
000000000x
13 Publicações

000000000x
Denunciar
Bloquear Utilizador
一个小目标
4 A seguir
0 Seguidores
0 Gostaram
Publicações
Tudo
Vídeos
·
--
Ver tradução
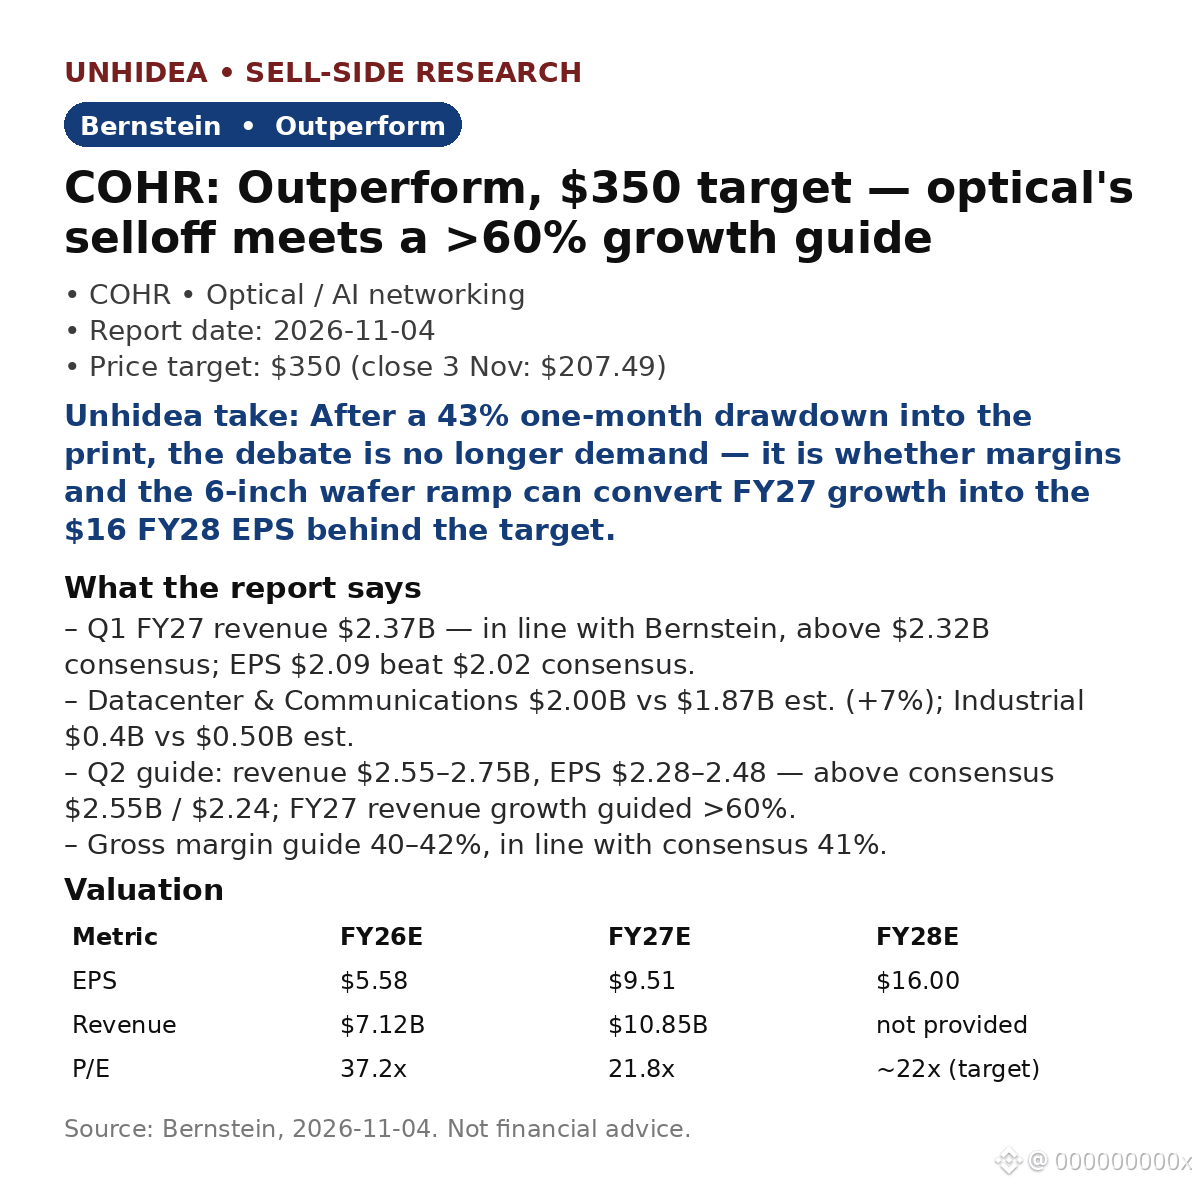
$COHR: Bernstein keeps Outperform, $350 target — ~69% above the $207.49 close on 3 Nov. Optical's selloff just met a >60% growth guide.
Q1 FY27: revenue $2.37B, in line with Bernstein's $2.37B estimate and above $2.32B consensus; EPS $2.09 beat $2.02 consensus. Datacenter did the work: $2.00B vs $1.87B expected (+7%).
- Q2 guide: revenue $2.55–2.75B and EPS $2.28–2.48, above consensus $2.55B/$2.24; FY27 revenue growth guided above 60%.
- Valuation: $350 = ~22x Bernstein's FY28E EPS of $16; FY27E EPS $9.51 on revenue of $10.85B; FY27E P/E 21.8x.
- Since the report: shares fell 6.75% on 16 Nov, then bounced ~11% premarket on 17 Nov as optical names recovered ahead of Nvidia earnings (market coverage, 17 Nov).
Unhidea take: after a 43% one-month drawdown, the repricing is about plumbing, not hype — the InP bottleneck is the moat, and the Marvell–Lumentum deal leaves Coherent the remaining independent optical pure-play.
Unhidea take: the open question is margins, not demand — Bernstein calls margins disappointing, and the 6-inch wafer ramp decides whether FY27 growth converts into that $16 FY28 EPS.
Risks: margin ramp slips; InP pricing fades; VCSEL scale-up unproven; the Lumentum deal reshapes competition.
Source: Bernstein, 4 Nov 2026. Not financial advice.
$COHR : Bernstein keeps Outperform, $350 target — ~69% above the $207.49 close on 3 Nov. Optical's selloff just met a >60% growth guide.
Q1 FY27: revenue $2.37B, in line with Bernstein's $2.37B estimate and above $2.32B consensus; EPS $2.09 beat $2.02 consensus. Datacenter did the work: $2.00B vs $1.87B expected (+7%).
- Q2 guide: revenue $2.55–2.75B and EPS $2.28–2.48, above consensus $2.55B/$2.24; FY27 revenue growth guided above 60%.
- Valuation: $350 = ~22x Bernstein's FY28E EPS of $16; FY27E EPS $9.51 on revenue of $10.85B; FY27E P/E 21.8x.
- Since the report: shares fell 6.75% on 16 Nov, then bounced ~11% premarket on 17 Nov as optical names recovered ahead of Nvidia earnings (market coverage, 17 Nov).
Unhidea take: after a 43% one-month drawdown, the repricing is about plumbing, not hype — the InP bottleneck is the moat, and the Marvell–Lumentum deal leaves Coherent the remaining independent optical pure-play.
Unhidea take: the open question is margins, not demand — Bernstein calls margins disappointing, and the 6-inch wafer ramp decides whether FY27 growth converts into that $16 FY28 EPS.
Risks: margin ramp slips; InP pricing fades; VCSEL scale-up unproven; the Lumentum deal reshapes competition.
Source: Bernstein, 4 Nov 2026. Not financial advice.
Q1 FY27: revenue $2.37B, in line with Bernstein's $2.37B estimate and above $2.32B consensus; EPS $2.09 beat $2.02 consensus. Datacenter did the work: $2.00B vs $1.87B expected (+7%).
- Q2 guide: revenue $2.55–2.75B and EPS $2.28–2.48, above consensus $2.55B/$2.24; FY27 revenue growth guided above 60%.
- Valuation: $350 = ~22x Bernstein's FY28E EPS of $16; FY27E EPS $9.51 on revenue of $10.85B; FY27E P/E 21.8x.
- Since the report: shares fell 6.75% on 16 Nov, then bounced ~11% premarket on 17 Nov as optical names recovered ahead of Nvidia earnings (market coverage, 17 Nov).
Unhidea take: after a 43% one-month drawdown, the repricing is about plumbing, not hype — the InP bottleneck is the moat, and the Marvell–Lumentum deal leaves Coherent the remaining independent optical pure-play.
Unhidea take: the open question is margins, not demand — Bernstein calls margins disappointing, and the 6-inch wafer ramp decides whether FY27 growth converts into that $16 FY28 EPS.
Risks: margin ramp slips; InP pricing fades; VCSEL scale-up unproven; the Lumentum deal reshapes competition.
Source: Bernstein, 4 Nov 2026. Not financial advice.
2
·
--
Ver tradução
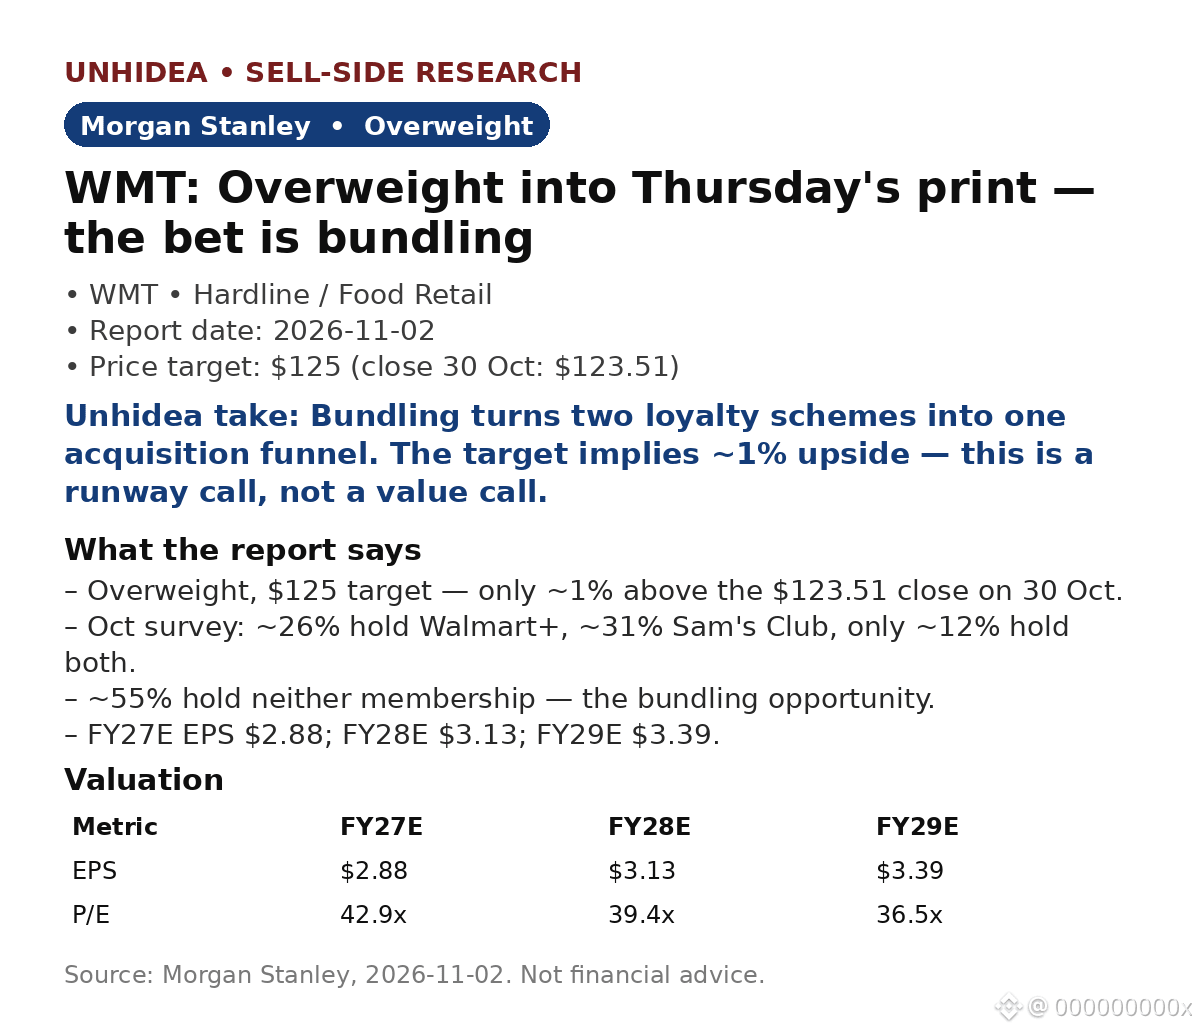
$WMT: Morgan Stanley stays Overweight into Thursday's print — the bet is bundling
MS's 2 Nov note: Overweight, $125 target — just ~1% above the $123.51 close on 30 Oct. The call is about membership: its Oct survey finds ~26% hold Walmart+, ~31% Sam's Club, only ~12% both — while ~55% hold neither.
- The gap is the opportunity: ~14% hold only Walmart+ and ~19% only Sam's — natural cross-sell targets.
- Valuation: $125 = ~36.8x F'29E EPS of $3.39, vs a 10-year average P/E of ~21x — a premium MS says the e-commerce shift earns.
- Estimates: FY27E EPS $2.88, FY28E $3.13, FY29E $3.39; Q3 FY27E EPS $0.63, actual print due Thu 19 Nov.
Unhidea take: the 55% holding neither is the real prize — bundling turns two loyalty schemes into one acquisition funnel, closer to Costco's flywheel than a grocery card.
Unhidea take: with the target ~1% above the Oct close, this Overweight is a runway call, not a value call — Thursday's print must show it in comps, not just a survey.
Risks: e-commerce losses could widen; US e-comm growth below 15% undercuts the thesis; Flipkart losses. Survey is a first read.
Source: Morgan Stanley, 2 Nov 2026. Not financial advice.
$WMT : Morgan Stanley stays Overweight into Thursday's print — the bet is bundling
MS's 2 Nov note: Overweight, $125 target — just ~1% above the $123.51 close on 30 Oct. The call is about membership: its Oct survey finds ~26% hold Walmart+, ~31% Sam's Club, only ~12% both — while ~55% hold neither.
- The gap is the opportunity: ~14% hold only Walmart+ and ~19% only Sam's — natural cross-sell targets.
- Valuation: $125 = ~36.8x F'29E EPS of $3.39, vs a 10-year average P/E of ~21x — a premium MS says the e-commerce shift earns.
- Estimates: FY27E EPS $2.88, FY28E $3.13, FY29E $3.39; Q3 FY27E EPS $0.63, actual print due Thu 19 Nov.
Unhidea take: the 55% holding neither is the real prize — bundling turns two loyalty schemes into one acquisition funnel, closer to Costco's flywheel than a grocery card.
Unhidea take: with the target ~1% above the Oct close, this Overweight is a runway call, not a value call — Thursday's print must show it in comps, not just a survey.
Risks: e-commerce losses could widen; US e-comm growth below 15% undercuts the thesis; Flipkart losses. Survey is a first read.
Source: Morgan Stanley, 2 Nov 2026. Not financial advice.
MS's 2 Nov note: Overweight, $125 target — just ~1% above the $123.51 close on 30 Oct. The call is about membership: its Oct survey finds ~26% hold Walmart+, ~31% Sam's Club, only ~12% both — while ~55% hold neither.
- The gap is the opportunity: ~14% hold only Walmart+ and ~19% only Sam's — natural cross-sell targets.
- Valuation: $125 = ~36.8x F'29E EPS of $3.39, vs a 10-year average P/E of ~21x — a premium MS says the e-commerce shift earns.
- Estimates: FY27E EPS $2.88, FY28E $3.13, FY29E $3.39; Q3 FY27E EPS $0.63, actual print due Thu 19 Nov.
Unhidea take: the 55% holding neither is the real prize — bundling turns two loyalty schemes into one acquisition funnel, closer to Costco's flywheel than a grocery card.
Unhidea take: with the target ~1% above the Oct close, this Overweight is a runway call, not a value call — Thursday's print must show it in comps, not just a survey.
Risks: e-commerce losses could widen; US e-comm growth below 15% undercuts the thesis; Flipkart losses. Survey is a first read.
Source: Morgan Stanley, 2 Nov 2026. Not financial advice.
3
·
--
Ver tradução
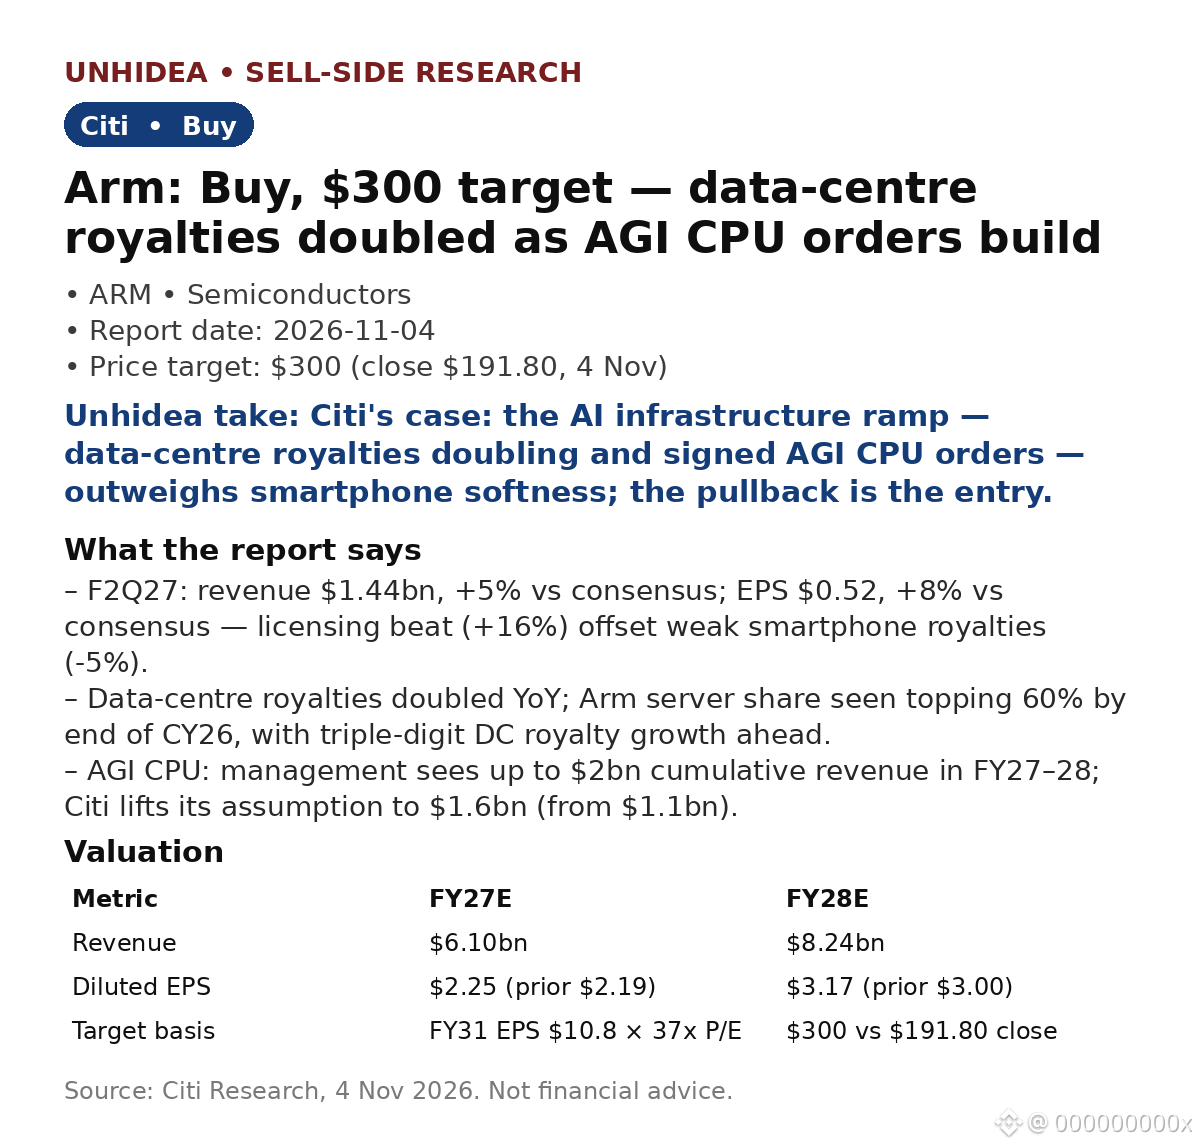
$ARM: Citi keeps Buy, $300 target — data-centre royalties doubled as AGI CPU orders build
Citi's 4 Nov note, after Arm's F2Q27 print: revenue $1.44bn (+5% vs consensus) and EPS $0.52 (+8%) — licensing beat (+16% vs consensus) more than offset smartphone royalty softness (-5%). F3Q27 guide of $1.54bn revenue and $0.56 EPS sits modestly ahead of consensus ($1.52bn / $0.55).
- Data centre: royalties doubled YoY; Arm server share seen above 60% by end of CY26, with triple-digit DC royalty growth expected in coming years.
- AGI CPU: management sees up to $2bn cumulative revenue in FY27–28; Citi lifts its assumption to $1.6bn (from $1.1bn) on signed purchase orders.
- Valuation: FY27E revenue $6.10bn, FY28E $8.24bn; EPS $2.25 / $3.17. Target $300 = FY31 EPS $10.8 at 37x P/E, discounted to 2028 — ~56% above the $191.80 close on 4 Nov.
Unhidea take: the quarter shows Arm monetising AI twice — licences today, royalties tomorrow — and the AGI CPU order book turns a story into contracted revenue.
Unhidea take: ARM shares were down ~8% intraday on 17 Nov in a broad chip sell-off — that's AI anxiety into Nvidia's print, not this report. The gap between Citi's $300 and the market's mood is the trade to watch.
Risks: execution and system deployment are the key constraint; smartphone royalties still weak; RISC-V competition; SoftBank holds ~90%.
Source: Citi Research, 4 Nov 2026. Not financial advice.
$ARM : Citi keeps Buy, $300 target — data-centre royalties doubled as AGI CPU orders build
Citi's 4 Nov note, after Arm's F2Q27 print: revenue $1.44bn (+5% vs consensus) and EPS $0.52 (+8%) — licensing beat (+16% vs consensus) more than offset smartphone royalty softness (-5%). F3Q27 guide of $1.54bn revenue and $0.56 EPS sits modestly ahead of consensus ($1.52bn / $0.55).
- Data centre: royalties doubled YoY; Arm server share seen above 60% by end of CY26, with triple-digit DC royalty growth expected in coming years.
- AGI CPU: management sees up to $2bn cumulative revenue in FY27–28; Citi lifts its assumption to $1.6bn (from $1.1bn) on signed purchase orders.
- Valuation: FY27E revenue $6.10bn, FY28E $8.24bn; EPS $2.25 / $3.17. Target $300 = FY31 EPS $10.8 at 37x P/E, discounted to 2028 — ~56% above the $191.80 close on 4 Nov.
Unhidea take: the quarter shows Arm monetising AI twice — licences today, royalties tomorrow — and the AGI CPU order book turns a story into contracted revenue.
Unhidea take: ARM shares were down ~8% intraday on 17 Nov in a broad chip sell-off — that's AI anxiety into Nvidia's print, not this report. The gap between Citi's $300 and the market's mood is the trade to watch.
Risks: execution and system deployment are the key constraint; smartphone royalties still weak; RISC-V competition; SoftBank holds ~90%.
Source: Citi Research, 4 Nov 2026. Not financial advice.
Citi's 4 Nov note, after Arm's F2Q27 print: revenue $1.44bn (+5% vs consensus) and EPS $0.52 (+8%) — licensing beat (+16% vs consensus) more than offset smartphone royalty softness (-5%). F3Q27 guide of $1.54bn revenue and $0.56 EPS sits modestly ahead of consensus ($1.52bn / $0.55).
- Data centre: royalties doubled YoY; Arm server share seen above 60% by end of CY26, with triple-digit DC royalty growth expected in coming years.
- AGI CPU: management sees up to $2bn cumulative revenue in FY27–28; Citi lifts its assumption to $1.6bn (from $1.1bn) on signed purchase orders.
- Valuation: FY27E revenue $6.10bn, FY28E $8.24bn; EPS $2.25 / $3.17. Target $300 = FY31 EPS $10.8 at 37x P/E, discounted to 2028 — ~56% above the $191.80 close on 4 Nov.
Unhidea take: the quarter shows Arm monetising AI twice — licences today, royalties tomorrow — and the AGI CPU order book turns a story into contracted revenue.
Unhidea take: ARM shares were down ~8% intraday on 17 Nov in a broad chip sell-off — that's AI anxiety into Nvidia's print, not this report. The gap between Citi's $300 and the market's mood is the trade to watch.
Risks: execution and system deployment are the key constraint; smartphone royalties still weak; RISC-V competition; SoftBank holds ~90%.
Source: Citi Research, 4 Nov 2026. Not financial advice.
6
·
--
Ver tradução
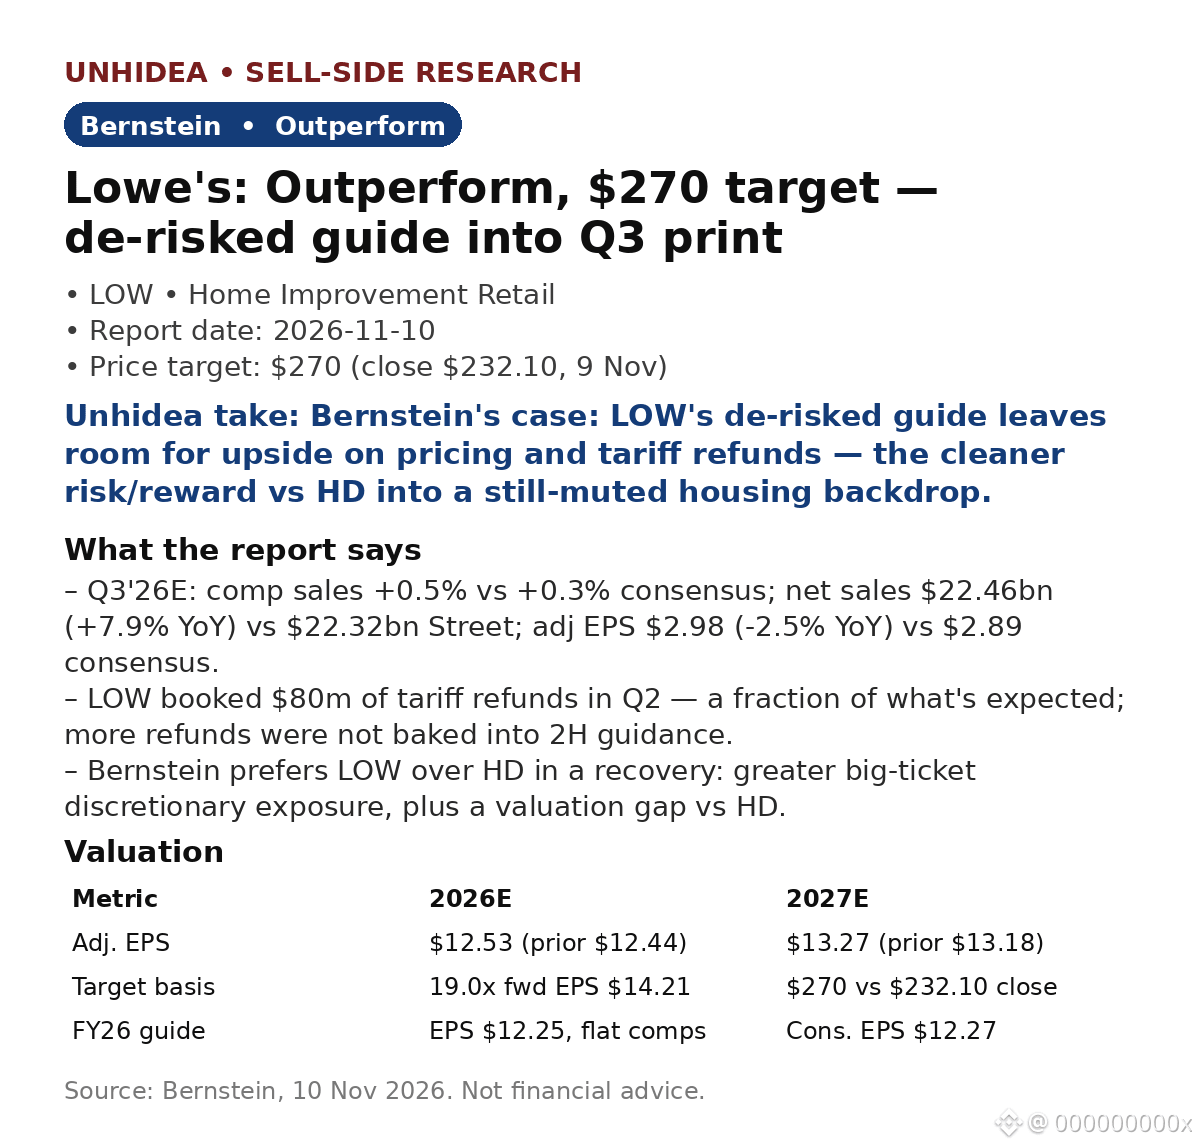
$LOW: Bernstein keeps Outperform, $270 target — guidance de-risked into today's Q3 print
Bernstein's 10 Nov preview: Lowe's reports Q3'26 before the open today (18 Nov). Its FY26 guide of flat comps assumes no weather benefit and no further tariff refunds. Target raised to $270 from $254 — ~16% above the $232.10 close on 9 Nov.
- Q3 preview: comp sales +0.5% vs +0.3% consensus; net sales $22.46bn (+7.9% YoY) vs $22.32bn Street; adj EPS $2.98 (-2.5% YoY) vs $2.89 consensus.
- Tariff refunds: LOW booked $80m in Q2, a fraction of what's expected — extra refunds could offset fuel/freight inflation or fund promotions.
- Valuation: FY26E adj EPS $12.53 (prior $12.44) vs $12.25 guide; FY27E $13.27. Target = 19.0x forward EPS $14.21 (was 18.0x).
Unhidea take: with the bar at flat comps, modest pricing power shows up as a beat — and tariff refunds are a free option the guide ignores.
Unhidea take: LOW is Bernstein's preferred recovery play over HD — bigger big-ticket exposure means a sharper rebound if housing turns, a deeper wait if it doesn't.
Risks: muted housing demand, tariff/freight inflation, weak resi construction hitting Pro.
Context: HD reported 17 Nov — sales $43.4bn beat ~$42.8bn expected, shares -2% (CNBC).
Source: Bernstein, 10 Nov 2026. Not financial advice.
https://unhidea.com/en/articles/research-972aba8288b2492db4a299efd9035504-en
$LOW: Bernstein keeps Outperform, $270 target — guidance de-risked into today's Q3 print
Bernstein's 10 Nov preview: Lowe's reports Q3'26 before the open today (18 Nov). Its FY26 guide of flat comps assumes no weather benefit and no further tariff refunds. Target raised to $270 from $254 — ~16% above the $232.10 close on 9 Nov.
- Q3 preview: comp sales +0.5% vs +0.3% consensus; net sales $22.46bn (+7.9% YoY) vs $22.32bn Street; adj EPS $2.98 (-2.5% YoY) vs $2.89 consensus.
- Tariff refunds: LOW booked $80m in Q2, a fraction of what's expected — extra refunds could offset fuel/freight inflation or fund promotions.
- Valuation: FY26E adj EPS $12.53 (prior $12.44) vs $12.25 guide; FY27E $13.27. Target = 19.0x forward EPS $14.21 (was 18.0x).
Unhidea take: with the bar at flat comps, modest pricing power shows up as a beat — and tariff refunds are a free option the guide ignores.
Unhidea take: LOW is Bernstein's preferred recovery play over HD — bigger big-ticket exposure means a sharper rebound if housing turns, a deeper wait if it doesn't.
Risks: muted housing demand, tariff/freight inflation, weak resi construction hitting Pro.
Context: HD reported 17 Nov — sales $43.4bn beat ~$42.8bn expected, shares -2% (CNBC).
Source: Bernstein, 10 Nov 2026. Not financial advice.
https://unhidea.com/en/articles/research-972aba8288b2492db4a299efd9035504-en
Bernstein's 10 Nov preview: Lowe's reports Q3'26 before the open today (18 Nov). Its FY26 guide of flat comps assumes no weather benefit and no further tariff refunds. Target raised to $270 from $254 — ~16% above the $232.10 close on 9 Nov.
- Q3 preview: comp sales +0.5% vs +0.3% consensus; net sales $22.46bn (+7.9% YoY) vs $22.32bn Street; adj EPS $2.98 (-2.5% YoY) vs $2.89 consensus.
- Tariff refunds: LOW booked $80m in Q2, a fraction of what's expected — extra refunds could offset fuel/freight inflation or fund promotions.
- Valuation: FY26E adj EPS $12.53 (prior $12.44) vs $12.25 guide; FY27E $13.27. Target = 19.0x forward EPS $14.21 (was 18.0x).
Unhidea take: with the bar at flat comps, modest pricing power shows up as a beat — and tariff refunds are a free option the guide ignores.
Unhidea take: LOW is Bernstein's preferred recovery play over HD — bigger big-ticket exposure means a sharper rebound if housing turns, a deeper wait if it doesn't.
Risks: muted housing demand, tariff/freight inflation, weak resi construction hitting Pro.
Context: HD reported 17 Nov — sales $43.4bn beat ~$42.8bn expected, shares -2% (CNBC).
Source: Bernstein, 10 Nov 2026. Not financial advice.
https://unhidea.com/en/articles/research-972aba8288b2492db4a299efd9035504-en
HD-2,26%
LOWUS-1,57%
·
--
Parcialmente verdadeiro
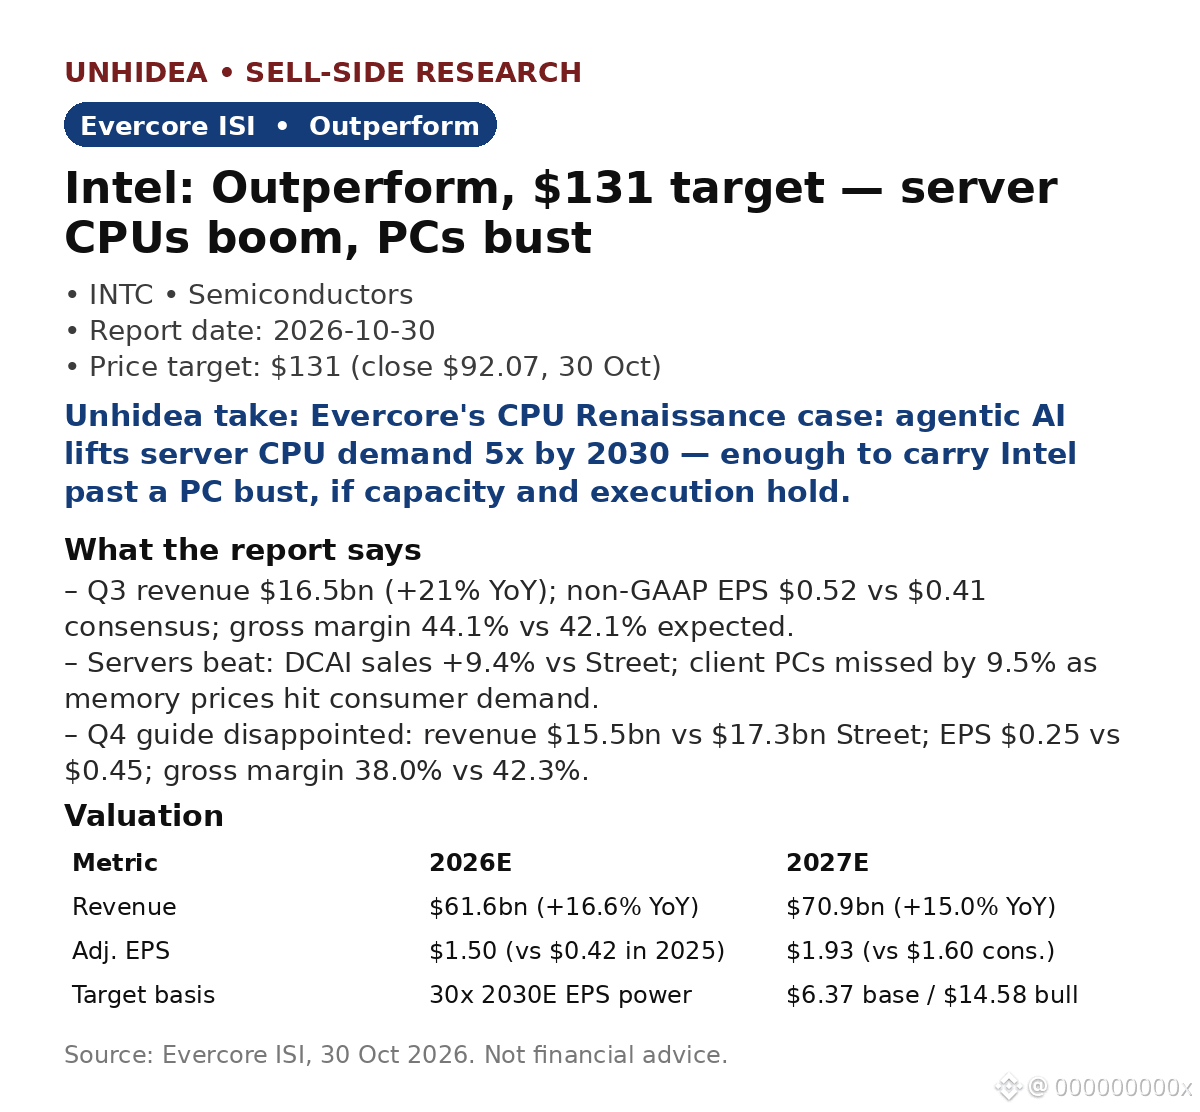
$INTC: Evercore mantém recomendação Outperform e preço-alvo de US$ 131 — boom das CPUs para servidores enquanto os PCs recuam
A nota da Evercore de 30 de outubro divide a Intel em duas frentes: CPUs para data centers superaram as expectativas (+9,4% em relação ao consenso do mercado), enquanto os PCs para clientes ficaram 9,5% aquém, com os preços da memória afetando a demanda. Receita no 3º trimestre: US$ 16,5 bilhões (+21% em relação ao ano anterior); LPA não GAAP de US$ 0,52 contra consenso de US$ 0,41; margem bruta de 44,1% contra expectativa de 42,1%.
- Projeção fraca: receita de US$ 15,5 bilhões no 4º trimestre contra US$ 17,3 bilhões esperados pelo mercado; LPA de US$ 0,25 contra US$ 0,45; margem bruta de 38,0% contra 42,3%.
- Tese para servidores: a administração prevê alta de >30% nas unidades de CPUs para servidores em 2026 e 2027; a DCAI se tornará a maior unidade da Intel a partir do 4º trimestre. O mercado total endereçável de unidades de PCs deve cair ~12% em 2026 e mais ~10% em 2027.
- Avaliação: o preço-alvo de US$ 131 equivale a 30x o potencial de LPA estimado para 2030 (US$ 6,37 no cenário-base e US$ 14,58 no otimista), ~42% acima do fechamento de US$ 92,07 em 30 de outubro.
Análise da Unhidea: a tese do renascimento das CPUs depende de a IA agêntica exigir muito mais CPUs por GPU — se isso se confirmar, os servidores sustentarão a Intel durante a retração dos PCs.
Análise da Unhidea: o limitador é a capacidade, não a demanda — a escassez de wafers e substratos deve persistir até 2028; transferir a capacidade destinada a clientes para servidores será decisivo para saber se os números de 2030 são realistas.
Riscos: queda dos PCs, custos da memória, execução na fundição, sustentabilidade dos gastos com IA.
Contexto: o formulário 13F da $NVDA mostrou um corte de 25% em sua participação na Intel; as ações da Intel caíram ~3% no pré-mercado hoje (Reuters, 17 de novembro).
Fonte: Evercore ISI, 30 de outubro de 2026. Isto não é aconselhamento financeiro.
$INTC : Evercore mantém recomendação Outperform e preço-alvo de US$ 131 — boom das CPUs para servidores enquanto os PCs recuam
A nota da Evercore de 30 de outubro divide a Intel em duas frentes: CPUs para data centers superaram as expectativas (+9,4% em relação ao consenso do mercado), enquanto os PCs para clientes ficaram 9,5% aquém, com os preços da memória afetando a demanda. Receita no 3º trimestre: US$ 16,5 bilhões (+21% em relação ao ano anterior); LPA não GAAP de US$ 0,52 contra consenso de US$ 0,41; margem bruta de 44,1% contra expectativa de 42,1%.
- Projeção fraca: receita de US$ 15,5 bilhões no 4º trimestre contra US$ 17,3 bilhões esperados pelo mercado; LPA de US$ 0,25 contra US$ 0,45; margem bruta de 38,0% contra 42,3%.
- Tese para servidores: a administração prevê alta de >30% nas unidades de CPUs para servidores em 2026 e 2027; a DCAI se tornará a maior unidade da Intel a partir do 4º trimestre. O mercado total endereçável de unidades de PCs deve cair ~12% em 2026 e mais ~10% em 2027.
- Avaliação: o preço-alvo de US$ 131 equivale a 30x o potencial de LPA estimado para 2030 (US$ 6,37 no cenário-base e US$ 14,58 no otimista), ~42% acima do fechamento de US$ 92,07 em 30 de outubro.
Análise da Unhidea: a tese do renascimento das CPUs depende de a IA agêntica exigir muito mais CPUs por GPU — se isso se confirmar, os servidores sustentarão a Intel durante a retração dos PCs.
Análise da Unhidea: o limitador é a capacidade, não a demanda — a escassez de wafers e substratos deve persistir até 2028; transferir a capacidade destinada a clientes para servidores será decisivo para saber se os números de 2030 são realistas.
Riscos: queda dos PCs, custos da memória, execução na fundição, sustentabilidade dos gastos com IA.
Contexto: o formulário 13F da $NVDA mostrou um corte de 25% em sua participação na Intel; as ações da Intel caíram ~3% no pré-mercado hoje (Reuters, 17 de novembro).
Fonte: Evercore ISI, 30 de outubro de 2026. Isto não é aconselhamento financeiro.
A nota da Evercore de 30 de outubro divide a Intel em duas frentes: CPUs para data centers superaram as expectativas (+9,4% em relação ao consenso do mercado), enquanto os PCs para clientes ficaram 9,5% aquém, com os preços da memória afetando a demanda. Receita no 3º trimestre: US$ 16,5 bilhões (+21% em relação ao ano anterior); LPA não GAAP de US$ 0,52 contra consenso de US$ 0,41; margem bruta de 44,1% contra expectativa de 42,1%.
- Projeção fraca: receita de US$ 15,5 bilhões no 4º trimestre contra US$ 17,3 bilhões esperados pelo mercado; LPA de US$ 0,25 contra US$ 0,45; margem bruta de 38,0% contra 42,3%.
- Tese para servidores: a administração prevê alta de >30% nas unidades de CPUs para servidores em 2026 e 2027; a DCAI se tornará a maior unidade da Intel a partir do 4º trimestre. O mercado total endereçável de unidades de PCs deve cair ~12% em 2026 e mais ~10% em 2027.
- Avaliação: o preço-alvo de US$ 131 equivale a 30x o potencial de LPA estimado para 2030 (US$ 6,37 no cenário-base e US$ 14,58 no otimista), ~42% acima do fechamento de US$ 92,07 em 30 de outubro.
Análise da Unhidea: a tese do renascimento das CPUs depende de a IA agêntica exigir muito mais CPUs por GPU — se isso se confirmar, os servidores sustentarão a Intel durante a retração dos PCs.
Análise da Unhidea: o limitador é a capacidade, não a demanda — a escassez de wafers e substratos deve persistir até 2028; transferir a capacidade destinada a clientes para servidores será decisivo para saber se os números de 2030 são realistas.
Riscos: queda dos PCs, custos da memória, execução na fundição, sustentabilidade dos gastos com IA.
Contexto: o formulário 13F da $NVDA mostrou um corte de 25% em sua participação na Intel; as ações da Intel caíram ~3% no pré-mercado hoje (Reuters, 17 de novembro).
Fonte: Evercore ISI, 30 de outubro de 2026. Isto não é aconselhamento financeiro.
771
·
--
Parcialmente verdadeiro
Ver tradução
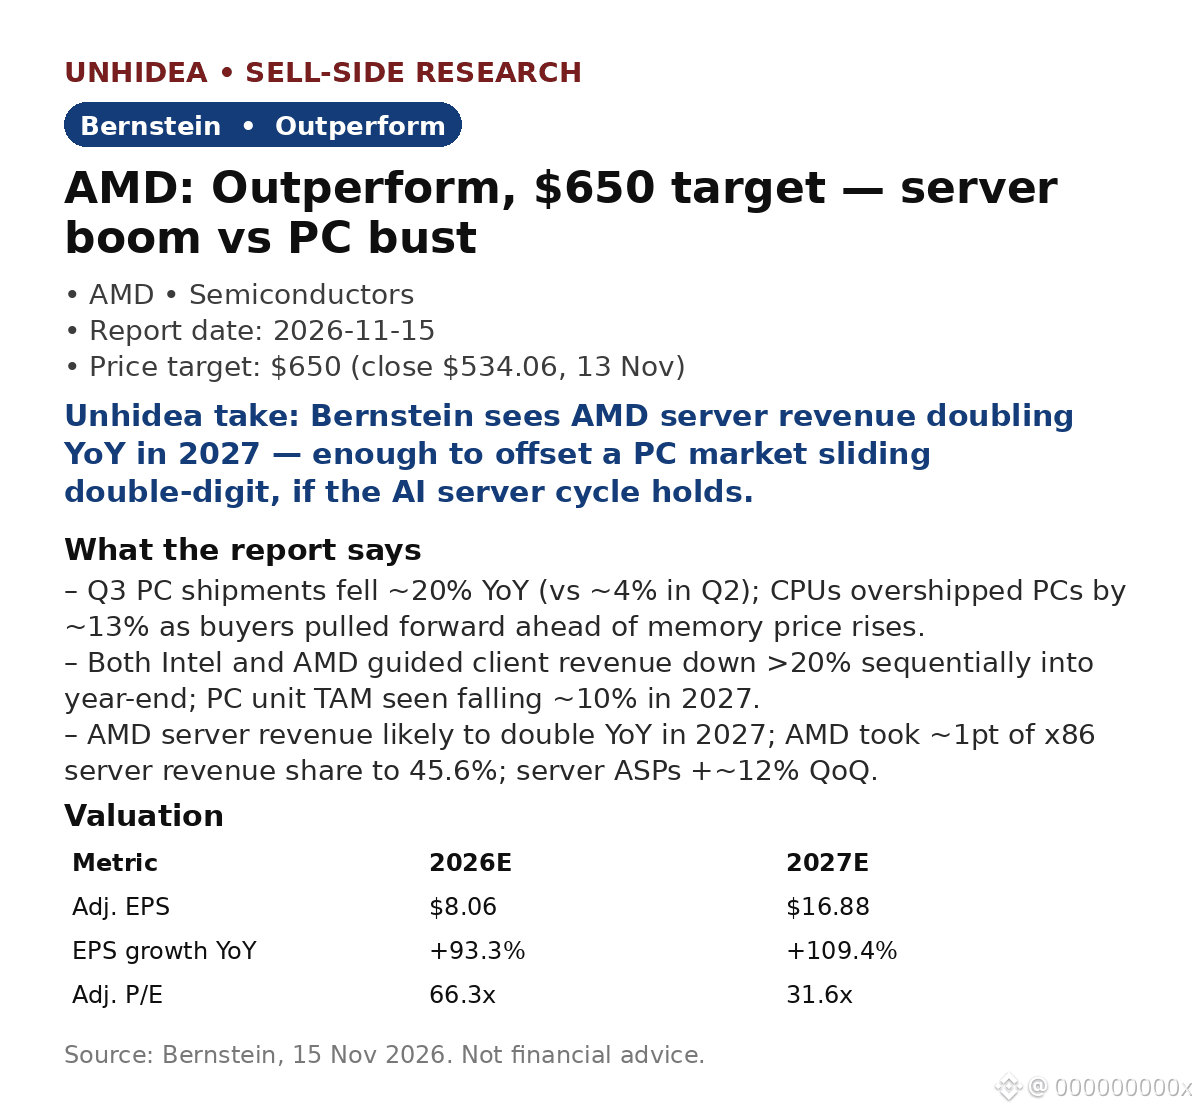
$AMD: Bernstein holds Outperform, $650 target — server revenues set to double in 2027 as the PC market cracks
Bernstein's 15 Nov note splits AMD in two: a PC business heading into a bust, and a server business about to double. Q3 PC shipments fell ~20% YoY (vs ~4% in Q2) as CPUs overshipped PCs by ~13% on pull-forward ahead of memory price rises. Both Intel and AMD guided client revenue down >20% sequentially into year-end.
- Server offset: AMD server revenue is likely to double YoY in 2027; AMD took ~1pt of x86 server revenue share to 45.6% as server ASPs rose ~12% QoQ (+34% YoY).
- Estimates: 2027E adj. EPS $16.88 vs $8.06 in 2026E (+109% YoY); the $650 target is ~31x avg FY27/28 EPS ($20.83), ~22% above the $534.06 close on 13 Nov.
Unhidea take: the PC bust is real, but for AMD it is a mix-shift story, not a demand story — servers and AI accelerators are where the growth lives.
Unhidea take: memory is the swing factor: rising prices deepen the pull-forward hangover, but tight memory also caps rival supply, rewarding AMD's better-managed supply chain.
Risks: PC declines, GPU customer concentration, margins, AI spending sustainability.
Context: $NVDA reports after the close today (17 Nov).
Source: Bernstein, 15 Nov 2026. Not financial advice.
$AMD : Bernstein holds Outperform, $650 target — server revenues set to double in 2027 as the PC market cracks
Bernstein's 15 Nov note splits AMD in two: a PC business heading into a bust, and a server business about to double. Q3 PC shipments fell ~20% YoY (vs ~4% in Q2) as CPUs overshipped PCs by ~13% on pull-forward ahead of memory price rises. Both Intel and AMD guided client revenue down >20% sequentially into year-end.
- Server offset: AMD server revenue is likely to double YoY in 2027; AMD took ~1pt of x86 server revenue share to 45.6% as server ASPs rose ~12% QoQ (+34% YoY).
- Estimates: 2027E adj. EPS $16.88 vs $8.06 in 2026E (+109% YoY); the $650 target is ~31x avg FY27/28 EPS ($20.83), ~22% above the $534.06 close on 13 Nov.
Unhidea take: the PC bust is real, but for AMD it is a mix-shift story, not a demand story — servers and AI accelerators are where the growth lives.
Unhidea take: memory is the swing factor: rising prices deepen the pull-forward hangover, but tight memory also caps rival supply, rewarding AMD's better-managed supply chain.
Risks: PC declines, GPU customer concentration, margins, AI spending sustainability.
Context: $NVDA reports after the close today (17 Nov).
Source: Bernstein, 15 Nov 2026. Not financial advice.
Bernstein's 15 Nov note splits AMD in two: a PC business heading into a bust, and a server business about to double. Q3 PC shipments fell ~20% YoY (vs ~4% in Q2) as CPUs overshipped PCs by ~13% on pull-forward ahead of memory price rises. Both Intel and AMD guided client revenue down >20% sequentially into year-end.
- Server offset: AMD server revenue is likely to double YoY in 2027; AMD took ~1pt of x86 server revenue share to 45.6% as server ASPs rose ~12% QoQ (+34% YoY).
- Estimates: 2027E adj. EPS $16.88 vs $8.06 in 2026E (+109% YoY); the $650 target is ~31x avg FY27/28 EPS ($20.83), ~22% above the $534.06 close on 13 Nov.
Unhidea take: the PC bust is real, but for AMD it is a mix-shift story, not a demand story — servers and AI accelerators are where the growth lives.
Unhidea take: memory is the swing factor: rising prices deepen the pull-forward hangover, but tight memory also caps rival supply, rewarding AMD's better-managed supply chain.
Risks: PC declines, GPU customer concentration, margins, AI spending sustainability.
Context: $NVDA reports after the close today (17 Nov).
Source: Bernstein, 15 Nov 2026. Not financial advice.
418
·
--
Ver tradução
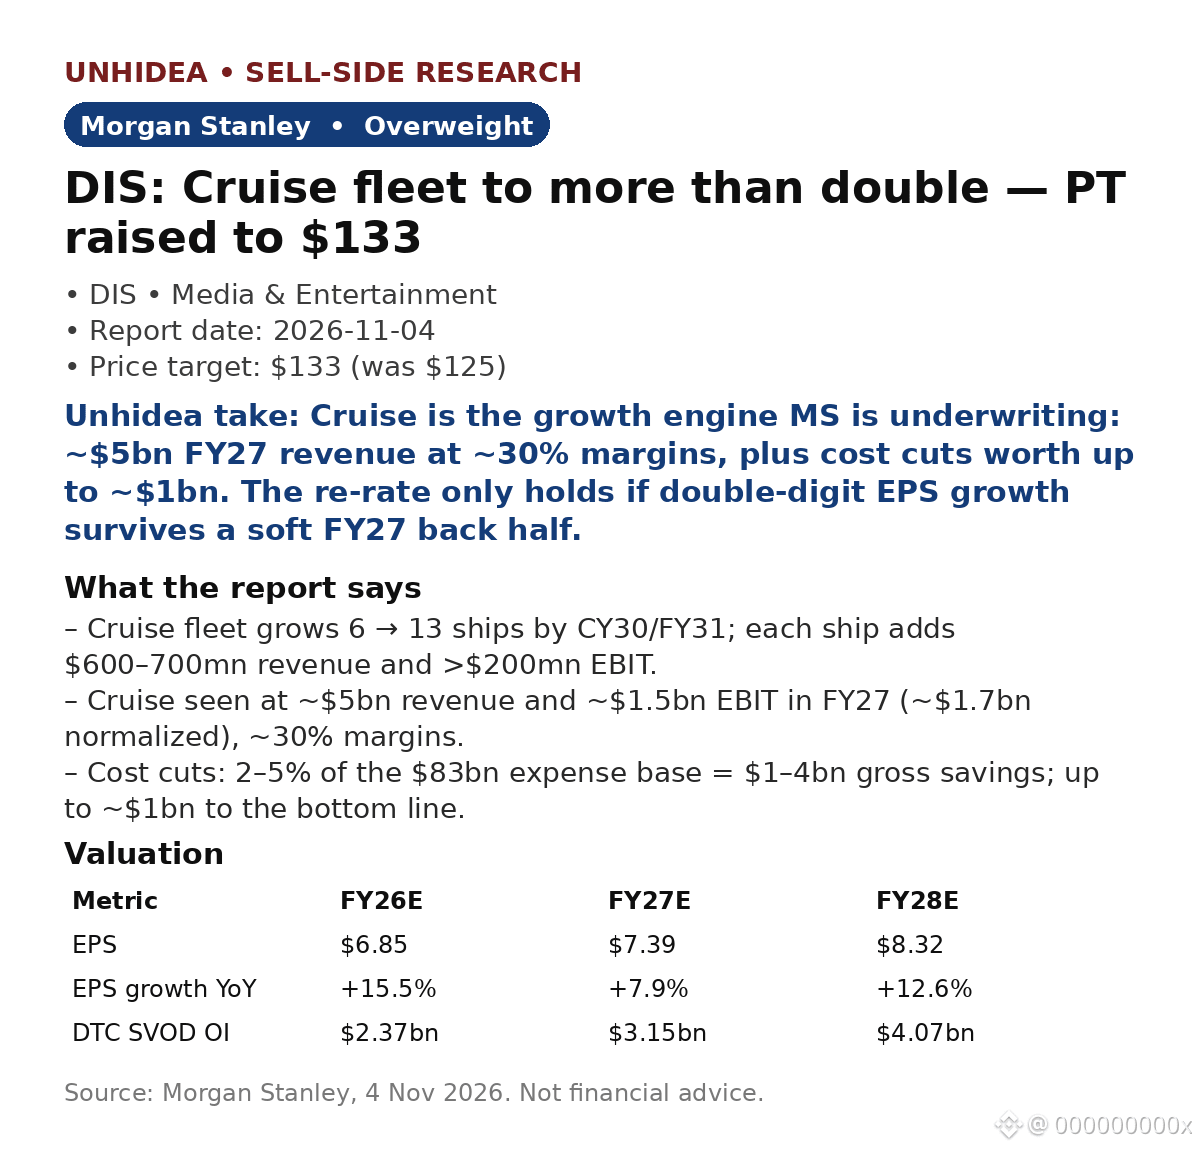
$DIS: Morgan Stanley raises PT to $133 from $125, reiterates Overweight — cruise is now the growth story
MS sees Disney "cruising to double-digit EPS growth": fleet 6 → 13 ships by CY30/FY31, each adding $600–700mn revenue and >$200mn EBIT. Cruise seen at ~$5bn revenue, ~$1.5bn EBIT in FY27 (~$1.7bn normalized), ~30% margins.
- Estimates: FY26E EPS $6.85 (+15.5% YoY) vs $7.19 consensus; FY27E $7.39 (+7.9%); FY28E $8.32 (+12.6%) — the base for the $133 PT at 16x (was 15x).
- Cost cuts are a new lever: 2–5% of the $83bn expense base = $1–4bn savings; up to ~$1bn to the bottom line.
- Streaming scales: DTC SVOD operating income $1.30bn in FY25 → $2.37bn FY26E → $4.07bn FY28E.
Unhidea take: MS is underwriting a cruise-led re-rate, not a parks recovery — the fleet is the cleanest incremental capex in the portfolio.
Unhidea take: watch the timing — FY27 is front-half weighted and F4Q faces a 53rd-week headwind.
Fresh print (17 Nov, after the report): Disney beat — revenue +16% to $25.95bn, adj EPS $1.77 vs ~$1.67 expected; parks, streaming, ESPN all grew.
Risks: macro weakness, pay-TV cord-cutting, franchise fatigue. Bull $152 / bear $97. Source: Morgan Stanley, 4 Nov 2026. Not financial advice.
$DIS : Morgan Stanley raises PT to $133 from $125, reiterates Overweight — cruise is now the growth story
MS sees Disney "cruising to double-digit EPS growth": fleet 6 → 13 ships by CY30/FY31, each adding $600–700mn revenue and >$200mn EBIT. Cruise seen at ~$5bn revenue, ~$1.5bn EBIT in FY27 (~$1.7bn normalized), ~30% margins.
- Estimates: FY26E EPS $6.85 (+15.5% YoY) vs $7.19 consensus; FY27E $7.39 (+7.9%); FY28E $8.32 (+12.6%) — the base for the $133 PT at 16x (was 15x).
- Cost cuts are a new lever: 2–5% of the $83bn expense base = $1–4bn savings; up to ~$1bn to the bottom line.
- Streaming scales: DTC SVOD operating income $1.30bn in FY25 → $2.37bn FY26E → $4.07bn FY28E.
Unhidea take: MS is underwriting a cruise-led re-rate, not a parks recovery — the fleet is the cleanest incremental capex in the portfolio.
Unhidea take: watch the timing — FY27 is front-half weighted and F4Q faces a 53rd-week headwind.
Fresh print (17 Nov, after the report): Disney beat — revenue +16% to $25.95bn, adj EPS $1.77 vs ~$1.67 expected; parks, streaming, ESPN all grew.
Risks: macro weakness, pay-TV cord-cutting, franchise fatigue. Bull $152 / bear $97. Source: Morgan Stanley, 4 Nov 2026. Not financial advice.
MS sees Disney "cruising to double-digit EPS growth": fleet 6 → 13 ships by CY30/FY31, each adding $600–700mn revenue and >$200mn EBIT. Cruise seen at ~$5bn revenue, ~$1.5bn EBIT in FY27 (~$1.7bn normalized), ~30% margins.
- Estimates: FY26E EPS $6.85 (+15.5% YoY) vs $7.19 consensus; FY27E $7.39 (+7.9%); FY28E $8.32 (+12.6%) — the base for the $133 PT at 16x (was 15x).
- Cost cuts are a new lever: 2–5% of the $83bn expense base = $1–4bn savings; up to ~$1bn to the bottom line.
- Streaming scales: DTC SVOD operating income $1.30bn in FY25 → $2.37bn FY26E → $4.07bn FY28E.
Unhidea take: MS is underwriting a cruise-led re-rate, not a parks recovery — the fleet is the cleanest incremental capex in the portfolio.
Unhidea take: watch the timing — FY27 is front-half weighted and F4Q faces a 53rd-week headwind.
Fresh print (17 Nov, after the report): Disney beat — revenue +16% to $25.95bn, adj EPS $1.77 vs ~$1.67 expected; parks, streaming, ESPN all grew.
Risks: macro weakness, pay-TV cord-cutting, franchise fatigue. Bull $152 / bear $97. Source: Morgan Stanley, 4 Nov 2026. Not financial advice.
35
·
--
Ver tradução
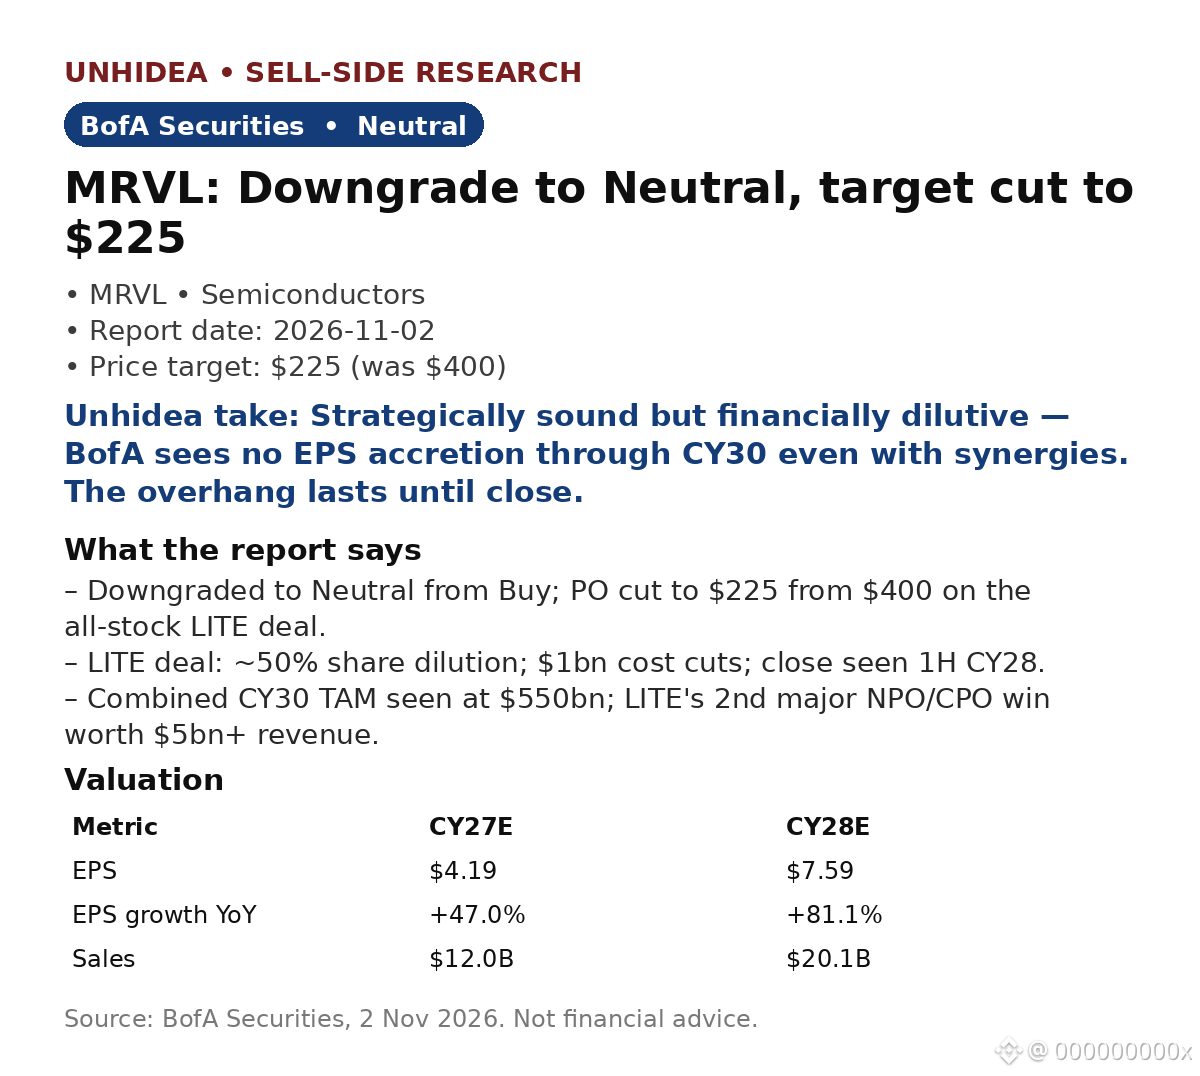
$MRVL: BofA cuts to Neutral, target $225 from $400 — the Lumentum deal muddies the Buy case
BofA cut Marvell to Neutral from Buy on 2 Nov, slashing its target to $225 from $400. The all-stock Lumentum deal adds ~50% share dilution, with no EPS accretion through CY30 — even with $1bn of cost cuts and 5% revenue synergies, dilution is -3.0% (CY28E), -7.0% (CY29E) and -12.4% (CY30E).
- Deal logic: LITE adds lasers, optical switches and scarce InP capacity; combined CY30 TAM seen at $550bn.
- Estimates intact: CY27E EPS $4.19 (+47.0% YoY) vs $4.22 consensus; CY28E $7.59 (+81.1%) vs $7.28 consensus; CY27E sales +46.5% to $12.0B.
- Multiple reset: PO now 20x CY28E PE vs 33x before, after the SOX fell 19% in a month.
Unhidea take: the debate is no longer Marvell's AI content — it's whether the deal's dilution is the price of owning the optical stack.
Unhidea take: $MRVL is +5.0% premarket at $152.30, where $225 implies ~48% upside — but BofA's own math says that upside waits until after close.
Risks: close not seen until 1H CY28 (China review); break fees; ASIC visibility at AWS/Microsoft.
Source: BofA Securities, 2 Nov 2026. Premarket: The Right Trader, 17 Nov. Not financial advice.
$MRVL : BofA cuts to Neutral, target $225 from $400 — the Lumentum deal muddies the Buy case
BofA cut Marvell to Neutral from Buy on 2 Nov, slashing its target to $225 from $400. The all-stock Lumentum deal adds ~50% share dilution, with no EPS accretion through CY30 — even with $1bn of cost cuts and 5% revenue synergies, dilution is -3.0% (CY28E), -7.0% (CY29E) and -12.4% (CY30E).
- Deal logic: LITE adds lasers, optical switches and scarce InP capacity; combined CY30 TAM seen at $550bn.
- Estimates intact: CY27E EPS $4.19 (+47.0% YoY) vs $4.22 consensus; CY28E $7.59 (+81.1%) vs $7.28 consensus; CY27E sales +46.5% to $12.0B.
- Multiple reset: PO now 20x CY28E PE vs 33x before, after the SOX fell 19% in a month.
Unhidea take: the debate is no longer Marvell's AI content — it's whether the deal's dilution is the price of owning the optical stack.
Unhidea take: $MRVL is +5.0% premarket at $152.30, where $225 implies ~48% upside — but BofA's own math says that upside waits until after close.
Risks: close not seen until 1H CY28 (China review); break fees; ASIC visibility at AWS/Microsoft.
Source: BofA Securities, 2 Nov 2026. Premarket: The Right Trader, 17 Nov. Not financial advice.
BofA cut Marvell to Neutral from Buy on 2 Nov, slashing its target to $225 from $400. The all-stock Lumentum deal adds ~50% share dilution, with no EPS accretion through CY30 — even with $1bn of cost cuts and 5% revenue synergies, dilution is -3.0% (CY28E), -7.0% (CY29E) and -12.4% (CY30E).
- Deal logic: LITE adds lasers, optical switches and scarce InP capacity; combined CY30 TAM seen at $550bn.
- Estimates intact: CY27E EPS $4.19 (+47.0% YoY) vs $4.22 consensus; CY28E $7.59 (+81.1%) vs $7.28 consensus; CY27E sales +46.5% to $12.0B.
- Multiple reset: PO now 20x CY28E PE vs 33x before, after the SOX fell 19% in a month.
Unhidea take: the debate is no longer Marvell's AI content — it's whether the deal's dilution is the price of owning the optical stack.
Unhidea take: $MRVL is +5.0% premarket at $152.30, where $225 implies ~48% upside — but BofA's own math says that upside waits until after close.
Risks: close not seen until 1H CY28 (China review); break fees; ASIC visibility at AWS/Microsoft.
Source: BofA Securities, 2 Nov 2026. Premarket: The Right Trader, 17 Nov. Not financial advice.
322
·
--
Ver tradução
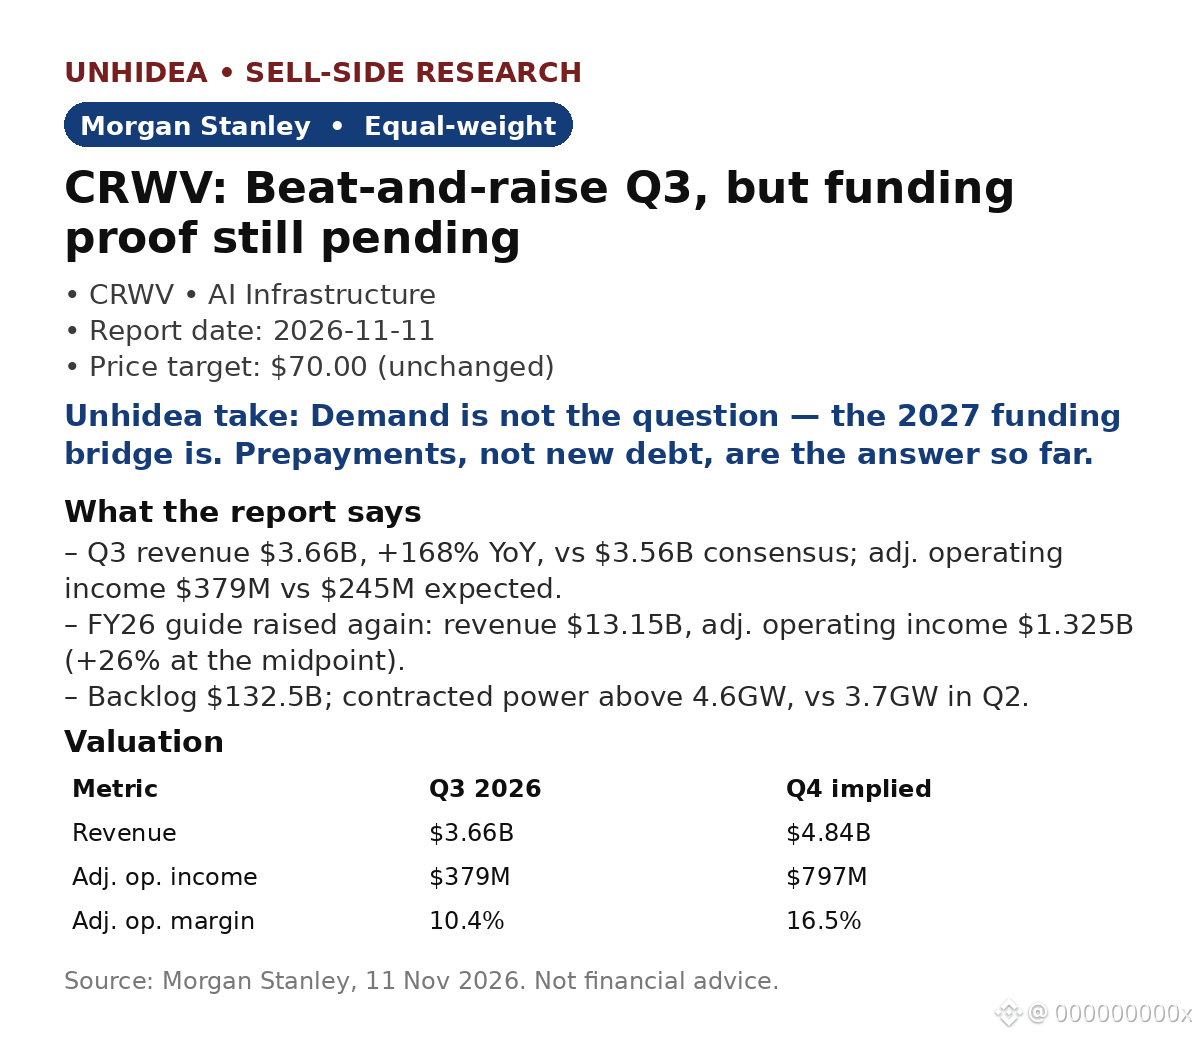
$CRWV: Morgan Stanley stays Equal-weight at $70 after a beat-and-raise Q3
CoreWeave beat Q3: revenue $3.66B, +168% YoY, vs $3.56B consensus. Adj. operating income $379M vs $245M expected — 10.4% margin vs 6.9% expected. FY26 guide rose again: revenue $13.15B, adj. operating income $1.325B (+26%).
- Exit ARR guided to $20–21B (was $18.5–19.5B); backlog $132.5B; contracted power above 4.6GW vs 3.7GW in Q2.
- Demand ~10x capacity through end-2027; new 4–5yr deals at $20–25M per MW, short-term above $40M.
- 2027 funding: $6.5B cash, ~$5B undrawn lines, ~$9B prepayments expected; 75% of 2027 capex covered by IG/enterprise contracts.
- Valuation: $70 is 8x 2030 unlevered FCF of $21.2B — ~44% above the Nov 10 close of $48.73.
Unhidea take: the funding bridge, not demand, was the debate — management answered it with customer prepayments, not new bonds.
Unhidea take: recontracting is the quiet upside — ~$4B of extra annual revenue from 2027 GPU renewals, with no new capex.
Risks: the new IG loan facility is still unclosed; FY26 capex stays huge at $37–39B.
Source: Morgan Stanley, 11 Nov 2026. Shares slipped ~2% premarket Nov 17 (Reuters). Not financial advice.
$CRWV : Morgan Stanley stays Equal-weight at $70 after a beat-and-raise Q3
CoreWeave beat Q3: revenue $3.66B, +168% YoY, vs $3.56B consensus. Adj. operating income $379M vs $245M expected — 10.4% margin vs 6.9% expected. FY26 guide rose again: revenue $13.15B, adj. operating income $1.325B (+26%).
- Exit ARR guided to $20–21B (was $18.5–19.5B); backlog $132.5B; contracted power above 4.6GW vs 3.7GW in Q2.
- Demand ~10x capacity through end-2027; new 4–5yr deals at $20–25M per MW, short-term above $40M.
- 2027 funding: $6.5B cash, ~$5B undrawn lines, ~$9B prepayments expected; 75% of 2027 capex covered by IG/enterprise contracts.
- Valuation: $70 is 8x 2030 unlevered FCF of $21.2B — ~44% above the Nov 10 close of $48.73.
Unhidea take: the funding bridge, not demand, was the debate — management answered it with customer prepayments, not new bonds.
Unhidea take: recontracting is the quiet upside — ~$4B of extra annual revenue from 2027 GPU renewals, with no new capex.
Risks: the new IG loan facility is still unclosed; FY26 capex stays huge at $37–39B.
Source: Morgan Stanley, 11 Nov 2026. Shares slipped ~2% premarket Nov 17 (Reuters). Not financial advice.
CoreWeave beat Q3: revenue $3.66B, +168% YoY, vs $3.56B consensus. Adj. operating income $379M vs $245M expected — 10.4% margin vs 6.9% expected. FY26 guide rose again: revenue $13.15B, adj. operating income $1.325B (+26%).
- Exit ARR guided to $20–21B (was $18.5–19.5B); backlog $132.5B; contracted power above 4.6GW vs 3.7GW in Q2.
- Demand ~10x capacity through end-2027; new 4–5yr deals at $20–25M per MW, short-term above $40M.
- 2027 funding: $6.5B cash, ~$5B undrawn lines, ~$9B prepayments expected; 75% of 2027 capex covered by IG/enterprise contracts.
- Valuation: $70 is 8x 2030 unlevered FCF of $21.2B — ~44% above the Nov 10 close of $48.73.
Unhidea take: the funding bridge, not demand, was the debate — management answered it with customer prepayments, not new bonds.
Unhidea take: recontracting is the quiet upside — ~$4B of extra annual revenue from 2027 GPU renewals, with no new capex.
Risks: the new IG loan facility is still unclosed; FY26 capex stays huge at $37–39B.
Source: Morgan Stanley, 11 Nov 2026. Shares slipped ~2% premarket Nov 17 (Reuters). Not financial advice.
105
·
--
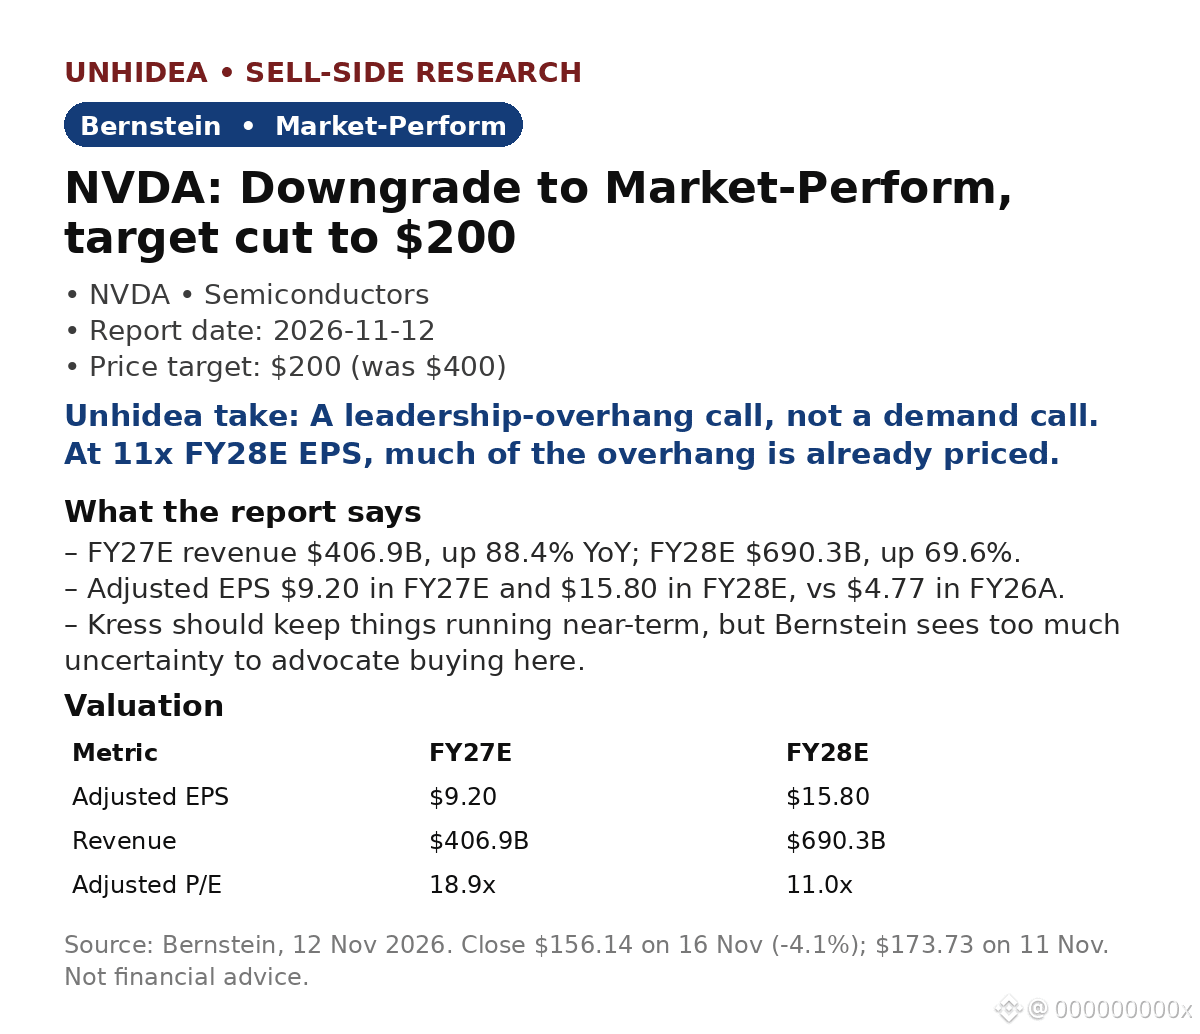
$NVDA: Bernstein rebaixa para desempenho em linha com o mercado e reduz preço-alvo pela metade, para US$ 200
A Bernstein rebaixou a NVIDIA para desempenho em linha com o mercado e reduziu seu preço-alvo de US$ 400 para US$ 200, após o CEO Jensen Huang renunciar em 11 de novembro. Colette Kress é a CEO interina. A divulgação dos resultados está prevista para 17 de novembro, sem anúncio prévio.
- Receita estimada para o exercício fiscal de 2027: US$ 406,9 bi, alta anual de 88,4%; para o exercício fiscal de 2028: US$ 690,3 bi, alta de 69,6%.
- Lucro por ação ajustado estimado em US$ 9,20 no exercício fiscal de 2027 e US$ 15,80 no exercício fiscal de 2028, ante US$ 4,77 no exercício fiscal de 2026.
- Avaliação: 11 vezes a média do lucro por ação dos exercícios fiscais de 2028 e 2029, de US$ 19,04, sustenta o preço-alvo de US$ 200; as ações fecharam a US$ 156,14 em 16 de novembro, queda de 4,1% no dia, o que implica potencial de valorização de cerca de 28% (ante cerca de 15% no fechamento de 11 de novembro, a US$ 173,73).
- Bernstein: Kress deve manter as operações funcionando no curto prazo, mas a incerteza sobre novas informações e sobre um novo CEO capaz de ocupar o lugar de Huang é grande demais para recomendar compras neste momento.
Opinião da Unhidea: esta é uma avaliação motivada pelas incertezas em torno da liderança, não pela demanda — a oportunidade em data centers continua sendo descrita como enorme.
Opinião da Unhidea: a 11 vezes o lucro por ação estimado para o exercício fiscal de 2028, grande parte dessas incertezas já está precificada; os resultados de 17 de novembro serão o próximo teste de verdade.
Riscos: novas informações, desaceleração do crescimento, concorrência, chips desenvolvidos internamente e controles de exportação.
Fonte: Bernstein, 12 de novembro de 2026. Isto não é uma recomendação financeira.
$NVDA : Bernstein rebaixa para desempenho em linha com o mercado e reduz preço-alvo pela metade, para US$ 200
A Bernstein rebaixou a NVIDIA para desempenho em linha com o mercado e reduziu seu preço-alvo de US$ 400 para US$ 200, após o CEO Jensen Huang renunciar em 11 de novembro. Colette Kress é a CEO interina. A divulgação dos resultados está prevista para 17 de novembro, sem anúncio prévio.
- Receita estimada para o exercício fiscal de 2027: US$ 406,9 bi, alta anual de 88,4%; para o exercício fiscal de 2028: US$ 690,3 bi, alta de 69,6%.
- Lucro por ação ajustado estimado em US$ 9,20 no exercício fiscal de 2027 e US$ 15,80 no exercício fiscal de 2028, ante US$ 4,77 no exercício fiscal de 2026.
- Avaliação: 11 vezes a média do lucro por ação dos exercícios fiscais de 2028 e 2029, de US$ 19,04, sustenta o preço-alvo de US$ 200; as ações fecharam a US$ 156,14 em 16 de novembro, queda de 4,1% no dia, o que implica potencial de valorização de cerca de 28% (ante cerca de 15% no fechamento de 11 de novembro, a US$ 173,73).
- Bernstein: Kress deve manter as operações funcionando no curto prazo, mas a incerteza sobre novas informações e sobre um novo CEO capaz de ocupar o lugar de Huang é grande demais para recomendar compras neste momento.
Opinião da Unhidea: esta é uma avaliação motivada pelas incertezas em torno da liderança, não pela demanda — a oportunidade em data centers continua sendo descrita como enorme.
Opinião da Unhidea: a 11 vezes o lucro por ação estimado para o exercício fiscal de 2028, grande parte dessas incertezas já está precificada; os resultados de 17 de novembro serão o próximo teste de verdade.
Riscos: novas informações, desaceleração do crescimento, concorrência, chips desenvolvidos internamente e controles de exportação.
Fonte: Bernstein, 12 de novembro de 2026. Isto não é uma recomendação financeira.
A Bernstein rebaixou a NVIDIA para desempenho em linha com o mercado e reduziu seu preço-alvo de US$ 400 para US$ 200, após o CEO Jensen Huang renunciar em 11 de novembro. Colette Kress é a CEO interina. A divulgação dos resultados está prevista para 17 de novembro, sem anúncio prévio.
- Receita estimada para o exercício fiscal de 2027: US$ 406,9 bi, alta anual de 88,4%; para o exercício fiscal de 2028: US$ 690,3 bi, alta de 69,6%.
- Lucro por ação ajustado estimado em US$ 9,20 no exercício fiscal de 2027 e US$ 15,80 no exercício fiscal de 2028, ante US$ 4,77 no exercício fiscal de 2026.
- Avaliação: 11 vezes a média do lucro por ação dos exercícios fiscais de 2028 e 2029, de US$ 19,04, sustenta o preço-alvo de US$ 200; as ações fecharam a US$ 156,14 em 16 de novembro, queda de 4,1% no dia, o que implica potencial de valorização de cerca de 28% (ante cerca de 15% no fechamento de 11 de novembro, a US$ 173,73).
- Bernstein: Kress deve manter as operações funcionando no curto prazo, mas a incerteza sobre novas informações e sobre um novo CEO capaz de ocupar o lugar de Huang é grande demais para recomendar compras neste momento.
Opinião da Unhidea: esta é uma avaliação motivada pelas incertezas em torno da liderança, não pela demanda — a oportunidade em data centers continua sendo descrita como enorme.
Opinião da Unhidea: a 11 vezes o lucro por ação estimado para o exercício fiscal de 2028, grande parte dessas incertezas já está precificada; os resultados de 17 de novembro serão o próximo teste de verdade.
Riscos: novas informações, desaceleração do crescimento, concorrência, chips desenvolvidos internamente e controles de exportação.
Fonte: Bernstein, 12 de novembro de 2026. Isto não é uma recomendação financeira.
114
·
--
Ver tradução
谷歌最猛的一季,为什么被砸盘
10月28日谷歌三季报:收入涨25%,云涨103%,股价当天却跌了10%。砸的不是增长,是增长的质量。
· 搜索增速连续下滑:19% → 17% → 12%
· 自由现金流:2024/2025 各730亿 → 2026E -200亿 → 2027E -620亿
· 3Q26资本开支514亿美元,全年预计2011亿,2027年预计3299亿
· 伯恩斯坦目标价325美元,一刀砍60美元,评级与大盘同步
报告原话:AI赢家,但不是今天。
观察点:云积压订单5610亿美元、Gemini月活破10亿;真正的多米诺是搜索增速掉到个位数——到那天,故事才重新开始。
#谷歌 #GOOGL #美股 #AI #财报
谷歌最猛的一季,为什么被砸盘
10月28日谷歌三季报:收入涨25%,云涨103%,股价当天却跌了10%。砸的不是增长,是增长的质量。
· 搜索增速连续下滑:19% → 17% → 12%
· 自由现金流:2024/2025 各730亿 → 2026E -200亿 → 2027E -620亿
· 3Q26资本开支514亿美元,全年预计2011亿,2027年预计3299亿
· 伯恩斯坦目标价325美元,一刀砍60美元,评级与大盘同步
报告原话:AI赢家,但不是今天。
观察点:云积压订单5610亿美元、Gemini月活破10亿;真正的多米诺是搜索增速掉到个位数——到那天,故事才重新开始。
#谷歌 #GOOGL #美股 #AI #财报
10月28日谷歌三季报:收入涨25%,云涨103%,股价当天却跌了10%。砸的不是增长,是增长的质量。
· 搜索增速连续下滑:19% → 17% → 12%
· 自由现金流:2024/2025 各730亿 → 2026E -200亿 → 2027E -620亿
· 3Q26资本开支514亿美元,全年预计2011亿,2027年预计3299亿
· 伯恩斯坦目标价325美元,一刀砍60美元,评级与大盘同步
报告原话:AI赢家,但不是今天。
观察点:云积压订单5610亿美元、Gemini月活破10亿;真正的多米诺是搜索增速掉到个位数——到那天,故事才重新开始。
#谷歌 #GOOGL #美股 #AI #财报
107
·
--
#MyFirstSquarePost Bem-vindo à Binance Square! #sats
#MyFirstSquarePost Bem-vindo à Binance Square! #sats
94
Inicia sessão para explorar mais conteúdos
Junta-te a utilizadores de criptomoedas de todo o mundo na Binance Square
⚡️ Obtém informações úteis e recentes sobre criptomoedas.
💬 Com a confiança da maior exchange de criptomoedas do mundo.
👍 Descobre perspetivas reais de criadores verificados.
E-mail/Número de telefone
Tópicos em Tendência
NvidiaEarningsTonight:AIStocks’NextMove?
100,225 visualizações
1,181 a discutir
Dia dos resultados da Nvidia: primeira aparição da CEO interina — a história da IA vai se sustentar?
Binance News
·18 gostos
·8k visualizações
A Packed Week of Earnings and Data Tests Markets
137,358 visualizações
640 a discutir
AnthropicIPOTestsInvestorAppetiteForAI
304,291 visualizações
2,807 a discutir