$INTC: Evercore keeps Outperform, $131 target — server CPUs boom while PCs bust
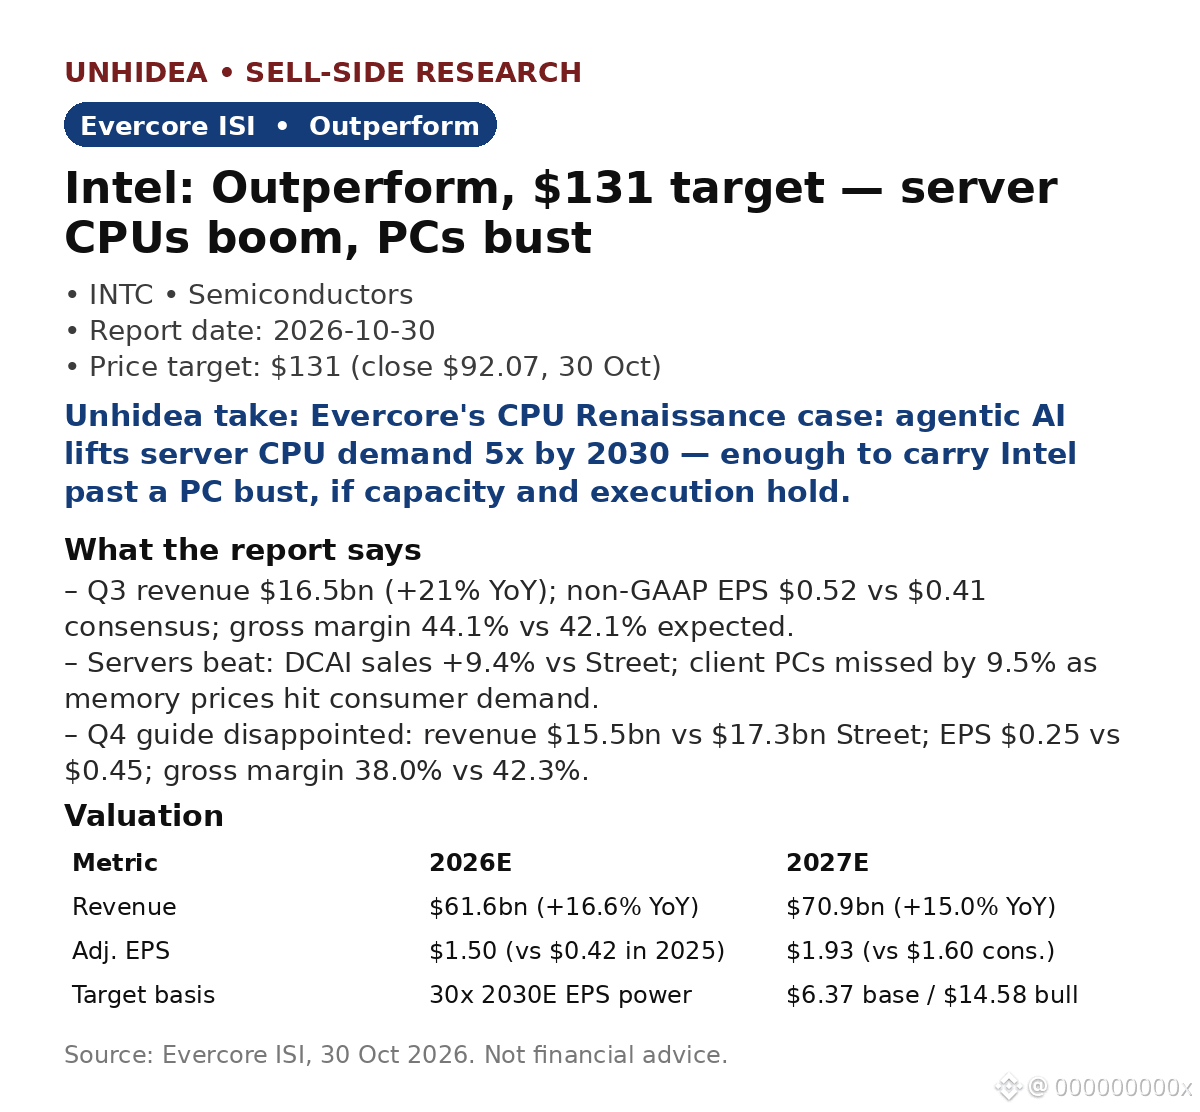
Evercore's 30 Oct note splits Intel in two: data-center CPUs beat (+9.4% vs Street) while client PCs missed by 9.5% as memory prices hit demand. Q3 revenue $16.5bn (+21% YoY); non-GAAP EPS $0.52 vs $0.41 consensus; gross margin 44.1% vs 42.1% expected.
- Weak guide: Q4 revenue $15.5bn vs $17.3bn Street; EPS $0.25 vs $0.45; gross margin 38.0% vs 42.3%.
- Server thesis: mgmt sees server CPU units up >30% in 2026 and 2027; DCAI becomes Intel's largest unit from Q4. PC unit TAM down ~12% in 2026, ~10% more in 2027.
- Valuation: the $131 target is 30x 2030E EPS power ($6.37 base, $14.58 bull), ~42% above the $92.07 close on 30 Oct.
Unhidea take: the CPU Renaissance case rests on agentic AI needing far more CPUs per GPU — if that holds, servers carry Intel through the PC downturn.
Unhidea take: capacity, not demand, is the constraint — wafer/substrate tightness runs into 2028, so shifting client capacity to server decides if the 2030 numbers are real.
Risks: PC declines, memory costs, foundry execution, AI spending sustainability.
Context: $NVDA's 13F showed a 25% cut in its Intel stake; Intel fell ~3% premarket today (Reuters, 17 Nov).
Source: Evercore ISI, 30 Oct 2026. Not financial advice.
Evercore's 30 Oct note splits Intel in two: data-center CPUs beat (+9.4% vs Street) while client PCs missed by 9.5% as memory prices hit demand. Q3 revenue $16.5bn (+21% YoY); non-GAAP EPS $0.52 vs $0.41 consensus; gross margin 44.1% vs 42.1% expected.
- Weak guide: Q4 revenue $15.5bn vs $17.3bn Street; EPS $0.25 vs $0.45; gross margin 38.0% vs 42.3%.
- Server thesis: mgmt sees server CPU units up >30% in 2026 and 2027; DCAI becomes Intel's largest unit from Q4. PC unit TAM down ~12% in 2026, ~10% more in 2027.
- Valuation: the $131 target is 30x 2030E EPS power ($6.37 base, $14.58 bull), ~42% above the $92.07 close on 30 Oct.
Unhidea take: the CPU Renaissance case rests on agentic AI needing far more CPUs per GPU — if that holds, servers carry Intel through the PC downturn.
Unhidea take: capacity, not demand, is the constraint — wafer/substrate tightness runs into 2028, so shifting client capacity to server decides if the 2030 numbers are real.
Risks: PC declines, memory costs, foundry execution, AI spending sustainability.
Context: $NVDA's 13F showed a 25% cut in its Intel stake; Intel fell ~3% premarket today (Reuters, 17 Nov).
Source: Evercore ISI, 30 Oct 2026. Not financial advice.