

SKATS
866 Publications
SKATS
Signaler
Bloquer l’utilisateur
Ouvert au trading

Détenteur pour AUCTION
Trade fréquemment
1.7 an(s)
4 Suivis
345 Abonnés
1.3K+ J’aime
Publications
Portefeuille
Tous
Citations
Vidéos
Direct
PINNED
·
--
2021This is more than a portfolio. It's a journey built on research, patience, and continuous learning. 📊
2021
This is more than a portfolio. It's a journey built on research, patience, and continuous learning. 📊
1
9
3.3k
·
--
Baissier
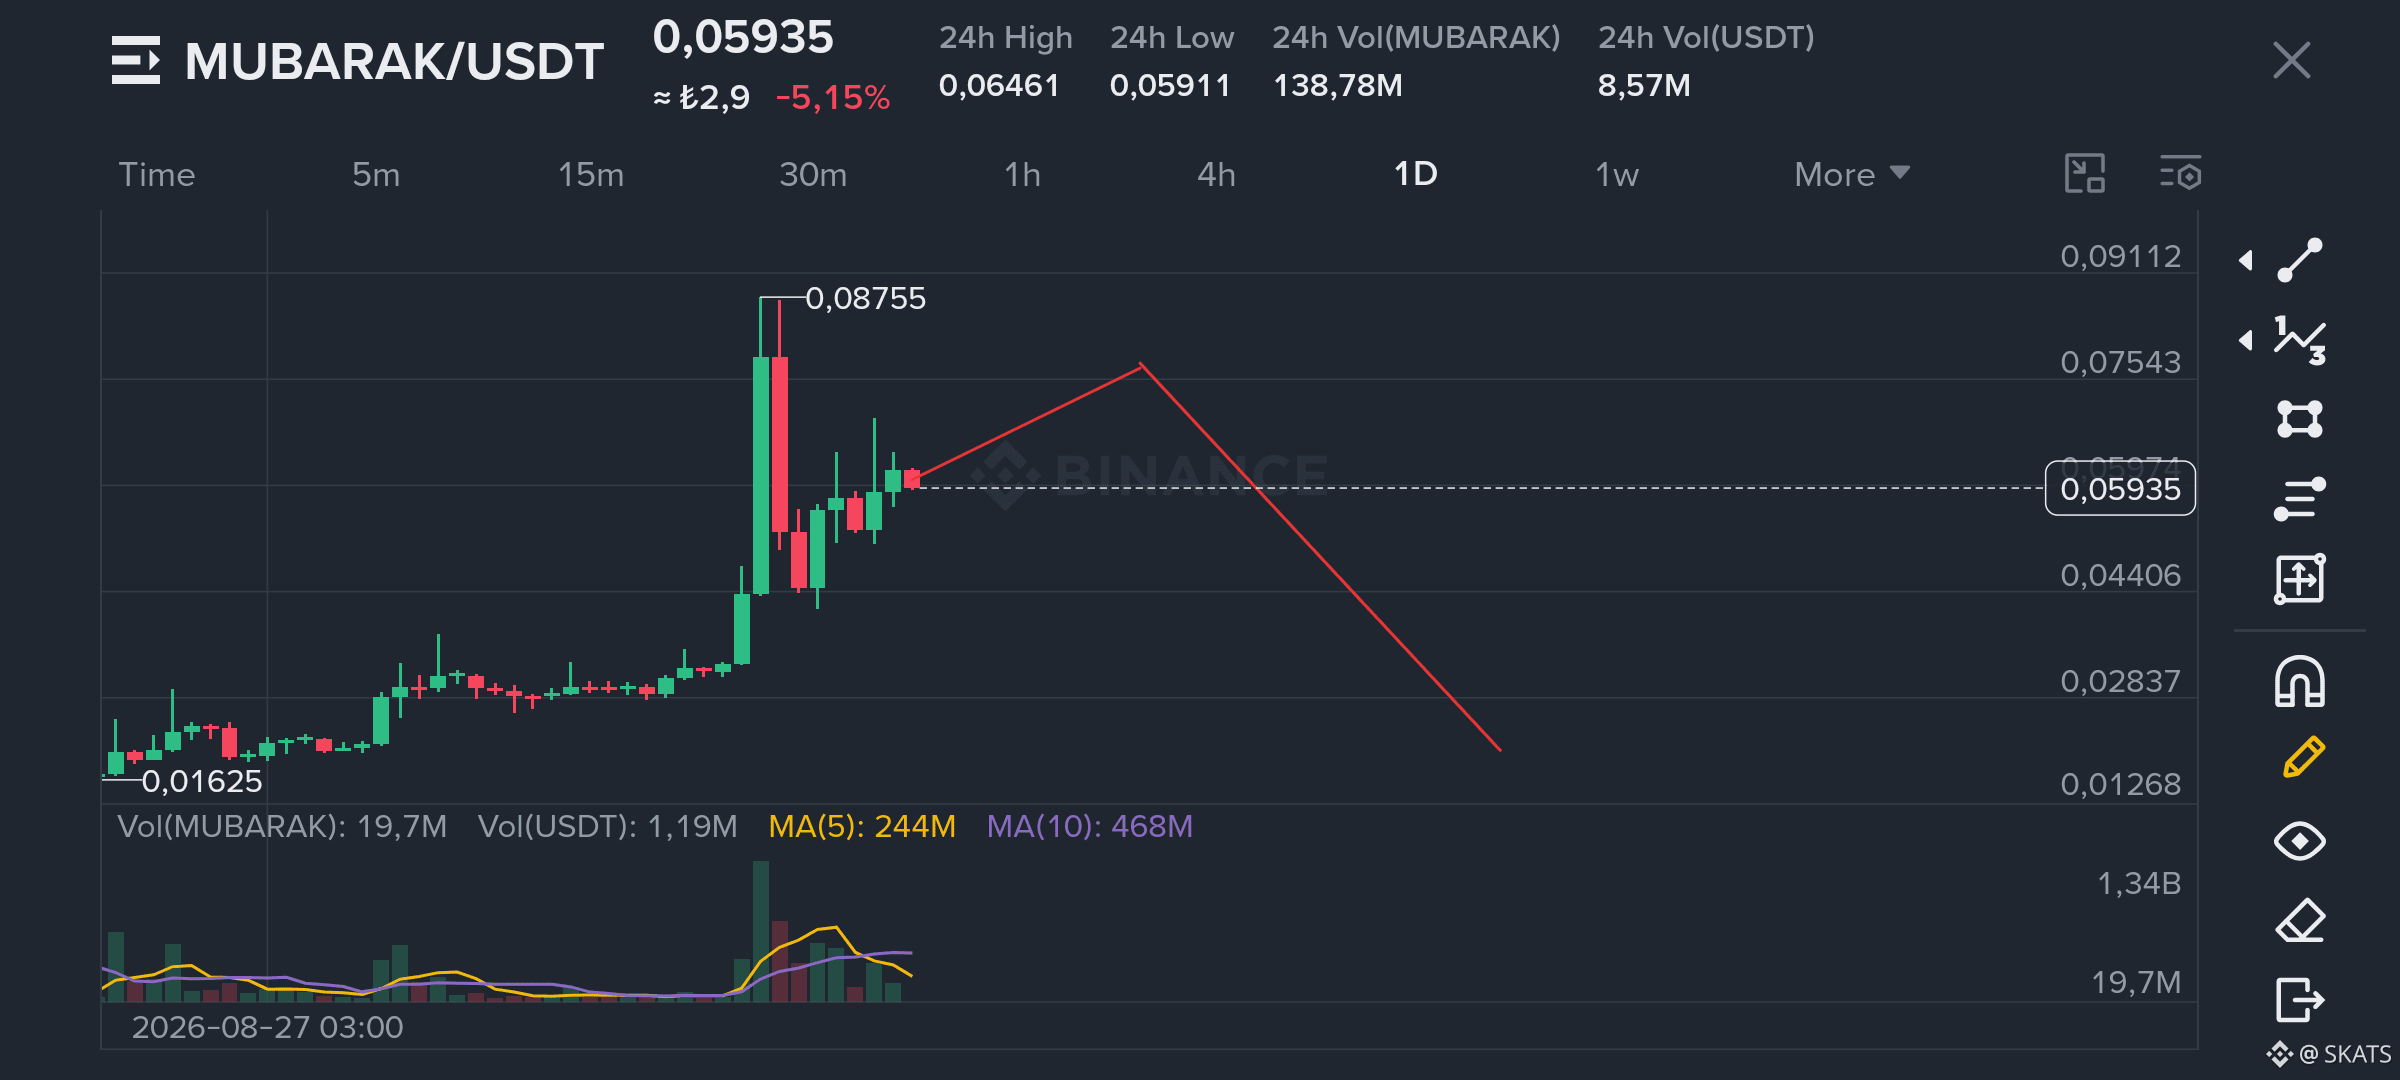
With MUBARAK, I’m watching something more specific than resistance
I think the market may be building what I would call an acceptance debt
The move toward 0.08755 happened so quickly that price passed through several areas without spending enough time there to build a real balance
For me, speed does not always mean strength. Sometimes it simply leaves behind price zones that were never fully tested
That is why even if MUBARAK extends toward the 0.07–0.075 area, I would not automatically read that as continuation
Volume has already narrowed after the first impulse. If price moves higher without broader participation, the structure may become thinner rather than stronger
That is the reason behind the red path on the chart
I am not trying to predict the exact top
I am trying to identify which levels the market never truly accepted
If the 0.05–0.06 area fails to become a lasting reference zone, then the current pricing still looks incomplete to me and a deeper retracement would not be surprising
Fast rallies do not always tell you where strength is going
Sometimes they only leave behind areas the market may have to come back and answer later $MUBARAK
#TufanSalur #Binance #MUBARAK
1
1
70
·
--
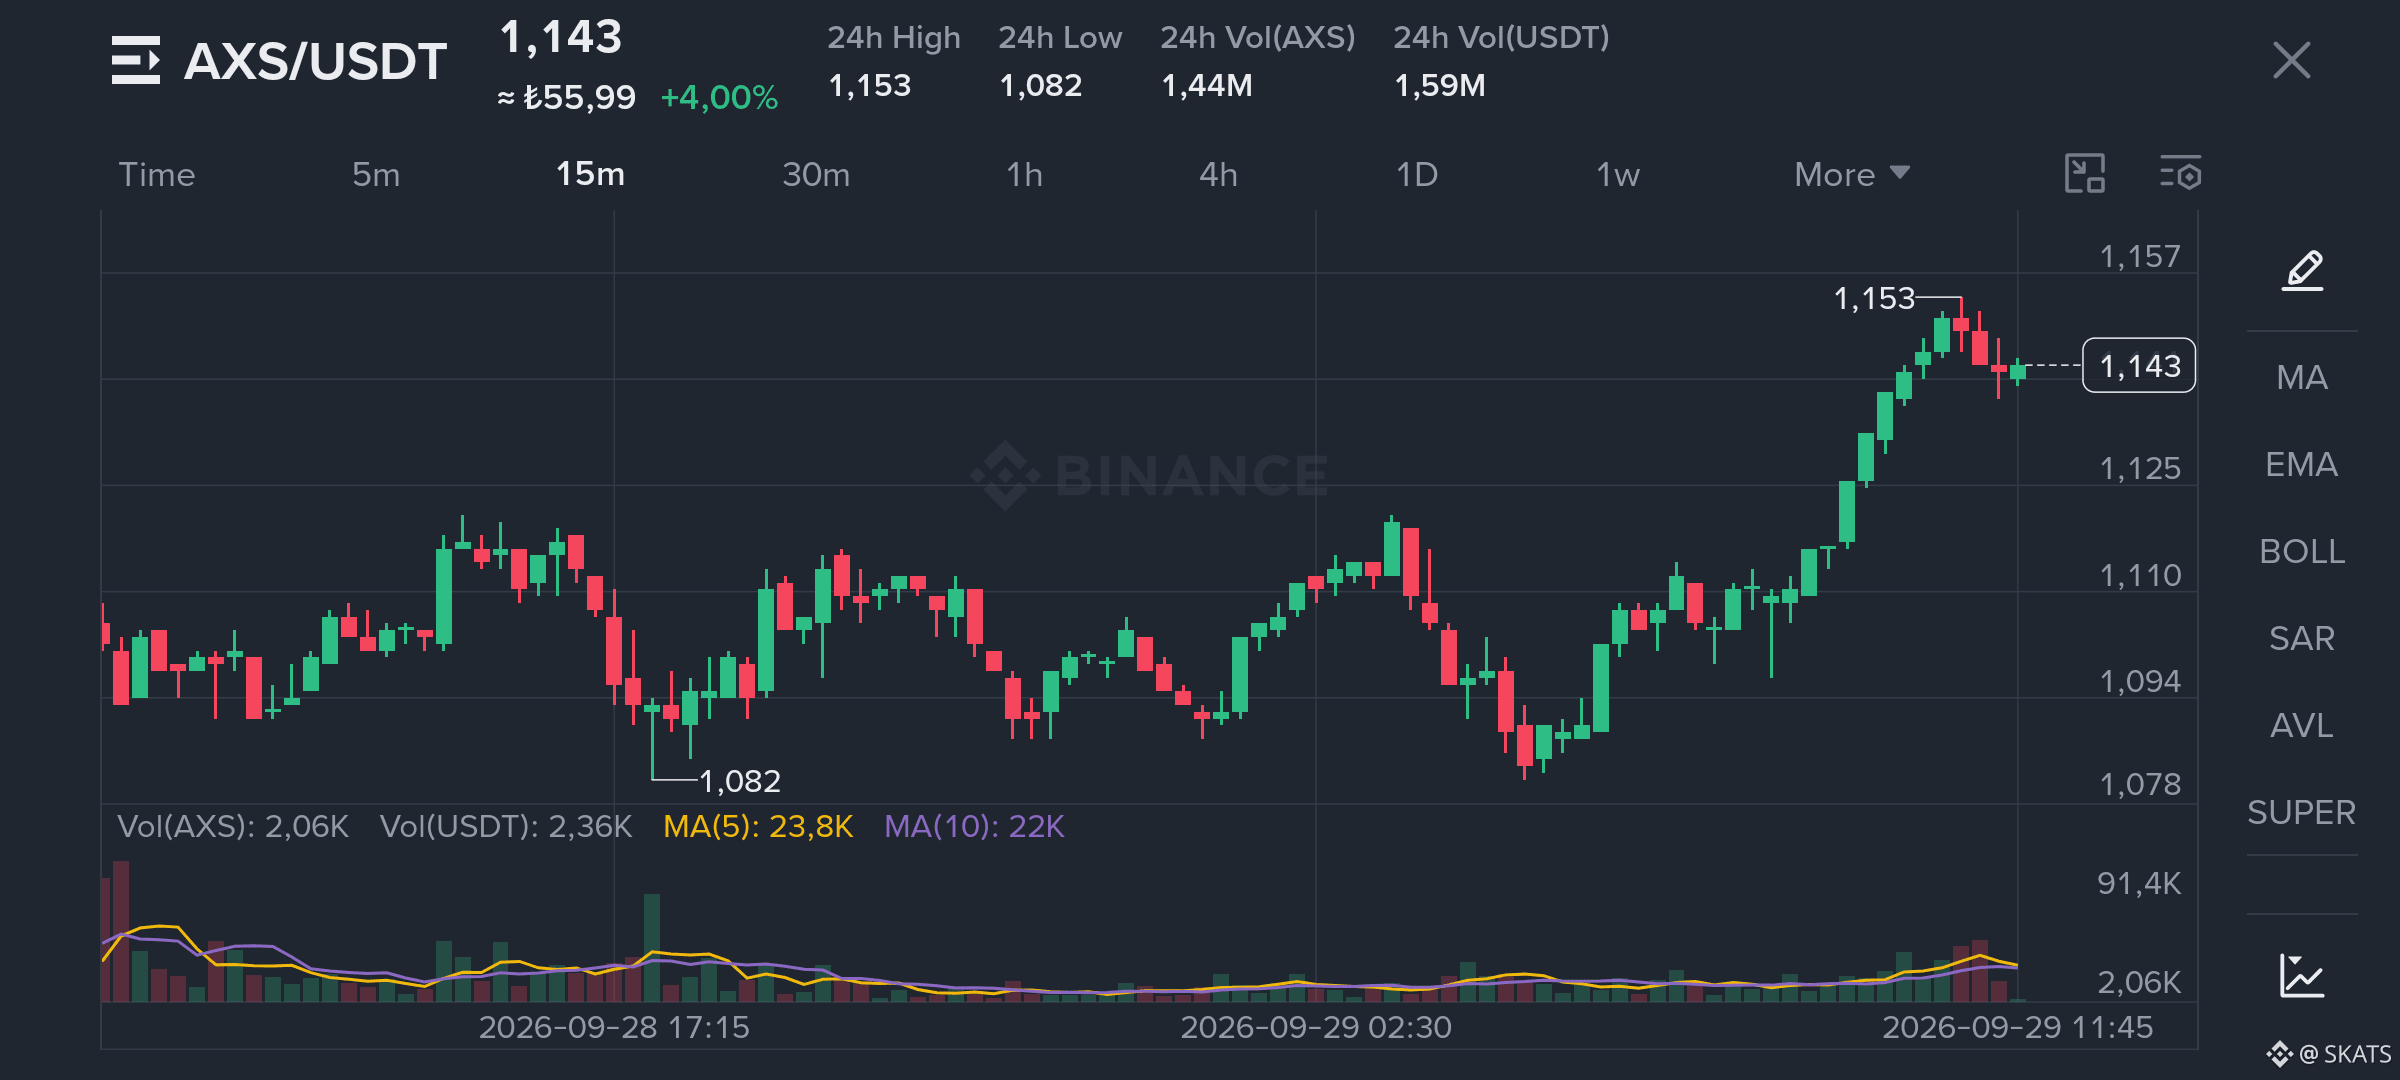
I’m looking at AXS right now and I have the 15-minute chart open. After 1.236, selling pushed it into the 1.154 area and it is now trying to hold around 1.16. There is some short-term pressure, but I’m not focused only on the candles.
I think the market may still be reading AXS through the old high-reward, high-sell-pressure cycle. But today’s structure is not the same.
What I care about is not simply how much AXS exists. I care about how quickly AXS moves from the reward side into real sell pressure.
That distinction matters. Even if the token count stays the same, slower conversion into sell pressure can change the balance the market has become used to.
Despite the pullback on the chart, I’m still watching the upside for now. If demand strengthens while supply turns into sell pressure more slowly than it used to, the market reaction could look very different from what people expect.
I think that is the blind spot in AXS.
Sometimes a move does not begin because there is less supply. It begins because the same supply reaches the market more slowly.
#AXS #CryptoMarket #Tokenomics
1
460
·
--
Haussier
$AUCTION stays on the table.
I’ve made a note of $TRB and $MUBARAK too.
Let’s come back to this post in 2030
#SKATS
$AUCTION stays on the table.
I’ve made a note of $TRB and $MUBARAK too.
Let’s come back to this post in 2030
#SKATS
I’ve made a note of $TRB and $MUBARAK too.
Let’s come back to this post in 2030
#SKATS
Mon portefeuille Spot
2 / 300
10 USDT minimum
Public
G et P sur 7 j
(USDT)
128.58
RSI sur 7 J
+1.72%
ASG
$8945.09
Taux de réussite
62.69%
2
106
·
--
I think we may be measuring oracle security with the wrong metrics
Most people focus on speed, the number of data sources or how quickly an update reaches the chain
What interests me about Tellor is a different question
How expensive is it to keep false data alive long enough to create a real economic consequence
An attacker does not need a lie to survive forever. Sometimes a few blocks, one liquidation or a single critical transaction can be enough
That is why I do not look at Tellor only as a system that delivers data
I am more interested in whether its design can make a false answer too expensive to keep alive long enough to matter
For me, that is a much more important test than speed alone
Because the strongest oracle may not be the one that gives the right answer first
It may be the one that makes the wrong answer economically unsustainable
That is the Tellor thesis I find more interesting
$TRB
#BinanceSquareFamily #TradingTales #TellorTributes
2
4.3k
·
--
On August 19, Bitcoin was trading around $64,000 and by August 25 it had moved above $81,000
Now we are seeing a similar setup again, with price moving from the $75,000 region to above $86,000
At first glance, the two rallies look alike. I don’t think they are
This time, parts of the altcoin market are accelerating as well, while strong ETF demand and significant short covering are adding another layer to the move
What interests me is not the $86,000 level itself
The real question is how far capital can spread beyond Bitcoin from here
Two rallies can produce a similar chart without creating the same market structure
In one, liquidity remains concentrated in the leading asset
In the other, risk appetite begins to rotate across the broader market
For me, the real confirmation would be broader altcoin participation, easing BTC dominance and spot volume expanding across the market
That is where I would start reading this as genuine capital rotation rather than just another price reaction
Maybe the real story will not be where this rally stops, but where capital flows next
#Bitcoin #Altcoins #CryptoMarket
#TufanSalur
2
19.4k
·
--
Haussier
Vérifié
Everyone is debating the same thing around AI stocks
How long can this growth continue
I’m looking somewhere else
As a technology scales, what does it make abundant and what does it make more valuable
Nvidia generating $96.2 billion in revenue last quarter, with $89 billion coming from Data Center, already shows how strong the demand is. Broadcom reaching $16.7 billion in AI semiconductor revenue points in the same direction
But I’m no longer focused only on the product itself
I’m looking at the narrow paths this growth has to pass through
Software can scale. Code can be copied. Models can improve
Electricity capacity, grid access, advanced memory, packaging and cooling cannot expand at the same speed
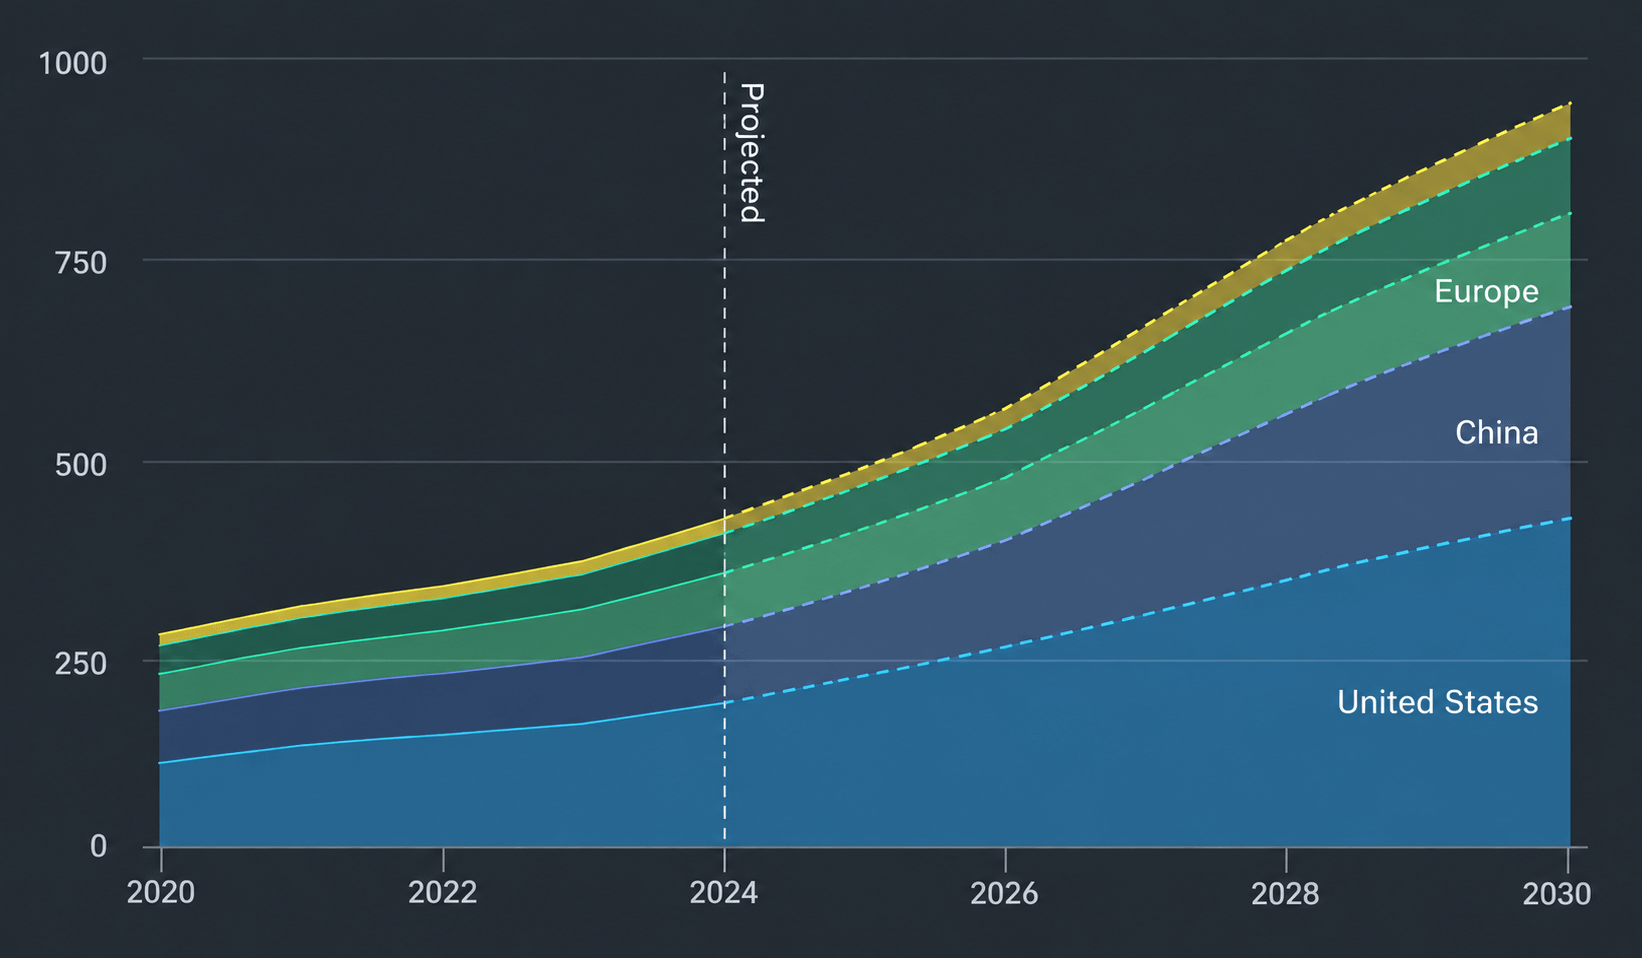
The IEA expects data center electricity consumption to rise from around 485 TWh in 2025 to close to 950 TWh by 2030
That’s why I’m bullish on this space, but I don’t look at every company with an AI label the same way
I’m more interested in the things this technology cannot multiply easily
Because the faster growth becomes, the more visible the physical limits become
And sometimes the strongest pricing power does not sit with the product everyone is talking about
It sits at the narrow point the entire expansion has to pass through
I think the first phase was the race to create intelligence
The next phase may be about who controls the resources that intelligence cannot operate without
So for me, the next opportunity is not about finding another AI story
It is about finding the scarcity that does not disappear as growth continues
Because the more a technology scales, the more valuable the things that cannot keep up with it can become @Binance_Square_Official
#AIStocksWhatNext #AIInfrastructure #Nvidia #Binance #TufanSalur
Everyone is debating the same thing around AI stocks
How long can this growth continue
I’m looking somewhere else
As a technology scales, what does it make abundant and what does it make more valuable
Nvidia generating $96.2 billion in revenue last quarter, with $89 billion coming from Data Center, already shows how strong the demand is. Broadcom reaching $16.7 billion in AI semiconductor revenue points in the same direction
But I’m no longer focused only on the product itself
I’m looking at the narrow paths this growth has to pass through
Software can scale. Code can be copied. Models can improve
Electricity capacity, grid access, advanced memory, packaging and cooling cannot expand at the same speed
The IEA expects data center electricity consumption to rise from around 485 TWh in 2025 to close to 950 TWh by 2030
That’s why I’m bullish on this space, but I don’t look at every company with an AI label the same way
I’m more interested in the things this technology cannot multiply easily
Because the faster growth becomes, the more visible the physical limits become
And sometimes the strongest pricing power does not sit with the product everyone is talking about
It sits at the narrow point the entire expansion has to pass through
I think the first phase was the race to create intelligence
The next phase may be about who controls the resources that intelligence cannot operate without
So for me, the next opportunity is not about finding another AI story
It is about finding the scarcity that does not disappear as growth continues
Because the more a technology scales, the more valuable the things that cannot keep up with it can become @Binance Square Official
#AIStocksWhatNext #AIInfrastructure #Nvidia #Binance #TufanSalur
2
15.9k
·
--
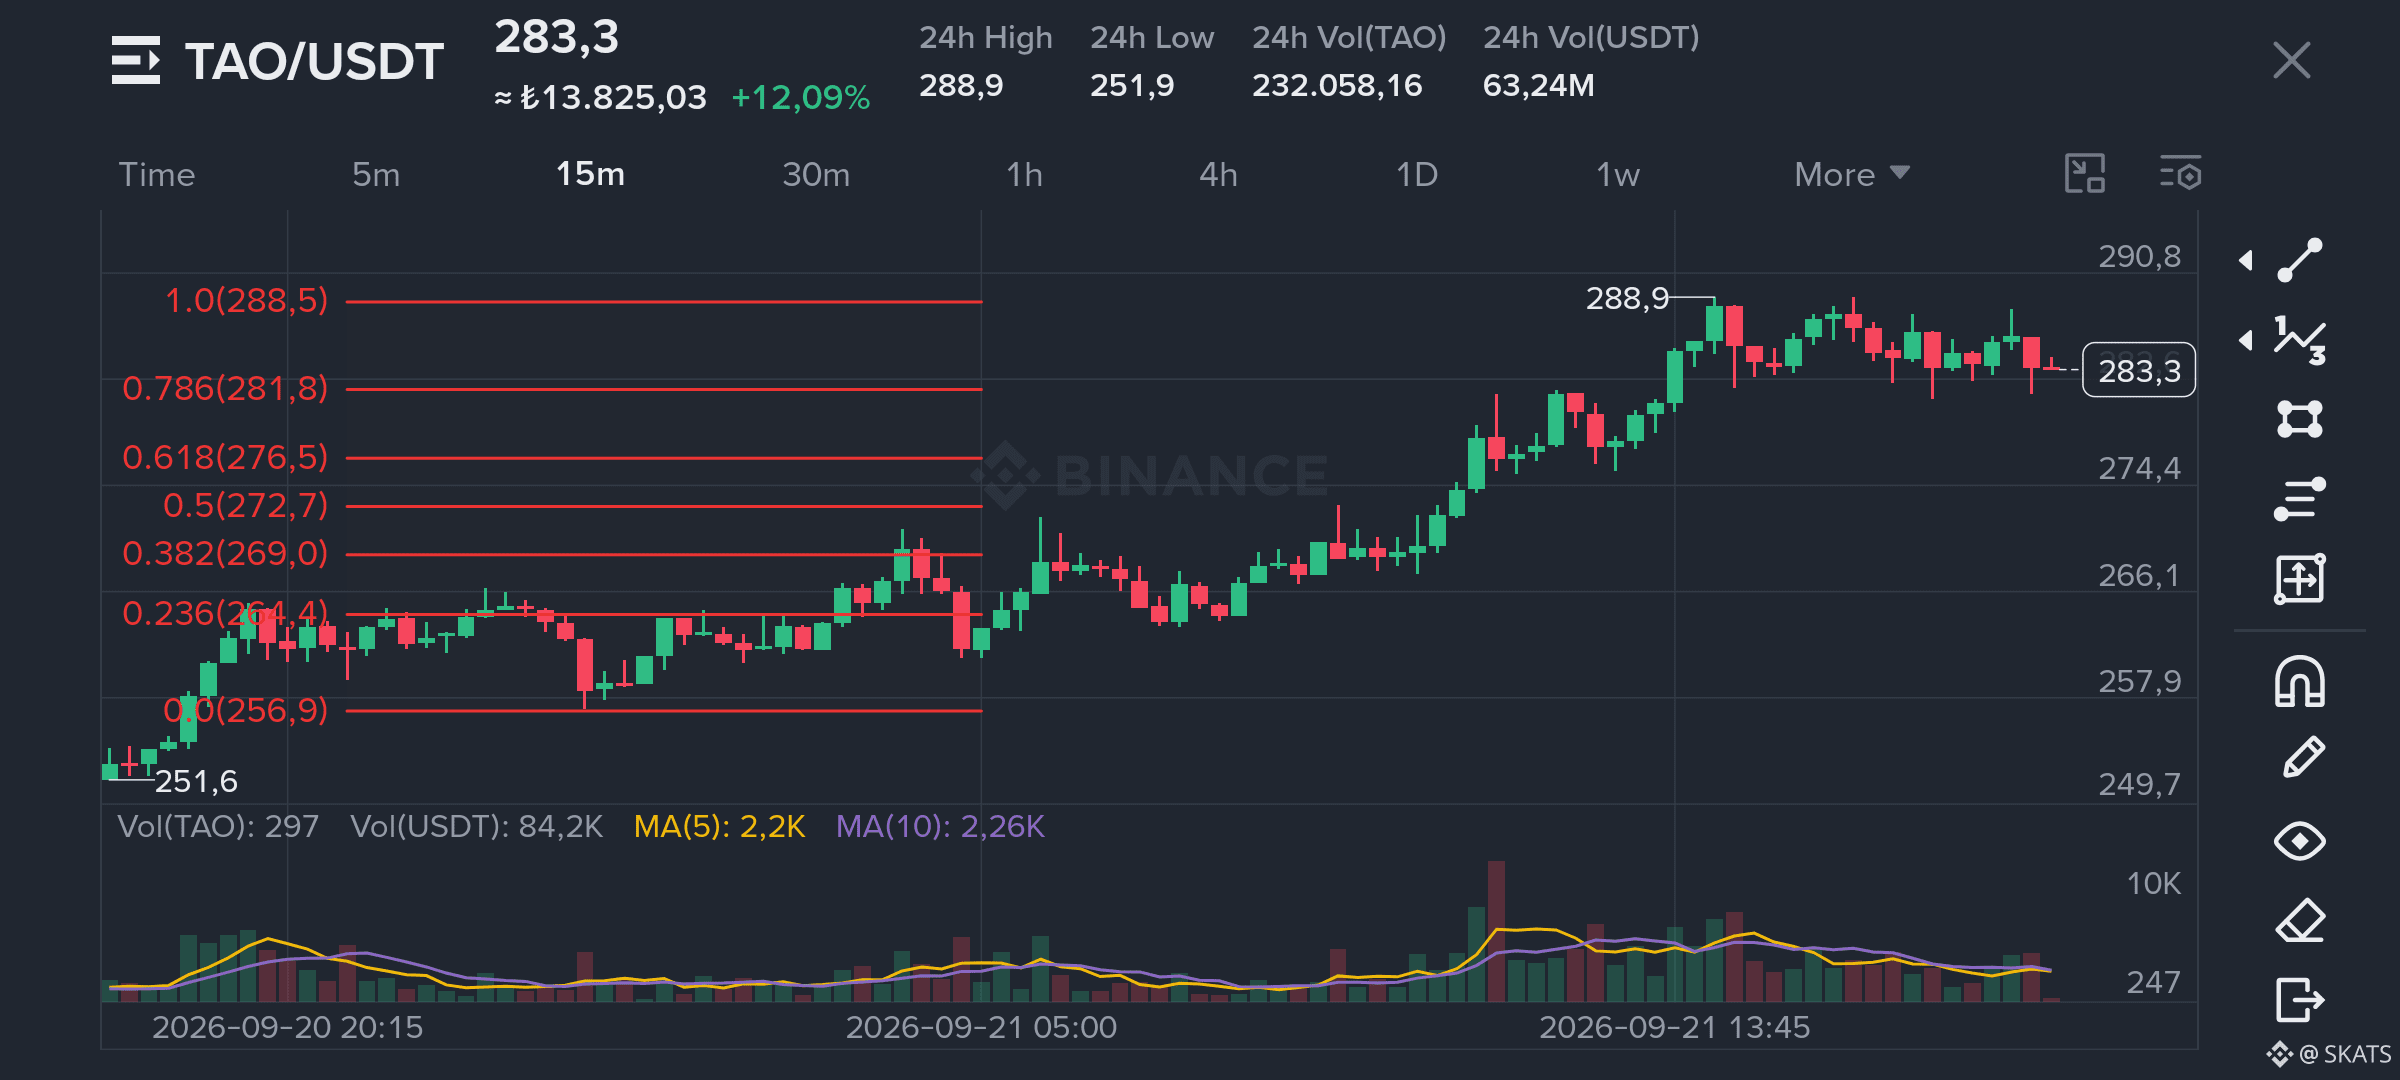
When I look at the TAO chart, I’m not interested in explaining the price. Everyone can already see that.
What I keep thinking about is how capital may start making decisions inside Bittensor over time.
Building strong technology may not be enough. Different subnets are also competing for attention and capital, and that creates a more interesting problem for me.
If a system keeps rewarding what already looks strongest, it may end up losing something that simply hasn’t had enough time to prove itself.
Capital naturally moves toward what has already shown results. But when the same preference keeps repeating, the winners attract more capital, gain more visibility and then attract even more capital.
At some point, Bittensor may not only be selecting what is best. It may also be making what people already believe is best even stronger.
That balance is what I’m watching with TAO.
The long-term quality of the network may not depend only on how well it rewards the strongest subnets. It may also depend on how much room it leaves for ideas that are still early, uncertain or simply different.
If capital reaches the same conclusion too quickly, the system can look efficient while slowly losing its ability to discover something new.
Consensus can make capital feel safer, but new value is often found before consensus exists.
So when I look at TAO, I’m not only thinking about which part of the network is gaining attention.
I’m thinking about how long Bittensor can allow a different idea to survive before the market fully understands whether it was right or wrong.
Because maybe the quality of a network is not measured by how quickly everyone reaches the same conclusion.
Maybe it is measured by how much space it gives an unproven idea to prove itself.$TAO
#TAO #Bittensor #Crypto #Binance
#TufanSalur
3
10.5k
·
--
Most people will probably read S&P Global’s move to acquire OpenZeppelin as another sign of traditional finance moving closer to crypto
I’m looking at it from a different angle
When financial products become programmable, I think the way we measure risk may need to change as well
In traditional finance we usually look at the issuer, the balance sheet, the collateral and who holds custody. On-chain finance adds another layer to all of this, the code itself
A tokenized bond can have a strong issuer, attractive yield and solid collateral, but if the smart contract controlling ownership, transfers or access has a critical weakness, part of the risk may sit somewhere traditional analysis does not fully capture
That’s what makes S&P Global’s agreement to acquire OpenZeppelin interesting to me. Not simply because another major financial company is moving closer to crypto, but because it points to something more fundamental
As finance becomes programmable, code quality may stop being a technical detail and start becoming part of the financial product itself
That could also change the questions institutions ask before committing capital. It may no longer be only about who issued the asset, but also who verified the code behind it
Tokenization is often described as moving stocks, bonds, funds and other assets onto blockchain infrastructure. But putting an asset on-chain does not automatically make its risk easier to understand
It may create a new type of risk that capital still needs to learn how to measure
So maybe the next stage of on-chain finance is not simply about bringing more assets onto blockchains
It may be about making the risks inside the code measurable enough for large capital to trust
If that happens, the infrastructure that verifies financial code may eventually become just as important as the infrastructure that executes it
#Tokenization #DigitalAssets #SmartContracts #Binance
2
23.1k
·
--
Haussier
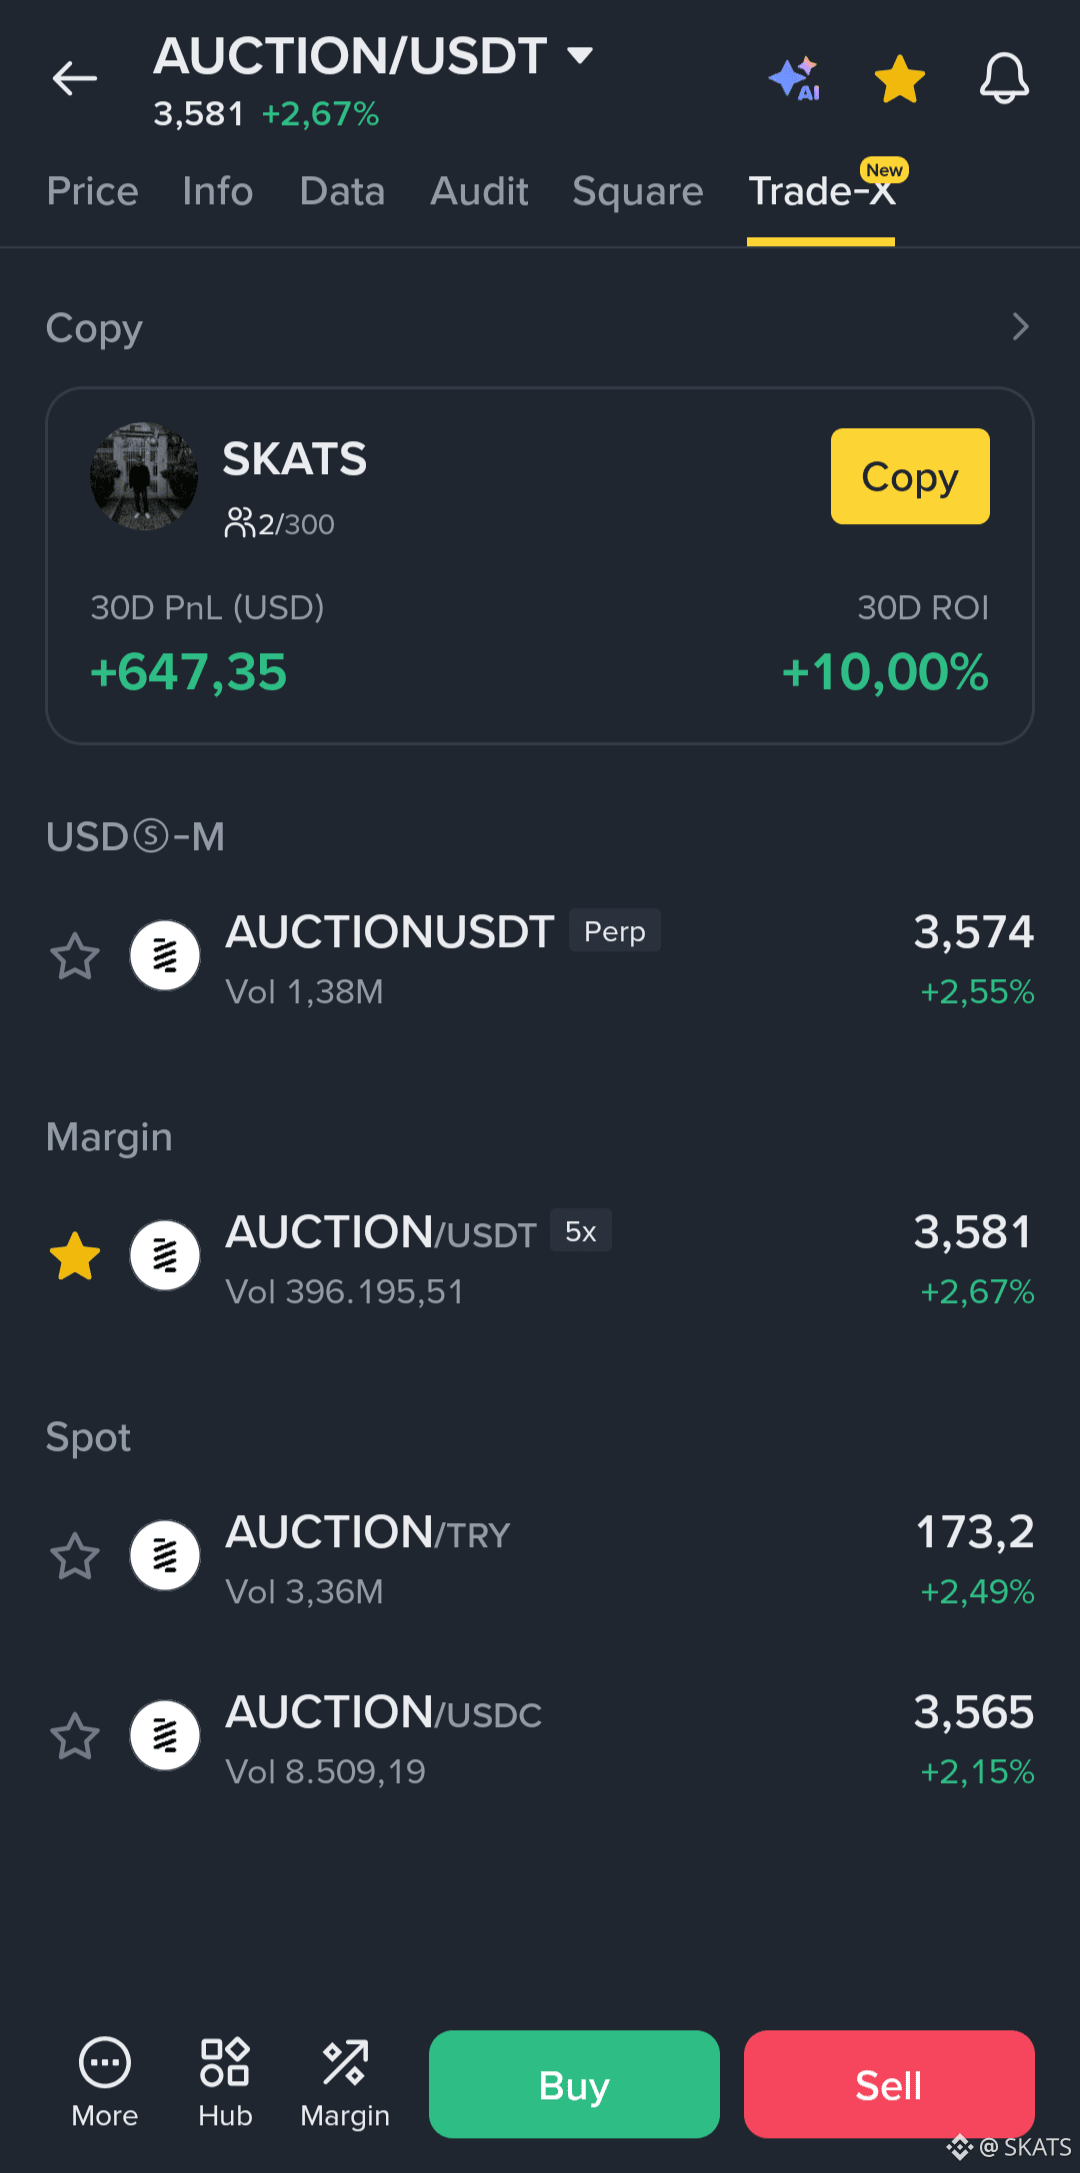
My AUCTION strategy is now active in the Copy section.
The numbers are already on the screen, so I won’t write an epic on top of them. The market is dramatic enough 😄
$AUCTION #Binance
My AUCTION strategy is now active in the Copy section.
The numbers are already on the screen, so I won’t write an epic on top of them. The market is dramatic enough 😄
$AUCTION #Binance
The numbers are already on the screen, so I won’t write an epic on top of them. The market is dramatic enough 😄
$AUCTION #Binance
2
18.2k
·
--
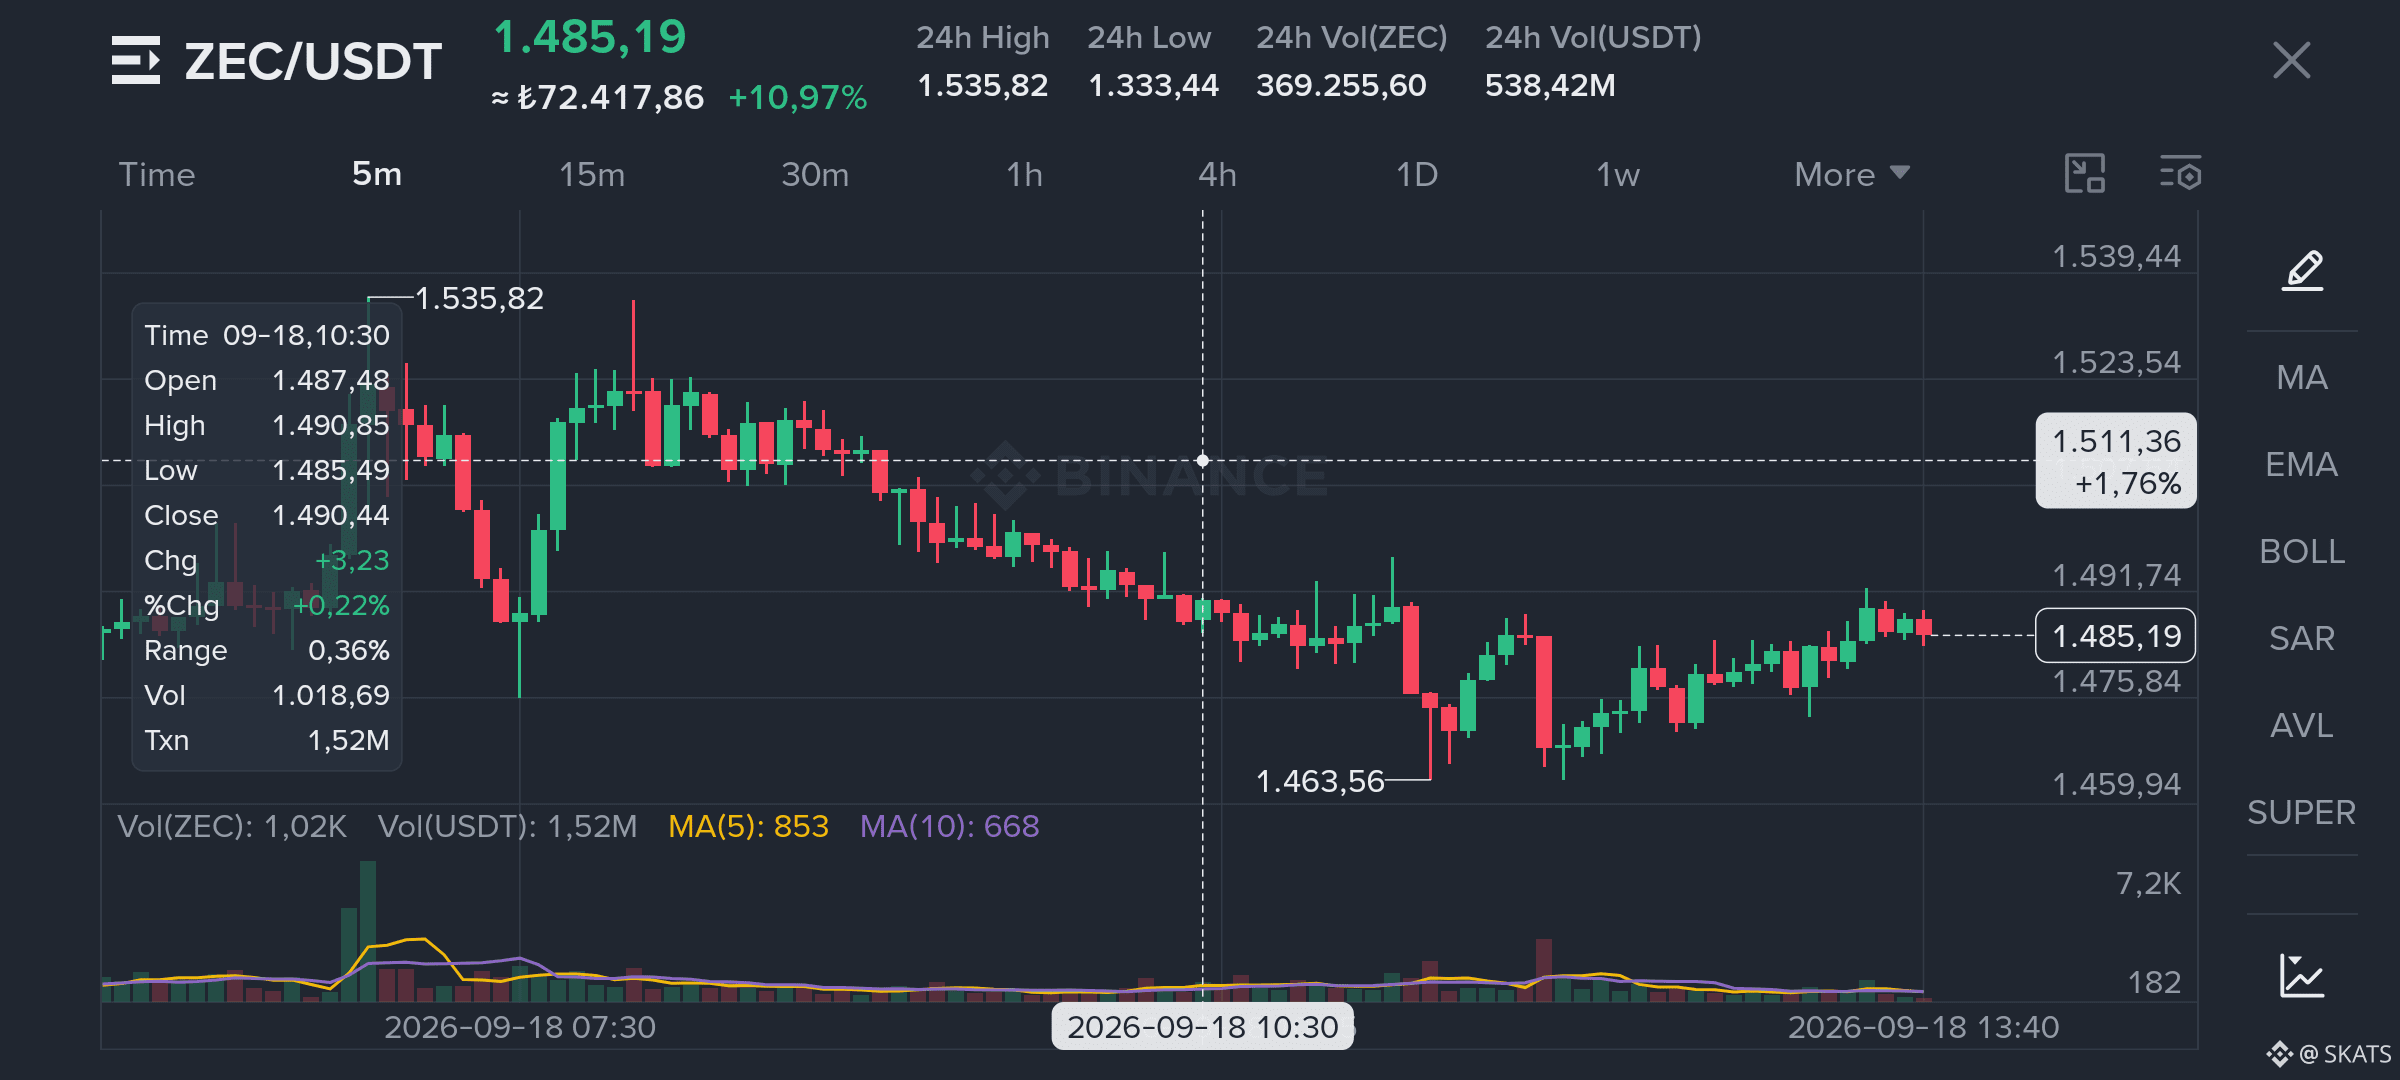
With ZEC, I’m less interested in how fast the price moved and more interested in how this move has redistributed positions across the market.
We’ve seen a double-digit move in 24 hours, a clear expansion in volume, and price testing the 1,535 area before settling around 1,485.
Short liquidations may have accelerated part of that move.
But I wouldn’t reduce the whole move to that.
Because several things changed at the same time.
Capital positioned much lower is now sitting on meaningful profits.
New money that didn’t want to miss the move entered at a much higher cost basis.
And on the short side, some positions may have been forced out or reduced their risk.
So while the price changed, something else changed with it:
The level at which different participants start to feel uncomfortable.
That matters more to me now.
After a strong move, price doesn’t always need more money to keep moving.
Sometimes it only needs existing positions to start behaving differently.
If earlier buyers are in no rush to take profits, newer buyers can tolerate the first pullback, and shorts don’t immediately rebuild aggressive exposure, the market may begin accepting a higher price range.
But the opposite can happen just as quickly.
If late buyers become the first group to lose conviction, what looks strong today can become fragile very fast.
So I’m not looking at ZEC and thinking:
“Shorts got liquidated, therefore it goes higher.”
I’m asking a different question.
Who is most likely to be forced into changing their decision first?
The earlier capital sitting on profits?
The newer capital that entered at a higher price?
Or the short side trying to rebuild exposure?
Because sometimes the next move isn’t decided by the strongest side.
It’s decided by the side that becomes uncomfortable first.
#ZEC #MarketStructure #Binance
2
5.3k
·
--
Vérifié
One of crypto’s earliest ideas was simple:
If you hold the keys, you truly hold the asset.
That idea moved financial responsibility away from institutions and toward the individual.
Years later, something interesting is happening in the opposite direction.
Deutsche Bank is preparing a digital asset custody service for institutional clients. Under the plan, managing wallets and private keys for Bitcoin, Ether and selected stablecoins will become part of the service it provides.
But Bitcoin isn’t what caught my attention.
It’s the fact that a bank is preparing to take responsibility for the keys.
For an individual, controlling the keys can mean independence. For an institution, it means responsibility.
Who controls access, and who carries the responsibility when something goes wrong?
At some point, the problem stops being only about storing the asset.
You have to custody the responsibility too.
I think this is one of the overlooked parts of institutional crypto.
For years, we’ve asked whether banks would buy Bitcoin, put it on their balance sheets or give clients access to it.
Maybe the bigger change is happening somewhere else.
Banks may not simply be adopting crypto. They may be turning a new kind of responsibility created by crypto into a financial service.
And that becomes even more interesting if stocks, bonds, funds and other assets gradually move onto on-chain infrastructure.
In that world, custody may no longer be simply about saying:
“Your assets are stored here.”
The more valuable promise could become:
“We take responsibility for the keys.”
So with Deutsche Bank’s move, I’m not watching how much Bitcoin it may eventually custody.
I’m watching something else.
What does banking start selling when crypto becomes infrastructure?
Because one of crypto’s earliest questions was:
“Why do I need a bank?”
If the institutional question eventually becomes:
“Which institution can I trust with this responsibility?”
#DigitalAssetCustody #Bitcoin #InstitutionalCrypto #Binance
3
12.7k
·
--
Article
What Institutional Money TrustsWhen institutional interest in crypto comes up, most people tend to look at the same thing: How much money is coming in?
Lately, I’ve been looking one step further back.
What does that money need to trust before it can make a decision?
That’s why S&P Global leading a strategic investment that extended Kaiko’s Series B to $110 million caught my attention. Kaiko provides data infrastructure for crypto and on-chain markets.
And this isn’t an isolated development. S&P Dow Jones Indices and Kaiko have also brought their digital asset indices together under a shared framework.
I don’t just see this as another sign of traditional finance moving closer to crypto. I see something more fundamental.
Before large pools of capital move deeper into crypto, they are starting to take seriously how crypto itself is measured.
Because millions of people trading the same asset doesn’t necessarily mean its price carries the same meaning for everyone.
Which market is the price coming from? How deep is the liquidity? Which reference price can actually be trusted?
And among prices formed across different platforms, which one is reliable enough to make a decision on?
A retail investor can move past most of these questions in seconds. Large capital can’t.
And I think this is one of the overlooked parts of crypto becoming institutional.
A market doesn’t mature simply because it gets bigger.
Scale that cannot be measured reliably is still uncertainty for institutions.
If tokenized stocks, bonds, funds and other assets really do move toward 24-hour on-chain markets, some of the most valuable infrastructure may not only be the systems that execute transactions.
The systems that can tell us which price deserves to be trusted may become just as important.
So from now on, I won’t measure institutional interest in crypto only through ETF flows, investments or market caps.
I’ll also be watching which data institutions are beginning to trust.
Because maybe institutionalization doesn’t truly begin on the day large capital enters the market.
Maybe it begins on the day that capital develops a common language for deciding which price is “real.
#Crypto #DigitalAssets #Binance
What Institutional Money Trusts
When institutional interest in crypto comes up, most people tend to look at the same thing: How much money is coming in?
Lately, I’ve been looking one step further back.
What does that money need to trust before it can make a decision?
That’s why S&P Global leading a strategic investment that extended Kaiko’s Series B to $110 million caught my attention. Kaiko provides data infrastructure for crypto and on-chain markets.
And this isn’t an isolated development. S&P Dow Jones Indices and Kaiko have also brought their digital asset indices together under a shared framework.
I don’t just see this as another sign of traditional finance moving closer to crypto. I see something more fundamental.
Before large pools of capital move deeper into crypto, they are starting to take seriously how crypto itself is measured.
Because millions of people trading the same asset doesn’t necessarily mean its price carries the same meaning for everyone.
Which market is the price coming from? How deep is the liquidity? Which reference price can actually be trusted?
And among prices formed across different platforms, which one is reliable enough to make a decision on?
A retail investor can move past most of these questions in seconds. Large capital can’t.
And I think this is one of the overlooked parts of crypto becoming institutional.
A market doesn’t mature simply because it gets bigger.
Scale that cannot be measured reliably is still uncertainty for institutions.
If tokenized stocks, bonds, funds and other assets really do move toward 24-hour on-chain markets, some of the most valuable infrastructure may not only be the systems that execute transactions.
The systems that can tell us which price deserves to be trusted may become just as important.
So from now on, I won’t measure institutional interest in crypto only through ETF flows, investments or market caps.
I’ll also be watching which data institutions are beginning to trust.
Because maybe institutionalization doesn’t truly begin on the day large capital enters the market.
Maybe it begins on the day that capital develops a common language for deciding which price is “real.
#Crypto #DigitalAssets #Binance
2
5.1k
·
--
Vérifié
As the Fed meeting approaches, everyone is preparing for the same question: Will we get a 25bp rate hike?
This time, I’m looking less at the decision itself and more at what happened before the Fed even announced it.
Because the bond market didn’t wait for the Fed.
With the U.S. 10-year Treasury yield around 5%, a 25bp hike has already been largely priced in.
So if the Fed raises rates tomorrow, I won’t necessarily see it as the beginning of a new round of tightening.
There’s another possibility.
The Fed may simply be formalizing a tightening that the bond market has already started.
I think that distinction matters.
Because everything from corporate borrowing costs to investors’ willingness to take risk depends on more than the rate set by the Fed. Long-term yields also change the value of the alternatives available to capital.
That’s why I think looking only at the decision itself misses part of the picture for BTC, technology stocks and gold.
For me, the more interesting information comes afterward.
What happens to the 10-year Treasury yield after a 25bp hike?
Does it retreat?
Or does it remain elevated, keeping financial conditions tight independently of the Fed?
The second scenario would create something much more interesting.
The Fed could hike once while the market delivers a much larger tightening to the economy.
So tomorrow, I won’t be trying to predict the first reaction on the screen.
I’ll be less interested in which direction BTC moves in the first few minutes and more interested in which level of interest rates capital accepts after the decision.
Because for me, the most important question tomorrow isn’t whether the Fed raises rates.
Is the Fed still leading financial conditions?
Or is it simply catching up with a bond market that has already moved ahead of it?
#FedRateWatch #BTC #Fed #Binance
2
2.4k
·
--
What has been making me think most about stablecoins lately isn’t their market cap.
It’s the behavior of banks.
In the U.S., the banking industry is increasingly concerned that stablecoins could compete directly with bank deposits. The discussion is no longer just about regulation or whether crypto is safe.
It’s becoming a question of where money will be held.
That’s why even the yields and rewards offered to stablecoin holders have become part of a serious debate.
But at the same time, something else is happening.
A group of 21 major financial institutions, including Bank of America, Citi, Goldman Sachs and Deutsche Bank, is preparing to launch its own dollar-based stablecoin solution in the first half of 2027.
I see an interesting contradiction here.
On one side, we have a banking system concerned about stablecoins competing with deposits. On the other, some of the biggest players in that same system are preparing to enter stablecoin infrastructure themselves.
Maybe measuring the importance of stablecoins in finance only by the number of dollars in circulation misses something bigger.
I’m watching something else.
Has the existing system started changing its own behavior?
Because real competition doesn’t always begin when a new product replaces the old system.
Sometimes it begins when the old system starts changing its position because of the new one.
So in the period ahead, I won’t only be watching how much the stablecoin market grows.
I’ll also be watching the distance between what banks say about stablecoins and what they are building for their own customers.
Because that may be where the real signal is.
Sometimes the clearest sign of how powerful a financial innovation has become isn’t who is investing in it, but who is being forced to change their behavior because of it.
#Stablecoins #Crypto #Binance #TufanSalur
2
3
737
·
--
Will the opening bell of a stock exchange still mark the beginning of price discovery in the future?
Most of the discussion around tokenization lately has focused on the ability to trade 24 hours a day.
What interests me is the possibility of something much bigger.
Because if price discovery is no longer limited to the hours when a market is open, the opening of a traditional exchange may eventually lose the meaning it has today.
We are already seeing a small but very interesting example of this.
According to Binance Research, the price formed by bStocks over weekends reflected a median of 92% of the price gap that followed at the Monday open.
Even more interesting, in all 41 observed cases where the opening gap was larger than 3%, the direction was correct.
The important part for me isn’t the 92% or the 41 out of 41.
It’s that price is beginning to form before the traditional market even opens.
Because when the market closes on Friday, the world doesn’t stop.
News keeps coming.
Companies keep making announcements.
Macroeconomic conditions keep changing.
Investor expectations keep shifting.
In the past, all of this had to wait until Monday to find a real reflection in price.
If tokenization starts removing that waiting period, I don’t think the only thing that changes will be trading hours.
The place where price is discovered first could change too.
And that’s why I find Nasdaq’s $100 million investment in Payward so interesting.
Because the question is no longer, “Can we put stocks on the blockchain?”
It’s what happens to the traditional structure of finance if price discovery, trading, and settlement are redesigned around blockchain infrastructure.
Maybe in the future, the Monday open won’t be the moment when a new price is discovered.
It will simply be the moment when a price discovered over the weekend finds its place in the traditional market.
I think that’s where the real breakthrough in tokenization could happen.
#RWA #Tokenization #Crypto #bStocks
2
1.2k
·
--
Haussier
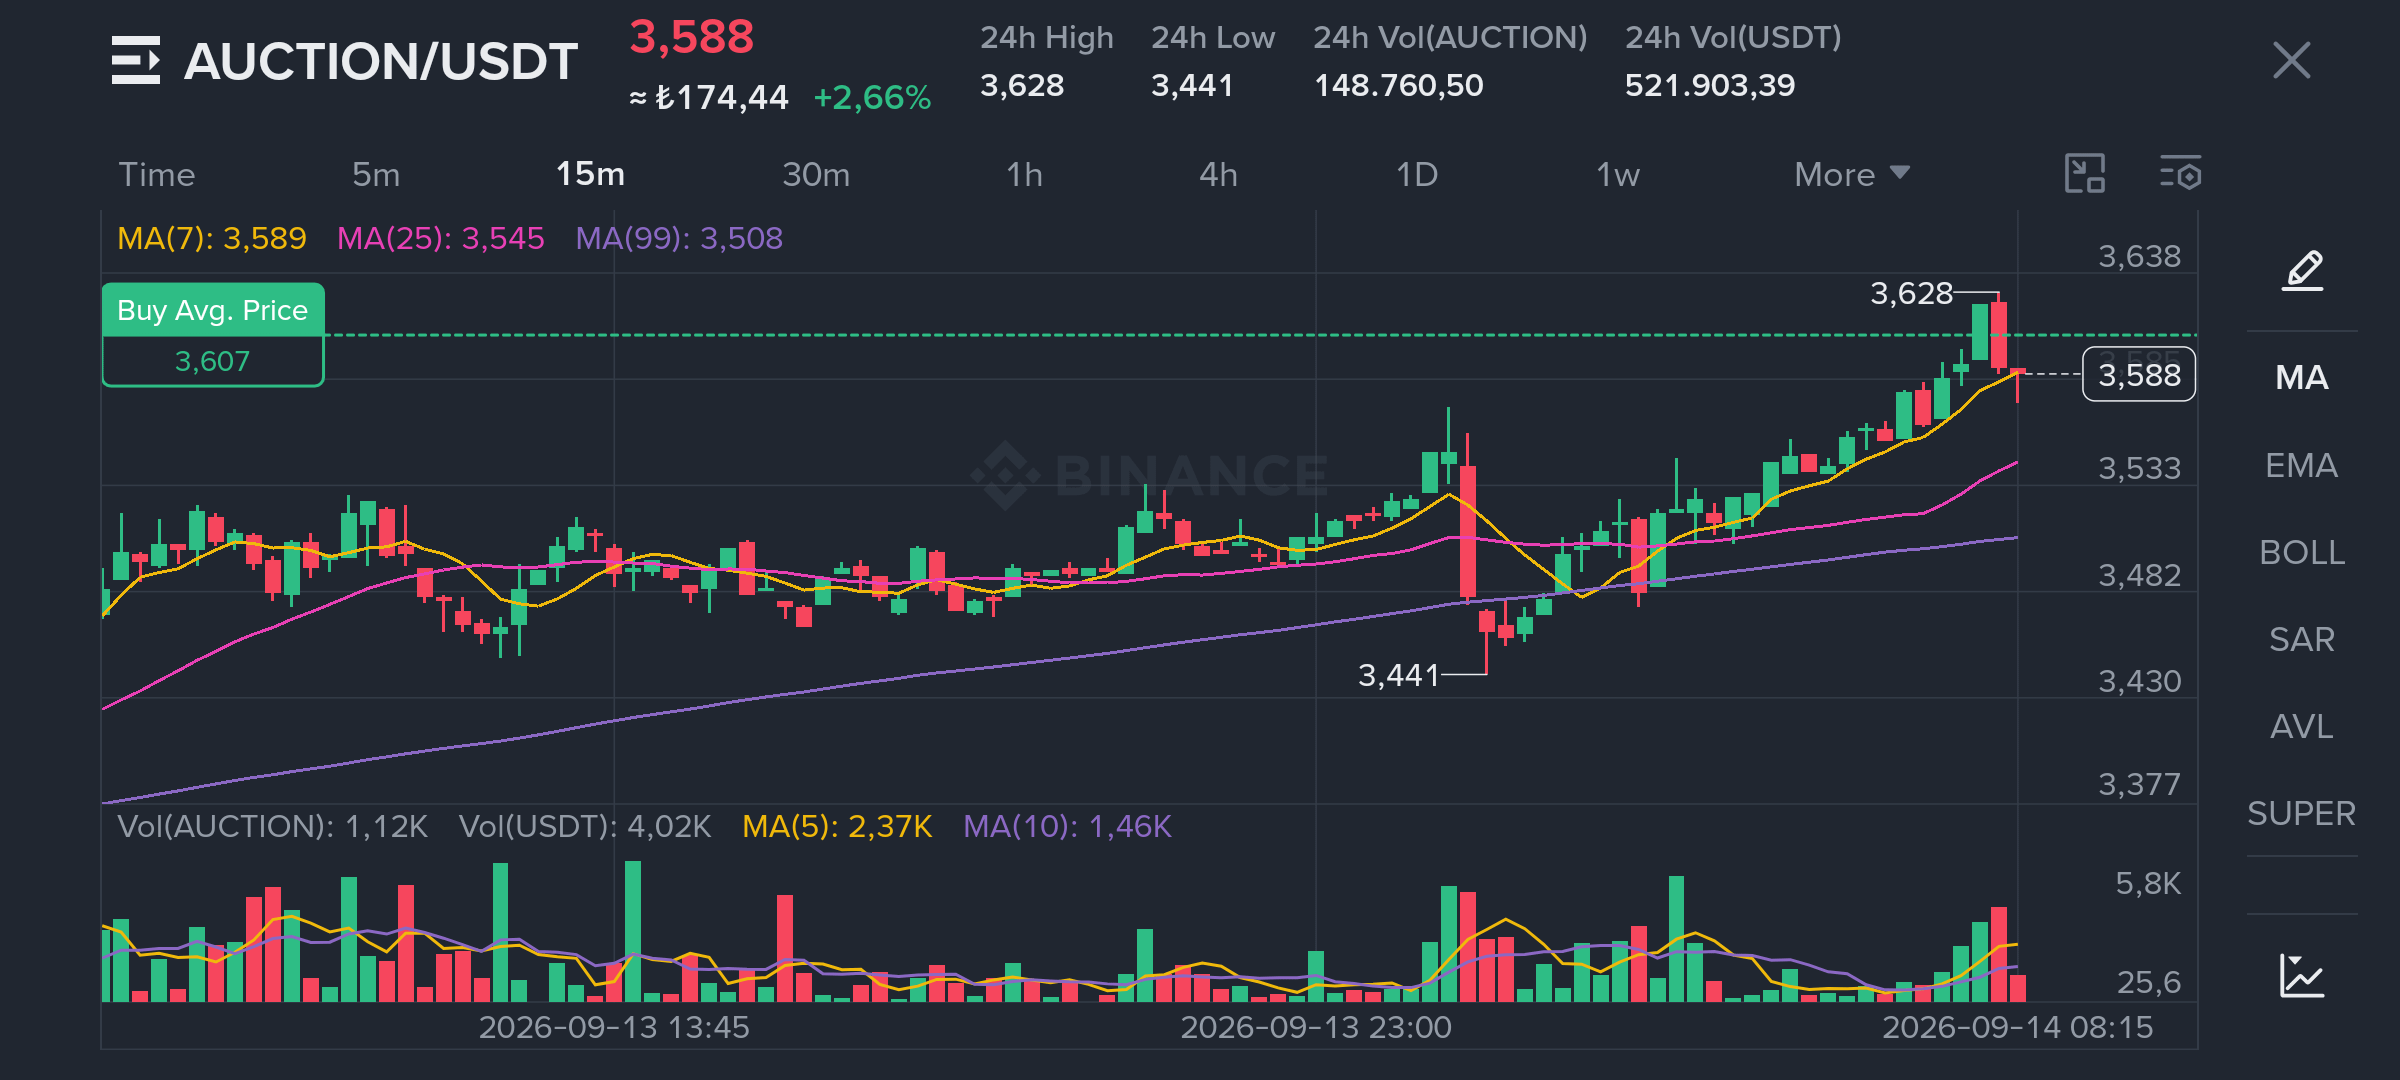
What interests me about AUCTION today isn’t simply that the price has moved back above $3.50.
A few weeks ago, something much more interesting happened.
AUCTION’s daily trading volume moved above $100 million.
Then the price pulled back, and the market cap returned to around $26 million.
Normally, after a move like that, I would first look at how much of the move was given back.
This time, I’m looking at it differently.
Because instead of completely returning to its previous range, price has started building strength around $3.50 again.
And now another thing is standing out on the chart.
Volume is expanding again, momentum is strengthening, and price is testing the short-term resistance around $3.52.
For me, the important question isn’t whether $3.52 is simply broken.
It’s whether the structure that formed after that previous surge in volume is now creating a new price area.
Because sometimes the real meaning of a strong move doesn’t become visible during the move.
It appears afterward.
If AUCTION can establish a lasting structure above this area, I would find it difficult to view the $100 million-plus volume from a few weeks ago as simply a large trading day that came and went.
Then I would be asking a different question:
Was that volume the beginning of renewed interest, or was it only a temporary burst of activity?
The chart hasn’t given me a definitive answer yet.
But it has definitely started asking the question again.
#AUCTİON #Crypto #Binance
2
775
·
--
Vérifié
This CPI report didn’t give the Fed a clear escape route.
Headline inflation came in exactly where expectations were, at 0.4% month over month and 3.4% year over year.
But I’m paying more attention to what happened underneath it.
Core CPI accelerated to 0.3% monthly, after 0% in June and 0.2% in July.
Then look at the rest of the picture.
Payrolls increased by 162,000 in August, unemployment stayed at 4.1%, and PPI is running at 5.4% year over year.
The market now puts the probability of a September rate hike around 82%.
I’m bearish on risk assets in the short term.
But I don’t think the most interesting part is the possibility of a hike.
It’s that the Fed may be responding to an inflation problem that monetary policy cannot fully solve.
The Fed can suppress demand. It cannot manufacture supply.
That distinction matters.
If energy supply improves in the months ahead, especially as more Venezuelan oil potentially returns to global markets, today’s inflation pressure could look very different later.
But the Fed has to make its decision with today’s numbers.
That creates an uncomfortable situation.
The Fed may have to tighten financial conditions because inflation is still too persistent, even while part of that inflation is coming from forces that higher rates cannot directly fix.
That’s why I’m not treating this CPI as a simple “hawkish” signal.
For me, the bigger question is whether this becomes the beginning of a new tightening cycle — or simply a policy response to an inflation problem that may eventually ease from the supply side.
That difference could matter far more for markets than today’s 0.4%.
#CPIWatch #Fed #Crypto #Binance
1
2
1k
·
--
The addition of HIMS and Salesforce to bStocks isn’t just about having two new names available to trade for me.
Because the fact that an asset becomes easier to access isn’t enough to change how I look at it.
What interests me more is this:
When access becomes easier, how much does an investor’s view of an asset they were previously watching from a distance actually change?
Because sometimes a new opportunity isn’t created.
The distance between you and a decision simply becomes shorter.
That’s exactly what I’ll be watching with HIMS and Salesforce.
A new listing can attract attention, create trading activity, and put these assets in front of more investors.
But none of that changes the investment thesis by itself.
For me, the real value isn’t that they are now on the screen. It’s whether, after they get there, I can still explain why they deserve a place in my portfolio.
I think that’s where the difference between good investing and easy access really becomes visible
$HIMSB $CRMB
#HIMS #CRM #bStocks #Binance
2
5.6k
Connectez-vous pour découvrir plus de contenu
Rejoignez la communauté mondiale des adeptes de cryptomonnaies sur Binance Square
⚡️ Suviez les dernières informations importantes sur les cryptomonnaies.
💬 Jugé digne de confiance par la plus grande plateforme d’échange de cryptomonnaies au monde.
👍 Découvrez les connaissances que partagent les créateurs vérifiés.
Adresse e-mail/Nº de téléphone
Sujets d’actualité
QNTRises287%
6,052 vues
209 mentions
🚨 QNT JUST EXPLODED +287%! 🔥
+287% is NOT a normal move. 👀
QNT has suddenly gone parabolic, putting traders on high alert as momentum and volume surge.
⚠️ After a move this violent, FOMO can be dangerous — volatility
can go both ways.
📈 Watch: sustained volume + breakout confirmation
📉 Risk: sharp profit-taking / pullback
🔥 Is QNT just getting started… or is this move ready for a major correction?
What’s your QNT target? 👇
#qntrises287% #QNT #Quant #crypto #BinanceSquare
$QNT
ASHFAQ NAEEM
·6 mentions J’aime
·3.9k vues
HSBCNamesStablecoinRedCoinForPhasedLaunch
326 vues
29 mentions
TrumpRejectsAIRulesForVoluntaryAudits
9,953 vues
328 mentions