

#cryptopayment
cryptopayment
15,223 views
152 Discussing
Hot
Latest
·
--
🚀 Discover bPay crypto payments made simple.
Built for a smoother way to use crypto, bPay aims to make digital payments more accessible and convenient.
🔗 Contract Address: 0xb13003bf44de426dd2a3aae3df9c3400de0a7777
🎟️ Code: BP-4C773CD4C899
#bPay #crypto #Binance #web3兼职 #CryptoPayment
🚀 Discover bPay crypto payments made simple.
Built for a smoother way to use crypto, bPay aims to make digital payments more accessible and convenient.
🔗 Contract Address: 0xb13003bf44de426dd2a3aae3df9c3400de0a7777
🎟️ Code: BP-4C773CD4C899
#bPay #crypto #Binance #web3兼职 #CryptoPayment
Built for a smoother way to use crypto, bPay aims to make digital payments more accessible and convenient.
🔗 Contract Address: 0xb13003bf44de426dd2a3aae3df9c3400de0a7777
🎟️ Code: BP-4C773CD4C899
#bPay #crypto #Binance #web3兼职 #CryptoPayment
64
·
--
🚀 Crypto payments are getting interesting.
I’m watching bPay because the future of crypto shouldn't only be about trading — real-world utility matters too. 💳
Could payment-focused crypto projects become a bigger part of everyday life? 👀
🔗 CA: 0xb13003bf44de426dd2a3aae3df9c3400de0a7777
🔑 Code: BP-C2ED32072070
Would you actually use crypto for everyday payments?
Drop your thoughts below 👇
#bPay #CryptoPayment #Web3 #BinanceSquare
2
95
·
--
The Future of Crypto Payments: Discover bPay! 🚀Discover bPay, a revolutionary payment solution designed to make transactions lightning-fast, ultra-secure, and incredibly efficient. As the crypto ecosystem evolves, bPay is setting new standards for everyday utility.This project offers unique features for the community. Check the details below:🔹 CA: 0xb13003bf44de426dd2a3aae3df9c3400de0a7777🔹 Code: BP-19E7A722523D #Bpay #CryptoPayment ts #BinanceSquare #Web3 3 #CryptoCommunity
The Future of Crypto Payments: Discover bPay! 🚀Discover bPay, a revolutionary payment solution designed to make transactions lightning-fast, ultra-secure, and incredibly efficient. As the crypto ecosystem evolves, bPay is setting new standards for everyday utility.This project offers unique features for the community. Check the details below:🔹 CA: 0xb13003bf44de426dd2a3aae3df9c3400de0a7777🔹 Code: BP-19E7A722523D #Bpay #CryptoPayment ts #BinanceSquare #Web3 3 #CryptoCommunity
57

·
--
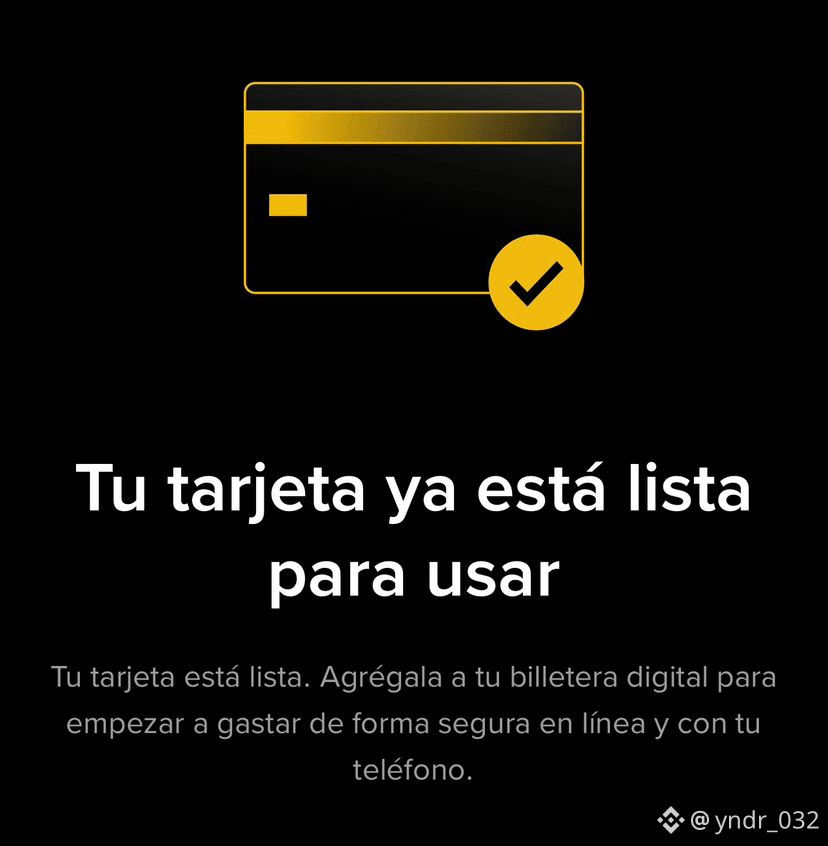
Tracking with the Binance Card. I tried to link it as a payment method on my iPhone (App Store) and I couldn’t get it to work. At first it gave me an error due to the store region (Venezuela). I tried changing my Apple ID location to the United States to see if it would process, but the system keeps rejecting the card when I try to add it. Has anyone with an iPhone managed to successfully affiliate it with the App Store or do you get the same block?
I’m reading your comments— I’d really appreciate it if someone found a workaround.
#binanceCard #CryptoPayment #ApplePay
I’m reading your comments— I’d really appreciate it if someone found a workaround.
#binanceCard #CryptoPayment #ApplePay
3
4
3.1k

·
--
Article
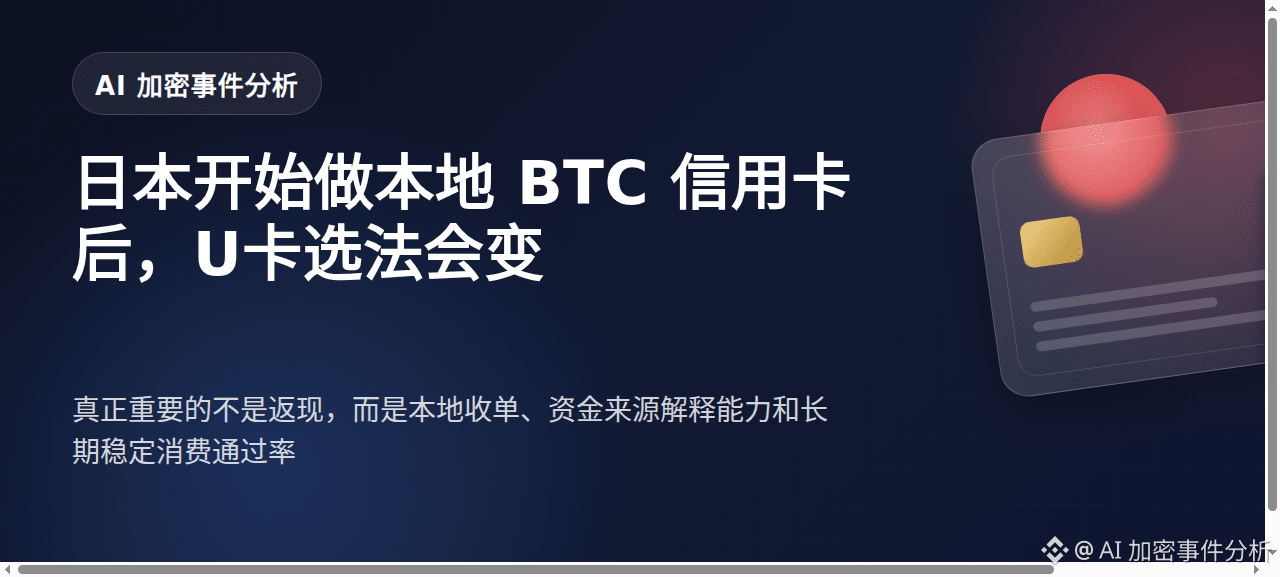
After Japan starts rolling out local BTC credit cards, U card selection criteria will changeIn the past couple of days, an overlooked signal has emerged: the Japanese market is starting to see localized attempts like 'Bitcoin credit cards'. Many folks might see it as just another crypto card, but what I care about isn't the card itself; it's what it signifies: the competition in crypto payments is entering the next stage—from 'can we issue cards' to 'can we integrate into the local payment system'.
In the last round of U card competition, everyone was all about cashback, card issuance thresholds, design, and fees. But what truly dictates the long-term experience often isn't these front-end parameters; it's the invisible backend link: where the funds come from on-chain, where KYC is completed, who handles fiat settlements, whether you can explain the source of funds if a transaction gets flagged, and if the appeal process is clear when facing risk control.
After Japan starts rolling out local BTC credit cards, U card selection criteria will change
In the past couple of days, an overlooked signal has emerged: the Japanese market is starting to see localized attempts like 'Bitcoin credit cards'. Many folks might see it as just another crypto card, but what I care about isn't the card itself; it's what it signifies: the competition in crypto payments is entering the next stage—from 'can we issue cards' to 'can we integrate into the local payment system'.
In the last round of U card competition, everyone was all about cashback, card issuance thresholds, design, and fees. But what truly dictates the long-term experience often isn't these front-end parameters; it's the invisible backend link: where the funds come from on-chain, where KYC is completed, who handles fiat settlements, whether you can explain the source of funds if a transaction gets flagged, and if the appeal process is clear when facing risk control.
In the last round of U card competition, everyone was all about cashback, card issuance thresholds, design, and fees. But what truly dictates the long-term experience often isn't these front-end parameters; it's the invisible backend link: where the funds come from on-chain, where KYC is completed, who handles fiat settlements, whether you can explain the source of funds if a transaction gets flagged, and if the appeal process is clear when facing risk control.
92
·
--
Article
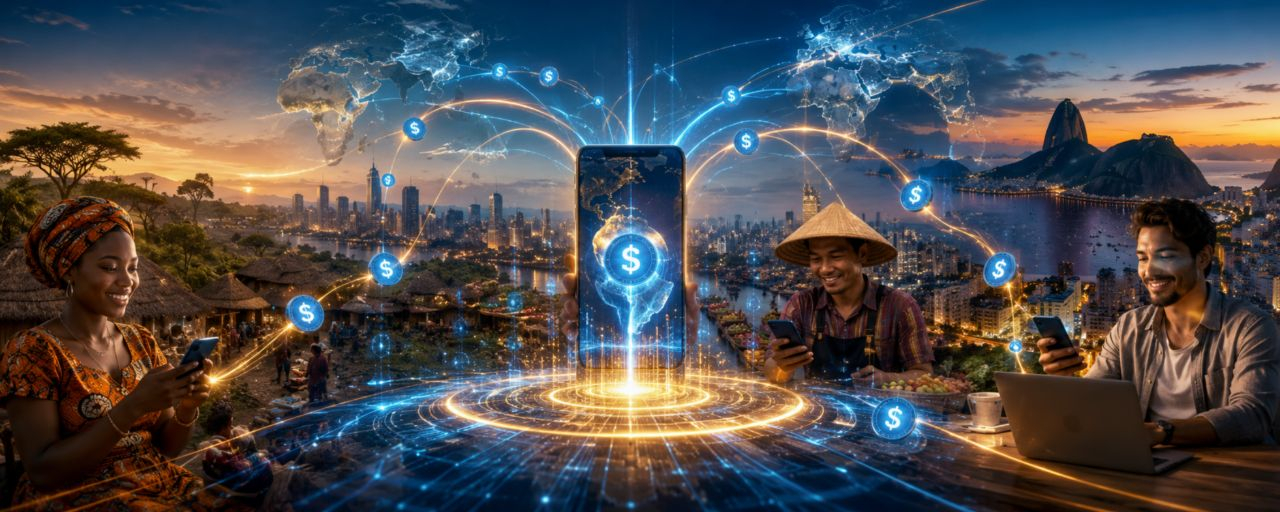
Finance Without Frontiers: How Binance Is Banking the Unbanked Through StablecoinsImagine living in a world where opening a bank account is nearly impossible.
No nearby bank branch. No access to savings products. No affordable way to send money abroad. No opportunity to earn interest on your savings.
For more than 1.3 billion adults worldwide, this is still reality today. Yet a quiet financial revolution is changing that story—and it is happening through smartphones, stablecoins, and crypto platforms.
The Global Financial Gap
Traditional banking has expanded dramatically over the past decade, but large gaps remain.
According to the World Bank's Global Findex Report, mobile technology has become one of the most powerful drivers of financial inclusion, helping millions access savings and digital payments for the first time. In developing economies, formal saving has reached record levels as mobile-based financial services become more accessible.
Yet access is still uneven.
Many people face barriers such as minimum account balances, documentation requirements, expensive international transfers, limited banking infrastructure, and restricted access to investment products.
This is where crypto—and particularly stablecoins—enters the picture.
Stablecoins: The Digital Dollars Changing Lives
Stablecoins are cryptocurrencies designed to maintain a stable value, often pegged to the U.S. dollar.
Unlike traditional cryptocurrencies that can experience large price swings, stablecoins provide a familiar unit of value while retaining the speed and accessibility of blockchain networks.
For users in emerging markets, stablecoins are becoming much more than trading tools.
They are digital savings accounts.
They are payment networks.
They are remittance solutions.
And increasingly, they are a gateway to the global economy.
A user with only a smartphone and internet connection can hold dollar-denominated assets, transfer funds internationally, save capital, and participate in financial services that may have previously been unavailable.
Binance Users Are Showing a New Trend
According to Binance Research's latest report, emerging markets now account for 77% of Binance users, a significant increase from just 49% in 2020. Even more interesting, 83% of users engaging with multiple Binance products are located in emerging economies.
This tells an important story.
People are not simply using crypto exchanges to speculate.
They are using them as financial platforms.
Research cited by CoinDesk describes this trend as users treating crypto platforms like "banking apps" for savings, payments, and investments.
The growth of stablecoin usage reinforces this narrative.
Users who may never have had access to reliable financial products are now storing value in digital dollars, sending funds across borders in minutes, and participating in global commerce from their mobile phones.
Why Emerging Markets Are Leading Adoption
In many developed countries, banking infrastructure is already mature.
But in emerging economies, financial access remains a challenge.
For millions of people, stablecoins solve practical problems:
Protection against local currency volatilityFaster and cheaper international transfersAccess to dollar-denominated savings24/7 financial services without banking hoursParticipation in the global digital economy
This explains why stablecoin adoption is accelerating fastest in regions across Asia, Africa, and Latin America.
Rather than replacing traditional finance, crypto is filling gaps where traditional systems have struggled to reach.
The Smartphone Is Becoming the New Bank Branch
The World Bank's latest research highlights how mobile technology is powering a surge in savings across developing economies. Mobile financial services are helping people save, transact, and participate in formal financial systems at unprecedented levels.
Crypto takes that evolution one step further.
A smartphone connected to a blockchain network can now provide access to:
SavingsPaymentsRemittancesInvestmentsGlobal markets
Without requiring a physical bank branch.
Without geographic limitations.
And often with lower barriers to entry.
For many users, the first financial account they truly control may not be a traditional bank account at all—it may be a crypto wallet.
The Future of Financial Inclusion
The next billion users entering the financial system may not do so through traditional banking.
They may enter through mobile phones, stablecoins, and blockchain-powered financial platforms.
What began as an alternative financial technology is increasingly becoming financial infrastructure.
The numbers tell the story.
Millions of people who were previously excluded are now saving, investing, and transacting globally. Emerging markets are driving the majority of crypto adoption, and stablecoins are becoming one of the most important tools for financial inclusion in the digital age.
The future of finance may not be about replacing banks.
It may be about bringing financial access to everyone—regardless of where they live.
And for millions around the world, that future has already begun.
#Stablecoins #CryptoPayment #Banking
$U
{spot}(UUSDT)
$USD1
{spot}(USD1USDT)
$USDC
{future}(USDCUSDT)
Finance Without Frontiers: How Binance Is Banking the Unbanked Through Stablecoins
Imagine living in a world where opening a bank account is nearly impossible.
No nearby bank branch. No access to savings products. No affordable way to send money abroad. No opportunity to earn interest on your savings.
For more than 1.3 billion adults worldwide, this is still reality today. Yet a quiet financial revolution is changing that story—and it is happening through smartphones, stablecoins, and crypto platforms.
The Global Financial Gap
Traditional banking has expanded dramatically over the past decade, but large gaps remain.
According to the World Bank's Global Findex Report, mobile technology has become one of the most powerful drivers of financial inclusion, helping millions access savings and digital payments for the first time. In developing economies, formal saving has reached record levels as mobile-based financial services become more accessible.
Yet access is still uneven.
Many people face barriers such as minimum account balances, documentation requirements, expensive international transfers, limited banking infrastructure, and restricted access to investment products.
This is where crypto—and particularly stablecoins—enters the picture.
Stablecoins: The Digital Dollars Changing Lives
Stablecoins are cryptocurrencies designed to maintain a stable value, often pegged to the U.S. dollar.
Unlike traditional cryptocurrencies that can experience large price swings, stablecoins provide a familiar unit of value while retaining the speed and accessibility of blockchain networks.
For users in emerging markets, stablecoins are becoming much more than trading tools.
They are digital savings accounts.
They are payment networks.
They are remittance solutions.
And increasingly, they are a gateway to the global economy.
A user with only a smartphone and internet connection can hold dollar-denominated assets, transfer funds internationally, save capital, and participate in financial services that may have previously been unavailable.
Binance Users Are Showing a New Trend
According to Binance Research's latest report, emerging markets now account for 77% of Binance users, a significant increase from just 49% in 2020. Even more interesting, 83% of users engaging with multiple Binance products are located in emerging economies.
This tells an important story.
People are not simply using crypto exchanges to speculate.
They are using them as financial platforms.
Research cited by CoinDesk describes this trend as users treating crypto platforms like "banking apps" for savings, payments, and investments.
The growth of stablecoin usage reinforces this narrative.
Users who may never have had access to reliable financial products are now storing value in digital dollars, sending funds across borders in minutes, and participating in global commerce from their mobile phones.
Why Emerging Markets Are Leading Adoption
In many developed countries, banking infrastructure is already mature.
But in emerging economies, financial access remains a challenge.
For millions of people, stablecoins solve practical problems:
Protection against local currency volatilityFaster and cheaper international transfersAccess to dollar-denominated savings24/7 financial services without banking hoursParticipation in the global digital economy
This explains why stablecoin adoption is accelerating fastest in regions across Asia, Africa, and Latin America.
Rather than replacing traditional finance, crypto is filling gaps where traditional systems have struggled to reach.
The Smartphone Is Becoming the New Bank Branch
The World Bank's latest research highlights how mobile technology is powering a surge in savings across developing economies. Mobile financial services are helping people save, transact, and participate in formal financial systems at unprecedented levels.
Crypto takes that evolution one step further.
A smartphone connected to a blockchain network can now provide access to:
SavingsPaymentsRemittancesInvestmentsGlobal markets
Without requiring a physical bank branch.
Without geographic limitations.
And often with lower barriers to entry.
For many users, the first financial account they truly control may not be a traditional bank account at all—it may be a crypto wallet.
The Future of Financial Inclusion
The next billion users entering the financial system may not do so through traditional banking.
They may enter through mobile phones, stablecoins, and blockchain-powered financial platforms.
What began as an alternative financial technology is increasingly becoming financial infrastructure.
The numbers tell the story.
Millions of people who were previously excluded are now saving, investing, and transacting globally. Emerging markets are driving the majority of crypto adoption, and stablecoins are becoming one of the most important tools for financial inclusion in the digital age.
The future of finance may not be about replacing banks.
It may be about bringing financial access to everyone—regardless of where they live.
And for millions around the world, that future has already begun.
#Stablecoins #CryptoPayment #Banking
$U
$USD1
$USDC
1
143
·
--
Bullish
🚨 BREAKING NEWS: Massive Update for Content Creators from Meta! 🚨
Getting paid just got a whole lot faster and smarter! Meta (the parent company of Facebook and Instagram) has introduced an amazing feature allowing content creators to receive their payouts in cryptocurrency!
Creators can now get their hard-earned revenue directly into their crypto wallets using USDC (USD Coin), one of the world’s most trusted and reliable stablecoins! ✨
💡 Why is this a Game-Changer for Creators?
Zero Volatility Risks: Since USDC is a pegged 'stablecoin', 1 USDC is always equal to 1 USD. You don't have to worry about crypto market crashes or price drops!
Lightning-Fast & Low Fees: Powered by top-tier payment processors like Stripe and efficient networks like Polygon/Solana, making transactions incredibly fast and seamless.
Global Accessibility: No more traditional banking delays or borders. Creators worldwide can now manage their earnings with full control and ease.
This revolutionary move by Meta is a massive bridge connecting Web2 content creation with the future of Web3 finance.
Are you ready to receive your next payout in crypto? Let me know your thoughts in the comments below! 👇
#meta #USDC #CryptoPayment #ContentCreator #breakingnews #We$USDC #FacebookUpdate #CryptoShahin
2
192
·
--
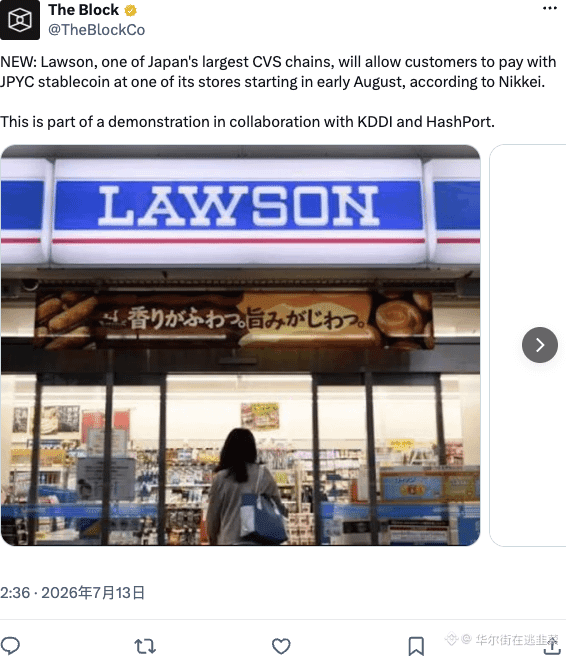
Lawson, one of Japan’s three major convenience store chains, is piloting JPYC stablecoin payments at a store under its umbrella starting in early August.
Compared with projects that only “promise” on-chain, this real-world retail use case is what truly moves stablecoins one step closer to everyday payments.
As for how far JPYC can reach, it remains to be seen whether it will expand to thousands of stores or wrap up after the pilot.
| #JPYC #CryptoPayment
52

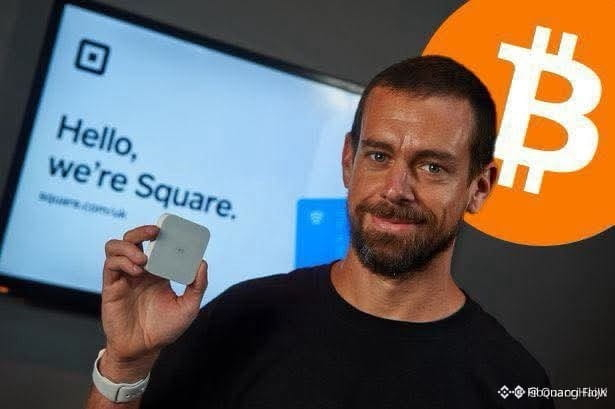
$BTC IS GETTING MAINSTREAM VALIDATION RIGHT NOW 🚀
Block CEO Jack Dorsey just announced he chose to pay with $BTC at the counter, this kind of real-world use case is surging right now and volume is spiking, are you accumulating here or waiting for a dip?
Not financial advice, manage your risk.
#BTC #MainstreamAdoption #CryptoPayment
💥
Block CEO Jack Dorsey just announced he chose to pay with $BTC at the counter, this kind of real-world use case is surging right now and volume is spiking, are you accumulating here or waiting for a dip?
Not financial advice, manage your risk.
#BTC #MainstreamAdoption #CryptoPayment
💥
35
·
--
BiyaPay U-Card Exclusive Campaign Goes Live — Digital Assets Can Be Spent by Card Anywhere in the World
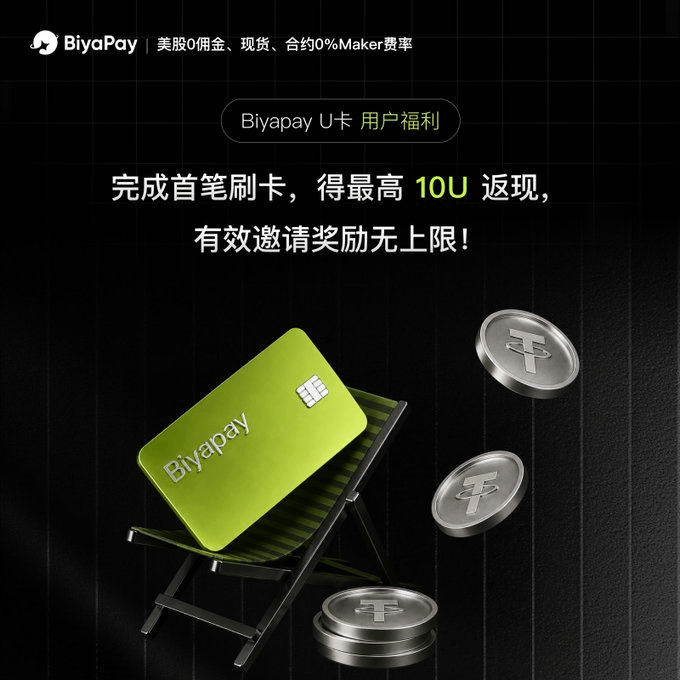
I’ve been using BiyaPay to manage digital assets and invest in US and Hong Kong stocks. Besides core features like currency exchange, cross-border remittances, and zero-commission US stock trading, the U-Card payment card is also a daily, high-frequency tool. It lets you convert USDT directly into fiat currency, and use your card to make purchases both online and offline worldwide—covering scenarios such as overseas subscriptions, international shopping (haitao), and payments at merchants abroad.
Now the platform has launched a time-limited, U-Card exclusive promotion. The campaign period runs from August 1 to September 15. The rewards are simple and substantial:
For new users’ first card payment with U-Card, enjoy 50% cashback on your spending, up to a maximum of 10 USDT. Invite friends to register and meet the usage requirements—each successfully invited new user earns you 5 USDT. There’s no cap on the number of invitees. Invite more, earn more.
One U-Card connects digital assets with real-world spending. No more tedious steps of exchanging and cashing out. Combined with this high cashback offer and unlimited invite-new-user rewards, it’s a great fit whether you frequently shop internationally, subscribe to overseas software, or have spending needs abroad.
Official Twitter: @BIYAPAYOFFICIAL
#biyapay #Ucard #CryptoPayment
1
2
206
Verified
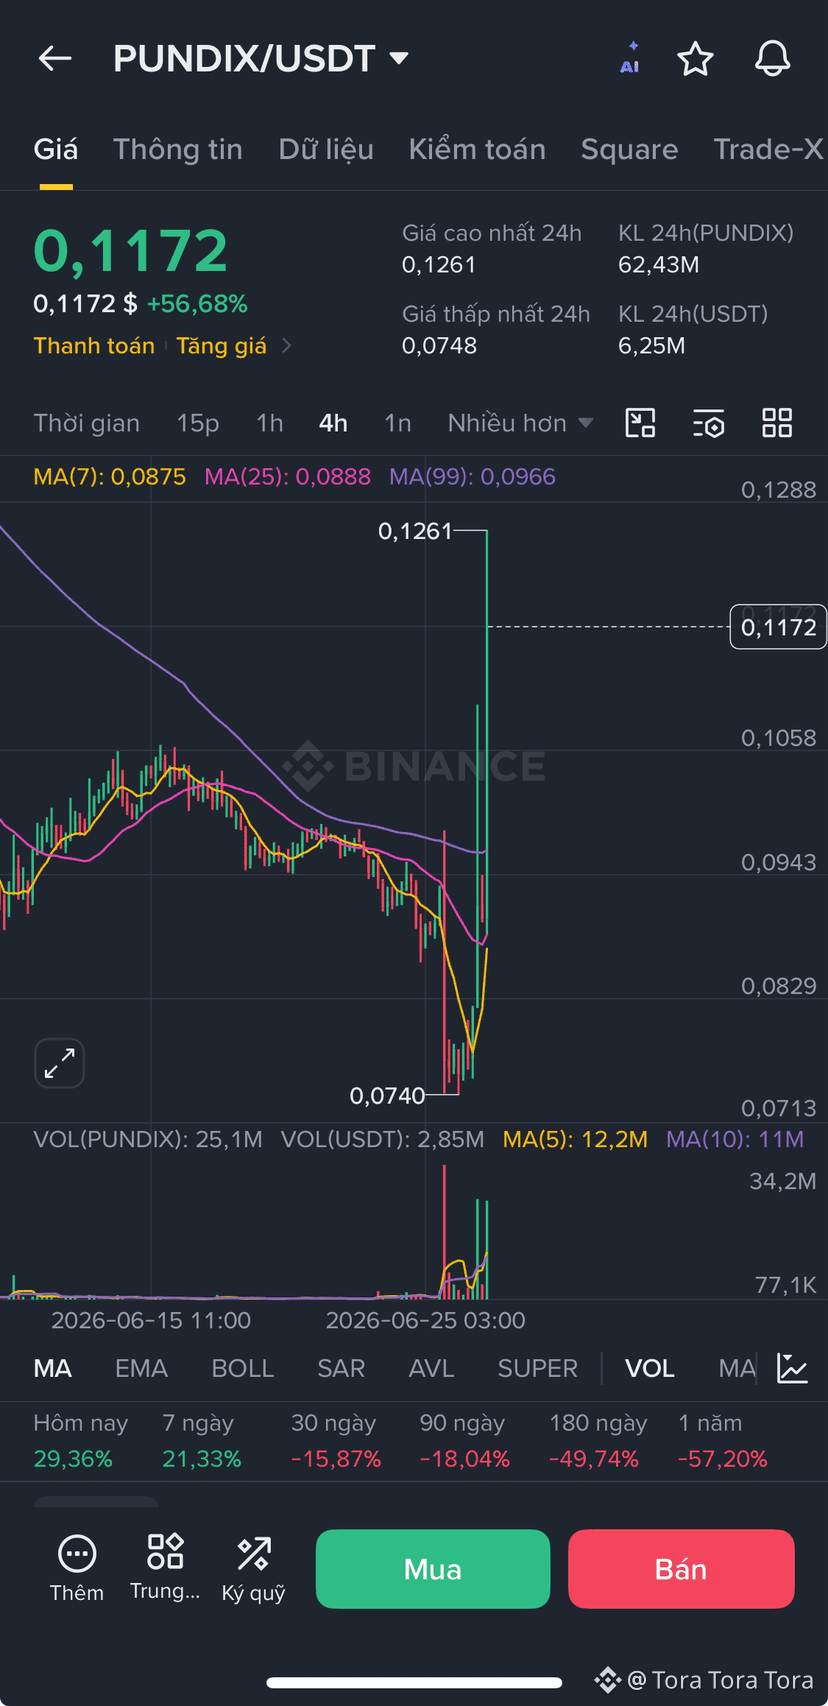
🚀 Pundi X ($PUNDIX ) explodes +56% in a short time!
#pundix is currently one of the hottest tokens as PUNDIX surges +56% in just 24h, pushing the price up from the low range to over 0.117 USDT. Trading volume has spiked sharply, showing clear community pull.
What is Pundi X?
Pundi X is a pioneering project in crypto payments at the point of sale (Point-of-Sale). The project provides a comprehensive ecosystem including:
• XPOS — a blockchain POS device that lets merchants accept crypto payments (BTC, ETH, USDT, PUNDIX…) as well as fiat quickly.
• XWallet — a mobile wallet that supports multiple DApps.
• XPASS — a contactless payment card.
PUNDIX is the main utility token of the ecosystem, used to pay fees, rewards, incentives, and to operate the network. Launched in 2018, Pundi X focuses on bringing crypto into real life, helping users spend crypto easily at physical stores.
With a market cap of only about $30.7M and a circulating supply of ~258 million tokens, PUNDIX still has plenty of room to grow if XPOS adoption continues to expand—especially as the project is integrating AI and modern payment solutions.
Why did it pump strongly recently?
• The overall altcoin momentum.
• The real-world payment ecosystem is drawing attention.
• Volume and liquidity have surged dramatically.
However, crypto is always highly volatile. This is not investment advice—please DYOR and manage risk carefully before getting involved!
Are you holding PUNDIX or just watching it? Comment below and share! #PUNDIXUSDT #CryptoPayment #XPost #BinanceSquare
158
·
--
Today, we need to look at two signals together: one is that BIS has continued to pour cold water on stablecoins in their research, and the other is that the stance of the central banks in the US and UK regarding stablecoins is starting to show clear divergence.
Many folks interpret this as 'regulation is still up for debate, so hold off on the U card.' I actually think the opposite.
When regulation starts to diverge, what gets eliminated first isn't the coins, but rather the cards with incomplete pathways. In the next phase, users won’t just be comparing how fast they can get a card or how high the cashback is, but rather three key things: whether the source of funds can be clearly explained, whether spending can be consistently processed, and whether issues can be managed effectively in terms of complaints and withdrawal routes.
So, the U card will increasingly resemble the 'frontend of payment infrastructure,' not just a simple card. The platforms that will endure long-term aren't necessarily the ones that issue the most cards, but rather those that can integrate stablecoins, clearing, merchant acceptance rates, and anomaly handling into a seamless loop.
This is also why I’ve been checking out tools like Payall.ai: the real value isn’t just in finding you a card, but in helping you understand which withdrawal and spending routes suit you best.
#Stablecoin #CryptoPayment #BinanceSquare
154
·
--
Bullish
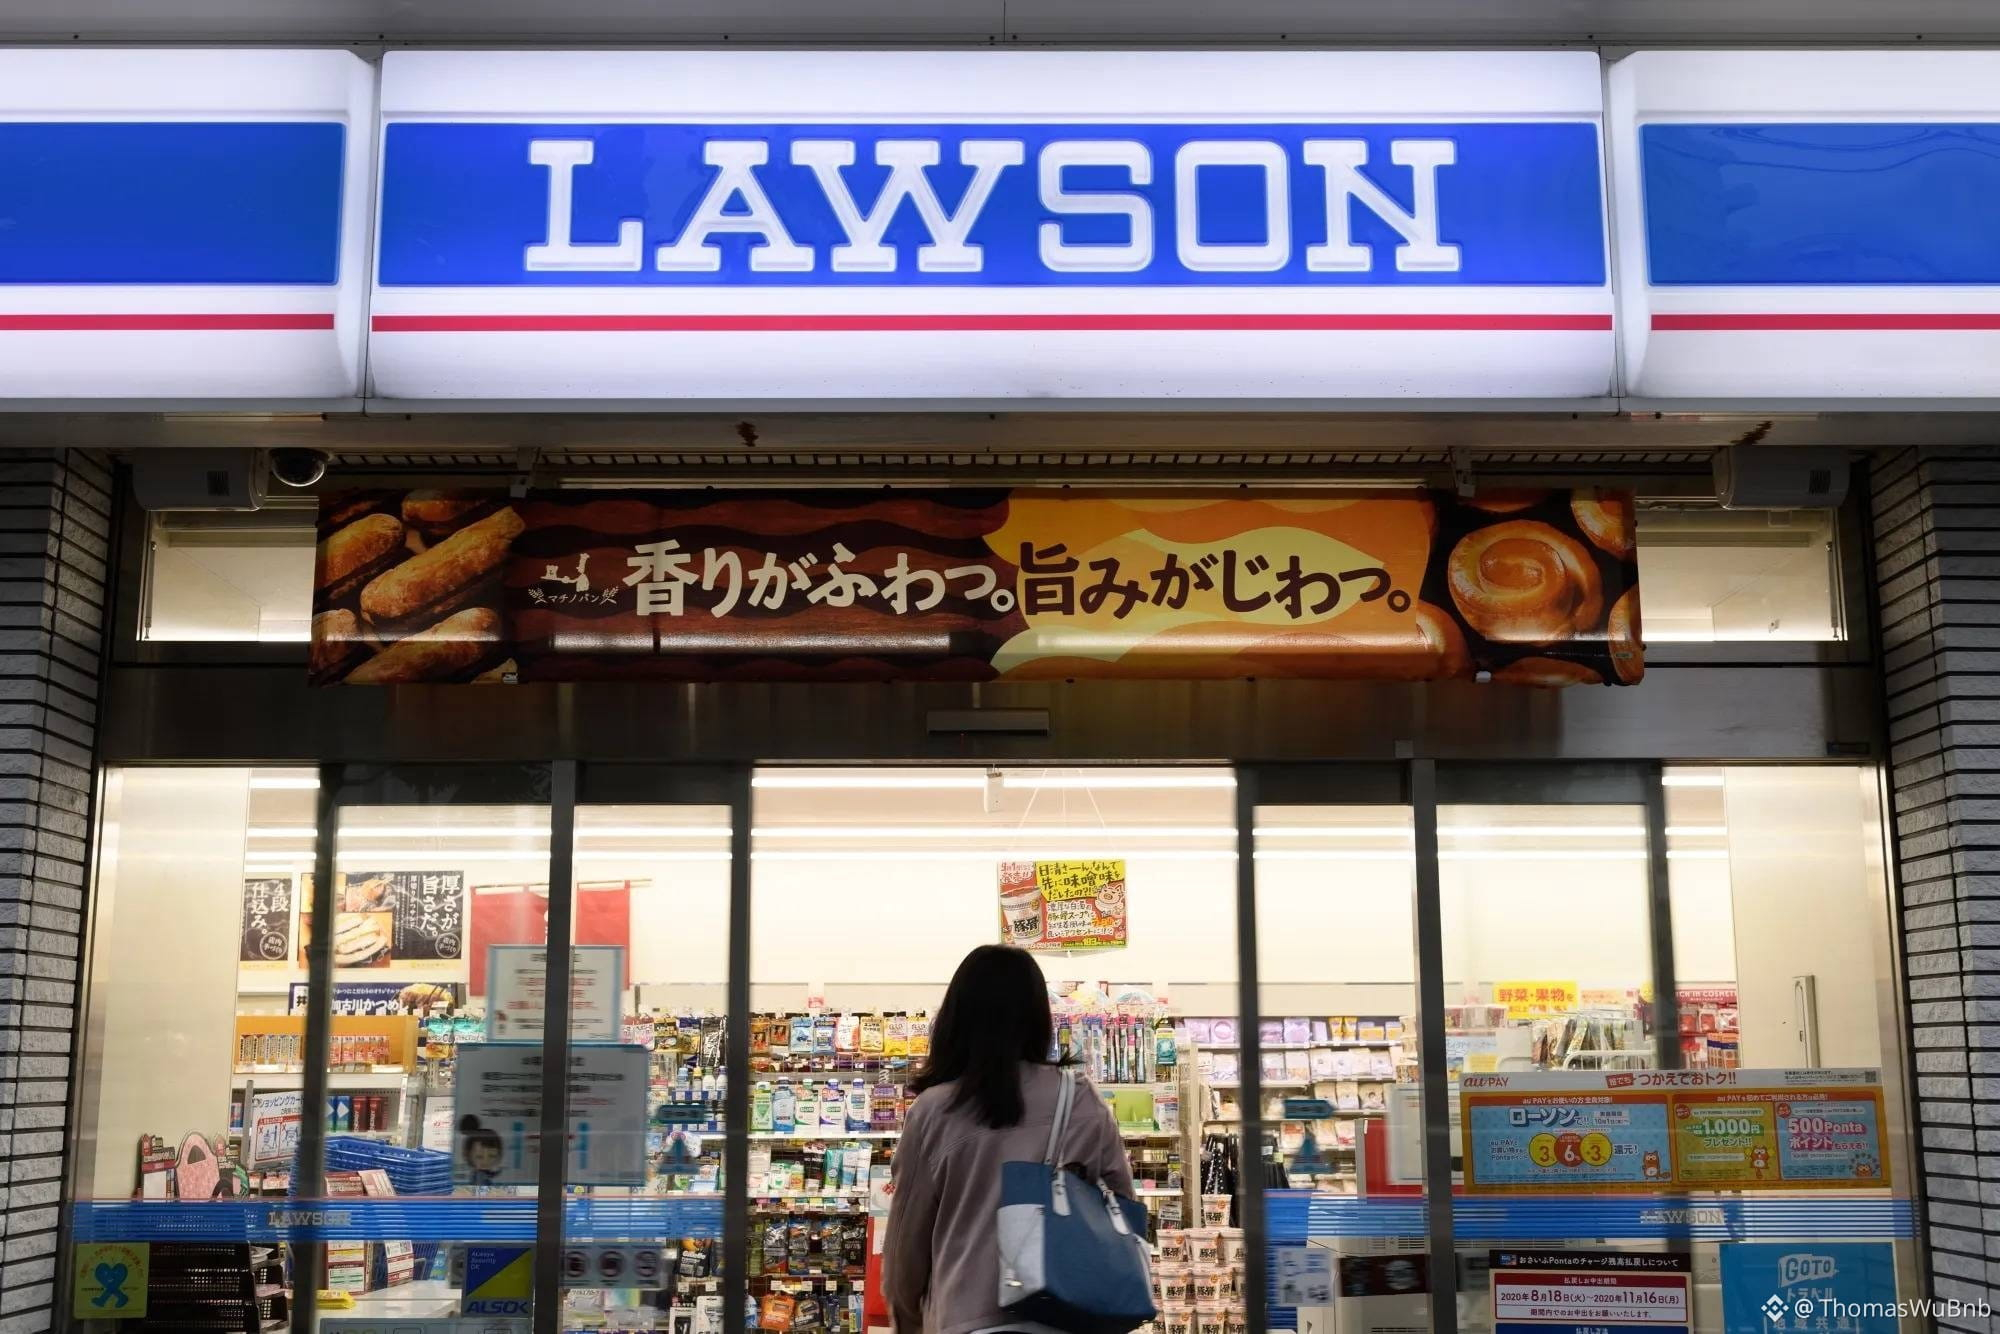
Lawson Pilots Stablecoin Payments in Tokyo
Japan’s third-largest convenience store chain, Lawson, is piloting yen-backed JPYC stablecoin payments integrated into its POS system. Partnering with KDDI and HashPort, the trial tests system stability. Like USDC, these digital assets offer distinct advantages over traditional payments, including instant settlement, near-zero transaction fees, and secure, fully backed stability.
#stablecoin #CryptoPayment $USDC #JapanCrypto
14
6.1k
ASIA PAYMENT GAP PUTS $USDC IN FOCUS 🚨
Saber’s whitepaper says Asia leads in domestic digital payments but still faces major friction in cross-border settlement. The report highlights $BTC trillion sitting idle in pre-funded correspondent accounts globally, with some $200 transfers costing 6-10% and taking days to clear.
Stablecoins are being pushed as a faster settlement layer, but the real battle is compliance, liquidity depth, and last-mile payout infrastructure. This is where institutional rails get separated from hype. Watch the payment stack, not just the token noise.
Not financial advice. Manage your risk.
#Stablecoins #CryptoPayment #web #BinanceSquare
⚡
29
·
--
Article
With Bitcoin making its way back into payment scenarios, the real thing that needs reevaluation isn't speed, but cash flowThere's an often-overlooked signal in the market these days: Bitcoin payment protocols are once again pushing into everyday consumption scenarios. On the surface, it seems like the old debate of 'can you buy stuff with BTC directly' is back; but what's really worth noting this time isn't just the payment button itself, but how the industry is scrambling to reclaim the last mile of crypto funding.
During the last bull run, everyone was obsessed with gains, leverage, and narrative shifts. But as volatility increases and profits shrink, the real concerns for users will quickly shift to another class of questions: How do I cash out my earnings? How do I convert my on-chain balance into spendable cash flow? When do I stay in crypto, when do I switch to stable assets, and when do I directly move funds into my daily spending account?
With Bitcoin making its way back into payment scenarios, the real thing that needs reevaluation isn't speed, but cash flow
There's an often-overlooked signal in the market these days: Bitcoin payment protocols are once again pushing into everyday consumption scenarios. On the surface, it seems like the old debate of 'can you buy stuff with BTC directly' is back; but what's really worth noting this time isn't just the payment button itself, but how the industry is scrambling to reclaim the last mile of crypto funding.
During the last bull run, everyone was obsessed with gains, leverage, and narrative shifts. But as volatility increases and profits shrink, the real concerns for users will quickly shift to another class of questions: How do I cash out my earnings? How do I convert my on-chain balance into spendable cash flow? When do I stay in crypto, when do I switch to stable assets, and when do I directly move funds into my daily spending account?
During the last bull run, everyone was obsessed with gains, leverage, and narrative shifts. But as volatility increases and profits shrink, the real concerns for users will quickly shift to another class of questions: How do I cash out my earnings? How do I convert my on-chain balance into spendable cash flow? When do I stay in crypto, when do I switch to stable assets, and when do I directly move funds into my daily spending account?
120
·
--
BPAYLooking for a fast and secure way to pay with crypto? Try bPay now!
Use the information below to join:
🔹 Contract Address (CA): 0xb13003bf44de426dd2a3aae3df9c3400de0a7777
🔹 Referral Code: BP-DF963433F43F
#Bpay #CryptoPayment #blockchain
BPAY
Looking for a fast and secure way to pay with crypto? Try bPay now!
Use the information below to join:
🔹 Contract Address (CA): 0xb13003bf44de426dd2a3aae3df9c3400de0a7777
🔹 Referral Code: BP-DF963433F43F
#Bpay #CryptoPayment #blockchain
Use the information below to join:
🔹 Contract Address (CA): 0xb13003bf44de426dd2a3aae3df9c3400de0a7777
🔹 Referral Code: BP-DF963433F43F
#Bpay #CryptoPayment #blockchain
84

🔥 At 3am UTC, $400M moved out of exchanges, sparking a 0.93% surge in BTC to $63,820, as extreme fear turned to cautious optimism, with #Bitcoin $60K $70KRangeHits307DayConsolidation still on the radar.
📊 The WeFi collaboration with Visa is the latest in a string of initiatives bridging traditional payment networks and digital asset firms, with #cryptopayment solutions and #blockchain innovation driving growth, while #BTC enthusiasts watch with bated breath as the RSI hits 56.9, a bullish sign.
💡 But here's the twist: as institutional players like BlackRock and Visa tap into crypto, the narrative shifts from speculative asset to mainstream payment solution, with Smart Money BUYING signals from ANSEM and Tardy on Solana, and top traders net long on BTC and ETH.
❓ Will the $6.62B Open Interest in BTC futures and $4.07B in ETH be the catalyst for the next major price move, or will the market succumb to the lingering fear, leaving retail investors on the wrong side of the trade?
52

Article
BNB Chain is leading the wave of Stablecoin Adoption?🔶 Is BNB Chain leading the wave of Stablecoin Adoption? What does on-chain data say? 😎
Which chain is processing the most strong stablecoin activity right now? Many people would think of Ethereum or Solana, but recent on-chain data shows that BNB Chain is emerging as one of the ecosystems with the highest real-world stablecoin usage in the market.
📊 A few noteworthy figures:
• Over 10 million active addresses using stablecoins every month on BNB Chain.
BNB Chain is leading the wave of Stablecoin Adoption?
🔶 Is BNB Chain leading the wave of Stablecoin Adoption? What does on-chain data say? 😎
Which chain is processing the most strong stablecoin activity right now? Many people would think of Ethereum or Solana, but recent on-chain data shows that BNB Chain is emerging as one of the ecosystems with the highest real-world stablecoin usage in the market.
📊 A few noteworthy figures:
• Over 10 million active addresses using stablecoins every month on BNB Chain.
79
·
--
📰 Crypto Market Hotspot Dispatch
1. AI Deep Research Agents Expose New Privacy Risks
Recent studies highlight that when AI deep research agents simultaneously access local private documents and perform external web searches, there's a high chance of unintentionally leaking sensitive information during multi-hop reasoning. The new task, MosaicLeaks, reveals that focusing solely on task success rates can inadvertently increase leak risks by interspersing private and public sub-problems. To address this, researchers propose a privacy-aware deep research training program that enhances task completion rates while significantly reducing information leakage at the answer level, showing that balancing AI security and performance is becoming a key concern in the industry.
2. Dubai's Crypto Payment Gateway Heating Up, UAE Fintech Continues to Benefit
Recently, the Dubai crypto payment sector has gained momentum, with a clear regulatory framework and official support boosting businesses' confidence in adopting digital asset payments. Multiple payment platforms now allow merchants to accept BTC, ETH, USDT, and other cryptocurrencies, automatically converting them to AED for settlement into local bank accounts, thus minimizing merchants' exposure to volatility. Market observers believe that compliant payment gateways are driving crypto payments from concept to real-world application, and the combination of stablecoin and fiat settlement models is poised to be a significant growth direction in the next phase.
#AI安全 #CryptoPayment #ETH
234
·
--
Tonight’s worth watching isn’t just another stablecoin “adoption headline,” but the fact that DoorDash is preparing to expand stablecoin payouts to more than 40 countries—already bringing a more realistic threshold into view.
Most people think competition in the crypto world is still about who pumps faster and whose narrative is stronger. In reality, since this year, more and more real-money use cases are reassessing a different question: once your money earns on-chain, can it flow into real life?
Rider payments, remote team reimbursements, subscription renewals, and travel expenses—none of these are grand narratives, but they determine whether funds are “paper assets” or “discretionary cash flow.” Many people trade, but don’t seriously handle the back half of the money flow. That’s precisely where the losses are most easily overlooked.
My take is straightforward: in the next round, the truly valuable ones won’t be only those who can capture volatility, but those who can smoothly connect stablecoin balances to payments, withdrawals, and everyday spending.
So instead of only watching the market, it’s better to get your funds’ flow mapped out early. Gateways that focus more on real payment and settlement—like payall.pro—will become increasingly useful at this stage.
#Stablecoin #CryptoPayment
21
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#SECHaltsCryptoETFReviewsAmidFundingLapse
51,908 views
612 Discussing
2
#ZcashETFPostsFirstWeeklyOutflow$93.6M
64,318 views
199 Discussing
3
#GreekPoliceBustCryptoScamRingArrest17
211,623 views
1,500 Discussing
4
#BitcoinRejectedAt$87K
168,545 views
253 Discussing
5
#FedOctoberRateHikeOddsFallTo17%
233,990 views
1,682 Discussing
6
#NvidiaHitsRecordHighUp2.4%
164,783 views
1,174 Discussing
7
#CanaryFilesAmendedS1ForPEPEETF
48,368 views
792 Discussing
8
#BitcoinParesGainsAfterRallyTo$86.5K
59,443 views
175 Discussing
9
#CerebrasSinksNearly20%OnReportNvidiaToPowerOpenAI
159,450 views
1,390 Discussing
10
#SECProposesCryptoCustodyRules
218,313 views
1,717 Discussing