
#kalshi
kalshi
閲覧回数 277,280
1,416人が討論中
注目
最新
·
--
翻訳参照
Kalshi开放个股永续合约,AAPL和AMZN合约估算杠杆接近五倍。
The Defiant报道称,这两份合约的估算杠杆水平接近五倍;报道同时提到,一场司法挑战正威胁这类股票永续合约的监管基础。也就是说,产品已上线,但其合规支撑仍处在被质疑的状态。
· 五倍是报道给出的估算杠杆,不是合约条款里的固定倍数
· 报道指向的是股票永续这一品类的监管基础,而非单只股票
对想交易个股永续的人,你会先看杠杆条款还是等司法结果?
#Kalshi
Kalshi开放个股永续合约,AAPL和AMZN合约估算杠杆接近五倍。
The Defiant报道称,这两份合约的估算杠杆水平接近五倍;报道同时提到,一场司法挑战正威胁这类股票永续合约的监管基础。也就是说,产品已上线,但其合规支撑仍处在被质疑的状态。
· 五倍是报道给出的估算杠杆,不是合约条款里的固定倍数
· 报道指向的是股票永续这一品类的监管基础,而非单只股票
对想交易个股永续的人,你会先看杠杆条款还是等司法结果?
#Kalshi
The Defiant报道称,这两份合约的估算杠杆水平接近五倍;报道同时提到,一场司法挑战正威胁这类股票永续合约的监管基础。也就是说,产品已上线,但其合规支撑仍处在被质疑的状态。
· 五倍是报道给出的估算杠杆,不是合约条款里的固定倍数
· 报道指向的是股票永续这一品类的监管基础,而非单只股票
对想交易个股永续的人,你会先看杠杆条款还是等司法结果?
#Kalshi
78

·
--
アーカンソー州がKalshiを提訴した7番目の州となりました――今回の訴訟は、予測市場のビジネスモデルの核心を真っ向から攻撃しています。
事実:アーカンソー州のティム・グリフィン司法長官は2026年11月4日、KalshiEX LLCとKalshi Inc.を提訴しました。同州で、18歳以上のユーザーが利用できる無許可のスポーツ賭博を運営し、アーカンソー州欺瞞的取引慣行法に違反したと主張しています。57ページに及ぶ訴状は、返還金、民事制裁金、滞納税の支払い、および裁判所命令を求めています。この訴訟はインディペンデンス郡巡回裁判所に、事件番号32CV-26-717として登録されています。Kalshiはこれまで、同社の契約は賭博ではなく、CFTC(米商品先物取引委員会)が規制する金融デリバティブだと主張してきました。アーカンソー州の主張について、裁判所の判断はまだ出ていません。
私の見解:これはもはや一つの州だけの訴訟ではなく、ひとつのパターンです。ユタ州はすでにKalshiとその創業者らを14件の刑事罪で起訴しており、これで7つの州が行動を起こしたことになります。本当の争点は管轄権です。州は「手のひらサイズの賭博業者」と見なし、CFTCは連邦先物取引所と見ています。この問いに最高裁判所か議会が答えない限り、新たな訴訟が起きるたびに、類似プラットフォームで取引される暗号資産関連の契約も含め、予測市場全体の法的リスクが高まります。このニュースが広まった際、BTCは約80,300ドルで落ち着いていたため、市場はまだこれを衝撃として織り込んでいません。ただし、規制の風向きは明らかです。
今後注目しているのは、この訴訟に対するKalshiの回答、株式パーペチュアルをめぐる別件でのCFTCの11月6日の回答期限、そして他の州も同様の訴訟を起こすかどうかです。
皆さんは、Kalshiのイベント契約は金融商品だと思いますか、それとも賭博でしょうか――そして、誰が規制すべきでしょうか?
これは私の分析であり、金融上の助言ではありません。常にDYOR(自分で調べて判断)を。
#Kalshi #PredictionMarket #規制
アーカンソー州がKalshiを提訴した7番目の州となりました――今回の訴訟は、予測市場のビジネスモデルの核心を真っ向から攻撃しています。
事実:アーカンソー州のティム・グリフィン司法長官は2026年11月4日、KalshiEX LLCとKalshi Inc.を提訴しました。同州で、18歳以上のユーザーが利用できる無許可のスポーツ賭博を運営し、アーカンソー州欺瞞的取引慣行法に違反したと主張しています。57ページに及ぶ訴状は、返還金、民事制裁金、滞納税の支払い、および裁判所命令を求めています。この訴訟はインディペンデンス郡巡回裁判所に、事件番号32CV-26-717として登録されています。Kalshiはこれまで、同社の契約は賭博ではなく、CFTC(米商品先物取引委員会)が規制する金融デリバティブだと主張してきました。アーカンソー州の主張について、裁判所の判断はまだ出ていません。
私の見解:これはもはや一つの州だけの訴訟ではなく、ひとつのパターンです。ユタ州はすでにKalshiとその創業者らを14件の刑事罪で起訴しており、これで7つの州が行動を起こしたことになります。本当の争点は管轄権です。州は「手のひらサイズの賭博業者」と見なし、CFTCは連邦先物取引所と見ています。この問いに最高裁判所か議会が答えない限り、新たな訴訟が起きるたびに、類似プラットフォームで取引される暗号資産関連の契約も含め、予測市場全体の法的リスクが高まります。このニュースが広まった際、BTCは約80,300ドルで落ち着いていたため、市場はまだこれを衝撃として織り込んでいません。ただし、規制の風向きは明らかです。
今後注目しているのは、この訴訟に対するKalshiの回答、株式パーペチュアルをめぐる別件でのCFTCの11月6日の回答期限、そして他の州も同様の訴訟を起こすかどうかです。
皆さんは、Kalshiのイベント契約は金融商品だと思いますか、それとも賭博でしょうか――そして、誰が規制すべきでしょうか?
これは私の分析であり、金融上の助言ではありません。常にDYOR(自分で調べて判断)を。
#Kalshi #PredictionMarket #規制
事実:アーカンソー州のティム・グリフィン司法長官は2026年11月4日、KalshiEX LLCとKalshi Inc.を提訴しました。同州で、18歳以上のユーザーが利用できる無許可のスポーツ賭博を運営し、アーカンソー州欺瞞的取引慣行法に違反したと主張しています。57ページに及ぶ訴状は、返還金、民事制裁金、滞納税の支払い、および裁判所命令を求めています。この訴訟はインディペンデンス郡巡回裁判所に、事件番号32CV-26-717として登録されています。Kalshiはこれまで、同社の契約は賭博ではなく、CFTC(米商品先物取引委員会)が規制する金融デリバティブだと主張してきました。アーカンソー州の主張について、裁判所の判断はまだ出ていません。
私の見解:これはもはや一つの州だけの訴訟ではなく、ひとつのパターンです。ユタ州はすでにKalshiとその創業者らを14件の刑事罪で起訴しており、これで7つの州が行動を起こしたことになります。本当の争点は管轄権です。州は「手のひらサイズの賭博業者」と見なし、CFTCは連邦先物取引所と見ています。この問いに最高裁判所か議会が答えない限り、新たな訴訟が起きるたびに、類似プラットフォームで取引される暗号資産関連の契約も含め、予測市場全体の法的リスクが高まります。このニュースが広まった際、BTCは約80,300ドルで落ち着いていたため、市場はまだこれを衝撃として織り込んでいません。ただし、規制の風向きは明らかです。
今後注目しているのは、この訴訟に対するKalshiの回答、株式パーペチュアルをめぐる別件でのCFTCの11月6日の回答期限、そして他の州も同様の訴訟を起こすかどうかです。
皆さんは、Kalshiのイベント契約は金融商品だと思いますか、それとも賭博でしょうか――そして、誰が規制すべきでしょうか?
これは私の分析であり、金融上の助言ではありません。常にDYOR(自分で調べて判断)を。
#Kalshi #PredictionMarket #規制
8
·
--
アーカンソー州がKalshiを提訴、予測市場へのコンプライアンス圧力が強まる
米アーカンソー州司法長官事務所は、予測市場プラットフォームのKalshiを正式に提訴し、違法賭博によるものとされる収益の返還を求めた。これは単独の動きではなく、オンライン予測市場のビジネスモデルの適法性をめぐり、各州の規制当局が圧力を強めていることを示す最新の事例だ。こうした訴訟が増えるにつれ、業界を取り巻く規制上の不確実性は大きく高まっている。
Decryptの報道によると、アーカンソー州のティム・グリフィン司法長官は声明で、プラットフォーム上で「アーカンソー・レイザーバックスが勝つかどうか」に賭ける行為は賭博に当たると指摘し、Kalshiに賠償(restitution)を明確に求めた。この訴訟により、アーカンソー州は予測市場への規制取り締まりに正式に加わった。これは、先に他州が取った措置に呼応するものだ。
予測市場は長らく、従来の金融規制と賭博関連法のグレーゾーンに置かれてきた。連邦レベルでは統一された明確な法律がまだ制定されていない一方、各州は独自の賭博の定義と執行権限を持つ。このように規制が分断された環境では、プラットフォームのコンプライアンスコストが高くなり、判決の結果も、各地の法律を裁判官がどう解釈するかに大きく左右される。今回のアーカンソー州の訴訟は、まさにこの問題を象徴する事例だ。
市場への影響という点では、規制強化の兆しが予測市場のビジネスモデルを直接揺るがす。コンプライアンス上の圧力が強まれば、プラットフォームの運営が制限され、流動性が低下する可能性があり、その結果、POLYやUMAMIなど関連資産の評価見通しにも影響が及ぶ。さらに多くの州がアーカンソー州に続いて訴訟を起こせば、業界全体がより大きなコンプライアンス上の課題に直面し、市場流動性の縮小につながるおそれもある。
ただし、各州の賭博に関する法律の定義が曖昧であることも、判決の不確実性につながっている点には注意が必要だ。同じ法律の条項でも、裁判官によって解釈が異なる可能性があり、プラットフォーム側には一定の反論の余地がある。また、政策が変更されるリスクも依然として存在し、今後の連邦レベルでの立法の進展によって、現在の規制環境が変わる可能性もある。
今後注目すべきは、他州が同様の訴訟に続くかどうか、そしてKalshiの訴訟対応方針や最終的な判決の行方だ。こうした動きは、予測市場業界のコンプライアンスの見通しと、関連資産の市場での動向に直接影響する。
#PredictionMarkets #Regulation #Kalshi
以上は情報の整理と個人的な分析であり、投資助言を構成するものではありません。
今後、政策の詳細がさらに明らかになり次第、引き続き更新します。
アーカンソー州がKalshiを提訴、予測市場へのコンプライアンス圧力が強まる
米アーカンソー州司法長官事務所は、予測市場プラットフォームのKalshiを正式に提訴し、違法賭博によるものとされる収益の返還を求めた。これは単独の動きではなく、オンライン予測市場のビジネスモデルの適法性をめぐり、各州の規制当局が圧力を強めていることを示す最新の事例だ。こうした訴訟が増えるにつれ、業界を取り巻く規制上の不確実性は大きく高まっている。
Decryptの報道によると、アーカンソー州のティム・グリフィン司法長官は声明で、プラットフォーム上で「アーカンソー・レイザーバックスが勝つかどうか」に賭ける行為は賭博に当たると指摘し、Kalshiに賠償(restitution)を明確に求めた。この訴訟により、アーカンソー州は予測市場への規制取り締まりに正式に加わった。これは、先に他州が取った措置に呼応するものだ。
予測市場は長らく、従来の金融規制と賭博関連法のグレーゾーンに置かれてきた。連邦レベルでは統一された明確な法律がまだ制定されていない一方、各州は独自の賭博の定義と執行権限を持つ。このように規制が分断された環境では、プラットフォームのコンプライアンスコストが高くなり、判決の結果も、各地の法律を裁判官がどう解釈するかに大きく左右される。今回のアーカンソー州の訴訟は、まさにこの問題を象徴する事例だ。
市場への影響という点では、規制強化の兆しが予測市場のビジネスモデルを直接揺るがす。コンプライアンス上の圧力が強まれば、プラットフォームの運営が制限され、流動性が低下する可能性があり、その結果、POLYやUMAMIなど関連資産の評価見通しにも影響が及ぶ。さらに多くの州がアーカンソー州に続いて訴訟を起こせば、業界全体がより大きなコンプライアンス上の課題に直面し、市場流動性の縮小につながるおそれもある。
ただし、各州の賭博に関する法律の定義が曖昧であることも、判決の不確実性につながっている点には注意が必要だ。同じ法律の条項でも、裁判官によって解釈が異なる可能性があり、プラットフォーム側には一定の反論の余地がある。また、政策が変更されるリスクも依然として存在し、今後の連邦レベルでの立法の進展によって、現在の規制環境が変わる可能性もある。
今後注目すべきは、他州が同様の訴訟に続くかどうか、そしてKalshiの訴訟対応方針や最終的な判決の行方だ。こうした動きは、予測市場業界のコンプライアンスの見通しと、関連資産の市場での動向に直接影響する。
#PredictionMarkets #Regulation #Kalshi
以上は情報の整理と個人的な分析であり、投資助言を構成するものではありません。
今後、政策の詳細がさらに明らかになり次第、引き続き更新します。
米アーカンソー州司法長官事務所は、予測市場プラットフォームのKalshiを正式に提訴し、違法賭博によるものとされる収益の返還を求めた。これは単独の動きではなく、オンライン予測市場のビジネスモデルの適法性をめぐり、各州の規制当局が圧力を強めていることを示す最新の事例だ。こうした訴訟が増えるにつれ、業界を取り巻く規制上の不確実性は大きく高まっている。
Decryptの報道によると、アーカンソー州のティム・グリフィン司法長官は声明で、プラットフォーム上で「アーカンソー・レイザーバックスが勝つかどうか」に賭ける行為は賭博に当たると指摘し、Kalshiに賠償(restitution)を明確に求めた。この訴訟により、アーカンソー州は予測市場への規制取り締まりに正式に加わった。これは、先に他州が取った措置に呼応するものだ。
予測市場は長らく、従来の金融規制と賭博関連法のグレーゾーンに置かれてきた。連邦レベルでは統一された明確な法律がまだ制定されていない一方、各州は独自の賭博の定義と執行権限を持つ。このように規制が分断された環境では、プラットフォームのコンプライアンスコストが高くなり、判決の結果も、各地の法律を裁判官がどう解釈するかに大きく左右される。今回のアーカンソー州の訴訟は、まさにこの問題を象徴する事例だ。
市場への影響という点では、規制強化の兆しが予測市場のビジネスモデルを直接揺るがす。コンプライアンス上の圧力が強まれば、プラットフォームの運営が制限され、流動性が低下する可能性があり、その結果、POLYやUMAMIなど関連資産の評価見通しにも影響が及ぶ。さらに多くの州がアーカンソー州に続いて訴訟を起こせば、業界全体がより大きなコンプライアンス上の課題に直面し、市場流動性の縮小につながるおそれもある。
ただし、各州の賭博に関する法律の定義が曖昧であることも、判決の不確実性につながっている点には注意が必要だ。同じ法律の条項でも、裁判官によって解釈が異なる可能性があり、プラットフォーム側には一定の反論の余地がある。また、政策が変更されるリスクも依然として存在し、今後の連邦レベルでの立法の進展によって、現在の規制環境が変わる可能性もある。
今後注目すべきは、他州が同様の訴訟に続くかどうか、そしてKalshiの訴訟対応方針や最終的な判決の行方だ。こうした動きは、予測市場業界のコンプライアンスの見通しと、関連資産の市場での動向に直接影響する。
#PredictionMarkets #Regulation #Kalshi
以上は情報の整理と個人的な分析であり、投資助言を構成するものではありません。
今後、政策の詳細がさらに明らかになり次第、引き続き更新します。
28

·
--
アーカンソー州のティム・グリフィン司法長官がKalshiを直接提訴し、テキサス州の予測市場は完全におしまい。「ワイルドキャッツの勝敗に賭けるのはギャンブルじゃないの?」というのはもっともな話で、規制の火はますます燃え広がっています。
#Kalshi #予測市場
アーカンソー州のティム・グリフィン司法長官がKalshiを直接提訴し、テキサス州の予測市場は完全におしまい。「ワイルドキャッツの勝敗に賭けるのはギャンブルじゃないの?」というのはもっともな話で、規制の火はますます燃え広がっています。
#Kalshi #予測市場
#Kalshi #予測市場
3

·
--
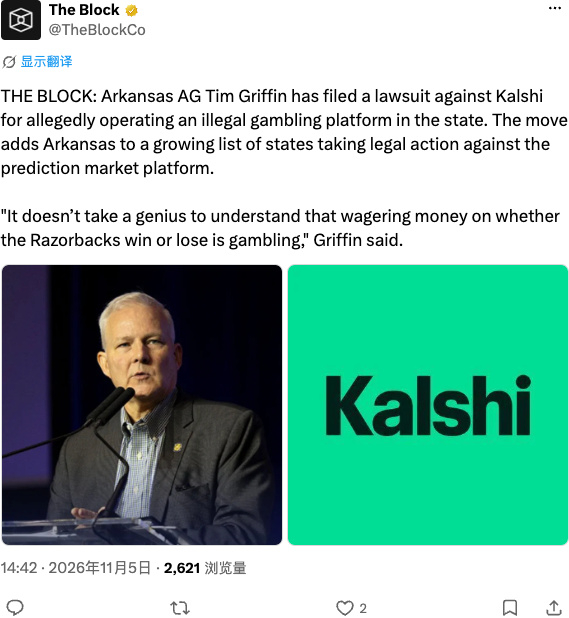
予測市場をめぐる争いに、また一州が加わった。アーカンソー州のティム・グリフィン司法長官がKalshiを提訴し、州の許可を得ずに、実際のお金を賭けるスポーツやエンターテインメントの結果に関する契約を提供していたと主張している。
訴状はインディペンデンス郡巡回裁判所に提出され、KalshiEX LLC / Kalshi Inc.を名指しし、アーカンソー州欺瞞的取引慣行法への違反を主張。返金、罰金、税金の支払い、差し止めによる救済を求めている。グリフィンは公式発表で、チームの勝敗に賭ける行為は州法の規制対象だと明言した。プラットフォームは州の免許取得や規制、納税の手続きを経ておらず、18歳の利用者にもスポーツやエンターテインメント関連の契約への参加を認めていたという。訴状ではKalshiを「ポケットサイズの賭け屋」とまで呼んでいる。
Kalshiの一貫した主張は、スポーツ関連の契約はCFTCの規制を受ける金融デリバティブだというものだ。連邦政府と州の主張は食い違っている。ユタ州は先週、すでに刑事訴追に踏み切り、アリゾナ州、コネチカット州、マサチューセッツ州、ミシガン州、ネバダ州なども提訴や利用制限を進めている。一方、CFTCはユタ州を逆に提訴し、「規制できるのはワシントンだけだ」と争っている。今回のアーカンソー州の動きは、民事訴訟の面でもう一州が加わった形だ。
州レベルでの包囲網はさらに強まり、予測市場がコンプライアンスを守れる範囲はますます狭まっている。#预测市场 #Kalshi #暗号資産規制
予測市場をめぐる争いに、また一州が加わった。アーカンソー州のティム・グリフィン司法長官がKalshiを提訴し、州の許可を得ずに、実際のお金を賭けるスポーツやエンターテインメントの結果に関する契約を提供していたと主張している。
訴状はインディペンデンス郡巡回裁判所に提出され、KalshiEX LLC / Kalshi Inc.を名指しし、アーカンソー州欺瞞的取引慣行法への違反を主張。返金、罰金、税金の支払い、差し止めによる救済を求めている。グリフィンは公式発表で、チームの勝敗に賭ける行為は州法の規制対象だと明言した。プラットフォームは州の免許取得や規制、納税の手続きを経ておらず、18歳の利用者にもスポーツやエンターテインメント関連の契約への参加を認めていたという。訴状ではKalshiを「ポケットサイズの賭け屋」とまで呼んでいる。
Kalshiの一貫した主張は、スポーツ関連の契約はCFTCの規制を受ける金融デリバティブだというものだ。連邦政府と州の主張は食い違っている。ユタ州は先週、すでに刑事訴追に踏み切り、アリゾナ州、コネチカット州、マサチューセッツ州、ミシガン州、ネバダ州なども提訴や利用制限を進めている。一方、CFTCはユタ州を逆に提訴し、「規制できるのはワシントンだけだ」と争っている。今回のアーカンソー州の動きは、民事訴訟の面でもう一州が加わった形だ。
州レベルでの包囲網はさらに強まり、予測市場がコンプライアンスを守れる範囲はますます狭まっている。#预测市场 #Kalshi #暗号資産規制
訴状はインディペンデンス郡巡回裁判所に提出され、KalshiEX LLC / Kalshi Inc.を名指しし、アーカンソー州欺瞞的取引慣行法への違反を主張。返金、罰金、税金の支払い、差し止めによる救済を求めている。グリフィンは公式発表で、チームの勝敗に賭ける行為は州法の規制対象だと明言した。プラットフォームは州の免許取得や規制、納税の手続きを経ておらず、18歳の利用者にもスポーツやエンターテインメント関連の契約への参加を認めていたという。訴状ではKalshiを「ポケットサイズの賭け屋」とまで呼んでいる。
Kalshiの一貫した主張は、スポーツ関連の契約はCFTCの規制を受ける金融デリバティブだというものだ。連邦政府と州の主張は食い違っている。ユタ州は先週、すでに刑事訴追に踏み切り、アリゾナ州、コネチカット州、マサチューセッツ州、ミシガン州、ネバダ州なども提訴や利用制限を進めている。一方、CFTCはユタ州を逆に提訴し、「規制できるのはワシントンだけだ」と争っている。今回のアーカンソー州の動きは、民事訴訟の面でもう一州が加わった形だ。
州レベルでの包囲網はさらに強まり、予測市場がコンプライアンスを守れる範囲はますます狭まっている。#预测市场 #Kalshi #暗号資産規制
7

Kalshi、違法賭博の疑いでアーカンソー州から提訴!
- **アーカンソー州、違法賭博を主張:** アーカンソー州は、予測市場のKalshiが違法賭博を運営しているとして、正式に提訴しました。
- **ユタ州など複数の州も追随:** ユタ州をはじめとする複数の州も、同様の刑事または民事上の申し立てを行っています。
- **法的措置が拡大:** 訴訟が相次ぎ、予測市場プラットフォームの将来に大きな課題を突きつけています。
#BinanceSquare #CryptoNews #Kalshi #PredictionMarket
$btc $eth
#vlikevn Titanbot
出典:CoinDesk
Kalshi、違法賭博の疑いでアーカンソー州から提訴!
- **アーカンソー州、違法賭博を主張:** アーカンソー州は、予測市場のKalshiが違法賭博を運営しているとして、正式に提訴しました。
- **ユタ州など複数の州も追随:** ユタ州をはじめとする複数の州も、同様の刑事または民事上の申し立てを行っています。
- **法的措置が拡大:** 訴訟が相次ぎ、予測市場プラットフォームの将来に大きな課題を突きつけています。
#BinanceSquare #CryptoNews #Kalshi #PredictionMarket
$btc $eth
#vlikevn Titanbot
出典:CoinDesk
- **アーカンソー州、違法賭博を主張:** アーカンソー州は、予測市場のKalshiが違法賭博を運営しているとして、正式に提訴しました。
- **ユタ州など複数の州も追随:** ユタ州をはじめとする複数の州も、同様の刑事または民事上の申し立てを行っています。
- **法的措置が拡大:** 訴訟が相次ぎ、予測市場プラットフォームの将来に大きな課題を突きつけています。
#BinanceSquare #CryptoNews #Kalshi #PredictionMarket
$btc $eth
#vlikevn Titanbot
出典:CoinDesk
157
Kalshiに新たな訴訟、訴訟の山がさらに膨らむ
- アーカンソー州がKalshiを提訴。
- Kalshiは違法賭博を運営しているとして告発される。
- ユタ州と他の複数の州も提訴。
- 刑事・民事の訴追。
#BinanceSquare #CryptoNews #Kalshi
$btc $eth
#vlikevn #Titanbot
出典:CoinDesk
Kalshiに新たな訴訟、訴訟の山がさらに膨らむ
- アーカンソー州がKalshiを提訴。
- Kalshiは違法賭博を運営しているとして告発される。
- ユタ州と他の複数の州も提訴。
- 刑事・民事の訴追。
#BinanceSquare #CryptoNews #Kalshi
$btc $eth
#vlikevn #Titanbot
出典:CoinDesk
- アーカンソー州がKalshiを提訴。
- Kalshiは違法賭博を運営しているとして告発される。
- ユタ州と他の複数の州も提訴。
- 刑事・民事の訴追。
#BinanceSquare #CryptoNews #Kalshi
$btc $eth
#vlikevn #Titanbot
出典:CoinDesk
168
·
--
米国第2巡回区控訴裁判所は、KalshiとCoinbaseが申請した「控訴中の仮差し止め命令」を退けた。ニューヨーク州とコネティカット州は、州法に基づく関連の執行を引き続き進めることができる。
3人の裁判官による2ページの決定は簡潔で、申立人が差し止め命令の必要性を立証できなかったとだけ述べている。連邦法の優先(イベント契約をCFTCが管轄するのか、それとも州法も適用できるのか)という実体的な問題には今回は踏み込まず、プラットフォームに取引停止やポジション解消も求めなかった。しかし、州レベルでの訴訟圧力はひとまず現実のものとなった。
報道によると、ニューヨーク州がKalshiに求める民事賠償額は少なくとも約360億ドルに達する可能性がある。Coinbaseは四半期報告書で、予測市場の年換算収益がすでに2億ドルを超えたと言及している。連邦と州の争いは続いているが、当面の盾はなくなった。
$COIN #预测市场 #Kalshi #規制
米国第2巡回区控訴裁判所は、KalshiとCoinbaseが申請した「控訴中の仮差し止め命令」を退けた。ニューヨーク州とコネティカット州は、州法に基づく関連の執行を引き続き進めることができる。
3人の裁判官による2ページの決定は簡潔で、申立人が差し止め命令の必要性を立証できなかったとだけ述べている。連邦法の優先(イベント契約をCFTCが管轄するのか、それとも州法も適用できるのか)という実体的な問題には今回は踏み込まず、プラットフォームに取引停止やポジション解消も求めなかった。しかし、州レベルでの訴訟圧力はひとまず現実のものとなった。
報道によると、ニューヨーク州がKalshiに求める民事賠償額は少なくとも約360億ドルに達する可能性がある。Coinbaseは四半期報告書で、予測市場の年換算収益がすでに2億ドルを超えたと言及している。連邦と州の争いは続いているが、当面の盾はなくなった。
$COIN #预测市场 #Kalshi #規制
3人の裁判官による2ページの決定は簡潔で、申立人が差し止め命令の必要性を立証できなかったとだけ述べている。連邦法の優先(イベント契約をCFTCが管轄するのか、それとも州法も適用できるのか)という実体的な問題には今回は踏み込まず、プラットフォームに取引停止やポジション解消も求めなかった。しかし、州レベルでの訴訟圧力はひとまず現実のものとなった。
報道によると、ニューヨーク州がKalshiに求める民事賠償額は少なくとも約360億ドルに達する可能性がある。Coinbaseは四半期報告書で、予測市場の年換算収益がすでに2億ドルを超えたと言及している。連邦と州の争いは続いているが、当面の盾はなくなった。
$COIN #预测市场 #Kalshi #規制
20
·
--
記事
Kalshiのパーレーでテイカーは10億ドル超を損失、マーケットメーカーは5億2,000万ドルを獲得InGameの分析で確認されたとおり、Kalshiが2025年9月にパーレーを開始して以来、テイカーは合計10億400万ドルの損失を出しています。
内訳:
· 予測市場での純損失:6億890万ドル
· 支払われた手数料:4億ドル
· テイカーの賭け金総額:71億ドル
勝者は誰か:マーケットメーカーは手数料差し引き後に5億1,980万ドルを得ました。Kalshiがマーケットメーカー手数料の徴収を始めたのは8月20日からで、それ以前はマーケットメーカーがスプレッドのほぼ全額を手にしていました。
損失が膨らんだ時期:テイカーの損失全体のほぼ半分は、2026年のNFLシーズン開幕後の8週間に発生しました。10月31日〜11月1日の週末だけで、賭け金は約2億ドル、損失は1,700万ドル超でした。
Kalshiのパーレーでテイカーは10億ドル超を損失、マーケットメーカーは5億2,000万ドルを獲得
InGameの分析で確認されたとおり、Kalshiが2025年9月にパーレーを開始して以来、テイカーは合計10億400万ドルの損失を出しています。
内訳:
· 予測市場での純損失:6億890万ドル
· 支払われた手数料:4億ドル
· テイカーの賭け金総額:71億ドル
勝者は誰か:マーケットメーカーは手数料差し引き後に5億1,980万ドルを得ました。Kalshiがマーケットメーカー手数料の徴収を始めたのは8月20日からで、それ以前はマーケットメーカーがスプレッドのほぼ全額を手にしていました。
損失が膨らんだ時期:テイカーの損失全体のほぼ半分は、2026年のNFLシーズン開幕後の8週間に発生しました。10月31日〜11月1日の週末だけで、賭け金は約2億ドル、損失は1,700万ドル超でした。
内訳:
· 予測市場での純損失:6億890万ドル
· 支払われた手数料:4億ドル
· テイカーの賭け金総額:71億ドル
勝者は誰か:マーケットメーカーは手数料差し引き後に5億1,980万ドルを得ました。Kalshiがマーケットメーカー手数料の徴収を始めたのは8月20日からで、それ以前はマーケットメーカーがスプレッドのほぼ全額を手にしていました。
損失が膨らんだ時期:テイカーの損失全体のほぼ半分は、2026年のNFLシーズン開幕後の8週間に発生しました。10月31日〜11月1日の週末だけで、賭け金は約2億ドル、損失は1,700万ドル超でした。
24
·
--
本人確認中
📢 PolymarketとKalshi、2026年は民主党に賭け
予測市場では、2026年の中間選挙で民主党が上下両院を制する可能性が高いと見られています。Polymarketでは確率が78%で、取引額は5,800万ドル超。一方、Kalshiでは74%で、取引高は1億ドルを超えています。
上院選の個別市場も同じ傾向を示しています。テキサス州のJames Talaricoは74~76%、メイン州のTroy Jacksonは約73%、ミシガン州のAbdul El-Sayedは約78%と予想されています。従来型の世論調査も、青い波が起こる可能性を示しています。
KalshiのCEO、Tarek Mansourは、予測市場の賭け金が14億ドルを超えた初めての選挙だと述べました。ただし、これらのプラットフォームが過去に予想を外したこともあります。ブラジルの決選投票でLula da Silvaが勝利することを予測できませんでした。オッズが示しているのは、今どこに資金が流れているかであり、結果が保証されているわけではありません。
#CRYPTO #POLYMARKET #KALSHI $USDC
{spot}(USDCUSDT)
📢 PolymarketとKalshi、2026年は民主党に賭け
予測市場では、2026年の中間選挙で民主党が上下両院を制する可能性が高いと見られています。Polymarketでは確率が78%で、取引額は5,800万ドル超。一方、Kalshiでは74%で、取引高は1億ドルを超えています。
上院選の個別市場も同じ傾向を示しています。テキサス州のJames Talaricoは74~76%、メイン州のTroy Jacksonは約73%、ミシガン州のAbdul El-Sayedは約78%と予想されています。従来型の世論調査も、青い波が起こる可能性を示しています。
KalshiのCEO、Tarek Mansourは、予測市場の賭け金が14億ドルを超えた初めての選挙だと述べました。ただし、これらのプラットフォームが過去に予想を外したこともあります。ブラジルの決選投票でLula da Silvaが勝利することを予測できませんでした。オッズが示しているのは、今どこに資金が流れているかであり、結果が保証されているわけではありません。
#CRYPTO #POLYMARKET #KALSHI $USDC
予測市場では、2026年の中間選挙で民主党が上下両院を制する可能性が高いと見られています。Polymarketでは確率が78%で、取引額は5,800万ドル超。一方、Kalshiでは74%で、取引高は1億ドルを超えています。
上院選の個別市場も同じ傾向を示しています。テキサス州のJames Talaricoは74~76%、メイン州のTroy Jacksonは約73%、ミシガン州のAbdul El-Sayedは約78%と予想されています。従来型の世論調査も、青い波が起こる可能性を示しています。
KalshiのCEO、Tarek Mansourは、予測市場の賭け金が14億ドルを超えた初めての選挙だと述べました。ただし、これらのプラットフォームが過去に予想を外したこともあります。ブラジルの決選投票でLula da Silvaが勝利することを予測できませんでした。オッズが示しているのは、今どこに資金が流れているかであり、結果が保証されているわけではありません。
#CRYPTO #POLYMARKET #KALSHI $USDC
1
1.1k

予測市場は、片隅の存在から一気にメインステージへ躍り出た。Kalshiは10月29日、セコイアとWellingtonが共同で主導し、a16z、Coatue、モルガン・スタンレー・インベストメント・マネジメントなども参加する、10億ドルのシリーズG資金調達を発表。調達後の評価額は400億ドルとなった。5月時点では220億ドルで、わずか5カ月でほぼ倍増した。年間換算の取引高はすでに1兆ドルを突破し、スポーツ以外の事業の年間換算売上高は10億ドル超、登録アカウント数は3,000万件を超えている。資金はラテンアメリカや欧州への進出に加え、指数、個別株の永久先物、計算能力市場などの新商品に投じられる。明日はアメリカの中間選挙。KalshiとPolymarketでは、中間選挙関連の契約にすでに14億ドル超が賭けられている。予測市場を信じるかどうかはともかく、すでに世界の不確実性に値を付けている。Polymarketの8月時点の評価額は210億ドルで、Kalshiは今やそのほぼ2倍。差はさらに広がっている。#预测市场 #Kalshi
予測市場は、片隅の存在から一気にメインステージへ躍り出た。Kalshiは10月29日、セコイアとWellingtonが共同で主導し、a16z、Coatue、モルガン・スタンレー・インベストメント・マネジメントなども参加する、10億ドルのシリーズG資金調達を発表。調達後の評価額は400億ドルとなった。5月時点では220億ドルで、わずか5カ月でほぼ倍増した。年間換算の取引高はすでに1兆ドルを突破し、スポーツ以外の事業の年間換算売上高は10億ドル超、登録アカウント数は3,000万件を超えている。資金はラテンアメリカや欧州への進出に加え、指数、個別株の永久先物、計算能力市場などの新商品に投じられる。明日はアメリカの中間選挙。KalshiとPolymarketでは、中間選挙関連の契約にすでに14億ドル超が賭けられている。予測市場を信じるかどうかはともかく、すでに世界の不確実性に値を付けている。Polymarketの8月時点の評価額は210億ドルで、Kalshiは今やそのほぼ2倍。差はさらに広がっている。#预测市场 #Kalshi
96
·
--
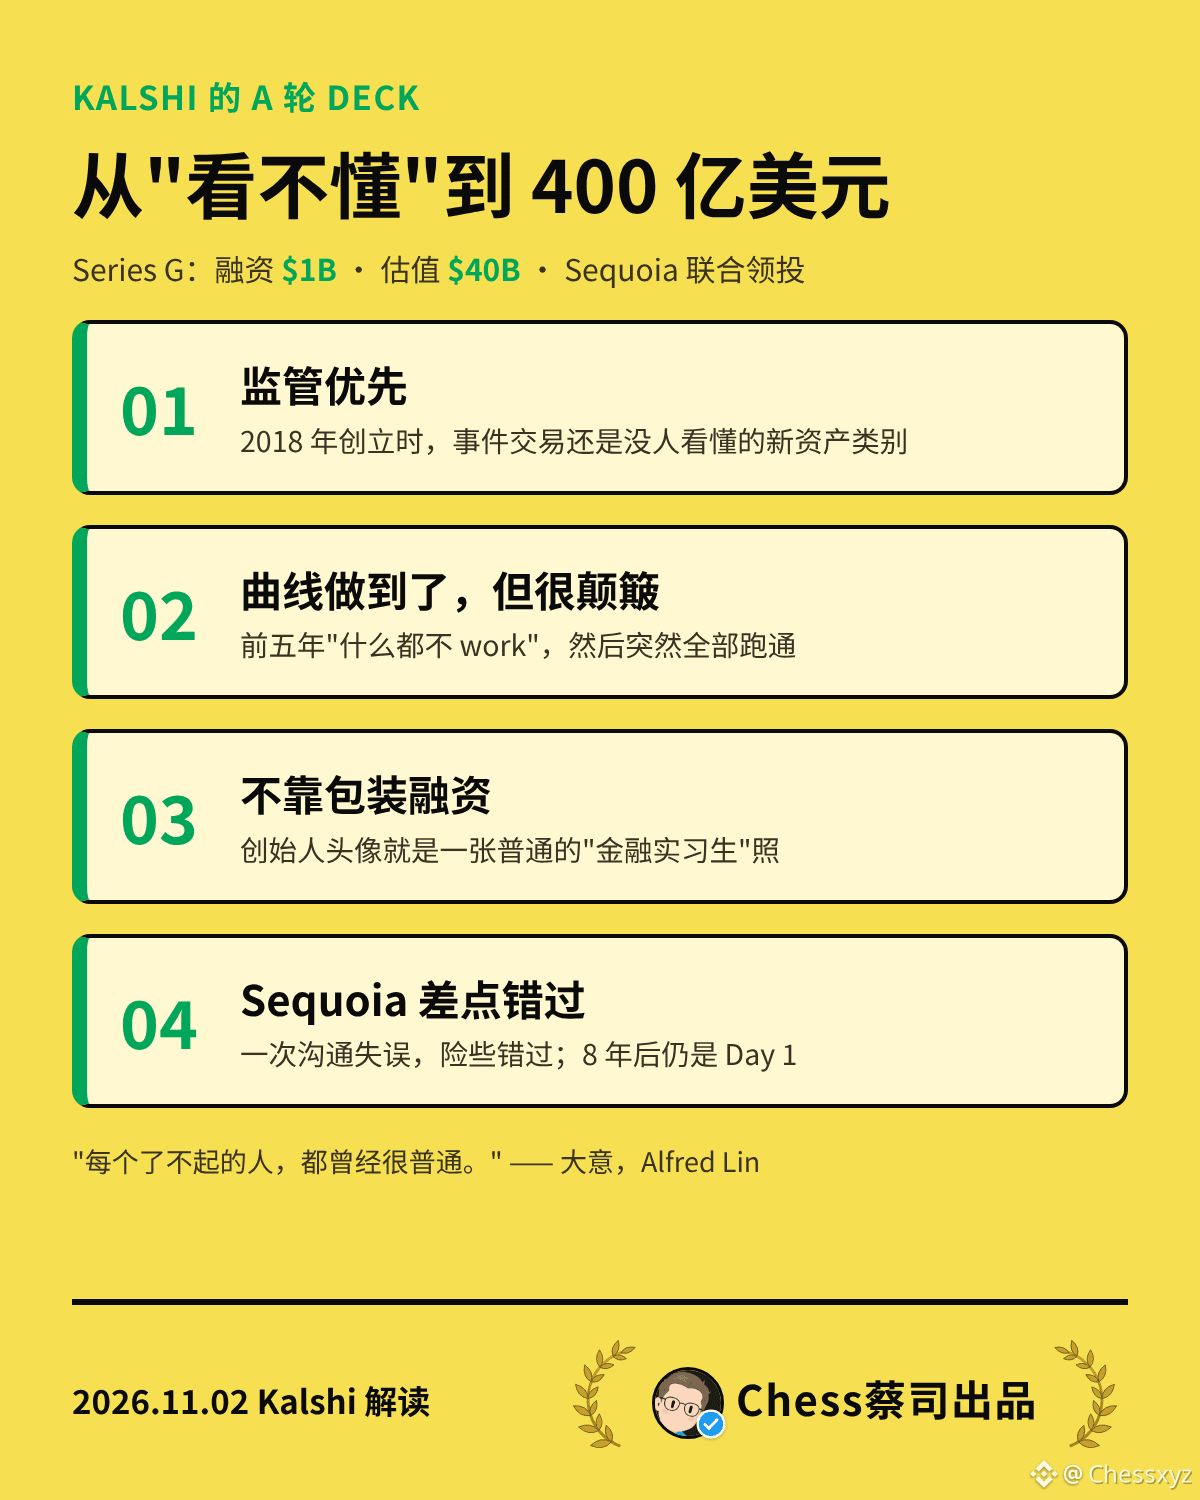
Kalshiが400億ドルの評価額に達する前にも、「パッとしない」シリーズAのピッチデックがあった
SequoiaのAlfred Linが、KalshiがシリーズAの資金調達に使った当時のピッチデックを全編公開した。背景として、KalshiはシリーズGで10億ドルを調達し、評価額は400億ドルに。Sequoiaが共同で主導した。
注目しておきたいポイント:
1. 初日から規制対応を最優先
Kalshiは最初からコンプライアンス重視の道を選んだ。今では「イベントの結果を取引する」ことは当たり前に思えるが、2018年の創業時も、Sequoiaが投資した2020年も、これは理解されにくい新しい資産クラスだった。
2. ホッケースティック型の成長曲線は実現したが、道のりは計画よりずっと険しかった
デックに記された成長予測は、Kalshiはその後、達成しただけでなく上回った。しかしTarek自身が語ったように、最初の5年間は何をやってもうまくいかないと感じていた。ある時を境に、突然すべてがうまく回り始めた。
3. 資金調達に見栄えは必要ない
デックに載っていた創業者の写真は、ごく普通の「金融インターン」の写真だった。Alfredの言葉の趣旨はこうだ。偉大な人も、かつてはみなごく普通だった。
4. Sequoiaは危うく投資機会を逃すところだった
コミュニケーションの行き違いがあり、この投資を完全に逃すところだった。8年が経った今も、KalshiはDay 1のままだ。
私の見解:
Bagelや予測市場、AI取引に取り組んできたこの一年で、最も共感したのは2つ目だ。外から見えるのは一本の成長曲線。でも中にいる人たちが経験したのは、「何をやってもうまくいかない」5年間だった。
今、予測市場は注目の分野に見える。でもKalshiは、誰も信じていない時期に、最も難しく、最も時間のかかる規制対応を先にやり遂げた。本当の競争優位性は、当時はいちばん不器用に見えた部分にあることが多い。
AIエージェントも今、同じ段階にある。誰もがストーリーを語る一方で、土台を先に磨こうとする人はほとんどいない。私たちが取り組んでいることも同じ。まずは地力をつける。成長曲線は後からついてくる。
まだ「何をやってもうまくいかない」段階にいる起業家へ。Kalshiも同じ経験をしてきた。
原文:https://x.com/Alfred_Lin/status/2116924431960535365
この内容は本人がまとめたものです(AIの支援を含む場合があります)。個人的な見解の共有であり、投資助言を構成するものではありません。
#Kalshi #预测市场 #起業
Kalshiが400億ドルの評価額に達する前にも、「パッとしない」シリーズAのピッチデックがあった
SequoiaのAlfred Linが、KalshiがシリーズAの資金調達に使った当時のピッチデックを全編公開した。背景として、KalshiはシリーズGで10億ドルを調達し、評価額は400億ドルに。Sequoiaが共同で主導した。
注目しておきたいポイント:
1. 初日から規制対応を最優先
Kalshiは最初からコンプライアンス重視の道を選んだ。今では「イベントの結果を取引する」ことは当たり前に思えるが、2018年の創業時も、Sequoiaが投資した2020年も、これは理解されにくい新しい資産クラスだった。
2. ホッケースティック型の成長曲線は実現したが、道のりは計画よりずっと険しかった
デックに記された成長予測は、Kalshiはその後、達成しただけでなく上回った。しかしTarek自身が語ったように、最初の5年間は何をやってもうまくいかないと感じていた。ある時を境に、突然すべてがうまく回り始めた。
3. 資金調達に見栄えは必要ない
デックに載っていた創業者の写真は、ごく普通の「金融インターン」の写真だった。Alfredの言葉の趣旨はこうだ。偉大な人も、かつてはみなごく普通だった。
4. Sequoiaは危うく投資機会を逃すところだった
コミュニケーションの行き違いがあり、この投資を完全に逃すところだった。8年が経った今も、KalshiはDay 1のままだ。
私の見解:
Bagelや予測市場、AI取引に取り組んできたこの一年で、最も共感したのは2つ目だ。外から見えるのは一本の成長曲線。でも中にいる人たちが経験したのは、「何をやってもうまくいかない」5年間だった。
今、予測市場は注目の分野に見える。でもKalshiは、誰も信じていない時期に、最も難しく、最も時間のかかる規制対応を先にやり遂げた。本当の競争優位性は、当時はいちばん不器用に見えた部分にあることが多い。
AIエージェントも今、同じ段階にある。誰もがストーリーを語る一方で、土台を先に磨こうとする人はほとんどいない。私たちが取り組んでいることも同じ。まずは地力をつける。成長曲線は後からついてくる。
まだ「何をやってもうまくいかない」段階にいる起業家へ。Kalshiも同じ経験をしてきた。
原文:https://x.com/Alfred_Lin/status/2116924431960535365
この内容は本人がまとめたものです(AIの支援を含む場合があります)。個人的な見解の共有であり、投資助言を構成するものではありません。
#Kalshi #预测市场 #起業
SequoiaのAlfred Linが、KalshiがシリーズAの資金調達に使った当時のピッチデックを全編公開した。背景として、KalshiはシリーズGで10億ドルを調達し、評価額は400億ドルに。Sequoiaが共同で主導した。
注目しておきたいポイント:
1. 初日から規制対応を最優先
Kalshiは最初からコンプライアンス重視の道を選んだ。今では「イベントの結果を取引する」ことは当たり前に思えるが、2018年の創業時も、Sequoiaが投資した2020年も、これは理解されにくい新しい資産クラスだった。
2. ホッケースティック型の成長曲線は実現したが、道のりは計画よりずっと険しかった
デックに記された成長予測は、Kalshiはその後、達成しただけでなく上回った。しかしTarek自身が語ったように、最初の5年間は何をやってもうまくいかないと感じていた。ある時を境に、突然すべてがうまく回り始めた。
3. 資金調達に見栄えは必要ない
デックに載っていた創業者の写真は、ごく普通の「金融インターン」の写真だった。Alfredの言葉の趣旨はこうだ。偉大な人も、かつてはみなごく普通だった。
4. Sequoiaは危うく投資機会を逃すところだった
コミュニケーションの行き違いがあり、この投資を完全に逃すところだった。8年が経った今も、KalshiはDay 1のままだ。
私の見解:
Bagelや予測市場、AI取引に取り組んできたこの一年で、最も共感したのは2つ目だ。外から見えるのは一本の成長曲線。でも中にいる人たちが経験したのは、「何をやってもうまくいかない」5年間だった。
今、予測市場は注目の分野に見える。でもKalshiは、誰も信じていない時期に、最も難しく、最も時間のかかる規制対応を先にやり遂げた。本当の競争優位性は、当時はいちばん不器用に見えた部分にあることが多い。
AIエージェントも今、同じ段階にある。誰もがストーリーを語る一方で、土台を先に磨こうとする人はほとんどいない。私たちが取り組んでいることも同じ。まずは地力をつける。成長曲線は後からついてくる。
まだ「何をやってもうまくいかない」段階にいる起業家へ。Kalshiも同じ経験をしてきた。
原文:https://x.com/Alfred_Lin/status/2116924431960535365
この内容は本人がまとめたものです(AIの支援を含む場合があります)。個人的な見解の共有であり、投資助言を構成するものではありません。
#Kalshi #预测市场 #起業
71

Kalshiの評価額は400億ドル。いちばん冷静になるべきなのは、まさに暗号資産界隈だ。
10月29日、シリーズGで10億ドルを調達したと発表。セコイアとウェリントンが主導し、調達後の評価額は400億ドル。5月のラウンドでは220億ドルだったので、半年も経たずにほぼ倍増だ。公式発表によると、年間換算の取引高は1兆ドルを突破し、月間では978億ドル。
でも、私がもっと気になるのはある細部だ。あるメディアは、Kalshiが「暗号資産と永久先物でこの評価額を支えている」とはっきり書いている。暗号資産関連の取引高は年間換算で約1,400億ドル。つまり、イベント契約のビジネスを400億ドルの評価額に値する話として語るには、結局こちらの領域にも手を伸ばす必要があるということだ。暗号資産価格の上げ下げを予測する契約や永久先物で、取引所と同じ個人投資家を奪い合っている。
もう一つ、かなり目を引くデータがある。今週の暗号資産関連の資金調達は合計12.4億ドルで、そのうち10億ドルをKalshi一社が獲得。約8割だ。資金が一つの分野のトップ企業に集中するのは、業界の繁栄とは言わない。VCが次のCoinbaseを探して、こぞって群がっているだけだ。
確実に儲かるのは誰か? 手数料を取るプラットフォーム、スプレッドで稼ぐマーケットメーカー、次のラウンドや上場でのイグジットを待つVCだ。必ずしも儲かるとは限らないのは誰か? そこでYes/Noを選ぶあなた。予測市場の価格がある程度、世の中の空気を反映するのは確かだ。でも「プラットフォームの評価額が倍増した」ことを、「そこで遊べば自分も倍増できる」と考えてはいけない。この二つには、これっぽっちも関係がない。
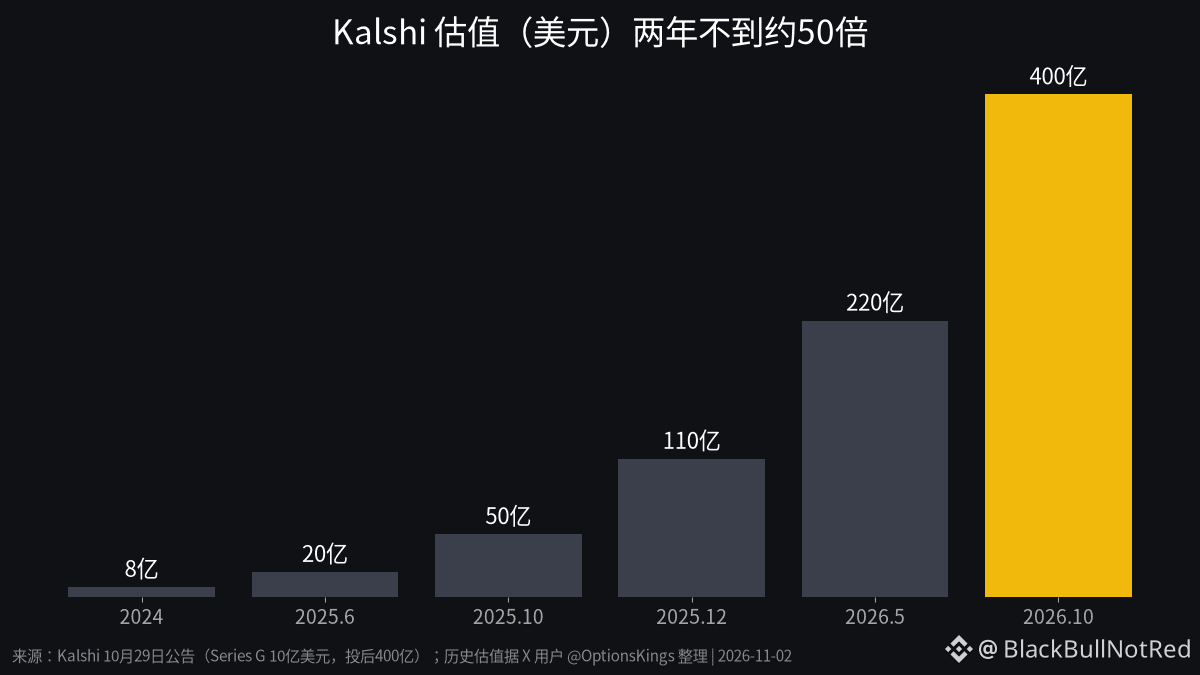
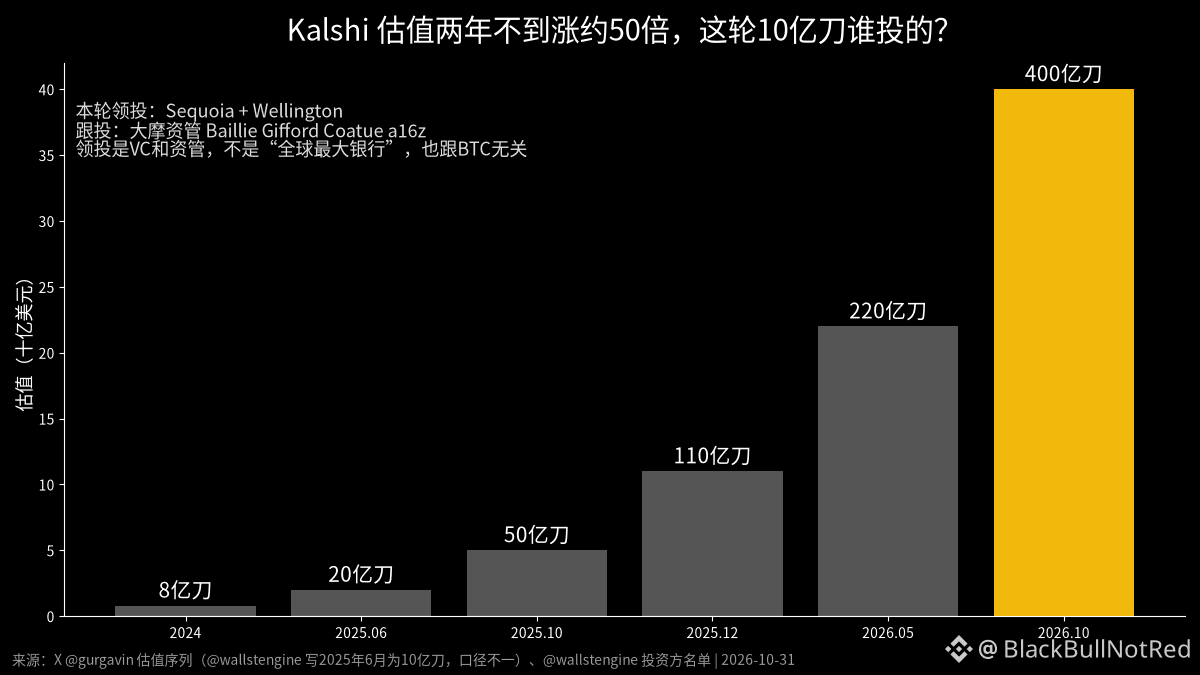
画像の過去の評価額は、Xで誰かがまとめたもの。公式発表の数字なのは最後の棒だけだ。
#预测市场 #Kalshi
Kalshiの評価額は400億ドル。いちばん冷静になるべきなのは、まさに暗号資産界隈だ。
10月29日、シリーズGで10億ドルを調達したと発表。セコイアとウェリントンが主導し、調達後の評価額は400億ドル。5月のラウンドでは220億ドルだったので、半年も経たずにほぼ倍増だ。公式発表によると、年間換算の取引高は1兆ドルを突破し、月間では978億ドル。
でも、私がもっと気になるのはある細部だ。あるメディアは、Kalshiが「暗号資産と永久先物でこの評価額を支えている」とはっきり書いている。暗号資産関連の取引高は年間換算で約1,400億ドル。つまり、イベント契約のビジネスを400億ドルの評価額に値する話として語るには、結局こちらの領域にも手を伸ばす必要があるということだ。暗号資産価格の上げ下げを予測する契約や永久先物で、取引所と同じ個人投資家を奪い合っている。
もう一つ、かなり目を引くデータがある。今週の暗号資産関連の資金調達は合計12.4億ドルで、そのうち10億ドルをKalshi一社が獲得。約8割だ。資金が一つの分野のトップ企業に集中するのは、業界の繁栄とは言わない。VCが次のCoinbaseを探して、こぞって群がっているだけだ。
確実に儲かるのは誰か? 手数料を取るプラットフォーム、スプレッドで稼ぐマーケットメーカー、次のラウンドや上場でのイグジットを待つVCだ。必ずしも儲かるとは限らないのは誰か? そこでYes/Noを選ぶあなた。予測市場の価格がある程度、世の中の空気を反映するのは確かだ。でも「プラットフォームの評価額が倍増した」ことを、「そこで遊べば自分も倍増できる」と考えてはいけない。この二つには、これっぽっちも関係がない。
画像の過去の評価額は、Xで誰かがまとめたもの。公式発表の数字なのは最後の棒だけだ。
#预测市场 #Kalshi
10月29日、シリーズGで10億ドルを調達したと発表。セコイアとウェリントンが主導し、調達後の評価額は400億ドル。5月のラウンドでは220億ドルだったので、半年も経たずにほぼ倍増だ。公式発表によると、年間換算の取引高は1兆ドルを突破し、月間では978億ドル。
でも、私がもっと気になるのはある細部だ。あるメディアは、Kalshiが「暗号資産と永久先物でこの評価額を支えている」とはっきり書いている。暗号資産関連の取引高は年間換算で約1,400億ドル。つまり、イベント契約のビジネスを400億ドルの評価額に値する話として語るには、結局こちらの領域にも手を伸ばす必要があるということだ。暗号資産価格の上げ下げを予測する契約や永久先物で、取引所と同じ個人投資家を奪い合っている。
もう一つ、かなり目を引くデータがある。今週の暗号資産関連の資金調達は合計12.4億ドルで、そのうち10億ドルをKalshi一社が獲得。約8割だ。資金が一つの分野のトップ企業に集中するのは、業界の繁栄とは言わない。VCが次のCoinbaseを探して、こぞって群がっているだけだ。
確実に儲かるのは誰か? 手数料を取るプラットフォーム、スプレッドで稼ぐマーケットメーカー、次のラウンドや上場でのイグジットを待つVCだ。必ずしも儲かるとは限らないのは誰か? そこでYes/Noを選ぶあなた。予測市場の価格がある程度、世の中の空気を反映するのは確かだ。でも「プラットフォームの評価額が倍増した」ことを、「そこで遊べば自分も倍増できる」と考えてはいけない。この二つには、これっぽっちも関係がない。
画像の過去の評価額は、Xで誰かがまとめたもの。公式発表の数字なのは最後の棒だけだ。
#预测市场 #Kalshi
33
記事
翻訳参照
TOKENIZED KALSHI: ARE YOU BUYING PRE-IPO SHARES — OR SOMEONE ELSE'S PROMISE?BitChoice | Satya — RWA & Market Structure Intelligence
November 2, 2026
Private-Market Exposure Is Not the Same as Share Ownership
The race to tokenize traditional financial assets is expanding beyond publicly traded stocks and ETFs.
LBank has introduced a Pre-IPO offering linked to Kalshi, the US prediction-market company, through two instruments:
xKLSH — a product designed for earlier trading access.cKLSH — a locked product with a conditional conversion mechanism.
At first glance, these instruments appear to offer access to the potential future value of a private company.
But the central question is more complicated:
What exactly does a tokenholder legally own?
The answer matters much more than the token's price.
1. What LBank Actually Offers
According to LBank's October 26 announcement, the Kalshi-linked subscription includes two structures.
xKLSH — Unlock Mode
Subscription price: 39 USDTIntended for spot trading on LBankExpected trading launch: November 3, 2026, at 09:00 UTCLiquidity and execution prices are not guaranteed.
cKLSH — Lock Mode
Subscription price: 28 USDTSubject to lock-up conditionsPotential conversion into 1.4 xKLSH per cKLSH, according to the published termsConversion depends on the applicable contractual conditions.
The combined subscription allocation is capped at 500,000 USDT.
The published subscription window runs from October 29 to November 2, 2026.
Importantly, these are subscription terms — not guaranteed future market valuations.
2. The Most Important Detail: These Are Not Kalshi Shares
LBank explicitly states that subscribing to these instruments does not create direct ownership of Kalshi shares or standard shareholder rights.
That means holders should not assume they receive:
Direct voting rights in KalshiOrdinary shareholder statusDirect ownership of company equityGuaranteed access to an eventual IPOGuaranteed conversion into publicly traded shares.
Instead, the structure provides contractual economic exposure through a third-party arrangement.
The named issuing and managing entity is Paimon Limited.
LBank acts as a distribution and platform-services provider.
The distinction is fundamental: exposure to a company's value is not the same as ownership of that company.
3. Who Actually Owes the Investor?
The legal structure introduces additional parties between the investor and the underlying company.
A simplified chain looks like this:
Investor → LBank platform → Paimon product → SPV-linked economic exposure → Kalshi
Each layer has a different role.
LBank provides platform access and associated services.
Paimon is responsible for issuing and managing the product under its contractual documentation.
The SPV arrangement is intended to connect the token's economic exposure with underlying private-market interests.
But the existence of a token does not eliminate contractual, custody or counterparty risk.
If an issuer or intermediary fails to perform its obligations, the tokenholder's recovery depends on the enforceability of the relevant agreements and the status of underlying assets.
This is why understanding the legal issuer matters more than recognizing the company name featured in the marketing.
4. The cKLSH Lock-Up Deserves Special Attention
A longer holding period is often presented as the price of accessing a lower entry valuation.
But investors should examine the precise conditions.
LBank's announcement describes the lock-up as extending until six months after Kalshi's IPO.
The Paimon product website, however, describes a six-month locked tranche.
These descriptions are not obviously equivalent.
The final, binding product documents must determine which condition applies to a specific purchase.
If an IPO is delayed, never occurs or triggers alternative settlement provisions, the exit process may differ significantly from what a simplified promotional description suggests.
A fixed six-month lock-up and an IPO-dependent lock-up can create radically different liquidity risks.
That difference should be resolved before treating the product as a conventional short-term investment.
5. Does the 1.4× Conversion Mean a 40% Profit?
No.
The published conversion ratio concerns token quantities, not guaranteed investment returns.
Imagine a hypothetical position converting into 1.4 times as many tokens.
The economic result still depends on the market price of those tokens when conversion becomes available.
If the value per token falls sufficiently, receiving more tokens does not prevent a loss.
Other factors may include costs, settlement conditions, redemption limitations and the time value of locked capital.
More tokens do not automatically mean more money.
The conversion mechanism must be evaluated together with the expected underlying value and the contractual risks.
6. xKLSH: Tradable Does Not Mean Liquid
The unlocked product is intended to provide earlier access to secondary-market trading.
But there is an important difference between a token being listed and a token having a functional market.
Consider a product with a quoted price of 39 USDT.
A trader might assume that a position worth 3,900 USDT can be sold at that valuation.
In reality, the order book may contain very little buying interest near that price.
A market sell order could execute substantially lower.
Alternatively, there may be insufficient liquidity to close the full position promptly.
Important metrics include:
Bid and ask spreadOrder-book depthTrading volumeAvailable market makersPrice impact for meaningful order sizesConcentration of token holdings.
LBank's announcement also states that deposits and withdrawals are not supported for the event assets.
This creates an additional limitation: users cannot assume that they can transfer the instrument to another exchange or personal wallet through LBank.
A token can be tradable within one platform while remaining difficult to exit economically.
7. What Happens if Kalshi Never Goes Public?
This is one of the most important unresolved investment scenarios.
There is no guaranteed IPO date.
A private company can remain private for longer than investors expect.
Its valuation can change substantially.
Corporate restructurings, financing rounds and regulatory developments can affect the economics of a structured exposure product.
LBank's master agreement describes a potential repurchase opportunity if no IPO or other agreed exit event occurs within twelve months after the relevant Paimon closing date.
However, this is not a guaranteed redemption.
Paimon may offer repurchase only under the applicable conditions, and the proceeds depend on actual realization of the underlying interests.
LBank explicitly disclaims any guarantee of a repurchase, minimum quantity or price.
That means investors should not treat the twelve-month provision as an unconditional maturity date or a guaranteed route back to USDT.
8. The Hidden Valuation Problem
Private-market assets lack the continuous, transparent price discovery associated with highly liquid public shares.
A token can reference an estimated company valuation, while its own secondary-market price reflects a different set of forces.
These may include:
Private-company valuation risk
The reference valuation may be uncertain or change before an eventual liquidity event.
Token liquidity premium or discount
A tradable instrument may trade above or below the value implied by its contractual exposure.
Issuer and settlement risk
The market must assess whether the promised economic relationship can be fulfilled.
Information asymmetry
Public investors may have less access to financial disclosures than investors in conventional public equity markets.
Consequently, a rising token price does not necessarily prove that the underlying company has increased in value.
And a falling token price does not always measure a corresponding change in the company's fundamentals.
9. Can Tokenized Pre-IPO Products Improve Market Access?
Potentially, yes.
Tokenization can simplify distribution, introduce smaller subscription amounts and provide alternative market structures for eligible users.
LBank's published minimum subscription is 10 USDT, subject to allocation and eligibility rules.
That lowers the nominal entry threshold compared with many traditional private-market opportunities.
But reducing the minimum amount does not eliminate structural complexity.
A product can be easier to access while remaining difficult to value, verify or exit.
For these instruments to develop into credible financial infrastructure, several conditions matter:
Transparent legal documentationVerifiable underlying exposureClear investor rightsIndependent custody and valuation controlsReliable secondary-market liquidityPredictable conversion and settlement mechanismsEnforceable investor protections.
Accessibility without clarity is not necessarily financial progress.
10. What Serious Investors Should Verify
Before evaluating any tokenized private-company exposure, the relevant questions are:
Who is the legal issuer?
The issuer is not necessarily the private company named in the product.
What is the underlying claim?
Does it represent shares, an SPV interest or a contractual promise linked to economic performance?
Who holds the underlying assets?
What evidence supports the stated holdings, and who can independently verify it?
What happens if a counterparty fails?
Which entity is responsible for settlement, and what legal remedies are available?
What does "liquid" actually mean?
Is there deep executable demand, or merely an exchange listing?
How does the product terminate?
What happens after an IPO, without an IPO or during an issuer-level failure?
Without clear answers, the token's headline price tells only a small part of the story.
Final Perspective: The Wrapper Is Part of the Investment
The Kalshi-linked offering illustrates both the promise and complexity of tokenized private markets.
Investors may gain new methods of accessing economic exposure associated with private companies.
But these arrangements can introduce multiple layers of counterparty, legal, valuation and liquidity risk.
For xKLSH and cKLSH, the key issue is not simply whether Kalshi's business grows.
It is whether the product's contractual structure can reliably translate that growth into an enforceable economic outcome for the tokenholder.
Tokenized exposure ≠ direct equity ownership.
A quoted price ≠ guaranteed liquidity.
A conversion ratio ≠ guaranteed profit.
The future of RWA tokenization will depend on closing the gap between the financial asset being promoted and the legal rights investors actually receive.
Discussion
Would you prefer direct equity ownership with limited access — or easier tokenized access with additional issuer and liquidity risks?
Sources
LBank — LBank Announces Kalshi Pre-IPO Product Subscriptions, October 26, 2026.
LBank — Pre-IPO Locked Product Subscription & Platform Services Master Agreement, October 28, 2026.
Paimon Finance — Paimon Kalshi SPV Token Product Documentation.
Editorial disclosure: The product is issued and managed by a third party. Its contractual rights, underlying holdings, lock-up conditions and settlement procedures are governed by the applicable binding documents. Inconsistent descriptions of lock-up terms require clarification; neither future liquidity nor an IPO is guaranteed.
Educational and informational content only. Not financial or investment advice.
#Kalshi #PreIPO #RWA #Tokenization #InvestorProtection
TOKENIZED KALSHI: ARE YOU BUYING PRE-IPO SHARES — OR SOMEONE ELSE'S PROMISE?
BitChoice | Satya — RWA & Market Structure Intelligence
November 2, 2026
Private-Market Exposure Is Not the Same as Share Ownership
The race to tokenize traditional financial assets is expanding beyond publicly traded stocks and ETFs.
LBank has introduced a Pre-IPO offering linked to Kalshi, the US prediction-market company, through two instruments:
xKLSH — a product designed for earlier trading access.cKLSH — a locked product with a conditional conversion mechanism.
At first glance, these instruments appear to offer access to the potential future value of a private company.
But the central question is more complicated:
What exactly does a tokenholder legally own?
The answer matters much more than the token's price.
1. What LBank Actually Offers
According to LBank's October 26 announcement, the Kalshi-linked subscription includes two structures.
xKLSH — Unlock Mode
Subscription price: 39 USDTIntended for spot trading on LBankExpected trading launch: November 3, 2026, at 09:00 UTCLiquidity and execution prices are not guaranteed.
cKLSH — Lock Mode
Subscription price: 28 USDTSubject to lock-up conditionsPotential conversion into 1.4 xKLSH per cKLSH, according to the published termsConversion depends on the applicable contractual conditions.
The combined subscription allocation is capped at 500,000 USDT.
The published subscription window runs from October 29 to November 2, 2026.
Importantly, these are subscription terms — not guaranteed future market valuations.
2. The Most Important Detail: These Are Not Kalshi Shares
LBank explicitly states that subscribing to these instruments does not create direct ownership of Kalshi shares or standard shareholder rights.
That means holders should not assume they receive:
Direct voting rights in KalshiOrdinary shareholder statusDirect ownership of company equityGuaranteed access to an eventual IPOGuaranteed conversion into publicly traded shares.
Instead, the structure provides contractual economic exposure through a third-party arrangement.
The named issuing and managing entity is Paimon Limited.
LBank acts as a distribution and platform-services provider.
The distinction is fundamental: exposure to a company's value is not the same as ownership of that company.
3. Who Actually Owes the Investor?
The legal structure introduces additional parties between the investor and the underlying company.
A simplified chain looks like this:
Investor → LBank platform → Paimon product → SPV-linked economic exposure → Kalshi
Each layer has a different role.
LBank provides platform access and associated services.
Paimon is responsible for issuing and managing the product under its contractual documentation.
The SPV arrangement is intended to connect the token's economic exposure with underlying private-market interests.
But the existence of a token does not eliminate contractual, custody or counterparty risk.
If an issuer or intermediary fails to perform its obligations, the tokenholder's recovery depends on the enforceability of the relevant agreements and the status of underlying assets.
This is why understanding the legal issuer matters more than recognizing the company name featured in the marketing.
4. The cKLSH Lock-Up Deserves Special Attention
A longer holding period is often presented as the price of accessing a lower entry valuation.
But investors should examine the precise conditions.
LBank's announcement describes the lock-up as extending until six months after Kalshi's IPO.
The Paimon product website, however, describes a six-month locked tranche.
These descriptions are not obviously equivalent.
The final, binding product documents must determine which condition applies to a specific purchase.
If an IPO is delayed, never occurs or triggers alternative settlement provisions, the exit process may differ significantly from what a simplified promotional description suggests.
A fixed six-month lock-up and an IPO-dependent lock-up can create radically different liquidity risks.
That difference should be resolved before treating the product as a conventional short-term investment.
5. Does the 1.4× Conversion Mean a 40% Profit?
No.
The published conversion ratio concerns token quantities, not guaranteed investment returns.
Imagine a hypothetical position converting into 1.4 times as many tokens.
The economic result still depends on the market price of those tokens when conversion becomes available.
If the value per token falls sufficiently, receiving more tokens does not prevent a loss.
Other factors may include costs, settlement conditions, redemption limitations and the time value of locked capital.
More tokens do not automatically mean more money.
The conversion mechanism must be evaluated together with the expected underlying value and the contractual risks.
6. xKLSH: Tradable Does Not Mean Liquid
The unlocked product is intended to provide earlier access to secondary-market trading.
But there is an important difference between a token being listed and a token having a functional market.
Consider a product with a quoted price of 39 USDT.
A trader might assume that a position worth 3,900 USDT can be sold at that valuation.
In reality, the order book may contain very little buying interest near that price.
A market sell order could execute substantially lower.
Alternatively, there may be insufficient liquidity to close the full position promptly.
Important metrics include:
Bid and ask spreadOrder-book depthTrading volumeAvailable market makersPrice impact for meaningful order sizesConcentration of token holdings.
LBank's announcement also states that deposits and withdrawals are not supported for the event assets.
This creates an additional limitation: users cannot assume that they can transfer the instrument to another exchange or personal wallet through LBank.
A token can be tradable within one platform while remaining difficult to exit economically.
7. What Happens if Kalshi Never Goes Public?
This is one of the most important unresolved investment scenarios.
There is no guaranteed IPO date.
A private company can remain private for longer than investors expect.
Its valuation can change substantially.
Corporate restructurings, financing rounds and regulatory developments can affect the economics of a structured exposure product.
LBank's master agreement describes a potential repurchase opportunity if no IPO or other agreed exit event occurs within twelve months after the relevant Paimon closing date.
However, this is not a guaranteed redemption.
Paimon may offer repurchase only under the applicable conditions, and the proceeds depend on actual realization of the underlying interests.
LBank explicitly disclaims any guarantee of a repurchase, minimum quantity or price.
That means investors should not treat the twelve-month provision as an unconditional maturity date or a guaranteed route back to USDT.
8. The Hidden Valuation Problem
Private-market assets lack the continuous, transparent price discovery associated with highly liquid public shares.
A token can reference an estimated company valuation, while its own secondary-market price reflects a different set of forces.
These may include:
Private-company valuation risk
The reference valuation may be uncertain or change before an eventual liquidity event.
Token liquidity premium or discount
A tradable instrument may trade above or below the value implied by its contractual exposure.
Issuer and settlement risk
The market must assess whether the promised economic relationship can be fulfilled.
Information asymmetry
Public investors may have less access to financial disclosures than investors in conventional public equity markets.
Consequently, a rising token price does not necessarily prove that the underlying company has increased in value.
And a falling token price does not always measure a corresponding change in the company's fundamentals.
9. Can Tokenized Pre-IPO Products Improve Market Access?
Potentially, yes.
Tokenization can simplify distribution, introduce smaller subscription amounts and provide alternative market structures for eligible users.
LBank's published minimum subscription is 10 USDT, subject to allocation and eligibility rules.
That lowers the nominal entry threshold compared with many traditional private-market opportunities.
But reducing the minimum amount does not eliminate structural complexity.
A product can be easier to access while remaining difficult to value, verify or exit.
For these instruments to develop into credible financial infrastructure, several conditions matter:
Transparent legal documentationVerifiable underlying exposureClear investor rightsIndependent custody and valuation controlsReliable secondary-market liquidityPredictable conversion and settlement mechanismsEnforceable investor protections.
Accessibility without clarity is not necessarily financial progress.
10. What Serious Investors Should Verify
Before evaluating any tokenized private-company exposure, the relevant questions are:
Who is the legal issuer?
The issuer is not necessarily the private company named in the product.
What is the underlying claim?
Does it represent shares, an SPV interest or a contractual promise linked to economic performance?
Who holds the underlying assets?
What evidence supports the stated holdings, and who can independently verify it?
What happens if a counterparty fails?
Which entity is responsible for settlement, and what legal remedies are available?
What does "liquid" actually mean?
Is there deep executable demand, or merely an exchange listing?
How does the product terminate?
What happens after an IPO, without an IPO or during an issuer-level failure?
Without clear answers, the token's headline price tells only a small part of the story.
Final Perspective: The Wrapper Is Part of the Investment
The Kalshi-linked offering illustrates both the promise and complexity of tokenized private markets.
Investors may gain new methods of accessing economic exposure associated with private companies.
But these arrangements can introduce multiple layers of counterparty, legal, valuation and liquidity risk.
For xKLSH and cKLSH, the key issue is not simply whether Kalshi's business grows.
It is whether the product's contractual structure can reliably translate that growth into an enforceable economic outcome for the tokenholder.
Tokenized exposure ≠ direct equity ownership.
A quoted price ≠ guaranteed liquidity.
A conversion ratio ≠ guaranteed profit.
The future of RWA tokenization will depend on closing the gap between the financial asset being promoted and the legal rights investors actually receive.
Discussion
Would you prefer direct equity ownership with limited access — or easier tokenized access with additional issuer and liquidity risks?
Sources
LBank — LBank Announces Kalshi Pre-IPO Product Subscriptions, October 26, 2026.
LBank — Pre-IPO Locked Product Subscription & Platform Services Master Agreement, October 28, 2026.
Paimon Finance — Paimon Kalshi SPV Token Product Documentation.
Editorial disclosure: The product is issued and managed by a third party. Its contractual rights, underlying holdings, lock-up conditions and settlement procedures are governed by the applicable binding documents. Inconsistent descriptions of lock-up terms require clarification; neither future liquidity nor an IPO is guaranteed.
Educational and informational content only. Not financial or investment advice.
#Kalshi #PreIPO #RWA #Tokenization #InvestorProtection
November 2, 2026
Private-Market Exposure Is Not the Same as Share Ownership
The race to tokenize traditional financial assets is expanding beyond publicly traded stocks and ETFs.
LBank has introduced a Pre-IPO offering linked to Kalshi, the US prediction-market company, through two instruments:
xKLSH — a product designed for earlier trading access.cKLSH — a locked product with a conditional conversion mechanism.
At first glance, these instruments appear to offer access to the potential future value of a private company.
But the central question is more complicated:
What exactly does a tokenholder legally own?
The answer matters much more than the token's price.
1. What LBank Actually Offers
According to LBank's October 26 announcement, the Kalshi-linked subscription includes two structures.
xKLSH — Unlock Mode
Subscription price: 39 USDTIntended for spot trading on LBankExpected trading launch: November 3, 2026, at 09:00 UTCLiquidity and execution prices are not guaranteed.
cKLSH — Lock Mode
Subscription price: 28 USDTSubject to lock-up conditionsPotential conversion into 1.4 xKLSH per cKLSH, according to the published termsConversion depends on the applicable contractual conditions.
The combined subscription allocation is capped at 500,000 USDT.
The published subscription window runs from October 29 to November 2, 2026.
Importantly, these are subscription terms — not guaranteed future market valuations.
2. The Most Important Detail: These Are Not Kalshi Shares
LBank explicitly states that subscribing to these instruments does not create direct ownership of Kalshi shares or standard shareholder rights.
That means holders should not assume they receive:
Direct voting rights in KalshiOrdinary shareholder statusDirect ownership of company equityGuaranteed access to an eventual IPOGuaranteed conversion into publicly traded shares.
Instead, the structure provides contractual economic exposure through a third-party arrangement.
The named issuing and managing entity is Paimon Limited.
LBank acts as a distribution and platform-services provider.
The distinction is fundamental: exposure to a company's value is not the same as ownership of that company.
3. Who Actually Owes the Investor?
The legal structure introduces additional parties between the investor and the underlying company.
A simplified chain looks like this:
Investor → LBank platform → Paimon product → SPV-linked economic exposure → Kalshi
Each layer has a different role.
LBank provides platform access and associated services.
Paimon is responsible for issuing and managing the product under its contractual documentation.
The SPV arrangement is intended to connect the token's economic exposure with underlying private-market interests.
But the existence of a token does not eliminate contractual, custody or counterparty risk.
If an issuer or intermediary fails to perform its obligations, the tokenholder's recovery depends on the enforceability of the relevant agreements and the status of underlying assets.
This is why understanding the legal issuer matters more than recognizing the company name featured in the marketing.
4. The cKLSH Lock-Up Deserves Special Attention
A longer holding period is often presented as the price of accessing a lower entry valuation.
But investors should examine the precise conditions.
LBank's announcement describes the lock-up as extending until six months after Kalshi's IPO.
The Paimon product website, however, describes a six-month locked tranche.
These descriptions are not obviously equivalent.
The final, binding product documents must determine which condition applies to a specific purchase.
If an IPO is delayed, never occurs or triggers alternative settlement provisions, the exit process may differ significantly from what a simplified promotional description suggests.
A fixed six-month lock-up and an IPO-dependent lock-up can create radically different liquidity risks.
That difference should be resolved before treating the product as a conventional short-term investment.
5. Does the 1.4× Conversion Mean a 40% Profit?
No.
The published conversion ratio concerns token quantities, not guaranteed investment returns.
Imagine a hypothetical position converting into 1.4 times as many tokens.
The economic result still depends on the market price of those tokens when conversion becomes available.
If the value per token falls sufficiently, receiving more tokens does not prevent a loss.
Other factors may include costs, settlement conditions, redemption limitations and the time value of locked capital.
More tokens do not automatically mean more money.
The conversion mechanism must be evaluated together with the expected underlying value and the contractual risks.
6. xKLSH: Tradable Does Not Mean Liquid
The unlocked product is intended to provide earlier access to secondary-market trading.
But there is an important difference between a token being listed and a token having a functional market.
Consider a product with a quoted price of 39 USDT.
A trader might assume that a position worth 3,900 USDT can be sold at that valuation.
In reality, the order book may contain very little buying interest near that price.
A market sell order could execute substantially lower.
Alternatively, there may be insufficient liquidity to close the full position promptly.
Important metrics include:
Bid and ask spreadOrder-book depthTrading volumeAvailable market makersPrice impact for meaningful order sizesConcentration of token holdings.
LBank's announcement also states that deposits and withdrawals are not supported for the event assets.
This creates an additional limitation: users cannot assume that they can transfer the instrument to another exchange or personal wallet through LBank.
A token can be tradable within one platform while remaining difficult to exit economically.
7. What Happens if Kalshi Never Goes Public?
This is one of the most important unresolved investment scenarios.
There is no guaranteed IPO date.
A private company can remain private for longer than investors expect.
Its valuation can change substantially.
Corporate restructurings, financing rounds and regulatory developments can affect the economics of a structured exposure product.
LBank's master agreement describes a potential repurchase opportunity if no IPO or other agreed exit event occurs within twelve months after the relevant Paimon closing date.
However, this is not a guaranteed redemption.
Paimon may offer repurchase only under the applicable conditions, and the proceeds depend on actual realization of the underlying interests.
LBank explicitly disclaims any guarantee of a repurchase, minimum quantity or price.
That means investors should not treat the twelve-month provision as an unconditional maturity date or a guaranteed route back to USDT.
8. The Hidden Valuation Problem
Private-market assets lack the continuous, transparent price discovery associated with highly liquid public shares.
A token can reference an estimated company valuation, while its own secondary-market price reflects a different set of forces.
These may include:
Private-company valuation risk
The reference valuation may be uncertain or change before an eventual liquidity event.
Token liquidity premium or discount
A tradable instrument may trade above or below the value implied by its contractual exposure.
Issuer and settlement risk
The market must assess whether the promised economic relationship can be fulfilled.
Information asymmetry
Public investors may have less access to financial disclosures than investors in conventional public equity markets.
Consequently, a rising token price does not necessarily prove that the underlying company has increased in value.
And a falling token price does not always measure a corresponding change in the company's fundamentals.
9. Can Tokenized Pre-IPO Products Improve Market Access?
Potentially, yes.
Tokenization can simplify distribution, introduce smaller subscription amounts and provide alternative market structures for eligible users.
LBank's published minimum subscription is 10 USDT, subject to allocation and eligibility rules.
That lowers the nominal entry threshold compared with many traditional private-market opportunities.
But reducing the minimum amount does not eliminate structural complexity.
A product can be easier to access while remaining difficult to value, verify or exit.
For these instruments to develop into credible financial infrastructure, several conditions matter:
Transparent legal documentationVerifiable underlying exposureClear investor rightsIndependent custody and valuation controlsReliable secondary-market liquidityPredictable conversion and settlement mechanismsEnforceable investor protections.
Accessibility without clarity is not necessarily financial progress.
10. What Serious Investors Should Verify
Before evaluating any tokenized private-company exposure, the relevant questions are:
Who is the legal issuer?
The issuer is not necessarily the private company named in the product.
What is the underlying claim?
Does it represent shares, an SPV interest or a contractual promise linked to economic performance?
Who holds the underlying assets?
What evidence supports the stated holdings, and who can independently verify it?
What happens if a counterparty fails?
Which entity is responsible for settlement, and what legal remedies are available?
What does "liquid" actually mean?
Is there deep executable demand, or merely an exchange listing?
How does the product terminate?
What happens after an IPO, without an IPO or during an issuer-level failure?
Without clear answers, the token's headline price tells only a small part of the story.
Final Perspective: The Wrapper Is Part of the Investment
The Kalshi-linked offering illustrates both the promise and complexity of tokenized private markets.
Investors may gain new methods of accessing economic exposure associated with private companies.
But these arrangements can introduce multiple layers of counterparty, legal, valuation and liquidity risk.
For xKLSH and cKLSH, the key issue is not simply whether Kalshi's business grows.
It is whether the product's contractual structure can reliably translate that growth into an enforceable economic outcome for the tokenholder.
Tokenized exposure ≠ direct equity ownership.
A quoted price ≠ guaranteed liquidity.
A conversion ratio ≠ guaranteed profit.
The future of RWA tokenization will depend on closing the gap between the financial asset being promoted and the legal rights investors actually receive.
Discussion
Would you prefer direct equity ownership with limited access — or easier tokenized access with additional issuer and liquidity risks?
Sources
LBank — LBank Announces Kalshi Pre-IPO Product Subscriptions, October 26, 2026.
LBank — Pre-IPO Locked Product Subscription & Platform Services Master Agreement, October 28, 2026.
Paimon Finance — Paimon Kalshi SPV Token Product Documentation.
Editorial disclosure: The product is issued and managed by a third party. Its contractual rights, underlying holdings, lock-up conditions and settlement procedures are governed by the applicable binding documents. Inconsistent descriptions of lock-up terms require clarification; neither future liquidity nor an IPO is guaranteed.
Educational and informational content only. Not financial or investment advice.
#Kalshi #PreIPO #RWA #Tokenization #InvestorProtection
1
94
·
--
記事
速報:Kalshi、評価額400億ドルでさらに10億ドルを調達—5月から82%増。セコイア・キャピタルとウェリントン・マネジメントが共同で今回の資金調達を主導しました。5カ月前、Kalshiは企業評価額220億ドルで10億ドルを調達しました。
しかし、評価額の急上昇が本題ではありません。重要なのは、その向かう先です。
Kalshiは、この資金を活用して取引所の幅を広げると述べています。レバレッジ型イベント契約、無期限先物、計算資源価格市場などです。イベント契約は足がかりでした。目指すのは、CMEやICEと競合するマルチアセット取引所です。
その主張を支える数字:
• 年間換算取引高:1兆ドル超**
• スポーツ以外の年間換算収益:**10億ドル超
速報:Kalshi、評価額400億ドルでさらに10億ドルを調達—5月から82%増。
セコイア・キャピタルとウェリントン・マネジメントが共同で今回の資金調達を主導しました。5カ月前、Kalshiは企業評価額220億ドルで10億ドルを調達しました。
しかし、評価額の急上昇が本題ではありません。重要なのは、その向かう先です。
Kalshiは、この資金を活用して取引所の幅を広げると述べています。レバレッジ型イベント契約、無期限先物、計算資源価格市場などです。イベント契約は足がかりでした。目指すのは、CMEやICEと競合するマルチアセット取引所です。
その主張を支える数字:
• 年間換算取引高:1兆ドル超**
• スポーツ以外の年間換算収益:**10億ドル超
しかし、評価額の急上昇が本題ではありません。重要なのは、その向かう先です。
Kalshiは、この資金を活用して取引所の幅を広げると述べています。レバレッジ型イベント契約、無期限先物、計算資源価格市場などです。イベント契約は足がかりでした。目指すのは、CMEやICEと競合するマルチアセット取引所です。
その主張を支える数字:
• 年間換算取引高:1兆ドル超**
• スポーツ以外の年間換算収益:**10億ドル超
9
·
--
さっき見かけた話:米上院議員のウォーレン氏とカーティス氏(超党派)が、KalshiとPolymarketのCEO宛てに書簡を送り、選挙関連の予測市場について質問。候補者本人が自分の選挙戦に賭けることや、インサイダー取引、取引量の水増しなどを、プラットフォームがどこまで防げるのかを問いただしています。
重要な点:約7項目について書面で回答を求めており、今年に入ってから発見した疑わしい選挙関連契約の数、取引成立前に阻止した数、CFTCや法執行機関に報告した数などが含まれます。回答期限は中間選挙当日の11/3。書簡では、Kalshiで候補者が自分の選挙戦に賭けた事例や、Polymarketで取引量を水増しした疑いをめぐる調査にも言及しています。
投票まであと数日。選挙関連契約は盛り上がる一方で、コンプライアンス面の圧力も高まっています。
#预测市场 #Polymarket #Kalshi
さっき見かけた話:米上院議員のウォーレン氏とカーティス氏(超党派)が、KalshiとPolymarketのCEO宛てに書簡を送り、選挙関連の予測市場について質問。候補者本人が自分の選挙戦に賭けることや、インサイダー取引、取引量の水増しなどを、プラットフォームがどこまで防げるのかを問いただしています。
重要な点:約7項目について書面で回答を求めており、今年に入ってから発見した疑わしい選挙関連契約の数、取引成立前に阻止した数、CFTCや法執行機関に報告した数などが含まれます。回答期限は中間選挙当日の11/3。書簡では、Kalshiで候補者が自分の選挙戦に賭けた事例や、Polymarketで取引量を水増しした疑いをめぐる調査にも言及しています。
投票まであと数日。選挙関連契約は盛り上がる一方で、コンプライアンス面の圧力も高まっています。
#预测市场 #Polymarket #Kalshi
重要な点:約7項目について書面で回答を求めており、今年に入ってから発見した疑わしい選挙関連契約の数、取引成立前に阻止した数、CFTCや法執行機関に報告した数などが含まれます。回答期限は中間選挙当日の11/3。書簡では、Kalshiで候補者が自分の選挙戦に賭けた事例や、Polymarketで取引量を水増しした疑いをめぐる調査にも言及しています。
投票まであと数日。選挙関連契約は盛り上がる一方で、コンプライアンス面の圧力も高まっています。
#预测市场 #Polymarket #Kalshi
25

Kalshiが10億ドルを調達し、評価額は400億ドル。これは本当のニュースだ。暗号資産界隈の大物がリポストした途端、話が別物になった。
Pete Rizzoの投稿は全文大文字でこうだ。「世界最大の銀行がKalshiに10億ドルを投じた。君たちが恐怖に駆られている間に、数十億ドルが予測市場を通じてビットコインに流れ込んでいる。とにかくHODLしろ」。閲覧数は1万2000超。
投資家リストを確認してみよう。主導したのはSequoiaとWellington。VCと資産運用会社だ。参加したのはMorgan Stanleyの資産運用部門、Baillie Gifford、Coatue、a16z。「世界最大の銀行」はどこから出てきたのか? 彼が挙げたBlackRockやTiger Globalは、私が確認した公開報道の投資家リストには見当たらなかった。「資金がBTCに流れ込んでいる」というのも違う。この資金調達はKalshiが新商品を開発し、海外展開するためのもので、あなたが持っているコインとは何の関係もない。
本当に話す価値があるのは評価額の推移だ。@gurgavinのまとめによると、2024年は8億ドル、今年5月は220億ドル、そして現在は400億ドル。2年足らずで約50倍だ。ただ、出発点の数字すら一致していない。Wall St Engineによれば、去年6月の評価額は10億ドルだった。年換算売上高は10億ドル超とのことだが、年換算取引高が1兆ドル超というのは名目上の売買額のこと。売上高と混同してはいけない。
VCが稼ぐのは評価額、大物インフルエンサーが稼ぐのはあなたの注目だ。ついでに見出しを借りて、持ち続けろと叫ぶ。相場が下がると、他人の資金調達ニュースを使って自分のポジションを正当化する。こういう手口は何度も見てきた。
#Kalshi #予測市場
Kalshiが10億ドルを調達し、評価額は400億ドル。これは本当のニュースだ。暗号資産界隈の大物がリポストした途端、話が別物になった。
Pete Rizzoの投稿は全文大文字でこうだ。「世界最大の銀行がKalshiに10億ドルを投じた。君たちが恐怖に駆られている間に、数十億ドルが予測市場を通じてビットコインに流れ込んでいる。とにかくHODLしろ」。閲覧数は1万2000超。
投資家リストを確認してみよう。主導したのはSequoiaとWellington。VCと資産運用会社だ。参加したのはMorgan Stanleyの資産運用部門、Baillie Gifford、Coatue、a16z。「世界最大の銀行」はどこから出てきたのか? 彼が挙げたBlackRockやTiger Globalは、私が確認した公開報道の投資家リストには見当たらなかった。「資金がBTCに流れ込んでいる」というのも違う。この資金調達はKalshiが新商品を開発し、海外展開するためのもので、あなたが持っているコインとは何の関係もない。
本当に話す価値があるのは評価額の推移だ。@gurgavinのまとめによると、2024年は8億ドル、今年5月は220億ドル、そして現在は400億ドル。2年足らずで約50倍だ。ただ、出発点の数字すら一致していない。Wall St Engineによれば、去年6月の評価額は10億ドルだった。年換算売上高は10億ドル超とのことだが、年換算取引高が1兆ドル超というのは名目上の売買額のこと。売上高と混同してはいけない。
VCが稼ぐのは評価額、大物インフルエンサーが稼ぐのはあなたの注目だ。ついでに見出しを借りて、持ち続けろと叫ぶ。相場が下がると、他人の資金調達ニュースを使って自分のポジションを正当化する。こういう手口は何度も見てきた。
#Kalshi #予測市場
Pete Rizzoの投稿は全文大文字でこうだ。「世界最大の銀行がKalshiに10億ドルを投じた。君たちが恐怖に駆られている間に、数十億ドルが予測市場を通じてビットコインに流れ込んでいる。とにかくHODLしろ」。閲覧数は1万2000超。
投資家リストを確認してみよう。主導したのはSequoiaとWellington。VCと資産運用会社だ。参加したのはMorgan Stanleyの資産運用部門、Baillie Gifford、Coatue、a16z。「世界最大の銀行」はどこから出てきたのか? 彼が挙げたBlackRockやTiger Globalは、私が確認した公開報道の投資家リストには見当たらなかった。「資金がBTCに流れ込んでいる」というのも違う。この資金調達はKalshiが新商品を開発し、海外展開するためのもので、あなたが持っているコインとは何の関係もない。
本当に話す価値があるのは評価額の推移だ。@gurgavinのまとめによると、2024年は8億ドル、今年5月は220億ドル、そして現在は400億ドル。2年足らずで約50倍だ。ただ、出発点の数字すら一致していない。Wall St Engineによれば、去年6月の評価額は10億ドルだった。年換算売上高は10億ドル超とのことだが、年換算取引高が1兆ドル超というのは名目上の売買額のこと。売上高と混同してはいけない。
VCが稼ぐのは評価額、大物インフルエンサーが稼ぐのはあなたの注目だ。ついでに見出しを借りて、持ち続けろと叫ぶ。相場が下がると、他人の資金調達ニュースを使って自分のポジションを正当化する。こういう手口は何度も見てきた。
#Kalshi #予測市場
25


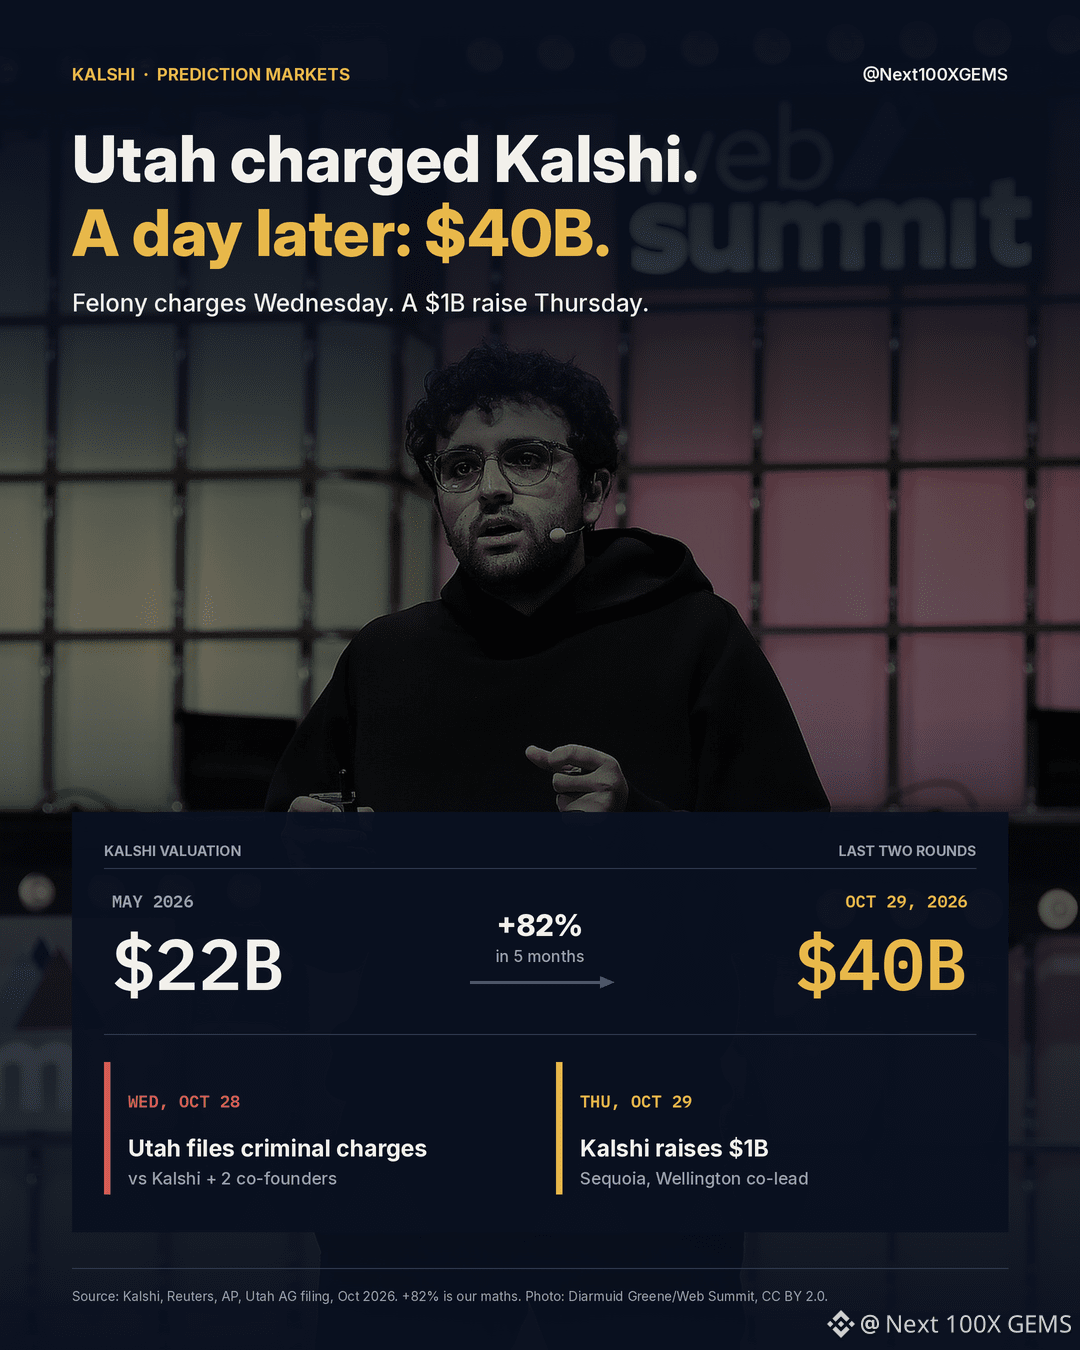
ユタ州は水曜日、Kalshiと共同創業者2人を刑事訴追した。木曜日、Kalshiは企業評価額400億ドルで10億ドルを調達したと発表した。
SequoiaとWellingtonが共同でラウンドを主導し、Andreessen Horowitz、Coatue、Baillie Gifford、Morgan Stanley Investment Managementなども参加した。5月には、Kalshiは企業評価額220億ドルで10億ドルを調達している。単純計算では、約5か月で82%の上昇だ。
ユタ州の訴訟は軽いものではない。APによると、9月に覆面捜査官がソルトレイク郡で行ったスポーツ賭博を根拠に、州の賭博禁止法違反13件と、違法行為による利益獲得1件の罪が問われている。CEOのTarek MansourとCOOのLuana Lopes Laraも個人として名指しされている。CFTCはユタ州による執行を阻止するために動いており、APによれば、イベント契約が連邦政府の管轄するデリバティブなのか、州法上の賭博なのかをめぐる争いは、最高裁判所に持ち込まれる見通しだ。
Kalshiによると、予測市場、コモディティ、暗号資産、無期限先物を合わせた年間換算取引高は、現在1兆ドルを超えており、今回の資金で、より幅広い取引所を構築する計画だ。
テクノロジー業界の大手投資家たちは、予測市場が州裁判所で生き残ることに賭けた。その賭けには今や、400億ドルの値札が付いている。
#Kalshi #予測市場
これは金融アドバイスではありません。ご自身で調査してください。
ユタ州は水曜日、Kalshiと共同創業者2人を刑事訴追した。木曜日、Kalshiは企業評価額400億ドルで10億ドルを調達したと発表した。
SequoiaとWellingtonが共同でラウンドを主導し、Andreessen Horowitz、Coatue、Baillie Gifford、Morgan Stanley Investment Managementなども参加した。5月には、Kalshiは企業評価額220億ドルで10億ドルを調達している。単純計算では、約5か月で82%の上昇だ。
ユタ州の訴訟は軽いものではない。APによると、9月に覆面捜査官がソルトレイク郡で行ったスポーツ賭博を根拠に、州の賭博禁止法違反13件と、違法行為による利益獲得1件の罪が問われている。CEOのTarek MansourとCOOのLuana Lopes Laraも個人として名指しされている。CFTCはユタ州による執行を阻止するために動いており、APによれば、イベント契約が連邦政府の管轄するデリバティブなのか、州法上の賭博なのかをめぐる争いは、最高裁判所に持ち込まれる見通しだ。
Kalshiによると、予測市場、コモディティ、暗号資産、無期限先物を合わせた年間換算取引高は、現在1兆ドルを超えており、今回の資金で、より幅広い取引所を構築する計画だ。
テクノロジー業界の大手投資家たちは、予測市場が州裁判所で生き残ることに賭けた。その賭けには今や、400億ドルの値札が付いている。
#Kalshi #予測市場
これは金融アドバイスではありません。ご自身で調査してください。
SequoiaとWellingtonが共同でラウンドを主導し、Andreessen Horowitz、Coatue、Baillie Gifford、Morgan Stanley Investment Managementなども参加した。5月には、Kalshiは企業評価額220億ドルで10億ドルを調達している。単純計算では、約5か月で82%の上昇だ。
ユタ州の訴訟は軽いものではない。APによると、9月に覆面捜査官がソルトレイク郡で行ったスポーツ賭博を根拠に、州の賭博禁止法違反13件と、違法行為による利益獲得1件の罪が問われている。CEOのTarek MansourとCOOのLuana Lopes Laraも個人として名指しされている。CFTCはユタ州による執行を阻止するために動いており、APによれば、イベント契約が連邦政府の管轄するデリバティブなのか、州法上の賭博なのかをめぐる争いは、最高裁判所に持ち込まれる見通しだ。
Kalshiによると、予測市場、コモディティ、暗号資産、無期限先物を合わせた年間換算取引高は、現在1兆ドルを超えており、今回の資金で、より幅広い取引所を構築する計画だ。
テクノロジー業界の大手投資家たちは、予測市場が州裁判所で生き残ることに賭けた。その賭けには今や、400億ドルの値札が付いている。
#Kalshi #予測市場
これは金融アドバイスではありません。ご自身で調査してください。
1
1.9k
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号
トレンドトピック
1
#BinanceReopensWithdrawalsForMoreAssets
閲覧回数 967,507
4,976人が討論中
2
#AnthropicIPOValuationDoubts
閲覧回数 93
24人が討論中
3
#USStocksSlipandCryptoMarketUnderBroadPressure
閲覧回数 45,793
434人が討論中
4
#StrategySTRCResumesIssuanceAfterOver170Days
閲覧回数 37,056
528人が討論中
5
#Nasdaq100Tumbles6%
閲覧回数 731
50人が討論中
6
#GreekParliamentPasses10%CryptoCapitalGainsTaxBill
閲覧回数 288
35人が討論中
7
#KospiSlideTriggersCircuitBreaker
閲覧回数 467
31人が討論中
8
#ADPUSPrivateEmployersAdd86000JobsInOctober
閲覧回数 55,046
654人が討論中
9
#KazakhstanReportedlyInvests$100MInCryptoFunds
閲覧回数 4,004
65人が討論中
10
#SouthKoreaSeeksCryptoTaxDelayUntil2029
閲覧回数 31,672
304人が討論中