

ARIA Web3
69 Beiträge

ARIA Web3
Melden
Nutzer blockieren
15 Following
15 Follower
44 Like gegeben
Beiträge
PINNED
·
--
Bullisch
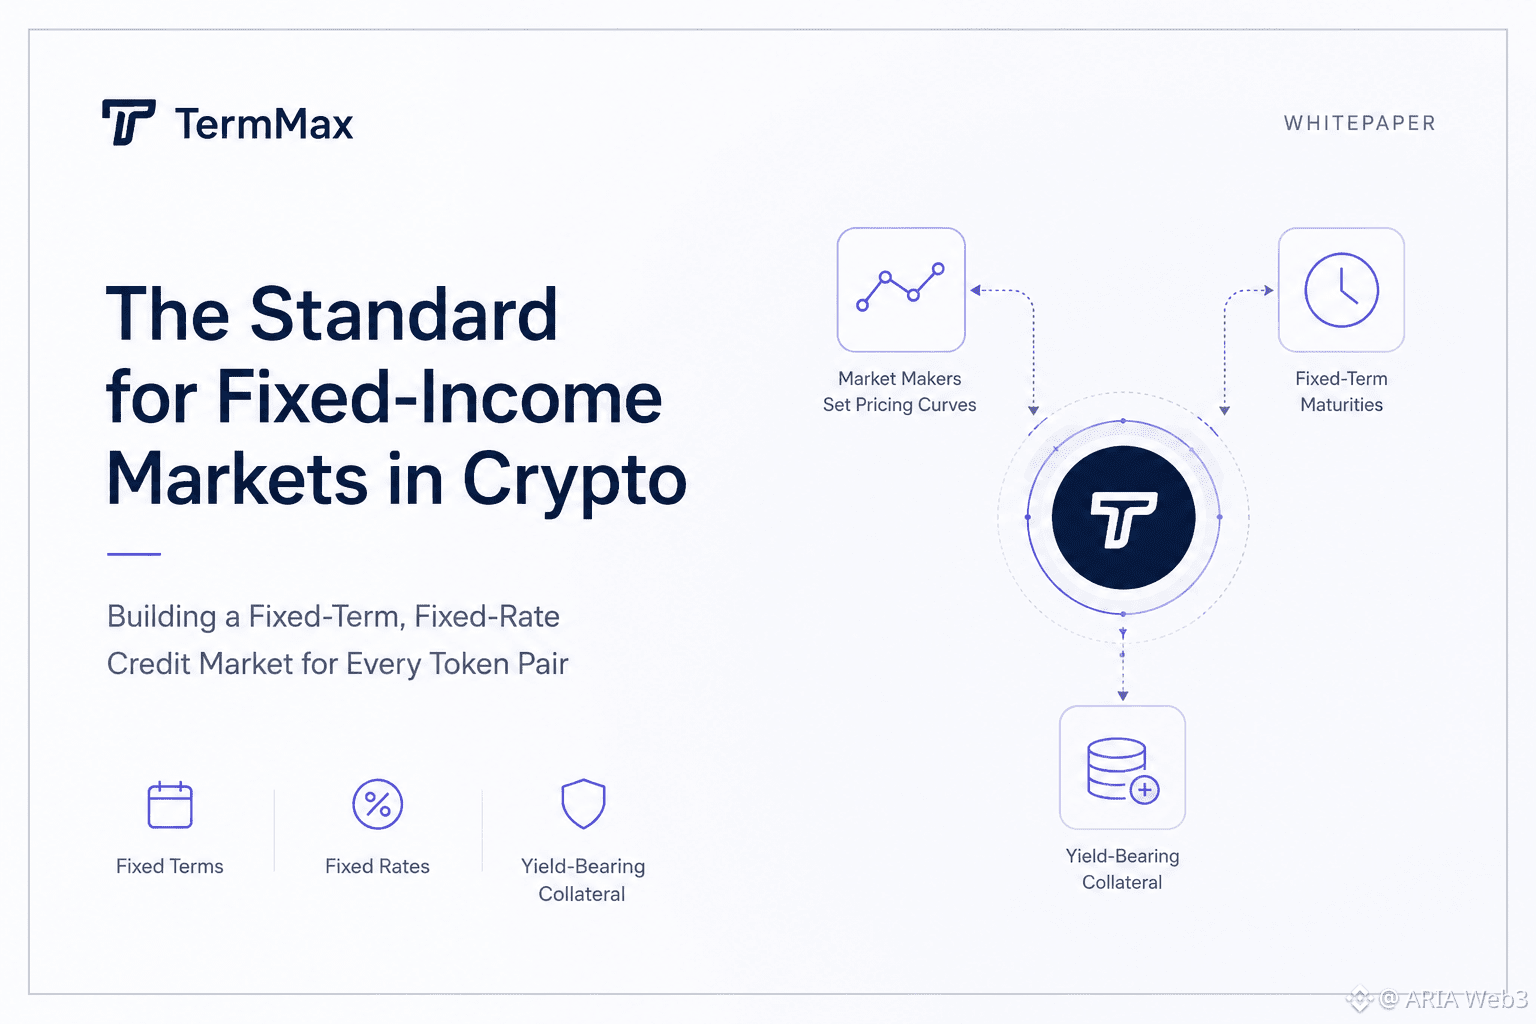
Ich habe die Dokumentation von TermMax gelesen und versucht herauszufinden, was sie damit meinen, sich als „den Standard für festverzinsliche Märkte“ im Kryptobereich zu bezeichnen. Zunächst dachte ich, es wäre einfach ein weiteres Kreditprotokoll, das über die Zinssätze konkurriert.
Nachdem ich mir die offizielle Vision-Seite angesehen hatte, fiel mir ein Detail auf: Sie sprechen davon, „für jedes Token-Paar einen ganzen Kreditmarkt aufzubauen, genau wie es ihn auch in der realen Welt gibt“. Dieser Satz ist mir im Gedächtnis geblieben – das ist ein ganz anderer Ansatz als bei den meisten DeFi-Kreditangeboten.
Da wurde es mir klar. Es geht nicht einfach nur ums Verleihen, sondern darum, für jedes Asset-Paar einen eigenen Markt mit fester Laufzeit und festem Zinssatz zu schaffen, in dem Market Maker die Preiskurven festlegen. Außerdem dienen ertragsbringende Token als Sicherheiten. So sorgen feste Laufzeiten für Vorhersehbarkeit, während die Sicherheiten selbst weiterhin Erträge erwirtschaften.
Überrascht hat mich, wie bewusst die Grenzen gesetzt wirken. Feste Laufzeiten bedeuten weniger Flexibilität als unbefristete Kreditvergabe, aber genau dieser Kompromiss macht einen echten Kreditmarkt überhaupt erst on-chain möglich.
Da das TGE für den 25. August 2026 angesetzt ist, wirkt es weniger wie ein eigenständiger Launch und mehr wie der nächste Meilenstein beim Ausbau dieses Kreditmarkts. Ich frage mich noch immer, wie viel von der Festlegung der Kurven sich irgendwann auch außerhalb der Kuratoren öffnen wird.
#termmax @termmax
Ich habe die Dokumentation von TermMax gelesen und versucht herauszufinden, was sie damit meinen, sich als „den Standard für festverzinsliche Märkte“ im Kryptobereich zu bezeichnen. Zunächst dachte ich, es wäre einfach ein weiteres Kreditprotokoll, das über die Zinssätze konkurriert.
Nachdem ich mir die offizielle Vision-Seite angesehen hatte, fiel mir ein Detail auf: Sie sprechen davon, „für jedes Token-Paar einen ganzen Kreditmarkt aufzubauen, genau wie es ihn auch in der realen Welt gibt“. Dieser Satz ist mir im Gedächtnis geblieben – das ist ein ganz anderer Ansatz als bei den meisten DeFi-Kreditangeboten.
Da wurde es mir klar. Es geht nicht einfach nur ums Verleihen, sondern darum, für jedes Asset-Paar einen eigenen Markt mit fester Laufzeit und festem Zinssatz zu schaffen, in dem Market Maker die Preiskurven festlegen. Außerdem dienen ertragsbringende Token als Sicherheiten. So sorgen feste Laufzeiten für Vorhersehbarkeit, während die Sicherheiten selbst weiterhin Erträge erwirtschaften.
Überrascht hat mich, wie bewusst die Grenzen gesetzt wirken. Feste Laufzeiten bedeuten weniger Flexibilität als unbefristete Kreditvergabe, aber genau dieser Kompromiss macht einen echten Kreditmarkt überhaupt erst on-chain möglich.
Da das TGE für den 25. August 2026 angesetzt ist, wirkt es weniger wie ein eigenständiger Launch und mehr wie der nächste Meilenstein beim Ausbau dieses Kreditmarkts. Ich frage mich noch immer, wie viel von der Festlegung der Kurven sich irgendwann auch außerhalb der Kuratoren öffnen wird.
#termmax @TermMax
1
1
85
·
--
Übersetzung ansehen
today live match, AS Roma vs Cagliari: Roma look like the clear favorites with a 74% win probability, while Cagliari have just 8%. I’m leaning towards a Roma win. #BinancePick
today live match, AS Roma vs Cagliari: Roma look like the clear favorites with a 74% win probability, while Cagliari have just 8%. I’m leaning towards a Roma win. #BinancePick
81
·
--
Übersetzung ansehen
Inter Milan win congratulations, already winlook like the clear favorites team, with. I’m leaning towards an Inter win, but football can always surprise us. #BinancePick
Inter Milan win congratulations, already winlook like the clear favorites team, with. I’m leaning towards an Inter win, but football can always surprise us. #BinancePick
87
·
--
#BinancePick Live, G2 Esports gegen Dplus KIA
DK scheint mit einer Siegwahrscheinlichkeit von 60 % der Favorit zu sein, während G2 bei 39 % liegt. Kann G2 für eine Überraschung sorgen,
oder wird DK den Sieg holen?
#BinancePick Live, G2 Esports gegen Dplus KIA
DK scheint mit einer Siegwahrscheinlichkeit von 60 % der Favorit zu sein, während G2 bei 39 % liegt. Kann G2 für eine Überraschung sorgen,
oder wird DK den Sieg holen?
DK scheint mit einer Siegwahrscheinlichkeit von 60 % der Favorit zu sein, während G2 bei 39 % liegt. Kann G2 für eine Überraschung sorgen,
oder wird DK den Sieg holen?
67
·
--
Übersetzung ansehen
#BinancePick today live match, Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction.
#BinancePick today live match, Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction.
·
--
Bullisch
#BinancePick Heute sieht gen.g vor diesem Spiel wie die stärkere Mannschaft aus.
#BinancePick Heute sieht gen.g vor diesem Spiel wie die stärkere Mannschaft aus.
63
·
--
Übersetzung ansehen
#BinancePick Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction?
#BinancePick Gen.G looks like the stronger side going into this match. IG can still surprise us, but I’m backing GEN to take the win! What’s your prediction?
78
·
--
Bullisch
Übersetzung ansehen
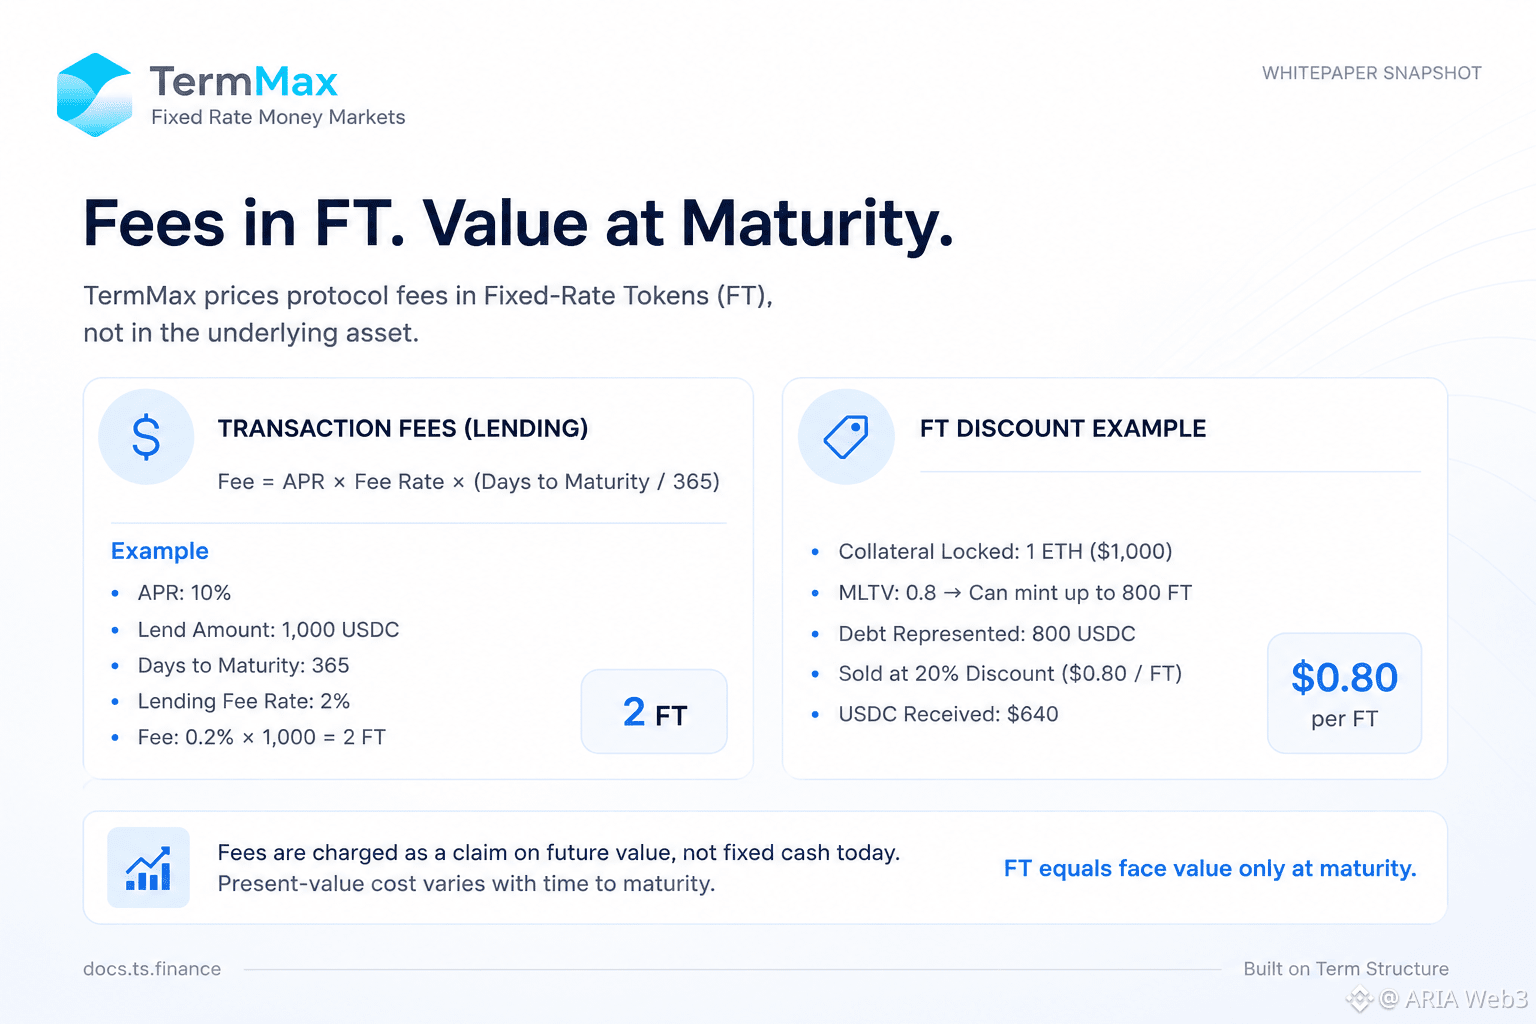
I was reading TermMax's transaction fees page on docs.ts.finance. The formulas are simple — APR × fee rate × (days to maturity/365) — but one detail caught my attention: fees resolve "in unit of FT," not USDC. Their own example: lending 1,000 USDC at 10% APR for 365 days, at a 2% fee rate, costs just 2 FT.
I assumed that was just a display convention. After checking the Fixed-Rate Tokenization docs, it turned out more deliberate. FT is a discount instrument, only worth face value at maturity. In their example, 800 FT sells at a 20% discount ($0.80 each) — $640, not $800.
That's when it clicked: pricing fees in FT means charging a claim on future value, not fixed cash today. Two lenders paying "the same" 2% fee at different points before maturity pay different present-value costs.
Feels less like a flaw, more a trade-off of tying fees to the unit lenders already hold, instead of converting through USDC each time. Still unclear how this reconciles when the protocol reports aggregate fee revenue in one denomination.
Anyone know where that's documented?#termmax @termmax
I was reading TermMax's transaction fees page on docs.ts.finance. The formulas are simple — APR × fee rate × (days to maturity/365) — but one detail caught my attention: fees resolve "in unit of FT," not USDC. Their own example: lending 1,000 USDC at 10% APR for 365 days, at a 2% fee rate, costs just 2 FT.
I assumed that was just a display convention. After checking the Fixed-Rate Tokenization docs, it turned out more deliberate. FT is a discount instrument, only worth face value at maturity. In their example, 800 FT sells at a 20% discount ($0.80 each) — $640, not $800.
That's when it clicked: pricing fees in FT means charging a claim on future value, not fixed cash today. Two lenders paying "the same" 2% fee at different points before maturity pay different present-value costs.
Feels less like a flaw, more a trade-off of tying fees to the unit lenders already hold, instead of converting through USDC each time. Still unclear how this reconciles when the protocol reports aggregate fee revenue in one denomination.
Anyone know where that's documented?#termmax @TermMax
4
5
80
·
--
Bullisch
Ich habe die Landingpage von Dusk Trade gelesen und eine typische Seite für den Zugang zu RWA erwartet: auf die Warteliste setzen lassen, verifizieren, investieren. Ein Detail fiel mir auf, als ich über diese Oberfläche hinaus zu den Dokumenten vorgedrungen bin.
Ich nahm an, dass das Produkt selbst so einfach wäre, wie es auf der Seite klingt: drei Schritte, nicht mehr. Nach einem Blick in die offiziellen Dokumente ändert sich die Beschreibung. Dusk Trade wird als Anwendungsschicht über dem Basisprotokoll bezeichnet, und in den Dokumenten wird ausdrücklich klargestellt, dass es nicht selbst das Basisprotokoll ist. Es wandelt grundlegende Infrastrukturbausteine des Marktes in Abläufe um, die die Suche nach Vermögenswerten, das Onboarding von Anlegern, die Wallet-Verbindung, die Zahlungsabwicklung und das Settlement abdecken.
Überrascht hat mich die Diskrepanz zwischen den beiden offiziellen Quellen. Die Landingpage wirbt für den Zugang in drei Schritten. Die Dokumente beschreiben Eignungsprüfungen, Offenlegungslogik und ein Settlement, bei dem Vermögenswert- und Zahlungsseite miteinander abgeglichen werden, bevor etwas endgültig abgeschlossen wird. Da wurde mir klar: Der Zielgruppe entsprechend ergibt dieser Kompromiss Sinn. Eine Wartelistenseite muss Besucher schnell überzeugen, während die Dokumentation den Anforderungen von Entwicklern und Aufsichtsbehörden genügen muss, die wissen müssen, wie Eignung und Settlement tatsächlich On-Chain durchgesetzt werden. Trotzdem frage ich mich, wie viel von dieser Komplexität Anleger tatsächlich zu sehen bekommen, sobald die Benutzeroberfläche live geht – oder ob sie hinter dem übersichtlichen Ablauf in drei Schritten verborgen bleibt.
Die Landingpage wirbt für den Zugang in drei Schritten. Die Dokumente beschreiben die dahinterliegende Logik für Eignungsprüfungen, Offenlegung und Settlement.
Was ist für den Erfolg von Dusk Trade am wichtigsten?
#dusk $DUSK @Dusk_Foundation
Ich habe die Landingpage von Dusk Trade gelesen und eine typische Seite für den Zugang zu RWA erwartet: auf die Warteliste setzen lassen, verifizieren, investieren. Ein Detail fiel mir auf, als ich über diese Oberfläche hinaus zu den Dokumenten vorgedrungen bin.
Ich nahm an, dass das Produkt selbst so einfach wäre, wie es auf der Seite klingt: drei Schritte, nicht mehr. Nach einem Blick in die offiziellen Dokumente ändert sich die Beschreibung. Dusk Trade wird als Anwendungsschicht über dem Basisprotokoll bezeichnet, und in den Dokumenten wird ausdrücklich klargestellt, dass es nicht selbst das Basisprotokoll ist. Es wandelt grundlegende Infrastrukturbausteine des Marktes in Abläufe um, die die Suche nach Vermögenswerten, das Onboarding von Anlegern, die Wallet-Verbindung, die Zahlungsabwicklung und das Settlement abdecken.
Überrascht hat mich die Diskrepanz zwischen den beiden offiziellen Quellen. Die Landingpage wirbt für den Zugang in drei Schritten. Die Dokumente beschreiben Eignungsprüfungen, Offenlegungslogik und ein Settlement, bei dem Vermögenswert- und Zahlungsseite miteinander abgeglichen werden, bevor etwas endgültig abgeschlossen wird. Da wurde mir klar: Der Zielgruppe entsprechend ergibt dieser Kompromiss Sinn. Eine Wartelistenseite muss Besucher schnell überzeugen, während die Dokumentation den Anforderungen von Entwicklern und Aufsichtsbehörden genügen muss, die wissen müssen, wie Eignung und Settlement tatsächlich On-Chain durchgesetzt werden. Trotzdem frage ich mich, wie viel von dieser Komplexität Anleger tatsächlich zu sehen bekommen, sobald die Benutzeroberfläche live geht – oder ob sie hinter dem übersichtlichen Ablauf in drei Schritten verborgen bleibt.
Die Landingpage wirbt für den Zugang in drei Schritten. Die Dokumente beschreiben die dahinterliegende Logik für Eignungsprüfungen, Offenlegung und Settlement.
Was ist für den Erfolg von Dusk Trade am wichtigsten?
#dusk $DUSK @Dusk
Compliance design
50%
Liquidity depth
50%
Onboarding speed
0%
Investor trust
0%
4 Stimmen • Abstimmung beendet
1
1
83
·
--
Bullisch
Übersetzung ansehen
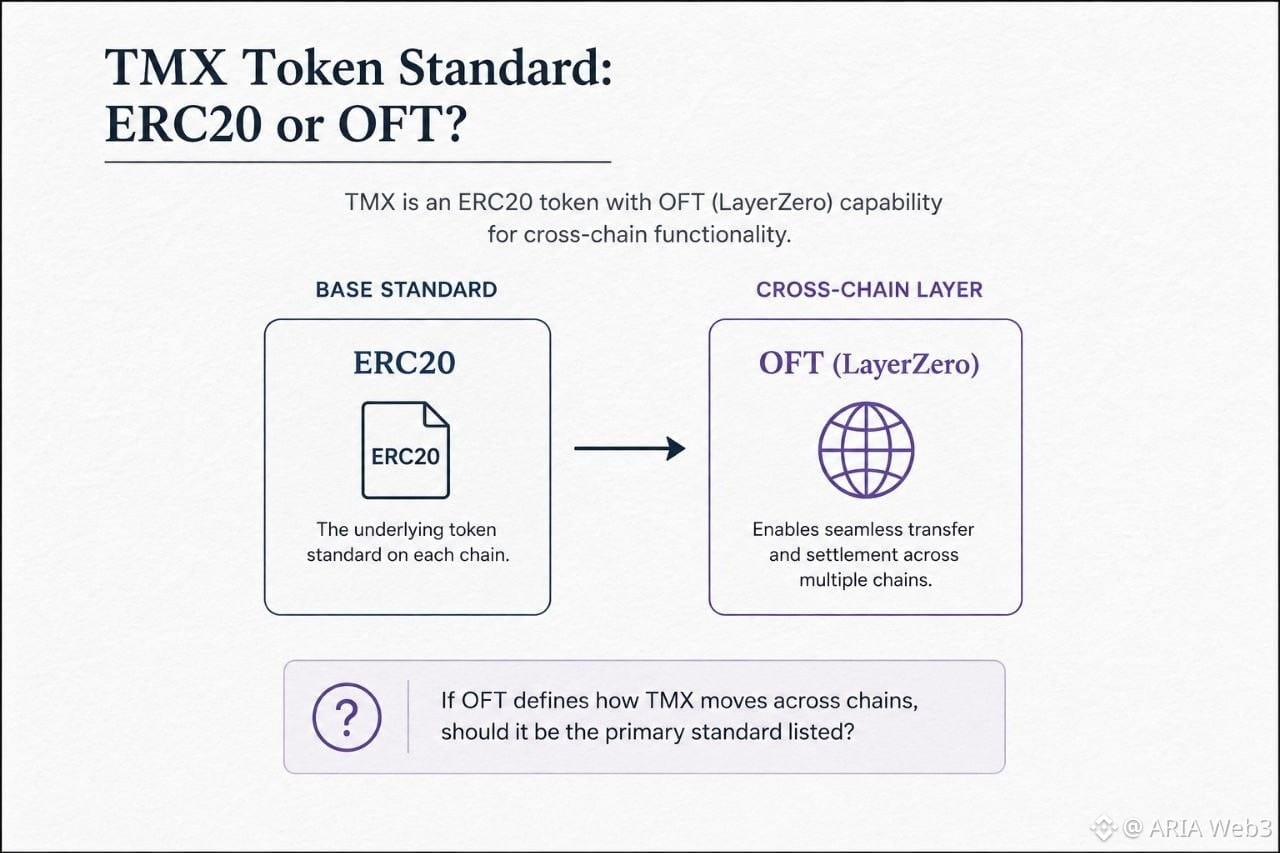
I was scrolling through the TMX tokenomics table and stopped at the Standard field. It just says ERC20, listed as a plain, separate line item from the token address and total supply. One detail caught my attention a few lines above it though. The Bridge Mechanism field describes TMX as a LayerZero OFT, an Omnichain Fungible Token, deployed on Ethereum and BNB Chain with more EVM chains supported. I assumed OFT would replace ERC20 as the listed standard, since it's the newer cross-chain spec.
After checking the executive summary section of the same whitepaper, the terminology got less consistent, not more. There, the token standard is written as ERC20 (OFT on multiple blockchains), treating OFT as a bracketed extension rather than the primary classification. So within the same document, TMX is presented once as ERC20 with OFT as a side note, and once as ERC20 sitting quietly next to a full OFT description with no explicit link between the two. That's when it clicked that this isn't really a contradiction, LayerZero's OFT standard is built as a wrapper around ERC20, adding cross-chain messaging without changing the base token behavior on any single chain. So calling it ERC20 isn't wrong, it's just incomplete without the bridge mechanism line filling in the rest.
Still, it raises a fair question: if OFT defines how the token actually moves and settles across chains, should it be the primary standard listed, with ERC20 treated as the underlying implementation detail instead of the headline?
#termmax @termmax
I was scrolling through the TMX tokenomics table and stopped at the Standard field. It just says ERC20, listed as a plain, separate line item from the token address and total supply. One detail caught my attention a few lines above it though. The Bridge Mechanism field describes TMX as a LayerZero OFT, an Omnichain Fungible Token, deployed on Ethereum and BNB Chain with more EVM chains supported. I assumed OFT would replace ERC20 as the listed standard, since it's the newer cross-chain spec.
After checking the executive summary section of the same whitepaper, the terminology got less consistent, not more. There, the token standard is written as ERC20 (OFT on multiple blockchains), treating OFT as a bracketed extension rather than the primary classification. So within the same document, TMX is presented once as ERC20 with OFT as a side note, and once as ERC20 sitting quietly next to a full OFT description with no explicit link between the two. That's when it clicked that this isn't really a contradiction, LayerZero's OFT standard is built as a wrapper around ERC20, adding cross-chain messaging without changing the base token behavior on any single chain. So calling it ERC20 isn't wrong, it's just incomplete without the bridge mechanism line filling in the rest.
Still, it raises a fair question: if OFT defines how the token actually moves and settles across chains, should it be the primary standard listed, with ERC20 treated as the underlying implementation detail instead of the headline?
#termmax @TermMax
10
4
76
·
--
Bullisch
Übersetzung ansehen
I was reading the section on borrowing range order setters and one number stopped me: in the example, Alice locks 1 ETH, gets matched for 500 USDC, and her GT ends up recording 535 FTs as debt. My first read was that she'd somehow borrowed more than she received.
After checking the mechanics section again, that's not what's happening. The 500 USDC funds 500 FTs (principal) and 500 XTs (interest). The XTs get exchanged inside her own range order for 35 additional FTs, minted from her GT, which is what pushes her recorded debt to 535. She never touches the XT herself.
What surprised me was realizing XT isn't idle here, it's the mechanism that converts a floating interest obligation into a fixed one before the loan even settles. Instead of interest accruing over time, it's priced and locked into extra FTs at the moment of matching. The trade-off is that a borrowing order setter's GT debt isn't just "what I borrowed" but "what I borrowed plus the interest I already agreed to pay," visible on-chain from day one rather than accruing quietly. That seems deliberate: fixed-rate borrowing needs the full obligation locked in upfront, not calculated later. Still curious how the pricing curve decides the split between early fills at 8% versus later fills closer to 6% within the same order.
#termmax @termmax
I was reading the section on borrowing range order setters and one number stopped me: in the example, Alice locks 1 ETH, gets matched for 500 USDC, and her GT ends up recording 535 FTs as debt. My first read was that she'd somehow borrowed more than she received.
After checking the mechanics section again, that's not what's happening. The 500 USDC funds 500 FTs (principal) and 500 XTs (interest). The XTs get exchanged inside her own range order for 35 additional FTs, minted from her GT, which is what pushes her recorded debt to 535. She never touches the XT herself.
What surprised me was realizing XT isn't idle here, it's the mechanism that converts a floating interest obligation into a fixed one before the loan even settles. Instead of interest accruing over time, it's priced and locked into extra FTs at the moment of matching. The trade-off is that a borrowing order setter's GT debt isn't just "what I borrowed" but "what I borrowed plus the interest I already agreed to pay," visible on-chain from day one rather than accruing quietly. That seems deliberate: fixed-rate borrowing needs the full obligation locked in upfront, not calculated later. Still curious how the pricing curve decides the split between early fills at 8% versus later fills closer to 6% within the same order.
#termmax @TermMax

6
1
80
·
--
Bullisch
Übersetzung ansehen
I was reading through TermMax's docs to understand how they handle leveraged positions, and one detail caught my attention: the Gearing Token isn't an ERC-20 like everything else in the system.
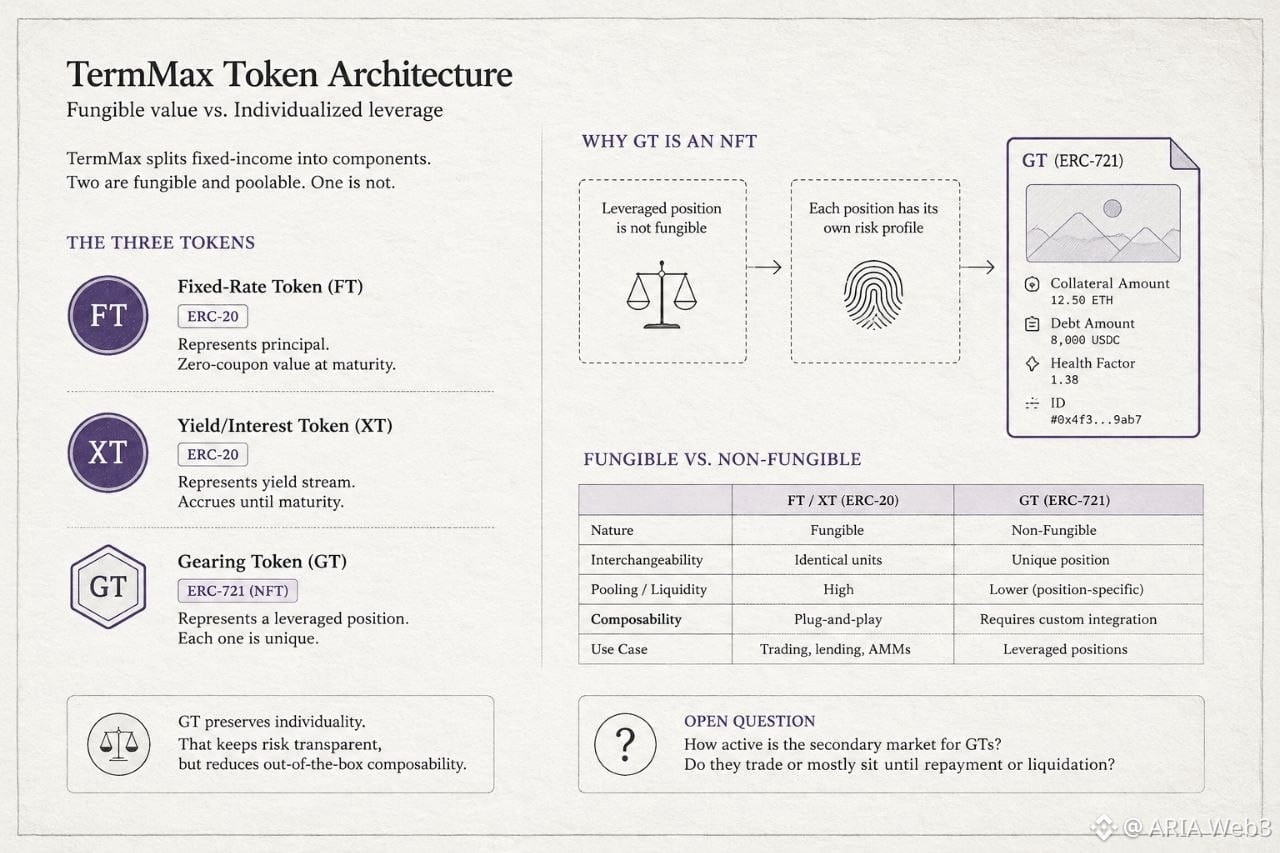
I assumed all three of TermMax's tokens — FT, XT, and GT — would follow the same standard, since the introduction page talks about "Gearing Token and Fixed-rate Token trading" almost interchangeably, like they're just different flavors of the same tradable asset. After checking the docs page on token components, that assumption didn't hold. FT and XT are both ERC-20, representing principal and interest as fungible, poolable value. GT, though, is an ERC-721 NFT. Each one encapsulates a specific collateral amount, a specific debt, and its own health factor as metadata.
What surprised me was realizing why. A leveraged position isn't really a fungible claim — two GTs with the same face value could carry different collateral ratios or liquidation risk. Making it an NFT preserves that individuality instead of averaging it away in a shared pool. The trade-off is composability. Fungible tokens are easier to plug into other protocols; NFTs require more custom integration work from anyone building on top of TermMax.
Still not sure how that affects secondary-market liquidity for GT positions themselves. Anyone looked into whether GTs trade actively, or mostly just sit until repayment or liquidation? @termmax #termmax
I was reading through TermMax's docs to understand how they handle leveraged positions, and one detail caught my attention: the Gearing Token isn't an ERC-20 like everything else in the system.
I assumed all three of TermMax's tokens — FT, XT, and GT — would follow the same standard, since the introduction page talks about "Gearing Token and Fixed-rate Token trading" almost interchangeably, like they're just different flavors of the same tradable asset. After checking the docs page on token components, that assumption didn't hold. FT and XT are both ERC-20, representing principal and interest as fungible, poolable value. GT, though, is an ERC-721 NFT. Each one encapsulates a specific collateral amount, a specific debt, and its own health factor as metadata.
What surprised me was realizing why. A leveraged position isn't really a fungible claim — two GTs with the same face value could carry different collateral ratios or liquidation risk. Making it an NFT preserves that individuality instead of averaging it away in a shared pool. The trade-off is composability. Fungible tokens are easier to plug into other protocols; NFTs require more custom integration work from anyone building on top of TermMax.
Still not sure how that affects secondary-market liquidity for GT positions themselves. Anyone looked into whether GTs trade actively, or mostly just sit until repayment or liquidation? @TermMax #termmax
1
1
69
·
--
Bullisch
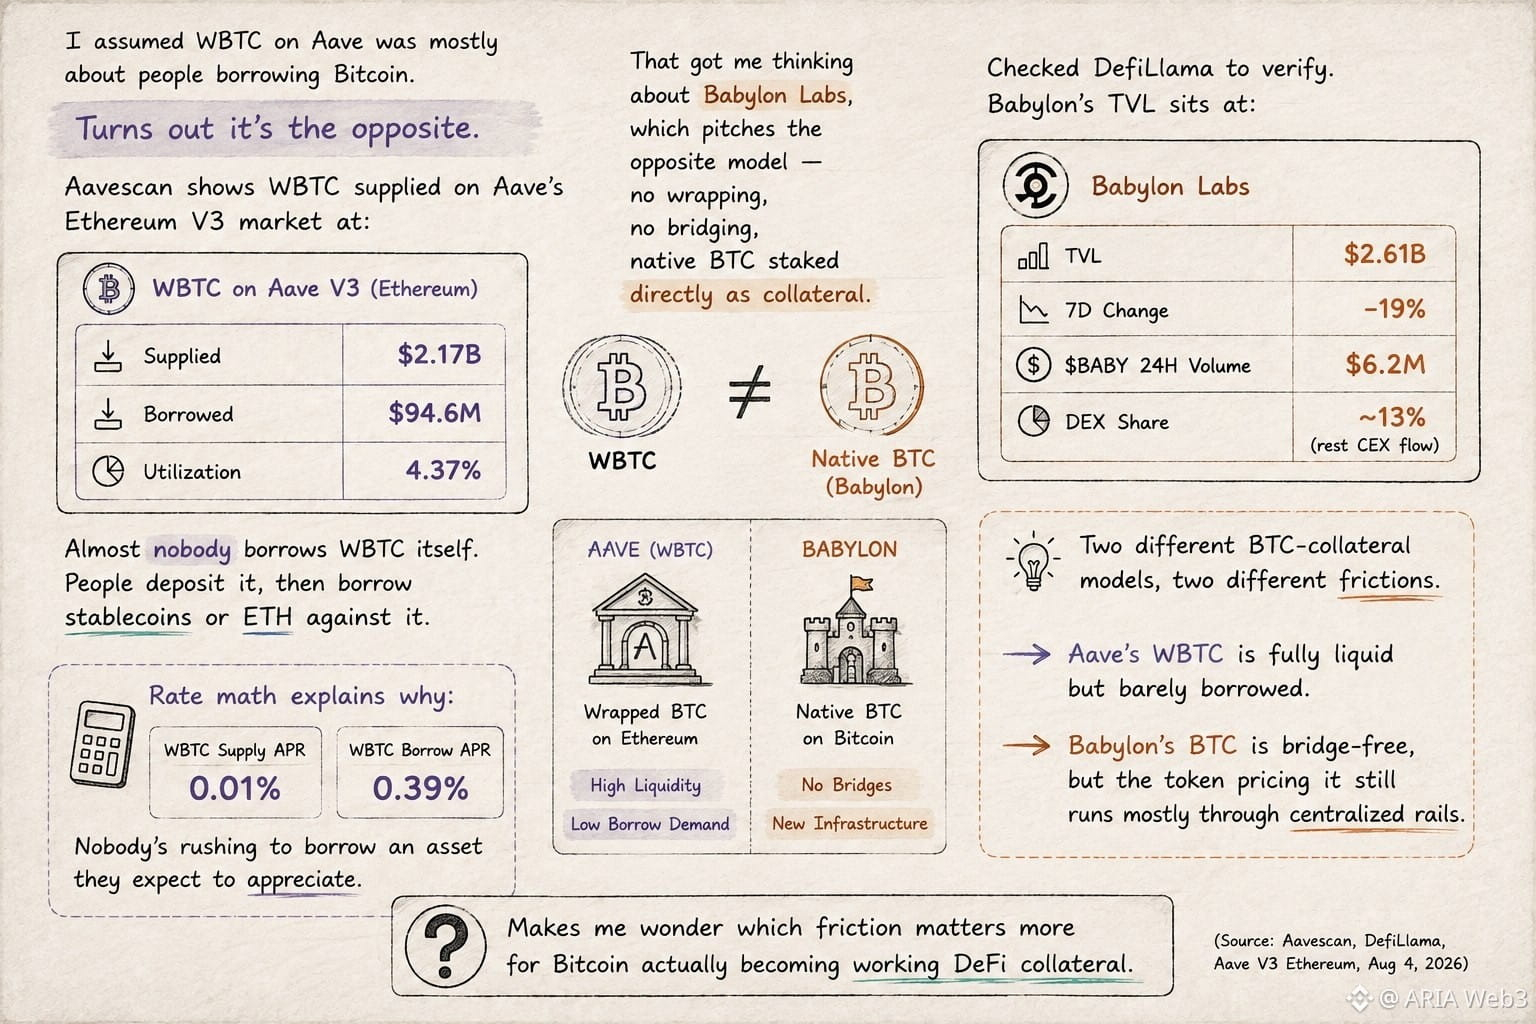
Ich dachte, bei WBTC auf Aave ginge es hauptsächlich darum, dass Leute Bitcoin leihen.
Es stellt sich heraus: Es ist genau umgekehrt.
Laut Aavescan wurden auf Aaves Ethereum-V3-Markt 2,17 Mrd. $ in WBTC eingezahlt. Geliehen wurden gerade einmal 94,6 Mio. $. Auslastung: 4,37 %.
Fast niemand leiht WBTC selbst. Die Leute zahlen es ein und leihen sich dann Stablecoins oder ETH dagegen.
Das brachte mich zum Nachdenken über @babylonlabs_io , das ein genau umgekehrtes Modell verfolgt – kein Wrapping, kein Bridging, natives BTC, das direkt als Sicherheit gestakt wird.
Ich habe bei DefiLlama nachgesehen. Babylons TVL liegt bei 2,61 Mrd. $, 19 % weniger als in der vergangenen Woche. $BABY macht in 24 Stunden ein Handelsvolumen von etwa 6,2 Mio. $, aber nur rund 13 % davon werden auf DEXs gehandelt – der Rest läuft über zentralisierte Börsen.
Zwei verschiedene BTC-Sicherheitenmodelle, zwei verschiedene Hürden. Aaves WBTC ist vollständig liquide, wird aber kaum geliehen. Babylon-BTC kommt ohne Bridge aus, aber der Token, über den es bewertet wird, läuft weiterhin größtenteils über zentralisierte Handelsplätze.
Da frage ich mich, welche Hürde wichtiger ist, damit Bitcoin tatsächlich als produktive DeFi-Sicherheit eingesetzt werden kann.
#baby
Ich dachte, bei WBTC auf Aave ginge es hauptsächlich darum, dass Leute Bitcoin leihen.
Es stellt sich heraus: Es ist genau umgekehrt.
Laut Aavescan wurden auf Aaves Ethereum-V3-Markt 2,17 Mrd. $ in WBTC eingezahlt. Geliehen wurden gerade einmal 94,6 Mio. $. Auslastung: 4,37 %.
Fast niemand leiht WBTC selbst. Die Leute zahlen es ein und leihen sich dann Stablecoins oder ETH dagegen.
Das brachte mich zum Nachdenken über @BabylonLabs_io , das ein genau umgekehrtes Modell verfolgt – kein Wrapping, kein Bridging, natives BTC, das direkt als Sicherheit gestakt wird.
Ich habe bei DefiLlama nachgesehen. Babylons TVL liegt bei 2,61 Mrd. $, 19 % weniger als in der vergangenen Woche. $BABY macht in 24 Stunden ein Handelsvolumen von etwa 6,2 Mio. $, aber nur rund 13 % davon werden auf DEXs gehandelt – der Rest läuft über zentralisierte Börsen.
Zwei verschiedene BTC-Sicherheitenmodelle, zwei verschiedene Hürden. Aaves WBTC ist vollständig liquide, wird aber kaum geliehen. Babylon-BTC kommt ohne Bridge aus, aber der Token, über den es bewertet wird, läuft weiterhin größtenteils über zentralisierte Handelsplätze.
Da frage ich mich, welche Hürde wichtiger ist, damit Bitcoin tatsächlich als produktive DeFi-Sicherheit eingesetzt werden kann.
#baby
2
99
·
--
Bullisch
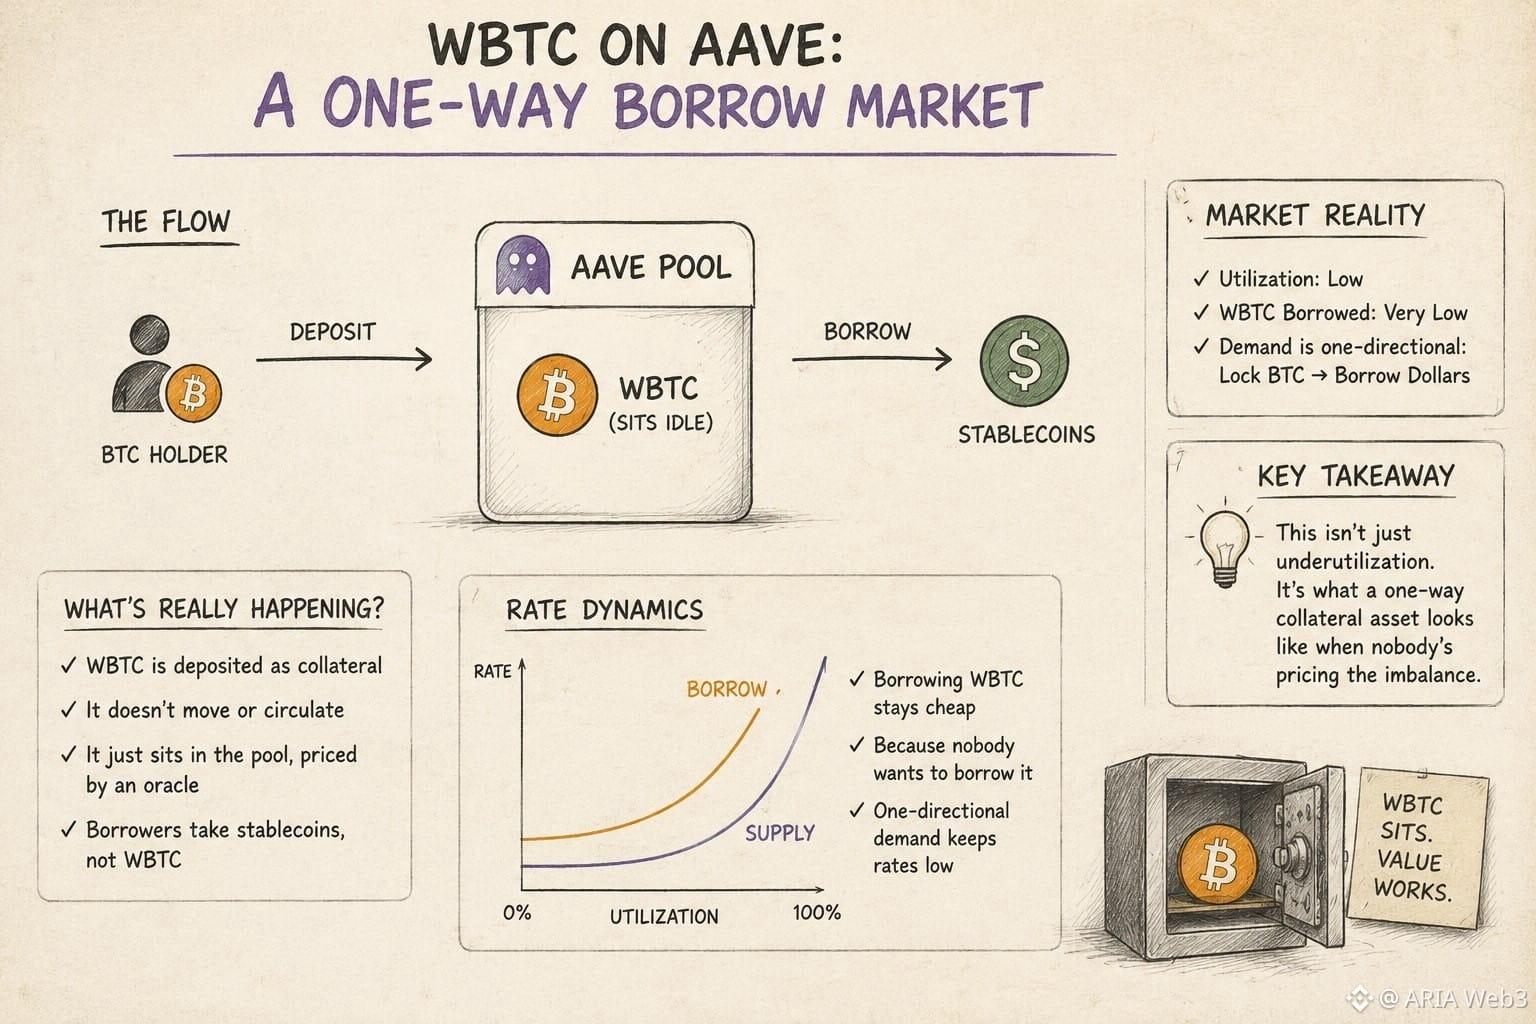
Ich dachte, WBTC auf Aave zu beleihen, bedeutete, dass Bitcoin doppelte Arbeit leistet — als Sicherheit hinterlegt ist und gleichzeitig mit seinem Wert einen Kredit anderswo absichert.
Es ist einfacher als das und zugleich seltsamer.
WBTC im Pool ist nicht im Umlauf. Es liegt einfach dort, von einem Orakel bewertet, während jemand dagegen die Stablecoins einer anderen Person leiht.
Ich habe Aaves Zinsverlauf und die Live-WBTC-Märkte von Aavescan geprüft, um das zu bestätigen. Die Auslastung bleibt niedrig. Fast niemand leiht WBTC selbst.
Was mir auffiel: Die Nachfrage geht nur in eine Richtung. Die Leute sperren BTC, um sich Dollar zu leihen, nicht umgekehrt.
Das prägt die Zinskurve. Aaves Modell bepreist jeweils die Seite, die knapp ist — und da BTC-Besitzer BTC nur selten verleihen wollen, bleibt es absichtlich günstig, sich BTC zu leihen, und nicht zufällig.
Es ist ein Markt, in dem die „Leihen“-Seite eines Kreditmarkts kaum genutzt wird.
Da frage ich mich, ob das wirklich eine Unterauslastung ist oder einfach das Bild eines einseitig als Sicherheit genutzten Vermögenswerts, wenn niemand das Ungleichgewicht einpreist.
#baby $BABY @babylonlabs_io
Ich dachte, WBTC auf Aave zu beleihen, bedeutete, dass Bitcoin doppelte Arbeit leistet — als Sicherheit hinterlegt ist und gleichzeitig mit seinem Wert einen Kredit anderswo absichert.
Es ist einfacher als das und zugleich seltsamer.
WBTC im Pool ist nicht im Umlauf. Es liegt einfach dort, von einem Orakel bewertet, während jemand dagegen die Stablecoins einer anderen Person leiht.
Ich habe Aaves Zinsverlauf und die Live-WBTC-Märkte von Aavescan geprüft, um das zu bestätigen. Die Auslastung bleibt niedrig. Fast niemand leiht WBTC selbst.
Was mir auffiel: Die Nachfrage geht nur in eine Richtung. Die Leute sperren BTC, um sich Dollar zu leihen, nicht umgekehrt.
Das prägt die Zinskurve. Aaves Modell bepreist jeweils die Seite, die knapp ist — und da BTC-Besitzer BTC nur selten verleihen wollen, bleibt es absichtlich günstig, sich BTC zu leihen, und nicht zufällig.
Es ist ein Markt, in dem die „Leihen“-Seite eines Kreditmarkts kaum genutzt wird.
Da frage ich mich, ob das wirklich eine Unterauslastung ist oder einfach das Bild eines einseitig als Sicherheit genutzten Vermögenswerts, wenn niemand das Ungleichgewicht einpreist.
#baby $BABY @BabylonLabs_io
2
90
·
--
Bullisch
Teilweise korrekt
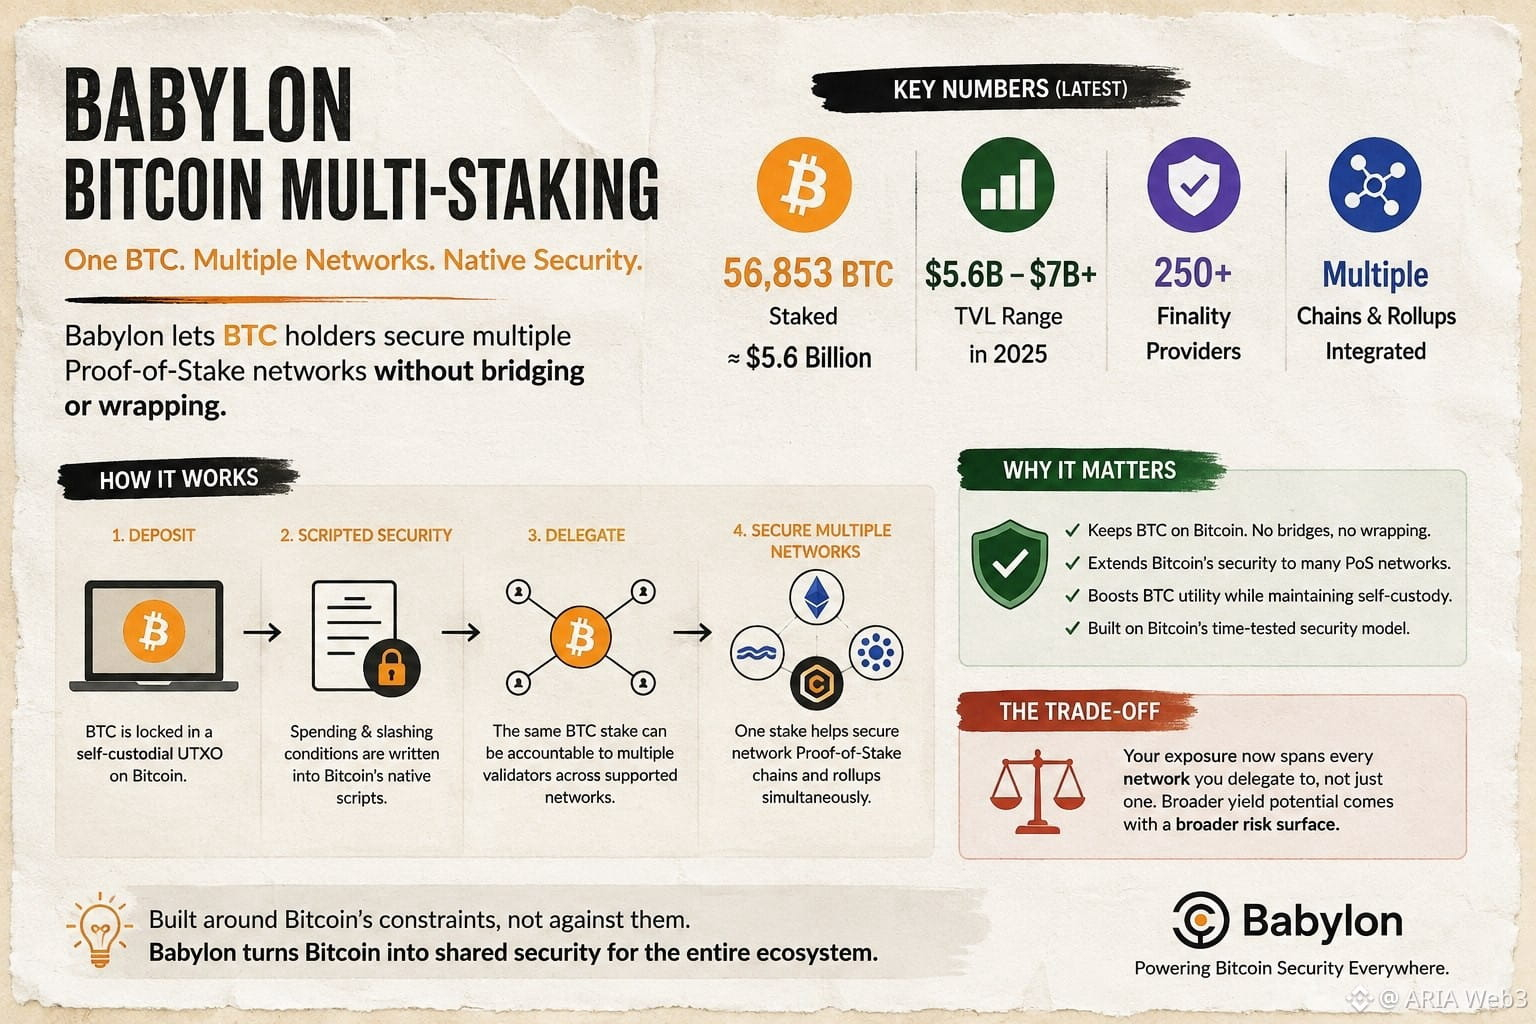
Ich ging davon aus, dass Bitcoin-Staking wie typisches Restaking funktioniert: eine Chain auswählen und seine Assets binden. Also habe ich in der offiziellen Dokumentation von Babylon nachgesehen, um mich zu vergewissern.
Da wurde es mir klar. Babylon sichert derzeit rund 56.853 BTC im Wert von etwa 5,6 Milliarden US-Dollar über mehr als 250 Finalitätsanbieter. Die BTC bleiben in einem selbstverwalteten UTXO direkt auf Bitcoin gesperrt – ohne Bridge, ohne Wrapping. Und derselbe Stake kann gleichzeitig mehrere Bitcoin Supercharged Networks absichern.
Überrascht hat mich der Mechanismus. Die Bedingungen für Ausgaben und Slashing sind direkt in die Skripting-Ebene von Bitcoin eingebettet. So kann eine einzige gesperrte Position gleichzeitig mehreren Validatoren unterliegen, ohne jemals die Bitcoin-Chain zu verlassen.
Der Kompromiss ist klar: Dein Risiko erstreckt sich nun auf jedes Netzwerk, an das du delegierst, und nicht nur auf eines. Das ist der Preis gemeinsamer Sicherheit: größeres Renditepotenzial im Austausch für eine breitere Risikoexposition.
Da der TVL in diesem Jahr zwischen 5,6 Milliarden und über 7 Milliarden US-Dollar lag, frage ich mich immer wieder, wie Staker diese Streuung tatsächlich ausbalancieren: ob sie auf höhere Rewards aus sind oder das Risiko sorgfältiger verteilen.#baby $BABY @babylonlabs_io
Ich ging davon aus, dass Bitcoin-Staking wie typisches Restaking funktioniert: eine Chain auswählen und seine Assets binden. Also habe ich in der offiziellen Dokumentation von Babylon nachgesehen, um mich zu vergewissern.
Da wurde es mir klar. Babylon sichert derzeit rund 56.853 BTC im Wert von etwa 5,6 Milliarden US-Dollar über mehr als 250 Finalitätsanbieter. Die BTC bleiben in einem selbstverwalteten UTXO direkt auf Bitcoin gesperrt – ohne Bridge, ohne Wrapping. Und derselbe Stake kann gleichzeitig mehrere Bitcoin Supercharged Networks absichern.
Überrascht hat mich der Mechanismus. Die Bedingungen für Ausgaben und Slashing sind direkt in die Skripting-Ebene von Bitcoin eingebettet. So kann eine einzige gesperrte Position gleichzeitig mehreren Validatoren unterliegen, ohne jemals die Bitcoin-Chain zu verlassen.
Der Kompromiss ist klar: Dein Risiko erstreckt sich nun auf jedes Netzwerk, an das du delegierst, und nicht nur auf eines. Das ist der Preis gemeinsamer Sicherheit: größeres Renditepotenzial im Austausch für eine breitere Risikoexposition.
Da der TVL in diesem Jahr zwischen 5,6 Milliarden und über 7 Milliarden US-Dollar lag, frage ich mich immer wieder, wie Staker diese Streuung tatsächlich ausbalancieren: ob sie auf höhere Rewards aus sind oder das Risiko sorgfältiger verteilen.#baby $BABY @BabylonLabs_io
6
1
81
·
--
Bullisch
Übersetzung ansehen
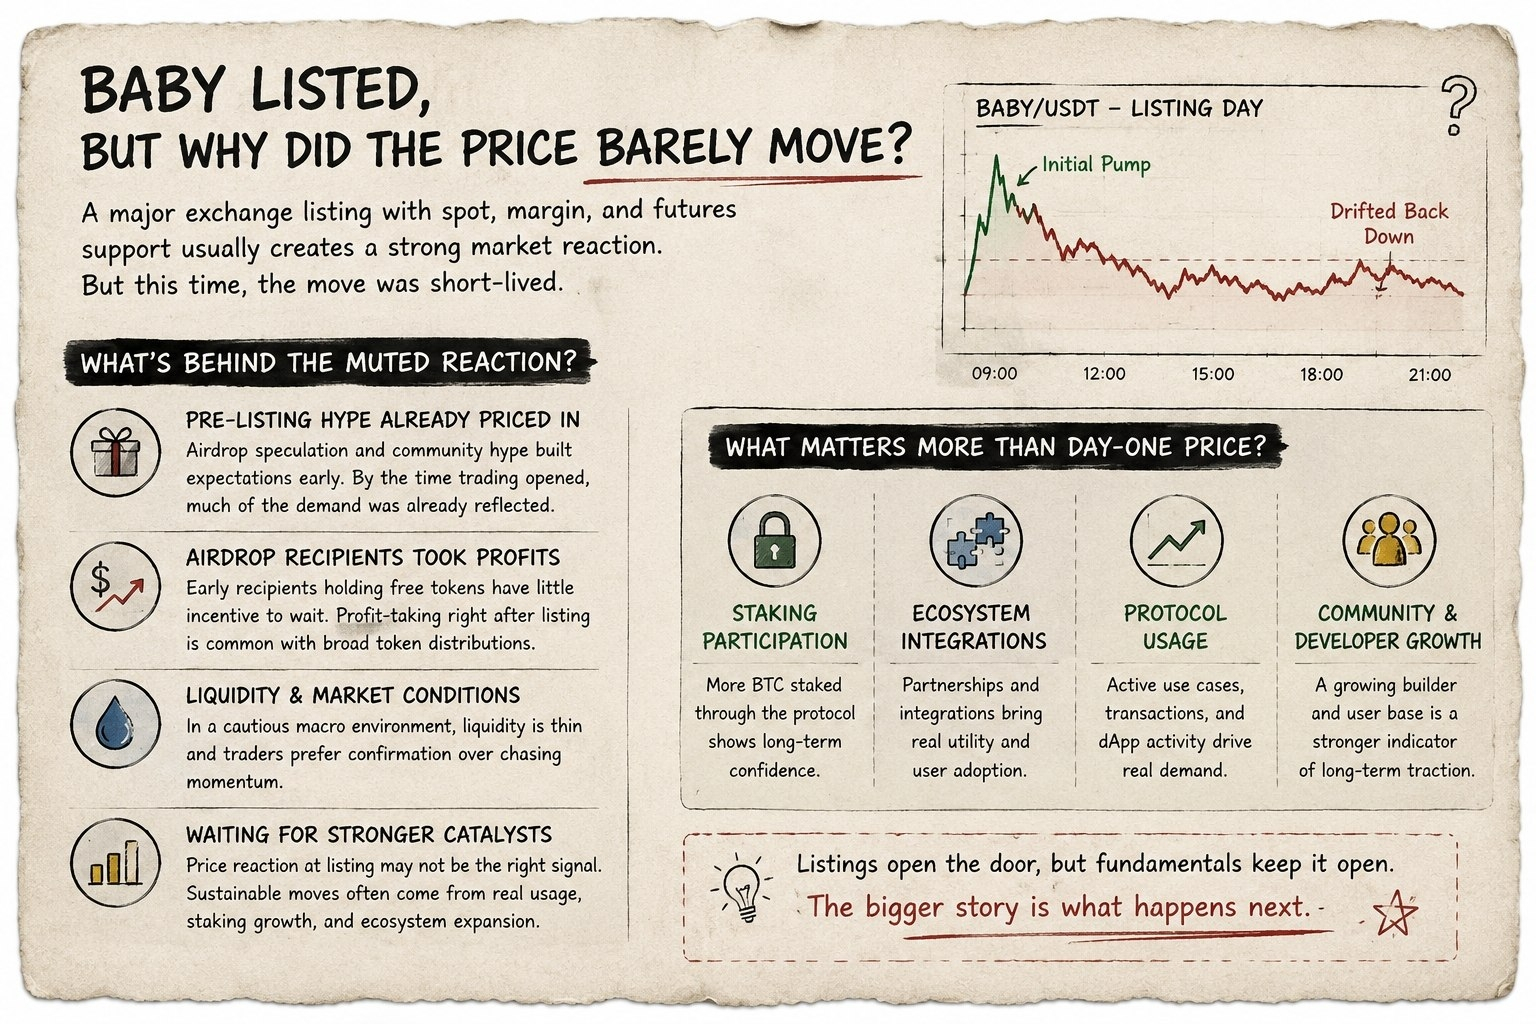
I was reading through recent listing data for BABY, and one detail caught my attention: despite landing on a major exchange with full spot, margin, and futures support, the price barely moved beyond an initial pop before drifting back down. I assumed a listing that big would trigger a sustained rally, so the muted follow-through confused me.
After checking exchange notices and on-chain activity around the listing date, a pattern emerged. Much of the anticipated demand had likely already been priced in through pre-listing airdrop speculation and community hype. That's when it clicked — by the time trading actually opened, a lot of the "buy the news" enthusiasm had already played out as "sell the news."
What surprised me was the airdrop angle. Early recipients holding free tokens have little incentive to wait, so a wave of profit-taking right after listing is a common trade-off of broad token distributions, not a flaw unique to this project.
Liquidity conditions and overall market sentiment matter too. In a cautious macro environment, traders tend to wait for confirmation rather than chase momentum.
It made me wonder whether price reaction at listing is even the right signal to watch. Maybe the more meaningful catalysts — staking participation, ecosystem integrations, actual protocol usage — simply haven't arrived yet. What would you consider a stronger indicator of long-term traction than day-one price action?#baby @babylonlabs_io $BABY
I was reading through recent listing data for BABY, and one detail caught my attention: despite landing on a major exchange with full spot, margin, and futures support, the price barely moved beyond an initial pop before drifting back down. I assumed a listing that big would trigger a sustained rally, so the muted follow-through confused me.
After checking exchange notices and on-chain activity around the listing date, a pattern emerged. Much of the anticipated demand had likely already been priced in through pre-listing airdrop speculation and community hype. That's when it clicked — by the time trading actually opened, a lot of the "buy the news" enthusiasm had already played out as "sell the news."
What surprised me was the airdrop angle. Early recipients holding free tokens have little incentive to wait, so a wave of profit-taking right after listing is a common trade-off of broad token distributions, not a flaw unique to this project.
Liquidity conditions and overall market sentiment matter too. In a cautious macro environment, traders tend to wait for confirmation rather than chase momentum.
It made me wonder whether price reaction at listing is even the right signal to watch. Maybe the more meaningful catalysts — staking participation, ecosystem integrations, actual protocol usage — simply haven't arrived yet. What would you consider a stronger indicator of long-term traction than day-one price action?#baby @BabylonLabs_io $BABY
6
2
75
·
--
Verifiziert
Übersetzung ansehen
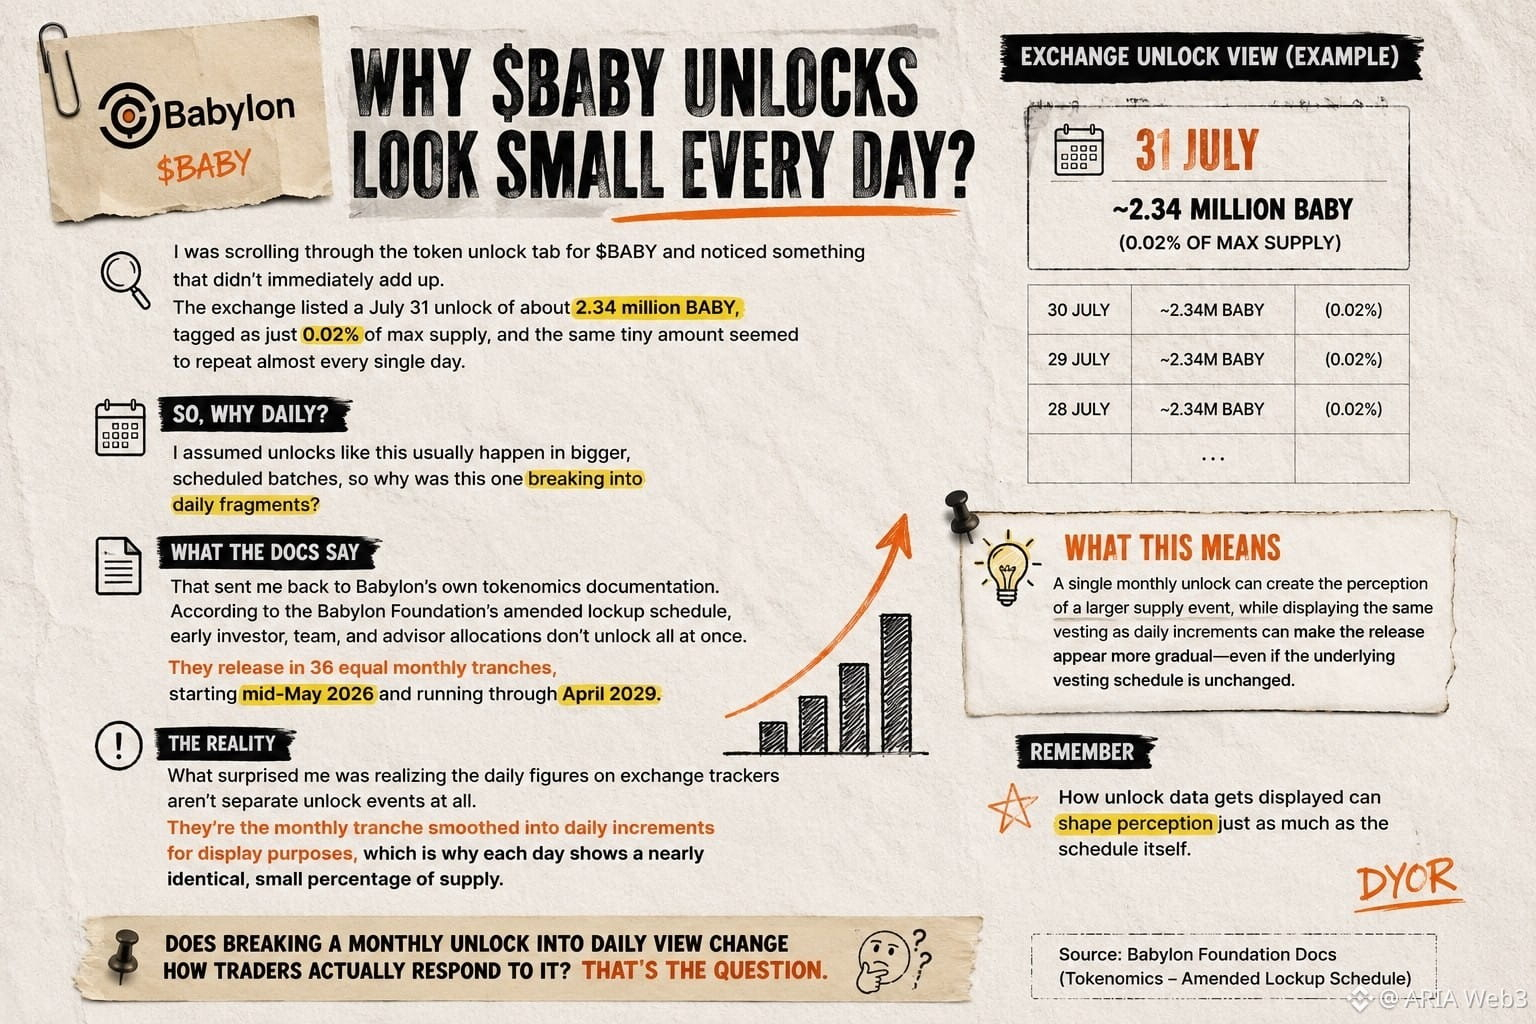
I was scrolling through the token unlock tab for BABY and noticed something that didn't immediately add up. The exchange listed a July 31 unlock of about 2.34 million BABY, tagged as just 0.02% of max supply, and the same tiny amount seemed to repeat almost every single day.
I assumed unlocks like this usually happen in bigger, scheduled batches, so why was this one breaking into daily fragments?
That sent me back to Babylon's own tokenomics documentation. According to the Babylon Foundation's amended lockup schedule, early investor, team, and advisor allocations don't unlock all at once. They release in 36 equal monthly tranches, starting mid-May 2026 and running through April 2029.
What surprised me was realizing the daily figures on exchange trackers aren't separate unlock events at all. They're the monthly tranche smoothed into daily increments for display purposes, which is why each day shows a nearly identical, small percentage of supply. That's the trade-off worth sitting with. A single large monthly cliff can shock the market with a sudden supply jump, while spreading it visually into daily slices makes the release feel gradual, even though the underlying vesting math hasn't changed at all.
It's a reminder that how unlock data gets displayed can shape perception just as much as the schedule itself. Does breaking a monthly unlock into daily view change how traders actually respond to it?
#baby $BABY @babylonlabs_io
I was scrolling through the token unlock tab for BABY and noticed something that didn't immediately add up. The exchange listed a July 31 unlock of about 2.34 million BABY, tagged as just 0.02% of max supply, and the same tiny amount seemed to repeat almost every single day.
I assumed unlocks like this usually happen in bigger, scheduled batches, so why was this one breaking into daily fragments?
That sent me back to Babylon's own tokenomics documentation. According to the Babylon Foundation's amended lockup schedule, early investor, team, and advisor allocations don't unlock all at once. They release in 36 equal monthly tranches, starting mid-May 2026 and running through April 2029.
What surprised me was realizing the daily figures on exchange trackers aren't separate unlock events at all. They're the monthly tranche smoothed into daily increments for display purposes, which is why each day shows a nearly identical, small percentage of supply. That's the trade-off worth sitting with. A single large monthly cliff can shock the market with a sudden supply jump, while spreading it visually into daily slices makes the release feel gradual, even though the underlying vesting math hasn't changed at all.
It's a reminder that how unlock data gets displayed can shape perception just as much as the schedule itself. Does breaking a monthly unlock into daily view change how traders actually respond to it?
#baby $BABY @BabylonLabs_io
4
3
69
·
--
Bullisch
Übersetzung ansehen
I've read "slashing" in every Babylon post I've seen, and pictured the same thing every time: a validator misbehaves, and some rule takes their money.
That picture held up until I tried to explain who actually enforces it.
Is there a vote? A dispute period? Someone reviewing evidence?
I went looking for that process, expecting a committee.
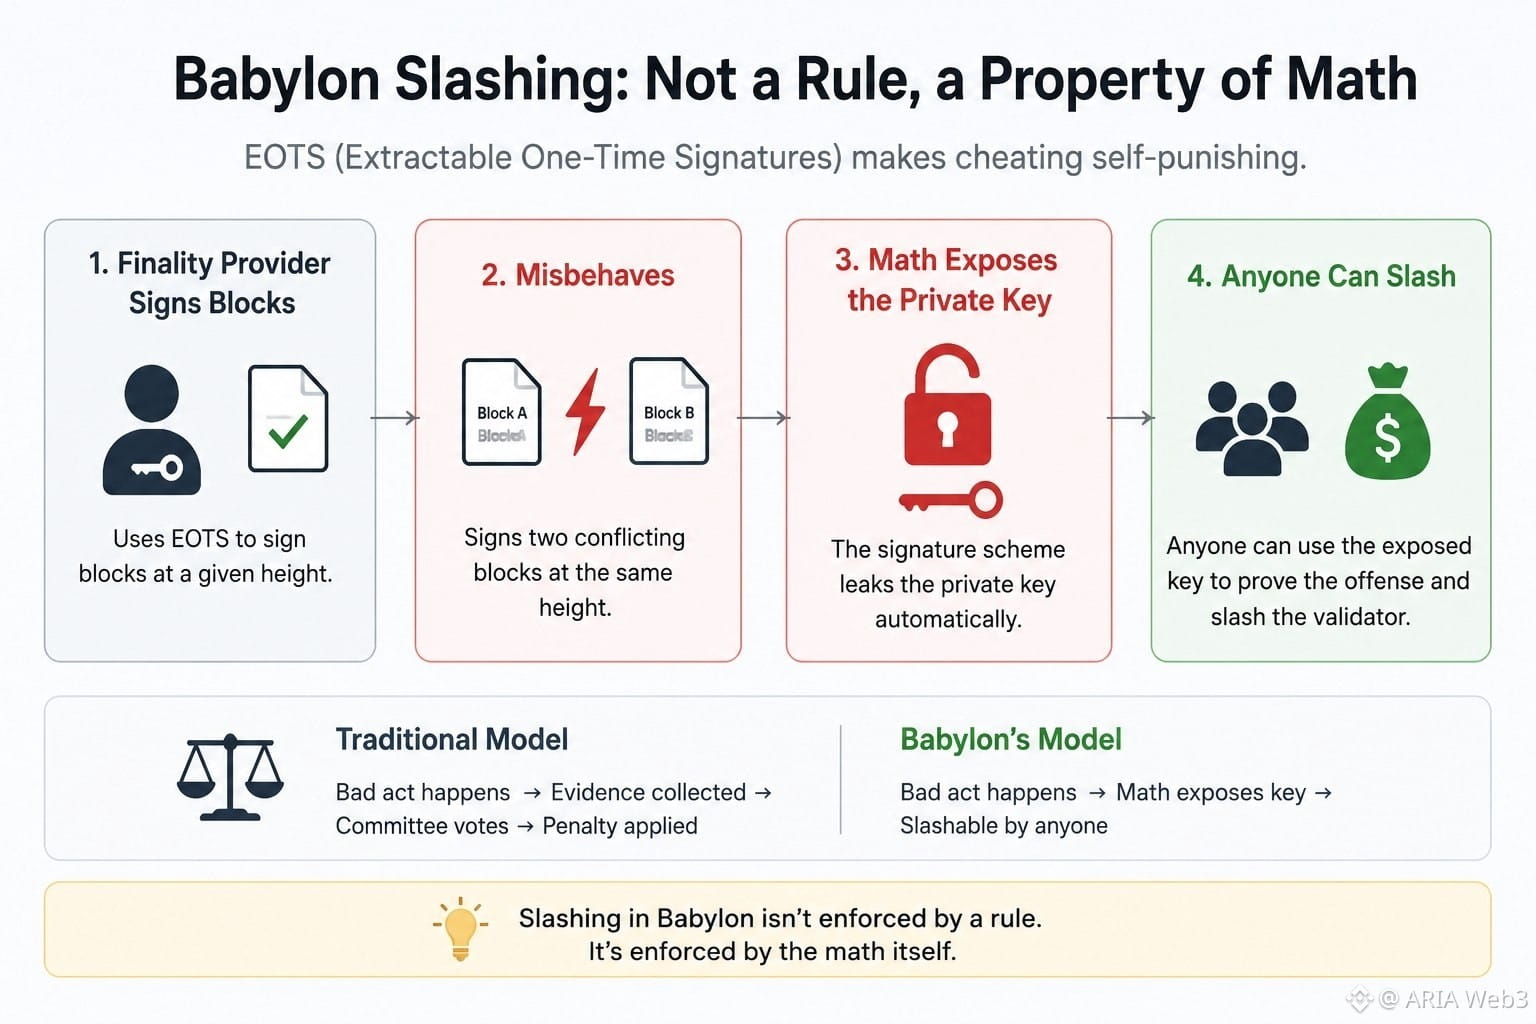
Instead I found something called EOTS — Extractable One-Time Signatures — the way Babylon's finality providers sign blocks.
I assumed it was just a fancier signature scheme. Then I read what "extractable" means.
If a finality provider signs two conflicting blocks at the same height, the signature math itself leaks their private key. Not as a penalty applied afterward. As a direct result of the act.
I sat with that for a second. There's no judge deciding guilt. The cheating and the exposure are the same event. That's different from how I usually think about enforcement — a bad act happens, then a separate process decides the consequence. Here, doing the bad thing is handing over the key to punish yourself.
Once I saw that, "slashing" stopped feeling like a rule Babylon enforces, and started feeling like something the math simply makes true on its own.
I still don't know how that holds up outside clean theory — implementation bugs, edge cases nobody planned for. Cryptography being correct on paper isn't the same as behaving correctly under real network stress.
But I like sitting with the idea that punishment here isn't a decision. It's a fact that reveals itself.
#baby $BABY @babylonlabs_io
I've read "slashing" in every Babylon post I've seen, and pictured the same thing every time: a validator misbehaves, and some rule takes their money.
That picture held up until I tried to explain who actually enforces it.
Is there a vote? A dispute period? Someone reviewing evidence?
I went looking for that process, expecting a committee.
Instead I found something called EOTS — Extractable One-Time Signatures — the way Babylon's finality providers sign blocks.
I assumed it was just a fancier signature scheme. Then I read what "extractable" means.
If a finality provider signs two conflicting blocks at the same height, the signature math itself leaks their private key. Not as a penalty applied afterward. As a direct result of the act.
I sat with that for a second. There's no judge deciding guilt. The cheating and the exposure are the same event. That's different from how I usually think about enforcement — a bad act happens, then a separate process decides the consequence. Here, doing the bad thing is handing over the key to punish yourself.
Once I saw that, "slashing" stopped feeling like a rule Babylon enforces, and started feeling like something the math simply makes true on its own.
I still don't know how that holds up outside clean theory — implementation bugs, edge cases nobody planned for. Cryptography being correct on paper isn't the same as behaving correctly under real network stress.
But I like sitting with the idea that punishment here isn't a decision. It's a fact that reveals itself.
#baby $BABY @BabylonLabs_io
1
1
72
·
--
Übersetzung ansehen
The more I read through Babylon's code this week, the more one small detail kept sticking in my head.
Every checkpoint sent to Bitcoin actually goes out as two separate transactions, not one. My first thought was redundancy, like a backup copy in case something gets orphaned. Turns out that's not it at all. A Bitcoin OP_RETURN output only holds 80 bytes, and a full checkpoint just doesn't fit in that space. So it gets split in half and sent as two txs, then pieced back together once both confirm. Simple once you know it, but I hadn't seen anyone point it out before.
What actually got me curious was who submits these.
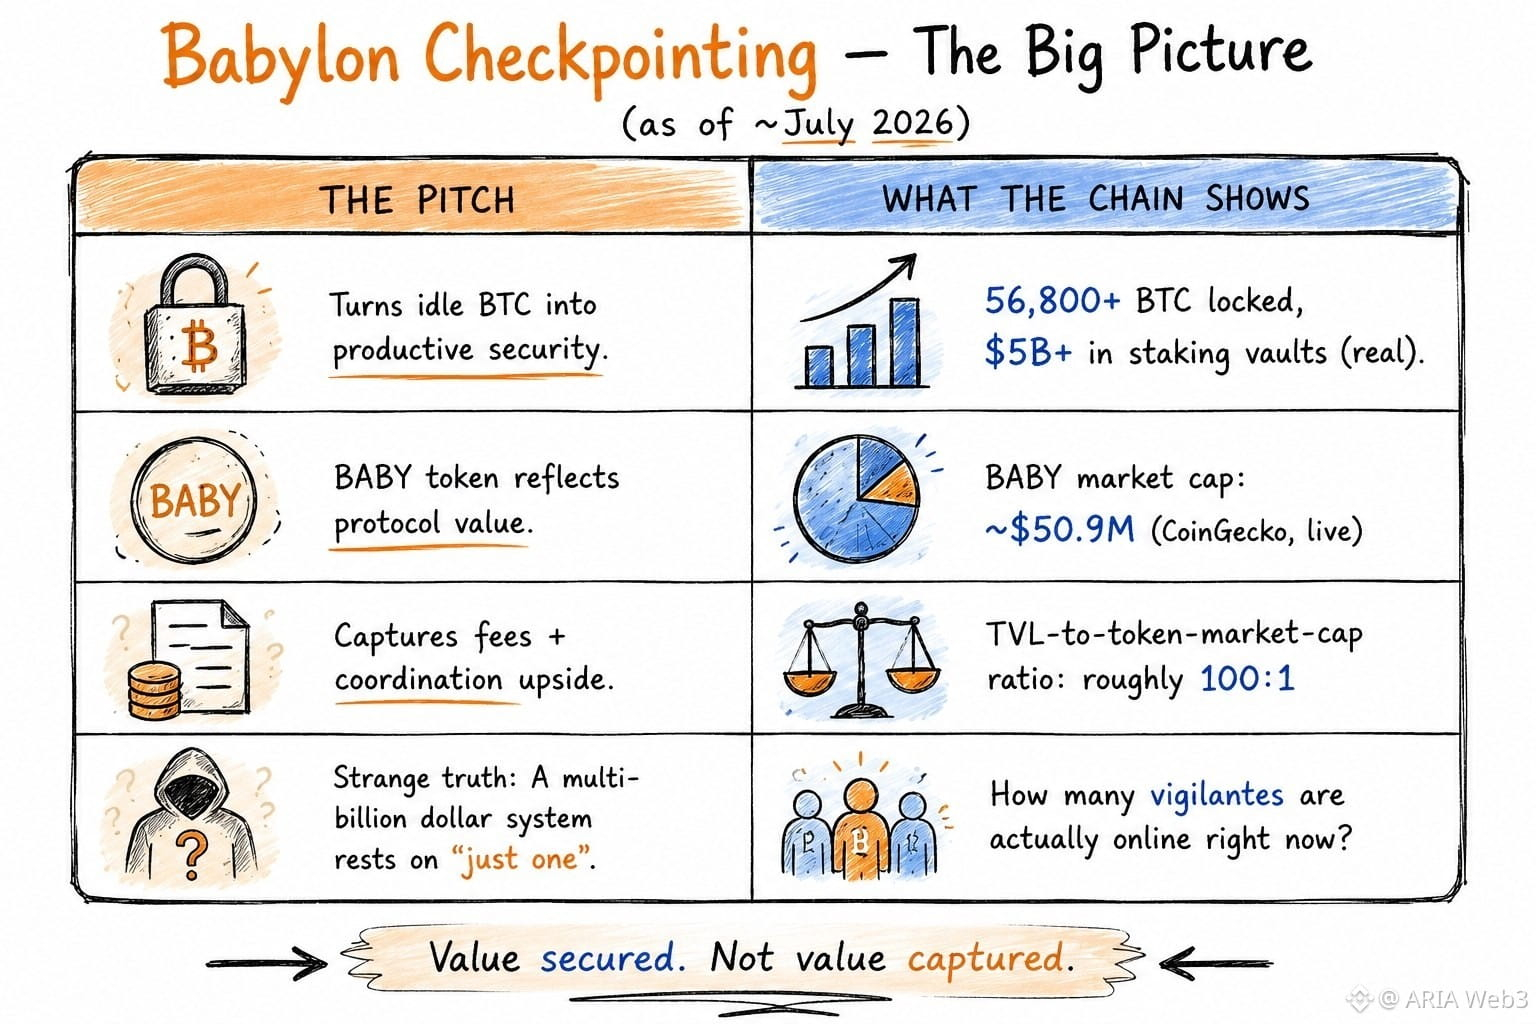
Not validators, not @babylonlabs_io itself, just anyone who wants to. They're called "vigilantes." You run the software, grab the checkpoint, pay the Bitcoin fee out of your own pocket, and broadcast it. No bond, no whitelist, nothing stopping you from just... stopping. And the whole system only needs one of these people online and honest at any given moment. Not a majority, just one.
Feels strange knowing a multi-billion dollar staking system quietly rests on that. Makes me wonder how many vigilantes are actually running right now, and whether most people staking through Babylon even know this part exists.
$BABY #baby
The more I read through Babylon's code this week, the more one small detail kept sticking in my head.
Every checkpoint sent to Bitcoin actually goes out as two separate transactions, not one. My first thought was redundancy, like a backup copy in case something gets orphaned. Turns out that's not it at all. A Bitcoin OP_RETURN output only holds 80 bytes, and a full checkpoint just doesn't fit in that space. So it gets split in half and sent as two txs, then pieced back together once both confirm. Simple once you know it, but I hadn't seen anyone point it out before.
What actually got me curious was who submits these.
Not validators, not @BabylonLabs_io itself, just anyone who wants to. They're called "vigilantes." You run the software, grab the checkpoint, pay the Bitcoin fee out of your own pocket, and broadcast it. No bond, no whitelist, nothing stopping you from just... stopping. And the whole system only needs one of these people online and honest at any given moment. Not a majority, just one.
Feels strange knowing a multi-billion dollar staking system quietly rests on that. Makes me wonder how many vigilantes are actually running right now, and whether most people staking through Babylon even know this part exists.
$BABY #baby
16
4
87
·
--
Übersetzung ansehen
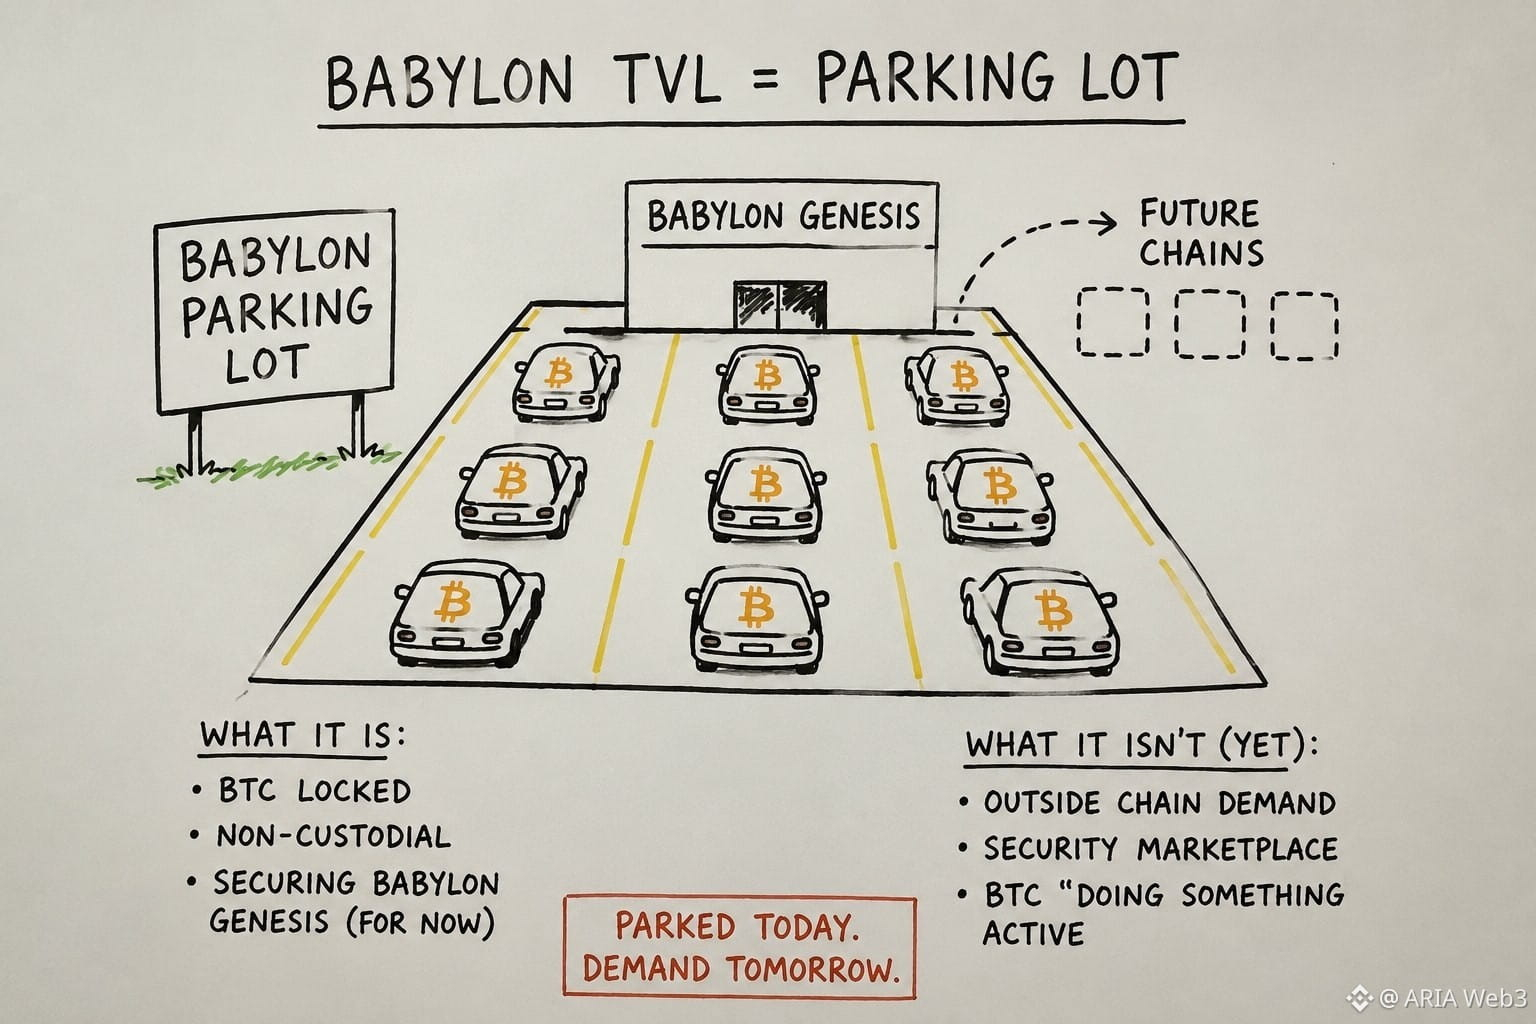
Kept assuming Babylon's TVL chart was a demand chart. It isn't. It's a parking lot.
Multi-staking, the feature that lets one BTC deposit secure several PoS chains at once, is still the headline pitch.
But almost all the staked BTC right now backs one chain: Babylon Genesis, which also happens to be the control plane for every future network that's supposed to plug in later. So the number being read as "security demand" is mostly capital sitting inside the system that built the measuring stick. Not dishonest, just sequencing. Bootstrap supply first, prove the mechanism, let demand catch up. Every security marketplace starts this way.
But it means TVL answers a question nobody's really asking, can BTC be locked non-custodially to back validators, instead of the one that matters: do outside chains value that security enough to pay for it over their own token inflation. You can feel the market already sensing this. BABY's valuation against the BTC parked behind it doesn't move like a demand asset. It moves like a token still waiting to find out what it's for. The uncomfortable read: Babylon may have solved the harder cryptographic problem before solving the easier economic one. Most infrastructure bets assume the tech is the bottleneck. What if here it never was?
#baby $BABY @babylonlabs_io
Kept assuming Babylon's TVL chart was a demand chart. It isn't. It's a parking lot.
Multi-staking, the feature that lets one BTC deposit secure several PoS chains at once, is still the headline pitch.
But almost all the staked BTC right now backs one chain: Babylon Genesis, which also happens to be the control plane for every future network that's supposed to plug in later. So the number being read as "security demand" is mostly capital sitting inside the system that built the measuring stick. Not dishonest, just sequencing. Bootstrap supply first, prove the mechanism, let demand catch up. Every security marketplace starts this way.
But it means TVL answers a question nobody's really asking, can BTC be locked non-custodially to back validators, instead of the one that matters: do outside chains value that security enough to pay for it over their own token inflation. You can feel the market already sensing this. BABY's valuation against the BTC parked behind it doesn't move like a demand asset. It moves like a token still waiting to find out what it's for. The uncomfortable read: Babylon may have solved the harder cryptographic problem before solving the easier economic one. Most infrastructure bets assume the tech is the bottleneck. What if here it never was?
#baby $BABY @BabylonLabs_io
6
3
86
Anmelden und weiter Inhalte entdecken
Krypto-Nutzer weltweit auf Binance Square kennenlernen
⚡️ Bleib in Sachen Krypto stets am Puls.
💬 Die weltgrößte Kryptobörse vertraut darauf.
👍 Erhalte verlässliche Einblicke von verifizierten Creators.
E-Mail-Adresse/Telefonnummer
Trendthemen
EarningsSeason
6.6M Aufrufe
33,056 Kommentare
Berichtssaison, Session 3: Übertreffen Google und Microsoft die Gewinnerwartungen?
Binance Square Official
·184 Likes
·109.8k Aufrufe
USMidtermElections
83,914 Aufrufe
1,092 Kommentare
StrategySTRCReaches$99.95ForFirstTimeIn165Days
605 Aufrufe
31 Kommentare