
#bp
bp
15,123 views
106 Discussing
Hot
Latest

·
--
Verified
BP made a killing this quarter: Q3 underlying RC profit was $8.46 billion, versus market expectations of just $7.33 billion.
I looked through BP’s official 3Q26 announcement. Here are a few key figures:
1️⃣ Profit: $8.46 billion, up from $5.73 billion last quarter and just $2.21 billion in the same quarter last year—nearly 4 times higher
2️⃣ Cash flow: $14.8 billion in operating cash flow
3️⃣ Debt: Net debt fell from $22.25 billion to $13.87 billion, down $8.4 billion in a single quarter and reaching its target a year ahead of schedule
4️⃣ Drivers: The company’s exact words were that refining margins and oil and gas trading were “significantly higher”
5️⃣ The other side: Reported profit was only $4.7 billion, including around $4 billion in after-tax impairments; the dividend was held at 8.66 cents per share
My take: This is an earnings report where “the environment served up the profits.” Refining margins and the trading desk did most of the heavy lifting. BP is using the cash to pay down debt rather than rushing to hand it back to shareholders—a rare bit of clear-headedness in recent years.
But cyclical stocks are cyclical stocks. When refining margins fall, quarters like this will too. What really determines the ceiling for energy stocks is still global demand and the electricity bill for AI data centers.
Data source: BP’s official 3Q 2026 results announcement (RNS); consensus estimates from the analyst survey commissioned by BP (as reported by Reuters).
This is not investment advice.
#BP #财报 #Energy
BP made a killing this quarter: Q3 underlying RC profit was $8.46 billion, versus market expectations of just $7.33 billion.
I looked through BP’s official 3Q26 announcement. Here are a few key figures:
1️⃣ Profit: $8.46 billion, up from $5.73 billion last quarter and just $2.21 billion in the same quarter last year—nearly 4 times higher
2️⃣ Cash flow: $14.8 billion in operating cash flow
3️⃣ Debt: Net debt fell from $22.25 billion to $13.87 billion, down $8.4 billion in a single quarter and reaching its target a year ahead of schedule
4️⃣ Drivers: The company’s exact words were that refining margins and oil and gas trading were “significantly higher”
5️⃣ The other side: Reported profit was only $4.7 billion, including around $4 billion in after-tax impairments; the dividend was held at 8.66 cents per share
My take: This is an earnings report where “the environment served up the profits.” Refining margins and the trading desk did most of the heavy lifting. BP is using the cash to pay down debt rather than rushing to hand it back to shareholders—a rare bit of clear-headedness in recent years.
But cyclical stocks are cyclical stocks. When refining margins fall, quarters like this will too. What really determines the ceiling for energy stocks is still global demand and the electricity bill for AI data centers.
Data source: BP’s official 3Q 2026 results announcement (RNS); consensus estimates from the analyst survey commissioned by BP (as reported by Reuters).
This is not investment advice.
#BP #财报 #Energy
I looked through BP’s official 3Q26 announcement. Here are a few key figures:
1️⃣ Profit: $8.46 billion, up from $5.73 billion last quarter and just $2.21 billion in the same quarter last year—nearly 4 times higher
2️⃣ Cash flow: $14.8 billion in operating cash flow
3️⃣ Debt: Net debt fell from $22.25 billion to $13.87 billion, down $8.4 billion in a single quarter and reaching its target a year ahead of schedule
4️⃣ Drivers: The company’s exact words were that refining margins and oil and gas trading were “significantly higher”
5️⃣ The other side: Reported profit was only $4.7 billion, including around $4 billion in after-tax impairments; the dividend was held at 8.66 cents per share
My take: This is an earnings report where “the environment served up the profits.” Refining margins and the trading desk did most of the heavy lifting. BP is using the cash to pay down debt rather than rushing to hand it back to shareholders—a rare bit of clear-headedness in recent years.
But cyclical stocks are cyclical stocks. When refining margins fall, quarters like this will too. What really determines the ceiling for energy stocks is still global demand and the electricity bill for AI data centers.
Data source: BP’s official 3Q 2026 results announcement (RNS); consensus estimates from the analyst survey commissioned by BP (as reported by Reuters).
This is not investment advice.
#BP #财报 #Energy
BPUS-0.92%
594
·
--
Two concrete developments in the Backpack product line on the same day (10/29), both at the intersection of “regulated brokerages × on-chain distribution”:
① Strategic partnership with South Korean listed brokerage SK Securities (KRX: 001510): eligible non-resident foreign investors can access Korean stock trading through the Backpack App; the offering could later expand to tokenized securities and RWAs.
② Kamino has launched Backpack Securities tokenized stocks as collateral: MU, SKHY, SPCX, SNDK, and others are now available in Kamino’s Backpack isolated market. Eligible holders can borrow USDC while retaining exposure to the underlying stocks (liquidation risk still applies). The tokens are backed 1:1 by underlying U.S. stocks/ETFs and can be redeemed through an account; the underlying assets are held under New York UCC Article 8, with custody/clearing involving RQD Clearing and Atomic Vault. Kamino says deposits of tokenized stocks as collateral are around $50M (as of 2026-10).
By comparison: Backpack’s weekly trading volume has topped roughly $500 million, accounting for more than 60% of comparable platforms, but competitors still lead in supply share—lending access is a key step toward closing the gap between “hot trading volume and cold supply.”
What to watch next: the jurisdictions and timing for the Korean stock service launch, more assets being added to Kamino’s collateral list, and whether product expansion is accompanied by synchronized pricing.
#Backpack #BP #RWA #Solana
For reference only; not investment advice / NFA
Two concrete developments in the Backpack product line on the same day (10/29), both at the intersection of “regulated brokerages × on-chain distribution”:
① Strategic partnership with South Korean listed brokerage SK Securities (KRX: 001510): eligible non-resident foreign investors can access Korean stock trading through the Backpack App; the offering could later expand to tokenized securities and RWAs.
② Kamino has launched Backpack Securities tokenized stocks as collateral: MU, SKHY, SPCX, SNDK, and others are now available in Kamino’s Backpack isolated market. Eligible holders can borrow USDC while retaining exposure to the underlying stocks (liquidation risk still applies). The tokens are backed 1:1 by underlying U.S. stocks/ETFs and can be redeemed through an account; the underlying assets are held under New York UCC Article 8, with custody/clearing involving RQD Clearing and Atomic Vault. Kamino says deposits of tokenized stocks as collateral are around $50M (as of 2026-10).
By comparison: Backpack’s weekly trading volume has topped roughly $500 million, accounting for more than 60% of comparable platforms, but competitors still lead in supply share—lending access is a key step toward closing the gap between “hot trading volume and cold supply.”
What to watch next: the jurisdictions and timing for the Korean stock service launch, more assets being added to Kamino’s collateral list, and whether product expansion is accompanied by synchronized pricing.
#Backpack #BP #RWA #Solana
For reference only; not investment advice / NFA
① Strategic partnership with South Korean listed brokerage SK Securities (KRX: 001510): eligible non-resident foreign investors can access Korean stock trading through the Backpack App; the offering could later expand to tokenized securities and RWAs.
② Kamino has launched Backpack Securities tokenized stocks as collateral: MU, SKHY, SPCX, SNDK, and others are now available in Kamino’s Backpack isolated market. Eligible holders can borrow USDC while retaining exposure to the underlying stocks (liquidation risk still applies). The tokens are backed 1:1 by underlying U.S. stocks/ETFs and can be redeemed through an account; the underlying assets are held under New York UCC Article 8, with custody/clearing involving RQD Clearing and Atomic Vault. Kamino says deposits of tokenized stocks as collateral are around $50M (as of 2026-10).
By comparison: Backpack’s weekly trading volume has topped roughly $500 million, accounting for more than 60% of comparable platforms, but competitors still lead in supply share—lending access is a key step toward closing the gap between “hot trading volume and cold supply.”
What to watch next: the jurisdictions and timing for the Korean stock service launch, more assets being added to Kamino’s collateral list, and whether product expansion is accompanied by synchronized pricing.
#Backpack #BP #RWA #Solana
For reference only; not investment advice / NFA
113
·
--
Backpack (BP) tokenomics are once again drawing heightened discussion (2026-10-23): total supply of 1 billion tokens; 25% released at TGE (240 million for points users + 10 million for Mad Lads); the remaining 37.5% is allocated to the Pre-IPO milestone pool and 37.5% to the Post-IPO treasury (locked for ≥1 year after the IPO). The founder, executives, and investors receive zero tokens and zero warrants. Staking offers fee discounts; Pre-IPO tokens may be mapped to an equity pool of up to ~20%. Current price is about ~$0.99, with a staking rate of about ~56.4% (around 140.88 million tokens).
Key mechanics: This is a “zero insider allocation + dual-track milestone/treasury” structure, tying supply releases to post-listing governance rather than using the traditional linear unlock schedule for team/VC allocations. A staking rate above 50% suggests significant ties between circulating supply friction and fees, but the pace of milestone fulfillment and the details of equity mapping still need to be monitored.
Next things to watch: Whether the Pre-IPO milestone triggers are publicly disclosed and verifiable, and whether the staking rate stays above 50% in volatile markets.
Sources: Crypto Briefing https://cryptobriefing.com/backpack-founder-extreme-tokenomics-no-insider-tokens/ ; Backpack https://backpack.exchange/bp ; Official Backpack https://x.com/Backpack/status/2113643108449837214
#Backpack #BP #Web3 #Tokenomics $BP
For informational purposes only; this is not investment advice / NFA
Backpack (BP) tokenomics are once again drawing heightened discussion (2026-10-23): total supply of 1 billion tokens; 25% released at TGE (240 million for points users + 10 million for Mad Lads); the remaining 37.5% is allocated to the Pre-IPO milestone pool and 37.5% to the Post-IPO treasury (locked for ≥1 year after the IPO). The founder, executives, and investors receive zero tokens and zero warrants. Staking offers fee discounts; Pre-IPO tokens may be mapped to an equity pool of up to ~20%. Current price is about ~$0.99, with a staking rate of about ~56.4% (around 140.88 million tokens).
Key mechanics: This is a “zero insider allocation + dual-track milestone/treasury” structure, tying supply releases to post-listing governance rather than using the traditional linear unlock schedule for team/VC allocations. A staking rate above 50% suggests significant ties between circulating supply friction and fees, but the pace of milestone fulfillment and the details of equity mapping still need to be monitored.
Next things to watch: Whether the Pre-IPO milestone triggers are publicly disclosed and verifiable, and whether the staking rate stays above 50% in volatile markets.
Sources: Crypto Briefing https://cryptobriefing.com/backpack-founder-extreme-tokenomics-no-insider-tokens/ ; Backpack https://backpack.exchange/bp ; Official Backpack https://x.com/Backpack/status/2113643108449837214
#Backpack #BP #Web3 #Tokenomics $BP
For informational purposes only; this is not investment advice / NFA
Key mechanics: This is a “zero insider allocation + dual-track milestone/treasury” structure, tying supply releases to post-listing governance rather than using the traditional linear unlock schedule for team/VC allocations. A staking rate above 50% suggests significant ties between circulating supply friction and fees, but the pace of milestone fulfillment and the details of equity mapping still need to be monitored.
Next things to watch: Whether the Pre-IPO milestone triggers are publicly disclosed and verifiable, and whether the staking rate stays above 50% in volatile markets.
Sources: Crypto Briefing https://cryptobriefing.com/backpack-founder-extreme-tokenomics-no-insider-tokens/ ; Backpack https://backpack.exchange/bp ; Official Backpack https://x.com/Backpack/status/2113643108449837214
#Backpack #BP #Web3 #Tokenomics $BP
For informational purposes only; this is not investment advice / NFA
46

·
--
Bullish
My follow-up thoughts on Backpack! (It has 100x potential)
I've held it for almost a year and followed the project for two years. My average cost is 0.24. It peaked at 1.6, gaining nearly 800%, and there's still room for a 5x return. I shared this coin, BP, a long time ago—from completing tasks to earn the airdrop, to buying the dip after it was listed. I also staked my BP on the platform to get IPO equity; I'll hold it for a year and see how it goes. It's a compliant trading platform with a market cap of under 300 million. The token currently has relatively little utility, so there's plenty of room for speculation down the road. I'm looking at 3–5 USDT for the long term.#比特币突破8.3万美元 #bp #中国三季度经济增速加快至4.5%
My follow-up thoughts on Backpack! (It has 100x potential)
I've held it for almost a year and followed the project for two years. My average cost is 0.24. It peaked at 1.6, gaining nearly 800%, and there's still room for a 5x return. I shared this coin, BP, a long time ago—from completing tasks to earn the airdrop, to buying the dip after it was listed. I also staked my BP on the platform to get IPO equity; I'll hold it for a year and see how it goes. It's a compliant trading platform with a market cap of under 300 million. The token currently has relatively little utility, so there's plenty of room for speculation down the road. I'm looking at 3–5 USDT for the long term.#比特币突破8.3万美元 #bp #中国三季度经济增速加快至4.5%
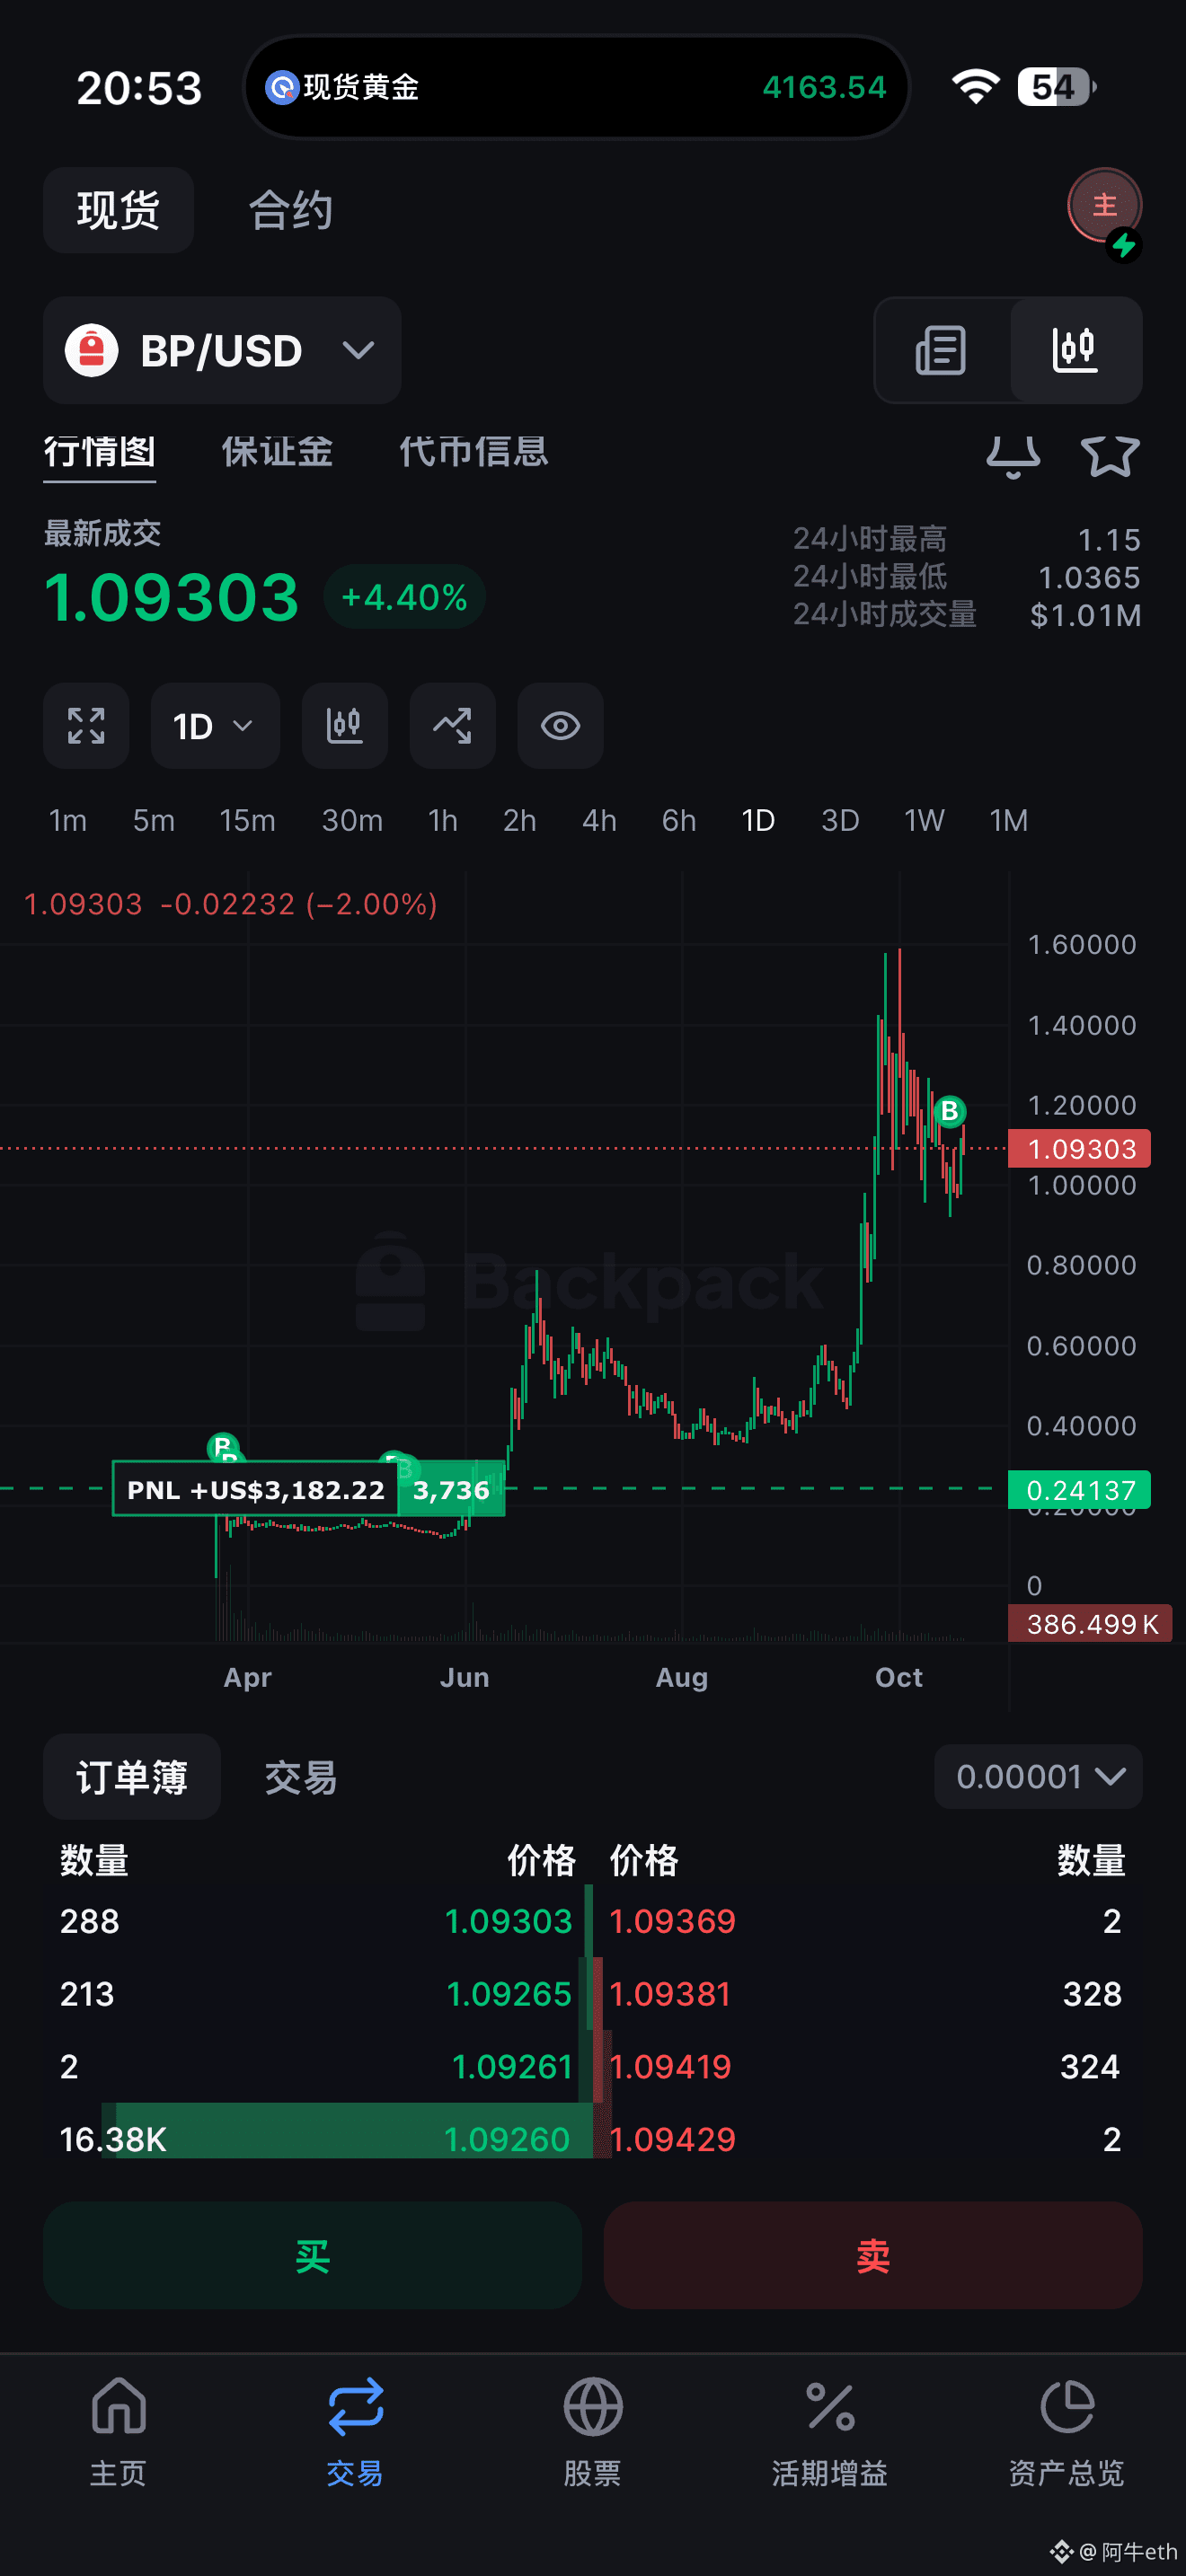
I've held it for almost a year and followed the project for two years. My average cost is 0.24. It peaked at 1.6, gaining nearly 800%, and there's still room for a 5x return. I shared this coin, BP, a long time ago—from completing tasks to earn the airdrop, to buying the dip after it was listed. I also staked my BP on the platform to get IPO equity; I'll hold it for a year and see how it goes. It's a compliant trading platform with a market cap of under 300 million. The token currently has relatively little utility, so there's plenty of room for speculation down the road. I'm looking at 3–5 USDT for the long term.#比特币突破8.3万美元 #bp #中国三季度经济增速加快至4.5%
2
679

·
--
🚨 $BP ROCKETS 22% AS SEC APPROVAL UNLOCKS REAL ON-CHAIN U.S. EQUITY TRADING! 📈
Entry: 1.479 ⚡
$BP just ripped over 22% in 24 hours, pressing right against the $1.50 psychological barrier. 📊 Traditional market infrastructure is officially bleeding into decentralized finance as regulatory approval enables 24/7 real U.S. stock ownership on-chain.
📌 This represents direct equity backing with continuous price discovery and instant stablecoin settlement, moving far beyond synthetic derivatives. 🌊 Capital flow is aggressively re-pricing the asset as order flow absorbs heavy spot bid momentum.
💬 Is this real-world asset shift the catalyst that sends $BP into price discovery, or do we pull back first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #RWA #DeFi #Breakout #Crypto
⚡ 💎
🚨 $BP ROCKETS 22% AS SEC APPROVAL UNLOCKS REAL ON-CHAIN U.S. EQUITY TRADING! 📈
Entry: 1.479 ⚡
$BP just ripped over 22% in 24 hours, pressing right against the $1.50 psychological barrier. 📊 Traditional market infrastructure is officially bleeding into decentralized finance as regulatory approval enables 24/7 real U.S. stock ownership on-chain.
📌 This represents direct equity backing with continuous price discovery and instant stablecoin settlement, moving far beyond synthetic derivatives. 🌊 Capital flow is aggressively re-pricing the asset as order flow absorbs heavy spot bid momentum.
💬 Is this real-world asset shift the catalyst that sends $BP into price discovery, or do we pull back first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #RWA #DeFi #Breakout #Crypto
⚡ 💎
Entry: 1.479 ⚡
$BP just ripped over 22% in 24 hours, pressing right against the $1.50 psychological barrier. 📊 Traditional market infrastructure is officially bleeding into decentralized finance as regulatory approval enables 24/7 real U.S. stock ownership on-chain.
📌 This represents direct equity backing with continuous price discovery and instant stablecoin settlement, moving far beyond synthetic derivatives. 🌊 Capital flow is aggressively re-pricing the asset as order flow absorbs heavy spot bid momentum.
💬 Is this real-world asset shift the catalyst that sends $BP into price discovery, or do we pull back first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #RWA #DeFi #Breakout #Crypto
⚡ 💎
1
9
·
--
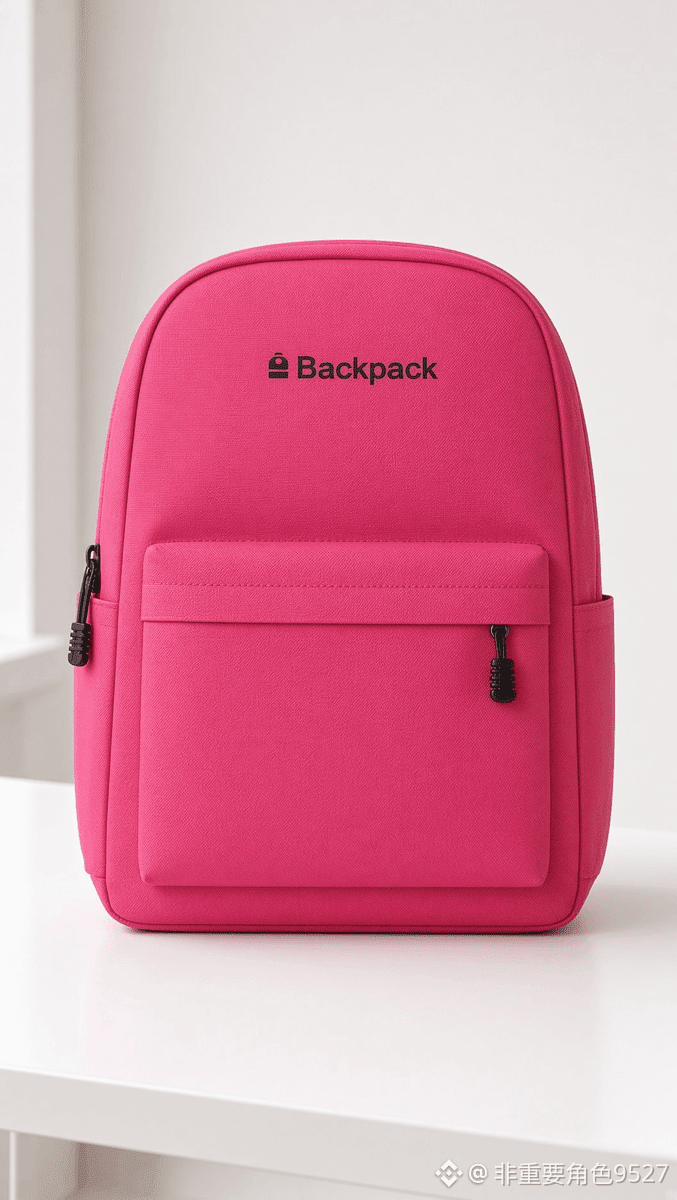
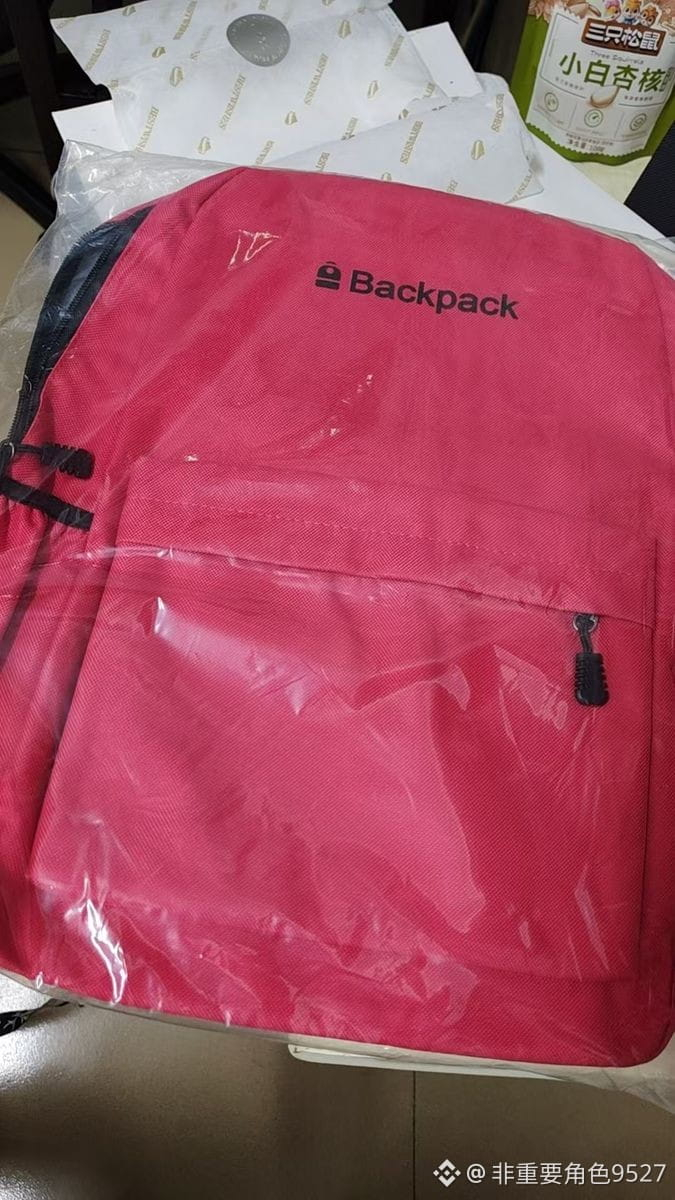
My backpack arrived!! Thank you so much
@CryptoPikachu @Miiiho420, you two lovely ladies 🥰
I never expected that casually making a short video would earn me such a beautiful piece of merch.
I’m not very good at taking photos, so I got AI to help touch them up. Hahaha
As soon as I opened the package, I put the backpack to the test. It’s smooth and sturdy! I’m planning to let my family use this merch backpack and turn them into a walking advertisement. It’s not that I won’t use it—I already have two backpacks in use.
👉 If you’d like to get some merch like this too, I think you could try making some images or videos for BP, or even volunteer with BP. Who knows, you might get a lovely surprise just like I did!
#BP #BP志愿者 solana:BPxxfRCXkUVhig4HS1Lh7kZqV6SPJhzfEk4x6fVBjPCy
Quoted @wen394428142129: $BP is taking off!! Chinese people really can fly 🤣🤣 @CryptoPikachu
My backpack arrived!! Thank you so much
@CryptoPikachu @Miiiho420, you two lovely ladies 🥰
I never expected that casually making a short video would earn me such a beautiful piece of merch.
I’m not very good at taking photos, so I got AI to help touch them up. Hahaha
As soon as I opened the package, I put the backpack to the test. It’s smooth and sturdy! I’m planning to let my family use this merch backpack and turn them into a walking advertisement. It’s not that I won’t use it—I already have two backpacks in use.
👉 If you’d like to get some merch like this too, I think you could try making some images or videos for BP, or even volunteer with BP. Who knows, you might get a lovely surprise just like I did!
#BP #BP志愿者 solana:BPxxfRCXkUVhig4HS1Lh7kZqV6SPJhzfEk4x6fVBjPCy
Quoted @wen394428142129: $BP is taking off!! Chinese people really can fly 🤣🤣 @CryptoPikachu
@CryptoPikachu @Miiiho420, you two lovely ladies 🥰
I never expected that casually making a short video would earn me such a beautiful piece of merch.
I’m not very good at taking photos, so I got AI to help touch them up. Hahaha
As soon as I opened the package, I put the backpack to the test. It’s smooth and sturdy! I’m planning to let my family use this merch backpack and turn them into a walking advertisement. It’s not that I won’t use it—I already have two backpacks in use.
👉 If you’d like to get some merch like this too, I think you could try making some images or videos for BP, or even volunteer with BP. Who knows, you might get a lovely surprise just like I did!
#BP #BP志愿者 solana:BPxxfRCXkUVhig4HS1Lh7kZqV6SPJhzfEk4x6fVBjPCy
Quoted @wen394428142129: $BP is taking off!! Chinese people really can fly 🤣🤣 @CryptoPikachu
14

⚡ $BP EXPLODES NEAR $1 AS TOKENIZED EQUITY NARRATIVE REWRITES VALUATION LOGIC! 📈
$BP pushed toward the $1 mark with a sharp 20% expansion, ignited by breakthrough developments in SEC tokenized stock trading approvals. ⚡ Smart capital is actively repricing this asset as 24/7 real equity settlement bridges traditional finance directly into on-chain liquidity. 📊
💡 With continuous price discovery and instant settlement taking center stage, order flow is reflecting a completely updated valuation framework. 🌊 Solid spot demand indicates buyers are aggressively positioning around this real-world asset catalyst. 💬 Do you expect $BP to cleanly flip $1 into support, or are you anticipating a retest first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #TokenizedStocks #RWA #Crypto #Breakout
⚡ 💎
⚡ $BP EXPLODES NEAR $1 AS TOKENIZED EQUITY NARRATIVE REWRITES VALUATION LOGIC! 📈
$BP pushed toward the $1 mark with a sharp 20% expansion, ignited by breakthrough developments in SEC tokenized stock trading approvals. ⚡ Smart capital is actively repricing this asset as 24/7 real equity settlement bridges traditional finance directly into on-chain liquidity. 📊
💡 With continuous price discovery and instant settlement taking center stage, order flow is reflecting a completely updated valuation framework. 🌊 Solid spot demand indicates buyers are aggressively positioning around this real-world asset catalyst. 💬 Do you expect $BP to cleanly flip $1 into support, or are you anticipating a retest first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #TokenizedStocks #RWA #Crypto #Breakout
⚡ 💎
$BP pushed toward the $1 mark with a sharp 20% expansion, ignited by breakthrough developments in SEC tokenized stock trading approvals. ⚡ Smart capital is actively repricing this asset as 24/7 real equity settlement bridges traditional finance directly into on-chain liquidity. 📊
💡 With continuous price discovery and instant settlement taking center stage, order flow is reflecting a completely updated valuation framework. 🌊 Solid spot demand indicates buyers are aggressively positioning around this real-world asset catalyst. 💬 Do you expect $BP to cleanly flip $1 into support, or are you anticipating a retest first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #TokenizedStocks #RWA #Crypto #Breakout
⚡ 💎
24

·
--
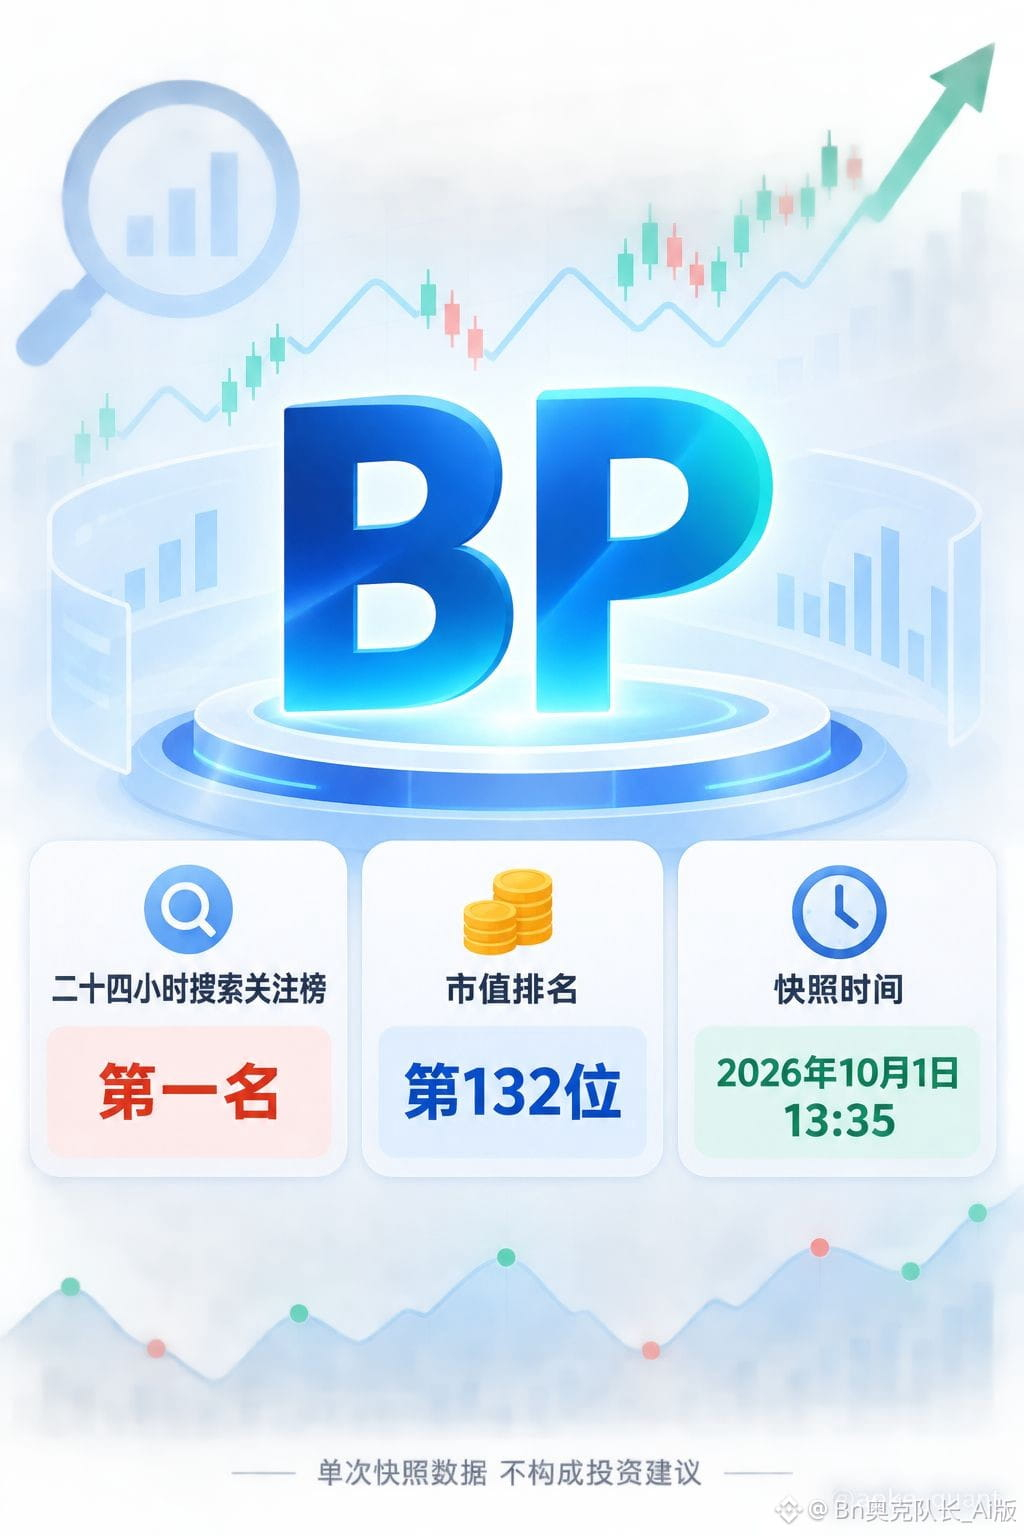
Backpack Token BP Ranks No. 1 on CoinGecko Search Watchlist
According to a CoinGecko snapshot of the past 24 hours’ search watchlist, published at 13:35 Beijing time on October 1, 2026, Backpack (BP) ranked first on the list. The same snapshot shows its market-cap rank was 132nd. The above are all the core verifiable facts for this update. First, clearly define the scope of the metrics. The search watchlist measures users’ search behavior and falls under the category of attention, not equivalent to buy orders, net capital inflows, or predictions of price trends. This dataset is a single snapshot, with no prior records in the same format available for comparison; therefore, it is not possible to determine whether BP’s attention is rising, falling, or staying flat, nor should the list position be directly interpreted as a market signal. In addition, this leaderboard is compiled by CoinGecko using a different methodology than exchanges’ trading volume or listing arrangements, so they cannot be mixed or used interchangeably. Next, address the unknowns. Currently, there is no event-driven evidence explaining the ranking’s cause. Any claim linking BP’s attention level to project progress, partnerships, or institutional actions lacks support and amounts to unverified speculation. Market-cap rank reflects scale, while the watchlist rank reflects search heat—these two dimensions cannot be inferred from one another. Three areas are worth monitoring next: (1) whether BP can maintain a top position consistently across subsequent snapshots to form a comparable time series; (2) whether search attention translates into verifiable changes in trading activity and liquidity; and (3) whether the project team releases announcements or data that can help explain changes in attention. Until the above information is supplemented, this ranking should be treated only as a record of attention—not as confirmation of a trend, and not as any investment advice.
#BP #BTC #ETH #BNB
Backpack Token BP Ranks No. 1 on CoinGecko Search Watchlist
According to a CoinGecko snapshot of the past 24 hours’ search watchlist, published at 13:35 Beijing time on October 1, 2026, Backpack (BP) ranked first on the list. The same snapshot shows its market-cap rank was 132nd. The above are all the core verifiable facts for this update. First, clearly define the scope of the metrics. The search watchlist measures users’ search behavior and falls under the category of attention, not equivalent to buy orders, net capital inflows, or predictions of price trends. This dataset is a single snapshot, with no prior records in the same format available for comparison; therefore, it is not possible to determine whether BP’s attention is rising, falling, or staying flat, nor should the list position be directly interpreted as a market signal. In addition, this leaderboard is compiled by CoinGecko using a different methodology than exchanges’ trading volume or listing arrangements, so they cannot be mixed or used interchangeably. Next, address the unknowns. Currently, there is no event-driven evidence explaining the ranking’s cause. Any claim linking BP’s attention level to project progress, partnerships, or institutional actions lacks support and amounts to unverified speculation. Market-cap rank reflects scale, while the watchlist rank reflects search heat—these two dimensions cannot be inferred from one another. Three areas are worth monitoring next: (1) whether BP can maintain a top position consistently across subsequent snapshots to form a comparable time series; (2) whether search attention translates into verifiable changes in trading activity and liquidity; and (3) whether the project team releases announcements or data that can help explain changes in attention. Until the above information is supplemented, this ranking should be treated only as a record of attention—not as confirmation of a trend, and not as any investment advice.
#BP #BTC #ETH #BNB
According to a CoinGecko snapshot of the past 24 hours’ search watchlist, published at 13:35 Beijing time on October 1, 2026, Backpack (BP) ranked first on the list. The same snapshot shows its market-cap rank was 132nd. The above are all the core verifiable facts for this update. First, clearly define the scope of the metrics. The search watchlist measures users’ search behavior and falls under the category of attention, not equivalent to buy orders, net capital inflows, or predictions of price trends. This dataset is a single snapshot, with no prior records in the same format available for comparison; therefore, it is not possible to determine whether BP’s attention is rising, falling, or staying flat, nor should the list position be directly interpreted as a market signal. In addition, this leaderboard is compiled by CoinGecko using a different methodology than exchanges’ trading volume or listing arrangements, so they cannot be mixed or used interchangeably. Next, address the unknowns. Currently, there is no event-driven evidence explaining the ranking’s cause. Any claim linking BP’s attention level to project progress, partnerships, or institutional actions lacks support and amounts to unverified speculation. Market-cap rank reflects scale, while the watchlist rank reflects search heat—these two dimensions cannot be inferred from one another. Three areas are worth monitoring next: (1) whether BP can maintain a top position consistently across subsequent snapshots to form a comparable time series; (2) whether search attention translates into verifiable changes in trading activity and liquidity; and (3) whether the project team releases announcements or data that can help explain changes in attention. Until the above information is supplemented, this ranking should be treated only as a record of attention—not as confirmation of a trend, and not as any investment advice.
#BP #BTC #ETH #BNB
449
💡 Useful information: BP unexpectedly surges, valuation reassessed thanks to a boost from U.S. stocks!
BP is drawing everyone’s attention after recording impressive growth over the past 24 hours. Let’s take a look at the numbers:
📈 Current price: 1.479 USD
🚀 Growth: 22.2% (over 24 hours)
🎯 Short-term peak: Almost hit the 1.5 USD mark
*Why does it matter?*
🔹 The main driver is that the SEC has allowed trading tokenized stock shares on on-chain platforms, opening a new era for real-world assets (RWA).
🔹 Backpack is pioneering a setup that lets international investors trade real U.S. stocks 24/7—not derivatives—improving transparency and liquidity.
🔹 This model completely changes BP’s valuation logic, turning it from a typical token into a bridge between traditional finance and crypto.
What do you think about the potential of putting stocks on-chain? Will BP keep breaking its highs?
👉 Get early market signals — Follow the Channel https://app.binance.com/uni-qr/cpro/Square-Creator-4a0f2008149d?l=en&r=BOZMO8A1
#BP #Backpack #RWA. $TRX
💡 Useful information: BP unexpectedly surges, valuation reassessed thanks to a boost from U.S. stocks!
BP is drawing everyone’s attention after recording impressive growth over the past 24 hours. Let’s take a look at the numbers:
📈 Current price: 1.479 USD
🚀 Growth: 22.2% (over 24 hours)
🎯 Short-term peak: Almost hit the 1.5 USD mark
*Why does it matter?*
🔹 The main driver is that the SEC has allowed trading tokenized stock shares on on-chain platforms, opening a new era for real-world assets (RWA).
🔹 Backpack is pioneering a setup that lets international investors trade real U.S. stocks 24/7—not derivatives—improving transparency and liquidity.
🔹 This model completely changes BP’s valuation logic, turning it from a typical token into a bridge between traditional finance and crypto.
What do you think about the potential of putting stocks on-chain? Will BP keep breaking its highs?
👉 Get early market signals — Follow the Channel https://app.binance.com/uni-qr/cpro/Square-Creator-4a0f2008149d?l=en&r=BOZMO8A1
#BP #Backpack #RWA. $TRX
BP is drawing everyone’s attention after recording impressive growth over the past 24 hours. Let’s take a look at the numbers:
📈 Current price: 1.479 USD
🚀 Growth: 22.2% (over 24 hours)
🎯 Short-term peak: Almost hit the 1.5 USD mark
*Why does it matter?*
🔹 The main driver is that the SEC has allowed trading tokenized stock shares on on-chain platforms, opening a new era for real-world assets (RWA).
🔹 Backpack is pioneering a setup that lets international investors trade real U.S. stocks 24/7—not derivatives—improving transparency and liquidity.
🔹 This model completely changes BP’s valuation logic, turning it from a typical token into a bridge between traditional finance and crypto.
What do you think about the potential of putting stocks on-chain? Will BP keep breaking its highs?
👉 Get early market signals — Follow the Channel https://app.binance.com/uni-qr/cpro/Square-Creator-4a0f2008149d?l=en&r=BOZMO8A1
#BP #Backpack #RWA. $TRX
124
·
--
Article
BP — Knocking on the Door of a Major Breakout💫💥🤟Hey everyone :-D
June 14, 2026
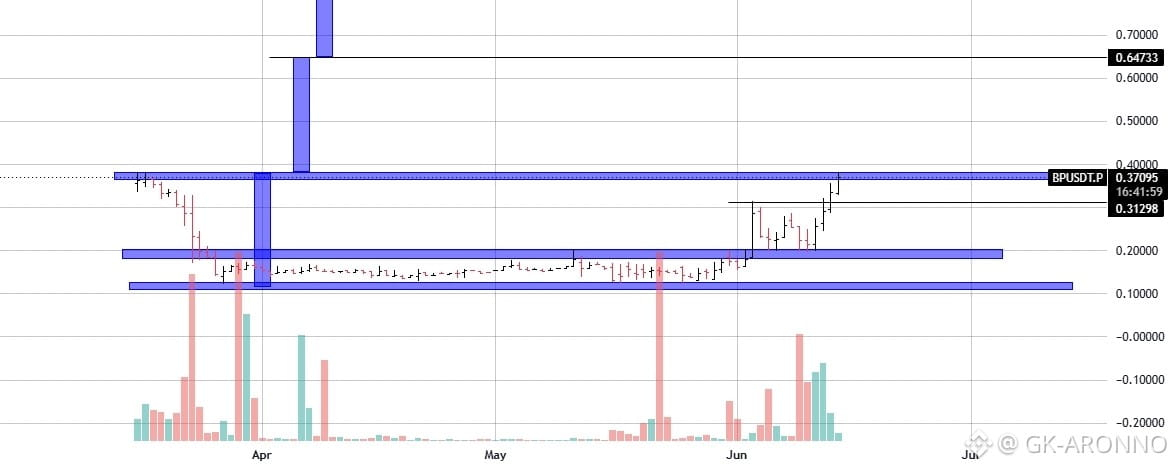
🚀 BP — Knocking on the Door of a Major Breakout
BP is approaching one of the most important technical levels on its chart after spending months building a broad accumulation structure.
The recent recovery has been aggressive, and price is now pressing directly into a key resistance zone that could determine the next major leg higher.
🧠 Stage 1 → Stage 2 Transition
BP is showing a classic trend-development structure:
✔ Long accumulation → completed
✔ Higher lows → established
✔ Resistance retest → underway
✔ Volume expansion → returning
After finding support around the $0.12–$0.20 range, buyers have steadily regained control and pushed price back toward the upper boundary of the range.
🔍 Current Setup
Price: ~$0.37
BP is now:
Testing a major resistance zone around $0.37
Printing a strong recovery from recent lows
Building momentum with improving volume
The current move suggests demand is beginning to overwhelm supply at a level that has historically acted as a significant barrier.
🧱 Key Levels
Support:
$0.31 → short-term support
$0.20 → major accumulation zone
$0.12 → macro base
Resistance / Targets:
$0.37 → immediate breakout level
$0.65 → first expansion target
$0.91 → major liquidity objective
🎯 Scenario
✅ Bullish Case (Stage 2 Confirmation)
If BP:
Breaks and holds above $0.37
Turns resistance into support
Continues attracting volume
→ A move toward $0.65 becomes increasingly likely.
A successful breakout would confirm a transition from range-bound trading into a fully developed trend structure.
⚠️ Weak Case
Failure to clear resistance:
→ Consolidation below the breakout level
→ Additional accumulation before another attempt
(No meaningful structural damage unless the $0.20 support zone fails)
🚀 Final Thought
BP has spent months building a foundation while volatility compressed.
Now it is testing the ceiling of that structure.
👉 The market has already shown accumulation.
The next question is whether it can convert accumulation into expansion.
If the breakout confirms:
➡ accumulation → breakout → trend expansion
And that's typically where the strongest repricing phases begin.
Good trading!
#BP
BP — Knocking on the Door of a Major Breakout💫💥🤟
Hey everyone :-D
June 14, 2026
🚀 BP — Knocking on the Door of a Major Breakout
BP is approaching one of the most important technical levels on its chart after spending months building a broad accumulation structure.
The recent recovery has been aggressive, and price is now pressing directly into a key resistance zone that could determine the next major leg higher.
🧠 Stage 1 → Stage 2 Transition
BP is showing a classic trend-development structure:
✔ Long accumulation → completed
✔ Higher lows → established
✔ Resistance retest → underway
✔ Volume expansion → returning
After finding support around the $0.12–$0.20 range, buyers have steadily regained control and pushed price back toward the upper boundary of the range.
🔍 Current Setup
Price: ~$0.37
BP is now:
Testing a major resistance zone around $0.37
Printing a strong recovery from recent lows
Building momentum with improving volume
The current move suggests demand is beginning to overwhelm supply at a level that has historically acted as a significant barrier.
🧱 Key Levels
Support:
$0.31 → short-term support
$0.20 → major accumulation zone
$0.12 → macro base
Resistance / Targets:
$0.37 → immediate breakout level
$0.65 → first expansion target
$0.91 → major liquidity objective
🎯 Scenario
✅ Bullish Case (Stage 2 Confirmation)
If BP:
Breaks and holds above $0.37
Turns resistance into support
Continues attracting volume
→ A move toward $0.65 becomes increasingly likely.
A successful breakout would confirm a transition from range-bound trading into a fully developed trend structure.
⚠️ Weak Case
Failure to clear resistance:
→ Consolidation below the breakout level
→ Additional accumulation before another attempt
(No meaningful structural damage unless the $0.20 support zone fails)
🚀 Final Thought
BP has spent months building a foundation while volatility compressed.
Now it is testing the ceiling of that structure.
👉 The market has already shown accumulation.
The next question is whether it can convert accumulation into expansion.
If the breakout confirms:
➡ accumulation → breakout → trend expansion
And that's typically where the strongest repricing phases begin.
Good trading!
#BP
June 14, 2026
🚀 BP — Knocking on the Door of a Major Breakout
BP is approaching one of the most important technical levels on its chart after spending months building a broad accumulation structure.
The recent recovery has been aggressive, and price is now pressing directly into a key resistance zone that could determine the next major leg higher.
🧠 Stage 1 → Stage 2 Transition
BP is showing a classic trend-development structure:
✔ Long accumulation → completed
✔ Higher lows → established
✔ Resistance retest → underway
✔ Volume expansion → returning
After finding support around the $0.12–$0.20 range, buyers have steadily regained control and pushed price back toward the upper boundary of the range.
🔍 Current Setup
Price: ~$0.37
BP is now:
Testing a major resistance zone around $0.37
Printing a strong recovery from recent lows
Building momentum with improving volume
The current move suggests demand is beginning to overwhelm supply at a level that has historically acted as a significant barrier.
🧱 Key Levels
Support:
$0.31 → short-term support
$0.20 → major accumulation zone
$0.12 → macro base
Resistance / Targets:
$0.37 → immediate breakout level
$0.65 → first expansion target
$0.91 → major liquidity objective
🎯 Scenario
✅ Bullish Case (Stage 2 Confirmation)
If BP:
Breaks and holds above $0.37
Turns resistance into support
Continues attracting volume
→ A move toward $0.65 becomes increasingly likely.
A successful breakout would confirm a transition from range-bound trading into a fully developed trend structure.
⚠️ Weak Case
Failure to clear resistance:
→ Consolidation below the breakout level
→ Additional accumulation before another attempt
(No meaningful structural damage unless the $0.20 support zone fails)
🚀 Final Thought
BP has spent months building a foundation while volatility compressed.
Now it is testing the ceiling of that structure.
👉 The market has already shown accumulation.
The next question is whether it can convert accumulation into expansion.
If the breakout confirms:
➡ accumulation → breakout → trend expansion
And that's typically where the strongest repricing phases begin.
Good trading!
#BP
216

·
--
🚀 $BP SKYROCKETS 13% IN 24H – LIQUIDITY SWEEP IGNITES RALLY! 🟢
Entry: $0.5893 ⚡
📊 The 13% surge in a single day aligns with a fresh liquidity grab, confirming smart‑money accumulation around the $0.59 zone. 🦈 With a 30‑day gain of 44.2% and an FDV tightening to $587.4 M, the order block is now a magnet for aggressive buyers. 💡 Volume spikes on the 4‑hour chart suggest the next upward thrust could test the $0.65 resistance, while the market cap’s $146.9 M lift reinforces the bullish narrative.
💬 How are you positioning as $BP rides this institutional wave? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #LongSetup #Momentum #Crypto
🔥 💎
🚀 $BP SKYROCKETS 13% IN 24H – LIQUIDITY SWEEP IGNITES RALLY! 🟢
Entry: $0.5893 ⚡
📊 The 13% surge in a single day aligns with a fresh liquidity grab, confirming smart‑money accumulation around the $0.59 zone. 🦈 With a 30‑day gain of 44.2% and an FDV tightening to $587.4 M, the order block is now a magnet for aggressive buyers. 💡 Volume spikes on the 4‑hour chart suggest the next upward thrust could test the $0.65 resistance, while the market cap’s $146.9 M lift reinforces the bullish narrative.
💬 How are you positioning as $BP rides this institutional wave? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #LongSetup #Momentum #Crypto
🔥 💎
Entry: $0.5893 ⚡
📊 The 13% surge in a single day aligns with a fresh liquidity grab, confirming smart‑money accumulation around the $0.59 zone. 🦈 With a 30‑day gain of 44.2% and an FDV tightening to $587.4 M, the order block is now a magnet for aggressive buyers. 💡 Volume spikes on the 4‑hour chart suggest the next upward thrust could test the $0.65 resistance, while the market cap’s $146.9 M lift reinforces the bullish narrative.
💬 How are you positioning as $BP rides this institutional wave? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #LongSetup #Momentum #Crypto
🔥 💎
13

🚀 $BP BREAKS ATH WITH 48% RALLY AS TOKENIZED US STOCKS RE-RATE THE NARRATIVE! 💥
📌 $BP just blasted through all-time highs to touch $1.277, driven by a massive 48% vertical expansion over the last 24 hours. Buyers are aggressively front-running a fundamental paradigm shift as regulatory momentum opens the doors for 24/7 real U.S. equity trading on-chain. 📈
💡 Moving beyond synthetic derivatives into real equity ownership with instant fiat and stablecoin settlement changes the valuation framework entirely. 🌊 Smart money is locking into this institutional merge as real-world equity volume meets crypto liquidity. 💬 Is $BP laying the blueprint for the next major RWA cycle, or are you waiting for a retest before bidding? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #RWA #Altcoins #Breakout #Crypto
🎯 🦈
🚀 $BP BREAKS ATH WITH 48% RALLY AS TOKENIZED US STOCKS RE-RATE THE NARRATIVE! 💥
📌 $BP just blasted through all-time highs to touch $1.277, driven by a massive 48% vertical expansion over the last 24 hours. Buyers are aggressively front-running a fundamental paradigm shift as regulatory momentum opens the doors for 24/7 real U.S. equity trading on-chain. 📈
💡 Moving beyond synthetic derivatives into real equity ownership with instant fiat and stablecoin settlement changes the valuation framework entirely. 🌊 Smart money is locking into this institutional merge as real-world equity volume meets crypto liquidity. 💬 Is $BP laying the blueprint for the next major RWA cycle, or are you waiting for a retest before bidding? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #RWA #Altcoins #Breakout #Crypto
🎯 🦈
📌 $BP just blasted through all-time highs to touch $1.277, driven by a massive 48% vertical expansion over the last 24 hours. Buyers are aggressively front-running a fundamental paradigm shift as regulatory momentum opens the doors for 24/7 real U.S. equity trading on-chain. 📈
💡 Moving beyond synthetic derivatives into real equity ownership with instant fiat and stablecoin settlement changes the valuation framework entirely. 🌊 Smart money is locking into this institutional merge as real-world equity volume meets crypto liquidity. 💬 Is $BP laying the blueprint for the next major RWA cycle, or are you waiting for a retest before bidding? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #RWA #Altcoins #Breakout #Crypto
🎯 🦈
21
·
--
$BP has been holding above $0.70 for several consecutive days, and the short-term sentiment is definitely heating up. However, with small-cap assets, the core risks become more pronounced: thin liquidity and insufficient order book depth can amplify volatility with just a small amount of funds. If the narrative primarily relies on Backpack / memecoin hype, once the heat dies down, the pullback speed is often quicker than the rise.
In this kind of market, it's better to focus on trading volume, position distribution, and unlock/selling pressure changes, rather than just looking for price breakouts. Before chasing the pump, think clearly: are you trading the trend, or just grabbing the last baton?
#Backpack #memecoin #BP
$BP has been holding above $0.70 for several consecutive days, and the short-term sentiment is definitely heating up. However, with small-cap assets, the core risks become more pronounced: thin liquidity and insufficient order book depth can amplify volatility with just a small amount of funds. If the narrative primarily relies on Backpack / memecoin hype, once the heat dies down, the pullback speed is often quicker than the rise.
In this kind of market, it's better to focus on trading volume, position distribution, and unlock/selling pressure changes, rather than just looking for price breakouts. Before chasing the pump, think clearly: are you trading the trend, or just grabbing the last baton?
#Backpack #memecoin #BP
In this kind of market, it's better to focus on trading volume, position distribution, and unlock/selling pressure changes, rather than just looking for price breakouts. Before chasing the pump, think clearly: are you trading the trend, or just grabbing the last baton?
#Backpack #memecoin #BP
22

🚨 $BP ACCELERATES TO NEW ALL-TIME HIGH AS REAL-WORLD ASSET VALUATION SHIFTS! 💥
$BP delivered a violent expansion leg, printing a 48% daily push to hit a new peak of $1.277. 📊 Smart money is clearly pricing in a structural re-valuation following protocol developments around tokenized U.S. stock infrastructure.
By bridging continuous 24/7 equity settlement with traditional liquidity depth, the underlying model captures genuine institutional order flow. 💡 This continuous price discovery mechanism is driving heavy expansion past prior high-timeframe resistance. 💬 Are you treating this ATH expansion as a sustained structural trend or waiting for a Fair Value Gap retest? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Altcoins #RWA #Breakout #Crypto
🔥 🎯
🚨 $BP ACCELERATES TO NEW ALL-TIME HIGH AS REAL-WORLD ASSET VALUATION SHIFTS! 💥
$BP delivered a violent expansion leg, printing a 48% daily push to hit a new peak of $1.277. 📊 Smart money is clearly pricing in a structural re-valuation following protocol developments around tokenized U.S. stock infrastructure.
By bridging continuous 24/7 equity settlement with traditional liquidity depth, the underlying model captures genuine institutional order flow. 💡 This continuous price discovery mechanism is driving heavy expansion past prior high-timeframe resistance. 💬 Are you treating this ATH expansion as a sustained structural trend or waiting for a Fair Value Gap retest? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Altcoins #RWA #Breakout #Crypto
🔥 🎯
$BP delivered a violent expansion leg, printing a 48% daily push to hit a new peak of $1.277. 📊 Smart money is clearly pricing in a structural re-valuation following protocol developments around tokenized U.S. stock infrastructure.
By bridging continuous 24/7 equity settlement with traditional liquidity depth, the underlying model captures genuine institutional order flow. 💡 This continuous price discovery mechanism is driving heavy expansion past prior high-timeframe resistance. 💬 Are you treating this ATH expansion as a sustained structural trend or waiting for a Fair Value Gap retest? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Altcoins #RWA #Breakout #Crypto
🔥 🎯
1
18

⚡ $BP EXPANDS PAST $0.53 AS ON-CHAIN EQUITY TOKENIZATION GETS REGULATORY BACKING! 💥
📌 Market structure shifted fast as $BP ripped past $0.53 with an 18.4% single-day push following green lights for on-chain equity trading. Order flow confirms buyers bidding aggressively into 24/7 continuous settlement infrastructure. 📊
⚡ Traditional order books are connecting directly to blockchain rails, bypassing legacy market hours. By offering genuine equity backing rather than synthetic derivatives, the platform is absorbing real liquidity with instant stablecoin settlement. 💡
💬 Will equity tokenization become the dominant market narrative this quarter, or are you looking elsewhere? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Tokenization #RWA #Crypto
🔥 💎
⚡ $BP EXPANDS PAST $0.53 AS ON-CHAIN EQUITY TOKENIZATION GETS REGULATORY BACKING! 💥
📌 Market structure shifted fast as $BP ripped past $0.53 with an 18.4% single-day push following green lights for on-chain equity trading. Order flow confirms buyers bidding aggressively into 24/7 continuous settlement infrastructure. 📊
⚡ Traditional order books are connecting directly to blockchain rails, bypassing legacy market hours. By offering genuine equity backing rather than synthetic derivatives, the platform is absorbing real liquidity with instant stablecoin settlement. 💡
💬 Will equity tokenization become the dominant market narrative this quarter, or are you looking elsewhere? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Tokenization #RWA #Crypto
🔥 💎
📌 Market structure shifted fast as $BP ripped past $0.53 with an 18.4% single-day push following green lights for on-chain equity trading. Order flow confirms buyers bidding aggressively into 24/7 continuous settlement infrastructure. 📊
⚡ Traditional order books are connecting directly to blockchain rails, bypassing legacy market hours. By offering genuine equity backing rather than synthetic derivatives, the platform is absorbing real liquidity with instant stablecoin settlement. 💡
💬 Will equity tokenization become the dominant market narrative this quarter, or are you looking elsewhere? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Tokenization #RWA #Crypto
🔥 💎
90

·
--
Bearish
⁉️BREAKING: Energy giant $BP is reportedly in advanced negotiations to sell its Lightsource solar business to a consortium backed by Kuwait's sovereign wealth fund, according to Reuters.
The leading bidders include Qualitas Energy and Wren House (the infrastructure arm of the Kuwait Investment Authority). The move highlights BP's strategic shift back toward its core oil and gas business as it aims to reduce debt, strengthen cash flow, and maximize shareholder returns.
Will this mark a major turning point in BP's long-term energy strategy?
#BP #StockMarket #Energy #Investing #BreakingNews $BP.US
{stock_us}(BP.US)
⁉️BREAKING: Energy giant $BP is reportedly in advanced negotiations to sell its Lightsource solar business to a consortium backed by Kuwait's sovereign wealth fund, according to Reuters.
The leading bidders include Qualitas Energy and Wren House (the infrastructure arm of the Kuwait Investment Authority). The move highlights BP's strategic shift back toward its core oil and gas business as it aims to reduce debt, strengthen cash flow, and maximize shareholder returns.
Will this mark a major turning point in BP's long-term energy strategy?
#BP #StockMarket #Energy #Investing #BreakingNews $BP.US
The leading bidders include Qualitas Energy and Wren House (the infrastructure arm of the Kuwait Investment Authority). The move highlights BP's strategic shift back toward its core oil and gas business as it aims to reduce debt, strengthen cash flow, and maximize shareholder returns.
Will this mark a major turning point in BP's long-term energy strategy?
#BP #StockMarket #Energy #Investing #BreakingNews $BP.US
BPUS-0.92%
1
127
·
--
Bullish
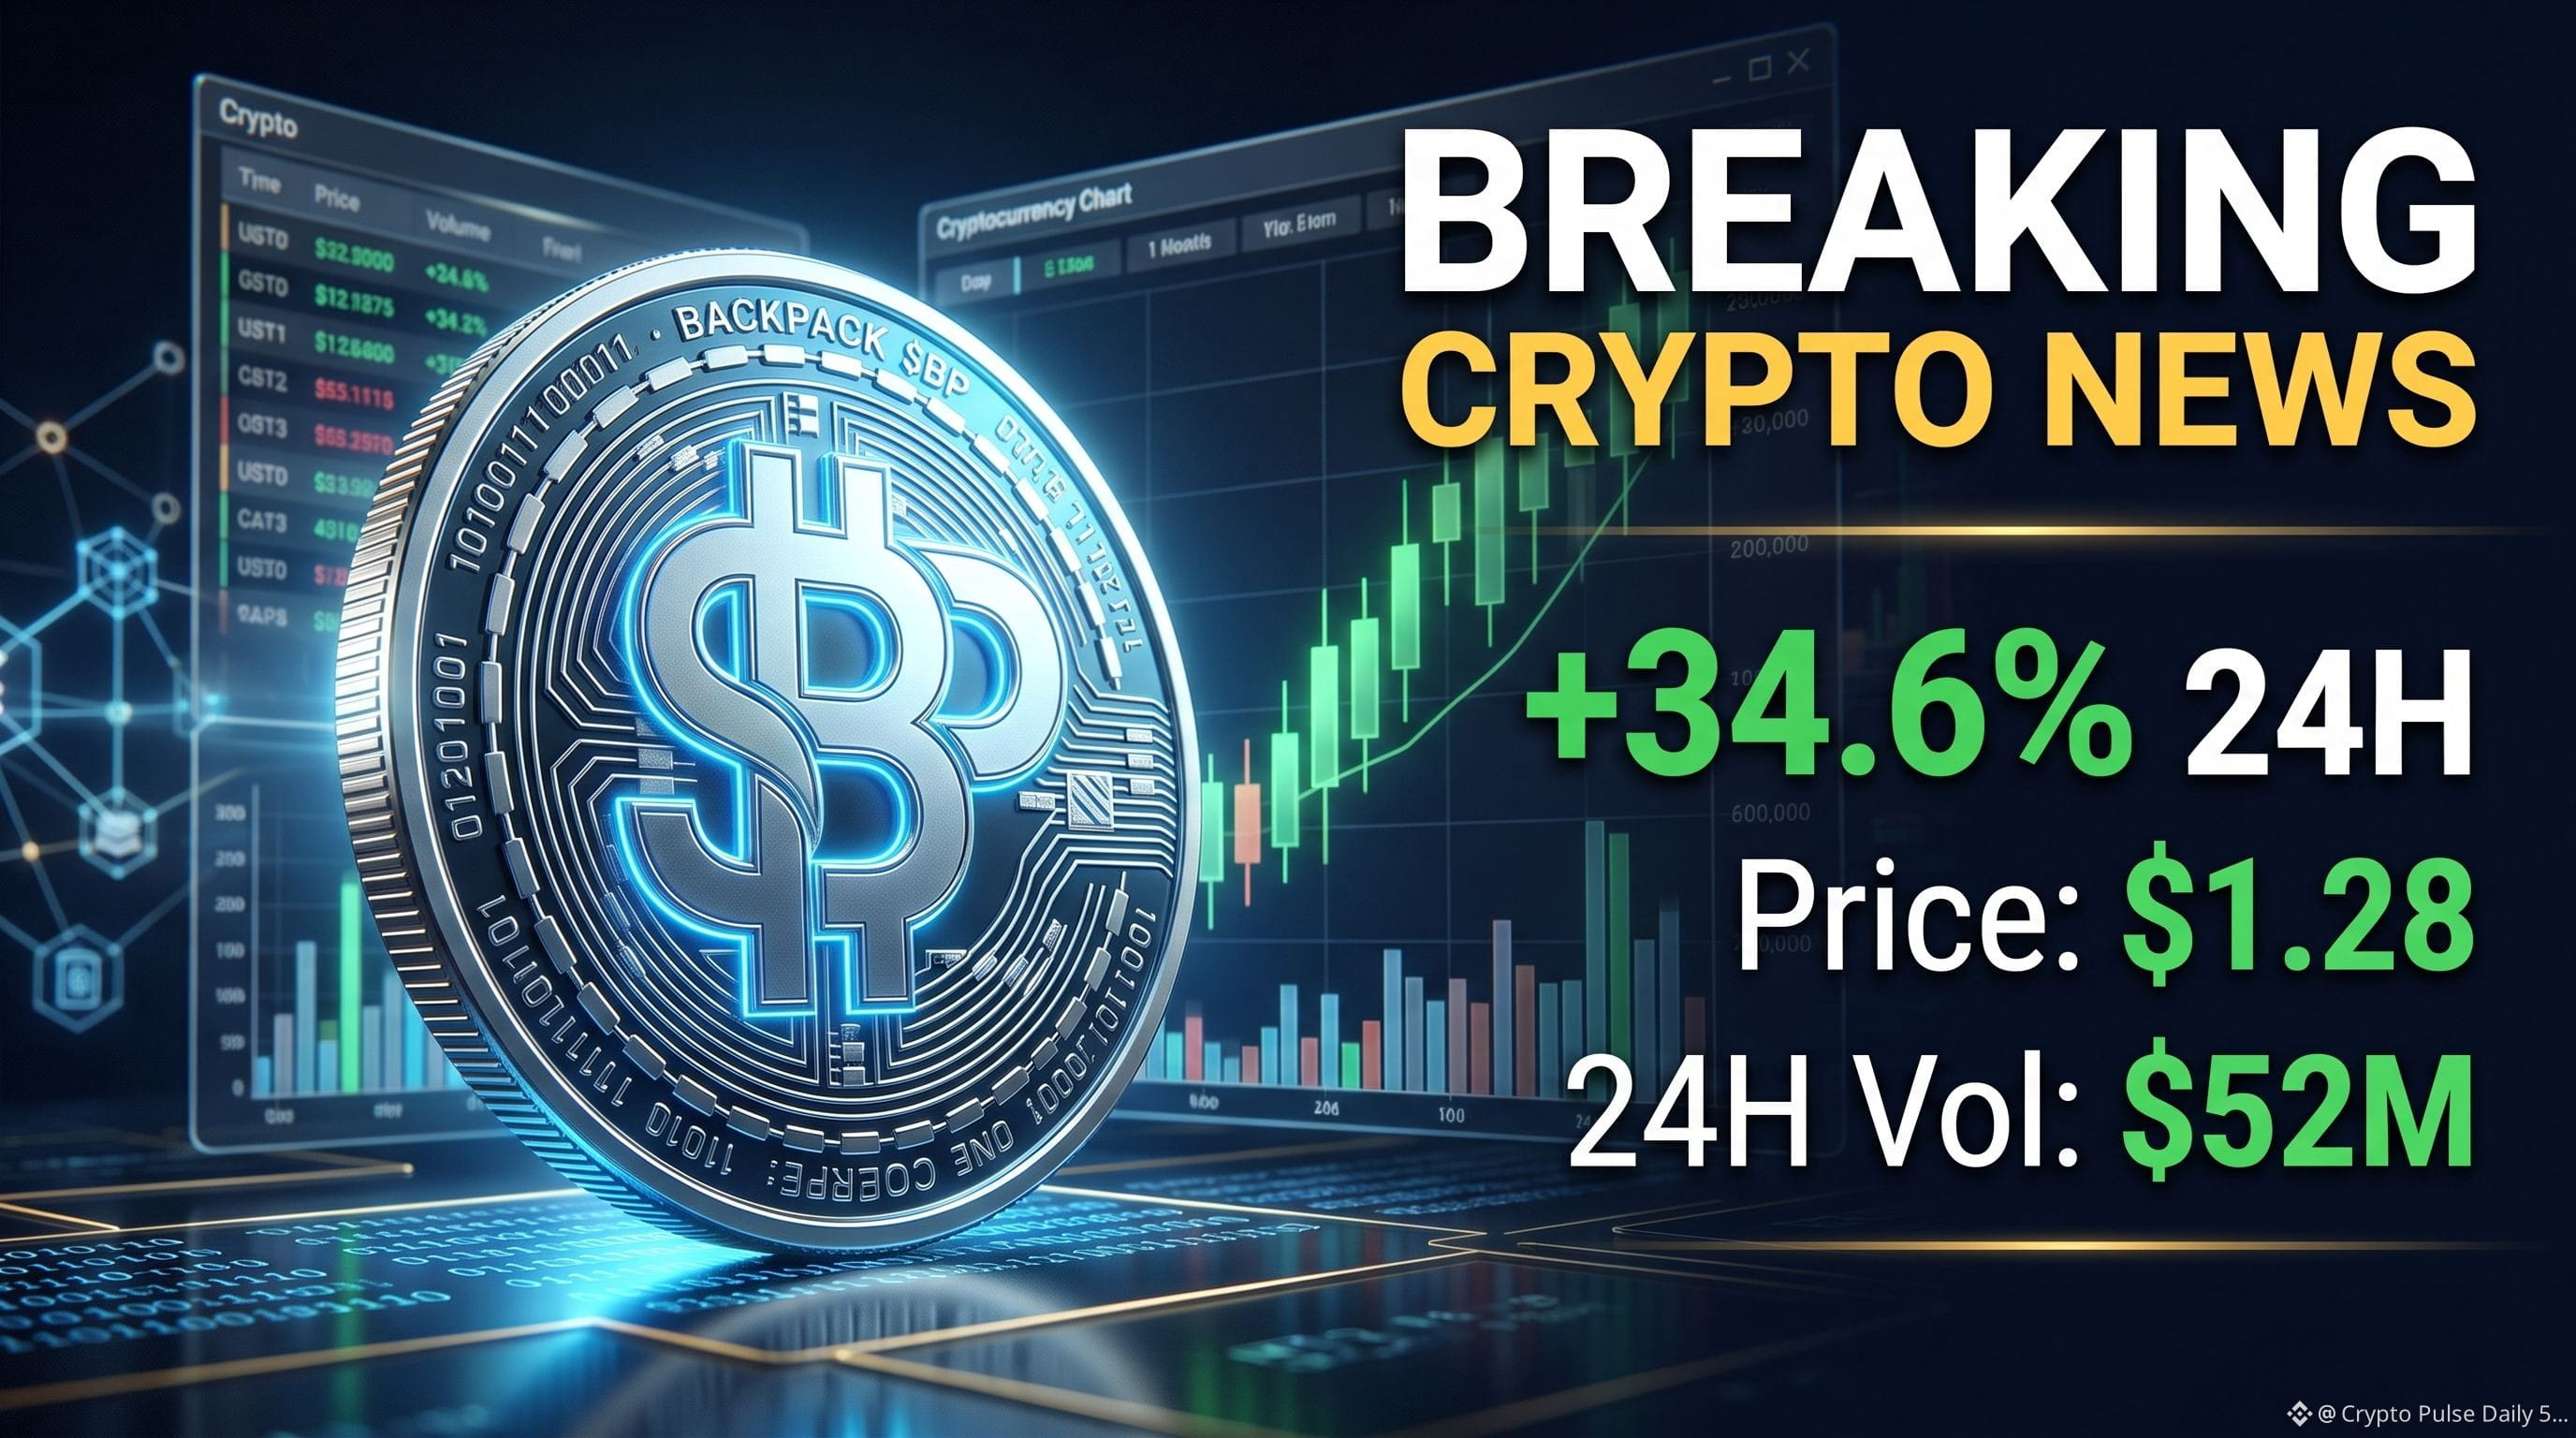
🚨 BACKPACK ($BP) LEADS TODAY’S CRYPTO GAINERS 🔥
Backpack ($BP) is currently showing the strongest 24-hour move on the latest gainer data, up around 34.6%.
The token is trading near $1.28, with roughly $52M in reported 24-hour volume.
BP is now one of the major movers on the crypto leaderboard, putting fresh attention on the token and its market activity.
#BP #backpack #CryptoNewss #Altcoin #CryptoMarketMoves
$BP.US
{stock_us}(BP.US)
🚨 BACKPACK ($BP) LEADS TODAY’S CRYPTO GAINERS 🔥
Backpack ($BP) is currently showing the strongest 24-hour move on the latest gainer data, up around 34.6%.
The token is trading near $1.28, with roughly $52M in reported 24-hour volume.
BP is now one of the major movers on the crypto leaderboard, putting fresh attention on the token and its market activity.
#BP #backpack #CryptoNewss #Altcoin #CryptoMarketMoves
$BP.US
Backpack ($BP) is currently showing the strongest 24-hour move on the latest gainer data, up around 34.6%.
The token is trading near $1.28, with roughly $52M in reported 24-hour volume.
BP is now one of the major movers on the crypto leaderboard, putting fresh attention on the token and its market activity.
#BP #backpack #CryptoNewss #Altcoin #CryptoMarketMoves
$BP.US
BPUS-0.92%
134

·
--
$BP SMASHES NEW ALL-TIME HIGH AS REAL-WORLD EQUITY TOKENIZATION DRIVES BID VELOCITY! 🚀 💥
$BP recently ripped to a fresh all-time high of $1.42 before consolidating near $1.297, posting a clean 9.2% daily gain as institutional interest surges. 📈 Price action is responding aggressively to regulatory tailwinds following SEC approval for limited on-chain trading of real tokenized equities. ⚡
By granting continuous 24/7 access to actual U.S. stock ownership with instant fiat settlement rather than synthetic derivatives, the platform is tapping into a massive traditional finance liquidity bridge. 📊 Order flow shows smart capital actively absorbing pullbacks as this structural narrative unfolds. 💡
💬 Do you see continuous equity settlement as the primary driver for platform token valuations moving forward? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Altcoins #RWA #Breakout
🔥 ⚡
$BP SMASHES NEW ALL-TIME HIGH AS REAL-WORLD EQUITY TOKENIZATION DRIVES BID VELOCITY! 🚀 💥
$BP recently ripped to a fresh all-time high of $1.42 before consolidating near $1.297, posting a clean 9.2% daily gain as institutional interest surges. 📈 Price action is responding aggressively to regulatory tailwinds following SEC approval for limited on-chain trading of real tokenized equities. ⚡
By granting continuous 24/7 access to actual U.S. stock ownership with instant fiat settlement rather than synthetic derivatives, the platform is tapping into a massive traditional finance liquidity bridge. 📊 Order flow shows smart capital actively absorbing pullbacks as this structural narrative unfolds. 💡
💬 Do you see continuous equity settlement as the primary driver for platform token valuations moving forward? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Altcoins #RWA #Breakout
🔥 ⚡
$BP recently ripped to a fresh all-time high of $1.42 before consolidating near $1.297, posting a clean 9.2% daily gain as institutional interest surges. 📈 Price action is responding aggressively to regulatory tailwinds following SEC approval for limited on-chain trading of real tokenized equities. ⚡
By granting continuous 24/7 access to actual U.S. stock ownership with instant fiat settlement rather than synthetic derivatives, the platform is tapping into a massive traditional finance liquidity bridge. 📊 Order flow shows smart capital actively absorbing pullbacks as this structural narrative unfolds. 💡
💬 Do you see continuous equity settlement as the primary driver for platform token valuations moving forward? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Altcoins #RWA #Breakout
🔥 ⚡
24
🚨 $BP IGNITES A 28% IMPULSE EXPANSION AS LIQUIDITY ACCELERATES THROUGH KEY RESISTANCE! 📈
Smart money momentum has driven $BP through the $0.74 inefficiency barrier, registering an aggressive 28% expansion over 24 hours to hold near $0.738. 📊 This rapid volume influx reflects institutional repricing and a strong structural reclaim above prior high-timeframe pivot zones.
The sharp velocity suggests buy-side liquidity sweeping overhead levels while establishing a fresh high-timeframe demand baseline. 🔍 Traders should monitor whether order flow consolidates above this reclaimed handle or seeks a fair value gap fill before continuation. 💬 Are you treating this surge as structural continuation or waiting for a retest of demand? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Crypto #Breakout #Altcoins
⚡ 📊
🚨 $BP IGNITES A 28% IMPULSE EXPANSION AS LIQUIDITY ACCELERATES THROUGH KEY RESISTANCE! 📈
Smart money momentum has driven $BP through the $0.74 inefficiency barrier, registering an aggressive 28% expansion over 24 hours to hold near $0.738. 📊 This rapid volume influx reflects institutional repricing and a strong structural reclaim above prior high-timeframe pivot zones.
The sharp velocity suggests buy-side liquidity sweeping overhead levels while establishing a fresh high-timeframe demand baseline. 🔍 Traders should monitor whether order flow consolidates above this reclaimed handle or seeks a fair value gap fill before continuation. 💬 Are you treating this surge as structural continuation or waiting for a retest of demand? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Crypto #Breakout #Altcoins
⚡ 📊
Smart money momentum has driven $BP through the $0.74 inefficiency barrier, registering an aggressive 28% expansion over 24 hours to hold near $0.738. 📊 This rapid volume influx reflects institutional repricing and a strong structural reclaim above prior high-timeframe pivot zones.
The sharp velocity suggests buy-side liquidity sweeping overhead levels while establishing a fresh high-timeframe demand baseline. 🔍 Traders should monitor whether order flow consolidates above this reclaimed handle or seeks a fair value gap fill before continuation. 💬 Are you treating this surge as structural continuation or waiting for a retest of demand? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Crypto #Breakout #Altcoins
⚡ 📊
21
⚡ $BP EXPLODES 25% TO STRIKE $0.91 AS BULLISH MOMENTUM RIPS THROUGH RESISTANCE! 💥
📌 Momentum buyers just pushed $BP through $0.91 in an aggressive 25% single-day expansion, driving market capitalization up to $227.3 million. 📊 High-velocity order flow is now consolidating around $0.9089 as early breakout traders digest the move.
⚡ This price zone represents a critical battleground where buyers are actively absorbing profit-taking following the initial impulse. 🔍 Holding above $0.90 keeps the market structure intact for another potential liquidity sweep higher. 💬 Are you bidding this consolidation zone or waiting for a deeper retest before entering? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Breakout #Altcoins #Crypto
🔥 💎
⚡ $BP EXPLODES 25% TO STRIKE $0.91 AS BULLISH MOMENTUM RIPS THROUGH RESISTANCE! 💥
📌 Momentum buyers just pushed $BP through $0.91 in an aggressive 25% single-day expansion, driving market capitalization up to $227.3 million. 📊 High-velocity order flow is now consolidating around $0.9089 as early breakout traders digest the move.
⚡ This price zone represents a critical battleground where buyers are actively absorbing profit-taking following the initial impulse. 🔍 Holding above $0.90 keeps the market structure intact for another potential liquidity sweep higher. 💬 Are you bidding this consolidation zone or waiting for a deeper retest before entering? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Breakout #Altcoins #Crypto
🔥 💎
📌 Momentum buyers just pushed $BP through $0.91 in an aggressive 25% single-day expansion, driving market capitalization up to $227.3 million. 📊 High-velocity order flow is now consolidating around $0.9089 as early breakout traders digest the move.
⚡ This price zone represents a critical battleground where buyers are actively absorbing profit-taking following the initial impulse. 🔍 Holding above $0.90 keeps the market structure intact for another potential liquidity sweep higher. 💬 Are you bidding this consolidation zone or waiting for a deeper retest before entering? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BP #Breakout #Altcoins #Crypto
🔥 💎
29
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceIncidentReport
116 views
36 Discussing
2
#BinanceReopensWithdrawalsForMoreAssets
78,478 views
1,381 Discussing
3
#BinanceHourlyDepositsExceedWithdrawals
32,821 views
568 Discussing
4
#AnthropicIPOPricedDownasInvestorsEye$1.5T
685 views
31 Discussing
5
#AppleReportsMixedResults
41,901 views
859 Discussing
6
#PalantirSlides3PercentOn$2BRevenue
2,418 views
36 Discussing
7
#FrenchAssemblyRejectsTwoCryptoExitTaxProposals
3,893 views
124 Discussing
8
#USMidtermElections
797,430 views
4,310 Discussing
9
#Nasdaq100EntersCorrection
8,045 views
153 Discussing
10
#USOctoberNFP-AreRateCutsStillPossible
144,771 views
1,134 Discussing