
#rates
rates
Просмотров: 110,748
432 обсуждают
Популярные
Новые
·
--
Частичная правда
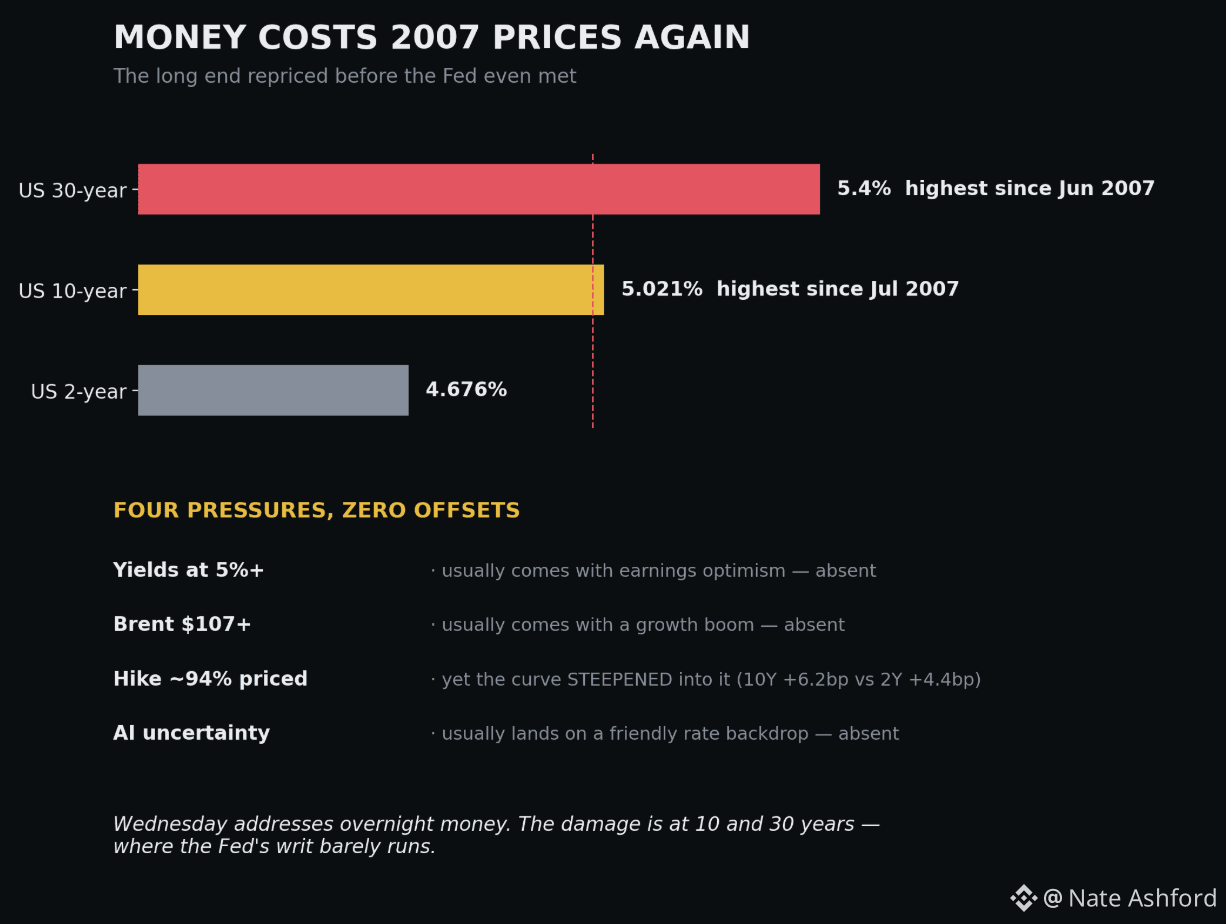
5.04%. The 10-year just printed its highest yield since July 2007. The 30-year at 5.40%, also a 2007 number. The long end didn't wait for Wednesday.
On this feed for weeks: the story was never the hike, it was the long bond quietly repricing what money costs. Today it stopped being quiet.
Here's the detail that matters most. Markets price 94% odds of tomorrow's hike — and the curve STEEPENED into it, the 10-year rising faster than the 2-year. A hike should calm the long end. It isn't. Because the long end isn't trading the Fed anymore: it's trading debt supply, the fiscal path, and an AI capex boom borrowing against the same pool of capital. Only one of those ends when the tightening cycle does.
Four pressures at once — 5% yields, $107 Brent, a priced hike, AI doubt — and the real problem is what's missing: every offset that usually cushions one of them. Energy shocks usually come with growth. Rising yields usually come with earnings optimism. Neither is on the table.
Wednesday addresses overnight money. The damage is being done at the far end of the curve, where the Fed's writ barely runs. #rates #Fed
5.04%. The 10-year just printed its highest yield since July 2007. The 30-year at 5.40%, also a 2007 number. The long end didn't wait for Wednesday.
On this feed for weeks: the story was never the hike, it was the long bond quietly repricing what money costs. Today it stopped being quiet.
Here's the detail that matters most. Markets price 94% odds of tomorrow's hike — and the curve STEEPENED into it, the 10-year rising faster than the 2-year. A hike should calm the long end. It isn't. Because the long end isn't trading the Fed anymore: it's trading debt supply, the fiscal path, and an AI capex boom borrowing against the same pool of capital. Only one of those ends when the tightening cycle does.
Four pressures at once — 5% yields, $107 Brent, a priced hike, AI doubt — and the real problem is what's missing: every offset that usually cushions one of them. Energy shocks usually come with growth. Rising yields usually come with earnings optimism. Neither is on the table.
Wednesday addresses overnight money. The damage is being done at the far end of the curve, where the Fed's writ barely runs. #rates #Fed
On this feed for weeks: the story was never the hike, it was the long bond quietly repricing what money costs. Today it stopped being quiet.
Here's the detail that matters most. Markets price 94% odds of tomorrow's hike — and the curve STEEPENED into it, the 10-year rising faster than the 2-year. A hike should calm the long end. It isn't. Because the long end isn't trading the Fed anymore: it's trading debt supply, the fiscal path, and an AI capex boom borrowing against the same pool of capital. Only one of those ends when the tightening cycle does.
Four pressures at once — 5% yields, $107 Brent, a priced hike, AI doubt — and the real problem is what's missing: every offset that usually cushions one of them. Energy shocks usually come with growth. Rising yields usually come with earnings optimism. Neither is on the table.
Wednesday addresses overnight money. The damage is being done at the far end of the curve, where the Fed's writ barely runs. #rates #Fed
AngelOfCrypto_-:
nice
2
1.3k

·
--
Проверено
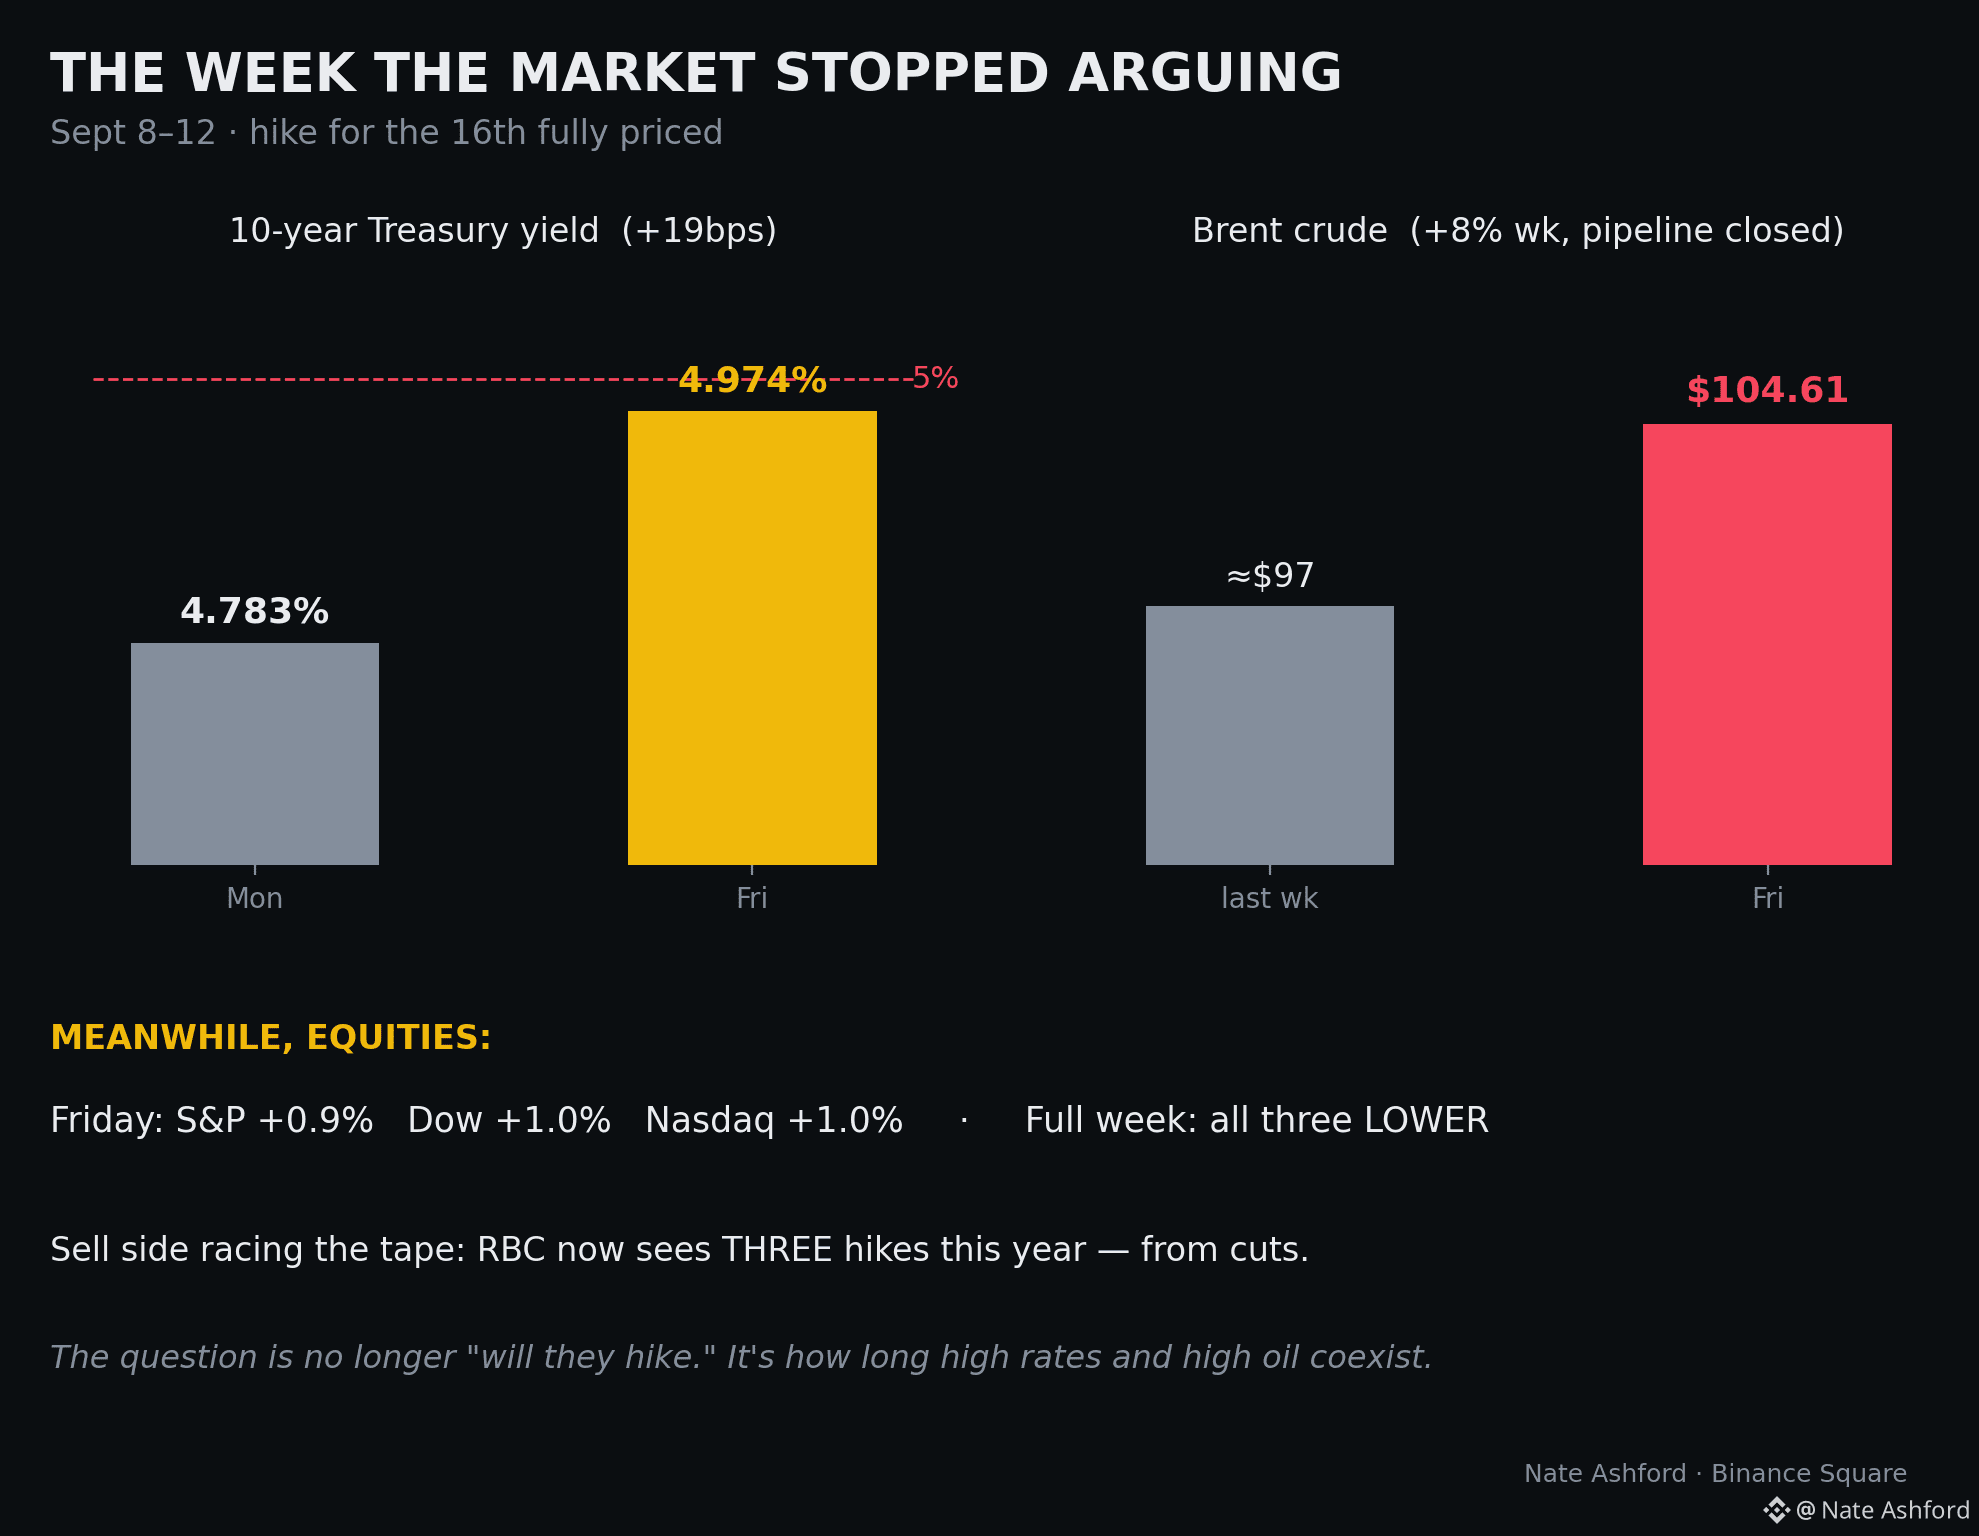
The week the market stopped arguing. Core CPI hot, hike locked for the 16th — and stocks rallied Friday on the certainty itself. S&P +0.9%, Dow +1%, Nasdaq +1%. All three still down on the week.
The bond market kept score differently: 10-year at 4.974%, from 4.783% a week ago. Nineteen basis points in five sessions, knocking on 5%.
And the sell side is now racing the tape — RBC has gone from cuts this year to THREE hikes. That's not a forecast revision. That's a regime acknowledgment.
Add Brent at $104.61, up 8% on the week with the East-West pipeline closed, and Wall Street's question has properly changed. Not "will they hike." How long do high rates and high oil coexist before something in earnings gives.
That question doesn't resolve on the 16th. It starts there. #Fed #rates
The week the market stopped arguing. Core CPI hot, hike locked for the 16th — and stocks rallied Friday on the certainty itself. S&P +0.9%, Dow +1%, Nasdaq +1%. All three still down on the week.
The bond market kept score differently: 10-year at 4.974%, from 4.783% a week ago. Nineteen basis points in five sessions, knocking on 5%.
And the sell side is now racing the tape — RBC has gone from cuts this year to THREE hikes. That's not a forecast revision. That's a regime acknowledgment.
Add Brent at $104.61, up 8% on the week with the East-West pipeline closed, and Wall Street's question has properly changed. Not "will they hike." How long do high rates and high oil coexist before something in earnings gives.
That question doesn't resolve on the 16th. It starts there. #Fed #rates
The bond market kept score differently: 10-year at 4.974%, from 4.783% a week ago. Nineteen basis points in five sessions, knocking on 5%.
And the sell side is now racing the tape — RBC has gone from cuts this year to THREE hikes. That's not a forecast revision. That's a regime acknowledgment.
Add Brent at $104.61, up 8% on the week with the East-West pipeline closed, and Wall Street's question has properly changed. Not "will they hike." How long do high rates and high oil coexist before something in earnings gives.
That question doesn't resolve on the 16th. It starts there. #Fed #rates
572
·
--
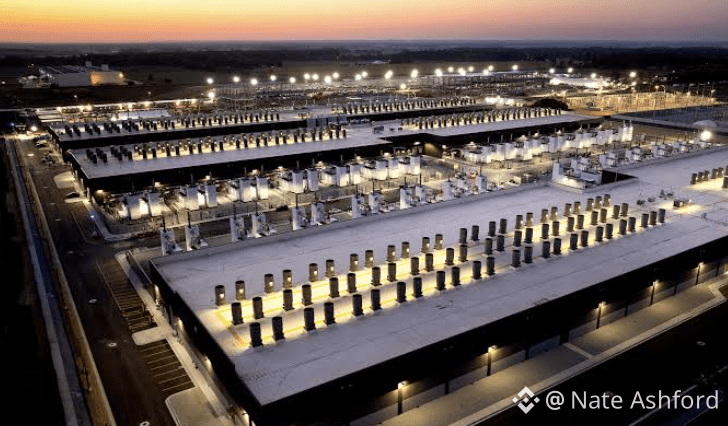
Another week, another AI infrastructure deal — Amazon backing Qualcomm into data center chips, with up to $4B in equity attached.
Add the running total: two labs alone have contracted compute implying $500B to $750B of spend this decade. Now the chip layer is spawning funded competitors.
Here's why this belongs on a macro feed. Williams named the drivers of high yields two weeks ago: strong economy, robust investment demand. This is the investment demand. Capex at this scale is a structural bid for capital that keeps real rates elevated no matter what the Fed does on the 16th.
The long bond has held above 5% for weeks. Everyone argues about the Fed. Almost nobody prices the simpler force: the biggest industrial buildout since the postwar era, all of it borrowing and spending at once.
The AI trade isn't just in equities. It's in your discount rate. #rates #macro
Another week, another AI infrastructure deal — Amazon backing Qualcomm into data center chips, with up to $4B in equity attached.
Add the running total: two labs alone have contracted compute implying $500B to $750B of spend this decade. Now the chip layer is spawning funded competitors.
Here's why this belongs on a macro feed. Williams named the drivers of high yields two weeks ago: strong economy, robust investment demand. This is the investment demand. Capex at this scale is a structural bid for capital that keeps real rates elevated no matter what the Fed does on the 16th.
The long bond has held above 5% for weeks. Everyone argues about the Fed. Almost nobody prices the simpler force: the biggest industrial buildout since the postwar era, all of it borrowing and spending at once.
The AI trade isn't just in equities. It's in your discount rate. #rates #macro
Add the running total: two labs alone have contracted compute implying $500B to $750B of spend this decade. Now the chip layer is spawning funded competitors.
Here's why this belongs on a macro feed. Williams named the drivers of high yields two weeks ago: strong economy, robust investment demand. This is the investment demand. Capex at this scale is a structural bid for capital that keeps real rates elevated no matter what the Fed does on the 16th.
The long bond has held above 5% for weeks. Everyone argues about the Fed. Almost nobody prices the simpler force: the biggest industrial buildout since the postwar era, all of it borrowing and spending at once.
The AI trade isn't just in equities. It's in your discount rate. #rates #macro
388
·
--
Проверено
Payrolls: 162K. Unemployment steady at 4.1%. After a negative July, the labor market just voted, and it voted strong.
On the record all week here: weak data was the only thing that could stop this hike, and a positive print settles it. So it went. Odds at 58.4% for the 16th, and the sell side is falling in line — UBS now sees hikes in September AND December, Macquarie and BofA moving the same way. The debate Waller opened is losing to the data.
But the real story now isn't the market. It's the collision nobody's pricing. The White House is publicly pressing for CUTS — rates hurting competitiveness, housing affordability — at the exact moment the market prices a HIKE at 58%. Warsh is being pulled in opposite directions by his two audiences.
One of them has to be disappointed on the 16th. Central bank independence isn't a speech topic anymore. It's this meeting.
CPI on the 11th is the last input. #Fed #rates
Payrolls: 162K. Unemployment steady at 4.1%. After a negative July, the labor market just voted, and it voted strong.
On the record all week here: weak data was the only thing that could stop this hike, and a positive print settles it. So it went. Odds at 58.4% for the 16th, and the sell side is falling in line — UBS now sees hikes in September AND December, Macquarie and BofA moving the same way. The debate Waller opened is losing to the data.
But the real story now isn't the market. It's the collision nobody's pricing. The White House is publicly pressing for CUTS — rates hurting competitiveness, housing affordability — at the exact moment the market prices a HIKE at 58%. Warsh is being pulled in opposite directions by his two audiences.
One of them has to be disappointed on the 16th. Central bank independence isn't a speech topic anymore. It's this meeting.
CPI on the 11th is the last input. #Fed #rates
On the record all week here: weak data was the only thing that could stop this hike, and a positive print settles it. So it went. Odds at 58.4% for the 16th, and the sell side is falling in line — UBS now sees hikes in September AND December, Macquarie and BofA moving the same way. The debate Waller opened is losing to the data.
But the real story now isn't the market. It's the collision nobody's pricing. The White House is publicly pressing for CUTS — rates hurting competitiveness, housing affordability — at the exact moment the market prices a HIKE at 58%. Warsh is being pulled in opposite directions by his two audiences.
One of them has to be disappointed on the 16th. Central bank independence isn't a speech topic anymore. It's this meeting.
CPI on the 11th is the last input. #Fed #rates
1
1.5k

·
--
#FedHikeOddsRiseTo68%
CME FedWatch now prices a 68% chance the Fed hikes rates by 25 bps at the September 16 meeting. Just a week ago it was sitting under 40%.
What changed? Fed Chair Kevin Warsh went full hawk at Jackson Hole. He basically said inflation is still running nearly double the target and the current stance isn’t restrictive enough. Traders heard him loud and clear.
Oil is climbing, yields are rising, and the “soft landing + eventual cuts” narrative is getting shredded in real time.
This isn’t just a numbers game. Higher rates for longer hit mortgages, car loans, and business borrowing. Risk assets are already feeling the heat.
Two weeks of data left before the decision. One hot CPI print and 68% could turn into 80% real quick.
Are you still positioned for cuts… or have you already adjusted?
#Fed #Rates
#FedHikeOddsRiseTo68%
CME FedWatch now prices a 68% chance the Fed hikes rates by 25 bps at the September 16 meeting. Just a week ago it was sitting under 40%.
What changed? Fed Chair Kevin Warsh went full hawk at Jackson Hole. He basically said inflation is still running nearly double the target and the current stance isn’t restrictive enough. Traders heard him loud and clear.
Oil is climbing, yields are rising, and the “soft landing + eventual cuts” narrative is getting shredded in real time.
This isn’t just a numbers game. Higher rates for longer hit mortgages, car loans, and business borrowing. Risk assets are already feeling the heat.
Two weeks of data left before the decision. One hot CPI print and 68% could turn into 80% real quick.
Are you still positioned for cuts… or have you already adjusted?
#Fed #Rates
CME FedWatch now prices a 68% chance the Fed hikes rates by 25 bps at the September 16 meeting. Just a week ago it was sitting under 40%.
What changed? Fed Chair Kevin Warsh went full hawk at Jackson Hole. He basically said inflation is still running nearly double the target and the current stance isn’t restrictive enough. Traders heard him loud and clear.
Oil is climbing, yields are rising, and the “soft landing + eventual cuts” narrative is getting shredded in real time.
This isn’t just a numbers game. Higher rates for longer hit mortgages, car loans, and business borrowing. Risk assets are already feeling the heat.
Two weeks of data left before the decision. One hot CPI print and 68% could turn into 80% real quick.
Are you still positioned for cuts… or have you already adjusted?
#Fed #Rates
99
·
--
Проверено
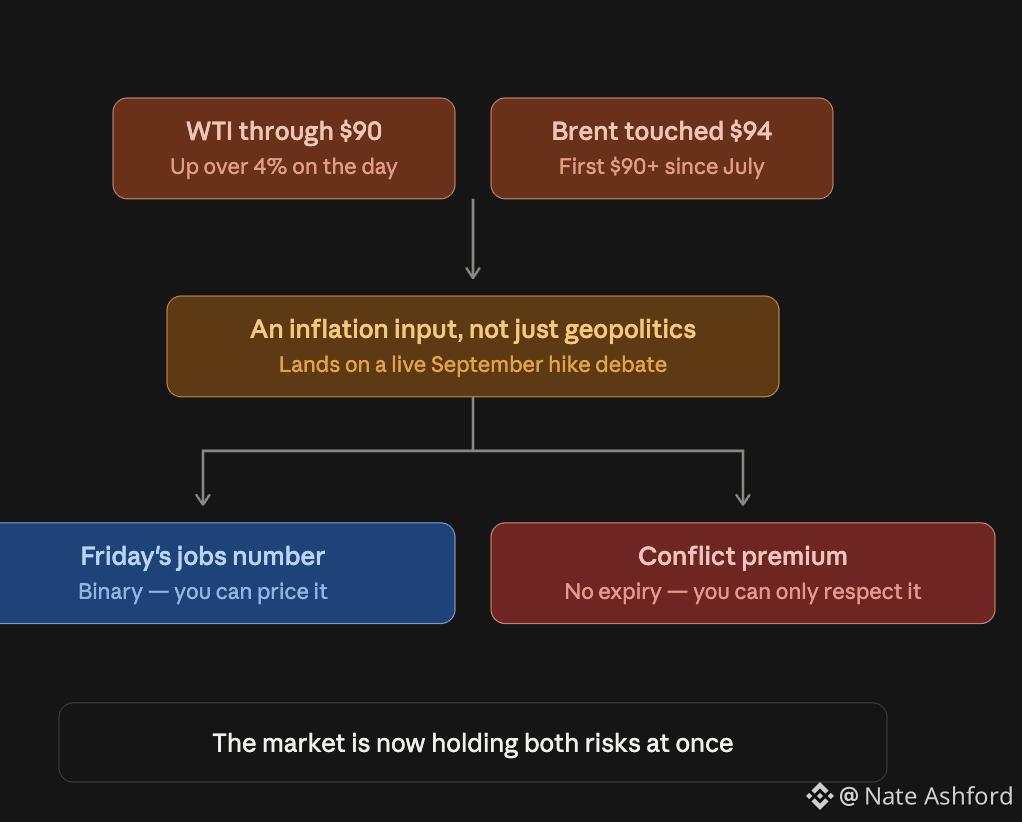
WTI through $90, up over 4% on the day. Brent touched $94. First time above $90 since late July.
The driver is on every front page. US-Iran escalation, missiles in the air, threats going both directions.
Here's what the oil move does that the headlines don't: it lands on a Fed already debating a September hike.
Crude up 4% in a session is an inflation input, not just a geopolitics story. The "hike is live" case just got a supply-side tailwind it didn't ask for.
So the market is now holding two risks at once. A binary jobs number Friday and an open-ended conflict premium with no expiry date.
One of those you can price. The other you can only respect. #macro #rates
WTI through $90, up over 4% on the day. Brent touched $94. First time above $90 since late July.
The driver is on every front page. US-Iran escalation, missiles in the air, threats going both directions.
Here's what the oil move does that the headlines don't: it lands on a Fed already debating a September hike.
Crude up 4% in a session is an inflation input, not just a geopolitics story. The "hike is live" case just got a supply-side tailwind it didn't ask for.
So the market is now holding two risks at once. A binary jobs number Friday and an open-ended conflict premium with no expiry date.
One of those you can price. The other you can only respect. #macro #rates
The driver is on every front page. US-Iran escalation, missiles in the air, threats going both directions.
Here's what the oil move does that the headlines don't: it lands on a Fed already debating a September hike.
Crude up 4% in a session is an inflation input, not just a geopolitics story. The "hike is live" case just got a supply-side tailwind it didn't ask for.
So the market is now holding two risks at once. A binary jobs number Friday and an open-ended conflict premium with no expiry date.
One of those you can price. The other you can only respect. #macro #rates
738
·
--
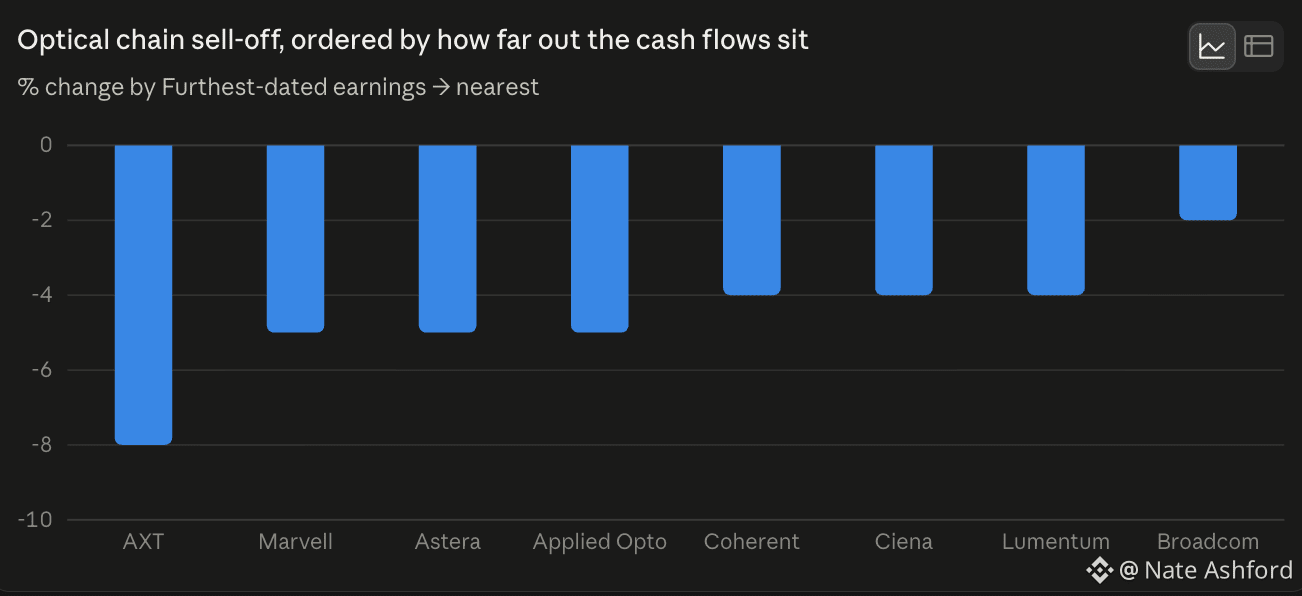
AXT down 8%. Marvell, Astera, Applied Opto down 5%. Coherent, Ciena, Lumentum down 4%. Broadcom off 2%.
That's the entire optical chain, in order of how far out the cash flows sit.
This isn't a sector story. It's a rates story with a semiconductor logo on it.
When a September hike is a coin flip, the first thing to get sold is anything priced on 2028 earnings. Optical is priced on 2028 earnings.
Notice Broadcom is the least bad. Biggest balance sheet, nearest cash flows. Same pattern as the Dow beating the Nasdaq this morning.
The AI trade isn't breaking. It's being discounted at a higher rate. Different thing. #rates #macro
AXT down 8%. Marvell, Astera, Applied Opto down 5%. Coherent, Ciena, Lumentum down 4%. Broadcom off 2%.
That's the entire optical chain, in order of how far out the cash flows sit.
This isn't a sector story. It's a rates story with a semiconductor logo on it.
When a September hike is a coin flip, the first thing to get sold is anything priced on 2028 earnings. Optical is priced on 2028 earnings.
Notice Broadcom is the least bad. Biggest balance sheet, nearest cash flows. Same pattern as the Dow beating the Nasdaq this morning.
The AI trade isn't breaking. It's being discounted at a higher rate. Different thing. #rates #macro
That's the entire optical chain, in order of how far out the cash flows sit.
This isn't a sector story. It's a rates story with a semiconductor logo on it.
When a September hike is a coin flip, the first thing to get sold is anything priced on 2028 earnings. Optical is priced on 2028 earnings.
Notice Broadcom is the least bad. Biggest balance sheet, nearest cash flows. Same pattern as the Dow beating the Nasdaq this morning.
The AI trade isn't breaking. It's being discounted at a higher rate. Different thing. #rates #macro
533
·
--
Nasdaq futures down 1% before the cash open. S&P off half a percent. Dow a touch less.
Nothing was released overnight. Read that again.
This is the hike-odds story from yesterday finding its way into equities. Rates traders repriced last week. Stock traders are catching up this morning.
Growth getting hit hardest is exactly what you'd expect if the market believes the Fed isn't done. Long-duration assets don't like a live September.
The tell is that the Dow is the least bad. That's a rates trade wearing an equity costume.
Payrolls Friday. Until then this is positioning, not news. #rates #macro
Nasdaq futures down 1% before the cash open. S&P off half a percent. Dow a touch less.
Nothing was released overnight. Read that again.
This is the hike-odds story from yesterday finding its way into equities. Rates traders repriced last week. Stock traders are catching up this morning.
Growth getting hit hardest is exactly what you'd expect if the market believes the Fed isn't done. Long-duration assets don't like a live September.
The tell is that the Dow is the least bad. That's a rates trade wearing an equity costume.
Payrolls Friday. Until then this is positioning, not news. #rates #macro
Nothing was released overnight. Read that again.
This is the hike-odds story from yesterday finding its way into equities. Rates traders repriced last week. Stock traders are catching up this morning.
Growth getting hit hardest is exactly what you'd expect if the market believes the Fed isn't done. Long-duration assets don't like a live September.
The tell is that the Dow is the least bad. That's a rates trade wearing an equity costume.
Payrolls Friday. Until then this is positioning, not news. #rates #macro
1
340
Over 98% odds the Fed holds in June — so don’t expect a “rate-cut pump” to save bad trades.
This is a patience market:
Risk assets can grind up… then snap on one hot CPI print.
Liquidity stays picky: quality wins, hype gets rugged.
Trade the chart, respect the macro, keep dry powder.
#Rates #Macro #Crypto #Altcoins!
#FedJuneRateHoldOver98Pct
Over 98% odds the Fed holds in June — so don’t expect a “rate-cut pump” to save bad trades.
This is a patience market:
Risk assets can grind up… then snap on one hot CPI print.
Liquidity stays picky: quality wins, hype gets rugged.
Trade the chart, respect the macro, keep dry powder.
#Rates #Macro #Crypto #Altcoins!
#FedJuneRateHoldOver98Pct
This is a patience market:
Risk assets can grind up… then snap on one hot CPI print.
Liquidity stays picky: quality wins, hype gets rugged.
Trade the chart, respect the macro, keep dry powder.
#Rates #Macro #Crypto #Altcoins!
#FedJuneRateHoldOver98Pct
146
·
--
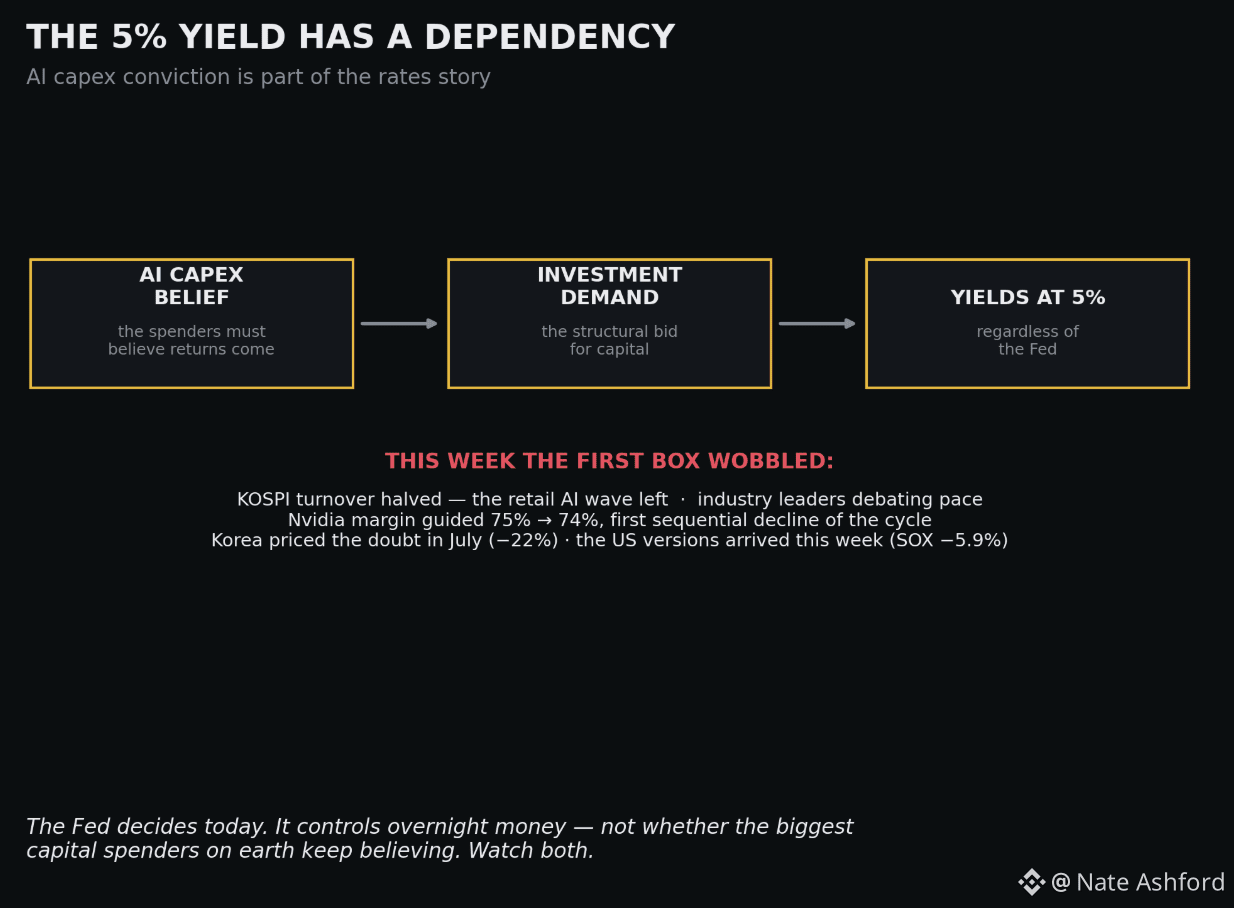
Korea just sent the macro signal everyone's been arguing about, and it isn't in the price — it's in the participation. KOSPI turnover has halved from its peak. The AI retail wave that drove the rally is gone.
Why this belongs on a macro feed, today of all days. My standing argument: the AI buildout is a structural bid for capital — the investment demand holding real yields up regardless of the Fed. That thesis has a dependency: the spenders must believe the returns are coming.
This week the belief wobbled in public. Industry leaders debating whether to slow down. Nvidia guiding gross margin DOWN sequentially for the first time this cycle — costs rising faster than pricing. Korea's memory-heavy market registered the doubt in July, 22% worth; the US versions arrived this week, 5.9% in a session.
If capex conviction cracks, the yield story changes too — the "robust investment demand" leg under 5% Treasuries is the same trade as the KOSPI's missing volume.
The Fed decides in hours. It controls overnight money. It doesn't control whether the biggest capital spenders on earth keep believing. Watch both. #macro #rates
Korea just sent the macro signal everyone's been arguing about, and it isn't in the price — it's in the participation. KOSPI turnover has halved from its peak. The AI retail wave that drove the rally is gone.
Why this belongs on a macro feed, today of all days. My standing argument: the AI buildout is a structural bid for capital — the investment demand holding real yields up regardless of the Fed. That thesis has a dependency: the spenders must believe the returns are coming.
This week the belief wobbled in public. Industry leaders debating whether to slow down. Nvidia guiding gross margin DOWN sequentially for the first time this cycle — costs rising faster than pricing. Korea's memory-heavy market registered the doubt in July, 22% worth; the US versions arrived this week, 5.9% in a session.
If capex conviction cracks, the yield story changes too — the "robust investment demand" leg under 5% Treasuries is the same trade as the KOSPI's missing volume.
The Fed decides in hours. It controls overnight money. It doesn't control whether the biggest capital spenders on earth keep believing. Watch both. #macro #rates
Why this belongs on a macro feed, today of all days. My standing argument: the AI buildout is a structural bid for capital — the investment demand holding real yields up regardless of the Fed. That thesis has a dependency: the spenders must believe the returns are coming.
This week the belief wobbled in public. Industry leaders debating whether to slow down. Nvidia guiding gross margin DOWN sequentially for the first time this cycle — costs rising faster than pricing. Korea's memory-heavy market registered the doubt in July, 22% worth; the US versions arrived this week, 5.9% in a session.
If capex conviction cracks, the yield story changes too — the "robust investment demand" leg under 5% Treasuries is the same trade as the KOSPI's missing volume.
The Fed decides in hours. It controls overnight money. It doesn't control whether the biggest capital spenders on earth keep believing. Watch both. #macro #rates
247
·
--
📊 FOMC POLL: What’s the Fed’s next move?
With inflation still in focus, will the Fed stay hawkish—or surprise markets? 👀
$BTC
{future}(BTCUSDT)
#FedRateWatch #Rates #FOMOisReal
📊 FOMC POLL: What’s the Fed’s next move?
With inflation still in focus, will the Fed stay hawkish—or surprise markets? 👀
$BTC
#FedRateWatch #Rates #FOMOisReal
With inflation still in focus, will the Fed stay hawkish—or surprise markets? 👀
$BTC
#FedRateWatch #Rates #FOMOisReal
📉 Rate Cut
45%
⏸️ Hold Rates
22%
🔺 25bp Hike
33%
27 проголосовали • Голосование закрыто
1
2
3
452
·
--
China added 20 tons of gold in August. Reserves now 2,386 tons. That's 22 consecutive months of buying.
Twenty-two months is not a trade. It's a policy.
The context that gives it teeth: this run continued straight through gold's pullback, through a US hike debate, through everything. Central banks don't chase price. They accumulate against a scenario — and the scenario a 22-month gold bid hedges is less dollar dependence, fewer Treasury claims, sanction-proofing reserves.
Put it next to this week's other tape: the 10-year at 2023 highs, the long bond above 5% for weeks. The largest official buyers diversifying away from the paper the US needs to sell more of than ever. Those two facts are having a conversation, and yields are how it sounds.
Nobody announces a reserve regime change. It just shows up, 20 tons at a time. #macro #rates
China added 20 tons of gold in August. Reserves now 2,386 tons. That's 22 consecutive months of buying.
Twenty-two months is not a trade. It's a policy.
The context that gives it teeth: this run continued straight through gold's pullback, through a US hike debate, through everything. Central banks don't chase price. They accumulate against a scenario — and the scenario a 22-month gold bid hedges is less dollar dependence, fewer Treasury claims, sanction-proofing reserves.
Put it next to this week's other tape: the 10-year at 2023 highs, the long bond above 5% for weeks. The largest official buyers diversifying away from the paper the US needs to sell more of than ever. Those two facts are having a conversation, and yields are how it sounds.
Nobody announces a reserve regime change. It just shows up, 20 tons at a time. #macro #rates
Twenty-two months is not a trade. It's a policy.
The context that gives it teeth: this run continued straight through gold's pullback, through a US hike debate, through everything. Central banks don't chase price. They accumulate against a scenario — and the scenario a 22-month gold bid hedges is less dollar dependence, fewer Treasury claims, sanction-proofing reserves.
Put it next to this week's other tape: the 10-year at 2023 highs, the long bond above 5% for weeks. The largest official buyers diversifying away from the paper the US needs to sell more of than ever. Those two facts are having a conversation, and yields are how it sounds.
Nobody announces a reserve regime change. It just shows up, 20 tons at a time. #macro #rates
469
·
--
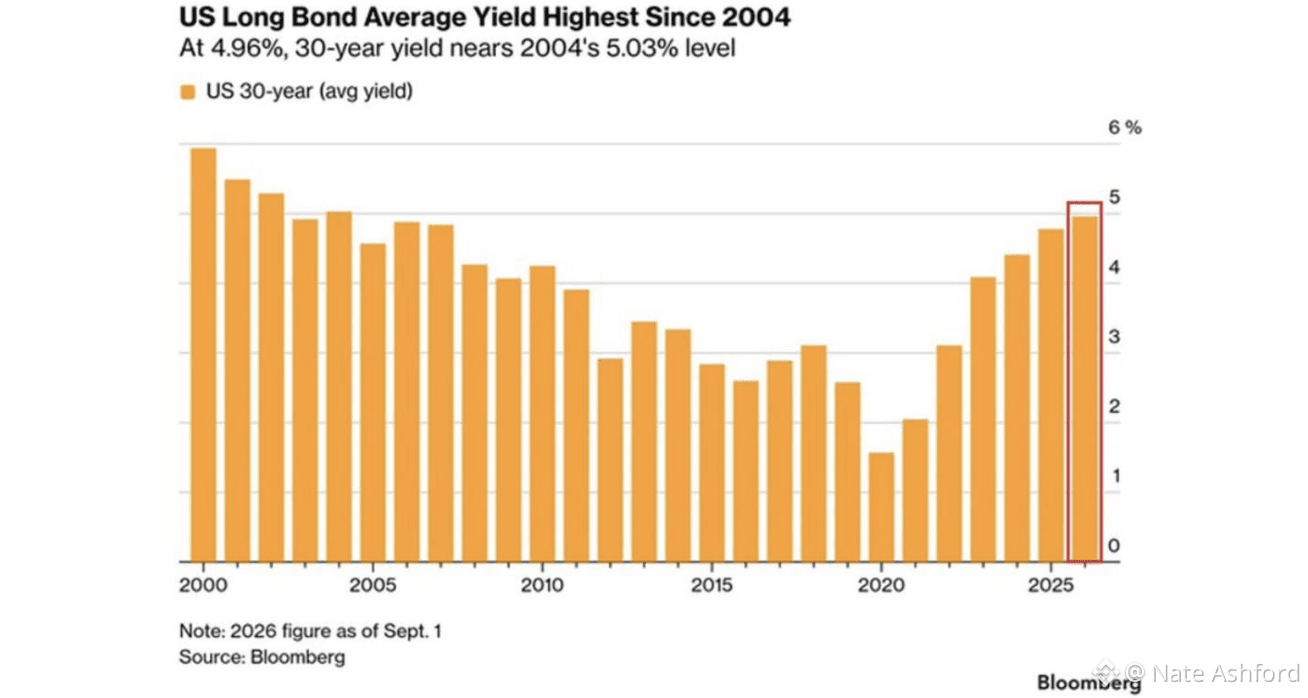
Quite a reversal to sit inside of. The 30-year backed off 5bps from the intraday high to 5.25%. Dow and S&P futures clawed back their losses and went green. Oil round-tripped from up 2% to down 1%.
All three moved together, and that's the tell. This was the conflict premium deflating, not a view change on the Fed.
One session of de-escalation trading. The hike odds didn't go anywhere.
Enjoy the green. The two events that matter — payrolls Friday, the Fed on the 16th — are still exactly where they were this morning. #rates #macro
Quite a reversal to sit inside of. The 30-year backed off 5bps from the intraday high to 5.25%. Dow and S&P futures clawed back their losses and went green. Oil round-tripped from up 2% to down 1%.
All three moved together, and that's the tell. This was the conflict premium deflating, not a view change on the Fed.
One session of de-escalation trading. The hike odds didn't go anywhere.
Enjoy the green. The two events that matter — payrolls Friday, the Fed on the 16th — are still exactly where they were this morning. #rates #macro
All three moved together, and that's the tell. This was the conflict premium deflating, not a view change on the Fed.
One session of de-escalation trading. The hike odds didn't go anywhere.
Enjoy the green. The two events that matter — payrolls Friday, the Fed on the 16th — are still exactly where they were this morning. #rates #macro
398
·
--
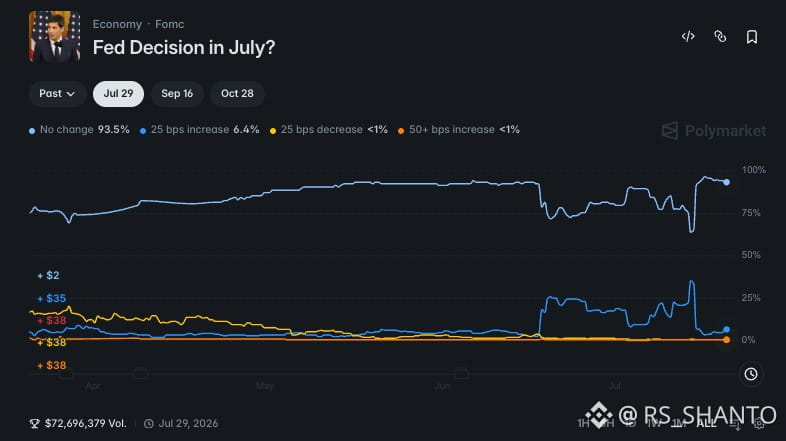
🔴 The Iran deal just torched $246M in shorts and sent oil prices into a nosedive 🩸. Anyone still betting on Fed rate hikes is smoking hopium. This isn't a pivot, it's a full-blown capitulation of the hawkish narrative. Where does BTC land before the next FOMC meeting? Drop your target 👇
#btc #oil #rates
🔴 The Iran deal just torched $246M in shorts and sent oil prices into a nosedive 🩸. Anyone still betting on Fed rate hikes is smoking hopium. This isn't a pivot, it's a full-blown capitulation of the hawkish narrative. Where does BTC land before the next FOMC meeting? Drop your target 👇
#btc #oil #rates
#btc #oil #rates
2
42
·
--
🔴 Впервые с 2006 года три крупных центральных банка ужесточают политику одновременно ⚡ создавая глобальное сжатие ликвидности. В то время как криптовалюта остается уязвимой для сворачивания кэрри-трейдов, американские спотовые ETF на Биткоин поглотили более трех с половиной миллиардов долларов в прошлом месяце 💰 помогая смягчить системное давление. Внимательно следите за потоками спотовых ETF на этой неделе, когда макро-волатильность достигнет пика.
Будут ли притоки в спотовые ETF достаточно сильными, чтобы поглотить глобальное сворачивание кэрри-трейдов во время решений по ставкам центральных банков на этой неделе? 👇
#macro #bitcoin #fed #ecb #rates
🔴 Впервые с 2006 года три крупных центральных банка ужесточают политику одновременно ⚡ создавая глобальное сжатие ликвидности. В то время как криптовалюта остается уязвимой для сворачивания кэрри-трейдов, американские спотовые ETF на Биткоин поглотили более трех с половиной миллиардов долларов в прошлом месяце 💰 помогая смягчить системное давление. Внимательно следите за потоками спотовых ETF на этой неделе, когда макро-волатильность достигнет пика.
Будут ли притоки в спотовые ETF достаточно сильными, чтобы поглотить глобальное сворачивание кэрри-трейдов во время решений по ставкам центральных банков на этой неделе? 👇
#macro #bitcoin #fed #ecb #rates
Будут ли притоки в спотовые ETF достаточно сильными, чтобы поглотить глобальное сворачивание кэрри-трейдов во время решений по ставкам центральных банков на этой неделе? 👇
#macro #bitcoin #fed #ecb #rates
166
·
--
🔴 Биткоин торгуется около $77 250, поскольку рынки оценивают 87-процентную вероятность повышения ставки ФРС в эту среду. 📉 Данные по инфляции за август прервали предыдущий восходящий импульс, в то время как обратные выкупы казначейских облигаций пытаются управлять долгосрочной доходностью. Ликвидность крипторынка ⚡ сталкивается с жесткой макроэкономической ситуацией, поскольку трейдеры готовятся к официальным указаниям.
Компенсируют ли обратные выкупы облигаций Казначейства «ястребиное» повышение ставки ФРС для Биткоина, или грядут более низкие ценовые уровни? 👇
#bitcoin #macro #fed #treasury #rates
🔴 Биткоин торгуется около $77 250, поскольку рынки оценивают 87-процентную вероятность повышения ставки ФРС в эту среду. 📉 Данные по инфляции за август прервали предыдущий восходящий импульс, в то время как обратные выкупы казначейских облигаций пытаются управлять долгосрочной доходностью. Ликвидность крипторынка ⚡ сталкивается с жесткой макроэкономической ситуацией, поскольку трейдеры готовятся к официальным указаниям.
Компенсируют ли обратные выкупы облигаций Казначейства «ястребиное» повышение ставки ФРС для Биткоина, или грядут более низкие ценовые уровни? 👇
#bitcoin #macro #fed #treasury #rates
Компенсируют ли обратные выкупы облигаций Казначейства «ястребиное» повышение ставки ФРС для Биткоина, или грядут более низкие ценовые уровни? 👇
#bitcoin #macro #fed #treasury #rates
919

·
--
🚨 $BTC LIQUIDITY TAP OPENS IF RATES FALL 90% 🦈
A confirmed 90% rate collapse would be a liquidity cannon aimed straight at $BTC . 🟢 Lower cost of capital means leverage, risk appetite, and macro flows can all snap back fast.
📊 The market will stop pricing duration risk and start pricing scarcity. If that drop is real, dips become buy zones while sellers scramble for fresh bids. ⚡
Watch volume and bid depth as the first fingerprints. 👇 Are you positioning for the repricing now or waiting for confirmation candles?
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Rates #Liquidity #Macro #Crypto
💎 🎯
🚨 $BTC LIQUIDITY TAP OPENS IF RATES FALL 90% 🦈
A confirmed 90% rate collapse would be a liquidity cannon aimed straight at $BTC . 🟢 Lower cost of capital means leverage, risk appetite, and macro flows can all snap back fast.
📊 The market will stop pricing duration risk and start pricing scarcity. If that drop is real, dips become buy zones while sellers scramble for fresh bids. ⚡
Watch volume and bid depth as the first fingerprints. 👇 Are you positioning for the repricing now or waiting for confirmation candles?
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Rates #Liquidity #Macro #Crypto
💎 🎯
A confirmed 90% rate collapse would be a liquidity cannon aimed straight at $BTC . 🟢 Lower cost of capital means leverage, risk appetite, and macro flows can all snap back fast.
📊 The market will stop pricing duration risk and start pricing scarcity. If that drop is real, dips become buy zones while sellers scramble for fresh bids. ⚡
Watch volume and bid depth as the first fingerprints. 👇 Are you positioning for the repricing now or waiting for confirmation candles?
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Rates #Liquidity #Macro #Crypto
💎 🎯
57
Войдите, чтобы посмотреть больше материала
Присоединяйтесь к пользователям криптовалют по всему миру на Binance Square
⚡️ Получайте новейшую и полезную информацию о криптоактивах.
💬 Нам доверяет крупнейшая в мире криптобиржа.
👍 Получите достоверные аналитические данные от верифицированных создателей контента.
Эл. почта/номер телефона
В тренде
1
#FedRateWatch
Просмотров: 1.2M
5,842 обсуждают
2
#ZcashRises6%
Просмотров: 15,296
289 обсуждают
3
#XRPSinks10%
Просмотров: 8,828
185 обсуждают
4
#BitcoinETFsShed$450M
Просмотров: 1,168
43 обсуждают
5
#CircleOpensArcMainnet
Просмотров: 5,226
125 обсуждают
6
#ZcashHoldersBackNU7Upgrade
Просмотров: 13,995
284 обсуждают
7
#MSTRTradingVolumeSurpassesMorganStanley
Просмотров: 16,771
474 обсуждают
8
#BitcoinFalls4%
Просмотров: 35,121
759 обсуждают
9
#SKHynixInTalksToMakeMemoryChipsInUS
Просмотров: 16,055
313 обсуждают
10
#OpenAIDiscussesNewFundingAt$1.2TValuation
Просмотров: 3,587
52 обсуждают