
#chinatech
chinatech
閲覧回数 46,182
171人が討論中
注目
最新

·
--
弱気相場
翻訳参照
🚨 DEEPSEEK ATTRACTS MAJOR CHINESE BROKERAGE INVESTORS! 🚨
🇨🇳 Wall Street-Style Capital Is Moving Into China's AI Sector!
📍 What's Happening?
Hangzhou Chengyan Enterprise Management Consulting Partnership became a shareholder of DeepSeek for the first time on November 17, reportedly ranking as its 3rd-largest shareholder.
💰 Major Brokerage Backing: Several major Chinese financial institutions reportedly invested in Hangzhou Chengyan, including:
🔹 CITIC Securities
🔹 China International Capital Corporation (CICC)
🔹 China Securities
🔹 Shenwan Hongyuan
👤 Liang Wenfeng's Position: Following the new shareholder entry, Liang Wenfeng's direct ownership reportedly decreased, but he remains DeepSeek's 2nd-largest direct shareholder.
📈 Why This Matters: • Institutional capital is increasingly targeting high-value AI companies.
• DeepSeek's private equity structure is attracting attention from major financial players.
• Potential AI IPOs and private-market valuations could unlock significant opportunities for brokerage firms.
• China's AI investment landscape may be entering a new phase of institutional participation.
💡 Analysts suggest that high-quality private industrial investments could become a major growth driver for traditional brokerage firms beyond their conventional securities business.
🔥 AI, Capital, and Institutional Investment—The Next Big Narrative?
📢 Post by @DeFiTitan
👍 Like 🔁 Share 💬 Comment
#DeepSeek #AI #ChinaTech #AIInvesting #BinanceSquare
$BTC $SOL $ETH
🚨 DEEPSEEK ATTRACTS MAJOR CHINESE BROKERAGE INVESTORS! 🚨
🇨🇳 Wall Street-Style Capital Is Moving Into China's AI Sector!
📍 What's Happening?
Hangzhou Chengyan Enterprise Management Consulting Partnership became a shareholder of DeepSeek for the first time on November 17, reportedly ranking as its 3rd-largest shareholder.
💰 Major Brokerage Backing: Several major Chinese financial institutions reportedly invested in Hangzhou Chengyan, including:
🔹 CITIC Securities
🔹 China International Capital Corporation (CICC)
🔹 China Securities
🔹 Shenwan Hongyuan
👤 Liang Wenfeng's Position: Following the new shareholder entry, Liang Wenfeng's direct ownership reportedly decreased, but he remains DeepSeek's 2nd-largest direct shareholder.
📈 Why This Matters: • Institutional capital is increasingly targeting high-value AI companies.
• DeepSeek's private equity structure is attracting attention from major financial players.
• Potential AI IPOs and private-market valuations could unlock significant opportunities for brokerage firms.
• China's AI investment landscape may be entering a new phase of institutional participation.
💡 Analysts suggest that high-quality private industrial investments could become a major growth driver for traditional brokerage firms beyond their conventional securities business.
🔥 AI, Capital, and Institutional Investment—The Next Big Narrative?
📢 Post by @DeFiTitan
👍 Like 🔁 Share 💬 Comment
#DeepSeek #AI #ChinaTech #AIInvesting #BinanceSquare
$BTC $SOL $ETH
🇨🇳 Wall Street-Style Capital Is Moving Into China's AI Sector!
📍 What's Happening?
Hangzhou Chengyan Enterprise Management Consulting Partnership became a shareholder of DeepSeek for the first time on November 17, reportedly ranking as its 3rd-largest shareholder.
💰 Major Brokerage Backing: Several major Chinese financial institutions reportedly invested in Hangzhou Chengyan, including:
🔹 CITIC Securities
🔹 China International Capital Corporation (CICC)
🔹 China Securities
🔹 Shenwan Hongyuan
👤 Liang Wenfeng's Position: Following the new shareholder entry, Liang Wenfeng's direct ownership reportedly decreased, but he remains DeepSeek's 2nd-largest direct shareholder.
📈 Why This Matters: • Institutional capital is increasingly targeting high-value AI companies.
• DeepSeek's private equity structure is attracting attention from major financial players.
• Potential AI IPOs and private-market valuations could unlock significant opportunities for brokerage firms.
• China's AI investment landscape may be entering a new phase of institutional participation.
💡 Analysts suggest that high-quality private industrial investments could become a major growth driver for traditional brokerage firms beyond their conventional securities business.
🔥 AI, Capital, and Institutional Investment—The Next Big Narrative?
📢 Post by @DeFiTitan
👍 Like 🔁 Share 💬 Comment
#DeepSeek #AI #ChinaTech #AIInvesting #BinanceSquare
$BTC $SOL $ETH
292

百度股价在其2026年第三季度财报发布前徘徊在77.67美元附近。分析师预计,每股收益为0.92美元,营收为45.9亿美元。尽管传统广告业务面临宏观经济和竞争压力,投资者正密切关注人工智能云业务的增长以及萝卜快跑的规模扩张能否抵消下滑,并为未来增长提供更强劲的动力。
{stock_us}(BIDU.US)
$BIDU.US #CoinVahini #Baidu #EarningsPreview #CloudComputing #ChinaTech
百度股价在其2026年第三季度财报发布前徘徊在77.67美元附近。分析师预计,每股收益为0.92美元,营收为45.9亿美元。尽管传统广告业务面临宏观经济和竞争压力,投资者正密切关注人工智能云业务的增长以及萝卜快跑的规模扩张能否抵消下滑,并为未来增长提供更强劲的动力。
$BIDU.US #CoinVahini #Baidu #EarningsPreview #CloudComputing #ChinaTech
$BIDU.US #CoinVahini #Baidu #EarningsPreview #CloudComputing #ChinaTech
86

·
--
ブリッシュ
北京は再びNvidiaに門戸を開く可能性があるかもしれません 🚨 中国当局が、アルババ、バイトダンス、DeepSeekに対し、$NVDAB
{spot}(NVDABUSDT)
H200チップを限られた数量で購入することについて、近いうちに許可が下りる可能性があると伝えたと報じられています。
合計は200,000チップ未満となる見込みで、これらの企業が申請した数の半分にも満たない可能性があります。中国のAI企業は計算能力(コンピューティングパワー)不足に直面しており、北京が国内の半導体メーカーを引き続き支援しながら姿勢を軟化させることにつながっている可能性があります。
このニュースは、AI取引(AIトークンを含む)を押し上げますか? 👇
#NVIDIA #AI #ChinaTech
北京は再びNvidiaに門戸を開く可能性があるかもしれません 🚨 中国当局が、アルババ、バイトダンス、DeepSeekに対し、$NVDAB
H200チップを限られた数量で購入することについて、近いうちに許可が下りる可能性があると伝えたと報じられています。
合計は200,000チップ未満となる見込みで、これらの企業が申請した数の半分にも満たない可能性があります。中国のAI企業は計算能力(コンピューティングパワー)不足に直面しており、北京が国内の半導体メーカーを引き続き支援しながら姿勢を軟化させることにつながっている可能性があります。
このニュースは、AI取引(AIトークンを含む)を押し上げますか? 👇
#NVIDIA #AI #ChinaTech
H200チップを限られた数量で購入することについて、近いうちに許可が下りる可能性があると伝えたと報じられています。
合計は200,000チップ未満となる見込みで、これらの企業が申請した数の半分にも満たない可能性があります。中国のAI企業は計算能力(コンピューティングパワー)不足に直面しており、北京が国内の半導体メーカーを引き続き支援しながら姿勢を軟化させることにつながっている可能性があります。
このニュースは、AI取引(AIトークンを含む)を押し上げますか? 👇
#NVIDIA #AI #ChinaTech
2
19
·
--
未来は今だ!中国はヒューマノイドロボットの時代に巨大な一歩を踏み出す
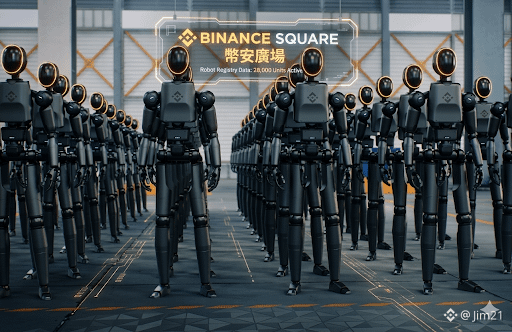
テクノロジーは急速に進化しており、中国がそのリズムを刻んでいます。北京の経済技術開発区で、ヒューマノイドロボットのライフサイクル管理プラットフォームが発表されました。これはまるでSFから飛び出したような措置で、各ロボットに29文字のユニークなIDが付与されます。
これは何を意味するのか?
各ユニットは今や、その原産国、製造業者、モデル、シリアル番号を詳述した標準化されたコードを持っています。
プロジェクトの背後にある数字:
すでに28,000のロボットがシステムに登録されています。
100社以上のトップ企業が関与しています。
この規制の下、すでに200種類の異なるモデルが流通しています。
行政管理を超えて、これは産業および社会のロボティクスに関するグローバルインフラの基盤を築き、トレーサビリティと日常生活へのAIの統合を容易にします。
標準化は、大規模な導入への前段階です。ロボットが自分の「DNI」を持つ世界に私たちは準備ができているのでしょうか? 🌐
#Robotics #ChinaTech #INNOVATION #HumanoidRobots #Web3
{future}(BTCUSDT)
{future}(BNBUSDT)
{future}(SOLUSDT)
未来は今だ!中国はヒューマノイドロボットの時代に巨大な一歩を踏み出す
テクノロジーは急速に進化しており、中国がそのリズムを刻んでいます。北京の経済技術開発区で、ヒューマノイドロボットのライフサイクル管理プラットフォームが発表されました。これはまるでSFから飛び出したような措置で、各ロボットに29文字のユニークなIDが付与されます。
これは何を意味するのか?
各ユニットは今や、その原産国、製造業者、モデル、シリアル番号を詳述した標準化されたコードを持っています。
プロジェクトの背後にある数字:
すでに28,000のロボットがシステムに登録されています。
100社以上のトップ企業が関与しています。
この規制の下、すでに200種類の異なるモデルが流通しています。
行政管理を超えて、これは産業および社会のロボティクスに関するグローバルインフラの基盤を築き、トレーサビリティと日常生活へのAIの統合を容易にします。
標準化は、大規模な導入への前段階です。ロボットが自分の「DNI」を持つ世界に私たちは準備ができているのでしょうか? 🌐
#Robotics #ChinaTech #INNOVATION #HumanoidRobots #Web3
テクノロジーは急速に進化しており、中国がそのリズムを刻んでいます。北京の経済技術開発区で、ヒューマノイドロボットのライフサイクル管理プラットフォームが発表されました。これはまるでSFから飛び出したような措置で、各ロボットに29文字のユニークなIDが付与されます。
これは何を意味するのか?
各ユニットは今や、その原産国、製造業者、モデル、シリアル番号を詳述した標準化されたコードを持っています。
プロジェクトの背後にある数字:
すでに28,000のロボットがシステムに登録されています。
100社以上のトップ企業が関与しています。
この規制の下、すでに200種類の異なるモデルが流通しています。
行政管理を超えて、これは産業および社会のロボティクスに関するグローバルインフラの基盤を築き、トレーサビリティと日常生活へのAIの統合を容易にします。
標準化は、大規模な導入への前段階です。ロボットが自分の「DNI」を持つ世界に私たちは準備ができているのでしょうか? 🌐
#Robotics #ChinaTech #INNOVATION #HumanoidRobots #Web3
300
#chinatodropolderwindowsfromstateagencies
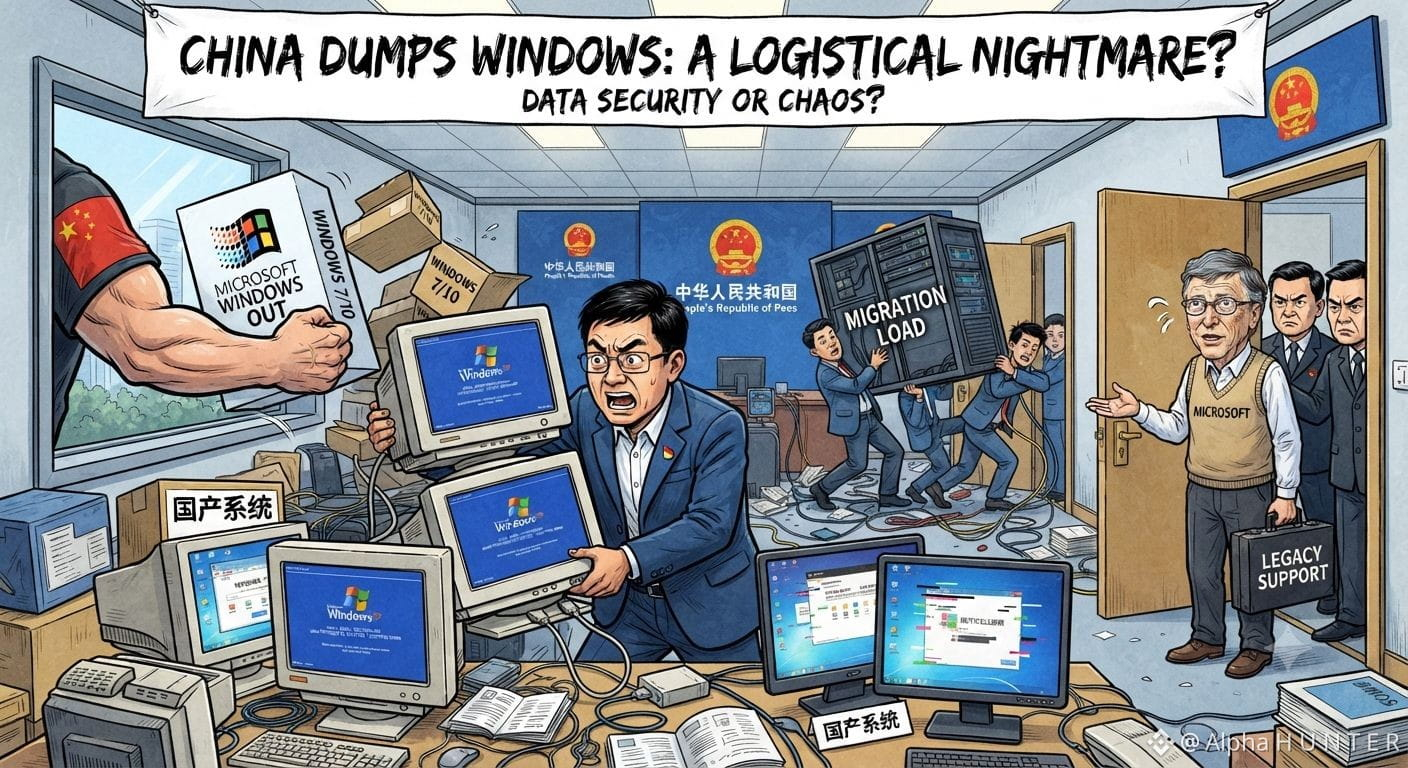
北京は、データの安全性と完全な技術的独立を目指す大規模な取り組みの中で、公的機関から公式にMicrosoftを排除する。
しかし正直に言おう:数百万のレガシーシステムを、実証されていない国内製のOSに置き換えるのは、混乱なしには進まない。複数年にわたって続く、めちゃくちゃなロジスティクスの悪夢を覚悟しておいてほしい。その間、地元のテックは途方もない負荷を吸収しようとするだろう。💥💻
トレーダーのゲームガイド:大規模な混乱は最大のボラティリティを生む。資本移動の最中は、中国のソフトウェア大手と世界のテック株を細かく監視してほしい。キャッシュフローを追跡し、その変動を取引せよ。📈📉
(注意:これは金融助言ではない。必ず自分で調べてください。)
#TechSovereignty #Microsoft #ChinaTech
$BTW
{future}(BTWUSDT)
$HEMI
{future}(HEMIUSDT)
$BTC
{future}(BTCUSDT)
#chinatodropolderwindowsfromstateagencies
北京は、データの安全性と完全な技術的独立を目指す大規模な取り組みの中で、公的機関から公式にMicrosoftを排除する。
しかし正直に言おう:数百万のレガシーシステムを、実証されていない国内製のOSに置き換えるのは、混乱なしには進まない。複数年にわたって続く、めちゃくちゃなロジスティクスの悪夢を覚悟しておいてほしい。その間、地元のテックは途方もない負荷を吸収しようとするだろう。💥💻
トレーダーのゲームガイド:大規模な混乱は最大のボラティリティを生む。資本移動の最中は、中国のソフトウェア大手と世界のテック株を細かく監視してほしい。キャッシュフローを追跡し、その変動を取引せよ。📈📉
(注意:これは金融助言ではない。必ず自分で調べてください。)
#TechSovereignty #Microsoft #ChinaTech
$BTW
$HEMI
$BTC
北京は、データの安全性と完全な技術的独立を目指す大規模な取り組みの中で、公的機関から公式にMicrosoftを排除する。
しかし正直に言おう:数百万のレガシーシステムを、実証されていない国内製のOSに置き換えるのは、混乱なしには進まない。複数年にわたって続く、めちゃくちゃなロジスティクスの悪夢を覚悟しておいてほしい。その間、地元のテックは途方もない負荷を吸収しようとするだろう。💥💻
トレーダーのゲームガイド:大規模な混乱は最大のボラティリティを生む。資本移動の最中は、中国のソフトウェア大手と世界のテック株を細かく監視してほしい。キャッシュフローを追跡し、その変動を取引せよ。📈📉
(注意:これは金融助言ではない。必ず自分で調べてください。)
#TechSovereignty #Microsoft #ChinaTech
$BTW
$HEMI
$BTC
1
1.5k

📉 中国のテクノロジーセクターに対する投資家心理が4年ぶりの低水準まで悪化
電子部品関連株の下落を受け、中国のテクノロジー機器セクターに対する投資家心理は4年ぶりの低水準となりました。この下落は、2026年の第2四半期にSTAR 50指数が60%超の大幅上昇を記録したことに続くものです。
━━━━━━━━━━━━━━
📊 影響: 📊 中程度
🏷️ OTHER
#ChinaTech #InvestorSentiment #ChipStocks #MarketDownturn #STAR50
🔗 出典: https://cryptobriefing.com/china-tech-hardware-sentiment-four-year-low/
📉 中国のテクノロジーセクターに対する投資家心理が4年ぶりの低水準まで悪化
電子部品関連株の下落を受け、中国のテクノロジー機器セクターに対する投資家心理は4年ぶりの低水準となりました。この下落は、2026年の第2四半期にSTAR 50指数が60%超の大幅上昇を記録したことに続くものです。
━━━━━━━━━━━━━━
📊 影響: 📊 中程度
🏷️ OTHER
#ChinaTech #InvestorSentiment #ChipStocks #MarketDownturn #STAR50
🔗 出典: https://cryptobriefing.com/china-tech-hardware-sentiment-four-year-low/
電子部品関連株の下落を受け、中国のテクノロジー機器セクターに対する投資家心理は4年ぶりの低水準となりました。この下落は、2026年の第2四半期にSTAR 50指数が60%超の大幅上昇を記録したことに続くものです。
━━━━━━━━━━━━━━
📊 影響: 📊 中程度
🏷️ OTHER
#ChinaTech #InvestorSentiment #ChipStocks #MarketDownturn #STAR50
🔗 出典: https://cryptobriefing.com/china-tech-hardware-sentiment-four-year-low/
9

·
--
中国は今、AIの支配を狙っています。
DeepSeekは独自のClaudeコードを構築中です。北京は全スタックを望んでいます。
DeepSeekが独自のClaudeコードを構築する動きは、戦略的なパワープレイであり、企業がテクノロジースタック全体をコントロールし、世界のAI市場に潜在的に影響を与えることを可能にします。この展開は、トレーダーやホルダーにとって重要であり、AI関連資産の価値に影響を与える可能性があります。トレーダーは、DeepSeekやその競合からのさらなる発表に注目すべきです。
#AI #Crypto #Tech #Innovation #ChinaTech
中国は今、AIの支配を狙っています。
DeepSeekは独自のClaudeコードを構築中です。北京は全スタックを望んでいます。
DeepSeekが独自のClaudeコードを構築する動きは、戦略的なパワープレイであり、企業がテクノロジースタック全体をコントロールし、世界のAI市場に潜在的に影響を与えることを可能にします。この展開は、トレーダーやホルダーにとって重要であり、AI関連資産の価値に影響を与える可能性があります。トレーダーは、DeepSeekやその競合からのさらなる発表に注目すべきです。
#AI #Crypto #Tech #Innovation #ChinaTech
DeepSeekは独自のClaudeコードを構築中です。北京は全スタックを望んでいます。
DeepSeekが独自のClaudeコードを構築する動きは、戦略的なパワープレイであり、企業がテクノロジースタック全体をコントロールし、世界のAI市場に潜在的に影響を与えることを可能にします。この展開は、トレーダーやホルダーにとって重要であり、AI関連資産の価値に影響を与える可能性があります。トレーダーは、DeepSeekやその競合からのさらなる発表に注目すべきです。
#AI #Crypto #Tech #Innovation #ChinaTech
19
📉 中国のテクノロジー業界に対する投資家のセンチメント後退:暗号資産マイニングに影響するのか?
中国のSTAR 50 指数(恐怖/強欲)の値が、2022年4月以来の最低水準に下落しました。6月のピークから16%下落したことを受けての動きです。この下落は、中国がこの分野の主要プレイヤーであり続けていることから、暗号資産のマイニング機器市場への潜在的な影響について疑問を呼び起こしています。
━━━━━━━━━━━━━━
📊 影響:📈 高い
🏷️ OTHER
#ChinaTech #CryptoMining #MarketSentiment #STAR50 #Hardware
🔗 出典: https://cryptobriefing.com/china-tech-hardware-sentiment-lowest-since-2022/
📉 中国のテクノロジー業界に対する投資家のセンチメント後退:暗号資産マイニングに影響するのか?
中国のSTAR 50 指数(恐怖/強欲)の値が、2022年4月以来の最低水準に下落しました。6月のピークから16%下落したことを受けての動きです。この下落は、中国がこの分野の主要プレイヤーであり続けていることから、暗号資産のマイニング機器市場への潜在的な影響について疑問を呼び起こしています。
━━━━━━━━━━━━━━
📊 影響:📈 高い
🏷️ OTHER
#ChinaTech #CryptoMining #MarketSentiment #STAR50 #Hardware
🔗 出典: https://cryptobriefing.com/china-tech-hardware-sentiment-lowest-since-2022/
中国のSTAR 50 指数(恐怖/強欲)の値が、2022年4月以来の最低水準に下落しました。6月のピークから16%下落したことを受けての動きです。この下落は、中国がこの分野の主要プレイヤーであり続けていることから、暗号資産のマイニング機器市場への潜在的な影響について疑問を呼び起こしています。
━━━━━━━━━━━━━━
📊 影響:📈 高い
🏷️ OTHER
#ChinaTech #CryptoMining #MarketSentiment #STAR50 #Hardware
🔗 出典: https://cryptobriefing.com/china-tech-hardware-sentiment-lowest-since-2022/
32
DeepSeekの創業者は、次の中国のIPOラッシュに向けて静かに布石を打っている。
DeepSeekの創業者である梁文鋒氏は、DeepSeekの背後にある量的ファンドHigh-Flyerを通じて、中国のプレIPO市場にさらに踏み込んでいるとされる。
High-Flyerは、AI、半導体、ロボティクスといった北京が優先する分野で、これまで複数のIPO前案件に関与してきたとみられており、その中にはCXMTやUnitree Roboticsが含まれる。
注目すべきは、この戦略が投資だけにとどまらないことだ。
DeepSeekは、上海のSTAR市場でIPOを狙っているとされており、世界の市場を揺さぶったAI企業そのものが、中国のテックIPOの波における有力候補の一つになろうとしている。
もしこのモデルが成功すれば、梁文鋒氏は単にAIラボを作っているだけではない。
同氏は、クオンツ+AI+プライベート市場を組み合わせ、技術エコシステムが一般市場に上場する前にその全体へアクセスしようとしている。
AI競争は、IPO競争にもなりつつある。
あなたは、DeepSeekのIPOがChina Techにとって次の追い風になると思うか、それとも中国市場はAIをファンダメンタルズから見て行き過ぎた水準で評価しすぎているのだろうか?
#DeepSeek #Aİ #ChinaTech #IPOWave
DeepSeekの創業者は、次の中国のIPOラッシュに向けて静かに布石を打っている。
DeepSeekの創業者である梁文鋒氏は、DeepSeekの背後にある量的ファンドHigh-Flyerを通じて、中国のプレIPO市場にさらに踏み込んでいるとされる。
High-Flyerは、AI、半導体、ロボティクスといった北京が優先する分野で、これまで複数のIPO前案件に関与してきたとみられており、その中にはCXMTやUnitree Roboticsが含まれる。
注目すべきは、この戦略が投資だけにとどまらないことだ。
DeepSeekは、上海のSTAR市場でIPOを狙っているとされており、世界の市場を揺さぶったAI企業そのものが、中国のテックIPOの波における有力候補の一つになろうとしている。
もしこのモデルが成功すれば、梁文鋒氏は単にAIラボを作っているだけではない。
同氏は、クオンツ+AI+プライベート市場を組み合わせ、技術エコシステムが一般市場に上場する前にその全体へアクセスしようとしている。
AI競争は、IPO競争にもなりつつある。
あなたは、DeepSeekのIPOがChina Techにとって次の追い風になると思うか、それとも中国市場はAIをファンダメンタルズから見て行き過ぎた水準で評価しすぎているのだろうか?
#DeepSeek #Aİ #ChinaTech #IPOWave
DeepSeekの創業者である梁文鋒氏は、DeepSeekの背後にある量的ファンドHigh-Flyerを通じて、中国のプレIPO市場にさらに踏み込んでいるとされる。
High-Flyerは、AI、半導体、ロボティクスといった北京が優先する分野で、これまで複数のIPO前案件に関与してきたとみられており、その中にはCXMTやUnitree Roboticsが含まれる。
注目すべきは、この戦略が投資だけにとどまらないことだ。
DeepSeekは、上海のSTAR市場でIPOを狙っているとされており、世界の市場を揺さぶったAI企業そのものが、中国のテックIPOの波における有力候補の一つになろうとしている。
もしこのモデルが成功すれば、梁文鋒氏は単にAIラボを作っているだけではない。
同氏は、クオンツ+AI+プライベート市場を組み合わせ、技術エコシステムが一般市場に上場する前にその全体へアクセスしようとしている。
AI競争は、IPO競争にもなりつつある。
あなたは、DeepSeekのIPOがChina Techにとって次の追い風になると思うか、それとも中国市場はAIをファンダメンタルズから見て行き過ぎた水準で評価しすぎているのだろうか?
#DeepSeek #Aİ #ChinaTech #IPOWave
473
·
--
🚀 中国の「インスタグラム」が上場へ!
小紅書(Xiaohongshu)は、企業価値が700億ドル以上になる可能性のある香港IPOの準備を進めていると報じられています💰
📱 何が起こっているの?
このプラットフォームは、世界の投資家が中国のテック市場に戻る中で、主要な公開上場に向けて動いています。
⚡ なぜこれが重要なのか:
• 📊 世界中で4億人以上のユーザー
• 📸 ライフスタイルとショートフォームコンテンツにおける強力なポジション
• 🌍 TikTokの不確実性の後、世界的な注目が高まる
• 🚀 IPO市場でのメガバリュエーションの可能性
📈
このIPOが成功裏に進めば、以下のことが期待されます:
• 🇨🇳 中国のテック株への信頼感を高める
• 💸 ソーシャルメディアセクターに新しい流動性をもたらす
• 📊 コンテンツプラットフォームのバリュエーション基準をリセットする
小紅書は、TikTokやInstagramのような次のグローバルソーシャルメディアの巨人になることができるのでしょうか?
💬 あなたの意見を下に書いてください👇
#IPO #ChinaTech #SocialMedia #HKEX XiaohongshuHKIPOValuationAbove$70B $
🚀 中国の「インスタグラム」が上場へ!
小紅書(Xiaohongshu)は、企業価値が700億ドル以上になる可能性のある香港IPOの準備を進めていると報じられています💰
📱 何が起こっているの?
このプラットフォームは、世界の投資家が中国のテック市場に戻る中で、主要な公開上場に向けて動いています。
⚡ なぜこれが重要なのか:
• 📊 世界中で4億人以上のユーザー
• 📸 ライフスタイルとショートフォームコンテンツにおける強力なポジション
• 🌍 TikTokの不確実性の後、世界的な注目が高まる
• 🚀 IPO市場でのメガバリュエーションの可能性
📈
このIPOが成功裏に進めば、以下のことが期待されます:
• 🇨🇳 中国のテック株への信頼感を高める
• 💸 ソーシャルメディアセクターに新しい流動性をもたらす
• 📊 コンテンツプラットフォームのバリュエーション基準をリセットする
小紅書は、TikTokやInstagramのような次のグローバルソーシャルメディアの巨人になることができるのでしょうか?
💬 あなたの意見を下に書いてください👇
#IPO #ChinaTech #SocialMedia #HKEX XiaohongshuHKIPOValuationAbove$70B $
小紅書(Xiaohongshu)は、企業価値が700億ドル以上になる可能性のある香港IPOの準備を進めていると報じられています💰
📱 何が起こっているの?
このプラットフォームは、世界の投資家が中国のテック市場に戻る中で、主要な公開上場に向けて動いています。
⚡ なぜこれが重要なのか:
• 📊 世界中で4億人以上のユーザー
• 📸 ライフスタイルとショートフォームコンテンツにおける強力なポジション
• 🌍 TikTokの不確実性の後、世界的な注目が高まる
• 🚀 IPO市場でのメガバリュエーションの可能性
📈
このIPOが成功裏に進めば、以下のことが期待されます:
• 🇨🇳 中国のテック株への信頼感を高める
• 💸 ソーシャルメディアセクターに新しい流動性をもたらす
• 📊 コンテンツプラットフォームのバリュエーション基準をリセットする
小紅書は、TikTokやInstagramのような次のグローバルソーシャルメディアの巨人になることができるのでしょうか?
💬 あなたの意見を下に書いてください👇
#IPO #ChinaTech #SocialMedia #HKEX XiaohongshuHKIPOValuationAbove$70B $
87

$ASML AND $BESI HALTED AFTER EIGHT PERCENT PLUNGE! CHINA STRIKES BACK WITH DOMESTIC DUV MACHINES 💥
Body
🔴 半導体の戦場が、さらに血なまぐさくなりました。ASMLとBesi Semiconductorは、アムステルダム取引所で取引停止に追い込まれました。数分で8%超下落したためです。引き金は? 中国の官民支援を受けた企業が、国産のDUV(深紫外)リソグラフィ装置の量産を開始したこと。これにより、オランダの独占に正面から挑みます。🦈
📌 これは噂ではなく、構造的な転換です。中国は2026年に5台、2027年までに20台の導入を計画しており、SMICやChangXin Memoryのような巨大メーカーを狙っています。昨年のASMLの131台の没入型DUV装置にはまだ及ばないものの、「自前で賄える」という物語は、もはや市場価格に織り込まれています。💡 市場は不確実性を嫌います――そしてこれは、サプライチェーンの混乱を狙った直接的な一手です。🤔 あなたは半導体株でのさらなる下落に備えているのか、それとも押し目の買い場として見ていますか?👇
⚠️ 金融アドバイスではありません。常にリスクを管理してください。🛡️
🏷️ $ASML $BESI #Semiconductors #ChinaTech #MarketCrash
🔴 🛡️
$ASML AND $BESI HALTED AFTER EIGHT PERCENT PLUNGE! CHINA STRIKES BACK WITH DOMESTIC DUV MACHINES 💥
Body
🔴 半導体の戦場が、さらに血なまぐさくなりました。ASMLとBesi Semiconductorは、アムステルダム取引所で取引停止に追い込まれました。数分で8%超下落したためです。引き金は? 中国の官民支援を受けた企業が、国産のDUV(深紫外)リソグラフィ装置の量産を開始したこと。これにより、オランダの独占に正面から挑みます。🦈
📌 これは噂ではなく、構造的な転換です。中国は2026年に5台、2027年までに20台の導入を計画しており、SMICやChangXin Memoryのような巨大メーカーを狙っています。昨年のASMLの131台の没入型DUV装置にはまだ及ばないものの、「自前で賄える」という物語は、もはや市場価格に織り込まれています。💡 市場は不確実性を嫌います――そしてこれは、サプライチェーンの混乱を狙った直接的な一手です。🤔 あなたは半導体株でのさらなる下落に備えているのか、それとも押し目の買い場として見ていますか?👇
⚠️ 金融アドバイスではありません。常にリスクを管理してください。🛡️
🏷️ $ASML $BESI #Semiconductors #ChinaTech #MarketCrash
🔴 🛡️
Body
🔴 半導体の戦場が、さらに血なまぐさくなりました。ASMLとBesi Semiconductorは、アムステルダム取引所で取引停止に追い込まれました。数分で8%超下落したためです。引き金は? 中国の官民支援を受けた企業が、国産のDUV(深紫外)リソグラフィ装置の量産を開始したこと。これにより、オランダの独占に正面から挑みます。🦈
📌 これは噂ではなく、構造的な転換です。中国は2026年に5台、2027年までに20台の導入を計画しており、SMICやChangXin Memoryのような巨大メーカーを狙っています。昨年のASMLの131台の没入型DUV装置にはまだ及ばないものの、「自前で賄える」という物語は、もはや市場価格に織り込まれています。💡 市場は不確実性を嫌います――そしてこれは、サプライチェーンの混乱を狙った直接的な一手です。🤔 あなたは半導体株でのさらなる下落に備えているのか、それとも押し目の買い場として見ていますか?👇
⚠️ 金融アドバイスではありません。常にリスクを管理してください。🛡️
🏷️ $ASML $BESI #Semiconductors #ChinaTech #MarketCrash
🔴 🛡️
46
#AIrotation #韓国のチップメーカー #ChinaTech #SKHYNIX
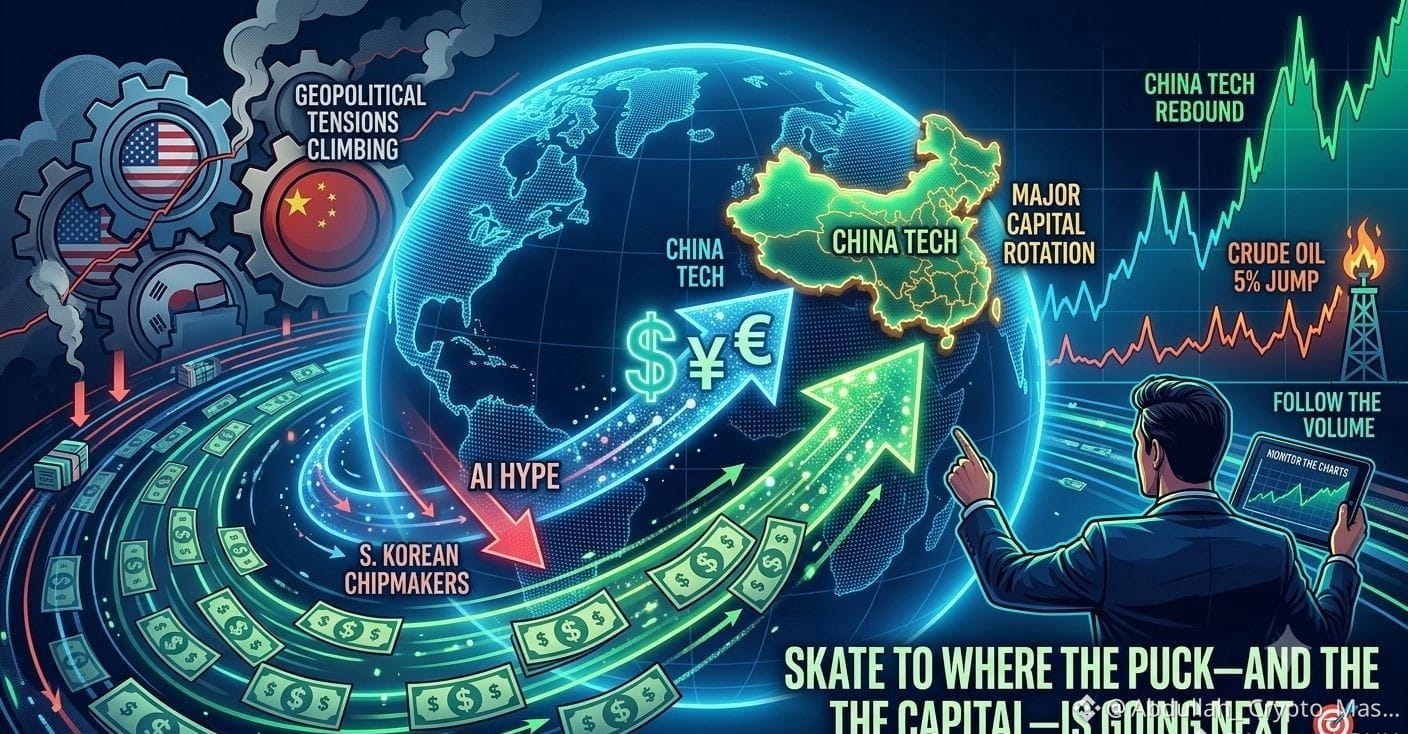
💰 お金が中国のテックへ動いています! 🇨🇳📈
市場の変化により、大口投資家がAI銘柄から中国のテックへ資金を移しています。
👉 起きていること:
✅ 中国テックで強い買いが入っている 🚀
✅ AI銘柄はひとまず失速 ⏳
✅ 原油価格の上昇&世界の緊張がこの動きを後押し 🌍⚠️
📊 取引アイデア:
👉 トレンドが上向きの間に、中国のテックの強い銘柄を買う 📈
👉 強さが再び出るまで弱いAI銘柄を追いかけない ❌
👇 下の黄色いコインをタップして取引ページへ行き、この波を掴もう 💰🔥
$SKHYNIX $SAMSUNG
{future}(SAMSUNGUSDT)
{future}(SKHYNIXUSDT)
#AIrotation #韓国のチップメーカー #ChinaTech #SKHYNIX
💰 お金が中国のテックへ動いています! 🇨🇳📈
市場の変化により、大口投資家がAI銘柄から中国のテックへ資金を移しています。
👉 起きていること:
✅ 中国テックで強い買いが入っている 🚀
✅ AI銘柄はひとまず失速 ⏳
✅ 原油価格の上昇&世界の緊張がこの動きを後押し 🌍⚠️
📊 取引アイデア:
👉 トレンドが上向きの間に、中国のテックの強い銘柄を買う 📈
👉 強さが再び出るまで弱いAI銘柄を追いかけない ❌
👇 下の黄色いコインをタップして取引ページへ行き、この波を掴もう 💰🔥
$SKHYNIX $SAMSUNG
💰 お金が中国のテックへ動いています! 🇨🇳📈
市場の変化により、大口投資家がAI銘柄から中国のテックへ資金を移しています。
👉 起きていること:
✅ 中国テックで強い買いが入っている 🚀
✅ AI銘柄はひとまず失速 ⏳
✅ 原油価格の上昇&世界の緊張がこの動きを後押し 🌍⚠️
📊 取引アイデア:
👉 トレンドが上向きの間に、中国のテックの強い銘柄を買う 📈
👉 強さが再び出るまで弱いAI銘柄を追いかけない ❌
👇 下の黄色いコインをタップして取引ページへ行き、この波を掴もう 💰🔥
$SKHYNIX $SAMSUNG
79
·
--
中国の技術推進は新たな局面に入る中国のテクノロジー分野は、急速な拡大を超えて自立に、そして先進的な製造と戦略的なイノベーションへと、ますます重点を移している。人工知能や半導体から、ロボット、電気自動車、次世代コンピューティングに至るまで、中国企業は世界でもっとも重要な技術市場のいくつかで、積極的に競争している。
大きな物語は、単に中国が技術をどれだけ速く発展させているかだけではなく、それを取り巻くエコシステムをいかに素早く構築しているかにある。国内の半導体生産、AIインフラ、自動化、高度な製造への巨額投資により、海外のサプライチェーンへの依存が減りつつ、同時に現地企業に新たな機会が生まれている。
中国の技術推進は新たな局面に入る
中国のテクノロジー分野は、急速な拡大を超えて自立に、そして先進的な製造と戦略的なイノベーションへと、ますます重点を移している。人工知能や半導体から、ロボット、電気自動車、次世代コンピューティングに至るまで、中国企業は世界でもっとも重要な技術市場のいくつかで、積極的に競争している。
大きな物語は、単に中国が技術をどれだけ速く発展させているかだけではなく、それを取り巻くエコシステムをいかに素早く構築しているかにある。国内の半導体生産、AIインフラ、自動化、高度な製造への巨額投資により、海外のサプライチェーンへの依存が減りつつ、同時に現地企業に新たな機会が生まれている。
大きな物語は、単に中国が技術をどれだけ速く発展させているかだけではなく、それを取り巻くエコシステムをいかに素早く構築しているかにある。国内の半導体生産、AIインフラ、自動化、高度な製造への巨額投資により、海外のサプライチェーンへの依存が減りつつ、同時に現地企業に新たな機会が生まれている。
1
99

#chinatodropolderwindowsfromstateagencies
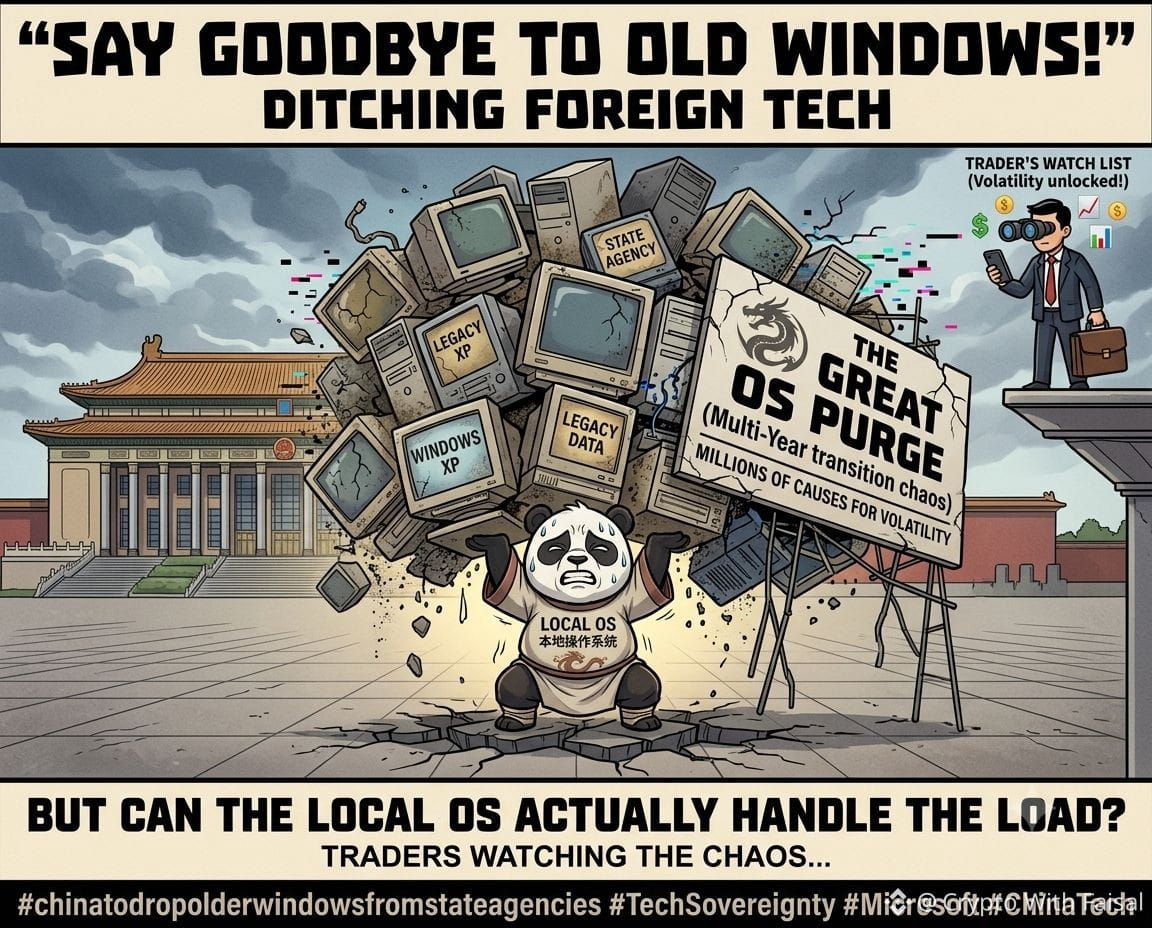
北京はデータセキュリティ強化と完全な技術的自立を目指し、大規模な取り組みの一環として、国家機関からマイクロソフトを正式に排除しようとしている。
だが正直に言えば、何百万もの既存システムを実証されていない国内のOSに入れ替えるのは、スムーズには進まないだろう。現地の技術が膨大な負荷を処理しようとするにつれ、カオスで、複数年に及ぶ物流の悪夢が待っているはずだ。💥💻
トレーダーの教本:大きな混乱は、大きなボラティリティにつながる。資本の流れが移る中、中国の国内ソフトウェア大手と世界のハイテク株を注意深く監視しよう。資金の流れを追い、値動きの波に乗る。📈📉
(免責事項:これは投資助言ではありません。必ず自分で調べてください。)
#TechSovereignty #Microsoft #ChinaTech
$BTW
{future}(BTWUSDT)
$HEMI
{future}(HEMIUSDT)
$ACE
{future}(ACEUSDT)
#chinatodropolderwindowsfromstateagencies
北京はデータセキュリティ強化と完全な技術的自立を目指し、大規模な取り組みの一環として、国家機関からマイクロソフトを正式に排除しようとしている。
だが正直に言えば、何百万もの既存システムを実証されていない国内のOSに入れ替えるのは、スムーズには進まないだろう。現地の技術が膨大な負荷を処理しようとするにつれ、カオスで、複数年に及ぶ物流の悪夢が待っているはずだ。💥💻
トレーダーの教本:大きな混乱は、大きなボラティリティにつながる。資本の流れが移る中、中国の国内ソフトウェア大手と世界のハイテク株を注意深く監視しよう。資金の流れを追い、値動きの波に乗る。📈📉
(免責事項:これは投資助言ではありません。必ず自分で調べてください。)
#TechSovereignty #Microsoft #ChinaTech
$BTW
$HEMI
$ACE
北京はデータセキュリティ強化と完全な技術的自立を目指し、大規模な取り組みの一環として、国家機関からマイクロソフトを正式に排除しようとしている。
だが正直に言えば、何百万もの既存システムを実証されていない国内のOSに入れ替えるのは、スムーズには進まないだろう。現地の技術が膨大な負荷を処理しようとするにつれ、カオスで、複数年に及ぶ物流の悪夢が待っているはずだ。💥💻
トレーダーの教本:大きな混乱は、大きなボラティリティにつながる。資本の流れが移る中、中国の国内ソフトウェア大手と世界のハイテク株を注意深く監視しよう。資金の流れを追い、値動きの波に乗る。📈📉
(免責事項:これは投資助言ではありません。必ず自分で調べてください。)
#TechSovereignty #Microsoft #ChinaTech
$BTW
$HEMI
$ACE
1
3.2k
🔥 あなたが眠っている間に、AI領域で **歴史的** な動きがありました: DeepSeekがHuaweiチップ上でV4モデルをリリースしました。誰もこれを予想していなかった、特にホワイトハウスが中国に対してアメリカのAIを盗んだと非難した同じ日にです。#AIwarfare と#ChinaTech がすでにトレンドになっています。
📊 その影響は巨大で、DeepSeekのV4モデルはHuaweiのAscendチッププラットフォーム向けに明示的に最適化されており、これはアメリカのAIセクターにおける支配権の終焉を意味するかもしれません。BTCのオープンインタレストは$7.92Bで、資金調達のセンチメントは強気です。ロング/ショート比は1.36、そして#BitcoinBreaksBelow75KAsWarshTakesFedHelm がすでに1,755人によって議論されています。
💡 これは高い賭けを意味し、賢いお金がすでにSolanaのようなコインに流れ込んでいます。トップトレーダーは53.8%のネットロングポジションを持ち、相対力指数は54.9で中立的なトレンドを示していますが、MACDはベアリッシュクロスオーバーを示し、#SuiGaslessStablecoinTransfers が注目を集めています。
❓ このAI戦争は暗号空間に火をつけるのでしょうか?そして、この技術的競争の新しい時代から最初に恩恵を受けるコインはどれでしょうか?
🔥 あなたが眠っている間に、AI領域で **歴史的** な動きがありました: DeepSeekがHuaweiチップ上でV4モデルをリリースしました。誰もこれを予想していなかった、特にホワイトハウスが中国に対してアメリカのAIを盗んだと非難した同じ日にです。#AIwarfare と#ChinaTech がすでにトレンドになっています。
📊 その影響は巨大で、DeepSeekのV4モデルはHuaweiのAscendチッププラットフォーム向けに明示的に最適化されており、これはアメリカのAIセクターにおける支配権の終焉を意味するかもしれません。BTCのオープンインタレストは$7.92Bで、資金調達のセンチメントは強気です。ロング/ショート比は1.36、そして#BitcoinBreaksBelow75KAsWarshTakesFedHelm がすでに1,755人によって議論されています。
💡 これは高い賭けを意味し、賢いお金がすでにSolanaのようなコインに流れ込んでいます。トップトレーダーは53.8%のネットロングポジションを持ち、相対力指数は54.9で中立的なトレンドを示していますが、MACDはベアリッシュクロスオーバーを示し、#SuiGaslessStablecoinTransfers が注目を集めています。
❓ このAI戦争は暗号空間に火をつけるのでしょうか?そして、この技術的競争の新しい時代から最初に恩恵を受けるコインはどれでしょうか?
📊 その影響は巨大で、DeepSeekのV4モデルはHuaweiのAscendチッププラットフォーム向けに明示的に最適化されており、これはアメリカのAIセクターにおける支配権の終焉を意味するかもしれません。BTCのオープンインタレストは$7.92Bで、資金調達のセンチメントは強気です。ロング/ショート比は1.36、そして#BitcoinBreaksBelow75KAsWarshTakesFedHelm がすでに1,755人によって議論されています。
💡 これは高い賭けを意味し、賢いお金がすでにSolanaのようなコインに流れ込んでいます。トップトレーダーは53.8%のネットロングポジションを持ち、相対力指数は54.9で中立的なトレンドを示していますが、MACDはベアリッシュクロスオーバーを示し、#SuiGaslessStablecoinTransfers が注目を集めています。
❓ このAI戦争は暗号空間に火をつけるのでしょうか?そして、この技術的競争の新しい時代から最初に恩恵を受けるコインはどれでしょうか?
73
·
--
本人確認中
#ChinaToDropOlderWindowsFromStateAgencies #ChinaTech #Software
🚨 中国のWindowsの動きが国内のソフトウェア株を急騰させた。
$BTW ,$VELVET ,$HEMI
{spot}(HEMIUSDT)
{future}(VELVETUSDT)
{future}(BTWUSDT)
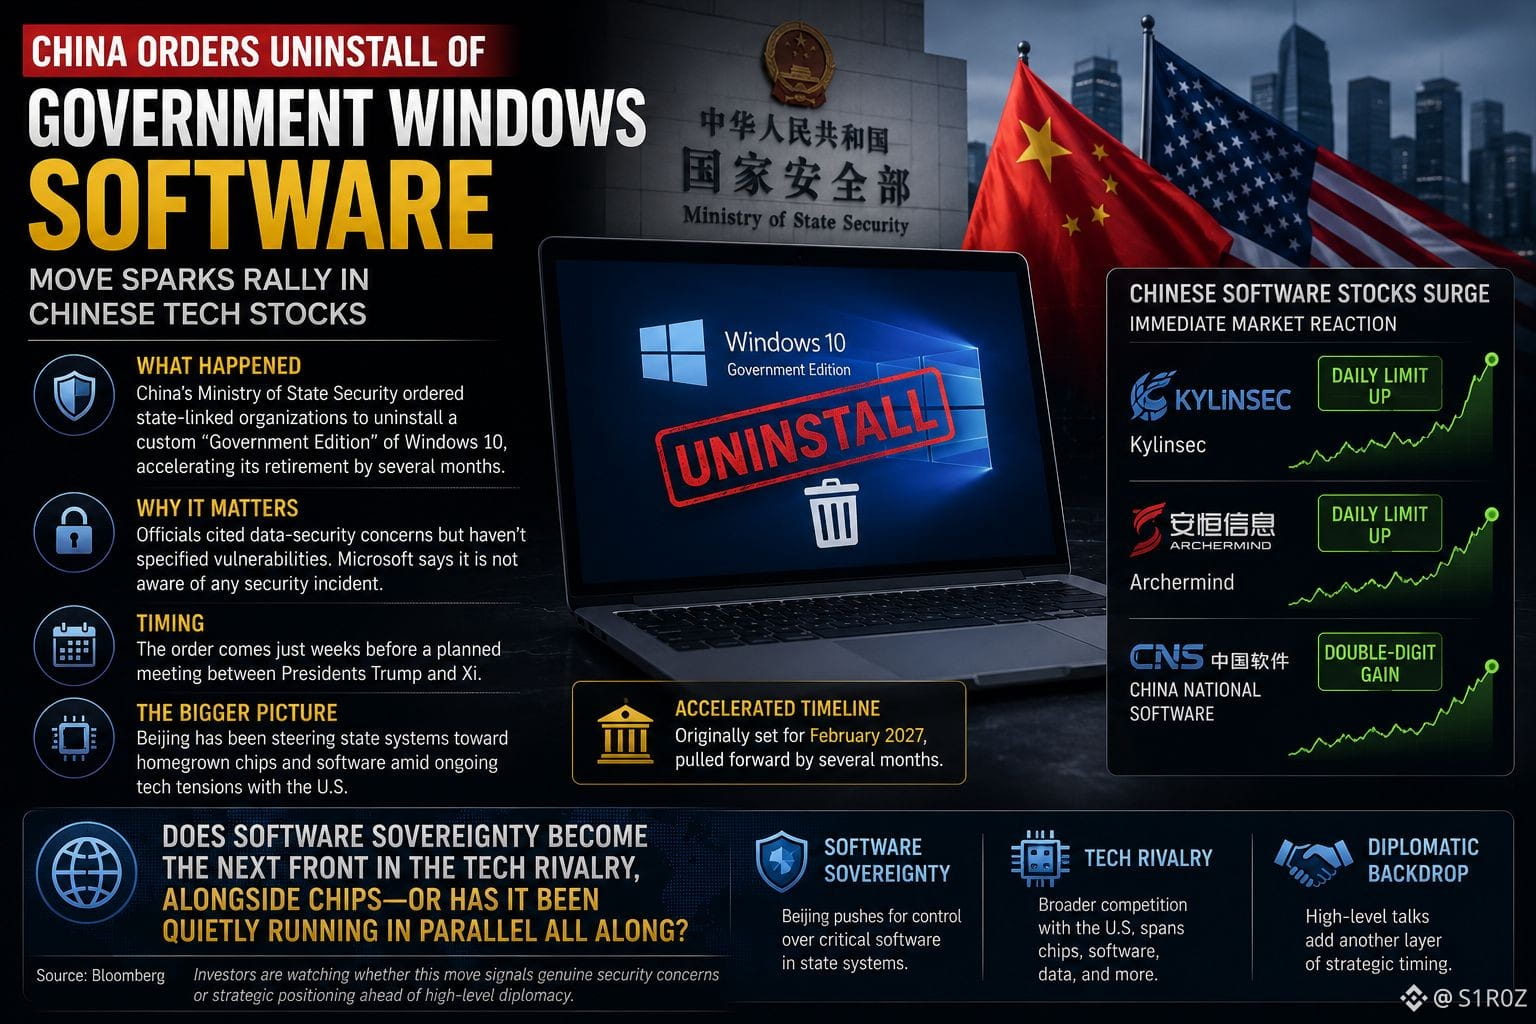
ブルームバーグによると、中国の国家安全保障省が、州・国営系の一部組織に対し、カスタマイズされた「政府版」Windows 10のアンインストールを指示したと報じられており、予定されているWindows 10の退役(更新終了)を前倒しする可能性がある。
市場の反応は即座だった:
📈 Kylinsec & Archermind:デイリー上限の値上がり
📈 中国国営ソフト:2桁の上昇
🛡️ 北京はデータ・セキュリティ上の懸念を主張
🇨🇳 国内ソフトウェア導入の追い風となる可能性
この動きは、米中の技術摩擦が続く中で、国産のチップやソフトウェアを後押しするより大きな流れに合致している。
投資家にとってのより大きな論点は、これが一過性の反応にとどまるのか、それともより長期にわたり中国のソフトウェア供給元へのシフトを加速させるのか、という点だ。
ソフトウェアの主権が、米中の技術競争における次の主要戦線になりつつあるのだろうか?
#USChina #TechStocks #Trading
#ChinaToDropOlderWindowsFromStateAgencies #ChinaTech #Software
🚨 中国のWindowsの動きが国内のソフトウェア株を急騰させた。
$BTW ,$VELVET ,$HEMI
ブルームバーグによると、中国の国家安全保障省が、州・国営系の一部組織に対し、カスタマイズされた「政府版」Windows 10のアンインストールを指示したと報じられており、予定されているWindows 10の退役(更新終了)を前倒しする可能性がある。
市場の反応は即座だった:
📈 Kylinsec & Archermind:デイリー上限の値上がり
📈 中国国営ソフト:2桁の上昇
🛡️ 北京はデータ・セキュリティ上の懸念を主張
🇨🇳 国内ソフトウェア導入の追い風となる可能性
この動きは、米中の技術摩擦が続く中で、国産のチップやソフトウェアを後押しするより大きな流れに合致している。
投資家にとってのより大きな論点は、これが一過性の反応にとどまるのか、それともより長期にわたり中国のソフトウェア供給元へのシフトを加速させるのか、という点だ。
ソフトウェアの主権が、米中の技術競争における次の主要戦線になりつつあるのだろうか?
#USChina #TechStocks #Trading
🚨 中国のWindowsの動きが国内のソフトウェア株を急騰させた。
$BTW ,$VELVET ,$HEMI
ブルームバーグによると、中国の国家安全保障省が、州・国営系の一部組織に対し、カスタマイズされた「政府版」Windows 10のアンインストールを指示したと報じられており、予定されているWindows 10の退役(更新終了)を前倒しする可能性がある。
市場の反応は即座だった:
📈 Kylinsec & Archermind:デイリー上限の値上がり
📈 中国国営ソフト:2桁の上昇
🛡️ 北京はデータ・セキュリティ上の懸念を主張
🇨🇳 国内ソフトウェア導入の追い風となる可能性
この動きは、米中の技術摩擦が続く中で、国産のチップやソフトウェアを後押しするより大きな流れに合致している。
投資家にとってのより大きな論点は、これが一過性の反応にとどまるのか、それともより長期にわたり中国のソフトウェア供給元へのシフトを加速させるのか、という点だ。
ソフトウェアの主権が、米中の技術競争における次の主要戦線になりつつあるのだろうか?
#USChina #TechStocks #Trading
1
234
#airotationkoreanchipmakersslumpchinatechsurges
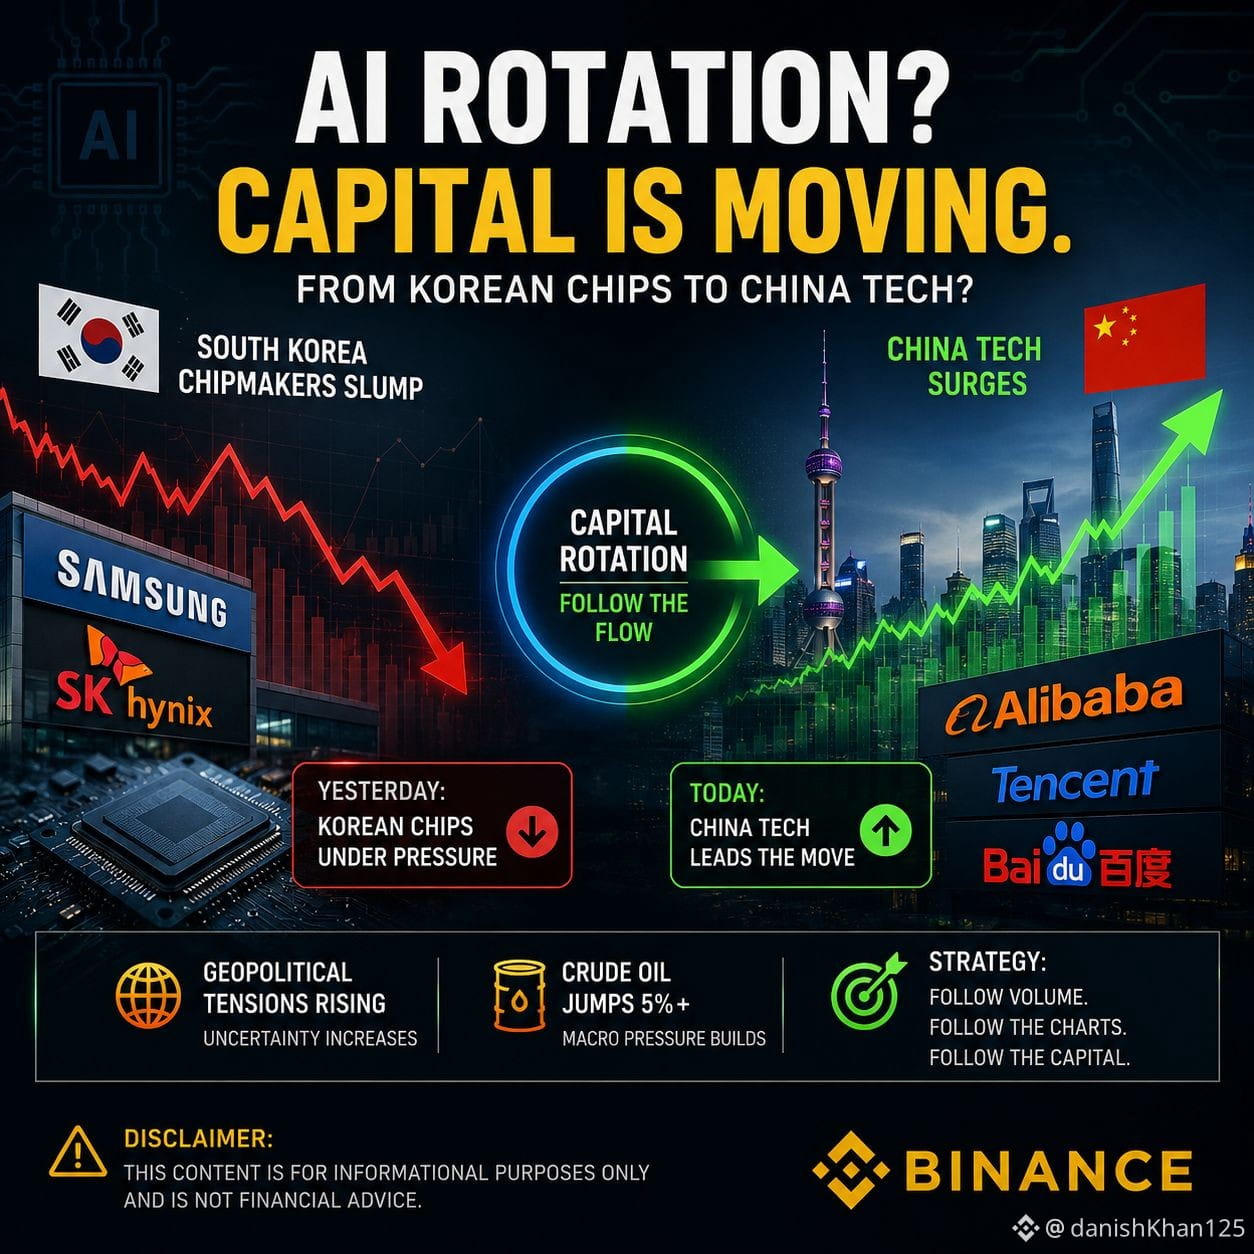
🤖📊 AIの取引は一息ついていて、資金が他へシフトしているのでしょうか?
数カ月にわたる強いAI主導の勢いの後、市場ではローテーション(資金の入れ替わり)の兆しが見えています。韓国の主要な半導体株が弱含む一方で、中国のテクノロジー関連株には改めて買いが集まっています。
同時に、地政学的不確実性の高まりと原油価格の急騰が、市場全体のセンチメントを組み替えています。昨日の勝ち組を追いかけるのではなく、新たな流動性がどこに入ってきているのかを見ているトレーダーが多くいます。
📌 注目ポイント:
• AIセクターの勢い
• 中国テックの値動き
• 取引量と資金フロー
• 原油価格とマクロの見出し
市場は周期で動きます。そうしたローテーションをいち早く見極めることは、正しい資産を選ぶのと同じくらい重要になることもよくあります。
⚠️ 本投稿は教育目的のみであり、金融アドバイスではありません。
#AITrend #ChinaTech #SouthKorea #Crypto #Trading #BinanceSquare
$SAMSUNG $SKHYNIX $AMDB
#airotationkoreanchipmakersslumpchinatechsurges
🤖📊 AIの取引は一息ついていて、資金が他へシフトしているのでしょうか?
数カ月にわたる強いAI主導の勢いの後、市場ではローテーション(資金の入れ替わり)の兆しが見えています。韓国の主要な半導体株が弱含む一方で、中国のテクノロジー関連株には改めて買いが集まっています。
同時に、地政学的不確実性の高まりと原油価格の急騰が、市場全体のセンチメントを組み替えています。昨日の勝ち組を追いかけるのではなく、新たな流動性がどこに入ってきているのかを見ているトレーダーが多くいます。
📌 注目ポイント:
• AIセクターの勢い
• 中国テックの値動き
• 取引量と資金フロー
• 原油価格とマクロの見出し
市場は周期で動きます。そうしたローテーションをいち早く見極めることは、正しい資産を選ぶのと同じくらい重要になることもよくあります。
⚠️ 本投稿は教育目的のみであり、金融アドバイスではありません。
#AITrend #ChinaTech #SouthKorea #Crypto #Trading #BinanceSquare
$SAMSUNG $SKHYNIX $AMDB
🤖📊 AIの取引は一息ついていて、資金が他へシフトしているのでしょうか?
数カ月にわたる強いAI主導の勢いの後、市場ではローテーション(資金の入れ替わり)の兆しが見えています。韓国の主要な半導体株が弱含む一方で、中国のテクノロジー関連株には改めて買いが集まっています。
同時に、地政学的不確実性の高まりと原油価格の急騰が、市場全体のセンチメントを組み替えています。昨日の勝ち組を追いかけるのではなく、新たな流動性がどこに入ってきているのかを見ているトレーダーが多くいます。
📌 注目ポイント:
• AIセクターの勢い
• 中国テックの値動き
• 取引量と資金フロー
• 原油価格とマクロの見出し
市場は周期で動きます。そうしたローテーションをいち早く見極めることは、正しい資産を選ぶのと同じくらい重要になることもよくあります。
⚠️ 本投稿は教育目的のみであり、金融アドバイスではありません。
#AITrend #ChinaTech #SouthKorea #Crypto #Trading #BinanceSquare
$SAMSUNG $SKHYNIX $AMDB
1
2.2k

·
--
記事
翻訳参照
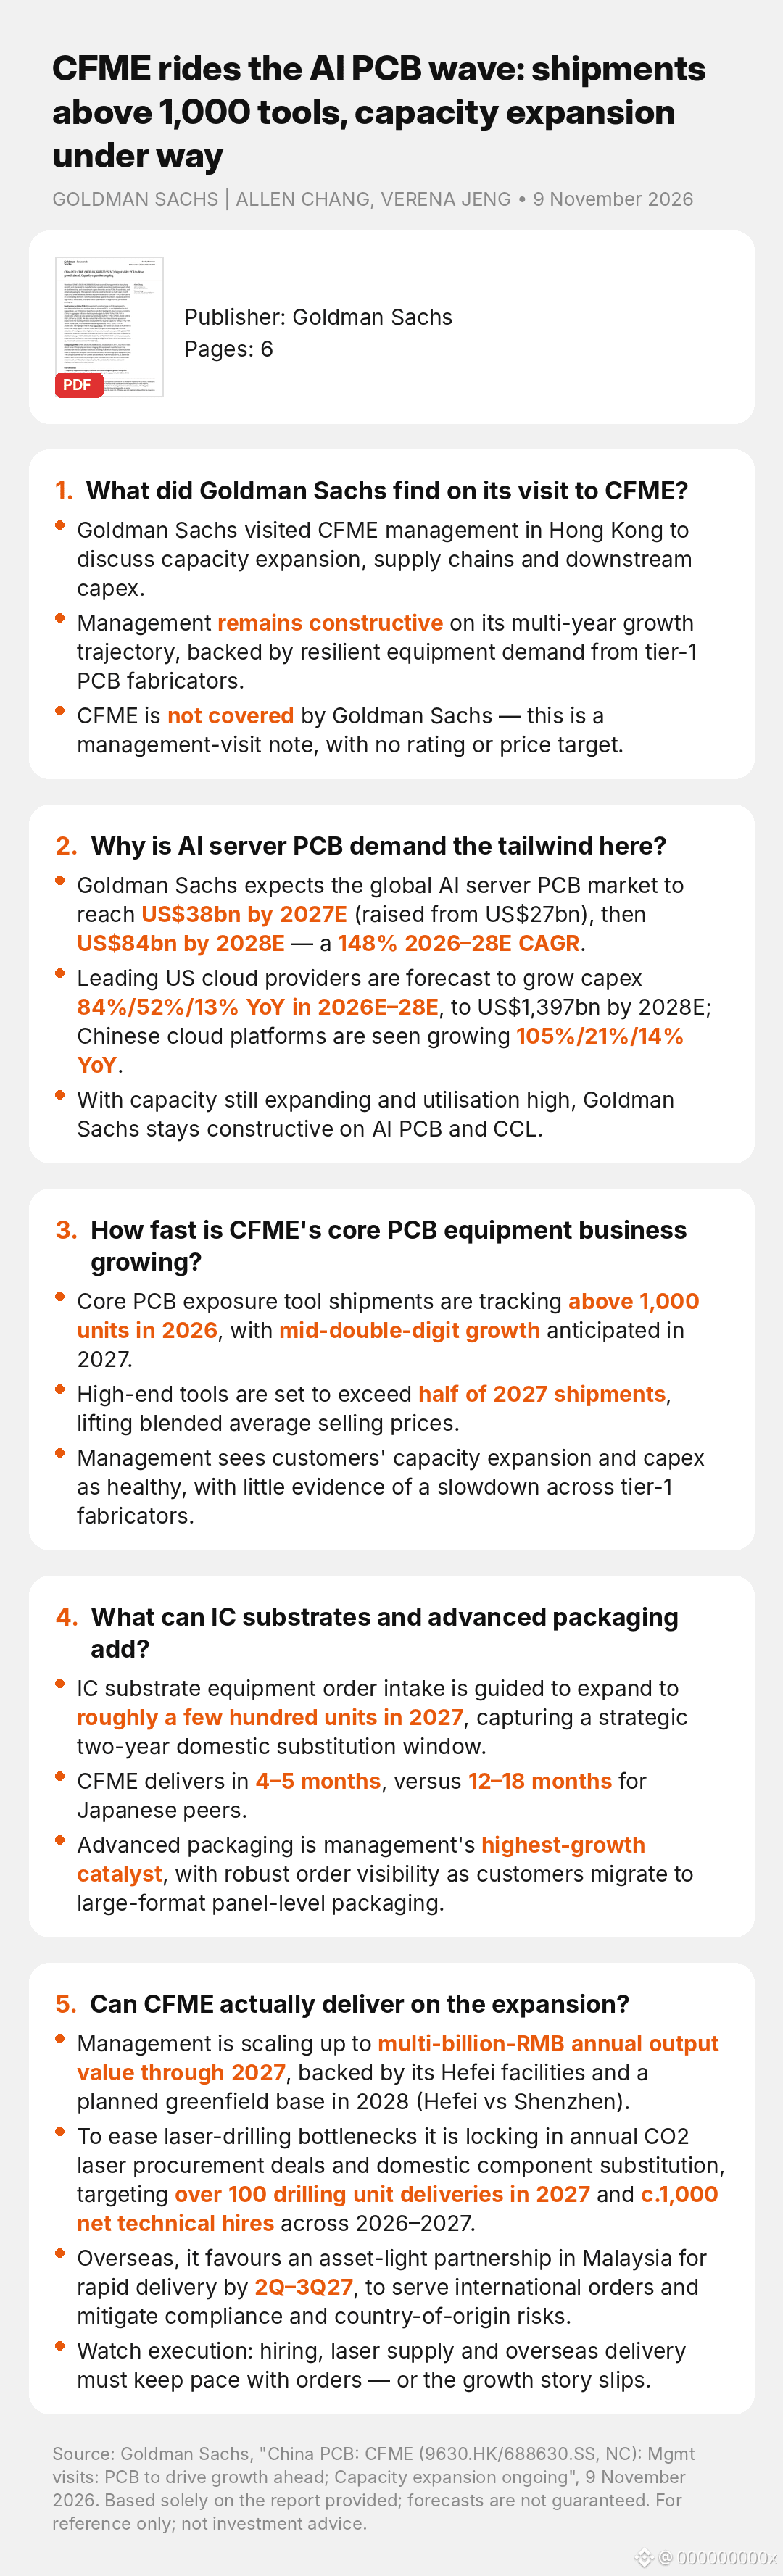
CFME rides the AI PCB wave: shipments above 1,000 tools, capacity expansion under wayCFME rides the AI PCB wave: shipments above 1,000 tools, capacity expansion under way
$9630.HK
GOLDMAN SACHS | ALLEN CHANG, VERENA JENG • 9 November 2026
1. What did Goldman Sachs find on its visit to CFME?
• Goldman Sachs visited CFME management in Hong Kong to discuss capacity expansion, supply chains and downstream capex.
• Management remains constructive on its multi-year growth trajectory, backed by resilient equipment demand from tier-1 PCB fabricators.
• CFME is not covered by Goldman Sachs — this is a management-visit note, with no rating or price target.
2. Why is AI server PCB demand the tailwind here?
• Goldman Sachs expects the global AI server PCB market to reach US$38bn by 2027E (raised from US$27bn), then US$84bn by 2028E — a 148% 2026–28E CAGR.
• Leading US cloud providers are forecast to grow capex 84%/52%/13% YoY in 2026E–28E, to US$1,397bn by 2028E; Chinese cloud platforms are seen growing 105%/21%/14% YoY.
• With capacity still expanding and utilisation high, Goldman Sachs stays constructive on AI PCB and CCL.
3. How fast is CFME's core PCB equipment business growing?
• Core PCB exposure tool shipments are tracking above 1,000 units in 2026, with mid-double-digit growth anticipated in 2027.
• High-end tools are set to exceed half of 2027 shipments, lifting blended average selling prices.
• Management sees customers' capacity expansion and capex as healthy, with little evidence of a slowdown across tier-1 fabricators.
4. What can IC substrates and advanced packaging add?
• IC substrate equipment order intake is guided to expand to roughly a few hundred units in 2027, capturing a strategic two-year domestic substitution window.
• CFME delivers in 4–5 months, versus 12–18 months for Japanese peers.
• Advanced packaging is management's highest-growth catalyst, with robust order visibility as customers migrate to large-format panel-level packaging.
5. Can CFME actually deliver on the expansion?
• Management is scaling up to multi-billion-RMB annual output value through 2027, backed by its Hefei facilities and a planned greenfield base in 2028 (Hefei vs Shenzhen).
• To ease laser-drilling bottlenecks it is locking in annual CO2 laser procurement deals and domestic component substitution, targeting over 100 drilling unit deliveries in 2027 and c.1,000 net technical hires across 2026–2027.
• Overseas, it favours an asset-light partnership in Malaysia for rapid delivery by 2Q–3Q27, to serve international orders and mitigate compliance and country-of-origin risks.
• Watch execution: hiring, laser supply and overseas delivery must keep pace with orders — or the growth story slips.
#PCB #AIServers #Semiconductors #ChinaTech #AdvancedPackaging
Source: Goldman Sachs, "China PCB: CFME (9630.HK/688630.SS, NC): Mgmt visits: PCB to drive growth ahead; Capacity expansion ongoing", 9 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-e89d12082b51444ea649f2905787cb0e-en
Visit unhidea.com for more of the latest sell-side research interpretations.
CFME rides the AI PCB wave: shipments above 1,000 tools, capacity expansion under way
CFME rides the AI PCB wave: shipments above 1,000 tools, capacity expansion under way
$9630.HK
GOLDMAN SACHS | ALLEN CHANG, VERENA JENG • 9 November 2026
1. What did Goldman Sachs find on its visit to CFME?
• Goldman Sachs visited CFME management in Hong Kong to discuss capacity expansion, supply chains and downstream capex.
• Management remains constructive on its multi-year growth trajectory, backed by resilient equipment demand from tier-1 PCB fabricators.
• CFME is not covered by Goldman Sachs — this is a management-visit note, with no rating or price target.
2. Why is AI server PCB demand the tailwind here?
• Goldman Sachs expects the global AI server PCB market to reach US$38bn by 2027E (raised from US$27bn), then US$84bn by 2028E — a 148% 2026–28E CAGR.
• Leading US cloud providers are forecast to grow capex 84%/52%/13% YoY in 2026E–28E, to US$1,397bn by 2028E; Chinese cloud platforms are seen growing 105%/21%/14% YoY.
• With capacity still expanding and utilisation high, Goldman Sachs stays constructive on AI PCB and CCL.
3. How fast is CFME's core PCB equipment business growing?
• Core PCB exposure tool shipments are tracking above 1,000 units in 2026, with mid-double-digit growth anticipated in 2027.
• High-end tools are set to exceed half of 2027 shipments, lifting blended average selling prices.
• Management sees customers' capacity expansion and capex as healthy, with little evidence of a slowdown across tier-1 fabricators.
4. What can IC substrates and advanced packaging add?
• IC substrate equipment order intake is guided to expand to roughly a few hundred units in 2027, capturing a strategic two-year domestic substitution window.
• CFME delivers in 4–5 months, versus 12–18 months for Japanese peers.
• Advanced packaging is management's highest-growth catalyst, with robust order visibility as customers migrate to large-format panel-level packaging.
5. Can CFME actually deliver on the expansion?
• Management is scaling up to multi-billion-RMB annual output value through 2027, backed by its Hefei facilities and a planned greenfield base in 2028 (Hefei vs Shenzhen).
• To ease laser-drilling bottlenecks it is locking in annual CO2 laser procurement deals and domestic component substitution, targeting over 100 drilling unit deliveries in 2027 and c.1,000 net technical hires across 2026–2027.
• Overseas, it favours an asset-light partnership in Malaysia for rapid delivery by 2Q–3Q27, to serve international orders and mitigate compliance and country-of-origin risks.
• Watch execution: hiring, laser supply and overseas delivery must keep pace with orders — or the growth story slips.
#PCB #AIServers #Semiconductors #ChinaTech #AdvancedPackaging
Source: Goldman Sachs, "China PCB: CFME (9630.HK/688630.SS, NC): Mgmt visits: PCB to drive growth ahead; Capacity expansion ongoing", 9 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-e89d12082b51444ea649f2905787cb0e-en
Visit unhidea.com for more of the latest sell-side research interpretations.
$9630.HK
GOLDMAN SACHS | ALLEN CHANG, VERENA JENG • 9 November 2026
1. What did Goldman Sachs find on its visit to CFME?
• Goldman Sachs visited CFME management in Hong Kong to discuss capacity expansion, supply chains and downstream capex.
• Management remains constructive on its multi-year growth trajectory, backed by resilient equipment demand from tier-1 PCB fabricators.
• CFME is not covered by Goldman Sachs — this is a management-visit note, with no rating or price target.
2. Why is AI server PCB demand the tailwind here?
• Goldman Sachs expects the global AI server PCB market to reach US$38bn by 2027E (raised from US$27bn), then US$84bn by 2028E — a 148% 2026–28E CAGR.
• Leading US cloud providers are forecast to grow capex 84%/52%/13% YoY in 2026E–28E, to US$1,397bn by 2028E; Chinese cloud platforms are seen growing 105%/21%/14% YoY.
• With capacity still expanding and utilisation high, Goldman Sachs stays constructive on AI PCB and CCL.
3. How fast is CFME's core PCB equipment business growing?
• Core PCB exposure tool shipments are tracking above 1,000 units in 2026, with mid-double-digit growth anticipated in 2027.
• High-end tools are set to exceed half of 2027 shipments, lifting blended average selling prices.
• Management sees customers' capacity expansion and capex as healthy, with little evidence of a slowdown across tier-1 fabricators.
4. What can IC substrates and advanced packaging add?
• IC substrate equipment order intake is guided to expand to roughly a few hundred units in 2027, capturing a strategic two-year domestic substitution window.
• CFME delivers in 4–5 months, versus 12–18 months for Japanese peers.
• Advanced packaging is management's highest-growth catalyst, with robust order visibility as customers migrate to large-format panel-level packaging.
5. Can CFME actually deliver on the expansion?
• Management is scaling up to multi-billion-RMB annual output value through 2027, backed by its Hefei facilities and a planned greenfield base in 2028 (Hefei vs Shenzhen).
• To ease laser-drilling bottlenecks it is locking in annual CO2 laser procurement deals and domestic component substitution, targeting over 100 drilling unit deliveries in 2027 and c.1,000 net technical hires across 2026–2027.
• Overseas, it favours an asset-light partnership in Malaysia for rapid delivery by 2Q–3Q27, to serve international orders and mitigate compliance and country-of-origin risks.
• Watch execution: hiring, laser supply and overseas delivery must keep pace with orders — or the growth story slips.
#PCB #AIServers #Semiconductors #ChinaTech #AdvancedPackaging
Source: Goldman Sachs, "China PCB: CFME (9630.HK/688630.SS, NC): Mgmt visits: PCB to drive growth ahead; Capacity expansion ongoing", 9 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-e89d12082b51444ea649f2905787cb0e-en
Visit unhidea.com for more of the latest sell-side research interpretations.
·
--
記事
翻訳参照
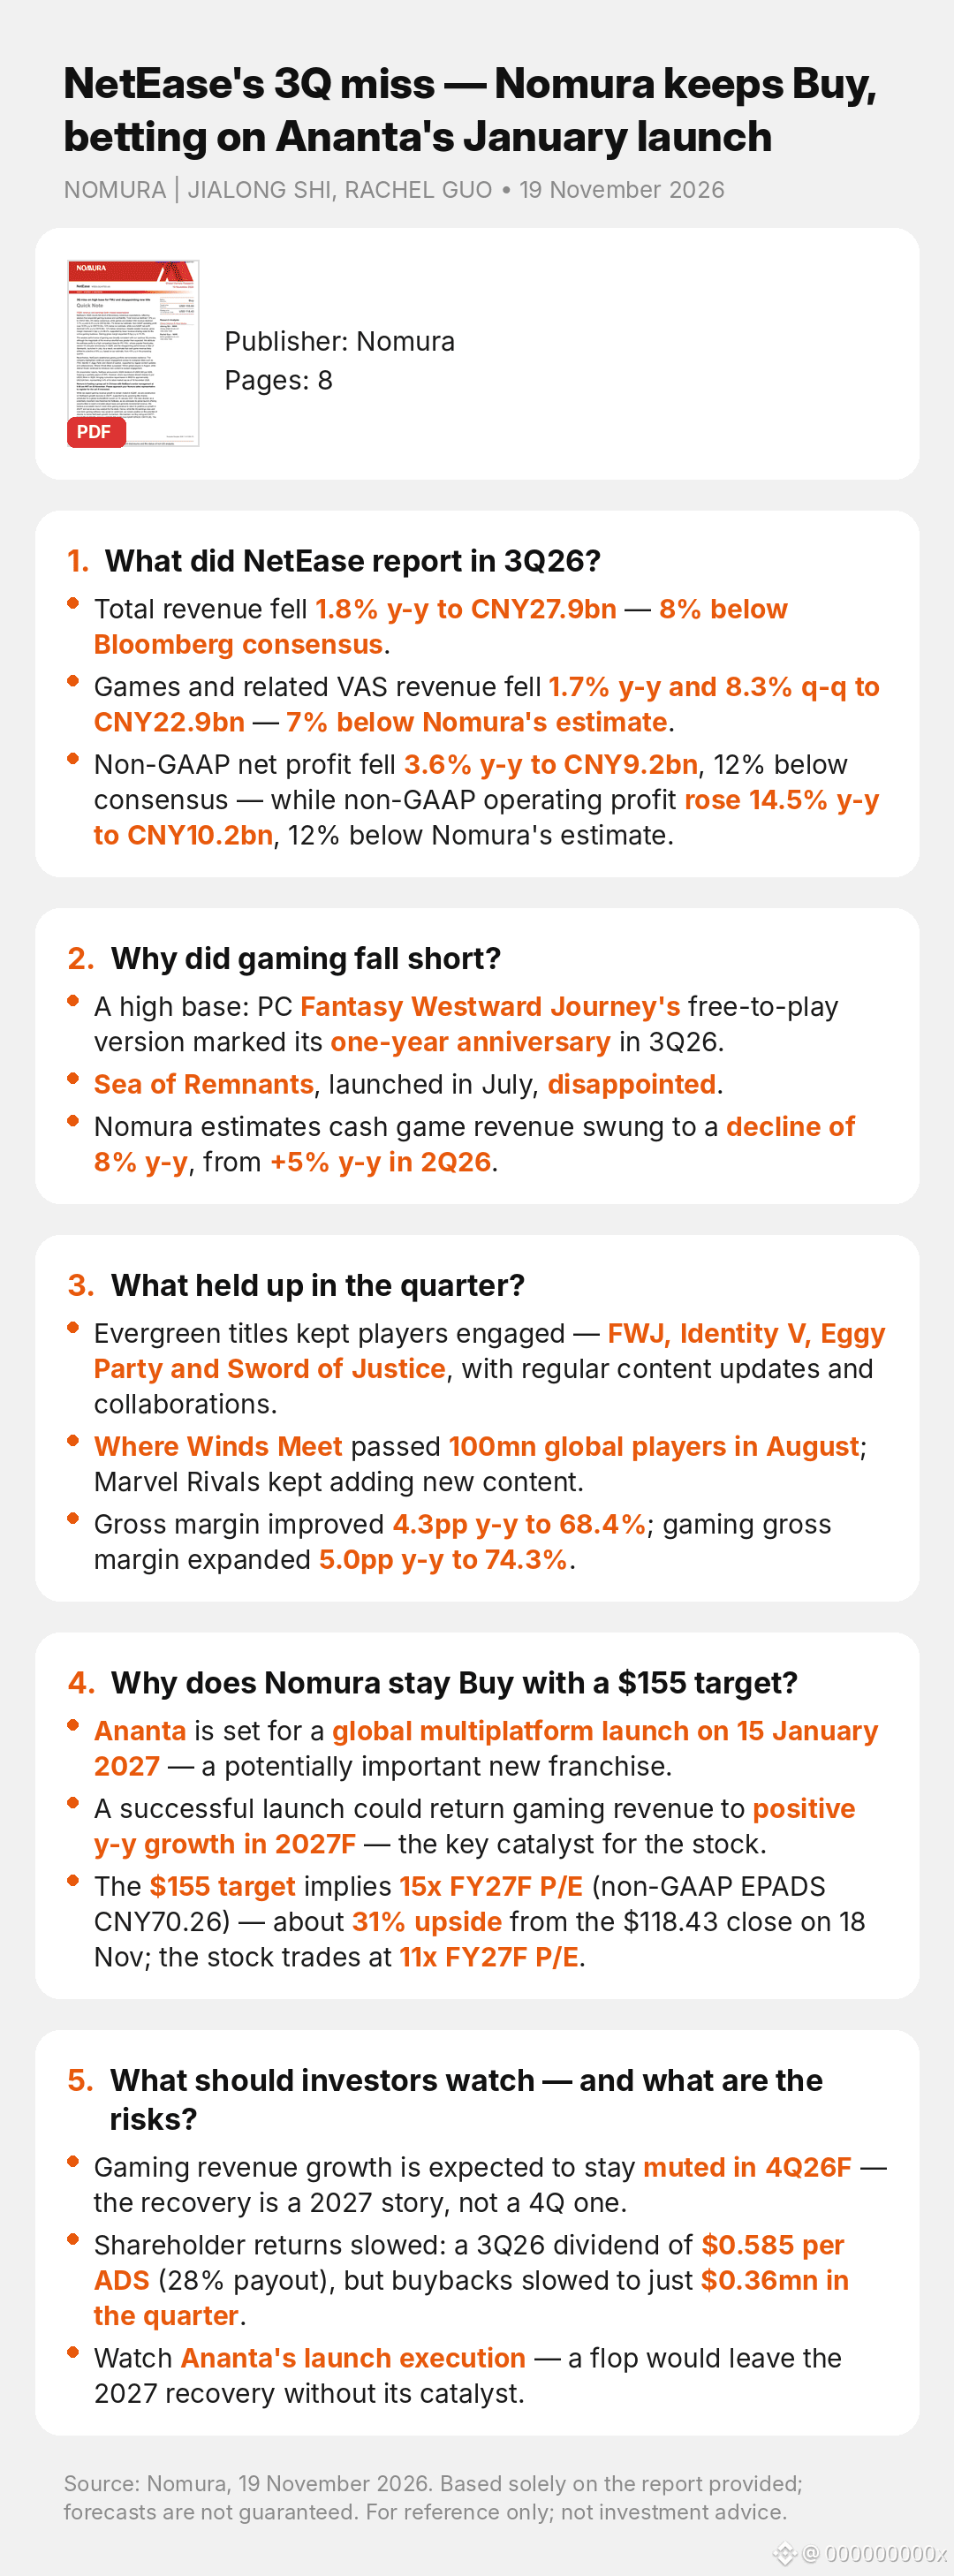
NetEase's 3Q miss — Nomura keeps Buy, betting on Ananta's January launchNetEase's 3Q miss — Nomura keeps Buy, betting on Ananta's January launch
$NTES
NOMURA | JIALONG SHI, RACHEL GUO • 19 November 2026
1. What did NetEase report in 3Q26?
• Total revenue fell 1.8% y-y to CNY27.9bn — 8% below Bloomberg consensus.
• Games and related VAS revenue fell 1.7% y-y and 8.3% q-q to CNY22.9bn — 7% below Nomura's estimate.
• Non-GAAP net profit fell 3.6% y-y to CNY9.2bn, 12% below consensus — while non-GAAP operating profit rose 14.5% y-y to CNY10.2bn, 12% below Nomura's estimate.
2. Why did gaming fall short?
• A high base: PC Fantasy Westward Journey's free-to-play version marked its one-year anniversary in 3Q26.
• Sea of Remnants, launched in July, disappointed.
• Nomura estimates cash game revenue swung to a decline of 8% y-y, from +5% y-y in 2Q26.
3. What held up in the quarter?
• Evergreen titles kept players engaged — FWJ, Identity V, Eggy Party and Sword of Justice, with regular content updates and collaborations.
• Where Winds Meet passed 100mn global players in August; Marvel Rivals kept adding new content.
• Gross margin improved 4.3pp y-y to 68.4%; gaming gross margin expanded 5.0pp y-y to 74.3%.
4. Why does Nomura stay Buy with a $155 target?
• Ananta is set for a global multiplatform launch on 15 January 2027 — a potentially important new franchise.
• A successful launch could return gaming revenue to positive y-y growth in 2027F — the key catalyst for the stock.
• The $155 target implies 15x FY27F P/E (non-GAAP EPADS CNY70.26) — about 31% upside from the $118.43 close on 18 Nov; the stock trades at 11x FY27F P/E.
5. What should investors watch — and what are the risks?
• Gaming revenue growth is expected to stay muted in 4Q26F — the recovery is a 2027 story, not a 4Q one.
• Shareholder returns slowed: a 3Q26 dividend of $0.585 per ADS (28% payout), but buybacks slowed to just $0.36mn in the quarter.
• Watch Ananta's launch execution — a flop would leave the 2027 recovery without its catalyst.
#Gaming #ChinaTech #Ananta #MobileGames #Earnings
Source: Nomura, "3Q miss on high base for FWJ and disappointing new title", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Since the report: NTES ADSs fell 11.4% to $104.94 on 19 Nov, and Hong Kong-listed shares fell 17.6% to HK$154 on 20 Nov (Yicai). NetEase's CEO also flagged AI-generated short dramas competing for gamers' time.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
NetEase's 3Q miss — Nomura keeps Buy, betting on Ananta's January launch
NetEase's 3Q miss — Nomura keeps Buy, betting on Ananta's January launch
$NTES
NOMURA | JIALONG SHI, RACHEL GUO • 19 November 2026
1. What did NetEase report in 3Q26?
• Total revenue fell 1.8% y-y to CNY27.9bn — 8% below Bloomberg consensus.
• Games and related VAS revenue fell 1.7% y-y and 8.3% q-q to CNY22.9bn — 7% below Nomura's estimate.
• Non-GAAP net profit fell 3.6% y-y to CNY9.2bn, 12% below consensus — while non-GAAP operating profit rose 14.5% y-y to CNY10.2bn, 12% below Nomura's estimate.
2. Why did gaming fall short?
• A high base: PC Fantasy Westward Journey's free-to-play version marked its one-year anniversary in 3Q26.
• Sea of Remnants, launched in July, disappointed.
• Nomura estimates cash game revenue swung to a decline of 8% y-y, from +5% y-y in 2Q26.
3. What held up in the quarter?
• Evergreen titles kept players engaged — FWJ, Identity V, Eggy Party and Sword of Justice, with regular content updates and collaborations.
• Where Winds Meet passed 100mn global players in August; Marvel Rivals kept adding new content.
• Gross margin improved 4.3pp y-y to 68.4%; gaming gross margin expanded 5.0pp y-y to 74.3%.
4. Why does Nomura stay Buy with a $155 target?
• Ananta is set for a global multiplatform launch on 15 January 2027 — a potentially important new franchise.
• A successful launch could return gaming revenue to positive y-y growth in 2027F — the key catalyst for the stock.
• The $155 target implies 15x FY27F P/E (non-GAAP EPADS CNY70.26) — about 31% upside from the $118.43 close on 18 Nov; the stock trades at 11x FY27F P/E.
5. What should investors watch — and what are the risks?
• Gaming revenue growth is expected to stay muted in 4Q26F — the recovery is a 2027 story, not a 4Q one.
• Shareholder returns slowed: a 3Q26 dividend of $0.585 per ADS (28% payout), but buybacks slowed to just $0.36mn in the quarter.
• Watch Ananta's launch execution — a flop would leave the 2027 recovery without its catalyst.
#Gaming #ChinaTech #Ananta #MobileGames #Earnings
Source: Nomura, "3Q miss on high base for FWJ and disappointing new title", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Since the report: NTES ADSs fell 11.4% to $104.94 on 19 Nov, and Hong Kong-listed shares fell 17.6% to HK$154 on 20 Nov (Yicai). NetEase's CEO also flagged AI-generated short dramas competing for gamers' time.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
$NTES
NOMURA | JIALONG SHI, RACHEL GUO • 19 November 2026
1. What did NetEase report in 3Q26?
• Total revenue fell 1.8% y-y to CNY27.9bn — 8% below Bloomberg consensus.
• Games and related VAS revenue fell 1.7% y-y and 8.3% q-q to CNY22.9bn — 7% below Nomura's estimate.
• Non-GAAP net profit fell 3.6% y-y to CNY9.2bn, 12% below consensus — while non-GAAP operating profit rose 14.5% y-y to CNY10.2bn, 12% below Nomura's estimate.
2. Why did gaming fall short?
• A high base: PC Fantasy Westward Journey's free-to-play version marked its one-year anniversary in 3Q26.
• Sea of Remnants, launched in July, disappointed.
• Nomura estimates cash game revenue swung to a decline of 8% y-y, from +5% y-y in 2Q26.
3. What held up in the quarter?
• Evergreen titles kept players engaged — FWJ, Identity V, Eggy Party and Sword of Justice, with regular content updates and collaborations.
• Where Winds Meet passed 100mn global players in August; Marvel Rivals kept adding new content.
• Gross margin improved 4.3pp y-y to 68.4%; gaming gross margin expanded 5.0pp y-y to 74.3%.
4. Why does Nomura stay Buy with a $155 target?
• Ananta is set for a global multiplatform launch on 15 January 2027 — a potentially important new franchise.
• A successful launch could return gaming revenue to positive y-y growth in 2027F — the key catalyst for the stock.
• The $155 target implies 15x FY27F P/E (non-GAAP EPADS CNY70.26) — about 31% upside from the $118.43 close on 18 Nov; the stock trades at 11x FY27F P/E.
5. What should investors watch — and what are the risks?
• Gaming revenue growth is expected to stay muted in 4Q26F — the recovery is a 2027 story, not a 4Q one.
• Shareholder returns slowed: a 3Q26 dividend of $0.585 per ADS (28% payout), but buybacks slowed to just $0.36mn in the quarter.
• Watch Ananta's launch execution — a flop would leave the 2027 recovery without its catalyst.
#Gaming #ChinaTech #Ananta #MobileGames #Earnings
Source: Nomura, "3Q miss on high base for FWJ and disappointing new title", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Since the report: NTES ADSs fell 11.4% to $104.94 on 19 Nov, and Hong Kong-listed shares fell 17.6% to HK$154 on 20 Nov (Yicai). NetEase's CEO also flagged AI-generated short dramas competing for gamers' time.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
1
·
--
記事
翻訳参照
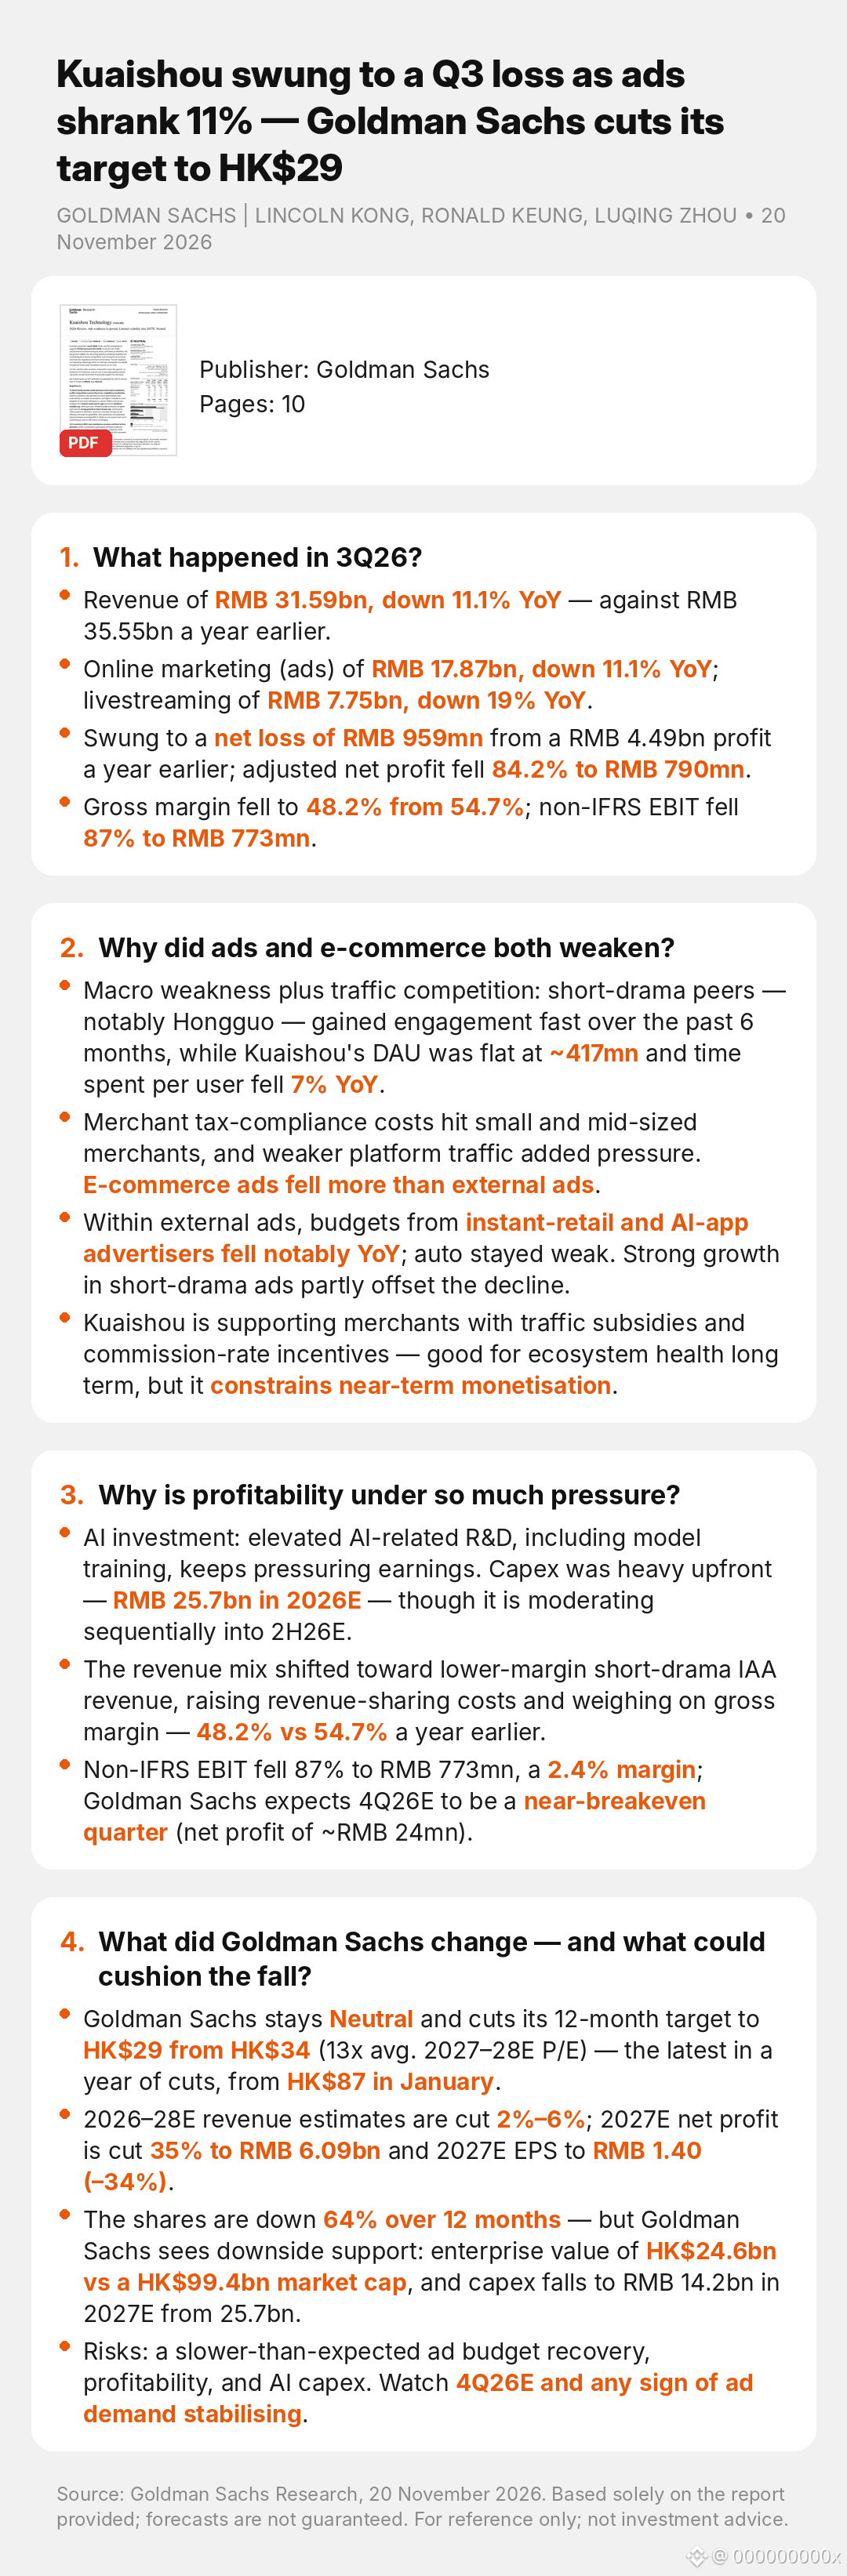
Kuaishou swung to a Q3 loss as ads shrank 11% — Goldman Sachs cuts its target to HK$29Kuaishou swung to a Q3 loss as ads shrank 11% — Goldman Sachs cuts its target to HK$29
$1024.HK
GOLDMAN SACHS | LINCOLN KONG, RONALD KEUNG, LUQING ZHOU • 20 November 2026
1. What happened in 3Q26?
• Revenue of RMB 31.59bn, down 11.1% YoY — against RMB 35.55bn a year earlier.
• Online marketing (ads) of RMB 17.87bn, down 11.1% YoY; livestreaming of RMB 7.75bn, down 19% YoY.
• Swung to a net loss of RMB 959mn from a RMB 4.49bn profit a year earlier; adjusted net profit fell 84.2% to RMB 790mn.
• Gross margin fell to 48.2% from 54.7%; non-IFRS EBIT fell 87% to RMB 773mn.
2. Why did ads and e-commerce both weaken?
• Macro weakness plus traffic competition: short-drama peers — notably Hongguo — gained engagement fast over the past 6 months, while Kuaishou's DAU was flat at ~417mn and time spent per user fell 7% YoY.
• Merchant tax-compliance costs hit small and mid-sized merchants, and weaker platform traffic added pressure. E-commerce ads fell more than external ads.
• Within external ads, budgets from instant-retail and AI-app advertisers fell notably YoY; auto stayed weak. Strong growth in short-drama ads partly offset the decline.
• Kuaishou is supporting merchants with traffic subsidies and commission-rate incentives — good for ecosystem health long term, but it constrains near-term monetisation.
3. Why is profitability under so much pressure?
• AI investment: elevated AI-related R&D, including model training, keeps pressuring earnings. Capex was heavy upfront — RMB 25.7bn in 2026E — though it is moderating sequentially into 2H26E.
• The revenue mix shifted toward lower-margin short-drama IAA revenue, raising revenue-sharing costs and weighing on gross margin — 48.2% vs 54.7% a year earlier.
• Non-IFRS EBIT fell 87% to RMB 773mn, a 2.4% margin; Goldman Sachs expects 4Q26E to be a near-breakeven quarter (net profit of ~RMB 24mn).
4. What did Goldman Sachs change — and what could cushion the fall?
• Goldman Sachs stays Neutral and cuts its 12-month target to HK$29 from HK$34 (13x avg. 2027–28E P/E) — the latest in a year of cuts, from HK$87 in January.
• 2026–28E revenue estimates are cut 2%–6%; 2027E net profit is cut 35% to RMB 6.09bn and 2027E EPS to RMB 1.40 (–34%).
• The shares are down 64% over 12 months — but Goldman Sachs sees downside support: enterprise value of HK$24.6bn vs a HK$99.4bn market cap, and capex falls to RMB 14.2bn in 2027E from 25.7bn.
• Risks: a slower-than-expected ad budget recovery, profitability, and AI capex. Watch 4Q26E and any sign of ad demand stabilising.
Post-report market data, 20 Nov: shares fell 11.4% to HK$20.42 after the results, hitting a record intraday low of HK$19.97 (Yicai / Finwire).
#Kuaishou #ChinaTech #ShortVideo #Advertising #AI
Source: Goldman Sachs, "3Q26 Review: Ads weakness to persist; Limited visibility into 2027E", 20 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
Kuaishou swung to a Q3 loss as ads shrank 11% — Goldman Sachs cuts its target to HK$29
Kuaishou swung to a Q3 loss as ads shrank 11% — Goldman Sachs cuts its target to HK$29
$1024.HK
GOLDMAN SACHS | LINCOLN KONG, RONALD KEUNG, LUQING ZHOU • 20 November 2026
1. What happened in 3Q26?
• Revenue of RMB 31.59bn, down 11.1% YoY — against RMB 35.55bn a year earlier.
• Online marketing (ads) of RMB 17.87bn, down 11.1% YoY; livestreaming of RMB 7.75bn, down 19% YoY.
• Swung to a net loss of RMB 959mn from a RMB 4.49bn profit a year earlier; adjusted net profit fell 84.2% to RMB 790mn.
• Gross margin fell to 48.2% from 54.7%; non-IFRS EBIT fell 87% to RMB 773mn.
2. Why did ads and e-commerce both weaken?
• Macro weakness plus traffic competition: short-drama peers — notably Hongguo — gained engagement fast over the past 6 months, while Kuaishou's DAU was flat at ~417mn and time spent per user fell 7% YoY.
• Merchant tax-compliance costs hit small and mid-sized merchants, and weaker platform traffic added pressure. E-commerce ads fell more than external ads.
• Within external ads, budgets from instant-retail and AI-app advertisers fell notably YoY; auto stayed weak. Strong growth in short-drama ads partly offset the decline.
• Kuaishou is supporting merchants with traffic subsidies and commission-rate incentives — good for ecosystem health long term, but it constrains near-term monetisation.
3. Why is profitability under so much pressure?
• AI investment: elevated AI-related R&D, including model training, keeps pressuring earnings. Capex was heavy upfront — RMB 25.7bn in 2026E — though it is moderating sequentially into 2H26E.
• The revenue mix shifted toward lower-margin short-drama IAA revenue, raising revenue-sharing costs and weighing on gross margin — 48.2% vs 54.7% a year earlier.
• Non-IFRS EBIT fell 87% to RMB 773mn, a 2.4% margin; Goldman Sachs expects 4Q26E to be a near-breakeven quarter (net profit of ~RMB 24mn).
4. What did Goldman Sachs change — and what could cushion the fall?
• Goldman Sachs stays Neutral and cuts its 12-month target to HK$29 from HK$34 (13x avg. 2027–28E P/E) — the latest in a year of cuts, from HK$87 in January.
• 2026–28E revenue estimates are cut 2%–6%; 2027E net profit is cut 35% to RMB 6.09bn and 2027E EPS to RMB 1.40 (–34%).
• The shares are down 64% over 12 months — but Goldman Sachs sees downside support: enterprise value of HK$24.6bn vs a HK$99.4bn market cap, and capex falls to RMB 14.2bn in 2027E from 25.7bn.
• Risks: a slower-than-expected ad budget recovery, profitability, and AI capex. Watch 4Q26E and any sign of ad demand stabilising.
Post-report market data, 20 Nov: shares fell 11.4% to HK$20.42 after the results, hitting a record intraday low of HK$19.97 (Yicai / Finwire).
#Kuaishou #ChinaTech #ShortVideo #Advertising #AI
Source: Goldman Sachs, "3Q26 Review: Ads weakness to persist; Limited visibility into 2027E", 20 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
$1024.HK
GOLDMAN SACHS | LINCOLN KONG, RONALD KEUNG, LUQING ZHOU • 20 November 2026
1. What happened in 3Q26?
• Revenue of RMB 31.59bn, down 11.1% YoY — against RMB 35.55bn a year earlier.
• Online marketing (ads) of RMB 17.87bn, down 11.1% YoY; livestreaming of RMB 7.75bn, down 19% YoY.
• Swung to a net loss of RMB 959mn from a RMB 4.49bn profit a year earlier; adjusted net profit fell 84.2% to RMB 790mn.
• Gross margin fell to 48.2% from 54.7%; non-IFRS EBIT fell 87% to RMB 773mn.
2. Why did ads and e-commerce both weaken?
• Macro weakness plus traffic competition: short-drama peers — notably Hongguo — gained engagement fast over the past 6 months, while Kuaishou's DAU was flat at ~417mn and time spent per user fell 7% YoY.
• Merchant tax-compliance costs hit small and mid-sized merchants, and weaker platform traffic added pressure. E-commerce ads fell more than external ads.
• Within external ads, budgets from instant-retail and AI-app advertisers fell notably YoY; auto stayed weak. Strong growth in short-drama ads partly offset the decline.
• Kuaishou is supporting merchants with traffic subsidies and commission-rate incentives — good for ecosystem health long term, but it constrains near-term monetisation.
3. Why is profitability under so much pressure?
• AI investment: elevated AI-related R&D, including model training, keeps pressuring earnings. Capex was heavy upfront — RMB 25.7bn in 2026E — though it is moderating sequentially into 2H26E.
• The revenue mix shifted toward lower-margin short-drama IAA revenue, raising revenue-sharing costs and weighing on gross margin — 48.2% vs 54.7% a year earlier.
• Non-IFRS EBIT fell 87% to RMB 773mn, a 2.4% margin; Goldman Sachs expects 4Q26E to be a near-breakeven quarter (net profit of ~RMB 24mn).
4. What did Goldman Sachs change — and what could cushion the fall?
• Goldman Sachs stays Neutral and cuts its 12-month target to HK$29 from HK$34 (13x avg. 2027–28E P/E) — the latest in a year of cuts, from HK$87 in January.
• 2026–28E revenue estimates are cut 2%–6%; 2027E net profit is cut 35% to RMB 6.09bn and 2027E EPS to RMB 1.40 (–34%).
• The shares are down 64% over 12 months — but Goldman Sachs sees downside support: enterprise value of HK$24.6bn vs a HK$99.4bn market cap, and capex falls to RMB 14.2bn in 2027E from 25.7bn.
• Risks: a slower-than-expected ad budget recovery, profitability, and AI capex. Watch 4Q26E and any sign of ad demand stabilising.
Post-report market data, 20 Nov: shares fell 11.4% to HK$20.42 after the results, hitting a record intraday low of HK$19.97 (Yicai / Finwire).
#Kuaishou #ChinaTech #ShortVideo #Advertising #AI
Source: Goldman Sachs, "3Q26 Review: Ads weakness to persist; Limited visibility into 2027E", 20 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
29
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号
トレンドトピック
1
#NvidiaLoses$2.7TrillionInMonthAndAHalf
閲覧回数 5,208
74人が討論中
2
#CanBTCReboundAfterFallingBelow60K?
閲覧回数 611,302
2,647人が討論中
3
#GlobalStocksFaceLongestLosingStreakSince2023
閲覧回数 214,271
1,817人が討論中
4
#BlackRockIBITPostsRecord$541MSingleDayOutflow
閲覧回数 20,803
64人が討論中
5
#AnthropicPlungesTowardIPOPriceonDay2
閲覧回数 106,425
1,075人が討論中
6
#TwentyOneCapitalAdds172.25BTC
閲覧回数 44,955
556人が討論中
7
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
閲覧回数 5,006
48人が討論中
8
#BNBDropsBelow540USDTWith8.46%DailyDecline
閲覧回数 60,939
567人が討論中
9
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
閲覧回数 2,033
21人が討論中
10
#BitMineFaces$10.1BUnrealizedETHLoss
閲覧回数 4,291
25人が討論中