
#semiconductors
semiconductors
683,790 views
4,106 Discussing
Hot
Latest
Article
SanDisk (SNDK): The 64% Crash Explained(This Articleis only for those who really wants to know the company details and investors or traders)
🚨 HEADLINE: 64% CRASH — Opportunity or Trap?
SanDisk's stock has fallen -64% from its June high. But this is not the company's downfall — it is a "valuation reset for a cyclical stock."
📊 NUMBERS THAT MATTER (Hard Figures)
| Metric | Figure | What it means |
| Stock fall | -64% from June high | Violent correction, not bankruptcy risk |
| Revenue growth | +378% YoY | Sales exploded due to AI storage shortage |
| Gross Margin | 85% | Cyclical PEAK — not normal |
| Forward P/E | ~3.7x | Tech average 19x — very cheap (or an illusion?) |
| Next Q growth guidance | ~13% (vs near-doubling) | This was the trigger — growth momentum gone |
| 2027 supply locked | ~50% long-term contracts | Earnings visibility |
| 2028 supply locked | ~66% long-term contracts | Earnings visibility |
| Contract floor margin | ~80% | Strong even in worst case |
| Wall St. avg target | $2,056 | Huge implied upside (bulls) |
| Key support | $800–820 | Technical stabilization zone |
📉 THE 3 REAL REASONS FOR THE CRASH
1. "Good news priced in" + Growth deceleration
The market already knew about 378% revenue and 85% margin. The real shock: management said next quarter's growth would slow from "near-doubling" to ~13%. For a high-valuation stock, growth stalling is a fatal signal.
2. Fear of memory cycle peaking
Memory is classically cyclical. 85% margin could be the peak. Micron and SK Hynix are raising CAPEX + Chinese players (CXMT, YMTC) are ramping capacity → shortage → oversupply → fear of profit collapse.
3. Macro + sentiment
- Democratic sweep in US midterms → fear of tighter data center regulation → AI infrastructure demand could be suppressed
- 1-for-8 stock split coming → added volatility
⚖️ BULL vs BEAR — Sharp Edges on Both Sides
🐂 BULL CASE (Golden Opportunity)
- Forward P/E ~3.7x — worst-case "profit collapse" already priced in
- ~50% of 2027 and ~66% of 2028 NAND supply locked — tremendous earnings visibility
- ~80% gross margin even at contract floor price — safety cushion
- Humanoid robots = new demand narrative (each robot needs several TB of storage)
- Wall St. target $2,056 — significant upside
🐻 BEAR CASE (Value Trap)
- If this is the cycle peak → 3.7x P/E is an illusion — once earnings normalize/fall, P/E goes back up
- CXMT sales surged 8x (first 9 months) + YMTC expansion → erodes pricing power and market share
- Clear technical downtrend — without stabilization at $800–820 support, it's "catching a falling knife"
- If oversupply materializes, further downside is possible
💎 BOTTOM LINE
The 64% crash = a "valuation reset," not bankruptcy risk.
| Who are you? | Strategy |
| Short-term trader | Downtrend is active. Extreme volatility around the stock split date. Bottom-fishing = high risk. Strict stop-loss is mandatory.|
| Long-term investor | If you believe AI storage demand is a multi-year structural trend (not a short-term shortage) → ultra-low valuation + long-term contracts provide a thick safety cushion. But: wait for stabilization + volume at $800–820 support first, then build positions in batches (DCA). |
🔥 In one line: Is it cheap or does it just look cheap — that depends on how AI/memory demand plays out over the next 2-3 years. Don't put all your money in at once. Respect the levels and the volume.
Sources: Earnings report (Revenue +378% YoY, GM 85%), management guidance (~13% growth), long-term contract disclosures (~50% 2027, ~66% 2028, ~80% floor margin), analyst targets ($2,056 avg), technical support ($800–820).
$SNDK $CXMT
{future}(CXMTUSDT)
{future}(SNDKUSDT)
#Semiconductors #ValueInvesting #artificialintelligence #Binance #stockmarket
SanDisk (SNDK): The 64% Crash Explained
(This Articleis only for those who really wants to know the company details and investors or traders)
🚨 HEADLINE: 64% CRASH — Opportunity or Trap?
SanDisk's stock has fallen -64% from its June high. But this is not the company's downfall — it is a "valuation reset for a cyclical stock."
📊 NUMBERS THAT MATTER (Hard Figures)
| Metric | Figure | What it means |
| Stock fall | -64% from June high | Violent correction, not bankruptcy risk |
| Revenue growth | +378% YoY | Sales exploded due to AI storage shortage |
| Gross Margin | 85% | Cyclical PEAK — not normal |
| Forward P/E | ~3.7x | Tech average 19x — very cheap (or an illusion?) |
| Next Q growth guidance | ~13% (vs near-doubling) | This was the trigger — growth momentum gone |
| 2027 supply locked | ~50% long-term contracts | Earnings visibility |
| 2028 supply locked | ~66% long-term contracts | Earnings visibility |
| Contract floor margin | ~80% | Strong even in worst case |
| Wall St. avg target | $2,056 | Huge implied upside (bulls) |
| Key support | $800–820 | Technical stabilization zone |
📉 THE 3 REAL REASONS FOR THE CRASH
1. "Good news priced in" + Growth deceleration
The market already knew about 378% revenue and 85% margin. The real shock: management said next quarter's growth would slow from "near-doubling" to ~13%. For a high-valuation stock, growth stalling is a fatal signal.
2. Fear of memory cycle peaking
Memory is classically cyclical. 85% margin could be the peak. Micron and SK Hynix are raising CAPEX + Chinese players (CXMT, YMTC) are ramping capacity → shortage → oversupply → fear of profit collapse.
3. Macro + sentiment
- Democratic sweep in US midterms → fear of tighter data center regulation → AI infrastructure demand could be suppressed
- 1-for-8 stock split coming → added volatility
⚖️ BULL vs BEAR — Sharp Edges on Both Sides
🐂 BULL CASE (Golden Opportunity)
- Forward P/E ~3.7x — worst-case "profit collapse" already priced in
- ~50% of 2027 and ~66% of 2028 NAND supply locked — tremendous earnings visibility
- ~80% gross margin even at contract floor price — safety cushion
- Humanoid robots = new demand narrative (each robot needs several TB of storage)
- Wall St. target $2,056 — significant upside
🐻 BEAR CASE (Value Trap)
- If this is the cycle peak → 3.7x P/E is an illusion — once earnings normalize/fall, P/E goes back up
- CXMT sales surged 8x (first 9 months) + YMTC expansion → erodes pricing power and market share
- Clear technical downtrend — without stabilization at $800–820 support, it's "catching a falling knife"
- If oversupply materializes, further downside is possible
💎 BOTTOM LINE
The 64% crash = a "valuation reset," not bankruptcy risk.
| Who are you? | Strategy |
| Short-term trader | Downtrend is active. Extreme volatility around the stock split date. Bottom-fishing = high risk. Strict stop-loss is mandatory.|
| Long-term investor | If you believe AI storage demand is a multi-year structural trend (not a short-term shortage) → ultra-low valuation + long-term contracts provide a thick safety cushion. But: wait for stabilization + volume at $800–820 support first, then build positions in batches (DCA). |
🔥 In one line: Is it cheap or does it just look cheap — that depends on how AI/memory demand plays out over the next 2-3 years. Don't put all your money in at once. Respect the levels and the volume.
Sources: Earnings report (Revenue +378% YoY, GM 85%), management guidance (~13% growth), long-term contract disclosures (~50% 2027, ~66% 2028, ~80% floor margin), analyst targets ($2,056 avg), technical support ($800–820).
$SNDK $CXMT
#Semiconductors #ValueInvesting #artificialintelligence #Binance #stockmarket
🚨 HEADLINE: 64% CRASH — Opportunity or Trap?
SanDisk's stock has fallen -64% from its June high. But this is not the company's downfall — it is a "valuation reset for a cyclical stock."
📊 NUMBERS THAT MATTER (Hard Figures)
| Metric | Figure | What it means |
| Stock fall | -64% from June high | Violent correction, not bankruptcy risk |
| Revenue growth | +378% YoY | Sales exploded due to AI storage shortage |
| Gross Margin | 85% | Cyclical PEAK — not normal |
| Forward P/E | ~3.7x | Tech average 19x — very cheap (or an illusion?) |
| Next Q growth guidance | ~13% (vs near-doubling) | This was the trigger — growth momentum gone |
| 2027 supply locked | ~50% long-term contracts | Earnings visibility |
| 2028 supply locked | ~66% long-term contracts | Earnings visibility |
| Contract floor margin | ~80% | Strong even in worst case |
| Wall St. avg target | $2,056 | Huge implied upside (bulls) |
| Key support | $800–820 | Technical stabilization zone |
📉 THE 3 REAL REASONS FOR THE CRASH
1. "Good news priced in" + Growth deceleration
The market already knew about 378% revenue and 85% margin. The real shock: management said next quarter's growth would slow from "near-doubling" to ~13%. For a high-valuation stock, growth stalling is a fatal signal.
2. Fear of memory cycle peaking
Memory is classically cyclical. 85% margin could be the peak. Micron and SK Hynix are raising CAPEX + Chinese players (CXMT, YMTC) are ramping capacity → shortage → oversupply → fear of profit collapse.
3. Macro + sentiment
- Democratic sweep in US midterms → fear of tighter data center regulation → AI infrastructure demand could be suppressed
- 1-for-8 stock split coming → added volatility
⚖️ BULL vs BEAR — Sharp Edges on Both Sides
🐂 BULL CASE (Golden Opportunity)
- Forward P/E ~3.7x — worst-case "profit collapse" already priced in
- ~50% of 2027 and ~66% of 2028 NAND supply locked — tremendous earnings visibility
- ~80% gross margin even at contract floor price — safety cushion
- Humanoid robots = new demand narrative (each robot needs several TB of storage)
- Wall St. target $2,056 — significant upside
🐻 BEAR CASE (Value Trap)
- If this is the cycle peak → 3.7x P/E is an illusion — once earnings normalize/fall, P/E goes back up
- CXMT sales surged 8x (first 9 months) + YMTC expansion → erodes pricing power and market share
- Clear technical downtrend — without stabilization at $800–820 support, it's "catching a falling knife"
- If oversupply materializes, further downside is possible
💎 BOTTOM LINE
The 64% crash = a "valuation reset," not bankruptcy risk.
| Who are you? | Strategy |
| Short-term trader | Downtrend is active. Extreme volatility around the stock split date. Bottom-fishing = high risk. Strict stop-loss is mandatory.|
| Long-term investor | If you believe AI storage demand is a multi-year structural trend (not a short-term shortage) → ultra-low valuation + long-term contracts provide a thick safety cushion. But: wait for stabilization + volume at $800–820 support first, then build positions in batches (DCA). |
🔥 In one line: Is it cheap or does it just look cheap — that depends on how AI/memory demand plays out over the next 2-3 years. Don't put all your money in at once. Respect the levels and the volume.
Sources: Earnings report (Revenue +378% YoY, GM 85%), management guidance (~13% growth), long-term contract disclosures (~50% 2027, ~66% 2028, ~80% floor margin), analyst targets ($2,056 avg), technical support ($800–820).
$SNDK $CXMT
#Semiconductors #ValueInvesting #artificialintelligence #Binance #stockmarket
1
424
🚨 NVIDIA faces fresh scrutiny over alleged $7.5 BILLION in chip shipments linked to Chinese firms.
According to The Information, a network involving companies in China and Singapore allegedly facilitated the movement of approximately 240,000 NVIDIA chips into China since 2023, including models subject to US export restrictions.
NVIDIA says its partners must follow US export rules. CEO Jensen Huang has not been shown to have personally authorized any illegal shipments.
The independent investigation is ongoing.
Market impact: Potential regulatory pressure, geopolitical tensions, and risks to NVIDIA's China business.
#NVIDIA #China #AI #Semiconductors #StockMarket
🚨 NVIDIA faces fresh scrutiny over alleged $7.5 BILLION in chip shipments linked to Chinese firms.
According to The Information, a network involving companies in China and Singapore allegedly facilitated the movement of approximately 240,000 NVIDIA chips into China since 2023, including models subject to US export restrictions.
NVIDIA says its partners must follow US export rules. CEO Jensen Huang has not been shown to have personally authorized any illegal shipments.
The independent investigation is ongoing.
Market impact: Potential regulatory pressure, geopolitical tensions, and risks to NVIDIA's China business.
#NVIDIA #China #AI #Semiconductors #StockMarket
According to The Information, a network involving companies in China and Singapore allegedly facilitated the movement of approximately 240,000 NVIDIA chips into China since 2023, including models subject to US export restrictions.
NVIDIA says its partners must follow US export rules. CEO Jensen Huang has not been shown to have personally authorized any illegal shipments.
The independent investigation is ongoing.
Market impact: Potential regulatory pressure, geopolitical tensions, and risks to NVIDIA's China business.
#NVIDIA #China #AI #Semiconductors #StockMarket
1
399
Article
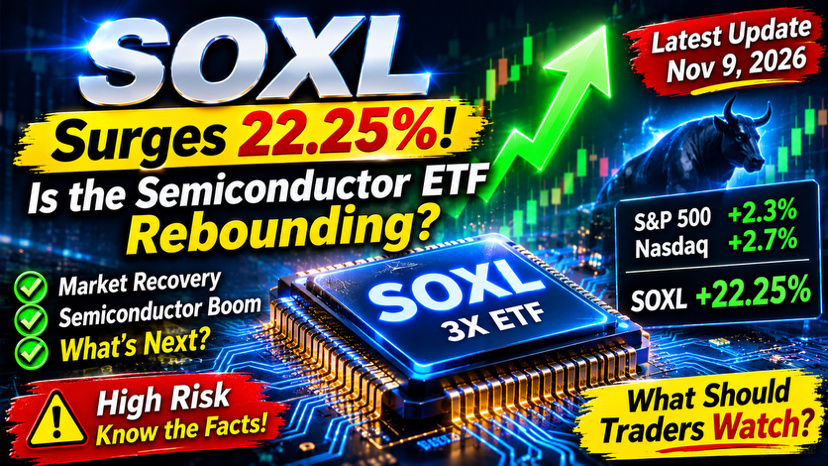
SOXL Surges 22.25%: Is the Semiconductor ETF Rebounding After a Brutal Selloff?SOXL Surges 22.25%: What Happened in the Semiconductor Market?
The semiconductor market has attracted major attention following a sharp move in the Direxion Daily Semiconductor Bull 3X ETF (SOXL).
On November 9, 2026, SOXL closed at approximately $56.20, gaining 22.25% compared with its previous close. This move came during a strong recovery across major US stock indexes.
But what is behind this sudden movement, and what should market observers understand?
1. SOXL's Latest Market Update
SOXL recorded a significant daily gain on November 9.
According to reported market data:
Closing price: approximately $56.20Daily change: +22.25%Trading interest: Increased attention around semiconductor stocks
The move followed a difficult period for semiconductor-related investments, showing just how quickly leveraged ETFs can change direction.
2. Why Did the Market Recover?
The broader US stock market also experienced a strong session on November 9.
The S&P 500 gained 2.3%, while the Nasdaq Composite rose 2.7%. Falling oil prices were among the factors supporting the wider market recovery.
This broader improvement helped create a more positive market environment, although individual semiconductor stocks did not all move in the same direction.
3. Why SOXL Is Different From Ordinary ETFs
SOXL is designed to seek 300% of the daily performance of its semiconductor benchmark, before fees and expenses.
That means daily movements can be amplified in both directions.
For example, a 2% daily increase in the benchmark would theoretically correspond to approximately a 6% increase in SOXL before fees and tracking differences.
However, the same leverage also magnifies losses.
Importantly, the daily objective does not mean SOXL will deliver three times the benchmark's return over several days or weeks. Compounding and volatility can produce very different results.
4. What Should the Market Watch Next?
There are several important factors worth monitoring:
Performance of major semiconductor companiesAI infrastructure and chip-industry developmentsBroader Nasdaq market directionChanges in investor sentimentSOXL's daily price and volatility
These factors can help explain why the ETF moves sharply from one session to another.
5. The Biggest Risk to Understand
A 22.25% daily gain may attract attention, but it should not be confused with a predictable future trend.
SOXL can experience equally dramatic declines. Its leveraged daily structure makes it a high-risk financial product, and it is not suitable for everyone.
Understanding the product is just as important as following its latest price movement.
Final Thoughts
SOXL's November 9 rally was a major development for the semiconductor ETF, especially after recent market weakness.
The bigger story is whether semiconductor-sector strength can continue and how broader market conditions evolve.
What do you think is driving the semiconductor market right now: AI demand, broader market recovery, or changing investor sentiment?
Share your perspective in the comments and keep the discussion focused on verified market information.
Disclaimer: This article is for educational purposes only and is not financial advice or a recommendation to buy or sell SOXL. Leveraged ETFs carry substantial risk and can lose value rapidly.
#SOXL #Semiconductors #etf #stockmarket #AI #MarketNews
SOXL Surges 22.25%: Is the Semiconductor ETF Rebounding After a Brutal Selloff?
SOXL Surges 22.25%: What Happened in the Semiconductor Market?
The semiconductor market has attracted major attention following a sharp move in the Direxion Daily Semiconductor Bull 3X ETF (SOXL).
On November 9, 2026, SOXL closed at approximately $56.20, gaining 22.25% compared with its previous close. This move came during a strong recovery across major US stock indexes.
But what is behind this sudden movement, and what should market observers understand?
1. SOXL's Latest Market Update
SOXL recorded a significant daily gain on November 9.
According to reported market data:
Closing price: approximately $56.20Daily change: +22.25%Trading interest: Increased attention around semiconductor stocks
The move followed a difficult period for semiconductor-related investments, showing just how quickly leveraged ETFs can change direction.
2. Why Did the Market Recover?
The broader US stock market also experienced a strong session on November 9.
The S&P 500 gained 2.3%, while the Nasdaq Composite rose 2.7%. Falling oil prices were among the factors supporting the wider market recovery.
This broader improvement helped create a more positive market environment, although individual semiconductor stocks did not all move in the same direction.
3. Why SOXL Is Different From Ordinary ETFs
SOXL is designed to seek 300% of the daily performance of its semiconductor benchmark, before fees and expenses.
That means daily movements can be amplified in both directions.
For example, a 2% daily increase in the benchmark would theoretically correspond to approximately a 6% increase in SOXL before fees and tracking differences.
However, the same leverage also magnifies losses.
Importantly, the daily objective does not mean SOXL will deliver three times the benchmark's return over several days or weeks. Compounding and volatility can produce very different results.
4. What Should the Market Watch Next?
There are several important factors worth monitoring:
Performance of major semiconductor companiesAI infrastructure and chip-industry developmentsBroader Nasdaq market directionChanges in investor sentimentSOXL's daily price and volatility
These factors can help explain why the ETF moves sharply from one session to another.
5. The Biggest Risk to Understand
A 22.25% daily gain may attract attention, but it should not be confused with a predictable future trend.
SOXL can experience equally dramatic declines. Its leveraged daily structure makes it a high-risk financial product, and it is not suitable for everyone.
Understanding the product is just as important as following its latest price movement.
Final Thoughts
SOXL's November 9 rally was a major development for the semiconductor ETF, especially after recent market weakness.
The bigger story is whether semiconductor-sector strength can continue and how broader market conditions evolve.
What do you think is driving the semiconductor market right now: AI demand, broader market recovery, or changing investor sentiment?
Share your perspective in the comments and keep the discussion focused on verified market information.
Disclaimer: This article is for educational purposes only and is not financial advice or a recommendation to buy or sell SOXL. Leveraged ETFs carry substantial risk and can lose value rapidly.
#SOXL #Semiconductors #etf #stockmarket #AI #MarketNews
The semiconductor market has attracted major attention following a sharp move in the Direxion Daily Semiconductor Bull 3X ETF (SOXL).
On November 9, 2026, SOXL closed at approximately $56.20, gaining 22.25% compared with its previous close. This move came during a strong recovery across major US stock indexes.
But what is behind this sudden movement, and what should market observers understand?
1. SOXL's Latest Market Update
SOXL recorded a significant daily gain on November 9.
According to reported market data:
Closing price: approximately $56.20Daily change: +22.25%Trading interest: Increased attention around semiconductor stocks
The move followed a difficult period for semiconductor-related investments, showing just how quickly leveraged ETFs can change direction.
2. Why Did the Market Recover?
The broader US stock market also experienced a strong session on November 9.
The S&P 500 gained 2.3%, while the Nasdaq Composite rose 2.7%. Falling oil prices were among the factors supporting the wider market recovery.
This broader improvement helped create a more positive market environment, although individual semiconductor stocks did not all move in the same direction.
3. Why SOXL Is Different From Ordinary ETFs
SOXL is designed to seek 300% of the daily performance of its semiconductor benchmark, before fees and expenses.
That means daily movements can be amplified in both directions.
For example, a 2% daily increase in the benchmark would theoretically correspond to approximately a 6% increase in SOXL before fees and tracking differences.
However, the same leverage also magnifies losses.
Importantly, the daily objective does not mean SOXL will deliver three times the benchmark's return over several days or weeks. Compounding and volatility can produce very different results.
4. What Should the Market Watch Next?
There are several important factors worth monitoring:
Performance of major semiconductor companiesAI infrastructure and chip-industry developmentsBroader Nasdaq market directionChanges in investor sentimentSOXL's daily price and volatility
These factors can help explain why the ETF moves sharply from one session to another.
5. The Biggest Risk to Understand
A 22.25% daily gain may attract attention, but it should not be confused with a predictable future trend.
SOXL can experience equally dramatic declines. Its leveraged daily structure makes it a high-risk financial product, and it is not suitable for everyone.
Understanding the product is just as important as following its latest price movement.
Final Thoughts
SOXL's November 9 rally was a major development for the semiconductor ETF, especially after recent market weakness.
The bigger story is whether semiconductor-sector strength can continue and how broader market conditions evolve.
What do you think is driving the semiconductor market right now: AI demand, broader market recovery, or changing investor sentiment?
Share your perspective in the comments and keep the discussion focused on verified market information.
Disclaimer: This article is for educational purposes only and is not financial advice or a recommendation to buy or sell SOXL. Leveraged ETFs carry substantial risk and can lose value rapidly.
#SOXL #Semiconductors #etf #stockmarket #AI #MarketNews
1
466
·
--
Bullish
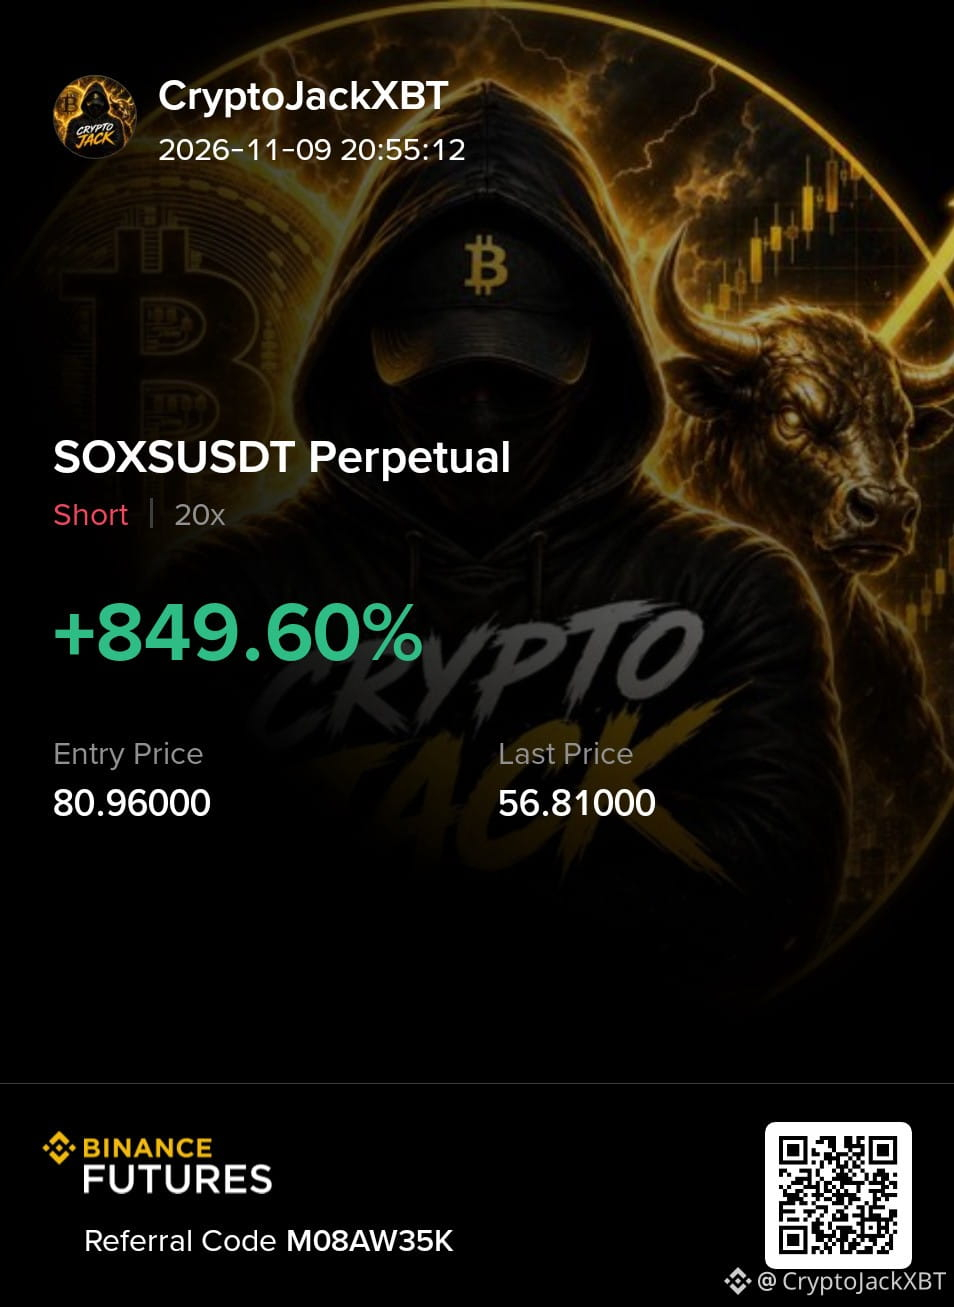
I SHORTED $SOXS Top with 20x leverage and it Plunged 🔻🔻
.
I LONGED $SOXL Bottom with 4x leverage and it pumped ✅✅
.
Perfect Dose for me on #Semiconductors
.
#CPITestsDecemberRateOutlook
I SHORTED $SOXS Top with 20x leverage and it Plunged 🔻🔻
.
I LONGED $SOXL Bottom with 4x leverage and it pumped ✅✅
.
Perfect Dose for me on #Semiconductors
.
#CPITestsDecemberRateOutlook
.
I LONGED $SOXL Bottom with 4x leverage and it pumped ✅✅
.
Perfect Dose for me on #Semiconductors
.
#CPITestsDecemberRateOutlook
CryptoJackXBT
·
--
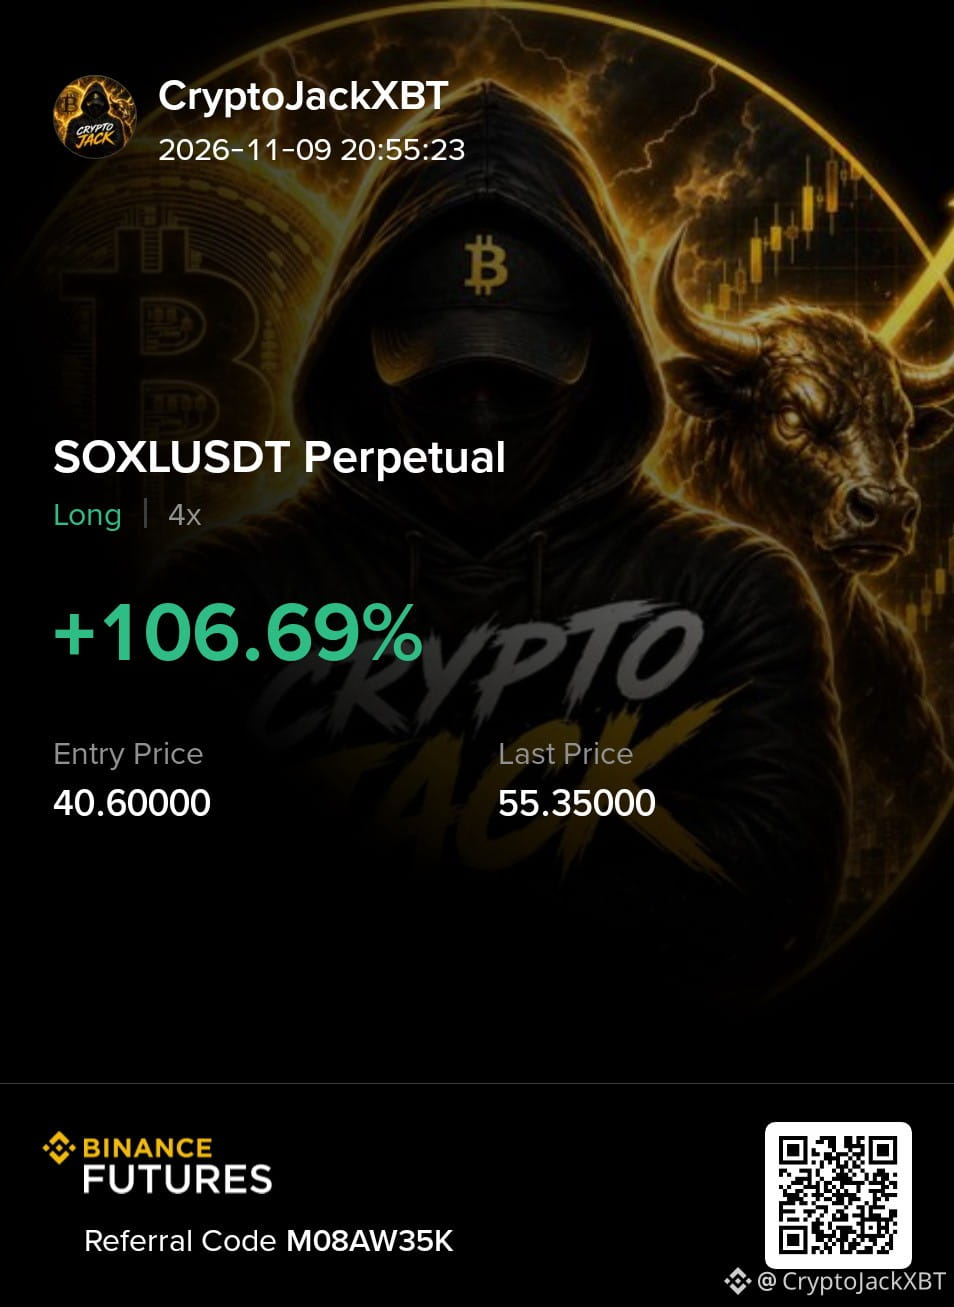
BullishI'm SHORT $SOXS @ $80
.
I'm LONG $SOXL @ $40
.
It's 3rd time we're I'm going to make huge money on this #Semiconductors duo etf pair!
#USStocksSlipandCryptoMarketUnderBroadPressure
.
I'm LONG $SOXL @ $40
.
It's 3rd time we're I'm going to make huge money on this #Semiconductors duo etf pair!
#USStocksSlipandCryptoMarketUnderBroadPressure
802

·
--
#AIChipSlumpNasdaq
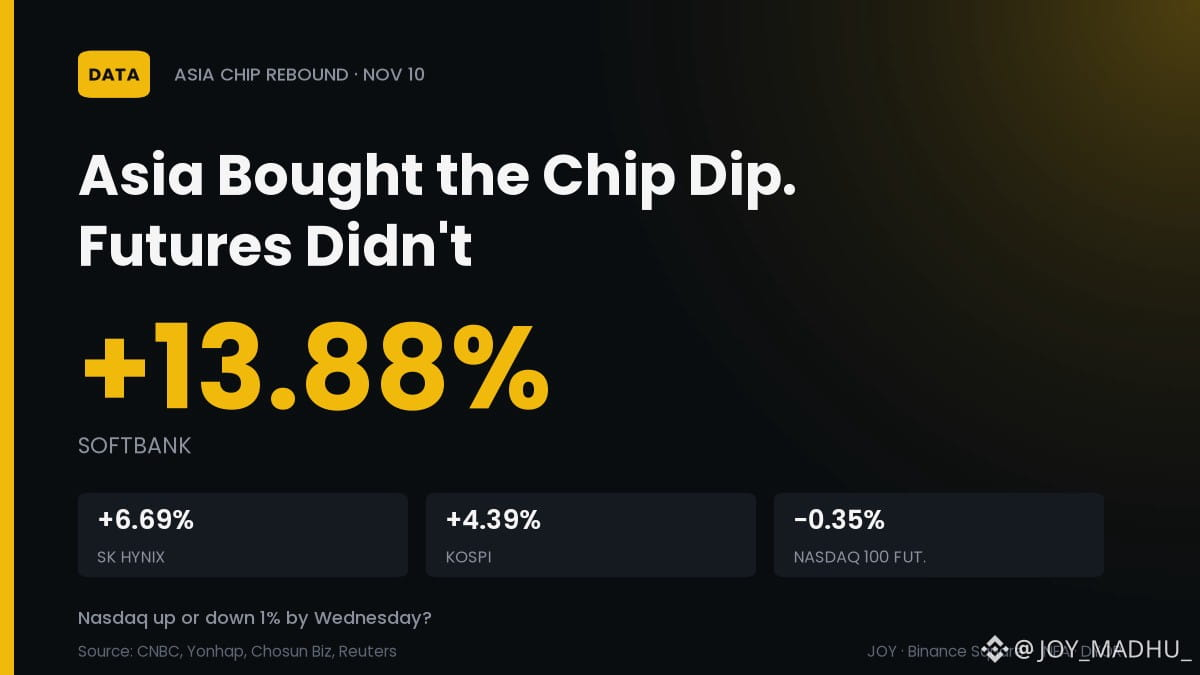
🌏 Seoul Hit a Buy Halt in 6 Minutes. US Futures Shrugged
Asia's chip stocks extended Monday's Wall Street rebound today, but Nasdaq futures dipped before tonight's CPI.
📈 SoftBank +13.88%, Tokyo Electron +6.05% in Tokyo
📈 SK Hynix +6.69%, Samsung +4.74%, back above 2,000T won combined
📊 KOSPI +4.39% to 5,239.13; buy-sidecar triggered at 9:06 a.m.
📉 Nasdaq 100 futures -0.35% at 6:04 a.m. ET
My read: Asia bought the dip; CPI decides if New York follows.
Nasdaq up or down 1% by Wednesday's close? 👇
$BTC $ETH
#AIChipSlumpNasdaq #Semiconductors #Macro
#AIChipSlumpNasdaq
🌏 Seoul Hit a Buy Halt in 6 Minutes. US Futures Shrugged
Asia's chip stocks extended Monday's Wall Street rebound today, but Nasdaq futures dipped before tonight's CPI.
📈 SoftBank +13.88%, Tokyo Electron +6.05% in Tokyo
📈 SK Hynix +6.69%, Samsung +4.74%, back above 2,000T won combined
📊 KOSPI +4.39% to 5,239.13; buy-sidecar triggered at 9:06 a.m.
📉 Nasdaq 100 futures -0.35% at 6:04 a.m. ET
My read: Asia bought the dip; CPI decides if New York follows.
Nasdaq up or down 1% by Wednesday's close? 👇
$BTC $ETH
#AIChipSlumpNasdaq #Semiconductors #Macro
🌏 Seoul Hit a Buy Halt in 6 Minutes. US Futures Shrugged
Asia's chip stocks extended Monday's Wall Street rebound today, but Nasdaq futures dipped before tonight's CPI.
📈 SoftBank +13.88%, Tokyo Electron +6.05% in Tokyo
📈 SK Hynix +6.69%, Samsung +4.74%, back above 2,000T won combined
📊 KOSPI +4.39% to 5,239.13; buy-sidecar triggered at 9:06 a.m.
📉 Nasdaq 100 futures -0.35% at 6:04 a.m. ET
My read: Asia bought the dip; CPI decides if New York follows.
Nasdaq up or down 1% by Wednesday's close? 👇
$BTC $ETH
#AIChipSlumpNasdaq #Semiconductors #Macro
11
·
--
Bullish
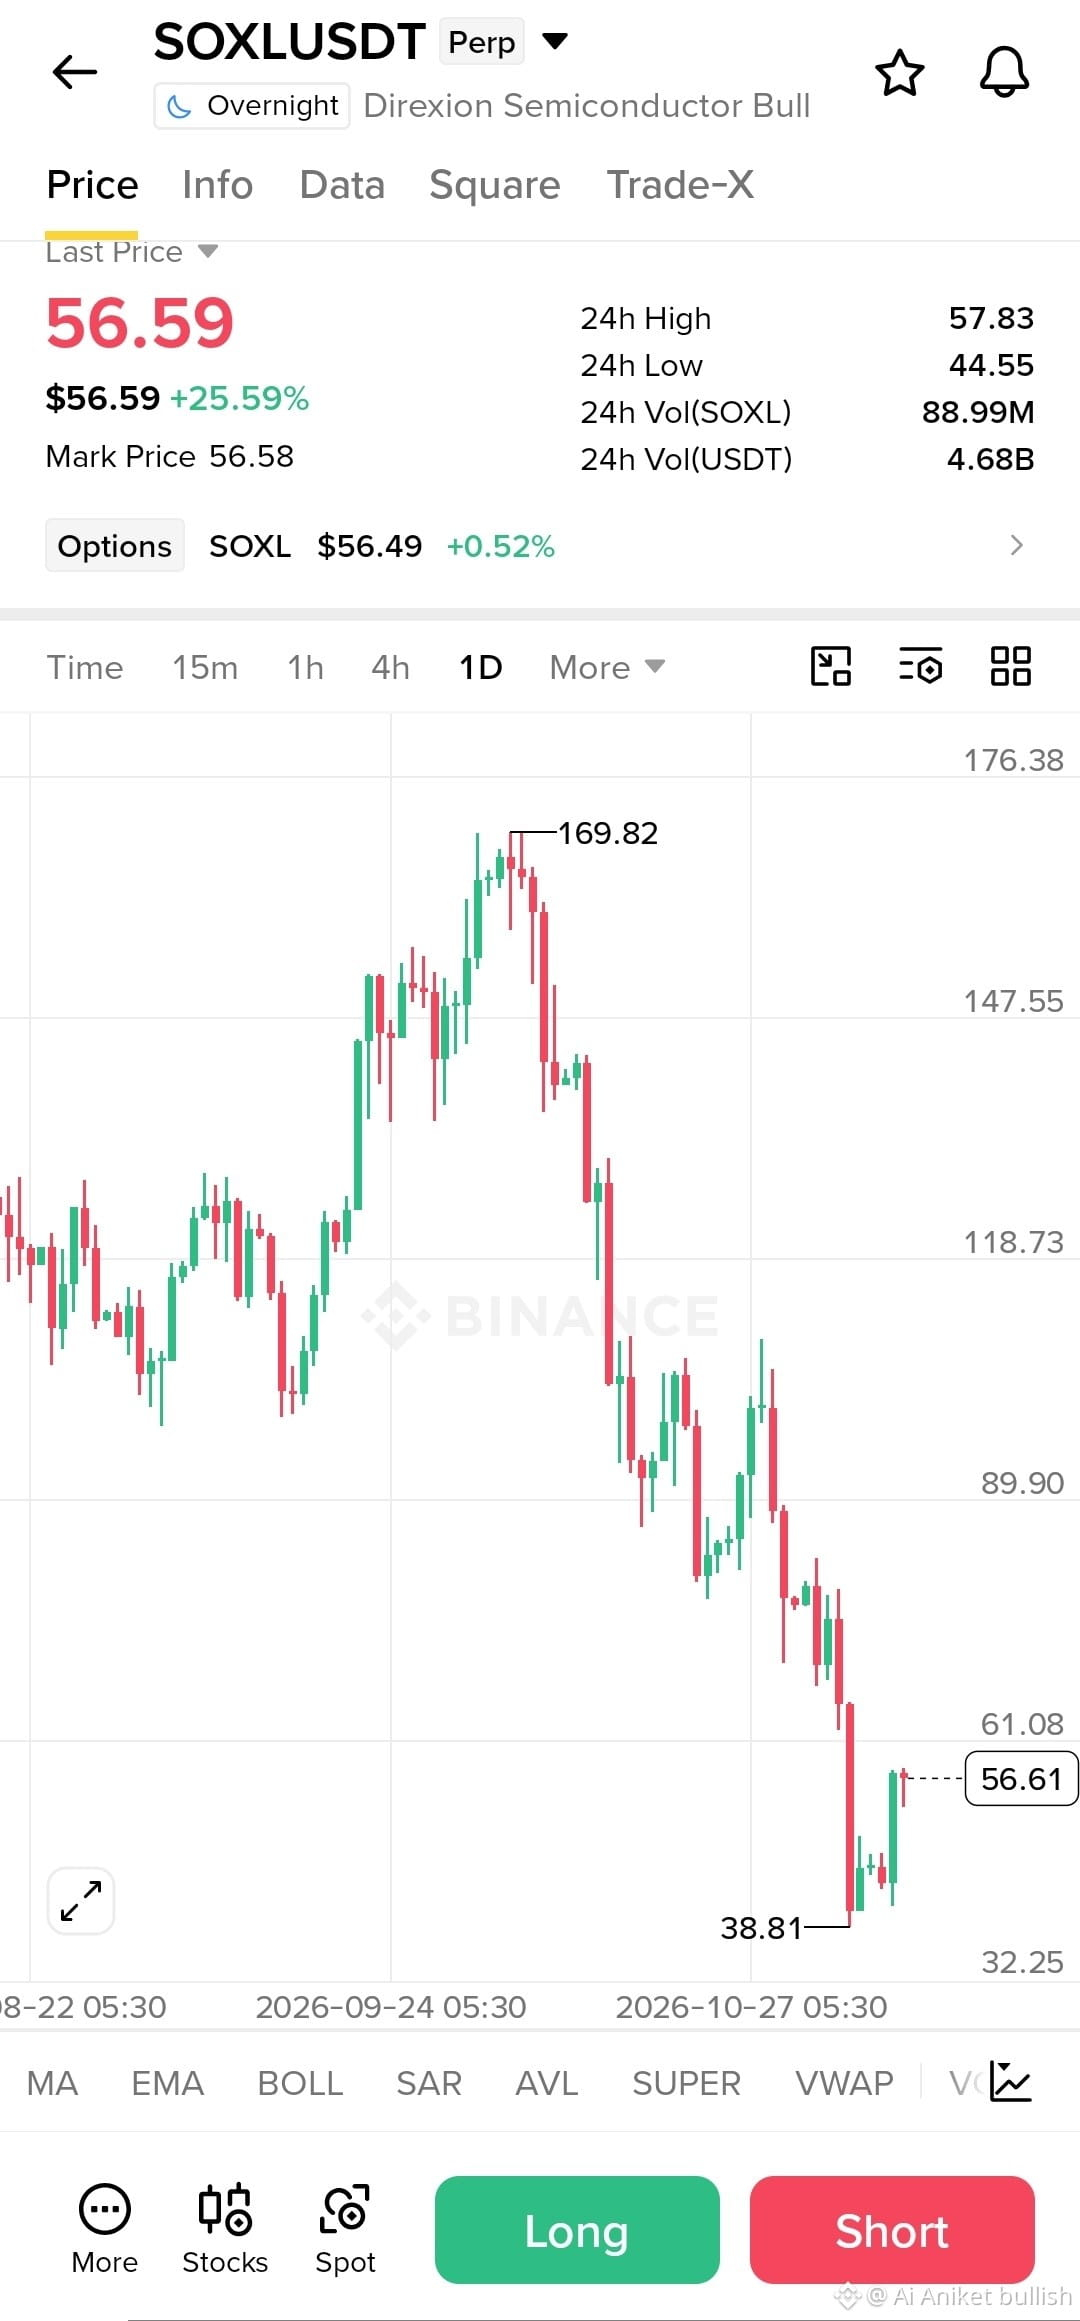
🚀 $SOXL is bouncing hard after a brutal sell-off — could bulls be preparing a recovery?
$SOXL is trading near $56.59, up around 25.59% in 24 hours. After falling from the $169 area to a recent low near $38.81, the chart is showing a strong rebound.
📊 Key levels to watch:
Resistance: $61.08
Next upside zone: $89.90
Support: $44.55
Major support: $38.81
Bullish scenario: If SOXL holds its recovery and breaks above $61.08, further upside could develop.
My approach: I'm watching for a confirmed breakout and a successful retest before considering a LONG. If price loses support, the bullish idea weakens.
⚠️ SOXL is a leveraged semiconductor ETF, so volatility and risk are high. No need to chase a sudden pump.
Can SOXL reclaim $61 and continue its recovery?
{future}(SOXLUSDT)
$SOXL #SOXL #Semiconductors #cryptotrading
🚀 $SOXL is bouncing hard after a brutal sell-off — could bulls be preparing a recovery?
$SOXL is trading near $56.59, up around 25.59% in 24 hours. After falling from the $169 area to a recent low near $38.81, the chart is showing a strong rebound.
📊 Key levels to watch:
Resistance: $61.08
Next upside zone: $89.90
Support: $44.55
Major support: $38.81
Bullish scenario: If SOXL holds its recovery and breaks above $61.08, further upside could develop.
My approach: I'm watching for a confirmed breakout and a successful retest before considering a LONG. If price loses support, the bullish idea weakens.
⚠️ SOXL is a leveraged semiconductor ETF, so volatility and risk are high. No need to chase a sudden pump.
Can SOXL reclaim $61 and continue its recovery?
$SOXL #SOXL #Semiconductors #cryptotrading
$SOXL is trading near $56.59, up around 25.59% in 24 hours. After falling from the $169 area to a recent low near $38.81, the chart is showing a strong rebound.
📊 Key levels to watch:
Resistance: $61.08
Next upside zone: $89.90
Support: $44.55
Major support: $38.81
Bullish scenario: If SOXL holds its recovery and breaks above $61.08, further upside could develop.
My approach: I'm watching for a confirmed breakout and a successful retest before considering a LONG. If price loses support, the bullish idea weakens.
⚠️ SOXL is a leveraged semiconductor ETF, so volatility and risk are high. No need to chase a sudden pump.
Can SOXL reclaim $61 and continue its recovery?
$SOXL #SOXL #Semiconductors #cryptotrading
1
1
136
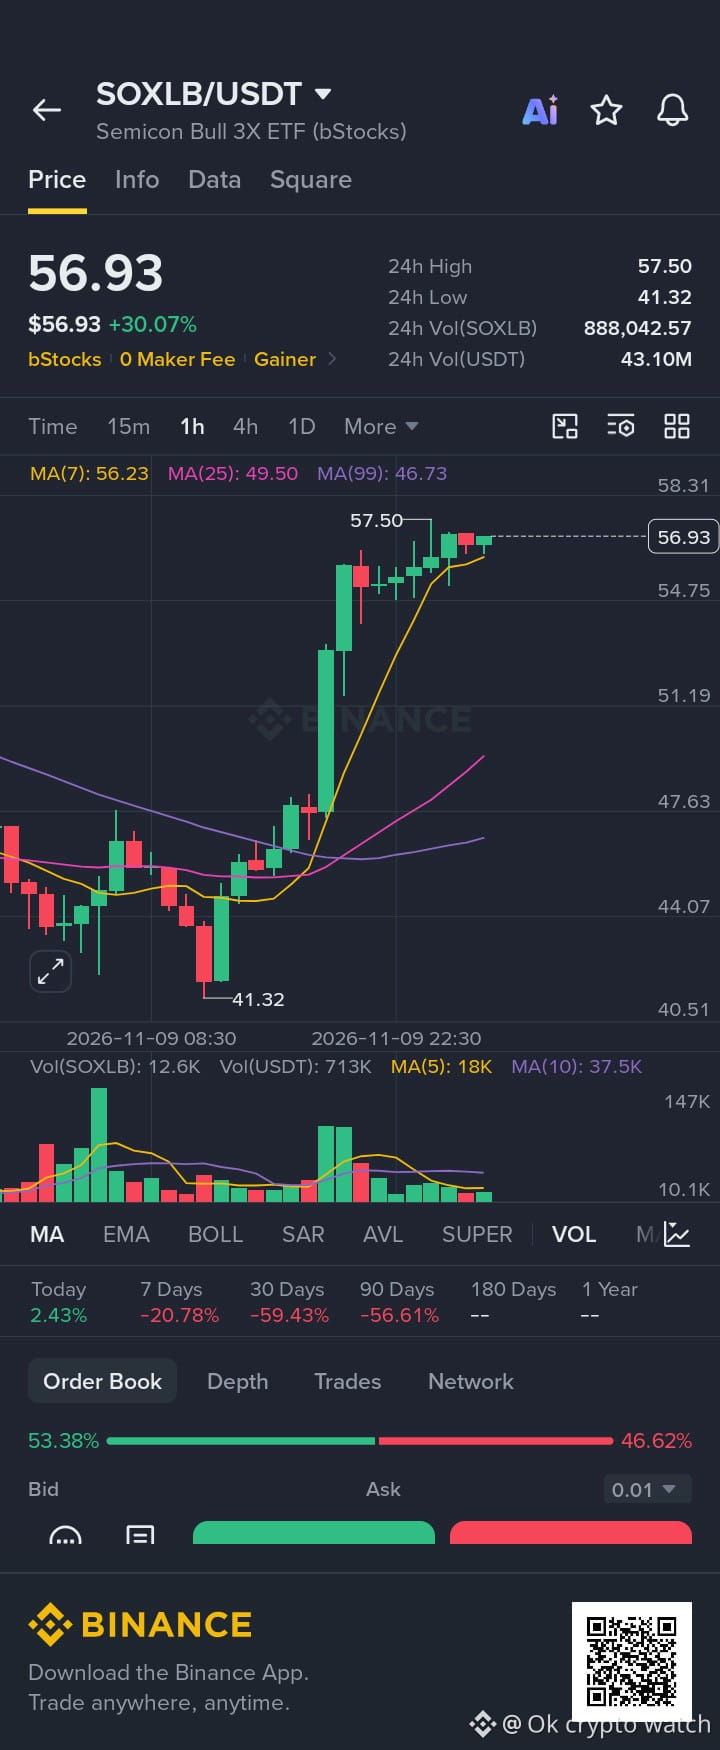
🚨 SOXLB IS MAKING A BIG MOVE! 🔥
$SOXLB /USDT — Semiconductor Momentum Alert
The market is watching this move closely!
📊 What the chart shows:
🟢 Current Price: $56.93
🚀 24H Change: +30.07%
📈 24H High: $57.50
💰 24H Volume: $43.10M
What's interesting?
• Strong bullish breakout on the 1H chart.
• Price is holding above MA(7), MA(25), and MA(99).
• Consolidation near the recent high could be an important signal.
🎯 Key Level to Watch: $57.50
A breakout above this level could attract further attention. A rejection could bring short-term profit-taking.
⚠️ Remember: SOXLB tracks a 3X leveraged semiconductor ETF exposure. Volatility and downside risk can be significant.
🔥 THE BIG QUESTION:
Will SOXLB break $57.50 and continue higher, or is a pullback coming?
👇 Bullish or bearish? Share your analysis!
#SOXLB #Semiconductors #RWA #BinanceSquare #cryptotrading
{spot}(SOXLBUSDT)
🚨 SOXLB IS MAKING A BIG MOVE! 🔥
$SOXLB /USDT — Semiconductor Momentum Alert
The market is watching this move closely!
📊 What the chart shows:
🟢 Current Price: $56.93
🚀 24H Change: +30.07%
📈 24H High: $57.50
💰 24H Volume: $43.10M
What's interesting?
• Strong bullish breakout on the 1H chart.
• Price is holding above MA(7), MA(25), and MA(99).
• Consolidation near the recent high could be an important signal.
🎯 Key Level to Watch: $57.50
A breakout above this level could attract further attention. A rejection could bring short-term profit-taking.
⚠️ Remember: SOXLB tracks a 3X leveraged semiconductor ETF exposure. Volatility and downside risk can be significant.
🔥 THE BIG QUESTION:
Will SOXLB break $57.50 and continue higher, or is a pullback coming?
👇 Bullish or bearish? Share your analysis!
#SOXLB #Semiconductors #RWA #BinanceSquare #cryptotrading
$SOXLB /USDT — Semiconductor Momentum Alert
The market is watching this move closely!
📊 What the chart shows:
🟢 Current Price: $56.93
🚀 24H Change: +30.07%
📈 24H High: $57.50
💰 24H Volume: $43.10M
What's interesting?
• Strong bullish breakout on the 1H chart.
• Price is holding above MA(7), MA(25), and MA(99).
• Consolidation near the recent high could be an important signal.
🎯 Key Level to Watch: $57.50
A breakout above this level could attract further attention. A rejection could bring short-term profit-taking.
⚠️ Remember: SOXLB tracks a 3X leveraged semiconductor ETF exposure. Volatility and downside risk can be significant.
🔥 THE BIG QUESTION:
Will SOXLB break $57.50 and continue higher, or is a pullback coming?
👇 Bullish or bearish? Share your analysis!
#SOXLB #Semiconductors #RWA #BinanceSquare #cryptotrading
80

·
--
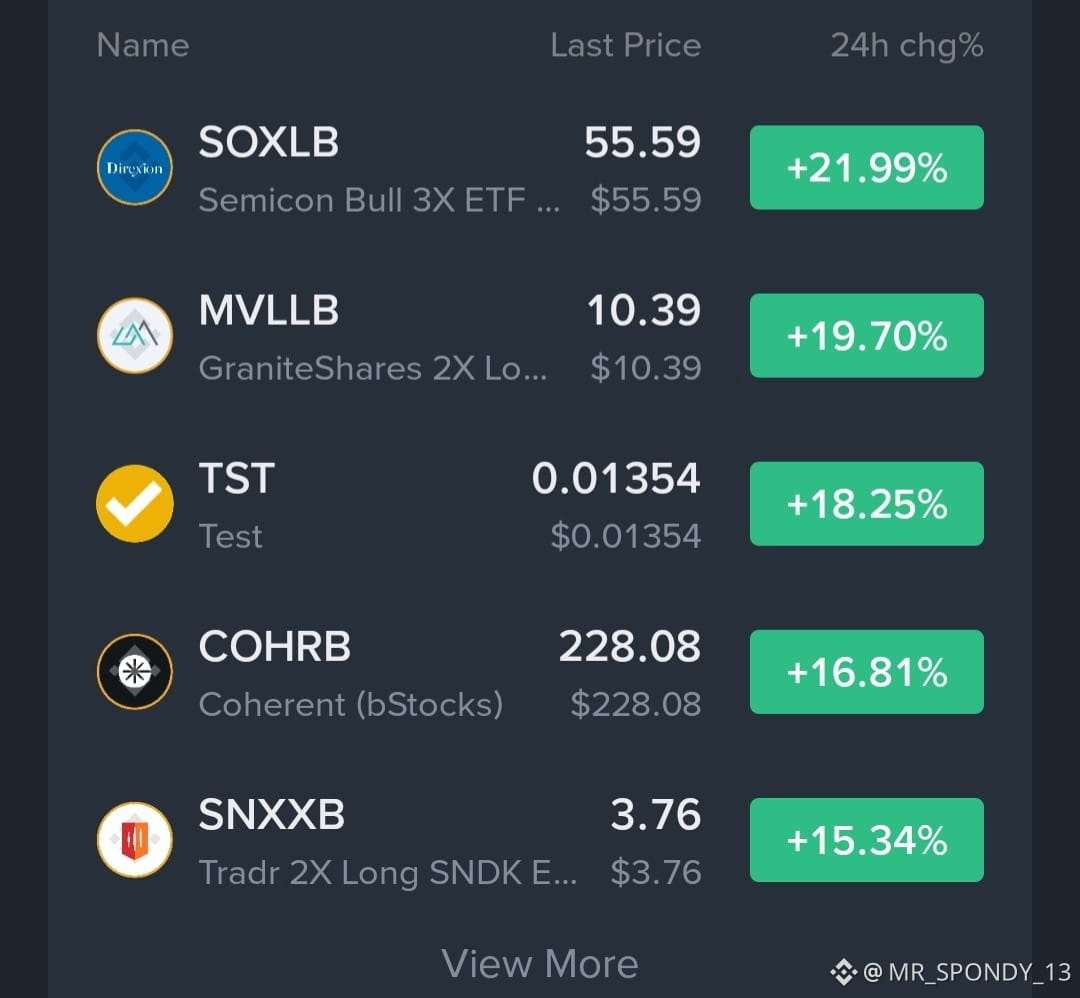
🚀 MARKET MOMENTUM IS HEATING UP! TOP GAINERS TO WATCH TODAY
The market is showing impressive buying momentum, with semiconductor stocks, leveraged ETFs and selected crypto assets leading the move.
📊 Today's Top Performers:
🔥 SOXLB: +21.99% at $55.59
🔥 MVLLB: +19.70% at $10.39
🚀 TST: +18.25% at $0.01354
📈 COHRB: +16.81% at $228.08
⚡ SNXXB: +15.34% at $3.76
What makes this interesting?
Semiconductor exposure is attracting attention, reflecting growing interest in AI infrastructure, computing power and the technology sector.
But remember, leveraged ETFs can carry significant volatility, and today's biggest gainers aren't necessarily tomorrow's winners.
The real opportunity is identifying momentum early while understanding the risks.
Which one is on your watchlist? 👇
#MarketUpdate #Semiconductors #AI #Trading #Mr_SPONDY_13
$SOXLB
{spot}(SOXLBUSDT)
$MVLLB
{spot}(MVLLBUSDT)
$TST
{future}(TSTUSDT)
🚀 MARKET MOMENTUM IS HEATING UP! TOP GAINERS TO WATCH TODAY
The market is showing impressive buying momentum, with semiconductor stocks, leveraged ETFs and selected crypto assets leading the move.
📊 Today's Top Performers:
🔥 SOXLB: +21.99% at $55.59
🔥 MVLLB: +19.70% at $10.39
🚀 TST: +18.25% at $0.01354
📈 COHRB: +16.81% at $228.08
⚡ SNXXB: +15.34% at $3.76
What makes this interesting?
Semiconductor exposure is attracting attention, reflecting growing interest in AI infrastructure, computing power and the technology sector.
But remember, leveraged ETFs can carry significant volatility, and today's biggest gainers aren't necessarily tomorrow's winners.
The real opportunity is identifying momentum early while understanding the risks.
Which one is on your watchlist? 👇
#MarketUpdate #Semiconductors #AI #Trading #Mr_SPONDY_13
$SOXLB
$MVLLB
$TST
The market is showing impressive buying momentum, with semiconductor stocks, leveraged ETFs and selected crypto assets leading the move.
📊 Today's Top Performers:
🔥 SOXLB: +21.99% at $55.59
🔥 MVLLB: +19.70% at $10.39
🚀 TST: +18.25% at $0.01354
📈 COHRB: +16.81% at $228.08
⚡ SNXXB: +15.34% at $3.76
What makes this interesting?
Semiconductor exposure is attracting attention, reflecting growing interest in AI infrastructure, computing power and the technology sector.
But remember, leveraged ETFs can carry significant volatility, and today's biggest gainers aren't necessarily tomorrow's winners.
The real opportunity is identifying momentum early while understanding the risks.
Which one is on your watchlist? 👇
#MarketUpdate #Semiconductors #AI #Trading #Mr_SPONDY_13
$SOXLB
$MVLLB
$TST
479

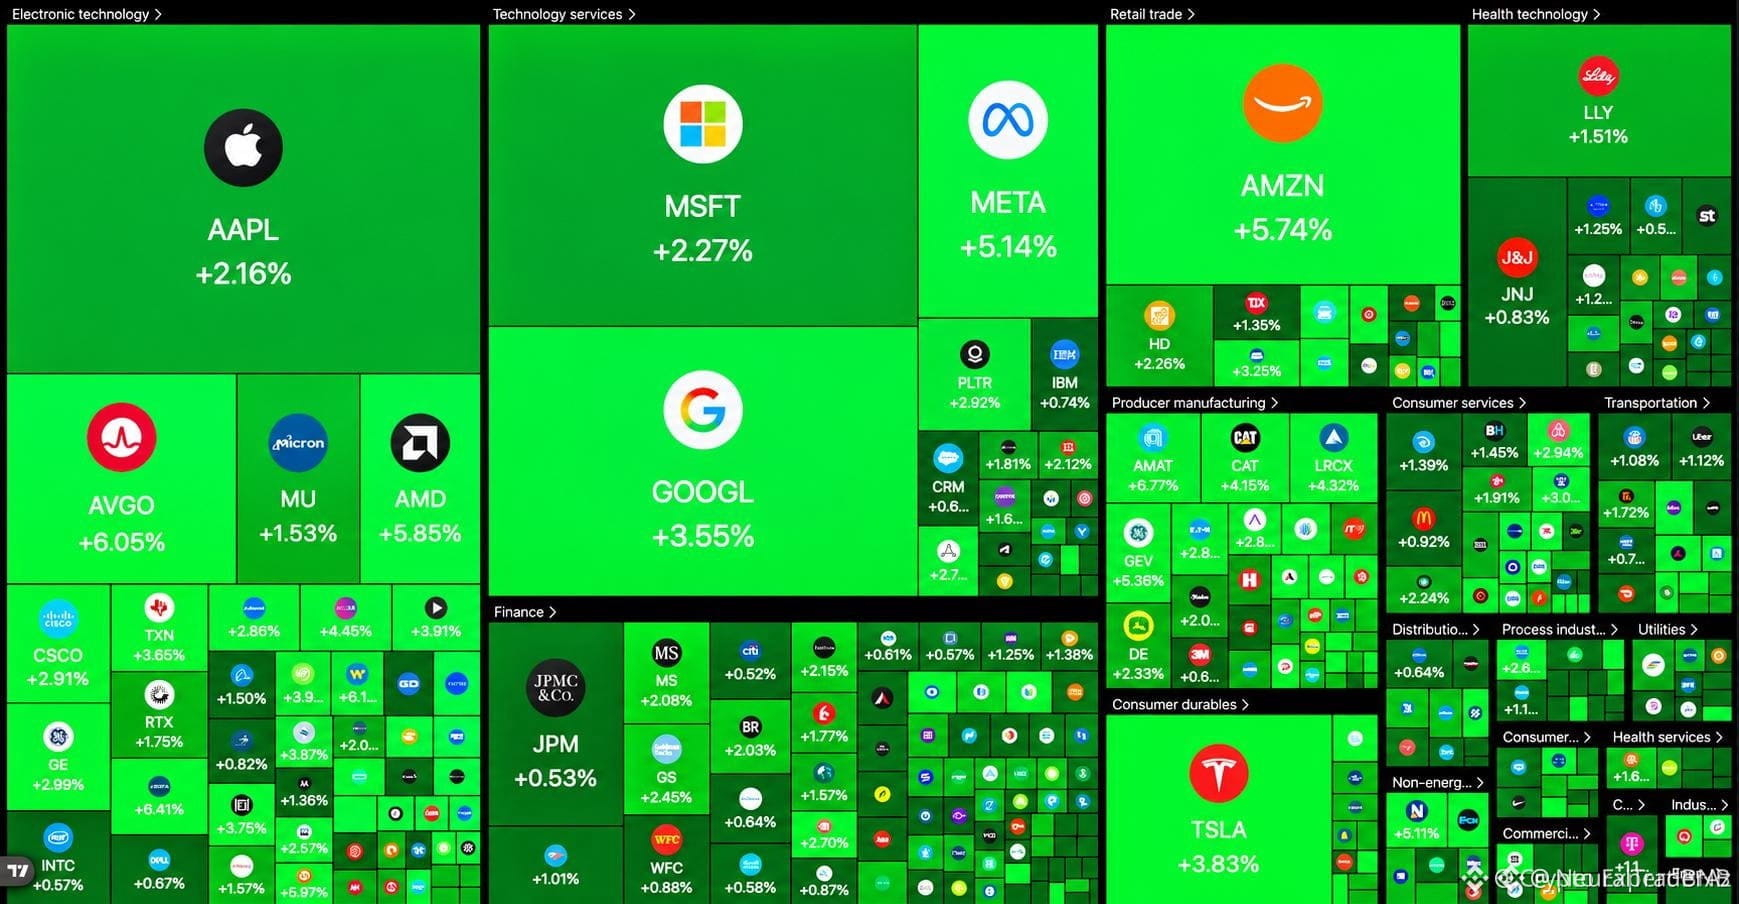
🚨 $SOXL SURGES AS NINE HUNDRED BILLION FLOODS US STOCKS IN TEN MINUTES! 💥
An unprecedented nine hundred billion liquidity injection during the opening bell has completely dismantled standard order flow mechanics across major indices. 🌊 This massive institutional capital wave is triggering aggressive momentum algorithms across leveraged semiconductor proxies like $SOXL . ⚡
Such violent capital influxes instantly generate massive fair value imbalances that demand careful structural retests rather than emotional chasing. 📊 How are you positioning your portfolio around this sudden macro liquidity shock? 🤔
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXL #MarketLiquidity #Macro #Semiconductors
🔥 🦈
🚨 $SOXL SURGES AS NINE HUNDRED BILLION FLOODS US STOCKS IN TEN MINUTES! 💥
An unprecedented nine hundred billion liquidity injection during the opening bell has completely dismantled standard order flow mechanics across major indices. 🌊 This massive institutional capital wave is triggering aggressive momentum algorithms across leveraged semiconductor proxies like $SOXL . ⚡
Such violent capital influxes instantly generate massive fair value imbalances that demand careful structural retests rather than emotional chasing. 📊 How are you positioning your portfolio around this sudden macro liquidity shock? 🤔
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXL #MarketLiquidity #Macro #Semiconductors
🔥 🦈
An unprecedented nine hundred billion liquidity injection during the opening bell has completely dismantled standard order flow mechanics across major indices. 🌊 This massive institutional capital wave is triggering aggressive momentum algorithms across leveraged semiconductor proxies like $SOXL . ⚡
Such violent capital influxes instantly generate massive fair value imbalances that demand careful structural retests rather than emotional chasing. 📊 How are you positioning your portfolio around this sudden macro liquidity shock? 🤔
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXL #MarketLiquidity #Macro #Semiconductors
🔥 🦈
25

·
--
#aichipslumpnasdaq
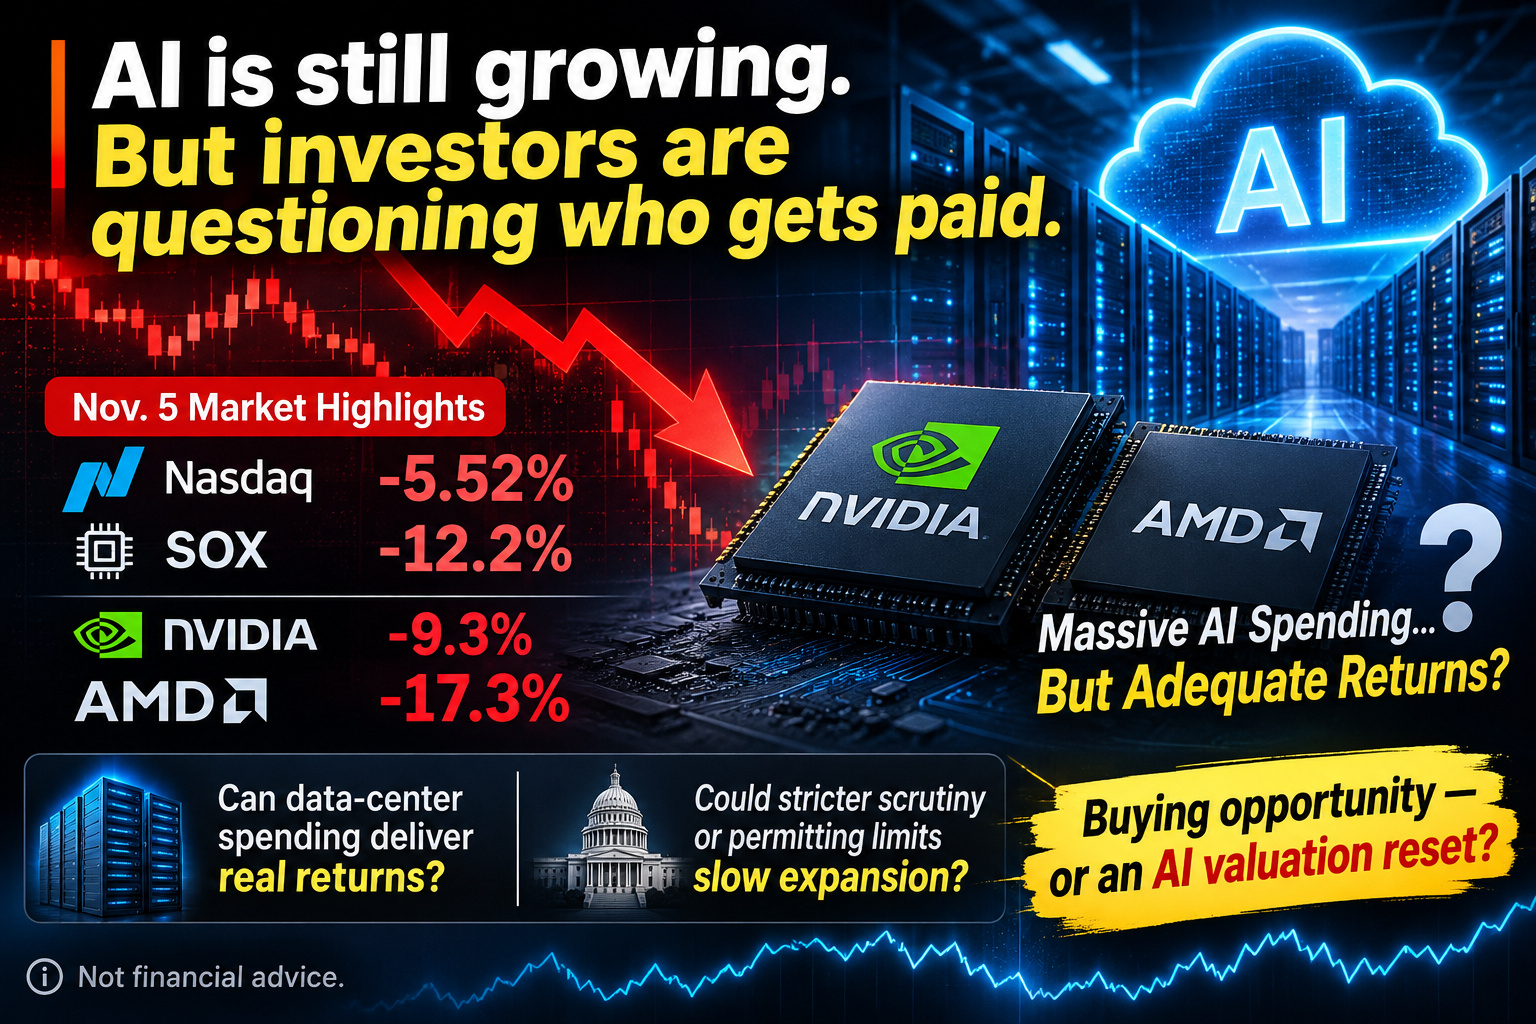
🚨 AI is still growing. But investors are questioning who gets paid.
On Nov. 5, the Nasdaq fell 5.52% and the Philadelphia Semiconductor Index plunged 12.2%. $NVDA lost 9.3%; $AMD dropped 17.3%.
Why? The market is reassessing the AI trade from two angles: can massive data-center spending generate adequate returns, and could tougher scrutiny or permitting limits slow infrastructure expansion? Weak chip-sector results added pressure. But this is not proof that AI demand has disappeared.
The twist: chip stocks rebounded on Friday, yet the Nasdaq still recorded a fourth straight weekly decline. One green session can ease selling pressure without answering the bigger question.
My read: watch hyperscaler capex guidance, chip orders and cash-flow conversion—not just the next candle. If spending keeps rising while returns disappoint, volatility may persist. If earnings and demand hold up, this could be a painful reset, not the end of the AI cycle.
Buying opportunity—or an AI valuation reset?
Not financial advice.
#Nasdaq #Semiconductors #Aİ
{future}(AMDUSDT)
{future}(NVDAUSDT)
#aichipslumpnasdaq
🚨 AI is still growing. But investors are questioning who gets paid.
On Nov. 5, the Nasdaq fell 5.52% and the Philadelphia Semiconductor Index plunged 12.2%. $NVDA lost 9.3%; $AMD dropped 17.3%.
Why? The market is reassessing the AI trade from two angles: can massive data-center spending generate adequate returns, and could tougher scrutiny or permitting limits slow infrastructure expansion? Weak chip-sector results added pressure. But this is not proof that AI demand has disappeared.
The twist: chip stocks rebounded on Friday, yet the Nasdaq still recorded a fourth straight weekly decline. One green session can ease selling pressure without answering the bigger question.
My read: watch hyperscaler capex guidance, chip orders and cash-flow conversion—not just the next candle. If spending keeps rising while returns disappoint, volatility may persist. If earnings and demand hold up, this could be a painful reset, not the end of the AI cycle.
Buying opportunity—or an AI valuation reset?
Not financial advice.
#Nasdaq #Semiconductors #Aİ
🚨 AI is still growing. But investors are questioning who gets paid.
On Nov. 5, the Nasdaq fell 5.52% and the Philadelphia Semiconductor Index plunged 12.2%. $NVDA lost 9.3%; $AMD dropped 17.3%.
Why? The market is reassessing the AI trade from two angles: can massive data-center spending generate adequate returns, and could tougher scrutiny or permitting limits slow infrastructure expansion? Weak chip-sector results added pressure. But this is not proof that AI demand has disappeared.
The twist: chip stocks rebounded on Friday, yet the Nasdaq still recorded a fourth straight weekly decline. One green session can ease selling pressure without answering the bigger question.
My read: watch hyperscaler capex guidance, chip orders and cash-flow conversion—not just the next candle. If spending keeps rising while returns disappoint, volatility may persist. If earnings and demand hold up, this could be a painful reset, not the end of the AI cycle.
Buying opportunity—or an AI valuation reset?
Not financial advice.
#Nasdaq #Semiconductors #Aİ
234
·
--
🔥 xTXN: THE CHIP POWER BEHIND TOMORROW!
Texas Instruments plays an important role in semiconductors, industrial technology, automotive electronics, and advanced devices. As global demand for intelligent technology expands, $TXN deserves attention. Manufacturing costs and semiconductor market cycles remain risks, but long-term technological demand creates an interesting growth opportunity.
#xTXN #Semiconductors #TechnologyNews #USDTfree
🔥 xTXN: THE CHIP POWER BEHIND TOMORROW!
Texas Instruments plays an important role in semiconductors, industrial technology, automotive electronics, and advanced devices. As global demand for intelligent technology expands, $TXN deserves attention. Manufacturing costs and semiconductor market cycles remain risks, but long-term technological demand creates an interesting growth opportunity.
#xTXN #Semiconductors #TechnologyNews #USDTfree
Texas Instruments plays an important role in semiconductors, industrial technology, automotive electronics, and advanced devices. As global demand for intelligent technology expands, $TXN deserves attention. Manufacturing costs and semiconductor market cycles remain risks, but long-term technological demand creates an interesting growth opportunity.
#xTXN #Semiconductors #TechnologyNews #USDTfree
16
Verified
🚨 TAIWAN JUST STEPPED IN AFTER A 12% STOCK MARKET CRASH. THE AI SELLOFF IS GETTING SERIOUS.
Taiwan's stock market has been hit hard by the global AI selloff, forcing financial authorities to introduce emergency measures to stop the bleeding.
The numbers are alarming.
The TAIEX plunged as much as 9% on Friday before recovering to close down 4.5%. Its weekly loss reached a staggering 12.2%, pushing the market into bear-market territory.
Now, authorities are fighting back.
Here's what they're doing:
🔴 SHORT-SELLING RESTRICTIONS: Intraday borrowed-share selling limits are being slashed from 30% to just 3% of average daily trading volume.
🔴 HIGHER MARGIN REQUIREMENTS: Minimum short-sale margin is increasing from 90% to 130%, making bearish bets more expensive.
🔴 $15 BILLION STABILIZATION FUND: Authorities have authorized intervention to support the stock market if necessary.
And there's another major concern.
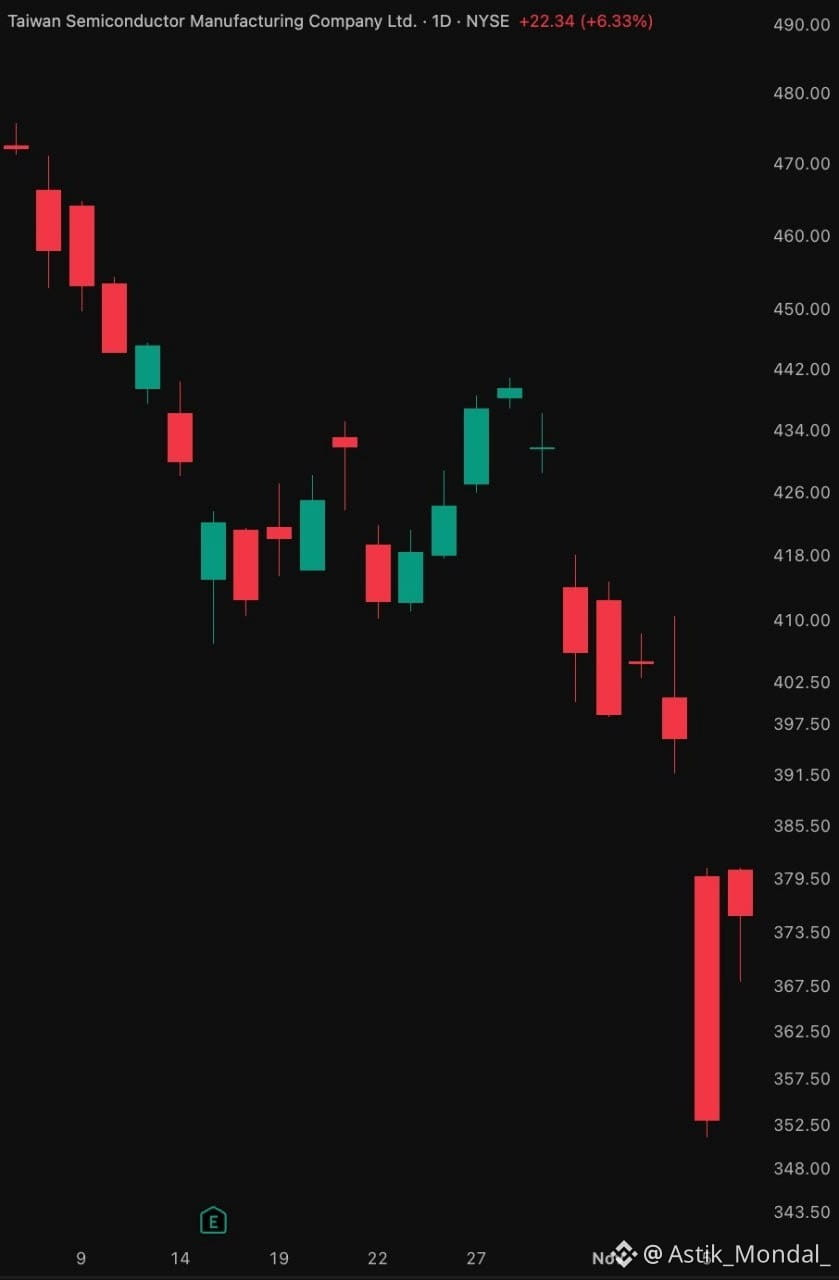
TSMC, Taiwan's largest listed company and a critical player in the global AI supply chain, plunged 4.7% in Taipei on Friday.
Its US-listed shares later rebounded 6.3%.
But here's the bigger picture:
This isn't just about Taiwan.
The global AI trade is facing a serious test.
Investors are increasingly questioning whether massive AI infrastructure spending can generate the returns the market expects.
If confidence in AI demand weakens, semiconductor stocks could face further pressure.
MY MARKET TAKE:
Emergency restrictions can reduce immediate selling pressure, but they cannot fix a deeper problem of valuation, demand expectations, or investor confidence.
Watch TSMC, Nvidia, semiconductor stocks, Nasdaq and global AI-related capital expenditure.
The real question is no longer how much money companies are spending on AI.
It's whether the returns will justify the spending.
#Taiwan #TSMC #AIStocks #StockMarket #Semiconductors
🚨 TAIWAN JUST STEPPED IN AFTER A 12% STOCK MARKET CRASH. THE AI SELLOFF IS GETTING SERIOUS.
Taiwan's stock market has been hit hard by the global AI selloff, forcing financial authorities to introduce emergency measures to stop the bleeding.
The numbers are alarming.
The TAIEX plunged as much as 9% on Friday before recovering to close down 4.5%. Its weekly loss reached a staggering 12.2%, pushing the market into bear-market territory.
Now, authorities are fighting back.
Here's what they're doing:
🔴 SHORT-SELLING RESTRICTIONS: Intraday borrowed-share selling limits are being slashed from 30% to just 3% of average daily trading volume.
🔴 HIGHER MARGIN REQUIREMENTS: Minimum short-sale margin is increasing from 90% to 130%, making bearish bets more expensive.
🔴 $15 BILLION STABILIZATION FUND: Authorities have authorized intervention to support the stock market if necessary.
And there's another major concern.
TSMC, Taiwan's largest listed company and a critical player in the global AI supply chain, plunged 4.7% in Taipei on Friday.
Its US-listed shares later rebounded 6.3%.
But here's the bigger picture:
This isn't just about Taiwan.
The global AI trade is facing a serious test.
Investors are increasingly questioning whether massive AI infrastructure spending can generate the returns the market expects.
If confidence in AI demand weakens, semiconductor stocks could face further pressure.
MY MARKET TAKE:
Emergency restrictions can reduce immediate selling pressure, but they cannot fix a deeper problem of valuation, demand expectations, or investor confidence.
Watch TSMC, Nvidia, semiconductor stocks, Nasdaq and global AI-related capital expenditure.
The real question is no longer how much money companies are spending on AI.
It's whether the returns will justify the spending.
#Taiwan #TSMC #AIStocks #StockMarket #Semiconductors
Taiwan's stock market has been hit hard by the global AI selloff, forcing financial authorities to introduce emergency measures to stop the bleeding.
The numbers are alarming.
The TAIEX plunged as much as 9% on Friday before recovering to close down 4.5%. Its weekly loss reached a staggering 12.2%, pushing the market into bear-market territory.
Now, authorities are fighting back.
Here's what they're doing:
🔴 SHORT-SELLING RESTRICTIONS: Intraday borrowed-share selling limits are being slashed from 30% to just 3% of average daily trading volume.
🔴 HIGHER MARGIN REQUIREMENTS: Minimum short-sale margin is increasing from 90% to 130%, making bearish bets more expensive.
🔴 $15 BILLION STABILIZATION FUND: Authorities have authorized intervention to support the stock market if necessary.
And there's another major concern.
TSMC, Taiwan's largest listed company and a critical player in the global AI supply chain, plunged 4.7% in Taipei on Friday.
Its US-listed shares later rebounded 6.3%.
But here's the bigger picture:
This isn't just about Taiwan.
The global AI trade is facing a serious test.
Investors are increasingly questioning whether massive AI infrastructure spending can generate the returns the market expects.
If confidence in AI demand weakens, semiconductor stocks could face further pressure.
MY MARKET TAKE:
Emergency restrictions can reduce immediate selling pressure, but they cannot fix a deeper problem of valuation, demand expectations, or investor confidence.
Watch TSMC, Nvidia, semiconductor stocks, Nasdaq and global AI-related capital expenditure.
The real question is no longer how much money companies are spending on AI.
It's whether the returns will justify the spending.
#Taiwan #TSMC #AIStocks #StockMarket #Semiconductors
Square Crypt:
Aber dass ist doch auch klar .Taiwan muß jetzt wirklich dringend handeln.
1
1
883
{stock_us}(AMD.US)
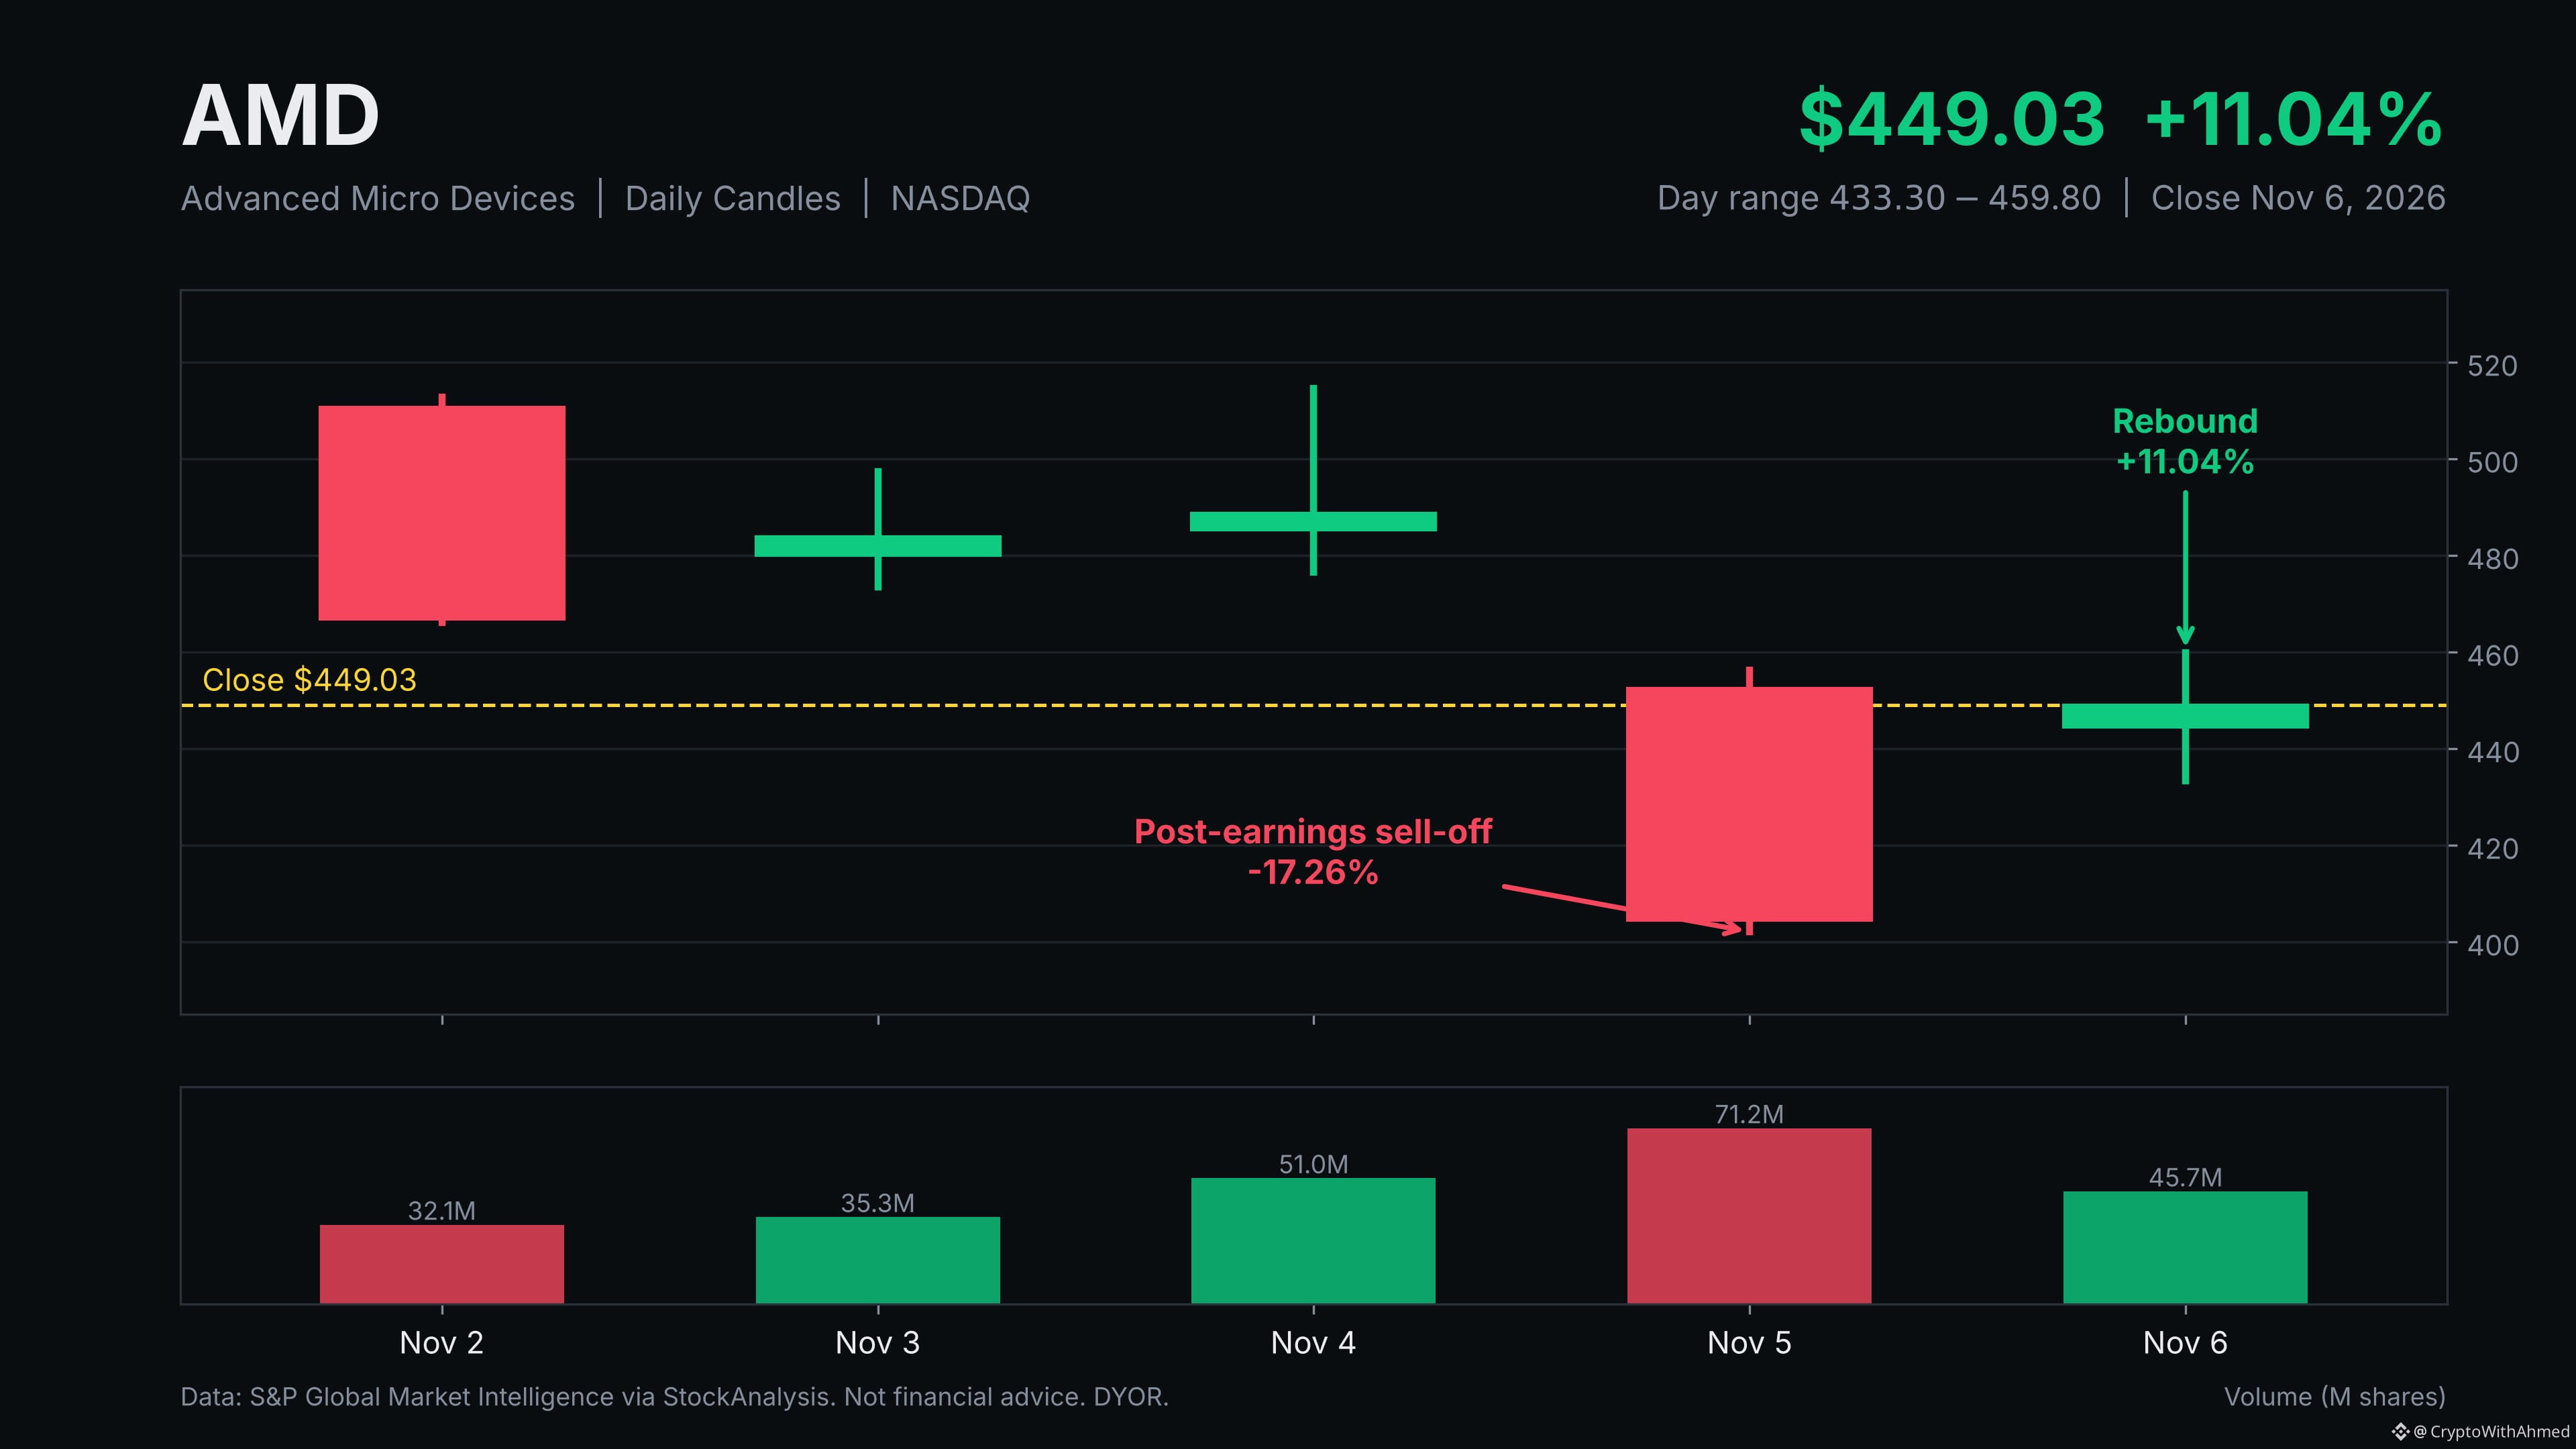
$AMD.US Just Rebounded +11%!
After a brutal -17% post-earnings drop on Nov 5, AMD bounced back hard and closed at $449.03 (+11.04%) on Nov 6. The company reported record quarterly revenue and a stronger growth outlook, powered by the AI chip boom.
📊 Key Values:
• Close: $449.03
• Day Range: $433.30 – $459.80
• Nov 5 Low: $402.10
• 52-Week High: $658.52
Big volatility, big volume, big attention. Are dip buyers back in control? 👀
Not financial advice. Always DYOR.
#TradFi #BinanceSquare #stocks #Semiconductors #trading
$AMD.US Just Rebounded +11%!
After a brutal -17% post-earnings drop on Nov 5, AMD bounced back hard and closed at $449.03 (+11.04%) on Nov 6. The company reported record quarterly revenue and a stronger growth outlook, powered by the AI chip boom.
📊 Key Values:
• Close: $449.03
• Day Range: $433.30 – $459.80
• Nov 5 Low: $402.10
• 52-Week High: $658.52
Big volatility, big volume, big attention. Are dip buyers back in control? 👀
Not financial advice. Always DYOR.
#TradFi #BinanceSquare #stocks #Semiconductors #trading
After a brutal -17% post-earnings drop on Nov 5, AMD bounced back hard and closed at $449.03 (+11.04%) on Nov 6. The company reported record quarterly revenue and a stronger growth outlook, powered by the AI chip boom.
📊 Key Values:
• Close: $449.03
• Day Range: $433.30 – $459.80
• Nov 5 Low: $402.10
• 52-Week High: $658.52
Big volatility, big volume, big attention. Are dip buyers back in control? 👀
Not financial advice. Always DYOR.
#TradFi #BinanceSquare #stocks #Semiconductors #trading
AMDUS+4.25%
1
241
Verified
🚨 🇺🇸🇨🇳 WASHINGTON APPROVED NVIDIA AI CHIP SALES TO CHINESE FIRMS WITH EMPTY OFFICES AND SUSPICIOUS CONNECTIONS.
A potentially explosive national security controversy is emerging around America's AI chip export policy.
According to a new report by The New York Times, the US government cleared Nvidia chip sales to Chinese companies despite warning signs involving empty offices and questionable business connections.
Think about the implications.
🇨🇳 Chinese-linked entities may have gained access to powerful American AI technology through companies whose legitimacy and connections raised serious questions.
⚠️ THE BIGGER PROBLEM:
Washington has spent years restricting China's access to advanced AI chips over fears they could strengthen Beijing's military and technological capabilities.
Yet questions are now emerging about whether US approval procedures and customer verification safeguards were strong enough.
🔥 WHY THIS MATTERS:
NVIDIA sits at the center of the global AI arms race.
Any evidence of weak export controls could trigger congressional investigations, tighter restrictions and renewed US-China technology tensions.
For $NVDA investors, the stakes extend beyond chip sales.
More restrictions could threaten access to China's massive AI market, while geopolitical uncertainty could increase volatility across semiconductor stocks.
AMERICA IS TRYING TO CONTROL WHO GETS ITS MOST POWERFUL AI CHIPS. BUT WHO IS REALLY CHECKING THE BUYERS?
#NVIDIA #NVDA #China #ArtificialIntelligence #Semiconductors $NVDA
🚨 🇺🇸🇨🇳 WASHINGTON APPROVED NVIDIA AI CHIP SALES TO CHINESE FIRMS WITH EMPTY OFFICES AND SUSPICIOUS CONNECTIONS.
A potentially explosive national security controversy is emerging around America's AI chip export policy.
According to a new report by The New York Times, the US government cleared Nvidia chip sales to Chinese companies despite warning signs involving empty offices and questionable business connections.
Think about the implications.
🇨🇳 Chinese-linked entities may have gained access to powerful American AI technology through companies whose legitimacy and connections raised serious questions.
⚠️ THE BIGGER PROBLEM:
Washington has spent years restricting China's access to advanced AI chips over fears they could strengthen Beijing's military and technological capabilities.
Yet questions are now emerging about whether US approval procedures and customer verification safeguards were strong enough.
🔥 WHY THIS MATTERS:
NVIDIA sits at the center of the global AI arms race.
Any evidence of weak export controls could trigger congressional investigations, tighter restrictions and renewed US-China technology tensions.
For $NVDA investors, the stakes extend beyond chip sales.
More restrictions could threaten access to China's massive AI market, while geopolitical uncertainty could increase volatility across semiconductor stocks.
AMERICA IS TRYING TO CONTROL WHO GETS ITS MOST POWERFUL AI CHIPS. BUT WHO IS REALLY CHECKING THE BUYERS?
#NVIDIA #NVDA #China #ArtificialIntelligence #Semiconductors $NVDA
A potentially explosive national security controversy is emerging around America's AI chip export policy.
According to a new report by The New York Times, the US government cleared Nvidia chip sales to Chinese companies despite warning signs involving empty offices and questionable business connections.
Think about the implications.
🇨🇳 Chinese-linked entities may have gained access to powerful American AI technology through companies whose legitimacy and connections raised serious questions.
⚠️ THE BIGGER PROBLEM:
Washington has spent years restricting China's access to advanced AI chips over fears they could strengthen Beijing's military and technological capabilities.
Yet questions are now emerging about whether US approval procedures and customer verification safeguards were strong enough.
🔥 WHY THIS MATTERS:
NVIDIA sits at the center of the global AI arms race.
Any evidence of weak export controls could trigger congressional investigations, tighter restrictions and renewed US-China technology tensions.
For $NVDA investors, the stakes extend beyond chip sales.
More restrictions could threaten access to China's massive AI market, while geopolitical uncertainty could increase volatility across semiconductor stocks.
AMERICA IS TRYING TO CONTROL WHO GETS ITS MOST POWERFUL AI CHIPS. BUT WHO IS REALLY CHECKING THE BUYERS?
#NVIDIA #NVDA #China #ArtificialIntelligence #Semiconductors $NVDA
2
1.2k
Bank of America removes Nvidia and Micron from its select listBank of America removed Nvidia and Micron from its list of top picks; the change applies to the list, not the ratings of the two stocks. $NVDA
Is this a downgrade? The notes don't mention one, and removal from a select list may simply indicate a decline in relative confidence in the two stocks.
Does the decision cover the entire AI sector? Only the two companies are mentioned, and any claims about the sector need further confirmation.
Bank of America removes Nvidia and Micron from its select list
Bank of America removed Nvidia and Micron from its list of top picks; the change applies to the list, not the ratings of the two stocks. $NVDA
Is this a downgrade? The notes don't mention one, and removal from a select list may simply indicate a decline in relative confidence in the two stocks.
Does the decision cover the entire AI sector? Only the two companies are mentioned, and any claims about the sector need further confirmation.
Is this a downgrade? The notes don't mention one, and removal from a select list may simply indicate a decline in relative confidence in the two stocks.
Does the decision cover the entire AI sector? Only the two companies are mentioned, and any claims about the sector need further confirmation.
15
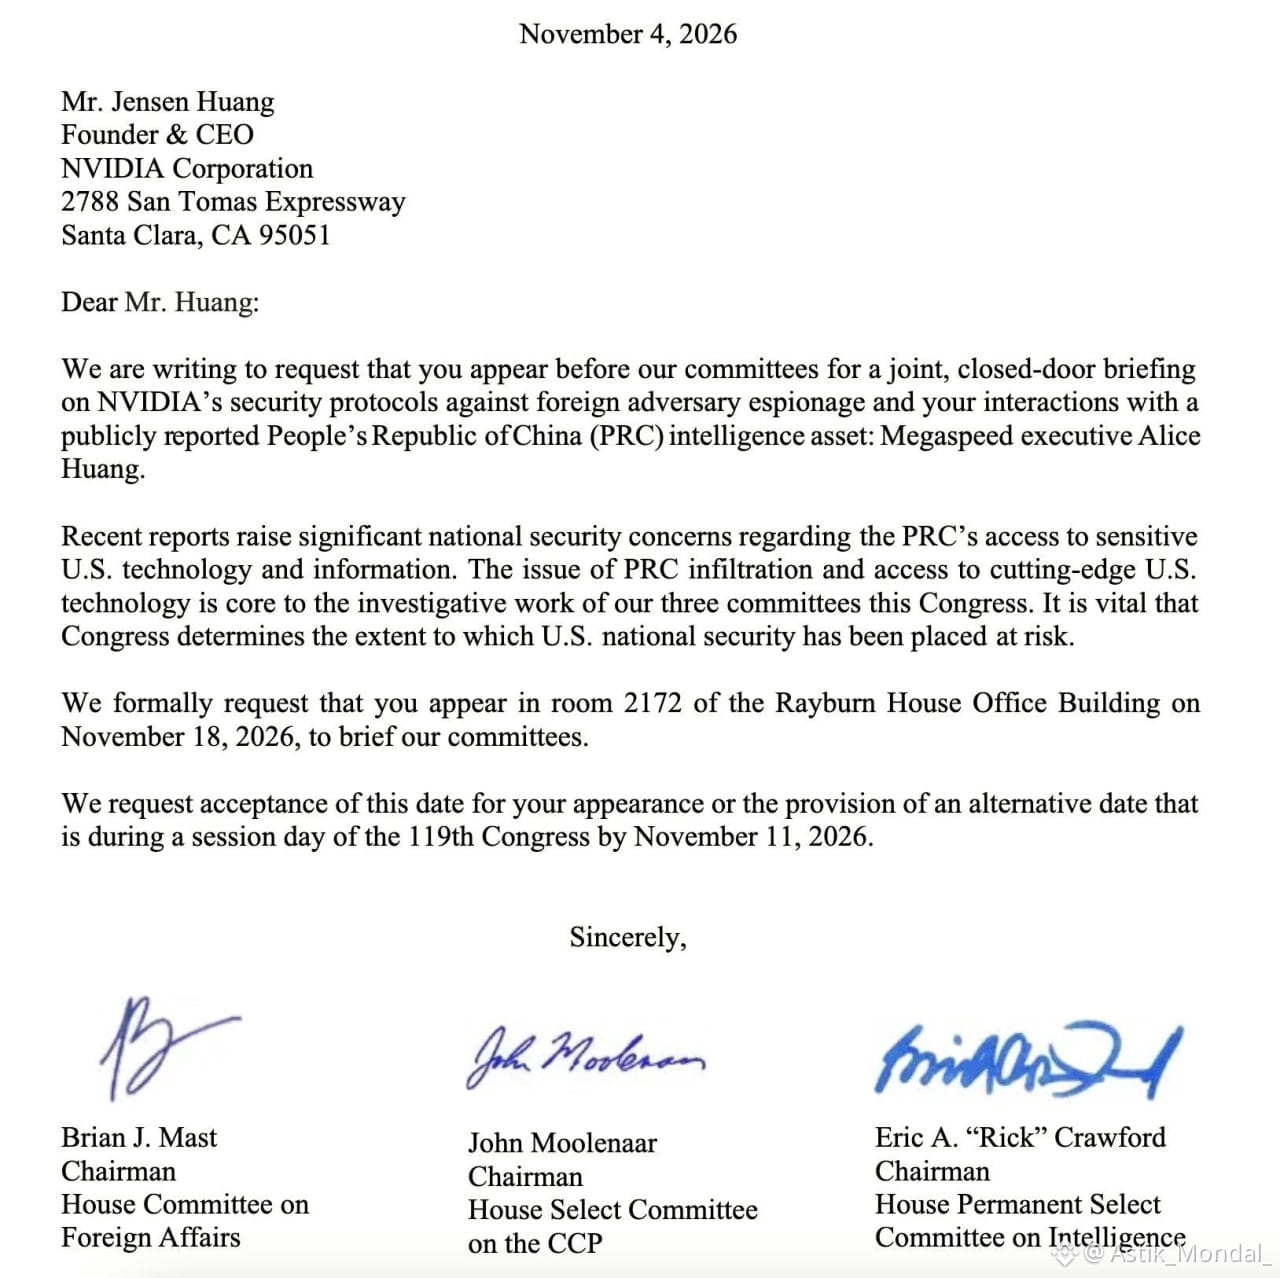
🚨 🇺🇸 NVIDIA CEO JENSEN HUANG SUMMONED BY CONGRESS OVER SUSPECTED CHINESE ESPIONAGE OPERATION.
Washington is turning its attention to one of the world's most powerful AI companies.
Three Republican-led House committees have formally requested a closed-door briefing with NVIDIA CEO Jensen Huang on November 18.
The investigation centers on a suspected Chinese intelligence operation involving Alice Huang, an executive at Singapore-based Megaspeed, a reported NVIDIA customer.
According to the Financial Times, US intelligence officials suspect Chinese intelligence may have recruited Alice Huang to obtain information about American AI chips and potentially influence NVIDIA's efforts to sell advanced processors to China.
⚠️ THE NATIONAL SECURITY ANGLE IS HUGE.
The concern is whether sensitive American AI technology could have been exposed to foreign intelligence networks.
Congress wants answers about NVIDIA's security protocols, customer relationships and safeguards against foreign espionage.
NVIDIA has pushed back, saying Huang's interactions with customer executives were routine and no sensitive information was shared.
Importantly, there is currently no publicly established evidence that Jensen Huang knowingly participated in espionage or that NVIDIA technology was compromised.
🔥 WHY THIS MATTERS FOR MARKETS:
NVIDIA sits at the center of the global AI revolution.
Any escalation in US-China technology tensions could mean tighter export restrictions, increased regulatory scrutiny and uncertainty for the semiconductor industry.
This investigation could become another major flashpoint in the battle for AI supremacy between Washington and Beijing.
The bigger question: Could national security concerns reshape the future of NVIDIA's business in China?
#NVIDIA #JensenHuang #China #AI #Semiconductors $NVDA
🚨 🇺🇸 NVIDIA CEO JENSEN HUANG SUMMONED BY CONGRESS OVER SUSPECTED CHINESE ESPIONAGE OPERATION.
Washington is turning its attention to one of the world's most powerful AI companies.
Three Republican-led House committees have formally requested a closed-door briefing with NVIDIA CEO Jensen Huang on November 18.
The investigation centers on a suspected Chinese intelligence operation involving Alice Huang, an executive at Singapore-based Megaspeed, a reported NVIDIA customer.
According to the Financial Times, US intelligence officials suspect Chinese intelligence may have recruited Alice Huang to obtain information about American AI chips and potentially influence NVIDIA's efforts to sell advanced processors to China.
⚠️ THE NATIONAL SECURITY ANGLE IS HUGE.
The concern is whether sensitive American AI technology could have been exposed to foreign intelligence networks.
Congress wants answers about NVIDIA's security protocols, customer relationships and safeguards against foreign espionage.
NVIDIA has pushed back, saying Huang's interactions with customer executives were routine and no sensitive information was shared.
Importantly, there is currently no publicly established evidence that Jensen Huang knowingly participated in espionage or that NVIDIA technology was compromised.
🔥 WHY THIS MATTERS FOR MARKETS:
NVIDIA sits at the center of the global AI revolution.
Any escalation in US-China technology tensions could mean tighter export restrictions, increased regulatory scrutiny and uncertainty for the semiconductor industry.
This investigation could become another major flashpoint in the battle for AI supremacy between Washington and Beijing.
The bigger question: Could national security concerns reshape the future of NVIDIA's business in China?
#NVIDIA #JensenHuang #China #AI #Semiconductors $NVDA
Washington is turning its attention to one of the world's most powerful AI companies.
Three Republican-led House committees have formally requested a closed-door briefing with NVIDIA CEO Jensen Huang on November 18.
The investigation centers on a suspected Chinese intelligence operation involving Alice Huang, an executive at Singapore-based Megaspeed, a reported NVIDIA customer.
According to the Financial Times, US intelligence officials suspect Chinese intelligence may have recruited Alice Huang to obtain information about American AI chips and potentially influence NVIDIA's efforts to sell advanced processors to China.
⚠️ THE NATIONAL SECURITY ANGLE IS HUGE.
The concern is whether sensitive American AI technology could have been exposed to foreign intelligence networks.
Congress wants answers about NVIDIA's security protocols, customer relationships and safeguards against foreign espionage.
NVIDIA has pushed back, saying Huang's interactions with customer executives were routine and no sensitive information was shared.
Importantly, there is currently no publicly established evidence that Jensen Huang knowingly participated in espionage or that NVIDIA technology was compromised.
🔥 WHY THIS MATTERS FOR MARKETS:
NVIDIA sits at the center of the global AI revolution.
Any escalation in US-China technology tensions could mean tighter export restrictions, increased regulatory scrutiny and uncertainty for the semiconductor industry.
This investigation could become another major flashpoint in the battle for AI supremacy between Washington and Beijing.
The bigger question: Could national security concerns reshape the future of NVIDIA's business in China?
#NVIDIA #JensenHuang #China #AI #Semiconductors $NVDA
3
2.7k
·
--
Bullish
### 🚨 $SOXLB sparks a showdown! Are semiconductor stocks beginning their comeback here? 🔥
$SOXLB is entering a highly volatile phase amid notable moves in the technology and semiconductor markets.
📊 Technical analysis:
* 🚀 It rose by around 4.11% over the past 24 hours, according to one market snapshot.
* 📉 It is still down around 50.88% over the past 30 days.
* 💥 A return of buying momentum and a break above resistance could support a strong rebound, while a break below support could open the door to a new wave of declines. cexscan
🐋 What should you watch? Trading volume, semiconductor sector performance, and the direction of the underlying asset.
⚠️ Important note: SOXLB is a 3X leveraged tokenized ETF product, not an ordinary cryptocurrency; it therefore carries high risks and volatility, and losses can mount quickly. Binance +1
🔥 The big question: Is SOXLB gearing up for a rally that will restore buyers' confidence, or does the decline still have more to say?
$SOXLB
{spot}(SOXLBUSDT)
#SOXLB #Binance #Crypto #Semiconductors #Trading
### 🚨 $SOXLB sparks a showdown! Are semiconductor stocks beginning their comeback here? 🔥
$SOXLB is entering a highly volatile phase amid notable moves in the technology and semiconductor markets.
📊 Technical analysis:
* 🚀 It rose by around 4.11% over the past 24 hours, according to one market snapshot.
* 📉 It is still down around 50.88% over the past 30 days.
* 💥 A return of buying momentum and a break above resistance could support a strong rebound, while a break below support could open the door to a new wave of declines. cexscan
🐋 What should you watch? Trading volume, semiconductor sector performance, and the direction of the underlying asset.
⚠️ Important note: SOXLB is a 3X leveraged tokenized ETF product, not an ordinary cryptocurrency; it therefore carries high risks and volatility, and losses can mount quickly. Binance +1
🔥 The big question: Is SOXLB gearing up for a rally that will restore buyers' confidence, or does the decline still have more to say?
$SOXLB
#SOXLB #Binance #Crypto #Semiconductors #Trading
$SOXLB is entering a highly volatile phase amid notable moves in the technology and semiconductor markets.
📊 Technical analysis:
* 🚀 It rose by around 4.11% over the past 24 hours, according to one market snapshot.
* 📉 It is still down around 50.88% over the past 30 days.
* 💥 A return of buying momentum and a break above resistance could support a strong rebound, while a break below support could open the door to a new wave of declines. cexscan
🐋 What should you watch? Trading volume, semiconductor sector performance, and the direction of the underlying asset.
⚠️ Important note: SOXLB is a 3X leveraged tokenized ETF product, not an ordinary cryptocurrency; it therefore carries high risks and volatility, and losses can mount quickly. Binance +1
🔥 The big question: Is SOXLB gearing up for a rally that will restore buyers' confidence, or does the decline still have more to say?
$SOXLB
#SOXLB #Binance #Crypto #Semiconductors #Trading
1
130

Partly True
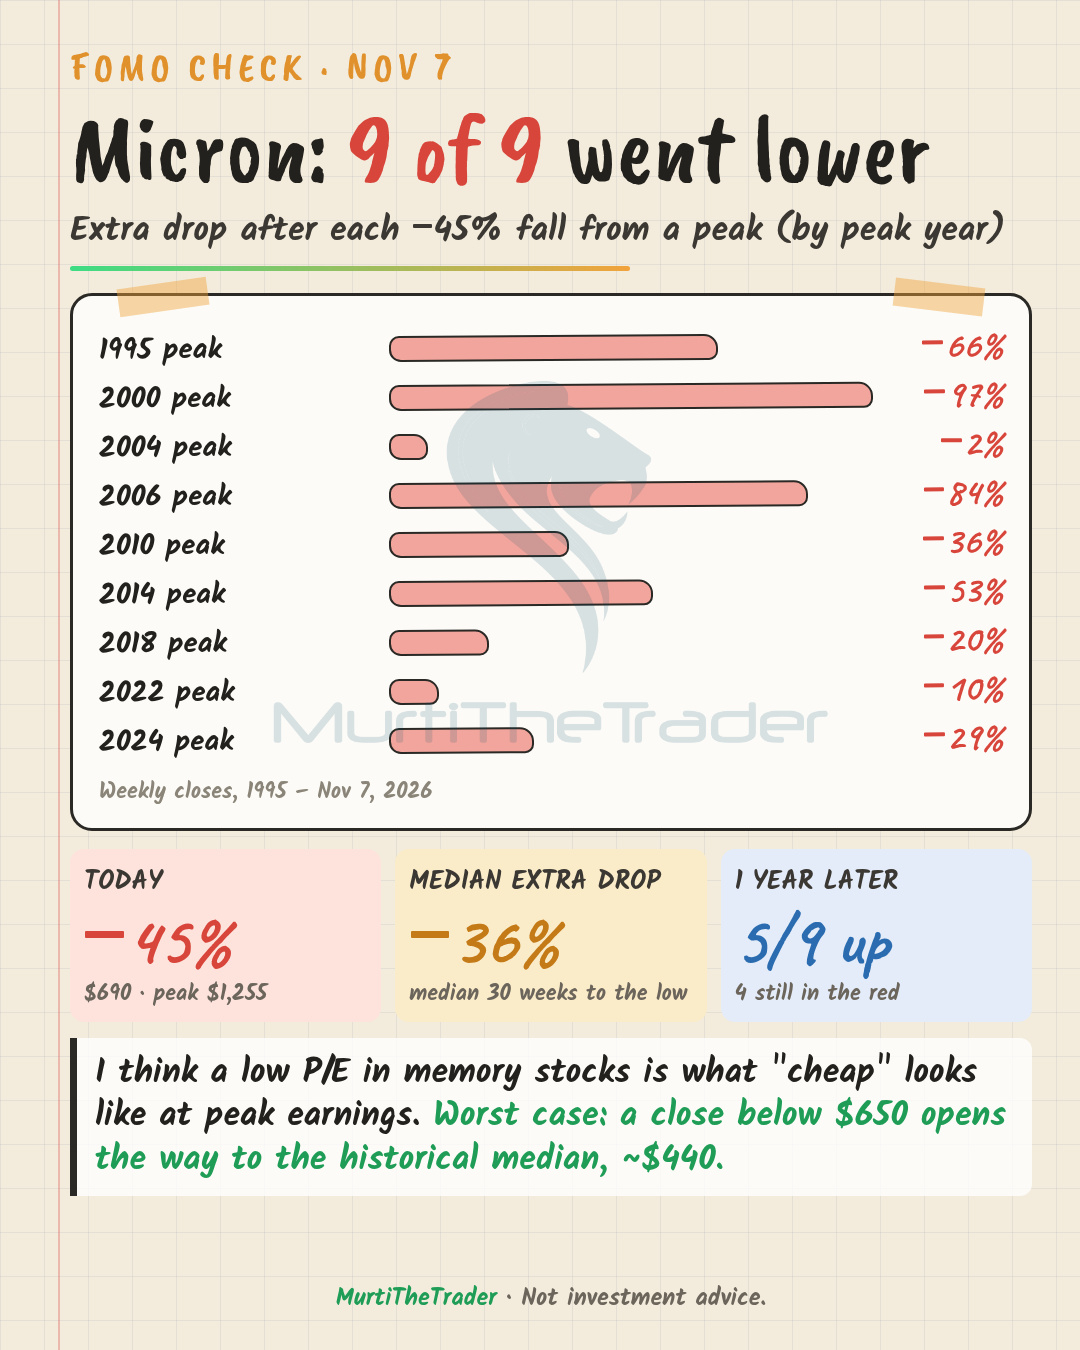
FOMO check: Everyone's saying "Micron is cheap, the P/E is at the bottom, buy now." The stock is −45% from its peak.
→ Since 1995 Micron has fallen 45% from a peak 9 times — and all 9 times the bottom came lower
→ From that point, the median extra drop was −36%, with a median 30 weeks to the low
→ One year later: up in 5 of 9 cases, still in the red in 4
I think a low P/E in memory stocks is just what "cheap" looks like when earnings are at the peak. Worst case: if Micron closes below $650, the historical median opens the way to ~$440 — that's where my eyes are.
Watching: $MU $QQQ $SPY
#Stocks #AI #Semiconductors
FOMO check: Everyone's saying "Micron is cheap, the P/E is at the bottom, buy now." The stock is −45% from its peak.
→ Since 1995 Micron has fallen 45% from a peak 9 times — and all 9 times the bottom came lower
→ From that point, the median extra drop was −36%, with a median 30 weeks to the low
→ One year later: up in 5 of 9 cases, still in the red in 4
I think a low P/E in memory stocks is just what "cheap" looks like when earnings are at the peak. Worst case: if Micron closes below $650, the historical median opens the way to ~$440 — that's where my eyes are.
Watching: $MU $QQQ $SPY
#Stocks #AI #Semiconductors
→ Since 1995 Micron has fallen 45% from a peak 9 times — and all 9 times the bottom came lower
→ From that point, the median extra drop was −36%, with a median 30 weeks to the low
→ One year later: up in 5 of 9 cases, still in the red in 4
I think a low P/E in memory stocks is just what "cheap" looks like when earnings are at the peak. Worst case: if Micron closes below $650, the historical median opens the way to ~$440 — that's where my eyes are.
Watching: $MU $QQQ $SPY
#Stocks #AI #Semiconductors
888
Chip Stocks Look Cheap -But Sentiment Is Still Fragile 💾
Semiconductor stocks are trading well below recent highs, with the SMH ETF at $463.96, about 31% below its 52-week high of $671.83. The rebound is real -SMH rose 3.62% and SOXX 3.51% in the latest session- but investors remain cautious after the AI-infrastructure selloff.
{spot}(SMHBUSDT)
{etf_us}(SOXX.ETF)
The valuation gap is clearest in TSM, trading near $375 with a 21.7x P/E, versus AMD at 97.6x and Broadcom at 37.5x. Nvidia remains near $186.64 with a 23.6x P/E, showing that not every “chip discount” is equally cheap.
The opportunity may be real, but confidence will return only when AI capex, demand, and earnings visibility stabilize.
$NVDAB $AMDB $TSMB #Semiconductors #NVDA #AMD #TSM #CoinVahini
Chip Stocks Look Cheap -But Sentiment Is Still Fragile 💾
Semiconductor stocks are trading well below recent highs, with the SMH ETF at $463.96, about 31% below its 52-week high of $671.83. The rebound is real -SMH rose 3.62% and SOXX 3.51% in the latest session- but investors remain cautious after the AI-infrastructure selloff.
The valuation gap is clearest in TSM, trading near $375 with a 21.7x P/E, versus AMD at 97.6x and Broadcom at 37.5x. Nvidia remains near $186.64 with a 23.6x P/E, showing that not every “chip discount” is equally cheap.
The opportunity may be real, but confidence will return only when AI capex, demand, and earnings visibility stabilize.
$NVDAB $AMDB $TSMB #Semiconductors #NVDA #AMD #TSM #CoinVahini
Semiconductor stocks are trading well below recent highs, with the SMH ETF at $463.96, about 31% below its 52-week high of $671.83. The rebound is real -SMH rose 3.62% and SOXX 3.51% in the latest session- but investors remain cautious after the AI-infrastructure selloff.
The valuation gap is clearest in TSM, trading near $375 with a 21.7x P/E, versus AMD at 97.6x and Broadcom at 37.5x. Nvidia remains near $186.64 with a 23.6x P/E, showing that not every “chip discount” is equally cheap.
The opportunity may be real, but confidence will return only when AI capex, demand, and earnings visibility stabilize.
$NVDAB $AMDB $TSMB #Semiconductors #NVDA #AMD #TSM #CoinVahini
67
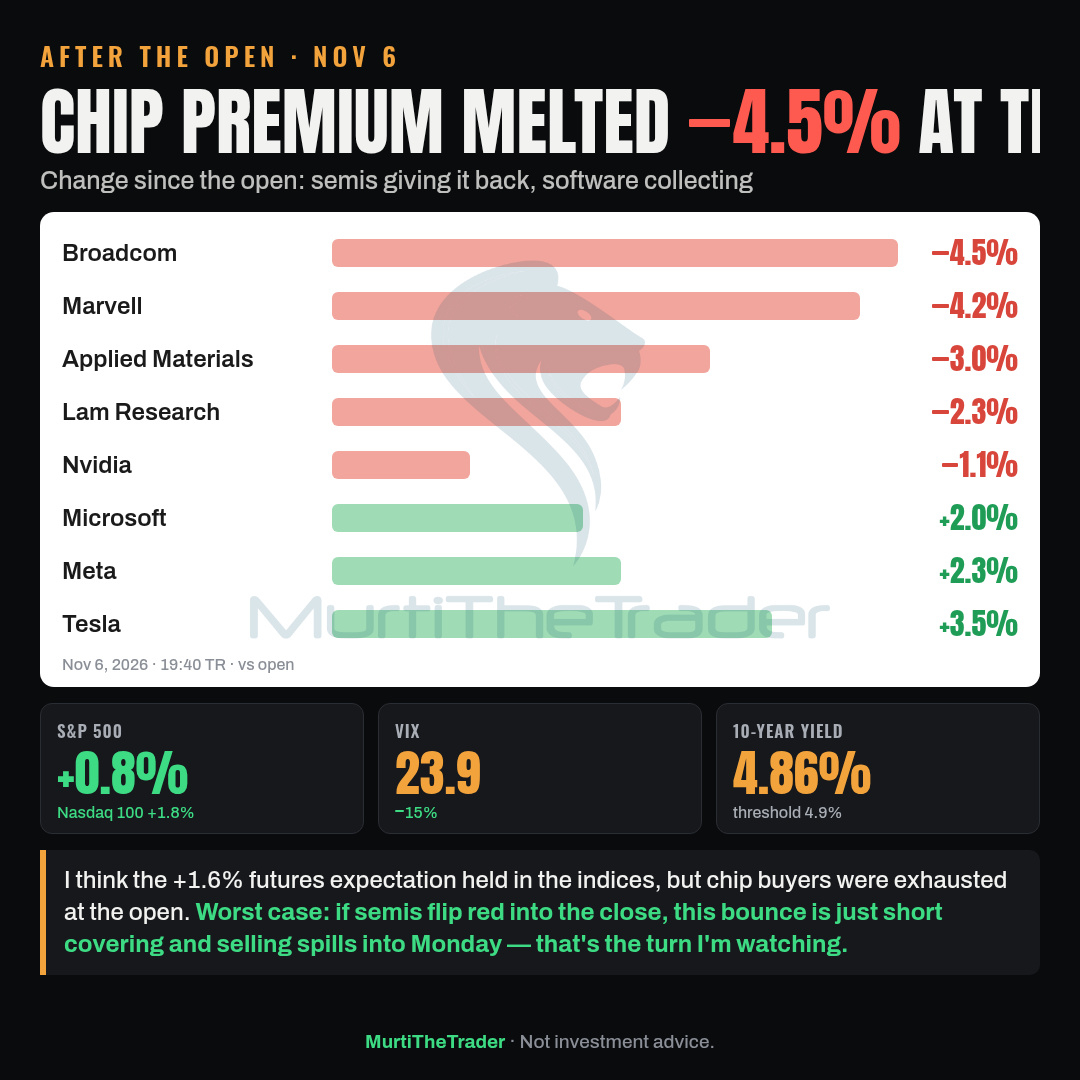
After the open: Broadcom ($AVGO ) started the day +6.7%, melted −4.5% from the open and is now only +1.9%.
→ Marvell ($MRVL ) −4.2%, Applied Materials −3.0%, Lam Research −2.3%
→ Microsoft ($MSFT ) has picked up +2.0% since the open
→ S&P 500 +0.8%, Nasdaq 100 +1.8%, VIX 23.9
I think the +1.6% futures expectation held in the indices, but chip buyers were exhausted at the open. Worst case: if semis flip red into the close, this bounce is just short covering and selling spills into Monday — that's the turn I'm watching.
Watching: $AVGO $MRVL $MSFT
#Semiconductors #AI #Stocks
After the open: Broadcom ($AVGO ) started the day +6.7%, melted −4.5% from the open and is now only +1.9%.
→ Marvell ($MRVL ) −4.2%, Applied Materials −3.0%, Lam Research −2.3%
→ Microsoft ($MSFT ) has picked up +2.0% since the open
→ S&P 500 +0.8%, Nasdaq 100 +1.8%, VIX 23.9
I think the +1.6% futures expectation held in the indices, but chip buyers were exhausted at the open. Worst case: if semis flip red into the close, this bounce is just short covering and selling spills into Monday — that's the turn I'm watching.
Watching: $AVGO $MRVL $MSFT
#Semiconductors #AI #Stocks
→ Marvell ($MRVL ) −4.2%, Applied Materials −3.0%, Lam Research −2.3%
→ Microsoft ($MSFT ) has picked up +2.0% since the open
→ S&P 500 +0.8%, Nasdaq 100 +1.8%, VIX 23.9
I think the +1.6% futures expectation held in the indices, but chip buyers were exhausted at the open. Worst case: if semis flip red into the close, this bounce is just short covering and selling spills into Monday — that's the turn I'm watching.
Watching: $AVGO $MRVL $MSFT
#Semiconductors #AI #Stocks
Red Zone 07:
Follow me 🙏
1
405
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#HotCPIDecemberHikePriced
7,338 views
338 Discussing
2
#AnthropicRejectsIPODelayValuationinQuestion
137,969 views
1,331 Discussing
3
#NvidiaInvestigatesAfterHuang’sAffairApology
385,545 views
2,798 Discussing
4
#CanNvidiaEarningsEaseMarketConcerns?
12,064 views
294 Discussing
5
#ADPWeeklyEstimateShowsUSPrivatePayrollsUp19750
1,756 views
103 Discussing
6
#US-IranTalksFuelStrongStockMarketRebound
57,349 views
475 Discussing
7
#BitcoinFiveWeeklyLosses
406,050 views
2,994 Discussing
8
#AIChipSlumpNasdaq
225,718 views
1,713 Discussing
9
#BitcoinSpotETFsPost$201MNetOutflowForThirdStraightDay
1,124 views
17 Discussing
10
#CryptoLiquidationsReach$1.16BIn24Hours
52,050 views
73 Discussing