
#tokenizeddeposits
tokenizeddeposits
6,047 views
103 Discussing
Hot
Latest

·
--
Article
HKMA and Swift explore interoperability for tokenized deposits: a settlement infrastructure test, not an ETH buying spreeHKMA and Swift explore interoperability for tokenized deposits: a settlement infrastructure test, not an ETH buying spree
At around 18:30 Beijing time on November 17, Binance Square’s trending page showed `#HKMAAndSwiftExploreTokenizedDepositInteroperability` in the top 10, with around 15 people visibly discussing it; the list rotated quickly afterward. The real event behind the topic was that on November 16, the Hong Kong Monetary Authority announced closer cooperation with Swift to explore interoperability between the Swift ledger and the Project Ensemble settlement layer.
To be clear about the boundaries: this is not an announcement that “Hong Kong is starting to use ETH for cross-border settlement,” nor does it mean that any institution has already bought ETH. The HKMA’s official release confirms only that it is exploring a cross-border payment mechanism for tokenized deposits in multiple currencies. Participating banks include Bank of China (Hong Kong), Standard Chartered, and HSBC. The announcement gives no commercial launch date, transaction volume, or token procurement arrangements.
HKMA and Swift explore interoperability for tokenized deposits: a settlement infrastructure test, not an ETH buying spree
HKMA and Swift explore interoperability for tokenized deposits: a settlement infrastructure test, not an ETH buying spree
At around 18:30 Beijing time on November 17, Binance Square’s trending page showed `#HKMAAndSwiftExploreTokenizedDepositInteroperability` in the top 10, with around 15 people visibly discussing it; the list rotated quickly afterward. The real event behind the topic was that on November 16, the Hong Kong Monetary Authority announced closer cooperation with Swift to explore interoperability between the Swift ledger and the Project Ensemble settlement layer.
To be clear about the boundaries: this is not an announcement that “Hong Kong is starting to use ETH for cross-border settlement,” nor does it mean that any institution has already bought ETH. The HKMA’s official release confirms only that it is exploring a cross-border payment mechanism for tokenized deposits in multiple currencies. Participating banks include Bank of China (Hong Kong), Standard Chartered, and HSBC. The announcement gives no commercial launch date, transaction volume, or token procurement arrangements.
At around 18:30 Beijing time on November 17, Binance Square’s trending page showed `#HKMAAndSwiftExploreTokenizedDepositInteroperability` in the top 10, with around 15 people visibly discussing it; the list rotated quickly afterward. The real event behind the topic was that on November 16, the Hong Kong Monetary Authority announced closer cooperation with Swift to explore interoperability between the Swift ledger and the Project Ensemble settlement layer.
To be clear about the boundaries: this is not an announcement that “Hong Kong is starting to use ETH for cross-border settlement,” nor does it mean that any institution has already bought ETH. The HKMA’s official release confirms only that it is exploring a cross-border payment mechanism for tokenized deposits in multiple currencies. Participating banks include Bank of China (Hong Kong), Standard Chartered, and HSBC. The announcement gives no commercial launch date, transaction volume, or token procurement arrangements.
260
DBS and J.P. Morgan’s Kinexys launched institutional transfers of tokenized dollar deposits between the US and Singapore. Ant International is the first client.
These are bank deposits recorded on permissioned blockchains. Transfers operate 24/7, but moving funds between traditional accounts and Kinexys blockchain accounts pauses Saturdays, 3–6 p.m. ET.
#TokenizedDeposits #blockchain
DBS and J.P. Morgan’s Kinexys launched institutional transfers of tokenized dollar deposits between the US and Singapore. Ant International is the first client.
These are bank deposits recorded on permissioned blockchains. Transfers operate 24/7, but moving funds between traditional accounts and Kinexys blockchain accounts pauses Saturdays, 3–6 p.m. ET.
#TokenizedDeposits #blockchain
These are bank deposits recorded on permissioned blockchains. Transfers operate 24/7, but moving funds between traditional accounts and Kinexys blockchain accounts pauses Saturdays, 3–6 p.m. ET.
#TokenizedDeposits #blockchain
102

·
--
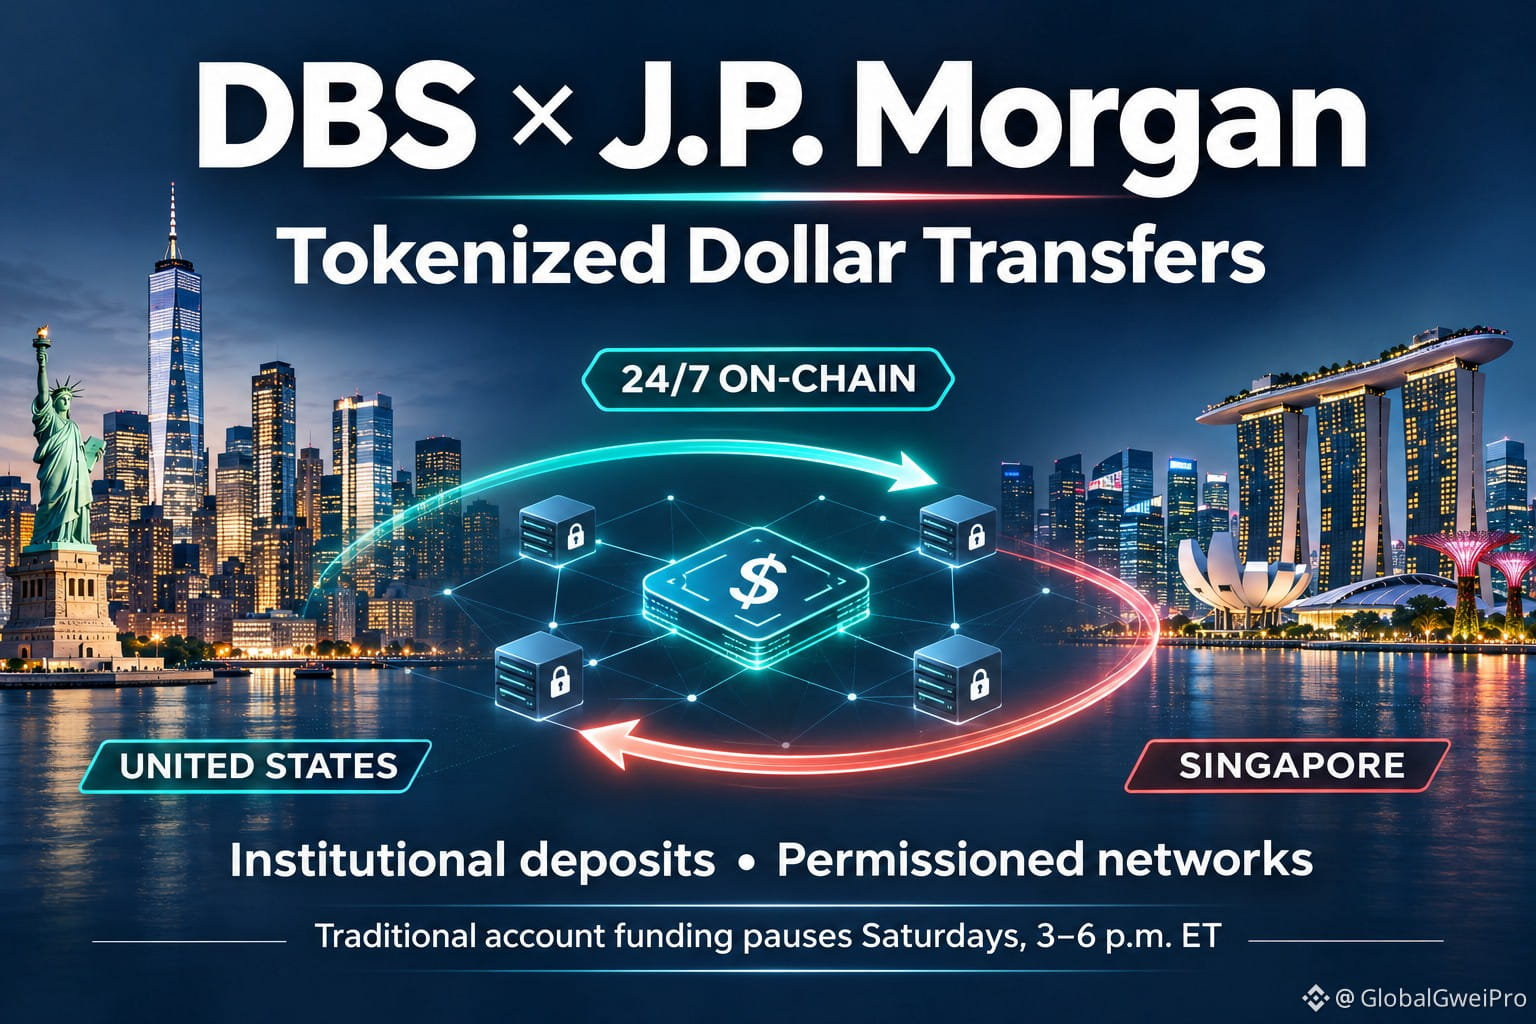
DBS and JPMorgan launch 24/7 cross-border transfers of tokenized deposits, expanding access to stablecoin settlement
Traditional financial giants are moving fiat deposits directly onto on-chain settlement networks. According to Cointelegraph, DBS and Kinexys, a division of JPMorgan, have partnered to launch a 24/7 cross-border transfer service for tokenized deposits. Its first client is Ant International, which can now transfer U.S. dollar deposits in real time between locations including Singapore.
The significance lies not in individual transactions, but in the infrastructure model. Over the past decade, the use case in which stablecoins have truly gained widespread institutional adoption has been cross-border payments and settlement—because they bypass the operating hours and intermediaries of the traditional SWIFT system. Now, established banks and top-tier investment banks are entering the space themselves, turning “deposit tokenization + real-time cross-border transfers” into a standardized capability. This effectively creates an institutional-grade official channel for stablecoin settlement.
From a capital-flow perspective, this is a classic signal of “expanded access.” Stablecoins are valuable not only as a unit of account, but also as an entry point for fiat currency into the crypto ecosystem. The more numerous and seamless these entry points are, the more efficiently capital can move on-chain, and the more active the ecosystem’s overall liquidity pools become. Tokenized deposits themselves are not crypto-native stablecoins, so their direct impact on token prices is limited, but their infrastructure significance deserves attention.
The scale and pace are what to watch. So far, only the first client has been disclosed, and the rollout remains at an early stage, with both the number of clients and transfer volumes quite limited. The true impact of institutional-grade infrastructure will depend on whether it can move from pilot programs to large-scale adoption.
One countervailing factor is that tokenized deposits are deeply tied to the traditional banking system. Their expansion is constrained by regulation, compliance, and banks’ own strategies, so they may not spread as quickly as decentralized stablecoins. Their effect on token prices is also indirect and long-term, making it difficult to trigger price moves in the short term.
What to watch next: Focus on additional clients and actual transfer volumes, as well as whether more banks join this settlement network. If volumes continue to grow, stablecoins’ position as a leading means of cross-border settlement will be further reinforced. From a trading perspective, this kind of infrastructure news is more of a long-term positive. In the short term, it is more worthwhile to watch whether overall liquidity and funding rates provide meaningful confirmation, rather than chase a rally.
#Stablecoins #TokenizedDeposits #InstitutionalAdoption
The above is a summary of information and personal analysis, and does not constitute investment advice.
Follow me for ongoing coverage of key market developments and data.
DBS and JPMorgan launch 24/7 cross-border transfers of tokenized deposits, expanding access to stablecoin settlement
Traditional financial giants are moving fiat deposits directly onto on-chain settlement networks. According to Cointelegraph, DBS and Kinexys, a division of JPMorgan, have partnered to launch a 24/7 cross-border transfer service for tokenized deposits. Its first client is Ant International, which can now transfer U.S. dollar deposits in real time between locations including Singapore.
The significance lies not in individual transactions, but in the infrastructure model. Over the past decade, the use case in which stablecoins have truly gained widespread institutional adoption has been cross-border payments and settlement—because they bypass the operating hours and intermediaries of the traditional SWIFT system. Now, established banks and top-tier investment banks are entering the space themselves, turning “deposit tokenization + real-time cross-border transfers” into a standardized capability. This effectively creates an institutional-grade official channel for stablecoin settlement.
From a capital-flow perspective, this is a classic signal of “expanded access.” Stablecoins are valuable not only as a unit of account, but also as an entry point for fiat currency into the crypto ecosystem. The more numerous and seamless these entry points are, the more efficiently capital can move on-chain, and the more active the ecosystem’s overall liquidity pools become. Tokenized deposits themselves are not crypto-native stablecoins, so their direct impact on token prices is limited, but their infrastructure significance deserves attention.
The scale and pace are what to watch. So far, only the first client has been disclosed, and the rollout remains at an early stage, with both the number of clients and transfer volumes quite limited. The true impact of institutional-grade infrastructure will depend on whether it can move from pilot programs to large-scale adoption.
One countervailing factor is that tokenized deposits are deeply tied to the traditional banking system. Their expansion is constrained by regulation, compliance, and banks’ own strategies, so they may not spread as quickly as decentralized stablecoins. Their effect on token prices is also indirect and long-term, making it difficult to trigger price moves in the short term.
What to watch next: Focus on additional clients and actual transfer volumes, as well as whether more banks join this settlement network. If volumes continue to grow, stablecoins’ position as a leading means of cross-border settlement will be further reinforced. From a trading perspective, this kind of infrastructure news is more of a long-term positive. In the short term, it is more worthwhile to watch whether overall liquidity and funding rates provide meaningful confirmation, rather than chase a rally.
#Stablecoins #TokenizedDeposits #InstitutionalAdoption
The above is a summary of information and personal analysis, and does not constitute investment advice.
Follow me for ongoing coverage of key market developments and data.
Traditional financial giants are moving fiat deposits directly onto on-chain settlement networks. According to Cointelegraph, DBS and Kinexys, a division of JPMorgan, have partnered to launch a 24/7 cross-border transfer service for tokenized deposits. Its first client is Ant International, which can now transfer U.S. dollar deposits in real time between locations including Singapore.
The significance lies not in individual transactions, but in the infrastructure model. Over the past decade, the use case in which stablecoins have truly gained widespread institutional adoption has been cross-border payments and settlement—because they bypass the operating hours and intermediaries of the traditional SWIFT system. Now, established banks and top-tier investment banks are entering the space themselves, turning “deposit tokenization + real-time cross-border transfers” into a standardized capability. This effectively creates an institutional-grade official channel for stablecoin settlement.
From a capital-flow perspective, this is a classic signal of “expanded access.” Stablecoins are valuable not only as a unit of account, but also as an entry point for fiat currency into the crypto ecosystem. The more numerous and seamless these entry points are, the more efficiently capital can move on-chain, and the more active the ecosystem’s overall liquidity pools become. Tokenized deposits themselves are not crypto-native stablecoins, so their direct impact on token prices is limited, but their infrastructure significance deserves attention.
The scale and pace are what to watch. So far, only the first client has been disclosed, and the rollout remains at an early stage, with both the number of clients and transfer volumes quite limited. The true impact of institutional-grade infrastructure will depend on whether it can move from pilot programs to large-scale adoption.
One countervailing factor is that tokenized deposits are deeply tied to the traditional banking system. Their expansion is constrained by regulation, compliance, and banks’ own strategies, so they may not spread as quickly as decentralized stablecoins. Their effect on token prices is also indirect and long-term, making it difficult to trigger price moves in the short term.
What to watch next: Focus on additional clients and actual transfer volumes, as well as whether more banks join this settlement network. If volumes continue to grow, stablecoins’ position as a leading means of cross-border settlement will be further reinforced. From a trading perspective, this kind of infrastructure news is more of a long-term positive. In the short term, it is more worthwhile to watch whether overall liquidity and funding rates provide meaningful confirmation, rather than chase a rally.
#Stablecoins #TokenizedDeposits #InstitutionalAdoption
The above is a summary of information and personal analysis, and does not constitute investment advice.
Follow me for ongoing coverage of key market developments and data.
42

DBS and JPMorgan’s Kinexys launch 24/7 tokenized deposit transfers
- DBS and JPMorgan’s Kinexys launch a 24/7 tokenized deposit transfer service.
- Customers can transfer USD deposits between Singapore and the United States.
- Ant International is the first customer to use the service.
- The RSS description provides no further details.
#BinanceSquare #CryptoNews #Blockchain #RWA #TokenizedDeposits
$btc $eth
vlikevn Titanbot
Source: CoinTelegraph
DBS and JPMorgan’s Kinexys launch 24/7 tokenized deposit transfers
- DBS and JPMorgan’s Kinexys launch a 24/7 tokenized deposit transfer service.
- Customers can transfer USD deposits between Singapore and the United States.
- Ant International is the first customer to use the service.
- The RSS description provides no further details.
#BinanceSquare #CryptoNews #Blockchain #RWA #TokenizedDeposits
$btc $eth
vlikevn Titanbot
Source: CoinTelegraph
- DBS and JPMorgan’s Kinexys launch a 24/7 tokenized deposit transfer service.
- Customers can transfer USD deposits between Singapore and the United States.
- Ant International is the first customer to use the service.
- The RSS description provides no further details.
#BinanceSquare #CryptoNews #Blockchain #RWA #TokenizedDeposits
$btc $eth
vlikevn Titanbot
Source: CoinTelegraph
DBS and JPMorgan’s Kinexys launch 24/7 tokenized US dollar transfers
- DBS and JPMorgan’s Kinexys launch 24/7 transfers of tokenized deposits.
- Ant International is the first customer.
- Transfers US dollar deposits between Singapore and the US.
#BinanceSquare #CryptoNews #TokenizedDeposits
$btc $eth
#vlikevn #Titanbot
Source: CoinTelegraph
DBS and JPMorgan’s Kinexys launch 24/7 tokenized US dollar transfers
- DBS and JPMorgan’s Kinexys launch 24/7 transfers of tokenized deposits.
- Ant International is the first customer.
- Transfers US dollar deposits between Singapore and the US.
#BinanceSquare #CryptoNews #TokenizedDeposits
$btc $eth
#vlikevn #Titanbot
Source: CoinTelegraph
- DBS and JPMorgan’s Kinexys launch 24/7 transfers of tokenized deposits.
- Ant International is the first customer.
- Transfers US dollar deposits between Singapore and the US.
#BinanceSquare #CryptoNews #TokenizedDeposits
$btc $eth
#vlikevn #Titanbot
Source: CoinTelegraph
199

#RWA Standard Chartered has launched tokenized deposits for corporate clients in Hong Kong, the first market in its network to offer the service. Built on the bank’s blockchain and the HKMA’s EnsembleTX infrastructure, it enables 24/7 real-time transfers between banks with settlement in central bank money, including wholesale CBDC.
$PAXG $XAUT $ONDO #CoinVahini #StandardChartered #TokenizedDeposits
#RWA Standard Chartered has launched tokenized deposits for corporate clients in Hong Kong, the first market in its network to offer the service. Built on the bank’s blockchain and the HKMA’s EnsembleTX infrastructure, it enables 24/7 real-time transfers between banks with settlement in central bank money, including wholesale CBDC.
$PAXG $XAUT $ONDO #CoinVahini #StandardChartered #TokenizedDeposits
$PAXG $XAUT $ONDO #CoinVahini #StandardChartered #TokenizedDeposits
11

Standard Chartered has launched a tokenized deposit service in Hong Kong, using the local EnsembleTX system to enable 24/7 interbank fund transfers settled in central bank money. 🪙 💬
- Fact: The service is aimed at corporate clients and uses blockchain technology to package traditional deposits as programmable tokens, theoretically improving liquidity and the efficiency of cross-border settlement.
- Unanswered questions: It remains unclear how the regulatory framework for these tokenized deposits will be developed. The actual scale of usage and the extent of their impact on existing interbank settlement networks have also not been disclosed.
- Explanation: If regulators keep pace and businesses adopt the service, it could become an important pilot for the digital transformation of traditional banks. Conversely, regulatory uncertainty and the cost of integrating the technology could limit its adoption.
🔍 How do you think tokenized deposits will change the way businesses make cross-border payments?
This is not investment advice.
#TokenizedDeposits #香港金融 #区块链创新 #Write2Earn
Standard Chartered has launched a tokenized deposit service in Hong Kong, using the local EnsembleTX system to enable 24/7 interbank fund transfers settled in central bank money. 🪙 💬
- Fact: The service is aimed at corporate clients and uses blockchain technology to package traditional deposits as programmable tokens, theoretically improving liquidity and the efficiency of cross-border settlement.
- Unanswered questions: It remains unclear how the regulatory framework for these tokenized deposits will be developed. The actual scale of usage and the extent of their impact on existing interbank settlement networks have also not been disclosed.
- Explanation: If regulators keep pace and businesses adopt the service, it could become an important pilot for the digital transformation of traditional banks. Conversely, regulatory uncertainty and the cost of integrating the technology could limit its adoption.
🔍 How do you think tokenized deposits will change the way businesses make cross-border payments?
This is not investment advice.
#TokenizedDeposits #香港金融 #区块链创新 #Write2Earn
- Fact: The service is aimed at corporate clients and uses blockchain technology to package traditional deposits as programmable tokens, theoretically improving liquidity and the efficiency of cross-border settlement.
- Unanswered questions: It remains unclear how the regulatory framework for these tokenized deposits will be developed. The actual scale of usage and the extent of their impact on existing interbank settlement networks have also not been disclosed.
- Explanation: If regulators keep pace and businesses adopt the service, it could become an important pilot for the digital transformation of traditional banks. Conversely, regulatory uncertainty and the cost of integrating the technology could limit its adoption.
🔍 How do you think tokenized deposits will change the way businesses make cross-border payments?
This is not investment advice.
#TokenizedDeposits #香港金融 #区块链创新 #Write2Earn
4

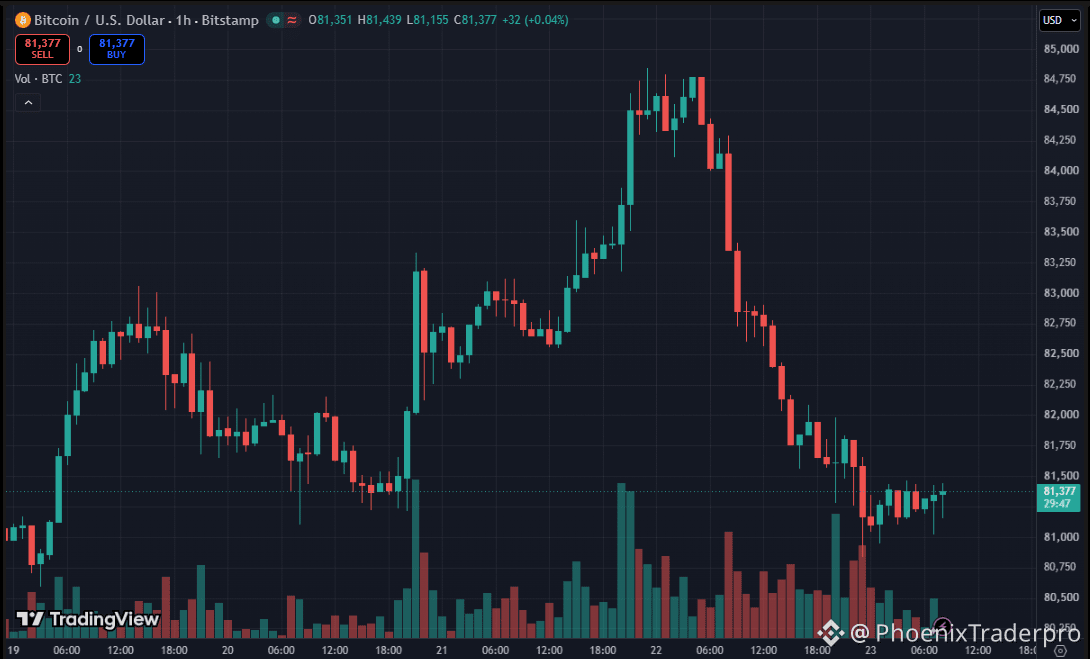
🚀 $BTC HITS $81.3K AS REGULATORY WAVES & TOKENIZED DEPOSITS SURGE! 📈
📊 Bitcoin steadies near $81,300 while Ireland’s fine on a major exchange fuels a short‑term liquidity squeeze. Smart‑money 🦈 eyes the dip, anticipating a rebound as institutional interest stays iron‑clad. ⚡ SoFi’s 4.4% tokenized deposit launch adds a fresh yield‑play, nudging capital toward crypto‑linked assets. Ripple’s RLUSD partnership and Uniswap’s new aggregator hooks broaden cross‑chain flow, hinting at deeper order‑book depth for $BTC and alt‑coins alike.
💬 Which angle are you riding – the regulatory dip or the token‑driven inflow? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Regulation #TokenizedDeposits #CryptoNews
🔥 💎
🚀 $BTC HITS $81.3K AS REGULATORY WAVES & TOKENIZED DEPOSITS SURGE! 📈
📊 Bitcoin steadies near $81,300 while Ireland’s fine on a major exchange fuels a short‑term liquidity squeeze. Smart‑money 🦈 eyes the dip, anticipating a rebound as institutional interest stays iron‑clad. ⚡ SoFi’s 4.4% tokenized deposit launch adds a fresh yield‑play, nudging capital toward crypto‑linked assets. Ripple’s RLUSD partnership and Uniswap’s new aggregator hooks broaden cross‑chain flow, hinting at deeper order‑book depth for $BTC and alt‑coins alike.
💬 Which angle are you riding – the regulatory dip or the token‑driven inflow? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Regulation #TokenizedDeposits #CryptoNews
🔥 💎
📊 Bitcoin steadies near $81,300 while Ireland’s fine on a major exchange fuels a short‑term liquidity squeeze. Smart‑money 🦈 eyes the dip, anticipating a rebound as institutional interest stays iron‑clad. ⚡ SoFi’s 4.4% tokenized deposit launch adds a fresh yield‑play, nudging capital toward crypto‑linked assets. Ripple’s RLUSD partnership and Uniswap’s new aggregator hooks broaden cross‑chain flow, hinting at deeper order‑book depth for $BTC and alt‑coins alike.
💬 Which angle are you riding – the regulatory dip or the token‑driven inflow? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Regulation #TokenizedDeposits #CryptoNews
🔥 💎
19

·
--
SoFi just put a bank deposit on-chain for everyday customers — with FDIC cover and a yield.
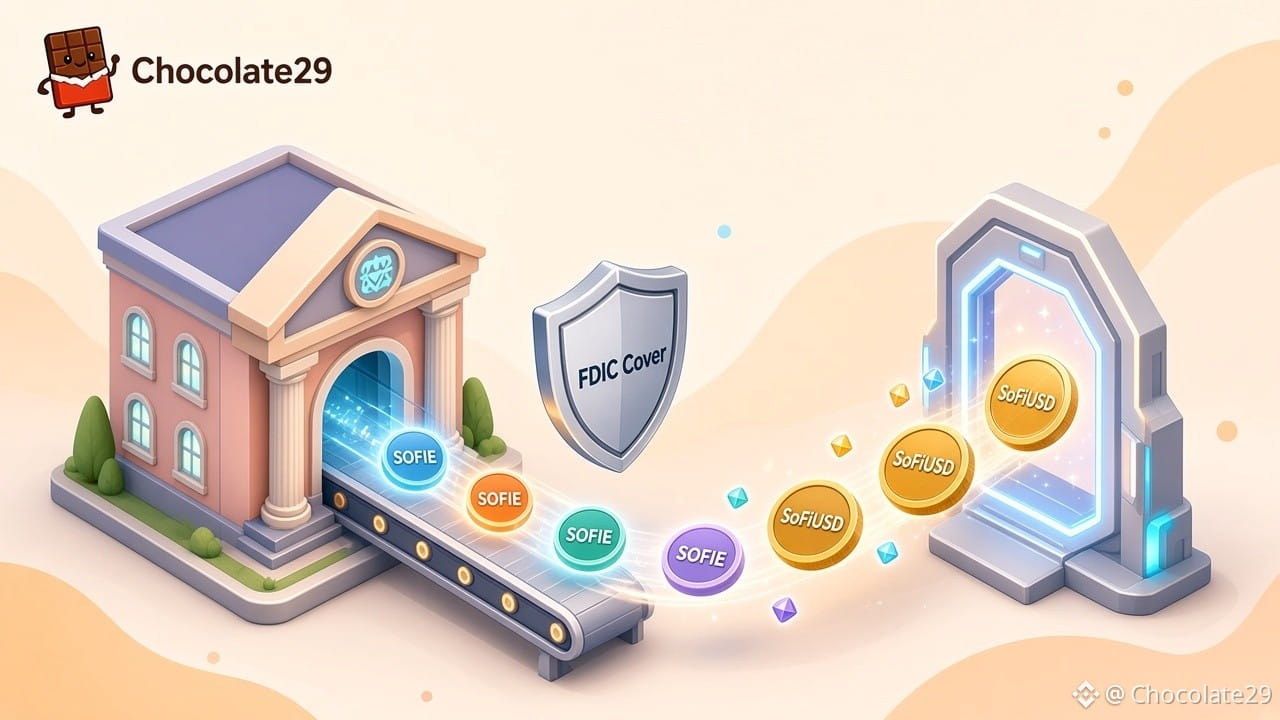
On October 22, 2026, SoFi Technologies launched SoFi Earn (SOFIE), calling it the first national bank-issued tokenized deposit for U.S. consumers. Each SOFIE represents one U.S. dollar held on deposit at SoFi Bank, earns a variable 4.40% APY (rate as of October 20, 2026), and is FDIC-insured up to standard limits. SoFi frames the launch as its fifth crypto-related product in less than a year.
SOFIE is not a payment stablecoin. Members can convert it 1:1 into SoFiUSD when they want to buy crypto in-app or move funds over blockchain rails around the clock; once converted, those dollars leave the insured deposit product. SoFi expects the rollout to crypto customers to finish in November 2026. Tokenized bank deposits sit in a different risk box than exchange stablecoins — read the disclosures before parking cash.
#SoFi #SOFIE #TokenizedDeposits #Stablecoins #Crypto
DYOR. Not financial advice.
{future}(SOFIUSDT)
SoFi just put a bank deposit on-chain for everyday customers — with FDIC cover and a yield.
On October 22, 2026, SoFi Technologies launched SoFi Earn (SOFIE), calling it the first national bank-issued tokenized deposit for U.S. consumers. Each SOFIE represents one U.S. dollar held on deposit at SoFi Bank, earns a variable 4.40% APY (rate as of October 20, 2026), and is FDIC-insured up to standard limits. SoFi frames the launch as its fifth crypto-related product in less than a year.
SOFIE is not a payment stablecoin. Members can convert it 1:1 into SoFiUSD when they want to buy crypto in-app or move funds over blockchain rails around the clock; once converted, those dollars leave the insured deposit product. SoFi expects the rollout to crypto customers to finish in November 2026. Tokenized bank deposits sit in a different risk box than exchange stablecoins — read the disclosures before parking cash.
#SoFi #SOFIE #TokenizedDeposits #Stablecoins #Crypto
DYOR. Not financial advice.
On October 22, 2026, SoFi Technologies launched SoFi Earn (SOFIE), calling it the first national bank-issued tokenized deposit for U.S. consumers. Each SOFIE represents one U.S. dollar held on deposit at SoFi Bank, earns a variable 4.40% APY (rate as of October 20, 2026), and is FDIC-insured up to standard limits. SoFi frames the launch as its fifth crypto-related product in less than a year.
SOFIE is not a payment stablecoin. Members can convert it 1:1 into SoFiUSD when they want to buy crypto in-app or move funds over blockchain rails around the clock; once converted, those dollars leave the insured deposit product. SoFi expects the rollout to crypto customers to finish in November 2026. Tokenized bank deposits sit in a different risk box than exchange stablecoins — read the disclosures before parking cash.
#SoFi #SOFIE #TokenizedDeposits #Stablecoins #Crypto
DYOR. Not financial advice.
11
·
--
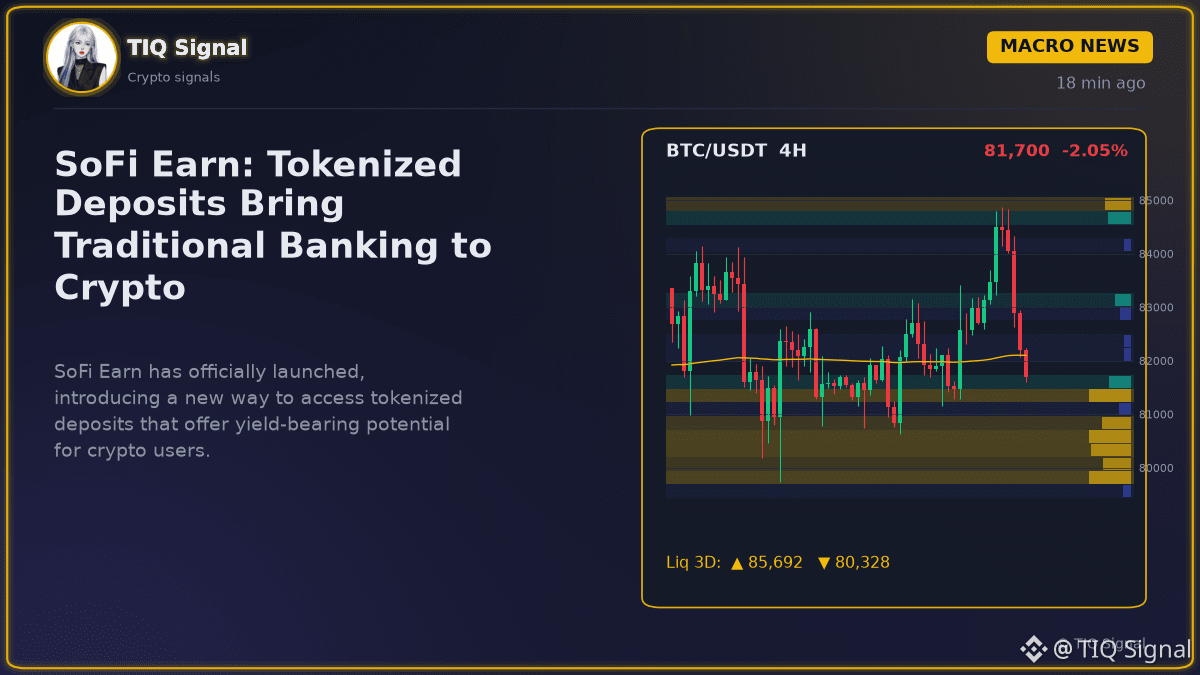
🍿 Today's crypto drama: SoFi Earn: Tokenized Deposits Bring Traditional Banking to Crypto
Quick version: SoFi Earn has officially launched, introducing a new way to access tokenized deposits that offer yield-bearing potential for crypto users.
This service provides a 4.40% APY on deposits while maintaining FDIC coverage, bridging the gap between traditional banking and digital assets. Users can convert their funds into stablecoins at any time, giving them 24/7 access to their capital. It is a clever way to keep your cash working hard while you decide on your next move in the market. 🏦
👉 What to watch: Crypto traders often watch these developments because they signal how traditional finance is integrating with blockchain to improve liquidity and risk management. Keep an eye on how these regulated yield products influence overall market sentiment regarding stablecoin utility. 📈
#Macro #TokenizedDeposits #Stablecoins #Fintech #CryptoNews
ℹ️ News roundup from public sources, not financial advice.
🍿 Today's crypto drama: SoFi Earn: Tokenized Deposits Bring Traditional Banking to Crypto
Quick version: SoFi Earn has officially launched, introducing a new way to access tokenized deposits that offer yield-bearing potential for crypto users.
This service provides a 4.40% APY on deposits while maintaining FDIC coverage, bridging the gap between traditional banking and digital assets. Users can convert their funds into stablecoins at any time, giving them 24/7 access to their capital. It is a clever way to keep your cash working hard while you decide on your next move in the market. 🏦
👉 What to watch: Crypto traders often watch these developments because they signal how traditional finance is integrating with blockchain to improve liquidity and risk management. Keep an eye on how these regulated yield products influence overall market sentiment regarding stablecoin utility. 📈
#Macro #TokenizedDeposits #Stablecoins #Fintech #CryptoNews
ℹ️ News roundup from public sources, not financial advice.
Quick version: SoFi Earn has officially launched, introducing a new way to access tokenized deposits that offer yield-bearing potential for crypto users.
This service provides a 4.40% APY on deposits while maintaining FDIC coverage, bridging the gap between traditional banking and digital assets. Users can convert their funds into stablecoins at any time, giving them 24/7 access to their capital. It is a clever way to keep your cash working hard while you decide on your next move in the market. 🏦
👉 What to watch: Crypto traders often watch these developments because they signal how traditional finance is integrating with blockchain to improve liquidity and risk management. Keep an eye on how these regulated yield products influence overall market sentiment regarding stablecoin utility. 📈
#Macro #TokenizedDeposits #Stablecoins #Fintech #CryptoNews
ℹ️ News roundup from public sources, not financial advice.
7

𝚈𝙸𝙴𝙻𝙳 𝙼𝙴𝙴𝚃𝚂 𝚂𝙴𝙲𝚄𝚁𝙸𝚃𝚈.
SoFi is bridging the gap between traditional banking and crypto by launching the SOFIE token. This tokenized deposit offers a competitive 4.4 percent APY backed by FDIC insurance which provides a level of safety that most decentralized stablecoins cannot match. For traders this represents a significant step in the institutional adoption of real world assets and could drive more liquidity into regulated fintech ecosystems.
#SoFi #TokenizedDeposits ⠀
𝚈𝙸𝙴𝙻𝙳 𝙼𝙴𝙴𝚃𝚂 𝚂𝙴𝙲𝚄𝚁𝙸𝚃𝚈.
SoFi is bridging the gap between traditional banking and crypto by launching the SOFIE token. This tokenized deposit offers a competitive 4.4 percent APY backed by FDIC insurance which provides a level of safety that most decentralized stablecoins cannot match. For traders this represents a significant step in the institutional adoption of real world assets and could drive more liquidity into regulated fintech ecosystems.
#SoFi #TokenizedDeposits ⠀
SoFi is bridging the gap between traditional banking and crypto by launching the SOFIE token. This tokenized deposit offers a competitive 4.4 percent APY backed by FDIC insurance which provides a level of safety that most decentralized stablecoins cannot match. For traders this represents a significant step in the institutional adoption of real world assets and could drive more liquidity into regulated fintech ecosystems.
#SoFi #TokenizedDeposits ⠀
11

🏛 $SOFIE: SoFi Unveils First National Bank Tokenized Deposit
SoFi launched SoFi Earn ($SOFIE), introducing the first consumer tokenized deposit issued by a U.S. national bank. Each token represents $1 held on deposit, delivering a 4.40% annual percentage yield backed by FDIC insurance. Tokens convert 1:1 into the bank's stablecoin for trading or on-chain settlement, though FDIC protections apply only up to standard statutory limits.
#SOFIE #TokenizedDeposits #Banking
🏛 $SOFIE: SoFi Unveils First National Bank Tokenized Deposit
SoFi launched SoFi Earn ($SOFIE), introducing the first consumer tokenized deposit issued by a U.S. national bank. Each token represents $1 held on deposit, delivering a 4.40% annual percentage yield backed by FDIC insurance. Tokens convert 1:1 into the bank's stablecoin for trading or on-chain settlement, though FDIC protections apply only up to standard statutory limits.
#SOFIE #TokenizedDeposits #Banking
SoFi launched SoFi Earn ($SOFIE), introducing the first consumer tokenized deposit issued by a U.S. national bank. Each token represents $1 held on deposit, delivering a 4.40% annual percentage yield backed by FDIC insurance. Tokens convert 1:1 into the bank's stablecoin for trading or on-chain settlement, though FDIC protections apply only up to standard statutory limits.
#SOFIE #TokenizedDeposits #Banking
51
·
--
Something in the news just caught my attention.
The news about America's biggest banks launching tokenized deposits to compete with stablecoins is huge.
It shows traditional finance is really leaning into blockchain, trying to get a piece of the action. This isn't just about stablecoins; it's about mainstream adoption of the underlying tech.
Banks wanting to issue their own digital cash on-chain means more legitimacy for the whole crypto space. It’s a move that could bring massive institutional liquidity down the line.
Even with $BTC trading around $62530.00 today and $ETH at $1633.47, this kind of development is a long-term bullish signal.
Sure, it means more competition for existing stablecoins, but the overall pie is expanding. More players, more capital.
I'm feeling cautiously bullish on the long-term outlook for crypto. The fundamental tech is getting adopted by the big guns. This is a big deal, imo. LFG! 🚀
#CryptoOutlook #TokenizedDeposits #TradFi #BlockchainAdoption #Bullish
Something in the news just caught my attention.
The news about America's biggest banks launching tokenized deposits to compete with stablecoins is huge.
It shows traditional finance is really leaning into blockchain, trying to get a piece of the action. This isn't just about stablecoins; it's about mainstream adoption of the underlying tech.
Banks wanting to issue their own digital cash on-chain means more legitimacy for the whole crypto space. It’s a move that could bring massive institutional liquidity down the line.
Even with $BTC trading around $62530.00 today and $ETH at $1633.47, this kind of development is a long-term bullish signal.
Sure, it means more competition for existing stablecoins, but the overall pie is expanding. More players, more capital.
I'm feeling cautiously bullish on the long-term outlook for crypto. The fundamental tech is getting adopted by the big guns. This is a big deal, imo. LFG! 🚀
#CryptoOutlook #TokenizedDeposits #TradFi #BlockchainAdoption #Bullish
The news about America's biggest banks launching tokenized deposits to compete with stablecoins is huge.
It shows traditional finance is really leaning into blockchain, trying to get a piece of the action. This isn't just about stablecoins; it's about mainstream adoption of the underlying tech.
Banks wanting to issue their own digital cash on-chain means more legitimacy for the whole crypto space. It’s a move that could bring massive institutional liquidity down the line.
Even with $BTC trading around $62530.00 today and $ETH at $1633.47, this kind of development is a long-term bullish signal.
Sure, it means more competition for existing stablecoins, but the overall pie is expanding. More players, more capital.
I'm feeling cautiously bullish on the long-term outlook for crypto. The fundamental tech is getting adopted by the big guns. This is a big deal, imo. LFG! 🚀
#CryptoOutlook #TokenizedDeposits #TradFi #BlockchainAdoption #Bullish
97
Tokenized Deposits: Banks Move Funds On-Chain
- Banks transfer savings deposits to the blockchain (on-chain) using permitted systems
- Tokenization helps strengthen security and regulatory compliance
- Privacy and legal compliance are driving this trend
#BinanceSquare #CryptoNews #TokenizedDeposits
$btc $eth
#vlikevn #Titanbot
Source: CoinDesk
Tokenized Deposits: Banks Move Funds On-Chain
- Banks transfer savings deposits to the blockchain (on-chain) using permitted systems
- Tokenization helps strengthen security and regulatory compliance
- Privacy and legal compliance are driving this trend
#BinanceSquare #CryptoNews #TokenizedDeposits
$btc $eth
#vlikevn #Titanbot
Source: CoinDesk
- Banks transfer savings deposits to the blockchain (on-chain) using permitted systems
- Tokenization helps strengthen security and regulatory compliance
- Privacy and legal compliance are driving this trend
#BinanceSquare #CryptoNews #TokenizedDeposits
$btc $eth
#vlikevn #Titanbot
Source: CoinDesk
288

·
--
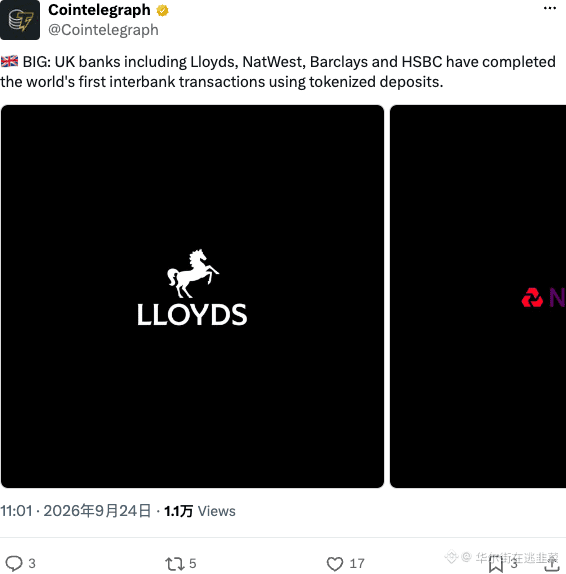
The UK’s four major banks have turned tokenized deposits from PPT to real-world action. Lloyds, NatWest, Barclays, and HSBC have just completed the world’s first batch of interbank tokenized deposit transactions. Simply put, it turns deposits into programmable tokens that can be directly used for interbank payments and clearing. Why are traditional banks so enthusiastic? Cut out the middle layers, and capital efficiency jumps to the next level. For the RWA/tokenization sector, this is a milestone-level endorsement. Next time someone says blockchain is useless, just point them to this news. But don’t rush to buy into it with Bitcoin—this is a permissioned-chain approach, not much to do with public chains in the short term. In the long run, it’s laying the groundwork for traditional capital to move in. Focus on projects that truly tokenize assets; don’t touch too much “air.”🚀
$BTC $ETH #RWA #TokenizedDeposits
The UK’s four major banks have turned tokenized deposits from PPT to real-world action. Lloyds, NatWest, Barclays, and HSBC have just completed the world’s first batch of interbank tokenized deposit transactions. Simply put, it turns deposits into programmable tokens that can be directly used for interbank payments and clearing. Why are traditional banks so enthusiastic? Cut out the middle layers, and capital efficiency jumps to the next level. For the RWA/tokenization sector, this is a milestone-level endorsement. Next time someone says blockchain is useless, just point them to this news. But don’t rush to buy into it with Bitcoin—this is a permissioned-chain approach, not much to do with public chains in the short term. In the long run, it’s laying the groundwork for traditional capital to move in. Focus on projects that truly tokenize assets; don’t touch too much “air.”🚀
$BTC $ETH #RWA #TokenizedDeposits
$BTC $ETH #RWA #TokenizedDeposits
186
·
--
$QNT exploding on real news!
Quant just partnered with The Clearing House (TCH) to power tokenized deposits for the U.S. banking system.
This is institutional adoption on another level.
Whales already moving. Volume spiking.
Smart money is loading $QNT before the next leg.
Don’t sleep on this one.
Trade $QNT now 👇
#QNT #Quant #TokenizedDeposits #crypto
{future}(QNTUSDT)
$QNT exploding on real news!
Quant just partnered with The Clearing House (TCH) to power tokenized deposits for the U.S. banking system.
This is institutional adoption on another level.
Whales already moving. Volume spiking.
Smart money is loading $QNT before the next leg.
Don’t sleep on this one.
Trade $QNT now 👇
#QNT #Quant #TokenizedDeposits #crypto
Quant just partnered with The Clearing House (TCH) to power tokenized deposits for the U.S. banking system.
This is institutional adoption on another level.
Whales already moving. Volume spiking.
Smart money is loading $QNT before the next leg.
Don’t sleep on this one.
Trade $QNT now 👇
#QNT #Quant #TokenizedDeposits #crypto
178
·
--
"It's not that Swift couldn't handle the decentralized memepool, but this blockchain ledger thing is low-key fire. Swift just launched a blockchain-based ledger for 17 banks to pilot 24/7 cross-border payments using tokenized deposits. This basically means banks get to be part of the blockchain squad and make cross-border payments less cringey #BlockchainForBanks #CrossBorderPayments #TokenizedDeposits.
The alpha is that this is a big deal, folks. It shows the banks are finally taking our 'decentralize and survive' advice. The punchline insight? Centralized powers are slowly embracing the decentralized ethos and that's like, totally a meme.
So, what do you think? Is this the beginning of banks finally getting with the blockchain times, or are they just trying to stay relevant?"
"It's not that Swift couldn't handle the decentralized memepool, but this blockchain ledger thing is low-key fire. Swift just launched a blockchain-based ledger for 17 banks to pilot 24/7 cross-border payments using tokenized deposits. This basically means banks get to be part of the blockchain squad and make cross-border payments less cringey #BlockchainForBanks #CrossBorderPayments #TokenizedDeposits.
The alpha is that this is a big deal, folks. It shows the banks are finally taking our 'decentralize and survive' advice. The punchline insight? Centralized powers are slowly embracing the decentralized ethos and that's like, totally a meme.
So, what do you think? Is this the beginning of banks finally getting with the blockchain times, or are they just trying to stay relevant?"
The alpha is that this is a big deal, folks. It shows the banks are finally taking our 'decentralize and survive' advice. The punchline insight? Centralized powers are slowly embracing the decentralized ethos and that's like, totally a meme.
So, what do you think? Is this the beginning of banks finally getting with the blockchain times, or are they just trying to stay relevant?"
47

·
--
Verified
🏦 Top US Banks Launch Tokenized Deposit Network in 2027 🚀
Wall Street’s biggest banks team up with The Clearing House to build “the bridge” – a tokenized deposit network linking traditional banking rails to blockchain for 24/7 instant settlement ⏱️
🌉 The Bridge Project 🔗
⏩ Who Led by The Clearing House. Co-owned by JPMorgan, Bank of America, Citi, Wells Fargo 🏦
⏩ What Connects legacy payment systems → blockchain infra so tokenized deposits move instantly 24/7 🌙 Blockchain built with yet-to-be-named third-party vendor 💻
⏩ Why now Banks face “radically different” on-chain future per CEO David Watson 📊 Citi: cements banks’ role in finance + capital markets 💰
⚖️ Stablecoin Tension + Adoption 🐢
⏩ Stablecoin war Banks wary stablecoins drain deposits 🪙 vs crypto firms want interest-paying stablecoins 📈 legislative fight ongoing
⏩ Use cases Real-time liquidity mgmt, programmable treasury, cross-border payments 🌍 multinationals = first users
⏩ Reality check BofA: clients not “beating down the door” yet 🐌 but interest growing 📈 adoption = gradual
⏩ Precedent JPMorgan already runs JPM Coin + Base token for institutions 🟧 last year banks discussed joint stablecoin via Clearing House + Early Warning
Bottom line 🎯 TradFi going on-chain 📲 Tokenized deposits = banks’ answer to stablecoins/CBDCs. 2027 launch, but demand still warming up 🔥
#TokenizedDeposits #TheBridge #WallStreet #Banking
🏦 Top US Banks Launch Tokenized Deposit Network in 2027 🚀
Wall Street’s biggest banks team up with The Clearing House to build “the bridge” – a tokenized deposit network linking traditional banking rails to blockchain for 24/7 instant settlement ⏱️
🌉 The Bridge Project 🔗
⏩ Who Led by The Clearing House. Co-owned by JPMorgan, Bank of America, Citi, Wells Fargo 🏦
⏩ What Connects legacy payment systems → blockchain infra so tokenized deposits move instantly 24/7 🌙 Blockchain built with yet-to-be-named third-party vendor 💻
⏩ Why now Banks face “radically different” on-chain future per CEO David Watson 📊 Citi: cements banks’ role in finance + capital markets 💰
⚖️ Stablecoin Tension + Adoption 🐢
⏩ Stablecoin war Banks wary stablecoins drain deposits 🪙 vs crypto firms want interest-paying stablecoins 📈 legislative fight ongoing
⏩ Use cases Real-time liquidity mgmt, programmable treasury, cross-border payments 🌍 multinationals = first users
⏩ Reality check BofA: clients not “beating down the door” yet 🐌 but interest growing 📈 adoption = gradual
⏩ Precedent JPMorgan already runs JPM Coin + Base token for institutions 🟧 last year banks discussed joint stablecoin via Clearing House + Early Warning
Bottom line 🎯 TradFi going on-chain 📲 Tokenized deposits = banks’ answer to stablecoins/CBDCs. 2027 launch, but demand still warming up 🔥
#TokenizedDeposits #TheBridge #WallStreet #Banking
Wall Street’s biggest banks team up with The Clearing House to build “the bridge” – a tokenized deposit network linking traditional banking rails to blockchain for 24/7 instant settlement ⏱️
🌉 The Bridge Project 🔗
⏩ Who Led by The Clearing House. Co-owned by JPMorgan, Bank of America, Citi, Wells Fargo 🏦
⏩ What Connects legacy payment systems → blockchain infra so tokenized deposits move instantly 24/7 🌙 Blockchain built with yet-to-be-named third-party vendor 💻
⏩ Why now Banks face “radically different” on-chain future per CEO David Watson 📊 Citi: cements banks’ role in finance + capital markets 💰
⚖️ Stablecoin Tension + Adoption 🐢
⏩ Stablecoin war Banks wary stablecoins drain deposits 🪙 vs crypto firms want interest-paying stablecoins 📈 legislative fight ongoing
⏩ Use cases Real-time liquidity mgmt, programmable treasury, cross-border payments 🌍 multinationals = first users
⏩ Reality check BofA: clients not “beating down the door” yet 🐌 but interest growing 📈 adoption = gradual
⏩ Precedent JPMorgan already runs JPM Coin + Base token for institutions 🟧 last year banks discussed joint stablecoin via Clearing House + Early Warning
Bottom line 🎯 TradFi going on-chain 📲 Tokenized deposits = banks’ answer to stablecoins/CBDCs. 2027 launch, but demand still warming up 🔥
#TokenizedDeposits #TheBridge #WallStreet #Banking
2
7
621
#CanadaOSFISaysTokenizedDepositsEqualTraditional
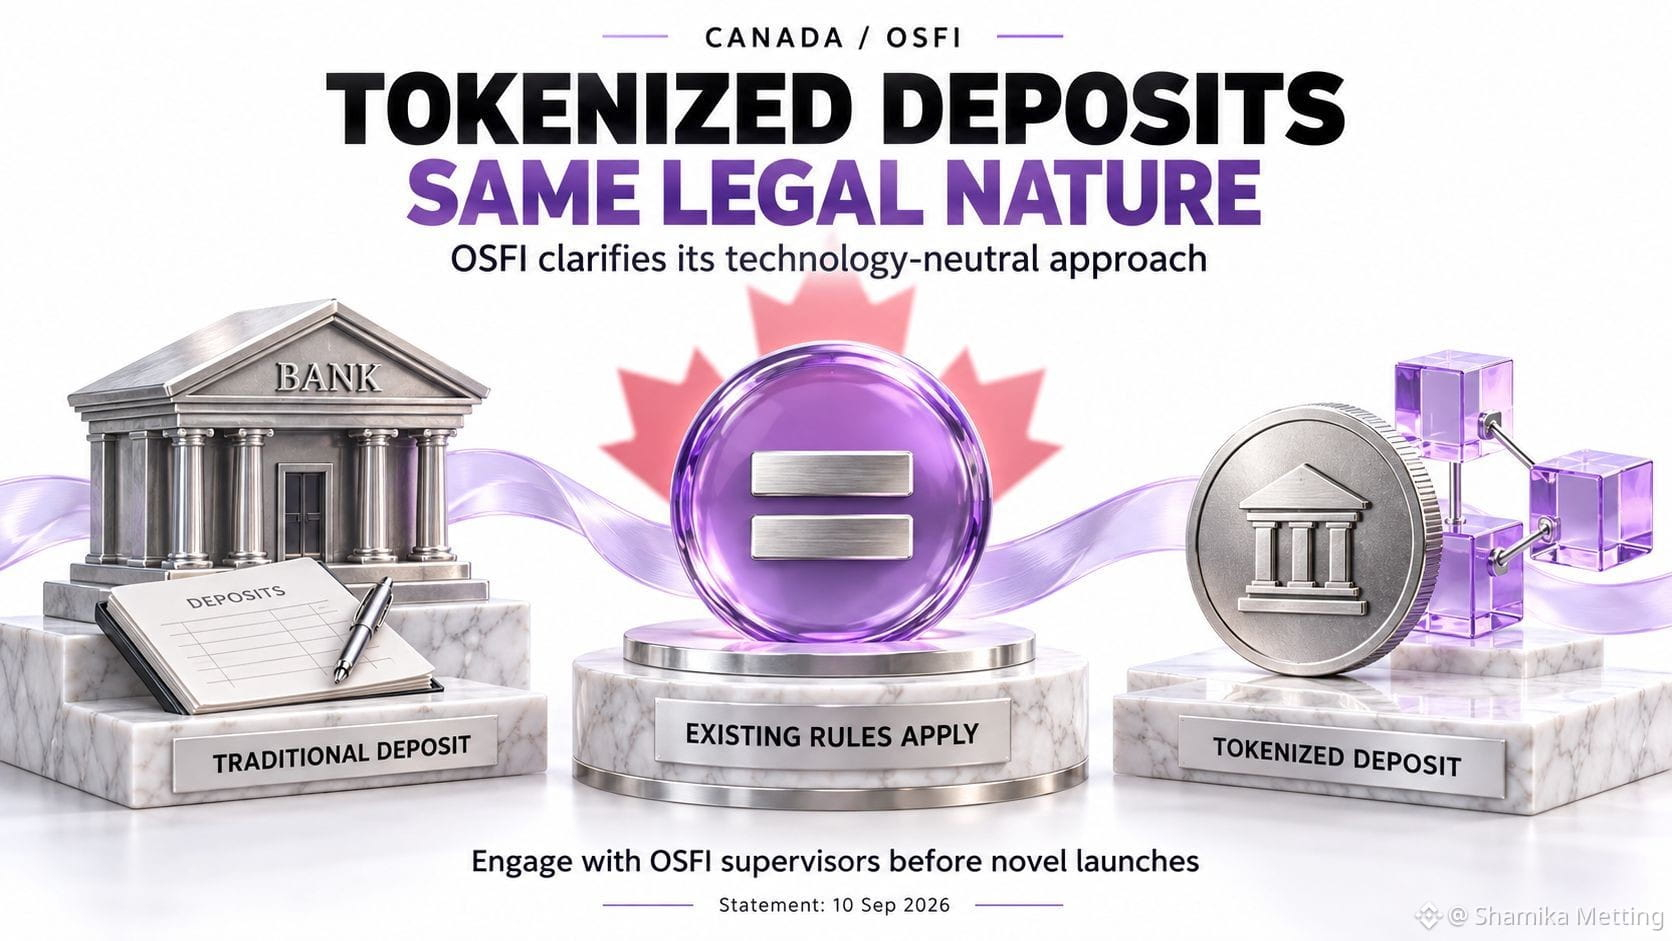
Canada clarified an important point regarding digitized asset banking (tokenized banking): changes in technology do not alter the legal nature of deposits.
In a statement dated September 10, Canada’s financial regulator, OSFI, said that tokenized deposits are legally equivalent to traditional deposits under its “technically neutral” approach.
Federally regulated financial institutions remain responsible for compliance with relevant laws, including when third parties provide services on their behalf. Requirements related to technology and cybersecurity, as well as third-party risk management, continue to apply.
Institutions are also expected to engage with their key OSFI supervisors before launching new products or services.
My view: this reduces one source of uncertainty for banks considering a move to tokenization. It also gives product teams a clearer basis for designing services within the existing banking framework.
But the business case still needs evidence. I will watch whether these products improve settlement times, reduce reconciliation work, and allow funds to move smoothly between participating institutions.
What would convince you that tokenized deposits are gaining momentum: more bank launches, or proof that customers save time and money?
Please continue
#TokenizedDeposits $VTHO
#CanadaOSFISaysTokenizedDepositsEqualTraditional
Canada clarified an important point regarding digitized asset banking (tokenized banking): changes in technology do not alter the legal nature of deposits.
In a statement dated September 10, Canada’s financial regulator, OSFI, said that tokenized deposits are legally equivalent to traditional deposits under its “technically neutral” approach.
Federally regulated financial institutions remain responsible for compliance with relevant laws, including when third parties provide services on their behalf. Requirements related to technology and cybersecurity, as well as third-party risk management, continue to apply.
Institutions are also expected to engage with their key OSFI supervisors before launching new products or services.
My view: this reduces one source of uncertainty for banks considering a move to tokenization. It also gives product teams a clearer basis for designing services within the existing banking framework.
But the business case still needs evidence. I will watch whether these products improve settlement times, reduce reconciliation work, and allow funds to move smoothly between participating institutions.
What would convince you that tokenized deposits are gaining momentum: more bank launches, or proof that customers save time and money?
Please continue
#TokenizedDeposits $VTHO
Canada clarified an important point regarding digitized asset banking (tokenized banking): changes in technology do not alter the legal nature of deposits.
In a statement dated September 10, Canada’s financial regulator, OSFI, said that tokenized deposits are legally equivalent to traditional deposits under its “technically neutral” approach.
Federally regulated financial institutions remain responsible for compliance with relevant laws, including when third parties provide services on their behalf. Requirements related to technology and cybersecurity, as well as third-party risk management, continue to apply.
Institutions are also expected to engage with their key OSFI supervisors before launching new products or services.
My view: this reduces one source of uncertainty for banks considering a move to tokenization. It also gives product teams a clearer basis for designing services within the existing banking framework.
But the business case still needs evidence. I will watch whether these products improve settlement times, reduce reconciliation work, and allow funds to move smoothly between participating institutions.
What would convince you that tokenized deposits are gaining momentum: more bank launches, or proof that customers save time and money?
Please continue
#TokenizedDeposits $VTHO
1
65
·
--
#CanadaOSFISaysTokenizedDepositsEqualTraditionalDeposits
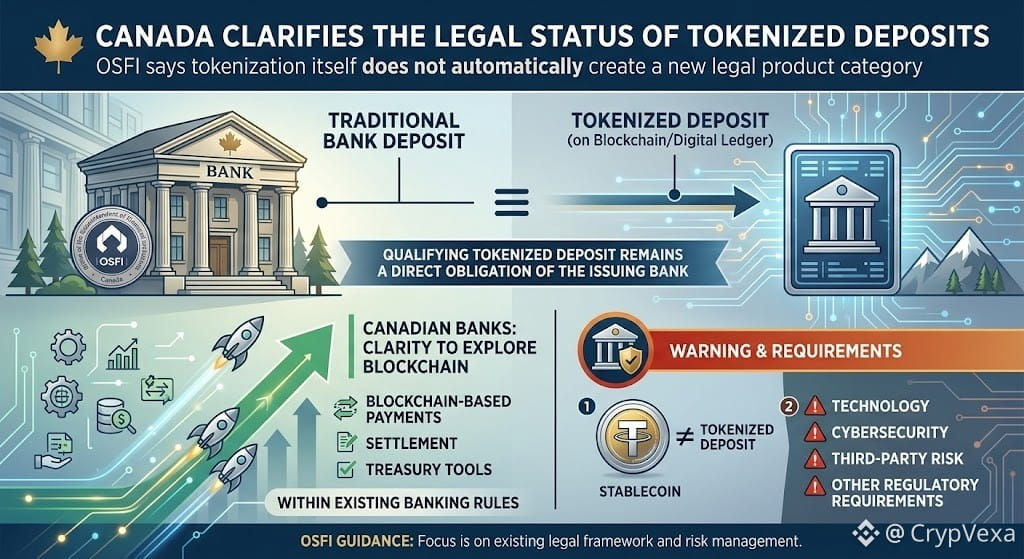
🇨🇦 Canada Clarifies the Legal Status of Tokenized Deposits
🏦 Canada’s banking regulator, OSFI, said tokenized deposits are not legally distinct from traditional bank deposits simply because they use blockchain or another digital ledger.
🔗 A qualifying tokenized deposit remains a direct obligation of the issuing bank, meaning tokenization itself does not automatically create a new legal product category.
🚀 This could give Canadian banks more clarity to explore blockchain-based payments, settlement, and treasury tools within existing banking rules.
⚠️ But tokenized deposits are not automatically the same as stablecoins, and banks still face technology, cybersecurity, third-party-risk, and other regulatory requirements.
👀 Could clearer rules accelerate blockchain adoption by Canadian banks?
#TokenizedDeposits #Blockchain #RWA #CryptoRegulation
#CanadaOSFISaysTokenizedDepositsEqualTraditionalDeposits
🇨🇦 Canada Clarifies the Legal Status of Tokenized Deposits
🏦 Canada’s banking regulator, OSFI, said tokenized deposits are not legally distinct from traditional bank deposits simply because they use blockchain or another digital ledger.
🔗 A qualifying tokenized deposit remains a direct obligation of the issuing bank, meaning tokenization itself does not automatically create a new legal product category.
🚀 This could give Canadian banks more clarity to explore blockchain-based payments, settlement, and treasury tools within existing banking rules.
⚠️ But tokenized deposits are not automatically the same as stablecoins, and banks still face technology, cybersecurity, third-party-risk, and other regulatory requirements.
👀 Could clearer rules accelerate blockchain adoption by Canadian banks?
#TokenizedDeposits #Blockchain #RWA #CryptoRegulation
🇨🇦 Canada Clarifies the Legal Status of Tokenized Deposits
🏦 Canada’s banking regulator, OSFI, said tokenized deposits are not legally distinct from traditional bank deposits simply because they use blockchain or another digital ledger.
🔗 A qualifying tokenized deposit remains a direct obligation of the issuing bank, meaning tokenization itself does not automatically create a new legal product category.
🚀 This could give Canadian banks more clarity to explore blockchain-based payments, settlement, and treasury tools within existing banking rules.
⚠️ But tokenized deposits are not automatically the same as stablecoins, and banks still face technology, cybersecurity, third-party-risk, and other regulatory requirements.
👀 Could clearer rules accelerate blockchain adoption by Canadian banks?
#TokenizedDeposits #Blockchain #RWA #CryptoRegulation
1
19
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#CanBTCReboundAfterFallingBelow60K?
308,519 views
1,301 Discussing
2
#GlobalStocksFaceLongestLosingStreakSince2023
101,315 views
942 Discussing
3
#BlackRockIBITPostsRecord$541MSingleDayOutflow
0 views
0 Discussing
4
#AnthropicPlungesTowardIPOPriceonDay2
49,796 views
497 Discussing
5
#TwentyOneCapitalAdds172.25BTC
876 views
73 Discussing
6
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
232 views
11 Discussing
7
#BNBDropsBelow540USDTWith8.46%DailyDecline
24,235 views
189 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
795 views
12 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
1,735 views
15 Discussing
10
#StrategyReports$35BNetReserves
1,436 views
15 Discussing