
#swift
swift
1.3M නැරඹීම්
1,114 සාකච්ඡා කරමින්
උණුසුම්
නවතම

stablecoin-backed prefunding rails reduce FX and treasury management costs compared to traditionalComparing stablecoin-backed prefunding rails (such as Visa Direct’s integration with USDC) to traditional SWIFT wires highlights how structural changes in technology directly alter the economics of liquidity and foreign exchange (FX) management.
Traditional cross-border payments rely on the correspondent banking network, which creates severe capital inefficiencies. Stablecoins reshape these dynamics through several distinct mechanisms:
1. Elimination of Fragmented Nostro/Vostro Account Capital
The SWIFT Problem: Under traditional rails, a payout provider or financial institution must "pre-fund" multiple foreign bank accounts (nostro/vostro accounts) globally to ensure they can settle outgoing payments in local currencies instantly. This locks up millions of dollars in idle capital across different time zones, jurisdictions, and currencies just to cover weekend or after-hours gaps.The Stablecoin Advantage: Stablecoin prefunding introduces shared, centralized liquidity pools. Instead of fragmenting working capital across a dozen local bank accounts worldwide, treasury teams can hold a unified digital asset pool (e.g., USDC) and dynamically deploy funds on-chain within minutes to wherever payout demand spikes.
2. Radical Reduction of Intermediary & "Lifting" Fees
The SWIFT Problem: A standard cross-border wire often hops through 2 to 5 intermediary correspondent banks before reaching the destination. Each intermediary bank in the chain takes a cut—deducting sending fees, intermediary wire fees, and receiving "lifting charges"—making low-value or high-frequency transfers cost-prohibitive.The Stablecoin Advantage: Blockchain rails bypass multi-hop intermediary chains. Value transfers directly from the sender’s wallet to the network settlement layer in seconds or minutes, reducing intermediary overhead to negligible on-chain network costs (often fractions of a dollar).
3. Tighter FX Spreads & Predictable Conversions
The SWIFT Problem: Traditional SWIFT FX conversions are prone to opaque, multi-layered markups. Because conversion rates are handled sequentially by multiple banks along the route, treasury teams frequently face unpredictable FX slippage and lack real-time visibility into the exact landed cost.The Stablecoin Advantage: By utilizing regulated infrastructure partners (such as Triple-A or Circle) to handle edge conversions, stablecoin rails isolate the FX conversion to a single transparent leg. Businesses can execute conversions programmatically at exact, published rates before the value moves on-chain, eliminating hidden mid-route currency devaluation.
4. Mitigation of Weekend and Cut-off Time Risk
The SWIFT Problem: Traditional banking windows are restricted to local business hours and cut-off times, closing entirely over weekends and national holidays. If an unexpected liquidity shortfall occurs on a Friday evening, treasury teams must either over-buffer capital defensively or absorb severe delays until Monday morning.The Stablecoin Advantage: Operating 24/7/365, blockchain networks allow treasuries to move funds instantly outside banking hours. This operational continuity eliminates the need to hold extra "buffer capital" specifically to guard against weekend market shocks or unexpected payout surges.
Summary Cost & Operational Comparison
#Swift #BTC #ETH
stablecoin-backed prefunding rails reduce FX and treasury management costs compared to traditional
Comparing stablecoin-backed prefunding rails (such as Visa Direct’s integration with USDC) to traditional SWIFT wires highlights how structural changes in technology directly alter the economics of liquidity and foreign exchange (FX) management.
Traditional cross-border payments rely on the correspondent banking network, which creates severe capital inefficiencies. Stablecoins reshape these dynamics through several distinct mechanisms:
1. Elimination of Fragmented Nostro/Vostro Account Capital
The SWIFT Problem: Under traditional rails, a payout provider or financial institution must "pre-fund" multiple foreign bank accounts (nostro/vostro accounts) globally to ensure they can settle outgoing payments in local currencies instantly. This locks up millions of dollars in idle capital across different time zones, jurisdictions, and currencies just to cover weekend or after-hours gaps.The Stablecoin Advantage: Stablecoin prefunding introduces shared, centralized liquidity pools. Instead of fragmenting working capital across a dozen local bank accounts worldwide, treasury teams can hold a unified digital asset pool (e.g., USDC) and dynamically deploy funds on-chain within minutes to wherever payout demand spikes.
2. Radical Reduction of Intermediary & "Lifting" Fees
The SWIFT Problem: A standard cross-border wire often hops through 2 to 5 intermediary correspondent banks before reaching the destination. Each intermediary bank in the chain takes a cut—deducting sending fees, intermediary wire fees, and receiving "lifting charges"—making low-value or high-frequency transfers cost-prohibitive.The Stablecoin Advantage: Blockchain rails bypass multi-hop intermediary chains. Value transfers directly from the sender’s wallet to the network settlement layer in seconds or minutes, reducing intermediary overhead to negligible on-chain network costs (often fractions of a dollar).
3. Tighter FX Spreads & Predictable Conversions
The SWIFT Problem: Traditional SWIFT FX conversions are prone to opaque, multi-layered markups. Because conversion rates are handled sequentially by multiple banks along the route, treasury teams frequently face unpredictable FX slippage and lack real-time visibility into the exact landed cost.The Stablecoin Advantage: By utilizing regulated infrastructure partners (such as Triple-A or Circle) to handle edge conversions, stablecoin rails isolate the FX conversion to a single transparent leg. Businesses can execute conversions programmatically at exact, published rates before the value moves on-chain, eliminating hidden mid-route currency devaluation.
4. Mitigation of Weekend and Cut-off Time Risk
The SWIFT Problem: Traditional banking windows are restricted to local business hours and cut-off times, closing entirely over weekends and national holidays. If an unexpected liquidity shortfall occurs on a Friday evening, treasury teams must either over-buffer capital defensively or absorb severe delays until Monday morning.The Stablecoin Advantage: Operating 24/7/365, blockchain networks allow treasuries to move funds instantly outside banking hours. This operational continuity eliminates the need to hold extra "buffer capital" specifically to guard against weekend market shocks or unexpected payout surges.
Summary Cost & Operational Comparison
#Swift #BTC #ETH
Traditional cross-border payments rely on the correspondent banking network, which creates severe capital inefficiencies. Stablecoins reshape these dynamics through several distinct mechanisms:
1. Elimination of Fragmented Nostro/Vostro Account Capital
The SWIFT Problem: Under traditional rails, a payout provider or financial institution must "pre-fund" multiple foreign bank accounts (nostro/vostro accounts) globally to ensure they can settle outgoing payments in local currencies instantly. This locks up millions of dollars in idle capital across different time zones, jurisdictions, and currencies just to cover weekend or after-hours gaps.The Stablecoin Advantage: Stablecoin prefunding introduces shared, centralized liquidity pools. Instead of fragmenting working capital across a dozen local bank accounts worldwide, treasury teams can hold a unified digital asset pool (e.g., USDC) and dynamically deploy funds on-chain within minutes to wherever payout demand spikes.
2. Radical Reduction of Intermediary & "Lifting" Fees
The SWIFT Problem: A standard cross-border wire often hops through 2 to 5 intermediary correspondent banks before reaching the destination. Each intermediary bank in the chain takes a cut—deducting sending fees, intermediary wire fees, and receiving "lifting charges"—making low-value or high-frequency transfers cost-prohibitive.The Stablecoin Advantage: Blockchain rails bypass multi-hop intermediary chains. Value transfers directly from the sender’s wallet to the network settlement layer in seconds or minutes, reducing intermediary overhead to negligible on-chain network costs (often fractions of a dollar).
3. Tighter FX Spreads & Predictable Conversions
The SWIFT Problem: Traditional SWIFT FX conversions are prone to opaque, multi-layered markups. Because conversion rates are handled sequentially by multiple banks along the route, treasury teams frequently face unpredictable FX slippage and lack real-time visibility into the exact landed cost.The Stablecoin Advantage: By utilizing regulated infrastructure partners (such as Triple-A or Circle) to handle edge conversions, stablecoin rails isolate the FX conversion to a single transparent leg. Businesses can execute conversions programmatically at exact, published rates before the value moves on-chain, eliminating hidden mid-route currency devaluation.
4. Mitigation of Weekend and Cut-off Time Risk
The SWIFT Problem: Traditional banking windows are restricted to local business hours and cut-off times, closing entirely over weekends and national holidays. If an unexpected liquidity shortfall occurs on a Friday evening, treasury teams must either over-buffer capital defensively or absorb severe delays until Monday morning.The Stablecoin Advantage: Operating 24/7/365, blockchain networks allow treasuries to move funds instantly outside banking hours. This operational continuity eliminates the need to hold extra "buffer capital" specifically to guard against weekend market shocks or unexpected payout surges.
Summary Cost & Operational Comparison
#Swift #BTC #ETH
1
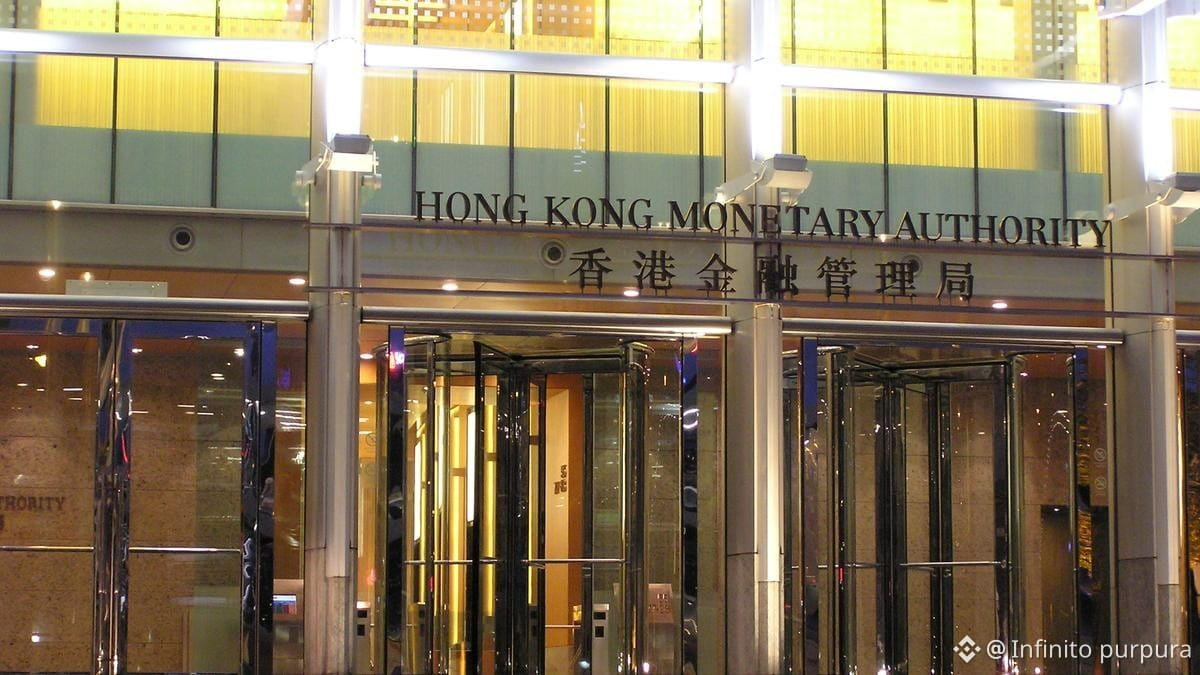
Гонконг і Swift тестують токенізовані депозити, оскільки банки женуться за швидкістю стейблкоїнівЦентральний банк Гонконгу та Swift, 53-річний сервіс міжбанківського обміну повідомленнями, об'єднують зусилля з великими банками для тестування міжнародних платежів з використанням токенізованих депозитів у кількох валютах, що може запропонувати кредиторам варіант на основі блокчейну, що виходить за рамки стейблкоїнів.
Гонконзьке валютне управління (HKMA) заявило в понеділок, що HSBC, Standard Chartered та Bank of China беруть участь у зусиллях щодо підключення блокчейн-реєстру Swift до Project Ensemble, гонконгської платформи для розрахунків за токенізованими активами та депозитами.
Проєкт може надати банкам можливість переміщувати гроші через кордони в будь-яку годину, що допомогло стейблкоїнам закріпитися в міжнародних платежах. На відміну від стейблкоїнів, які випускаються приватними компаніями, токенізовані депозити являють собою гроші, що зберігаються на банківських рахунках та записуються в блокчейні.
Гонконг і Swift почали співпрацювати у 2023 році, щоб дослідити, як системи цифрових валют центральних банків (CBDC) можуть взаємодіяти одна з одною. CBDC – це цифрові версії національних валют, що випускаються центральними банками, а не приватними компаніями.
«Стейблкоїни показали, що гроші можуть переміщатися цілодобово, через кордони», – сказав Віш Ву, генеральний директор Pharos, блокчейн-мережі для токенізованих активів. «Банки тепер хочуть робити те саме, не відмовляючись від депозитів чи відносин з клієнтами. Вони не намагаються замінити стейблкоїни. Вони хочуть іншого варіанту, який також міг би використовувати CBDC для розрахунків».
Ву сказав, що новий проєкт є продовженням існуючої роботи, але з більшим акцентом на комерційні платежі.
«Токенізовані депозити можуть стати фронтендом цифрового банкінгу, тоді як гроші центрального банку займатимуться розрахунками. Справжнім переможцем буде той, хто об’єднає ці різні системи», – сказав він.
Говард Лі, заступник головного виконавчого директора HKMA, заявив, що в рамках співпраці буде досліджено, як токенізовані депозити можуть підтримувати міжнародні транзакції, що працюють цілодобово.
Swift, яка об'єднує понад 11 500 фінансових установ по всьому світу, заявила, що її метою є об'єднання нових платіжних систем через кордони. Проєкт залишається на стадії дослідження.
Цей крок відбувається на тлі активізації банків та центральних банків у всьому світі зусиль щодо модернізації міжнародних платежів.
У понеділок JPMorgan та DBS заявили, що вони підключили свою мережу депозитів на блокчейні, що дозволить схваленим клієнтам переказувати токенізовані долари США між Сінгапуром та США, зокрема у вихідні.
Також у понеділок Сінгапур та Німеччина оголосили про успішне випробування використання CBDC для обміну євро та сінгапурських доларів. Система була розроблена для того, щоб запобігти надсиланню грошей одним банком без отримання валюти іншого банку натомість.
Окремий експеримент за участю центральних банків Великої Британії, Сінгапуру та Таїланду продемонстрував, як традиційні платіжні системи та платіжні системи на основі блокчейну можуть координувати валютні транзакції, не працюючи в одній мережі.
Разом ці ініціативи показують, як банки намагаються запропонувати певну швидкість та цілодобову доступність, пов'язані зі стейблкоїнами, водночас зберігаючи платежі в межах регульованих банківських систем.
#Swift #Stablecoins
Гонконг і Swift тестують токенізовані депозити, оскільки банки женуться за швидкістю стейблкоїнів
Центральний банк Гонконгу та Swift, 53-річний сервіс міжбанківського обміну повідомленнями, об'єднують зусилля з великими банками для тестування міжнародних платежів з використанням токенізованих депозитів у кількох валютах, що може запропонувати кредиторам варіант на основі блокчейну, що виходить за рамки стейблкоїнів.
Гонконзьке валютне управління (HKMA) заявило в понеділок, що HSBC, Standard Chartered та Bank of China беруть участь у зусиллях щодо підключення блокчейн-реєстру Swift до Project Ensemble, гонконгської платформи для розрахунків за токенізованими активами та депозитами.
Проєкт може надати банкам можливість переміщувати гроші через кордони в будь-яку годину, що допомогло стейблкоїнам закріпитися в міжнародних платежах. На відміну від стейблкоїнів, які випускаються приватними компаніями, токенізовані депозити являють собою гроші, що зберігаються на банківських рахунках та записуються в блокчейні.
Гонконг і Swift почали співпрацювати у 2023 році, щоб дослідити, як системи цифрових валют центральних банків (CBDC) можуть взаємодіяти одна з одною. CBDC – це цифрові версії національних валют, що випускаються центральними банками, а не приватними компаніями.
«Стейблкоїни показали, що гроші можуть переміщатися цілодобово, через кордони», – сказав Віш Ву, генеральний директор Pharos, блокчейн-мережі для токенізованих активів. «Банки тепер хочуть робити те саме, не відмовляючись від депозитів чи відносин з клієнтами. Вони не намагаються замінити стейблкоїни. Вони хочуть іншого варіанту, який також міг би використовувати CBDC для розрахунків».
Ву сказав, що новий проєкт є продовженням існуючої роботи, але з більшим акцентом на комерційні платежі.
«Токенізовані депозити можуть стати фронтендом цифрового банкінгу, тоді як гроші центрального банку займатимуться розрахунками. Справжнім переможцем буде той, хто об’єднає ці різні системи», – сказав він.
Говард Лі, заступник головного виконавчого директора HKMA, заявив, що в рамках співпраці буде досліджено, як токенізовані депозити можуть підтримувати міжнародні транзакції, що працюють цілодобово.
Swift, яка об'єднує понад 11 500 фінансових установ по всьому світу, заявила, що її метою є об'єднання нових платіжних систем через кордони. Проєкт залишається на стадії дослідження.
Цей крок відбувається на тлі активізації банків та центральних банків у всьому світі зусиль щодо модернізації міжнародних платежів.
У понеділок JPMorgan та DBS заявили, що вони підключили свою мережу депозитів на блокчейні, що дозволить схваленим клієнтам переказувати токенізовані долари США між Сінгапуром та США, зокрема у вихідні.
Також у понеділок Сінгапур та Німеччина оголосили про успішне випробування використання CBDC для обміну євро та сінгапурських доларів. Система була розроблена для того, щоб запобігти надсиланню грошей одним банком без отримання валюти іншого банку натомість.
Окремий експеримент за участю центральних банків Великої Британії, Сінгапуру та Таїланду продемонстрував, як традиційні платіжні системи та платіжні системи на основі блокчейну можуть координувати валютні транзакції, не працюючи в одній мережі.
Разом ці ініціативи показують, як банки намагаються запропонувати певну швидкість та цілодобову доступність, пов'язані зі стейблкоїнами, водночас зберігаючи платежі в межах регульованих банківських систем.
#Swift #Stablecoins
Гонконзьке валютне управління (HKMA) заявило в понеділок, що HSBC, Standard Chartered та Bank of China беруть участь у зусиллях щодо підключення блокчейн-реєстру Swift до Project Ensemble, гонконгської платформи для розрахунків за токенізованими активами та депозитами.
Проєкт може надати банкам можливість переміщувати гроші через кордони в будь-яку годину, що допомогло стейблкоїнам закріпитися в міжнародних платежах. На відміну від стейблкоїнів, які випускаються приватними компаніями, токенізовані депозити являють собою гроші, що зберігаються на банківських рахунках та записуються в блокчейні.
Гонконг і Swift почали співпрацювати у 2023 році, щоб дослідити, як системи цифрових валют центральних банків (CBDC) можуть взаємодіяти одна з одною. CBDC – це цифрові версії національних валют, що випускаються центральними банками, а не приватними компаніями.
«Стейблкоїни показали, що гроші можуть переміщатися цілодобово, через кордони», – сказав Віш Ву, генеральний директор Pharos, блокчейн-мережі для токенізованих активів. «Банки тепер хочуть робити те саме, не відмовляючись від депозитів чи відносин з клієнтами. Вони не намагаються замінити стейблкоїни. Вони хочуть іншого варіанту, який також міг би використовувати CBDC для розрахунків».
Ву сказав, що новий проєкт є продовженням існуючої роботи, але з більшим акцентом на комерційні платежі.
«Токенізовані депозити можуть стати фронтендом цифрового банкінгу, тоді як гроші центрального банку займатимуться розрахунками. Справжнім переможцем буде той, хто об’єднає ці різні системи», – сказав він.
Говард Лі, заступник головного виконавчого директора HKMA, заявив, що в рамках співпраці буде досліджено, як токенізовані депозити можуть підтримувати міжнародні транзакції, що працюють цілодобово.
Swift, яка об'єднує понад 11 500 фінансових установ по всьому світу, заявила, що її метою є об'єднання нових платіжних систем через кордони. Проєкт залишається на стадії дослідження.
Цей крок відбувається на тлі активізації банків та центральних банків у всьому світі зусиль щодо модернізації міжнародних платежів.
У понеділок JPMorgan та DBS заявили, що вони підключили свою мережу депозитів на блокчейні, що дозволить схваленим клієнтам переказувати токенізовані долари США між Сінгапуром та США, зокрема у вихідні.
Також у понеділок Сінгапур та Німеччина оголосили про успішне випробування використання CBDC для обміну євро та сінгапурських доларів. Система була розроблена для того, щоб запобігти надсиланню грошей одним банком без отримання валюти іншого банку натомість.
Окремий експеримент за участю центральних банків Великої Британії, Сінгапуру та Таїланду продемонстрував, як традиційні платіжні системи та платіжні системи на основі блокчейну можуть координувати валютні транзакції, не працюючи в одній мережі.
Разом ці ініціативи показують, як банки намагаються запропонувати певну швидкість та цілодобову доступність, пов'язані зі стейблкоїнами, водночас зберігаючи платежі в межах регульованих банківських систем.
#Swift #Stablecoins
JPM-2.18%
HSBCUS+0.33%
38


HONG KONG & SWIFT ARE PUSHING BANKING TOWARD 24/7 BLOCKCHAIN PAYMENTS!
Traditional finance is accelerating its move into tokenization!
⚡ What's happening?
- SWIFT and Hong Kong are exploring tokenized bank deposits.
- The goal is to enable faster around-the-clock cross-border payments.
- Major banks are testing blockchain-based financial infrastructure.
- Tokenized deposits could become another competitor to stablecoins in digital payments
🔥 Why it matters:
Blockchain technology is increasingly attracting traditional banking giants not just crypto companies.
Will tokenized bank deposits challenge stablecoins in the global payments market?
#SWIFT #HongKong #Blockchain #Stablecoins
HONG KONG & SWIFT ARE PUSHING BANKING TOWARD 24/7 BLOCKCHAIN PAYMENTS!
Traditional finance is accelerating its move into tokenization!
⚡ What's happening?
- SWIFT and Hong Kong are exploring tokenized bank deposits.
- The goal is to enable faster around-the-clock cross-border payments.
- Major banks are testing blockchain-based financial infrastructure.
- Tokenized deposits could become another competitor to stablecoins in digital payments
🔥 Why it matters:
Blockchain technology is increasingly attracting traditional banking giants not just crypto companies.
Will tokenized bank deposits challenge stablecoins in the global payments market?
#SWIFT #HongKong #Blockchain #Stablecoins
Traditional finance is accelerating its move into tokenization!
⚡ What's happening?
- SWIFT and Hong Kong are exploring tokenized bank deposits.
- The goal is to enable faster around-the-clock cross-border payments.
- Major banks are testing blockchain-based financial infrastructure.
- Tokenized deposits could become another competitor to stablecoins in digital payments
🔥 Why it matters:
Blockchain technology is increasingly attracting traditional banking giants not just crypto companies.
Will tokenized bank deposits challenge stablecoins in the global payments market?
#SWIFT #HongKong #Blockchain #Stablecoins
10
Hong Kong y Swift exploran depósitos tokenizados para pagos bancarios 24/7
La Autoridad Monetaria de Hong Kong y Swift colaboran con HSBC, Standard Chartered y Bank of China para probar pagos transfronterizos con depósitos tokenizados en varias monedas. Este proyecto conecta el libro mayor blockchain de Swift con Project Ensemble de Hong Kong. A diferencia de las stablecoins, los depósitos tokenizados mantienen la relación de depósito bancario mientras ofrecen velocidad continua en pagos internacionales.
$ENA $SOL $BTC
#HongKong #Swift #Pagos
Hong Kong y Swift exploran depósitos tokenizados para pagos bancarios 24/7
La Autoridad Monetaria de Hong Kong y Swift colaboran con HSBC, Standard Chartered y Bank of China para probar pagos transfronterizos con depósitos tokenizados en varias monedas. Este proyecto conecta el libro mayor blockchain de Swift con Project Ensemble de Hong Kong. A diferencia de las stablecoins, los depósitos tokenizados mantienen la relación de depósito bancario mientras ofrecen velocidad continua en pagos internacionales.
$ENA $SOL $BTC
#HongKong #Swift #Pagos
La Autoridad Monetaria de Hong Kong y Swift colaboran con HSBC, Standard Chartered y Bank of China para probar pagos transfronterizos con depósitos tokenizados en varias monedas. Este proyecto conecta el libro mayor blockchain de Swift con Project Ensemble de Hong Kong. A diferencia de las stablecoins, los depósitos tokenizados mantienen la relación de depósito bancario mientras ofrecen velocidad continua en pagos internacionales.
$ENA $SOL $BTC
#HongKong #Swift #Pagos
99
Hong Kong y Swift exploran depósitos tokenizados para pagos bancarios 24/7
La Autoridad Monetaria de Hong Kong y Swift colaboran con HSBC, Standard Chartered y Bank of China para probar pagos transfronterizos con depósitos tokenizados en varias monedas. Este proyecto conecta el libro mayor blockchain de Swift con Project Ensemble de Hong Kong. A diferencia de las stablecoins, los depósitos tokenizados mantienen la relación de depósito bancario mientras ofrecen velocidad continua en pagos internacionales.
$ENA $SOL $BTC
#HongKong #Swift #Pagos
Hong Kong y Swift exploran depósitos tokenizados para pagos bancarios 24/7
La Autoridad Monetaria de Hong Kong y Swift colaboran con HSBC, Standard Chartered y Bank of China para probar pagos transfronterizos con depósitos tokenizados en varias monedas. Este proyecto conecta el libro mayor blockchain de Swift con Project Ensemble de Hong Kong. A diferencia de las stablecoins, los depósitos tokenizados mantienen la relación de depósito bancario mientras ofrecen velocidad continua en pagos internacionales.
$ENA $SOL $BTC
#HongKong #Swift #Pagos
La Autoridad Monetaria de Hong Kong y Swift colaboran con HSBC, Standard Chartered y Bank of China para probar pagos transfronterizos con depósitos tokenizados en varias monedas. Este proyecto conecta el libro mayor blockchain de Swift con Project Ensemble de Hong Kong. A diferencia de las stablecoins, los depósitos tokenizados mantienen la relación de depósito bancario mientras ofrecen velocidad continua en pagos internacionales.
$ENA $SOL $BTC
#HongKong #Swift #Pagos
106
·
--
උසබ තත්ත්වය
🚨 TRADITIONAL BANKING IS MOVING DEEPER INTO BLOCKCHAIN.
Hong Kong is taking another major step toward the future of digital finance.
The Hong Kong Monetary Authority (HKMA) and SWIFT have strengthened their collaboration to explore cross-border payments using tokenized bank deposits.
The initiative will investigate connecting SWIFT's blockchain based ledger with Hong Kong's Project Ensemble settlement infrastructure, supporting payments involving multiple currencies.
Major financial institutions including HSBC, Standard Chartered and Bank of China (Hong Kong) are participating.
Today, international payments can involve multiple intermediaries, settlement delays and operational costs. Tokenized deposits could help make these transactions faster, more efficient and potentially available around the clock.
Even more interesting is the possibility of programmable payments, where transactions can automatically execute when predefined conditions are met.
This isn't simply about putting money on a blockchain. It's about connecting traditional banking infrastructure with the emerging tokenized financial system.
And SWIFT's involvement makes this particularly significant because it already connects financial institutions across the world.
Traditional finance isn't necessarily fighting blockchain technology. Some of its biggest players are exploring how to integrate it.
Will tokenized deposits become the foundation of the next generation of global payments?
#blockchain #Tokenization #Swift #DigitalFinance
🚨 TRADITIONAL BANKING IS MOVING DEEPER INTO BLOCKCHAIN.
Hong Kong is taking another major step toward the future of digital finance.
The Hong Kong Monetary Authority (HKMA) and SWIFT have strengthened their collaboration to explore cross-border payments using tokenized bank deposits.
The initiative will investigate connecting SWIFT's blockchain based ledger with Hong Kong's Project Ensemble settlement infrastructure, supporting payments involving multiple currencies.
Major financial institutions including HSBC, Standard Chartered and Bank of China (Hong Kong) are participating.
Today, international payments can involve multiple intermediaries, settlement delays and operational costs. Tokenized deposits could help make these transactions faster, more efficient and potentially available around the clock.
Even more interesting is the possibility of programmable payments, where transactions can automatically execute when predefined conditions are met.
This isn't simply about putting money on a blockchain. It's about connecting traditional banking infrastructure with the emerging tokenized financial system.
And SWIFT's involvement makes this particularly significant because it already connects financial institutions across the world.
Traditional finance isn't necessarily fighting blockchain technology. Some of its biggest players are exploring how to integrate it.
Will tokenized deposits become the foundation of the next generation of global payments?
#blockchain #Tokenization #Swift #DigitalFinance
Hong Kong is taking another major step toward the future of digital finance.
The Hong Kong Monetary Authority (HKMA) and SWIFT have strengthened their collaboration to explore cross-border payments using tokenized bank deposits.
The initiative will investigate connecting SWIFT's blockchain based ledger with Hong Kong's Project Ensemble settlement infrastructure, supporting payments involving multiple currencies.
Major financial institutions including HSBC, Standard Chartered and Bank of China (Hong Kong) are participating.
Today, international payments can involve multiple intermediaries, settlement delays and operational costs. Tokenized deposits could help make these transactions faster, more efficient and potentially available around the clock.
Even more interesting is the possibility of programmable payments, where transactions can automatically execute when predefined conditions are met.
This isn't simply about putting money on a blockchain. It's about connecting traditional banking infrastructure with the emerging tokenized financial system.
And SWIFT's involvement makes this particularly significant because it already connects financial institutions across the world.
Traditional finance isn't necessarily fighting blockchain technology. Some of its biggest players are exploring how to integrate it.
Will tokenized deposits become the foundation of the next generation of global payments?
#blockchain #Tokenization #Swift #DigitalFinance
HSBCUS+0.33%
4
219

HKMA và Swift nghiên cứu tiền gửi mã hóa cho thanh toán xuyên biên giới
- HKMA và Swift liên kết Dự án Ensemble với sổ cái Swift.
- Dùng tiền gửi mã hóa cho thanh toán ngân hàng xuyên biên giới.
- Hỗ trợ nhiều loại tiền tệ.
- RSS chưa cung cấp chi tiết thêm.
#BinanceSquare #CryptoNews #Blockchain #Swift #HKMA
$btc $eth
vlikevn Titanbot
Nguồn: CoinTelegraph
HKMA và Swift nghiên cứu tiền gửi mã hóa cho thanh toán xuyên biên giới
- HKMA và Swift liên kết Dự án Ensemble với sổ cái Swift.
- Dùng tiền gửi mã hóa cho thanh toán ngân hàng xuyên biên giới.
- Hỗ trợ nhiều loại tiền tệ.
- RSS chưa cung cấp chi tiết thêm.
#BinanceSquare #CryptoNews #Blockchain #Swift #HKMA
$btc $eth
vlikevn Titanbot
Nguồn: CoinTelegraph
- HKMA và Swift liên kết Dự án Ensemble với sổ cái Swift.
- Dùng tiền gửi mã hóa cho thanh toán ngân hàng xuyên biên giới.
- Hỗ trợ nhiều loại tiền tệ.
- RSS chưa cung cấp chi tiết thêm.
#BinanceSquare #CryptoNews #Blockchain #Swift #HKMA
$btc $eth
vlikevn Titanbot
Nguồn: CoinTelegraph
142

·
--
🌐 Chainlink e Swift: Unindo Finanças Tradicionais e Blockchain
A adopção de ativos tokenizados deu um passo gigante:
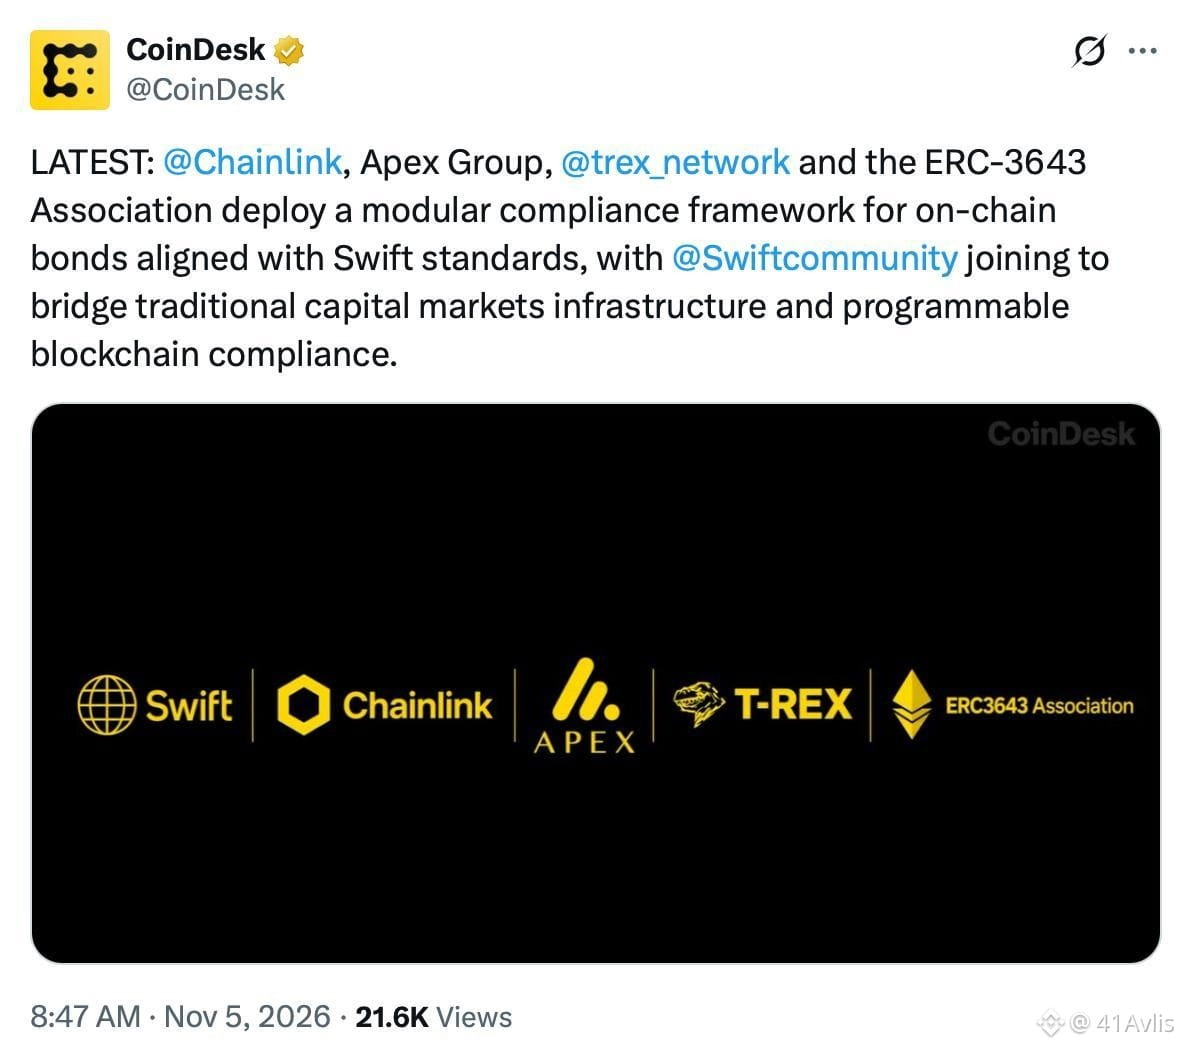
* Nova Aliança: Chainlink, Apex Group, T-REX Network e a Associação ERC-3633 lançaram uma estrutura modular de conformidade regulatória.
* Padrão Swift: O projeto foi desenvolvido para seguir os padrões da Swift.
* O Impacto: O objetivo é conectar os mercados financeiros tradicionais à blockchain, impulsionando os ativos tokenizados.
💡 O que achou dessa novidade para o mercado? Deixe sua opinião nos comentários!
#Chainlink #Swift #RWA
🌐 Chainlink e Swift: Unindo Finanças Tradicionais e Blockchain
A adopção de ativos tokenizados deu um passo gigante:
* Nova Aliança: Chainlink, Apex Group, T-REX Network e a Associação ERC-3633 lançaram uma estrutura modular de conformidade regulatória.
* Padrão Swift: O projeto foi desenvolvido para seguir os padrões da Swift.
* O Impacto: O objetivo é conectar os mercados financeiros tradicionais à blockchain, impulsionando os ativos tokenizados.
💡 O que achou dessa novidade para o mercado? Deixe sua opinião nos comentários!
#Chainlink #Swift #RWA
A adopção de ativos tokenizados deu um passo gigante:
* Nova Aliança: Chainlink, Apex Group, T-REX Network e a Associação ERC-3633 lançaram uma estrutura modular de conformidade regulatória.
* Padrão Swift: O projeto foi desenvolvido para seguir os padrões da Swift.
* O Impacto: O objetivo é conectar os mercados financeiros tradicionais à blockchain, impulsionando os ativos tokenizados.
💡 O que achou dessa novidade para o mercado? Deixe sua opinião nos comentários!
#Chainlink #Swift #RWA
76
·
--
ලිපිය
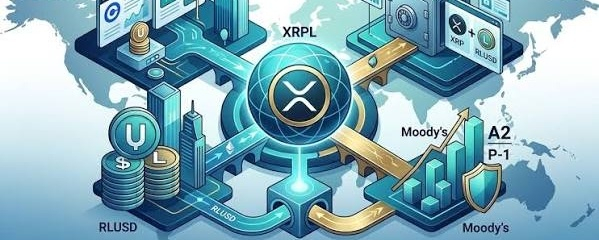
Xrp làm cầu nối hay độc lập ? Giả sử 10% hoạt động của SWIFT chuyển sang hệ sinh thái XRPL
🫱#Swift chủ yếu là mạng truyền thông điệp tài chính, không trực tiếp sở hữu hay chuyển toàn bộ số tiền trong các giao dịch.
SWIFT công bố trung bình 59,8 triệu thông điệp thanh toán mỗi ngày trong năm 2025. Con số 14.000 tỷ USD/ngày cần được xem là một ước tính về giá trị luân chuyển, không phải con số xác nhận được từ trang thống kê chính thức hiện tại. 👌
Giả sử tổng giá trị giao dịch là 14.000 tỷ USD/ngày
10% là 1,4000 tỷ/ngày
1.000.000$ >> 0.00001xrp
1,4000 tỷ>> 14 xrp
Ngay cả khi giả định 1,4 nghìn tỷ USD đi qua XRPL mỗi ngày, với mỗi giao dịch trung bình 1 triệu USD và phí 10 drops, lượng XRP bị đốt chỉ khoảng 14 XRP/ngày.
Điều đó không có nghĩa XRPL không cần $XRP . Nó có nghĩa là không thể lấy tổng giá trị giao dịch chia cho 100 tỷ XRP rồi kết luận giá XRP bắt buộc phải đạt 1.000 USD, 100.000 USD hay hơn nữa
🤩Vậy nếu #Xrp🔥🔥 phải làm tài sản cầu nối thì cần giá bao nhiêu?.
Bài sau mình bốc phét tiếp vậy🤪
#Write2Earn #Write2Earn!
Xrp làm cầu nối hay độc lập ?
Giả sử 10% hoạt động của SWIFT chuyển sang hệ sinh thái XRPL
🫱#Swift chủ yếu là mạng truyền thông điệp tài chính, không trực tiếp sở hữu hay chuyển toàn bộ số tiền trong các giao dịch.
SWIFT công bố trung bình 59,8 triệu thông điệp thanh toán mỗi ngày trong năm 2025. Con số 14.000 tỷ USD/ngày cần được xem là một ước tính về giá trị luân chuyển, không phải con số xác nhận được từ trang thống kê chính thức hiện tại. 👌
Giả sử tổng giá trị giao dịch là 14.000 tỷ USD/ngày
10% là 1,4000 tỷ/ngày
1.000.000$ >> 0.00001xrp
1,4000 tỷ>> 14 xrp
Ngay cả khi giả định 1,4 nghìn tỷ USD đi qua XRPL mỗi ngày, với mỗi giao dịch trung bình 1 triệu USD và phí 10 drops, lượng XRP bị đốt chỉ khoảng 14 XRP/ngày.
Điều đó không có nghĩa XRPL không cần $XRP . Nó có nghĩa là không thể lấy tổng giá trị giao dịch chia cho 100 tỷ XRP rồi kết luận giá XRP bắt buộc phải đạt 1.000 USD, 100.000 USD hay hơn nữa
🤩Vậy nếu #Xrp🔥🔥 phải làm tài sản cầu nối thì cần giá bao nhiêu?.
Bài sau mình bốc phét tiếp vậy🤪
#Write2Earn #Write2Earn!
🫱#Swift chủ yếu là mạng truyền thông điệp tài chính, không trực tiếp sở hữu hay chuyển toàn bộ số tiền trong các giao dịch.
SWIFT công bố trung bình 59,8 triệu thông điệp thanh toán mỗi ngày trong năm 2025. Con số 14.000 tỷ USD/ngày cần được xem là một ước tính về giá trị luân chuyển, không phải con số xác nhận được từ trang thống kê chính thức hiện tại. 👌
Giả sử tổng giá trị giao dịch là 14.000 tỷ USD/ngày
10% là 1,4000 tỷ/ngày
1.000.000$ >> 0.00001xrp
1,4000 tỷ>> 14 xrp
Ngay cả khi giả định 1,4 nghìn tỷ USD đi qua XRPL mỗi ngày, với mỗi giao dịch trung bình 1 triệu USD và phí 10 drops, lượng XRP bị đốt chỉ khoảng 14 XRP/ngày.
Điều đó không có nghĩa XRPL không cần $XRP . Nó có nghĩa là không thể lấy tổng giá trị giao dịch chia cho 100 tỷ XRP rồi kết luận giá XRP bắt buộc phải đạt 1.000 USD, 100.000 USD hay hơn nữa
🤩Vậy nếu #Xrp🔥🔥 phải làm tài sản cầu nối thì cần giá bao nhiêu?.
Bài sau mình bốc phét tiếp vậy🤪
#Write2Earn #Write2Earn!
4
4
3.8k

·
--
📰 XRP Researcher: My Full Conversation With Tom Alaerts Who Spent Over 27 Years At SWIFT
Tom Alaerts, a former SWIFT standards expert with more than 27 years of experience at the global financial messaging network, has explained why ISO 20022 could play an important role in bringing digital assets into traditional banking infrastructure. In a lengthy conversation on X with Crypto Researcher SMQKE, Alaerts discussed SWIFT’s future, the relationship between […] The post XRP Researcher: My Full Conversation With Tom Alaerts Who Spent Over 27 Years At SWIFT appeared first on Times Tabloid.
Source : Times Tabloid
Time : 2026-11-01 13:00:46
Credit : solomon odunayo
#xrp #cryptocurrency #swift #news
$XRP
Share your opinion in the comment section below
📰 XRP Researcher: My Full Conversation With Tom Alaerts Who Spent Over 27 Years At SWIFT
Tom Alaerts, a former SWIFT standards expert with more than 27 years of experience at the global financial messaging network, has explained why ISO 20022 could play an important role in bringing digital assets into traditional banking infrastructure. In a lengthy conversation on X with Crypto Researcher SMQKE, Alaerts discussed SWIFT’s future, the relationship between […] The post XRP Researcher: My Full Conversation With Tom Alaerts Who Spent Over 27 Years At SWIFT appeared first on Times Tabloid.
Source : Times Tabloid
Time : 2026-11-01 13:00:46
Credit : solomon odunayo
#xrp #cryptocurrency #swift #news
$XRP
Share your opinion in the comment section below
Tom Alaerts, a former SWIFT standards expert with more than 27 years of experience at the global financial messaging network, has explained why ISO 20022 could play an important role in bringing digital assets into traditional banking infrastructure. In a lengthy conversation on X with Crypto Researcher SMQKE, Alaerts discussed SWIFT’s future, the relationship between […] The post XRP Researcher: My Full Conversation With Tom Alaerts Who Spent Over 27 Years At SWIFT appeared first on Times Tabloid.
Source : Times Tabloid
Time : 2026-11-01 13:00:46
Credit : solomon odunayo
#xrp #cryptocurrency #swift #news
$XRP
Share your opinion in the comment section below
151

·
--
🚨 SWIFT is talking about the future of finance, and $XRP holders are paying attention. 👀🔥
24/7 cross-border payments, programmable digital cash, tokenized securities, and atomic settlement are becoming important parts of the financial industry's evolution.
Ripple is building within this broader blockchain payments landscape, making the overlap worth watching.
But here’s the key point: SWIFT discussing blockchain infrastructure does not automatically mean an official partnership or direct XRP adoption.
The real question is whether XRP and the XRP Ledger will capture a meaningful role in this changing financial system. 🌎
That’s what I’ll be watching closely. 🚀
#XRP #Ripple #SWIFT
🚨 SWIFT is talking about the future of finance, and $XRP holders are paying attention. 👀🔥
24/7 cross-border payments, programmable digital cash, tokenized securities, and atomic settlement are becoming important parts of the financial industry's evolution.
Ripple is building within this broader blockchain payments landscape, making the overlap worth watching.
But here’s the key point: SWIFT discussing blockchain infrastructure does not automatically mean an official partnership or direct XRP adoption.
The real question is whether XRP and the XRP Ledger will capture a meaningful role in this changing financial system. 🌎
That’s what I’ll be watching closely. 🚀
#XRP #Ripple #SWIFT
24/7 cross-border payments, programmable digital cash, tokenized securities, and atomic settlement are becoming important parts of the financial industry's evolution.
Ripple is building within this broader blockchain payments landscape, making the overlap worth watching.
But here’s the key point: SWIFT discussing blockchain infrastructure does not automatically mean an official partnership or direct XRP adoption.
The real question is whether XRP and the XRP Ledger will capture a meaningful role in this changing financial system. 🌎
That’s what I’ll be watching closely. 🚀
#XRP #Ripple #SWIFT
3
1
10
5.8k

·
--
Two giant banks just moved real dollars as tokens, and almost nobody holding crypto was in the trade.
That is the trap. Every time a headline like this hits, people FOMO into whatever ticker sounds vaguely like payments or real-world assets, then find out the product never needed their coin. You do not get rugged by a contract. You get rugged by a story you did not read.
On September 2, First Abu Dhabi Bank and Citi settled an actual USD payment with tokenized deposits on Swift's shared ledger. A tokenized deposit is just a bank IOU in a new format. It is a claim on that bank's balance sheet, written so two institutions can move it on a shared record instead of waiting on the old message chain. It is not $BTC. You cannot pull it to a wallet and leave. The promise is still the bank's, and Swift still runs the room.
The risk is treating that as a win for whatever you already hold. These tokens can be frozen or reversed because a regulated bank issued them, not a neutral chain. If the bank has a problem, you are in line with every other depositor, token or not. And if treasurers actually like this rail, a lot of the cross-border flow people keep pricing into $XRP or loose $ETH tokenization bets may never leave the banking system. Faster money for banks is not the same as money showing up on the chains you trade.
If the banks can do this without public crypto, what are we actually pricing in?
#Tokenization #RWA #Swift
Two giant banks just moved real dollars as tokens, and almost nobody holding crypto was in the trade.
That is the trap. Every time a headline like this hits, people FOMO into whatever ticker sounds vaguely like payments or real-world assets, then find out the product never needed their coin. You do not get rugged by a contract. You get rugged by a story you did not read.
On September 2, First Abu Dhabi Bank and Citi settled an actual USD payment with tokenized deposits on Swift's shared ledger. A tokenized deposit is just a bank IOU in a new format. It is a claim on that bank's balance sheet, written so two institutions can move it on a shared record instead of waiting on the old message chain. It is not $BTC . You cannot pull it to a wallet and leave. The promise is still the bank's, and Swift still runs the room.
The risk is treating that as a win for whatever you already hold. These tokens can be frozen or reversed because a regulated bank issued them, not a neutral chain. If the bank has a problem, you are in line with every other depositor, token or not. And if treasurers actually like this rail, a lot of the cross-border flow people keep pricing into $XRP or loose $ETH tokenization bets may never leave the banking system. Faster money for banks is not the same as money showing up on the chains you trade.
If the banks can do this without public crypto, what are we actually pricing in?
#Tokenization #RWA #Swift
That is the trap. Every time a headline like this hits, people FOMO into whatever ticker sounds vaguely like payments or real-world assets, then find out the product never needed their coin. You do not get rugged by a contract. You get rugged by a story you did not read.
On September 2, First Abu Dhabi Bank and Citi settled an actual USD payment with tokenized deposits on Swift's shared ledger. A tokenized deposit is just a bank IOU in a new format. It is a claim on that bank's balance sheet, written so two institutions can move it on a shared record instead of waiting on the old message chain. It is not $BTC . You cannot pull it to a wallet and leave. The promise is still the bank's, and Swift still runs the room.
The risk is treating that as a win for whatever you already hold. These tokens can be frozen or reversed because a regulated bank issued them, not a neutral chain. If the bank has a problem, you are in line with every other depositor, token or not. And if treasurers actually like this rail, a lot of the cross-border flow people keep pricing into $XRP or loose $ETH tokenization bets may never leave the banking system. Faster money for banks is not the same as money showing up on the chains you trade.
If the banks can do this without public crypto, what are we actually pricing in?
#Tokenization #RWA #Swift
6

If you're still treating SWIFT as some relic that crypto already beat, stop now.
Traders keep getting chopped up rotating into the latest hype while the real cash movement happens in quiet bank experiments. That's how you miss the liquidity that actually sticks around.
On September 2 First Abu Dhabi Bank and Citi settled a genuine USD payment using tokenized deposits on SWIFT's shared ledger. I forwarded it to a treasury ops colleague expecting some blockchain excitement. He just asked how it would cut the daily grind of reconciling positions and chasing failed wires.
This sits differently from the years of $XRP trying to replace SWIFT or the slow corporate crawl of $USDC and $USDT onto new rails. Those always felt like extra steps. Tokenized deposits let the same banks keep their existing setup while using a shared ledger. Most earlier PoCs never left the lab. This one moved actual dollars.
The people who will actually use it don't care about our narratives. They care about fewer emails and faster visibility. When ops folks start asking practical questions, the shift is already underway.
Where do you think this leaves the old disruption story versus banks just getting more efficient on-chain?
#Tokenization #TradFi #SWIFT
If you're still treating SWIFT as some relic that crypto already beat, stop now.
Traders keep getting chopped up rotating into the latest hype while the real cash movement happens in quiet bank experiments. That's how you miss the liquidity that actually sticks around.
On September 2 First Abu Dhabi Bank and Citi settled a genuine USD payment using tokenized deposits on SWIFT's shared ledger. I forwarded it to a treasury ops colleague expecting some blockchain excitement. He just asked how it would cut the daily grind of reconciling positions and chasing failed wires.
This sits differently from the years of $XRP trying to replace SWIFT or the slow corporate crawl of $USDC and $USDT onto new rails. Those always felt like extra steps. Tokenized deposits let the same banks keep their existing setup while using a shared ledger. Most earlier PoCs never left the lab. This one moved actual dollars.
The people who will actually use it don't care about our narratives. They care about fewer emails and faster visibility. When ops folks start asking practical questions, the shift is already underway.
Where do you think this leaves the old disruption story versus banks just getting more efficient on-chain?
#Tokenization #TradFi #SWIFT
Traders keep getting chopped up rotating into the latest hype while the real cash movement happens in quiet bank experiments. That's how you miss the liquidity that actually sticks around.
On September 2 First Abu Dhabi Bank and Citi settled a genuine USD payment using tokenized deposits on SWIFT's shared ledger. I forwarded it to a treasury ops colleague expecting some blockchain excitement. He just asked how it would cut the daily grind of reconciling positions and chasing failed wires.
This sits differently from the years of $XRP trying to replace SWIFT or the slow corporate crawl of $USDC and $USDT onto new rails. Those always felt like extra steps. Tokenized deposits let the same banks keep their existing setup while using a shared ledger. Most earlier PoCs never left the lab. This one moved actual dollars.
The people who will actually use it don't care about our narratives. They care about fewer emails and faster visibility. When ops folks start asking practical questions, the shift is already underway.
Where do you think this leaves the old disruption story versus banks just getting more efficient on-chain?
#Tokenization #TradFi #SWIFT
19
·
--
උසබ තත්ත්වය
සත්යායනය කළ
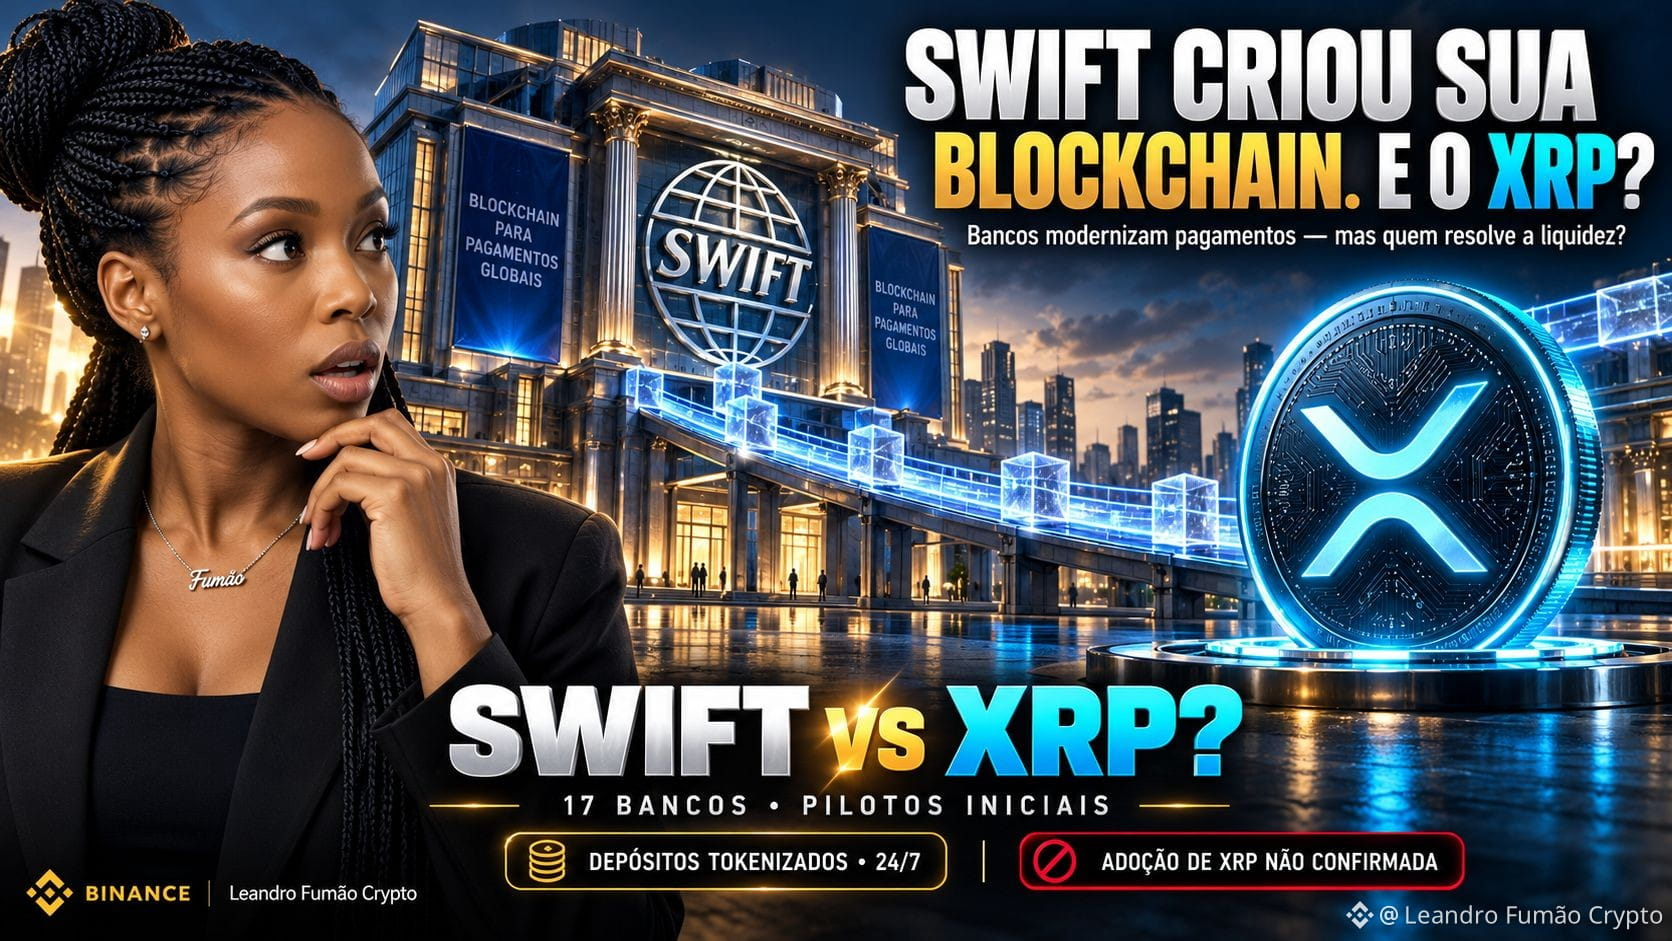
🚨જ⁀➴ SWIFT CRIOU SUA BLOCKCHAIN ⥱ E AGORA ⋙ $XRP ❓
✔️O sistema financeiro internacional está passando por uma transformação gigantesca.
A SWIFT, responsável por conectar milhares de instituições financeiras, já desenvolveu seu próprio ledger blockchain para modernizar pagamentos internacionais.
🔥 17 BANCOS FORAM ANUNCIADOS PARA OS PILOTOS INICIAIS.
A proposta é permitir pagamentos 24 horas por dia usando depósitos bancários tokenizados.
Mas existe um detalhe que quase ninguém está discutindo.
BLOCKCHAIN NÃO RESOLVE AUTOMATICAMENTE O PROBLEMA DA LIQUIDEZ.
Mesmo com uma infraestrutura compartilhada, bancos ainda precisam lidar com moedas diferentes, disponibilidade de recursos e mecanismos de liquidação.
É justamente aqui que surge uma pergunta⤵
ONDE ENTRA O $XRP ?
O XRP pode funcionar como ativo intermediário na conversão entre moedas, permitindo transferências sem depender necessariamente de saldos previamente mantidos em cada mercado.
Imagine a diferença⤵
🏦 SWIFT » Coordenação de pagamentos e integração entre instituições.
⚡ XRP » Potencial ponte de liquidez entre diferentes moedas e mercados.
Mas atenção⤵
⚠️ A SWIFT NÃO ANUNCIOU ADOÇÃO DE XRP EM SEU NOVO LEDGER.
Também não está comprovado que a infraestrutura exigirá XRP para funcionar.
O avanço da SWIFT pode representar competição para algumas soluções da Ripple e, ao mesmo tempo, demonstrar que o setor bancário está adotando tecnologias que antes pareciam restritas ao universo cripto.
O verdadeiro desafio agora é conectar sistemas, moedas e liquidez com eficiência.
🔥 A SWIFT ESTÁ CONSTRUINDO NOVOS TRILHOS. MAS QUEM VAI FORNECER AS PONTES?
VOCÊ ACREDITA QUE $XRP E SWIFT SERÃO CONCORRENTES OU COMPLEMENTARES?
⚠️ O canal @Fumao aqui na Binance Square 🗣️ Lembra » Esta é uma análise informativa e educativa » Isso não é um conselho financeiro » Sempre faça seu próprio estudo antes de investir. 👨🎓📚
#xrp #Swift #RippleXRP
🚨જ⁀➴ SWIFT CRIOU SUA BLOCKCHAIN ⥱ E AGORA ⋙ $XRP ❓
✔️O sistema financeiro internacional está passando por uma transformação gigantesca.
A SWIFT, responsável por conectar milhares de instituições financeiras, já desenvolveu seu próprio ledger blockchain para modernizar pagamentos internacionais.
🔥 17 BANCOS FORAM ANUNCIADOS PARA OS PILOTOS INICIAIS.
A proposta é permitir pagamentos 24 horas por dia usando depósitos bancários tokenizados.
Mas existe um detalhe que quase ninguém está discutindo.
BLOCKCHAIN NÃO RESOLVE AUTOMATICAMENTE O PROBLEMA DA LIQUIDEZ.
Mesmo com uma infraestrutura compartilhada, bancos ainda precisam lidar com moedas diferentes, disponibilidade de recursos e mecanismos de liquidação.
É justamente aqui que surge uma pergunta⤵
ONDE ENTRA O $XRP ?
O XRP pode funcionar como ativo intermediário na conversão entre moedas, permitindo transferências sem depender necessariamente de saldos previamente mantidos em cada mercado.
Imagine a diferença⤵
🏦 SWIFT » Coordenação de pagamentos e integração entre instituições.
⚡ XRP » Potencial ponte de liquidez entre diferentes moedas e mercados.
Mas atenção⤵
⚠️ A SWIFT NÃO ANUNCIOU ADOÇÃO DE XRP EM SEU NOVO LEDGER.
Também não está comprovado que a infraestrutura exigirá XRP para funcionar.
O avanço da SWIFT pode representar competição para algumas soluções da Ripple e, ao mesmo tempo, demonstrar que o setor bancário está adotando tecnologias que antes pareciam restritas ao universo cripto.
O verdadeiro desafio agora é conectar sistemas, moedas e liquidez com eficiência.
🔥 A SWIFT ESTÁ CONSTRUINDO NOVOS TRILHOS. MAS QUEM VAI FORNECER AS PONTES?
VOCÊ ACREDITA QUE $XRP E SWIFT SERÃO CONCORRENTES OU COMPLEMENTARES?
⚠️ O canal @Leandro Fumão Crypto aqui na Binance Square 🗣️ Lembra » Esta é uma análise informativa e educativa » Isso não é um conselho financeiro » Sempre faça seu próprio estudo antes de investir. 👨🎓📚
#xrp #Swift #RippleXRP
✔️O sistema financeiro internacional está passando por uma transformação gigantesca.
A SWIFT, responsável por conectar milhares de instituições financeiras, já desenvolveu seu próprio ledger blockchain para modernizar pagamentos internacionais.
🔥 17 BANCOS FORAM ANUNCIADOS PARA OS PILOTOS INICIAIS.
A proposta é permitir pagamentos 24 horas por dia usando depósitos bancários tokenizados.
Mas existe um detalhe que quase ninguém está discutindo.
BLOCKCHAIN NÃO RESOLVE AUTOMATICAMENTE O PROBLEMA DA LIQUIDEZ.
Mesmo com uma infraestrutura compartilhada, bancos ainda precisam lidar com moedas diferentes, disponibilidade de recursos e mecanismos de liquidação.
É justamente aqui que surge uma pergunta⤵
ONDE ENTRA O $XRP ?
O XRP pode funcionar como ativo intermediário na conversão entre moedas, permitindo transferências sem depender necessariamente de saldos previamente mantidos em cada mercado.
Imagine a diferença⤵
🏦 SWIFT » Coordenação de pagamentos e integração entre instituições.
⚡ XRP » Potencial ponte de liquidez entre diferentes moedas e mercados.
Mas atenção⤵
⚠️ A SWIFT NÃO ANUNCIOU ADOÇÃO DE XRP EM SEU NOVO LEDGER.
Também não está comprovado que a infraestrutura exigirá XRP para funcionar.
O avanço da SWIFT pode representar competição para algumas soluções da Ripple e, ao mesmo tempo, demonstrar que o setor bancário está adotando tecnologias que antes pareciam restritas ao universo cripto.
O verdadeiro desafio agora é conectar sistemas, moedas e liquidez com eficiência.
🔥 A SWIFT ESTÁ CONSTRUINDO NOVOS TRILHOS. MAS QUEM VAI FORNECER AS PONTES?
VOCÊ ACREDITA QUE $XRP E SWIFT SERÃO CONCORRENTES OU COMPLEMENTARES?
⚠️ O canal @Leandro Fumão Crypto aqui na Binance Square 🗣️ Lembra » Esta é uma análise informativa e educativa » Isso não é um conselho financeiro » Sempre faça seu próprio estudo antes de investir. 👨🎓📚
#xrp #Swift #RippleXRP
3
138
·
--
උසබ තත්ත්වය
🏗️🛠️ O SWIFT ESTÁ CONSTRUINDO ALGO MUITO MAIOR DO QUE APENAS MAIS UMA ATUALIZAÇÃO DE PAGAMENTOS✨🌱
Quanto mais fundo eu olho para onde isso está indo, mais otimista fico em relação a $HBAR ▸ 💲LINK ▸ $XRP ✔️
No HederaCon 2025, Alisa DiCaprio alertou: com stablecoins explodindo e novos instrumentos financeiros se multiplicando, o desafio seria manter o valor fluindo num sistema cada vez mais fragmentado. Em 2026, o SWIFT está construindo exatamente a resposta.
📌 SWIFT: Seu ledger blockchain compartilhado já tem 17 bancos em seis continentes (Citi, HSBC, BNY, DBS, Itaú, UBS, Wells Fargo e outros) preparando transações de depósitos tokenizados 24/7. A rede conecta +11.500 instituições em mais de 200 países.
A parte difícil agora não é criar ativos digitais, mas conectá-los e encontrar liquidez entre eles. Três papéis distintos:
🔗 LINK (Chainlink): A conexão mais direta com o SWIFT. Testou interoperabilidade via CCIP, demonstrou subscrição e resgate de fundos tokenizados com a UBS AM e venceu o hackathon do SWIFT em 2025. A DTCC também usa a Chainlink na Collateral AppChain (previsão: 4º tri/2026).
🏛️ HBAR (Hedera): Shinhan Bank, Standard Bank e SCB TechX testaram remessas multimoeda com liquidação em 3-5 segundos. A Australian Payments Plus usou a HashSphere no Projeto Acacia do Banco da Reserva da Austrália. O CCIP já está ativo na mainnet da Hedera.
💱 XRP (XRPL): Conectividade técnica não cria liquidez cambial. O XRPL oferece pagamentos cross-currency, DEX on-chain, liquidação atômica e auto-bridging. Ripple e Bitso trazem MXNB e RLUSD ao XRPL conceitualmente, MXNB → XRP → RLUSD, se o XRP for a melhor rota.
💡 A Tese: Não é HBAR vs $LINK vs XRP. A Hedera hospeda valor regulado, a Chainlink conecta as redes e o XRP ajuda a conectar liquidez entre moedas.
A fragmentação virou realidade, e as finanças globais já constroem a resposta. Quem ainda precifica esses ativos como se nada disso estivesse acontecendo?
#hbar #LINK #xrp #Swift
🏗️🛠️ O SWIFT ESTÁ CONSTRUINDO ALGO MUITO MAIOR DO QUE APENAS MAIS UMA ATUALIZAÇÃO DE PAGAMENTOS✨🌱
Quanto mais fundo eu olho para onde isso está indo, mais otimista fico em relação a $HBAR ▸ 💲LINK ▸ $XRP ✔️
No HederaCon 2025, Alisa DiCaprio alertou: com stablecoins explodindo e novos instrumentos financeiros se multiplicando, o desafio seria manter o valor fluindo num sistema cada vez mais fragmentado. Em 2026, o SWIFT está construindo exatamente a resposta.
📌 SWIFT: Seu ledger blockchain compartilhado já tem 17 bancos em seis continentes (Citi, HSBC, BNY, DBS, Itaú, UBS, Wells Fargo e outros) preparando transações de depósitos tokenizados 24/7. A rede conecta +11.500 instituições em mais de 200 países.
A parte difícil agora não é criar ativos digitais, mas conectá-los e encontrar liquidez entre eles. Três papéis distintos:
🔗 LINK (Chainlink): A conexão mais direta com o SWIFT. Testou interoperabilidade via CCIP, demonstrou subscrição e resgate de fundos tokenizados com a UBS AM e venceu o hackathon do SWIFT em 2025. A DTCC também usa a Chainlink na Collateral AppChain (previsão: 4º tri/2026).
🏛️ HBAR (Hedera): Shinhan Bank, Standard Bank e SCB TechX testaram remessas multimoeda com liquidação em 3-5 segundos. A Australian Payments Plus usou a HashSphere no Projeto Acacia do Banco da Reserva da Austrália. O CCIP já está ativo na mainnet da Hedera.
💱 XRP (XRPL): Conectividade técnica não cria liquidez cambial. O XRPL oferece pagamentos cross-currency, DEX on-chain, liquidação atômica e auto-bridging. Ripple e Bitso trazem MXNB e RLUSD ao XRPL conceitualmente, MXNB → XRP → RLUSD, se o XRP for a melhor rota.
💡 A Tese: Não é HBAR vs $LINK vs XRP. A Hedera hospeda valor regulado, a Chainlink conecta as redes e o XRP ajuda a conectar liquidez entre moedas.
A fragmentação virou realidade, e as finanças globais já constroem a resposta. Quem ainda precifica esses ativos como se nada disso estivesse acontecendo?
#hbar #LINK #xrp #Swift
Quanto mais fundo eu olho para onde isso está indo, mais otimista fico em relação a $HBAR ▸ 💲LINK ▸ $XRP ✔️
No HederaCon 2025, Alisa DiCaprio alertou: com stablecoins explodindo e novos instrumentos financeiros se multiplicando, o desafio seria manter o valor fluindo num sistema cada vez mais fragmentado. Em 2026, o SWIFT está construindo exatamente a resposta.
📌 SWIFT: Seu ledger blockchain compartilhado já tem 17 bancos em seis continentes (Citi, HSBC, BNY, DBS, Itaú, UBS, Wells Fargo e outros) preparando transações de depósitos tokenizados 24/7. A rede conecta +11.500 instituições em mais de 200 países.
A parte difícil agora não é criar ativos digitais, mas conectá-los e encontrar liquidez entre eles. Três papéis distintos:
🔗 LINK (Chainlink): A conexão mais direta com o SWIFT. Testou interoperabilidade via CCIP, demonstrou subscrição e resgate de fundos tokenizados com a UBS AM e venceu o hackathon do SWIFT em 2025. A DTCC também usa a Chainlink na Collateral AppChain (previsão: 4º tri/2026).
🏛️ HBAR (Hedera): Shinhan Bank, Standard Bank e SCB TechX testaram remessas multimoeda com liquidação em 3-5 segundos. A Australian Payments Plus usou a HashSphere no Projeto Acacia do Banco da Reserva da Austrália. O CCIP já está ativo na mainnet da Hedera.
💱 XRP (XRPL): Conectividade técnica não cria liquidez cambial. O XRPL oferece pagamentos cross-currency, DEX on-chain, liquidação atômica e auto-bridging. Ripple e Bitso trazem MXNB e RLUSD ao XRPL conceitualmente, MXNB → XRP → RLUSD, se o XRP for a melhor rota.
💡 A Tese: Não é HBAR vs $LINK vs XRP. A Hedera hospeda valor regulado, a Chainlink conecta as redes e o XRP ajuda a conectar liquidez entre moedas.
A fragmentação virou realidade, e as finanças globais já constroem a resposta. Quem ainda precifica esses ativos como se nada disso estivesse acontecendo?
#hbar #LINK #xrp #Swift
2
200

Swift 区块链账本正式进入初期可用阶段,仅用 9 个月就从概念走到落地,17 家覆盖六大洲的全球银行成为首批试点方——澳新、法巴、纽约梅隆、花旗、星展、汇丰、渣打、瑞银、富国等悉数在列。
这次试点的核心,是用代币化存款打通 24/7 跨境支付:在传统结算系统完成最终清算之前,资金已可实时或在非工作时间流动,同时保留原有的合规、信用与风控框架。
值得留意的是,Swift 明确把这个账本定位成"编排层",未来还会延伸到可编程货币与代理商务(agentic commerce)的底层设施。这意味着传统跨境金融基建正在向链上世界主动靠拢,而不是被动被替代。
对市场的信号也很清晰:机构级代币化不再停留于白皮书,稳定币、RWA、支付类公链的中长期叙事都会因此得到再一次背书。
#Swift #代币化 #跨境支付
Swift 区块链账本正式进入初期可用阶段,仅用 9 个月就从概念走到落地,17 家覆盖六大洲的全球银行成为首批试点方——澳新、法巴、纽约梅隆、花旗、星展、汇丰、渣打、瑞银、富国等悉数在列。
这次试点的核心,是用代币化存款打通 24/7 跨境支付:在传统结算系统完成最终清算之前,资金已可实时或在非工作时间流动,同时保留原有的合规、信用与风控框架。
值得留意的是,Swift 明确把这个账本定位成"编排层",未来还会延伸到可编程货币与代理商务(agentic commerce)的底层设施。这意味着传统跨境金融基建正在向链上世界主动靠拢,而不是被动被替代。
对市场的信号也很清晰:机构级代币化不再停留于白皮书,稳定币、RWA、支付类公链的中长期叙事都会因此得到再一次背书。
#Swift #代币化 #跨境支付
这次试点的核心,是用代币化存款打通 24/7 跨境支付:在传统结算系统完成最终清算之前,资金已可实时或在非工作时间流动,同时保留原有的合规、信用与风控框架。
值得留意的是,Swift 明确把这个账本定位成"编排层",未来还会延伸到可编程货币与代理商务(agentic commerce)的底层设施。这意味着传统跨境金融基建正在向链上世界主动靠拢,而不是被动被替代。
对市场的信号也很清晰:机构级代币化不再停留于白皮书,稳定币、RWA、支付类公链的中长期叙事都会因此得到再一次背书。
#Swift #代币化 #跨境支付
26
·
--
SWIFT XRP Speculation Hits Wall
Former SWIFT Chief Innovation Officer Tom Zschach has dismissed claims that SWIFT plans to support #XRP .
Responding on X, Zschach said the rumored integration is "not happening."
The comments follow viral posts claiming #Swift would support $XRP instead of launching its own digital asset, a claim presented without evidence.
SWIFT XRP Speculation Hits Wall
Former SWIFT Chief Innovation Officer Tom Zschach has dismissed claims that SWIFT plans to support #XRP .
Responding on X, Zschach said the rumored integration is "not happening."
The comments follow viral posts claiming #Swift would support $XRP instead of launching its own digital asset, a claim presented without evidence.
Former SWIFT Chief Innovation Officer Tom Zschach has dismissed claims that SWIFT plans to support #XRP .
Responding on X, Zschach said the rumored integration is "not happening."
The comments follow viral posts claiming #Swift would support $XRP instead of launching its own digital asset, a claim presented without evidence.
109

·
--
Swift acaba de completar su primera transacción bancaria real en vivo.
HSBC y Standard Chartered fueron los encargados de realizar este movimiento.
Lo interesante es que este proyecto piloto busca agilizar las liquidaciones internacionales.
Es un movimiento claro para seguir siendo relevantes frente al crecimiento de las stablecoins y los depósitos tokenizados.
Parece que el sistema financiero tradicional se está moviendo rápido.
¿Crees que esto les ayudará a competir con las criptomonedas?
$BTC #Swift #Fintech
Swift acaba de completar su primera transacción bancaria real en vivo.
HSBC y Standard Chartered fueron los encargados de realizar este movimiento.
Lo interesante es que este proyecto piloto busca agilizar las liquidaciones internacionales.
Es un movimiento claro para seguir siendo relevantes frente al crecimiento de las stablecoins y los depósitos tokenizados.
Parece que el sistema financiero tradicional se está moviendo rápido.
¿Crees que esto les ayudará a competir con las criptomonedas?
$BTC #Swift #Fintech
HSBC y Standard Chartered fueron los encargados de realizar este movimiento.
Lo interesante es que este proyecto piloto busca agilizar las liquidaciones internacionales.
Es un movimiento claro para seguir siendo relevantes frente al crecimiento de las stablecoins y los depósitos tokenizados.
Parece que el sistema financiero tradicional se está moviendo rápido.
¿Crees que esto les ayudará a competir con las criptomonedas?
$BTC #Swift #Fintech
213
තවත් අන්තර්ගතයන් ගවේෂණය කිරීමට ඇතුල් වන්න
Binance චතුරශ්රය හි ගෝලීය ක්රිප්ටෝ පරිශීලකයින් හා එක්වන්න
⚡️ ක්රිප්ටෝ පිළිබඳ නවතම සහ ප්රයෝජනවත් තොරතුරු ලබා ගන්න.
💬 ලොව විශාලතම ක්රිප්ටෝ හුවමාරුව මගින් විශ්වාස කෙරේ.
👍 සත්යායනය කරන ලද නිර්මාණකරුවන්ගෙන් සැබෑ විදසුන් සොයා ගන්න.
විද්යුත් තැපෑල / දුරකථන අංකය
නැගී එන මාතෘකා
1
#MoreHikesExpectedIsBTCUnderPressure
19,628 නැරඹීම්
202 සාකච්ඡා කරමින්
2
#NvidiaBeatsEstimatesWith$130BQ4Outlook
84,890 නැරඹීම්
318 සාකච්ඡා කරමින්
3
#AnthropicIPOPriceCouldExceed$80
80,621 නැරඹීම්
262 සාකච්ඡා කරමින්
4
#RussiaCentralBankAddsAlfaBankToCryptoExchangeRegister
6,276 නැරඹීම්
73 සාකච්ඡා කරමින්
5
#VisaPlansStablecoinPrefundingForAPACCrossBorderPayments
6,631 නැරඹීම්
61 සාකච්ඡා කරමින්
6
#CanadaAndUSLaunchOperationNiagaraAgainstApprovalPhishing
53,428 නැරඹීම්
70 සාකච්ඡා කරමින්
7
#BankOfEnglandUnveilsClearingHousePathwayCoveringDLTFirms
5,146 නැරඹීම්
69 සාකච්ඡා කරමින්
8
#DBSAndCirclePartnerToExpandAsianInstitutionsUSDCAccess
6,536 නැරඹීම්
69 සාකච්ඡා කරමින්
9
#LedgerHardwareImplantReportsExtendToDubai
121,339 නැරඹීම්
979 සාකච්ඡා කරමින්
10
#NvidiaBoardNotConsideringHuang’sReturnasCEO
298,770 නැරඹීම්
1,756 සාකච්ඡා කරමින්