

sSumons
53 投稿

sSumons
報告
ユーザーをブロック
20 フォロー
31 フォロワー
52 いいね
投稿
·
--
翻訳参照
TermMax caught my attention because the usage numbers tell an interesting story, but the structure is what really stands out.
With TVL around $33M and roughly $22M in active loans, there’s clearly capital being put to work. But I think the bigger question is whether fixed-rate borrowing becomes something users consistently return to.
Being able to lock a borrowing rate until a defined maturity gives borrowers more predictability than constantly navigating changing variable rates.
That could become even more relevant as tokenized stocks and other real-world assets move further onchain.
For me, the key metric to watch is simple: what happens at maturity?
Do borrowers walk away, or do they roll into another term?
That repeat behavior could be the real test of TermMax’s model.
@termmax #TermMax
TermMax caught my attention because the usage numbers tell an interesting story, but the structure is what really stands out.
With TVL around $33M and roughly $22M in active loans, there’s clearly capital being put to work. But I think the bigger question is whether fixed-rate borrowing becomes something users consistently return to.
Being able to lock a borrowing rate until a defined maturity gives borrowers more predictability than constantly navigating changing variable rates.
That could become even more relevant as tokenized stocks and other real-world assets move further onchain.
For me, the key metric to watch is simple: what happens at maturity?
Do borrowers walk away, or do they roll into another term?
That repeat behavior could be the real test of TermMax’s model.
@TermMax #TermMax
2
·
--
翻訳参照
While looking deeper into @termmax Alpha, I started thinking about how different market views can be turned into more structured positions.
If you’re bullish, a Call can express that view. If you’re bearish, a Put can do the same from the other side. You can then define the position around a specific strike price and maturity.
That’s what makes the idea interesting to me.
Instead of simply buying or selling the underlying asset, you can build a position around a specific expectation and timeframe.
For traders who like clearly defined strategies, TermMax Alpha is definitely something worth watching.
Sometimes it’s not about predicting the market perfectly — it’s about having more ways to express your view.
#TermMax #TermMax
While looking deeper into @TermMax Alpha, I started thinking about how different market views can be turned into more structured positions.
If you’re bullish, a Call can express that view. If you’re bearish, a Put can do the same from the other side. You can then define the position around a specific strike price and maturity.
That’s what makes the idea interesting to me.
Instead of simply buying or selling the underlying asset, you can build a position around a specific expectation and timeframe.
For traders who like clearly defined strategies, TermMax Alpha is definitely something worth watching.
Sometimes it’s not about predicting the market perfectly — it’s about having more ways to express your view.
#TermMax #TermMax
28
·
--
翻訳参照
1.5M+ Wallets: The Bigger Question for TermMax
I keep coming back to one detail when looking at @termmax : scale is interesting, but repeat usage is what really matters.
TermMax has now crossed 1.5M+ registered wallets, building on the growth it reported earlier in 2026 across TVL, active users, and 100+ markets.
But registered wallets alone don’t tell the full story. A wallet can connect once and never return.
What I find more interesting is how V2 tries to reduce the friction after that first interaction.
With markets and vaults brought into one view, plus curator range orders and individual limit orders, users can compare terms without constantly jumping between different flows.
Lenders can define the minimum rate they want. Borrowers can set the maximum rate they’re willing to accept. And fixed maturities make the timing explicit.
So the real metric I’m watching isn’t just 1.5M wallets.
It’s whether those wallets become active participants.
If easier market discovery turns more wallets into repeat lenders and borrowers, then the headline number starts carrying much more weight.
#termmax @termmax
1.5M+ Wallets: The Bigger Question for TermMax
I keep coming back to one detail when looking at @TermMax : scale is interesting, but repeat usage is what really matters.
TermMax has now crossed 1.5M+ registered wallets, building on the growth it reported earlier in 2026 across TVL, active users, and 100+ markets.
But registered wallets alone don’t tell the full story. A wallet can connect once and never return.
What I find more interesting is how V2 tries to reduce the friction after that first interaction.
With markets and vaults brought into one view, plus curator range orders and individual limit orders, users can compare terms without constantly jumping between different flows.
Lenders can define the minimum rate they want. Borrowers can set the maximum rate they’re willing to accept. And fixed maturities make the timing explicit.
So the real metric I’m watching isn’t just 1.5M wallets.
It’s whether those wallets become active participants.
If easier market discovery turns more wallets into repeat lenders and borrowers, then the headline number starts carrying much more weight.
#termmax @TermMax
340
·
--
#TermMax @termmax
タスクをラップした後、TermMaxの数字の中のあることをずっと考えていました。
DefiLlamaではTVLが$31.22Mだった一方で、アクティブな貸付(ローン)は約$27.28Mでした。
つまり、すでにTVLの約87%がアクティブな融資ポジションの中に収まっていることになります。
最初は、それは単なる別の利用率(ユーティライゼーション)指標なのだと思いました。ですがTermMaxの設計をよく見るほど、ますます面白くなってきました。
これは、資本が誰かが借りるまでアイドル状態になり得る、従来のプールド・レンディング市場と同じ構造ではありません。
TermMaxは固定期間の仕組みを使い、貸し手はFTを受け取り、借り手はそれに対してGTポジションを取ります。固定リターンは、最初から価格設定に実質的に組み込まれています。
そのため、資本がシステムに入ってきたときの問いは、単に「プールにどれだけ資金があるのか?」ではありません。
それよりも、その資本のうち実際に、プロトコルの固定金利市場を通じて“働かされている”割合がどれくらいか、ということになります。
それによって、私のTVLの見方が変わりました。
利用率が高いということは、資本の効率的な運用を示している可能性があります。
しかし、単に流動性が集中している、より小さな市場を反映しているだけかもしれません。
私はその点をまだ見守っています。
この比率は興味深いです。
次に重要なのは、流動性とユーザーが拡大していく中で、TermMaxがその水準の資本効率を維持できるかどうかです。
#TMX
#TermMax @TermMax
タスクをラップした後、TermMaxの数字の中のあることをずっと考えていました。
DefiLlamaではTVLが$31.22Mだった一方で、アクティブな貸付(ローン)は約$27.28Mでした。
つまり、すでにTVLの約87%がアクティブな融資ポジションの中に収まっていることになります。
最初は、それは単なる別の利用率(ユーティライゼーション)指標なのだと思いました。ですがTermMaxの設計をよく見るほど、ますます面白くなってきました。
これは、資本が誰かが借りるまでアイドル状態になり得る、従来のプールド・レンディング市場と同じ構造ではありません。
TermMaxは固定期間の仕組みを使い、貸し手はFTを受け取り、借り手はそれに対してGTポジションを取ります。固定リターンは、最初から価格設定に実質的に組み込まれています。
そのため、資本がシステムに入ってきたときの問いは、単に「プールにどれだけ資金があるのか?」ではありません。
それよりも、その資本のうち実際に、プロトコルの固定金利市場を通じて“働かされている”割合がどれくらいか、ということになります。
それによって、私のTVLの見方が変わりました。
利用率が高いということは、資本の効率的な運用を示している可能性があります。
しかし、単に流動性が集中している、より小さな市場を反映しているだけかもしれません。
私はその点をまだ見守っています。
この比率は興味深いです。
次に重要なのは、流動性とユーザーが拡大していく中で、TermMaxがその水準の資本効率を維持できるかどうかです。
#TMX
47
·
--
翻訳参照
🔥 With the #TMX launch getting closer, I’ve been looking deeper into why $TMX could become one of the most interesting DeFi tokens to watch.
💎 Why $TMX Could Have Serious Potential
Unlike tokens that launch before their product is proven, @termmax is building around an already-developed DeFi infrastructure focused on fixed-rate, fixed-term lending and borrowing across multiple markets.
⚡ Why #TermMax Could Stand Out in 2026
DeFi has traditionally relied heavily on floating rates, making borrowing costs unpredictable and making long-term strategies harder to plan.
@termmax takes a different approach with maturity-based markets and its loan AMM, enabling users to access fixed rates and fixed terms instead of depending entirely on constantly changing rates.
That could make DeFi more predictable, capital-efficient, and potentially more attractive to larger users.
$TMX + real infrastructure + fixed-rate DeFi = a combination worth watching closely. 🚀
Not financial advice. DYOR.
#TMX #TermMax #Web3
🔥 With the #TMX launch getting closer, I’ve been looking deeper into why $TMX could become one of the most interesting DeFi tokens to watch.
💎 Why $TMX Could Have Serious Potential
Unlike tokens that launch before their product is proven, @TermMax is building around an already-developed DeFi infrastructure focused on fixed-rate, fixed-term lending and borrowing across multiple markets.
⚡ Why #TermMax Could Stand Out in 2026
DeFi has traditionally relied heavily on floating rates, making borrowing costs unpredictable and making long-term strategies harder to plan.
@TermMax takes a different approach with maturity-based markets and its loan AMM, enabling users to access fixed rates and fixed terms instead of depending entirely on constantly changing rates.
That could make DeFi more predictable, capital-efficient, and potentially more attractive to larger users.
$TMX + real infrastructure + fixed-rate DeFi = a combination worth watching closely. 🚀
Not financial advice. DYOR.
#TMX #TermMax #Web3
66
·
--
翻訳参照
🚨 #TermMax TMX: 5 Signals I’m Watching as the Ecosystem Grows 🚀
When I look at an early DeFi ecosystem like @termmax , I’m less interested in short-term noise and more focused on whether the underlying network is actually getting stronger.
Here are 5 things I’ll be watching:
1. Product Expansion: How TermMax continues developing fixed-rate, fixed-term lending, borrowing, leverage, and other DeFi products.
2. Liquidity & Users: Growing liquidity and consistent user activity could be strong signals that the products are finding real demand.
3. $TMX Utility: I’ll be watching how TMX becomes integrated into the ecosystem and whether new utilities emerge as the protocol develops.
4. RWA Growth: The connection between DeFi and real-world assets could become increasingly important, making TermMax’s RWA direction worth following.
5. Partnerships & Integrations: New integrations, ecosystem collaborations, and strategic partnerships could expand TermMax’s reach and bring more activity on-chain.
It’s still early, especially with TGE approaching.
For me, the bigger question isn’t simply what happens to TMX.
It’s whether TermMax can keep turning its products, liquidity, users, and partnerships into a growing ecosystem.
That’s the story I’ll be watching. 👀
#TermMax #TMX #DeFi
🚨 #TermMax TMX: 5 Signals I’m Watching as the Ecosystem Grows 🚀
When I look at an early DeFi ecosystem like @TermMax , I’m less interested in short-term noise and more focused on whether the underlying network is actually getting stronger.
Here are 5 things I’ll be watching:
1. Product Expansion: How TermMax continues developing fixed-rate, fixed-term lending, borrowing, leverage, and other DeFi products.
2. Liquidity & Users: Growing liquidity and consistent user activity could be strong signals that the products are finding real demand.
3. $TMX Utility: I’ll be watching how TMX becomes integrated into the ecosystem and whether new utilities emerge as the protocol develops.
4. RWA Growth: The connection between DeFi and real-world assets could become increasingly important, making TermMax’s RWA direction worth following.
5. Partnerships & Integrations: New integrations, ecosystem collaborations, and strategic partnerships could expand TermMax’s reach and bring more activity on-chain.
It’s still early, especially with TGE approaching.
For me, the bigger question isn’t simply what happens to TMX.
It’s whether TermMax can keep turning its products, liquidity, users, and partnerships into a growing ecosystem.
That’s the story I’ll be watching. 👀
#TermMax #TMX #DeFi
1
6
·
--
翻訳参照
The more I explore @termmax , the more I realize fixed-rate DeFi is not only about locking in a predictable number.
It’s also about having more control over how that rate is applied.
That’s what makes Range Orders interesting to me.
Instead of forcing liquidity into one fixed rate, lenders can structure different rates across different fill sizes. Borrowers can approach the market from the other side in a similar way.
That creates a more flexible way to manage capital.
Maybe I’m comfortable lending a smaller amount at one rate, but if significantly more capital gets deployed, I may want the pricing to change.
So the order itself can reflect both my rate preference and my willingness to provide more liquidity.
Of course, more flexibility means there’s more to understand.
But that’s what good DeFi infrastructure should do: not pretend complexity doesn’t exist, but give users better tools to manage it.
That’s one of the TermMax mechanics I’m watching closely.
$TMX #TermMax @TermMax
The more I explore @TermMax , the more I realize fixed-rate DeFi is not only about locking in a predictable number.
It’s also about having more control over how that rate is applied.
That’s what makes Range Orders interesting to me.
Instead of forcing liquidity into one fixed rate, lenders can structure different rates across different fill sizes. Borrowers can approach the market from the other side in a similar way.
That creates a more flexible way to manage capital.
Maybe I’m comfortable lending a smaller amount at one rate, but if significantly more capital gets deployed, I may want the pricing to change.
So the order itself can reflect both my rate preference and my willingness to provide more liquidity.
Of course, more flexibility means there’s more to understand.
But that’s what good DeFi infrastructure should do: not pretend complexity doesn’t exist, but give users better tools to manage it.
That’s one of the TermMax mechanics I’m watching closely.
$TMX #TermMax @TermMax
27
·
--
翻訳参照
#TermMax @termmax
The more I look at TermMax’s Vault and Curator model, the more I think the interesting part isn’t simply the yield.
At first, a vault sounds straightforward: deposit capital, let the strategy handle allocation, and earn returns. But fixed-rate markets make the allocation decision much more important.
The Curator has to think about which market deserves capital, which maturity makes sense, how much liquidity is needed, and what level of risk is acceptable.
That changes how I look at APY.
A higher number on the screen doesn’t automatically mean a better strategy. The real question is what is required to generate that yield.
Capital deployed into different fixed-rate markets can face different maturity and liquidity conditions. So the quality of the strategy depends not only on return, but also on how intelligently capital is allocated.
That’s what I find interesting about TermMax.
The user experience may feel passive, but the decisions behind that passive yield are anything but passive.
I’ll be watching how the vault model performs when markets become volatile, liquidity gets tighter, and different maturities start creating real pressure on capital allocation.
#TermMax @TermMax
The more I look at TermMax’s Vault and Curator model, the more I think the interesting part isn’t simply the yield.
At first, a vault sounds straightforward: deposit capital, let the strategy handle allocation, and earn returns. But fixed-rate markets make the allocation decision much more important.
The Curator has to think about which market deserves capital, which maturity makes sense, how much liquidity is needed, and what level of risk is acceptable.
That changes how I look at APY.
A higher number on the screen doesn’t automatically mean a better strategy. The real question is what is required to generate that yield.
Capital deployed into different fixed-rate markets can face different maturity and liquidity conditions. So the quality of the strategy depends not only on return, but also on how intelligently capital is allocated.
That’s what I find interesting about TermMax.
The user experience may feel passive, but the decisions behind that passive yield are anything but passive.
I’ll be watching how the vault model performs when markets become volatile, liquidity gets tighter, and different maturities start creating real pressure on capital allocation.
2
1
36
·
--
翻訳参照
@termmax The more I look at TermMax, the more I think the headline fee numbers need more context.
A 2% lending fee can sound expensive at first glance. But if that fee is applied to the interest generated rather than the full principal, the actual economic cost can be much smaller than the headline suggests.
That makes the bigger question more interesting.
For borrowers, fixed-rate debt is valuable because it removes uncertainty. You know the cost upfront instead of watching variable rates move against your position.
But there is a tradeoff.
Fixed maturity means less flexibility. Borrowers need to think about timing, liquidity, and what happens when the position reaches maturity.
So I’m less interested in whether a fee looks high on paper and more interested in whether users believe predictable financing is worth paying for.
A small borrower and a large institution can face the same percentage fee, yet create completely different economics for the protocol.
The real test for TermMax isn’t just pricing.
It’s whether fixed-rate certainty becomes something users actively prefer when markets get volatile.
That’s where I’ll be watching.
#termmax
@TermMax The more I look at TermMax, the more I think the headline fee numbers need more context.
A 2% lending fee can sound expensive at first glance. But if that fee is applied to the interest generated rather than the full principal, the actual economic cost can be much smaller than the headline suggests.
That makes the bigger question more interesting.
For borrowers, fixed-rate debt is valuable because it removes uncertainty. You know the cost upfront instead of watching variable rates move against your position.
But there is a tradeoff.
Fixed maturity means less flexibility. Borrowers need to think about timing, liquidity, and what happens when the position reaches maturity.
So I’m less interested in whether a fee looks high on paper and more interested in whether users believe predictable financing is worth paying for.
A small borrower and a large institution can face the same percentage fee, yet create completely different economics for the protocol.
The real test for TermMax isn’t just pricing.
It’s whether fixed-rate certainty becomes something users actively prefer when markets get volatile.
That’s where I’ll be watching.
#termmax
1
61
·
--
#termmax @termmax 今年の夏の初め、私はある人との会話をきっかけに、ひとつの疑問を抱いたことからDeFiをより深く掘り下げ始めました。その疑問とは:金利が動き続ける中で、分散型金融は本当に予測可能になるのでしょうか?
この問いがやがて@termmax へと私を導きました。
何が私の関心を引いたのでしょう?
固定金利――借入コストや貸付リターンを事前に確定して固定します。
ワンクリックのレバレッジ――複雑なループを毎回手作業で組まずに、レバレッジ戦略をよりシンプルにします。
資本効率――未使用の流動性を、待機したままにせず、確立された貸付市場へ振り向けます。
ただ、私がより惹かれているのは、その先の大きな構想です。
@termmax が、トークン化された株式ファイナンスや実世界資産などの領域へ広がっていくにつれ、私は考え続けています。
固定金利のDeFiが、従来の金融の流動性とオンチェーン市場をつなぐインフラになり得るのではないでしょうか?
もしかすると、未来はDeFiがTradFiを一夜にして置き換えることではないのかもしれません。
あるいは、両者がゆっくりと同じ金融システムへ近づいていくのかもしれません。
#TermMax
#termmax @TermMax 今年の夏の初め、私はある人との会話をきっかけに、ひとつの疑問を抱いたことからDeFiをより深く掘り下げ始めました。その疑問とは:金利が動き続ける中で、分散型金融は本当に予測可能になるのでしょうか?
この問いがやがて@TermMax へと私を導きました。
何が私の関心を引いたのでしょう?
固定金利――借入コストや貸付リターンを事前に確定して固定します。
ワンクリックのレバレッジ――複雑なループを毎回手作業で組まずに、レバレッジ戦略をよりシンプルにします。
資本効率――未使用の流動性を、待機したままにせず、確立された貸付市場へ振り向けます。
ただ、私がより惹かれているのは、その先の大きな構想です。
@TermMax が、トークン化された株式ファイナンスや実世界資産などの領域へ広がっていくにつれ、私は考え続けています。
固定金利のDeFiが、従来の金融の流動性とオンチェーン市場をつなぐインフラになり得るのではないでしょうか?
もしかすると、未来はDeFiがTradFiを一夜にして置き換えることではないのかもしれません。
あるいは、両者がゆっくりと同じ金融システムへ近づいていくのかもしれません。
#TermMax
1
2
81
·
--
TermMaxの固定期間市場について考えているうちに、どんどん深掘りしたくなってきました。
最初は、固定金利の借入がDeFiをより予測可能にする単純な方法に思えました。けれども@termmax を見れば見るほど、市場構造がいかに興味深いものかが見えてきます。
金利、満期、流動性、そして注文の出し方がすべて噛み合っているとき、目標は単に金利を固定することではありません。DeFiの中で資本が移動していくための、より構造化された仕組みを作ることです。
それが私の興味を引きつけています。
私がずっと立ち返ってしまうのは、この構造によって固定金利の市場が本当に使いやすくなるのか、それとも追加された柔軟性が、利用者が理解するのに時間を要する複雑さの層を生んでしまうのか、という点です。
設計は期待できると思います。
あとは本当の試練として、ユーザーが実際にその違いを体感できるかどうかです。
@termmax #TermMax
TermMaxの固定期間市場について考えているうちに、どんどん深掘りしたくなってきました。
最初は、固定金利の借入がDeFiをより予測可能にする単純な方法に思えました。けれども@TermMax を見れば見るほど、市場構造がいかに興味深いものかが見えてきます。
金利、満期、流動性、そして注文の出し方がすべて噛み合っているとき、目標は単に金利を固定することではありません。DeFiの中で資本が移動していくための、より構造化された仕組みを作ることです。
それが私の興味を引きつけています。
私がずっと立ち返ってしまうのは、この構造によって固定金利の市場が本当に使いやすくなるのか、それとも追加された柔軟性が、利用者が理解するのに時間を要する複雑さの層を生んでしまうのか、という点です。
設計は期待できると思います。
あとは本当の試練として、ユーザーが実際にその違いを体感できるかどうかです。
@TermMax #TermMax
28
·
--
翻訳参照
#termmax @termmax
TermMax Vaults: Delegated Risk, Not Just Yield
I was digging deeper into TermMax’s Vault architecture, and one thing stood out to me: the Curator isn’t simply managing liquidity. They’re effectively making ongoing credit-allocation decisions.
The ability to adjust order sizes and pricing curves gives the Curator room to respond to market conditions without waiting for governance every time.
But changes that expand the vault’s risk exposure, like adding new markets or modifying certain parameters, come with more friction through fees and timelocks.
That asymmetry is interesting.
Risk-reducing adjustments can move faster, while decisions that increase the vault’s risk perimeter face additional constraints.
Then there’s the withdrawal side. Queued withdrawals mean depositors aren’t necessarily holding instantly liquid capital. Their liquidity depends partly on how the Curator positions the vault across different markets.
So the deeper thesis for me is this:
TermMax vault governance is less about voting on every decision and more about delegating credit underwriting to a Curator within defined guardrails.
The Guardian and timelocks add protection, but they don’t eliminate human judgment.
And that leaves the biggest question:
As vaults scale and markets move faster, will those guardrails be strong enough to keep delegated discretion aligned with depositor risk?
#termmax @TermMax
TermMax Vaults: Delegated Risk, Not Just Yield
I was digging deeper into TermMax’s Vault architecture, and one thing stood out to me: the Curator isn’t simply managing liquidity. They’re effectively making ongoing credit-allocation decisions.
The ability to adjust order sizes and pricing curves gives the Curator room to respond to market conditions without waiting for governance every time.
But changes that expand the vault’s risk exposure, like adding new markets or modifying certain parameters, come with more friction through fees and timelocks.
That asymmetry is interesting.
Risk-reducing adjustments can move faster, while decisions that increase the vault’s risk perimeter face additional constraints.
Then there’s the withdrawal side. Queued withdrawals mean depositors aren’t necessarily holding instantly liquid capital. Their liquidity depends partly on how the Curator positions the vault across different markets.
So the deeper thesis for me is this:
TermMax vault governance is less about voting on every decision and more about delegating credit underwriting to a Curator within defined guardrails.
The Guardian and timelocks add protection, but they don’t eliminate human judgment.
And that leaves the biggest question:
As vaults scale and markets move faster, will those guardrails be strong enough to keep delegated discretion aligned with depositor risk?
1
203
·
--
翻訳参照
The closer I look at @termmax , the more I think the August 25 $TMX TGE is only the beginning.
XP, AP, and MP rewards are expected to become claimable at TGE, with allocation checks, vesting, and staking details also part of the launch process.
But the bigger story is what comes after.
TermMax V2 is already live with unified routing, limit orders across markets, and a single dashboard for positions across supported chains. Instead of forcing users to manage fragmented liquidity manually, the app can combine curator ranges and individual limit orders into one transaction.
That makes the token launch more interesting because the underlying product is already being used and developed.
The App V2 also entered Immunefi’s bug-bounty scope on August 17, adding another layer of external security scrutiny.
Of course, fixed rates don’t remove every DeFi risk. Liquidity, collateral, liquidation, and smart-contract risks still matter.
So after TGE, I’ll be watching the metrics that matter more than the first $TMX price move:
Deeper liquidity.
More filled orders.
More repeat borrowers and lenders.
A token can create attention.
A useful fixed-rate market has to create retention.
#TermMax
The closer I look at @TermMax , the more I think the August 25 $TMX TGE is only the beginning.
XP, AP, and MP rewards are expected to become claimable at TGE, with allocation checks, vesting, and staking details also part of the launch process.
But the bigger story is what comes after.
TermMax V2 is already live with unified routing, limit orders across markets, and a single dashboard for positions across supported chains. Instead of forcing users to manage fragmented liquidity manually, the app can combine curator ranges and individual limit orders into one transaction.
That makes the token launch more interesting because the underlying product is already being used and developed.
The App V2 also entered Immunefi’s bug-bounty scope on August 17, adding another layer of external security scrutiny.
Of course, fixed rates don’t remove every DeFi risk. Liquidity, collateral, liquidation, and smart-contract risks still matter.
So after TGE, I’ll be watching the metrics that matter more than the first $TMX price move:
Deeper liquidity.
More filled orders.
More repeat borrowers and lenders.
A token can create attention.
A useful fixed-rate market has to create retention.
#TermMax
1
55
·
--
なぜ#TermMax はDeFiの融資に対する考え方を変えうるのか
数日前、私はDeFiの領域を調べていたのですが、@termmax についてのある事実が特に印象に残りました。
融資または借入のポジションを取ったあと、市場の動きに合わせて金利がずっと変わり続けていくのを見たことはありませんか?
その不確実性は、先の計画を立てにくくします。
そこで、@termmax は別のアプローチを取ります。
変動金利に主に依存するのではなく、TermMaxは固定金利・固定期間での貸し借りに焦点を当てることで、ユーザーが定められた期間における借入または貸付のポジションの見通しをより明確に把握できるようにしています。
私にとって興味深いのは、「固定」という言葉そのものだけではありません。
より大きな問いは、DeFiが目まぐるしく変化する環境の中で、固定金利の融資をどのように維持しつつ、DeFiの魅力である柔軟性と効率性も保てるか、という点です。
エコシステムの中心に#TMX を据え、TermMaxは、DeFiが成熟するにつれてますます重要になり得る考え方を形にしようとしています:
分散型市場のメリットを手放さずに、より予測可能な金融ポジションを実現すること。
シンプルなコンセプトですが、その背後にあるインフラこそが、注目する価値を生んでいます。
エコシステムが次の段階へ進むにつれて、#TermMax $PORTALに注目してください。
#defi #TermMax
なぜ#TermMax はDeFiの融資に対する考え方を変えうるのか
数日前、私はDeFiの領域を調べていたのですが、@TermMax についてのある事実が特に印象に残りました。
融資または借入のポジションを取ったあと、市場の動きに合わせて金利がずっと変わり続けていくのを見たことはありませんか?
その不確実性は、先の計画を立てにくくします。
そこで、@TermMax は別のアプローチを取ります。
変動金利に主に依存するのではなく、TermMaxは固定金利・固定期間での貸し借りに焦点を当てることで、ユーザーが定められた期間における借入または貸付のポジションの見通しをより明確に把握できるようにしています。
私にとって興味深いのは、「固定」という言葉そのものだけではありません。
より大きな問いは、DeFiが目まぐるしく変化する環境の中で、固定金利の融資をどのように維持しつつ、DeFiの魅力である柔軟性と効率性も保てるか、という点です。
エコシステムの中心に#TMX を据え、TermMaxは、DeFiが成熟するにつれてますます重要になり得る考え方を形にしようとしています:
分散型市場のメリットを手放さずに、より予測可能な金融ポジションを実現すること。
シンプルなコンセプトですが、その背後にあるインフラこそが、注目する価値を生んでいます。
エコシステムが次の段階へ進むにつれて、#TermMax $PORTALに注目してください。
#defi #TermMax
2
78
·
--
私は @termmax をより深く調べていて、際立っている点が一つあります。固定金利での貸付は、方程式の一部にすぎないということです。
より大きな問いは、市場環境が急激に変わるときに、プロトコルがどのようにリスクを管理するのかです。
固定金利の借入・貸付では、ユーザーはより高い予測可能性を得られますが、それでもプロトコルは流動性、ボラティリティ、満期の不一致、そして資産価格の急変に対処しなければなりません。そこで、特に流動性が薄くなったり市場が急に動いたりするときに、TermMax がさまざまなプロダクト間でどのようにリスクを分離し、管理しているのかが気になります。
また、オプション側も興味深い問いを投げかけます。プロトコルは、オプションポジションによって生じるリスクを、固定金利の貸付インフラストラクチャとどのように両立させているのでしょうか。
ガバナンスも、私が注視している領域です。重要なパラメータがガバナンスによって調整可能である場合、拙速な判断や、十分に連携されていない変更によってプロトコル全体により大きなリスクが波及しないようにする仕組みは何が用意されているのでしょうか。
そしてスマートコントラクトのセキュリティだけでなく、市場リスクや流動性リスクにも同じくらい注意が払われるべきだと思います。
TermMax を掘り下げるほど、面白いのは単に固定金利を提供することではなく、変化し続ける DeFi 環境においてその金利を持続可能にするリスク管理の枠組みを構築することなのだと感じます。
TermMax のアーキテクチャは、リスク隔離、流動性管理、ガバナンスにどのようにアプローチしているのか、ぜひ聞いてみたいです。
@termmax $TERMINUS #TERM #termmax
私は @TermMax をより深く調べていて、際立っている点が一つあります。固定金利での貸付は、方程式の一部にすぎないということです。
より大きな問いは、市場環境が急激に変わるときに、プロトコルがどのようにリスクを管理するのかです。
固定金利の借入・貸付では、ユーザーはより高い予測可能性を得られますが、それでもプロトコルは流動性、ボラティリティ、満期の不一致、そして資産価格の急変に対処しなければなりません。そこで、特に流動性が薄くなったり市場が急に動いたりするときに、TermMax がさまざまなプロダクト間でどのようにリスクを分離し、管理しているのかが気になります。
また、オプション側も興味深い問いを投げかけます。プロトコルは、オプションポジションによって生じるリスクを、固定金利の貸付インフラストラクチャとどのように両立させているのでしょうか。
ガバナンスも、私が注視している領域です。重要なパラメータがガバナンスによって調整可能である場合、拙速な判断や、十分に連携されていない変更によってプロトコル全体により大きなリスクが波及しないようにする仕組みは何が用意されているのでしょうか。
そしてスマートコントラクトのセキュリティだけでなく、市場リスクや流動性リスクにも同じくらい注意が払われるべきだと思います。
TermMax を掘り下げるほど、面白いのは単に固定金利を提供することではなく、変化し続ける DeFi 環境においてその金利を持続可能にするリスク管理の枠組みを構築することなのだと感じます。
TermMax のアーキテクチャは、リスク隔離、流動性管理、ガバナンスにどのようにアプローチしているのか、ぜひ聞いてみたいです。
@TermMax $TERMINUS #TERM #termmax
3
46
·
--
翻訳参照
There’s a part of DeFi borrowing that I think deserves more attention: certainty.
When rates are constantly moving, it becomes difficult to know what your capital will actually cost over time. A strategy can be solid, but changing borrowing rates can still change the outcome.
That’s why the fixed-rate approach from @termmax stands out to me.
With a fixed rate, borrowers can plan around a known cost instead of constantly reacting to market movements. Lenders can also get clearer expectations around their returns.
It’s not simply about finding the highest yield.
It’s about making the cost of capital more predictable.
DeFi has already made financial markets more accessible and composable. The next step could be making those markets easier to plan around.
Sometimes, certainty is the real yield.
#TermMax @termmax
There’s a part of DeFi borrowing that I think deserves more attention: certainty.
When rates are constantly moving, it becomes difficult to know what your capital will actually cost over time. A strategy can be solid, but changing borrowing rates can still change the outcome.
That’s why the fixed-rate approach from @TermMax stands out to me.
With a fixed rate, borrowers can plan around a known cost instead of constantly reacting to market movements. Lenders can also get clearer expectations around their returns.
It’s not simply about finding the highest yield.
It’s about making the cost of capital more predictable.
DeFi has already made financial markets more accessible and composable. The next step could be making those markets easier to plan around.
Sometimes, certainty is the real yield.
#TermMax @TermMax
3
279
·
--
#termmax @termmax 今日、TermMaxの設計をより深く掘り下げました。今回は「固定金利DeFi」の見出しにばかり注目するのではなく、システムが実際にスケールするにはどう動くのかに焦点を当てました。
私が注目しているのは、@termmax が固定金利、定義された満期、トークン化、AMMベースのマーケットによって、借り入れと貸し出しにより高い予測可能性をもたらそうとしている点です。
一見するとシンプルに聞こえますが、面白いのはその下で何が起きるかです。
金利が固定されているなら、流動性は異なる満期や市場環境の中でも効率的に保たれている必要があります。そうすると、流動性提供者はどのようにインセンティブを与えられるのか、またプロトコルは高ボラティリティの時期をどう扱うのかが気になります。
さらに、TMXにもより注意を向けています。
総供給が1Bトークンで固定され、ガバナンス、ステーキング、そしてエコシステム・インセンティブといった役割がある中で、実際の問いは「供給量」だけではありません。
「分配」です。
時間とともにガバナンスはどれほど分散されていくのか?
初期保有者の影響力はどれくらいになるのか?
そしてインセンティブは、短期的な活動ではなく持続可能な参加を生み出せるのか?
これらはまだ、私が検討している問いであって、結論ではありません。
TermMaxについて読むほど、真の試練は、その固定金利モデルが持続可能な流動性と実際のユーザー需要を生み出せるかどうかになるのではないかと思えてきます。
あなたなら、次にTermMaxエコシステムのどの部分を調べますか?
@termmax #TermMax
#termmax @TermMax 今日、TermMaxの設計をより深く掘り下げました。今回は「固定金利DeFi」の見出しにばかり注目するのではなく、システムが実際にスケールするにはどう動くのかに焦点を当てました。
私が注目しているのは、@TermMax が固定金利、定義された満期、トークン化、AMMベースのマーケットによって、借り入れと貸し出しにより高い予測可能性をもたらそうとしている点です。
一見するとシンプルに聞こえますが、面白いのはその下で何が起きるかです。
金利が固定されているなら、流動性は異なる満期や市場環境の中でも効率的に保たれている必要があります。そうすると、流動性提供者はどのようにインセンティブを与えられるのか、またプロトコルは高ボラティリティの時期をどう扱うのかが気になります。
さらに、TMXにもより注意を向けています。
総供給が1Bトークンで固定され、ガバナンス、ステーキング、そしてエコシステム・インセンティブといった役割がある中で、実際の問いは「供給量」だけではありません。
「分配」です。
時間とともにガバナンスはどれほど分散されていくのか?
初期保有者の影響力はどれくらいになるのか?
そしてインセンティブは、短期的な活動ではなく持続可能な参加を生み出せるのか?
これらはまだ、私が検討している問いであって、結論ではありません。
TermMaxについて読むほど、真の試練は、その固定金利モデルが持続可能な流動性と実際のユーザー需要を生み出せるかどうかになるのではないかと思えてきます。
あなたなら、次にTermMaxエコシステムのどの部分を調べますか?
@TermMax #TermMax
1
3
151
·
--
翻訳参照
What Makes #TermMax Different From Traditional DeFi Lending? @termmax
The more I explore DeFi, the more I realize that predictability can be just as important as yield.
In many traditional DeFi lending protocols, interest rates are variable, which means borrowing costs can change as market conditions shift. That can make it difficult to plan ahead, especially when you’re holding a position for longer periods.
@termmax takes a different approach by focusing on fixed-rate and fixed-term lending.
Instead of constantly wondering where the interest rate might move next, users can have a clearer idea of their borrowing costs and maturity from the beginning.
What I find interesting is that TermMax isn’t trying to remove the flexibility that makes DeFi powerful. It’s building a more structured lending experience around predictability, defined terms, and better financial planning.
And with #TMX at the center of the ecosystem, it will be interesting to see how this model develops as DeFi continues to mature.
Simple idea, but potentially a meaningful upgrade for users who want more certainty in their DeFi strategies.
Keep watching @termmax 👀
#TermMax #defi #alpha
What Makes #TermMax Different From Traditional DeFi Lending? @TermMax
The more I explore DeFi, the more I realize that predictability can be just as important as yield.
In many traditional DeFi lending protocols, interest rates are variable, which means borrowing costs can change as market conditions shift. That can make it difficult to plan ahead, especially when you’re holding a position for longer periods.
@TermMax takes a different approach by focusing on fixed-rate and fixed-term lending.
Instead of constantly wondering where the interest rate might move next, users can have a clearer idea of their borrowing costs and maturity from the beginning.
What I find interesting is that TermMax isn’t trying to remove the flexibility that makes DeFi powerful. It’s building a more structured lending experience around predictability, defined terms, and better financial planning.
And with #TMX at the center of the ecosystem, it will be interesting to see how this model develops as DeFi continues to mature.
Simple idea, but potentially a meaningful upgrade for users who want more certainty in their DeFi strategies.
Keep watching @TermMax 👀
#TermMax #defi #alpha
3
32
·
--
@termmax を掘り下げれば掘り下げるほど、真のチャンスは単に「固定金利」にあるわけではないのではないかと思えてきます。
それは、DeFiのファイナンスをより予測可能にすることです。
変動金利は、市場が落ち着いていて流動性が豊富なときにはうまく機能します。ですが、てこ(レバレッジ)を管理したり、戦略を立てたり、あらかじめ自分の正確な資金調達コストを把握しようとしたりする局面では、不確実性が高くついてしまいます。
そこでTermMaxの出番です。
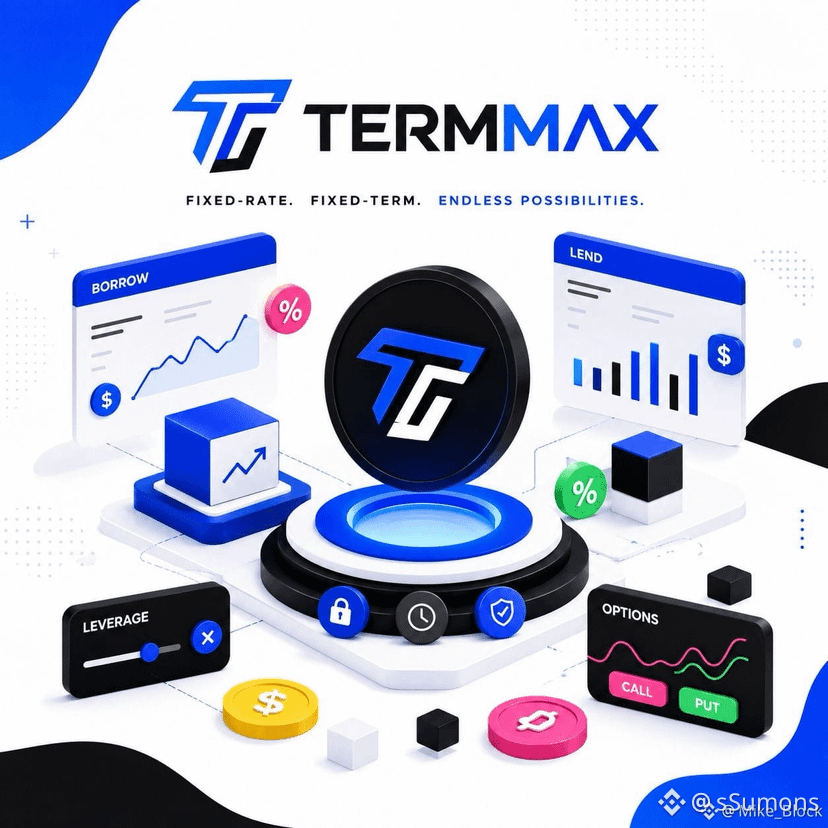
固定金利の貸し借り、明確な満期、ヴォールト(資産管理機構)、そしてレバレッジにより、プロトコルは「ただの別のマネーマーケット」というより、実際の固定金利(固定収益)インフラに近いものを構築しようとしています。
それでも、最大の疑問は技術が機能するかどうかではありません。
ユーザーが、すでに慣れ親しんでいる柔軟性よりも、予測可能性を選ぶかどうかです。
XPやアクティビティ・ポイントは注目や流動性を呼び込めるかもしれませんが、持続可能な需要が最終的に生まれてくるのは、やはりプロダクトそのものからである必要があります。
DeFiがさらに成熟していくなら、固定金利の市場はますます重要になると思います。
もしかすると、問題はTermMaxが早すぎるかどうかではないのかもしれません。
もしかすると、市場がようやく追いつき始めているのかもしれません。
@termmax #termmax
@TermMax を掘り下げれば掘り下げるほど、真のチャンスは単に「固定金利」にあるわけではないのではないかと思えてきます。
それは、DeFiのファイナンスをより予測可能にすることです。
変動金利は、市場が落ち着いていて流動性が豊富なときにはうまく機能します。ですが、てこ(レバレッジ)を管理したり、戦略を立てたり、あらかじめ自分の正確な資金調達コストを把握しようとしたりする局面では、不確実性が高くついてしまいます。
そこでTermMaxの出番です。
固定金利の貸し借り、明確な満期、ヴォールト(資産管理機構)、そしてレバレッジにより、プロトコルは「ただの別のマネーマーケット」というより、実際の固定金利(固定収益)インフラに近いものを構築しようとしています。
それでも、最大の疑問は技術が機能するかどうかではありません。
ユーザーが、すでに慣れ親しんでいる柔軟性よりも、予測可能性を選ぶかどうかです。
XPやアクティビティ・ポイントは注目や流動性を呼び込めるかもしれませんが、持続可能な需要が最終的に生まれてくるのは、やはりプロダクトそのものからである必要があります。
DeFiがさらに成熟していくなら、固定金利の市場はますます重要になると思います。
もしかすると、問題はTermMaxが早すぎるかどうかではないのかもしれません。
もしかすると、市場がようやく追いつき始めているのかもしれません。
@TermMax #termmax
3
29
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号
トレンドトピック
EtherGains70.9%InQ3
閲覧回数 101,691
937人が討論中
🧭🧭🧭 代替コイン・シーズン分析 🧭🧭🧭
💡 代替コインのシーズン指標 💡
🚨🚨🚨 第3四半期(T3)が終了しました。ETHの価格は71%上昇、BTCは43%上昇。 🚨🚨🚨
これは代替コイン・シーズンの始まりだったのでしょうか?
上位100の中で:
🌐🌐🌐 57銘柄が過去90日でBTCを上回りました
代替コイン・シーズンは75から始まるので、まだ
また、年初来最高値67からはあと10ポイントしか進んでいません 🌐🌐
💥💥💥 でもちょっと待って、先月は指標が23に過ぎなかった!
10月がこれを75まで押し上げられるでしょうか? 👀💥💥💥
フォローをお願いします
#EtherGains70.9%InQ3
$GRAM
Shamika Metting
·いいね:2件
·閲覧回数 938
TreasuryLetsStatesFileStablecoinCertificationsEarly
閲覧回数 5,165
61人が討論中
US10YearYieldNears5.3%
閲覧回数 122,787
997人が討論中