

#layer1
layer1
5.1M views
28,293 Discussing
Hot
Latest
·
--
See translation
$SOL at $95.67 is being sold like it broke. It hasn’t.
Up 1.34% today, +0.8% in the last 4h, while 4h RSI sits at 39. That’s not euphoria. That’s a washed-out chart with price still below the 20d and 50d MAs. 📉
Volume is only 0.3x its 20d average, so this bounce has no crowd behind it yet. Even $ETH looks more loved right now.
At $100, I’d trim risk, not chase. Longs paying 0.007% into this setup is the tell. 🔥
#Solana #Layer1 #Altcoin
1

See translation
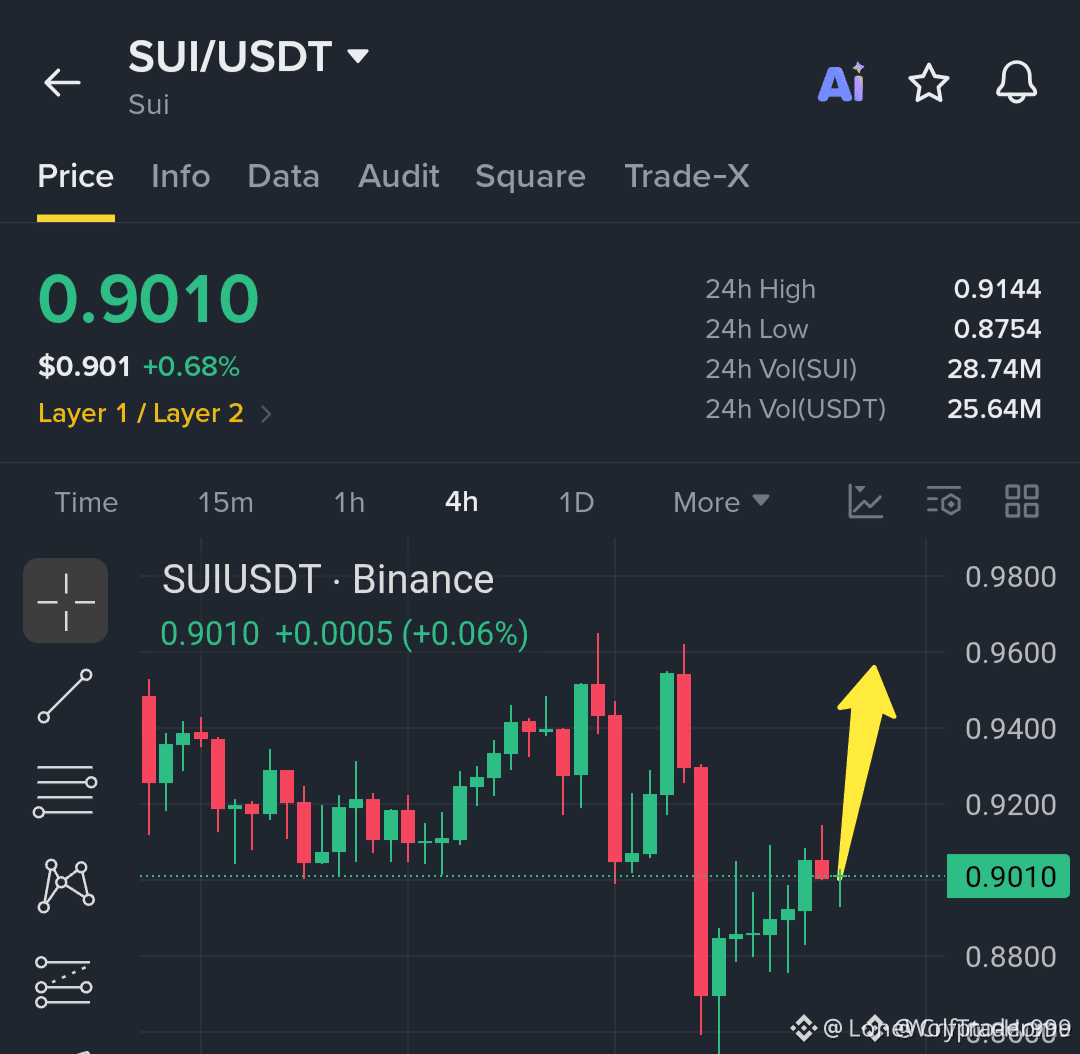
⚡ $SUI ABSORBS THE LOWS AND CARVES OUT AN AGGRESSIVE RANGE RECLAIM! 🟢
Entry: 0.9010 ⚡
The bid has firmly stepped in at $0.9010 as buyers aggressively soak up selling pressure across the lower boundary. 📊 When an asset abruptly halts downward expansion and prints consecutive green momentum candles, smart money is usually positioning for the flip.
⚡ Order books are tightening fast as spot demand begins punching straight through localized supply. 💡 If buyers hold ground above this structural pivot, the runway for a broader liquidity sweep opens up significantly.
💬 Are you loading spot on this reversal or waiting for higher confirmation? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SUI #Layer1 #Altcoins #CryptoMomentum
⚡ 💎
6
·
--
See translation
🌐 $NEAR : The Chain That Bet on AI Early
NEAR has been one of the most searched coins recently. Here's what it's about 👇
What NEAR does:
🔹 A sharded layer-1 designed to scale
🔹 Focus on "chain abstraction" — using crypto apps without worrying about which chain you're on
🔹 A strong push into AI-related products and agents
Why it gets attention:
When the AI narrative heats up, NEAR is often grouped with AI tokens like $FET and $TAO .
⚠️ Risks:
🔻 Competition from many other layer-1s
🔻 Narrative-driven moves can reverse fast
💬 Is NEAR an AI play or a layer-1 play for you? 👇
⚠️ Educational content only, not financial advice. DYOR.
#NEAR #AI #Layer1 #BinanceSquare
1
45
·
--
See translation
🔺 $AVAX : Avalanche and the "Launch Your Own Chain" Model
AVAX powers Avalanche, which lets projects launch their own custom blockchains (L1s) connected to the network.
Why that matters 👇
🔹 Games, institutions and apps can have their own rules
🔹 Interest from tokenization and finance projects
🔹 Fast finality on the main chain
Comparison: similar to the multi-chain ideas of $DOT , while competing with $SOL for apps and users.
⚠️ Risks: custom chains must bring real activity back to AVAX's value.
💬 Do you think every big app will eventually have its own chain? 👇
⚠️ Educational content only, not financial advice. DYOR.
#AVAX #Avalanche #Layer1 #BinanceSquare
1
174

·
--
See translation
📡 $S | Layer 1
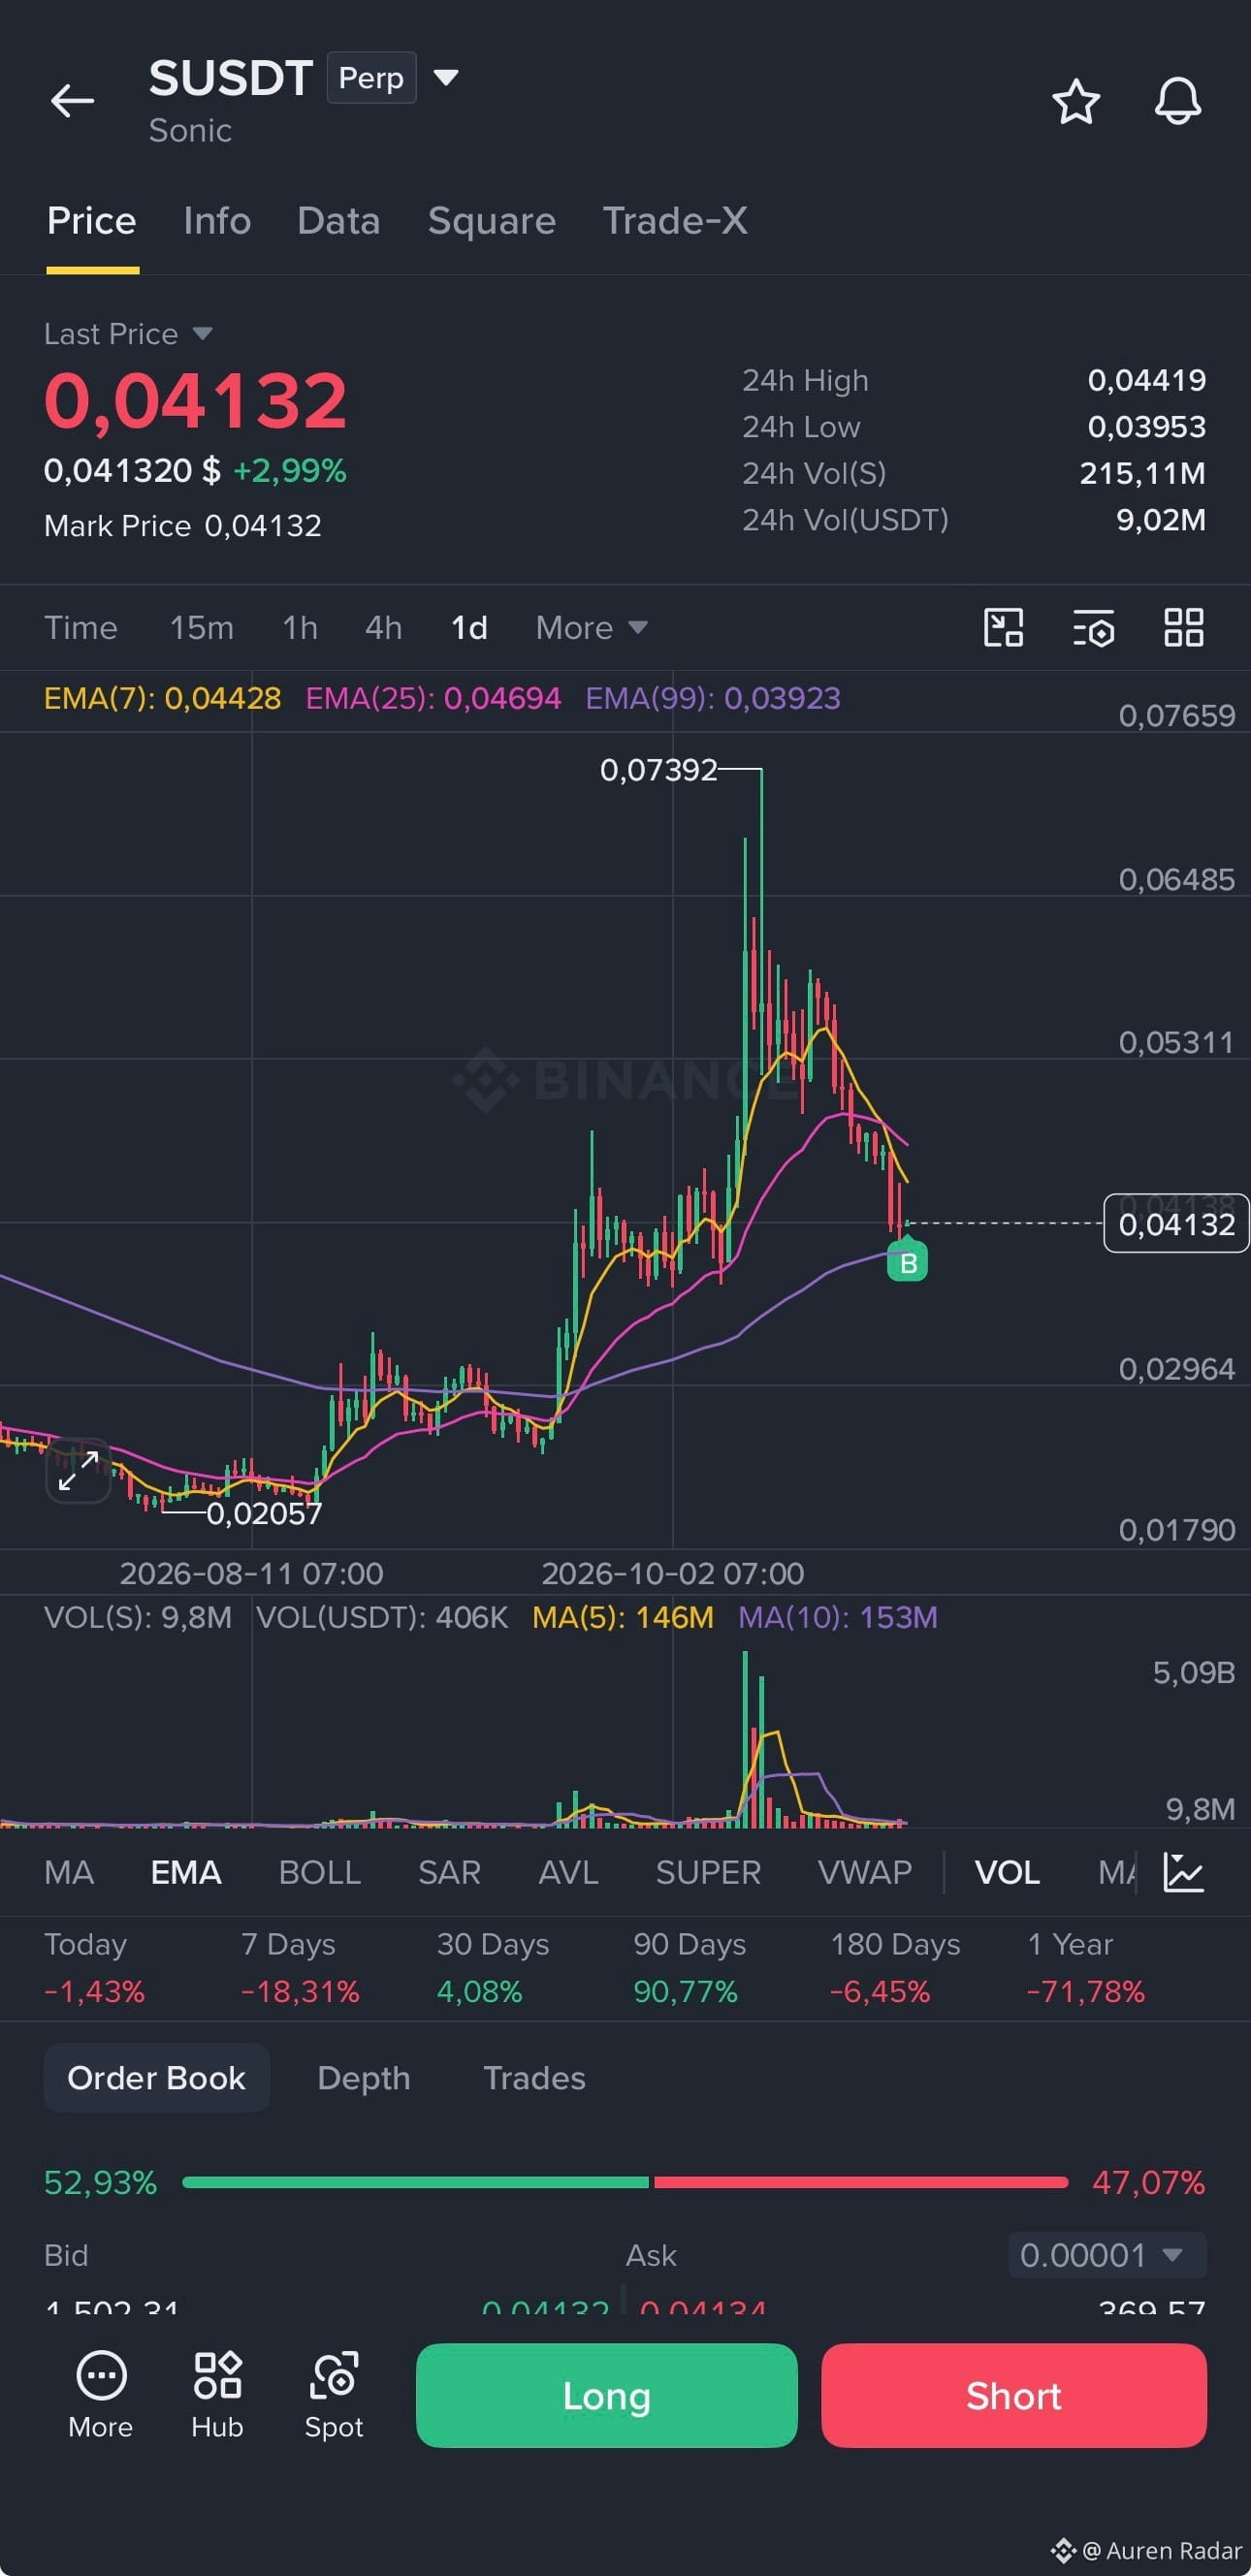
$S is back at strong support around $0.041 after a deep drop from its peak, with the market starting to recover.
Holding this zone could set up a strong recovery leg for $S along with the broader market.
✅ TP: 0.0435 / 0.0455 / 0.055 / 0.069
❌ STL: 0.0365
📌 Personal opinion, not financial advice. DYOR.
#S #Sonic #Layer1 #Altcoins
$SUSDT
1
454
See translation
⚡ $SUI ABSORBS THE SECTOR SHOCKWAVE WITH RELENTLESS BID STRENGTH! 📈
When broad sector shockwaves hit the tape, true relative strength reveals itself immediately. While panic sellers dumped across the market following yesterday's exchange security incident, $SUI absorbed the entire wave of liquidity sweeps like a sponge. 🌊
Institutional bids stepped in with conviction, aggressively defending key structure and triggering a clean reclaim. 📊 Order books show steady accumulation while sideline bears hesitate, caught off-guard by the velocity of this bounce.
This degree of price insulation often signals serious capital preparing to front-run the next expansion phase. 🤔 Are you buying into this relative strength or waiting for another market sweep? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SUI #Layer1 #RelativeStrength #Altcoins
🔥 💎
3
·
--
See translation
🧪 $ADA : Cardano's Slow-and-Steady Approach
ADA is famous for doing things differently: peer-reviewed research before shipping features.
What defines Cardano 👇
🔹 Proof-of-stake (Ouroboros) with a large staking community
🔹 Strong focus on governance by token holders
🔹 A loyal, long-term community
The debate:
Supporters call it careful engineering. Critics say it's too slow vs fast movers like $SOL and $SUI .
⚠️ What to watch: real DeFi activity and developer adoption.
💬 Is slow and careful a strength or a weakness in crypto? 👇
⚠️ Educational content only, not financial advice. DYOR.
#ADA #Cardano #Layer1 #BinanceSquare
1
130
·
--
See translation
💧 $SUI : The Layer-1 Built for Speed and Objects
SUI has become one of the most talked-about newer layer-1s. Here's why 👇
What makes it different:
🔹 Built with the Move programming language
🔹 An "object-based" model that allows parallel transactions
🔹 Fast finality, aimed at games, payments and DeFi
Comparison:
It's often compared to $APT (also Move-based) and $SOL (also built for speed).
⚠️ Risks to watch:
🔻 Token unlock schedules
🔻 Ecosystem activity vs hype
🔻 Competition from established chains
💬 SUI, APT or SOL — which fast chain wins? 👇
⚠️ Educational content only, not financial advice. DYOR.
#SUI #Layer1 #Move #BinanceSquare
146

·
--
See translation
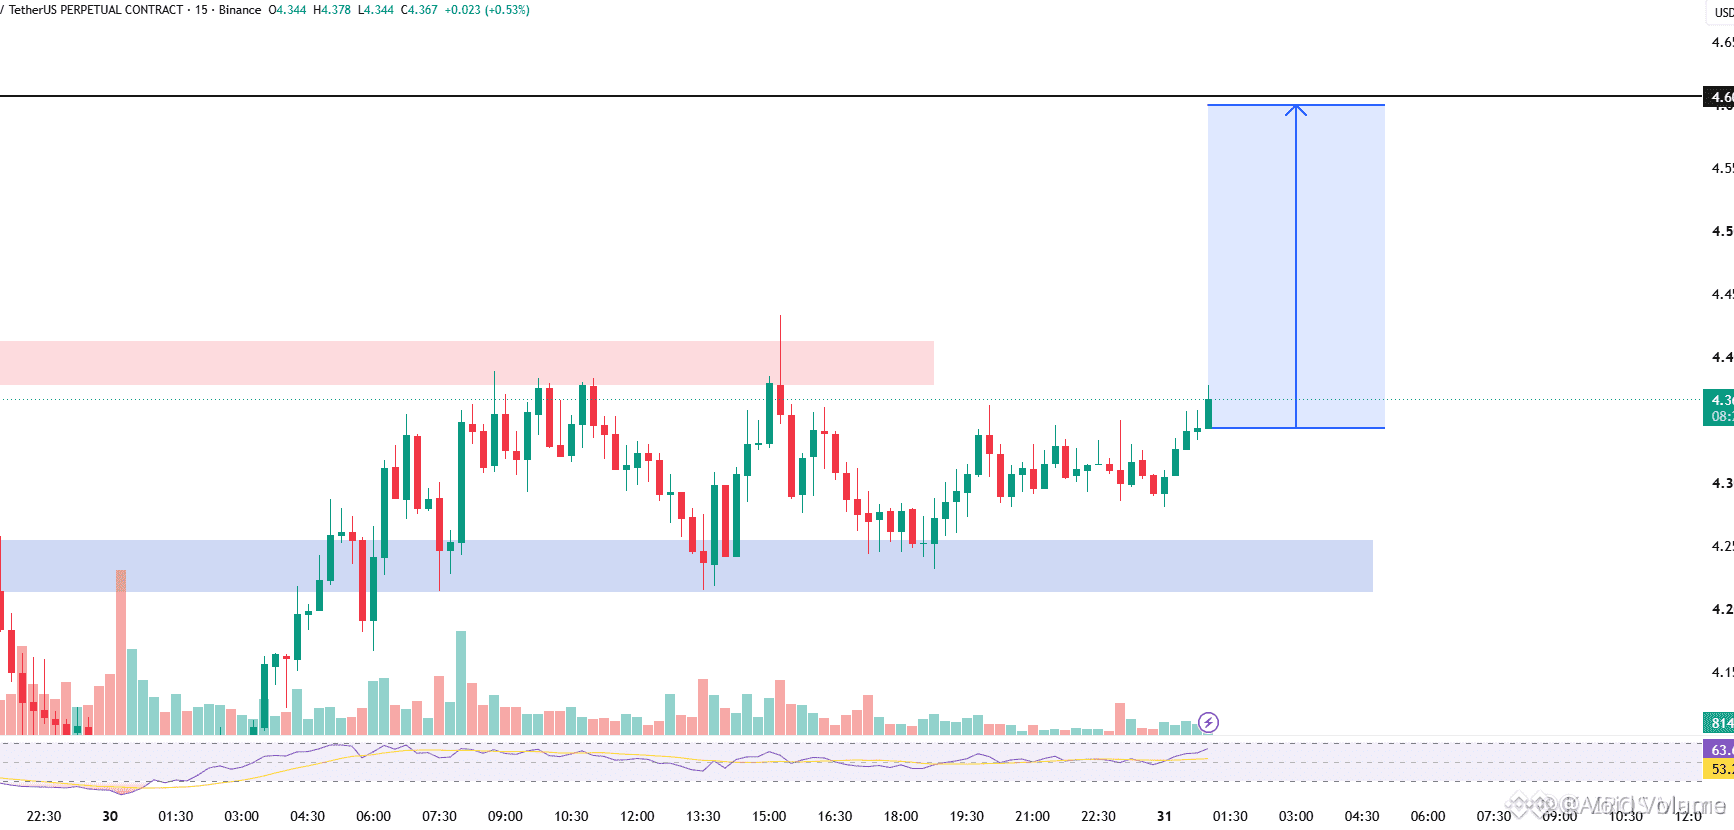
$NEAR SHAKES OUT SPECULATORS AS INSTITUTIONAL ACCUMULATION EYES RESISTANCE RECLAIM ⚡ 🦈
Target: 4.60 🎯
The recent wash-out across $NEAR effectively engineered sell-side liquidity, clearing late positions right into an institutional demand zone. 🌊 Order flow demonstrates aggressive absorption at the lows, with smart money defending the structural floor and driving price straight into overhead supply.
📌 Chasing momentum into major resistance offers poor risk asymmetry, while a clean structural close opens an efficient path toward liquidity resting above. 📊 As order books tighten near this inflection point, the priority remains disciplined execution over premature entries.
🤔 Are you anticipating a clean breakout retest here, or waiting for another liquidity sweep below the range?
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #NEAR #MarketStructure #CryptoTrading #Layer1
🎯 🦈
12
·
--
See translation
🅰️ $APT : Aptos and the Legacy of Meta's Blockchain Project
APT was built by a team that came from Meta's Diem blockchain project. When Diem ended, the technology lived on.
What Aptos focuses on 👇
🔹 Move language for safer smart contracts
🔹 Parallel execution for high throughput
🔹 Partnerships with traditional finance and big brands
Comparison: often grouped with $SUI , its Move-based sibling, and competing with $SOL for speed-focused users.
⚠️ Keep an eye on:
🔻 Token unlocks
🔻 Real user activity vs announcements
💬 Do big-company partnerships matter in crypto, or only users? 👇
⚠️ Educational content only, not financial advice. DYOR.
#APT #Aptos #Layer1 #BinanceSquare
224
·
--
See translation
🔗 $DOT : Is Polkadot Ready for a Comeback?
DOT is back on the most-searched lists. Polkadot was one of the hottest projects of the last cycle — so what now?
The idea behind Polkadot 👇
A network of connected chains that share security, allowing different blockchains to communicate.
What to watch:
✅ Real activity on its connected chains
✅ Upgrades that simplify the network
✅ How DOT performs vs other older layer-1s like $ADA and $AVAX
⚠️ Reality:
Being an "old favorite" doesn't guarantee a comeback. Old leaders don't always lead again.
💬 Polkadot: comeback candidate or past cycle story? 👇
⚠️ Educational content only, not financial advice. DYOR.
#DOT #Polkadot #Layer1 #BinanceSquare
217
See translation
Several layer-1 networks are competing for developer activity and user adoption.
$HBAR — Hedera's enterprise-focused network model remains a key part of its market narrative.
$SUI — Sui's ecosystem growth and network activity are important signals for traders.
$APT — Aptos continues to develop its ecosystem, with adoption and liquidity worth monitoring.
#HBAR #SUI #APT #Layer1 #CryptoMarket
11
See translation
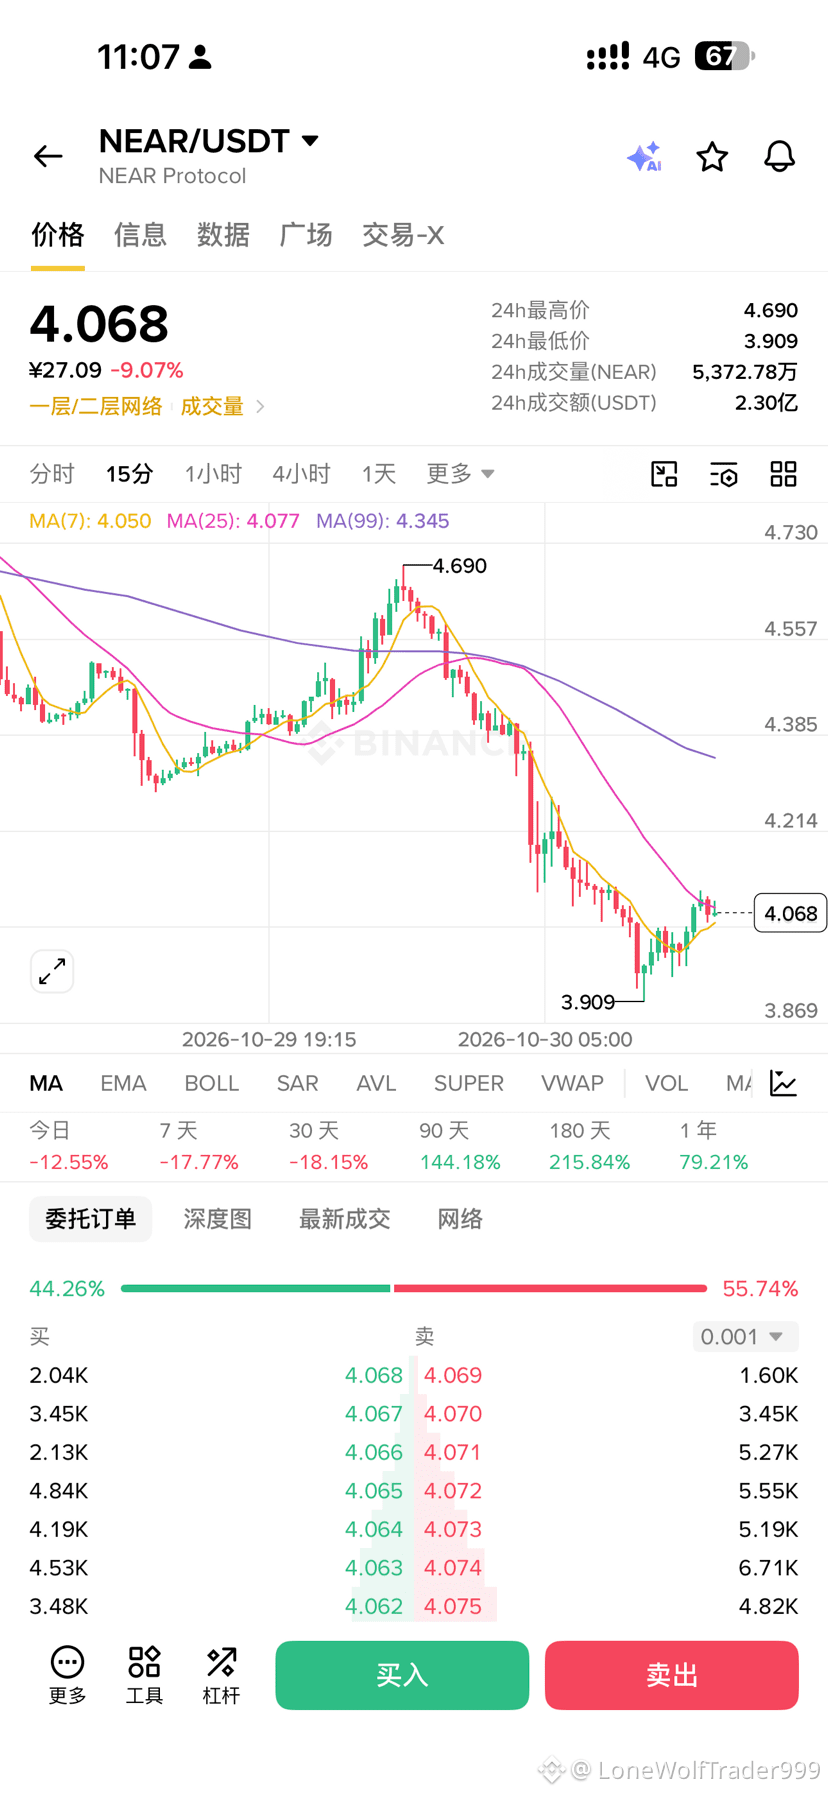
⚡ $NEAR CATALYSTS STACK UP WHILE PRICE DIGESTS TOWARD KEY ACCUMULATION 🎯
Entry: 3.8 ⚡
💡 Next week brings a stacked slate of ecosystem rollouts powered by NEAR Intents, covering equity perps, privacy protocols, and meme markets. Yet the order book tells a cautious story, with price moving sideways to digest earlier aggressive expansions.
📊 Chasing green candles into overhead resistance makes little sense when liquidity favors a cleaner reset. Patient money is watching for bids to fill around 3.8 where structural demand can absorb the chop. 💬 Are you front-running this ecosystem catalyst now, or waiting for 3.8 to trigger your bid? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #NEAR #Altcoins #Layer1 #CryptoTrading
🎯 🦈
7
·
--
See translation
Sui just lost 30% while Samsung, Brazil and $500M in Bitcoin capital are all moving onto it.
Who's wrong? 👀
Samsung Wallet is bringing USDC on Sui to 82M phones. Mercado Bitcoin just opened Sui to 4.5M clients. Hashi is coming with $500M+ committed.
The price still fell to 0.8934. The reason is leverage: about $1.37B in perp open interest, nearly a third of its market cap.
When longs get flushed, good news doesn't matter.
0.8277 is the line. If it holds, I'm in above 0.96, targeting 1.11 then 1.29.
If it breaks, I'm out.
Are you buying the news or fearing the flush? 👇
#SUI #Layer1 #CryptoTrading $SUI
DYOR / NFA
198

·
--
See translation
Layer-1 Rotation Battle: Why Smart Money Is Watching $SUI, $APT, and$SEI Before the Weekend
Every Friday before the weekend session, liquidity rotates out of slow large-caps and into high-speed Layer-1 chains where retail scalpers love to trade volatility.
Looking at the 4H order books right now, here is how the top three Move/parallel chains stack up:
$SUI: Still the undisputed king of retail volume on dips. Every time it sweeps local 4H liquidity, buyers step in aggressively.
$APT (Aptos): Quietly building a tight consolidation base while funding rates stay neutral—textbook setup for a volatility expansion move.
$SEI: High-beta playground for futures traders. When SUI moves 5%,$SEI often follows with an 8–12% impulse candle.
My Friday Rule: Avoid holding heavy leverage into late Friday night when market makers thin out the order books. Take your 4H scalp profits early.
If you are opening ONE Layer-1 trade today, which ticker are you clicking—$SUI, $APT, or$SEI? Drop your pick below! 👇🔥
#Layer1 #CryptoTrading #Altcoins #BinanceSquare
{spot}(SEIUSDT)
{spot}(APTUSDT)
{spot}(SUIUSDT)
Layer-1 Rotation Battle: Why Smart Money Is Watching $SUI, $APT , and$SEI Before the Weekend
Every Friday before the weekend session, liquidity rotates out of slow large-caps and into high-speed Layer-1 chains where retail scalpers love to trade volatility.
Looking at the 4H order books right now, here is how the top three Move/parallel chains stack up:
$SUI: Still the undisputed king of retail volume on dips. Every time it sweeps local 4H liquidity, buyers step in aggressively.
$APT (Aptos): Quietly building a tight consolidation base while funding rates stay neutral—textbook setup for a volatility expansion move.
$SEI : High-beta playground for futures traders. When SUI moves 5%,$SEI often follows with an 8–12% impulse candle.
My Friday Rule: Avoid holding heavy leverage into late Friday night when market makers thin out the order books. Take your 4H scalp profits early.
If you are opening ONE Layer-1 trade today, which ticker are you clicking—$SUI, $APT , or$SEI ? Drop your pick below! 👇🔥
#Layer1 #CryptoTrading #Altcoins #BinanceSquare
468
See translation
$PARTI MASSIVE EXPLOSION! +47% MEGA SURGE — OVER 40M VOL LAYER 1 / LAYER 2 GAINER HOLDING HIGHER-LOW BASE — RSI RESET AT 43.09 TARGETING A BREAKOUT PAST $0.0622 SAR RESISTANCE?
Binance Layer 1 / Layer 2 top gainers are dominating the morning market session! PARTI (Particle Network) has logged an explosive +47.30% daily surge, backed by an enormous 40.57M USDT (815.64M $PARTI) in 24-hour trading volume!
After rocketing off its 0.0313 daily bottom floor and recovering cleanly from its 0.0524 local swing support base, price action launched a vertical surge toward 0.0639 before testing a 24-hour peak high of 0.0659. Following a healthy cooling-off retrace, $PARTI is consolidating steadily near 0.0572 with a strong higher-low structure.
Master Scalp Setup & Strategic Levels:
Trade Bias: Strong Bullish Rebound / Scalp Long
Accumulation Entry Zone: 0.0546 – 0.0573 (Local demand support consolidation range)
Key Targets: 0.0603 ➡️ 0.0622 ➡️ 0.0659 (24h Peak Retest)
Stop Loss: Below 0.0518
Why This Setup is Primed for Expansion:
Clean RSI Neutral Reset: The 15m RSI (6) has cleanly reset from overbought levels down to a healthy 43.09. This cool-down offers buyers optimal upside breathing room for the next upward expansion leg.
Overhead SAR Breakout Trigger: Dynamic Parabolic SAR overhead resistance currently sits right above at 0.0622. A decisive 15m candle close above 0.0603 will flip momentum bullish and clear the pathway toward the SAR resistance at 0.0622 and a full retest of the 0.0659 peak high.
Are you taking a long entry on PARTI at this $0.0546–$0.0573 support consolidation base, or waiting for a breakout close above $0.0603? Share your strategy in the comments below!
Trade Now $PARTI
{spot}(PARTIUSDT)
#PARTI #ParticleNetwork #FedWatch
#Layer1
$PARTI MASSIVE EXPLOSION! +47% MEGA SURGE — OVER 40M VOL LAYER 1 / LAYER 2 GAINER HOLDING HIGHER-LOW BASE — RSI RESET AT 43.09 TARGETING A BREAKOUT PAST $0.0622 SAR RESISTANCE?
Binance Layer 1 / Layer 2 top gainers are dominating the morning market session! PARTI (Particle Network) has logged an explosive +47.30% daily surge, backed by an enormous 40.57M USDT (815.64M $PARTI ) in 24-hour trading volume!
After rocketing off its 0.0313 daily bottom floor and recovering cleanly from its 0.0524 local swing support base, price action launched a vertical surge toward 0.0639 before testing a 24-hour peak high of 0.0659. Following a healthy cooling-off retrace, $PARTI is consolidating steadily near 0.0572 with a strong higher-low structure.
Master Scalp Setup & Strategic Levels:
Trade Bias: Strong Bullish Rebound / Scalp Long
Accumulation Entry Zone: 0.0546 – 0.0573 (Local demand support consolidation range)
Key Targets: 0.0603 ➡️ 0.0622 ➡️ 0.0659 (24h Peak Retest)
Stop Loss: Below 0.0518
Why This Setup is Primed for Expansion:
Clean RSI Neutral Reset: The 15m RSI (6) has cleanly reset from overbought levels down to a healthy 43.09. This cool-down offers buyers optimal upside breathing room for the next upward expansion leg.
Overhead SAR Breakout Trigger: Dynamic Parabolic SAR overhead resistance currently sits right above at 0.0622. A decisive 15m candle close above 0.0603 will flip momentum bullish and clear the pathway toward the SAR resistance at 0.0622 and a full retest of the 0.0659 peak high.
Are you taking a long entry on PARTI at this $0.0546–$0.0573 support consolidation base, or waiting for a breakout close above $0.0603? Share your strategy in the comments below!
Trade Now $PARTI
#PARTI #ParticleNetwork #FedWatch
#Layer1
1
88
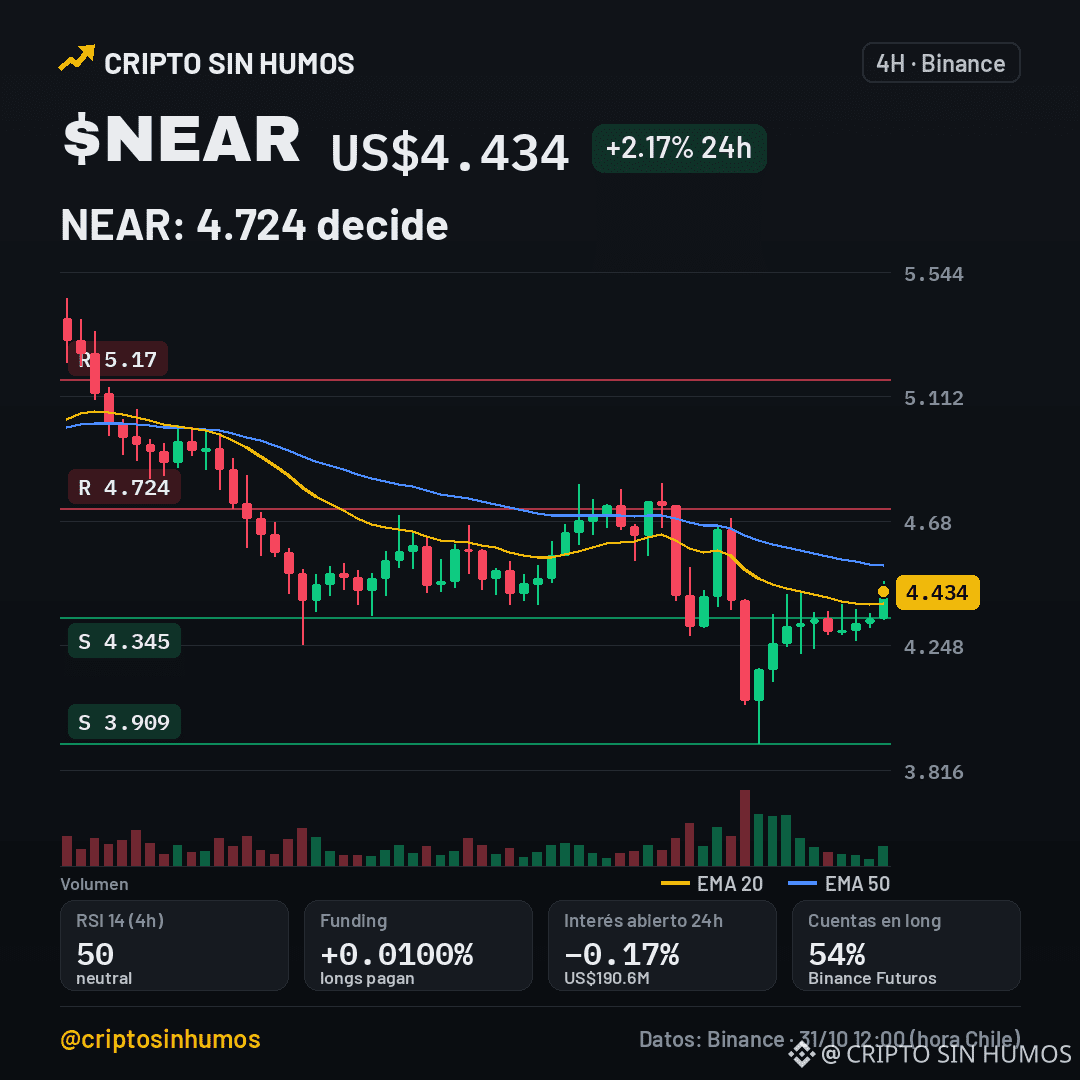
$NEAR a US$4.434: Does it break 4.724 or retreat to 4.345?
$NEAR is trading at US$4.434, up 2.17% in 24h, within the 4.239‑4.469 range. The EMAs are at 4.395 (20) and 4.527 (50), and the RSI at 50.3 indicates neutrality.
The price is respecting support at 4.345 and resistance at 4.724. If it retests 4.345, the next floor is 3.909; if it rises above 4.724, the next ceiling is 5.17.
On Binance Futures, funding is at +0.0100% and open interest fell 0.2%, with 54% of accounts long. Meanwhile, $PEPE is down 3.3% and $ZEC is up 3.0% in 24h, with volumes of 74 M and 105 M, respectively.
My take: the market is moving sideways, so I wouldn’t jump in now; a clear breakout to the upside would make me enter, but a break below 4.345 would signal weakness. On the downside, a drop below 4.345 would invalidate any bullish rebound.
Will it break 4.724 or return to 4.345? 🟢/🔴
#NEAR #Layer1 #FuturosBinance
This is not financial advice. Do your own research before investing.
159

·
--
Monad launched 11 months ago: $889 million on-chain, but the token has fallen below its $0.025 sale price
From November 17 to 22 last year, Monad sold 7.5 billion MON on Coinbase for $0.025 per token, raising about $269 million in total, with 85,800 participants. Two days later, the mainnet and token launched together, and the price briefly climbed to around $0.048—roughly 90% above the sale price. The excitement at the time was easy to understand: a new chain claiming to make Ethereum run faster, combined with the first project on Coinbase’s new token sale platform, was bound to attract plenty of attention.
So what exactly is Monad? It’s an Ethereum Virtual Machine-compatible Layer 1, meaning applications and tools on Ethereum can be moved over without changing their code. The difference is in how transactions are processed. Ethereum executes transactions one by one, while Monad assumes that most transactions won’t interfere with each other and runs them in parallel. It then checks for conflicts; any transaction that clashes is rerun with the correct data. The final result is the same as if transactions had been executed sequentially. Block times are about 0.4 seconds, and around 10,000 transactions per second is a design target, not a measured result. The aim is to support high-frequency trading and high-traffic applications. Its consensus mechanism is called MonadBFT, which advances in a pipelined fashion. The state layer has its own system, MonadDB, designed specifically to address data read and write bottlenecks under heavy concurrency.
Eleven months after launch, here’s what the on-chain ledger looks like. According to DefiLlama data from October 31, Monad had $889.04 million in DeFi TVL, $632.74 million in on-chain stablecoin market capitalization, $28.45 million in decentralized exchange volume over the past 24 hours, $12.71 million in perpetuals volume, 5.85 million transactions in 24 hours, and 10,710 active addresses. TVL and transaction counts show that the chain isn’t just spinning its wheels—people are genuinely putting money and transactions on it. Compare that with Nansen’s figures from the first day after launch: more than 3 million transactions, 140,000 addresses, and over 18,000 contracts. But be careful about the metrics: the 140,000 figure from the early days was cumulative addresses, while the 10,710 figure for October 31 is daily active addresses. The two numbers can’t be directly compared to measure growth or decline. Spread across just over 10,000 active addresses, 5.85 million transactions in a day works out to more than 500 per address on average. Activity is heavily concentrated among a small number of high-frequency addresses; ordinary users aren’t making anywhere near that many transactions.
But there’s a striking contrast in the same table. Over the past 24 hours, the chain itself collected just $11,224 in fees, while applications on the chain collected $254,725—more than 20 times as much. The chain gets plenty of use but collects little. That’s where Monad stands right now. Low fees are good for users, but token holders need to look at the other side of the equation: fees are not yet a major source of value for MON. At a little over $10,000 a day, that comes to just over $4 million a year. Compared with $889 million in TVL, that’s a very thin margin.
Now let’s look at the token ledger. MON has a total supply of 100 billion tokens, with about 10.8 billion in circulation at launch, including 7.5 billion sold publicly and 3.3 billion airdropped. Circulating supply is now about 11.8 billion, which also checks out when calculated from DefiLlama’s October 31 market cap of $226.64 million and the current price of $0.019. The team holds 27%, investors 19.7%, and the treasury and other allocations about 4%; roughly half the supply is still locked up, with all of it scheduled to be released by the fourth quarter of 2029. At $0.019, the current price is about 24% below the $0.025 sale price. The gains made by those who bought at the launch spike have long since evaporated, and anyone still holding tokens bought at the sale price is sitting on a paper loss.
For retail investors, there are really three takeaways here. First, TVL and transaction counts are worth watching, but don’t focus only on those two figures. How much a chain collects in fees each day is a better indicator of whether the token has a source of value. Second, applications making money doesn’t mean the token is making money. Application fees and chain fees are two separate ledgers, so be clear about where the money is going. Third, circulating supply is still gradually increasing, with new supply coming until 2029. Whenever the price rises, there may be newly unlocked tokens waiting to be sold.
My view is that Monad’s technical story makes sense, and its on-chain ledger doesn’t look bad, but the token’s ledger still doesn’t add up. At $0.019, three things are true at once: the price is below the sale price, unlocks are still ongoing, and fees remain very thin. It’s too early to rush to a conclusion, whether bullish or bearish.
When you look at a new chain, do you check its TVL first, or how much it collects in fees each day?
#Monad #并行EVM #Layer1 #项目拆解 $MON
—— web3 Leek Xiao Kai
The views expressed above are personal opinions only and do not constitute investment advice.
88
·
--
See translation
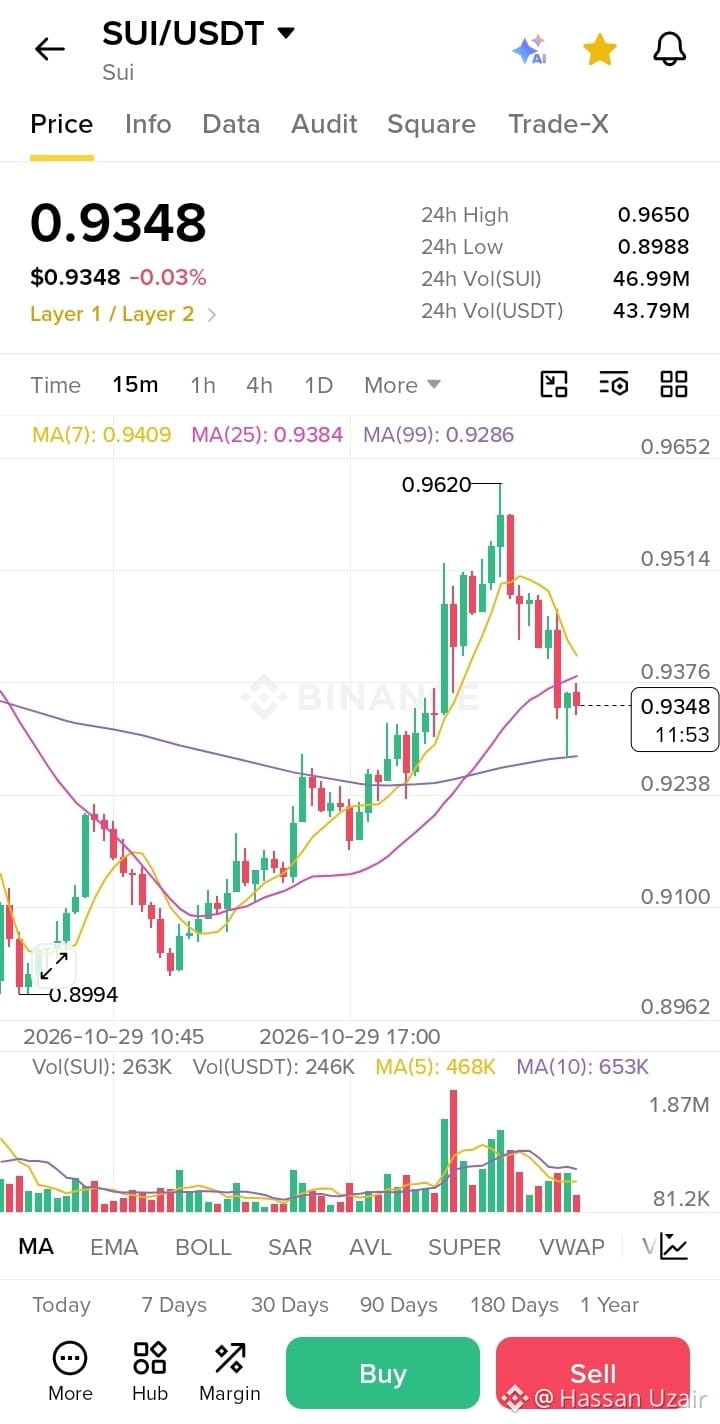
🚀 $SUI / USDT 15m Chart Update: Healthy Pullback & Rebound Setup! 🔥
According to the latest 15m chart, $SUI is consolidating around $0.9348 (-0.03%) after testing a 24h high of $0.9650 and dipping to a low of $0.8988.
💡 Key Technical Highlights:
🔹 Current Price: $0.9348
🔹 24h Range: $0.8988 - $0.9650
🔹 Moving Averages: Price is holding steady near MA(7) ($0.9409), MA(25) ($0.9384), and staying well above MA(99) ($0.9286), showing solid short-term support.
🔹 Market Outlook: After a sharp rally toward $0.9620, the price is undergoing a controlled retest. If momentum picks up, we could see another push to break past the upper resistance level.
Kya aap is dip par accumulation kar rahe hain ya breakout ka intezar? Apni strategy zaroor share karein! 👇
#SUI #SUIUSDT #CryptoTrading #BinanceSquare #TechnicalAnalysis #Layer1 #Altcoins
1
113
·
--
New All-Time High: Miner Numbers Reach Their Peak! ⛏️🔥
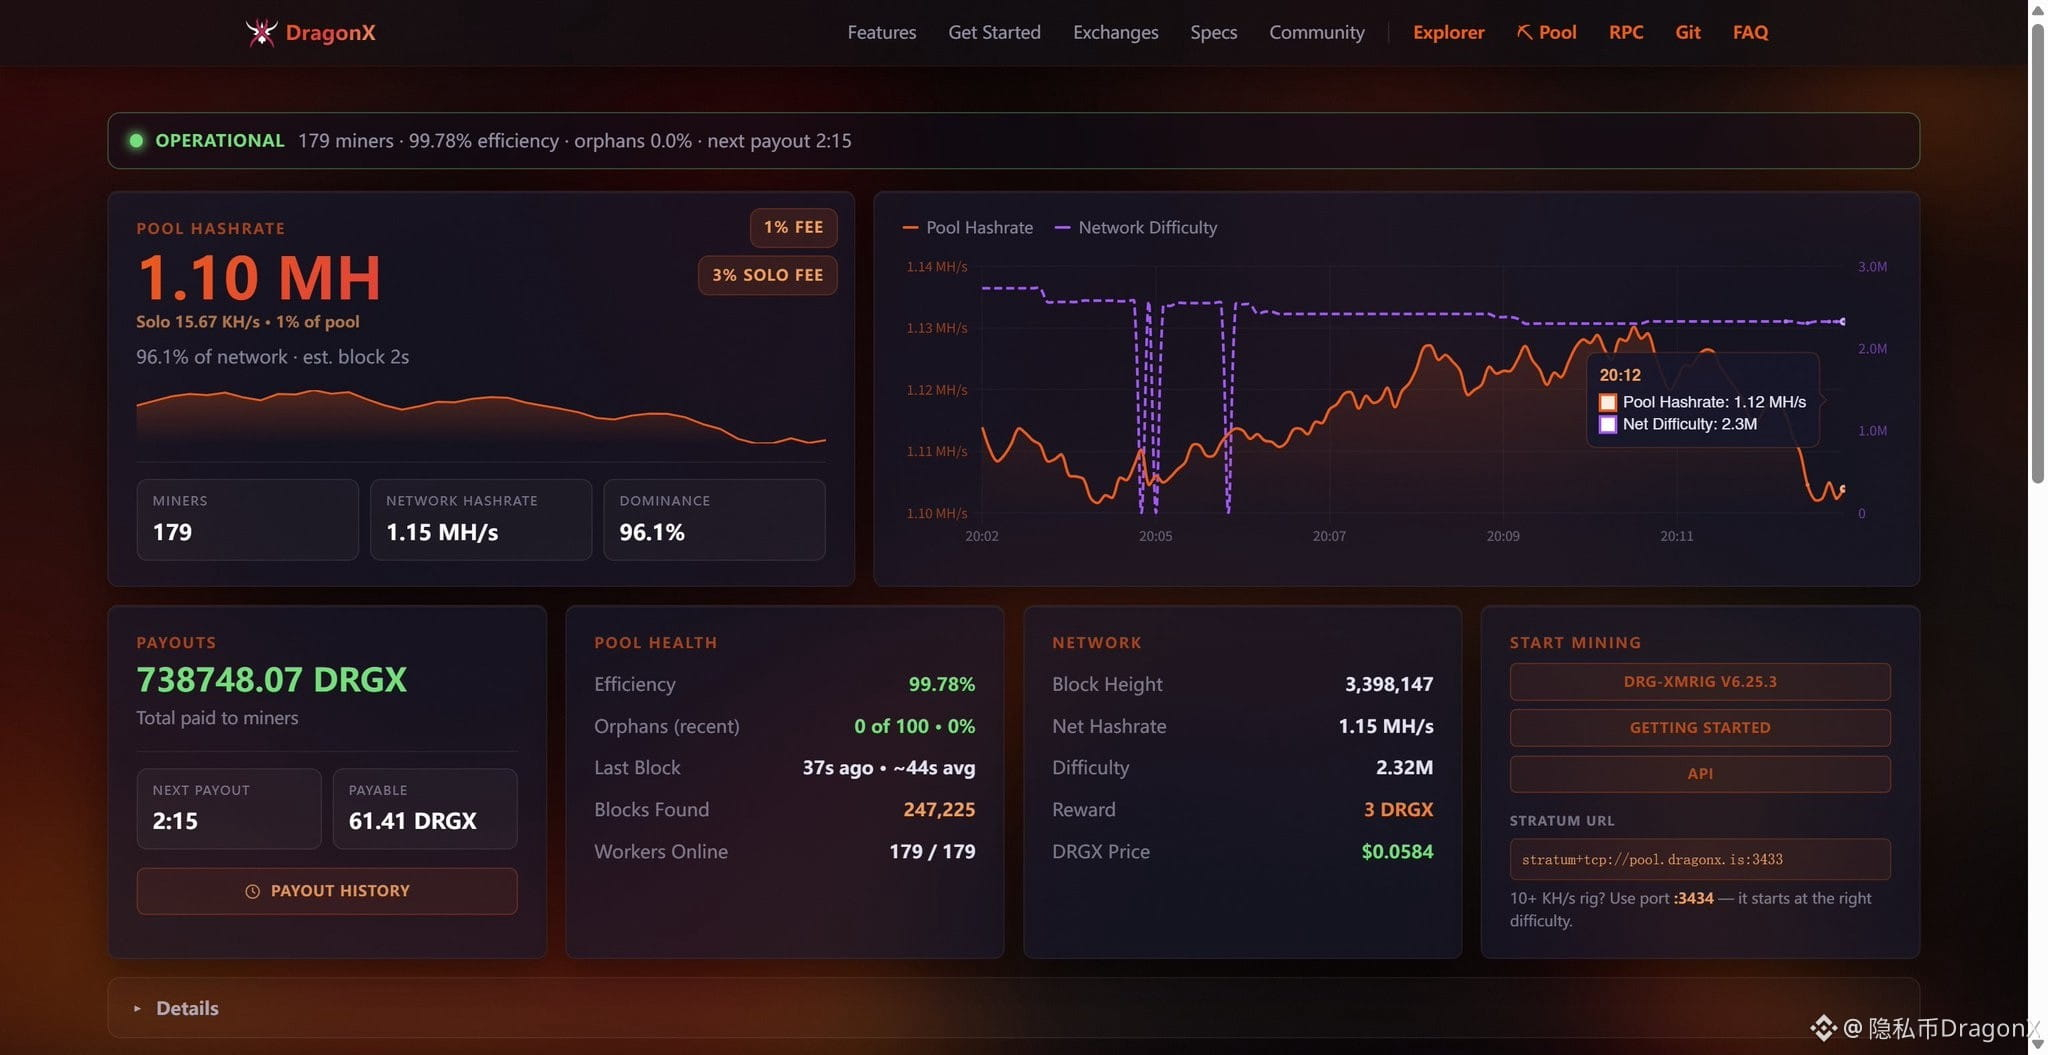
The DragonX ($DRGX) mining network is stronger than ever!
Active miners have officially reached a new record high, demonstrating the power of truly decentralized hashrate.
📊 Latest network metrics:
👷 Active miners: 179 (New ATH!)
⏱️ Block time: ~36 seconds (超-fast blocks!)
⚙️ Pool hashrate: 1.10 MH/s (peak ~1.12 MH/s)
🌐 Network hashrate: 1.15 MH/s
👑 Dominance: 96.1%
⚡ Efficiency: 99.78% (0% orphan blocks)
Freedom isn't given; it's computed. Join 179+ miners worldwide and point your CPU hashrate toward truly censorship-resistant L1 privacy. 🛡️ Dual modes available: PPLNS (steady rewards) or SOLO (block hunting).
🔗 Start mining now: pool.dragonx.is
#Layer1 #zec #BTC #XMR #DASH
69
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceSAFUFundTransferCompleted7499BTC
159 views
47 Discussing
2
#BinanceRecovery90% of stolen assets
24,916 views
80 Discussing
3
#YiHe:ProofOfReserves:10TokensAt100%Backing
63,688 views
276 Discussing
4
#BackedNotBroken:RichardTengSaysUsersBearNoLoss
3,553 views
141 Discussing
5
#CZSaysCompensationIsinPlaceUsersAreProtected
72,677 views
970 Discussing
6
#IntelHasItsWorstDaySince1974
19,272 views
428 Discussing
7
#TRMCambodianCasinosReceived$1.07BInCrypto
4,531 views
57 Discussing
8
#USDCCirculationFallsAbout800MInSevenDays
40,019 views
577 Discussing
9
#SuspectedNorthKoreaAttacksAccountForNearly89%OfCryptoHackLosses
10,564 views
80 Discussing
10
#OpenAICutsFundraisingTargetBy$10B
2,491 views
65 Discussing