bondmarket

100,455 views
404 Discussing
CryptoWithGanesh
·
--
Article
Bond market ka bahut important concept hai. Simple line meBond market ka bahut important concept hai. Simple line me: Jitna bond ka maturity period lamba hota hai, utne zyada saal tak uske fixed coupon payments aur principal repayment purane interest rate par locked rehte hain. Jab market interest rates badalte hain, un future fixed cash flows ki aaj ki value zyada badalti hai. Isi ko interest-rate sensitivity kehte hain. Pehle basic mechanism samjho Bond kharidte waqt aapko do tarah ke cash flows milte hain: Coupon/interest payment — jaise har saal ₹50 Face value/principal — maturity par, jaise ₹1,000 wapas Agar market interest rate badh jaaye, naye bonds higher coupon dene lagte hain. Aapka purana low-coupon bond comparatively kam attractive ho jata hai, isliye uski market price girti hai. Agar market interest rate gire, naye bonds kam coupon dene lagte hain. Aapka purana high-coupon bond attractive ho jata hai, isliye uski market price badhti hai. So: Interest rates ↑ → Bond prices ↓ Interest rates ↓ → Bond prices ↑ Long-term bond zyada sensitive kyun? Cash flows bahut door future me milte hain Long-term bond me principal aur kai coupon payments bahut baad milte hain—10, 20, ya 30 saal baad. Future me milne wale paise ki aaj ki value discounting se nikalti hai: \[ PV = \frac{Future\ Cash\ Flow}{(1+r)^n} \] Yahan: r = market interest rate / yield n = kitne saal baad payment milega Jab n bada hota hai, r me chhota sa change bhi denominator par bada effect daalta hai. Isliye bond price me larger movement hota hai. Intuition Aaj se 1 saal baad milne wale ₹1,000 ki value rate change se thodi badlegi. Lekin 30 saal baad milne wale ₹1,000 ki present value rate change ke saath kaafi badal sakti hai, kyunki change 30 saal tak compounding/discounting me apply hota hai. Ek simple example Maan lo do zero-coupon bonds hain—dono maturity par ₹1,000 denge: Bond A: 1 saal baad ₹1,000 Bond B: 10 saal baad ₹1,000 Agar market rate 5% ho: \[ Price = \frac{1000}{(1.05)^n} \] 1-year bond ki value lagbhag ₹952.38 10-year bond ki value lagbhag ₹613.91 Agar rate 6% ho jaaye: 1-year bond ki value lagbhag ₹943.40 10-year bond ki value lagbhag ₹558.39 Matlab rate me sirf 1% badhotri par: 1-year bond ki price around 0.94% giri 10-year bond ki price around 9.04% giri Yehi core reason hai: distant future cash flow ki present value rate change ke liye far more sensitive hoti hai. Long-term bond ka “problem” kya hota hai? Long-term bond holder ne apna coupon rate zyada samay ke liye lock kar liya hota hai. Maan lo aapke paas 20-year bond hai jo 5% coupon de raha hai. Kuch time baad market rates 7% ho gaye. Ab investor ke paas choice hai: aapka old bond: 5% coupon naya bond: 7% coupon Koi investor old 5% bond ko face value par kyun lega, jab naya 7% mil raha hai? Old bond tabhi bikega jab uski price neeche aaye, taaki lower coupon ke bawajood buyer ko market ke aas-paas return mil sake. Aur kyunki 5% vs 7% ka gap agle kai saalon tak effect karega, long-term bond ki price ko zyada adjust hona padta hai. Short-term bond me investor ko jaldi principal wapas mil jayega aur woh usse new, higher-rate bond me reinvest kar sakega. Isliye uska loss comparatively limited hota hai. Short-term bond kam sensitive kyun hota hai? Short-term bond ki maturity jaldi hoti hai—maan lo 1–2 saal me. Rate badhne par bhi: uska principal jaldi wapas aa jayega; investor jaldi new higher-interest-rate environment me reinvest kar sakta hai; purane low coupon ka disadvantage sirf kuch samay ke liye hota hai. Isliye uski price me zyada adjustment ki zarurat nahi padti. Short-term bond = “jaldi reset/reinvest karne ka option.” Long-term bond = “purane coupon rate me lamba lock-in.” Duration: sensitivity measure karne ka technical tool Bond ki interest-rate sensitivity ko measure karne ke liye duration use hota hai. Rough rule: \[ \%\ Price\ Change \approx - Duration \times Yield\ Change \] Example: Bond duration = 2 Yield change = +1% To approximate price change: \[ -2 \times 1\% = -2\% \] Aur agar: Bond duration = 10 Yield change = +1% To approximate price change: \[ -10 \times 1\% = -10\% \] Isliye long maturity bonds generally high-duration hote hain aur rate movement par unki prices zyada fluctuate karti hain. Ye approximation hai; actual price movement convexity ki wajah se thoda alag ho sakta hai. Coupon bhi matter karta hai—sirf maturity nahi Ek important nuance: same maturity ke do bonds me lower-coupon bond generally zyada sensitive hota hai. Kyun? Kyuki low-coupon bond me aapko kam cash jaldi milta hai aur value ka bada hissa maturity ke end me milta hai. Cash flows aur door shift ho jaate hain. Isliye: Long maturity + low coupon = high interest-rate risk Short maturity + high coupon = comparatively low interest-rate risk Zero-coupon bond sabse extreme example hai: usme koi annual coupon nahi hota; pura paisa maturity par milta hai. Isliye uski duration lagbhag maturity ke barabar hoti hai. “Long-term bond hi kyun?” ka exact answer Long-term bond hi zyada sensitive isliye hota hai kyunki: Uske cash flows zyada door future me hote hain Future cash flow ko discount karte waqt interest-rate change ka effect zyada compound hota hai. Low coupon ka disadvantage lambi duration tak chalta hai Naye bonds high yield dene lagen to purana bond bahut saalon tak lower coupon deta rahega. Principal jaldi recover nahi hota Short-term bond holder jaldi maturity amount lekar new rate par reinvest kar sakta hai; long-term holder ko wait karna padta hai. Price ko market yield ke saath align hone ke liye zyada adjust karna hota hai Long period ke fixed payments ko current market return ke equivalent banane ke liye price me bada change chahiye. Ek daily-life analogy Socho do job contracts hain: Contract A: 1 saal ke liye fixed salary Contract B: 20 saal ke liye fixed salary Agar market me salaries suddenly bahut badh jaayein, kaunsa contract comparatively zyada unattractive lagega? 20-year fixed-salary contract, kyunki aap bahut lambi period tak low pay par locked ho. Bond me bhi same idea hai: coupon = fixed salary maturity = contract duration market yield = market salary level bond price = contract ko kisi aur ko transfer karne ki value Ek line me final clarity Interest rate change ka impact jitne zyada saalon ke cash flows par padega, bond price utni zyada move karegi. Long-term bonds me ye impact many years tak chalta hai; short-term bonds me jaldi khatam ho jata hai. {future}(TMFUSDT) #Agar meri jankari apko acchi lagi to ise like jada logo ke sath share karo kyuki jankari hi satarkta ki chhavi he Bina jankari ke aap na satark re payenge na sahi fesla le payenge Apko kis vishay par jankari chahiye muje comment likho or saval ya confusion he kis vishay ko leke market outlook or financial discipline ko lekar muje batao me apki madat karunga #BondMarkets #bondmarket ,#crypto ,#Intrestrate Mere sath jude rahne ke liye muje follow karo follow@GaneshCrypto

Bond market ka bahut important concept hai. Simple line me

Bond market ka bahut important concept hai. Simple line me:
Jitna bond ka maturity period lamba hota hai, utne zyada saal tak uske fixed coupon payments aur principal repayment purane interest rate par locked rehte hain. Jab market interest rates badalte hain, un future fixed cash flows ki aaj ki value zyada badalti hai. Isi ko interest-rate sensitivity kehte hain.
Pehle basic mechanism samjho
Bond kharidte waqt aapko do tarah ke cash flows milte hain:
Coupon/interest payment — jaise har saal ₹50
Face value/principal — maturity par, jaise ₹1,000 wapas
Agar market interest rate badh jaaye, naye bonds higher coupon dene lagte hain. Aapka purana low-coupon bond comparatively kam attractive ho jata hai, isliye uski market price girti hai.
Agar market interest rate gire, naye bonds kam coupon dene lagte hain. Aapka purana high-coupon bond attractive ho jata hai, isliye uski market price badhti hai.
So:
Interest rates ↑ → Bond prices ↓
Interest rates ↓ → Bond prices ↑
Long-term bond zyada sensitive kyun?
Cash flows bahut door future me milte hain
Long-term bond me principal aur kai coupon payments bahut baad milte hain—10, 20, ya 30 saal baad.
Future me milne wale paise ki aaj ki value discounting se nikalti hai:
\[
PV = \frac{Future\ Cash\ Flow}{(1+r)^n}
\]
Yahan:
r = market interest rate / yield
n = kitne saal baad payment milega
Jab n bada hota hai, r me chhota sa change bhi denominator par bada effect daalta hai. Isliye bond price me larger movement hota hai.
Intuition
Aaj se 1 saal baad milne wale ₹1,000 ki value rate change se thodi badlegi.
Lekin 30 saal baad milne wale ₹1,000 ki present value rate change ke saath kaafi badal sakti hai, kyunki change 30 saal tak compounding/discounting me apply hota hai.
Ek simple example
Maan lo do zero-coupon bonds hain—dono maturity par ₹1,000 denge:
Bond A: 1 saal baad ₹1,000
Bond B: 10 saal baad ₹1,000
Agar market rate 5% ho:
\[
Price = \frac{1000}{(1.05)^n}
\]
1-year bond ki value lagbhag ₹952.38
10-year bond ki value lagbhag ₹613.91
Agar rate 6% ho jaaye:
1-year bond ki value lagbhag ₹943.40
10-year bond ki value lagbhag ₹558.39
Matlab rate me sirf 1% badhotri par:
1-year bond ki price around 0.94% giri
10-year bond ki price around 9.04% giri
Yehi core reason hai: distant future cash flow ki present value rate change ke liye far more sensitive hoti hai.
Long-term bond ka “problem” kya hota hai?
Long-term bond holder ne apna coupon rate zyada samay ke liye lock kar liya hota hai.
Maan lo aapke paas 20-year bond hai jo 5% coupon de raha hai. Kuch time baad market rates 7% ho gaye.
Ab investor ke paas choice hai:
aapka old bond: 5% coupon
naya bond: 7% coupon
Koi investor old 5% bond ko face value par kyun lega, jab naya 7% mil raha hai?
Old bond tabhi bikega jab uski price neeche aaye, taaki lower coupon ke bawajood buyer ko market ke aas-paas return mil sake.
Aur kyunki 5% vs 7% ka gap agle kai saalon tak effect karega, long-term bond ki price ko zyada adjust hona padta hai.
Short-term bond me investor ko jaldi principal wapas mil jayega aur woh usse new, higher-rate bond me reinvest kar sakega. Isliye uska loss comparatively limited hota hai.
Short-term bond kam sensitive kyun hota hai?
Short-term bond ki maturity jaldi hoti hai—maan lo 1–2 saal me.
Rate badhne par bhi:
uska principal jaldi wapas aa jayega;
investor jaldi new higher-interest-rate environment me reinvest kar sakta hai;
purane low coupon ka disadvantage sirf kuch samay ke liye hota hai.
Isliye uski price me zyada adjustment ki zarurat nahi padti.
Short-term bond = “jaldi reset/reinvest karne ka option.”
Long-term bond = “purane coupon rate me lamba lock-in.”
Duration: sensitivity measure karne ka technical tool
Bond ki interest-rate sensitivity ko measure karne ke liye duration use hota hai.
Rough rule:
\[
\%\ Price\ Change \approx - Duration \times Yield\ Change
\]
Example:
Bond duration = 2
Yield change = +1%
To approximate price change:
\[
-2 \times 1\% = -2\%
\]
Aur agar:
Bond duration = 10
Yield change = +1%
To approximate price change:
\[
-10 \times 1\% = -10\%
\]
Isliye long maturity bonds generally high-duration hote hain aur rate movement par unki prices zyada fluctuate karti hain.
Ye approximation hai; actual price movement convexity ki wajah se thoda alag ho sakta hai.
Coupon bhi matter karta hai—sirf maturity nahi
Ek important nuance: same maturity ke do bonds me lower-coupon bond generally zyada sensitive hota hai.
Kyun?
Kyuki low-coupon bond me aapko kam cash jaldi milta hai aur value ka bada hissa maturity ke end me milta hai. Cash flows aur door shift ho jaate hain.
Isliye:
Long maturity + low coupon = high interest-rate risk
Short maturity + high coupon = comparatively low interest-rate risk
Zero-coupon bond sabse extreme example hai: usme koi annual coupon nahi hota; pura paisa maturity par milta hai. Isliye uski duration lagbhag maturity ke barabar hoti hai.
“Long-term bond hi kyun?” ka exact answer
Long-term bond hi zyada sensitive isliye hota hai kyunki:
Uske cash flows zyada door future me hote hain
Future cash flow ko discount karte waqt interest-rate change ka effect zyada compound hota hai.
Low coupon ka disadvantage lambi duration tak chalta hai
Naye bonds high yield dene lagen to purana bond bahut saalon tak lower coupon deta rahega.
Principal jaldi recover nahi hota
Short-term bond holder jaldi maturity amount lekar new rate par reinvest kar sakta hai; long-term holder ko wait karna padta hai.
Price ko market yield ke saath align hone ke liye zyada adjust karna hota hai
Long period ke fixed payments ko current market return ke equivalent banane ke liye price me bada change chahiye.
Ek daily-life analogy
Socho do job contracts hain:
Contract A: 1 saal ke liye fixed salary
Contract B: 20 saal ke liye fixed salary
Agar market me salaries suddenly bahut badh jaayein, kaunsa contract comparatively zyada unattractive lagega?
20-year fixed-salary contract, kyunki aap bahut lambi period tak low pay par locked ho.
Bond me bhi same idea hai:
coupon = fixed salary
maturity = contract duration
market yield = market salary level
bond price = contract ko kisi aur ko transfer karne ki value
Ek line me final clarity
Interest rate change ka impact jitne zyada saalon ke cash flows par padega, bond price utni zyada move karegi. Long-term bonds me ye impact many years tak chalta hai; short-term bonds me jaldi khatam ho jata hai.
#Agar meri jankari apko acchi lagi to ise like jada logo ke sath share karo kyuki
jankari hi satarkta ki chhavi he
Bina jankari ke aap na satark re payenge na sahi fesla le payenge
Apko kis vishay par jankari chahiye muje comment likho or saval ya confusion he kis vishay ko leke market outlook or financial discipline ko lekar muje batao me apki madat karunga #BondMarkets
#bondmarket ,#crypto ,#Intrestrate
Mere sath jude rahne ke liye muje follow karo follow@CryptoWithGanesh
美债10年期竞标结果10分钟后公布!收益率和投标倍数将出炉,这可能影响市场流动性。#债券市场 #美债 $BTC $ETH US 10-year Treasury auction results in 10 minutes! Yields and bid-to-cover ratios coming up, this could impact market liquidity. #BondMarket #USTreasuries $BTC $ETH
美债10年期竞标结果10分钟后公布!收益率和投标倍数将出炉,这可能影响市场流动性。#债券市场 #美债 $BTC $ETH

US 10-year Treasury auction results in 10 minutes! Yields and bid-to-cover ratios coming up, this could impact market liquidity. #BondMarket #USTreasuries $BTC $ETH
IEFETF+0.95%
🚨 $BMT BONDS SPARK AI LIQUIDITY SURGE – META'S $25B PLAY 📈 📊 Meta’s $25 billion bond series, spanning 5‑ to 30‑year maturities, draws institutional capital into its AI runway, creating a fresh liquidity pool that smart‑money eyes for downstream allocation. 🦈 The tranche mix signals confidence in long‑term AI spend, yet the added leverage flags a balance‑sheet watch as credit conditions tighten. ⚡ Crypto assets, especially those linked to AI narratives, may feel the ripple as investors rebalance risk across equity, debt, and digital realms. 💬 How will this bond flow reshape AI‑centric token demand in the coming weeks? 👇 ⚠️ Not financial advice. Always manage your risk. 🛡️ 🏷️ #BMT #BondMarket #AIInvestments #CryptoLiquidity 🦈 💎
🚨 $BMT BONDS SPARK AI LIQUIDITY SURGE – META'S $25B PLAY 📈

📊 Meta’s $25 billion bond series, spanning 5‑ to 30‑year maturities, draws institutional capital into its AI runway, creating a fresh liquidity pool that smart‑money eyes for downstream allocation. 🦈 The tranche mix signals confidence in long‑term AI spend, yet the added leverage flags a balance‑sheet watch as credit conditions tighten. ⚡ Crypto assets, especially those linked to AI narratives, may feel the ripple as investors rebalance risk across equity, debt, and digital realms.

💬 How will this bond flow reshape AI‑centric token demand in the coming weeks? 👇

⚠️ Not financial advice. Always manage your risk. 🛡️

🏷️ #BMT #BondMarket #AIInvestments #CryptoLiquidity

🦈 💎
France's benchmark 10-year government bond yield rose by 4 basis points to reach 5.039%, hitting its highest level in 24 years. This sharp surge highlights escalating pressure across European sovereign debt markets. Breaching the critical 5% threshold is a major milestone that catches global macro desks off guard. The move reflects deepening investor anxiety over persistent European fiscal deficits and elevated long-term refinancing costs. Surging yields across core European economies tighten financial conditions and lift sovereign borrowing expenses. This dynamic strengthens yields relative to equities, creating sustained headwinds for risk-sensitive global assets. For digital assets, elevated risk-free yields continue to drain speculative liquidity from the broader ecosystem. While $BTC maintains resilience, persistent macro headwinds suggest cautious price action until global bond volatility stabilizes. #EurozoneDebt #BondMarket #MacroEconomy
France's benchmark 10-year government bond yield rose by 4 basis points to reach 5.039%, hitting its highest level in 24 years. This sharp surge highlights escalating pressure across European sovereign debt markets.

Breaching the critical 5% threshold is a major milestone that catches global macro desks off guard. The move reflects deepening investor anxiety over persistent European fiscal deficits and elevated long-term refinancing costs.

Surging yields across core European economies tighten financial conditions and lift sovereign borrowing expenses. This dynamic strengthens yields relative to equities, creating sustained headwinds for risk-sensitive global assets.

For digital assets, elevated risk-free yields continue to drain speculative liquidity from the broader ecosystem. While $BTC maintains resilience, persistent macro headwinds suggest cautious price action until global bond volatility stabilizes.

#EurozoneDebt #BondMarket #MacroEconomy
欧洲主权债务市场近日再度拉响警报,法国10年期国债收益率正式触及5%关口,创下自2002年7月以来的最高水平。与此同时,衡量法国主权违约风险的风险溢价指数已逼近160个基点,攀升至近15年来的历史高位,凸显出市场对其财政健康状况与政治不确定性的深度焦虑。 这一异动极其关键,标志着核心欧元区国家的信用风险正在被市场重新定价。在通胀粘性与主要央行紧缩立场的双重压制下,过去被视为低风险资产的核心欧债正遭遇猛烈抛售。借贷成本的失控飙升不仅打破了市场对财政温和复苏的预期,更可能在欧洲引发新一轮系统性债务重构压力。 主权收益率的剧烈抬升迅速传导至全球宏观金融体系。欧债收益率破位上行加剧了欧洲央行的政策两难,同时推高了跨市场无风险基准利率,压制了美元计价体系下的整体流动性。传统资金在避险情绪驱动下出现分化,部分防御性资金倾向于持有高息现金资产,对风险资产估值构成持续压制。 对于加密资产而言,核心主权债市场的动荡绝非单纯的外部利空,而是宏观流动性环境进一步恶化的信号。当无风险资产收益率居高不下且主权信用承压时,机构资金的风险偏好将显著降温,流入加密市场的增量流动性或被进一步抽离。投资者应保持警惕,在流动性收缩周期中切忌盲目博弈反弹风险。 $BTC #BondMarket #Eurozone #MacroEconomy
欧洲主权债务市场近日再度拉响警报,法国10年期国债收益率正式触及5%关口,创下自2002年7月以来的最高水平。与此同时,衡量法国主权违约风险的风险溢价指数已逼近160个基点,攀升至近15年来的历史高位,凸显出市场对其财政健康状况与政治不确定性的深度焦虑。

这一异动极其关键,标志着核心欧元区国家的信用风险正在被市场重新定价。在通胀粘性与主要央行紧缩立场的双重压制下,过去被视为低风险资产的核心欧债正遭遇猛烈抛售。借贷成本的失控飙升不仅打破了市场对财政温和复苏的预期,更可能在欧洲引发新一轮系统性债务重构压力。

主权收益率的剧烈抬升迅速传导至全球宏观金融体系。欧债收益率破位上行加剧了欧洲央行的政策两难,同时推高了跨市场无风险基准利率,压制了美元计价体系下的整体流动性。传统资金在避险情绪驱动下出现分化,部分防御性资金倾向于持有高息现金资产,对风险资产估值构成持续压制。

对于加密资产而言,核心主权债市场的动荡绝非单纯的外部利空,而是宏观流动性环境进一步恶化的信号。当无风险资产收益率居高不下且主权信用承压时,机构资金的风险偏好将显著降温,流入加密市场的增量流动性或被进一步抽离。投资者应保持警惕,在流动性收缩周期中切忌盲目博弈反弹风险。 $BTC

#BondMarket #Eurozone #MacroEconomy
欧洲央行行长拉加德于周六在曼谷举行的央行行长与财长会议上公开发出警告,指出近期全球债券市场的剧烈抛售推高了长期借贷成本。这一金融环境的显著收紧正在直接抑制欧元区的经济扩张,并削弱此前的通胀传导机制。 在全球主权债务担忧、通胀黏性以及人工智能投资对信贷需求剧增的共同作用下,全球债券收益率在过去数周内持续飙升。拉加德强调,借贷成本高企使法国等高负债国家的财政承压,更导致消费者难以承受中东地缘冲突引发的原油价格上涨,整体形势比欧洲央行9月的预估更为严峻。 长端债券收益率的被动走高相当于在央行政策之外施加了额外的紧缩效应,压制了整体金融市场的风险偏好。在主权债务承压与能源成本反弹的双重夹击下,传统资本市场正面临经济放缓与流动性分流的现实考验。 对于加密资产而言,全球无风险利率的高企持续对宏观流动性构成压制,加剧了投资者的避险倾向。若欧元区经济承压与借贷成本上升进一步削弱全球风险资产的流动性,$BTC 等主要资产短期内或将维持承压震荡格局。📉 #ECB #BondMarket #GlobalEconomy
欧洲央行行长拉加德于周六在曼谷举行的央行行长与财长会议上公开发出警告,指出近期全球债券市场的剧烈抛售推高了长期借贷成本。这一金融环境的显著收紧正在直接抑制欧元区的经济扩张,并削弱此前的通胀传导机制。

在全球主权债务担忧、通胀黏性以及人工智能投资对信贷需求剧增的共同作用下,全球债券收益率在过去数周内持续飙升。拉加德强调,借贷成本高企使法国等高负债国家的财政承压,更导致消费者难以承受中东地缘冲突引发的原油价格上涨,整体形势比欧洲央行9月的预估更为严峻。

长端债券收益率的被动走高相当于在央行政策之外施加了额外的紧缩效应,压制了整体金融市场的风险偏好。在主权债务承压与能源成本反弹的双重夹击下,传统资本市场正面临经济放缓与流动性分流的现实考验。

对于加密资产而言,全球无风险利率的高企持续对宏观流动性构成压制,加剧了投资者的避险倾向。若欧元区经济承压与借贷成本上升进一步削弱全球风险资产的流动性,$BTC 等主要资产短期内或将维持承压震荡格局。📉

#ECB #BondMarket #GlobalEconomy
BOE GIỮ LÃI SUẤT, DỪNG BÁN TRÁI PHIẾU DÀI HẠN ​Ngân hàng Trung ương Anh (BoE) vừa đưa ra quyết định quan trọng nhằm giảm áp lực cho thị trường tài chính. ​Giữ nguyên lãi suất: BoE quyết định duy trì mức lãi suất ở 3,75% với tỷ lệ biểu quyết 6–3. ​Dừng bán trái phiếu dài hạn: Động thái mang tính bước ngoặt giúp tháo gỡ căng thẳng cho thị trường trái phiếu. ​Phản ứng từ thị trường: Thị trường trái phiếu lập tức bật tăng, lợi suất trái phiếu chính phủ Anh kỳ hạn 30 năm giảm khoảng 12 bps, đồng thời hạ nhiệt làn sóng tăng lợi suất trên toàn cầu. ​Định hướng chính sách: BoE đang chấp nhận ưu tiên ổn định thị trường trái phiếu, dù bài toán lạm phát vẫn chưa hoàn toàn hạ nhiệt. {spot}(BTCUSDT) {spot}(XAUTUSDT) ​Thông tin trên chỉ mang tính chất cập nhật diễn biến vĩ mô toàn cầu, tuyệt đối không phải lời khuyên đầu tư hay phán đoán để "đặt cược" tỷ giá. Nếu bạn lỡ nghe tin này rồi nhảy vào "múa may" với trái phiếu hay tiền tệ để rồi cháy tài khoản, ad xin phép đứng ngoài vỗ tay chia buồn chứ không cứu nổi ví của bạn đâu nhé! ​#BankOfEngland #InterestRates #BondMarket #GlobalEconomy #MacroNews
BOE GIỮ LÃI SUẤT, DỪNG BÁN TRÁI PHIẾU DÀI HẠN

​Ngân hàng Trung ương Anh (BoE) vừa đưa ra quyết định quan trọng nhằm giảm áp lực cho thị trường tài chính.

​Giữ nguyên lãi suất: BoE quyết định duy trì mức lãi suất ở 3,75% với tỷ lệ biểu quyết 6–3.

​Dừng bán trái phiếu dài hạn: Động thái mang tính bước ngoặt giúp tháo gỡ căng thẳng cho thị trường trái phiếu.

​Phản ứng từ thị trường: Thị trường trái phiếu lập tức bật tăng, lợi suất trái phiếu chính phủ Anh kỳ hạn 30 năm giảm khoảng 12 bps, đồng thời hạ nhiệt làn sóng tăng lợi suất trên toàn cầu.

​Định hướng chính sách: BoE đang chấp nhận ưu tiên ổn định thị trường trái phiếu, dù bài toán lạm phát vẫn chưa hoàn toàn hạ nhiệt.


​Thông tin trên chỉ mang tính chất cập nhật diễn biến vĩ mô toàn cầu, tuyệt đối không phải lời khuyên đầu tư hay phán đoán để "đặt cược" tỷ giá. Nếu bạn lỡ nghe tin này rồi nhảy vào "múa may" với trái phiếu hay tiền tệ để rồi cháy tài khoản, ad xin phép đứng ngoài vỗ tay chia buồn chứ không cứu nổi ví của bạn đâu nhé!

​#BankOfEngland #InterestRates #BondMarket #GlobalEconomy #MacroNews
AMD'S $4.75B RECORD BOND DEAL — THE AI RACE JUST GOT PRICIER 💰🔥 AMD just dropped a $4.75B four-tranche bond — its largest USD debt raise ever. The 10-year tranche tightened 25bps from guidance, a clear signal institutions are hungry for AI exposure. 📊 This isn't a liquidity squeeze — with $13.1B in cash and high investment-grade status, AMD is borrowing for optionality: AI accelerators, data center scale, and the $5B Anthropic bet. 💳 The AI capex loop keeps widening. Revenue is projected above $51B (47% growth), and this raise dwarfs its $1.5B note issuance last March — the sector has entered a persistent capital expansion phase. The question: at what price does this story get fully discounted? Would you scale into $AMD on a structural pullback, or wait for confirmation? 👇 ⚠️ Not financial advice. Always manage your risk. 🛡️ 🏷️ $AMD #AIInfrastructure #BondMarket #Semiconductor #InstitutionalFlow 🧠💼
AMD'S $4.75B RECORD BOND DEAL — THE AI RACE JUST GOT PRICIER 💰🔥

AMD just dropped a $4.75B four-tranche bond — its largest USD debt raise ever. The 10-year tranche tightened 25bps from guidance, a clear signal institutions are hungry for AI exposure. 📊

This isn't a liquidity squeeze — with $13.1B in cash and high investment-grade status, AMD is borrowing for optionality: AI accelerators, data center scale, and the $5B Anthropic bet. 💳

The AI capex loop keeps widening. Revenue is projected above $51B (47% growth), and this raise dwarfs its $1.5B note issuance last March — the sector has entered a persistent capital expansion phase. The question: at what price does this story get fully discounted? Would you scale into $AMD on a structural pullback, or wait for confirmation? 👇

⚠️ Not financial advice. Always manage your risk. 🛡️

🏷️ $AMD #AIInfrastructure #BondMarket #Semiconductor #InstitutionalFlow

🧠💼
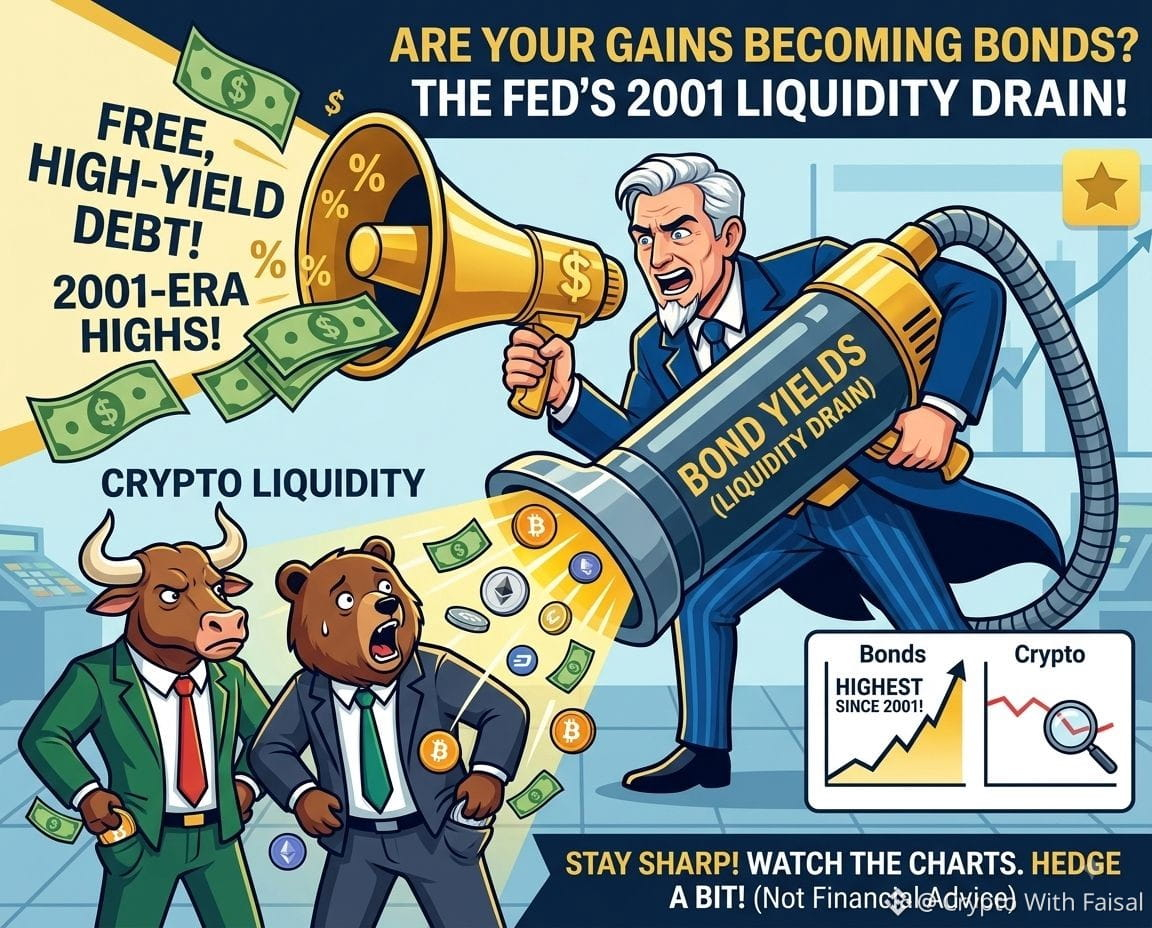
​#us30ybondauctionyieldhighestsince2001 ​🚨 BOND MARKET SHOCKWAVE: YIELDS HIT 2001 HIGHS! 🚨 ​The latest US 30-Year Bond Auction just concluded, and the results are setting off alarms across the financial world. Yields have officially skyrocketed to levels we haven't witnessed since 2001! 🤯 ​What caused this massive spike? A severe lack of market demand. The bid-to-cover ratio plummeted to a dismal 2.39, indicating that buyers for US debt were practically non-existent. To successfully auction off these bonds, the Treasury was forced to entice investors by offering aggressively higher interest rates. Essentially, they had to pay a premium to find buyers. 💸 ​The Crypto Connection: Why should crypto traders care about government bonds? It all comes down to liquidity. Capital naturally flows toward attractive, lower-risk yields. With traditional bonds now offering such hefty payouts, we could witness a significant liquidity drain from risk-on asset classes—including crypto. ​Trader Action Plan: When macroeconomic shifts happen, preparation is key: ​Stay Vigilant: Monitor the charts closely for sudden volume drops. ​Manage Risk: Tighten your stop-losses. ​Protect Capital: Seriously consider hedging your portfolio to brace for potential market volatility. 📉📈 ​(Disclaimer: This is market commentary and should not be taken as financial advice! Do your own research.) #MacroEconomics #BondMarket #FederalReserve $BTC {future}(BTCUSDT) $ETH {future}(ETHUSDT) $BNB {future}(BNBUSDT)
​#us30ybondauctionyieldhighestsince2001
​🚨 BOND MARKET SHOCKWAVE: YIELDS HIT 2001 HIGHS! 🚨

​The latest US 30-Year Bond Auction just concluded, and the results are setting off alarms across the financial world. Yields have officially skyrocketed to levels we haven't witnessed since 2001! 🤯

​What caused this massive spike?

A severe lack of market demand. The bid-to-cover ratio plummeted to a dismal 2.39, indicating that buyers for US debt were practically non-existent. To successfully auction off these bonds, the Treasury was forced to entice investors by offering aggressively higher interest rates. Essentially, they had to pay a premium to find buyers. 💸

​The Crypto Connection:

Why should crypto traders care about government bonds? It all comes down to liquidity. Capital naturally flows toward attractive, lower-risk yields. With traditional bonds now offering such hefty payouts, we could witness a significant liquidity drain from risk-on asset classes—including crypto.

​Trader Action Plan:

When macroeconomic shifts happen, preparation is key:

​Stay Vigilant: Monitor the charts closely for sudden volume drops.

​Manage Risk: Tighten your stop-losses.

​Protect Capital: Seriously consider hedging your portfolio to brace for potential market volatility. 📉📈

​(Disclaimer: This is market commentary and should not be taken as financial advice! Do your own research.)

#MacroEconomics #BondMarket #FederalReserve
$BTC
$ETH
$BNB
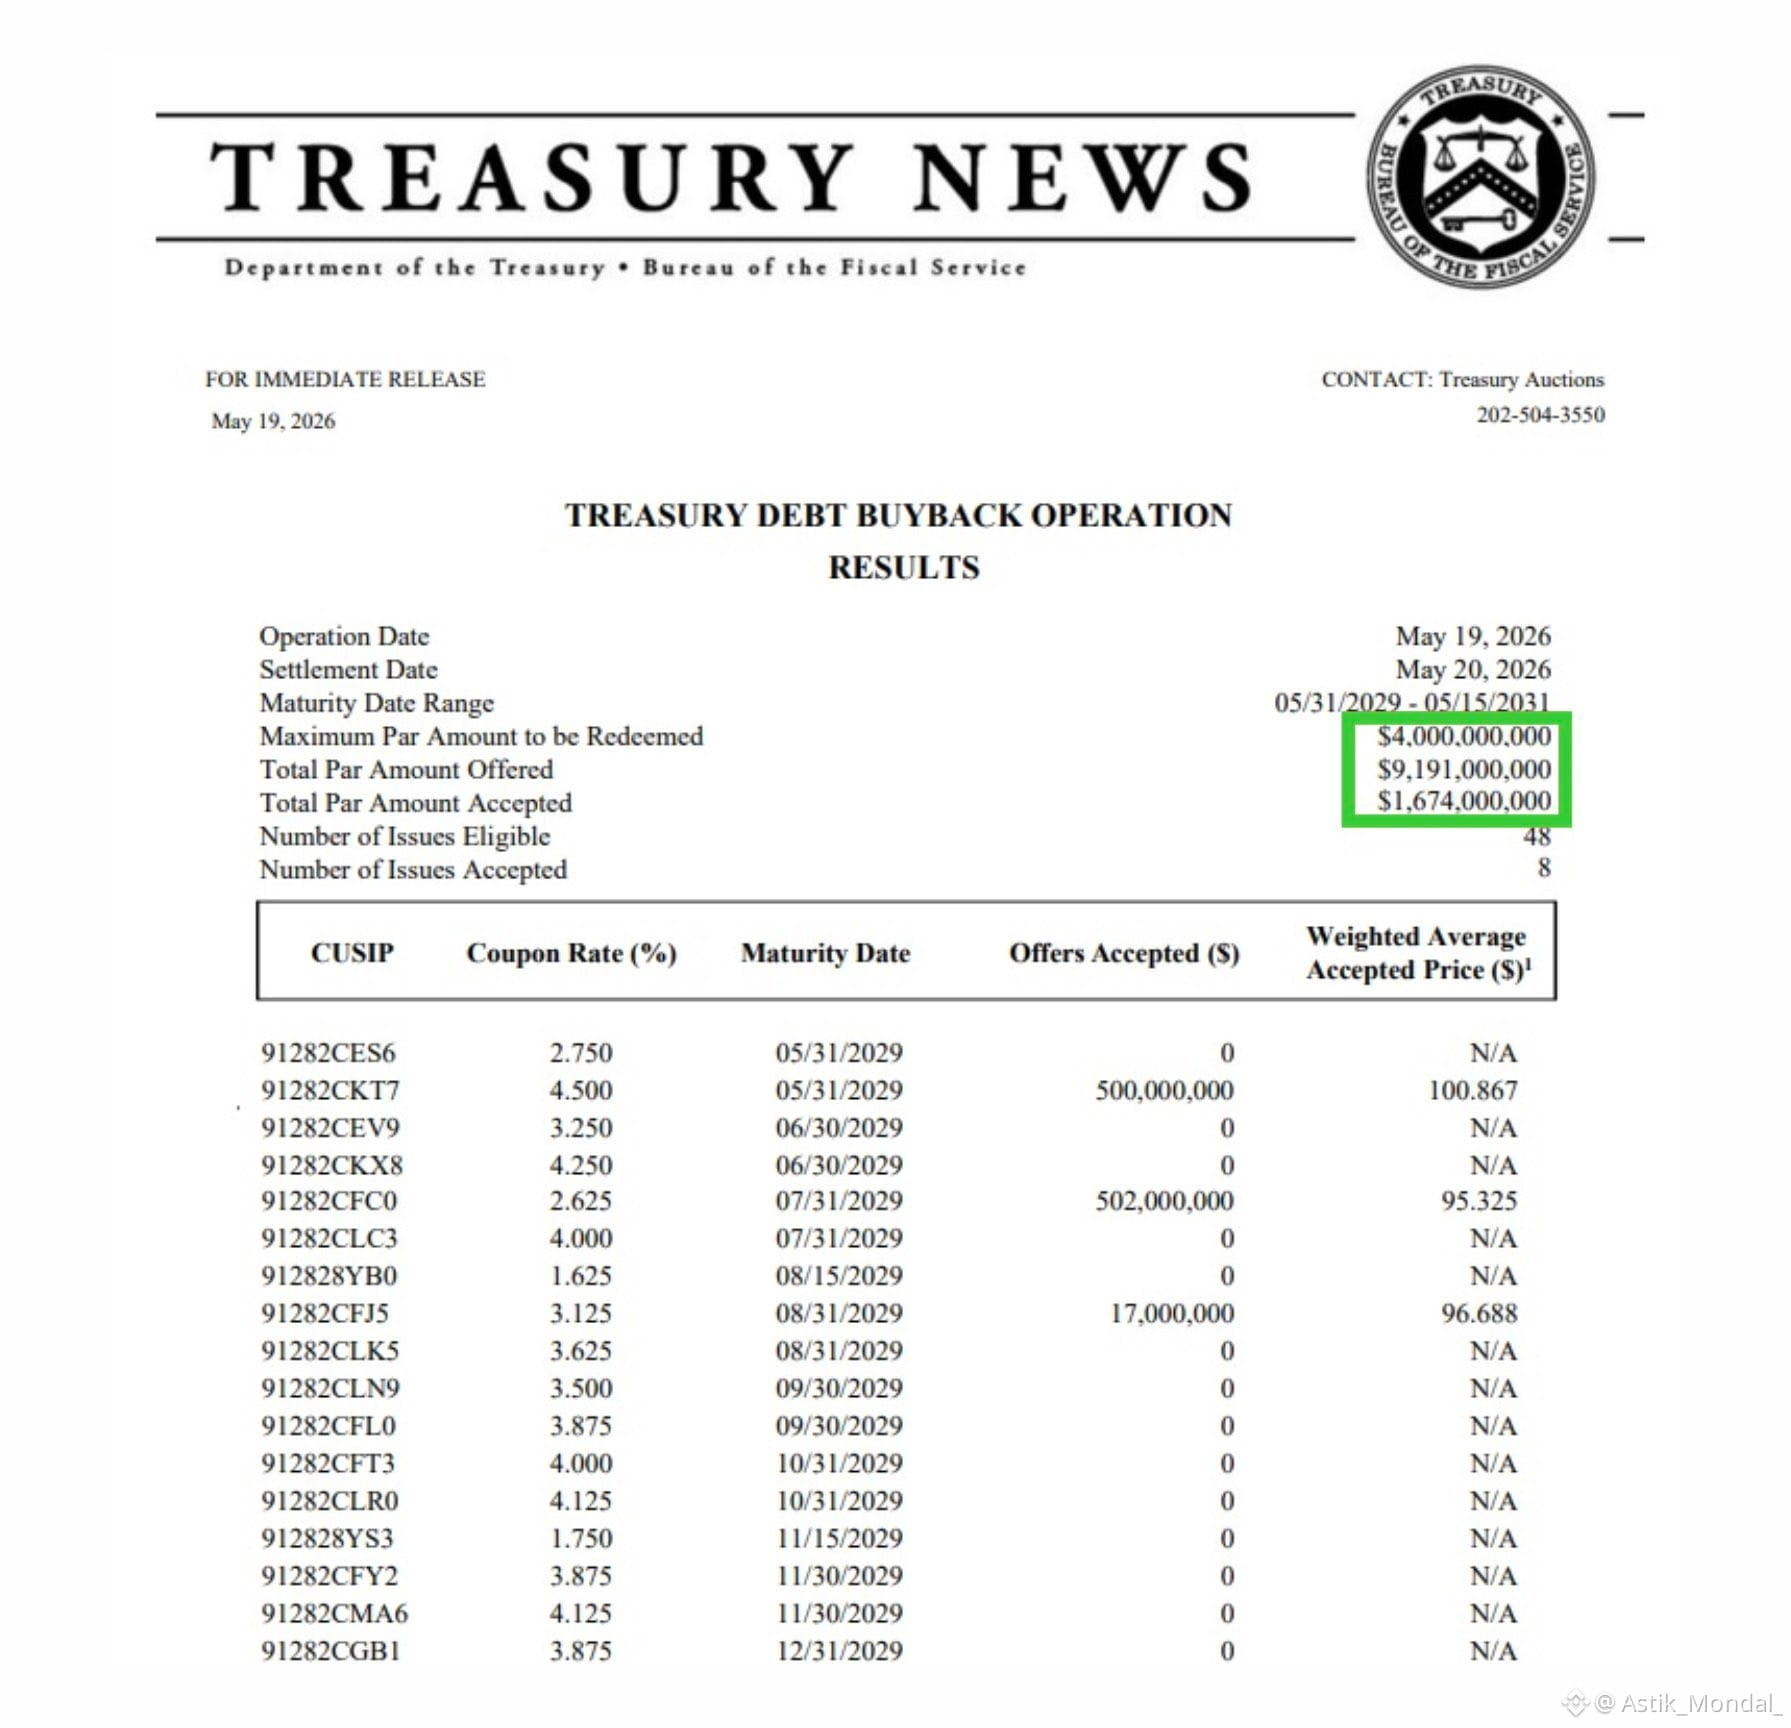
🚨 The US Treasury just spent $1,674,000,000 buying back its own debt. Read that again. The government is now purchasing its own IOUs and most people have zero idea what this actually means for your money. Here's what's really happening They're calling it a "liquidity improvement." Translation: the bond market is getting choppy, and the Treasury is stepping in to smooth it out before something breaks. This isn't routine housekeeping. You don't deploy $1.67 billion unless you're worried about the plumbing. The mechanics are simple. The optics are terrifying. When the government buys its own debt, it's injecting cash directly into the financial system without calling it QE, without a Fed meeting, without a press conference. Quiet. Surgical. Deliberate. The bond market has been flashing warning signs for months. Bid-ask spreads widening. Auction demand softening. Foreign buyers stepping back. This buyback is the Treasury saying: we'll be the buyer of last resort if we have to be. What this means for you: More dollars chasing the same assets. Pressure on the dollar. A Fed that's boxed in. And a bond market that increasingly needs life support to function "normally." This is what the endgame of debt monetization looks like in slow motion. The number that matters isn't $1.67B. It's the precedent. Once you normalize the government buying its own debt to "improve liquidity," where exactly does that stop? Watch this space closely. The next move will be bigger. #Macro #BondMarket #USTreasury #DollarCollapse #FinanceTwitter
🚨 The US Treasury just spent $1,674,000,000 buying back its own debt.
Read that again.
The government is now purchasing its own IOUs and most people have zero idea what this actually means for your money.
Here's what's really happening
They're calling it a "liquidity improvement."
Translation: the bond market is getting choppy, and the Treasury is stepping in to smooth it out before something breaks.
This isn't routine housekeeping. You don't deploy $1.67 billion unless you're worried about the plumbing.
The mechanics are simple. The optics are terrifying.
When the government buys its own debt, it's injecting cash directly into the financial system without calling it QE, without a Fed meeting, without a press conference.
Quiet. Surgical. Deliberate.
The bond market has been flashing warning signs for months.
Bid-ask spreads widening. Auction demand softening. Foreign buyers stepping back.
This buyback is the Treasury saying: we'll be the buyer of last resort if we have to be.
What this means for you:
More dollars chasing the same assets. Pressure on the dollar. A Fed that's boxed in. And a bond market that increasingly needs life support to function "normally."
This is what the endgame of debt monetization looks like in slow motion.
The number that matters isn't $1.67B.
It's the precedent.
Once you normalize the government buying its own debt to "improve liquidity," where exactly does that stop?
Watch this space closely. The next move will be bigger.
#Macro #BondMarket #USTreasury #DollarCollapse #FinanceTwitter
Article
Microsoft-Linked Project Odyssey Bond Draws More Than Twice the DemandThe bond issuance linked to Microsoft Corp., known as Project Odyssey, is attracting significant investor interest, with demand now exceeding twice the initial offering target. Bloomberg reports that the corporate bond sale, which is focused on financing data-center projects, may be increased to as much as $3.9 billion due to the overwhelming demand. This bond offering is notable for offering yields that resemble those typically associated with junk bonds, which are higher than investment-grade debt. The higher yields reflect the perceived risk in the financing, aligned with the nature of the project and the sector it serves. The strong investor appetite indicates confidence in Microsoft’s strategic investments in data-center infrastructure, despite the somewhat higher risk profile implied by the junk-like yields. The demand suggests that investors see value in the long-term growth prospects tied to cloud computing and data center expansion, especially as digital transformation accelerates. As the potential increase in bond issuance approaches, market participants will be watching how Microsoft manages its financing strategies and whether this trend signifies broader investor interest in tech-related debt with higher yields. The success of Project Odyssey underscores the ongoing appetite for risk in the corporate bond market, driven by the expansion of digital services and infrastructure. #Microsoft #BondMarket #DataCenters

Microsoft-Linked Project Odyssey Bond Draws More Than Twice the Demand

The bond issuance linked to Microsoft Corp., known as Project Odyssey, is attracting significant investor interest, with demand now exceeding twice the initial offering target. Bloomberg reports that the corporate bond sale, which is focused on financing data-center projects, may be increased to as much as $3.9 billion due to the overwhelming demand.
This bond offering is notable for offering yields that resemble those typically associated with junk bonds, which are higher than investment-grade debt. The higher yields reflect the perceived risk in the financing, aligned with the nature of the project and the sector it serves.
The strong investor appetite indicates confidence in Microsoft’s strategic investments in data-center infrastructure, despite the somewhat higher risk profile implied by the junk-like yields. The demand suggests that investors see value in the long-term growth prospects tied to cloud computing and data center expansion, especially as digital transformation accelerates.
As the potential increase in bond issuance approaches, market participants will be watching how Microsoft manages its financing strategies and whether this trend signifies broader investor interest in tech-related debt with higher yields. The success of Project Odyssey underscores the ongoing appetite for risk in the corporate bond market, driven by the expansion of digital services and infrastructure. #Microsoft #BondMarket #DataCenters
美国财政部长耶伦(Janet Yellen)将于今晚 22:00 出席众议院金融服务委员会听证会,就“国际金融体系现状年度报告”作证。在当前 10 年期美债收益率已突破 5% 的敏感时刻,市场目光全部集中在财政部的下一步动作上。 这次听证会之所以备受瞩目,核心在于财政部的发债计划与债务管理策略。市场正在密切观察耶伦是否会释放关于控制财政赤字、调整国债发行与回购节奏的新信号,这直接关系到市场此前对长期高利率环境的预期是否需要修正。 从宏观资产角度来看,若耶伦释出稳固债市、控制赤字的偏温和信号,长期美债收益率的上涨压力或将有所缓解;反之,若财政扩张意图明显或对高利率维持更高容忍度,美债收益率与美元指数可能面临新一轮波动,进而牵动黄金及美股走势。 对于加密市场而言,高企的无风险利率持续考验着流动性环境。投资者正保持观望态势,$BTC 等风险资产的表现将取决于听证会后流动性预期的微妙变化,短期内市场或维持双向波动态势。 👀 #JanetYellen #BondMarket #InterestRates
美国财政部长耶伦(Janet Yellen)将于今晚 22:00 出席众议院金融服务委员会听证会,就“国际金融体系现状年度报告”作证。在当前 10 年期美债收益率已突破 5% 的敏感时刻,市场目光全部集中在财政部的下一步动作上。

这次听证会之所以备受瞩目,核心在于财政部的发债计划与债务管理策略。市场正在密切观察耶伦是否会释放关于控制财政赤字、调整国债发行与回购节奏的新信号,这直接关系到市场此前对长期高利率环境的预期是否需要修正。

从宏观资产角度来看,若耶伦释出稳固债市、控制赤字的偏温和信号,长期美债收益率的上涨压力或将有所缓解;反之,若财政扩张意图明显或对高利率维持更高容忍度,美债收益率与美元指数可能面临新一轮波动,进而牵动黄金及美股走势。

对于加密市场而言,高企的无风险利率持续考验着流动性环境。投资者正保持观望态势,$BTC 等风险资产的表现将取决于听证会后流动性预期的微妙变化,短期内市场或维持双向波动态势。 👀

#JanetYellen #BondMarket #InterestRates
·
--
Bearish
Bitcoin Up or Down on October 6?

Bitcoin Up or Down on October 6?

99%Up1%Down
Volume $71,262.59
$TLT OPTIONS DATA FLASHES BULLISH SIGNAL AHEAD OF FED DECISION 🚨 📊 The iShares 20+ Year Treasury Bond ETF has seen its put/call ratio drop to 0.63 — the lowest since May — with call trading volume surging to 171,000 contracts. That's triple the put activity. 💡 This isn't random retail euphoria; institutions are positioning for a potential "rate hike rally." ⚡ Citadel Securities predicts an unexpected rate hike this week. The logic? If Fed Chair Kevin Wash hikes decisively, long-term inflation expectations may collapse, driving long-term yields down and bond prices up. 🦈 That could also ignite a relief rally in rate-sensitive tech stocks like $QQQ . 💬 Do you see the Fed actually hiking, or is this a liquidity trap to force shorts to cover? 👇 ⚠️ Not financial advice. Always manage your risk. 🛡️ 🏷️ $TLT $QQQ #Fed #BondMarket #Nasdaq 📊 🔍
$TLT OPTIONS DATA FLASHES BULLISH SIGNAL AHEAD OF FED DECISION 🚨

📊 The iShares 20+ Year Treasury Bond ETF has seen its put/call ratio drop to 0.63 — the lowest since May — with call trading volume surging to 171,000 contracts. That's triple the put activity. 💡 This isn't random retail euphoria; institutions are positioning for a potential "rate hike rally."

⚡ Citadel Securities predicts an unexpected rate hike this week. The logic? If Fed Chair Kevin Wash hikes decisively, long-term inflation expectations may collapse, driving long-term yields down and bond prices up. 🦈 That could also ignite a relief rally in rate-sensitive tech stocks like $QQQ .

💬 Do you see the Fed actually hiking, or is this a liquidity trap to force shorts to cover? 👇

⚠️ Not financial advice. Always manage your risk. 🛡️

🏷️ $TLT $QQQ #Fed #BondMarket #Nasdaq

📊 🔍
TLTETF+1.55%
QQQETF-4.69%
$XAU {future}(XAUUSDT) $NVDA.US {stock_us}(NVDA.US) Asian Bonds Slide as Rising Oil Stoking Fresh Inflation Fears ⚠️ Macro pressures are intensifying across traditional markets today. Asian bonds followed US Treasuries lower as concerns over government finances mounted significantly, while higher oil prices continue to fuel renewed inflation fears worldwide. When energy prices climb and bond markets face pressure, macroeconomic volatility tends to affect all risk assets, including crypto. Keeping a close eye on these global economic shifts is crucial for proper risk management. How are you protecting your portfolio against rising inflation? 🛡️ 🟢$XAU #Inflation #MacroEconomics #bondmarket #BinanceSquare #GlobalMarkets
$XAU
$NVDA.US
Asian Bonds Slide as Rising Oil Stoking Fresh Inflation Fears ⚠️

Macro pressures are intensifying across traditional markets today.

Asian bonds followed US Treasuries lower as concerns over government finances mounted significantly, while higher oil prices continue to fuel renewed inflation fears worldwide.

When energy prices climb and bond markets face pressure, macroeconomic volatility tends to affect all risk assets, including crypto.

Keeping a close eye on these global economic shifts is crucial for proper risk management. How are you protecting your portfolio against rising inflation? 🛡️

🟢$XAU

#Inflation #MacroEconomics #bondmarket #BinanceSquare #GlobalMarkets
XAU-3.99%
NVDAUS-11.37%
Chủ tịch ECB Christine Lagarde vừa lên tiếng cảnh báo hôm thứ Bảy tại Bangkok trong cuộc gặp với các lãnh đạo ngân hàng trung ương và bộ trưởng tài chính. Bà nhấn mạnh làn sóng bán tháo trái phiếu gần đây đang đẩy chi phí vay mượn lên cao, làm thắt chặt điều kiện tài chính và trực tiếp kìm hãm tăng trưởng kinh tế khu vực Eurozone. Thông điệp này đặc biệt quan trọng vì nó cho thấy áp lực kép từ nợ công leo thang, nhu cầu tín dụng cho AI và rủi ro giá dầu thô tăng do xung đột Iran. Mức độ thắt chặt tài chính thực tế đang diễn ra nhanh hơn và nguy hiểm hơn so với các kịch bản dự báo hồi tháng 9 của ECB. Đối với thị trường tài chính truyền thống, lợi suất trái phiếu dài hạn tăng vọt đè nặng lên các quốc gia có gánh nặng nợ lớn như Pháp. Chi phí vốn đắt đỏ hơn cũng sẽ kìm hãm sức mua của người tiêu dùng và gây áp lực giảm định giá lên thị trường chứng khoán toàn cầu. Với thị trường tiền mã hóa, môi trường thanh khoản thắt chặt và lợi suất phi rủi ro neo cao thường khiến dòng vốn lớn thận trọng hơn. $BTC và các tài sản rủi ro có thể đối mặt với giai đoạn biến động đi ngang khi giới đầu tư cân đối lại dòng tiền phòng hộ vĩ mô. #ECB #BondMarket #MacroEconomy
Chủ tịch ECB Christine Lagarde vừa lên tiếng cảnh báo hôm thứ Bảy tại Bangkok trong cuộc gặp với các lãnh đạo ngân hàng trung ương và bộ trưởng tài chính. Bà nhấn mạnh làn sóng bán tháo trái phiếu gần đây đang đẩy chi phí vay mượn lên cao, làm thắt chặt điều kiện tài chính và trực tiếp kìm hãm tăng trưởng kinh tế khu vực Eurozone.

Thông điệp này đặc biệt quan trọng vì nó cho thấy áp lực kép từ nợ công leo thang, nhu cầu tín dụng cho AI và rủi ro giá dầu thô tăng do xung đột Iran. Mức độ thắt chặt tài chính thực tế đang diễn ra nhanh hơn và nguy hiểm hơn so với các kịch bản dự báo hồi tháng 9 của ECB.

Đối với thị trường tài chính truyền thống, lợi suất trái phiếu dài hạn tăng vọt đè nặng lên các quốc gia có gánh nặng nợ lớn như Pháp. Chi phí vốn đắt đỏ hơn cũng sẽ kìm hãm sức mua của người tiêu dùng và gây áp lực giảm định giá lên thị trường chứng khoán toàn cầu.

Với thị trường tiền mã hóa, môi trường thanh khoản thắt chặt và lợi suất phi rủi ro neo cao thường khiến dòng vốn lớn thận trọng hơn. $BTC và các tài sản rủi ro có thể đối mặt với giai đoạn biến động đi ngang khi giới đầu tư cân đối lại dòng tiền phòng hộ vĩ mô.

#ECB #BondMarket #MacroEconomy
TRUMP JUST THREW ANOTHER WRENCH INTO THE BOND MARKET Tổng thống Trump vừa đưa ra cam kết $5,000 cho mỗi người dân Mỹ nếu Đảng Cộng hòa giành chiến thắng trong cuộc bầu cử giữa nhiệm kỳ, nhưng không đưa ra chi tiết về cách triển khai. Timing khá nhạy cảm: thị trường đang hướng tới phiên đấu thầu Treasury 30 năm trị giá $22B vào thứ Năm, với trái phiếu đáo hạn năm 2056. Lợi suất Treasury 30Y hiện đang ở gần vùng cao nhất kể từ khủng hoảng tài chính toàn cầu, trong khi giới đầu tư vốn đã lo ngại về thâm hụt ngân sách và kỷ luật tài khóa của Mỹ. Góc nhìn của mình: $5,000 nghe rất hấp dẫn với người nhận, nhưng với bond market thì câu hỏi đầu tiên sẽ là “tiền đâu ra?” Nếu thị trường bắt đầu định giá thêm áp lực tài khóa và lạm phát, lợi suất dài hạn có thể tiếp tục chịu áp lực. Và trớ trêu là CPI Mỹ cũng sắp được công bố nghĩa là Treasury market đang phải xử lý cả câu chuyện tài khóa lẫn lạm phát cùng lúc. $5,000 for every American? Bond traders just found another reason to ask “who’s paying?” Bạn nghĩ phiên đấu thầu Treasury 30Y $22B hôm nay sẽ hấp thụ tốt, hay lợi suất sẽ tiếp tục bị đẩy lên? #BrainrotCrypto #Treasury #bondmarket #TRUMP
TRUMP JUST THREW ANOTHER WRENCH INTO THE BOND MARKET

Tổng thống Trump vừa đưa ra cam kết $5,000 cho mỗi người dân Mỹ nếu Đảng Cộng hòa giành chiến thắng trong cuộc bầu cử giữa nhiệm kỳ, nhưng không đưa ra chi tiết về cách triển khai.

Timing khá nhạy cảm: thị trường đang hướng tới phiên đấu thầu Treasury 30 năm trị giá $22B vào thứ Năm, với trái phiếu đáo hạn năm 2056.

Lợi suất Treasury 30Y hiện đang ở gần vùng cao nhất kể từ khủng hoảng tài chính toàn cầu, trong khi giới đầu tư vốn đã lo ngại về thâm hụt ngân sách và kỷ luật tài khóa của Mỹ.

Góc nhìn của mình: $5,000 nghe rất hấp dẫn với người nhận, nhưng với bond market thì câu hỏi đầu tiên sẽ là “tiền đâu ra?”

Nếu thị trường bắt đầu định giá thêm áp lực tài khóa và lạm phát, lợi suất dài hạn có thể tiếp tục chịu áp lực.

Và trớ trêu là CPI Mỹ cũng sắp được công bố nghĩa là Treasury market đang phải xử lý cả câu chuyện tài khóa lẫn lạm phát cùng lúc.

$5,000 for every American? Bond traders just found another reason to ask “who’s paying?”

Bạn nghĩ phiên đấu thầu Treasury 30Y $22B hôm nay sẽ hấp thụ tốt, hay lợi suất sẽ tiếp tục bị đẩy lên?

#BrainrotCrypto #Treasury #bondmarket #TRUMP
🚨 INDIA BOND MARKET UNDER PRESSURE — 10-YEAR YIELD HITS HIGHEST LEVEL SINCE NOVEMBER 2023! 🇮🇳📉 India’s government bond prices fell after the Reserve Bank of India introduced emergency measures to support the rupee. 📊 $KEY $MARKET UPDATE: 🔹 10-Year Government Bond Yield: 7.35% 🔹 Daily Increase: 5 basis points 🔹 Highest Level Since: November 2023 ⚠️ Rising bond yields signal increased pressure in India’s debt market as authorities work to stabilize the rupee. Investors will closely watch the RBI’s next moves and currency market developments. #India #RBI #BondMarket
🚨 INDIA BOND MARKET UNDER PRESSURE — 10-YEAR YIELD HITS HIGHEST LEVEL SINCE NOVEMBER 2023! 🇮🇳📉

India’s government bond prices fell after the Reserve Bank of India introduced emergency measures to support the rupee.

📊 $KEY $MARKET UPDATE: 🔹 10-Year Government Bond Yield: 7.35% 🔹 Daily Increase: 5 basis points 🔹 Highest Level Since: November 2023

⚠️ Rising bond yields signal increased pressure in India’s debt market as authorities work to stabilize the rupee. Investors will closely watch the RBI’s next moves and currency market developments.

#India #RBI #BondMarket
欧洲主权债务市场今日迎来重大异动。根据最新交易数据,法国与德国10年期国债收益率利差在今日欧盘交易时段持续走阔,盘中强势突破150个基点整数大关。这一关键利差指标直接刷新了自2012年1月欧债危机以来的最高纪录,标志着欧元区核心主权信用风险溢价正迎来十余年未见的极端波动。 从宏观背景与技术指标来看,该利差走阔主要源于市场对法国财政预算赤字及政治博弈不确定性的集中定价。不过从量化分析角度来看,150个基点恰好对应着长周期图表上的强阻力密集区。动量指标已深度进入极端超买状态,历史经验表明,在极值区间出现恐慌性溢价释放,通常意味着利空情绪正在步入最后加速探顶的衰竭阶段。 在宏观跨资产层面,这一波动正重塑资金流向格局。尽管利差飙升短期内对欧元兑美元汇率构成技术性下行压力,并引发欧洲股市的防御性轮动,但这同样加速了主权债务风险的集中释放。随着最悲观的市场预期被充分消化,一旦利差在技术阻力位受阻回落,跨市场套利资金的介入将有效提振整体风险偏好。 对于加密市场而言,传统法币主权债务与财政压力的显现,再度凸显了去中心化数字资产在资产配置中的抗脆弱性。当主权信用利差触顶并带动传统避险情绪边际放缓时,宏观流动性将重新倾向于具有高弹性的风险资产,$BTC 等核心品种的技术面支撑将进一步巩固并吸引增量资金进场。🚀 #BondMarket #Eurozone #MacroEconomy
欧洲主权债务市场今日迎来重大异动。根据最新交易数据,法国与德国10年期国债收益率利差在今日欧盘交易时段持续走阔,盘中强势突破150个基点整数大关。这一关键利差指标直接刷新了自2012年1月欧债危机以来的最高纪录,标志着欧元区核心主权信用风险溢价正迎来十余年未见的极端波动。

从宏观背景与技术指标来看,该利差走阔主要源于市场对法国财政预算赤字及政治博弈不确定性的集中定价。不过从量化分析角度来看,150个基点恰好对应着长周期图表上的强阻力密集区。动量指标已深度进入极端超买状态,历史经验表明,在极值区间出现恐慌性溢价释放,通常意味着利空情绪正在步入最后加速探顶的衰竭阶段。

在宏观跨资产层面,这一波动正重塑资金流向格局。尽管利差飙升短期内对欧元兑美元汇率构成技术性下行压力,并引发欧洲股市的防御性轮动,但这同样加速了主权债务风险的集中释放。随着最悲观的市场预期被充分消化,一旦利差在技术阻力位受阻回落,跨市场套利资金的介入将有效提振整体风险偏好。

对于加密市场而言,传统法币主权债务与财政压力的显现,再度凸显了去中心化数字资产在资产配置中的抗脆弱性。当主权信用利差触顶并带动传统避险情绪边际放缓时,宏观流动性将重新倾向于具有高弹性的风险资产,$BTC 等核心品种的技术面支撑将进一步巩固并吸引增量资金进场。🚀

#BondMarket #Eurozone #MacroEconomy
品浩(PIMCO)高级顾问兼投资组合经理Rupert Harrison周二在伦敦出席TS Lombard经济咨询活动时指出,美国10年期与30年期国债收益率本周均攀升至24年以来的最高水平。Harrison强调,在经历了近期收益率的剧烈上行后,美债资产的估值已经展现出极具吸引力的配置价值,PIMCO目前正在维持一定的久期风险敞口。 长端美债收益率创下近四分之一世纪新高,反映出市场对美国持续高企的财政赤字及长期通胀粘性的极度担忧。这一轮债券抛售潮不仅推高了无风险利率基准,也显著重塑了机构对资产安全边际的预期。 从宏观金融市场来看,创纪录的高收益率正强力虹吸全球流动性,强化美元指数的韧性,并对高估值权益资产构成沉重的折现压力。若未来经济增长放缓或科技股出现深度回调,资金可能加速向高票息的长端国债回流,从而抑制整体风险偏好。 对于加密资产而言,无风险收益率维持在历史高位意味着机构配置加密货币的机会成本大幅上升。在宏观流动性持续收紧和流动性抽离的双重压力下,以 $BTC 为代表的风险资产短期内或将面临更严峻的估值承压与震荡调整。 #US10Y #BondMarket #MacroEconomy
品浩(PIMCO)高级顾问兼投资组合经理Rupert Harrison周二在伦敦出席TS Lombard经济咨询活动时指出,美国10年期与30年期国债收益率本周均攀升至24年以来的最高水平。Harrison强调,在经历了近期收益率的剧烈上行后,美债资产的估值已经展现出极具吸引力的配置价值,PIMCO目前正在维持一定的久期风险敞口。

长端美债收益率创下近四分之一世纪新高,反映出市场对美国持续高企的财政赤字及长期通胀粘性的极度担忧。这一轮债券抛售潮不仅推高了无风险利率基准,也显著重塑了机构对资产安全边际的预期。

从宏观金融市场来看,创纪录的高收益率正强力虹吸全球流动性,强化美元指数的韧性,并对高估值权益资产构成沉重的折现压力。若未来经济增长放缓或科技股出现深度回调,资金可能加速向高票息的长端国债回流,从而抑制整体风险偏好。

对于加密资产而言,无风险收益率维持在历史高位意味着机构配置加密货币的机会成本大幅上升。在宏观流动性持续收紧和流动性抽离的双重压力下,以 $BTC 为代表的风险资产短期内或将面临更严峻的估值承压与震荡调整。 #US10Y #BondMarket #MacroEconomy
BTC-6.29%
TLTETF+1.55%
AGGETF+0.72%
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number