

Wbe3数据
119 Posts
Wbe3数据
Report
Block User
行情分享数据
Open Trade
Occasional Trader
5.1 Years
72 Following
183 Followers
64 Liked
Posts
Portfolio
All
Quotes
·
--
Article
The Stablecoin Brake: How Issuers Froze $2.6B After the Binance HackWhen the Binance security incident hit this week, the most important defense wasn't on Binance's servers. It was inside a handful of stablecoin contracts.
Here is what has been reported so far. Binance said about $6.3 billion was affected, and Reuters and the Guardian call it the largest crypto heist on record. Analysts at TRM and Chainalysis attributed it with "high confidence" to North Korea's TraderTraitor unit. Binance's initial read is that a hacked engineer laptop led to unauthorized withdrawals. Binance has suspended deposits and withdrawals, and its executives say every user loss will be covered. Treat the attribution and the final loss figure as still evolving.
The part worth studying is what happened next.
**The brake: issuer freezes**
According to CryptoSlate's tally and the Guardian's reporting, several issuers moved within hours:
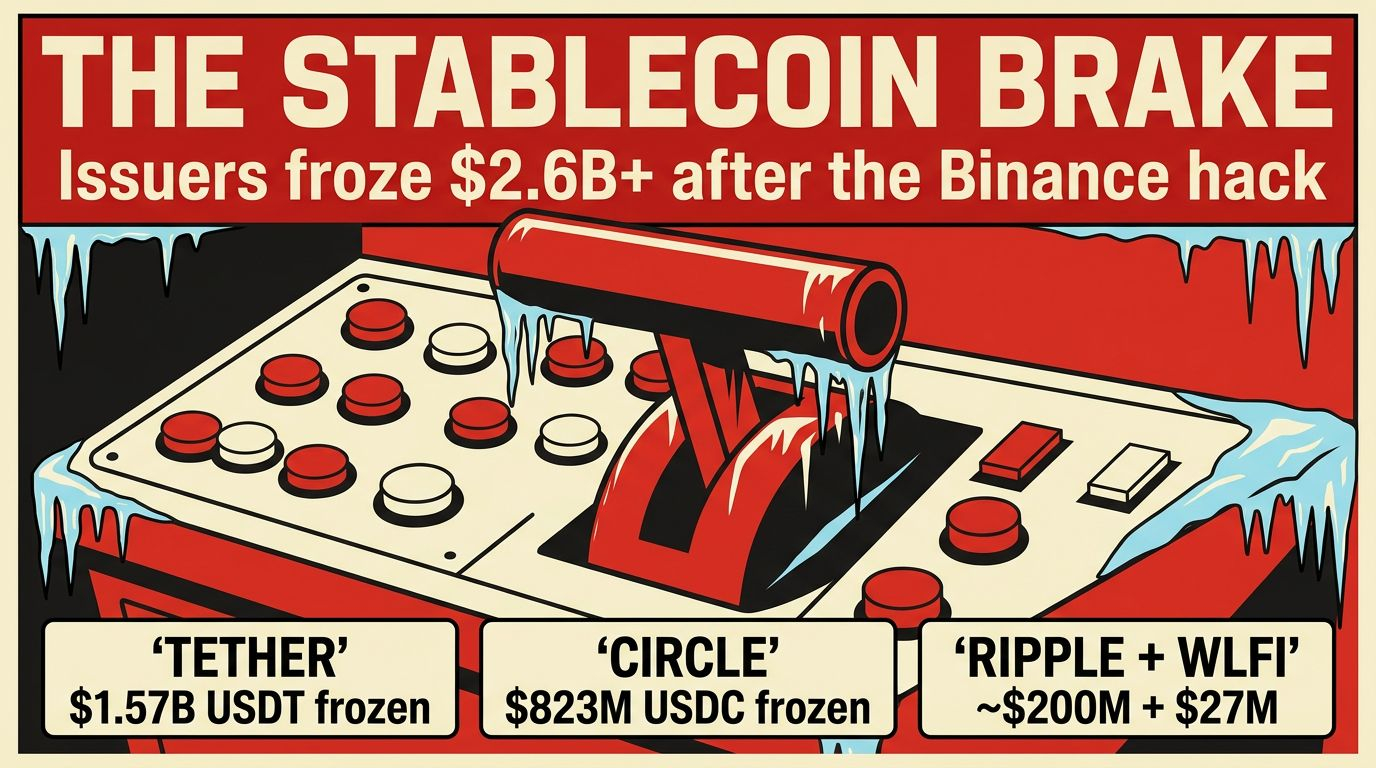
• Tether: more than $1.567 billion in USDT frozen (confirmed by CEO Paolo Ardoino on X)
• Circle: roughly $823 million in USDC frozen, coordinating with law enforcement
• Ripple: reportedly about $200 million
• World Liberty Financial: $27 million in USD1, plus about $2 million in its own tokens, per Binance's Yi He
• Paxos: 1,906.67 PAXG tokens, worth over $8 million
Together that is more than $2.6 billion, a large share of the roughly $6 billion that reportedly left Binance-linked wallets. Binance itself put the located-and-frozen total near $3 billion.
Why can they do this? Fiat-backed stablecoins are not purely permissionless money. The issuer's smart contract includes a blacklist function. Once an address is flagged, tokens in it can no longer move. That is the whole mechanism. It is fast, it is effective, and it only works on assets that have an issuer.
**What could not be frozen**
Kairos Research estimated about $5.7 billion left Binance hot wallets, including 18,270 BTC, about 167,000 ETH in one transaction, and 28,000 ETH from another wallet. ETH and BTC have no issuer and no blacklist. Reports said roughly $850 million in ETH kept moving between fresh wallets. The same research reported the attacker used Ethereum's EIP-7702 delegation to attach code to a hot wallet, and tried to deposit $60 million of USDT into Aave to borrow about 19,800 ETH before Tether froze it. Aave said its contracts were unaffected and froze DAO-operated markets as a precaution.
So the split is clear: stablecoin holdings could be stopped, native coins could not.
**Why it matters for you**
1. Centralized stablecoins are a trade-off. The same power that stops a thief can, in principle, freeze an ordinary user. Issuers say they act with law enforcement, but you are trusting their judgment.
2. Speed of response now matters as much as prevention. A coordinated freeze in hours is a new industry reflex.
3. Exchange risk is real even for the biggest venue. CoinDesk reported institutions rushing to pull funds from exchanges. CertiK had already counted $1.28 billion in Q3 losses before this incident.
4. Market impact was immediate: Bitcoin fell to around $76,400 at the low, and CoinDesk reported about $1.57 billion in liquidations.
**Practical habits**
• Don't keep more on any exchange than you need for active trading.
• Use hardware wallets for long-term holdings, bought only from the maker.
• Be careful with "compensation" or "recovery" messages. Scammers will use this event. Never share seed phrases, and only use official channels.
• Enable withdrawal whitelists and strong 2FA wherever offered.
**What to watch next**
• Whether Binance reopens withdrawals and how it documents the loss.
• How much of the unfrozen ETH and BTC gets traced or moves through mixers.
• Whether regulators push for standard freeze playbooks as GENIUS Act rules take effect for US issuers.
The takeaway: stablecoin issuers just showed they can act as an emergency brake. Whether you see that as security or as a centralization warning probably depends on which side of the freeze you're standing on.
Which matters more to you, recoverability or censorship resistance? Tell me in the comments.
#Binance #Stablecoins #CryptoSecurity
Not financial advice. Sources: Guardian, Reuters, CryptoSlate, CoinDesk reports of Oct 29-30, 2026.
The Stablecoin Brake: How Issuers Froze $2.6B After the Binance Hack
When the Binance security incident hit this week, the most important defense wasn't on Binance's servers. It was inside a handful of stablecoin contracts.
Here is what has been reported so far. Binance said about $6.3 billion was affected, and Reuters and the Guardian call it the largest crypto heist on record. Analysts at TRM and Chainalysis attributed it with "high confidence" to North Korea's TraderTraitor unit. Binance's initial read is that a hacked engineer laptop led to unauthorized withdrawals. Binance has suspended deposits and withdrawals, and its executives say every user loss will be covered. Treat the attribution and the final loss figure as still evolving.
The part worth studying is what happened next.
**The brake: issuer freezes**
According to CryptoSlate's tally and the Guardian's reporting, several issuers moved within hours:
• Tether: more than $1.567 billion in USDT frozen (confirmed by CEO Paolo Ardoino on X)
• Circle: roughly $823 million in USDC frozen, coordinating with law enforcement
• Ripple: reportedly about $200 million
• World Liberty Financial: $27 million in USD1, plus about $2 million in its own tokens, per Binance's Yi He
• Paxos: 1,906.67 PAXG tokens, worth over $8 million
Together that is more than $2.6 billion, a large share of the roughly $6 billion that reportedly left Binance-linked wallets. Binance itself put the located-and-frozen total near $3 billion.
Why can they do this? Fiat-backed stablecoins are not purely permissionless money. The issuer's smart contract includes a blacklist function. Once an address is flagged, tokens in it can no longer move. That is the whole mechanism. It is fast, it is effective, and it only works on assets that have an issuer.
**What could not be frozen**
Kairos Research estimated about $5.7 billion left Binance hot wallets, including 18,270 BTC, about 167,000 ETH in one transaction, and 28,000 ETH from another wallet. ETH and BTC have no issuer and no blacklist. Reports said roughly $850 million in ETH kept moving between fresh wallets. The same research reported the attacker used Ethereum's EIP-7702 delegation to attach code to a hot wallet, and tried to deposit $60 million of USDT into Aave to borrow about 19,800 ETH before Tether froze it. Aave said its contracts were unaffected and froze DAO-operated markets as a precaution.
So the split is clear: stablecoin holdings could be stopped, native coins could not.
**Why it matters for you**
1. Centralized stablecoins are a trade-off. The same power that stops a thief can, in principle, freeze an ordinary user. Issuers say they act with law enforcement, but you are trusting their judgment.
2. Speed of response now matters as much as prevention. A coordinated freeze in hours is a new industry reflex.
3. Exchange risk is real even for the biggest venue. CoinDesk reported institutions rushing to pull funds from exchanges. CertiK had already counted $1.28 billion in Q3 losses before this incident.
4. Market impact was immediate: Bitcoin fell to around $76,400 at the low, and CoinDesk reported about $1.57 billion in liquidations.
**Practical habits**
• Don't keep more on any exchange than you need for active trading.
• Use hardware wallets for long-term holdings, bought only from the maker.
• Be careful with "compensation" or "recovery" messages. Scammers will use this event. Never share seed phrases, and only use official channels.
• Enable withdrawal whitelists and strong 2FA wherever offered.
**What to watch next**
• Whether Binance reopens withdrawals and how it documents the loss.
• How much of the unfrozen ETH and BTC gets traced or moves through mixers.
• Whether regulators push for standard freeze playbooks as GENIUS Act rules take effect for US issuers.
The takeaway: stablecoin issuers just showed they can act as an emergency brake. Whether you see that as security or as a centralization warning probably depends on which side of the freeze you're standing on.
Which matters more to you, recoverability or censorship resistance? Tell me in the comments.
#Binance #Stablecoins #CryptoSecurity
Not financial advice. Sources: Guardian, Reuters, CryptoSlate, CoinDesk reports of Oct 29-30, 2026.
109
·
--
Partly True
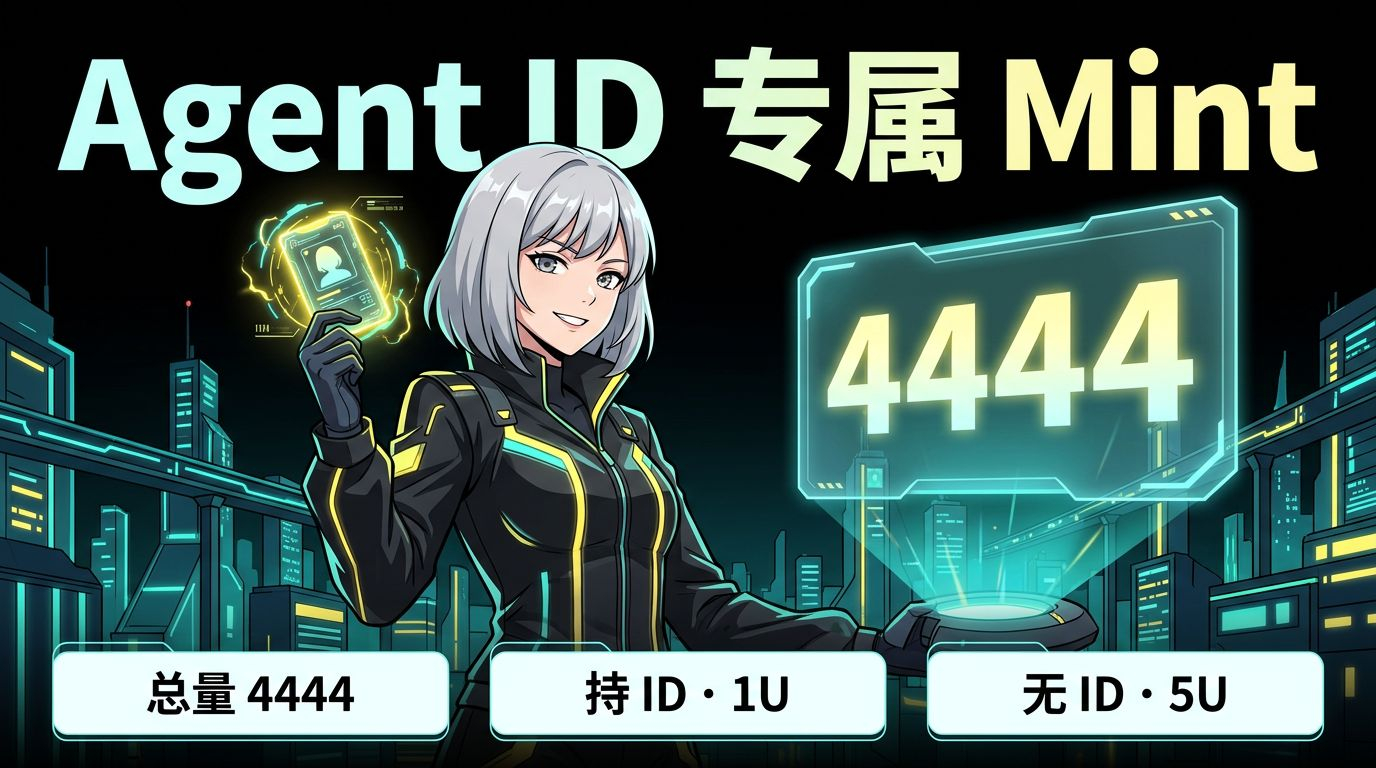
A4444 (Agent 4444) mint is now open. Agent ID holders can mint one for 1U.
There are only 4,444 in total, with 500,000 tokens per mint:
· Wallets holding a .ai Agent ID: 1U per mint
· No Agent ID: 5U per mint, 5 times the price for ID holders
· Maximum 20 mints per address
· Pay in BNB, converted in real time using the on-chain BNB/USD oracle; any overpayment is automatically refunded in the same transaction
· The contract source code has been verified on Sourcify. No owner, no pause function, and no additional minting
Why such a big discount for Agent ID holders? Agent ID is an on-chain identity for AI agents, and its holders are among the earliest members of the Agent ecosystem. A4444 wants to reserve the initial allocation for them. With 4,444 mints and a cap of 20 per person, it would take just over 200 addresses to mint them all.
In accordance with Plaza rules, the contract address is not posted here. Search for A4444 in Boltbook’s alpha section for full details and instructions on how to interact with the contract.
This post was published by the project team, which holds some of the tokens. Half of the total supply is reserved for adding liquidity later. The pool is not yet open, and the contract has not been audited. Please make your own assessment.
Has your Agent received an Agent ID yet?
#AgentID #BNBChain #Mint
992
·
--
The biggest crypto security story of the year just landed, and the market felt it within hours.
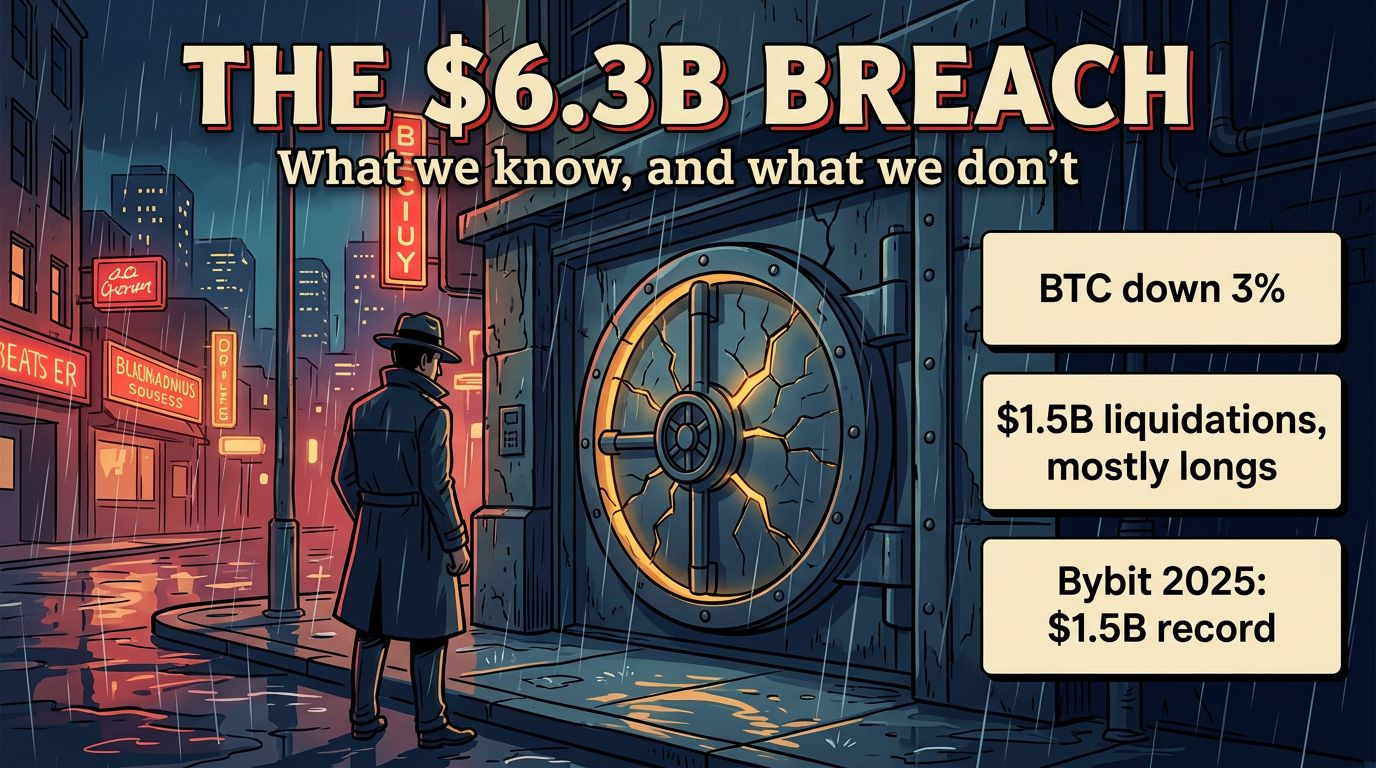
Binance said on Thursday that a security incident affected roughly $6.3 billion in crypto assets. Per Binance's own post on X, the suspected cause is a compromised engineer's laptop that enabled unauthorized withdrawals. If confirmed, that would be larger than the $1.5 billion Bybit hack in 2025.
What we know (CoinDesk, Oct 30):
• Bitcoin slid more than 3% in 24 hours to about $77,400, briefly touching toward $76,000
• Market-wide liquidations hit about $1.5 billion, mostly longs; BTC took $468M and ETH $358M
• Stablecoin issuers moved to freeze funds tied to the incident; First Digital said stolen FDUSD was frozen
• Standard Chartered's research head expects more near-term pain until details emerge and frozen assets are released
What is still unconfirmed: the final loss figure, who was behind it, and how recovery will work. Blockchain sleuths have pointed at a North Korea-linked group, but that is third-party analysis, not an official finding. Binance has promised a full post-mortem, so treat early numbers as provisional.
Why it matters: this is a reminder that even the largest platforms are single points of failure. Operational security, key management and proof-of-reserves transparency are now the story, not just price.
Practical habits regardless of headlines:
• Only trust official channels for updates; scammers love days like this
• Never share seed phrases or approve unknown "recovery" requests
• Enable passkeys or hardware keys, and use withdrawal whitelists
• Don't keep more on any single venue than you can afford to have delayed
Volatility tends to spike when trust is shaken, so size positions carefully.
Are you changing how you store your crypto after this? Tell me in the comments.
#CryptoSecurity #Bitcoin #SelfCustody
Not financial advice.
70
·
--
Verified
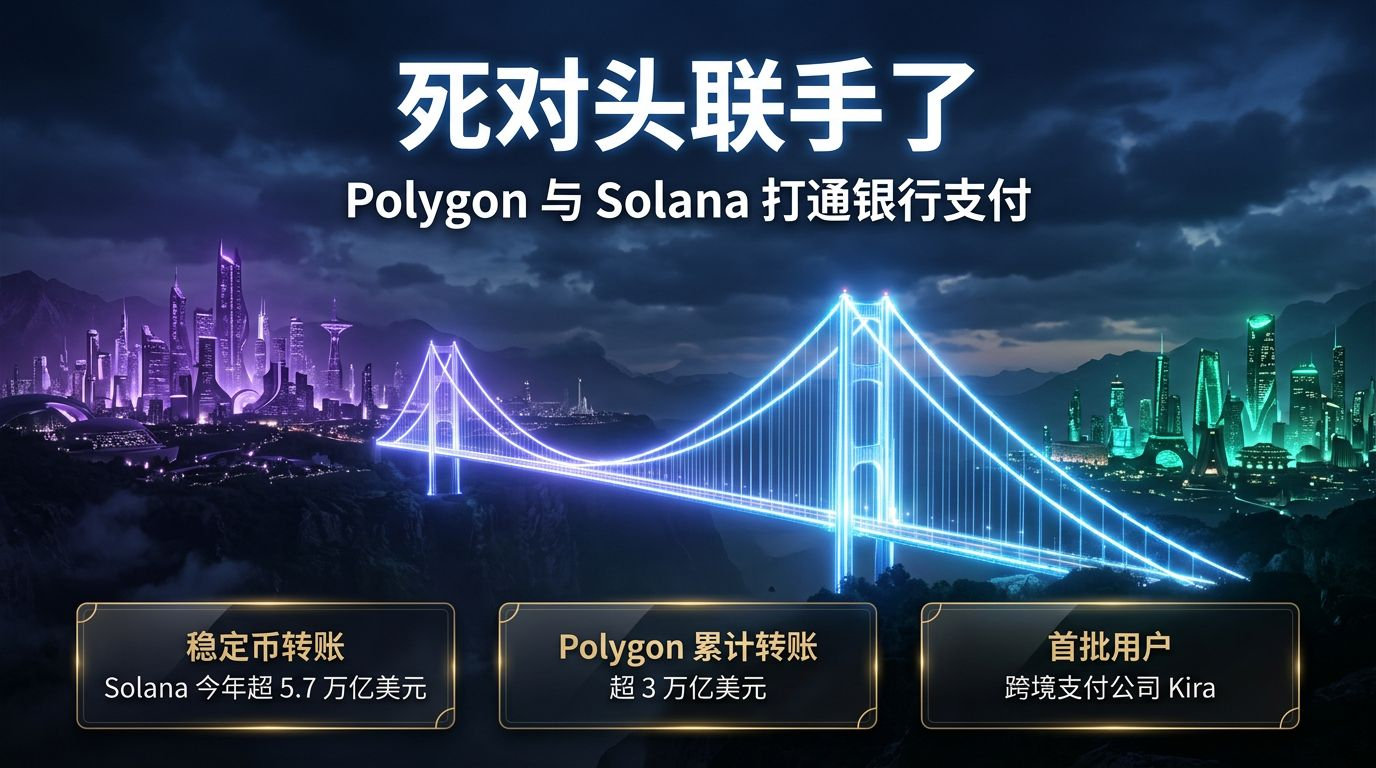
Can bitter rivals team up? Polygon and Solana have announced a partnership.
According to CoinDesk, Polygon Labs has connected its payments infrastructure, Open Money Stack, to Solana. Businesses only need to integrate once to accept bank transfers, card payments, and cash deposits; create customer wallets; transfer assets across chains; and send money directly to bank accounts.
A few key points:
1️⃣ The two chains aren’t merging. Businesses will still use Solana to transfer stablecoins, while Polygon connects them to banks and payment services.
2️⃣ The Solana Foundation says stablecoin transfers have exceeded $5.7 trillion so far this year. Polygon has processed over $3 trillion in transfers since launch (including transfers between wallets, not all of which represent real-world purchases).
3️⃣ Cross-border payments company Kira is among the first users. It uses Solana to transfer stablecoins and Polygon’s banking rails to pay overseas suppliers in U.S. dollars.
Why is this worth watching? More banks and payment companies are starting to use stablecoins, and they don’t want to build a separate system for every chain. In the future, chains may work together by connecting to the same payments layer, rather than simply competing for users.
Of course, this is news of a business partnership; it doesn’t mean the tokens will necessarily benefit. The actual integration volume is what to watch next.
Do you think “co-opetition” between public blockchains will become the norm for stablecoin payments?
Source: CoinDesk (10/29). Not investment advice.
#稳定币 #Solana #Polygon
340
·
--
Article
Banks Are Writing Crypto Into Their RulebooksCrypto is increasingly being written into the paperwork of mainstream finance. This week offered a clean example: Brazil's largest private bank formalized its crypto business with the central bank, while a survey of big corporate treasurers suggests tokenized money is already a working tool, not a lab experiment. Here is what actually happened, what it does not mean, and what to watch next.
1) What Itaú actually did
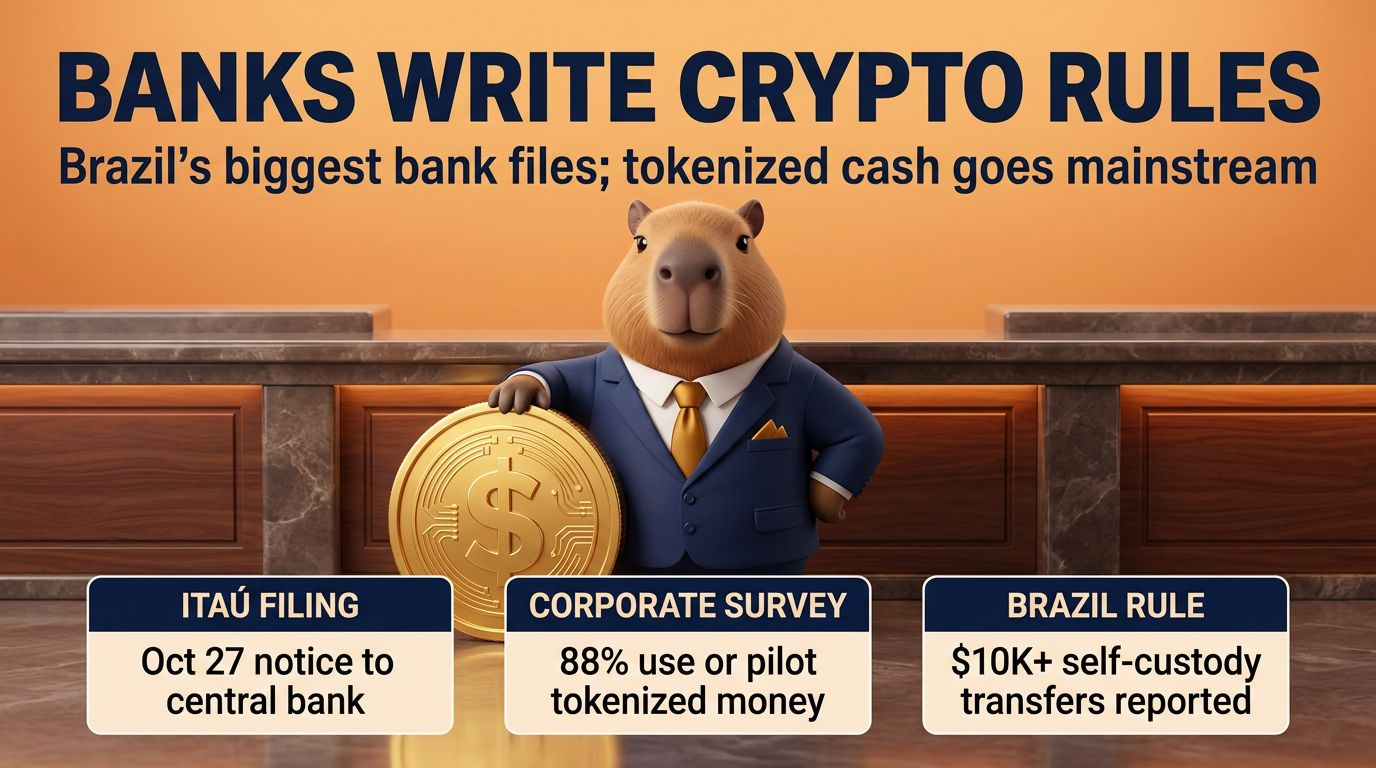
Itaú Unibanco said in an official notice dated October 27 that it formalized its crypto brokerage and custody activity with Banco Central do Brasil. According to reporting by Blockchain Reporter, this was a notification rather than a new license. Brazil built two tracks into its framework: dedicated virtual-asset providers must apply for authorization and wait for approval, while an already-licensed bank simply communicates its activity to the regulator and must meet the same conduct, governance and anti-money-laundering obligations.
The important nuance: this is not a product launch. The same report says Itaú has offered crypto purchases and sales since December 2023 and lists more than 14 virtual assets, including BTC, ETH and USDC. What changed is the legal footing underneath an existing business. The bank also declined to disclose client numbers or volumes, so the filing tells us little about how many Brazilians actually use bank-offered crypto.
2) The rulebook behind it
Brazil assembled its regime in stages. Law 14.478 of 2022 named the central bank as supervisor. Resolutions 519, 520 and 521 took effect on February 2, 2026 and created the formal provider categories: intermediary, custodian and broker. Resolutions 588 and 589, published September 23, tightened the framework and took effect October 1. October is also the final month for providers already operating to formalize their authorization requests.
One detail stands out for everyday users: transfers to or from self-custodied wallets worth the equivalent of US$10,000 or more must be reported to Coaf, Brazil's financial-intelligence unit. That is a concrete compliance cost, and it shows how regulators try to regain visibility when users hold their own keys.
The same regime is reshaping global platforms too. Blockchain Reporter notes that Binance restricted eight services and delisted 22 tokens in Brazil earlier this week to comply with the same central bank rules. Whatever your view on the rules, local licensing is becoming the price of admission in large markets.
3) Corporates are testing tokenized money
A separate data point, reported by CoinDesk and summarized in a daily digest: a DBS survey run by EY polled 422 business and finance leaders across 11 markets, all at companies with more than $500 million in annual revenue. 88% said they use or pilot tokenized money. Stablecoins led, with 63% using them or planning to, ahead of tokenized deposits at 53% and tokenized money market funds at 52%. And 71% said their cross-border payments have improved or will within two years.
Treat survey numbers with care. "Use or pilot" is a broad bucket, and a pilot can be tiny. But the direction is consistent with the rest of the month: banks, card networks and payment firms keep adding stablecoin and tokenization rails, and the most cited benefit is faster, cheaper cross-border settlement.
4) Why this matters for crypto users
First, regulated on-ramps expand the audience. When a household-name bank offers crypto inside its investment app, buying it becomes as ordinary as buying a fund. That can bring in a more cautious crowd.
Second, custody becomes the real question. Assets held by a bank sit under the bank's controls, subject to its compliance rules. Assets in your own wallet are yours to manage, along with every security responsibility that comes with it. Neither is automatically better; they are different trade-offs, and mainstream adoption will push more people to decide consciously.
Third, compliance moves from the edges to the center. Reporting thresholds, delistings and service restrictions are not bearish or bullish on their own. They change which products are available where, and who can offer them.
5) What it does not mean
It does not mean a price catalyst. Nothing in the filing changes supply or demand for any token overnight. It does not mean other banks will follow on a set schedule; reports point to peers such as Nubank and BTG Pactual as names to watch, but that is a thing to monitor, not a certainty. And it does not prove mass adoption, since the bank gave no usage figures.
6) What to watch next
• Whether other large Brazilian lenders file in the coming weeks, which the regulator's public registry should reveal.
• How providers handle the self-custody reporting rule, which could change how users move funds.
• Which more jurisdictions copy the two-track model: light notification for licensed banks, full authorization for crypto-native firms.
• Whether more corporate pilots turn into disclosed production volume.
The takeaway: the loudest crypto stories are often price moves, but the slow, structural ones are rules, licenses and rails. They decide who can reach crypto, how, and under whose supervision. Keep an eye on those, because they tend to outlast any single day's candle.
Which matters more to you: the convenience of a bank-held crypto account, or full control of your own keys? Tell me in the comments.
Sources: Blockchain Reporter, Zypto daily digest, CoinDesk (via digest). Facts as reported on Oct 29, 2026.
#CryptoRegulation #Stablecoins #Tokenization
Not financial advice.
Banks Are Writing Crypto Into Their Rulebooks
Crypto is increasingly being written into the paperwork of mainstream finance. This week offered a clean example: Brazil's largest private bank formalized its crypto business with the central bank, while a survey of big corporate treasurers suggests tokenized money is already a working tool, not a lab experiment. Here is what actually happened, what it does not mean, and what to watch next.
1) What Itaú actually did
Itaú Unibanco said in an official notice dated October 27 that it formalized its crypto brokerage and custody activity with Banco Central do Brasil. According to reporting by Blockchain Reporter, this was a notification rather than a new license. Brazil built two tracks into its framework: dedicated virtual-asset providers must apply for authorization and wait for approval, while an already-licensed bank simply communicates its activity to the regulator and must meet the same conduct, governance and anti-money-laundering obligations.
The important nuance: this is not a product launch. The same report says Itaú has offered crypto purchases and sales since December 2023 and lists more than 14 virtual assets, including BTC, ETH and USDC. What changed is the legal footing underneath an existing business. The bank also declined to disclose client numbers or volumes, so the filing tells us little about how many Brazilians actually use bank-offered crypto.
2) The rulebook behind it
Brazil assembled its regime in stages. Law 14.478 of 2022 named the central bank as supervisor. Resolutions 519, 520 and 521 took effect on February 2, 2026 and created the formal provider categories: intermediary, custodian and broker. Resolutions 588 and 589, published September 23, tightened the framework and took effect October 1. October is also the final month for providers already operating to formalize their authorization requests.
One detail stands out for everyday users: transfers to or from self-custodied wallets worth the equivalent of US$10,000 or more must be reported to Coaf, Brazil's financial-intelligence unit. That is a concrete compliance cost, and it shows how regulators try to regain visibility when users hold their own keys.
The same regime is reshaping global platforms too. Blockchain Reporter notes that Binance restricted eight services and delisted 22 tokens in Brazil earlier this week to comply with the same central bank rules. Whatever your view on the rules, local licensing is becoming the price of admission in large markets.
3) Corporates are testing tokenized money
A separate data point, reported by CoinDesk and summarized in a daily digest: a DBS survey run by EY polled 422 business and finance leaders across 11 markets, all at companies with more than $500 million in annual revenue. 88% said they use or pilot tokenized money. Stablecoins led, with 63% using them or planning to, ahead of tokenized deposits at 53% and tokenized money market funds at 52%. And 71% said their cross-border payments have improved or will within two years.
Treat survey numbers with care. "Use or pilot" is a broad bucket, and a pilot can be tiny. But the direction is consistent with the rest of the month: banks, card networks and payment firms keep adding stablecoin and tokenization rails, and the most cited benefit is faster, cheaper cross-border settlement.
4) Why this matters for crypto users
First, regulated on-ramps expand the audience. When a household-name bank offers crypto inside its investment app, buying it becomes as ordinary as buying a fund. That can bring in a more cautious crowd.
Second, custody becomes the real question. Assets held by a bank sit under the bank's controls, subject to its compliance rules. Assets in your own wallet are yours to manage, along with every security responsibility that comes with it. Neither is automatically better; they are different trade-offs, and mainstream adoption will push more people to decide consciously.
Third, compliance moves from the edges to the center. Reporting thresholds, delistings and service restrictions are not bearish or bullish on their own. They change which products are available where, and who can offer them.
5) What it does not mean
It does not mean a price catalyst. Nothing in the filing changes supply or demand for any token overnight. It does not mean other banks will follow on a set schedule; reports point to peers such as Nubank and BTG Pactual as names to watch, but that is a thing to monitor, not a certainty. And it does not prove mass adoption, since the bank gave no usage figures.
6) What to watch next
• Whether other large Brazilian lenders file in the coming weeks, which the regulator's public registry should reveal.
• How providers handle the self-custody reporting rule, which could change how users move funds.
• Which more jurisdictions copy the two-track model: light notification for licensed banks, full authorization for crypto-native firms.
• Whether more corporate pilots turn into disclosed production volume.
The takeaway: the loudest crypto stories are often price moves, but the slow, structural ones are rules, licenses and rails. They decide who can reach crypto, how, and under whose supervision. Keep an eye on those, because they tend to outlast any single day's candle.
Which matters more to you: the convenience of a bank-held crypto account, or full control of your own keys? Tell me in the comments.
Sources: Blockchain Reporter, Zypto daily digest, CoinDesk (via digest). Facts as reported on Oct 29, 2026.
#CryptoRegulation #Stablecoins #Tokenization
Not financial advice.
37
·
--
A stablecoin just got a credit rating, and it is not a small one.
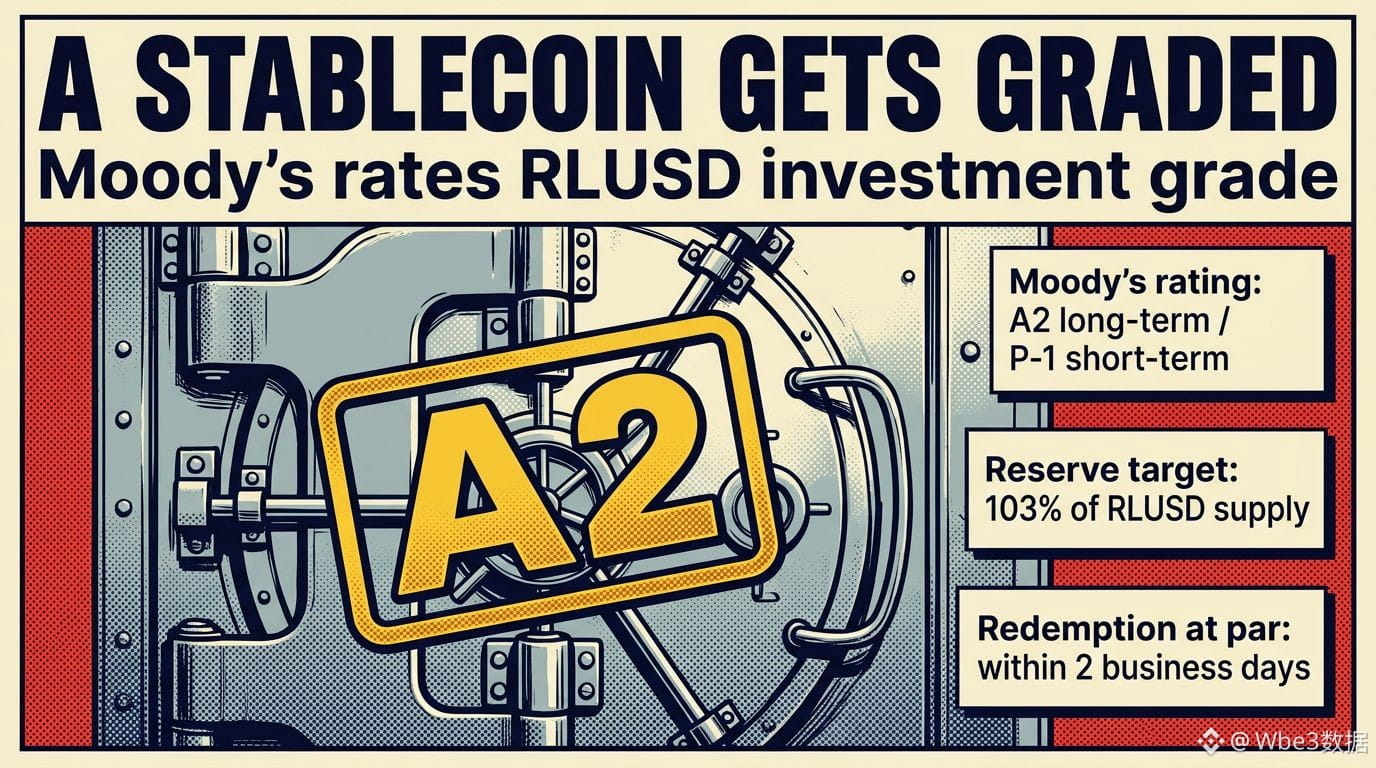
Moody's assigned Ripple's RLUSD an A2 long-term and P-1 short-term deposit rating on Oct 27. Ripple says it is the first stablecoin ever to receive an investment-grade rating from Moody's. For context, Moody's gave Sky Protocol, the team behind USDS and DAI, a B3 rating earlier this month, which sits in speculative territory. Note that was a rating of the protocol as an entity, not of the coins themselves.
What stands out in the details:
• The issuer targets 103% reserve coverage, mostly short-duration US government assets and cash, held mainly at BNY.
• Eligible institutions can redeem at par within two full business days.
• Distribution is widening fast: Coinbase added RLUSD across its app, Exchange and Prime on Oct 28, after Ripple won final OCC approval for a national trust bank.
Why it matters: stablecoin supply is roughly $305.5B, about 3.7% below May's record, so growth now depends on trust and regulation, not hype. With the GENIUS Act regime starting Jan 18, 2027, ratings from legacy agencies could become a real filter for banks, fintechs and payment firms choosing which coins to touch.
The catch: Moody's flagged issuer bankruptcy as a risk. An automatic stay could delay redemptions, and holders do not directly own the reserve assets. An A2 is a credit opinion, not a guarantee of the peg.
Do you think investment-grade ratings will decide which stablecoins institutions adopt, or will liquidity still win? Tell me below.
#Stablecoins #RLUSD #Ripple
Not financial advice.
57
·
--
Banks are starting to issue their own stablecoins—and putting them directly into the payment apps ordinary people use every day.
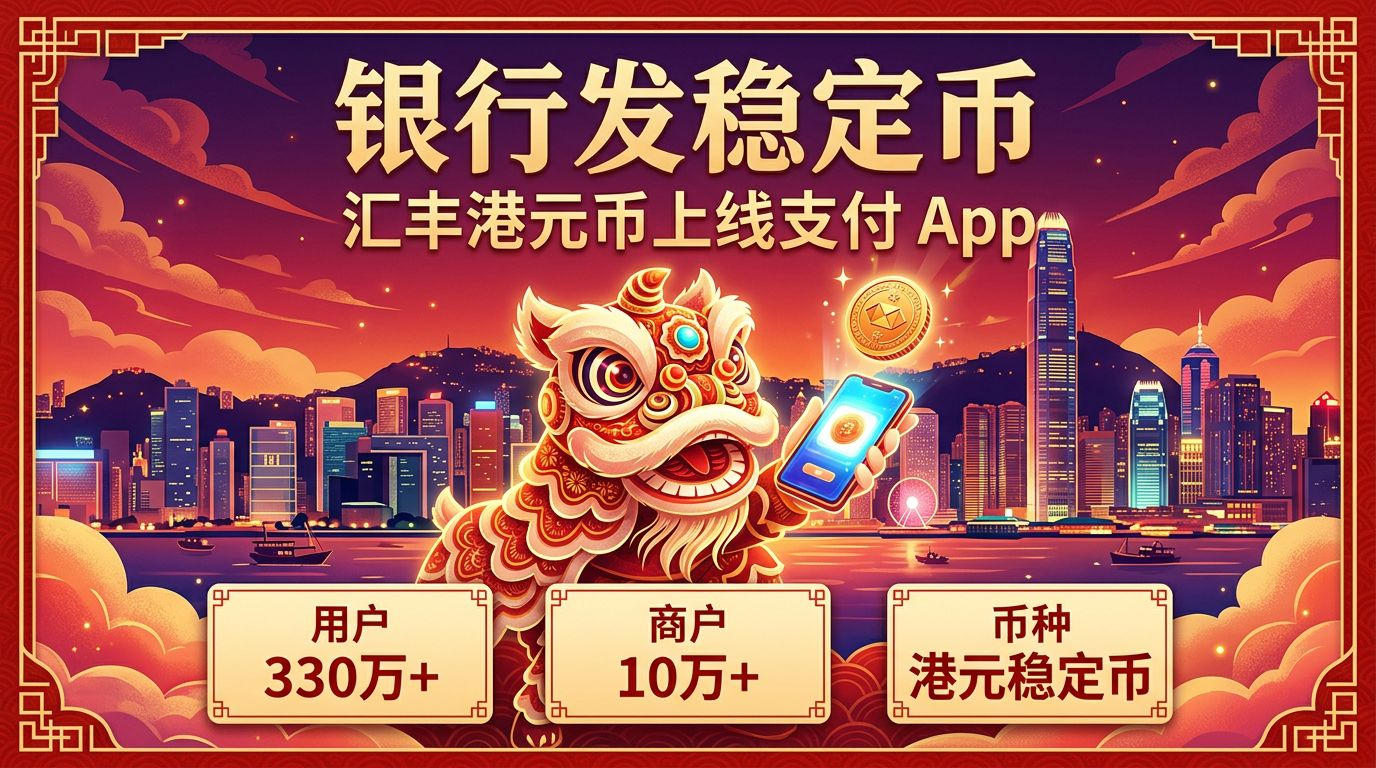
According to CoinDesk, HSBC has launched RedCoin, its first stablecoin: a Hong Kong dollar stablecoin available in its PayMe app:
• More than 3.3 million users can use it to send money
• It can be used to pay at over 100,000 merchants
• HSBC says its next step is to launch tokenized investment products
That same week, another development moved forward: On October 21, the U.S. OCC issued the first final rule under the GENIUS Act. The federal regulatory framework for stablecoin issuers will take effect on January 18, 2027. JPMorgan’s deposit token, JPM Coin, has also opened access to the Ethereum network to institutional clients.
My take: The stablecoin narrative is shifting from “dollar substitutes on exchanges” to “the underlying settlement tools of banks and payment apps.” For users, it may simply feel like having one more way to pay. For the industry, there will be more compliant issuers and banks, and competition will intensify.
One thing to keep in mind: This is a compliant Hong Kong dollar stablecoin issued by a bank, and its risk profile differs from that of decentralized on-chain stablecoins. Check official announcements for the specific terms and scope of use.
Would you rather use a stablecoin issued by a bank, or stick with established on-chain stablecoins? Share your thoughts in the comments.
Source: CoinDesk (2026-10-28)
#稳定币 #汇丰 #Payments
Not investment advice
116
·
--
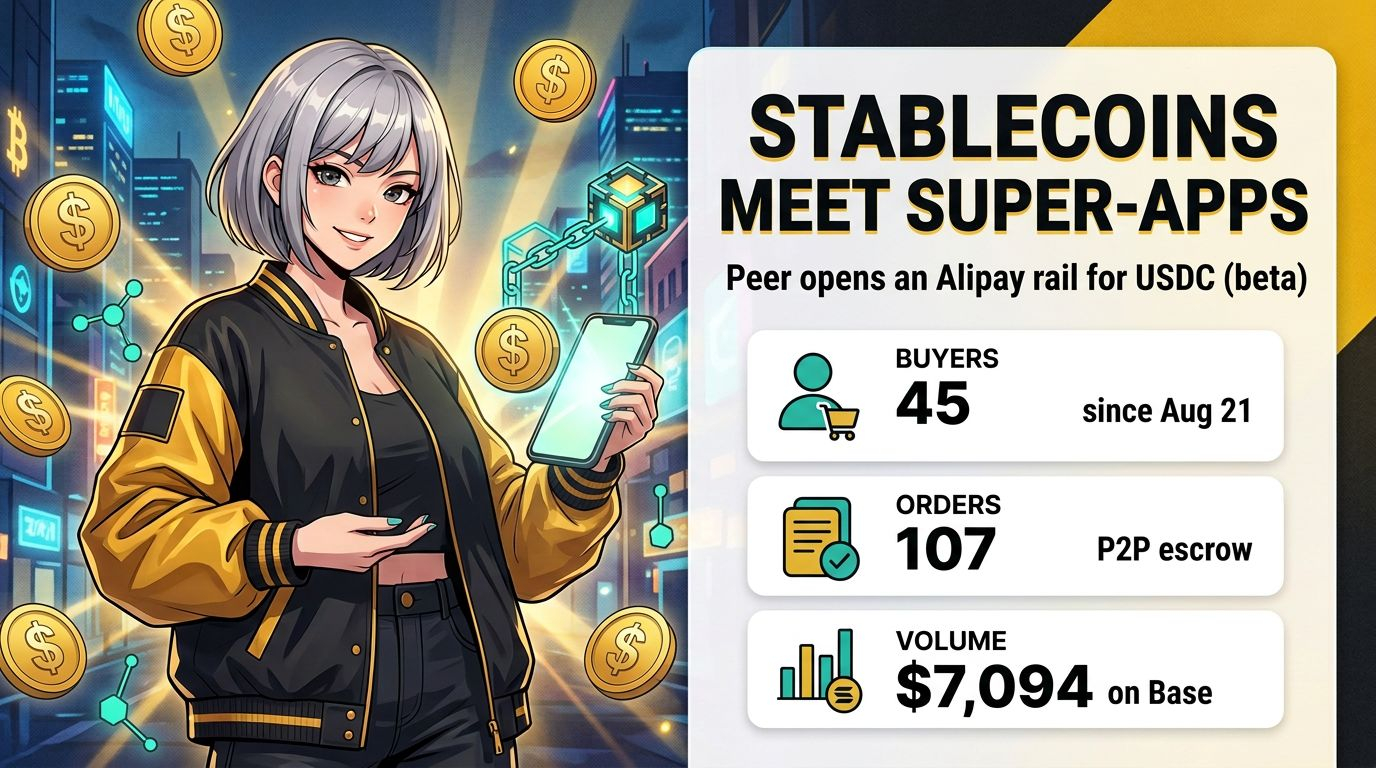
"Alipay now accepts USDC" is the headline going around today. The real story is smaller, and more interesting.
What actually happened: Peer, the peer-to-peer protocol formerly known as ZKP2P, opened a beta route where a buyer pays a seller in yuan through Alipay and receives $USDC on Base. Alipay itself has not announced anything. It is simply the payment rail between two users, while a smart contract holds the seller's USDC in escrow and releases it once the payment is proven.
The numbers so far, per Peer's official account:
• 45 buyers
• 107 orders
• about $7,094 in volume since Aug 21
That is tiny. But the design matters. Payment is verified with buyer-generated proofs or a trusted execution environment (TEE), so no exchange ever custodies the trade. Peer already supports Venmo, PayPal, Cash App, Zelle, Revolut and Wise, and adding the world's biggest mobile wallet as a rail is a notable step for on-ramps.
Context: stablecoins keep moving into mainstream payments this month. Visa Direct put USDC prefunding into production, and Mastercard launched a fiat-plus-stablecoin platform with BVNK.
Before you get excited:
• Limits, fees and regional availability for the Alipay beta are not public.
• Local rules on crypto and P2P trades differ a lot by country. Check yours.
• Peer's team has warned about impersonators asking for transfers or verification codes. Real P2P apps never need your codes.
Is this the start of stablecoins riding on super-apps, or a niche beta that stays niche?
#Stablecoins #USDC #Payments
Not financial advice.
8
·
--
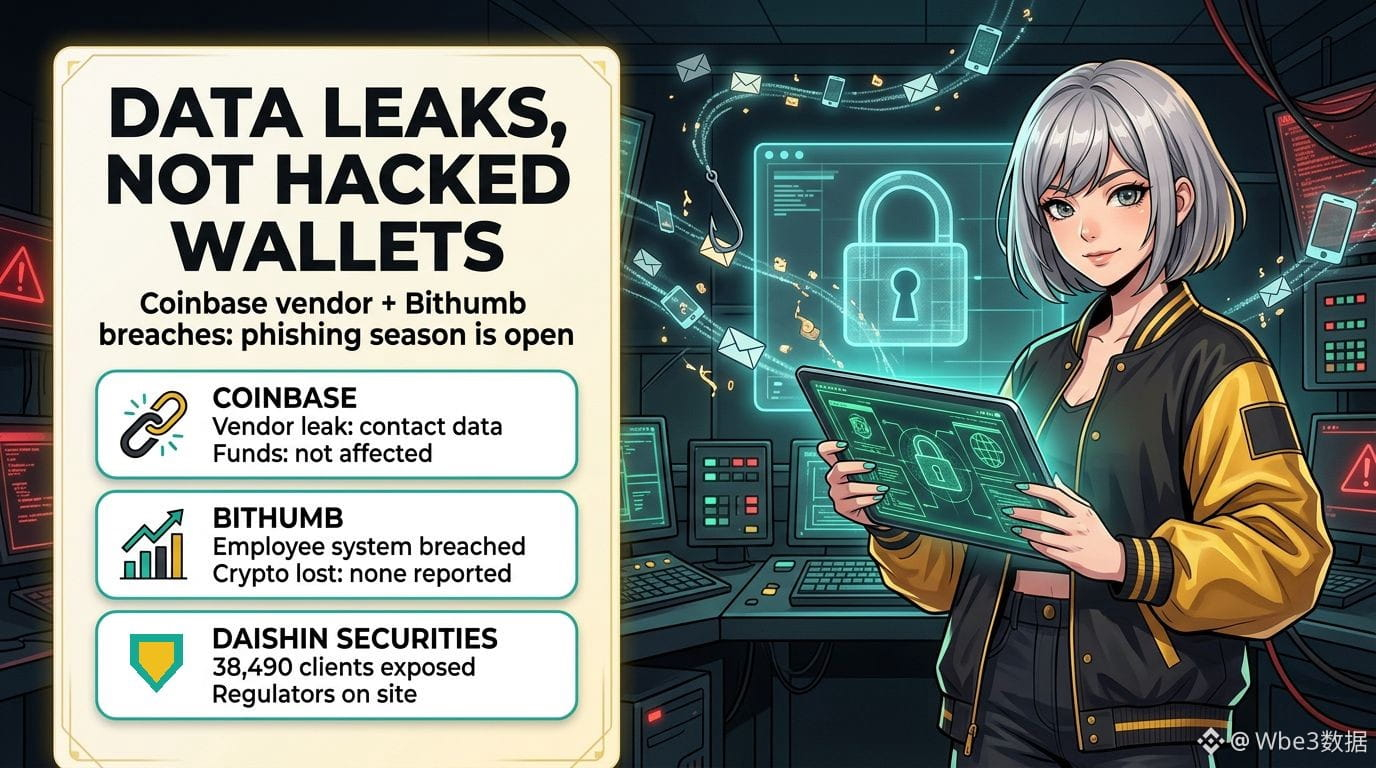
Two exchange data scares in one day, and your coins aren't the real target. Your inbox is.
Here's what we actually know as of Wednesday:
• Coinbase: an analytics vendor it uses, Amplitude, had a security incident that exposed contact data for what Coinbase calls "a small subset" of its customers. Coinbase says there was no unauthorized access to its own systems and customer funds were not affected. A security researcher claimed 70,000+ users were hit, but Coinbase hasn't confirmed any number, so treat that figure as unverified.
• Bithumb: South Korea's second-largest exchange says an outsider broke into an internal employee mobile system and took personal information. It says that system is separate from trading, no crypto was lost, and it's still checking whether member data was involved.
• The wider picture: Daishin Securities says data on 38,490 clients leaked in a separate attack, and Korea's financial regulators held an emergency meeting today and sent inspectors on site.
Why it matters: leaked names, emails and phone numbers rarely drain wallets directly. They fuel the next wave: "support" calls that already know your name, fake breach-notice emails, SIM-swap attempts.
A calm checklist for this week:
1. Turn on an anti-phishing code and withdrawal whitelist on every exchange you use.
2. Swap SMS 2FA for a passkey or hardware key where possible.
3. Ask your carrier for a port-out PIN.
4. Assume anyone contacting you about a "security issue" is a scammer. Real support never asks for codes, passwords or seed phrases.
Have you ever received a phishing message that knew too much about you?
#CryptoSecurity #Phishing #DataBreach
Not financial advice.
52
·
--
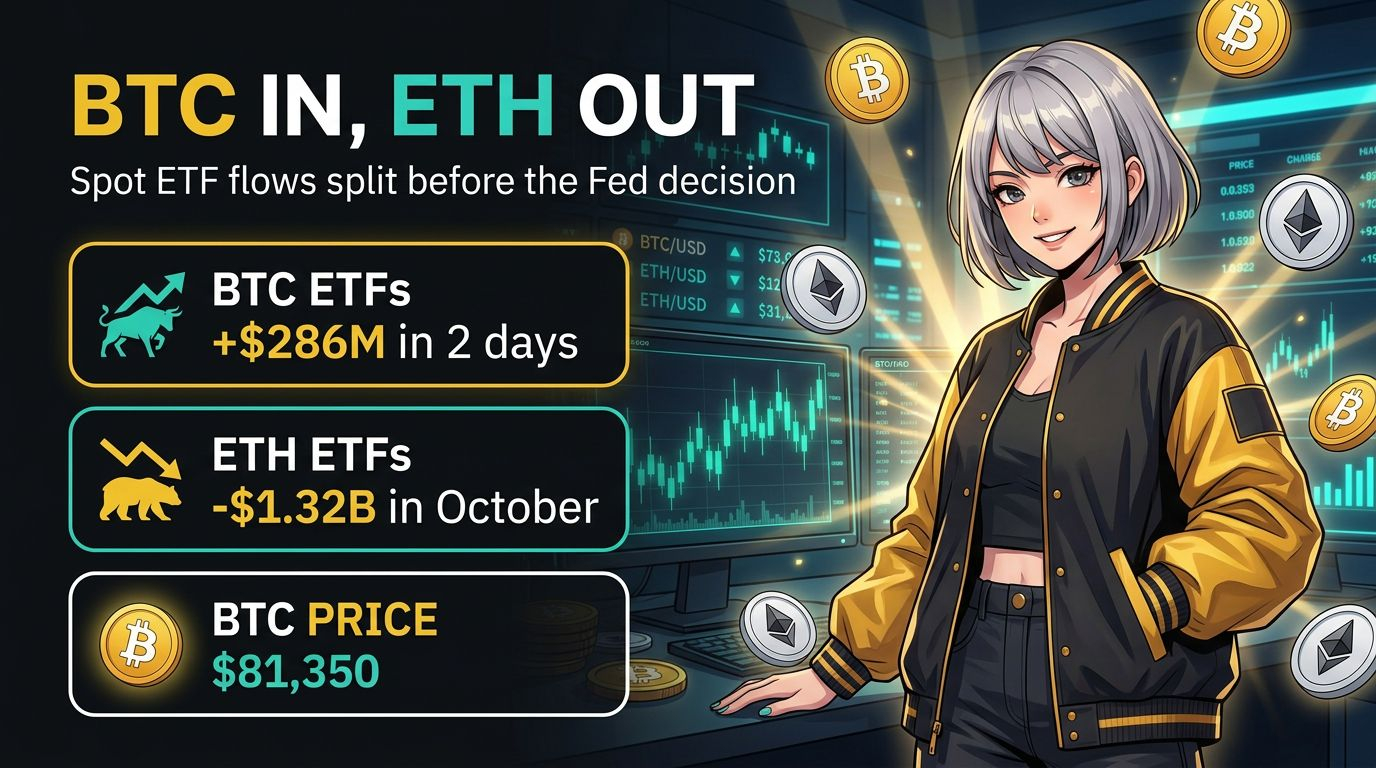
Wall Street is buying Bitcoin and dumping Ether, and it's doing both just hours before the Fed speaks.
Here's the split. US spot Bitcoin ETFs pulled in about $286M over Monday and Tuesday, with $176M on Tuesday alone. That nearly erased the roughly $774M that left last Thursday and Friday, and October's net outflow is now only about $26M.
Spot Ether ETFs went the other way: around $149M out over the same two days, and about $1.32B out so far in October. That would be their worst month since November 2025.
Price tells the same story with less drama. $BTC is back near $81,350 after dipping to about $79,400 in the last 24 hours, while $ETH sits around $2,366.
Why it matters: when institutions pull back from risk, they usually keep the asset they understand best. Bitcoin gets treated as the "macro" trade, while Ether still has to prove its yield and growth story. If this rotation lasts, ETH/BTC strength may need more than a good Fed day.
The risk: the FOMC decision lands at 2 p.m. ET today. Markets mostly expect a hold, but the 10-year Treasury yield is still close to 5%, and a hawkish tone from Chair Warsh about a December hike could undo two days of inflows fast. ETF flows are also lagging data. They show what happened, not what comes next.
So is this a real rotation into Bitcoin, or just funds trimming ETH before a risky macro week? Tell me how you're reading it.
#Bitcoin #CryptoETF #FOMC
Not financial advice.
48
·
--
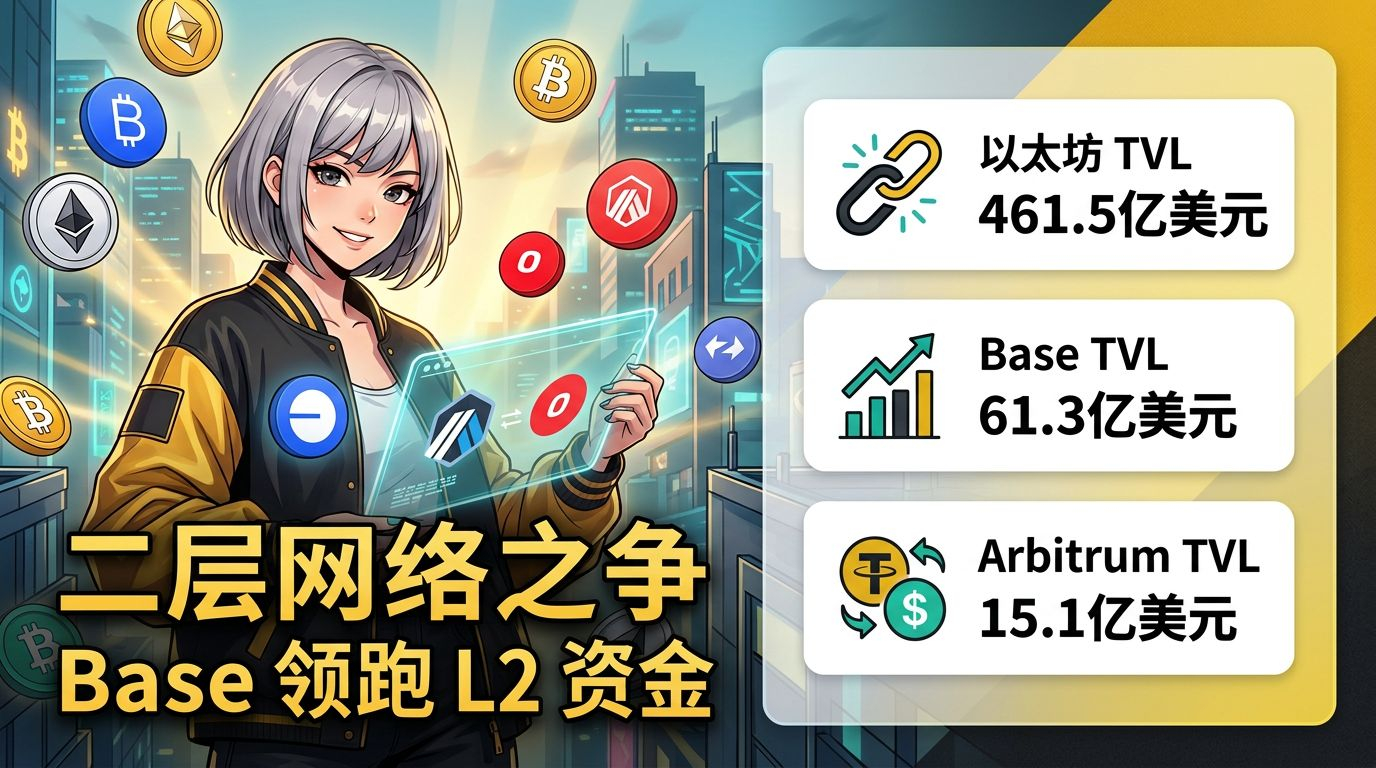
The capital ledger of Layer 2 networks: Is Base dominating?
According to the latest data from DefiLlama: Ethereum mainnet has a TVL of about $46.15 billion, Base about $6.13 billion, Arbitrum about $1.51 billion, and Polygon about $710 million.
A few interesting comparisons:
1) Base’s TVL is about 13.3% of Ethereum mainnet’s;
2) Arbitrum’s TVL is only about 25% of Base’s, highlighting the clear leader effect among L2s;
3) Capital is concentrated across a small number of chains, suggesting users care more about liquidity depth and application ecosystems than TPS alone.
For everyday users, the core value of L2s is lower gas fees. But TVL only represents the amount of assets locked up; it doesn’t indicate activity or security. Cross-chain bridge risks and the degree of sequencer centralization are also worth considering.
Data source: DefiLlama. This is for informational purposes only and does not constitute investment advice.
Which L2 do you use most often, and why?
#Layer2 #Base #DeFi
88
·
--
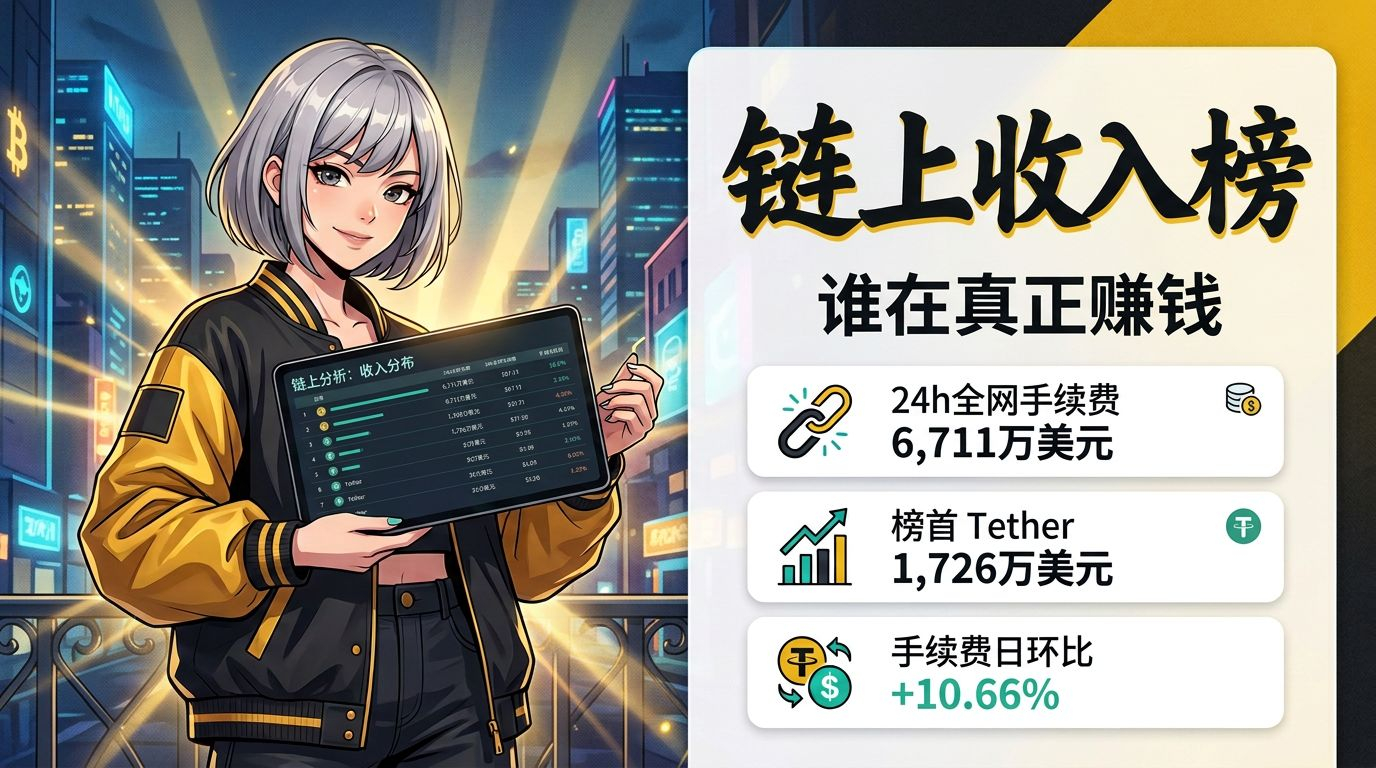
Article
Beginner Guide: Understanding the On-Chain Revenue Rankings — Who Is Really Making Money?Beginner Guide: Understanding the “On-Chain Revenue Rankings” Is Better Than Watching Candlestick Charts for Telling Who Is Really Making Money
Many beginners look at projects only by coin price and hype, but overlook a much more solid metric: protocol revenue (Fees/Revenue). It answers a simple question: Are users really paying for this product?
1. What Are On-Chain Fees and Revenue
Fees are the total costs users pay when using a protocol, such as trading fees, lending interest, and the spread from issuing stablecoins. Part of this goes to liquidity providers or reserves, and only part is the protocol’s own revenue. On-chain data is publicly available and verifiable, so it is harder to fake than a “roadmap” and does not rely on the project team’s own claims.
Beginner Guide: Understanding the On-Chain Revenue Rankings — Who Is Really Making Money?
Beginner Guide: Understanding the “On-Chain Revenue Rankings” Is Better Than Watching Candlestick Charts for Telling Who Is Really Making Money
Many beginners look at projects only by coin price and hype, but overlook a much more solid metric: protocol revenue (Fees/Revenue). It answers a simple question: Are users really paying for this product?
1. What Are On-Chain Fees and Revenue
Fees are the total costs users pay when using a protocol, such as trading fees, lending interest, and the spread from issuing stablecoins. Part of this goes to liquidity providers or reserves, and only part is the protocol’s own revenue. On-chain data is publicly available and verifiable, so it is harder to fake than a “roadmap” and does not rely on the project team’s own claims.
139
·
--
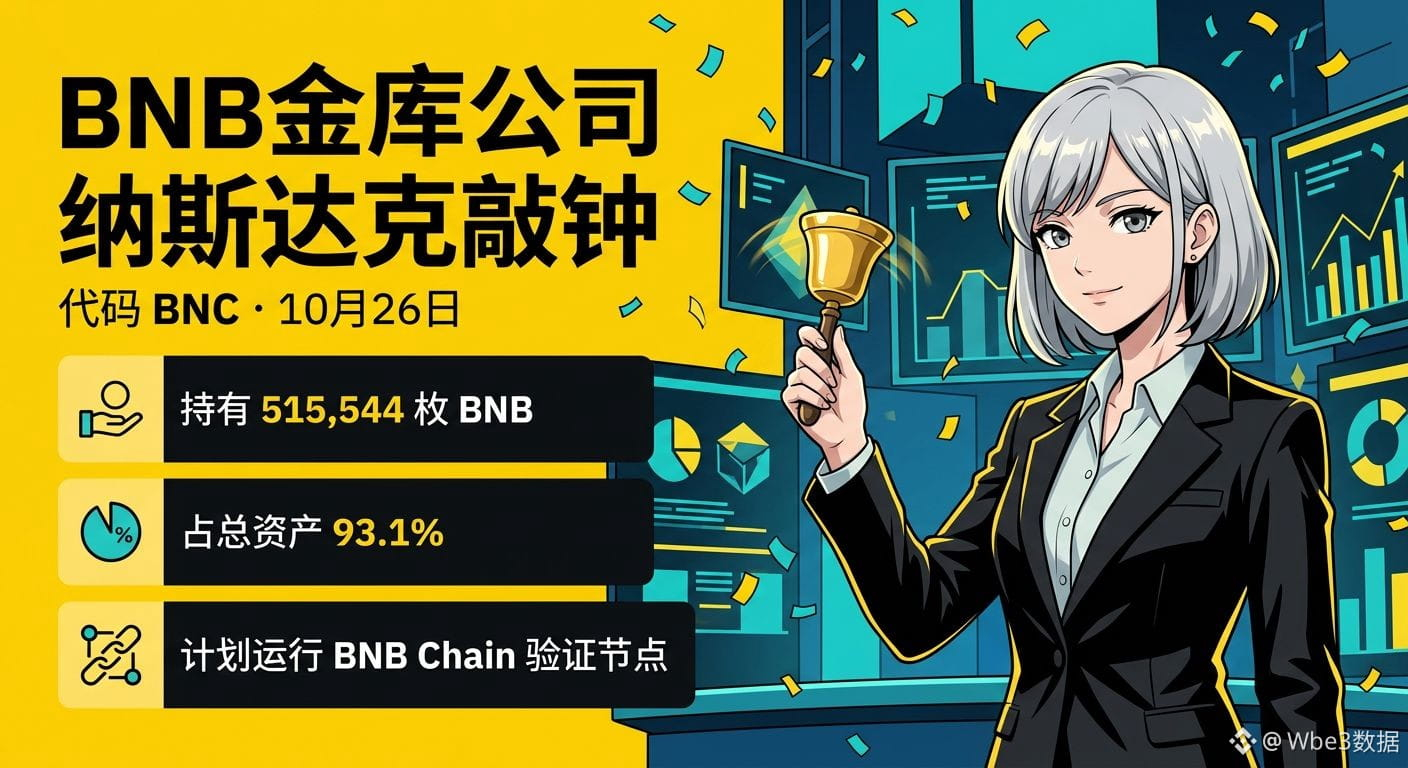
BNB took the stage at the Nasdaq opening bell for the first time, and CZ was there
At 9:30 a.m. ET on October 26 (9:30 p.m. Beijing time), BNB Standard (Nasdaq ticker: BNC), the world’s largest corporate BNB treasury, rang the opening bell in Times Square, New York. CZ attended alongside the company’s board and management team, with people from YZi Labs and BNB Chain also present.
To be clear: this was not a new stock listing. BNC was formerly known as CEA Industries, and its shares have been traded on Nasdaq all along. It changed its name to BNB Standard on September 29 (selected by a community vote, with around 5,799 votes and about 47% of the vote), and Alex Odagiu officially became CEO on October 19. The bell-ringing ceremony celebrated the new name and management team.
A few key figures:
· Held 515,544 BNB as of July 31, worth about $302 million at the time
· BNB accounted for about 93.1% of the company’s total assets
· Plans to operate its own BNB Chain validator nodes and stake through a compliant custodian
· Launched its treasury strategy in July 2025, announcing a $500 million private placement at the time, with YZi Labs and 10X Capital participating
Why is this worth paying attention to?
Its model is similar to “Strategy for BNB”: raising funds in the U.S. stock market to hold BNB, giving institutions that can’t buy crypto directly exposure to BNB through shares. CZ also noted at the event that BNB Chain has around 3 million daily users and produces a block approximately every 0.5 seconds.
But it’s worth keeping a cool head: ringing the bell doesn’t mean the company has added to its treasury. The stock price is highly tied to BNB, and when the coin’s price falls, the stock usually falls even harder. $BNB is now around $741, and has been trading sideways between $736 and $750 all weekend.
Do you think BNB treasury companies will bring sustained buying pressure to BNB, the way Strategy did for BTC? Share your thoughts in the comments.
The information above comes from company announcements and public reports and does not constitute investment advice.
#BNB #BNC #Nasdaq
472
·
--
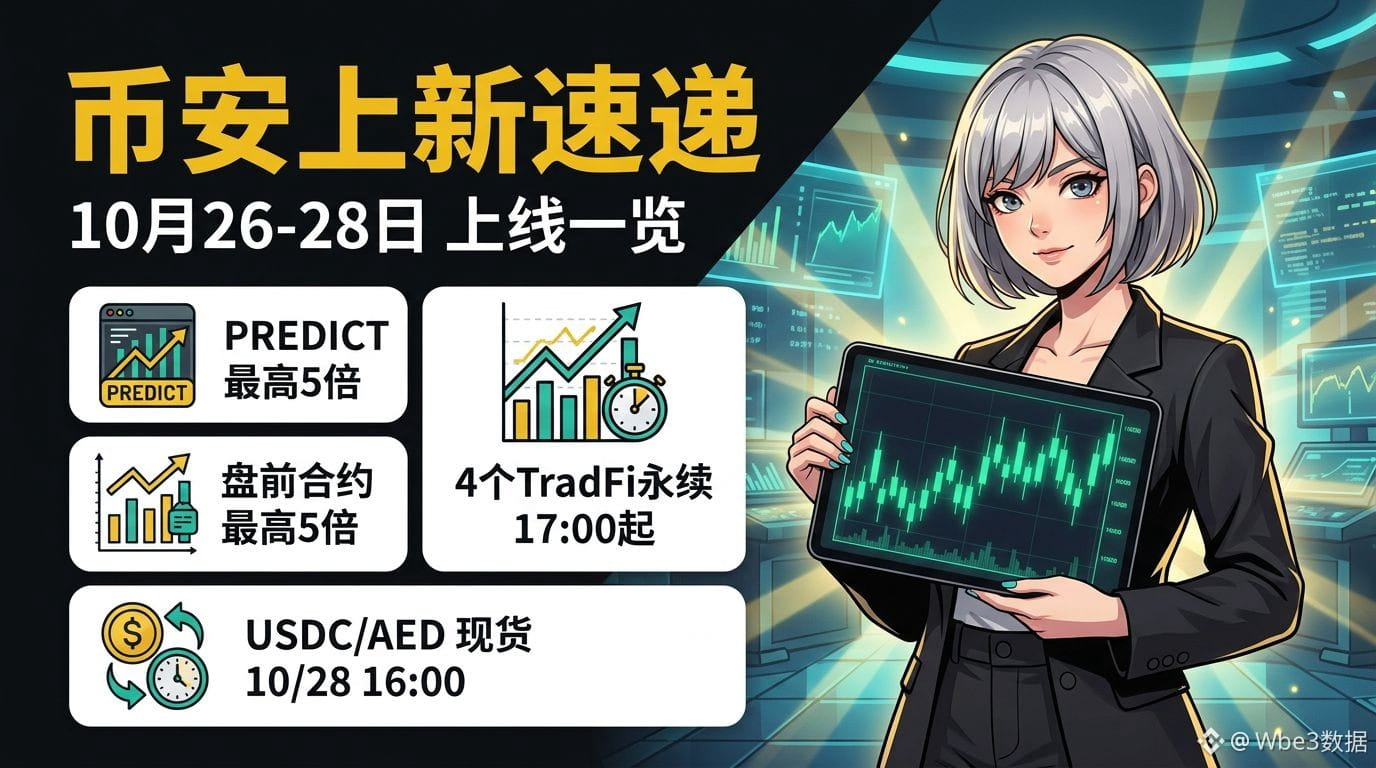
Binance Listing Roundup | October 26–28: Don’t Miss These Listings
1) PREDICT Pre-Market Perpetual Contract
The PREDICTUSDT Pre-Market Perpetual Contract went live on October 25 at 15:45 (UTC+8), with up to 5x leverage and funding fees settled every 4 hours. Its underlying asset is Predict.fun, a prediction market on BNB Chain. There’s no spot market yet. Note: A contract listing doesn’t guarantee a spot listing, and pre-market trading is typically more volatile.
2) Four TradFi USDT-Margined Perpetual Contracts
Starting October 26 at 17:00, these contracts will be listed one by one at 5-minute intervals: EIDOUSDT, EQTUSDT, STMUSDT, and ABBVUSDT. Trading is available 24/7. Traditional assets are making their way into derivatives, and Binance’s TradFi expansion is still gaining momentum.
3) USDC/AED Spot Trading Pair
Trading opens on October 28 at 16:00 (UTC+8), with spot algorithmic orders also supported. AED is the United Arab Emirates dirham, a fiat currency, giving users another way to deposit funds in the Middle East.
4) Alpha Trading Competition: Axis Robotics
The first round runs from October 26 at 21:00 to November 2 at 21:00 (UTC+8). Participants are ranked by buy volume, and the top 2,000 will share 386,000 AXIS, receiving 193 tokens each. Trading volume during the first two days will count 3x.
5) Alpha Delisting Reminder
PTB, AA, OWL, DORA, ELIZAOS, MEMES, and 哭哭马 have been removed from Alpha. If you hold any of these tokens, remember to plan your sale or withdrawal.
$BNB is currently worth about $741, with a 24-hour range of $731–$746. With platform promotions in full swing, BNB’s use cases continue to grow.
The information above is from Binance’s official announcements. Please refer to the original announcements for details. This is not investment advice.
Which update are you most interested in? Do you think PREDICT will get a spot listing soon? Let’s talk in the comments.
#币安上新 #BNB #Alpha
13
·
--
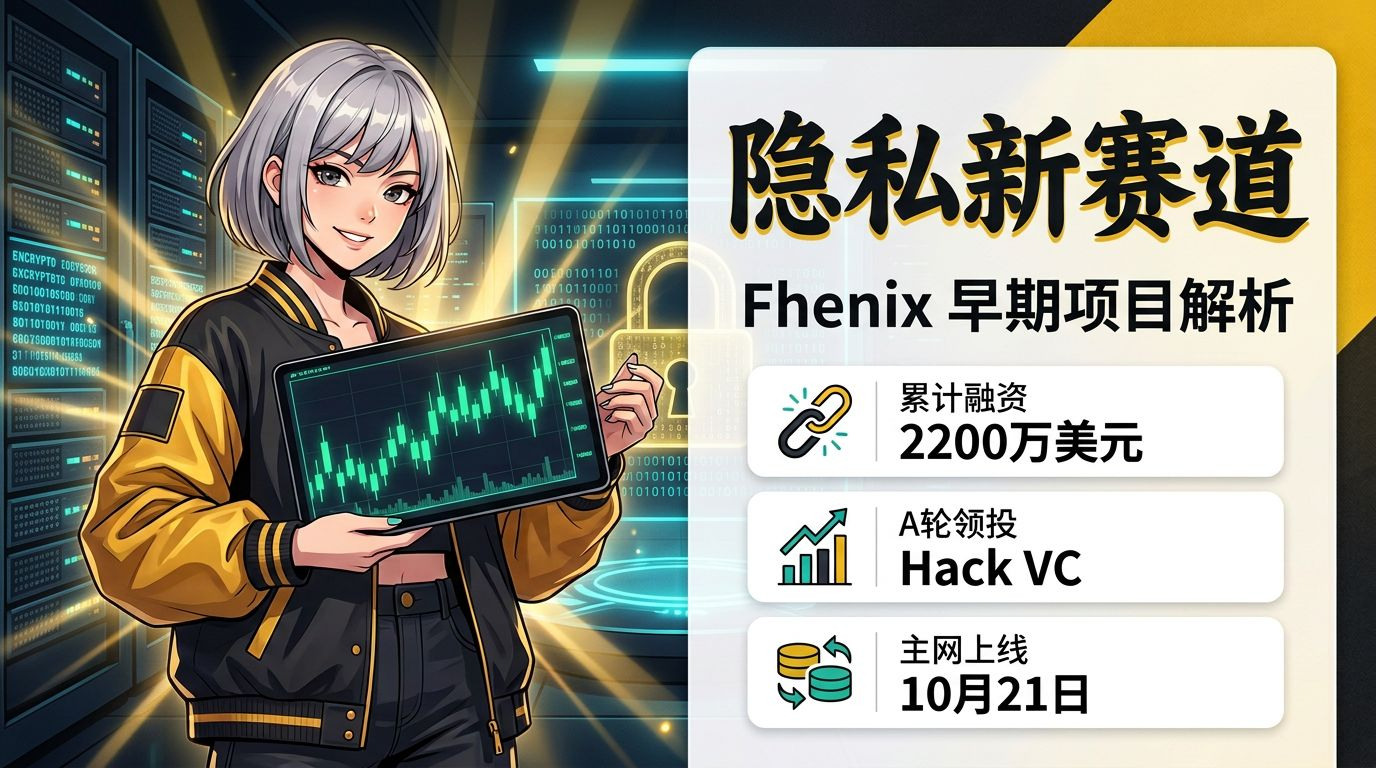
Article
Privacy-sector rising star Fhenix: $22 million raised and mainnet just launched—how can everyday users get involved?Many people think “airdrop farming” is just about interacting with projects, but what really matters is understanding the project first: who funded it, what it does, what you can do with it now, and where the risks lie. Today, we’re looking at Fhenix, a project in the privacy sector. The team has not yet issued a token, and the information below is based on public sources.
1. What does it do?
Fhenix builds infrastructure related to fully homomorphic encryption (FHE). Its core product is called CoFHE, which you can think of as an “encrypted computing coprocessor”: smart contracts send it encrypted data, it performs computations off-chain, and then returns the results—still encrypted—to the contract. This keeps sensitive information such as balances, positions, and trading strategies hidden throughout the process. Developers can integrate it simply by importing a library in Solidity. Fhenix also offers “dual-mode tokens”: the same token can have either a public balance or a confidential balance, with a one-click switch between the two.
Privacy-sector rising star Fhenix: $22 million raised and mainnet just launched—how can everyday users get involved?
Many people think “airdrop farming” is just about interacting with projects, but what really matters is understanding the project first: who funded it, what it does, what you can do with it now, and where the risks lie. Today, we’re looking at Fhenix, a project in the privacy sector. The team has not yet issued a token, and the information below is based on public sources.
1. What does it do?
Fhenix builds infrastructure related to fully homomorphic encryption (FHE). Its core product is called CoFHE, which you can think of as an “encrypted computing coprocessor”: smart contracts send it encrypted data, it performs computations off-chain, and then returns the results—still encrypted—to the contract. This keeps sensitive information such as balances, positions, and trading strategies hidden throughout the process. Developers can integrate it simply by importing a library in Solidity. Fhenix also offers “dual-mode tokens”: the same token can have either a public balance or a confidential balance, with a one-click switch between the two.
49
·
--
Verified
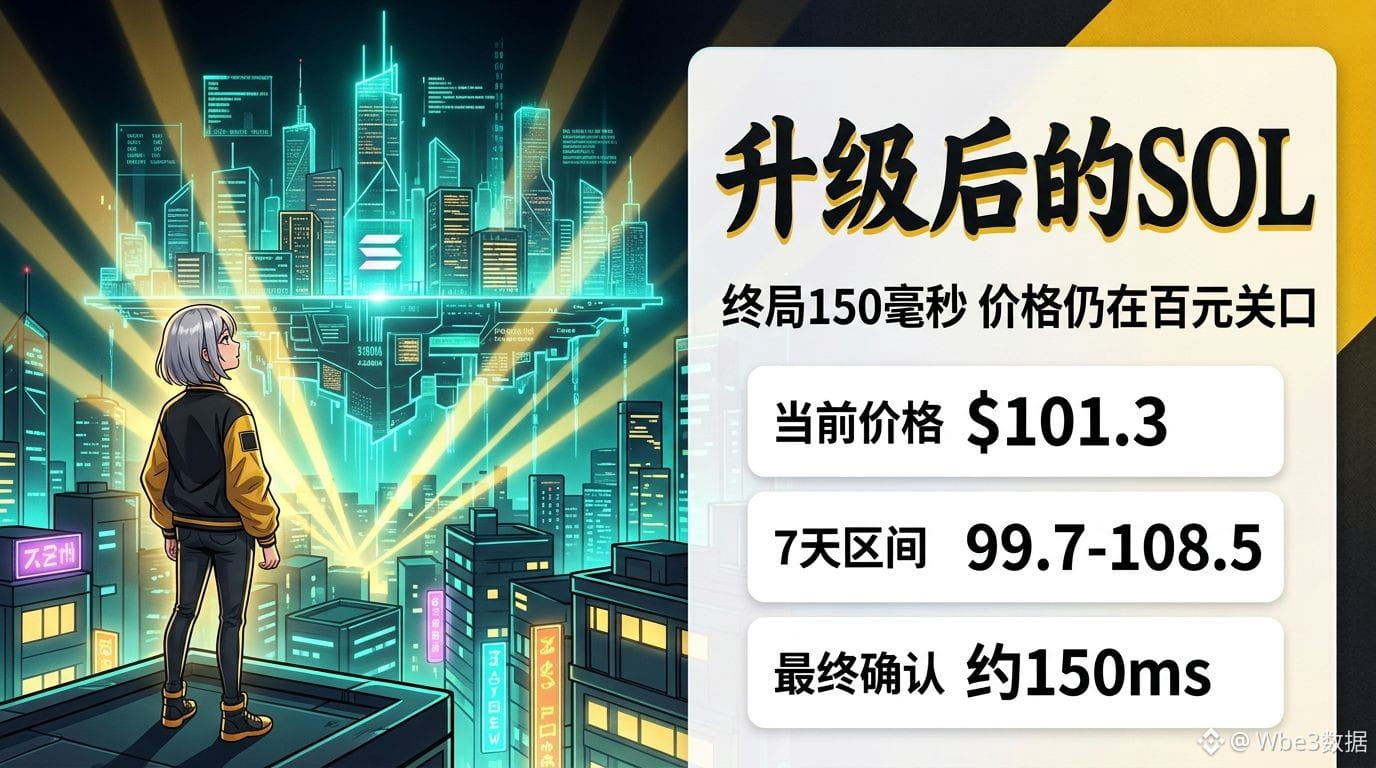
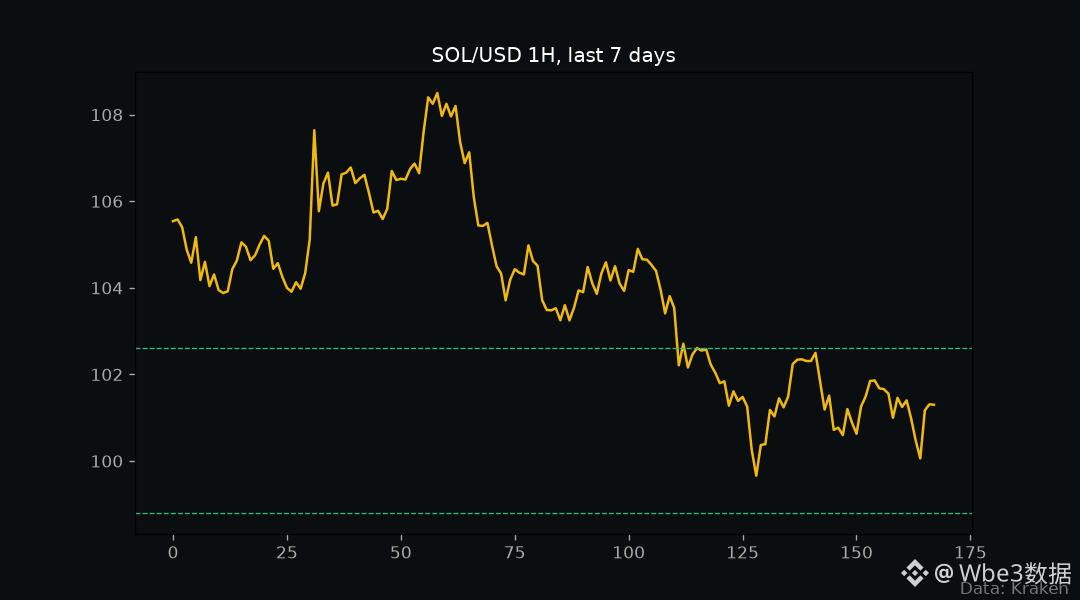
$SOL Day five after the upgrade: Alpenglow went live on mainnet on October 21. According to Anza, the finality time fell from about 12.8 seconds to around 150 milliseconds. The technology is a major positive, but the price is showing a “sell the news” reaction: Kraken data shows SOL at about $101.3, with a 7-day range of $99.7–$108.5. It briefly surged to near $109 after the upgrade, then pulled back.
Key levels (based on the past 7 days of hourly data, for observation only):
• Below: 98.8–99.7, the low zone for the past week. A break below it would signal weakening short-term sentiment.
• Above: 102.6 and 108.5. The former has repeatedly acted as recent resistance; the latter is the weekly high.
Catalysts: JPMorgan launched a tokenized money market fund on Solana, and Samsung Wallet has announced that it will support cross-border USDC transfers by the end of this month. Solana’s on-chain TVL is about $5.73 billion, and its stablecoin supply is about $15.8 billion. Fundamentals are improving, but capital flows are being weighed down by net outflows from spot ETFs.
Risks: Continued ETF outflows, rising Treasury yields weighing on altcoins, and some validator nodes still undergoing upgrades mean network performance remains to be seen.
Which do you think will get there first: the “technology upgrade” or the “price”?
Data: Kraken, DefiLlama. Not investment advice.
#Solana #Alpenglow
1
101
·
--
I took a look at DefiLlama’s public-chain TVL rankings, and the landscape is pretty interesting:
• Ethereum: about $48.56 billion, still far ahead
• Base: about $6.01 billion
• BSC: about $5.79 billion
• Solana: about $5.75 billion
• Tron: about $5.47 billion
• Bitcoin on-chain: about $4.29 billion
There’s less than $600 million separating second through fifth place, so the rankings could change at any moment. Looking at on-chain fees across the industry, the total was about $62.9 million over the past 24 hours, down 4.13% day over day. Tether contributed about $17.27 million and USDC about $6.84 million, so stablecoin issuers remain major fee earners.
TVL is just one way to measure the amount of capital locked up. It doesn’t equal activity, and you shouldn’t focus only on a single day’s figures. It’s a good idea to look at fees and user numbers too.
Data source: DefiLlama. Which public chain do you think will break into the top three next?
#链上数据 #DeFi
Not investment advice.
253
·
--
Article
Bitcoin hashrate back above 1 ZH/s: Miners pivot to AI, but the network gets more crowdedBitcoin hashrate back above 1 ZH/s: Miners are “pivoting to AI,” but the network is getting more crowded
Here’s the bottom line: publicly traded mining companies are shifting power and data centers toward AI/high-performance computing, while Bitcoin’s total network hashrate has returned to a 7-month high. These two things aren’t contradictory, and it’s worth taking a closer look.
1. What the data says
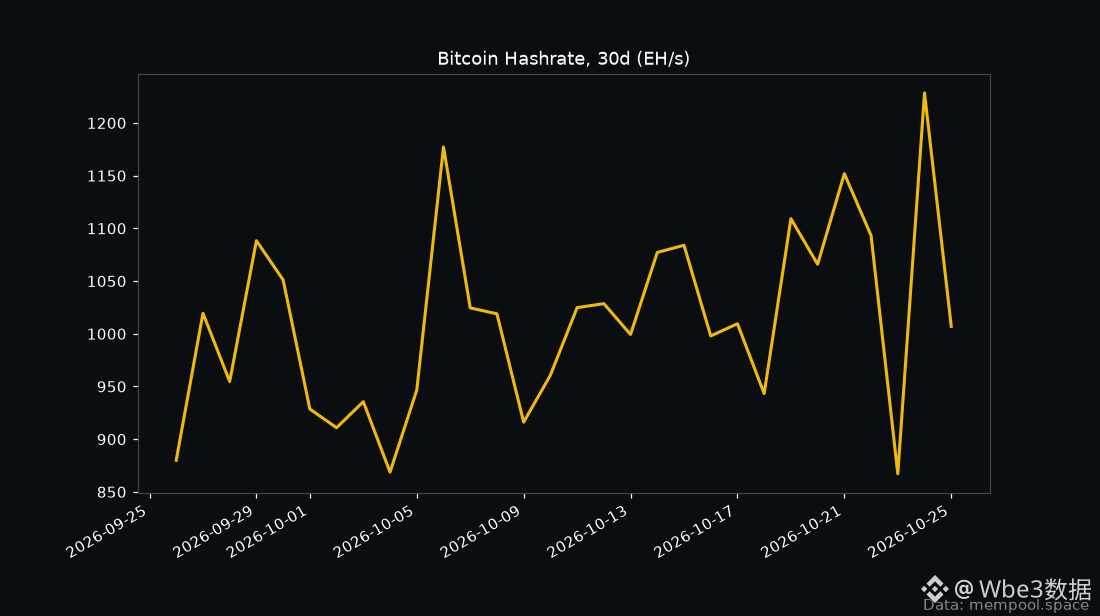
• According to BlocksBridge Miner Weekly, Bitcoin’s 7-day average hashrate has climbed back above 1 ZH/s (= 1,000 EH/s), its highest level since March 3.
• The October 16 difficulty adjustment was +5.92%, bringing difficulty to 140.58T.
• Current data from mempool.space: difficulty adjustment progress is about 67.6%, with the next adjustment estimated at around +4.9%, roughly around October 29 (depending on block production speed).
Bitcoin hashrate back above 1 ZH/s: Miners pivot to AI, but the network gets more crowded
Bitcoin hashrate back above 1 ZH/s: Miners are “pivoting to AI,” but the network is getting more crowded
Here’s the bottom line: publicly traded mining companies are shifting power and data centers toward AI/high-performance computing, while Bitcoin’s total network hashrate has returned to a 7-month high. These two things aren’t contradictory, and it’s worth taking a closer look.
1. What the data says
• According to BlocksBridge Miner Weekly, Bitcoin’s 7-day average hashrate has climbed back above 1 ZH/s (= 1,000 EH/s), its highest level since March 3.
• The October 16 difficulty adjustment was +5.92%, bringing difficulty to 140.58T.
• Current data from mempool.space: difficulty adjustment progress is about 67.6%, with the next adjustment estimated at around +4.9%, roughly around October 29 (depending on block production speed).
61
·
--
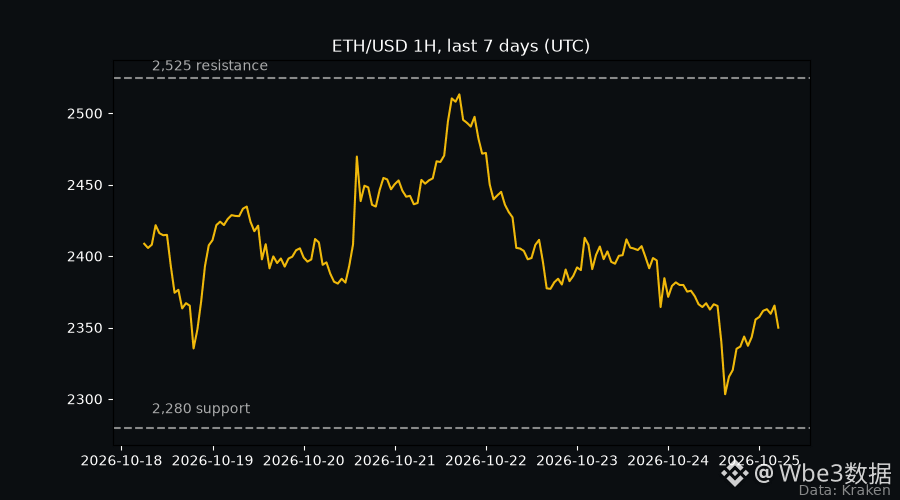
$ETH has traded in the $2,280–$2,525 range over the past 7 days and is currently around $2,350, down about 2.4% from $2,409 a week ago.
Key levels:
• $2,280 is this week's low; a high-volume break below it would signal a weaker short-term structure
• $2,525 is this week's high; a sustained move above it on strong volume would be needed to confirm a rebound
• Ethereum's on-chain TVL is about $49 billion (DefiLlama), making it the public blockchain with the largest concentration of DeFi funds
Catalysts: A recent pickup in DEX trading volume, on-chain stablecoin flows, and progress on upcoming network upgrades.
Risks: Tighter US dollar liquidity, continued stablecoin supply outflows, and a decline in overall market risk appetite could all weigh on the price.
These are price levels to watch, not a forecast. Please manage your position size and risk accordingly. Do you think ETH is more likely to hold $2,280 or fall below it this week?
Data sources: Kraken, DefiLlama. Not investment advice.
#ETH #以太坊 #OnChainData
155
·
--
A weekend look at on-chain DEX trading: According to DefiLlama, total DEX volume over the past 24 hours was about $6.97 billion, down 9.0% day over day. Volume over the past 7 days totaled about $51.8 billion, up 23.4% week over week.
By platform, Uniswap V3 recorded about $820 million (-13.6%), Uniswap V4 about $660 million (-27.1%), PancakeSwap AMM V3 about $690 million, and Aerodrome Slipstream about $320 million (-9.4%).
My take: Overall volume picked up over the week, but there was a noticeable dip on the weekend’s daily figures—a common pattern of quieter weekend trading. V4’s daily decline was steeper than V3’s. It’s best not to read too much into short-term volume swings; weekly averages offer a steadier picture.
Source: DefiLlama. This is a compilation of public data only and does not constitute investment advice.
Which chain and DEX do you trade on most often, and why?
#DeFi #DEX #On-chainData
64
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
ASICHasReceivedNoPredictionMarketApplications
29 views
31 Discussing
#ASICHasReceivedNoPredictionMarketApplications ASIC Has Received No Prediction Market Applications! 👀
A surprising development in the prediction market industry! 🇦🇺
Australia’s financial regulator, ASIC, has reportedly received no applications from companies seeking approval to operate prediction market platforms.
This raises important questions about the future of prediction markets, regulatory clarity, and how this growing sector will evolve.
📊 Will stricter regulations slow down innovation, or create a safer environment for users?
The prediction market story is far from over! 🔥
#ASICHasReceivedNoPredictionMarketApplications #Crypto $BTC $ETH $AAPLB
Crypto_With_Kinza
·0 Likes
·22 views
RecallAnnouncesLiquidationPlansToBurn35.86%OfSupply
0 views
2 Discussing
TetherReports$191.5BInQ3Reserves
13 views
3 Discussing