

#cryptopayments
cryptopayments
486,966 views
3,537 Discussing
Hot
Latest
·
--
Bullish
{spot}(PARTIUSDT)
{spot}(OSMOUSDT)
{spot}(CHIPUSDT)
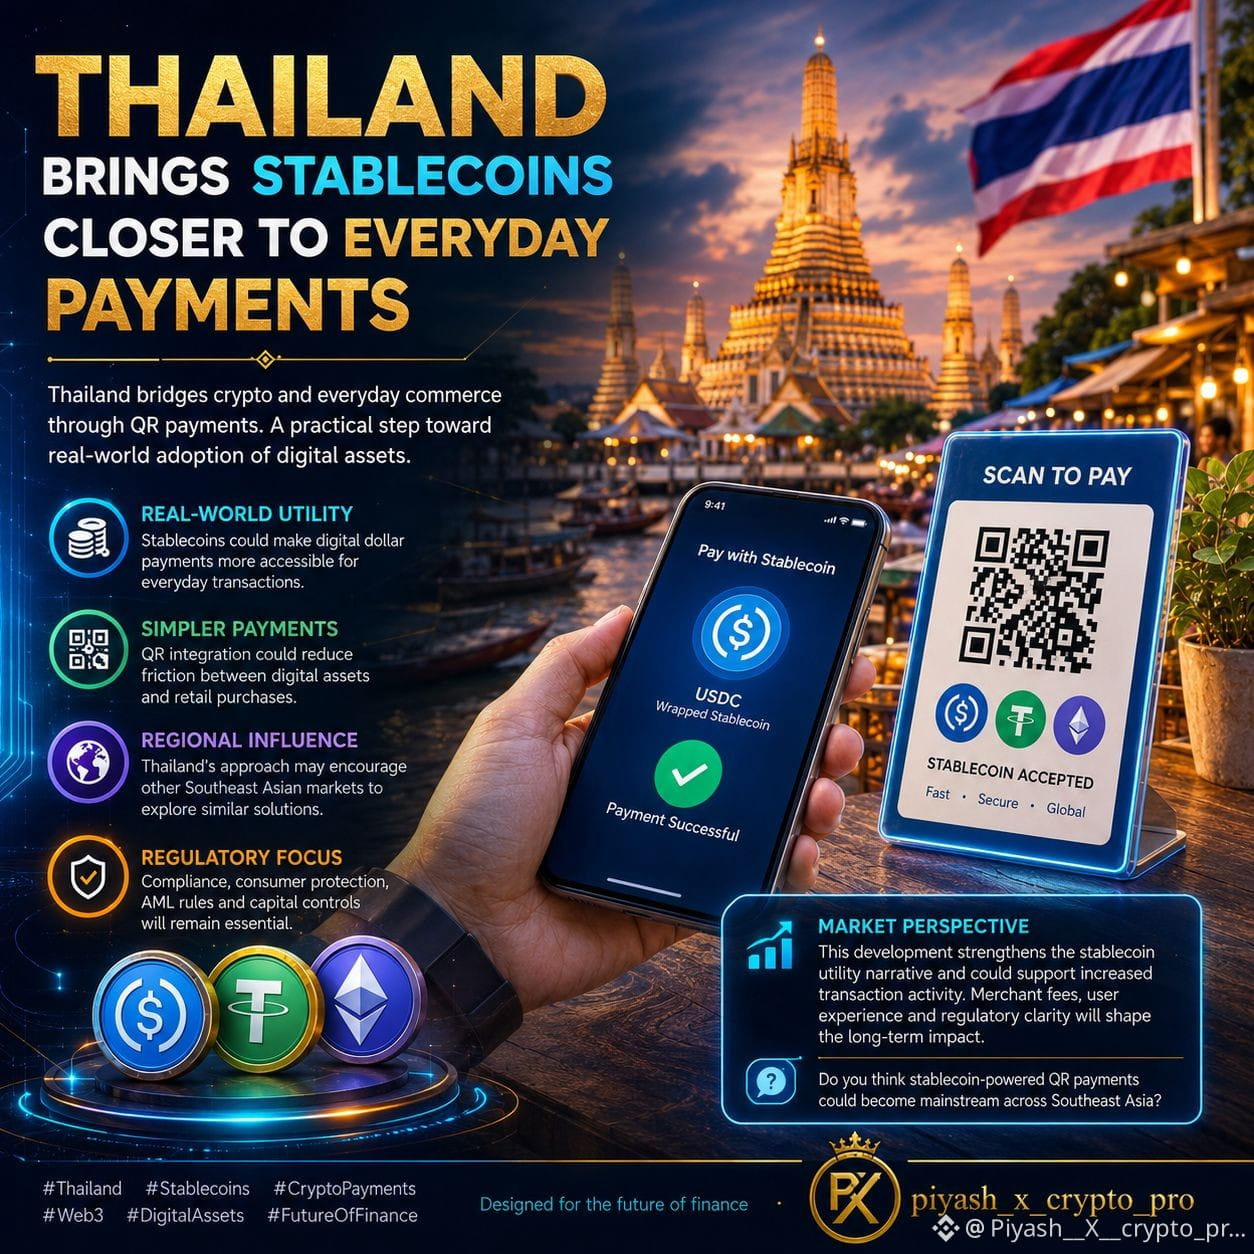
#EthereumDropsBelow$2300🚀🌏 THAILAND IS BRINGING CRYPTO CLOSER TO EVERYDAY LIFE! 💳🔥
💰 From Digital Dollars to Real-World Payments — Is This the Future of Crypto?
Thailand is making waves in the digital finance space! 🇹🇭 The reported integration of wrapped stablecoins into QR payment systems highlights an exciting direction for crypto adoption, connecting digital assets with everyday commerce. ⚡
🔥 WHY DOES THIS MATTER?
💵 $ Stablecoin Utility — Digital dollars could become more practical for everyday transactions.
📲 QR Payment Innovation — Connecting blockchain-based assets with familiar payment systems could make crypto easier to use.
🌏 Southeast Asia's Next Chapter — Thailand's approach could encourage further discussion about digital payments across the region.
📈 A New Narrative for Crypto — Beyond trading and speculation, real-world payment applications could become an important driver of blockchain adoption.
🔍 3 TOKENS TO WATCH 👀
🟢 $PARTI — Watch how Web3 adoption and ecosystem development evolve.
🔵 $OSMO — Keep an eye on Cosmos ecosystem growth and cross-chain activity.
🟡 $CHIP — Monitor its project developments, liquidity, and potential real-world use cases.
⚠️ WHAT SHOULD TRADERS WATCH?
The bigger opportunity depends on actual adoption, regulatory approval, transaction costs, and user experience. Thailand's reported development does not automatically guarantee that these tokens will benefit.
💭 YOUR TURN!
If crypto payments become part of everyday shopping across Southeast Asia, which token do you think could attract the most attention?
🔥 $PARTI | $OSMO | $CHIP
👇 Drop your pick in the comments and tell us WHY!
📌 DYOR — Do Your Own Research.
⚠️ NFA — Not Financial Advice.
#Thailand #Stablecoins #CryptoPayments #Web3 #PARTI #OSMO #CHIP #CryptoAdoption #Blockchain #BinanceSquare
80

·
--
🚀 $XRP POISED TO CAPTURE G20 FAST‑PAYMENT SWEEP! 🟢
📊 The G20’s pledge to settle 75% of cross‑border moves within an hour by 2027 lights up a massive liquidity corridor for $XRP . Smart money is already stacking positions as the protocol’s speed advantage aligns perfectly with the upcoming regulatory push. 🌊 Institutional corridors are primed to flood the order books, turning every tick into a potential wave of buying pressure.
💡 With a clear narrative and a global mandate, the upside narrative feels like a runway ready for take‑off. 👇 What’s your play on the $XRP surge as the world tightens its payment clocks? 💬
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #XRP #CrossBorder #CryptoPayments #Momentum
🚀 ⚡
14
·
--
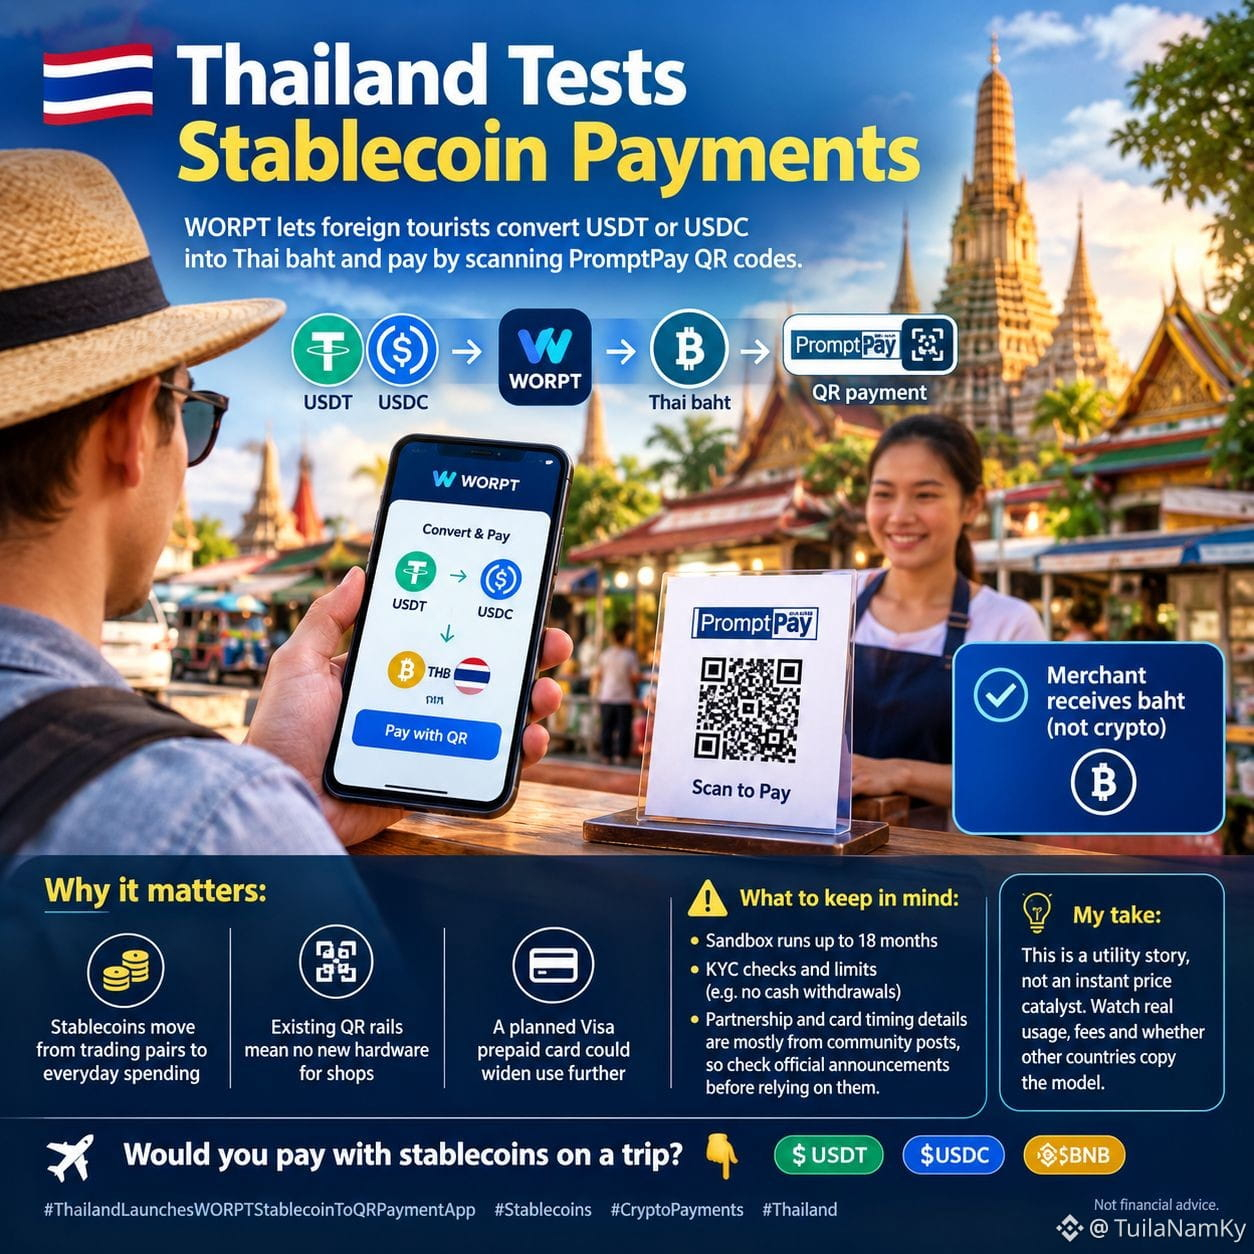
#thailandlaunchesworptstablecointoqrpaymentapp
Thailand is testing a very practical stablecoin use case. 🇹🇭
WORPT, a wallet running under the SEC’s TouristDigiPay sandbox, lets foreign tourists convert USDT or USDC into Thai baht and pay by scanning PromptPay QR codes. Merchants are paid in baht, not crypto, so they carry no token risk.
Why it matters:
• Stablecoins move from trading pairs to everyday spending
• Existing QR rails mean no new hardware for shops
• A planned Visa prepaid card could widen use further
What to keep in mind:
The sandbox runs up to 18 months, with KYC checks and limits such as no cash withdrawals. Partnership and card-timing details are mostly reported by community posts, so check official announcements before relying on them.
My take: this is a utility story, not an instant price catalyst. Watch real usage, fees and whether other countries copy the model.
Would you pay with stablecoins on a trip? 👇
$USDT $USDC $BNB
{future}(BNBUSDT)
#Stablecoins #CryptoPayments #Thailand
Not financial advice.
#thailandlaunchesworptstablecointoqrpaymentapp
Thailand is testing a very practical stablecoin use case. 🇹🇭
WORPT, a wallet running under the SEC’s TouristDigiPay sandbox, lets foreign tourists convert USDT or USDC into Thai baht and pay by scanning PromptPay QR codes. Merchants are paid in baht, not crypto, so they carry no token risk.
Why it matters:
• Stablecoins move from trading pairs to everyday spending
• Existing QR rails mean no new hardware for shops
• A planned Visa prepaid card could widen use further
What to keep in mind:
The sandbox runs up to 18 months, with KYC checks and limits such as no cash withdrawals. Partnership and card-timing details are mostly reported by community posts, so check official announcements before relying on them.
My take: this is a utility story, not an instant price catalyst. Watch real usage, fees and whether other countries copy the model.
Would you pay with stablecoins on a trip? 👇
$USDT $USDC $BNB
#Stablecoins #CryptoPayments #Thailand
Not financial advice.
1
52
·
--
Small banks getting a push into stablecoins? That caught my attention. 👀
The OCC, a U.S. banking regulator, is encouraging community banks to develop stablecoin services as new federal licensing requirements approach, according to CoinDesk.
What stands out to me: this isn’t just banks watching crypto from the sidelines. The regulator is calling on smaller lenders to enter the stablecoin payments market. 🏦
Would you use stablecoin payments through your local bank, or prefer a crypto-native service?
#Stablecoins #CryptoPayments #CryptoRegulation
5

·
--
Mastercard Calls Out the Stablecoin “Sandwich” Bottleneck: Payment Speed Gains Stalled at Conversion
Stablecoins are widely seen as key infrastructure for speeding up payments. But in its first public use of a “sandwich” metaphor, Mastercard pointed out that what often holds efficiency back is not the stablecoin itself, but the conversion processes behind it. This view adds an infrastructure perspective to the current liquidity narrative.
According to CNBC, Mastercard wrote that stablecoins could theoretically enable faster payments, but “slow conversions” in the supporting systems may limit their real-world benefits. The “sandwich” refers to stablecoins being caught between traditional financial infrastructure in the payment chain: if settlement at either end cannot keep pace, the speed gains in the middle are diluted.
This assessment is worth noting because it shifts the discussion away from the grand narrative of whether stablecoins will replace traditional payments and back toward the more practical issue of the real obstacles to adoption at scale. Investors focused on liquidity typically pay attention to where money comes from and where it flows; the efficiency of infrastructure conversions directly determines the friction costs of those flows.
Fundamentally, the value of stablecoins lies not only in the tokens themselves, but also in whether they can integrate seamlessly with bank clearing, merchant acquiring, and cross-border settlement. If conversions are slow, the improvements to the payment experience are diminished—which also helps explain why institutions remain cautious about adoption. It is important to note that this is Mastercard’s expressed view, not hard data. Its perspective leans toward traditional payments and may underestimate stablecoins’ long-term efficiency, so its immediate market impact is limited.
At the market level, views like this typically do not trigger direct asset-price reactions, but they can gradually shape institutional expectations for the stablecoin payments sector. It reminds observers focused on liquidity that the central tension in the stablecoin narrative is shifting from “issuance scale” to “implementation efficiency.”
One counterpoint is that, as a traditional payments giant, Mastercard may have an inclination to protect its existing interests. Meanwhile, several stablecoin payment solutions in the industry already perform well in terms of speed and cost. Whether the “sandwich” bottleneck is widespread remains to be demonstrated with more evidence.
What to watch next: Competition in stablecoin payments will center on continually improving conversion speed and cost. At the trading level, the more important thing is to wait for tangible evidence of infrastructure improvements rather than overinterpreting a single viewpoint.
#Stablecoins #Mastercard #CryptoPayments
The above is a compilation of information and personal analysis, and does not constitute investment advice.
28

·
--
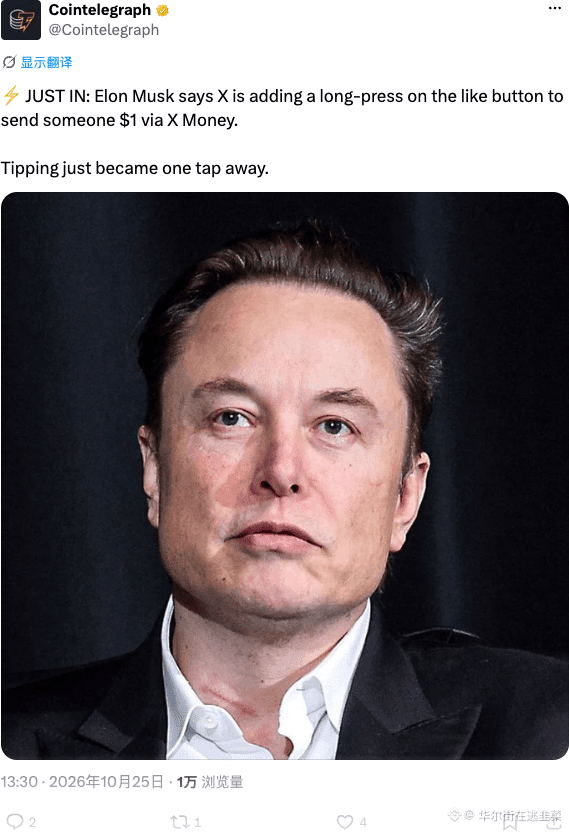
Musk has finally brought X Money to the table. Just long-press a like to send $1—the barrier to entry is ridiculously low. This isn’t just social media; it’s quietly laying the groundwork for a payment network. Once people get used to paying this way, rolling out X Token or X Pay could bring years of infrastructure-driven gains.
$X #XMoney #CryptoPayments
$X #XMoney #CryptoPayments
1
98
·
--
Bullish
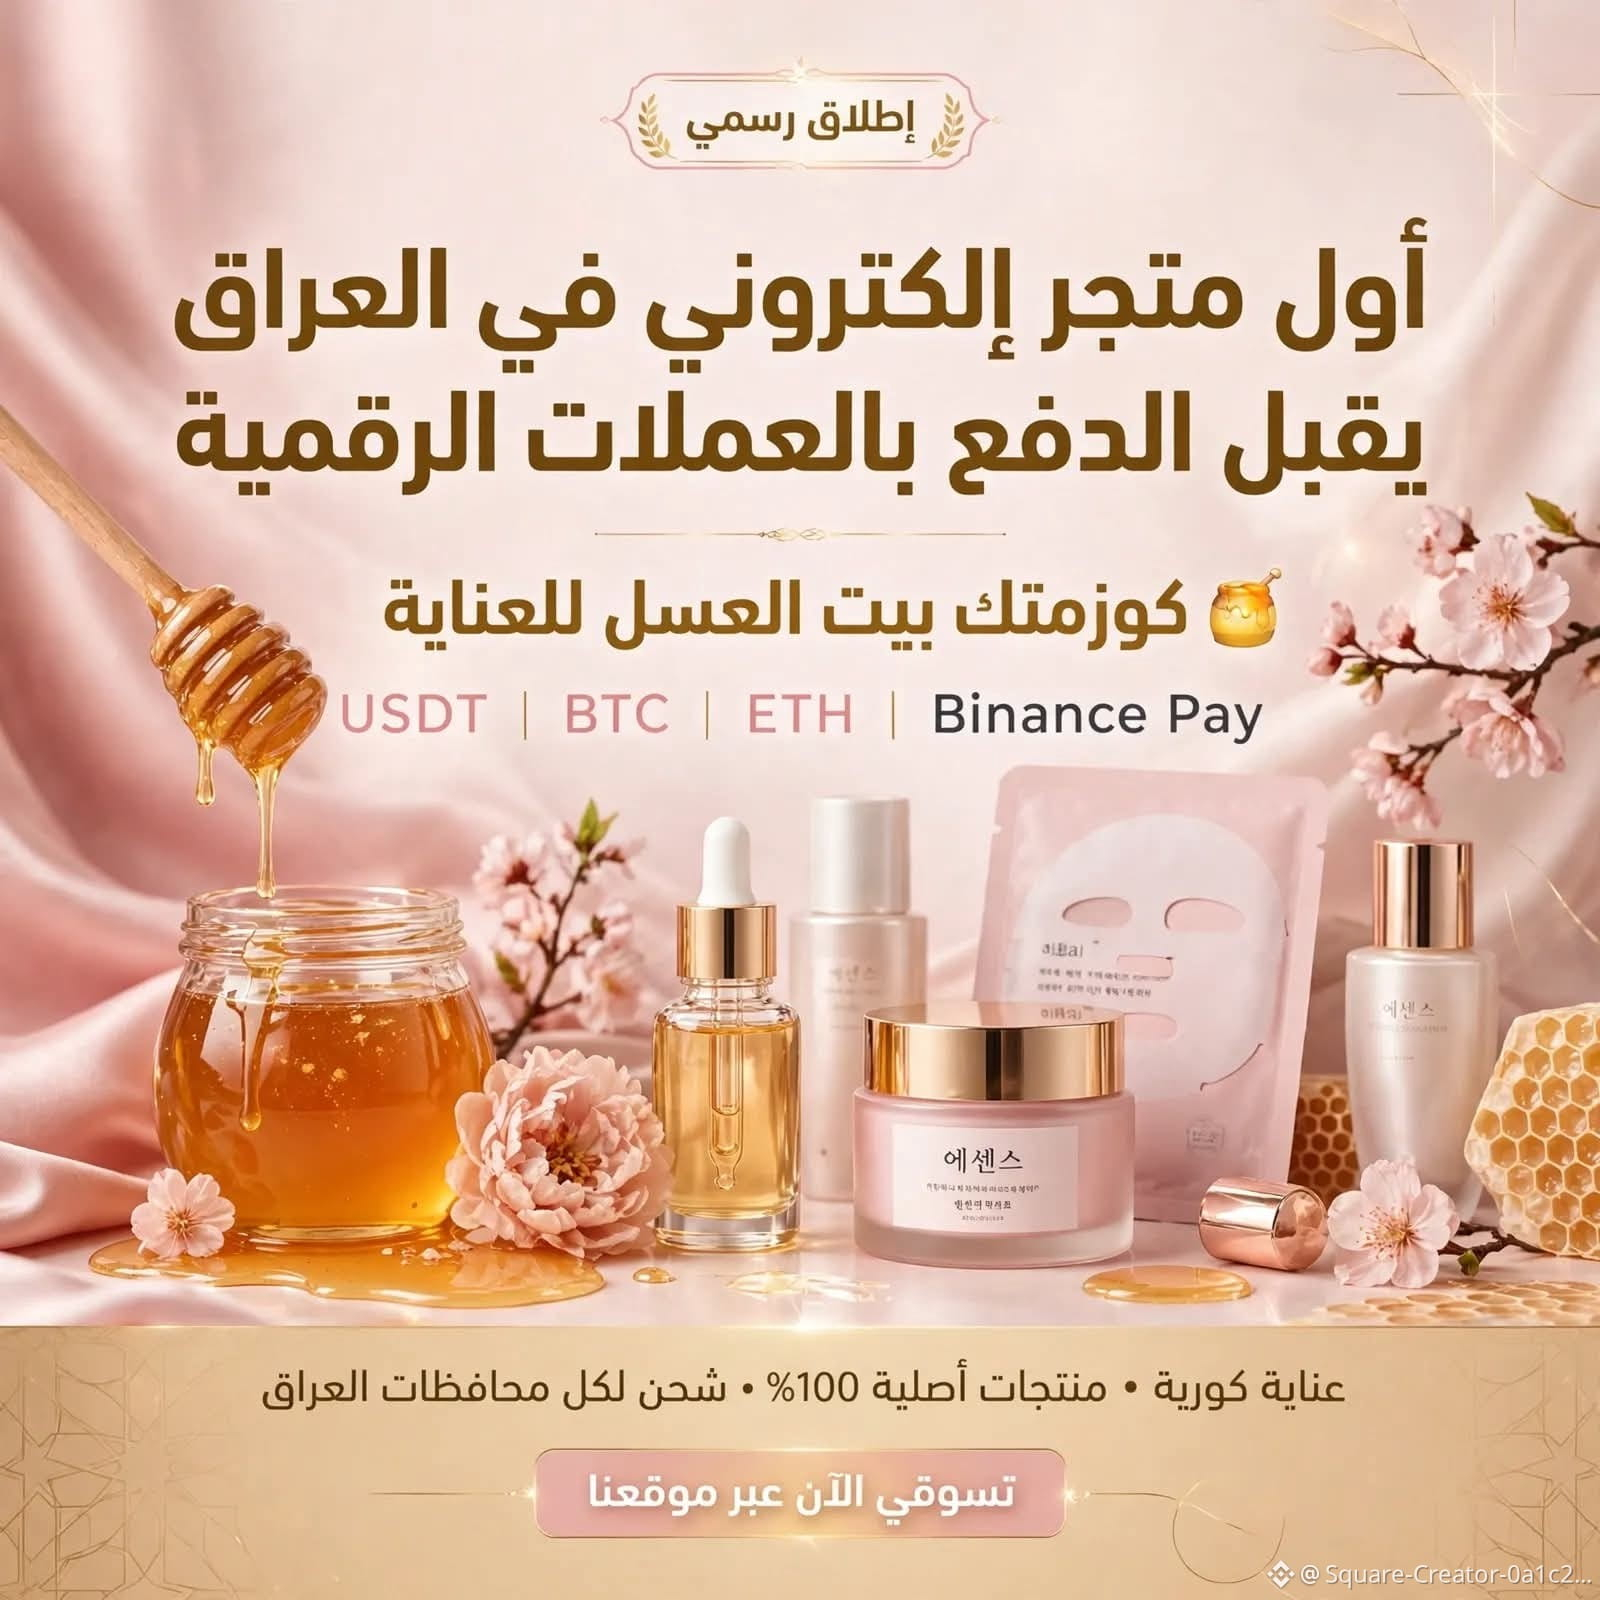
*🍯 Official Announcement: Launch of Iraq’s First Beauty Store Accepting Cryptocurrency*
Binance friends in Iraq, peace be upon you!
I’m the owner of *Cosmetic Bait Al Asal Skincare - Cosmetic Bait Al Asal* — a store specializing in Korean skincare and makeup.
*Today, I’m officially announcing that our store has become the first online store in Iraq to accept direct cryptocurrency payments.*
*Accepted payment methods:*
✅ USDT (TRC20 / BEP20)
✅ BTC
✅ Binance Pay — instant payment with no fees
*What do we sell?*
100% authentic Korean skincare and makeup products (masks, serums, creams, moisturizers)
*Benefits:*
🔒 Direct payment to my Binance wallet — no middleman
💸 No extra commission — the same price in Iraqi dinars
🚚 Delivery to all Iraqi governorates (Baghdad and all other governorates)
📦 Same-day shipping after payment is confirmed
If you have digital assets and want to turn them into a useful, tangible product, you’re very welcome.
To order or ask questions: message me privately on Binance Square, and I’ll send you the store link and step-by-step payment instructions.
*#BinanceIraq #USDT #IraqCrypto #BinancePay #CryptoPayments $
123

·
--
Dogecoin wallet teams are joining forces! $DOGE is set to become an everyday payment tool! Labs is combining MyDoge, DogeOS, and payment tools so people can actually buy things with DOGE instead of just holding it. Dogecoin is finally moving from meme coin to real-world utility! #Dogecoin #加密货币支付
Dogecoin wallet teams unite! $DOGE is getting practical. Labs combining MyDoge, DogeOS and payment tools to make DOGE actually usable for everyday purchases, not just hodling. Dogecoin moving from meme to real utility! #Dogecoin #CryptoPayments
Dogecoin wallet teams unite! $DOGE is getting practical. Labs combining MyDoge, DogeOS and payment tools to make DOGE actually usable for everyday purchases, not just hodling. Dogecoin moving from meme to real utility! #Dogecoin #CryptoPayments
80

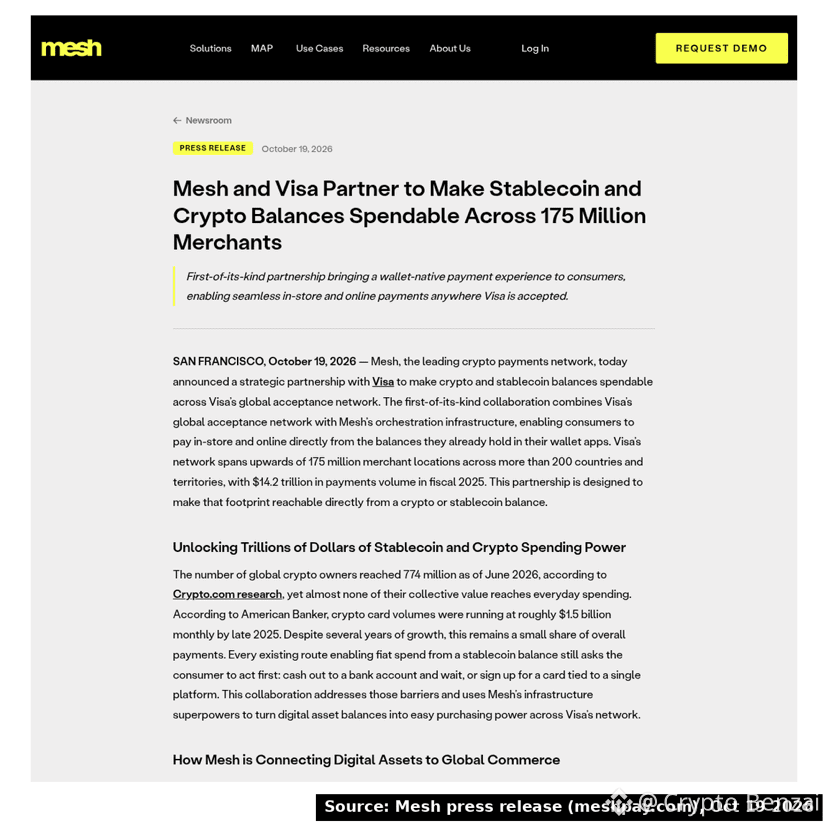
🚨BREAKING News: Mesh and Visa make wallet crypto spendable at 175M merchants
Mesh partnered with Visa so users can spend crypto and stablecoin balances straight from participating wallet apps. No separate card. Mesh sets up a Visa credential in the background and converts at checkout. Merchants change nothing. Launch date, wallets and supported assets aren't announced yet.
What would you buy with $BTC first?
#CryptoPayments #Stablecoins #VİSA
Source: Mesh press release
170

·
--
Stablecoins Are Quietly Becoming the Most Important Layer in Crypto
When people debate $BTC as digital gold or $ETH as a settlement layer, the unglamorous story underneath is stablecoins — and they may matter more for adoption than any L1.
Global remittances are a $900B+ annual market. Traditional rails charge 5-8% and take days. Stablecoin transfers on fast, low-fee chains settle in seconds for fractions of a cent. That is not a marginal improvement — it is a category reset.
The infrastructure is already being built. $BNB Chain and Solana process millions of USDC/USDT transfers daily, often for sub-$0.01 fees. Circle and Tether are competing aggressively for payment corridor dominance in Southeast Asia, Latin America, and Sub-Saharan Africa. Visa and Mastercard settlement pilots using stablecoins are live, not theoretical.
The strategic implication: whichever chain captures stablecoin payment volume builds a defensible moat. Volume attracts liquidity. Liquidity attracts DeFi. DeFi attracts developers. The flywheel is payment-first, not speculation-first.
Most crypto analysis focuses on price. The more durable question is: which chain is moving the most real-world value? Watch stablecoin transfer volume, not just TVL.
Payment rails are not exciting. Adoption is.
$BTC $ETH $BNB
#Stablecoins #CryptoPayments #Crypto
25

·
--
Visa Partners with Mesh to Bring Crypto Payments to 175 Million Merchant Locations
Visa and Mesh have announced a partnership to connect crypto and stablecoin wallets to Visa’s global payment network, which covers 175 million merchant locations. According to Cointelegraph, users may eventually be able to spend digital assets directly in traditional retail settings without first converting them into fiat currency.
The significance is that stablecoins are being integrated into the core infrastructure layer of a “payment network” for the first time. Until now, crypto payments have relied mostly on standalone apps or specific merchants, while Visa’s merchant network is already established and global. If Mesh’s wallets can integrate smoothly, stablecoin use cases could expand from “holding and transferring” to “everyday spending”—a sign of real growth in demand.
The 175 million merchant locations refers to the size of Visa’s existing network, not newly added crypto merchants. The partnership has only been announced so far, and the number of merchants actually onboarded, transaction volume, and settlement fees have not been disclosed. The rollout timeline, user adoption, and regulatory compliance all remain uncertain.
The market may interpret this news as positive for the stablecoin ecosystem, particularly for stablecoin issuers and payment infrastructure projects that work with Visa. But it remains to be seen whether this is merely a brand-level partnership or whether it truly connects the clearing and settlement rails.
A potential obstacle is that connecting crypto assets to traditional payment networks could create compliance challenges. Some merchants may also hesitate because of tax or accounting considerations. In addition, whether users are willing to pay with stablecoins at supermarkets and restaurants will depend on exchange-rate volatility, fees, and convenience—all of which will take time to assess.
What to watch next: First, whether Mesh announces the first merchants to join and the pilot locations. Second, whether Visa discloses transaction volume data for stablecoin settlements. Third, regulators’ stance on the compliance of “paying directly with a crypto wallet.” If you’re following the stablecoin sector, it’s more important to wait for actual transaction volume data than to chase prices based solely on a partnership announcement.
#Stablecoin #CryptoPayments
The above is a summary of information and personal analysis, and does not constitute investment advice.
70

🦈 MASTERCARD UNLOCKS GLOBAL SETTLEMENT RAILS AS $AVA LIQUIDITY PREPARES TO SURGE ⚡
Traditional payment giants are actively constructing global risk and compliance rails across thirty countries to normalize stablecoin transactions. Smart money understands this shift de-risks payment flows, positioning high-utility ecosystems like $AVA , $PHA , and $BR to capture long-term transaction volume. 🌊
📊 Bringing institutional-grade risk telemetry to merchants effectively flips historical skepticism into mainstream commercial adoption. 💡 The friction points keeping retail capital on the sidelines are steadily evaporating. 💬 Do you view strict transaction screening as the catalyst for mainstream volume or a bottleneck to decentralization? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #AVA #Stablecoins #CryptoPayments #Web3
🎯 🦈
10
·
--
Visa and crypto payments network Mesh have teamed up to let users spend cryptocurrency and stablecoin balances straight from their digital wallets at any merchant that accepts Visa.
The integration works through existing Visa credentials provisioned by participating wallet apps, so shoppers do not need a separate crypto card or to move funds to a bank account, and merchants receive payment via Visa’s network without changing their checkout.
Visa’s network reaches more than 175 million merchant locations across over 200 countries and territories. Mesh will handle funding, conversion between crypto, stablecoins and fiat, and manage customer onboarding and KYC.
The partnership follows Mesh’s September integration with Bybit Pay and its January $75 million funding round led by Dragonfly that valued the company at $1 billion.
#VisaMesh #CryptoPayments #StablecoinSpend
47

·
--
Paying with crypto anywhere is about to get much easier.
Visa partnered with Mesh to connect digital wallets to its global payments network.
What’s interesting is that you won’t need an additional physical card to spend your assets or stablecoins.
The infrastructure handles everything directly from your current wallet.
It’s a big step forward for using crypto at traditional merchants.
Do you think this will make it easier to use your assets every day?
$BTC $ETH
#Visa #CryptoPayments
32
·
--
Payment network effects are one of the most underappreciated forces in crypto valuation.
When a payment network gains adoption — more corridors, more institutions, more settlement volume — each new participant makes the network exponentially more valuable for everyone already on it. This is Metcalfe's Law in action, and it explains why payment-focused L1s can be sleeper assets during infrastructure build-out phases.
Here's what makes this cycle different for crypto payment rails:
1. **Regulatory runway is opening.** Stablecoin legislation in the US, MiCA in Europe, and CBUAE frameworks in the Middle East are giving institutions a clear compliance path to deploy on-chain settlement — something that was legally murky just two years ago.
2. **Correspondent banking is expensive.** SWIFT cross-border payments still cost 2–6% and settle in 1–5 days. Any blockchain network that can undercut both metrics while meeting AML/KYC requirements becomes structurally attractive to banks, not just retail users.
3. **Volume creates defensibility.** Once a payment corridor is established on-chain, switching costs compound. Liquidity pools deepen, slippage narrows, and competing networks face an uphill battle — exactly how Visa and Mastercard built their moats.
The market often prices payment-layer tokens on speculation. The smarter frame is to watch transaction volume growth, institutional corridor adoption, and regulatory approvals as leading indicators of real network value.
Position conviction should follow infrastructure signals — not just price action.
$XRP $BNB $ADA
#CryptoPayments #BlockchainAdoption #NetworkEffects #XRP #BinanceSquare
91
·
--
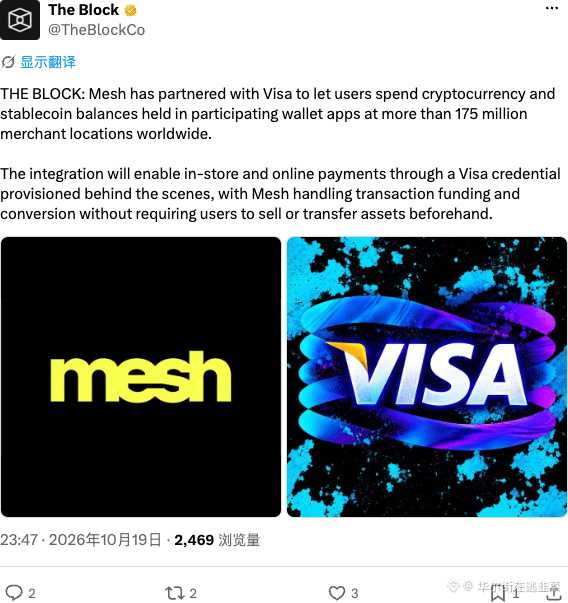
Mesh has finally teamed up with Visa, letting users spend on-chain coins at 175 million merchants worldwide.
This time, they’ve truly made it usable. While other wallets are still dreaming, Mesh can already turn on-chain U into real-world spending power. Stablecoin payments are finally more than just talk, and a surge in wallet activity is just around the corner.
$MESH #CryptoPayments #DeFi
This time, they’ve truly made it usable. While other wallets are still dreaming, Mesh can already turn on-chain U into real-world spending power. Stablecoin payments are finally more than just talk, and a surge in wallet activity is just around the corner.
$MESH #CryptoPayments #DeFi
18
🦈 $USDT PAYMENT VELOCITY EXPLODES AS REAL-WORLD UTILITY SURGES 45%! ⚡
📊 Circulating market cap sits virtually flat at $305 billion, yet payment velocity is shattering records with $482 billion settled and transactions surging 71% past the one billion mark. Smart money knows that when raw velocity outpaces float expansion, underlying network utility is quietly turning parabolic.
🏦 Traditional payment rails are aggressively locking in rails behind the scenes, evidenced by card volumes multiplying tenfold to $3.9 billion. 💡 Capital is actively circulating on-chain rather than sitting idle as dry powder on the sidelines. 🤔 Are you watching transactional velocity to gauge the next macro expansion, or just tracking raw market cap?
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #USDT #Stablecoins #CryptoPayments #OnChain
⚡ 🦈
4
·
--
The use of stablecoins for real-world payments is growing rapidly.
The firm Allium reported that stablecoin payments reached 482 billion dollars this year.
This represents a 45 percent jump.
The interesting thing is that this growth is happening while the total supply of stablecoins remains stagnant.
The momentum comes from the integration of Visa, Mastercard, and Stripe.
They are directly connecting crypto with fiat money.
The infrastructure for spending $USDT or $USDC seems ready for mass use.
Do you think this is the real adoption that was missing?
#Stablecoins #CryptoPayments $BTC
13
💳 $482 BILLION IN STABLECOIN PAYMENTS — CRYPTO IS ENTERING THE REAL ECONOMY! 🌍
While traders focus on Bitcoin prices and market volatility, something important is happening behind the scenes.
According to Allium's latest report, stablecoin payments reached $482 billion in the first nine months of 2026 — a 45% increase year over year! 📈
📊 Key highlights:
🔹 $482B in stablecoin payments (+45%)
🔹 1.04 billion payment transactions (+71%)
🔹 $72B in payments during September alone
🔹 Stablecoin supply grew just 0.4%
Meanwhile, companies like Visa, Mastercard and Stripe are expanding their involvement in blockchain-based payment infrastructure.
⚡ The interesting part?
Crypto adoption isn't just about buying tokens and waiting for prices to rise.
It's increasingly about moving money, making payments and connecting traditional finance with blockchain technology.
And this may be one of the most important developments in the entire industry.
💬 Would you use stablecoins like $USDT or $USDC for everyday purchases instead of traditional payment methods?
Source: Allium — State of Stablecoins and Payments, October 2026.
#Stablecoins #CryptoPayments #CryptoAdoption
1
86
·
--
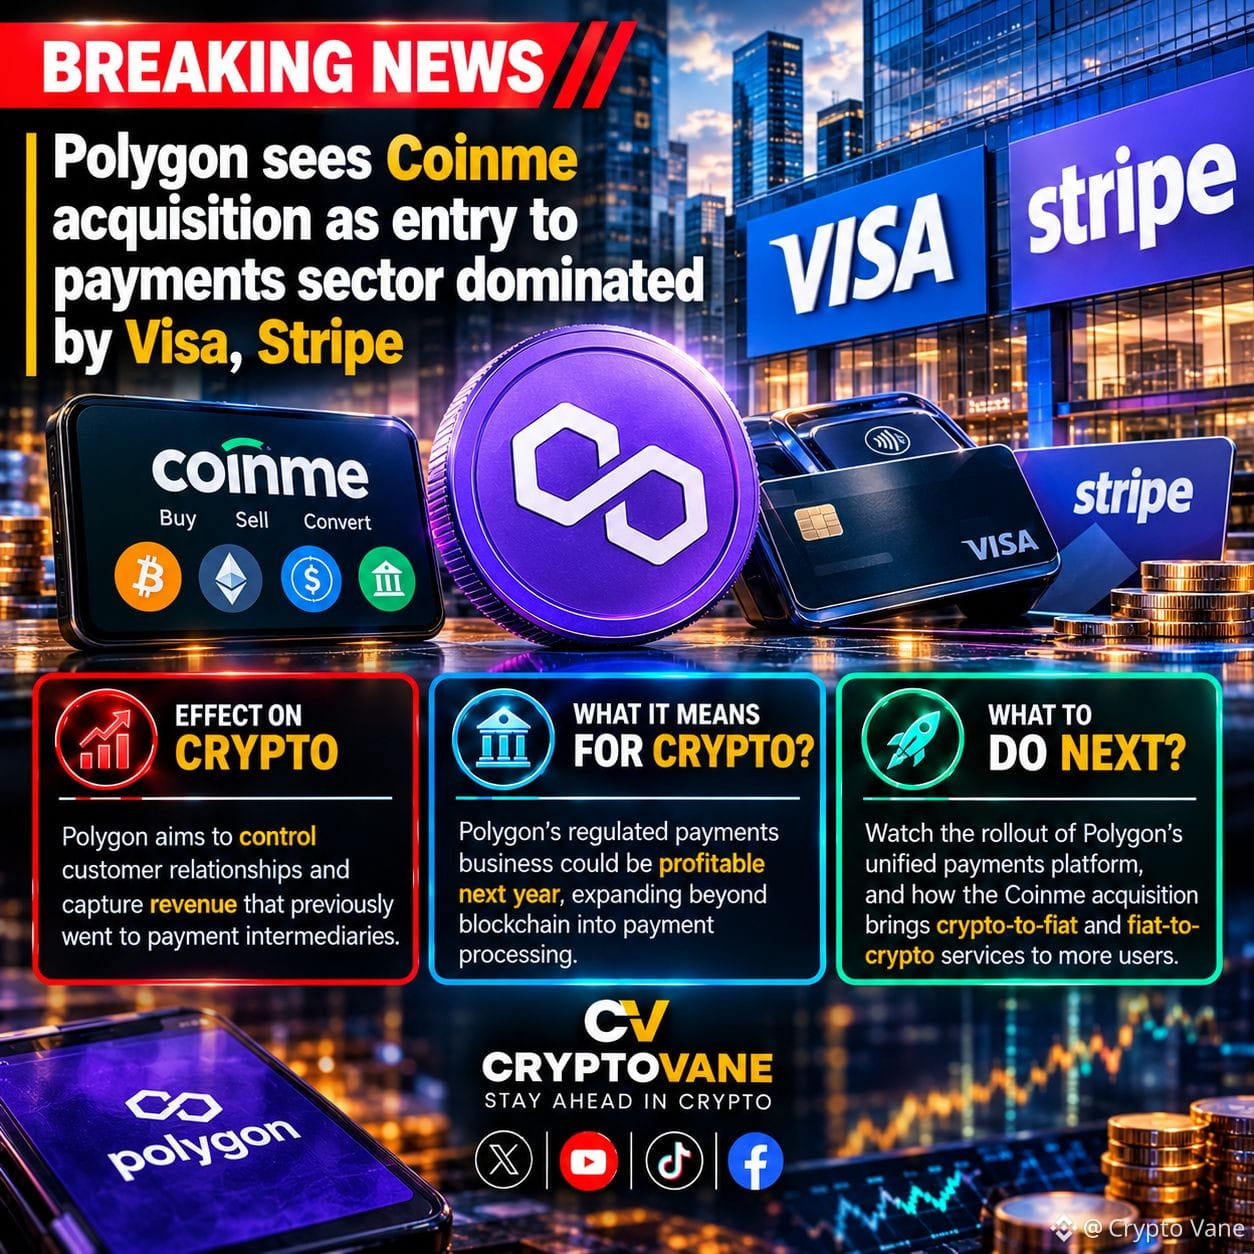
$POL Expands Into Payments: Can the Coinme Deal Challenge Visa and Stripe?
$POL is moving beyond blockchain infrastructure with its Coinme acquisition, targeting the payments industry dominated by Visa and Stripe. The expansion could strengthen $POL ’s regulated payments business, unlock new revenue streams, and accelerate crypto-to-fiat adoption as its unified payments platform develops.
#Polygon #POL #CryptoNews #blockchain #CryptoPayments
{spot}(POLUSDT)
$POL Expands Into Payments: Can the Coinme Deal Challenge Visa and Stripe?
$POL is moving beyond blockchain infrastructure with its Coinme acquisition, targeting the payments industry dominated by Visa and Stripe. The expansion could strengthen $POL ’s regulated payments business, unlock new revenue streams, and accelerate crypto-to-fiat adoption as its unified payments platform develops.
#Polygon #POL #CryptoNews #blockchain #CryptoPayments
152
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#CanMicrosoftDeliverOnAI
665,705 views
4,406 Discussing
2
#CanGoogleDefindItsCore
412,637 views
3,111 Discussing
3
#FedWatch
16.1M views
37,465 Discussing
4
#BitcoinCore32.1RaisesPeerConnectionLimit
7,909 views
259 Discussing
5
#VisaStablecoinSettlementTops$25BAnnualized
0 views
1 Discussing
6
#WestpacToCapCryptoPaymentsAtAUD10KPerMonth
1,039 views
46 Discussing
7
#RussiaPlansStandardizedTestForCryptoInvestors
1,943 views
98 Discussing
8
#EarningsSeason
6.2M views
30,534 Discussing
9
#BitcoinCoreIdentifiesThreeVulnerabilities
17,488 views
352 Discussing
10
#RippleExpects$900MAnnualizedProductRevenueRunRate
1,760 views
11 Discussing