
MurtiTheTrader
500 Posts

MurtiTheTrader
Report
Block User
US stocks, options flow and crypto. Data-driven daily market notes, no FOMO. Risk first, always. Not financial advice.
0 Following
55 Followers
4 Liked
Posts
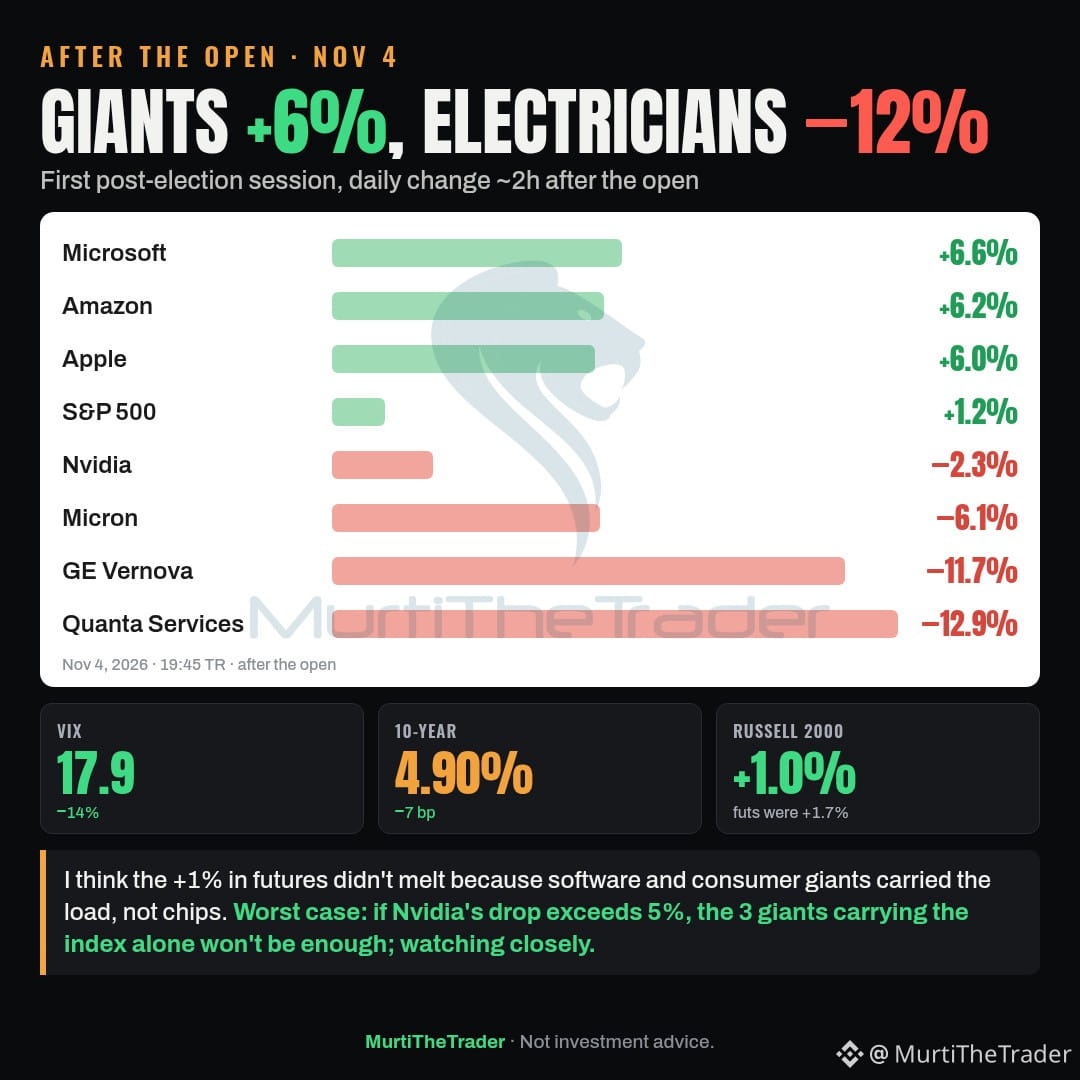
After the open: Money ran to the giants; Microsoft +6.6%, Amazon +6.2%, Apple +6.0% and S&P 500 +1.2%.
→ Losses deepened in the power infrastructure sold this morning: Quanta −12.9%, GE Vernova −11.7%
→ Nvidia −2.3%, Micron −6.1%
→ VIX −14% to 17.9, 10-year yield 4.90%
I think the +1% in futures didn't melt because software and consumer giants carried the load, not chips. Worst case: if Nvidia's drop exceeds 5%, the 3 giants carrying the index alone won't be enough; watching closely.
Watching: $BTC $SOL
#Investing #NASDAQ
After the open: Money ran to the giants; Microsoft +6.6%, Amazon +6.2%, Apple +6.0% and S&P 500 +1.2%.
→ Losses deepened in the power infrastructure sold this morning: Quanta −12.9%, GE Vernova −11.7%
→ Nvidia −2.3%, Micron −6.1%
→ VIX −14% to 17.9, 10-year yield 4.90%
I think the +1% in futures didn't melt because software and consumer giants carried the load, not chips. Worst case: if Nvidia's drop exceeds 5%, the 3 giants carrying the index alone won't be enough; watching closely.
Watching: $BTC $SOL
#Investing #NASDAQ
→ Losses deepened in the power infrastructure sold this morning: Quanta −12.9%, GE Vernova −11.7%
→ Nvidia −2.3%, Micron −6.1%
→ VIX −14% to 17.9, 10-year yield 4.90%
I think the +1% in futures didn't melt because software and consumer giants carried the load, not chips. Worst case: if Nvidia's drop exceeds 5%, the 3 giants carrying the index alone won't be enough; watching closely.
Watching: $BTC $SOL
#Investing #NASDAQ
104
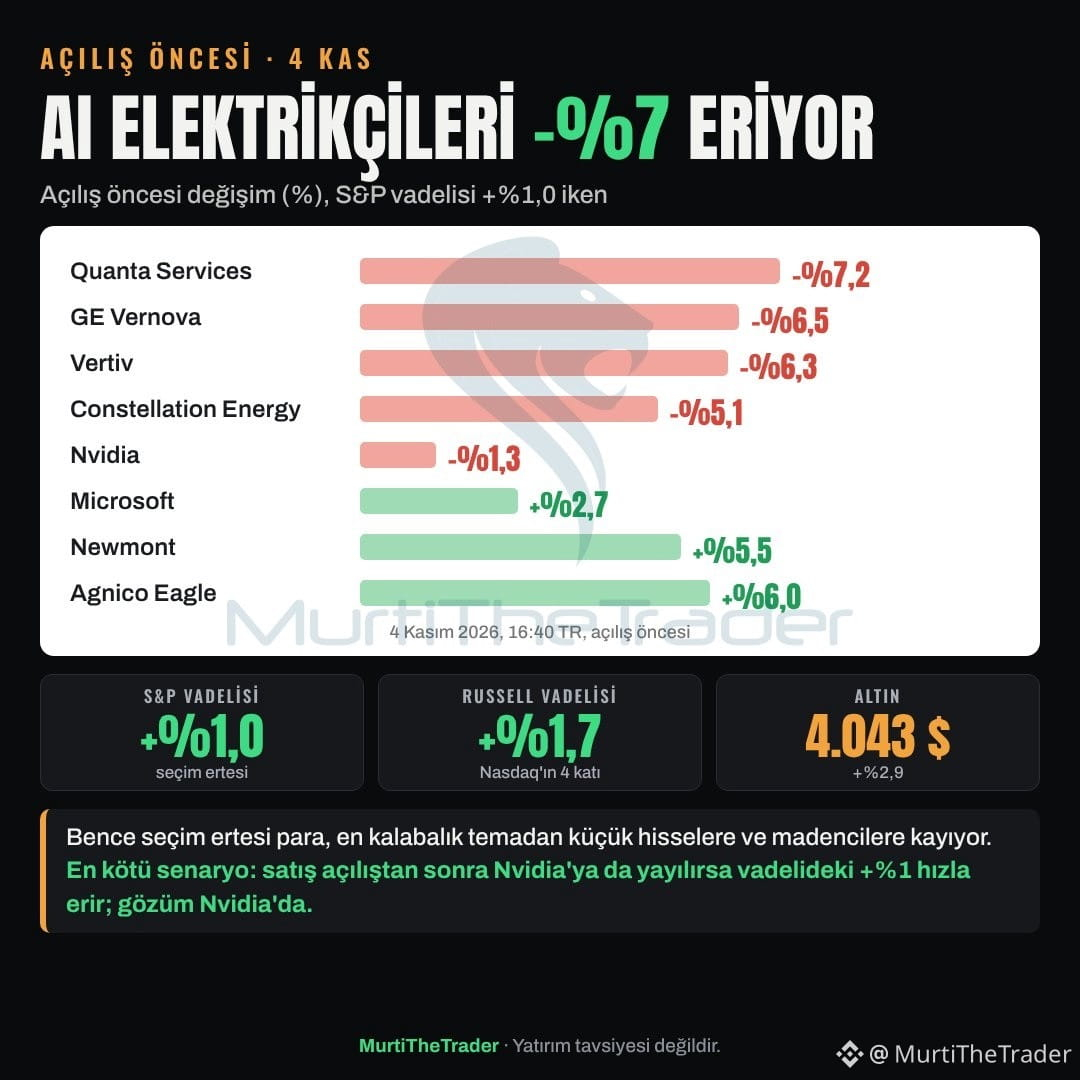
Pre-market: S&P futures are up 1.0%, but AI's power infrastructure is getting sold; Quanta −7.2%, GE Vernova −6.5%.
→ Vertiv −6.3%, Constellation −5.1%, Nvidia −1.3%
→ Miners lead with Newmont +5.5% and Agnico Eagle +6.0%
→ Russell 2000 futures +1.7%, 4x Nasdaq's
My take: post-election money is rotating out of the most crowded theme into small caps and miners. Worst case: if the selling spreads to Nvidia after the open, the +1% in futures melts fast. My eye is on Nvidia.
#Stocks #AI $GEV $PWR
Pre-market: S&P futures are up 1.0%, but AI's power infrastructure is getting sold; Quanta −7.2%, GE Vernova −6.5%.
→ Vertiv −6.3%, Constellation −5.1%, Nvidia −1.3%
→ Miners lead with Newmont +5.5% and Agnico Eagle +6.0%
→ Russell 2000 futures +1.7%, 4x Nasdaq's
My take: post-election money is rotating out of the most crowded theme into small caps and miners. Worst case: if the selling spreads to Nvidia after the open, the +1% in futures melts fast. My eye is on Nvidia.
#Stocks #AI $GEV $PWR
→ Vertiv −6.3%, Constellation −5.1%, Nvidia −1.3%
→ Miners lead with Newmont +5.5% and Agnico Eagle +6.0%
→ Russell 2000 futures +1.7%, 4x Nasdaq's
My take: post-election money is rotating out of the most crowded theme into small caps and miners. Worst case: if the selling spreads to Nvidia after the open, the +1% in futures melts fast. My eye is on Nvidia.
#Stocks #AI $GEV $PWR
1
1
680
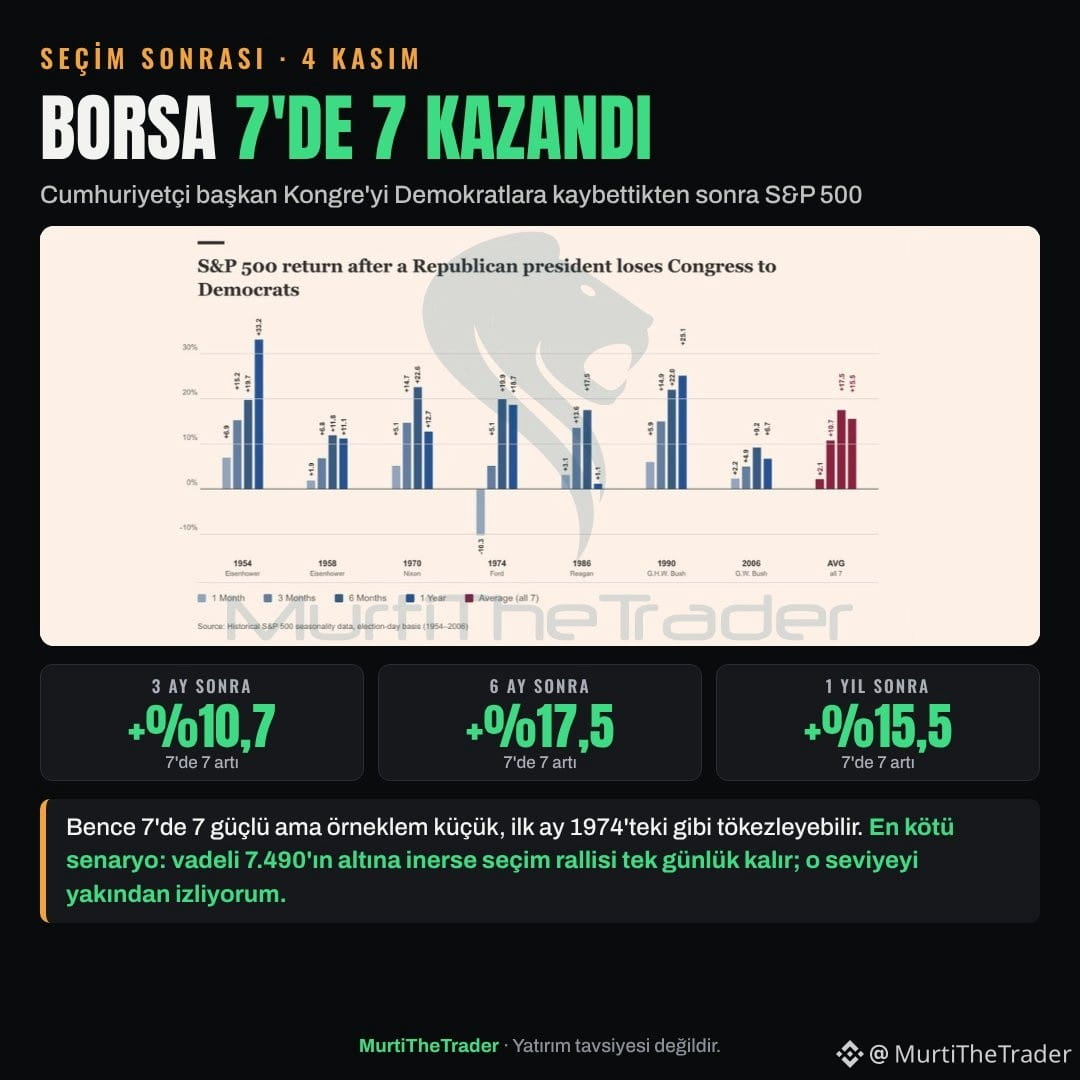
Post-election: Democrats took both chambers of Congress. In the previous 7 instances since 1954, the S&P 500 was higher one year later 7 out of 7 times.
→ Average: +10.7% in 3 months, +17.5% in 6 months, +15.5% in 1 year
→ First month positive in 6 of 7, with a double-digit drop in 1974
→ ES futures tagged 7,490 overnight, then flipped to +1.1%
My take: 7 for 7 is strong, but the sample is small, and the first month could stumble like 1974. Worst case: if futures drop below 7,490, the election rally lasts a single day. I'm watching that level closely.
#Investing #SP500
Post-election: Democrats took both chambers of Congress. In the previous 7 instances since 1954, the S&P 500 was higher one year later 7 out of 7 times.
→ Average: +10.7% in 3 months, +17.5% in 6 months, +15.5% in 1 year
→ First month positive in 6 of 7, with a double-digit drop in 1974
→ ES futures tagged 7,490 overnight, then flipped to +1.1%
My take: 7 for 7 is strong, but the sample is small, and the first month could stumble like 1974. Worst case: if futures drop below 7,490, the election rally lasts a single day. I'm watching that level closely.
#Investing #SP500
→ Average: +10.7% in 3 months, +17.5% in 6 months, +15.5% in 1 year
→ First month positive in 6 of 7, with a double-digit drop in 1974
→ ES futures tagged 7,490 overnight, then flipped to +1.1%
My take: 7 for 7 is strong, but the sample is small, and the first month could stumble like 1974. Worst case: if futures drop below 7,490, the election rally lasts a single day. I'm watching that level closely.
#Investing #SP500
1
121
Partly True
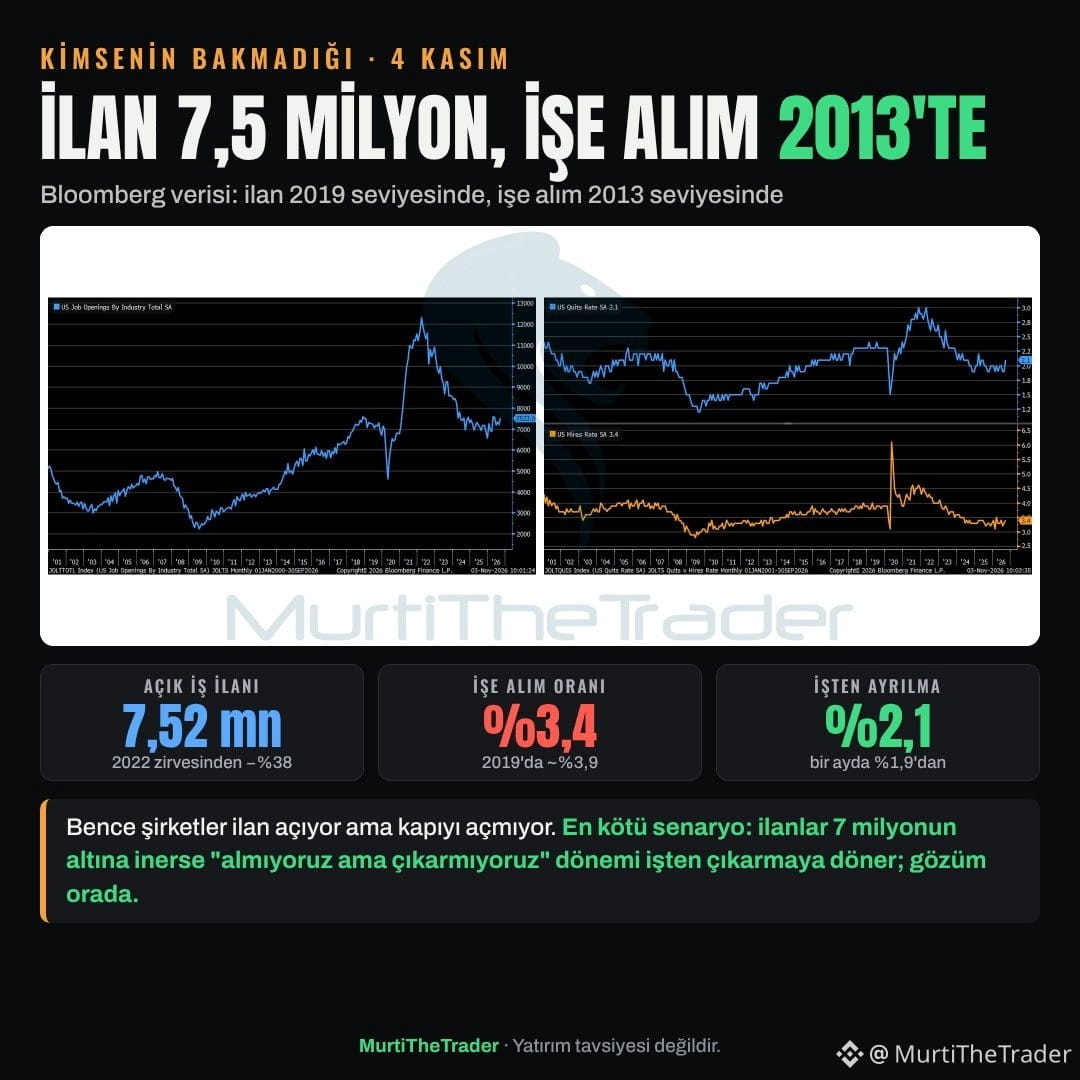
What nobody's watching: per Bloomberg data, the US has 7.5 million job openings, the same as 2019 levels, but the hiring rate is at 3.4%, a 2013 level.
→ In 2019, with a similar number of openings, the hiring rate was ~3.9%
→ Openings are 38% below the March 2022 peak (12.2M)
→ Layoffs rose from 1.9% to 2.1% in a single month
My take: companies are posting jobs but not opening the door. Worst case: if openings drop below 7 million, the "not hiring, but not firing" phase turns into layoffs. That's what I'm watching.
#Economy #Fed
What nobody's watching: per Bloomberg data, the US has 7.5 million job openings, the same as 2019 levels, but the hiring rate is at 3.4%, a 2013 level.
→ In 2019, with a similar number of openings, the hiring rate was ~3.9%
→ Openings are 38% below the March 2022 peak (12.2M)
→ Layoffs rose from 1.9% to 2.1% in a single month
My take: companies are posting jobs but not opening the door. Worst case: if openings drop below 7 million, the "not hiring, but not firing" phase turns into layoffs. That's what I'm watching.
#Economy #Fed
→ In 2019, with a similar number of openings, the hiring rate was ~3.9%
→ Openings are 38% below the March 2022 peak (12.2M)
→ Layoffs rose from 1.9% to 2.1% in a single month
My take: companies are posting jobs but not opening the door. Worst case: if openings drop below 7 million, the "not hiring, but not firing" phase turns into layoffs. That's what I'm watching.
#Economy #Fed
889
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BTCRebounds80K
2,158 views
210 Discussing
#BTCRebounds80K 🚀 BTC RECLAIMS $80K AS ALTCOINS RALLY!
Bitcoin's recovery above $80,000 is boosting market sentiment, while three altcoins are showing strong momentum.
📊 TOP PERFORMERS
CLANKER: $19.89 | +70.88%
JCT: $0.005364 | +23.65%
ELSA: $0.07942 | +23.65%
🔥 Key Highlights:
CLANKER leads daily gains.
JCT dominates the 30-day performance with +220.18%.
ELSA shows steady growth but has comparatively lower trading volume.
🎯 Market Watch: BTC's next resistance zone is $82K–$84K.
⚠️ High volatility remains. Manage risk carefully.
Not financial advice. Always do your own research.
#BTCRebounds80K #CLANKER #JCT #ELSA #CryptoMarket
CHASEPA SULUXù
·0 Likes
·59 views
Binance98PercentReplenished
5,167 views
302 Discussing
USMidterms-WhatAreMarketsExpecting?
225,613 views
1,741 Discussing