Binance Square
#micron

micron

87,130 views
632 Discussing
Master 774
ยท
--
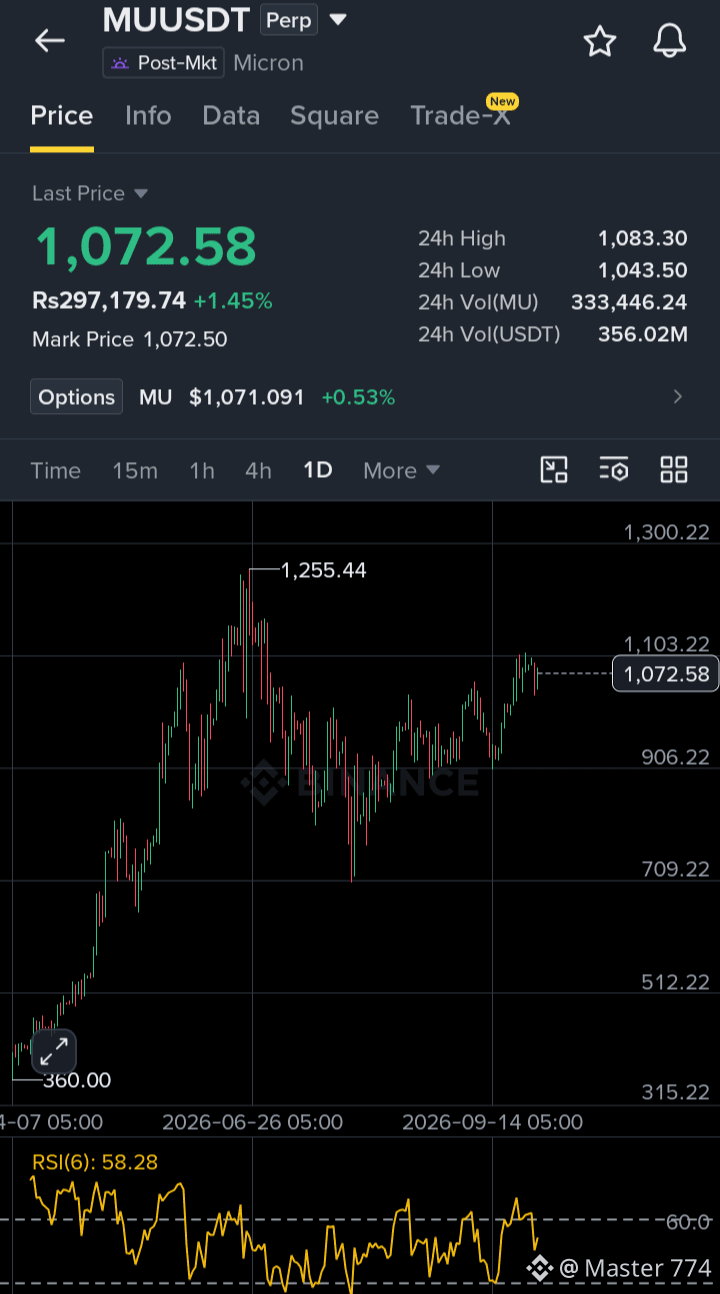
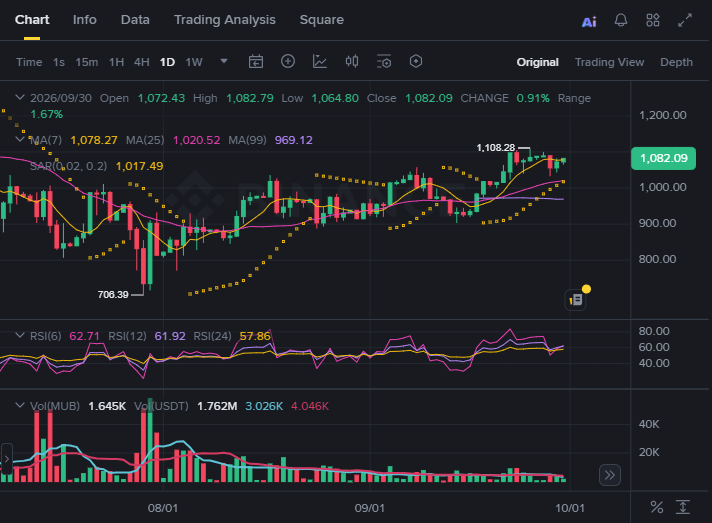
#EarningsSeason ๐Ÿš—โšก MU Daily Chart โ€” AI Memory Story Micron is sitting near $1,073, with the daily chart showing strong recovery momentum. The bigger story is AI infrastructure: autonomous vehicles need ultra-fast memory to process camera, LiDAR and radar data in real time. ๐Ÿ“ˆ If MU holds the current momentum, $1,103 is the first key area to watch, followed by the previous high zone around $1,255. AI demand isnโ€™t only about GPUs โ€” memory is becoming a major part of the AI hardware race. ๐Ÿ‘€ $MUB #Micron #AI #Semiconductors
#EarningsSeason ๐Ÿš—โšก MU Daily Chart โ€” AI Memory Story

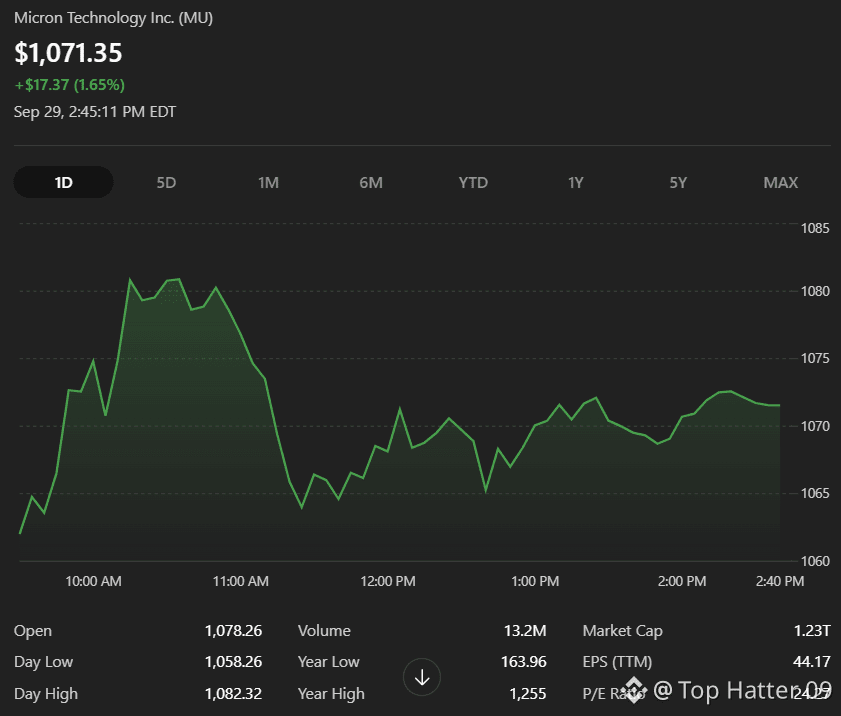
Micron is sitting near $1,073, with the daily chart showing strong recovery momentum.

The bigger story is AI infrastructure: autonomous vehicles need ultra-fast memory to process camera, LiDAR and radar data in real time.

๐Ÿ“ˆ If MU holds the current momentum, $1,103 is the first key area to watch, followed by the previous high zone around $1,255.

AI demand isnโ€™t only about GPUs โ€” memory is becoming a major part of the AI hardware race. ๐Ÿ‘€

$MUB #Micron #AI #Semiconductors
Micron Q4 Earnings: Bullish or Bearish? ๐Ÿ” $MU reports this week, and it's more than one stock's quarter. It's a test of the whole memory supercycle narrative. ๐Ÿ‚ Bull case AI demand keeps pulling HBM and high-capacity DRAM Tight supply could support pricing and margins Strong guidance would confirm the cycle has room to run. ๐Ÿป Bear case Expectations are already high, so "good" may not be enough Any softness in guidance could hit the whole memory sector Cyclical stocks often peak while the news still looks great. ๐Ÿ‘€ What I'm watching HBM revenue and next-quarter guidance Gross margin trend How the stock moves after the report, since the reaction matters more than the headline. Beat-and-drop and miss-and-rally both happen on earnings day, so I'll be waiting for the reaction before making any move. Where do you stand: ๐Ÿ‚ Bullish or ๐Ÿป Bearish on $MU? Drop your take below ๐Ÿ‘‡ #EarningsSeason #MU #Micron $BTC $ETH
Micron Q4 Earnings: Bullish or Bearish? ๐Ÿ”

$MU reports this week, and it's more than one stock's quarter. It's a test of the whole memory supercycle narrative.

๐Ÿ‚ Bull case

AI demand keeps pulling HBM and high-capacity DRAM
Tight supply could support pricing and margins
Strong guidance would confirm the cycle has room to run.

๐Ÿป Bear case

Expectations are already high, so "good" may not be enough
Any softness in guidance could hit the whole memory sector
Cyclical stocks often peak while the news still looks great.

๐Ÿ‘€ What I'm watching

HBM revenue and next-quarter guidance
Gross margin trend
How the stock moves after the report, since the reaction matters more than the headline.

Beat-and-drop and miss-and-rally both happen on earnings day, so I'll be waiting for the reaction before making any move.
Where do you stand: ๐Ÿ‚ Bullish or ๐Ÿป Bearish on $MU ? Drop your take below ๐Ÿ‘‡

#EarningsSeason #MU #Micron $BTC $ETH
ยท
--
Verified
๐ŸšจMicron reports today, and the key question is whether Q4 revenue can meetโ€”or beatโ€”its prior guidance of $50B ยฑ $1B Hereโ€™s the simple setup: 1๏ธโƒฃBeat + raised guidance: Confirms the AI memory boom is still intact. A strong +8% to +15% move is possible 2๏ธโƒฃIn line, but no upside surprise: The classic โ€œgood, but already priced inโ€ scenario. Shares could trade in a -3% to +3% range 3๏ธโƒฃSoft guidance / more cautious HBM outlook: The market may quickly cut future expectations. In a high-volatility reaction, a -10% to -18% pullback would not be surprising #EarningsSeason #micron
๐ŸšจMicron reports today, and the key question is whether Q4 revenue can meetโ€”or beatโ€”its prior guidance of $50B ยฑ $1B

Hereโ€™s the simple setup:

1๏ธโƒฃBeat + raised guidance:
Confirms the AI memory boom is still intact. A strong +8% to +15% move is possible

2๏ธโƒฃIn line, but no upside surprise:
The classic โ€œgood, but already priced inโ€ scenario. Shares could trade in a -3% to +3% range

3๏ธโƒฃSoft guidance / more cautious HBM outlook:
The market may quickly cut future expectations. In a high-volatility reaction, a -10% to -18% pullback would not be surprising #EarningsSeason #micron
BSDurrani:
Holding $MUB too! Watching earnings closely. If Micron beats $50B guidance and raises next Q, we can see new ATH. If they miss, this bStocks selloff will be a buying opportunity. I'm holding small spot for earnings gamble. Are you bullish or bearish before report? #MUB #Micron #Earnings
Verified
Article
ONE QUARTER CAN MOVE $MU. MULTI-YEAR COMMITMENTS BUILD THE THESIS.$MU: ONE QUARTER CAN MOVE THE STOCK. CAN IT BREAK THE THESIS? Micron reports FY2026 Q4 today. Most people will watch one thing: Did $MU beat or miss? I think the more important question is different: Is Micron building a business that can remain strong AFTER this earnings report? Before Q4 even lands, Micron was already guiding for: $50B ยฑ $1B revenue ~86% gross margin ~$31 non-GAAP EPS Those numbers are huge. But a great quarter alone doesn't create long-term confidence. The real signal is what sits behind the quarter. Micron has signed 16 Strategic Customer Agreements. 14 of those agreements represent approximately $100B of cumulative minimum-price revenue over their remaining terms. Micron also expects around $22B in cash deposits and related financial commitments from signed agreements. And these aren't one-quarter commitments. Most agreements have five-year terms, with binding take-or-pay commitments for specific volumes. That changes how I look at $MU. This isn't simply: AI hype โ†’ earnings beat โ†’ stock pumps. The bigger story is: AI infrastructure demand โ†“ HBM / DRAM demand โ†“ customers securing long-term supply โ†“ Micron expanding capacity + technology investment โ†“ greater revenue visibility Micron itself says these agreements are intended to improve the durability, stability and predictability of its financial performance. And the recent numbers already show how dramatically the business has changed. Q3 FY2026 revenue reached $41.46B, versus $23.86B in Q2. GAAP gross margin jumped from 74.4% โ†’ 84.6%. Operating cash flow increased from $11.90B โ†’ $25.39B. So here's the question I actually want to debate: Is this just another memory-cycle peak โ€” or is AI fundamentally changing the economics of memory? Because these are two completely different theses. If it's just a cycle, extraordinary margins eventually normalize. If AI has structurally increased the value of high-performance memory, then today's numbers could be part of a much longer transformation. That's why I don't think one earnings report should decide your entire view of $MU. One quarter can change the price. Multiple years of demand, customer commitments, technology leadership and disciplined capacity investment are what determine whether the thesis survives. My question for #EarningsSeason: Can Micron sustain this memory supercycle beyond the next few quarters? ๐ŸŸข BULL: AI demand + HBM + long-term contracts can support a multi-year cycle. ๐Ÿ”ด BEAR: Today's margins are cyclical and expectations are already too high. Don't just tell me BULL or BEAR. Tell me what breaks your thesis first. #EarningsSeason #Micron #AI #Semiconductors Nguแป“n: Micron Investor Relations โ€” Q3 FY2026 results & Strategic Customer Agreements.

ONE QUARTER CAN MOVE $MU. MULTI-YEAR COMMITMENTS BUILD THE THESIS.

$MU : ONE QUARTER CAN MOVE THE STOCK. CAN IT BREAK THE THESIS?
Micron reports FY2026 Q4 today.
Most people will watch one thing:
Did $MU beat or miss?
I think the more important question is different:
Is Micron building a business that can remain strong AFTER this earnings report?
Before Q4 even lands, Micron was already guiding for:
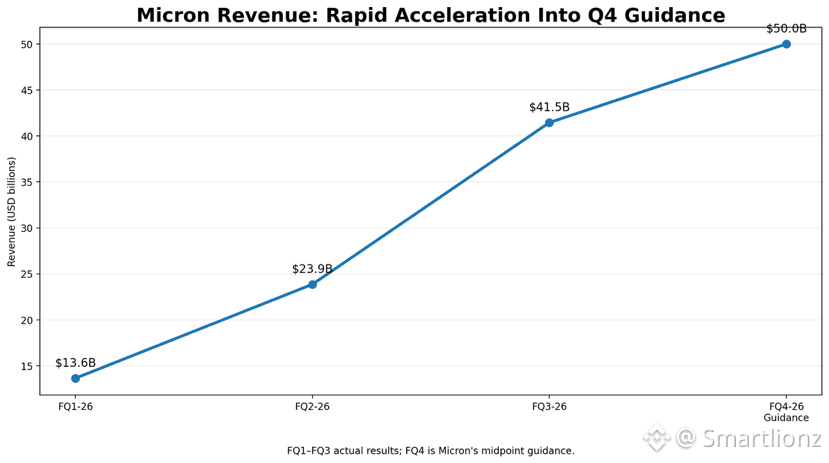
$50B ยฑ $1B revenue
~86% gross margin
~$31 non-GAAP EPS
Those numbers are huge.
But a great quarter alone doesn't create long-term confidence.
The real signal is what sits behind the quarter.
Micron has signed 16 Strategic Customer Agreements.
14 of those agreements represent approximately $100B of cumulative minimum-price revenue over their remaining terms.
Micron also expects around $22B in cash deposits and related financial commitments from signed agreements.
And these aren't one-quarter commitments.
Most agreements have five-year terms, with binding take-or-pay commitments for specific volumes.
That changes how I look at $MU .
This isn't simply:
AI hype โ†’ earnings beat โ†’ stock pumps.
The bigger story is:
AI infrastructure demand
โ†“
HBM / DRAM demand
โ†“
customers securing long-term supply
โ†“
Micron expanding capacity + technology investment
โ†“
greater revenue visibility
Micron itself says these agreements are intended to improve the durability, stability and predictability of its financial performance.
And the recent numbers already show how dramatically the business has changed.
Q3 FY2026 revenue reached $41.46B, versus $23.86B in Q2.
GAAP gross margin jumped from 74.4% โ†’ 84.6%.
Operating cash flow increased from $11.90B โ†’ $25.39B.
So here's the question I actually want to debate:
Is this just another memory-cycle peak โ€” or is AI fundamentally changing the economics of memory?
Because these are two completely different theses.
If it's just a cycle, extraordinary margins eventually normalize.
If AI has structurally increased the value of high-performance memory, then today's numbers could be part of a much longer transformation.
That's why I don't think one earnings report should decide your entire view of $MU .
One quarter can change the price.
Multiple years of demand, customer commitments, technology leadership and disciplined capacity investment are what determine whether the thesis survives.
My question for #EarningsSeason:
Can Micron sustain this memory supercycle beyond the next few quarters?
๐ŸŸข BULL: AI demand + HBM + long-term contracts can support a multi-year cycle.
๐Ÿ”ด BEAR: Today's margins are cyclical and expectations are already too high.
Don't just tell me BULL or BEAR.
Tell me what breaks your thesis first.
#EarningsSeason #Micron #AI #Semiconductors
Nguแป“n: Micron Investor Relations โ€” Q3 FY2026 results & Strategic Customer Agreements.
Fualnguyen:
$MU delivers strong earnings but weak guidanceโ€”does the dip still look cheap? ๐Ÿ‘€ Which matters more for your next trade: this quarterโ€™s beat or next quarterโ€™s outlook? ๐Ÿ‘‡
Picture this: the memory supercycle story that pulled in so many traders is about to face a real stress test with Micron's Q4 earnings this week. Crypto investors have been using these semiconductor reports as signals for AI token plays, only to get blindsided when the data doesn't match the hype and they have no clear exit. Micron's FY2026 Q4 results drop this week and they go far beyond just $MU. This report will show whether the memory supercycle narrative can actually survive contact with reality. Most people are watching for confirmation of the boom. They are not preparing for what happens if it falls short. A disappointing print could quickly unwind the optimism that has been lifting related assets. That includes knock-on effects for $BTC as risk sentiment shifts and for $ETH where AI narratives have been a quiet tailwind. The pain comes from treating these earnings as guaranteed fuel instead of a potential turning point. Where do you think this goes from here? #EarningsSeason #Micron #CryptoMarkets
Picture this: the memory supercycle story that pulled in so many traders is about to face a real stress test with Micron's Q4 earnings this week.
Crypto investors have been using these semiconductor reports as signals for AI token plays, only to get blindsided when the data doesn't match the hype and they have no clear exit.
Micron's FY2026 Q4 results drop this week and they go far beyond just $MU . This report will show whether the memory supercycle narrative can actually survive contact with reality. Most people are watching for confirmation of the boom. They are not preparing for what happens if it falls short.
A disappointing print could quickly unwind the optimism that has been lifting related assets. That includes knock-on effects for $BTC as risk sentiment shifts and for $ETH where AI narratives have been a quiet tailwind. The pain comes from treating these earnings as guaranteed fuel instead of a potential turning point.
Where do you think this goes from here?
#EarningsSeason #Micron #CryptoMarkets
ยท
--
Verified
Micron Earnings Day: What I'm Watching Today is the big day for $MU. Micron is set to report its fiscal Q4 results after the US market close, so I'm less focused on simply whether the company beats expectations and more interested in what the numbers say about the memory cycle. Micron previously guided for around $50B in Q4 revenue and approximately 86% gross margin. Its fiscal Q3 revenue was $41.46B with a 84.9% non GAAP gross margin. For me, the key things to watch are gross margin, AI memory demand, HBM progress, and management's outlook for the next quarter. The earnings number matters, but the guidance could tell us more about how durable this memory cycle really is. What will you be watching most closely from Micron tonight? #EarningsSeason #Micron #MU
Micron Earnings Day: What I'm Watching
Today is the big day for $MU.
Micron is set to report its fiscal Q4 results after the US market close, so I'm less focused on simply whether the company beats expectations and more interested in what the numbers say about the memory cycle.
Micron previously guided for around $50B in Q4 revenue and approximately 86% gross margin. Its fiscal Q3 revenue was $41.46B with a 84.9% non GAAP gross margin.
For me, the key things to watch are gross margin, AI memory demand, HBM progress, and management's outlook for the next quarter.
The earnings number matters, but the guidance could tell us more about how durable this memory cycle really is.
What will you be watching most closely from Micron tonight?
#EarningsSeason #Micron #MU
ยท
--
I think the memory super cycle could run for another 12โ€“24 months, driven by AI and data-center demand. But supply growth and slowing AI spending remain key risks. Iโ€™m cautiously bullish on $MU , but expectations are already high. What do you think? Are we still early, or near the top? $MU #Micron #Semiconductors #EarningsSeason
I think the memory super cycle could run for another 12โ€“24 months, driven by AI and data-center demand. But supply growth and slowing AI spending remain key risks.
Iโ€™m cautiously bullish on $MU , but expectations are already high.
What do you think? Are we still early, or near the top?
$MU #Micron #Semiconductors #EarningsSeason
ยท
--
Bullish
Verified
Micron could beat its 86% gross-margin target and still disappoint investors. Hereโ€™s why Iโ€™m watching what comes AFTER the beat. Ahead of $MUB September 30 earnings, my bias is bullish on the memory business. But the strength of that thesis depends on how long todayโ€™s profitability can last. One revealing detail from Q3: Micronโ€™s Mobile & Client division delivered an 87% gross margin. That tells me the profitability story extends beyond the cloud business. It also raises the stakes: how much of that strength can survive when supply expands? My earnings checklist: โ‘  MARGINS Does the next-quarter outlook support continued strength? An impressive Q4 wonโ€™t answer that by itself. โ‘ก HBM4 Micron already reported high-volume shipments for its lead customer. I want updates on additional customer qualifications and the production ramp. โ‘ข CUSTOMER COMMITMENTS What do long-term agreements actually protect: volumes, pricing, or both? My bullish case strengthens if Micron shows durable demand and credible visibility into future profitability. Iโ€™d become more cautious if the outlook points to weaker pricing or supply catching up faster than demand. Thatโ€™s the test Iโ€™ll use after the reportโ€”even if the headline numbers look spectacular. Source: Micronโ€™s official FY2026 Q3 earnings release, including Q4 guidance: https://www.sec.gov/Archives/edgar/data/723125/000072312526000013/a2026q3ex991-pressrelease.htm Your turn: If Micron beats Q4 expectations but guides lower margins, would you remain bullish? What would change YOUR mind? #EarningsSeason #Micron $MU $MUB {spot}(MUBUSDT) {future}(MUUSDT)
Micron could beat its 86% gross-margin target and still disappoint investors.

Hereโ€™s why Iโ€™m watching what comes AFTER the beat.

Ahead of $MUB September 30 earnings, my bias is bullish on the memory business. But the strength of that thesis depends on how long todayโ€™s profitability can last.

One revealing detail from Q3:

Micronโ€™s Mobile & Client division delivered an 87% gross margin.

That tells me the profitability story extends beyond the cloud business. It also raises the stakes: how much of that strength can survive when supply expands?

My earnings checklist:

โ‘  MARGINS
Does the next-quarter outlook support continued strength? An impressive Q4 wonโ€™t answer that by itself.

โ‘ก HBM4
Micron already reported high-volume shipments for its lead customer. I want updates on additional customer qualifications and the production ramp.

โ‘ข CUSTOMER COMMITMENTS
What do long-term agreements actually protect: volumes, pricing, or both?

My bullish case strengthens if Micron shows durable demand and credible visibility into future profitability.

Iโ€™d become more cautious if the outlook points to weaker pricing or supply catching up faster than demand.

Thatโ€™s the test Iโ€™ll use after the reportโ€”even if the headline numbers look spectacular.

Source: Micronโ€™s official FY2026 Q3 earnings release, including Q4 guidance:
https://www.sec.gov/Archives/edgar/data/723125/000072312526000013/a2026q3ex991-pressrelease.htm

Your turn:

If Micron beats Q4 expectations but guides lower margins, would you remain bullish?

What would change YOUR mind?

#EarningsSeason #Micron
$MU $MUB
ALร˜NDRACRYPTร˜1:
Excelente anรกlisis! Totalmente de acuerdo en que lo importante no es solo el resultado de hoy, sino lo que pase a futuro.
ยท
--
Bullish
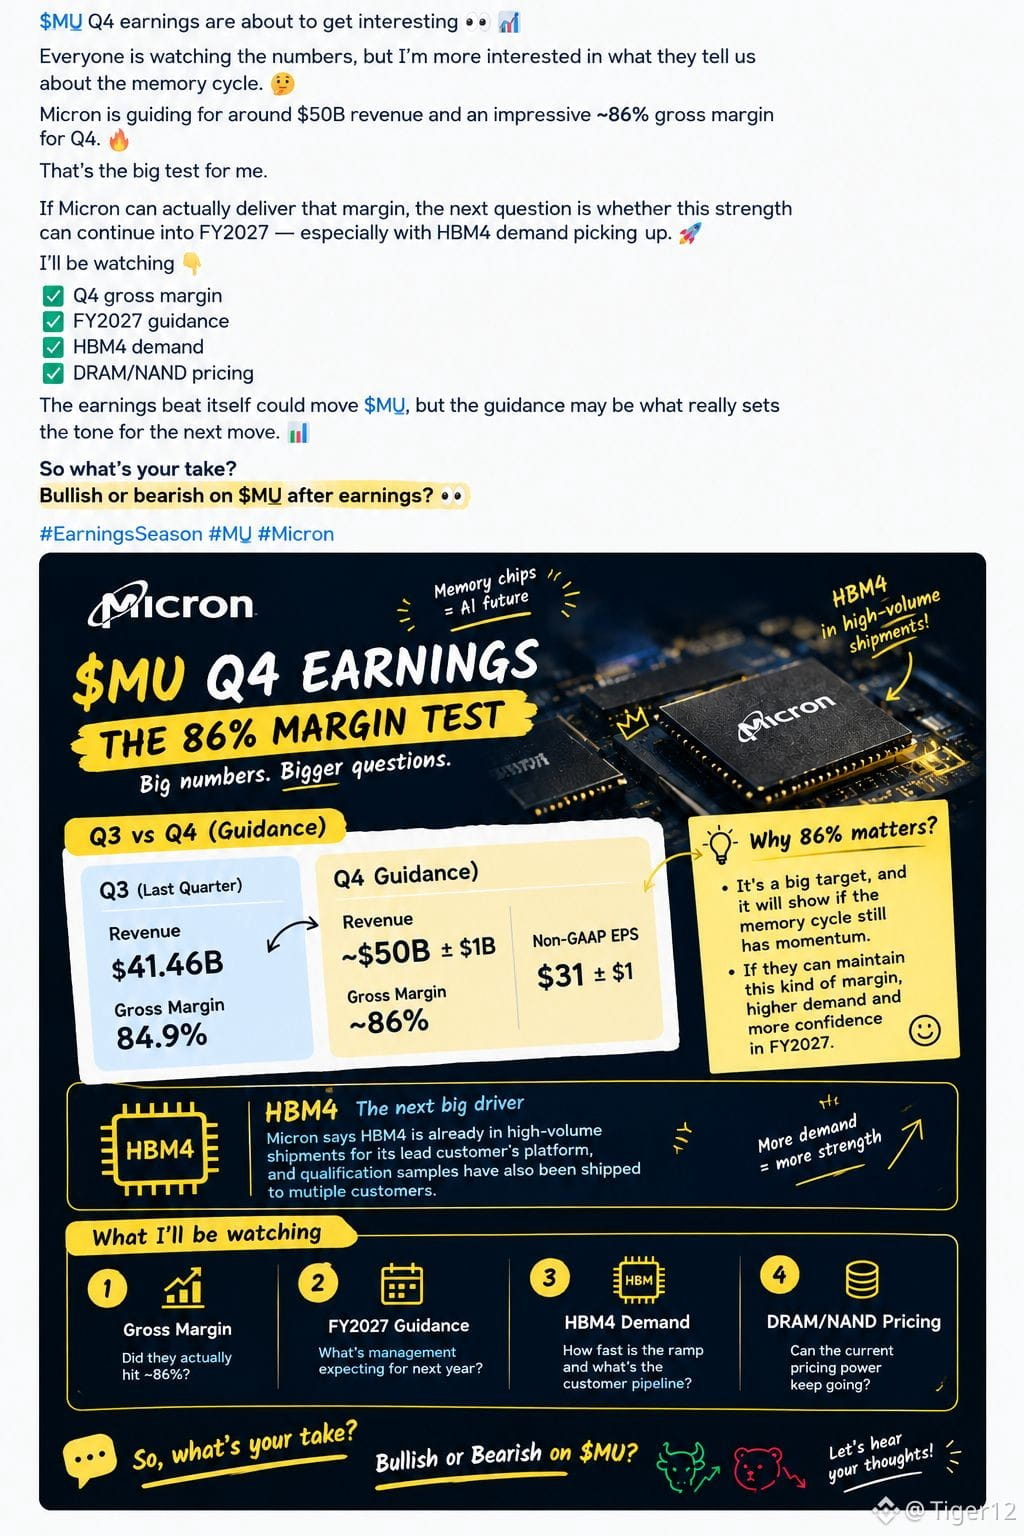
$#EarningsSeason $MU Q4 earnings are about to get interesting ๐Ÿ‘€ Everyone is watching the numbers, but Iโ€™m more interested in what they tell us about the memory cycle. Micron is guiding for around $50B revenue and an impressive ~86% gross margin for Q4. Thatโ€™s the big test for me. If Micron can actually deliver that margin, the next question is whether this strength can continue into FY2027 โ€” especially with HBM4 demand picking up. Iโ€™ll be watching ๐Ÿ‘‡ ๐Ÿ”น Q4 gross margin ๐Ÿ”น FY2027 guidance ๐Ÿ”น HBM4 demand ๐Ÿ”น DRAM/NAND pricing The earnings beat itself could move $MU, but the guidance may be what really sets the tone for the next move. So whatโ€™s your take? Bullish or bearish on $MU after earnings? ๐Ÿ‘€ #EarningsSeason #MU #Micron
$#EarningsSeason
$MU Q4 earnings are about to get interesting ๐Ÿ‘€

Everyone is watching the numbers, but Iโ€™m more interested in what they tell us about the memory cycle.

Micron is guiding for around $50B revenue and an impressive ~86% gross margin for Q4.

Thatโ€™s the big test for me.

If Micron can actually deliver that margin, the next question is whether this strength can continue into FY2027 โ€” especially with HBM4 demand picking up.

Iโ€™ll be watching ๐Ÿ‘‡

๐Ÿ”น Q4 gross margin
๐Ÿ”น FY2027 guidance
๐Ÿ”น HBM4 demand
๐Ÿ”น DRAM/NAND pricing

The earnings beat itself could move $MU , but the guidance may be what really sets the tone for the next move.

So whatโ€™s your take?

Bullish or bearish on $MU after earnings? ๐Ÿ‘€

#EarningsSeason #MU #Micron
#EarningsSeason{future}(MUUSDT) $MU Micron Technology $MU reports its FY2026 Q4 earnings today, September 30, 2026. As AI hardware demand accelerates, key operational metrics outline the stock's multi-year outlook. Core Q4 Metrics & Expectations Gross Margin Target: Guided around 86.0% (up from 84.9% in Q3), fueled by premium HBM4 (High Bandwidth Memory) shipments and 1-gamma DRAM efficiency gains. Revenue & Earnings Baseline: Consensus expects ~$50.97B in revenue (+350% YoY) and $31.52 EPS, hitting upper guidance bounds. Key Insights & Market Dynamics Memory Supercycle Runway: HBM manufacturing requires ~3x the silicon wafer space of standard DDR5 DRAM, restricting broad market supply and protecting long-term contract pricing into FY2027. #mu #micron #EarningsSeason

#EarningsSeason

$MU
Micron Technology $MU reports its FY2026 Q4 earnings today, September 30, 2026. As AI hardware demand accelerates, key operational metrics outline the stock's multi-year outlook.
Core Q4 Metrics & Expectations
Gross Margin Target: Guided around 86.0% (up from 84.9% in Q3), fueled by premium HBM4 (High Bandwidth Memory) shipments and 1-gamma DRAM efficiency gains.
Revenue & Earnings Baseline: Consensus expects ~$50.97B in revenue (+350% YoY) and $31.52 EPS, hitting upper guidance bounds.
Key Insights & Market Dynamics
Memory Supercycle Runway: HBM manufacturing requires ~3x the silicon wafer space of standard DDR5 DRAM, restricting broad market supply and protecting long-term contract pricing into FY2027.
#mu #micron #EarningsSeason
ยท
--
Bullish
Micron Q4: Bullish or Bearish? My Take ๐Ÿ“Š Micron reports FY2026 Q4 earnings today, guiding to $50B revenue, ~86% non-GAAP gross margin, and $31 EPS. The number everyone's watching: can gross margin actually push past 86%? Here's the nuance most people are missing โ€” Micron's own guidance language already flags a "moderation in the rate of price increases." That's not the same as falling prices, but it tells you management is managing expectations slightly below where spot pricing trends might have implied. Why this matters: - If margin beats 86% clearly โ†’ genuinely bullish, confirms the memory super-cycle has more room to run into FY27 - If margin lands right at 86% (in-line) โ†’ could read as "priced in," especially with $MU already up 276% YTD - HBM demand looks structural (AI servers need way more advanced memory), which is the strongest argument for this cycle lasting longer than past ones My lean: cautiously bullish on the structural HBM story, but this print needs a clear beat โ€” not just an in-line number โ€” to justify meaningfully more upside from current levels. How much longer do you think the memory super-cycle can run? $MU #EarningsSeason #Micron
Micron Q4: Bullish or Bearish? My Take ๐Ÿ“Š

Micron reports FY2026 Q4 earnings today, guiding to $50B revenue, ~86% non-GAAP gross margin, and $31 EPS.

The number everyone's watching: can gross margin actually push past 86%?

Here's the nuance most people are missing โ€” Micron's own guidance language already flags a "moderation in the rate of price increases." That's not the same as falling prices, but it tells you management is managing expectations slightly below where spot pricing trends might have implied.

Why this matters:

- If margin beats 86% clearly โ†’ genuinely bullish, confirms the memory super-cycle has more room to run into FY27
- If margin lands right at 86% (in-line) โ†’ could read as "priced in," especially with $MU already up 276% YTD
- HBM demand looks structural (AI servers need way more advanced memory), which is the strongest argument for this cycle lasting longer than past ones

My lean: cautiously bullish on the structural HBM story, but this print needs a clear beat โ€” not just an in-line number โ€” to justify meaningfully more upside from current levels.

How much longer do you think the memory super-cycle can run?

$MU

#EarningsSeason #Micron
Binance Square Official
ยท
--
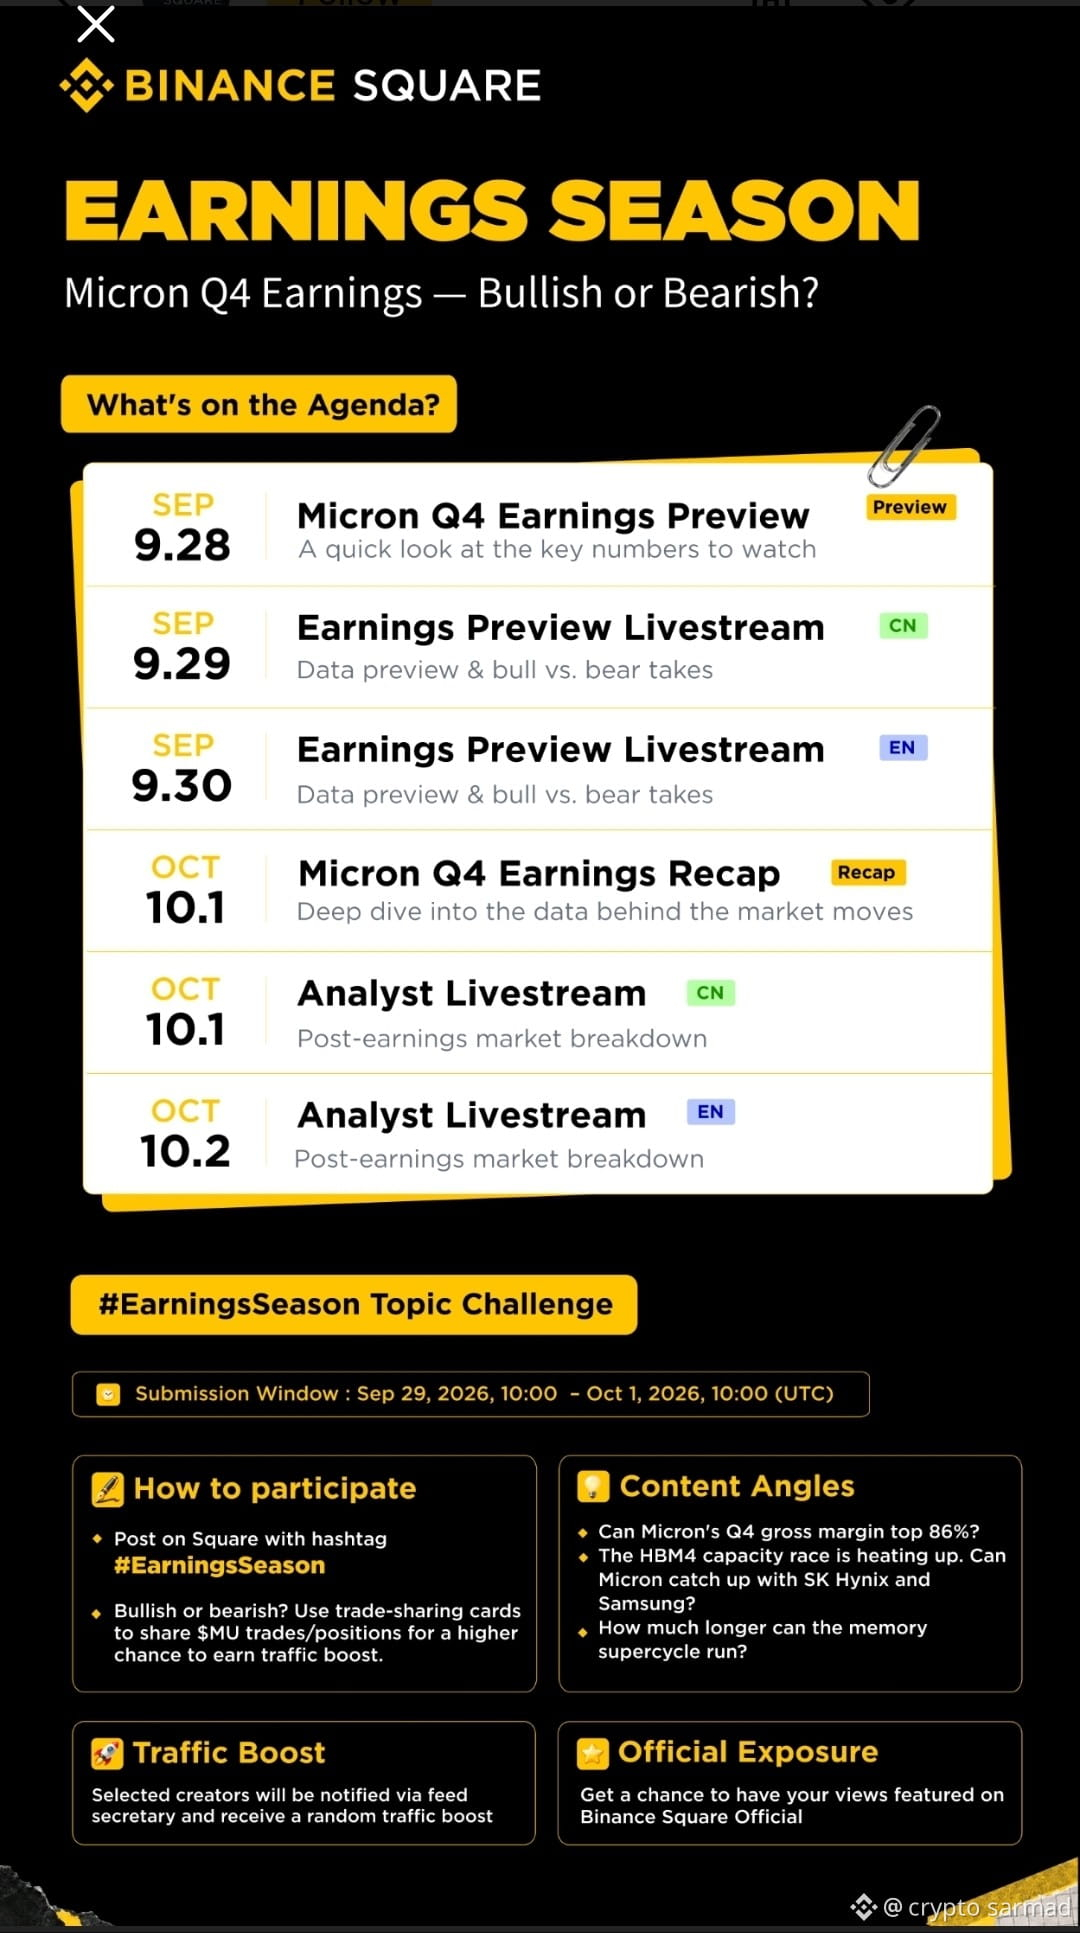
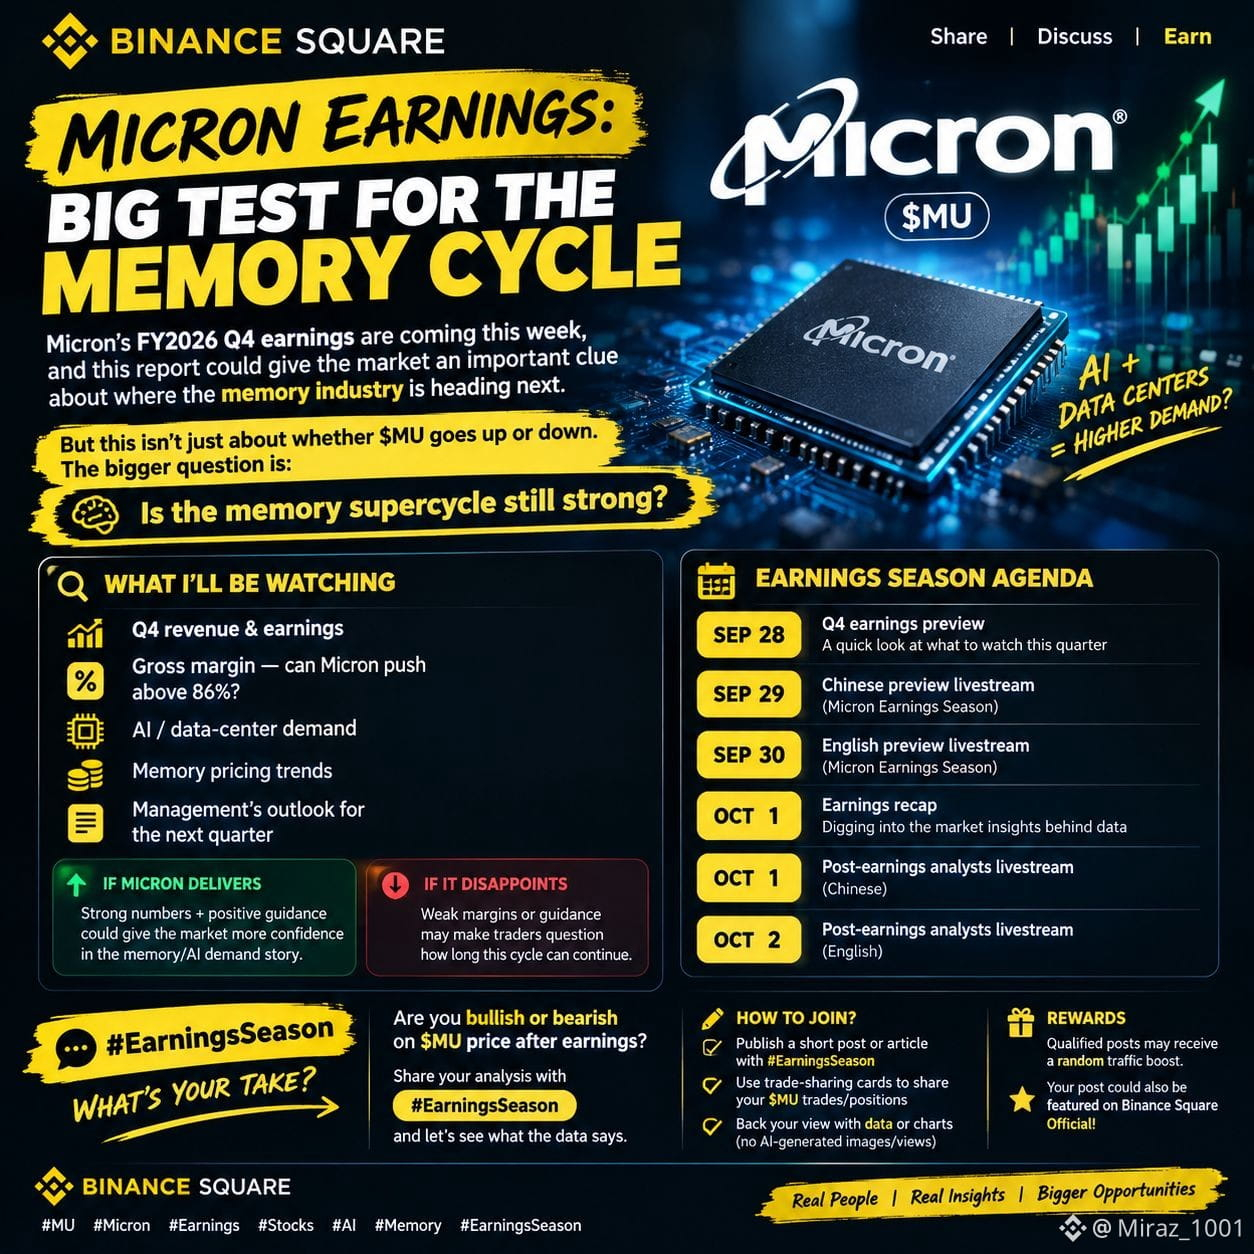
Earnings Season: Micron Q4 Earnings โ€” Bullish or Bearish?
Binance Square is launching the Earnings Season! Join us as we breakdown the market data before and after earnings from the hottest stocks.ย 
Micron's FY2026 Q4 earnings are about to drop this week. The results aren't just about $MU prices, it becomes a key test of whether the whole memory supercycle narrative can hold up.ย 
Stay tuned to Binance Square Earnings Season โ€” be the first to know and act around the biggest earnings!
What's on the Agenda?
Sep 28 โ€” Micron FY2026 Q4 earnings preview: a quick look at what to watch this quarterSep 29 โ€” Micron Earnings Season preview livestream (Chinese)Sep 30 โ€” Micron Earnings Season preview livestream (English)Oct 1 โ€” Micron FY2026 Q4 earnings recap: digging into the market insights behind dataOct 1 โ€” Post-earnings analysts livestream (Chinese)Oct 2 โ€” Post-earnings analysts livestream (English)
#EarningsSeason Topic Challenge
How to join:
Publish a short post or article with hashtag #EarningsSeason How will you adjust your trades/positions before/after the report? Use trade-sharing cards to share your $MU trades/positions for a higher chance to earn a traffic boost.Back up your view with data or charts, and avoid AI-generated images/views.Try to answer one of the following questions in your post:Are you bullish or bearish on $MU price once Q4 earnings are out?Read Micron FY2026 Q4 earnings preview, and share your take: will Micron really be able to push its gross margin past 86% in Q4?ย How much longer do you think the memory super cycle can run?ย 
Submission window:
Sep 29, 2026, 10:00ย  โ€“ Oct 1, 2026, 10:00 (UTC)
Rewards:
Qualified posts that comply with the above guidelines will be reviewed and may receive a random traffic boost in views. Use trade-sharing cards to share your $MU trades/positions for a higher chance to earn a traffic boost. You will receive a notification from your feed secretary if your post is selected.ย Get a chance to have your views featured on Binance Square Official.
Need ideas for your post? Visit #EarningsSeason or the Square Guide on How to Post for Better Reach.
Can this print still supports valuation ?? **Micron Technology heads into its fiscal fourth-quarter earnings report with lofty valuations and high expectations driven by soaring Al memory demand and tight DRAM supplies. Future market momentum will largely depend on fiscal 2027 guidance and ongoing supply constraints. Read the full story at Binance Square. #Micron
Can this print still supports valuation ??

**Micron Technology heads into its fiscal fourth-quarter earnings report with lofty valuations and high expectations driven by soaring Al memory demand and tight DRAM supplies. Future market momentum will largely depend on fiscal 2027 guidance and ongoing supply constraints. Read the full story at Binance Square. #Micron
Binance News
ยท
--
Micron Heads Into Fiscal Q4 Earnings With the Barโ€”and the Stockโ€”Already High
Micron Technology (Nasdaq: MU) $MUB reports fiscal fourth-quarter results after the market close on Sept. 30, closing out a fiscal year in which the stock has surged. The question for investors is no longer whether the memory maker can beat estimates. It is whether the results, and especially the guidance, can justify a valuation that has run well ahead of the sector.
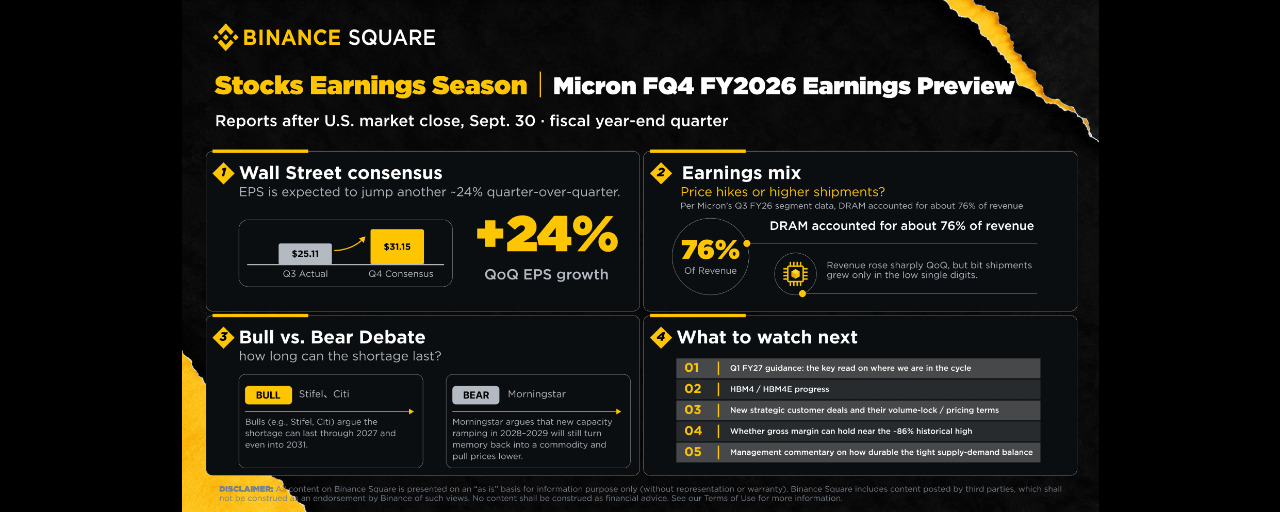
For the August quarter, Micron guided to revenue of 1 billion; non-GAAP earnings of 1; GAAP diluted earnings of 1; and gross margin of roughly 86%. Wall Street sits at or slightly above the midpoint of that range. According to TipRanks, the sell-side consensus calls for revenue of about 50.6 billion and adjusted earnings near 31.16. A quarter ago, in fiscal Q3, Micron earned $25.11 a share as revenue jumped about 346% from a year earlier. Hitting consensus would mean another roughly 24% sequential jump in earningsโ€”a steep step-up for any chipmaker.
The earnings are coming from price, not volume
Most analysts trace this quarter's profit swing to tight supply and rising prices in high-bandwidth memory and AI-related DRAM, rather than to a surge in units shipped.
The mix in fiscal Q3 makes the point. DRAM accounted for about 76% of revenue, and while that revenue climbed sharply from the prior quarter, bit shipments rose only in the low single digits. The gains came from higher average selling prices; incremental volume contributed little.
What separates this cycle from earlier ones is the role of long-term supply agreements. On its earnings call, management said demand from some key customers now runs about 50% above the volume Micron can commit to supply. As of last quarter the company had signed 16 strategic customer agreements covering roughly 20% of its DRAM bits and about 30% of its NAND bits, tied to some 22 billion in customer cash deposits and commitments.
Analysts lean bullish, but price targets are all over the map
TipRanks data as of Sept. 24 shows 29 analysts rating the stock over the prior three months, with a consensus of Strong Buyโ€”28 buys, one hold and no sells. The average price target is about 2,200 and a low of $1,100. That spread reflects a real disagreement about where the cycle stands.
Stifel rates Micron a buy with a $1,500 target and expects both the Q4 results and the guidance to top consensus, though it sees the upside as more measured than in recent quarters, given supply agreements with banded pricing and near-term limits on bit shipments. The firm also expects HBM4 pricing per bit to roughly double, with 2027 negotiations near a close.
TD Cowen analyst Krish Sankar carries a buy rating and a $1,600 target, and frames the case as a re-rating rather than an earnings story: Micron is about 80% of the way through an 18-month stretch of margin expansion, but growing confidence in the cycle's durability could still push the multiple higher.
Citi is bullish as well, arguing that AI demand can keep the memory market undersupplied through 2031.
Melius Research analyst Ben Reitzes holds the Street's highest target at $2,200, citing years of sold-out HBM capacity and the revenue visibility that comes with locked-in long-term contracts.
The cautious camp worries about normalization and valuation
The counterargument, from several named institutions and investors, centers less on any collapse in AI demand than on high margins reverting to normal and a stock that has already priced in a lot.
Goldman Sachs analyst James Schneider is the most cautious of the three major banks, with a neutral rating and a 62 in earnings. Even so, Goldman's own forecast for the quarter sits a few percent above consensusโ€”32.54โ€”and it looks for low-double-digit sequential revenue growth in fiscal Q1, flagging long-run capacity additions from Chinese producers as the main risk. In other words, Goldman's neutral stance rests on valuation, not on any doubt about the fundamentals.
Morningstar analyst William Kerwin rates the shares two stars, calls the business no-moat and assigns it "Very High" uncertainty. After the June quarter he raised his fair value to 455, yet still views the stock as expensive. His bearishness comes down to cyclicality: Kerwin sees memory as a fundamentally cyclical business and expects a wave of new capacity in 2028 and 2029 to create oversupply and pull prices down. Long-term agreements soften the blow, in his view, but do not prevent the downturn, since the revenue genuinely locked in by customer contracts covers only a fraction of the total.
Michael Burry, the "Big Short" investor and founder of Scion Asset Management, has added to bearish bets against Micron. According to Yahoo Finance, he is short the shares along with the iShares Semiconductor ETF. His fundamental case leans on industry signals: he has cited Acer's chairman describing a DDR4 market with more sellers than buyers, and he is watching China's CXMT, whose progress on DDR5 yields and volume production could add supply and cap any durable rise in memory prices.
The bull-bear split on supply ultimately turns on timing. The bullsโ€”Stifel and Citi among themโ€”see the shortage lasting into 2027 and even 2031. Morningstar counters that the capacity coming online in 2028 and 2029 will return memory to its commodity roots and drag prices back down.
Other variables worth watching
Tariffs.ย Investing.com reports that the Trump administration is weighing broader semiconductor tariffs that would reach servers and laptops, a move the industry fears could slow the pace of AI infrastructure spending.
Patent litigation. Netlist has filed a complaint against Micron's DDR5 memory with the U.S. International Trade Commission, and Micron recently lost a patent appeal against the company. An exclusion order looks unlikely in the near term but would be a material risk.
Capital returns. Per CNBC, Micron's roughly $6.165 billion in direct CHIPS Act funding, awarded in December 2024, came with guardrails restricting large-scale buybacks and dividends for recipients. Those company-specific restrictions expire after Dec. 9 this year. Chief Financial Officer Mark Murphy has said the company intends to step up capital returns after that date, with a long-term plan to return 100% of excess cash flow to shareholders. With rivals such as SK Hynix already announcing multibillion-dollar buybacks, investors will listen for any commitment on the call.
R&D. Micron plans to invest $10 billion over the next decade in a Boise, Idaho research center called Micron Research Labs.
What matters most on Sept. 30
The consensus view is that next quarter's guidance will count for more than the current quarter's numbers.
Fiscal Q1 guidance is the key read on where the cycle stands. TipRanks puts the sell-side consensus for the November quarter at about 46.9 billion to 31.49 in earnings (35.11); Goldman's own model for the quarter runs to about $57.7 billion, above the market figure it cites.HBM4 and HBM4E progress, and whether Micron can hold or grow its roughly 20% share of the HBM market.New strategic customer agreements, and their volume and pricing termsโ€”particularly progress toward locking in half of revenue.Whether gross margin holds near its 86% high, and whether the pace of price increases is starting to flatten.Management's language on the durability of supply and demand. Any softening on HBM pricing or demand could trigger a sell-the-news reaction, even on a beat.
ยท
--
$MU earnings are coming. ๐Ÿ‘€ The big question isn't just revenue: Can Micron really push gross margins past 86%? ๐ŸŸข Bullish surprise? ๐Ÿ”ด Sell the news? ๐Ÿง  Or is the memory supercycle already priced in? What's your take? #EarningsSeason #Micron
$MU earnings are coming. ๐Ÿ‘€
The big question isn't just revenue:

Can Micron really push gross margins past 86%?
๐ŸŸข Bullish surprise?
๐Ÿ”ด Sell the news?
๐Ÿง  Or is the memory supercycle already priced in?
What's your take?

#EarningsSeason #Micron
๐Ÿ”ฅ Micron's Q4 earnings drop today, Sep 30, and the stakes are massive โ€” the company is guiding for ~$50B revenue and ~$31 non-GAAP EPS, both records built entirely on the AI memory boom. This follows a jaw-dropping Q3, where revenue jumped 346% YoY to $41.46B on surging DRAM and HBM demand. Shares have pulled back ~22% from highs heading into today's print, so the market is clearly nervous despite the strong fundamentals. Big beats in AI-adjacent stocks like Micron often spill over into positive sentiment for AI-narrative crypto tokens too. Beat or miss โ€” what's your call? ๐Ÿ‘‡ #EarningsSeason #Micron #AI
๐Ÿ”ฅ Micron's Q4 earnings drop today, Sep 30, and the stakes are massive โ€” the company is guiding for ~$50B revenue and ~$31 non-GAAP EPS, both records built entirely on the AI memory boom.

This follows a jaw-dropping Q3, where revenue jumped 346% YoY to $41.46B on surging DRAM and HBM demand. Shares have pulled back ~22% from highs heading into today's print, so the market is clearly nervous despite the strong fundamentals.

Big beats in AI-adjacent stocks like Micron often spill over into positive sentiment for AI-narrative crypto tokens too.

Beat or miss โ€” what's your call? ๐Ÿ‘‡

#EarningsSeason #Micron #AI
$MU is heading into a major earnings catalyst today. Micron reports Q4 FY2026 results after the market close, with AI-driven memory demand in focus. Analysts expect roughly $50B+ revenue, with earnings growth remaining extremely strong. The key question: can Micron maintain tight supply, strong pricing and elevated HBM demand? MU has already delivered a huge 2026 rally, so expectations are high going into earnings. Watch price reaction around the earnings release โ€” volatility could be significant. #MU #Micron #Stocks #EarningsSeason #EarningsSeason {future}(MUUSDT)
$MU is heading into a major earnings catalyst today.
Micron reports Q4 FY2026 results after the market close, with AI-driven memory demand in focus.
Analysts expect roughly $50B+ revenue, with earnings growth remaining extremely strong.
The key question: can Micron maintain tight supply, strong pricing and elevated HBM demand?
MU has already delivered a huge 2026 rally, so expectations are high going into earnings.
Watch price reaction around the earnings release โ€” volatility could be significant.
#MU #Micron #Stocks #EarningsSeason #EarningsSeason
ยท
--
The Real Signal Micronโ€™s Q4 earnings could reveal whether the AI memory boom is becoming a lasting cycle. But the real signal may come from what management says about the future ahead. Micron is targeting roughly $50 billion in Q4 revenue, around 86% gross margin and about $31 in adjusted EPS. Iโ€™m watching three key things very closely: margins, FY2027 guidance and HBM demand. If AI customers continue competing for high-bandwidth memory, the memory cycle could remain tight. But if supply catches up, pricing could change quickly. The forward outlook matters more than one impressive quarter alone. #EarningsSeason #MU #Micron #AI
The Real Signal
Micronโ€™s Q4 earnings could reveal whether the AI memory boom is becoming a lasting cycle. But the real signal may come from what management says about the future ahead. Micron is targeting roughly $50 billion in Q4 revenue, around 86% gross margin and about $31 in adjusted EPS. Iโ€™m watching three key things very closely: margins, FY2027 guidance and HBM demand. If AI customers continue competing for high-bandwidth memory, the memory cycle could remain tight. But if supply catches up, pricing could change quickly. The forward outlook matters more than one impressive quarter alone.
#EarningsSeason #MU #Micron #AI
206 Atlas:
HBM supply constraints are real, but margin compression risks are underpriced if demand normalizes.
$MU EARNINGS IN FOCUS ๐Ÿ‘€ $MU is sitting around $1,073 ahead of tomorrowโ€™s earnings, with the chart still holding well above the 25D MA at $1,018.58. The level Iโ€™m watching is $1,080โ€“$1,100. A clean break above that zone could bring the previous $1,200โ€“$1,255 area back into focus. But earnings are the real test. Micron is guiding for roughly $50B revenue, ~86% gross margin and $31 non-GAAP EPS for Q4. For me, the key question isn't just whether MU {future}(MUUSDT) beats. What matters is the FY2027 guidance and the outlook for memory/HBM demand. Iโ€™m watching $1,100 above and $1,020โ€“$1,040 below. $MU #EarningsSeason #Micron #Semiconductors #BinanceSquare
$MU EARNINGS IN FOCUS ๐Ÿ‘€
$MU is sitting around $1,073 ahead of tomorrowโ€™s earnings, with the chart still holding well above the 25D MA at $1,018.58.
The level Iโ€™m watching is $1,080โ€“$1,100. A clean break above that zone could bring the previous $1,200โ€“$1,255 area back into focus.
But earnings are the real test. Micron is guiding for roughly $50B revenue, ~86% gross margin and $31 non-GAAP EPS for Q4.
For me, the key question isn't just whether MU
beats. What matters is the FY2027 guidance and the outlook for memory/HBM demand.
Iโ€™m watching $1,100 above and $1,020โ€“$1,040 below.
$MU #EarningsSeason #Micron #Semiconductors #BinanceSquare
ยท
--
๐Ÿ”ฅ Micron ($MU) Earnings Season โ€” Big Test for the Memory Supercycle! Micron Technologyโ€™s FY2026 Q4 earnings are coming this week. ๐Ÿ“Š The big question: Can Micronโ€™s results confirm that the memory-chip supercycle is still strong? ๐Ÿง ๐Ÿ’พ Watch closely: โ€ข Revenue & EPS โ€ข DRAM/NAND pricing โ€ข AI-related memory demand โ€ข Q1 FY2027 guidance โ€ข Market reaction after earnings โš ๏ธ Earnings can bring major volatility. Do your own research before making any investment decision. #Micron #MU #EarningsSeason #AI #Semiconductors #MemoryChips #BinanceSquare
๐Ÿ”ฅ Micron ($MU) Earnings Season โ€” Big Test for the Memory Supercycle!

Micron Technologyโ€™s FY2026 Q4 earnings are coming this week. ๐Ÿ“Š

The big question: Can Micronโ€™s results confirm that the memory-chip supercycle is still strong? ๐Ÿง ๐Ÿ’พ

Watch closely:
โ€ข Revenue & EPS
โ€ข DRAM/NAND pricing
โ€ข AI-related memory demand
โ€ข Q1 FY2027 guidance
โ€ข Market reaction after earnings

โš ๏ธ Earnings can bring major volatility. Do your own research before making any investment decision.

#Micron #MU #EarningsSeason #AI #Semiconductors #MemoryChips #BinanceSquare
ยท
--
๐Ÿšจ MICRON EARNINGS ARE HERE โ€” $MU IS IN FOCUS! ๐Ÿ”ฅ Micronโ€™s FY2026 Q4 earnings are coming this week, and this report could give the market an important clue about where the memory industry is heading next. But this isnโ€™t just about whether $MU goes up or down. ๐Ÿ‘€ The bigger question is: ๐Ÿง  Is the memory supercycle still strong? ๐Ÿ“Š Hereโ€™s what Iโ€™ll be watching: โ€ข Q4 revenue & earnings โ€ข Gross margin โ€” can Micron push above 86%? โ€ข AI/data-center demand โ€ข Memory pricing trends โ€ข Managementโ€™s outlook for the next quarter ๐Ÿ”ฅ If Micron delivers strong numbers + positive guidance, the market may get more confidence in the memory/AI demand story. โš ๏ธ But if margins or guidance disappoint, traders may start questioning how long this cycle can continue. ๐Ÿ“… Earnings Season Schedule Sep 28 โ€” Q4 earnings preview Sep 29 โ€” Chinese preview livestream Sep 30 โ€” English preview livestream Oct 1 โ€” Earnings recap + Chinese analyst livestream Oct 2 โ€” English analyst livestream ๐Ÿ’ฌ Whatโ€™s your view on $MU after earnings โ€” bullish or bearish? Share your analysis with and letโ€™s see what the data says. ๐Ÿ“ˆ๐Ÿ“‰ #MU #Micron #Earnings #EarningsSeason
๐Ÿšจ MICRON EARNINGS ARE HERE โ€” $MU IS IN FOCUS! ๐Ÿ”ฅ

Micronโ€™s FY2026 Q4 earnings are coming this week, and this report could give the market an important clue about where the memory industry is heading next.

But this isnโ€™t just about whether $MU goes up or down. ๐Ÿ‘€

The bigger question is:

๐Ÿง  Is the memory supercycle still strong?

๐Ÿ“Š Hereโ€™s what Iโ€™ll be watching:
โ€ข Q4 revenue & earnings
โ€ข Gross margin โ€” can Micron push above 86%?
โ€ข AI/data-center demand
โ€ข Memory pricing trends
โ€ข Managementโ€™s outlook for the next quarter

๐Ÿ”ฅ If Micron delivers strong numbers + positive guidance, the market may get more confidence in the memory/AI demand story.

โš ๏ธ But if margins or guidance disappoint, traders may start questioning how long this cycle can continue.

๐Ÿ“… Earnings Season Schedule
Sep 28 โ€” Q4 earnings preview
Sep 29 โ€” Chinese preview livestream
Sep 30 โ€” English preview livestream
Oct 1 โ€” Earnings recap + Chinese analyst livestream
Oct 2 โ€” English analyst livestream

๐Ÿ’ฌ Whatโ€™s your view on $MU after earnings โ€” bullish or bearish?

Share your analysis with and letโ€™s see what the data says. ๐Ÿ“ˆ๐Ÿ“‰

#MU #Micron #Earnings #EarningsSeason
ยท
--
Bullish
Verified
{stock_us}(MU.US) #EarningsSeason ๐Ÿ”ฅ $MU โ€” BULLISH, BUT THE CHART IS AT A DECISION POINT Micron is still structurally bullish. ๐ŸŸข ๐Ÿ“Š 1D: Price ~$1,066, above MA25 $992 & MA99 $947; RSI 61 โ†’ bullish structure. โฑ๏ธ 4H: RSI 51 and price sitting around MA7/MA25 โ†’ neutral consolidation. โšก 1H: RSI 49 โ†’ short-term momentum has cooled. ๐ŸŽฏ Levels that matter Resistance: $1,074 โ†’ $1,109 ๐Ÿ”ฅ Break & hold above $1,109 = bullish continuation signal Support: ~$1,028 โš ๏ธ Lose $1,028 = setup weakens materially The fundamental backdrop remains strong: Micron guided Q4 revenue at $50B ยฑ$1B, ~86% gross margin and $31 ยฑ$1 EPS, while HBM4 is already in high-volume shipments. Micron Investors +1 And tomorrow's earnings could be explosive: options pricing is implying roughly a ยฑ7% move. Investopedia My read: ๐ŸŸข Medium-term: BULLISH ๐ŸŸก Pre-earnings: NEUTRAL/volatile ๐Ÿš€ Above $1,109: momentum can accelerate ๐Ÿ”ป Below $1,028: caution The biggest question isn't whether MU beats Q4. It's whether FY2027 guidance proves this memory supercycle can continue. #MU #Micron #EarningsSeason #AI #HBM #Stocks Not financial advice. DYOR & manage risk.
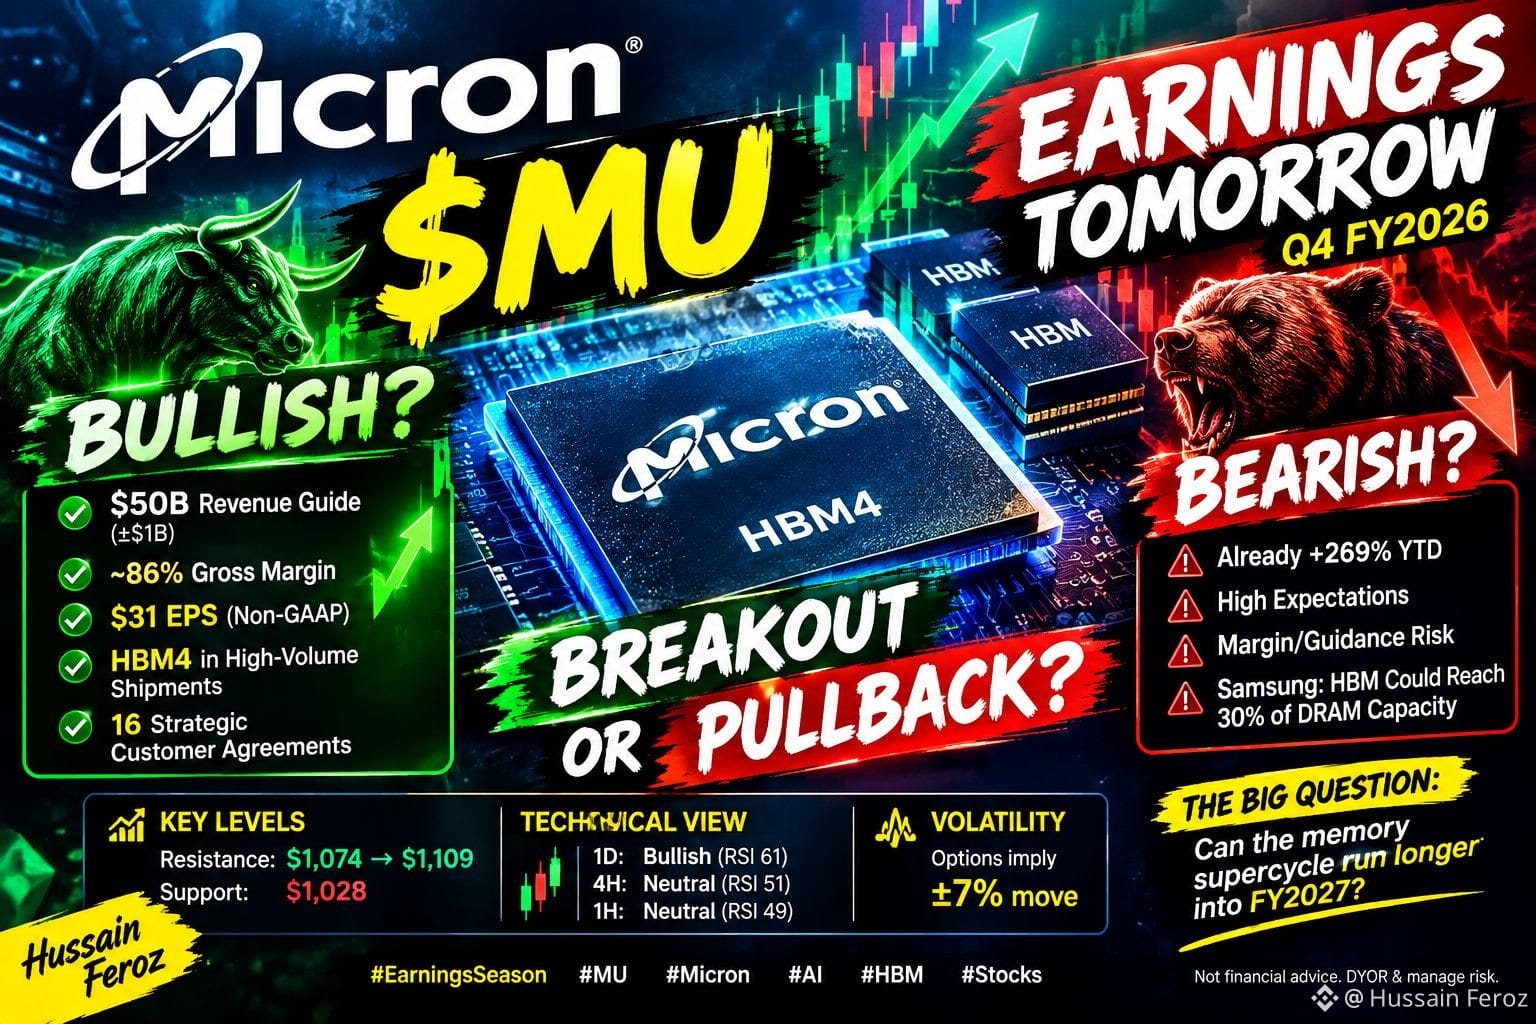
#EarningsSeason ๐Ÿ”ฅ $MU โ€” BULLISH, BUT THE CHART IS AT A DECISION POINT
Micron is still structurally bullish. ๐ŸŸข
๐Ÿ“Š 1D: Price ~$1,066, above MA25 $992 & MA99 $947; RSI 61 โ†’ bullish structure.
โฑ๏ธ 4H: RSI 51 and price sitting around MA7/MA25 โ†’ neutral consolidation.
โšก 1H: RSI 49 โ†’ short-term momentum has cooled.
๐ŸŽฏ Levels that matter
Resistance: $1,074 โ†’ $1,109
๐Ÿ”ฅ Break & hold above $1,109 = bullish continuation signal
Support: ~$1,028
โš ๏ธ Lose $1,028 = setup weakens materially
The fundamental backdrop remains strong: Micron guided Q4 revenue at $50B ยฑ$1B, ~86% gross margin and $31 ยฑ$1 EPS, while HBM4 is already in high-volume shipments.
Micron Investors +1
And tomorrow's earnings could be explosive: options pricing is implying roughly a ยฑ7% move.
Investopedia
My read:
๐ŸŸข Medium-term: BULLISH
๐ŸŸก Pre-earnings: NEUTRAL/volatile
๐Ÿš€ Above $1,109: momentum can accelerate
๐Ÿ”ป Below $1,028: caution
The biggest question isn't whether MU beats Q4.
It's whether FY2027 guidance proves this memory supercycle can continue.
#MU #Micron #EarningsSeason #AI #HBM #Stocks
Not financial advice. DYOR & manage risk.
MU+0.79%
MUUS+1.20%
Log in to explore more content
Join global crypto users on Binance Square
โšก๏ธ Get latest and useful information about crypto.
๐Ÿ’ฌ Trusted by the worldโ€™s largest crypto exchange.
๐Ÿ‘ Discover real insights from verified creators.
Email / Phone number