
#cryptosellofftriggersmultiplewhaleliquidations
cryptosellofftriggersmultiplewhaleliquidations
ມາແຮງ
ຫຼ້າສຸດ


·
--
Crypto Liquidations Top $2B in 24 Hours as 329,000 Traders Are Wiped OutCrypto futures liquidations reached $2.058 billion in the past 24 hours, according to CoinGlass data reported by BlockBeats on November 15, with long positions accounting for nearly all liquidations.Long positions made up $1.922 billion, about 93% of the total, while short positions contributed $142 million. The imbalance points to a one-directional flush rather than a two-way shakeout. Leveraged buyers were carried out as prices fell.A total of 329,339 traders were liquidated. The largest single order was a $16.17 million ETHUSDT position on Binance, a size that points to a whale-scale account.
Crypto Liquidations Top $2B in 24 Hours as 329,000 Traders Are Wiped Out
Crypto futures liquidations reached $2.058 billion in the past 24 hours, according to CoinGlass data reported by BlockBeats on November 15, with long positions accounting for nearly all liquidations.Long positions made up $1.922 billion, about 93% of the total, while short positions contributed $142 million. The imbalance points to a one-directional flush rather than a two-way shakeout. Leveraged buyers were carried out as prices fell.A total of 329,339 traders were liquidated. The largest single order was a $16.17 million ETHUSDT position on Binance, a size that points to a whale-scale account.
BlockchainBuller:
oh god
7
1
31
30.1k
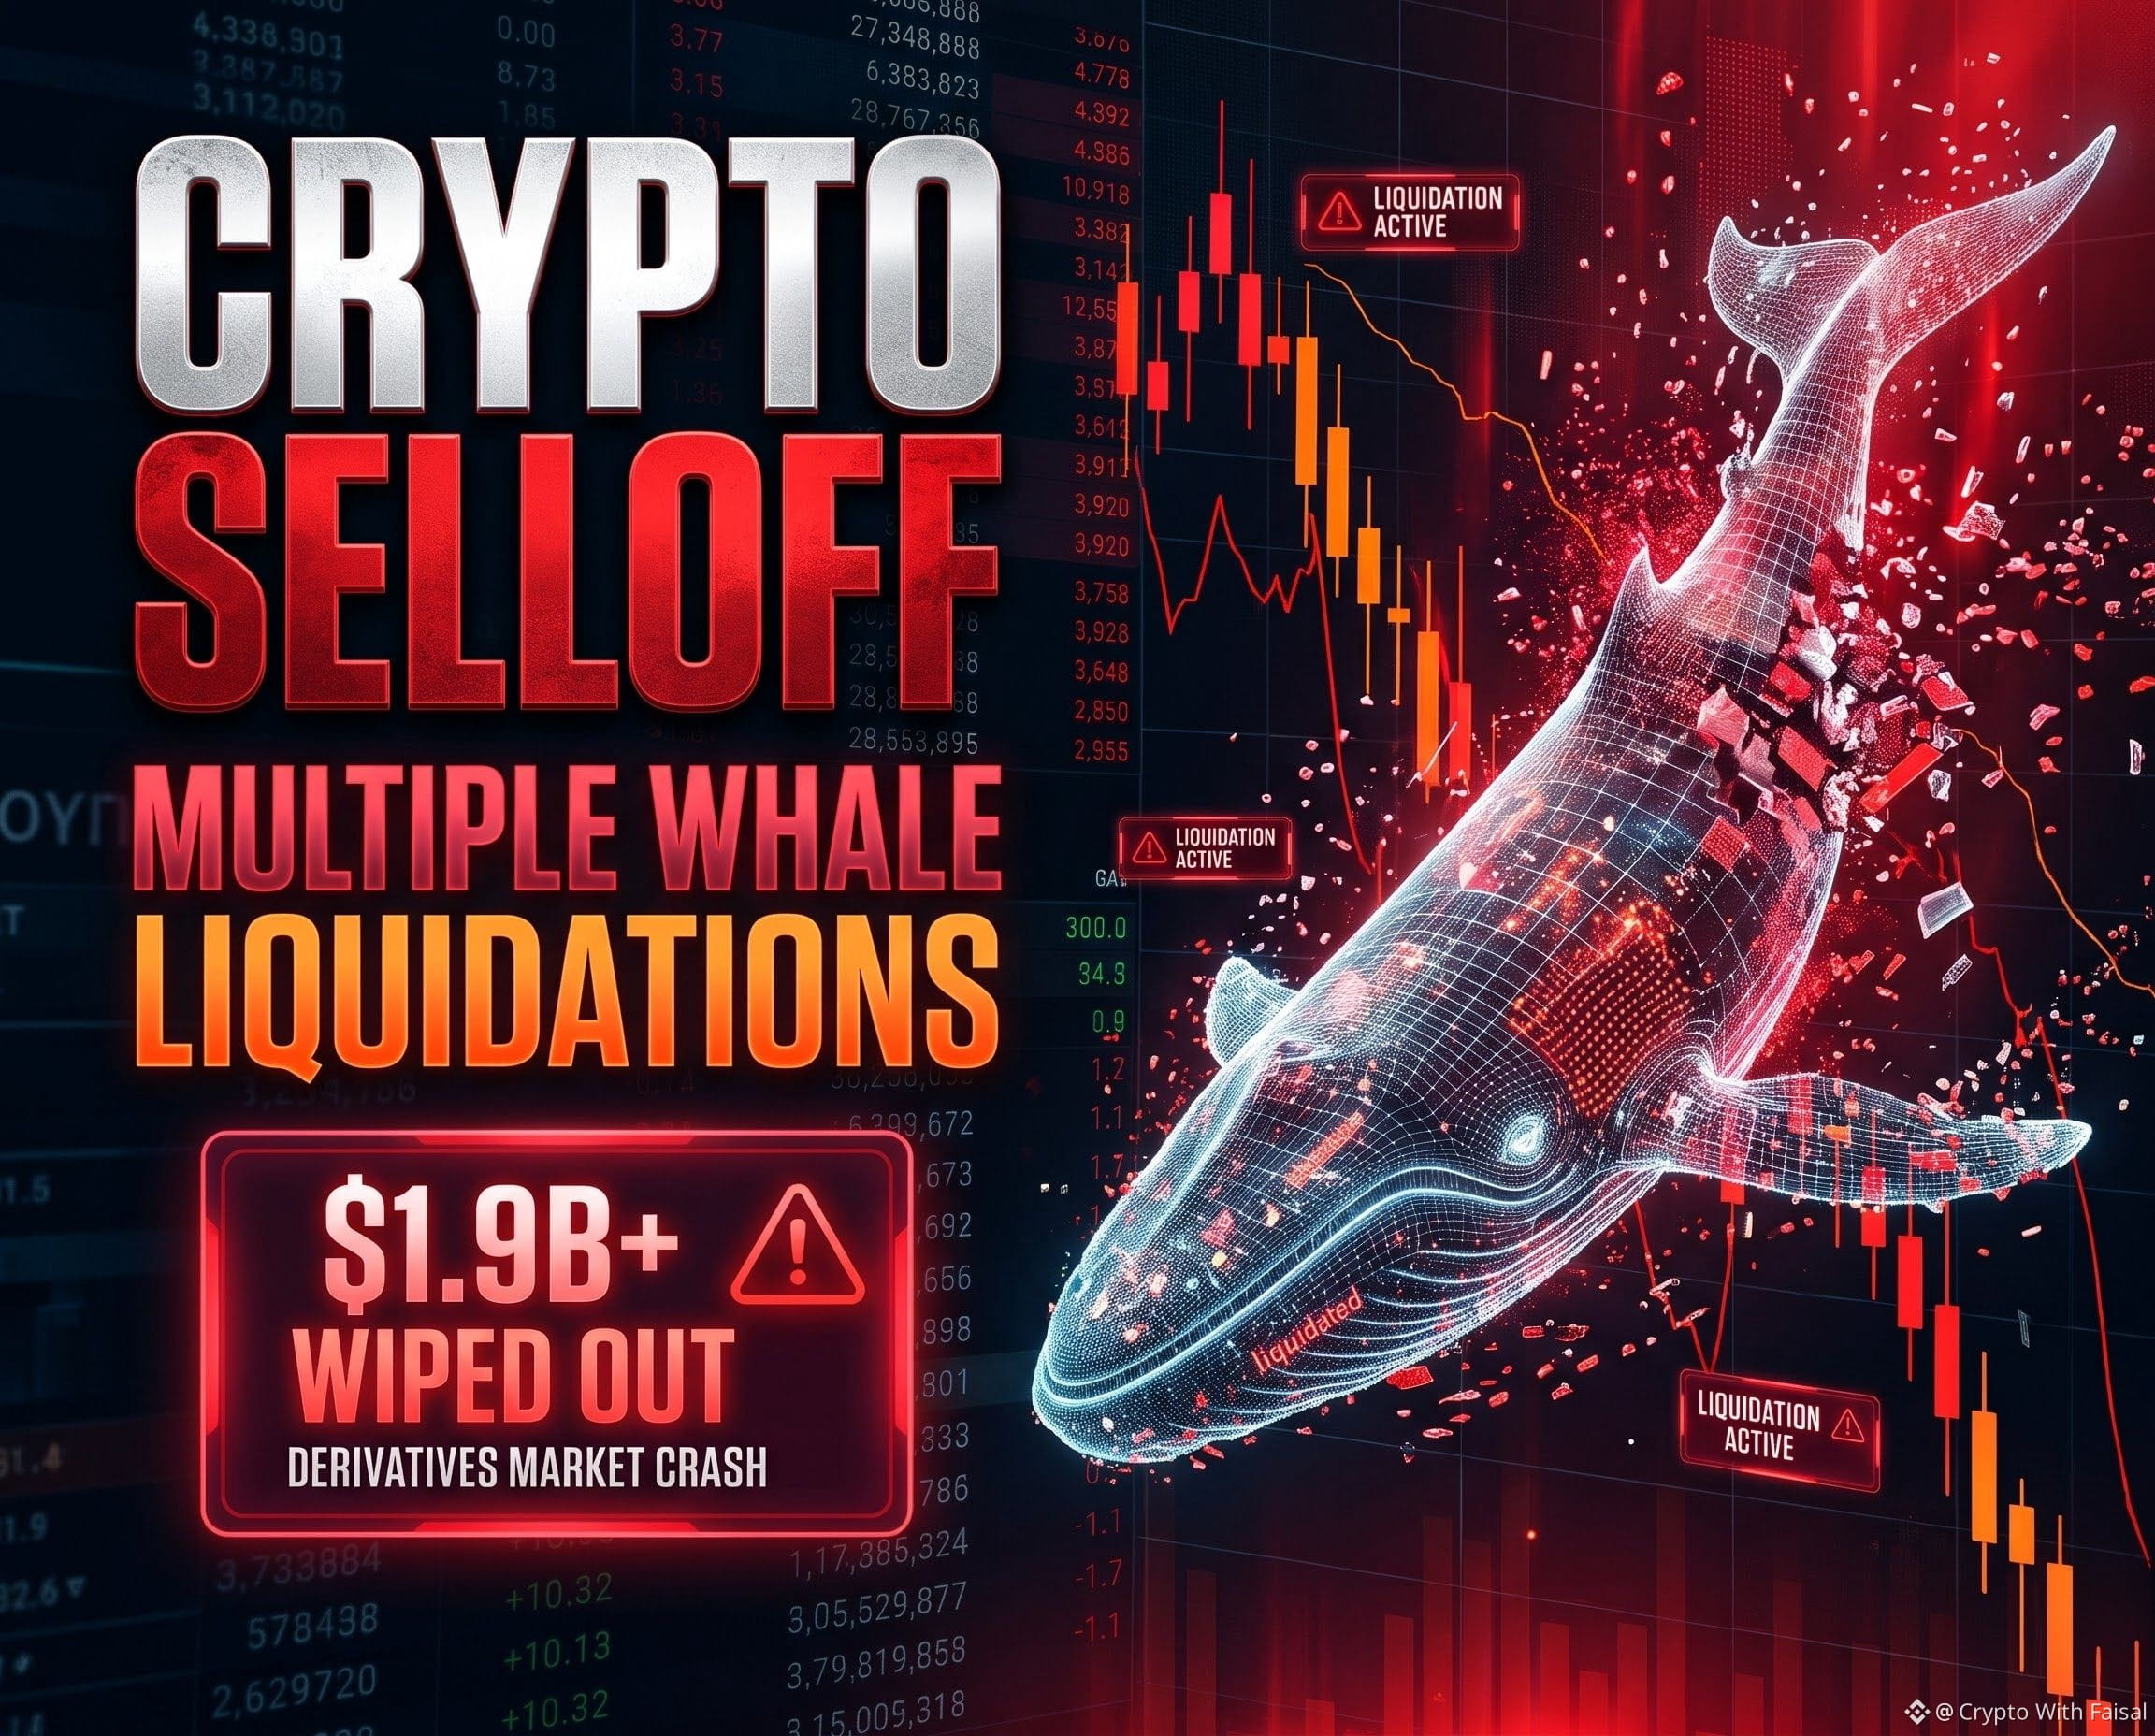
Over-leveraged whales just got caught on the wrong side of the tape.
As BTC slipped toward $63,300—its lowest level since August—cascading margin calls wiped out over $1.9B in 24h derivatives positions, with longs taking 90%+ of the hit.
What the order flow is showing right now:
Whale Wipeouts: Four individual traders lost over $10M apiece, while the largest single BTC long liquidation topped $31M.
Macro & Flow Pressure: Seven straight days of U.S. spot Bitcoin ETF outflows ($1.07B this week) and renewed Fed rate-hike jitters drained spot bid liquidity.
Next Liquidity Magnet: Glassnode flags $59,500–$62,600 as the next major long-liquidation cluster if $63K fails to hold.
Trader Takeaway:
When funding stays crowded into macro uncertainty, high-leverage clusters get hunted first. Keep leverage low, protect margin, and wait for spot absorption before catching knives.
Are you scaling into spot here or waiting for a sweep of $60K? Drop your plan below 👇
$BTC $ETH $EVAA
{future}(EVAAUSDT)
{future}(ETHUSDT)
{future}(BTCUSDT)
#cryptosellofftriggersmultiplewhaleliquidations
#BTC #ETH #CryptoLiquidations #WhaleAlert
Over-leveraged whales just got caught on the wrong side of the tape.
As BTC slipped toward $63,300—its lowest level since August—cascading margin calls wiped out over $1.9B in 24h derivatives positions, with longs taking 90%+ of the hit.
What the order flow is showing right now:
Whale Wipeouts: Four individual traders lost over $10M apiece, while the largest single BTC long liquidation topped $31M.
Macro & Flow Pressure: Seven straight days of U.S. spot Bitcoin ETF outflows ($1.07B this week) and renewed Fed rate-hike jitters drained spot bid liquidity.
Next Liquidity Magnet: Glassnode flags $59,500–$62,600 as the next major long-liquidation cluster if $63K fails to hold.
Trader Takeaway:
When funding stays crowded into macro uncertainty, high-leverage clusters get hunted first. Keep leverage low, protect margin, and wait for spot absorption before catching knives.
Are you scaling into spot here or waiting for a sweep of $60K? Drop your plan below 👇
$BTC $ETH $EVAA
#cryptosellofftriggersmultiplewhaleliquidations
#BTC #ETH #CryptoLiquidations #WhaleAlert
As BTC slipped toward $63,300—its lowest level since August—cascading margin calls wiped out over $1.9B in 24h derivatives positions, with longs taking 90%+ of the hit.
What the order flow is showing right now:
Whale Wipeouts: Four individual traders lost over $10M apiece, while the largest single BTC long liquidation topped $31M.
Macro & Flow Pressure: Seven straight days of U.S. spot Bitcoin ETF outflows ($1.07B this week) and renewed Fed rate-hike jitters drained spot bid liquidity.
Next Liquidity Magnet: Glassnode flags $59,500–$62,600 as the next major long-liquidation cluster if $63K fails to hold.
Trader Takeaway:
When funding stays crowded into macro uncertainty, high-leverage clusters get hunted first. Keep leverage low, protect margin, and wait for spot absorption before catching knives.
Are you scaling into spot here or waiting for a sweep of $60K? Drop your plan below 👇
$BTC $ETH $EVAA
#cryptosellofftriggersmultiplewhaleliquidations
#BTC #ETH #CryptoLiquidations #WhaleAlert
YevhenCrypto:
Spot only, and no rush. I'd rather miss the bottom than force an entry
3
4
4.4k

ບົດຄວາມ
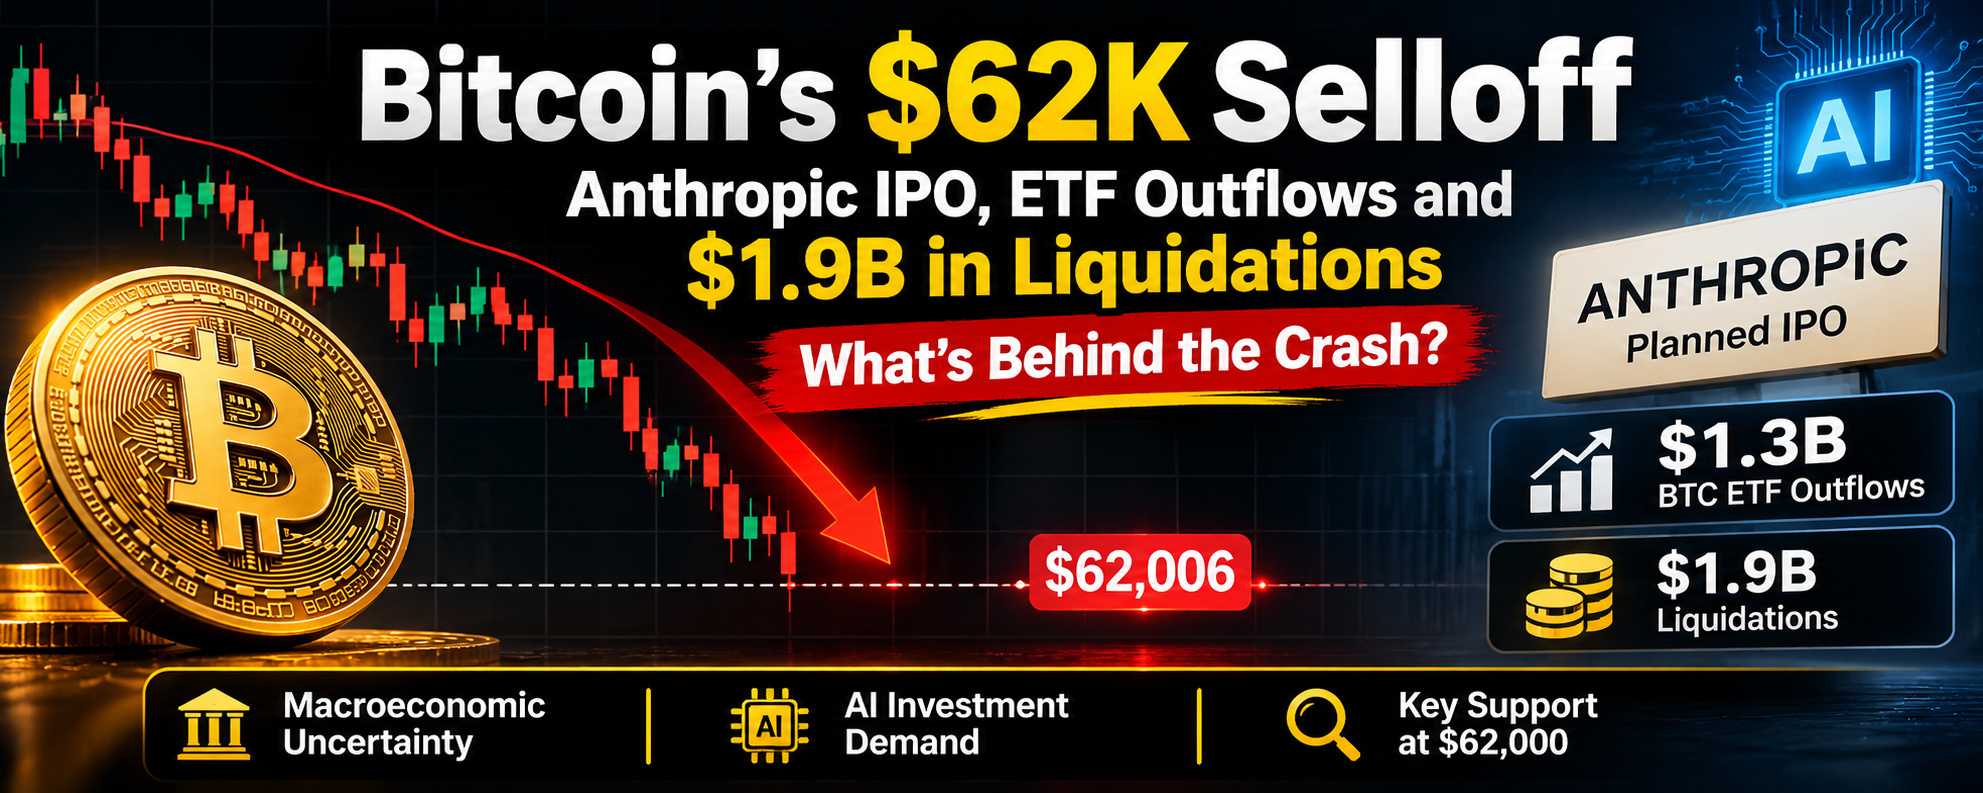
Bitcoin's $62K Selloff:Anthropic IPO, ETF Outflows and $1.9B in Liquidations What's Behind the CrashBitcoin's latest selloff is highlighting a connection between crypto markets, institutional liquidity and the growing demand for capital in the artificial intelligence sector.
One development worth watching is Anthropic's planned IPO. According to Binance Research's November 10 report, the company's pre-IPO perpetual market price had declined approximately 28% since its filing, compared with a roughly 7% decline in Bitcoin over the same period.
This is an interesting divergence because the AI investment cycle is increasingly becoming a major focus for financial markets.
There are several developments adding pressure to crypto:
1. Anthropic's planned IPO
Reuters reported on November 13 that Anthropic's approximately $64 billion IPO had attracted strong institutional demand. Its order book was reportedly six times oversubscribed by Thursday. Some market participants believe investors may be moving capital out of liquid assets to pursue IPO allocations, although direct Bitcoin-to-IPO fund flows have not been established.
2. Bitcoin ETF outflows
Binance Research reported approximately $1.3 billion in net outflows from spot Bitcoin ETFs during the week covered by its November 10 report. This reflects weaker institutional demand during the market decline.
3. Heavy leveraged liquidations
Bloomberg reported, citing CoinGlass data, approximately $1.9 billion in crypto liquidations over the 24 hours through 7 AM Singapore time on November 15. Bitcoin accounted for approximately $684 million and Ethereum $466 million, with long positions representing the vast majority.
4. Broader AI and macroeconomic uncertainty
Binance Research also highlighted concerns around debt-funded AI infrastructure spending, technology-sector weakness and expectations of higher US interest rates. These developments can affect risk appetite across both traditional and crypto markets.
What does this mean for Bitcoin?
Binance BTCUSDT historical market data recorded an intraday low of approximately $62,006 on November 15.
I am watching whether buyers can defend this region and whether stronger spot demand returns. A recovery needs confirmation rather than simply relying on a decline in liquidation activity.
My takeaway is that this selloff deserves a broader explanation. ETF withdrawals, macroeconomic uncertainty, AI-sector capital requirements and leveraged liquidations are all important parts of the current market picture.
Anthropic's IPO may add another liquidity consideration, but it would be incorrect to claim that it alone caused Bitcoin's decline or that every liquidation represents a whale selling.
Do you think the Anthropic IPO could increase competition for investment capital, or are macroeconomic conditions and ETF outflows the bigger reasons behind Bitcoin's weakness? #CryptoSelloffTriggersMultipleWhaleLiquidations
{spot}(BTCUSDT)
{spot}(BNBUSDT)
{future}(ANTHROPICUSDT)
Bitcoin's $62K Selloff:Anthropic IPO, ETF Outflows and $1.9B in Liquidations What's Behind the Crash
Bitcoin's latest selloff is highlighting a connection between crypto markets, institutional liquidity and the growing demand for capital in the artificial intelligence sector.
One development worth watching is Anthropic's planned IPO. According to Binance Research's November 10 report, the company's pre-IPO perpetual market price had declined approximately 28% since its filing, compared with a roughly 7% decline in Bitcoin over the same period.
This is an interesting divergence because the AI investment cycle is increasingly becoming a major focus for financial markets.
There are several developments adding pressure to crypto:
1. Anthropic's planned IPO
Reuters reported on November 13 that Anthropic's approximately $64 billion IPO had attracted strong institutional demand. Its order book was reportedly six times oversubscribed by Thursday. Some market participants believe investors may be moving capital out of liquid assets to pursue IPO allocations, although direct Bitcoin-to-IPO fund flows have not been established.
2. Bitcoin ETF outflows
Binance Research reported approximately $1.3 billion in net outflows from spot Bitcoin ETFs during the week covered by its November 10 report. This reflects weaker institutional demand during the market decline.
3. Heavy leveraged liquidations
Bloomberg reported, citing CoinGlass data, approximately $1.9 billion in crypto liquidations over the 24 hours through 7 AM Singapore time on November 15. Bitcoin accounted for approximately $684 million and Ethereum $466 million, with long positions representing the vast majority.
4. Broader AI and macroeconomic uncertainty
Binance Research also highlighted concerns around debt-funded AI infrastructure spending, technology-sector weakness and expectations of higher US interest rates. These developments can affect risk appetite across both traditional and crypto markets.
What does this mean for Bitcoin?
Binance BTCUSDT historical market data recorded an intraday low of approximately $62,006 on November 15.
I am watching whether buyers can defend this region and whether stronger spot demand returns. A recovery needs confirmation rather than simply relying on a decline in liquidation activity.
My takeaway is that this selloff deserves a broader explanation. ETF withdrawals, macroeconomic uncertainty, AI-sector capital requirements and leveraged liquidations are all important parts of the current market picture.
Anthropic's IPO may add another liquidity consideration, but it would be incorrect to claim that it alone caused Bitcoin's decline or that every liquidation represents a whale selling.
Do you think the Anthropic IPO could increase competition for investment capital, or are macroeconomic conditions and ETF outflows the bigger reasons behind Bitcoin's weakness? #CryptoSelloffTriggersMultipleWhaleLiquidations
One development worth watching is Anthropic's planned IPO. According to Binance Research's November 10 report, the company's pre-IPO perpetual market price had declined approximately 28% since its filing, compared with a roughly 7% decline in Bitcoin over the same period.
This is an interesting divergence because the AI investment cycle is increasingly becoming a major focus for financial markets.
There are several developments adding pressure to crypto:
1. Anthropic's planned IPO
Reuters reported on November 13 that Anthropic's approximately $64 billion IPO had attracted strong institutional demand. Its order book was reportedly six times oversubscribed by Thursday. Some market participants believe investors may be moving capital out of liquid assets to pursue IPO allocations, although direct Bitcoin-to-IPO fund flows have not been established.
2. Bitcoin ETF outflows
Binance Research reported approximately $1.3 billion in net outflows from spot Bitcoin ETFs during the week covered by its November 10 report. This reflects weaker institutional demand during the market decline.
3. Heavy leveraged liquidations
Bloomberg reported, citing CoinGlass data, approximately $1.9 billion in crypto liquidations over the 24 hours through 7 AM Singapore time on November 15. Bitcoin accounted for approximately $684 million and Ethereum $466 million, with long positions representing the vast majority.
4. Broader AI and macroeconomic uncertainty
Binance Research also highlighted concerns around debt-funded AI infrastructure spending, technology-sector weakness and expectations of higher US interest rates. These developments can affect risk appetite across both traditional and crypto markets.
What does this mean for Bitcoin?
Binance BTCUSDT historical market data recorded an intraday low of approximately $62,006 on November 15.
I am watching whether buyers can defend this region and whether stronger spot demand returns. A recovery needs confirmation rather than simply relying on a decline in liquidation activity.
My takeaway is that this selloff deserves a broader explanation. ETF withdrawals, macroeconomic uncertainty, AI-sector capital requirements and leveraged liquidations are all important parts of the current market picture.
Anthropic's IPO may add another liquidity consideration, but it would be incorrect to claim that it alone caused Bitcoin's decline or that every liquidation represents a whale selling.
Do you think the Anthropic IPO could increase competition for investment capital, or are macroeconomic conditions and ETF outflows the bigger reasons behind Bitcoin's weakness? #CryptoSelloffTriggersMultipleWhaleLiquidations
1.1k
🚨 $2 BILLION WIPED OUT! EVEN THE WHALES GOT LIQUIDATED!
The crypto market just delivered one of its nastiest liquidation events. Over $2.05 BILLION in leveraged positions were wiped out in just 24 hours!
#CryptoSelloffTriggersMultipleWhaleLiquidations
📉 $1.922B came from LONG positions, accounting for 93% of total liquidations.
329,339 traders liquidated
$142M in short liquidations
Largest single liquidation: $16.17M $ETH on Binance
This wasn't just a market shakeout. It was a one-sided massacre of leveraged bulls.
When over 329K traders get wiped out and even whale-sized positions disappear, you know how brutal this selloff has become.
The big question now: Is this the final flush before a relief rally, or are we about to witness another wave of liquidations?
The market is showing no mercy to leveraged buyers.
🚨 $2 BILLION WIPED OUT! EVEN THE WHALES GOT LIQUIDATED!
The crypto market just delivered one of its nastiest liquidation events. Over $2.05 BILLION in leveraged positions were wiped out in just 24 hours!
#CryptoSelloffTriggersMultipleWhaleLiquidations
📉 $1.922B came from LONG positions, accounting for 93% of total liquidations.
329,339 traders liquidated
$142M in short liquidations
Largest single liquidation: $16.17M $ETH on Binance
This wasn't just a market shakeout. It was a one-sided massacre of leveraged bulls.
When over 329K traders get wiped out and even whale-sized positions disappear, you know how brutal this selloff has become.
The big question now: Is this the final flush before a relief rally, or are we about to witness another wave of liquidations?
The market is showing no mercy to leveraged buyers.
The crypto market just delivered one of its nastiest liquidation events. Over $2.05 BILLION in leveraged positions were wiped out in just 24 hours!
#CryptoSelloffTriggersMultipleWhaleLiquidations
📉 $1.922B came from LONG positions, accounting for 93% of total liquidations.
329,339 traders liquidated
$142M in short liquidations
Largest single liquidation: $16.17M $ETH on Binance
This wasn't just a market shakeout. It was a one-sided massacre of leveraged bulls.
When over 329K traders get wiped out and even whale-sized positions disappear, you know how brutal this selloff has become.
The big question now: Is this the final flush before a relief rally, or are we about to witness another wave of liquidations?
The market is showing no mercy to leveraged buyers.
Crypto Scientist Expert44:
i followed you sweet brother please follows me back
10
1
34
18.5k
·
--
ສັນຍານໝີ
📰 CRYPTO CARNAGE
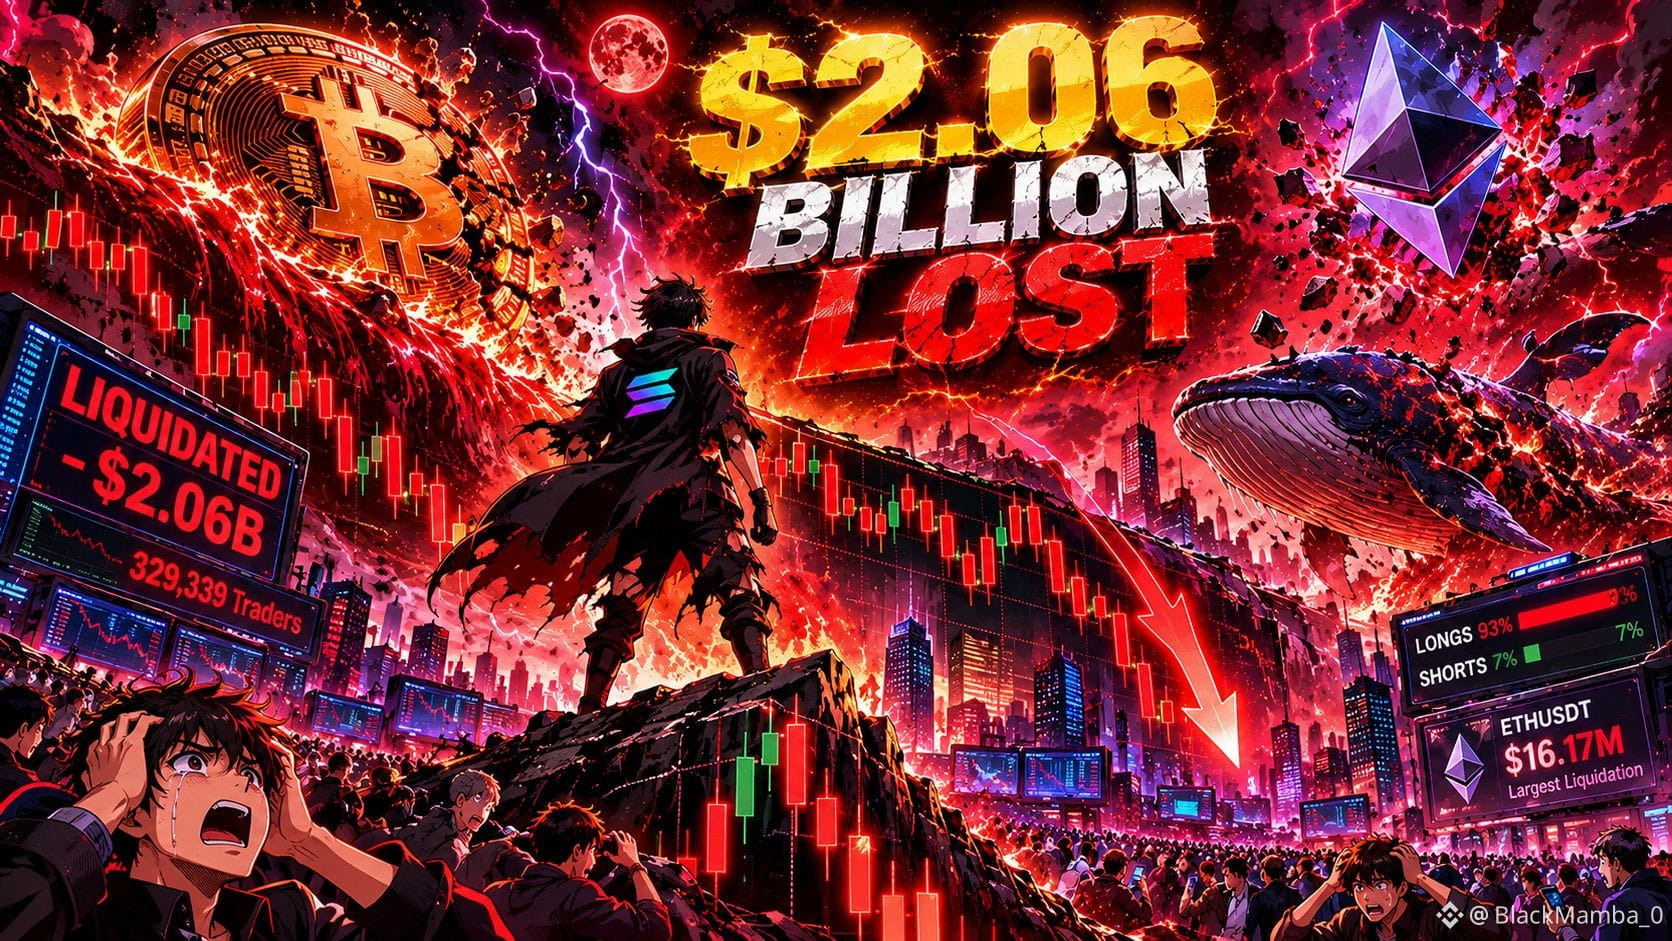
$2.06 BILLION LIQUIDATED IN 24 HOURS
329,339 Traders Wiped Out as Bullish Bets Collapse
📉 Market Crash Snapshot
The crypto derivatives market witnessed a massive liquidation event as over $2.058 Billion in leveraged positions were wiped out within 24 hours.
⚠️ 329,339 traders were liquidated globally, making it one of the largest leverage flushes in recent months.
📊 Liquidation Breakdown
💥 Total Liquidations: $2.058B
🔴 Long Positions: $1.922B (93%)
🟢 Short Positions: $142M (7%)
The numbers reveal an overwhelmingly one-sided event, with bullish traders absorbing nearly all losses as markets moved sharply lower.
🐋 Biggest Casualty
Largest Single Liquidation
ETHUSDT Position: $16.17 Million
A whale-sized account saw a massive ETHUSDT position forcefully closed, highlighting how even large traders can be caught in extreme market volatility.
⚡ What This Means
✅ Excessive leverage built up across the market.
✅ A rapid price decline triggered forced liquidations.
✅ Liquidation engines accelerated selling pressure.
✅ Billions were erased within hours.
📈 At a Glance
_________________
TOTAL LIQUIDATIONS
$2.058 BILLION
LONGS ███████████████████ 93%
SHORTS ██ 7%
TRADERS LIQUIDATED
= 329,339
LARGEST LOSS
= $16.17M ETHUSDT
#cryptosellofftriggersmultiplewhaleliquidations #liquidation #BitcoinActiveSupplyInProfitDropsBelow45%
Trade Now 👇
{future}(BTCUSDT)
{future}(ETHUSDT)
{future}(SOLUSDT)
📰 CRYPTO CARNAGE
$2.06 BILLION LIQUIDATED IN 24 HOURS
329,339 Traders Wiped Out as Bullish Bets Collapse
📉 Market Crash Snapshot
The crypto derivatives market witnessed a massive liquidation event as over $2.058 Billion in leveraged positions were wiped out within 24 hours.
⚠️ 329,339 traders were liquidated globally, making it one of the largest leverage flushes in recent months.
📊 Liquidation Breakdown
💥 Total Liquidations: $2.058B
🔴 Long Positions: $1.922B (93%)
🟢 Short Positions: $142M (7%)
The numbers reveal an overwhelmingly one-sided event, with bullish traders absorbing nearly all losses as markets moved sharply lower.
🐋 Biggest Casualty
Largest Single Liquidation
ETHUSDT Position: $16.17 Million
A whale-sized account saw a massive ETHUSDT position forcefully closed, highlighting how even large traders can be caught in extreme market volatility.
⚡ What This Means
✅ Excessive leverage built up across the market.
✅ A rapid price decline triggered forced liquidations.
✅ Liquidation engines accelerated selling pressure.
✅ Billions were erased within hours.
📈 At a Glance
_________________
TOTAL LIQUIDATIONS
$2.058 BILLION
LONGS ███████████████████ 93%
SHORTS ██ 7%
TRADERS LIQUIDATED
= 329,339
LARGEST LOSS
= $16.17M ETHUSDT
#cryptosellofftriggersmultiplewhaleliquidations #liquidation #BitcoinActiveSupplyInProfitDropsBelow45%
Trade Now 👇
$2.06 BILLION LIQUIDATED IN 24 HOURS
329,339 Traders Wiped Out as Bullish Bets Collapse
📉 Market Crash Snapshot
The crypto derivatives market witnessed a massive liquidation event as over $2.058 Billion in leveraged positions were wiped out within 24 hours.
⚠️ 329,339 traders were liquidated globally, making it one of the largest leverage flushes in recent months.
📊 Liquidation Breakdown
💥 Total Liquidations: $2.058B
🔴 Long Positions: $1.922B (93%)
🟢 Short Positions: $142M (7%)
The numbers reveal an overwhelmingly one-sided event, with bullish traders absorbing nearly all losses as markets moved sharply lower.
🐋 Biggest Casualty
Largest Single Liquidation
ETHUSDT Position: $16.17 Million
A whale-sized account saw a massive ETHUSDT position forcefully closed, highlighting how even large traders can be caught in extreme market volatility.
⚡ What This Means
✅ Excessive leverage built up across the market.
✅ A rapid price decline triggered forced liquidations.
✅ Liquidation engines accelerated selling pressure.
✅ Billions were erased within hours.
📈 At a Glance
_________________
TOTAL LIQUIDATIONS
$2.058 BILLION
LONGS ███████████████████ 93%
SHORTS ██ 7%
TRADERS LIQUIDATED
= 329,339
LARGEST LOSS
= $16.17M ETHUSDT
#cryptosellofftriggersmultiplewhaleliquidations #liquidation #BitcoinActiveSupplyInProfitDropsBelow45%
Trade Now 👇
thesolidoke:
93% longs is the number that matters here. I tested buying right after flushes like this: my flush bot buys an altcoin when price drops more than 5% in 24h and open interest drops more than 8%, then sells 24h later. the 2021-26 backtest said +1.15% per trade. live, 20 trades: +0.11 USDT total. the bounce after a cascade looks clear on a chart and is much thinner with real fills and fees. anyone here tracking how fast liquidations shrink back to normal after a 2B day?
2
1
2.6k
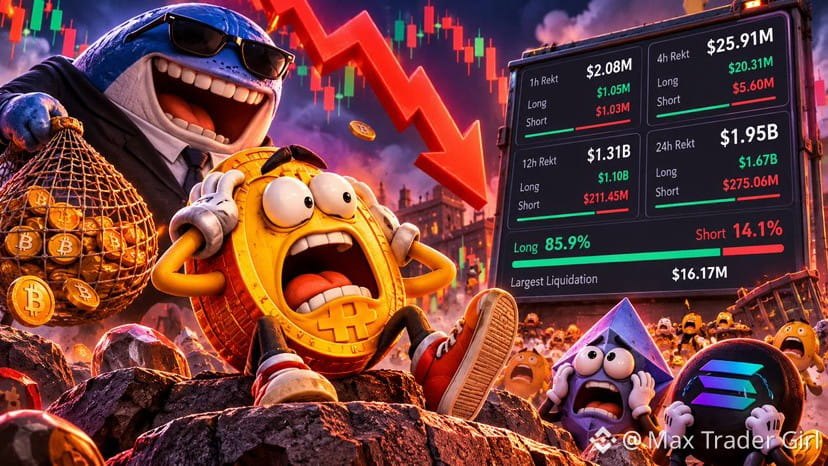
HOW MUCH LOWER CAN $BTC GO?
#Bitcoin’s latest drop has triggered another massive liquidation wave. Nearly $1.95 billion in positions were wiped out over the past 24 hours, and $1.67 billion of that came from LONG positions.
Around 310,000 traders got liquidated. The largest single liquidation was worth $16.17 million on Binance’s ETH pair. #cryptosellofftriggersmultiplewhaleliquidations
At this point, I’m more interested in where this selling pressure finally runs out than how far BTC has already fallen. Once excessive leverage gets flushed out, the market could start looking very different.
But have we actually found a bottom, or is there another painful move ahead?
What do you think?
HOW MUCH LOWER CAN $BTC GO?
#Bitcoin’s latest drop has triggered another massive liquidation wave. Nearly $1.95 billion in positions were wiped out over the past 24 hours, and $1.67 billion of that came from LONG positions.
Around 310,000 traders got liquidated. The largest single liquidation was worth $16.17 million on Binance’s ETH pair. #cryptosellofftriggersmultiplewhaleliquidations
At this point, I’m more interested in where this selling pressure finally runs out than how far BTC has already fallen. Once excessive leverage gets flushed out, the market could start looking very different.
But have we actually found a bottom, or is there another painful move ahead?
What do you think?
#Bitcoin’s latest drop has triggered another massive liquidation wave. Nearly $1.95 billion in positions were wiped out over the past 24 hours, and $1.67 billion of that came from LONG positions.
Around 310,000 traders got liquidated. The largest single liquidation was worth $16.17 million on Binance’s ETH pair. #cryptosellofftriggersmultiplewhaleliquidations
At this point, I’m more interested in where this selling pressure finally runs out than how far BTC has already fallen. Once excessive leverage gets flushed out, the market could start looking very different.
But have we actually found a bottom, or is there another painful move ahead?
What do you think?
1.7k
·
--
🚨 CRYPTO BLOODBATH — WHALES ARE GETTING LIQUIDATED! 🐋📉
The latest crypto sell-off is wiping out leveraged positions, and even large traders aren't escaping the pain.
As forced liquidations accelerate, selling pressure could push $BTC and major altcoins into another volatile session.
But here's the twist: massive liquidations can also flush out excessive leverage and create opportunities for a sharp relief bounce.
ARE WHALES CAPITULATING — OR IS THIS THE RESET BEFORE THE NEXT RALLY? 👀
$BTC $ETH $SOL
#cryptosellofftriggersmultiplewhaleliquidations #USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months #WillFOMCMinutesReinforceRateHikeExpectations? #BitcoinActiveSupplyInProfitDropsBelow45% #TONStrategyReports$23.97MQ3NetLoss
🚨 CRYPTO BLOODBATH — WHALES ARE GETTING LIQUIDATED! 🐋📉
The latest crypto sell-off is wiping out leveraged positions, and even large traders aren't escaping the pain.
As forced liquidations accelerate, selling pressure could push $BTC and major altcoins into another volatile session.
But here's the twist: massive liquidations can also flush out excessive leverage and create opportunities for a sharp relief bounce.
ARE WHALES CAPITULATING — OR IS THIS THE RESET BEFORE THE NEXT RALLY? 👀
$BTC $ETH $SOL
#cryptosellofftriggersmultiplewhaleliquidations #USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months #WillFOMCMinutesReinforceRateHikeExpectations? #BitcoinActiveSupplyInProfitDropsBelow45% #TONStrategyReports$23.97MQ3NetLoss
The latest crypto sell-off is wiping out leveraged positions, and even large traders aren't escaping the pain.
As forced liquidations accelerate, selling pressure could push $BTC and major altcoins into another volatile session.
But here's the twist: massive liquidations can also flush out excessive leverage and create opportunities for a sharp relief bounce.
ARE WHALES CAPITULATING — OR IS THIS THE RESET BEFORE THE NEXT RALLY? 👀
$BTC $ETH $SOL
#cryptosellofftriggersmultiplewhaleliquidations #USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months #WillFOMCMinutesReinforceRateHikeExpectations? #BitcoinActiveSupplyInProfitDropsBelow45% #TONStrategyReports$23.97MQ3NetLoss
1
2k
·
--
🚨 CRYPTO MARKET BLOODBATH: WHALES ARE GETTING WIPED OUT!
The latest crypto selloff is triggering massive liquidations, and even large traders are struggling to survive the market pressure.
On November 14, tracked whale positions worth approximately $188 million were liquidated across 89 of 95 monitored markets that declined.
🔥 Key developments:
• 96% of tracked whale liquidation exposure came from LONG positions.
• Bitcoin led the damage, with one whale losing $13.1 million on a liquidated BTC long.
• BTC and ETH faced significant leveraged selling pressure.
• Total crypto liquidations reached approximately $1.45 billion on November 14, according to another liquidation tracker.
Why this matters: When leveraged whales are forced out, cascading liquidations can accelerate volatility and push prices lower.
But extreme liquidation events can also flush excessive leverage from the market and create conditions for a recovery.
Are we witnessing a major market shakeout, or is another wave of liquidations coming?
#cryptosellofftriggersmultiplewhaleliquidations $BTC $XRP $BNB
{spot}(BNBUSDT)
{spot}(XRPUSDT)
{spot}(BTCUSDT)
🚨 CRYPTO MARKET BLOODBATH: WHALES ARE GETTING WIPED OUT!
The latest crypto selloff is triggering massive liquidations, and even large traders are struggling to survive the market pressure.
On November 14, tracked whale positions worth approximately $188 million were liquidated across 89 of 95 monitored markets that declined.
🔥 Key developments:
• 96% of tracked whale liquidation exposure came from LONG positions.
• Bitcoin led the damage, with one whale losing $13.1 million on a liquidated BTC long.
• BTC and ETH faced significant leveraged selling pressure.
• Total crypto liquidations reached approximately $1.45 billion on November 14, according to another liquidation tracker.
Why this matters: When leveraged whales are forced out, cascading liquidations can accelerate volatility and push prices lower.
But extreme liquidation events can also flush excessive leverage from the market and create conditions for a recovery.
Are we witnessing a major market shakeout, or is another wave of liquidations coming?
#cryptosellofftriggersmultiplewhaleliquidations $BTC $XRP $BNB
The latest crypto selloff is triggering massive liquidations, and even large traders are struggling to survive the market pressure.
On November 14, tracked whale positions worth approximately $188 million were liquidated across 89 of 95 monitored markets that declined.
🔥 Key developments:
• 96% of tracked whale liquidation exposure came from LONG positions.
• Bitcoin led the damage, with one whale losing $13.1 million on a liquidated BTC long.
• BTC and ETH faced significant leveraged selling pressure.
• Total crypto liquidations reached approximately $1.45 billion on November 14, according to another liquidation tracker.
Why this matters: When leveraged whales are forced out, cascading liquidations can accelerate volatility and push prices lower.
But extreme liquidation events can also flush excessive leverage from the market and create conditions for a recovery.
Are we witnessing a major market shakeout, or is another wave of liquidations coming?
#cryptosellofftriggersmultiplewhaleliquidations $BTC $XRP $BNB
Crypto Scientist Expert44:
i followed you sweet brother please follows me back
1
1
15
20.2k
·
--
#cryptosellofftriggersmultiplewhaleliquidations
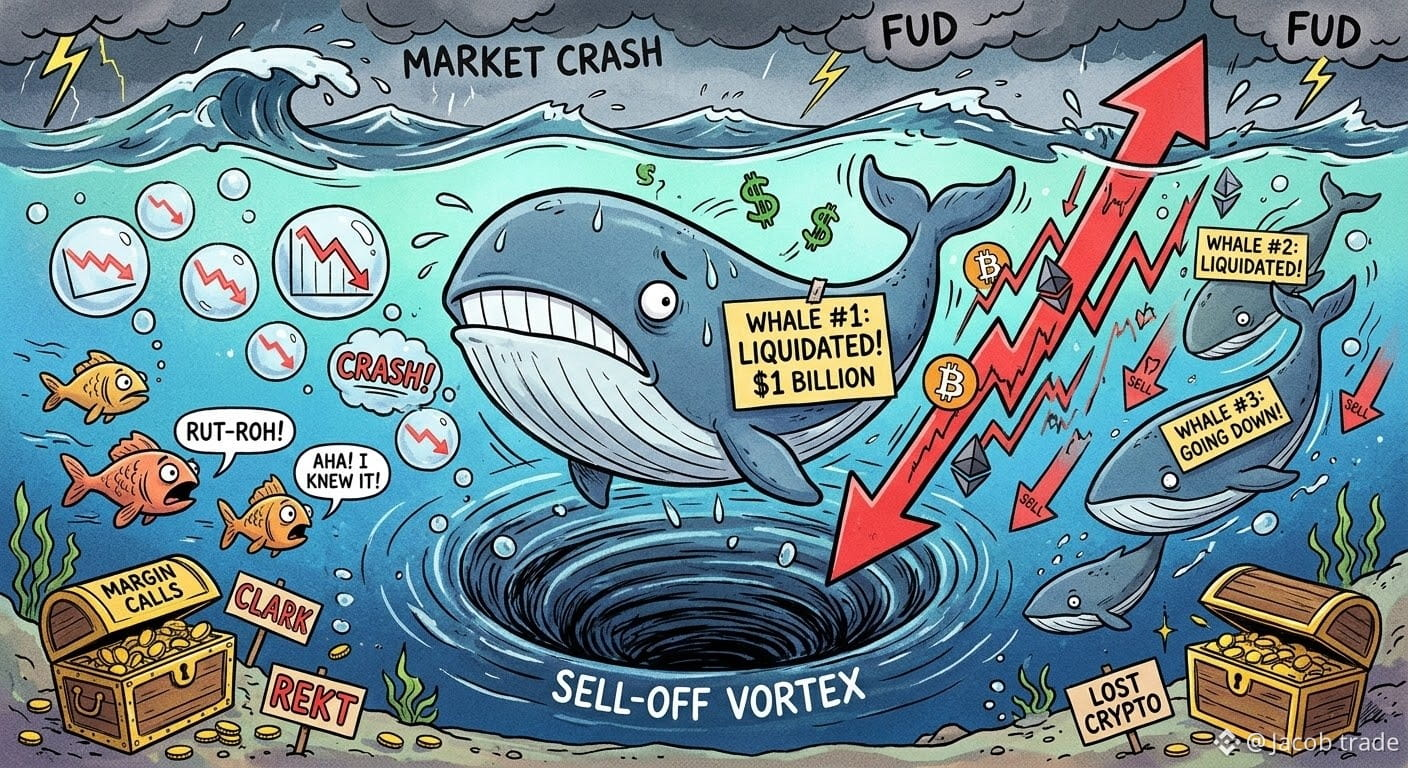
🚨 Mer déchaînée : même les « baleines » échouent ! Plus de 2 milliards de dollars évaporés en 24 h, 329 000 comptes liquidés (93 % étaient en position longue). Une baleine a été liquidée 7 fois en 10 h et a perdu la somme colossale de 16,45 millions de dollars !
🔍 Analyse rapide :
Les ETF ont enregistré des sorties nettes de plus d’un milliard de dollars la semaine dernière. Ajoutez à cela la crainte d’une hausse des taux de la Fed en décembre, et le marché plonge dans le rouge. Le BTC s’approche de la zone de liquidation située entre 59 500 $ et 62 600 $, où les positions à fort effet de levier risquent d’être balayées.
💡 Que devraient faire les traders ?
• Réduisez l’effet de levier, placez des stop-loss serrés et évitez absolument de conserver des positions perdantes ou de tenter d’attraper un couteau qui tombe.
• Patientez jusqu’à ce que le BTC ait réagi dans la zone de support inférieure avant de décider de la suite.
⚠️ Ceci ne constitue pas un conseil financier.
👇 Cliquez sur les liens de trading ci-dessous pour me soutenir :
$EVAA
{future}(EVAAUSDT)
$INIT
{future}(INITUSDT)
$BLESS
{future}(BLESSUSDT)
#cryptosellofftriggersmultiplewhaleliquidations
🚨 Mer déchaînée : même les « baleines » échouent ! Plus de 2 milliards de dollars évaporés en 24 h, 329 000 comptes liquidés (93 % étaient en position longue). Une baleine a été liquidée 7 fois en 10 h et a perdu la somme colossale de 16,45 millions de dollars !
🔍 Analyse rapide :
Les ETF ont enregistré des sorties nettes de plus d’un milliard de dollars la semaine dernière. Ajoutez à cela la crainte d’une hausse des taux de la Fed en décembre, et le marché plonge dans le rouge. Le BTC s’approche de la zone de liquidation située entre 59 500 $ et 62 600 $, où les positions à fort effet de levier risquent d’être balayées.
💡 Que devraient faire les traders ?
• Réduisez l’effet de levier, placez des stop-loss serrés et évitez absolument de conserver des positions perdantes ou de tenter d’attraper un couteau qui tombe.
• Patientez jusqu’à ce que le BTC ait réagi dans la zone de support inférieure avant de décider de la suite.
⚠️ Ceci ne constitue pas un conseil financier.
👇 Cliquez sur les liens de trading ci-dessous pour me soutenir :
$EVAA
$INIT
$BLESS
🚨 Mer déchaînée : même les « baleines » échouent ! Plus de 2 milliards de dollars évaporés en 24 h, 329 000 comptes liquidés (93 % étaient en position longue). Une baleine a été liquidée 7 fois en 10 h et a perdu la somme colossale de 16,45 millions de dollars !
🔍 Analyse rapide :
Les ETF ont enregistré des sorties nettes de plus d’un milliard de dollars la semaine dernière. Ajoutez à cela la crainte d’une hausse des taux de la Fed en décembre, et le marché plonge dans le rouge. Le BTC s’approche de la zone de liquidation située entre 59 500 $ et 62 600 $, où les positions à fort effet de levier risquent d’être balayées.
💡 Que devraient faire les traders ?
• Réduisez l’effet de levier, placez des stop-loss serrés et évitez absolument de conserver des positions perdantes ou de tenter d’attraper un couteau qui tombe.
• Patientez jusqu’à ce que le BTC ait réagi dans la zone de support inférieure avant de décider de la suite.
⚠️ Ceci ne constitue pas un conseil financier.
👇 Cliquez sur les liens de trading ci-dessous pour me soutenir :
$EVAA
$INIT
$BLESS
3
4k
🚨 CARNAGE CRYPTO — LES BALEINES SE FONT LIQUIDER ! 🐋📉
La dernière vague de ventes de cryptomonnaies anéantit les positions à effet de levier, et même les gros investisseurs n’échappent pas à la douleur.
Alors que les liquidations forcées s’accélèrent, la pression vendeuse pourrait entraîner BTC et les principaux altcoins dans une nouvelle séance volatile.
Mais voici le rebondissement : des liquidations massives peuvent aussi éliminer l’effet de levier excessif et créer des occasions de rebond marqué.
LES BALEINES CAPITULENT-ELLES — OU EST-CE LA REMISE À ZÉRO AVANT LA PROCHAINE HAUSSE ? 👀
#CryptoSelloffTriggersMultipleWhaleLiquidations
$INIT
{future}(INITUSDT)
$EVAA
{future}(EVAAUSDT)
$SOPH
{future}(SOPHUSDT)
🚨 CARNAGE CRYPTO — LES BALEINES SE FONT LIQUIDER ! 🐋📉
La dernière vague de ventes de cryptomonnaies anéantit les positions à effet de levier, et même les gros investisseurs n’échappent pas à la douleur.
Alors que les liquidations forcées s’accélèrent, la pression vendeuse pourrait entraîner BTC et les principaux altcoins dans une nouvelle séance volatile.
Mais voici le rebondissement : des liquidations massives peuvent aussi éliminer l’effet de levier excessif et créer des occasions de rebond marqué.
LES BALEINES CAPITULENT-ELLES — OU EST-CE LA REMISE À ZÉRO AVANT LA PROCHAINE HAUSSE ? 👀
#CryptoSelloffTriggersMultipleWhaleLiquidations
$INIT
$EVAA
$SOPH
La dernière vague de ventes de cryptomonnaies anéantit les positions à effet de levier, et même les gros investisseurs n’échappent pas à la douleur.
Alors que les liquidations forcées s’accélèrent, la pression vendeuse pourrait entraîner BTC et les principaux altcoins dans une nouvelle séance volatile.
Mais voici le rebondissement : des liquidations massives peuvent aussi éliminer l’effet de levier excessif et créer des occasions de rebond marqué.
LES BALEINES CAPITULENT-ELLES — OU EST-CE LA REMISE À ZÉRO AVANT LA PROCHAINE HAUSSE ? 👀
#CryptoSelloffTriggersMultipleWhaleLiquidations
$INIT
$EVAA
$SOPH
1.8k
·
--
ສັນຍານໝີ
$2B wiped out in 24 hours. The most dangerous chain in crypto isn't a blockchain. It's a chain reaction.
CoinGlass data, reported by BlockBeats on Nov 15: $2.058B of crypto futures positions were force-closed, hitting 329,339 traders. The biggest single order, a $16.17M ETH long on Binance, was under 1% of the total. By my math, the average position was about $6,250. Not one whale. A crowd.
Many traders use leverage. They borrow to hold a bigger bet than their cash allows, with a small deposit as collateral. When price falls far enough, the deposit is nearly gone and the exchange sells the position automatically. No warning, no vote.
That forced sale is itself a sell order. It pushes price a little lower, which pushes the next trader past their line, which triggers the next forced sale. One domino hits the next. TokenPost reported about $925M of an earlier $1.9B tally landed in just the last four hours: the chain speeding up.
It was one-way, too: $1.922B of the $2.058B (about 93%) were longs, bets on price rising. Shorts, bets on price falling, were only $142M. When a crowd stands on one side, one push clears it together.
What pushed first? Reports point to hotter inflation, rising odds of a Fed rate hike in December (about 88% on CME FedWatch, per CryptoTicker) and seven straight sessions of US spot Bitcoin ETF outflows, about $1.91B (TokenPost). Bitcoin touched about $62,000, its lowest since mid-August. Those are reporters' explanations, not proven causes.
Two things the number hides:
- $2B is the size of the closed positions, not the cash lost. Traders lost the deposit they put up
- A big liquidation number says forced sellers were active. It does not say they are done
2 scenarios I am thinking of:
- If liquidations shrink and price stops falling, forced selling may be running out
- If price keeps sliding and liquidations stay huge, the chain is still running
Be honest, were you one of the 329,339?
Experience, not financial advice. $BTC
{future}(BTCUSDT)
#cryptosellofftriggersmultiplewhaleliquidations
$2B wiped out in 24 hours. The most dangerous chain in crypto isn't a blockchain. It's a chain reaction.
CoinGlass data, reported by BlockBeats on Nov 15: $2.058B of crypto futures positions were force-closed, hitting 329,339 traders. The biggest single order, a $16.17M ETH long on Binance, was under 1% of the total. By my math, the average position was about $6,250. Not one whale. A crowd.
Many traders use leverage. They borrow to hold a bigger bet than their cash allows, with a small deposit as collateral. When price falls far enough, the deposit is nearly gone and the exchange sells the position automatically. No warning, no vote.
That forced sale is itself a sell order. It pushes price a little lower, which pushes the next trader past their line, which triggers the next forced sale. One domino hits the next. TokenPost reported about $925M of an earlier $1.9B tally landed in just the last four hours: the chain speeding up.
It was one-way, too: $1.922B of the $2.058B (about 93%) were longs, bets on price rising. Shorts, bets on price falling, were only $142M. When a crowd stands on one side, one push clears it together.
What pushed first? Reports point to hotter inflation, rising odds of a Fed rate hike in December (about 88% on CME FedWatch, per CryptoTicker) and seven straight sessions of US spot Bitcoin ETF outflows, about $1.91B (TokenPost). Bitcoin touched about $62,000, its lowest since mid-August. Those are reporters' explanations, not proven causes.
Two things the number hides:
- $2B is the size of the closed positions, not the cash lost. Traders lost the deposit they put up
- A big liquidation number says forced sellers were active. It does not say they are done
2 scenarios I am thinking of:
- If liquidations shrink and price stops falling, forced selling may be running out
- If price keeps sliding and liquidations stay huge, the chain is still running
Be honest, were you one of the 329,339?
Experience, not financial advice. $BTC
#cryptosellofftriggersmultiplewhaleliquidations
CoinGlass data, reported by BlockBeats on Nov 15: $2.058B of crypto futures positions were force-closed, hitting 329,339 traders. The biggest single order, a $16.17M ETH long on Binance, was under 1% of the total. By my math, the average position was about $6,250. Not one whale. A crowd.
Many traders use leverage. They borrow to hold a bigger bet than their cash allows, with a small deposit as collateral. When price falls far enough, the deposit is nearly gone and the exchange sells the position automatically. No warning, no vote.
That forced sale is itself a sell order. It pushes price a little lower, which pushes the next trader past their line, which triggers the next forced sale. One domino hits the next. TokenPost reported about $925M of an earlier $1.9B tally landed in just the last four hours: the chain speeding up.
It was one-way, too: $1.922B of the $2.058B (about 93%) were longs, bets on price rising. Shorts, bets on price falling, were only $142M. When a crowd stands on one side, one push clears it together.
What pushed first? Reports point to hotter inflation, rising odds of a Fed rate hike in December (about 88% on CME FedWatch, per CryptoTicker) and seven straight sessions of US spot Bitcoin ETF outflows, about $1.91B (TokenPost). Bitcoin touched about $62,000, its lowest since mid-August. Those are reporters' explanations, not proven causes.
Two things the number hides:
- $2B is the size of the closed positions, not the cash lost. Traders lost the deposit they put up
- A big liquidation number says forced sellers were active. It does not say they are done
2 scenarios I am thinking of:
- If liquidations shrink and price stops falling, forced selling may be running out
- If price keeps sliding and liquidations stay huge, the chain is still running
Be honest, were you one of the 329,339?
Experience, not financial advice. $BTC
#cryptosellofftriggersmultiplewhaleliquidations
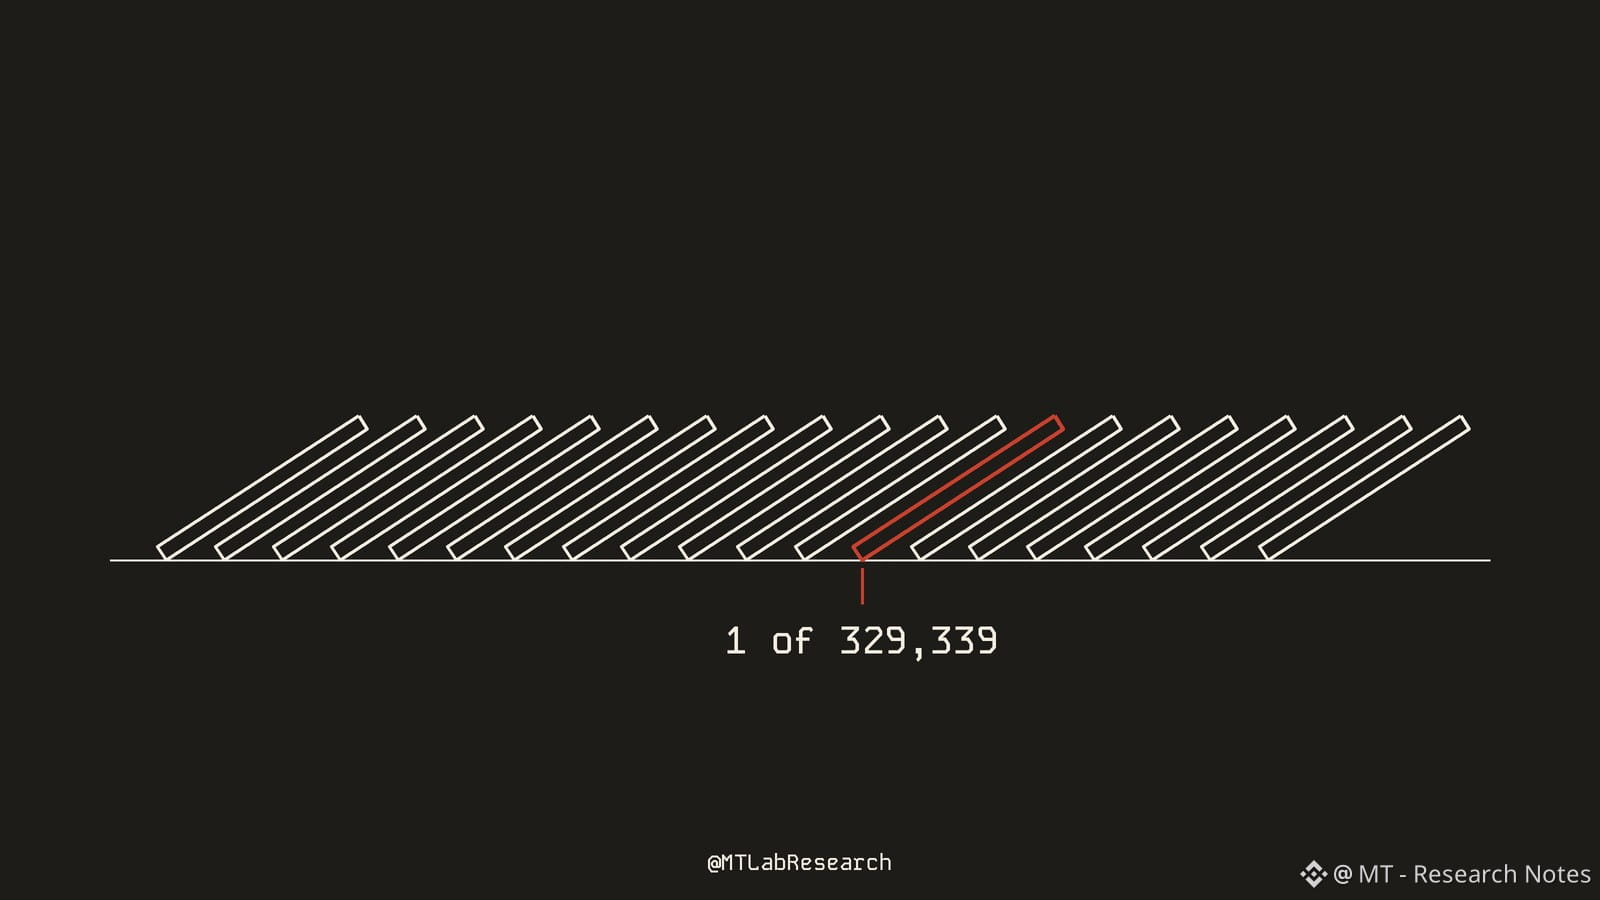
4
3.3k
𝐒𝐓𝐎𝐏..... 𝐒𝐓𝐎𝐏..... 𝐒𝐓𝐎𝐏 🚨
$BTC IS CLOSER TO A MAJOR REVERSAL THAN YOU THINK!
I didn't expect Bitcoin to drop this aggressively.
BTC touched $62K, triggering massive liquidations across the market.
My downside targets were $68K–$70K, but volatility pushed price even lower.
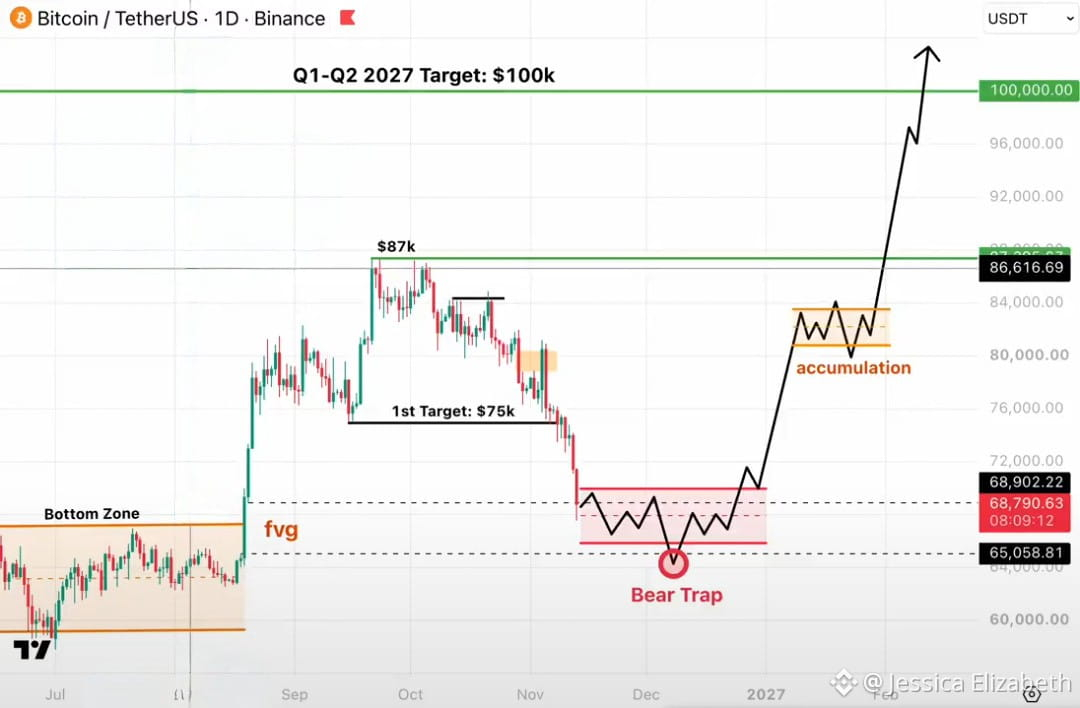
Here's my roadmap:
1. Relief bounce toward $70K–$72K
2. Final liquidity sweep near $63K
3. Bear trap and accumulation phase
4. First recovery rally
5. Breakout above $87K
6. Target: $100K in Q1–Q2 2027
The downside targets are getting tested. Now I'm watching closely for signs of a confirmed reversal.
Stay patient. Watch the levels. Don't FOMO.
Turn on notifications so you don't miss my next BTC update! 🚀
#CryptoSelloffTriggersMultipleWhaleLiquidations
𝐒𝐓𝐎𝐏..... 𝐒𝐓𝐎𝐏..... 𝐒𝐓𝐎𝐏 🚨
$BTC IS CLOSER TO A MAJOR REVERSAL THAN YOU THINK!
I didn't expect Bitcoin to drop this aggressively.
BTC touched $62K, triggering massive liquidations across the market.
My downside targets were $68K–$70K, but volatility pushed price even lower.
Here's my roadmap:
1. Relief bounce toward $70K–$72K
2. Final liquidity sweep near $63K
3. Bear trap and accumulation phase
4. First recovery rally
5. Breakout above $87K
6. Target: $100K in Q1–Q2 2027
The downside targets are getting tested. Now I'm watching closely for signs of a confirmed reversal.
Stay patient. Watch the levels. Don't FOMO.
Turn on notifications so you don't miss my next BTC update! 🚀
#CryptoSelloffTriggersMultipleWhaleLiquidations
$BTC IS CLOSER TO A MAJOR REVERSAL THAN YOU THINK!
I didn't expect Bitcoin to drop this aggressively.
BTC touched $62K, triggering massive liquidations across the market.
My downside targets were $68K–$70K, but volatility pushed price even lower.
Here's my roadmap:
1. Relief bounce toward $70K–$72K
2. Final liquidity sweep near $63K
3. Bear trap and accumulation phase
4. First recovery rally
5. Breakout above $87K
6. Target: $100K in Q1–Q2 2027
The downside targets are getting tested. Now I'm watching closely for signs of a confirmed reversal.
Stay patient. Watch the levels. Don't FOMO.
Turn on notifications so you don't miss my next BTC update! 🚀
#CryptoSelloffTriggersMultipleWhaleLiquidations
771
#cryptosellofftriggersmultiplewhaleliquidations Follow my profile. I write research for ordinary traders.
WAS THIS FALL JUST LIQUIDATIONS, OR AN OPPORTUNITY FOR BIG BUYERS?
Around $2 billion in crypto positions were liquidated in 24 hours. More than 329,000 traders were affected, and 93% were long positions.
Bitcoin touched $62,000 before bouncing nearly 5% towards $65,000.
What happened?
Selling pressure pushed Bitcoin lower. Then leveraged long positions were force-sold, creating a chain reaction:
Price falls → longs are liquidated → more selling → price falls further.
Who benefited?
Leveraged longs suffered the biggest damage.
Short traders could profit.
Liquidity providers earned from trading activity, but volatility also brings risks.
Buyers with cash and no leverage had a chance to buy cheaper.
I have no proof this was deliberately planned against retail traders. We should understand the mechanics before making accusations.
What I am watching:
Support: $61,946, then $60,000.
Resistance: $65,564 and $67,442.
ETF flows and stablecoin supply.
My view: BTC remains bearish. This bounce is not yet proof of a new uptrend.
I don't claim to predict every candle. I want to understand WHY.
To the 90% of retail traders: borrowed money can turn you into fuel for a liquidation chain. Protect your capital. I would rather miss the bottom than be forced out.
Question: Was selling pressure or forced liquidation the bigger reason for this fall?
Experience, not financial advice.
$BTC
{spot}(BTCUSDT)
#Bitcoin #CryptoLiquidations
#cryptosellofftriggersmultiplewhaleliquidations Follow my profile. I write research for ordinary traders.
WAS THIS FALL JUST LIQUIDATIONS, OR AN OPPORTUNITY FOR BIG BUYERS?
Around $2 billion in crypto positions were liquidated in 24 hours. More than 329,000 traders were affected, and 93% were long positions.
Bitcoin touched $62,000 before bouncing nearly 5% towards $65,000.
What happened?
Selling pressure pushed Bitcoin lower. Then leveraged long positions were force-sold, creating a chain reaction:
Price falls → longs are liquidated → more selling → price falls further.
Who benefited?
Leveraged longs suffered the biggest damage.
Short traders could profit.
Liquidity providers earned from trading activity, but volatility also brings risks.
Buyers with cash and no leverage had a chance to buy cheaper.
I have no proof this was deliberately planned against retail traders. We should understand the mechanics before making accusations.
What I am watching:
Support: $61,946, then $60,000.
Resistance: $65,564 and $67,442.
ETF flows and stablecoin supply.
My view: BTC remains bearish. This bounce is not yet proof of a new uptrend.
I don't claim to predict every candle. I want to understand WHY.
To the 90% of retail traders: borrowed money can turn you into fuel for a liquidation chain. Protect your capital. I would rather miss the bottom than be forced out.
Question: Was selling pressure or forced liquidation the bigger reason for this fall?
Experience, not financial advice.
$BTC
#Bitcoin #CryptoLiquidations
WAS THIS FALL JUST LIQUIDATIONS, OR AN OPPORTUNITY FOR BIG BUYERS?
Around $2 billion in crypto positions were liquidated in 24 hours. More than 329,000 traders were affected, and 93% were long positions.
Bitcoin touched $62,000 before bouncing nearly 5% towards $65,000.
What happened?
Selling pressure pushed Bitcoin lower. Then leveraged long positions were force-sold, creating a chain reaction:
Price falls → longs are liquidated → more selling → price falls further.
Who benefited?
Leveraged longs suffered the biggest damage.
Short traders could profit.
Liquidity providers earned from trading activity, but volatility also brings risks.
Buyers with cash and no leverage had a chance to buy cheaper.
I have no proof this was deliberately planned against retail traders. We should understand the mechanics before making accusations.
What I am watching:
Support: $61,946, then $60,000.
Resistance: $65,564 and $67,442.
ETF flows and stablecoin supply.
My view: BTC remains bearish. This bounce is not yet proof of a new uptrend.
I don't claim to predict every candle. I want to understand WHY.
To the 90% of retail traders: borrowed money can turn you into fuel for a liquidation chain. Protect your capital. I would rather miss the bottom than be forced out.
Question: Was selling pressure or forced liquidation the bigger reason for this fall?
Experience, not financial advice.
$BTC
#Bitcoin #CryptoLiquidations
Abu Fahadأ:
💛
2
6
11.3k

·
--
ສັນຍານໝີ
#cryptosellofftriggersmultiplewhaleliquidations
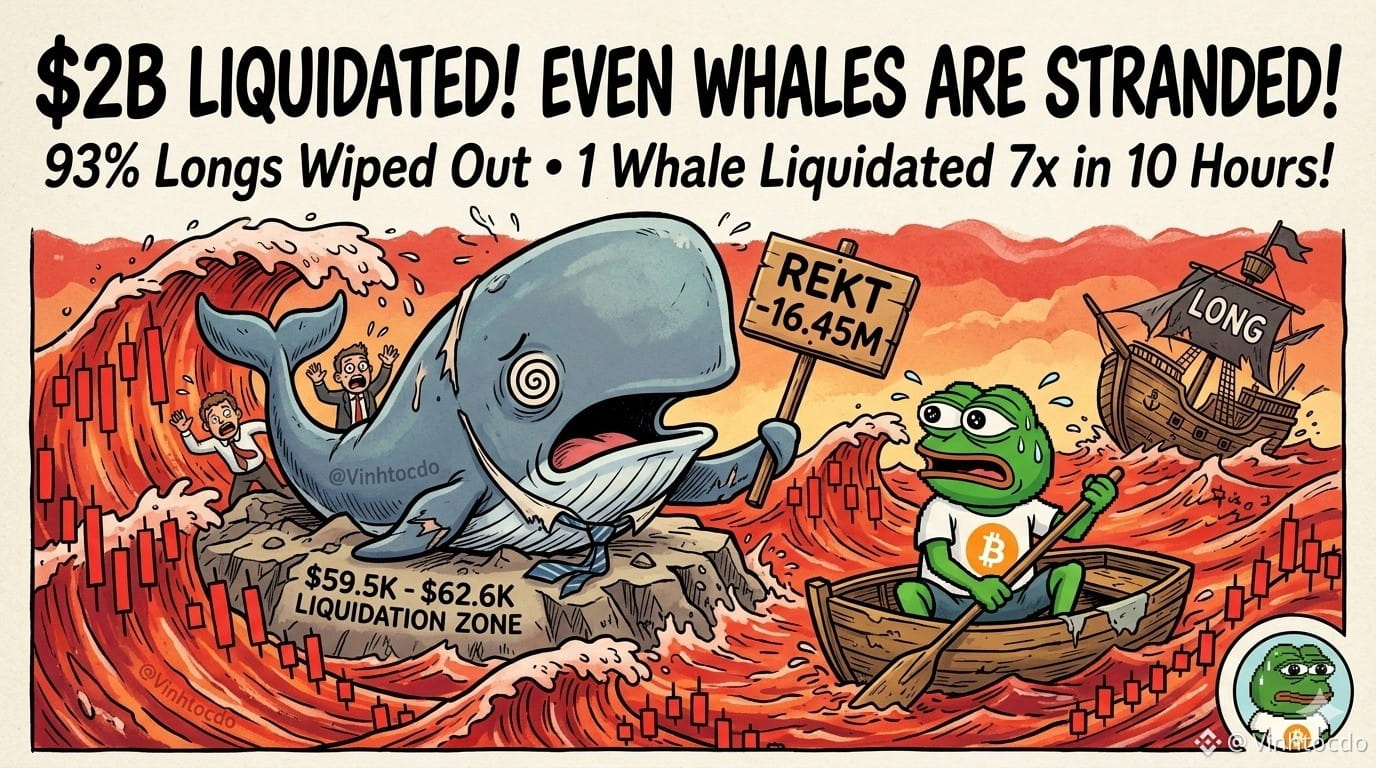
🚨 Biển động dữ dội, đến "cá voi" cũng mắc cạn! Hơn 2 tỷ USD bốc hơi trong 24h, 329.000 tài khoản "bay màu" (93% là phe Long). Có bác cá voi bị thanh lý 7 lần trong 10h, mất đứt 16,45 triệu USD!
🔍 Phân tích nhanh:
Quỹ ETF rút ròng hơn 1 tỷ USD tuần qua cộng thêm nỗi lo Fed tăng lãi suất tháng 12 khiến thị trường đỏ lửa. BTC đang áp sát vùng thanh lý $59.500 - $62.600, quét sạch đòn bẩy cao.
💡 Trader nên làm gì?
• Hạ đòn bẩy, cài Stop-Loss chặt và tuyệt đối không "gồng lỗ" hay bắt dao rơi lúc này.
• Kiên nhẫn đợi BTC phản ứng xong ở vùng hỗ trợ dưới rồi mới tính tiếp.
⚠️ Đây không phải lời khuyên tài chính.
👇 Click giao dịch bên dưới để ủng hộ tôi:
$BTC
{spot}(BTCUSDT)
$ETH
{spot}(ETHUSDT)
$KAVA
{future}(KAVAUSDT)
#CryptoCrash #Liquidation #Bitcoin #TradingTips #WhaleAlert #VINHTOCDO
#cryptosellofftriggersmultiplewhaleliquidations
🚨 Biển động dữ dội, đến "cá voi" cũng mắc cạn! Hơn 2 tỷ USD bốc hơi trong 24h, 329.000 tài khoản "bay màu" (93% là phe Long). Có bác cá voi bị thanh lý 7 lần trong 10h, mất đứt 16,45 triệu USD!
🔍 Phân tích nhanh:
Quỹ ETF rút ròng hơn 1 tỷ USD tuần qua cộng thêm nỗi lo Fed tăng lãi suất tháng 12 khiến thị trường đỏ lửa. BTC đang áp sát vùng thanh lý $59.500 - $62.600, quét sạch đòn bẩy cao.
💡 Trader nên làm gì?
• Hạ đòn bẩy, cài Stop-Loss chặt và tuyệt đối không "gồng lỗ" hay bắt dao rơi lúc này.
• Kiên nhẫn đợi BTC phản ứng xong ở vùng hỗ trợ dưới rồi mới tính tiếp.
⚠️ Đây không phải lời khuyên tài chính.
👇 Click giao dịch bên dưới để ủng hộ tôi:
$BTC
$ETH
$KAVA
#CryptoCrash #Liquidation #Bitcoin #TradingTips #WhaleAlert #VINHTOCDO
🚨 Biển động dữ dội, đến "cá voi" cũng mắc cạn! Hơn 2 tỷ USD bốc hơi trong 24h, 329.000 tài khoản "bay màu" (93% là phe Long). Có bác cá voi bị thanh lý 7 lần trong 10h, mất đứt 16,45 triệu USD!
🔍 Phân tích nhanh:
Quỹ ETF rút ròng hơn 1 tỷ USD tuần qua cộng thêm nỗi lo Fed tăng lãi suất tháng 12 khiến thị trường đỏ lửa. BTC đang áp sát vùng thanh lý $59.500 - $62.600, quét sạch đòn bẩy cao.
💡 Trader nên làm gì?
• Hạ đòn bẩy, cài Stop-Loss chặt và tuyệt đối không "gồng lỗ" hay bắt dao rơi lúc này.
• Kiên nhẫn đợi BTC phản ứng xong ở vùng hỗ trợ dưới rồi mới tính tiếp.
⚠️ Đây không phải lời khuyên tài chính.
👇 Click giao dịch bên dưới để ủng hộ tôi:
$BTC
$ETH
$KAVA
#CryptoCrash #Liquidation #Bitcoin #TradingTips #WhaleAlert #VINHTOCDO
8
2.4k

·
--
ສັນຍານໝີ
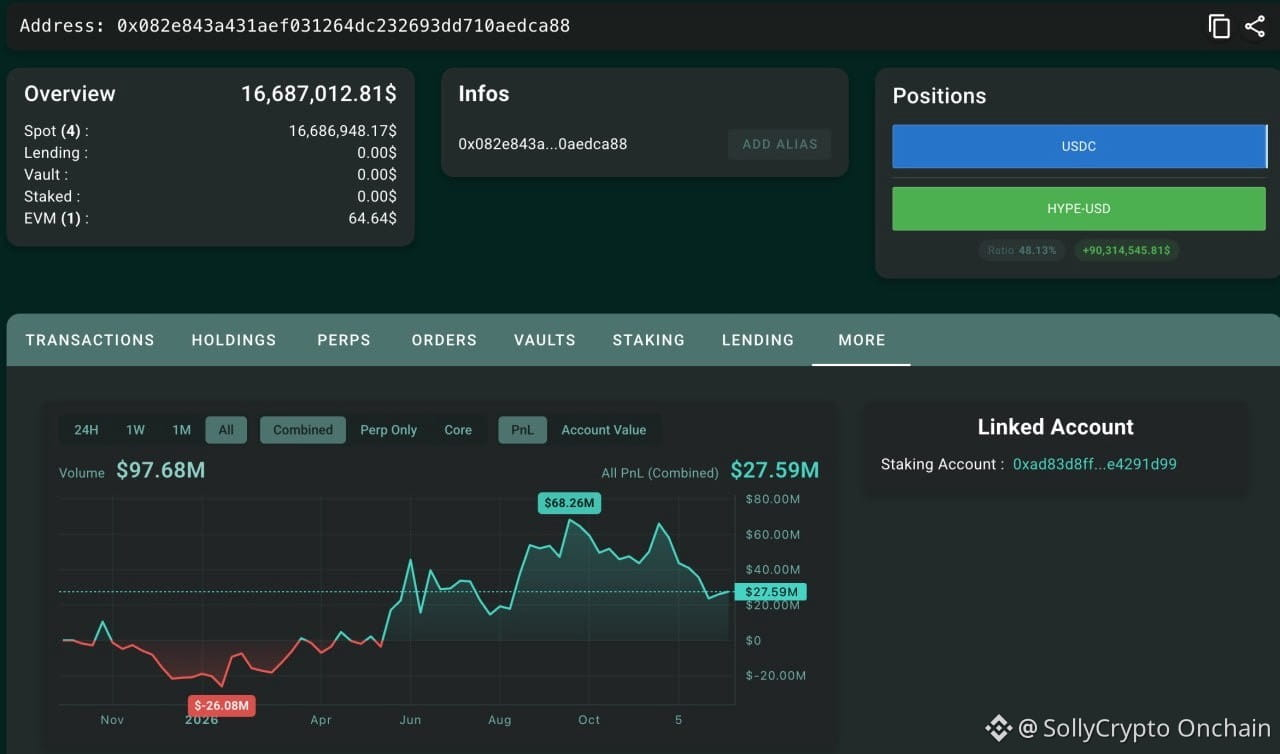
GREEDY WHALE WATCHED $68.26M IN PROFIT SHRINK TO $27.59M AND JUST ADDED $8.3M TO DODGE WIPEOUT AT $58.47! — EPIC COMEBACK OR LIQUIDATION HUNT?
The biggest $HYPE bull on Hyperliquid refused to take profits at the top—and now he is throwing millions of emergency cash into the fire just to stay alive!
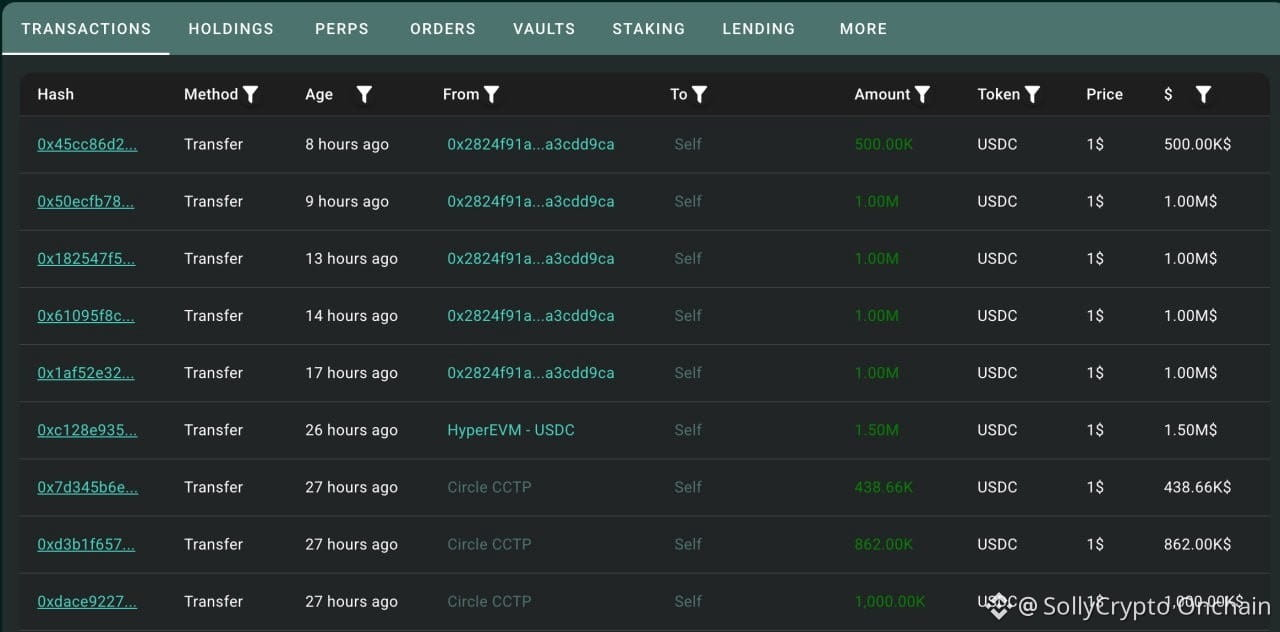
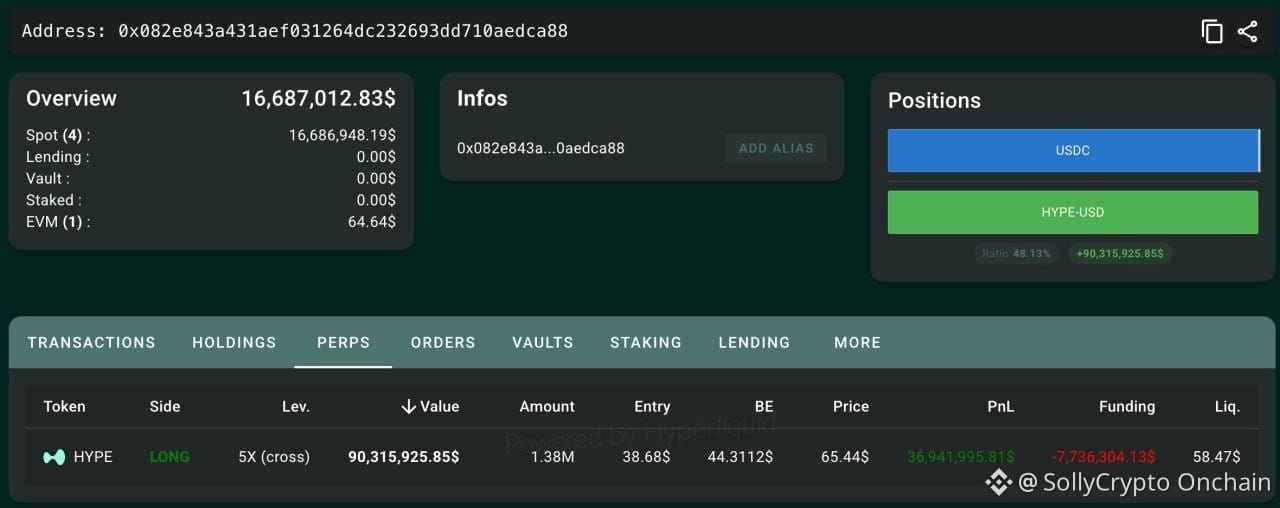
On-chain tracking confirms that whale wallet 0x082e held onto a massive $HYPE long position even when unrealized profits reached a jaw-dropping $68.26 million. As $HYPE tumbled into the low-$60s, those paper gains shrank all the way down to $27.59 million, pushing the giant position dangerously close to forced closure. Over the past two days, the whale rushed to deposit $8.3 million in $USDC onto Hyperliquid to add margin, lowering his new liquidation price to $58.47.
This should lean as a bearish short-term warning for $HYPE because a visible, ultra-large whale liquidation wall sitting right at $58.47 acts like a giant magnet for market makers during volatile sell-offs.
Here is the secret most everyday traders miss: when a whale refuses to lock in $68 million in profit and has to keep injecting fresh cash (8.3MUSDC) to defend a position, the entire market can see his exact breaking point on-chain. Big players know that if $HYPE dips just a few dollars lower to touch $58.47, forced liquidation orders will flood the market and trigger a rapid cascade—meaning sellers often target that exact price zone before letting the token recover.
The real trap for everyday traders is copying a stubborn whale's leveraged long just because he hasn't been wiped out yet. A whale with millions of extra $USDC in reserve can keep topping up margin to survive dips, while everyday traders using high leverage get liquidated instantly on the way down toward $58.47.
Do you think this giant $HYPE bull survives the storm and bounces back, or will the market hunt his $58.47 liquidation price first?
#CryptoSelloffTriggersMultipleWhaleLiquidations
GREEDY WHALE WATCHED $68.26M IN PROFIT SHRINK TO $27.59M AND JUST ADDED $8.3M TO DODGE WIPEOUT AT $58.47! — EPIC COMEBACK OR LIQUIDATION HUNT?
The biggest $HYPE bull on Hyperliquid refused to take profits at the top—and now he is throwing millions of emergency cash into the fire just to stay alive!
On-chain tracking confirms that whale wallet 0x082e held onto a massive $HYPE long position even when unrealized profits reached a jaw-dropping $68.26 million. As $HYPE tumbled into the low-$60s, those paper gains shrank all the way down to $27.59 million, pushing the giant position dangerously close to forced closure. Over the past two days, the whale rushed to deposit $8.3 million in $USDC onto Hyperliquid to add margin, lowering his new liquidation price to $58.47.
This should lean as a bearish short-term warning for $HYPE because a visible, ultra-large whale liquidation wall sitting right at $58.47 acts like a giant magnet for market makers during volatile sell-offs.
Here is the secret most everyday traders miss: when a whale refuses to lock in $68 million in profit and has to keep injecting fresh cash (8.3MUSDC) to defend a position, the entire market can see his exact breaking point on-chain. Big players know that if $HYPE dips just a few dollars lower to touch $58.47, forced liquidation orders will flood the market and trigger a rapid cascade—meaning sellers often target that exact price zone before letting the token recover.
The real trap for everyday traders is copying a stubborn whale's leveraged long just because he hasn't been wiped out yet. A whale with millions of extra $USDC in reserve can keep topping up margin to survive dips, while everyday traders using high leverage get liquidated instantly on the way down toward $58.47.
Do you think this giant $HYPE bull survives the storm and bounces back, or will the market hunt his $58.47 liquidation price first?
#CryptoSelloffTriggersMultipleWhaleLiquidations
The biggest $HYPE bull on Hyperliquid refused to take profits at the top—and now he is throwing millions of emergency cash into the fire just to stay alive!
On-chain tracking confirms that whale wallet 0x082e held onto a massive $HYPE long position even when unrealized profits reached a jaw-dropping $68.26 million. As $HYPE tumbled into the low-$60s, those paper gains shrank all the way down to $27.59 million, pushing the giant position dangerously close to forced closure. Over the past two days, the whale rushed to deposit $8.3 million in $USDC onto Hyperliquid to add margin, lowering his new liquidation price to $58.47.
This should lean as a bearish short-term warning for $HYPE because a visible, ultra-large whale liquidation wall sitting right at $58.47 acts like a giant magnet for market makers during volatile sell-offs.
Here is the secret most everyday traders miss: when a whale refuses to lock in $68 million in profit and has to keep injecting fresh cash (8.3MUSDC) to defend a position, the entire market can see his exact breaking point on-chain. Big players know that if $HYPE dips just a few dollars lower to touch $58.47, forced liquidation orders will flood the market and trigger a rapid cascade—meaning sellers often target that exact price zone before letting the token recover.
The real trap for everyday traders is copying a stubborn whale's leveraged long just because he hasn't been wiped out yet. A whale with millions of extra $USDC in reserve can keep topping up margin to survive dips, while everyday traders using high leverage get liquidated instantly on the way down toward $58.47.
Do you think this giant $HYPE bull survives the storm and bounces back, or will the market hunt his $58.47 liquidation price first?
#CryptoSelloffTriggersMultipleWhaleLiquidations
2
241

·
--
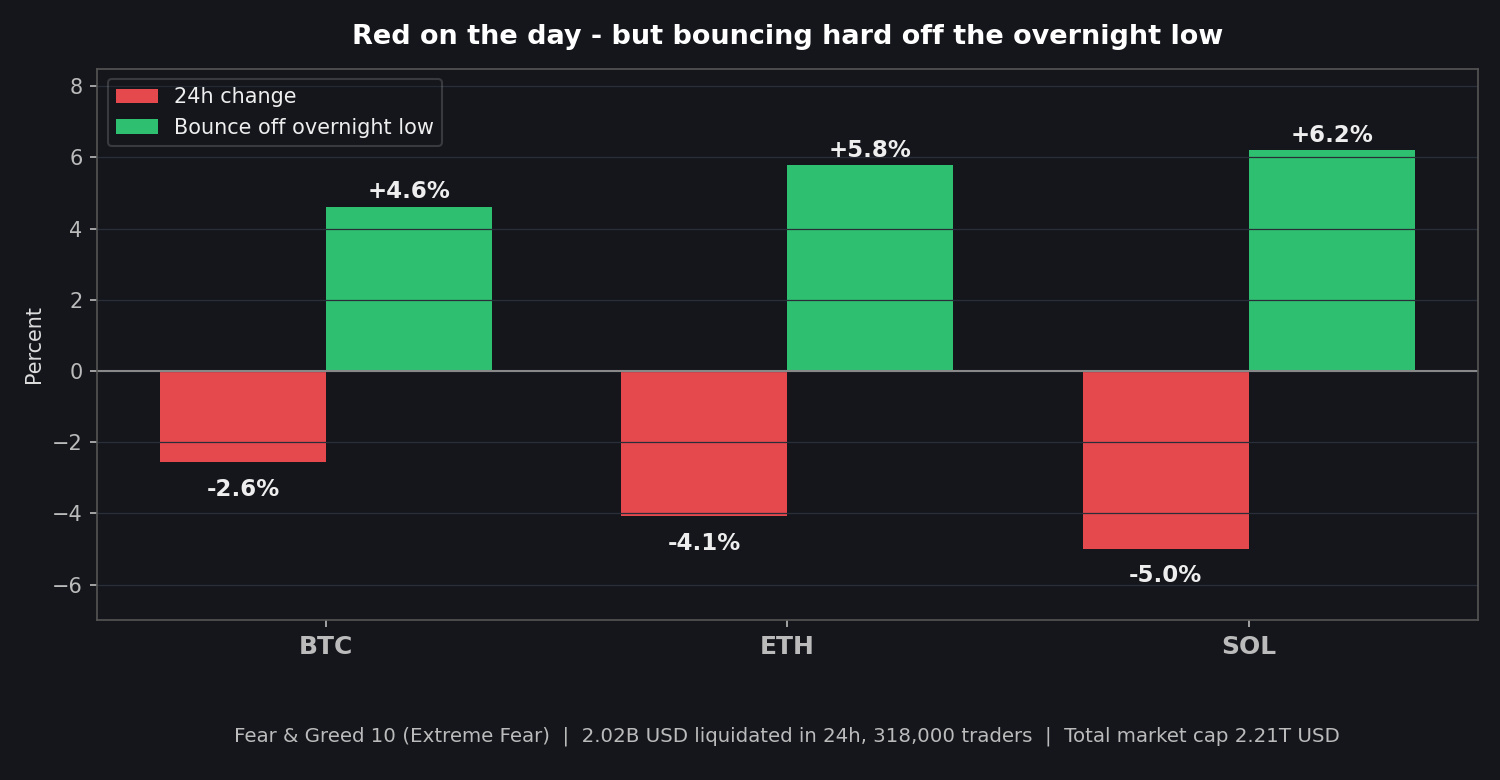
🚨 $BTC JUST CRASHED TO 62,000 USD — THEN BOUNCED 4.6% IN HOURS. WHAT STOPPED THE FALL? 👀
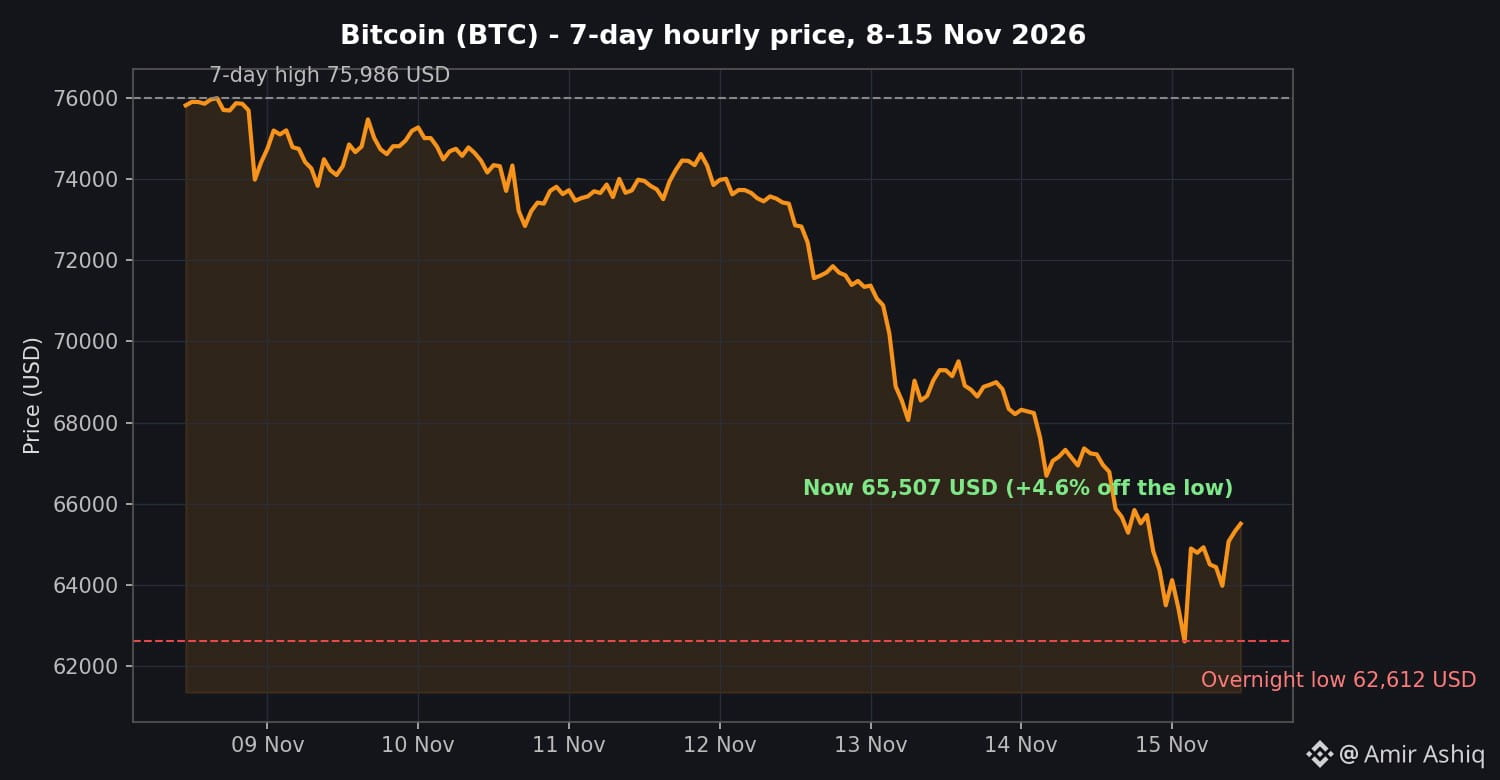
Bitcoin fell to 62,612 USD overnight — its lowest since early July and now about 48% below its 126,080 USD record high.
Then buyers stepped in. $BTC reclaimed 65,507 USD within hours, and $ETH and $SOL bounced even harder off their lows.
Here's what the data shows:
📉 2.02B USD liquidated in 24 hours — over 318,000 traders wiped out, 86.7% of them longs.
📊 Fear & Greed is at 10 — Extreme Fear, the lowest reading of the week.
💧 $ETH bounced 5.8% off its 1,729 USD low and $SOL 6.2% off 67.86 USD — the coins that fell hardest bounced hardest.
A liquidation cascade feeds on itself: forced selling pushes prices down, which triggers more liquidations — until the forced sellers are gone and even small buying lifts prices fast.
Volatility usually stays elevated after a flush like this, and Tuesday brings retail sales plus Nvidia earnings — the next big tests for the market.
Did the 62,000 USD level just become the line everyone watches? 👇
Not financial advice — educational purposes only.
#CryptoSelloffTriggersMultipleWhaleLiquidations #Bitcoin #crypto #Ethereum
🚨 $BTC JUST CRASHED TO 62,000 USD — THEN BOUNCED 4.6% IN HOURS. WHAT STOPPED THE FALL? 👀
Bitcoin fell to 62,612 USD overnight — its lowest since early July and now about 48% below its 126,080 USD record high.
Then buyers stepped in. $BTC reclaimed 65,507 USD within hours, and $ETH and $SOL bounced even harder off their lows.
Here's what the data shows:
📉 2.02B USD liquidated in 24 hours — over 318,000 traders wiped out, 86.7% of them longs.
📊 Fear & Greed is at 10 — Extreme Fear, the lowest reading of the week.
💧 $ETH bounced 5.8% off its 1,729 USD low and $SOL 6.2% off 67.86 USD — the coins that fell hardest bounced hardest.
A liquidation cascade feeds on itself: forced selling pushes prices down, which triggers more liquidations — until the forced sellers are gone and even small buying lifts prices fast.
Volatility usually stays elevated after a flush like this, and Tuesday brings retail sales plus Nvidia earnings — the next big tests for the market.
Did the 62,000 USD level just become the line everyone watches? 👇
Not financial advice — educational purposes only.
#CryptoSelloffTriggersMultipleWhaleLiquidations #Bitcoin #crypto #Ethereum
Bitcoin fell to 62,612 USD overnight — its lowest since early July and now about 48% below its 126,080 USD record high.
Then buyers stepped in. $BTC reclaimed 65,507 USD within hours, and $ETH and $SOL bounced even harder off their lows.
Here's what the data shows:
📉 2.02B USD liquidated in 24 hours — over 318,000 traders wiped out, 86.7% of them longs.
📊 Fear & Greed is at 10 — Extreme Fear, the lowest reading of the week.
💧 $ETH bounced 5.8% off its 1,729 USD low and $SOL 6.2% off 67.86 USD — the coins that fell hardest bounced hardest.
A liquidation cascade feeds on itself: forced selling pushes prices down, which triggers more liquidations — until the forced sellers are gone and even small buying lifts prices fast.
Volatility usually stays elevated after a flush like this, and Tuesday brings retail sales plus Nvidia earnings — the next big tests for the market.
Did the 62,000 USD level just become the line everyone watches? 👇
Not financial advice — educational purposes only.
#CryptoSelloffTriggersMultipleWhaleLiquidations #Bitcoin #crypto #Ethereum
Phoenix Crypto:
That liquidation flush explains the sharp rebound, but the real test is whether BTC can hold above $65K. The next few sessions should reveal a lot! 👀
1
1
484
·
--
#CryptoSelloffTriggersMultipleWhaleLiquidations
🩸 THIS IS ABSOLUTELY INSANE...
OVER $350 BILLION WIPED OUT FROM THE CRYPTO MARKET IN JUST ONE WEEK! 💀
Bitcoin has crashed toward $62,000, triggering a massive wave of panic across the entire market.
🚨 OVER $1.9 BILLION in leveraged positions liquidated in just 24 HOURS!
Bulls are getting completely destroyed.
Altcoins are bleeding.
Investors are running for the exits.
#KavaSaysAbnormalActivityLimitedToKavaLend
But what is driving this nightmare?
#KavaSaysAbnormalActivityLimitedToKavaLend
📉 Massive Bitcoin ETF outflows. 📉 Renewed fears of Federal Reserve rate hikes. 📉 Billions in leveraged long positions getting wiped out. 📉 Weak investor sentiment and declining market liquidity.
This is turning into one brutal week for crypto.
#WillFOMCMinutesReinforceRateHikeExpectations?
ARE WE WITNESSING A MAJOR BUYING OPPORTUNITY OR IS THE WORST YET TO COME? 🐻
$BTC $ETH $SOL
#USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months
#CryptoSelloffTriggersMultipleWhaleLiquidations
🩸 THIS IS ABSOLUTELY INSANE...
OVER $350 BILLION WIPED OUT FROM THE CRYPTO MARKET IN JUST ONE WEEK! 💀
Bitcoin has crashed toward $62,000, triggering a massive wave of panic across the entire market.
🚨 OVER $1.9 BILLION in leveraged positions liquidated in just 24 HOURS!
Bulls are getting completely destroyed.
Altcoins are bleeding.
Investors are running for the exits.
#KavaSaysAbnormalActivityLimitedToKavaLend
But what is driving this nightmare?
#KavaSaysAbnormalActivityLimitedToKavaLend
📉 Massive Bitcoin ETF outflows. 📉 Renewed fears of Federal Reserve rate hikes. 📉 Billions in leveraged long positions getting wiped out. 📉 Weak investor sentiment and declining market liquidity.
This is turning into one brutal week for crypto.
#WillFOMCMinutesReinforceRateHikeExpectations?
ARE WE WITNESSING A MAJOR BUYING OPPORTUNITY OR IS THE WORST YET TO COME? 🐻
$BTC $ETH $SOL
#USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months
🩸 THIS IS ABSOLUTELY INSANE...
OVER $350 BILLION WIPED OUT FROM THE CRYPTO MARKET IN JUST ONE WEEK! 💀
Bitcoin has crashed toward $62,000, triggering a massive wave of panic across the entire market.
🚨 OVER $1.9 BILLION in leveraged positions liquidated in just 24 HOURS!
Bulls are getting completely destroyed.
Altcoins are bleeding.
Investors are running for the exits.
#KavaSaysAbnormalActivityLimitedToKavaLend
But what is driving this nightmare?
#KavaSaysAbnormalActivityLimitedToKavaLend
📉 Massive Bitcoin ETF outflows. 📉 Renewed fears of Federal Reserve rate hikes. 📉 Billions in leveraged long positions getting wiped out. 📉 Weak investor sentiment and declining market liquidity.
This is turning into one brutal week for crypto.
#WillFOMCMinutesReinforceRateHikeExpectations?
ARE WE WITNESSING A MAJOR BUYING OPPORTUNITY OR IS THE WORST YET TO COME? 🐻
$BTC $ETH $SOL
#USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months
1
39
·
--
About $2 billion in crypto bets got liquidated in 24 hours. Most of it was longs.
Bitcoin touched about $62,000 this weekend. It dropped over 8% and Ether lost more than 10% in that window. More than 320,000 traders got liquidated.
The whales got hit too. Four of them were liquidated for more than $10M each when BTC slipped under $69K, about $144M combined. One had BTC and ETH longs worth over $140M. Both got fully liquidated, and the loss was more than $17M.
A few things stacked up. Bitcoin broke below its 200-day average near $73K. Spot BTC ETFs saw outflows seven trading days in a row, about $1.9B total. Rate markets now fully price a Fed hike in December, and October CPI rose 0.4% on the month.
That's the leverage problem. Price drops, longs get forced out, and the forced selling pushes it lower.
No one knows where the bottom is. $60K is the level people are watching next.
Liquidation numbers move fast...
#CryptoSelloffTriggersMultipleWhaleLiquidations
About $2 billion in crypto bets got liquidated in 24 hours. Most of it was longs.
Bitcoin touched about $62,000 this weekend. It dropped over 8% and Ether lost more than 10% in that window. More than 320,000 traders got liquidated.
The whales got hit too. Four of them were liquidated for more than $10M each when BTC slipped under $69K, about $144M combined. One had BTC and ETH longs worth over $140M. Both got fully liquidated, and the loss was more than $17M.
A few things stacked up. Bitcoin broke below its 200-day average near $73K. Spot BTC ETFs saw outflows seven trading days in a row, about $1.9B total. Rate markets now fully price a Fed hike in December, and October CPI rose 0.4% on the month.
That's the leverage problem. Price drops, longs get forced out, and the forced selling pushes it lower.
No one knows where the bottom is. $60K is the level people are watching next.
Liquidation numbers move fast...
#CryptoSelloffTriggersMultipleWhaleLiquidations
Bitcoin touched about $62,000 this weekend. It dropped over 8% and Ether lost more than 10% in that window. More than 320,000 traders got liquidated.
The whales got hit too. Four of them were liquidated for more than $10M each when BTC slipped under $69K, about $144M combined. One had BTC and ETH longs worth over $140M. Both got fully liquidated, and the loss was more than $17M.
A few things stacked up. Bitcoin broke below its 200-day average near $73K. Spot BTC ETFs saw outflows seven trading days in a row, about $1.9B total. Rate markets now fully price a Fed hike in December, and October CPI rose 0.4% on the month.
That's the leverage problem. Price drops, longs get forced out, and the forced selling pushes it lower.
No one knows where the bottom is. $60K is the level people are watching next.
Liquidation numbers move fast...
#CryptoSelloffTriggersMultipleWhaleLiquidations
JMH_CRYPTO:
great info
1
5
912
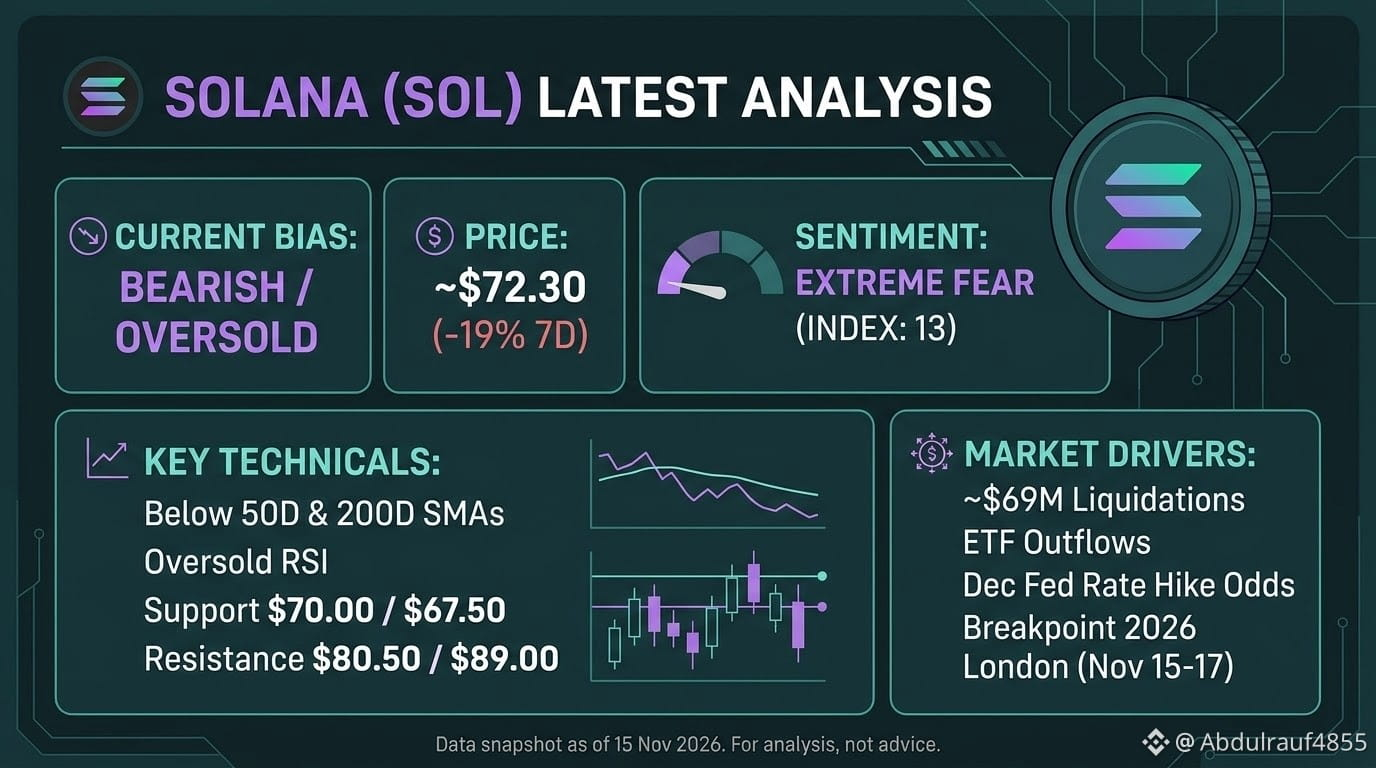
$SOL SOL is trading around $72.30 (having dipped as low as $71.13–$71.61), marking a roughly 19.4% drop over the past 7 days and erasing its autumn gains. The selloff triggered roughly $69 million in 24-hour liquidations (97% from long positions) alongside an 11.4% drop in futures open interest.
{spot}(SOLUSDT)
#CryptoSelloffTriggersMultipleWhaleLiquidations #USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months #WillFOMCMinutesReinforceRateHikeExpectations? #BitcoinActiveSupplyInProfitDropsBelow45% #KavaSaysAbnormalActivityLimitedToKavaLend
$SOL SOL is trading around $72.30 (having dipped as low as $71.13–$71.61), marking a roughly 19.4% drop over the past 7 days and erasing its autumn gains. The selloff triggered roughly $69 million in 24-hour liquidations (97% from long positions) alongside an 11.4% drop in futures open interest.
#CryptoSelloffTriggersMultipleWhaleLiquidations #USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months #WillFOMCMinutesReinforceRateHikeExpectations? #BitcoinActiveSupplyInProfitDropsBelow45% #KavaSaysAbnormalActivityLimitedToKavaLend
#CryptoSelloffTriggersMultipleWhaleLiquidations #USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months #WillFOMCMinutesReinforceRateHikeExpectations? #BitcoinActiveSupplyInProfitDropsBelow45% #KavaSaysAbnormalActivityLimitedToKavaLend
2
189
·
--
🚨 CRYPTO MARKET UNDER PRESSURE: LEVERAGED TRADERS FACE HUGE LOSSES!
The crypto market experienced another wave of intense selling on November 14, putting enormous pressure on leveraged traders. Even major market participants were unable to escape the sudden price movements.
📉 Here’s what caught everyone's attention:
• Around $188 million in tracked whale positions were wiped out across 89 monitored declining markets. • Nearly 96% of whale liquidation exposure came from bullish LONG trades. • One major BTC trader reportedly suffered a loss of approximately $13.1 million. • Bitcoin and Ethereum experienced heavy selling pressure from leveraged positions. • Overall crypto liquidations reportedly climbed to nearly $1.45 billion in a single day.
🔥 The bigger picture:
Large-scale liquidations can create a domino effect, forcing more traders out of their positions and increasing market volatility. However, these events may also remove excessive leverage and potentially prepare the market for a healthier rebound.
The big question now is: Is this just a temporary correction before the next bullish move, or should traders prepare for another major downturn?
What's your take on the current crypto market? 👀
$BNB
{future}(BNBUSDT)
$BTC
{future}(BTCUSDT)
$XRP
{future}(XRPUSDT)
#cryptosellofftriggersmultiplewhaleliquidations #BTC☀ #bnb #XRP’
🚨 CRYPTO MARKET UNDER PRESSURE: LEVERAGED TRADERS FACE HUGE LOSSES!
The crypto market experienced another wave of intense selling on November 14, putting enormous pressure on leveraged traders. Even major market participants were unable to escape the sudden price movements.
📉 Here’s what caught everyone's attention:
• Around $188 million in tracked whale positions were wiped out across 89 monitored declining markets. • Nearly 96% of whale liquidation exposure came from bullish LONG trades. • One major BTC trader reportedly suffered a loss of approximately $13.1 million. • Bitcoin and Ethereum experienced heavy selling pressure from leveraged positions. • Overall crypto liquidations reportedly climbed to nearly $1.45 billion in a single day.
🔥 The bigger picture:
Large-scale liquidations can create a domino effect, forcing more traders out of their positions and increasing market volatility. However, these events may also remove excessive leverage and potentially prepare the market for a healthier rebound.
The big question now is: Is this just a temporary correction before the next bullish move, or should traders prepare for another major downturn?
What's your take on the current crypto market? 👀
$BNB
$BTC
$XRP
#cryptosellofftriggersmultiplewhaleliquidations #BTC☀ #bnb #XRP’
The crypto market experienced another wave of intense selling on November 14, putting enormous pressure on leveraged traders. Even major market participants were unable to escape the sudden price movements.
📉 Here’s what caught everyone's attention:
• Around $188 million in tracked whale positions were wiped out across 89 monitored declining markets. • Nearly 96% of whale liquidation exposure came from bullish LONG trades. • One major BTC trader reportedly suffered a loss of approximately $13.1 million. • Bitcoin and Ethereum experienced heavy selling pressure from leveraged positions. • Overall crypto liquidations reportedly climbed to nearly $1.45 billion in a single day.
🔥 The bigger picture:
Large-scale liquidations can create a domino effect, forcing more traders out of their positions and increasing market volatility. However, these events may also remove excessive leverage and potentially prepare the market for a healthier rebound.
The big question now is: Is this just a temporary correction before the next bullish move, or should traders prepare for another major downturn?
What's your take on the current crypto market? 👀
$BNB
$BTC
$XRP
#cryptosellofftriggersmultiplewhaleliquidations #BTC☀ #bnb #XRP’
703
UMA SANGRIA HISTÓRICA VARRENDO MAIS DE DOIS BILHÕES DE DÓLARES DO MERCADO
જ⁀➴
A tempestade é violenta. Mais de 329.000 traders foram liquidados em 24 horas e a esmagadora maioria, cerca de 93 por cento, estava a apostar na subida. Até as baleias estão a falhar. Uma delas foi liquidada 7 vezes em 10 horas e amargou um prejuízo de 16,45 milhões de dólares.
O motivo é uma mistura tóxica de saídas massivas dos ETFs, que passaram de 1 bilhão de dólares na semana passada, e o medo de um aperto de juros pelo Fed em dezembro. O BTC está perigosamente perto da zona de 59.500 a 62.600 dólares, onde as posições altamente alavancadas serão varridas do mapa.
A regra é clara. Reduza a alavancagem, defina stop loss rigorosos e não tente apanhar a faca a cair. Aguarde uma reação no suporte antes de dar o próximo passo.
Isto não constitui aconselhamento financeiro.
Clique nos links de trading abaixo para me apoiar.
$EVAA
$INIT
$JELLYJELLY
Siga a página e ative as notificações. Não se atrase. Seja qual for a próxima atualização, vou publicá la aqui primeiro.
#cryptosellofftriggersmultiplewhaleliquidations
{future}(EVAAUSDT)
{spot}(INITUSDT)
{future}(JELLYJELLYUSDT)
UMA SANGRIA HISTÓRICA VARRENDO MAIS DE DOIS BILHÕES DE DÓLARES DO MERCADO
જ⁀➴
A tempestade é violenta. Mais de 329.000 traders foram liquidados em 24 horas e a esmagadora maioria, cerca de 93 por cento, estava a apostar na subida. Até as baleias estão a falhar. Uma delas foi liquidada 7 vezes em 10 horas e amargou um prejuízo de 16,45 milhões de dólares.
O motivo é uma mistura tóxica de saídas massivas dos ETFs, que passaram de 1 bilhão de dólares na semana passada, e o medo de um aperto de juros pelo Fed em dezembro. O BTC está perigosamente perto da zona de 59.500 a 62.600 dólares, onde as posições altamente alavancadas serão varridas do mapa.
A regra é clara. Reduza a alavancagem, defina stop loss rigorosos e não tente apanhar a faca a cair. Aguarde uma reação no suporte antes de dar o próximo passo.
Isto não constitui aconselhamento financeiro.
Clique nos links de trading abaixo para me apoiar.
$EVAA
$INIT
$JELLYJELLY
Siga a página e ative as notificações. Não se atrase. Seja qual for a próxima atualização, vou publicá la aqui primeiro.
#cryptosellofftriggersmultiplewhaleliquidations
જ⁀➴
A tempestade é violenta. Mais de 329.000 traders foram liquidados em 24 horas e a esmagadora maioria, cerca de 93 por cento, estava a apostar na subida. Até as baleias estão a falhar. Uma delas foi liquidada 7 vezes em 10 horas e amargou um prejuízo de 16,45 milhões de dólares.
O motivo é uma mistura tóxica de saídas massivas dos ETFs, que passaram de 1 bilhão de dólares na semana passada, e o medo de um aperto de juros pelo Fed em dezembro. O BTC está perigosamente perto da zona de 59.500 a 62.600 dólares, onde as posições altamente alavancadas serão varridas do mapa.
A regra é clara. Reduza a alavancagem, defina stop loss rigorosos e não tente apanhar a faca a cair. Aguarde uma reação no suporte antes de dar o próximo passo.
Isto não constitui aconselhamento financeiro.
Clique nos links de trading abaixo para me apoiar.
$EVAA
$INIT
$JELLYJELLY
Siga a página e ative as notificações. Não se atrase. Seja qual for a próxima atualização, vou publicá la aqui primeiro.
#cryptosellofftriggersmultiplewhaleliquidations
1
364
ເຂົ້າສູ່ລະບົບເພື່ອສຳຫຼວດເນື້ອຫາເພີ່ມເຕີມ
ເຂົ້າຮ່ວມກຸ່ມຜູ້ໃຊ້ຄຣິບໂຕທົ່ວໂລກໃນ Binance Square.
⚡️ ໄດ້ຮັບຂໍ້ມູນຫຼ້າສຸດ ແລະ ທີ່ມີປະໂຫຍດກ່ຽວກັບຄຣິບໂຕ.
💬 ໄດ້ຮັບຄວາມໄວ້ວາງໃຈຈາກຕະຫຼາດແລກປ່ຽນຄຣິບໂຕທີ່ໃຫຍ່ທີ່ສຸດໃນໂລກ.
👍 ຄົ້ນຫາຂໍ້ມູນເຊີງເລິກທີ່ແທ້ຈາກນັກສ້າງທີ່ໄດ້ຮັບການຢືນຢັນ.
ອີເມວ / ເບີໂທລະສັບ
ຫົວຂໍ້ທີ່ກໍາລັງນິຍົມ
1
#CryptoSelloffTriggersMultipleWhaleLiquidations
70,774 ຄັ້ງທີ່ເບິ່ງ
904 ກຳລັງສົນທະນາ
2
#USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months
90,052 ຄັ້ງທີ່ເບິ່ງ
1,055 ກຳລັງສົນທະນາ
3
#WillFOMCMinutesReinforceRateHikeExpectations?
16,630 ຄັ້ງທີ່ເບິ່ງ
372 ກຳລັງສົນທະນາ
4
#BitcoinActiveSupplyInProfitDropsBelow45%
160,322 ຄັ້ງທີ່ເບິ່ງ
1,386 ກຳລັງສົນທະນາ
5
#TONStrategyReports$23.97MQ3NetLoss
15,881 ຄັ້ງທີ່ເບິ່ງ
110 ກຳລັງສົນທະນາ
6
#KavaSaysAbnormalActivityLimitedToKavaLend
104,560 ຄັ້ງທີ່ເບິ່ງ
762 ກຳລັງສົນທະນາ
7
#WORPTLetsTouristsConvertCryptoToThaiBaht
28,775 ຄັ້ງທີ່ເບິ່ງ
276 ກຳລັງສົນທະນາ
8
#WhoWillSucceedJensenHuangatNvidia?
287,001 ຄັ້ງທີ່ເບິ່ງ
2,026 ກຳລັງສົນທະນາ
9
#WhatWillDriveCryptoandStocks’NextRebound?
773,095 ຄັ້ງທີ່ເບິ່ງ
3,824 ກຳລັງສົນທະນາ
10
#TradFiForBeginners
803,345 ຄັ້ງທີ່ເບິ່ງ
4,823 ກຳລັງສົນທະນາ