

x_Rex
X @x_Rex_yhy |Social Butterfly🌸😋😸| Gold Trader😎✨🌼|
取引を発注

NILホルダー
高頻度トレーダー
1.6年
355 フォロー
20.9K+ フォロワー
10.8K+ いいね
投稿
ポートフォリオ
すべて
引用
動画
ライブ
PINNED
x_Rex
·
--
#KiteBBW $KITE
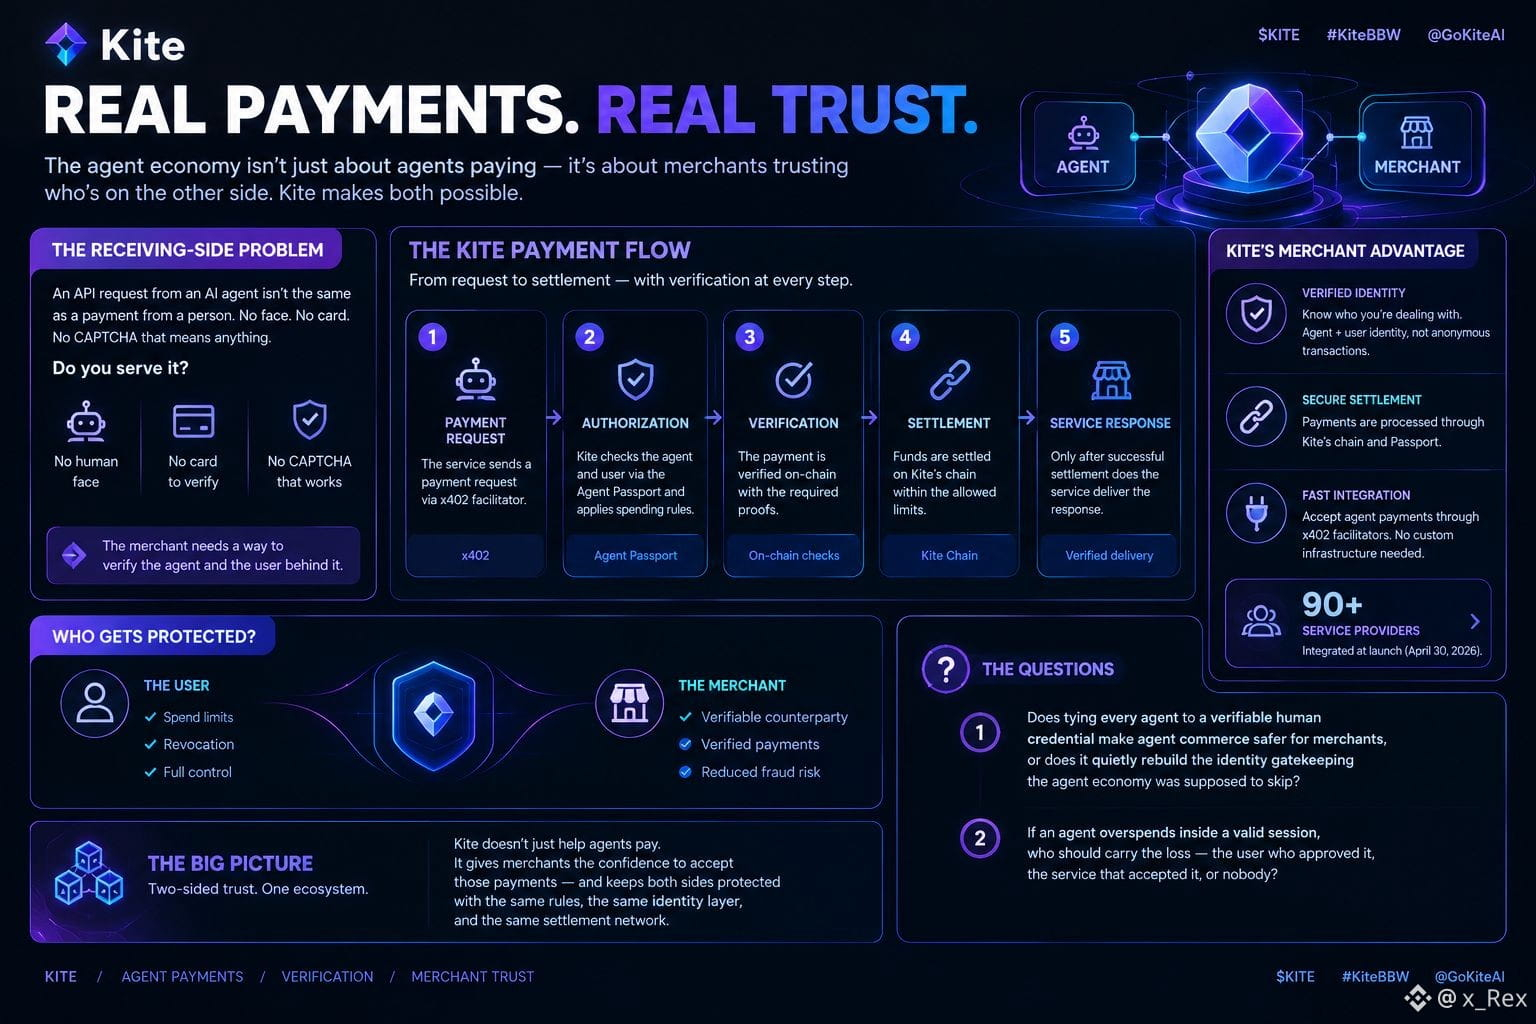
カード決済は買い手を守り、売り手を危険にさらす😒。
顧客は数か月後に請求に異議を申し立てることができ、そのチャージバックの負担は加盟店が負う。
Kiteのサービスプロバイダー向けガイドには、この流れを逆転させる仕組みが説明されている。エージェント経済において、この逆転こそ最も過小評価されている設計上の選択だと思う😁。
流れはシンプルだ。
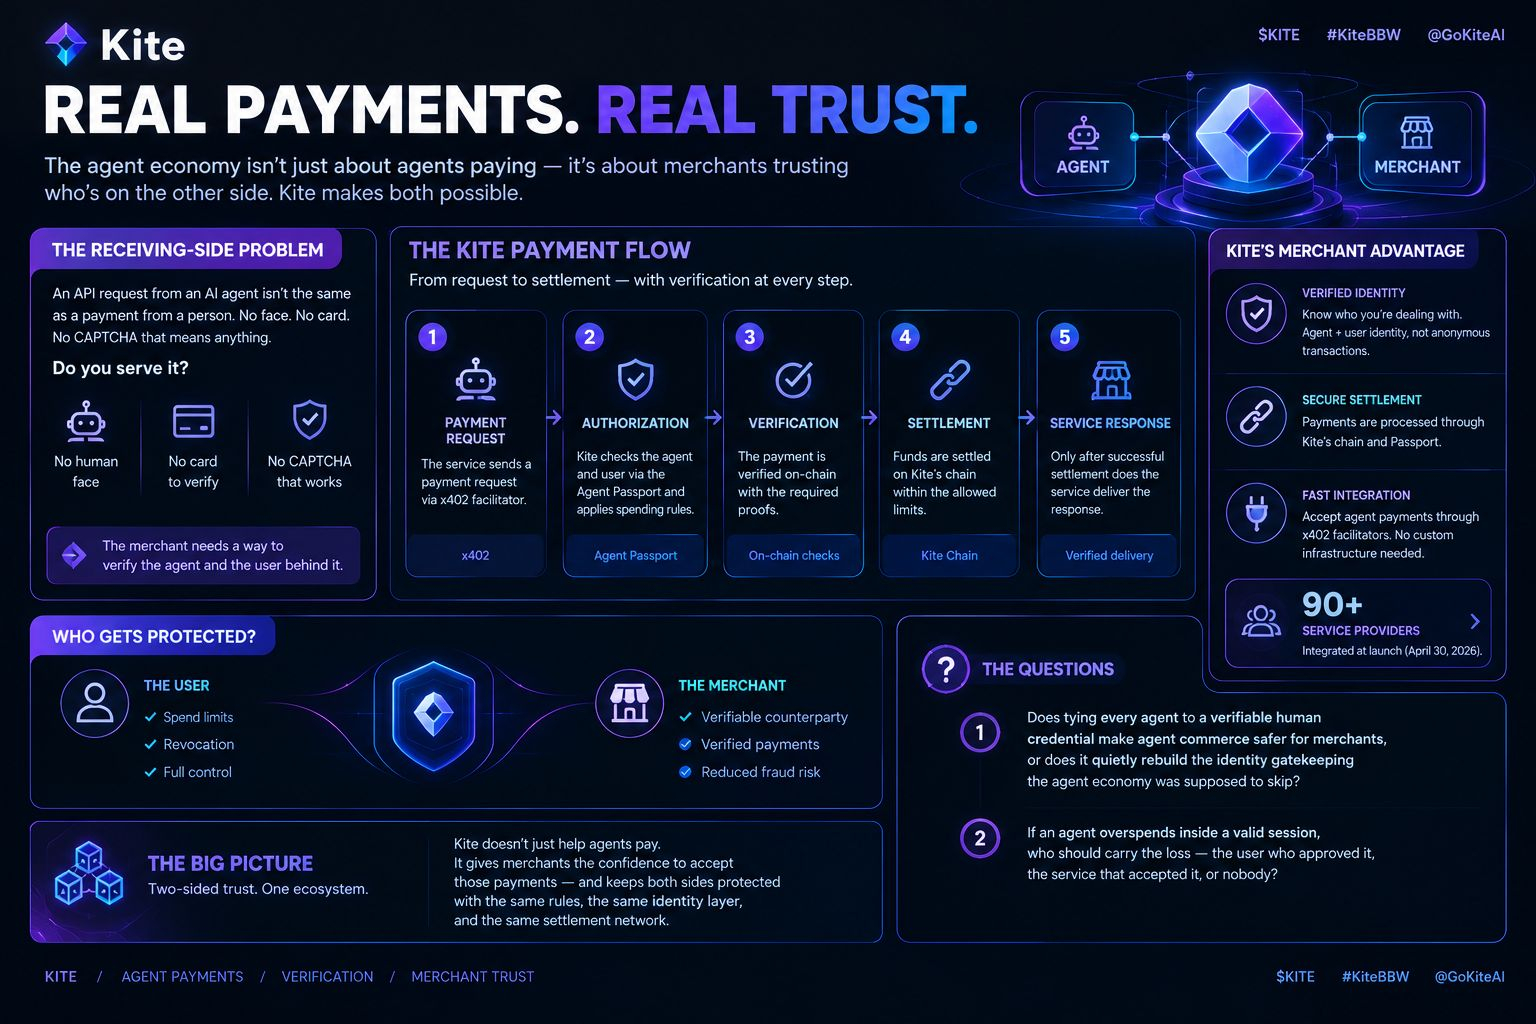
エージェントがエンドポイントを呼び出すと、サービスは価格、支払い先アドレス、タイムアウトを示す「402 Payment Required」を返す。
エージェントは、ユーザーが承認したセッションから生成された署名付きの承認情報を返す。
サービスがそれを検証し、ファシリテーターがオンチェーンで送金を決済してから、初めてサービスが応答を返す。
先に決済、後から提供🤷♀️。
加盟店は信用を供与する必要も、請求書の支払いを待つ必要もない。
だからこそ、原理上はリクエストごとの少額課金が成り立つ🤓。
カード決済網では取引ごとに固定費がかかり、少額決済ではその費用を吸収できない。リクエストごとの課金が機能するには、決済自体がほぼ無料でなければならない。
このガイドによると、すでにx402、またはStripeが共同開発したマシン決済プロトコルに対応しているサービスなら、Passportエージェントから今すぐ支払いを受けられる。
2026年4月30日のメインネットローンチ時には、90を超えるプロバイダーが統合されていた。
しかし、リスクが消えたわけではない。買い手側に移ったのだ。
提供前に決済が確定する以上、役に立たないものを返すサービスでも、すでに代金を受け取っている。私が読んだプロバイダー向けガイドには、返金や異議申し立ての手順は説明されていない。
ユーザーを守るのはセッション😃。取引ごとの上限と総額の上限によって、悪質な呼び出し1回で発生し得る損失を制限する。
私の考えでは、これらの上限はカード決済の世界でチャージバックが果たす役割を担う。ただし、損害が起きた後ではなく、起きる前に防ぐ😌。
リクエストごとの価格が少額なら、このトレードオフは問題ない。深刻な問題になるのは、エージェントに高額な買い物をさせる場合だ。
サービスが応答する前に決済が確定し、有料の呼び出しで役に立たないものが返ってきた場合、チャージバックに代わるものは何であるべきだろう?サービスの評判スコア、プロトコルに組み込まれた返金用エスクロー、それとも、リクエストごとの価格が小さすぎて仕組みを整える価値がないとして、何も設けないことだろうか?
ここで役立つ情報を得られたら「kite」とコメントしてね
x_Rex
·
--
#KiteBBW $KITE
カード決済は買い手を守り、売り手を危険にさらす😒。
顧客は数か月後に請求に異議を申し立てることができ、そのチャージバックの負担は加盟店が負う。
Kiteのサービスプロバイダー向けガイドには、この流れを逆転させる仕組みが説明されている。エージェント経済において、この逆転こそ最も過小評価されている設計上の選択だと思う😁。
流れはシンプルだ。
エージェントがエンドポイントを呼び出すと、サービスは価格、支払い先アドレス、タイムアウトを示す「402 Payment Required」を返す。
エージェントは、ユーザーが承認したセッションから生成された署名付きの承認情報を返す。
サービスがそれを検証し、ファシリテーターがオンチェーンで送金を決済してから、初めてサービスが応答を返す。
先に決済、後から提供🤷♀️。
加盟店は信用を供与する必要も、請求書の支払いを待つ必要もない。
だからこそ、原理上はリクエストごとの少額課金が成り立つ🤓。
カード決済網では取引ごとに固定費がかかり、少額決済ではその費用を吸収できない。リクエストごとの課金が機能するには、決済自体がほぼ無料でなければならない。
このガイドによると、すでにx402、またはStripeが共同開発したマシン決済プロトコルに対応しているサービスなら、Passportエージェントから今すぐ支払いを受けられる。
2026年4月30日のメインネットローンチ時には、90を超えるプロバイダーが統合されていた。
しかし、リスクが消えたわけではない。買い手側に移ったのだ。
提供前に決済が確定する以上、役に立たないものを返すサービスでも、すでに代金を受け取っている。私が読んだプロバイダー向けガイドには、返金や異議申し立ての手順は説明されていない。
ユーザーを守るのはセッション😃。取引ごとの上限と総額の上限によって、悪質な呼び出し1回で発生し得る損失を制限する。
私の考えでは、これらの上限はカード決済の世界でチャージバックが果たす役割を担う。ただし、損害が起きた後ではなく、起きる前に防ぐ😌。
リクエストごとの価格が少額なら、このトレードオフは問題ない。深刻な問題になるのは、エージェントに高額な買い物をさせる場合だ。
サービスが応答する前に決済が確定し、有料の呼び出しで役に立たないものが返ってきた場合、チャージバックに代わるものは何であるべきだろう?サービスの評判スコア、プロトコルに組み込まれた返金用エスクロー、それとも、リクエストごとの価格が小さすぎて仕組みを整える価値がないとして、何も設けないことだろうか?
ここで役立つ情報を得られたら「kite」とコメントしてね
カード決済は買い手を守り、売り手を危険にさらす😒。
顧客は数か月後に請求に異議を申し立てることができ、そのチャージバックの負担は加盟店が負う。
Kiteのサービスプロバイダー向けガイドには、この流れを逆転させる仕組みが説明されている。エージェント経済において、この逆転こそ最も過小評価されている設計上の選択だと思う😁。
流れはシンプルだ。
エージェントがエンドポイントを呼び出すと、サービスは価格、支払い先アドレス、タイムアウトを示す「402 Payment Required」を返す。
エージェントは、ユーザーが承認したセッションから生成された署名付きの承認情報を返す。
サービスがそれを検証し、ファシリテーターがオンチェーンで送金を決済してから、初めてサービスが応答を返す。
先に決済、後から提供🤷♀️。
加盟店は信用を供与する必要も、請求書の支払いを待つ必要もない。
だからこそ、原理上はリクエストごとの少額課金が成り立つ🤓。
カード決済網では取引ごとに固定費がかかり、少額決済ではその費用を吸収できない。リクエストごとの課金が機能するには、決済自体がほぼ無料でなければならない。
このガイドによると、すでにx402、またはStripeが共同開発したマシン決済プロトコルに対応しているサービスなら、Passportエージェントから今すぐ支払いを受けられる。
2026年4月30日のメインネットローンチ時には、90を超えるプロバイダーが統合されていた。
しかし、リスクが消えたわけではない。買い手側に移ったのだ。
提供前に決済が確定する以上、役に立たないものを返すサービスでも、すでに代金を受け取っている。私が読んだプロバイダー向けガイドには、返金や異議申し立ての手順は説明されていない。
ユーザーを守るのはセッション😃。取引ごとの上限と総額の上限によって、悪質な呼び出し1回で発生し得る損失を制限する。
私の考えでは、これらの上限はカード決済の世界でチャージバックが果たす役割を担う。ただし、損害が起きた後ではなく、起きる前に防ぐ😌。
リクエストごとの価格が少額なら、このトレードオフは問題ない。深刻な問題になるのは、エージェントに高額な買い物をさせる場合だ。
サービスが応答する前に決済が確定し、有料の呼び出しで役に立たないものが返ってきた場合、チャージバックに代わるものは何であるべきだろう?サービスの評判スコア、プロトコルに組み込まれた返金用エスクロー、それとも、リクエストごとの価格が小さすぎて仕組みを整える価値がないとして、何も設けないことだろうか?
ここで役立つ情報を得られたら「kite」とコメントしてね
Luke_龙
·
--
#KiteBBW $KITE
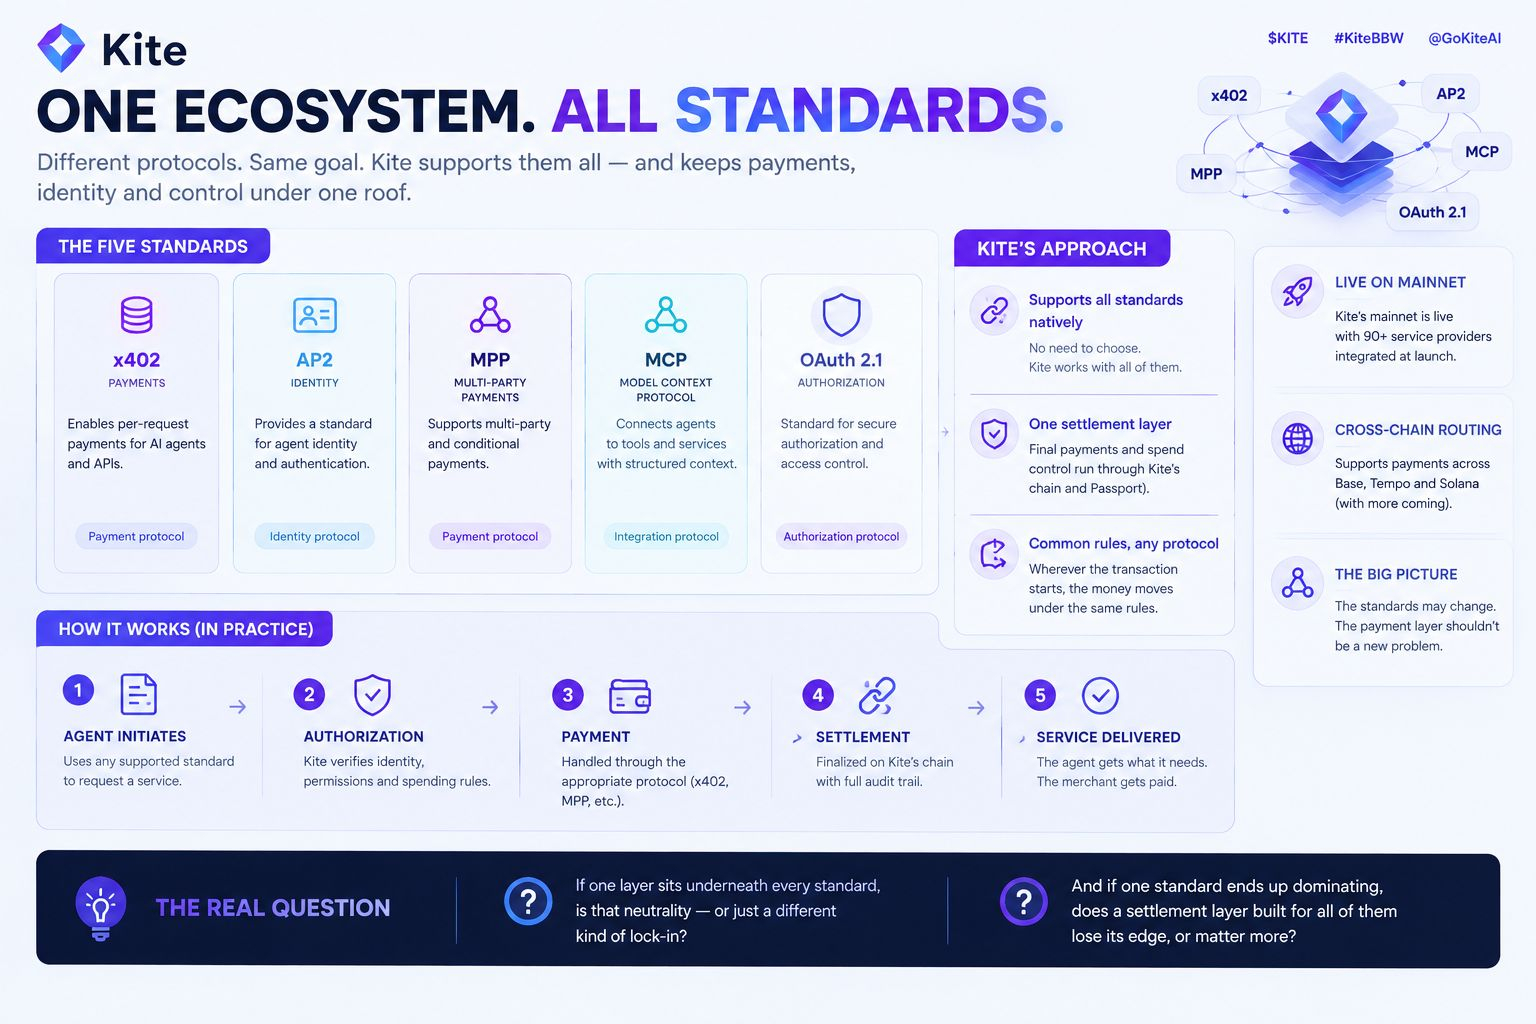
x402、AP2、MPP、MCP、OAuth 2.1。
エージェントが対応を求められる可能性のある5つのプロトコル。どれが勝つのかは誰にもわからない。
Kiteの答えは、どれか一つを選ばないこと。
それぞれが異なる役割を担う。x402はHTTPの「支払いが必要」ステータスを復活させ、サービスがリクエストごとに課金できるようにする。
AP2はGoogleのエージェント向け決済プロトコル、MPPはStripeの機械向け決済プロトコル、MCPはAnthropicがエージェントとツールを接続するための仕組みで、OAuth 2.1は認可を担う。
ある調査レポートの説明によると、x402を使うエージェントはリクエストごとに支払いができる一方で、別個のウォレット、独立したIDレイヤー、そして独自の支出上限ロジックが依然として必要になる。
Kiteが掲げる方針は、それらすべてをネイティブにサポートしつつ、重要な部分である最終決済と支出管理を、自社のチェーンとPassportに紐づけておくことだ。
どのプロトコルで取引が始まっても、資金はユーザーが設定した同じルールのもとで動くことを目指している。予算、時間制限、パスキーによる承認、即時取り消しだ。
Kiteはさらに、サブ秒の決定論的ファイナリティと、エージェント専用の決済レーンも挙げている。これらは人間よりもエージェントにとって重要だ。
人間なら、確認を待つことができる。
単独で行動するエージェントには、支払いが本当に完了したと把握できることが必要だ。この考え方は、標準規格をめぐる争いを回避できるので、理にかなっていると思う。
また、エージェント経済で価値がどこに宿るのかについて、静かな賭けでもある。
毎年変わる可能性のあるリクエストレイヤーではなく、支払いを承認して決済を完了させるかどうかを決めるレイヤーに価値がある、という賭けだ。
KiteはLinux FoundationのAgentic AI Foundationにも参加している。これは、標準化の議論の外側ではなく、その内側に席を確保したいという意向を示している。
メインネットは2026年4月30日にローンチし、すでに90以上のサービスプロバイダーが統合済みだ。実際のトラフィックのもとで、この中立性と決済レーンが機能し続けるかどうかが、本当の試金石となる。
皆さんの意見も聞きたい。
1. すべての標準規格の下に一つのレイヤーが存在するのは、中立性なのか、それとも別種のロックインにすぎないのか?
2. いずれか一つの標準規格が結局優勢になった場合、それらすべてに対応するよう構築された決済レイヤーの優位性は失われるのか。それとも、すべてがそこを通るからこそ、重要性が増すのか?
🚀 Yes — want early access
63%
😐 Too risky for me
25%
🤔 Interesting but need info
6%
💀 A trap to lose money faster
6%
16 投票 • 投票は終了しました
本人確認中
🎰 Aping in for the meme
33%
👀 Watching from far away
45%
💀 Political memecoins = scams
0%
😂 Just here for the drama
22%
9 投票 • 投票は終了しました
ログインして、さらにコンテンツを読む