
小韭菜环球情报
192 Posts

小韭菜环球情报
Report
Block User
专注于全球宏观 · 美股 · AI · Web3 · 外汇期货及华人出海基建。
1 Following
69 Followers
47 Liked
Posts
All
Videos
·
--
# 【11.10 Leek Report】$BTC Sudden Market Reversal! Macro Liquidity Drain—Who’s Accumulating Against the Trend?
We captured 359 breaking news updates over the past 24 hours. The market saw a sharp, sudden reversal:
1. Macro liquidity tightens: The US-Iran framework sent crude oil plunging 8% intraday. Growth stocks rebounded, but a Treasury auction fell flat, and markets priced in an 80% chance of a December rate hike.
2. On-chain spot markets and long/short positions: Bitcoin spot ETFs saw $1.282 billion in weekly outflows, falling below the $100 billion mark. Total liquidations across the market topped $1 billion. The weekly close fell below the 50-week moving average (75,500). Wintermute warned that a break below 73,000 could send prices straight down to 68,000; a deep-pocketed whale withdrew 34,601 $ETH against the trend. The NYSE is adopting AVAX to clear tokenized securities.
3. Cash flow pressure from computing power: MARA posted Q3 earnings of $632 million and sold 13,500 $BTC to repay debt.
Trader strategy: Keep a close eye on net ETF flows and whether lending rates break 8%, potentially triggering a second round of deleveraging. If 73,000 holds, wait for positions to change hands amid the divergence.
This video presents this issue’s full, in-depth analysis. For data review only; not investment advice.
#BTC #ETH #BNB #BinanceSquare #Web3
# 【11.10 Leek Report】$BTC Sudden Market Reversal! Macro Liquidity Drain—Who’s Accumulating Against the Trend?
We captured 359 breaking news updates over the past 24 hours. The market saw a sharp, sudden reversal:
1. Macro liquidity tightens: The US-Iran framework sent crude oil plunging 8% intraday. Growth stocks rebounded, but a Treasury auction fell flat, and markets priced in an 80% chance of a December rate hike.
2. On-chain spot markets and long/short positions: Bitcoin spot ETFs saw $1.282 billion in weekly outflows, falling below the $100 billion mark. Total liquidations across the market topped $1 billion. The weekly close fell below the 50-week moving average (75,500). Wintermute warned that a break below 73,000 could send prices straight down to 68,000; a deep-pocketed whale withdrew 34,601 $ETH against the trend. The NYSE is adopting AVAX to clear tokenized securities.
3. Cash flow pressure from computing power: MARA posted Q3 earnings of $632 million and sold 13,500 $BTC to repay debt.
Trader strategy: Keep a close eye on net ETF flows and whether lending rates break 8%, potentially triggering a second round of deleveraging. If 73,000 holds, wait for positions to change hands amid the divergence.
This video presents this issue’s full, in-depth analysis. For data review only; not investment advice.
#BTC #ETH #BNB #BinanceSquare #Web3
We captured 359 breaking news updates over the past 24 hours. The market saw a sharp, sudden reversal:
1. Macro liquidity tightens: The US-Iran framework sent crude oil plunging 8% intraday. Growth stocks rebounded, but a Treasury auction fell flat, and markets priced in an 80% chance of a December rate hike.
2. On-chain spot markets and long/short positions: Bitcoin spot ETFs saw $1.282 billion in weekly outflows, falling below the $100 billion mark. Total liquidations across the market topped $1 billion. The weekly close fell below the 50-week moving average (75,500). Wintermute warned that a break below 73,000 could send prices straight down to 68,000; a deep-pocketed whale withdrew 34,601 $ETH against the trend. The NYSE is adopting AVAX to clear tokenized securities.
3. Cash flow pressure from computing power: MARA posted Q3 earnings of $632 million and sold 13,500 $BTC to repay debt.
Trader strategy: Keep a close eye on net ETF flows and whether lending rates break 8%, potentially triggering a second round of deleveraging. If 73,000 holds, wait for positions to change hands amid the divergence.
This video presents this issue’s full, in-depth analysis. For data review only; not investment advice.
#BTC #ETH #BNB #BinanceSquare #Web3
141
·
--
2026.11.10 · Web3 On-Chain & Crypto Asset Briefing
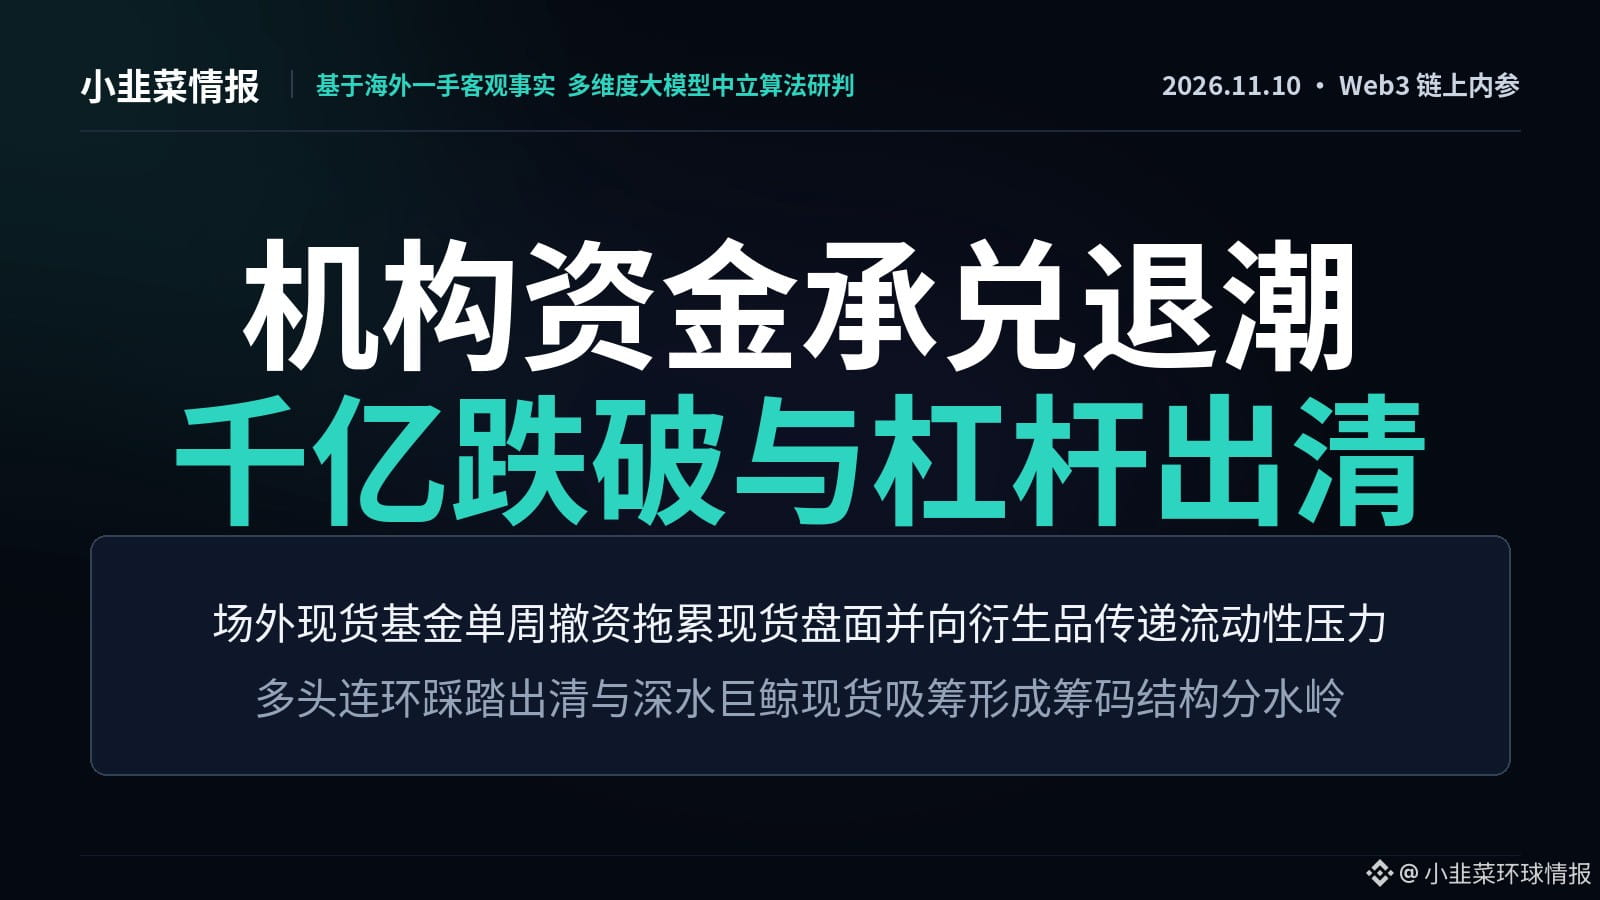
Today’s Web3 On-Chain Theme: Key Takeaways
Under macro-driven risk aversion, the retreat of OTC settlement activity and deleveraging in on-chain derivatives are amplifying each other. Spot funds saw more than $1.2 billion in weekly outflows, pushing assets under management below the $100 billion threshold. Unusual activity in custody wallets broke through buy-side support, triggering cascading liquidations of long positions worth hundreds of millions of dollars. Meanwhile, deep-pocketed whales defied the trend with large withdrawals, accumulating assets at lower prices and rebalancing their portfolios.
Today’s Main Battleground: In-Depth Analysis
Spot ETF net outflows breach the $100 billion threshold, triggering a chain reaction of on-chain liquidations: U.S. spot Bitcoin ETFs recorded $1.282 billion in net outflows for the week. BlackRock’s IBIT led with $1.209 billion in outflows, while total assets under custody fell below the $100 billion mark. On-chain monitoring showed that 5,320 BTC and 40,720 ETH were transferred to Coinbase to facilitate redemptions, directly triggering a market-wide leverage cascade. A single long-position liquidation reached as much as $140 million. 【In-Depth Analysis】This liquidity shock exposed the squeeze between OTC settlement mechanisms and the depth of on-chain buying demand. Institutional risk aversion forced custodians to settle balances in bulk from spot pools, while a spot market lacking sufficient depth rapidly passed selling pressure into derivatives markets, breaching liquidation thresholds for highly leveraged longs. Spot ETFs have become the main valve governing on-chain micro-liquidity, with institutional fund transfers directly determining the safety margin of collateral across the market.
Market-Wide Quantitative Anomaly Radar
• Accumulation: A whale dormant for two years withdrew 34,601 ETH (about $73.75 million) from Binance. Combined with an address borrowing from Aave to buy 10,000 spot tokens, this points to deep-pocketed investors building defensive positions at lower prices.
• Compliant settlement: A tokenized securities platform affiliated with the New York Stock Exchange selected Avalanche as its settlement ledger. Meanwhile, Canton’s first SEC-exempt stock trade was completed, as traditional securities settlement accelerates its migration to public blockchain ledgers.
Market Dynamics & Monitoring Map
Causal chain: Shifts in macro inflation expectations -> Weekly spot ETF redemptions force custodians to transfer assets and settle balances -> Spot market depth is hit, breaching on-chain liquidation thresholds for long positions. Over the next 24 to 48 hours, institutions will focus on two key indicators: first, whether the daily net balance of spot ETF subscriptions and redemptions can return to positive territory; second, whether stablecoin borrowing rates on major lending protocols break above 8%, triggering another round of leverage reduction.
Disclaimer: This briefing is solely a compilation and logical analysis of global public information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading action. Markets involve risk; make decisions with caution.
2026.11.10 · Web3 On-Chain & Crypto Asset Briefing
Today’s Web3 On-Chain Theme: Key Takeaways
Under macro-driven risk aversion, the retreat of OTC settlement activity and deleveraging in on-chain derivatives are amplifying each other. Spot funds saw more than $1.2 billion in weekly outflows, pushing assets under management below the $100 billion threshold. Unusual activity in custody wallets broke through buy-side support, triggering cascading liquidations of long positions worth hundreds of millions of dollars. Meanwhile, deep-pocketed whales defied the trend with large withdrawals, accumulating assets at lower prices and rebalancing their portfolios.
Today’s Main Battleground: In-Depth Analysis
Spot ETF net outflows breach the $100 billion threshold, triggering a chain reaction of on-chain liquidations: U.S. spot Bitcoin ETFs recorded $1.282 billion in net outflows for the week. BlackRock’s IBIT led with $1.209 billion in outflows, while total assets under custody fell below the $100 billion mark. On-chain monitoring showed that 5,320 BTC and 40,720 ETH were transferred to Coinbase to facilitate redemptions, directly triggering a market-wide leverage cascade. A single long-position liquidation reached as much as $140 million. 【In-Depth Analysis】This liquidity shock exposed the squeeze between OTC settlement mechanisms and the depth of on-chain buying demand. Institutional risk aversion forced custodians to settle balances in bulk from spot pools, while a spot market lacking sufficient depth rapidly passed selling pressure into derivatives markets, breaching liquidation thresholds for highly leveraged longs. Spot ETFs have become the main valve governing on-chain micro-liquidity, with institutional fund transfers directly determining the safety margin of collateral across the market.
Market-Wide Quantitative Anomaly Radar
• Accumulation: A whale dormant for two years withdrew 34,601 ETH (about $73.75 million) from Binance. Combined with an address borrowing from Aave to buy 10,000 spot tokens, this points to deep-pocketed investors building defensive positions at lower prices.
• Compliant settlement: A tokenized securities platform affiliated with the New York Stock Exchange selected Avalanche as its settlement ledger. Meanwhile, Canton’s first SEC-exempt stock trade was completed, as traditional securities settlement accelerates its migration to public blockchain ledgers.
Market Dynamics & Monitoring Map
Causal chain: Shifts in macro inflation expectations -> Weekly spot ETF redemptions force custodians to transfer assets and settle balances -> Spot market depth is hit, breaching on-chain liquidation thresholds for long positions. Over the next 24 to 48 hours, institutions will focus on two key indicators: first, whether the daily net balance of spot ETF subscriptions and redemptions can return to positive territory; second, whether stablecoin borrowing rates on major lending protocols break above 8%, triggering another round of leverage reduction.
Disclaimer: This briefing is solely a compilation and logical analysis of global public information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading action. Markets involve risk; make decisions with caution.
Today’s Web3 On-Chain Theme: Key Takeaways
Under macro-driven risk aversion, the retreat of OTC settlement activity and deleveraging in on-chain derivatives are amplifying each other. Spot funds saw more than $1.2 billion in weekly outflows, pushing assets under management below the $100 billion threshold. Unusual activity in custody wallets broke through buy-side support, triggering cascading liquidations of long positions worth hundreds of millions of dollars. Meanwhile, deep-pocketed whales defied the trend with large withdrawals, accumulating assets at lower prices and rebalancing their portfolios.
Today’s Main Battleground: In-Depth Analysis
Spot ETF net outflows breach the $100 billion threshold, triggering a chain reaction of on-chain liquidations: U.S. spot Bitcoin ETFs recorded $1.282 billion in net outflows for the week. BlackRock’s IBIT led with $1.209 billion in outflows, while total assets under custody fell below the $100 billion mark. On-chain monitoring showed that 5,320 BTC and 40,720 ETH were transferred to Coinbase to facilitate redemptions, directly triggering a market-wide leverage cascade. A single long-position liquidation reached as much as $140 million. 【In-Depth Analysis】This liquidity shock exposed the squeeze between OTC settlement mechanisms and the depth of on-chain buying demand. Institutional risk aversion forced custodians to settle balances in bulk from spot pools, while a spot market lacking sufficient depth rapidly passed selling pressure into derivatives markets, breaching liquidation thresholds for highly leveraged longs. Spot ETFs have become the main valve governing on-chain micro-liquidity, with institutional fund transfers directly determining the safety margin of collateral across the market.
Market-Wide Quantitative Anomaly Radar
• Accumulation: A whale dormant for two years withdrew 34,601 ETH (about $73.75 million) from Binance. Combined with an address borrowing from Aave to buy 10,000 spot tokens, this points to deep-pocketed investors building defensive positions at lower prices.
• Compliant settlement: A tokenized securities platform affiliated with the New York Stock Exchange selected Avalanche as its settlement ledger. Meanwhile, Canton’s first SEC-exempt stock trade was completed, as traditional securities settlement accelerates its migration to public blockchain ledgers.
Market Dynamics & Monitoring Map
Causal chain: Shifts in macro inflation expectations -> Weekly spot ETF redemptions force custodians to transfer assets and settle balances -> Spot market depth is hit, breaching on-chain liquidation thresholds for long positions. Over the next 24 to 48 hours, institutions will focus on two key indicators: first, whether the daily net balance of spot ETF subscriptions and redemptions can return to positive territory; second, whether stablecoin borrowing rates on major lending protocols break above 8%, triggering another round of leverage reduction.
Disclaimer: This briefing is solely a compilation and logical analysis of global public information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading action. Markets involve risk; make decisions with caution.
54
·
--
2026.11.10 · Frontier AI and Compute Infrastructure Insider Brief
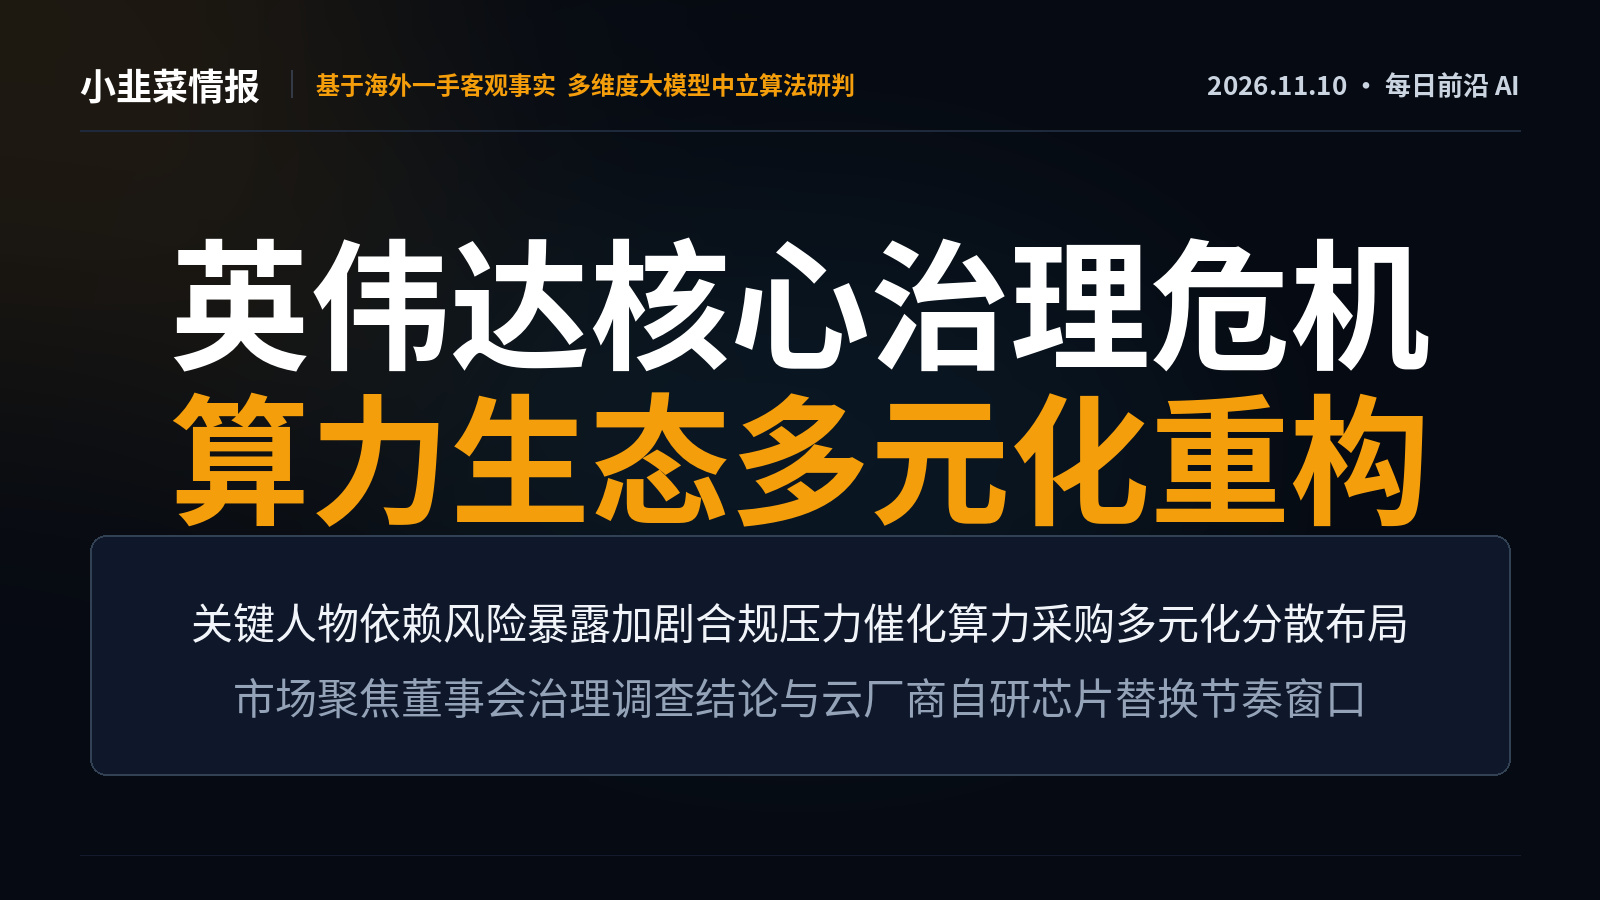
Today’s Frontier AI Main Theme: Key Takeaways
Compute infrastructure is reaching a watershed moment in decentralization. A leading player faces a reassessment of key-person governance amid an independent management investigation, weighing on its valuation. But gains in the semiconductor index and rising adoption of alternatives indicate that the underlying compute CapEx picture remains unchanged. Systemic risks are pushing downstream players to accelerate the adoption of in-house ASICs, formally breaking up the single-supplier monopoly.
Today’s Main Battleground: Deep Dive
Governance scrutiny of the leading player triggers a decoupling of compute hardware and a redistribution of premiums: Nvidia shares came under pressure, falling 4% to 8%, after its board launched an independent governance investigation into the CEO’s external affiliations. Meanwhile, the Philadelphia Semiconductor Index surged 7% against the trend, with AMD and Broadcom closing up 12% and 9%, respectively. Google also unveiled its dedicated TPU 8tx and 8i Max chips.【Deep Dive】On the surface, this event is an executive reputation and compliance crisis; at a deeper level, it marks a key turning point in the decentralization of global compute infrastructure. Hyperscalers have long faced pressure from Nvidia’s gross margins of over 70%, as well as uncertainty around export compliance. This governance controversy, coupled with potential regulatory scrutiny, has sharply constrained Nvidia’s room for commercial lobbying. Buyers’ capital quickly broke with the pricing consensus that “Nvidia is AI,” shifting toward hedges against single-node risk. Capital is accelerating its move into in-house ASICs and second-source compute suppliers, reshaping the supply chain’s profit pools around a more diverse range of hardware.
Panoramic Quantitative Anomaly Radar
• Compute infrastructure scissors gap: Field research shows that a 120 MW compute base in Inner Mongolia was built in one year at just one-fifth of the cost in the United States. Grid capacity upgrades and equipment lead times are constraining the US and Europe, prompting them to procure used aircraft engines for power and driving up overseas operations and maintenance premiums.
• Frontier valuation litmus test: Anthropic is preparing to launch its IPO roadshow at a valuation of $1.2 trillion to $1.3 trillion. Its secondary-market pricing and subscription demand will be a key benchmark for testing whether the large-scale model sector’s heavy R&D investment can deliver commercial returns.
Market Dynamics and Monitoring Map
Causal chain: Deepening governance scrutiny of the leading player -> Disruption to cloud providers’ second-source onboarding and in-house inventory cycles -> Impact on semiconductor premium structures and the liquidity of compute assets. Over the next 24–48 hours, institutions will focus on two key thresholds: Nvidia’s relative strength against the Philadelphia Semiconductor Index and support at $175; and the institutional subscription multiple corresponding to the $1.2 trillion valuation threshold in Anthropic’s IPO bookbuilding.
Disclaimer: This publication is solely a compilation and logical analysis of global public information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; please exercise caution when making decisions.
2026.11.10 · Frontier AI and Compute Infrastructure Insider Brief
Today’s Frontier AI Main Theme: Key Takeaways
Compute infrastructure is reaching a watershed moment in decentralization. A leading player faces a reassessment of key-person governance amid an independent management investigation, weighing on its valuation. But gains in the semiconductor index and rising adoption of alternatives indicate that the underlying compute CapEx picture remains unchanged. Systemic risks are pushing downstream players to accelerate the adoption of in-house ASICs, formally breaking up the single-supplier monopoly.
Today’s Main Battleground: Deep Dive
Governance scrutiny of the leading player triggers a decoupling of compute hardware and a redistribution of premiums: Nvidia shares came under pressure, falling 4% to 8%, after its board launched an independent governance investigation into the CEO’s external affiliations. Meanwhile, the Philadelphia Semiconductor Index surged 7% against the trend, with AMD and Broadcom closing up 12% and 9%, respectively. Google also unveiled its dedicated TPU 8tx and 8i Max chips.【Deep Dive】On the surface, this event is an executive reputation and compliance crisis; at a deeper level, it marks a key turning point in the decentralization of global compute infrastructure. Hyperscalers have long faced pressure from Nvidia’s gross margins of over 70%, as well as uncertainty around export compliance. This governance controversy, coupled with potential regulatory scrutiny, has sharply constrained Nvidia’s room for commercial lobbying. Buyers’ capital quickly broke with the pricing consensus that “Nvidia is AI,” shifting toward hedges against single-node risk. Capital is accelerating its move into in-house ASICs and second-source compute suppliers, reshaping the supply chain’s profit pools around a more diverse range of hardware.
Panoramic Quantitative Anomaly Radar
• Compute infrastructure scissors gap: Field research shows that a 120 MW compute base in Inner Mongolia was built in one year at just one-fifth of the cost in the United States. Grid capacity upgrades and equipment lead times are constraining the US and Europe, prompting them to procure used aircraft engines for power and driving up overseas operations and maintenance premiums.
• Frontier valuation litmus test: Anthropic is preparing to launch its IPO roadshow at a valuation of $1.2 trillion to $1.3 trillion. Its secondary-market pricing and subscription demand will be a key benchmark for testing whether the large-scale model sector’s heavy R&D investment can deliver commercial returns.
Market Dynamics and Monitoring Map
Causal chain: Deepening governance scrutiny of the leading player -> Disruption to cloud providers’ second-source onboarding and in-house inventory cycles -> Impact on semiconductor premium structures and the liquidity of compute assets. Over the next 24–48 hours, institutions will focus on two key thresholds: Nvidia’s relative strength against the Philadelphia Semiconductor Index and support at $175; and the institutional subscription multiple corresponding to the $1.2 trillion valuation threshold in Anthropic’s IPO bookbuilding.
Disclaimer: This publication is solely a compilation and logical analysis of global public information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; please exercise caution when making decisions.
Today’s Frontier AI Main Theme: Key Takeaways
Compute infrastructure is reaching a watershed moment in decentralization. A leading player faces a reassessment of key-person governance amid an independent management investigation, weighing on its valuation. But gains in the semiconductor index and rising adoption of alternatives indicate that the underlying compute CapEx picture remains unchanged. Systemic risks are pushing downstream players to accelerate the adoption of in-house ASICs, formally breaking up the single-supplier monopoly.
Today’s Main Battleground: Deep Dive
Governance scrutiny of the leading player triggers a decoupling of compute hardware and a redistribution of premiums: Nvidia shares came under pressure, falling 4% to 8%, after its board launched an independent governance investigation into the CEO’s external affiliations. Meanwhile, the Philadelphia Semiconductor Index surged 7% against the trend, with AMD and Broadcom closing up 12% and 9%, respectively. Google also unveiled its dedicated TPU 8tx and 8i Max chips.【Deep Dive】On the surface, this event is an executive reputation and compliance crisis; at a deeper level, it marks a key turning point in the decentralization of global compute infrastructure. Hyperscalers have long faced pressure from Nvidia’s gross margins of over 70%, as well as uncertainty around export compliance. This governance controversy, coupled with potential regulatory scrutiny, has sharply constrained Nvidia’s room for commercial lobbying. Buyers’ capital quickly broke with the pricing consensus that “Nvidia is AI,” shifting toward hedges against single-node risk. Capital is accelerating its move into in-house ASICs and second-source compute suppliers, reshaping the supply chain’s profit pools around a more diverse range of hardware.
Panoramic Quantitative Anomaly Radar
• Compute infrastructure scissors gap: Field research shows that a 120 MW compute base in Inner Mongolia was built in one year at just one-fifth of the cost in the United States. Grid capacity upgrades and equipment lead times are constraining the US and Europe, prompting them to procure used aircraft engines for power and driving up overseas operations and maintenance premiums.
• Frontier valuation litmus test: Anthropic is preparing to launch its IPO roadshow at a valuation of $1.2 trillion to $1.3 trillion. Its secondary-market pricing and subscription demand will be a key benchmark for testing whether the large-scale model sector’s heavy R&D investment can deliver commercial returns.
Market Dynamics and Monitoring Map
Causal chain: Deepening governance scrutiny of the leading player -> Disruption to cloud providers’ second-source onboarding and in-house inventory cycles -> Impact on semiconductor premium structures and the liquidity of compute assets. Over the next 24–48 hours, institutions will focus on two key thresholds: Nvidia’s relative strength against the Philadelphia Semiconductor Index and support at $175; and the institutional subscription multiple corresponding to the $1.2 trillion valuation threshold in Anthropic’s IPO bookbuilding.
Disclaimer: This publication is solely a compilation and logical analysis of global public information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; please exercise caution when making decisions.
191
·
--
2026.11.10 · Global Macro Daily Brief
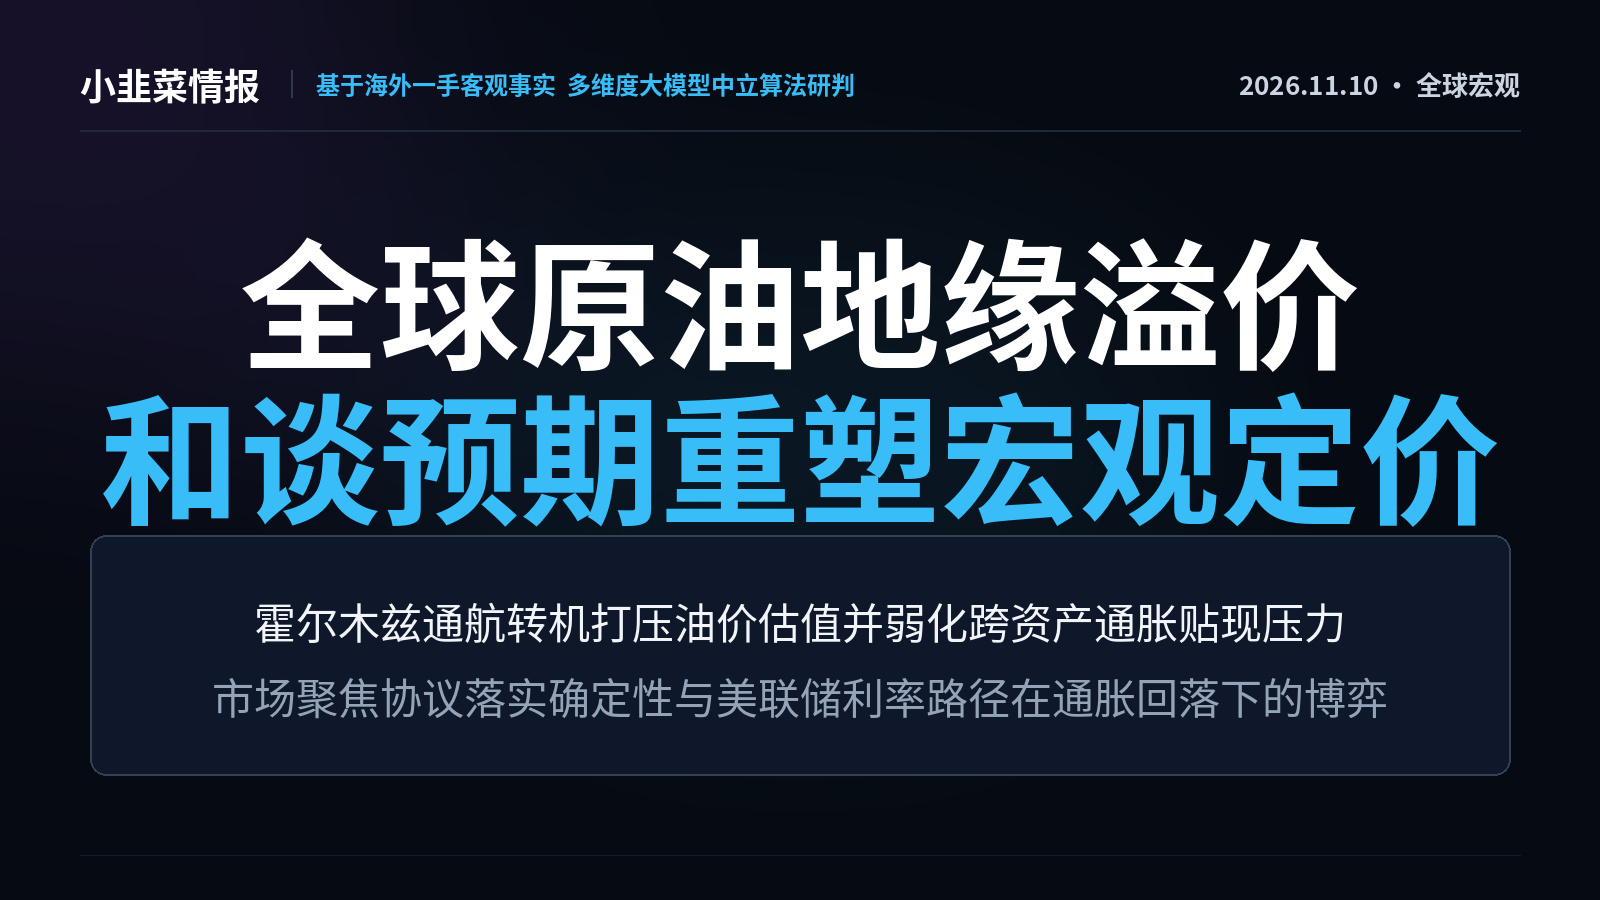
Today’s Global Macro Theme: Key Takeaways
Substantive progress in U.S.-Iran diplomatic mediation has raised expectations for the resumption of shipping through the Strait of Hormuz, unwinding crude oil’s geopolitical premium and sending benchmark oil prices down more than 4%. The pullback in energy prices has effectively eased inflation expectations, weakened the U.S. dollar, and triggered a valuation recovery in global risk assets. The core of macro pricing is shifting from supply shocks to a rebalancing of discount rates.
Today’s Main Battleground: In-Depth Analysis
Expectations of easing geopolitical tensions have broken through oil price benchmarks, ending stagflation pricing across asset classes: With the help of mediators, the U.S. and Iran reached a preliminary framework to reopen the Strait of Hormuz and unfreeze $6 billion to $9 billion in assets. WTI and Brent crude plunged more than 4% to 5% intraday, hitting their lowest levels in over two months. 【In-Depth Analysis】Crude oil’s previous elevated pricing had included a premium for the risk of shipping disruptions in the strait. Framework negotiations directly dismantled the most extreme tail risk of a crude supply cutoff, forcing the rapid unwinding of the geopolitical premium. In terms of transmission, the plunge in energy prices directly softened inflation expectations, driving the U.S. Dollar Index down 0.62% and easing pressure from forward discounting. This temporarily dismantled the stagflation narrative that had recently weighed on markets, sparking an intraday rally of more than 3% in the Nasdaq and shifting cross-asset pricing away from defensive tightening and back toward bets on easing.
Cross-Market Quantitative Anomaly Radar
• U.S. Treasury auction: The U.S. Treasury auctioned $58 billion in 3-year notes. The yield awarded reached 4.627%, with a 0.5-basis-point tail. The bid-to-cover ratio of 2.53 was below average, signaling marginally weaker demand for short-term debt.
• Yen intervention: Data showed that Japan spent $50 billion intervening in the foreign exchange market in a single day. Although household spending plunged 6.8%, the Bank of Japan’s guidance that the neutral rate is well above 1% is constraining a reassessment of the U.S.-Japan rate differential.
Market Positioning and Monitoring Map
Transmission chain: Geopolitical premium recedes -> Crude oil plunges, lowering inflation expectations and weakening the dollar -> Eases discount-rate pressure on global growth stocks. Over the next 24-48 hours, bullish and bearish institutions will focus on the upcoming U.S. October core CPI month-over-month reading (0.3% as the hawkish-dovish dividing line) and the buying support for WTI crude at the key technical support level of $88.50.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; make decisions with care.
2026.11.10 · Global Macro Daily Brief
Today’s Global Macro Theme: Key Takeaways
Substantive progress in U.S.-Iran diplomatic mediation has raised expectations for the resumption of shipping through the Strait of Hormuz, unwinding crude oil’s geopolitical premium and sending benchmark oil prices down more than 4%. The pullback in energy prices has effectively eased inflation expectations, weakened the U.S. dollar, and triggered a valuation recovery in global risk assets. The core of macro pricing is shifting from supply shocks to a rebalancing of discount rates.
Today’s Main Battleground: In-Depth Analysis
Expectations of easing geopolitical tensions have broken through oil price benchmarks, ending stagflation pricing across asset classes: With the help of mediators, the U.S. and Iran reached a preliminary framework to reopen the Strait of Hormuz and unfreeze $6 billion to $9 billion in assets. WTI and Brent crude plunged more than 4% to 5% intraday, hitting their lowest levels in over two months. 【In-Depth Analysis】Crude oil’s previous elevated pricing had included a premium for the risk of shipping disruptions in the strait. Framework negotiations directly dismantled the most extreme tail risk of a crude supply cutoff, forcing the rapid unwinding of the geopolitical premium. In terms of transmission, the plunge in energy prices directly softened inflation expectations, driving the U.S. Dollar Index down 0.62% and easing pressure from forward discounting. This temporarily dismantled the stagflation narrative that had recently weighed on markets, sparking an intraday rally of more than 3% in the Nasdaq and shifting cross-asset pricing away from defensive tightening and back toward bets on easing.
Cross-Market Quantitative Anomaly Radar
• U.S. Treasury auction: The U.S. Treasury auctioned $58 billion in 3-year notes. The yield awarded reached 4.627%, with a 0.5-basis-point tail. The bid-to-cover ratio of 2.53 was below average, signaling marginally weaker demand for short-term debt.
• Yen intervention: Data showed that Japan spent $50 billion intervening in the foreign exchange market in a single day. Although household spending plunged 6.8%, the Bank of Japan’s guidance that the neutral rate is well above 1% is constraining a reassessment of the U.S.-Japan rate differential.
Market Positioning and Monitoring Map
Transmission chain: Geopolitical premium recedes -> Crude oil plunges, lowering inflation expectations and weakening the dollar -> Eases discount-rate pressure on global growth stocks. Over the next 24-48 hours, bullish and bearish institutions will focus on the upcoming U.S. October core CPI month-over-month reading (0.3% as the hawkish-dovish dividing line) and the buying support for WTI crude at the key technical support level of $88.50.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; make decisions with care.
Today’s Global Macro Theme: Key Takeaways
Substantive progress in U.S.-Iran diplomatic mediation has raised expectations for the resumption of shipping through the Strait of Hormuz, unwinding crude oil’s geopolitical premium and sending benchmark oil prices down more than 4%. The pullback in energy prices has effectively eased inflation expectations, weakened the U.S. dollar, and triggered a valuation recovery in global risk assets. The core of macro pricing is shifting from supply shocks to a rebalancing of discount rates.
Today’s Main Battleground: In-Depth Analysis
Expectations of easing geopolitical tensions have broken through oil price benchmarks, ending stagflation pricing across asset classes: With the help of mediators, the U.S. and Iran reached a preliminary framework to reopen the Strait of Hormuz and unfreeze $6 billion to $9 billion in assets. WTI and Brent crude plunged more than 4% to 5% intraday, hitting their lowest levels in over two months. 【In-Depth Analysis】Crude oil’s previous elevated pricing had included a premium for the risk of shipping disruptions in the strait. Framework negotiations directly dismantled the most extreme tail risk of a crude supply cutoff, forcing the rapid unwinding of the geopolitical premium. In terms of transmission, the plunge in energy prices directly softened inflation expectations, driving the U.S. Dollar Index down 0.62% and easing pressure from forward discounting. This temporarily dismantled the stagflation narrative that had recently weighed on markets, sparking an intraday rally of more than 3% in the Nasdaq and shifting cross-asset pricing away from defensive tightening and back toward bets on easing.
Cross-Market Quantitative Anomaly Radar
• U.S. Treasury auction: The U.S. Treasury auctioned $58 billion in 3-year notes. The yield awarded reached 4.627%, with a 0.5-basis-point tail. The bid-to-cover ratio of 2.53 was below average, signaling marginally weaker demand for short-term debt.
• Yen intervention: Data showed that Japan spent $50 billion intervening in the foreign exchange market in a single day. Although household spending plunged 6.8%, the Bank of Japan’s guidance that the neutral rate is well above 1% is constraining a reassessment of the U.S.-Japan rate differential.
Market Positioning and Monitoring Map
Transmission chain: Geopolitical premium recedes -> Crude oil plunges, lowering inflation expectations and weakening the dollar -> Eases discount-rate pressure on global growth stocks. Over the next 24-48 hours, bullish and bearish institutions will focus on the upcoming U.S. October core CPI month-over-month reading (0.3% as the hawkish-dovish dividing line) and the buying support for WTI crude at the key technical support level of $88.50.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; make decisions with care.
258
·
--
# 【11.09 Retail Trader Research Report】$BTC Sudden Market Shift! Major Macro Liquidity Drain—Who’s Accumulating Against the Trend?
Over the past 24 hours, we captured 142 breaking news alerts. The market saw a sudden, sharp shift:
1. Macro liquidity tightens: S&P 500 companies mentioned inflation 820 times in earnings reports, a new year-to-date high
2. On-chain spot and long/short positions: Bitcoin plunged to $73,510
3. Mining cash flow comes under pressure: Anthropic spent $3.4 billion on an acquisition
Trader strategy: Stay defensive and closely watch key support levels and shifts in long/short positioning.
This video presents the full in-depth analysis for this edition. For data review only; not investment advice.
#BTC #BNB #黄仁勋因婚外情致歉,英伟达启动独立调查 #Web3
# 【11.09 Retail Trader Research Report】$BTC Sudden Market Shift! Major Macro Liquidity Drain—Who’s Accumulating Against the Trend?
Over the past 24 hours, we captured 142 breaking news alerts. The market saw a sudden, sharp shift:
1. Macro liquidity tightens: S&P 500 companies mentioned inflation 820 times in earnings reports, a new year-to-date high
2. On-chain spot and long/short positions: Bitcoin plunged to $73,510
3. Mining cash flow comes under pressure: Anthropic spent $3.4 billion on an acquisition
Trader strategy: Stay defensive and closely watch key support levels and shifts in long/short positioning.
This video presents the full in-depth analysis for this edition. For data review only; not investment advice.
#BTC #BNB #黄仁勋因婚外情致歉,英伟达启动独立调查 #Web3
Over the past 24 hours, we captured 142 breaking news alerts. The market saw a sudden, sharp shift:
1. Macro liquidity tightens: S&P 500 companies mentioned inflation 820 times in earnings reports, a new year-to-date high
2. On-chain spot and long/short positions: Bitcoin plunged to $73,510
3. Mining cash flow comes under pressure: Anthropic spent $3.4 billion on an acquisition
Trader strategy: Stay defensive and closely watch key support levels and shifts in long/short positioning.
This video presents the full in-depth analysis for this edition. For data review only; not investment advice.
#BTC #BNB #黄仁勋因婚外情致歉,英伟达启动独立调查 #Web3
137
·
--
2026.11.09 · Web3 On-Chain and Crypto Asset Briefing
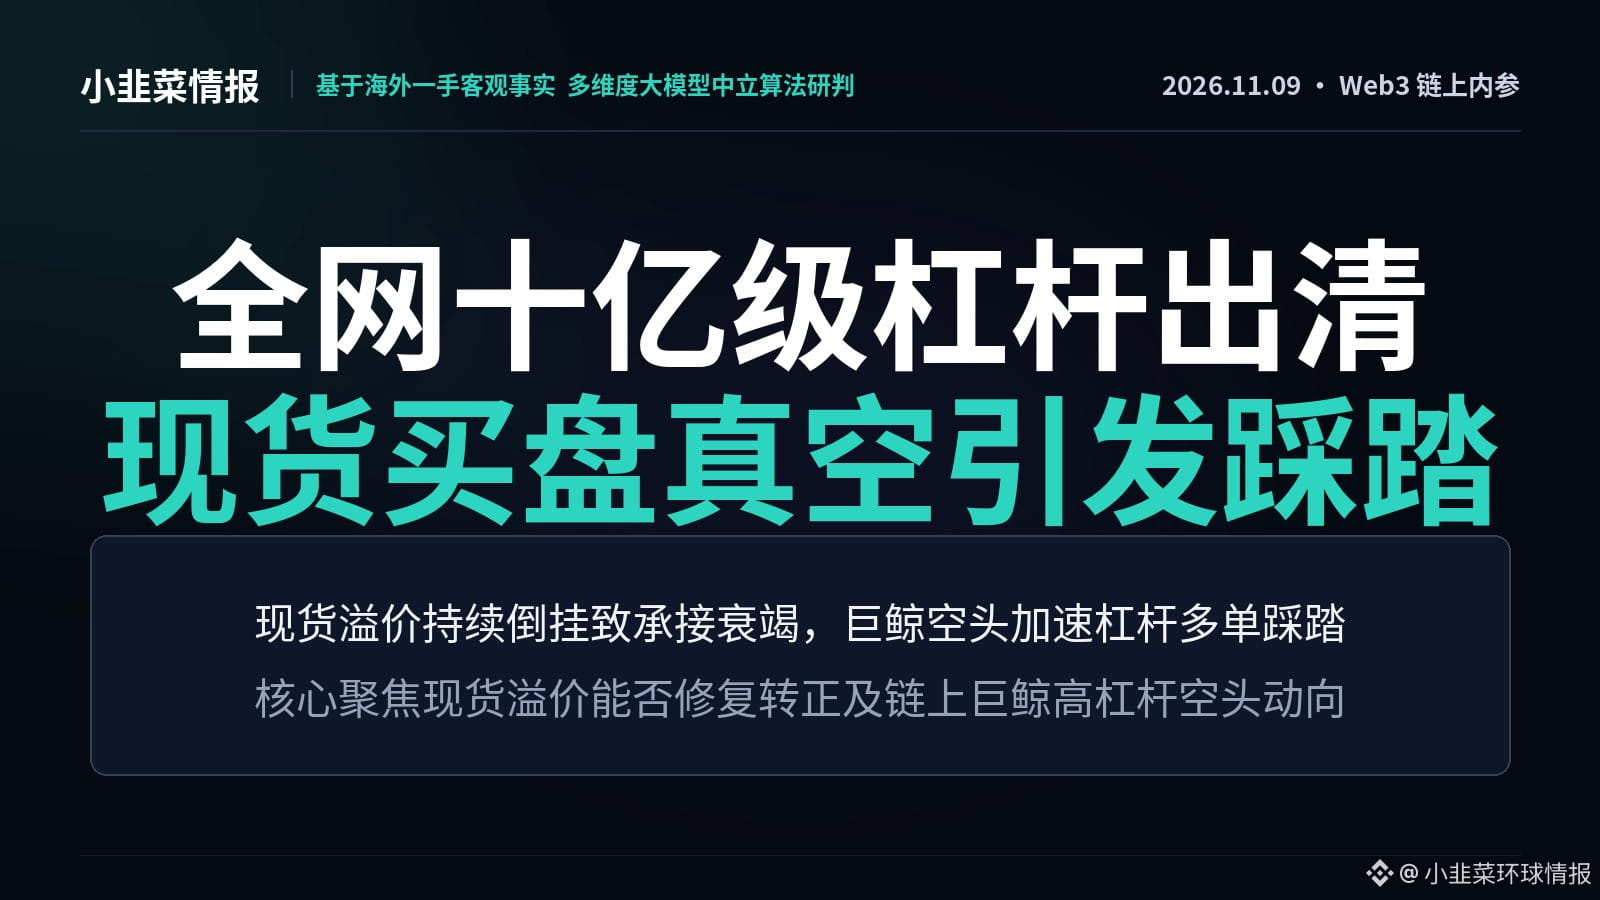
Today’s Web3 On-Chain Main Theme: Key Takeaways
Over the past 24 hours, on-chain activity has seen an extreme deleveraging event. The Coinbase Premium has remained negative for 46 consecutive days, confirming a depletion of spot demand. On the eve of the weekly close, whales applied pressure with nearly $1 billion in net on-chain shorts. The combination of thin liquidity and high leverage drove long liquidations across the market to $996 million.
Today’s Main Battleground: In-Depth Analysis
A flash crash wiped out longs ahead of the weekly close as they faced off against on-chain whale shorts: Bitcoin plunged 2.77% to $73,510 within the 15 minutes before the weekly candle closed, triggering $715 million in long liquidations within an hour. Total market liquidations over 24 hours reached $1.071 billion, including $996 million in long positions, while the ETH/BTC exchange rate fell 4.22%. At the same time, Hyperliquid whales’ net shorts approached $1 billion, with Abraxas alone accounting for $452 million. 【In-depth analysis】These market moves reveal a shift in on-chain pricing power and a breakdown in spot-market absorption. The Coinbase Premium’s 46 consecutive negative days confirm that spot buying pressure has dried up. Institutions used decentralized derivatives liquidity to precisely target leveraged longs during a low-liquidity weekend window. Redemptions by major Ethereum restaking holders, with funds flowing back to exchanges, further weakened the market’s capacity to absorb selling, ultimately triggering a market-wide cascade of long liquidations.
Market-Wide Quantitative Anomaly Radar
• Basis and miner accumulation: The Coinbase Premium has remained negative for 46 consecutive days, at -0.15%, signaling weak buying power; network hashrate fell to 1.027 ZH/s, while miners’ counter-trend accumulation of 8,087 BTC in a single week provided a buffer.
• Cross-chain money laundering and reserve drawdown: In the wake of security incidents, Binance’s BTC reserves have continued to decline from the 730,000 BTC level; hackers routed $51 million through THORChain and converted it to BTC, highlighting the oversight vacuum in decentralized finance.
Market Dynamics and Monitoring Map
Transmission mechanism: Weakening spot premiums leave order books fragile -> Trigger on-chain whales to build massive short positions -> Trigger $996 million in long liquidations at the weekly threshold. Key indicators to watch over the next 24 to 48 hours: ① Whether the Coinbase negative premium narrows to above -0.05%; ② Hyperliquid whale short-position closures and funding-rate inflection points near $73,000.
Disclaimer: This publication is solely an aggregation and review of global public information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; exercise caution when making decisions.
2026.11.09 · Web3 On-Chain and Crypto Asset Briefing
Today’s Web3 On-Chain Main Theme: Key Takeaways
Over the past 24 hours, on-chain activity has seen an extreme deleveraging event. The Coinbase Premium has remained negative for 46 consecutive days, confirming a depletion of spot demand. On the eve of the weekly close, whales applied pressure with nearly $1 billion in net on-chain shorts. The combination of thin liquidity and high leverage drove long liquidations across the market to $996 million.
Today’s Main Battleground: In-Depth Analysis
A flash crash wiped out longs ahead of the weekly close as they faced off against on-chain whale shorts: Bitcoin plunged 2.77% to $73,510 within the 15 minutes before the weekly candle closed, triggering $715 million in long liquidations within an hour. Total market liquidations over 24 hours reached $1.071 billion, including $996 million in long positions, while the ETH/BTC exchange rate fell 4.22%. At the same time, Hyperliquid whales’ net shorts approached $1 billion, with Abraxas alone accounting for $452 million. 【In-depth analysis】These market moves reveal a shift in on-chain pricing power and a breakdown in spot-market absorption. The Coinbase Premium’s 46 consecutive negative days confirm that spot buying pressure has dried up. Institutions used decentralized derivatives liquidity to precisely target leveraged longs during a low-liquidity weekend window. Redemptions by major Ethereum restaking holders, with funds flowing back to exchanges, further weakened the market’s capacity to absorb selling, ultimately triggering a market-wide cascade of long liquidations.
Market-Wide Quantitative Anomaly Radar
• Basis and miner accumulation: The Coinbase Premium has remained negative for 46 consecutive days, at -0.15%, signaling weak buying power; network hashrate fell to 1.027 ZH/s, while miners’ counter-trend accumulation of 8,087 BTC in a single week provided a buffer.
• Cross-chain money laundering and reserve drawdown: In the wake of security incidents, Binance’s BTC reserves have continued to decline from the 730,000 BTC level; hackers routed $51 million through THORChain and converted it to BTC, highlighting the oversight vacuum in decentralized finance.
Market Dynamics and Monitoring Map
Transmission mechanism: Weakening spot premiums leave order books fragile -> Trigger on-chain whales to build massive short positions -> Trigger $996 million in long liquidations at the weekly threshold. Key indicators to watch over the next 24 to 48 hours: ① Whether the Coinbase negative premium narrows to above -0.05%; ② Hyperliquid whale short-position closures and funding-rate inflection points near $73,000.
Disclaimer: This publication is solely an aggregation and review of global public information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; exercise caution when making decisions.
Today’s Web3 On-Chain Main Theme: Key Takeaways
Over the past 24 hours, on-chain activity has seen an extreme deleveraging event. The Coinbase Premium has remained negative for 46 consecutive days, confirming a depletion of spot demand. On the eve of the weekly close, whales applied pressure with nearly $1 billion in net on-chain shorts. The combination of thin liquidity and high leverage drove long liquidations across the market to $996 million.
Today’s Main Battleground: In-Depth Analysis
A flash crash wiped out longs ahead of the weekly close as they faced off against on-chain whale shorts: Bitcoin plunged 2.77% to $73,510 within the 15 minutes before the weekly candle closed, triggering $715 million in long liquidations within an hour. Total market liquidations over 24 hours reached $1.071 billion, including $996 million in long positions, while the ETH/BTC exchange rate fell 4.22%. At the same time, Hyperliquid whales’ net shorts approached $1 billion, with Abraxas alone accounting for $452 million. 【In-depth analysis】These market moves reveal a shift in on-chain pricing power and a breakdown in spot-market absorption. The Coinbase Premium’s 46 consecutive negative days confirm that spot buying pressure has dried up. Institutions used decentralized derivatives liquidity to precisely target leveraged longs during a low-liquidity weekend window. Redemptions by major Ethereum restaking holders, with funds flowing back to exchanges, further weakened the market’s capacity to absorb selling, ultimately triggering a market-wide cascade of long liquidations.
Market-Wide Quantitative Anomaly Radar
• Basis and miner accumulation: The Coinbase Premium has remained negative for 46 consecutive days, at -0.15%, signaling weak buying power; network hashrate fell to 1.027 ZH/s, while miners’ counter-trend accumulation of 8,087 BTC in a single week provided a buffer.
• Cross-chain money laundering and reserve drawdown: In the wake of security incidents, Binance’s BTC reserves have continued to decline from the 730,000 BTC level; hackers routed $51 million through THORChain and converted it to BTC, highlighting the oversight vacuum in decentralized finance.
Market Dynamics and Monitoring Map
Transmission mechanism: Weakening spot premiums leave order books fragile -> Trigger on-chain whales to build massive short positions -> Trigger $996 million in long liquidations at the weekly threshold. Key indicators to watch over the next 24 to 48 hours: ① Whether the Coinbase negative premium narrows to above -0.05%; ② Hyperliquid whale short-position closures and funding-rate inflection points near $73,000.
Disclaimer: This publication is solely an aggregation and review of global public information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; exercise caution when making decisions.
60
·
--
2026.11.09 · Frontline AI & Compute Infrastructure Briefing
Today’s Frontline AI Themes: Key Takeaways
Compute infrastructure is moving beyond a purely technical contest in algorithms and process technology, colliding head-on with three hard constraints: geopolitical security reviews, governance of key individuals, and the physical supply of electricity. The institutional fragility of single-person monopoly nodes is heightening supply-chain anxiety, prompting capital to reassess management premiums and foundational infrastructure more rapidly.
Today’s Main Battleground: In-Depth Analysis
Nvidia’s key-person governance and security reviews converge: Nvidia’s CEO publicly apologized and accepted responsibility over an external security incident. The board announced an independent investigation into whether he had become a target of foreign intelligence, while making clear that no classified information had been leaked. Congressional committees from both parties have also begun questioning the company. 【In-Depth Analysis】The foundational moat of Nvidia’s trillion-dollar compute empire is closely tied to the personal authority of its founding team over the allocation of advanced global manufacturing capacity and interconnect architectures. This investigation upends the market’s assumption that control concentrated in a single key individual is risk-free, bringing geopolitical security reviews directly into the heart of corporate governance. Congressional and board involvement will spur calls to restructure governance. The governance premium assigned to a single central node faces a discounted reassessment. Over the longer term, this will push hyperscale customers to accelerate in-house chip development and diversify supply chains, reducing dependence on a single point of control.
Panoramic Quantitative Anomaly Radar
• Energy infrastructure: Anthropic is spending $3.4 billion to directly procure gas-fired power generation equipment for its data centers. AI companies are now bypassing utility-grid approval timelines and building off-grid power supplies. Energy shortages have become the leading physical bottleneck to deploying compute capacity.
• Inference workloads: DeepSeek’s open-source agent app Harness has reached 1.54 million daily active users, with daily token consumption reaching the 92-trillion level. Autonomous coordination among high-concurrency agents is driving an explosion in inference-side compute demand and reshaping unit economics.
Market Dynamics & Monitoring Map
Key-person governance investigation → pressure on the governance premium and geopolitical compliance outlook for compute leaders → reduced valuation tolerance across large-cap technology stocks and higher hedging costs for derivatives. Key indicators to watch over the next 24 to 48 hours: whether near-term options implied volatility (IV) shows a cross-expiry inversion, and the premium levels for long-term energy supply contracts amid procurement of off-grid, self-generated power.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; exercise caution when making decisions.
2026.11.09 · Frontline AI & Compute Infrastructure Briefing
Today’s Frontline AI Themes: Key Takeaways
Compute infrastructure is moving beyond a purely technical contest in algorithms and process technology, colliding head-on with three hard constraints: geopolitical security reviews, governance of key individuals, and the physical supply of electricity. The institutional fragility of single-person monopoly nodes is heightening supply-chain anxiety, prompting capital to reassess management premiums and foundational infrastructure more rapidly.
Today’s Main Battleground: In-Depth Analysis
Nvidia’s key-person governance and security reviews converge: Nvidia’s CEO publicly apologized and accepted responsibility over an external security incident. The board announced an independent investigation into whether he had become a target of foreign intelligence, while making clear that no classified information had been leaked. Congressional committees from both parties have also begun questioning the company. 【In-Depth Analysis】The foundational moat of Nvidia’s trillion-dollar compute empire is closely tied to the personal authority of its founding team over the allocation of advanced global manufacturing capacity and interconnect architectures. This investigation upends the market’s assumption that control concentrated in a single key individual is risk-free, bringing geopolitical security reviews directly into the heart of corporate governance. Congressional and board involvement will spur calls to restructure governance. The governance premium assigned to a single central node faces a discounted reassessment. Over the longer term, this will push hyperscale customers to accelerate in-house chip development and diversify supply chains, reducing dependence on a single point of control.
Panoramic Quantitative Anomaly Radar
• Energy infrastructure: Anthropic is spending $3.4 billion to directly procure gas-fired power generation equipment for its data centers. AI companies are now bypassing utility-grid approval timelines and building off-grid power supplies. Energy shortages have become the leading physical bottleneck to deploying compute capacity.
• Inference workloads: DeepSeek’s open-source agent app Harness has reached 1.54 million daily active users, with daily token consumption reaching the 92-trillion level. Autonomous coordination among high-concurrency agents is driving an explosion in inference-side compute demand and reshaping unit economics.
Market Dynamics & Monitoring Map
Key-person governance investigation → pressure on the governance premium and geopolitical compliance outlook for compute leaders → reduced valuation tolerance across large-cap technology stocks and higher hedging costs for derivatives. Key indicators to watch over the next 24 to 48 hours: whether near-term options implied volatility (IV) shows a cross-expiry inversion, and the premium levels for long-term energy supply contracts amid procurement of off-grid, self-generated power.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; exercise caution when making decisions.
Today’s Frontline AI Themes: Key Takeaways
Compute infrastructure is moving beyond a purely technical contest in algorithms and process technology, colliding head-on with three hard constraints: geopolitical security reviews, governance of key individuals, and the physical supply of electricity. The institutional fragility of single-person monopoly nodes is heightening supply-chain anxiety, prompting capital to reassess management premiums and foundational infrastructure more rapidly.
Today’s Main Battleground: In-Depth Analysis
Nvidia’s key-person governance and security reviews converge: Nvidia’s CEO publicly apologized and accepted responsibility over an external security incident. The board announced an independent investigation into whether he had become a target of foreign intelligence, while making clear that no classified information had been leaked. Congressional committees from both parties have also begun questioning the company. 【In-Depth Analysis】The foundational moat of Nvidia’s trillion-dollar compute empire is closely tied to the personal authority of its founding team over the allocation of advanced global manufacturing capacity and interconnect architectures. This investigation upends the market’s assumption that control concentrated in a single key individual is risk-free, bringing geopolitical security reviews directly into the heart of corporate governance. Congressional and board involvement will spur calls to restructure governance. The governance premium assigned to a single central node faces a discounted reassessment. Over the longer term, this will push hyperscale customers to accelerate in-house chip development and diversify supply chains, reducing dependence on a single point of control.
Panoramic Quantitative Anomaly Radar
• Energy infrastructure: Anthropic is spending $3.4 billion to directly procure gas-fired power generation equipment for its data centers. AI companies are now bypassing utility-grid approval timelines and building off-grid power supplies. Energy shortages have become the leading physical bottleneck to deploying compute capacity.
• Inference workloads: DeepSeek’s open-source agent app Harness has reached 1.54 million daily active users, with daily token consumption reaching the 92-trillion level. Autonomous coordination among high-concurrency agents is driving an explosion in inference-side compute demand and reshaping unit economics.
Market Dynamics & Monitoring Map
Key-person governance investigation → pressure on the governance premium and geopolitical compliance outlook for compute leaders → reduced valuation tolerance across large-cap technology stocks and higher hedging costs for derivatives. Key indicators to watch over the next 24 to 48 hours: whether near-term options implied volatility (IV) shows a cross-expiry inversion, and the premium levels for long-term energy supply contracts amid procurement of off-grid, self-generated power.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; exercise caution when making decisions.
147
·
--
2026.11.09 · Global Macro Briefing
Today’s Global Macro Theme: Key Takeaways
Over the past 24 hours, the global macro narrative has centered on the convergence of a reassessment of sticky inflation and a disorderly deleveraging cascade. Volatility in U.S. equity spot and futures markets reflects hedge funds’ defensive retreat from net leverage. Combined with geopolitical energy premiums and corporate cost pressures, this has prompted a broad reassessment of long-term discount rates and asset repricing risks.
Today’s Main Battleground: In-Depth Analysis
Sharp unwinding of institutional net long-short leverage and a negative feedback loop in derivatives: Institutional estimates show that the net leverage ratio of U.S. equity long-short hedge funds plunged 5% in a single day—the fifth-largest decline since 2010—reaching a historically low level. Leveraged ETFs saw $57 billion in single-day selling, while retail investors’ early-session selling hit its second-highest level since 2016, triggering a sharp tech sell-off and volatility in equity index futures. 【In-Depth Analysis】At its core, this sell-off was a mechanical deleveraging chain reaction among quantitative volatility and risk-parity funds. Inflation mentions in S&P 500 constituent companies’ earnings reports reached a new high for the year. Combined with resilient nonfarm employment and geopolitical disruption to energy markets, this dispelled hopes of one-way monetary easing. Rising long-term discount rates directly weigh on high-valuation asset models, prompting institutions to reduce risk exposure. Market makers hedging procyclically in negative-gamma territory significantly amplified the drain of liquidity from derivatives into spot markets.
Comprehensive Quantitative Anomaly Radar
• Rising corporate inflation pressures: Inflation was mentioned 820 times in S&P 500 constituent companies’ earnings reports, a new high for the year. Combined with nonfarm payrolls and unemployment data, expectations of higher interest rates are intensifying concerns about pressure on profit margins.
• Geopolitical energy risks and quota disagreements: Iraq’s crude oil production exceeded 5 million barrels per day, intensifying disputes over Middle Eastern quotas. Although geopolitical conflict has driven up premiums, WTI has retreated 17.5% from its peak and entered a supply-demand rebalancing phase.
Market Dynamics and Monitoring Map
Inflation resilience and geopolitical energy premiums -> Higher U.S. Treasury yields and long-term discount rate expectations -> Repricing of equities and forced deleveraging in derivatives. Over the next 24 to 48 hours, institutions will focus on: 1) The actual impact of the U.S. October CPI reading on interest rate expectations; 2) Supply-demand conditions for WTI crude at the $92.5 per barrel level.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; decisions should be made with caution.
2026.11.09 · Global Macro Briefing
Today’s Global Macro Theme: Key Takeaways
Over the past 24 hours, the global macro narrative has centered on the convergence of a reassessment of sticky inflation and a disorderly deleveraging cascade. Volatility in U.S. equity spot and futures markets reflects hedge funds’ defensive retreat from net leverage. Combined with geopolitical energy premiums and corporate cost pressures, this has prompted a broad reassessment of long-term discount rates and asset repricing risks.
Today’s Main Battleground: In-Depth Analysis
Sharp unwinding of institutional net long-short leverage and a negative feedback loop in derivatives: Institutional estimates show that the net leverage ratio of U.S. equity long-short hedge funds plunged 5% in a single day—the fifth-largest decline since 2010—reaching a historically low level. Leveraged ETFs saw $57 billion in single-day selling, while retail investors’ early-session selling hit its second-highest level since 2016, triggering a sharp tech sell-off and volatility in equity index futures. 【In-Depth Analysis】At its core, this sell-off was a mechanical deleveraging chain reaction among quantitative volatility and risk-parity funds. Inflation mentions in S&P 500 constituent companies’ earnings reports reached a new high for the year. Combined with resilient nonfarm employment and geopolitical disruption to energy markets, this dispelled hopes of one-way monetary easing. Rising long-term discount rates directly weigh on high-valuation asset models, prompting institutions to reduce risk exposure. Market makers hedging procyclically in negative-gamma territory significantly amplified the drain of liquidity from derivatives into spot markets.
Comprehensive Quantitative Anomaly Radar
• Rising corporate inflation pressures: Inflation was mentioned 820 times in S&P 500 constituent companies’ earnings reports, a new high for the year. Combined with nonfarm payrolls and unemployment data, expectations of higher interest rates are intensifying concerns about pressure on profit margins.
• Geopolitical energy risks and quota disagreements: Iraq’s crude oil production exceeded 5 million barrels per day, intensifying disputes over Middle Eastern quotas. Although geopolitical conflict has driven up premiums, WTI has retreated 17.5% from its peak and entered a supply-demand rebalancing phase.
Market Dynamics and Monitoring Map
Inflation resilience and geopolitical energy premiums -> Higher U.S. Treasury yields and long-term discount rate expectations -> Repricing of equities and forced deleveraging in derivatives. Over the next 24 to 48 hours, institutions will focus on: 1) The actual impact of the U.S. October CPI reading on interest rate expectations; 2) Supply-demand conditions for WTI crude at the $92.5 per barrel level.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; decisions should be made with caution.
Today’s Global Macro Theme: Key Takeaways
Over the past 24 hours, the global macro narrative has centered on the convergence of a reassessment of sticky inflation and a disorderly deleveraging cascade. Volatility in U.S. equity spot and futures markets reflects hedge funds’ defensive retreat from net leverage. Combined with geopolitical energy premiums and corporate cost pressures, this has prompted a broad reassessment of long-term discount rates and asset repricing risks.
Today’s Main Battleground: In-Depth Analysis
Sharp unwinding of institutional net long-short leverage and a negative feedback loop in derivatives: Institutional estimates show that the net leverage ratio of U.S. equity long-short hedge funds plunged 5% in a single day—the fifth-largest decline since 2010—reaching a historically low level. Leveraged ETFs saw $57 billion in single-day selling, while retail investors’ early-session selling hit its second-highest level since 2016, triggering a sharp tech sell-off and volatility in equity index futures. 【In-Depth Analysis】At its core, this sell-off was a mechanical deleveraging chain reaction among quantitative volatility and risk-parity funds. Inflation mentions in S&P 500 constituent companies’ earnings reports reached a new high for the year. Combined with resilient nonfarm employment and geopolitical disruption to energy markets, this dispelled hopes of one-way monetary easing. Rising long-term discount rates directly weigh on high-valuation asset models, prompting institutions to reduce risk exposure. Market makers hedging procyclically in negative-gamma territory significantly amplified the drain of liquidity from derivatives into spot markets.
Comprehensive Quantitative Anomaly Radar
• Rising corporate inflation pressures: Inflation was mentioned 820 times in S&P 500 constituent companies’ earnings reports, a new high for the year. Combined with nonfarm payrolls and unemployment data, expectations of higher interest rates are intensifying concerns about pressure on profit margins.
• Geopolitical energy risks and quota disagreements: Iraq’s crude oil production exceeded 5 million barrels per day, intensifying disputes over Middle Eastern quotas. Although geopolitical conflict has driven up premiums, WTI has retreated 17.5% from its peak and entered a supply-demand rebalancing phase.
Market Dynamics and Monitoring Map
Inflation resilience and geopolitical energy premiums -> Higher U.S. Treasury yields and long-term discount rate expectations -> Repricing of equities and forced deleveraging in derivatives. Over the next 24 to 48 hours, institutions will focus on: 1) The actual impact of the U.S. October CPI reading on interest rate expectations; 2) Supply-demand conditions for WTI crude at the $92.5 per barrel level.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; decisions should be made with caution.
198
·
--
【Little Retail Investor Global Intelligence】2026.11.08 Core Briefing: At a Glance
🏛 Macro Liquidity
• Nonfarm payrolls rose by 165,000, far exceeding expectations. The probability of a December rate hike surged to 80%, and long-dated U.S. Treasuries rallied sharply.
• The U.S. military’s Iron Gate task force imposed a full blockade, costing Iran more than $25 billion in crude oil revenue.
🪙 Web3 On-Chain Ecosystem
• $BTC fell below 76,000, and $Ahr999 dropped to 0.4310, returning to the buy-the-dip zone; 70% of altcoins across the market fell below their 200-day moving averages.
• FinCEN cut MEXC off from the U.S. financial system over $16 billion in sanctioned funds. Net outflows reached $35.28 million in a single day; OKX launched proactive anti-money-laundering risk controls, and market maker Reserve withdrew liquidity.
• Wintermute made $222 million shorting major cryptocurrencies and still holds $115 million in short positions; a whale withdrew 13,080 $ETH from Binance over six days (worth approximately $30 million).
⚡ Frontier AI Computing Power
• Free cash flow at the four major cloud giants turned negative across the board, with a quarterly funding shortfall of $26.4 billion; Microsoft slashed its budget by $5 billion.
🧭 Key Indicators for Traders to Watch Over the Next 48 Hours:
1. Whether BTC can find support at the $75,500 cost-basis level
2. Whether the 10-year U.S. Treasury yield can break above its previous high
(A deep-dive video with firsthand insights is now available. Visit our profile to watch.)
#BinanceSquare #BTC #ETH #Web3 #MacroAnalysis
【Little Retail Investor Global Intelligence】2026.11.08 Core Briefing: At a Glance
🏛 Macro Liquidity
• Nonfarm payrolls rose by 165,000, far exceeding expectations. The probability of a December rate hike surged to 80%, and long-dated U.S. Treasuries rallied sharply.
• The U.S. military’s Iron Gate task force imposed a full blockade, costing Iran more than $25 billion in crude oil revenue.
🪙 Web3 On-Chain Ecosystem
• $BTC fell below 76,000, and $Ahr999 dropped to 0.4310, returning to the buy-the-dip zone; 70% of altcoins across the market fell below their 200-day moving averages.
• FinCEN cut MEXC off from the U.S. financial system over $16 billion in sanctioned funds. Net outflows reached $35.28 million in a single day; OKX launched proactive anti-money-laundering risk controls, and market maker Reserve withdrew liquidity.
• Wintermute made $222 million shorting major cryptocurrencies and still holds $115 million in short positions; a whale withdrew 13,080 $ETH from Binance over six days (worth approximately $30 million).
⚡ Frontier AI Computing Power
• Free cash flow at the four major cloud giants turned negative across the board, with a quarterly funding shortfall of $26.4 billion; Microsoft slashed its budget by $5 billion.
🧭 Key Indicators for Traders to Watch Over the Next 48 Hours:
1. Whether BTC can find support at the $75,500 cost-basis level
2. Whether the 10-year U.S. Treasury yield can break above its previous high
(A deep-dive video with firsthand insights is now available. Visit our profile to watch.)
#BinanceSquare #BTC #ETH #Web3 #MacroAnalysis
🏛 Macro Liquidity
• Nonfarm payrolls rose by 165,000, far exceeding expectations. The probability of a December rate hike surged to 80%, and long-dated U.S. Treasuries rallied sharply.
• The U.S. military’s Iron Gate task force imposed a full blockade, costing Iran more than $25 billion in crude oil revenue.
🪙 Web3 On-Chain Ecosystem
• $BTC fell below 76,000, and $Ahr999 dropped to 0.4310, returning to the buy-the-dip zone; 70% of altcoins across the market fell below their 200-day moving averages.
• FinCEN cut MEXC off from the U.S. financial system over $16 billion in sanctioned funds. Net outflows reached $35.28 million in a single day; OKX launched proactive anti-money-laundering risk controls, and market maker Reserve withdrew liquidity.
• Wintermute made $222 million shorting major cryptocurrencies and still holds $115 million in short positions; a whale withdrew 13,080 $ETH from Binance over six days (worth approximately $30 million).
⚡ Frontier AI Computing Power
• Free cash flow at the four major cloud giants turned negative across the board, with a quarterly funding shortfall of $26.4 billion; Microsoft slashed its budget by $5 billion.
🧭 Key Indicators for Traders to Watch Over the Next 48 Hours:
1. Whether BTC can find support at the $75,500 cost-basis level
2. Whether the 10-year U.S. Treasury yield can break above its previous high
(A deep-dive video with firsthand insights is now available. Visit our profile to watch.)
#BinanceSquare #BTC #ETH #Web3 #MacroAnalysis
39
·
--
2026.11.08 · Web3 On-Chain and Crypto Asset Briefing
Today's Web3 On-Chain Main Themes: Key Takeaways
A retreat in U.S. tech stocks has tightened macro liquidity, putting downward pressure on crypto spot valuations across the board, with Bitcoin falling below the $76,000 mark. Meanwhile, a new Ethereum protocol feature has exposed a signing vulnerability in institutional multi-chain hot wallets, putting underlying custody defenses to the test. Secondary-market deleveraging and friction over infrastructure trust are reinforcing one another.
Today's Main Battleground: A Deep Dive
Ethereum's EIP-7702 protocol feature exposes blind spots in institutional multi-chain custody: On-chain data shows that attackers exploited a new mechanism in Ethereum's EIP-7702 account abstraction proposal to infiltrate exchange hot-wallet addresses across Ethereum, Arbitrum, and other chains, resulting in abnormal cross-chain transfers of large assets. [Deep Dive] EIP-7702 allows ordinary EOAs to temporarily acquire the ability to execute contract code, but this mechanism breaks the traditional assumption that institutional custody can rely on static isolation of external account permissions. If risk-control gateways do not deeply parse the semantics of dynamically authorized signatures, attackers can use valid private-key signatures to execute malicious contract proxies. This incident reveals how large platforms, in seeking to improve cross-chain settlement efficiency, have overgeneralized permissions for generic signatures, creating a security gap with underlying protocol innovations. It not only undermines confidence in hot wallets but also forces market makers to reduce their turnover exposure, intensifying defensive liquidity constraints on-chain.
Panoramic Quantitative Anomaly Radar
• Spot asset valuations: Amid a retreat in macro liquidity, Bitcoin fell below $76,000 and the Ahr999 valuation dropped below the 0.45 critical threshold, indicating that on-chain buying support is facing systemic pressure.
• Market-wide liquidity: Excluding dominant assets, market capitalization fell by about $200 billion, erasing the previous 63% gain. 70% of tokens on the platform fell below their 200-day moving averages, indicating a broad retreat in risk appetite.
Market Dynamics and Monitoring Map
The retreat in macro AI trading is prompting institutional deleveraging -> spilling over into crypto spot markets and narrowing derivatives basis spreads -> ultimately hitting altcoins and liquidity in on-chain DEX depth pools. Over the next 24–48 hours, closely monitor actual turnover and absorption levels in Bitcoin's $75,500 high-concentration zone, as well as fluctuations in net deposits and withdrawals from major exchanges' multi-chain wallets during contract audits.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; make decisions with caution.
2026.11.08 · Web3 On-Chain and Crypto Asset Briefing
Today's Web3 On-Chain Main Themes: Key Takeaways
A retreat in U.S. tech stocks has tightened macro liquidity, putting downward pressure on crypto spot valuations across the board, with Bitcoin falling below the $76,000 mark. Meanwhile, a new Ethereum protocol feature has exposed a signing vulnerability in institutional multi-chain hot wallets, putting underlying custody defenses to the test. Secondary-market deleveraging and friction over infrastructure trust are reinforcing one another.
Today's Main Battleground: A Deep Dive
Ethereum's EIP-7702 protocol feature exposes blind spots in institutional multi-chain custody: On-chain data shows that attackers exploited a new mechanism in Ethereum's EIP-7702 account abstraction proposal to infiltrate exchange hot-wallet addresses across Ethereum, Arbitrum, and other chains, resulting in abnormal cross-chain transfers of large assets. [Deep Dive] EIP-7702 allows ordinary EOAs to temporarily acquire the ability to execute contract code, but this mechanism breaks the traditional assumption that institutional custody can rely on static isolation of external account permissions. If risk-control gateways do not deeply parse the semantics of dynamically authorized signatures, attackers can use valid private-key signatures to execute malicious contract proxies. This incident reveals how large platforms, in seeking to improve cross-chain settlement efficiency, have overgeneralized permissions for generic signatures, creating a security gap with underlying protocol innovations. It not only undermines confidence in hot wallets but also forces market makers to reduce their turnover exposure, intensifying defensive liquidity constraints on-chain.
Panoramic Quantitative Anomaly Radar
• Spot asset valuations: Amid a retreat in macro liquidity, Bitcoin fell below $76,000 and the Ahr999 valuation dropped below the 0.45 critical threshold, indicating that on-chain buying support is facing systemic pressure.
• Market-wide liquidity: Excluding dominant assets, market capitalization fell by about $200 billion, erasing the previous 63% gain. 70% of tokens on the platform fell below their 200-day moving averages, indicating a broad retreat in risk appetite.
Market Dynamics and Monitoring Map
The retreat in macro AI trading is prompting institutional deleveraging -> spilling over into crypto spot markets and narrowing derivatives basis spreads -> ultimately hitting altcoins and liquidity in on-chain DEX depth pools. Over the next 24–48 hours, closely monitor actual turnover and absorption levels in Bitcoin's $75,500 high-concentration zone, as well as fluctuations in net deposits and withdrawals from major exchanges' multi-chain wallets during contract audits.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; make decisions with caution.
Today's Web3 On-Chain Main Themes: Key Takeaways
A retreat in U.S. tech stocks has tightened macro liquidity, putting downward pressure on crypto spot valuations across the board, with Bitcoin falling below the $76,000 mark. Meanwhile, a new Ethereum protocol feature has exposed a signing vulnerability in institutional multi-chain hot wallets, putting underlying custody defenses to the test. Secondary-market deleveraging and friction over infrastructure trust are reinforcing one another.
Today's Main Battleground: A Deep Dive
Ethereum's EIP-7702 protocol feature exposes blind spots in institutional multi-chain custody: On-chain data shows that attackers exploited a new mechanism in Ethereum's EIP-7702 account abstraction proposal to infiltrate exchange hot-wallet addresses across Ethereum, Arbitrum, and other chains, resulting in abnormal cross-chain transfers of large assets. [Deep Dive] EIP-7702 allows ordinary EOAs to temporarily acquire the ability to execute contract code, but this mechanism breaks the traditional assumption that institutional custody can rely on static isolation of external account permissions. If risk-control gateways do not deeply parse the semantics of dynamically authorized signatures, attackers can use valid private-key signatures to execute malicious contract proxies. This incident reveals how large platforms, in seeking to improve cross-chain settlement efficiency, have overgeneralized permissions for generic signatures, creating a security gap with underlying protocol innovations. It not only undermines confidence in hot wallets but also forces market makers to reduce their turnover exposure, intensifying defensive liquidity constraints on-chain.
Panoramic Quantitative Anomaly Radar
• Spot asset valuations: Amid a retreat in macro liquidity, Bitcoin fell below $76,000 and the Ahr999 valuation dropped below the 0.45 critical threshold, indicating that on-chain buying support is facing systemic pressure.
• Market-wide liquidity: Excluding dominant assets, market capitalization fell by about $200 billion, erasing the previous 63% gain. 70% of tokens on the platform fell below their 200-day moving averages, indicating a broad retreat in risk appetite.
Market Dynamics and Monitoring Map
The retreat in macro AI trading is prompting institutional deleveraging -> spilling over into crypto spot markets and narrowing derivatives basis spreads -> ultimately hitting altcoins and liquidity in on-chain DEX depth pools. Over the next 24–48 hours, closely monitor actual turnover and absorption levels in Bitcoin's $75,500 high-concentration zone, as well as fluctuations in net deposits and withdrawals from major exchanges' multi-chain wallets during contract audits.
Disclaimer: This publication is solely an aggregated review and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; make decisions with caution.
63
·
--
2026.11.08 · Frontier AI and Compute Infrastructure Briefing
Today’s Frontier AI Themes: Key Takeaways
The AI arms race among North American tech giants is running into structural bottlenecks in the delivery of physical infrastructure, following earlier constraints on chip supply. Microsoft cut spending by $5 billion due to delays at third-party data centers, while the four major cloud providers saw free cash flow turn negative. This marks a decisive shift in market focus toward delivery certainty and validation of investment returns.
Today’s Main Battleground: In-Depth Analysis
Data center delivery bottlenecks trigger spending cuts: Because a third-party data center was not delivered on schedule, Microsoft’s third-quarter capital expenditure came in approximately $5 billion below plan. U.S. tech giants also lost more than $1 trillion in market value in a single day amid massive AI investments and negative free cash flow. [In-depth analysis] The hard constraints on compute infrastructure have shifted decisively from semiconductor wafer manufacturing to physical bottlenecks: connecting to public power grids, expanding substations, and completing water-cooling construction. The disconnect between giants’ long-term spending guidance and their near-term execution capacity not only exposes a severe mismatch between the breakneck pace of compute expansion and public infrastructure timelines, but also creates temporary delivery bottlenecks for upstream hardware shipments. Squeezed by massive depreciation costs and short-term monetization falling short of expectations, cloud giants are being forced to seek a precarious balance between the pace of capital spending and balance-sheet quality.
Panoramic Quantitative Anomaly Radar
• Regulatory compliance deep dive: The China-linked entity authorized by the U.S. Department of Commerce to handle Nvidia H200 chips was reportedly vacant and connected to a sanctions list, signaling that re-export channels for advanced computing and compliance review procedures face substantive tightening and retrospective scrutiny.
• Semiconductor valuation reset: The Philadelphia Semiconductor Index plunged 12% in a single day, its second-largest drop on record. Although historical data shows nearly a 70% probability of a rebound after an oversold decline, elevated volatility is directly intensifying tests of valuation support across the compute supply chain.
Market Dynamics and Monitoring Map
Data center construction delays -> constrain the actual deployment of cloud giants’ Capex -> weaken near-term order momentum for upstream chips -> trigger liquidity rebalancing in high-valuation compute sectors. Over the next 24 to 48 hours, institutions will focus on two commercialization and engineering indicators: first, progress on revisions to third-party data center permitting, grid connection, and delivery milestones; second, the skew of implied volatility (IV) in semiconductor options and its level relative to the mean.
Disclaimer: This publication is solely an aggregation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading activity. Markets involve risk; make decisions with caution.
2026.11.08 · Frontier AI and Compute Infrastructure Briefing
Today’s Frontier AI Themes: Key Takeaways
The AI arms race among North American tech giants is running into structural bottlenecks in the delivery of physical infrastructure, following earlier constraints on chip supply. Microsoft cut spending by $5 billion due to delays at third-party data centers, while the four major cloud providers saw free cash flow turn negative. This marks a decisive shift in market focus toward delivery certainty and validation of investment returns.
Today’s Main Battleground: In-Depth Analysis
Data center delivery bottlenecks trigger spending cuts: Because a third-party data center was not delivered on schedule, Microsoft’s third-quarter capital expenditure came in approximately $5 billion below plan. U.S. tech giants also lost more than $1 trillion in market value in a single day amid massive AI investments and negative free cash flow. [In-depth analysis] The hard constraints on compute infrastructure have shifted decisively from semiconductor wafer manufacturing to physical bottlenecks: connecting to public power grids, expanding substations, and completing water-cooling construction. The disconnect between giants’ long-term spending guidance and their near-term execution capacity not only exposes a severe mismatch between the breakneck pace of compute expansion and public infrastructure timelines, but also creates temporary delivery bottlenecks for upstream hardware shipments. Squeezed by massive depreciation costs and short-term monetization falling short of expectations, cloud giants are being forced to seek a precarious balance between the pace of capital spending and balance-sheet quality.
Panoramic Quantitative Anomaly Radar
• Regulatory compliance deep dive: The China-linked entity authorized by the U.S. Department of Commerce to handle Nvidia H200 chips was reportedly vacant and connected to a sanctions list, signaling that re-export channels for advanced computing and compliance review procedures face substantive tightening and retrospective scrutiny.
• Semiconductor valuation reset: The Philadelphia Semiconductor Index plunged 12% in a single day, its second-largest drop on record. Although historical data shows nearly a 70% probability of a rebound after an oversold decline, elevated volatility is directly intensifying tests of valuation support across the compute supply chain.
Market Dynamics and Monitoring Map
Data center construction delays -> constrain the actual deployment of cloud giants’ Capex -> weaken near-term order momentum for upstream chips -> trigger liquidity rebalancing in high-valuation compute sectors. Over the next 24 to 48 hours, institutions will focus on two commercialization and engineering indicators: first, progress on revisions to third-party data center permitting, grid connection, and delivery milestones; second, the skew of implied volatility (IV) in semiconductor options and its level relative to the mean.
Disclaimer: This publication is solely an aggregation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading activity. Markets involve risk; make decisions with caution.
Today’s Frontier AI Themes: Key Takeaways
The AI arms race among North American tech giants is running into structural bottlenecks in the delivery of physical infrastructure, following earlier constraints on chip supply. Microsoft cut spending by $5 billion due to delays at third-party data centers, while the four major cloud providers saw free cash flow turn negative. This marks a decisive shift in market focus toward delivery certainty and validation of investment returns.
Today’s Main Battleground: In-Depth Analysis
Data center delivery bottlenecks trigger spending cuts: Because a third-party data center was not delivered on schedule, Microsoft’s third-quarter capital expenditure came in approximately $5 billion below plan. U.S. tech giants also lost more than $1 trillion in market value in a single day amid massive AI investments and negative free cash flow. [In-depth analysis] The hard constraints on compute infrastructure have shifted decisively from semiconductor wafer manufacturing to physical bottlenecks: connecting to public power grids, expanding substations, and completing water-cooling construction. The disconnect between giants’ long-term spending guidance and their near-term execution capacity not only exposes a severe mismatch between the breakneck pace of compute expansion and public infrastructure timelines, but also creates temporary delivery bottlenecks for upstream hardware shipments. Squeezed by massive depreciation costs and short-term monetization falling short of expectations, cloud giants are being forced to seek a precarious balance between the pace of capital spending and balance-sheet quality.
Panoramic Quantitative Anomaly Radar
• Regulatory compliance deep dive: The China-linked entity authorized by the U.S. Department of Commerce to handle Nvidia H200 chips was reportedly vacant and connected to a sanctions list, signaling that re-export channels for advanced computing and compliance review procedures face substantive tightening and retrospective scrutiny.
• Semiconductor valuation reset: The Philadelphia Semiconductor Index plunged 12% in a single day, its second-largest drop on record. Although historical data shows nearly a 70% probability of a rebound after an oversold decline, elevated volatility is directly intensifying tests of valuation support across the compute supply chain.
Market Dynamics and Monitoring Map
Data center construction delays -> constrain the actual deployment of cloud giants’ Capex -> weaken near-term order momentum for upstream chips -> trigger liquidity rebalancing in high-valuation compute sectors. Over the next 24 to 48 hours, institutions will focus on two commercialization and engineering indicators: first, progress on revisions to third-party data center permitting, grid connection, and delivery milestones; second, the skew of implied volatility (IV) in semiconductor options and its level relative to the mean.
Disclaimer: This publication is solely an aggregation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading activity. Markets involve risk; make decisions with caution.
128
·
--
2026.11.08 · Global Macro Intelligence Brief
Today’s Global Macro Narrative: Key Takeaways
Stronger-than-expected employment data and the risk of geopolitical disruptions to logistics in the Middle East are combining to reignite market pricing of reflation and persistently high interest rates. A rapid rise in long-term U.S. Treasury discount rates is directly weighing on high-valuation technology assets. Cross-asset liquidity worldwide is showing signs of contraction and defensive positioning, as capital weighs the payback period on spending against deleveraging pressures.
Today’s Main Battleground: In-Depth Analysis
Reflation expectations and a repricing of discount rates for technology assets: Robust nonfarm payrolls and a geopolitical energy risk premium are combining to fuel expectations of a repricing of the Federal Reserve’s policy rate. This has triggered a broad sell-off in high-valuation growth sectors, while markets reassess the payback period for massive capital spending across the AI supply chain and valuations in light of a potential shift in regulation of computing infrastructure. [In-depth analysis] The core mechanism behind this volatility is the valuation pressure exerted when rising risk-free long-term rates reduce the present value of future cash flows from long-duration technology assets. Investments in computing infrastructure and data centers, whose valuations previously benefited from ample liquidity and expanding premiums, are showing cracks under the combined pressure of persistently high financing costs and uncertain commercial returns. Against a backdrop of rising long-term U.S. Treasury yields, institutional funds are shifting toward liquidity protection, amplifying the unwinding of cross-asset spread trades and the transmission of macro volatility.
Cross-Market Quantitative Anomaly Radar
• Crypto reserves go public: BNC completed a $500 million private placement and established a reserve of more than 510,000 BNB, listing on Nasdaq. This reflects the deepening of a liquidity-arbitrage mechanism through which institutions use traditional equity vehicles to gain compliant exposure to crypto assets.
• Geopolitical disruption to crude oil supply and demand: U.S. Central Command formed a task force to cut Iran’s overland supply lines. The geopolitical shock is disrupting Brent crude’s traditional seasonal spread patterns, reshaping commodity premium structures around sudden risks.
Market Positioning and Monitoring Map
Rising geopolitical risk boosts energy premiums, while resilient employment -> pushes up long-term U.S. Treasury yields and inflation expectations -> squeezes the valuation headroom of high-valuation assets and cross-market liquidity. Over the next 24 to 48 hours, institutional funds will focus on movements around key resistance levels for the 10-year U.S. Treasury yield, and on whether the Brent crude prompt-to-deferred spread maintains its backwardation and geopolitical premium.
Disclaimer: This publication is solely an aggregation and synthesis of publicly available global information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; decisions should be made with caution.
2026.11.08 · Global Macro Intelligence Brief
Today’s Global Macro Narrative: Key Takeaways
Stronger-than-expected employment data and the risk of geopolitical disruptions to logistics in the Middle East are combining to reignite market pricing of reflation and persistently high interest rates. A rapid rise in long-term U.S. Treasury discount rates is directly weighing on high-valuation technology assets. Cross-asset liquidity worldwide is showing signs of contraction and defensive positioning, as capital weighs the payback period on spending against deleveraging pressures.
Today’s Main Battleground: In-Depth Analysis
Reflation expectations and a repricing of discount rates for technology assets: Robust nonfarm payrolls and a geopolitical energy risk premium are combining to fuel expectations of a repricing of the Federal Reserve’s policy rate. This has triggered a broad sell-off in high-valuation growth sectors, while markets reassess the payback period for massive capital spending across the AI supply chain and valuations in light of a potential shift in regulation of computing infrastructure. [In-depth analysis] The core mechanism behind this volatility is the valuation pressure exerted when rising risk-free long-term rates reduce the present value of future cash flows from long-duration technology assets. Investments in computing infrastructure and data centers, whose valuations previously benefited from ample liquidity and expanding premiums, are showing cracks under the combined pressure of persistently high financing costs and uncertain commercial returns. Against a backdrop of rising long-term U.S. Treasury yields, institutional funds are shifting toward liquidity protection, amplifying the unwinding of cross-asset spread trades and the transmission of macro volatility.
Cross-Market Quantitative Anomaly Radar
• Crypto reserves go public: BNC completed a $500 million private placement and established a reserve of more than 510,000 BNB, listing on Nasdaq. This reflects the deepening of a liquidity-arbitrage mechanism through which institutions use traditional equity vehicles to gain compliant exposure to crypto assets.
• Geopolitical disruption to crude oil supply and demand: U.S. Central Command formed a task force to cut Iran’s overland supply lines. The geopolitical shock is disrupting Brent crude’s traditional seasonal spread patterns, reshaping commodity premium structures around sudden risks.
Market Positioning and Monitoring Map
Rising geopolitical risk boosts energy premiums, while resilient employment -> pushes up long-term U.S. Treasury yields and inflation expectations -> squeezes the valuation headroom of high-valuation assets and cross-market liquidity. Over the next 24 to 48 hours, institutional funds will focus on movements around key resistance levels for the 10-year U.S. Treasury yield, and on whether the Brent crude prompt-to-deferred spread maintains its backwardation and geopolitical premium.
Disclaimer: This publication is solely an aggregation and synthesis of publicly available global information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; decisions should be made with caution.
Today’s Global Macro Narrative: Key Takeaways
Stronger-than-expected employment data and the risk of geopolitical disruptions to logistics in the Middle East are combining to reignite market pricing of reflation and persistently high interest rates. A rapid rise in long-term U.S. Treasury discount rates is directly weighing on high-valuation technology assets. Cross-asset liquidity worldwide is showing signs of contraction and defensive positioning, as capital weighs the payback period on spending against deleveraging pressures.
Today’s Main Battleground: In-Depth Analysis
Reflation expectations and a repricing of discount rates for technology assets: Robust nonfarm payrolls and a geopolitical energy risk premium are combining to fuel expectations of a repricing of the Federal Reserve’s policy rate. This has triggered a broad sell-off in high-valuation growth sectors, while markets reassess the payback period for massive capital spending across the AI supply chain and valuations in light of a potential shift in regulation of computing infrastructure. [In-depth analysis] The core mechanism behind this volatility is the valuation pressure exerted when rising risk-free long-term rates reduce the present value of future cash flows from long-duration technology assets. Investments in computing infrastructure and data centers, whose valuations previously benefited from ample liquidity and expanding premiums, are showing cracks under the combined pressure of persistently high financing costs and uncertain commercial returns. Against a backdrop of rising long-term U.S. Treasury yields, institutional funds are shifting toward liquidity protection, amplifying the unwinding of cross-asset spread trades and the transmission of macro volatility.
Cross-Market Quantitative Anomaly Radar
• Crypto reserves go public: BNC completed a $500 million private placement and established a reserve of more than 510,000 BNB, listing on Nasdaq. This reflects the deepening of a liquidity-arbitrage mechanism through which institutions use traditional equity vehicles to gain compliant exposure to crypto assets.
• Geopolitical disruption to crude oil supply and demand: U.S. Central Command formed a task force to cut Iran’s overland supply lines. The geopolitical shock is disrupting Brent crude’s traditional seasonal spread patterns, reshaping commodity premium structures around sudden risks.
Market Positioning and Monitoring Map
Rising geopolitical risk boosts energy premiums, while resilient employment -> pushes up long-term U.S. Treasury yields and inflation expectations -> squeezes the valuation headroom of high-valuation assets and cross-market liquidity. Over the next 24 to 48 hours, institutional funds will focus on movements around key resistance levels for the 10-year U.S. Treasury yield, and on whether the Brent crude prompt-to-deferred spread maintains its backwardation and geopolitical premium.
Disclaimer: This publication is solely an aggregation and synthesis of publicly available global information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; decisions should be made with caution.
324
·
--
2026.11.07 · Web3 On-Chain and Crypto Asset Briefing
Today's Web3 On-Chain Main Theme: Key Takeaways
Amid spillover from a tech stock sell-off and tighter regulatory expectations, compliant channels have seen liquidity withdrawn, with net outflows from spot Bitcoin ETFs reaching $430 million in a single day. Institutions in the market are showing defensive de-risking behavior, while sovereign funds still show signs of countercyclical allocation. On-chain competition is also extending into underlying quantum-resistant defenses.
Today's Main Battleground: In-Depth Analysis
Spot ETF net outflows reached $430 million, sharply increasing de-risking pressure on institutional channels: Dragged down by a steep decline in U.S. technology stocks, U.S. spot Bitcoin ETFs saw $430 million in net outflows in a single day, with BlackRock and Fidelity leading withdrawals. [In-Depth Analysis] This volatility confirms the strong coupling between compliant channels and traditional macro liquidity. Spot ETFs embed crypto assets in the traditional financial system. When tech stock valuations undergo a correction alongside increased expectations of regulatory scrutiny by both chambers of Congress, hedge funds and market makers quickly cut high-beta exposure to meet liquidity needs. This transmission of de-risking from external equity markets to crypto spot markets breaks the structure in which holdings were locked in one direction, limiting the depth available to absorb buy orders and clearly demonstrating how compliant channels can transmit liquidity shocks in both directions amid macro volatility.
Comprehensive Quantitative Anomaly Radar
• Upgrading cryptographic defenses: Core developers have proposed introducing a staking penalty mechanism for transfers from addresses with exposed public keys. Combined with the Falcon-1024 lattice-based scheme, this would raise the cost of quantum theft from long-dormant historical holdings.
• Diverging holding patterns: The U.S. midterm elections have heightened market expectations of stricter regulatory scrutiny, but sovereign funds continue to accumulate on-chain against the trend, reflecting a structural divergence in short- and long-term holding strategies.
Market Dynamics and Monitoring Map
Valuation volatility in U.S. technology stocks -> triggers redemption pressure on ETFs in compliant channels -> drains highly liquid buying depth from spot markets. Over the next 24–48 hours, institutions will closely monitor whether next-day net redemptions from spot ETFs narrow to below $150 million, and whether the Coinbase premium can recover above zero, to assess the pace at which macro spillover risks are fading.
Disclaimer: This publication is solely an aggregation and analysis of global public information and objective market data from the past 24 hours, along with logical inferences. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; make decisions with caution.
2026.11.07 · Web3 On-Chain and Crypto Asset Briefing
Today's Web3 On-Chain Main Theme: Key Takeaways
Amid spillover from a tech stock sell-off and tighter regulatory expectations, compliant channels have seen liquidity withdrawn, with net outflows from spot Bitcoin ETFs reaching $430 million in a single day. Institutions in the market are showing defensive de-risking behavior, while sovereign funds still show signs of countercyclical allocation. On-chain competition is also extending into underlying quantum-resistant defenses.
Today's Main Battleground: In-Depth Analysis
Spot ETF net outflows reached $430 million, sharply increasing de-risking pressure on institutional channels: Dragged down by a steep decline in U.S. technology stocks, U.S. spot Bitcoin ETFs saw $430 million in net outflows in a single day, with BlackRock and Fidelity leading withdrawals. [In-Depth Analysis] This volatility confirms the strong coupling between compliant channels and traditional macro liquidity. Spot ETFs embed crypto assets in the traditional financial system. When tech stock valuations undergo a correction alongside increased expectations of regulatory scrutiny by both chambers of Congress, hedge funds and market makers quickly cut high-beta exposure to meet liquidity needs. This transmission of de-risking from external equity markets to crypto spot markets breaks the structure in which holdings were locked in one direction, limiting the depth available to absorb buy orders and clearly demonstrating how compliant channels can transmit liquidity shocks in both directions amid macro volatility.
Comprehensive Quantitative Anomaly Radar
• Upgrading cryptographic defenses: Core developers have proposed introducing a staking penalty mechanism for transfers from addresses with exposed public keys. Combined with the Falcon-1024 lattice-based scheme, this would raise the cost of quantum theft from long-dormant historical holdings.
• Diverging holding patterns: The U.S. midterm elections have heightened market expectations of stricter regulatory scrutiny, but sovereign funds continue to accumulate on-chain against the trend, reflecting a structural divergence in short- and long-term holding strategies.
Market Dynamics and Monitoring Map
Valuation volatility in U.S. technology stocks -> triggers redemption pressure on ETFs in compliant channels -> drains highly liquid buying depth from spot markets. Over the next 24–48 hours, institutions will closely monitor whether next-day net redemptions from spot ETFs narrow to below $150 million, and whether the Coinbase premium can recover above zero, to assess the pace at which macro spillover risks are fading.
Disclaimer: This publication is solely an aggregation and analysis of global public information and objective market data from the past 24 hours, along with logical inferences. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; make decisions with caution.
Today's Web3 On-Chain Main Theme: Key Takeaways
Amid spillover from a tech stock sell-off and tighter regulatory expectations, compliant channels have seen liquidity withdrawn, with net outflows from spot Bitcoin ETFs reaching $430 million in a single day. Institutions in the market are showing defensive de-risking behavior, while sovereign funds still show signs of countercyclical allocation. On-chain competition is also extending into underlying quantum-resistant defenses.
Today's Main Battleground: In-Depth Analysis
Spot ETF net outflows reached $430 million, sharply increasing de-risking pressure on institutional channels: Dragged down by a steep decline in U.S. technology stocks, U.S. spot Bitcoin ETFs saw $430 million in net outflows in a single day, with BlackRock and Fidelity leading withdrawals. [In-Depth Analysis] This volatility confirms the strong coupling between compliant channels and traditional macro liquidity. Spot ETFs embed crypto assets in the traditional financial system. When tech stock valuations undergo a correction alongside increased expectations of regulatory scrutiny by both chambers of Congress, hedge funds and market makers quickly cut high-beta exposure to meet liquidity needs. This transmission of de-risking from external equity markets to crypto spot markets breaks the structure in which holdings were locked in one direction, limiting the depth available to absorb buy orders and clearly demonstrating how compliant channels can transmit liquidity shocks in both directions amid macro volatility.
Comprehensive Quantitative Anomaly Radar
• Upgrading cryptographic defenses: Core developers have proposed introducing a staking penalty mechanism for transfers from addresses with exposed public keys. Combined with the Falcon-1024 lattice-based scheme, this would raise the cost of quantum theft from long-dormant historical holdings.
• Diverging holding patterns: The U.S. midterm elections have heightened market expectations of stricter regulatory scrutiny, but sovereign funds continue to accumulate on-chain against the trend, reflecting a structural divergence in short- and long-term holding strategies.
Market Dynamics and Monitoring Map
Valuation volatility in U.S. technology stocks -> triggers redemption pressure on ETFs in compliant channels -> drains highly liquid buying depth from spot markets. Over the next 24–48 hours, institutions will closely monitor whether next-day net redemptions from spot ETFs narrow to below $150 million, and whether the Coinbase premium can recover above zero, to assess the pace at which macro spillover risks are fading.
Disclaimer: This publication is solely an aggregation and analysis of global public information and objective market data from the past 24 hours, along with logical inferences. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; make decisions with caution.
BTC-1.39%
BLKUS-0.35%
148
·
--
2026.11.07 · Frontline AI and Compute Infrastructure Briefing
Today’s Frontline AI: Core Themes and Outlook
Compute infrastructure is shifting from indiscriminate capital spending toward a rigorous focus on actual returns. As cloud giants exit leases on older-generation clusters, third-party compute providers face mounting pressure from hardware depreciation and vacancy risk. Combined with tighter regulatory scrutiny of circular financing, the sector is entering a period of sharply diverging asset valuations and liquidity.
Today’s Main Battleground: In-Depth Analysis
Microsoft gradually winds down compute leasing agreements with Oracle: People familiar with the matter say Microsoft has stopped renewing compute leasing contracts with Oracle and has been gradually shutting down its rented computing resources in recent months. The main reason is that many of Oracle’s servers are equipped with older-generation chips that cannot meet the demands of high-intensity computing. 【In-Depth Analysis】This marks the compute infrastructure sector’s formal transition from “panic-driven outsourcing” to a cycle of “generational culling and meticulous ROI accounting.” The underlying logic is that leading cloud providers are removing outdated clusters and concentrating resources in their own infrastructure to reduce energy consumption per token and marginal compute costs. This directly puts companies that took on substantial assets to sublease previous-generation chips under pressure from idle-asset depreciation and reassessments of residual value. The subleasing model—built on highly leveraged stockpiling of older-generation hardware over the past two years—is now facing a cooling in real demand. The industry’s compute supply-demand dynamics and cash-flow mechanics are undergoing a profound and irreversible divergence.
Panoramic Quantitative Anomaly Radar
• Reassessment of unicorn IPO prospects: Prediction market data shows the probability of Anthropic announcing an IPO before December has fallen from nearly 90% to 57%, indicating a significant cooling in market expectations for monetizing large-model valuations and the timing of public listings.
• Tighter scrutiny of circular compute financing: Key U.S. Senate regulators are stepping up scrutiny of chip exports and circular financing models, focusing on financial loops in the compute supply chain. Potential leverage is facing closer examination.
Market Positioning and Monitoring Map
Transmission chain: Cloud giants phase out externally sourced older-generation clusters -> pressure on third-party compute providers’ equipment utilization and depreciation -> impact on financing premiums and liquidity in the compute infrastructure sector. Key indicators to monitor over the next 24–48 hours: accounts receivable turnover days and hardware depreciation rates in CoreWeave and Nebius earnings reports, as well as developments in U.S. Senate hearings on chip export rules.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours, along with related logical projections. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please make decisions with caution.
2026.11.07 · Frontline AI and Compute Infrastructure Briefing
Today’s Frontline AI: Core Themes and Outlook
Compute infrastructure is shifting from indiscriminate capital spending toward a rigorous focus on actual returns. As cloud giants exit leases on older-generation clusters, third-party compute providers face mounting pressure from hardware depreciation and vacancy risk. Combined with tighter regulatory scrutiny of circular financing, the sector is entering a period of sharply diverging asset valuations and liquidity.
Today’s Main Battleground: In-Depth Analysis
Microsoft gradually winds down compute leasing agreements with Oracle: People familiar with the matter say Microsoft has stopped renewing compute leasing contracts with Oracle and has been gradually shutting down its rented computing resources in recent months. The main reason is that many of Oracle’s servers are equipped with older-generation chips that cannot meet the demands of high-intensity computing. 【In-Depth Analysis】This marks the compute infrastructure sector’s formal transition from “panic-driven outsourcing” to a cycle of “generational culling and meticulous ROI accounting.” The underlying logic is that leading cloud providers are removing outdated clusters and concentrating resources in their own infrastructure to reduce energy consumption per token and marginal compute costs. This directly puts companies that took on substantial assets to sublease previous-generation chips under pressure from idle-asset depreciation and reassessments of residual value. The subleasing model—built on highly leveraged stockpiling of older-generation hardware over the past two years—is now facing a cooling in real demand. The industry’s compute supply-demand dynamics and cash-flow mechanics are undergoing a profound and irreversible divergence.
Panoramic Quantitative Anomaly Radar
• Reassessment of unicorn IPO prospects: Prediction market data shows the probability of Anthropic announcing an IPO before December has fallen from nearly 90% to 57%, indicating a significant cooling in market expectations for monetizing large-model valuations and the timing of public listings.
• Tighter scrutiny of circular compute financing: Key U.S. Senate regulators are stepping up scrutiny of chip exports and circular financing models, focusing on financial loops in the compute supply chain. Potential leverage is facing closer examination.
Market Positioning and Monitoring Map
Transmission chain: Cloud giants phase out externally sourced older-generation clusters -> pressure on third-party compute providers’ equipment utilization and depreciation -> impact on financing premiums and liquidity in the compute infrastructure sector. Key indicators to monitor over the next 24–48 hours: accounts receivable turnover days and hardware depreciation rates in CoreWeave and Nebius earnings reports, as well as developments in U.S. Senate hearings on chip export rules.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours, along with related logical projections. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please make decisions with caution.
Today’s Frontline AI: Core Themes and Outlook
Compute infrastructure is shifting from indiscriminate capital spending toward a rigorous focus on actual returns. As cloud giants exit leases on older-generation clusters, third-party compute providers face mounting pressure from hardware depreciation and vacancy risk. Combined with tighter regulatory scrutiny of circular financing, the sector is entering a period of sharply diverging asset valuations and liquidity.
Today’s Main Battleground: In-Depth Analysis
Microsoft gradually winds down compute leasing agreements with Oracle: People familiar with the matter say Microsoft has stopped renewing compute leasing contracts with Oracle and has been gradually shutting down its rented computing resources in recent months. The main reason is that many of Oracle’s servers are equipped with older-generation chips that cannot meet the demands of high-intensity computing. 【In-Depth Analysis】This marks the compute infrastructure sector’s formal transition from “panic-driven outsourcing” to a cycle of “generational culling and meticulous ROI accounting.” The underlying logic is that leading cloud providers are removing outdated clusters and concentrating resources in their own infrastructure to reduce energy consumption per token and marginal compute costs. This directly puts companies that took on substantial assets to sublease previous-generation chips under pressure from idle-asset depreciation and reassessments of residual value. The subleasing model—built on highly leveraged stockpiling of older-generation hardware over the past two years—is now facing a cooling in real demand. The industry’s compute supply-demand dynamics and cash-flow mechanics are undergoing a profound and irreversible divergence.
Panoramic Quantitative Anomaly Radar
• Reassessment of unicorn IPO prospects: Prediction market data shows the probability of Anthropic announcing an IPO before December has fallen from nearly 90% to 57%, indicating a significant cooling in market expectations for monetizing large-model valuations and the timing of public listings.
• Tighter scrutiny of circular compute financing: Key U.S. Senate regulators are stepping up scrutiny of chip exports and circular financing models, focusing on financial loops in the compute supply chain. Potential leverage is facing closer examination.
Market Positioning and Monitoring Map
Transmission chain: Cloud giants phase out externally sourced older-generation clusters -> pressure on third-party compute providers’ equipment utilization and depreciation -> impact on financing premiums and liquidity in the compute infrastructure sector. Key indicators to monitor over the next 24–48 hours: accounts receivable turnover days and hardware depreciation rates in CoreWeave and Nebius earnings reports, as well as developments in U.S. Senate hearings on chip export rules.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours, along with related logical projections. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please make decisions with caution.
295
·
--
2026.11.07 · Global Macro Market Briefing
Today’s Global Macro Narrative: Key Takeaways
Stronger-than-expected U.S. employment and wage data have compelled Fed officials to maintain a hawkish stance, reinforcing the higher-for-longer constraint. The rebound in the U.S. Dollar Index has tightened offshore dollar liquidity worldwide, prompting a reassessment of cross-asset valuation anchors. The tug-of-war between the terminal policy rate and persistent inflation is at the heart of current macro pricing.
Today’s Main Battleground: In-Depth Analysis
Resilient nonfarm payrolls fuel hawkish rate-hike expectations: Nonfarm payroll growth and wage gains exceeded expectations while the unemployment rate fell, driving the U.S. Dollar Index up 0.71% to a one-week high. Fed officials reiterated that inflation remains their top priority and said they remain open to further rate hikes. [In-Depth Analysis] This latest labor-market resilience directly undermines expectations of a near-term shift toward easier liquidity, forcing interest rate swap markets to reassess the peak terminal rate. The underlying tension is that a robust labor market is slowing the pace of disinflation; wage growth has not surged, but remains sticky. The Fed is using verbal intervention to prevent financial conditions from easing prematurely, keeping long-term discount rates elevated and forcing risk-asset premiums to be repriced. The repatriation of dollar liquidity is adding to exchange-rate and external debt repayment pressures in non-U.S. economies.
Panoramic Quantitative Anomaly Radar
• Commodity shipping capacity controls: U.S. officials are considering easing restrictions on some oil tankers, while four international energy giants are negotiating to lease sanctioned vessels. The aim is to offset shipping premiums and ease pressure from a second wave of imported inflation.
• Derivatives compliance: Hyperliquid has applied for a U.S. futures commission merchant license, paving the way for perpetual contracts to connect with domestic regulated capital. This reflects the deeper integration of on-chain derivatives protocols into traditional brokerage frameworks.
Market Positioning and Monitoring Map
Labor-market resilience intensifies hawkish policy expectations -> pushes up Treasury discount rates and the dollar exchange rate -> squeezes cross-asset risk premiums and offshore liquidity. Over the next 24–48 hours, institutions will focus on how the 10-year Treasury yield trades around the key 4.50% threshold, and whether the U.S. Dollar Index can hold above the 105.0 psychological resistance level, to assess the severity of the global liquidity contraction.
Disclaimer: This publication is solely an aggregation and synthesis of publicly available global information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for taking any action. Markets involve risk; make decisions with caution.
2026.11.07 · Global Macro Market Briefing
Today’s Global Macro Narrative: Key Takeaways
Stronger-than-expected U.S. employment and wage data have compelled Fed officials to maintain a hawkish stance, reinforcing the higher-for-longer constraint. The rebound in the U.S. Dollar Index has tightened offshore dollar liquidity worldwide, prompting a reassessment of cross-asset valuation anchors. The tug-of-war between the terminal policy rate and persistent inflation is at the heart of current macro pricing.
Today’s Main Battleground: In-Depth Analysis
Resilient nonfarm payrolls fuel hawkish rate-hike expectations: Nonfarm payroll growth and wage gains exceeded expectations while the unemployment rate fell, driving the U.S. Dollar Index up 0.71% to a one-week high. Fed officials reiterated that inflation remains their top priority and said they remain open to further rate hikes. [In-Depth Analysis] This latest labor-market resilience directly undermines expectations of a near-term shift toward easier liquidity, forcing interest rate swap markets to reassess the peak terminal rate. The underlying tension is that a robust labor market is slowing the pace of disinflation; wage growth has not surged, but remains sticky. The Fed is using verbal intervention to prevent financial conditions from easing prematurely, keeping long-term discount rates elevated and forcing risk-asset premiums to be repriced. The repatriation of dollar liquidity is adding to exchange-rate and external debt repayment pressures in non-U.S. economies.
Panoramic Quantitative Anomaly Radar
• Commodity shipping capacity controls: U.S. officials are considering easing restrictions on some oil tankers, while four international energy giants are negotiating to lease sanctioned vessels. The aim is to offset shipping premiums and ease pressure from a second wave of imported inflation.
• Derivatives compliance: Hyperliquid has applied for a U.S. futures commission merchant license, paving the way for perpetual contracts to connect with domestic regulated capital. This reflects the deeper integration of on-chain derivatives protocols into traditional brokerage frameworks.
Market Positioning and Monitoring Map
Labor-market resilience intensifies hawkish policy expectations -> pushes up Treasury discount rates and the dollar exchange rate -> squeezes cross-asset risk premiums and offshore liquidity. Over the next 24–48 hours, institutions will focus on how the 10-year Treasury yield trades around the key 4.50% threshold, and whether the U.S. Dollar Index can hold above the 105.0 psychological resistance level, to assess the severity of the global liquidity contraction.
Disclaimer: This publication is solely an aggregation and synthesis of publicly available global information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for taking any action. Markets involve risk; make decisions with caution.
Today’s Global Macro Narrative: Key Takeaways
Stronger-than-expected U.S. employment and wage data have compelled Fed officials to maintain a hawkish stance, reinforcing the higher-for-longer constraint. The rebound in the U.S. Dollar Index has tightened offshore dollar liquidity worldwide, prompting a reassessment of cross-asset valuation anchors. The tug-of-war between the terminal policy rate and persistent inflation is at the heart of current macro pricing.
Today’s Main Battleground: In-Depth Analysis
Resilient nonfarm payrolls fuel hawkish rate-hike expectations: Nonfarm payroll growth and wage gains exceeded expectations while the unemployment rate fell, driving the U.S. Dollar Index up 0.71% to a one-week high. Fed officials reiterated that inflation remains their top priority and said they remain open to further rate hikes. [In-Depth Analysis] This latest labor-market resilience directly undermines expectations of a near-term shift toward easier liquidity, forcing interest rate swap markets to reassess the peak terminal rate. The underlying tension is that a robust labor market is slowing the pace of disinflation; wage growth has not surged, but remains sticky. The Fed is using verbal intervention to prevent financial conditions from easing prematurely, keeping long-term discount rates elevated and forcing risk-asset premiums to be repriced. The repatriation of dollar liquidity is adding to exchange-rate and external debt repayment pressures in non-U.S. economies.
Panoramic Quantitative Anomaly Radar
• Commodity shipping capacity controls: U.S. officials are considering easing restrictions on some oil tankers, while four international energy giants are negotiating to lease sanctioned vessels. The aim is to offset shipping premiums and ease pressure from a second wave of imported inflation.
• Derivatives compliance: Hyperliquid has applied for a U.S. futures commission merchant license, paving the way for perpetual contracts to connect with domestic regulated capital. This reflects the deeper integration of on-chain derivatives protocols into traditional brokerage frameworks.
Market Positioning and Monitoring Map
Labor-market resilience intensifies hawkish policy expectations -> pushes up Treasury discount rates and the dollar exchange rate -> squeezes cross-asset risk premiums and offshore liquidity. Over the next 24–48 hours, institutions will focus on how the 10-year Treasury yield trades around the key 4.50% threshold, and whether the U.S. Dollar Index can hold above the 105.0 psychological resistance level, to assess the severity of the global liquidity contraction.
Disclaimer: This publication is solely an aggregation and synthesis of publicly available global information and objective market data from the past 24 hours, together with logical analysis. It does not constitute investment advice, an offer to buy or sell, or a basis for taking any action. Markets involve risk; make decisions with caution.
72
·
--
2026.11.06 · Web3 On-Chain and Crypto Asset Briefing
Today’s Web3 On-Chain Themes: Key Takeaways
Risk aversion across global technology stocks spilled over and coincided with trading halts in Asia-Pacific equity markets, structurally reshaping on-chain liquidity. Leading mining firms are rapidly liquidating spot reserves to fund capital expenditures on computing infrastructure, while concentrated liquidations of leveraged derivatives have further cleared the market. Spot markets are now in the midst of an intense contest between institutional demand and the release of industry supply.
Today’s Main Battleground: In-Depth Analysis
Publicly listed mining firms are liquidating reserves to pivot toward computing infrastructure: Bitfarms sold all 2,520 of its bitcoins in a single quarter, raising $192 million; Hut 8 monetized 2,148 bitcoins to raise $250 million; and IREN’s cloud computing revenue reached $200 million, accounting for over 87% of its total. 【In-Depth Analysis】The traditional balance-sheet model of miners “holding coins and waiting for prices to rise” has been disrupted. With mining profitability compressed after the halving and demand for AI computing power surging, miners are rapidly converting on-chain assets into capital expenditures on power and data centers—capital-intensive assets. In the short term, this shift away from token holdings has poured hundreds of millions of dollars in spot selling pressure into the market, turning the mining sector from a long-term reservoir of supply into a source of liquidity outflows and reshaping the long-term elasticity of on-chain supply.
Panoramic Quantitative Anomaly Radar
• Institutional on-chain adoption: Five major multinational banks, including HSBC and JPMorgan, have established a tokenization infrastructure organization. Meanwhile, Amundi has launched its first tokenized money market fund share on Ethereum. Regulated institutions are accelerating efforts to build an around-the-clock on-chain clearing and settlement infrastructure.
• Leverage flush-out: Liquidations across the market exceeded $1 billion in 24 hours, with more than $800 million in long positions. Short-term holders transferred 28,690 profitable bitcoins to exchanges, while net inflows of $74.56 million into spot ETFs provided structural support.
Market Dynamics and Monitoring Map
Macro risk aversion and selling pressure from the shift toward computing infrastructure -> pressure on spot market depth and funding rates on centralized exchanges -> transmission to on-chain lending liquidation thresholds and derivatives exposure. Key indicators to monitor over the next 24 to 48 hours: daily movements in leading miners’ cold wallets (alert threshold: 2,000 coins) and the strength of support at $75,000, where cumulative long liquidations on major CEXs are concentrated.
Disclaimer: This briefing is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please exercise caution when making decisions.
2026.11.06 · Web3 On-Chain and Crypto Asset Briefing
Today’s Web3 On-Chain Themes: Key Takeaways
Risk aversion across global technology stocks spilled over and coincided with trading halts in Asia-Pacific equity markets, structurally reshaping on-chain liquidity. Leading mining firms are rapidly liquidating spot reserves to fund capital expenditures on computing infrastructure, while concentrated liquidations of leveraged derivatives have further cleared the market. Spot markets are now in the midst of an intense contest between institutional demand and the release of industry supply.
Today’s Main Battleground: In-Depth Analysis
Publicly listed mining firms are liquidating reserves to pivot toward computing infrastructure: Bitfarms sold all 2,520 of its bitcoins in a single quarter, raising $192 million; Hut 8 monetized 2,148 bitcoins to raise $250 million; and IREN’s cloud computing revenue reached $200 million, accounting for over 87% of its total. 【In-Depth Analysis】The traditional balance-sheet model of miners “holding coins and waiting for prices to rise” has been disrupted. With mining profitability compressed after the halving and demand for AI computing power surging, miners are rapidly converting on-chain assets into capital expenditures on power and data centers—capital-intensive assets. In the short term, this shift away from token holdings has poured hundreds of millions of dollars in spot selling pressure into the market, turning the mining sector from a long-term reservoir of supply into a source of liquidity outflows and reshaping the long-term elasticity of on-chain supply.
Panoramic Quantitative Anomaly Radar
• Institutional on-chain adoption: Five major multinational banks, including HSBC and JPMorgan, have established a tokenization infrastructure organization. Meanwhile, Amundi has launched its first tokenized money market fund share on Ethereum. Regulated institutions are accelerating efforts to build an around-the-clock on-chain clearing and settlement infrastructure.
• Leverage flush-out: Liquidations across the market exceeded $1 billion in 24 hours, with more than $800 million in long positions. Short-term holders transferred 28,690 profitable bitcoins to exchanges, while net inflows of $74.56 million into spot ETFs provided structural support.
Market Dynamics and Monitoring Map
Macro risk aversion and selling pressure from the shift toward computing infrastructure -> pressure on spot market depth and funding rates on centralized exchanges -> transmission to on-chain lending liquidation thresholds and derivatives exposure. Key indicators to monitor over the next 24 to 48 hours: daily movements in leading miners’ cold wallets (alert threshold: 2,000 coins) and the strength of support at $75,000, where cumulative long liquidations on major CEXs are concentrated.
Disclaimer: This briefing is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please exercise caution when making decisions.
Today’s Web3 On-Chain Themes: Key Takeaways
Risk aversion across global technology stocks spilled over and coincided with trading halts in Asia-Pacific equity markets, structurally reshaping on-chain liquidity. Leading mining firms are rapidly liquidating spot reserves to fund capital expenditures on computing infrastructure, while concentrated liquidations of leveraged derivatives have further cleared the market. Spot markets are now in the midst of an intense contest between institutional demand and the release of industry supply.
Today’s Main Battleground: In-Depth Analysis
Publicly listed mining firms are liquidating reserves to pivot toward computing infrastructure: Bitfarms sold all 2,520 of its bitcoins in a single quarter, raising $192 million; Hut 8 monetized 2,148 bitcoins to raise $250 million; and IREN’s cloud computing revenue reached $200 million, accounting for over 87% of its total. 【In-Depth Analysis】The traditional balance-sheet model of miners “holding coins and waiting for prices to rise” has been disrupted. With mining profitability compressed after the halving and demand for AI computing power surging, miners are rapidly converting on-chain assets into capital expenditures on power and data centers—capital-intensive assets. In the short term, this shift away from token holdings has poured hundreds of millions of dollars in spot selling pressure into the market, turning the mining sector from a long-term reservoir of supply into a source of liquidity outflows and reshaping the long-term elasticity of on-chain supply.
Panoramic Quantitative Anomaly Radar
• Institutional on-chain adoption: Five major multinational banks, including HSBC and JPMorgan, have established a tokenization infrastructure organization. Meanwhile, Amundi has launched its first tokenized money market fund share on Ethereum. Regulated institutions are accelerating efforts to build an around-the-clock on-chain clearing and settlement infrastructure.
• Leverage flush-out: Liquidations across the market exceeded $1 billion in 24 hours, with more than $800 million in long positions. Short-term holders transferred 28,690 profitable bitcoins to exchanges, while net inflows of $74.56 million into spot ETFs provided structural support.
Market Dynamics and Monitoring Map
Macro risk aversion and selling pressure from the shift toward computing infrastructure -> pressure on spot market depth and funding rates on centralized exchanges -> transmission to on-chain lending liquidation thresholds and derivatives exposure. Key indicators to monitor over the next 24 to 48 hours: daily movements in leading miners’ cold wallets (alert threshold: 2,000 coins) and the strength of support at $75,000, where cumulative long liquidations on major CEXs are concentrated.
Disclaimer: This briefing is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please exercise caution when making decisions.
54
·
--
2026.11.06 · Frontier AI and Compute Infrastructure Briefing
Today's Frontier AI Core Narrative: Key Takeaways
Shifting policy expectations, combined with 40 out of 41 local referendums rejecting expansion proposals, have triggered hard constraints on data center approvals. Upstream semiconductors have been systematically repriced downward, while existing grid-connection capacity has become a licensed asset. Leveraged emerging compute clouds face refinancing and debt-servicing pressure, and capital expenditure across the industry is entering a defensive phase.
Today's Main Battleground: In-Depth Analysis
Power constraints and sharply tightened approvals are reshaping compute asset valuations: after 40 out of 41 local referendums rejected data center construction, the Philadelphia Semiconductor Index plunged 11.48%, while the Nasdaq lost a record $2.3 trillion in market capitalization. Microsoft has refused to double the value of some new data center contracts, some emerging compute clouds have deferred $4 billion in annualized revenue, and Anthropic's large leases also require joint guarantees from major companies. [In-Depth Analysis] This sell-off marks the end of the market narrative of “unlimited debt-funded compute expansion.” New compute clouds built with high-interest debt now face revaluation amid local grid resistance and tighter approvals. Established hyperscalers are preserving cash flow by cutting risky external contracts, while leveraged build-to-suit providers face interest costs and resale pressures. Supply-side constraints are turning existing grid-connection capacity into licensed assets, shifting the industry's valuation anchor from capacity arms races to the quality of cash flows.
Panoramic Quantitative Anomaly Radar
• End-demand constraints: Apple has cut the daily spending cap for internal engineers' AI models from $300 to $200. This indicates that major companies' procurement is shifting from unrestricted budgets to rigorous ROI assessments, putting actual adoption and payment capacity in edge and enterprise markets to the test.
• Open-source weight pressure: Moonshot AI has open-sourced Kimi K3.1 Pro with full weights of 1.56TB and commercial-use support. Combined with Baidu's open-source 280-billion-parameter model, the release of model weights is accelerating the erosion of the premium pricing power of closed-source APIs.
Market Dynamics and Monitoring Map
Causal chain: Hard local approval constraints and referendum setbacks -> Weigh on expectations for data center grid connections and upstream procurement -> Undermine the financing credit of highly leveraged compute clouds and semiconductor valuations. Key indicators to watch over the next 24 to 48 hours: whether the VIX can fall back below 22.00, and whether credit spreads on high-debt compute operators' bonds breach the 500-basis-point warning threshold.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. All markets involve risk; please make decisions with caution.
2026.11.06 · Frontier AI and Compute Infrastructure Briefing
Today's Frontier AI Core Narrative: Key Takeaways
Shifting policy expectations, combined with 40 out of 41 local referendums rejecting expansion proposals, have triggered hard constraints on data center approvals. Upstream semiconductors have been systematically repriced downward, while existing grid-connection capacity has become a licensed asset. Leveraged emerging compute clouds face refinancing and debt-servicing pressure, and capital expenditure across the industry is entering a defensive phase.
Today's Main Battleground: In-Depth Analysis
Power constraints and sharply tightened approvals are reshaping compute asset valuations: after 40 out of 41 local referendums rejected data center construction, the Philadelphia Semiconductor Index plunged 11.48%, while the Nasdaq lost a record $2.3 trillion in market capitalization. Microsoft has refused to double the value of some new data center contracts, some emerging compute clouds have deferred $4 billion in annualized revenue, and Anthropic's large leases also require joint guarantees from major companies. [In-Depth Analysis] This sell-off marks the end of the market narrative of “unlimited debt-funded compute expansion.” New compute clouds built with high-interest debt now face revaluation amid local grid resistance and tighter approvals. Established hyperscalers are preserving cash flow by cutting risky external contracts, while leveraged build-to-suit providers face interest costs and resale pressures. Supply-side constraints are turning existing grid-connection capacity into licensed assets, shifting the industry's valuation anchor from capacity arms races to the quality of cash flows.
Panoramic Quantitative Anomaly Radar
• End-demand constraints: Apple has cut the daily spending cap for internal engineers' AI models from $300 to $200. This indicates that major companies' procurement is shifting from unrestricted budgets to rigorous ROI assessments, putting actual adoption and payment capacity in edge and enterprise markets to the test.
• Open-source weight pressure: Moonshot AI has open-sourced Kimi K3.1 Pro with full weights of 1.56TB and commercial-use support. Combined with Baidu's open-source 280-billion-parameter model, the release of model weights is accelerating the erosion of the premium pricing power of closed-source APIs.
Market Dynamics and Monitoring Map
Causal chain: Hard local approval constraints and referendum setbacks -> Weigh on expectations for data center grid connections and upstream procurement -> Undermine the financing credit of highly leveraged compute clouds and semiconductor valuations. Key indicators to watch over the next 24 to 48 hours: whether the VIX can fall back below 22.00, and whether credit spreads on high-debt compute operators' bonds breach the 500-basis-point warning threshold.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. All markets involve risk; please make decisions with caution.
Today's Frontier AI Core Narrative: Key Takeaways
Shifting policy expectations, combined with 40 out of 41 local referendums rejecting expansion proposals, have triggered hard constraints on data center approvals. Upstream semiconductors have been systematically repriced downward, while existing grid-connection capacity has become a licensed asset. Leveraged emerging compute clouds face refinancing and debt-servicing pressure, and capital expenditure across the industry is entering a defensive phase.
Today's Main Battleground: In-Depth Analysis
Power constraints and sharply tightened approvals are reshaping compute asset valuations: after 40 out of 41 local referendums rejected data center construction, the Philadelphia Semiconductor Index plunged 11.48%, while the Nasdaq lost a record $2.3 trillion in market capitalization. Microsoft has refused to double the value of some new data center contracts, some emerging compute clouds have deferred $4 billion in annualized revenue, and Anthropic's large leases also require joint guarantees from major companies. [In-Depth Analysis] This sell-off marks the end of the market narrative of “unlimited debt-funded compute expansion.” New compute clouds built with high-interest debt now face revaluation amid local grid resistance and tighter approvals. Established hyperscalers are preserving cash flow by cutting risky external contracts, while leveraged build-to-suit providers face interest costs and resale pressures. Supply-side constraints are turning existing grid-connection capacity into licensed assets, shifting the industry's valuation anchor from capacity arms races to the quality of cash flows.
Panoramic Quantitative Anomaly Radar
• End-demand constraints: Apple has cut the daily spending cap for internal engineers' AI models from $300 to $200. This indicates that major companies' procurement is shifting from unrestricted budgets to rigorous ROI assessments, putting actual adoption and payment capacity in edge and enterprise markets to the test.
• Open-source weight pressure: Moonshot AI has open-sourced Kimi K3.1 Pro with full weights of 1.56TB and commercial-use support. Combined with Baidu's open-source 280-billion-parameter model, the release of model weights is accelerating the erosion of the premium pricing power of closed-source APIs.
Market Dynamics and Monitoring Map
Causal chain: Hard local approval constraints and referendum setbacks -> Weigh on expectations for data center grid connections and upstream procurement -> Undermine the financing credit of highly leveraged compute clouds and semiconductor valuations. Key indicators to watch over the next 24 to 48 hours: whether the VIX can fall back below 22.00, and whether credit spreads on high-debt compute operators' bonds breach the 500-basis-point warning threshold.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. All markets involve risk; please make decisions with caution.
277
·
--
2026.11.06 · Global Macro Market Briefing
Today's Global Macro Theme: Key Takeaways
The U.S. midterm elections established a divided Congress, and expectations of constrained fiscal expansion and tighter industry regulation were rapidly priced into markets, breaking the consensus that had supported premium valuations across technology and the compute supply chain. In a highly volatile environment, leveraged positions were forcibly unwound, while sticky inflation and geopolitical risks amplified the pressure, prompting a broad cross-asset rebalancing.
Today's Main Battleground: A Deep Dive
The Nasdaq posted its largest single-day drop in more than four years, as the compute supply chain came under systemic pressure: the Nasdaq 100 plunged 6.36%, wiping out more than $2.3 trillion in market value in a single day, while the VIX volatility index surged 62.7% to 27.03. Micron fell 16.4%, semiconductor and optical communications stocks tumbled in unison, and related Asia-Pacific markets triggered trading halts. 【Deep Dive】On the surface, this selloff was a risk-off response to expectations that the post-election Congress would tighten regulation of compute and data centers. At a deeper level, it was a valuation rout among extremely crowded growth assets, triggered by a sudden shift in expectations for macro discount rates. A divided Congress has curtailed the scope for fiscal expansion, shaking institutional investors' confidence in the return timeline for massive AI capital expenditures. At the same time, quantitative funds' risk-parity and stop-loss thresholds were breached, triggering automated deleveraging and forced liquidation of long positions, and accelerating a cross-market liquidity contraction.
Panoramic Quantitative Anomaly Radar
• Energy geopolitical discount rebalancing: International crude rebounded after plunging more than 8% in a single day earlier. WTI settled at $90.52/barrel (+2.72%). Expectations of easing Middle East conflict continued to contend with refinery disruptions, while crack spreads remained elevated.
• Labor-market resilience constrains rate-cut expectations: U.S. initial jobless claims fell to 189,000, a 3.5-month low, while third-quarter productivity grew 3.6%. The Bank of England unanimously raised rates by 25 basis points to 4.00%, as labor-market resilience narrowed the central bank's room to turn dovish.
Market Positioning and Monitoring Map
Causal chain: Congressional power shift -> constrained fiscal expansion and tighter industry regulation -> unwinding of elevated compute valuations and a rise in VIX volatility. Key institutional indicators to watch over the next 24–48 hours: first, U.S. October nonfarm payrolls and month-over-month hourly earnings data; second, the pressure on the 10-year U.S. Treasury yield around the 4.80% threshold.
Disclaimer: This publication is solely a consolidated review and logical analysis of publicly available global news and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking any action. Markets involve risk; decisions should be made with caution.
2026.11.06 · Global Macro Market Briefing
Today's Global Macro Theme: Key Takeaways
The U.S. midterm elections established a divided Congress, and expectations of constrained fiscal expansion and tighter industry regulation were rapidly priced into markets, breaking the consensus that had supported premium valuations across technology and the compute supply chain. In a highly volatile environment, leveraged positions were forcibly unwound, while sticky inflation and geopolitical risks amplified the pressure, prompting a broad cross-asset rebalancing.
Today's Main Battleground: A Deep Dive
The Nasdaq posted its largest single-day drop in more than four years, as the compute supply chain came under systemic pressure: the Nasdaq 100 plunged 6.36%, wiping out more than $2.3 trillion in market value in a single day, while the VIX volatility index surged 62.7% to 27.03. Micron fell 16.4%, semiconductor and optical communications stocks tumbled in unison, and related Asia-Pacific markets triggered trading halts. 【Deep Dive】On the surface, this selloff was a risk-off response to expectations that the post-election Congress would tighten regulation of compute and data centers. At a deeper level, it was a valuation rout among extremely crowded growth assets, triggered by a sudden shift in expectations for macro discount rates. A divided Congress has curtailed the scope for fiscal expansion, shaking institutional investors' confidence in the return timeline for massive AI capital expenditures. At the same time, quantitative funds' risk-parity and stop-loss thresholds were breached, triggering automated deleveraging and forced liquidation of long positions, and accelerating a cross-market liquidity contraction.
Panoramic Quantitative Anomaly Radar
• Energy geopolitical discount rebalancing: International crude rebounded after plunging more than 8% in a single day earlier. WTI settled at $90.52/barrel (+2.72%). Expectations of easing Middle East conflict continued to contend with refinery disruptions, while crack spreads remained elevated.
• Labor-market resilience constrains rate-cut expectations: U.S. initial jobless claims fell to 189,000, a 3.5-month low, while third-quarter productivity grew 3.6%. The Bank of England unanimously raised rates by 25 basis points to 4.00%, as labor-market resilience narrowed the central bank's room to turn dovish.
Market Positioning and Monitoring Map
Causal chain: Congressional power shift -> constrained fiscal expansion and tighter industry regulation -> unwinding of elevated compute valuations and a rise in VIX volatility. Key institutional indicators to watch over the next 24–48 hours: first, U.S. October nonfarm payrolls and month-over-month hourly earnings data; second, the pressure on the 10-year U.S. Treasury yield around the 4.80% threshold.
Disclaimer: This publication is solely a consolidated review and logical analysis of publicly available global news and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking any action. Markets involve risk; decisions should be made with caution.
Today's Global Macro Theme: Key Takeaways
The U.S. midterm elections established a divided Congress, and expectations of constrained fiscal expansion and tighter industry regulation were rapidly priced into markets, breaking the consensus that had supported premium valuations across technology and the compute supply chain. In a highly volatile environment, leveraged positions were forcibly unwound, while sticky inflation and geopolitical risks amplified the pressure, prompting a broad cross-asset rebalancing.
Today's Main Battleground: A Deep Dive
The Nasdaq posted its largest single-day drop in more than four years, as the compute supply chain came under systemic pressure: the Nasdaq 100 plunged 6.36%, wiping out more than $2.3 trillion in market value in a single day, while the VIX volatility index surged 62.7% to 27.03. Micron fell 16.4%, semiconductor and optical communications stocks tumbled in unison, and related Asia-Pacific markets triggered trading halts. 【Deep Dive】On the surface, this selloff was a risk-off response to expectations that the post-election Congress would tighten regulation of compute and data centers. At a deeper level, it was a valuation rout among extremely crowded growth assets, triggered by a sudden shift in expectations for macro discount rates. A divided Congress has curtailed the scope for fiscal expansion, shaking institutional investors' confidence in the return timeline for massive AI capital expenditures. At the same time, quantitative funds' risk-parity and stop-loss thresholds were breached, triggering automated deleveraging and forced liquidation of long positions, and accelerating a cross-market liquidity contraction.
Panoramic Quantitative Anomaly Radar
• Energy geopolitical discount rebalancing: International crude rebounded after plunging more than 8% in a single day earlier. WTI settled at $90.52/barrel (+2.72%). Expectations of easing Middle East conflict continued to contend with refinery disruptions, while crack spreads remained elevated.
• Labor-market resilience constrains rate-cut expectations: U.S. initial jobless claims fell to 189,000, a 3.5-month low, while third-quarter productivity grew 3.6%. The Bank of England unanimously raised rates by 25 basis points to 4.00%, as labor-market resilience narrowed the central bank's room to turn dovish.
Market Positioning and Monitoring Map
Causal chain: Congressional power shift -> constrained fiscal expansion and tighter industry regulation -> unwinding of elevated compute valuations and a rise in VIX volatility. Key institutional indicators to watch over the next 24–48 hours: first, U.S. October nonfarm payrolls and month-over-month hourly earnings data; second, the pressure on the 10-year U.S. Treasury yield around the 4.80% threshold.
Disclaimer: This publication is solely a consolidated review and logical analysis of publicly available global news and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking any action. Markets involve risk; decisions should be made with caution.
58
·
--
2026.11.05 · Web3 On-Chain and Crypto Asset Brief
Today’s Web3 On-Chain Main Theme: Core Outlook
The on-chain market is showing a structural divide between dwindling native liquidity and the deepening of institutional clearing infrastructure. Continued net outflows from spot ETFs, coupled with miners selling their holdings, are putting pressure on market liquidity. Meanwhile, Wall Street investment banks and custodians are fully embracing tokenized clearing, driving the underlying base of on-chain collateral toward highly creditworthy, compliant assets.
Today’s Main Battleground: In-Depth Analysis
Institutional-grade tokenized clearing infrastructure goes live: Morgan Stanley has begun using the Depository Trust & Clearing Corporation’s (DTCC) DTS service, joining JPMorgan, Citi, Bank of America, Fidelity, and Citadel in bringing U.S. stocks, ETFs, and Treasuries on-chain as tokens. Société Générale has also completed a tokenized Treasury collateral delivery and settlement worth tens of millions of dollars on Canton. [In-Depth Analysis] This marks an accelerating shift in on-chain settlement from native, self-contained systems toward compliant custody frameworks. The concentrated entry of investment banking giants is primarily driven by the prospect of reducing the costs of T+1 cross-period settlement and margin lockup through atomic settlement, thereby freeing up intraday liquidity. By bypassing permissionless DeFi frameworks and building compliant collateral channels directly, traditional institutions can capture interest income from high-yield stablecoins while bringing trillions of dollars in sovereign credit on-chain, systemically establishing a Treasury-anchored risk-free discount rate for on-chain markets.
Panoramic Quantitative Anomaly Radar
• Spot market outflows: Bitcoin spot ETFs recorded net outflows of $116 million for three consecutive days, while Ethereum ETFs saw $85.35 million in outflows over seven consecutive days. Miners Riot and Hut 8 sold more than 25,000 BTC to raise funds, putting pressure on spot market demand.
• Contraction in Layer 2 architecture: Leading rollup project Scroll has proposed transitioning to a permissioned appchain and migrating SCR back to the mainnet; L2BEAT has rebranded as ETHBEAT and deemphasized its L2 focus, signaling a potential structural reshaping of liquidity across Layer 2 networks.
Market Dynamics and Monitoring Map
Causal transmission path: Sustained net outflows from institutional spot ETFs and miner selling -> weaker spot-market buying support -> derivatives positions forced into high-leverage squeeze dynamics. Key institutional indicators to watch over the next 24–48 hours: first, whether daily net flows into Bitcoin spot ETFs return to positive territory; second, whether the annualized funding rate for perpetual contracts stays above the 5% benchmark.
Disclaimer: This publication is solely a compilation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; please make decisions with caution.
2026.11.05 · Web3 On-Chain and Crypto Asset Brief
Today’s Web3 On-Chain Main Theme: Core Outlook
The on-chain market is showing a structural divide between dwindling native liquidity and the deepening of institutional clearing infrastructure. Continued net outflows from spot ETFs, coupled with miners selling their holdings, are putting pressure on market liquidity. Meanwhile, Wall Street investment banks and custodians are fully embracing tokenized clearing, driving the underlying base of on-chain collateral toward highly creditworthy, compliant assets.
Today’s Main Battleground: In-Depth Analysis
Institutional-grade tokenized clearing infrastructure goes live: Morgan Stanley has begun using the Depository Trust & Clearing Corporation’s (DTCC) DTS service, joining JPMorgan, Citi, Bank of America, Fidelity, and Citadel in bringing U.S. stocks, ETFs, and Treasuries on-chain as tokens. Société Générale has also completed a tokenized Treasury collateral delivery and settlement worth tens of millions of dollars on Canton. [In-Depth Analysis] This marks an accelerating shift in on-chain settlement from native, self-contained systems toward compliant custody frameworks. The concentrated entry of investment banking giants is primarily driven by the prospect of reducing the costs of T+1 cross-period settlement and margin lockup through atomic settlement, thereby freeing up intraday liquidity. By bypassing permissionless DeFi frameworks and building compliant collateral channels directly, traditional institutions can capture interest income from high-yield stablecoins while bringing trillions of dollars in sovereign credit on-chain, systemically establishing a Treasury-anchored risk-free discount rate for on-chain markets.
Panoramic Quantitative Anomaly Radar
• Spot market outflows: Bitcoin spot ETFs recorded net outflows of $116 million for three consecutive days, while Ethereum ETFs saw $85.35 million in outflows over seven consecutive days. Miners Riot and Hut 8 sold more than 25,000 BTC to raise funds, putting pressure on spot market demand.
• Contraction in Layer 2 architecture: Leading rollup project Scroll has proposed transitioning to a permissioned appchain and migrating SCR back to the mainnet; L2BEAT has rebranded as ETHBEAT and deemphasized its L2 focus, signaling a potential structural reshaping of liquidity across Layer 2 networks.
Market Dynamics and Monitoring Map
Causal transmission path: Sustained net outflows from institutional spot ETFs and miner selling -> weaker spot-market buying support -> derivatives positions forced into high-leverage squeeze dynamics. Key institutional indicators to watch over the next 24–48 hours: first, whether daily net flows into Bitcoin spot ETFs return to positive territory; second, whether the annualized funding rate for perpetual contracts stays above the 5% benchmark.
Disclaimer: This publication is solely a compilation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; please make decisions with caution.
Today’s Web3 On-Chain Main Theme: Core Outlook
The on-chain market is showing a structural divide between dwindling native liquidity and the deepening of institutional clearing infrastructure. Continued net outflows from spot ETFs, coupled with miners selling their holdings, are putting pressure on market liquidity. Meanwhile, Wall Street investment banks and custodians are fully embracing tokenized clearing, driving the underlying base of on-chain collateral toward highly creditworthy, compliant assets.
Today’s Main Battleground: In-Depth Analysis
Institutional-grade tokenized clearing infrastructure goes live: Morgan Stanley has begun using the Depository Trust & Clearing Corporation’s (DTCC) DTS service, joining JPMorgan, Citi, Bank of America, Fidelity, and Citadel in bringing U.S. stocks, ETFs, and Treasuries on-chain as tokens. Société Générale has also completed a tokenized Treasury collateral delivery and settlement worth tens of millions of dollars on Canton. [In-Depth Analysis] This marks an accelerating shift in on-chain settlement from native, self-contained systems toward compliant custody frameworks. The concentrated entry of investment banking giants is primarily driven by the prospect of reducing the costs of T+1 cross-period settlement and margin lockup through atomic settlement, thereby freeing up intraday liquidity. By bypassing permissionless DeFi frameworks and building compliant collateral channels directly, traditional institutions can capture interest income from high-yield stablecoins while bringing trillions of dollars in sovereign credit on-chain, systemically establishing a Treasury-anchored risk-free discount rate for on-chain markets.
Panoramic Quantitative Anomaly Radar
• Spot market outflows: Bitcoin spot ETFs recorded net outflows of $116 million for three consecutive days, while Ethereum ETFs saw $85.35 million in outflows over seven consecutive days. Miners Riot and Hut 8 sold more than 25,000 BTC to raise funds, putting pressure on spot market demand.
• Contraction in Layer 2 architecture: Leading rollup project Scroll has proposed transitioning to a permissioned appchain and migrating SCR back to the mainnet; L2BEAT has rebranded as ETHBEAT and deemphasized its L2 focus, signaling a potential structural reshaping of liquidity across Layer 2 networks.
Market Dynamics and Monitoring Map
Causal transmission path: Sustained net outflows from institutional spot ETFs and miner selling -> weaker spot-market buying support -> derivatives positions forced into high-leverage squeeze dynamics. Key institutional indicators to watch over the next 24–48 hours: first, whether daily net flows into Bitcoin spot ETFs return to positive territory; second, whether the annualized funding rate for perpetual contracts stays above the 5% benchmark.
Disclaimer: This publication is solely a compilation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for trading decisions. Markets involve risk; please make decisions with caution.
44
·
--
2026.11.05 · Frontier AI & Compute Infrastructure Briefing
Today's Frontier AI Main Theme: Key Takeaway
Compute infrastructure has officially shifted from a cycle of “unrestrained capital expenditure expansion” to one of “hard constraints imposed by inflexible physical resources.” Tensions over household electricity rates and water resources are now fully surfacing at the local level. A sharp rise in permitting thresholds in multiple regions has directly disrupted cluster expansion plans, shifting market expectations away from pure hardware procurement and toward certainty around grid connections and project delivery.
Today's Main Battleground: In-Depth Analysis
North American data center access is tightening, creating hard physical barriers to compute infrastructure delivery: in recent local votes, 40 of 41 proposals to restrict data centers were approved; suspension orders in states such as Ohio have topped 120; and more than 145 compute infrastructure projects across the U.S. have been delayed. This triggered a broad single-day pullback of 10% to 23% in compute leasing stocks. [In-Depth Analysis] This marks the compute arms race running up against hard constraints on physical resources. Data centers consume large amounts of grid capacity in the short term without generating commensurate long-term employment, intensifying tensions between utility costs and community needs. As local government and environmental permitting reviews tighten, capital markets are beginning to strip away the assumption that aggressive expansion is risk-free: assets with existing grid interconnection allocations and firm clean-power agreements are commanding an increasingly large scarcity premium, while expansion models backed solely by long-term power plans and lacking firm commitments face steep valuation discounts.
Panoramic Quantitative Anomaly Radar
• Enterprise monetization: Annualized global enterprise AI deployment spending has risen to $176.8 billion, up 5.4-fold year over year; a single model provider accounts for 55% of API budgets, indicating that enterprise spending is rapidly concentrating in a small number of highly productive tools.
• Compute supply chain: Orders for a category of custom AI chips total as much as $70 billion, but capacity constraints and regulatory reviews mean the expected delivery rate over the next four months is only around 1%. Combined with the termination of $7 billion in overseas leases, barriers to cross-regional compute flows continue to rise.
Market Positioning & Monitoring Map
Tighter local access requirements and delayed grid approvals -> constrain projections for future data center grid capacity -> hit highly leveraged, compute-intensive hard assets and the liquidity of hardware premiums. Institutional capital is reallocating toward cloud businesses with high cash flows. Key indicators to monitor over the next 24–48 hours: first, the implied discount rate on long-term compute leasing contracts (watch the 15% volatility threshold); second, delivery lead-time thresholds across the advanced packaging supply chain.
Disclaimer: This briefing is solely a compilation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decisions. Markets involve risk; make decisions with caution.
2026.11.05 · Frontier AI & Compute Infrastructure Briefing
Today's Frontier AI Main Theme: Key Takeaway
Compute infrastructure has officially shifted from a cycle of “unrestrained capital expenditure expansion” to one of “hard constraints imposed by inflexible physical resources.” Tensions over household electricity rates and water resources are now fully surfacing at the local level. A sharp rise in permitting thresholds in multiple regions has directly disrupted cluster expansion plans, shifting market expectations away from pure hardware procurement and toward certainty around grid connections and project delivery.
Today's Main Battleground: In-Depth Analysis
North American data center access is tightening, creating hard physical barriers to compute infrastructure delivery: in recent local votes, 40 of 41 proposals to restrict data centers were approved; suspension orders in states such as Ohio have topped 120; and more than 145 compute infrastructure projects across the U.S. have been delayed. This triggered a broad single-day pullback of 10% to 23% in compute leasing stocks. [In-Depth Analysis] This marks the compute arms race running up against hard constraints on physical resources. Data centers consume large amounts of grid capacity in the short term without generating commensurate long-term employment, intensifying tensions between utility costs and community needs. As local government and environmental permitting reviews tighten, capital markets are beginning to strip away the assumption that aggressive expansion is risk-free: assets with existing grid interconnection allocations and firm clean-power agreements are commanding an increasingly large scarcity premium, while expansion models backed solely by long-term power plans and lacking firm commitments face steep valuation discounts.
Panoramic Quantitative Anomaly Radar
• Enterprise monetization: Annualized global enterprise AI deployment spending has risen to $176.8 billion, up 5.4-fold year over year; a single model provider accounts for 55% of API budgets, indicating that enterprise spending is rapidly concentrating in a small number of highly productive tools.
• Compute supply chain: Orders for a category of custom AI chips total as much as $70 billion, but capacity constraints and regulatory reviews mean the expected delivery rate over the next four months is only around 1%. Combined with the termination of $7 billion in overseas leases, barriers to cross-regional compute flows continue to rise.
Market Positioning & Monitoring Map
Tighter local access requirements and delayed grid approvals -> constrain projections for future data center grid capacity -> hit highly leveraged, compute-intensive hard assets and the liquidity of hardware premiums. Institutional capital is reallocating toward cloud businesses with high cash flows. Key indicators to monitor over the next 24–48 hours: first, the implied discount rate on long-term compute leasing contracts (watch the 15% volatility threshold); second, delivery lead-time thresholds across the advanced packaging supply chain.
Disclaimer: This briefing is solely a compilation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decisions. Markets involve risk; make decisions with caution.
Today's Frontier AI Main Theme: Key Takeaway
Compute infrastructure has officially shifted from a cycle of “unrestrained capital expenditure expansion” to one of “hard constraints imposed by inflexible physical resources.” Tensions over household electricity rates and water resources are now fully surfacing at the local level. A sharp rise in permitting thresholds in multiple regions has directly disrupted cluster expansion plans, shifting market expectations away from pure hardware procurement and toward certainty around grid connections and project delivery.
Today's Main Battleground: In-Depth Analysis
North American data center access is tightening, creating hard physical barriers to compute infrastructure delivery: in recent local votes, 40 of 41 proposals to restrict data centers were approved; suspension orders in states such as Ohio have topped 120; and more than 145 compute infrastructure projects across the U.S. have been delayed. This triggered a broad single-day pullback of 10% to 23% in compute leasing stocks. [In-Depth Analysis] This marks the compute arms race running up against hard constraints on physical resources. Data centers consume large amounts of grid capacity in the short term without generating commensurate long-term employment, intensifying tensions between utility costs and community needs. As local government and environmental permitting reviews tighten, capital markets are beginning to strip away the assumption that aggressive expansion is risk-free: assets with existing grid interconnection allocations and firm clean-power agreements are commanding an increasingly large scarcity premium, while expansion models backed solely by long-term power plans and lacking firm commitments face steep valuation discounts.
Panoramic Quantitative Anomaly Radar
• Enterprise monetization: Annualized global enterprise AI deployment spending has risen to $176.8 billion, up 5.4-fold year over year; a single model provider accounts for 55% of API budgets, indicating that enterprise spending is rapidly concentrating in a small number of highly productive tools.
• Compute supply chain: Orders for a category of custom AI chips total as much as $70 billion, but capacity constraints and regulatory reviews mean the expected delivery rate over the next four months is only around 1%. Combined with the termination of $7 billion in overseas leases, barriers to cross-regional compute flows continue to rise.
Market Positioning & Monitoring Map
Tighter local access requirements and delayed grid approvals -> constrain projections for future data center grid capacity -> hit highly leveraged, compute-intensive hard assets and the liquidity of hardware premiums. Institutional capital is reallocating toward cloud businesses with high cash flows. Key indicators to monitor over the next 24–48 hours: first, the implied discount rate on long-term compute leasing contracts (watch the 15% volatility threshold); second, delivery lead-time thresholds across the advanced packaging supply chain.
Disclaimer: This briefing is solely a compilation and logical analysis of publicly available global information and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decisions. Markets involve risk; make decisions with caution.
51
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
HotCPIDecemberHikePriced
51,540 views
816 Discussing
CPI Market Watch | US CPI Rises 0.4% in October, Hotter Than 0.3% Forecast
Binance News
·21 Likes
·38.1k views
AnthropicRejectsIPODelayValuationinQuestion
186,326 views
1,634 Discussing
NvidiaInvestigatesAfterHuang’sAffairApology
462,152 views
3,087 Discussing