2026.11.07 · Frontline AI and Compute Infrastructure Briefing
Today’s Frontline AI: Core Themes and Outlook
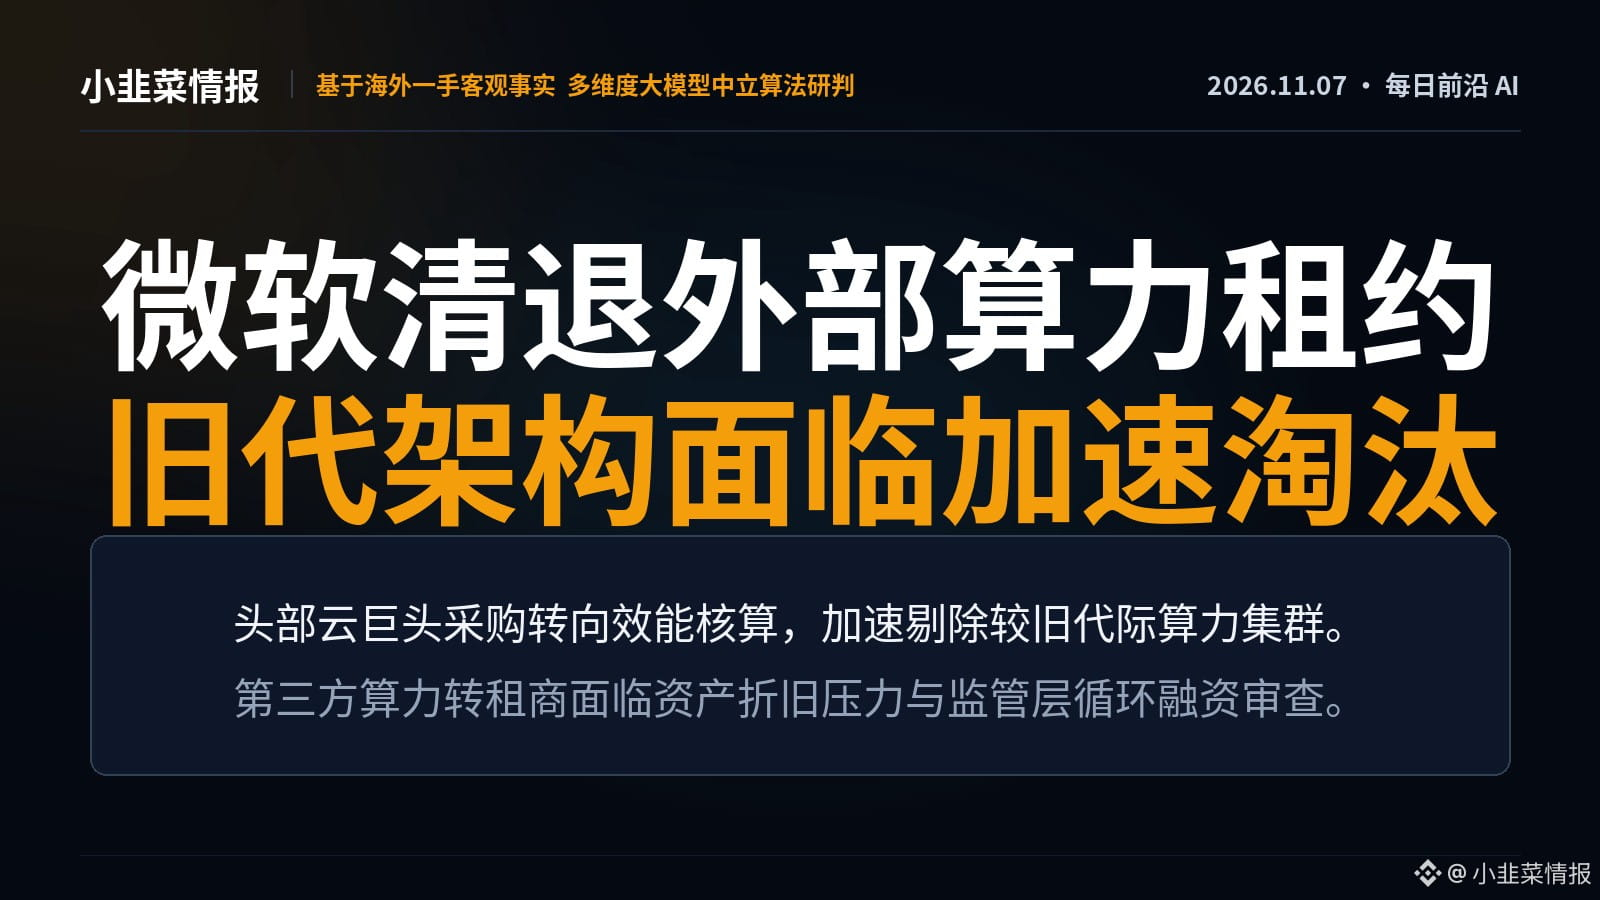
Compute infrastructure is shifting from indiscriminate capital spending toward a rigorous focus on actual returns. As cloud giants exit leases on older-generation clusters, third-party compute providers face mounting pressure from hardware depreciation and vacancy risk. Combined with tighter regulatory scrutiny of circular financing, the sector is entering a period of sharply diverging asset valuations and liquidity.
Today’s Main Battleground: In-Depth Analysis
Microsoft gradually winds down compute leasing agreements with Oracle: People familiar with the matter say Microsoft has stopped renewing compute leasing contracts with Oracle and has been gradually shutting down its rented computing resources in recent months. The main reason is that many of Oracle’s servers are equipped with older-generation chips that cannot meet the demands of high-intensity computing. 【In-Depth Analysis】This marks the compute infrastructure sector’s formal transition from “panic-driven outsourcing” to a cycle of “generational culling and meticulous ROI accounting.” The underlying logic is that leading cloud providers are removing outdated clusters and concentrating resources in their own infrastructure to reduce energy consumption per token and marginal compute costs. This directly puts companies that took on substantial assets to sublease previous-generation chips under pressure from idle-asset depreciation and reassessments of residual value. The subleasing model—built on highly leveraged stockpiling of older-generation hardware over the past two years—is now facing a cooling in real demand. The industry’s compute supply-demand dynamics and cash-flow mechanics are undergoing a profound and irreversible divergence.
Panoramic Quantitative Anomaly Radar
• Reassessment of unicorn IPO prospects: Prediction market data shows the probability of Anthropic announcing an IPO before December has fallen from nearly 90% to 57%, indicating a significant cooling in market expectations for monetizing large-model valuations and the timing of public listings.
• Tighter scrutiny of circular compute financing: Key U.S. Senate regulators are stepping up scrutiny of chip exports and circular financing models, focusing on financial loops in the compute supply chain. Potential leverage is facing closer examination.
Market Positioning and Monitoring Map
Transmission chain: Cloud giants phase out externally sourced older-generation clusters -> pressure on third-party compute providers’ equipment utilization and depreciation -> impact on financing premiums and liquidity in the compute infrastructure sector. Key indicators to monitor over the next 24–48 hours: accounts receivable turnover days and hardware depreciation rates in CoreWeave and Nebius earnings reports, as well as developments in U.S. Senate hearings on chip export rules.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours, along with related logical projections. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please make decisions with caution.
Today’s Frontline AI: Core Themes and Outlook
Compute infrastructure is shifting from indiscriminate capital spending toward a rigorous focus on actual returns. As cloud giants exit leases on older-generation clusters, third-party compute providers face mounting pressure from hardware depreciation and vacancy risk. Combined with tighter regulatory scrutiny of circular financing, the sector is entering a period of sharply diverging asset valuations and liquidity.
Today’s Main Battleground: In-Depth Analysis
Microsoft gradually winds down compute leasing agreements with Oracle: People familiar with the matter say Microsoft has stopped renewing compute leasing contracts with Oracle and has been gradually shutting down its rented computing resources in recent months. The main reason is that many of Oracle’s servers are equipped with older-generation chips that cannot meet the demands of high-intensity computing. 【In-Depth Analysis】This marks the compute infrastructure sector’s formal transition from “panic-driven outsourcing” to a cycle of “generational culling and meticulous ROI accounting.” The underlying logic is that leading cloud providers are removing outdated clusters and concentrating resources in their own infrastructure to reduce energy consumption per token and marginal compute costs. This directly puts companies that took on substantial assets to sublease previous-generation chips under pressure from idle-asset depreciation and reassessments of residual value. The subleasing model—built on highly leveraged stockpiling of older-generation hardware over the past two years—is now facing a cooling in real demand. The industry’s compute supply-demand dynamics and cash-flow mechanics are undergoing a profound and irreversible divergence.
Panoramic Quantitative Anomaly Radar
• Reassessment of unicorn IPO prospects: Prediction market data shows the probability of Anthropic announcing an IPO before December has fallen from nearly 90% to 57%, indicating a significant cooling in market expectations for monetizing large-model valuations and the timing of public listings.
• Tighter scrutiny of circular compute financing: Key U.S. Senate regulators are stepping up scrutiny of chip exports and circular financing models, focusing on financial loops in the compute supply chain. Potential leverage is facing closer examination.
Market Positioning and Monitoring Map
Transmission chain: Cloud giants phase out externally sourced older-generation clusters -> pressure on third-party compute providers’ equipment utilization and depreciation -> impact on financing premiums and liquidity in the compute infrastructure sector. Key indicators to monitor over the next 24–48 hours: accounts receivable turnover days and hardware depreciation rates in CoreWeave and Nebius earnings reports, as well as developments in U.S. Senate hearings on chip export rules.
Disclaimer: This publication is solely an aggregation and analysis of publicly available global information and objective market data from the past 24 hours, along with related logical projections. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please make decisions with caution.