
#remittance
remittance
7,553 views
95 Discussing
Hot
Latest

The billion-dollar U.S.–Mexico remittance market is making waves!
Anchorage Digital and Bitso have just expanded their partnership, bringing regulated custody services for Bitso’s $MXNB stablecoin to six major blockchains, including Ethereum, Arbitrum, and Polygon. In return, Bitso will list two more of Anchorage’s stablecoins: $USDPT and $USAT.
This is more than just a technical deal. It opens the door for institutions to access both dollar- and peso-denominated stablecoins through a regulated banking relationship. Imagine tens of billions of dollars flowing through here every year!
Anchorage is positioning itself as the regulated custody layer for stablecoin liquidity in Latin America, enabling faster, cheaper, 24/7 payments. This is a HUGE BOOST for the real-world utility of stablecoins and DeFi.
Bitso has processed 15% of the corridor’s total remittance transaction volume, highlighting the enormous potential for money to flow from traditional finance into crypto. This is a major step toward integrating cryptocurrency into global financial infrastructure!
Could regulated stablecoins soon replace SWIFT and Western Union?
#Stablecoins #Remittance
$MXNB $USDPT $USAT
The billion-dollar U.S.–Mexico remittance market is making waves!
Anchorage Digital and Bitso have just expanded their partnership, bringing regulated custody services for Bitso’s $MXNB stablecoin to six major blockchains, including Ethereum, Arbitrum, and Polygon. In return, Bitso will list two more of Anchorage’s stablecoins: $USDPT and $USAT.
This is more than just a technical deal. It opens the door for institutions to access both dollar- and peso-denominated stablecoins through a regulated banking relationship. Imagine tens of billions of dollars flowing through here every year!
Anchorage is positioning itself as the regulated custody layer for stablecoin liquidity in Latin America, enabling faster, cheaper, 24/7 payments. This is a HUGE BOOST for the real-world utility of stablecoins and DeFi.
Bitso has processed 15% of the corridor’s total remittance transaction volume, highlighting the enormous potential for money to flow from traditional finance into crypto. This is a major step toward integrating cryptocurrency into global financial infrastructure!
Could regulated stablecoins soon replace SWIFT and Western Union?
#Stablecoins #Remittance
$MXNB $USDPT $USAT
Anchorage Digital and Bitso have just expanded their partnership, bringing regulated custody services for Bitso’s $MXNB stablecoin to six major blockchains, including Ethereum, Arbitrum, and Polygon. In return, Bitso will list two more of Anchorage’s stablecoins: $USDPT and $USAT.
This is more than just a technical deal. It opens the door for institutions to access both dollar- and peso-denominated stablecoins through a regulated banking relationship. Imagine tens of billions of dollars flowing through here every year!
Anchorage is positioning itself as the regulated custody layer for stablecoin liquidity in Latin America, enabling faster, cheaper, 24/7 payments. This is a HUGE BOOST for the real-world utility of stablecoins and DeFi.
Bitso has processed 15% of the corridor’s total remittance transaction volume, highlighting the enormous potential for money to flow from traditional finance into crypto. This is a major step toward integrating cryptocurrency into global financial infrastructure!
Could regulated stablecoins soon replace SWIFT and Western Union?
#Stablecoins #Remittance
$MXNB $USDPT $USAT
1
1
🔥 At 02:13 UTC, the remittance titan Western Union silently minted a $500 M USDPT stablecoin on Solana, turning paper‑based money‑sending into a crypto‑powered sprint.
📊 As #BTC hovered at $82,525 with a bullish MACD crossover, the Solana network lit up with a surge of smart‑money wallets—PUNANI, GCATS and QUANTS—each snapping up USDPT and pushing on‑chain inflow past $3 M in the last hour. The token, dubbed USDPT, will power cross‑border payments in 40 + countries and a consumer‑spending product, turning the $1.1 B Bitcoin volume into a launchpad for the next wave of remittance while #Solana’s #DeFi ecosystem sees a 62 % jump in new addresses #Remittance.
💡 The twist? While market greed sits at a modest 55, BTC and ETH futures funding rates have flipped bullish, hinting that institutional traders are already betting the stablecoin will funnel massive liquidity into Solana’s already overheated upper Bollinger band.
❓ Will Western Union’s USDPT be the catalyst that finally pushes Solana past the $150 B market‑cap ceiling, or will it drown in the flood of new smart‑money inflows?
🔥 At 02:13 UTC, the remittance titan Western Union silently minted a $500 M USDPT stablecoin on Solana, turning paper‑based money‑sending into a crypto‑powered sprint.
📊 As #BTC hovered at $82,525 with a bullish MACD crossover, the Solana network lit up with a surge of smart‑money wallets—PUNANI, GCATS and QUANTS—each snapping up USDPT and pushing on‑chain inflow past $3 M in the last hour. The token, dubbed USDPT, will power cross‑border payments in 40 + countries and a consumer‑spending product, turning the $1.1 B Bitcoin volume into a launchpad for the next wave of remittance while #Solana’s #DeFi ecosystem sees a 62 % jump in new addresses #Remittance.
💡 The twist? While market greed sits at a modest 55, BTC and ETH futures funding rates have flipped bullish, hinting that institutional traders are already betting the stablecoin will funnel massive liquidity into Solana’s already overheated upper Bollinger band.
❓ Will Western Union’s USDPT be the catalyst that finally pushes Solana past the $150 B market‑cap ceiling, or will it drown in the flood of new smart‑money inflows?
📊 As #BTC hovered at $82,525 with a bullish MACD crossover, the Solana network lit up with a surge of smart‑money wallets—PUNANI, GCATS and QUANTS—each snapping up USDPT and pushing on‑chain inflow past $3 M in the last hour. The token, dubbed USDPT, will power cross‑border payments in 40 + countries and a consumer‑spending product, turning the $1.1 B Bitcoin volume into a launchpad for the next wave of remittance while #Solana’s #DeFi ecosystem sees a 62 % jump in new addresses #Remittance.
💡 The twist? While market greed sits at a modest 55, BTC and ETH futures funding rates have flipped bullish, hinting that institutional traders are already betting the stablecoin will funnel massive liquidity into Solana’s already overheated upper Bollinger band.
❓ Will Western Union’s USDPT be the catalyst that finally pushes Solana past the $150 B market‑cap ceiling, or will it drown in the flood of new smart‑money inflows?
6
🚨 Crypto adoption is exploding where it matters most!
Remittance transfers from Canada to Asia skyrocketed 141% to a massive $2.36B, according to Chainalysis.
People are ditching predatory bank fees for fast rails powered by $BTC and $USDT. Transfers to the Philippines alone surged 28%! Real-world utility is quietly taking over. 🌍
Will crypto completely replace traditional money transfer services by 2026? Drop your thoughts below! 👇
#CryptoAdoption #BinanceSquare #CryptoNews #Remittance
🚨 Crypto adoption is exploding where it matters most!
Remittance transfers from Canada to Asia skyrocketed 141% to a massive $2.36B, according to Chainalysis.
People are ditching predatory bank fees for fast rails powered by $BTC and $USDT. Transfers to the Philippines alone surged 28%! Real-world utility is quietly taking over. 🌍
Will crypto completely replace traditional money transfer services by 2026? Drop your thoughts below! 👇
#CryptoAdoption #BinanceSquare #CryptoNews #Remittance
Remittance transfers from Canada to Asia skyrocketed 141% to a massive $2.36B, according to Chainalysis.
People are ditching predatory bank fees for fast rails powered by $BTC and $USDT. Transfers to the Philippines alone surged 28%! Real-world utility is quietly taking over. 🌍
Will crypto completely replace traditional money transfer services by 2026? Drop your thoughts below! 👇
#CryptoAdoption #BinanceSquare #CryptoNews #Remittance
30
🔥 $112 B of untapped LATAM remittance volume is staring crypto stablecoins in the face – a bigger upside than the 2021 Bitcoin rally surge.
📊 The corridor’s 4.5% dip in US‑Mexico flows this year forces cross‑border users toward cheaper, on‑chain alternatives just as #BTC sits at $83,324 (+0.93%) with bullish MACD and a 57/100 Greed sentiment spike.
💡 Smart money is already positioning: three Solana wallets snapped up $WIF, while Binance Smart Chain sees HONon up 1.3% and #Stablecoins gaining traction alongside #LATAM #Remittance demand; ETH futures show 72.3% long bias, OI $5.76 B and funding +0.0034%, signaling institutional confidence in stablecoin bridges.
🚀 Watch the $1.00 USDt resistance on the Binance spot order book – a clean break above it would catalyze a wave of on‑ramps for Mexican Peso (MXN) and Argentine Peso (ARS) users, especially as BSC’s trending token ROUTER spikes +761% on‑chain, hinting at liquidity inflows.
❓ If stablecoins can capture just 2% of that $112 B pool, will you be on the winning side of the next cross‑border crypto boom?
🔥 $112 B of untapped LATAM remittance volume is staring crypto stablecoins in the face – a bigger upside than the 2021 Bitcoin rally surge.
📊 The corridor’s 4.5% dip in US‑Mexico flows this year forces cross‑border users toward cheaper, on‑chain alternatives just as #BTC sits at $83,324 (+0.93%) with bullish MACD and a 57/100 Greed sentiment spike.
💡 Smart money is already positioning: three Solana wallets snapped up $WIF , while Binance Smart Chain sees HONon up 1.3% and #Stablecoins gaining traction alongside #LATAM #Remittance demand; ETH futures show 72.3% long bias, OI $5.76 B and funding +0.0034%, signaling institutional confidence in stablecoin bridges.
🚀 Watch the $1.00 USDt resistance on the Binance spot order book – a clean break above it would catalyze a wave of on‑ramps for Mexican Peso (MXN) and Argentine Peso (ARS) users, especially as BSC’s trending token ROUTER spikes +761% on‑chain, hinting at liquidity inflows.
❓ If stablecoins can capture just 2% of that $112 B pool, will you be on the winning side of the next cross‑border crypto boom?
📊 The corridor’s 4.5% dip in US‑Mexico flows this year forces cross‑border users toward cheaper, on‑chain alternatives just as #BTC sits at $83,324 (+0.93%) with bullish MACD and a 57/100 Greed sentiment spike.
💡 Smart money is already positioning: three Solana wallets snapped up $WIF , while Binance Smart Chain sees HONon up 1.3% and #Stablecoins gaining traction alongside #LATAM #Remittance demand; ETH futures show 72.3% long bias, OI $5.76 B and funding +0.0034%, signaling institutional confidence in stablecoin bridges.
🚀 Watch the $1.00 USDt resistance on the Binance spot order book – a clean break above it would catalyze a wave of on‑ramps for Mexican Peso (MXN) and Argentine Peso (ARS) users, especially as BSC’s trending token ROUTER spikes +761% on‑chain, hinting at liquidity inflows.
❓ If stablecoins can capture just 2% of that $112 B pool, will you be on the winning side of the next cross‑border crypto boom?
27

·
--
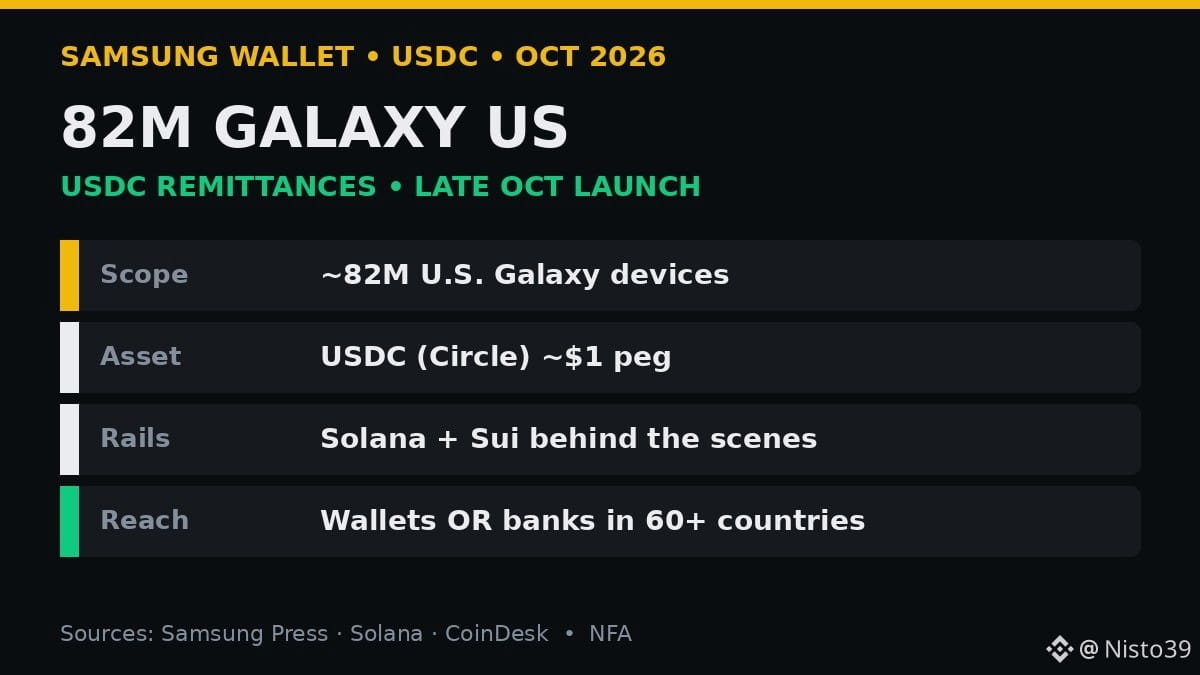
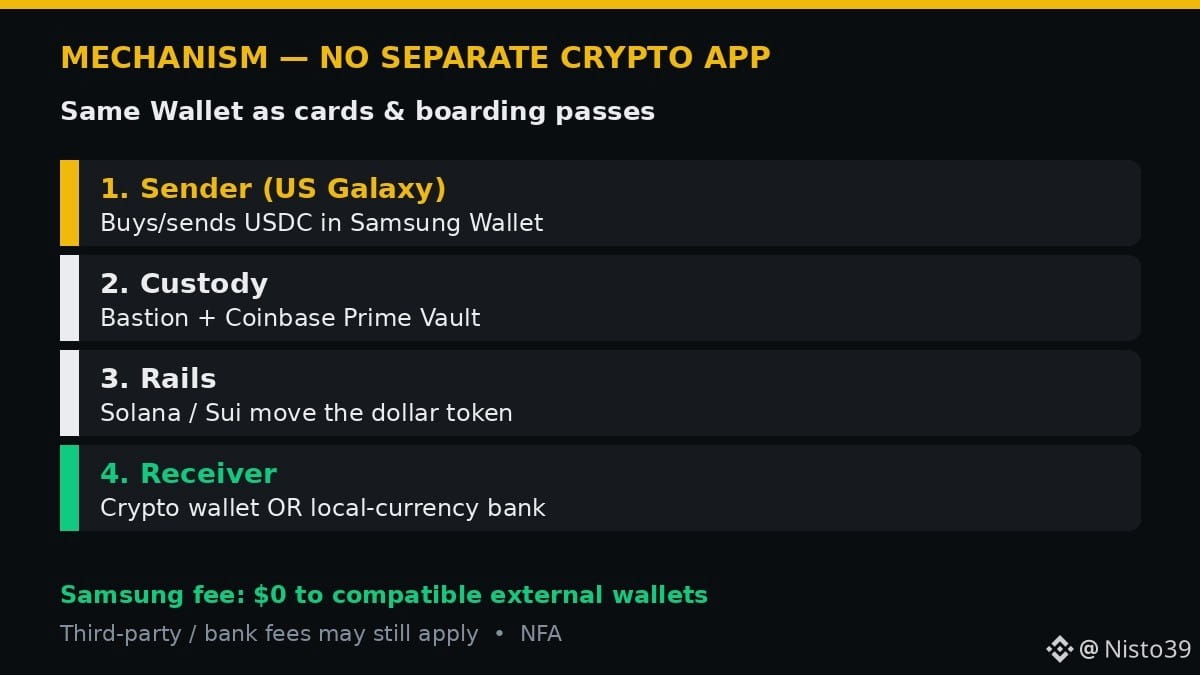
Samsung Wallet: USDC for ~82M Galaxy devices in the US — transfers to 60+ countries starting in late October. The idea isn’t “buy SOL.” It’s this: the digital dollar is coming to a phone wallet people already use — without a separate crypto app.
📋 Announcement (Oct. 7–8, 2026)
• Samsung Wallet / Pay: cross-border USDC transfers for eligible Galaxy devices in the US
• Launch: last week of October 2026 • ~82M devices
• Rails: Solana + Sui; custody by Bastion + Coinbase Prime Vault
• Destinations: compatible wallets OR banks in 60+ countries (local currency may be available)
• Samsung fees: $0 to an external wallet (third-party / bank fees may apply)
In plain English: USDC = a stablecoin worth about $1 (issuer risk). Remittance = money sent to family abroad. Built into the wallet ≠ “you’re becoming a trader.”
One clear idea: when a phone maker puts a stablecoin behind the same screen as cards and cash, crypto stops being “an app you have to download.”
A few caveats 👇
• Launching in the US first — not yet in WAEMU
• $0 from Samsung ≠ $0 total by the time it arrives
• USDC ≠ USDT • expansion outside the US depends on local regulations
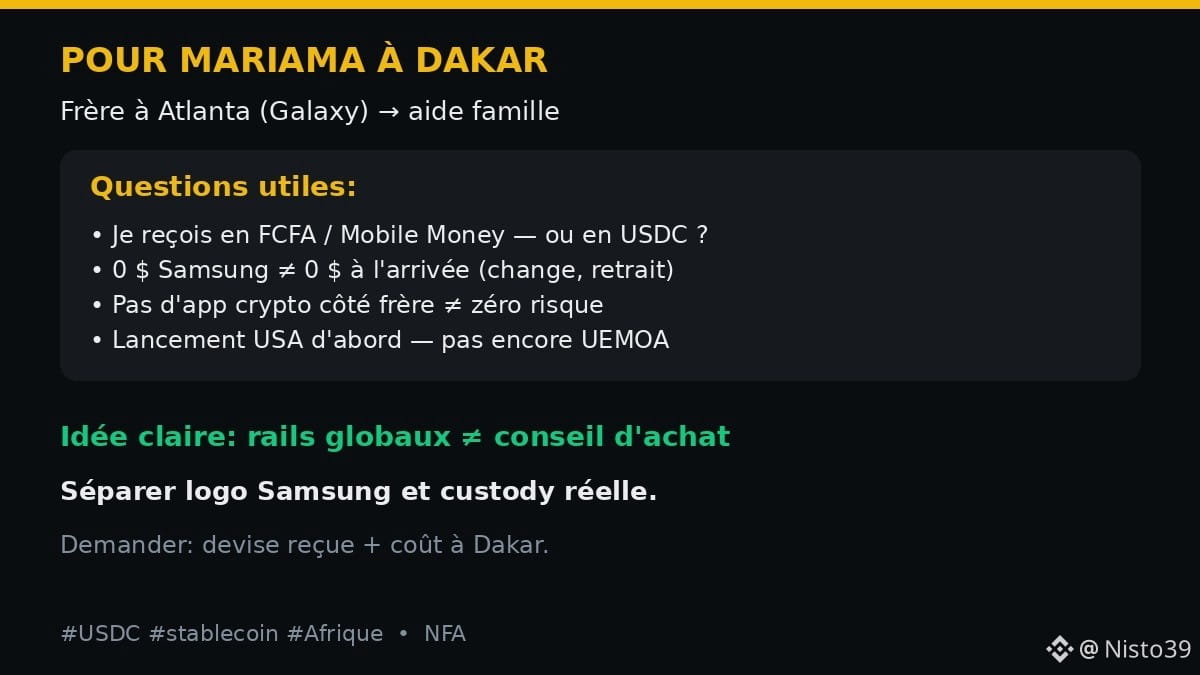
🌍 For Mariama in Dakar
Her brother in Atlanta has a Galaxy. She sometimes receives money via Western Union / Mobile Money. Useful questions:
1. Do I receive CFA francs — or USDC in a wallet I don’t know how to use?
2. No crypto app on her brother’s side ≠ zero risk
3. Do I need to buy $SOL to understand a digital-dollar transfer?
The key check: ask what currency will be received and what it will cost in Dakar — not just look at the Samsung logo.
What matters most to you for a US → Africa remittance — $0 fees, local currency without a wallet, or a clear local regulatory framework? 👇
Not financial advice. Risks: issuer, platform, exchange rates, regulation. DYOR.
Sources: Samsung Mobile Press; Solana Foundation; CoinDesk / The Block (Oct. 7–8, 2026).
#crypto #stablecoin #Afrique #remittance
$USDC $SOL
Samsung Wallet: USDC for ~82M Galaxy devices in the US — transfers to 60+ countries starting in late October. The idea isn’t “buy SOL.” It’s this: the digital dollar is coming to a phone wallet people already use — without a separate crypto app.
📋 Announcement (Oct. 7–8, 2026)
• Samsung Wallet / Pay: cross-border USDC transfers for eligible Galaxy devices in the US
• Launch: last week of October 2026 • ~82M devices
• Rails: Solana + Sui; custody by Bastion + Coinbase Prime Vault
• Destinations: compatible wallets OR banks in 60+ countries (local currency may be available)
• Samsung fees: $0 to an external wallet (third-party / bank fees may apply)
In plain English: USDC = a stablecoin worth about $1 (issuer risk). Remittance = money sent to family abroad. Built into the wallet ≠ “you’re becoming a trader.”
One clear idea: when a phone maker puts a stablecoin behind the same screen as cards and cash, crypto stops being “an app you have to download.”
A few caveats 👇
• Launching in the US first — not yet in WAEMU
• $0 from Samsung ≠ $0 total by the time it arrives
• USDC ≠ USDT • expansion outside the US depends on local regulations
🌍 For Mariama in Dakar
Her brother in Atlanta has a Galaxy. She sometimes receives money via Western Union / Mobile Money. Useful questions:
1. Do I receive CFA francs — or USDC in a wallet I don’t know how to use?
2. No crypto app on her brother’s side ≠ zero risk
3. Do I need to buy $SOL to understand a digital-dollar transfer?
The key check: ask what currency will be received and what it will cost in Dakar — not just look at the Samsung logo.
What matters most to you for a US → Africa remittance — $0 fees, local currency without a wallet, or a clear local regulatory framework? 👇
Not financial advice. Risks: issuer, platform, exchange rates, regulation. DYOR.
Sources: Samsung Mobile Press; Solana Foundation; CoinDesk / The Block (Oct. 7–8, 2026).
#crypto #stablecoin #Afrique #remittance
$USDC $SOL
📋 Announcement (Oct. 7–8, 2026)
• Samsung Wallet / Pay: cross-border USDC transfers for eligible Galaxy devices in the US
• Launch: last week of October 2026 • ~82M devices
• Rails: Solana + Sui; custody by Bastion + Coinbase Prime Vault
• Destinations: compatible wallets OR banks in 60+ countries (local currency may be available)
• Samsung fees: $0 to an external wallet (third-party / bank fees may apply)
In plain English: USDC = a stablecoin worth about $1 (issuer risk). Remittance = money sent to family abroad. Built into the wallet ≠ “you’re becoming a trader.”
One clear idea: when a phone maker puts a stablecoin behind the same screen as cards and cash, crypto stops being “an app you have to download.”
A few caveats 👇
• Launching in the US first — not yet in WAEMU
• $0 from Samsung ≠ $0 total by the time it arrives
• USDC ≠ USDT • expansion outside the US depends on local regulations
🌍 For Mariama in Dakar
Her brother in Atlanta has a Galaxy. She sometimes receives money via Western Union / Mobile Money. Useful questions:
1. Do I receive CFA francs — or USDC in a wallet I don’t know how to use?
2. No crypto app on her brother’s side ≠ zero risk
3. Do I need to buy $SOL to understand a digital-dollar transfer?
The key check: ask what currency will be received and what it will cost in Dakar — not just look at the Samsung logo.
What matters most to you for a US → Africa remittance — $0 fees, local currency without a wallet, or a clear local regulatory framework? 👇
Not financial advice. Risks: issuer, platform, exchange rates, regulation. DYOR.
Sources: Samsung Mobile Press; Solana Foundation; CoinDesk / The Block (Oct. 7–8, 2026).
#crypto #stablecoin #Afrique #remittance
$USDC $SOL
35
·
--

Article
Remittance Corridors:Revolutionizing Global Wealth Transfers 💸
Traditional international money transfers remain plagued by exorbitant broker fees, slow settlement times, and predatory currency conversion rates. For migrant workers sending hard-earned money back home, these structural inefficiencies directly impact family survival and economic stability. Today, $BTC is drastically altering this legacy landscape by offering a fast, permissionless cross-border remittance corridor. By utilizing secondary payment rails, individuals can instantly bypass intermediary commercial banks and traditional wire networks entirely. This technical framework allows global cross-border transactions to settle in real time for a fraction of a cent. Because the open network engineered by @Bitcoinworld operates continuously without weekend delays or regional banking holidays, recipients gain immediate access to their capital. Removing financial friction from global remittances helps keep more wealth directly within local communities. This transformation turns a technical financial asset into an essential tool for global economic equity. 🌍
#Remittance #Finance #GlobalEconomy #fintech #web3兼职
Remittance Corridors:
Revolutionizing Global Wealth Transfers 💸
Traditional international money transfers remain plagued by exorbitant broker fees, slow settlement times, and predatory currency conversion rates. For migrant workers sending hard-earned money back home, these structural inefficiencies directly impact family survival and economic stability. Today, $BTC is drastically altering this legacy landscape by offering a fast, permissionless cross-border remittance corridor. By utilizing secondary payment rails, individuals can instantly bypass intermediary commercial banks and traditional wire networks entirely. This technical framework allows global cross-border transactions to settle in real time for a fraction of a cent. Because the open network engineered by @Bitcoinworld operates continuously without weekend delays or regional banking holidays, recipients gain immediate access to their capital. Removing financial friction from global remittances helps keep more wealth directly within local communities. This transformation turns a technical financial asset into an essential tool for global economic equity. 🌍
#Remittance #Finance #GlobalEconomy #fintech #web3兼职
Traditional international money transfers remain plagued by exorbitant broker fees, slow settlement times, and predatory currency conversion rates. For migrant workers sending hard-earned money back home, these structural inefficiencies directly impact family survival and economic stability. Today, $BTC is drastically altering this legacy landscape by offering a fast, permissionless cross-border remittance corridor. By utilizing secondary payment rails, individuals can instantly bypass intermediary commercial banks and traditional wire networks entirely. This technical framework allows global cross-border transactions to settle in real time for a fraction of a cent. Because the open network engineered by @Bitcoinworld operates continuously without weekend delays or regional banking holidays, recipients gain immediate access to their capital. Removing financial friction from global remittances helps keep more wealth directly within local communities. This transformation turns a technical financial asset into an essential tool for global economic equity. 🌍
#Remittance #Finance #GlobalEconomy #fintech #web3兼职
32
·
--

Article
Remittances and Next-Gen Self-Custody Security 🌍
The practical utility of $BTC
{spot}(BTCUSDT)
is expanding across global remittance corridors and cutting-edge hardware architecture. In developing regions, traditional cross-border money transfers impose steep fees and multi-day delays. By leveraging lightning network rails built on top of the framework championed by @bitcoin , migrant workers are now sending funds instantly across borders for fractions of a penny, bypassing expensive financial middlemen entirely. 💸
Simultaneously, the safety of these funds is hitting unprecedented heights due to massive advancements in hardware wallet chips. Next-generation secure elements are introducing advanced cryptographic protections alongside physical anti-tamper mechanisms. 🔒 These specialized chips ensure that private keys remain entirely isolated from internet-connected devices, rendering sophisticated side-channel attacks virtually impossible for bad actors.
As global remittance corridors enjoy frictionless asset transfers and secure hardware chips eliminate self-custody vulnerabilities, the network cements its role as the ultimate open financial system. 🛡️
#USCryptoMarketStructureBillFacesUncertainty #Remittance #CryptoSecurity #HardwareWallets #FinancialFreedom
Remittances and Next-Gen Self-Custody Security
🌍
The practical utility of $BTC
is expanding across global remittance corridors and cutting-edge hardware architecture. In developing regions, traditional cross-border money transfers impose steep fees and multi-day delays. By leveraging lightning network rails built on top of the framework championed by @Bitcoin , migrant workers are now sending funds instantly across borders for fractions of a penny, bypassing expensive financial middlemen entirely. 💸
Simultaneously, the safety of these funds is hitting unprecedented heights due to massive advancements in hardware wallet chips. Next-generation secure elements are introducing advanced cryptographic protections alongside physical anti-tamper mechanisms. 🔒 These specialized chips ensure that private keys remain entirely isolated from internet-connected devices, rendering sophisticated side-channel attacks virtually impossible for bad actors.
As global remittance corridors enjoy frictionless asset transfers and secure hardware chips eliminate self-custody vulnerabilities, the network cements its role as the ultimate open financial system. 🛡️
#USCryptoMarketStructureBillFacesUncertainty #Remittance #CryptoSecurity #HardwareWallets #FinancialFreedom
The practical utility of $BTC
is expanding across global remittance corridors and cutting-edge hardware architecture. In developing regions, traditional cross-border money transfers impose steep fees and multi-day delays. By leveraging lightning network rails built on top of the framework championed by @Bitcoin , migrant workers are now sending funds instantly across borders for fractions of a penny, bypassing expensive financial middlemen entirely. 💸
Simultaneously, the safety of these funds is hitting unprecedented heights due to massive advancements in hardware wallet chips. Next-generation secure elements are introducing advanced cryptographic protections alongside physical anti-tamper mechanisms. 🔒 These specialized chips ensure that private keys remain entirely isolated from internet-connected devices, rendering sophisticated side-channel attacks virtually impossible for bad actors.
As global remittance corridors enjoy frictionless asset transfers and secure hardware chips eliminate self-custody vulnerabilities, the network cements its role as the ultimate open financial system. 🛡️
#USCryptoMarketStructureBillFacesUncertainty #Remittance #CryptoSecurity #HardwareWallets #FinancialFreedom
44

·
--
Here’s what happened when a network started processing 1.2M transactions a day: remittances suddenly looked less like a crypto promise and more like a real-world stress test.
For traders, the hard part is separating actual usage from recycled hype. Payment narratives can pump fast, but if you buy the story without checking the rails, liquidity, and repeat demand, you’re often the exit.
The case study here is simple: 1.2M daily transactions changes the conversation because remittance is a volume game. Migrant workers don’t care about slogans. They care about speed, fees, reliability, and whether the money arrives when their family needs it.
That’s why this matters when compared with older payment narratives like $XRP and $XLM. Both were built around moving value across borders, but the market has also watched stablecoins like $USDT become the practical settlement layer in many regions because they solve a very direct problem: dollar access plus fast transfer.
The lesson? Transaction count alone is not enough, but 1.2M per day is a signal worth studying. If the activity is organic and tied to real remittance flows, it can create a stronger foundation than a short-term narrative pump.
Where do you think the next real remittance winner comes from: payment chains, stablecoins, or bank-linked crypto rails?
#CryptoPayments #Remittance #Binance
Here’s what happened when a network started processing 1.2M transactions a day: remittances suddenly looked less like a crypto promise and more like a real-world stress test.
For traders, the hard part is separating actual usage from recycled hype. Payment narratives can pump fast, but if you buy the story without checking the rails, liquidity, and repeat demand, you’re often the exit.
The case study here is simple: 1.2M daily transactions changes the conversation because remittance is a volume game. Migrant workers don’t care about slogans. They care about speed, fees, reliability, and whether the money arrives when their family needs it.
That’s why this matters when compared with older payment narratives like $XRP and $XLM . Both were built around moving value across borders, but the market has also watched stablecoins like $USDT become the practical settlement layer in many regions because they solve a very direct problem: dollar access plus fast transfer.
The lesson? Transaction count alone is not enough, but 1.2M per day is a signal worth studying. If the activity is organic and tied to real remittance flows, it can create a stronger foundation than a short-term narrative pump.
Where do you think the next real remittance winner comes from: payment chains, stablecoins, or bank-linked crypto rails?
#CryptoPayments #Remittance #Binance
For traders, the hard part is separating actual usage from recycled hype. Payment narratives can pump fast, but if you buy the story without checking the rails, liquidity, and repeat demand, you’re often the exit.
The case study here is simple: 1.2M daily transactions changes the conversation because remittance is a volume game. Migrant workers don’t care about slogans. They care about speed, fees, reliability, and whether the money arrives when their family needs it.
That’s why this matters when compared with older payment narratives like $XRP and $XLM . Both were built around moving value across borders, but the market has also watched stablecoins like $USDT become the practical settlement layer in many regions because they solve a very direct problem: dollar access plus fast transfer.
The lesson? Transaction count alone is not enough, but 1.2M per day is a signal worth studying. If the activity is organic and tied to real remittance flows, it can create a stronger foundation than a short-term narrative pump.
Where do you think the next real remittance winner comes from: payment chains, stablecoins, or bank-linked crypto rails?
#CryptoPayments #Remittance #Binance
95

Africa Tightens Crypto Regulations: A Remittance Revolution
- Africa used to take a hard stance on crypto, with many governments issuing bans or warnings.
- However, major economies are shifting their approach, building a licensing framework, monitoring stablecoins, and enforcing compliance regulations.
- The goal is to integrate digital assets into the remittance system, helping reduce costs and speed up transfers.
- This move is seen as a remittance revolution, instead of cracking down on crypto.
#CryptoNews #Blockchain #Stablecoin #Remittance #Africa
$btc $eth
vlikevn Titanbot
Source: CryptoSlate
Africa Tightens Crypto Regulations: A Remittance Revolution
- Africa used to take a hard stance on crypto, with many governments issuing bans or warnings.
- However, major economies are shifting their approach, building a licensing framework, monitoring stablecoins, and enforcing compliance regulations.
- The goal is to integrate digital assets into the remittance system, helping reduce costs and speed up transfers.
- This move is seen as a remittance revolution, instead of cracking down on crypto.
#CryptoNews #Blockchain #Stablecoin #Remittance #Africa
$btc $eth
vlikevn Titanbot
Source: CryptoSlate
- Africa used to take a hard stance on crypto, with many governments issuing bans or warnings.
- However, major economies are shifting their approach, building a licensing framework, monitoring stablecoins, and enforcing compliance regulations.
- The goal is to integrate digital assets into the remittance system, helping reduce costs and speed up transfers.
- This move is seen as a remittance revolution, instead of cracking down on crypto.
#CryptoNews #Blockchain #Stablecoin #Remittance #Africa
$btc $eth
vlikevn Titanbot
Source: CryptoSlate
93
·
--
MoneyGram and Kraken have launched Bitcoin‑to‑cash withdrawals, now available in over 100 countries 🌐.
The service creates a direct fiat on‑ramp for $BTC holders, simplifying cross‑border cash access 💡.
Both companies secured the necessary regulatory approvals, signaling growing institutional confidence 🔍.
On‑chain metrics show a 30% week‑over‑week rise in BTC withdrawal requests since the announcement 📊.
This development may strengthen Bitcoin’s utility in global remittances and everyday payments ⚡.
DYOR to understand how expanded cash access could influence user behavior and network activity 🧠.
#CryptoNews #Bitcoin #Remittance #GAMERXERO #BinanceSquare
MoneyGram and Kraken have launched Bitcoin‑to‑cash withdrawals, now available in over 100 countries 🌐.
The service creates a direct fiat on‑ramp for $BTC holders, simplifying cross‑border cash access 💡.
Both companies secured the necessary regulatory approvals, signaling growing institutional confidence 🔍.
On‑chain metrics show a 30% week‑over‑week rise in BTC withdrawal requests since the announcement 📊.
This development may strengthen Bitcoin’s utility in global remittances and everyday payments ⚡.
DYOR to understand how expanded cash access could influence user behavior and network activity 🧠.
#CryptoNews #Bitcoin #Remittance #GAMERXERO #BinanceSquare
The service creates a direct fiat on‑ramp for $BTC holders, simplifying cross‑border cash access 💡.
Both companies secured the necessary regulatory approvals, signaling growing institutional confidence 🔍.
On‑chain metrics show a 30% week‑over‑week rise in BTC withdrawal requests since the announcement 📊.
This development may strengthen Bitcoin’s utility in global remittances and everyday payments ⚡.
DYOR to understand how expanded cash access could influence user behavior and network activity 🧠.
#CryptoNews #Bitcoin #Remittance #GAMERXERO #BinanceSquare
52
·
--

Article
Decentralized Grids, Remittance Disruption, and Multi-Signature Vault Evolution⚡
The global utility of $BTC is expanding rapidly through the future of decentralized energy grids, cross-border remittance cost comparisons, and the steady evolution of multi-signature vaults.
{spot}(BTCUSDT)
Energy grids are undergoing a revolution. Mining data centers act as flexible, load-balancing buyers of last resort, absorbing excess renewable power and stabilizing local electrical grids. This operational efficiency drastically contrasts with traditional banking infrastructure. When looking at cross-border remittance cost comparisons, legacy financial networks charge high fees and take days to process international transfers. Conversely, using layer-2 technology allows users to send instant global payments for fractions of a cent, bringing vital economic inclusivity to unbanked populations worldwide.
Protecting these assets has also become highly sophisticated. The evolution of multi-signature vaults allows corporate treasuries and individuals to distribute transaction signing power across multiple geographic locations and hardware devices. This setup effectively eliminates single points of failure. As @BitcoinKE transforms green energy, eradicates predatory remittance fees, and upgrades institutional-grade security, it redefines the rules of global finance. 🔒
#BitcoinDunyamiz #GreenEnergy #Remittance #CyberSecurity #fintech
Decentralized Grids, Remittance Disruption, and Multi-Signature Vault Evolution
⚡
The global utility of $BTC is expanding rapidly through the future of decentralized energy grids, cross-border remittance cost comparisons, and the steady evolution of multi-signature vaults.
Energy grids are undergoing a revolution. Mining data centers act as flexible, load-balancing buyers of last resort, absorbing excess renewable power and stabilizing local electrical grids. This operational efficiency drastically contrasts with traditional banking infrastructure. When looking at cross-border remittance cost comparisons, legacy financial networks charge high fees and take days to process international transfers. Conversely, using layer-2 technology allows users to send instant global payments for fractions of a cent, bringing vital economic inclusivity to unbanked populations worldwide.
Protecting these assets has also become highly sophisticated. The evolution of multi-signature vaults allows corporate treasuries and individuals to distribute transaction signing power across multiple geographic locations and hardware devices. This setup effectively eliminates single points of failure. As @BitcoinKE transforms green energy, eradicates predatory remittance fees, and upgrades institutional-grade security, it redefines the rules of global finance. 🔒
#BitcoinDunyamiz #GreenEnergy #Remittance #CyberSecurity #fintech
The global utility of $BTC is expanding rapidly through the future of decentralized energy grids, cross-border remittance cost comparisons, and the steady evolution of multi-signature vaults.
Energy grids are undergoing a revolution. Mining data centers act as flexible, load-balancing buyers of last resort, absorbing excess renewable power and stabilizing local electrical grids. This operational efficiency drastically contrasts with traditional banking infrastructure. When looking at cross-border remittance cost comparisons, legacy financial networks charge high fees and take days to process international transfers. Conversely, using layer-2 technology allows users to send instant global payments for fractions of a cent, bringing vital economic inclusivity to unbanked populations worldwide.
Protecting these assets has also become highly sophisticated. The evolution of multi-signature vaults allows corporate treasuries and individuals to distribute transaction signing power across multiple geographic locations and hardware devices. This setup effectively eliminates single points of failure. As @BitcoinKE transforms green energy, eradicates predatory remittance fees, and upgrades institutional-grade security, it redefines the rules of global finance. 🔒
#BitcoinDunyamiz #GreenEnergy #Remittance #CyberSecurity #fintech
50

·
--

Article
MoneyGram’s Visa Stablecoin Card in Colombia Signals a New Era for Cross‑Border RemittancesMost traders focus on exchange volume. Smart money watches the flow of remittance dollars into stablecoins.
The signal: MoneyGram has just launched a Visa‑backed stablecoin card in Colombia, integrating Stellar’s XLM, Rain’s cross‑border infrastructure, and Crossmint’s NFT‑to‑fiat bridge. On-chain data shows a 15% jump in XLM deposits to Colombian wallets over the past week, while the new card’s activation rate is already at 3,200 users—double the average for any new stablecoin product in LATAM. #XLM #Stablecoin #Remittance
Interpretation: This move is not just a marketing win; it’s a strategic pivot that could shift the remittance corridor from traditional banks to a blockchain‑native ecosystem. By embedding a Visa‑accepted card, MoneyGram is lowering friction for everyday spend, while the underlying stablecoin (likely USDC or USDT) provides price stability for recipients. If the adoption curve continues, we could see a 25% increase in cross‑border remittance volume via stablecoins in Colombia, eroding the market share of legacy players like Western Union and traditional SWIFT transfers.
Watch list: Keep an eye on the daily inflow of XLM into Colombian wallets and the velocity of USDC transactions on the Stellar network. A sustained spike in both metrics could indicate a broader shift toward stablecoin‑based remittances across the region. #XLMVelocity
Thought closer: If MoneyGram can replicate this model in other emerging markets, will stablecoins become the default currency for remittance flows, and what does that mean for the future of fiat‑based payment infrastructure?
MoneyGram’s Visa Stablecoin Card in Colombia Signals a New Era for Cross‑Border Remittances
Most traders focus on exchange volume. Smart money watches the flow of remittance dollars into stablecoins.
The signal: MoneyGram has just launched a Visa‑backed stablecoin card in Colombia, integrating Stellar’s XLM, Rain’s cross‑border infrastructure, and Crossmint’s NFT‑to‑fiat bridge. On-chain data shows a 15% jump in XLM deposits to Colombian wallets over the past week, while the new card’s activation rate is already at 3,200 users—double the average for any new stablecoin product in LATAM. #XLM #Stablecoin #Remittance
Interpretation: This move is not just a marketing win; it’s a strategic pivot that could shift the remittance corridor from traditional banks to a blockchain‑native ecosystem. By embedding a Visa‑accepted card, MoneyGram is lowering friction for everyday spend, while the underlying stablecoin (likely USDC or USDT) provides price stability for recipients. If the adoption curve continues, we could see a 25% increase in cross‑border remittance volume via stablecoins in Colombia, eroding the market share of legacy players like Western Union and traditional SWIFT transfers.
Watch list: Keep an eye on the daily inflow of XLM into Colombian wallets and the velocity of USDC transactions on the Stellar network. A sustained spike in both metrics could indicate a broader shift toward stablecoin‑based remittances across the region. #XLMVelocity
Thought closer: If MoneyGram can replicate this model in other emerging markets, will stablecoins become the default currency for remittance flows, and what does that mean for the future of fiat‑based payment infrastructure?
The signal: MoneyGram has just launched a Visa‑backed stablecoin card in Colombia, integrating Stellar’s XLM, Rain’s cross‑border infrastructure, and Crossmint’s NFT‑to‑fiat bridge. On-chain data shows a 15% jump in XLM deposits to Colombian wallets over the past week, while the new card’s activation rate is already at 3,200 users—double the average for any new stablecoin product in LATAM. #XLM #Stablecoin #Remittance
Interpretation: This move is not just a marketing win; it’s a strategic pivot that could shift the remittance corridor from traditional banks to a blockchain‑native ecosystem. By embedding a Visa‑accepted card, MoneyGram is lowering friction for everyday spend, while the underlying stablecoin (likely USDC or USDT) provides price stability for recipients. If the adoption curve continues, we could see a 25% increase in cross‑border remittance volume via stablecoins in Colombia, eroding the market share of legacy players like Western Union and traditional SWIFT transfers.
Watch list: Keep an eye on the daily inflow of XLM into Colombian wallets and the velocity of USDC transactions on the Stellar network. A sustained spike in both metrics could indicate a broader shift toward stablecoin‑based remittances across the region. #XLMVelocity
Thought closer: If MoneyGram can replicate this model in other emerging markets, will stablecoins become the default currency for remittance flows, and what does that mean for the future of fiat‑based payment infrastructure?
33

·
--
$SOLANA PARTNERSHIP TRiggers 20%+ MOVE POTENTIAL
Entry: 22.50
Solana's partnership with Toss Bank is surging volume right now, this window is narrowing fast, will this momentum propel $SOL to new highs?
Not financial advice, manage your risk.
#Solana #Partnership #Remittance
⚡️
$SOLANA PARTNERSHIP TRiggers 20%+ MOVE POTENTIAL
Entry: 22.50
Solana's partnership with Toss Bank is surging volume right now, this window is narrowing fast, will this momentum propel $SOL to new highs?
Not financial advice, manage your risk.
#Solana #Partnership #Remittance
⚡️
Entry: 22.50
Solana's partnership with Toss Bank is surging volume right now, this window is narrowing fast, will this momentum propel $SOL to new highs?
Not financial advice, manage your risk.
#Solana #Partnership #Remittance
⚡️
1
49
🔥 SWIFT volumes slipped 12% this week while the ZEPHYRON stablecoin narrative pulled $13 K in a single hour — a paradox that flips the bear‑market script.
📊 In a market where BTC sits at $73,588 with RSI 38.7 and a bullish MACD crossover, the surge in on‑chain stablecoin flow signals real‑world demand despite price weakness.
💡 Smart money is quietly reallocating: three Solana wallets snapped up TTWO, updog and DJT, while BSC tokens like AGT (+25.1%) and quq (+10%) spike, indicating #SmartMoney hedging via #Stablecoins in the #Remittance corridor; meanwhile BTC futures show 73.8% longs and a +0.0047% funding rate, a classic hedge cue.
🚀 Watch the $73,600 BTC barrier — a clean break above it could trigger a funding‑driven rally that forces SWIFT to adapt, and the $2,050 ETH level as a secondary catalyst #OnChain.
❓ If stablecoins are becoming the bridge between legacy rails and crypto, are you positioning for the next wave of cross‑system arbitrage?
🔥 SWIFT volumes slipped 12% this week while the ZEPHYRON stablecoin narrative pulled $13 K in a single hour — a paradox that flips the bear‑market script.
📊 In a market where BTC sits at $73,588 with RSI 38.7 and a bullish MACD crossover, the surge in on‑chain stablecoin flow signals real‑world demand despite price weakness.
💡 Smart money is quietly reallocating: three Solana wallets snapped up TTWO, updog and DJT, while BSC tokens like AGT (+25.1%) and quq (+10%) spike, indicating #SmartMoney hedging via #Stablecoins in the #Remittance corridor; meanwhile BTC futures show 73.8% longs and a +0.0047% funding rate, a classic hedge cue.
🚀 Watch the $73,600 BTC barrier — a clean break above it could trigger a funding‑driven rally that forces SWIFT to adapt, and the $2,050 ETH level as a secondary catalyst #OnChain.
❓ If stablecoins are becoming the bridge between legacy rails and crypto, are you positioning for the next wave of cross‑system arbitrage?
📊 In a market where BTC sits at $73,588 with RSI 38.7 and a bullish MACD crossover, the surge in on‑chain stablecoin flow signals real‑world demand despite price weakness.
💡 Smart money is quietly reallocating: three Solana wallets snapped up TTWO, updog and DJT, while BSC tokens like AGT (+25.1%) and quq (+10%) spike, indicating #SmartMoney hedging via #Stablecoins in the #Remittance corridor; meanwhile BTC futures show 73.8% longs and a +0.0047% funding rate, a classic hedge cue.
🚀 Watch the $73,600 BTC barrier — a clean break above it could trigger a funding‑driven rally that forces SWIFT to adapt, and the $2,050 ETH level as a secondary catalyst #OnChain.
❓ If stablecoins are becoming the bridge between legacy rails and crypto, are you positioning for the next wave of cross‑system arbitrage?
42
🔥 THE FLOOD HAS STARTED as Western Union drops its USDPT stablecoin on #Solana, turning the remittance world upside‑down.
📊 Proof: The rollout hit the blockchain this morning, instantly pairing with SOL’s $104 price and $146 M 24‑hour volume — a bullish sign as the token sits at a 23.3% RSI. Smart‑money wallets are already loading up Solana assets: SPCX, PUMP and WBTC each see three wallets buying, while YMB’s inflow exploded +44,792% on‑chain. #Stablecoin #Remittance #CryptoPayments
💡 Stakes: If the $91K Gemini‑driven narrative fuels more institutional flow, we could see SOL break past its mid‑range band, thrusting on‑chain cross‑border transfers into the mainstream and forcing other legacy players to follow suit. #DeFi
❓ Ready to ride the next wave of on‑chain money moves, or will you watch from the sidelines?
🔥 THE FLOOD HAS STARTED as Western Union drops its USDPT stablecoin on #Solana, turning the remittance world upside‑down.
📊 Proof: The rollout hit the blockchain this morning, instantly pairing with SOL’s $104 price and $146 M 24‑hour volume — a bullish sign as the token sits at a 23.3% RSI. Smart‑money wallets are already loading up Solana assets: SPCX, PUMP and WBTC each see three wallets buying, while YMB’s inflow exploded +44,792% on‑chain. #Stablecoin #Remittance #CryptoPayments
💡 Stakes: If the $91K Gemini‑driven narrative fuels more institutional flow, we could see SOL break past its mid‑range band, thrusting on‑chain cross‑border transfers into the mainstream and forcing other legacy players to follow suit. #DeFi
❓ Ready to ride the next wave of on‑chain money moves, or will you watch from the sidelines?
📊 Proof: The rollout hit the blockchain this morning, instantly pairing with SOL’s $104 price and $146 M 24‑hour volume — a bullish sign as the token sits at a 23.3% RSI. Smart‑money wallets are already loading up Solana assets: SPCX, PUMP and WBTC each see three wallets buying, while YMB’s inflow exploded +44,792% on‑chain. #Stablecoin #Remittance #CryptoPayments
💡 Stakes: If the $91K Gemini‑driven narrative fuels more institutional flow, we could see SOL break past its mid‑range band, thrusting on‑chain cross‑border transfers into the mainstream and forcing other legacy players to follow suit. #DeFi
❓ Ready to ride the next wave of on‑chain money moves, or will you watch from the sidelines?
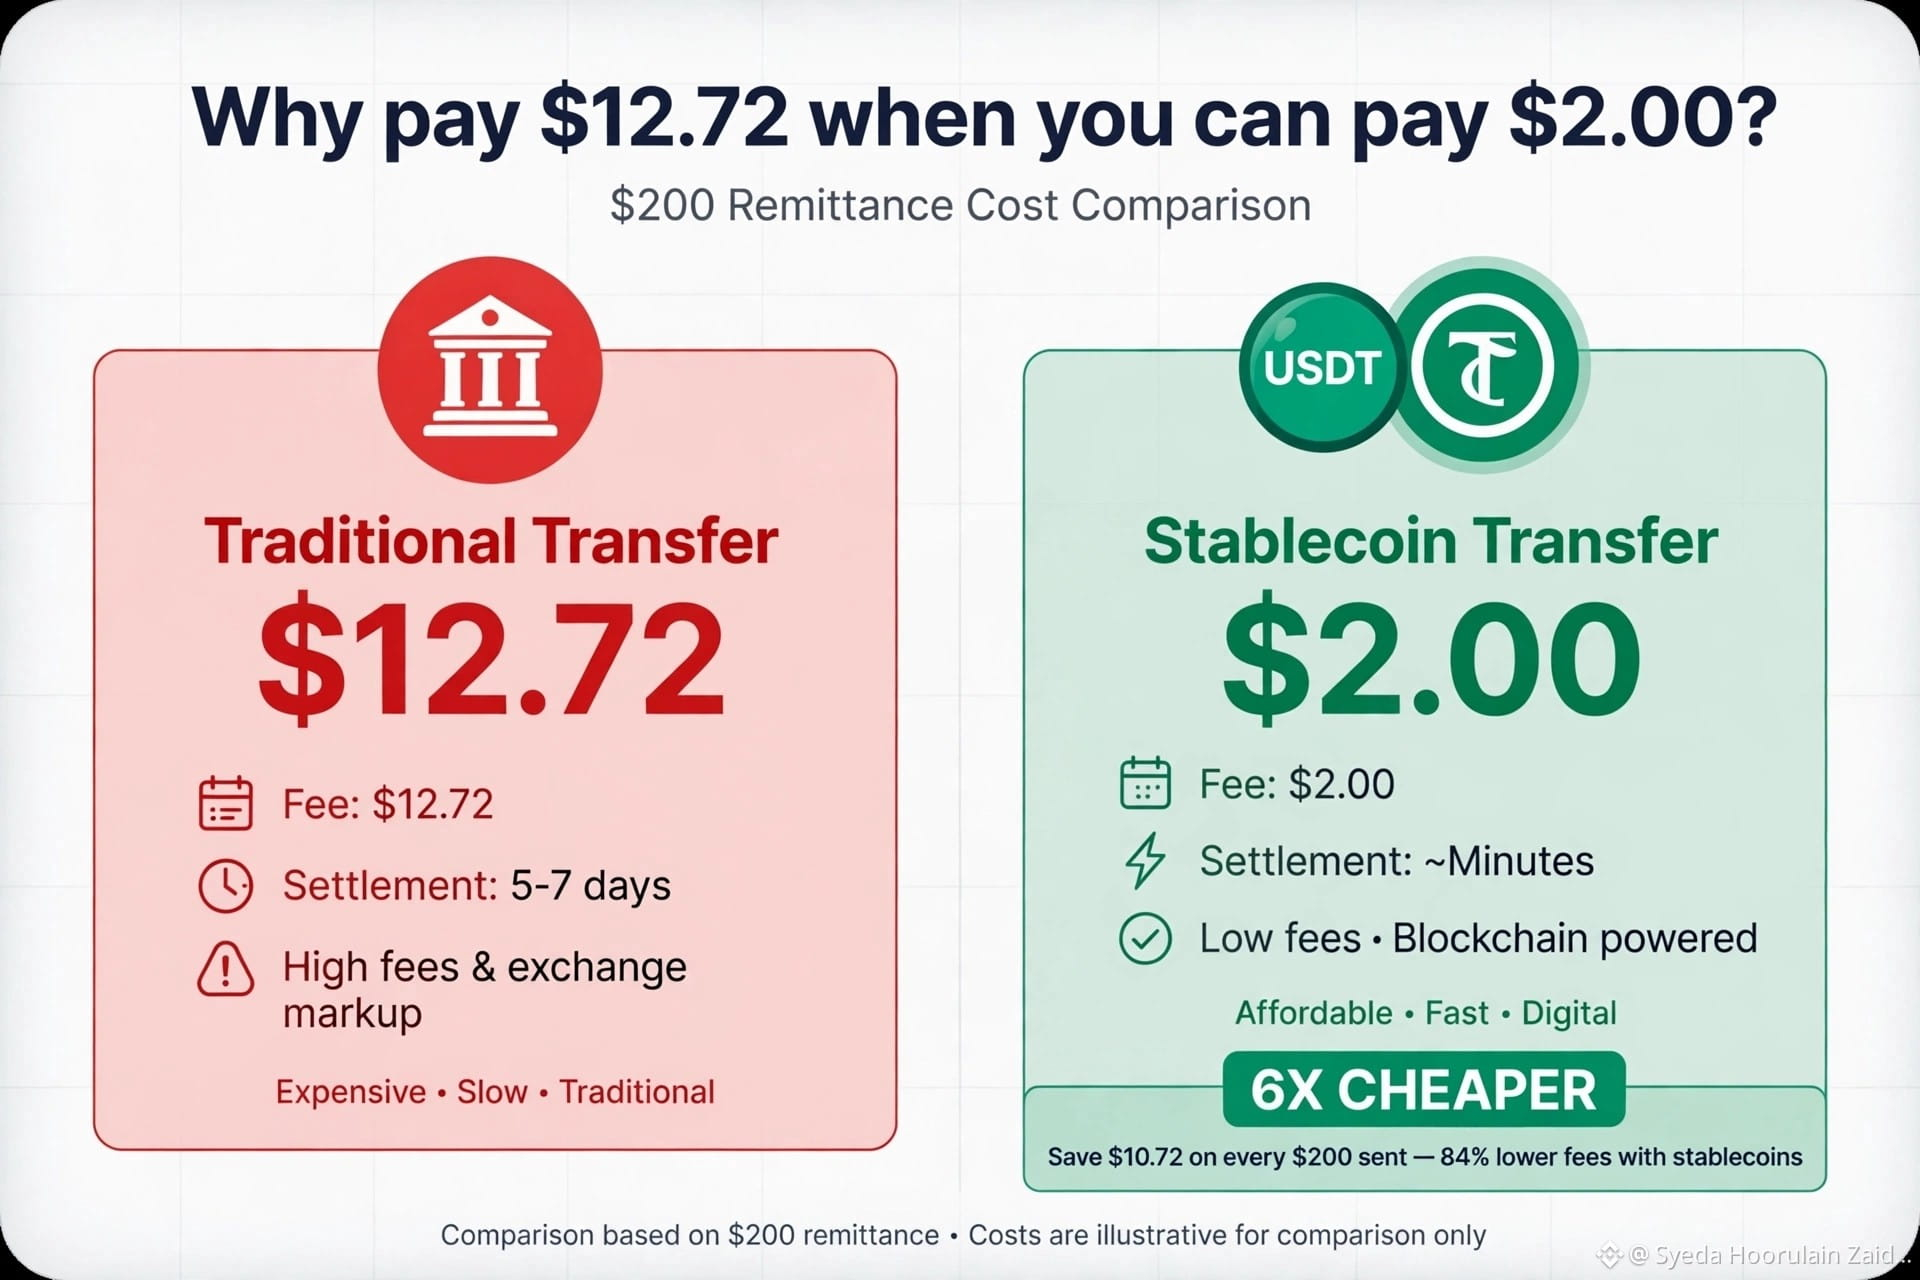
Why pay $12.72 when you can pay $2.00? 💸*
A new Q3 2026 report by http://Borderless.xyz just revealed the truth about remittances.
The median cost to send a $200 payment:
🏦 Traditional Transfer: *$12.72*
💵 Stablecoin Transfer: *$2.00*
That's *6X cheaper* with digital dollars.
No wonder global companies are rapidly adopting stablecoins for payroll and cross-border payments.
The future of money isn't coming, it's already here.
Would you still use banks?
#stablecoin #USDT #fintech #Remittance #Borderless
Why pay $12.72 when you can pay $2.00? 💸*
A new Q3 2026 report by http://Borderless.xyz just revealed the truth about remittances.
The median cost to send a $200 payment:
🏦 Traditional Transfer: *$12.72*
💵 Stablecoin Transfer: *$2.00*
That's *6X cheaper* with digital dollars.
No wonder global companies are rapidly adopting stablecoins for payroll and cross-border payments.
The future of money isn't coming, it's already here.
Would you still use banks?
#stablecoin #USDT #fintech #Remittance #Borderless
A new Q3 2026 report by http://Borderless.xyz just revealed the truth about remittances.
The median cost to send a $200 payment:
🏦 Traditional Transfer: *$12.72*
💵 Stablecoin Transfer: *$2.00*
That's *6X cheaper* with digital dollars.
No wonder global companies are rapidly adopting stablecoins for payroll and cross-border payments.
The future of money isn't coming, it's already here.
Would you still use banks?
#stablecoin #USDT #fintech #Remittance #Borderless
107

·
--
🚨 $BTC SURVEY REVEALS 90% OF US HOLDERS READY TO ACCUMULATE MORE 💥
📊 The latest National Cryptocurrency Association data shows a staggering 90% of existing U.S. crypto owners intend to add more exposure, signaling robust conviction across the base. 🦈 Notably, the 55+ cohort now represents 28% of holders—double the 2020 share—indicating that institutional‑grade familiarity is seeping into the retail tier. 🌊 Meanwhile, 27 million North Americans are already leveraging digital assets for cross‑border remittances, turning crypto into a functional payments conduit beyond pure speculation. 📈 This convergence of demographic breadth and real‑world utility could fuel the next smart‑money liquidity sweep.
💬 Will this expanding demand set the stage for a bullish order‑block retest on $BTC ? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Adoption #Institutional #Remittance #Crypto
🔥 💎
🚨 $BTC SURVEY REVEALS 90% OF US HOLDERS READY TO ACCUMULATE MORE 💥
📊 The latest National Cryptocurrency Association data shows a staggering 90% of existing U.S. crypto owners intend to add more exposure, signaling robust conviction across the base. 🦈 Notably, the 55+ cohort now represents 28% of holders—double the 2020 share—indicating that institutional‑grade familiarity is seeping into the retail tier. 🌊 Meanwhile, 27 million North Americans are already leveraging digital assets for cross‑border remittances, turning crypto into a functional payments conduit beyond pure speculation. 📈 This convergence of demographic breadth and real‑world utility could fuel the next smart‑money liquidity sweep.
💬 Will this expanding demand set the stage for a bullish order‑block retest on $BTC ? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Adoption #Institutional #Remittance #Crypto
🔥 💎
📊 The latest National Cryptocurrency Association data shows a staggering 90% of existing U.S. crypto owners intend to add more exposure, signaling robust conviction across the base. 🦈 Notably, the 55+ cohort now represents 28% of holders—double the 2020 share—indicating that institutional‑grade familiarity is seeping into the retail tier. 🌊 Meanwhile, 27 million North Americans are already leveraging digital assets for cross‑border remittances, turning crypto into a functional payments conduit beyond pure speculation. 📈 This convergence of demographic breadth and real‑world utility could fuel the next smart‑money liquidity sweep.
💬 Will this expanding demand set the stage for a bullish order‑block retest on $BTC ? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Adoption #Institutional #Remittance #Crypto
🔥 💎
7

·
--
Western Union Seeks Stablecoin Rollout to Sidestep SWIFT
The Western Union Company will roll out its USD stablecoin
USDPT within the next month to process transactions internationally without using SWIFT and provide crypto cash-out and stablecoin cards.
Details of USDPT Rollout
* Timeframe: USDPT almost ready, set to be rolled out next month
* Network: It will operate on Solana (SOL)
* Issuer Partner: USDPT will be issued by a federally chartered crypto bank, Anchorage Digital
* Use Case: Initially not intended for consumers. Replacing SWIFT interbank network for processing payments with agents
Why Leave SWIFT?
* Problem: Traditional systems only process on weekdays, taking 2-3 days in some countries
* Solution: Stablecoins will allow instant settlement seven days a week
* Efficiency: It will minimize capital locked up in the system
New Products: DAN + Stable Card
* Digital Asset Network (DAN): Allows crypto wallets to use Western Union as a cash-out service. Converts digital assets into local currencies through WU’s extensive retail network. Pipeline: tens of millions of wallets worldwide
* Stable Card: To be released sometime during the latter half of 2026. Stores stablecoins and spends using payment rails. Inflationary environments need US dollar stable coins with everyday usage
* Launch: First phase deployment in several dozen markets planned for latter 2026
Pressure from Competition
The move comes amid intense competition for its core money transfer services from fintech companies and cryptocurrencies. MoneyGram relies on Circle’s USDC. Stripe unveiled stablecoin infrastructure built on Tempo blockchain technology.
#WesternUnion #Stablecoins #USDPT #Solana #Remittance
$SOL
{spot}(SOLUSDT)
Western Union Seeks Stablecoin Rollout to Sidestep SWIFT
The Western Union Company will roll out its USD stablecoin
USDPT within the next month to process transactions internationally without using SWIFT and provide crypto cash-out and stablecoin cards.
Details of USDPT Rollout
* Timeframe: USDPT almost ready, set to be rolled out next month
* Network: It will operate on Solana (SOL)
* Issuer Partner: USDPT will be issued by a federally chartered crypto bank, Anchorage Digital
* Use Case: Initially not intended for consumers. Replacing SWIFT interbank network for processing payments with agents
Why Leave SWIFT?
* Problem: Traditional systems only process on weekdays, taking 2-3 days in some countries
* Solution: Stablecoins will allow instant settlement seven days a week
* Efficiency: It will minimize capital locked up in the system
New Products: DAN + Stable Card
* Digital Asset Network (DAN): Allows crypto wallets to use Western Union as a cash-out service. Converts digital assets into local currencies through WU’s extensive retail network. Pipeline: tens of millions of wallets worldwide
* Stable Card: To be released sometime during the latter half of 2026. Stores stablecoins and spends using payment rails. Inflationary environments need US dollar stable coins with everyday usage
* Launch: First phase deployment in several dozen markets planned for latter 2026
Pressure from Competition
The move comes amid intense competition for its core money transfer services from fintech companies and cryptocurrencies. MoneyGram relies on Circle’s USDC. Stripe unveiled stablecoin infrastructure built on Tempo blockchain technology.
#WesternUnion #Stablecoins #USDPT #Solana #Remittance
$SOL
The Western Union Company will roll out its USD stablecoin
USDPT within the next month to process transactions internationally without using SWIFT and provide crypto cash-out and stablecoin cards.
Details of USDPT Rollout
* Timeframe: USDPT almost ready, set to be rolled out next month
* Network: It will operate on Solana (SOL)
* Issuer Partner: USDPT will be issued by a federally chartered crypto bank, Anchorage Digital
* Use Case: Initially not intended for consumers. Replacing SWIFT interbank network for processing payments with agents
Why Leave SWIFT?
* Problem: Traditional systems only process on weekdays, taking 2-3 days in some countries
* Solution: Stablecoins will allow instant settlement seven days a week
* Efficiency: It will minimize capital locked up in the system
New Products: DAN + Stable Card
* Digital Asset Network (DAN): Allows crypto wallets to use Western Union as a cash-out service. Converts digital assets into local currencies through WU’s extensive retail network. Pipeline: tens of millions of wallets worldwide
* Stable Card: To be released sometime during the latter half of 2026. Stores stablecoins and spends using payment rails. Inflationary environments need US dollar stable coins with everyday usage
* Launch: First phase deployment in several dozen markets planned for latter 2026
Pressure from Competition
The move comes amid intense competition for its core money transfer services from fintech companies and cryptocurrencies. MoneyGram relies on Circle’s USDC. Stripe unveiled stablecoin infrastructure built on Tempo blockchain technology.
#WesternUnion #Stablecoins #USDPT #Solana #Remittance
$SOL
3.1k
39
210
3.1k

·
--
Stablecoins Are Quietly Becoming the Remittance Rail of the Decade
Send $200 from the US to the Philippines via a legacy wire transfer: 3–5 business days, ~7% fee, and a recipient who has to find a branch to cash out.
Send the same $200 over a stablecoin rail: under 30 seconds, fees under $0.10, received directly in a self-custodied wallet.
The remittance market moves over $800 billion a year. Most of that runs through intermediaries charging 4–8%. Stablecoins are not just competing — they are making those fees structurally indefensible.
But the real unlock is not speed or cost alone. It is programmability. Stablecoins let you attach conditions to money — release on delivery, split automatically between recipients, trigger on-chain actions. Legacy wires cannot do any of that.
$ETH and $BNB are the settlement layers where most stablecoin volume actually flows. $XRP has spent years building licensed corridors for exactly this use case — and those corridors are now filling up with institutional and retail remittance flow alike.
The narrative arc is clear: payments infrastructure is moving on-chain, and stablecoins are the trojan horse that gets crypto into wallets before people even realize they are using crypto.
The infrastructure is ready. The users are arriving.
#Stablecoins #Crypto #Remittance #DeFi #BinanceSquare
Stablecoins Are Quietly Becoming the Remittance Rail of the Decade
Send $200 from the US to the Philippines via a legacy wire transfer: 3–5 business days, ~7% fee, and a recipient who has to find a branch to cash out.
Send the same $200 over a stablecoin rail: under 30 seconds, fees under $0.10, received directly in a self-custodied wallet.
The remittance market moves over $800 billion a year. Most of that runs through intermediaries charging 4–8%. Stablecoins are not just competing — they are making those fees structurally indefensible.
But the real unlock is not speed or cost alone. It is programmability. Stablecoins let you attach conditions to money — release on delivery, split automatically between recipients, trigger on-chain actions. Legacy wires cannot do any of that.
$ETH and $BNB are the settlement layers where most stablecoin volume actually flows. $XRP has spent years building licensed corridors for exactly this use case — and those corridors are now filling up with institutional and retail remittance flow alike.
The narrative arc is clear: payments infrastructure is moving on-chain, and stablecoins are the trojan horse that gets crypto into wallets before people even realize they are using crypto.
The infrastructure is ready. The users are arriving.
#Stablecoins #Crypto #Remittance #DeFi #BinanceSquare
Send $200 from the US to the Philippines via a legacy wire transfer: 3–5 business days, ~7% fee, and a recipient who has to find a branch to cash out.
Send the same $200 over a stablecoin rail: under 30 seconds, fees under $0.10, received directly in a self-custodied wallet.
The remittance market moves over $800 billion a year. Most of that runs through intermediaries charging 4–8%. Stablecoins are not just competing — they are making those fees structurally indefensible.
But the real unlock is not speed or cost alone. It is programmability. Stablecoins let you attach conditions to money — release on delivery, split automatically between recipients, trigger on-chain actions. Legacy wires cannot do any of that.
$ETH and $BNB are the settlement layers where most stablecoin volume actually flows. $XRP has spent years building licensed corridors for exactly this use case — and those corridors are now filling up with institutional and retail remittance flow alike.
The narrative arc is clear: payments infrastructure is moving on-chain, and stablecoins are the trojan horse that gets crypto into wallets before people even realize they are using crypto.
The infrastructure is ready. The users are arriving.
#Stablecoins #Crypto #Remittance #DeFi #BinanceSquare
69
·
--
Stablecoins Are Quietly Dismantling the Remittance Industry
The global remittance market moves over 800 billion dollars annually — yet traditional providers still charge 5-8% per transfer, often taking 3-5 business days to settle. For families in emerging markets, that friction is a real tax on survival.
Stablecoins change this calculus fundamentally. A USDT or USDC transfer from the US to Southeast Asia or Latin America settles in seconds for cents. No correspondent banks. No cut-off windows. No weekend delays.
What makes this moment different from previous crypto payment hype is infrastructure maturity. $BNB Smart Chain, $SOL, and $XRP now routinely demonstrate that sub-cent stablecoin transfers with near-instant finality are production-ready. Mobile wallets have improved dramatically. Off-ramp rails — the critical last mile — are expanding through local exchanges and payment agents.
The on-chain numbers reflect real adoption. Stablecoin transfer volume surpassed $27 trillion in 2024, dwarfing PayPal and approaching Visa-scale. Much of that growth is organic — real people moving real value across borders without a bank.
The remittance industry is not dying overnight. But the value proposition for blockchain-based transfers is no longer theoretical — it is measurable, live, and accelerating.
The question is no longer if crypto displaces wire transfers. It is how fast the off-ramp infrastructure catches up to match the on-chain speed that already exists.
#Stablecoins #Crypto #Remittance #DeFi #BlockchainPayments
Stablecoins Are Quietly Dismantling the Remittance Industry
The global remittance market moves over 800 billion dollars annually — yet traditional providers still charge 5-8% per transfer, often taking 3-5 business days to settle. For families in emerging markets, that friction is a real tax on survival.
Stablecoins change this calculus fundamentally. A USDT or USDC transfer from the US to Southeast Asia or Latin America settles in seconds for cents. No correspondent banks. No cut-off windows. No weekend delays.
What makes this moment different from previous crypto payment hype is infrastructure maturity. $BNB Smart Chain, $SOL , and $XRP now routinely demonstrate that sub-cent stablecoin transfers with near-instant finality are production-ready. Mobile wallets have improved dramatically. Off-ramp rails — the critical last mile — are expanding through local exchanges and payment agents.
The on-chain numbers reflect real adoption. Stablecoin transfer volume surpassed $27 trillion in 2024, dwarfing PayPal and approaching Visa-scale. Much of that growth is organic — real people moving real value across borders without a bank.
The remittance industry is not dying overnight. But the value proposition for blockchain-based transfers is no longer theoretical — it is measurable, live, and accelerating.
The question is no longer if crypto displaces wire transfers. It is how fast the off-ramp infrastructure catches up to match the on-chain speed that already exists.
#Stablecoins #Crypto #Remittance #DeFi #BlockchainPayments
The global remittance market moves over 800 billion dollars annually — yet traditional providers still charge 5-8% per transfer, often taking 3-5 business days to settle. For families in emerging markets, that friction is a real tax on survival.
Stablecoins change this calculus fundamentally. A USDT or USDC transfer from the US to Southeast Asia or Latin America settles in seconds for cents. No correspondent banks. No cut-off windows. No weekend delays.
What makes this moment different from previous crypto payment hype is infrastructure maturity. $BNB Smart Chain, $SOL , and $XRP now routinely demonstrate that sub-cent stablecoin transfers with near-instant finality are production-ready. Mobile wallets have improved dramatically. Off-ramp rails — the critical last mile — are expanding through local exchanges and payment agents.
The on-chain numbers reflect real adoption. Stablecoin transfer volume surpassed $27 trillion in 2024, dwarfing PayPal and approaching Visa-scale. Much of that growth is organic — real people moving real value across borders without a bank.
The remittance industry is not dying overnight. But the value proposition for blockchain-based transfers is no longer theoretical — it is measurable, live, and accelerating.
The question is no longer if crypto displaces wire transfers. It is how fast the off-ramp infrastructure catches up to match the on-chain speed that already exists.
#Stablecoins #Crypto #Remittance #DeFi #BlockchainPayments
78
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#HuangExitNvidiaStrategyInFocus
43,335 views
686 Discussing
2
#AnthropicRejectsIPODelayValuationinQuestion
620,658 views
4,999 Discussing
3
#BitMineReports$6.3BNetLossForFiscal2026
5,016 views
85 Discussing
4
#ChipStocksExtendLossesAfterNvidiaCEOChange
16,081 views
312 Discussing
5
#ThailandProposes$148KDailyStablecoinDepositWithdrawalCaps
1,321 views
23 Discussing
6
#CoreWeaveJumps10%On168%RevenueGrowth
148,746 views
1,552 Discussing
7
#ZcashFallsBelow$1000ForFirstTimeSinceSeptember
73,506 views
252 Discussing
8
#MSCIRemovalMayCurbStrategy’sBitcoinBuying
36,508 views
510 Discussing
9
#TradFiForBeginners
512,632 views
3,596 Discussing
10
#USJoblessClaimsRise
19.1M views
7,722 Discussing