
#bankofengland
bankofengland
357,482 views
236 Discussing
Hot
Latest

·
--
UK Bank of England Governor Andrew Bailey formally announced in the latest policy decision that the central bank has decided to cancel the originally planned long-term gilt sales program and postpone all quantitative tightening (QT) auctions to April next year. Under the new plan, the Bank of England’s £4.88 trillion asset portfolio will be gradually unwound by September 2034, with £1.2 trillion in ultra-long gilts maturing in 2049 or later being retained; the remaining assets will be processed in stages in batches. This move signals a major shift in the timing of the Bank of England’s balance-sheet contraction.
This adjustment is notable because the market had previously widely worried that aggressive tightening would create heavy selling pressure on the already fragile UK long-end gilt market. The Bank of England chose to slow its exit pace at the current juncture. The core logic is to balance fiscal costs against market stability. Bailey emphasized that the plan is intended to take into account both monetary-policy independence and fiscal efficiency—essentially applying the brakes to an overheated supply of government bonds and preventing uncontrollable, sharp volatility in interest-rate markets.
Judging by reactions in traditional financial markets, pausing the sale of long-dated bonds directly lifted some of the near-term upward pressure on UK gilt yields. Liquidity in the long end has received temporary protection, and tensions in the pound exchange rate and related interest-rate swap markets have also been eased to a certain extent. For global macro liquidity, any tweaks and slowdowns by major central banks in quantitative tightening send the market a clear signal that central banks remain highly alert to the risks of balance-sheet contraction.
For our crypto community, such liquidity adjustments are also worth continuous monitoring. While the Bank of England’s delay of QT does not mean starting a new round of “water release,” it does reduce the pressure of liquidity being drained from offshore markets. Currently, mainstream assets such as $BTC are in a phase of intense macro-liquidity-sensitive, range-bound observation. As the marginal pressure from external liquidity weakens, the market gets some breathing room, but the global major central banks’ overall contest between inflation and tightening still needs to be watched closely going forward.
#BankOfEngland #QuantitativeTightening #GlobalMacro
UK Bank of England Governor Andrew Bailey formally announced in the latest policy decision that the central bank has decided to cancel the originally planned long-term gilt sales program and postpone all quantitative tightening (QT) auctions to April next year. Under the new plan, the Bank of England’s £4.88 trillion asset portfolio will be gradually unwound by September 2034, with £1.2 trillion in ultra-long gilts maturing in 2049 or later being retained; the remaining assets will be processed in stages in batches. This move signals a major shift in the timing of the Bank of England’s balance-sheet contraction.
This adjustment is notable because the market had previously widely worried that aggressive tightening would create heavy selling pressure on the already fragile UK long-end gilt market. The Bank of England chose to slow its exit pace at the current juncture. The core logic is to balance fiscal costs against market stability. Bailey emphasized that the plan is intended to take into account both monetary-policy independence and fiscal efficiency—essentially applying the brakes to an overheated supply of government bonds and preventing uncontrollable, sharp volatility in interest-rate markets.
Judging by reactions in traditional financial markets, pausing the sale of long-dated bonds directly lifted some of the near-term upward pressure on UK gilt yields. Liquidity in the long end has received temporary protection, and tensions in the pound exchange rate and related interest-rate swap markets have also been eased to a certain extent. For global macro liquidity, any tweaks and slowdowns by major central banks in quantitative tightening send the market a clear signal that central banks remain highly alert to the risks of balance-sheet contraction.
For our crypto community, such liquidity adjustments are also worth continuous monitoring. While the Bank of England’s delay of QT does not mean starting a new round of “water release,” it does reduce the pressure of liquidity being drained from offshore markets. Currently, mainstream assets such as $BTC are in a phase of intense macro-liquidity-sensitive, range-bound observation. As the marginal pressure from external liquidity weakens, the market gets some breathing room, but the global major central banks’ overall contest between inflation and tightening still needs to be watched closely going forward.
#BankOfEngland #QuantitativeTightening #GlobalMacro
This adjustment is notable because the market had previously widely worried that aggressive tightening would create heavy selling pressure on the already fragile UK long-end gilt market. The Bank of England chose to slow its exit pace at the current juncture. The core logic is to balance fiscal costs against market stability. Bailey emphasized that the plan is intended to take into account both monetary-policy independence and fiscal efficiency—essentially applying the brakes to an overheated supply of government bonds and preventing uncontrollable, sharp volatility in interest-rate markets.
Judging by reactions in traditional financial markets, pausing the sale of long-dated bonds directly lifted some of the near-term upward pressure on UK gilt yields. Liquidity in the long end has received temporary protection, and tensions in the pound exchange rate and related interest-rate swap markets have also been eased to a certain extent. For global macro liquidity, any tweaks and slowdowns by major central banks in quantitative tightening send the market a clear signal that central banks remain highly alert to the risks of balance-sheet contraction.
For our crypto community, such liquidity adjustments are also worth continuous monitoring. While the Bank of England’s delay of QT does not mean starting a new round of “water release,” it does reduce the pressure of liquidity being drained from offshore markets. Currently, mainstream assets such as $BTC are in a phase of intense macro-liquidity-sensitive, range-bound observation. As the marginal pressure from external liquidity weakens, the market gets some breathing room, but the global major central banks’ overall contest between inflation and tightening still needs to be watched closely going forward.
#BankOfEngland #QuantitativeTightening #GlobalMacro
2

In the latest balance-sheet policy adjustment, Andrew Bailey, Governor of the Bank of England, announced the formal cancellation of the plan to sell long-dated government bonds and that all quantitative tightening (QT) auctions will be postponed until next April. Under the new scheme, the Bank of England’s total asset portfolio of £4.88 trillion will be wound down gradually by September 2034, with £1.2 trillion in ultra-long bonds maturing in 2049 or later being retained, while the disposal period for the remainder will be extended substantially.
This major shift is ostensibly aimed at improving fiscal efficiency and policy independence, but in reality it highlights the extreme fragility of the sovereign debt market. During the balance-sheet shrinking process, the central bank has had to compromise with market liquidity realities; the delay in selling directly reflects deep concerns about weak demand for long-term gilts and renewed worries about a spike in yields. The previously aggressive tightening path is now facing tangible resistance amid the broader backdrop of elevated global debt.
For traditional macro markets, pausing the sale of ultra-long bonds may ease near-term selling pressure on UK gilts, but extending the balance-sheet adjustment timeline also implies that inflation persistence may be harder to eliminate. The wavering of major central banks worldwide between tightening and backstopping signals that sovereign liquidity management has entered a high-risk corridor, and the bond market’s underlying crisis of trust has not been fundamentally resolved.
For crypto assets, the central bank’s retreat from its balance-sheet policy signals that liquidity stress may have peaked—at least temporarily. However, this passive compromise reflects wider macroeconomic fragility and geopolitical inflation pressures (such as the Ukrainian central bank being forced to hike to 16% on the same day). Until macro liquidity is genuinely and broadly eased, risk assets represented by $BTC must still be on guard against secondary volatility caused by contagion from debt risks.
#BankOfEngland #QuantitativeTightening #MacroEconomics
In the latest balance-sheet policy adjustment, Andrew Bailey, Governor of the Bank of England, announced the formal cancellation of the plan to sell long-dated government bonds and that all quantitative tightening (QT) auctions will be postponed until next April. Under the new scheme, the Bank of England’s total asset portfolio of £4.88 trillion will be wound down gradually by September 2034, with £1.2 trillion in ultra-long bonds maturing in 2049 or later being retained, while the disposal period for the remainder will be extended substantially.
This major shift is ostensibly aimed at improving fiscal efficiency and policy independence, but in reality it highlights the extreme fragility of the sovereign debt market. During the balance-sheet shrinking process, the central bank has had to compromise with market liquidity realities; the delay in selling directly reflects deep concerns about weak demand for long-term gilts and renewed worries about a spike in yields. The previously aggressive tightening path is now facing tangible resistance amid the broader backdrop of elevated global debt.
For traditional macro markets, pausing the sale of ultra-long bonds may ease near-term selling pressure on UK gilts, but extending the balance-sheet adjustment timeline also implies that inflation persistence may be harder to eliminate. The wavering of major central banks worldwide between tightening and backstopping signals that sovereign liquidity management has entered a high-risk corridor, and the bond market’s underlying crisis of trust has not been fundamentally resolved.
For crypto assets, the central bank’s retreat from its balance-sheet policy signals that liquidity stress may have peaked—at least temporarily. However, this passive compromise reflects wider macroeconomic fragility and geopolitical inflation pressures (such as the Ukrainian central bank being forced to hike to 16% on the same day). Until macro liquidity is genuinely and broadly eased, risk assets represented by $BTC must still be on guard against secondary volatility caused by contagion from debt risks.
#BankOfEngland #QuantitativeTightening #MacroEconomics
This major shift is ostensibly aimed at improving fiscal efficiency and policy independence, but in reality it highlights the extreme fragility of the sovereign debt market. During the balance-sheet shrinking process, the central bank has had to compromise with market liquidity realities; the delay in selling directly reflects deep concerns about weak demand for long-term gilts and renewed worries about a spike in yields. The previously aggressive tightening path is now facing tangible resistance amid the broader backdrop of elevated global debt.
For traditional macro markets, pausing the sale of ultra-long bonds may ease near-term selling pressure on UK gilts, but extending the balance-sheet adjustment timeline also implies that inflation persistence may be harder to eliminate. The wavering of major central banks worldwide between tightening and backstopping signals that sovereign liquidity management has entered a high-risk corridor, and the bond market’s underlying crisis of trust has not been fundamentally resolved.
For crypto assets, the central bank’s retreat from its balance-sheet policy signals that liquidity stress may have peaked—at least temporarily. However, this passive compromise reflects wider macroeconomic fragility and geopolitical inflation pressures (such as the Ukrainian central bank being forced to hike to 16% on the same day). Until macro liquidity is genuinely and broadly eased, risk assets represented by $BTC must still be on guard against secondary volatility caused by contagion from debt risks.
#BankOfEngland #QuantitativeTightening #MacroEconomics
1

Bank of England Governor Andrew Bailey announced at the latest policy meeting a major liquidity tailwind shift: the plan to sell long-dated government bonds has been formally cancelled, and all quantitative tightening (QT) auctions will be postponed to April next year. Under the revised plan, of the UK’s total £4.88 trillion asset portfolio, £1.2 trillion of long-dated government bonds maturing in 2049 and beyond will be retained, while the liquidation pace for the remaining assets will be significantly slowed to minimize market volatility and selling pressure as much as possible.
From a macro-technical perspective, the central bank’s pause in selling long-dated bonds is a notable marginal improvement in liquidity conditions. This move directly removes the “mountain” of sell pressure weighing on UK long-end gilt yields, signaling that major central banks, when facing financial stability risks, are more inclined to provide liquidity backstops. Against the backdrop of policy divergence among central banks and lingering geopolitical inflation pressures, the Bank of England’s substantial slowdown in balance-sheet reduction injects a strong dose of confidence into global fixed-income markets.
In traditional financial markets, this decision will effectively suppress global long-end borrowing costs, support fixed-income asset prices, and ease pressure on widening credit spreads. As technical relief from sell pressure on the sovereign bond yield curve takes hold, the allocation logic for both safe-haven and arbitrage capital is likely to tilt back toward risk assets, improving the overall macro environment’s risk appetite (Risk-On).
For the crypto market, the major central banks’ pause in tightening is an extremely positive liquidity signal. The market often “quietly” finds a bottom at the turning point of global liquidity before risk assets fully surge. With the suppression on long-dated government bond yields lifted and funding opportunity costs falling, core crypto assets such as $BTC are expected to see sustained long momentum and valuation repair driven by improving liquidity expectations.📈
#BankOfEngland #QuantitativeTightening #Liquidity
Bank of England Governor Andrew Bailey announced at the latest policy meeting a major liquidity tailwind shift: the plan to sell long-dated government bonds has been formally cancelled, and all quantitative tightening (QT) auctions will be postponed to April next year. Under the revised plan, of the UK’s total £4.88 trillion asset portfolio, £1.2 trillion of long-dated government bonds maturing in 2049 and beyond will be retained, while the liquidation pace for the remaining assets will be significantly slowed to minimize market volatility and selling pressure as much as possible.
From a macro-technical perspective, the central bank’s pause in selling long-dated bonds is a notable marginal improvement in liquidity conditions. This move directly removes the “mountain” of sell pressure weighing on UK long-end gilt yields, signaling that major central banks, when facing financial stability risks, are more inclined to provide liquidity backstops. Against the backdrop of policy divergence among central banks and lingering geopolitical inflation pressures, the Bank of England’s substantial slowdown in balance-sheet reduction injects a strong dose of confidence into global fixed-income markets.
In traditional financial markets, this decision will effectively suppress global long-end borrowing costs, support fixed-income asset prices, and ease pressure on widening credit spreads. As technical relief from sell pressure on the sovereign bond yield curve takes hold, the allocation logic for both safe-haven and arbitrage capital is likely to tilt back toward risk assets, improving the overall macro environment’s risk appetite (Risk-On).
For the crypto market, the major central banks’ pause in tightening is an extremely positive liquidity signal. The market often “quietly” finds a bottom at the turning point of global liquidity before risk assets fully surge. With the suppression on long-dated government bond yields lifted and funding opportunity costs falling, core crypto assets such as $BTC are expected to see sustained long momentum and valuation repair driven by improving liquidity expectations.📈
#BankOfEngland #QuantitativeTightening #Liquidity
From a macro-technical perspective, the central bank’s pause in selling long-dated bonds is a notable marginal improvement in liquidity conditions. This move directly removes the “mountain” of sell pressure weighing on UK long-end gilt yields, signaling that major central banks, when facing financial stability risks, are more inclined to provide liquidity backstops. Against the backdrop of policy divergence among central banks and lingering geopolitical inflation pressures, the Bank of England’s substantial slowdown in balance-sheet reduction injects a strong dose of confidence into global fixed-income markets.
In traditional financial markets, this decision will effectively suppress global long-end borrowing costs, support fixed-income asset prices, and ease pressure on widening credit spreads. As technical relief from sell pressure on the sovereign bond yield curve takes hold, the allocation logic for both safe-haven and arbitrage capital is likely to tilt back toward risk assets, improving the overall macro environment’s risk appetite (Risk-On).
For the crypto market, the major central banks’ pause in tightening is an extremely positive liquidity signal. The market often “quietly” finds a bottom at the turning point of global liquidity before risk assets fully surge. With the suppression on long-dated government bond yields lifted and funding opportunity costs falling, core crypto assets such as $BTC are expected to see sustained long momentum and valuation repair driven by improving liquidity expectations.📈
#BankOfEngland #QuantitativeTightening #Liquidity
40

·
--
See translation
Thống đốc Ngân hàng Trung ương Anh (BoE) Andrew Bailey vừa công bố điều chỉnh chiến lược thắt chặt định lượng (QT), chính thức hủy bỏ kế hoạch bán trái phiếu chính phủ dài hạn và hoãn toàn bộ các phiên đấu giá QT đến tháng 4 năm sau. Theo lộ trình mới, danh mục 4.880 tỷ bảng sẽ được xử lý dần đến tháng 9/2034, trong đó BoE giữ lại 1.200 tỷ bảng trái phiếu đáo hạn từ năm 2049 trở đi.
Động thái bất ngờ này cho thấy BoE đang chủ động hạ nhiệt áp lực lên thị trường nợ công trong bối cảnh lợi suất dài hạn chịu nhiều biến động. Thay vì đẩy mạnh rút thanh khoản một cách cứng nhắc, việc giãn tiến độ bán trái phiếu và kéo dài thời gian xử lý sang giai đoạn 2035-2049 giúp hạn chế rủi ro xáo trộn cấu trúc tài chính.
Quyết định của BoE ngay lập tức giải tỏa áp lực tăng lợi suất trái phiếu chính phủ Anh (gilts), mang lại sự ổn định tâm lý cho thị trường tài chính châu Âu. Lợi suất hạ nhiệt cũng làm giảm chi phí vốn cho nền kinh tế, đồng thời phát đi tín hiệu rằng các ngân hàng trung ương lớn đang rất thận trọng với rủi ro thanh khoản hệ thống.
Đối với thị trường crypto, việc BoE tạm dừng rút thanh khoản dài hạn là một tín hiệu tích cực về mặt dòng tiền toàn cầu. Khi áp lực QT từ các ngân hàng trung ương dịu bớt, tâm lý ưa thích rủi ro có xu hướng quay trở lại, hỗ trợ cho $BTC và các tài sản số duy trì đà tích lũy trong ngắn và trung hạn. 🏛️
#BankOfEngland #QuantitativeTightening #BondMarket
Thống đốc Ngân hàng Trung ương Anh (BoE) Andrew Bailey vừa công bố điều chỉnh chiến lược thắt chặt định lượng (QT), chính thức hủy bỏ kế hoạch bán trái phiếu chính phủ dài hạn và hoãn toàn bộ các phiên đấu giá QT đến tháng 4 năm sau. Theo lộ trình mới, danh mục 4.880 tỷ bảng sẽ được xử lý dần đến tháng 9/2034, trong đó BoE giữ lại 1.200 tỷ bảng trái phiếu đáo hạn từ năm 2049 trở đi.
Động thái bất ngờ này cho thấy BoE đang chủ động hạ nhiệt áp lực lên thị trường nợ công trong bối cảnh lợi suất dài hạn chịu nhiều biến động. Thay vì đẩy mạnh rút thanh khoản một cách cứng nhắc, việc giãn tiến độ bán trái phiếu và kéo dài thời gian xử lý sang giai đoạn 2035-2049 giúp hạn chế rủi ro xáo trộn cấu trúc tài chính.
Quyết định của BoE ngay lập tức giải tỏa áp lực tăng lợi suất trái phiếu chính phủ Anh (gilts), mang lại sự ổn định tâm lý cho thị trường tài chính châu Âu. Lợi suất hạ nhiệt cũng làm giảm chi phí vốn cho nền kinh tế, đồng thời phát đi tín hiệu rằng các ngân hàng trung ương lớn đang rất thận trọng với rủi ro thanh khoản hệ thống.
Đối với thị trường crypto, việc BoE tạm dừng rút thanh khoản dài hạn là một tín hiệu tích cực về mặt dòng tiền toàn cầu. Khi áp lực QT từ các ngân hàng trung ương dịu bớt, tâm lý ưa thích rủi ro có xu hướng quay trở lại, hỗ trợ cho $BTC và các tài sản số duy trì đà tích lũy trong ngắn và trung hạn. 🏛️
#BankOfEngland #QuantitativeTightening #BondMarket
Động thái bất ngờ này cho thấy BoE đang chủ động hạ nhiệt áp lực lên thị trường nợ công trong bối cảnh lợi suất dài hạn chịu nhiều biến động. Thay vì đẩy mạnh rút thanh khoản một cách cứng nhắc, việc giãn tiến độ bán trái phiếu và kéo dài thời gian xử lý sang giai đoạn 2035-2049 giúp hạn chế rủi ro xáo trộn cấu trúc tài chính.
Quyết định của BoE ngay lập tức giải tỏa áp lực tăng lợi suất trái phiếu chính phủ Anh (gilts), mang lại sự ổn định tâm lý cho thị trường tài chính châu Âu. Lợi suất hạ nhiệt cũng làm giảm chi phí vốn cho nền kinh tế, đồng thời phát đi tín hiệu rằng các ngân hàng trung ương lớn đang rất thận trọng với rủi ro thanh khoản hệ thống.
Đối với thị trường crypto, việc BoE tạm dừng rút thanh khoản dài hạn là một tín hiệu tích cực về mặt dòng tiền toàn cầu. Khi áp lực QT từ các ngân hàng trung ương dịu bớt, tâm lý ưa thích rủi ro có xu hướng quay trở lại, hỗ trợ cho $BTC và các tài sản số duy trì đà tích lũy trong ngắn và trung hạn. 🏛️
#BankOfEngland #QuantitativeTightening #BondMarket
31

According to reports published by the Financial Times ahead of the Bank of England's upcoming policy meeting, escalating conflict in the Middle East is driving energy prices higher and reigniting intense internal debate over potential interest rate hikes before year-end.
This shift comes at a critical juncture as markets had previously priced in less than a one-third probability of a rate increase at this Thursday's September meeting. However, resilient UK GDP growth coupled with mounting geopolitical oil shocks is squeezing policymakers, with Deutsche Bank economist Sanjay Raja warning that the BoE's patience may be wearing thin as the justification for holding rates at 3.75% weakens.
The prospect of renewed monetary tightening is already rattling global bond markets and strengthening sovereign yields, compounding pressure on fiscal authorities ahead of the October 28 budget. A prolonged higher-for-longer regime across major central banks threatens to dry up liquidity conditions and elevate cross-asset volatility.
For the crypto sector, persistent macro headwinds and sticky inflation typically dampen risk-on sentiment in the near term, potentially capping upside momentum for $BTC as capital retreats to safety. Investors should closely monitor the central bank's forward guidance for broader macroeconomic trajectory.
#BankOfEngland #EnergyCrisis #MacroEconomics
According to reports published by the Financial Times ahead of the Bank of England's upcoming policy meeting, escalating conflict in the Middle East is driving energy prices higher and reigniting intense internal debate over potential interest rate hikes before year-end.
This shift comes at a critical juncture as markets had previously priced in less than a one-third probability of a rate increase at this Thursday's September meeting. However, resilient UK GDP growth coupled with mounting geopolitical oil shocks is squeezing policymakers, with Deutsche Bank economist Sanjay Raja warning that the BoE's patience may be wearing thin as the justification for holding rates at 3.75% weakens.
The prospect of renewed monetary tightening is already rattling global bond markets and strengthening sovereign yields, compounding pressure on fiscal authorities ahead of the October 28 budget. A prolonged higher-for-longer regime across major central banks threatens to dry up liquidity conditions and elevate cross-asset volatility.
For the crypto sector, persistent macro headwinds and sticky inflation typically dampen risk-on sentiment in the near term, potentially capping upside momentum for $BTC as capital retreats to safety. Investors should closely monitor the central bank's forward guidance for broader macroeconomic trajectory.
#BankOfEngland #EnergyCrisis #MacroEconomics
This shift comes at a critical juncture as markets had previously priced in less than a one-third probability of a rate increase at this Thursday's September meeting. However, resilient UK GDP growth coupled with mounting geopolitical oil shocks is squeezing policymakers, with Deutsche Bank economist Sanjay Raja warning that the BoE's patience may be wearing thin as the justification for holding rates at 3.75% weakens.
The prospect of renewed monetary tightening is already rattling global bond markets and strengthening sovereign yields, compounding pressure on fiscal authorities ahead of the October 28 budget. A prolonged higher-for-longer regime across major central banks threatens to dry up liquidity conditions and elevate cross-asset volatility.
For the crypto sector, persistent macro headwinds and sticky inflation typically dampen risk-on sentiment in the near term, potentially capping upside momentum for $BTC as capital retreats to safety. Investors should closely monitor the central bank's forward guidance for broader macroeconomic trajectory.
#BankOfEngland #EnergyCrisis #MacroEconomics
10
·
--
The Bank of England is reported to be preparing to pause the sale of long-dated government bonds before UK Chancellor of the Exchequer Jeremy Hunt releases his first Budget on October 28. According to The Daily Telegraph, the central bank plans to stop offloading the 20- and 30-year gilts it accumulated during the previous financial crisis, in order to ease the pressure on the Treasury caused by rising borrowing costs.
The key behind this is the scale of fiscal losses. Economists estimate that since the sale of these long-term debts began in 2022, it has already cost UK taxpayers around £22 billion. Against the backdrop of global bond sell-offs, halting this discount-driven selling could save the Treasury about £2.5 billion per year, giving the newly appointed chancellor some policy room to manoeuvre, even though it also makes the budget rules for balancing day-to-day spending more complicated.
From a traditional macro market perspective, adjustments to the pace of central bank balance-sheet shrinkage directly affect the supply-and-demand dynamics in the bond market. Pausing the sale of long-dated gilts can help temporarily relieve upward pressure on long-end yields and, to some extent, stabilize market sentiment toward the UK’s sovereign credit. It may also lead to minor tweaks in the liquidity tug-of-war between the US dollar and the pound.
For the crypto market, this reflects the real trade-offs major central banks face between tightening liquidity and their ability to bear fiscal strain. While this does not mean a full pivot to easing, reduced pressure from long-end selling may slightly ease the overall liquidity environment. Crypto investors can continue to monitor how sovereign bond markets in major economies react, and to view structural changes in liquidity conditions rationally. $BTC
#BankOfEngland #Bonds #MacroEconomy
The Bank of England is reported to be preparing to pause the sale of long-dated government bonds before UK Chancellor of the Exchequer Jeremy Hunt releases his first Budget on October 28. According to The Daily Telegraph, the central bank plans to stop offloading the 20- and 30-year gilts it accumulated during the previous financial crisis, in order to ease the pressure on the Treasury caused by rising borrowing costs.
The key behind this is the scale of fiscal losses. Economists estimate that since the sale of these long-term debts began in 2022, it has already cost UK taxpayers around £22 billion. Against the backdrop of global bond sell-offs, halting this discount-driven selling could save the Treasury about £2.5 billion per year, giving the newly appointed chancellor some policy room to manoeuvre, even though it also makes the budget rules for balancing day-to-day spending more complicated.
From a traditional macro market perspective, adjustments to the pace of central bank balance-sheet shrinkage directly affect the supply-and-demand dynamics in the bond market. Pausing the sale of long-dated gilts can help temporarily relieve upward pressure on long-end yields and, to some extent, stabilize market sentiment toward the UK’s sovereign credit. It may also lead to minor tweaks in the liquidity tug-of-war between the US dollar and the pound.
For the crypto market, this reflects the real trade-offs major central banks face between tightening liquidity and their ability to bear fiscal strain. While this does not mean a full pivot to easing, reduced pressure from long-end selling may slightly ease the overall liquidity environment. Crypto investors can continue to monitor how sovereign bond markets in major economies react, and to view structural changes in liquidity conditions rationally. $BTC
#BankOfEngland #Bonds #MacroEconomy
The key behind this is the scale of fiscal losses. Economists estimate that since the sale of these long-term debts began in 2022, it has already cost UK taxpayers around £22 billion. Against the backdrop of global bond sell-offs, halting this discount-driven selling could save the Treasury about £2.5 billion per year, giving the newly appointed chancellor some policy room to manoeuvre, even though it also makes the budget rules for balancing day-to-day spending more complicated.
From a traditional macro market perspective, adjustments to the pace of central bank balance-sheet shrinkage directly affect the supply-and-demand dynamics in the bond market. Pausing the sale of long-dated gilts can help temporarily relieve upward pressure on long-end yields and, to some extent, stabilize market sentiment toward the UK’s sovereign credit. It may also lead to minor tweaks in the liquidity tug-of-war between the US dollar and the pound.
For the crypto market, this reflects the real trade-offs major central banks face between tightening liquidity and their ability to bear fiscal strain. While this does not mean a full pivot to easing, reduced pressure from long-end selling may slightly ease the overall liquidity environment. Crypto investors can continue to monitor how sovereign bond markets in major economies react, and to view structural changes in liquidity conditions rationally. $BTC
#BankOfEngland #Bonds #MacroEconomy
48
According to the latest report by the British newspaper The Daily Telegraph, ahead of the presentation of Chancellor Jeremy Hunt’s first budget on October 28, the Bank of England (BoE) is preparing to stop selling long-dated gilts with maturities of 20 and 30 years. The policy adjustment is intended to ease the immense pressure on the Treasury from a surge in borrowing costs. These long-term debts accumulated during the financial crisis have, since being sold in 2022, already caused losses of around £22 billion to taxpayers.
From a deep macroeconomic perspective, against the backdrop of a global sell-off in bonds, the Bank of England’s reluctant stepping on the brakes of quantitative tightening (QT) essentially reflects the sharp conflict between sovereign debt sustainability and a contractionary monetary policy. While halting the loss-making sale of long-dated gilts could save around £2.5 billion per year in accounting losses, this compromise cannot disguise the UK’s underlying fiscal fragility and may even make it more complicated—and more passive—for the Chancellor to achieve the rule of balancing the day-to-day spending budget.
For traditional financial markets, the pause in the sell-off of long-dated gilts may, in the short term, curb the spike in yields on long-end UK government bonds and temporarily relieve liquidity pressures. However, this forced policy adjustment sends a warning signal to the market: the asset-liability normalization process of major central banks is running into a hard ceiling imposed by sovereign debt costs. If pressure from continued budget deficits keeps forcing central banks to slow balance-sheet reduction, the risks of fiat-credit expansion and a resurgence of inflation would further build up.
For the cryptocurrency market, this policy wavering triggered by a debt crisis is not entirely positive. Although easing expectations of tighter liquidity may provide a brief breathing space for risk assets such as $BTC , the fragility of the sovereign credit system and macro uncertainty reflected behind it may, in the short term, intensify risk-off-driven asset volatility. Investors should remain alert to downside risks arising from liquidity divergence.
#BankOfEngland #Bonds #MacroEconomy
According to the latest report by the British newspaper The Daily Telegraph, ahead of the presentation of Chancellor Jeremy Hunt’s first budget on October 28, the Bank of England (BoE) is preparing to stop selling long-dated gilts with maturities of 20 and 30 years. The policy adjustment is intended to ease the immense pressure on the Treasury from a surge in borrowing costs. These long-term debts accumulated during the financial crisis have, since being sold in 2022, already caused losses of around £22 billion to taxpayers.
From a deep macroeconomic perspective, against the backdrop of a global sell-off in bonds, the Bank of England’s reluctant stepping on the brakes of quantitative tightening (QT) essentially reflects the sharp conflict between sovereign debt sustainability and a contractionary monetary policy. While halting the loss-making sale of long-dated gilts could save around £2.5 billion per year in accounting losses, this compromise cannot disguise the UK’s underlying fiscal fragility and may even make it more complicated—and more passive—for the Chancellor to achieve the rule of balancing the day-to-day spending budget.
For traditional financial markets, the pause in the sell-off of long-dated gilts may, in the short term, curb the spike in yields on long-end UK government bonds and temporarily relieve liquidity pressures. However, this forced policy adjustment sends a warning signal to the market: the asset-liability normalization process of major central banks is running into a hard ceiling imposed by sovereign debt costs. If pressure from continued budget deficits keeps forcing central banks to slow balance-sheet reduction, the risks of fiat-credit expansion and a resurgence of inflation would further build up.
For the cryptocurrency market, this policy wavering triggered by a debt crisis is not entirely positive. Although easing expectations of tighter liquidity may provide a brief breathing space for risk assets such as $BTC , the fragility of the sovereign credit system and macro uncertainty reflected behind it may, in the short term, intensify risk-off-driven asset volatility. Investors should remain alert to downside risks arising from liquidity divergence.
#BankOfEngland #Bonds #MacroEconomy
From a deep macroeconomic perspective, against the backdrop of a global sell-off in bonds, the Bank of England’s reluctant stepping on the brakes of quantitative tightening (QT) essentially reflects the sharp conflict between sovereign debt sustainability and a contractionary monetary policy. While halting the loss-making sale of long-dated gilts could save around £2.5 billion per year in accounting losses, this compromise cannot disguise the UK’s underlying fiscal fragility and may even make it more complicated—and more passive—for the Chancellor to achieve the rule of balancing the day-to-day spending budget.
For traditional financial markets, the pause in the sell-off of long-dated gilts may, in the short term, curb the spike in yields on long-end UK government bonds and temporarily relieve liquidity pressures. However, this forced policy adjustment sends a warning signal to the market: the asset-liability normalization process of major central banks is running into a hard ceiling imposed by sovereign debt costs. If pressure from continued budget deficits keeps forcing central banks to slow balance-sheet reduction, the risks of fiat-credit expansion and a resurgence of inflation would further build up.
For the cryptocurrency market, this policy wavering triggered by a debt crisis is not entirely positive. Although easing expectations of tighter liquidity may provide a brief breathing space for risk assets such as $BTC , the fragility of the sovereign credit system and macro uncertainty reflected behind it may, in the short term, intensify risk-off-driven asset volatility. Investors should remain alert to downside risks arising from liquidity divergence.
#BankOfEngland #Bonds #MacroEconomy
2
According to a report by the British newspaper The Daily Telegraph, the Bank of England (BoE) plans to officially stop selling long-dated government bonds such as 20-year and 30-year gilts before the Chancellor of the Exchequer, Jeremy Hunt, unveils his first budget on October 28. Long-dated gilts accumulated to deal with the crisis have been offloaded since 2022, resulting in losses to taxpayers of about £22 billion. This move is intended to directly curb the runaway surge in borrowing costs.
From a technical and macro-liquidity perspective, this policy shift carries extremely critical “market rescue” significance. Global bond markets have been under sustained pressure, with the yield curve becoming extremely steep. By halting the massive selling of long bonds that are driving large losses, it is expected to save £2.5 billion in costs each year. This marks a substantive loosening at the margin along the Bank of England’s quantitative tightening (QT) path, effectively plugging the broken gap in long-end liquidity that has been bleeding continuously.
The decision is directly positive for traditional financial markets. A spike-and-retracement in long-dated gilt yields will prompt a technical adjustment to global risk-free rates, easing sovereign debt pressure and suppressing the one-way upward push of the U.S. dollar index. Risk-on sentiment is forming a resonance at a key support level, and a potential peak in funding costs will open a technical path for base-building and rebound in equities and other risk assets.
For crypto assets, the slight moderation in the marginal tightening pace by major central banks is an extremely positive macro signal. Expectations for liquidity typically bottom out and recover ahead of technical breakouts in coin prices. As the high-rate “cloud” that has been suppressing valuations gradually dissipates, core assets such as $BTC that have been building strength at the bottom may be positioned to see a volume-expansion rebound driven by liquidity spillover.📈
#BankOfEngland #QuantitativeTightening #GlobalMacro
According to a report by the British newspaper The Daily Telegraph, the Bank of England (BoE) plans to officially stop selling long-dated government bonds such as 20-year and 30-year gilts before the Chancellor of the Exchequer, Jeremy Hunt, unveils his first budget on October 28. Long-dated gilts accumulated to deal with the crisis have been offloaded since 2022, resulting in losses to taxpayers of about £22 billion. This move is intended to directly curb the runaway surge in borrowing costs.
From a technical and macro-liquidity perspective, this policy shift carries extremely critical “market rescue” significance. Global bond markets have been under sustained pressure, with the yield curve becoming extremely steep. By halting the massive selling of long bonds that are driving large losses, it is expected to save £2.5 billion in costs each year. This marks a substantive loosening at the margin along the Bank of England’s quantitative tightening (QT) path, effectively plugging the broken gap in long-end liquidity that has been bleeding continuously.
The decision is directly positive for traditional financial markets. A spike-and-retracement in long-dated gilt yields will prompt a technical adjustment to global risk-free rates, easing sovereign debt pressure and suppressing the one-way upward push of the U.S. dollar index. Risk-on sentiment is forming a resonance at a key support level, and a potential peak in funding costs will open a technical path for base-building and rebound in equities and other risk assets.
For crypto assets, the slight moderation in the marginal tightening pace by major central banks is an extremely positive macro signal. Expectations for liquidity typically bottom out and recover ahead of technical breakouts in coin prices. As the high-rate “cloud” that has been suppressing valuations gradually dissipates, core assets such as $BTC that have been building strength at the bottom may be positioned to see a volume-expansion rebound driven by liquidity spillover.📈
#BankOfEngland #QuantitativeTightening #GlobalMacro
From a technical and macro-liquidity perspective, this policy shift carries extremely critical “market rescue” significance. Global bond markets have been under sustained pressure, with the yield curve becoming extremely steep. By halting the massive selling of long bonds that are driving large losses, it is expected to save £2.5 billion in costs each year. This marks a substantive loosening at the margin along the Bank of England’s quantitative tightening (QT) path, effectively plugging the broken gap in long-end liquidity that has been bleeding continuously.
The decision is directly positive for traditional financial markets. A spike-and-retracement in long-dated gilt yields will prompt a technical adjustment to global risk-free rates, easing sovereign debt pressure and suppressing the one-way upward push of the U.S. dollar index. Risk-on sentiment is forming a resonance at a key support level, and a potential peak in funding costs will open a technical path for base-building and rebound in equities and other risk assets.
For crypto assets, the slight moderation in the marginal tightening pace by major central banks is an extremely positive macro signal. Expectations for liquidity typically bottom out and recover ahead of technical breakouts in coin prices. As the high-rate “cloud” that has been suppressing valuations gradually dissipates, core assets such as $BTC that have been building strength at the bottom may be positioned to see a volume-expansion rebound driven by liquidity spillover.📈
#BankOfEngland #QuantitativeTightening #GlobalMacro
52
·
--
According to a report by the Financial Times, as the escalation of geopolitical tensions in the Middle East drives up energy prices, internal disagreement within the Bank of England over the interest-rate path is intensifying. The policy makers have scheduled a monetary policy meeting for this week, focusing on the benchmark interest rate and the pace of balance-sheet runoff. While the market currently broadly expects the odds of a rate hike at Thursday’s meeting to be less than one-third, the continued rise in oil prices is increasing pressures for a rebound in inflation. Combined with steady growth in UK GDP, this has forced policy makers to reassess the likely direction of rates before year-end.
Sanjay Raja, an economist at Deutsche Bank, said that the rationale for the Bank of England to maintain the status quo is weakening, and its tolerance may be nearing its limit. The situation is complicated by the fact that the market is not only facing higher energy costs from geopolitical factors; the UK gilt market is also coming under significant pressure from the government ahead of the budget statement to be released on October 28. Any previously expected path of rate cuts or a smooth transition is likely to be disrupted by this wave of imported inflation.
From the perspective of macro financial markets, the Middle East conflict lifting oil prices not only directly suppresses global expectations for rate cuts, but also raises sovereign bond yields and provides interim support for the US dollar index. If the Bank of England were forced by inflation pressures to keep rates at 3.75% or to signal a tightening bias, policy divergence among major global central banks could intensify, leading to wider swings in both traditional FX and commodity markets.
For the crypto market, macro liquidity expectations remain a key factor influencing investors’ risk appetite. The delayed effect of energy-driven inflation and the expectation of high interest rates may, in the short term, limit the pace at which incremental capital flows in, keeping $BTC and mainstream tokens locked in a range-bound, choppy pattern. Investors are currently staying cautious and on the sidelines, and should closely monitor the Middle East situation and the actual impact of central bank decisions on peripheral liquidity.
#BankOfEngland #Inflation #Geopolitics
According to a report by the Financial Times, as the escalation of geopolitical tensions in the Middle East drives up energy prices, internal disagreement within the Bank of England over the interest-rate path is intensifying. The policy makers have scheduled a monetary policy meeting for this week, focusing on the benchmark interest rate and the pace of balance-sheet runoff. While the market currently broadly expects the odds of a rate hike at Thursday’s meeting to be less than one-third, the continued rise in oil prices is increasing pressures for a rebound in inflation. Combined with steady growth in UK GDP, this has forced policy makers to reassess the likely direction of rates before year-end.
Sanjay Raja, an economist at Deutsche Bank, said that the rationale for the Bank of England to maintain the status quo is weakening, and its tolerance may be nearing its limit. The situation is complicated by the fact that the market is not only facing higher energy costs from geopolitical factors; the UK gilt market is also coming under significant pressure from the government ahead of the budget statement to be released on October 28. Any previously expected path of rate cuts or a smooth transition is likely to be disrupted by this wave of imported inflation.
From the perspective of macro financial markets, the Middle East conflict lifting oil prices not only directly suppresses global expectations for rate cuts, but also raises sovereign bond yields and provides interim support for the US dollar index. If the Bank of England were forced by inflation pressures to keep rates at 3.75% or to signal a tightening bias, policy divergence among major global central banks could intensify, leading to wider swings in both traditional FX and commodity markets.
For the crypto market, macro liquidity expectations remain a key factor influencing investors’ risk appetite. The delayed effect of energy-driven inflation and the expectation of high interest rates may, in the short term, limit the pace at which incremental capital flows in, keeping $BTC and mainstream tokens locked in a range-bound, choppy pattern. Investors are currently staying cautious and on the sidelines, and should closely monitor the Middle East situation and the actual impact of central bank decisions on peripheral liquidity.
#BankOfEngland #Inflation #Geopolitics
Sanjay Raja, an economist at Deutsche Bank, said that the rationale for the Bank of England to maintain the status quo is weakening, and its tolerance may be nearing its limit. The situation is complicated by the fact that the market is not only facing higher energy costs from geopolitical factors; the UK gilt market is also coming under significant pressure from the government ahead of the budget statement to be released on October 28. Any previously expected path of rate cuts or a smooth transition is likely to be disrupted by this wave of imported inflation.
From the perspective of macro financial markets, the Middle East conflict lifting oil prices not only directly suppresses global expectations for rate cuts, but also raises sovereign bond yields and provides interim support for the US dollar index. If the Bank of England were forced by inflation pressures to keep rates at 3.75% or to signal a tightening bias, policy divergence among major global central banks could intensify, leading to wider swings in both traditional FX and commodity markets.
For the crypto market, macro liquidity expectations remain a key factor influencing investors’ risk appetite. The delayed effect of energy-driven inflation and the expectation of high interest rates may, in the short term, limit the pace at which incremental capital flows in, keeping $BTC and mainstream tokens locked in a range-bound, choppy pattern. Investors are currently staying cautious and on the sidelines, and should closely monitor the Middle East situation and the actual impact of central bank decisions on peripheral liquidity.
#BankOfEngland #Inflation #Geopolitics
46
According to a report by the Financial Times, as the Middle East conflict escalates and pushes global energy prices higher, the Bank of England’s (BoE) policymakers face a harsher interest-rate dilemma at this week’s policy meeting. Currently, the UK’s benchmark interest rate stands at 3.75%, while the government budget statement to be released on October 28 and pressure in the bond market are further intensifying fierce internal debate within the Monetary Policy Committee over whether another rate hike is needed before year-end.
At the heart of this development is the resurgence of imported inflation risk. Although markets previously expected less than a one-in-three chance that the Bank of England would raise rates at Thursday’s meeting, Deutsche Bank economist Sanjay Raja said that with the UK’s GDP showing robust growth and oil prices rising, the rationale for keeping existing policy is being steadily eroded, and policymakers’ patience may soon be exhausted. This indicates that the easing expectations held by major central banks are running into serious re-inflation headwinds.
From the perspective of macro financial markets, the specter of stagflation and a potential hawkish shift in central bank stance will substantially weigh on risk assets. Soaring energy costs combined with interest rates staying high for longer will not only lift the pound and global bond yields, but also directly squeeze corporate profit margins. That, in turn, will raise the risk of valuation re-pricing in global equity and credit markets and intensify concerns about tightening liquidity.
For the cryptocurrency market, the repeated twists in macro-tightening expectations are a clear headwind. If global central banks—represented by the Bank of England—are forced to extend the tightening cycle due to geopolitical factors and inflation rebounds, the global liquidity environment will face further strain. Under the dual squeeze of risk-off sentiment and elevated funding costs, risk assets such as $BTC may, in the near term, be tested by capital outflows and heightened volatility. Investors should watch out for the risk of valuation pullbacks.📊
#BankOfEngland #InflationRisk #MacroEconomics
According to a report by the Financial Times, as the Middle East conflict escalates and pushes global energy prices higher, the Bank of England’s (BoE) policymakers face a harsher interest-rate dilemma at this week’s policy meeting. Currently, the UK’s benchmark interest rate stands at 3.75%, while the government budget statement to be released on October 28 and pressure in the bond market are further intensifying fierce internal debate within the Monetary Policy Committee over whether another rate hike is needed before year-end.
At the heart of this development is the resurgence of imported inflation risk. Although markets previously expected less than a one-in-three chance that the Bank of England would raise rates at Thursday’s meeting, Deutsche Bank economist Sanjay Raja said that with the UK’s GDP showing robust growth and oil prices rising, the rationale for keeping existing policy is being steadily eroded, and policymakers’ patience may soon be exhausted. This indicates that the easing expectations held by major central banks are running into serious re-inflation headwinds.
From the perspective of macro financial markets, the specter of stagflation and a potential hawkish shift in central bank stance will substantially weigh on risk assets. Soaring energy costs combined with interest rates staying high for longer will not only lift the pound and global bond yields, but also directly squeeze corporate profit margins. That, in turn, will raise the risk of valuation re-pricing in global equity and credit markets and intensify concerns about tightening liquidity.
For the cryptocurrency market, the repeated twists in macro-tightening expectations are a clear headwind. If global central banks—represented by the Bank of England—are forced to extend the tightening cycle due to geopolitical factors and inflation rebounds, the global liquidity environment will face further strain. Under the dual squeeze of risk-off sentiment and elevated funding costs, risk assets such as $BTC may, in the near term, be tested by capital outflows and heightened volatility. Investors should watch out for the risk of valuation pullbacks.📊
#BankOfEngland #InflationRisk #MacroEconomics
At the heart of this development is the resurgence of imported inflation risk. Although markets previously expected less than a one-in-three chance that the Bank of England would raise rates at Thursday’s meeting, Deutsche Bank economist Sanjay Raja said that with the UK’s GDP showing robust growth and oil prices rising, the rationale for keeping existing policy is being steadily eroded, and policymakers’ patience may soon be exhausted. This indicates that the easing expectations held by major central banks are running into serious re-inflation headwinds.
From the perspective of macro financial markets, the specter of stagflation and a potential hawkish shift in central bank stance will substantially weigh on risk assets. Soaring energy costs combined with interest rates staying high for longer will not only lift the pound and global bond yields, but also directly squeeze corporate profit margins. That, in turn, will raise the risk of valuation re-pricing in global equity and credit markets and intensify concerns about tightening liquidity.
For the cryptocurrency market, the repeated twists in macro-tightening expectations are a clear headwind. If global central banks—represented by the Bank of England—are forced to extend the tightening cycle due to geopolitical factors and inflation rebounds, the global liquidity environment will face further strain. Under the dual squeeze of risk-off sentiment and elevated funding costs, risk assets such as $BTC may, in the near term, be tested by capital outflows and heightened volatility. Investors should watch out for the risk of valuation pullbacks.📊
#BankOfEngland #InflationRisk #MacroEconomics

🏦 Bank of England holds interest rates steady amid inflation concerns
The Bank of England has indicated it will keep interest rates unchanged, which could affect risk assets. This step comes as geopolitical tensions related to energy continue to escalate, raising concerns about future inflation and complicating the bank’s policy decisions.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ REGULATION
#BankOfEngland #InterestRates #GlobalEconomy #Inflation #MonetaryPolicy
📰 Source: cryptobriefing.com
🏦 Bank of England holds interest rates steady amid inflation concerns
The Bank of England has indicated it will keep interest rates unchanged, which could affect risk assets. This step comes as geopolitical tensions related to energy continue to escalate, raising concerns about future inflation and complicating the bank’s policy decisions.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ REGULATION
#BankOfEngland #InterestRates #GlobalEconomy #Inflation #MonetaryPolicy
📰 Source: cryptobriefing.com
The Bank of England has indicated it will keep interest rates unchanged, which could affect risk assets. This step comes as geopolitical tensions related to energy continue to escalate, raising concerns about future inflation and complicating the bank’s policy decisions.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ REGULATION
#BankOfEngland #InterestRates #GlobalEconomy #Inflation #MonetaryPolicy
📰 Source: cryptobriefing.com
12

·
--
Article
Market Raises 2026 Bank of England Rate-Hike BetsMarket expectations for the Bank of England’s interest rate path have shifted, with bets on a rate hike in 2026 increasing notably. According to data from Jin10 and the London Stock Exchange Group, investors now anticipate a 30-basis-point increase in the bank’s rate next year, representing a rise of 5 basis points from the previous week.
This change suggests that market participants are increasingly concerned about inflationary pressures and the potential for the Bank of England to tighten monetary policy sooner rather than later. Rising oil prices are cited by analysts as a contributing factor, with Tickmill Group’s Patrick Munnelly noting that higher energy costs are likely to push overall inflation upward by increasing gasoline and energy expenses for consumers and businesses.
Munnelly also highlighted the broader risk of a second wave of inflationary pressures, which could compel the Bank of England to adopt a more aggressive stance on interest rates. This outlook is reflected in the market’s pricing, which now incorporates a higher probability of future rate hikes to combat persistent inflation concerns.
Investors will continue to monitor economic data and geopolitical developments that could influence the Bank of England’s decisions in the coming months. The current expectations underscore a cautious approach amid ongoing economic uncertainties, with the possibility of further adjustments to interest rate forecasts as new information emerges. #BankOfEngland #InterestRates #Inflation
Market Raises 2026 Bank of England Rate-Hike Bets
Market expectations for the Bank of England’s interest rate path have shifted, with bets on a rate hike in 2026 increasing notably. According to data from Jin10 and the London Stock Exchange Group, investors now anticipate a 30-basis-point increase in the bank’s rate next year, representing a rise of 5 basis points from the previous week.
This change suggests that market participants are increasingly concerned about inflationary pressures and the potential for the Bank of England to tighten monetary policy sooner rather than later. Rising oil prices are cited by analysts as a contributing factor, with Tickmill Group’s Patrick Munnelly noting that higher energy costs are likely to push overall inflation upward by increasing gasoline and energy expenses for consumers and businesses.
Munnelly also highlighted the broader risk of a second wave of inflationary pressures, which could compel the Bank of England to adopt a more aggressive stance on interest rates. This outlook is reflected in the market’s pricing, which now incorporates a higher probability of future rate hikes to combat persistent inflation concerns.
Investors will continue to monitor economic data and geopolitical developments that could influence the Bank of England’s decisions in the coming months. The current expectations underscore a cautious approach amid ongoing economic uncertainties, with the possibility of further adjustments to interest rate forecasts as new information emerges. #BankOfEngland #InterestRates #Inflation
This change suggests that market participants are increasingly concerned about inflationary pressures and the potential for the Bank of England to tighten monetary policy sooner rather than later. Rising oil prices are cited by analysts as a contributing factor, with Tickmill Group’s Patrick Munnelly noting that higher energy costs are likely to push overall inflation upward by increasing gasoline and energy expenses for consumers and businesses.
Munnelly also highlighted the broader risk of a second wave of inflationary pressures, which could compel the Bank of England to adopt a more aggressive stance on interest rates. This outlook is reflected in the market’s pricing, which now incorporates a higher probability of future rate hikes to combat persistent inflation concerns.
Investors will continue to monitor economic data and geopolitical developments that could influence the Bank of England’s decisions in the coming months. The current expectations underscore a cautious approach amid ongoing economic uncertainties, with the possibility of further adjustments to interest rate forecasts as new information emerges. #BankOfEngland #InterestRates #Inflation
19
·
--
🚨 BIG WIN FOR STABLECOINS IN THE UK? 🇬🇧
The UK House of Lords is pushing back against the Bank of England’s proposed stablecoin restrictions, arguing that strict limits could slow innovation before the market has a chance to mature.
The central bank had suggested capping individual stablecoin holdings at £20,000 and business holdings at £10 million. However, lawmakers believe regulators should monitor market growth first and only introduce restrictions if real financial stability risks emerge.
They also questioned rules requiring stablecoin issuers to keep at least 40% of reserves in non-interest-bearing central bank deposits.
🔥 This signals a more balanced approach to crypto regulation and could be a bullish development for stablecoin adoption across the UK.
$GUN | $GENIUS | $NEAR
#Crypto #Stablecoins #UKCrypto #BankOfEngland
🚨 BIG WIN FOR STABLECOINS IN THE UK? 🇬🇧
The UK House of Lords is pushing back against the Bank of England’s proposed stablecoin restrictions, arguing that strict limits could slow innovation before the market has a chance to mature.
The central bank had suggested capping individual stablecoin holdings at £20,000 and business holdings at £10 million. However, lawmakers believe regulators should monitor market growth first and only introduce restrictions if real financial stability risks emerge.
They also questioned rules requiring stablecoin issuers to keep at least 40% of reserves in non-interest-bearing central bank deposits.
🔥 This signals a more balanced approach to crypto regulation and could be a bullish development for stablecoin adoption across the UK.
$GUN | $GENIUS | $NEAR
#Crypto #Stablecoins #UKCrypto #BankOfEngland
The UK House of Lords is pushing back against the Bank of England’s proposed stablecoin restrictions, arguing that strict limits could slow innovation before the market has a chance to mature.
The central bank had suggested capping individual stablecoin holdings at £20,000 and business holdings at £10 million. However, lawmakers believe regulators should monitor market growth first and only introduce restrictions if real financial stability risks emerge.
They also questioned rules requiring stablecoin issuers to keep at least 40% of reserves in non-interest-bearing central bank deposits.
🔥 This signals a more balanced approach to crypto regulation and could be a bullish development for stablecoin adoption across the UK.
$GUN | $GENIUS | $NEAR
#Crypto #Stablecoins #UKCrypto #BankOfEngland
1
3
190

·
--
The Bank of England just pulled a major U-turn on stablecoin regulation. Instead of strict individual holding limits, the UK central bank is setting a $50 billion aggregate issuance cap for stablecoins ahead of a 2027 market launch. Token issuers get sweetened yield terms, signaling the BoE wants to compete rather than crush innovation.
This is massive for crypto. Stablecoins are the backbone of DeFi and cross-border payments. A $50B cap means room for explosive growth while maintaining guardrails. $BTC $ETH $SOL all stand to benefit as institutional confidence in stablecoin infrastructure hits new highs.
The shift from retail limits to an aggregate cap shows regulators are learning that heavy-handed restrictions push activity offshore. The UK is positioning itself as crypto-friendly while the US still debates its own stablecoin framework.
Will other central banks follow the BoE's approach or double down? Drop your take below.
#BankOfEngland #Stablecoin #Regulation #Crypto
The Bank of England just pulled a major U-turn on stablecoin regulation. Instead of strict individual holding limits, the UK central bank is setting a $50 billion aggregate issuance cap for stablecoins ahead of a 2027 market launch. Token issuers get sweetened yield terms, signaling the BoE wants to compete rather than crush innovation.
This is massive for crypto. Stablecoins are the backbone of DeFi and cross-border payments. A $50B cap means room for explosive growth while maintaining guardrails. $BTC $ETH $SOL all stand to benefit as institutional confidence in stablecoin infrastructure hits new highs.
The shift from retail limits to an aggregate cap shows regulators are learning that heavy-handed restrictions push activity offshore. The UK is positioning itself as crypto-friendly while the US still debates its own stablecoin framework.
Will other central banks follow the BoE's approach or double down? Drop your take below.
#BankOfEngland #Stablecoin #Regulation #Crypto
This is massive for crypto. Stablecoins are the backbone of DeFi and cross-border payments. A $50B cap means room for explosive growth while maintaining guardrails. $BTC $ETH $SOL all stand to benefit as institutional confidence in stablecoin infrastructure hits new highs.
The shift from retail limits to an aggregate cap shows regulators are learning that heavy-handed restrictions push activity offshore. The UK is positioning itself as crypto-friendly while the US still debates its own stablecoin framework.
Will other central banks follow the BoE's approach or double down? Drop your take below.
#BankOfEngland #Stablecoin #Regulation #Crypto
43
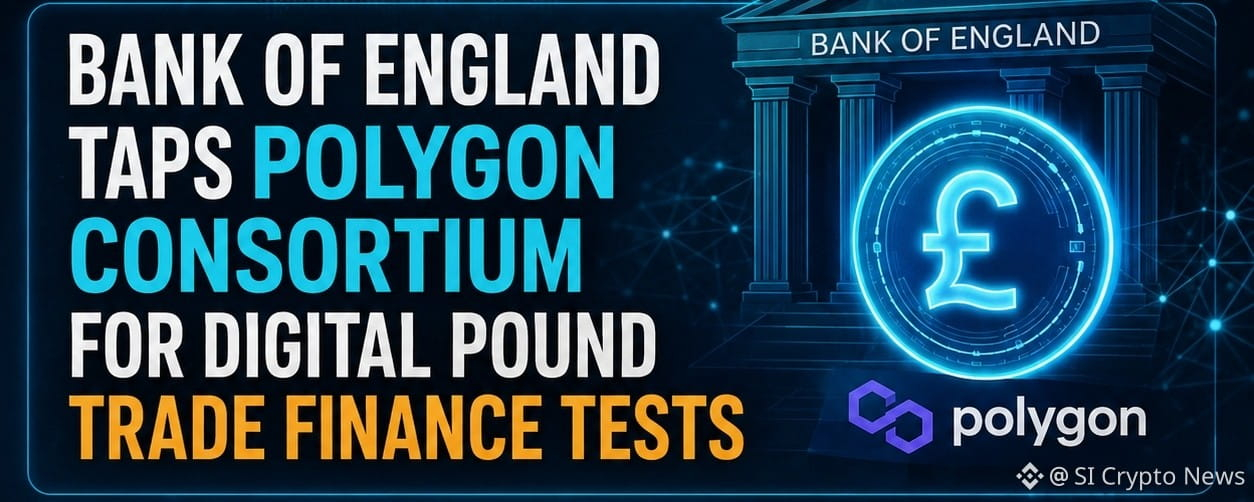
Article
Bank of England and Polygon’s New Experiment: Can a Digital Pound and Stablecoins Work Together?The world’s financial system is gradually moving toward an era in which, alongside traditional money, stablecoins, blockchain, and digital currencies may play an important role.
An interesting move in this direction has emerged from the UK. In its Digital Pound Lab Phase 2, the Bank of England has included Polygon Labs, NOBO Finance, and Dun & Bradstreet. The goal is to see how blockchain, stablecoins, and a potential digital pound could be used in business transactions—especially international trade finance.
Bank of England and Polygon’s New Experiment: Can a Digital Pound and Stablecoins Work Together?
The world’s financial system is gradually moving toward an era in which, alongside traditional money, stablecoins, blockchain, and digital currencies may play an important role.
An interesting move in this direction has emerged from the UK. In its Digital Pound Lab Phase 2, the Bank of England has included Polygon Labs, NOBO Finance, and Dun & Bradstreet. The goal is to see how blockchain, stablecoins, and a potential digital pound could be used in business transactions—especially international trade finance.
An interesting move in this direction has emerged from the UK. In its Digital Pound Lab Phase 2, the Bank of England has included Polygon Labs, NOBO Finance, and Dun & Bradstreet. The goal is to see how blockchain, stablecoins, and a potential digital pound could be used in business transactions—especially international trade finance.
67
🏦 Bank of England slows down quantitative tightening
The Bank of England announced a slowdown in the pace of its quantitative tightening program, a decision that aligns with market expectations. This step may help stabilize government bond yields, which could ease pressures in broader financial markets.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ REGULATION
#BankOfEngland #QuantitativeTightening #MacroEconomy #FinancialMarkets #CentralBanks
📰 Source: cryptobriefing.com
🏦 Bank of England slows down quantitative tightening
The Bank of England announced a slowdown in the pace of its quantitative tightening program, a decision that aligns with market expectations. This step may help stabilize government bond yields, which could ease pressures in broader financial markets.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ REGULATION
#BankOfEngland #QuantitativeTightening #MacroEconomy #FinancialMarkets #CentralBanks
📰 Source: cryptobriefing.com
The Bank of England announced a slowdown in the pace of its quantitative tightening program, a decision that aligns with market expectations. This step may help stabilize government bond yields, which could ease pressures in broader financial markets.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ REGULATION
#BankOfEngland #QuantitativeTightening #MacroEconomy #FinancialMarkets #CentralBanks
📰 Source: cryptobriefing.com
11
·
--
The Bank of England just flipped its stablecoin playbook. Instead of capping wallet holdings, the regulator will impose a £40 billion issuance ceiling on systemic stablecoins — reshaping how digital pounds scale across institutions.
This signals a shift favoring institutional infrastructure over retail controls. By removing wallet-level restrictions, the BoE opens the door for larger capital allocators without friction. Issuers now face a single transparent cap rather than fragmented rules that slowed adoption.
The move aligns with global trends. The BIS has pushed for regulated stablecoins as cross-border settlement backbone. With the UK setting clear issuance boundaries, expect other G7 regulators to follow a framework balancing growth with systemic risk. $BTC $ETH $SOL
Does a blanket issuance cap strike the right balance between innovation and risk, or push activity to less regulated jurisdictions? Drop your take. #BankOfEngland #Stablecoins #Regulation #Crypto
The Bank of England just flipped its stablecoin playbook. Instead of capping wallet holdings, the regulator will impose a £40 billion issuance ceiling on systemic stablecoins — reshaping how digital pounds scale across institutions.
This signals a shift favoring institutional infrastructure over retail controls. By removing wallet-level restrictions, the BoE opens the door for larger capital allocators without friction. Issuers now face a single transparent cap rather than fragmented rules that slowed adoption.
The move aligns with global trends. The BIS has pushed for regulated stablecoins as cross-border settlement backbone. With the UK setting clear issuance boundaries, expect other G7 regulators to follow a framework balancing growth with systemic risk. $BTC $ETH $SOL
Does a blanket issuance cap strike the right balance between innovation and risk, or push activity to less regulated jurisdictions? Drop your take. #BankOfEngland #Stablecoins #Regulation #Crypto
This signals a shift favoring institutional infrastructure over retail controls. By removing wallet-level restrictions, the BoE opens the door for larger capital allocators without friction. Issuers now face a single transparent cap rather than fragmented rules that slowed adoption.
The move aligns with global trends. The BIS has pushed for regulated stablecoins as cross-border settlement backbone. With the UK setting clear issuance boundaries, expect other G7 regulators to follow a framework balancing growth with systemic risk. $BTC $ETH $SOL
Does a blanket issuance cap strike the right balance between innovation and risk, or push activity to less regulated jurisdictions? Drop your take. #BankOfEngland #Stablecoins #Regulation #Crypto
62
·
--
⚡️ **BOE BOMBSHELL: Frontier AI is a Ticking Time Bomb for Financial Stability** 🚨
The Bank of England just dropped a major warning: Rapid advances in cutting-edge AI are **amplifying systemic risks** across global finance — think lightning-fast trading glitches, black swan events, and cascading failures.
$BLUR
Crypto markets? Already volatile as hell. AI-powered algos + DeFi could either supercharge gains… or trigger the next meltdown.
Are we building the future or the next 2008?
What’s your take — AI savior or destroyer for crypto? Drop it below 👇
#BankOfEngland #Crypto #FinTech #CryptoRisks #Web3
$EVAA $TAC
⚡️ **BOE BOMBSHELL: Frontier AI is a Ticking Time Bomb for Financial Stability** 🚨
The Bank of England just dropped a major warning: Rapid advances in cutting-edge AI are **amplifying systemic risks** across global finance — think lightning-fast trading glitches, black swan events, and cascading failures.
$BLUR
Crypto markets? Already volatile as hell. AI-powered algos + DeFi could either supercharge gains… or trigger the next meltdown.
Are we building the future or the next 2008?
What’s your take — AI savior or destroyer for crypto? Drop it below 👇
#BankOfEngland #Crypto #FinTech #CryptoRisks #Web3
$EVAA $TAC
The Bank of England just dropped a major warning: Rapid advances in cutting-edge AI are **amplifying systemic risks** across global finance — think lightning-fast trading glitches, black swan events, and cascading failures.
$BLUR
Crypto markets? Already volatile as hell. AI-powered algos + DeFi could either supercharge gains… or trigger the next meltdown.
Are we building the future or the next 2008?
What’s your take — AI savior or destroyer for crypto? Drop it below 👇
#BankOfEngland #Crypto #FinTech #CryptoRisks #Web3
$EVAA $TAC
1
226
·
--
🇬🇧 JUST IN: A BANK OF ENGLAND POLICYMAKER SAYS STABLECOINS MAY NOT BE THE FUTURE.$STG
Megan Greene predicts demand for stablecoins could eventually fade as tokenized bank deposits take over, offering a more integrated bridge between traditional finance and blockchain.$FF
THE NEXT BIG BATTLE IN DIGITAL MONEY MAY ALREADY BE STARTING. 🚨$WLD
{spot}(WLDUSDT)
{spot}(FFUSDT)
{spot}(SUIUSDT)
#England #BankOfEngland #Stablecoins #ECBHighlightsStablecoinRisks #OverlayPhantomTargetsCryptoApps
🇬🇧 JUST IN: A BANK OF ENGLAND POLICYMAKER SAYS STABLECOINS MAY NOT BE THE FUTURE.$STG
Megan Greene predicts demand for stablecoins could eventually fade as tokenized bank deposits take over, offering a more integrated bridge between traditional finance and blockchain.$FF
THE NEXT BIG BATTLE IN DIGITAL MONEY MAY ALREADY BE STARTING. 🚨$WLD
#England #BankOfEngland #Stablecoins #ECBHighlightsStablecoinRisks #OverlayPhantomTargetsCryptoApps
Megan Greene predicts demand for stablecoins could eventually fade as tokenized bank deposits take over, offering a more integrated bridge between traditional finance and blockchain.$FF
THE NEXT BIG BATTLE IN DIGITAL MONEY MAY ALREADY BE STARTING. 🚨$WLD
#England #BankOfEngland #Stablecoins #ECBHighlightsStablecoinRisks #OverlayPhantomTargetsCryptoApps
3
1
3
397
#BankOfEngland & #Stablecoins
🇬🇧 Bank of England eases rules for stablecoins
The regulator has revised its tough approach to future sterling stablecoins. This is a major concession to the fintech market.
Key changes:
🚫 Wallet limits removed: The previous limits (£20k for individuals and £10m for companies) have been completely removed as they would have hindered scaling.
⬆️ New issuer cap: Instead of user limits, a temporary overall limit on issuance of up to £40 billion per issuer is introduced.
💼 More profitable reserves: Up to 70% of collateral is allowed to be held in short-term UK government bonds. This will allow issuers to generate income and make the business viable.
➡️ Context: The market is still dominated by dollar tokens. The UK is trying to catch up with the US and EU in regulation to attract capital and companies building the future infrastructure for tokenized payments.
⚠️ Important: This is not yet the launch of a retail stablecoin, but only an update to the rules in the development process. However, for banks and crypto companies, it is a clear green light for product planning.
#BankOfEngland & #Stablecoins
🇬🇧 Bank of England eases rules for stablecoins
The regulator has revised its tough approach to future sterling stablecoins. This is a major concession to the fintech market.
Key changes:
🚫 Wallet limits removed: The previous limits (£20k for individuals and £10m for companies) have been completely removed as they would have hindered scaling.
⬆️ New issuer cap: Instead of user limits, a temporary overall limit on issuance of up to £40 billion per issuer is introduced.
💼 More profitable reserves: Up to 70% of collateral is allowed to be held in short-term UK government bonds. This will allow issuers to generate income and make the business viable.
➡️ Context: The market is still dominated by dollar tokens. The UK is trying to catch up with the US and EU in regulation to attract capital and companies building the future infrastructure for tokenized payments.
⚠️ Important: This is not yet the launch of a retail stablecoin, but only an update to the rules in the development process. However, for banks and crypto companies, it is a clear green light for product planning.
🇬🇧 Bank of England eases rules for stablecoins
The regulator has revised its tough approach to future sterling stablecoins. This is a major concession to the fintech market.
Key changes:
🚫 Wallet limits removed: The previous limits (£20k for individuals and £10m for companies) have been completely removed as they would have hindered scaling.
⬆️ New issuer cap: Instead of user limits, a temporary overall limit on issuance of up to £40 billion per issuer is introduced.
💼 More profitable reserves: Up to 70% of collateral is allowed to be held in short-term UK government bonds. This will allow issuers to generate income and make the business viable.
➡️ Context: The market is still dominated by dollar tokens. The UK is trying to catch up with the US and EU in regulation to attract capital and companies building the future infrastructure for tokenized payments.
⚠️ Important: This is not yet the launch of a retail stablecoin, but only an update to the rules in the development process. However, for banks and crypto companies, it is a clear green light for product planning.
1
41
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#ElSalvadorBTCHoldingsRiseTo7777
1,983 views
82 Discussing
2
#MemeLaunchpads82%OfArcDayOneVolume
10,748 views
307 Discussing
3
#OstiumLoanDisputeHearingSetInNYFederalCourt
10,939 views
257 Discussing
4
#HyperliquidUSDCSupplyOvertakesSolana
1,668 views
81 Discussing
5
#SKPoliceRefer18PolymarketUsersToProsecutors
8,447 views
261 Discussing
6
#FedSEPProjects2026RateAt4.1%
20,702 views
367 Discussing
7
#USHouseAdvancesBitcoinReserveBill
10,570 views
245 Discussing
8
#AmazonGetsWarrantsToBuyGeneracStock
10,233 views
224 Discussing
9
#DotPlotSignalsOneMoreHikeIn2026
35,085 views
616 Discussing
10
#RobinhoodToSupportCircleArcNetwork
12,461 views
228 Discussing