
CryptoWolf-
68 Beiträge
CryptoWolf-
Melden
Nutzer blockieren
21 Following
36 Follower
56 Like gegeben
Beiträge
·
--
Übersetzung ansehen
#BinancePick ghuttt hdruyrgytgurr ydfyhrghr yfhgcggggffhh hh
#BinancePick ghuttt hdruyrgytgurr ydfyhrghr yfhgcggggffhh hh
·
--
Übersetzung ansehen
#BinancePick hhuvgvv hgdrredgh gvvghjhtfyu bhhhhhvfdhygg
#BinancePick hhuvgvv hgdrredgh gvvghjhtfyu bhhhhhvfdhygg
·
--
Übersetzung ansehen
#BinancePick hhhhhyyyy77777yuu777777ghyyhyyyyyy huh huuuu hhhhv
#BinancePick hhhhhyyyy77777yuu777777ghyyhyyyyyy huh huuuu hhhhv
·
--
#BinancePick hjjjhhhhhhhgghhh hhhhggrruhhdgu hhggihhhhggjjhh
#BinancePick hjjjhhhhhhhgghhh hhhhggrruhhdgu hhggihhhhggjjhh
1
·
--
#BinancePick ffffgffdd dbdjjdjdhdhdhdhehdhdbdbbdhdhf
#BinancePick ffffgffdd dbdjjdjdhdhdhdhehdhdbdbbdhdhf
·
--
Übersetzung ansehen
#BinancePick ga s shdhdhd djushddjddbbd ueuehd d dhhdbdbebebebee
#BinancePick ga s shdhdhd djushddjddbbd ueuehd d dhhdbdbebebebee
·
--
Übersetzung ansehen
#BinancePick interest on same is my said like or ehkshs ausa hsuvs
#BinancePick interest on same is my said like or ehkshs ausa hsuvs
·
--
·
--
@termmax #TermMax
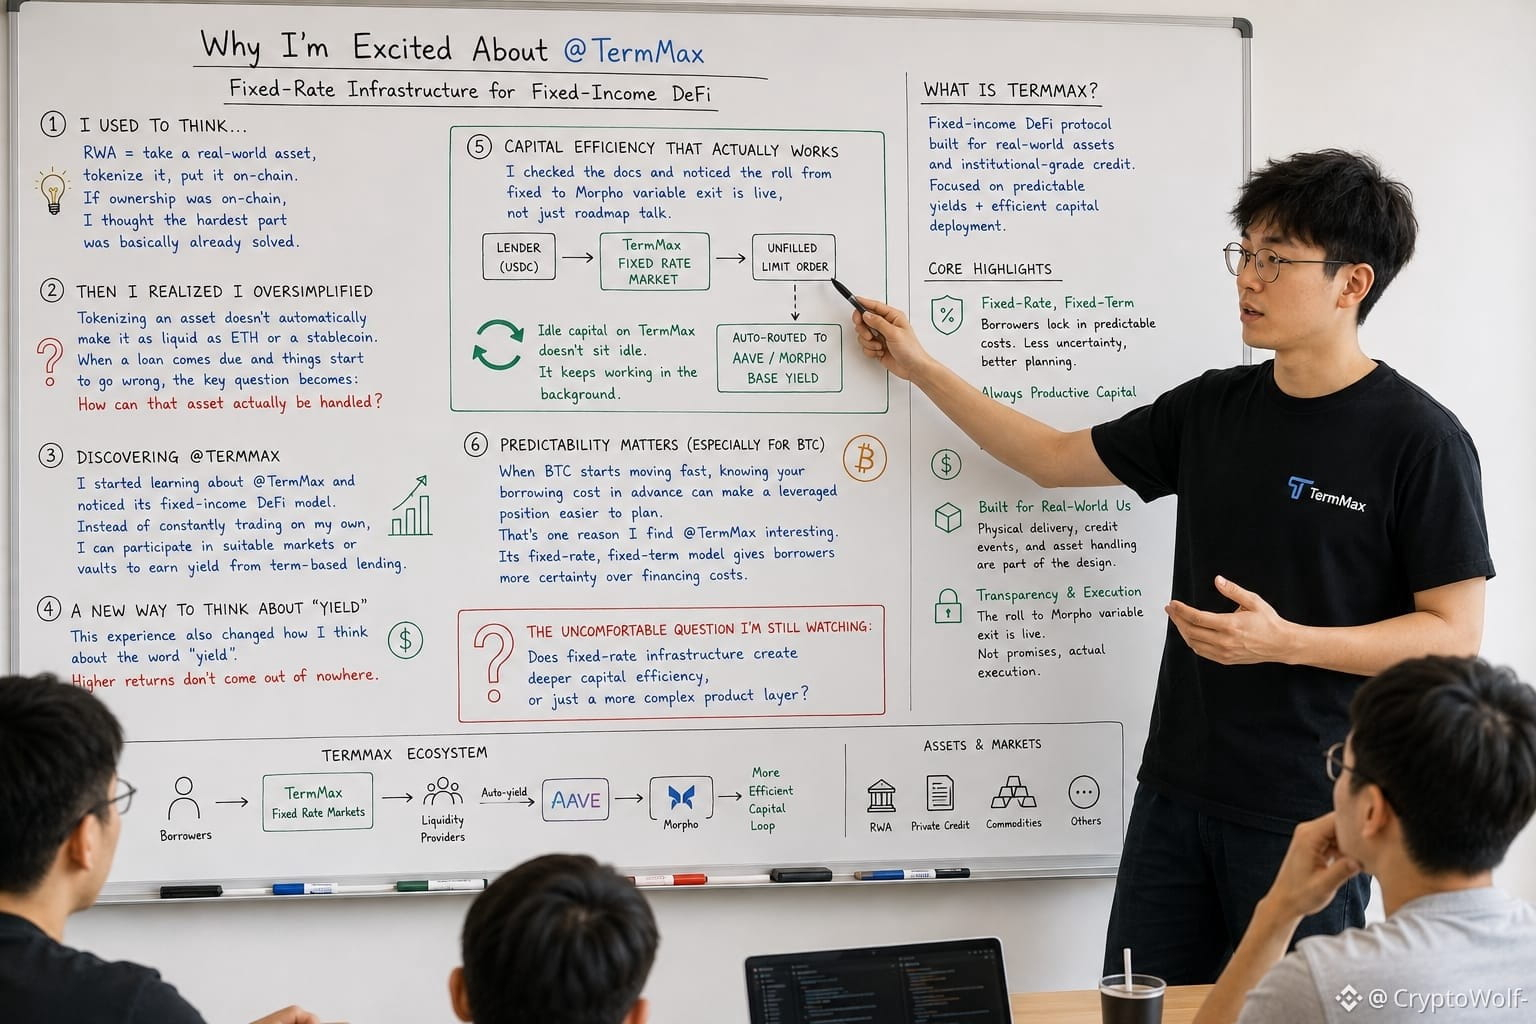
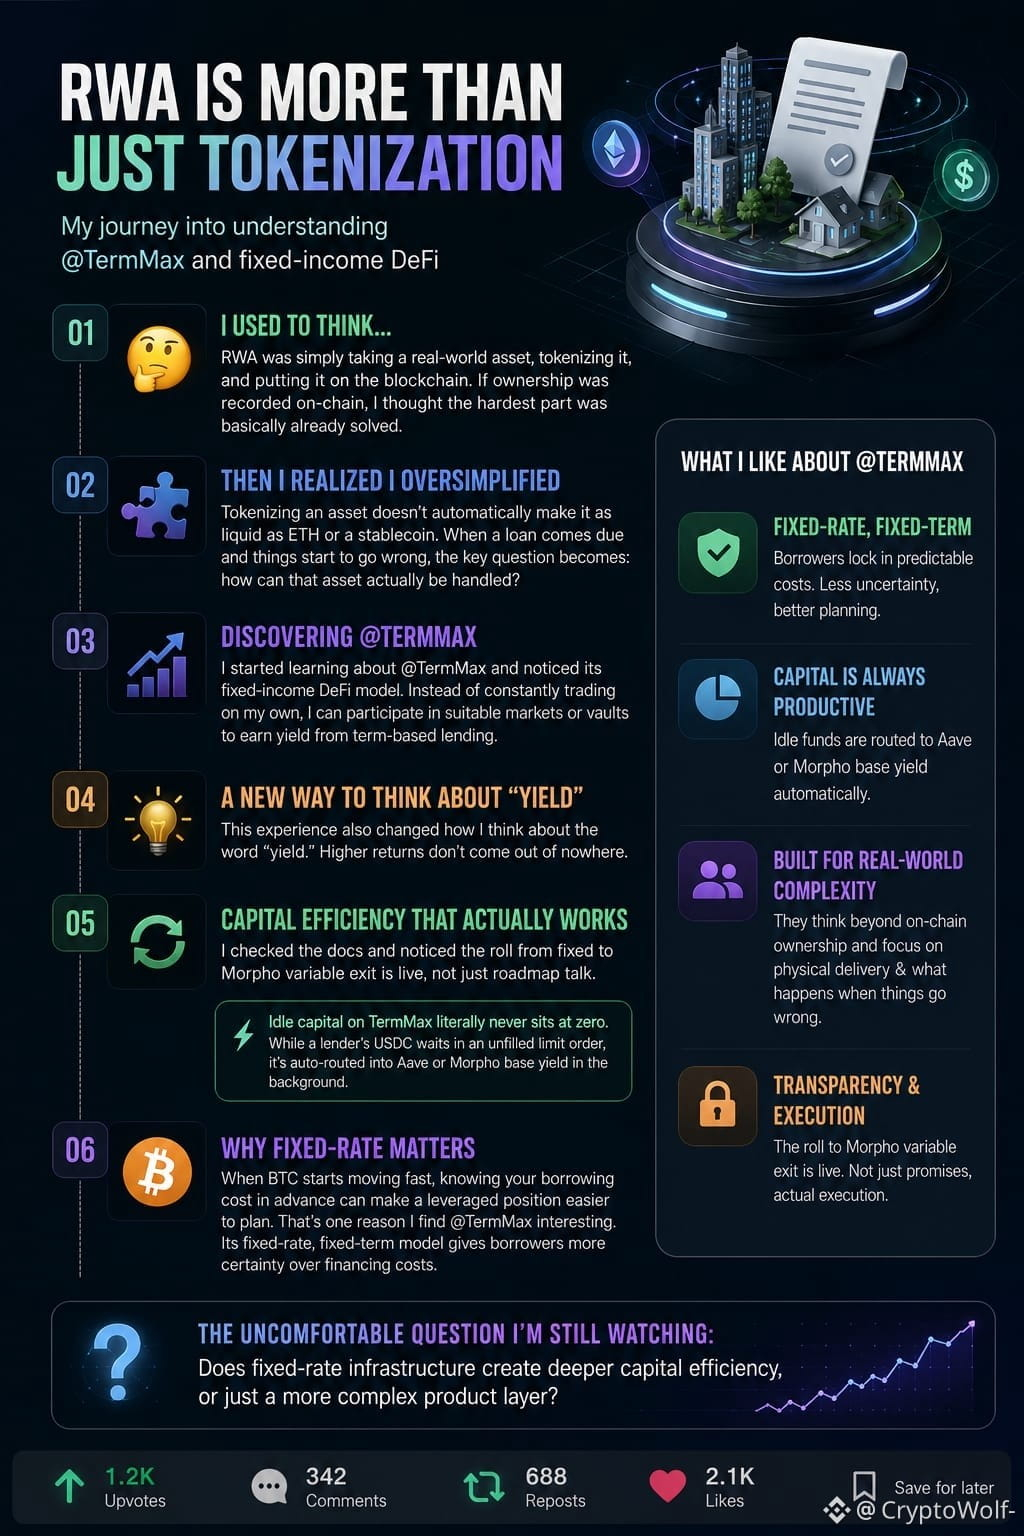
Früher dachte ich, RWA sei im Grunde einfach die Tokenisierung eines realen Vermögenswerts und das Platzieren auf der Blockchain. Wenn das Eigentum dann On-Chain erfasst wird, dachte ich, dass der schwierigste Teil im Grunde schon gelöst wäre.
Aber als ich mir @TermMax angesehen habe—insbesondere ihren Ansatz für die physische Lieferung—wurde mir klar, dass ich das Problem zu stark vereinfacht hatte. Ein Vermögenswert zu tokenisieren macht ihn nicht automatisch so liquide wie ETH oder ein Stablecoin. Wenn ein Kredit fällig wird und die Dinge schiefzugehen beginnen, lautet die entscheidende Frage: Wie kann dieser Vermögenswert tatsächlich gehandhabt werden?
Dann habe ich angefangen, mehr über @TermMax zu lernen und habe sein DeFi-Modell für festverzinsliche Anlagen entdeckt. Anstatt ständig in Eigenregie zu traden, kann ich an passenden Märkten oder in Vaults teilnehmen, um Rendite aus termbasiertem Lending zu erzielen.
Diese Erfahrung hat aber auch meine Sicht auf das Wort „Rendite“ verändert. Höhere Erträge kommen nicht einfach aus dem Nichts.
Ich habe die Doku geprüft und festgestellt, dass der Wechsel von Fixed zu Morpho variable Exit bereits live ist—kein bloßes Roadmap-Gerede. Brachliegendes Kapital bei TermMax sitzt buchstäblich nie bei Null. Während ein USDC eines Kreditgebers auf eine unbesetzte Limit-Order wartet, wird es im Hintergrund automatisch in Aave oder die Morpho-Basisrendite umgeroutet.
Noch eine Sache ist mir letzte Nacht aufgefallen: Wenn sich BTC schnell bewegt, kann es einfacher sein, eine gehebelte Position zu planen, wenn man die eigenen Borrowing-Kosten im Voraus kennt. Genau deshalb finde ich @TermMax interessant. Sein Modell mit festem Zinssatz und fester Laufzeit gibt Kreditnehmern mehr Sicherheit bei den Finanzierungskosten.
@TermMax #TermMax
Früher dachte ich, RWA sei im Grunde einfach die Tokenisierung eines realen Vermögenswerts und das Platzieren auf der Blockchain. Wenn das Eigentum dann On-Chain erfasst wird, dachte ich, dass der schwierigste Teil im Grunde schon gelöst wäre.
Aber als ich mir @TermMax angesehen habe—insbesondere ihren Ansatz für die physische Lieferung—wurde mir klar, dass ich das Problem zu stark vereinfacht hatte. Ein Vermögenswert zu tokenisieren macht ihn nicht automatisch so liquide wie ETH oder ein Stablecoin. Wenn ein Kredit fällig wird und die Dinge schiefzugehen beginnen, lautet die entscheidende Frage: Wie kann dieser Vermögenswert tatsächlich gehandhabt werden?
Dann habe ich angefangen, mehr über @TermMax zu lernen und habe sein DeFi-Modell für festverzinsliche Anlagen entdeckt. Anstatt ständig in Eigenregie zu traden, kann ich an passenden Märkten oder in Vaults teilnehmen, um Rendite aus termbasiertem Lending zu erzielen.
Diese Erfahrung hat aber auch meine Sicht auf das Wort „Rendite“ verändert. Höhere Erträge kommen nicht einfach aus dem Nichts.
Ich habe die Doku geprüft und festgestellt, dass der Wechsel von Fixed zu Morpho variable Exit bereits live ist—kein bloßes Roadmap-Gerede. Brachliegendes Kapital bei TermMax sitzt buchstäblich nie bei Null. Während ein USDC eines Kreditgebers auf eine unbesetzte Limit-Order wartet, wird es im Hintergrund automatisch in Aave oder die Morpho-Basisrendite umgeroutet.
Noch eine Sache ist mir letzte Nacht aufgefallen: Wenn sich BTC schnell bewegt, kann es einfacher sein, eine gehebelte Position zu planen, wenn man die eigenen Borrowing-Kosten im Voraus kennt. Genau deshalb finde ich @TermMax interessant. Sein Modell mit festem Zinssatz und fester Laufzeit gibt Kreditnehmern mehr Sicherheit bei den Finanzierungskosten.
Früher dachte ich, RWA sei im Grunde einfach die Tokenisierung eines realen Vermögenswerts und das Platzieren auf der Blockchain. Wenn das Eigentum dann On-Chain erfasst wird, dachte ich, dass der schwierigste Teil im Grunde schon gelöst wäre.
Aber als ich mir @TermMax angesehen habe—insbesondere ihren Ansatz für die physische Lieferung—wurde mir klar, dass ich das Problem zu stark vereinfacht hatte. Ein Vermögenswert zu tokenisieren macht ihn nicht automatisch so liquide wie ETH oder ein Stablecoin. Wenn ein Kredit fällig wird und die Dinge schiefzugehen beginnen, lautet die entscheidende Frage: Wie kann dieser Vermögenswert tatsächlich gehandhabt werden?
Dann habe ich angefangen, mehr über @TermMax zu lernen und habe sein DeFi-Modell für festverzinsliche Anlagen entdeckt. Anstatt ständig in Eigenregie zu traden, kann ich an passenden Märkten oder in Vaults teilnehmen, um Rendite aus termbasiertem Lending zu erzielen.
Diese Erfahrung hat aber auch meine Sicht auf das Wort „Rendite“ verändert. Höhere Erträge kommen nicht einfach aus dem Nichts.
Ich habe die Doku geprüft und festgestellt, dass der Wechsel von Fixed zu Morpho variable Exit bereits live ist—kein bloßes Roadmap-Gerede. Brachliegendes Kapital bei TermMax sitzt buchstäblich nie bei Null. Während ein USDC eines Kreditgebers auf eine unbesetzte Limit-Order wartet, wird es im Hintergrund automatisch in Aave oder die Morpho-Basisrendite umgeroutet.
Noch eine Sache ist mir letzte Nacht aufgefallen: Wenn sich BTC schnell bewegt, kann es einfacher sein, eine gehebelte Position zu planen, wenn man die eigenen Borrowing-Kosten im Voraus kennt. Genau deshalb finde ich @TermMax interessant. Sein Modell mit festem Zinssatz und fester Laufzeit gibt Kreditnehmern mehr Sicherheit bei den Finanzierungskosten.
21
2
12
89
·
--
Verifiziert
Übersetzung ansehen
The more I look into @TermMax, the more it makes me reconsider how I think about fixed-rate lending.
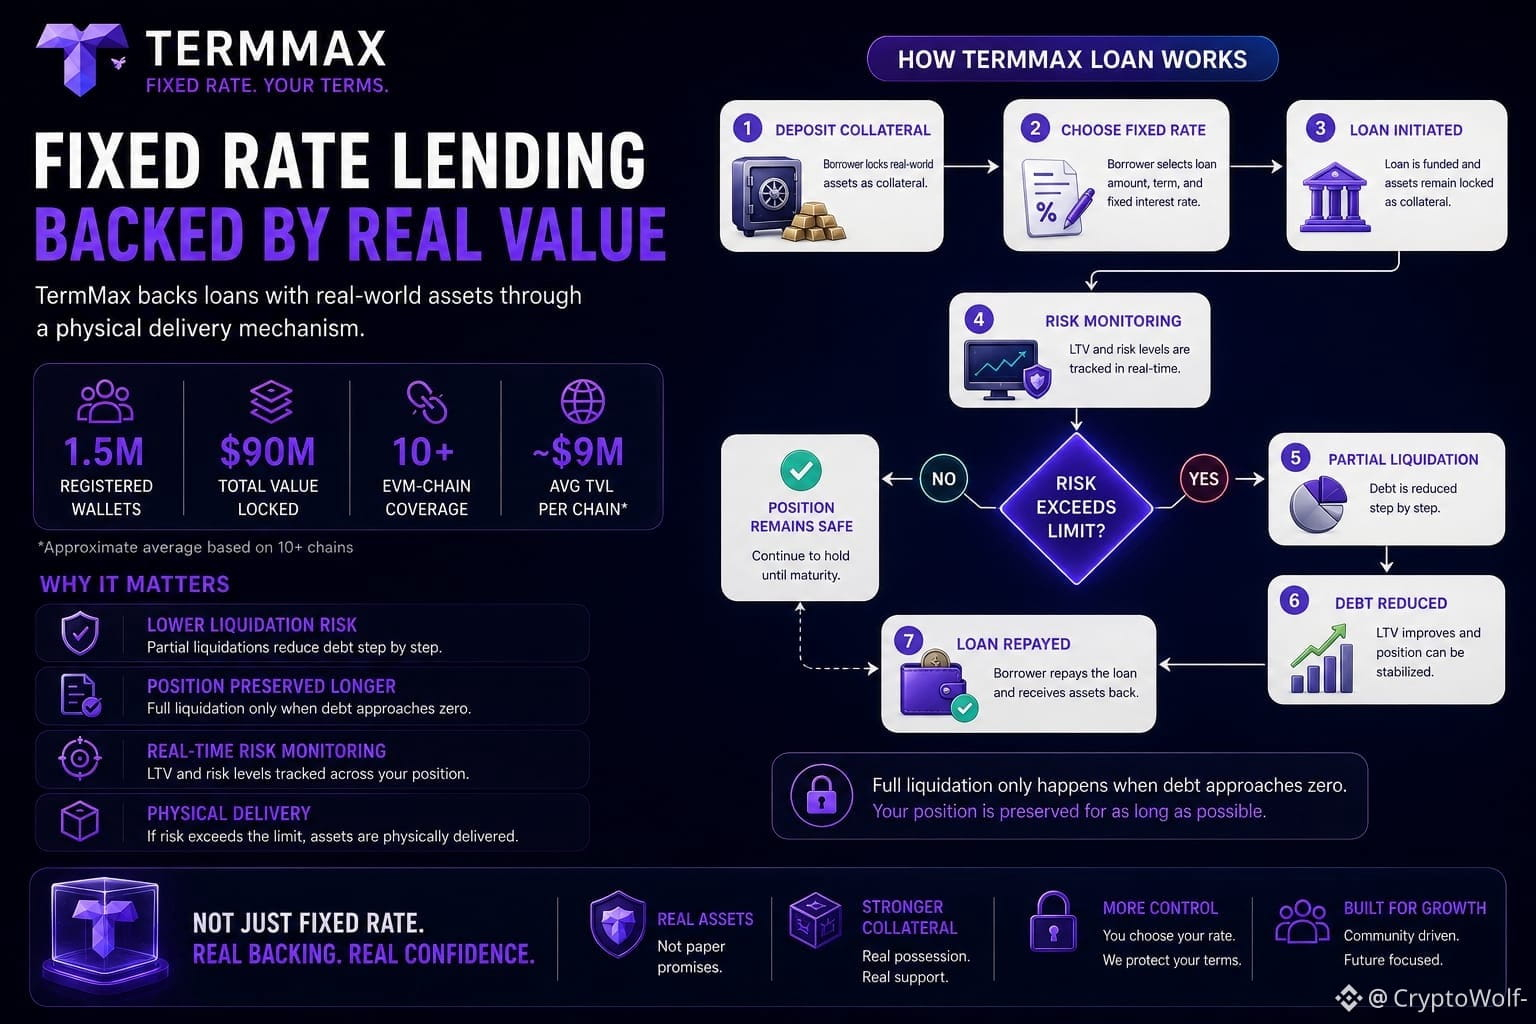
One thing that caught my attention was the liquidation mechanism. Instead of simply selling assets on the market to handle the loan, the way the mechanism works gives me a different perspective on how collateral can back the loan when things don't go as expected.
I also noticed the reported 1.5M registered wallets and $90M TVL. Dividing the TVL across that number gives a very different picture than simply looking at the clean $1B fixed-supply story.
The EVM-chain coverage sounds broad, but a simple average would put roughly $9M TVL per chain. Still, fixed-rate markets need real liquidity and depth, not just deployment across many chains.
Another point I noticed is the liquidation design. In other systems I've used, crossing the danger line can mean losing the whole position in one shot. With @termmax the way LTV changes after liquidation caught my attention. If full liquidation only happens as the debt is reduced toward zero, that could make a difference in how liquidity and risk are managed.
I like thinking about the downside before focusing on the upside. We can't control where the market moves, but we can decide how much risk we're willing to take before opening a position.
Do you think TermMax’s physical delivery mechanism can really handle truly illiquid real-world assets, or is that where the real challenge begins?
@TermMax #TermMax
The more I look into @TermMax, the more it makes me reconsider how I think about fixed-rate lending.
One thing that caught my attention was the liquidation mechanism. Instead of simply selling assets on the market to handle the loan, the way the mechanism works gives me a different perspective on how collateral can back the loan when things don't go as expected.
I also noticed the reported 1.5M registered wallets and $90M TVL. Dividing the TVL across that number gives a very different picture than simply looking at the clean $1B fixed-supply story.
The EVM-chain coverage sounds broad, but a simple average would put roughly $9M TVL per chain. Still, fixed-rate markets need real liquidity and depth, not just deployment across many chains.
Another point I noticed is the liquidation design. In other systems I've used, crossing the danger line can mean losing the whole position in one shot. With @TermMax the way LTV changes after liquidation caught my attention. If full liquidation only happens as the debt is reduced toward zero, that could make a difference in how liquidity and risk are managed.
I like thinking about the downside before focusing on the upside. We can't control where the market moves, but we can decide how much risk we're willing to take before opening a position.
Do you think TermMax’s physical delivery mechanism can really handle truly illiquid real-world assets, or is that where the real challenge begins?
@TermMax #TermMax
One thing that caught my attention was the liquidation mechanism. Instead of simply selling assets on the market to handle the loan, the way the mechanism works gives me a different perspective on how collateral can back the loan when things don't go as expected.
I also noticed the reported 1.5M registered wallets and $90M TVL. Dividing the TVL across that number gives a very different picture than simply looking at the clean $1B fixed-supply story.
The EVM-chain coverage sounds broad, but a simple average would put roughly $9M TVL per chain. Still, fixed-rate markets need real liquidity and depth, not just deployment across many chains.
Another point I noticed is the liquidation design. In other systems I've used, crossing the danger line can mean losing the whole position in one shot. With @TermMax the way LTV changes after liquidation caught my attention. If full liquidation only happens as the debt is reduced toward zero, that could make a difference in how liquidity and risk are managed.
I like thinking about the downside before focusing on the upside. We can't control where the market moves, but we can decide how much risk we're willing to take before opening a position.
Do you think TermMax’s physical delivery mechanism can really handle truly illiquid real-world assets, or is that where the real challenge begins?
@TermMax #TermMax
11
1
10
69
·
--
Verifiziert
Übersetzung ansehen
#termmax
Is new TMX being absorbed by staking governance use and real demand or simply becoming more available liquidity?
That changes how I judge TermMax. The real question is not whether the fee rate looks high or low. It is whether users value predictable debt enough to accept fixed maturity reduced flexibility and the need to manage rollover timing.
That makes governance important.
If $TMX stakers can influence risk parameters and curator permissions, they’re potentially helping shape how the protocol handles risk.
That balance is what I’ll be watching with TermMax.
For me, the interesting question isn’t just how much the protocol can grow.
But when I looked into TermMax’s Vault and Curator model, I started to realize that this understanding was a bit superficial. The Curator isn’t simply someone who “seeks high APY.” They have to decide which market the capital should go into, what maturity to choose, and what level of risk to take on.I like how this model makes a fairly invisible problem—capital risk and allocation—more apparent.
TermMax has been working on institutional fixed rate markets since 2024, including Fireblocks secured infrastructure for KYC institutions. Its roadmap now points toward institutional structured products, market maker partnerships and broader RWA integration.
The best infrastructure is often the part that makes a complicated strategy feel simple without hiding the risk.
After going through the markets, the order I’d use is: choose the asset pair → check maturity → understand the FT/XT structure → then compare the fixed rate. That feels much more logical to me than starting with the yield.
I like the thinking behind it, but I’m still cautious. Predictability in one area doesn’t make DeFi predictable overall. Collateral can still fall, liquidity can still disappear, and fixed maturities can become uncomfortable when the market moves the wrong way.
@termmax #TermMax
#termmax
Is new TMX being absorbed by staking governance use and real demand or simply becoming more available liquidity?
That changes how I judge TermMax. The real question is not whether the fee rate looks high or low. It is whether users value predictable debt enough to accept fixed maturity reduced flexibility and the need to manage rollover timing.
That makes governance important.
If $TMX stakers can influence risk parameters and curator permissions, they’re potentially helping shape how the protocol handles risk.
That balance is what I’ll be watching with TermMax.
For me, the interesting question isn’t just how much the protocol can grow.
But when I looked into TermMax’s Vault and Curator model, I started to realize that this understanding was a bit superficial. The Curator isn’t simply someone who “seeks high APY.” They have to decide which market the capital should go into, what maturity to choose, and what level of risk to take on.I like how this model makes a fairly invisible problem—capital risk and allocation—more apparent.
TermMax has been working on institutional fixed rate markets since 2024, including Fireblocks secured infrastructure for KYC institutions. Its roadmap now points toward institutional structured products, market maker partnerships and broader RWA integration.
The best infrastructure is often the part that makes a complicated strategy feel simple without hiding the risk.
After going through the markets, the order I’d use is: choose the asset pair → check maturity → understand the FT/XT structure → then compare the fixed rate. That feels much more logical to me than starting with the yield.
I like the thinking behind it, but I’m still cautious. Predictability in one area doesn’t make DeFi predictable overall. Collateral can still fall, liquidity can still disappear, and fixed maturities can become uncomfortable when the market moves the wrong way.
@TermMax #TermMax
Is new TMX being absorbed by staking governance use and real demand or simply becoming more available liquidity?
That changes how I judge TermMax. The real question is not whether the fee rate looks high or low. It is whether users value predictable debt enough to accept fixed maturity reduced flexibility and the need to manage rollover timing.
That makes governance important.
If $TMX stakers can influence risk parameters and curator permissions, they’re potentially helping shape how the protocol handles risk.
That balance is what I’ll be watching with TermMax.
For me, the interesting question isn’t just how much the protocol can grow.
But when I looked into TermMax’s Vault and Curator model, I started to realize that this understanding was a bit superficial. The Curator isn’t simply someone who “seeks high APY.” They have to decide which market the capital should go into, what maturity to choose, and what level of risk to take on.I like how this model makes a fairly invisible problem—capital risk and allocation—more apparent.
TermMax has been working on institutional fixed rate markets since 2024, including Fireblocks secured infrastructure for KYC institutions. Its roadmap now points toward institutional structured products, market maker partnerships and broader RWA integration.
The best infrastructure is often the part that makes a complicated strategy feel simple without hiding the risk.
After going through the markets, the order I’d use is: choose the asset pair → check maturity → understand the FT/XT structure → then compare the fixed rate. That feels much more logical to me than starting with the yield.
I like the thinking behind it, but I’m still cautious. Predictability in one area doesn’t make DeFi predictable overall. Collateral can still fall, liquidity can still disappear, and fixed maturities can become uncomfortable when the market moves the wrong way.
@TermMax #TermMax
1
71
·
--
Übersetzung ansehen
#termmax
TermMax is also expanding beyond traditional lend/borrow markets with managed wallets and options-style products.
TermMax lets users enter markets with a defined rate and maturity.
TermMax Alpha is built around options-style trading, so traders can position themselves around different market views while taking a defined-risk approach.
PIEVERSE just got another interesting boost it’s now listed on TermMax Alpha.the Pieverse ecosystem continues giving people reasons to stay involved.seeing $PIEVERSE expand into another DeFi environment.
A debt token can be represented through two complementary pieces, where 1 FT + 1 XT makes up the full debt position. The FT carries the face-value claim toward maturity, while XT represents the remaining side of that position.
TermMax are worth watching for their potential to reshape how users interact with On-chain financial products.For crypto enthusiasts, @TermMaxremains a project to research closely as the market develops.TermMax approaches this by making the fixed term claim transferable as an FT, giving the position a life beyond the original agreements.
the bigger experiment here isn’t really “can DeFi offer fixed rates?
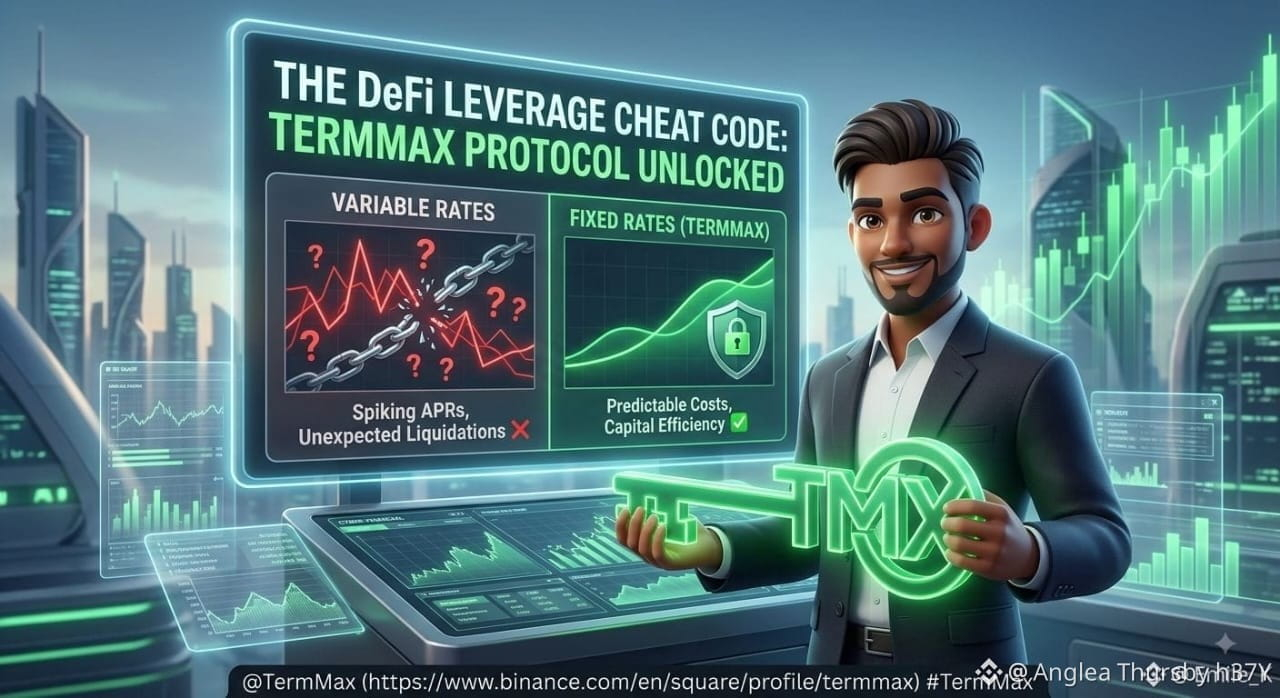
TermMax I assumed liquidation on TermMax meant the same thing it means everywhere else I've used — cross the danger line, lose the whole position in one shot, no in-between.
If outstanding debt exceeds $10,000, liquidators are capped at 50% of total debt value per event.The penalty is 10% of liquidated debt value, split exactly in half — 5% to the liquidator as reward, 5% to the protocol's reserve vault.TMX is whether that 50% cap protects large borrowers meaningfully, or just turns one liquidation into two smaller ones back to back. $CYS?
#TermMax @termmax
#termmax
TermMax is also expanding beyond traditional lend/borrow markets with managed wallets and options-style products.
TermMax lets users enter markets with a defined rate and maturity.
TermMax Alpha is built around options-style trading, so traders can position themselves around different market views while taking a defined-risk approach.
PIEVERSE just got another interesting boost it’s now listed on TermMax Alpha.the Pieverse ecosystem continues giving people reasons to stay involved.seeing $PIEVERSE expand into another DeFi environment.
A debt token can be represented through two complementary pieces, where 1 FT + 1 XT makes up the full debt position. The FT carries the face-value claim toward maturity, while XT represents the remaining side of that position.
TermMax are worth watching for their potential to reshape how users interact with On-chain financial products.For crypto enthusiasts, @TermMaxremains a project to research closely as the market develops.TermMax approaches this by making the fixed term claim transferable as an FT, giving the position a life beyond the original agreements.
the bigger experiment here isn’t really “can DeFi offer fixed rates?
TermMax I assumed liquidation on TermMax meant the same thing it means everywhere else I've used — cross the danger line, lose the whole position in one shot, no in-between.
If outstanding debt exceeds $10,000, liquidators are capped at 50% of total debt value per event.The penalty is 10% of liquidated debt value, split exactly in half — 5% to the liquidator as reward, 5% to the protocol's reserve vault.TMX is whether that 50% cap protects large borrowers meaningfully, or just turns one liquidation into two smaller ones back to back. $CYS?
#TermMax @TermMax
TermMax is also expanding beyond traditional lend/borrow markets with managed wallets and options-style products.
TermMax lets users enter markets with a defined rate and maturity.
TermMax Alpha is built around options-style trading, so traders can position themselves around different market views while taking a defined-risk approach.
PIEVERSE just got another interesting boost it’s now listed on TermMax Alpha.the Pieverse ecosystem continues giving people reasons to stay involved.seeing $PIEVERSE expand into another DeFi environment.
A debt token can be represented through two complementary pieces, where 1 FT + 1 XT makes up the full debt position. The FT carries the face-value claim toward maturity, while XT represents the remaining side of that position.
TermMax are worth watching for their potential to reshape how users interact with On-chain financial products.For crypto enthusiasts, @TermMaxremains a project to research closely as the market develops.TermMax approaches this by making the fixed term claim transferable as an FT, giving the position a life beyond the original agreements.
the bigger experiment here isn’t really “can DeFi offer fixed rates?
TermMax I assumed liquidation on TermMax meant the same thing it means everywhere else I've used — cross the danger line, lose the whole position in one shot, no in-between.
If outstanding debt exceeds $10,000, liquidators are capped at 50% of total debt value per event.The penalty is 10% of liquidated debt value, split exactly in half — 5% to the liquidator as reward, 5% to the protocol's reserve vault.TMX is whether that 50% cap protects large borrowers meaningfully, or just turns one liquidation into two smaller ones back to back. $CYS?
#TermMax @TermMax
5
3
73
·
--
Übersetzung ansehen
#termmax
A normal DeFi loan bundles collateral, debt, interest and maturity into one position. Curators like MEV Capital and Keyrock can manage ERC-4626 vaults across different term markets Traditional finance solved this centuries ago with bonds. Not "estimated APY." Not "up to." Locked.The borrower gets certainty about the maturity obligation, yet that certainty is tied to a market where the corresponding FTs can trade at different prices before maturity.It's whether tokenizing the obligation creates a better way to manage the uncertainty that remains around it? FT is a zero coupon bond. It pays exactly 1 USDC at maturity.Say someone opens a leveraged ETH position through a GT and sets Smart Unwind at 20% APR.
@termmax #TermMax
#termmax
A normal DeFi loan bundles collateral, debt, interest and maturity into one position. Curators like MEV Capital and Keyrock can manage ERC-4626 vaults across different term markets Traditional finance solved this centuries ago with bonds. Not "estimated APY." Not "up to." Locked.The borrower gets certainty about the maturity obligation, yet that certainty is tied to a market where the corresponding FTs can trade at different prices before maturity.It's whether tokenizing the obligation creates a better way to manage the uncertainty that remains around it? FT is a zero coupon bond. It pays exactly 1 USDC at maturity.Say someone opens a leveraged ETH position through a GT and sets Smart Unwind at 20% APR.
@TermMax #TermMax
A normal DeFi loan bundles collateral, debt, interest and maturity into one position. Curators like MEV Capital and Keyrock can manage ERC-4626 vaults across different term markets Traditional finance solved this centuries ago with bonds. Not "estimated APY." Not "up to." Locked.The borrower gets certainty about the maturity obligation, yet that certainty is tied to a market where the corresponding FTs can trade at different prices before maturity.It's whether tokenizing the obligation creates a better way to manage the uncertainty that remains around it? FT is a zero coupon bond. It pays exactly 1 USDC at maturity.Say someone opens a leveraged ETH position through a GT and sets Smart Unwind at 20% APR.
@TermMax #TermMax
5
6
91
·
--
Übersetzung ansehen
Football is better together. I check Task
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
Football is better together. I check Task
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
1
·
--
Übersetzung ansehen
Football is better together. I check Task
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
Football is better together. I check Task
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
2
·
--
Übersetzung ansehen
Happy 9th Anniversary to @binance! 9 years of innovation, security and empowering millions worldwide. Here's to many more years of building the future of crypto together. #BinanceTurns9
Happy 9th Anniversary to @binance! 9 years of innovation, security and empowering millions worldwide. Here's to many more years of building the future of crypto together. #BinanceTurns9
72
·
--
Übersetzung ansehen
Football is better together. I check Task
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
Football is better together. I check Task
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
Completion History daily and compare picks
with friends. The 2026 Football Challenge
Group Stage feels like a mini tournament with
everyone. Drop your favorite team below!
#BinancePickAndWin
1
Anmelden und weiter Inhalte entdecken
Krypto-Nutzer weltweit auf Binance Square kennenlernen
⚡️ Bleib in Sachen Krypto stets am Puls.
💬 Die weltgrößte Kryptobörse vertraut darauf.
👍 Erhalte verlässliche Einblicke von verifizierten Creators.
E-Mail-Adresse/Telefonnummer
Trendthemen
BitcoinRebounds$75KAsChipsLead
6,623 Aufrufe
107 Kommentare
Marktüberblick | Bitcoin erholt sich nach Rückgang unter 75.000 $ auf 75.600 $, während Chip-Aktien nach überraschend starken Arbeitsmarktdaten die Rally anführen
Binance News
·13 Likes
·4.5k Aufrufe
JobsReportRaisesHikeOdds
92,239 Aufrufe
887 Kommentare
US Data Center Rules May Constrain AI Expansion
11,825 Aufrufe
94 Kommentare