

#canmicrosoftdeliveronai
canmicrosoftdeliveronai
Microsoft continues to increase its AI investment, with Azure and its Copilot products in the spotlight. Will this quarter's earnings show revenue growth from its AI investment? Share your predictions and analysis of Microsoft's ($MSFT) quarterly earnings, show your Binance Pick prediction positions or your trades/positions, and join the discussion on whether Microsoft can deliver on AI.
Ommabop
Eng so‘nggi


Maqola
Daromadlar mavsumining 3-sessiyasi: Google va Microsoft moliyaviy natijalari kutilganidan yaxshiroq bo‘ladimi?Binance Square #EarningsSeason yangi sessiya bilan yangilandi. Ushbu sessiyada Google va Microsoftga e’tibor qaratamiz. Eng so‘nggi yangiliklar va ma’lumotlar tahlilini olish uchun Google va Microsoft daromadlarini Square’da kuzatib boring, [Binance Pick](https://app.binance.com/uni-qr/prophet?seasonId=prophet_1019_s1) orqali daromadlar bo‘yicha bashoratlaringizni qiling va Binance Pick ballari hamda trafikni oshirish imkoniyatini qo‘lga kiritish uchun taxminlaringizni ulashing. Daromadlar mavsumidan unumli foydalaning — barchasi Binance Square’da!
Binance Square’da #EarningsSeason uchun eng mukammal qo‘llanma.
1-qadam: Google va Microsoft daromadlari bo‘yicha muhim ma’lumotlar va tahlillarni kuzatib boring
Daromadlar mavsumining 3-sessiyasi: Google va Microsoft moliyaviy natijalari kutilganidan yaxshiroq bo‘ladimi?
Binance Square #EarningsSeason yangi sessiya bilan yangilandi. Ushbu sessiyada Google va Microsoftga e’tibor qaratamiz. Eng so‘nggi yangiliklar va ma’lumotlar tahlilini olish uchun Google va Microsoft daromadlarini Square’da kuzatib boring, Binance Pick orqali daromadlar bo‘yicha bashoratlaringizni qiling va Binance Pick ballari hamda trafikni oshirish imkoniyatini qo‘lga kiritish uchun taxminlaringizni ulashing. Daromadlar mavsumidan unumli foydalaning — barchasi Binance Square’da!
Binance Square’da #EarningsSeason uchun eng mukammal qo‘llanma.
1-qadam: Google va Microsoft daromadlari bo‘yicha muhim ma’lumotlar va tahlillarni kuzatib boring
Binance Square’da #EarningsSeason uchun eng mukammal qo‘llanma.
1-qadam: Google va Microsoft daromadlari bo‘yicha muhim ma’lumotlar va tahlillarni kuzatib boring
BitScopeX:
I think $GOOGL has a strong chance of beating earnings expectations, thanks to its advertising business and AI development. But AI competition could also create challenges.
7
5
53
13.6k

·
--
Tarjimani ko‘rish
#CanMicrosoftDeliverOnAI
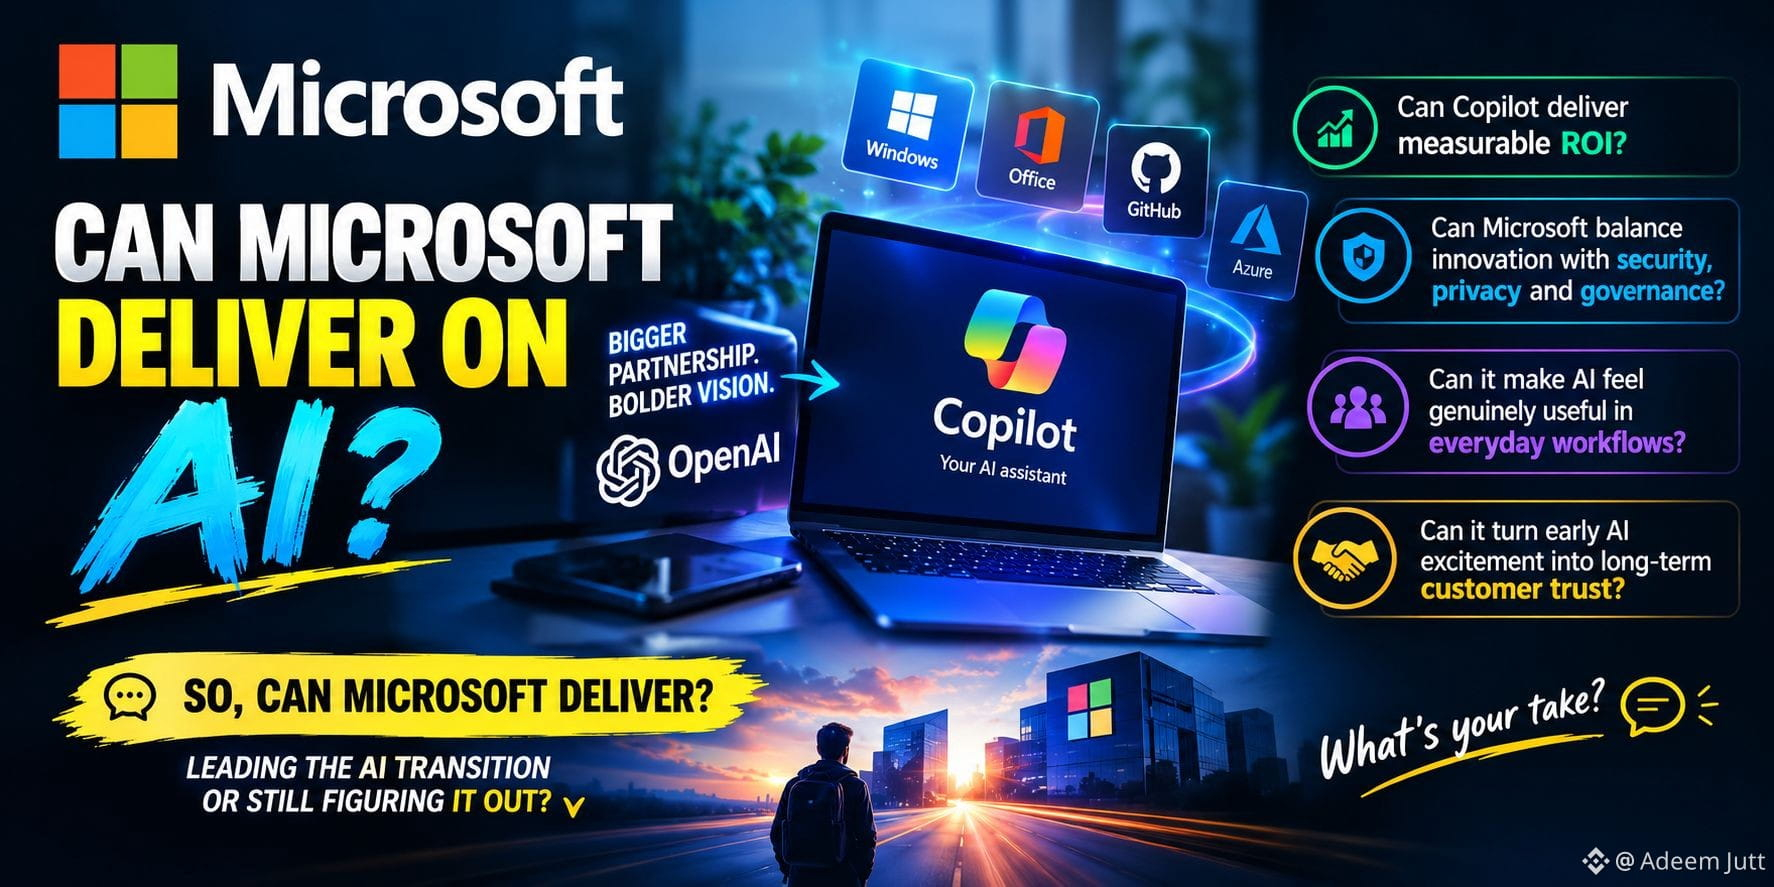
Microsoft moved faster than almost anyone: Copilot across Windows, Office, #Github and Azure; a massive OpenAI partnership; and AI woven into its enterprise stack. On paper, it looks like a masterstroke.
But execution is where the story gets complicated.
Can Copilot deliver measurable ROI—or does it risk becoming another “nice-to-have” subscription?
Can Microsoft balance innovation with enterprise-grade security, privacy, and governance?
Can it make AI feel genuinely useful across everyday workflows—not just impressive in demos?
And can it turn early AI excitement into long-term customer trust?
Microsoft doesn’t just need to ship AI features. It needs to prove reliability, value, and adoption at scale.
The AI race won’t be won by the loudest launch. It will be won by the company that makes AI dependable, affordable, and truly embedded in how people work.
So, can Microsoft deliver? The next 12–18 months will tell.
What’s your take is Microsoft leading the AI transition, or still figuring out how to monetize it? 👇
$MSFT $OPENAI
{future}(OPENAIUSDT)
{future}(MSFTUSDT)
#CanGoogleDefindItsCore
#CanMicrosoftDeliverOnAI
Microsoft moved faster than almost anyone: Copilot across Windows, Office, #Github and Azure; a massive OpenAI partnership; and AI woven into its enterprise stack. On paper, it looks like a masterstroke.
But execution is where the story gets complicated.
Can Copilot deliver measurable ROI—or does it risk becoming another “nice-to-have” subscription?
Can Microsoft balance innovation with enterprise-grade security, privacy, and governance?
Can it make AI feel genuinely useful across everyday workflows—not just impressive in demos?
And can it turn early AI excitement into long-term customer trust?
Microsoft doesn’t just need to ship AI features. It needs to prove reliability, value, and adoption at scale.
The AI race won’t be won by the loudest launch. It will be won by the company that makes AI dependable, affordable, and truly embedded in how people work.
So, can Microsoft deliver? The next 12–18 months will tell.
What’s your take is Microsoft leading the AI transition, or still figuring out how to monetize it? 👇
$MSFT $OPENAI
#CanGoogleDefindItsCore
2
1
137
Tarjimani ko‘rish
#canmicrosoftdeliveronai
🤖 Can Microsoft Deliver on AI?
Microsoft is making a massive bet on AI, from Azure cloud infrastructure to Copilot and next-generation AI systems.
The opportunity is huge, but so are the challenges: rising infrastructure costs, intense competition, and the need to turn AI adoption into sustainable profits.
📈 The real question: Can Microsoft turn its AI investments into long-term growth while staying ahead of competitors?
Is Microsoft positioned to dominate the AI era, or is the market expecting too much?
Share your thoughts below. 👇
#Microsoft #Copilot #TechStocks #artificialintelligence
8

·
--
Maqola
Tarjimani ko‘rish
CanMicrosoftDeliverOnAI 🤖#CanMicrosoftDeliverOnAI Microsoft is not just investing in artificial intelligence; it is trying to make AI a practical part of everyday life. From Microsoft Copilot to Azure AI and AI-powered productivity tools, the company is building an ecosystem designed to help people work smarter, businesses grow faster, and developers create new possibilities.
But the real question is not how much Microsoft invests in AI. The real question is whether it can turn that investment into real value.
The opportunities are huge, but so are the challenges. Competition is growing, computing costs remain significant, and users expect AI tools to be accurate, reliable, secure, and genuinely useful. Simply adding AI to every product will not guarantee success.
In my view, Microsoft has the technology, infrastructure, and global reach to become one of the biggest winners in the AI revolution. However, long-term success will depend on execution, customer trust, and whether its AI products deliver measurable results rather than just impressive demonstrations.
My takeaway: Microsoft has the potential to deliver on AI, but the real test is turning innovation into sustainable business value.
What do you think? Can Microsoft lead the next era of AI, or will competitors take the advantage?
Share your thoughts below! 👇
#ArtificialIntelligence #MicrosoftCopilo #AzureAI $MSFTB #AIRevolution
$MSFTB
{spot}(MSFTBUSDT)
CanMicrosoftDeliverOnAI 🤖
#CanMicrosoftDeliverOnAI Microsoft is not just investing in artificial intelligence; it is trying to make AI a practical part of everyday life. From Microsoft Copilot to Azure AI and AI-powered productivity tools, the company is building an ecosystem designed to help people work smarter, businesses grow faster, and developers create new possibilities.
But the real question is not how much Microsoft invests in AI. The real question is whether it can turn that investment into real value.
The opportunities are huge, but so are the challenges. Competition is growing, computing costs remain significant, and users expect AI tools to be accurate, reliable, secure, and genuinely useful. Simply adding AI to every product will not guarantee success.
In my view, Microsoft has the technology, infrastructure, and global reach to become one of the biggest winners in the AI revolution. However, long-term success will depend on execution, customer trust, and whether its AI products deliver measurable results rather than just impressive demonstrations.
My takeaway: Microsoft has the potential to deliver on AI, but the real test is turning innovation into sustainable business value.
What do you think? Can Microsoft lead the next era of AI, or will competitors take the advantage?
Share your thoughts below! 👇
#ArtificialIntelligence #MicrosoftCopilo #AzureAI $MSFTB #AIRevolution
$MSFTB
32

·
--
Tarjimani ko‘rish
$MSFTB
{spot}(MSFTBUSDT)
💡 Can Microsoft Maintain Its AI Momentum?
$MSFT
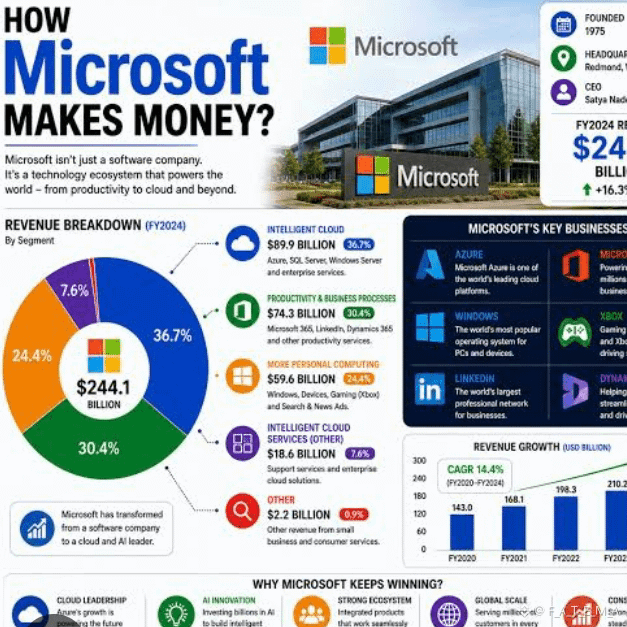
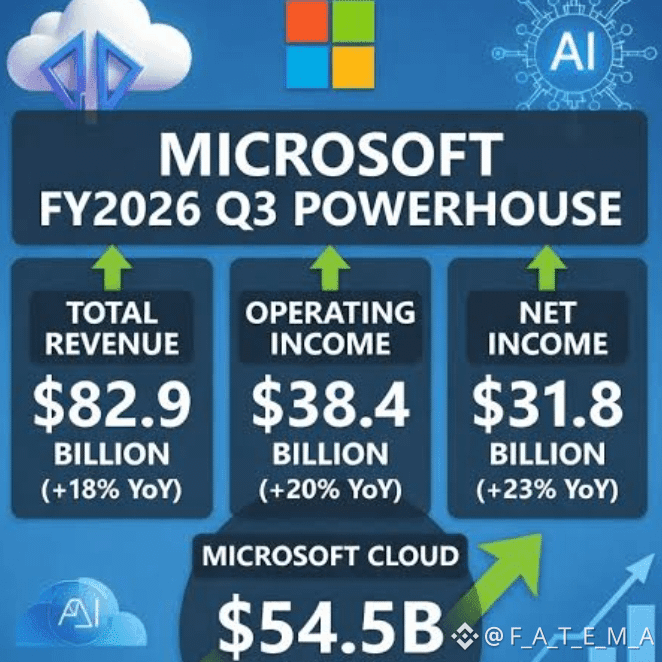
Microsoft continues to set the benchmark for enterprise AI monetization. With Azure growing at 40% YoY and Microsoft 365 Copilot surpassing 20 million paid seats (+250% YoY), their AI business has scaled to a staggering $37 billion annual run rate (ARR).
However, with massive calendar 2026 CapEx projected around $190 billion to tackle infrastructure constraints, the real question is: can revenue keep outpacing infrastructure spending?
What’s your outlook on MSFT this earnings season? Share below!
#CanMicrosoftDeliverOnAI #MSFT #Azure #TechEarnings
$MSFTB
💡 Can Microsoft Maintain Its AI Momentum?
$MSFT
Microsoft continues to set the benchmark for enterprise AI monetization. With Azure growing at 40% YoY and Microsoft 365 Copilot surpassing 20 million paid seats (+250% YoY), their AI business has scaled to a staggering $37 billion annual run rate (ARR).
However, with massive calendar 2026 CapEx projected around $190 billion to tackle infrastructure constraints, the real question is: can revenue keep outpacing infrastructure spending?
What’s your outlook on MSFT this earnings season? Share below!
#CanMicrosoftDeliverOnAI #MSFT #Azure #TechEarnings
1
82

Tarjimani ko‘rish
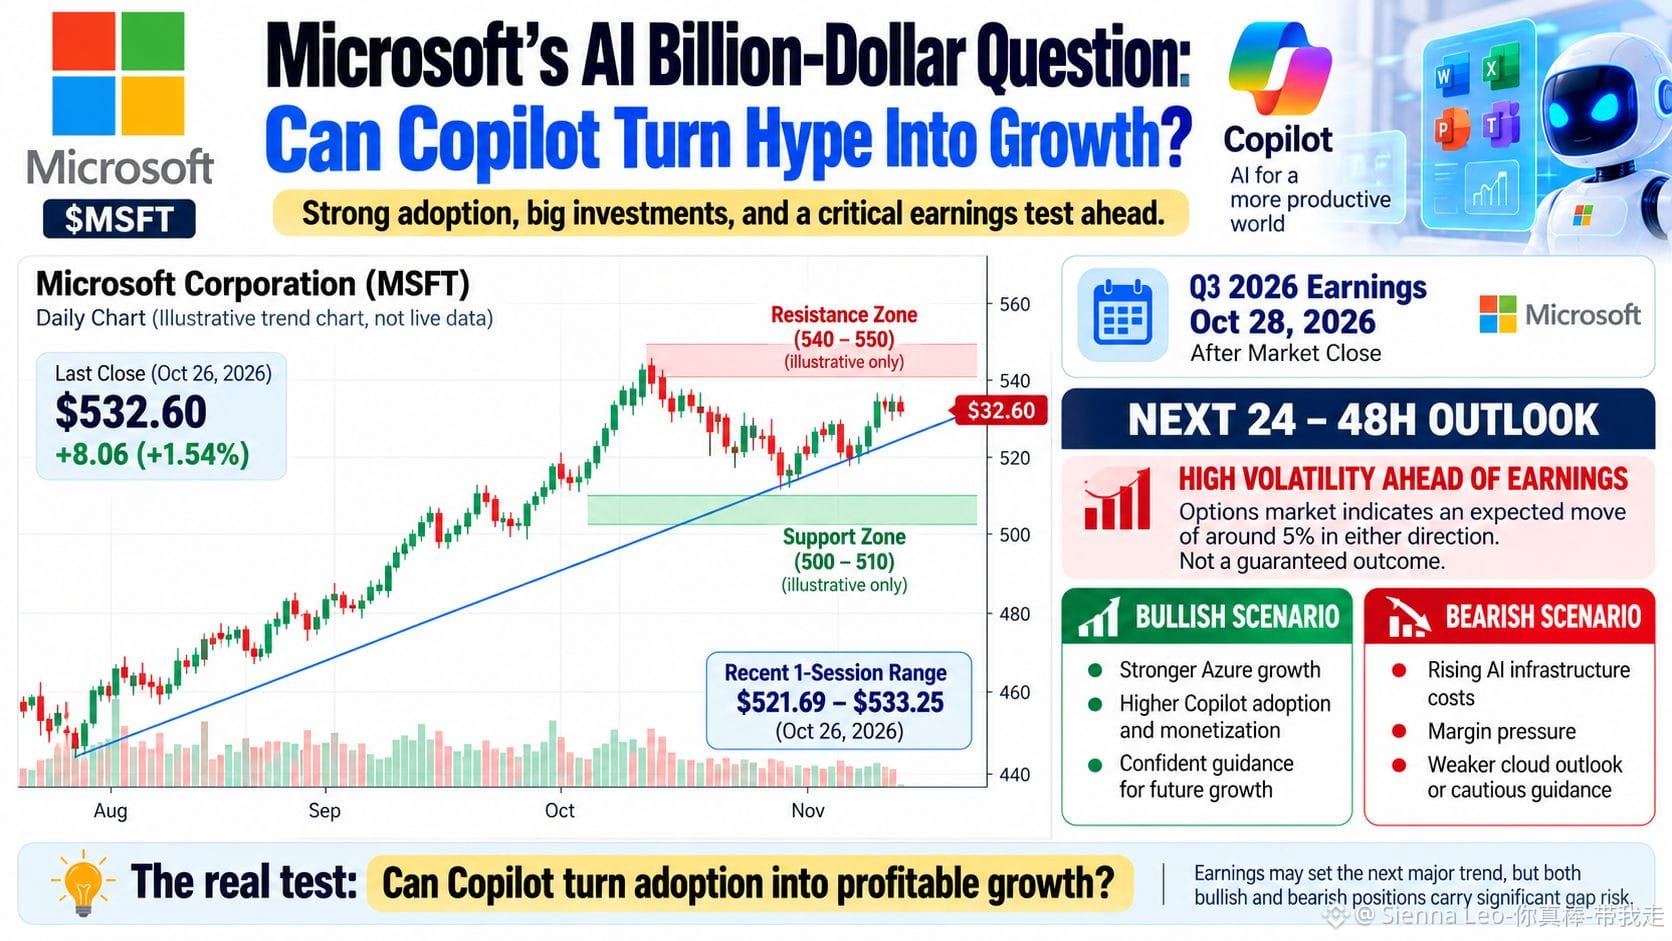
Microsoft's AI Billion-Dollar Question: Can Copilot Turn Hype Into Growth? 🤖
The future belongs not to the company with the smartest AI, but to the one that makes it indispensable.
Microsoft is approaching a critical test: can Copilot turn AI excitement into recurring revenue?
The Evidence: In July 2026, Microsoft reported $90 billion in quarterly revenue, up 18% year over year. Microsoft 365 Copilot had surpassed 30 million paid seats, while Azure revenue grew 43%. These are meaningful signs of demand, but adoption alone does not guarantee attractive returns.
The real question is whether businesses will keep paying for AI tools that deliver measurable productivity gains.
What the Market May Be Missing
AI infrastructure requires enormous investment. If Copilot increases customer spending, strengthens Microsoft's ecosystem, and improves productivity, those investments could pay off. If monetization fails to keep pace with computing costs, margins could face pressure.
MSFT Price: The latest reliably retrieved quote was $521.20, dated October 22, 2026, at 3:06 p.m. ET. A verified live price is unavailable here.
Prediction | Next 24–48 Hours: Microsoft's October 28 earnings are the major catalyst. Strong Azure growth, Copilot adoption, and confident guidance could support bullish momentum. Disappointing cloud growth, weak monetization, or higher-than-expected AI spending could trigger a pullback. Options markets indicate an expected move of approximately 5% in either direction, not a guarantee.
Short-term traders may find opportunities around earnings, but both bullish and bearish positions carry substantial gap risk.
The bottom line: AI hype attracts attention. Profitable adoption creates lasting value.
Will Copilot become Microsoft's next growth engine, or will its costs outrun its commercial rewards?
For educational purposes only. Not financial advice.
#GrowWithSAC #EarningsSeason #BinancePick $MSFT
$MSFTB
#CanGoogleDefindItsCore #CanMicrosoftDeliverOnAI
176
·
--
Tarjimani ko‘rish
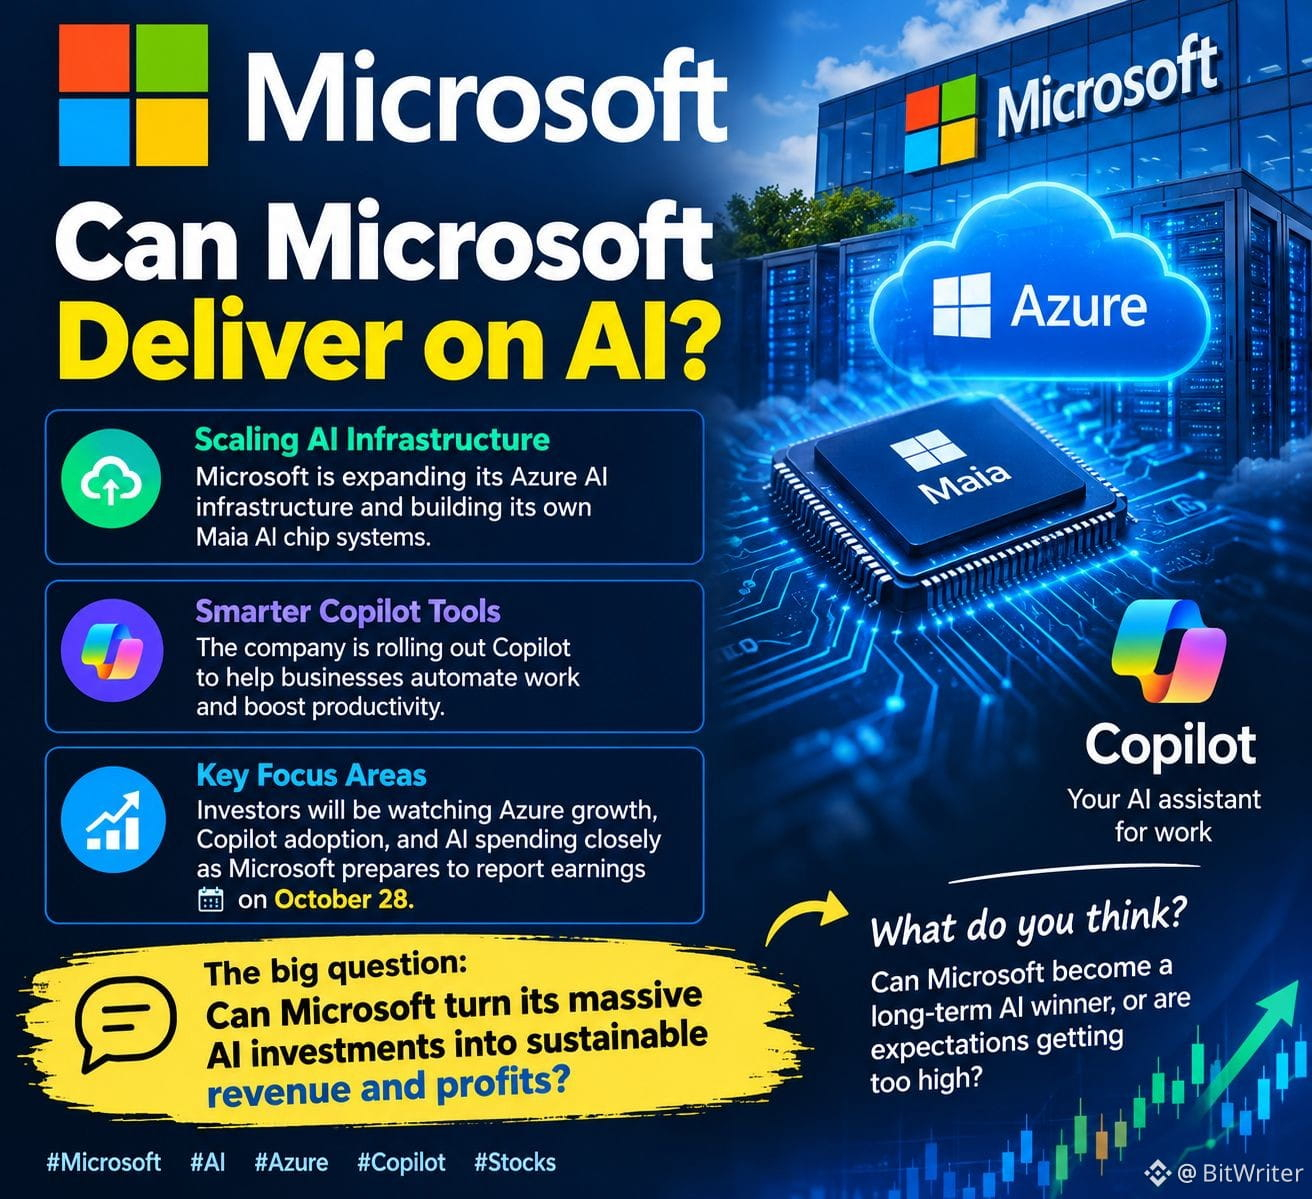
#CanMicrosoftDeliverOnAI CanMicrosoftDeliverOnAI? 🤖📈
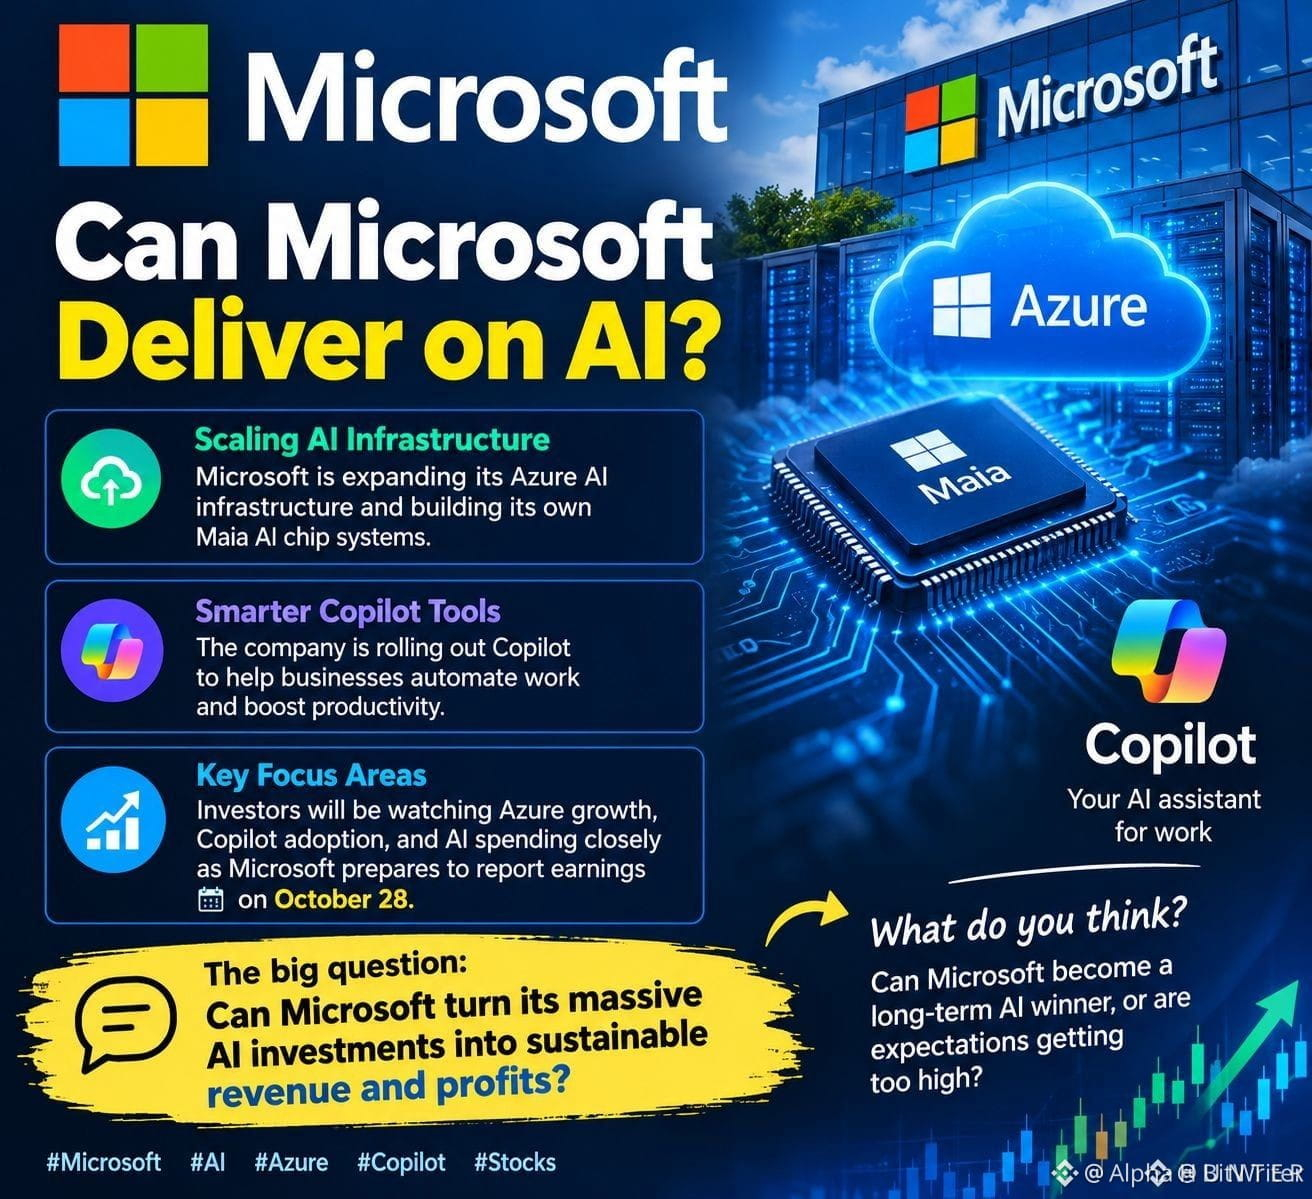
Microsoft is doubling down on AI, expanding its Azure AI infrastructure and developing smarter Copilot tools to help businesses automate work. Its latest plans include scaling its own Maia AI chip systems.
🚨 The big question: Can Microsoft turn its massive AI investments into sustainable revenue and profits?
Investors will be watching Azure growth, Copilot adoption, and AI spending closely as Microsoft prepares to report earnings on October 28.
💬 What do you think? Can Microsoft become a long-term AI winner, or are expectations getting too high?
#Microsoft #AI #Azure
10
·
--
O‘suvchi
Tarjimani ko‘rish
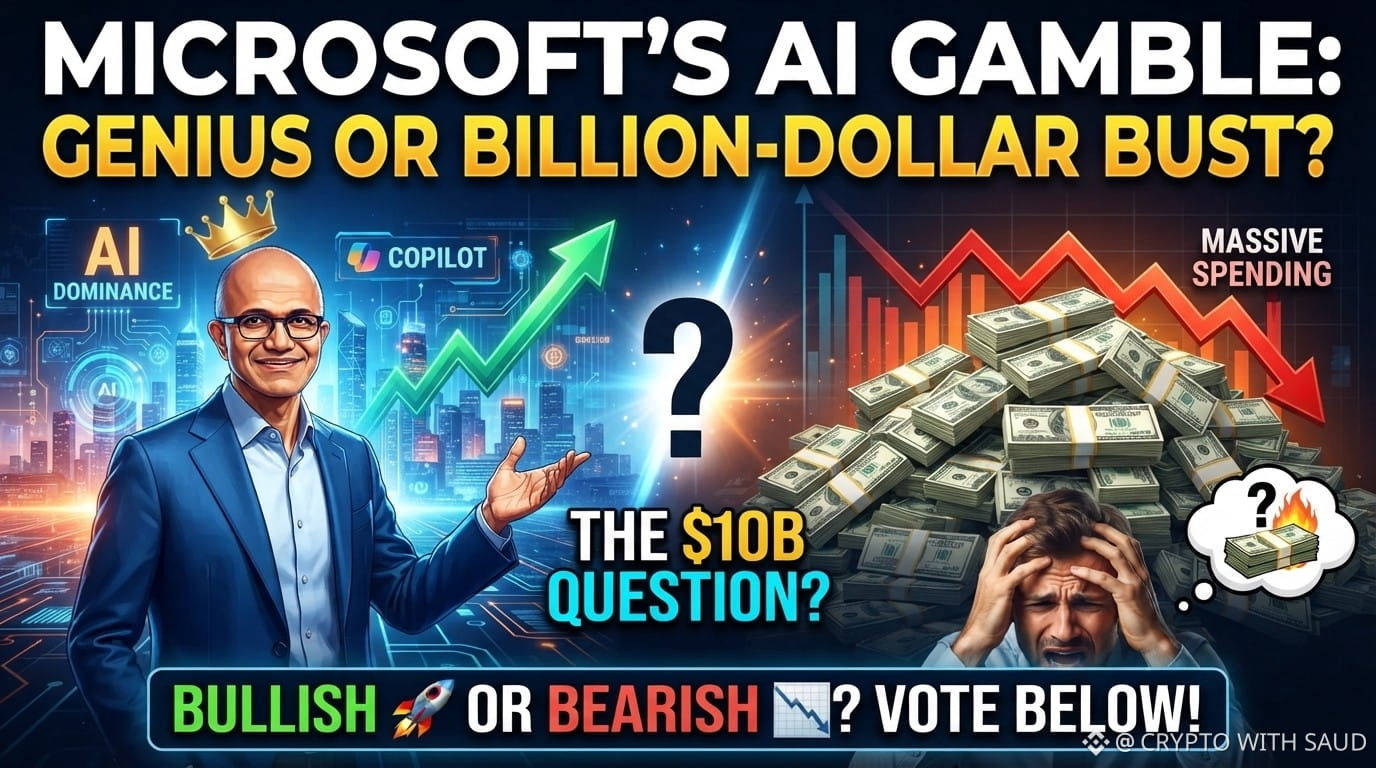
🚨🤖 MICROSOFT AI GAMBLE: GENIUS MOVE OR BILLION-DOLLAR GAMBLE? 💸🔥
Microsoft is going ALL IN on AI! But will this tech giant hit the jackpot 🎰 or discover that even billions can’t buy success? 👀👇
💰 1. The Money Machine Is ON! 🏗️⚡
Microsoft is pouring huge amounts of money into AI, cloud computing, and data centers. Those servers aren’t going to build themselves! 😂💻$GOOGL
{future}(GOOGLUSDT)
🔄 2. Humans vs. AI? 🤖👨💻
The company is reshaping parts of its workforce while pushing harder into AI. The big question: can it become more efficient without losing the human talent that makes innovation happen? 🧠⚡
🚀 3. Microsoft Is Building Its Own AI Empire! 🌐🔥
With its MAI models, smarter Microsoft 365 Copilot, and AI agents across its ecosystem, Microsoft wants AI to be more than just a chatbot. It wants an AI assistant for almost everything! 😎🤖
📉 4. The Billion-Dollar Question! 💰👀
Investing billions is one thing. Turning that spending into sustainable profits is another! Wall Street wants results, not just fancy AI demos. 📊🎯
🧠 YOUR TURN! 👇$MSFTB
{spot}(MSFTBUSDT)
Will Microsoft become the KING of the AI era 👑🤖, or is it spending too much chasing the next big thing? 💸😂
🔥 BULLISH on Microsoft’s AI future or BEARISH on the massive spending? Drop your thoughts below! 👇💬
#CanMicrosoftDeliverOnAI #CanGoogleDefindItsCore #FOMCWatch #EthereumDropsBelow$2300
🚨🤖 MICROSOFT AI GAMBLE: GENIUS MOVE OR BILLION-DOLLAR GAMBLE? 💸🔥
Microsoft is going ALL IN on AI! But will this tech giant hit the jackpot 🎰 or discover that even billions can’t buy success? 👀👇
💰 1. The Money Machine Is ON! 🏗️⚡
Microsoft is pouring huge amounts of money into AI, cloud computing, and data centers. Those servers aren’t going to build themselves! 😂💻$GOOGL
🔄 2. Humans vs. AI? 🤖👨💻
The company is reshaping parts of its workforce while pushing harder into AI. The big question: can it become more efficient without losing the human talent that makes innovation happen? 🧠⚡
🚀 3. Microsoft Is Building Its Own AI Empire! 🌐🔥
With its MAI models, smarter Microsoft 365 Copilot, and AI agents across its ecosystem, Microsoft wants AI to be more than just a chatbot. It wants an AI assistant for almost everything! 😎🤖
📉 4. The Billion-Dollar Question! 💰👀
Investing billions is one thing. Turning that spending into sustainable profits is another! Wall Street wants results, not just fancy AI demos. 📊🎯
🧠 YOUR TURN! 👇$MSFTB
Will Microsoft become the KING of the AI era 👑🤖, or is it spending too much chasing the next big thing? 💸😂
🔥 BULLISH on Microsoft’s AI future or BEARISH on the massive spending? Drop your thoughts below! 👇💬
#CanMicrosoftDeliverOnAI #CanGoogleDefindItsCore #FOMCWatch #EthereumDropsBelow$2300
1
48
Tarjimani ko‘rish
#CanMicrosoftDeliverOnAI ❔$MSFTB
I feel that opportunity is huge, but execution will determine the winner.
The real challenge is turning AI into practical tools that millions of people and businesses use every day.
Next breakthrough may not simply be a smarter AI model, but an AI system that can reliably complete real tasks, save time, reduce costs, and solve everyday problems. #Mahanadi
{future}(MSFTUSDT)
{future}(BTCUSDT)
#CanMicrosoftDeliverOnAI ❔$MSFTB
I feel that opportunity is huge, but execution will determine the winner.
The real challenge is turning AI into practical tools that millions of people and businesses use every day.
Next breakthrough may not simply be a smarter AI model, but an AI system that can reliably complete real tasks, save time, reduce costs, and solve everyday problems. #Mahanadi

Q&A Session
Digital Mahanadi dan
2
71

·
--
O‘suvchi
Tarjimani ko‘rish
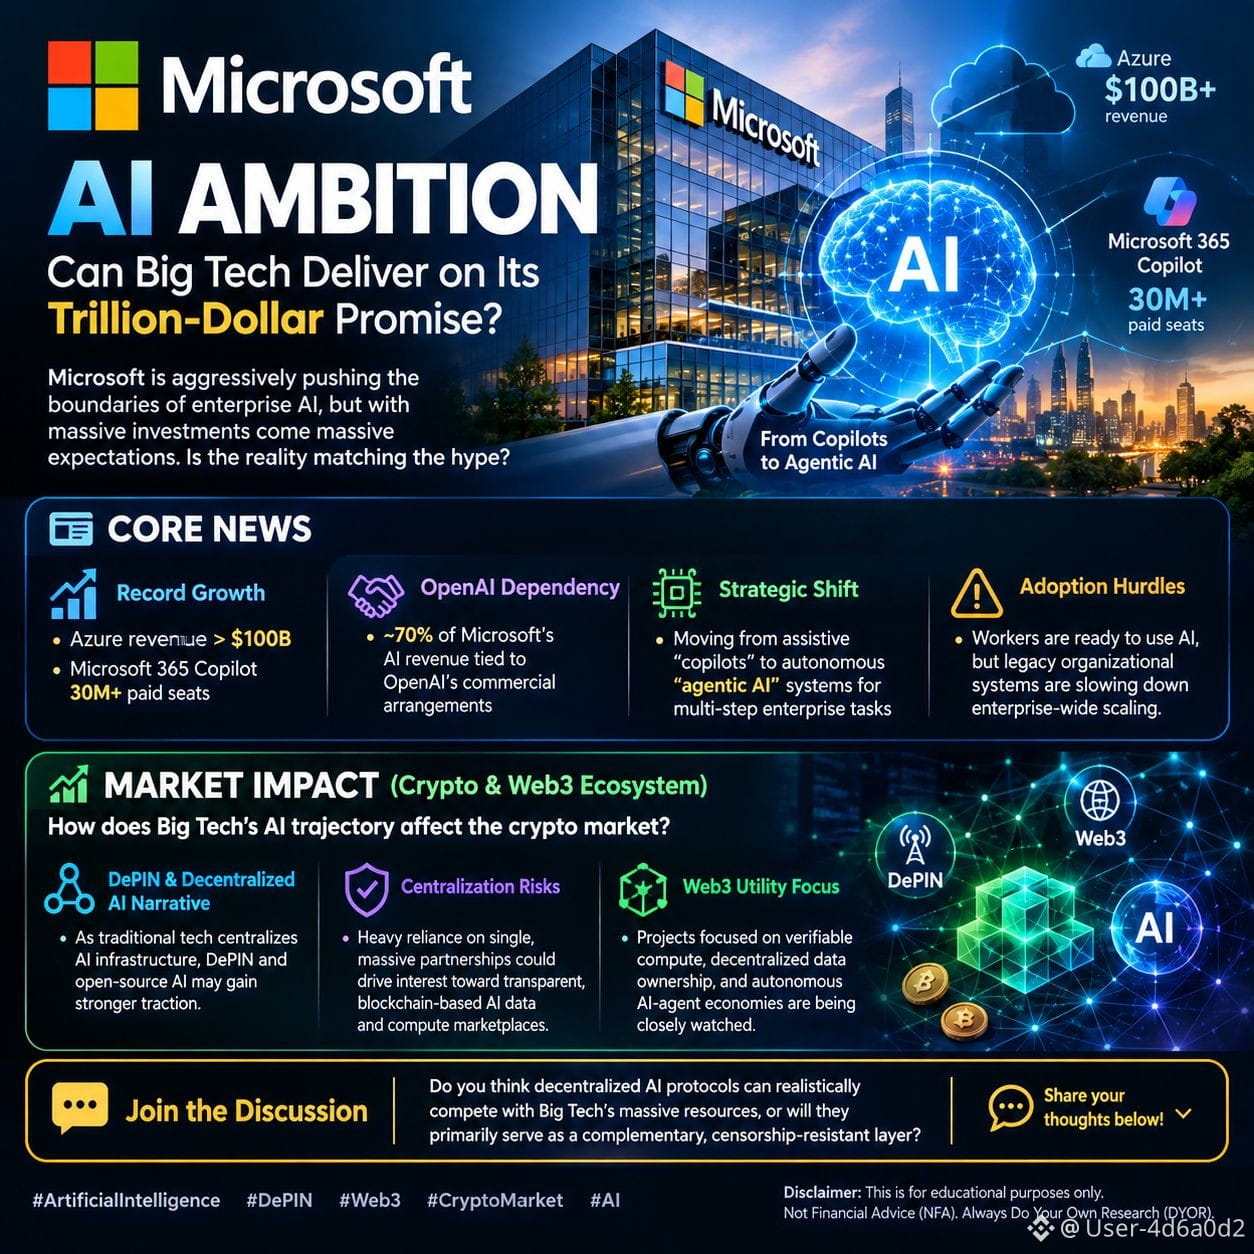
#canmicrosoftdeliveronai 🔍 Microsoft’s AI Ambition: Can Big Tech Deliver on Its Promise?
Microsoft is aggressively pushing enterprise AI, but massive investments bring massive expectations. Is reality matching the hype?
📰 Core News:
• 📈 Record Growth: Azure revenue surpassed $100B, with M365 Copilot exceeding 30M paid seats.
• 🤝 OpenAI Dependency: Recent filings show ~70% of Microsoft’s AI revenue is tied directly to OpenAI.
• ⚠️ Adoption Hurdles: The 2026 Work Trend Index highlights an "AI paradox"—workers are ready, but legacy systems slow enterprise scaling.
📊 Market Impact (Crypto & Web3):
• 🌐 DePIN Narrative: As Big Tech centralizes AI compute, crypto’s focus on Decentralized Physical Infrastructure Networks (DePIN) gains traction.
• ⚖️ Centralization Risks: Heavy reliance on single partnerships highlights systemic risks, driving interest toward blockchain-based AI compute marketplaces.
• 💡 Web3 Utility: Projects focusing on verifiable compute and decentralized data ownership are closely watched as traditional models face bottlenecks.
💬 Join the Discussion:
Can decentralized AI protocols realistically compete with Big Tech’s resources, or will they primarily serve as a complementary layer? Share your thoughts below! 👇
#ArtificialIntelligence #DePIN #Web3 #CryptoMarket #AI
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$HAEDAL $INIT $BANK
{future}(BANKUSDT)
{future}(INITUSDT)
{future}(HAEDALUSDT)
#canmicrosoftdeliveronai 🔍 Microsoft’s AI Ambition: Can Big Tech Deliver on Its Promise?
Microsoft is aggressively pushing enterprise AI, but massive investments bring massive expectations. Is reality matching the hype?
📰 Core News:
• 📈 Record Growth: Azure revenue surpassed $100B, with M365 Copilot exceeding 30M paid seats.
• 🤝 OpenAI Dependency: Recent filings show ~70% of Microsoft’s AI revenue is tied directly to OpenAI.
• ⚠️ Adoption Hurdles: The 2026 Work Trend Index highlights an "AI paradox"—workers are ready, but legacy systems slow enterprise scaling.
📊 Market Impact (Crypto & Web3):
• 🌐 DePIN Narrative: As Big Tech centralizes AI compute, crypto’s focus on Decentralized Physical Infrastructure Networks (DePIN) gains traction.
• ⚖️ Centralization Risks: Heavy reliance on single partnerships highlights systemic risks, driving interest toward blockchain-based AI compute marketplaces.
• 💡 Web3 Utility: Projects focusing on verifiable compute and decentralized data ownership are closely watched as traditional models face bottlenecks.
💬 Join the Discussion:
Can decentralized AI protocols realistically compete with Big Tech’s resources, or will they primarily serve as a complementary layer? Share your thoughts below! 👇
#ArtificialIntelligence #DePIN #Web3 #CryptoMarket #AI
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$HAEDAL $INIT $BANK
257

Tarjimani ko‘rish
O grande dilema da Microsoft: a corrida da IA está a pagar a conta?
A empresa investiu pesado para colocar o Copilot no centro do seu ecossistema (Windows, Office) e na infraestrutura do Azure. A tecnologia está lá, mas o mercado mudou o foco para a rentabilidade. O sucesso financeiro exige que os clientes paguem um prémio que justifique o custo massivo de poder computacional e R&D.
O que os investidores estão a monitorizar:
Crescimento do Azure.
Assinaturas pagas do Copilot.
Adoção real pelas empresas.
Evolução do capex.
A minha visão é que a distribuição é a arma secreta da Microsoft. Como o software já está no dia a dia das empresas, transformar a experimentação em adoção paga é mais fácil para eles do que para os concorrentes. No entanto, o risco de os custos superarem os retornos existe e é real.
Na corrida da IA, criar ferramentas poderosas é metade da vitória. A outra metade é fazer com que as pessoas queiram pagar por elas. Se a Microsoft falhar na execução da monetização, o mercado vai penalizar.
Aviso: Apenas para fins educacionais. Não é aconselhamento financeiro.
$JCT $MSFT.US $MSFTB
#canmicrosoftdeliveronai #MicrosoftAI #ArtificialIntelligence #GrowWithSAC #CanMicrosoftDeliverOnAI
{future}(JCTUSDT)
{stock_us}(MSFT.US)
{spot}(MSFTBUSDT)
O grande dilema da Microsoft: a corrida da IA está a pagar a conta?
A empresa investiu pesado para colocar o Copilot no centro do seu ecossistema (Windows, Office) e na infraestrutura do Azure. A tecnologia está lá, mas o mercado mudou o foco para a rentabilidade. O sucesso financeiro exige que os clientes paguem um prémio que justifique o custo massivo de poder computacional e R&D.
O que os investidores estão a monitorizar:
Crescimento do Azure.
Assinaturas pagas do Copilot.
Adoção real pelas empresas.
Evolução do capex.
A minha visão é que a distribuição é a arma secreta da Microsoft. Como o software já está no dia a dia das empresas, transformar a experimentação em adoção paga é mais fácil para eles do que para os concorrentes. No entanto, o risco de os custos superarem os retornos existe e é real.
Na corrida da IA, criar ferramentas poderosas é metade da vitória. A outra metade é fazer com que as pessoas queiram pagar por elas. Se a Microsoft falhar na execução da monetização, o mercado vai penalizar.
Aviso: Apenas para fins educacionais. Não é aconselhamento financeiro.
$JCT $MSFT.US $MSFTB
#canmicrosoftdeliveronai #MicrosoftAI #ArtificialIntelligence #GrowWithSAC #CanMicrosoftDeliverOnAI
1
35
·
--
O‘suvchi
Tarjimani ko‘rish
#CanMicrosoftDeliverOnAI
🚀 CAN MICROSOFT DELIVER ON THE AI REVOLUTION? OR WILL CRYPTO-AI STEAL THE SHOW? 🧵
The ultimate showdown on Wall Street and the digital asset space is here. Microsoft ($MSFT) is heading straight into a critical earnings test. Investors are asking one massive question: Can MSFT actually turn its colossal AI dominance into sustainable, long-term cash flow?
📊 The Cold, Hard Data
• The Big Spend: Microsoft is projected to inject a mind-boggling $175 Billion into AI Capital Expenditures by 2026.
• The Cost Optimization: To offset these soaring data center costs, they recently offered voluntary buyouts to 60,000 employees.
• The Momentum: Even with heavy spending, Microsoft Cloud surged 27% to $214.4 billion in annual revenue, while Azure grew 41% year-over-year.
$MSFTB $RNDR
#BinanceSquareTalks
{spot}(BTCUSDT)
#CanMicrosoftDeliverOnAI
🚀 CAN MICROSOFT DELIVER ON THE AI REVOLUTION? OR WILL CRYPTO-AI STEAL THE SHOW? 🧵
The ultimate showdown on Wall Street and the digital asset space is here. Microsoft ($MSFT) is heading straight into a critical earnings test. Investors are asking one massive question: Can MSFT actually turn its colossal AI dominance into sustainable, long-term cash flow?
📊 The Cold, Hard Data
• The Big Spend: Microsoft is projected to inject a mind-boggling $175 Billion into AI Capital Expenditures by 2026.
• The Cost Optimization: To offset these soaring data center costs, they recently offered voluntary buyouts to 60,000 employees.
• The Momentum: Even with heavy spending, Microsoft Cloud surged 27% to $214.4 billion in annual revenue, while Azure grew 41% year-over-year.
$MSFTB $RNDR
#BinanceSquareTalks
2
47
Tarjimani ko‘rish
#CanMicrosoftDeliverOnAI
Microsoft is making big moves in the AI industry, but can it turn its vision into real results? 🤖
From AI-powered tools to cloud computing, Microsoft has the technology and resources to compete with the biggest names in the market.
However, success will depend on innovation, user adoption, and the ability to make AI more useful in everyday life.
The potential is huge, but execution is everything! 🔥
Do you believe Microsoft can become the ultimate leader in AI? 👇
#Microsoft #ArtificialIntelligence #AI #BinanceSquare
83
Tarjimani ko‘rish
#canmicrosoftdeliveronai
🚨 LE PARI DE MICROSOFT SUR L’IA : DES MILLIARDS EN JEU ! 🤖💰
Microsoft mise tout sur l’intelligence artificielle, l’infrastructure cloud et les modèles d’IA de nouvelle génération. Mais pour les investisseurs, la grande question est simple : les dépenses massives en IA se traduiront-elles par des bénéfices durables ? 📊🔥
💰 1. Des investissements massifs dans l’IA
Les prévisions d’investissement de Microsoft pour 2026, telles qu’elles ont été rapportées, soulignent le coût considérable de l’augmentation de la puissance de calcul dédiée à l’IA, de l’infrastructure Azure et des centres de données. Les investisseurs attendent une forte croissance des revenus et un rendement clairement démontré sur ces dépenses.
🔄 2. Restructuration des effectifs
Alors que Microsoft remodèle une partie de ses effectifs et de ses activités, l’entreprise subit des pressions pour gagner en efficacité tout en réorientant ses ressources vers sa stratégie d’IA à long terme.
🚀 3. Construire son propre écosystème d’IA
Des modèles MAI propriétaires à Microsoft 365 Copilot, Windows et Azure, Microsoft étend ses capacités en IA et cherche à faire des outils propulsés par l’IA un élément essentiel du quotidien professionnel.
⚖️ 4. La grande question des investisseurs
L’adoption de l’IA progresse, mais les coûts liés aux infrastructures sont énormes. Le véritable enjeu sera de savoir si les activités de Microsoft dans l’IA et le cloud peuvent générer suffisamment de revenus, de marges et de flux de trésorerie pour justifier cet investissement.
📊 LES ÉLÉMENTS CLÉS À SURVEILLER :
Croissance du cloud Azure
Revenus liés à l’IA et adoption par les entreprises
Dépenses d’investissement et flux de trésorerie disponible
Marges bénéficiaires et prévisions futures
$AIN
{future}(AINUSDT)
$BTW
{future}(BTWUSDT)
$EVAA
{future}(EVAAUSDT)
#canmicrosoftdeliveronai
🚨 LE PARI DE MICROSOFT SUR L’IA : DES MILLIARDS EN JEU ! 🤖💰
Microsoft mise tout sur l’intelligence artificielle, l’infrastructure cloud et les modèles d’IA de nouvelle génération. Mais pour les investisseurs, la grande question est simple : les dépenses massives en IA se traduiront-elles par des bénéfices durables ? 📊🔥
💰 1. Des investissements massifs dans l’IA
Les prévisions d’investissement de Microsoft pour 2026, telles qu’elles ont été rapportées, soulignent le coût considérable de l’augmentation de la puissance de calcul dédiée à l’IA, de l’infrastructure Azure et des centres de données. Les investisseurs attendent une forte croissance des revenus et un rendement clairement démontré sur ces dépenses.
🔄 2. Restructuration des effectifs
Alors que Microsoft remodèle une partie de ses effectifs et de ses activités, l’entreprise subit des pressions pour gagner en efficacité tout en réorientant ses ressources vers sa stratégie d’IA à long terme.
🚀 3. Construire son propre écosystème d’IA
Des modèles MAI propriétaires à Microsoft 365 Copilot, Windows et Azure, Microsoft étend ses capacités en IA et cherche à faire des outils propulsés par l’IA un élément essentiel du quotidien professionnel.
⚖️ 4. La grande question des investisseurs
L’adoption de l’IA progresse, mais les coûts liés aux infrastructures sont énormes. Le véritable enjeu sera de savoir si les activités de Microsoft dans l’IA et le cloud peuvent générer suffisamment de revenus, de marges et de flux de trésorerie pour justifier cet investissement.
📊 LES ÉLÉMENTS CLÉS À SURVEILLER :
Croissance du cloud Azure
Revenus liés à l’IA et adoption par les entreprises
Dépenses d’investissement et flux de trésorerie disponible
Marges bénéficiaires et prévisions futures
$AIN
$BTW
$EVAA
114
·
--
O‘suvchi
Tarjimani ko‘rish
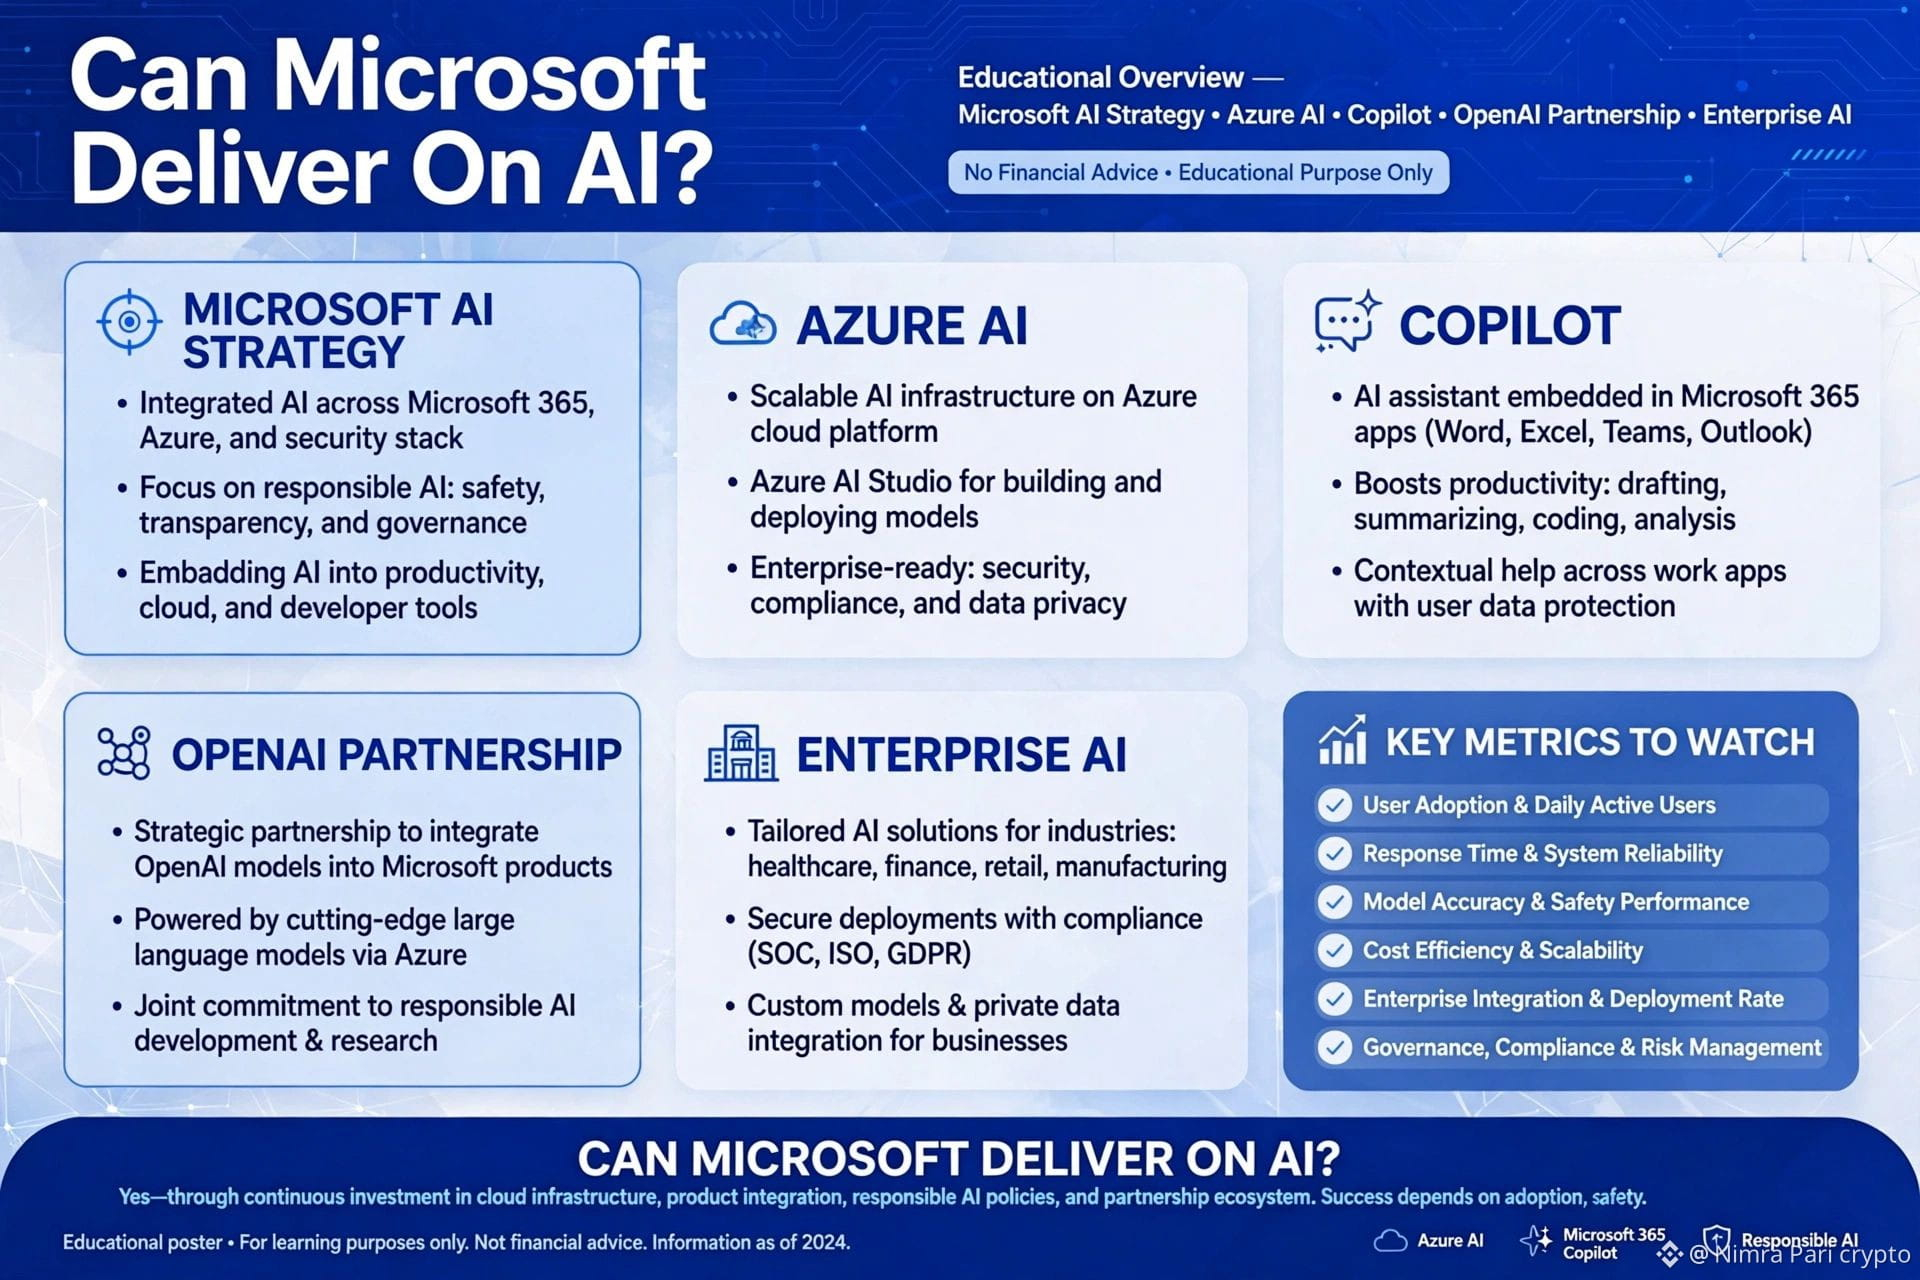
#CanMicrosoftDeliverOnAI CanMicrosoftDeliverOnAI 🤖🔥
> Microsoft's AI Game Plan Explained!
>
> 🎯 MICROSOFT AI STRATEGY
> Integrated AI across M365, Azure & Security. Focus on Responsible AI!
>
> ☁️ AZURE AI: Scalable cloud + Azure AI Studio + Enterprise security
> 💬 COPILOT: AI in Word, Excel, Teams, Outlook = Productivity 10x!
> 🤝 OPENAI PARTNERSHIP: Cutting-edge LLMs via Azure
> 🏢 ENTERPRISE AI: Healthcare, Finance, Retail + GDPR compliant
>
> 📊 KEY METRICS TO WATCH:
> User Adoption | Response Time | Model Accuracy | Cost Efficiency | Governance
>
> ANSWER: Yes — Through cloud, product integration & responsible AI! 🚀
>
> What do you think? Can Microsoft lead AI? 👇
> #EarningsSeason #CanMicrosoftDeliverOnAI #AI
> *Educational only
Isko #EarningsSeason + #CanMicrosoftDeliverOnAI dono hashtags ke sath post karo - double boost! 🚀
6
·
--
O‘suvchi
Tarjimani ko‘rish
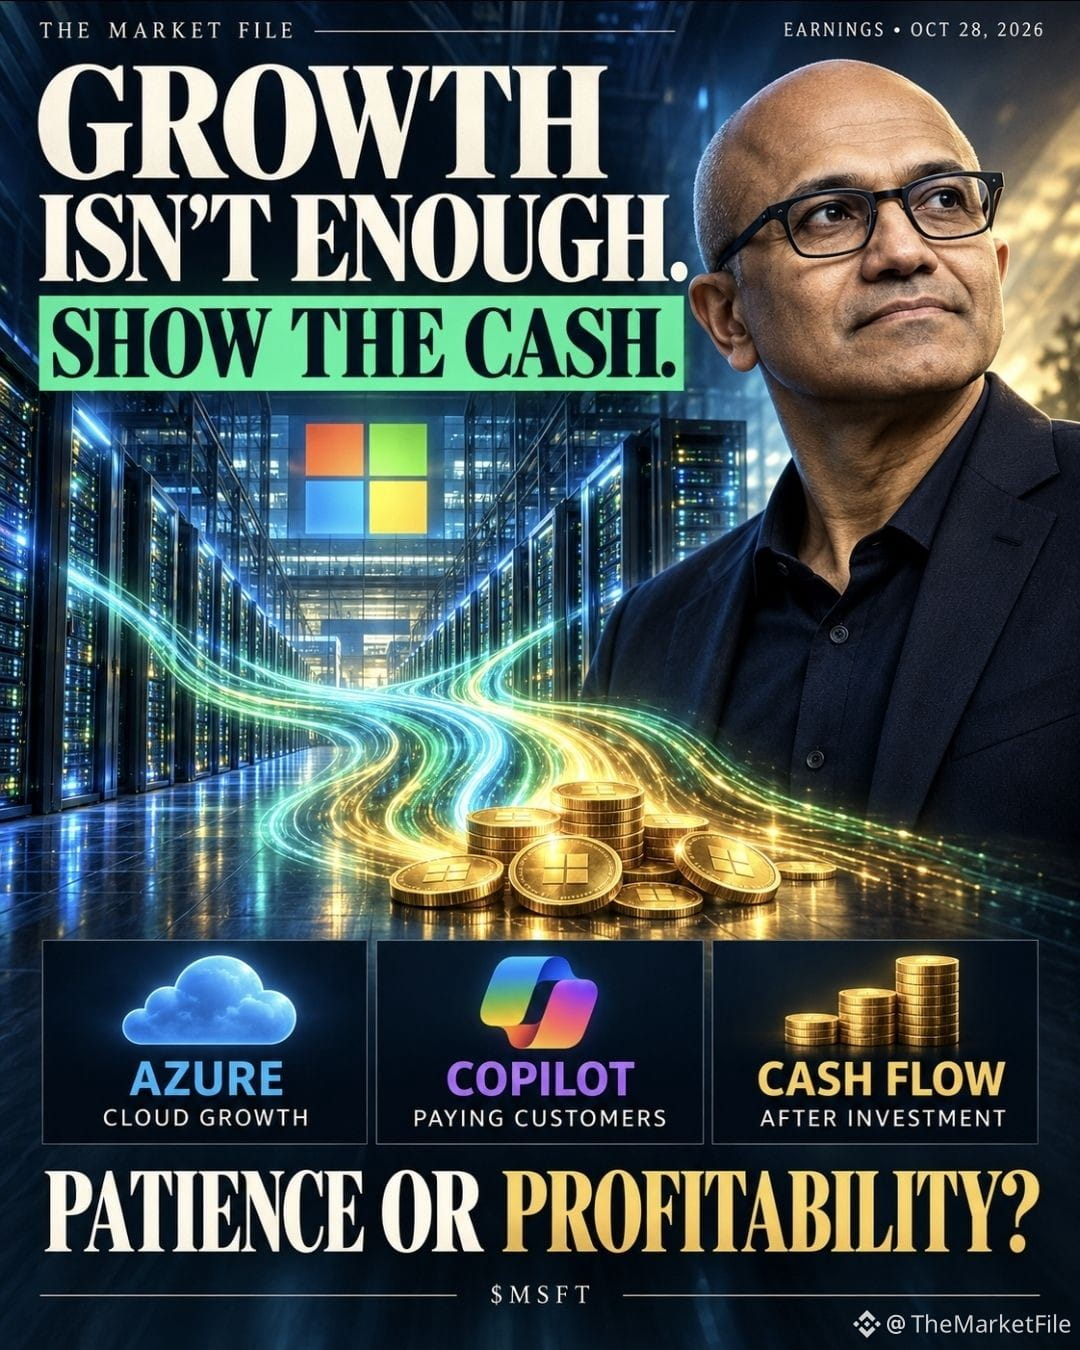
🚨 Microsoft can beat expectations… and still fall.
The question is how fast it must grow to justify the AI bill.
THE MARKET FILE — AI FACES ITS TEST
October 27, 2026
Microsoft reports earnings on October 28. Here are the benchmarks from its own guidance.
☁️ AZURE: IS GROWTH ENOUGH?
The company projected roughly 45% growth in constant currency.
My test: does new capacity translate into revenue, and does the next outlook sustain that momentum?
🤖 COPILOT: PAYING USERS
Microsoft ended fiscal 2026 with over 30 million paid Microsoft 365 Copilot seats.
I want to see growth in those seats and revenue per customer. Adding an AI feature doesn’t automatically mean monetizing it.
💰 THE BILL: OVER $50 BILLION
That was the quarter’s projected CapEx: total capital expenditure, not exclusively AI spending.
I’m watching margins, free cash flow and how much additional investment growth requires.
These are pre-earnings benchmarks, not results for the quarter Microsoft is about to report.
📖 MY POSITION:
Microsoft has an advantage: it can sell infrastructure through Azure and tools built on top through Copilot.
But that advantage must show up in the numbers.
🟢 Strong growth, paying customers and an outlook supporting margins and cash flow would build confidence.
🔴 A growing bill without enough improvement in monetization would concern me.
Results can beat consensus and still disappoint against expectations already reflected in the share price. That’s the risk of buying a great company with enormous expectations.
💬 If Azure grows strongly but investment weakens cash flow, do you give Microsoft more time—or demand results?
Pick: PATIENCE or PROFITABILITY. What number would make you switch sides?
$MSFTB $MSFT
{future}(MSFTUSDT)
{spot}(MSFTBUSDT)
#EarningsSeason #Microsoft
#CanMicrosoftDeliverOnAI
🚨 Microsoft can beat expectations… and still fall.
The question is how fast it must grow to justify the AI bill.
THE MARKET FILE — AI FACES ITS TEST
October 27, 2026
Microsoft reports earnings on October 28. Here are the benchmarks from its own guidance.
☁️ AZURE: IS GROWTH ENOUGH?
The company projected roughly 45% growth in constant currency.
My test: does new capacity translate into revenue, and does the next outlook sustain that momentum?
🤖 COPILOT: PAYING USERS
Microsoft ended fiscal 2026 with over 30 million paid Microsoft 365 Copilot seats.
I want to see growth in those seats and revenue per customer. Adding an AI feature doesn’t automatically mean monetizing it.
💰 THE BILL: OVER $50 BILLION
That was the quarter’s projected CapEx: total capital expenditure, not exclusively AI spending.
I’m watching margins, free cash flow and how much additional investment growth requires.
These are pre-earnings benchmarks, not results for the quarter Microsoft is about to report.
📖 MY POSITION:
Microsoft has an advantage: it can sell infrastructure through Azure and tools built on top through Copilot.
But that advantage must show up in the numbers.
🟢 Strong growth, paying customers and an outlook supporting margins and cash flow would build confidence.
🔴 A growing bill without enough improvement in monetization would concern me.
Results can beat consensus and still disappoint against expectations already reflected in the share price. That’s the risk of buying a great company with enormous expectations.
💬 If Azure grows strongly but investment weakens cash flow, do you give Microsoft more time—or demand results?
Pick: PATIENCE or PROFITABILITY. What number would make you switch sides?
$MSFTB $MSFT
#EarningsSeason #Microsoft
#CanMicrosoftDeliverOnAI
49
Tarjimani ko‘rish
#CanMicrosoftDeliverOnAI
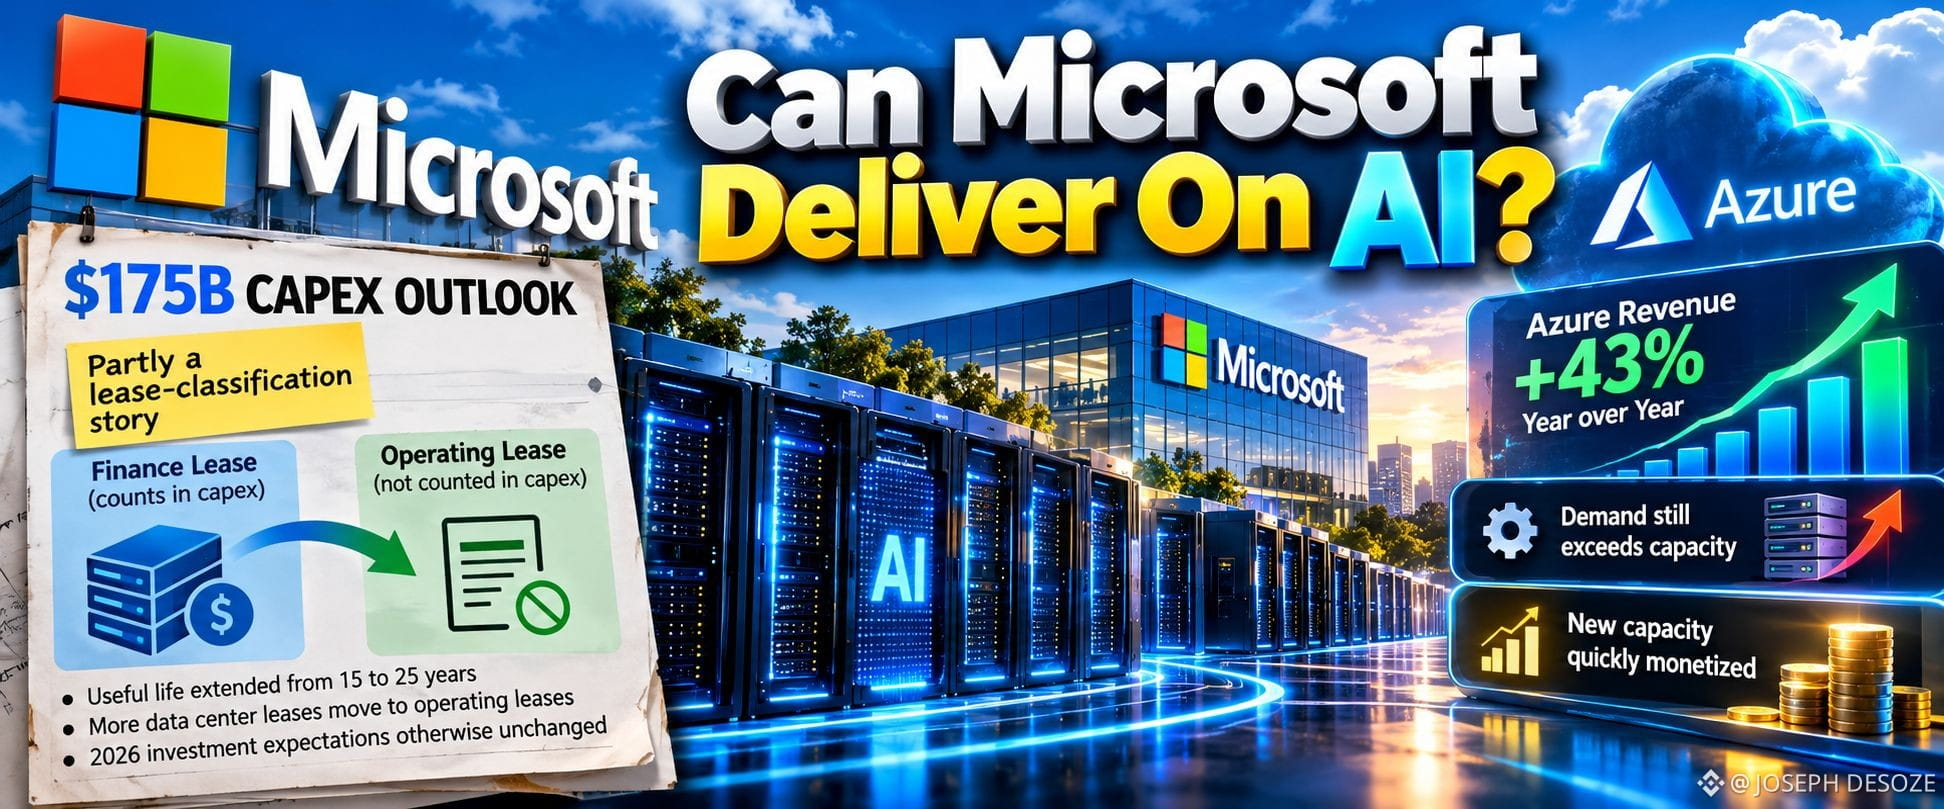
Why does this matter for CanMicrosoftDeliverOnAI? Spending is only an input. In Q4, Azure revenue grew 43% year over year, yet Microsoft said demand still exceeded available capacity. It also said new capacity delivered during the quarter was quickly monetized. That shows execution, but the supply gap remained.
I’d judge delivery by comparing capacity actually brought online with Azure growth and cloud gross-margin direction, not capex alone. Strong growth alongside improving margins would suggest infrastructure is becoming more productive; higher spending without those signals is harder to interpret.
The next report’s key detail is whether Microsoft is closing the capacity gap faster, while separating genuine build-out from lease-classification effects.
#AI
209
Tarjimani ko‘rish
📈 What Could Move $MSFT After Earnings?
Microsoft’s results could influence how investors view the wider AI sector. Azure performance, Copilot adoption, AI-related spending, and forward guidance will all be important signals.
⚖️ Strong results may support confidence, while weaker growth or rising costs could create uncertainty.
Are you bullish, bearish, or waiting for the numbers before deciding? Share your analysis and Binance Pick position! 👇
#canmicrosoftdeliveronai
3
Tarjimani ko‘rish
📊 AI Spending vs. Profitability
Microsoft’s $MSFT investment in AI infrastructure is substantial. More data centers and computing capacity can support future growth, but investors also want to understand the financial returns.
🔍 Watch revenue growth, capital expenditure, operating margins, and management’s outlook.
Would you prioritize faster AI expansion or stronger profitability? Let’s discuss!
#canmicrosoftdeliveronai
4
Tarjimani ko‘rish
💡 Will Copilot Become a Major Growth Engine?
Microsoft’s $MSFT Copilot products bring AI into everyday business workflows, from document creation to productivity tasks.
The big question is whether businesses will keep paying for these tools as adoption expands.
🚀 Can Copilot turn AI excitement into recurring revenue? What evidence will you watch in the earnings report?
#canmicrosoftdeliveronai
5
Tarjimani ko‘rish
☁️ Azure Growth in the Spotlight
Microsoft’s $MSFT cloud business remains a major part of its AI strategy. Businesses need computing power to build and run AI applications, but capacity and infrastructure costs also matter.
📈 Can Azure maintain strong growth while meeting rising AI demand?
Share your earnings expectations and Binance Pick prediction!
#canmicrosoftdeliveronai
3
Ko‘proq kontentni ko‘rish uchun tizimga kiring
Binance Square'da global kriptovalyuta foydalanuvchilariga qo‘shiling
⚡️ Kriptovalyuta haqida eng so‘nggi va foydali ma’lumotlarni oling.
💬 Dunyoning eng yirik kriptovalyuta birjasi tomonidan ishonchli deb topilgan.
👍 Tasdiqlangan mualliflardan haqiqiy tahlillarni kashf eting.
Email / telefon raqami
Tegishli tangalar
Trenddagi mavzular
1
#CanMicrosoftDeliverOnAI
44,121 marta koʻrilgan
593 muhokama qilmoqda
2
#CanGoogleDefindItsCore
22,069 marta koʻrilgan
445 muhokama qilmoqda
3
#FOMCWatch
9M marta koʻrilgan
27,767 muhokama qilmoqda
4
#EthereumDropsBelow$2300
9,530 marta koʻrilgan
148 muhokama qilmoqda
5
#BitcoinSlipsBelow$80KAgain
26,496 marta koʻrilgan
113 muhokama qilmoqda
6
#ThailandLaunchesWORPTStablecoinToQRPaymentApp
52,022 marta koʻrilgan
734 muhokama qilmoqda
7
#StrategySkipsBitcoinPurchasesSpends$205MOnSTRCBuybacks
10,164 marta koʻrilgan
94 muhokama qilmoqda
8
#BitmineAdds10452ETH
93,336 marta koʻrilgan
1,121 muhokama qilmoqda
9
#SouthKoreaConsidersEducationTaxOnCryptoExchanges
50,670 marta koʻrilgan
817 muhokama qilmoqda
10
#OCCUrgesCommunityBanksToEnterStablecoinPayments
38,460 marta koʻrilgan
581 muhokama qilmoqda