

Eric SJ
3.5k Posts

Eric SJ
 Square Verified+
Report
Block User
推特@sjbtc9丨内容输出:美股相关(科普和财报分析)、二级市场技术分析、Web3项目观点

Creator Awards 2024

原创之星
65 Following
56.6K+ Followers
140.8K+ Liked
3 Badges
Posts
All
Quotes
Videos
Live
Trending
·
--

Article
Taking Binance Square as an example, let’s think about: What strategic value does a content community have for a platform?For an exchange, its product form is essentially a trading tool. At the peak of the domestic Internet era, someone once said: "A good product should be used and then gone."
However, when a platform has gone through the initial growth period of high expansion, especially when the industry is currently in the stage of transitioning from high growth to stock, good products should not be used and then gone.
So what strategic value does the Binance Square product have for Binance?
🗝️Article title
1. Discuss the rationality of Binance Square
2. Why is this a product moat that is difficult to replicate?
Taking Binance Square as an example, let’s think about: What strategic value does a content community have for a platform?
For an exchange, its product form is essentially a trading tool. At the peak of the domestic Internet era, someone once said: "A good product should be used and then gone."
However, when a platform has gone through the initial growth period of high expansion, especially when the industry is currently in the stage of transitioning from high growth to stock, good products should not be used and then gone.
So what strategic value does the Binance Square product have for Binance?
🗝️Article title
1. Discuss the rationality of Binance Square
2. Why is this a product moat that is difficult to replicate?
44
13
927
3.3M
·
--
Bullish
This may be a genuine bottom signal.
Binance has suffered the largest crypto theft in the history of the industry.
After an incident this serious,
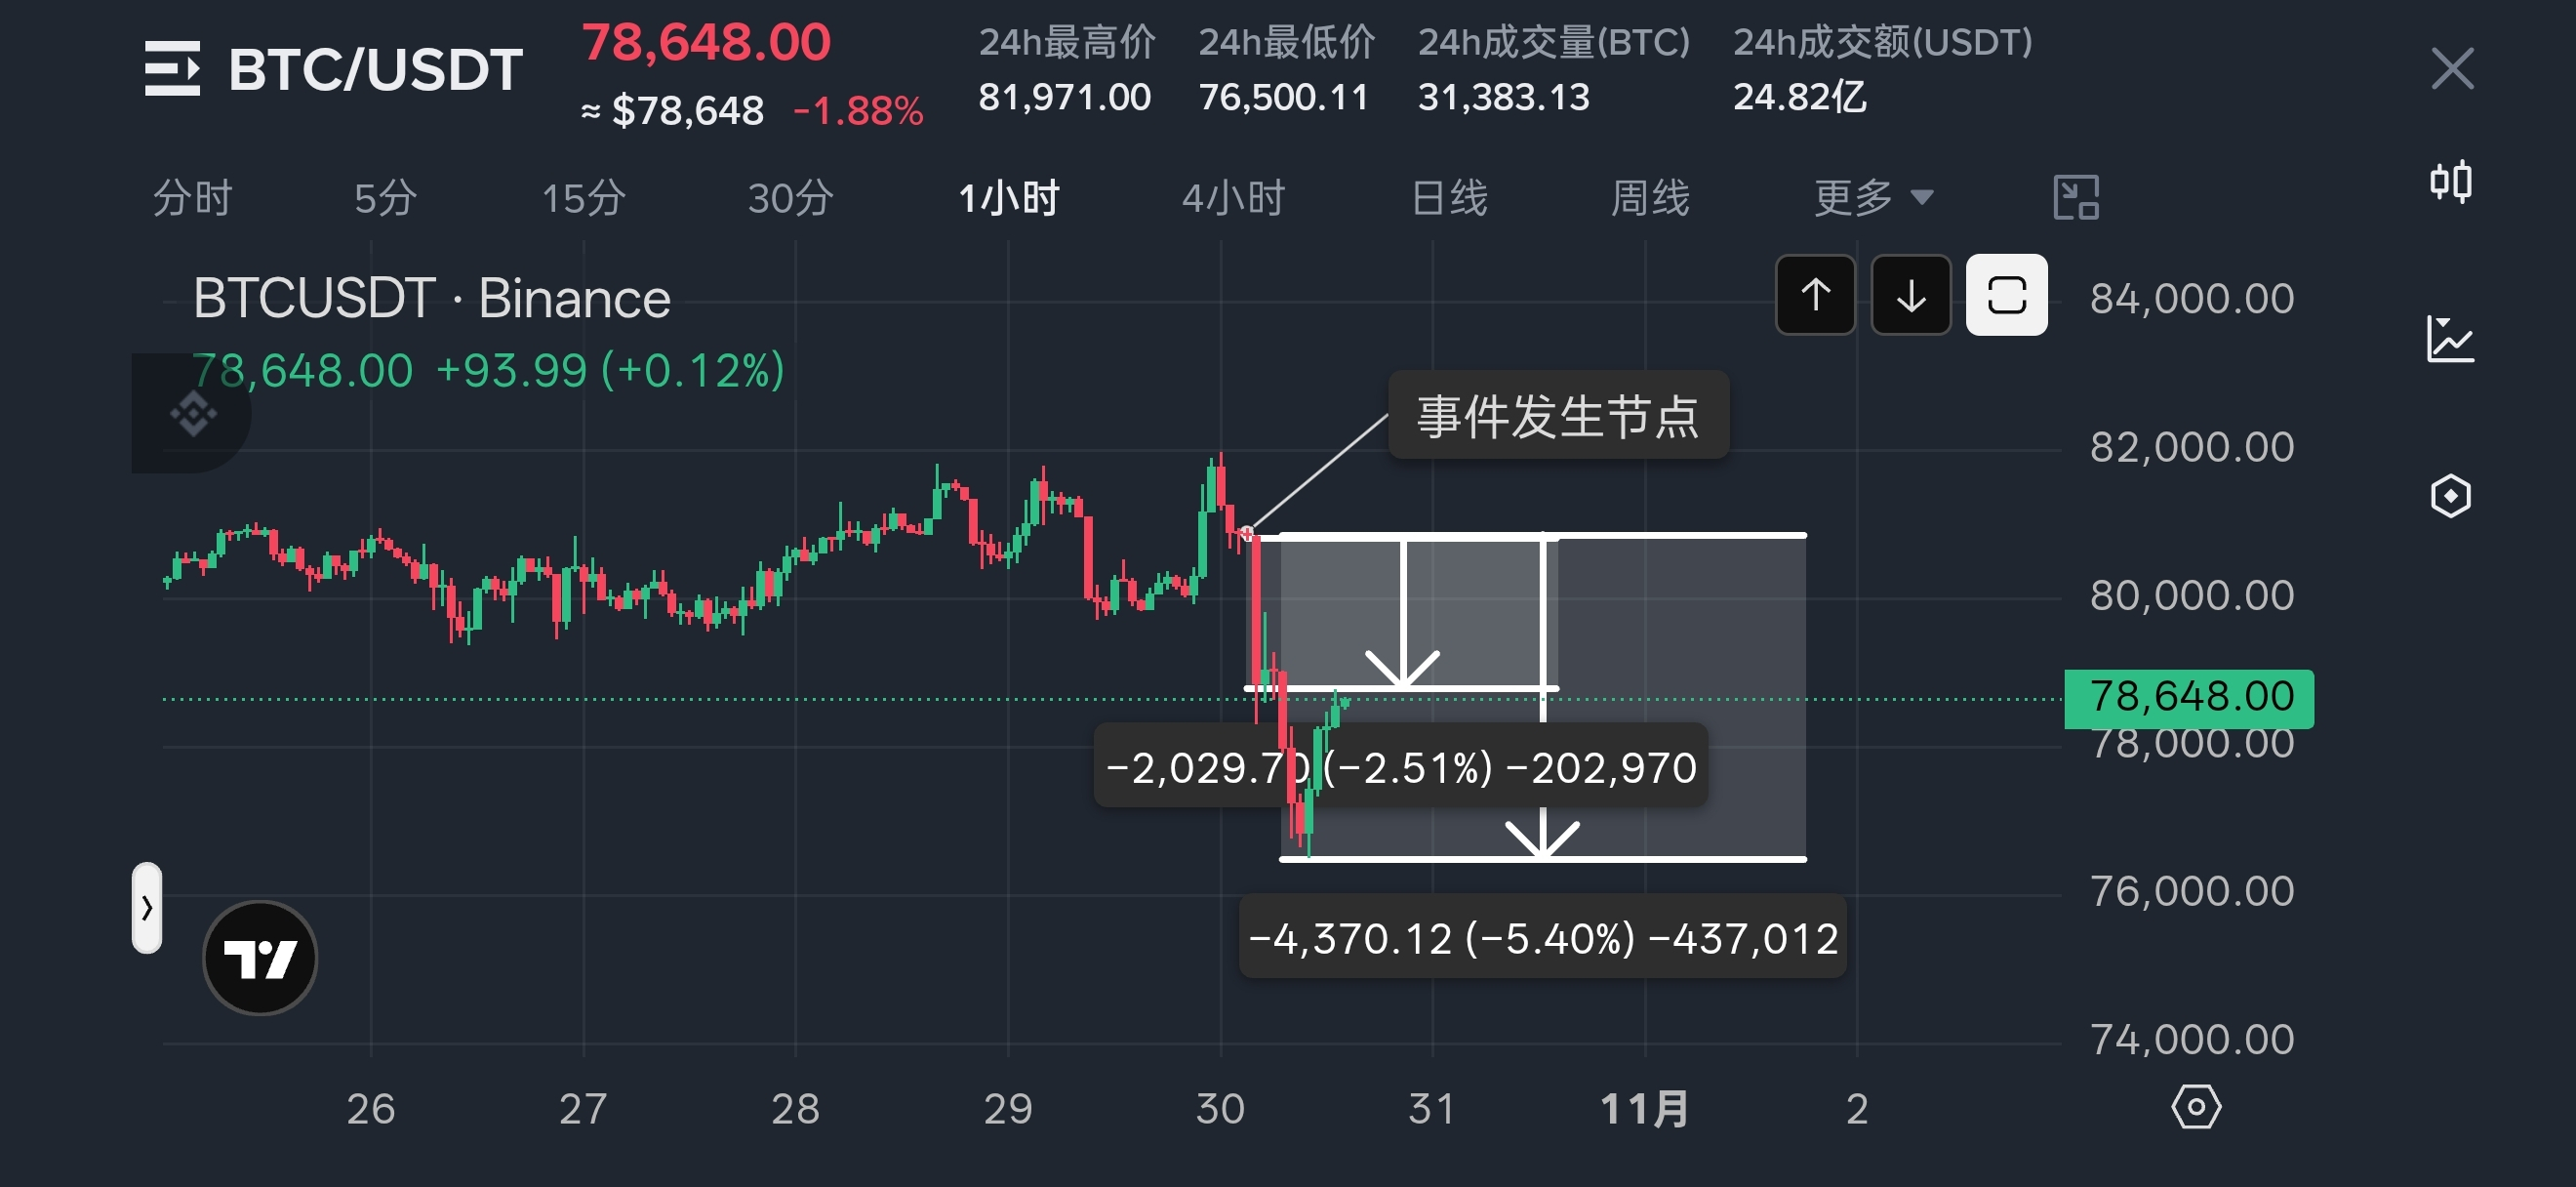
from the time of the incident to the lowest point, the price retraced $BTC (7w7)
{future}(BTCUSDT)
The drop was about 5.4%, not far off the retracement when Bybit was hacked.
And the amount involved in this Binance incident was more than four times that of the Bybit hack back then.
The impact has been much smaller than expected.
The current price has already recovered nearly half of its decline (the latest news is that half of the stolen funds have also been frozen).
I think this is a signal well worth viewing optimistically.
This may be a genuine bottom signal.
Binance has suffered the largest crypto theft in the history of the industry.
After an incident this serious,
from the time of the incident to the lowest point, the price retraced $BTC (7w7)
The drop was about 5.4%, not far off the retracement when Bybit was hacked.
And the amount involved in this Binance incident was more than four times that of the Bybit hack back then.
The impact has been much smaller than expected.
The current price has already recovered nearly half of its decline (the latest news is that half of the stolen funds have also been frozen).
I think this is a signal well worth viewing optimistically.
2
5.4k
·
--
Verified
A lot of people haven’t quite got this straight.
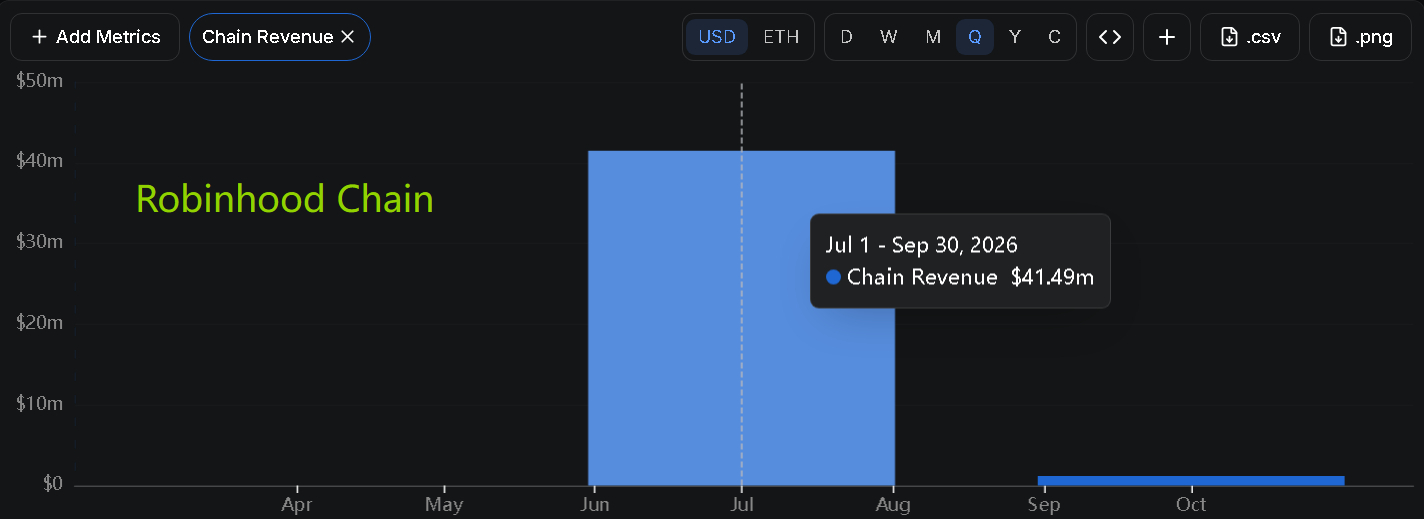
How much did Robinhood Chain actually earn in Q3?
According to DefiLlama, it was $41.49 million.
But $HOOD ’s financial report confirmed only $26 million.
To understand why, we need to break down the different ways revenue from a single gas fee is distributed:
1. Ethereum: Charges settlement and data fees required to run the chain. This isn’t the biggest expense.
2. 10% of net revenue goes to Arbitrum.
3. A share goes to other launch partners.
The chain revenue reported by DefiLlama has already been adjusted for the first two items above.
The additional item disclosed in the financial report is the final one: the share paid to “launch partners.”
These “launch partners” are partners who helped Robinhood build the chain and provided foundational services when it launched.
The full list hasn’t been disclosed. Arbitrum and Ethereum, mentioned above, could both be included.
According to the company, Robinhood initially retained only about 50% of its sequencer revenue.
That’s why management said on the earnings call that RHC actually generated about $50 million in gross revenue this quarter, with around $25 million left after revenue sharing.
DefiLlama’s $41.49 million figure reflects revenue after deducting some known fees. The difference arises because the company uses different accounting rules and includes a different scope of items.
To sum up:
1) About $50 million reflects the chain’s revenue-generating capacity.
2) $26 million is the revenue the company actually gets to keep.
3) $41.49 million is revenue calculated according to DefiLlama’s methodology.
Use DefiLlama to research the chain; to calculate its contribution to $HOOD ’s revenue, use the financial report.
1
3k
·
--
The topic we discussed a month ago: $BTC
{future}(BTCUSDT)
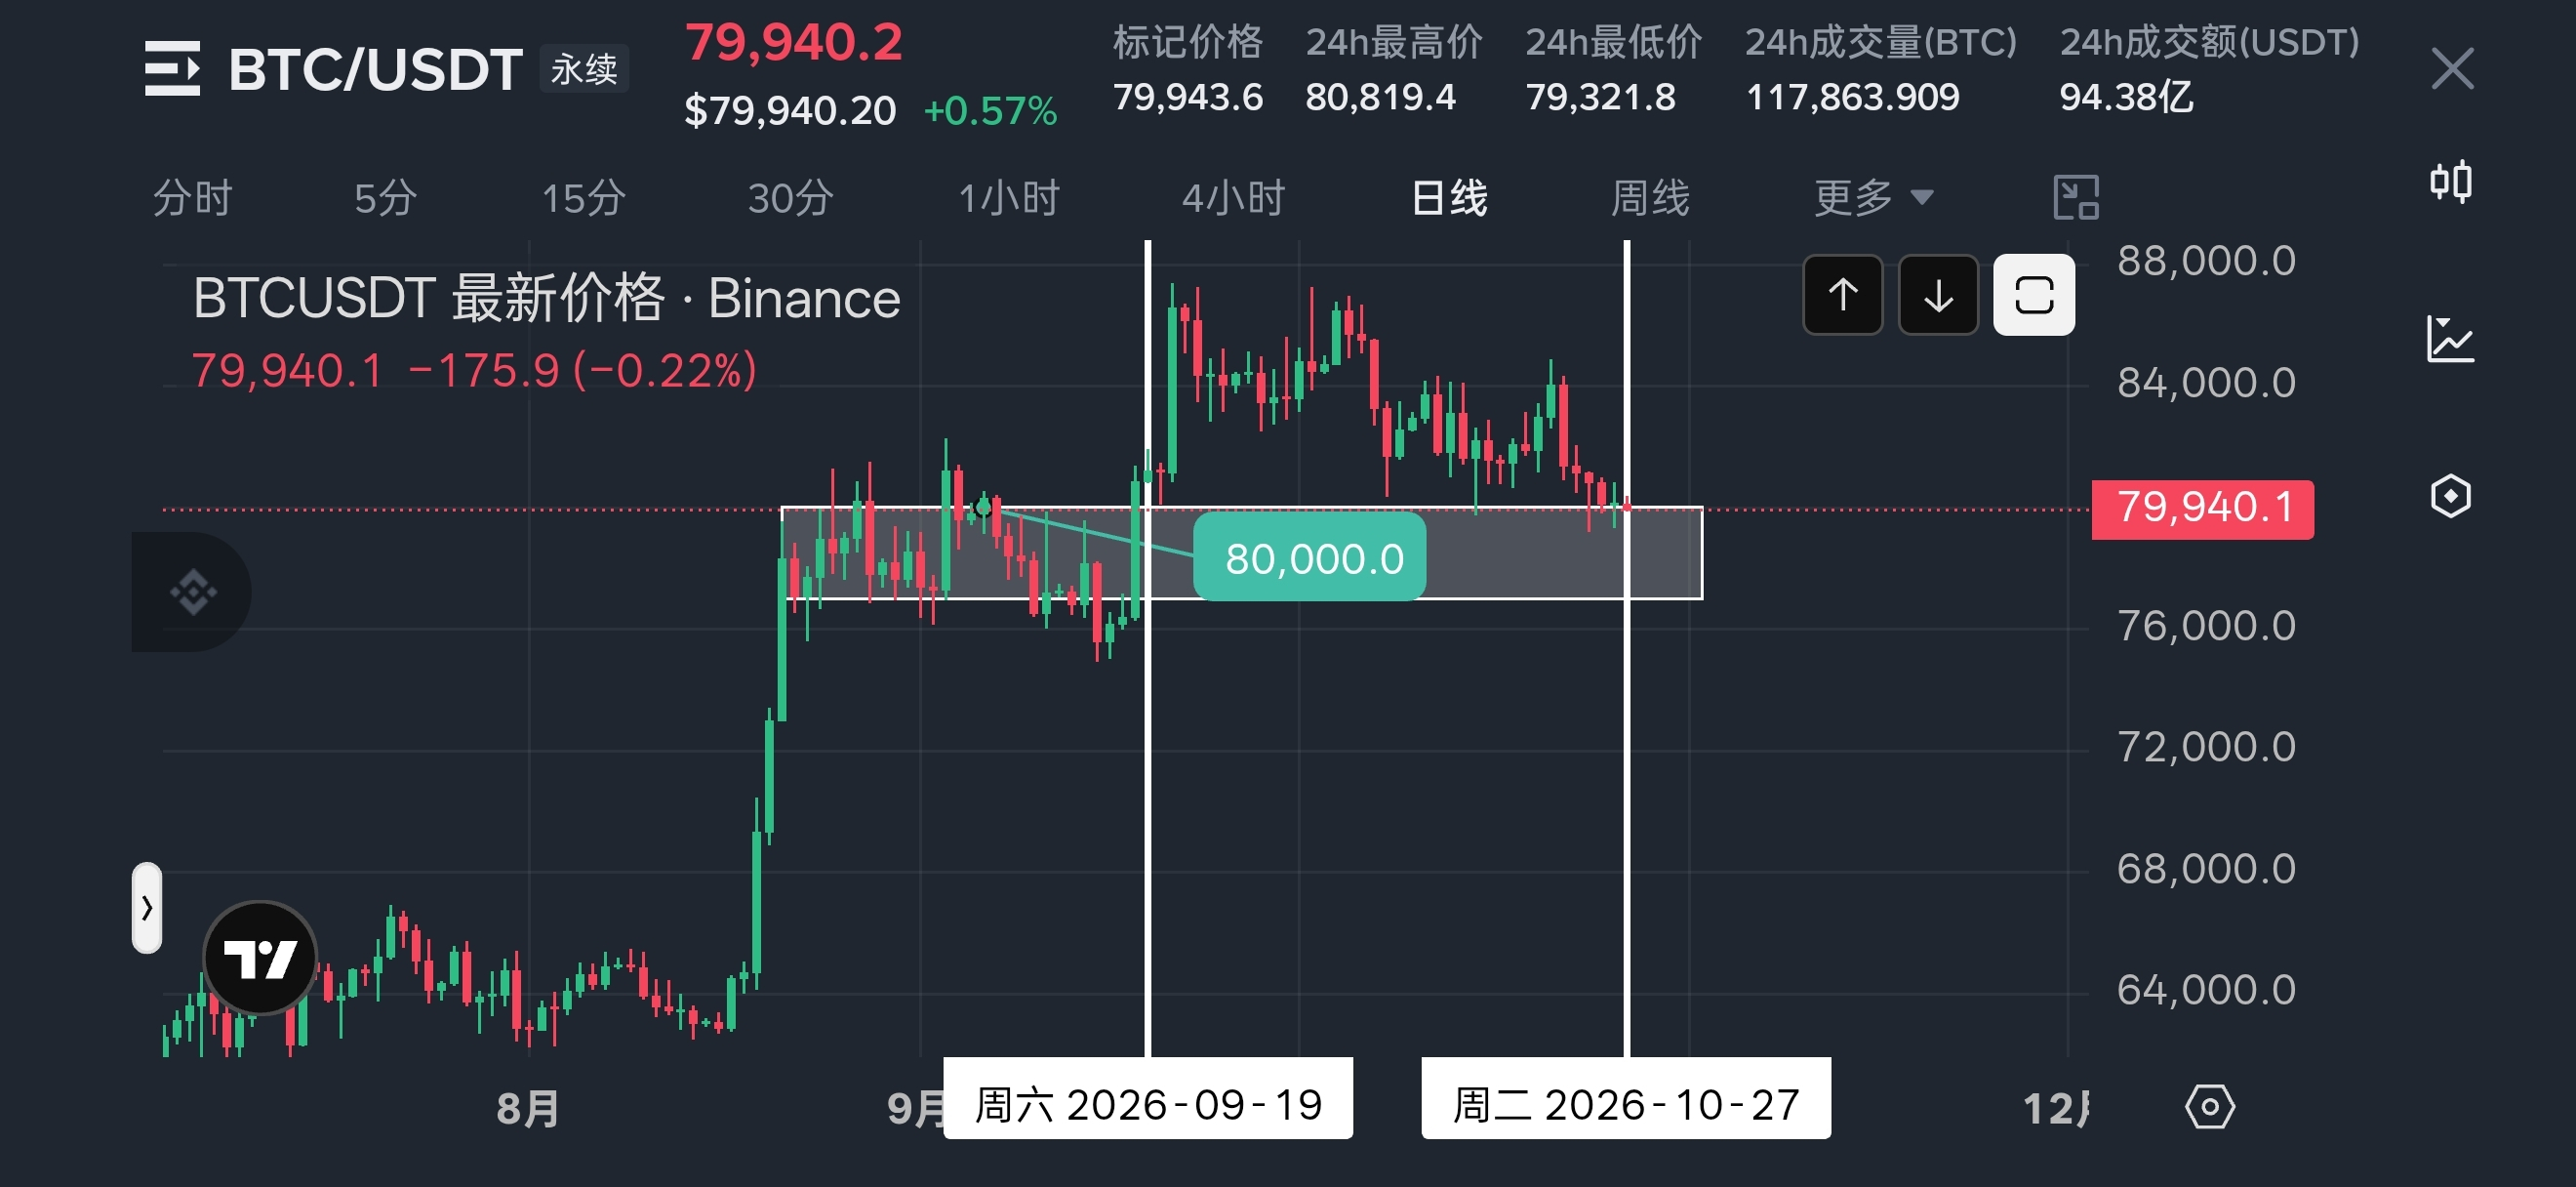
80,000 is strong resistance; a breakout would open up endless possibilities
The topic we're discussing now: $BTC 80,000 is strong support; if it breaks, I'm afraid it could fall back to 40,000
The topic we discussed a month ago: $BTC
80,000 is strong resistance; a breakout would open up endless possibilities
The topic we're discussing now: $BTC 80,000 is strong support; if it breaks, I'm afraid it could fall back to 40,000
80,000 is strong resistance; a breakout would open up endless possibilities
The topic we're discussing now: $BTC 80,000 is strong support; if it breaks, I'm afraid it could fall back to 40,000
2
5
3.4k
·
--
Verified
Article
Can this mechanism really turn early sell-off tokens into permanent market-making liquidity?When many developers launch a token, they use multiple wallets to buy up a large supply in advance. Once the project gains traction and the price rises, they sell those tokens to people who get in later.
That’s why many memecoins look like they have a widely distributed token supply at launch, yet after rising for a while, they can still suddenly get completely dumped.
What appeals to me most about Robinhood Chain is that, while it brings established DeFi protocols onto the chain, it has also given rise to many projects with innovative designs.
The solution Mosh offers addresses who holds these early tokens and how they can exit. In other words, it packages [bundled trading] into an [automated vault product].
Can this mechanism really turn early sell-off tokens into permanent market-making liquidity?
When many developers launch a token, they use multiple wallets to buy up a large supply in advance. Once the project gains traction and the price rises, they sell those tokens to people who get in later.
That’s why many memecoins look like they have a widely distributed token supply at launch, yet after rising for a while, they can still suddenly get completely dumped.
What appeals to me most about Robinhood Chain is that, while it brings established DeFi protocols onto the chain, it has also given rise to many projects with innovative designs.
The solution Mosh offers addresses who holds these early tokens and how they can exit. In other words, it packages [bundled trading] into an [automated vault product].
3
6
3k
·
--
I know
Pump fun$PUMP is going to get criticized again
{future}(PUMPUSDT)
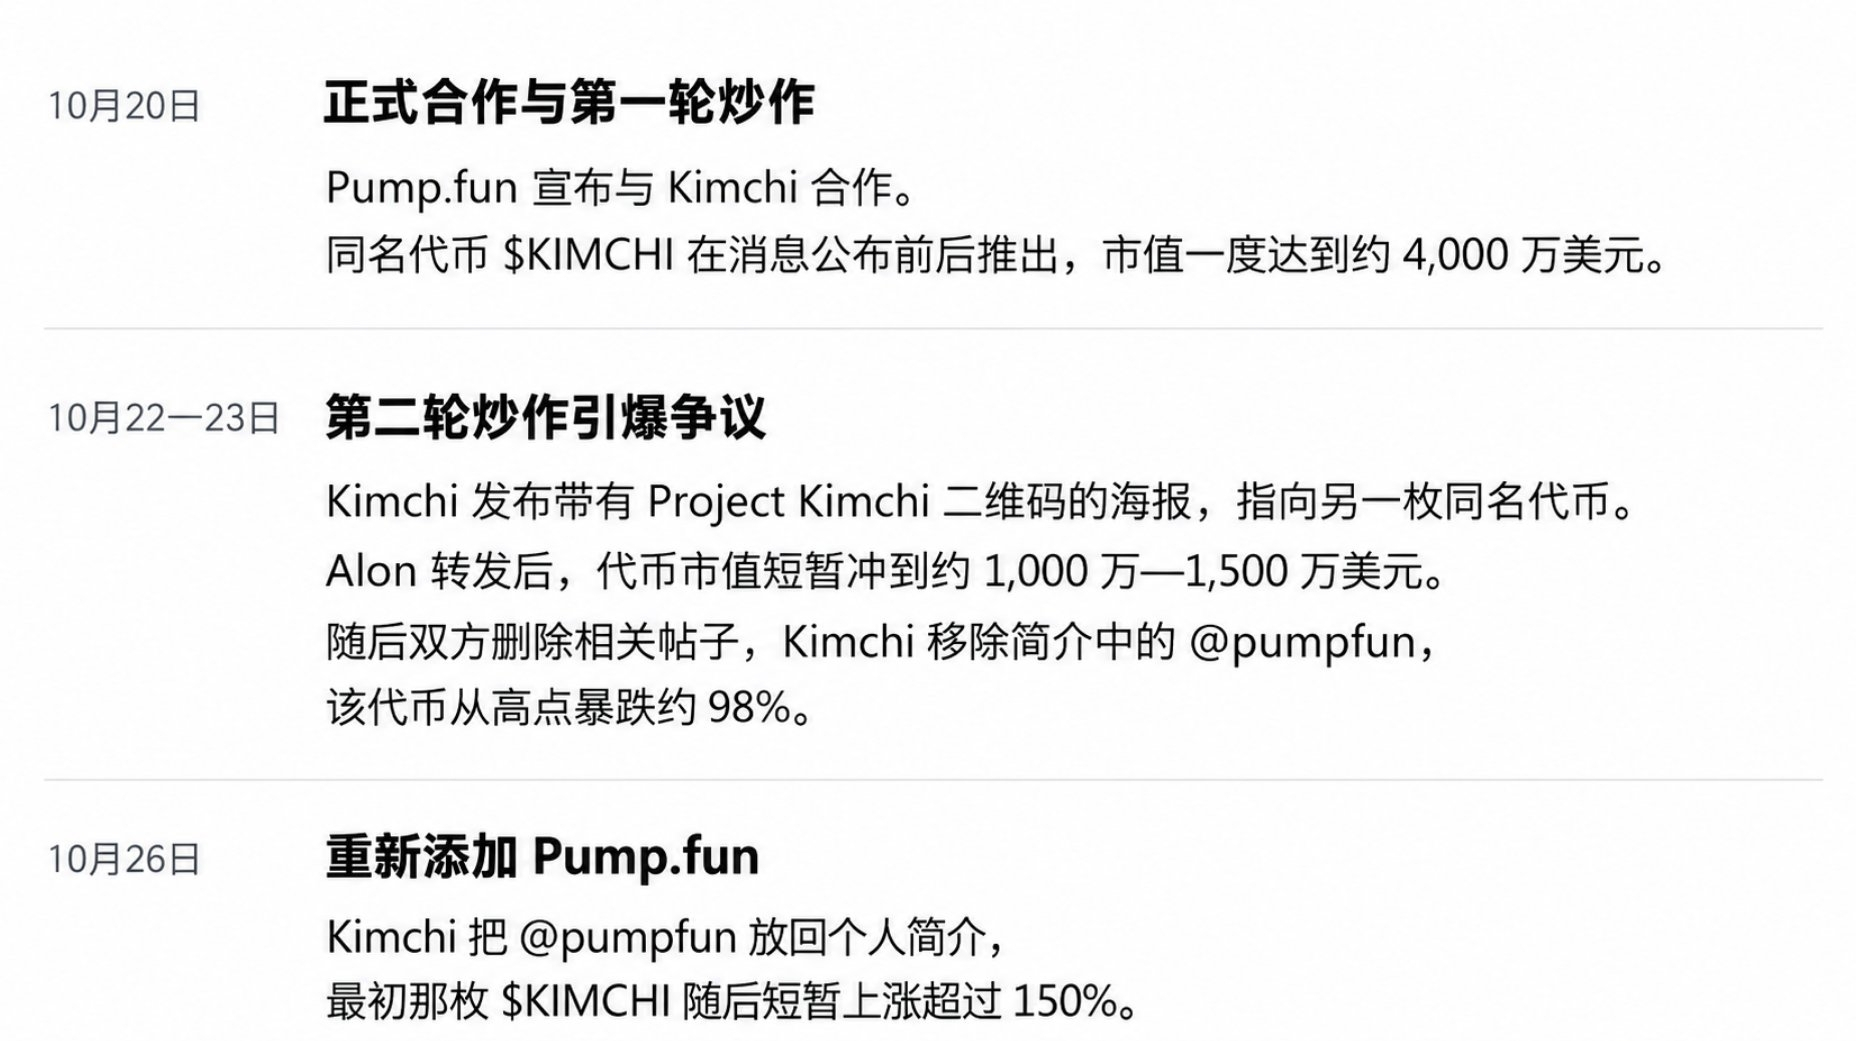
The collaboration between @pumpfun and @kimchi1x these past few days has gotten more and more bizarre.
Today, kimchi added pumpfun back to their bio.
To this day, I still don't know whether this farcical collaboration is over or if something just went wrong along the way 🤡
Here’s a line from a post by @FabianoSolana a few days ago:
“If you still support Pump Fun, I’ve completely lost respect for you.”
I know
Pump fun$PUMP is going to get criticized again
The collaboration between @pumpfun and @kimchi1x these past few days has gotten more and more bizarre.
Today, kimchi added pumpfun back to their bio.
To this day, I still don't know whether this farcical collaboration is over or if something just went wrong along the way 🤡
Here’s a line from a post by @FabianoSolana a few days ago:
“If you still support Pump Fun, I’ve completely lost respect for you.”
1
2.5k
·
--
The Air Force has no idea what it's about to go through right now.
The Air Force has no idea what it's about to go through right now.
1
1
3
1.4k
·
--
Verified
Putting the financial reports aside
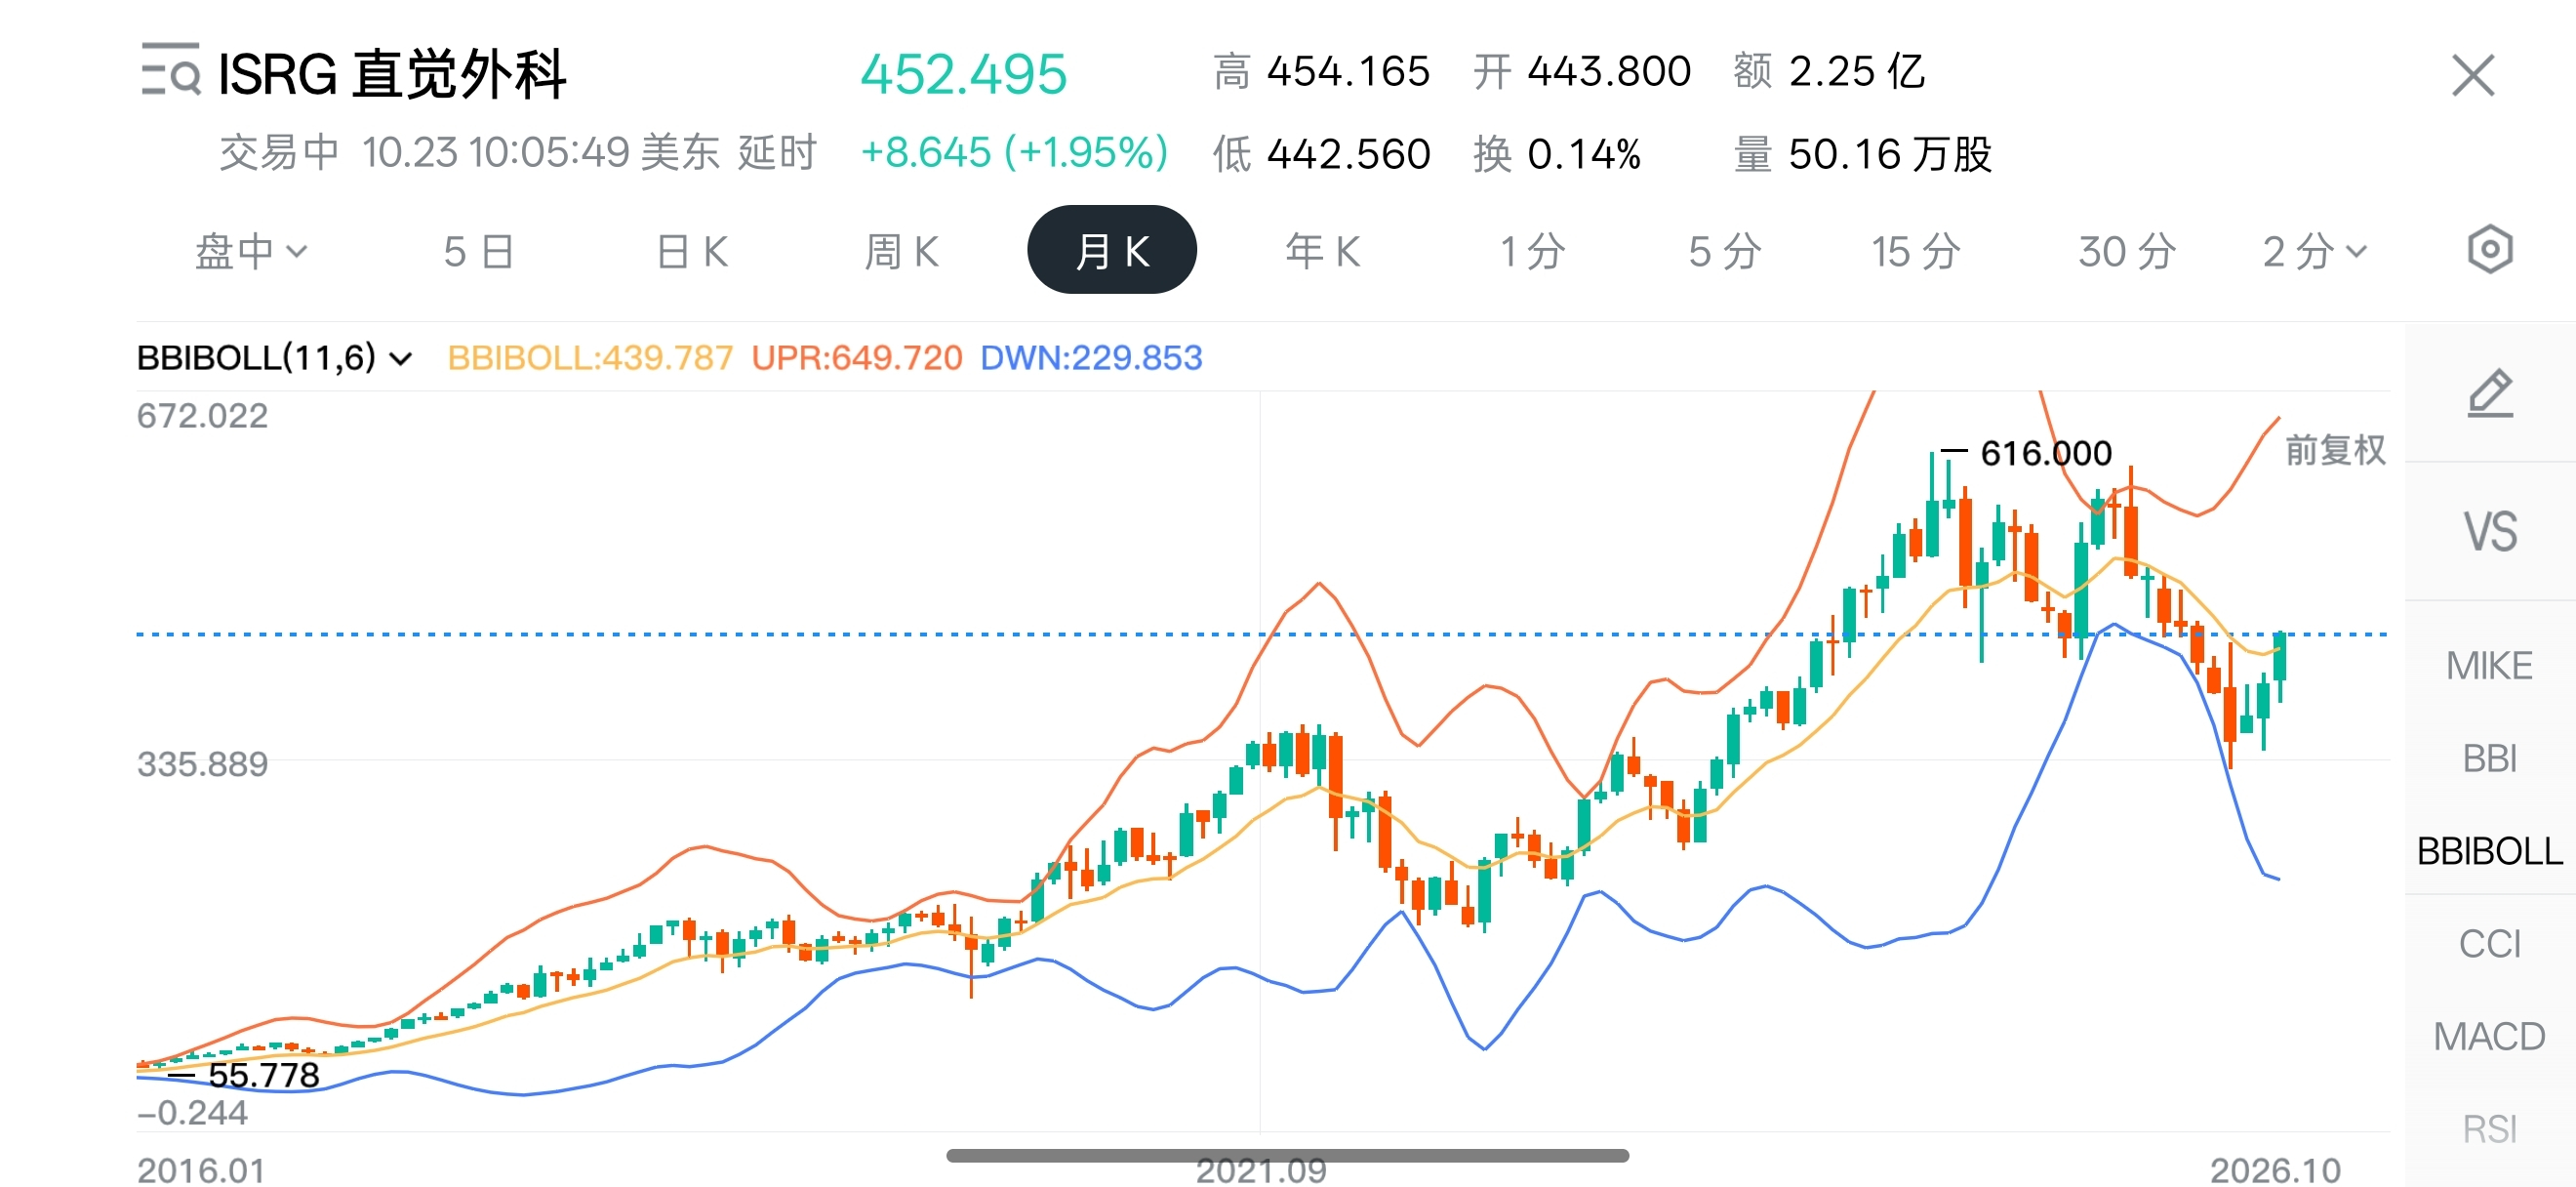
$ISRG.US is also a medical technology company well worth investing in for the long term
{stock_us}(ISRG.US)
1. Its business model is stable and clear
2. Its competitive moat deepens as the market grows
3. The development of AI will also give this company an even greater advantage
Its surgical robot was developed before the boom in large AI models
Previously, the robot mainly helped doctors perform surgeries with greater precision and consistency
But with the support of today’s AI, it can make robots easier for doctors to learn and use, encouraging more hospitals and doctors to perform robotic surgeries
It can also improve the utilization of existing equipment, giving each robot the opportunity to perform more surgeries
Lower barriers to entry = more customers
More surgeries = more consumables
It can attack when advancing and defend when retreating—either way, it wins
#股票财报季
Putting the financial reports aside
$ISRG.US is also a medical technology company well worth investing in for the long term
1. Its business model is stable and clear
2. Its competitive moat deepens as the market grows
3. The development of AI will also give this company an even greater advantage
Its surgical robot was developed before the boom in large AI models
Previously, the robot mainly helped doctors perform surgeries with greater precision and consistency
But with the support of today’s AI, it can make robots easier for doctors to learn and use, encouraging more hospitals and doctors to perform robotic surgeries
It can also improve the utilization of existing equipment, giving each robot the opportunity to perform more surgeries
Lower barriers to entry = more customers
More surgeries = more consumables
It can attack when advancing and defend when retreating—either way, it wins
#股票财报季
Eric SJ
·
--
Intuitive Surgical is voluntarily cutting prices—what’s the strategy?
A company that gets nearly 60% of its revenue from surgical instruments and consumables is actually preparing to voluntarily reduce the consumables revenue it earns per procedure.
This is what Intuitive Surgical $ISRG.US disclosed during its latest earnings call.
According to management:
“Once the next round of instrument pricing adjustments and policy-driven price reductions in China have been fully implemented, revenue from instruments and accessories per da Vinci (our flagship product) procedure is expected to decline by approximately 3%–5%, assuming the mix of procedures, geographies, and products remains unchanged.”
If you understand Intuitive Surgical’s business model, you’ll know that its most profitable business isn’t simply selling robots to hospitals. The bulk of its profits comes from the services and consumables that follow.
6
1.8k
·
--
Bitcoin $BTC can't fall any further
If you don't cash in your short today,
you'll have to take out a nude loan tomorrow.
Bitcoin $BTC can't fall any further
If you don't cash in your short today,
you'll have to take out a nude loan tomorrow.
If you don't cash in your short today,
you'll have to take out a nude loan tomorrow.
6
8
1.6k
·
--
Verified
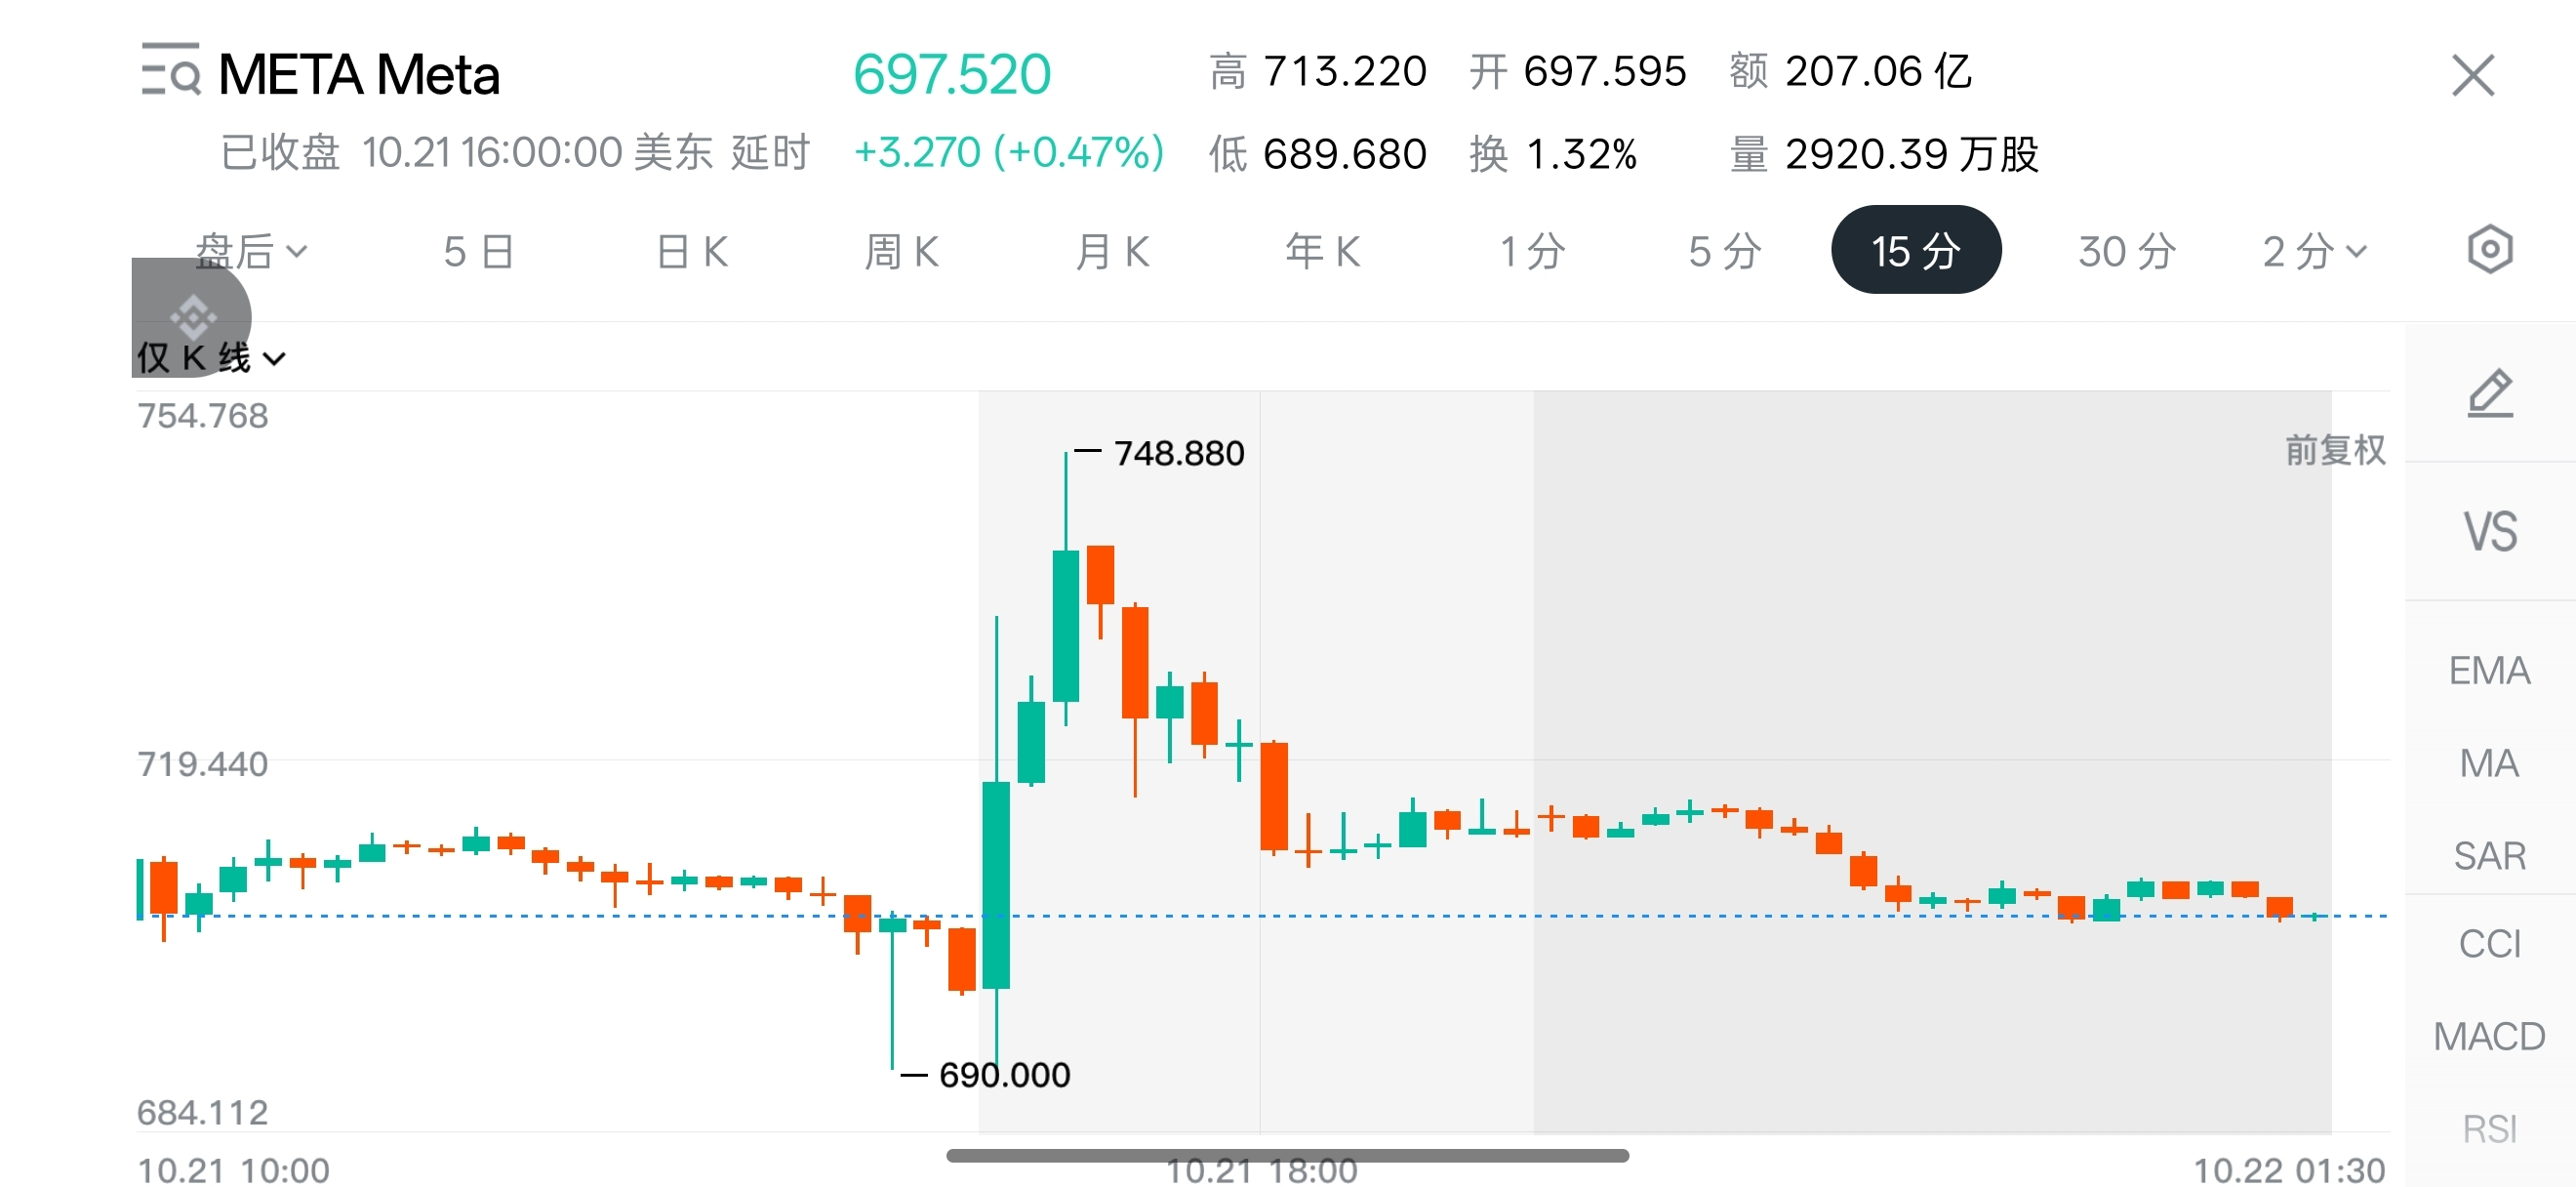
At this point, the gains after $META 's earnings are almost completely wiped out
A quick aside
The market is no longer as bullish on AI as it was before; attention is shifting back to tech stocks themselves
Most other tech giants have a clear, easy-to-understand core business, but Meta's is rather vague
The last time Meta's story felt “sexy” to me was when it changed its name. Unfortunately, the metaverse has yet to prove itself (or perhaps it was simply too far ahead of its time)
Since then, it has made bets in several areas, including virtual reality, AI glasses, large language models, and AI agents
But so far, none of them have really taken off
The vast majority of Meta's revenue today comes from advertising
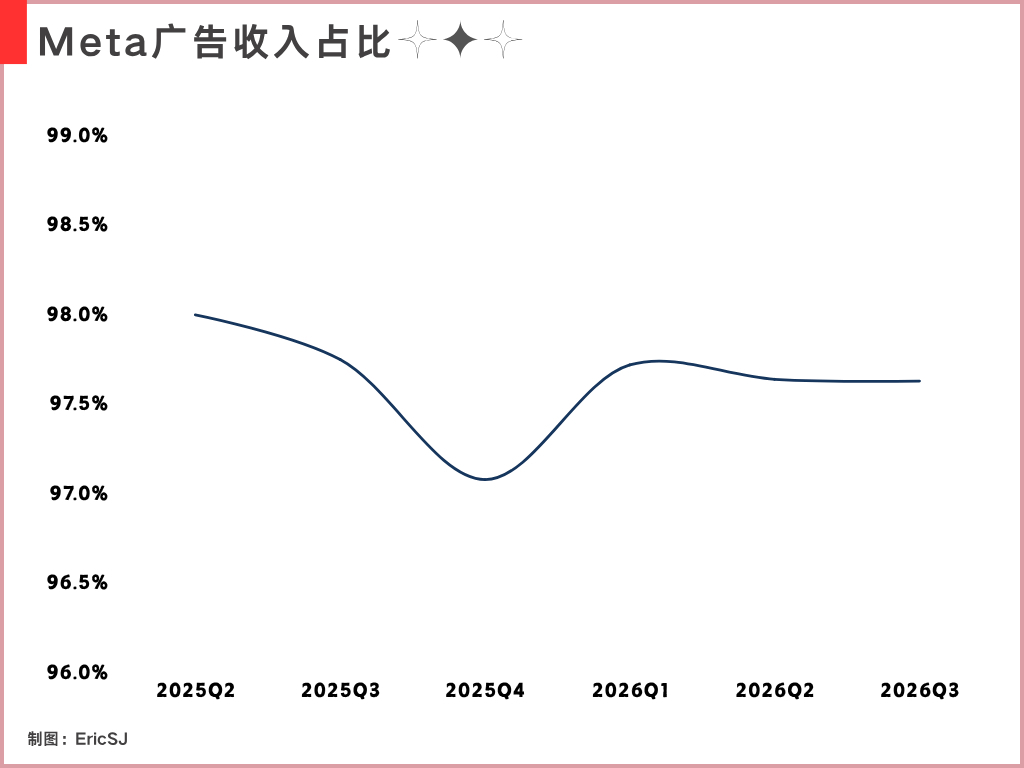
This was especially clear in its recently released Q3 earnings report: advertising accounted for nearly 98% of Meta's total revenue
Looking at Meta's revenue mix over the past six quarters, this share has barely fluctuated. In Q3, it fell by just 0.12 percentage points
Although Google earns more from advertising, Meta is undoubtedly more reliant on this business and is therefore more vulnerable to platform rules (in its annual report last year, it explicitly listed its reliance on third-party platforms such as Android and iOS as a significant business risk)
Perhaps it's also because Meta's products just don't really resonate with me compared with those of other tech giants
So in my eyes, although it's a very profitable advertising company, Meta still feels like the most ordinary of the major tech giants
#股票财报季
32
24.3k
·
--
Verified
Article
Intuitive Surgical is voluntarily cutting prices—what’s the strategy?A company that gets nearly 60% of its revenue from surgical instruments and consumables is actually preparing to voluntarily reduce the consumables revenue it earns per procedure.
This is what Intuitive Surgical $ISRG.US disclosed during its latest earnings call.
According to management:
“Once the next round of instrument pricing adjustments and policy-driven price reductions in China have been fully implemented, revenue from instruments and accessories per da Vinci (our flagship product) procedure is expected to decline by approximately 3%–5%, assuming the mix of procedures, geographies, and products remains unchanged.”
If you understand Intuitive Surgical’s business model, you’ll know that its most profitable business isn’t simply selling robots to hospitals. The bulk of its profits comes from the services and consumables that follow.
Intuitive Surgical is voluntarily cutting prices—what’s the strategy?
A company that gets nearly 60% of its revenue from surgical instruments and consumables is actually preparing to voluntarily reduce the consumables revenue it earns per procedure.
This is what Intuitive Surgical $ISRG.US disclosed during its latest earnings call.
According to management:
“Once the next round of instrument pricing adjustments and policy-driven price reductions in China have been fully implemented, revenue from instruments and accessories per da Vinci (our flagship product) procedure is expected to decline by approximately 3%–5%, assuming the mix of procedures, geographies, and products remains unchanged.”
If you understand Intuitive Surgical’s business model, you’ll know that its most profitable business isn’t simply selling robots to hospitals. The bulk of its profits comes from the services and consumables that follow.
This is what Intuitive Surgical $ISRG.US disclosed during its latest earnings call.
According to management:
“Once the next round of instrument pricing adjustments and policy-driven price reductions in China have been fully implemented, revenue from instruments and accessories per da Vinci (our flagship product) procedure is expected to decline by approximately 3%–5%, assuming the mix of procedures, geographies, and products remains unchanged.”
If you understand Intuitive Surgical’s business model, you’ll know that its most profitable business isn’t simply selling robots to hospitals. The bulk of its profits comes from the services and consumables that follow.
1
2
2.2k
·
--
Recently, 𝕏 has been acting weird.
Blue-check subscriptions are taking a long time to get approved.
They used to show up within an hour.
So now, when I see projects on-chain whose Twitter accounts don't have a subscription checkmark, I wait and watch for a while first.
That’s saved me quite a bit of money lately.
Blue-check subscriptions are taking a long time to get approved.
They used to show up within an hour.
So now, when I see projects on-chain whose Twitter accounts don't have a subscription checkmark, I wait and watch for a while first.
That’s saved me quite a bit of money lately.
1
4
1.5k
·
--
Verified
Boss, is looking at financial reports really useful at this stage when we’re buying $SPCX ?
{future}(SPCXUSDT)
I’ve seen a lot of people discussing its latest financial report, especially the fact that revenue from its AI business surged 830% year over year.
To be sure, by its second earnings report after going public, SpaceX had already turned profitable.
The numbers are certainly impressive.
But at least at this stage, I don’t think SpaceX’s investment value has much to do with how much it earns in any given quarter.
There are plenty of companies on the market that make more money and have higher profit margins.
Why is the market willing to give SpaceX such a high valuation?
So we should focus more on whether the reasons underpinning the company’s high valuation have actually been validated.
SpaceX already has several businesses generating real revenue,
to the point that many people have lost sight of its original core narrative.
In a nutshell, the question is whether SpaceX, under Musk’s leadership, can reduce the cost of reaching space enough to give rise to a whole range of new commercial markets.
If you’re going to follow the business, Starship is actually the area that most needs to be tracked over the long term in its financial reports.
Whether it’s expanding the Starlink network or deploying AI data centers in space, a lot of equipment needs to be sent into orbit.
If every launch comes at a high cost, the scale of these businesses will be limited.
Getting something into space and being able to do it repeatedly, at a sufficiently low cost and high frequency, are two entirely different things.
That’s the key to the [space infrastructure operator] narrative.
➠ In late September, Starship completed its first orbital flight, deploying 26 V3 Starlink satellites in a single launch.
Starship hasn’t yet reached the point where it can validate the core narrative; it has only demonstrated that it can reliably deliver actual commercial payloads.
Musk also said on the earnings call that the next Starship test flight would attempt to successfully recover both the rocket’s first-stage booster and its second-stage spacecraft.
So, looking again at the growth in the AI business reported this time,
it shows that SpaceX can make money from the AI market, but it has little to do with the main story of space transportation.
In fact, this is precisely what I think we should be most careful not to conflate.
#股票财报季
Boss, is looking at financial reports really useful at this stage when we’re buying $SPCX ?
I’ve seen a lot of people discussing its latest financial report, especially the fact that revenue from its AI business surged 830% year over year.
To be sure, by its second earnings report after going public, SpaceX had already turned profitable.
The numbers are certainly impressive.
But at least at this stage, I don’t think SpaceX’s investment value has much to do with how much it earns in any given quarter.
There are plenty of companies on the market that make more money and have higher profit margins.
Why is the market willing to give SpaceX such a high valuation?
So we should focus more on whether the reasons underpinning the company’s high valuation have actually been validated.
SpaceX already has several businesses generating real revenue,
to the point that many people have lost sight of its original core narrative.
In a nutshell, the question is whether SpaceX, under Musk’s leadership, can reduce the cost of reaching space enough to give rise to a whole range of new commercial markets.
If you’re going to follow the business, Starship is actually the area that most needs to be tracked over the long term in its financial reports.
Whether it’s expanding the Starlink network or deploying AI data centers in space, a lot of equipment needs to be sent into orbit.
If every launch comes at a high cost, the scale of these businesses will be limited.
Getting something into space and being able to do it repeatedly, at a sufficiently low cost and high frequency, are two entirely different things.
That’s the key to the [space infrastructure operator] narrative.
➠ In late September, Starship completed its first orbital flight, deploying 26 V3 Starlink satellites in a single launch.
Starship hasn’t yet reached the point where it can validate the core narrative; it has only demonstrated that it can reliably deliver actual commercial payloads.
Musk also said on the earnings call that the next Starship test flight would attempt to successfully recover both the rocket’s first-stage booster and its second-stage spacecraft.
So, looking again at the growth in the AI business reported this time,
it shows that SpaceX can make money from the AI market, but it has little to do with the main story of space transportation.
In fact, this is precisely what I think we should be most careful not to conflate.
#股票财报季
2
17
25.8k
·
--
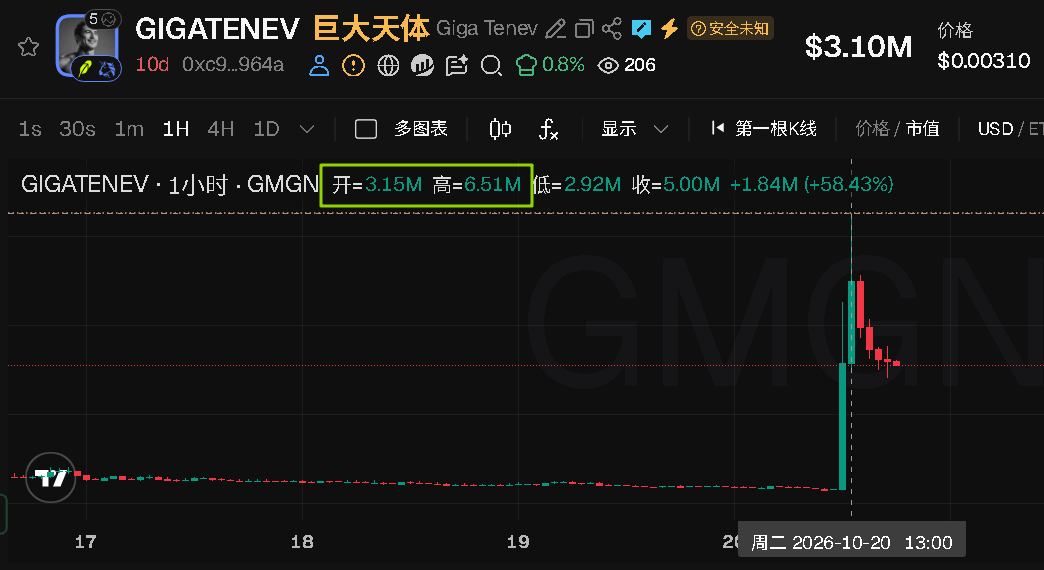
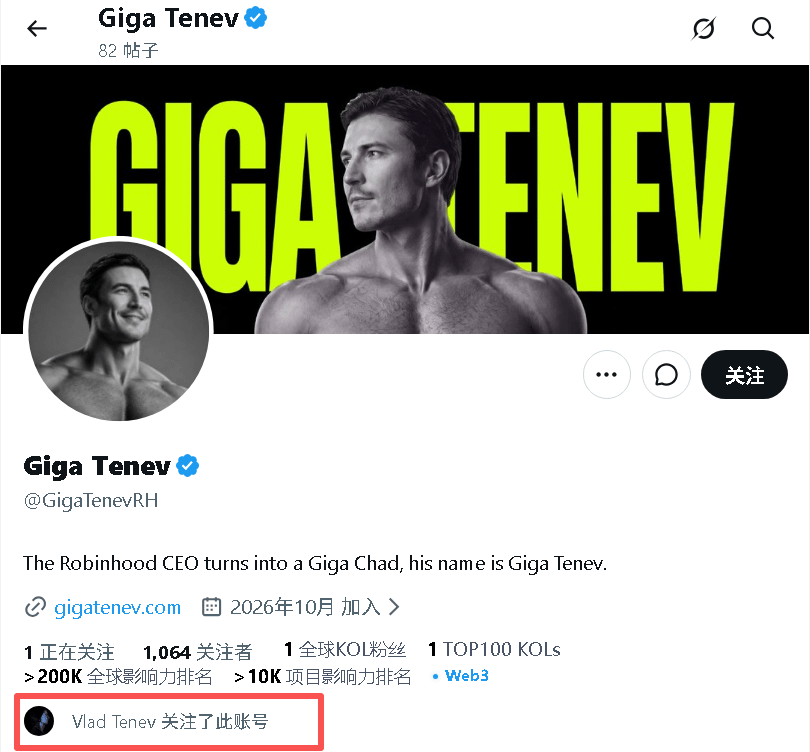
RH chain @vladtenev — one follow, whether it was intentional or just a fat-finger.
And just like that, it went from 300k to 6.5M.
So,
Robinhood can’t possibly do nothing in the final quarter of this year, right?
$PONS has really got me bagholding to the point where I can barely take it anymore.
“Waiting for the storm”
And just like that, it went from 300k to 6.5M.
So,
Robinhood can’t possibly do nothing in the final quarter of this year, right?
$PONS has really got me bagholding to the point where I can barely take it anymore.
“Waiting for the storm”
5
4.6k
·
--
Verified
Musk will be handing out tens of billions of dollars next year???
Interesting.
SpaceX is releasing its financial results tomorrow.
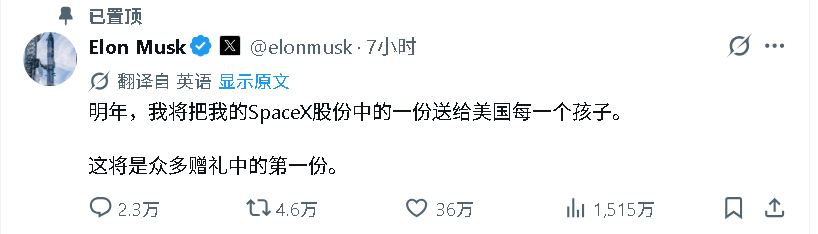
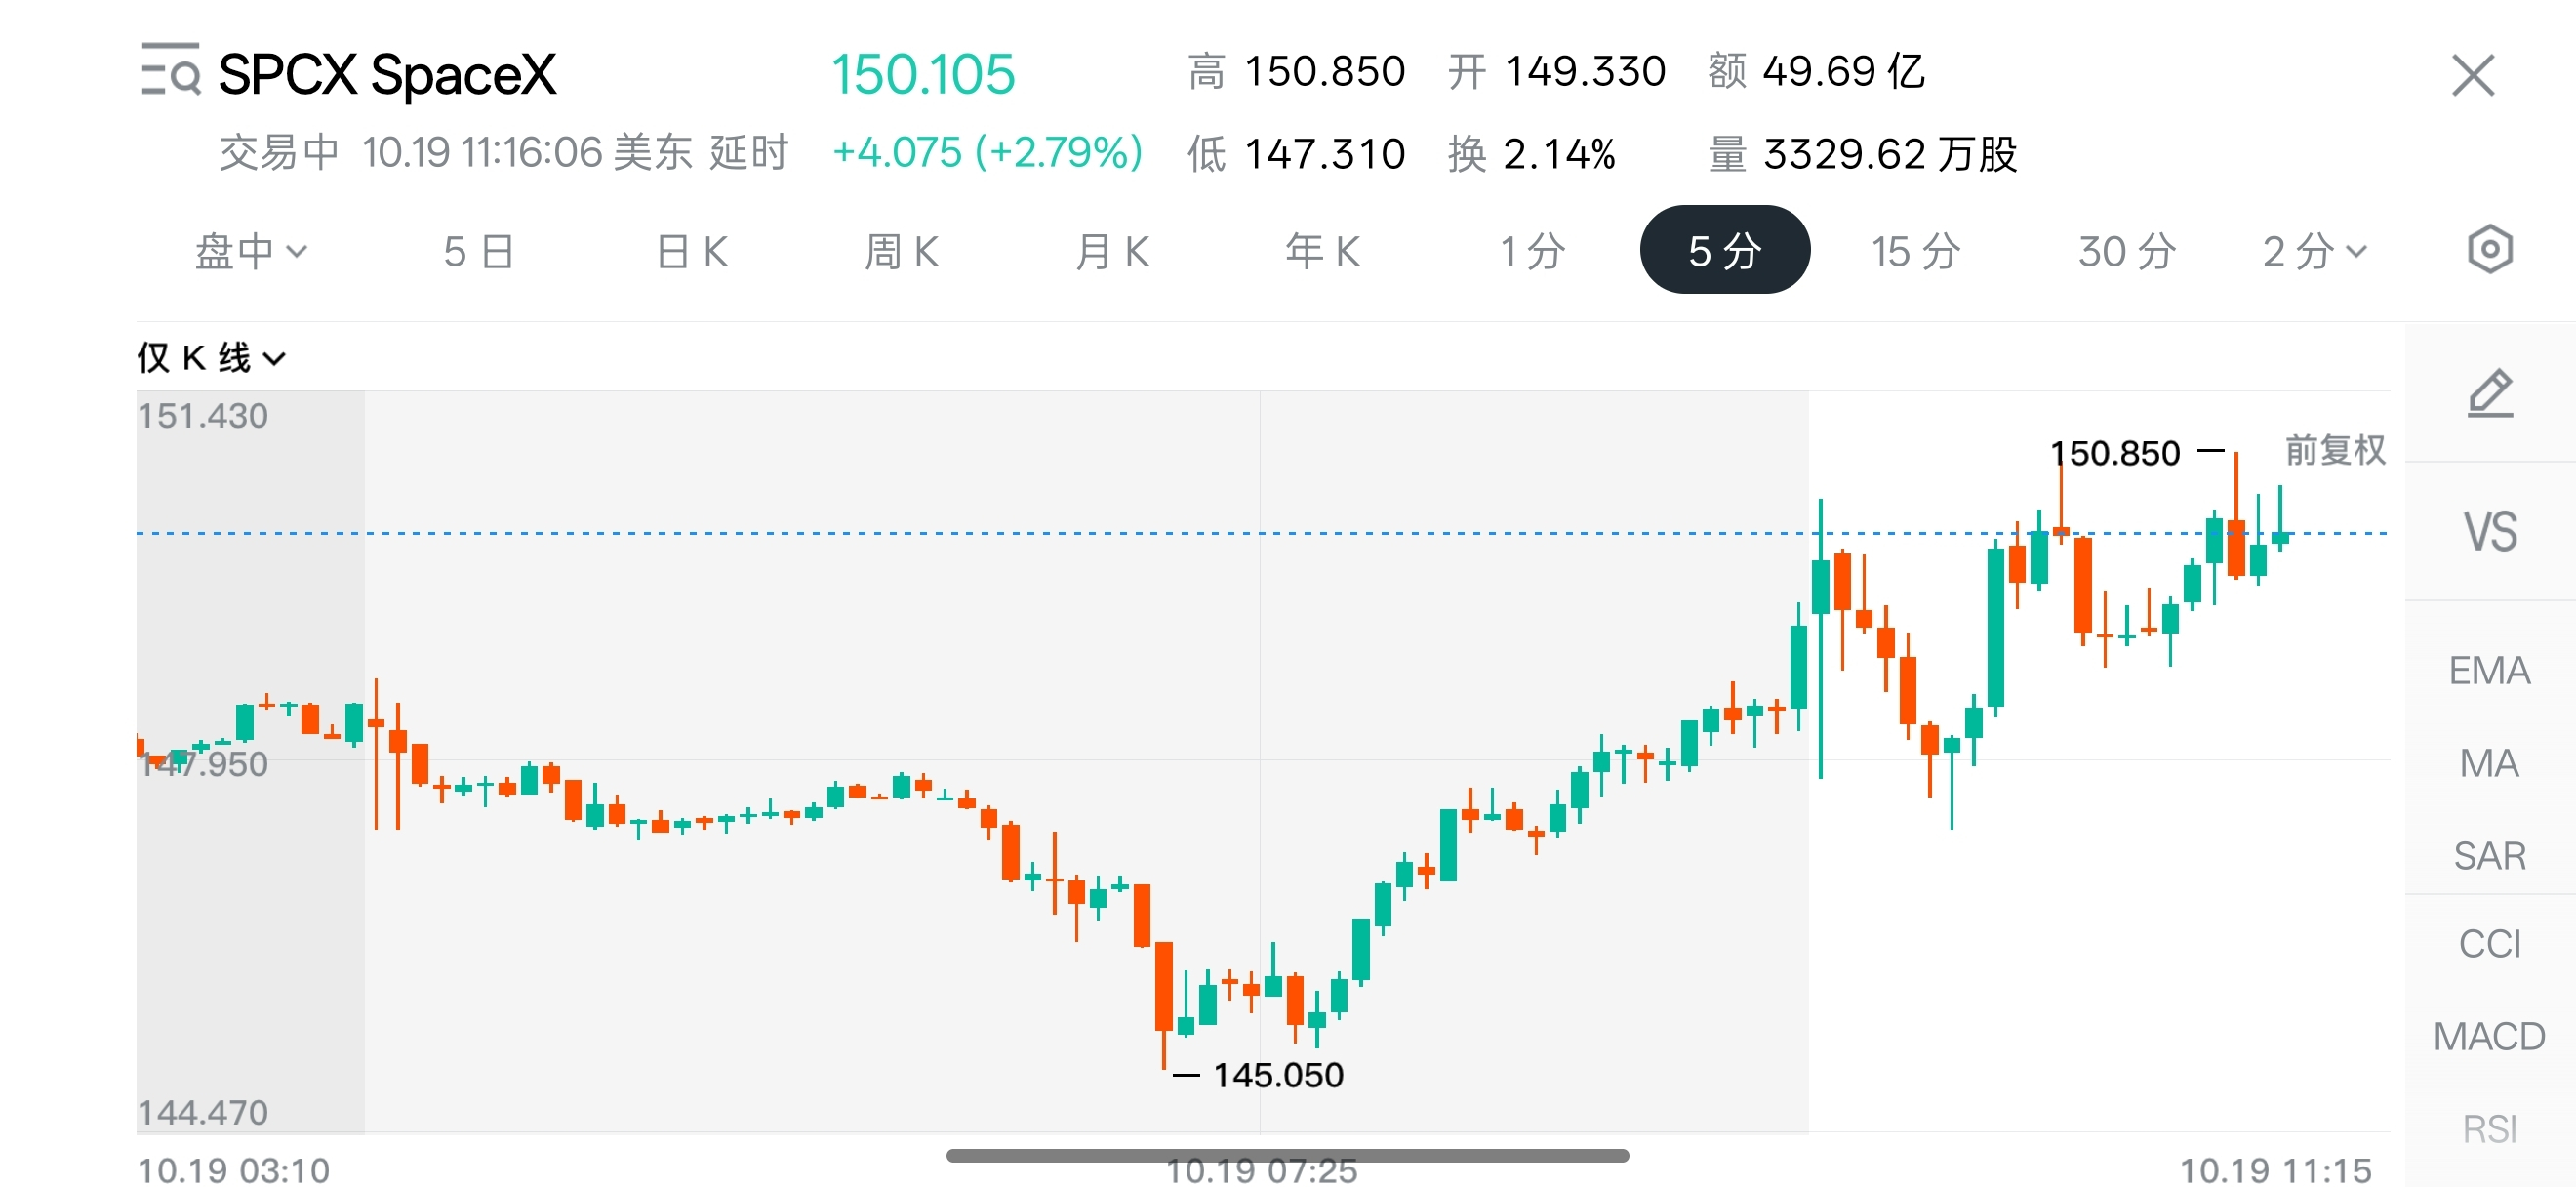
At this point, Musk announced that next year he’ll collectively airdrop one share of $SPCX to American children (possibly meaning anyone under 18?). What does this mean?
It’s estimated that there are about 72 million U.S. residents under the age of 18.
At the current price, the shares being distributed are worth over $10 billion.
It looks like a giveaway, but really it’s telling the market, “Guys, next year I’m effectively locking up some of my $SPCX shares.”
➠ (New rules announced by the U.S. Treasury on September 30, 2026, allow eligible stocks to be donated directly into children’s investment accounts, subject to a specific minimum holding period.)
I used AI to look up these rules. For eligible stocks contributed directly to these accounts, the minimum holding period lasts until whichever of these two dates comes first:
(1) Five years after the stock enters the account
(2) The account holder turns 18
Thanks to this news, SPCX is temporarily trending upward today.
However, based on Musk’s personal ownership stake, even if the shares are distributed to 72 million people, it would amount to less than 2% of his personal holdings.
So, looking at it purely from a trading perspective, I don’t think this is a lockup measure substantial enough to noticeably drive up SpaceX’s share price.
But because the airdrop is so broad, it will also greatly expand SpaceX’s long-term influence among ordinary American families.
Could think of it as spending tens of billions on a long-term brand-awareness campaign???
{future}(SPCXUSDT)
Musk will be handing out tens of billions of dollars next year???
Interesting.
SpaceX is releasing its financial results tomorrow.
At this point, Musk announced that next year he’ll collectively airdrop one share of $SPCX to American children (possibly meaning anyone under 18?). What does this mean?
It’s estimated that there are about 72 million U.S. residents under the age of 18.
At the current price, the shares being distributed are worth over $10 billion.
It looks like a giveaway, but really it’s telling the market, “Guys, next year I’m effectively locking up some of my $SPCX shares.”
➠ (New rules announced by the U.S. Treasury on September 30, 2026, allow eligible stocks to be donated directly into children’s investment accounts, subject to a specific minimum holding period.)
I used AI to look up these rules. For eligible stocks contributed directly to these accounts, the minimum holding period lasts until whichever of these two dates comes first:
(1) Five years after the stock enters the account
(2) The account holder turns 18
Thanks to this news, SPCX is temporarily trending upward today.
However, based on Musk’s personal ownership stake, even if the shares are distributed to 72 million people, it would amount to less than 2% of his personal holdings.
So, looking at it purely from a trading perspective, I don’t think this is a lockup measure substantial enough to noticeably drive up SpaceX’s share price.
But because the airdrop is so broad, it will also greatly expand SpaceX’s long-term influence among ordinary American families.
Could think of it as spending tens of billions on a long-term brand-awareness campaign???
1
2.8k
·
--
$币安人生 What the hell is going on?
I just saw a top female influencer retweet CZ's post about the Japanese version of Binance Life going on sale.
That was already 8 hours ago.
Got curious and checked the price action.
tm
Not moving at all?
Has liquidity dried up, or is the market maker trapped too?
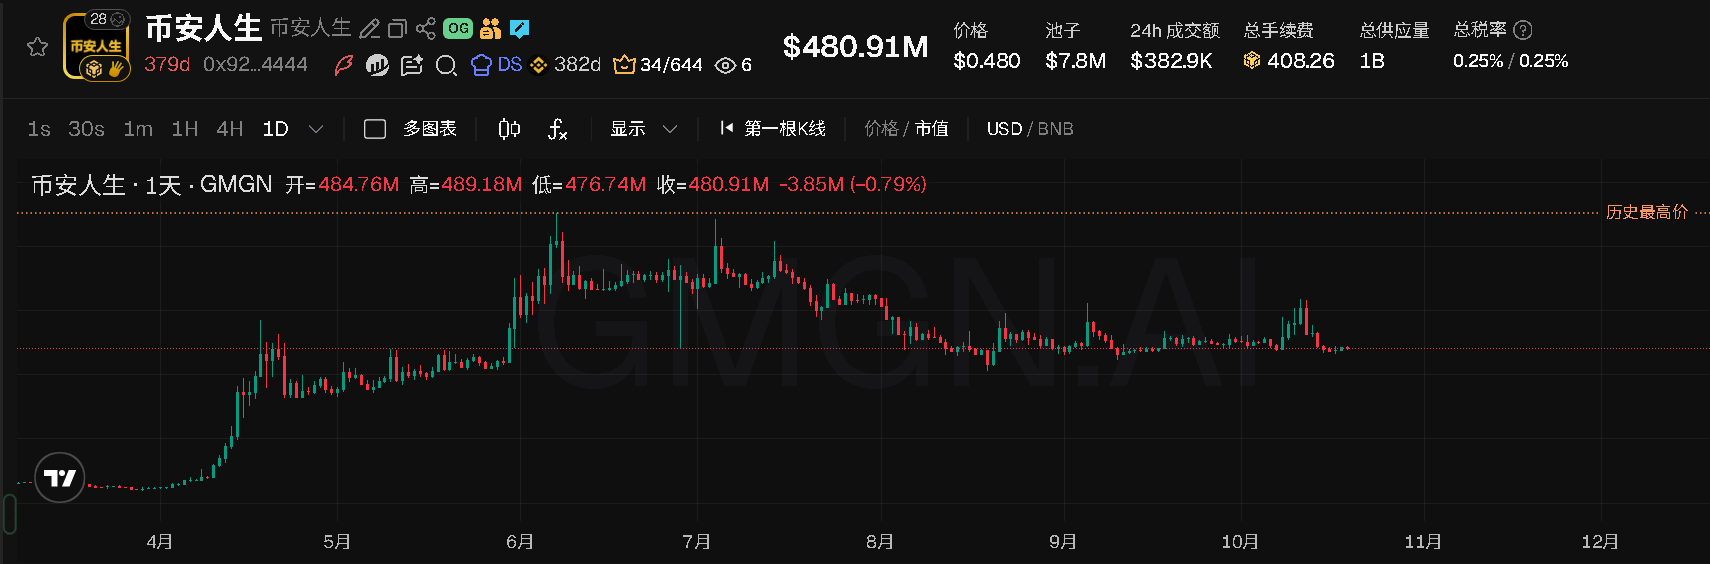
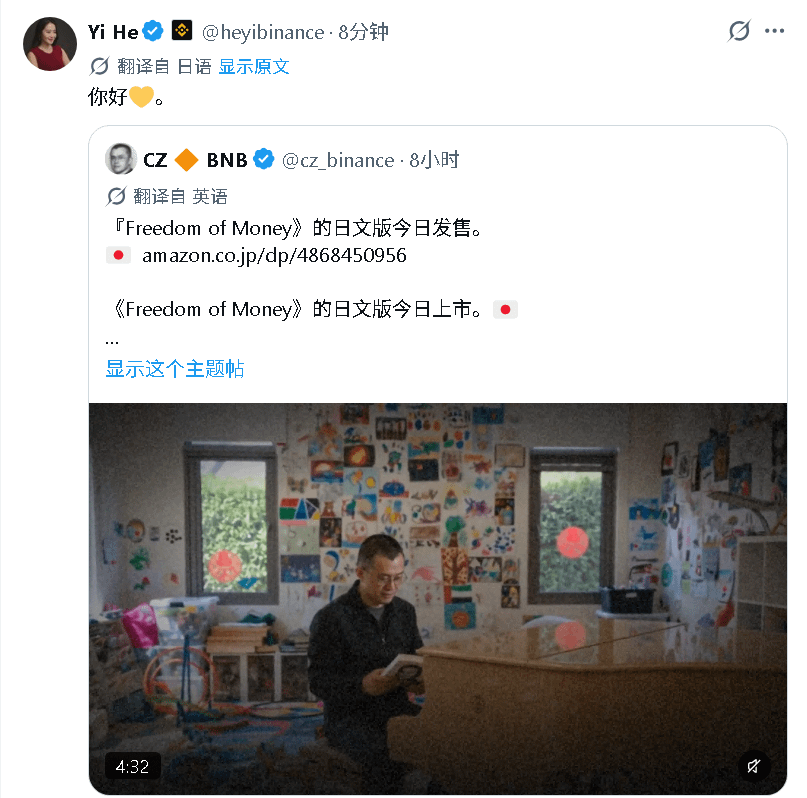
$币安人生 What the hell is going on?
I just saw a top female influencer retweet CZ's post about the Japanese version of Binance Life going on sale.
That was already 8 hours ago.
Got curious and checked the price action.
tm
Not moving at all?
Has liquidity dried up, or is the market maker trapped too?
I just saw a top female influencer retweet CZ's post about the Japanese version of Binance Life going on sale.
That was already 8 hours ago.
Got curious and checked the price action.
tm
Not moving at all?
Has liquidity dried up, or is the market maker trapped too?
3
1
11.8k
·
--
Partly True
Article
What are this week’s earnings reports from the four largest U.S. banks telling us?The four largest U.S. banks together added about $6.852 billion in revenue in the third quarter, but their net interest income increased by $6.895 billion.
In other words, nearly all of the four banks’ combined revenue growth came from net interest income.
So here’s the question:
Other businesses that were still growing in the first half of the year—why did they suddenly lose momentum in the third quarter?
First, let’s explain what net interest income is:
Banks take in customer deposits and use the funds to invest in interest-earning assets, such as bonds and loans. The interest these assets and products generate, minus the interest banks pay to depositors and other providers of funds, is net interest income.
What are this week’s earnings reports from the four largest U.S. banks telling us?
The four largest U.S. banks together added about $6.852 billion in revenue in the third quarter, but their net interest income increased by $6.895 billion.
In other words, nearly all of the four banks’ combined revenue growth came from net interest income.
So here’s the question:
Other businesses that were still growing in the first half of the year—why did they suddenly lose momentum in the third quarter?
First, let’s explain what net interest income is:
Banks take in customer deposits and use the funds to invest in interest-earning assets, such as bonds and loans. The interest these assets and products generate, minus the interest banks pay to depositors and other providers of funds, is net interest income.
4
3.4k
·
--
Charlie Munger once said: Go fishing where the fish are.
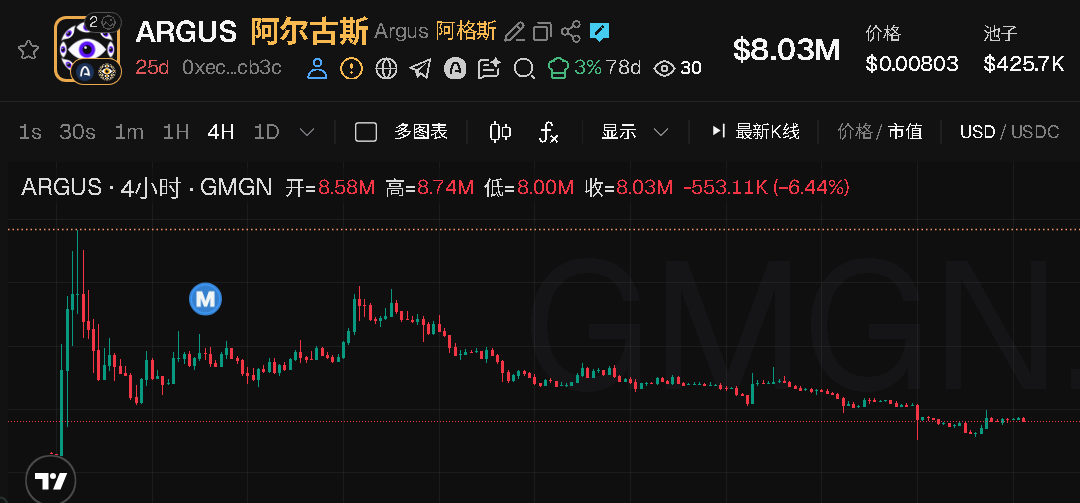
It’s been exactly one month since ARC launched.
Longyi $ARGUS isn’t even at 10M yet, and a few days ago it almost fell below 5M.
If you’re still paying too much attention to ARC right now,
then I don’t want to talk to you!
Charlie Munger once said: Go fishing where the fish are.
It’s been exactly one month since ARC launched.
Longyi $ARGUS isn’t even at 10M yet, and a few days ago it almost fell below 5M.
If you’re still paying too much attention to ARC right now,
then I don’t want to talk to you!
It’s been exactly one month since ARC launched.
Longyi $ARGUS isn’t even at 10M yet, and a few days ago it almost fell below 5M.
If you’re still paying too much attention to ARC right now,
then I don’t want to talk to you!
1
2
2.4k
·
--
Verified
However, TSMC's $TSM HPC growth has been rapid for some time; this is not a new development that began in the third quarter.
In each of the first two quarters, HPC grew by at least 20% quarter over quarter. What makes this especially impressive is that it has continued to grow by around 20% per quarter even as it has come to account for nearly 70% of total revenue.
Is HPC contributing such a large share of incremental revenue because TSMC is selling more wafers, or because these orders generate more revenue to begin with?
Considering the gap between wafer shipment growth and revenue growth discussed earlier, I’m inclined to think the latter is playing an increasingly important role in this growth cycle.
The revenue mix of advanced process nodes this quarter also offers some supporting evidence.
For example, wafers made using the 2nm process accounted for just 3% of revenue last quarter, but that share rose to 8% this quarter. The share for 3nm also increased, from 30% to 33%.
Together, the two now account for 41% of wafer revenue, up 8 percentage points from last quarter.
Looking at the data from the past few quarters, one possible interpretation is that TSMC may no longer need wafer shipments to grow at the same rate in order to generate higher revenue.
Growth is highly concentrated in high-performance computing and related demand for advanced manufacturing.
And because advanced manufacturing demand is the main driver of growth, TSMC's results alone cannot be taken as proof that the semiconductor industry as a whole is recovering in tandem.
That is also why many market observers say the semiconductor industry has yet to recover.
After all, for manufacturers that mainly produce chips using mature process nodes, customer demand and market conditions may be an entirely different story.
{future}(TSMUSDT)
However, TSMC's $TSM HPC growth has been rapid for some time; this is not a new development that began in the third quarter.
In each of the first two quarters, HPC grew by at least 20% quarter over quarter. What makes this especially impressive is that it has continued to grow by around 20% per quarter even as it has come to account for nearly 70% of total revenue.
Is HPC contributing such a large share of incremental revenue because TSMC is selling more wafers, or because these orders generate more revenue to begin with?
Considering the gap between wafer shipment growth and revenue growth discussed earlier, I’m inclined to think the latter is playing an increasingly important role in this growth cycle.
The revenue mix of advanced process nodes this quarter also offers some supporting evidence.
For example, wafers made using the 2nm process accounted for just 3% of revenue last quarter, but that share rose to 8% this quarter. The share for 3nm also increased, from 30% to 33%.
Together, the two now account for 41% of wafer revenue, up 8 percentage points from last quarter.
Looking at the data from the past few quarters, one possible interpretation is that TSMC may no longer need wafer shipments to grow at the same rate in order to generate higher revenue.
Growth is highly concentrated in high-performance computing and related demand for advanced manufacturing.
And because advanced manufacturing demand is the main driver of growth, TSMC's results alone cannot be taken as proof that the semiconductor industry as a whole is recovering in tandem.
That is also why many market observers say the semiconductor industry has yet to recover.
After all, for manufacturers that mainly produce chips using mature process nodes, customer demand and market conditions may be an entirely different story.
Eric SJ
·
--
TSMC's latest earnings data is out
$TSM
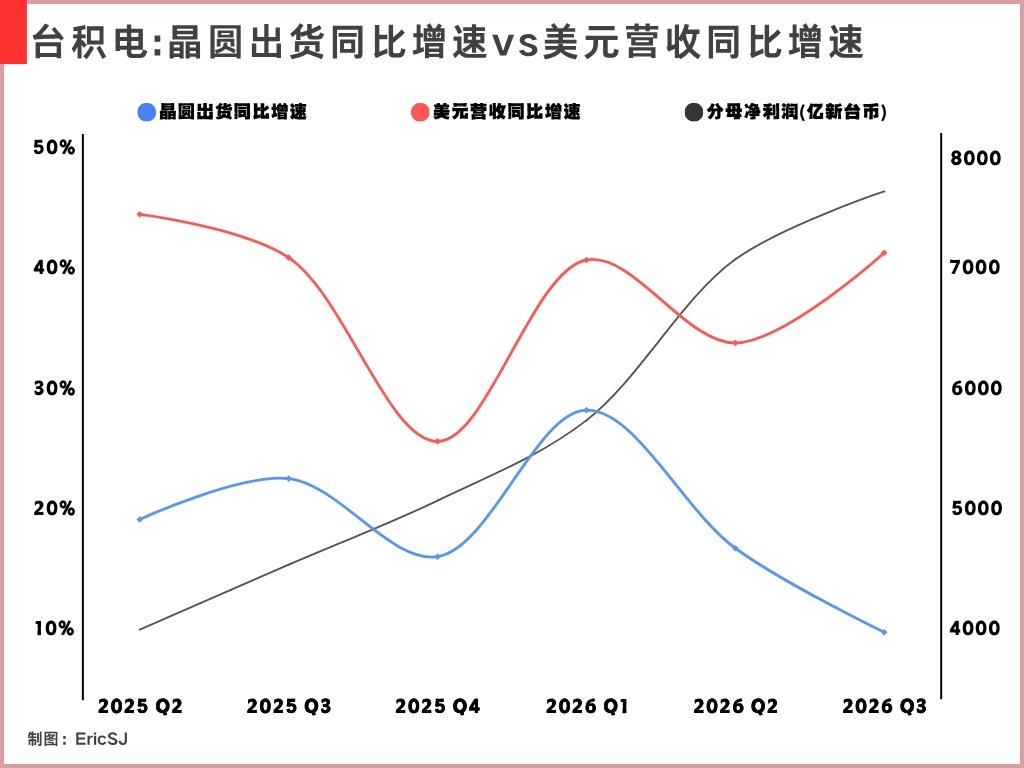
Net profit has hit a new record for six consecutive quarters
But
we can see that in the third quarter, TSMC's wafer shipments grew just 9.6% year over year—the lowest level in these six quarters
The figures that contrast with this are not only net profit, but also revenue growth
As shown in my chart, the red and blue lines have moved almost in tandem over the past few quarters. This quarter, however, they diverged far more sharply than in recent quarters
(1) Year-over-year wafer shipment growth slowed further, from 16.6% to 9.6%, while revenue growth in U.S. dollars rose from 33.7% to 41.2%
(2) The gap between them was 31.6 percentage points—the widest divergence in the past six quarters
If this were simply a broad recovery in the semiconductor industry, bringing in more chip orders,
we would expect to see wafer shipment volumes rise in tandem
But revenue is now growing far faster than shipment volumes. This suggests that simply shipping more wafers is not enough to explain this growth, nor does it support the conclusion that the semiconductor industry is broadly recovering
A more likely explanation is a shift in the mix of products customers are buying
So, what type of customer is driving this shift?
The answer is high-performance computing (HPC)
HPC is a business category TSMC defines by end application. It includes AI accelerators, server processors, and other chips related to high-performance computing
These chips typically have demanding performance, power consumption, and manufacturing requirements. Many products require advanced process nodes, and some also need complex advanced packaging
In the same quarter last year, HPC accounted for 57% of TSMC's total revenue. In its latest earnings data, that figure had risen to 68%
Based on a rough estimate using quarterly revenue and business mix, HPC revenue grew approximately 80% year over year in the third quarter
Even more strikingly, HPC growth can explain nearly 90% of TSMC's year-over-year revenue increase this quarter
In other words, other businesses are certainly generating revenue too, but the growth driving TSMC is now heavily concentrated in orders related to high-performance computing
This also explains why TSMC's revenue and wafer shipment volumes are becoming increasingly out of proportion
1.3k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BinanceSAFUFundTransferCompleted7499BTC
22,418 views
610 Discussing
Binance Says SAFU Fund Transfer Completed, Covering 7,499 BTC
Binance News
·27 Likes
·12.9k views
BinanceRecovery90% of stolen assets
94,303 views
147 Discussing
YiHe:ProofOfReserves:10TokensAt100%Backing
107,618 views
635 Discussing