
#googlestock
googlestock
1,114 views
8 Discussing
Hot
Latest
·
--
Article
Why I’m not worried about Alphabet’s drop (and what I’m watching instead)Alphabet ($GOOGLB ) is down hard, and my timeline is full of people calling it broken. I don’t see it that way. If you plan to hold for years, this looks more like an opening than a warning.
Start with the monthly chart. Alphabet ran from about $141 to a high near $407, one of the strongest moves in Big Tech. A pullback after a run like that is normal. Price has now come back to roughly $279, almost exactly the 50% retracement of the whole move at $274. That’s the line between “premium” and “discount” territory, and it’s the area where long-term buyers have historically started paying attention.
If selling continues, the next level to watch is the 61.8% retracement near $243. There’s also a bullish fair value gap sitting in that zone, an area where price moved up so fast it left little trading behind. Price often returns to fill gaps like that before continuing higher. I’m not saying it will go there. I’m saying that’s where I’d expect buyers to show up if it does.
Some traders think big institutions push price down on purpose to build positions at better prices before the next leg up. I can’t prove that, and nobody outside those desks can. What I can say is that sharp drops on bad headlines are when large buyers tend to get the best entries, and when retail tends to sell.
The headlines aren’t pretty. Earnings missed on profit, Search growth slowed, and free cash flow went negative because of heavy AI spending. But Cloud revenue more than doubled, and the spending is building capacity the company expects to use for years. A business that still grew revenue 25% is not a broken business.
I’d rather buy something good while people are scared than chase it after the recovery. If you’re investing for five or ten years, the daily noise matters a lot less than the price you pay. Scaling in across the 50% to 61.8% zone beats betting everything at one level.
None of this is a guarantee. Fibonacci levels are guides, not floors, and price can slice through them. The AI spending bet could take longer to pay off than investors will tolerate. Size your position so a further drop doesn’t force you to sell.
Found this helpful? 👍 Like it, 🔁 share it, and ➕ follow so you don’t miss the next one.
$GOOGLB #LongTermGain #Googlestock #TrendingTopic
Why I’m not worried about Alphabet’s drop (and what I’m watching instead)
Alphabet ($GOOGLB ) is down hard, and my timeline is full of people calling it broken. I don’t see it that way. If you plan to hold for years, this looks more like an opening than a warning.
Start with the monthly chart. Alphabet ran from about $141 to a high near $407, one of the strongest moves in Big Tech. A pullback after a run like that is normal. Price has now come back to roughly $279, almost exactly the 50% retracement of the whole move at $274. That’s the line between “premium” and “discount” territory, and it’s the area where long-term buyers have historically started paying attention.
If selling continues, the next level to watch is the 61.8% retracement near $243. There’s also a bullish fair value gap sitting in that zone, an area where price moved up so fast it left little trading behind. Price often returns to fill gaps like that before continuing higher. I’m not saying it will go there. I’m saying that’s where I’d expect buyers to show up if it does.
Some traders think big institutions push price down on purpose to build positions at better prices before the next leg up. I can’t prove that, and nobody outside those desks can. What I can say is that sharp drops on bad headlines are when large buyers tend to get the best entries, and when retail tends to sell.
The headlines aren’t pretty. Earnings missed on profit, Search growth slowed, and free cash flow went negative because of heavy AI spending. But Cloud revenue more than doubled, and the spending is building capacity the company expects to use for years. A business that still grew revenue 25% is not a broken business.
I’d rather buy something good while people are scared than chase it after the recovery. If you’re investing for five or ten years, the daily noise matters a lot less than the price you pay. Scaling in across the 50% to 61.8% zone beats betting everything at one level.
None of this is a guarantee. Fibonacci levels are guides, not floors, and price can slice through them. The AI spending bet could take longer to pay off than investors will tolerate. Size your position so a further drop doesn’t force you to sell.
Found this helpful? 👍 Like it, 🔁 share it, and ➕ follow so you don’t miss the next one.
$GOOGLB #LongTermGain #Googlestock #TrendingTopic
Start with the monthly chart. Alphabet ran from about $141 to a high near $407, one of the strongest moves in Big Tech. A pullback after a run like that is normal. Price has now come back to roughly $279, almost exactly the 50% retracement of the whole move at $274. That’s the line between “premium” and “discount” territory, and it’s the area where long-term buyers have historically started paying attention.
If selling continues, the next level to watch is the 61.8% retracement near $243. There’s also a bullish fair value gap sitting in that zone, an area where price moved up so fast it left little trading behind. Price often returns to fill gaps like that before continuing higher. I’m not saying it will go there. I’m saying that’s where I’d expect buyers to show up if it does.
Some traders think big institutions push price down on purpose to build positions at better prices before the next leg up. I can’t prove that, and nobody outside those desks can. What I can say is that sharp drops on bad headlines are when large buyers tend to get the best entries, and when retail tends to sell.
The headlines aren’t pretty. Earnings missed on profit, Search growth slowed, and free cash flow went negative because of heavy AI spending. But Cloud revenue more than doubled, and the spending is building capacity the company expects to use for years. A business that still grew revenue 25% is not a broken business.
I’d rather buy something good while people are scared than chase it after the recovery. If you’re investing for five or ten years, the daily noise matters a lot less than the price you pay. Scaling in across the 50% to 61.8% zone beats betting everything at one level.
None of this is a guarantee. Fibonacci levels are guides, not floors, and price can slice through them. The AI spending bet could take longer to pay off than investors will tolerate. Size your position so a further drop doesn’t force you to sell.
Found this helpful? 👍 Like it, 🔁 share it, and ➕ follow so you don’t miss the next one.
$GOOGLB #LongTermGain #Googlestock #TrendingTopic
1
431
·
--
Bullish
Verified
#Alphabet ($GOOGL /$GOOG.US ) q3 2026 earnings announcement is scheduled to be published as following :
1. Report Date: 28 October 2026
2. Results Coverage: July-September 2026
3. Earnings Call: 4:30 PM US Eastern
Watch out #GoogleStock and position yourself accordingly. Sentiment is bullish till now.
{future}(GOOGLUSDT)
{stock_us}(GOOGL.US)
#BinancePick
#EarningsSeason
#Alphabet ($GOOGL /$GOOG.US ) q3 2026 earnings announcement is scheduled to be published as following :
1. Report Date: 28 October 2026
2. Results Coverage: July-September 2026
3. Earnings Call: 4:30 PM US Eastern
Watch out #GoogleStock and position yourself accordingly. Sentiment is bullish till now.
#BinancePick
#EarningsSeason
1. Report Date: 28 October 2026
2. Results Coverage: July-September 2026
3. Earnings Call: 4:30 PM US Eastern
Watch out #GoogleStock and position yourself accordingly. Sentiment is bullish till now.
#BinancePick
#EarningsSeason
1
1.2k

·
--
Bullish
Holding $GOOGLB 3K USDT
$GOOGLB I never bought #bstocks活动 but look at the chart it's already at lowest point, it's right time to buy and hold for potential 1x profit. simple rules, buy when nobody wants to.
#EarningsSeason
#GoogleStock
$GOOGLB I never bought #bstocks活动 but look at the chart it's already at lowest point, it's right time to buy and hold for potential 1x profit. simple rules, buy when nobody wants to.
#EarningsSeason
#GoogleStock
#EarningsSeason
#GoogleStock
85

·
--
Bullish
#BinancePick
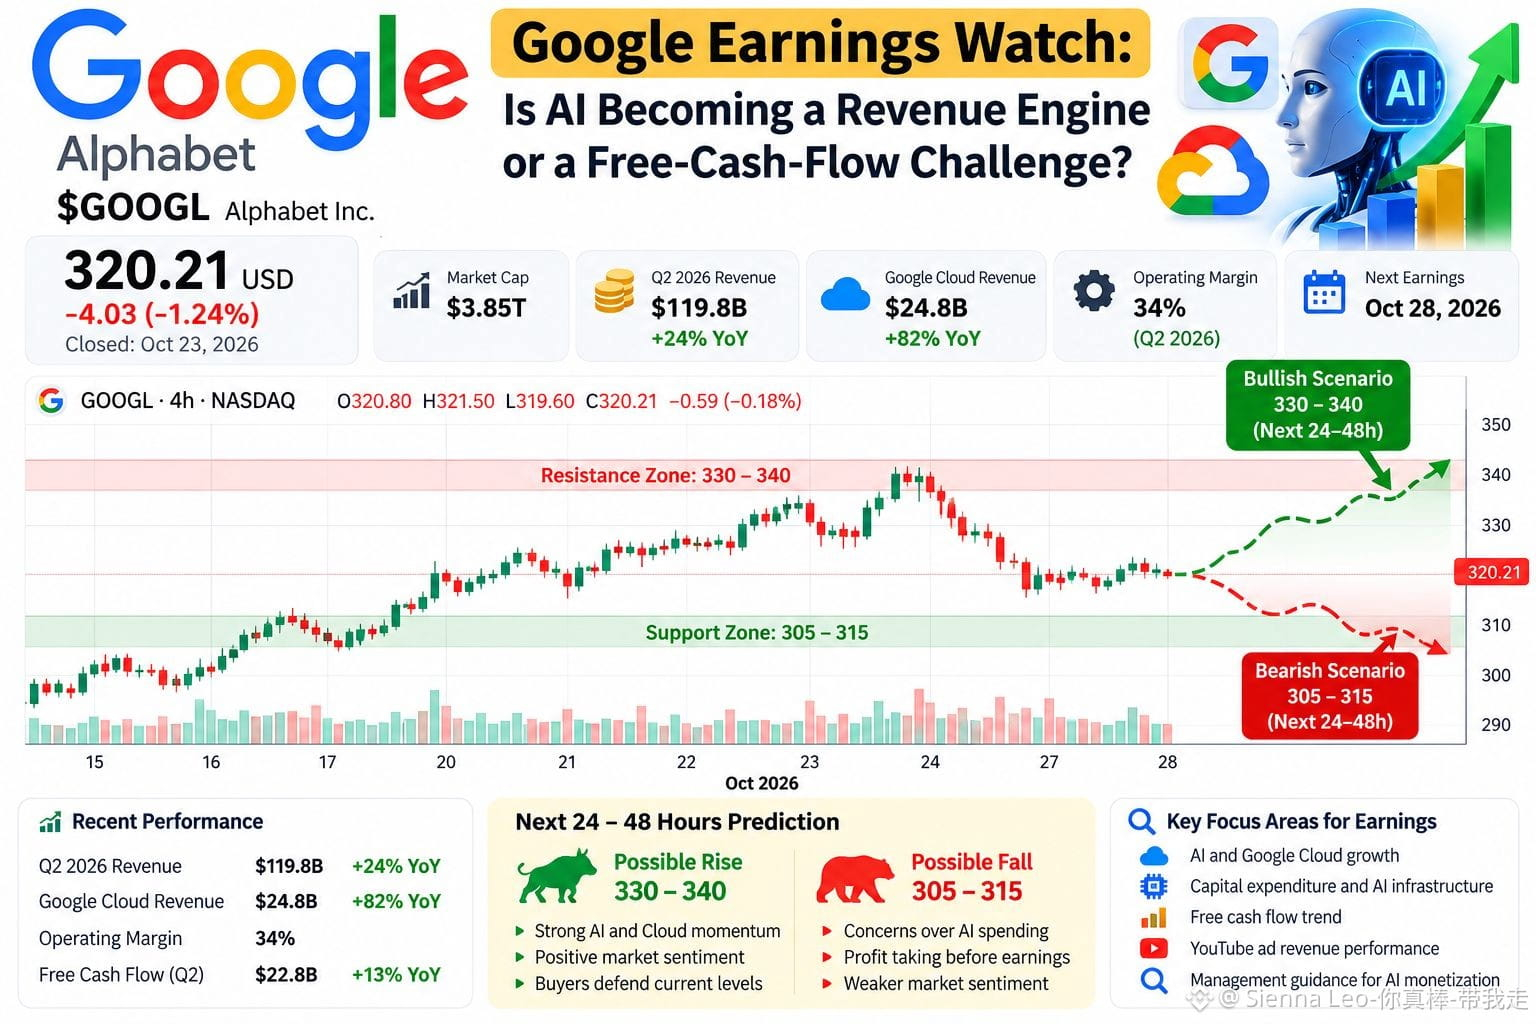
Google Earnings Watch: Is AI Becoming a Revenue Engine or a Free-Cash-Flow Challenge?
The AI race is no longer just about building smarter machines. It is about turning intelligence into sustainable profit. 🤖💰
Alphabet ($GOOGL ) faces a crucial test ahead of its October 28 earnings report: can AI growth justify the enormous cost of building the infrastructure behind it?
In Q2 2026, Alphabet generated $119.8 billion in revenue, up 24% year over year. Google Cloud revenue surged 82% to $24.8 billion, while operating margin expanded to 34%.
That is powerful evidence of demand. But revenue growth alone cannot tell the whole story.
AI infrastructure requires expensive data centers, advanced chips, and massive computing capacity. If spending rises faster than cash generation, even impressive growth could disappoint investors.
Stock update: $GOOGL closed at $320.21 on October 23, down 1.24% for the session.
Prediction: Next 24 to 48 hours
My near-term outlook is cautious ahead of earnings.
Bullish scenario: Improving sentiment and optimism about Cloud and AI monetization could support a rebound.
Bearish scenario: Investors may sell further if concerns about AI spending outweigh expectations for future revenue.
These are conditional scenarios, not guaranteed outcomes. With markets closed over the weekend, the next regular session is the key test. No reliable live price is available here to establish confirmed breakout levels.
Active traders may find opportunities in either direction, but earnings volatility can quickly magnify losses.
The real AI winner will not simply spend the most. It will convert computing power into lasting cash flow.
Would you prioritize Google Cloud's explosive growth or its ability to turn AI investment into free cash flow?
For educational purposes only. Not financial advice.
#GoogleStock #ArtificialIntelligence #GrowWithSAC #EarningsSeason $GOOGL
#BinancePick
Google Earnings Watch: Is AI Becoming a Revenue Engine or a Free-Cash-Flow Challenge?
The AI race is no longer just about building smarter machines. It is about turning intelligence into sustainable profit. 🤖💰
Alphabet ($GOOGL ) faces a crucial test ahead of its October 28 earnings report: can AI growth justify the enormous cost of building the infrastructure behind it?
In Q2 2026, Alphabet generated $119.8 billion in revenue, up 24% year over year. Google Cloud revenue surged 82% to $24.8 billion, while operating margin expanded to 34%.
That is powerful evidence of demand. But revenue growth alone cannot tell the whole story.
AI infrastructure requires expensive data centers, advanced chips, and massive computing capacity. If spending rises faster than cash generation, even impressive growth could disappoint investors.
Stock update: $GOOGL closed at $320.21 on October 23, down 1.24% for the session.
Prediction: Next 24 to 48 hours
My near-term outlook is cautious ahead of earnings.
Bullish scenario: Improving sentiment and optimism about Cloud and AI monetization could support a rebound.
Bearish scenario: Investors may sell further if concerns about AI spending outweigh expectations for future revenue.
These are conditional scenarios, not guaranteed outcomes. With markets closed over the weekend, the next regular session is the key test. No reliable live price is available here to establish confirmed breakout levels.
Active traders may find opportunities in either direction, but earnings volatility can quickly magnify losses.
The real AI winner will not simply spend the most. It will convert computing power into lasting cash flow.
Would you prioritize Google Cloud's explosive growth or its ability to turn AI investment into free cash flow?
For educational purposes only. Not financial advice.
#GoogleStock #ArtificialIntelligence #GrowWithSAC #EarningsSeason $GOOGL
Google Earnings Watch: Is AI Becoming a Revenue Engine or a Free-Cash-Flow Challenge?
The AI race is no longer just about building smarter machines. It is about turning intelligence into sustainable profit. 🤖💰
Alphabet ($GOOGL ) faces a crucial test ahead of its October 28 earnings report: can AI growth justify the enormous cost of building the infrastructure behind it?
In Q2 2026, Alphabet generated $119.8 billion in revenue, up 24% year over year. Google Cloud revenue surged 82% to $24.8 billion, while operating margin expanded to 34%.
That is powerful evidence of demand. But revenue growth alone cannot tell the whole story.
AI infrastructure requires expensive data centers, advanced chips, and massive computing capacity. If spending rises faster than cash generation, even impressive growth could disappoint investors.
Stock update: $GOOGL closed at $320.21 on October 23, down 1.24% for the session.
Prediction: Next 24 to 48 hours
My near-term outlook is cautious ahead of earnings.
Bullish scenario: Improving sentiment and optimism about Cloud and AI monetization could support a rebound.
Bearish scenario: Investors may sell further if concerns about AI spending outweigh expectations for future revenue.
These are conditional scenarios, not guaranteed outcomes. With markets closed over the weekend, the next regular session is the key test. No reliable live price is available here to establish confirmed breakout levels.
Active traders may find opportunities in either direction, but earnings volatility can quickly magnify losses.
The real AI winner will not simply spend the most. It will convert computing power into lasting cash flow.
Would you prioritize Google Cloud's explosive growth or its ability to turn AI investment into free cash flow?
For educational purposes only. Not financial advice.
#GoogleStock #ArtificialIntelligence #GrowWithSAC #EarningsSeason $GOOGL
168
·
--
Bullish
🚨 $GOOGLB: PANIC FOR SOME, OPPORTUNITY FOR OTHERS? 📉📈
The market is testing investors’ emotions, and that’s where discipline matters most. 🧠
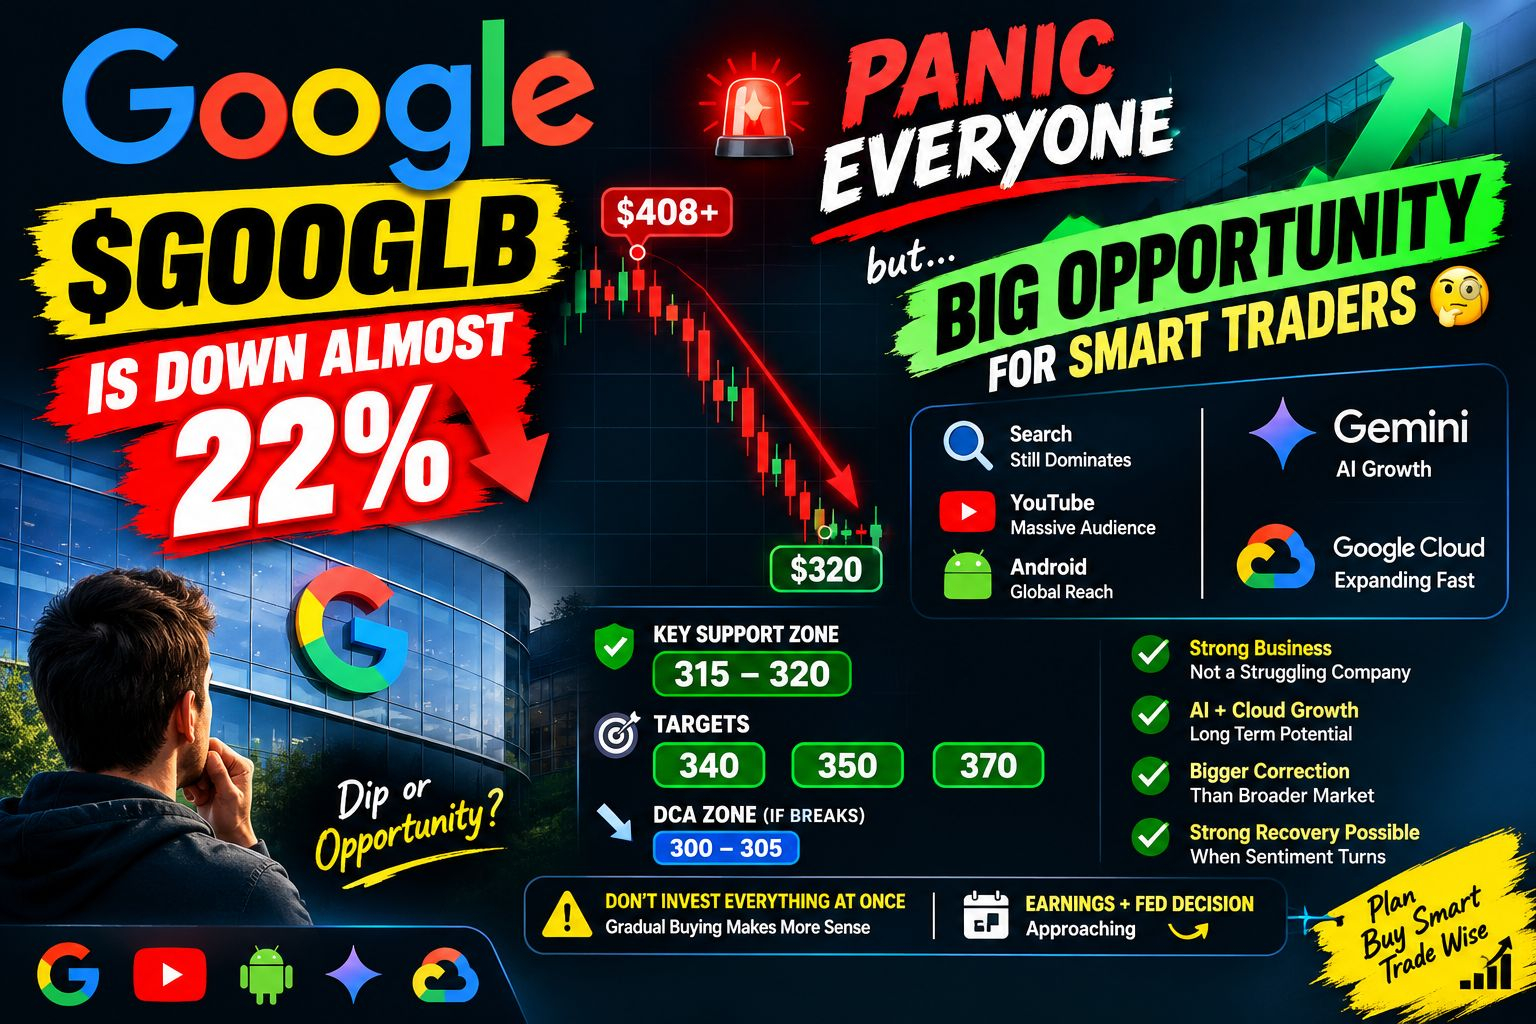
Google reportedly dropped from above $408 to around $320, putting a major question on the table: Is this a bargain, or is the market warning us about something bigger? 👀
Here’s my perspective: a strong business can experience a weak stock price without losing its long-term potential. Google still has powerful businesses in Search, YouTube, Android, Gemini AI, and Google Cloud. However, rising AI expenses, competition, and future profitability remain real risks.
🎯 My key levels to watch: 🟢 Support zone: $315–$320 🎯 Potential upside levels: $340 → $350 → $370 🔵 If support fails: $300–$305 could become another area to evaluate.
But remember, support is not guaranteed to hold, and a falling stock can always fall further. I’d rather scale in gradually than spend all my capital on the first dip.
My unique thought: The biggest opportunity isn't simply buying a stock because it has fallen 22%—it's identifying whether the market has become too pessimistic about a fundamentally strong business.
⚠️ Earnings, AI spending, and the Fed decision could change the picture quickly. These are levels to watch, not guaranteed targets. Do your own research and manage risk carefully.
What’s your move? 👇 🟢 Buy the dip 🔴 Wait for confirmation 🔵 Wait for $300–$305
#GOOGLB #GoogleStock #StockMarket #Investing #AIStocks #TradingStrategy
$GOOGLB
{spot}(GOOGLBUSDT)
🚨 $GOOGLB : PANIC FOR SOME, OPPORTUNITY FOR OTHERS? 📉📈
The market is testing investors’ emotions, and that’s where discipline matters most. 🧠
Google reportedly dropped from above $408 to around $320, putting a major question on the table: Is this a bargain, or is the market warning us about something bigger? 👀
Here’s my perspective: a strong business can experience a weak stock price without losing its long-term potential. Google still has powerful businesses in Search, YouTube, Android, Gemini AI, and Google Cloud. However, rising AI expenses, competition, and future profitability remain real risks.
🎯 My key levels to watch: 🟢 Support zone: $315–$320 🎯 Potential upside levels: $340 → $350 → $370 🔵 If support fails: $300–$305 could become another area to evaluate.
But remember, support is not guaranteed to hold, and a falling stock can always fall further. I’d rather scale in gradually than spend all my capital on the first dip.
My unique thought: The biggest opportunity isn't simply buying a stock because it has fallen 22%—it's identifying whether the market has become too pessimistic about a fundamentally strong business.
⚠️ Earnings, AI spending, and the Fed decision could change the picture quickly. These are levels to watch, not guaranteed targets. Do your own research and manage risk carefully.
What’s your move? 👇 🟢 Buy the dip 🔴 Wait for confirmation 🔵 Wait for $300–$305
#GOOGLB #GoogleStock #StockMarket #Investing #AIStocks #TradingStrategy
$GOOGLB
The market is testing investors’ emotions, and that’s where discipline matters most. 🧠
Google reportedly dropped from above $408 to around $320, putting a major question on the table: Is this a bargain, or is the market warning us about something bigger? 👀
Here’s my perspective: a strong business can experience a weak stock price without losing its long-term potential. Google still has powerful businesses in Search, YouTube, Android, Gemini AI, and Google Cloud. However, rising AI expenses, competition, and future profitability remain real risks.
🎯 My key levels to watch: 🟢 Support zone: $315–$320 🎯 Potential upside levels: $340 → $350 → $370 🔵 If support fails: $300–$305 could become another area to evaluate.
But remember, support is not guaranteed to hold, and a falling stock can always fall further. I’d rather scale in gradually than spend all my capital on the first dip.
My unique thought: The biggest opportunity isn't simply buying a stock because it has fallen 22%—it's identifying whether the market has become too pessimistic about a fundamentally strong business.
⚠️ Earnings, AI spending, and the Fed decision could change the picture quickly. These are levels to watch, not guaranteed targets. Do your own research and manage risk carefully.
What’s your move? 👇 🟢 Buy the dip 🔴 Wait for confirmation 🔵 Wait for $300–$305
#GOOGLB #GoogleStock #StockMarket #Investing #AIStocks #TradingStrategy
$GOOGLB
1
95
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceIncidentReport
5,373 views
232 Discussing
2
#BinanceReopensWithdrawalsForMoreAssets
96,357 views
1,535 Discussing
3
#BinanceHourlyDepositsExceedWithdrawals
45,794 views
666 Discussing
4
#USMidtermElections
825,486 views
4,435 Discussing
5
#AnthropicIPOPricedDownasInvestorsEye$1.5T
1,544 views
39 Discussing
6
#USOctoberNFP-AreRateCutsStillPossible
151,666 views
1,195 Discussing
7
#AppleReportsMixedResults
49,408 views
930 Discussing
8
#PalantirSlides3PercentOn$2BRevenue
3,270 views
40 Discussing
9
#FrenchAssemblyRejectsTwoCryptoExitTaxProposals
6,987 views
159 Discussing
10
#Nasdaq100EntersCorrection
11,259 views
167 Discussing