
#backtesting
backtesting
30,760 නැරඹීම්
2,145 සාකච්ඡා කරමින්
උණුසුම්
නවතම
·
--
Backtesting methodologies help traders evaluate strategy performance. This is done by simulating trades on historical data. For example, a strategy is at 80% success rate on $BTC data from 2020. Forward-testing frameworks take this a step further by testing on new, unseen data. This helps confirm if a strategy is sitting at a high success rate. Traders use both methods to refine their approach, often using $ETH and $LTC data. By combining backtesting and forward-testing, traders can gain advanced insights into their strategy's effectiveness. Trading strategies can be improved with a success rate of 70% or higher. tradingstrategies #backtesting #cryptotrading
Backtesting methodologies help traders evaluate strategy performance. This is done by simulating trades on historical data. For example, a strategy is at 80% success rate on $BTC data from 2020. Forward-testing frameworks take this a step further by testing on new, unseen data. This helps confirm if a strategy is sitting at a high success rate. Traders use both methods to refine their approach, often using $ETH and $LTC data. By combining backtesting and forward-testing, traders can gain advanced insights into their strategy's effectiveness. Trading strategies can be improved with a success rate of 70% or higher. tradingstrategies #backtesting #cryptotrading
95

·
--
7 versions of my bot, running side by side
My futures bot (testnet funds) has a "shadow lab": alternative rule sets trade the same market on paper, each starting from 5,000 USDT. After 30 days, here is the table:
• Channel breakout 55/20: +1.3%, max drawdown −5.0%, 16 trades, 19% winners
• EMA 20/50 cross: +1.2%, max drawdown −3.0%, 8 trades, 12% winners
• RSI 30/70 pullback: +0.8%, max drawdown −0.2%, 1 trade
• Shorts only: +0.7%, max drawdown −0.5%, 2 trades still open
• Longs only: −0.5%, 1 trade
• Current rules without news mode: −0.9%, 4 trades, 0 winners
• No $BTC filter: −2.1%, 7 trades, 0 winners
What I take from it: not much yet. The two leaders are up thanks to open positions and a few winners; their average trade is still negative (−0.52R and −0.85R). Most variants have fewer than 10 closed trades, and my own rule is to compare only after 20–30 trades each.
One thing is already visible: removing the BTC trend filter made results worse, 7 trades and not a single winner.
How many trades do you need before you trust a paper or backtest result?
#TradingBot #Backtesting #Testnet
7 versions of my bot, running side by side
My futures bot (testnet funds) has a "shadow lab": alternative rule sets trade the same market on paper, each starting from 5,000 USDT. After 30 days, here is the table:
• Channel breakout 55/20: +1.3%, max drawdown −5.0%, 16 trades, 19% winners
• EMA 20/50 cross: +1.2%, max drawdown −3.0%, 8 trades, 12% winners
• RSI 30/70 pullback: +0.8%, max drawdown −0.2%, 1 trade
• Shorts only: +0.7%, max drawdown −0.5%, 2 trades still open
• Longs only: −0.5%, 1 trade
• Current rules without news mode: −0.9%, 4 trades, 0 winners
• No $BTC filter: −2.1%, 7 trades, 0 winners
What I take from it: not much yet. The two leaders are up thanks to open positions and a few winners; their average trade is still negative (−0.52R and −0.85R). Most variants have fewer than 10 closed trades, and my own rule is to compare only after 20–30 trades each.
One thing is already visible: removing the BTC trend filter made results worse, 7 trades and not a single winner.
How many trades do you need before you trust a paper or backtest result?
#TradingBot #Backtesting #Testnet
My futures bot (testnet funds) has a "shadow lab": alternative rule sets trade the same market on paper, each starting from 5,000 USDT. After 30 days, here is the table:
• Channel breakout 55/20: +1.3%, max drawdown −5.0%, 16 trades, 19% winners
• EMA 20/50 cross: +1.2%, max drawdown −3.0%, 8 trades, 12% winners
• RSI 30/70 pullback: +0.8%, max drawdown −0.2%, 1 trade
• Shorts only: +0.7%, max drawdown −0.5%, 2 trades still open
• Longs only: −0.5%, 1 trade
• Current rules without news mode: −0.9%, 4 trades, 0 winners
• No $BTC filter: −2.1%, 7 trades, 0 winners
What I take from it: not much yet. The two leaders are up thanks to open positions and a few winners; their average trade is still negative (−0.52R and −0.85R). Most variants have fewer than 10 closed trades, and my own rule is to compare only after 20–30 trades each.
One thing is already visible: removing the BTC trend filter made results worse, 7 trades and not a single winner.
How many trades do you need before you trust a paper or backtest result?
#TradingBot #Backtesting #Testnet
1
99

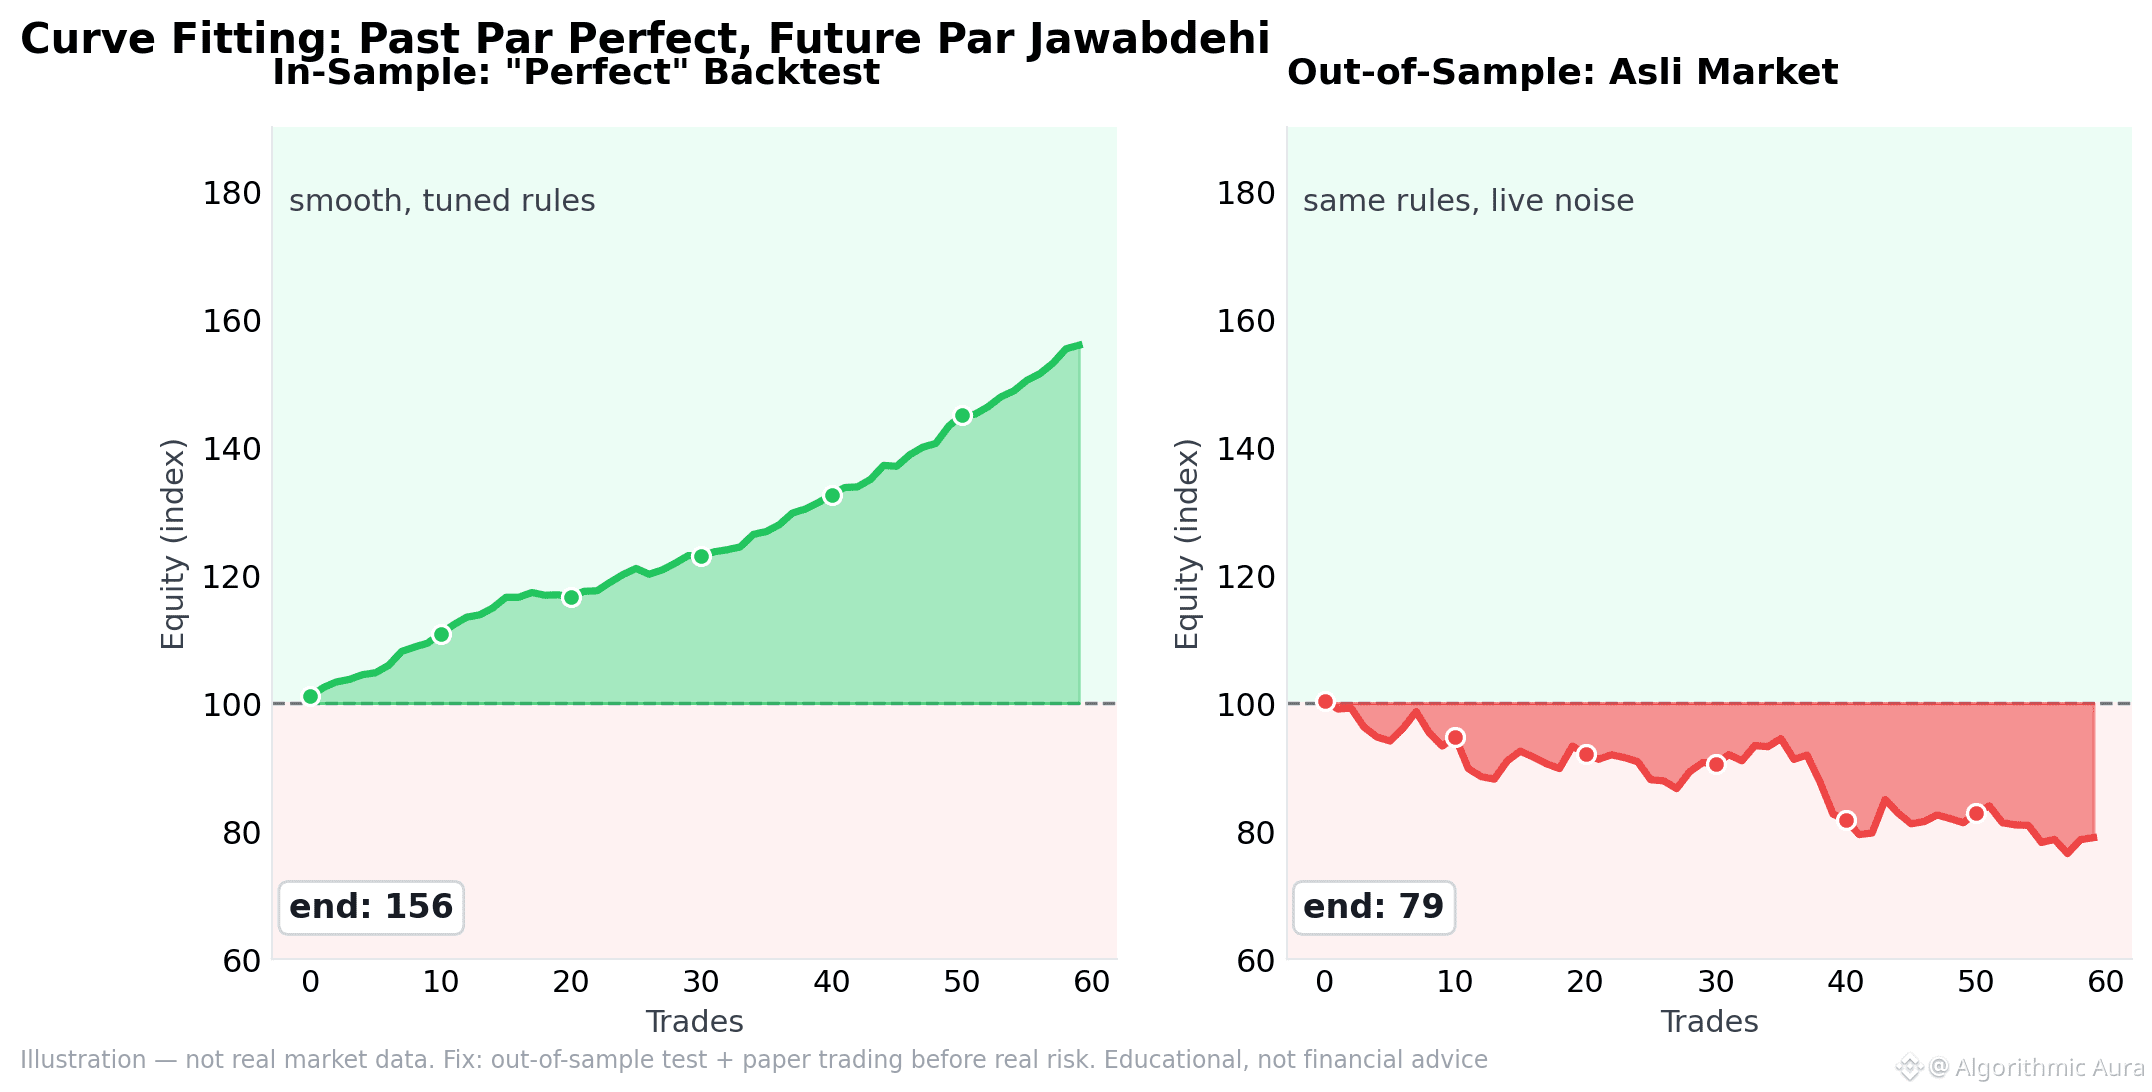
🧪 Ek chart: backtest ka sab se common dhoka — curve fitting.
Left: in-sample result smooth upar (rules past par tune). Right: same rules out-of-sample — live noise, kahani alag.
1️⃣ Fit karna asaan: 15 conditions lagao to past perfect ban jata hai
2️⃣ Lekin wo strategy nahi, memory hai — future ka data us shape se milta nahi
3️⃣ Fix: out-of-sample test, phir paper trading
4️⃣ Sample size: 20 trades statistics nahi
Backtest ka matlab: candidate milta hai, yaqeen nahi. Illustration — real data nahi.
$BTC #CryptoEducation #Backtesting #TradingStrategy
🧪 Ek chart: backtest ka sab se common dhoka — curve fitting.
Left: in-sample result smooth upar (rules past par tune). Right: same rules out-of-sample — live noise, kahani alag.
1️⃣ Fit karna asaan: 15 conditions lagao to past perfect ban jata hai
2️⃣ Lekin wo strategy nahi, memory hai — future ka data us shape se milta nahi
3️⃣ Fix: out-of-sample test, phir paper trading
4️⃣ Sample size: 20 trades statistics nahi
Backtest ka matlab: candidate milta hai, yaqeen nahi. Illustration — real data nahi.
$BTC #CryptoEducation #Backtesting #TradingStrategy
Left: in-sample result smooth upar (rules past par tune). Right: same rules out-of-sample — live noise, kahani alag.
1️⃣ Fit karna asaan: 15 conditions lagao to past perfect ban jata hai
2️⃣ Lekin wo strategy nahi, memory hai — future ka data us shape se milta nahi
3️⃣ Fix: out-of-sample test, phir paper trading
4️⃣ Sample size: 20 trades statistics nahi
Backtest ka matlab: candidate milta hai, yaqeen nahi. Illustration — real data nahi.
$BTC #CryptoEducation #Backtesting #TradingStrategy
8
🧪 Backtesting — past par test, lekin traps wahi hain.
1️⃣ Fayda: rough expectancy estimate, feeling ke baghair
2️⃣ Trap 1 — curve fitting: past par perfect tune kiya to future nahi pehchanta; 15 conditions = strategy nahi, memory
3️⃣ Trap 2 — chhota sample: 20 trades statistics nahi
4️⃣ Trap 3 — survivorship: dead coins ka data chhor kar sirf winners test karna
5️⃣ Fix: out-of-sample test + paper trading — aaj bhi kaam karta hai? past nahi batata
Backtest candidate deta hai, yaqeen nahi. Ye farq samajhne wala lambi race jeetta hai.
$BTC #CryptoEducation #TradingStrategy #Backtesting
🧪 Backtesting — past par test, lekin traps wahi hain.
1️⃣ Fayda: rough expectancy estimate, feeling ke baghair
2️⃣ Trap 1 — curve fitting: past par perfect tune kiya to future nahi pehchanta; 15 conditions = strategy nahi, memory
3️⃣ Trap 2 — chhota sample: 20 trades statistics nahi
4️⃣ Trap 3 — survivorship: dead coins ka data chhor kar sirf winners test karna
5️⃣ Fix: out-of-sample test + paper trading — aaj bhi kaam karta hai? past nahi batata
Backtest candidate deta hai, yaqeen nahi. Ye farq samajhne wala lambi race jeetta hai.
$BTC #CryptoEducation #TradingStrategy #Backtesting
1️⃣ Fayda: rough expectancy estimate, feeling ke baghair
2️⃣ Trap 1 — curve fitting: past par perfect tune kiya to future nahi pehchanta; 15 conditions = strategy nahi, memory
3️⃣ Trap 2 — chhota sample: 20 trades statistics nahi
4️⃣ Trap 3 — survivorship: dead coins ka data chhor kar sirf winners test karna
5️⃣ Fix: out-of-sample test + paper trading — aaj bhi kaam karta hai? past nahi batata
Backtest candidate deta hai, yaqeen nahi. Ye farq samajhne wala lambi race jeetta hai.
$BTC #CryptoEducation #TradingStrategy #Backtesting
9
·
--
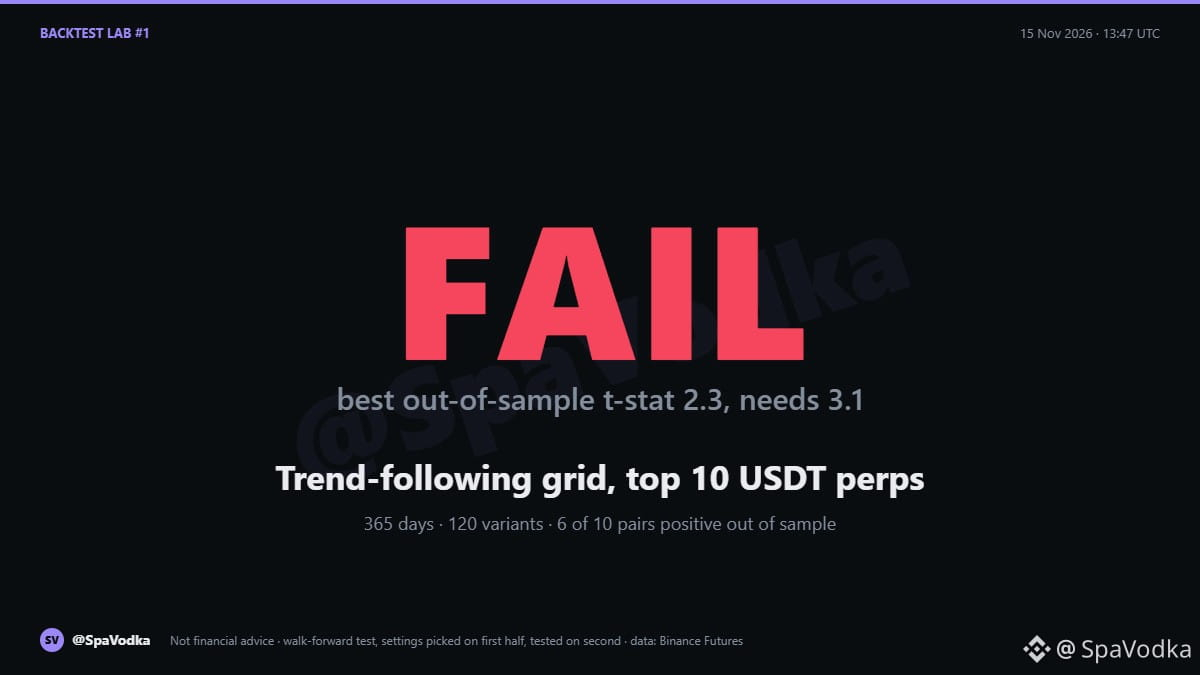
$NEAR made the most money out of sample, and the strategy still failed.
Backtest Lab #1: does a grid that follows the trend actually work?
The idea: run a futures grid, but pick its direction from the daily trend. Long grid when price is above MA20 and MA7 is above MA25, short grid when both are below, neutral when MA7 and MA25 are within 3% of each other. Seven day runs, 3x, stop 1.5% outside the range, Binance fees included.
Data: top 10 USDT perps by volume, 365 days of 15m candles. Settings picked on the first half of the year only (12 variants per pair, 120 in total), then tested on the second half that the model never saw.
Result on unseen data: 6 of 10 pairs stayed positive. The best t-stat was 2.3 (SOL and NEAR). After trying 120 variants, a real edge needs at least 3.1. NEAR hit its stop in 38% of weekly runs. HYPE went from profit in training to a loss out of sample.
Verdict: FAIL. Positive numbers here are what you get by trying 120 versions and keeping the best one, not proof of an edge.
What I do with it: not trading it. Same verdict as my first run on 4 Nov, fresh data did not change it.
Next on the list: unlock windows, alt minus BTC beta, extreme funding reversals. Which one should I test next?
Not financial advice.
#Backtesting #tradingStrategy #gridtrading
{future}(NEARUSDT)
$NEAR made the most money out of sample, and the strategy still failed.
Backtest Lab #1: does a grid that follows the trend actually work?
The idea: run a futures grid, but pick its direction from the daily trend. Long grid when price is above MA20 and MA7 is above MA25, short grid when both are below, neutral when MA7 and MA25 are within 3% of each other. Seven day runs, 3x, stop 1.5% outside the range, Binance fees included.
Data: top 10 USDT perps by volume, 365 days of 15m candles. Settings picked on the first half of the year only (12 variants per pair, 120 in total), then tested on the second half that the model never saw.
Result on unseen data: 6 of 10 pairs stayed positive. The best t-stat was 2.3 (SOL and NEAR). After trying 120 variants, a real edge needs at least 3.1. NEAR hit its stop in 38% of weekly runs. HYPE went from profit in training to a loss out of sample.
Verdict: FAIL. Positive numbers here are what you get by trying 120 versions and keeping the best one, not proof of an edge.
What I do with it: not trading it. Same verdict as my first run on 4 Nov, fresh data did not change it.
Next on the list: unlock windows, alt minus BTC beta, extreme funding reversals. Which one should I test next?
Not financial advice.
#Backtesting #tradingStrategy #gridtrading
Backtest Lab #1: does a grid that follows the trend actually work?
The idea: run a futures grid, but pick its direction from the daily trend. Long grid when price is above MA20 and MA7 is above MA25, short grid when both are below, neutral when MA7 and MA25 are within 3% of each other. Seven day runs, 3x, stop 1.5% outside the range, Binance fees included.
Data: top 10 USDT perps by volume, 365 days of 15m candles. Settings picked on the first half of the year only (12 variants per pair, 120 in total), then tested on the second half that the model never saw.
Result on unseen data: 6 of 10 pairs stayed positive. The best t-stat was 2.3 (SOL and NEAR). After trying 120 variants, a real edge needs at least 3.1. NEAR hit its stop in 38% of weekly runs. HYPE went from profit in training to a loss out of sample.
Verdict: FAIL. Positive numbers here are what you get by trying 120 versions and keeping the best one, not proof of an edge.
What I do with it: not trading it. Same verdict as my first run on 4 Nov, fresh data did not change it.
Next on the list: unlock windows, alt minus BTC beta, extreme funding reversals. Which one should I test next?
Not financial advice.
#Backtesting #tradingStrategy #gridtrading
254
🧪 Strategy pehle demo par test karo — paper trading ka fayda.
1️⃣ Real market data, fake money — rules bina financial risk ke test
2️⃣ Backtesting: purane data par rule run karo — wins, losses, max drawdown
3️⃣ Forward testing: live conditions mein discipline check
Kyun: aaj BTC $74.8K→$77K bounce tha — choppy dinon wali strategy real data par hi verify hogi, feelings par nahi.
30–50 paper trades ke baad pattern saaf: rules asli edge hain ya mood-based decisions?
Demo mein galti sasti hai, live mein mehngi. Pehle test, phir trust. 🔬
$BTC
#PaperTrading #Backtesting #CryptoEducation
🧪 Strategy pehle demo par test karo — paper trading ka fayda.
1️⃣ Real market data, fake money — rules bina financial risk ke test
2️⃣ Backtesting: purane data par rule run karo — wins, losses, max drawdown
3️⃣ Forward testing: live conditions mein discipline check
Kyun: aaj BTC $74.8K→$77K bounce tha — choppy dinon wali strategy real data par hi verify hogi, feelings par nahi.
30–50 paper trades ke baad pattern saaf: rules asli edge hain ya mood-based decisions?
Demo mein galti sasti hai, live mein mehngi. Pehle test, phir trust. 🔬
$BTC
#PaperTrading #Backtesting #CryptoEducation
1️⃣ Real market data, fake money — rules bina financial risk ke test
2️⃣ Backtesting: purane data par rule run karo — wins, losses, max drawdown
3️⃣ Forward testing: live conditions mein discipline check
Kyun: aaj BTC $74.8K→$77K bounce tha — choppy dinon wali strategy real data par hi verify hogi, feelings par nahi.
30–50 paper trades ke baad pattern saaf: rules asli edge hain ya mood-based decisions?
Demo mein galti sasti hai, live mein mehngi. Pehle test, phir trust. 🔬
$BTC
#PaperTrading #Backtesting #CryptoEducation
·
--
I tested 144 trading strategies on BTC, ETH and SOL. Here's what happened 🧪
I built a bot on my phone (Termux) and backtested it on 1 year of hourly data from MEXC, with fees included and 10x leverage.
The setup:
• 70% of the data for training, 30% kept hidden for testing
• EMA crossovers and breakouts, with and without a trend filter
• ATR-based stops and different risk/reward ratios
The results:
• Only 22 of 144 combinations were profitable on the unseen data
• The "best" strategy in training LOST 61% on the test period
• Max drawdowns were over 100% at 10x leverage, which means a wiped account
• Simply holding $BTC, $ETH or $SOL returned about +18-20% in the same period, with no leverage
What I learned:
1. A strategy that looks great on past data often fails on new data (overfitting)
2. High leverage makes most edges disappear
3. Beating the market is much harder than it looks
I'm not trading real money with this. Next I'm testing slower timeframes and lower leverage, and I'll share the results either way.
Not financial advice. Past performance doesn't predict future results.
#BinanceSquare #crypto #Backtesting #TradingBots101 $BTC $ETH
I tested 144 trading strategies on BTC, ETH and SOL. Here's what happened 🧪
I built a bot on my phone (Termux) and backtested it on 1 year of hourly data from MEXC, with fees included and 10x leverage.
The setup:
• 70% of the data for training, 30% kept hidden for testing
• EMA crossovers and breakouts, with and without a trend filter
• ATR-based stops and different risk/reward ratios
The results:
• Only 22 of 144 combinations were profitable on the unseen data
• The "best" strategy in training LOST 61% on the test period
• Max drawdowns were over 100% at 10x leverage, which means a wiped account
• Simply holding $BTC , $ETH or $SOL returned about +18-20% in the same period, with no leverage
What I learned:
1. A strategy that looks great on past data often fails on new data (overfitting)
2. High leverage makes most edges disappear
3. Beating the market is much harder than it looks
I'm not trading real money with this. Next I'm testing slower timeframes and lower leverage, and I'll share the results either way.
Not financial advice. Past performance doesn't predict future results.
#BinanceSquare #crypto #Backtesting #TradingBots101 $BTC $ETH
I built a bot on my phone (Termux) and backtested it on 1 year of hourly data from MEXC, with fees included and 10x leverage.
The setup:
• 70% of the data for training, 30% kept hidden for testing
• EMA crossovers and breakouts, with and without a trend filter
• ATR-based stops and different risk/reward ratios
The results:
• Only 22 of 144 combinations were profitable on the unseen data
• The "best" strategy in training LOST 61% on the test period
• Max drawdowns were over 100% at 10x leverage, which means a wiped account
• Simply holding $BTC , $ETH or $SOL returned about +18-20% in the same period, with no leverage
What I learned:
1. A strategy that looks great on past data often fails on new data (overfitting)
2. High leverage makes most edges disappear
3. Beating the market is much harder than it looks
I'm not trading real money with this. Next I'm testing slower timeframes and lower leverage, and I'll share the results either way.
Not financial advice. Past performance doesn't predict future results.
#BinanceSquare #crypto #Backtesting #TradingBots101 $BTC $ETH
148
·
--
Backtesting is a crucial step in evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy based on moving averages can be backtested on $BTC data from the past year. Forward-testing frameworks take it a step further by testing a strategy on new, unseen data. This helps to validate the strategy's performance. A strategy sitting at 80% success rate in backtesting may not perform as well in forward testing. For instance, a strategy that performed well on $ETH data may struggle with $BTC data. Understanding these methodologies is key to successful trading. Trading strategies and advanced analytics require careful evaluation. tradingstrategies #backtesting #cryptotrading
Backtesting is a crucial step in evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy based on moving averages can be backtested on $BTC data from the past year. Forward-testing frameworks take it a step further by testing a strategy on new, unseen data. This helps to validate the strategy's performance. A strategy sitting at 80% success rate in backtesting may not perform as well in forward testing. For instance, a strategy that performed well on $ETH data may struggle with $BTC data. Understanding these methodologies is key to successful trading. Trading strategies and advanced analytics require careful evaluation. tradingstrategies #backtesting #cryptotrading
24
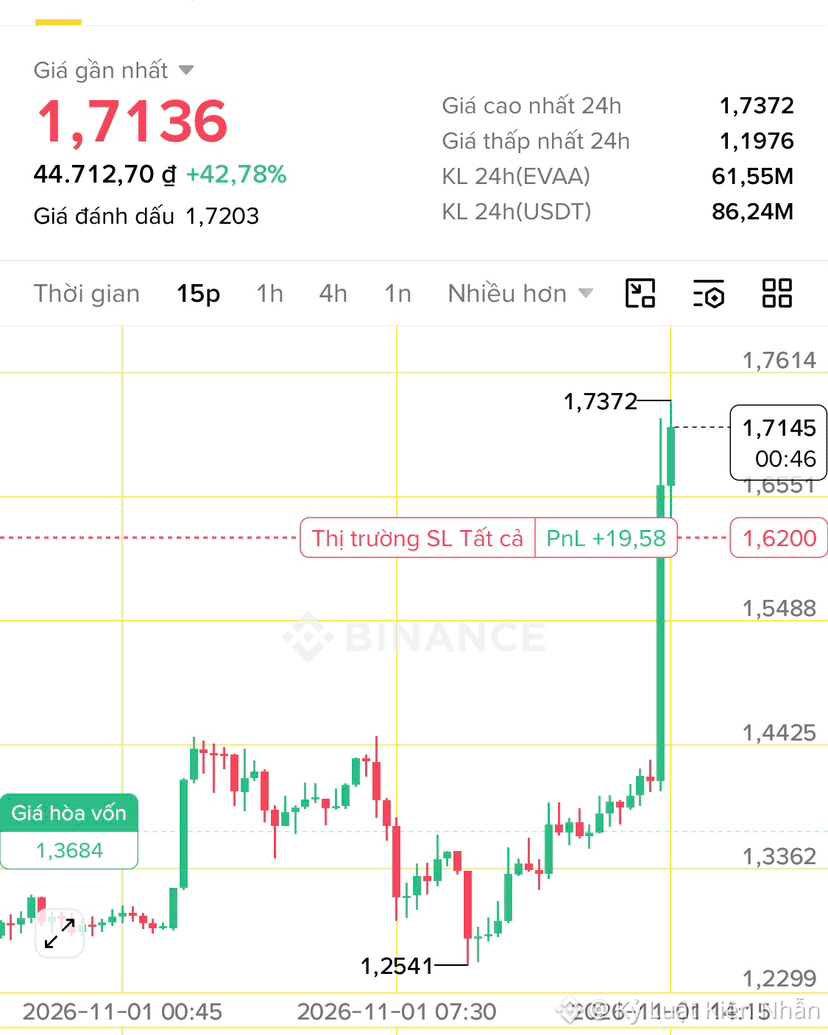
Khi dữ liệu lịch sử không bảo đảm tương lai
Mình từng thấy một phương pháp hoạt động tốt trong dữ liệu quá khứ và kỳ vọng nó sẽ tiếp tục hiệu quả.
Nhưng khi điều kiện thị trường thay đổi, kết quả thực tế không còn giống như mình hình dung.
Bài học của mình là dữ liệu quá khứ rất hữu ích để nghiên cứu, nhưng không thể bảo đảm kết quả của những giao dịch tiếp theo.
$ETH $EVAA
Anh em có thường kiểm tra lại phương pháp khi thị trường thay đổi không? Cùng trao đổi nhé!
#Backtesting
Khi dữ liệu lịch sử không bảo đảm tương lai
Mình từng thấy một phương pháp hoạt động tốt trong dữ liệu quá khứ và kỳ vọng nó sẽ tiếp tục hiệu quả.
Nhưng khi điều kiện thị trường thay đổi, kết quả thực tế không còn giống như mình hình dung.
Bài học của mình là dữ liệu quá khứ rất hữu ích để nghiên cứu, nhưng không thể bảo đảm kết quả của những giao dịch tiếp theo.
$ETH $EVAA
Anh em có thường kiểm tra lại phương pháp khi thị trường thay đổi không? Cùng trao đổi nhé!
#Backtesting
Mình từng thấy một phương pháp hoạt động tốt trong dữ liệu quá khứ và kỳ vọng nó sẽ tiếp tục hiệu quả.
Nhưng khi điều kiện thị trường thay đổi, kết quả thực tế không còn giống như mình hình dung.
Bài học của mình là dữ liệu quá khứ rất hữu ích để nghiên cứu, nhưng không thể bảo đảm kết quả của những giao dịch tiếp theo.
$ETH $EVAA
Anh em có thường kiểm tra lại phương pháp khi thị trường thay đổi không? Cùng trao đổi nhé!
#Backtesting
1
1
229
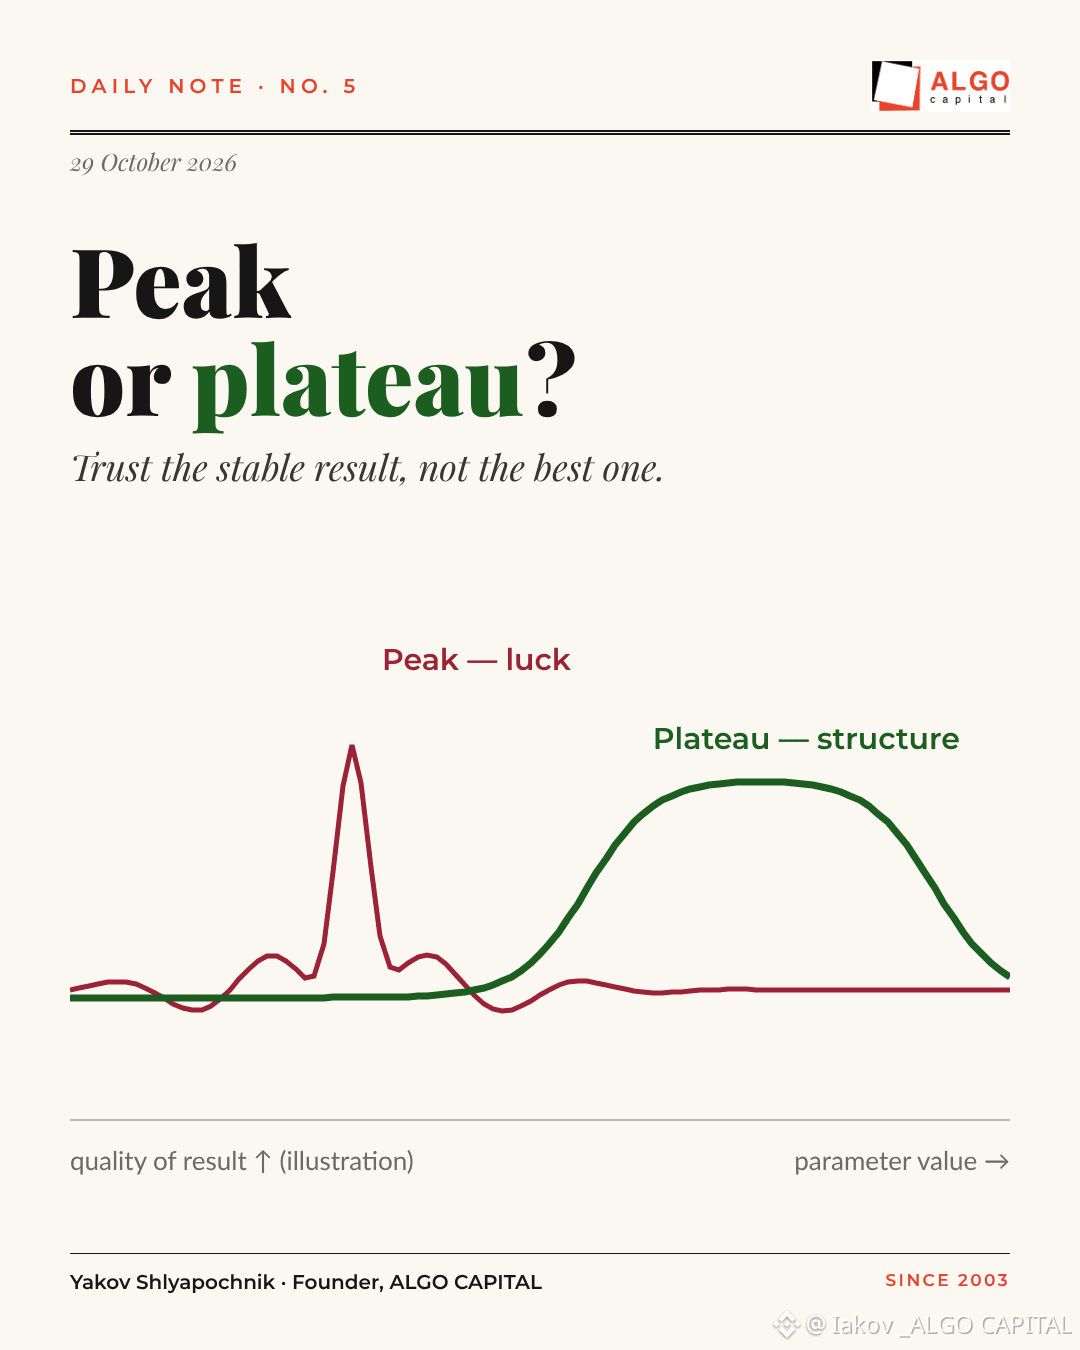
The most dangerous object in finance is a beautiful backtest.
With enough parameters you can fit any history. The curve goes up and to the right — and tells you nothing about the future.
Three rules we use against self-deception:
1️⃣ Plateau, not peak. We choose parameters in the middle of a wide stable area, not at the single best point. A peak is luck; a plateau is structure.
2️⃣ Random in-sample and out-of-sample months, different for every test — so the hard months cannot hide.
3️⃣ Live trading is the only final judge. A backtest is a hypothesis; a real account is evidence.
If you remember one thing: be suspicious of the best result, trust the stable one.
#backtesting #quant #crypto
The most dangerous object in finance is a beautiful backtest.
With enough parameters you can fit any history. The curve goes up and to the right — and tells you nothing about the future.
Three rules we use against self-deception:
1️⃣ Plateau, not peak. We choose parameters in the middle of a wide stable area, not at the single best point. A peak is luck; a plateau is structure.
2️⃣ Random in-sample and out-of-sample months, different for every test — so the hard months cannot hide.
3️⃣ Live trading is the only final judge. A backtest is a hypothesis; a real account is evidence.
If you remember one thing: be suspicious of the best result, trust the stable one.
#backtesting #quant #crypto
With enough parameters you can fit any history. The curve goes up and to the right — and tells you nothing about the future.
Three rules we use against self-deception:
1️⃣ Plateau, not peak. We choose parameters in the middle of a wide stable area, not at the single best point. A peak is luck; a plateau is structure.
2️⃣ Random in-sample and out-of-sample months, different for every test — so the hard months cannot hide.
3️⃣ Live trading is the only final judge. A backtest is a hypothesis; a real account is evidence.
If you remember one thing: be suspicious of the best result, trust the stable one.
#backtesting #quant #crypto
80
·
--
Backtesting is key to evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy using $BTC and $ETH can be backtested on data from the last year to see if it would have been profitable. Forward-testing frameworks take this a step further by testing the strategy on new, unseen data. This helps to confirm if the strategy is still effective when the market is sitting at current levels. Using a combination of backtesting and forward-testing can help traders refine their strategies and make more informed decisions. Trading with $BTC can be challenging but with the right approach it can be rewarding. tradingstrategies #backtesting #cryptotrading
Backtesting is key to evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy using $BTC and $ETH can be backtested on data from the last year to see if it would have been profitable. Forward-testing frameworks take this a step further by testing the strategy on new, unseen data. This helps to confirm if the strategy is still effective when the market is sitting at current levels. Using a combination of backtesting and forward-testing can help traders refine their strategies and make more informed decisions. Trading with $BTC can be challenging but with the right approach it can be rewarding. tradingstrategies #backtesting #cryptotrading
19
“You don’t want to backtest? Someone has done the homework for you.”
Backtesting may be time consuming and tiring, but it reveals your strategy’s win rate, risk-to-reward ratio, maximum drawndown, and whether you can trust it with real money.
I’ve tested my trading strategy across 1,000+ trades—focusing on maximizing returns with proper risk management.
Don’t want to do the research yourself?
You can build your own edge—or follow someone who already has.
You’re welcome to copy me, but remember: everyone has different risk appetite & stress tolerance. P.S. past performance doesn’t guarantee future results.
Trade smart and copy me.
#CryptoTrading #Backtesting #RiskManagement #CopyTrading
“You don’t want to backtest? Someone has done the homework for you.”
Backtesting may be time consuming and tiring, but it reveals your strategy’s win rate, risk-to-reward ratio, maximum drawndown, and whether you can trust it with real money.
I’ve tested my trading strategy across 1,000+ trades—focusing on maximizing returns with proper risk management.
Don’t want to do the research yourself?
You can build your own edge—or follow someone who already has.
You’re welcome to copy me, but remember: everyone has different risk appetite & stress tolerance. P.S. past performance doesn’t guarantee future results.
Trade smart and copy me.
#CryptoTrading #Backtesting #RiskManagement #CopyTrading
Backtesting may be time consuming and tiring, but it reveals your strategy’s win rate, risk-to-reward ratio, maximum drawndown, and whether you can trust it with real money.
I’ve tested my trading strategy across 1,000+ trades—focusing on maximizing returns with proper risk management.
Don’t want to do the research yourself?
You can build your own edge—or follow someone who already has.
You’re welcome to copy me, but remember: everyone has different risk appetite & stress tolerance. P.S. past performance doesn’t guarantee future results.
Trade smart and copy me.
#CryptoTrading #Backtesting #RiskManagement #CopyTrading
1
1
223
🧠 EVERYONE HAS A STRATEGY. VERY FEW HAVE PROOF OF AN EDGE.
A chart setup that worked three times is not statistical evidence.
Serious traders test:
📈 Performance across different market regimes
📉 Maximum drawdown
🧮 Expectancy after fees
🔁 Out-of-sample results
⚙️ Sensitivity to entry and exit rules
A strategy that only works after endless adjustments may be overfitted.
If your edge disappears when conditions change slightly, how robust was it?
Less storytelling. More data.
What’s your minimum backtest sample before trusting a setup?
#Backtesting #Quantitativetrading #TradingSystems #CryptoMarkets #BinanceSquare
🧠 EVERYONE HAS A STRATEGY. VERY FEW HAVE PROOF OF AN EDGE.
A chart setup that worked three times is not statistical evidence.
Serious traders test:
📈 Performance across different market regimes
📉 Maximum drawdown
🧮 Expectancy after fees
🔁 Out-of-sample results
⚙️ Sensitivity to entry and exit rules
A strategy that only works after endless adjustments may be overfitted.
If your edge disappears when conditions change slightly, how robust was it?
Less storytelling. More data.
What’s your minimum backtest sample before trusting a setup?
#Backtesting #Quantitativetrading #TradingSystems #CryptoMarkets #BinanceSquare
A chart setup that worked three times is not statistical evidence.
Serious traders test:
📈 Performance across different market regimes
📉 Maximum drawdown
🧮 Expectancy after fees
🔁 Out-of-sample results
⚙️ Sensitivity to entry and exit rules
A strategy that only works after endless adjustments may be overfitted.
If your edge disappears when conditions change slightly, how robust was it?
Less storytelling. More data.
What’s your minimum backtest sample before trusting a setup?
#Backtesting #Quantitativetrading #TradingSystems #CryptoMarkets #BinanceSquare
18
ලිපිය
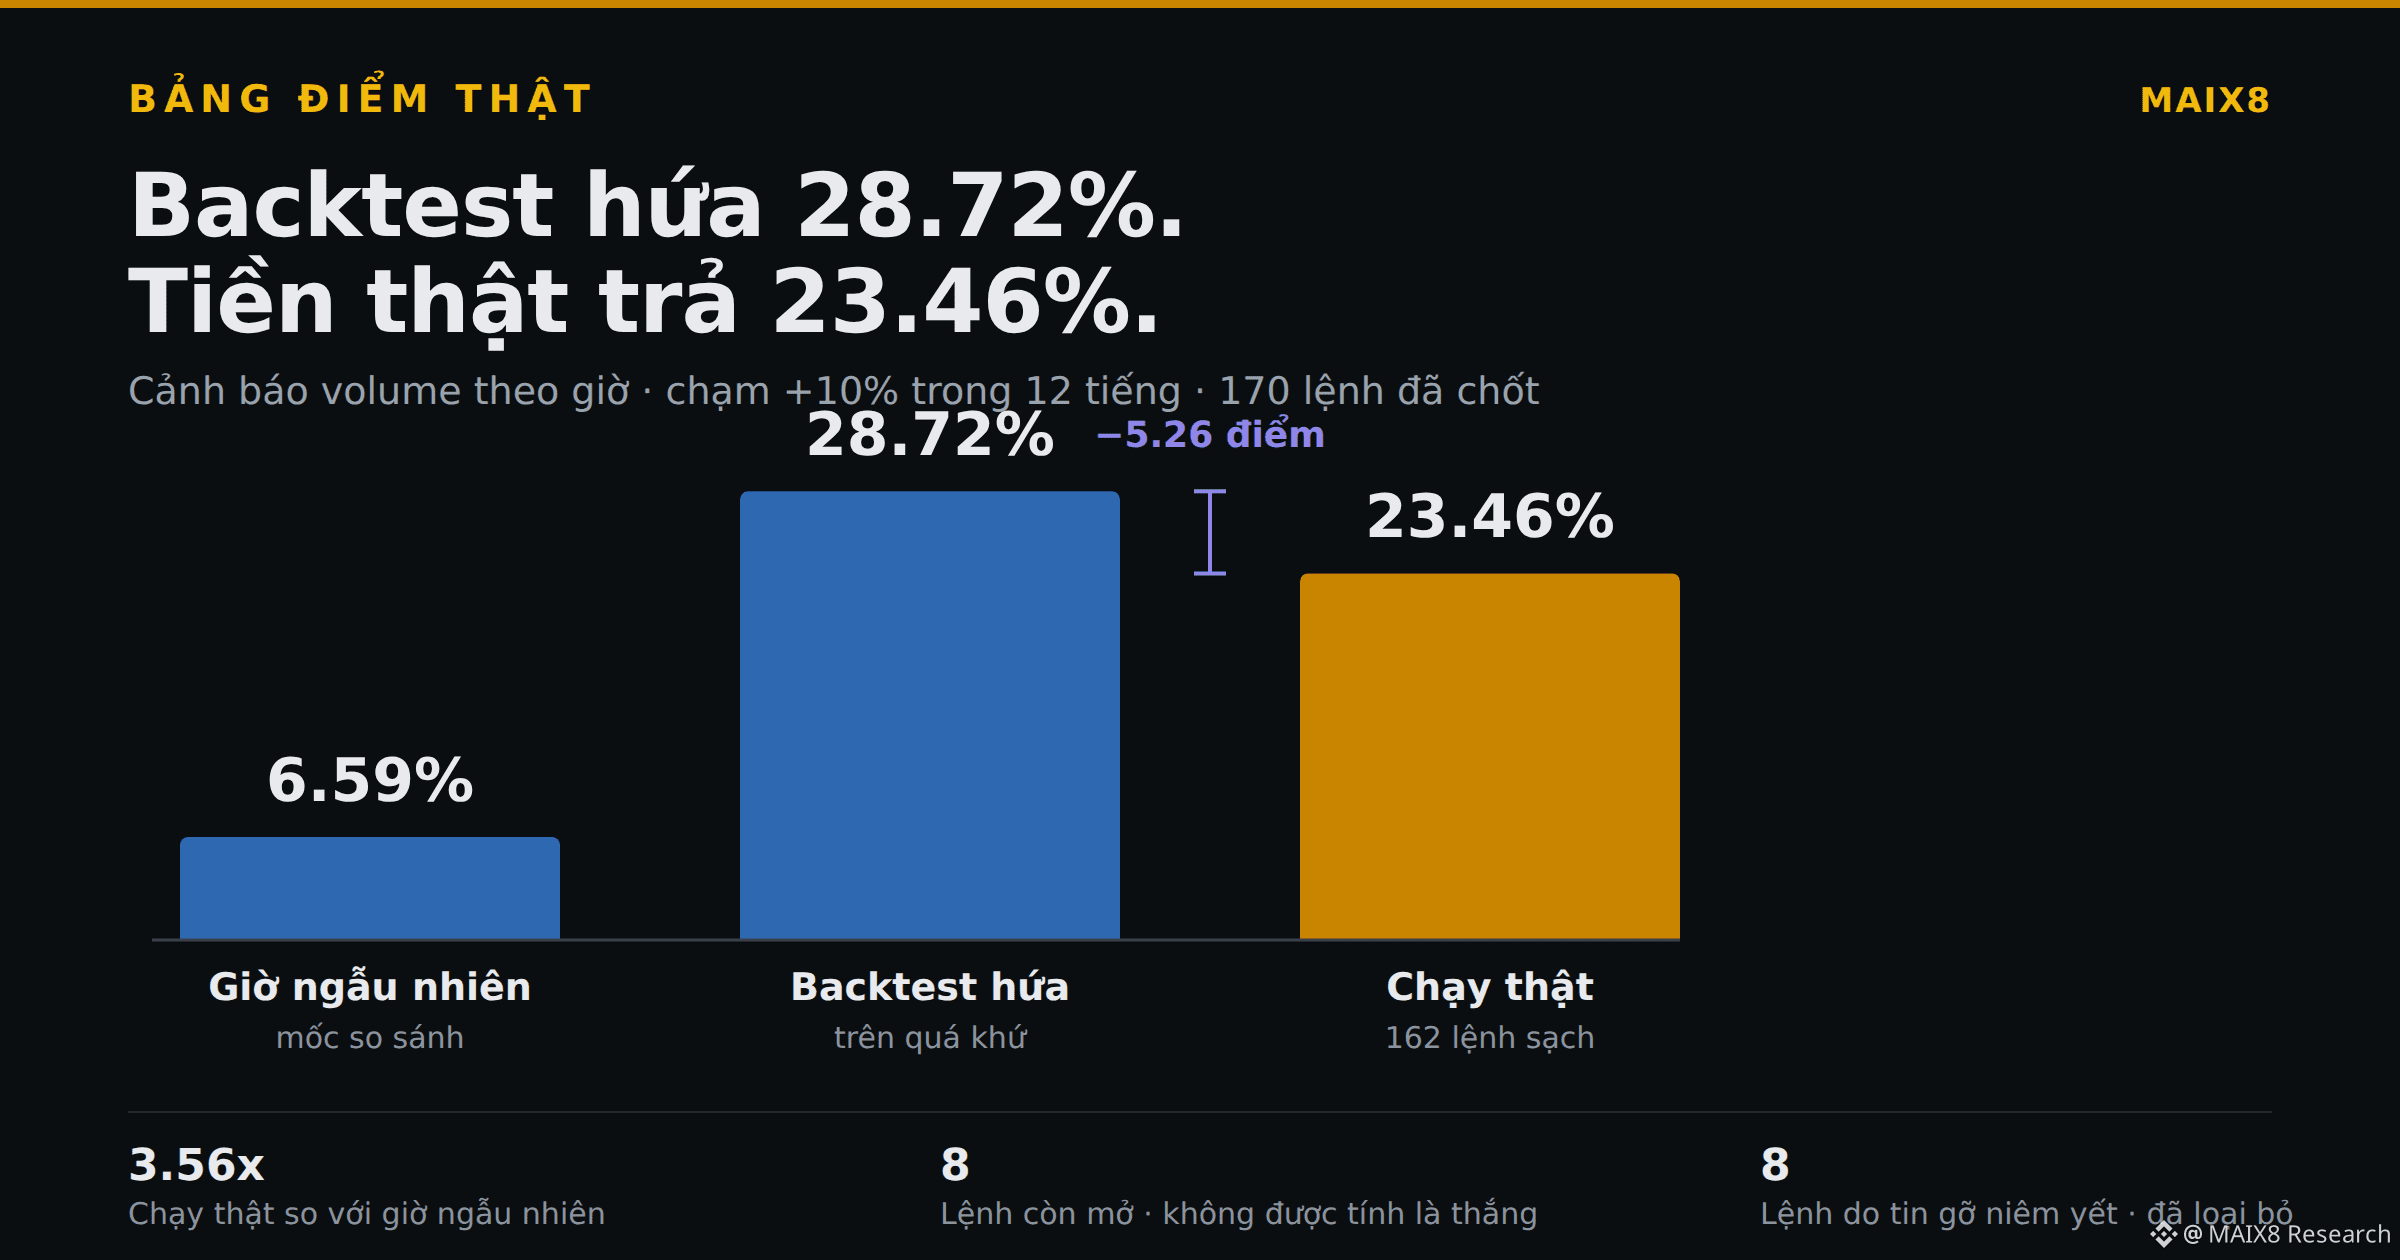
Backtest Hứa 28.72%. Chạy Bằng Tiền Thật Trả 23.46%.Backtest hứa cảnh báo volume theo giờ của tôi chạm +10% trong 12 tiếng 28.72% số lần.
Máy đã chạy thật. 170 cảnh báo đóng cửa sổ. Điểm số:
**23.46%** trên 162 lệnh sạch.
Thấp hơn backtest 5.26 điểm. Đúng như mọi backtest: chạy thật luôn kém hơn chạy trên giấy.
Nhưng vẫn gấp **3.56 lần** một giờ ngẫu nhiên (6.59%). Edge có thật, chỉ nhỏ hơn tờ quảng cáo.
Ba điều đi kèm con số đó.
**Một.** 8 cảnh báo còn mở và **không được tính**. Vị thế chưa hết khung giờ không phải chiến thắng.
**Hai.** Tôi bỏ 8 cảnh báo sinh từ tin gỡ niêm yết — chỉ 4.49% tổng số nhưng bơm mạnh nhất bảng. Bỏ chúng làm điểm **giảm** từ 25.88% xuống 23.46%. Vẫn bỏ: thanh lý cưỡng bức là cách dễ nhất chế ra volume, và nói ít nhất về nhu cầu.
**Ba, quan trọng nhất:** hơn ba phần tư số cảnh báo **không chạm mục tiêu**. Đó là hình dạng thật của một edge nhỏ. Ai bán cho bạn tỷ lệ thắng bảy trên mười đang bán thứ khác.
Quan điểm: CHỜ. Tôi thích 23.46% đo trên tiền thật hơn 28.72% đo trên quá khứ.
Bạn đã đối chiếu backtest của mình với kết quả chạy thật chưa?
Nghiên cứu giáo dục, không phải lời khuyên đầu tư.
$BTC #TradingSignals #Backtesting #WriteToEarn
Backtest Hứa 28.72%. Chạy Bằng Tiền Thật Trả 23.46%.
Backtest hứa cảnh báo volume theo giờ của tôi chạm +10% trong 12 tiếng 28.72% số lần.
Máy đã chạy thật. 170 cảnh báo đóng cửa sổ. Điểm số:
**23.46%** trên 162 lệnh sạch.
Thấp hơn backtest 5.26 điểm. Đúng như mọi backtest: chạy thật luôn kém hơn chạy trên giấy.
Nhưng vẫn gấp **3.56 lần** một giờ ngẫu nhiên (6.59%). Edge có thật, chỉ nhỏ hơn tờ quảng cáo.
Ba điều đi kèm con số đó.
**Một.** 8 cảnh báo còn mở và **không được tính**. Vị thế chưa hết khung giờ không phải chiến thắng.
**Hai.** Tôi bỏ 8 cảnh báo sinh từ tin gỡ niêm yết — chỉ 4.49% tổng số nhưng bơm mạnh nhất bảng. Bỏ chúng làm điểm **giảm** từ 25.88% xuống 23.46%. Vẫn bỏ: thanh lý cưỡng bức là cách dễ nhất chế ra volume, và nói ít nhất về nhu cầu.
**Ba, quan trọng nhất:** hơn ba phần tư số cảnh báo **không chạm mục tiêu**. Đó là hình dạng thật của một edge nhỏ. Ai bán cho bạn tỷ lệ thắng bảy trên mười đang bán thứ khác.
Quan điểm: CHỜ. Tôi thích 23.46% đo trên tiền thật hơn 28.72% đo trên quá khứ.
Bạn đã đối chiếu backtest của mình với kết quả chạy thật chưa?
Nghiên cứu giáo dục, không phải lời khuyên đầu tư.
$BTC #TradingSignals #Backtesting #WriteToEarn
Máy đã chạy thật. 170 cảnh báo đóng cửa sổ. Điểm số:
**23.46%** trên 162 lệnh sạch.
Thấp hơn backtest 5.26 điểm. Đúng như mọi backtest: chạy thật luôn kém hơn chạy trên giấy.
Nhưng vẫn gấp **3.56 lần** một giờ ngẫu nhiên (6.59%). Edge có thật, chỉ nhỏ hơn tờ quảng cáo.
Ba điều đi kèm con số đó.
**Một.** 8 cảnh báo còn mở và **không được tính**. Vị thế chưa hết khung giờ không phải chiến thắng.
**Hai.** Tôi bỏ 8 cảnh báo sinh từ tin gỡ niêm yết — chỉ 4.49% tổng số nhưng bơm mạnh nhất bảng. Bỏ chúng làm điểm **giảm** từ 25.88% xuống 23.46%. Vẫn bỏ: thanh lý cưỡng bức là cách dễ nhất chế ra volume, và nói ít nhất về nhu cầu.
**Ba, quan trọng nhất:** hơn ba phần tư số cảnh báo **không chạm mục tiêu**. Đó là hình dạng thật của một edge nhỏ. Ai bán cho bạn tỷ lệ thắng bảy trên mười đang bán thứ khác.
Quan điểm: CHỜ. Tôi thích 23.46% đo trên tiền thật hơn 28.72% đo trên quá khứ.
Bạn đã đối chiếu backtest của mình với kết quả chạy thật chưa?
Nghiên cứu giáo dục, không phải lời khuyên đầu tư.
$BTC #TradingSignals #Backtesting #WriteToEarn
120
·
--
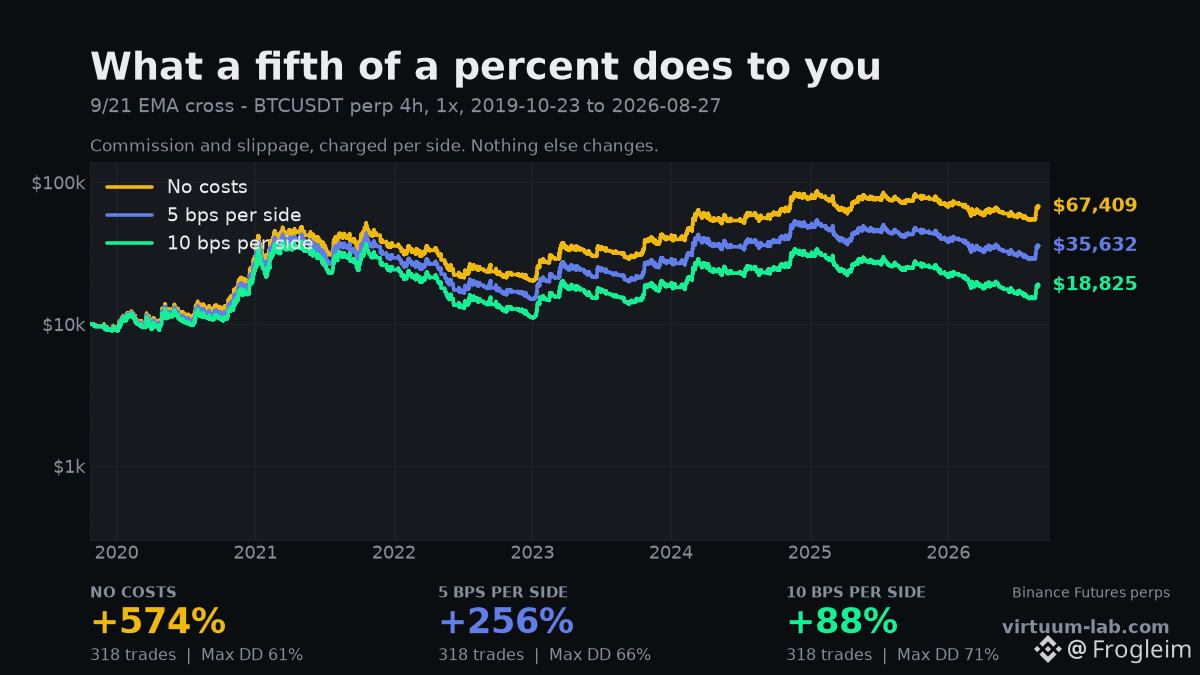
0.1% a trade cost this strategy 486 points.
9/21 EMA cross on BTCUSDT perp, 4 hour bars, 1x, 2019-10-23 to today. 318 trades. The strategy never changes — only what each trade costs.
No costs at all: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps is 0.1%. It is roughly what you actually pay as a taker once spread and slippage are counted, and it turns a spectacular backtest into an ordinary one.
The reason it bites this hard is 318 trades. Cost is charged per trade, so it scales with activity while your edge does not. A slow strategy can ignore fees. A strategy that trades every few days cannot — it is paying rent 318 times.
This is why the most common backtesting mistake isn't a bad indicator. It's a zero in the fee box. Every high-frequency strategy looks brilliant at 0 bps.
If your backtester doesn't charge commission and slippage per side, it isn't testing your strategy. It's testing a fantasy version that trades for free.
Charge yourself what your exchange charges you 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
0.1% a trade cost this strategy 486 points.
9/21 EMA cross on BTCUSDT perp, 4 hour bars, 1x, 2019-10-23 to today. 318 trades. The strategy never changes — only what each trade costs.
No costs at all: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps is 0.1%. It is roughly what you actually pay as a taker once spread and slippage are counted, and it turns a spectacular backtest into an ordinary one.
The reason it bites this hard is 318 trades. Cost is charged per trade, so it scales with activity while your edge does not. A slow strategy can ignore fees. A strategy that trades every few days cannot — it is paying rent 318 times.
This is why the most common backtesting mistake isn't a bad indicator. It's a zero in the fee box. Every high-frequency strategy looks brilliant at 0 bps.
If your backtester doesn't charge commission and slippage per side, it isn't testing your strategy. It's testing a fantasy version that trades for free.
Charge yourself what your exchange charges you 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
9/21 EMA cross on BTCUSDT perp, 4 hour bars, 1x, 2019-10-23 to today. 318 trades. The strategy never changes — only what each trade costs.
No costs at all: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps is 0.1%. It is roughly what you actually pay as a taker once spread and slippage are counted, and it turns a spectacular backtest into an ordinary one.
The reason it bites this hard is 318 trades. Cost is charged per trade, so it scales with activity while your edge does not. A slow strategy can ignore fees. A strategy that trades every few days cannot — it is paying rent 318 times.
This is why the most common backtesting mistake isn't a bad indicator. It's a zero in the fee box. Every high-frequency strategy looks brilliant at 0 bps.
If your backtester doesn't charge commission and slippage per side, it isn't testing your strategy. It's testing a fantasy version that trades for free.
Charge yourself what your exchange charges you 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
153
·
--
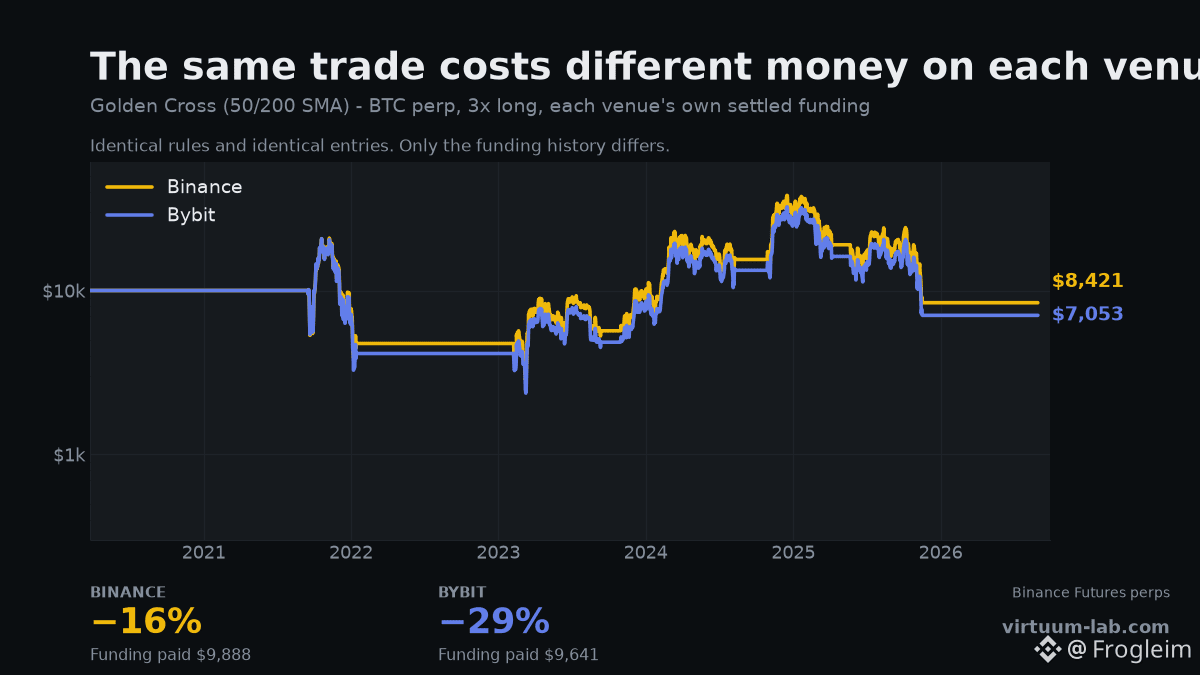
Same strategy. Same pair. Same five trades, on the same days. Two exchanges, 14 points apart.
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 to today, each venue charged its own settled funding.
Binance: −16% — $9,888 of funding paid
Bybit: −29% — $9,641 of funding paid
The entries and exits are identical. Same signal dates, all 5 of them. And the funding bills are within a few hundred dollars of each other, so that isn't the explanation either.
The gap is the candles. Every exchange prints its own price, and a rule that reads "close above the 200 SMA" reads a slightly different close on each one. Same rule, different prints, different fills — and 14 points of difference by the end.
Which means a backtest is only as real as the venue it was run on. If you tested on one exchange's data and traded on another's, you tested a strategy you did not deploy.
It also puts a floor on precision. If two honest data sources disagree by 14 points on the same rules, no backtest result is accurate to the decimal place, and anyone quoting you one is selling something.
Pick the exchange you actually trade on 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
Same strategy. Same pair. Same five trades, on the same days. Two exchanges, 14 points apart.
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 to today, each venue charged its own settled funding.
Binance: −16% — $9,888 of funding paid
Bybit: −29% — $9,641 of funding paid
The entries and exits are identical. Same signal dates, all 5 of them. And the funding bills are within a few hundred dollars of each other, so that isn't the explanation either.
The gap is the candles. Every exchange prints its own price, and a rule that reads "close above the 200 SMA" reads a slightly different close on each one. Same rule, different prints, different fills — and 14 points of difference by the end.
Which means a backtest is only as real as the venue it was run on. If you tested on one exchange's data and traded on another's, you tested a strategy you did not deploy.
It also puts a floor on precision. If two honest data sources disagree by 14 points on the same rules, no backtest result is accurate to the decimal place, and anyone quoting you one is selling something.
Pick the exchange you actually trade on 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 to today, each venue charged its own settled funding.
Binance: −16% — $9,888 of funding paid
Bybit: −29% — $9,641 of funding paid
The entries and exits are identical. Same signal dates, all 5 of them. And the funding bills are within a few hundred dollars of each other, so that isn't the explanation either.
The gap is the candles. Every exchange prints its own price, and a rule that reads "close above the 200 SMA" reads a slightly different close on each one. Same rule, different prints, different fills — and 14 points of difference by the end.
Which means a backtest is only as real as the venue it was run on. If you tested on one exchange's data and traded on another's, you tested a strategy you did not deploy.
It also puts a floor on precision. If two honest data sources disagree by 14 points on the same rules, no backtest result is accurate to the decimal place, and anyone quoting you one is selling something.
Pick the exchange you actually trade on 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
140
This is tail capture, not income. Realistically it does nothing in calm markets and pays during sharp selloffs. Expecting it to earn every month is how people quit a strategy right before it works.
Here is what that came from.
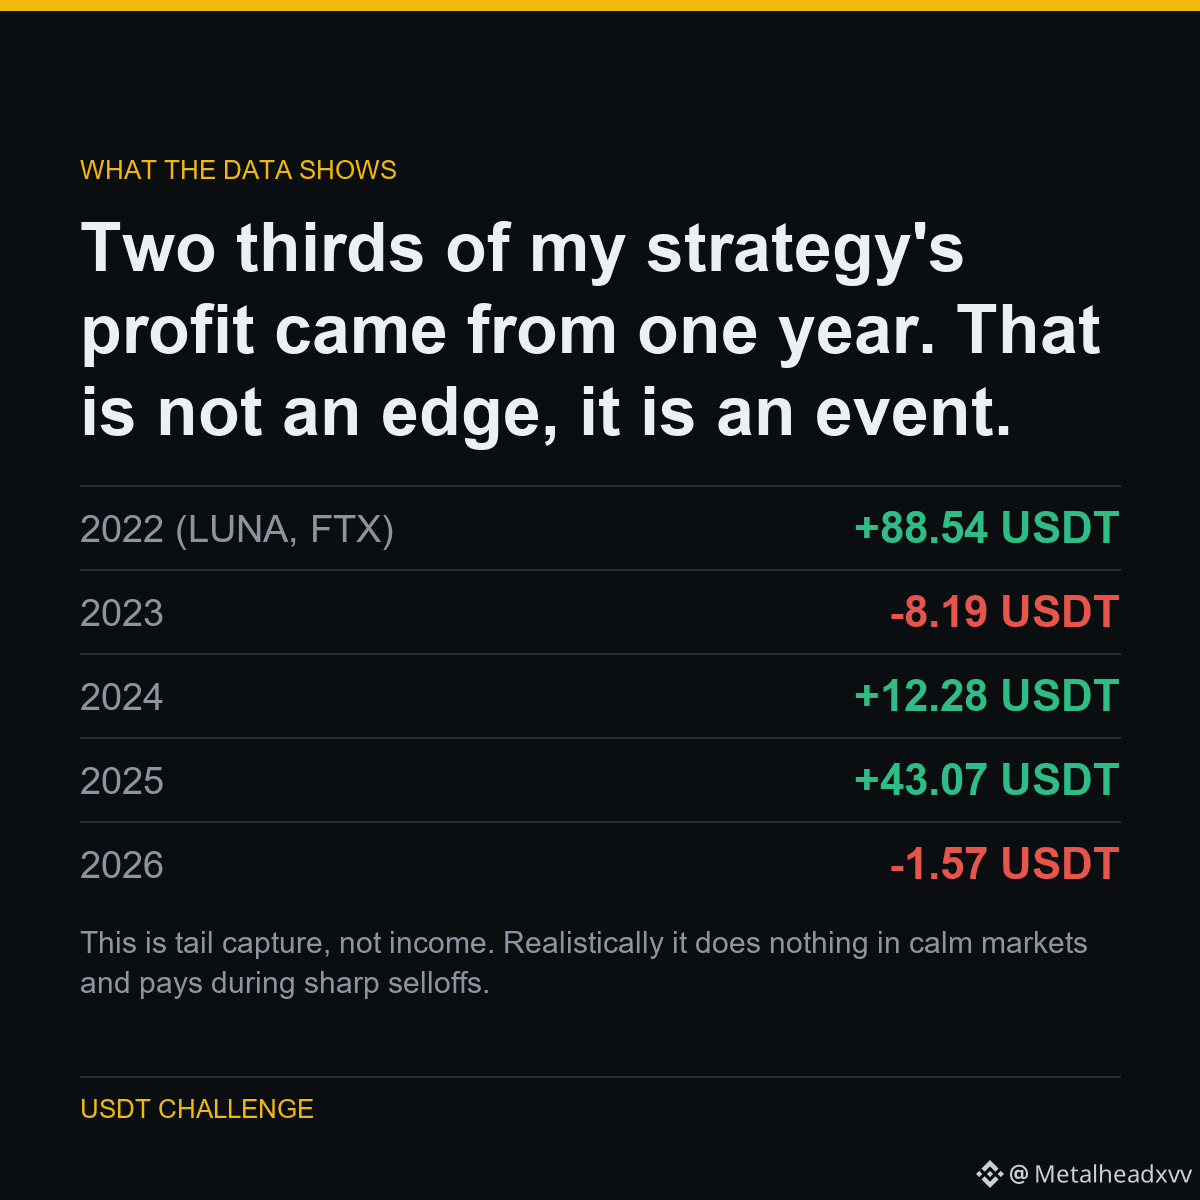
Two thirds of my strategy's profit came from one year. That is not an edge, it is an event.
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
This is tail capture, not income. Realistically it does nothing in calm markets and pays during sharp selloffs. Expecting it to earn every month is how people quit a strategy right before it works.
Here is what that came from.
Two thirds of my strategy's profit came from one year. That is not an edge, it is an event.
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
Here is what that came from.
Two thirds of my strategy's profit came from one year. That is not an edge, it is an event.
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
61

·
--
ලිපිය
EL TRADING ES COMO EL MUSTANG: SE GESTA EN UN LABORATORIOEn mis confesiones de un trader novato, hoy quiero hablarte de por qué operar sin un sistema es como conducir a ciegas...
Debo confesar que cuando empecé en esto, una de las cosas que más me costó fue recordar que un RSI en 70 significaba sobrecompra y en 30 sobreventa. Algo tan 'básico' creaba un vacío aterrador en mi mente. Y no, no era por falta de inteligencia; era porque hacer trading con dislexia y discalculia te obliga a vivir en un universo donde los números y las direcciones a veces se transforman en un túnel sin salida.
Esto me hizo recordar al samurái Musashi (del que he hablado un par de veces) y la máxima platónica de 'Conócete a ti mismo'. Ellos sabían que para hacer cualquier cosa bien en la vida, primero debes mirar de frente a tus sombras. En el trading, mi sombra eran los números cruzándose en mi pantalla; mi luz fue aceptar esa realidad.
Los manuales tradicionales te venden una fantasía: configuraciones de velas perfectas, niveles mágicos de Fibonacci o la idea de que si el mercado está sobrecomprado caerá en cualquier momento, haciéndote esperar con ansiedad.
Nos alimentan con historias épicas de grandes hombres que se hicieron millonarios, impulsándonos a apostar más, a intentar movernos como ballenas o a copiar ratios de retorno (ROI) que solo existen en sueños.
Pasamos horas viendo fijamente los gráficos repitiendo teorías ajenas, pagando grupos de señales o siguiendo a gurús porque desconocemos por qué el mercado hace lo que hace.
Nos dicen que debemos ser 'resilientes', levantarnos rápido y aprender de los errores. Pero cuando estás a oscuras, no sabes cómo levantarte. Y muchas veces, quienes venden los cursos no te dejan saber cómo hacerlo por ti mismo.
Los libros están ahí y los conceptos son públicos. Sin embargo, lo que no te dicen es que el trading profesional y rentable no se gesta persiguiendo el precio en vivo; se gesta en el laboratorio, en el backtesting y la simulación matemática.
Antes de abrir un gráfico y poner una sola orden, un trader de sistemas ya sabe exactamente dónde entrar, dónde salir, cuándo hacerlo, por qué lo hace y qué probabilidades estadísticas tiene a su favor. Sabe cuántas pérdidas consecutivas representan una bandera roja matemática y no una simple mala racha emocional.
Conocerte a ti mismo tiene la gran ventaja de ayudarte en la ejecución diaria y en proteger tu mente, pero lo que realmente va a sostener tu rentabilidad a largo plazo es probar científicamente tus estrategias antes de arriesgar un solo centavo en el mercado.
Si quieres dejar de adivinar y empezar a operar como un profesional de sistemas, estos son los tres pasos más básicos para construir tu propio laboratorio de backtesting:
1. Define reglas fijas sin emociones: Escribe en un papel exactamente qué triggers técnicos causan tu entrada y tu salida. Si la regla tiene espacio para la intuición, no es una estrategia; es una corazonada.
2. Recopila y registra el pasado: Toma una muestra mínima de 100 operaciones en el histórico del gráfico aplicando tus reglas de forma estricta. Registra cada ganancia, pérdida, drawdown máximo y racha consecutiva en una hoja de cálculo.
3. Busca la esperanza matemática: Suma tus ganancias totales y réstales tus pérdidas. Si el resultado neto es positivo tras esa muestra, tienes un sistema viable. Si es negativo, el mercado te acaba de salvar dinero real avisando en el papel.
El trading es mucho más que poner una orden; es el arte de conocer tus sombras y el rigor científico de probar tus ideas antes de abrir un gráfico.
Son tiempos de lectura.
{future}(BTCUSDT)
#tradingdesimulacion #Backtesting #PsicologiaDelMercado #BinanceSquare #bitcoin
EL TRADING ES COMO EL MUSTANG: SE GESTA EN UN LABORATORIO
En mis confesiones de un trader novato, hoy quiero hablarte de por qué operar sin un sistema es como conducir a ciegas...
Debo confesar que cuando empecé en esto, una de las cosas que más me costó fue recordar que un RSI en 70 significaba sobrecompra y en 30 sobreventa. Algo tan 'básico' creaba un vacío aterrador en mi mente. Y no, no era por falta de inteligencia; era porque hacer trading con dislexia y discalculia te obliga a vivir en un universo donde los números y las direcciones a veces se transforman en un túnel sin salida.
Esto me hizo recordar al samurái Musashi (del que he hablado un par de veces) y la máxima platónica de 'Conócete a ti mismo'. Ellos sabían que para hacer cualquier cosa bien en la vida, primero debes mirar de frente a tus sombras. En el trading, mi sombra eran los números cruzándose en mi pantalla; mi luz fue aceptar esa realidad.
Los manuales tradicionales te venden una fantasía: configuraciones de velas perfectas, niveles mágicos de Fibonacci o la idea de que si el mercado está sobrecomprado caerá en cualquier momento, haciéndote esperar con ansiedad.
Nos alimentan con historias épicas de grandes hombres que se hicieron millonarios, impulsándonos a apostar más, a intentar movernos como ballenas o a copiar ratios de retorno (ROI) que solo existen en sueños.
Pasamos horas viendo fijamente los gráficos repitiendo teorías ajenas, pagando grupos de señales o siguiendo a gurús porque desconocemos por qué el mercado hace lo que hace.
Nos dicen que debemos ser 'resilientes', levantarnos rápido y aprender de los errores. Pero cuando estás a oscuras, no sabes cómo levantarte. Y muchas veces, quienes venden los cursos no te dejan saber cómo hacerlo por ti mismo.
Los libros están ahí y los conceptos son públicos. Sin embargo, lo que no te dicen es que el trading profesional y rentable no se gesta persiguiendo el precio en vivo; se gesta en el laboratorio, en el backtesting y la simulación matemática.
Antes de abrir un gráfico y poner una sola orden, un trader de sistemas ya sabe exactamente dónde entrar, dónde salir, cuándo hacerlo, por qué lo hace y qué probabilidades estadísticas tiene a su favor. Sabe cuántas pérdidas consecutivas representan una bandera roja matemática y no una simple mala racha emocional.
Conocerte a ti mismo tiene la gran ventaja de ayudarte en la ejecución diaria y en proteger tu mente, pero lo que realmente va a sostener tu rentabilidad a largo plazo es probar científicamente tus estrategias antes de arriesgar un solo centavo en el mercado.
Si quieres dejar de adivinar y empezar a operar como un profesional de sistemas, estos son los tres pasos más básicos para construir tu propio laboratorio de backtesting:
1. Define reglas fijas sin emociones: Escribe en un papel exactamente qué triggers técnicos causan tu entrada y tu salida. Si la regla tiene espacio para la intuición, no es una estrategia; es una corazonada.
2. Recopila y registra el pasado: Toma una muestra mínima de 100 operaciones en el histórico del gráfico aplicando tus reglas de forma estricta. Registra cada ganancia, pérdida, drawdown máximo y racha consecutiva en una hoja de cálculo.
3. Busca la esperanza matemática: Suma tus ganancias totales y réstales tus pérdidas. Si el resultado neto es positivo tras esa muestra, tienes un sistema viable. Si es negativo, el mercado te acaba de salvar dinero real avisando en el papel.
El trading es mucho más que poner una orden; es el arte de conocer tus sombras y el rigor científico de probar tus ideas antes de abrir un gráfico.
Son tiempos de lectura.
#tradingdesimulacion #Backtesting #PsicologiaDelMercado #BinanceSquare #bitcoin
Debo confesar que cuando empecé en esto, una de las cosas que más me costó fue recordar que un RSI en 70 significaba sobrecompra y en 30 sobreventa. Algo tan 'básico' creaba un vacío aterrador en mi mente. Y no, no era por falta de inteligencia; era porque hacer trading con dislexia y discalculia te obliga a vivir en un universo donde los números y las direcciones a veces se transforman en un túnel sin salida.
Esto me hizo recordar al samurái Musashi (del que he hablado un par de veces) y la máxima platónica de 'Conócete a ti mismo'. Ellos sabían que para hacer cualquier cosa bien en la vida, primero debes mirar de frente a tus sombras. En el trading, mi sombra eran los números cruzándose en mi pantalla; mi luz fue aceptar esa realidad.
Los manuales tradicionales te venden una fantasía: configuraciones de velas perfectas, niveles mágicos de Fibonacci o la idea de que si el mercado está sobrecomprado caerá en cualquier momento, haciéndote esperar con ansiedad.
Nos alimentan con historias épicas de grandes hombres que se hicieron millonarios, impulsándonos a apostar más, a intentar movernos como ballenas o a copiar ratios de retorno (ROI) que solo existen en sueños.
Pasamos horas viendo fijamente los gráficos repitiendo teorías ajenas, pagando grupos de señales o siguiendo a gurús porque desconocemos por qué el mercado hace lo que hace.
Nos dicen que debemos ser 'resilientes', levantarnos rápido y aprender de los errores. Pero cuando estás a oscuras, no sabes cómo levantarte. Y muchas veces, quienes venden los cursos no te dejan saber cómo hacerlo por ti mismo.
Los libros están ahí y los conceptos son públicos. Sin embargo, lo que no te dicen es que el trading profesional y rentable no se gesta persiguiendo el precio en vivo; se gesta en el laboratorio, en el backtesting y la simulación matemática.
Antes de abrir un gráfico y poner una sola orden, un trader de sistemas ya sabe exactamente dónde entrar, dónde salir, cuándo hacerlo, por qué lo hace y qué probabilidades estadísticas tiene a su favor. Sabe cuántas pérdidas consecutivas representan una bandera roja matemática y no una simple mala racha emocional.
Conocerte a ti mismo tiene la gran ventaja de ayudarte en la ejecución diaria y en proteger tu mente, pero lo que realmente va a sostener tu rentabilidad a largo plazo es probar científicamente tus estrategias antes de arriesgar un solo centavo en el mercado.
Si quieres dejar de adivinar y empezar a operar como un profesional de sistemas, estos son los tres pasos más básicos para construir tu propio laboratorio de backtesting:
1. Define reglas fijas sin emociones: Escribe en un papel exactamente qué triggers técnicos causan tu entrada y tu salida. Si la regla tiene espacio para la intuición, no es una estrategia; es una corazonada.
2. Recopila y registra el pasado: Toma una muestra mínima de 100 operaciones en el histórico del gráfico aplicando tus reglas de forma estricta. Registra cada ganancia, pérdida, drawdown máximo y racha consecutiva en una hoja de cálculo.
3. Busca la esperanza matemática: Suma tus ganancias totales y réstales tus pérdidas. Si el resultado neto es positivo tras esa muestra, tienes un sistema viable. Si es negativo, el mercado te acaba de salvar dinero real avisando en el papel.
El trading es mucho más que poner una orden; es el arte de conocer tus sombras y el rigor científico de probar tus ideas antes de abrir un gráfico.
Son tiempos de lectura.
#tradingdesimulacion #Backtesting #PsicologiaDelMercado #BinanceSquare #bitcoin
1
650
·
--
උසබ තත්ත්වය
We believe crypto should feel less like a casino.
And more like a well-tested system for sustainable growth.
That's why CryptoGates exists:
→ Build strategies — don't guess them
→ Backtest on real historical data — don't assume
→ Predict & optimize — don't hope
→ Automate with discipline — don't react
Earning without stress.
Participating without obsession.
Growing without gambling.
No signup. No credit card. Just build.👇
$BTC $BNB #Backtesting
We believe crypto should feel less like a casino.
And more like a well-tested system for sustainable growth.
That's why CryptoGates exists:
→ Build strategies — don't guess them
→ Backtest on real historical data — don't assume
→ Predict & optimize — don't hope
→ Automate with discipline — don't react
Earning without stress.
Participating without obsession.
Growing without gambling.
No signup. No credit card. Just build.👇
$BTC $BNB #Backtesting
And more like a well-tested system for sustainable growth.
That's why CryptoGates exists:
→ Build strategies — don't guess them
→ Backtest on real historical data — don't assume
→ Predict & optimize — don't hope
→ Automate with discipline — don't react
Earning without stress.
Participating without obsession.
Growing without gambling.
No signup. No credit card. Just build.👇
$BTC $BNB #Backtesting
136
·
--
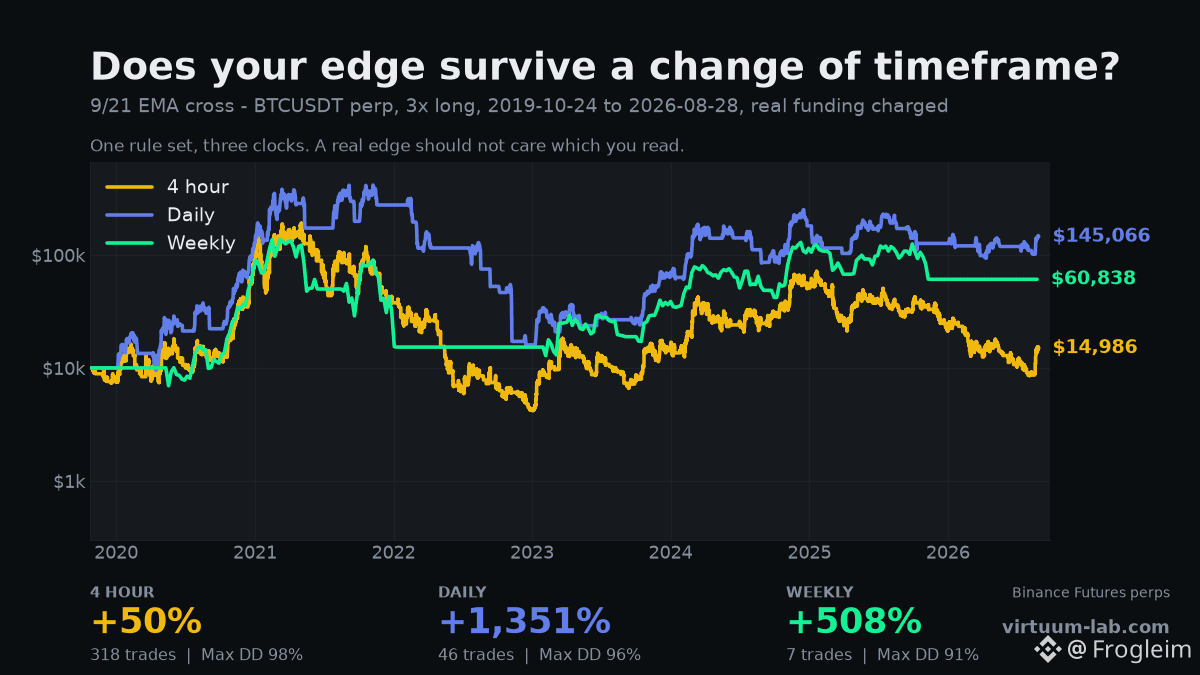
Same rule. Three clocks. 1,301 points apart.
9/21 EMA cross, 3x long BTCUSDT perp, real Binance funding, same window on all three so nothing gets a head start.
4 hour: +50% — 318 trades, max drawdown 98%
Daily: +1,351% — 46 trades, max drawdown 96%
Weekly: +508% — 7 trades, max drawdown 91%
Nobody chose a timeframe for a reason. You picked the one your chart opened on.
The 4 hour version trades 318 times and hands almost all of it back — every crossing costs fees, slippage and funding, and on a fast clock most crossings are noise. The weekly version takes 7 trades in 41 years and keeps more of what it makes.
The uncomfortable read: if a strategy only works on one timeframe, the timeframe is doing the work, not the strategy. A real edge degrades gracefully when you change the clock. This one doesn't — it swings by 1,301 points.
Before you trust a backtest, run it on the timeframe either side of the one you like.
Change the clock and see what survives 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
Same rule. Three clocks. 1,301 points apart.
9/21 EMA cross, 3x long BTCUSDT perp, real Binance funding, same window on all three so nothing gets a head start.
4 hour: +50% — 318 trades, max drawdown 98%
Daily: +1,351% — 46 trades, max drawdown 96%
Weekly: +508% — 7 trades, max drawdown 91%
Nobody chose a timeframe for a reason. You picked the one your chart opened on.
The 4 hour version trades 318 times and hands almost all of it back — every crossing costs fees, slippage and funding, and on a fast clock most crossings are noise. The weekly version takes 7 trades in 41 years and keeps more of what it makes.
The uncomfortable read: if a strategy only works on one timeframe, the timeframe is doing the work, not the strategy. A real edge degrades gracefully when you change the clock. This one doesn't — it swings by 1,301 points.
Before you trust a backtest, run it on the timeframe either side of the one you like.
Change the clock and see what survives 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
9/21 EMA cross, 3x long BTCUSDT perp, real Binance funding, same window on all three so nothing gets a head start.
4 hour: +50% — 318 trades, max drawdown 98%
Daily: +1,351% — 46 trades, max drawdown 96%
Weekly: +508% — 7 trades, max drawdown 91%
Nobody chose a timeframe for a reason. You picked the one your chart opened on.
The 4 hour version trades 318 times and hands almost all of it back — every crossing costs fees, slippage and funding, and on a fast clock most crossings are noise. The weekly version takes 7 trades in 41 years and keeps more of what it makes.
The uncomfortable read: if a strategy only works on one timeframe, the timeframe is doing the work, not the strategy. A real edge degrades gracefully when you change the clock. This one doesn't — it swings by 1,301 points.
Before you trust a backtest, run it on the timeframe either side of the one you like.
Change the clock and see what survives 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
124
තවත් අන්තර්ගතයන් ගවේෂණය කිරීමට ඇතුල් වන්න
Binance චතුරශ්රය හි ගෝලීය ක්රිප්ටෝ පරිශීලකයින් හා එක්වන්න
⚡️ ක්රිප්ටෝ පිළිබඳ නවතම සහ ප්රයෝජනවත් තොරතුරු ලබා ගන්න.
💬 ලොව විශාලතම ක්රිප්ටෝ හුවමාරුව මගින් විශ්වාස කෙරේ.
👍 සත්යායනය කරන ලද නිර්මාණකරුවන්ගෙන් සැබෑ විදසුන් සොයා ගන්න.
විද්යුත් තැපෑල / දුරකථන අංකය
නැගී එන මාතෘකා
1
#BTCReboundsAbove$60KAmidWhaleDipBuying
7,570 නැරඹීම්
76 සාකච්ඡා කරමින්
2
#CaliforniaNvidiaProbeExaminesPotentialCriminalViolations
155 නැරඹීම්
12 සාකච්ඡා කරමින්
3
#BlackRockLaunchesHKDollarDigitalLiquidityFund
245 නැරඹීම්
39 සාකච්ඡා කරමින්
4
#NvidiaLoses$2.7TrillionInMonthAndAHalf
46,362 නැරඹීම්
216 සාකච්ඡා කරමින්
5
#GlobalStocksFaceLongestLosingStreakSince2023
412,869 නැරඹීම්
2,735 සාකච්ඡා කරමින්
6
#BlackRockIBITPostsRecord$541MSingleDayOutflow
61,432 නැරඹීම්
149 සාකච්ඡා කරමින්
7
#AnthropicPlungesTowardIPOPriceonDay2
222,333 නැරඹීම්
1,760 සාකච්ඡා කරමින්
8
#TwentyOneCapitalAdds172.25BTC
108,081 නැරඹීම්
1,149 සාකච්ඡා කරමින්
9
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
14,745 නැරඹීම්
69 සාකච්ඡා කරමින්
10
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
3,665 නැරඹීම්
31 සාකච්ඡා කරමින්