


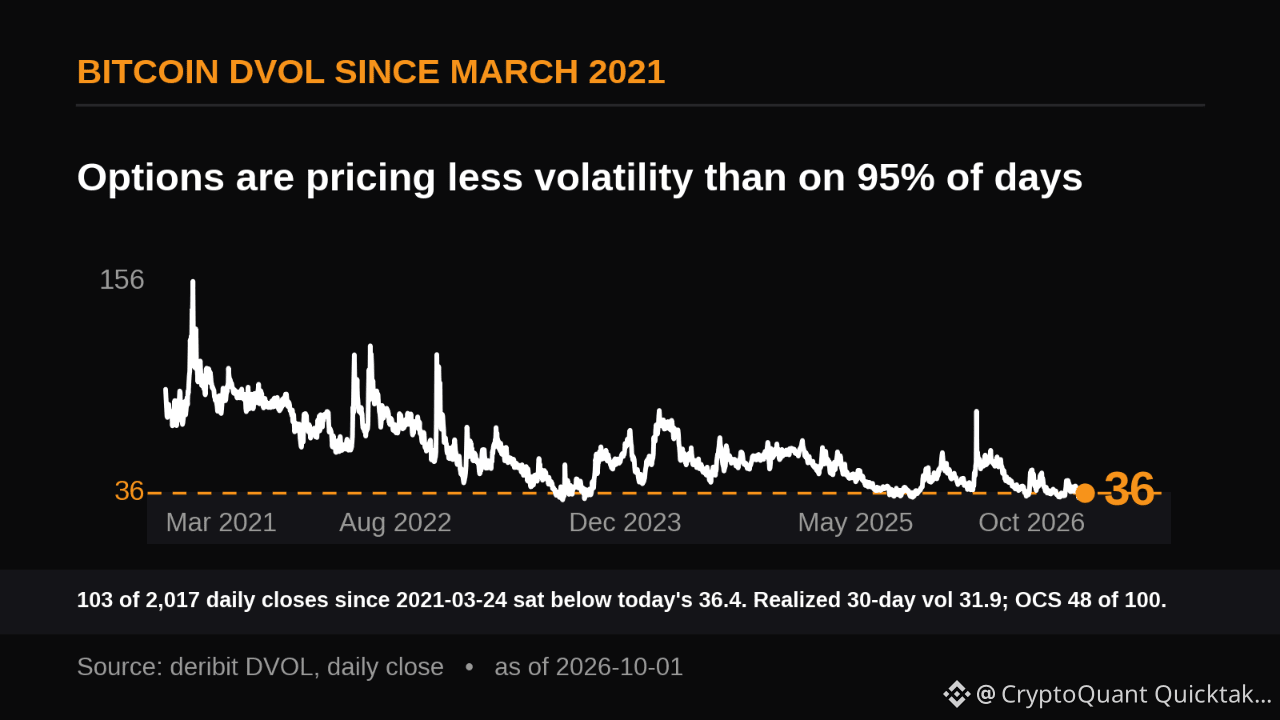
Deribit's DVOL index, the 30-day implied volatility for bitcoin options, sits at 36.42. That is lower than on 95% of days since March 2021. Options are pricing a calm month.
For that print to hold, option sellers have to be comfortable with the risk they carry. The tape gives them cover. Realized 30-day volatility is 31.9, so implied still sits 4.52 points above what the market has delivered. Traders are paying a little extra for downside protection: the 25-delta risk reversal on the 30 October expiry is -2.45.
CryptoQuant's all-exchange Funding Rates tell the same story from the futures side. Funding was 0.0062% on 30 September, inside its 30-day range of 0.0004% to 0.0085%. Perp traders are neither crowded long nor running for the exit.
The caveat matters here. A low implied volatility reading does not make options cheap. Across 1,588 days, DVOL priced more volatility than the next 30 days delivered on 73.4% of them, by a median 10.8 points. A low print shows what the market expects, not what it is missing.
The October expiry has its own tell. The $95,000 call holds $2.0 billion of open interest, the largest strike on the board. Max pain, the price where option holders collectively lose the most and not a target, sits at $77,000 with spot at $84,501.
Bitcoin's options market is priced for a quiet October, and the futures market agrees with it.
What reverses the read: DVOL back above 45 before the 30 October expiry says the calm broke. Realized volatility climbing above 36.42 while DVOL stays flat says sellers underpriced the month.
Written by The Daily Digits