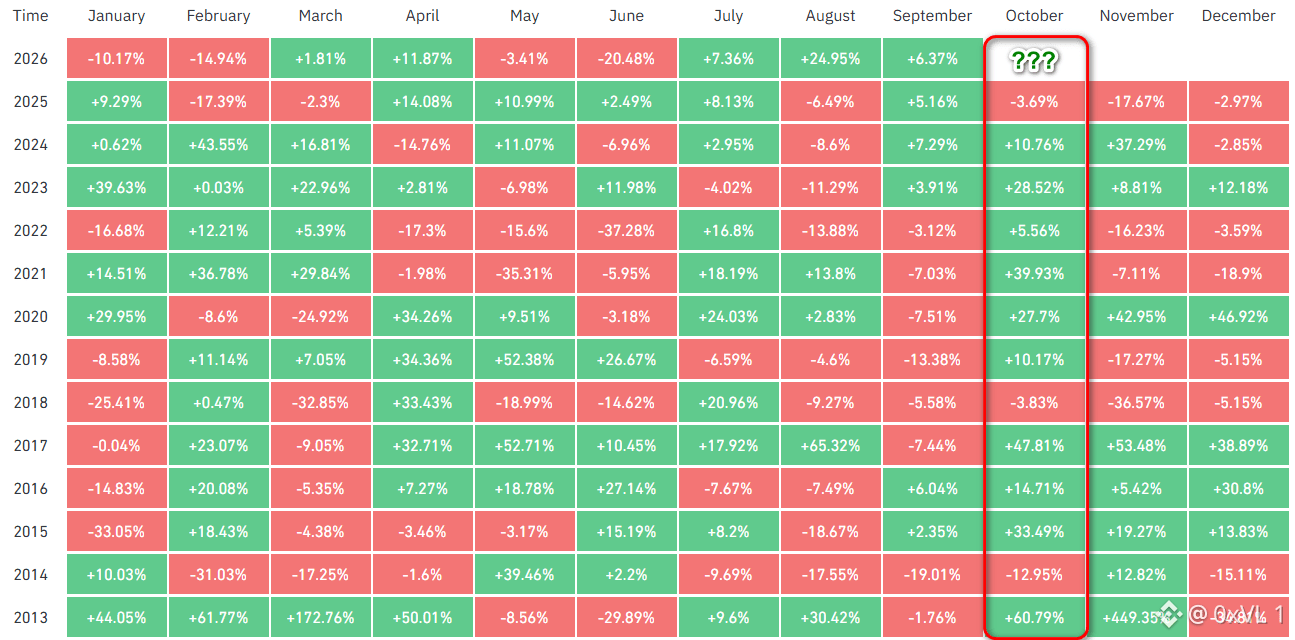
Spot on breakdown of the seasonal tendencies the historical hit rate for October is definitely one of the cleanest patterns across crypto cycles, and it makes total sense why liquidity providers and swing traders lean heavily into Q4 setups. When you look at the structural tailwinds historically lined up around this window, especially post-halving quarters and the usual resurgence in institutional volume after September’s risk-off behavior, the statistical bias toward an "Uptober" rally has solid precedent behind it.
That said, relying purely on seasonal calendar math without factoring in current market regime shifts feels like a dangerous trap. Seasonality is a descriptive observation of past flows, not a predictive fundamental law. The macro environment, structural changes in ETF net flows, and shifting open-interest concentrations can easily override historical averages. I’m pretty skeptical about treating a calendar anomaly as high-conviction alpha, especially when positioning gets this crowded on the long side. If broader macroeconomic liquidity tightens or derivative funding rates overheat prematurely, front-running past history usually ends in a sharp liquidity flush rather than a clean continuation rally. History gives context, but order flow dictates reality. $BTC
That said, relying purely on seasonal calendar math without factoring in current market regime shifts feels like a dangerous trap. Seasonality is a descriptive observation of past flows, not a predictive fundamental law. The macro environment, structural changes in ETF net flows, and shifting open-interest concentrations can easily override historical averages. I’m pretty skeptical about treating a calendar anomaly as high-conviction alpha, especially when positioning gets this crowded on the long side. If broader macroeconomic liquidity tightens or derivative funding rates overheat prematurely, front-running past history usually ends in a sharp liquidity flush rather than a clean continuation rally. History gives context, but order flow dictates reality. $BTC