

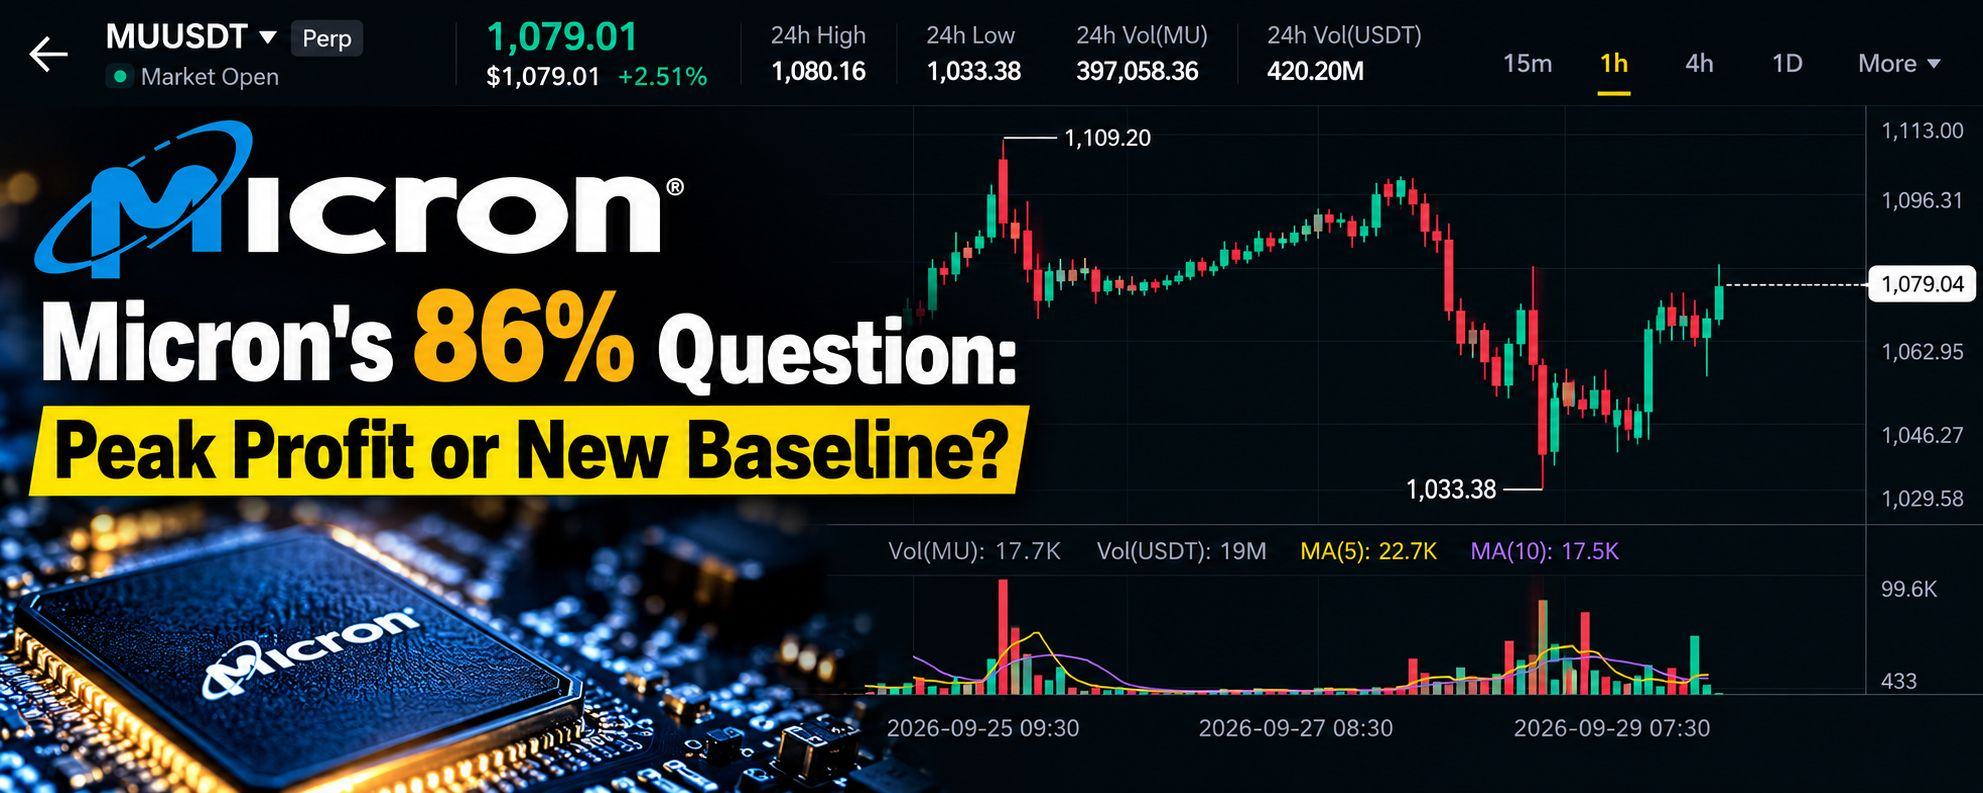

Micron Technology $MU is approaching its FY2026 Q4 earnings report, and one number has caught my attention: 86% gross margin.
For me, the bigger question isn't simply whether Micron can meet its forecast. It's whether the company can maintain such high profitability as the memory market evolves.
What the official numbers tell us
Micron reported $41.456 billion in revenue and an 84.9% non-GAAP gross margin in fiscal Q3 2026. For Q4, management guided for revenue of $50 billion, plus or minus $1 billion, and gross margin of approximately 86%.
That is an ambitious target, but it is important to separate guidance from actual results. The company has not confirmed its Q4 performance until it releases the report.
Why the bullish case still matters
AI infrastructure requires advanced memory, including high-bandwidth memory (HBM). If demand remains strong and supply stays tight, Micron could continue to benefit from favorable pricing and a product mix that supports profitability.
That is the part of the story I will be watching closely. Can demand translate into sustainable earnings growth rather than just another strong quarter?
What could go wrong?
I don't think the risks should be ignored. Memory is a cyclical industry, and supply conditions can change as manufacturers expand production.
There is also the question of expectations. Even if Micron reports strong numbers, the stock could react negatively if investors were expecting even more. Slower memory price increases or weaker forward guidance could also challenge the bullish case.
A good earnings report and a good stock entry are not necessarily the same thing.
What I will watch before considering $MU
I don't currently hold a position in Micron, so my approach is to wait for the actual results rather than make a rushed decision before earnings.
I want to see whether the company delivers its margin outlook, what management says about HBM demand and pricing, and whether its next-quarter guidance supports the current growth story.
For me, confirmation matters more than excitement. I would rather reassess the opportunity after seeing the numbers than assume that strong AI demand guarantees further upside.
Final thoughts
Micron's Q4 report could provide important clues about the health of the memory supercycle. The approximately 86% gross-margin outlook gives investors a clear benchmark, but sustaining that profitability may be just as important as achieving it once.
What do you think: can Micron maintain margins around 86%, or could slower price increases signal that the memory cycle is approaching a turning point?
