

#hbm
hbm
Просмотров: 92,699
381 обсуждают
Популярные
Новые
·
--
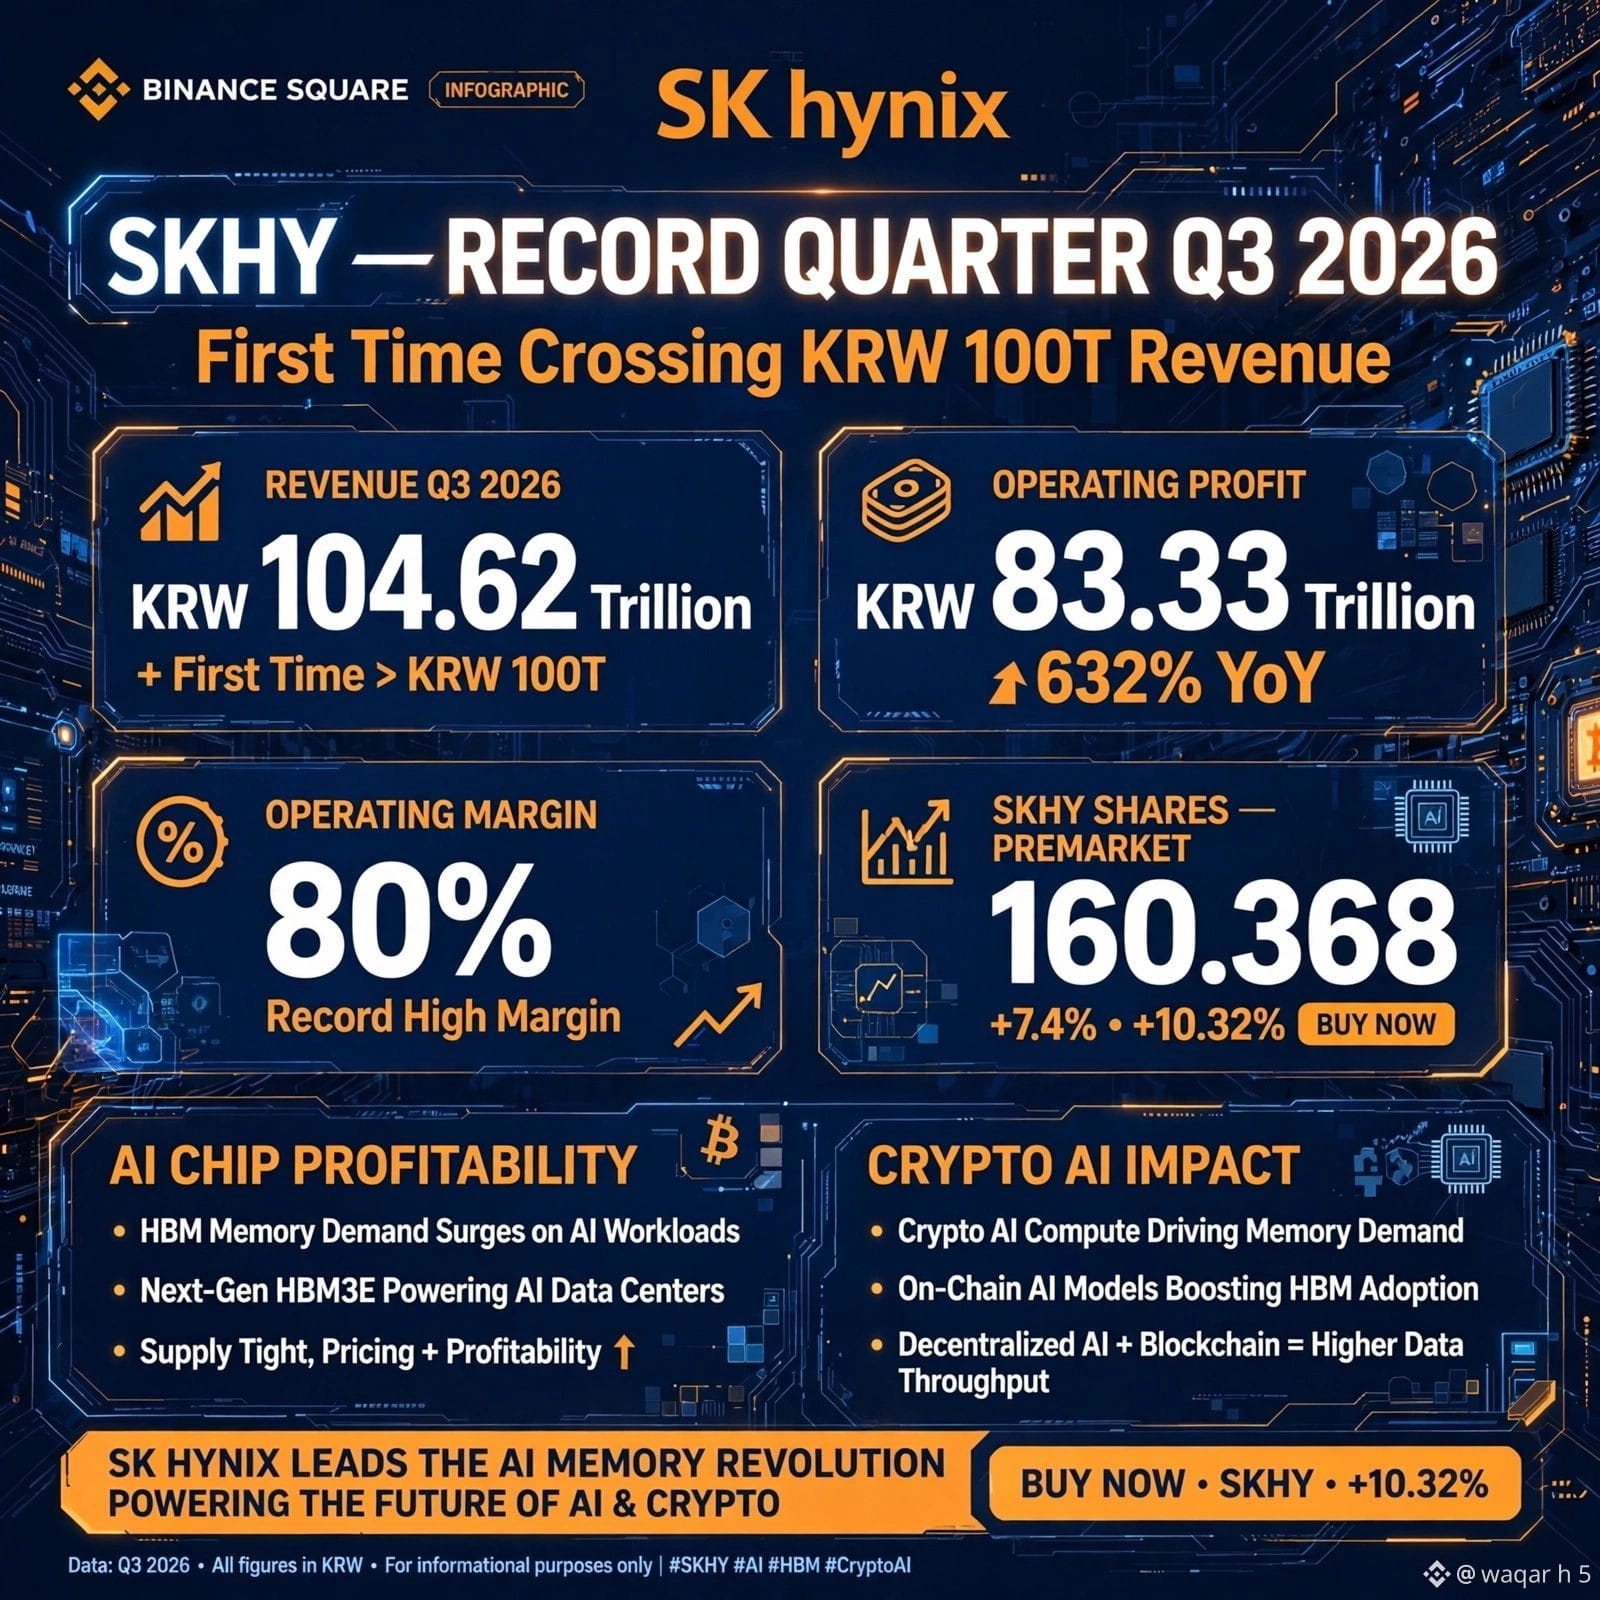
SK Hynix (SKHY) — RECORD QUARTER! Shares +7.4% Premarket 🔥
SK Hynix just delivered one of the STRONGEST earnings in chip sector history — Q3 2026:
📊 Revenue Q3 2026: KRW 104.62 TRILLION — First time ever crossing KRW 100T! 💥
💰 Operating Profit: KRW 83.33 Trillion — UP 632% YoY
📈 Operating Margin: 80% — Record High, showing insane AI chip profitability
🚀 SKHY Shares: 160.368 (+7.4% premarket, +10.32%) — BUY NOW momentum
Why This Matters for Crypto AI?
✅ HBM Memory Demand Surging — AI workloads + Crypto AI compute driving it
✅ Next-Gen HBM3E Powering AI Data Centers — tight supply = higher pricing
✅ Crypto AI Impact: Decentralized AI + Blockchain = Higher Data Throughput, On-Chain AI models boosting HBM adoption
SK Hynix Leads The AI Memory Revolution — Powering Future of AI & Crypto!
Is AI chip boom fueling next Crypto AI rally? 👀
#SKHY #SKHynix #AI #HBM #CryptoAI #Binance #Earnings #ChipStocks
$SKHY $BTC $AI
{future}(SKHYUSDT)
{alpha}(46630x2e8c31162b855a2ffa90f6f8634643ad6f111e18)
SK Hynix (SKHY) — RECORD QUARTER! Shares +7.4% Premarket 🔥
SK Hynix just delivered one of the STRONGEST earnings in chip sector history — Q3 2026:
📊 Revenue Q3 2026: KRW 104.62 TRILLION — First time ever crossing KRW 100T! 💥
💰 Operating Profit: KRW 83.33 Trillion — UP 632% YoY
📈 Operating Margin: 80% — Record High, showing insane AI chip profitability
🚀 SKHY Shares: 160.368 (+7.4% premarket, +10.32%) — BUY NOW momentum
Why This Matters for Crypto AI?
✅ HBM Memory Demand Surging — AI workloads + Crypto AI compute driving it
✅ Next-Gen HBM3E Powering AI Data Centers — tight supply = higher pricing
✅ Crypto AI Impact: Decentralized AI + Blockchain = Higher Data Throughput, On-Chain AI models boosting HBM adoption
SK Hynix Leads The AI Memory Revolution — Powering Future of AI & Crypto!
Is AI chip boom fueling next Crypto AI rally? 👀
#SKHY #SKHynix #AI #HBM #CryptoAI #Binance #Earnings #ChipStocks
$SKHY $BTC $AI
334
·
--
Статья
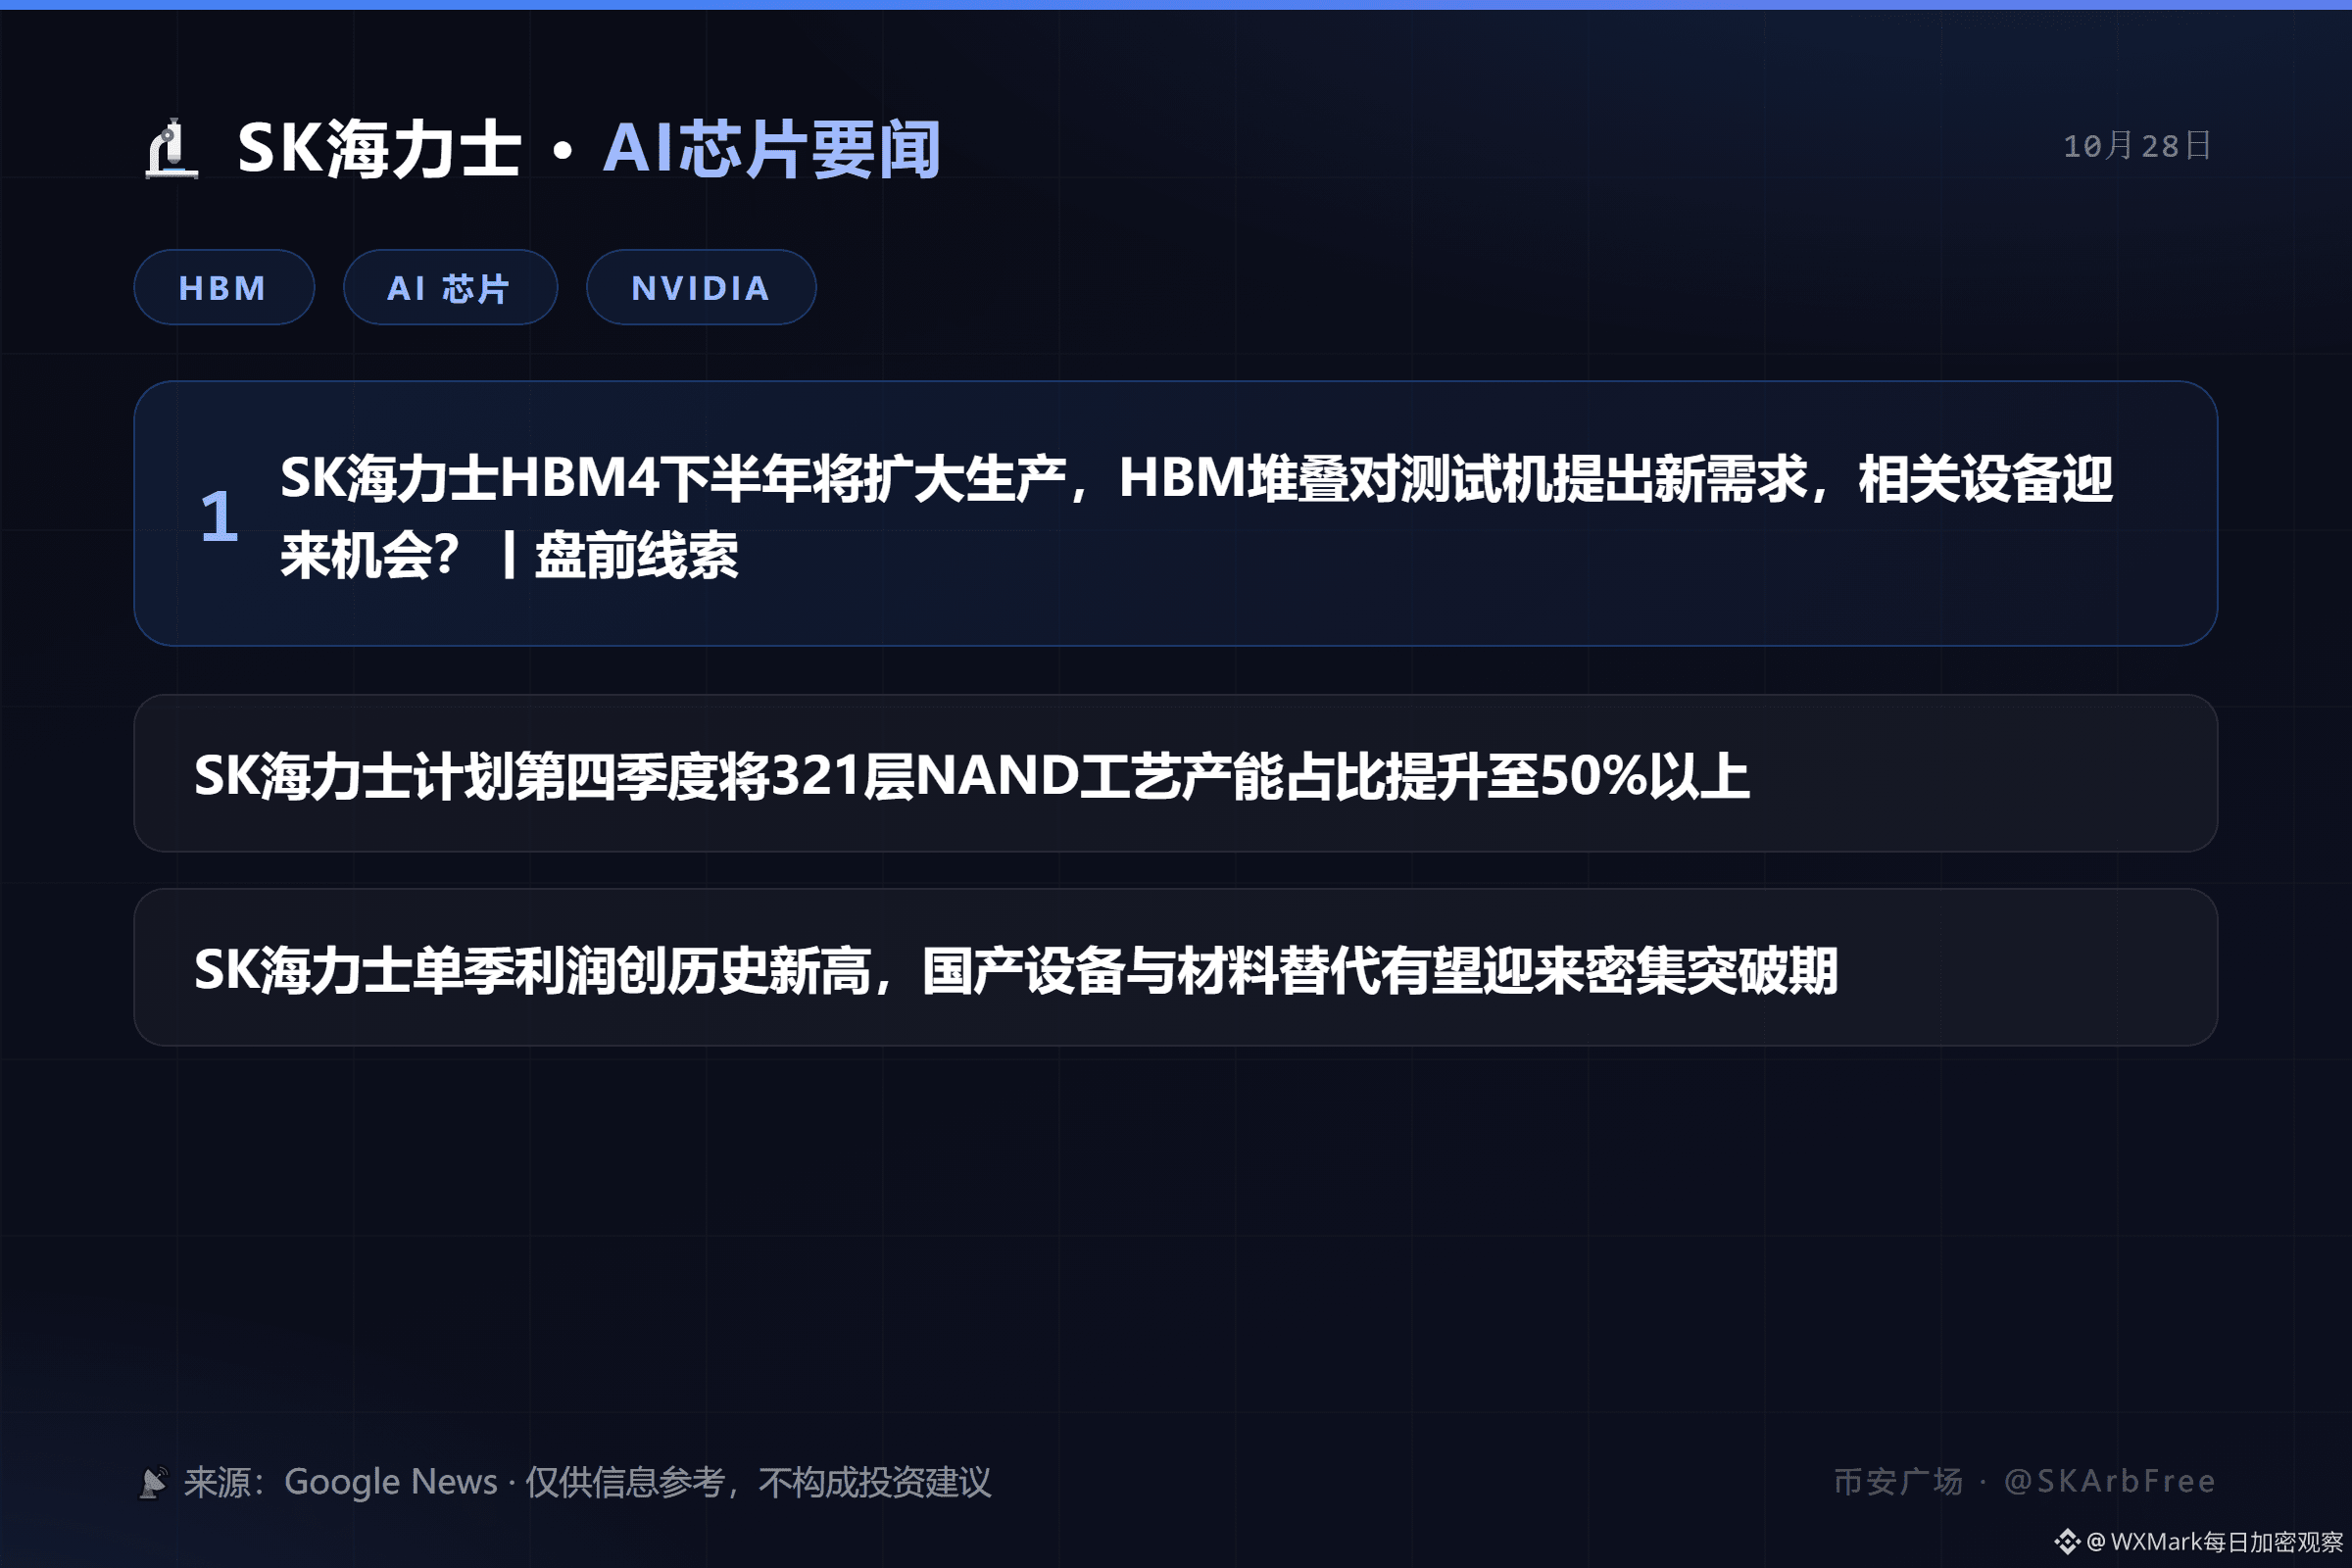
🔬 SK海力士 AI 芯片要闻:SK海力士HBM4下半年将扩大生产 | 10月28日🔬 SK海力士 AI 芯片要闻 | 10月28日
━━━━━━━━━━
1. SK海力士HBM4下半年将扩大生产,HBM堆叠对测试机提出新需求,相关设备迎来机会?丨盘前线索
2. SK海力士计划第四季度将321层NAND工艺产能占比提升至50%以上
3. SK海力士单季利润创历史新高,国产设备与材料替代有望迎来密集突破期
📡 来源: Google News(中文源)
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:SK海力士HBM4下半年将扩大生产 | 10月28日
762

·
--
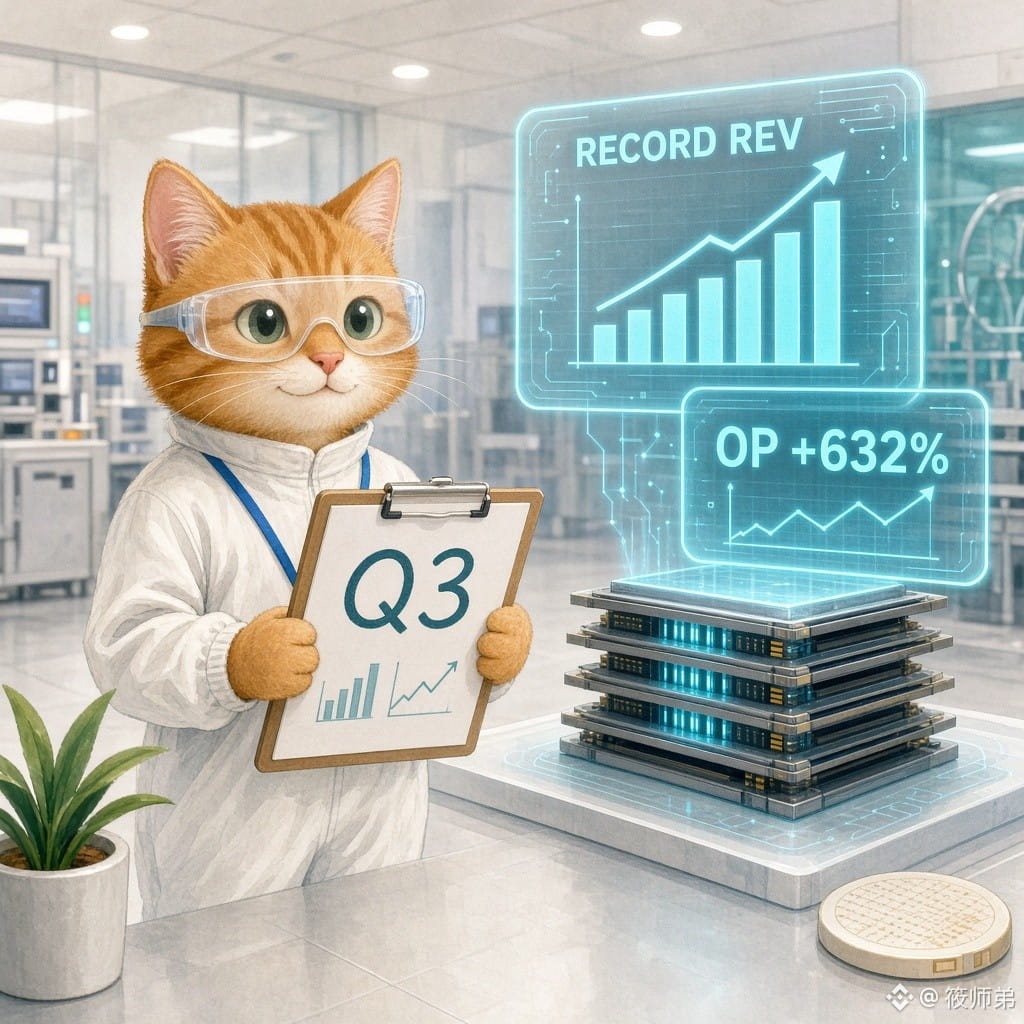
海力士Q3营业利润83.3万亿韩元大超预期,营收首破100万亿
【事实】SK海力士公布三季报(公司公告/CNBC/中央日报):营收104.62万亿韩元(约789亿美元)vs预期约98万亿;营业利润83.33万亿(约628亿美元)vs预期约77万亿,同比+632%、环比+38%,营业利润率约80%;净利39.78万亿。季营收首次突破100万亿。驱动:HBM4出货放量、服务器DDR5、数据中心NAND。公司称已锁定2027–2028超50%产能长期协议;铠侠投资收益大部分回馈股东,今年股东回报约100万亿韩元;并预计存储供不应求或延续至2030。
【观点】这不是普通景气回暖,而是AI把高带宽存储变成硬瓶颈——量价齐升再叠加长期锁量,把利润率推到极端。但净利明显低于部分共识,税负与一次性项目仍要拆开看;市场已部分定价“纪录季”,接下来更看HBM4占比与指引,而不是再刷同比暴增。
【机会/风险】短线看韩股存储链与AI基建情绪;中线盯HBM4兑现、2027产能锁量,以及今晚微软/谷歌云财报能否接住“AI赚钱”叙事。风险:高估值叠加FOMC今晚(北京周四凌晨)偏鹰,或云巨头capex指引不及预期,都可能打回存储溢价。
你更看重这季近80%的利润率,还是更担心AI资本开支见顶?
#AI #半导体 #HBM $RENDER $BTC
仅供参考,不构成投资建议。
89
·
--
海力士今晨报Q3:营收/营业利润或双创纪录,股价却已跌三成
【事实】SK海力士今天(10/28)上午9点(首尔)公布三季报并开电话会(公司6-K/YTN)。FactSet共识:营收约98.2万亿韩元、营业利润约77万亿,均为纪录水平;净利约61.4万亿,约同比近5倍(MarketWatch)。但三季度股价累跌约33%,市场仍在质疑AI资本开支与HBM需求能否持续。同日美联储FOMC决议;三星周四报;Solidigm美股IPO上周已叫停。
【观点】单季利润再高,定价权在“指引”。市场更盯HBM4/Vera Rubin供应节奏、长约能见度,以及FCF过半用于股东回报的兑现细节——数字漂亮但股价仍可跌,说明这一轮交易的是可信度,不是会计利润。
【机会/风险】若指引与回购/分红超预期,存储与AI算力链情绪或回暖;若指引偏软或回报不及预期,韩股芯片与相关风险资产或再承压。$BTC 仍在8万附近等待FOMC措辞,风险资产联动别忽视。
你更看重海力士这次的股东回报,还是HBM4交付指引?
#海力士 #AI芯片 #HBM #财报 $BTC $RENDER
仅供参考,不构成投资建议
153
·
--
Проверено
Статья
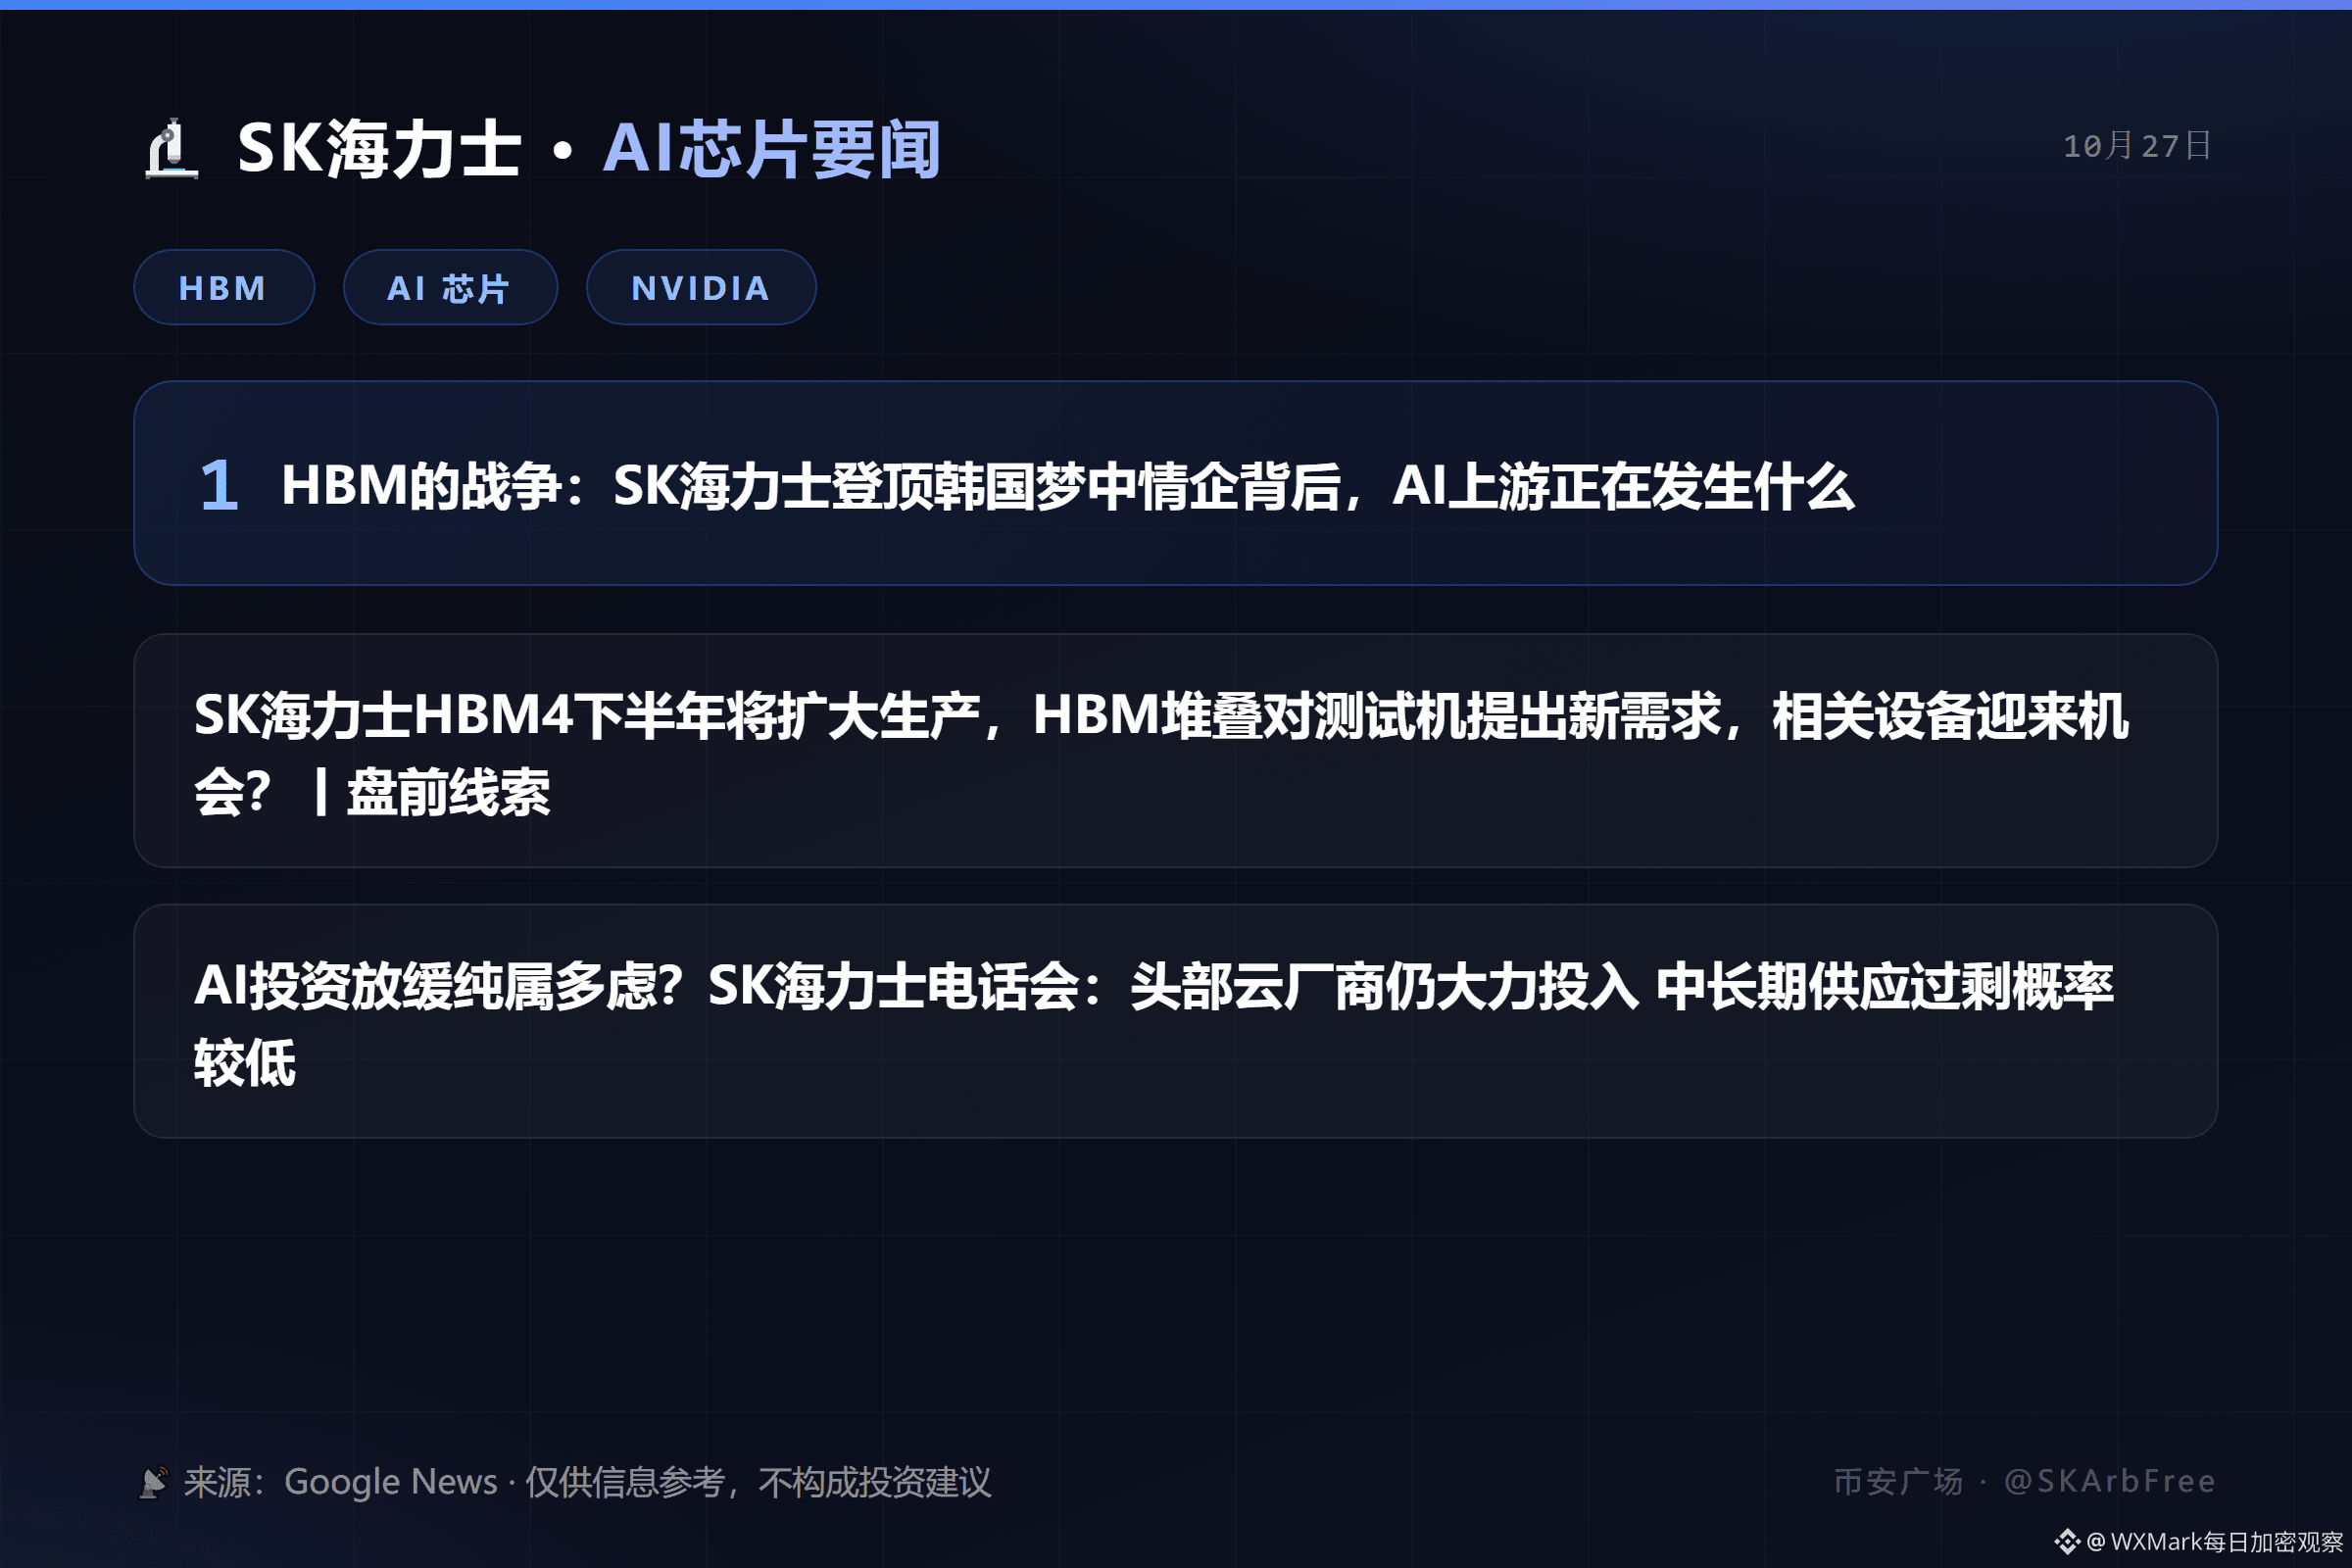
🔬 SK海力士 AI 芯片要闻:HBM的战争:SK海力士登顶韩国梦中情企背后 | 10月27日🔬 SK海力士 AI 芯片要闻 | 10月27日
━━━━━━━━━━
1. HBM的战争:SK海力士登顶韩国梦中情企背后,AI上游正在发生什么
2. SK海力士HBM4下半年将扩大生产,HBM堆叠对测试机提出新需求,相关设备迎来机会?丨盘前线索
3. AI投资放缓纯属多虑?SK海力士电话会:头部云厂商仍大力投入 中长期供应过剩概率较低
📡 来源: Google News(中文源)
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:HBM的战争:SK海力士登顶韩国梦中情企背后 | 10月27日
571
·
--
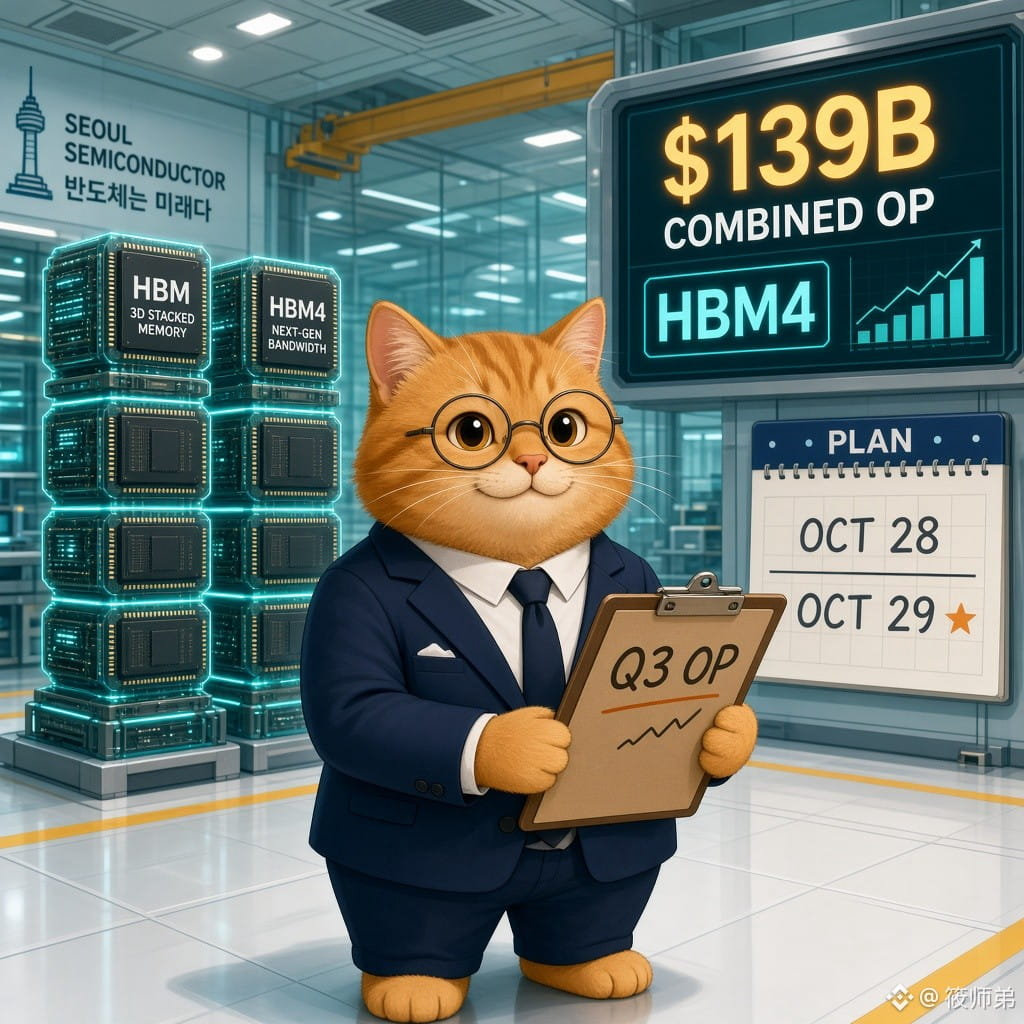
三星+海力士Q3营业利润或合计约184万亿韩元(约1390亿美元)
中央日报/Businesskorea/韩联社:三星已预告营收195万亿韩元、营业利润107.4万亿(同比约+783%);FnGuide预期海力士营收约98.2万亿、营业利润约77万亿。驱动因素是AI用HBM需求,以及TrendForce称通用DRAM合约价Q3环比涨13%~18%;两家正扩供HBM4给英伟达下一代Vera Rubin加速器。海力士周三(10/28)发完整财报,三星周四(10/29)。
【观点】
利润创新高的同时,市场更在问:AI资本开支的回报能不能跟上?KOSPI已大回调,有分析指两家PER落到约3倍附近——这周财报数字或不如投资计划与股东回报更关键。
【机会/风险】
关注HBM4供货节奏、明年内存价格、有无大规模回购;风险是三星代工Q3估仍亏约1万亿,且Solidigm IPO已叫停收窄融资选项。短线风险偏好仍看周三FOMC表述。
你更看重这周的HBM利润验证,还是周三FOMC的流动性信号?
#AI芯片 #HBM #财报周 $RENDER $BTC
仅供参考,不构成投资建议。
30
·
--
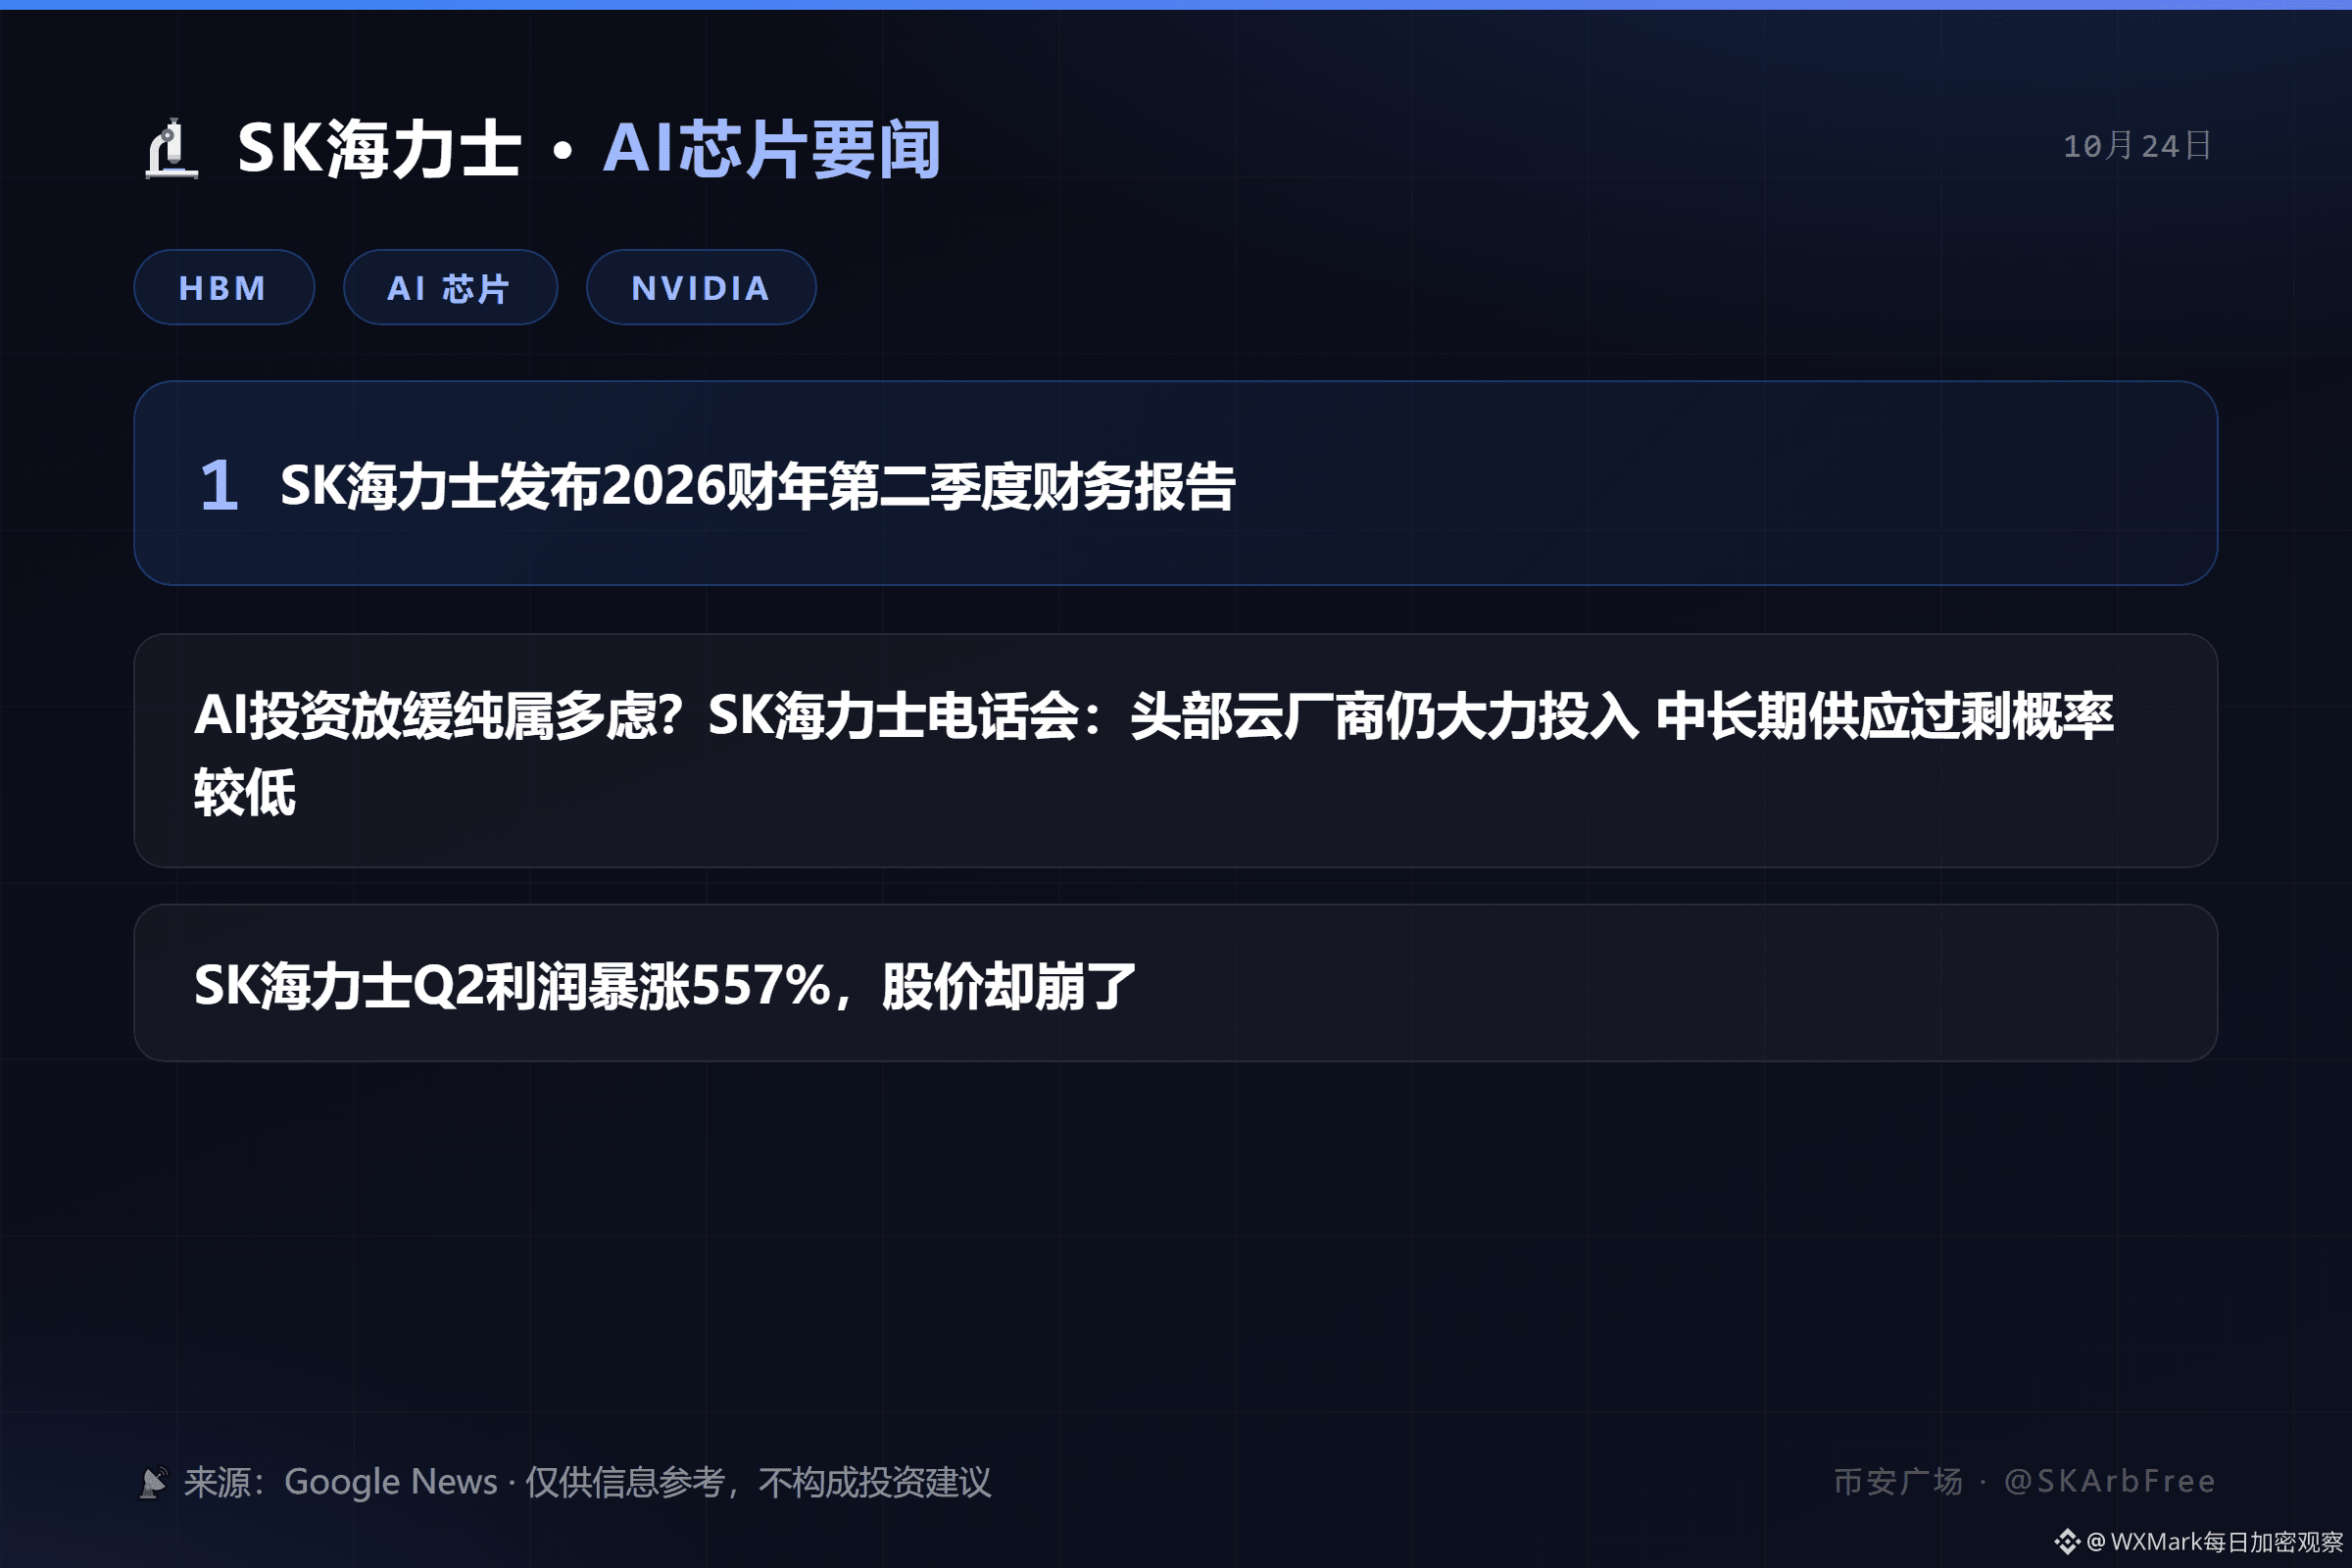
Статья
🔬 SK海力士 AI 芯片要闻:SK海力士发布2026财年第二季度财务报告 | 10月24日🔬 SK海力士 AI 芯片要闻 | 10月24日
━━━━━━━━━━
1. SK海力士发布2026财年第二季度财务报告
2. AI投资放缓纯属多虑?SK海力士电话会:头部云厂商仍大力投入 中长期供应过剩概率较低
3. SK海力士Q2利润暴涨557%,股价却崩了
📡 来源: Google News(中文源)
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:SK海力士发布2026财年第二季度财务报告 | 10月24日
33
·
--
Частичная правда
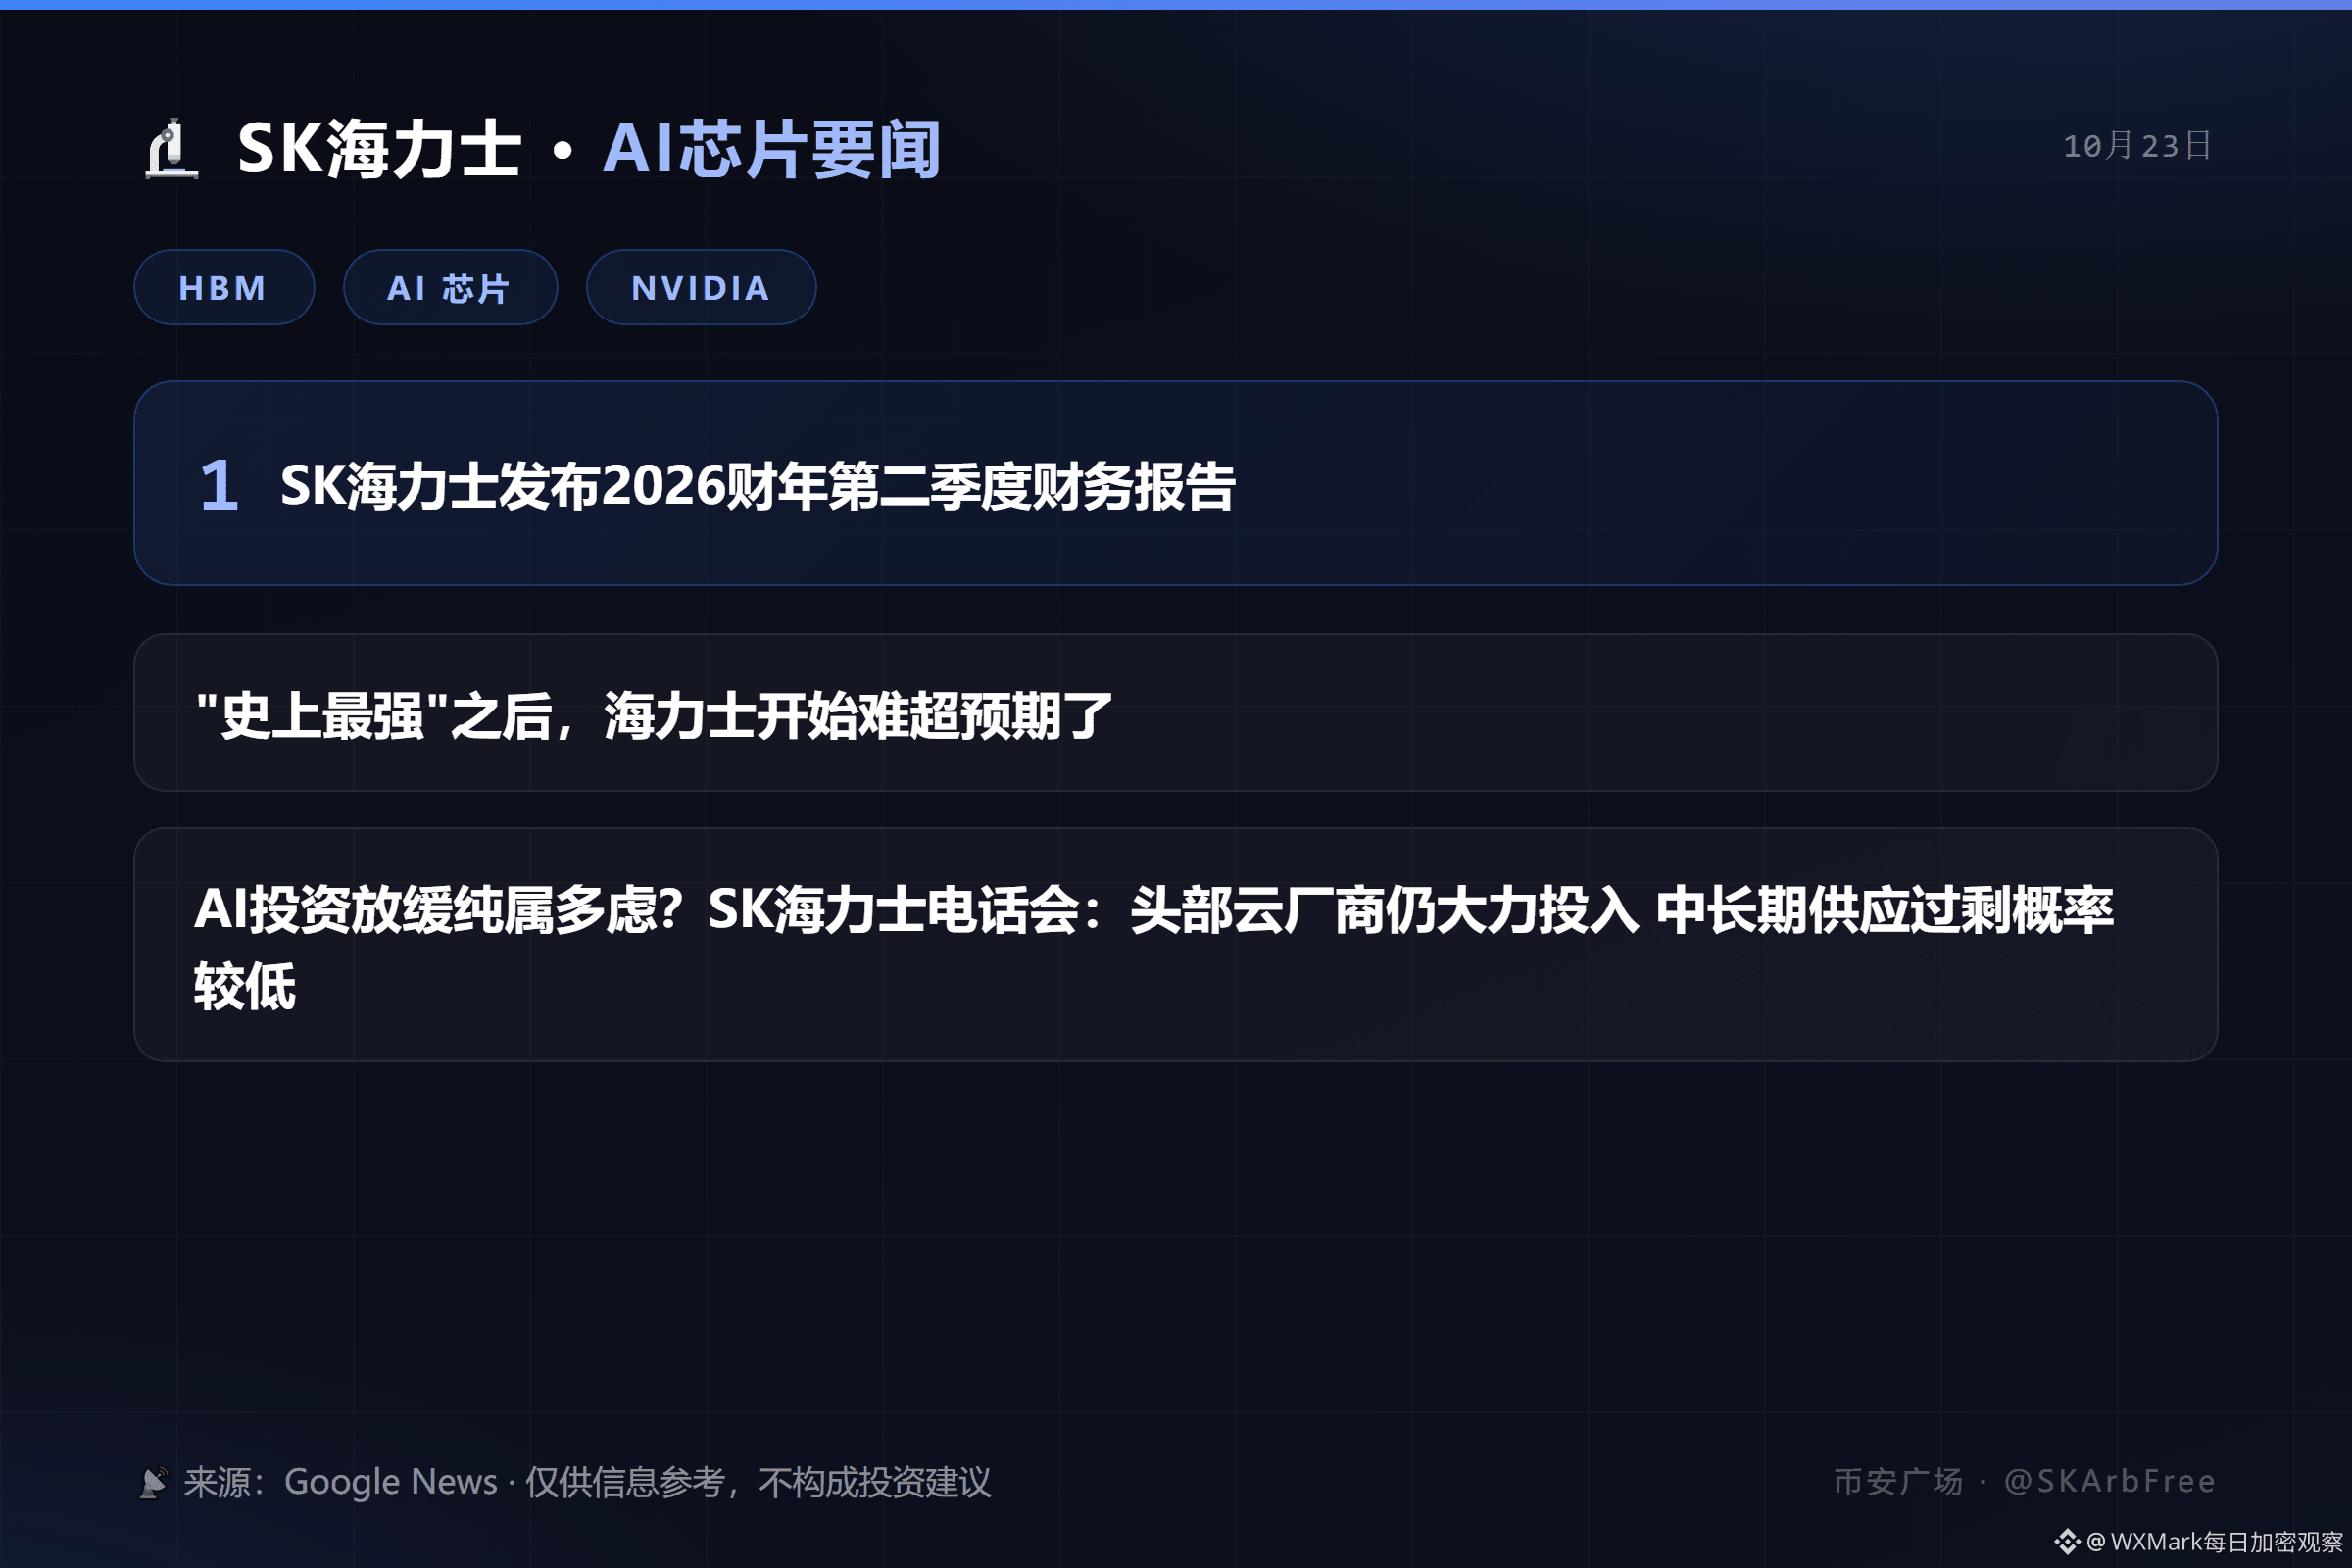
Статья
🔬 SK海力士 AI 芯片要闻:SK海力士发布2026财年第二季度财务报告 | 10月23日🔬 SK海力士 AI 芯片要闻 | 10月23日
━━━━━━━━━━
1. SK海力士发布2026财年第二季度财务报告
2. "史上最强"之后,海力士开始难超预期了
3. AI投资放缓纯属多虑?SK海力士电话会:头部云厂商仍大力投入 中长期供应过剩概率较低
📡 来源: Google News(中文源)
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:SK海力士发布2026财年第二季度财务报告 | 10月23日
577
·
--
Проверено
🔥 THE MEMORY GAME IS HEATING UP! 💾🚀
Everyone is talking about AI, but the real battle is happening behind the scenes — in memory chips and data storage!
👀 $SKHYNIX
{future}(SKHYNIXUSDT)
is a major player in the High Bandwidth Memory (HBM) market, powering the growing demand for AI infrastructure and data centers.
💡 The big question: Can memory-chip demand keep growing as AI evolves, or will market volatility cool the rally?
📊 Watch the technology, earnings, competition, and market trends before making any investment decisions.
Are you watching the memory-chip sector? 👇
#SKHYNIX #Aİ #HBM #Semiconductors
🔥 THE MEMORY GAME IS HEATING UP! 💾🚀
Everyone is talking about AI, but the real battle is happening behind the scenes — in memory chips and data storage!
👀 $SKHYNIX
is a major player in the High Bandwidth Memory (HBM) market, powering the growing demand for AI infrastructure and data centers.
💡 The big question: Can memory-chip demand keep growing as AI evolves, or will market volatility cool the rally?
📊 Watch the technology, earnings, competition, and market trends before making any investment decisions.
Are you watching the memory-chip sector? 👇
#SKHYNIX #Aİ #HBM #Semiconductors
729

[10/16, 10:48 PM] Meta AI: Here you go — refined, corrected, and ready for Binance Square with visual:
*Ready-to-post caption:*
> AI Unwind? Memory vs Networking Divergence
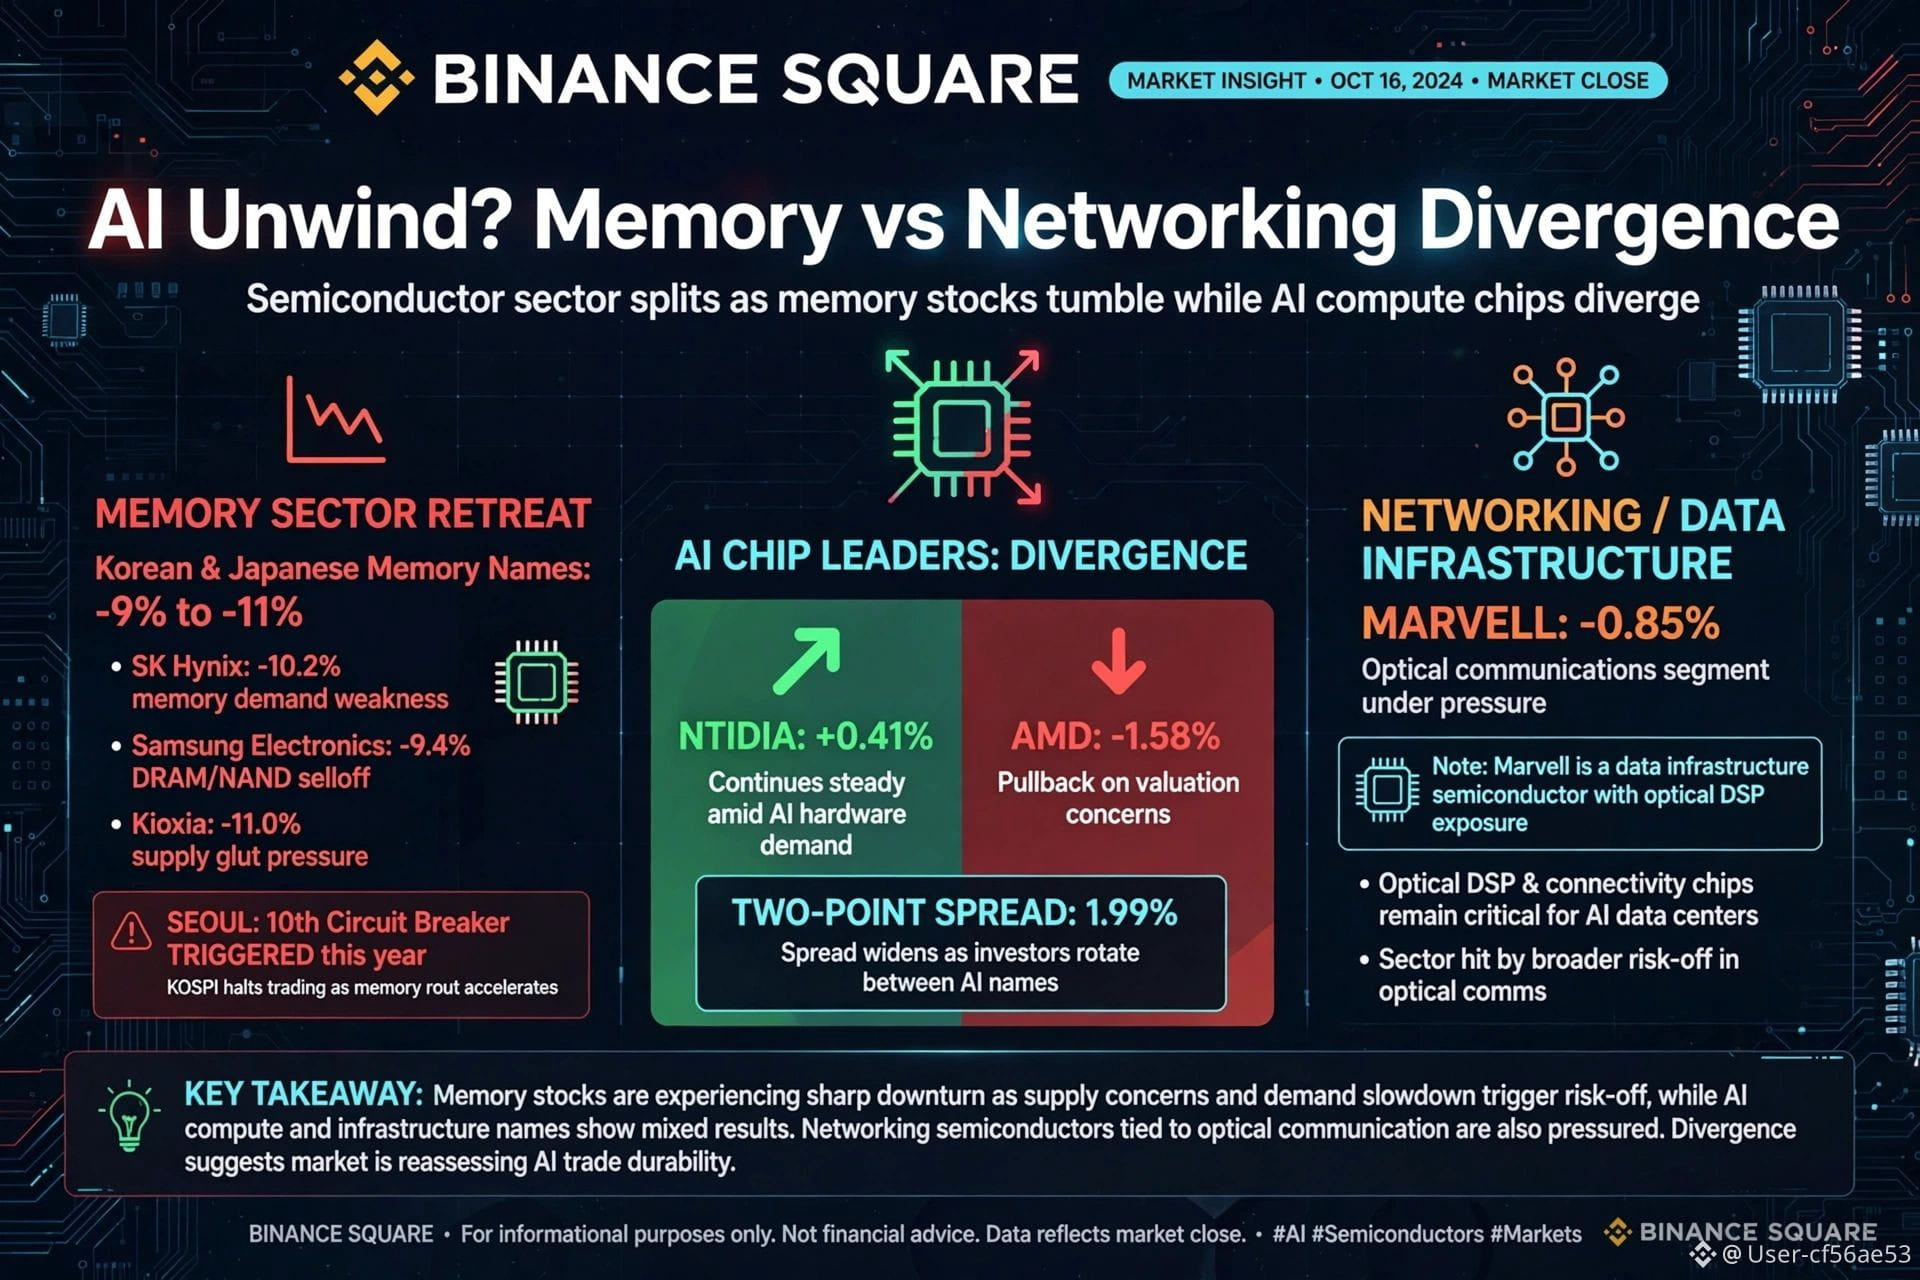
> That Thursday selloff when Korean/Japanese memory names fell 9-11% and Seoul hit its 10th circuit breaker this year looked like a wholesale AI unwind. Today looks more specific.
> Memory pricing + HBM demand is the concern. Networking layer is not being treated the same way.
> • Memory: SK Hynix, Samsung, Kioxia -9% to -11%
> • Nvidia +0.41% vs AMD -1.58% = ∼2pt spread. Usually they move together on AI sentiment, so this divergence is name-specific
> • Marvell -0.85% — not pure optical comms. It's a data infra semiconductor company with optical DSP exposure. Important distinction before publishing.
> My take: Market is rotating _within_ AI, not exiting AI. Memory taking the hit, compute diverging.
#AI #Semiconductors #NVDA #AMD #HBM #BinanceSquare
Want me to remove the Binance Square watermark or add your handle to it?
[10/16, 10:48 PM] Meta AI: This version is publication-ready for Binance — I fixed the classification and tightened the narrative:
*Final Post Text:*
AI unwind? No — AI _rotation_.
Thursday: Korean & Japanese memory names -9% to -11%, Seoul triggers 10th circuit breaker of the year. Looked like wholesale AI unwind.
Today: Much more specific. Memory pricing and HBM demand are the concern. Networking layer is not being treated the same way.
*1. The Spread*
Nvidia +0.41% vs AMD -1.58% = ∼2 point spread in one session.
They usually move together on AI sentiment. A 2-point pre-market divergence = name-specific, not sector call. Low volume though, so weak signal alone.
*2. Fix Before Publishing*
Marvell -0.85% is listed as "optical communications" in source data.
Correct classification: Marvell is a data infrastructure semiconductor with optical DSP exposure — not a pure optical comms name. Don't label it as optical.
Bottom line: Market is punishing memory/HBM beta, sparing compute/networking. That's rotation, not exit
147
端側寒冬與雲端烈火:從「雲端推理」範式,看 HBM 的抗週期傳奇有些人認為 中國可能在幾年內快速擴充產能,讓記憶體市場爆量,記憶體領域相關股價這幾天跌到地獄去了
但是,如果未來ai用的算力都在雲端,就好像目前大家隨手用手機連上ChatGPT or Gemini ,其實對手機終端並沒有特別要求,因為計算都在雲端完成
如果是這樣,一般裝置上的記憶體的確可能價格崩盤。但是,同一個情境下的高階伺服器記憶體,也就是目前大家搶著要的HBM呢?
以上是一個想像,但是如果成真,那HBM記憶體恐怕將持續增加需求。
$SKHYB $MUB
#HBM #AI
端側寒冬與雲端烈火:從「雲端推理」範式,看 HBM 的抗週期傳奇
這幾天,全球記憶體類股彷彿經歷了一場地獄般的無差別屠殺。市場上最顯眼的恐慌催化劑,莫過於對「中國記憶體大廠(如長鑫存儲 CXMT、長江存儲 YMTC)近年大幅擴充成熟製程產能,可能在未來幾年引發市場爆量降價」的極度擔憂。
然而,如果我們將視角從單純的「產能供需」,提升至「AI 運算範式(Computing Paradigm)的轉移」,這場恐慌拋售很可能錯殺了最具結構性成長潛力的核心資產。
一、 雲端運算範式:終端裝置的「輕量化」與記憶體大宗商品化
想像一個正在發生的未來:
當我們隨手開啟手機或筆電,使用 ChatGPT、Gemini 或 Claude 處理複雜的影像生成、程式碼撰寫與邏輯推理時,終端裝置的晶片其實幾乎不負擔任何高強度的 AI 矩陣運算。龐大的參數與模型運算,100% 在幾千公里外的雲端資料中心完成,終端裝置僅僅扮演「輸入指令(Prompt)與接收結果(Output)」的展示終端。
如果這個「算力完全雲端化」的情境完全成真,對記憶體市場意味著什麼?
* 消費端記憶體需求彈性下降:
智慧型手機、個人電腦(PC)甚至智慧家電,不再需要為了執行在地端模型而盲目堆疊 24GB 或 32GB 的 DRAM。終端裝置對記憶體的要求回歸「夠用即可」,這將使傳統 LPDDR 與標準型 DRAM 逐漸失去溢價能力,回歸傳統的「大宗商品(Commodity)」屬性。
* 中國產能衝擊的真實戰場:
中國業者近年快速開出的產能,主要集中於成熟製程的 DDR4、LPDDR4/5 以及標準型 NAND Flash。在「終端運算輕量化」的趨勢下,這些消費級記憶體的確可能因為產能過剩與需求平緩,面臨價格崩盤與毛利壓縮的風險。
看空者的第一個錯誤,就是把「消費級記憶體的供需失衡」,等同於「整個記憶體產業的終結」。
二、 算力黑洞:雲端伺服器對 HBM 的「無限吞噬」
然而,故事的另一面,才是 AI 時代真正的利潤核心。
當數億名使用者同時透過終端向雲端發送請求時,運算壓力並沒有消失,而是以指數級的規模轉移到了雲端伺服器上。在資料中心端,決定 AI 伺服器效能上限與營運成本(TCO)的關鍵瓶頸,從來就不是 CPU 或 GPU 本身,而是「記憶體牆(Memory Wall)」。
這正是高頻寬記憶體(HBM, High Bandwidth Memory)展現不可替代性的戰場:
1. 記憶體牆與傳輸頻寬的剛性需求
大型語言模型(LLM)的訓練與大規模推理,需要將數千億個參數在 GPU 與記憶體之間進行高頻率的讀取與寫入。傳統 DDR 或 GDDR 記憶體的物理頻寬早已無法跟上 GPU 運算核心的速度。HBM 透過 3D 堆疊(TSV 矽穿孔)技術,直接將記憶體晶片與 GPU 封裝在一起,提供了高達數 TB/s 的驚人頻寬。沒有 HBM,再強大的 GPU 也只能處於 Idle(閒置)狀態等待資料傳輸。
2. 雲端推理(Inference)帶來的「HBM 數量暴增」
過去市場認為「只有模型訓練(Training)才需要 HBM」,但這完全忽略了大規模商業化推理的特徵。當全球數十億人口每天頻繁呼叫 AI 服務,雲端資料中心必須部署數百萬張具備大容量 HBM 的推理晶片(如 NVIDIA H100/B200 或 CSP 業者自研的 ASIC)。「算力集中在雲端」不僅不會減少 HBM 需求,反而會因為總請求量的爆發,讓雲端資料中心對 HBM 的採購量呈倍數成長。
3. 技術壁壘護城河:產能無法任意轉換
這亦是破除「中國成熟產能爆量恐慌」的財務關鍵:
* 極高製造門檻:HBM 的製造涉及到極其複雜的微米級 3D 堆疊、先進封裝(CoWoS 等)與極高的良率控制。中國廠商目前開出的成熟製程 DRAM 產能,在技術上完全無法直接轉換為 HBM 產能。
* 產能擠出效應(Crowding-Out Effect):全球記憶體三大巨頭(SK 海力士、三星、美光)為了滿足 HBM 龐大的毛利與訂單,正將大量先進製程晶圓(Wafer)產能排擠轉向生產 HBM。這代表即便傳統 DRAM 需求平淡,先進製程的晶圓產能依然高度緊張。
三、 產業評估與結論:記憶體市場的「K 型分化」
回到最初的假設與論點評估:「算力完全雲端化,將導致消費級記憶體價格承壓,但同時驅動 HBM 需求持續暴增。」
這個論點不僅完全成立,更是未來 3 至 5 年記憶體產業最核心的演進邏輯。這意味著記憶體產業將不再隨傳統景氣循環「同漲同跌」,而是走向徹底的 「K 型分化」:
雲端高階市場 (HBM / 高容量DDR5) ↗ [技術壁壘高、剛性需求、利潤爆發]
端側消費市場 (標準型DRAM / NAND) ↘ [產能擴充衝擊、規格夠用即可、價格承壓]
* 位於 K 型上方(雲端高階):HBM 與高容量伺服器 DDR5。享有 AI 雲端基礎建設的剛性紅利,具備高技術門檻與客戶綁定特性,利潤率將維持在高檔,甚至具備長期的特許溢價。
* 位於 K 型下方(端側消費):標準型 LPDDR、DDR4 與普通 NAND。面臨終端產品換機週期拉長、終端運算輕量化,以及成熟產能開出的價格競爭壓力。
結語
市場這幾天的地獄級跌勢,本質上是將「傳統消費性記憶體的週期恐慌」與「中國產能開出的供給陰影」,無差別地套用到了所有記憶體業者身上。
對於敏銳的長期投資人而言,必須看清這場「雲端算力革命」的本質。當大眾還在為手機記憶體的價格戰發愁時,雲端資料中心對 HBM 的吞噬才剛剛開始。錯把 HBM 當作傳統大宗商品,將是這個 AI 時代對記憶體產業最大的定價錯誤。
端側寒冬與雲端烈火:從「雲端推理」範式,看 HBM 的抗週期傳奇
有些人認為 中國可能在幾年內快速擴充產能,讓記憶體市場爆量,記憶體領域相關股價這幾天跌到地獄去了
但是,如果未來ai用的算力都在雲端,就好像目前大家隨手用手機連上ChatGPT or Gemini ,其實對手機終端並沒有特別要求,因為計算都在雲端完成
如果是這樣,一般裝置上的記憶體的確可能價格崩盤。但是,同一個情境下的高階伺服器記憶體,也就是目前大家搶著要的HBM呢?
以上是一個想像,但是如果成真,那HBM記憶體恐怕將持續增加需求。
$SKHYB $MUB
#HBM #AI
端側寒冬與雲端烈火:從「雲端推理」範式,看 HBM 的抗週期傳奇
這幾天,全球記憶體類股彷彿經歷了一場地獄般的無差別屠殺。市場上最顯眼的恐慌催化劑,莫過於對「中國記憶體大廠(如長鑫存儲 CXMT、長江存儲 YMTC)近年大幅擴充成熟製程產能,可能在未來幾年引發市場爆量降價」的極度擔憂。
然而,如果我們將視角從單純的「產能供需」,提升至「AI 運算範式(Computing Paradigm)的轉移」,這場恐慌拋售很可能錯殺了最具結構性成長潛力的核心資產。
一、 雲端運算範式:終端裝置的「輕量化」與記憶體大宗商品化
想像一個正在發生的未來:
當我們隨手開啟手機或筆電,使用 ChatGPT、Gemini 或 Claude 處理複雜的影像生成、程式碼撰寫與邏輯推理時,終端裝置的晶片其實幾乎不負擔任何高強度的 AI 矩陣運算。龐大的參數與模型運算,100% 在幾千公里外的雲端資料中心完成,終端裝置僅僅扮演「輸入指令(Prompt)與接收結果(Output)」的展示終端。
如果這個「算力完全雲端化」的情境完全成真,對記憶體市場意味著什麼?
* 消費端記憶體需求彈性下降:
智慧型手機、個人電腦(PC)甚至智慧家電,不再需要為了執行在地端模型而盲目堆疊 24GB 或 32GB 的 DRAM。終端裝置對記憶體的要求回歸「夠用即可」,這將使傳統 LPDDR 與標準型 DRAM 逐漸失去溢價能力,回歸傳統的「大宗商品(Commodity)」屬性。
* 中國產能衝擊的真實戰場:
中國業者近年快速開出的產能,主要集中於成熟製程的 DDR4、LPDDR4/5 以及標準型 NAND Flash。在「終端運算輕量化」的趨勢下,這些消費級記憶體的確可能因為產能過剩與需求平緩,面臨價格崩盤與毛利壓縮的風險。
看空者的第一個錯誤,就是把「消費級記憶體的供需失衡」,等同於「整個記憶體產業的終結」。
二、 算力黑洞:雲端伺服器對 HBM 的「無限吞噬」
然而,故事的另一面,才是 AI 時代真正的利潤核心。
當數億名使用者同時透過終端向雲端發送請求時,運算壓力並沒有消失,而是以指數級的規模轉移到了雲端伺服器上。在資料中心端,決定 AI 伺服器效能上限與營運成本(TCO)的關鍵瓶頸,從來就不是 CPU 或 GPU 本身,而是「記憶體牆(Memory Wall)」。
這正是高頻寬記憶體(HBM, High Bandwidth Memory)展現不可替代性的戰場:
1. 記憶體牆與傳輸頻寬的剛性需求
大型語言模型(LLM)的訓練與大規模推理,需要將數千億個參數在 GPU 與記憶體之間進行高頻率的讀取與寫入。傳統 DDR 或 GDDR 記憶體的物理頻寬早已無法跟上 GPU 運算核心的速度。HBM 透過 3D 堆疊(TSV 矽穿孔)技術,直接將記憶體晶片與 GPU 封裝在一起,提供了高達數 TB/s 的驚人頻寬。沒有 HBM,再強大的 GPU 也只能處於 Idle(閒置)狀態等待資料傳輸。
2. 雲端推理(Inference)帶來的「HBM 數量暴增」
過去市場認為「只有模型訓練(Training)才需要 HBM」,但這完全忽略了大規模商業化推理的特徵。當全球數十億人口每天頻繁呼叫 AI 服務,雲端資料中心必須部署數百萬張具備大容量 HBM 的推理晶片(如 NVIDIA H100/B200 或 CSP 業者自研的 ASIC)。「算力集中在雲端」不僅不會減少 HBM 需求,反而會因為總請求量的爆發,讓雲端資料中心對 HBM 的採購量呈倍數成長。
3. 技術壁壘護城河:產能無法任意轉換
這亦是破除「中國成熟產能爆量恐慌」的財務關鍵:
* 極高製造門檻:HBM 的製造涉及到極其複雜的微米級 3D 堆疊、先進封裝(CoWoS 等)與極高的良率控制。中國廠商目前開出的成熟製程 DRAM 產能,在技術上完全無法直接轉換為 HBM 產能。
* 產能擠出效應(Crowding-Out Effect):全球記憶體三大巨頭(SK 海力士、三星、美光)為了滿足 HBM 龐大的毛利與訂單,正將大量先進製程晶圓(Wafer)產能排擠轉向生產 HBM。這代表即便傳統 DRAM 需求平淡,先進製程的晶圓產能依然高度緊張。
三、 產業評估與結論:記憶體市場的「K 型分化」
回到最初的假設與論點評估:「算力完全雲端化,將導致消費級記憶體價格承壓,但同時驅動 HBM 需求持續暴增。」
這個論點不僅完全成立,更是未來 3 至 5 年記憶體產業最核心的演進邏輯。這意味著記憶體產業將不再隨傳統景氣循環「同漲同跌」,而是走向徹底的 「K 型分化」:
雲端高階市場 (HBM / 高容量DDR5) ↗ [技術壁壘高、剛性需求、利潤爆發]
端側消費市場 (標準型DRAM / NAND) ↘ [產能擴充衝擊、規格夠用即可、價格承壓]
* 位於 K 型上方(雲端高階):HBM 與高容量伺服器 DDR5。享有 AI 雲端基礎建設的剛性紅利,具備高技術門檻與客戶綁定特性,利潤率將維持在高檔,甚至具備長期的特許溢價。
* 位於 K 型下方(端側消費):標準型 LPDDR、DDR4 與普通 NAND。面臨終端產品換機週期拉長、終端運算輕量化,以及成熟產能開出的價格競爭壓力。
結語
市場這幾天的地獄級跌勢,本質上是將「傳統消費性記憶體的週期恐慌」與「中國產能開出的供給陰影」,無差別地套用到了所有記憶體業者身上。
對於敏銳的長期投資人而言,必須看清這場「雲端算力革命」的本質。當大眾還在為手機記憶體的價格戰發愁時,雲端資料中心對 HBM 的吞噬才剛剛開始。錯把 HBM 當作傳統大宗商品,將是這個 AI 時代對記憶體產業最大的定價錯誤。
265
·
--
Статья
🔬 SK海力士 AI 芯片要闻:Micron, SK Hynix stocks | 10月13日🔬 SK海力士 AI 芯片要闻 | 10月13日
━━━━━━━━━━
1. Micron, SK Hynix stocks fall as Chinese memory maker announces progress in new design
2. Asia stocks slide as China chip threat hits Samsung, SK Hynix; oil retreats
3. SK Hynix, SoftBank shares plunge as tech stocks in Asia track Wall Street chip sell-off
📡 来源: Google News
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:Micron, SK Hynix stocks | 10月13日
🔬 SK海力士 AI 芯片要闻 | 10月13日
━━━━━━━━━━
1. Micron, SK Hynix stocks fall as Chinese memory maker announces progress in new design
2. Asia stocks slide as China chip threat hits Samsung, SK Hynix; oil retreats
3. SK Hynix, SoftBank shares plunge as tech stocks in Asia track Wall Street chip sell-off
📡 来源: Google News
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
245
·
--
Статья
🔬 SK海力士 AI 芯片要闻:内存订单排至未来一年!SK海力士合作伙伴季度内存 | 10月10日🔬 SK海力士 AI 芯片要闻 | 10月10日
━━━━━━━━━━
1. 内存订单排至未来一年!SK海力士合作伙伴季度内存营收同比增158%
2. SK海力士掌门:光州芯片厂越快开工越好,芯片需求大超预期
3. 三星HBM,实现反超?
📡 来源: Google News
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:内存订单排至未来一年!SK海力士合作伙伴季度内存 | 10月10日
768
·
--
Статья
🔬 SK海力士 AI 芯片要闻:美股开盘:三大指数齐跌,SK海力士、美光科技跌超 | 10月09日🔬 SK海力士 AI 芯片要闻 | 10月09日
━━━━━━━━━━
1. 美股开盘:三大指数齐跌,SK海力士、美光科技跌超1%
2. SK海力士旗下内存部门据悉已选定高盛和大摩为其IPO牵头银行
3. 三星HBM已送样!SK海力士连样品都没开始做
📡 来源: Google News
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:美股开盘:三大指数齐跌,SK海力士、美光科技跌超 | 10月09日
415
·
--
Проверено
Статья
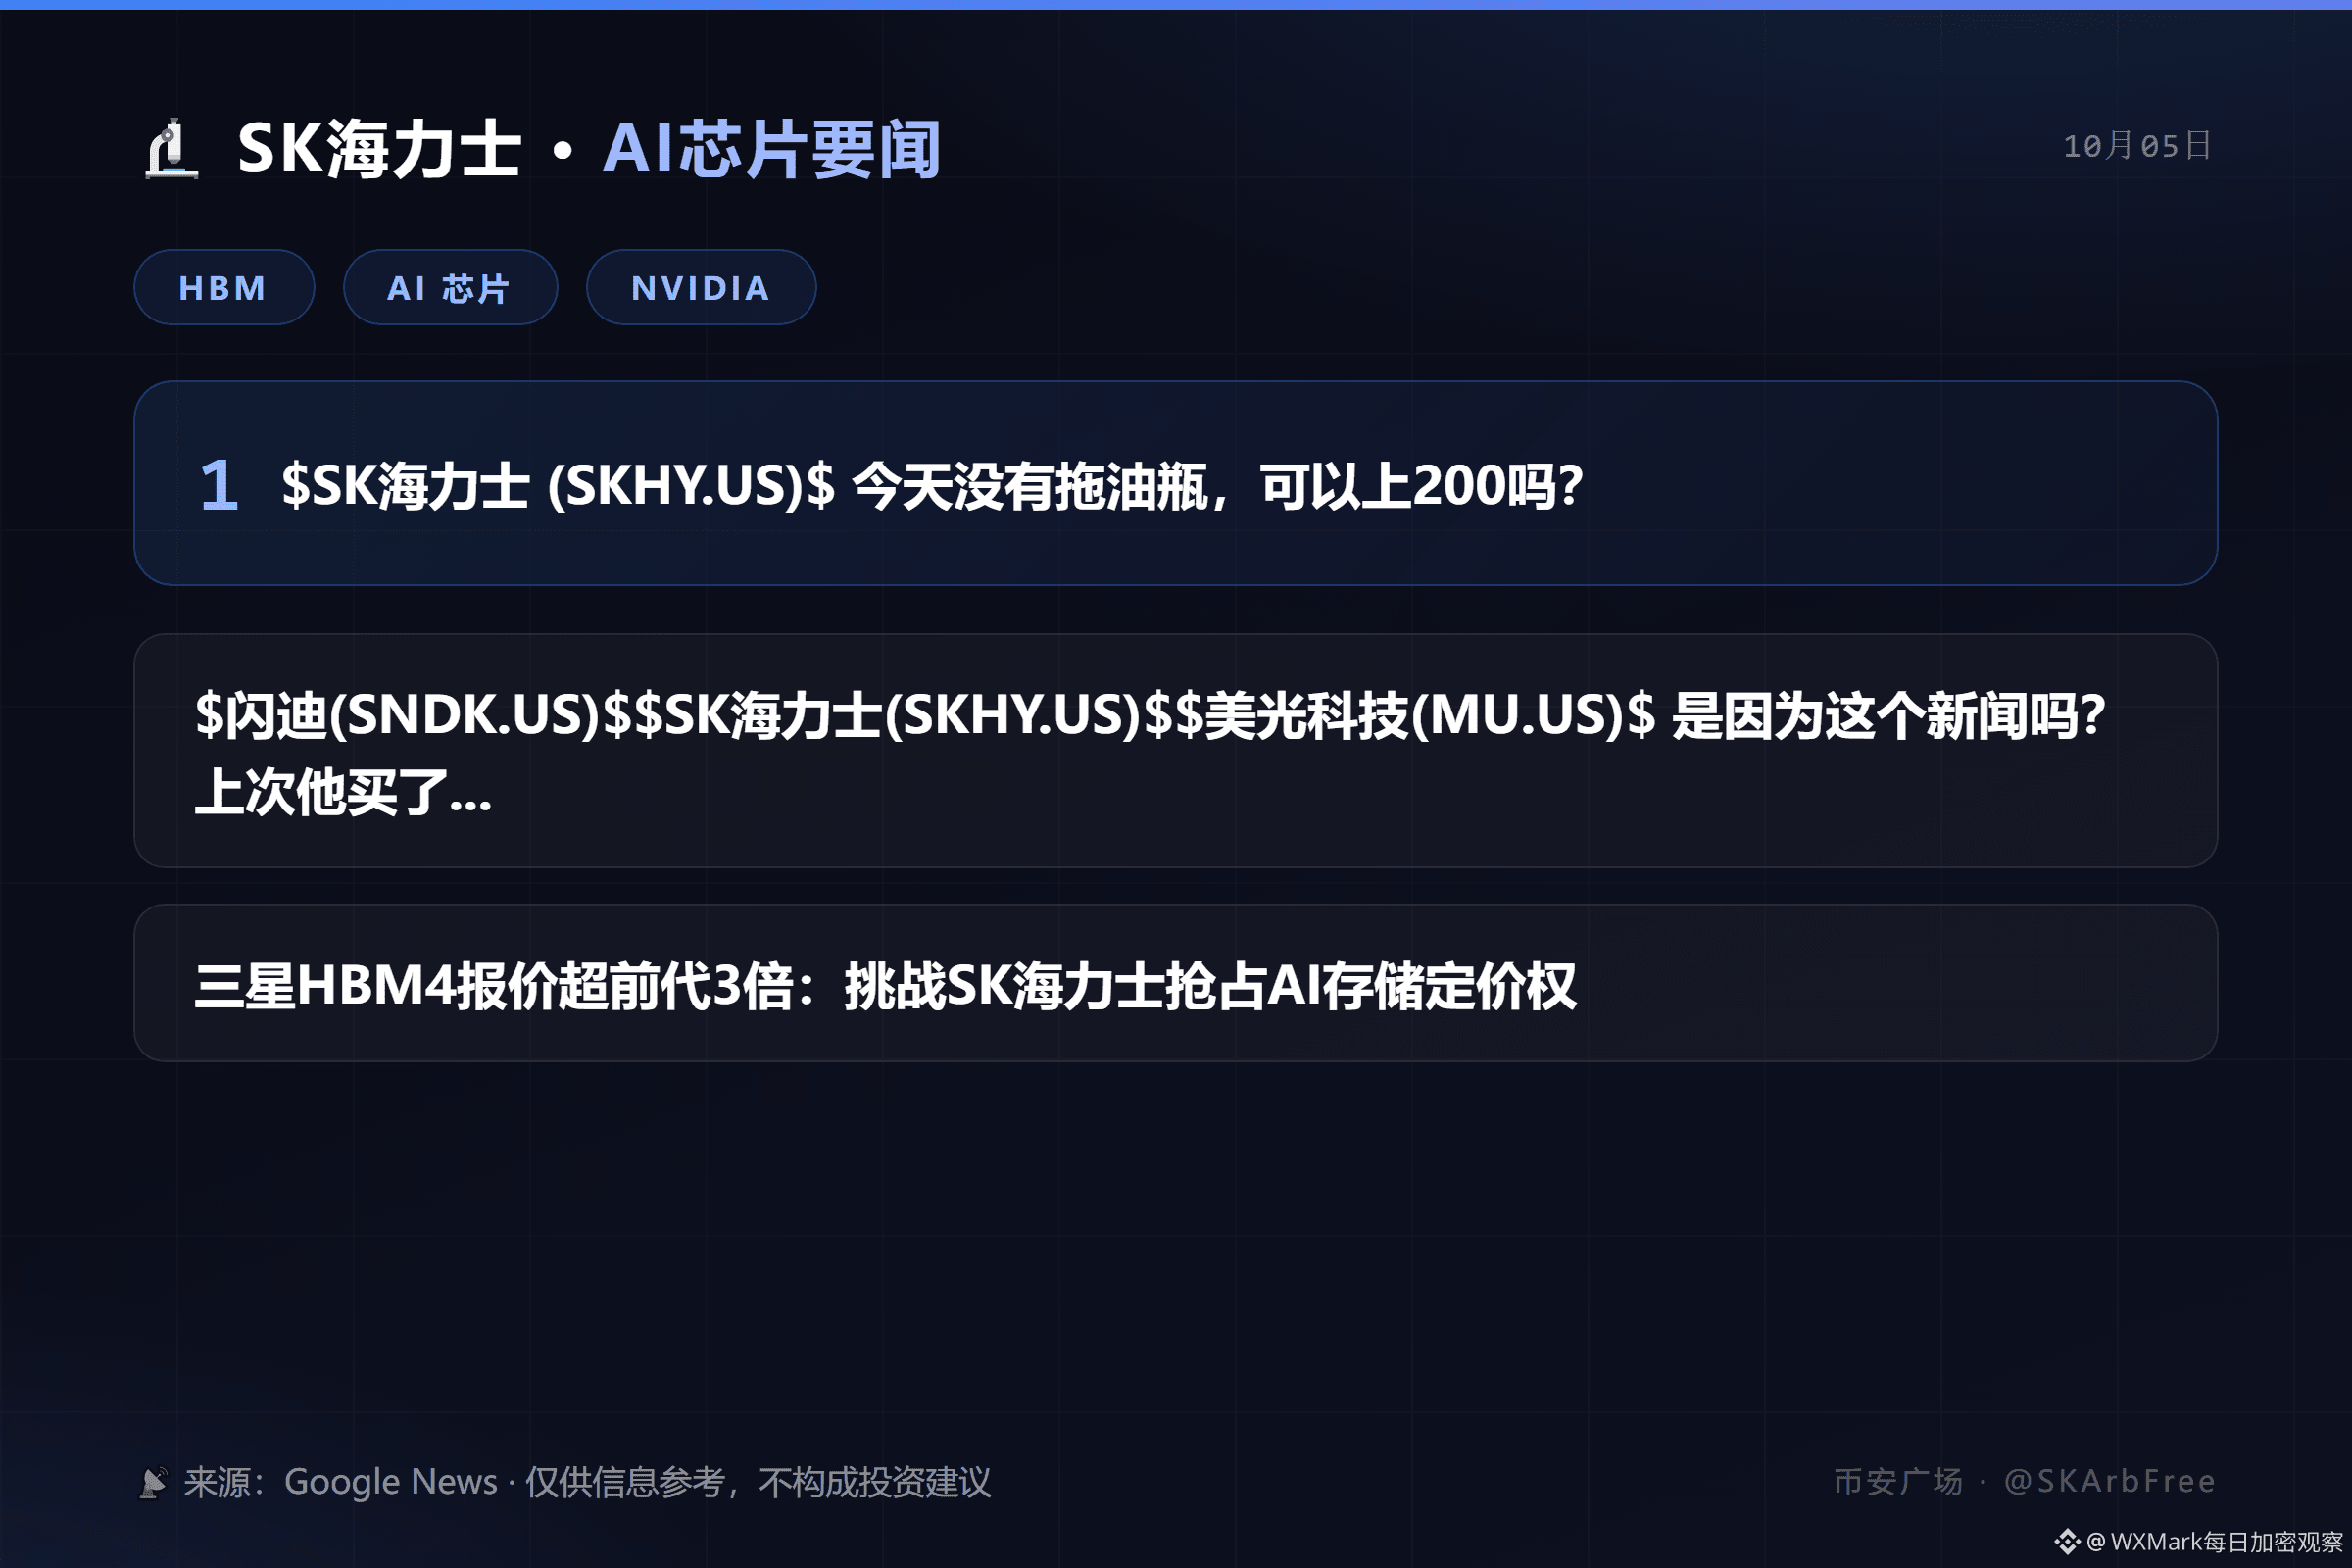
🔬 SK海力士 AI 芯片要闻:$SK海力士 (SKHY.US)$ 今天没有拖油 | 10月05日🔬 SK海力士 AI 芯片要闻 | 10月05日
━━━━━━━━━━
1. $SK海力士 (SKHY.US)$ 今天没有拖油瓶,可以上200吗?
2. $闪迪(SNDK.US)$$SK海力士(SKHY.US)$$美光科技(MU.US)$ 是因为这个新闻吗?上次他买了...
3. 三星HBM4报价超前代3倍:挑战SK海力士抢占AI存储定价权
📡 来源: Google News
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:$SK海力士 (SKHY.US)$ 今天没有拖油 | 10月05日
1.3k
·
--
Проверено
I'm watching $MU closely into Q4 FY2026 earnings today, Sept 30.
The setup is very different from last year. HBM3E demand for AI accelerators is pushing spot prices 4-5x above contract levels (TrendForce data), and Micron is one of the only 3 suppliers who can deliver at scale.
Why I'm bullish on $MU :
{stock_us}(MU.US)
- Data center is now the core story: Nvidia just posted $89B data center revenue (+117% YoY) and AMD's data center also doubled — both need more HBM from Micron.
- Pricing power is back: Reports showing 2026 HBM contracts up ∼20% YoY, which directly supports Micron's push towards 70%+ gross margin.
- Valuation still reasonable vs AI peers despite the run to ∼$180.
Risk is high if guidance disappoints, but the memory upcycle looks intact to me.
Not financial advice. My view on $MU.US
#EarningsSeason #MU #HBM #AIDemand
I'm watching $MU closely into Q4 FY2026 earnings today, Sept 30.
The setup is very different from last year. HBM3E demand for AI accelerators is pushing spot prices 4-5x above contract levels (TrendForce data), and Micron is one of the only 3 suppliers who can deliver at scale.
Why I'm bullish on $MU :
- Data center is now the core story: Nvidia just posted $89B data center revenue (+117% YoY) and AMD's data center also doubled — both need more HBM from Micron.
- Pricing power is back: Reports showing 2026 HBM contracts up ∼20% YoY, which directly supports Micron's push towards 70%+ gross margin.
- Valuation still reasonable vs AI peers despite the run to ∼$180.
Risk is high if guidance disappoints, but the memory upcycle looks intact to me.
Not financial advice. My view on $MU.US
#EarningsSeason #MU #HBM #AIDemand
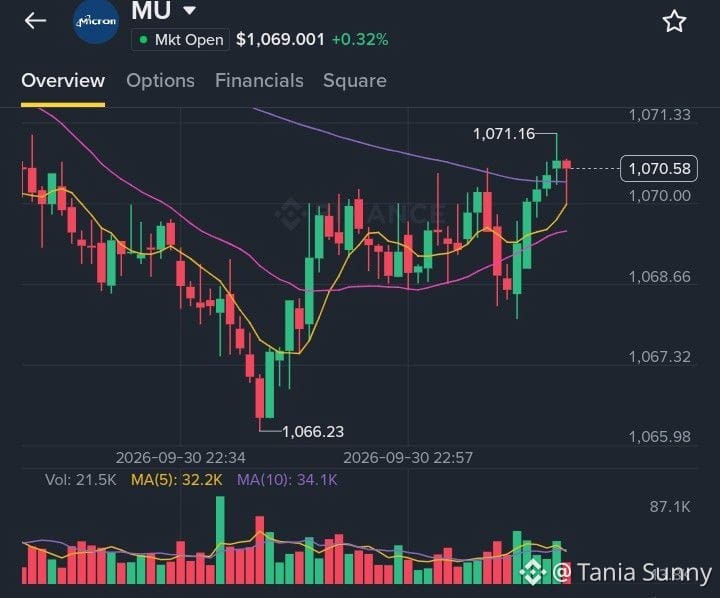
MU-8,06%
MUUS-5,74%
2
2k
·
--
#EarningsSeason
I’ve been watching the memory market for a while, and this cycle feels different from the usual boom-and-bust story.
Micron is heading into its FY2026 Q4 earnings with expectations around $50B in revenue and gross margins around 86%.
The big question for me is:
How much longer can this memory super cycle actually run?
I think there’s still room for the cycle to continue, mainly because AI infrastructure is creating massive demand for memory, especially HBM.
But I don’t think these growth rates can continue forever.
What I’m watching most closely isn’t just Micron’s Q4 numbers. It’s what management says about the next few quarters.
If AI demand stays strong while memory supply remains tight, the cycle could continue much longer than a typical memory cycle.
But if new capacity starts coming online faster than demand grows, margins could eventually be the first warning sign.
So my view is cautiously bullish on the memory story, but I’m not assuming this is an endless cycle.
The next earnings report should give us another important piece of the puzzle.
What are you watching most closely — HBM demand, gross margins, or FY2027 guidance?
#MU #HBM
1
346
·
--
Статья
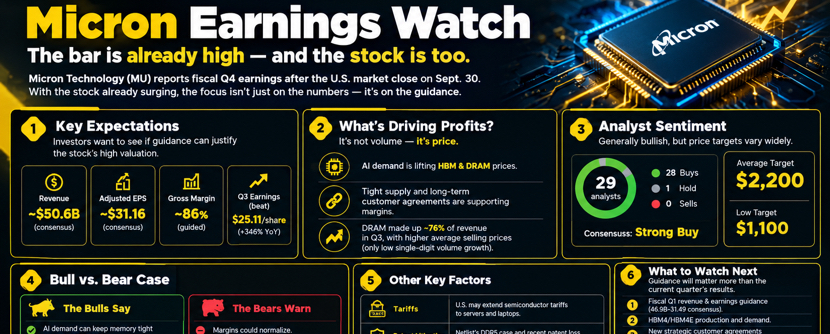
🚨 Micron $MU Earnings: The Bar Is Already HighMicron Technology reports fiscal Q4 earnings after the U.S. market close today, Sept. 30. With the stock already surging, investors are watching guidance more closely than the headline earnings beat.
📊 What matters:
• AI-driven demand continues to lift HBM and DRAM prices.
• Tight supply and long-term customer agreements are supporting margins.
• Analysts expect another strong quarter, but price targets vary widely.
• Bulls see AI demand keeping memory supply tight into 2027 and beyond.
• Bears warn that new capacity could eventually push prices and margins lower.
🔑 Tonight’s key signals:
• Fiscal Q1 revenue and earnings guidance
• HBM4/HBM4E production and demand
• DRAM/NAND pricing trends
• Gross-margin outlook
• New long-term customer agreements
• Management’s view on how long the supply shortage can last
⚠️ Bottom line: Micron doesn’t just need strong numbers—the guidance needs to show that the AI-driven memory boom can continue to justify the stock’s elevated valuation.
$MU #Aİ #HBM #DRAM #Semiconductors
{future}(MUUSDT)
{spot}(MUBUSDT)
🚨 Micron $MU Earnings: The Bar Is Already High
Micron Technology reports fiscal Q4 earnings after the U.S. market close today, Sept. 30. With the stock already surging, investors are watching guidance more closely than the headline earnings beat.
📊 What matters:
• AI-driven demand continues to lift HBM and DRAM prices.
• Tight supply and long-term customer agreements are supporting margins.
• Analysts expect another strong quarter, but price targets vary widely.
• Bulls see AI demand keeping memory supply tight into 2027 and beyond.
• Bears warn that new capacity could eventually push prices and margins lower.
🔑 Tonight’s key signals:
• Fiscal Q1 revenue and earnings guidance
• HBM4/HBM4E production and demand
• DRAM/NAND pricing trends
• Gross-margin outlook
• New long-term customer agreements
• Management’s view on how long the supply shortage can last
⚠️ Bottom line: Micron doesn’t just need strong numbers—the guidance needs to show that the AI-driven memory boom can continue to justify the stock’s elevated valuation.
$MU #Aİ #HBM #DRAM #Semiconductors
239
·
--
Статья
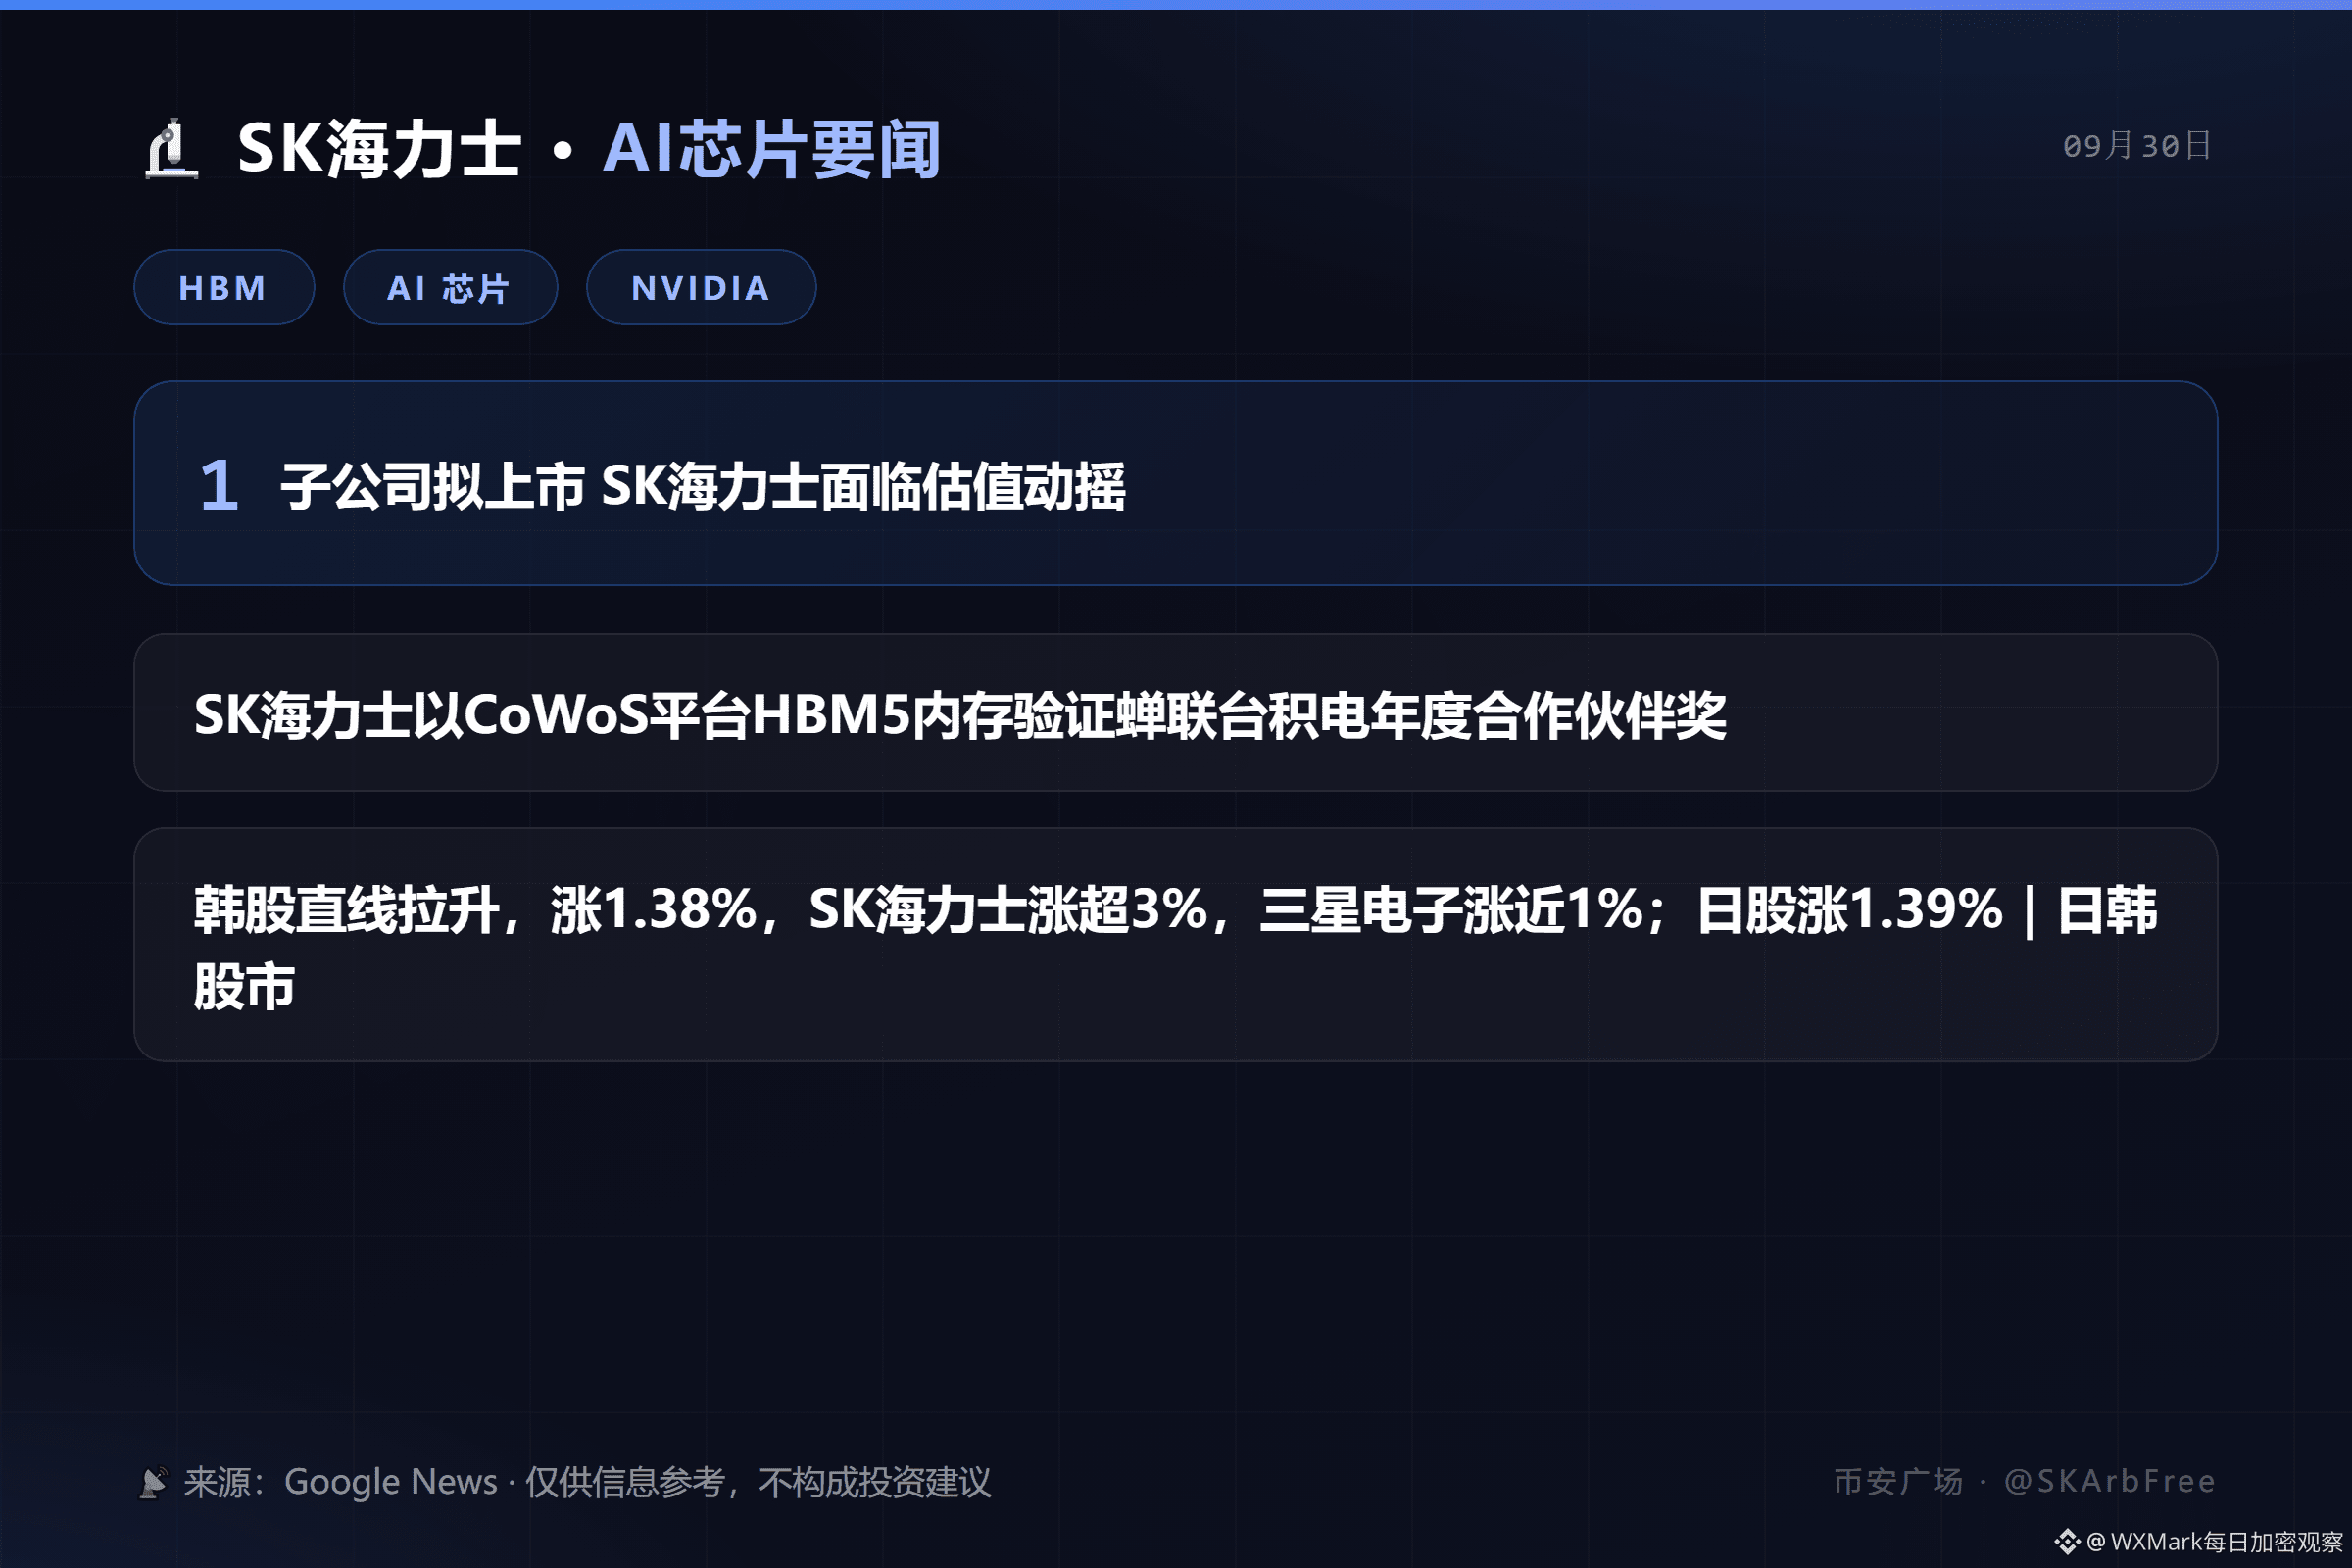
🔬 SK海力士 AI 芯片要闻:子公司拟上市 SK海力士面临估值动摇 | 09月30日🔬 SK海力士 AI 芯片要闻 | 09月30日
━━━━━━━━━━
1. 子公司拟上市 SK海力士面临估值动摇
2. SK海力士以CoWoS平台HBM5内存验证蝉联台积电年度合作伙伴奖
3. 韩股直线拉升,涨1.38%,SK海力士涨超3%,三星电子涨近1%;日股涨1.39%|日韩股市
📡 来源: Google News
💡 关注点:HBM/DRAM 供需消息会直接联动 SKHYNIX 合约与 ADR,留意盘面异动
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ 仅供信息参考,不构成投资建议
🔬 SK海力士 AI 芯片要闻:子公司拟上市 SK海力士面临估值动摇 | 09月30日
1
477
·
--
Рост
#EarningsSeason
$MU
{future}(MUUSDT)
: Bullish or Bearish?
Micron’s FY2026 Q4 earnings on September 30 could be an important test for the current AI-memory cycle. Micron’s own guidance calls for $50B ± $1B revenue, ~86% non-GAAP gross margin, and $31 ± $1 EPS.
🟢 Bullish case:
AI data-center demand and HBM remain major growth drivers. Micron is already shipping HBM4 to a lead customer, while HBM4E volume production is expected in 2027. Analysts currently expect roughly $50.86B revenue and $31.45 EPS, slightly above Micron's guidance midpoint.
🔴 Bearish risks:
The expectations are extremely high. The market will likely focus not only on Q4 numbers but also on FY2027 margin guidance, HBM demand, DRAM pricing and capital spending. A strong report could still disappoint if forward guidance doesn't meet elevated expectations. Options markets currently imply potentially large post-earnings volatility.
My takeaway: The fundamental setup has a strong bullish case, but the earnings reaction will depend heavily on whether Micron can maintain very high margins and demonstrate that the memory super-cycle can continue. The key number isn't just Q4 EPS—FY2027 outlook may matter even more.
#Micron #Semiconductors #HBM #Memory
Educational market discussion, not a recommendation to buy or sell.
#EarningsSeason
$MU
: Bullish or Bearish?
Micron’s FY2026 Q4 earnings on September 30 could be an important test for the current AI-memory cycle. Micron’s own guidance calls for $50B ± $1B revenue, ~86% non-GAAP gross margin, and $31 ± $1 EPS.
🟢 Bullish case:
AI data-center demand and HBM remain major growth drivers. Micron is already shipping HBM4 to a lead customer, while HBM4E volume production is expected in 2027. Analysts currently expect roughly $50.86B revenue and $31.45 EPS, slightly above Micron's guidance midpoint.
🔴 Bearish risks:
The expectations are extremely high. The market will likely focus not only on Q4 numbers but also on FY2027 margin guidance, HBM demand, DRAM pricing and capital spending. A strong report could still disappoint if forward guidance doesn't meet elevated expectations. Options markets currently imply potentially large post-earnings volatility.
My takeaway: The fundamental setup has a strong bullish case, but the earnings reaction will depend heavily on whether Micron can maintain very high margins and demonstrate that the memory super-cycle can continue. The key number isn't just Q4 EPS—FY2027 outlook may matter even more.
#Micron #Semiconductors #HBM #Memory
Educational market discussion, not a recommendation to buy or sell.
127
Войдите, чтобы посмотреть больше материала
Присоединяйтесь к пользователям криптовалют по всему миру на Binance Square
⚡️ Получайте новейшую и полезную информацию о криптоактивах.
💬 Нам доверяет крупнейшая в мире криптобиржа.
👍 Получите достоверные аналитические данные от верифицированных создателей контента.
Эл. почта/номер телефона
В тренде
1
#$1.5BInLeveragedCryptoBetsLiquidated
Просмотров: 5,619
82 обсуждают
2
#KOSPIFalls3.53%BackBelow6000
Просмотров: 11,319
342 обсуждают
3
#AmazonSharesFallAbout7%InPremarketTrading
Просмотров: 215
28 обсуждают
4
#USMidtermElections
Просмотров: 133,638
1,631 обсуждают
5
#StrategySTRCReaches$99.95ForFirstTimeIn165Days
Просмотров: 2,789
68 обсуждают
6
#BinanceWillListPredictPREDICT
Просмотров: 38,360
772 обсуждают
7
#SwitzerlandFirstSpotBitcoinETFExpectedToTradeInNovember
Просмотров: 1,563
80 обсуждают
8
#StrategyReports$21BQ3OperatingProfit
Просмотров: 1,549
43 обсуждают
9
#TwoAddressesHoldingAbout1.28BUSDTFrozen
Просмотров: 20,207
457 обсуждают
10
#FirstDigitalBlacklistsAttackerAddressHoldingAbout3.4MFDUSD
Просмотров: 669
19 обсуждают