
MacroMicro
46 Публикации
MacroMicro
Отправить жалобу
Заблокировать пользователя
Global Data and AI Decision Platform. Over 100 million data points and years of research to help you make smarter decisions: https://en.macromicro.me
0 подписок(и/а)
369 подписчиков(а)
91 понравилось
Посты
PINNED
·
--
👋🏻 Meet MacroMicro — Global Data & AI Decision Platform
Founded in 2015, we started with one belief: economic data shouldn't belong to a select few — it should be intuitive, visual, and accessible to everyone.
What began as a macro data platform has grown into a one-stop financial decision-making ecosystem, now powered by AI to connect economic fundamentals with industry trends and company financials.
📊 100M+ data points, 900K+ interactive charts
🌍 600K+ users worldwide, 9.5M+ monthly visits
🤝 Trusted by 150+ companies worldwide, including TSMC, moomoo and Yahoo Finance.
We help you go beyond price charts, understanding why markets move, not just that they moved. From central bank policy to the AI capex cycle to global supply chains, we connect the dots across macro fundamentals, industries and company data.
🔗 Explore MacroMicro: https://en.macromicro.me/
#MacroMicro #MacroEconomics #AI #DataDriven #GlobalMarkets
👋🏻 Meet MacroMicro — Global Data & AI Decision Platform
Founded in 2015, we started with one belief: economic data shouldn't belong to a select few — it should be intuitive, visual, and accessible to everyone.
What began as a macro data platform has grown into a one-stop financial decision-making ecosystem, now powered by AI to connect economic fundamentals with industry trends and company financials.
📊 100M+ data points, 900K+ interactive charts
🌍 600K+ users worldwide, 9.5M+ monthly visits
🤝 Trusted by 150+ companies worldwide, including TSMC, moomoo and Yahoo Finance.
We help you go beyond price charts, understanding why markets move, not just that they moved. From central bank policy to the AI capex cycle to global supply chains, we connect the dots across macro fundamentals, industries and company data.
🔗 Explore MacroMicro: https://en.macromicro.me/
#MacroMicro #MacroEconomics #AI #DataDriven #GlobalMarkets
Founded in 2015, we started with one belief: economic data shouldn't belong to a select few — it should be intuitive, visual, and accessible to everyone.
What began as a macro data platform has grown into a one-stop financial decision-making ecosystem, now powered by AI to connect economic fundamentals with industry trends and company financials.
📊 100M+ data points, 900K+ interactive charts
🌍 600K+ users worldwide, 9.5M+ monthly visits
🤝 Trusted by 150+ companies worldwide, including TSMC, moomoo and Yahoo Finance.
We help you go beyond price charts, understanding why markets move, not just that they moved. From central bank policy to the AI capex cycle to global supply chains, we connect the dots across macro fundamentals, industries and company data.
🔗 Explore MacroMicro: https://en.macromicro.me/
#MacroMicro #MacroEconomics #AI #DataDriven #GlobalMarkets
1
5
6.3k
·
--
Проверено
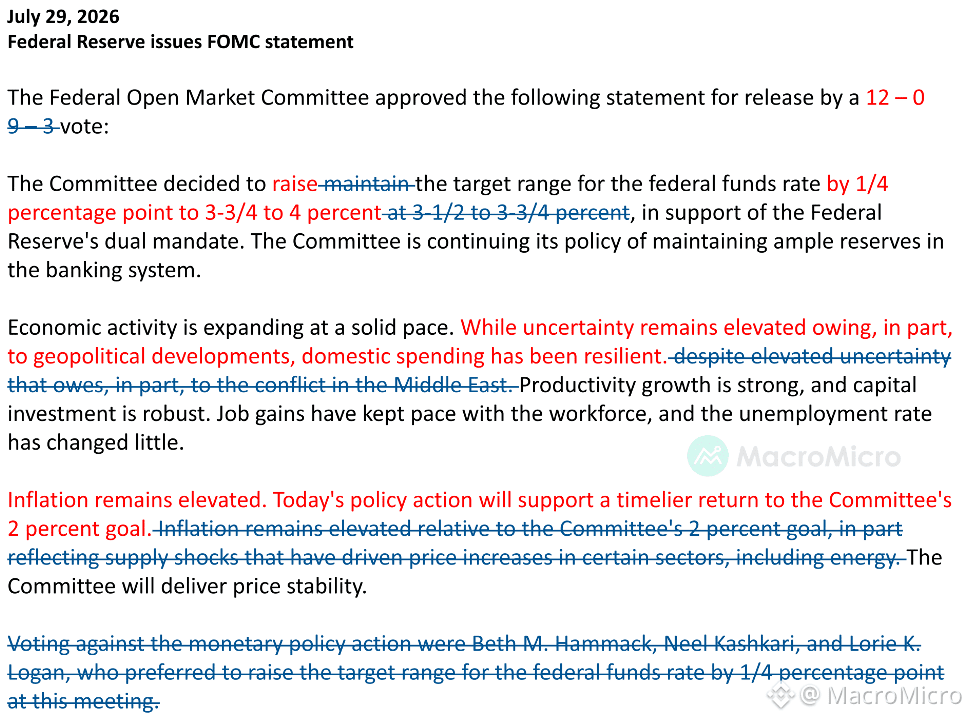
🔥 September 2026 FOMC Meeting: Key Takeaways 🔎
📌 The Fed hiked rates 25bp to 3.75%-4.00%, unanimously (12-0), citing solid economic growth and a push to accelerate progress toward the 2% inflation target.
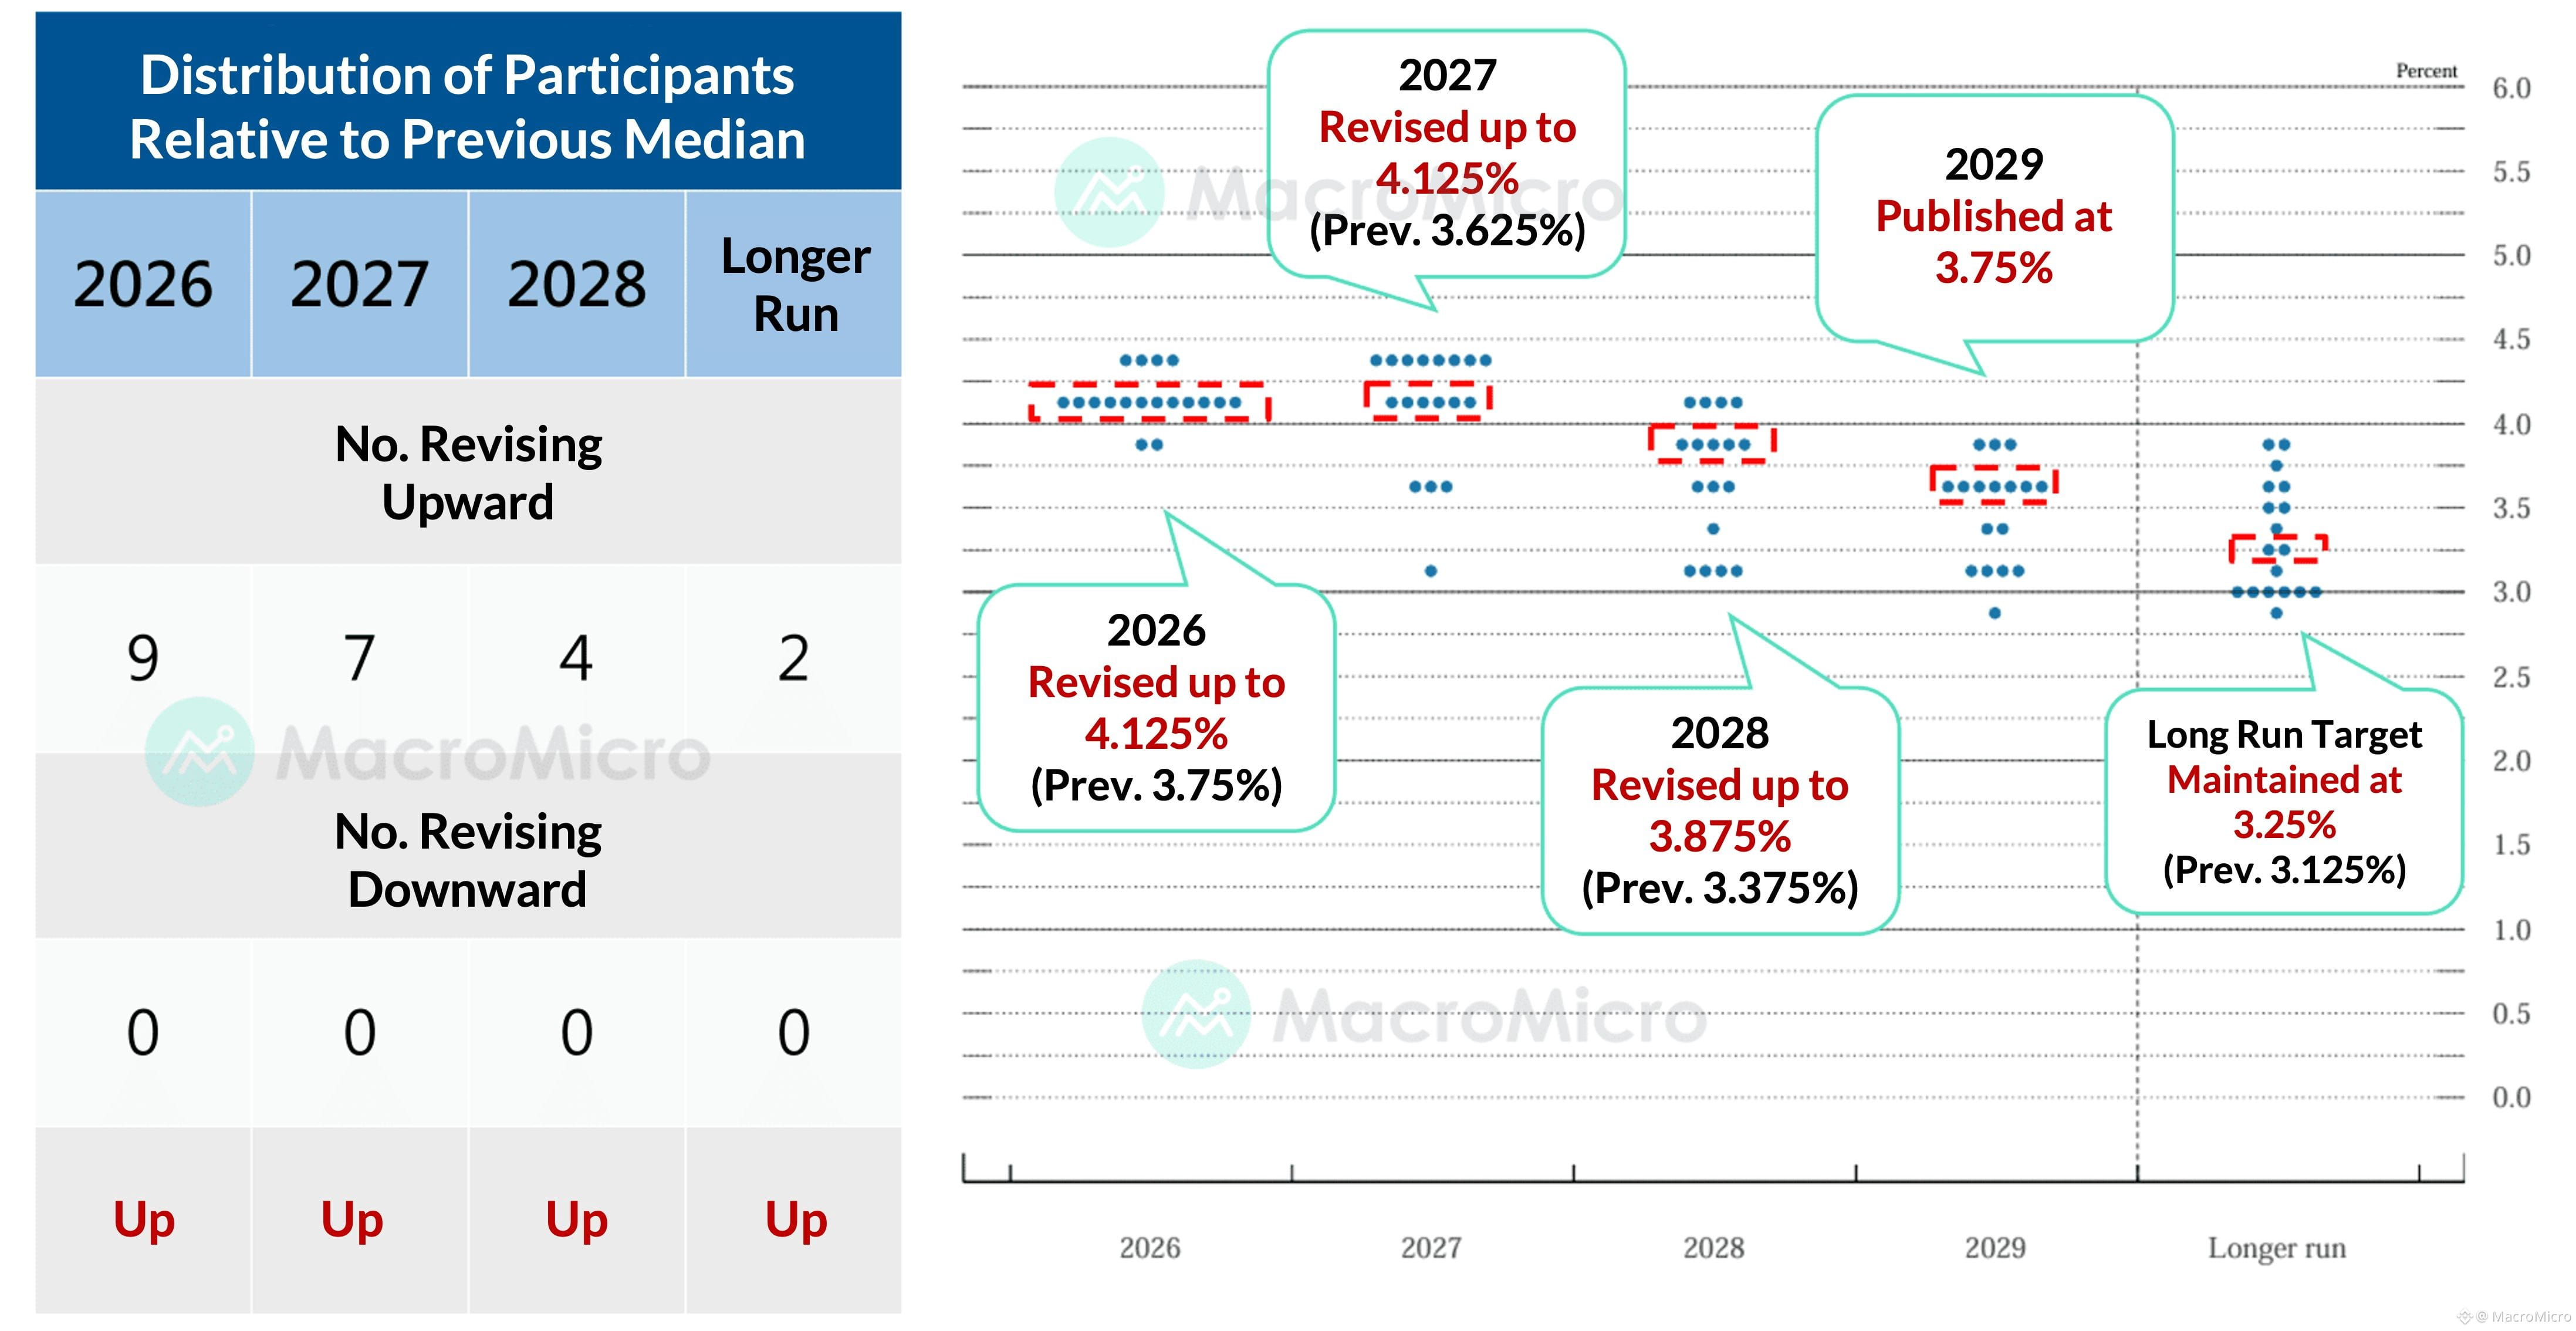
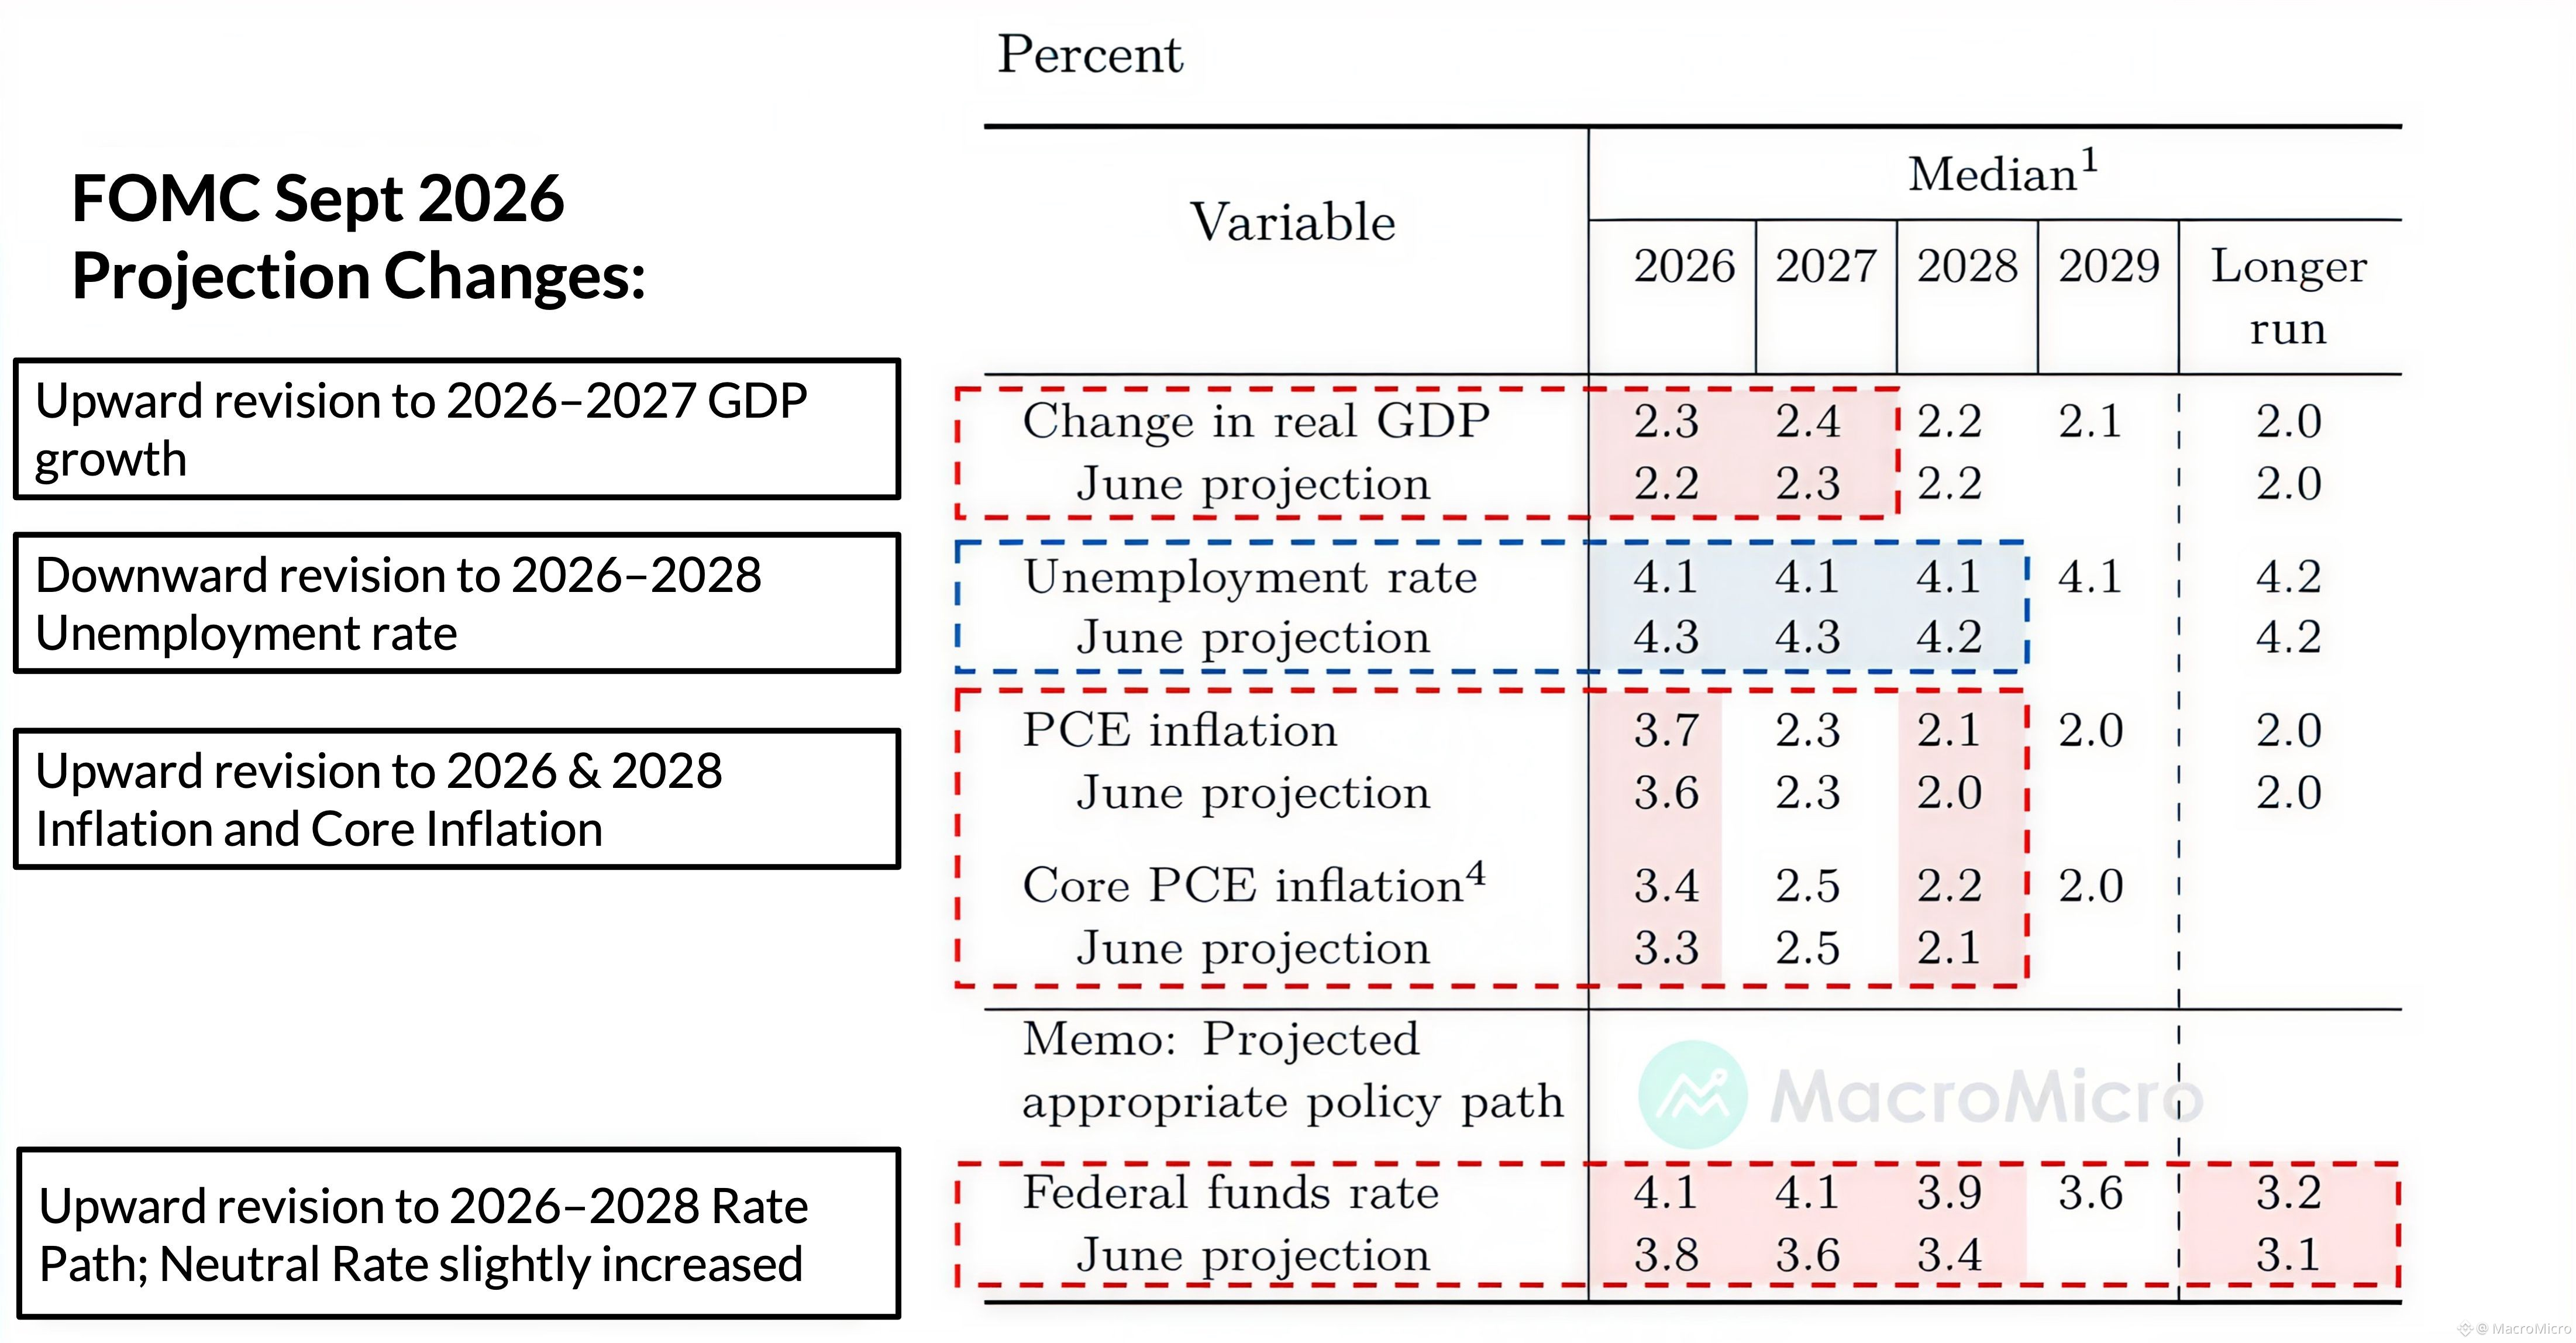
📌 The dot plot shifted sharply hawkish: 2026-2027 median rate projections jumped to 4.00%-4.25%, with 16 and 14 members respectively backing further hikes, meaning 1-2 more hikes are possible this year and next before the rate path turns lower again, eventually moving toward a higher long-run rate of 3.25%.
📌 SEP forecasts show the Fed turning more hawkish across the board: 2026-2027 GDP raised to 2.3% and 2.4%, unemployment lowered to 4.1% (from 4.3%, below the long-run average), while inflation and core inflation were revised up to 3.7% and 3.4% (from 3.6% and 3.3%).
📌 Warsh said the economy is at full employment with no conflict between the Fed's dual mandate goals, called it hard to describe current financial conditions as restrictive, and pointed to resilient labor data, unresolved underlying inflation trends, and rising geopolitical risk as the three reasons behind the hike.
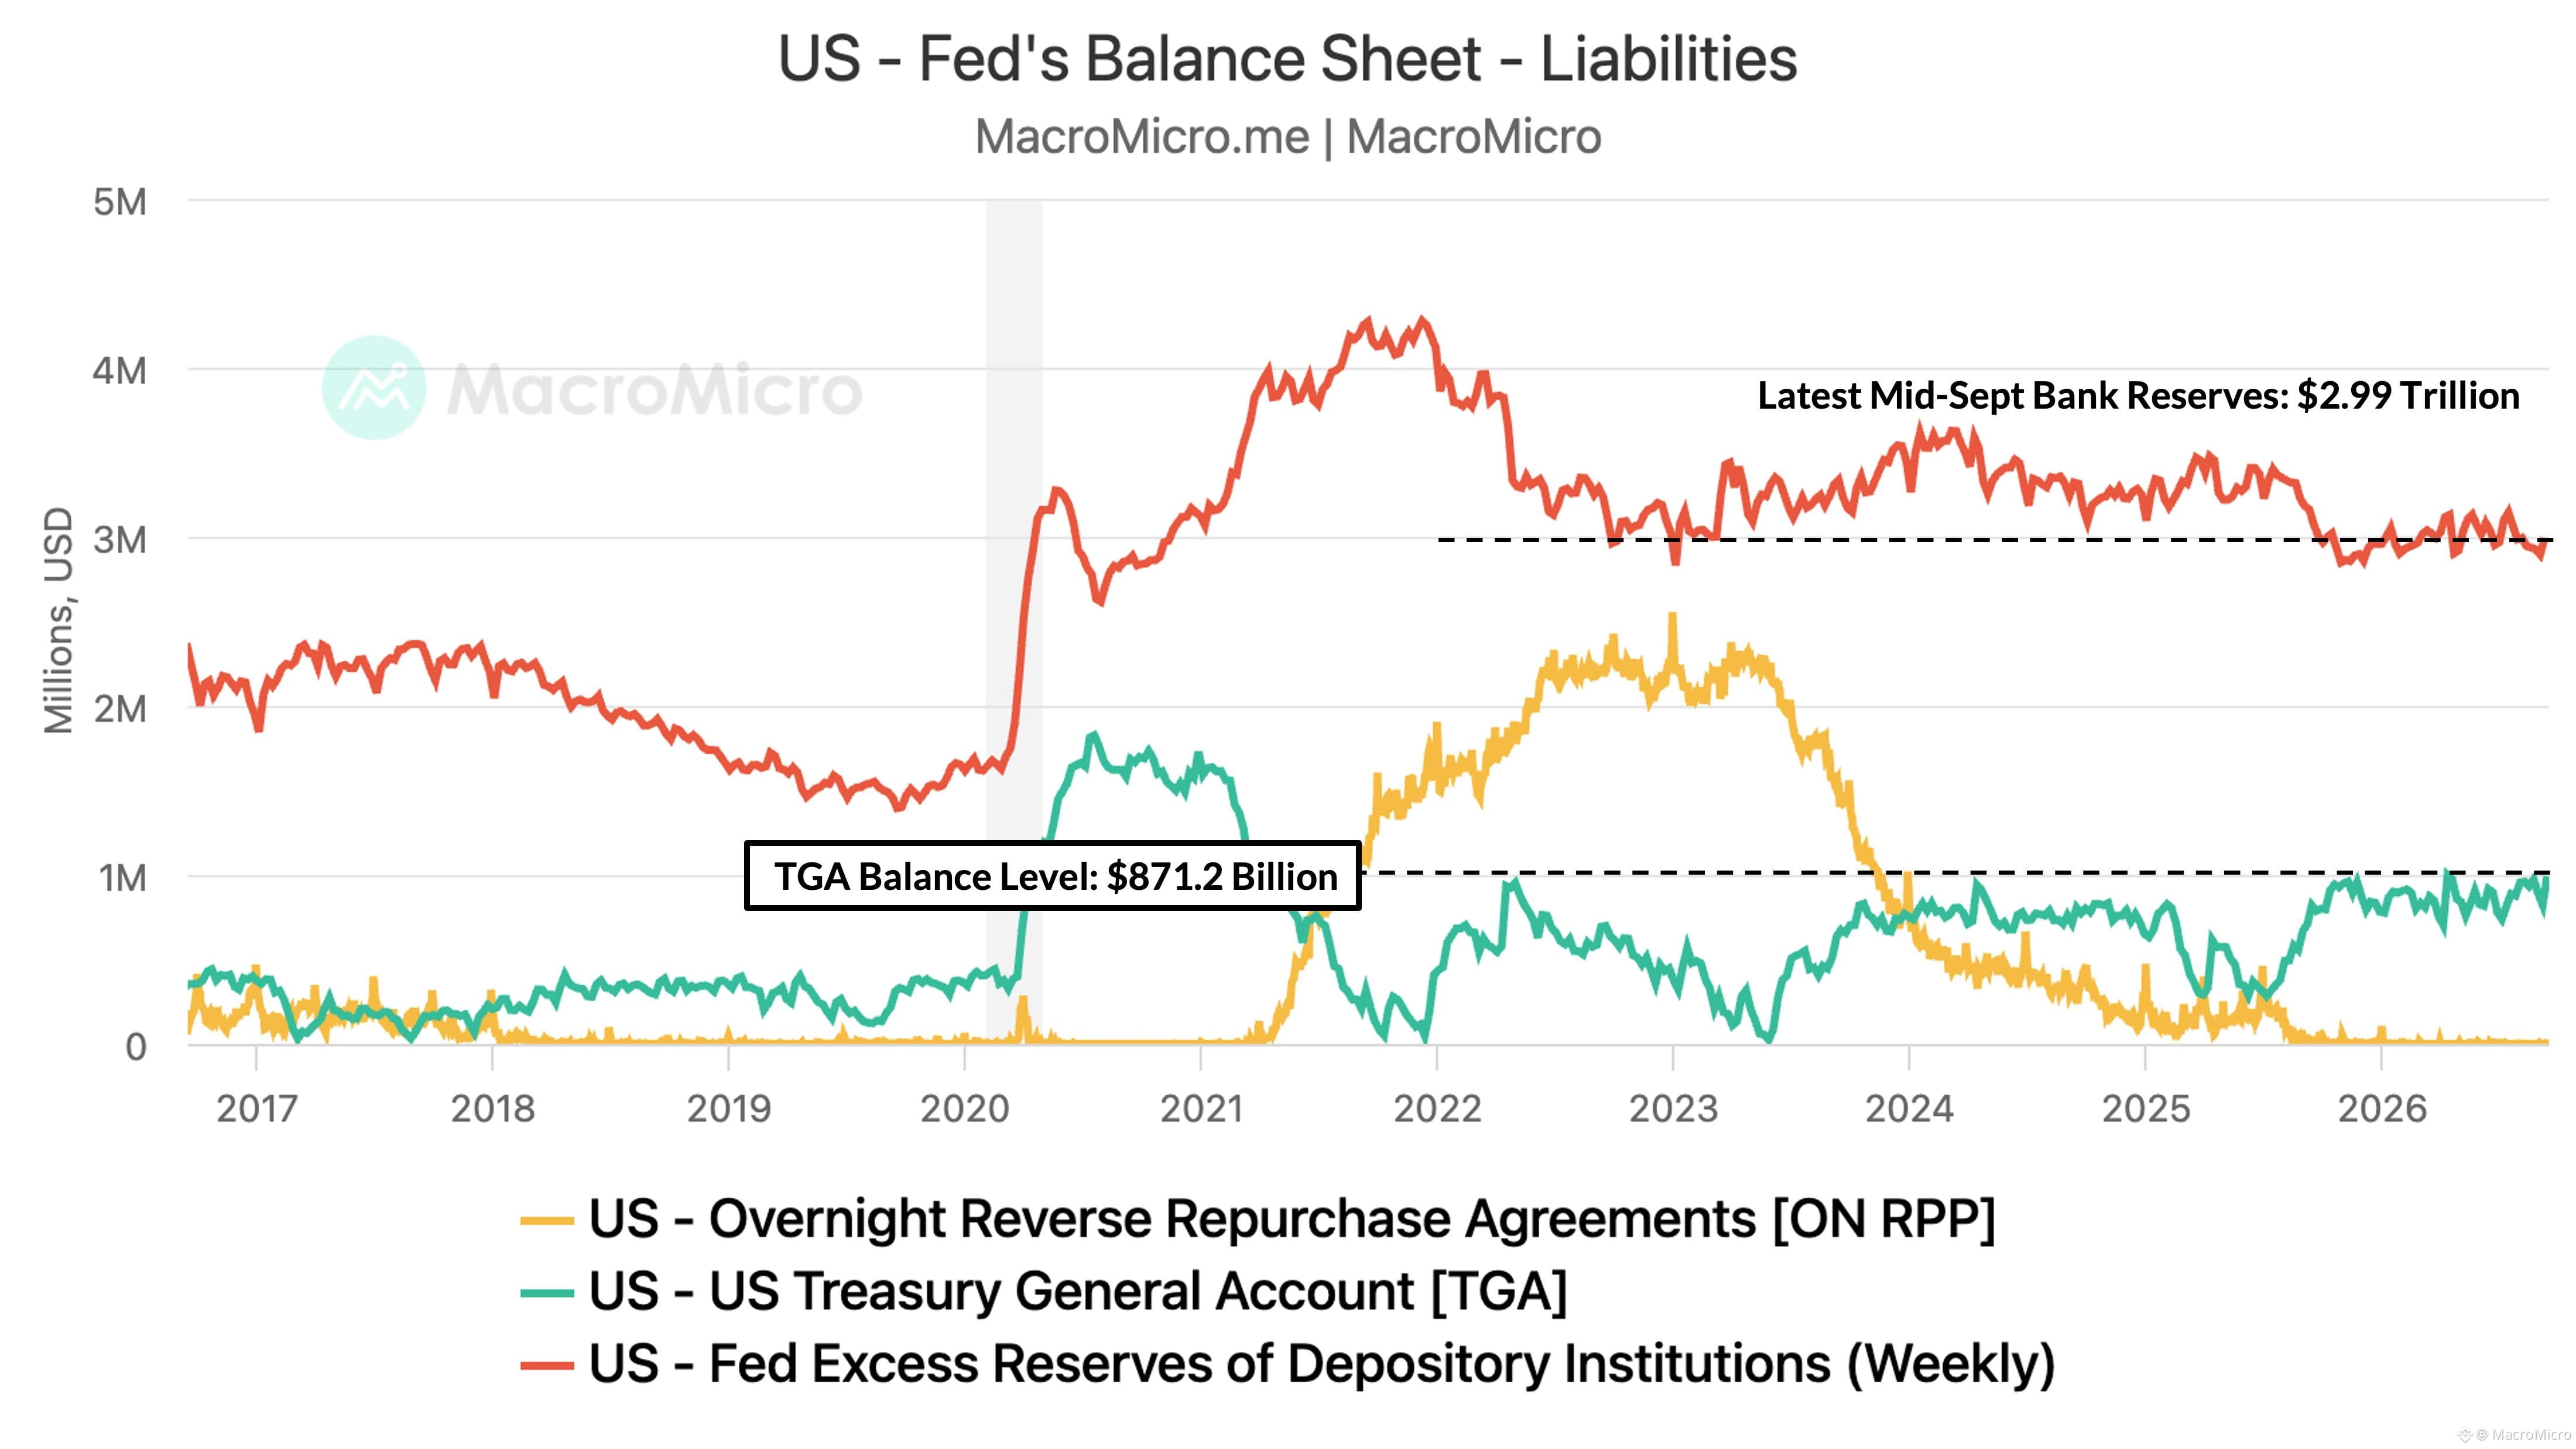
📌 The Fed reaffirmed its ample reserves policy after ending short-term bill purchases in August. Bank reserves hold steady near $2.99T, with TGA expected to approach $1T by September-October on corporate tax receipts against a year-end target of $850B, implying $100-200B of liquidity release to keep reserves supported.
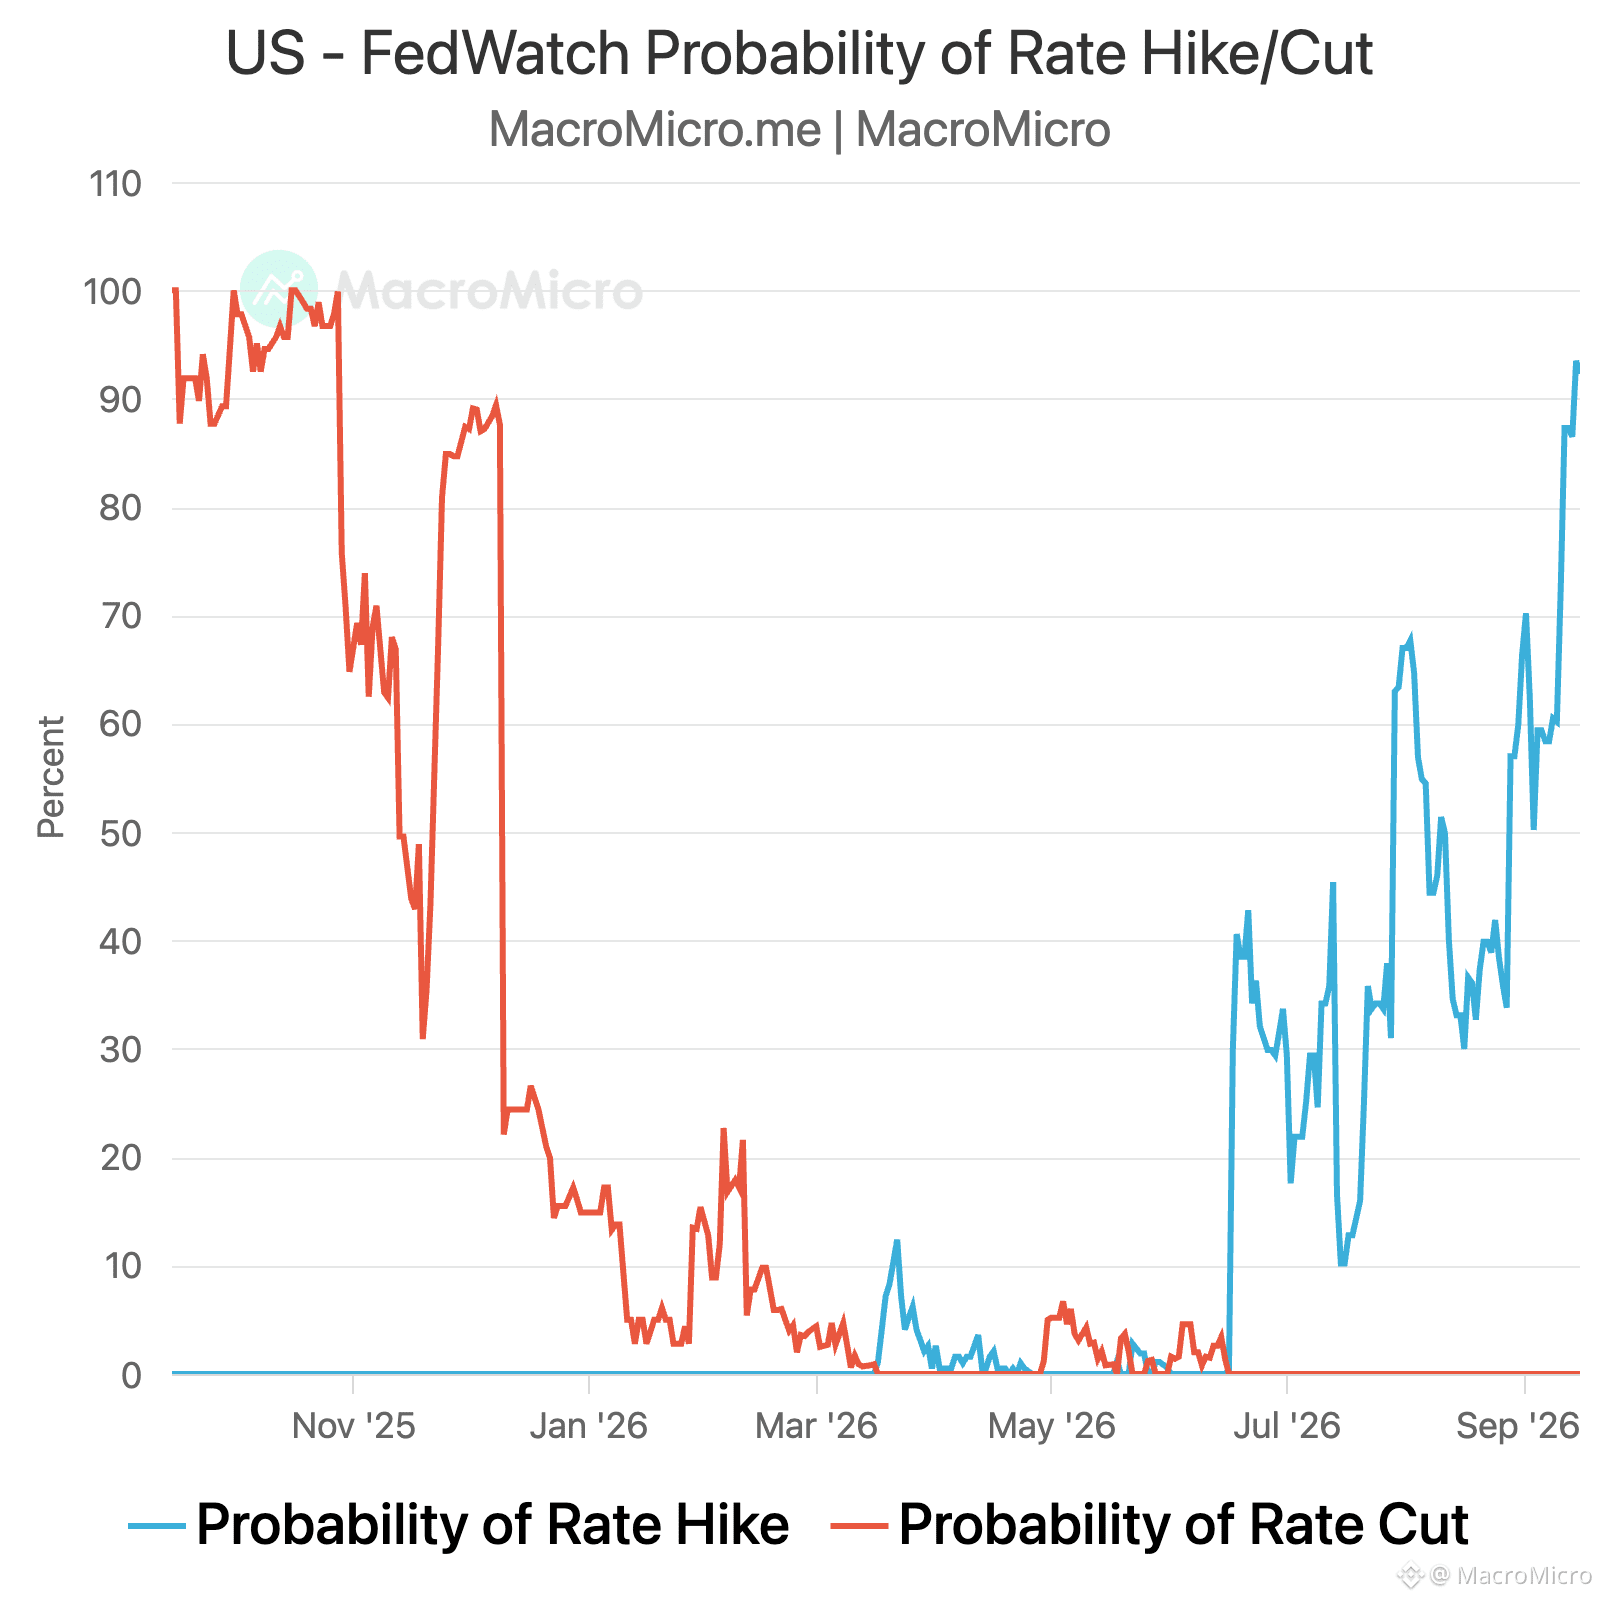
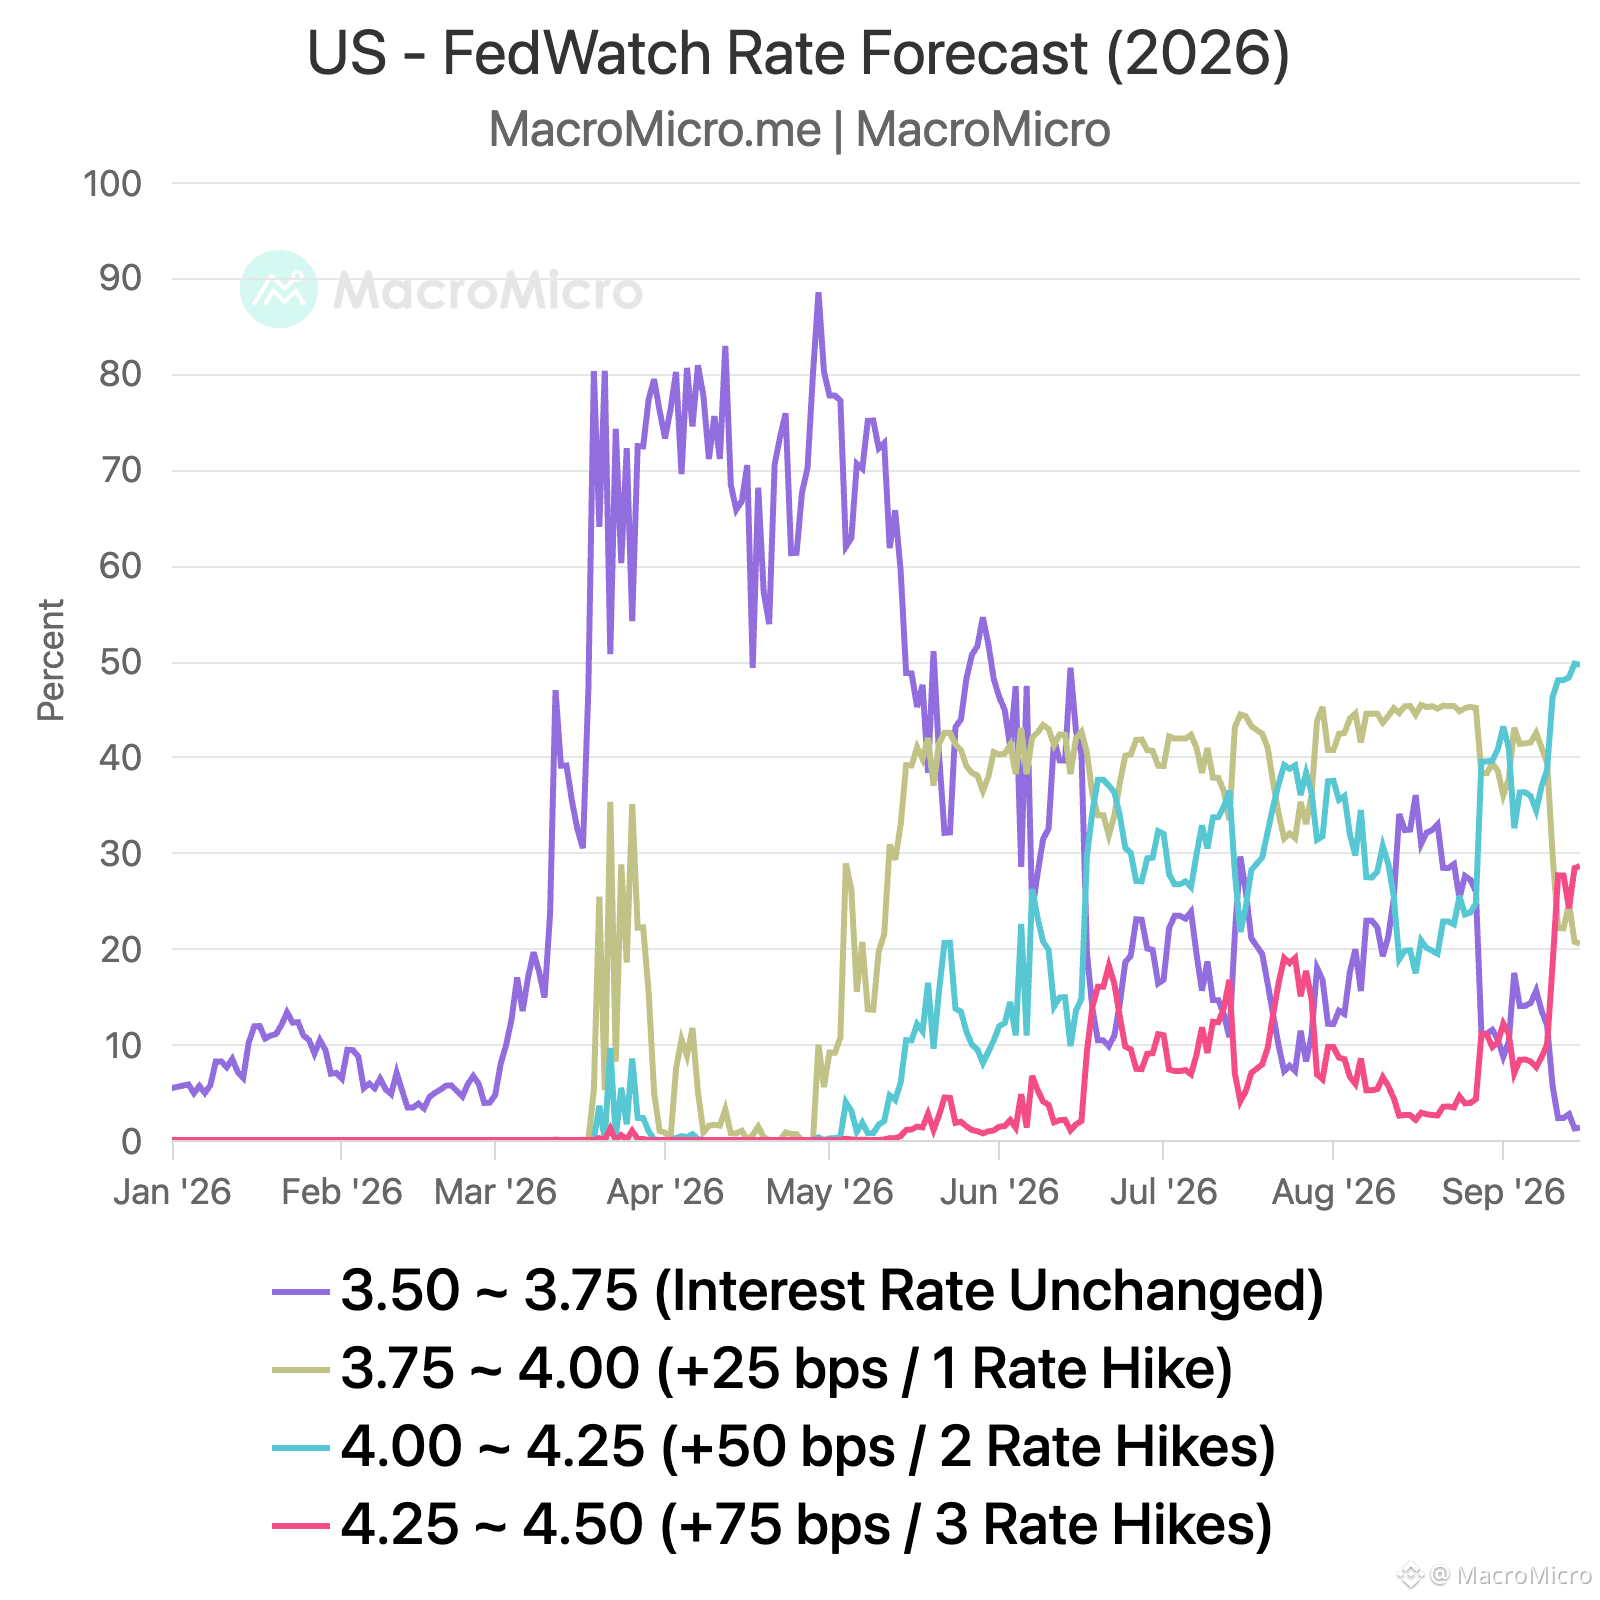
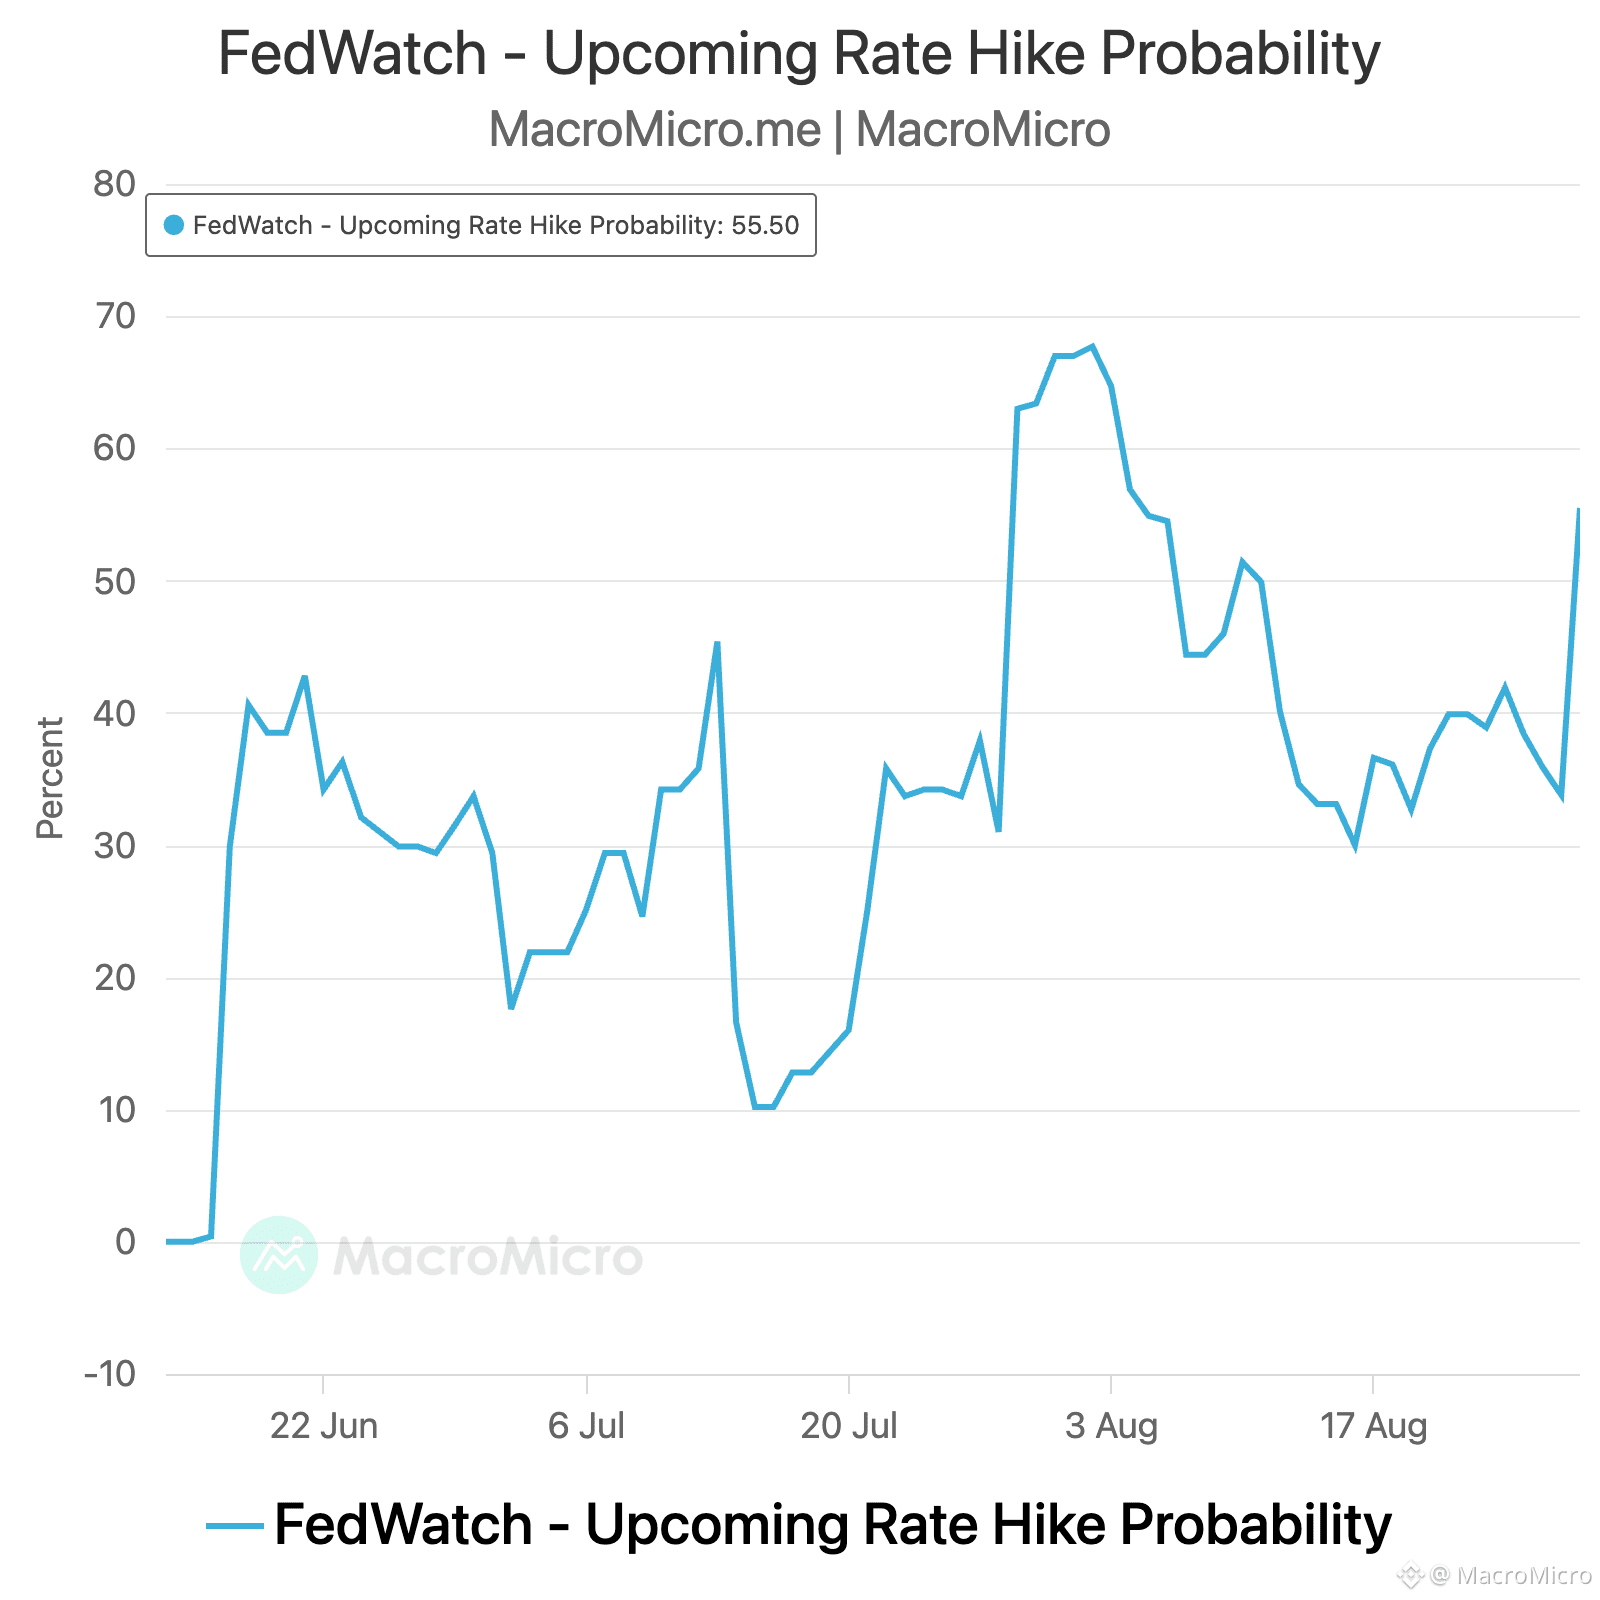
📌 Markets read it hawkish: October hike odds jumped from 41% to 51% and 2026 three-hike odds rose from 28% to 39% on FedWatch, while the 10-year yield climbed above 4.74% and the 30-year held at 5.36%, the highest since July 2007.
#FedRateWatch
🔥 September 2026 FOMC Meeting: Key Takeaways 🔎
📌 The Fed hiked rates 25bp to 3.75%-4.00%, unanimously (12-0), citing solid economic growth and a push to accelerate progress toward the 2% inflation target.
📌 The dot plot shifted sharply hawkish: 2026-2027 median rate projections jumped to 4.00%-4.25%, with 16 and 14 members respectively backing further hikes, meaning 1-2 more hikes are possible this year and next before the rate path turns lower again, eventually moving toward a higher long-run rate of 3.25%.
📌 SEP forecasts show the Fed turning more hawkish across the board: 2026-2027 GDP raised to 2.3% and 2.4%, unemployment lowered to 4.1% (from 4.3%, below the long-run average), while inflation and core inflation were revised up to 3.7% and 3.4% (from 3.6% and 3.3%).
📌 Warsh said the economy is at full employment with no conflict between the Fed's dual mandate goals, called it hard to describe current financial conditions as restrictive, and pointed to resilient labor data, unresolved underlying inflation trends, and rising geopolitical risk as the three reasons behind the hike.
📌 The Fed reaffirmed its ample reserves policy after ending short-term bill purchases in August. Bank reserves hold steady near $2.99T, with TGA expected to approach $1T by September-October on corporate tax receipts against a year-end target of $850B, implying $100-200B of liquidity release to keep reserves supported.
📌 Markets read it hawkish: October hike odds jumped from 41% to 51% and 2026 three-hike odds rose from 28% to 39% on FedWatch, while the 10-year yield climbed above 4.74% and the 30-year held at 5.36%, the highest since July 2007.
#FedRateWatch
📌 The Fed hiked rates 25bp to 3.75%-4.00%, unanimously (12-0), citing solid economic growth and a push to accelerate progress toward the 2% inflation target.
📌 The dot plot shifted sharply hawkish: 2026-2027 median rate projections jumped to 4.00%-4.25%, with 16 and 14 members respectively backing further hikes, meaning 1-2 more hikes are possible this year and next before the rate path turns lower again, eventually moving toward a higher long-run rate of 3.25%.
📌 SEP forecasts show the Fed turning more hawkish across the board: 2026-2027 GDP raised to 2.3% and 2.4%, unemployment lowered to 4.1% (from 4.3%, below the long-run average), while inflation and core inflation were revised up to 3.7% and 3.4% (from 3.6% and 3.3%).
📌 Warsh said the economy is at full employment with no conflict between the Fed's dual mandate goals, called it hard to describe current financial conditions as restrictive, and pointed to resilient labor data, unresolved underlying inflation trends, and rising geopolitical risk as the three reasons behind the hike.
📌 The Fed reaffirmed its ample reserves policy after ending short-term bill purchases in August. Bank reserves hold steady near $2.99T, with TGA expected to approach $1T by September-October on corporate tax receipts against a year-end target of $850B, implying $100-200B of liquidity release to keep reserves supported.
📌 Markets read it hawkish: October hike odds jumped from 41% to 51% and 2026 three-hike odds rose from 28% to 39% on FedWatch, while the 10-year yield climbed above 4.74% and the 30-year held at 5.36%, the highest since July 2007.
#FedRateWatch
1
1
2.3k
·
--
Проверено
The September FOMC decision is coming in just hours, with markets almost universally expecting a rate hike after last week's inflation data and oil futures living above $100.
The key question is how the dot plot changes alongside the decision.
We see three possible scenarios:
📌 Dovish: Rates remain unchanged, while the median dot rises to signal one rate hike this year.
📌 Neutral: Rates rise 25bp, with the median dot also signaling one rate hike this year, implying no further hikes after September.
📌 Hawkish: Rates rise 25bp, while the median dot signals two rate hikes this year, leaving room for another hike after September.
Before last week’s CPI and PPI releases, we viewed the dovish scenario as our base case. With inflation coming in above expectations and oil prices moving above $100, the probability of a September hike has increased significantly.
Still, a hike would not necessarily mean the Fed is turning firmly hawkish. Core inflation has not shown a broad-based reacceleration, so even if the Fed resumes tightening, the move could represent one or two precautionary hikes rather than the start of a sustained hiking cycle.
That distinction will matter for markets. Under the neutral scenario, a September hike could represent “bad news already priced in”: once the hike is delivered, uncertainty around this year’s rate path would diminish, potentially allowing long-term Treasury yields to peak and retreat.
The SEP will provide another important signal. If economic projections are maintained or raised while inflation projections remain unchanged, it would reinforce the view that any shift toward rate hikes is precautionary, with a low probability of consecutive hikes.
The decision arrives in hours. The hike matters, but the dot plot will tell us what comes next.
#FedRateWatch
The September FOMC decision is coming in just hours, with markets almost universally expecting a rate hike after last week's inflation data and oil futures living above $100.
The key question is how the dot plot changes alongside the decision.
We see three possible scenarios:
📌 Dovish: Rates remain unchanged, while the median dot rises to signal one rate hike this year.
📌 Neutral: Rates rise 25bp, with the median dot also signaling one rate hike this year, implying no further hikes after September.
📌 Hawkish: Rates rise 25bp, while the median dot signals two rate hikes this year, leaving room for another hike after September.
Before last week’s CPI and PPI releases, we viewed the dovish scenario as our base case. With inflation coming in above expectations and oil prices moving above $100, the probability of a September hike has increased significantly.
Still, a hike would not necessarily mean the Fed is turning firmly hawkish. Core inflation has not shown a broad-based reacceleration, so even if the Fed resumes tightening, the move could represent one or two precautionary hikes rather than the start of a sustained hiking cycle.
That distinction will matter for markets. Under the neutral scenario, a September hike could represent “bad news already priced in”: once the hike is delivered, uncertainty around this year’s rate path would diminish, potentially allowing long-term Treasury yields to peak and retreat.
The SEP will provide another important signal. If economic projections are maintained or raised while inflation projections remain unchanged, it would reinforce the view that any shift toward rate hikes is precautionary, with a low probability of consecutive hikes.
The decision arrives in hours. The hike matters, but the dot plot will tell us what comes next.
#FedRateWatch
The key question is how the dot plot changes alongside the decision.
We see three possible scenarios:
📌 Dovish: Rates remain unchanged, while the median dot rises to signal one rate hike this year.
📌 Neutral: Rates rise 25bp, with the median dot also signaling one rate hike this year, implying no further hikes after September.
📌 Hawkish: Rates rise 25bp, while the median dot signals two rate hikes this year, leaving room for another hike after September.
Before last week’s CPI and PPI releases, we viewed the dovish scenario as our base case. With inflation coming in above expectations and oil prices moving above $100, the probability of a September hike has increased significantly.
Still, a hike would not necessarily mean the Fed is turning firmly hawkish. Core inflation has not shown a broad-based reacceleration, so even if the Fed resumes tightening, the move could represent one or two precautionary hikes rather than the start of a sustained hiking cycle.
That distinction will matter for markets. Under the neutral scenario, a September hike could represent “bad news already priced in”: once the hike is delivered, uncertainty around this year’s rate path would diminish, potentially allowing long-term Treasury yields to peak and retreat.
The SEP will provide another important signal. If economic projections are maintained or raised while inflation projections remain unchanged, it would reinforce the view that any shift toward rate hikes is precautionary, with a low probability of consecutive hikes.
The decision arrives in hours. The hike matters, but the dot plot will tell us what comes next.
#FedRateWatch
3
1
1.8k
·
--
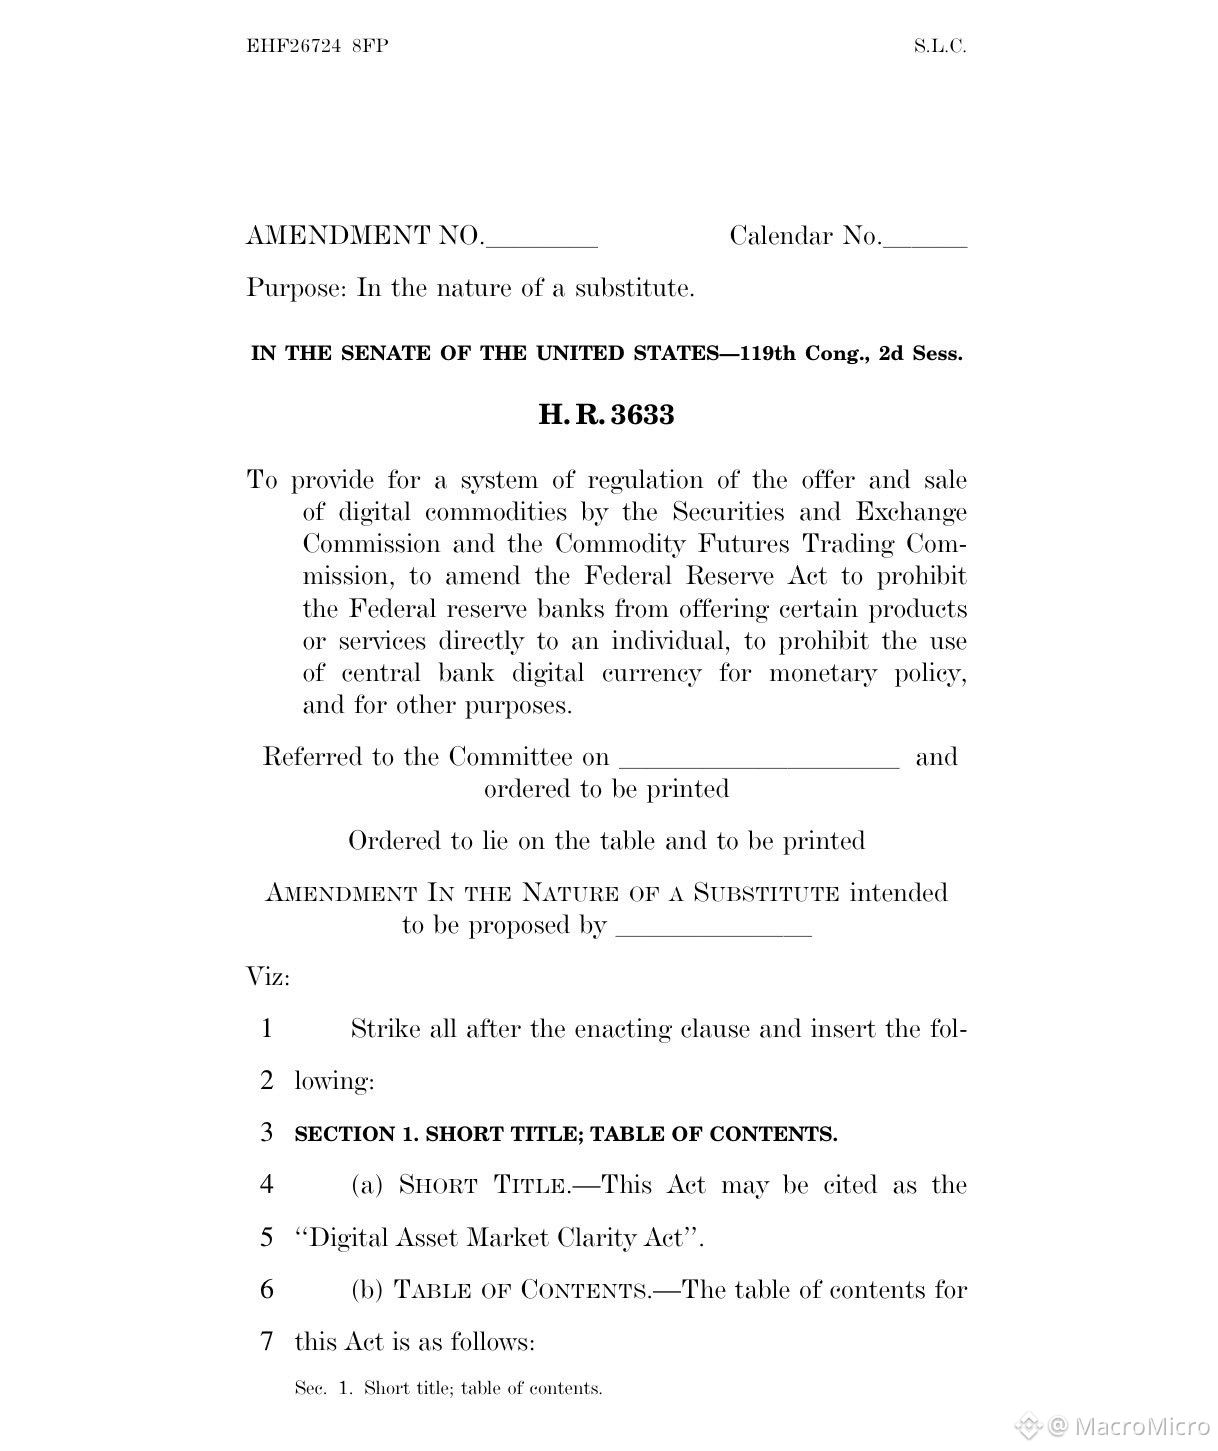
🚨 BREAKING: 🇺🇸 Senate Republicans have released another revised 635-page CLARITY Act, calling it their “last, best and final” offer ahead of Tuesday’s critical cloture vote.
The revised bill includes major changes:
📌 Trump-backed ethics rules would bar the president and other federal officials from issuing or sponsoring digital assets.
📌 Stablecoin rules add a “circuit breaker” allowing federal intervention if community banks face widespread deposit flight into stablecoins.
📌 BRCA protections have been narrowed, removing language that explicitly extended certain protections to criminal cases.
📌 New conflict-of-interest rules target affiliate trading involving digital commodity exchanges, brokers and dealers.
The White House has agreed to the ethics provisions in a last-minute push to secure enough support for the bill.
The legislation now heads toward Tuesday’s Senate vote, where it will need 60 votes to advance.
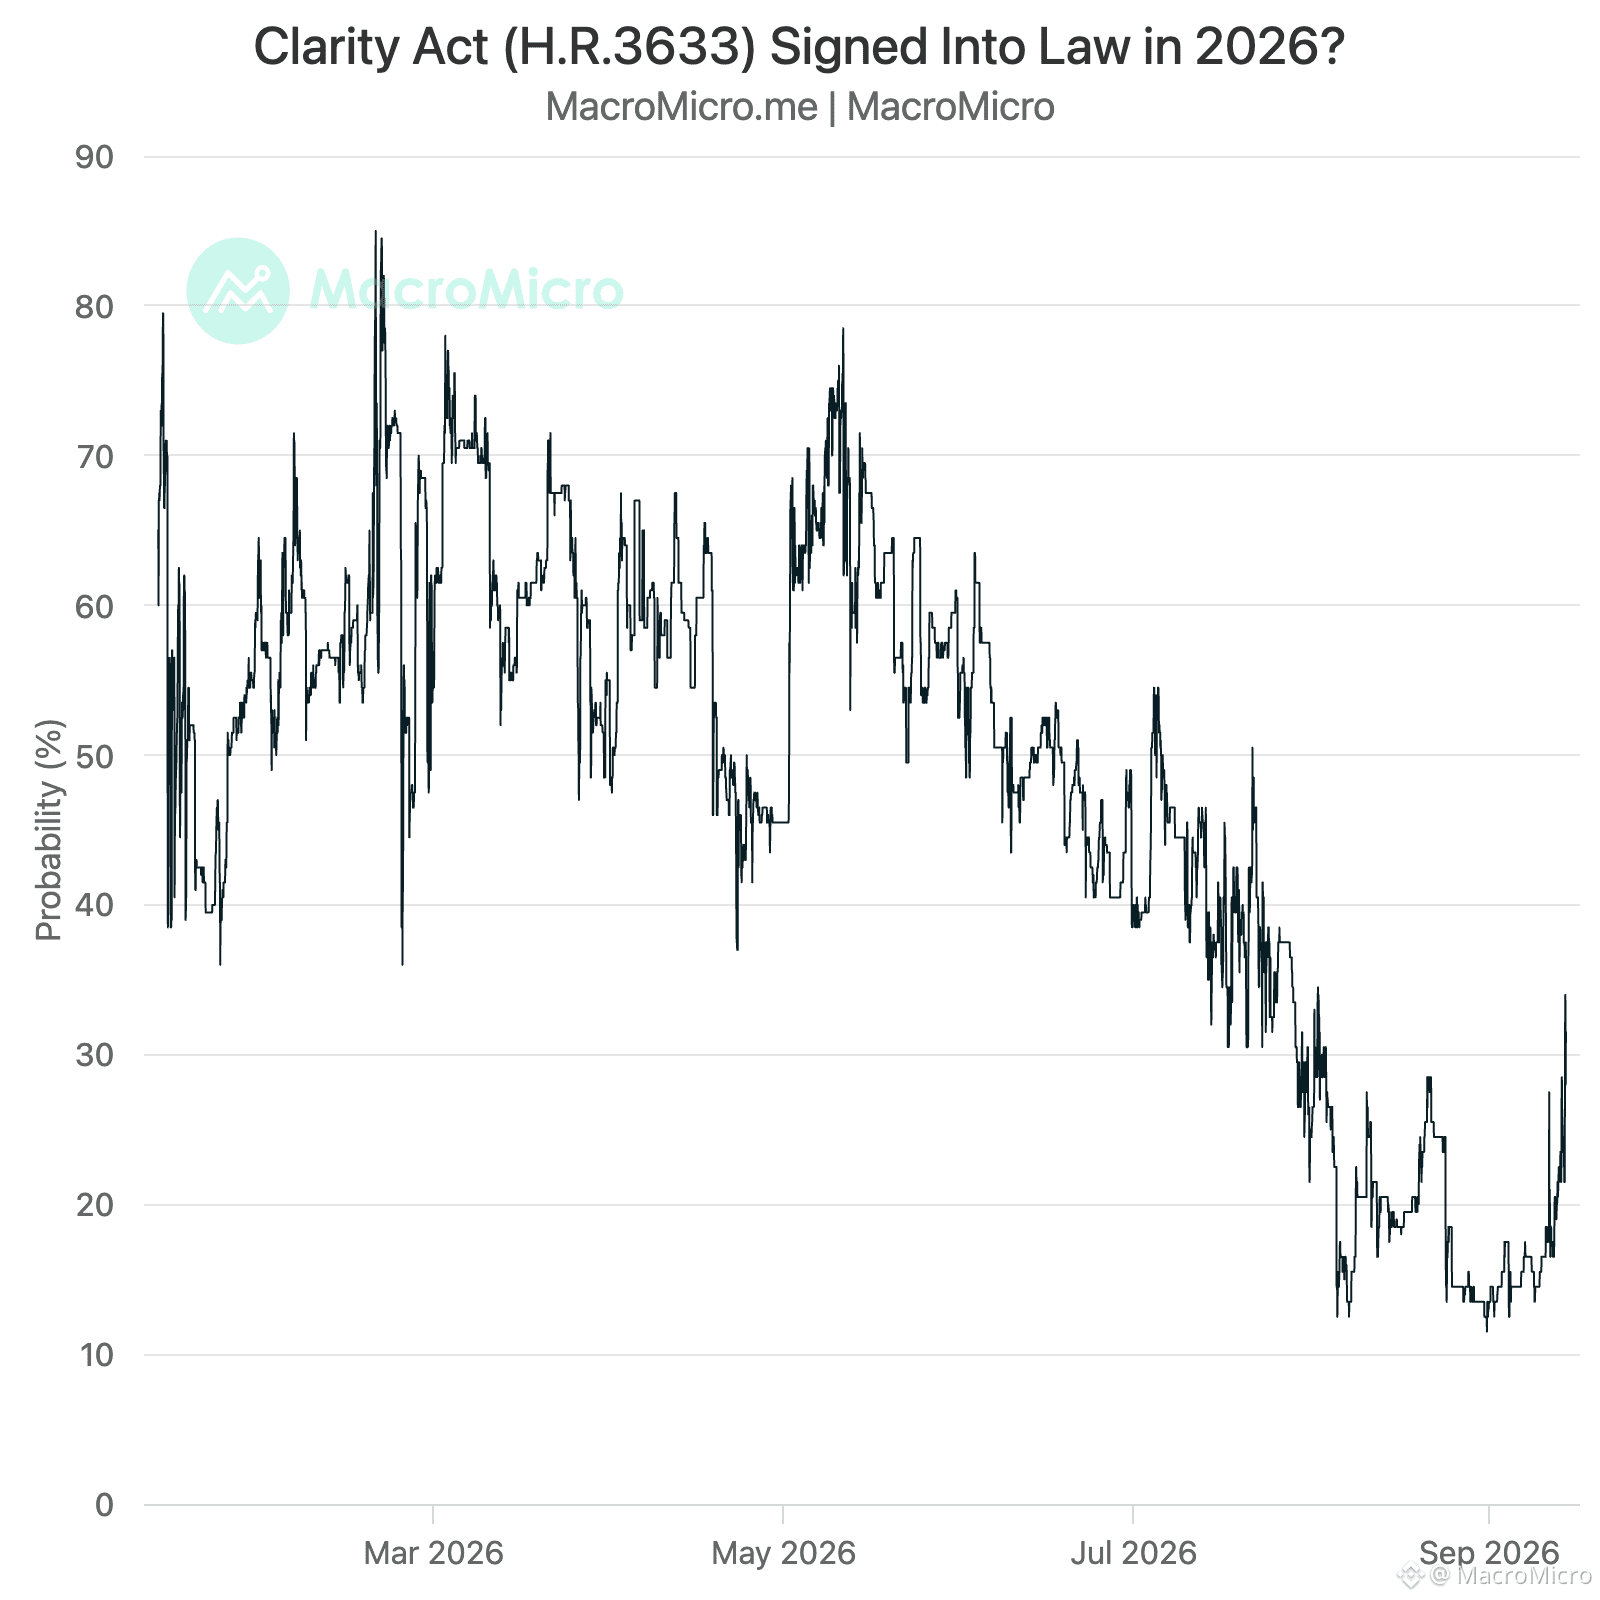
This could be the final Republican attempt to break the impasse and move the long-awaited crypto market structure bill forward. Prediction market odds for a 2026 passing have shot up to 32% 🚀
🚨 BREAKING: 🇺🇸 Senate Republicans have released another revised 635-page CLARITY Act, calling it their “last, best and final” offer ahead of Tuesday’s critical cloture vote.
The revised bill includes major changes:
📌 Trump-backed ethics rules would bar the president and other federal officials from issuing or sponsoring digital assets.
📌 Stablecoin rules add a “circuit breaker” allowing federal intervention if community banks face widespread deposit flight into stablecoins.
📌 BRCA protections have been narrowed, removing language that explicitly extended certain protections to criminal cases.
📌 New conflict-of-interest rules target affiliate trading involving digital commodity exchanges, brokers and dealers.
The White House has agreed to the ethics provisions in a last-minute push to secure enough support for the bill.
The legislation now heads toward Tuesday’s Senate vote, where it will need 60 votes to advance.
This could be the final Republican attempt to break the impasse and move the long-awaited crypto market structure bill forward. Prediction market odds for a 2026 passing have shot up to 32% 🚀
The revised bill includes major changes:
📌 Trump-backed ethics rules would bar the president and other federal officials from issuing or sponsoring digital assets.
📌 Stablecoin rules add a “circuit breaker” allowing federal intervention if community banks face widespread deposit flight into stablecoins.
📌 BRCA protections have been narrowed, removing language that explicitly extended certain protections to criminal cases.
📌 New conflict-of-interest rules target affiliate trading involving digital commodity exchanges, brokers and dealers.
The White House has agreed to the ethics provisions in a last-minute push to secure enough support for the bill.
The legislation now heads toward Tuesday’s Senate vote, where it will need 60 votes to advance.
This could be the final Republican attempt to break the impasse and move the long-awaited crypto market structure bill forward. Prediction market odds for a 2026 passing have shot up to 32% 🚀
8
1
7
9.5k
·
--
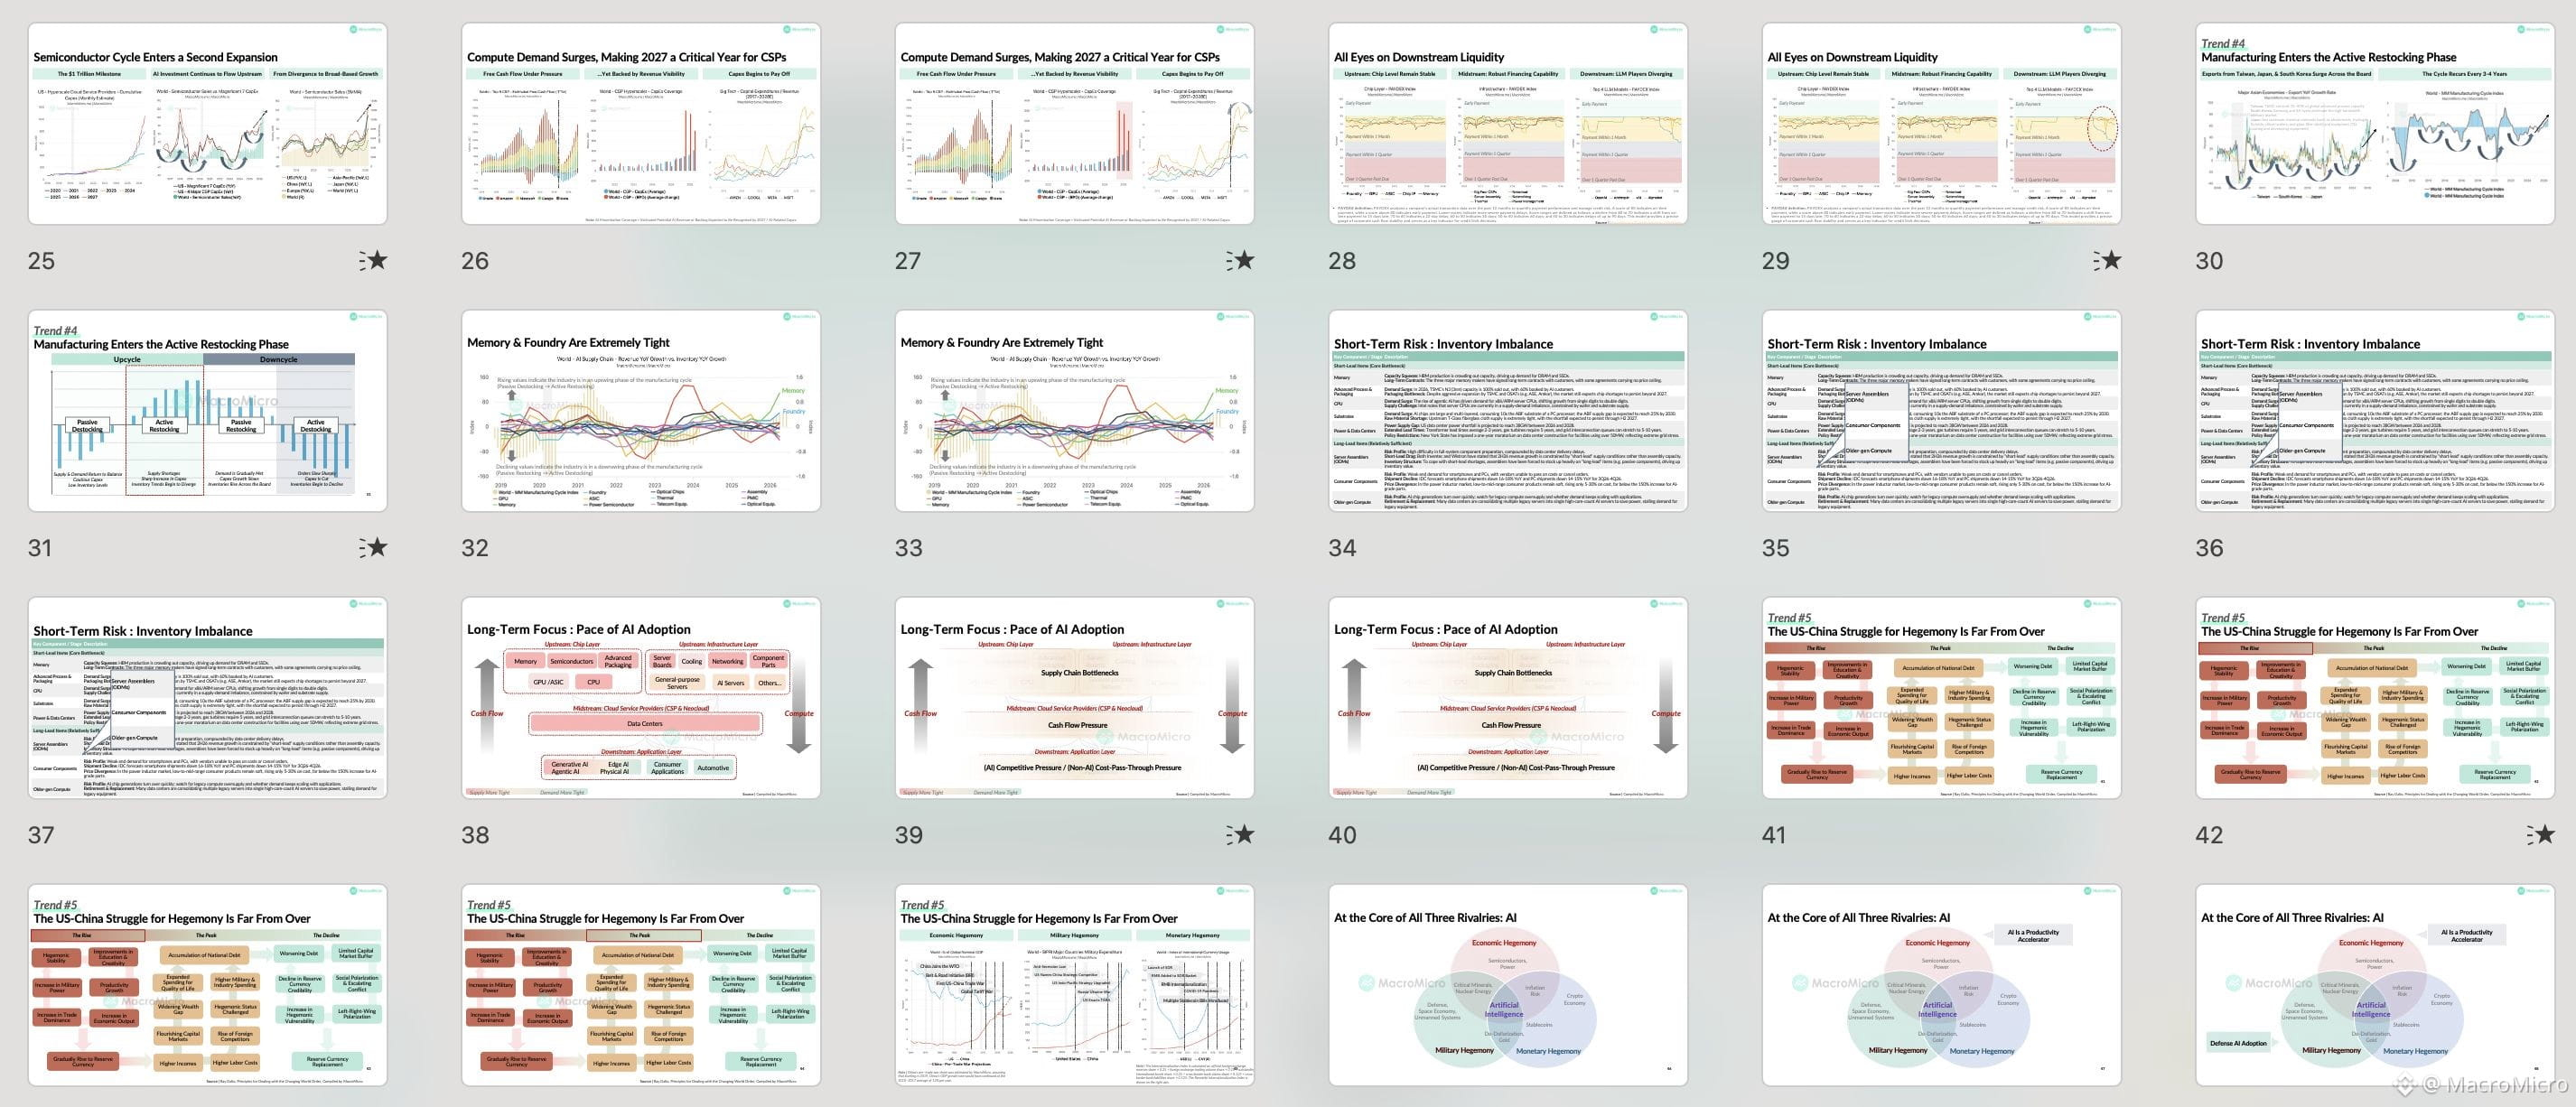
We just released a preview of THE $1T MEGATRENDS: Money, Margin, & Macro — covering the $1 trillion CapEx milestone, why memory and foundry are extremely tight, and where the short-term risks are building.
Want the full breakdown? It's live now, free with Max AI Annual — plus 1-year access to the AI Supply Chain Intelligence Hub.
View the preview: https://drive.google.com/file/d/1r-_vuihG9HmDNeKNxjPqh2IHprpxqf7K/view
We just released a preview of THE $1T MEGATRENDS: Money, Margin, & Macro — covering the $1 trillion CapEx milestone, why memory and foundry are extremely tight, and where the short-term risks are building.
Want the full breakdown? It's live now, free with Max AI Annual — plus 1-year access to the AI Supply Chain Intelligence Hub.
View the preview: https://drive.google.com/file/d/1r-_vuihG9HmDNeKNxjPqh2IHprpxqf7K/view
Want the full breakdown? It's live now, free with Max AI Annual — plus 1-year access to the AI Supply Chain Intelligence Hub.
View the preview: https://drive.google.com/file/d/1r-_vuihG9HmDNeKNxjPqh2IHprpxqf7K/view
416
·
--
🚨 Senate Republicans have released revised CLARITY Act text following August recess negotiations. 114+ Democratic asks were incorporated, but the two sections Dems have fought hardest over (ethics, stablecoin yield) are untouched.
The latest text appears to tighten the regulatory perimeter around DeFi while carving out a clearer path for regulated financial institutions to participate in crypto.
Key changes:
📌 Non-decentralized DeFi comes further into the regulatory perimeter. Protocols with identifiable parties able to control or materially alter functionality, operate outside transparent code-based rules, or restrict users would face CFTC registration and related conduct, disclosure, recordkeeping and supervision requirements.
📌 DeFi provisions are narrowed to spot/cash digital commodity transactions. This appears designed in part to address concerns around blockchain-based prediction markets, limiting how broadly the DeFi framework can reach activities that are not conventional spot commodity markets.
📌 Credit-union authority is explicitly clarified. Federal credit unions would be able to use digital assets and DLT to provide activities they are otherwise authorized to conduct, creating greater parity with the bill’s broader banking provisions.
No changes to the ethics provisions, while the BRCA and stablecoin-yield provisions remain intact.
Bottom line: the revisions appear calibrated to attract 60 votes while preserving the bill’s core structure. The question now is whether Democrats view the 114 provisions as substantive concessions or as an effort to make limited changes look broader than they are.
#CLARITYAct
🚨 Senate Republicans have released revised CLARITY Act text following August recess negotiations. 114+ Democratic asks were incorporated, but the two sections Dems have fought hardest over (ethics, stablecoin yield) are untouched.
The latest text appears to tighten the regulatory perimeter around DeFi while carving out a clearer path for regulated financial institutions to participate in crypto.
Key changes:
📌 Non-decentralized DeFi comes further into the regulatory perimeter. Protocols with identifiable parties able to control or materially alter functionality, operate outside transparent code-based rules, or restrict users would face CFTC registration and related conduct, disclosure, recordkeeping and supervision requirements.
📌 DeFi provisions are narrowed to spot/cash digital commodity transactions. This appears designed in part to address concerns around blockchain-based prediction markets, limiting how broadly the DeFi framework can reach activities that are not conventional spot commodity markets.
📌 Credit-union authority is explicitly clarified. Federal credit unions would be able to use digital assets and DLT to provide activities they are otherwise authorized to conduct, creating greater parity with the bill’s broader banking provisions.
No changes to the ethics provisions, while the BRCA and stablecoin-yield provisions remain intact.
Bottom line: the revisions appear calibrated to attract 60 votes while preserving the bill’s core structure. The question now is whether Democrats view the 114 provisions as substantive concessions or as an effort to make limited changes look broader than they are.
#CLARITYAct
The latest text appears to tighten the regulatory perimeter around DeFi while carving out a clearer path for regulated financial institutions to participate in crypto.
Key changes:
📌 Non-decentralized DeFi comes further into the regulatory perimeter. Protocols with identifiable parties able to control or materially alter functionality, operate outside transparent code-based rules, or restrict users would face CFTC registration and related conduct, disclosure, recordkeeping and supervision requirements.
📌 DeFi provisions are narrowed to spot/cash digital commodity transactions. This appears designed in part to address concerns around blockchain-based prediction markets, limiting how broadly the DeFi framework can reach activities that are not conventional spot commodity markets.
📌 Credit-union authority is explicitly clarified. Federal credit unions would be able to use digital assets and DLT to provide activities they are otherwise authorized to conduct, creating greater parity with the bill’s broader banking provisions.
No changes to the ethics provisions, while the BRCA and stablecoin-yield provisions remain intact.
Bottom line: the revisions appear calibrated to attract 60 votes while preserving the bill’s core structure. The question now is whether Democrats view the 114 provisions as substantive concessions or as an effort to make limited changes look broader than they are.
#CLARITYAct

3
10
9.4k
·
--
Рост
Проверено
🇺🇸 August CPI is due in a few hours, and coming a week after nonfarm payrolls beat, provides an important test of whether higher energy prices are feeding into core inflation.
Fed Chair Warsh has said the decision comes down to this print: a core reading broadly in line with expectations supports a hold, a surprise to the upside opens the door to a September hike. Waller has said much the same, and adds that stripping out the imputed non-market services component, underlying inflation already looks better than core suggests, with energy and tariffs not yet showing up as a persistent source of pressure.
Core is expected near 0.2% MoM, which brings the annual rate down to 2.4% from 2.5%. We're not seeing oil, despite renewed Iran tensions and elevated prices, feed through into core goods or services. We lean toward a hold.
Our prediction market implied forecast puts August headline CPI at 3.34% YoY and core CPI at 2.33% YoY.
#CPIWatch
📍 https://en.macromicro.me/charts/154402/us-cpi-yoy-prediction-market-implied-forecast
🇺🇸 August CPI is due in a few hours, and coming a week after nonfarm payrolls beat, provides an important test of whether higher energy prices are feeding into core inflation.
Fed Chair Warsh has said the decision comes down to this print: a core reading broadly in line with expectations supports a hold, a surprise to the upside opens the door to a September hike. Waller has said much the same, and adds that stripping out the imputed non-market services component, underlying inflation already looks better than core suggests, with energy and tariffs not yet showing up as a persistent source of pressure.
Core is expected near 0.2% MoM, which brings the annual rate down to 2.4% from 2.5%. We're not seeing oil, despite renewed Iran tensions and elevated prices, feed through into core goods or services. We lean toward a hold.
Our prediction market implied forecast puts August headline CPI at 3.34% YoY and core CPI at 2.33% YoY.
#CPIWatch
📍 https://en.macromicro.me/charts/154402/us-cpi-yoy-prediction-market-implied-forecast
Fed Chair Warsh has said the decision comes down to this print: a core reading broadly in line with expectations supports a hold, a surprise to the upside opens the door to a September hike. Waller has said much the same, and adds that stripping out the imputed non-market services component, underlying inflation already looks better than core suggests, with energy and tariffs not yet showing up as a persistent source of pressure.
Core is expected near 0.2% MoM, which brings the annual rate down to 2.4% from 2.5%. We're not seeing oil, despite renewed Iran tensions and elevated prices, feed through into core goods or services. We lean toward a hold.
Our prediction market implied forecast puts August headline CPI at 3.34% YoY and core CPI at 2.33% YoY.
#CPIWatch
📍 https://en.macromicro.me/charts/154402/us-cpi-yoy-prediction-market-implied-forecast

1
2
1.8k
·
--
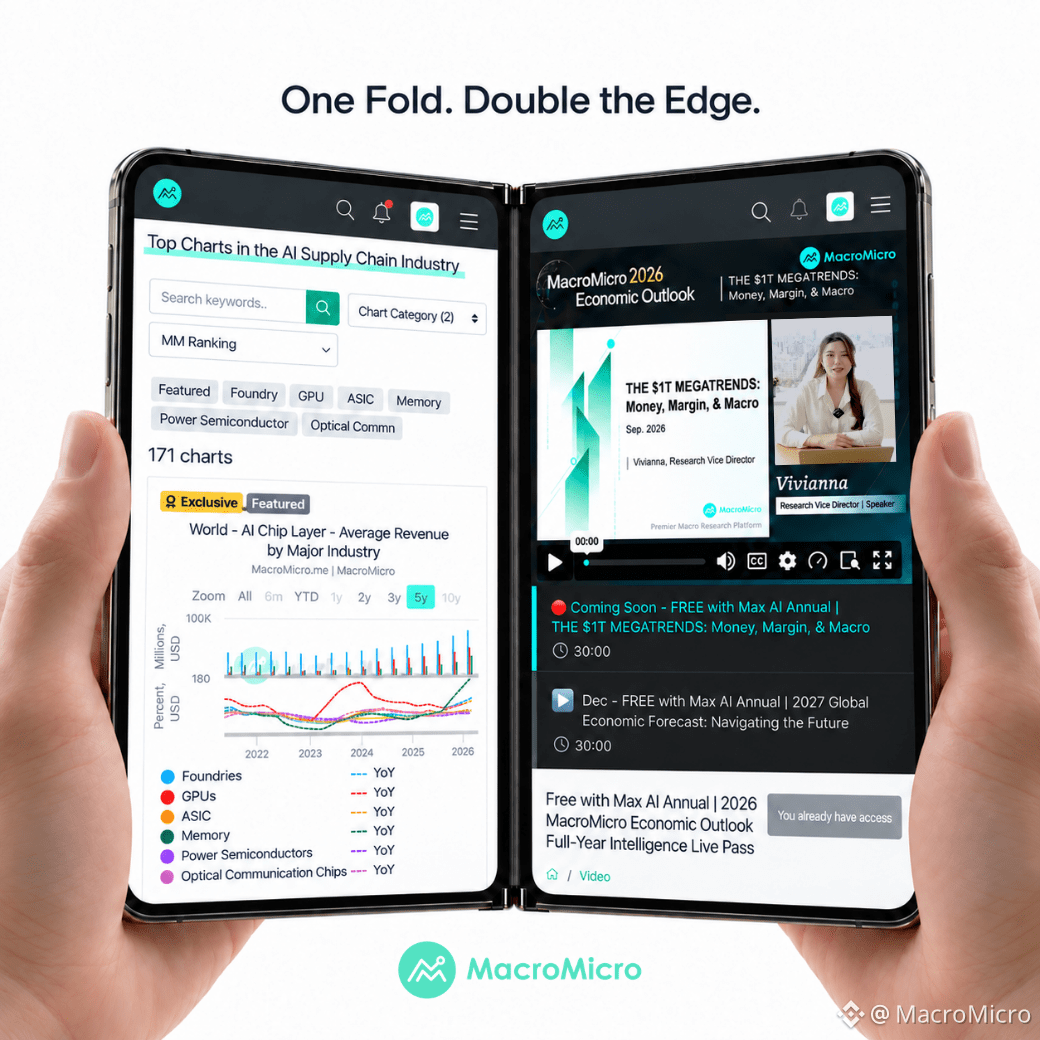
The new iPhone folds open to reveal two screens.
Our Max AI Annual Plan folds open to reveal two perks.
Coincidence? We think not...
Before iPhone Duo goes on sale, grab this one first — our offer ends soon, and once it's gone, it's gone.
Link in this post👇🏻
The new iPhone folds open to reveal two screens.
Our Max AI Annual Plan folds open to reveal two perks.
Coincidence? We think not...
Before iPhone Duo goes on sale, grab this one first — our offer ends soon, and once it's gone, it's gone.
Link in this post👇🏻
Our Max AI Annual Plan folds open to reveal two perks.
Coincidence? We think not...
Before iPhone Duo goes on sale, grab this one first — our offer ends soon, and once it's gone, it's gone.
Link in this post👇🏻
3
2
1.5k
·
--
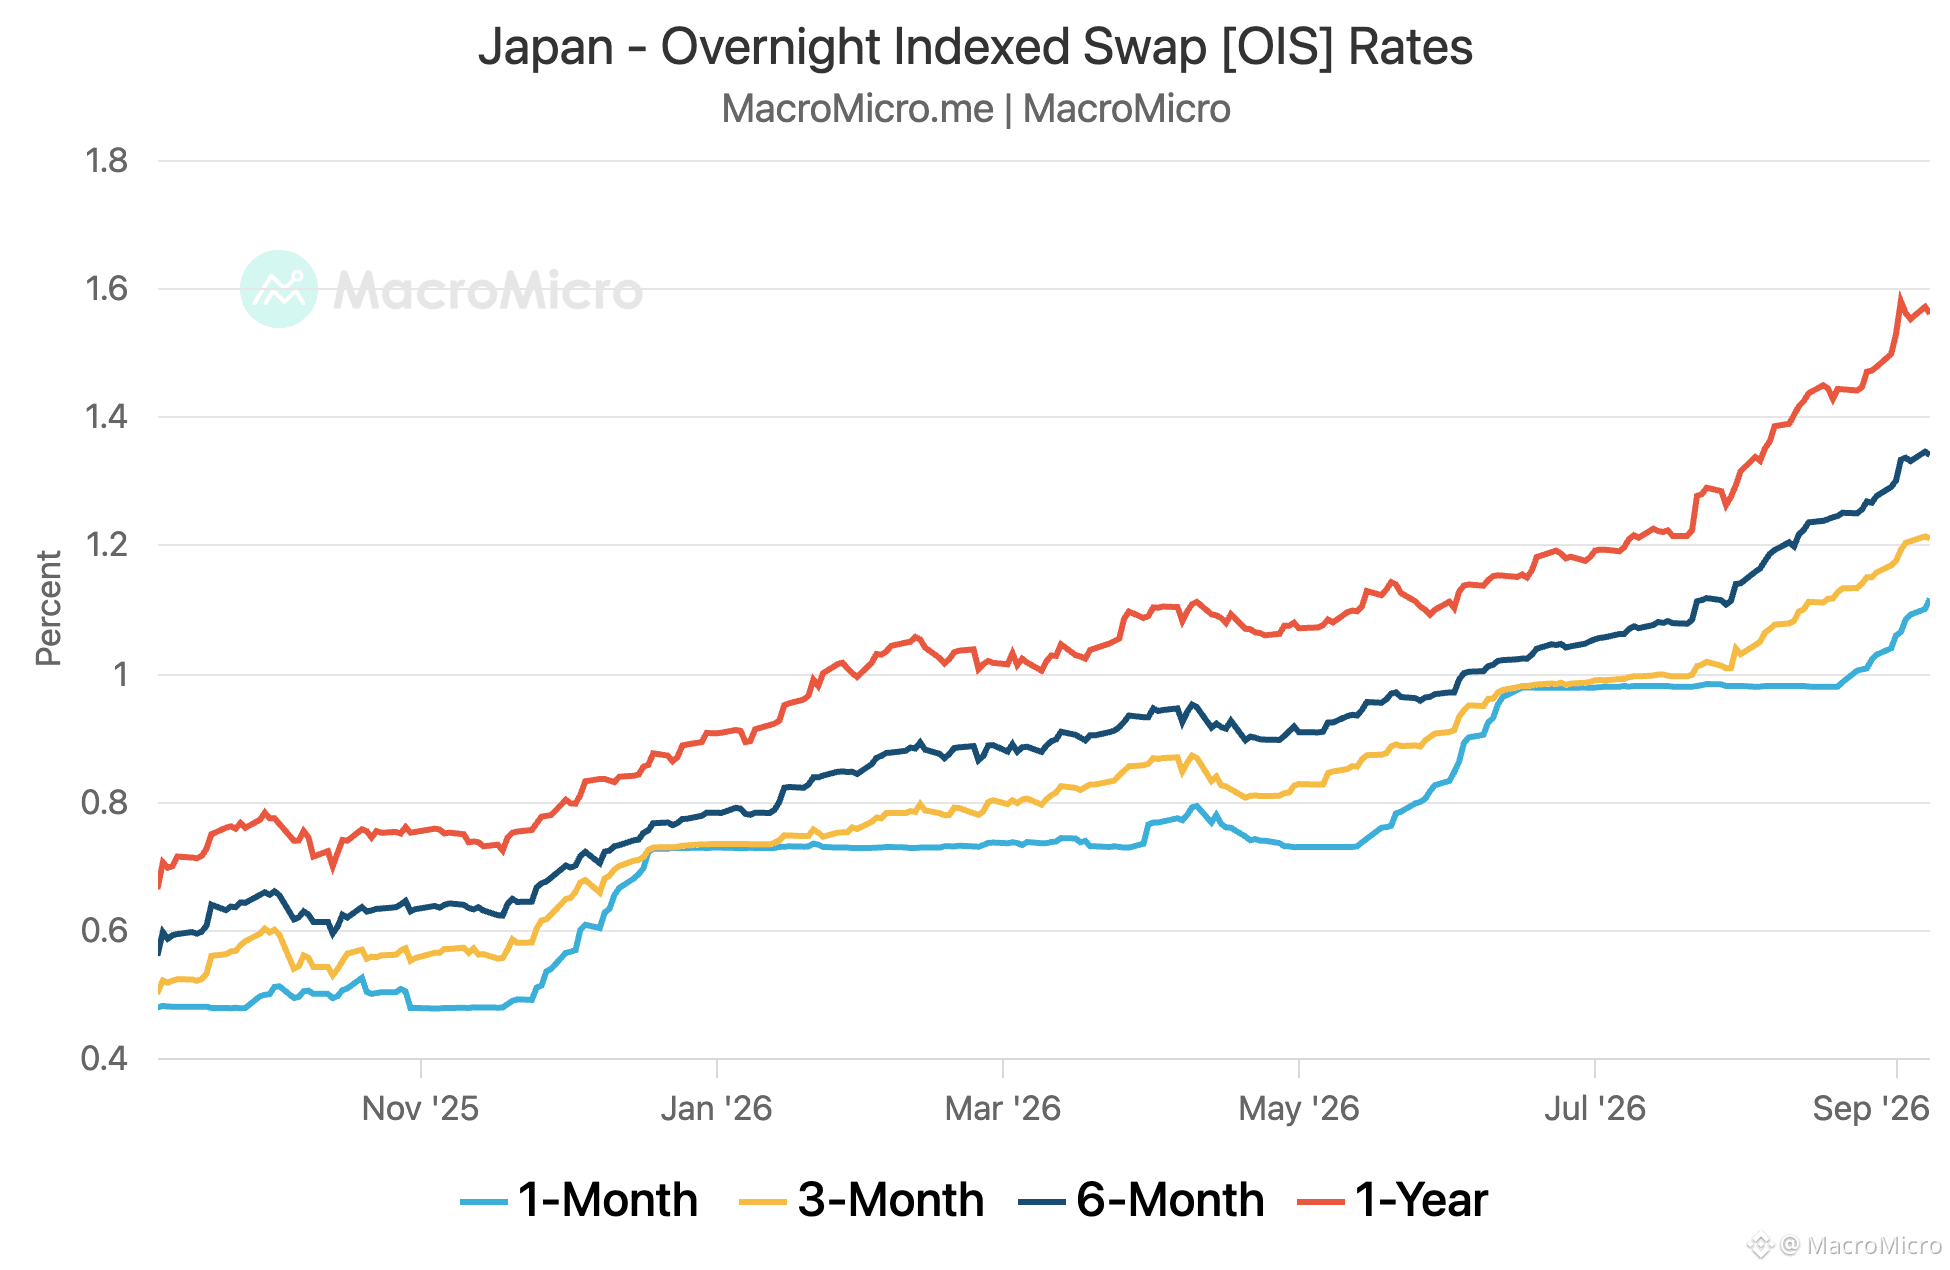
🔴 BREAKING: USD/JPY breaks 153, yen strongest since February!
Three things hit at once:
▸ Q2 GDP revised up to 1.4% annualized, vs 1.1% preliminary
▸ August cash earnings +4.7% YoY — beats 3.9% consensus, fastest since 1997
▸ 1M OIS at 1.12%, fully pricing a 25bp hike next week
🔴 BREAKING: USD/JPY breaks 153, yen strongest since February!
Three things hit at once:
▸ Q2 GDP revised up to 1.4% annualized, vs 1.1% preliminary
▸ August cash earnings +4.7% YoY — beats 3.9% consensus, fastest since 1997
▸ 1M OIS at 1.12%, fully pricing a 25bp hike next week
Three things hit at once:
▸ Q2 GDP revised up to 1.4% annualized, vs 1.1% preliminary
▸ August cash earnings +4.7% YoY — beats 3.9% consensus, fastest since 1997
▸ 1M OIS at 1.12%, fully pricing a 25bp hike next week
1
324
·
--
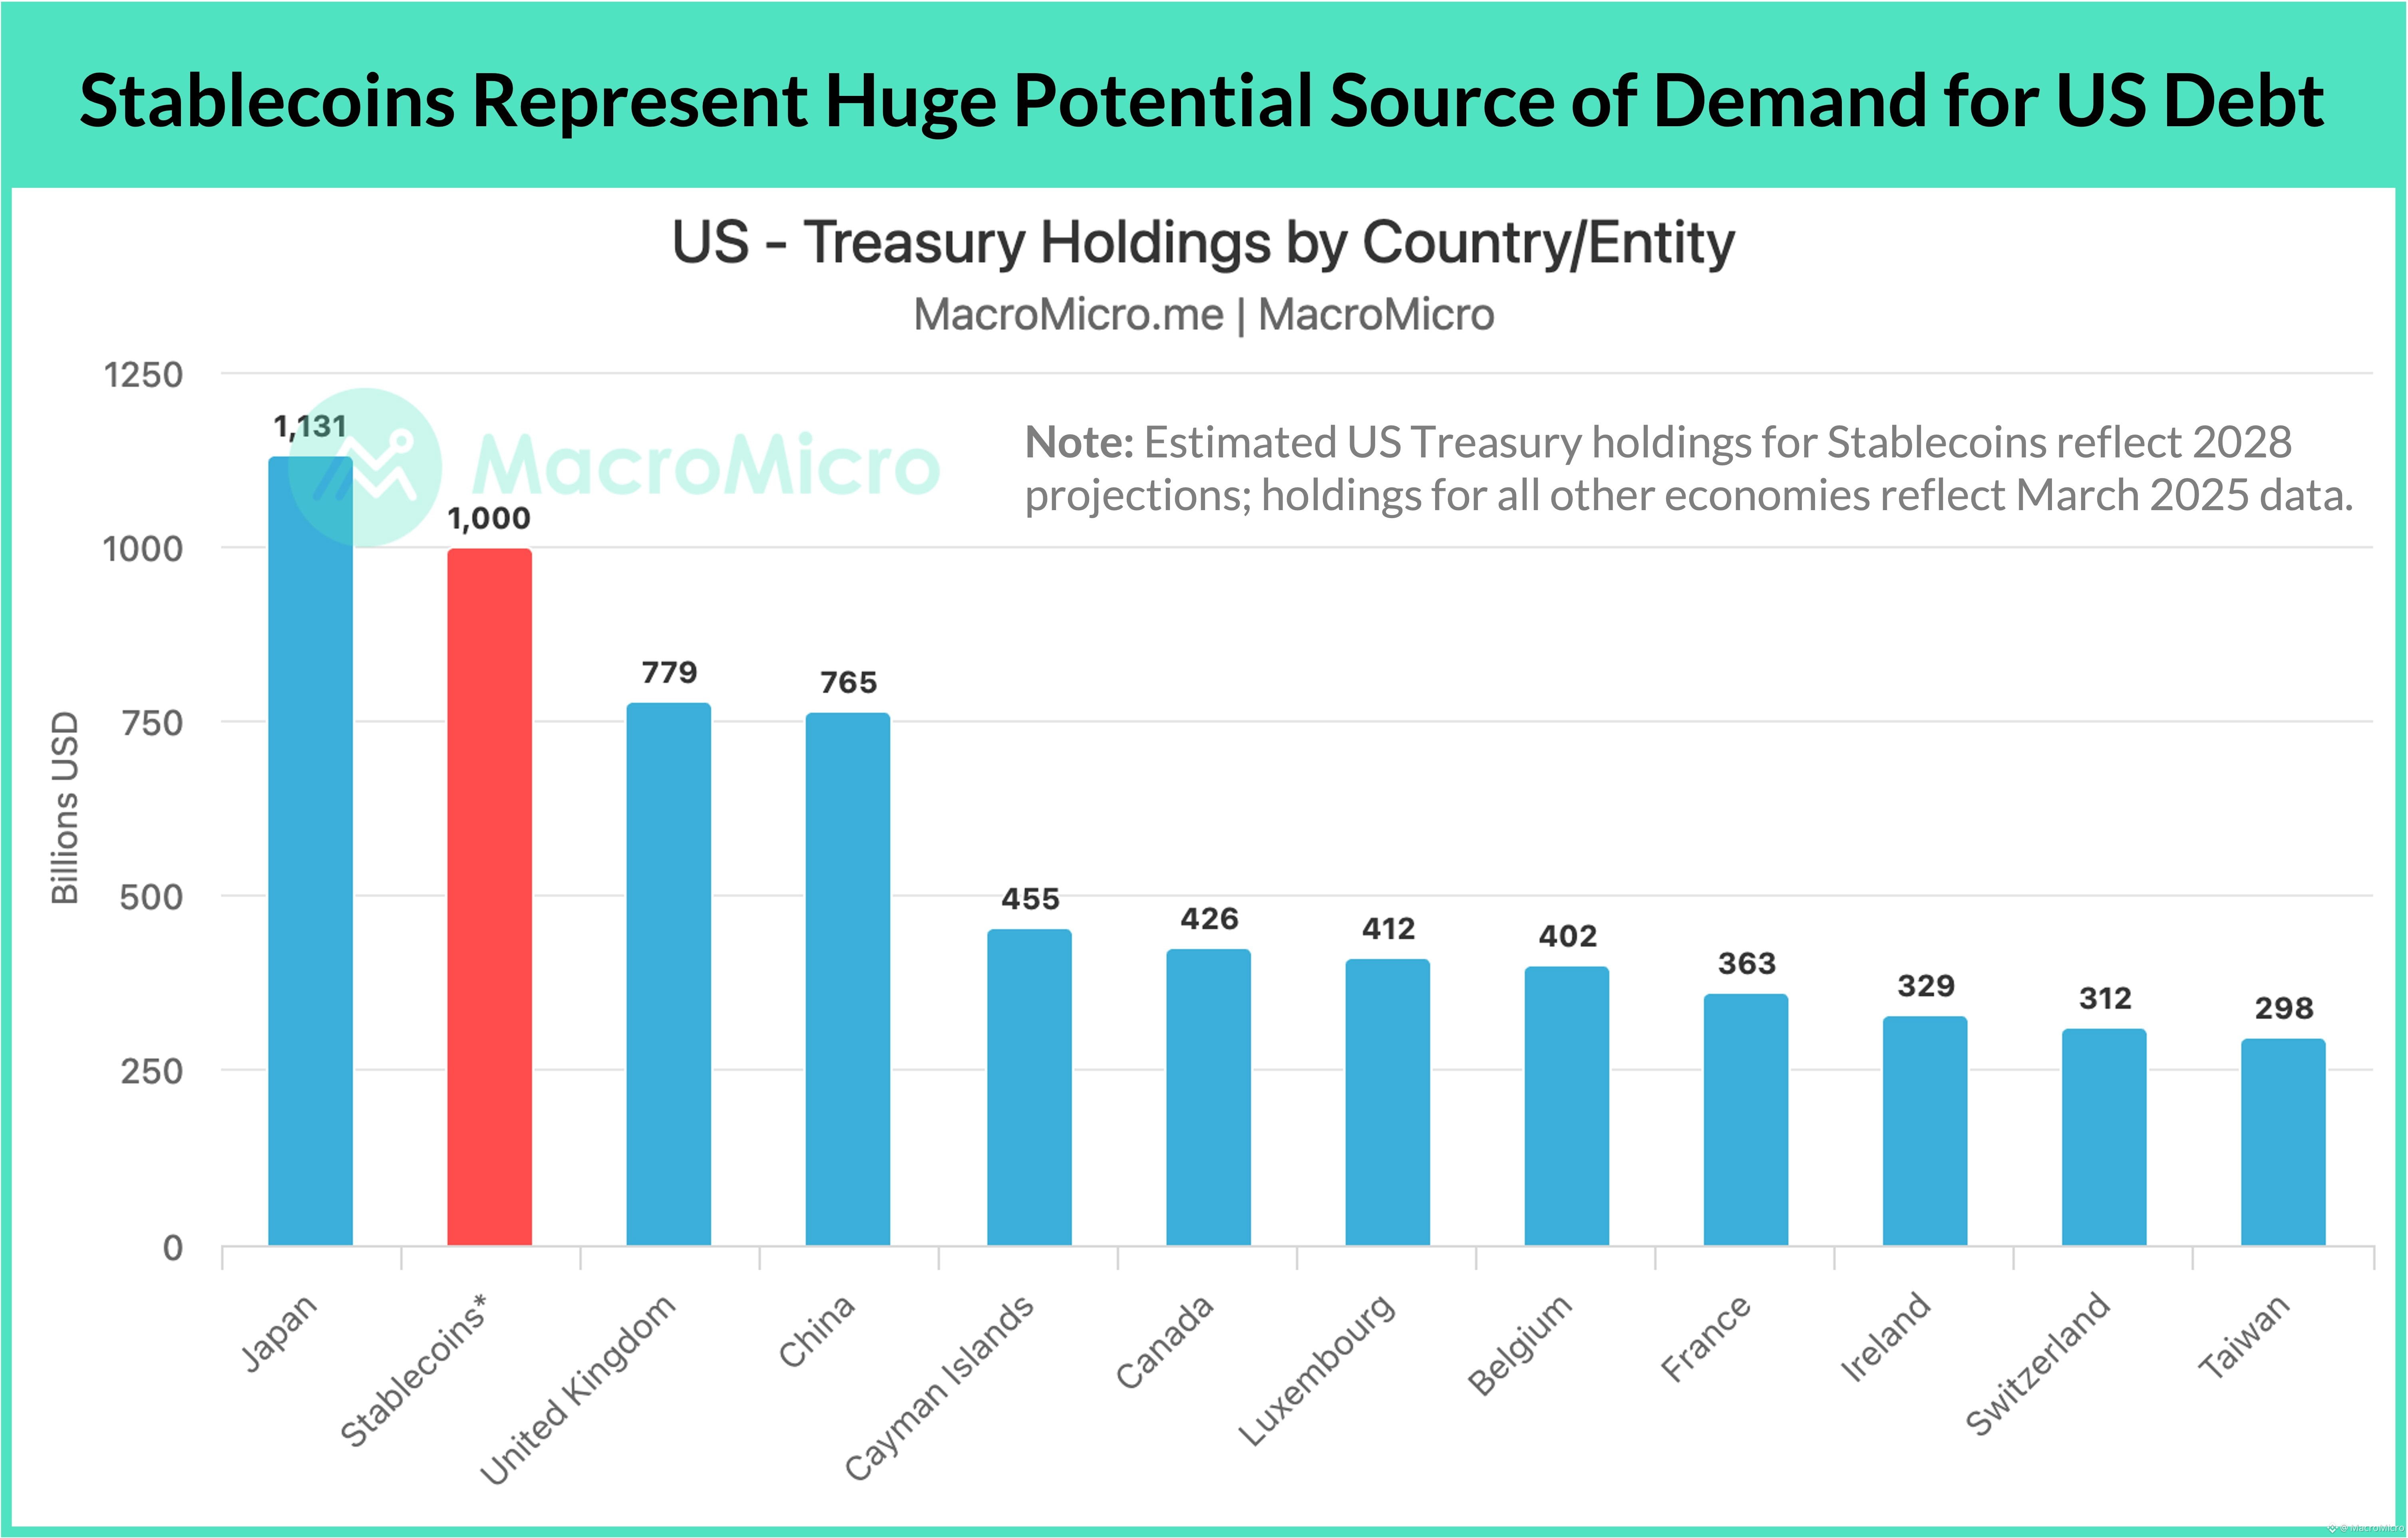
The most consequential shift in stablecoins is not payment volume, but their emergence as a major buyer of US sovereign debt.
According to Treasury Borrowing Advisory Committee (TBAC) estimates, the stablecoin market could reach $2 trillion by 2028. Backing that expansion would require roughly $1 trillion in short-term Treasury bills, up from approximately $120 billion today. That reserve scale would put stablecoin issuers roughly on par with Japan ($1.1trillion) as the largest holder of US debt.
This demand arrives precisely as the Treasury Department alters its debt management strategy. In its August quarterly refunding statement, the Treasury altered its guidance on coupon auction sizes from assessing "increases" to assessing "changes." The shift points toward higher bill issuance and fewer long-dated auctions to suppress the term premium on long-term yields. T-bills already make up 22% of outstanding marketable Treasuries, up from 15% pre-pandemic.
With money market funds sitting near $8 trillion and the Federal Reserve directing maturing MBS principal into T-bills, stablecoins provide an expanding, price-insensitive buyer base. For Washington, digital dollars have quietly become a tool to absorb short-term deficit financing.
🔗 Read more: https://en.macromicro.me/blog/treasury-yields-are-surging-three-ways-out-of-the-debt-trap
The most consequential shift in stablecoins is not payment volume, but their emergence as a major buyer of US sovereign debt.
According to Treasury Borrowing Advisory Committee (TBAC) estimates, the stablecoin market could reach $2 trillion by 2028. Backing that expansion would require roughly $1 trillion in short-term Treasury bills, up from approximately $120 billion today. That reserve scale would put stablecoin issuers roughly on par with Japan ($1.1trillion) as the largest holder of US debt.
This demand arrives precisely as the Treasury Department alters its debt management strategy. In its August quarterly refunding statement, the Treasury altered its guidance on coupon auction sizes from assessing "increases" to assessing "changes." The shift points toward higher bill issuance and fewer long-dated auctions to suppress the term premium on long-term yields. T-bills already make up 22% of outstanding marketable Treasuries, up from 15% pre-pandemic.
With money market funds sitting near $8 trillion and the Federal Reserve directing maturing MBS principal into T-bills, stablecoins provide an expanding, price-insensitive buyer base. For Washington, digital dollars have quietly become a tool to absorb short-term deficit financing.
🔗 Read more: https://en.macromicro.me/blog/treasury-yields-are-surging-three-ways-out-of-the-debt-trap
According to Treasury Borrowing Advisory Committee (TBAC) estimates, the stablecoin market could reach $2 trillion by 2028. Backing that expansion would require roughly $1 trillion in short-term Treasury bills, up from approximately $120 billion today. That reserve scale would put stablecoin issuers roughly on par with Japan ($1.1trillion) as the largest holder of US debt.
This demand arrives precisely as the Treasury Department alters its debt management strategy. In its August quarterly refunding statement, the Treasury altered its guidance on coupon auction sizes from assessing "increases" to assessing "changes." The shift points toward higher bill issuance and fewer long-dated auctions to suppress the term premium on long-term yields. T-bills already make up 22% of outstanding marketable Treasuries, up from 15% pre-pandemic.
With money market funds sitting near $8 trillion and the Federal Reserve directing maturing MBS principal into T-bills, stablecoins provide an expanding, price-insensitive buyer base. For Washington, digital dollars have quietly become a tool to absorb short-term deficit financing.
🔗 Read more: https://en.macromicro.me/blog/treasury-yields-are-surging-three-ways-out-of-the-debt-trap
434
·
--
📈 AI capex is on pace to cross $1 trillion by 2027 and the supply chain is already showing the strain. Memory and foundry capacity are maxed out, hardware prices are back above 2021 peaks, and pricing power is moving upstream, away from the apps everyone's trading.
We're covering all of it this Sep, with two things unlocked in one plan:
📌 Live Outlook (Sep 11) — our Research VP walks through the $1T AI megatrends live
📌 1-Year Full Access to the AI Supply Chain Hub — 18 exclusive charts across chips, infrastructure and compute
Whether this bottleneck holds or breaks comes down to real demand, not just tight supply.
That's what both are built to help you track.
Track it before the market prices it in. Ends Sep 30.
🔗 https://mmgo.me/xxv4q3
📈 AI capex is on pace to cross $1 trillion by 2027 and the supply chain is already showing the strain. Memory and foundry capacity are maxed out, hardware prices are back above 2021 peaks, and pricing power is moving upstream, away from the apps everyone's trading.
We're covering all of it this Sep, with two things unlocked in one plan:
📌 Live Outlook (Sep 11) — our Research VP walks through the $1T AI megatrends live
📌 1-Year Full Access to the AI Supply Chain Hub — 18 exclusive charts across chips, infrastructure and compute
Whether this bottleneck holds or breaks comes down to real demand, not just tight supply.
That's what both are built to help you track.
Track it before the market prices it in. Ends Sep 30.
🔗 https://mmgo.me/xxv4q3
We're covering all of it this Sep, with two things unlocked in one plan:
📌 Live Outlook (Sep 11) — our Research VP walks through the $1T AI megatrends live
📌 1-Year Full Access to the AI Supply Chain Hub — 18 exclusive charts across chips, infrastructure and compute
Whether this bottleneck holds or breaks comes down to real demand, not just tight supply.
That's what both are built to help you track.
Track it before the market prices it in. Ends Sep 30.
🔗 https://mmgo.me/xxv4q3
421
·
--
Проверено
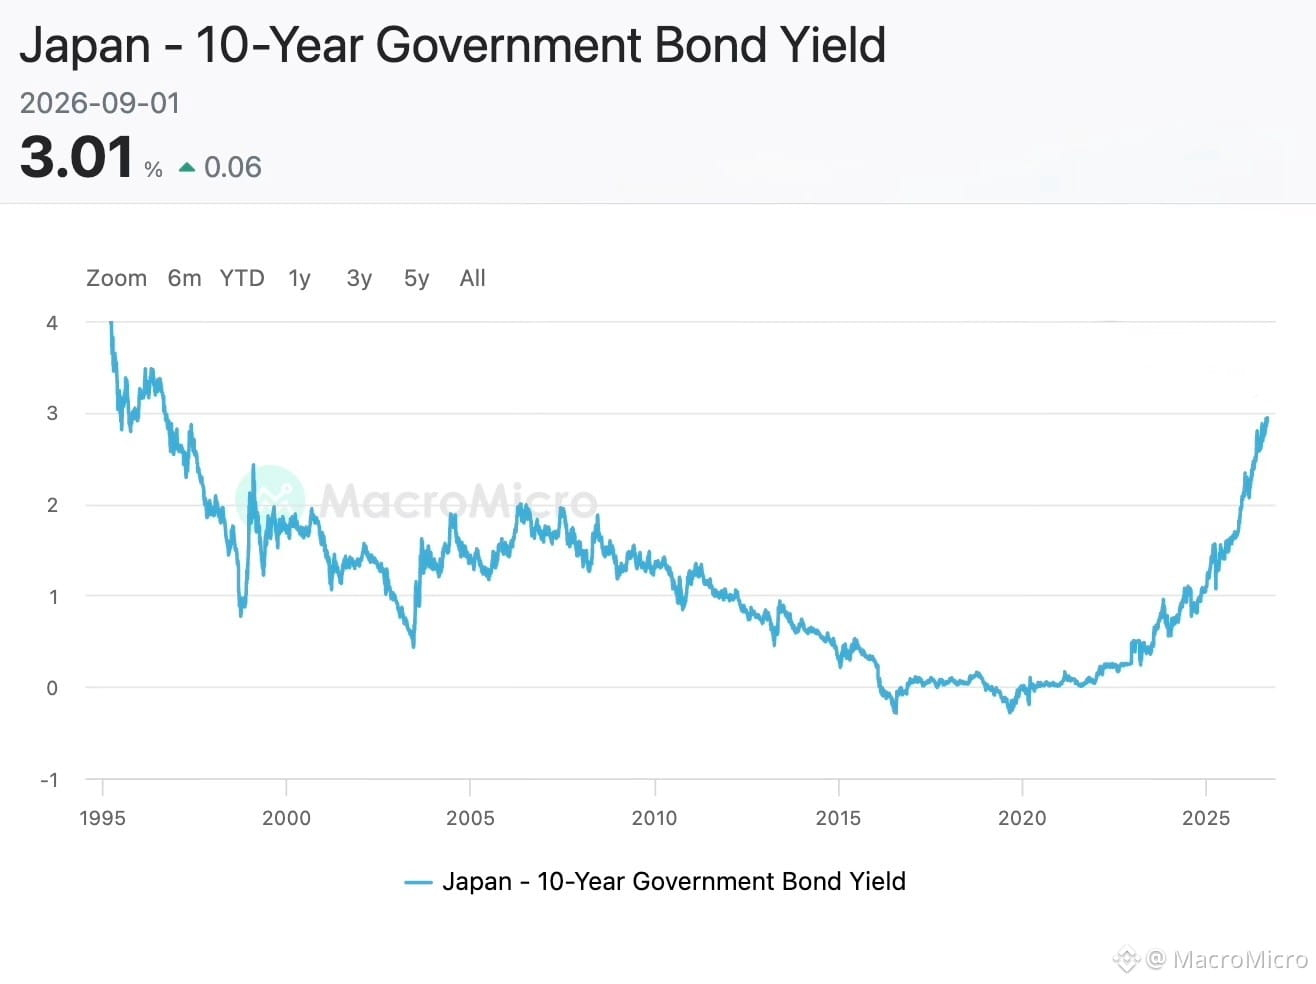
🔴 BREAKING: Japan's 10-year government bond yield rose to 3.00%, the highest level since September 1996.
$EWJ
🔴 BREAKING: Japan's 10-year government bond yield rose to 3.00%, the highest level since September 1996.
$EWJ
$EWJ
1
717
·
--
🔴 65 Months Above Target: Inflation Dominates Warsh's Jackson Hole Speech
"The Fed's preferred measure of inflation, the 12-month change in the PCE price index, stands at 3.7 percent, while the six-month change is 4.1 percent."
"on the price-stability side of our mandate, the numbers are more concerning."
"So the Fed's predominant focus right now should be on prices."
"And while this summer's PCE and CPI readings were better than expected, they do not tell me that underlying trends have meaningfully improved."
"Over the past 12 months, 54 percent of goods and services in the PCE basket showed price increases above 3 percent. This is well below the post-pandemic highs of about 77 percent, but it remains well above the level of 32 percent in the two decades that preceded the pandemic."
"The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs."
"Price stability is not self-executing, nor is inflation necessarily mean-reverting."
"We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do."
"But inflation remained too high."
"The comparable measures from the consumer price index (CPI) are also elevated, as are the core measures of both PCE and CPI inflation."
"None of these measures are perfect, but they all tell a similar story: Inflation is running above our 2 percent target."
"The recent rise in overall commodity prices also bears watching."
"Certain sectors—like housing and agriculture—are showing strains. But, on balance, I would be hard pressed to describe broad financial conditions as restrictive."
"It's the Fed's job to make sure that inflation expectations do not get unanchored."
"It matters, too, whether the inflation readings of the past five-plus years have seeped into expectations."
$SHY.ETF
🔴 65 Months Above Target: Inflation Dominates Warsh's Jackson Hole Speech
"The Fed's preferred measure of inflation, the 12-month change in the PCE price index, stands at 3.7 percent, while the six-month change is 4.1 percent."
"on the price-stability side of our mandate, the numbers are more concerning."
"So the Fed's predominant focus right now should be on prices."
"And while this summer's PCE and CPI readings were better than expected, they do not tell me that underlying trends have meaningfully improved."
"Over the past 12 months, 54 percent of goods and services in the PCE basket showed price increases above 3 percent. This is well below the post-pandemic highs of about 77 percent, but it remains well above the level of 32 percent in the two decades that preceded the pandemic."
"The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs."
"Price stability is not self-executing, nor is inflation necessarily mean-reverting."
"We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do."
"But inflation remained too high."
"The comparable measures from the consumer price index (CPI) are also elevated, as are the core measures of both PCE and CPI inflation."
"None of these measures are perfect, but they all tell a similar story: Inflation is running above our 2 percent target."
"The recent rise in overall commodity prices also bears watching."
"Certain sectors—like housing and agriculture—are showing strains. But, on balance, I would be hard pressed to describe broad financial conditions as restrictive."
"It's the Fed's job to make sure that inflation expectations do not get unanchored."
"It matters, too, whether the inflation readings of the past five-plus years have seeped into expectations."
$SHY.ETF
"The Fed's preferred measure of inflation, the 12-month change in the PCE price index, stands at 3.7 percent, while the six-month change is 4.1 percent."
"on the price-stability side of our mandate, the numbers are more concerning."
"So the Fed's predominant focus right now should be on prices."
"And while this summer's PCE and CPI readings were better than expected, they do not tell me that underlying trends have meaningfully improved."
"Over the past 12 months, 54 percent of goods and services in the PCE basket showed price increases above 3 percent. This is well below the post-pandemic highs of about 77 percent, but it remains well above the level of 32 percent in the two decades that preceded the pandemic."
"The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs."
"Price stability is not self-executing, nor is inflation necessarily mean-reverting."
"We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do."
"But inflation remained too high."
"The comparable measures from the consumer price index (CPI) are also elevated, as are the core measures of both PCE and CPI inflation."
"None of these measures are perfect, but they all tell a similar story: Inflation is running above our 2 percent target."
"The recent rise in overall commodity prices also bears watching."
"Certain sectors—like housing and agriculture—are showing strains. But, on balance, I would be hard pressed to describe broad financial conditions as restrictive."
"It's the Fed's job to make sure that inflation expectations do not get unanchored."
"It matters, too, whether the inflation readings of the past five-plus years have seeped into expectations."
$SHY.ETF
SHYETF+0,00%
1
494
·
--
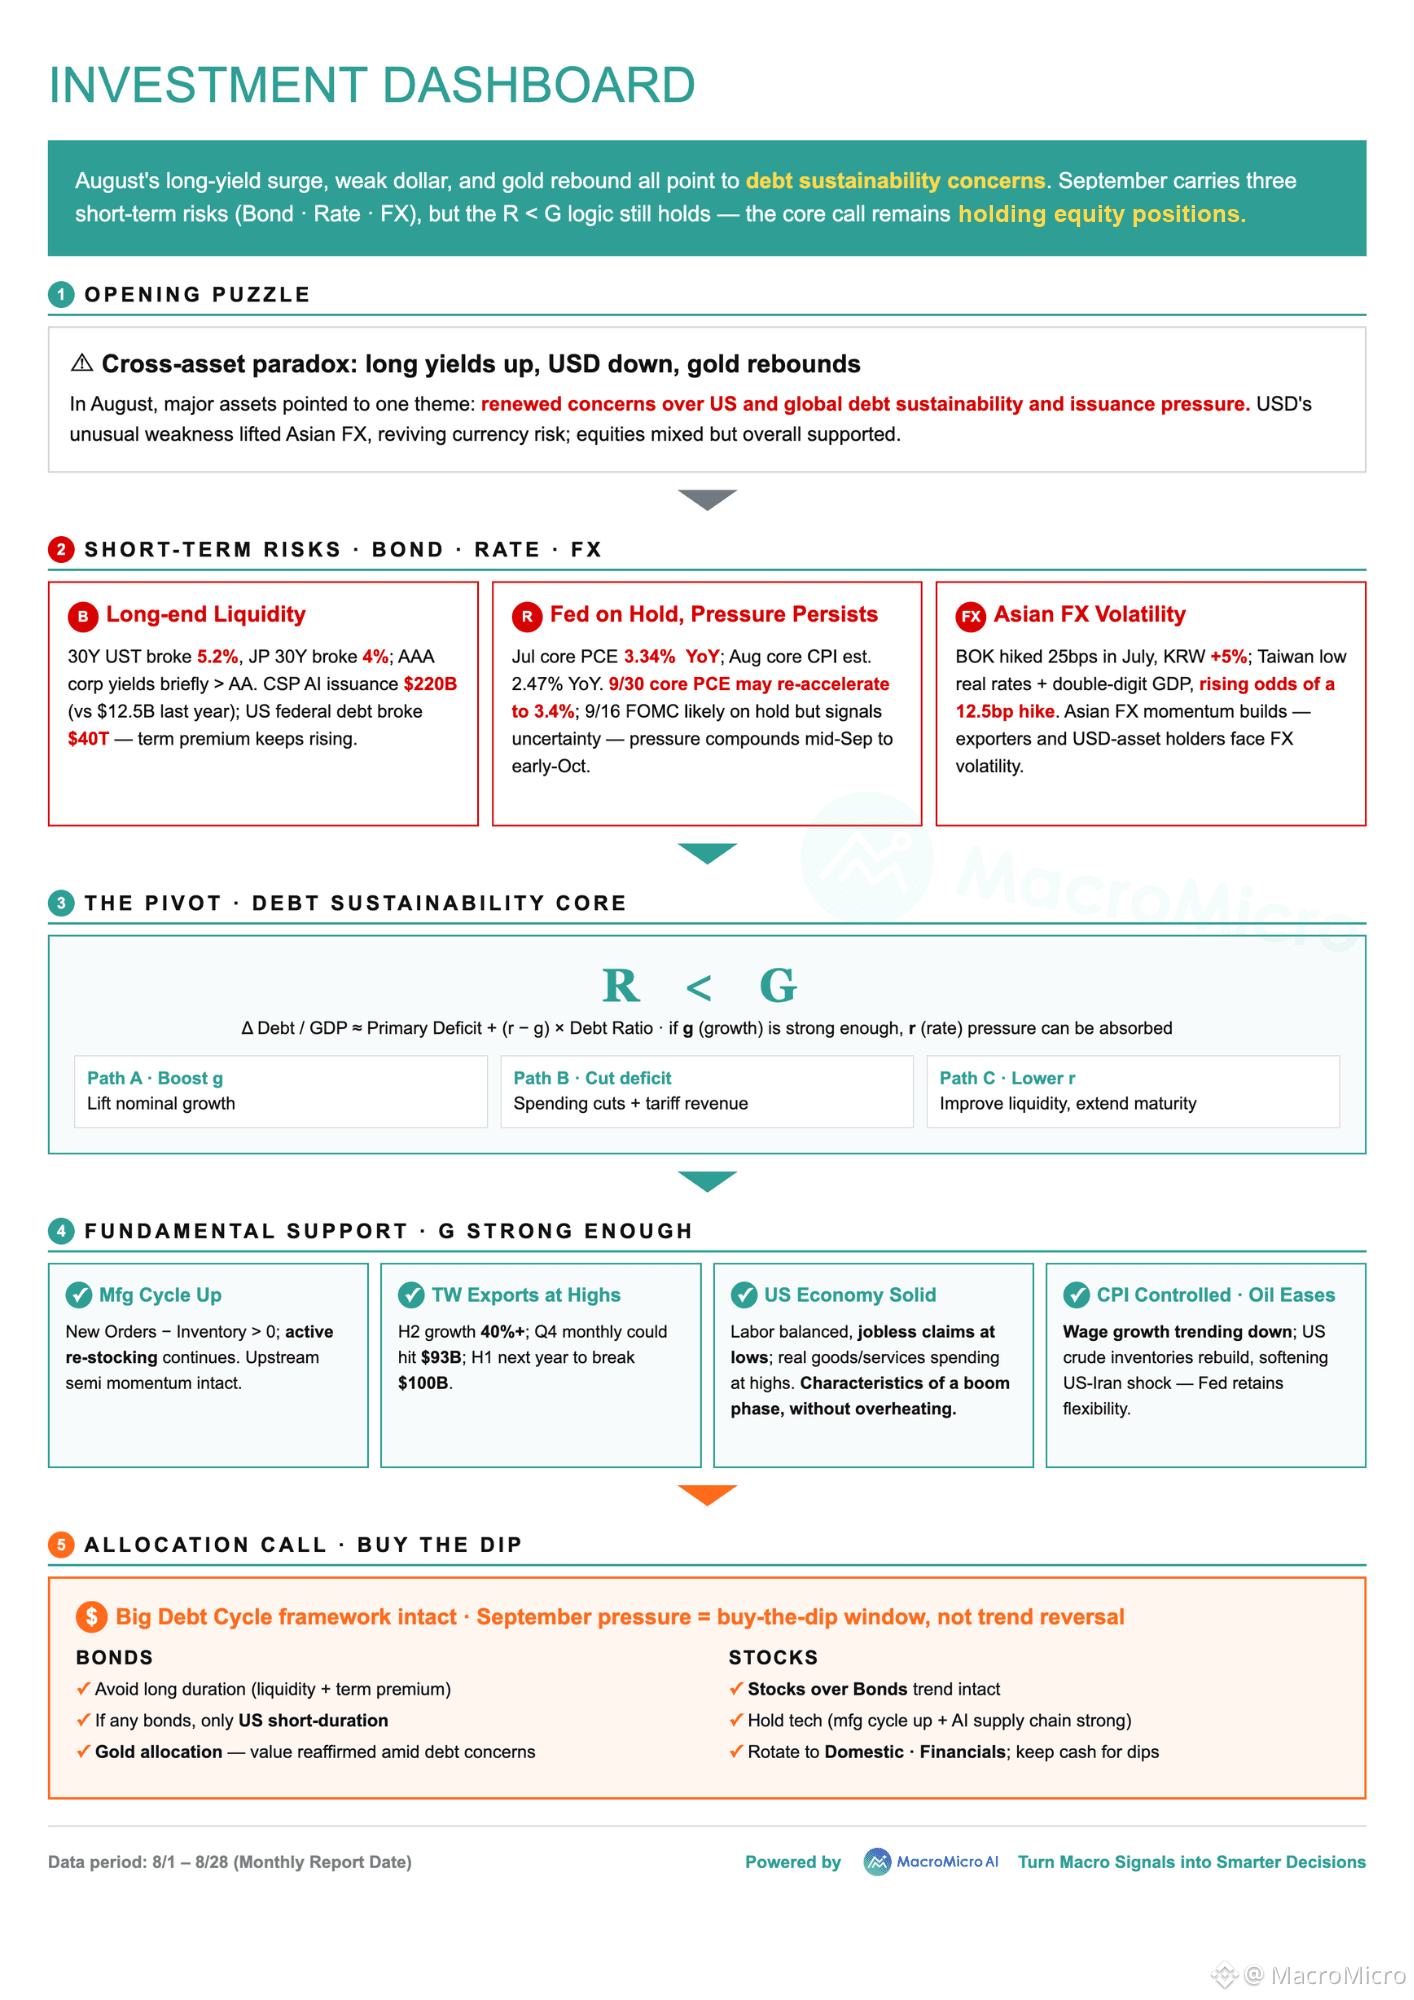
📊 The latest Investment Dashboard is out!
Feel free to save it, share it — you'll want this one on hand.
August's asset moves all pointed the same direction: long yields spiked, the dollar sank, and gold rebounded — three separate signals, one shared theme: debt sustainability concerns are back.
Heading into September, the real question isn't whether this pressure fades. It's whether growth (G) is still strong enough to outrun it.
We're breaking it down into 3 themes — full view in the dashboard below.
👋🏻Feel free to share or repost. Follow MacroMicro to stay ahead of market risk before the next move: https://mmgo.me/y6cugk
📊 The latest Investment Dashboard is out!
Feel free to save it, share it — you'll want this one on hand.
August's asset moves all pointed the same direction: long yields spiked, the dollar sank, and gold rebounded — three separate signals, one shared theme: debt sustainability concerns are back.
Heading into September, the real question isn't whether this pressure fades. It's whether growth (G) is still strong enough to outrun it.
We're breaking it down into 3 themes — full view in the dashboard below.
👋🏻Feel free to share or repost. Follow MacroMicro to stay ahead of market risk before the next move: https://mmgo.me/y6cugk
Feel free to save it, share it — you'll want this one on hand.
August's asset moves all pointed the same direction: long yields spiked, the dollar sank, and gold rebounded — three separate signals, one shared theme: debt sustainability concerns are back.
Heading into September, the real question isn't whether this pressure fades. It's whether growth (G) is still strong enough to outrun it.
We're breaking it down into 3 themes — full view in the dashboard below.
👋🏻Feel free to share or repost. Follow MacroMicro to stay ahead of market risk before the next move: https://mmgo.me/y6cugk
623
·
--
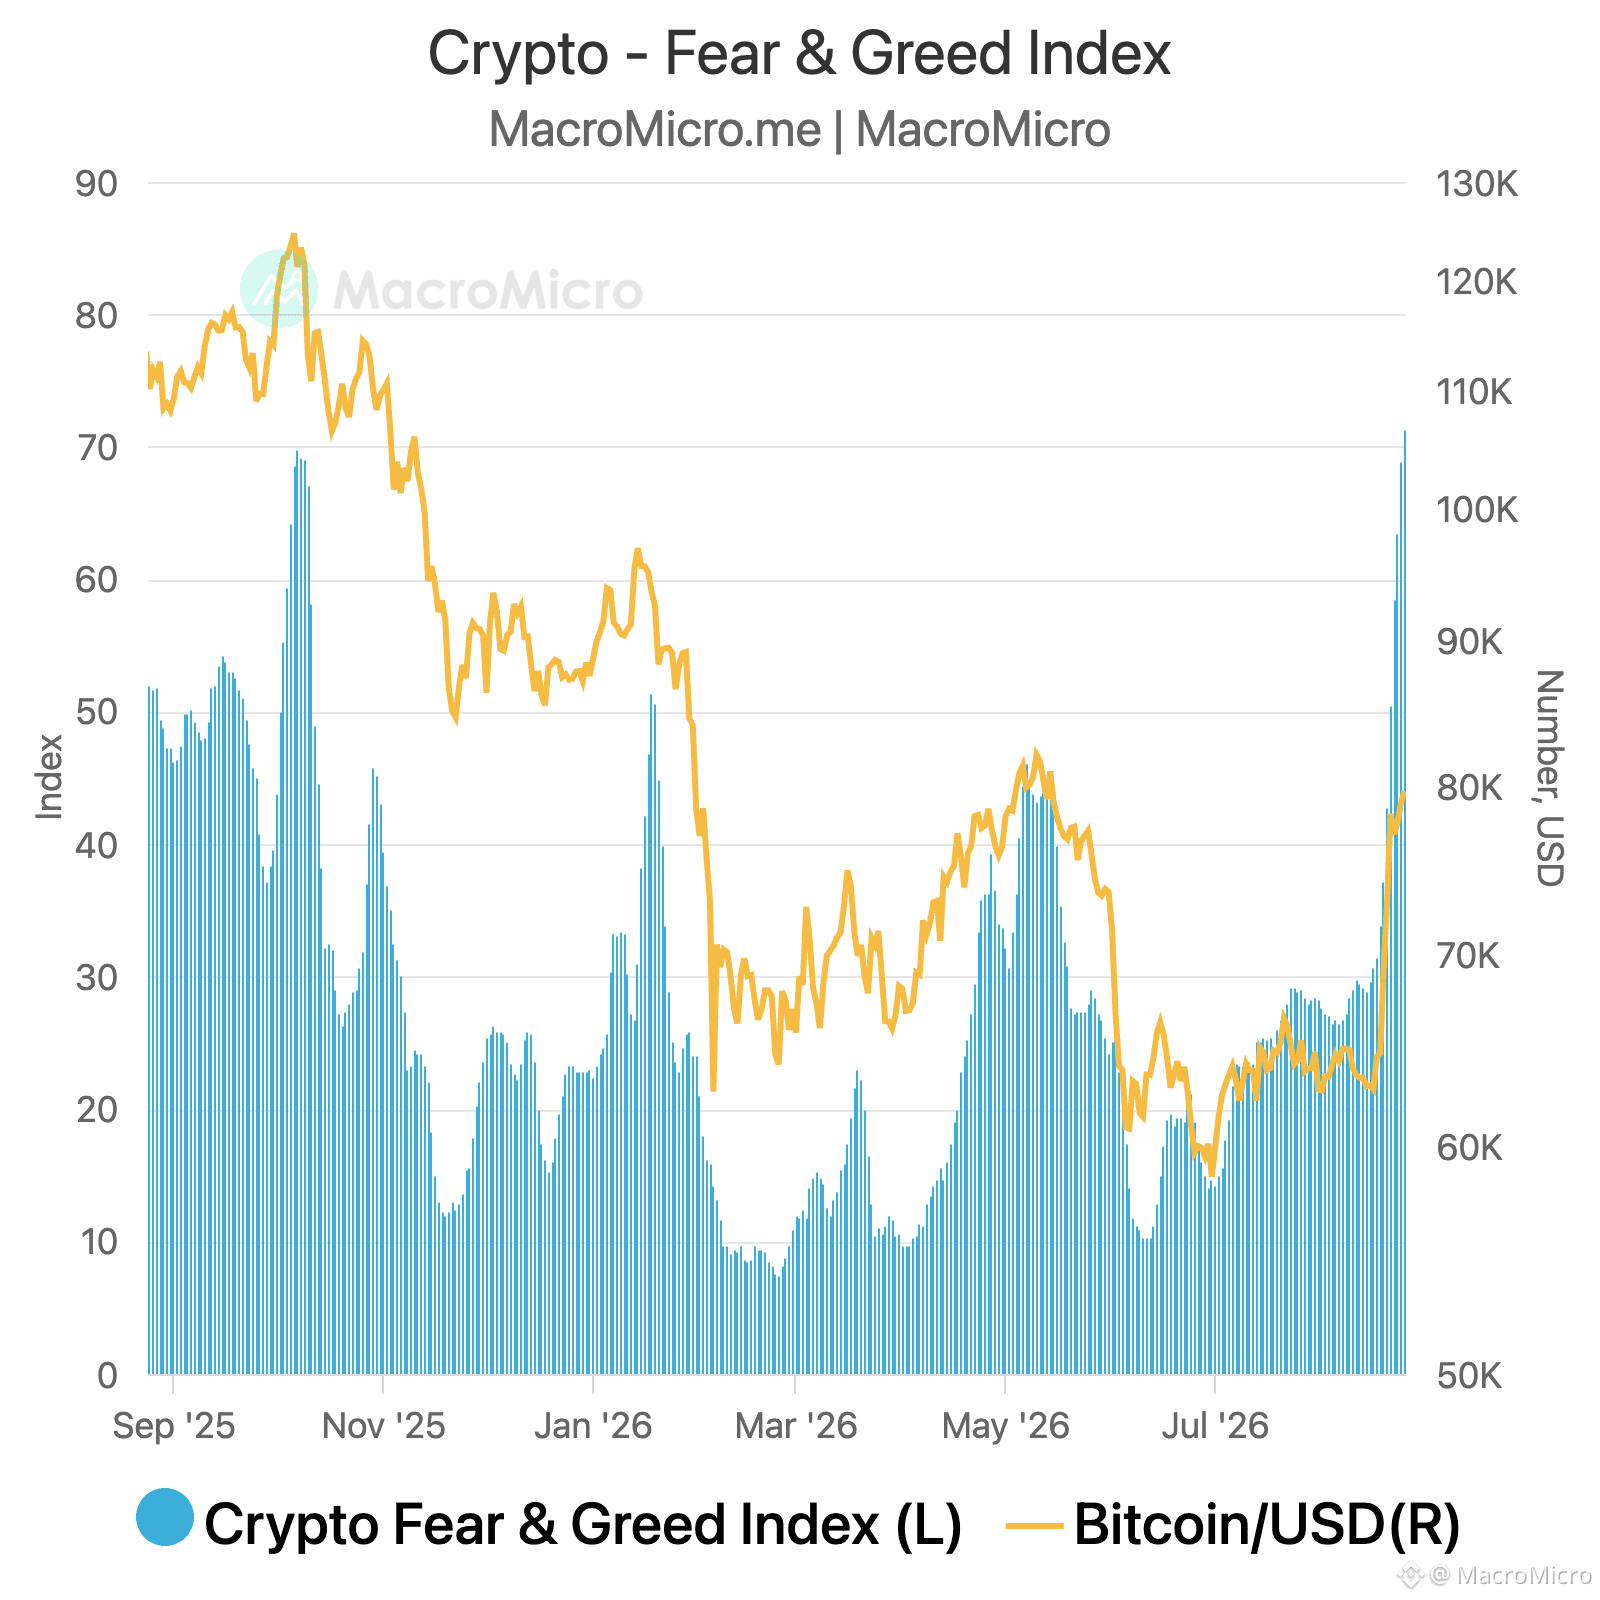
📈 Bitcoin hit $80,000 for the first time since May 2026. Gold is making the same move.
The Fed has stopped adding T-bill purchases and the Treasury is expanding its long-end buyback capacity. Together those moves ease pressure on short-end funding markets, the same repo channels behind TGCR, BGCR, and SOFR.
Nonfarm and CPI have already taken any near-term hike off the table. Markets are pricing that improvement in now, ahead of the clarity September's FOMC and Jackson Hole discussions are expected to bring.
$BTC
{spot}(BTCUSDT)
📈 Bitcoin hit $80,000 for the first time since May 2026. Gold is making the same move.
The Fed has stopped adding T-bill purchases and the Treasury is expanding its long-end buyback capacity. Together those moves ease pressure on short-end funding markets, the same repo channels behind TGCR, BGCR, and SOFR.
Nonfarm and CPI have already taken any near-term hike off the table. Markets are pricing that improvement in now, ahead of the clarity September's FOMC and Jackson Hole discussions are expected to bring.
$BTC
The Fed has stopped adding T-bill purchases and the Treasury is expanding its long-end buyback capacity. Together those moves ease pressure on short-end funding markets, the same repo channels behind TGCR, BGCR, and SOFR.
Nonfarm and CPI have already taken any near-term hike off the table. Markets are pricing that improvement in now, ahead of the clarity September's FOMC and Jackson Hole discussions are expected to bring.
$BTC
2
16
19.5k
·
--
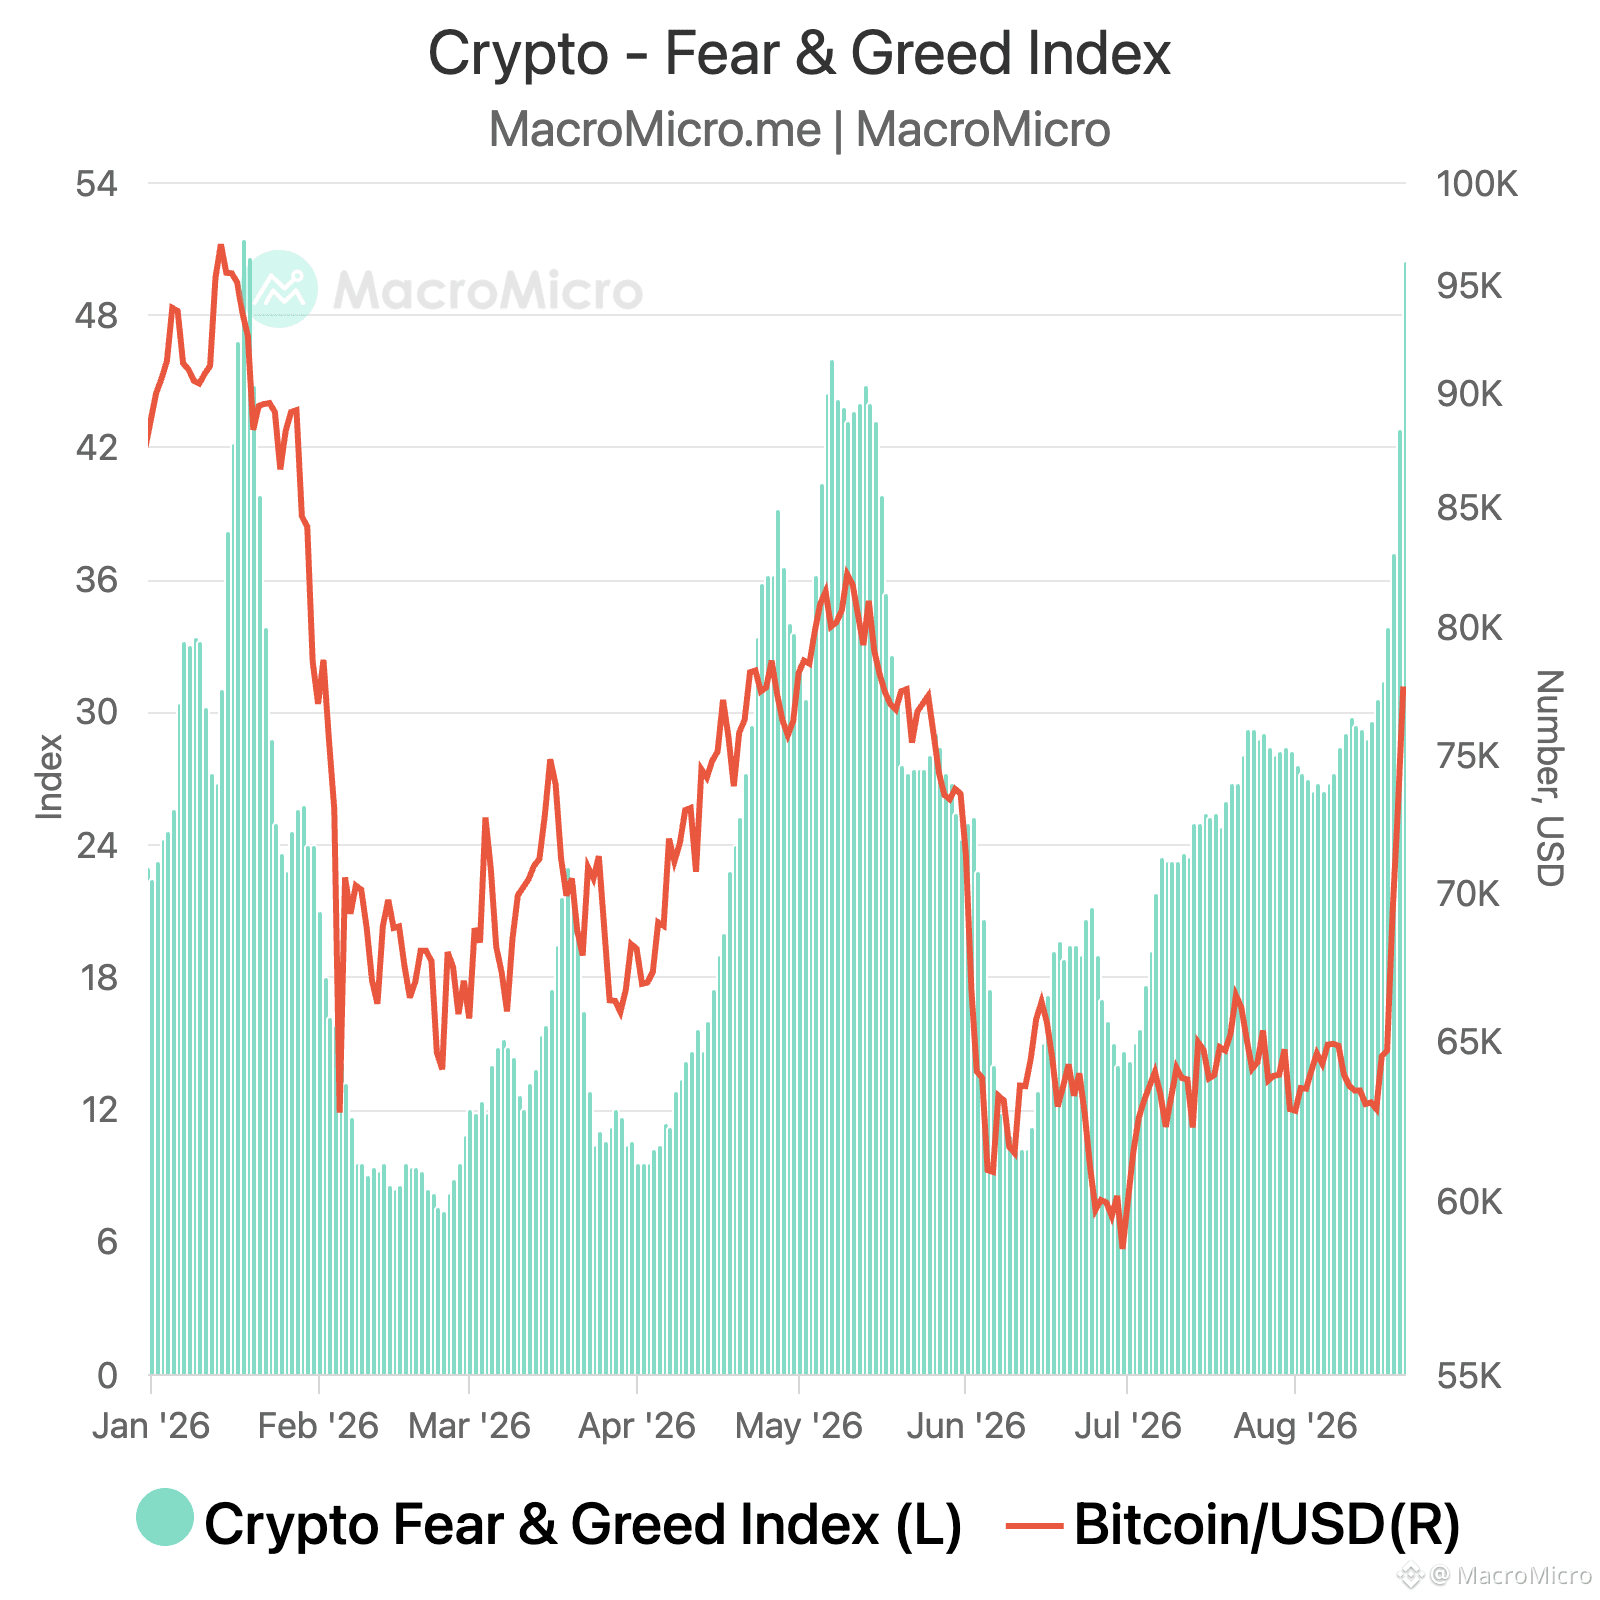
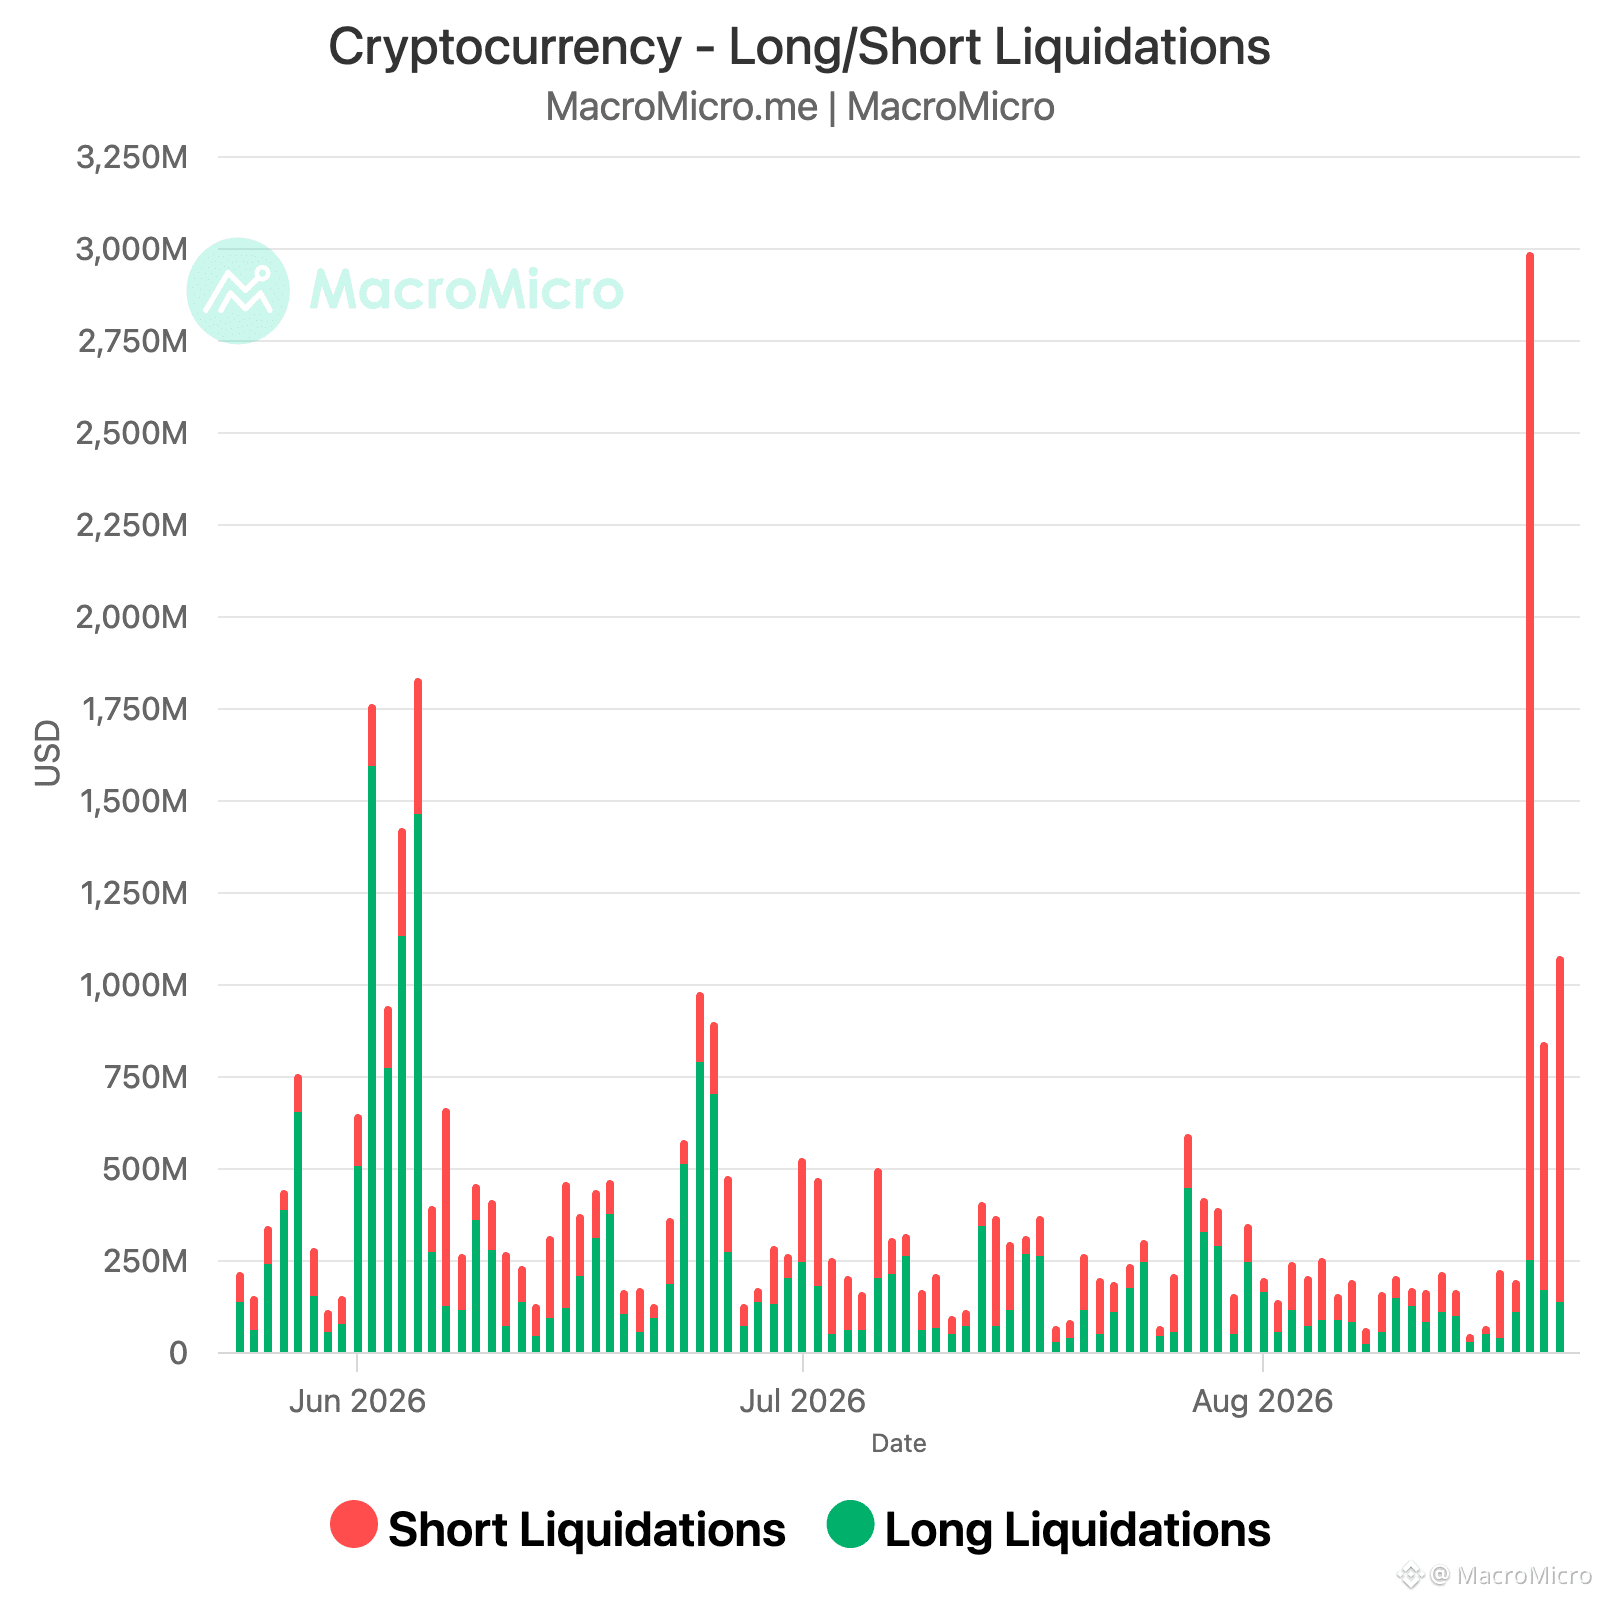
🚨 Bitcoin above $78,000, up over 30% in four days. Crypto market cap has added $450 billion since Monday.
$1.24 billion worth of shorts liquidated from the crypto market in the past 24 hours alone!
$BTC
{spot}(BTCUSDT)
🚨 Bitcoin above $78,000, up over 30% in four days. Crypto market cap has added $450 billion since Monday.
$1.24 billion worth of shorts liquidated from the crypto market in the past 24 hours alone!
$BTC
$1.24 billion worth of shorts liquidated from the crypto market in the past 24 hours alone!
$BTC
3
5.5k
·
--
Проверено
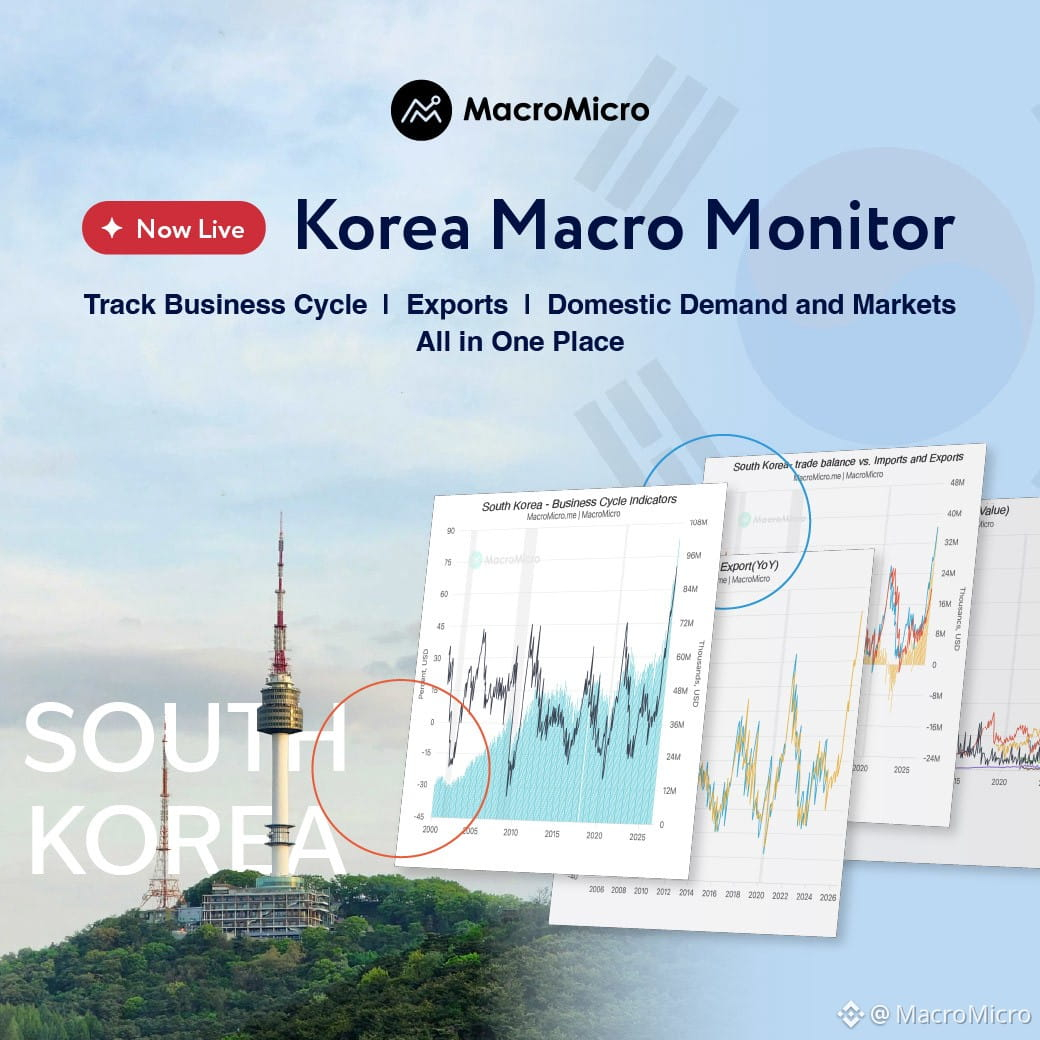
🇰🇷Now Live! Korea Macro Monitor — is the bull market backed by fundamentals?
Today's the proof: KOSPI snapped back +5.9% to 6,852.58, triggering a buy sidecar — the 49th of the year. Samsung +9%, SK Hynix +12%, as a $29B buyback announcement from SK Hynix and falling US Treasury yields fueled the rebound.
Korea just round-tripped, fundamentals haven't caught up yet:
Leverage-fueled rally → Sharp correction → Back to bull territory.
Why it matters: Samsung + SK Hynix make most of the world's HBM/DRAM — the memory chips behind the AI buildout. Korea's export data leads names like Micron and the broader memory cycle.
Five charts on Korea's fundamentals + the memory cycle:
1. Is the recovery real? Business Cycle Indicators
2. Is export momentum holding? Total Exports in the First 20 Days
3. Memory cycle bellwether? Export Price Index - Memory(YoY)
4. Real demand or just price hikes? Semiconductors & Parts Inventory-to-Shipment Ratio
5. Does the rally have liquidity behind it? — Investor Deposits
👇Chart links in the comments
🇰🇷Now Live! Korea Macro Monitor — is the bull market backed by fundamentals?
Today's the proof: KOSPI snapped back +5.9% to 6,852.58, triggering a buy sidecar — the 49th of the year. Samsung +9%, SK Hynix +12%, as a $29B buyback announcement from SK Hynix and falling US Treasury yields fueled the rebound.
Korea just round-tripped, fundamentals haven't caught up yet:
Leverage-fueled rally → Sharp correction → Back to bull territory.
Why it matters: Samsung + SK Hynix make most of the world's HBM/DRAM — the memory chips behind the AI buildout. Korea's export data leads names like Micron and the broader memory cycle.
Five charts on Korea's fundamentals + the memory cycle:
1. Is the recovery real? Business Cycle Indicators
2. Is export momentum holding? Total Exports in the First 20 Days
3. Memory cycle bellwether? Export Price Index - Memory(YoY)
4. Real demand or just price hikes? Semiconductors & Parts Inventory-to-Shipment Ratio
5. Does the rally have liquidity behind it? — Investor Deposits
👇Chart links in the comments
Today's the proof: KOSPI snapped back +5.9% to 6,852.58, triggering a buy sidecar — the 49th of the year. Samsung +9%, SK Hynix +12%, as a $29B buyback announcement from SK Hynix and falling US Treasury yields fueled the rebound.
Korea just round-tripped, fundamentals haven't caught up yet:
Leverage-fueled rally → Sharp correction → Back to bull territory.
Why it matters: Samsung + SK Hynix make most of the world's HBM/DRAM — the memory chips behind the AI buildout. Korea's export data leads names like Micron and the broader memory cycle.
Five charts on Korea's fundamentals + the memory cycle:
1. Is the recovery real? Business Cycle Indicators
2. Is export momentum holding? Total Exports in the First 20 Days
3. Memory cycle bellwether? Export Price Index - Memory(YoY)
4. Real demand or just price hikes? Semiconductors & Parts Inventory-to-Shipment Ratio
5. Does the rally have liquidity behind it? — Investor Deposits
👇Chart links in the comments
1
1.2k
·
--
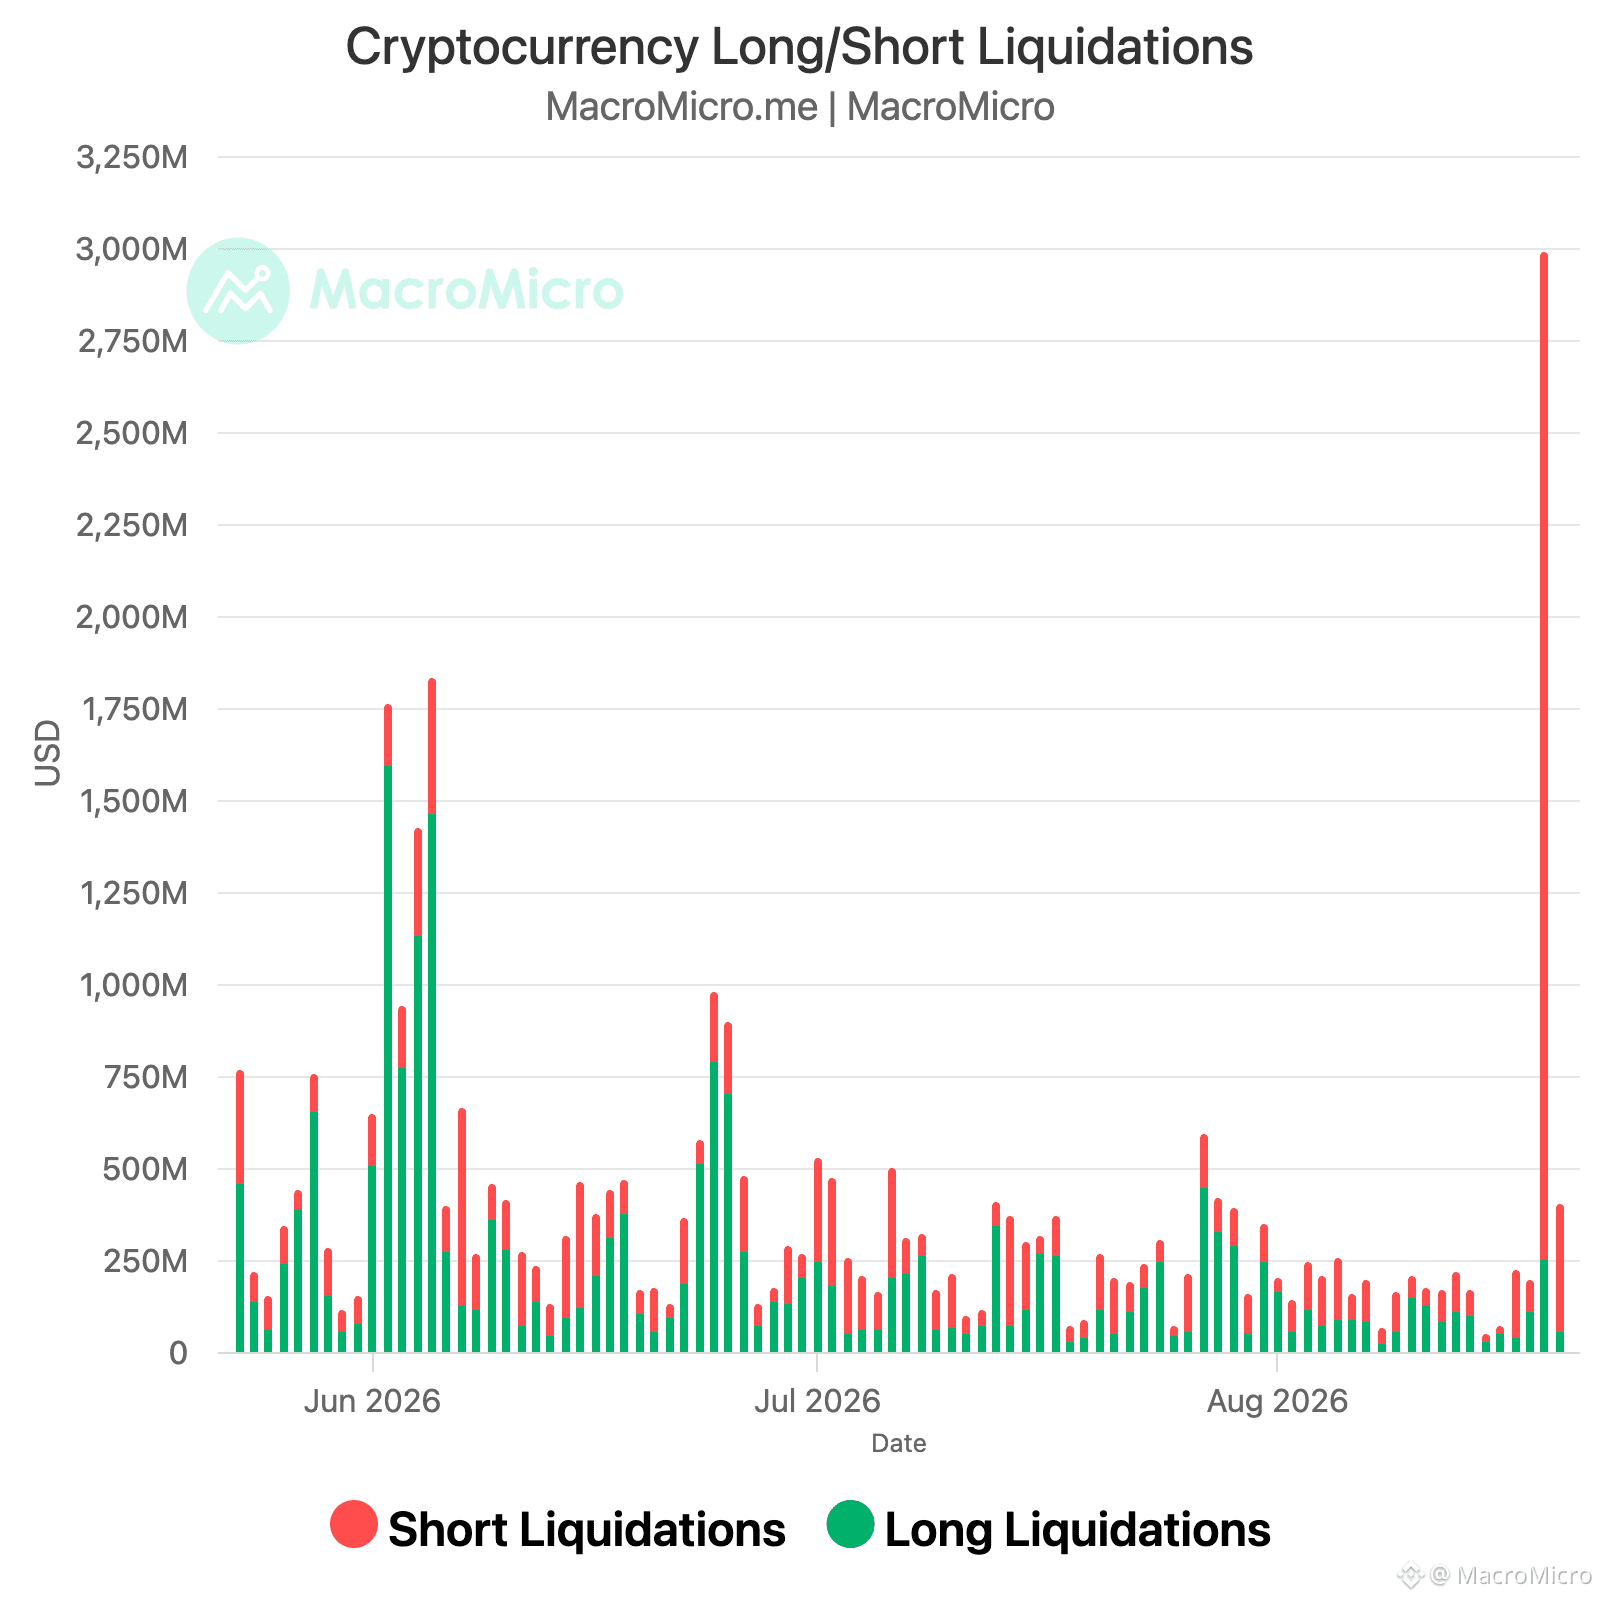
📈 Bitcoin had gone from $65,400 to $69,700 in under an hour, with $746 million in shorts wiped out in a single one-minute candle as the move trapped leveraged sellers. Total crypto liquidations hit $3 billion in 24 hours.
The move traces back to the bond market. Treasury doubled its long-term buyback cap from $2B to $4B per operation, targeting 10 to 30-year debt from September 9 through November 4. The announcement came a day after the 30-year yield hit 5.337%, its highest since 2007. The 10-year fell 6bps to 4.647%, the 30-year fell 9bps to 5.196%.
This is not QE. The Fed did not expand its balance sheet. Treasury bought back its own existing debt to smooth liquidity in the long end, at a scale still small relative to a $32 trillion market. But falling long-term yields lowered the discount rate on risk assets at the exact moment leveraged shorts were positioned against Bitcoin, and the squeeze did the rest.
$BTC
{spot}(BTCUSDT)
📈 Bitcoin had gone from $65,400 to $69,700 in under an hour, with $746 million in shorts wiped out in a single one-minute candle as the move trapped leveraged sellers. Total crypto liquidations hit $3 billion in 24 hours.
The move traces back to the bond market. Treasury doubled its long-term buyback cap from $2B to $4B per operation, targeting 10 to 30-year debt from September 9 through November 4. The announcement came a day after the 30-year yield hit 5.337%, its highest since 2007. The 10-year fell 6bps to 4.647%, the 30-year fell 9bps to 5.196%.
This is not QE. The Fed did not expand its balance sheet. Treasury bought back its own existing debt to smooth liquidity in the long end, at a scale still small relative to a $32 trillion market. But falling long-term yields lowered the discount rate on risk assets at the exact moment leveraged shorts were positioned against Bitcoin, and the squeeze did the rest.
$BTC
The move traces back to the bond market. Treasury doubled its long-term buyback cap from $2B to $4B per operation, targeting 10 to 30-year debt from September 9 through November 4. The announcement came a day after the 30-year yield hit 5.337%, its highest since 2007. The 10-year fell 6bps to 4.647%, the 30-year fell 9bps to 5.196%.
This is not QE. The Fed did not expand its balance sheet. Treasury bought back its own existing debt to smooth liquidity in the long end, at a scale still small relative to a $32 trillion market. But falling long-term yields lowered the discount rate on risk assets at the exact moment leveraged shorts were positioned against Bitcoin, and the squeeze did the rest.
$BTC
8
11
26.7k
·
--
Проверено
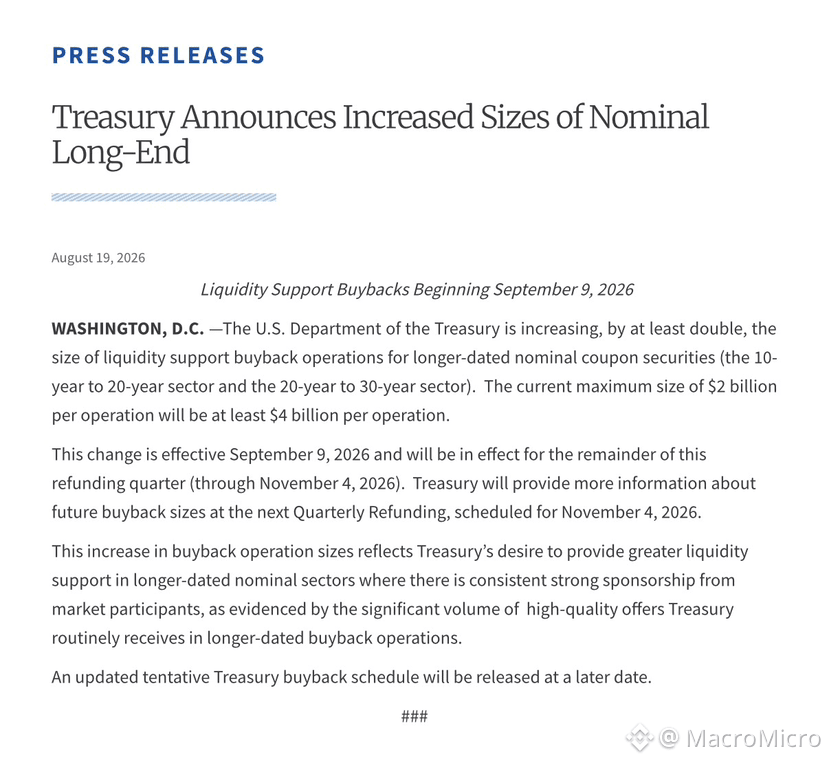
🔴BREAKING: US Treasury increasing size of liquidity support buyback operations for longer-dated nominal coupon securities.
The Treasury is doubling buybacks for 10- to 30-year securities to at least $4 billion per operation.
Timeline: The new limits are effective from September 9 to November 4, 2026.
Goal: The change aims to boost market liquidity in these longer-dated sectors.
🔴BREAKING: US Treasury increasing size of liquidity support buyback operations for longer-dated nominal coupon securities.
The Treasury is doubling buybacks for 10- to 30-year securities to at least $4 billion per operation.
Timeline: The new limits are effective from September 9 to November 4, 2026.
Goal: The change aims to boost market liquidity in these longer-dated sectors.
The Treasury is doubling buybacks for 10- to 30-year securities to at least $4 billion per operation.
Timeline: The new limits are effective from September 9 to November 4, 2026.
Goal: The change aims to boost market liquidity in these longer-dated sectors.
901
·
--
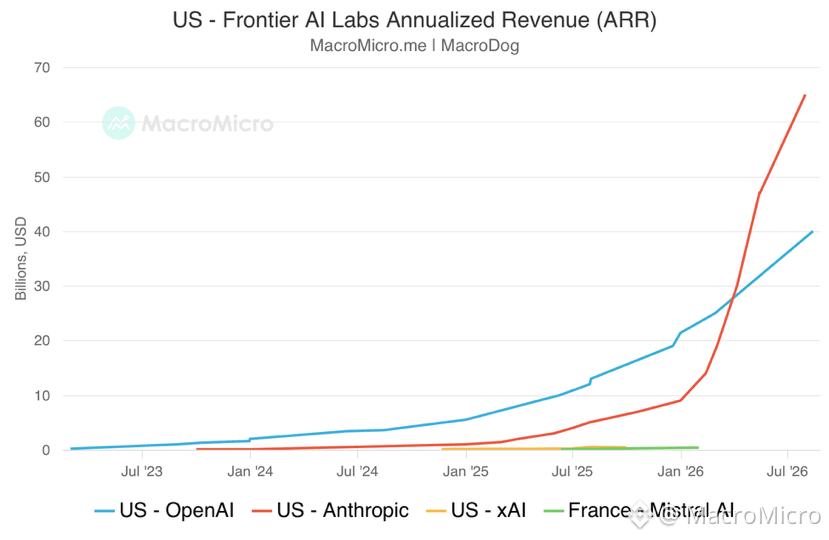
Anthropic’s annualized revenue run rate topped $65B by end-July, up from just ~$9B at year-end.
But momentum has slowed: it rose ~$18B from early May to July, versus ~$17B in just one month from April to May.
Market expectations were much higher, with some third-party estimates previously near $80B.
Anthropic’s annualized revenue run rate topped $65B by end-July, up from just ~$9B at year-end.
But momentum has slowed: it rose ~$18B from early May to July, versus ~$17B in just one month from April to May.
Market expectations were much higher, with some third-party estimates previously near $80B.
But momentum has slowed: it rose ~$18B from early May to July, versus ~$17B in just one month from April to May.
Market expectations were much higher, with some third-party estimates previously near $80B.
2.5k
Войдите, чтобы посмотреть больше материала
Присоединяйтесь к пользователям криптовалют по всему миру на Binance Square
⚡️ Получайте новейшую и полезную информацию о криптоактивах.
💬 Нам доверяет крупнейшая в мире криптобиржа.
👍 Получите достоверные аналитические данные от верифицированных создателей контента.
Эл. почта/номер телефона