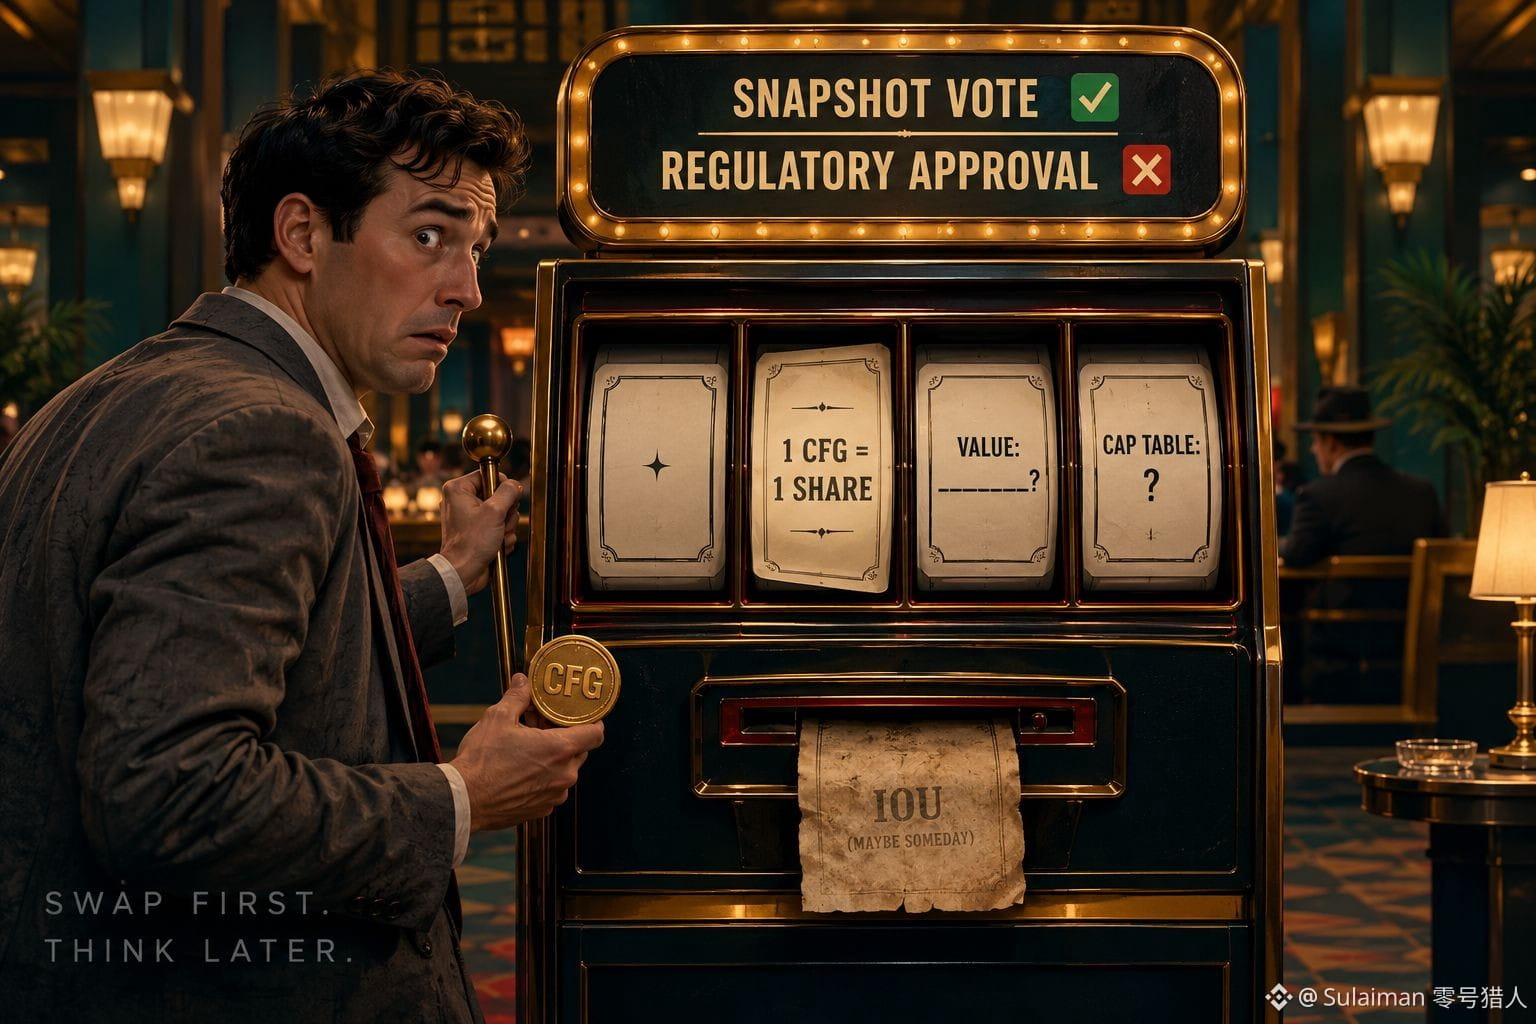
Imagine your project asks you to swap your token for shares in the company.
Centrifuge just did that to CFG holders.
1 CFG = 1 share.
Sounds clean. But 1 share of what?
CP172 passed the Snapshot vote (Sept 3-10) but still needs regulatory approval. The terms aren't set yet: no valuation, no cap table, no share rights, no window date. Holders with 100,000+ CFG would register directly. Smaller holders would go through a CoinList trust. It's voluntary.
Why offer this at all? DefiLlama's token-rights page shows the fee switch off and no dividend or burn. Token-holder net income is $0, while gross protocol revenue was $12.16M in Q2 2026 (partial quarter).
Holders already tried to fix this once. CP162, a fee-capture proposal, missed its 4M-CFG quorum and was rejected. And in Oct 2025, CP171 said CFG would be the single value-accrual mechanism. The equity route reverses that.
The business itself looks real. JAAA, JTRSY and HYB went live on Arc on Oct 1. TVL is anywhere from $1.6B to $1.8B+ depending on the source, and I couldn't reconcile the gap. But a growing protocol and a growing token are not the same thing.
My read: Centrifuge may be doing fine. What nobody has answered is what CFG is after the conversion window. A liquid token for an illiquid share, at a ratio no one can check.
What I'm watching: the published terms, the cap table, and whether the token keeps any role at all. If equity becomes the only route to value and the token is left with nothing, I'm out.
If you hold CFG, would you swap before seeing the cap table?
#Centrifuge #RWA #Tokenization #DeFi #ZeroHunter
$CFG $PLUME $BNB