🚨 The SEC’s $75M crypto-fundraising headline hides the part that could matter more...
#sectoclarifyonchainfundraisingrules
On Aug. 18, the SEC proposed Regulation Crypto Assets — but this is not yet a final rule. Comments are open until Oct. 20.
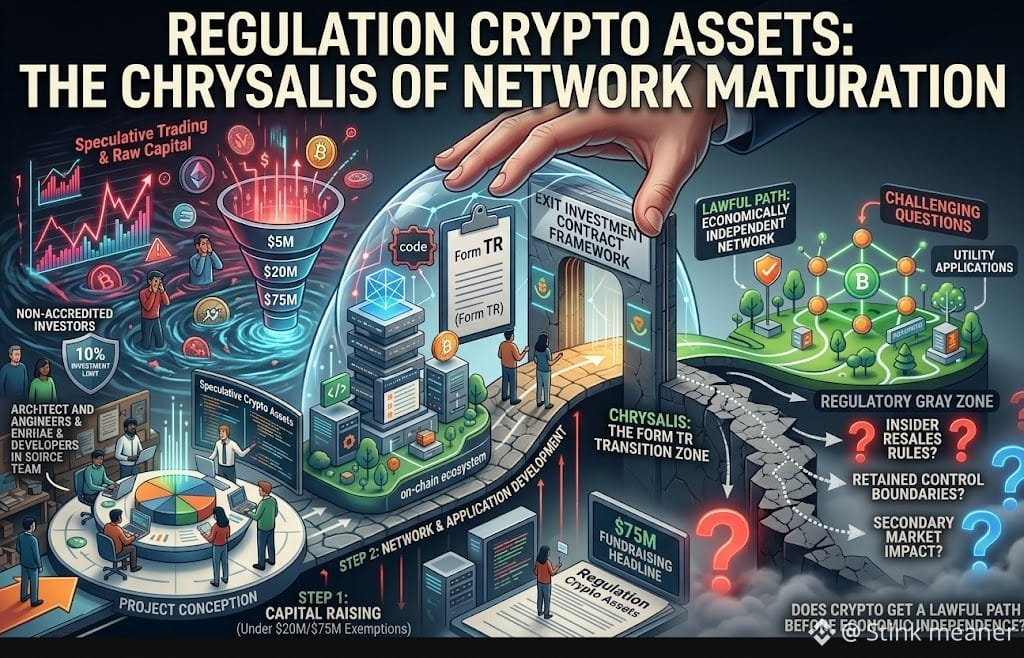
The headline: projects could potentially raise $5M over four years through a startup exemption, or $20M/$75M over 12 months under Tier 1/2 fundraising exemptions. Non-accredited investors would generally face a 10% of income-or-net-worth purchase limit.
But the deeper mechanism is a regulatory lifecycle:
Raise capital → build the network/application → complete or permanently cease promised “essential managerial efforts” → file Form TR → potentially exit the investment-contract framework.
And the SEC isn't treating crypto like ordinary securities paperwork. Proposed disclosures specifically address source code, network security, token supply/allocation, governance, ecosystem and ways to verify transaction history.
That could turn token launches from a legal gray zone into a defined capital-formation process — while leaving difficult questions around insider resales, retained control and secondary markets. Recent SEC comments are already challenging those gaps.
The real question: does crypto finally get a lawful path to fund a network before it becomes economically independent?
DYOR. This remains a proposal, not law, and any transition out of the investment-contract framework would depend on satisfying the SEC’s proposed conditions
$ETH $SOL $BNB
#SECToClarifyOnChainFundraisingRules #CryptoRegulation #Stinkmeanerinsights #blockchain