

Trade with Ju
6 投稿
Trade with Ju
報告
ユーザーをブロック
never give up everyone has bad days
取引を発注
16日
0 フォロー
0 フォロワー
0 いいね
投稿
ポートフォリオ
記事
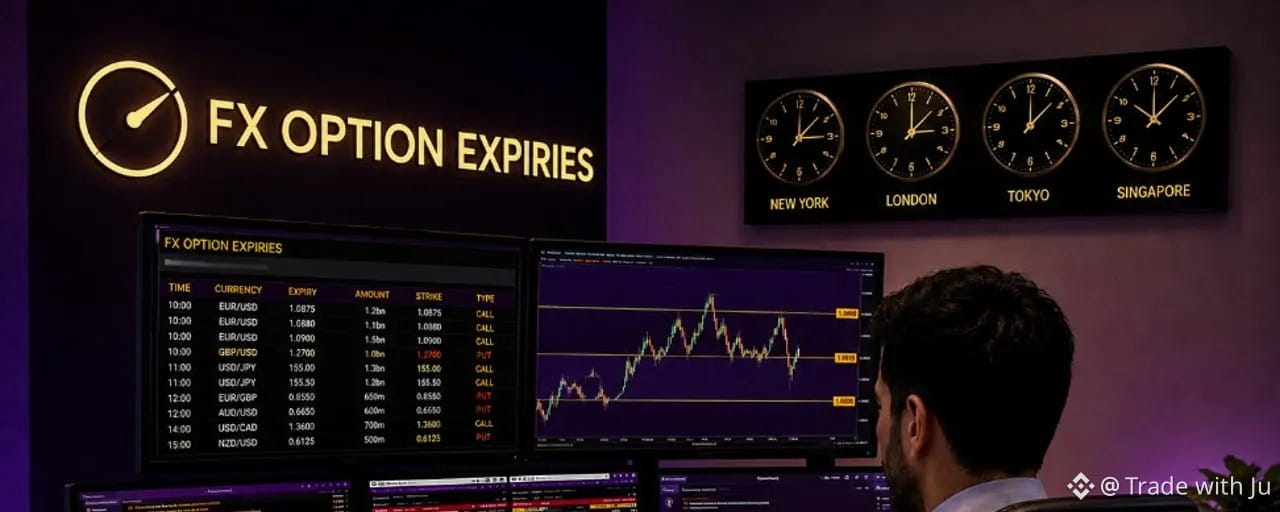
9月30日(米東部時間)午前10時のFXオプション満期の注目点今日の注目ポイント:まず押さえるべきこと今日は、下の太字で示した通り、注目すべき満期水準が2つあります。
1つ目はEUR/USDで1.1300の水準です。ストライクは現在のスポット価格からおおむね30ピップほど離れています。満期の規模が大きく、すでに価格が比較的近いことから、カット(満期が近づく局面)に向けて1.1300へ引っ張られる可能性があります。特に、ドルが引き続き上方向に押し上げるならです。トレジャリーの下落(売り)が通貨の下支えになっているためです。
9月30日(米東部時間)午前10時のFXオプション満期の注目点
今日の注目ポイント:まず押さえるべきこと今日は、下の太字で示した通り、注目すべき満期水準が2つあります。
1つ目はEUR/USDで1.1300の水準です。ストライクは現在のスポット価格からおおむね30ピップほど離れています。満期の規模が大きく、すでに価格が比較的近いことから、カット(満期が近づく局面)に向けて1.1300へ引っ張られる可能性があります。特に、ドルが引き続き上方向に押し上げるならです。トレジャリーの下落(売り)が通貨の下支えになっているためです。
1つ目はEUR/USDで1.1300の水準です。ストライクは現在のスポット価格からおおむね30ピップほど離れています。満期の規模が大きく、すでに価格が比較的近いことから、カット(満期が近づく局面)に向けて1.1300へ引っ張られる可能性があります。特に、ドルが引き続き上方向に押し上げるならです。トレジャリーの下落(売り)が通貨の下支えになっているためです。
45
記事
イランはホルムズ提案に関して今日の米国からの返答を見込む中、原油価格が再び上昇テヘランは、強化された外交がホルムズ海峡をめぐる状況について原油トレーダーの思惑をかき立てる中で、今日ワシントンからの返答を待っているイランの外相、アッバス・アラクチ氏は、テヘランはホルムズ海峡の再開をめぐる最新の提案に関して、今日米国からの回答を受け取ることを見込んでいると述べた。それにより、週末にトランプ米大統領がイランの当初の7日間の提案を公に拒否した後でも、ある程度は外交の扉が開かれたままだ。以降、状況はわずかにより複雑になっている。
イランはホルムズ提案に関して今日の米国からの返答を見込む中、原油価格が再び上昇
テヘランは、強化された外交がホルムズ海峡をめぐる状況について原油トレーダーの思惑をかき立てる中で、今日ワシントンからの返答を待っているイランの外相、アッバス・アラクチ氏は、テヘランはホルムズ海峡の再開をめぐる最新の提案に関して、今日米国からの回答を受け取ることを見込んでいると述べた。それにより、週末にトランプ米大統領がイランの当初の7日間の提案を公に拒否した後でも、ある程度は外交の扉が開かれたままだ。以降、状況はわずかにより複雑になっている。
221
記事
翻訳参照
investingLive Asia-Pacific market news: Yen, Nikkei firmer2 hours ago, published 30/09/2026 at 09:40 AM
Summary
Market moving news for Asian trading on Wednesday, September 30, 2026 Oil was lower after Tuesday's slide on SPR and Russia sanctions reports, while USD/JPY dropped to around 156.4 on half-year-end flows. Australian CPI hit 4.0% y/y, China's official PMIs rose above 50 and the Nikkei gained 1.0%. Gold edged higher.
Goldman: Persian Gulf oil exports back at 2025 average after doubling in SeptemberUSD/JPY slips to around 156.4 as half-year-end flows and Fed comments weighChina official manufacturing PMI returns to growth at 50.1, non-manufacturing 50.2RatingDog China manufacturing PMI 52.1 tops forecast, services 51.6 also beatsAustralia August CPI 4.0% as fuel jumps, trimmed mean below forecast at 0.2% m/mPBOC sets USD/ CNY mid-point today at 6.7351 (vs. estimate at 6.7025)ANZ survey: NZ business confidence eases to +52 as oil rise hits late responsesJapan August factory output falls 1.7% against forecast rise, retail sales slowICYMI: BlackRock says AI agents could be an overlooked source of crypto demandOil: OPEC+ seen holding November quotas steady at Sunday meeting, delegates sayWestpac sees RBA hiking again in November after 25bp move to 4.6% yesterdayCiti sees Starship flight as step toward $900 SpaceX targetUS-Iran talks stall as Qatar mediation yields little, raising risk of renewed combatBoeing shares rise on $20 billion Navy fighter win as Northrop Grumman slipsTrump, tech leaders sign voluntary "morally binding" AI accord at White HouseFed officials lean hawkish, though Williams sees no urgency for another hike
Summary:
Oil extended some of Tuesday's losses after several downside catalysts, including a report that Trump backs easing Russia sanctions for the release of political prisoners and a US offer of up to 40 million barrels from the Strategic Petroleum Reserve. Gold made a small gain.On the other hand, Axios reported that Qatari mediation this week produced little progress between the US and Iran, and that US officials think Trump could order a return to major combat after the midterms.Japan's August industrial output fell 1.7% m/m against a forecast rise of 1.7%, and retail sales slowed to 2.7% y/y against 3.3% expected. USD/JPY fell from around 157.5 to around 156.4 on Japanese half-year-end flows.Australian CPI rose 4.0% y/y in August as expected, with fuel driving the rise, while trimmed mean rose 0.2% m/m against 0.3% forecast and held at 3.6% y/y. Market pricing implies around a 25% chance of an RBA hike in November, and the Australian dollar was lower.China's official manufacturing PMI rose to 50.1 and non-manufacturing to 50.2. RatingDog manufacturing was 52.1, services 51.6 and composite 52.4.The Nikkei rose 1.0%, the KOSPI fell 0.1%, the Hang Seng was flat and the Shanghai Composite rose 0.3%.
Oil and geopolitics
Oil prices saw some further losses on Wednesday after sliding on Tuesday, when Brent settled down circa 2.5% at around $103 a barrel and WTI closed at around $89. Several downside catalysts contributed. The Atlantic reported that US President Donald Trump backs a strategy to ease Russia sanctions in exchange for the release of political prisoners, which could open the way for the US to sign deals involving Russian oil, diesel, rare earth minerals and other commodities. The US Department of Energy also offered up to 40 million barrels from the Strategic Petroleum Reserve. Separately, Goldman Sachs estimated that Persian Gulf oil exports, including dark exports, recovered to their 2025 average after doubling in September, with Saudi exports leading the rebound and Iran shipping no crude by sea.
Qatar persisted with mediation, but Axios, citing three sources, reported that this week's efforts yielded little progress between the US and Iran. Axios said the stalemate has strengthened the belief on both sides that renewed conflict is more likely, and that US officials think Trump could order a return to major combat operations after the midterms. Trump has said he offered Iran nothing. Gold made a small gain.
Japan and the yen
Japan's August industrial output fell 1.7% from July against a forecast rise of 1.7%, and rose 3.4% y/y. Retail sales slowed to 2.7% y/y, below the 3.3% expected, and fell 1.2% m/m. Manufacturers surveyed by the Ministry of Economy, Trade and Industry (METI) expect output to increase 3.2% in September and 3.1% in October.
The yen was a large mover. USD/JPY fell from around 157.5 to around 156.4 in Asia as Japanese investors and exporters sold foreign currency into the fiscal half-year end. Fed President John Williams said on Tuesday there is no urgency to raise rates again, although he said one more increase may be appropriate late this year. Comments from US and Japanese officials also weighed on the pair.
Australia
Australian consumer prices rose 4.0% y/y in August, in line with forecasts and up from 3.5%, with fuel driving the rise. Trimmed mean, the Reserve Bank of Australia's preferred gauge of underlying inflation, rose 0.2% m/m against a forecast of 0.3% and held at 3.6% y/y. Reuters said the softer core reading lessened pressure for a near-term rate rise. The RBA lifted its cash rate to 4.6% on Tuesday, and Westpac has said a November follow-up is its base case, while market pricing implies around a 25% chance. The Australian dollar was lower.
China
China's official manufacturing PMI rose to 50.1 in September from 49.8, matching forecasts and ending two months of contraction, while the non-manufacturing PMI rose to 50.2 from 49.0, above the 49.3 forecast. The private RatingDog surveys also improved: manufacturing rose to 52.1 (forecast 51.6, prior 51.5), a five-month high with input costs driven by metals and oil, services to 51.6 (forecast 51.1, prior 51.4) and composite to 52.4 from 52.1. The data came ahead of the week-long National Day holiday, with mainland markets closed from October 1 to 7 and the Hong Kong exchange shut on Thursday.
Equities
The Nikkei 225 rose 1.0% despite the Japanese data, which included a contraction in industrial output against a forecast for growth. The KOSPI fell 0.1%, fading initial gains, as weak data and tensions with North Korea weighed on sentiment after a landmine explosion in the demilitarised zone injured three South Korean officers. The Hang Seng was flat and the Shanghai Composite rose 0.3%.
investingLive Asia-Pacific market news: Yen, Nikkei firmer
2 hours ago, published 30/09/2026 at 09:40 AM
Summary
Market moving news for Asian trading on Wednesday, September 30, 2026 Oil was lower after Tuesday's slide on SPR and Russia sanctions reports, while USD/JPY dropped to around 156.4 on half-year-end flows. Australian CPI hit 4.0% y/y, China's official PMIs rose above 50 and the Nikkei gained 1.0%. Gold edged higher.
Goldman: Persian Gulf oil exports back at 2025 average after doubling in SeptemberUSD/JPY slips to around 156.4 as half-year-end flows and Fed comments weighChina official manufacturing PMI returns to growth at 50.1, non-manufacturing 50.2RatingDog China manufacturing PMI 52.1 tops forecast, services 51.6 also beatsAustralia August CPI 4.0% as fuel jumps, trimmed mean below forecast at 0.2% m/mPBOC sets USD/ CNY mid-point today at 6.7351 (vs. estimate at 6.7025)ANZ survey: NZ business confidence eases to +52 as oil rise hits late responsesJapan August factory output falls 1.7% against forecast rise, retail sales slowICYMI: BlackRock says AI agents could be an overlooked source of crypto demandOil: OPEC+ seen holding November quotas steady at Sunday meeting, delegates sayWestpac sees RBA hiking again in November after 25bp move to 4.6% yesterdayCiti sees Starship flight as step toward $900 SpaceX targetUS-Iran talks stall as Qatar mediation yields little, raising risk of renewed combatBoeing shares rise on $20 billion Navy fighter win as Northrop Grumman slipsTrump, tech leaders sign voluntary "morally binding" AI accord at White HouseFed officials lean hawkish, though Williams sees no urgency for another hike
Summary:
Oil extended some of Tuesday's losses after several downside catalysts, including a report that Trump backs easing Russia sanctions for the release of political prisoners and a US offer of up to 40 million barrels from the Strategic Petroleum Reserve. Gold made a small gain.On the other hand, Axios reported that Qatari mediation this week produced little progress between the US and Iran, and that US officials think Trump could order a return to major combat after the midterms.Japan's August industrial output fell 1.7% m/m against a forecast rise of 1.7%, and retail sales slowed to 2.7% y/y against 3.3% expected. USD/JPY fell from around 157.5 to around 156.4 on Japanese half-year-end flows.Australian CPI rose 4.0% y/y in August as expected, with fuel driving the rise, while trimmed mean rose 0.2% m/m against 0.3% forecast and held at 3.6% y/y. Market pricing implies around a 25% chance of an RBA hike in November, and the Australian dollar was lower.China's official manufacturing PMI rose to 50.1 and non-manufacturing to 50.2. RatingDog manufacturing was 52.1, services 51.6 and composite 52.4.The Nikkei rose 1.0%, the KOSPI fell 0.1%, the Hang Seng was flat and the Shanghai Composite rose 0.3%.
Oil and geopolitics
Oil prices saw some further losses on Wednesday after sliding on Tuesday, when Brent settled down circa 2.5% at around $103 a barrel and WTI closed at around $89. Several downside catalysts contributed. The Atlantic reported that US President Donald Trump backs a strategy to ease Russia sanctions in exchange for the release of political prisoners, which could open the way for the US to sign deals involving Russian oil, diesel, rare earth minerals and other commodities. The US Department of Energy also offered up to 40 million barrels from the Strategic Petroleum Reserve. Separately, Goldman Sachs estimated that Persian Gulf oil exports, including dark exports, recovered to their 2025 average after doubling in September, with Saudi exports leading the rebound and Iran shipping no crude by sea.
Qatar persisted with mediation, but Axios, citing three sources, reported that this week's efforts yielded little progress between the US and Iran. Axios said the stalemate has strengthened the belief on both sides that renewed conflict is more likely, and that US officials think Trump could order a return to major combat operations after the midterms. Trump has said he offered Iran nothing. Gold made a small gain.
Japan and the yen
Japan's August industrial output fell 1.7% from July against a forecast rise of 1.7%, and rose 3.4% y/y. Retail sales slowed to 2.7% y/y, below the 3.3% expected, and fell 1.2% m/m. Manufacturers surveyed by the Ministry of Economy, Trade and Industry (METI) expect output to increase 3.2% in September and 3.1% in October.
The yen was a large mover. USD/JPY fell from around 157.5 to around 156.4 in Asia as Japanese investors and exporters sold foreign currency into the fiscal half-year end. Fed President John Williams said on Tuesday there is no urgency to raise rates again, although he said one more increase may be appropriate late this year. Comments from US and Japanese officials also weighed on the pair.
Australia
Australian consumer prices rose 4.0% y/y in August, in line with forecasts and up from 3.5%, with fuel driving the rise. Trimmed mean, the Reserve Bank of Australia's preferred gauge of underlying inflation, rose 0.2% m/m against a forecast of 0.3% and held at 3.6% y/y. Reuters said the softer core reading lessened pressure for a near-term rate rise. The RBA lifted its cash rate to 4.6% on Tuesday, and Westpac has said a November follow-up is its base case, while market pricing implies around a 25% chance. The Australian dollar was lower.
China
China's official manufacturing PMI rose to 50.1 in September from 49.8, matching forecasts and ending two months of contraction, while the non-manufacturing PMI rose to 50.2 from 49.0, above the 49.3 forecast. The private RatingDog surveys also improved: manufacturing rose to 52.1 (forecast 51.6, prior 51.5), a five-month high with input costs driven by metals and oil, services to 51.6 (forecast 51.1, prior 51.4) and composite to 52.4 from 52.1. The data came ahead of the week-long National Day holiday, with mainland markets closed from October 1 to 7 and the Hong Kong exchange shut on Thursday.
Equities
The Nikkei 225 rose 1.0% despite the Japanese data, which included a contraction in industrial output against a forecast for growth. The KOSPI fell 0.1%, fading initial gains, as weak data and tensions with North Korea weighed on sentiment after a landmine explosion in the demilitarised zone injured three South Korean officers. The Hang Seng was flat and the Shanghai Composite rose 0.3%.
114
記事
翻訳参照
What are the main events for today?The highlights include the Spanish CPI, the Canadian monthly GDP, the US Consumer Confidence report and the US Job Openings data. The focus, though, will remain mostly on US-Iran headlines.EUROPEAN SESSIONIn the European session, the main highlight is the Spanish CPI report. Headline CPI Y/Y is expected to rise further to 4.6% vs 4.3% prior, but the focus will be on the Core measure which has ticked lower to 2.9% in the prior reading.The market is currently pricing roughly a 31% chance of an ECB rate hike in October, so if we get hot inflation numbers this week, we should see those odds rising above 50% and the central bank following suit.If we get a surprising breakthrough in US-Iran relations before the next ECB meeting, then we might see a dovish repricing across the board, with the central bank holding off from raising rates in October.AMERICAN SESSIONIn the American session, we have the Canadian monthly GDP, the US Consumer Confidence report and the US Job Openings data. None of the data is going to change much for the respective central banks, as both the BoC and the Fed are mainly focused on inflation.The more important event should actually be a potential additional round of US-Iran talks as mediators try to bridge the gap between the two sides to reopen the Strait of Hormuz.We've already got a taste of the volatility around these talks yesterday, with positive and negative headlines triggering spikes in the markets. The focus will remain on the Middle East developments given their enormous influence of pretty much everything now.CENTRAL BANK SPEAKERS08:00 GMT/04:00 ET - ECB's Kazimir (hawkish - voter)10:00 GMT/06:00 ET - ECB's Nagel (hawkish - voter)11:30 GMT/07:30 ET - ECB's Escriva (neutral - voter)13:15 GMT/11:15 ET - ECB's Cipollone (neutral - voter)15:00 GMT/11:00 ET - Fed's Bowman (dovish - voter)15:00 GMT/11:00 ET - BoE's Mann (hawkish - voter)15:00 GMT/11:00 ET - BoE's Taylor (dovish - voter)16:30 GMT/12:30 ET - Fed's Barr (neutral - voter)17:00 GMT/13:00 ET - Fed's Goolsbee (hawkish - non voter)17:20 GMT/13:20 ET - BoC's Gravelle (neutral - voter)17:30 GMT/13:30 ET - Fed's Musalem (hawkish - non voter)18:00 GMT/14:00 ET - Fed's Williams (neutral - voter)19:00 GMT/15:00 ET - Fed's Waller (hawkish - voter)
What are the main events for today?
The highlights include the Spanish CPI, the Canadian monthly GDP, the US Consumer Confidence report and the US Job Openings data. The focus, though, will remain mostly on US-Iran headlines.EUROPEAN SESSIONIn the European session, the main highlight is the Spanish CPI report. Headline CPI Y/Y is expected to rise further to 4.6% vs 4.3% prior, but the focus will be on the Core measure which has ticked lower to 2.9% in the prior reading.The market is currently pricing roughly a 31% chance of an ECB rate hike in October, so if we get hot inflation numbers this week, we should see those odds rising above 50% and the central bank following suit.If we get a surprising breakthrough in US-Iran relations before the next ECB meeting, then we might see a dovish repricing across the board, with the central bank holding off from raising rates in October.AMERICAN SESSIONIn the American session, we have the Canadian monthly GDP, the US Consumer Confidence report and the US Job Openings data. None of the data is going to change much for the respective central banks, as both the BoC and the Fed are mainly focused on inflation.The more important event should actually be a potential additional round of US-Iran talks as mediators try to bridge the gap between the two sides to reopen the Strait of Hormuz.We've already got a taste of the volatility around these talks yesterday, with positive and negative headlines triggering spikes in the markets. The focus will remain on the Middle East developments given their enormous influence of pretty much everything now.CENTRAL BANK SPEAKERS08:00 GMT/04:00 ET - ECB's Kazimir (hawkish - voter)10:00 GMT/06:00 ET - ECB's Nagel (hawkish - voter)11:30 GMT/07:30 ET - ECB's Escriva (neutral - voter)13:15 GMT/11:15 ET - ECB's Cipollone (neutral - voter)15:00 GMT/11:00 ET - Fed's Bowman (dovish - voter)15:00 GMT/11:00 ET - BoE's Mann (hawkish - voter)15:00 GMT/11:00 ET - BoE's Taylor (dovish - voter)16:30 GMT/12:30 ET - Fed's Barr (neutral - voter)17:00 GMT/13:00 ET - Fed's Goolsbee (hawkish - non voter)17:20 GMT/13:20 ET - BoC's Gravelle (neutral - voter)17:30 GMT/13:30 ET - Fed's Musalem (hawkish - non voter)18:00 GMT/14:00 ET - Fed's Williams (neutral - voter)19:00 GMT/15:00 ET - Fed's Waller (hawkish - voter)
1
242
記事
投資ライブ:アジア太平洋市場ニュース—アジア株下落2026年9月29日(火)のアジア取引向けの市場を動かすニュース米10年債利回りがイラン攻撃以来の高水準で着地し、イラン関連の見出しが交錯する中で原油が上昇したことを受けて、火曜日のアジア太平洋株は概ね下落した。日経平均は1.2%下落、KOSPIは0.6%下落、そして金は0.5%上昇となった。これは、月曜の急落の後の動き。
投資ライブ:アジア太平洋市場ニュース—アジア株下落
2026年9月29日(火)のアジア取引向けの市場を動かすニュース米10年債利回りがイラン攻撃以来の高水準で着地し、イラン関連の見出しが交錯する中で原油が上昇したことを受けて、火曜日のアジア太平洋株は概ね下落した。日経平均は1.2%下落、KOSPIは0.6%下落、そして金は0.5%上昇となった。これは、月曜の急落の後の動き。
1
306
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号
トレンドトピック
BitcoinSlipsBelow$84000
閲覧回数 5
22人が討論中
9.30大饼
$BTC
反発して84000-84300の区間に触れたら、直接カンに入る。
昨晩82800付近まで叩きつけて底を作り、今朝の寄り付きは落ち着いてから反発開始。全体としてはカン頭が主導している。
上の84000-84300のあたりはちょうど移動平均線に押さえられており、ここまで反発しても売り圧力が強く、根本的に突き上げるのは難しい。まずは83000-82800のサポートを注視し、守れなければさらに下へ行って底探りが続く。
取引としては、価格が84000-84300に反発したら分割でカン単(買い)に入る。笋(スン)位置は84500の上に少し安全策を置く。芷楹はまず83100-82900を見ている。#股票财报季
晓东Crypto
·いいね:0件
·閲覧回数 106
SECToClarifyOnChainFundraisingRules
閲覧回数 1,016
86人が討論中
UKFCAOpensCryptoFirmAuthorization
閲覧回数 2,701
115人が討論中