

Polius2007
2 投稿
Polius2007
報告
ユーザーをブロック
I build XTester Studio and CopyTrader. Sharing strategy research, product development and lessons from building tools for crypto traders.
2 フォロー
9 フォロワー
3 いいね
投稿
PINNED
·
--
暗号トレーダーのためにソフトウェアを開発しています:戦略リサーチとバックテストのためのXTester Studio、そして自分のオーディエンスにトレードコピーを提供したいトレーダー向けのCopyTrader。
ここでは、私が取り組んでいること、その裏で行っている実験、そして途中でのプロダクト決定について共有します。戦略アイデアをどう検証するのか、バックテストから何が分かるのか、そしてコピー取引サービスを構築する実務的な作業まで含みます。
もしあなたが戦略をリサーチしていたり、トレーディングのコミュニティを運営していたりするなら、あなたのワークフローでいちばん時間がかかるのは何かぜひ聞かせてください。
プロジェクト: https://easytrading.pw
#Backtesting #CopyTrading
ここでは、私が取り組んでいること、その裏で行っている実験、そして途中でのプロダクト決定について共有します。戦略アイデアをどう検証するのか、バックテストから何が分かるのか、そしてコピー取引サービスを構築する実務的な作業まで含みます。
もしあなたが戦略をリサーチしていたり、トレーディングのコミュニティを運営していたりするなら、あなたのワークフローでいちばん時間がかかるのは何かぜひ聞かせてください。
プロジェクト: https://easytrading.pw
#Backtesting #CopyTrading
384
·
--
翻訳参照
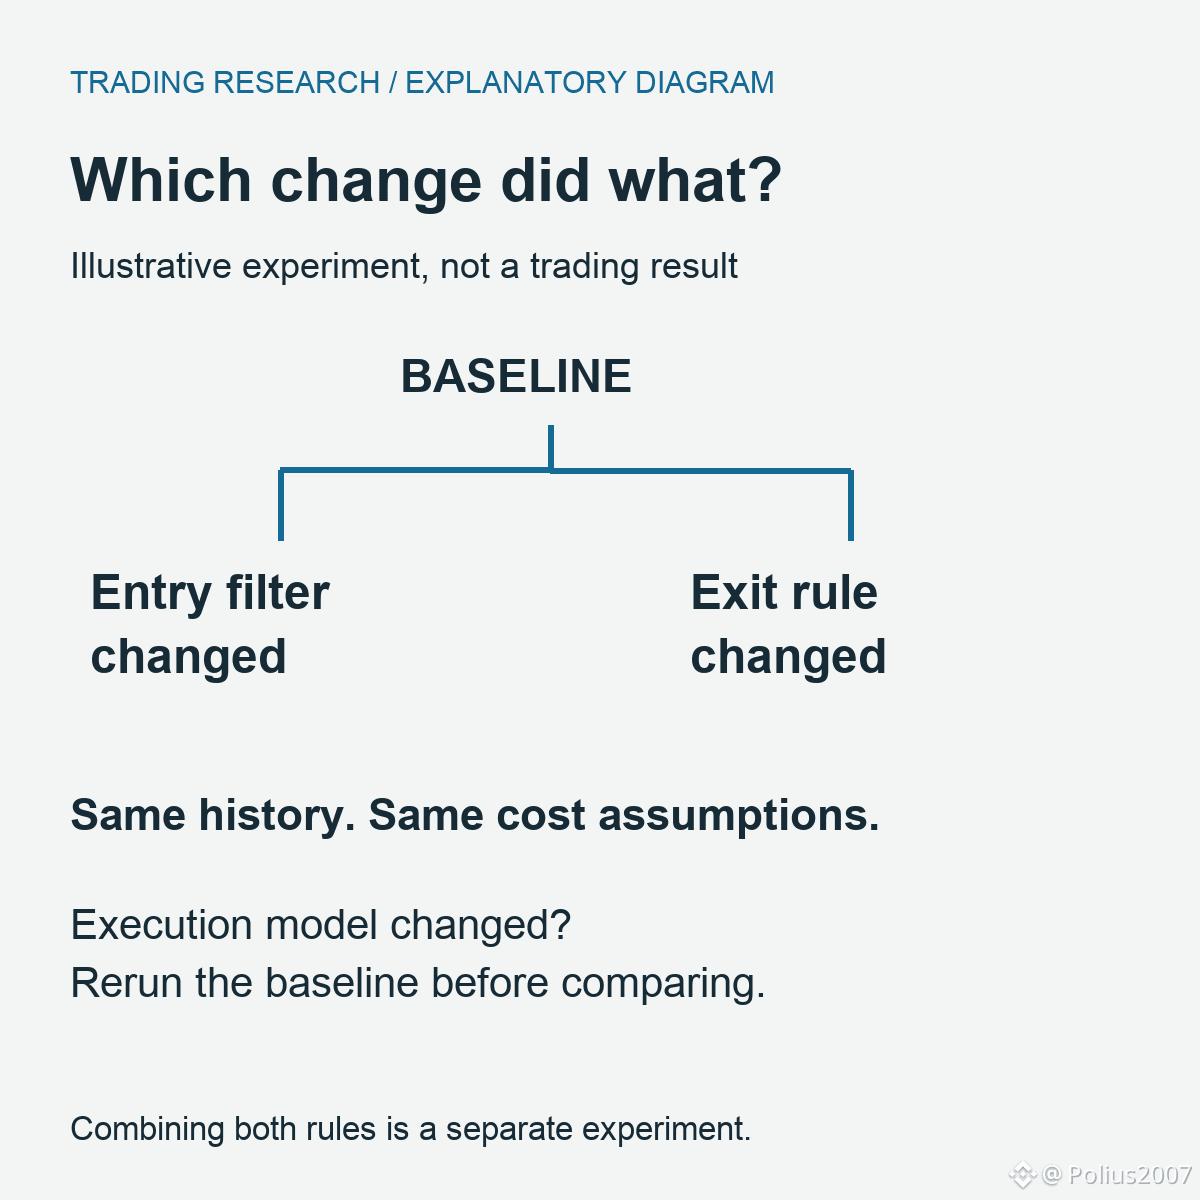
Change an entry filter, then change an exit rule. The second backtest looks better. Which change deserves the credit?
That's one of the problems I'm working on in XTester Studio. A result needs to stay attached to the version that produced it and the question being tested. Otherwise, the next experiment starts with guesswork.
Here's how I'd set up that comparison: keep the original strategy as a baseline, test the entry filter on its own, then test the exit rule from that same baseline. Keep the historical period and trading-cost assumptions the same. Combining both changes can be a separate experiment.
There's a less obvious complication in this work: the simulator can change too. A recent fix in Studio corrected slippage on market orders placed at minute boundaries. If an older test used that behavior, rerun the baseline before comparing it with a new strategy version. A different result may come from the execution model.
Before keeping a new rule, I'd want to answer one question: did I change the strategy, the test conditions, or both?
30
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号
トレンドトピック
BitcoinClears$85200
閲覧回数 16,063
237人が討論中
動きが出て、$BTC はデータがあった直前にあった場所にそのまま立っています。取引における本当の忍耐ってこういうことです。
データは混ざって入ってきましたが、いくつか重要な数字がありました。ADP 非農業部門雇用者数は予想の73Kに対して90Kでした。一方でコアPCEは、予想の0.3%に対して0.2%です。最終的なGDPも予想の1.5%に対して2.2%と強めでした。個人消費は予想の0.8%に対して0.9%でした。同時に、個人所得は予想の0.5%に対して0.2%で未達でした。
BTCは最初に85,600ドルまで急騰しましたが、今は必要なところに戻っています。私は引き続き、82,759ドルと80,000ドルの流動性の低いレンジを見ています。上側の流動性はもう終わって、あとは塵も残っていないからです。
データ発表中にライブセッションを行いました。その中で、市場は83,800ドル→85,600ドル→そして83,000ドル付近へと戻っていくのを見ました。それでも私たちは取引に入りませんでした。
それが忍耐です。
市場に明確な方向性がないときは、無理にエントリーはできません。同じレンジがまだ注目ポイントで、相場がセットアップを提示してくれるまで待ちます。
みなさん、セッションはどうでしたか? それから、尊敬するメンバーの皆さんともっと定期的にセッションをするべきでしょうか。そうすれば、市場について適切に議論できます。
#BitcoinClears$85200 #AltcoinSeasonIndexHoldsAbove60For5Days #USADPAdds90000JobsInSeptember #BitcoinSlipsBelow$84000 #SECToClarifyOnChainFundraisingRules
Crypto_LUX
·いいね:27件
·閲覧回数 23.2k
AltcoinSeasonIndexHoldsAbove60For5Days
閲覧回数 80,360
1,308人が討論中
USADPAdds90000JobsInSeptember
閲覧回数 35,288
722人が討論中