

Coincamps
509 投稿

Coincamps
報告
ユーザーをブロック
🔍 Where Crypto & AI Minds Gather,Signal for Crypto & AI Builders
https://coincamps.ai
取引を発注
低高頻度トレーダー
2.4年
5 フォロー
1.3K+ フォロワー
51 いいね
投稿
ポートフォリオ
·
--
記事
翻訳参照
Solana today launches its largest upgrade to date, Alpenglow: which ecosystem projects will benefit from 150-millisecond transaction confirmations?Later today, the Solana mainnet will officially activate its largest and most hardcore consensus upgrade since its 2020 launch: Alpenglow.
Solana’s official social media channels are also announcing this upgrade, generating buzz through profile picture changes.
In a crypto market saturated with short-term sentiment and noise, underlying infrastructure upgrades are often overlooked. While the community has long lost its mystique surrounding TPS, consensus mechanisms, and technological iterations, this Alpenglow upgrade marks a significant qualitative shift that directly impacts the on-chain interaction experience for all participants and quietly reconstructs the fundamental economics of SOL.
For the SOL token itself, this upgrade brings little direct impact, but it provides a positive boost to the fundamentals of the entire ecosystem. If you are still following projects within the Solana ecosystem but haven’t delved into the specifics of this upgrade, this article is well worth reading.
Setting aside the cryptic client technical documentation, we need to examine this upgrade from two dimensions: mechanism principles and ecological implications, to see what exactly has changed and which asset categories will become the true beneficiaries.
Deconstructing Alpenglow: Everything Comes Down to Transaction Finality Speed
The core changes brought by this Alpenglow upgrade to the network ecosystem can be condensed into two points:
First, ultra-fast finality.
After the upgrade, transaction confirmation times on the Solana chain have been compressed from 6 seconds to 150 milliseconds. Under the old consensus mechanism, although Solana produces blocks incredibly fast, a transaction typically takes about 6 to 12 seconds to reach the state of “final irreversible confirmation (Finality).” For retail users, the most intuitive pain point is “Schrödinger’s execution”: after clicking Swap on a decentralized exchange, you’re always forced to stare at the screen during a few seconds of suspense, even worrying about potential network rollbacks.
Once Alpenglow is activated, Solana’s transaction finality time will be compressed to 150 milliseconds (and can even reach 100 milliseconds on the fast path). This means that future on-chain interactions, from click to complete settlement, will theoretically occur faster than a blink of an eye.
Second, a dramatic drop in node operating costs.
In the past, Solana validator nodes had to frequently send voting transactions on-chain to maintain network consensus, requiring continuous payment of high gas fees (consuming approximately 1 SOL per Epoch).
The new mechanism moves this massive voting action off-chain (using BLS signature aggregation), and changes the node’s voting cost to purchasing fixed-consumption “admission tickets” priced at 0.8 SOL, which are fully burned).
This underlying optimization directly reduces the daily operating costs for validator nodes by approximately 60%.
Who Are the True Beneficiaries of This Upgrade?
The implementation of Alpenglow may not become a short-term hype gimmick to instantly pump token prices, but it addresses Solana’s weaknesses in competing for mainstream institutional capital. Deduced from business logic, the following sectors are expected to receive substantial benefits in my view:
On-chain perpetual contracts and DEX aggregators (complete CEX-like experience)
Benefit logic: Elimination of finality risk and significant increase in capital turnover rate. This is the most direct business beneficiary of this upgrade. For Jupiter, Raydium, Drift, Flash Trade, and other perpetual contract platforms, 150 milliseconds means user experience is infinitely close to that of centralized exchanges (CEX).
The more profound impact likely lies in the institutional sector. The upgrade also means that high-frequency market makers and arbitrage bots providing liquidity on-chain no longer need to widen spreads to hedge against the 6-second rollback risk.
With decreased settlement friction, professional market-making funds previously stationed in CEXs will inevitably be attracted to permanently reside on Solana, thereby bringing superior trading depth.
Liquid staking (LST) sector and Solana’s decentralization narrative
Benefit logic: Significant reduction in the break-even threshold for nodes. A 60% drop in node operating costs yields the most straightforward economic calculation.
In the past, a node needed to attract nearly 5,000 SOL in staked amounts to break even; now, this pass mark has been drastically lowered to the hundreds of SOL range.
Although the LSD/LST narrative is no longer the hot topic, the extremely low barrier to entry will greatly stimulate the participation of mid-to-small-sized validators. This not only reinforces the decentralized foundation of the Solana network but also provides broader node allocation strategies and profit margins for LST protocols like Jito and Sanctum. In the long run, this still counts as a positive development;
As for whether secondary capital will leverage this for speculation, that is beyond the scope of this article to answer.
High-frequency payments and cross-chain bridges
Benefit logic: Elimination of waiting anxiety and reduction of temporal exposure risk. Whether for daily high-frequency payments based on USDC or fund transfers via cross-chain bridges like Wormhole, a 150-millisecond confirmation speed will completely eliminate user waiting anxiety and drastically reduce the temporal exposure risk of cross-chain funds in transit.
Conclusion
In the crypto market, history proves that capital always flows to where friction is minimal.
When a public chain can reduce underlying settlement latency to a level imperceptible to retail traders and worry-free for market makers, while achieving highly cost-effective economic self-sufficiency at the foundational mechanism level, its financial capacity truly reaches its ceiling.
This Solana technical upgrade mainly serves to unlock theoretical ceilings. How it performs once fully deployed on the mainnet requires further observation; after all, cases of hyped TPS figures accompanied by mainnet outages have occurred before.
Technology primarily paves the road. As for when traffic will arrive, or if it will come at all, perhaps only the market can provide the answer.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Solana today launches its largest upgrade to date, Alpenglow: which ecosystem projects will benefit from 150-millisecond transaction confirmations?
Later today, the Solana mainnet will officially activate its largest and most hardcore consensus upgrade since its 2020 launch: Alpenglow.
Solana’s official social media channels are also announcing this upgrade, generating buzz through profile picture changes.
In a crypto market saturated with short-term sentiment and noise, underlying infrastructure upgrades are often overlooked. While the community has long lost its mystique surrounding TPS, consensus mechanisms, and technological iterations, this Alpenglow upgrade marks a significant qualitative shift that directly impacts the on-chain interaction experience for all participants and quietly reconstructs the fundamental economics of SOL.
For the SOL token itself, this upgrade brings little direct impact, but it provides a positive boost to the fundamentals of the entire ecosystem. If you are still following projects within the Solana ecosystem but haven’t delved into the specifics of this upgrade, this article is well worth reading.
Setting aside the cryptic client technical documentation, we need to examine this upgrade from two dimensions: mechanism principles and ecological implications, to see what exactly has changed and which asset categories will become the true beneficiaries.
Deconstructing Alpenglow: Everything Comes Down to Transaction Finality Speed
The core changes brought by this Alpenglow upgrade to the network ecosystem can be condensed into two points:
First, ultra-fast finality.
After the upgrade, transaction confirmation times on the Solana chain have been compressed from 6 seconds to 150 milliseconds. Under the old consensus mechanism, although Solana produces blocks incredibly fast, a transaction typically takes about 6 to 12 seconds to reach the state of “final irreversible confirmation (Finality).” For retail users, the most intuitive pain point is “Schrödinger’s execution”: after clicking Swap on a decentralized exchange, you’re always forced to stare at the screen during a few seconds of suspense, even worrying about potential network rollbacks.
Once Alpenglow is activated, Solana’s transaction finality time will be compressed to 150 milliseconds (and can even reach 100 milliseconds on the fast path). This means that future on-chain interactions, from click to complete settlement, will theoretically occur faster than a blink of an eye.
Second, a dramatic drop in node operating costs.
In the past, Solana validator nodes had to frequently send voting transactions on-chain to maintain network consensus, requiring continuous payment of high gas fees (consuming approximately 1 SOL per Epoch).
The new mechanism moves this massive voting action off-chain (using BLS signature aggregation), and changes the node’s voting cost to purchasing fixed-consumption “admission tickets” priced at 0.8 SOL, which are fully burned).
This underlying optimization directly reduces the daily operating costs for validator nodes by approximately 60%.
Who Are the True Beneficiaries of This Upgrade?
The implementation of Alpenglow may not become a short-term hype gimmick to instantly pump token prices, but it addresses Solana’s weaknesses in competing for mainstream institutional capital. Deduced from business logic, the following sectors are expected to receive substantial benefits in my view:
On-chain perpetual contracts and DEX aggregators (complete CEX-like experience)
Benefit logic: Elimination of finality risk and significant increase in capital turnover rate. This is the most direct business beneficiary of this upgrade. For Jupiter, Raydium, Drift, Flash Trade, and other perpetual contract platforms, 150 milliseconds means user experience is infinitely close to that of centralized exchanges (CEX).
The more profound impact likely lies in the institutional sector. The upgrade also means that high-frequency market makers and arbitrage bots providing liquidity on-chain no longer need to widen spreads to hedge against the 6-second rollback risk.
With decreased settlement friction, professional market-making funds previously stationed in CEXs will inevitably be attracted to permanently reside on Solana, thereby bringing superior trading depth.
Liquid staking (LST) sector and Solana’s decentralization narrative
Benefit logic: Significant reduction in the break-even threshold for nodes. A 60% drop in node operating costs yields the most straightforward economic calculation.
In the past, a node needed to attract nearly 5,000 SOL in staked amounts to break even; now, this pass mark has been drastically lowered to the hundreds of SOL range.
Although the LSD/LST narrative is no longer the hot topic, the extremely low barrier to entry will greatly stimulate the participation of mid-to-small-sized validators. This not only reinforces the decentralized foundation of the Solana network but also provides broader node allocation strategies and profit margins for LST protocols like Jito and Sanctum. In the long run, this still counts as a positive development;
As for whether secondary capital will leverage this for speculation, that is beyond the scope of this article to answer.
High-frequency payments and cross-chain bridges
Benefit logic: Elimination of waiting anxiety and reduction of temporal exposure risk. Whether for daily high-frequency payments based on USDC or fund transfers via cross-chain bridges like Wormhole, a 150-millisecond confirmation speed will completely eliminate user waiting anxiety and drastically reduce the temporal exposure risk of cross-chain funds in transit.
Conclusion
In the crypto market, history proves that capital always flows to where friction is minimal.
When a public chain can reduce underlying settlement latency to a level imperceptible to retail traders and worry-free for market makers, while achieving highly cost-effective economic self-sufficiency at the foundational mechanism level, its financial capacity truly reaches its ceiling.
This Solana technical upgrade mainly serves to unlock theoretical ceilings. How it performs once fully deployed on the mainnet requires further observation; after all, cases of hyped TPS figures accompanied by mainnet outages have occurred before.
Technology primarily paves the road. As for when traffic will arrive, or if it will come at all, perhaps only the market can provide the answer.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
11
·
--
記事
翻訳参照
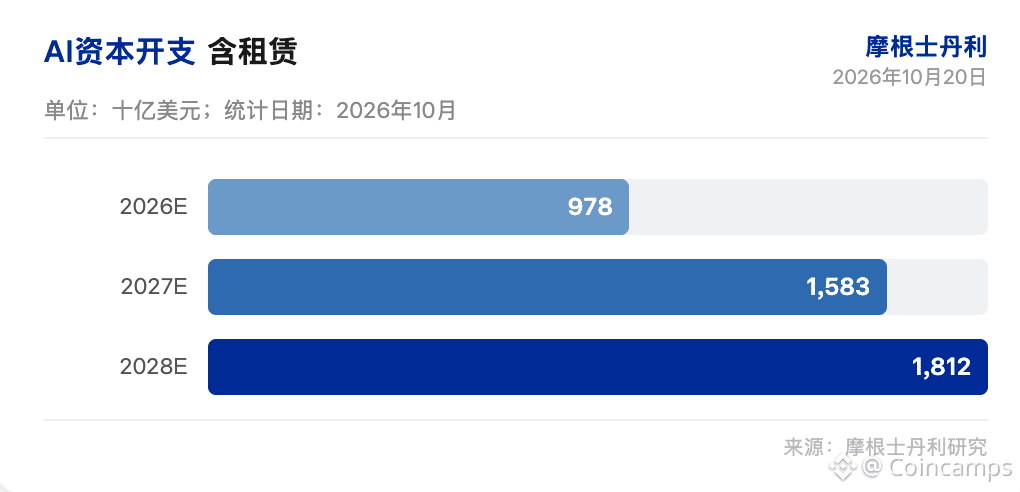
Morgan Stanley Research Analysis: $1.6 Trillion AI Capex, AI Accounts for a Quarter of S&P 500 Growth$1.6 trillion in capital expenditure corresponds to approximately 5% of S&P 500 revenue and 25% of revenue growth. In its October 20, 2026 report, Morgan Stanley summed up the cash and lease expenditures of hyperscalers and emerging cloud vendors, arriving at $1.58 trillion for 2027 and $1.81 trillion for 2028. The report projects that AI capex growth will decelerate from approximately 100% in 2026 to around 60% in 2027 and roughly 14% in 2028.
The market is concerned about the slowdown in 2028. Morgan Stanley's calculations show that S&P 500 revenue growth will reach 8.6% in 2027, remaining at 6.6% after excluding direct AI revenue. The report tracks approximately 65% of 2027 capex flowing to S&P 500 companies, with NVIDIA as the largest beneficiary.
Lease expenditure is a new variable added to this report. Hyperscalers have already disclosed over $1.1 trillion in lease commitments that have not yet commenced; these commitments do not fall under the capex line item on the cash flow statement. Morgan Stanley incorporates lease capex into cash capex, estimating the lease portion at $195 billion for 2027 and $246 billion for 2028.
Lease Expenditure is a New Variable
2027 cash capex stands at approximately $1.4 trillion, reaching $1.58 trillion when leases are included. 2028 cash capex is around $1.57 trillion, rising to $1.81 trillion with leases added. Lease expenditures amount to $195 billion in 2027 and $246 billion in 2028, primarily driven by Oracle, Microsoft, Meta, Amazon, and Google.
Uncommenced lease commitments reached $1.118 trillion in Q2 2026. These break down as follows: Oracle $288 billion, Microsoft $329 billion, Meta $279 billion, Amazon $137 billion, and Google $85 billion. Economically, these leases resemble debt-financed capex, bypassing GAAP cash flow statements. Morgan Stanley estimates them using three metrics: signed but uncommenced leases, annual incremental capacity, and the lease spend ratio per GW.
Capex growth is slowing. From approximately 100% in 2026, it drops to around 60% in 2027 and roughly 14% in 2028. However, the absolute scale continues to rise. Approximately $700 billion in incremental AI spend is added between 2026 and 2027. Morgan Stanley tracks that about 65% flows into the S&P 500.
AI Contributes One-Quarter of Revenue Growth
In 2027, customer revenue from hyperscalers and emerging cloud vendors accounts for 5% of total S&P 500 revenue, driving approximately 25% of year-over-year growth. S&P 500 revenue growth stands at 8.6%, remaining at 6.6% after stripping out direct AI revenue. Morgan Stanley believes S&P 500 broadening is underway, with growth remaining robust even without AI investment.
Of the $1.6 trillion in capex, approximately $1.0 trillion flows into S&P 500 revenue, with NVIDIA capturing about $690 billion. NVIDIA accounts for two-thirds of the S&P 500 absorption share, representing roughly 1.6% of the index's 2027 sales. The remaining $339 billion flows to other S&P 500 companies.
AI names in the S&P 500 see sales growth of 28% in 2027, compared to 5% for non-AI companies. Profit growth stands at 25% for AI firms and 4% for non-AI firms. AI names contribute 78% of the S&P 500's 2027 profit growth, accounting for 37% of the index's net income. The Magnificent 7 comprise 70% of AI cohort sales and 75% of their profits.
NVIDIA Captures Two-Thirds
NVIDIA generates approximately $690 billion in revenue from hyperscalers and emerging cloud vendors in 2027. Morgan Stanley estimates NVIDIA's share of hyperscaler capex: SPCX at roughly 79%, and AWS at about 29%. SPCX and AWS combined account for 54% of NVIDIA's hyperscaler revenue, while the remaining 46% comes from Microsoft, Oracle, Meta, and Google.
NVIDIA's data center revenue reaches $630.9 billion in 2027, with the hyperscaler segment contributing $337.5 billion, or 53.5%. Morgan Stanley believes NVIDIA trades at 15x FY28 EPS, making it reasonably valued; stock price appreciation can be driven by earnings growth even without multiple expansion.
Other beneficiaries include Broadcom, AMD, Micron, Samsung, and SK Hynix. AI chips, memory, networking, and ODMs capture the bulk of capex. Exposure to data centers for industrial goods and power suppliers is increasing.
A 2028 Slowdown Does Not Signal a Peak
With capex growth at 14% in 2028, the market fears AI investment may be peaking. Morgan Stanley views 2027 as a pivotal year for adopters, as AI productivity opportunities expand for both enterprises and individuals. Forward margin expectations improve most noticeably for companies with strong AI adoption and high pricing power.
The risk lies in power bottlenecks. Morgan Stanley's $1.6 trillion 2027 capex assumption assumes every ordered chip can be powered and run. Their Powering AI model indicates that after accounting for time-to-power solutions, the U.S. still faces a net shortfall of 32GW by 2028 and approximately 72GW by 2029. If commissioned capacity fails to keep pace with chip deliveries, the capex risk becomes a timing mismatch.
Memory, networking, optical modules, and ODM servers are most sensitive to the power wall. Power solution providers are relative beneficiaries. Capex may shift overseas, as power constraints in the U.S. drive hyperscalers to build facilities abroad.
Leadership among AI names shifts from pure enablers to mixed enabler/adopters and adopters. S&P 500 sales growth hits 9% in 2027, or approximately 7% excluding AI investment, which still aligns with nominal GDP and historical sales growth regression. AI spending incrementally drives growth, and index broadening has fully unfolded.
Whether the 2028 slowdown will be amplified by power bottlenecks is the key variable to watch next.
Disclaimer
This article is a compilation and interpretation by TechFlow Research of a third-party broker research report (Morgan Stanley, October 20, 2026), combined with publicly available market information. The ratings, target prices, earnings forecasts, and related judgments cited herein reflect the views of that broker's analysts, representing only the stance of their respective institutions, and do not represent the views of TechFlow Research nor constitute any investment advice.
Markets carry risks, and decisions must be independent. This article should not serve as the basis for trading any securities.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Morgan Stanley Research Analysis: $1.6 Trillion AI Capex, AI Accounts for a Quarter of S&P 500 Growth
$1.6 trillion in capital expenditure corresponds to approximately 5% of S&P 500 revenue and 25% of revenue growth. In its October 20, 2026 report, Morgan Stanley summed up the cash and lease expenditures of hyperscalers and emerging cloud vendors, arriving at $1.58 trillion for 2027 and $1.81 trillion for 2028. The report projects that AI capex growth will decelerate from approximately 100% in 2026 to around 60% in 2027 and roughly 14% in 2028.
The market is concerned about the slowdown in 2028. Morgan Stanley's calculations show that S&P 500 revenue growth will reach 8.6% in 2027, remaining at 6.6% after excluding direct AI revenue. The report tracks approximately 65% of 2027 capex flowing to S&P 500 companies, with NVIDIA as the largest beneficiary.
Lease expenditure is a new variable added to this report. Hyperscalers have already disclosed over $1.1 trillion in lease commitments that have not yet commenced; these commitments do not fall under the capex line item on the cash flow statement. Morgan Stanley incorporates lease capex into cash capex, estimating the lease portion at $195 billion for 2027 and $246 billion for 2028.
Lease Expenditure is a New Variable
2027 cash capex stands at approximately $1.4 trillion, reaching $1.58 trillion when leases are included. 2028 cash capex is around $1.57 trillion, rising to $1.81 trillion with leases added. Lease expenditures amount to $195 billion in 2027 and $246 billion in 2028, primarily driven by Oracle, Microsoft, Meta, Amazon, and Google.
Uncommenced lease commitments reached $1.118 trillion in Q2 2026. These break down as follows: Oracle $288 billion, Microsoft $329 billion, Meta $279 billion, Amazon $137 billion, and Google $85 billion. Economically, these leases resemble debt-financed capex, bypassing GAAP cash flow statements. Morgan Stanley estimates them using three metrics: signed but uncommenced leases, annual incremental capacity, and the lease spend ratio per GW.
Capex growth is slowing. From approximately 100% in 2026, it drops to around 60% in 2027 and roughly 14% in 2028. However, the absolute scale continues to rise. Approximately $700 billion in incremental AI spend is added between 2026 and 2027. Morgan Stanley tracks that about 65% flows into the S&P 500.
AI Contributes One-Quarter of Revenue Growth
In 2027, customer revenue from hyperscalers and emerging cloud vendors accounts for 5% of total S&P 500 revenue, driving approximately 25% of year-over-year growth. S&P 500 revenue growth stands at 8.6%, remaining at 6.6% after stripping out direct AI revenue. Morgan Stanley believes S&P 500 broadening is underway, with growth remaining robust even without AI investment.
Of the $1.6 trillion in capex, approximately $1.0 trillion flows into S&P 500 revenue, with NVIDIA capturing about $690 billion. NVIDIA accounts for two-thirds of the S&P 500 absorption share, representing roughly 1.6% of the index's 2027 sales. The remaining $339 billion flows to other S&P 500 companies.
AI names in the S&P 500 see sales growth of 28% in 2027, compared to 5% for non-AI companies. Profit growth stands at 25% for AI firms and 4% for non-AI firms. AI names contribute 78% of the S&P 500's 2027 profit growth, accounting for 37% of the index's net income. The Magnificent 7 comprise 70% of AI cohort sales and 75% of their profits.
NVIDIA Captures Two-Thirds
NVIDIA generates approximately $690 billion in revenue from hyperscalers and emerging cloud vendors in 2027. Morgan Stanley estimates NVIDIA's share of hyperscaler capex: SPCX at roughly 79%, and AWS at about 29%. SPCX and AWS combined account for 54% of NVIDIA's hyperscaler revenue, while the remaining 46% comes from Microsoft, Oracle, Meta, and Google.
NVIDIA's data center revenue reaches $630.9 billion in 2027, with the hyperscaler segment contributing $337.5 billion, or 53.5%. Morgan Stanley believes NVIDIA trades at 15x FY28 EPS, making it reasonably valued; stock price appreciation can be driven by earnings growth even without multiple expansion.
Other beneficiaries include Broadcom, AMD, Micron, Samsung, and SK Hynix. AI chips, memory, networking, and ODMs capture the bulk of capex. Exposure to data centers for industrial goods and power suppliers is increasing.
A 2028 Slowdown Does Not Signal a Peak
With capex growth at 14% in 2028, the market fears AI investment may be peaking. Morgan Stanley views 2027 as a pivotal year for adopters, as AI productivity opportunities expand for both enterprises and individuals. Forward margin expectations improve most noticeably for companies with strong AI adoption and high pricing power.
The risk lies in power bottlenecks. Morgan Stanley's $1.6 trillion 2027 capex assumption assumes every ordered chip can be powered and run. Their Powering AI model indicates that after accounting for time-to-power solutions, the U.S. still faces a net shortfall of 32GW by 2028 and approximately 72GW by 2029. If commissioned capacity fails to keep pace with chip deliveries, the capex risk becomes a timing mismatch.
Memory, networking, optical modules, and ODM servers are most sensitive to the power wall. Power solution providers are relative beneficiaries. Capex may shift overseas, as power constraints in the U.S. drive hyperscalers to build facilities abroad.
Leadership among AI names shifts from pure enablers to mixed enabler/adopters and adopters. S&P 500 sales growth hits 9% in 2027, or approximately 7% excluding AI investment, which still aligns with nominal GDP and historical sales growth regression. AI spending incrementally drives growth, and index broadening has fully unfolded.
Whether the 2028 slowdown will be amplified by power bottlenecks is the key variable to watch next.
Disclaimer
This article is a compilation and interpretation by TechFlow Research of a third-party broker research report (Morgan Stanley, October 20, 2026), combined with publicly available market information. The ratings, target prices, earnings forecasts, and related judgments cited herein reflect the views of that broker's analysts, representing only the stance of their respective institutions, and do not represent the views of TechFlow Research nor constitute any investment advice.
Markets carry risks, and decisions must be independent. This article should not serve as the basis for trading any securities.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
321
·
--
記事
翻訳参照
Why Doesn't Papertrade Allow Token Trading? Deconstructing the Fatal Loophole of Shorting Its Own CasinoTechFlow Editorial: On Monday, the team behind this perpetual contract exchange, which offers up to 1000x ultra-high leverage in the Hyperliquid ecosystem, made it clear that there are no plans in the short term to allow PAPER to exit its staking contracts: “At this stage, we have no plans to allow free transfer and circulation of tokens outside the contract.”
This marks a complete reversal from the roadmap initially promised to the community. Earlier this month, when we previewed the launch of Papertrade, official planning clearly stated that PAPER would eventually be allowed for free transfer; and in an official announcement on October 1, the team firmly declared that the token transfer feature would be officially activated “after sufficient time has passed.”
Now, this activation plan has been indefinitely shelved for the foreseeable future. Hit directly by this development, several trading platforms such as Aster and Paragon, which had previously rushed to list PAPER pre-market perpetual contracts, have urgently delisted them. Understandably, those airdrop farmers who deliberately lost real money in trades to “farm tokens” earlier are now furious.
However, no matter how strongly the community reacts negatively to this “breach of promise,” the underlying economic logic behind the team’s decision ruthlessly reveals the most fatal native flaw of these emerging “House Pool” exchanges: when a token essentially serves as a claim on ownership of the casino, shorting that token is equivalent to betting on the casino’s bankruptcy; and the huge profits from this external shorting can directly fund a malicious attack designed to drain the casino.
A Difficult Choice: From Promising Circulability to Indefinite Lockdown
For readers unfamiliar with this mechanism, let’s quickly review the background: on the Papertrade platform, the exchange itself acts as the counterparty to all users through a unified, shared USDC pool, whose funding source relies entirely on traders’ actual liquidations and losses.
When you lose money in a trade, the system mints a corresponding amount of PAPER tokens for you; and by staking these PAPER tokens, you can receive a pro-rata share of the protocol’s collected USDC fees, as well as the abundant profits that spill over once the pool exceeds its size cap. As we analyzed back in May: here, losing gamblers gradually become new shareholders of the casino.
However, the technical adjustments announced this Monday completely rewrote the rules of the game:
• Locking Token Circulation: PAPER can still be freely staked and unstaked, but absolutely cannot be sent to other external wallet addresses, nor freely sold off on secondary markets, and the team currently has no plans to lift the restrictions;
• Dilution and Sharp Reduction in Incentives: Under the future mechanism, for every $1 million loss incurred by traders, only approximately 0.1% of PAPER’s total supply at that time will be minted, tilting new token issuance toward new users and continuously diluting early holders’ shares. Meanwhile, loss incentives have shrunk drastically: when the platform first launched, users could earn up to 100 PAPER tokens for every $1 lost; now that number has plummeted to around 10. The only exception occurs during critical moments when the pool nears depletion: the system triggers additional reward mechanisms to attract more losing trades into the market to bail it out. The team vividly describes this mechanism as “the casino auctioning off its future cash flow at a discount.”
These key parameter modifications have been submitted to the timelock queue and will go live 24 hours after completing final security audit verification. So why did the team make such a drastic move at this critical juncture?
The trigger was precisely the external derivatives market mentioned earlier. Platform Paragon rushed to list PAPER perpetual contracts just 8 days after Papertrade’s initial launch, on October 18, followed closely by Aster on Monday morning. As co-founder Jez later admitted, “I severely underestimated the external market’s frenzied demand for pre-market perpetual contracts.”
Tradable Tokens Turn Into Lethal Attack Weapons
PAPER’s revenue comes entirely from the casino’s actual take, so its intrinsic value is tightly bound to the health of the underlying pool. If someone drains the liquidity pool or causes winning traders to get stuck in the withdrawal queue (i.e., unpaid profits queuing up while waiting for new losing funds to cover them), PAPER’s market valuation will instantly drop to zero.
This is where the most fatal security vulnerability lies. Papertrade’s matching mechanism directly anchors to Hyperliquid’s mid-price (the median between the highest bid and lowest ask). This means that if an attacker can push up or crash quotes on Hyperliquid within an extremely short timeframe, they can simultaneously shake Papertrade’s settlement benchmark.
A real warning occurred on the night the platform launched: according to The Block, a mysterious wallet merely nudged Ethereum’s price slightly upward by about 0.12% on Hyperliquid, then pocketed approximately $1.28 million in net profit and exited on Papertrade. Although Papertrade officials later stated that the trader subsequently lost most of those profits through other new accounts, the extreme danger of this attack vector has been laid bare.
The team has been quite candid about this vulnerability. In a technical note released on October 11, they frankly wrote: “Price manipulation attacks are technically always feasible; the only question is whether launching such an attack makes economic sense.”
Under normal conditions, the default way to prevent attacks is to ensure the attacker finds no positive mathematical expectation. The core defense lies in strictly capping the total size of the house pool: the smaller the pot, the lower the maximum amount an attacker can plunder. However, once external exchanges list freely tradable and shortable PAPER contracts, the entire game-theory mathematical model is completely overturned.
Let’s look at the team’s own calculations: assume the pool’s current base capital is $10 million. To manipulate BTC or ETH prices in the spot or main market to completely drain this $10 million pool, an attacker would need to absorb roughly $15 million in liquidity slippage and trading friction. Under a single-legged play, this attack is obviously unprofitable, summarized by the team in one sentence: “purely spending your own money to run a loss-making business.”
But suppose this attacker, while executing the manipulation, simultaneously opens a $10 million PAPER perpetual short position on an external exchange. At that moment, when he successfully drains the internal pool and triggers a solvency crisis, PAPER’s valuation instantly collapses; the massive profits harvested from his external short position not only completely cover the $15 million cost of market manipulation, but also yield substantial net profit. In an instant, what was originally a loss-inducing suicide mission transforms into a “highly economically viable” risk-free ATM.
In the words of Papertrade’s official statements, once a token can be freely shorted externally, perpetual contracts targeting that token are directly mutated into “leveraged shorting poison pills aimed at the house’s solvency.”
More problematically, these lethal shorting derivatives are scattered across various exchanges controlled by third parties, giving Papertrade absolutely no power to intervene. It can cap its own pool limits, but cannot stop Paragon, Aster, or any other platform from independently listing PAPER contracts. The platform’s only passive defense is left to severely compress its maximum single-position size limit. This means that for every new PAPER trading pair added externally, Papertrade’s own business ceiling gets dragged down a notch.
When backed to the brink, facing a life-or-death choice between “having a freely circulating token” or “having an exchange capable of healthy expansion,” the team unhesitatingly chose to save the exchange itself.
Ironically, this fatal blind spot was completely overlooked even in the most authoritative stress test before the project went live. Back in August, security firm Sumcap fed nearly 3.6 million real historical trades from Hyperliquid into Papertrade’s underlying architecture, comprehensively replaying them across more than 600 rigorous extreme scenarios. The results showed that the pool maintained 100% solvency under all tested conditions. However, the model carried a fatal prerequisite assumption: it completely excluded PAPER’s external secondary market price from the simulation, whereas the true lethal threat lurks precisely in that external price.
Analyzing the Status Quo: Holders' Rights and Yield Collapse
So, what exactly do current PAPER holders hold in their hands? Simply put, you possess a voucher that allows continuous receipt of the protocol’s USDC profit dividends, but this voucher itself can never be liquidated on secondary markets. As co-founder Jez explained, “You’re best off understanding PAPER as an internal profit-sharing right (Revenue Share) within the exchange, rather than a traditional cryptocurrency token.”
Undeniably, since its official launch on October 10, Papertrade’s cumulative dividend amounts have indeed been impressive. Data monitored by DefiLlama shows that to date, the protocol has distributed approximately $58 million in real USDC dividends to PAPER holders. However, this cash flow surge has recently cooled off precipitously: daily dividends dropped from a peak of around $6.7 million on October 15 to a daily average of about $1.5 million between October 17 and 19.
Meanwhile, the economic ledger for newly entering losers is becoming increasingly brutal.
Based on recent dividend levels of approximately $0.00017 per token daily, the 10 PAPER tokens exchanged for every $1 lost by a trader yield only a meager $0.002 in daily dividends. This means users must wait nearly 600 days (about 1.6 years) to barely break even on their lost $1 principal solely through dividends. In reality, even the earliest entrants—the largest early-volume-farming whales—have mostly failed to recoup their costs yet. Monitoring by on-chain analytics firm Lookonchain indicates that among the top 25 largest losers network-wide, a full 21 still show a net negative account balance even after factoring in staking dividends.
Furthermore, the final pricing offered by the secondary market for PAPER before delisting clearly confirms the collapse of market confidence. Platform Paragon set its settlement price at $0.026 when liquidating its perpetual contracts, corresponding to a total supply of roughly 8.85 billion PAPER tokens at the time, yielding an implied valuation of only about $230 million. If the recent daily dividend rhythm of $1.5 million could miraculously persist for a full year, stakers would cumulatively collect about $560 million, more than double that valuation. Such a massive valuation discount clearly signals that market traders fundamentally do not believe such high-intensity dividends can sustain long-term.
The Papertrade team fully understands this stark reality. In Monday’s announcement, the official stance framed this underlying architectural restructuring as returning PAPER to its roots: “Aligning it more closely with its original design intent: serving as a transaction volume rebate (Rakeback) for the exchange—that is, returning part of the house’s taken profits back to the genuine players who inject fuel into the casino.”
In other words, PAPER is rapidly shedding its characteristics as an investment-grade financial asset, evolving into a “loss reimbursement voucher” redeemed at an extremely slow pace in installments.
Soul-Searching Questions: Who Will Continue to Act as Loss Fuel?
• Who would willingly continue to lose money?: Every cent flowing to stakers has only one source: traders’ liquidation losses. Previously, many farmers dared to deliberately lose money under 1000x leverage purely because they bet on PAPER eventually being freely circulateable and cashing out at high prices on secondary markets. Now that the liquidity escape route has been completely cut off, volume-farming mining has turned into a grueling ordeal lasting 600 days with yields that could degrade at any time. Once this wave of speculative volume-farmers fully withdraws, the protocol will be left counting only on native retail gamblers who voluntarily participate in the game purely for the extreme thrill of 1000x leverage. This is Papertrade’s most authentic business foundation, and we are about to see exactly how large this base truly is.
• Can external shorting forces really be completely eliminated?: To some extent, it can indeed achieve a blocking effect. Paragon’s pre-market perpetual contracts operate entirely on the expectation that the token will eventually have a spot price and undergo basis convergence; once the spot anchor disappears, derivatives become water without a source, forcing exchanges to proactively close the market. However, hidden “side doors” remain. For example, PaperDAO traded on Uniswap (token symbol PULP) is essentially a decentralized vault holding substantial PAPER staking positions; although its whitepaper claims redemption is only possible “after Papertrade opens transfers,” the emergence of such tokenized wrapped vouchers proves that external capital’s impulse to seek short exposure can never be completely sealed shut.
• Can betting-style exchanges have freely circulating native tokens?: For comparison, Jupiter’s ultra-high leverage product YOLO, launched on October 15, uses the exact same house-betting algorithm, but they brilliantly abandoned native tokens from day one. YOLO’s house pool is directly funded by losers’ capital and is physically isolated from Jupiter’s core JLP pool, leaving no target in the market that can be shorted. In contrast, similar competitor Cardboard in the Solana ecosystem, which also offers 1000x leverage, took a path identical to Papertrade: for every $1 users lose, 100 CARDBOARD tokens are minted, and the token is similarly strictly restricted from transfer. Data from Pine Analytics shows that between October 15 and 19, Cardboard recorded open interest nominal principal of up to $4.48 billion, a significant proportion of which consists of suspected hedging farming wash-trade transactions. With the Papertrade case leading the way, Cardboard’s farmers are forced to reassess the massive risks of their locked tokens.
• Is this lockdown permanent?: The phrasing “at this stage” in the announcement obviously leaves room for future variables. Papertrade acknowledges that the security of its system is entirely dependent on the depth of Hyperliquid’s price feeds, and they are betting that liquidity on Hyperliquid’s underlying order book will expand exponentially. Because the deeper the depth, the higher the cost to manipulate spot prices; only when manipulation costs become so high that external short profits can never cover them does theoretically restoring PAPER to free circulation become safe. Additionally, introducing a delayed oracle feed mechanism like YOLO’s is another effective path to avoid real-time spike manipulation. But until these prerequisites are fully mature, PAPER will likely remain tightly locked within staking contracts.
Macro Perspective: Common Exam Questions for Betting-Style Exchange Tracks
Without a doubt, Papertrade’s emergency pivot has cost the team enormous reputation and community trust. Those early believers who absorbed losses to chase liquidity premiums are now forced to accept an unliquidatable, continually diluted ultra-long-term cash flow, which starkly contradicts the psychological contract they initially signed.
However, from a purely systemic architecture and financial engineering perspective, I believe the team made a completely defensible, and arguably correct, decision to save the platform from sudden collapse. The ultimate duty of a pool is to pay out profits to compliant winning traders on schedule; if the existence of a native token instead gives attackers a risk-free arbitrage model to plunder the pool via shorting, then not only will stakers lose everything, but all normal users participating in trading on the platform will be placed at immense risk of a systemic solvency crisis.
The implications of this incident for the entire on-chain derivatives sector are profound: in all decentralized exchanges adopting a “house-betting pool” architecture, the token itself represents the casino’s total net assets; allowing the casino’s equity to be freely shorted without barriers or high leverage in external financial markets is tantamount to directly gifting a hedging tool to malicious predators. It is foreseeable that any future project attempting to replicate this model must confront this insurmountable institutional chasm.
In this game of wagers, the iron rule that “the house always wins” still holds, but Papertrade’s self-rescue also proves that collapsing the house in a decentralized jungle is far more complex than ordinary people imagine. This epic struggle revolving around liquidity, tokenization, and attack costs is destined to see even more dramatic chapters unfold.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Why Doesn't Papertrade Allow Token Trading? Deconstructing the Fatal Loophole of Shorting Its Own Casino
TechFlow Editorial: On Monday, the team behind this perpetual contract exchange, which offers up to 1000x ultra-high leverage in the Hyperliquid ecosystem, made it clear that there are no plans in the short term to allow PAPER to exit its staking contracts: “At this stage, we have no plans to allow free transfer and circulation of tokens outside the contract.”
This marks a complete reversal from the roadmap initially promised to the community. Earlier this month, when we previewed the launch of Papertrade, official planning clearly stated that PAPER would eventually be allowed for free transfer; and in an official announcement on October 1, the team firmly declared that the token transfer feature would be officially activated “after sufficient time has passed.”
Now, this activation plan has been indefinitely shelved for the foreseeable future. Hit directly by this development, several trading platforms such as Aster and Paragon, which had previously rushed to list PAPER pre-market perpetual contracts, have urgently delisted them. Understandably, those airdrop farmers who deliberately lost real money in trades to “farm tokens” earlier are now furious.
However, no matter how strongly the community reacts negatively to this “breach of promise,” the underlying economic logic behind the team’s decision ruthlessly reveals the most fatal native flaw of these emerging “House Pool” exchanges: when a token essentially serves as a claim on ownership of the casino, shorting that token is equivalent to betting on the casino’s bankruptcy; and the huge profits from this external shorting can directly fund a malicious attack designed to drain the casino.
A Difficult Choice: From Promising Circulability to Indefinite Lockdown
For readers unfamiliar with this mechanism, let’s quickly review the background: on the Papertrade platform, the exchange itself acts as the counterparty to all users through a unified, shared USDC pool, whose funding source relies entirely on traders’ actual liquidations and losses.
When you lose money in a trade, the system mints a corresponding amount of PAPER tokens for you; and by staking these PAPER tokens, you can receive a pro-rata share of the protocol’s collected USDC fees, as well as the abundant profits that spill over once the pool exceeds its size cap. As we analyzed back in May: here, losing gamblers gradually become new shareholders of the casino.
However, the technical adjustments announced this Monday completely rewrote the rules of the game:
• Locking Token Circulation: PAPER can still be freely staked and unstaked, but absolutely cannot be sent to other external wallet addresses, nor freely sold off on secondary markets, and the team currently has no plans to lift the restrictions;
• Dilution and Sharp Reduction in Incentives: Under the future mechanism, for every $1 million loss incurred by traders, only approximately 0.1% of PAPER’s total supply at that time will be minted, tilting new token issuance toward new users and continuously diluting early holders’ shares. Meanwhile, loss incentives have shrunk drastically: when the platform first launched, users could earn up to 100 PAPER tokens for every $1 lost; now that number has plummeted to around 10. The only exception occurs during critical moments when the pool nears depletion: the system triggers additional reward mechanisms to attract more losing trades into the market to bail it out. The team vividly describes this mechanism as “the casino auctioning off its future cash flow at a discount.”
These key parameter modifications have been submitted to the timelock queue and will go live 24 hours after completing final security audit verification. So why did the team make such a drastic move at this critical juncture?
The trigger was precisely the external derivatives market mentioned earlier. Platform Paragon rushed to list PAPER perpetual contracts just 8 days after Papertrade’s initial launch, on October 18, followed closely by Aster on Monday morning. As co-founder Jez later admitted, “I severely underestimated the external market’s frenzied demand for pre-market perpetual contracts.”
Tradable Tokens Turn Into Lethal Attack Weapons
PAPER’s revenue comes entirely from the casino’s actual take, so its intrinsic value is tightly bound to the health of the underlying pool. If someone drains the liquidity pool or causes winning traders to get stuck in the withdrawal queue (i.e., unpaid profits queuing up while waiting for new losing funds to cover them), PAPER’s market valuation will instantly drop to zero.
This is where the most fatal security vulnerability lies. Papertrade’s matching mechanism directly anchors to Hyperliquid’s mid-price (the median between the highest bid and lowest ask). This means that if an attacker can push up or crash quotes on Hyperliquid within an extremely short timeframe, they can simultaneously shake Papertrade’s settlement benchmark.
A real warning occurred on the night the platform launched: according to The Block, a mysterious wallet merely nudged Ethereum’s price slightly upward by about 0.12% on Hyperliquid, then pocketed approximately $1.28 million in net profit and exited on Papertrade. Although Papertrade officials later stated that the trader subsequently lost most of those profits through other new accounts, the extreme danger of this attack vector has been laid bare.
The team has been quite candid about this vulnerability. In a technical note released on October 11, they frankly wrote: “Price manipulation attacks are technically always feasible; the only question is whether launching such an attack makes economic sense.”
Under normal conditions, the default way to prevent attacks is to ensure the attacker finds no positive mathematical expectation. The core defense lies in strictly capping the total size of the house pool: the smaller the pot, the lower the maximum amount an attacker can plunder. However, once external exchanges list freely tradable and shortable PAPER contracts, the entire game-theory mathematical model is completely overturned.
Let’s look at the team’s own calculations: assume the pool’s current base capital is $10 million. To manipulate BTC or ETH prices in the spot or main market to completely drain this $10 million pool, an attacker would need to absorb roughly $15 million in liquidity slippage and trading friction. Under a single-legged play, this attack is obviously unprofitable, summarized by the team in one sentence: “purely spending your own money to run a loss-making business.”
But suppose this attacker, while executing the manipulation, simultaneously opens a $10 million PAPER perpetual short position on an external exchange. At that moment, when he successfully drains the internal pool and triggers a solvency crisis, PAPER’s valuation instantly collapses; the massive profits harvested from his external short position not only completely cover the $15 million cost of market manipulation, but also yield substantial net profit. In an instant, what was originally a loss-inducing suicide mission transforms into a “highly economically viable” risk-free ATM.
In the words of Papertrade’s official statements, once a token can be freely shorted externally, perpetual contracts targeting that token are directly mutated into “leveraged shorting poison pills aimed at the house’s solvency.”
More problematically, these lethal shorting derivatives are scattered across various exchanges controlled by third parties, giving Papertrade absolutely no power to intervene. It can cap its own pool limits, but cannot stop Paragon, Aster, or any other platform from independently listing PAPER contracts. The platform’s only passive defense is left to severely compress its maximum single-position size limit. This means that for every new PAPER trading pair added externally, Papertrade’s own business ceiling gets dragged down a notch.
When backed to the brink, facing a life-or-death choice between “having a freely circulating token” or “having an exchange capable of healthy expansion,” the team unhesitatingly chose to save the exchange itself.
Ironically, this fatal blind spot was completely overlooked even in the most authoritative stress test before the project went live. Back in August, security firm Sumcap fed nearly 3.6 million real historical trades from Hyperliquid into Papertrade’s underlying architecture, comprehensively replaying them across more than 600 rigorous extreme scenarios. The results showed that the pool maintained 100% solvency under all tested conditions. However, the model carried a fatal prerequisite assumption: it completely excluded PAPER’s external secondary market price from the simulation, whereas the true lethal threat lurks precisely in that external price.
Analyzing the Status Quo: Holders' Rights and Yield Collapse
So, what exactly do current PAPER holders hold in their hands? Simply put, you possess a voucher that allows continuous receipt of the protocol’s USDC profit dividends, but this voucher itself can never be liquidated on secondary markets. As co-founder Jez explained, “You’re best off understanding PAPER as an internal profit-sharing right (Revenue Share) within the exchange, rather than a traditional cryptocurrency token.”
Undeniably, since its official launch on October 10, Papertrade’s cumulative dividend amounts have indeed been impressive. Data monitored by DefiLlama shows that to date, the protocol has distributed approximately $58 million in real USDC dividends to PAPER holders. However, this cash flow surge has recently cooled off precipitously: daily dividends dropped from a peak of around $6.7 million on October 15 to a daily average of about $1.5 million between October 17 and 19.
Meanwhile, the economic ledger for newly entering losers is becoming increasingly brutal.
Based on recent dividend levels of approximately $0.00017 per token daily, the 10 PAPER tokens exchanged for every $1 lost by a trader yield only a meager $0.002 in daily dividends. This means users must wait nearly 600 days (about 1.6 years) to barely break even on their lost $1 principal solely through dividends. In reality, even the earliest entrants—the largest early-volume-farming whales—have mostly failed to recoup their costs yet. Monitoring by on-chain analytics firm Lookonchain indicates that among the top 25 largest losers network-wide, a full 21 still show a net negative account balance even after factoring in staking dividends.
Furthermore, the final pricing offered by the secondary market for PAPER before delisting clearly confirms the collapse of market confidence. Platform Paragon set its settlement price at $0.026 when liquidating its perpetual contracts, corresponding to a total supply of roughly 8.85 billion PAPER tokens at the time, yielding an implied valuation of only about $230 million. If the recent daily dividend rhythm of $1.5 million could miraculously persist for a full year, stakers would cumulatively collect about $560 million, more than double that valuation. Such a massive valuation discount clearly signals that market traders fundamentally do not believe such high-intensity dividends can sustain long-term.
The Papertrade team fully understands this stark reality. In Monday’s announcement, the official stance framed this underlying architectural restructuring as returning PAPER to its roots: “Aligning it more closely with its original design intent: serving as a transaction volume rebate (Rakeback) for the exchange—that is, returning part of the house’s taken profits back to the genuine players who inject fuel into the casino.”
In other words, PAPER is rapidly shedding its characteristics as an investment-grade financial asset, evolving into a “loss reimbursement voucher” redeemed at an extremely slow pace in installments.
Soul-Searching Questions: Who Will Continue to Act as Loss Fuel?
• Who would willingly continue to lose money?: Every cent flowing to stakers has only one source: traders’ liquidation losses. Previously, many farmers dared to deliberately lose money under 1000x leverage purely because they bet on PAPER eventually being freely circulateable and cashing out at high prices on secondary markets. Now that the liquidity escape route has been completely cut off, volume-farming mining has turned into a grueling ordeal lasting 600 days with yields that could degrade at any time. Once this wave of speculative volume-farmers fully withdraws, the protocol will be left counting only on native retail gamblers who voluntarily participate in the game purely for the extreme thrill of 1000x leverage. This is Papertrade’s most authentic business foundation, and we are about to see exactly how large this base truly is.
• Can external shorting forces really be completely eliminated?: To some extent, it can indeed achieve a blocking effect. Paragon’s pre-market perpetual contracts operate entirely on the expectation that the token will eventually have a spot price and undergo basis convergence; once the spot anchor disappears, derivatives become water without a source, forcing exchanges to proactively close the market. However, hidden “side doors” remain. For example, PaperDAO traded on Uniswap (token symbol PULP) is essentially a decentralized vault holding substantial PAPER staking positions; although its whitepaper claims redemption is only possible “after Papertrade opens transfers,” the emergence of such tokenized wrapped vouchers proves that external capital’s impulse to seek short exposure can never be completely sealed shut.
• Can betting-style exchanges have freely circulating native tokens?: For comparison, Jupiter’s ultra-high leverage product YOLO, launched on October 15, uses the exact same house-betting algorithm, but they brilliantly abandoned native tokens from day one. YOLO’s house pool is directly funded by losers’ capital and is physically isolated from Jupiter’s core JLP pool, leaving no target in the market that can be shorted. In contrast, similar competitor Cardboard in the Solana ecosystem, which also offers 1000x leverage, took a path identical to Papertrade: for every $1 users lose, 100 CARDBOARD tokens are minted, and the token is similarly strictly restricted from transfer. Data from Pine Analytics shows that between October 15 and 19, Cardboard recorded open interest nominal principal of up to $4.48 billion, a significant proportion of which consists of suspected hedging farming wash-trade transactions. With the Papertrade case leading the way, Cardboard’s farmers are forced to reassess the massive risks of their locked tokens.
• Is this lockdown permanent?: The phrasing “at this stage” in the announcement obviously leaves room for future variables. Papertrade acknowledges that the security of its system is entirely dependent on the depth of Hyperliquid’s price feeds, and they are betting that liquidity on Hyperliquid’s underlying order book will expand exponentially. Because the deeper the depth, the higher the cost to manipulate spot prices; only when manipulation costs become so high that external short profits can never cover them does theoretically restoring PAPER to free circulation become safe. Additionally, introducing a delayed oracle feed mechanism like YOLO’s is another effective path to avoid real-time spike manipulation. But until these prerequisites are fully mature, PAPER will likely remain tightly locked within staking contracts.
Macro Perspective: Common Exam Questions for Betting-Style Exchange Tracks
Without a doubt, Papertrade’s emergency pivot has cost the team enormous reputation and community trust. Those early believers who absorbed losses to chase liquidity premiums are now forced to accept an unliquidatable, continually diluted ultra-long-term cash flow, which starkly contradicts the psychological contract they initially signed.
However, from a purely systemic architecture and financial engineering perspective, I believe the team made a completely defensible, and arguably correct, decision to save the platform from sudden collapse. The ultimate duty of a pool is to pay out profits to compliant winning traders on schedule; if the existence of a native token instead gives attackers a risk-free arbitrage model to plunder the pool via shorting, then not only will stakers lose everything, but all normal users participating in trading on the platform will be placed at immense risk of a systemic solvency crisis.
The implications of this incident for the entire on-chain derivatives sector are profound: in all decentralized exchanges adopting a “house-betting pool” architecture, the token itself represents the casino’s total net assets; allowing the casino’s equity to be freely shorted without barriers or high leverage in external financial markets is tantamount to directly gifting a hedging tool to malicious predators. It is foreseeable that any future project attempting to replicate this model must confront this insurmountable institutional chasm.
In this game of wagers, the iron rule that “the house always wins” still holds, but Papertrade’s self-rescue also proves that collapsing the house in a decentralized jungle is far more complex than ordinary people imagine. This epic struggle revolving around liquidity, tokenization, and attack costs is destined to see even more dramatic chapters unfold.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
1
·
--
翻訳参照
Polymarket founder faces controversy over misuse of funds, Dragonfly's Haseeb speaks out to clarifyOn October 21, 2026, according to a public statement released by Dragonfly Managing Partner Haseeb Qureshi, the allegations regarding prediction market leader Polymarket founder and CEO Shayne Coplan allegedly misappropriating company funds to pay for personal expenses such as a private jet are entirely baseless smears.
As one of the earliest core lead investors of the platform, Dragonfly has rarely publicly disclosed the true financial details and difficult uphill climb during Polymarket's early startup phase, comprehensively countering the continuously fermenting malicious speech on social networks.
Startup in the Bathroom: From Zero-Salary Survival to a Valuation Miracle
This public opinion storm originated from an anonymous leak tweet circulated on social media accounts, which accused Shayne of using investor funds as a personal wallet to pay for luxury charters, apartment rent, and haute couture clothing, and even stated that a major backer ordered a full refund.
In response to these sensational accusations, Haseeb restored the little-known full picture of the early startup days. When Shayne founded the platform at age 21, he took absolutely no salary and lived extremely frugally, using his apartment bathroom as a makeshift office desk, and even propping up his computer with a basket of miscellaneous items to write code.
According to Dragonfly's official portfolio records, the institution was the first backer to issue a term sheet to him, having grown so concerned about his basic livelihood that they proactively offered to provide a personal bridge loan.
Engineer-Level Annual Salary Travel: Proactive Accounting and Refunds Instead of Breach of Trust
Haseeb further pointed out that throughout the turbulence of the global pandemic and the heavy pressure of strict regulatory rectification orders from the US CFTC, the vast majority of startups in the industry have experienced extremely chaotic management phases.
But in terms of financial records, Shayne proactively disclosed every business expense to the board. After conversion, the total annualized expenditure was merely equivalent to the annual salary of an ordinary junior software engineer, including travel flights that were all standard business trips, with absolutely no private vacation charters.
The core fact is that the relevant accounting reconciliation and refund procedures were initiated and fully settled with the company by Shayne himself, rather than being caught by external auditors. He has since taken a regular salary according to standard employee compensation, and the essence of this incident belongs to early-stage accounting standardization processes rather than moral flaws.
Countering Baseless Panic: Management Transforms Rapidly Alongside the Platform
Facing the recent baseless negative noise stemming from the explosive growth of the prediction market, Haseeb emphasized that Polymarket has transformed from a precarious, day-to-day exploratory venture of the past into a fast-growing, highly culturally penetrating consumer-grade flagship standard across the United States.
Investment institutions have witnessed the synchronous evolution and management maturity of the young founder throughout its entire growth cycle. Dragonfly has explicitly stated its absolute confidence in his long-term leadership and solemnly called on the industry to stop maliciously manufacturing panic and taking statements out of context.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Polymarket founder faces controversy over misuse of funds, Dragonfly's Haseeb speaks out to clarify
On October 21, 2026, according to a public statement released by Dragonfly Managing Partner Haseeb Qureshi, the allegations regarding prediction market leader Polymarket founder and CEO Shayne Coplan allegedly misappropriating company funds to pay for personal expenses such as a private jet are entirely baseless smears.
As one of the earliest core lead investors of the platform, Dragonfly has rarely publicly disclosed the true financial details and difficult uphill climb during Polymarket's early startup phase, comprehensively countering the continuously fermenting malicious speech on social networks.
Startup in the Bathroom: From Zero-Salary Survival to a Valuation Miracle
This public opinion storm originated from an anonymous leak tweet circulated on social media accounts, which accused Shayne of using investor funds as a personal wallet to pay for luxury charters, apartment rent, and haute couture clothing, and even stated that a major backer ordered a full refund.
In response to these sensational accusations, Haseeb restored the little-known full picture of the early startup days. When Shayne founded the platform at age 21, he took absolutely no salary and lived extremely frugally, using his apartment bathroom as a makeshift office desk, and even propping up his computer with a basket of miscellaneous items to write code.
According to Dragonfly's official portfolio records, the institution was the first backer to issue a term sheet to him, having grown so concerned about his basic livelihood that they proactively offered to provide a personal bridge loan.
Engineer-Level Annual Salary Travel: Proactive Accounting and Refunds Instead of Breach of Trust
Haseeb further pointed out that throughout the turbulence of the global pandemic and the heavy pressure of strict regulatory rectification orders from the US CFTC, the vast majority of startups in the industry have experienced extremely chaotic management phases.
But in terms of financial records, Shayne proactively disclosed every business expense to the board. After conversion, the total annualized expenditure was merely equivalent to the annual salary of an ordinary junior software engineer, including travel flights that were all standard business trips, with absolutely no private vacation charters.
The core fact is that the relevant accounting reconciliation and refund procedures were initiated and fully settled with the company by Shayne himself, rather than being caught by external auditors. He has since taken a regular salary according to standard employee compensation, and the essence of this incident belongs to early-stage accounting standardization processes rather than moral flaws.
Countering Baseless Panic: Management Transforms Rapidly Alongside the Platform
Facing the recent baseless negative noise stemming from the explosive growth of the prediction market, Haseeb emphasized that Polymarket has transformed from a precarious, day-to-day exploratory venture of the past into a fast-growing, highly culturally penetrating consumer-grade flagship standard across the United States.
Investment institutions have witnessed the synchronous evolution and management maturity of the young founder throughout its entire growth cycle. Dragonfly has explicitly stated its absolute confidence in his long-term leadership and solemnly called on the industry to stop maliciously manufacturing panic and taking statements out of context.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
翻訳参照
Morgan Stanley: What Can the U.S. Midterm Elections Really Change? AI and Fiscal Policy Take Center StageAs the U.S. midterm elections approach in November, Wall Street is beginning to reassess the potential impact of the election results on financial markets. If Democrats regain control of Congress, will the Trump administration's economic policies shift? How long can U.S. fiscal stimulus be sustained? And will the rapidly expanding AI data center investment slow down due to political pressure?
Morgan Stanley noted in its latest analysis that this midterm election could change the power structure of Congress, but may not necessarily change the fundamental direction of U.S. economic policy. Rather than the election results themselves, investors should focus more on the continuity of fiscal policy and the increasing regulatory constraints surrounding artificial intelligence and data center construction.
Ariana Salvatore, Head of U.S. Public Policy Research at Morgan Stanley, believes that the midterm elections are unlikely to change the Trump administration's core policy agenda, which is dominated by executive power. Even if Democrats win the House, or even control both the House and Senate, policies on tariffs, trade, immigration, and deregulation may still continue to advance through the executive branch and federal agencies.
But an unchanged policy direction does not mean markets will be unaffected. Morgan Stanley believes that post-election fiscal negotiations may become more complex, and AI infrastructure investment may also face more restrictions from state and local governments.
What can the midterm elections change? Congressional control and policy direction may not move in sync
The most direct impact of the midterm elections is determining the political landscape of the U.S. Congress for the next two years. However, Morgan Stanley points out that even if congressional control changes, it does not mean the Trump administration's existing policies will be overturned.
First, divided government will make major legislation more difficult.
If Democrats win the House, or control both the House and Senate, the Trump administration will face greater resistance in pushing new large-scale fiscal bills. The budget reconciliation process previously used to advance major fiscal legislation will also be difficult to use when congressional power is fragmented.
At the same time, even if Democrats control both chambers of Congress, the president still holds veto power over legislation. This means Democrats will likewise find it difficult to unilaterally push through large-scale policy changes opposite to the current administration's direction.
Second, many of the Trump administration's core policies do not entirely depend on congressional legislation in the first place.
Morgan Stanley points out that tariffs and trade, deregulation, immigration, and some geopolitical policies are mainly implemented through the executive branch and federal agencies. Therefore, even if congressional control changes, these policies may still continue.
However, the election results may still change the political environment for policy implementation.
If a divided government takes shape, congressional oversight of the president and the executive branch may intensify, and the executive branch's role in policy implementation will become more prominent.
In other words, what the midterm elections are most likely to change is the difficulty of passing new policies, the intensity of congressional oversight, and the way the executive and legislative branches contend with each other—not an immediate rewrite of U.S. economic policy.
Fiscal Policy in Focus: Stimulus Hard to Expand, Debt Disputes May Heat Up
On economic policy, fiscal matters are one of the most closely watched areas in the midterm elections.
Morgan Stanley believes that although fiscal policy is more susceptible to changes in congressional control, the election results are unlikely to lead to a fundamental adjustment in the direction of U.S. fiscal policy.
The reason is that both parties lack strong incentives to push for large-scale cuts in government spending or tax increases. Therefore, even if the congressional political landscape changes, the existing U.S. fiscal policy framework is likely to continue.
However, a divided government may make it harder for new fiscal support measures to pass.
Without the support of the budget reconciliation process, advancing large-scale fiscal stimulus bills in Congress will become more difficult. At the same time, issues such as government funding, the debt ceiling, and the defense budget may trigger more intense partisan negotiations.
This issue is particularly prominent against the backdrop of the continued expansion of U.S. debt.
According to the Morgan Stanley article, U.S. federal debt exceeded $40 trillion for the first time in August 2026. As the debt burden increases, uncertainty surrounding government financing arrangements and fiscal policy may rise further.
However, Morgan Stanley believes that political disputes over the budget and the debt ceiling may be more significant than actual fiscal policy adjustments.
From a financial market perspective, tariffs, taxes, and deregulation will remain important drivers.
The Morgan Stanley research team noted that since January 2025, rising U.S. policy uncertainty and related market volatility have mainly come from the executive branch rather than congressional legislative action. This means that even if the midterm elections change the congressional landscape, investors still need to focus on the actual policies of the White House and federal agencies.
Historical market performance also provides a reference.
Research from the Morgan Stanley Wealth Management Global Investment Office shows that under a Republican president with Congress split between the parties, the S&P 500 rose an average of 23% in the year after the midterm elections; under a Republican president with Democrats controlling Congress, the average gain was 15%.
But Morgan Stanley cautions that a divided government cannot simply be equated with stock market gains. The current U.S. economy and financial markets are significantly affected by fiscal stimulus, tax and regulatory policies, and if these policies undergo substantive changes, they could also alter the previous trend of stock market gains spreading to more sectors.
Therefore, for investors, what truly matters is not which party controls Congress, but whether fiscal policy can continue to support U.S. economic growth, and whether political brinkmanship will affect policy implementation.
AI Becomes a Bipartisan Focus: Data Center Construction May Face More Restrictions
Beyond fiscal policy, AI infrastructure construction is becoming an important policy issue in the midterm elections.
Morgan Stanley believes that, unlike traditional economic policies such as tariffs and taxes, the political pressure facing AI data center construction has a distinctly local character. Even if the policy direction in Washington remains unchanged, state and local governments may still exert substantive influence on AI investment through energy management, project approvals, and community protection measures.
Currently, disputes surrounding data centers have crossed party lines. States governed by both Democrats and Republicans have begun to focus on the potential electricity cost increases, infrastructure burdens, and community interest issues that large-scale data centers may bring.
The state governments of New York, Virginia, and Texas have already adopted executive orders, policy frameworks, or review measures to reassess the impact of data center development.
Morgan Stanley summarizes this trend as "conditional buildout." This does not mean that the United States will stop investing in AI infrastructure, but rather that whether future data center projects can materialize will increasingly depend on whether developers can meet the requirements set by local governments.
Specifically, local governments may require data center operators to bear more of the added electricity costs, participate in infrastructure construction such as power grids, accept new tax or utility arrangements, and take measures to mitigate the impact of projects on local communities.
These conditions may increase project development costs and may also change the distribution of AI investment across different regions.
Nevertheless, Morgan Stanley still expects AI infrastructure investment to remain at a large scale. Its research team forecasts that capital expenditure by hyperscale cloud computing companies will reach $1.5 trillion in 2027.
At the same time, power supply has become an important factor constraining U.S. data center expansion. Morgan Stanley previously forecast that by 2028, the power supply gap facing U.S. data center developers could exceed 30%.
Policy debates surrounding AI infrastructure have thus produced two forces: local governments want to control energy costs, infrastructure burdens, and community impact; while supporters of continued AI infrastructure expansion emphasize national security and U.S.-China tech competition, arguing that excessive restrictions on data center construction could weaken America's long-term competitiveness.
Morgan Stanley believes that federal-level AI legislation may advance slowly, and a nationwide moratorium on data center construction is unlikely. By contrast, state and local governments will continue to play an important role in the implementation of specific projects.
This means the impact of the midterm elections on the AI industry may not manifest as a sudden shift in federal policy, but rather as differences in construction conditions, development costs, and investment progress across different regions.
What should the market watch after the midterm elections?
Morgan Stanley believes investors should not simply view divided government as a bullish signal for stocks, nor should they judge long-term trends solely based on short-term market reactions after the elections.
Jim Caron, Chief Investment Officer at Morgan Stanley Investment Management, noted that the current U.S. market is significantly influenced by fiscal policy, tax policy, and the regulatory environment. If relevant policies reverse, the market's previous broadening rally could also be affected.
Monica Guerra, Head of Policy and Geopolitical Strategy at Morgan Stanley Wealth Management's Investment Office, believes that congressional political gridlock and legislative stagnation can sometimes bring policy stability. Rather than short-term volatility triggered by political news, investors should focus more on the actual policy actions taken by the government.
For companies, a divided Congress does not mean the policy environment remains static. Josh Wilsusen, Head of Government Relations at Morgan Stanley, cautioned that companies still need to navigate changes in congressional oversight intensity, continued enforcement of existing policies by federal agencies, and the growing influence of state and local governments over AI infrastructure construction.
Based on Morgan Stanley's analysis, the impact of the 2026 U.S. midterm elections on financial markets is mainly concentrated in two aspects.
First, whether fiscal policy can maintain continuity. Even if congressional control changes, existing tax, tariff, and fiscal policies may continue, but new fiscal stimulus measures may be harder to introduce, and government funding and debt ceiling negotiations could also increase market uncertainty.
Second, what new constraints AI investment will face. Tech giants' capital expenditure plans remain massive, but data center construction is being affected by factors such as energy supply, local regulation, and community costs. A divergence may emerge between future investment scale and the actual pace of project implementation.
Therefore, Morgan Stanley's core judgment is: the midterm elections may change the political landscape of the U.S. Congress, but may not necessarily change the fundamental direction of economic policy. The continuity of fiscal policy, as well as the process of AI infrastructure investment transitioning from large-scale expansion to conditional construction, are the market variables worth continuous attention after the elections.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Morgan Stanley: What Can the U.S. Midterm Elections Really Change? AI and Fiscal Policy Take Center Stage
As the U.S. midterm elections approach in November, Wall Street is beginning to reassess the potential impact of the election results on financial markets. If Democrats regain control of Congress, will the Trump administration's economic policies shift? How long can U.S. fiscal stimulus be sustained? And will the rapidly expanding AI data center investment slow down due to political pressure?
Morgan Stanley noted in its latest analysis that this midterm election could change the power structure of Congress, but may not necessarily change the fundamental direction of U.S. economic policy. Rather than the election results themselves, investors should focus more on the continuity of fiscal policy and the increasing regulatory constraints surrounding artificial intelligence and data center construction.
Ariana Salvatore, Head of U.S. Public Policy Research at Morgan Stanley, believes that the midterm elections are unlikely to change the Trump administration's core policy agenda, which is dominated by executive power. Even if Democrats win the House, or even control both the House and Senate, policies on tariffs, trade, immigration, and deregulation may still continue to advance through the executive branch and federal agencies.
But an unchanged policy direction does not mean markets will be unaffected. Morgan Stanley believes that post-election fiscal negotiations may become more complex, and AI infrastructure investment may also face more restrictions from state and local governments.
What can the midterm elections change? Congressional control and policy direction may not move in sync
The most direct impact of the midterm elections is determining the political landscape of the U.S. Congress for the next two years. However, Morgan Stanley points out that even if congressional control changes, it does not mean the Trump administration's existing policies will be overturned.
First, divided government will make major legislation more difficult.
If Democrats win the House, or control both the House and Senate, the Trump administration will face greater resistance in pushing new large-scale fiscal bills. The budget reconciliation process previously used to advance major fiscal legislation will also be difficult to use when congressional power is fragmented.
At the same time, even if Democrats control both chambers of Congress, the president still holds veto power over legislation. This means Democrats will likewise find it difficult to unilaterally push through large-scale policy changes opposite to the current administration's direction.
Second, many of the Trump administration's core policies do not entirely depend on congressional legislation in the first place.
Morgan Stanley points out that tariffs and trade, deregulation, immigration, and some geopolitical policies are mainly implemented through the executive branch and federal agencies. Therefore, even if congressional control changes, these policies may still continue.
However, the election results may still change the political environment for policy implementation.
If a divided government takes shape, congressional oversight of the president and the executive branch may intensify, and the executive branch's role in policy implementation will become more prominent.
In other words, what the midterm elections are most likely to change is the difficulty of passing new policies, the intensity of congressional oversight, and the way the executive and legislative branches contend with each other—not an immediate rewrite of U.S. economic policy.
Fiscal Policy in Focus: Stimulus Hard to Expand, Debt Disputes May Heat Up
On economic policy, fiscal matters are one of the most closely watched areas in the midterm elections.
Morgan Stanley believes that although fiscal policy is more susceptible to changes in congressional control, the election results are unlikely to lead to a fundamental adjustment in the direction of U.S. fiscal policy.
The reason is that both parties lack strong incentives to push for large-scale cuts in government spending or tax increases. Therefore, even if the congressional political landscape changes, the existing U.S. fiscal policy framework is likely to continue.
However, a divided government may make it harder for new fiscal support measures to pass.
Without the support of the budget reconciliation process, advancing large-scale fiscal stimulus bills in Congress will become more difficult. At the same time, issues such as government funding, the debt ceiling, and the defense budget may trigger more intense partisan negotiations.
This issue is particularly prominent against the backdrop of the continued expansion of U.S. debt.
According to the Morgan Stanley article, U.S. federal debt exceeded $40 trillion for the first time in August 2026. As the debt burden increases, uncertainty surrounding government financing arrangements and fiscal policy may rise further.
However, Morgan Stanley believes that political disputes over the budget and the debt ceiling may be more significant than actual fiscal policy adjustments.
From a financial market perspective, tariffs, taxes, and deregulation will remain important drivers.
The Morgan Stanley research team noted that since January 2025, rising U.S. policy uncertainty and related market volatility have mainly come from the executive branch rather than congressional legislative action. This means that even if the midterm elections change the congressional landscape, investors still need to focus on the actual policies of the White House and federal agencies.
Historical market performance also provides a reference.
Research from the Morgan Stanley Wealth Management Global Investment Office shows that under a Republican president with Congress split between the parties, the S&P 500 rose an average of 23% in the year after the midterm elections; under a Republican president with Democrats controlling Congress, the average gain was 15%.
But Morgan Stanley cautions that a divided government cannot simply be equated with stock market gains. The current U.S. economy and financial markets are significantly affected by fiscal stimulus, tax and regulatory policies, and if these policies undergo substantive changes, they could also alter the previous trend of stock market gains spreading to more sectors.
Therefore, for investors, what truly matters is not which party controls Congress, but whether fiscal policy can continue to support U.S. economic growth, and whether political brinkmanship will affect policy implementation.
AI Becomes a Bipartisan Focus: Data Center Construction May Face More Restrictions
Beyond fiscal policy, AI infrastructure construction is becoming an important policy issue in the midterm elections.
Morgan Stanley believes that, unlike traditional economic policies such as tariffs and taxes, the political pressure facing AI data center construction has a distinctly local character. Even if the policy direction in Washington remains unchanged, state and local governments may still exert substantive influence on AI investment through energy management, project approvals, and community protection measures.
Currently, disputes surrounding data centers have crossed party lines. States governed by both Democrats and Republicans have begun to focus on the potential electricity cost increases, infrastructure burdens, and community interest issues that large-scale data centers may bring.
The state governments of New York, Virginia, and Texas have already adopted executive orders, policy frameworks, or review measures to reassess the impact of data center development.
Morgan Stanley summarizes this trend as "conditional buildout." This does not mean that the United States will stop investing in AI infrastructure, but rather that whether future data center projects can materialize will increasingly depend on whether developers can meet the requirements set by local governments.
Specifically, local governments may require data center operators to bear more of the added electricity costs, participate in infrastructure construction such as power grids, accept new tax or utility arrangements, and take measures to mitigate the impact of projects on local communities.
These conditions may increase project development costs and may also change the distribution of AI investment across different regions.
Nevertheless, Morgan Stanley still expects AI infrastructure investment to remain at a large scale. Its research team forecasts that capital expenditure by hyperscale cloud computing companies will reach $1.5 trillion in 2027.
At the same time, power supply has become an important factor constraining U.S. data center expansion. Morgan Stanley previously forecast that by 2028, the power supply gap facing U.S. data center developers could exceed 30%.
Policy debates surrounding AI infrastructure have thus produced two forces: local governments want to control energy costs, infrastructure burdens, and community impact; while supporters of continued AI infrastructure expansion emphasize national security and U.S.-China tech competition, arguing that excessive restrictions on data center construction could weaken America's long-term competitiveness.
Morgan Stanley believes that federal-level AI legislation may advance slowly, and a nationwide moratorium on data center construction is unlikely. By contrast, state and local governments will continue to play an important role in the implementation of specific projects.
This means the impact of the midterm elections on the AI industry may not manifest as a sudden shift in federal policy, but rather as differences in construction conditions, development costs, and investment progress across different regions.
What should the market watch after the midterm elections?
Morgan Stanley believes investors should not simply view divided government as a bullish signal for stocks, nor should they judge long-term trends solely based on short-term market reactions after the elections.
Jim Caron, Chief Investment Officer at Morgan Stanley Investment Management, noted that the current U.S. market is significantly influenced by fiscal policy, tax policy, and the regulatory environment. If relevant policies reverse, the market's previous broadening rally could also be affected.
Monica Guerra, Head of Policy and Geopolitical Strategy at Morgan Stanley Wealth Management's Investment Office, believes that congressional political gridlock and legislative stagnation can sometimes bring policy stability. Rather than short-term volatility triggered by political news, investors should focus more on the actual policy actions taken by the government.
For companies, a divided Congress does not mean the policy environment remains static. Josh Wilsusen, Head of Government Relations at Morgan Stanley, cautioned that companies still need to navigate changes in congressional oversight intensity, continued enforcement of existing policies by federal agencies, and the growing influence of state and local governments over AI infrastructure construction.
Based on Morgan Stanley's analysis, the impact of the 2026 U.S. midterm elections on financial markets is mainly concentrated in two aspects.
First, whether fiscal policy can maintain continuity. Even if congressional control changes, existing tax, tariff, and fiscal policies may continue, but new fiscal stimulus measures may be harder to introduce, and government funding and debt ceiling negotiations could also increase market uncertainty.
Second, what new constraints AI investment will face. Tech giants' capital expenditure plans remain massive, but data center construction is being affected by factors such as energy supply, local regulation, and community costs. A divergence may emerge between future investment scale and the actual pace of project implementation.
Therefore, Morgan Stanley's core judgment is: the midterm elections may change the political landscape of the U.S. Congress, but may not necessarily change the fundamental direction of economic policy. The continuity of fiscal policy, as well as the process of AI infrastructure investment transitioning from large-scale expansion to conditional construction, are the market variables worth continuous attention after the elections.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
翻訳参照
Mastercard Agent Pay for Machines: How x402 Agent Payments SettleMastercard Agent Pay for Machines is now open to developers: on Tuesday, 20 October 2026, Mastercard opened Early Access to the service, which lets AI agents pay for digital services on a business's behalf inside a pre-approved budget, and showed it running live at Cloudflare Connect, according to Mastercard's announcement.
The service builds on x402, the open protocol that lets a website or API answer a request with "402 Payment Required". In the demo, Coinbase Developer Platform funded the agent's wallet, Base provided onchain settlement, and BVNK settled both sides in fiat or stablecoins through Mastercard's Global Money Platform, per Mastercard. Decrypt, The Block and PYMNTS reported the launch on Tuesday evening, Central European time.
Below: what Mastercard actually opened, how a voucher payment moves from an HTTP 402 response to a stablecoin settlement, how the model differs from plain x402, and what is still missing before a business can run it in production.
Key Takeaways
Mastercard opened Agent Pay for Machines Early Access on 20 October 2026, with buyer and seller APIs, a toolkit, a sandbox and documentation (Mastercard).
Agents pay with digitally signed vouchers inside a business-set budget; vouchers are checked offchain and can be combined and redeemed later (Decrypt).
The demo used Coinbase Developer Platform wallets, Base for onchain settlement and BVNK to settle in fiat or stablecoins (CoinMarketCap).
Cloudflare's Monetization Gateway, the seller side in the demo, settles x402 payments on Base in USDC (Cloudflare).
Pricing, supported stablecoins, dispute rules and a general availability date are not in the announcement (Mastercard).
🔎What Mastercard has not disclosed: fees for buyers or sellers, which stablecoins and chains settle in production beyond the Base demo, how often vouchers are redeemed and settled, who carries the loss if a voucher is never honoured, dispute and chargeback rules, which countries Early Access covers, and when the service becomes generally available. Where this article discusses those points, it says so.
What Mastercard opened on 20 October
Mastercard first launched Agent Pay for Machines on 10 June 2026 with more than 30 named supporters, including Adyen, BVNK, Checkout.com, Cloudflare, Coinbase, Stripe and Tempo, per its June release. Tuesday's step moves it from a partner programme to something outside developers can build against. The confirmed facts:
Access: Agent Pay for Machines Early Access, with the first version of the buyer-side and seller-side APIs, a toolkit, a sandbox and developer documentation (Mastercard).
Pilots completed first: end-to-end pilots with Cloudflare, Ant International, AIsa, Base, BVNK, Coinbase and Hype (Mastercard).
Protocol: builds on x402, with Mastercard positioned as a common trust layer across agent platforms, wallets, payment providers and merchants (Mastercard).
Venue: demonstrated at Cloudflare Connect by Mastercard chief product officer Jorn Lambert (Decrypt).
Status: still early access. Mastercard says the roadmap will be shaped by customer and partner feedback (Mastercard).
One reporting difference is worth flagging. Decrypt lists the pilot partners as Cloudflare, Ant International, AWS, BVNK and Coinbase. Mastercard's own announcement names AIsa, Base and Hype instead of AWS and mentions Amazon Bedrock AgentCore only as an example agent platform. This article follows Mastercard's list.
How a Mastercard Agent Pay for Machines payment works
Mastercard sums up the model as "Authorize once. Transact many times. Guarantee payment now. Settle later." The flow from the announcement, step by step:
StepWhat happensOnchain?
1. MandateA business gives an agent a task and a spending limit (Mastercard)No
2. DiscoveryThe agent finds registered Agent Pay for Machines providers and proposes a plan; the business approves the fundingNo
3. 402 responseA paid service answers with "402 Payment Required", the x402 signal that payment is needed (x402)No
4. VoucherThe agent signs a payment voucher, a promise to pay within its approved limit; the seller verifies it and deliversNo, offchain at machine speed
5. RedemptionSellers combine vouchers and redeem them laterSettlement leg
6. SettlementIn the demo, Base carried onchain settlement and BVNK settled both sides in fiat or stablecoins (CoinMarketCap)Yes, on Base in the demo
The demo made the model concrete. Marketing agency Hype gave an agent a budget to plan a protein bar campaign; the agent bought social media research from AIsa and eight campaign images through Cloudflare AI Gateway. That came to nine payments to two independent merchants under one approved budget, with no separate accounts, API keys or invoices, per Mastercard. AIsa is the pay-per-call API marketplace that Tether Capital backed this month, covered in our Tether AIsa analysis.
Where the stablecoins sit
Mastercard's announcement uses the word stablecoin once, but the plumbing behind the demo is stablecoin plumbing. Coinbase Developer Platform supplied the wallet that funded the agent, Base provided the settlement network, and BVNK acted as the agent wallet, using the Global Money Platform to handle payment and settlement "in fiat or stablecoins" so sellers get paid in their preferred currency, token or rail (Mastercard).
The seller side is more specific. Cloudflare's Monetization Gateway, which returned the 402 responses in the demo, handles verification and settlement through Coinbase's x402 facilitator, and its payments settle on Base in USDC, per Cloudflare's beta announcement from 30 September. The gateway uses x402 version 2 with PAYMENT-REQUIRED and PAYMENT-SIGNATURE headers, per Cloudflare's developer docs, and is a closed beta for eligible US-based sellers and buyers. We covered the gateway when Cloudflare opened its waitlist in July.
Mastercard has not said which stablecoin settled the demo payments, so the USDC detail is Cloudflare's general product rule, not a Mastercard disclosure. What the structure shows is the division of labour: x402 and a USDC wallet on the buyer side, Mastercard's voucher and guarantee in the middle, and BVNK converting to whatever the seller wants to receive. Our guide to the Mastercard Global Money Platform explains that conversion layer.
Agent Pay for Machines vs plain x402
Plain x402 was designed for direct, per-request payment: an agent pays a service from its own wallet, and a facilitator verifies and settles each payment onchain, per Coinbase's x402 documentation. Mastercard keeps the 402 handshake but changes what happens after it. Ledger Insights describes the result as batch settlement with Mastercard inserted into the flow, adding a credential registry and a guarantee, per its analysis.
Plain x402Mastercard Agent Pay for Machines
Payment signalHTTP 402 with payment requirements (x402)Same 402 signal (Mastercard)
What the agent sendsA signed payment authorization, settled per requestA signed voucher, a promise to pay within an approved limit
Settlement timingPer request, onchainVouchers combined and redeemed later, in batches
Payment guaranteeFinality comes from the onchain settlement itselfMastercard says payment is guaranteed now and settled later
Funding sourceThe agent's own stablecoin walletWallet funding via Coinbase in the demo; fiat or stablecoins through BVNK
What the seller receivesThe asset named in the 402 response, often USDCPreferred currency, token or rail
Who sits in the middleA facilitator such as Coinbase'sMastercard as trust layer, plus BVNK and the facilitator
The trade-off is clear. Plain x402 is open and settles each payment as it happens, but every seller must accept a specific token on a specific chain. Mastercard's version adds an intermediary and a delay, in return for spending limits, a promise of payment and a way for a business that funds agents from a bank account to pay sellers who want stablecoins, or the reverse. Our x402 vs AP2 vs ACK-Pay comparison covers the other agent payment protocols Mastercard is competing with.
Why machine payments lean on stablecoins
The economics explain why Mastercard built on a crypto protocol at all. More than 138 million x402 transactions had taken place on Base by mid-2026, and over 87% of x402 payments fell between a hundredth of a cent and ten cents, per Chainalysis. Payments that small rarely make sense on card rails, where fixed per-transaction costs can exceed the payment.
Circle described the split to Chainalysis as card rails for consumer-prompted agent payments and stablecoin rails for machine-to-machine settlements too small for card economics, per the same Chainalysis report. Agent Pay for Machines is Mastercard's attempt to sit across that line: it already supports settlement across cards, accounts and stablecoins, per the June release, and batching vouchers is one way to make tiny payments cheap enough to settle.
🧭Our take: Agent Pay for Machines is less a new payment rail than a control layer on top of x402. The useful part for businesses is the mandate: a budget, permissions and a guarantee that a finance team can approve once. The cost is that the open, per-request settlement x402 was built for becomes a Mastercard-mediated batch. For sellers already on Cloudflare or Coinbase rails, USDC on Base is still doing the settling underneath. Test it in the sandbox now, but wait for published fees and dispute rules before routing real spend through it.
Named downsides
No pricing. Neither buyer nor seller fees have been published, so cost against plain x402 cannot be compared.
Settlement opacity. Redemption frequency, chains and stablecoins beyond the Base demo are unstated.
Counterparty in the middle. Batching means sellers deliver on a promise and wait for settlement, which plain x402 avoids.
Early access only. A sandbox and first-version APIs are not a production service level.
Geography unclear. Cloudflare's gateway is limited to eligible US-based sellers and buyers during its beta.
Vendor concentration. Mastercard, its BVNK unit and the Global Money Platform would sit on both sides of the payment.
Who should test it now, and who should wait
Test now: API and data sellers already behind Cloudflare's Monetization Gateway, agent platforms whose business customers want a hard spending cap per task, and payment providers in the BVNK or Coinbase orbit that want to accept agent payments without asking every buyer to hold USDC.
Wait: crypto-native agents that already pay per request in USDC and gain little from a guarantee, and any business outside the United States until Mastercard says where Early Access applies. For the risk side, Mastercard's separate Stablecoin Security screening service, launched a day earlier, shows how the company plans to wrap stablecoin payments in its fraud and sanctions tooling.
FAQ
What is Mastercard Agent Pay for Machines?
A Mastercard service that lets AI agents pay for digital services such as AI models, data, computing power and APIs on behalf of businesses, within approved budgets and permissions. It builds on the x402 protocol (Mastercard).
Is Agent Pay for Machines live?
It is in Early Access as of 20 October 2026. Developers can use first-version buyer and seller APIs, a toolkit, a sandbox and documentation; Mastercard has not given a general availability date (Mastercard).
Does Agent Pay for Machines use stablecoins?
It can. In the demo, Base provided onchain settlement and BVNK settled in fiat or stablecoins (Mastercard). Cloudflare's Monetization Gateway, the seller side in the demo, settles x402 payments in USDC on Base (Cloudflare).
How is it different from plain x402?
Plain x402 settles each payment per request through a facilitator (Coinbase). Mastercard's version uses signed vouchers that sellers combine and redeem later, with Mastercard acting as a trust layer that guarantees payment (Ledger Insights).
How much does Agent Pay for Machines cost?
Mastercard has not published pricing for buyers or sellers; the Early Access announcement lists APIs, a toolkit, a sandbox and documentation but no fees (Mastercard).
What to watch next: published fees, a list of settlement chains and stablecoins beyond Base, dispute and chargeback rules for vouchers, and the first sellers outside the pilot group. Background on the protocol layer is in our agent payment protocol comparison.
This content is provided for informational and educational purposes only and does not constitute financial, investment, legal, or tax advice; it is not financial advice, and no material herein should be interpreted as a recommendation, endorsement, or solicitation to buy or sell any asset or token. Product scope, partners and availability are as described by Mastercard on 20 October 2026 and can change; check Mastercard's developer documentation and take legal advice before letting software spend on a business's behalf. Nothing here is a solicitation to buy or sell.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Mastercard Agent Pay for Machines: How x402 Agent Payments Settle
Mastercard Agent Pay for Machines is now open to developers: on Tuesday, 20 October 2026, Mastercard opened Early Access to the service, which lets AI agents pay for digital services on a business's behalf inside a pre-approved budget, and showed it running live at Cloudflare Connect, according to Mastercard's announcement.
The service builds on x402, the open protocol that lets a website or API answer a request with "402 Payment Required". In the demo, Coinbase Developer Platform funded the agent's wallet, Base provided onchain settlement, and BVNK settled both sides in fiat or stablecoins through Mastercard's Global Money Platform, per Mastercard. Decrypt, The Block and PYMNTS reported the launch on Tuesday evening, Central European time.
Below: what Mastercard actually opened, how a voucher payment moves from an HTTP 402 response to a stablecoin settlement, how the model differs from plain x402, and what is still missing before a business can run it in production.
Key Takeaways
Mastercard opened Agent Pay for Machines Early Access on 20 October 2026, with buyer and seller APIs, a toolkit, a sandbox and documentation (Mastercard).
Agents pay with digitally signed vouchers inside a business-set budget; vouchers are checked offchain and can be combined and redeemed later (Decrypt).
The demo used Coinbase Developer Platform wallets, Base for onchain settlement and BVNK to settle in fiat or stablecoins (CoinMarketCap).
Cloudflare's Monetization Gateway, the seller side in the demo, settles x402 payments on Base in USDC (Cloudflare).
Pricing, supported stablecoins, dispute rules and a general availability date are not in the announcement (Mastercard).
🔎What Mastercard has not disclosed: fees for buyers or sellers, which stablecoins and chains settle in production beyond the Base demo, how often vouchers are redeemed and settled, who carries the loss if a voucher is never honoured, dispute and chargeback rules, which countries Early Access covers, and when the service becomes generally available. Where this article discusses those points, it says so.
What Mastercard opened on 20 October
Mastercard first launched Agent Pay for Machines on 10 June 2026 with more than 30 named supporters, including Adyen, BVNK, Checkout.com, Cloudflare, Coinbase, Stripe and Tempo, per its June release. Tuesday's step moves it from a partner programme to something outside developers can build against. The confirmed facts:
Access: Agent Pay for Machines Early Access, with the first version of the buyer-side and seller-side APIs, a toolkit, a sandbox and developer documentation (Mastercard).
Pilots completed first: end-to-end pilots with Cloudflare, Ant International, AIsa, Base, BVNK, Coinbase and Hype (Mastercard).
Protocol: builds on x402, with Mastercard positioned as a common trust layer across agent platforms, wallets, payment providers and merchants (Mastercard).
Venue: demonstrated at Cloudflare Connect by Mastercard chief product officer Jorn Lambert (Decrypt).
Status: still early access. Mastercard says the roadmap will be shaped by customer and partner feedback (Mastercard).
One reporting difference is worth flagging. Decrypt lists the pilot partners as Cloudflare, Ant International, AWS, BVNK and Coinbase. Mastercard's own announcement names AIsa, Base and Hype instead of AWS and mentions Amazon Bedrock AgentCore only as an example agent platform. This article follows Mastercard's list.
How a Mastercard Agent Pay for Machines payment works
Mastercard sums up the model as "Authorize once. Transact many times. Guarantee payment now. Settle later." The flow from the announcement, step by step:
StepWhat happensOnchain?
1. MandateA business gives an agent a task and a spending limit (Mastercard)No
2. DiscoveryThe agent finds registered Agent Pay for Machines providers and proposes a plan; the business approves the fundingNo
3. 402 responseA paid service answers with "402 Payment Required", the x402 signal that payment is needed (x402)No
4. VoucherThe agent signs a payment voucher, a promise to pay within its approved limit; the seller verifies it and deliversNo, offchain at machine speed
5. RedemptionSellers combine vouchers and redeem them laterSettlement leg
6. SettlementIn the demo, Base carried onchain settlement and BVNK settled both sides in fiat or stablecoins (CoinMarketCap)Yes, on Base in the demo
The demo made the model concrete. Marketing agency Hype gave an agent a budget to plan a protein bar campaign; the agent bought social media research from AIsa and eight campaign images through Cloudflare AI Gateway. That came to nine payments to two independent merchants under one approved budget, with no separate accounts, API keys or invoices, per Mastercard. AIsa is the pay-per-call API marketplace that Tether Capital backed this month, covered in our Tether AIsa analysis.
Where the stablecoins sit
Mastercard's announcement uses the word stablecoin once, but the plumbing behind the demo is stablecoin plumbing. Coinbase Developer Platform supplied the wallet that funded the agent, Base provided the settlement network, and BVNK acted as the agent wallet, using the Global Money Platform to handle payment and settlement "in fiat or stablecoins" so sellers get paid in their preferred currency, token or rail (Mastercard).
The seller side is more specific. Cloudflare's Monetization Gateway, which returned the 402 responses in the demo, handles verification and settlement through Coinbase's x402 facilitator, and its payments settle on Base in USDC, per Cloudflare's beta announcement from 30 September. The gateway uses x402 version 2 with PAYMENT-REQUIRED and PAYMENT-SIGNATURE headers, per Cloudflare's developer docs, and is a closed beta for eligible US-based sellers and buyers. We covered the gateway when Cloudflare opened its waitlist in July.
Mastercard has not said which stablecoin settled the demo payments, so the USDC detail is Cloudflare's general product rule, not a Mastercard disclosure. What the structure shows is the division of labour: x402 and a USDC wallet on the buyer side, Mastercard's voucher and guarantee in the middle, and BVNK converting to whatever the seller wants to receive. Our guide to the Mastercard Global Money Platform explains that conversion layer.
Agent Pay for Machines vs plain x402
Plain x402 was designed for direct, per-request payment: an agent pays a service from its own wallet, and a facilitator verifies and settles each payment onchain, per Coinbase's x402 documentation. Mastercard keeps the 402 handshake but changes what happens after it. Ledger Insights describes the result as batch settlement with Mastercard inserted into the flow, adding a credential registry and a guarantee, per its analysis.
Plain x402Mastercard Agent Pay for Machines
Payment signalHTTP 402 with payment requirements (x402)Same 402 signal (Mastercard)
What the agent sendsA signed payment authorization, settled per requestA signed voucher, a promise to pay within an approved limit
Settlement timingPer request, onchainVouchers combined and redeemed later, in batches
Payment guaranteeFinality comes from the onchain settlement itselfMastercard says payment is guaranteed now and settled later
Funding sourceThe agent's own stablecoin walletWallet funding via Coinbase in the demo; fiat or stablecoins through BVNK
What the seller receivesThe asset named in the 402 response, often USDCPreferred currency, token or rail
Who sits in the middleA facilitator such as Coinbase'sMastercard as trust layer, plus BVNK and the facilitator
The trade-off is clear. Plain x402 is open and settles each payment as it happens, but every seller must accept a specific token on a specific chain. Mastercard's version adds an intermediary and a delay, in return for spending limits, a promise of payment and a way for a business that funds agents from a bank account to pay sellers who want stablecoins, or the reverse. Our x402 vs AP2 vs ACK-Pay comparison covers the other agent payment protocols Mastercard is competing with.
Why machine payments lean on stablecoins
The economics explain why Mastercard built on a crypto protocol at all. More than 138 million x402 transactions had taken place on Base by mid-2026, and over 87% of x402 payments fell between a hundredth of a cent and ten cents, per Chainalysis. Payments that small rarely make sense on card rails, where fixed per-transaction costs can exceed the payment.
Circle described the split to Chainalysis as card rails for consumer-prompted agent payments and stablecoin rails for machine-to-machine settlements too small for card economics, per the same Chainalysis report. Agent Pay for Machines is Mastercard's attempt to sit across that line: it already supports settlement across cards, accounts and stablecoins, per the June release, and batching vouchers is one way to make tiny payments cheap enough to settle.
🧭Our take: Agent Pay for Machines is less a new payment rail than a control layer on top of x402. The useful part for businesses is the mandate: a budget, permissions and a guarantee that a finance team can approve once. The cost is that the open, per-request settlement x402 was built for becomes a Mastercard-mediated batch. For sellers already on Cloudflare or Coinbase rails, USDC on Base is still doing the settling underneath. Test it in the sandbox now, but wait for published fees and dispute rules before routing real spend through it.
Named downsides
No pricing. Neither buyer nor seller fees have been published, so cost against plain x402 cannot be compared.
Settlement opacity. Redemption frequency, chains and stablecoins beyond the Base demo are unstated.
Counterparty in the middle. Batching means sellers deliver on a promise and wait for settlement, which plain x402 avoids.
Early access only. A sandbox and first-version APIs are not a production service level.
Geography unclear. Cloudflare's gateway is limited to eligible US-based sellers and buyers during its beta.
Vendor concentration. Mastercard, its BVNK unit and the Global Money Platform would sit on both sides of the payment.
Who should test it now, and who should wait
Test now: API and data sellers already behind Cloudflare's Monetization Gateway, agent platforms whose business customers want a hard spending cap per task, and payment providers in the BVNK or Coinbase orbit that want to accept agent payments without asking every buyer to hold USDC.
Wait: crypto-native agents that already pay per request in USDC and gain little from a guarantee, and any business outside the United States until Mastercard says where Early Access applies. For the risk side, Mastercard's separate Stablecoin Security screening service, launched a day earlier, shows how the company plans to wrap stablecoin payments in its fraud and sanctions tooling.
FAQ
What is Mastercard Agent Pay for Machines?
A Mastercard service that lets AI agents pay for digital services such as AI models, data, computing power and APIs on behalf of businesses, within approved budgets and permissions. It builds on the x402 protocol (Mastercard).
Is Agent Pay for Machines live?
It is in Early Access as of 20 October 2026. Developers can use first-version buyer and seller APIs, a toolkit, a sandbox and documentation; Mastercard has not given a general availability date (Mastercard).
Does Agent Pay for Machines use stablecoins?
It can. In the demo, Base provided onchain settlement and BVNK settled in fiat or stablecoins (Mastercard). Cloudflare's Monetization Gateway, the seller side in the demo, settles x402 payments in USDC on Base (Cloudflare).
How is it different from plain x402?
Plain x402 settles each payment per request through a facilitator (Coinbase). Mastercard's version uses signed vouchers that sellers combine and redeem later, with Mastercard acting as a trust layer that guarantees payment (Ledger Insights).
How much does Agent Pay for Machines cost?
Mastercard has not published pricing for buyers or sellers; the Early Access announcement lists APIs, a toolkit, a sandbox and documentation but no fees (Mastercard).
What to watch next: published fees, a list of settlement chains and stablecoins beyond Base, dispute and chargeback rules for vouchers, and the first sellers outside the pilot group. Background on the protocol layer is in our agent payment protocol comparison.
This content is provided for informational and educational purposes only and does not constitute financial, investment, legal, or tax advice; it is not financial advice, and no material herein should be interpreted as a recommendation, endorsement, or solicitation to buy or sell any asset or token. Product scope, partners and availability are as described by Mastercard on 20 October 2026 and can change; check Mastercard's developer documentation and take legal advice before letting software spend on a business's behalf. Nothing here is a solicitation to buy or sell.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
記事
翻訳参照
Gate Releases Latest Reserve Report: Total Reserves Rise to $8.688 Billion, Overall Reserve Ratio Reaches 118.49%According to an official announcement, Gate has published its latest reserve report. As of October 18, 2026, Gate's total reserves have risen to $8.688 billion, up 5.7% from the previous period; customer net assets reached $7.332 billion, with the overall reserve coverage ratio rising from 117.26% in the previous period to 118.49%.
In terms of core asset reserves, BTC user assets grew from 21,116 to 21,156 BTC, while platform reserves grew from 25,466 to 25,727 BTC, lifting the reserve coverage ratio from 120.32% to 121.60%; ETH user assets grew from 350,840 to 362,785 ETH, while platform reserves grew from 433,589 to 449,042 ETH, lifting the reserve coverage ratio from 123.59% to 123.78%.
In terms of stablecoin reserves, combined user assets in USDT, USD1, GUSD and USDC totaled approximately $1.497 billion, against corresponding platform reserves of approximately $1.746 billion, for a combined reserve ratio of 116.59%. In addition, this proof of reserves covers 500 assets in total, with major assets such as DOGE, GT and SOL also maintaining ample reserves that remain above the 100% industry safety benchmark, at 106.76%, 129.00% and 102.51% respectively.
Gate continues to refine its reserve verification mechanism, from being among the industry's earliest to introduce a 100% reserve commitment and the first to adopt zero-knowledge proof (ZKP) technology, to establishing a self-verifiable reserve transparency mechanism that integrates technical measures such as cold and hot wallet ownership verification, Merkle tree structures and user balance snapshots, enhancing the authenticity and verifiability of reserve data and providing a safeguard for the platform's long-term stable operations.
Currently, Gate serves more than 62 million users worldwide, supports over 5,400 crypto assets and over 12,800 stock assets, and offers trading in TradFi assets such as metals, indices, forex and commodities. Building on this diverse asset base, Gate continues to integrate digital asset and traditional financial services, creating Gate Money, a globally integrated financial services application that connects digital assets, fiat currencies, stocks, ETFs, gold, bank accounts, payments and asset management services into a single account, further expanding the platform's financial services boundaries.
Going forward, Gate will continue to deepen its reserve transparency efforts, improve its security infrastructure and risk management systems, and accelerate the building of a safer, more transparent and more efficient one-stop financial services ecosystem.
About Gate
Founded in 2013, with Dr. Han as its founder and CEO, Gate is one of the world's leading cryptocurrency and comprehensive financial services platforms, with businesses covering asset management, trading, payments and other financial and lifestyle scenarios. The platform has more than 62 million users, supports trading in 5,400+ crypto assets and 12,800+ stock assets, and also offers TradFi assets such as metals, indices, forex and commodities, meeting users' full-spectrum needs from asset holding and trading to everyday use. As an industry benchmark, Gate was the first to achieve 100% proof of reserves, and continues to build a diversified range of products and ecosystems including Gate Money, Gate Wallet, Gate Ventures and Gate for AI Agent.
To learn more, please visit: Website | X | Telegram | LinkedIn | Instagram | YouTube
Disclaimer:
This content does not constitute any invitation, solicitation or recommendation. You should always seek independent professional advice before making any investment decision. Please note that Gate may restrict or prohibit all or part of its services from restricted regions. Please read the User Agreement for more information.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Gate Releases Latest Reserve Report: Total Reserves Rise to $8.688 Billion, Overall Reserve Ratio Reaches 118.49%
According to an official announcement, Gate has published its latest reserve report. As of October 18, 2026, Gate's total reserves have risen to $8.688 billion, up 5.7% from the previous period; customer net assets reached $7.332 billion, with the overall reserve coverage ratio rising from 117.26% in the previous period to 118.49%.
In terms of core asset reserves, BTC user assets grew from 21,116 to 21,156 BTC, while platform reserves grew from 25,466 to 25,727 BTC, lifting the reserve coverage ratio from 120.32% to 121.60%; ETH user assets grew from 350,840 to 362,785 ETH, while platform reserves grew from 433,589 to 449,042 ETH, lifting the reserve coverage ratio from 123.59% to 123.78%.
In terms of stablecoin reserves, combined user assets in USDT, USD1, GUSD and USDC totaled approximately $1.497 billion, against corresponding platform reserves of approximately $1.746 billion, for a combined reserve ratio of 116.59%. In addition, this proof of reserves covers 500 assets in total, with major assets such as DOGE, GT and SOL also maintaining ample reserves that remain above the 100% industry safety benchmark, at 106.76%, 129.00% and 102.51% respectively.
Gate continues to refine its reserve verification mechanism, from being among the industry's earliest to introduce a 100% reserve commitment and the first to adopt zero-knowledge proof (ZKP) technology, to establishing a self-verifiable reserve transparency mechanism that integrates technical measures such as cold and hot wallet ownership verification, Merkle tree structures and user balance snapshots, enhancing the authenticity and verifiability of reserve data and providing a safeguard for the platform's long-term stable operations.
Currently, Gate serves more than 62 million users worldwide, supports over 5,400 crypto assets and over 12,800 stock assets, and offers trading in TradFi assets such as metals, indices, forex and commodities. Building on this diverse asset base, Gate continues to integrate digital asset and traditional financial services, creating Gate Money, a globally integrated financial services application that connects digital assets, fiat currencies, stocks, ETFs, gold, bank accounts, payments and asset management services into a single account, further expanding the platform's financial services boundaries.
Going forward, Gate will continue to deepen its reserve transparency efforts, improve its security infrastructure and risk management systems, and accelerate the building of a safer, more transparent and more efficient one-stop financial services ecosystem.
About Gate
Founded in 2013, with Dr. Han as its founder and CEO, Gate is one of the world's leading cryptocurrency and comprehensive financial services platforms, with businesses covering asset management, trading, payments and other financial and lifestyle scenarios. The platform has more than 62 million users, supports trading in 5,400+ crypto assets and 12,800+ stock assets, and also offers TradFi assets such as metals, indices, forex and commodities, meeting users' full-spectrum needs from asset holding and trading to everyday use. As an industry benchmark, Gate was the first to achieve 100% proof of reserves, and continues to build a diversified range of products and ecosystems including Gate Money, Gate Wallet, Gate Ventures and Gate for AI Agent.
To learn more, please visit: Website | X | Telegram | LinkedIn | Instagram | YouTube
Disclaimer:
This content does not constitute any invitation, solicitation or recommendation. You should always seek independent professional advice before making any investment decision. Please note that Gate may restrict or prohibit all or part of its services from restricted regions. Please read the User Agreement for more information.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
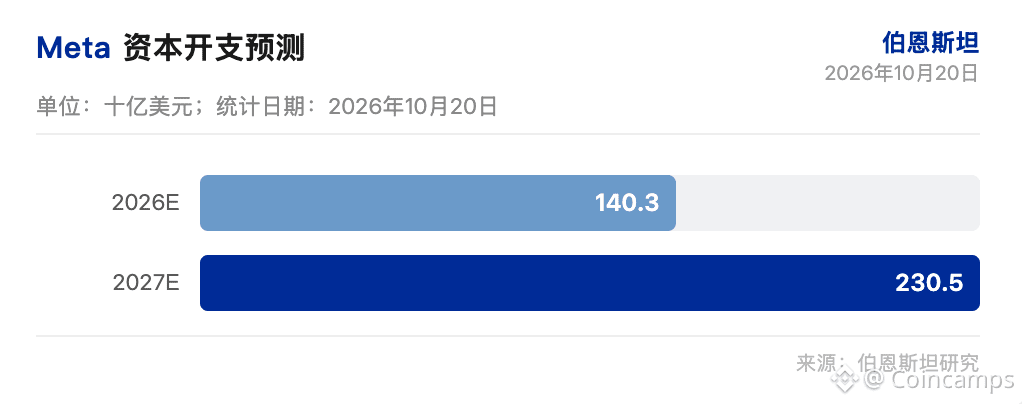
記事
翻訳参照
Bernstein Research Analysis: Meta Near-Term Expectations Run High, Muse Unlocks Path to AI ReturnsThe market views Muse as just another chat application, while Bernstein sees it in its October 20, 2026 report as Meta’s AI operating system. Launched on September 8, Muse topped the US App Store download charts within 10 days, accumulating approximately 2.5 million daily active users (DAU) in the US. Bernstein sets a price target of $800 for Meta, compared to its current price of $705.44, representing 13% upside.
The report maintains a long-term bullish stance but remains cautious in the near term. Muse provides Meta with its first consumer-facing AI product, demonstrating a return on AI investments and yielding a positive return on invested capital (ROIC). Valuations and expectations have already elevated, while Q3 2026 earnings before interest and taxes (EBIT) are weighed down by a $10 billion legal settlement.
Positioned at the center of the Meta ecosystem, hardware serves as the carrier while Muse is the product. The long-term narrative holds, though near-term earnings benchmarks have been set tighter.
Muse's Chart-Topping Rise Changes the Narrative
Launched on September 8, Muse reached number one on the US App Store download charts within 10 days, surpassing ChatGPT on September 17 and maintaining that position. Citing Sensor Tower data, Bernstein notes that Muse's post-launch download trajectory outpaces both ChatGPT's May 2023 launch and Meta's own AI app.
American DAU stands at approximately 2.5 million, with an average daily usage time of 16 minutes compared to ChatGPT's 19 minutes. Muse's retention curve outperforms ChatGPT's. Bernstein cautions that while early downloads and retention are strong, the initial buzz in the total addressable market (TAM) cannot be directly extrapolated, pointing to precedents like Facebook Shops and the Metaverse.
Muse has expanded from a chatbot to include real-time voice, customizable personas, avatars, email, and PC control integrations with Shopify, Walmart, Best Buy, Sephora, Ulta, Wayfair, Gap, Expedia, Instacart, Notion, GitHub, and Box. The hardware strategy revolves around "using Muse in any way," positioning glasses, virtual reality (VR) headsets, and pendants as endpoints.
Valuation Now Par with Google and Amazon
Following Muse's launch, Meta's stock has undergone repricing, aligning closely with the one-year forward P/E multiples of Google and Amazon. Bernstein's charts show all three trading around 20x. Muse has reignited discussions on the "iPhone moment" for consumer AI and revived debates surrounding agentic commerce and search displacement pressures.
Bernstein posits that Muse could evolve from a discovery platform into a decision-making layer, positioning itself closer to where purchase intent forms in the consumer funnel. Amazon is excluded from Muse's partner network, as it pursues its own agentic commerce initiatives. Meanwhile, Google faces concerns over AI accelerating the replacement of traditional search.
Higher valuations bring higher expectations. Bernstein maintains an Outperform rating with an $800 price target, utilizing a blended valuation model of 50% 2027 enterprise value-to-sales (EV/Sales) at 6.7x and 50% discounted cash flow (DCF), with a weighted average cost of capital (WACC) of 10% and terminal growth of 3.5%. At the current price of $705.44, this implies 13% upside.
Near-Term Expectations Outpace Fundamentals
For Q3 2026, Bernstein forecasts revenue at $64.058 billion against consensus of $63.312 billion. EBIT is projected at $11.338 billion versus consensus of $19.016 billion, including $10 billion in legal costs related to the minor media usage settlement. EPS is estimated at $3.95 against consensus of $3.56. Revenue beat estimates, while EBIT was suppressed by one-time charges.
Capex is forecast at $140.3 billion for 2026 and $230.5 billion for 2027, exceeding consensus of $201.6 billion. For 2027, Bernstein projects EBIT at $97.89 billion against consensus of $103.94 billion, and EPS at $33.21 versus consensus of $33.87. Bernstein has lowered 2027 EBIT and EPS forecasts to account for Muse investments, third-party cloud deals, and marketing expenditures.
Pressure on free cash flow (FCF) is even more pronounced. Bernstein forecasts 2027 FCF at -$59.684 billion versus consensus of -$33.418 billion, a divergence of $26.266 billion. Q3 2026 FCF is projected at -$13.756 billion against consensus of -$8.953 billion. 2027 capex is 14.3% above consensus, marketing spending rises due to Muse promotion, and third-party cloud transactions increase operating costs. These factors weigh on near-term profits and cash flows, though top-line strength remains intact.
Other revenue surpassed the $1 billion quarterly mark for the first time in Q2 2026, growing 73% year over year. Bernstein raised its other revenue forecast to reflect monetization from business messaging, commercial agents, subscriptions, and Muse. While early-stage monetization of Muse does not yet factor into baseline expectations, it could contribute visibly to other revenue growth in 2027. Muse's monetization hinges on four key metrics: subscription count, gross merchandise value (GMV), downloads, and engagement levels. An uplift in any single area would shift the gap between near-term expectations and fundamentals.
Muse turns Meta's AI investments from a mere narrative into a trackable consumer product, with near-term expectations already running ahead of realization.
Disclaimer
This article compiles and interprets a third-party broker research report (Bernstein, October 20, 2026) through TechFlow Research, alongside publicly available market information. All cited ratings, price targets, earnings forecasts, and related judgments represent the views of the broker's analysts, reflecting solely their institution's stance rather than those of TechFlow Research, and do not constitute investment advice.
Markets involve risks; decisions should be made independently. This article should not serve as a basis for buying or selling any securities.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Bernstein Research Analysis: Meta Near-Term Expectations Run High, Muse Unlocks Path to AI Returns
The market views Muse as just another chat application, while Bernstein sees it in its October 20, 2026 report as Meta’s AI operating system. Launched on September 8, Muse topped the US App Store download charts within 10 days, accumulating approximately 2.5 million daily active users (DAU) in the US. Bernstein sets a price target of $800 for Meta, compared to its current price of $705.44, representing 13% upside.
The report maintains a long-term bullish stance but remains cautious in the near term. Muse provides Meta with its first consumer-facing AI product, demonstrating a return on AI investments and yielding a positive return on invested capital (ROIC). Valuations and expectations have already elevated, while Q3 2026 earnings before interest and taxes (EBIT) are weighed down by a $10 billion legal settlement.
Positioned at the center of the Meta ecosystem, hardware serves as the carrier while Muse is the product. The long-term narrative holds, though near-term earnings benchmarks have been set tighter.
Muse's Chart-Topping Rise Changes the Narrative
Launched on September 8, Muse reached number one on the US App Store download charts within 10 days, surpassing ChatGPT on September 17 and maintaining that position. Citing Sensor Tower data, Bernstein notes that Muse's post-launch download trajectory outpaces both ChatGPT's May 2023 launch and Meta's own AI app.
American DAU stands at approximately 2.5 million, with an average daily usage time of 16 minutes compared to ChatGPT's 19 minutes. Muse's retention curve outperforms ChatGPT's. Bernstein cautions that while early downloads and retention are strong, the initial buzz in the total addressable market (TAM) cannot be directly extrapolated, pointing to precedents like Facebook Shops and the Metaverse.
Muse has expanded from a chatbot to include real-time voice, customizable personas, avatars, email, and PC control integrations with Shopify, Walmart, Best Buy, Sephora, Ulta, Wayfair, Gap, Expedia, Instacart, Notion, GitHub, and Box. The hardware strategy revolves around "using Muse in any way," positioning glasses, virtual reality (VR) headsets, and pendants as endpoints.
Valuation Now Par with Google and Amazon
Following Muse's launch, Meta's stock has undergone repricing, aligning closely with the one-year forward P/E multiples of Google and Amazon. Bernstein's charts show all three trading around 20x. Muse has reignited discussions on the "iPhone moment" for consumer AI and revived debates surrounding agentic commerce and search displacement pressures.
Bernstein posits that Muse could evolve from a discovery platform into a decision-making layer, positioning itself closer to where purchase intent forms in the consumer funnel. Amazon is excluded from Muse's partner network, as it pursues its own agentic commerce initiatives. Meanwhile, Google faces concerns over AI accelerating the replacement of traditional search.
Higher valuations bring higher expectations. Bernstein maintains an Outperform rating with an $800 price target, utilizing a blended valuation model of 50% 2027 enterprise value-to-sales (EV/Sales) at 6.7x and 50% discounted cash flow (DCF), with a weighted average cost of capital (WACC) of 10% and terminal growth of 3.5%. At the current price of $705.44, this implies 13% upside.
Near-Term Expectations Outpace Fundamentals
For Q3 2026, Bernstein forecasts revenue at $64.058 billion against consensus of $63.312 billion. EBIT is projected at $11.338 billion versus consensus of $19.016 billion, including $10 billion in legal costs related to the minor media usage settlement. EPS is estimated at $3.95 against consensus of $3.56. Revenue beat estimates, while EBIT was suppressed by one-time charges.
Capex is forecast at $140.3 billion for 2026 and $230.5 billion for 2027, exceeding consensus of $201.6 billion. For 2027, Bernstein projects EBIT at $97.89 billion against consensus of $103.94 billion, and EPS at $33.21 versus consensus of $33.87. Bernstein has lowered 2027 EBIT and EPS forecasts to account for Muse investments, third-party cloud deals, and marketing expenditures.
Pressure on free cash flow (FCF) is even more pronounced. Bernstein forecasts 2027 FCF at -$59.684 billion versus consensus of -$33.418 billion, a divergence of $26.266 billion. Q3 2026 FCF is projected at -$13.756 billion against consensus of -$8.953 billion. 2027 capex is 14.3% above consensus, marketing spending rises due to Muse promotion, and third-party cloud transactions increase operating costs. These factors weigh on near-term profits and cash flows, though top-line strength remains intact.
Other revenue surpassed the $1 billion quarterly mark for the first time in Q2 2026, growing 73% year over year. Bernstein raised its other revenue forecast to reflect monetization from business messaging, commercial agents, subscriptions, and Muse. While early-stage monetization of Muse does not yet factor into baseline expectations, it could contribute visibly to other revenue growth in 2027. Muse's monetization hinges on four key metrics: subscription count, gross merchandise value (GMV), downloads, and engagement levels. An uplift in any single area would shift the gap between near-term expectations and fundamentals.
Muse turns Meta's AI investments from a mere narrative into a trackable consumer product, with near-term expectations already running ahead of realization.
Disclaimer
This article compiles and interprets a third-party broker research report (Bernstein, October 20, 2026) through TechFlow Research, alongside publicly available market information. All cited ratings, price targets, earnings forecasts, and related judgments represent the views of the broker's analysts, reflecting solely their institution's stance rather than those of TechFlow Research, and do not constitute investment advice.
Markets involve risks; decisions should be made independently. This article should not serve as a basis for buying or selling any securities.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
翻訳参照
Accomplice in Qian Zhimin Money Laundering Case Has £5.6m Recovered as Ownership of 61,000 BTC (£3.8bn) Remains DisputedOn October 21, 2026, according to an exclusive judicial investigation report published by the UK Daily Mail, a key accomplice who assisted the ringleader of a massive transnational Ponzi scheme, Qian Zhimin, in money laundering has formally returned £5.6 million in full to the British government.
The 48-year-old Malaysian national Hok Seng Ling, who previously served as Qian Zhimin's personal butler, was sentenced to 4 years and 11 months in prison last November at the Southwark Crown Court in London for conspiring to launder money. The court subsequently issued a confiscation order against him.
Full Execution of £5.6 Million Recovery: Butler's Laundering Network Completely Collapses
According to an information disclosure response from the Crown Prosecution Service (CPS) in the UK, the court's confiscation order of £5,603,305 and £1,990 in interest have been fully executed. The funds primarily originated from encrypted assets seized upon his arrest.
During his assistance with her escape, Ling long concealed himself in Derbyshire, booking numerous temporary Airbnb accommodations, hiring logistical personnel, and building underground capital flow networks to help Qian Zhimin, dubbed the "Bitcoin Queen" by foreign media, evade pursuit by British police for an extended period.
With the full recovery of his concealed assets, the UK jurisdiction sees another substantive milestone in the financial liquidation of the Lantian Gearui major Ponzi scheme, which involved £5.5 billion and swept up 128,000 investors.
£3.8 Billion Asset Dispute: Applicable Law Ruling Triggers Ownership Determination Crisis
Compared to the fully recovered £5.6 million in this instance, the larger core assets tied to the case are settled within the Bitcoin network. According to a BBC follow-up report on the century-scale bitcoin case involving 61,000 BTC, the digital assets seized by London Police have seen their total market value surge to £3.8 billion amid rising prices.
Currently, Chinese victim investors are entrusting lawyers to initiate asset preservation lawsuits in British courts, striving to prevent the UK Treasury from appropriating all appreciation gains from this £3.8 billion bitcoin holding into the British national exchequer under the Proceeds of Crime Act.
The core dispute centers on whether victim claims should be governed by British law or Chinese law. If the UK equitable tracing principle applies, victims may assert ownership over all tokens; however, if compensation is limited to the original investment amount, the appreciation gains could be confiscated by the British government.
Dual-Track Judicial Sovereignty Contest: Victims Face Numerous Obstacles in Defending Rights
According to the latest civil forfeiture ruling issued by the UK High Court, Judge Sir Mark Turner officially ruled that this series of tortious acts occurred within Chinese territory, and the victims' creditor claims must be defined under Chinese substantive law.
This procedural ruling significantly raises the burden of proof for victims to recover complete bitcoin assets. The affected group must not only prove their proprietary rights over specific on-chain tokens under Chinese law but also withstand the rigorous scrutiny of British courts regarding the validity of those rights.
The London High Court will subsequently hear specialized cross-examination from Chinese law experts. Where these 61,000 bitcoins, which set global law enforcement records, ultimately flow will profoundly reshape precedential benchmarks for transnational crypto jurisdiction and the return of implicated assets.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Accomplice in Qian Zhimin Money Laundering Case Has £5.6m Recovered as Ownership of 61,000 BTC (£3.8bn) Remains Disputed
On October 21, 2026, according to an exclusive judicial investigation report published by the UK Daily Mail, a key accomplice who assisted the ringleader of a massive transnational Ponzi scheme, Qian Zhimin, in money laundering has formally returned £5.6 million in full to the British government.
The 48-year-old Malaysian national Hok Seng Ling, who previously served as Qian Zhimin's personal butler, was sentenced to 4 years and 11 months in prison last November at the Southwark Crown Court in London for conspiring to launder money. The court subsequently issued a confiscation order against him.
Full Execution of £5.6 Million Recovery: Butler's Laundering Network Completely Collapses
According to an information disclosure response from the Crown Prosecution Service (CPS) in the UK, the court's confiscation order of £5,603,305 and £1,990 in interest have been fully executed. The funds primarily originated from encrypted assets seized upon his arrest.
During his assistance with her escape, Ling long concealed himself in Derbyshire, booking numerous temporary Airbnb accommodations, hiring logistical personnel, and building underground capital flow networks to help Qian Zhimin, dubbed the "Bitcoin Queen" by foreign media, evade pursuit by British police for an extended period.
With the full recovery of his concealed assets, the UK jurisdiction sees another substantive milestone in the financial liquidation of the Lantian Gearui major Ponzi scheme, which involved £5.5 billion and swept up 128,000 investors.
£3.8 Billion Asset Dispute: Applicable Law Ruling Triggers Ownership Determination Crisis
Compared to the fully recovered £5.6 million in this instance, the larger core assets tied to the case are settled within the Bitcoin network. According to a BBC follow-up report on the century-scale bitcoin case involving 61,000 BTC, the digital assets seized by London Police have seen their total market value surge to £3.8 billion amid rising prices.
Currently, Chinese victim investors are entrusting lawyers to initiate asset preservation lawsuits in British courts, striving to prevent the UK Treasury from appropriating all appreciation gains from this £3.8 billion bitcoin holding into the British national exchequer under the Proceeds of Crime Act.
The core dispute centers on whether victim claims should be governed by British law or Chinese law. If the UK equitable tracing principle applies, victims may assert ownership over all tokens; however, if compensation is limited to the original investment amount, the appreciation gains could be confiscated by the British government.
Dual-Track Judicial Sovereignty Contest: Victims Face Numerous Obstacles in Defending Rights
According to the latest civil forfeiture ruling issued by the UK High Court, Judge Sir Mark Turner officially ruled that this series of tortious acts occurred within Chinese territory, and the victims' creditor claims must be defined under Chinese substantive law.
This procedural ruling significantly raises the burden of proof for victims to recover complete bitcoin assets. The affected group must not only prove their proprietary rights over specific on-chain tokens under Chinese law but also withstand the rigorous scrutiny of British courts regarding the validity of those rights.
The London High Court will subsequently hear specialized cross-examination from Chinese law experts. Where these 61,000 bitcoins, which set global law enforcement records, ultimately flow will profoundly reshape precedential benchmarks for transnational crypto jurisdiction and the return of implicated assets.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
1
·
--
記事
翻訳参照
Hyperliquid accounts for 58% of on-chain perpetual contract open interest, yet trading volume only represents 38.6%.TechFlow Guide:In the decentralized perpetual contract sector, trading volume has always been regarded as the primary indicator of platform activity; however, in Q3 2026, the on-chain derivatives landscape exhibited a highly disruptive divergence. According to the latest authoritative review report published by Alea Research, Hyperliquid captured 58.0% of the total network Open Interest (OI), while accounting for only 38.6% of total trading volume.
This anomaly of "open interest significantly surpassing trading volume" completely breaks the old model where derivative DEXs relied on short-term high-frequency volume spoofing to create a false sense of prosperity. Data shows that Hyperliquid traders' average holding period ranks first among the top ten mainstream exchanges across the entire network. A large number of professional institutions and quantitative hedge funds have selected it as their primary venue for executing cash-and-carry arbitrage and funding rate arbitrage (Carry Trade), accumulating an extremely large pool of sticky institutional capital.
This article provides an in-depth analysis of the competitive dynamics among the 121 perpetual contract venues across the network in Q3, examines the explosive growth logic behind the HIP-3 native ecosystem, the stunning data performance of trade.xyz, and how Hyperliquid's Assistance Fund establishes a powerful value loop by allocating nearly 90% of fees toward repurchasing HYPE tokens.
Tide Recedes in Market Trends: Network-Wide Perpetual Contract Volume Halved Amidst Counter-Cyclical Expansion
In Q3 2026, the on-chain perpetual contract market as a whole fell into a period of sluggish adjustment. Among the 121 tracked decentralized perpetual contract venues across the network, total trading volume contracted by half compared to the highs at the end of 2025, with the network-wide Q3 quarter-over-quarter decline reaching 2.5%.
However, amidst the network-wide winter, Hyperliquid demonstrated incredible counter-cyclical vitality. Its Q3 matched trading volume reached $688.7 billion, increasing by 9.2% quarter-over-quarter against the trend; this propelled its network-wide trading volume market share to achieve substantial jumps for three consecutive quarters, firmly locking in its position as the industry leader at 38.6%.
What is even more staggering is the battle for open interest (OI). Out of all newly added open contracts industry-wide, Hyperliquid alone captured 77%, maintaining a quarterly daily average OI of over $2.1 billion, with single-day peak values even surpassing a shocking monopoly ratio of 65% across the entire network.
Figure 1: Market share trend of Hyperliquid in the 30-day rolling trading volume of network-wide on-chain perpetual contracts. Steadily climbing to 38.6% for three consecutive quarters.
Anomaly in Position Structure: Why Is the Position Share Far Higher Than the Trading Volume Share?
In traditional derivatives understanding, an exchange's open contract share often closely aligns with its trading volume share; if the volume share is only 38.6%, logically its open interest should also hover around 40%. So why did Hyperliquid's open interest share surge to 58.0%?
Alea Research provided the core answer through long-term tracking of on-chain position addresses: Hyperliquid users hold positions for significantly longer periods than other top ten competitors. This is mainly attributed to the following two points:
• Zero gas fees and full-memory matching mechanism: The underlying high-performance L1 architecture built specifically for finance provides sub-second matching experiences and transparent liquidation comparable to centralized exchanges (CEX), attracting numerous professional hedge funds to use it as their primary position for large-scale basis arbitrage;
• Real liquidity without fabricated volume boosting: Many competing DEXs are flooded with fake wash trading (Wash Trading) aimed at earning points, resulting in artificially inflated volumes but extremely poor fund retention; whereas Hyperliquid's liquidity is entirely settled through organic trading and arbitrage market-making, resulting in extremely solid capital retention.
Figure 2: Hyperliquid's market share in total network-wide open interest (OI). Q3 average reached 58.0%, demonstrating deep accumulation of institutional-grade long-term capital.
HIP-3 Innovation Boom: trade.xyz Captures 98% of Native Ecosystem Fees
The most critical technological milestone achieved by the Hyperliquid ecosystem in Q3 was the launch of HIP-3 native spot and custom derivative markets. Anyone can establish an independent, exclusive derivative market on the Hyperliquid L1 through permissionless staking.
Among the two brand-new DEXs launched under the HIP-3 framework, trade.xyz displayed astonishing dominance. Within just one quarter of Q3, trade.xyz generated cumulative trading volume as high as $251.3 billion, directly surpassing the full-quarter performance of the independent legacy platform Aster ($160.3 billion).
At the level of ecosystem capture, trade.xyz contributed 97.9% of the fee revenue within the HIP-3 segmented market, delivering a continuous stream of genuine earnings to Hyperliquid's entire underlying public chain.
7% Fee Repurchase & Burn: Assistance Fund Forges a Sturdy Token Moat
Facing massive fee inflows, Hyperliquid established an exceptionally pure value capture loop. The report discloses that during Q3, the platform's total perpetual contract fee revenue grew 2.9% quarter-over-quarter to reach $165.5 million.
Its officially established Assistance Fund allocates up to 88.7% of the received fees directly toward continuously buying HYPE tokens on the open market; additionally, the revenue generated from its underlying hundreds-of-billions-USDC reserve pool contributed an extra $17.7 million in steady cash flow to the Assistance Fund in Q3.
Substantial real-capital buybacks enabled the HYPE token to exhibit strong price resilience amid the harsh macroeconomic environment of Q3, constructing a positive and healthy economic flywheel of "user trading -> position accumulation -> fee extraction -> strong buy-side support".
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Hyperliquid accounts for 58% of on-chain perpetual contract open interest, yet trading volume only represents 38.6%.
TechFlow Guide:In the decentralized perpetual contract sector, trading volume has always been regarded as the primary indicator of platform activity; however, in Q3 2026, the on-chain derivatives landscape exhibited a highly disruptive divergence. According to the latest authoritative review report published by Alea Research, Hyperliquid captured 58.0% of the total network Open Interest (OI), while accounting for only 38.6% of total trading volume.
This anomaly of "open interest significantly surpassing trading volume" completely breaks the old model where derivative DEXs relied on short-term high-frequency volume spoofing to create a false sense of prosperity. Data shows that Hyperliquid traders' average holding period ranks first among the top ten mainstream exchanges across the entire network. A large number of professional institutions and quantitative hedge funds have selected it as their primary venue for executing cash-and-carry arbitrage and funding rate arbitrage (Carry Trade), accumulating an extremely large pool of sticky institutional capital.
This article provides an in-depth analysis of the competitive dynamics among the 121 perpetual contract venues across the network in Q3, examines the explosive growth logic behind the HIP-3 native ecosystem, the stunning data performance of trade.xyz, and how Hyperliquid's Assistance Fund establishes a powerful value loop by allocating nearly 90% of fees toward repurchasing HYPE tokens.
Tide Recedes in Market Trends: Network-Wide Perpetual Contract Volume Halved Amidst Counter-Cyclical Expansion
In Q3 2026, the on-chain perpetual contract market as a whole fell into a period of sluggish adjustment. Among the 121 tracked decentralized perpetual contract venues across the network, total trading volume contracted by half compared to the highs at the end of 2025, with the network-wide Q3 quarter-over-quarter decline reaching 2.5%.
However, amidst the network-wide winter, Hyperliquid demonstrated incredible counter-cyclical vitality. Its Q3 matched trading volume reached $688.7 billion, increasing by 9.2% quarter-over-quarter against the trend; this propelled its network-wide trading volume market share to achieve substantial jumps for three consecutive quarters, firmly locking in its position as the industry leader at 38.6%.
What is even more staggering is the battle for open interest (OI). Out of all newly added open contracts industry-wide, Hyperliquid alone captured 77%, maintaining a quarterly daily average OI of over $2.1 billion, with single-day peak values even surpassing a shocking monopoly ratio of 65% across the entire network.
Figure 1: Market share trend of Hyperliquid in the 30-day rolling trading volume of network-wide on-chain perpetual contracts. Steadily climbing to 38.6% for three consecutive quarters.
Anomaly in Position Structure: Why Is the Position Share Far Higher Than the Trading Volume Share?
In traditional derivatives understanding, an exchange's open contract share often closely aligns with its trading volume share; if the volume share is only 38.6%, logically its open interest should also hover around 40%. So why did Hyperliquid's open interest share surge to 58.0%?
Alea Research provided the core answer through long-term tracking of on-chain position addresses: Hyperliquid users hold positions for significantly longer periods than other top ten competitors. This is mainly attributed to the following two points:
• Zero gas fees and full-memory matching mechanism: The underlying high-performance L1 architecture built specifically for finance provides sub-second matching experiences and transparent liquidation comparable to centralized exchanges (CEX), attracting numerous professional hedge funds to use it as their primary position for large-scale basis arbitrage;
• Real liquidity without fabricated volume boosting: Many competing DEXs are flooded with fake wash trading (Wash Trading) aimed at earning points, resulting in artificially inflated volumes but extremely poor fund retention; whereas Hyperliquid's liquidity is entirely settled through organic trading and arbitrage market-making, resulting in extremely solid capital retention.
Figure 2: Hyperliquid's market share in total network-wide open interest (OI). Q3 average reached 58.0%, demonstrating deep accumulation of institutional-grade long-term capital.
HIP-3 Innovation Boom: trade.xyz Captures 98% of Native Ecosystem Fees
The most critical technological milestone achieved by the Hyperliquid ecosystem in Q3 was the launch of HIP-3 native spot and custom derivative markets. Anyone can establish an independent, exclusive derivative market on the Hyperliquid L1 through permissionless staking.
Among the two brand-new DEXs launched under the HIP-3 framework, trade.xyz displayed astonishing dominance. Within just one quarter of Q3, trade.xyz generated cumulative trading volume as high as $251.3 billion, directly surpassing the full-quarter performance of the independent legacy platform Aster ($160.3 billion).
At the level of ecosystem capture, trade.xyz contributed 97.9% of the fee revenue within the HIP-3 segmented market, delivering a continuous stream of genuine earnings to Hyperliquid's entire underlying public chain.
7% Fee Repurchase & Burn: Assistance Fund Forges a Sturdy Token Moat
Facing massive fee inflows, Hyperliquid established an exceptionally pure value capture loop. The report discloses that during Q3, the platform's total perpetual contract fee revenue grew 2.9% quarter-over-quarter to reach $165.5 million.
Its officially established Assistance Fund allocates up to 88.7% of the received fees directly toward continuously buying HYPE tokens on the open market; additionally, the revenue generated from its underlying hundreds-of-billions-USDC reserve pool contributed an extra $17.7 million in steady cash flow to the Assistance Fund in Q3.
Substantial real-capital buybacks enabled the HYPE token to exhibit strong price resilience amid the harsh macroeconomic environment of Q3, constructing a positive and healthy economic flywheel of "user trading -> position accumulation -> fee extraction -> strong buy-side support".
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
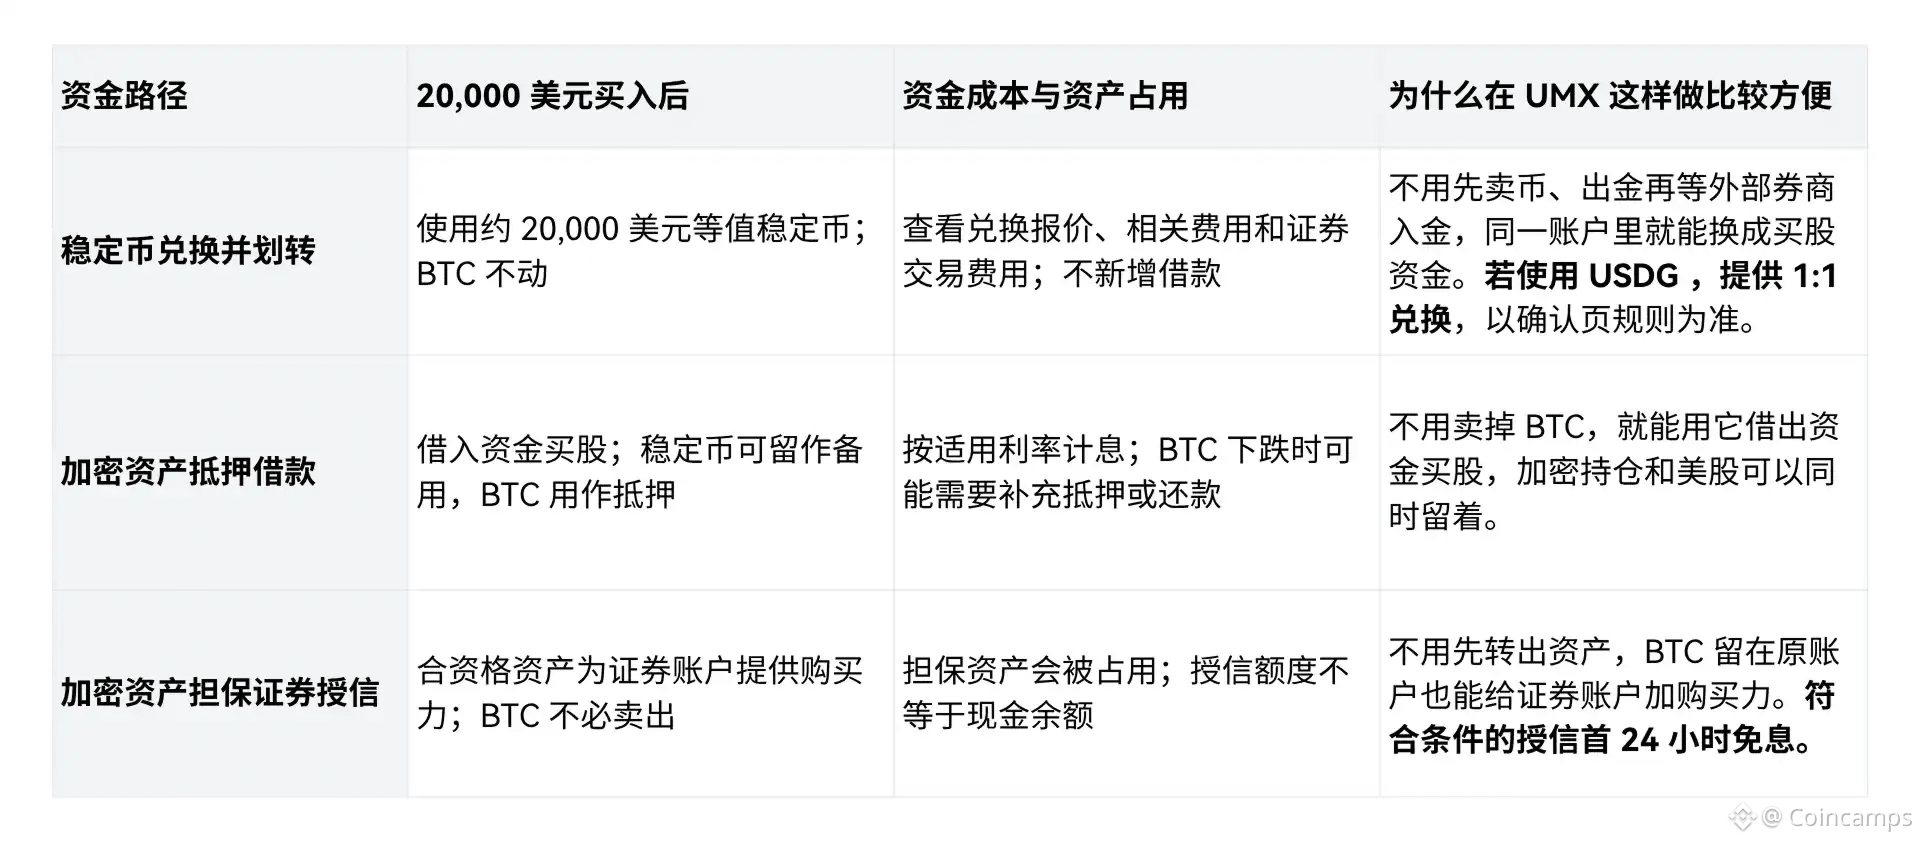
記事
翻訳参照
Holding BTC and want to buy US stocks? Check out UMX's three funding arrangements.Don't want to sell crypto just yet, but need to fund a stock purchase?
If you hold BTC and have your eye on a U.S. stock ETF, your first thought might be: do I have to sell my BTC first to buy stocks? The usual approach involves moving funds across crypto platforms, banks, and brokerages, possibly with currency conversion and waiting for settlement.
UMX puts crypto assets and securities trading on the same platform and offers several ways to arrange stock-buying funds: stablecoin conversion and transfer, borrowing against crypto collateral, or applying for securities credit using eligible crypto assets.
According to UMX, the product design was also inspired by founder Li Lin and his family office's experience managing their own assets, as well as client demand for cross-asset fund allocation. For investors, all three approaches address the question of how to arrange funds, but they differ in funding source, cost, and asset commitment. Below, we walk through the same stock-buying scenario one by one.
Buying $20,000 in U.S. stocks: how to choose among three funding arrangements?
Assume the account holds $100,000 equivalent in stablecoins and 1 BTC, and you plan to buy $20,000 of a U.S. stock ETF but don't want to sell BTC for now. The following is only a simulated scenario and does not represent BTC's current market price or actual available credit. Whether and how much you can use depends on account eligibility, collateral asset valuation, and the platform's risk parameters at the time.
Option 1 | Convert stablecoins to USD and buy directly
If you already planned to use some stablecoins to buy U.S. stocks, converting and transferring is a relatively straightforward arrangement. Once USD enters the securities account, it can be used to buy stocks; BTC is unaffected and no new borrowing is created.
Before proceeding, check the exchange rate, spread, fees, and estimated received amount on the conversion page, then add securities trading fees. If using USDG and the account page offers a 1:1 conversion option, the rules shown on the confirmation page prevail.
This path suits those willing to use existing stablecoins and who want to avoid borrowing and collateral arrangements. After buying stocks, the stablecoin balance available for other transactions will decrease accordingly.
Figure 1 | Unified account asset overview: view crypto assets, securities positions, and available buying power in the securities account.
Figure 2 | USDT conversion and transfer confirmation page: view the reference exchange rate, estimated arrival amount, quote validity period, and account changes after the transfer.
Option Two | Borrow against BTC, keep stablecoins as a reserve
If you want to keep your stablecoins, you can check whether your account supports using eligible assets such as BTC and ETH as collateral to borrow and buy stocks. Which assets are supported and how much you can borrow are subject to what is displayed on the account page.
This path keeps the stablecoins in your hands, but BTC will be used as collateral, and the loan will accrue interest. If the collateral asset declines in value or risk parameters change, you may need to add collateral, repay the loan, or have your assets handled according to the platform's rules.
Before proceeding, review the interest rate, repayment requirements, and risk disclosures, and consider whether you can withstand price volatility in the collateral asset.
Figure 3 | Crypto asset collateral loan confirmation page: verify the loan amount, interest rate, estimated arrival amount, and the collateral requirements and risk disclosures displayed on the page.
Option Three | Use BTC as collateral for securities credit to increase stock-buying power
Credit financing uses eligible crypto assets to provide collateral support for a securities account, increasing the purchasing power available for buying stocks. It differs from a collateral loan in the funding path: the former uses collateral assets to support the securities account limit, while the latter involves borrowing funds and then arranging them to buy stocks.
Convenience aside, remember: collateral assets will be locked up, and the credit limit does not equal cash in the account. Before confirming, verify the estimated increase in purchasing power, the collateral assets occupied, the applicable interest rate, and whether the limit will change with asset prices or account risk.
If the account meets the "first 24 hours interest-free" conditions, interest is subsequently calculated at the VIP0 USD financing annual interest rate of 5.74%. Taking $20,000 used for 7 days as an example, no interest is charged during the interest-free period, and interest is then calculated according to the page rules. Under this set of example conditions, compared with interest charged for the full 7 days, the interest is approximately 14.3% less. The actual interest rate, interest-free eligibility, and interest calculation period are subject to the account page, and other fees are charged separately.
Figure 4 | Securities Credit Confirmation Page: Verify the estimated increase in securities purchasing power, collateral asset occupation, as well as account changes and risk disclosures before and after credit extension.
Compare capital efficiency, and also consider capital cost
The difference among the three methods lies not only in whether stocks can be purchased, but also in how many stablecoins remain after purchase, whether BTC is occupied, and whether interest needs to be paid.
If you want something simple and direct, consider exchanging existing stablecoins; if you want to retain stablecoins, you can compare collateralized borrowing and securities credit. The former depends on interest rates, repayment, and collateral requirements, while the latter depends on collateral asset occupation and credit rules.
This simulated purchase of $20,000 can be compared across three cost items:
● Exchange cost: Verify the stablecoin exchange quote, exchange rate, and related fees.
● Financing cost: Estimate based on the loan amount, applicable annualized interest rate, and actual usage time.
● Asset occupation cost: Confirm whether the BTC used for collateral or credit can still be freely deployed.
Cross-market accounts can reduce some external transfers and waiting, but the actual savings must be compared item by item using quotes and fees at the same time and for the same amount.
Beyond U.S. stocks, Hong Kong stocks can also use these funding arrangements
UMX has also opened grayscale experience for Hong Kong stocks and ETFs. Eligible users can check whether they can obtain purchasing power through stablecoin transfers, crypto asset collateral financing, or securities credit arrangements; if the securities account already has USD, they can also check the option of exchanging to HKD before buying. Whether specific markets, underlying assets, and features apply to your account is subject to what is displayed on the page.
Before buying, first see whether the account can withstand volatility
The three methods suit different funding arrangements: stablecoin exchange is direct but uses up existing stablecoins; collateralized borrowing can retain stablecoins but requires interest payments and bears collateral risk; securities credit may increase stock purchasing power but occupies collateral assets and must comply with credit and risk control rules.
When comparing, first ask yourself three things: How much cash will you still need to put up when buying stocks? Which assets will be tied up as a result? If the price of the collateral assets or securities falls, is there still any buffer in the account?
The purchasing power displayed on the page is only part of the funding arrangement. Before use, you should also confirm account eligibility, supported assets, conversion quotes, interest rates, fees, conversion ratios, credit limits, as well as top-up, repayment, and liquidation rules.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Holding BTC and want to buy US stocks? Check out UMX's three funding arrangements.
Don't want to sell crypto just yet, but need to fund a stock purchase?
If you hold BTC and have your eye on a U.S. stock ETF, your first thought might be: do I have to sell my BTC first to buy stocks? The usual approach involves moving funds across crypto platforms, banks, and brokerages, possibly with currency conversion and waiting for settlement.
UMX puts crypto assets and securities trading on the same platform and offers several ways to arrange stock-buying funds: stablecoin conversion and transfer, borrowing against crypto collateral, or applying for securities credit using eligible crypto assets.
According to UMX, the product design was also inspired by founder Li Lin and his family office's experience managing their own assets, as well as client demand for cross-asset fund allocation. For investors, all three approaches address the question of how to arrange funds, but they differ in funding source, cost, and asset commitment. Below, we walk through the same stock-buying scenario one by one.
Buying $20,000 in U.S. stocks: how to choose among three funding arrangements?
Assume the account holds $100,000 equivalent in stablecoins and 1 BTC, and you plan to buy $20,000 of a U.S. stock ETF but don't want to sell BTC for now. The following is only a simulated scenario and does not represent BTC's current market price or actual available credit. Whether and how much you can use depends on account eligibility, collateral asset valuation, and the platform's risk parameters at the time.
Option 1 | Convert stablecoins to USD and buy directly
If you already planned to use some stablecoins to buy U.S. stocks, converting and transferring is a relatively straightforward arrangement. Once USD enters the securities account, it can be used to buy stocks; BTC is unaffected and no new borrowing is created.
Before proceeding, check the exchange rate, spread, fees, and estimated received amount on the conversion page, then add securities trading fees. If using USDG and the account page offers a 1:1 conversion option, the rules shown on the confirmation page prevail.
This path suits those willing to use existing stablecoins and who want to avoid borrowing and collateral arrangements. After buying stocks, the stablecoin balance available for other transactions will decrease accordingly.
Figure 1 | Unified account asset overview: view crypto assets, securities positions, and available buying power in the securities account.
Figure 2 | USDT conversion and transfer confirmation page: view the reference exchange rate, estimated arrival amount, quote validity period, and account changes after the transfer.
Option Two | Borrow against BTC, keep stablecoins as a reserve
If you want to keep your stablecoins, you can check whether your account supports using eligible assets such as BTC and ETH as collateral to borrow and buy stocks. Which assets are supported and how much you can borrow are subject to what is displayed on the account page.
This path keeps the stablecoins in your hands, but BTC will be used as collateral, and the loan will accrue interest. If the collateral asset declines in value or risk parameters change, you may need to add collateral, repay the loan, or have your assets handled according to the platform's rules.
Before proceeding, review the interest rate, repayment requirements, and risk disclosures, and consider whether you can withstand price volatility in the collateral asset.
Figure 3 | Crypto asset collateral loan confirmation page: verify the loan amount, interest rate, estimated arrival amount, and the collateral requirements and risk disclosures displayed on the page.
Option Three | Use BTC as collateral for securities credit to increase stock-buying power
Credit financing uses eligible crypto assets to provide collateral support for a securities account, increasing the purchasing power available for buying stocks. It differs from a collateral loan in the funding path: the former uses collateral assets to support the securities account limit, while the latter involves borrowing funds and then arranging them to buy stocks.
Convenience aside, remember: collateral assets will be locked up, and the credit limit does not equal cash in the account. Before confirming, verify the estimated increase in purchasing power, the collateral assets occupied, the applicable interest rate, and whether the limit will change with asset prices or account risk.
If the account meets the "first 24 hours interest-free" conditions, interest is subsequently calculated at the VIP0 USD financing annual interest rate of 5.74%. Taking $20,000 used for 7 days as an example, no interest is charged during the interest-free period, and interest is then calculated according to the page rules. Under this set of example conditions, compared with interest charged for the full 7 days, the interest is approximately 14.3% less. The actual interest rate, interest-free eligibility, and interest calculation period are subject to the account page, and other fees are charged separately.
Figure 4 | Securities Credit Confirmation Page: Verify the estimated increase in securities purchasing power, collateral asset occupation, as well as account changes and risk disclosures before and after credit extension.
Compare capital efficiency, and also consider capital cost
The difference among the three methods lies not only in whether stocks can be purchased, but also in how many stablecoins remain after purchase, whether BTC is occupied, and whether interest needs to be paid.
If you want something simple and direct, consider exchanging existing stablecoins; if you want to retain stablecoins, you can compare collateralized borrowing and securities credit. The former depends on interest rates, repayment, and collateral requirements, while the latter depends on collateral asset occupation and credit rules.
This simulated purchase of $20,000 can be compared across three cost items:
● Exchange cost: Verify the stablecoin exchange quote, exchange rate, and related fees.
● Financing cost: Estimate based on the loan amount, applicable annualized interest rate, and actual usage time.
● Asset occupation cost: Confirm whether the BTC used for collateral or credit can still be freely deployed.
Cross-market accounts can reduce some external transfers and waiting, but the actual savings must be compared item by item using quotes and fees at the same time and for the same amount.
Beyond U.S. stocks, Hong Kong stocks can also use these funding arrangements
UMX has also opened grayscale experience for Hong Kong stocks and ETFs. Eligible users can check whether they can obtain purchasing power through stablecoin transfers, crypto asset collateral financing, or securities credit arrangements; if the securities account already has USD, they can also check the option of exchanging to HKD before buying. Whether specific markets, underlying assets, and features apply to your account is subject to what is displayed on the page.
Before buying, first see whether the account can withstand volatility
The three methods suit different funding arrangements: stablecoin exchange is direct but uses up existing stablecoins; collateralized borrowing can retain stablecoins but requires interest payments and bears collateral risk; securities credit may increase stock purchasing power but occupies collateral assets and must comply with credit and risk control rules.
When comparing, first ask yourself three things: How much cash will you still need to put up when buying stocks? Which assets will be tied up as a result? If the price of the collateral assets or securities falls, is there still any buffer in the account?
The purchasing power displayed on the page is only part of the funding arrangement. Before use, you should also confirm account eligibility, supported assets, conversion quotes, interest rates, fees, conversion ratios, credit limits, as well as top-up, repayment, and liquidation rules.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
2
·
--
記事
翻訳参照
Hyperliquid holds 58% of on-chain perpetual open interest, yet trading volume accounts for only 38.6%.TechFlow Guide:In the decentralized perpetual contract sector, trading volume has always been regarded as the primary indicator of platform activity; however, in Q3 2026, the on-chain derivatives landscape exhibited a highly disruptive divergence. According to the latest authoritative review report published by Alea Research, Hyperliquid captured 58.0% of the total network Open Interest (OI), while accounting for only 38.6% of total trading volume.
This anomaly of "open interest significantly surpassing trading volume" completely breaks the old model where derivative DEXs relied on short-term high-frequency volume spoofing to create a false sense of prosperity. Data shows that Hyperliquid traders' average holding period ranks first among the top ten mainstream exchanges across the entire network. A large number of professional institutions and quantitative hedge funds have selected it as their primary venue for executing cash-and-carry arbitrage and funding rate arbitrage (Carry Trade), accumulating an extremely large pool of sticky institutional capital.
This article provides an in-depth analysis of the competitive dynamics among the 121 perpetual contract venues across the network in Q3, examines the explosive growth logic behind the HIP-3 native ecosystem, the stunning data performance of trade.xyz, and how Hyperliquid's Assistance Fund establishes a powerful value loop by allocating nearly 90% of fees toward repurchasing HYPE tokens.
Tide Recedes in Market Trends: Network-Wide Perpetual Contract Volume Halved Amidst Counter-Cyclical Expansion
In Q3 2026, the on-chain perpetual contract market as a whole fell into a period of sluggish adjustment. Among the 121 tracked decentralized perpetual contract venues across the network, total trading volume contracted by half compared to the highs at the end of 2025, with the network-wide Q3 quarter-over-quarter decline reaching 2.5%.
However, amidst the network-wide winter, Hyperliquid demonstrated incredible counter-cyclical vitality. Its Q3 matched trading volume reached $688.7 billion, increasing by 9.2% quarter-over-quarter against the trend; this propelled its network-wide trading volume market share to achieve substantial jumps for three consecutive quarters, firmly locking in its position as the industry leader at 38.6%.
What is even more staggering is the battle for open interest (OI). Out of all newly added open contracts industry-wide, Hyperliquid alone captured 77%, maintaining a quarterly daily average OI of over $2.1 billion, with single-day peak values even surpassing a shocking monopoly ratio of 65% across the entire network.
Figure 1: Market share trend of Hyperliquid in the 30-day rolling trading volume of network-wide on-chain perpetual contracts. Steadily climbing to 38.6% for three consecutive quarters.
Anomaly in Position Structure: Why Is the Position Share Far Higher Than the Trading Volume Share?
In traditional derivatives understanding, an exchange's open contract share often closely aligns with its trading volume share; if the volume share is only 38.6%, logically its open interest should also hover around 40%. So why did Hyperliquid's open interest share surge to 58.0%?
Alea Research provided the core answer through long-term tracking of on-chain position addresses: Hyperliquid users hold positions for significantly longer periods than other top ten competitors. This is mainly attributed to the following two points:
• Zero gas fees and full-memory matching mechanism: The underlying high-performance L1 architecture built specifically for finance provides sub-second matching experiences and transparent liquidation comparable to centralized exchanges (CEX), attracting numerous professional hedge funds to use it as their primary position for large-scale basis arbitrage;
• Real liquidity without fabricated volume boosting: Many competing DEXs are flooded with fake wash trading (Wash Trading) aimed at earning points, resulting in artificially inflated volumes but extremely poor fund retention; whereas Hyperliquid's liquidity is entirely settled through organic trading and arbitrage market-making, resulting in extremely solid capital retention.
Figure 2: Hyperliquid's market share in total network-wide open interest (OI). Q3 average reached 58.0%, demonstrating deep accumulation of institutional-grade long-term capital.
HIP-3 Innovation Boom: trade.xyz Captures 98% of Native Ecosystem Fees
The most critical technological milestone achieved by the Hyperliquid ecosystem in Q3 was the launch of HIP-3 native spot and custom derivative markets. Anyone can establish an independent, exclusive derivative market on the Hyperliquid L1 through permissionless staking.
Among the two brand-new DEXs launched under the HIP-3 framework, trade.xyz displayed astonishing dominance. Within just one quarter of Q3, trade.xyz generated cumulative trading volume as high as $251.3 billion, directly surpassing the full-quarter performance of the independent legacy platform Aster ($160.3 billion).
At the level of ecosystem capture, trade.xyz contributed 97.9% of the fee revenue within the HIP-3 segmented market, delivering a continuous stream of genuine earnings to Hyperliquid's entire underlying public chain.
7% Fee Repurchase & Burn: Assistance Fund Forges a Sturdy Token Moat
Facing massive fee inflows, Hyperliquid established an exceptionally pure value capture loop. The report discloses that during Q3, the platform's total perpetual contract fee revenue grew 2.9% quarter-over-quarter to reach $165.5 million.
Its officially established Assistance Fund allocates up to 88.7% of the received fees directly toward continuously buying HYPE tokens on the open market; additionally, the revenue generated from its underlying hundreds-of-billions-USDC reserve pool contributed an extra $17.7 million in steady cash flow to the Assistance Fund in Q3.
Substantial real-capital buybacks enabled the HYPE token to exhibit strong price resilience amid the harsh macroeconomic environment of Q3, constructing a positive and healthy economic flywheel of "user trading -> position accumulation -> fee extraction -> strong buy-side support".
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Hyperliquid holds 58% of on-chain perpetual open interest, yet trading volume accounts for only 38.6%.
TechFlow Guide:In the decentralized perpetual contract sector, trading volume has always been regarded as the primary indicator of platform activity; however, in Q3 2026, the on-chain derivatives landscape exhibited a highly disruptive divergence. According to the latest authoritative review report published by Alea Research, Hyperliquid captured 58.0% of the total network Open Interest (OI), while accounting for only 38.6% of total trading volume.
This anomaly of "open interest significantly surpassing trading volume" completely breaks the old model where derivative DEXs relied on short-term high-frequency volume spoofing to create a false sense of prosperity. Data shows that Hyperliquid traders' average holding period ranks first among the top ten mainstream exchanges across the entire network. A large number of professional institutions and quantitative hedge funds have selected it as their primary venue for executing cash-and-carry arbitrage and funding rate arbitrage (Carry Trade), accumulating an extremely large pool of sticky institutional capital.
This article provides an in-depth analysis of the competitive dynamics among the 121 perpetual contract venues across the network in Q3, examines the explosive growth logic behind the HIP-3 native ecosystem, the stunning data performance of trade.xyz, and how Hyperliquid's Assistance Fund establishes a powerful value loop by allocating nearly 90% of fees toward repurchasing HYPE tokens.
Tide Recedes in Market Trends: Network-Wide Perpetual Contract Volume Halved Amidst Counter-Cyclical Expansion
In Q3 2026, the on-chain perpetual contract market as a whole fell into a period of sluggish adjustment. Among the 121 tracked decentralized perpetual contract venues across the network, total trading volume contracted by half compared to the highs at the end of 2025, with the network-wide Q3 quarter-over-quarter decline reaching 2.5%.
However, amidst the network-wide winter, Hyperliquid demonstrated incredible counter-cyclical vitality. Its Q3 matched trading volume reached $688.7 billion, increasing by 9.2% quarter-over-quarter against the trend; this propelled its network-wide trading volume market share to achieve substantial jumps for three consecutive quarters, firmly locking in its position as the industry leader at 38.6%.
What is even more staggering is the battle for open interest (OI). Out of all newly added open contracts industry-wide, Hyperliquid alone captured 77%, maintaining a quarterly daily average OI of over $2.1 billion, with single-day peak values even surpassing a shocking monopoly ratio of 65% across the entire network.
Figure 1: Market share trend of Hyperliquid in the 30-day rolling trading volume of network-wide on-chain perpetual contracts. Steadily climbing to 38.6% for three consecutive quarters.
Anomaly in Position Structure: Why Is the Position Share Far Higher Than the Trading Volume Share?
In traditional derivatives understanding, an exchange's open contract share often closely aligns with its trading volume share; if the volume share is only 38.6%, logically its open interest should also hover around 40%. So why did Hyperliquid's open interest share surge to 58.0%?
Alea Research provided the core answer through long-term tracking of on-chain position addresses: Hyperliquid users hold positions for significantly longer periods than other top ten competitors. This is mainly attributed to the following two points:
• Zero gas fees and full-memory matching mechanism: The underlying high-performance L1 architecture built specifically for finance provides sub-second matching experiences and transparent liquidation comparable to centralized exchanges (CEX), attracting numerous professional hedge funds to use it as their primary position for large-scale basis arbitrage;
• Real liquidity without fabricated volume boosting: Many competing DEXs are flooded with fake wash trading (Wash Trading) aimed at earning points, resulting in artificially inflated volumes but extremely poor fund retention; whereas Hyperliquid's liquidity is entirely settled through organic trading and arbitrage market-making, resulting in extremely solid capital retention.
Figure 2: Hyperliquid's market share in total network-wide open interest (OI). Q3 average reached 58.0%, demonstrating deep accumulation of institutional-grade long-term capital.
HIP-3 Innovation Boom: trade.xyz Captures 98% of Native Ecosystem Fees
The most critical technological milestone achieved by the Hyperliquid ecosystem in Q3 was the launch of HIP-3 native spot and custom derivative markets. Anyone can establish an independent, exclusive derivative market on the Hyperliquid L1 through permissionless staking.
Among the two brand-new DEXs launched under the HIP-3 framework, trade.xyz displayed astonishing dominance. Within just one quarter of Q3, trade.xyz generated cumulative trading volume as high as $251.3 billion, directly surpassing the full-quarter performance of the independent legacy platform Aster ($160.3 billion).
At the level of ecosystem capture, trade.xyz contributed 97.9% of the fee revenue within the HIP-3 segmented market, delivering a continuous stream of genuine earnings to Hyperliquid's entire underlying public chain.
7% Fee Repurchase & Burn: Assistance Fund Forges a Sturdy Token Moat
Facing massive fee inflows, Hyperliquid established an exceptionally pure value capture loop. The report discloses that during Q3, the platform's total perpetual contract fee revenue grew 2.9% quarter-over-quarter to reach $165.5 million.
Its officially established Assistance Fund allocates up to 88.7% of the received fees directly toward continuously buying HYPE tokens on the open market; additionally, the revenue generated from its underlying hundreds-of-billions-USDC reserve pool contributed an extra $17.7 million in steady cash flow to the Assistance Fund in Q3.
Substantial real-capital buybacks enabled the HYPE token to exhibit strong price resilience amid the harsh macroeconomic environment of Q3, constructing a positive and healthy economic flywheel of "user trading -> position accumulation -> fee extraction -> strong buy-side support".
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
This anomaly of "open interest significantly surpassing trading volume" completely breaks the old model where derivative DEXs relied on short-term high-frequency volume spoofing to create a false sense of prosperity. Data shows that Hyperliquid traders' average holding period ranks first among the top ten mainstream exchanges across the entire network. A large number of professional institutions and quantitative hedge funds have selected it as their primary venue for executing cash-and-carry arbitrage and funding rate arbitrage (Carry Trade), accumulating an extremely large pool of sticky institutional capital.
This article provides an in-depth analysis of the competitive dynamics among the 121 perpetual contract venues across the network in Q3, examines the explosive growth logic behind the HIP-3 native ecosystem, the stunning data performance of trade.xyz, and how Hyperliquid's Assistance Fund establishes a powerful value loop by allocating nearly 90% of fees toward repurchasing HYPE tokens.
Tide Recedes in Market Trends: Network-Wide Perpetual Contract Volume Halved Amidst Counter-Cyclical Expansion
In Q3 2026, the on-chain perpetual contract market as a whole fell into a period of sluggish adjustment. Among the 121 tracked decentralized perpetual contract venues across the network, total trading volume contracted by half compared to the highs at the end of 2025, with the network-wide Q3 quarter-over-quarter decline reaching 2.5%.
However, amidst the network-wide winter, Hyperliquid demonstrated incredible counter-cyclical vitality. Its Q3 matched trading volume reached $688.7 billion, increasing by 9.2% quarter-over-quarter against the trend; this propelled its network-wide trading volume market share to achieve substantial jumps for three consecutive quarters, firmly locking in its position as the industry leader at 38.6%.
What is even more staggering is the battle for open interest (OI). Out of all newly added open contracts industry-wide, Hyperliquid alone captured 77%, maintaining a quarterly daily average OI of over $2.1 billion, with single-day peak values even surpassing a shocking monopoly ratio of 65% across the entire network.
Figure 1: Market share trend of Hyperliquid in the 30-day rolling trading volume of network-wide on-chain perpetual contracts. Steadily climbing to 38.6% for three consecutive quarters.
Anomaly in Position Structure: Why Is the Position Share Far Higher Than the Trading Volume Share?
In traditional derivatives understanding, an exchange's open contract share often closely aligns with its trading volume share; if the volume share is only 38.6%, logically its open interest should also hover around 40%. So why did Hyperliquid's open interest share surge to 58.0%?
Alea Research provided the core answer through long-term tracking of on-chain position addresses: Hyperliquid users hold positions for significantly longer periods than other top ten competitors. This is mainly attributed to the following two points:
• Zero gas fees and full-memory matching mechanism: The underlying high-performance L1 architecture built specifically for finance provides sub-second matching experiences and transparent liquidation comparable to centralized exchanges (CEX), attracting numerous professional hedge funds to use it as their primary position for large-scale basis arbitrage;
• Real liquidity without fabricated volume boosting: Many competing DEXs are flooded with fake wash trading (Wash Trading) aimed at earning points, resulting in artificially inflated volumes but extremely poor fund retention; whereas Hyperliquid's liquidity is entirely settled through organic trading and arbitrage market-making, resulting in extremely solid capital retention.
Figure 2: Hyperliquid's market share in total network-wide open interest (OI). Q3 average reached 58.0%, demonstrating deep accumulation of institutional-grade long-term capital.
HIP-3 Innovation Boom: trade.xyz Captures 98% of Native Ecosystem Fees
The most critical technological milestone achieved by the Hyperliquid ecosystem in Q3 was the launch of HIP-3 native spot and custom derivative markets. Anyone can establish an independent, exclusive derivative market on the Hyperliquid L1 through permissionless staking.
Among the two brand-new DEXs launched under the HIP-3 framework, trade.xyz displayed astonishing dominance. Within just one quarter of Q3, trade.xyz generated cumulative trading volume as high as $251.3 billion, directly surpassing the full-quarter performance of the independent legacy platform Aster ($160.3 billion).
At the level of ecosystem capture, trade.xyz contributed 97.9% of the fee revenue within the HIP-3 segmented market, delivering a continuous stream of genuine earnings to Hyperliquid's entire underlying public chain.
7% Fee Repurchase & Burn: Assistance Fund Forges a Sturdy Token Moat
Facing massive fee inflows, Hyperliquid established an exceptionally pure value capture loop. The report discloses that during Q3, the platform's total perpetual contract fee revenue grew 2.9% quarter-over-quarter to reach $165.5 million.
Its officially established Assistance Fund allocates up to 88.7% of the received fees directly toward continuously buying HYPE tokens on the open market; additionally, the revenue generated from its underlying hundreds-of-billions-USDC reserve pool contributed an extra $17.7 million in steady cash flow to the Assistance Fund in Q3.
Substantial real-capital buybacks enabled the HYPE token to exhibit strong price resilience amid the harsh macroeconomic environment of Q3, constructing a positive and healthy economic flywheel of "user trading -> position accumulation -> fee extraction -> strong buy-side support".
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
記事
翻訳参照
Putting Childhood on the Trading Table: TCG Might Be the Closest Today's Young People Get to Getting Rich QuickOn Courtyard's product page, collectors are presented with several choices: open a random pack, leave the card they pulled in the vault, request it be shipped home, or accept the platform's quote and sell immediately to recoup funds.
A Pokémon card sealed in a transparent hard case thus gains different destinations. For one person, it's exit capital after failing to pull the target; for another, it might be the version long missing from their collection binder. When a trade happens, the physical card stays where it is — what changes is ownership, and who is willing to pay for it.
After trading card games — TCG — moved on-chain, the most noteworthy change is hidden right here. In the past, once a pack was sold, the operator waited for the next customer; now, opening packs, quoting, buybacks, and repurchasing can be linked together. The same card, the same budget, has the chance to participate in multiple transactions in a row. Inventory doesn't move, but trading volume grows geometrically.
Human nature loves to gamble, which means: some people are willing to spend a little money to buy a chance at a big outcome. But where do they spend it? Some buy into wall-to-wall promotional posters, some into KOL endorsements, and some choose a cultural IP they're familiar with — TCG is that vehicle.
Rather than play a slot machine in a casino whose graphics you can't even understand, you might as well buy Pokémon cards — why? Pokémon, I know it~
A few numbers for context
As of the end of March 2026, cumulative Pokémon card production has exceeded 85 billion cards, with sales covering more than 90 countries and regions. The digital card app Pokémon TCG Pocket announced in October 2025 that cumulative downloads had surpassed 150 million.
Research firm Straits Research, in a report updated in October 2026, forecast the global trading card game market size for that year at roughly $16.3 billion.
Business Insider reported in December 2025, citing eBay data, that trading cards were the secondhand goods category most purchased by U.S. Gen Z on the platform that year as of the time of reporting.
Background
When it comes to TCG, this business is far older than cryptocurrency. In 1993, Magic: The Gathering debuted, and Wizards of the Coast co-founder Peter Adkison traveled along the U.S. West Coast visiting game stores, introducing players to this new way of buying cards, building decks, and battling through demonstrations. And so, one small shop after another opened up. Don't underestimate these unassuming
storefronts — they were both sales channels and social venues for fans.
More than thirty years later, the elementary school kids of back then have money now, and cards have transformed from game props into collectibles and investment assets. Some study deck builds, some chase illustrations and editions, and some buy back the "white moonlight" they couldn't bear to buy as children. Whatever the reason, the target audience keeps growing.
Hasbro's 2025 investor materials show that the average Magic: The Gathering tabletop player is about 35 years old, with average engagement exceeding five years, and the Wizards Play Network covers roughly 9,600 stores. In 2025, Magic: The Gathering tabletop and digital products combined revenue reached $1.72 billion, up 59% year over year.
Why are there so many participants?
The most obvious reason is that young people can't see hope anymore?
The threshold for traditional wealth accumulation keeps rising. A 2025 survey by the National Association of Realtors shows that first-time buyers fell to 21% of all homebuyers, and the median age of first-time buyers rose to 40. Northwestern Mutual's 2026 survey found that among U.S. Gen Z respondents who use or are considering high-risk speculative instruments, 80% said they are financially behind and hope these tools (aka TCG / Crypto) will help them reach their goals faster.
These figures present two realities that exist simultaneously: large assets require long-term accumulation; small, instant products with high-return imagination are competing for some people's attention.
Cards also have cultural familiarity as an entry point. A person may not understand a company's cash flow, but they know which character they like and which edition is popular in the community. Familiarity doesn't equal profit, but it makes participation easier; even if the price hasn't risen yet, collecting and displaying provide a reason to keep holding, because participants get a feeling that they "know better than the old-timers."
A 2025 Australian collectibles study commissioned by eBay and conducted by Deloitte found that 35% of surveyed collectors view collecting as a good investment; among those collecting for investment purposes, 40% expect returns above 50%. eBay data cited in the report also shows that One Piece OP-01 booster boxes have risen 200% in transaction price since 2022. We have to ask, who wouldn't love a story like that? These get-rich-quick stories easily turn a hobby into an investment attempt.
Buying the white moonlight of your childhood while the asset appreciates — why not?
So whether this card money counts as consumption or investment isn't something even the buyer strictly distinguishes.
A beloved character gives a reason to buy, a rare edition gives a reason to hold, and other people's profit stories provide the imagination of appreciation — and so it spreads from one to ten, from ten to a hundred.
But is that enough? No, because holding physical goods is too slow. Cards are non-standardized items (similar to NFTs), hard to price uniformly, so trading volume, turnover rate, and liquidity can't rise — and therefore there's no so-called derivatives trading market. So, to stimulate "spot" trading and the "get-rich-quick" effect, merchants put probability games like "blind boxes" and "card pulls" into a single sale.
Cards thus offer two different kinds of multiple imagination: buy a card and wait for it to rise from $100 to $300; or spend a few dozen dollars and pull a card worth far more. The former waits for the next buyer to raise the offer, the latter relies on prize-pool probability. But the problem is that the steps in the traditional model are either too slow or opaque, making it hard to scale.
To seat more people at this trading table, you first have to solve the problem of a card being shipped back and forth.
Traditional card selling requires photographing, confirming condition, packaging, and shipping, and cross-border transactions also face customs clearance and taxes. According to eBay's U.S. basic fee schedule, trading cards are charged a 13.25% final value fee on the first $7,500 of each item's total transaction amount, plus a per-order fee. Suppose this is a $100 order with no taxes or shipping — after deducting 13.25% and the $0.40 order fee, the seller takes home $86.35.
Under this cost structure, even if a card rises from $100 to $110, a 10% gain may not be worth taking profit. Because the "wear and tear" of the card market — including the condition risk from shipping — may not even be enough to cover the costs.
So some players (like Fanatics Collect) adopted centralized custody to separate physical movement from trading: once cards enter the warehouse, they can change owners multiple times, only leaving when someone requests withdrawal. This largely solves the efficiency problem.
But it's still not fast enough, and it doesn't solve the ownership problem.
On-chain credentials provide another layer of possibility on top of this: when the product allows, credentials can be transferred to external wallets, used by other marketplaces and smart contracts, and payments can connect with stablecoins. Custody solves the problem of cards not needing to be moved repeatedly; going on-chain expands where credentials can circulate and which services can call on them.
Price discovery and turnover rate are the two key words for understanding this business.
A card priced at $100, with a platform valuation of $100, doesn't mean someone is willing to pay $100 right now. The listing price expresses the seller's expectation, the transaction price records past trades, and the bid price tells the holder how much they can get by exiting now. The more independent buyers there are, the more complete the quotes and transactions, the easier it is for collectors to judge whether to hold or sell.
Turnover rate determines another thing: how many transactions the same batch of inventory can participate in. Suppose inventory is worth $1 million, with price and inventory scale unchanged — turning over once a month corresponds to $1 million in transaction volume; turning over ten times a month corresponds to $10 million. If it originally took an average of ten months to turn over once, and that rises to ten times a month, the turnover becomes 100 times the original.
Courtyard founder Nico Le Jeune once said that the same card sells an average of eight times a month on the platform. Sporting Crypto, compiling data from CryptoSlam, found that the platform's monthly sales grew from about $449,000 in April 2024 to about $66 million in April 2025. This case of a collectibles platform expanding from a small base demonstrates the potential when trading frequency and distribution range expand together.
In this system, random packs and instant buybacks further accelerate turnover. When users pull a card they don't like, they don't have to wait for someone else to buy it — they can accept the platform's quote and convert the result back into balance. The platform then reclaims the inventory and continues organizing sales.
From the perspective of random rewards and redemption mechanisms, this looks like a new gambling table dressed in IP clothing. But whether the operator can make money comes back to the probability, cost, and cash reserves of the entire card pool — you can't just look at how much of a discount the buyback is.
Suppose a user spends $50 to pull a card valued at $100, then sells it back to the platform for $85. After the full cycle, the card returns to the platform, and the cash change for the platform is:
50 - 85 = -$35
An example to illustrate: the pack sells for $50, the probability-weighted average card valuation is $45, and the buyback ratio is 85%. If all cards are sold back immediately, with probability and valuation unchanged, the average buyback expenditure per round is $38.25, leaving an average of $11.75 in cash (simplified calculation, excluding any costs).
$11.75 = the $5 between the sale price and average valuation, plus the $6.75 buyback on the $45 valuation.
How much capital users get back determines whether the next round can continue. In the above model, the average return ratio is 76.5%. If we further assume that funds can be infinitely subdivided, the return ratio is constant, all balance is reinvested, and there is no minimum purchase amount, then the theoretical cumulative purchase amount supported by a $50 initial budget is:
50 / (1 - 76.5%) = $212.77
Real products have pack denomination limits, and pull results fluctuate. If each pack is fixed at $50, after getting back $38.25 you'd need to top up or switch to cheaper products.
In reality it's of course not this simple — after all, users don't sell back every card. Some keep the cards they like, some request withdrawal, and some go to the secondary market for higher offers. Even if a card never leaves the warehouse, as long as it belongs to a user, it's no longer inventory the platform can freely put back into the prize pool. The platform needs to purchase new cards to maintain the pool's appeal, and also handle buyback expenditures when high-value results cluster.
Courtyard's fee arrangements reflect the difference between different lines of business:
The platform fee for peer-to-peer (P2P) secondary trading is zero; pack-pull buyback quotes have a seven-day acceptance window, with valuation referencing recent transactions, market trends, and grading differences; transfers triggered by accepting a pack-pull buyback incur a 6% fee, while ordinary market trades don't charge this fee.
Therefore, TCG platforms both operate a trading marketplace and bear the inventory risk of quoted buybacks.
This forms a noteworthy similarity with perpetual contracts: the same product reduces trading friction while accommodating different reasons for participation. In the perpetual market, some bet on direction, some hedge, some earn funding rates, some make markets; in the card market, some chase IP, some collect (hoard) cards (coins), some draw prizes, some play the game, some seek price spreads, and some manage inventory.
Outlook
More than thirty years ago, Magic: The Gathering brought people together through one game store after another. Today, card platforms try to get people scattered across different places, with different purposes, to trade around the same batch of physical goods. Culture lets them recognize what's on the table, mechanisms let them trade faster and more effectively, and custody and settlement mean the next round doesn't have to wait for a courier.
Some people are willing to spend a little money to buy a chance to change the outcome; others are willing to spend a certain amount to buy the outcome they like. Connecting these two kinds of people is the business most worth looking forward to in on-chain TCG.
Whether the platform can consistently deliver these things — a steady supply of cards, randomness/fairness, ongoing buybacks, and competitive quotes — matters far more than how many times a card gets flipped in a vault in determining how long and how big this trading table can run.
Afterword
If you've heard of Pokémon before, today allow me to introduce another Pokémon from this series: the Wish Pokémon — Jirachi. There's a touching story behind it.
There was a child named Avery who, from the age of four, endured the torment of cancer treatment. Pokémon cards were his spiritual refuge during those painful moments, and his favorite card was Jirachi — but sadly, he never managed to get it.
Just as he entered the final moments of his life, he finally pulled Jirachi.
The boy on screen stood frozen, exclaiming repeatedly: "I can't believe it..."
This recording turned out to be his last card-opening record in this world. Not long after, having endured the long torment of treatment, he passed away peacefully, bidding farewell to the world.
Through those long, cold chemotherapy years, it was these cards that gave him the strength to carry on. In this card community filled with gimmicks, hype, rarity, and investment returns, this twelve-year-old boy:
"What moves people is never the price or the card's grade, but the beauty you genuinely love from the bottom of your heart and are willing to treasure for a lifetime."
Legend has it that Jirachi sleeps for a thousand years, waking for only seven short days, and only a clear, pure voice can awaken it. May you, reading this, always keep that pure love.
Because only with purity is there hope.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Putting Childhood on the Trading Table: TCG Might Be the Closest Today's Young People Get to Getting Rich Quick
On Courtyard's product page, collectors are presented with several choices: open a random pack, leave the card they pulled in the vault, request it be shipped home, or accept the platform's quote and sell immediately to recoup funds.
A Pokémon card sealed in a transparent hard case thus gains different destinations. For one person, it's exit capital after failing to pull the target; for another, it might be the version long missing from their collection binder. When a trade happens, the physical card stays where it is — what changes is ownership, and who is willing to pay for it.
After trading card games — TCG — moved on-chain, the most noteworthy change is hidden right here. In the past, once a pack was sold, the operator waited for the next customer; now, opening packs, quoting, buybacks, and repurchasing can be linked together. The same card, the same budget, has the chance to participate in multiple transactions in a row. Inventory doesn't move, but trading volume grows geometrically.
Human nature loves to gamble, which means: some people are willing to spend a little money to buy a chance at a big outcome. But where do they spend it? Some buy into wall-to-wall promotional posters, some into KOL endorsements, and some choose a cultural IP they're familiar with — TCG is that vehicle.
Rather than play a slot machine in a casino whose graphics you can't even understand, you might as well buy Pokémon cards — why? Pokémon, I know it~
A few numbers for context
As of the end of March 2026, cumulative Pokémon card production has exceeded 85 billion cards, with sales covering more than 90 countries and regions. The digital card app Pokémon TCG Pocket announced in October 2025 that cumulative downloads had surpassed 150 million.
Research firm Straits Research, in a report updated in October 2026, forecast the global trading card game market size for that year at roughly $16.3 billion.
Business Insider reported in December 2025, citing eBay data, that trading cards were the secondhand goods category most purchased by U.S. Gen Z on the platform that year as of the time of reporting.
Background
When it comes to TCG, this business is far older than cryptocurrency. In 1993, Magic: The Gathering debuted, and Wizards of the Coast co-founder Peter Adkison traveled along the U.S. West Coast visiting game stores, introducing players to this new way of buying cards, building decks, and battling through demonstrations. And so, one small shop after another opened up. Don't underestimate these unassuming
storefronts — they were both sales channels and social venues for fans.
More than thirty years later, the elementary school kids of back then have money now, and cards have transformed from game props into collectibles and investment assets. Some study deck builds, some chase illustrations and editions, and some buy back the "white moonlight" they couldn't bear to buy as children. Whatever the reason, the target audience keeps growing.
Hasbro's 2025 investor materials show that the average Magic: The Gathering tabletop player is about 35 years old, with average engagement exceeding five years, and the Wizards Play Network covers roughly 9,600 stores. In 2025, Magic: The Gathering tabletop and digital products combined revenue reached $1.72 billion, up 59% year over year.
Why are there so many participants?
The most obvious reason is that young people can't see hope anymore?
The threshold for traditional wealth accumulation keeps rising. A 2025 survey by the National Association of Realtors shows that first-time buyers fell to 21% of all homebuyers, and the median age of first-time buyers rose to 40. Northwestern Mutual's 2026 survey found that among U.S. Gen Z respondents who use or are considering high-risk speculative instruments, 80% said they are financially behind and hope these tools (aka TCG / Crypto) will help them reach their goals faster.
These figures present two realities that exist simultaneously: large assets require long-term accumulation; small, instant products with high-return imagination are competing for some people's attention.
Cards also have cultural familiarity as an entry point. A person may not understand a company's cash flow, but they know which character they like and which edition is popular in the community. Familiarity doesn't equal profit, but it makes participation easier; even if the price hasn't risen yet, collecting and displaying provide a reason to keep holding, because participants get a feeling that they "know better than the old-timers."
A 2025 Australian collectibles study commissioned by eBay and conducted by Deloitte found that 35% of surveyed collectors view collecting as a good investment; among those collecting for investment purposes, 40% expect returns above 50%. eBay data cited in the report also shows that One Piece OP-01 booster boxes have risen 200% in transaction price since 2022. We have to ask, who wouldn't love a story like that? These get-rich-quick stories easily turn a hobby into an investment attempt.
Buying the white moonlight of your childhood while the asset appreciates — why not?
So whether this card money counts as consumption or investment isn't something even the buyer strictly distinguishes.
A beloved character gives a reason to buy, a rare edition gives a reason to hold, and other people's profit stories provide the imagination of appreciation — and so it spreads from one to ten, from ten to a hundred.
But is that enough? No, because holding physical goods is too slow. Cards are non-standardized items (similar to NFTs), hard to price uniformly, so trading volume, turnover rate, and liquidity can't rise — and therefore there's no so-called derivatives trading market. So, to stimulate "spot" trading and the "get-rich-quick" effect, merchants put probability games like "blind boxes" and "card pulls" into a single sale.
Cards thus offer two different kinds of multiple imagination: buy a card and wait for it to rise from $100 to $300; or spend a few dozen dollars and pull a card worth far more. The former waits for the next buyer to raise the offer, the latter relies on prize-pool probability. But the problem is that the steps in the traditional model are either too slow or opaque, making it hard to scale.
To seat more people at this trading table, you first have to solve the problem of a card being shipped back and forth.
Traditional card selling requires photographing, confirming condition, packaging, and shipping, and cross-border transactions also face customs clearance and taxes. According to eBay's U.S. basic fee schedule, trading cards are charged a 13.25% final value fee on the first $7,500 of each item's total transaction amount, plus a per-order fee. Suppose this is a $100 order with no taxes or shipping — after deducting 13.25% and the $0.40 order fee, the seller takes home $86.35.
Under this cost structure, even if a card rises from $100 to $110, a 10% gain may not be worth taking profit. Because the "wear and tear" of the card market — including the condition risk from shipping — may not even be enough to cover the costs.
So some players (like Fanatics Collect) adopted centralized custody to separate physical movement from trading: once cards enter the warehouse, they can change owners multiple times, only leaving when someone requests withdrawal. This largely solves the efficiency problem.
But it's still not fast enough, and it doesn't solve the ownership problem.
On-chain credentials provide another layer of possibility on top of this: when the product allows, credentials can be transferred to external wallets, used by other marketplaces and smart contracts, and payments can connect with stablecoins. Custody solves the problem of cards not needing to be moved repeatedly; going on-chain expands where credentials can circulate and which services can call on them.
Price discovery and turnover rate are the two key words for understanding this business.
A card priced at $100, with a platform valuation of $100, doesn't mean someone is willing to pay $100 right now. The listing price expresses the seller's expectation, the transaction price records past trades, and the bid price tells the holder how much they can get by exiting now. The more independent buyers there are, the more complete the quotes and transactions, the easier it is for collectors to judge whether to hold or sell.
Turnover rate determines another thing: how many transactions the same batch of inventory can participate in. Suppose inventory is worth $1 million, with price and inventory scale unchanged — turning over once a month corresponds to $1 million in transaction volume; turning over ten times a month corresponds to $10 million. If it originally took an average of ten months to turn over once, and that rises to ten times a month, the turnover becomes 100 times the original.
Courtyard founder Nico Le Jeune once said that the same card sells an average of eight times a month on the platform. Sporting Crypto, compiling data from CryptoSlam, found that the platform's monthly sales grew from about $449,000 in April 2024 to about $66 million in April 2025. This case of a collectibles platform expanding from a small base demonstrates the potential when trading frequency and distribution range expand together.
In this system, random packs and instant buybacks further accelerate turnover. When users pull a card they don't like, they don't have to wait for someone else to buy it — they can accept the platform's quote and convert the result back into balance. The platform then reclaims the inventory and continues organizing sales.
From the perspective of random rewards and redemption mechanisms, this looks like a new gambling table dressed in IP clothing. But whether the operator can make money comes back to the probability, cost, and cash reserves of the entire card pool — you can't just look at how much of a discount the buyback is.
Suppose a user spends $50 to pull a card valued at $100, then sells it back to the platform for $85. After the full cycle, the card returns to the platform, and the cash change for the platform is:
50 - 85 = -$35
An example to illustrate: the pack sells for $50, the probability-weighted average card valuation is $45, and the buyback ratio is 85%. If all cards are sold back immediately, with probability and valuation unchanged, the average buyback expenditure per round is $38.25, leaving an average of $11.75 in cash (simplified calculation, excluding any costs).
$11.75 = the $5 between the sale price and average valuation, plus the $6.75 buyback on the $45 valuation.
How much capital users get back determines whether the next round can continue. In the above model, the average return ratio is 76.5%. If we further assume that funds can be infinitely subdivided, the return ratio is constant, all balance is reinvested, and there is no minimum purchase amount, then the theoretical cumulative purchase amount supported by a $50 initial budget is:
50 / (1 - 76.5%) = $212.77
Real products have pack denomination limits, and pull results fluctuate. If each pack is fixed at $50, after getting back $38.25 you'd need to top up or switch to cheaper products.
In reality it's of course not this simple — after all, users don't sell back every card. Some keep the cards they like, some request withdrawal, and some go to the secondary market for higher offers. Even if a card never leaves the warehouse, as long as it belongs to a user, it's no longer inventory the platform can freely put back into the prize pool. The platform needs to purchase new cards to maintain the pool's appeal, and also handle buyback expenditures when high-value results cluster.
Courtyard's fee arrangements reflect the difference between different lines of business:
The platform fee for peer-to-peer (P2P) secondary trading is zero; pack-pull buyback quotes have a seven-day acceptance window, with valuation referencing recent transactions, market trends, and grading differences; transfers triggered by accepting a pack-pull buyback incur a 6% fee, while ordinary market trades don't charge this fee.
Therefore, TCG platforms both operate a trading marketplace and bear the inventory risk of quoted buybacks.
This forms a noteworthy similarity with perpetual contracts: the same product reduces trading friction while accommodating different reasons for participation. In the perpetual market, some bet on direction, some hedge, some earn funding rates, some make markets; in the card market, some chase IP, some collect (hoard) cards (coins), some draw prizes, some play the game, some seek price spreads, and some manage inventory.
Outlook
More than thirty years ago, Magic: The Gathering brought people together through one game store after another. Today, card platforms try to get people scattered across different places, with different purposes, to trade around the same batch of physical goods. Culture lets them recognize what's on the table, mechanisms let them trade faster and more effectively, and custody and settlement mean the next round doesn't have to wait for a courier.
Some people are willing to spend a little money to buy a chance to change the outcome; others are willing to spend a certain amount to buy the outcome they like. Connecting these two kinds of people is the business most worth looking forward to in on-chain TCG.
Whether the platform can consistently deliver these things — a steady supply of cards, randomness/fairness, ongoing buybacks, and competitive quotes — matters far more than how many times a card gets flipped in a vault in determining how long and how big this trading table can run.
Afterword
If you've heard of Pokémon before, today allow me to introduce another Pokémon from this series: the Wish Pokémon — Jirachi. There's a touching story behind it.
There was a child named Avery who, from the age of four, endured the torment of cancer treatment. Pokémon cards were his spiritual refuge during those painful moments, and his favorite card was Jirachi — but sadly, he never managed to get it.
Just as he entered the final moments of his life, he finally pulled Jirachi.
The boy on screen stood frozen, exclaiming repeatedly: "I can't believe it..."
This recording turned out to be his last card-opening record in this world. Not long after, having endured the long torment of treatment, he passed away peacefully, bidding farewell to the world.
Through those long, cold chemotherapy years, it was these cards that gave him the strength to carry on. In this card community filled with gimmicks, hype, rarity, and investment returns, this twelve-year-old boy:
"What moves people is never the price or the card's grade, but the beauty you genuinely love from the bottom of your heart and are willing to treasure for a lifetime."
Legend has it that Jirachi sleeps for a thousand years, waking for only seven short days, and only a clear, pure voice can awaken it. May you, reading this, always keep that pure love.
Because only with purity is there hope.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
2
·
--
記事
翻訳参照
The narrative must be sellable to the next round to avoid anxiety.Two things in the primary market have clearly inflated. One is called narrative, and the other is called outlier.
For a long time, after chatting with investors and entrepreneurs, we often have a slight sense of恍惚. People spend less and less time discussing product details and user retention, and more and more time discussing "narratives." It seems that as long as a company still applies the latest narrative that has become the "consensus" in the circle, it is as if they went out without clothes on, and it is absolutely impossible to push it to IC.
Along with narratives, the pricing of a set of casting aesthetics popular in Silicon Valley and domestic VC circles has also risen. The weirder the outlier, the more sought after.
In the context of many investors, conventional excellence is no longer sexy enough. It seems that as long as a person is sufficiently out of line and controversial enough, even if they tread on the edge of rules and morality, even if they maliciously poison and obstruct colleagues from training models, in the mouths of some VCs, it can still be described as "having a certain drive."
What is more subtle is the reaction around the card table. When an institution heavily bets on some out-of-line weirdo, it often wins applause from some onlookers, who think this is the courage to go against consensus.
There is actually a secretly swapped causality here. The quirks left by those great entrepreneurs were originally just shadows they dragged on the ground after accomplishing things; now, some capital has begun to pick people according to the shape of the shadow. As for whether the person standing under the shadow is a genius or a bastard, and whether there is anything real at all, fewer people ask.
It is also understandable. If the purpose of an investment is no longer to accompany a company through to producing a product that truly has user buy-in, but merely to sell the stake to the next round of buyers at double the valuation six months later, then whether the product actually works is indeed not so important. As long as the narrative can be sold to the next round, it does not burn.
Even the core operating numbers on the books are just a matter of the founder saying a sentence offhand.
Roy Lee, founder of AI startup Cluely, did exactly that. In July 2025, he told the media that the company's ARR had doubled to $7 million within a week.
This number ran for a full eight months in tech media headlines and in the benchmarking tables of countless peer financings. How many startups used it as a multiple reference, and how many investors used it at investment committee meetings to prove how explosive AI application growth was.
It wasn't until March 2026 that Roy Lee casually admitted on X that the numbers were made up. He said that on that day, he happened to receive a call from a strange woman asking about business data, and he just made something up on the spot. TechCrunch later pointed out that the interview was proactively arranged by Cluely's PR team, and the "strange woman" on the other end of the line was a TechCrunch reporter.
Why could a fake number blurted out on the spot spread unimpeded for over half a year and even become a reference for others' valuations? Because on this assembly line, the people who fabricate stories, spread stories, and pay for stories had long since become one and the same.
Just a few months earlier, a16z, which had invested in Cluely, laid out this logic openly in an article. In November 2025, this veteran fund founded in 2009 set up a new media team and published a long piece titled "What Is New Media," whose opening line stated that from its very first day, what this fund wanted to be was "the CAA of tech."
CAA is one of Hollywood's largest talent agencies, whose daily business is negotiating salaries for stars and managing their public personas. And in a16z's new media service menu, one offering is literally called "Win the Internet for a Day," promising to equip founders with everything they need to win the online narrative war—from legitimacy to momentum, dominating social media timelines on demand. That same year, a16z directly acquired Turpentine, the podcast network founded by Erik Torenberg, and Erik Torenberg pivoted to become a GP at the fund.
When a top-tier venture capital firm decides to step into the arena as a talent agency itself—running both the money printer and the TV station—narrative is no longer narrative.
In his 2023 book "The Crisis of Narration," Byung-Chul Han used the term storyselling. Once a story is used only to sell, it is no longer accountable to the real world—it only needs to serve the people paying for the next round.
Launch Tower
Following the logic of "VC media-ization" downward, the hottest infrastructure in the tech world in recent years, aside from compute clusters, is probably the content hub.
In the past, entrepreneurs and investors telling stories had to go through traditional tech media; now everyone finds the middlemen too slow and not obedient enough.
In April 2026, OpenAI spent hundreds of millions of dollars to directly acquire the tech podcast TBPN. The acquisition terms were interesting: editorial independence of the show was preserved, but the existing advertising business was shut down, and the team's new reporting line shifted to Chris Lehane, an executive who in his early years worked in the White House under Clinton, specifically handling scandals for the president.
Investment firms themselves started writing in-depth profile pieces even earlier. In September 2022, Sequoia specifically commissioned a freelance writer to produce a 13,000-word long-form profile, prominently displayed on Sequoia's official website, with a title styled like a religious gospel: "Sam Bankman-Fried Has a Savior Complex—and Maybe You Should Too."
Less than two months later, FTX filed for bankruptcy, and the article was urgently removed from the official website. Sequoia's $150 million investment was entirely written down to zero.
SBF's downfall taught Silicon Valley a hard lesson: glorifying founders as saints is too costly, and once the bubble bursts, the reputations of the institutions themselves shatter along with it.
Since positive glorification tends to fail, then use a cheaper fuel: public outrage.
In the formula where attention equals valuation, being praised by the entire internet and being cursed by the entire internet carry the same converted traffic weight. As long as the company's name can be inserted into investors' information feeds, infamy is still fame—even being reviled can be monetized.
Artisan's "Stop Hiring Humans" street advertisement in San Francisco
Image source: Artisan / San Francisco Chronicle
There have been many examples in the past two years. First, Artisan, a startup focused on AI sales agents, erected a billboard at the intersection of 10th Street and Folsom Street in San Francisco's SoMa district, reading "Stop Hiring Humans." Founder Jaspar Carmichael-Jack later admitted frankly that the primary purpose of these ads was to grab attention.
After the backlash fermented, Artisan smoothly secured $25 million in Series A funding. At the time, this company shouting "Stop Hiring Humans" had 35 human employees and planned to hire 22 more.
In September 2025, in New York subway cars, 22-year-old Avi Schiffmann also spent approximately $1 million to plaster over 11,000 ads for his AI pendant product Friend. Within days, enraged subway passengers covered the posters with marker scribbles, one of which read "AI doesn't care if you live or die." Facing the graffiti-covered walls, Avi Schiffmann responded publicly that everything was going according to plan, and casually dropped a quotable line: "Capitalism is the greatest art medium."
Silicon Valley has of course always been fascinated by those who can conjure hype out of thin air. In 1981, when Andy Hertzfeld first transferred into Apple's Mac team, software lead Bud Tribble used a term from Star Trek to name Jobs' storytelling ability: the "reality distortion field."
But Tribble also added the second half of the sentence at the time, saying that once Jobs left, the field would dissipate. After the field dissipates, code bugs won't listen to Jobs' keynote speeches, and the Mac would ultimately have to be put into a box, manufactured, and delivered into the hands of a real person. Whether this thing is actually any good—you just take it home, plug it in, and you know. Nobody can fool anybody.
The watershed moment came in 2011. That spring, Jobs spoke for the last time at the iPad 2 launch event about technology needing to intersect with the liberal arts; five months later, Marc Andreessen published "Why Software Is Eating the World" in The Wall Street Journal, and four days after that, Jobs resigned as Apple CEO.
Since then, the protagonists of Silicon Valley have changed to a different cast of characters. On the new gaming table where software, finance, and attention intertwine, if a product's real buyer is no longer the discerning end user but rather the next round of institutions afraid of missing out, that "reality distortion field" can persist indefinitely.
The music is still playing
Writing to this point, an unavoidable question emerges: since even bystanders can hear these calculations being made, can the professional buyers at the table really not see through it?
It's not that they can't see through it—the buyers at the table know better than anyone.
When I chat with some frontline investors about certain AI projects, they often give a wry smile and admit that yes, it's not solid enough, and the numbers are inflated. But once you press further—"Then why are you still rushing to hand out a TS?"—the usual response is silence, or a rhetorical question: "If you don't get in this round and it doubles next round, how do you explain that to your LPs?"
This is precisely the problem that Yale economist Robert Shiller wrote about in his 2019 book Narrative Economics. Shiller borrowed epidemiological models to describe how the amount of capital a narrative can mobilize depends on its transmission speed and coverage—and has absolutely nothing to do with whether the story itself is true or false.
In an industry where people answer to paper gains, truth and falsehood are concerns only for the final reckoning, while missing out is a problem that gets exposed within the quarter. As long as the narrative is told for the benefit of the next round of buyers, the baton can be passed along round after round.
This collective hysteria mentality played out once before in the 2020 SPAC frenzy.
On June 4, 2020, electric truck company Nikola went public on Nasdaq via a SPAC. Going public through a SPAC offers a huge loophole: it can bypass the strict scrutiny of a traditional IPO and stuff roadshow materials with extensive future financial projections.
Five days after listing, Nikola's market cap surged to nearly $29 billion, overtaking Ford in one stroke—even though Nikola had not delivered a single vehicle and its book revenue was zero. It was not until three and a half years later, in January 2024, that the U.S. SEC finally introduced new rules, removing the securities-litigation safe harbor protection for future performance projections by SPACs and their target companies.
In July 2007, Citigroup CEO Chuck Prince, interviewed by the Financial Times in Japan, summed up this institutional dilemma with remarkable honesty. Speaking of the leveraged buyout boom at the time, he said that when the music stops, things will get complicated in terms of liquidity, but as long as the music is playing, you've got to get up and dance.
During the 2023 OpenAI board turmoil
Sam Altman returned to the company office wearing a visitor badge
Image source: Sam Altman's own X post
Four months later, Chuck Prince resigned.
In the primary market, where valuation and paper gains do the talking, whoever stops first is the first to be out. Even when someone tries to turn off the music, the vested interests at the whole table will join forces to push him away.
Looking back at the OpenAI boardroom drama in November 2023 that shocked the world, stripping away all the rhetorical lines about "AI safety" and "accelerated development," the underlying color is in fact a battle to defend valuation—an asset-defense war.
At the time, the OpenAI board fired Sam Altman on the grounds that he was "not consistently candid in his communications." Right at that very moment, Thrive Capital was preparing to lead a tender offer to buy employee shares at an $86 billion valuation. As soon as the firing news broke, investors immediately let it be known that they were considering writing down their OpenAI shares to zero.
The $86 billion valuation was about to evaporate in an instant, and no one at the table could bear that cost. Within days, 738 of OpenAI's roughly 770 employees signed an open letter demanding the board resign and bring back Sam Altman, or they would all jump ship to Microsoft. Five days later, Sam Altman returned to OpenAI, and three of the four directors who fired him were gone.
Playing the Eccentric
Since the rule of the table is to sell the story to the next round, what is the most efficient fundraising strategy for an early-stage founder?
Building a product takes a long cycle; showing quirks or even crossing lines takes only a few minutes.
In early Silicon Valley, eccentricity was a byproduct left behind after getting things done. Young Steve Jobs liked to walk around the office barefoot, and for the latter half of his life wore almost exclusively Issey Miyake black turtlenecks. The reason people relish these details is the premise that he first built the Mac and the iPhone.
Later, the order of imitation was completely reversed.
In 2014, Elizabeth Holmes, wearing a black turtleneck, backstage at
TechCrunch Disrupt
Image source: Max Morse / TechCrunch
The first to learn this superficial trick was Elizabeth Holmes. She dressed like Jobs in a black turtleneck; a person who knew her family recalled that she even copied Jobs's gesture of pulling an iPhone from his trouser pocket exactly, except what she pulled out was swapped for a Theranos micro blood-collection tube.
If Holmes was still an individual-style imitation, then it was Peter Thiel who systematized the "cult of the eccentric" into venture-capital doctrine. By 2010, Peter Thiel established the Thiel Fellowship, giving each young person under 20 $100,000 on the condition that they drop out of college to start a company. Three years later, in Zero to One, he devoted a chapter to "The Founder's Paradox," arguing that successful founders often carry both the good and bad extremes of traits at once.
Fourteen years later, dropping out itself became a bonus point during pitch presentations.
At the YC Demo Day at the end of 2025, more and more founders, in their limited presentation time, could not be bothered to talk about the product and first made a point of emphasizing that they had just dropped out of school. Moxxie Ventures partner Katie Jacobs Stanton even publicly stated that dropping out is itself a credential, proving that a person has sufficiently deep conviction.
As for the results of multiple statistical studies on startups, they give exactly the opposite conclusion: the vast majority of successful startup founders hold university degrees. But in the FOMO atmosphere of the pitch hall, no one cares about such a buzz-killing statistic.
In recent years, just wearing a black turtleneck and going through the dropout paperwork is no longer thrilling enough. The new casting script demands that founders preferably bring some "antisocial" or "man-child" dramatic tension.
In May 2021, Musk hosted Saturday Night Live and said in his opening monologue that he was the first person with Asperger's syndrome to host the show, "or at least the first to admit it." Two years later, when Walter Isaacson finished his biography of Musk, he reflected at the end of the book that sometimes great innovators are just risk-loving man-children who refuse to be potty-trained, crazy enough to think they can change the world.
But some investors not only buy into this, they are happy to tell such offenses as flattering anecdotes.
In Sequoia's long article that has since been taken down, one story was recorded. SBF pitched Sequoia partners on Zoom about his vision for the future of money. After the meeting, an FTX employee sitting ten feet away from him walked over and discovered that he had been playing League of Legends the entire time while pitching. For an ordinary entrepreneur, this would be called bad manners and disrespect. Sequoia, however, treated it as a flattering anecdote and wrote it into the long article posted on its official website.
Once "outrageousness" can be directly converted into checks, public decency and bottom lines will be quickly breached.
Roy Lee, the founder of Cluely mentioned earlier, first became famous by developing a tool that helped people cheat in programmers' technical interviews, and personally filmed a video demonstrating himself using it to pass an Amazon interview. After Columbia University suspended him, he simply dropped out and founded Cluely, and soon received investment from a16z.
No matter how extreme the résumé, as long as it comes with话题度, it can find a buyer in Silicon Valley. In 2015, engineer Anthony Levandowski registered a church called "Way of the Future," claiming he wanted to develop an artificial-intelligence-based god. He was later sentenced to 18 months in prison for stealing Google's autonomous-driving trade secrets and received a presidential pardon in January 2021. By the spring of 2026, Travis Kalanick acquired Pronto, the autonomous mining-vehicle company Levandowski ran, confidently letting him continue at the helm and making Pronto the technical core of the mining division of the new company Atoms.
When we used to talk about good entrepreneurs who can survive cycles, one criterion we often cited was that they should have ambition but not too big an ego, and that they should do businesses that can actually be implemented. But in today's fast-money logic, as long as you perform your ego big enough and outrageous enough, investors eager to find outliers will come up to you and praise you for having the makings of a champion.
This casting logic has also spread to the Chinese venture capital circle, such as the recently much-buzzed-about Tian Keyu, whom VCs say "has a fire in his belly."
My view on this matter remains the same: if you know full well that someone has done something unethical—breaking rules and harming others—and you still think he "has a fire in his belly" and insist on investing in him, that only proves you are unethical too.
A couple of days ago, I discussed this view with a young investor, and he said, "How can an investor's business be called unethical?"
He probably really has mastered the four ways of investing in world models.
Failing Up
Common sense says that a setup built on acting and crossing lines will eventually be exposed. The company collapses, the scandal breaks, or even the court verdict comes down—surely this person should be out of the game by then?
Silicon Valley's answer is not only that they don't leave the table, but that their chips can keep growing the more they lose.
Silicon Valley has indeed had a tradition of tolerating failure—if a company flops, the founder can still raise money for the next one. But over the past few years, the pocket of "failure" has been stretched wider and wider, stuffing even fraud and workplace scandals into the narrative of "growing from lessons learned."
Tim White, a researcher at the London School of Economics, published a paper in 2026 specifically analyzing this phenomenon, using the term "failing up." His conclusion in the paper is that Silicon Valley's top VC system is structurally designed to reward serial entrepreneurs who commit extreme misconduct.
Why does the system reward those who make big mistakes?
Once you grasp the attention logic mentioned earlier, this is not surprising at all. For funds managing billions of dollars and needing to write large checks, the biggest headache is not founders with tainted records, but projects with no momentum. A star founder who drove a hundred-billion-dollar company into bankruptcy, even with a ruined reputation, still holds scarce assets that ordinary entrepreneurs couldn't accumulate in ten lifetimes—such as global attention, ready-made media headlines, and a capital-circle network that rallies at a call.
Adam Neumann at the Flow Fort Lauderdale project launch event
Image source: Romain Maurice/Getty Images
Adam Neumann is a typical case. In August 2019, WeWork, a subleasing company valued at $47 billion, filed its prospectus, opening with the company's mission to "elevate the world's consciousness." More than a month later, the IPO was shelved, Adam Neumann resigned as CEO, and WeWork, left in a mess, filed for bankruptcy in November 2023.
But more than a year before WeWork's bankruptcy, in August 2022, a16z wrote a check of about $350 million to his new real estate company Flow, setting the highest single investment record in the fund's history. Marc Andreessen praised Adam Neumann in a blog as a visionary leader and said the fund likes to see serial entrepreneurs grow from past lessons. By April 2025, Flow's valuation had risen to about $2.5 billion.
The same script played out with former Uber founder Travis Kalanick.
In 2017, Uber forced founder Travis Kalanick to step down as CEO after a series of sexual harassment and workplace discrimination complaints came to light. Nine years later, on July 22, 2026, it was again a16z that stepped up to lead a $1.7 billion funding round for Travis Kalanick's new company Atoms.
On the same day, a16z co-founder Ben Horowitz published an article titled "Travis Is Back" to boost his profile, while Travis Kalanick lightly described the return on X as "a bit of unfinished business."
As for those who accidentally crossed legal red lines and even had court verdicts handed down, they too have figured out another shortcut to turn the page.
Nikola, the company mentioned earlier that reached a $29 billion market cap on zero revenue, saw its founder Trevor Milton later convicted of securities fraud. But less than a month before the 2024 U.S. election, Trevor Milton and his wife donated more than $1.8 million to Donald Trump's campaign fund. On March 28, 2025, he smoothly received a presidential pardon, and the hundreds of millions of dollars he originally needed to pay investors were also waived.
With a clean slate, Trevor Milton immediately returned to the venture capital table. By the end of that year, he and a group of investors bought the near-bankrupt aircraft manufacturer SyberJet, and by the spring of 2026, he had skillfully switched to the narrative of AI-driven autonomous aircraft and begun seeking financing in the market.
02026
When a fund acts as both referee and media, when entrepreneurs can get checks by fabricating data and performing eccentricities, and even fraud convictions can be erased with political donations, this internal loop has only one hidden risk left: what if outside regulators, ethicists, or the general public can no longer stand it?
To prevent external regulation and moral scrutiny from interrupting this cycle, Silicon Valley has spent the past decade or so stitching together a larger ideological bulletproof vest for itself, step by step.
The original fabric of this bulletproof vest was the hybrid pointed out by British scholars Richard Barbrook and Andy Cameron in their 1995 article "The Californian Ideology," in which Silicon Valley fused the free spirit of hippies with the entrepreneurial fervor of yuppies, firmly believing that as long as the government stays out of the way, technology will solve all social problems on its own.
Travis Kalanick's Twitter avatar was once the cover of Ayn Rand's novel The Fountainhead; Facebook's internal slogan "move fast and break things" was also used until 2014. The implication is that as long as you run fast enough, the things that get broken don't need to be paid for by us.
Later, Peter Thiel pushed this kind of tech elite immunity to the institutional level. By 2014, Wired magazine excerpted a chapter from Zero to One, with the title directly taken as "You Should Run Your Startup Like a Cult."
In the past five years, this "elite immunity theory" has spawned two versions that appear to be diametrically opposed but actually lead to the same destination.
The first is called effective altruism (EA), whose core logic is to use "grand good deeds in the future" to exempt "money-grubbing means in the present." In 2012, Oxford University philosopher William MacAskill met with SBF, who was still studying at MIT, and advised him not to directly devote himself to public welfare, but to first make as much money as possible and then donate it, the so-called earn to give.
This rhetoric became SBF's best public relations shield. It was not until after the FTX collapse in November 2022 that Vox reporter Kelsey Piper asked him in a private message, for a person who treats everything as a win-or-lose game, you usually talk about ethics so eloquently. Only then did SBF drop the act and reply: "I had to be. It's what reputations are made of, to some extent."
The other is effective accelerationism (e/acc). Since pretending to be a philanthropist is too easy to expose, simply declare that "accelerating money-making and god-making is itself the highest morality."
This concept, proposed by the anonymous account Beff Jezos in 2022, argues that the universe thermodynamically naturally favors civilizations that become increasingly capable of utilizing energy. On October 16, 2023, Marc Andreessen published the "Techno-Optimist Manifesto," formally listing Beff Jezos among the "patron saints."
The manifesto was written with a murderous tone, stating that any attempt to slow down AI would lead to death, and that deaths that could have been avoided by AI "are a form of murder"; and in a section titled "Enemies," "social responsibility," "trust and safety," "tech ethics," and "risk management" were all listed on a blacklist.
When it came to Peter Thiel, the secular debate was directly elevated to theological intimidation.
In the fall of 2025, Peter Thiel gave four closed-door lectures on the "Antichrist" in San Francisco. Leaked recordings showed that he believed the Antichrist might appear in the form of someone obstructing scientific development, and he directly named environmental activist Greta Thunberg and AI safety researcher Eliezer Yudkowsky. By July 2026, he co-authored an article with Sam Wolfe in the religious publication First Things, depicting the Antichrist as a technocrat who constantly speaks of "safety, ethics, and global coordination."
Once "buckling up" is defined as "murder" and "the Antichrist," then whoever dares to audit Silicon Valley, whoever dares to step on the brakes of runaway capital, is a sinner against all humanity.
After the bulletproof vest was put on, the money began flowing directly toward ballots and legislation. In 2025, a16z and OpenAI President Greg Brockman and his wife each contributed $25 million to lead the creation of the super PAC Leading the Future, with the goal of promoting a unified national AI regulatory standard in the 2026 midterm elections and preventing states from legislating their own AI oversight. As of April 2026, the organization and its affiliated groups had raised more than $140 million, of which the $25 million received in the first quarter of 2026 came entirely from a16z and its two founders.
From fabricating ARR, buying media transmission towers, and mass-producing eccentrics, to using hundreds of millions of dollars in political donations to buy the right to interpret the rules, this closed loop ultimately converged seamlessly onto the same road, Sand Hill Road in Menlo Park, California, where a16z got its start.
Digging further along the place name Menlo Park, you will find a particularly ironic piece of history.
More than half a century ago, in the fall of 1968, Stewart Brand was also in the Menlo Park area, using a typewriter and scissors to assemble the first issue of the Whole Earth Catalog. In explaining his original purpose for the publication, he said that distant powers such as governments and large corporations had become riddled with problems, and that what the Whole Earth Catalog needed to do was serve as a tool for evaluation and access, selecting handy things for specific individuals, with readers then sending in their own usage feedback.
For that generation of Silicon Valley people, technology was a tool placed in the hands of specific individuals, and the makers of tools held a reverence for them. When the first-generation iPad launched in 2010, New York Times reporter Nick Bilton asked Steve Jobs, who had been deeply influenced by the Whole Earth Catalog, whether his children loved the iPad. Jobs replied that his children hadn't touched it yet, and that his family strictly limited their children's use of tech products.
Fifty-eight years later, a16z, also founded in Menlo Park, has had its media team shrink the unit of time to "winning the internet for a day."
As for what the tools ultimately turn people into, nobody cares—as long as today's timeline wins, tomorrow's valuation can go up.
And Stewart Brand, who made the Whole Earth Catalog in Menlo Park back then, later went on to reckon with another scale of time.
The mechanical structure of the 10,000-Year Clock inside the mountain
Image source: 10,000 Year Clock project website
In 1996, he and computer scientist Danny Hillis and others founded the Long Now Foundation, planning to build a mechanical clock inside a mountain that would run for ten thousand years, ticking once a year, with a cuckoo emerging only once every thousand years.
In all of the Long Now Foundation's documents, every year is preceded by an extra zero, to remind people to think about present decisions on a ten-thousand-year scale.
This year, in their reckoning, is 02026.
Original link
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
The narrative must be sellable to the next round to avoid anxiety.
Two things in the primary market have clearly inflated. One is called narrative, and the other is called outlier.
For a long time, after chatting with investors and entrepreneurs, we often have a slight sense of恍惚. People spend less and less time discussing product details and user retention, and more and more time discussing "narratives." It seems that as long as a company still applies the latest narrative that has become the "consensus" in the circle, it is as if they went out without clothes on, and it is absolutely impossible to push it to IC.
Along with narratives, the pricing of a set of casting aesthetics popular in Silicon Valley and domestic VC circles has also risen. The weirder the outlier, the more sought after.
In the context of many investors, conventional excellence is no longer sexy enough. It seems that as long as a person is sufficiently out of line and controversial enough, even if they tread on the edge of rules and morality, even if they maliciously poison and obstruct colleagues from training models, in the mouths of some VCs, it can still be described as "having a certain drive."
What is more subtle is the reaction around the card table. When an institution heavily bets on some out-of-line weirdo, it often wins applause from some onlookers, who think this is the courage to go against consensus.
There is actually a secretly swapped causality here. The quirks left by those great entrepreneurs were originally just shadows they dragged on the ground after accomplishing things; now, some capital has begun to pick people according to the shape of the shadow. As for whether the person standing under the shadow is a genius or a bastard, and whether there is anything real at all, fewer people ask.
It is also understandable. If the purpose of an investment is no longer to accompany a company through to producing a product that truly has user buy-in, but merely to sell the stake to the next round of buyers at double the valuation six months later, then whether the product actually works is indeed not so important. As long as the narrative can be sold to the next round, it does not burn.
Even the core operating numbers on the books are just a matter of the founder saying a sentence offhand.
Roy Lee, founder of AI startup Cluely, did exactly that. In July 2025, he told the media that the company's ARR had doubled to $7 million within a week.
This number ran for a full eight months in tech media headlines and in the benchmarking tables of countless peer financings. How many startups used it as a multiple reference, and how many investors used it at investment committee meetings to prove how explosive AI application growth was.
It wasn't until March 2026 that Roy Lee casually admitted on X that the numbers were made up. He said that on that day, he happened to receive a call from a strange woman asking about business data, and he just made something up on the spot. TechCrunch later pointed out that the interview was proactively arranged by Cluely's PR team, and the "strange woman" on the other end of the line was a TechCrunch reporter.
Why could a fake number blurted out on the spot spread unimpeded for over half a year and even become a reference for others' valuations? Because on this assembly line, the people who fabricate stories, spread stories, and pay for stories had long since become one and the same.
Just a few months earlier, a16z, which had invested in Cluely, laid out this logic openly in an article. In November 2025, this veteran fund founded in 2009 set up a new media team and published a long piece titled "What Is New Media," whose opening line stated that from its very first day, what this fund wanted to be was "the CAA of tech."
CAA is one of Hollywood's largest talent agencies, whose daily business is negotiating salaries for stars and managing their public personas. And in a16z's new media service menu, one offering is literally called "Win the Internet for a Day," promising to equip founders with everything they need to win the online narrative war—from legitimacy to momentum, dominating social media timelines on demand. That same year, a16z directly acquired Turpentine, the podcast network founded by Erik Torenberg, and Erik Torenberg pivoted to become a GP at the fund.
When a top-tier venture capital firm decides to step into the arena as a talent agency itself—running both the money printer and the TV station—narrative is no longer narrative.
In his 2023 book "The Crisis of Narration," Byung-Chul Han used the term storyselling. Once a story is used only to sell, it is no longer accountable to the real world—it only needs to serve the people paying for the next round.
Launch Tower
Following the logic of "VC media-ization" downward, the hottest infrastructure in the tech world in recent years, aside from compute clusters, is probably the content hub.
In the past, entrepreneurs and investors telling stories had to go through traditional tech media; now everyone finds the middlemen too slow and not obedient enough.
In April 2026, OpenAI spent hundreds of millions of dollars to directly acquire the tech podcast TBPN. The acquisition terms were interesting: editorial independence of the show was preserved, but the existing advertising business was shut down, and the team's new reporting line shifted to Chris Lehane, an executive who in his early years worked in the White House under Clinton, specifically handling scandals for the president.
Investment firms themselves started writing in-depth profile pieces even earlier. In September 2022, Sequoia specifically commissioned a freelance writer to produce a 13,000-word long-form profile, prominently displayed on Sequoia's official website, with a title styled like a religious gospel: "Sam Bankman-Fried Has a Savior Complex—and Maybe You Should Too."
Less than two months later, FTX filed for bankruptcy, and the article was urgently removed from the official website. Sequoia's $150 million investment was entirely written down to zero.
SBF's downfall taught Silicon Valley a hard lesson: glorifying founders as saints is too costly, and once the bubble bursts, the reputations of the institutions themselves shatter along with it.
Since positive glorification tends to fail, then use a cheaper fuel: public outrage.
In the formula where attention equals valuation, being praised by the entire internet and being cursed by the entire internet carry the same converted traffic weight. As long as the company's name can be inserted into investors' information feeds, infamy is still fame—even being reviled can be monetized.
Artisan's "Stop Hiring Humans" street advertisement in San Francisco
Image source: Artisan / San Francisco Chronicle
There have been many examples in the past two years. First, Artisan, a startup focused on AI sales agents, erected a billboard at the intersection of 10th Street and Folsom Street in San Francisco's SoMa district, reading "Stop Hiring Humans." Founder Jaspar Carmichael-Jack later admitted frankly that the primary purpose of these ads was to grab attention.
After the backlash fermented, Artisan smoothly secured $25 million in Series A funding. At the time, this company shouting "Stop Hiring Humans" had 35 human employees and planned to hire 22 more.
In September 2025, in New York subway cars, 22-year-old Avi Schiffmann also spent approximately $1 million to plaster over 11,000 ads for his AI pendant product Friend. Within days, enraged subway passengers covered the posters with marker scribbles, one of which read "AI doesn't care if you live or die." Facing the graffiti-covered walls, Avi Schiffmann responded publicly that everything was going according to plan, and casually dropped a quotable line: "Capitalism is the greatest art medium."
Silicon Valley has of course always been fascinated by those who can conjure hype out of thin air. In 1981, when Andy Hertzfeld first transferred into Apple's Mac team, software lead Bud Tribble used a term from Star Trek to name Jobs' storytelling ability: the "reality distortion field."
But Tribble also added the second half of the sentence at the time, saying that once Jobs left, the field would dissipate. After the field dissipates, code bugs won't listen to Jobs' keynote speeches, and the Mac would ultimately have to be put into a box, manufactured, and delivered into the hands of a real person. Whether this thing is actually any good—you just take it home, plug it in, and you know. Nobody can fool anybody.
The watershed moment came in 2011. That spring, Jobs spoke for the last time at the iPad 2 launch event about technology needing to intersect with the liberal arts; five months later, Marc Andreessen published "Why Software Is Eating the World" in The Wall Street Journal, and four days after that, Jobs resigned as Apple CEO.
Since then, the protagonists of Silicon Valley have changed to a different cast of characters. On the new gaming table where software, finance, and attention intertwine, if a product's real buyer is no longer the discerning end user but rather the next round of institutions afraid of missing out, that "reality distortion field" can persist indefinitely.
The music is still playing
Writing to this point, an unavoidable question emerges: since even bystanders can hear these calculations being made, can the professional buyers at the table really not see through it?
It's not that they can't see through it—the buyers at the table know better than anyone.
When I chat with some frontline investors about certain AI projects, they often give a wry smile and admit that yes, it's not solid enough, and the numbers are inflated. But once you press further—"Then why are you still rushing to hand out a TS?"—the usual response is silence, or a rhetorical question: "If you don't get in this round and it doubles next round, how do you explain that to your LPs?"
This is precisely the problem that Yale economist Robert Shiller wrote about in his 2019 book Narrative Economics. Shiller borrowed epidemiological models to describe how the amount of capital a narrative can mobilize depends on its transmission speed and coverage—and has absolutely nothing to do with whether the story itself is true or false.
In an industry where people answer to paper gains, truth and falsehood are concerns only for the final reckoning, while missing out is a problem that gets exposed within the quarter. As long as the narrative is told for the benefit of the next round of buyers, the baton can be passed along round after round.
This collective hysteria mentality played out once before in the 2020 SPAC frenzy.
On June 4, 2020, electric truck company Nikola went public on Nasdaq via a SPAC. Going public through a SPAC offers a huge loophole: it can bypass the strict scrutiny of a traditional IPO and stuff roadshow materials with extensive future financial projections.
Five days after listing, Nikola's market cap surged to nearly $29 billion, overtaking Ford in one stroke—even though Nikola had not delivered a single vehicle and its book revenue was zero. It was not until three and a half years later, in January 2024, that the U.S. SEC finally introduced new rules, removing the securities-litigation safe harbor protection for future performance projections by SPACs and their target companies.
In July 2007, Citigroup CEO Chuck Prince, interviewed by the Financial Times in Japan, summed up this institutional dilemma with remarkable honesty. Speaking of the leveraged buyout boom at the time, he said that when the music stops, things will get complicated in terms of liquidity, but as long as the music is playing, you've got to get up and dance.
During the 2023 OpenAI board turmoil
Sam Altman returned to the company office wearing a visitor badge
Image source: Sam Altman's own X post
Four months later, Chuck Prince resigned.
In the primary market, where valuation and paper gains do the talking, whoever stops first is the first to be out. Even when someone tries to turn off the music, the vested interests at the whole table will join forces to push him away.
Looking back at the OpenAI boardroom drama in November 2023 that shocked the world, stripping away all the rhetorical lines about "AI safety" and "accelerated development," the underlying color is in fact a battle to defend valuation—an asset-defense war.
At the time, the OpenAI board fired Sam Altman on the grounds that he was "not consistently candid in his communications." Right at that very moment, Thrive Capital was preparing to lead a tender offer to buy employee shares at an $86 billion valuation. As soon as the firing news broke, investors immediately let it be known that they were considering writing down their OpenAI shares to zero.
The $86 billion valuation was about to evaporate in an instant, and no one at the table could bear that cost. Within days, 738 of OpenAI's roughly 770 employees signed an open letter demanding the board resign and bring back Sam Altman, or they would all jump ship to Microsoft. Five days later, Sam Altman returned to OpenAI, and three of the four directors who fired him were gone.
Playing the Eccentric
Since the rule of the table is to sell the story to the next round, what is the most efficient fundraising strategy for an early-stage founder?
Building a product takes a long cycle; showing quirks or even crossing lines takes only a few minutes.
In early Silicon Valley, eccentricity was a byproduct left behind after getting things done. Young Steve Jobs liked to walk around the office barefoot, and for the latter half of his life wore almost exclusively Issey Miyake black turtlenecks. The reason people relish these details is the premise that he first built the Mac and the iPhone.
Later, the order of imitation was completely reversed.
In 2014, Elizabeth Holmes, wearing a black turtleneck, backstage at
TechCrunch Disrupt
Image source: Max Morse / TechCrunch
The first to learn this superficial trick was Elizabeth Holmes. She dressed like Jobs in a black turtleneck; a person who knew her family recalled that she even copied Jobs's gesture of pulling an iPhone from his trouser pocket exactly, except what she pulled out was swapped for a Theranos micro blood-collection tube.
If Holmes was still an individual-style imitation, then it was Peter Thiel who systematized the "cult of the eccentric" into venture-capital doctrine. By 2010, Peter Thiel established the Thiel Fellowship, giving each young person under 20 $100,000 on the condition that they drop out of college to start a company. Three years later, in Zero to One, he devoted a chapter to "The Founder's Paradox," arguing that successful founders often carry both the good and bad extremes of traits at once.
Fourteen years later, dropping out itself became a bonus point during pitch presentations.
At the YC Demo Day at the end of 2025, more and more founders, in their limited presentation time, could not be bothered to talk about the product and first made a point of emphasizing that they had just dropped out of school. Moxxie Ventures partner Katie Jacobs Stanton even publicly stated that dropping out is itself a credential, proving that a person has sufficiently deep conviction.
As for the results of multiple statistical studies on startups, they give exactly the opposite conclusion: the vast majority of successful startup founders hold university degrees. But in the FOMO atmosphere of the pitch hall, no one cares about such a buzz-killing statistic.
In recent years, just wearing a black turtleneck and going through the dropout paperwork is no longer thrilling enough. The new casting script demands that founders preferably bring some "antisocial" or "man-child" dramatic tension.
In May 2021, Musk hosted Saturday Night Live and said in his opening monologue that he was the first person with Asperger's syndrome to host the show, "or at least the first to admit it." Two years later, when Walter Isaacson finished his biography of Musk, he reflected at the end of the book that sometimes great innovators are just risk-loving man-children who refuse to be potty-trained, crazy enough to think they can change the world.
But some investors not only buy into this, they are happy to tell such offenses as flattering anecdotes.
In Sequoia's long article that has since been taken down, one story was recorded. SBF pitched Sequoia partners on Zoom about his vision for the future of money. After the meeting, an FTX employee sitting ten feet away from him walked over and discovered that he had been playing League of Legends the entire time while pitching. For an ordinary entrepreneur, this would be called bad manners and disrespect. Sequoia, however, treated it as a flattering anecdote and wrote it into the long article posted on its official website.
Once "outrageousness" can be directly converted into checks, public decency and bottom lines will be quickly breached.
Roy Lee, the founder of Cluely mentioned earlier, first became famous by developing a tool that helped people cheat in programmers' technical interviews, and personally filmed a video demonstrating himself using it to pass an Amazon interview. After Columbia University suspended him, he simply dropped out and founded Cluely, and soon received investment from a16z.
No matter how extreme the résumé, as long as it comes with话题度, it can find a buyer in Silicon Valley. In 2015, engineer Anthony Levandowski registered a church called "Way of the Future," claiming he wanted to develop an artificial-intelligence-based god. He was later sentenced to 18 months in prison for stealing Google's autonomous-driving trade secrets and received a presidential pardon in January 2021. By the spring of 2026, Travis Kalanick acquired Pronto, the autonomous mining-vehicle company Levandowski ran, confidently letting him continue at the helm and making Pronto the technical core of the mining division of the new company Atoms.
When we used to talk about good entrepreneurs who can survive cycles, one criterion we often cited was that they should have ambition but not too big an ego, and that they should do businesses that can actually be implemented. But in today's fast-money logic, as long as you perform your ego big enough and outrageous enough, investors eager to find outliers will come up to you and praise you for having the makings of a champion.
This casting logic has also spread to the Chinese venture capital circle, such as the recently much-buzzed-about Tian Keyu, whom VCs say "has a fire in his belly."
My view on this matter remains the same: if you know full well that someone has done something unethical—breaking rules and harming others—and you still think he "has a fire in his belly" and insist on investing in him, that only proves you are unethical too.
A couple of days ago, I discussed this view with a young investor, and he said, "How can an investor's business be called unethical?"
He probably really has mastered the four ways of investing in world models.
Failing Up
Common sense says that a setup built on acting and crossing lines will eventually be exposed. The company collapses, the scandal breaks, or even the court verdict comes down—surely this person should be out of the game by then?
Silicon Valley's answer is not only that they don't leave the table, but that their chips can keep growing the more they lose.
Silicon Valley has indeed had a tradition of tolerating failure—if a company flops, the founder can still raise money for the next one. But over the past few years, the pocket of "failure" has been stretched wider and wider, stuffing even fraud and workplace scandals into the narrative of "growing from lessons learned."
Tim White, a researcher at the London School of Economics, published a paper in 2026 specifically analyzing this phenomenon, using the term "failing up." His conclusion in the paper is that Silicon Valley's top VC system is structurally designed to reward serial entrepreneurs who commit extreme misconduct.
Why does the system reward those who make big mistakes?
Once you grasp the attention logic mentioned earlier, this is not surprising at all. For funds managing billions of dollars and needing to write large checks, the biggest headache is not founders with tainted records, but projects with no momentum. A star founder who drove a hundred-billion-dollar company into bankruptcy, even with a ruined reputation, still holds scarce assets that ordinary entrepreneurs couldn't accumulate in ten lifetimes—such as global attention, ready-made media headlines, and a capital-circle network that rallies at a call.
Adam Neumann at the Flow Fort Lauderdale project launch event
Image source: Romain Maurice/Getty Images
Adam Neumann is a typical case. In August 2019, WeWork, a subleasing company valued at $47 billion, filed its prospectus, opening with the company's mission to "elevate the world's consciousness." More than a month later, the IPO was shelved, Adam Neumann resigned as CEO, and WeWork, left in a mess, filed for bankruptcy in November 2023.
But more than a year before WeWork's bankruptcy, in August 2022, a16z wrote a check of about $350 million to his new real estate company Flow, setting the highest single investment record in the fund's history. Marc Andreessen praised Adam Neumann in a blog as a visionary leader and said the fund likes to see serial entrepreneurs grow from past lessons. By April 2025, Flow's valuation had risen to about $2.5 billion.
The same script played out with former Uber founder Travis Kalanick.
In 2017, Uber forced founder Travis Kalanick to step down as CEO after a series of sexual harassment and workplace discrimination complaints came to light. Nine years later, on July 22, 2026, it was again a16z that stepped up to lead a $1.7 billion funding round for Travis Kalanick's new company Atoms.
On the same day, a16z co-founder Ben Horowitz published an article titled "Travis Is Back" to boost his profile, while Travis Kalanick lightly described the return on X as "a bit of unfinished business."
As for those who accidentally crossed legal red lines and even had court verdicts handed down, they too have figured out another shortcut to turn the page.
Nikola, the company mentioned earlier that reached a $29 billion market cap on zero revenue, saw its founder Trevor Milton later convicted of securities fraud. But less than a month before the 2024 U.S. election, Trevor Milton and his wife donated more than $1.8 million to Donald Trump's campaign fund. On March 28, 2025, he smoothly received a presidential pardon, and the hundreds of millions of dollars he originally needed to pay investors were also waived.
With a clean slate, Trevor Milton immediately returned to the venture capital table. By the end of that year, he and a group of investors bought the near-bankrupt aircraft manufacturer SyberJet, and by the spring of 2026, he had skillfully switched to the narrative of AI-driven autonomous aircraft and begun seeking financing in the market.
02026
When a fund acts as both referee and media, when entrepreneurs can get checks by fabricating data and performing eccentricities, and even fraud convictions can be erased with political donations, this internal loop has only one hidden risk left: what if outside regulators, ethicists, or the general public can no longer stand it?
To prevent external regulation and moral scrutiny from interrupting this cycle, Silicon Valley has spent the past decade or so stitching together a larger ideological bulletproof vest for itself, step by step.
The original fabric of this bulletproof vest was the hybrid pointed out by British scholars Richard Barbrook and Andy Cameron in their 1995 article "The Californian Ideology," in which Silicon Valley fused the free spirit of hippies with the entrepreneurial fervor of yuppies, firmly believing that as long as the government stays out of the way, technology will solve all social problems on its own.
Travis Kalanick's Twitter avatar was once the cover of Ayn Rand's novel The Fountainhead; Facebook's internal slogan "move fast and break things" was also used until 2014. The implication is that as long as you run fast enough, the things that get broken don't need to be paid for by us.
Later, Peter Thiel pushed this kind of tech elite immunity to the institutional level. By 2014, Wired magazine excerpted a chapter from Zero to One, with the title directly taken as "You Should Run Your Startup Like a Cult."
In the past five years, this "elite immunity theory" has spawned two versions that appear to be diametrically opposed but actually lead to the same destination.
The first is called effective altruism (EA), whose core logic is to use "grand good deeds in the future" to exempt "money-grubbing means in the present." In 2012, Oxford University philosopher William MacAskill met with SBF, who was still studying at MIT, and advised him not to directly devote himself to public welfare, but to first make as much money as possible and then donate it, the so-called earn to give.
This rhetoric became SBF's best public relations shield. It was not until after the FTX collapse in November 2022 that Vox reporter Kelsey Piper asked him in a private message, for a person who treats everything as a win-or-lose game, you usually talk about ethics so eloquently. Only then did SBF drop the act and reply: "I had to be. It's what reputations are made of, to some extent."
The other is effective accelerationism (e/acc). Since pretending to be a philanthropist is too easy to expose, simply declare that "accelerating money-making and god-making is itself the highest morality."
This concept, proposed by the anonymous account Beff Jezos in 2022, argues that the universe thermodynamically naturally favors civilizations that become increasingly capable of utilizing energy. On October 16, 2023, Marc Andreessen published the "Techno-Optimist Manifesto," formally listing Beff Jezos among the "patron saints."
The manifesto was written with a murderous tone, stating that any attempt to slow down AI would lead to death, and that deaths that could have been avoided by AI "are a form of murder"; and in a section titled "Enemies," "social responsibility," "trust and safety," "tech ethics," and "risk management" were all listed on a blacklist.
When it came to Peter Thiel, the secular debate was directly elevated to theological intimidation.
In the fall of 2025, Peter Thiel gave four closed-door lectures on the "Antichrist" in San Francisco. Leaked recordings showed that he believed the Antichrist might appear in the form of someone obstructing scientific development, and he directly named environmental activist Greta Thunberg and AI safety researcher Eliezer Yudkowsky. By July 2026, he co-authored an article with Sam Wolfe in the religious publication First Things, depicting the Antichrist as a technocrat who constantly speaks of "safety, ethics, and global coordination."
Once "buckling up" is defined as "murder" and "the Antichrist," then whoever dares to audit Silicon Valley, whoever dares to step on the brakes of runaway capital, is a sinner against all humanity.
After the bulletproof vest was put on, the money began flowing directly toward ballots and legislation. In 2025, a16z and OpenAI President Greg Brockman and his wife each contributed $25 million to lead the creation of the super PAC Leading the Future, with the goal of promoting a unified national AI regulatory standard in the 2026 midterm elections and preventing states from legislating their own AI oversight. As of April 2026, the organization and its affiliated groups had raised more than $140 million, of which the $25 million received in the first quarter of 2026 came entirely from a16z and its two founders.
From fabricating ARR, buying media transmission towers, and mass-producing eccentrics, to using hundreds of millions of dollars in political donations to buy the right to interpret the rules, this closed loop ultimately converged seamlessly onto the same road, Sand Hill Road in Menlo Park, California, where a16z got its start.
Digging further along the place name Menlo Park, you will find a particularly ironic piece of history.
More than half a century ago, in the fall of 1968, Stewart Brand was also in the Menlo Park area, using a typewriter and scissors to assemble the first issue of the Whole Earth Catalog. In explaining his original purpose for the publication, he said that distant powers such as governments and large corporations had become riddled with problems, and that what the Whole Earth Catalog needed to do was serve as a tool for evaluation and access, selecting handy things for specific individuals, with readers then sending in their own usage feedback.
For that generation of Silicon Valley people, technology was a tool placed in the hands of specific individuals, and the makers of tools held a reverence for them. When the first-generation iPad launched in 2010, New York Times reporter Nick Bilton asked Steve Jobs, who had been deeply influenced by the Whole Earth Catalog, whether his children loved the iPad. Jobs replied that his children hadn't touched it yet, and that his family strictly limited their children's use of tech products.
Fifty-eight years later, a16z, also founded in Menlo Park, has had its media team shrink the unit of time to "winning the internet for a day."
As for what the tools ultimately turn people into, nobody cares—as long as today's timeline wins, tomorrow's valuation can go up.
And Stewart Brand, who made the Whole Earth Catalog in Menlo Park back then, later went on to reckon with another scale of time.
The mechanical structure of the 10,000-Year Clock inside the mountain
Image source: 10,000 Year Clock project website
In 1996, he and computer scientist Danny Hillis and others founded the Long Now Foundation, planning to build a mechanical clock inside a mountain that would run for ten thousand years, ticking once a year, with a cuckoo emerging only once every thousand years.
In all of the Long Now Foundation's documents, every year is preceded by an extra zero, to remind people to think about present decisions on a ten-thousand-year scale.
This year, in their reckoning, is 02026.
Original link
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
記事
翻訳参照
What are the key figures to watch in the potential merger of SpaceX and Tesla?TL;DR
· On the October 20 SpaceX earnings call, Musk confirmed that Tesla and SpaceX have each established independent special committees of their boards to discuss a potential merger; he recused himself due to a conflict of interest and said no terms have been reached.
· On the Tesla side, 50% approval of all outstanding shares is required, and abstentions count as opposition. This threshold conflicts with analysts' expectations of an "announcement before the annual meeting" and a "90% probability by the end of next year."
· Related tickers: Tesla (TSLA), SpaceX (SPCX). Verification points are Tesla's Q3 automotive gross margin, capital expenditures, and subsequent disclosures from the committees.
On October 20, Musk confirmed on SpaceX's Q3 earnings call that Tesla and SpaceX have each established independent special committees of their boards at shareholders' request to discuss a potential merger. He recused himself as a conflicted party and emphasized that the committees have not agreed on any terms, and "obviously there's no guarantee one will be reached."
This adds a procedural step beyond the rumors, but it is still far from a deal. What ordinary investors care about is whether Tesla shares would be exchanged for SpaceX shares, whether the exchange ratio would provide a sufficient premium, and whether Musk's voting power would become more concentrated after the merger.
The market has already offered two answers. Barclays analyst Dan Levy said in an October 14 client note that the merger "has increasingly become the consensus expectation" and could be announced before the annual shareholder meeting. CFRA's Garrett Nelson, after the Roadster presentation, gave a "90% probability of completing the merger by the end of next year." Musk, however, played down the certainty and described the Tesla-side threshold as "quite high."
Special committees put the conflict-isolation process on the table
Special committees are a standard isolation measure for conflicted transactions, but they do not mean the two sides have already agreed on a price. The CEO is simultaneously the largest individual shareholder of both companies, so independent directors must form a small group to negotiate the price for the deal to withstand scrutiny in Delaware courts.
Musk said the committees have not reached terms and there is no guarantee they will, and that he is not participating in the discussions. Tesla's October 19 proxy statement set the annual shareholder meeting for December 3, and the agenda contains no merger proposal.
Committee members, consideration, and timetable have not been disclosed, and there is no 8-K confirmation in public filings. What can be confirmed at present is only that "inquiries have been formalized."
Independence also warrants closer scrutiny. Ira Ehrenpreis, chairman of Tesla's compensation and governance committee, is still listed as an independent director, and according to public information he has also served as a SpaceX director since February. This does not automatically invalidate the committee, but it will subject the word "independent" to closer scrutiny.
SpaceX's AI Revenue Changes Acquirer Math
If a merger happens, who becomes the acquirer depends on whose stock is more expensive and whose growth story is stronger. SpaceX delivered stronger pricing power in the third quarter.
Revenue was $14.58 billion, up 161% year over year, net income was $4.4 billion, and adjusted EBITDA was $8.8 billion. Superintelligence business revenue was $7.56 billion, up 830% year over year, operating profit was $431 million, and margin was 5.7%. Starlink revenue was $5.25 billion, operating profit was $2.37 billion, and margin was 45.1%.
Starlink still contributes the main operating profit
Capex was $19.59 billion, fourth-quarter guidance is $35 billion to $40 billion, and the first nine months still showed a loss of $413 million.
Fourth-quarter capex guidance nearly doubles
AI revenue has expanded SpaceX's narrative from rockets and Starlink to compute leasing, but Starlink remains the main profit driver.
Based on current market valuations, SpaceX is about $2.1 trillion and Tesla is about $1.5 trillion, implying an exchange ratio of about 0.7 before any premium. Sell-side estimates put Musk's stake after a merger at about 37% and voting power at about 56%. This explains why the sell side favors an all-stock SpaceX acquisition: Musk's roughly 20% voting power in Tesla could be pulled toward about 56% after the merger.
Post-merger voting power could rise to 56%
Analysts' Calendar Collides With Musk's Threshold
Wall Street is giving a timetable and probabilities, while Musk is giving a legal threshold; the two have different evidentiary strength.
Levy's note was written before the committee disclosure. He said that if it drags into late October or early November, completing approval within the annual meeting window becomes harder, and the deal could still emerge in the next 6 to 12 months. "No later than December 6" is inferred from SEC deadlines, and after the proxy statement, December 3 should be the reference date.
RBC's Tom Narayan said it is "not easy," and in substance it can only be an all-stock SpaceX acquisition of Tesla. Tesla investors could accept $480 per share, a premium of about 30%, valuing the combined entity at about $3.74 trillion, with Tesla shareholders' stake falling from 54% to 48%. The $480 figure is a target price plus premium assumption, not a quote.
CFRA's Garrett Nelson raised his price target from $385 to $475, assigning a 90% probability by the end of next year, citing a resurgence of the "Musk magic" and technology convergence translating into products. The 90% points to the end of 2027, directly conflicting with Musk's "no guarantee" and "high threshold."
Levy provides the calendar window, Narayan provides the consideration difficulty, and Nelson provides the sentiment probability. Musk, meanwhile, stated that the Tesla side requires 50% approval of all outstanding shares, not just a majority of voting shares, with abstentions counting as opposition. This threshold is far tougher than "announcing before the shareholder meeting."
A votable proposal is unlikely to take shape before the annual meeting
Gross margin and document disclosure determine how far the story can go
For the merger to become a votable proposal, three hard elements are still missing: committee members and terms, formal documents, and whether Tesla's own finances can support AI investment.
Tesla's third-quarter earnings were released on October 21, with the market focused on automotive gross margin and AI capital expenditure. There are currently no verifiable figures, so they cannot be compared side by side with SpaceX's $14.58 billion in revenue. If gross margin is dragged down by AI investment, shareholder acceptance of a share exchange at a low premium will be even lower. If it holds steady, Narayan's $480 framework will have a basis for discussion.
On the committee front, there is currently only Musk's verbal confirmation, with no 8-K or DEFA14A-level documents. The December 3 shareholder meeting is set and has no merger proposal, so the window to form a votable proposal before the meeting is extremely short. If it drags past late October or early November, it is more likely to slip to 2027.
Current evidence supports only one judgment: the merger has entered formal exploration, while terms and consideration remain at zero. The core of the pricing disagreement is whether Tesla's third-quarter gross margin can sustain the AI narrative, whether the committee will disclose members and terms, and whether a formal proposal will appear before December 3. Without these three, the 90% probability is merely analysts' optimistic scenario, not a company commitment.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
What are the key figures to watch in the potential merger of SpaceX and Tesla?
TL;DR
· On the October 20 SpaceX earnings call, Musk confirmed that Tesla and SpaceX have each established independent special committees of their boards to discuss a potential merger; he recused himself due to a conflict of interest and said no terms have been reached.
· On the Tesla side, 50% approval of all outstanding shares is required, and abstentions count as opposition. This threshold conflicts with analysts' expectations of an "announcement before the annual meeting" and a "90% probability by the end of next year."
· Related tickers: Tesla (TSLA), SpaceX (SPCX). Verification points are Tesla's Q3 automotive gross margin, capital expenditures, and subsequent disclosures from the committees.
On October 20, Musk confirmed on SpaceX's Q3 earnings call that Tesla and SpaceX have each established independent special committees of their boards at shareholders' request to discuss a potential merger. He recused himself as a conflicted party and emphasized that the committees have not agreed on any terms, and "obviously there's no guarantee one will be reached."
This adds a procedural step beyond the rumors, but it is still far from a deal. What ordinary investors care about is whether Tesla shares would be exchanged for SpaceX shares, whether the exchange ratio would provide a sufficient premium, and whether Musk's voting power would become more concentrated after the merger.
The market has already offered two answers. Barclays analyst Dan Levy said in an October 14 client note that the merger "has increasingly become the consensus expectation" and could be announced before the annual shareholder meeting. CFRA's Garrett Nelson, after the Roadster presentation, gave a "90% probability of completing the merger by the end of next year." Musk, however, played down the certainty and described the Tesla-side threshold as "quite high."
Special committees put the conflict-isolation process on the table
Special committees are a standard isolation measure for conflicted transactions, but they do not mean the two sides have already agreed on a price. The CEO is simultaneously the largest individual shareholder of both companies, so independent directors must form a small group to negotiate the price for the deal to withstand scrutiny in Delaware courts.
Musk said the committees have not reached terms and there is no guarantee they will, and that he is not participating in the discussions. Tesla's October 19 proxy statement set the annual shareholder meeting for December 3, and the agenda contains no merger proposal.
Committee members, consideration, and timetable have not been disclosed, and there is no 8-K confirmation in public filings. What can be confirmed at present is only that "inquiries have been formalized."
Independence also warrants closer scrutiny. Ira Ehrenpreis, chairman of Tesla's compensation and governance committee, is still listed as an independent director, and according to public information he has also served as a SpaceX director since February. This does not automatically invalidate the committee, but it will subject the word "independent" to closer scrutiny.
SpaceX's AI Revenue Changes Acquirer Math
If a merger happens, who becomes the acquirer depends on whose stock is more expensive and whose growth story is stronger. SpaceX delivered stronger pricing power in the third quarter.
Revenue was $14.58 billion, up 161% year over year, net income was $4.4 billion, and adjusted EBITDA was $8.8 billion. Superintelligence business revenue was $7.56 billion, up 830% year over year, operating profit was $431 million, and margin was 5.7%. Starlink revenue was $5.25 billion, operating profit was $2.37 billion, and margin was 45.1%.
Starlink still contributes the main operating profit
Capex was $19.59 billion, fourth-quarter guidance is $35 billion to $40 billion, and the first nine months still showed a loss of $413 million.
Fourth-quarter capex guidance nearly doubles
AI revenue has expanded SpaceX's narrative from rockets and Starlink to compute leasing, but Starlink remains the main profit driver.
Based on current market valuations, SpaceX is about $2.1 trillion and Tesla is about $1.5 trillion, implying an exchange ratio of about 0.7 before any premium. Sell-side estimates put Musk's stake after a merger at about 37% and voting power at about 56%. This explains why the sell side favors an all-stock SpaceX acquisition: Musk's roughly 20% voting power in Tesla could be pulled toward about 56% after the merger.
Post-merger voting power could rise to 56%
Analysts' Calendar Collides With Musk's Threshold
Wall Street is giving a timetable and probabilities, while Musk is giving a legal threshold; the two have different evidentiary strength.
Levy's note was written before the committee disclosure. He said that if it drags into late October or early November, completing approval within the annual meeting window becomes harder, and the deal could still emerge in the next 6 to 12 months. "No later than December 6" is inferred from SEC deadlines, and after the proxy statement, December 3 should be the reference date.
RBC's Tom Narayan said it is "not easy," and in substance it can only be an all-stock SpaceX acquisition of Tesla. Tesla investors could accept $480 per share, a premium of about 30%, valuing the combined entity at about $3.74 trillion, with Tesla shareholders' stake falling from 54% to 48%. The $480 figure is a target price plus premium assumption, not a quote.
CFRA's Garrett Nelson raised his price target from $385 to $475, assigning a 90% probability by the end of next year, citing a resurgence of the "Musk magic" and technology convergence translating into products. The 90% points to the end of 2027, directly conflicting with Musk's "no guarantee" and "high threshold."
Levy provides the calendar window, Narayan provides the consideration difficulty, and Nelson provides the sentiment probability. Musk, meanwhile, stated that the Tesla side requires 50% approval of all outstanding shares, not just a majority of voting shares, with abstentions counting as opposition. This threshold is far tougher than "announcing before the shareholder meeting."
A votable proposal is unlikely to take shape before the annual meeting
Gross margin and document disclosure determine how far the story can go
For the merger to become a votable proposal, three hard elements are still missing: committee members and terms, formal documents, and whether Tesla's own finances can support AI investment.
Tesla's third-quarter earnings were released on October 21, with the market focused on automotive gross margin and AI capital expenditure. There are currently no verifiable figures, so they cannot be compared side by side with SpaceX's $14.58 billion in revenue. If gross margin is dragged down by AI investment, shareholder acceptance of a share exchange at a low premium will be even lower. If it holds steady, Narayan's $480 framework will have a basis for discussion.
On the committee front, there is currently only Musk's verbal confirmation, with no 8-K or DEFA14A-level documents. The December 3 shareholder meeting is set and has no merger proposal, so the window to form a votable proposal before the meeting is extremely short. If it drags past late October or early November, it is more likely to slip to 2027.
Current evidence supports only one judgment: the merger has entered formal exploration, while terms and consideration remain at zero. The core of the pricing disagreement is whether Tesla's third-quarter gross margin can sustain the AI narrative, whether the committee will disclose members and terms, and whether a formal proposal will appear before December 3. Without these three, the 90% probability is merely analysts' optimistic scenario, not a company commitment.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
361
·
--
翻訳参照
If Tesla and SpaceX merge, could TSLA hit $480?SpaceX's second quarterly report since going public, and it turned a profit for the first time. Revenue was $14.6 billion, up 161% year-over-year. Net income was $4.4 billion, compared with a loss of $1.1 billion in the same period last year.
The stock rose 8.06% after hours to close at $159.70.
The earnings themselves beat expectations. But what really got traders repositioning was a passage in the Q&A session of the earnings call.
Deutsche Bank analyst Edison Yu asked Musk how he viewed the pros and cons of a Tesla-SpaceX merger and what obstacles existed. Musk first acknowledged the awkwardness of his conflicted position, then laid things out clearly. He said the two companies had, at shareholders' request, each established special committees composed of independent directors.
"Especially on the Tesla side, we need 50% of all shares voting, not just those participating in the vote, but all shareholders. That's a fairly high threshold."
Texas law sets the default threshold for fundamental transactions like mergers at two-thirds of all outstanding shares. But the law allows companies to lower this in their charter, with a floor of a majority. After Tesla moved to Texas, its charter lowered the threshold to "a majority of all outstanding shares."
Musk holds about 20% of Tesla. That means even if the deal benefits him, he would still need to secure roughly another 30% of shares before the proposal could be put to a vote.
How the market views the merger
On Polymarket, the market for "merger announced by a certain date" stood at 18% probability by year-end and 64% by end-2027 on October 19. By the early hours of October 21, those figures had become 20.5% and 66.5%, with cumulative trading volume of $1.48 million across the event.
Future Fund managing partner Gary Black offered two judgments on X. One was that SpaceX's offer would land "around $420 per share." The other was that the merger is "inevitable," citing Musk's control of voting rights at both companies. Since it takes roughly 6 to 12 months from announcement to closing, he said the price "will likely be compressed by arbitrage."
Deepwater's Gene Munster put the probability at 95%. He added a time qualifier: "within the next two years."
Barclays' Dan Levy moved the timeline forward. In an October 15 report, he judged that an announcement could come before Tesla's annual shareholder meeting, which is in early December. He also offered an exchange ratio estimate: 1 Tesla share for about 0.7 SpaceX shares.
Amid a sea of probabilities and ranges, RBC put forth a specific number.
RBC Capital Markets analyst Tom Narayan set a price target of $480 per share for Tesla.
On July 7, RBC raised its price target from $475 to $500, citing the market beginning to price in the possibility of a SpaceX acquisition. He believes that excluding any SpaceX deal premium, Tesla alone is worth only about $435. A few days later, the $500 was cut to $480.
So where does $480 come from?
In RBC's assumed estimates, the combined company is valued at $3.74 trillion. Tesla shareholders get 48%, SpaceX shareholders get 52%. Converted into dollar amounts, the Tesla side is $1.795 trillion, and the SpaceX side is $1.945 trillion.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
If Tesla and SpaceX merge, could TSLA hit $480?
SpaceX's second quarterly report since going public, and it turned a profit for the first time. Revenue was $14.6 billion, up 161% year-over-year. Net income was $4.4 billion, compared with a loss of $1.1 billion in the same period last year.
The stock rose 8.06% after hours to close at $159.70.
The earnings themselves beat expectations. But what really got traders repositioning was a passage in the Q&A session of the earnings call.
Deutsche Bank analyst Edison Yu asked Musk how he viewed the pros and cons of a Tesla-SpaceX merger and what obstacles existed. Musk first acknowledged the awkwardness of his conflicted position, then laid things out clearly. He said the two companies had, at shareholders' request, each established special committees composed of independent directors.
"Especially on the Tesla side, we need 50% of all shares voting, not just those participating in the vote, but all shareholders. That's a fairly high threshold."
Texas law sets the default threshold for fundamental transactions like mergers at two-thirds of all outstanding shares. But the law allows companies to lower this in their charter, with a floor of a majority. After Tesla moved to Texas, its charter lowered the threshold to "a majority of all outstanding shares."
Musk holds about 20% of Tesla. That means even if the deal benefits him, he would still need to secure roughly another 30% of shares before the proposal could be put to a vote.
How the market views the merger
On Polymarket, the market for "merger announced by a certain date" stood at 18% probability by year-end and 64% by end-2027 on October 19. By the early hours of October 21, those figures had become 20.5% and 66.5%, with cumulative trading volume of $1.48 million across the event.
Future Fund managing partner Gary Black offered two judgments on X. One was that SpaceX's offer would land "around $420 per share." The other was that the merger is "inevitable," citing Musk's control of voting rights at both companies. Since it takes roughly 6 to 12 months from announcement to closing, he said the price "will likely be compressed by arbitrage."
Deepwater's Gene Munster put the probability at 95%. He added a time qualifier: "within the next two years."
Barclays' Dan Levy moved the timeline forward. In an October 15 report, he judged that an announcement could come before Tesla's annual shareholder meeting, which is in early December. He also offered an exchange ratio estimate: 1 Tesla share for about 0.7 SpaceX shares.
Amid a sea of probabilities and ranges, RBC put forth a specific number.
RBC Capital Markets analyst Tom Narayan set a price target of $480 per share for Tesla.
On July 7, RBC raised its price target from $475 to $500, citing the market beginning to price in the possibility of a SpaceX acquisition. He believes that excluding any SpaceX deal premium, Tesla alone is worth only about $435. A few days later, the $500 was cut to $480.
So where does $480 come from?
In RBC's assumed estimates, the combined company is valued at $3.74 trillion. Tesla shareholders get 48%, SpaceX shareholders get 52%. Converted into dollar amounts, the Tesla side is $1.795 trillion, and the SpaceX side is $1.945 trillion.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
26
·
--
記事
翻訳参照
Wall Street Morning Brief: AI jitters shake markets as healthcare leads, SpaceX and Super Micro ignite after-hours, Meta and Tesla face big testsEvery weekday morning, we focus on macro, US equities, AI, precious metals and crude oil, using data to review the market and trends to seize opportunities. Brought to you by us.
US stocks wobble as small caps lead; oil trades the rumor, then the denial
On Tuesday, US stocks were pulled back and forth between rumors of a "US-Iran compromise" and subsequent denials. The Dow rose 1.02%, the S&P 500 gained 0.28% (with more than 400 constituents advancing and the index reclaiming its 50-day moving average), the small-cap Russell 2000 led the way with a 1.66% surge, while the Nasdaq Composite slipped just 0.02%. Nine of the S&P 500's 11 sectors rose and two fell, with healthcare up 2.34% and real estate up 1.69% leading gains, while communication services fell 0.89% and technology fell 0.34% to bring up the rear.
In early trading overnight, Qatari media reported that the US and Iran had tentatively accepted a Pakistani-mediated proposal and could reach a ceasefire agreement as soon as this week. The news instantly detonated short positions, with Brent crude touching a five-month high of $111.99 intraday before plunging more than 3.3% in a straight line and briefly breaking below $106. However, shortly afterward, diplomats involved in the negotiations urgently denied the reports, calling claims that a deal was imminent seriously inaccurate. Tehran went further, reiterating in tougher terms that it would not compromise until the US met "seven conditions" including lifting sanctions and the blockade, and that "not a single particle of enriched nuclear material will leave Iran." Oil prices then sharply narrowed their losses from the lows, with Brent ultimately settling down 0.69% at $108.79, while the November WTI contract settled down 1.80% at $101.79.
In Europe, the energy crisis cloud shows no sign of lifting. The Dutch TTF benchmark natural gas price briefly broke above €90 per megawatt-hour intraday. Rabobank strategists expect that, with Asian LNG storage at its lowest level for this time of year since 2009, a winter energy scramble could be ignited. Meanwhile, France's sovereign debt and fiscal deficit crisis continues to fester. Although US Treasury Secretary Bessent publicly downplayed spillover risks, the French-German government bond spread still widened to a high of 153 basis points, with safe-haven funds accelerating into short-term German bunds and the Swiss franc. In addition, the US, Ukraine and Europe reached consensus on a peace framework, but the US government was thrown into disarray internally after Musk's "Starshield" system rate-limiting paralyzed Ukrainian military drones, further aggravating US-Ukraine differences over strikes on Russian oil refineries.
At the same time, the US dollar index weakened to the 101.7 area, a three-week low. Spot gold came under pressure late in New York trading, falling 0.45% to $4,122.38, while spot silver, buoyed by its industrial and catch-up attributes, extended its rebound, settling up 1.32% at $57.66. Gold's underlying support remains solid: Swiss gold exports rose 6% month-over-month in September to 165.2 tonnes, with exports to the UK surging 24% to 126.2 tonnes, a record high since 2012. World Gold Council data shows Q3 global physical gold ETF net inflows hit a record $31 billion (with the UK accounting for $7.5 billion). On the industrial metals front, Sonny McNess, a star aluminum trader formerly of JPMorgan and Mercuria, is aggressively going long October LME copper and short November copper through Hartree Partners, pushing the front-month spot premium to as much as $91.99 per tonne at one point.
Wall Street's "AI phobia" sees a turning point, but AI infrastructure expansion faces multiple challenges
The "AI capex phobia" that has hung over Wall Street over the past week saw a turning point. Goldman Sachs' risk appetite indicator turned negative for the first time since March, prompting Christian Mueller-Glissmann, the bank's London-based head of asset allocation, to tactically upgrade his three-month equity allocation to "overweight," noting that earnings support, light positioning and valuation pullbacks will fuel a year-end rally. At the same time, Wells Fargo's buy-sell sentiment indicator fell below -1 for the first time since June 2025, triggering a "buy" signal (historical data shows the S&P 500 has averaged a 6.5% gain over the following three months, with an 89% hit rate). Its chief strategist Ohsung Kwon said bluntly that the market has become overly pessimistic about AI financing and the Iran situation, and expects capital discipline to let hyperscale cloud providers replace chip stocks driven purely by cash burn as the new leaders, with the bullish case for AI infrastructure now pointing all the way to 2027.
Before the after-hours earnings bombs detonated, intraday traders were still voting with their feet, fleeing highly leveraged AI assets and rotating into defensive sectors such as healthcare (up 2.34%) and real estate (up 1.69%). Plante Moran chief investment officer Jim Baird said doubts about whether AI investment can be monetized are driving funds to rotate into small caps and healthcare stocks.
The panic was triggered by two factors: first, South Korea's rare profitable "new cloud" data center Elice plunged 32% on its first day of trading on October 20; second, The Wall Street Journal exposed a draft of Anthropic's IPO prospectus showing that although first-half revenue soared to $16.3 billion (with Q3 up another 45% quarter-over-quarter to $16.8 billion and adjusted profitability), its net loss reached a staggering $80.7 billion (including $72 billion in accounting charges from changes in the valuation of financing instruments), and future committed compute spending could reach an astonishing $750 billion at the high end. This directly led investors to slash their valuation expectations from $2 trillion to $1.5 trillion.
Moreover, the physical bottlenecks of AI expansion are becoming increasingly glaring. The US research group Center for Western Priorities revealed that there are already 35 data center and related applications on public lands across six western states (covering more than 24,000 acres, with one Utah project even proposing to use SMR nuclear power that has not yet been commercialized). Although the Trump administration views data center expansion as a national priority, public opposition to these projects is growing, with concerns centered on electricity demand, water consumption, wildlife impacts and the use of public lands.
Specific project moves and stock price swings:
Eli Lilly bucked the trend on Tuesday, surging 3.49% to another record high: The company announced that its Omvoh injection for pediatric ulcerative colitis patients achieved major success in late-stage clinical trials, and it plans to seek regulatory approval to expand the indication for this bowel disease therapy. Combined with intraday funds pulling out of tech stocks in search of a safe haven, this pushed the stock to a fresh all-time high.
The healthcare sector jumped 2.34% to lead the market: Weight-loss drug and biopharma themes broke out across the board, with Kailera Therapeutics soaring 12.77%, Viking Therapeutics up 6.63%, Moderna surging more than 6% to its highest since 2022 (up more than 720% year-to-date), Amgen up 3.29%, UnitedHealth up 3.04%, and Novo Nordisk up 2.42%.
SpaceX slipped 0.11%, then surged more than 8% in overnight trading: Third-quarter results crushed Wall Street across the board, with net profit of $4.4 billion far exceeding the expected $1.88 billion, and AI superintelligence (SI) business revenue soaring 830% to $7.56 billion while turning operating profit positive for the first time. On the earnings call, Musk confirmed that SpaceX and Tesla have each set up special committees to discuss a merger of the two giants, and declared that annual recurring revenue is sprinting toward $1 trillion and the compute payback period has shortened to six months, dispelling market doubts about whether infrastructure investment can be realized.
Super Micro Computer closed up 1.15%, then soared more than 15% after hours: The company's preliminary fiscal-quarter revenue estimate reached $18.5 billion–$19.5 billion (far exceeding the midpoint of its original guidance by 26.7% and analysts' expectations of $15.2 billion), with gross margin jumping to 12.0%–12.5%. Evercore ISI analyst Amit Daryanani noted that the combination of better-than-expected revenue and margins is striking, directly driving Dell Technologies up 6% in overnight trading, Hewlett Packard Enterprise up nearly 5%, and compute cloud firm CoreWeave up more than 4%.
Netflix closed down 1.66%, then plunged nearly 6% after hours: Fourth-quarter revenue growth guidance fell to 11.5% (slowing for a fourth consecutive quarter), net profit guidance missed expectations, and the company further cut its full-year advertising revenue forecast from $3 billion to $2.7 billion. Although third-quarter EPS beat expectations, management turmoil, layoff costs and the challenge of losing user time to YouTube sent funds fleeing.
CoreWeave & Nebius both surged more than 4% after hours: Boosted by Musk's massive GPU orders and the AI infrastructure boom, the US cloud services and compute leasing sector staged a dramatic comeback. CoreWeave, which had fallen as much as 6% intraday to a new post-IPO low, was supported by a Goldman Sachs rating upgrade to close up 1.65%, then soared more than 4% after hours along with the sector. Nebius rose 0.71% intraday and surged more than 4% after hours. Only data center operator IREN closed down 4.00% intraday.
The Philadelphia Semiconductor Index slipped 0.29%: Lam Research fell 3.21%, ARM fell 3.07%, ASML fell 0.99%, AMD fell 0.62%, Intel fell 0.37%, and Broadcom fell 0.07%.
The memory sector was mixed: Western Digital rose 3.44%, Seagate Technology rose 2.17%, SanDisk fell 0.42%, SK Hynix fell 2.16%, and Micron Technology fell 0.98% intraday (the company announced an investment in New York State's Indium Corporation to strengthen its high-purity mineral supply chain, but workers at its Taoyuan, Taiwan plant plan to strike this Thursday in solidarity with the Taichung union's push for profit sharing, which could severely disrupt chip production).
The optical communications sector broadly fell: AAOI fell 1.87%, Lumentum fell 1.44%, CRDO fell 0.75%, Coherent fell 0.09%, and only Marvell Technology rose 1.4%.
Tesla closed up 1.54% (extending gains of more than 1.5% in overnight trading): Ferrari's CEO publicly praised the new Roadster's design as showing bold innovation, and after hours Musk confirmed the formation of a special committee with SpaceX to explore a merger of the century, sending bullish sentiment into a frenzy. Watch for the earnings release after Wednesday's close.
Amazon edged up 0.07%: The company announced it will invest more than €16 billion in Germany in 2027 to expand AI and cloud infrastructure (full-year total capex is expected to reach $220 billion, with free cash flow already turning negative last quarter). However, internal emails revealed that AWS has activated an early-receipt process, taking delivery of $5 billion worth of Nvidia GB300 racks upfront (followed by $3 billion per month thereafter), but due to power shortages at some sites, the hardware can only be temporarily stored in transit warehouses awaiting deployment.
Nvidia closed down 0.29% (turning positive after hours, up more than 2.2%): Jensen Huang reached cooperation with the German government and Siemens at the Berlin summit on AI factories and startup investment, emphasizing that AI is a new tool to augment humans. After hours, Musk's announcement of a frenzied order to bring 200,000 GB300 units online each month and deploy 440,000 Vera Rubin units in Q2 next year directly injected a shot of adrenaline.
Microsoft slipped 0.31%: The company confirmed that Windows Server 2025 officially supports the fast machine recovery feature after installing the October security update.
Apple closed down 1.00%: Although the company, as part of its $600 billion "Made in America" plan, invested $100 million in Pennsylvania's Perryman to purchase recycled titanium and expanded its partnership with Qnity to produce variable-aperture film for the iPhone 18 Pro, the first foldable iPhone Duo going on sale this Friday is facing severe supply bottlenecks. Morgan Stanley noted that online delivery wait times have reached 14 weeks, the longest in a decade, while JPMorgan also cut its full-year shipment forecast from 10 million units to 8–9 million units due to capacity constraints.
Google fell 1.13%: Although its Waymo unit plans to use $5 billion in recently borrowed funds to double its autonomous vehicle fleet from 4,000 to 8,000 by the end of this year and expand to 20,000 by the end of next year, the stock was still dragged down intraday by selling pressure in the communication services sector.
Meta closed down 1.59%: As the first AI hyperscale giant to face the earnings gauntlet after Wednesday's close, funds chose to de-risk and front-run ahead of the results amid concerns over its massive capex guidance.
Other US stock moves: Braze soared 51.70% (Salesforce announced it will acquire the customer engagement platform Braze for $5.66 billion); Hasbro surged 11.2% to a one-year high (raising full-year revenue and digital gaming guidance); 3M rose 5.8% (announcing an expanded data center partnership with Amazon and raising its profit forecast); General Motors plunged 6.8% (warning of rising commodity costs and declining truck sales).
What to watch next:
October 21 (Wednesday)
17:00 Jensen Huang GTC keynote: European sovereign AI, inference demand, new architecture and partnership scale are the focus; the market needs concrete orders, not just long-term vision.
The World Intelligent Connected Vehicles Conference opens; the China-Europe Investment, Trade and Technology Cooperation Fair runs through the 23rd: watch for autonomous driving, vehicle-road-cloud standards and cross-border industrial cooperation.
Bessent and Druckenmiller attend the JPMorgan–Robinhood investor conference: the event is closed to media; if public information emerges, watch for views on fiscal financing, interest rates and market risk.
US earnings: IBM and AT&T before the open; Meta, Tesla, Lam Research and Texas Instruments after the close.
October 22 (Thursday)
Micron Taiwan Taoyuan plant strike and second round of negotiations with the Taichung union: Workers at Micron's Taoyuan plant are set to strike on Thursday in solidarity with the Taichung union's push for profit sharing. If negotiations break down and the strike is prolonged, it could directly cut off critical global DRAM and HBM chip production capacity, triggering sharp swings in memory chip prices and related stock prices.
04:30 Meta earnings call; 05:30 Tesla Q&A livestream: For Meta, the key is whether AI spending can be covered by advertising growth, with the market expecting revenue of $63.29 billion, capex of $40.97 billion and negative free cash flow of $9.14 billion; for Tesla, the key is how deliveries of more than 486,000 vehicles and 13.7 GWh of energy storage deployments translate into profit.
Bank of Korea rate decision: A pause is expected after consecutive hikes; if it tightens further, the won may find support, but chip stocks and companies with large financing needs would come under pressure.
US 20-year Treasury auction: The key is the strength of demand and whether the final yield comes in higher than expected, testing whether this round of the Treasury rally can continue and feeding through to gold and tech stocks.
Earnings: Nokia, Spotify, American Airlines, Procter & Gamble; after the close, watch Bloom Energy, Western Digital and Newmont.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Wall Street Morning Brief: AI jitters shake markets as healthcare leads, SpaceX and Super Micro ignite after-hours, Meta and Tesla face big tests
Every weekday morning, we focus on macro, US equities, AI, precious metals and crude oil, using data to review the market and trends to seize opportunities. Brought to you by us.
US stocks wobble as small caps lead; oil trades the rumor, then the denial
On Tuesday, US stocks were pulled back and forth between rumors of a "US-Iran compromise" and subsequent denials. The Dow rose 1.02%, the S&P 500 gained 0.28% (with more than 400 constituents advancing and the index reclaiming its 50-day moving average), the small-cap Russell 2000 led the way with a 1.66% surge, while the Nasdaq Composite slipped just 0.02%. Nine of the S&P 500's 11 sectors rose and two fell, with healthcare up 2.34% and real estate up 1.69% leading gains, while communication services fell 0.89% and technology fell 0.34% to bring up the rear.
In early trading overnight, Qatari media reported that the US and Iran had tentatively accepted a Pakistani-mediated proposal and could reach a ceasefire agreement as soon as this week. The news instantly detonated short positions, with Brent crude touching a five-month high of $111.99 intraday before plunging more than 3.3% in a straight line and briefly breaking below $106. However, shortly afterward, diplomats involved in the negotiations urgently denied the reports, calling claims that a deal was imminent seriously inaccurate. Tehran went further, reiterating in tougher terms that it would not compromise until the US met "seven conditions" including lifting sanctions and the blockade, and that "not a single particle of enriched nuclear material will leave Iran." Oil prices then sharply narrowed their losses from the lows, with Brent ultimately settling down 0.69% at $108.79, while the November WTI contract settled down 1.80% at $101.79.
In Europe, the energy crisis cloud shows no sign of lifting. The Dutch TTF benchmark natural gas price briefly broke above €90 per megawatt-hour intraday. Rabobank strategists expect that, with Asian LNG storage at its lowest level for this time of year since 2009, a winter energy scramble could be ignited. Meanwhile, France's sovereign debt and fiscal deficit crisis continues to fester. Although US Treasury Secretary Bessent publicly downplayed spillover risks, the French-German government bond spread still widened to a high of 153 basis points, with safe-haven funds accelerating into short-term German bunds and the Swiss franc. In addition, the US, Ukraine and Europe reached consensus on a peace framework, but the US government was thrown into disarray internally after Musk's "Starshield" system rate-limiting paralyzed Ukrainian military drones, further aggravating US-Ukraine differences over strikes on Russian oil refineries.
At the same time, the US dollar index weakened to the 101.7 area, a three-week low. Spot gold came under pressure late in New York trading, falling 0.45% to $4,122.38, while spot silver, buoyed by its industrial and catch-up attributes, extended its rebound, settling up 1.32% at $57.66. Gold's underlying support remains solid: Swiss gold exports rose 6% month-over-month in September to 165.2 tonnes, with exports to the UK surging 24% to 126.2 tonnes, a record high since 2012. World Gold Council data shows Q3 global physical gold ETF net inflows hit a record $31 billion (with the UK accounting for $7.5 billion). On the industrial metals front, Sonny McNess, a star aluminum trader formerly of JPMorgan and Mercuria, is aggressively going long October LME copper and short November copper through Hartree Partners, pushing the front-month spot premium to as much as $91.99 per tonne at one point.
Wall Street's "AI phobia" sees a turning point, but AI infrastructure expansion faces multiple challenges
The "AI capex phobia" that has hung over Wall Street over the past week saw a turning point. Goldman Sachs' risk appetite indicator turned negative for the first time since March, prompting Christian Mueller-Glissmann, the bank's London-based head of asset allocation, to tactically upgrade his three-month equity allocation to "overweight," noting that earnings support, light positioning and valuation pullbacks will fuel a year-end rally. At the same time, Wells Fargo's buy-sell sentiment indicator fell below -1 for the first time since June 2025, triggering a "buy" signal (historical data shows the S&P 500 has averaged a 6.5% gain over the following three months, with an 89% hit rate). Its chief strategist Ohsung Kwon said bluntly that the market has become overly pessimistic about AI financing and the Iran situation, and expects capital discipline to let hyperscale cloud providers replace chip stocks driven purely by cash burn as the new leaders, with the bullish case for AI infrastructure now pointing all the way to 2027.
Before the after-hours earnings bombs detonated, intraday traders were still voting with their feet, fleeing highly leveraged AI assets and rotating into defensive sectors such as healthcare (up 2.34%) and real estate (up 1.69%). Plante Moran chief investment officer Jim Baird said doubts about whether AI investment can be monetized are driving funds to rotate into small caps and healthcare stocks.
The panic was triggered by two factors: first, South Korea's rare profitable "new cloud" data center Elice plunged 32% on its first day of trading on October 20; second, The Wall Street Journal exposed a draft of Anthropic's IPO prospectus showing that although first-half revenue soared to $16.3 billion (with Q3 up another 45% quarter-over-quarter to $16.8 billion and adjusted profitability), its net loss reached a staggering $80.7 billion (including $72 billion in accounting charges from changes in the valuation of financing instruments), and future committed compute spending could reach an astonishing $750 billion at the high end. This directly led investors to slash their valuation expectations from $2 trillion to $1.5 trillion.
Moreover, the physical bottlenecks of AI expansion are becoming increasingly glaring. The US research group Center for Western Priorities revealed that there are already 35 data center and related applications on public lands across six western states (covering more than 24,000 acres, with one Utah project even proposing to use SMR nuclear power that has not yet been commercialized). Although the Trump administration views data center expansion as a national priority, public opposition to these projects is growing, with concerns centered on electricity demand, water consumption, wildlife impacts and the use of public lands.
Specific project moves and stock price swings:
Eli Lilly bucked the trend on Tuesday, surging 3.49% to another record high: The company announced that its Omvoh injection for pediatric ulcerative colitis patients achieved major success in late-stage clinical trials, and it plans to seek regulatory approval to expand the indication for this bowel disease therapy. Combined with intraday funds pulling out of tech stocks in search of a safe haven, this pushed the stock to a fresh all-time high.
The healthcare sector jumped 2.34% to lead the market: Weight-loss drug and biopharma themes broke out across the board, with Kailera Therapeutics soaring 12.77%, Viking Therapeutics up 6.63%, Moderna surging more than 6% to its highest since 2022 (up more than 720% year-to-date), Amgen up 3.29%, UnitedHealth up 3.04%, and Novo Nordisk up 2.42%.
SpaceX slipped 0.11%, then surged more than 8% in overnight trading: Third-quarter results crushed Wall Street across the board, with net profit of $4.4 billion far exceeding the expected $1.88 billion, and AI superintelligence (SI) business revenue soaring 830% to $7.56 billion while turning operating profit positive for the first time. On the earnings call, Musk confirmed that SpaceX and Tesla have each set up special committees to discuss a merger of the two giants, and declared that annual recurring revenue is sprinting toward $1 trillion and the compute payback period has shortened to six months, dispelling market doubts about whether infrastructure investment can be realized.
Super Micro Computer closed up 1.15%, then soared more than 15% after hours: The company's preliminary fiscal-quarter revenue estimate reached $18.5 billion–$19.5 billion (far exceeding the midpoint of its original guidance by 26.7% and analysts' expectations of $15.2 billion), with gross margin jumping to 12.0%–12.5%. Evercore ISI analyst Amit Daryanani noted that the combination of better-than-expected revenue and margins is striking, directly driving Dell Technologies up 6% in overnight trading, Hewlett Packard Enterprise up nearly 5%, and compute cloud firm CoreWeave up more than 4%.
Netflix closed down 1.66%, then plunged nearly 6% after hours: Fourth-quarter revenue growth guidance fell to 11.5% (slowing for a fourth consecutive quarter), net profit guidance missed expectations, and the company further cut its full-year advertising revenue forecast from $3 billion to $2.7 billion. Although third-quarter EPS beat expectations, management turmoil, layoff costs and the challenge of losing user time to YouTube sent funds fleeing.
CoreWeave & Nebius both surged more than 4% after hours: Boosted by Musk's massive GPU orders and the AI infrastructure boom, the US cloud services and compute leasing sector staged a dramatic comeback. CoreWeave, which had fallen as much as 6% intraday to a new post-IPO low, was supported by a Goldman Sachs rating upgrade to close up 1.65%, then soared more than 4% after hours along with the sector. Nebius rose 0.71% intraday and surged more than 4% after hours. Only data center operator IREN closed down 4.00% intraday.
The Philadelphia Semiconductor Index slipped 0.29%: Lam Research fell 3.21%, ARM fell 3.07%, ASML fell 0.99%, AMD fell 0.62%, Intel fell 0.37%, and Broadcom fell 0.07%.
The memory sector was mixed: Western Digital rose 3.44%, Seagate Technology rose 2.17%, SanDisk fell 0.42%, SK Hynix fell 2.16%, and Micron Technology fell 0.98% intraday (the company announced an investment in New York State's Indium Corporation to strengthen its high-purity mineral supply chain, but workers at its Taoyuan, Taiwan plant plan to strike this Thursday in solidarity with the Taichung union's push for profit sharing, which could severely disrupt chip production).
The optical communications sector broadly fell: AAOI fell 1.87%, Lumentum fell 1.44%, CRDO fell 0.75%, Coherent fell 0.09%, and only Marvell Technology rose 1.4%.
Tesla closed up 1.54% (extending gains of more than 1.5% in overnight trading): Ferrari's CEO publicly praised the new Roadster's design as showing bold innovation, and after hours Musk confirmed the formation of a special committee with SpaceX to explore a merger of the century, sending bullish sentiment into a frenzy. Watch for the earnings release after Wednesday's close.
Amazon edged up 0.07%: The company announced it will invest more than €16 billion in Germany in 2027 to expand AI and cloud infrastructure (full-year total capex is expected to reach $220 billion, with free cash flow already turning negative last quarter). However, internal emails revealed that AWS has activated an early-receipt process, taking delivery of $5 billion worth of Nvidia GB300 racks upfront (followed by $3 billion per month thereafter), but due to power shortages at some sites, the hardware can only be temporarily stored in transit warehouses awaiting deployment.
Nvidia closed down 0.29% (turning positive after hours, up more than 2.2%): Jensen Huang reached cooperation with the German government and Siemens at the Berlin summit on AI factories and startup investment, emphasizing that AI is a new tool to augment humans. After hours, Musk's announcement of a frenzied order to bring 200,000 GB300 units online each month and deploy 440,000 Vera Rubin units in Q2 next year directly injected a shot of adrenaline.
Microsoft slipped 0.31%: The company confirmed that Windows Server 2025 officially supports the fast machine recovery feature after installing the October security update.
Apple closed down 1.00%: Although the company, as part of its $600 billion "Made in America" plan, invested $100 million in Pennsylvania's Perryman to purchase recycled titanium and expanded its partnership with Qnity to produce variable-aperture film for the iPhone 18 Pro, the first foldable iPhone Duo going on sale this Friday is facing severe supply bottlenecks. Morgan Stanley noted that online delivery wait times have reached 14 weeks, the longest in a decade, while JPMorgan also cut its full-year shipment forecast from 10 million units to 8–9 million units due to capacity constraints.
Google fell 1.13%: Although its Waymo unit plans to use $5 billion in recently borrowed funds to double its autonomous vehicle fleet from 4,000 to 8,000 by the end of this year and expand to 20,000 by the end of next year, the stock was still dragged down intraday by selling pressure in the communication services sector.
Meta closed down 1.59%: As the first AI hyperscale giant to face the earnings gauntlet after Wednesday's close, funds chose to de-risk and front-run ahead of the results amid concerns over its massive capex guidance.
Other US stock moves: Braze soared 51.70% (Salesforce announced it will acquire the customer engagement platform Braze for $5.66 billion); Hasbro surged 11.2% to a one-year high (raising full-year revenue and digital gaming guidance); 3M rose 5.8% (announcing an expanded data center partnership with Amazon and raising its profit forecast); General Motors plunged 6.8% (warning of rising commodity costs and declining truck sales).
What to watch next:
October 21 (Wednesday)
17:00 Jensen Huang GTC keynote: European sovereign AI, inference demand, new architecture and partnership scale are the focus; the market needs concrete orders, not just long-term vision.
The World Intelligent Connected Vehicles Conference opens; the China-Europe Investment, Trade and Technology Cooperation Fair runs through the 23rd: watch for autonomous driving, vehicle-road-cloud standards and cross-border industrial cooperation.
Bessent and Druckenmiller attend the JPMorgan–Robinhood investor conference: the event is closed to media; if public information emerges, watch for views on fiscal financing, interest rates and market risk.
US earnings: IBM and AT&T before the open; Meta, Tesla, Lam Research and Texas Instruments after the close.
October 22 (Thursday)
Micron Taiwan Taoyuan plant strike and second round of negotiations with the Taichung union: Workers at Micron's Taoyuan plant are set to strike on Thursday in solidarity with the Taichung union's push for profit sharing. If negotiations break down and the strike is prolonged, it could directly cut off critical global DRAM and HBM chip production capacity, triggering sharp swings in memory chip prices and related stock prices.
04:30 Meta earnings call; 05:30 Tesla Q&A livestream: For Meta, the key is whether AI spending can be covered by advertising growth, with the market expecting revenue of $63.29 billion, capex of $40.97 billion and negative free cash flow of $9.14 billion; for Tesla, the key is how deliveries of more than 486,000 vehicles and 13.7 GWh of energy storage deployments translate into profit.
Bank of Korea rate decision: A pause is expected after consecutive hikes; if it tightens further, the won may find support, but chip stocks and companies with large financing needs would come under pressure.
US 20-year Treasury auction: The key is the strength of demand and whether the final yield comes in higher than expected, testing whether this round of the Treasury rally can continue and feeding through to gold and tech stocks.
Earnings: Nokia, Spotify, American Airlines, Procter & Gamble; after the close, watch Bloom Energy, Western Digital and Newmont.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
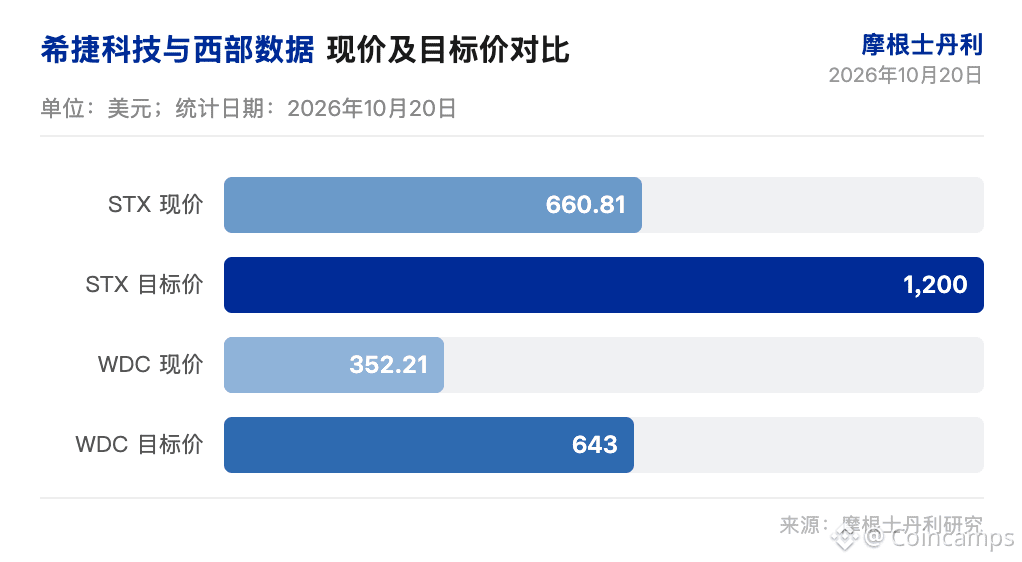
記事
翻訳参照
Morgan Stanley Research Report Analysis: The HDD Cycle Has Not Ended, Yet the Market Prices It as PeakedBy Rita
The market prices hard disk drives (HDDs) at an 8x P/E ratio, implying the cycle peaks in FY28. In its October 20, 2026 report, Morgan Stanley presents a contrary view: the cycle has not ended, and this pricing is overly punitive.
Demand is accelerating. Nearline HDD spot transaction prices are 4 to 7 cents/GB, while hybrid nearline contract prices are approximately 1.5 cents/GB. The industry faces a supply shortage of approximately 400 exabytes (EB) in CY27/CY28, compared to 300 EB in CY26. Customer bases are expanding from core cloud service providers (CSPs) to AI labs, which aim to secure 100% of EB capacity.
Morgan Stanley reiterates its Overweight ratings on Seagate Technology (STX) and Western Digital (WDC), with STX returning as its top pick in IT hardware. Target prices are $1,200 for STX and $643 for WDC. WDC features lower buy-side expectations and a more tactically favorable earnings setup.
8x P/E Ratio Implies Cycle Peak
Morgan Stanley backs into the valuation using FY28 earnings assumptions and an 80% price drop for solid-state drives (SSDs). The current ~8x P/E implies that HDD earnings peak in FY28, with SSD prices falling 80% from their C2Q26 levels. MS considers this assumption overly punitive.
HDD demand is accelerating, supply shortages are widening, and spot prices significantly exceed contract prices. Non-nearline HDD prices increased by 15% to 30% sequentially. Valuations exhibit positive asymmetry.
Morgan Stanley lowered its target multiple from 20x to 15x (STX) and 14x (WDC), reflecting market structural shifts and AI financing uncertainties. Target prices are $1,200 for STX (15x FY28 EPS of $80.10) and $643 for WDC (14x FY28 EPS of $45.95). Current prices are $660.81 for STX and $352.21 for WDC.
Spot Prices Far Exceed Contract Prices
Nearline HDD spot transaction prices range from 4 to 7 cents/GB, with hybrid nearline contract prices around 1.5 cents/GB. Clients seek to purchase 100% of the EB capacity, but supply shortages restrict procurement volumes. Storage capacity deficits are driving up spot prices.
Non-nearline HDD prices rose 15% to 30% sequentially. Seagate is more aggressive than Western Digital in capturing spot prices. Demand is expanding from core CSPs to AI labs. Toshiba is constrained by media and equipment, with CY27 capacity already sold out, leading to more aggressive pricing. Morgan Stanley is comfortable with Toshiba's risk profile.
December Quarter EPS Beats Consensus
Seagate's September quarter EPS is expected at $7.50 against a market consensus of $7.41; Western Digital's September quarter EPS stands at $4.13 versus a consensus of $4.09. Seagate's December quarter EPS is $9.54, 12% above market consensus. If spot pricing assumptions prove more aggressive, December EPS could rise another 5%.
Western Digital's December quarter EPS is $5.25, 10% above market consensus. Under more aggressive spot pricing assumptions, December EPS could reach $5.67. Buy-side expectations for WDC range from $4.75B to $4.95B in revenue, 59.5% to 61.0% gross margin, and $5.20 to $5.60 EPS. WDC guidance is typically conservative.
MS views WDC's earnings setup as tactically favorable due to lower buy-side hurdles. STX remains 10% above its high-conviction buy valuation level (10x CY27 EPS = $595), while WDC is only 3% above ($343).
Cycle Not Over, but Path Forward Blurs
MS acknowledges the catalyst path for HDDs is blurrier than a month ago. Markets hold uncertainty regarding vendor rationality and AI funding sources, which won't be resolved by earnings reports. Target multiples were reduced by 5 to 6x.
Demand checks support upside surprises and guide-up potential. MS focuses on four questions: whether STX/WDC will adjust capacity plans in response to Toshiba's targets; whether profit prioritization comes before market share gains; whether the supply/demand gap will widen; and whether more aggressive pricing emerges. Answers to these may not restore the stock to its narrative from four months ago, but will help investors recognize that certain risks are already priced in.
Morgan Stanley reiterates its Overweight ratings on STX and WDC, with STX back at Top Pick. The market prices in a cycle end, while MS prices in a cycle continuation.
Disclaimer
This article compiles and interprets a third-party broker research report (Morgan Stanley, October 20, 2026) by TechFlow Research, incorporating public market information. The ratings, target prices, earnings forecasts, and related assessments cited herein reflect the views of the broker's analysts, representing solely their institutional stance, not those of TechFlow Research, and do not constitute any investment advice.
Markets carry risks, and decisions must be independent. This article should not serve as the basis for buying or selling any securities.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Morgan Stanley Research Report Analysis: The HDD Cycle Has Not Ended, Yet the Market Prices It as Peaked
By Rita
The market prices hard disk drives (HDDs) at an 8x P/E ratio, implying the cycle peaks in FY28. In its October 20, 2026 report, Morgan Stanley presents a contrary view: the cycle has not ended, and this pricing is overly punitive.
Demand is accelerating. Nearline HDD spot transaction prices are 4 to 7 cents/GB, while hybrid nearline contract prices are approximately 1.5 cents/GB. The industry faces a supply shortage of approximately 400 exabytes (EB) in CY27/CY28, compared to 300 EB in CY26. Customer bases are expanding from core cloud service providers (CSPs) to AI labs, which aim to secure 100% of EB capacity.
Morgan Stanley reiterates its Overweight ratings on Seagate Technology (STX) and Western Digital (WDC), with STX returning as its top pick in IT hardware. Target prices are $1,200 for STX and $643 for WDC. WDC features lower buy-side expectations and a more tactically favorable earnings setup.
8x P/E Ratio Implies Cycle Peak
Morgan Stanley backs into the valuation using FY28 earnings assumptions and an 80% price drop for solid-state drives (SSDs). The current ~8x P/E implies that HDD earnings peak in FY28, with SSD prices falling 80% from their C2Q26 levels. MS considers this assumption overly punitive.
HDD demand is accelerating, supply shortages are widening, and spot prices significantly exceed contract prices. Non-nearline HDD prices increased by 15% to 30% sequentially. Valuations exhibit positive asymmetry.
Morgan Stanley lowered its target multiple from 20x to 15x (STX) and 14x (WDC), reflecting market structural shifts and AI financing uncertainties. Target prices are $1,200 for STX (15x FY28 EPS of $80.10) and $643 for WDC (14x FY28 EPS of $45.95). Current prices are $660.81 for STX and $352.21 for WDC.
Spot Prices Far Exceed Contract Prices
Nearline HDD spot transaction prices range from 4 to 7 cents/GB, with hybrid nearline contract prices around 1.5 cents/GB. Clients seek to purchase 100% of the EB capacity, but supply shortages restrict procurement volumes. Storage capacity deficits are driving up spot prices.
Non-nearline HDD prices rose 15% to 30% sequentially. Seagate is more aggressive than Western Digital in capturing spot prices. Demand is expanding from core CSPs to AI labs. Toshiba is constrained by media and equipment, with CY27 capacity already sold out, leading to more aggressive pricing. Morgan Stanley is comfortable with Toshiba's risk profile.
December Quarter EPS Beats Consensus
Seagate's September quarter EPS is expected at $7.50 against a market consensus of $7.41; Western Digital's September quarter EPS stands at $4.13 versus a consensus of $4.09. Seagate's December quarter EPS is $9.54, 12% above market consensus. If spot pricing assumptions prove more aggressive, December EPS could rise another 5%.
Western Digital's December quarter EPS is $5.25, 10% above market consensus. Under more aggressive spot pricing assumptions, December EPS could reach $5.67. Buy-side expectations for WDC range from $4.75B to $4.95B in revenue, 59.5% to 61.0% gross margin, and $5.20 to $5.60 EPS. WDC guidance is typically conservative.
MS views WDC's earnings setup as tactically favorable due to lower buy-side hurdles. STX remains 10% above its high-conviction buy valuation level (10x CY27 EPS = $595), while WDC is only 3% above ($343).
Cycle Not Over, but Path Forward Blurs
MS acknowledges the catalyst path for HDDs is blurrier than a month ago. Markets hold uncertainty regarding vendor rationality and AI funding sources, which won't be resolved by earnings reports. Target multiples were reduced by 5 to 6x.
Demand checks support upside surprises and guide-up potential. MS focuses on four questions: whether STX/WDC will adjust capacity plans in response to Toshiba's targets; whether profit prioritization comes before market share gains; whether the supply/demand gap will widen; and whether more aggressive pricing emerges. Answers to these may not restore the stock to its narrative from four months ago, but will help investors recognize that certain risks are already priced in.
Morgan Stanley reiterates its Overweight ratings on STX and WDC, with STX back at Top Pick. The market prices in a cycle end, while MS prices in a cycle continuation.
Disclaimer
This article compiles and interprets a third-party broker research report (Morgan Stanley, October 20, 2026) by TechFlow Research, incorporating public market information. The ratings, target prices, earnings forecasts, and related assessments cited herein reflect the views of the broker's analysts, representing solely their institutional stance, not those of TechFlow Research, and do not constitute any investment advice.
Markets carry risks, and decisions must be independent. This article should not serve as the basis for buying or selling any securities.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
·
--
記事
翻訳参照
AI business surges 830%! SpaceX earnings beat expectations, Musk: merging with Tesla is a good idea, revenue to hit $1 trillion in 2028Editor | Xinyuan
Musk: In 2028, $1 trillion in revenue is not impossible.
Zhidx, October 21 — Today, U.S. space and AI technology company SpaceX released its Q3 2026 earnings. Its third-quarter revenue was $14.575 billion (approximately RMB 97.358 billion), up 161% year-over-year; GAAP net profit was $4.404 billion (approximately RMB 29.418 billion), a significant improvement from a net loss of $1.054 billion in the same period last year.
In addition, SpaceX's operating profit was $2.791 billion (approximately RMB 18.643 billion), compared with an operating loss of $273 million in the same period last year; adjusted profit was $8.809 billion (approximately RMB 58.842 billion), up 306% year-over-year.
SpaceX's significant improvement in profitability this quarter was mainly driven by the explosive 830% growth of its Super Intelligence (SI) business, as well as the steady growth of its Connectivity business. The two businesses together contributed revenue of $12.808 billion (approximately RMB 85.555 billion), accounting for 87.9% of total revenue.
At yesterday's close in U.S. Eastern Time, SpaceX's market capitalization reached $1.947 trillion, just one step away from returning to the $2 trillion market cap club. Thanks to the better-than-expected earnings, SpaceX's stock surged in after-hours trading. As of 8:05 p.m. Eastern Time, its stock price had risen 8.01%, which translates to a market cap increase of more than $150 billion overnight (approximately RMB 1.00 trillion).
The earnings call became the focus of the evening. Musk turned the earnings call into a live show, and right off the bat he dropped a startling prediction: extrapolating from the current momentum, by the end of 2027, SpaceX's annual recurring revenue (ARR) would be between $500 billion and $1 trillion.
Musk's prediction posted on the X platform was even more aggressive. He believes that SpaceX reaching $1 trillion in revenue in 2028 is no longer impossible — he moved this timeline forward by two years from the previous 2030.
Musk also directly responded to questions about a potential merger with Tesla, calling it a "good idea," and revealed for the first time that both parties have, at the request of shareholders, formed special committees of independent directors to discuss the matter, but "it would be an overstatement to assume the merger is a certainty." Tesla would need 50% of all shareholders' votes in support, a very high threshold, and the special committees have not yet reached agreement on deal terms.
SpaceX CFO Bret Johnsen provided several pieces of forward guidance on the call: due to the large amount of new compute coming online this quarter, Q4 capital expenditure is expected to be $35 billion–$40 billion (approximately RMB 233.8 billion–267.2 billion), and Q4 total gross margin is expected to return to a level comparable to Q2 (Q3 included one-time gains and a favorable customer mix).
At the same time, SpaceX will maintain its goal of achieving $100 billion in ARR by the end of this year (annualized based on December's single-month revenue), and its Q1 2027 revenue guidance is $33 billion to $37 billion (approximately RMB 220.4 billion–247.2 billion).
01. Super Intelligence business revenue surges 830%, Cursor consolidation and Grok ramp-up
In Q3 2026, SpaceX's total revenue was $14.575 billion, up 161% year-over-year, coming from three business segments: Space business revenue of $1.767 billion, up 6% year-over-year and 84% quarter-over-quarter, accounting for 12.1% of total revenue; Connectivity business revenue of $5.248 billion, up 69% year-over-year and 22% quarter-over-quarter, accounting for 36.0%; Super Intelligence business revenue of $7.560 billion, up 830% year-over-year and 195% quarter-over-quarter, accounting for 51.9%, surpassing the Connectivity business for the first time to become the largest revenue source.
At the operating profit level, the Space segment posted an operating loss of $7 million, a significant narrowing of losses, compared with a profit of $259 million in the same period last year; the Connectivity segment posted an operating profit of $2.367 billion, up 99% year-over-year; the Super Intelligence segment posted an operating profit of $431 million, turning from loss to profit, compared with a loss of $1.722 billion in the same period last year.
It should be noted that the Super Intelligence segment's profit this quarter included $1.217 billion in stock-based compensation expenses from the Cursor acquisition; excluding this factor, its actual profit would be even higher.
In terms of cash flow and capital expenditure, SpaceX's Q3 capital expenditure reached as high as $19.593 billion, of which the Super Intelligence segment's capital expenditure was $16.444 billion, accounting for the bulk.
As of September 30, SpaceX held $51.294 billion in cash and cash equivalents, plus $38.561 billion in marketable securities, giving it ample ammunition on its balance sheet to support its large-scale compute buildout.
The biggest highlight of the earnings report was the Super Intelligence business. The growth in Super Intelligence segment revenue in Q3 was mainly driven by the activation of new cloud service agreements, the consolidation of the Cursor acquisition, and the accelerating penetration of Grok among enterprise customers and consumers.
Among these, Super Intelligence solutions and infrastructure revenue was $7.022 billion, up $6.63 billion year-over-year; advertising revenue was $538 million, up 19% year-over-year.
In terms of compute scale, SpaceX's nominal compute reached 1.7GW as of September 30, up from 1.4GW on June 30 and 0.6GW in the same period last year.
SpaceX is continuing to advance the construction of the COLOSSUS II supercomputing cluster in Memphis. On the product side, SpaceX accelerated the release and deployment of the Grok model and launched the around-the-clock agent system Grok Bot.
This year, SpaceX completed its acquisition of AI programming tool company Cursor. According to the earnings disclosure, the transaction was completed on August 14, 2026, with an implied equity valuation of $60 billion and a GAAP purchase consideration of $42.5 billion. Of this, approximately $23 billion (nearly 40% of the equity valuation) was attributed to core talent retention and the replacement of unvested equity, which will be recognized as stock-based compensation expense over a vesting period of approximately three years.
From the closing date to September 30, Cursor contributed $608 million in consolidated revenue to SpaceX. Even excluding Cursor, Super Intelligence solutions and infrastructure revenue still grew 192% quarter-over-quarter, mainly driven by the activation of new cloud service agreements.
SpaceX stated in its earnings report that the Cursor acquisition advanced its strategy of vertically integrating compute infrastructure, super intelligence models, and applications. The integration effect has already begun to show: including Cursor, the number of Grok Enterprise customers with annual revenue run-rate exceeding $1 million grew 50% quarter-over-quarter. Last week, SpaceX also announced the integration of Grok, Grok Bot, Cursor, and X Premium into a single subscription plan.
As of September 30, SpaceX's total order backlog reached $63 billion, of which approximately $42 billion is expected to be recognized as revenue within the next year.
On the funding side, Johnsen emphasized that SpaceX has an investment-grade rating and a strong balance sheet, and that in addition to operating cash flow, it has multiple debt capital market channels available, and that the compute business "can almost self-fund once it gets started."
02. Starship's first orbital-class flight succeeds and generates revenue for the first time, Starlink subscribers nearly double in a year
On the space business side, the biggest milestone this quarter was Starship Flight 14 — SpaceX completed its first orbital-class Starship flight and used it to carry out its first revenue-generating Starship mission, delivering 26 Starlink V3 satellites to the broadband constellation. The downlink capacity brought by a single Starlink mission is about 10 times that of a Falcon 9 Starlink launch.
During the quarter, SpaceX completed a total of 35 launches with 476 tons of mass to orbit, including using a Falcon Heavy rocket to send NASA's Nancy Grace Roman Space Telescope into deep space. On the order side, SpaceX signed three new NASA Crew Dragon missions, 18 National Security Space Launch missions, and a contract to use Starship to deliver payloads to the lunar surface, and announced the construction of the Louisiana Starbase spaceport, targeting a first launch in 2029.
SpaceX's Connectivity business is represented by Starlink. On user data, as of September 30, 2026, Starlink consumer subscribers reached 13.6 million, nearly double the 7.2 million in the same period last year, with an average monthly ARPU of $69. In terms of revenue structure, consumer revenue was $3.121 billion, up 57% year-over-year; enterprise and government revenue was $2.127 billion, up 91% year-over-year, making it the fastest-growing sub-business, with approximately 12,000 aircraft signed in the aviation segment, close to a quarter of the global available fleet. On the mobile side, Starlink Mobile monthly active users surpassed 22 million, up 37% quarter-over-quarter. On October 8, SpaceX announced the acquisition of a nationwide 800MHz low-band spectrum license portfolio to advance its Starlink Mobile strategy, with the transaction expected to close in the first half of 2027.
03. AI chips planned to tape out new deployment by mid-next year, compute payback period under one year
On SpaceX's earnings call, compute expansion became the main thread. Musk said that the bottleneck in Super Intelligence deployment is shifting from chips to power, cooling, and infrastructure, and that SpaceX has pulled in a team that accounts for nearly 90% of the world's mass to orbit to build ground-based compute, with a deployment speed that "may exceed the combined total of all other players."
SpaceX's specific goals include: building approximately 2.5–3GW of nominal compute by the end of this year, and adding 10GW of compute in 2027. Musk is "quite confident" about this. SpaceX is advancing at a pace of bringing online about 200,000 GB300 GPUs per month, for the rest of this year and unchanged next year, except that the mainstay will switch from GB300 to Vera Rubin GPUs.
The company is also planning 20GW of power and cooling infrastructure in parallel. Musk said that compute exceeding 20GW in 2027 "is unlikely, but no longer zero." By the end of October this year, nominal compute will reach about 2.2GW. Before the end of June next year, SpaceX also plans to bring online the world's strongest training cluster, deploying 440,000 Vera Rubin GPUs.
On self-developed AI chips, Musk revealed that SpaceX has set an aggressive goal: the R&D production line in Austin plans to tape out the first batch of test chips in May–June 2027, and the main Terafab production line at Gibbons Creek aims to achieve mass production in Q3 2028.
Musk emphasized that "this is an extremely aggressive timeline," and said that SpaceX holds "potentially breakthrough technology" in chip manufacturing processes. Terafab's ultimate goal is to produce 1 terawatt of compute chips per year.
Grok product data was equally impressive. Grok Bot launched in August this year, and by the beginning of this month its paid weekly active users had reached 800,000, doubling within a month. Musk called it "the fastest-growing product I have ever seen in my life," and said that user engagement time does not decline but rises over time.
The enterprise version of Grok Bot has already been deployed early among some customers and will be rolled out at scale within weeks. Musk expects that Grok Bot may eventually consume most of SpaceX's Super Intelligence compute.
On compute leasing strategy, SpaceX tends to sign short-term contracts at prices close to the spot market, with internal use and external leasing roughly dynamically allocated at 50:50. Musk judges that the effective intelligence produced per watt of compute will continue to rise, and that compute unit prices will rise over the long term. SpaceX's short-term contract renewal prices for compute are rising, and "if we agreed to all leasing requests, we could lease out the compute several times over."
SpaceX CFO Bret Johnsen added that the payback period for newly deployed compute is currently less than one year, and it is not ruled out that it could shorten to six months next year, with compute pricing already slightly above the upper end of the $30–50 per watt range given last quarter.
Regarding Starlink Mobile, SpaceX COO Gwynne Shotwell said that the S-band will carry the main traffic, while the 800MHz low band will be used for building penetration. Musk judged that SpaceX could achieve hundreds of billions of dollars in annual connectivity revenue in the future.
Regarding Starlink V3 satellites, Shotwell said that hundreds of satellites are needed before users can clearly perceive the improvement, a goal that could be achieved by mid-next year.
Speaking about the Louisiana Starbase under construction, Musk revealed that the internal target is actually a first launch in 2028, and "2029 is highly certain to achieve scaled launches."
04. Conclusion: SpaceX's transformation has substantively taken shape, whether it can sustain profitability deserves attention
Judging from the earnings data, SpaceX has clearly crossed the profitability inflection point. On one hand, Starship achieved its first orbital flight and began commercial monetization, and Starlink's user base nearly doubled in a year, with the core business still expanding.
On the other hand, the Super Intelligence business's single-quarter revenue of $7.56 billion and Adjusted EBITDA of $4.95 billion prove that SpaceX's second growth curve has substantively taken shape. SpaceX is transforming from a rocket launch company into an infrastructure company spanning three major fields: space, connectivity, and super intelligence.
Of course, concerns also exist: of the nearly $20 billion in capital expenditure in a single quarter, more than 80% went into Super Intelligence compute buildout. Whether this level of investment intensity can continue to generate returns will be the focus of market attention in the coming quarters.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
AI business surges 830%! SpaceX earnings beat expectations, Musk: merging with Tesla is a good idea, revenue to hit $1 trillion in 2028
Editor | Xinyuan
Musk: In 2028, $1 trillion in revenue is not impossible.
Zhidx, October 21 — Today, U.S. space and AI technology company SpaceX released its Q3 2026 earnings. Its third-quarter revenue was $14.575 billion (approximately RMB 97.358 billion), up 161% year-over-year; GAAP net profit was $4.404 billion (approximately RMB 29.418 billion), a significant improvement from a net loss of $1.054 billion in the same period last year.
In addition, SpaceX's operating profit was $2.791 billion (approximately RMB 18.643 billion), compared with an operating loss of $273 million in the same period last year; adjusted profit was $8.809 billion (approximately RMB 58.842 billion), up 306% year-over-year.
SpaceX's significant improvement in profitability this quarter was mainly driven by the explosive 830% growth of its Super Intelligence (SI) business, as well as the steady growth of its Connectivity business. The two businesses together contributed revenue of $12.808 billion (approximately RMB 85.555 billion), accounting for 87.9% of total revenue.
At yesterday's close in U.S. Eastern Time, SpaceX's market capitalization reached $1.947 trillion, just one step away from returning to the $2 trillion market cap club. Thanks to the better-than-expected earnings, SpaceX's stock surged in after-hours trading. As of 8:05 p.m. Eastern Time, its stock price had risen 8.01%, which translates to a market cap increase of more than $150 billion overnight (approximately RMB 1.00 trillion).
The earnings call became the focus of the evening. Musk turned the earnings call into a live show, and right off the bat he dropped a startling prediction: extrapolating from the current momentum, by the end of 2027, SpaceX's annual recurring revenue (ARR) would be between $500 billion and $1 trillion.
Musk's prediction posted on the X platform was even more aggressive. He believes that SpaceX reaching $1 trillion in revenue in 2028 is no longer impossible — he moved this timeline forward by two years from the previous 2030.
Musk also directly responded to questions about a potential merger with Tesla, calling it a "good idea," and revealed for the first time that both parties have, at the request of shareholders, formed special committees of independent directors to discuss the matter, but "it would be an overstatement to assume the merger is a certainty." Tesla would need 50% of all shareholders' votes in support, a very high threshold, and the special committees have not yet reached agreement on deal terms.
SpaceX CFO Bret Johnsen provided several pieces of forward guidance on the call: due to the large amount of new compute coming online this quarter, Q4 capital expenditure is expected to be $35 billion–$40 billion (approximately RMB 233.8 billion–267.2 billion), and Q4 total gross margin is expected to return to a level comparable to Q2 (Q3 included one-time gains and a favorable customer mix).
At the same time, SpaceX will maintain its goal of achieving $100 billion in ARR by the end of this year (annualized based on December's single-month revenue), and its Q1 2027 revenue guidance is $33 billion to $37 billion (approximately RMB 220.4 billion–247.2 billion).
01. Super Intelligence business revenue surges 830%, Cursor consolidation and Grok ramp-up
In Q3 2026, SpaceX's total revenue was $14.575 billion, up 161% year-over-year, coming from three business segments: Space business revenue of $1.767 billion, up 6% year-over-year and 84% quarter-over-quarter, accounting for 12.1% of total revenue; Connectivity business revenue of $5.248 billion, up 69% year-over-year and 22% quarter-over-quarter, accounting for 36.0%; Super Intelligence business revenue of $7.560 billion, up 830% year-over-year and 195% quarter-over-quarter, accounting for 51.9%, surpassing the Connectivity business for the first time to become the largest revenue source.
At the operating profit level, the Space segment posted an operating loss of $7 million, a significant narrowing of losses, compared with a profit of $259 million in the same period last year; the Connectivity segment posted an operating profit of $2.367 billion, up 99% year-over-year; the Super Intelligence segment posted an operating profit of $431 million, turning from loss to profit, compared with a loss of $1.722 billion in the same period last year.
It should be noted that the Super Intelligence segment's profit this quarter included $1.217 billion in stock-based compensation expenses from the Cursor acquisition; excluding this factor, its actual profit would be even higher.
In terms of cash flow and capital expenditure, SpaceX's Q3 capital expenditure reached as high as $19.593 billion, of which the Super Intelligence segment's capital expenditure was $16.444 billion, accounting for the bulk.
As of September 30, SpaceX held $51.294 billion in cash and cash equivalents, plus $38.561 billion in marketable securities, giving it ample ammunition on its balance sheet to support its large-scale compute buildout.
The biggest highlight of the earnings report was the Super Intelligence business. The growth in Super Intelligence segment revenue in Q3 was mainly driven by the activation of new cloud service agreements, the consolidation of the Cursor acquisition, and the accelerating penetration of Grok among enterprise customers and consumers.
Among these, Super Intelligence solutions and infrastructure revenue was $7.022 billion, up $6.63 billion year-over-year; advertising revenue was $538 million, up 19% year-over-year.
In terms of compute scale, SpaceX's nominal compute reached 1.7GW as of September 30, up from 1.4GW on June 30 and 0.6GW in the same period last year.
SpaceX is continuing to advance the construction of the COLOSSUS II supercomputing cluster in Memphis. On the product side, SpaceX accelerated the release and deployment of the Grok model and launched the around-the-clock agent system Grok Bot.
This year, SpaceX completed its acquisition of AI programming tool company Cursor. According to the earnings disclosure, the transaction was completed on August 14, 2026, with an implied equity valuation of $60 billion and a GAAP purchase consideration of $42.5 billion. Of this, approximately $23 billion (nearly 40% of the equity valuation) was attributed to core talent retention and the replacement of unvested equity, which will be recognized as stock-based compensation expense over a vesting period of approximately three years.
From the closing date to September 30, Cursor contributed $608 million in consolidated revenue to SpaceX. Even excluding Cursor, Super Intelligence solutions and infrastructure revenue still grew 192% quarter-over-quarter, mainly driven by the activation of new cloud service agreements.
SpaceX stated in its earnings report that the Cursor acquisition advanced its strategy of vertically integrating compute infrastructure, super intelligence models, and applications. The integration effect has already begun to show: including Cursor, the number of Grok Enterprise customers with annual revenue run-rate exceeding $1 million grew 50% quarter-over-quarter. Last week, SpaceX also announced the integration of Grok, Grok Bot, Cursor, and X Premium into a single subscription plan.
As of September 30, SpaceX's total order backlog reached $63 billion, of which approximately $42 billion is expected to be recognized as revenue within the next year.
On the funding side, Johnsen emphasized that SpaceX has an investment-grade rating and a strong balance sheet, and that in addition to operating cash flow, it has multiple debt capital market channels available, and that the compute business "can almost self-fund once it gets started."
02. Starship's first orbital-class flight succeeds and generates revenue for the first time, Starlink subscribers nearly double in a year
On the space business side, the biggest milestone this quarter was Starship Flight 14 — SpaceX completed its first orbital-class Starship flight and used it to carry out its first revenue-generating Starship mission, delivering 26 Starlink V3 satellites to the broadband constellation. The downlink capacity brought by a single Starlink mission is about 10 times that of a Falcon 9 Starlink launch.
During the quarter, SpaceX completed a total of 35 launches with 476 tons of mass to orbit, including using a Falcon Heavy rocket to send NASA's Nancy Grace Roman Space Telescope into deep space. On the order side, SpaceX signed three new NASA Crew Dragon missions, 18 National Security Space Launch missions, and a contract to use Starship to deliver payloads to the lunar surface, and announced the construction of the Louisiana Starbase spaceport, targeting a first launch in 2029.
SpaceX's Connectivity business is represented by Starlink. On user data, as of September 30, 2026, Starlink consumer subscribers reached 13.6 million, nearly double the 7.2 million in the same period last year, with an average monthly ARPU of $69. In terms of revenue structure, consumer revenue was $3.121 billion, up 57% year-over-year; enterprise and government revenue was $2.127 billion, up 91% year-over-year, making it the fastest-growing sub-business, with approximately 12,000 aircraft signed in the aviation segment, close to a quarter of the global available fleet. On the mobile side, Starlink Mobile monthly active users surpassed 22 million, up 37% quarter-over-quarter. On October 8, SpaceX announced the acquisition of a nationwide 800MHz low-band spectrum license portfolio to advance its Starlink Mobile strategy, with the transaction expected to close in the first half of 2027.
03. AI chips planned to tape out new deployment by mid-next year, compute payback period under one year
On SpaceX's earnings call, compute expansion became the main thread. Musk said that the bottleneck in Super Intelligence deployment is shifting from chips to power, cooling, and infrastructure, and that SpaceX has pulled in a team that accounts for nearly 90% of the world's mass to orbit to build ground-based compute, with a deployment speed that "may exceed the combined total of all other players."
SpaceX's specific goals include: building approximately 2.5–3GW of nominal compute by the end of this year, and adding 10GW of compute in 2027. Musk is "quite confident" about this. SpaceX is advancing at a pace of bringing online about 200,000 GB300 GPUs per month, for the rest of this year and unchanged next year, except that the mainstay will switch from GB300 to Vera Rubin GPUs.
The company is also planning 20GW of power and cooling infrastructure in parallel. Musk said that compute exceeding 20GW in 2027 "is unlikely, but no longer zero." By the end of October this year, nominal compute will reach about 2.2GW. Before the end of June next year, SpaceX also plans to bring online the world's strongest training cluster, deploying 440,000 Vera Rubin GPUs.
On self-developed AI chips, Musk revealed that SpaceX has set an aggressive goal: the R&D production line in Austin plans to tape out the first batch of test chips in May–June 2027, and the main Terafab production line at Gibbons Creek aims to achieve mass production in Q3 2028.
Musk emphasized that "this is an extremely aggressive timeline," and said that SpaceX holds "potentially breakthrough technology" in chip manufacturing processes. Terafab's ultimate goal is to produce 1 terawatt of compute chips per year.
Grok product data was equally impressive. Grok Bot launched in August this year, and by the beginning of this month its paid weekly active users had reached 800,000, doubling within a month. Musk called it "the fastest-growing product I have ever seen in my life," and said that user engagement time does not decline but rises over time.
The enterprise version of Grok Bot has already been deployed early among some customers and will be rolled out at scale within weeks. Musk expects that Grok Bot may eventually consume most of SpaceX's Super Intelligence compute.
On compute leasing strategy, SpaceX tends to sign short-term contracts at prices close to the spot market, with internal use and external leasing roughly dynamically allocated at 50:50. Musk judges that the effective intelligence produced per watt of compute will continue to rise, and that compute unit prices will rise over the long term. SpaceX's short-term contract renewal prices for compute are rising, and "if we agreed to all leasing requests, we could lease out the compute several times over."
SpaceX CFO Bret Johnsen added that the payback period for newly deployed compute is currently less than one year, and it is not ruled out that it could shorten to six months next year, with compute pricing already slightly above the upper end of the $30–50 per watt range given last quarter.
Regarding Starlink Mobile, SpaceX COO Gwynne Shotwell said that the S-band will carry the main traffic, while the 800MHz low band will be used for building penetration. Musk judged that SpaceX could achieve hundreds of billions of dollars in annual connectivity revenue in the future.
Regarding Starlink V3 satellites, Shotwell said that hundreds of satellites are needed before users can clearly perceive the improvement, a goal that could be achieved by mid-next year.
Speaking about the Louisiana Starbase under construction, Musk revealed that the internal target is actually a first launch in 2028, and "2029 is highly certain to achieve scaled launches."
04. Conclusion: SpaceX's transformation has substantively taken shape, whether it can sustain profitability deserves attention
Judging from the earnings data, SpaceX has clearly crossed the profitability inflection point. On one hand, Starship achieved its first orbital flight and began commercial monetization, and Starlink's user base nearly doubled in a year, with the core business still expanding.
On the other hand, the Super Intelligence business's single-quarter revenue of $7.56 billion and Adjusted EBITDA of $4.95 billion prove that SpaceX's second growth curve has substantively taken shape. SpaceX is transforming from a rocket launch company into an infrastructure company spanning three major fields: space, connectivity, and super intelligence.
Of course, concerns also exist: of the nearly $20 billion in capital expenditure in a single quarter, more than 80% went into Super Intelligence compute buildout. Whether this level of investment intensity can continue to generate returns will be the focus of market attention in the coming quarters.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
214
·
--
翻訳参照
Sui Basecamp 2026 Observations: From Performance and AI to Institutional Capital, Why Does the Future of Finance Need Sui?In 2026, the playbook for public blockchains is very clear:
Every chain wants to act as infrastructure, but real and sustainable economic activity is what truly determines competitive positioning.
From October 7 to 8, 2026, Sui Basecamp 2026 opened in Singapore, announcing a host of developments at once, including a world record TPS, AI infrastructure, and institutional partnerships. Technology, use cases, institutions... What is Sui fundamentally building?
Through this ecosystem conference, let us seriously examine the survival considerations of a public blockchain in today's market context.
AI Becomes the Absolute Protagonist
As Mysten Labs co-founder Adeniyi Abiodun stated: The next $5 trillion in transactions will no longer be driven by humans.
Connecting multiple details from the conference from this perspective reveals: Whatever the machine economy needs, Sui aims to solve it.
Speed is paramount. 40,614,180 transactions per second, independently verified by CertiK, was the most striking number on stage, backed by the Sui Tunnels (programmable off-chain channels) mechanism. Although this figure does not currently represent production throughput, it serves as proof of Sui's capacity to handle AI micro-transactions.
Speed alone isn't enough; it also needs to be cheap and smooth.
Sui has done two things in this regard: launching zero-Gas stablecoin transfers; and second, Agent Payments, which allows AI agents to autonomously and pay-per-use spend stablecoins for API or cloud service fees within user-predefined permissions and budgets. Alibaba Cloud has already announced a partnership.
Of course, amidst the current AI doomsday rhetoric, AI can act autonomously, but it must never operate without constraints.
To define AI permission boundaries, Sui delegated it to Agent Pass: users set rules to draw a boundary for AI, confining its operations within that predefined scope.
For verifiable AI behavior, Sui relies on VAA: jointly developed by Mysten Labs and Google Cloud, VAA aims to provide auditable records for AI authorization, actions, and outcomes.
The moves are multi-dimensional, but the logic is clear: Build infrastructure for the Agentic Economy, enabling faster AI transactions while ensuring controllable costs, clear permissions, and verifiable actions.
Enabling Capital to Flow Freely Across More Real-World Scenarios
If AI is the new transaction entity that must be embraced, then stablecoins are the indispensable medium of exchange.
On this front, Sui has already made significant progress.
Since August 2025, stablecoin transfer volume on the Sui network has exceeded $1 trillion. Additionally, the launch of zero-Gas stablecoin transfers lays the necessary foundation for stablecoins to enter daily consumer life.
Meanwhile, several stablecoin partnerships announced during Sui Basecamp 2026 also warrant attention.
On one hand, through a partnership with Circle CCTP V2, native Sui USDC can now be transferred across 29 chains, further reducing bridge risks and liquidity slippage, delivering a safer and more seamless experience that powers the financial arteries of the Web3 world.
On the other hand, through a partnership with Samsung Wallet, Sui ecosystem USDC is now accessible to 82 million Galaxy devices in the United States, further pushing stablecoins out of the crypto niche and into a feature millions of users already have in their phones, unlocking real-world B2C consumption scenarios.
Courting Institutions and Capital Simultaneously: What Is the Core Objective?
The highly anticipated Sui ecosystem Bitcoin finance platform Hashi has also seen recent developments:
On October 9, Hashi announced that its mainnet will roll out in phases starting this October. Additionally, with the announcement of a partnership with Anchorage Digital, America's first federally chartered crypto bank, Hashi has secured $500 million in committed funding support.Combined with backing from over 20 institutions at the project's inception, Hashi's partnership landscape now spans custody, liquidity, auditing, insurance, and applications.
Earlier this July, Hashi obtained legal opinion from U.S. law firm Fenwick West, confirming that deposit/redeem activities do not constitute taxable events, providing institutions with regulatory certainty.
This prestigious list of institutions serves both as pathways for institutional users to enter the Sui ecosystem and as a liquidity guarantee for Hashi.
A Converged Vision, and Yet-to-Come Tests
Laying out these moves openly is meant to clarify the fundamental logic behind them.
AI: Expanding the range of transaction entities
Stablecoins: Expanding the scenarios for capital flow
Bitcoin Finance: Expanding the assets eligible for financial participation
The convergence of these three lines ultimately points to a single goal: a complete financial infrastructure where more transaction entities, more assets, and more financial activities can thrive.
Of course, a comprehensive strategy does not automatically equate to a closed-loop business model. With the macro framework in place, several details remain under scrutiny, including the practical performance of the record-breaking TPS, how commercial partnerships will smoothly transition to real-world implementation, and whether Hashi's mainnet launch will see product experiences and institutional choices translate into retained funds and liquidity.
The market has always been slow to recognize infrastructure value; only after more real transactions start flowing will genuine recognition begin.
Moving from being "seen" to being "needed", for Sui, Sui Basecamp 2026 was perhaps never the end goal, but rather a clearer starting point.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
Sui Basecamp 2026 Observations: From Performance and AI to Institutional Capital, Why Does the Future of Finance Need Sui?
In 2026, the playbook for public blockchains is very clear:
Every chain wants to act as infrastructure, but real and sustainable economic activity is what truly determines competitive positioning.
From October 7 to 8, 2026, Sui Basecamp 2026 opened in Singapore, announcing a host of developments at once, including a world record TPS, AI infrastructure, and institutional partnerships. Technology, use cases, institutions... What is Sui fundamentally building?
Through this ecosystem conference, let us seriously examine the survival considerations of a public blockchain in today's market context.
AI Becomes the Absolute Protagonist
As Mysten Labs co-founder Adeniyi Abiodun stated: The next $5 trillion in transactions will no longer be driven by humans.
Connecting multiple details from the conference from this perspective reveals: Whatever the machine economy needs, Sui aims to solve it.
Speed is paramount. 40,614,180 transactions per second, independently verified by CertiK, was the most striking number on stage, backed by the Sui Tunnels (programmable off-chain channels) mechanism. Although this figure does not currently represent production throughput, it serves as proof of Sui's capacity to handle AI micro-transactions.
Speed alone isn't enough; it also needs to be cheap and smooth.
Sui has done two things in this regard: launching zero-Gas stablecoin transfers; and second, Agent Payments, which allows AI agents to autonomously and pay-per-use spend stablecoins for API or cloud service fees within user-predefined permissions and budgets. Alibaba Cloud has already announced a partnership.
Of course, amidst the current AI doomsday rhetoric, AI can act autonomously, but it must never operate without constraints.
To define AI permission boundaries, Sui delegated it to Agent Pass: users set rules to draw a boundary for AI, confining its operations within that predefined scope.
For verifiable AI behavior, Sui relies on VAA: jointly developed by Mysten Labs and Google Cloud, VAA aims to provide auditable records for AI authorization, actions, and outcomes.
The moves are multi-dimensional, but the logic is clear: Build infrastructure for the Agentic Economy, enabling faster AI transactions while ensuring controllable costs, clear permissions, and verifiable actions.
Enabling Capital to Flow Freely Across More Real-World Scenarios
If AI is the new transaction entity that must be embraced, then stablecoins are the indispensable medium of exchange.
On this front, Sui has already made significant progress.
Since August 2025, stablecoin transfer volume on the Sui network has exceeded $1 trillion. Additionally, the launch of zero-Gas stablecoin transfers lays the necessary foundation for stablecoins to enter daily consumer life.
Meanwhile, several stablecoin partnerships announced during Sui Basecamp 2026 also warrant attention.
On one hand, through a partnership with Circle CCTP V2, native Sui USDC can now be transferred across 29 chains, further reducing bridge risks and liquidity slippage, delivering a safer and more seamless experience that powers the financial arteries of the Web3 world.
On the other hand, through a partnership with Samsung Wallet, Sui ecosystem USDC is now accessible to 82 million Galaxy devices in the United States, further pushing stablecoins out of the crypto niche and into a feature millions of users already have in their phones, unlocking real-world B2C consumption scenarios.
Courting Institutions and Capital Simultaneously: What Is the Core Objective?
The highly anticipated Sui ecosystem Bitcoin finance platform Hashi has also seen recent developments:
On October 9, Hashi announced that its mainnet will roll out in phases starting this October. Additionally, with the announcement of a partnership with Anchorage Digital, America's first federally chartered crypto bank, Hashi has secured $500 million in committed funding support.Combined with backing from over 20 institutions at the project's inception, Hashi's partnership landscape now spans custody, liquidity, auditing, insurance, and applications.
Earlier this July, Hashi obtained legal opinion from U.S. law firm Fenwick West, confirming that deposit/redeem activities do not constitute taxable events, providing institutions with regulatory certainty.
This prestigious list of institutions serves both as pathways for institutional users to enter the Sui ecosystem and as a liquidity guarantee for Hashi.
A Converged Vision, and Yet-to-Come Tests
Laying out these moves openly is meant to clarify the fundamental logic behind them.
AI: Expanding the range of transaction entities
Stablecoins: Expanding the scenarios for capital flow
Bitcoin Finance: Expanding the assets eligible for financial participation
The convergence of these three lines ultimately points to a single goal: a complete financial infrastructure where more transaction entities, more assets, and more financial activities can thrive.
Of course, a comprehensive strategy does not automatically equate to a closed-loop business model. With the macro framework in place, several details remain under scrutiny, including the practical performance of the record-breaking TPS, how commercial partnerships will smoothly transition to real-world implementation, and whether Hashi's mainnet launch will see product experiences and institutional choices translate into retained funds and liquidity.
The market has always been slow to recognize infrastructure value; only after more real transactions start flowing will genuine recognition begin.
Moving from being "seen" to being "needed", for Sui, Sui Basecamp 2026 was perhaps never the end goal, but rather a clearer starting point.
Join the official Coincamps community:
X: https://x.com/coincamps
Telegram: https://t.me/coin_camps
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号