🚨SPX OPTIONS ALERT: THE MARKET LOOKS CALM. OPTIONS SAY OTHERWISE.
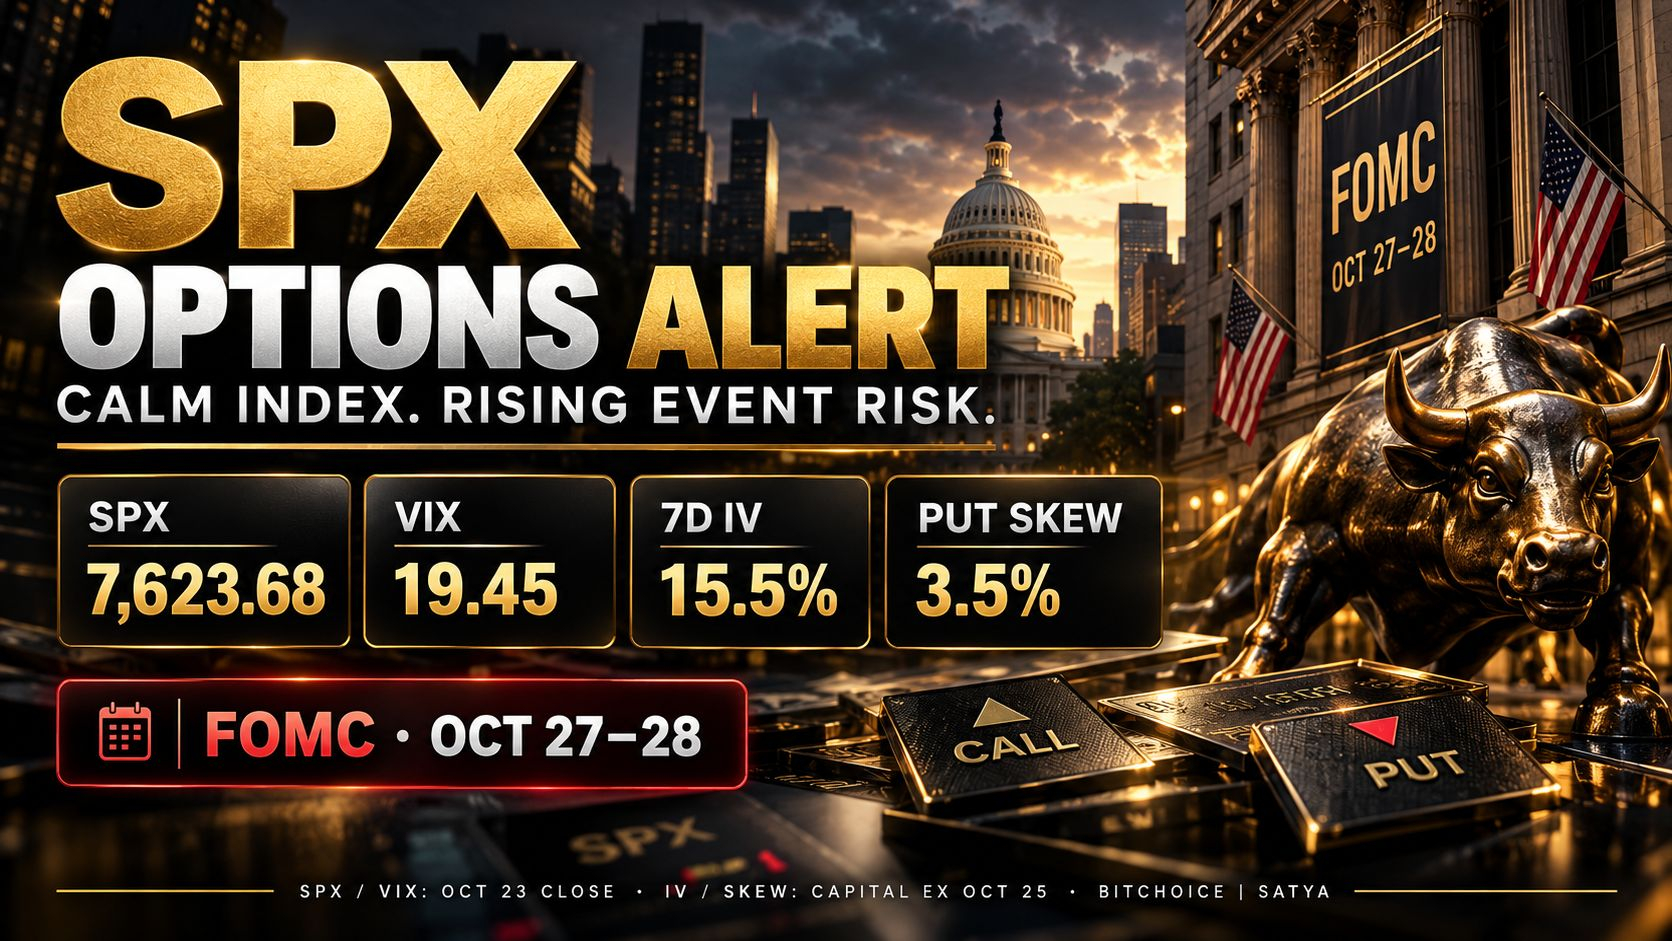
The S&P 500 closed Friday at 7,623.68, down roughly 0.5% for the week.
But beneath the surface, short-term options volatility is rising ahead of the Federal Reserve meeting.
THE NUMBERS:
• SPX: 7,623.68
• VIX: 19.45
• 7-day implied volatility: 15.5% (+1.9 percentage points)
• 14-day implied volatility: 15.2% (+1.1 percentage points)
• Put skew: 3.5%, down from 4.1%
The IV and skew figures come from the October 25 CAPITAL EX options snapshot and use provider-specific calculations.
WHY DOES THIS MATTER?
Short-term uncertainty is getting more expensive.
Rising near-term IV suggests that options markets are repricing event risk. It does not guarantee a selloff.
Downside protection is changing.
Lower put skew may reflect a reduced relative premium for downside protection, depending on strike selection and methodology. It is not proof that institutional investors have turned bullish.
The Fed is the next major catalyst.
The FOMC meets October 27–28. Its decision and guidance could affect Treasury yields, the US dollar and risk appetite.
And crypto traders should pay attention.
BTC and ETH do not directly follow SPX options, but shifts in macro liquidity expectations can influence both markets.
WHAT TO WATCH:
• Does short-term IV cool after the Fed?
• Does VIX remain elevated?
• Do dollar and Treasury yields confirm a change in risk sentiment?
• How do BTC and ETH spot volumes respond?
THE BIG QUESTION:
Is the options market pricing a temporary volatility spike — or warning of broader turbulence?
Share your view below.
Sources: SPX/VIX, Oct 23 close; CAPITAL EX, Oct 25 options snapshot; Federal Reserve calendar.
BitChoice | Satya | Educational analysis, not financial advice.
#SPX #OptionsTrading #FOMC #Volatility #MarketAnalysis