
#007
007
閲覧回数 1,101
12人が討論中
注目
最新
·
--
記事
翻訳参照
No Interest on the Coin. A Separate Fund Is HSBC's Next Plan.IKOL Note #007
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
No Interest on the Coin. A Separate Fund Is HSBC's Next Plan.
IKOL Note #007
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
22
·
--
翻訳参照
【结构观察 #007|BTC 4H】高低点同时外扩,价格卡在箱体下半区
上一条对账:昨天 20:00 划的 BTC 81,048–83,390,现价 81,908 还在里面,两条线都没碰到。
08:00 现价 81,908,24 小时 -0.21%,成交额 105.62 亿 U,日内 83,158 / 81,701。
① 结构:近 30 根高点抬高、低点降低,走的是扩张三角。箱体 80,841–83,961,宽度 3.9%,现价在 34% 分位,箱体下半区。MA25 在 81,810,就在现价下方,近 5 根斜率 +0.03%,基本是平的。
② 量价:近 10 根对前 30 根 0.89 倍,量能与前期接近,没有明显放量。近 10 根里 5 根收红,红绿各半,来回拉扯的味道。
③ 共振:上方 82,033–82,599 一带,Fib 0.618(82,033)和前高(82,599)压在一起;下方 81,320–81,810 一带,MA25(81,810)和前低(81,320)叠着。上下都是双来源,这点比单线可靠些。
④ 资金面:资金费率 +0.0092%,多头付费;持仓 7 根 4H 变化 +1.69%,持仓在加;多空账户比 1.62。价格没动多少,仓位在往里堆。
观察区间:上方 82,033–83,017,下方 80,829–81,810。
1H 视角:近 12 小时在 81,701–82,744 之间走,最新收盘落在 20% 分位,靠近这波的下沿。
失效条件:4H 收盘站上 83,017 或跌破 80,829,这组判断作废。
我自己的看法是,扩张三角里最值得盯的不是中间这段,而是上下沿被真正碰到的次数。上方 82,033 这条 Fib 和下方 81,810 这条 MA25,你画出来的位置跟我一致吗?
以上是公开数据的结构记录,不构成操作建议,盈亏自负。
$BTC
#技术分析 #合约交易 #比特币
【结构观察 #007|BTC 4H】高低点同时外扩,价格卡在箱体下半区
上一条对账:昨天 20:00 划的 BTC 81,048–83,390,现价 81,908 还在里面,两条线都没碰到。
08:00 现价 81,908,24 小时 -0.21%,成交额 105.62 亿 U,日内 83,158 / 81,701。
① 结构:近 30 根高点抬高、低点降低,走的是扩张三角。箱体 80,841–83,961,宽度 3.9%,现价在 34% 分位,箱体下半区。MA25 在 81,810,就在现价下方,近 5 根斜率 +0.03%,基本是平的。
② 量价:近 10 根对前 30 根 0.89 倍,量能与前期接近,没有明显放量。近 10 根里 5 根收红,红绿各半,来回拉扯的味道。
③ 共振:上方 82,033–82,599 一带,Fib 0.618(82,033)和前高(82,599)压在一起;下方 81,320–81,810 一带,MA25(81,810)和前低(81,320)叠着。上下都是双来源,这点比单线可靠些。
④ 资金面:资金费率 +0.0092%,多头付费;持仓 7 根 4H 变化 +1.69%,持仓在加;多空账户比 1.62。价格没动多少,仓位在往里堆。
观察区间:上方 82,033–83,017,下方 80,829–81,810。
1H 视角:近 12 小时在 81,701–82,744 之间走,最新收盘落在 20% 分位,靠近这波的下沿。
失效条件:4H 收盘站上 83,017 或跌破 80,829,这组判断作废。
我自己的看法是,扩张三角里最值得盯的不是中间这段,而是上下沿被真正碰到的次数。上方 82,033 这条 Fib 和下方 81,810 这条 MA25,你画出来的位置跟我一致吗?
以上是公开数据的结构记录,不构成操作建议,盈亏自负。
$BTC
#技术分析 #合约交易 #比特币
上一条对账:昨天 20:00 划的 BTC 81,048–83,390,现价 81,908 还在里面,两条线都没碰到。
08:00 现价 81,908,24 小时 -0.21%,成交额 105.62 亿 U,日内 83,158 / 81,701。
① 结构:近 30 根高点抬高、低点降低,走的是扩张三角。箱体 80,841–83,961,宽度 3.9%,现价在 34% 分位,箱体下半区。MA25 在 81,810,就在现价下方,近 5 根斜率 +0.03%,基本是平的。
② 量价:近 10 根对前 30 根 0.89 倍,量能与前期接近,没有明显放量。近 10 根里 5 根收红,红绿各半,来回拉扯的味道。
③ 共振:上方 82,033–82,599 一带,Fib 0.618(82,033)和前高(82,599)压在一起;下方 81,320–81,810 一带,MA25(81,810)和前低(81,320)叠着。上下都是双来源,这点比单线可靠些。
④ 资金面:资金费率 +0.0092%,多头付费;持仓 7 根 4H 变化 +1.69%,持仓在加;多空账户比 1.62。价格没动多少,仓位在往里堆。
观察区间:上方 82,033–83,017,下方 80,829–81,810。
1H 视角:近 12 小时在 81,701–82,744 之间走,最新收盘落在 20% 分位,靠近这波的下沿。
失效条件:4H 收盘站上 83,017 或跌破 80,829,这组判断作废。
我自己的看法是,扩张三角里最值得盯的不是中间这段,而是上下沿被真正碰到的次数。上方 82,033 这条 Fib 和下方 81,810 这条 MA25,你画出来的位置跟我一致吗?
以上是公开数据的结构记录,不构成操作建议,盈亏自负。
$BTC
#技术分析 #合约交易 #比特币
90
·
--
#广场运营手记 #007:初週のまとめ——実際に数字が伸びたのは、たった一つの法則
このシリーズも今日で7日目、連載開始からちょうど1週間。さっきプロフィールから最新データを確認したところ、1週間でいくつか発見があったので、記録しておきたい。
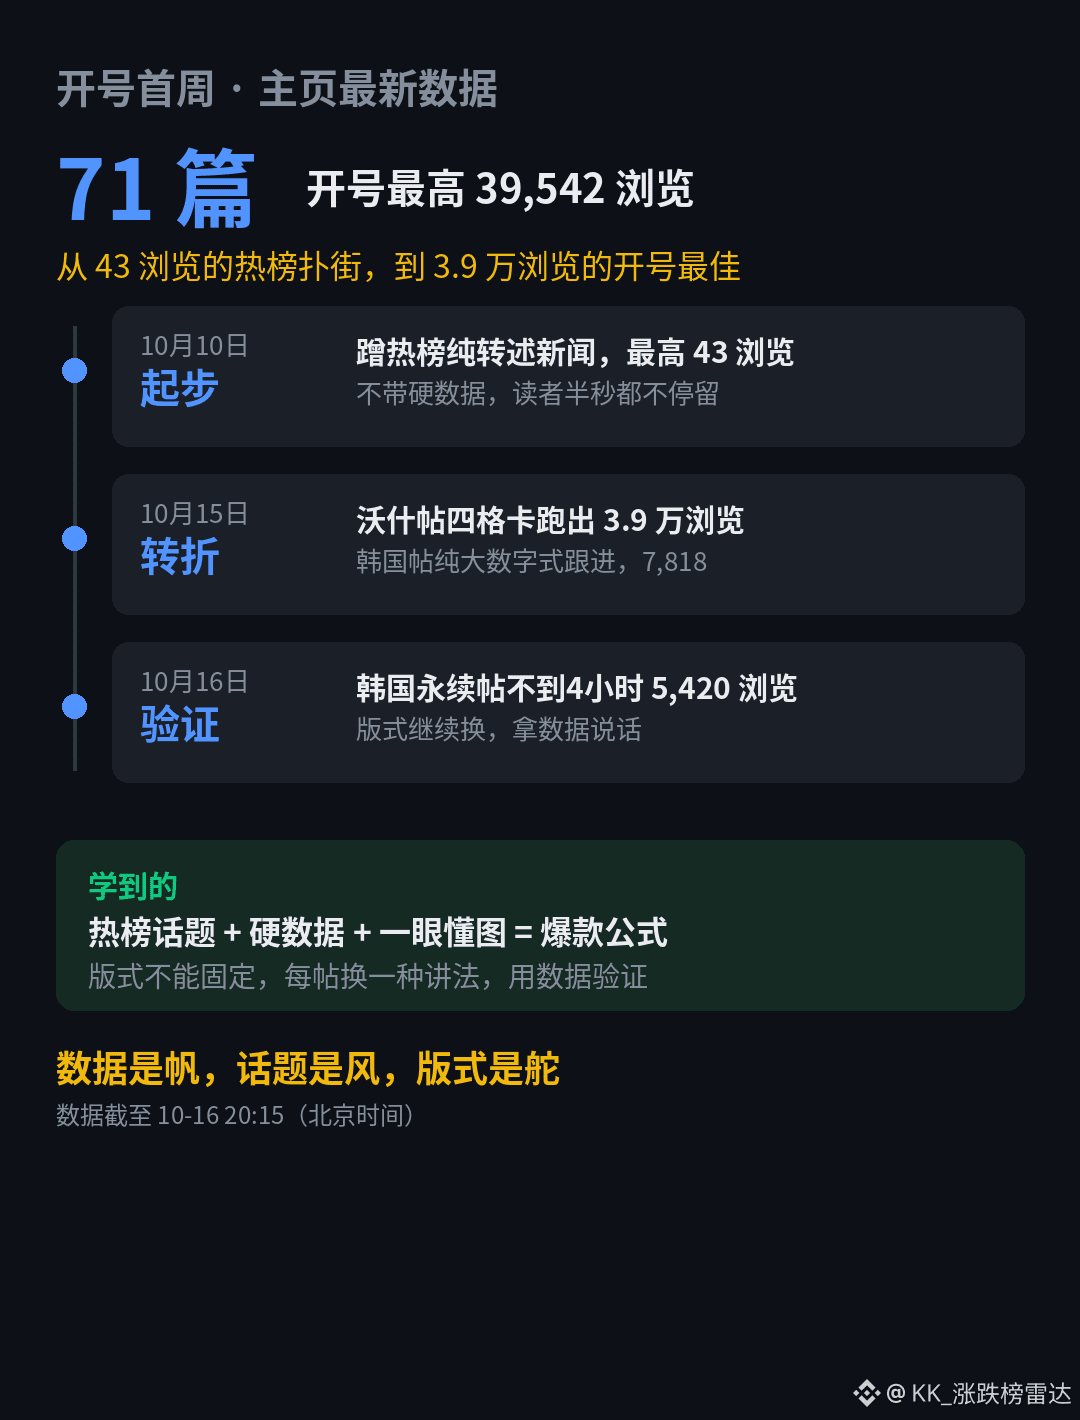
まず、最もわかりやすいことから。アカウント開設以来、最も閲覧数が多かった投稿は、昨日自分でもかなり手応えを感じていた韓国の投稿ではなく、ほとんど見過ごしかけていた10月15日のウォーシュ投稿(FRBの「シナリオ」が覆される?)だった。39,542閲覧、12いいね、5コメント。韓国が27の取引所サイトを遮断した投稿は7,818閲覧、3いいねで2位。今日の午後に投稿した韓国の無期限先物の投稿は、4時間足らずですでに5,420閲覧となり、ロングテールで伸び始めている。朝のブリーフィングは相変わらず安定していて、毎日およそ1,000閲覧。
この数本を並べて見ると、かえって結論がはっきりしてきた。ウォーシュ投稿は「過去/現在/未来/影響」の4コマカードで、1枚の画像にまとめたもの。数字が伸びた瞬間はとても興奮したけれど、今日、もう一つ学んだ。どんな形式もテンプレートとして固定してはいけない。ウォーシュ投稿が4コマカードで伸びた次の投稿では、シンプルな大きな数字の形式に変更(韓国の遮断投稿、7,818閲覧)。そして今日は、大きな数字に詳細を添える見せ方に変えた(韓国の無期限先物投稿、5,420閲覧で伸長中)。読者は飽きる。タイムラインには同じ形式を使い倒すアカウントが多すぎて、ユーザーは次のコマに何が出るか一目でわかり、そのままスクロールしてしまう。私の方針は、投稿ごとにやり方を変え、どの方法が本当に効果的かデータで検証すること。一つのヒット投稿だけで結論を出さない。
この7日間の試行錯誤についても振り返りたい。最初の数日は、私もトレンドに乗ろうとしていた。投稿は3本で、最も閲覧数が多かったものでも43回。ニュースをそのまま伝えただけで、自分なりのデータも切り口もなく、完全に失敗した。この7日間は、実は試行錯誤の一連のサイクルだった。最初は話題に乗ればいいと思っていたが、確かなデータがなければ、読者は0.5秒も立ち止まらないとわかった。途中で失敗が続き、このやり方では無理かもしれないと疑いかけたが、朝のブリーフィングがずっと安定していたおかげで、試行錯誤を続ける自信が持てた。転機は10月15日。韓国の投稿で「トレンドの話題+確かなデータ+ひと目でわかる図」を組み合わせ、7,818閲覧を記録。ウォーシュ投稿はさらに一気に3.9万まで伸びた。
もう一つ、失敗から学んだことがある。タグをむやみに付けると、流量が抑制される。内容とタグは同じテーマでなければならない。付けるなら厳選し、無理に増やさない。
来週やることは3つ。トレンドの話題を追うときは引き続き画像を付け、投稿ごとにやり方を変えて1週間検証する。朝のブリーフィングは毎日欠かさず続ける。これは毎日最も安定した基盤だから。そして確かなデータがないトレンドの話題は、投稿しないくらいでちょうどいい。質の低い投稿の代償は、投稿枠を一つ無駄にすることではなく、このアカウントに対する読者の信頼を損なうことだから。
7日間で71本。43閲覧で惨敗したところから、アカウント開設以来最高の3.9万閲覧まで。私はまだ小さなブロガーだけれど、進む道はだんだん見えてきた。データは帆、話題は風、形式は舵。
みなさんはタイムラインで「投稿ごとに形式を変える」ことを試したことがありますか?コメントでぜひ教えてください。
$BTC $ETH
#广场运营手记 #007:初週のまとめ——実際に数字が伸びたのは、たった一つの法則
このシリーズも今日で7日目、連載開始からちょうど1週間。さっきプロフィールから最新データを確認したところ、1週間でいくつか発見があったので、記録しておきたい。
まず、最もわかりやすいことから。アカウント開設以来、最も閲覧数が多かった投稿は、昨日自分でもかなり手応えを感じていた韓国の投稿ではなく、ほとんど見過ごしかけていた10月15日のウォーシュ投稿(FRBの「シナリオ」が覆される?)だった。39,542閲覧、12いいね、5コメント。韓国が27の取引所サイトを遮断した投稿は7,818閲覧、3いいねで2位。今日の午後に投稿した韓国の無期限先物の投稿は、4時間足らずですでに5,420閲覧となり、ロングテールで伸び始めている。朝のブリーフィングは相変わらず安定していて、毎日およそ1,000閲覧。
この数本を並べて見ると、かえって結論がはっきりしてきた。ウォーシュ投稿は「過去/現在/未来/影響」の4コマカードで、1枚の画像にまとめたもの。数字が伸びた瞬間はとても興奮したけれど、今日、もう一つ学んだ。どんな形式もテンプレートとして固定してはいけない。ウォーシュ投稿が4コマカードで伸びた次の投稿では、シンプルな大きな数字の形式に変更(韓国の遮断投稿、7,818閲覧)。そして今日は、大きな数字に詳細を添える見せ方に変えた(韓国の無期限先物投稿、5,420閲覧で伸長中)。読者は飽きる。タイムラインには同じ形式を使い倒すアカウントが多すぎて、ユーザーは次のコマに何が出るか一目でわかり、そのままスクロールしてしまう。私の方針は、投稿ごとにやり方を変え、どの方法が本当に効果的かデータで検証すること。一つのヒット投稿だけで結論を出さない。
この7日間の試行錯誤についても振り返りたい。最初の数日は、私もトレンドに乗ろうとしていた。投稿は3本で、最も閲覧数が多かったものでも43回。ニュースをそのまま伝えただけで、自分なりのデータも切り口もなく、完全に失敗した。この7日間は、実は試行錯誤の一連のサイクルだった。最初は話題に乗ればいいと思っていたが、確かなデータがなければ、読者は0.5秒も立ち止まらないとわかった。途中で失敗が続き、このやり方では無理かもしれないと疑いかけたが、朝のブリーフィングがずっと安定していたおかげで、試行錯誤を続ける自信が持てた。転機は10月15日。韓国の投稿で「トレンドの話題+確かなデータ+ひと目でわかる図」を組み合わせ、7,818閲覧を記録。ウォーシュ投稿はさらに一気に3.9万まで伸びた。
もう一つ、失敗から学んだことがある。タグをむやみに付けると、流量が抑制される。内容とタグは同じテーマでなければならない。付けるなら厳選し、無理に増やさない。
来週やることは3つ。トレンドの話題を追うときは引き続き画像を付け、投稿ごとにやり方を変えて1週間検証する。朝のブリーフィングは毎日欠かさず続ける。これは毎日最も安定した基盤だから。そして確かなデータがないトレンドの話題は、投稿しないくらいでちょうどいい。質の低い投稿の代償は、投稿枠を一つ無駄にすることではなく、このアカウントに対する読者の信頼を損なうことだから。
7日間で71本。43閲覧で惨敗したところから、アカウント開設以来最高の3.9万閲覧まで。私はまだ小さなブロガーだけれど、進む道はだんだん見えてきた。データは帆、話題は風、形式は舵。
みなさんはタイムラインで「投稿ごとに形式を変える」ことを試したことがありますか?コメントでぜひ教えてください。
$BTC $ETH
このシリーズも今日で7日目、連載開始からちょうど1週間。さっきプロフィールから最新データを確認したところ、1週間でいくつか発見があったので、記録しておきたい。
まず、最もわかりやすいことから。アカウント開設以来、最も閲覧数が多かった投稿は、昨日自分でもかなり手応えを感じていた韓国の投稿ではなく、ほとんど見過ごしかけていた10月15日のウォーシュ投稿(FRBの「シナリオ」が覆される?)だった。39,542閲覧、12いいね、5コメント。韓国が27の取引所サイトを遮断した投稿は7,818閲覧、3いいねで2位。今日の午後に投稿した韓国の無期限先物の投稿は、4時間足らずですでに5,420閲覧となり、ロングテールで伸び始めている。朝のブリーフィングは相変わらず安定していて、毎日およそ1,000閲覧。
この数本を並べて見ると、かえって結論がはっきりしてきた。ウォーシュ投稿は「過去/現在/未来/影響」の4コマカードで、1枚の画像にまとめたもの。数字が伸びた瞬間はとても興奮したけれど、今日、もう一つ学んだ。どんな形式もテンプレートとして固定してはいけない。ウォーシュ投稿が4コマカードで伸びた次の投稿では、シンプルな大きな数字の形式に変更(韓国の遮断投稿、7,818閲覧)。そして今日は、大きな数字に詳細を添える見せ方に変えた(韓国の無期限先物投稿、5,420閲覧で伸長中)。読者は飽きる。タイムラインには同じ形式を使い倒すアカウントが多すぎて、ユーザーは次のコマに何が出るか一目でわかり、そのままスクロールしてしまう。私の方針は、投稿ごとにやり方を変え、どの方法が本当に効果的かデータで検証すること。一つのヒット投稿だけで結論を出さない。
この7日間の試行錯誤についても振り返りたい。最初の数日は、私もトレンドに乗ろうとしていた。投稿は3本で、最も閲覧数が多かったものでも43回。ニュースをそのまま伝えただけで、自分なりのデータも切り口もなく、完全に失敗した。この7日間は、実は試行錯誤の一連のサイクルだった。最初は話題に乗ればいいと思っていたが、確かなデータがなければ、読者は0.5秒も立ち止まらないとわかった。途中で失敗が続き、このやり方では無理かもしれないと疑いかけたが、朝のブリーフィングがずっと安定していたおかげで、試行錯誤を続ける自信が持てた。転機は10月15日。韓国の投稿で「トレンドの話題+確かなデータ+ひと目でわかる図」を組み合わせ、7,818閲覧を記録。ウォーシュ投稿はさらに一気に3.9万まで伸びた。
もう一つ、失敗から学んだことがある。タグをむやみに付けると、流量が抑制される。内容とタグは同じテーマでなければならない。付けるなら厳選し、無理に増やさない。
来週やることは3つ。トレンドの話題を追うときは引き続き画像を付け、投稿ごとにやり方を変えて1週間検証する。朝のブリーフィングは毎日欠かさず続ける。これは毎日最も安定した基盤だから。そして確かなデータがないトレンドの話題は、投稿しないくらいでちょうどいい。質の低い投稿の代償は、投稿枠を一つ無駄にすることではなく、このアカウントに対する読者の信頼を損なうことだから。
7日間で71本。43閲覧で惨敗したところから、アカウント開設以来最高の3.9万閲覧まで。私はまだ小さなブロガーだけれど、進む道はだんだん見えてきた。データは帆、話題は風、形式は舵。
みなさんはタイムラインで「投稿ごとに形式を変える」ことを試したことがありますか?コメントでぜひ教えてください。
$BTC $ETH
175
·
--
#007
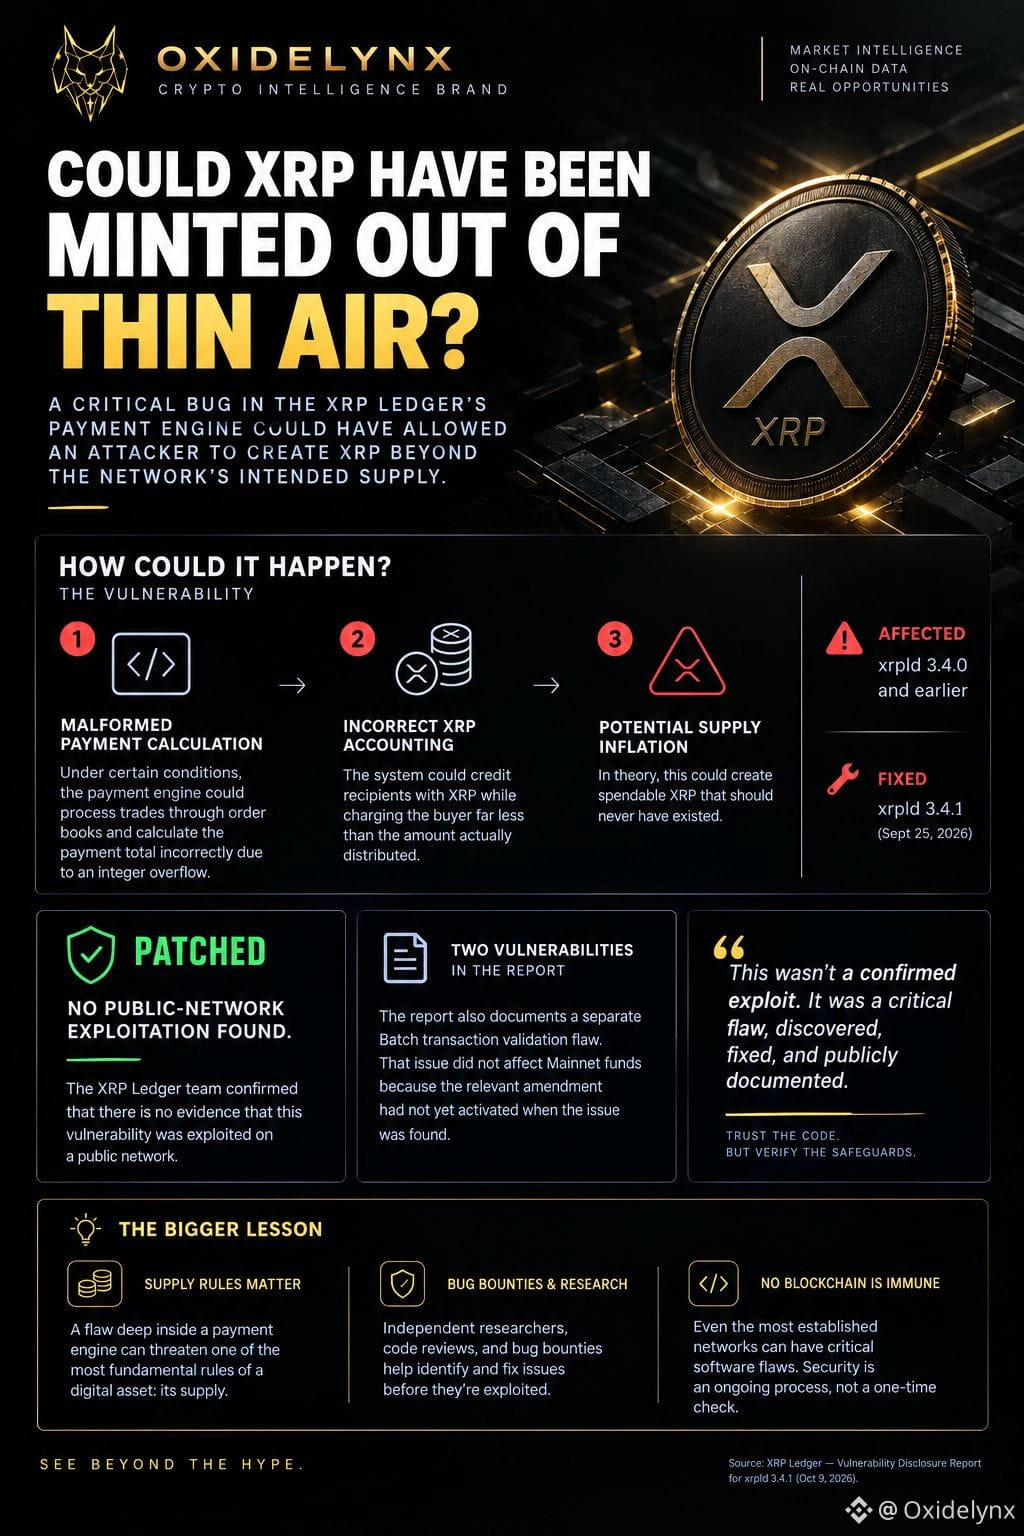
XRPは無から鋳造される可能性があったのか?
XRP Ledgerの決済エンジンに重大なバグがあり、理論上、攻撃者が想定された供給量を超える使用可能なXRPを生成できた可能性があります。
🔎 何が起きたのか?
この脆弱性は2015年から存在していた可能性があります。修正は2026年9月25日にxrpld 3.4.1でリリースされました。チームは、公開ネットワーク上で悪用された証拠はないと報告しています。
⚠️ 重要なポイント:深刻な脆弱性が発見されましたが、悪用されたことは確認されていません。
確立されたブロックチェーンであっても、継続的なセキュリティレビューが必要です。
コードを信頼し、安全対策を検証しましょう。
誇大宣伝の先を見よう。
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
#007
XRPは無から鋳造される可能性があったのか?
XRP Ledgerの決済エンジンに重大なバグがあり、理論上、攻撃者が想定された供給量を超える使用可能なXRPを生成できた可能性があります。
🔎 何が起きたのか?
この脆弱性は2015年から存在していた可能性があります。修正は2026年9月25日にxrpld 3.4.1でリリースされました。チームは、公開ネットワーク上で悪用された証拠はないと報告しています。
⚠️ 重要なポイント:深刻な脆弱性が発見されましたが、悪用されたことは確認されていません。
確立されたブロックチェーンであっても、継続的なセキュリティレビューが必要です。
コードを信頼し、安全対策を検証しましょう。
誇大宣伝の先を見よう。
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
XRPは無から鋳造される可能性があったのか?
XRP Ledgerの決済エンジンに重大なバグがあり、理論上、攻撃者が想定された供給量を超える使用可能なXRPを生成できた可能性があります。
🔎 何が起きたのか?
この脆弱性は2015年から存在していた可能性があります。修正は2026年9月25日にxrpld 3.4.1でリリースされました。チームは、公開ネットワーク上で悪用された証拠はないと報告しています。
⚠️ 重要なポイント:深刻な脆弱性が発見されましたが、悪用されたことは確認されていません。
確立されたブロックチェーンであっても、継続的なセキュリティレビューが必要です。
コードを信頼し、安全対策を検証しましょう。
誇大宣伝の先を見よう。
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
103
·
--
$WLD /USDT | MOMENTUM RADAR #007
{future}(WLDUSDT)
ステータス: 強気の継続セットアップ
WLDは4時間チャートのすべての主要移動平均の上に保持されており、MA7とMA25がダイナミックサポートとして機能しています。バイザーたちは$0.62エリアを守っており、$0.66を超えるブレイクがあれば、さらなる拡張ムーブを引き起こす可能性があります。
スマートマネープラン方向: ロング
エントリーゾーン: $0.638 – $0.648
レバレッジ: 5倍–8倍アイソレーテッド
ストップロス: $0.612
ターゲットマップ
ターゲット1: $0.670
ターゲット2: $0.695
ターゲット3: $0.725
マーケットトリガー
$0.66以上で4時間のキャンドルがクローズし、ボリュームが上昇すれば、$0.70以上のゾーンに向けてモメンタムが加速する可能性があります。
トレードマネジメント
TP1で30%の利益を確保し、SLをエントリーに移動し、残りのポジションを維持します。
エッジスコア: 8/10
無効化: $0.612のサポートを失うと、強気の構造が弱まります。
チャートは改善していますが、サポート付近でのエントリーは常にグリーンキャンドルを追いかけるよりも優れています。
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
$WLD /USDT | MOMENTUM RADAR #007
ステータス: 強気の継続セットアップ
WLDは4時間チャートのすべての主要移動平均の上に保持されており、MA7とMA25がダイナミックサポートとして機能しています。バイザーたちは$0.62エリアを守っており、$0.66を超えるブレイクがあれば、さらなる拡張ムーブを引き起こす可能性があります。
スマートマネープラン方向: ロング
エントリーゾーン: $0.638 – $0.648
レバレッジ: 5倍–8倍アイソレーテッド
ストップロス: $0.612
ターゲットマップ
ターゲット1: $0.670
ターゲット2: $0.695
ターゲット3: $0.725
マーケットトリガー
$0.66以上で4時間のキャンドルがクローズし、ボリュームが上昇すれば、$0.70以上のゾーンに向けてモメンタムが加速する可能性があります。
トレードマネジメント
TP1で30%の利益を確保し、SLをエントリーに移動し、残りのポジションを維持します。
エッジスコア: 8/10
無効化: $0.612のサポートを失うと、強気の構造が弱まります。
チャートは改善していますが、サポート付近でのエントリーは常にグリーンキャンドルを追いかけるよりも優れています。
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
ステータス: 強気の継続セットアップ
WLDは4時間チャートのすべての主要移動平均の上に保持されており、MA7とMA25がダイナミックサポートとして機能しています。バイザーたちは$0.62エリアを守っており、$0.66を超えるブレイクがあれば、さらなる拡張ムーブを引き起こす可能性があります。
スマートマネープラン方向: ロング
エントリーゾーン: $0.638 – $0.648
レバレッジ: 5倍–8倍アイソレーテッド
ストップロス: $0.612
ターゲットマップ
ターゲット1: $0.670
ターゲット2: $0.695
ターゲット3: $0.725
マーケットトリガー
$0.66以上で4時間のキャンドルがクローズし、ボリュームが上昇すれば、$0.70以上のゾーンに向けてモメンタムが加速する可能性があります。
トレードマネジメント
TP1で30%の利益を確保し、SLをエントリーに移動し、残りのポジションを維持します。
エッジスコア: 8/10
無効化: $0.612のサポートを失うと、強気の構造が弱まります。
チャートは改善していますが、サポート付近でのエントリーは常にグリーンキャンドルを追いかけるよりも優れています。
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
1
183
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号
トレンドトピック
1
#BinanceWithdrawalScamWarning
閲覧回数 10,848
369人が討論中
2
#USMidtermElections
閲覧回数 559,924
2,934人が討論中
3
#USOctoberNFP-AreRateCutsStillPossible
閲覧回数 19,868
383人が討論中
4
#AppleEarningsAhead-CanStockHitNewHigh
閲覧回数 6,489
276人が討論中
5
#Verify1to1BinanceReserves
閲覧回数 19,371
300人が討論中
6
#BinanceRestores28FiatWithdrawals
閲覧回数 96,642
936人が討論中
7
#StrategyRepurchases$208MSTRCAdds811Bitcoin
閲覧回数 2,787
13人が討論中
8
#FATFLaunchesReviewOfCryptoHubsMoneyLaunderingControls
閲覧回数 462
9人が討論中
9
#BinanceProcesses$4.65BWithdrawals
閲覧回数 96,645
355人が討論中
10
#HKMALaunchesSAGEAgenticFinanceProject
閲覧回数 2,562
148人が討論中