

Sheemo Queen
576 Publications
Sheemo Queen
Signaler
Bloquer l’utilisateur
222 Suivis
136 Abonnés
257 J’aime
Publications
PINNED
·
--
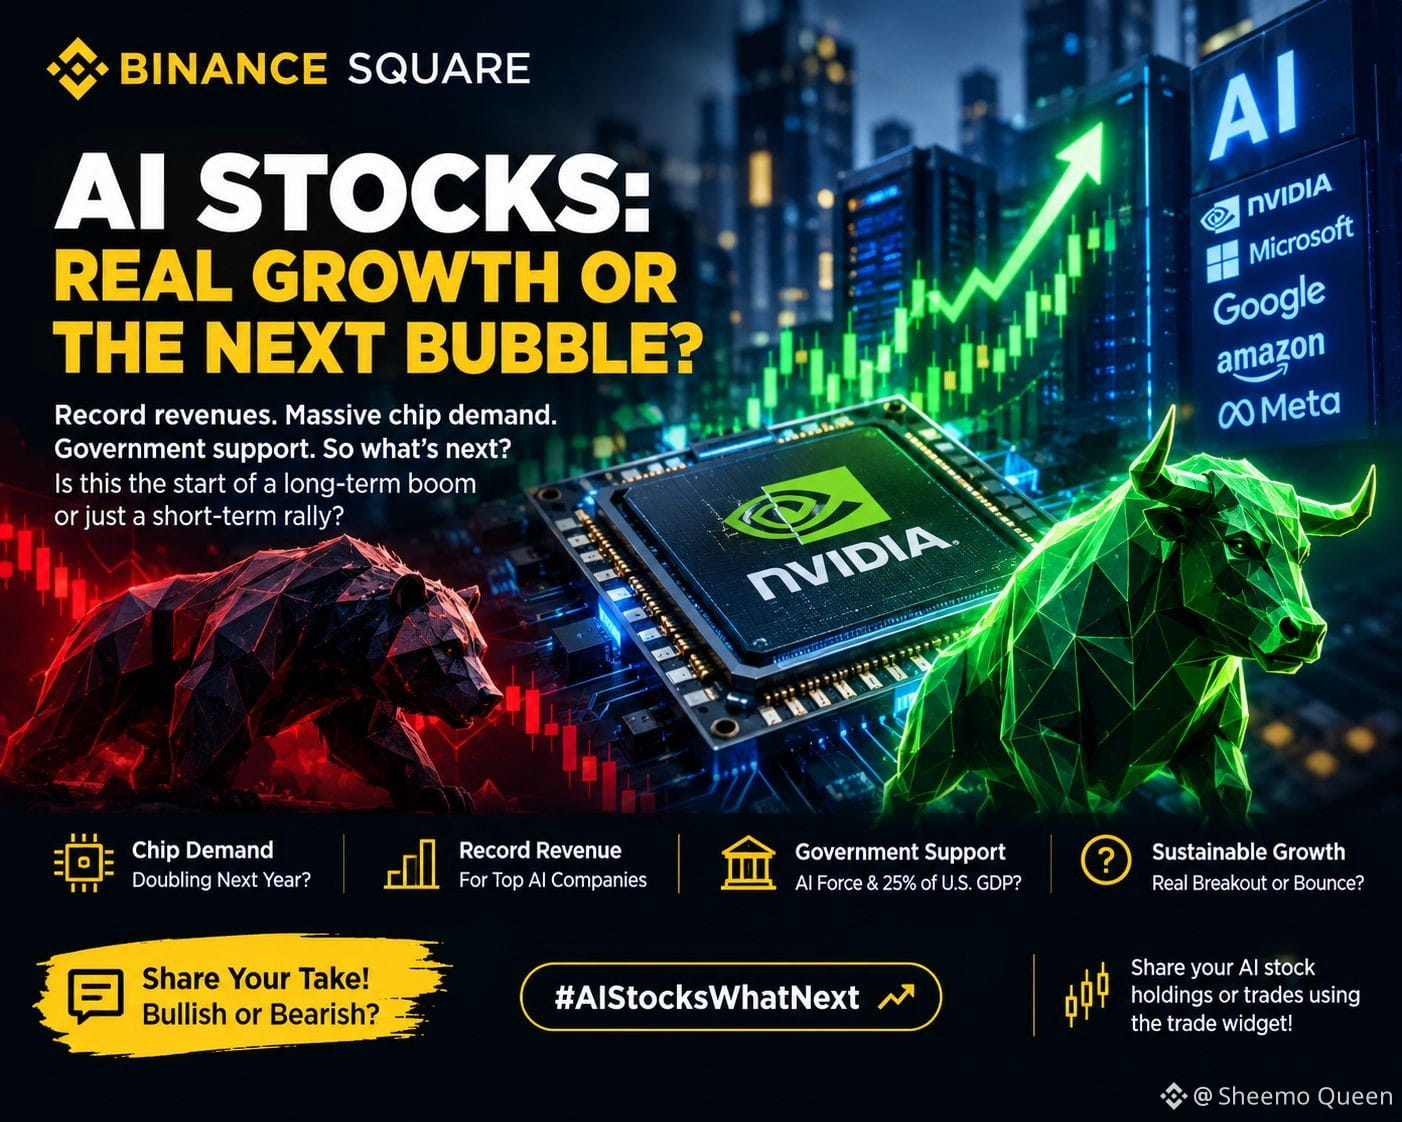
The AI revolution is clearly driving massive investments in computing power, data centers, and infrastructure. However, rising stock prices alone don't guarantee sustainable returns. Investors need to watch revenue growth, profitability, valuation, and whether AI companies can turn huge spending into long-term cash flow.
Government support for AI, including plans to strengthen U.S.AI capabilities, could accelerate the industry.But political backing doesn't eliminate market risks or guarantee that every AI stock will succeed.
Personally, I believe the next phase of AI investing will be about identifying real utility, sustainable earnings, and the infrastructure powering AI not simply chasing hype.
The opportunity may extend beyond chipmakers to data centers, energy infrastructure, cloud computing, and AI software.
Are AI stocks entering a long-term growth cycle, or are valuations getting ahead of reality? 👀
Bullish or bearish? What's your AI investment strategy?
#AIStocksWhatNext #AI #StockMarket #Investing #BinanceSquare
The AI revolution is clearly driving massive investments in computing power, data centers, and infrastructure. However, rising stock prices alone don't guarantee sustainable returns. Investors need to watch revenue growth, profitability, valuation, and whether AI companies can turn huge spending into long-term cash flow.
Government support for AI, including plans to strengthen U.S.AI capabilities, could accelerate the industry.But political backing doesn't eliminate market risks or guarantee that every AI stock will succeed.
Personally, I believe the next phase of AI investing will be about identifying real utility, sustainable earnings, and the infrastructure powering AI not simply chasing hype.
The opportunity may extend beyond chipmakers to data centers, energy infrastructure, cloud computing, and AI software.
Are AI stocks entering a long-term growth cycle, or are valuations getting ahead of reality? 👀
Bullish or bearish? What's your AI investment strategy?
#AIStocksWhatNext #AI #StockMarket #Investing #BinanceSquare
Government support for AI, including plans to strengthen U.S.AI capabilities, could accelerate the industry.But political backing doesn't eliminate market risks or guarantee that every AI stock will succeed.
Personally, I believe the next phase of AI investing will be about identifying real utility, sustainable earnings, and the infrastructure powering AI not simply chasing hype.
The opportunity may extend beyond chipmakers to data centers, energy infrastructure, cloud computing, and AI software.
Are AI stocks entering a long-term growth cycle, or are valuations getting ahead of reality? 👀
Bullish or bearish? What's your AI investment strategy?
#AIStocksWhatNext #AI #StockMarket #Investing #BinanceSquare
1
2
103
·
--
The Fed delivered the 25bp hike. Now the bigger question is: what comes next?
Rates are now at 3.75%–4.00%, while inflation remains elevated.
For markets, the next move may depend less on the hike itself and more on how long restrictive policy stays in place.
📌 BTC: Could face pressure if liquidity tightens further, but expectations and future guidance matter just as much as the hike.
📌 Tech stocks: Higher-for-longer rates can keep pressure on high-growth valuations.
📌 Gold: Could remain sensitive to real yields, inflation expectations and demand for defensive assets.
My focus now is not simply “bullish or bearish.”
It’s watching the Fed’s next signals and managing risk around BTC, stocks and gold accordingly.
What are you watching next?
#FedRateWatch
The Fed delivered the 25bp hike. Now the bigger question is: what comes next?
Rates are now at 3.75%–4.00%, while inflation remains elevated.
For markets, the next move may depend less on the hike itself and more on how long restrictive policy stays in place.
📌 BTC: Could face pressure if liquidity tightens further, but expectations and future guidance matter just as much as the hike.
📌 Tech stocks: Higher-for-longer rates can keep pressure on high-growth valuations.
📌 Gold: Could remain sensitive to real yields, inflation expectations and demand for defensive assets.
My focus now is not simply “bullish or bearish.”
It’s watching the Fed’s next signals and managing risk around BTC, stocks and gold accordingly.
What are you watching next?
#FedRateWatch
Rates are now at 3.75%–4.00%, while inflation remains elevated.
For markets, the next move may depend less on the hike itself and more on how long restrictive policy stays in place.
📌 BTC: Could face pressure if liquidity tightens further, but expectations and future guidance matter just as much as the hike.
📌 Tech stocks: Higher-for-longer rates can keep pressure on high-growth valuations.
📌 Gold: Could remain sensitive to real yields, inflation expectations and demand for defensive assets.
My focus now is not simply “bullish or bearish.”
It’s watching the Fed’s next signals and managing risk around BTC, stocks and gold accordingly.
What are you watching next?
#FedRateWatch
96
·
--
@Dusk_Foundation I’ve been thinking about Dusk’s privacy architecture as a problem of guarantee matching rather than maximum privacy.
The distinction between Hedger on DuskEVM and Zedger matters because the underlying data model sets a ceiling on what privacy can actually promise. An account-based EVM environment carries structural traces around accounts and state, even when transaction details are protected. A different architecture can make stronger anonymity guarantees because it starts with different assumptions.
That honesty is more interesting to me than a blanket claim that everything is private.
For users and institutions, overestimating a privacy guarantee can create its own form of risk. Capital may be routed through an application under one set of assumptions, only for metadata or account-level relationships to remain more observable than expected.
“Privacy is strongest when the guarantee matches the architecture.”
I suspect this distinction is easy to overlook because developers often value EVM compatibility, while privacy-sensitive users may value anonymity more than familiar tooling.
The weakness is clear: splitting privacy guarantees across Hedger and Zedger can fragment user flows and liquidity. If users must understand technical boundaries before choosing where to transact, the architecture itself becomes a source of friction.
Dusk’s challenge is making those different guarantees clear without making the user experience more complicated.
#dusk @Dusk_Foundation $DUSK $BTR $BMT
{future}(BMTUSDT)
{future}(BTRUSDT)
{future}(DUSKUSDT)
@Dusk I’ve been thinking about Dusk’s privacy architecture as a problem of guarantee matching rather than maximum privacy.
The distinction between Hedger on DuskEVM and Zedger matters because the underlying data model sets a ceiling on what privacy can actually promise. An account-based EVM environment carries structural traces around accounts and state, even when transaction details are protected. A different architecture can make stronger anonymity guarantees because it starts with different assumptions.
That honesty is more interesting to me than a blanket claim that everything is private.
For users and institutions, overestimating a privacy guarantee can create its own form of risk. Capital may be routed through an application under one set of assumptions, only for metadata or account-level relationships to remain more observable than expected.
“Privacy is strongest when the guarantee matches the architecture.”
I suspect this distinction is easy to overlook because developers often value EVM compatibility, while privacy-sensitive users may value anonymity more than familiar tooling.
The weakness is clear: splitting privacy guarantees across Hedger and Zedger can fragment user flows and liquidity. If users must understand technical boundaries before choosing where to transact, the architecture itself becomes a source of friction.
Dusk’s challenge is making those different guarantees clear without making the user experience more complicated.
#dusk @Dusk $DUSK $BTR $BMT
The distinction between Hedger on DuskEVM and Zedger matters because the underlying data model sets a ceiling on what privacy can actually promise. An account-based EVM environment carries structural traces around accounts and state, even when transaction details are protected. A different architecture can make stronger anonymity guarantees because it starts with different assumptions.
That honesty is more interesting to me than a blanket claim that everything is private.
For users and institutions, overestimating a privacy guarantee can create its own form of risk. Capital may be routed through an application under one set of assumptions, only for metadata or account-level relationships to remain more observable than expected.
“Privacy is strongest when the guarantee matches the architecture.”
I suspect this distinction is easy to overlook because developers often value EVM compatibility, while privacy-sensitive users may value anonymity more than familiar tooling.
The weakness is clear: splitting privacy guarantees across Hedger and Zedger can fragment user flows and liquidity. If users must understand technical boundaries before choosing where to transact, the architecture itself becomes a source of friction.
Dusk’s challenge is making those different guarantees clear without making the user experience more complicated.
#dusk @Dusk $DUSK $BTR $BMT
9
7
354
·
--
I found myself looking at Dusk’s XSC contracts as a question of data architecture rather than automation.
Traditional corporate actions create a strange duplication problem.The same dividend, split or voting event can be processed independently by multiple intermediaries, each maintaining its own records and then checking those records against everyone else afterward.
With native issuance, XSC can embed the corporate-action logic into the asset structure itself.The event and its execution share the same underlying state, which means the network is not simply moving instructions between separate ledgers.
That could change where operational risk actually sits.
“Reconciliation is expensive because disagreement is built into the architecture.”
For me, the investment angle is accounting reliability. If every participant can reference the same execution result, fewer resources may be needed to verify balances, entitlements and ownership after an event occurs. That is potentially more valuable than simply making corporate actions faster.
I think the market may still be underestimating the difference between tokenizing an existing workflow and redesigning the workflow around a native asset.
The weakness is equally important: concentrating execution into smart contracts concentrates the consequences of a mistake.A coding error or poorly designed upgrade process could affect every participant referencing that same source of truth.
The real test is whether Dusk can make shared execution as accountable as it is efficient.
#dusk $DUSK @Dusk_Foundation
{future}(DUSKUSDT)
I found myself looking at Dusk’s XSC contracts as a question of data architecture rather than automation.
Traditional corporate actions create a strange duplication problem.The same dividend, split or voting event can be processed independently by multiple intermediaries, each maintaining its own records and then checking those records against everyone else afterward.
With native issuance, XSC can embed the corporate-action logic into the asset structure itself.The event and its execution share the same underlying state, which means the network is not simply moving instructions between separate ledgers.
That could change where operational risk actually sits.
“Reconciliation is expensive because disagreement is built into the architecture.”
For me, the investment angle is accounting reliability. If every participant can reference the same execution result, fewer resources may be needed to verify balances, entitlements and ownership after an event occurs. That is potentially more valuable than simply making corporate actions faster.
I think the market may still be underestimating the difference between tokenizing an existing workflow and redesigning the workflow around a native asset.
The weakness is equally important: concentrating execution into smart contracts concentrates the consequences of a mistake.A coding error or poorly designed upgrade process could affect every participant referencing that same source of truth.
The real test is whether Dusk can make shared execution as accountable as it is efficient.
#dusk $DUSK @Dusk
Traditional corporate actions create a strange duplication problem.The same dividend, split or voting event can be processed independently by multiple intermediaries, each maintaining its own records and then checking those records against everyone else afterward.
With native issuance, XSC can embed the corporate-action logic into the asset structure itself.The event and its execution share the same underlying state, which means the network is not simply moving instructions between separate ledgers.
That could change where operational risk actually sits.
“Reconciliation is expensive because disagreement is built into the architecture.”
For me, the investment angle is accounting reliability. If every participant can reference the same execution result, fewer resources may be needed to verify balances, entitlements and ownership after an event occurs. That is potentially more valuable than simply making corporate actions faster.
I think the market may still be underestimating the difference between tokenizing an existing workflow and redesigning the workflow around a native asset.
The weakness is equally important: concentrating execution into smart contracts concentrates the consequences of a mistake.A coding error or poorly designed upgrade process could affect every participant referencing that same source of truth.
The real test is whether Dusk can make shared execution as accountable as it is efficient.
#dusk $DUSK @Dusk
11
11
110
·
--
Vérifié
I’ve started treating finality as an accounting property rather than a speed metric, and that makes Dusk’s Succinct Attestation mechanism more interesting to me.
A financial system needs to know when an entry can stop being provisional. With probabilistic finality, confidence increases over time as more blocks accumulate. That may work well for many crypto transactions, but institutional settlement has a different requirement: systems, counterparties and records eventually need a clear point at which the state is no longer open to revision.
Dusk’s SA mechanism is designed around committee voting, with a block becoming deterministically ratified after the required rounds of consensus.
That distinction changes how I think about settlement risk.
“Confidence can grow gradually. Finality should not.”
The investor question is whether deterministic finality creates measurable economic value. If institutions can reduce reconciliation delays, collateral buffers or uncertainty around ownership transfer, then the mechanism becomes part of the network’s financial utility rather than just a consensus specification.
There is an important trade-off, though. Committee-based systems concentrate security assumptions around validator selection, participation and governance. A deterministic outcome is only as reliable as the process that produces it.
I suspect the market may be underpricing that broader distinction: for financial infrastructure, knowing exactly when the ledger is done could matter as much as knowing how quickly it moved.
#dusk @Dusk_Foundation $DUSK
{future}(DUSKUSDT)
I’ve started treating finality as an accounting property rather than a speed metric, and that makes Dusk’s Succinct Attestation mechanism more interesting to me.
A financial system needs to know when an entry can stop being provisional. With probabilistic finality, confidence increases over time as more blocks accumulate. That may work well for many crypto transactions, but institutional settlement has a different requirement: systems, counterparties and records eventually need a clear point at which the state is no longer open to revision.
Dusk’s SA mechanism is designed around committee voting, with a block becoming deterministically ratified after the required rounds of consensus.
That distinction changes how I think about settlement risk.
“Confidence can grow gradually. Finality should not.”
The investor question is whether deterministic finality creates measurable economic value. If institutions can reduce reconciliation delays, collateral buffers or uncertainty around ownership transfer, then the mechanism becomes part of the network’s financial utility rather than just a consensus specification.
There is an important trade-off, though. Committee-based systems concentrate security assumptions around validator selection, participation and governance. A deterministic outcome is only as reliable as the process that produces it.
I suspect the market may be underpricing that broader distinction: for financial infrastructure, knowing exactly when the ledger is done could matter as much as knowing how quickly it moved.
#dusk @Dusk $DUSK
A financial system needs to know when an entry can stop being provisional. With probabilistic finality, confidence increases over time as more blocks accumulate. That may work well for many crypto transactions, but institutional settlement has a different requirement: systems, counterparties and records eventually need a clear point at which the state is no longer open to revision.
Dusk’s SA mechanism is designed around committee voting, with a block becoming deterministically ratified after the required rounds of consensus.
That distinction changes how I think about settlement risk.
“Confidence can grow gradually. Finality should not.”
The investor question is whether deterministic finality creates measurable economic value. If institutions can reduce reconciliation delays, collateral buffers or uncertainty around ownership transfer, then the mechanism becomes part of the network’s financial utility rather than just a consensus specification.
There is an important trade-off, though. Committee-based systems concentrate security assumptions around validator selection, participation and governance. A deterministic outcome is only as reliable as the process that produces it.
I suspect the market may be underpricing that broader distinction: for financial infrastructure, knowing exactly when the ledger is done could matter as much as knowing how quickly it moved.
#dusk @Dusk $DUSK
4
4
1k
·
--
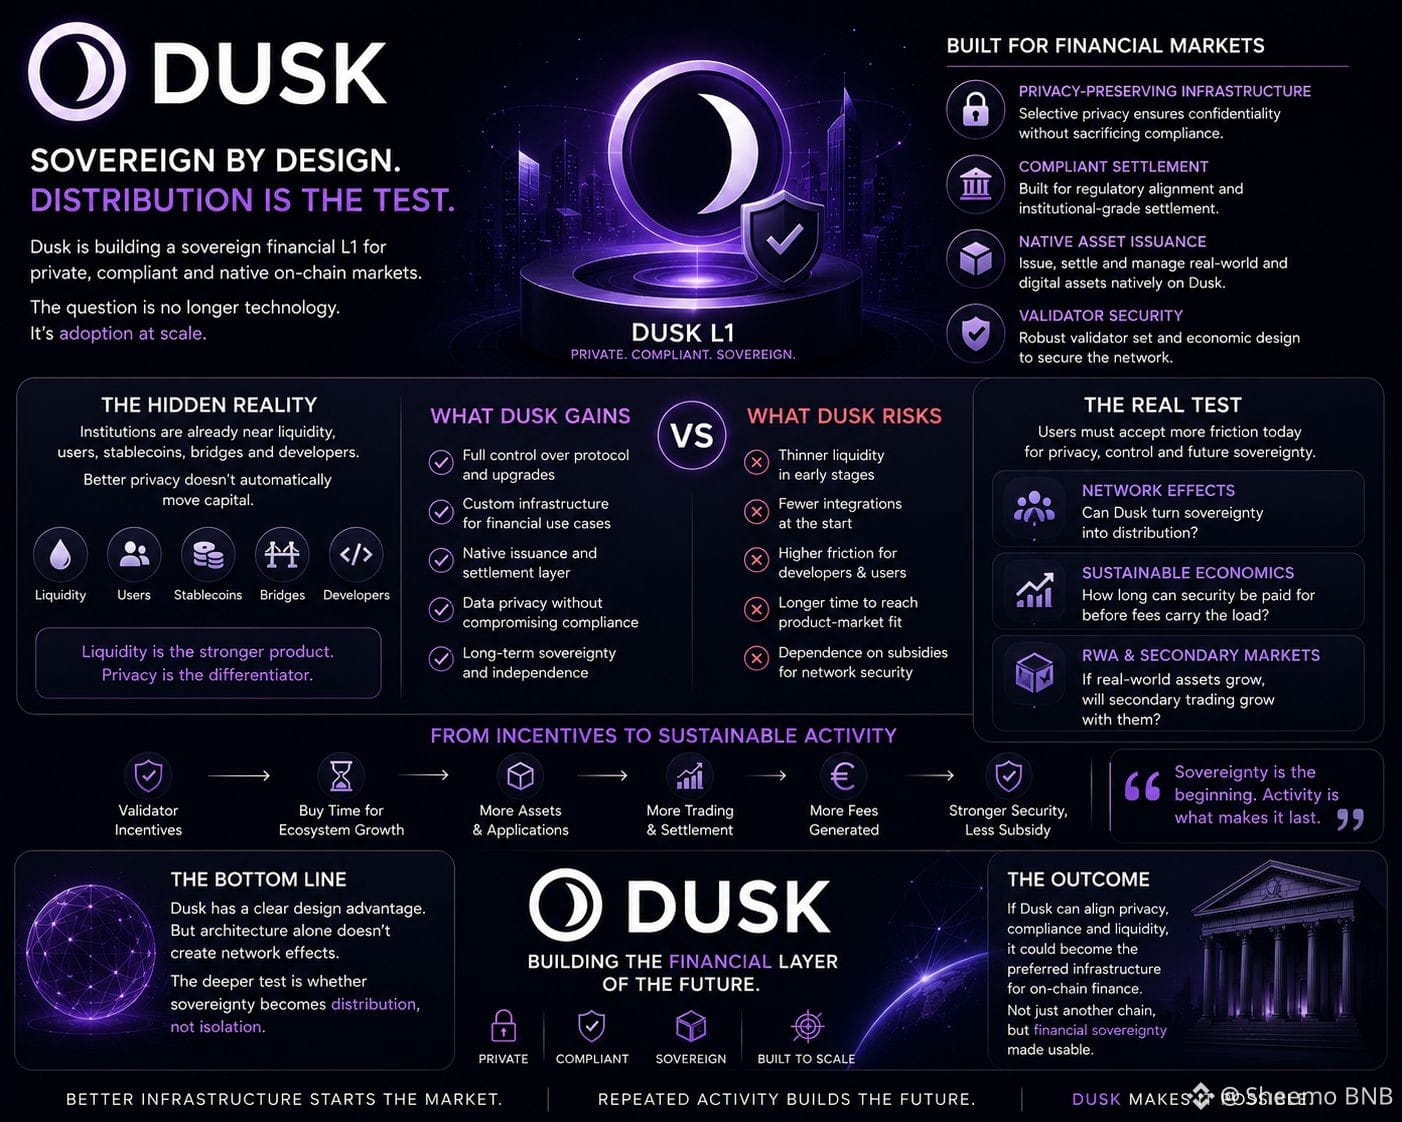
@Dusk_Foundation I’ve been looking at DUSK’s sovereign L1 design through a simpler lens: every layer of independence also creates another distribution problem.
A dedicated network can optimize privacy, compliant settlement and native asset infrastructure without inheriting another chain’s constraints. But it also means DUSK must attract the liquidity, applications and market participants that established ecosystems already aggregate.
For me, the important mechanism is native issuance. If regulated assets are issued and settled directly on Dusk, each new asset could create a reason for participants to remain within the network instead of treating it as a temporary execution layer.
That changes the economics of adoption.
“Distribution compounds when activity creates its own reason to stay.”
The point I’m still testing is whether RWA issuance can produce that loop. Primary issuance alone may generate impressive numbers while secondary liquidity remains thin. Without active trading, settlement demand and repeat capital flows, the network may still depend heavily on incentives to support security and participation.
I suspect the market may be focusing too much on what Dusk has built and not enough on whether each new financial product makes the next participant more likely to arrive.
Architecture starts the market. Recurring activity is what makes it durable.
#dusk @Dusk_Foundation $DUSK
{future}(DUSKUSDT)
$SPK
{future}(SPKUSDT)
$MORPHO
{future}(MORPHOUSDT)
@Dusk I’ve been looking at DUSK’s sovereign L1 design through a simpler lens: every layer of independence also creates another distribution problem.
A dedicated network can optimize privacy, compliant settlement and native asset infrastructure without inheriting another chain’s constraints. But it also means DUSK must attract the liquidity, applications and market participants that established ecosystems already aggregate.
For me, the important mechanism is native issuance. If regulated assets are issued and settled directly on Dusk, each new asset could create a reason for participants to remain within the network instead of treating it as a temporary execution layer.
That changes the economics of adoption.
“Distribution compounds when activity creates its own reason to stay.”
The point I’m still testing is whether RWA issuance can produce that loop. Primary issuance alone may generate impressive numbers while secondary liquidity remains thin. Without active trading, settlement demand and repeat capital flows, the network may still depend heavily on incentives to support security and participation.
I suspect the market may be focusing too much on what Dusk has built and not enough on whether each new financial product makes the next participant more likely to arrive.
Architecture starts the market. Recurring activity is what makes it durable.
#dusk @Dusk $DUSK
$SPK
$MORPHO
A dedicated network can optimize privacy, compliant settlement and native asset infrastructure without inheriting another chain’s constraints. But it also means DUSK must attract the liquidity, applications and market participants that established ecosystems already aggregate.
For me, the important mechanism is native issuance. If regulated assets are issued and settled directly on Dusk, each new asset could create a reason for participants to remain within the network instead of treating it as a temporary execution layer.
That changes the economics of adoption.
“Distribution compounds when activity creates its own reason to stay.”
The point I’m still testing is whether RWA issuance can produce that loop. Primary issuance alone may generate impressive numbers while secondary liquidity remains thin. Without active trading, settlement demand and repeat capital flows, the network may still depend heavily on incentives to support security and participation.
I suspect the market may be focusing too much on what Dusk has built and not enough on whether each new financial product makes the next participant more likely to arrive.
Architecture starts the market. Recurring activity is what makes it durable.
#dusk @Dusk $DUSK
$SPK
$MORPHO
7
10
178
·
--
#dusk $DUSK @Dusk_Foundation
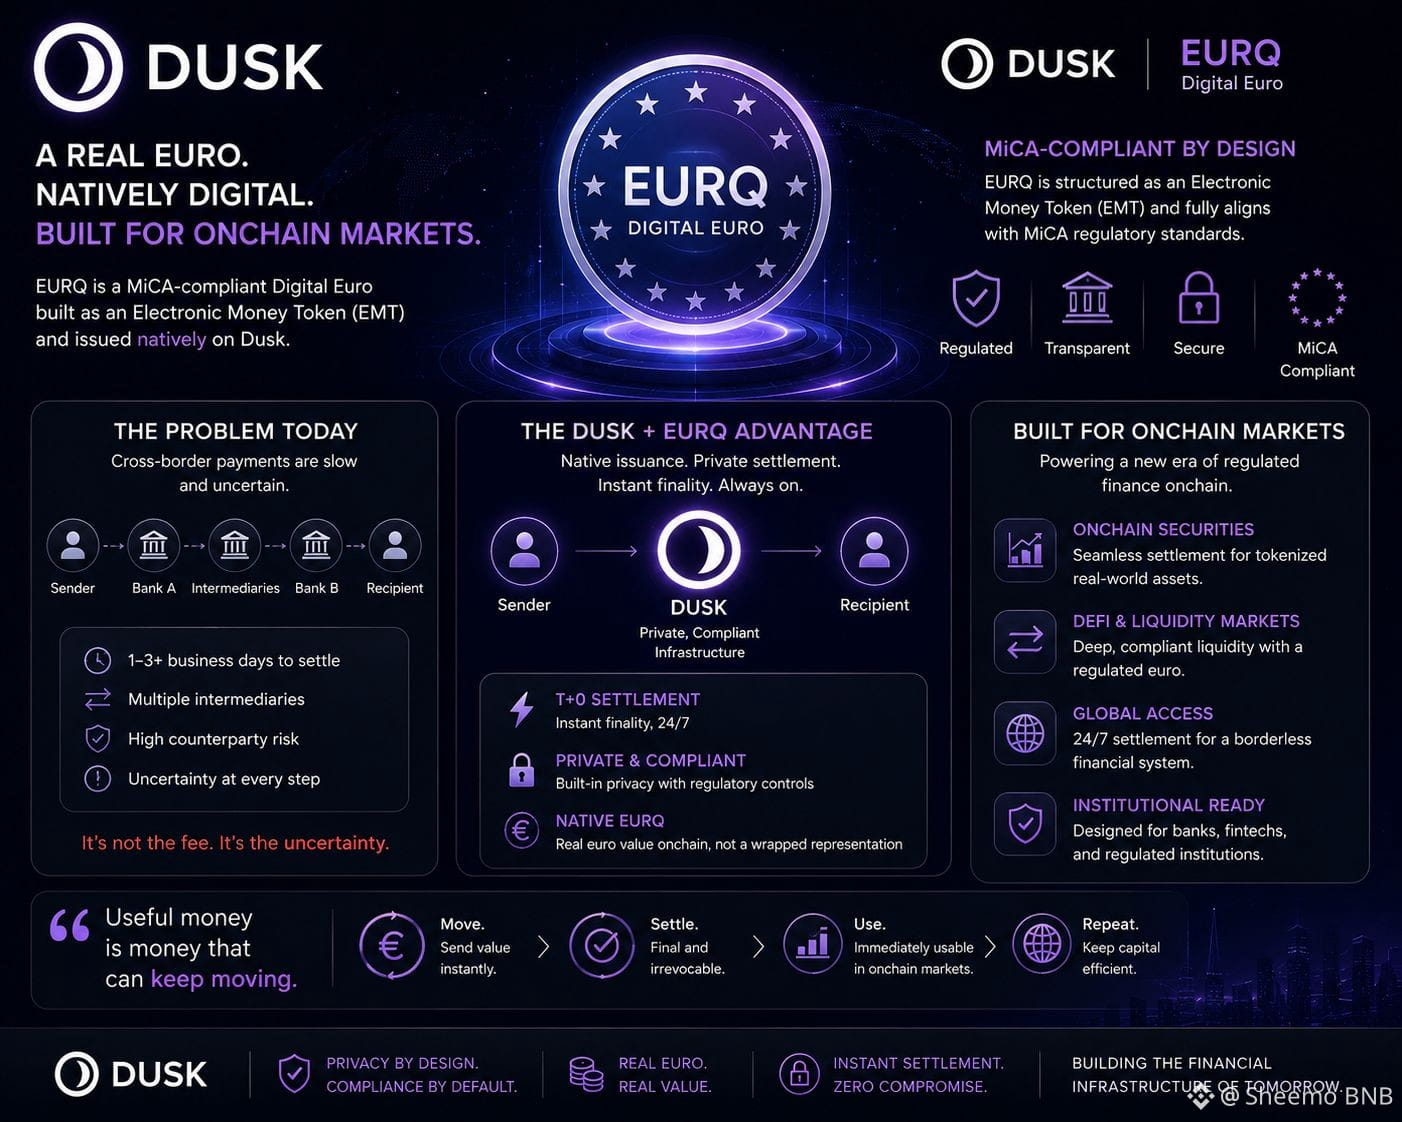
I keep coming back to one overlooked question around EURQ on Dusk: what makes a settlement asset economically useful after it becomes compliant?
EURQ’s structure as a MiCA-compliant Electronic Money Token matters because institutions do not assess money purely by technical speed. They need clarity around issuance, redemption and the rules governing the asset they are settling with.
Dusk adds another layer through native issuance and privacy-preserving infrastructure. In theory, that creates a cleaner route for regulated euro liquidity to interact with onchain securities and applications without relying on a wrapped representation moving across disconnected systems.
The part I would watch as an investor is velocity.
“Useful money is money that can keep moving.”
If EURQ can enter a transaction, settle an obligation and become immediately usable in the next compliant transaction, the value is not just faster payments. It is potentially less capital waiting between financial processes.
Still, regulation does not manufacture liquidity. A perfectly compliant settlement asset can remain economically quiet if market makers, venues and counterparties do not consistently route volume through it.
I suspect the market may be underestimating that distinction: compliance can open the door, but repeated settlement activity is what turns an asset into infrastructure.
#Dusk $TUT $TRUMP
{future}(TRUMPUSDT)
{future}(TUTUSDT)
{future}(DUSKUSDT)
#dusk $DUSK @Dusk
I keep coming back to one overlooked question around EURQ on Dusk: what makes a settlement asset economically useful after it becomes compliant?
EURQ’s structure as a MiCA-compliant Electronic Money Token matters because institutions do not assess money purely by technical speed. They need clarity around issuance, redemption and the rules governing the asset they are settling with.
Dusk adds another layer through native issuance and privacy-preserving infrastructure. In theory, that creates a cleaner route for regulated euro liquidity to interact with onchain securities and applications without relying on a wrapped representation moving across disconnected systems.
The part I would watch as an investor is velocity.
“Useful money is money that can keep moving.”
If EURQ can enter a transaction, settle an obligation and become immediately usable in the next compliant transaction, the value is not just faster payments. It is potentially less capital waiting between financial processes.
Still, regulation does not manufacture liquidity. A perfectly compliant settlement asset can remain economically quiet if market makers, venues and counterparties do not consistently route volume through it.
I suspect the market may be underestimating that distinction: compliance can open the door, but repeated settlement activity is what turns an asset into infrastructure.
#Dusk $TUT $TRUMP
I keep coming back to one overlooked question around EURQ on Dusk: what makes a settlement asset economically useful after it becomes compliant?
EURQ’s structure as a MiCA-compliant Electronic Money Token matters because institutions do not assess money purely by technical speed. They need clarity around issuance, redemption and the rules governing the asset they are settling with.
Dusk adds another layer through native issuance and privacy-preserving infrastructure. In theory, that creates a cleaner route for regulated euro liquidity to interact with onchain securities and applications without relying on a wrapped representation moving across disconnected systems.
The part I would watch as an investor is velocity.
“Useful money is money that can keep moving.”
If EURQ can enter a transaction, settle an obligation and become immediately usable in the next compliant transaction, the value is not just faster payments. It is potentially less capital waiting between financial processes.
Still, regulation does not manufacture liquidity. A perfectly compliant settlement asset can remain economically quiet if market makers, venues and counterparties do not consistently route volume through it.
I suspect the market may be underestimating that distinction: compliance can open the door, but repeated settlement activity is what turns an asset into infrastructure.
#Dusk $TUT $TRUMP
13
14
278
·
--
#dusk $DUSK @Dusk_Foundation
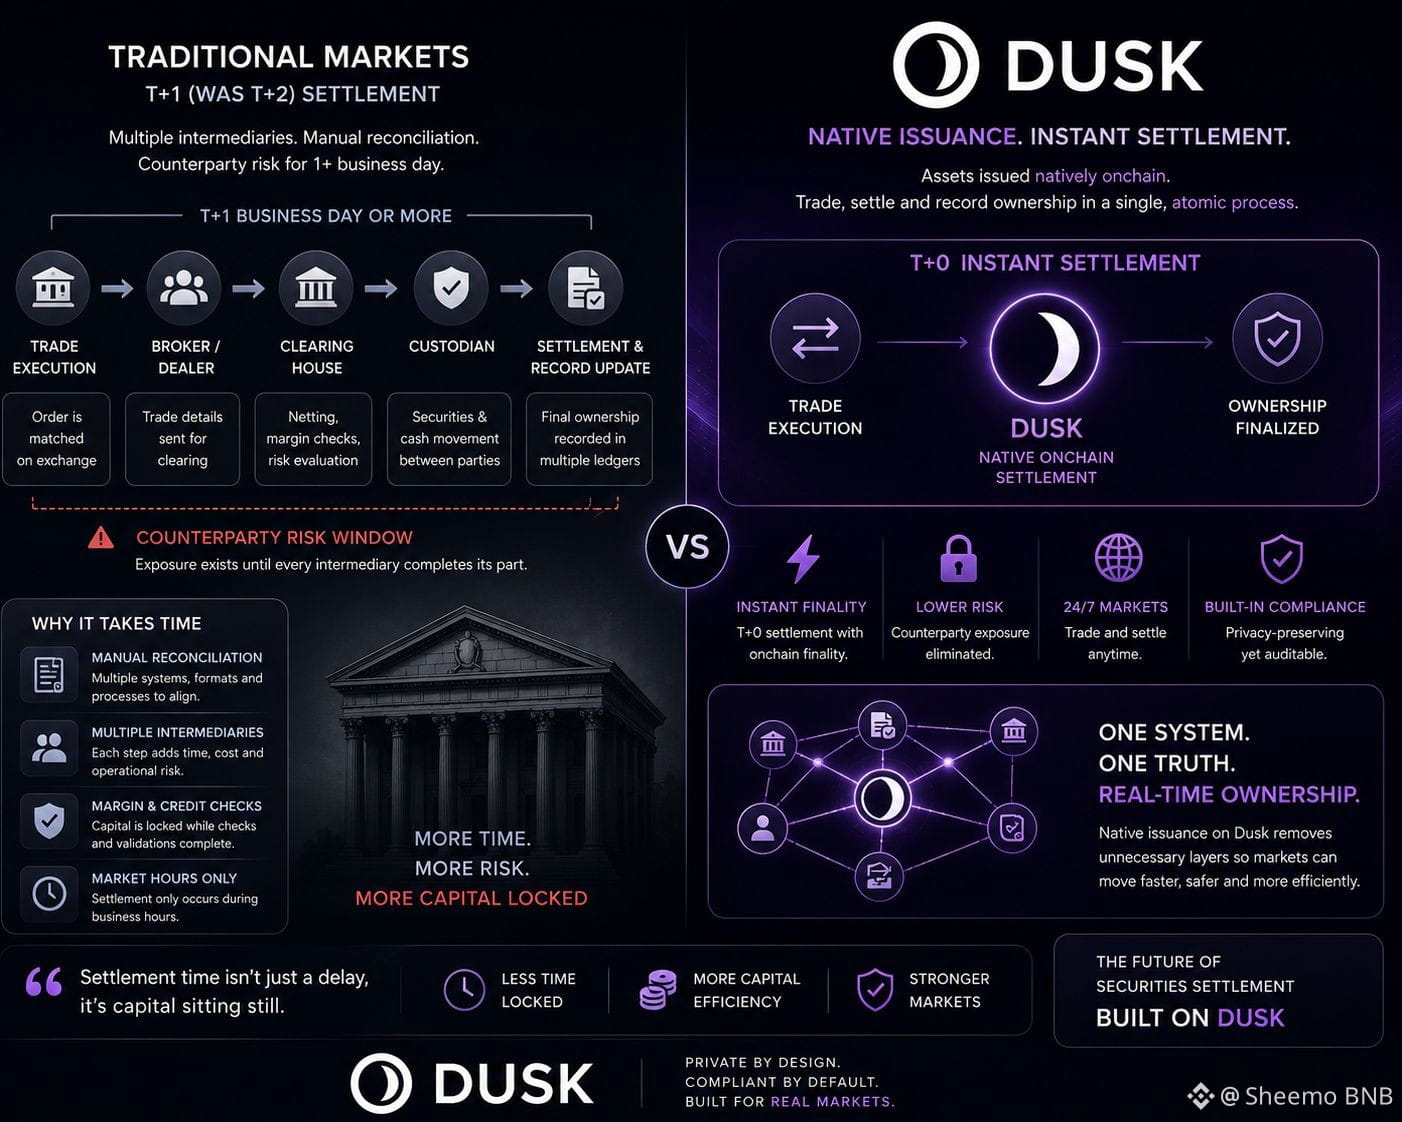
I’ve been thinking about Dusk’s native issuance model from a slightly different angle: settlement speed may matter less than balance-sheet efficiency.
When a security is issued natively onchain, ownership and settlement can happen within the same system.That potentially removes a layer of reconciliation between the trade and the final transfer of ownership.
For an investor, the interesting consequence is what happens to capital that would otherwise sit against unsettled positions. Faster finality could reduce the duration of counterparty exposure and the amount of collateral tied up waiting for multiple parties to complete their processes.
“Settlement time is also capital allocation time.”
That is why T+0 is more interesting to me than simply being faster than T+1 or T+2. If native issuance genuinely compresses the gap between execution and final ownership, it could change how efficiently regulated markets use liquidity.
Still, I think there is an important uncertainty here. Traditional settlement delays often contain operational safeguards, exception handling and compliance checks. Moving the asset onchain does not automatically remove those requirements.
The thesis becomes stronger only if Dusk can make compliance and instant settlement operate in the same workflow rather than shifting the old friction elsewhere.
#DUSK $BLESS $TUT
{future}(TUTUSDT)
{future}(BLESSUSDT)
{future}(DUSKUSDT)
#dusk $DUSK @Dusk
I’ve been thinking about Dusk’s native issuance model from a slightly different angle: settlement speed may matter less than balance-sheet efficiency.
When a security is issued natively onchain, ownership and settlement can happen within the same system.That potentially removes a layer of reconciliation between the trade and the final transfer of ownership.
For an investor, the interesting consequence is what happens to capital that would otherwise sit against unsettled positions. Faster finality could reduce the duration of counterparty exposure and the amount of collateral tied up waiting for multiple parties to complete their processes.
“Settlement time is also capital allocation time.”
That is why T+0 is more interesting to me than simply being faster than T+1 or T+2. If native issuance genuinely compresses the gap between execution and final ownership, it could change how efficiently regulated markets use liquidity.
Still, I think there is an important uncertainty here. Traditional settlement delays often contain operational safeguards, exception handling and compliance checks. Moving the asset onchain does not automatically remove those requirements.
The thesis becomes stronger only if Dusk can make compliance and instant settlement operate in the same workflow rather than shifting the old friction elsewhere.
#DUSK $BLESS $TUT
I’ve been thinking about Dusk’s native issuance model from a slightly different angle: settlement speed may matter less than balance-sheet efficiency.
When a security is issued natively onchain, ownership and settlement can happen within the same system.That potentially removes a layer of reconciliation between the trade and the final transfer of ownership.
For an investor, the interesting consequence is what happens to capital that would otherwise sit against unsettled positions. Faster finality could reduce the duration of counterparty exposure and the amount of collateral tied up waiting for multiple parties to complete their processes.
“Settlement time is also capital allocation time.”
That is why T+0 is more interesting to me than simply being faster than T+1 or T+2. If native issuance genuinely compresses the gap between execution and final ownership, it could change how efficiently regulated markets use liquidity.
Still, I think there is an important uncertainty here. Traditional settlement delays often contain operational safeguards, exception handling and compliance checks. Moving the asset onchain does not automatically remove those requirements.
The thesis becomes stronger only if Dusk can make compliance and instant settlement operate in the same workflow rather than shifting the old friction elsewhere.
#DUSK $BLESS $TUT
15
18
452
·
--
#dusk $DUSK @Dusk_Foundation
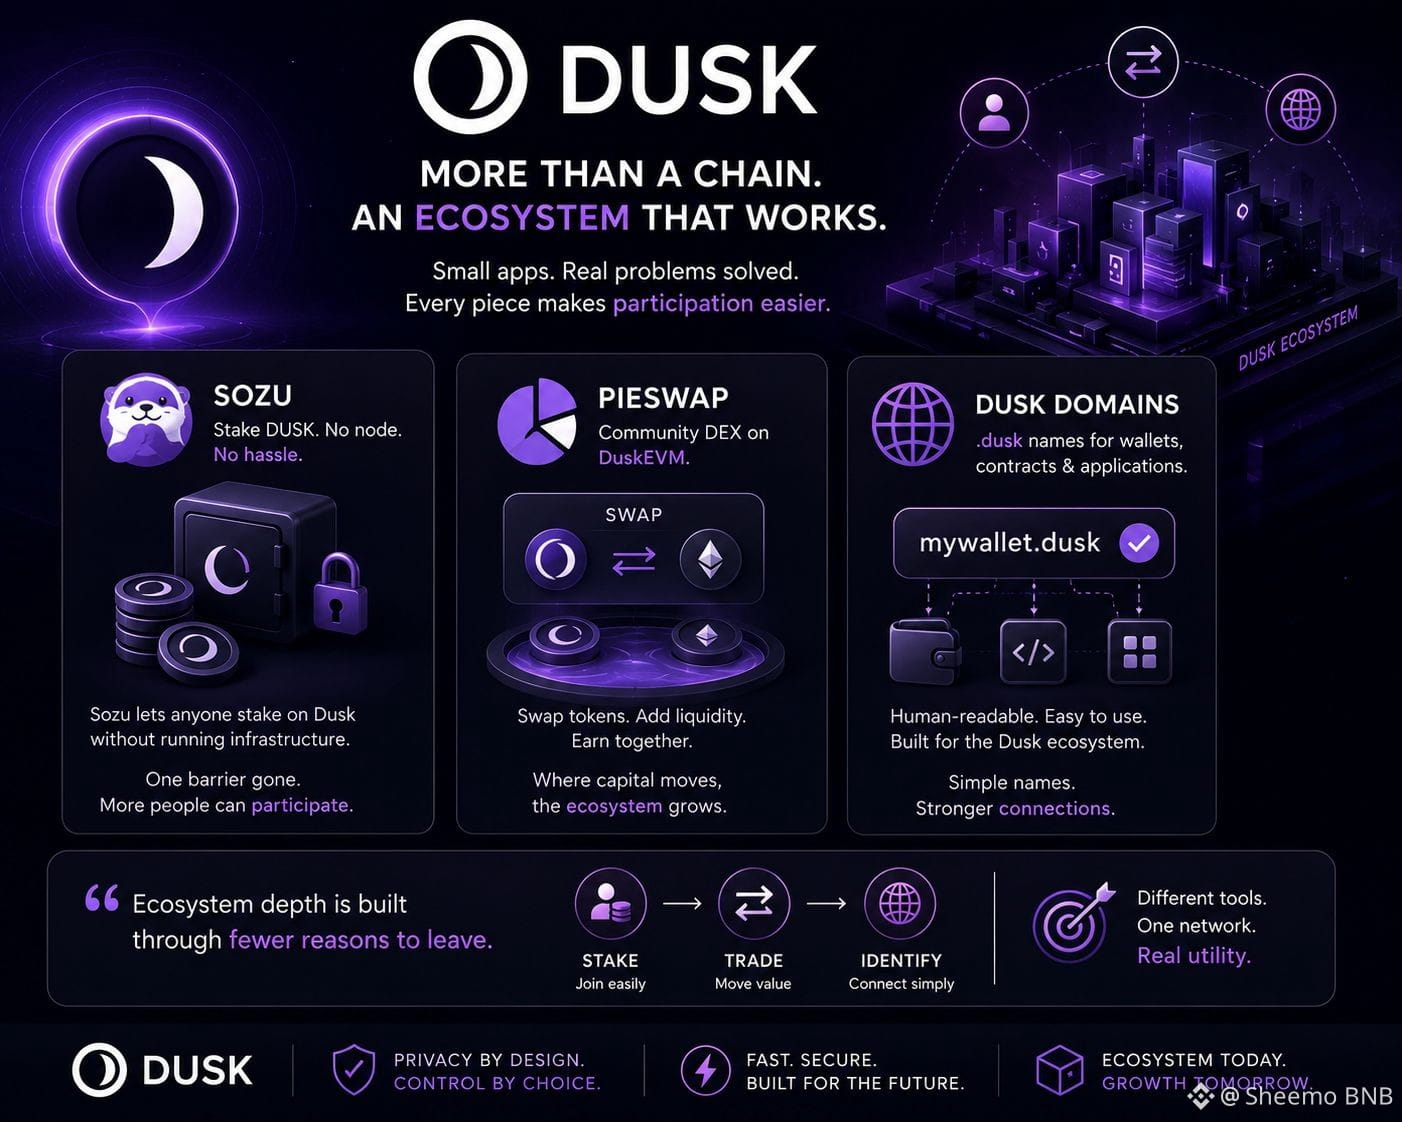
I’ve been paying more attention to the order in which a blockchain ecosystem becomes useful, and Dusk offers an interesting case.
Infrastructure usually gets the attention first, but participation often depends on smaller applications removing specific points of friction. Sozu, for example, changes the staking decision for users who want exposure to the network without taking on the operational burden of running infrastructure themselves.
PieSwap adds a different layer. As a DEX on DuskEVM, it gives capital somewhere to move after it enters the ecosystem. That distinction matters to me because staked capital and active liquidity serve very different economic roles.
Dusk Domains may look even smaller, but readable identities can reduce friction across wallets, contracts and applications.
“Ecosystem depth is built through fewer reasons to leave.”
I think the market can sometimes overestimate an ecosystem by counting applications rather than examining the handoffs between them. The stronger signal is whether one use naturally creates a reason to use the next.
The weakness is that convenience alone does not guarantee retention. These applications still need reliable liquidity and recurring user demand.
If Dusk’s ecosystem can turn participation into a connected sequence rather than isolated actions, that becomes a much more meaningful measure of network utility.
#Dusk
$ACE
$ONG
{future}(ONGUSDT)
{future}(ACEUSDT)
{future}(DUSKUSDT)
#dusk $DUSK @Dusk
I’ve been paying more attention to the order in which a blockchain ecosystem becomes useful, and Dusk offers an interesting case.
Infrastructure usually gets the attention first, but participation often depends on smaller applications removing specific points of friction. Sozu, for example, changes the staking decision for users who want exposure to the network without taking on the operational burden of running infrastructure themselves.
PieSwap adds a different layer. As a DEX on DuskEVM, it gives capital somewhere to move after it enters the ecosystem. That distinction matters to me because staked capital and active liquidity serve very different economic roles.
Dusk Domains may look even smaller, but readable identities can reduce friction across wallets, contracts and applications.
“Ecosystem depth is built through fewer reasons to leave.”
I think the market can sometimes overestimate an ecosystem by counting applications rather than examining the handoffs between them. The stronger signal is whether one use naturally creates a reason to use the next.
The weakness is that convenience alone does not guarantee retention. These applications still need reliable liquidity and recurring user demand.
If Dusk’s ecosystem can turn participation into a connected sequence rather than isolated actions, that becomes a much more meaningful measure of network utility.
#Dusk
$ACE
$ONG
I’ve been paying more attention to the order in which a blockchain ecosystem becomes useful, and Dusk offers an interesting case.
Infrastructure usually gets the attention first, but participation often depends on smaller applications removing specific points of friction. Sozu, for example, changes the staking decision for users who want exposure to the network without taking on the operational burden of running infrastructure themselves.
PieSwap adds a different layer. As a DEX on DuskEVM, it gives capital somewhere to move after it enters the ecosystem. That distinction matters to me because staked capital and active liquidity serve very different economic roles.
Dusk Domains may look even smaller, but readable identities can reduce friction across wallets, contracts and applications.
“Ecosystem depth is built through fewer reasons to leave.”
I think the market can sometimes overestimate an ecosystem by counting applications rather than examining the handoffs between them. The stronger signal is whether one use naturally creates a reason to use the next.
The weakness is that convenience alone does not guarantee retention. These applications still need reliable liquidity and recurring user demand.
If Dusk’s ecosystem can turn participation into a connected sequence rather than isolated actions, that becomes a much more meaningful measure of network utility.
#Dusk
$ACE
$ONG
8
6
225
·
--
#dusk $DUSK @Dusk_Foundation
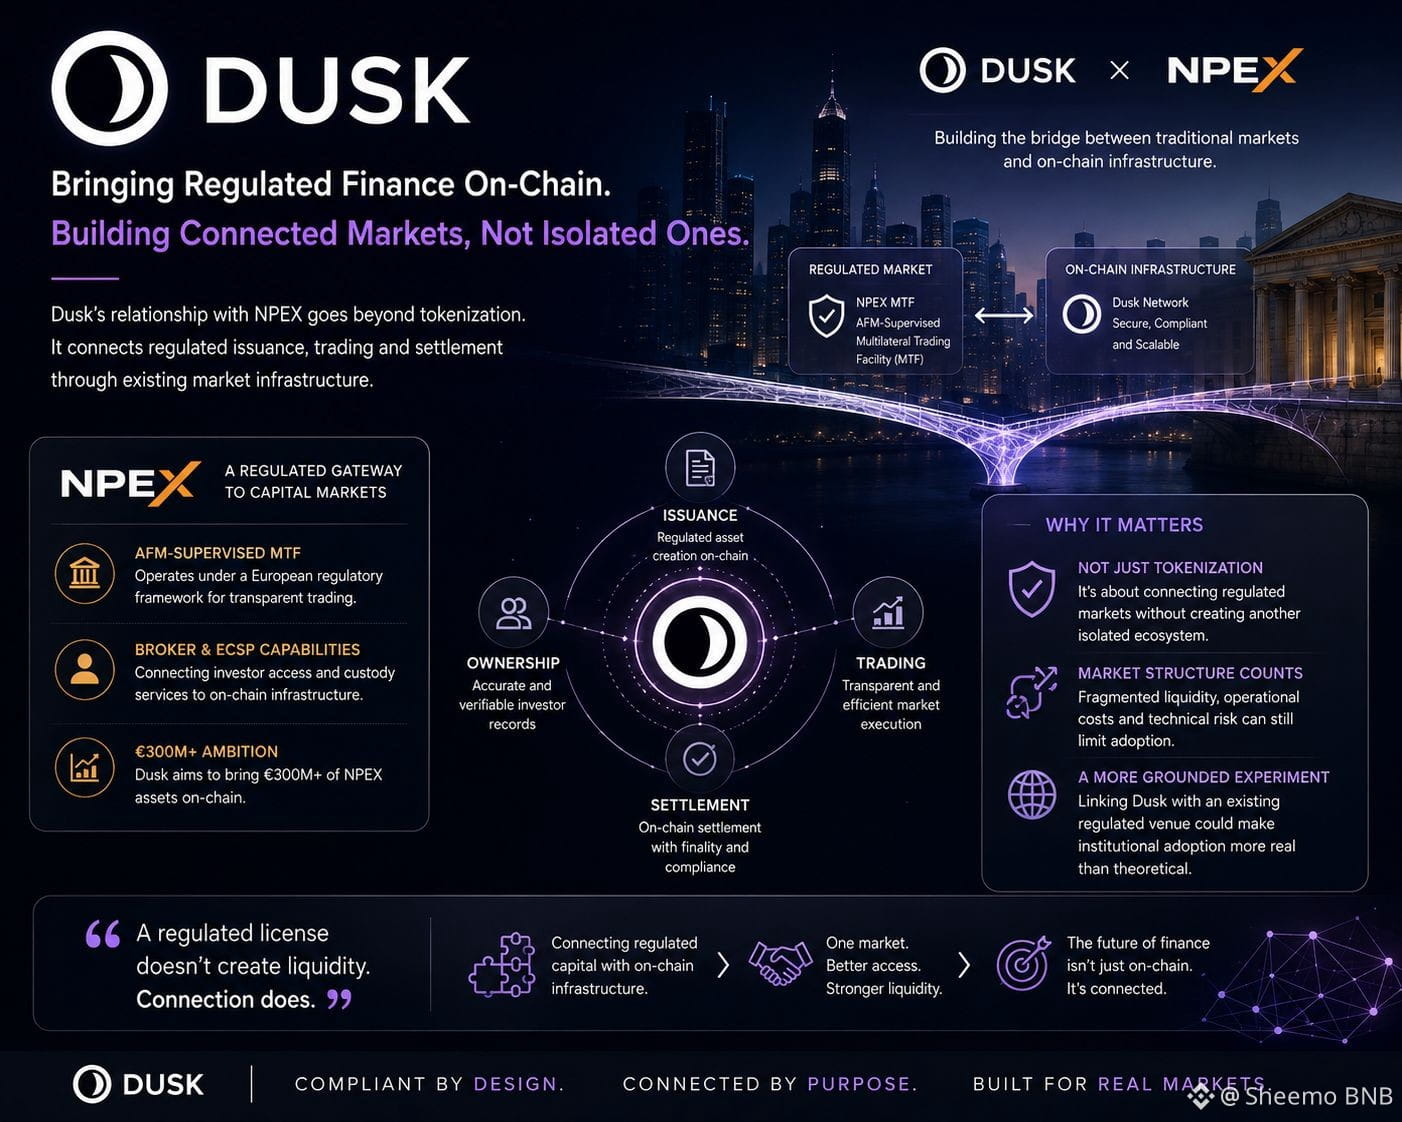
I’ve started viewing Dusk’s NPEX connection less as a tokenization milestone and more as a test of whether onchain infrastructure can preserve the quality of an existing market.
The interesting part is that NPEX already operates within a regulated trading environment. Bringing securities onchain therefore isn’t enough; the real challenge is keeping issuance, ownership records, trading and settlement consistent across systems.
That makes Dusk’s €300M+ ambition more interesting to me than the headline itself. If assets move onchain but liquidity, pricing and investor access remain fragmented, the blockchain layer may simply add another reconciliation burden.
“Tokenization only creates value when the market around the token improves.”
I also think the Broker and ECSP connection matters because it points toward infrastructure around the asset, not just the asset representation itself.
The weakness is that regulated integration can still be operationally heavy. Compliance requirements, venue liquidity and institutional workflows don’t disappear because settlement moves onto a blockchain.
What I’ll be watching is whether Dusk can reduce the number of disconnected steps between regulated capital and onchain settlement. If it can, the value proposition becomes much more measurable than simply putting securities on a ledger.
#DUSK $HEMI $TREE
{future}(TREEUSDT)
{future}(HEMIUSDT)
{future}(DUSKUSDT)
#dusk $DUSK @Dusk
I’ve started viewing Dusk’s NPEX connection less as a tokenization milestone and more as a test of whether onchain infrastructure can preserve the quality of an existing market.
The interesting part is that NPEX already operates within a regulated trading environment. Bringing securities onchain therefore isn’t enough; the real challenge is keeping issuance, ownership records, trading and settlement consistent across systems.
That makes Dusk’s €300M+ ambition more interesting to me than the headline itself. If assets move onchain but liquidity, pricing and investor access remain fragmented, the blockchain layer may simply add another reconciliation burden.
“Tokenization only creates value when the market around the token improves.”
I also think the Broker and ECSP connection matters because it points toward infrastructure around the asset, not just the asset representation itself.
The weakness is that regulated integration can still be operationally heavy. Compliance requirements, venue liquidity and institutional workflows don’t disappear because settlement moves onto a blockchain.
What I’ll be watching is whether Dusk can reduce the number of disconnected steps between regulated capital and onchain settlement. If it can, the value proposition becomes much more measurable than simply putting securities on a ledger.
#DUSK $HEMI $TREE
I’ve started viewing Dusk’s NPEX connection less as a tokenization milestone and more as a test of whether onchain infrastructure can preserve the quality of an existing market.
The interesting part is that NPEX already operates within a regulated trading environment. Bringing securities onchain therefore isn’t enough; the real challenge is keeping issuance, ownership records, trading and settlement consistent across systems.
That makes Dusk’s €300M+ ambition more interesting to me than the headline itself. If assets move onchain but liquidity, pricing and investor access remain fragmented, the blockchain layer may simply add another reconciliation burden.
“Tokenization only creates value when the market around the token improves.”
I also think the Broker and ECSP connection matters because it points toward infrastructure around the asset, not just the asset representation itself.
The weakness is that regulated integration can still be operationally heavy. Compliance requirements, venue liquidity and institutional workflows don’t disappear because settlement moves onto a blockchain.
What I’ll be watching is whether Dusk can reduce the number of disconnected steps between regulated capital and onchain settlement. If it can, the value proposition becomes much more measurable than simply putting securities on a ledger.
#DUSK $HEMI $TREE
16
11
461
·
--
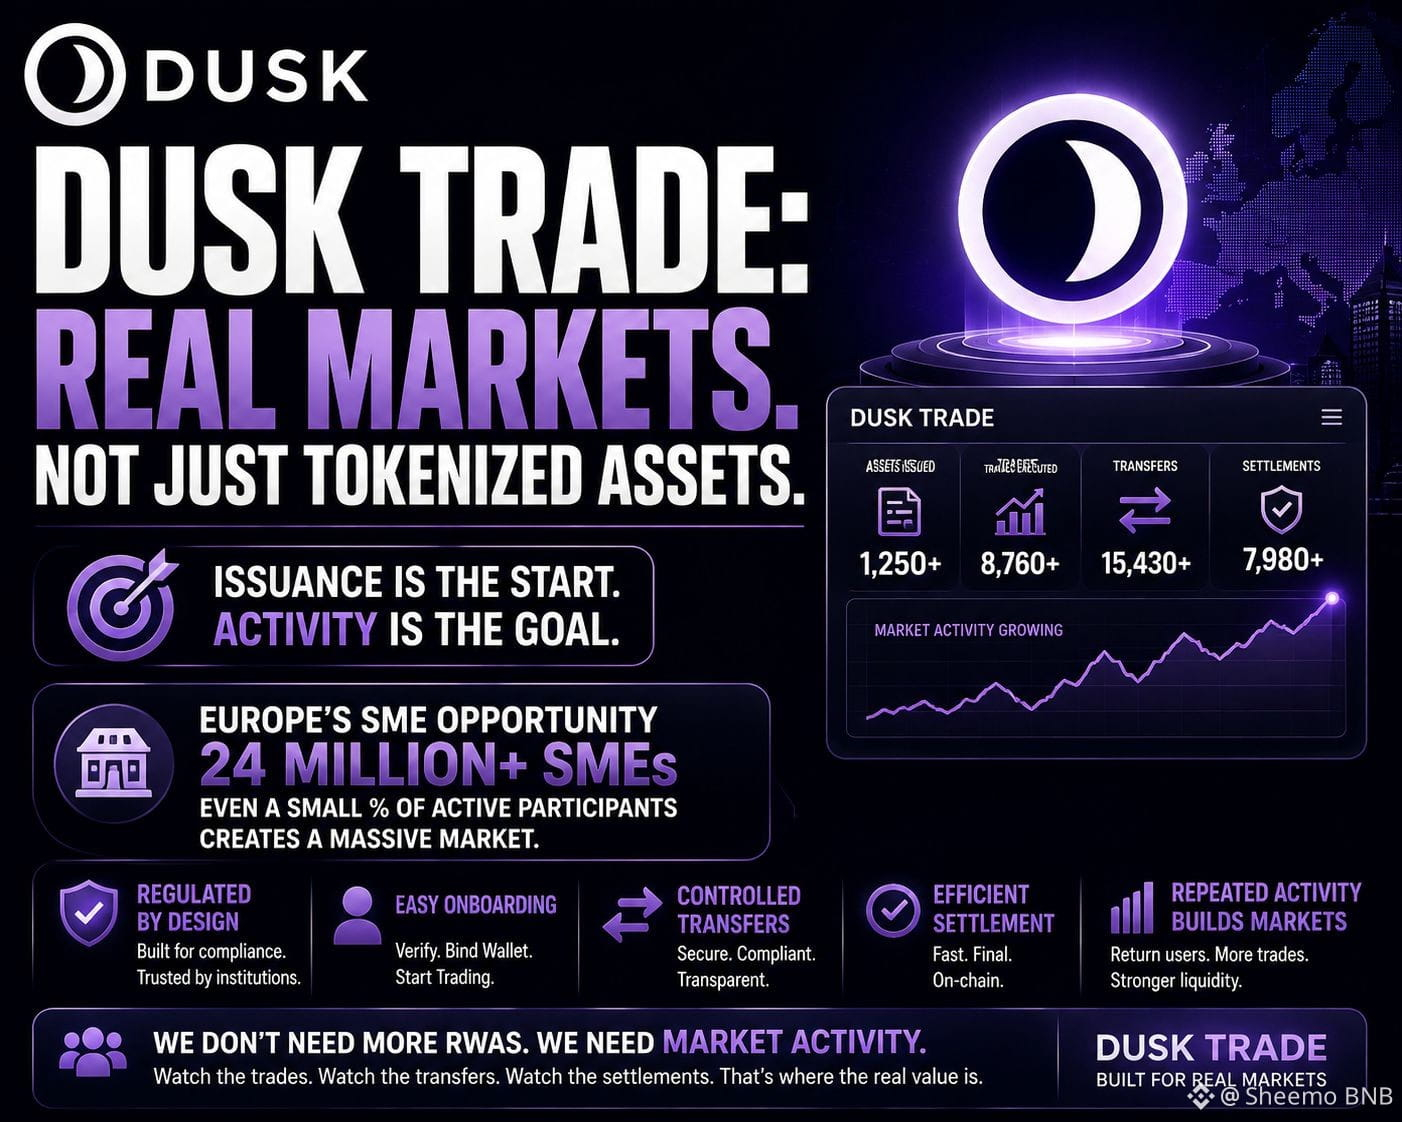
@Dusk_Foundation I’ve been looking at Dusk Trade through a slightly different lens: the quality of liquidity that remains after the first transaction.
A regulated RWA market can record successful onboarding, wallet binding, controlled transfers, and settlement while still producing very little organic trading. For me, the stronger signal would be whether participants begin routing activity through the same market repeatedly because execution is actually useful.
That makes secondary-market behavior important. If an asset is issued on Dusk but buyers rarely return, liquidity may be technically available without being economically reliable. Conversely, recurring transfers between unrelated participants would suggest the platform is becoming part of their normal workflow rather than a one-time issuance rail.
“Liquidity is proven by the second transaction, not the first.”
I’d therefore pay attention to participant concentration, transfer frequency, settlement volume, and how much activity comes from returning users rather than newly onboarded accounts.
There is a fair weakness here: early regulated markets naturally have slower liquidity formation because compliance and institutional onboarding add friction. Low initial turnover alone wouldn’t tell me much.
But if Dusk Trade can convert compliant onboarding into repeat market behavior, that would be a much stronger validation of the RWA thesis than the raw number of assets launched.
#dusk @Dusk_Foundation #Dusk $DUSK
{future}(DUSKUSDT)
@Dusk I’ve been looking at Dusk Trade through a slightly different lens: the quality of liquidity that remains after the first transaction.
A regulated RWA market can record successful onboarding, wallet binding, controlled transfers, and settlement while still producing very little organic trading. For me, the stronger signal would be whether participants begin routing activity through the same market repeatedly because execution is actually useful.
That makes secondary-market behavior important. If an asset is issued on Dusk but buyers rarely return, liquidity may be technically available without being economically reliable. Conversely, recurring transfers between unrelated participants would suggest the platform is becoming part of their normal workflow rather than a one-time issuance rail.
“Liquidity is proven by the second transaction, not the first.”
I’d therefore pay attention to participant concentration, transfer frequency, settlement volume, and how much activity comes from returning users rather than newly onboarded accounts.
There is a fair weakness here: early regulated markets naturally have slower liquidity formation because compliance and institutional onboarding add friction. Low initial turnover alone wouldn’t tell me much.
But if Dusk Trade can convert compliant onboarding into repeat market behavior, that would be a much stronger validation of the RWA thesis than the raw number of assets launched.
#dusk @Dusk #Dusk $DUSK
A regulated RWA market can record successful onboarding, wallet binding, controlled transfers, and settlement while still producing very little organic trading. For me, the stronger signal would be whether participants begin routing activity through the same market repeatedly because execution is actually useful.
That makes secondary-market behavior important. If an asset is issued on Dusk but buyers rarely return, liquidity may be technically available without being economically reliable. Conversely, recurring transfers between unrelated participants would suggest the platform is becoming part of their normal workflow rather than a one-time issuance rail.
“Liquidity is proven by the second transaction, not the first.”
I’d therefore pay attention to participant concentration, transfer frequency, settlement volume, and how much activity comes from returning users rather than newly onboarded accounts.
There is a fair weakness here: early regulated markets naturally have slower liquidity formation because compliance and institutional onboarding add friction. Low initial turnover alone wouldn’t tell me much.
But if Dusk Trade can convert compliant onboarding into repeat market behavior, that would be a much stronger validation of the RWA thesis than the raw number of assets launched.
#dusk @Dusk #Dusk $DUSK
17
10
99
·
--
@Dusk_Foundation I keep coming back to one operational detail in Dusk: selective disclosure only matters if it reduces the amount of information institutions need to exchange outside the ledger.
Phoenix is interesting here because privacy is not simply about hiding transaction data. It can let counterparties prove the information required for a regulated workflow without exposing everything else. In securities markets, that distinction could affect reconciliation, compliance checks, and how many parties need access to the same underlying data.
That creates a useful investor metric for me: how many manual verification steps can actually disappear?
If an issuer, venue, custodian, and settlement layer can independently verify the required state from the same infrastructure, Dusk may be creating value through fewer coordination points rather than simply faster transactions.
“Privacy becomes infrastructure when it removes operational friction.”
The weakness is that institutions may still maintain parallel records for legal, internal-control, or risk reasons. In that case, Dusk could technically compress settlement while leaving the surrounding accounting burden largely intact.
So I’d watch the workflow, not just throughput: how much reconciliation is eliminated, how often participants rely on the same settlement state, and whether that reliance persists beyond pilot deployments.
#dusk #Dusk $DUSK $GPS $TUT
{future}(DUSKUSDT)
{future}(GPSUSDT)
What matters most for Dusk’s institutional adoption?
@Dusk I keep coming back to one operational detail in Dusk: selective disclosure only matters if it reduces the amount of information institutions need to exchange outside the ledger.
Phoenix is interesting here because privacy is not simply about hiding transaction data. It can let counterparties prove the information required for a regulated workflow without exposing everything else. In securities markets, that distinction could affect reconciliation, compliance checks, and how many parties need access to the same underlying data.
That creates a useful investor metric for me: how many manual verification steps can actually disappear?
If an issuer, venue, custodian, and settlement layer can independently verify the required state from the same infrastructure, Dusk may be creating value through fewer coordination points rather than simply faster transactions.
“Privacy becomes infrastructure when it removes operational friction.”
The weakness is that institutions may still maintain parallel records for legal, internal-control, or risk reasons. In that case, Dusk could technically compress settlement while leaving the surrounding accounting burden largely intact.
So I’d watch the workflow, not just throughput: how much reconciliation is eliminated, how often participants rely on the same settlement state, and whether that reliance persists beyond pilot deployments.
#dusk #Dusk $DUSK $GPS $TUT
What matters most for Dusk’s institutional adoption?
Phoenix is interesting here because privacy is not simply about hiding transaction data. It can let counterparties prove the information required for a regulated workflow without exposing everything else. In securities markets, that distinction could affect reconciliation, compliance checks, and how many parties need access to the same underlying data.
That creates a useful investor metric for me: how many manual verification steps can actually disappear?
If an issuer, venue, custodian, and settlement layer can independently verify the required state from the same infrastructure, Dusk may be creating value through fewer coordination points rather than simply faster transactions.
“Privacy becomes infrastructure when it removes operational friction.”
The weakness is that institutions may still maintain parallel records for legal, internal-control, or risk reasons. In that case, Dusk could technically compress settlement while leaving the surrounding accounting burden largely intact.
So I’d watch the workflow, not just throughput: how much reconciliation is eliminated, how often participants rely on the same settlement state, and whether that reliance persists beyond pilot deployments.
#dusk #Dusk $DUSK $GPS $TUT
What matters most for Dusk’s institutional adoption?
🔐 Privacy
100%
⚡ Settlement
0%
📊 Reconciliation
0%
4 Votes • Vote fermé
17
8
282
·
--
@Dusk_Foundation
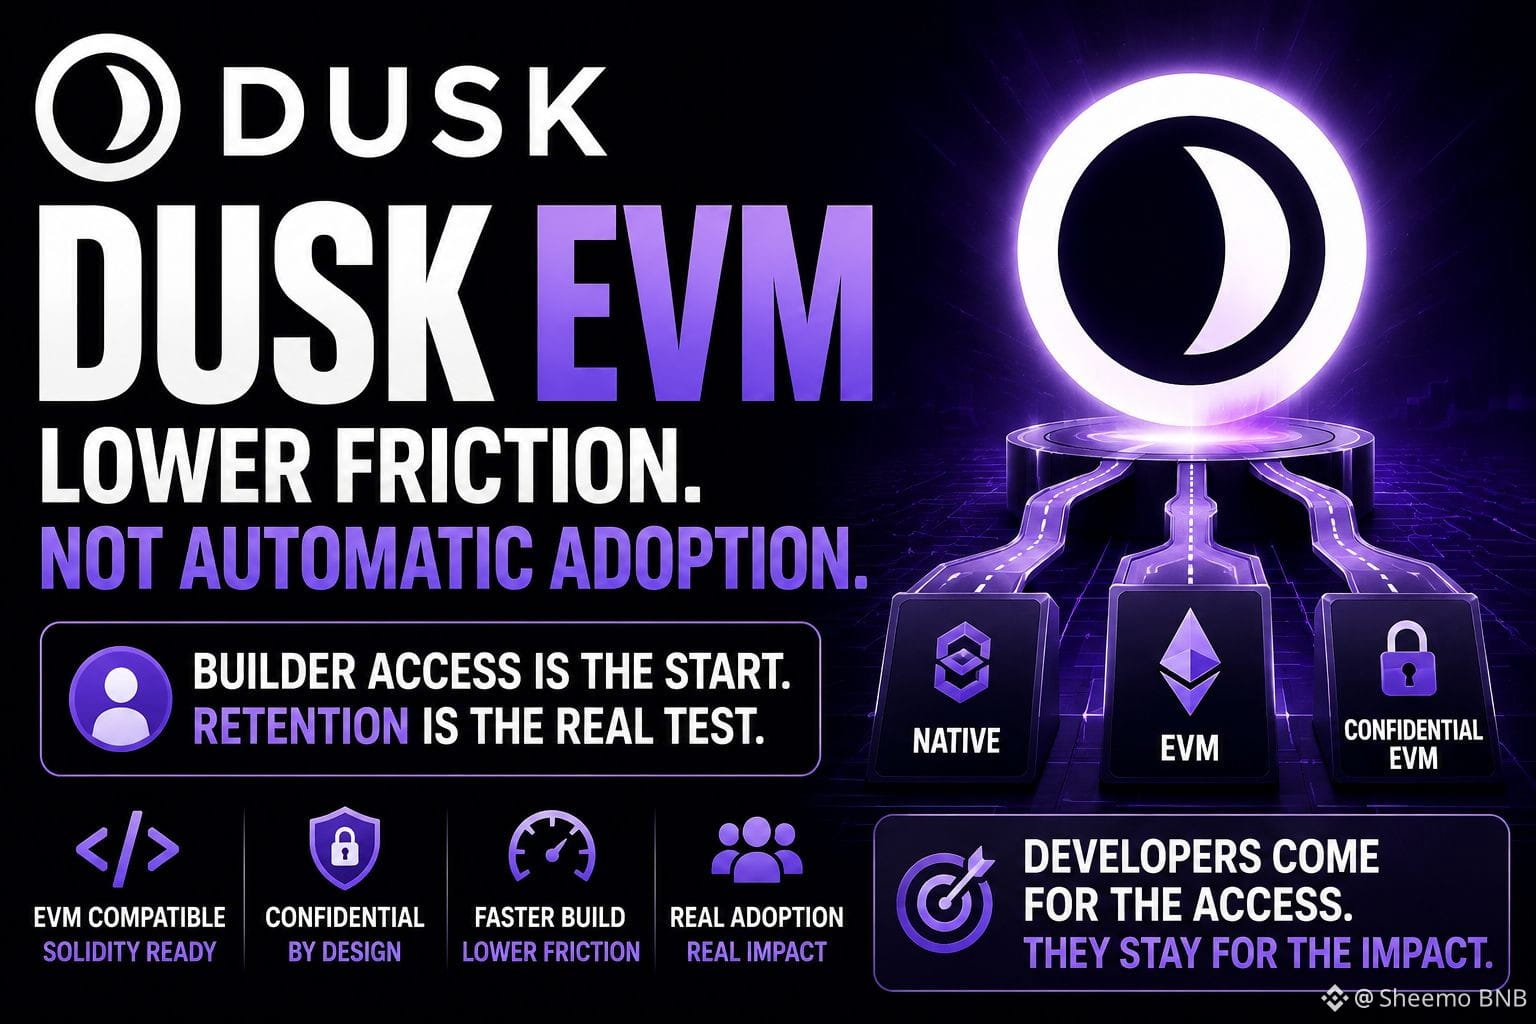
I’ve been looking at DuskEVM less as a developer acquisition tool and more as a routing problem.
Adding an EVM path gives Solidity teams a familiar execution environment, while Confidential EVM adds another option for applications that need privacy. That is useful, but it also creates a subtle measurement issue: activity can spread across three development environments without producing a stronger network effect.
For an investor, I’d want to know whether users and capital actually move between these paths.
A developer might deploy through EVM because onboarding is easy, while the application’s real advantage only appears once users interact with confidential transactions. If those users, assets, and liquidity remain isolated, Dusk has increased technical accessibility without necessarily increasing economic connectivity.
“More entry points only matter when they converge on the same network effect.”
That is the metric I’d watch: not deployments by environment, but how often applications graduate from experimentation into recurring usage, and whether liquidity follows them.
The weakness is obvious: early-stage infrastructure can look fragmented simply because adoption is still forming. So I wouldn’t treat separate activity as failure by itself.
But if DuskEVM becomes a convenient place to deploy rather than a bridge into Dusk’s privacy-focused economic layer, the developer story will be stronger than the adoption story.
#dusk #Dusk $DUSK $PORTAL $APR
{future}(APRUSDT)
{future}(PORTALUSDT)
{future}(DUSKUSDT)
@Dusk
I’ve been looking at DuskEVM less as a developer acquisition tool and more as a routing problem.
Adding an EVM path gives Solidity teams a familiar execution environment, while Confidential EVM adds another option for applications that need privacy. That is useful, but it also creates a subtle measurement issue: activity can spread across three development environments without producing a stronger network effect.
For an investor, I’d want to know whether users and capital actually move between these paths.
A developer might deploy through EVM because onboarding is easy, while the application’s real advantage only appears once users interact with confidential transactions. If those users, assets, and liquidity remain isolated, Dusk has increased technical accessibility without necessarily increasing economic connectivity.
“More entry points only matter when they converge on the same network effect.”
That is the metric I’d watch: not deployments by environment, but how often applications graduate from experimentation into recurring usage, and whether liquidity follows them.
The weakness is obvious: early-stage infrastructure can look fragmented simply because adoption is still forming. So I wouldn’t treat separate activity as failure by itself.
But if DuskEVM becomes a convenient place to deploy rather than a bridge into Dusk’s privacy-focused economic layer, the developer story will be stronger than the adoption story.
#dusk #Dusk $DUSK $PORTAL $APR
I’ve been looking at DuskEVM less as a developer acquisition tool and more as a routing problem.
Adding an EVM path gives Solidity teams a familiar execution environment, while Confidential EVM adds another option for applications that need privacy. That is useful, but it also creates a subtle measurement issue: activity can spread across three development environments without producing a stronger network effect.
For an investor, I’d want to know whether users and capital actually move between these paths.
A developer might deploy through EVM because onboarding is easy, while the application’s real advantage only appears once users interact with confidential transactions. If those users, assets, and liquidity remain isolated, Dusk has increased technical accessibility without necessarily increasing economic connectivity.
“More entry points only matter when they converge on the same network effect.”
That is the metric I’d watch: not deployments by environment, but how often applications graduate from experimentation into recurring usage, and whether liquidity follows them.
The weakness is obvious: early-stage infrastructure can look fragmented simply because adoption is still forming. So I wouldn’t treat separate activity as failure by itself.
But if DuskEVM becomes a convenient place to deploy rather than a bridge into Dusk’s privacy-focused economic layer, the developer story will be stronger than the adoption story.
#dusk #Dusk $DUSK $PORTAL $APR
23
11
783
·
--
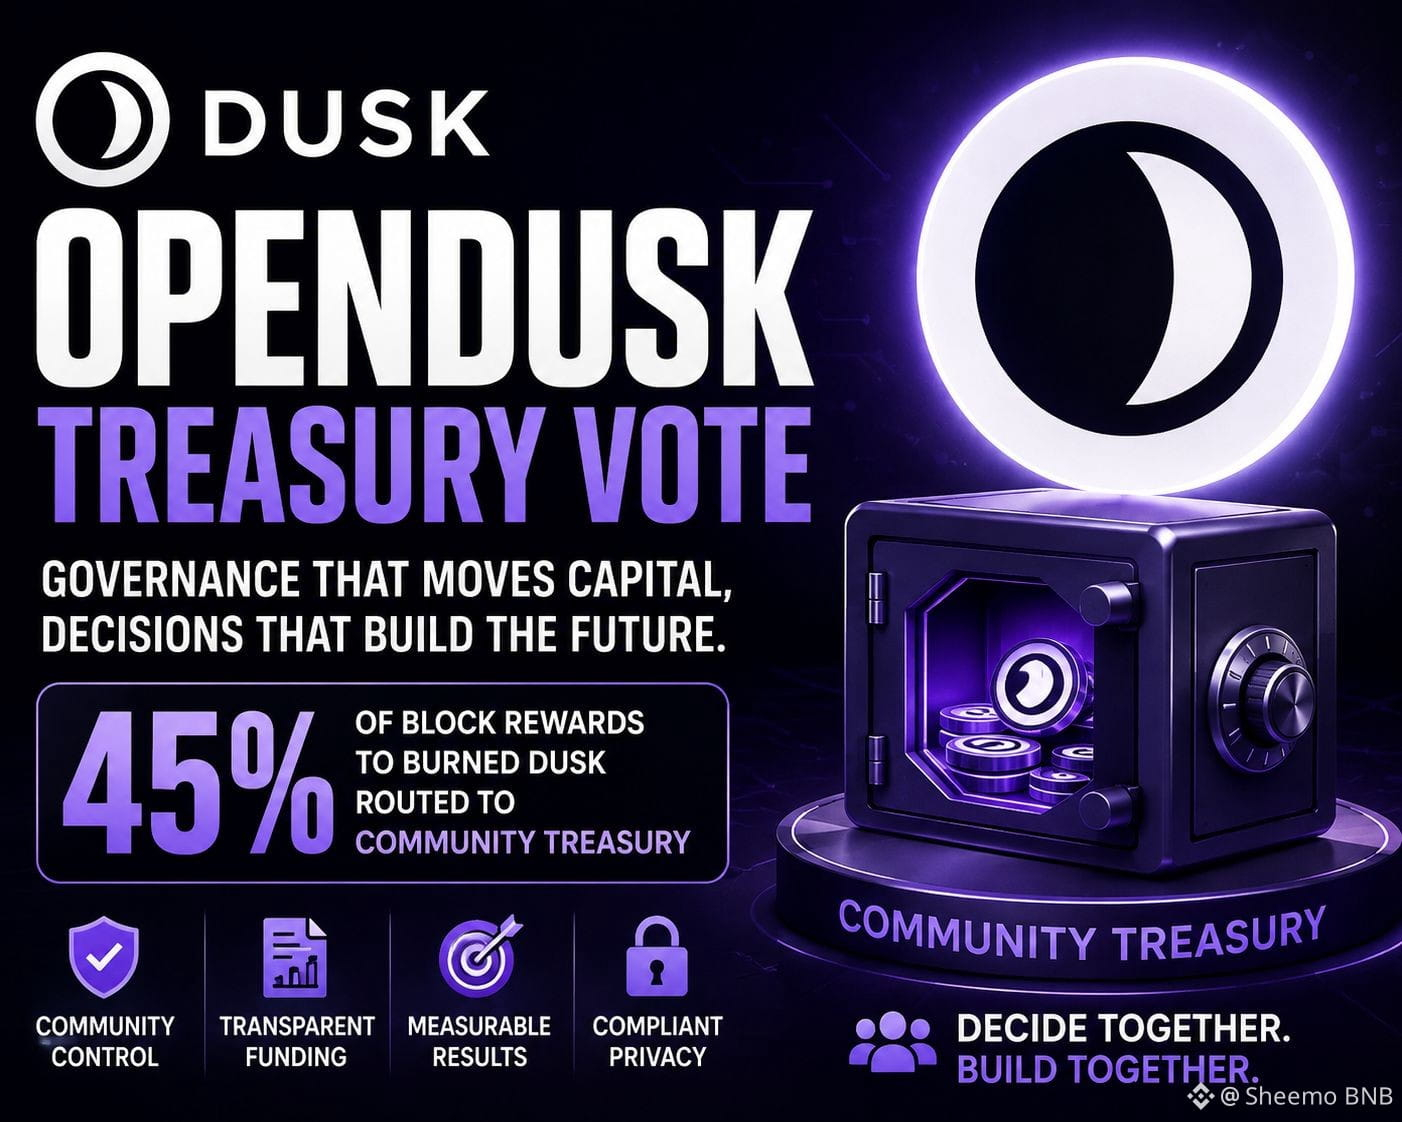
@Dusk_Foundation One detail I would watch in OpenDusk is not the size of the treasury, but how cleanly its spending can be traced back to network activity.
If the proposal redirects the portion of block rewards that would otherwise be burned into a community-controlled pool, DUSK effectively moves from an automatic protocol outcome into discretionary ecosystem capital. That changes the accounting problem.
For Dusk, this matters more than it might for a typical consumer L1. The thesis is tied to regulated assets, privacy, and settlement, where users and institutions care about reliability and measurable execution. So I would want funded initiatives to show a clear chain: DUSK received → milestone delivered → measurable usage or infrastructure improvement → continued demand.
“Capital is only productive when its outcome can be audited.”
That doesn’t mean every grant should be judged by immediate transactions. Institutional integrations can have long lead times, and forcing everything into short-term activity metrics could reject valuable infrastructure.
The weakness is that treasury reporting can still look impressive without proving economic value. A project can hit milestones, publish dashboards, and consume capital while adding little durable demand.
For me, OpenDusk becomes meaningful if it makes treasury performance easier to verify than ordinary ecosystem spending.
#dusk #Dusk @Dusk_Foundation $DUSK
{future}(DUSKUSDT)
$HEMI
{future}(HEMIUSDT)
$COW
{future}(COWUSDT)
@Dusk One detail I would watch in OpenDusk is not the size of the treasury, but how cleanly its spending can be traced back to network activity.
If the proposal redirects the portion of block rewards that would otherwise be burned into a community-controlled pool, DUSK effectively moves from an automatic protocol outcome into discretionary ecosystem capital. That changes the accounting problem.
For Dusk, this matters more than it might for a typical consumer L1. The thesis is tied to regulated assets, privacy, and settlement, where users and institutions care about reliability and measurable execution. So I would want funded initiatives to show a clear chain: DUSK received → milestone delivered → measurable usage or infrastructure improvement → continued demand.
“Capital is only productive when its outcome can be audited.”
That doesn’t mean every grant should be judged by immediate transactions. Institutional integrations can have long lead times, and forcing everything into short-term activity metrics could reject valuable infrastructure.
The weakness is that treasury reporting can still look impressive without proving economic value. A project can hit milestones, publish dashboards, and consume capital while adding little durable demand.
For me, OpenDusk becomes meaningful if it makes treasury performance easier to verify than ordinary ecosystem spending.
#dusk #Dusk @Dusk $DUSK
$HEMI
$COW
If the proposal redirects the portion of block rewards that would otherwise be burned into a community-controlled pool, DUSK effectively moves from an automatic protocol outcome into discretionary ecosystem capital. That changes the accounting problem.
For Dusk, this matters more than it might for a typical consumer L1. The thesis is tied to regulated assets, privacy, and settlement, where users and institutions care about reliability and measurable execution. So I would want funded initiatives to show a clear chain: DUSK received → milestone delivered → measurable usage or infrastructure improvement → continued demand.
“Capital is only productive when its outcome can be audited.”
That doesn’t mean every grant should be judged by immediate transactions. Institutional integrations can have long lead times, and forcing everything into short-term activity metrics could reject valuable infrastructure.
The weakness is that treasury reporting can still look impressive without proving economic value. A project can hit milestones, publish dashboards, and consume capital while adding little durable demand.
For me, OpenDusk becomes meaningful if it makes treasury performance easier to verify than ordinary ecosystem spending.
#dusk #Dusk @Dusk $DUSK
$HEMI
$COW
16
9
633
·
--
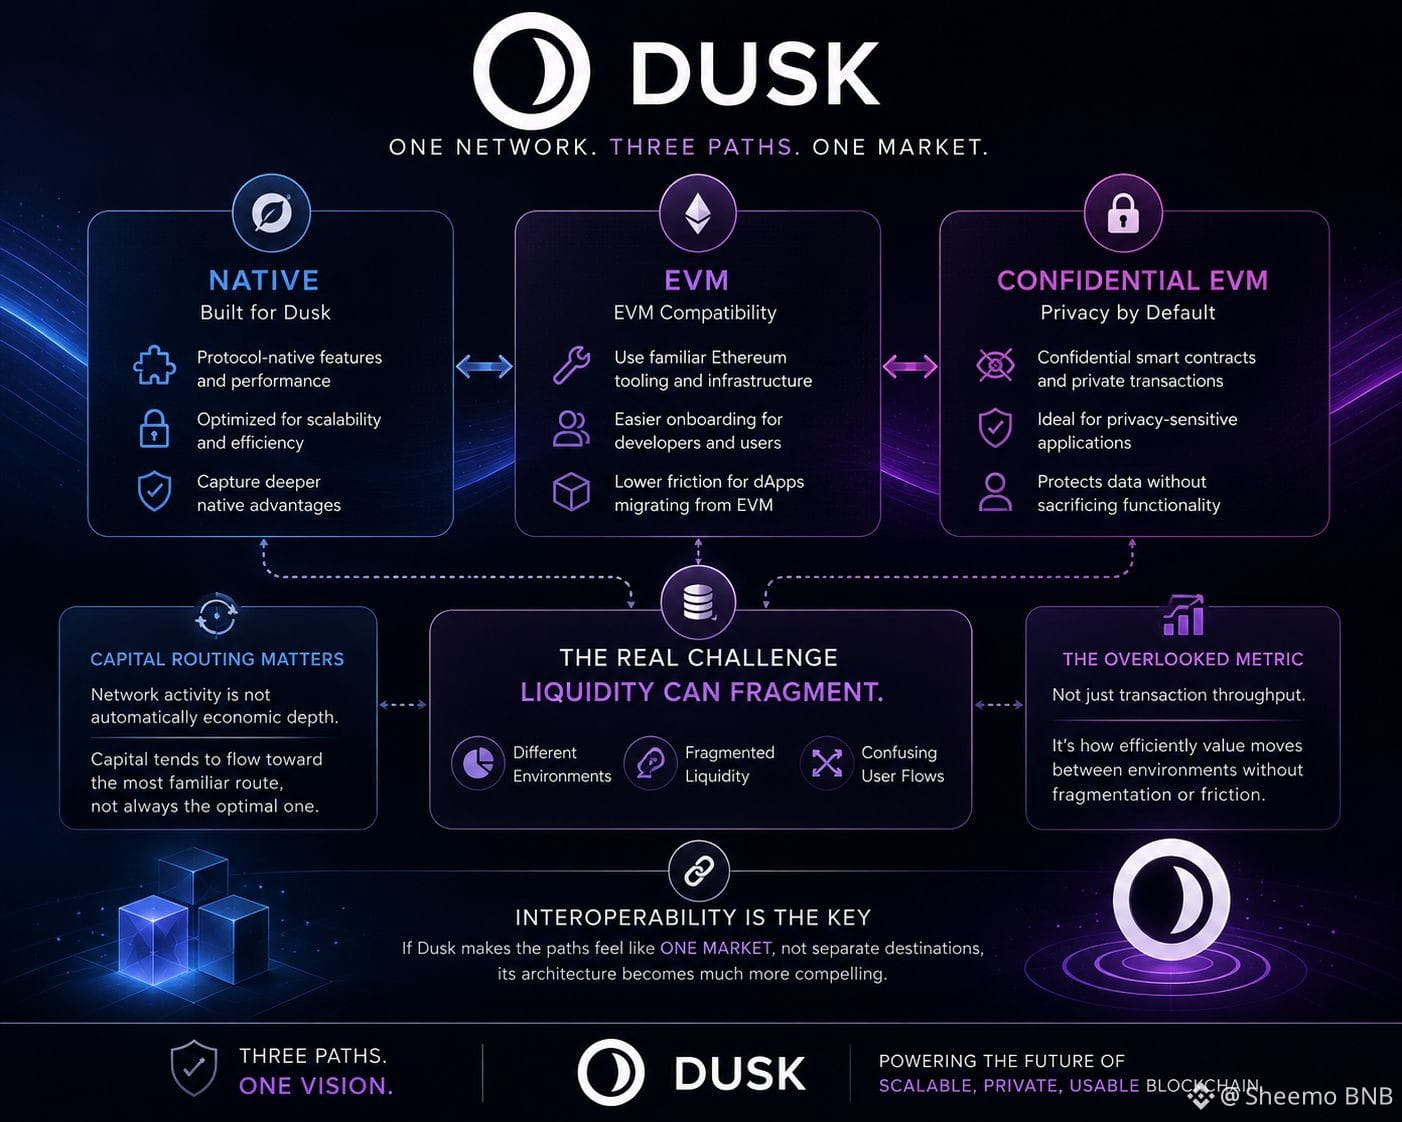
@Dusk_Foundation I’ve been thinking about Dusk’s three execution paths less as a developer feature and more as a capital-routing problem.
Native, EVM and confidential EVM can each attract a different type of application, but that also creates the possibility of liquidity becoming segmented by execution environment.
An EVM application may inherit familiar Ethereum tooling and make onboarding easier.A privacy-sensitive application may prefer confidential EVM. Native contracts can potentially capture deeper protocol-specific advantages.The important question is what happens to users and capital when those preferences diverge.
“More execution choices can also mean more places for liquidity to hide.”
That matters because network activity is not automatically economic depth.If users repeatedly have to understand which environment an application belongs to, capital may concentrate around the most familiar route rather than the technically optimal one.
I think the overlooked metric here is not simply transaction throughput.It is how efficiently value can move between Dusk’s environments without creating fragmented liquidity, duplicated integrations or confusing user flows.
The weakness is that three paths can become three ecosystems if interoperability and tooling don’t keep pace.
If Dusk makes the paths feel like one market rather than separate destinations, the architecture becomes much more compelling to me.
#DUSK #dusk $DUSK
{future}(DUSKUSDT)
$ACE
{future}(ACEUSDT)
@Dusk I’ve been thinking about Dusk’s three execution paths less as a developer feature and more as a capital-routing problem.
Native, EVM and confidential EVM can each attract a different type of application, but that also creates the possibility of liquidity becoming segmented by execution environment.
An EVM application may inherit familiar Ethereum tooling and make onboarding easier.A privacy-sensitive application may prefer confidential EVM. Native contracts can potentially capture deeper protocol-specific advantages.The important question is what happens to users and capital when those preferences diverge.
“More execution choices can also mean more places for liquidity to hide.”
That matters because network activity is not automatically economic depth.If users repeatedly have to understand which environment an application belongs to, capital may concentrate around the most familiar route rather than the technically optimal one.
I think the overlooked metric here is not simply transaction throughput.It is how efficiently value can move between Dusk’s environments without creating fragmented liquidity, duplicated integrations or confusing user flows.
The weakness is that three paths can become three ecosystems if interoperability and tooling don’t keep pace.
If Dusk makes the paths feel like one market rather than separate destinations, the architecture becomes much more compelling to me.
#DUSK #dusk $DUSK
$ACE
Native, EVM and confidential EVM can each attract a different type of application, but that also creates the possibility of liquidity becoming segmented by execution environment.
An EVM application may inherit familiar Ethereum tooling and make onboarding easier.A privacy-sensitive application may prefer confidential EVM. Native contracts can potentially capture deeper protocol-specific advantages.The important question is what happens to users and capital when those preferences diverge.
“More execution choices can also mean more places for liquidity to hide.”
That matters because network activity is not automatically economic depth.If users repeatedly have to understand which environment an application belongs to, capital may concentrate around the most familiar route rather than the technically optimal one.
I think the overlooked metric here is not simply transaction throughput.It is how efficiently value can move between Dusk’s environments without creating fragmented liquidity, duplicated integrations or confusing user flows.
The weakness is that three paths can become three ecosystems if interoperability and tooling don’t keep pace.
If Dusk makes the paths feel like one market rather than separate destinations, the architecture becomes much more compelling to me.
#DUSK #dusk $DUSK
$ACE
30
18
142
·
--
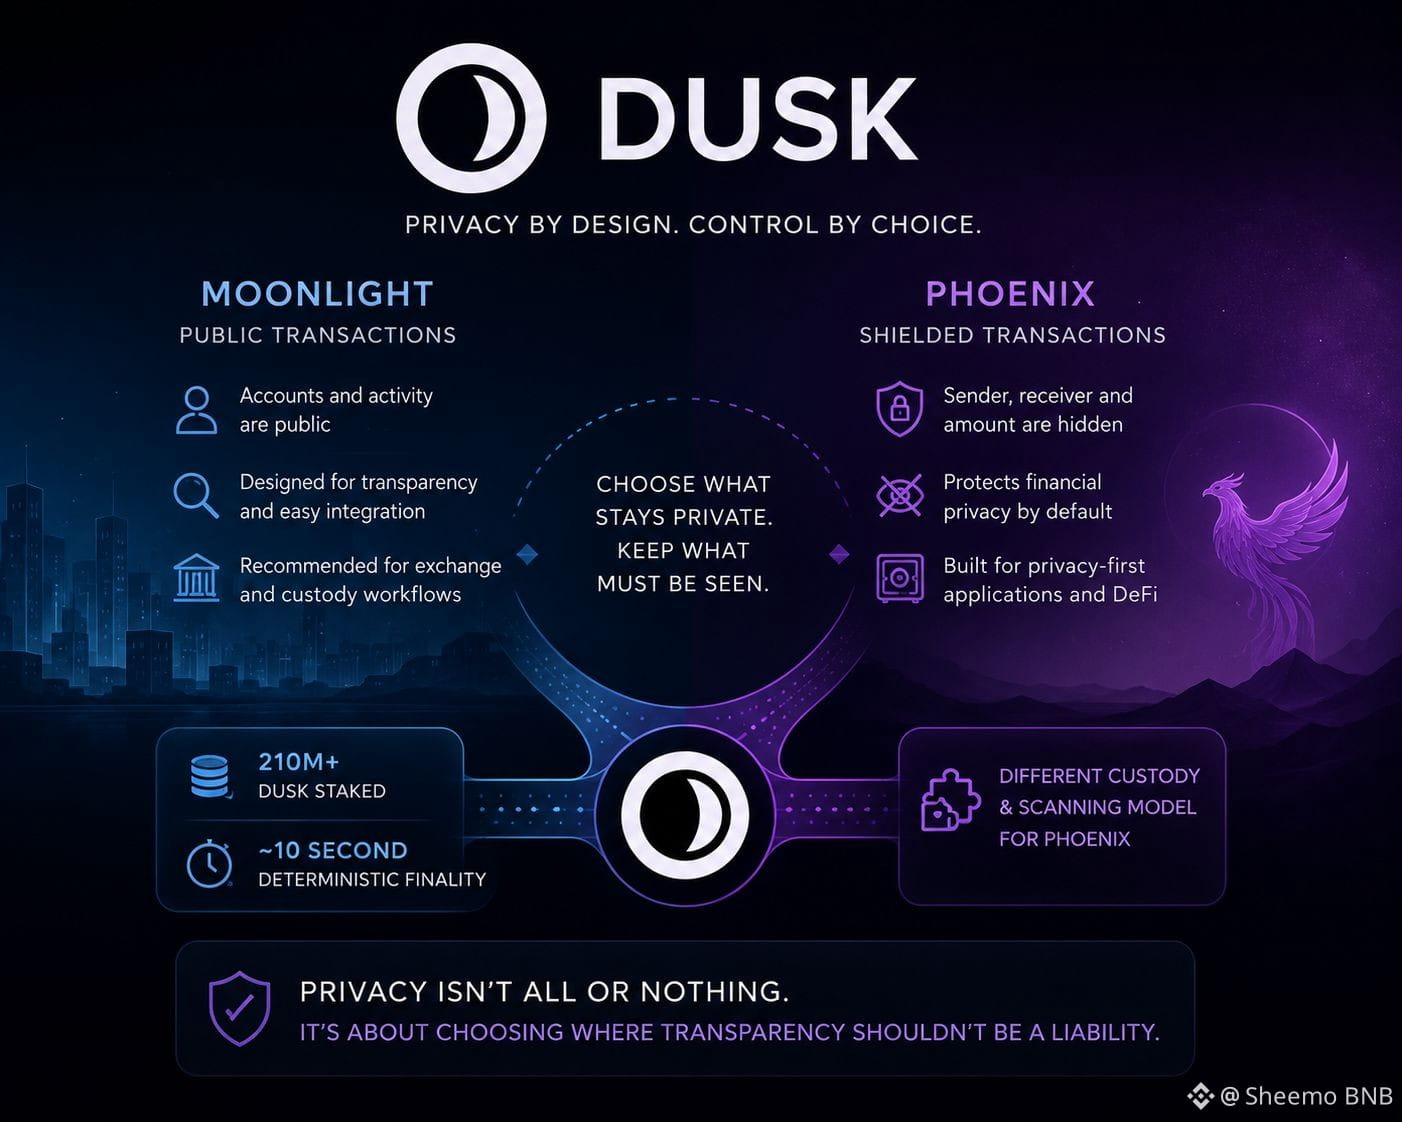
@Dusk_Foundation I’ve started looking at Dusk less as a privacy feature and more as an accounting design problem.
The interesting part is the ability to move between Moonlight’s public account model and Phoenix’s shielded notes. That creates a different question for capital providers: not simply “is this private?”, but “can I still reconcile where my capital went when it matters?”
That matters because institutional money rarely operates in one visibility regime. Trading, custody, settlement and compliance each need different levels of information.
The conversion path between Moonlight and Phoenix is therefore more important than either mode alone. If switching between them is reliable, users can choose privacy without permanently sacrificing operational transparency.
“Good privacy should reduce exposure without reducing accountability.”
The weakness is obvious: every additional transaction model increases the operational burden on wallets, exchanges and custodians. If those integrations remain awkward, users may default to the easier public path regardless of how strong Phoenix is technically.
For me, the investment signal is whether Dusk can make selective privacy operationally boring. That would be a much stronger form of adoption than privacy being merely impressive on paper.
#DUSK #dusk $DUSK
{future}(DUSKUSDT)
@Dusk I’ve started looking at Dusk less as a privacy feature and more as an accounting design problem.
The interesting part is the ability to move between Moonlight’s public account model and Phoenix’s shielded notes. That creates a different question for capital providers: not simply “is this private?”, but “can I still reconcile where my capital went when it matters?”
That matters because institutional money rarely operates in one visibility regime. Trading, custody, settlement and compliance each need different levels of information.
The conversion path between Moonlight and Phoenix is therefore more important than either mode alone. If switching between them is reliable, users can choose privacy without permanently sacrificing operational transparency.
“Good privacy should reduce exposure without reducing accountability.”
The weakness is obvious: every additional transaction model increases the operational burden on wallets, exchanges and custodians. If those integrations remain awkward, users may default to the easier public path regardless of how strong Phoenix is technically.
For me, the investment signal is whether Dusk can make selective privacy operationally boring. That would be a much stronger form of adoption than privacy being merely impressive on paper.
#DUSK #dusk $DUSK
The interesting part is the ability to move between Moonlight’s public account model and Phoenix’s shielded notes. That creates a different question for capital providers: not simply “is this private?”, but “can I still reconcile where my capital went when it matters?”
That matters because institutional money rarely operates in one visibility regime. Trading, custody, settlement and compliance each need different levels of information.
The conversion path between Moonlight and Phoenix is therefore more important than either mode alone. If switching between them is reliable, users can choose privacy without permanently sacrificing operational transparency.
“Good privacy should reduce exposure without reducing accountability.”
The weakness is obvious: every additional transaction model increases the operational burden on wallets, exchanges and custodians. If those integrations remain awkward, users may default to the easier public path regardless of how strong Phoenix is technically.
For me, the investment signal is whether Dusk can make selective privacy operationally boring. That would be a much stronger form of adoption than privacy being merely impressive on paper.
#DUSK #dusk $DUSK
12
8
341
·
--
@babylonlabs_io #baby
I've started paying closer attention to what protocols deliberately make impossible rather than what they make possible.
Babylon's Trustless Bitcoin Vaults caught my attention because the collateral remains native to Bitcoin while the vault is created for a specific application instead of becoming a broadly transferable asset. That design narrows the range of outcomes, but it also narrows the range of assumptions users have to trust.
From an investment perspective, that's an interesting trade-off. A system with fewer moving parts may not generate the same level of composability, yet it can produce cleaner risk accounting because every asset has a more defined purpose from the start.
"A protocol's limits often reveal its priorities."
$BABY
{future}(BABYUSDT)
Of course, there is a cost. Restricting collateral mobility can reduce capital efficiency and make integration with wider DeFi ecosystems slower than more flexible alternatives. Whether that trade-off succeeds depends on whether users continue valuing predictable security over maximum optionality.
I could be overlooking future design improvements, but it seems the market often rewards flexibility before asking whether that flexibility creates new trust assumptions. Over time, the protocols that define their boundaries most clearly may also be the easiest for capital to evaluate with confidence.
#Babylon $HEI
{future}(HEIUSDT)
$BLESS
{future}(BLESSUSDT)
What matters most in TBV?
@BabylonLabs_io #baby
I've started paying closer attention to what protocols deliberately make impossible rather than what they make possible.
Babylon's Trustless Bitcoin Vaults caught my attention because the collateral remains native to Bitcoin while the vault is created for a specific application instead of becoming a broadly transferable asset. That design narrows the range of outcomes, but it also narrows the range of assumptions users have to trust.
From an investment perspective, that's an interesting trade-off. A system with fewer moving parts may not generate the same level of composability, yet it can produce cleaner risk accounting because every asset has a more defined purpose from the start.
"A protocol's limits often reveal its priorities."
$BABY
Of course, there is a cost. Restricting collateral mobility can reduce capital efficiency and make integration with wider DeFi ecosystems slower than more flexible alternatives. Whether that trade-off succeeds depends on whether users continue valuing predictable security over maximum optionality.
I could be overlooking future design improvements, but it seems the market often rewards flexibility before asking whether that flexibility creates new trust assumptions. Over time, the protocols that define their boundaries most clearly may also be the easiest for capital to evaluate with confidence.
#Babylon $HEI
$BLESS
What matters most in TBV?
I've started paying closer attention to what protocols deliberately make impossible rather than what they make possible.
Babylon's Trustless Bitcoin Vaults caught my attention because the collateral remains native to Bitcoin while the vault is created for a specific application instead of becoming a broadly transferable asset. That design narrows the range of outcomes, but it also narrows the range of assumptions users have to trust.
From an investment perspective, that's an interesting trade-off. A system with fewer moving parts may not generate the same level of composability, yet it can produce cleaner risk accounting because every asset has a more defined purpose from the start.
"A protocol's limits often reveal its priorities."
$BABY
Of course, there is a cost. Restricting collateral mobility can reduce capital efficiency and make integration with wider DeFi ecosystems slower than more flexible alternatives. Whether that trade-off succeeds depends on whether users continue valuing predictable security over maximum optionality.
I could be overlooking future design improvements, but it seems the market often rewards flexibility before asking whether that flexibility creates new trust assumptions. Over time, the protocols that define their boundaries most clearly may also be the easiest for capital to evaluate with confidence.
#Babylon $HEI
$BLESS
What matters most in TBV?
🔹 Native BTC security
100%
🔹 Clear protocol boundaries
0%
🔹 Capital efficiency
0%
2 Votes • Vote fermé
11
6
126
·
--
I've found myself paying more attention to protocol coordination than transaction counts because that's often where the real scalability constraints appear.
In Babylon, vault creation depends on collecting the required signatures before the process can move on-chain.That step is easy to dismiss as operational overhead, but I think it reveals something more important: infrastructure is only as efficient as the participants coordinating behind it.
From an investor's perspective, successful vault creation isn't just a measure of demand.It's evidence that independent actors can reliably synchronize when security requires it.That makes coordination quality an overlooked metric alongside TVL or staking participation.
"Reliable coordination is a form of protocol liquidity."
The weakness,of course, is that every additional coordination requirement introduces another potential bottleneck..If signer availability becomes inconsistent, activation slows even if user interest remains high.That's not necessarily a security failure, but it can become a growth constraint.
I could be missing part of the picture, yet it seems the market pays far more attention to completed vaults than to the rate of failed or abandoned attempts. Understanding where coordination breaks down may tell us more about long-term network resilience than headline adoption numbers ever will.
#Babylon #baby @babylonlabs_io $BABY
{future}(BABYUSDT)
$CYS
{future}(CYSUSDT)
$HEI
{future}(HEIUSDT)
What's more important for Babylon's growth?
I've found myself paying more attention to protocol coordination than transaction counts because that's often where the real scalability constraints appear.
In Babylon, vault creation depends on collecting the required signatures before the process can move on-chain.That step is easy to dismiss as operational overhead, but I think it reveals something more important: infrastructure is only as efficient as the participants coordinating behind it.
From an investor's perspective, successful vault creation isn't just a measure of demand.It's evidence that independent actors can reliably synchronize when security requires it.That makes coordination quality an overlooked metric alongside TVL or staking participation.
"Reliable coordination is a form of protocol liquidity."
The weakness,of course, is that every additional coordination requirement introduces another potential bottleneck..If signer availability becomes inconsistent, activation slows even if user interest remains high.That's not necessarily a security failure, but it can become a growth constraint.
I could be missing part of the picture, yet it seems the market pays far more attention to completed vaults than to the rate of failed or abandoned attempts. Understanding where coordination breaks down may tell us more about long-term network resilience than headline adoption numbers ever will.
#Babylon #baby @BabylonLabs_io $BABY
$CYS
$HEI
What's more important for Babylon's growth?
In Babylon, vault creation depends on collecting the required signatures before the process can move on-chain.That step is easy to dismiss as operational overhead, but I think it reveals something more important: infrastructure is only as efficient as the participants coordinating behind it.
From an investor's perspective, successful vault creation isn't just a measure of demand.It's evidence that independent actors can reliably synchronize when security requires it.That makes coordination quality an overlooked metric alongside TVL or staking participation.
"Reliable coordination is a form of protocol liquidity."
The weakness,of course, is that every additional coordination requirement introduces another potential bottleneck..If signer availability becomes inconsistent, activation slows even if user interest remains high.That's not necessarily a security failure, but it can become a growth constraint.
I could be missing part of the picture, yet it seems the market pays far more attention to completed vaults than to the rate of failed or abandoned attempts. Understanding where coordination breaks down may tell us more about long-term network resilience than headline adoption numbers ever will.
#Babylon #baby @BabylonLabs_io $BABY
$CYS
$HEI
What's more important for Babylon's growth?
Reliable signer coordination
100%
Higher vault creation rate
0%
2 Votes • Vote fermé
28
25
614
·
--
#baby #Babylon @babylonlabs_io
I've become more interested in protocols that expand Bitcoin's role without asking Bitcoin holders to change what they fundamentally trust.
That's why Babylon stands out to me.
The real innovation isn't simply that BTC can contribute security beyond its own network. It's that the design tries to preserve Bitcoin's strongest property self-custody while allowing its economic weight to secure PoS ecosystems.
From an investor's perspective, that changes the discussion from "How much yield can BTC earn?" to "Can Bitcoin become the base security layer for an expanding crypto economy?"
Those are very different questions.
If that security model proves reliable, the value isn't limited to one application. It becomes infrastructure that other networks may choose to build around.
"Capital becomes more durable when utility grows without compromising ownership."
The thesis isn't risk-free. Adoption ultimately depends on whether PoS chains consistently find Bitcoin-backed security more valuable than existing alternatives. Strong technology alone doesn't guarantee lasting demand.
Even so, I think the market still spends too much time pricing incentives and not enough time pricing the quality of the security model itself.
#Babylon @babylonlabs_io
#baby $BABY
{future}(BABYUSDT)
$VIC
{future}(VICUSDT)
$BICO
{future}(BICOUSDT)
What's Babylon's biggest long-term advantage?
#baby #Babylon @BabylonLabs_io
I've become more interested in protocols that expand Bitcoin's role without asking Bitcoin holders to change what they fundamentally trust.
That's why Babylon stands out to me.
The real innovation isn't simply that BTC can contribute security beyond its own network. It's that the design tries to preserve Bitcoin's strongest property self-custody while allowing its economic weight to secure PoS ecosystems.
From an investor's perspective, that changes the discussion from "How much yield can BTC earn?" to "Can Bitcoin become the base security layer for an expanding crypto economy?"
Those are very different questions.
If that security model proves reliable, the value isn't limited to one application. It becomes infrastructure that other networks may choose to build around.
"Capital becomes more durable when utility grows without compromising ownership."
The thesis isn't risk-free. Adoption ultimately depends on whether PoS chains consistently find Bitcoin-backed security more valuable than existing alternatives. Strong technology alone doesn't guarantee lasting demand.
Even so, I think the market still spends too much time pricing incentives and not enough time pricing the quality of the security model itself.
#Babylon @BabylonLabs_io
#baby $BABY
$VIC
$BICO
What's Babylon's biggest long-term advantage?
I've become more interested in protocols that expand Bitcoin's role without asking Bitcoin holders to change what they fundamentally trust.
That's why Babylon stands out to me.
The real innovation isn't simply that BTC can contribute security beyond its own network. It's that the design tries to preserve Bitcoin's strongest property self-custody while allowing its economic weight to secure PoS ecosystems.
From an investor's perspective, that changes the discussion from "How much yield can BTC earn?" to "Can Bitcoin become the base security layer for an expanding crypto economy?"
Those are very different questions.
If that security model proves reliable, the value isn't limited to one application. It becomes infrastructure that other networks may choose to build around.
"Capital becomes more durable when utility grows without compromising ownership."
The thesis isn't risk-free. Adoption ultimately depends on whether PoS chains consistently find Bitcoin-backed security more valuable than existing alternatives. Strong technology alone doesn't guarantee lasting demand.
Even so, I think the market still spends too much time pricing incentives and not enough time pricing the quality of the security model itself.
#Babylon @BabylonLabs_io
#baby $BABY
$VIC
$BICO
What's Babylon's biggest long-term advantage?
Self-custodial BTC staking
0%
Bitcoin-powered security
100%
BTCFi infrastructure growth
0%
1 Votes • Vote fermé
22
17
254
Connectez-vous pour découvrir plus de contenu
Rejoignez la communauté mondiale des adeptes de cryptomonnaies sur Binance Square
⚡️ Suviez les dernières informations importantes sur les cryptomonnaies.
💬 Jugé digne de confiance par la plus grande plateforme d’échange de cryptomonnaies au monde.
👍 Découvrez les connaissances que partagent les créateurs vérifiés.
Adresse e-mail/Nº de téléphone
Sujets d’actualité
BitcoinSpotETFsNetInflow$191M
516 vues
68 mentions
#BitcoinFallsBelow$83,000
📉 Flash Dip: Bitcoin Drops Below $83,000—Shakeout or Trend Reversal?
Bitcoin ($BTC) briefly dipped below the key $83,000 support level, triggering liquidations and heightened volatility across derivatives markets.
The sudden pullback is driven by a combination of macroeconomic headwinds—specifically rising U.S. Treasury yields and a rising U.S. Dollar Index (DXY)—alongside profit-taking by long-term holders in the $83,000–$85,000 supply zone.
📌 Breakdown of Key Technical & On-Chain Indicators
🔻 Local Low: Bitcoin hit a 24-hour low around $82,889 on major exchanges before stabilizing back toward $83,500–$84,000.
🛡️ Immediate Support Levels: Traders are closely watching the $82,000 level as primary support, with a deeper downside safety net anchored at the $80,000 psychological floor.
🚀 Resistance Walls: To re-establish bullish momentum, $BTC needs to reclaim and hold above $84,600, opening the path toward $86,000.
⏳ Institutional Backstop: Despite spot price weakness, institutional spot BTC ETFs recorded $191 Million in net inflows, signaling that Wall Street buyers are absorbing sell-side pressure.
🎯 Strategic Takeaways: How to Navigate the Volatility
Avoid High-Leverage Trades: Sudden dips into major options expiry events cause sharp liquidation cascades—keep leverage low or spot position size controlled.
Watch Macro Signals: Rising 10-year Treasury yields and 69.7% odds of an October Fed rate hike are creating short-term risk-off sentiment.
Focus on Structural Demand: Sustained multi-day ETF inflows indicate that large capital allocators treat pullbacks below $83,000 as structural buying opportunities.
Are you panic selling the dip, or dollar-cost averaging (DCA) into key support? Drop your trading plan below! 💬👇
#BitcoinSpotETFsNetInflow$191M #bitcoin #BinanceSquare
Lily星星
·1 mentions J’aime
·26 vues
CFTCUpdatesGuidanceOnTokenizedAssets
9,981 vues
493 mentions
BitgetSays$352MAffectedInHack
1,994 vues
34 mentions