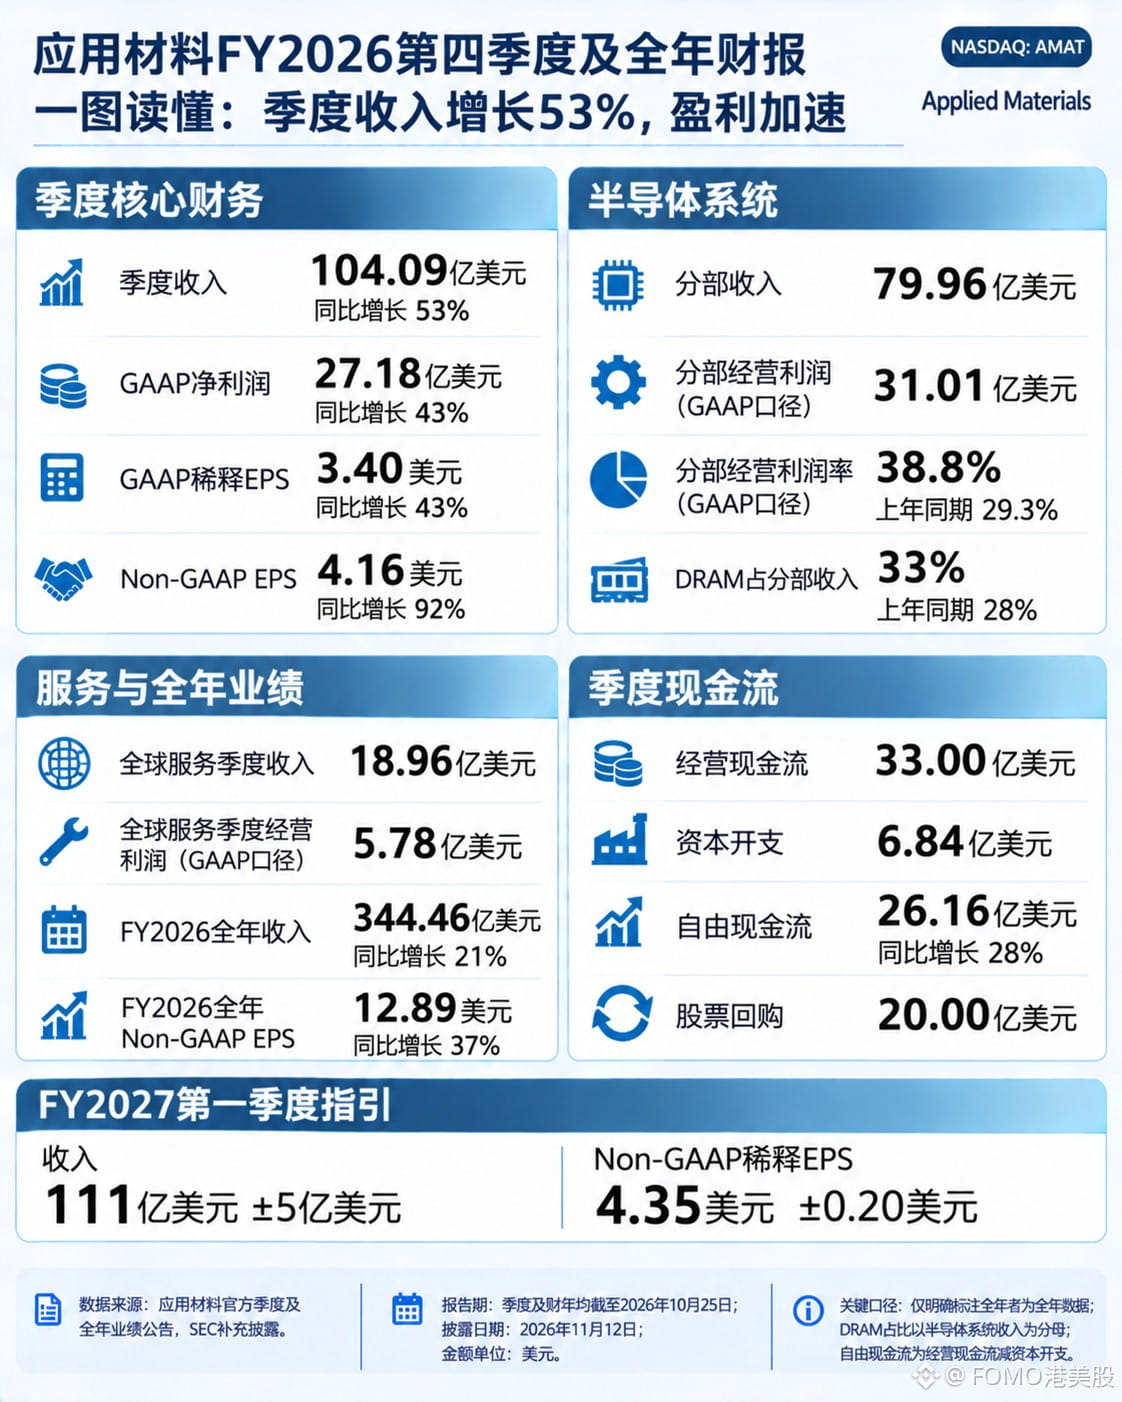
Applied Materials $AMATB reported FY2026 fourth-quarter revenue of $10.409 billion, up 53% year over year, and Non-GAAP EPS of $4.16, up 92%.
Nearly all the growth came from equipment. Semiconductor Systems revenue was $7.996 billion, up from $4.879 billion a year ago, while its operating margin rose from 29.3% to 38.8%. Within the segment, foundry and logic accounted for 58%, DRAM 33%, and flash 9%; a year ago, DRAM and flash accounted for 28% and 6%, respectively.
The difference between the two growth rates comes down to a non-operating item.
GAAP net income rose just 43% to $2.718 billion, $603 million below adjusted net income. That’s because this quarter included a $653 million unrealized loss on strategic investments, compared with a $467 million gain in the year-ago quarter—a $1.12 billion swing, greater than the Services segment’s quarterly earnings of $578 million.
Most of the cash went back to shareholders: free cash flow was $2.616 billion, and $2 billion in buybacks plus $421 million in dividends amounted to 92.5% of it. Q1 guidance is $11.1 billion ± $500 million, with the midpoint just 6.6% above this quarter’s revenue. Looking ahead, whether next quarter can reach the upper end of the $11.1 billion range is the first real test; don’t mistake the lower end of the range for a win.
The variable is Services. Its 30.5% segment margin is 8 points below equipment’s, and its 26% growth trails equipment’s 64%. Only if this segment holds steady can we start talking about a cycle.
#AMAT #BStocks #半导体
Nearly all the growth came from equipment. Semiconductor Systems revenue was $7.996 billion, up from $4.879 billion a year ago, while its operating margin rose from 29.3% to 38.8%. Within the segment, foundry and logic accounted for 58%, DRAM 33%, and flash 9%; a year ago, DRAM and flash accounted for 28% and 6%, respectively.
The difference between the two growth rates comes down to a non-operating item.
GAAP net income rose just 43% to $2.718 billion, $603 million below adjusted net income. That’s because this quarter included a $653 million unrealized loss on strategic investments, compared with a $467 million gain in the year-ago quarter—a $1.12 billion swing, greater than the Services segment’s quarterly earnings of $578 million.
Most of the cash went back to shareholders: free cash flow was $2.616 billion, and $2 billion in buybacks plus $421 million in dividends amounted to 92.5% of it. Q1 guidance is $11.1 billion ± $500 million, with the midpoint just 6.6% above this quarter’s revenue. Looking ahead, whether next quarter can reach the upper end of the $11.1 billion range is the first real test; don’t mistake the lower end of the range for a win.
The variable is Services. Its 30.5% segment margin is 8 points below equipment’s, and its 26% growth trails equipment’s 64%. Only if this segment holds steady can we start talking about a cycle.
#AMAT #BStocks #半导体