
Cerberus-
98 Posts

Cerberus-
Report
Block User
分享链上数据和宏观经济见解的主动式Dca现货大周期玩家😎
Open Trade

BTC Holder
Frequent Trader
2.8 Years
16 Following
102 Followers
141 Liked
Posts
Portfolio
All
Quotes
·
--
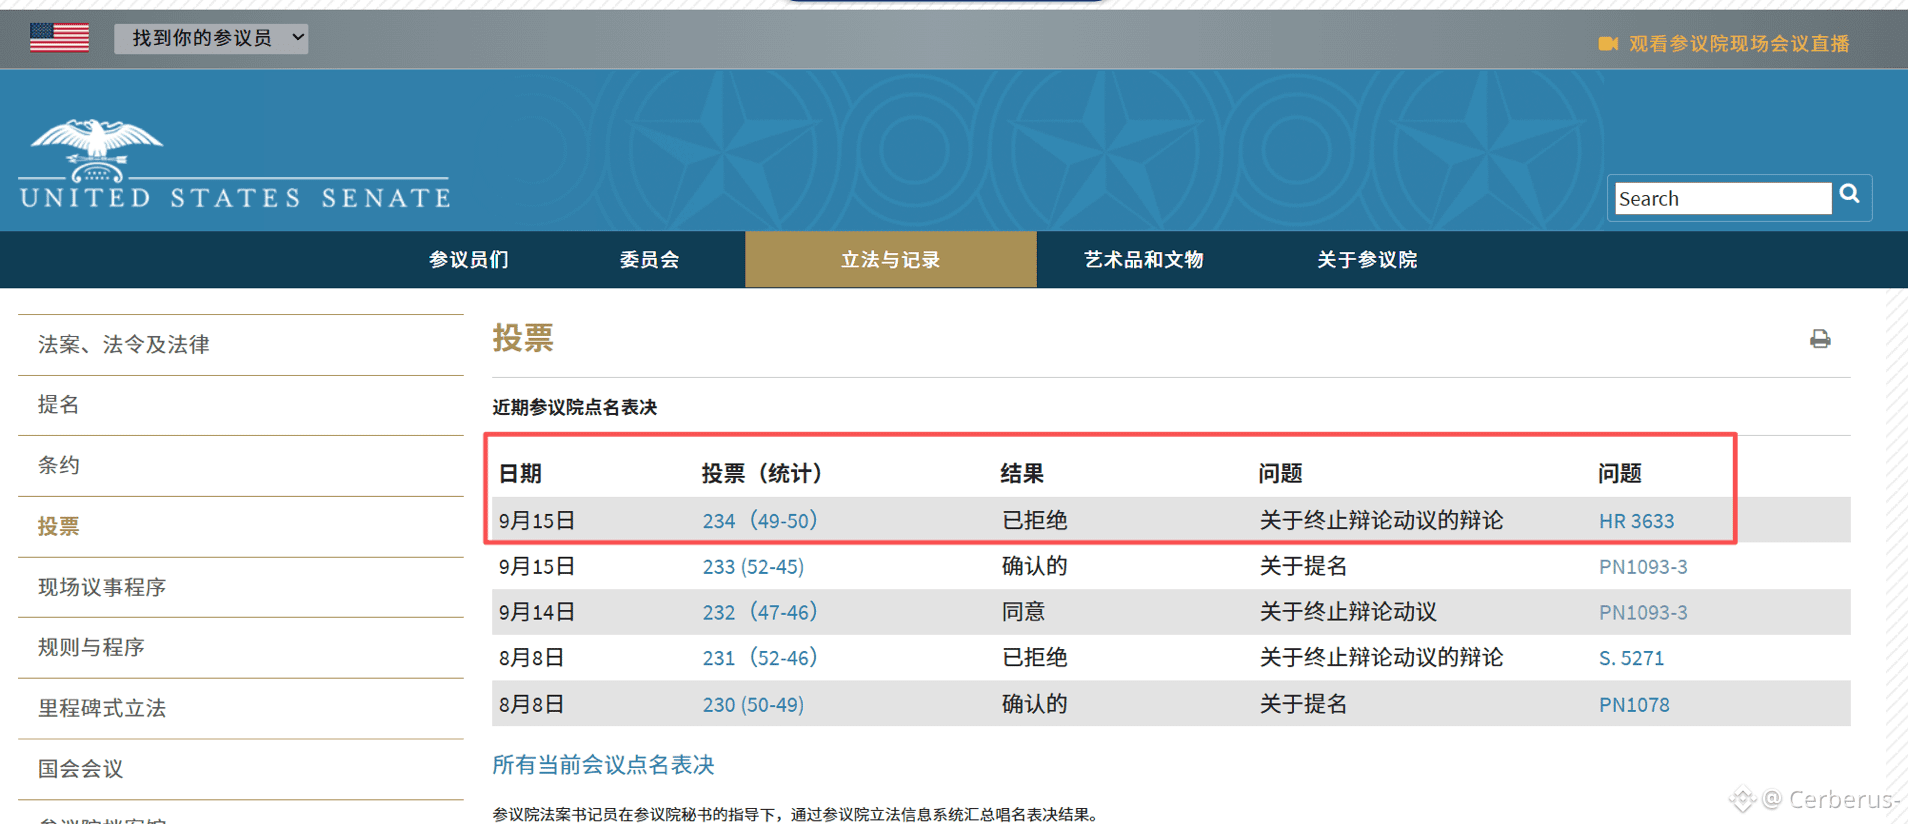
The U.S. Senate website has already shown that bill #CLARITYAct was rejected. It did not receive 60 votes and therefore could not move forward.
This outcome is clearly a negative regulatory development, especially since the market previously viewed the CLARITY Act as an important catalyst for implementing regulatory oversight for the U.S. crypto market structure. Now, at least in the short term, that catalyst is gone.
The U.S. Senate website has already shown that bill #CLARITYAct was rejected. It did not receive 60 votes and therefore could not move forward.
This outcome is clearly a negative regulatory development, especially since the market previously viewed the CLARITY Act as an important catalyst for implementing regulatory oversight for the U.S. crypto market structure. Now, at least in the short term, that catalyst is gone.
This outcome is clearly a negative regulatory development, especially since the market previously viewed the CLARITY Act as an important catalyst for implementing regulatory oversight for the U.S. crypto market structure. Now, at least in the short term, that catalyst is gone.
86
·
--
Article
The Fed’s next move: another hike—or the opening of a new cycle?A forward look at the September FOMC meeting—when an 88.5% probability of a rate hike is already priced in, where is the real trading opportunity? #美联储加息是否已成定局
At 2:00 a.m. on September 17 Beijing time, the white marble building on Washington’s Constitution Avenue will be lit up. Kevin Wosch—an “anti-forward-guidance” advocate who only took over as the chair of the Federal Reserve in May this year—will announce there his first interest-rate decision during his tenure. Less than 26 hours from now, #FedRateWatch the market has already written the answer into the price: on Polymarket, the probability of a 25-basis-point hike is 88.5%, holding steady is 11.5%, and a 20-basis-point cut is 0.2%. So this isn’t a meeting to “guess the outcome,” but one to “guess the follow-through.”
The Fed’s next move: another hike—or the opening of a new cycle?
A forward look at the September FOMC meeting—when an 88.5% probability of a rate hike is already priced in, where is the real trading opportunity? #美联储加息是否已成定局
At 2:00 a.m. on September 17 Beijing time, the white marble building on Washington’s Constitution Avenue will be lit up. Kevin Wosch—an “anti-forward-guidance” advocate who only took over as the chair of the Federal Reserve in May this year—will announce there his first interest-rate decision during his tenure. Less than 26 hours from now, #FedRateWatch the market has already written the answer into the price: on Polymarket, the probability of a 25-basis-point hike is 88.5%, holding steady is 11.5%, and a 20-basis-point cut is 0.2%. So this isn’t a meeting to “guess the outcome,” but one to “guess the follow-through.”
At 2:00 a.m. on September 17 Beijing time, the white marble building on Washington’s Constitution Avenue will be lit up. Kevin Wosch—an “anti-forward-guidance” advocate who only took over as the chair of the Federal Reserve in May this year—will announce there his first interest-rate decision during his tenure. Less than 26 hours from now, #FedRateWatch the market has already written the answer into the price: on Polymarket, the probability of a 25-basis-point hike is 88.5%, holding steady is 11.5%, and a 20-basis-point cut is 0.2%. So this isn’t a meeting to “guess the outcome,” but one to “guess the follow-through.”
2
3.6k
·
--
Financial Daily Report | September 15, 2026, Tuesday
📊 US Stocks
The Dow Jones closed at 52,421.20 (-0.29%), the S&P 500 at 7,619.98 (-0.48%), and the Nasdaq at 26,186.41 (-0.56%). All three major indexes ended lower collectively, but the declines were mild—more like high-level consolidation rather than a trend break.
Tech stocks are the hardest hit in this round of adjustment. Major AI companies such as Anthropic have publicly called for a slower development pace. The market immediately interpreted this as a signal that AI capital expenditures may have peaked. Chip stocks, which had been a “safe haven” for the past two years, overnight turned into a “pain trade.” SanDisk plunged 3.5%, Micron weakened, and Nvidia and Intel came under pressure. Notably, European equities closed higher against the trend, suggesting that capital hasn’t left—instead, it’s being reallocated between the AI narrative and traditional heavyweight sectors. It’s not a crash; it’s hesitation.
🪙 Cryptocurrency
$BTC 78,030.43 (+1.90%) rose against the trend despite the drop in US stocks, reclaiming above 78,000; $ETH 2,510.10 (+1.46%); BNB 719.43 (+0.53%); SOL 102.62 (+3.34%). ZEC surged 10.18%, leading the field. Gains for SUI, AVAX, and LINK were all above 3%.
Total market cap across the whole market is $2.67 trillion, with $91.0 billion in trading volume over the past 24 hours. BTC’s share is 58.5%. Fear & Greed Index: 69 (Greed). On the ETF side: IBIT 43.77 (+0.21%), FBTC 67.25 (+0.28%), ETHA 19.16 (+3.23%). Ethereum ETFs clearly outperformed Bitcoin ETFs, and incremental investor interest is shifting from top coins toward mainstream “blue-chip” alts.
🥇 Gold
$XAUT 4,288.93 (-1.14%). With oil prices rebounding and both the dollar and US Treasury yields rising in sync, gold prices faced short-term pressure and pulled back.
📰 Crypto Headlines
- The US Senate held a key vote on the “Clarity Act” on Tuesday. The odds of passage spiked, but 17 state attorneys general jointly signed a letter opposing it (TheBlock)
- A White House crypto adviser said the vote “feels great,” and Trump has agreed to tighten ethical provisions in exchange for pushing the bill forward. Bernstein believes the market has “priced in absolutely nothing” positive surprises (CoinDesk / Decrypt)
- Strive increased its holdings by 469 BTC to 25,000 BTC. Bitmine bought another 27,180 ETH, bringing its holdings close to 6 million coins (CoinTelegraph)
- Bank groups are calling for stricter stablecoin limits, escalating the debate over stablecoin rewards. New EU rules require wallet providers to report security incidents within 24 hours (Decrypt / CoinTelegraph)
🌐 Macro News
- The 10-year US Treasury yield broke above 5.0% intraday for the first time in nearly three years; traders are waiting for the Fed’s rate decision (FT)
- Consumer confidence fell sharply in September, inflation expectations worsened, and inflation again outpaced wage growth (CNBC)
- Trump called AI safety warnings a “scam,” saying it’s enough to have a “high-IQ president,” and he even called Nvidia CEO Jensen Huang (CNBC)
📅 Economic Data Preview This Week
Tuesday: Key vote in the Senate on the “Clarity Act”
Wednesday: Fed FOMC rate decision (to be released early Thursday Beijing time)
Thursday: Initial weekly jobless claims (US)
Financial Daily Report | September 15, 2026, Tuesday
📊 US Stocks
The Dow Jones closed at 52,421.20 (-0.29%), the S&P 500 at 7,619.98 (-0.48%), and the Nasdaq at 26,186.41 (-0.56%). All three major indexes ended lower collectively, but the declines were mild—more like high-level consolidation rather than a trend break.
Tech stocks are the hardest hit in this round of adjustment. Major AI companies such as Anthropic have publicly called for a slower development pace. The market immediately interpreted this as a signal that AI capital expenditures may have peaked. Chip stocks, which had been a “safe haven” for the past two years, overnight turned into a “pain trade.” SanDisk plunged 3.5%, Micron weakened, and Nvidia and Intel came under pressure. Notably, European equities closed higher against the trend, suggesting that capital hasn’t left—instead, it’s being reallocated between the AI narrative and traditional heavyweight sectors. It’s not a crash; it’s hesitation.
🪙 Cryptocurrency
$BTC 78,030.43 (+1.90%) rose against the trend despite the drop in US stocks, reclaiming above 78,000; $ETH 2,510.10 (+1.46%); BNB 719.43 (+0.53%); SOL 102.62 (+3.34%). ZEC surged 10.18%, leading the field. Gains for SUI, AVAX, and LINK were all above 3%.
Total market cap across the whole market is $2.67 trillion, with $91.0 billion in trading volume over the past 24 hours. BTC’s share is 58.5%. Fear & Greed Index: 69 (Greed). On the ETF side: IBIT 43.77 (+0.21%), FBTC 67.25 (+0.28%), ETHA 19.16 (+3.23%). Ethereum ETFs clearly outperformed Bitcoin ETFs, and incremental investor interest is shifting from top coins toward mainstream “blue-chip” alts.
🥇 Gold
$XAUT 4,288.93 (-1.14%). With oil prices rebounding and both the dollar and US Treasury yields rising in sync, gold prices faced short-term pressure and pulled back.
📰 Crypto Headlines
- The US Senate held a key vote on the “Clarity Act” on Tuesday. The odds of passage spiked, but 17 state attorneys general jointly signed a letter opposing it (TheBlock)
- A White House crypto adviser said the vote “feels great,” and Trump has agreed to tighten ethical provisions in exchange for pushing the bill forward. Bernstein believes the market has “priced in absolutely nothing” positive surprises (CoinDesk / Decrypt)
- Strive increased its holdings by 469 BTC to 25,000 BTC. Bitmine bought another 27,180 ETH, bringing its holdings close to 6 million coins (CoinTelegraph)
- Bank groups are calling for stricter stablecoin limits, escalating the debate over stablecoin rewards. New EU rules require wallet providers to report security incidents within 24 hours (Decrypt / CoinTelegraph)
🌐 Macro News
- The 10-year US Treasury yield broke above 5.0% intraday for the first time in nearly three years; traders are waiting for the Fed’s rate decision (FT)
- Consumer confidence fell sharply in September, inflation expectations worsened, and inflation again outpaced wage growth (CNBC)
- Trump called AI safety warnings a “scam,” saying it’s enough to have a “high-IQ president,” and he even called Nvidia CEO Jensen Huang (CNBC)
📅 Economic Data Preview This Week
Tuesday: Key vote in the Senate on the “Clarity Act”
Wednesday: Fed FOMC rate decision (to be released early Thursday Beijing time)
Thursday: Initial weekly jobless claims (US)
📊 US Stocks
The Dow Jones closed at 52,421.20 (-0.29%), the S&P 500 at 7,619.98 (-0.48%), and the Nasdaq at 26,186.41 (-0.56%). All three major indexes ended lower collectively, but the declines were mild—more like high-level consolidation rather than a trend break.
Tech stocks are the hardest hit in this round of adjustment. Major AI companies such as Anthropic have publicly called for a slower development pace. The market immediately interpreted this as a signal that AI capital expenditures may have peaked. Chip stocks, which had been a “safe haven” for the past two years, overnight turned into a “pain trade.” SanDisk plunged 3.5%, Micron weakened, and Nvidia and Intel came under pressure. Notably, European equities closed higher against the trend, suggesting that capital hasn’t left—instead, it’s being reallocated between the AI narrative and traditional heavyweight sectors. It’s not a crash; it’s hesitation.
🪙 Cryptocurrency
$BTC 78,030.43 (+1.90%) rose against the trend despite the drop in US stocks, reclaiming above 78,000; $ETH 2,510.10 (+1.46%); BNB 719.43 (+0.53%); SOL 102.62 (+3.34%). ZEC surged 10.18%, leading the field. Gains for SUI, AVAX, and LINK were all above 3%.
Total market cap across the whole market is $2.67 trillion, with $91.0 billion in trading volume over the past 24 hours. BTC’s share is 58.5%. Fear & Greed Index: 69 (Greed). On the ETF side: IBIT 43.77 (+0.21%), FBTC 67.25 (+0.28%), ETHA 19.16 (+3.23%). Ethereum ETFs clearly outperformed Bitcoin ETFs, and incremental investor interest is shifting from top coins toward mainstream “blue-chip” alts.
🥇 Gold
$XAUT 4,288.93 (-1.14%). With oil prices rebounding and both the dollar and US Treasury yields rising in sync, gold prices faced short-term pressure and pulled back.
📰 Crypto Headlines
- The US Senate held a key vote on the “Clarity Act” on Tuesday. The odds of passage spiked, but 17 state attorneys general jointly signed a letter opposing it (TheBlock)
- A White House crypto adviser said the vote “feels great,” and Trump has agreed to tighten ethical provisions in exchange for pushing the bill forward. Bernstein believes the market has “priced in absolutely nothing” positive surprises (CoinDesk / Decrypt)
- Strive increased its holdings by 469 BTC to 25,000 BTC. Bitmine bought another 27,180 ETH, bringing its holdings close to 6 million coins (CoinTelegraph)
- Bank groups are calling for stricter stablecoin limits, escalating the debate over stablecoin rewards. New EU rules require wallet providers to report security incidents within 24 hours (Decrypt / CoinTelegraph)
🌐 Macro News
- The 10-year US Treasury yield broke above 5.0% intraday for the first time in nearly three years; traders are waiting for the Fed’s rate decision (FT)
- Consumer confidence fell sharply in September, inflation expectations worsened, and inflation again outpaced wage growth (CNBC)
- Trump called AI safety warnings a “scam,” saying it’s enough to have a “high-IQ president,” and he even called Nvidia CEO Jensen Huang (CNBC)
📅 Economic Data Preview This Week
Tuesday: Key vote in the Senate on the “Clarity Act”
Wednesday: Fed FOMC rate decision (to be released early Thursday Beijing time)
Thursday: Initial weekly jobless claims (US)
362
·
--
Financial Daily | Monday, September 14, 2026
📊 U.S. Stocks
The Dow Jones 52,573.29 (+0.98%), the S&P 500 7,656.98 (+0.86%), and the Nasdaq 26,333.04 (+0.96%). Last Friday, all three major indexes rebounded collectively after inflation data landed—but the rally didn’t carry into the new week. On Monday, Nasdaq-100 futures fell about 1% in pre-market trading. The spark: three AI giants unusually and simultaneously called for a slowdown in the pace of frontier model development. Anthropic CEO’s “slowdown declaration” was publicly rejected by Trump, and the market priced in “narrative damage” first—SoftBank fell 11%, SK hynix dropped more than 5%, and Samsung Electronics fell more than 3%. AI is the main engine of this round of trading. Once the consensus on “investment growth pace” is questioned, valuations are hit first, and near-term volatility will be noticeably amplified.
🪙 Cryptoassets
$BTC 76,596 USD (-0.87%), $ETH 2,475.79 USD (-1.98%), BNB 715.77 USD (-1.64%), SOL 99.34 USD (-2.24%). The whole market saw broad losses over the past 24 hours. Total market cap: $2.60 trillion. Total 24-hour volume: $54.0 billion. BTC dominance: 58.9%. Fear & Greed Index: 57 (Greed).
The ETF side held up instead: IBIT 43.77 (+0.21%), FBTC 67.25 (+0.28%), ETHA 19.16 (+3.23%), with no sign of outflows. On the losers’ list, ZEC fell 5.84%, SUI fell 4.04%, and SOL losing the $100 level is worth watching. Institutional and on-chain news isn’t too bad. CryptoQuant believes BTC must stay above $81,700 to confirm the start of a new bull cycle. The “Clarity Act” remains undecided after the Senate reconvened. Bitcoin Suisse plans to cut up to half of its Swiss roles. Overall, it’s a wait-and-see pattern of “macro waiting for the Fed, industry waiting for legislation.”
🥇 Gold
$XAUT 4,337.74 USD (-0.29%). Gold prices are consolidating narrowly above $4,300. On one side, rate-hike expectations are heating up; on the other, geographic risk around the Strait of Hormuz. Neither bulls nor bears want to make the first move.
📰 Crypto News
- The U.S. Senate reconvened; the “Clarity Act” remains stuck in a “life-or-death overlap” stalemate, and industry legislation is unlikely to reach conclusions in the short term. (CoinDesk)
- CryptoQuant: BTC must break through the $81,700 resistance level to confirm the start of a new bull cycle. (The Block)
- Blockstream refused to pay a ransom for the remaining 600 BTC stolen from the Liquid sidechain; Symbiosis has recovered 15 BTC and offered a 20% bounty to the attacker. (The Block)
- Crypto tycoons Ben Delo and Christopher Harborne each donated £36 million to the UK’s Reform UK, totaling about $97 million within 24 hours. (CoinDesk)
🌐 Macro News
- The U.S. August core CPI rose 0.3% month-over-month, above expectations; market pricing for this week’s Fed rate hike climbed to nearly 90%. (CNBC)
- A ship was attacked in the Strait of Hormuz. Saudi Arabia shut an important oil pipeline, and the GCC and Iran talks were postponed. In early trading in Asia on Monday, international oil prices rose more than 3%. (CNBC)
- Trump rejected calls from tech giants to “slow down AI development,” saying the U.S. cannot concede in the race. (FT)
📅 Economic Data Preview This Week
- The Fed’s FOMC policy meeting will be held this week. The market expects a rate-hike probability of nearly 90%, and the decision will be released at around 4:00 a.m. Beijing time on Thursday.
- U.S. Initial Jobless Claims: Thursday
Financial Daily | Monday, September 14, 2026
📊 U.S. Stocks
The Dow Jones 52,573.29 (+0.98%), the S&P 500 7,656.98 (+0.86%), and the Nasdaq 26,333.04 (+0.96%). Last Friday, all three major indexes rebounded collectively after inflation data landed—but the rally didn’t carry into the new week. On Monday, Nasdaq-100 futures fell about 1% in pre-market trading. The spark: three AI giants unusually and simultaneously called for a slowdown in the pace of frontier model development. Anthropic CEO’s “slowdown declaration” was publicly rejected by Trump, and the market priced in “narrative damage” first—SoftBank fell 11%, SK hynix dropped more than 5%, and Samsung Electronics fell more than 3%. AI is the main engine of this round of trading. Once the consensus on “investment growth pace” is questioned, valuations are hit first, and near-term volatility will be noticeably amplified.
🪙 Cryptoassets
$BTC 76,596 USD (-0.87%), $ETH 2,475.79 USD (-1.98%), BNB 715.77 USD (-1.64%), SOL 99.34 USD (-2.24%). The whole market saw broad losses over the past 24 hours. Total market cap: $2.60 trillion. Total 24-hour volume: $54.0 billion. BTC dominance: 58.9%. Fear & Greed Index: 57 (Greed).
The ETF side held up instead: IBIT 43.77 (+0.21%), FBTC 67.25 (+0.28%), ETHA 19.16 (+3.23%), with no sign of outflows. On the losers’ list, ZEC fell 5.84%, SUI fell 4.04%, and SOL losing the $100 level is worth watching. Institutional and on-chain news isn’t too bad. CryptoQuant believes BTC must stay above $81,700 to confirm the start of a new bull cycle. The “Clarity Act” remains undecided after the Senate reconvened. Bitcoin Suisse plans to cut up to half of its Swiss roles. Overall, it’s a wait-and-see pattern of “macro waiting for the Fed, industry waiting for legislation.”
🥇 Gold
$XAUT 4,337.74 USD (-0.29%). Gold prices are consolidating narrowly above $4,300. On one side, rate-hike expectations are heating up; on the other, geographic risk around the Strait of Hormuz. Neither bulls nor bears want to make the first move.
📰 Crypto News
- The U.S. Senate reconvened; the “Clarity Act” remains stuck in a “life-or-death overlap” stalemate, and industry legislation is unlikely to reach conclusions in the short term. (CoinDesk)
- CryptoQuant: BTC must break through the $81,700 resistance level to confirm the start of a new bull cycle. (The Block)
- Blockstream refused to pay a ransom for the remaining 600 BTC stolen from the Liquid sidechain; Symbiosis has recovered 15 BTC and offered a 20% bounty to the attacker. (The Block)
- Crypto tycoons Ben Delo and Christopher Harborne each donated £36 million to the UK’s Reform UK, totaling about $97 million within 24 hours. (CoinDesk)
🌐 Macro News
- The U.S. August core CPI rose 0.3% month-over-month, above expectations; market pricing for this week’s Fed rate hike climbed to nearly 90%. (CNBC)
- A ship was attacked in the Strait of Hormuz. Saudi Arabia shut an important oil pipeline, and the GCC and Iran talks were postponed. In early trading in Asia on Monday, international oil prices rose more than 3%. (CNBC)
- Trump rejected calls from tech giants to “slow down AI development,” saying the U.S. cannot concede in the race. (FT)
📅 Economic Data Preview This Week
- The Fed’s FOMC policy meeting will be held this week. The market expects a rate-hike probability of nearly 90%, and the decision will be released at around 4:00 a.m. Beijing time on Thursday.
- U.S. Initial Jobless Claims: Thursday
📊 U.S. Stocks
The Dow Jones 52,573.29 (+0.98%), the S&P 500 7,656.98 (+0.86%), and the Nasdaq 26,333.04 (+0.96%). Last Friday, all three major indexes rebounded collectively after inflation data landed—but the rally didn’t carry into the new week. On Monday, Nasdaq-100 futures fell about 1% in pre-market trading. The spark: three AI giants unusually and simultaneously called for a slowdown in the pace of frontier model development. Anthropic CEO’s “slowdown declaration” was publicly rejected by Trump, and the market priced in “narrative damage” first—SoftBank fell 11%, SK hynix dropped more than 5%, and Samsung Electronics fell more than 3%. AI is the main engine of this round of trading. Once the consensus on “investment growth pace” is questioned, valuations are hit first, and near-term volatility will be noticeably amplified.
🪙 Cryptoassets
$BTC 76,596 USD (-0.87%), $ETH 2,475.79 USD (-1.98%), BNB 715.77 USD (-1.64%), SOL 99.34 USD (-2.24%). The whole market saw broad losses over the past 24 hours. Total market cap: $2.60 trillion. Total 24-hour volume: $54.0 billion. BTC dominance: 58.9%. Fear & Greed Index: 57 (Greed).
The ETF side held up instead: IBIT 43.77 (+0.21%), FBTC 67.25 (+0.28%), ETHA 19.16 (+3.23%), with no sign of outflows. On the losers’ list, ZEC fell 5.84%, SUI fell 4.04%, and SOL losing the $100 level is worth watching. Institutional and on-chain news isn’t too bad. CryptoQuant believes BTC must stay above $81,700 to confirm the start of a new bull cycle. The “Clarity Act” remains undecided after the Senate reconvened. Bitcoin Suisse plans to cut up to half of its Swiss roles. Overall, it’s a wait-and-see pattern of “macro waiting for the Fed, industry waiting for legislation.”
🥇 Gold
$XAUT 4,337.74 USD (-0.29%). Gold prices are consolidating narrowly above $4,300. On one side, rate-hike expectations are heating up; on the other, geographic risk around the Strait of Hormuz. Neither bulls nor bears want to make the first move.
📰 Crypto News
- The U.S. Senate reconvened; the “Clarity Act” remains stuck in a “life-or-death overlap” stalemate, and industry legislation is unlikely to reach conclusions in the short term. (CoinDesk)
- CryptoQuant: BTC must break through the $81,700 resistance level to confirm the start of a new bull cycle. (The Block)
- Blockstream refused to pay a ransom for the remaining 600 BTC stolen from the Liquid sidechain; Symbiosis has recovered 15 BTC and offered a 20% bounty to the attacker. (The Block)
- Crypto tycoons Ben Delo and Christopher Harborne each donated £36 million to the UK’s Reform UK, totaling about $97 million within 24 hours. (CoinDesk)
🌐 Macro News
- The U.S. August core CPI rose 0.3% month-over-month, above expectations; market pricing for this week’s Fed rate hike climbed to nearly 90%. (CNBC)
- A ship was attacked in the Strait of Hormuz. Saudi Arabia shut an important oil pipeline, and the GCC and Iran talks were postponed. In early trading in Asia on Monday, international oil prices rose more than 3%. (CNBC)
- Trump rejected calls from tech giants to “slow down AI development,” saying the U.S. cannot concede in the race. (FT)
📅 Economic Data Preview This Week
- The Fed’s FOMC policy meeting will be held this week. The market expects a rate-hike probability of nearly 90%, and the decision will be released at around 4:00 a.m. Beijing time on Thursday.
- U.S. Initial Jobless Claims: Thursday
1
324
·
--
Finance Daily Report | September 11, 2026, Friday
📊 US Stocks
The Dow Jones is at 52,064 points (-0.60%), the S&P 500 at 7,591 points (-0.58%), and the Nasdaq at 26,081 points (-0.65%). All three major indexes fell for the third consecutive day, but the decline narrowed. Ahead of tonight’s inflation data, the market clearly chose to wait. Inside the tech sector, the split was severe: memory chips continued to be treated as a safe haven for capital. Micron rose 2.75% and SanDisk rose 1.51%. Oracle’s cloud infrastructure revenue more than doubled year over year, and its results beat expectations—winning investor applause. Meanwhile, Adobe’s earnings report was criticized by Wall Street as “not surprising enough.” The real pressure came from the bond market—yields on the 30-year US Treasuries hit a 19-year high, and the 10-year yield rose to 4.94%. WTI oil surged more than 7% in a single day, reigniting inflation expectations. Markets have clearly been warming to the prospect of a Fed rate hike next week. In one sentence: the indexes are down, but panic hasn’t arrived—just the price of living the good days is getting higher.
🪙 Crypto
$BTC is at $76,800 (-1.86%). The $80,000 level was tested again but failed for the third consecutive day. $ETH is at $2,450 (-0.76%), comparatively holding up. BNB is $712 (-1.42%), and SOL is $98.8 (-2.47%). Mainstream coins show a watch-and-wait pattern of low-volume drifting lower. Bloodbath at the edge: ZEC plunged 12.07% in a day, yet 24h trading volume surged to $349 million—typical of a profit-taking stampede. SUI fell 4.69% and AVAX fell 4.05%. The only contrarians in the whole market were TON (+0.95%) and TRX (+0.44%). Total crypto market cap is $2.63 trillion, with about $89 billion in 24h trading volume. BTC’s share is 58.5%. The Fear & Greed Index is 56—pulling back from “greed” to neutral-to-warm, and sentiment and prices are cooling in sync. ETF flows were modestly out: IBIT 44.29 (-0.23%), FBTC 68.04 (-0.26%), and ETHA 18.58 (-0.75%). Institutions have not shown trend-like retreat yet.
🥇 Gold
$XAUT is at $4,324.5 (-1.63%). Soaring Treasury yields and a stronger dollar overwhelmed safe-haven demand, completing a healthy pullback from elevated levels.
📰 Crypto News
· Bitcoin fell back due to US PPI data coming in below expectations; 30-year US Treasury yields hit a 19-year high (CoinTelegraph)
· The Senate’s Republican Party released revised Clarity Act text; adjustments to DeFi and credit union provisions; key vote on September 15 (CoinDesk)
· Nasdaq invested $100 million in Kraken’s parent company Payward, valuing it at $21 billion (TheBlock)
· Liquid Network resumed block production after recovering from a $320 million attack (CoinTelegraph)
🌐 Macro News
· US August PPI rose 0.4% month over month, in line with expectations, but bond market pricing shows increasing policy risk for the Fed next week (CNBC)
· The US announced it would ban imports of a batch of Canadian goods; Canada’s retaliatory tariffs worth CAD 27.6 billion took effect at the same time (CNBC)
· Japan’s August corporate goods price index rose 7.6% year over year, exceeding expectations; the Nikkei fell more than 2% in the early session, and SK Hynix dropped more than 4% (Wall Street Insights)
📅 Economic Data Preview This Week
· Friday (tonight) 20:30 US August CPI—the last major inflation datapoint before the September 15–16 FOMC interest-rate decision meetings
· Next week, September 15–16: the Fed FOMC interest-rate decision meeting
Finance Daily Report | September 11, 2026, Friday
📊 US Stocks
The Dow Jones is at 52,064 points (-0.60%), the S&P 500 at 7,591 points (-0.58%), and the Nasdaq at 26,081 points (-0.65%). All three major indexes fell for the third consecutive day, but the decline narrowed. Ahead of tonight’s inflation data, the market clearly chose to wait. Inside the tech sector, the split was severe: memory chips continued to be treated as a safe haven for capital. Micron rose 2.75% and SanDisk rose 1.51%. Oracle’s cloud infrastructure revenue more than doubled year over year, and its results beat expectations—winning investor applause. Meanwhile, Adobe’s earnings report was criticized by Wall Street as “not surprising enough.” The real pressure came from the bond market—yields on the 30-year US Treasuries hit a 19-year high, and the 10-year yield rose to 4.94%. WTI oil surged more than 7% in a single day, reigniting inflation expectations. Markets have clearly been warming to the prospect of a Fed rate hike next week. In one sentence: the indexes are down, but panic hasn’t arrived—just the price of living the good days is getting higher.
🪙 Crypto
$BTC is at $76,800 (-1.86%). The $80,000 level was tested again but failed for the third consecutive day. $ETH is at $2,450 (-0.76%), comparatively holding up. BNB is $712 (-1.42%), and SOL is $98.8 (-2.47%). Mainstream coins show a watch-and-wait pattern of low-volume drifting lower. Bloodbath at the edge: ZEC plunged 12.07% in a day, yet 24h trading volume surged to $349 million—typical of a profit-taking stampede. SUI fell 4.69% and AVAX fell 4.05%. The only contrarians in the whole market were TON (+0.95%) and TRX (+0.44%). Total crypto market cap is $2.63 trillion, with about $89 billion in 24h trading volume. BTC’s share is 58.5%. The Fear & Greed Index is 56—pulling back from “greed” to neutral-to-warm, and sentiment and prices are cooling in sync. ETF flows were modestly out: IBIT 44.29 (-0.23%), FBTC 68.04 (-0.26%), and ETHA 18.58 (-0.75%). Institutions have not shown trend-like retreat yet.
🥇 Gold
$XAUT is at $4,324.5 (-1.63%). Soaring Treasury yields and a stronger dollar overwhelmed safe-haven demand, completing a healthy pullback from elevated levels.
📰 Crypto News
· Bitcoin fell back due to US PPI data coming in below expectations; 30-year US Treasury yields hit a 19-year high (CoinTelegraph)
· The Senate’s Republican Party released revised Clarity Act text; adjustments to DeFi and credit union provisions; key vote on September 15 (CoinDesk)
· Nasdaq invested $100 million in Kraken’s parent company Payward, valuing it at $21 billion (TheBlock)
· Liquid Network resumed block production after recovering from a $320 million attack (CoinTelegraph)
🌐 Macro News
· US August PPI rose 0.4% month over month, in line with expectations, but bond market pricing shows increasing policy risk for the Fed next week (CNBC)
· The US announced it would ban imports of a batch of Canadian goods; Canada’s retaliatory tariffs worth CAD 27.6 billion took effect at the same time (CNBC)
· Japan’s August corporate goods price index rose 7.6% year over year, exceeding expectations; the Nikkei fell more than 2% in the early session, and SK Hynix dropped more than 4% (Wall Street Insights)
📅 Economic Data Preview This Week
· Friday (tonight) 20:30 US August CPI—the last major inflation datapoint before the September 15–16 FOMC interest-rate decision meetings
· Next week, September 15–16: the Fed FOMC interest-rate decision meeting
📊 US Stocks
The Dow Jones is at 52,064 points (-0.60%), the S&P 500 at 7,591 points (-0.58%), and the Nasdaq at 26,081 points (-0.65%). All three major indexes fell for the third consecutive day, but the decline narrowed. Ahead of tonight’s inflation data, the market clearly chose to wait. Inside the tech sector, the split was severe: memory chips continued to be treated as a safe haven for capital. Micron rose 2.75% and SanDisk rose 1.51%. Oracle’s cloud infrastructure revenue more than doubled year over year, and its results beat expectations—winning investor applause. Meanwhile, Adobe’s earnings report was criticized by Wall Street as “not surprising enough.” The real pressure came from the bond market—yields on the 30-year US Treasuries hit a 19-year high, and the 10-year yield rose to 4.94%. WTI oil surged more than 7% in a single day, reigniting inflation expectations. Markets have clearly been warming to the prospect of a Fed rate hike next week. In one sentence: the indexes are down, but panic hasn’t arrived—just the price of living the good days is getting higher.
🪙 Crypto
$BTC is at $76,800 (-1.86%). The $80,000 level was tested again but failed for the third consecutive day. $ETH is at $2,450 (-0.76%), comparatively holding up. BNB is $712 (-1.42%), and SOL is $98.8 (-2.47%). Mainstream coins show a watch-and-wait pattern of low-volume drifting lower. Bloodbath at the edge: ZEC plunged 12.07% in a day, yet 24h trading volume surged to $349 million—typical of a profit-taking stampede. SUI fell 4.69% and AVAX fell 4.05%. The only contrarians in the whole market were TON (+0.95%) and TRX (+0.44%). Total crypto market cap is $2.63 trillion, with about $89 billion in 24h trading volume. BTC’s share is 58.5%. The Fear & Greed Index is 56—pulling back from “greed” to neutral-to-warm, and sentiment and prices are cooling in sync. ETF flows were modestly out: IBIT 44.29 (-0.23%), FBTC 68.04 (-0.26%), and ETHA 18.58 (-0.75%). Institutions have not shown trend-like retreat yet.
🥇 Gold
$XAUT is at $4,324.5 (-1.63%). Soaring Treasury yields and a stronger dollar overwhelmed safe-haven demand, completing a healthy pullback from elevated levels.
📰 Crypto News
· Bitcoin fell back due to US PPI data coming in below expectations; 30-year US Treasury yields hit a 19-year high (CoinTelegraph)
· The Senate’s Republican Party released revised Clarity Act text; adjustments to DeFi and credit union provisions; key vote on September 15 (CoinDesk)
· Nasdaq invested $100 million in Kraken’s parent company Payward, valuing it at $21 billion (TheBlock)
· Liquid Network resumed block production after recovering from a $320 million attack (CoinTelegraph)
🌐 Macro News
· US August PPI rose 0.4% month over month, in line with expectations, but bond market pricing shows increasing policy risk for the Fed next week (CNBC)
· The US announced it would ban imports of a batch of Canadian goods; Canada’s retaliatory tariffs worth CAD 27.6 billion took effect at the same time (CNBC)
· Japan’s August corporate goods price index rose 7.6% year over year, exceeding expectations; the Nikkei fell more than 2% in the early session, and SK Hynix dropped more than 4% (Wall Street Insights)
📅 Economic Data Preview This Week
· Friday (tonight) 20:30 US August CPI—the last major inflation datapoint before the September 15–16 FOMC interest-rate decision meetings
· Next week, September 15–16: the Fed FOMC interest-rate decision meeting
1
475
·
--
Briefly analyze this coin $ZEC based on various data.
First, this rally isn’t entirely driven by short squeezes. The core driver is a channel change: Grayscale has converted the Zcash Trust into an ETF, which has been trading since August 25. This opens a compliant funding channel for ZEC—structural rather than purely narrative-based as a catalyst.
Current futures structure: open interest stands at 558,000 coins (about $697 million), up 3.8% over 24 hours. Price rise together with rising open interest suggests new capital is driving the move, not just short covering. The long/short ratio in accounts is 0.44 (about 70% of accounts are net short), and the large-holder long/short ratio is 0.85. The short positioning is crowded and concentrated on the retail side.
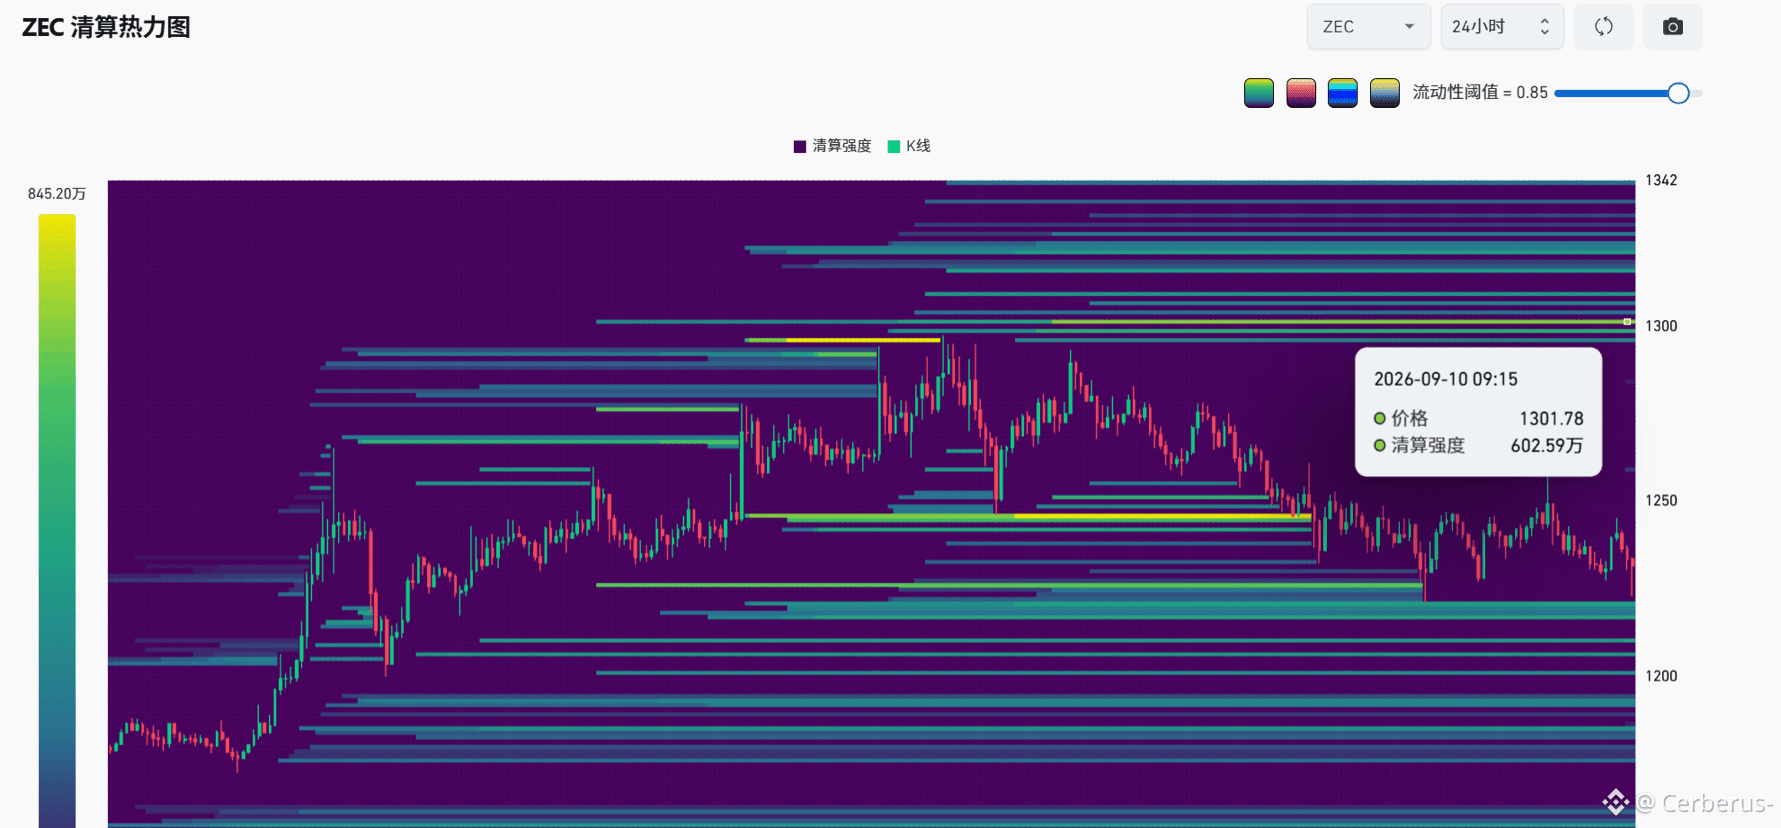
Key levels: the overhead 1,300–1,342 area is a buildup zone for short liquidation. A high-volume breakout above 1,300 is a confirmation of trend continuation. The downside 1,150–1,200 is a dense liquidation zone for longs, with 1,171 serving as a short-term line of defense.
The ETF channel provides a tangible support, but a 45% surge over one week has already priced in a lot of expectations. At the current price, the distance to the liquidation wall is less than 6%, so the risk-reward ratio of chasing is generally not favorable. It’s advisable to monitor the quality of the breakout above 1,300 and the durability of ETF-related capital flows.
Briefly analyze this coin $ZEC based on various data.
First, this rally isn’t entirely driven by short squeezes. The core driver is a channel change: Grayscale has converted the Zcash Trust into an ETF, which has been trading since August 25. This opens a compliant funding channel for ZEC—structural rather than purely narrative-based as a catalyst.
Current futures structure: open interest stands at 558,000 coins (about $697 million), up 3.8% over 24 hours. Price rise together with rising open interest suggests new capital is driving the move, not just short covering. The long/short ratio in accounts is 0.44 (about 70% of accounts are net short), and the large-holder long/short ratio is 0.85. The short positioning is crowded and concentrated on the retail side.
Key levels: the overhead 1,300–1,342 area is a buildup zone for short liquidation. A high-volume breakout above 1,300 is a confirmation of trend continuation. The downside 1,150–1,200 is a dense liquidation zone for longs, with 1,171 serving as a short-term line of defense.
The ETF channel provides a tangible support, but a 45% surge over one week has already priced in a lot of expectations. At the current price, the distance to the liquidation wall is less than 6%, so the risk-reward ratio of chasing is generally not favorable. It’s advisable to monitor the quality of the breakout above 1,300 and the durability of ETF-related capital flows.
First, this rally isn’t entirely driven by short squeezes. The core driver is a channel change: Grayscale has converted the Zcash Trust into an ETF, which has been trading since August 25. This opens a compliant funding channel for ZEC—structural rather than purely narrative-based as a catalyst.
Current futures structure: open interest stands at 558,000 coins (about $697 million), up 3.8% over 24 hours. Price rise together with rising open interest suggests new capital is driving the move, not just short covering. The long/short ratio in accounts is 0.44 (about 70% of accounts are net short), and the large-holder long/short ratio is 0.85. The short positioning is crowded and concentrated on the retail side.
Key levels: the overhead 1,300–1,342 area is a buildup zone for short liquidation. A high-volume breakout above 1,300 is a confirmation of trend continuation. The downside 1,150–1,200 is a dense liquidation zone for longs, with 1,171 serving as a short-term line of defense.
The ETF channel provides a tangible support, but a 45% surge over one week has already priced in a lot of expectations. At the current price, the distance to the liquidation wall is less than 6%, so the risk-reward ratio of chasing is generally not favorable. It’s advisable to monitor the quality of the breakout above 1,300 and the durability of ETF-related capital flows.
208
·
--
Financial Daily Report | September 10, 2026, Thursday
📊 US Stocks
The Dow was 52,381 points (-0.77%), the S&P 500 7,636 points (-0.48%), and the Nasdaq 26,253 points (-0.64%). US stocks fell for a second straight day: a $6 billion Treasury share buyback plan disappointed the market, U.S. Treasury yields jumped to 4.84%, and inflation concerns intensified after oil prices broke above $100, putting pressure on high-valuation growth stocks across the board. Storage-chip leaders from earlier saw a pullback at the highs: Micron fell 1.6% and SanDisk edged lower. The AI hardware main theme entered a consolidation phase.
🪙 Cryptocurrencies
$BTC is at $78,269 (-0.41%). The market again failed to break through the $80,000 level, and is trading in a tightening range around $78,000 with reduced volume. $ETH is at $2,469 (-0.79%), moving in line with the broader market. BNB at $721.5 (-4.44%) led the decline among major coins, while SOL at $101.3 (-2.16%). Notable movers: ZEC rose 4.4% against the trend, with 24h trading volume of $336 million and strength for a second consecutive day. DOT, which surged the day before, gave back 8.1%, while SUI fell 6.1%. Total crypto market cap: $2.68 trillion; 24h trading volume: about $95 billion. BTC dominance: 58.6%. Fear & Greed Index: 69 (Greed). Sentiment remains upbeat, but prices are stalling—watch out for repeated swings at high levels. ETF updates: IBIT 44.39 (-1.86%), FBTC 68.22 (-1.71%), ETHA 18.72 (+1.08%).
🥇 Gold
$XAUT is at $4,393 (+1.03%); COMEX gold futures are at $4,441 (+1.07%). With uncertainty from both tariffs and oil prices, safe-haven buying has pushed gold prices back into strength.
📰 Crypto News
· Consensys announced a split: MetaMask will operate independently; the company did not comment on IPO rumors (CoinDesk)
· Tether teams up with Fasanara to launch a $400 million private credit fund, targeting $3.0 billion (CoinTelegraph)
· Germany’s finance ministry new draft: cryptocurrencies such as Bitcoin would be taxed under stock rules; long-term holding tax-free benefits may be ended (CoinDesk)
· US Secret Service freezes $52.8 million in crypto funds related to Telegram scam “marketplaces” (Decrypt)
🌐 Macro News
· The US announced it would ban imports of a batch of Canadian goods, escalating the US–Canada trade war; Canada’s retaliatory tariffs worth 27.6 billion CAD take effect simultaneously (CNBC)
· The Treasury’s $6 billion buyback plan disappointed the market, sending U.S. Treasury yields higher; Finance Minister Bessent said “I am the market maker,” warning not to short the yen (FT)
· Brent crude returned above $100, and inflation worries resurfaced (MarketWatch)
📅 Economic Data Calendar This Week
· Thursday (tonight) 20:30 US weekly initial jobless claims
· Friday 20:30 US August CPI—last key inflation data before the September 15–16 FOMC meeting
Financial Daily Report | September 10, 2026, Thursday
📊 US Stocks
The Dow was 52,381 points (-0.77%), the S&P 500 7,636 points (-0.48%), and the Nasdaq 26,253 points (-0.64%). US stocks fell for a second straight day: a $6 billion Treasury share buyback plan disappointed the market, U.S. Treasury yields jumped to 4.84%, and inflation concerns intensified after oil prices broke above $100, putting pressure on high-valuation growth stocks across the board. Storage-chip leaders from earlier saw a pullback at the highs: Micron fell 1.6% and SanDisk edged lower. The AI hardware main theme entered a consolidation phase.
🪙 Cryptocurrencies
$BTC is at $78,269 (-0.41%). The market again failed to break through the $80,000 level, and is trading in a tightening range around $78,000 with reduced volume. $ETH is at $2,469 (-0.79%), moving in line with the broader market. BNB at $721.5 (-4.44%) led the decline among major coins, while SOL at $101.3 (-2.16%). Notable movers: ZEC rose 4.4% against the trend, with 24h trading volume of $336 million and strength for a second consecutive day. DOT, which surged the day before, gave back 8.1%, while SUI fell 6.1%. Total crypto market cap: $2.68 trillion; 24h trading volume: about $95 billion. BTC dominance: 58.6%. Fear & Greed Index: 69 (Greed). Sentiment remains upbeat, but prices are stalling—watch out for repeated swings at high levels. ETF updates: IBIT 44.39 (-1.86%), FBTC 68.22 (-1.71%), ETHA 18.72 (+1.08%).
🥇 Gold
$XAUT is at $4,393 (+1.03%); COMEX gold futures are at $4,441 (+1.07%). With uncertainty from both tariffs and oil prices, safe-haven buying has pushed gold prices back into strength.
📰 Crypto News
· Consensys announced a split: MetaMask will operate independently; the company did not comment on IPO rumors (CoinDesk)
· Tether teams up with Fasanara to launch a $400 million private credit fund, targeting $3.0 billion (CoinTelegraph)
· Germany’s finance ministry new draft: cryptocurrencies such as Bitcoin would be taxed under stock rules; long-term holding tax-free benefits may be ended (CoinDesk)
· US Secret Service freezes $52.8 million in crypto funds related to Telegram scam “marketplaces” (Decrypt)
🌐 Macro News
· The US announced it would ban imports of a batch of Canadian goods, escalating the US–Canada trade war; Canada’s retaliatory tariffs worth 27.6 billion CAD take effect simultaneously (CNBC)
· The Treasury’s $6 billion buyback plan disappointed the market, sending U.S. Treasury yields higher; Finance Minister Bessent said “I am the market maker,” warning not to short the yen (FT)
· Brent crude returned above $100, and inflation worries resurfaced (MarketWatch)
📅 Economic Data Calendar This Week
· Thursday (tonight) 20:30 US weekly initial jobless claims
· Friday 20:30 US August CPI—last key inflation data before the September 15–16 FOMC meeting
📊 US Stocks
The Dow was 52,381 points (-0.77%), the S&P 500 7,636 points (-0.48%), and the Nasdaq 26,253 points (-0.64%). US stocks fell for a second straight day: a $6 billion Treasury share buyback plan disappointed the market, U.S. Treasury yields jumped to 4.84%, and inflation concerns intensified after oil prices broke above $100, putting pressure on high-valuation growth stocks across the board. Storage-chip leaders from earlier saw a pullback at the highs: Micron fell 1.6% and SanDisk edged lower. The AI hardware main theme entered a consolidation phase.
🪙 Cryptocurrencies
$BTC is at $78,269 (-0.41%). The market again failed to break through the $80,000 level, and is trading in a tightening range around $78,000 with reduced volume. $ETH is at $2,469 (-0.79%), moving in line with the broader market. BNB at $721.5 (-4.44%) led the decline among major coins, while SOL at $101.3 (-2.16%). Notable movers: ZEC rose 4.4% against the trend, with 24h trading volume of $336 million and strength for a second consecutive day. DOT, which surged the day before, gave back 8.1%, while SUI fell 6.1%. Total crypto market cap: $2.68 trillion; 24h trading volume: about $95 billion. BTC dominance: 58.6%. Fear & Greed Index: 69 (Greed). Sentiment remains upbeat, but prices are stalling—watch out for repeated swings at high levels. ETF updates: IBIT 44.39 (-1.86%), FBTC 68.22 (-1.71%), ETHA 18.72 (+1.08%).
🥇 Gold
$XAUT is at $4,393 (+1.03%); COMEX gold futures are at $4,441 (+1.07%). With uncertainty from both tariffs and oil prices, safe-haven buying has pushed gold prices back into strength.
📰 Crypto News
· Consensys announced a split: MetaMask will operate independently; the company did not comment on IPO rumors (CoinDesk)
· Tether teams up with Fasanara to launch a $400 million private credit fund, targeting $3.0 billion (CoinTelegraph)
· Germany’s finance ministry new draft: cryptocurrencies such as Bitcoin would be taxed under stock rules; long-term holding tax-free benefits may be ended (CoinDesk)
· US Secret Service freezes $52.8 million in crypto funds related to Telegram scam “marketplaces” (Decrypt)
🌐 Macro News
· The US announced it would ban imports of a batch of Canadian goods, escalating the US–Canada trade war; Canada’s retaliatory tariffs worth 27.6 billion CAD take effect simultaneously (CNBC)
· The Treasury’s $6 billion buyback plan disappointed the market, sending U.S. Treasury yields higher; Finance Minister Bessent said “I am the market maker,” warning not to short the yen (FT)
· Brent crude returned above $100, and inflation worries resurfaced (MarketWatch)
📅 Economic Data Calendar This Week
· Thursday (tonight) 20:30 US weekly initial jobless claims
· Friday 20:30 US August CPI—last key inflation data before the September 15–16 FOMC meeting
379
·
--
Financial Daily | September 9, 2026, Wednesday
📊 US Stocks
The Dow Jones 52,786 points (-1.18%), the S&P 500 7,673 points (-0.58%), the Nasdaq 26,421 points (-0.32%). On Tuesday, US stocks collectively fell, with the trigger being the situation in the Middle East and oil prices: after the U.S. military destroyed five Iranian oil tankers, Brent crude pushed toward nearly $100 per barrel, reigniting worries about inflation and interest-rate hikes, and the Dow led the decline. Tech stocks held up relatively better—AI hardware remains the main storyline: Qualcomm secured an order from Amazon for chips; AI infrastructure stocks such as Corning rose; the storage supply-chain remained hot—SanDisk surged 11.9% and Micron rose 6.1%. In terms of sentiment, the market is being pulled between the “oil-price shock” and the “AI long-term logic.”
🪙 Crypto
The price of $BTC is $78,630 (24h -0.47%). It is currently struggling above the key $78,300 support level. CoinTelegraph says this area is the pivot between bulls and bears; US crude hitting a three-month high brings macro pressure. However, CoinDesk observed that when BTC pulled back, BNB and DeFi coins strengthened against the trend—funds rotated within the sector rather than exiting. $ETH is $2,491 (+0.29%): Bitmine bought 28,086 ETH in a single day (about $70 million), with its holdings nearing 5% of Ethereum’s total supply. Analyst Tom DeMark expects the uptrend to resume soon. BNB $755 (+2.26%) led major coins higher, while SOL $103.6 (+0.14%). Among the movers, DOT jumped 15.4% to lead, and ZEC rose 4.7%. Total crypto market cap is $2.70 trillion; 24h trading volume is about $91 billion. BTC dominance is 58.3%, and the Fear & Greed Index is 66 (Greed). ETFs followed their underlying assets lower: IBIT 45.23 (-2.42%), FBTC 69.41 (-2.53%), ETHA 18.52 (-2.63%). As of this year, BTC ETF assets still lag roughly $1 billion behind breakeven (CoinDesk).
🥇 Gold
$XAUT is $4,348 (24h -1.61%); COMEX gold futures are $4,392 (-0.85%). It’s rare to see an unusual divergence between oil and gold—safe-haven funds favor crude oil more, and gold prices are consolidating near recent highs ahead of CPI data.
📰 Crypto Headlines
· Bitmine buys another 28,086 ETH; its cold-storage accumulation target is already 97%, with holdings nearing 5% of Ethereum’s total supply (TheBlock)
· Strategy pauses buying coins, prioritizing a $176 million share buyback of STRC preferred stock; it returns to buying coins only for a week before stopping again (Decrypt)
· Circle acquires cross-border payments company Tazapay for $400 million, expanding the USDC footprint (CoinDesk)
· The Cronos chain executes a rollback, erasing two hours of transactions, and recovers losses of $111 million from a DeFi attack (CoinDesk)
🌐 Macroeconomic News
· The U.S. military destroyed five Iranian oil tankers; Iran’s missile attack on Jordan was intercepted; Brent crude is nearing $100 (CNBC/FT)
· Canada’s retaliatory tariffs of C$27.6 billion against the U.S. take effect, deepening the trade rift between the U.S. and Canada (CNBC)
· The oil-price shock reignites bets on Fed rate hikes, as Trump increases pressure on Fed Chair Waller (CNBC/Decrypt)
📅 This Week’s Economic Data Preview
· Thursday: US initial jobless claims for the week (20:30 Beijing time)
· Friday: US August CPI (20:30 Beijing time), the final key inflation data before the September 15–16 FOMC meeting
Financial Daily | September 9, 2026, Wednesday
📊 US Stocks
The Dow Jones 52,786 points (-1.18%), the S&P 500 7,673 points (-0.58%), the Nasdaq 26,421 points (-0.32%). On Tuesday, US stocks collectively fell, with the trigger being the situation in the Middle East and oil prices: after the U.S. military destroyed five Iranian oil tankers, Brent crude pushed toward nearly $100 per barrel, reigniting worries about inflation and interest-rate hikes, and the Dow led the decline. Tech stocks held up relatively better—AI hardware remains the main storyline: Qualcomm secured an order from Amazon for chips; AI infrastructure stocks such as Corning rose; the storage supply-chain remained hot—SanDisk surged 11.9% and Micron rose 6.1%. In terms of sentiment, the market is being pulled between the “oil-price shock” and the “AI long-term logic.”
🪙 Crypto
The price of $BTC is $78,630 (24h -0.47%). It is currently struggling above the key $78,300 support level. CoinTelegraph says this area is the pivot between bulls and bears; US crude hitting a three-month high brings macro pressure. However, CoinDesk observed that when BTC pulled back, BNB and DeFi coins strengthened against the trend—funds rotated within the sector rather than exiting. $ETH is $2,491 (+0.29%): Bitmine bought 28,086 ETH in a single day (about $70 million), with its holdings nearing 5% of Ethereum’s total supply. Analyst Tom DeMark expects the uptrend to resume soon. BNB $755 (+2.26%) led major coins higher, while SOL $103.6 (+0.14%). Among the movers, DOT jumped 15.4% to lead, and ZEC rose 4.7%. Total crypto market cap is $2.70 trillion; 24h trading volume is about $91 billion. BTC dominance is 58.3%, and the Fear & Greed Index is 66 (Greed). ETFs followed their underlying assets lower: IBIT 45.23 (-2.42%), FBTC 69.41 (-2.53%), ETHA 18.52 (-2.63%). As of this year, BTC ETF assets still lag roughly $1 billion behind breakeven (CoinDesk).
🥇 Gold
$XAUT is $4,348 (24h -1.61%); COMEX gold futures are $4,392 (-0.85%). It’s rare to see an unusual divergence between oil and gold—safe-haven funds favor crude oil more, and gold prices are consolidating near recent highs ahead of CPI data.
📰 Crypto Headlines
· Bitmine buys another 28,086 ETH; its cold-storage accumulation target is already 97%, with holdings nearing 5% of Ethereum’s total supply (TheBlock)
· Strategy pauses buying coins, prioritizing a $176 million share buyback of STRC preferred stock; it returns to buying coins only for a week before stopping again (Decrypt)
· Circle acquires cross-border payments company Tazapay for $400 million, expanding the USDC footprint (CoinDesk)
· The Cronos chain executes a rollback, erasing two hours of transactions, and recovers losses of $111 million from a DeFi attack (CoinDesk)
🌐 Macroeconomic News
· The U.S. military destroyed five Iranian oil tankers; Iran’s missile attack on Jordan was intercepted; Brent crude is nearing $100 (CNBC/FT)
· Canada’s retaliatory tariffs of C$27.6 billion against the U.S. take effect, deepening the trade rift between the U.S. and Canada (CNBC)
· The oil-price shock reignites bets on Fed rate hikes, as Trump increases pressure on Fed Chair Waller (CNBC/Decrypt)
📅 This Week’s Economic Data Preview
· Thursday: US initial jobless claims for the week (20:30 Beijing time)
· Friday: US August CPI (20:30 Beijing time), the final key inflation data before the September 15–16 FOMC meeting
📊 US Stocks
The Dow Jones 52,786 points (-1.18%), the S&P 500 7,673 points (-0.58%), the Nasdaq 26,421 points (-0.32%). On Tuesday, US stocks collectively fell, with the trigger being the situation in the Middle East and oil prices: after the U.S. military destroyed five Iranian oil tankers, Brent crude pushed toward nearly $100 per barrel, reigniting worries about inflation and interest-rate hikes, and the Dow led the decline. Tech stocks held up relatively better—AI hardware remains the main storyline: Qualcomm secured an order from Amazon for chips; AI infrastructure stocks such as Corning rose; the storage supply-chain remained hot—SanDisk surged 11.9% and Micron rose 6.1%. In terms of sentiment, the market is being pulled between the “oil-price shock” and the “AI long-term logic.”
🪙 Crypto
The price of $BTC is $78,630 (24h -0.47%). It is currently struggling above the key $78,300 support level. CoinTelegraph says this area is the pivot between bulls and bears; US crude hitting a three-month high brings macro pressure. However, CoinDesk observed that when BTC pulled back, BNB and DeFi coins strengthened against the trend—funds rotated within the sector rather than exiting. $ETH is $2,491 (+0.29%): Bitmine bought 28,086 ETH in a single day (about $70 million), with its holdings nearing 5% of Ethereum’s total supply. Analyst Tom DeMark expects the uptrend to resume soon. BNB $755 (+2.26%) led major coins higher, while SOL $103.6 (+0.14%). Among the movers, DOT jumped 15.4% to lead, and ZEC rose 4.7%. Total crypto market cap is $2.70 trillion; 24h trading volume is about $91 billion. BTC dominance is 58.3%, and the Fear & Greed Index is 66 (Greed). ETFs followed their underlying assets lower: IBIT 45.23 (-2.42%), FBTC 69.41 (-2.53%), ETHA 18.52 (-2.63%). As of this year, BTC ETF assets still lag roughly $1 billion behind breakeven (CoinDesk).
🥇 Gold
$XAUT is $4,348 (24h -1.61%); COMEX gold futures are $4,392 (-0.85%). It’s rare to see an unusual divergence between oil and gold—safe-haven funds favor crude oil more, and gold prices are consolidating near recent highs ahead of CPI data.
📰 Crypto Headlines
· Bitmine buys another 28,086 ETH; its cold-storage accumulation target is already 97%, with holdings nearing 5% of Ethereum’s total supply (TheBlock)
· Strategy pauses buying coins, prioritizing a $176 million share buyback of STRC preferred stock; it returns to buying coins only for a week before stopping again (Decrypt)
· Circle acquires cross-border payments company Tazapay for $400 million, expanding the USDC footprint (CoinDesk)
· The Cronos chain executes a rollback, erasing two hours of transactions, and recovers losses of $111 million from a DeFi attack (CoinDesk)
🌐 Macroeconomic News
· The U.S. military destroyed five Iranian oil tankers; Iran’s missile attack on Jordan was intercepted; Brent crude is nearing $100 (CNBC/FT)
· Canada’s retaliatory tariffs of C$27.6 billion against the U.S. take effect, deepening the trade rift between the U.S. and Canada (CNBC)
· The oil-price shock reignites bets on Fed rate hikes, as Trump increases pressure on Fed Chair Waller (CNBC/Decrypt)
📅 This Week’s Economic Data Preview
· Thursday: US initial jobless claims for the week (20:30 Beijing time)
· Friday: US August CPI (20:30 Beijing time), the final key inflation data before the September 15–16 FOMC meeting
1
2
452
·
--
Financial Daily Report | Tuesday, September 8, 2026
📊 U.S. Stocks
Dow Jones 53,414 points (-0.51%), S&P 500 7,718 points (-0.38%), Nasdaq 26,506 points (-0.29%). Markets were closed last Monday for Labor Day; the figures above are Friday’s close. U.S. stocks will reopen tonight after the holiday. The main narrative line remains storage chips: SanDisk and Micron lead the way, and the AI storage demand story is igniting investor enthusiasm. However, technical charts still suggest short-term pullback risks in the sector have not disappeared. In terms of sentiment, after August’s non-farm payrolls beat expectations, the market is instead worried about the Fed restarting rate hikes, and the tug-of-war between Trump and Fed Chair Waller has become a new source of uncertainty.
🪙 Crypto
$BTC traded at $78,990 (24h -1.53%). Efforts to reclaim the $80,000 level over the weekend fell short: CoinDesk says a “wall” at around $83,000 is overhead, and whales have turned to net selling. CoinShares, however, indicates ETF flows are driven by trading the Fed rate path rather than exiting the market—last week’s spot BTC ETF net inflow totaled $987 million. $ETH traded at $2,484 (-1.39%); BNB at $738 (-1.87%), SOL at $103 (-2.71%), and the weekend altcoin rebound fizzled out. DOT rose against the trend by 4.95% to lead the pack, while ZEC fell back from highs by about 7%. Total crypto market cap is $2.68 trillion; 24h trading volume is about $73 billion. BTC dominance is 59.1%, and the Fear & Greed Index is 69 (“Greed”).
🥇 Gold
$XAUT 4,419 at $1,721 (24h +0.10%); COMEX gold futures at $4,473 (+0.98%). Gold prices remain strong at elevated levels, and demand for safe-haven allocations persists.
📰 Crypto Headlines
• Progress on the Liquid white-hat incident: the attacker has returned about $270 million (3,400 BTC), but still holds nearly 600 BTC; the network was paused for a time (TheBlock/Decrypt)
• Hunter Biden officially announces the issuance of LAPTOP meme-coin(s), with an air drop to TRUMP holdings (WSJ; followed by CoinDesk and others)
• Citigroup and DBS Bank complete their first weekend cross-border U.S. dollar payment, based on Swift digital ledger and tokenized deposits (CoinDesk/TheBlock)
• Ethereum advances a “pay Gas without holding ETH” proposal; the foundation has earmarked two must-push EIPs for the Hegotá upgrade (CoinDesk/CoinTelegraph)
🌐 Macro News
• The U.S. added 162,000 jobs in August non-farm payrolls, far above expectations; unemployment rate 4.1% (CNBC)
• Fed Governor Waller supports holding steady in September; Trump increases pressure on the chair, and rate-hike speculation heats up (CNBC)
• Japan’s foreign exchange reserves fell by $80 billion in August, a record decline; nominal wages saw the largest increase since 1997. Expectations for a rate hike by the Bank of Japan are heating up next week (CNBC/Wall Street Insights)
📅 This Week’s Economic Data Preview
U.S. August CPI will be released this week. It is the last key inflation datapoint before the September policy meeting, and will test the market pricing of “hiking versus waiting.” Jobless claims data are scheduled for Thursday.
Financial Daily Report | Tuesday, September 8, 2026
📊 U.S. Stocks
Dow Jones 53,414 points (-0.51%), S&P 500 7,718 points (-0.38%), Nasdaq 26,506 points (-0.29%). Markets were closed last Monday for Labor Day; the figures above are Friday’s close. U.S. stocks will reopen tonight after the holiday. The main narrative line remains storage chips: SanDisk and Micron lead the way, and the AI storage demand story is igniting investor enthusiasm. However, technical charts still suggest short-term pullback risks in the sector have not disappeared. In terms of sentiment, after August’s non-farm payrolls beat expectations, the market is instead worried about the Fed restarting rate hikes, and the tug-of-war between Trump and Fed Chair Waller has become a new source of uncertainty.
🪙 Crypto
$BTC traded at $78,990 (24h -1.53%). Efforts to reclaim the $80,000 level over the weekend fell short: CoinDesk says a “wall” at around $83,000 is overhead, and whales have turned to net selling. CoinShares, however, indicates ETF flows are driven by trading the Fed rate path rather than exiting the market—last week’s spot BTC ETF net inflow totaled $987 million. $ETH traded at $2,484 (-1.39%); BNB at $738 (-1.87%), SOL at $103 (-2.71%), and the weekend altcoin rebound fizzled out. DOT rose against the trend by 4.95% to lead the pack, while ZEC fell back from highs by about 7%. Total crypto market cap is $2.68 trillion; 24h trading volume is about $73 billion. BTC dominance is 59.1%, and the Fear & Greed Index is 69 (“Greed”).
🥇 Gold
$XAUT 4,419 at $1,721 (24h +0.10%); COMEX gold futures at $4,473 (+0.98%). Gold prices remain strong at elevated levels, and demand for safe-haven allocations persists.
📰 Crypto Headlines
• Progress on the Liquid white-hat incident: the attacker has returned about $270 million (3,400 BTC), but still holds nearly 600 BTC; the network was paused for a time (TheBlock/Decrypt)
• Hunter Biden officially announces the issuance of LAPTOP meme-coin(s), with an air drop to TRUMP holdings (WSJ; followed by CoinDesk and others)
• Citigroup and DBS Bank complete their first weekend cross-border U.S. dollar payment, based on Swift digital ledger and tokenized deposits (CoinDesk/TheBlock)
• Ethereum advances a “pay Gas without holding ETH” proposal; the foundation has earmarked two must-push EIPs for the Hegotá upgrade (CoinDesk/CoinTelegraph)
🌐 Macro News
• The U.S. added 162,000 jobs in August non-farm payrolls, far above expectations; unemployment rate 4.1% (CNBC)
• Fed Governor Waller supports holding steady in September; Trump increases pressure on the chair, and rate-hike speculation heats up (CNBC)
• Japan’s foreign exchange reserves fell by $80 billion in August, a record decline; nominal wages saw the largest increase since 1997. Expectations for a rate hike by the Bank of Japan are heating up next week (CNBC/Wall Street Insights)
📅 This Week’s Economic Data Preview
U.S. August CPI will be released this week. It is the last key inflation datapoint before the September policy meeting, and will test the market pricing of “hiking versus waiting.” Jobless claims data are scheduled for Thursday.
📊 U.S. Stocks
Dow Jones 53,414 points (-0.51%), S&P 500 7,718 points (-0.38%), Nasdaq 26,506 points (-0.29%). Markets were closed last Monday for Labor Day; the figures above are Friday’s close. U.S. stocks will reopen tonight after the holiday. The main narrative line remains storage chips: SanDisk and Micron lead the way, and the AI storage demand story is igniting investor enthusiasm. However, technical charts still suggest short-term pullback risks in the sector have not disappeared. In terms of sentiment, after August’s non-farm payrolls beat expectations, the market is instead worried about the Fed restarting rate hikes, and the tug-of-war between Trump and Fed Chair Waller has become a new source of uncertainty.
🪙 Crypto
$BTC traded at $78,990 (24h -1.53%). Efforts to reclaim the $80,000 level over the weekend fell short: CoinDesk says a “wall” at around $83,000 is overhead, and whales have turned to net selling. CoinShares, however, indicates ETF flows are driven by trading the Fed rate path rather than exiting the market—last week’s spot BTC ETF net inflow totaled $987 million. $ETH traded at $2,484 (-1.39%); BNB at $738 (-1.87%), SOL at $103 (-2.71%), and the weekend altcoin rebound fizzled out. DOT rose against the trend by 4.95% to lead the pack, while ZEC fell back from highs by about 7%. Total crypto market cap is $2.68 trillion; 24h trading volume is about $73 billion. BTC dominance is 59.1%, and the Fear & Greed Index is 69 (“Greed”).
🥇 Gold
$XAUT 4,419 at $1,721 (24h +0.10%); COMEX gold futures at $4,473 (+0.98%). Gold prices remain strong at elevated levels, and demand for safe-haven allocations persists.
📰 Crypto Headlines
• Progress on the Liquid white-hat incident: the attacker has returned about $270 million (3,400 BTC), but still holds nearly 600 BTC; the network was paused for a time (TheBlock/Decrypt)
• Hunter Biden officially announces the issuance of LAPTOP meme-coin(s), with an air drop to TRUMP holdings (WSJ; followed by CoinDesk and others)
• Citigroup and DBS Bank complete their first weekend cross-border U.S. dollar payment, based on Swift digital ledger and tokenized deposits (CoinDesk/TheBlock)
• Ethereum advances a “pay Gas without holding ETH” proposal; the foundation has earmarked two must-push EIPs for the Hegotá upgrade (CoinDesk/CoinTelegraph)
🌐 Macro News
• The U.S. added 162,000 jobs in August non-farm payrolls, far above expectations; unemployment rate 4.1% (CNBC)
• Fed Governor Waller supports holding steady in September; Trump increases pressure on the chair, and rate-hike speculation heats up (CNBC)
• Japan’s foreign exchange reserves fell by $80 billion in August, a record decline; nominal wages saw the largest increase since 1997. Expectations for a rate hike by the Bank of Japan are heating up next week (CNBC/Wall Street Insights)
📅 This Week’s Economic Data Preview
U.S. August CPI will be released this week. It is the last key inflation datapoint before the September policy meeting, and will test the market pricing of “hiking versus waiting.” Jobless claims data are scheduled for Thursday.
215
·
--
Financial Daily | Monday, September 7, 2026
📊 U.S. Stocks
The Dow Jones closed at 53,414 points (-0.51%), the S&P 500 at 7,718 points (-0.38%), and the Nasdaq at 26,506 points (-0.29%) as of last Friday’s close; the U.S. market is closed today for Labor Day. The main theme on the board is memory chips: SanDisk surged nearly 12% last Friday and Micron rose more than 6%; this morning, Asia picked up the rally, with SK Hynix, Samsung Electronics, and Kioxia all strengthening together, showing AI hardware momentum spreading from U.S. stocks to Asia. On sentiment, after August nonfarm payrolls came in above expectations, the market instead worried that the Fed might "not cut, but raise" rates, and the tug-of-war between Trump and Fed Chair Waller has become a new source of uncertainty.
🪙 Cryptocurrencies
$BTC 80,118 USD (24h +0.27%), $ETH 2,513 USD (+1.01%); BNB 752 USD (-2.04%), SOL 106 USD (+2.55%). BTC briefly lost the 80,000 level last Friday after the nonfarm payroll shock, but stabilized and recovered over the weekend. The total crypto market cap is $2.71 trillion, with about $70 billion in 24h trading volume, BTC dominance at 59.2%, and the Fear & Greed Index at 71 (Greed). ETF net inflows over the past three weeks reached $3.8 billion, setting the strongest fundraising record of 2026. Altcoin highlights: ZEC rose nearly 17% to above $1,200, DOT climbed more than 10%, and LINK gained more than 9%.
🥇 Gold
$XAUT 4,417 USD (24h -0.21%); COMEX gold futures at $4,477 (+1.06%). Central bank buying and safe-haven demand are supporting prices, keeping gold in a high-level range.
📰 Crypto News
· The Liquid network had about 4,000 BTC (roughly $320 million) transferred out by a "white hat," and operations were suspended for investigation (The Block)
· Spot BTC ETFs recorded $3.8 billion in net inflows over three weeks, setting a 2026 record (CoinTelegraph)
· A wallet from the "Satoshi era" dormant for 16 years has been reactivated, with 600 BTC transferred out (CoinTelegraph)
· Polymarket has launched crypto perpetual contracts with up to 20x leverage (Decrypt)
🌐 Macro News
· U.S. August nonfarm payrolls added 162,000, far above expectations, while unemployment was 4.1% (CNBC)
· Fed Governor Waller supports standing pat in September, while Trump intensifies pressure on Chair Waller (CNBC)
· Japan’s foreign reserves declined for the fourth consecutive month, mainly due to intervention in the yen at the end of July (Wall Street Insights)
📅 This Week’s Economic Data Preview
The U.S. market is closed on Monday for Labor Day; U.S. data are relatively light this week, with attention shifting to officials’ comments ahead of the September policy meeting and Thursday’s initial jobless claims.
Financial Daily | Monday, September 7, 2026
📊 U.S. Stocks
The Dow Jones closed at 53,414 points (-0.51%), the S&P 500 at 7,718 points (-0.38%), and the Nasdaq at 26,506 points (-0.29%) as of last Friday’s close; the U.S. market is closed today for Labor Day. The main theme on the board is memory chips: SanDisk surged nearly 12% last Friday and Micron rose more than 6%; this morning, Asia picked up the rally, with SK Hynix, Samsung Electronics, and Kioxia all strengthening together, showing AI hardware momentum spreading from U.S. stocks to Asia. On sentiment, after August nonfarm payrolls came in above expectations, the market instead worried that the Fed might "not cut, but raise" rates, and the tug-of-war between Trump and Fed Chair Waller has become a new source of uncertainty.
🪙 Cryptocurrencies
$BTC 80,118 USD (24h +0.27%), $ETH 2,513 USD (+1.01%); BNB 752 USD (-2.04%), SOL 106 USD (+2.55%). BTC briefly lost the 80,000 level last Friday after the nonfarm payroll shock, but stabilized and recovered over the weekend. The total crypto market cap is $2.71 trillion, with about $70 billion in 24h trading volume, BTC dominance at 59.2%, and the Fear & Greed Index at 71 (Greed). ETF net inflows over the past three weeks reached $3.8 billion, setting the strongest fundraising record of 2026. Altcoin highlights: ZEC rose nearly 17% to above $1,200, DOT climbed more than 10%, and LINK gained more than 9%.
🥇 Gold
$XAUT 4,417 USD (24h -0.21%); COMEX gold futures at $4,477 (+1.06%). Central bank buying and safe-haven demand are supporting prices, keeping gold in a high-level range.
📰 Crypto News
· The Liquid network had about 4,000 BTC (roughly $320 million) transferred out by a "white hat," and operations were suspended for investigation (The Block)
· Spot BTC ETFs recorded $3.8 billion in net inflows over three weeks, setting a 2026 record (CoinTelegraph)
· A wallet from the "Satoshi era" dormant for 16 years has been reactivated, with 600 BTC transferred out (CoinTelegraph)
· Polymarket has launched crypto perpetual contracts with up to 20x leverage (Decrypt)
🌐 Macro News
· U.S. August nonfarm payrolls added 162,000, far above expectations, while unemployment was 4.1% (CNBC)
· Fed Governor Waller supports standing pat in September, while Trump intensifies pressure on Chair Waller (CNBC)
· Japan’s foreign reserves declined for the fourth consecutive month, mainly due to intervention in the yen at the end of July (Wall Street Insights)
📅 This Week’s Economic Data Preview
The U.S. market is closed on Monday for Labor Day; U.S. data are relatively light this week, with attention shifting to officials’ comments ahead of the September policy meeting and Thursday’s initial jobless claims.
📊 U.S. Stocks
The Dow Jones closed at 53,414 points (-0.51%), the S&P 500 at 7,718 points (-0.38%), and the Nasdaq at 26,506 points (-0.29%) as of last Friday’s close; the U.S. market is closed today for Labor Day. The main theme on the board is memory chips: SanDisk surged nearly 12% last Friday and Micron rose more than 6%; this morning, Asia picked up the rally, with SK Hynix, Samsung Electronics, and Kioxia all strengthening together, showing AI hardware momentum spreading from U.S. stocks to Asia. On sentiment, after August nonfarm payrolls came in above expectations, the market instead worried that the Fed might "not cut, but raise" rates, and the tug-of-war between Trump and Fed Chair Waller has become a new source of uncertainty.
🪙 Cryptocurrencies
$BTC 80,118 USD (24h +0.27%), $ETH 2,513 USD (+1.01%); BNB 752 USD (-2.04%), SOL 106 USD (+2.55%). BTC briefly lost the 80,000 level last Friday after the nonfarm payroll shock, but stabilized and recovered over the weekend. The total crypto market cap is $2.71 trillion, with about $70 billion in 24h trading volume, BTC dominance at 59.2%, and the Fear & Greed Index at 71 (Greed). ETF net inflows over the past three weeks reached $3.8 billion, setting the strongest fundraising record of 2026. Altcoin highlights: ZEC rose nearly 17% to above $1,200, DOT climbed more than 10%, and LINK gained more than 9%.
🥇 Gold
$XAUT 4,417 USD (24h -0.21%); COMEX gold futures at $4,477 (+1.06%). Central bank buying and safe-haven demand are supporting prices, keeping gold in a high-level range.
📰 Crypto News
· The Liquid network had about 4,000 BTC (roughly $320 million) transferred out by a "white hat," and operations were suspended for investigation (The Block)
· Spot BTC ETFs recorded $3.8 billion in net inflows over three weeks, setting a 2026 record (CoinTelegraph)
· A wallet from the "Satoshi era" dormant for 16 years has been reactivated, with 600 BTC transferred out (CoinTelegraph)
· Polymarket has launched crypto perpetual contracts with up to 20x leverage (Decrypt)
🌐 Macro News
· U.S. August nonfarm payrolls added 162,000, far above expectations, while unemployment was 4.1% (CNBC)
· Fed Governor Waller supports standing pat in September, while Trump intensifies pressure on Chair Waller (CNBC)
· Japan’s foreign reserves declined for the fourth consecutive month, mainly due to intervention in the yen at the end of July (Wall Street Insights)
📅 This Week’s Economic Data Preview
The U.S. market is closed on Monday for Labor Day; U.S. data are relatively light this week, with attention shifting to officials’ comments ahead of the September policy meeting and Thursday’s initial jobless claims.
252
·
--
Article
The 64-year-old man’s million-dollar gamble hides an on-chain undercurrent tied to Wall StreetFrom Bonk Guy’s meme legend to “coin-stock pair trading,” what may truly be worth betting on is perhaps the gambling table that has been repeatedly changing hands
A 64-year-old man, with $16,000 in principal and 6x leverage, rolled his position up to $20 million, only to be wiped out in a single crash — this is the story making the rounds in crypto circles over the past two days. The protagonist is called Bonk Guy, an anonymous trader nicknamed the “old man.” What is really worth pondering in this story is not his position, but something else: when he played out the same script for the fifth time, the gambling table he was betting on had already quietly changed hands.
The 64-year-old man’s million-dollar gamble hides an on-chain undercurrent tied to Wall Street
From Bonk Guy’s meme legend to “coin-stock pair trading,” what may truly be worth betting on is perhaps the gambling table that has been repeatedly changing hands
A 64-year-old man, with $16,000 in principal and 6x leverage, rolled his position up to $20 million, only to be wiped out in a single crash — this is the story making the rounds in crypto circles over the past two days. The protagonist is called Bonk Guy, an anonymous trader nicknamed the “old man.” What is really worth pondering in this story is not his position, but something else: when he played out the same script for the fifth time, the gambling table he was betting on had already quietly changed hands.
A 64-year-old man, with $16,000 in principal and 6x leverage, rolled his position up to $20 million, only to be wiped out in a single crash — this is the story making the rounds in crypto circles over the past two days. The protagonist is called Bonk Guy, an anonymous trader nicknamed the “old man.” What is really worth pondering in this story is not his position, but something else: when he played out the same script for the fifth time, the gambling table he was betting on had already quietly changed hands.
1
352
·
--
Article
Nonfarm payrolls triple expectations and the Fed’s “stay on hold” script has been blown apartIt took just one week to go from hawkish to dovish, and only 25 minutes to go from dovish to hawkish — Walsh’s September exam
At 20:30 Beijing time tonight, with a light click from the U.S. Bureau of Labor Statistics, the August nonfarm payrolls data hit the screen: 162,000 jobs were added, while market consensus was only about 53,000 — exactly three times as much. Over the past week, the market had just ridden an emotional roller coaster with Fed Chair Walsh: last Friday in Jackson Hole, he unveiled the most hawkish framework since taking office, pushing the probability of a September rate hike to 55.7% overnight; yesterday he changed his tone and leaned toward staying on hold, sending U.S. stocks, Bitcoin, and gold into a collective frenzy; tonight, with the 162,000 nonfarm payrolls print, everything fell back again. From hawkish to dovish took a week; from dovish to hawkish, only 25 minutes.
Nonfarm payrolls triple expectations and the Fed’s “stay on hold” script has been blown apart
It took just one week to go from hawkish to dovish, and only 25 minutes to go from dovish to hawkish — Walsh’s September exam
At 20:30 Beijing time tonight, with a light click from the U.S. Bureau of Labor Statistics, the August nonfarm payrolls data hit the screen: 162,000 jobs were added, while market consensus was only about 53,000 — exactly three times as much. Over the past week, the market had just ridden an emotional roller coaster with Fed Chair Walsh: last Friday in Jackson Hole, he unveiled the most hawkish framework since taking office, pushing the probability of a September rate hike to 55.7% overnight; yesterday he changed his tone and leaned toward staying on hold, sending U.S. stocks, Bitcoin, and gold into a collective frenzy; tonight, with the 162,000 nonfarm payrolls print, everything fell back again. From hawkish to dovish took a week; from dovish to hawkish, only 25 minutes.
At 20:30 Beijing time tonight, with a light click from the U.S. Bureau of Labor Statistics, the August nonfarm payrolls data hit the screen: 162,000 jobs were added, while market consensus was only about 53,000 — exactly three times as much. Over the past week, the market had just ridden an emotional roller coaster with Fed Chair Walsh: last Friday in Jackson Hole, he unveiled the most hawkish framework since taking office, pushing the probability of a September rate hike to 55.7% overnight; yesterday he changed his tone and leaned toward staying on hold, sending U.S. stocks, Bitcoin, and gold into a collective frenzy; tonight, with the 162,000 nonfarm payrolls print, everything fell back again. From hawkish to dovish took a week; from dovish to hawkish, only 25 minutes.
1
1
577
·
--
Financial Daily Report | Friday, September 4, 2026
📊 US Stocks
Overnight, the three major US indices all closed higher: Dow Jones 53,686.11 (+1.18%), S&P 500 7,747.71 (+1.06%), Nasdaq 26,584.06 (+1.40%). The Nasdaq led the gains, as sentiment in tech stocks improved. The biggest catalyst was Nvidia’s $12.9 billion acquisition of Hugging Face—opening up imagination for the AI software layer, while chip stocks surged across the board. Tonight, the US will release August Non-Farm Payrolls data, and the direction will be decided soon.
🪙 Cryptocurrencies
$BTC 81, $150 ( +5.35% ), back above $81,000; $ETH 2, $506 ( +5.27% ); BNB $726 (+5.58%); SOL $103.7 (+4.00%). Major coins broadly rose.
Notable movers: ZEC jumped 16.4% to lead the market, ADA rose 9.45%, and DOGE gained 7.44%.
Total crypto market cap is about $2.73 trillion, with $107 billion in 24-hour trading volume. BTC’s share is 59.4%. Fear & Greed Index is 74, in the “greed” zone.
ETF side: IBIT 43.79 (+0.07%), FBTC 67.29 (+0.16%) steadied, while ETHA 18.05 (-0.99%) saw a short-term pullback.
Driving logic: A sharp rise in the yen dragged the US dollar index below 99, US Treasury yields fell, and Fed officials signaled “hold rates steady” for September—leading risk assets to rally across the board (Decrypt/CoinTelegraph).
🥇 Gold
$XAUT (tokenized gold) $4,466 (+1.81%). Weak dollar and interest-rate cut expectations moving in tandem kept gold prices strong.
📰 Crypto Headlines
After the Fed floated the idea of holding steady in September, BTC broke above $80,000, with about $415 million in short liquidations (Decrypt)
Standard Chartered will bring spot crypto trading to the Dubai forex platform, accelerating traditional finance’s entry (CoinDesk)
Bitget is in talks with Wall Street giants such as BlackRock to expand distribution in Asia (CoinDesk)
Robinhood Chain ecosystem explodes: Pons has surged more than 18,000% since July; meme-coin launch applications top the on-chain fee revenue leaderboard (Decrypt)
🌐 Macro News
US August ADP private-sector employment rose by only 38,000, far below expectations; tonight’s Non-Farm Payrolls is the market’s focus (CNBC)
Fed Governor Waller said he supports keeping rates unchanged in September, creating a tug-of-war with the political sector’s calls for rate cuts (CNBC)
Eurozone inflation is back above 3%, with expectations for rate hikes warming (CNBC)
📅 Economic Data Preview This Week
Friday (today) evening: the US will release its August Non-Farm Employment Report (CNBC). If ADP’s weakness is confirmed by Non-Farm Payrolls, rate-cut expectations may return.
Financial Daily Report | Friday, September 4, 2026
📊 US Stocks
Overnight, the three major US indices all closed higher: Dow Jones 53,686.11 (+1.18%), S&P 500 7,747.71 (+1.06%), Nasdaq 26,584.06 (+1.40%). The Nasdaq led the gains, as sentiment in tech stocks improved. The biggest catalyst was Nvidia’s $12.9 billion acquisition of Hugging Face—opening up imagination for the AI software layer, while chip stocks surged across the board. Tonight, the US will release August Non-Farm Payrolls data, and the direction will be decided soon.
🪙 Cryptocurrencies
$BTC 81, $150 ( +5.35% ), back above $81,000; $ETH 2, $506 ( +5.27% ); BNB $726 (+5.58%); SOL $103.7 (+4.00%). Major coins broadly rose.
Notable movers: ZEC jumped 16.4% to lead the market, ADA rose 9.45%, and DOGE gained 7.44%.
Total crypto market cap is about $2.73 trillion, with $107 billion in 24-hour trading volume. BTC’s share is 59.4%. Fear & Greed Index is 74, in the “greed” zone.
ETF side: IBIT 43.79 (+0.07%), FBTC 67.29 (+0.16%) steadied, while ETHA 18.05 (-0.99%) saw a short-term pullback.
Driving logic: A sharp rise in the yen dragged the US dollar index below 99, US Treasury yields fell, and Fed officials signaled “hold rates steady” for September—leading risk assets to rally across the board (Decrypt/CoinTelegraph).
🥇 Gold
$XAUT (tokenized gold) $4,466 (+1.81%). Weak dollar and interest-rate cut expectations moving in tandem kept gold prices strong.
📰 Crypto Headlines
After the Fed floated the idea of holding steady in September, BTC broke above $80,000, with about $415 million in short liquidations (Decrypt)
Standard Chartered will bring spot crypto trading to the Dubai forex platform, accelerating traditional finance’s entry (CoinDesk)
Bitget is in talks with Wall Street giants such as BlackRock to expand distribution in Asia (CoinDesk)
Robinhood Chain ecosystem explodes: Pons has surged more than 18,000% since July; meme-coin launch applications top the on-chain fee revenue leaderboard (Decrypt)
🌐 Macro News
US August ADP private-sector employment rose by only 38,000, far below expectations; tonight’s Non-Farm Payrolls is the market’s focus (CNBC)
Fed Governor Waller said he supports keeping rates unchanged in September, creating a tug-of-war with the political sector’s calls for rate cuts (CNBC)
Eurozone inflation is back above 3%, with expectations for rate hikes warming (CNBC)
📅 Economic Data Preview This Week
Friday (today) evening: the US will release its August Non-Farm Employment Report (CNBC). If ADP’s weakness is confirmed by Non-Farm Payrolls, rate-cut expectations may return.
📊 US Stocks
Overnight, the three major US indices all closed higher: Dow Jones 53,686.11 (+1.18%), S&P 500 7,747.71 (+1.06%), Nasdaq 26,584.06 (+1.40%). The Nasdaq led the gains, as sentiment in tech stocks improved. The biggest catalyst was Nvidia’s $12.9 billion acquisition of Hugging Face—opening up imagination for the AI software layer, while chip stocks surged across the board. Tonight, the US will release August Non-Farm Payrolls data, and the direction will be decided soon.
🪙 Cryptocurrencies
$BTC 81, $150 ( +5.35% ), back above $81,000; $ETH 2, $506 ( +5.27% ); BNB $726 (+5.58%); SOL $103.7 (+4.00%). Major coins broadly rose.
Notable movers: ZEC jumped 16.4% to lead the market, ADA rose 9.45%, and DOGE gained 7.44%.
Total crypto market cap is about $2.73 trillion, with $107 billion in 24-hour trading volume. BTC’s share is 59.4%. Fear & Greed Index is 74, in the “greed” zone.
ETF side: IBIT 43.79 (+0.07%), FBTC 67.29 (+0.16%) steadied, while ETHA 18.05 (-0.99%) saw a short-term pullback.
Driving logic: A sharp rise in the yen dragged the US dollar index below 99, US Treasury yields fell, and Fed officials signaled “hold rates steady” for September—leading risk assets to rally across the board (Decrypt/CoinTelegraph).
🥇 Gold
$XAUT (tokenized gold) $4,466 (+1.81%). Weak dollar and interest-rate cut expectations moving in tandem kept gold prices strong.
📰 Crypto Headlines
After the Fed floated the idea of holding steady in September, BTC broke above $80,000, with about $415 million in short liquidations (Decrypt)
Standard Chartered will bring spot crypto trading to the Dubai forex platform, accelerating traditional finance’s entry (CoinDesk)
Bitget is in talks with Wall Street giants such as BlackRock to expand distribution in Asia (CoinDesk)
Robinhood Chain ecosystem explodes: Pons has surged more than 18,000% since July; meme-coin launch applications top the on-chain fee revenue leaderboard (Decrypt)
🌐 Macro News
US August ADP private-sector employment rose by only 38,000, far below expectations; tonight’s Non-Farm Payrolls is the market’s focus (CNBC)
Fed Governor Waller said he supports keeping rates unchanged in September, creating a tug-of-war with the political sector’s calls for rate cuts (CNBC)
Eurozone inflation is back above 3%, with expectations for rate hikes warming (CNBC)
📅 Economic Data Preview This Week
Friday (today) evening: the US will release its August Non-Farm Employment Report (CNBC). If ADP’s weakness is confirmed by Non-Farm Payrolls, rate-cut expectations may return.
335
·
--
Financial Daily | September 3, 2026, Thursday
📊 US Stocks
Dow Jones 53,061.95 (+0.56%)
S&P 500 7,666.60 (+0.46%)
Nasdaq 26,217.83 (+0.45%)
AI earnings season gains further momentum: Snowflake surged on AI-driven earnings guidance. HPE followed Dell by delivering an unexpectedly strong AI server performance. After-hours, Broadcom’s earnings guidance was strong, and the CEO publicly endorsed demand for its AI labs. The storage chip supply chain saw a pullback from high levels, but capital remains firmly committed to buying into the AI narrative—despite 10-year U.S. Treasury yields hitting a fresh high since November 2023, the three major U.S. stock indexes still closed higher across the board.
🪙 Cryptocurrencies
$BTC 77,023.07 (-0.28%)
$ETH 2,379.52 (-1.30%)
BNB 687.49 (+0.65%)
SOL 99.64 (-0.10%)
Bitcoin is repeatedly battling around the $77,000 level. Data shows that visible demand has turned negative. Ethereum is down more sharply, and overall altcoin sentiment remains weak. Total crypto market cap is $2.61 trillion, with $73 billion in 24-hour trading volume. BTC’s share is 59.0%, and the Fear & Greed Index is 65 (Greed). All three ETF lines fell: IBIT 43.76 (-2.04%), FBTC 67.18 (-2.08%), ETHA 18.23 (-2.62%). ADA and SUI rose against the trend by more than 2%, which are among the few bright spots on the day.
🥇 Gold
$XAUT 4,385.66 (+1.26%). Even as Treasury yields set new highs, gold prices strengthened against the trend. Safe-haven buying supported precious metals as tensions in the Iran–U.S. region heated up.
📰 Crypto News
1. 21 banks including Goldman Sachs and Bank of America plan to jointly issue USD stablecoins (Decrypt)
2. Kraken’s parent company Payward has postponed its IPO to after the second quarter of 2027 (CoinDesk)
3. Coinbase launches regulated crypto derivatives in Canada (CoinTelegraph)
4. Japan’s Remixpoint liquidates altcoin holdings and fully shifts to holding only Bitcoin (TheBlock)
🌐 Macro News
1. U.S. August ADP private payrolls increased by only 38,000, far below expectations (CNBC)
2. The 10-year U.S. Treasury yield hits the highest level since November 2023 (CNBC)
3. Eurozone inflation returns above 3%, and market expectations for rate hikes heat up (CNBC)
📅 Economic Data Preview This Week
Friday (9/4): U.S. August nonfarm payrolls report. After ADP came in unexpectedly weak, market sensitivity to nonfarm data has risen significantly.
Financial Daily | September 3, 2026, Thursday
📊 US Stocks
Dow Jones 53,061.95 (+0.56%)
S&P 500 7,666.60 (+0.46%)
Nasdaq 26,217.83 (+0.45%)
AI earnings season gains further momentum: Snowflake surged on AI-driven earnings guidance. HPE followed Dell by delivering an unexpectedly strong AI server performance. After-hours, Broadcom’s earnings guidance was strong, and the CEO publicly endorsed demand for its AI labs. The storage chip supply chain saw a pullback from high levels, but capital remains firmly committed to buying into the AI narrative—despite 10-year U.S. Treasury yields hitting a fresh high since November 2023, the three major U.S. stock indexes still closed higher across the board.
🪙 Cryptocurrencies
$BTC 77,023.07 (-0.28%)
$ETH 2,379.52 (-1.30%)
BNB 687.49 (+0.65%)
SOL 99.64 (-0.10%)
Bitcoin is repeatedly battling around the $77,000 level. Data shows that visible demand has turned negative. Ethereum is down more sharply, and overall altcoin sentiment remains weak. Total crypto market cap is $2.61 trillion, with $73 billion in 24-hour trading volume. BTC’s share is 59.0%, and the Fear & Greed Index is 65 (Greed). All three ETF lines fell: IBIT 43.76 (-2.04%), FBTC 67.18 (-2.08%), ETHA 18.23 (-2.62%). ADA and SUI rose against the trend by more than 2%, which are among the few bright spots on the day.
🥇 Gold
$XAUT 4,385.66 (+1.26%). Even as Treasury yields set new highs, gold prices strengthened against the trend. Safe-haven buying supported precious metals as tensions in the Iran–U.S. region heated up.
📰 Crypto News
1. 21 banks including Goldman Sachs and Bank of America plan to jointly issue USD stablecoins (Decrypt)
2. Kraken’s parent company Payward has postponed its IPO to after the second quarter of 2027 (CoinDesk)
3. Coinbase launches regulated crypto derivatives in Canada (CoinTelegraph)
4. Japan’s Remixpoint liquidates altcoin holdings and fully shifts to holding only Bitcoin (TheBlock)
🌐 Macro News
1. U.S. August ADP private payrolls increased by only 38,000, far below expectations (CNBC)
2. The 10-year U.S. Treasury yield hits the highest level since November 2023 (CNBC)
3. Eurozone inflation returns above 3%, and market expectations for rate hikes heat up (CNBC)
📅 Economic Data Preview This Week
Friday (9/4): U.S. August nonfarm payrolls report. After ADP came in unexpectedly weak, market sensitivity to nonfarm data has risen significantly.
📊 US Stocks
Dow Jones 53,061.95 (+0.56%)
S&P 500 7,666.60 (+0.46%)
Nasdaq 26,217.83 (+0.45%)
AI earnings season gains further momentum: Snowflake surged on AI-driven earnings guidance. HPE followed Dell by delivering an unexpectedly strong AI server performance. After-hours, Broadcom’s earnings guidance was strong, and the CEO publicly endorsed demand for its AI labs. The storage chip supply chain saw a pullback from high levels, but capital remains firmly committed to buying into the AI narrative—despite 10-year U.S. Treasury yields hitting a fresh high since November 2023, the three major U.S. stock indexes still closed higher across the board.
🪙 Cryptocurrencies
$BTC 77,023.07 (-0.28%)
$ETH 2,379.52 (-1.30%)
BNB 687.49 (+0.65%)
SOL 99.64 (-0.10%)
Bitcoin is repeatedly battling around the $77,000 level. Data shows that visible demand has turned negative. Ethereum is down more sharply, and overall altcoin sentiment remains weak. Total crypto market cap is $2.61 trillion, with $73 billion in 24-hour trading volume. BTC’s share is 59.0%, and the Fear & Greed Index is 65 (Greed). All three ETF lines fell: IBIT 43.76 (-2.04%), FBTC 67.18 (-2.08%), ETHA 18.23 (-2.62%). ADA and SUI rose against the trend by more than 2%, which are among the few bright spots on the day.
🥇 Gold
$XAUT 4,385.66 (+1.26%). Even as Treasury yields set new highs, gold prices strengthened against the trend. Safe-haven buying supported precious metals as tensions in the Iran–U.S. region heated up.
📰 Crypto News
1. 21 banks including Goldman Sachs and Bank of America plan to jointly issue USD stablecoins (Decrypt)
2. Kraken’s parent company Payward has postponed its IPO to after the second quarter of 2027 (CoinDesk)
3. Coinbase launches regulated crypto derivatives in Canada (CoinTelegraph)
4. Japan’s Remixpoint liquidates altcoin holdings and fully shifts to holding only Bitcoin (TheBlock)
🌐 Macro News
1. U.S. August ADP private payrolls increased by only 38,000, far below expectations (CNBC)
2. The 10-year U.S. Treasury yield hits the highest level since November 2023 (CNBC)
3. Eurozone inflation returns above 3%, and market expectations for rate hikes heat up (CNBC)
📅 Economic Data Preview This Week
Friday (9/4): U.S. August nonfarm payrolls report. After ADP came in unexpectedly weak, market sensitivity to nonfarm data has risen significantly.
1
614
·
--
Hahaha. Kuk just got removed from office and Apple has already unfollowed him.
Hahaha. Kuk just got removed from office and Apple has already unfollowed him.
14
5
3
33.9k
·
--
Financial Daily | September 2, 2026, Wednesday
📊 US Stocks
The Dow Jones 52,766.88 (-0.79%), S&P 500 7,631.47 (-0.71%), Nasdaq 26,099.77 (-1.03%). All three major indexes closed lower collectively, with the Nasdaq leading the decline. Inflation and rate-hike expectations have resurfaced. Eurozone inflation has returned above 3%, and successive hawkish signals from Federal Reserve officials have dented risk appetite. Technology stocks were generally under pressure, but AI hardware held up against the trend: Dell raised its full-year guidance, jumping 9%, as demand for AI servers remains strong.
🪙 Cryptocurrencies
$BTC 77,246 (-2.00%), $ETH 2,411 (-2.54%), BNB 683 (-1.40%), SOL 99.72 (-3.58%). Total crypto market cap is about $2.62 trillion, with about $82 billion in 24-hour trading. BTC dominance is 59.1%. Fear & Greed Index is 63 (Greed). After trading sideways around 78,000, BTC pulled back as rate-hike risks compounded with the seasonal “Rektember” curse—rallies met resistance. All ETFs were weak: IBIT -2.04%, FBTC -2.08%, ETHA -2.62%. Highlights on-chain: Robinhood Chain DEX trading volume surged to $1.6 billion, and ARB jumped 30%.
🥇 Gold
$XAUT 4,328.00 (-2.77%). Geopolitical safe-haven flows moved toward the US dollar and crude oil, causing gold prices to retreat from high levels.
📰 Crypto News
· Binance launches 1,000 options on US stocks and ETFs; TradFi monthly perpetual trading volume hits $433 billion (CoinTelegraph)
· 21 institutions including Bank of America, Citigroup, and Goldman Sachs plan to issue stablecoins (CoinTelegraph)
· Ethena launches USDe payment app, with up to 6% yield + 10% cashback (TheBlock)
· Singapore plans to require stablecoin issuers to hold 100% reserves and ban interest payments (CoinDesk)
🌐 Macro News
· The US airstrikes Iran; oil tankers in the Strait of Hormuz are attacked, sending oil prices to a six-week high (FT/CNBC)
· Eurozone inflation returns above 3%, with rate-hike expectations warming up (CNBC)
· Fed’s Hamack: “It’s time to raise rates now” (CNBC)
📅 Economic Data Preview This Week
Thursday: US initial jobless claims. Friday: US August nonfarm payroll employment report. If employment remains strong, it will further solidify the rate-hike path and weigh on risk assets.
Financial Daily | September 2, 2026, Wednesday
📊 US Stocks
The Dow Jones 52,766.88 (-0.79%), S&P 500 7,631.47 (-0.71%), Nasdaq 26,099.77 (-1.03%). All three major indexes closed lower collectively, with the Nasdaq leading the decline. Inflation and rate-hike expectations have resurfaced. Eurozone inflation has returned above 3%, and successive hawkish signals from Federal Reserve officials have dented risk appetite. Technology stocks were generally under pressure, but AI hardware held up against the trend: Dell raised its full-year guidance, jumping 9%, as demand for AI servers remains strong.
🪙 Cryptocurrencies
$BTC 77,246 (-2.00%), $ETH 2,411 (-2.54%), BNB 683 (-1.40%), SOL 99.72 (-3.58%). Total crypto market cap is about $2.62 trillion, with about $82 billion in 24-hour trading. BTC dominance is 59.1%. Fear & Greed Index is 63 (Greed). After trading sideways around 78,000, BTC pulled back as rate-hike risks compounded with the seasonal “Rektember” curse—rallies met resistance. All ETFs were weak: IBIT -2.04%, FBTC -2.08%, ETHA -2.62%. Highlights on-chain: Robinhood Chain DEX trading volume surged to $1.6 billion, and ARB jumped 30%.
🥇 Gold
$XAUT 4,328.00 (-2.77%). Geopolitical safe-haven flows moved toward the US dollar and crude oil, causing gold prices to retreat from high levels.
📰 Crypto News
· Binance launches 1,000 options on US stocks and ETFs; TradFi monthly perpetual trading volume hits $433 billion (CoinTelegraph)
· 21 institutions including Bank of America, Citigroup, and Goldman Sachs plan to issue stablecoins (CoinTelegraph)
· Ethena launches USDe payment app, with up to 6% yield + 10% cashback (TheBlock)
· Singapore plans to require stablecoin issuers to hold 100% reserves and ban interest payments (CoinDesk)
🌐 Macro News
· The US airstrikes Iran; oil tankers in the Strait of Hormuz are attacked, sending oil prices to a six-week high (FT/CNBC)
· Eurozone inflation returns above 3%, with rate-hike expectations warming up (CNBC)
· Fed’s Hamack: “It’s time to raise rates now” (CNBC)
📅 Economic Data Preview This Week
Thursday: US initial jobless claims. Friday: US August nonfarm payroll employment report. If employment remains strong, it will further solidify the rate-hike path and weigh on risk assets.
📊 US Stocks
The Dow Jones 52,766.88 (-0.79%), S&P 500 7,631.47 (-0.71%), Nasdaq 26,099.77 (-1.03%). All three major indexes closed lower collectively, with the Nasdaq leading the decline. Inflation and rate-hike expectations have resurfaced. Eurozone inflation has returned above 3%, and successive hawkish signals from Federal Reserve officials have dented risk appetite. Technology stocks were generally under pressure, but AI hardware held up against the trend: Dell raised its full-year guidance, jumping 9%, as demand for AI servers remains strong.
🪙 Cryptocurrencies
$BTC 77,246 (-2.00%), $ETH 2,411 (-2.54%), BNB 683 (-1.40%), SOL 99.72 (-3.58%). Total crypto market cap is about $2.62 trillion, with about $82 billion in 24-hour trading. BTC dominance is 59.1%. Fear & Greed Index is 63 (Greed). After trading sideways around 78,000, BTC pulled back as rate-hike risks compounded with the seasonal “Rektember” curse—rallies met resistance. All ETFs were weak: IBIT -2.04%, FBTC -2.08%, ETHA -2.62%. Highlights on-chain: Robinhood Chain DEX trading volume surged to $1.6 billion, and ARB jumped 30%.
🥇 Gold
$XAUT 4,328.00 (-2.77%). Geopolitical safe-haven flows moved toward the US dollar and crude oil, causing gold prices to retreat from high levels.
📰 Crypto News
· Binance launches 1,000 options on US stocks and ETFs; TradFi monthly perpetual trading volume hits $433 billion (CoinTelegraph)
· 21 institutions including Bank of America, Citigroup, and Goldman Sachs plan to issue stablecoins (CoinTelegraph)
· Ethena launches USDe payment app, with up to 6% yield + 10% cashback (TheBlock)
· Singapore plans to require stablecoin issuers to hold 100% reserves and ban interest payments (CoinDesk)
🌐 Macro News
· The US airstrikes Iran; oil tankers in the Strait of Hormuz are attacked, sending oil prices to a six-week high (FT/CNBC)
· Eurozone inflation returns above 3%, with rate-hike expectations warming up (CNBC)
· Fed’s Hamack: “It’s time to raise rates now” (CNBC)
📅 Economic Data Preview This Week
Thursday: US initial jobless claims. Friday: US August nonfarm payroll employment report. If employment remains strong, it will further solidify the rate-hike path and weigh on risk assets.
239
·
--
Financial Daily News | September 1, 2026, Tuesday
📊 US Stocks
US stocks collectively ended lower on the last trading day of August: the Dow stood at 53,185.90 points (-0.72%), the S&P 500 at 7,686.14 points (-0.58%), and the Nasdaq at 26,370.89 points (-0.64%). Storage chip stocks bucked the trend, with SanDisk up 5.51% and Micron up 2.50%; the software sector continued its August recovery, and Tesla led gains on expectations surrounding its Cybercab launch. With Fed officials turning hawkish in rapid succession and US Treasury yields approaching 20-year highs, risk appetite was kept under pressure.
🪙 Cryptocurrencies
$BTC rose to $78,891.93 (+1.28%). August gained about 25%, marking the best single-month performance since November 2024. $ETH was $2,476.80 (+1.94%); BNB was $693.09 (+0.94%); SOL was $103.47 (+1.32%). Crypto total market cap was $2.67 trillion, with $8 billion in 24-hour trading volume. BTC dominance was 59.2%, and the Fear & Greed Index was 69 (Greed). The corporate “crypto hoarding” wave intensified: Strategy’s total holdings reached 845,050 BTC, and Strive bought 1,800 BTC, moving it up to become the fifth-largest corporate holder. In terms of ETFs, IBIT, FBTC, and ETHA closed slightly lower.
🥇 Gold
$XAUT was $4,451.22 (+0.06%). Supported by geopolitical tensions and rate-cut expectations, gold prices traded in a range near high levels.
📰 Crypto Headlines
· Strategy bought another 4,603 BTC (about $370 million), bringing total holdings to 845,050 BTC (TheBlock)
· Bitmine bought 53,501 ETH in a single transaction, setting the biggest record since June. Tom Lee called it the best-performing macro asset (TheBlock)
· Treasury yields are nearing 20-year highs; BTC’s volatility increased toward month-end. A US airstrike on Iran did not affect the crypto market (CoinDesk)
· Russia’s Sberbank plans to use ETH and USDT as loan collateral; regulated trading volume in the first year could reach $46 billion (CoinDesk)
🌐 Macro News
· Fed Chair Warsh is concerned about inflation and argues the central bank should be quieter; Hammack said it’s time to raise rates (CNBC)
· China’s August factory activity contracted for the second consecutive month, with the contraction smaller than expected (CNBC)
· South Korea’s August exports surged 68.7% year-on-year, beating expectations (Quick News)
📅 This Week’s Economic Data Preview
Today: US August ISM Manufacturing PMI. Thursday: initial jobless claims. Friday: US August nonfarm payrolls—the biggest highlight of the week.
Financial Daily News | September 1, 2026, Tuesday
📊 US Stocks
US stocks collectively ended lower on the last trading day of August: the Dow stood at 53,185.90 points (-0.72%), the S&P 500 at 7,686.14 points (-0.58%), and the Nasdaq at 26,370.89 points (-0.64%). Storage chip stocks bucked the trend, with SanDisk up 5.51% and Micron up 2.50%; the software sector continued its August recovery, and Tesla led gains on expectations surrounding its Cybercab launch. With Fed officials turning hawkish in rapid succession and US Treasury yields approaching 20-year highs, risk appetite was kept under pressure.
🪙 Cryptocurrencies
$BTC rose to $78,891.93 (+1.28%). August gained about 25%, marking the best single-month performance since November 2024. $ETH was $2,476.80 (+1.94%); BNB was $693.09 (+0.94%); SOL was $103.47 (+1.32%). Crypto total market cap was $2.67 trillion, with $8 billion in 24-hour trading volume. BTC dominance was 59.2%, and the Fear & Greed Index was 69 (Greed). The corporate “crypto hoarding” wave intensified: Strategy’s total holdings reached 845,050 BTC, and Strive bought 1,800 BTC, moving it up to become the fifth-largest corporate holder. In terms of ETFs, IBIT, FBTC, and ETHA closed slightly lower.
🥇 Gold
$XAUT was $4,451.22 (+0.06%). Supported by geopolitical tensions and rate-cut expectations, gold prices traded in a range near high levels.
📰 Crypto Headlines
· Strategy bought another 4,603 BTC (about $370 million), bringing total holdings to 845,050 BTC (TheBlock)
· Bitmine bought 53,501 ETH in a single transaction, setting the biggest record since June. Tom Lee called it the best-performing macro asset (TheBlock)
· Treasury yields are nearing 20-year highs; BTC’s volatility increased toward month-end. A US airstrike on Iran did not affect the crypto market (CoinDesk)
· Russia’s Sberbank plans to use ETH and USDT as loan collateral; regulated trading volume in the first year could reach $46 billion (CoinDesk)
🌐 Macro News
· Fed Chair Warsh is concerned about inflation and argues the central bank should be quieter; Hammack said it’s time to raise rates (CNBC)
· China’s August factory activity contracted for the second consecutive month, with the contraction smaller than expected (CNBC)
· South Korea’s August exports surged 68.7% year-on-year, beating expectations (Quick News)
📅 This Week’s Economic Data Preview
Today: US August ISM Manufacturing PMI. Thursday: initial jobless claims. Friday: US August nonfarm payrolls—the biggest highlight of the week.
📊 US Stocks
US stocks collectively ended lower on the last trading day of August: the Dow stood at 53,185.90 points (-0.72%), the S&P 500 at 7,686.14 points (-0.58%), and the Nasdaq at 26,370.89 points (-0.64%). Storage chip stocks bucked the trend, with SanDisk up 5.51% and Micron up 2.50%; the software sector continued its August recovery, and Tesla led gains on expectations surrounding its Cybercab launch. With Fed officials turning hawkish in rapid succession and US Treasury yields approaching 20-year highs, risk appetite was kept under pressure.
🪙 Cryptocurrencies
$BTC rose to $78,891.93 (+1.28%). August gained about 25%, marking the best single-month performance since November 2024. $ETH was $2,476.80 (+1.94%); BNB was $693.09 (+0.94%); SOL was $103.47 (+1.32%). Crypto total market cap was $2.67 trillion, with $8 billion in 24-hour trading volume. BTC dominance was 59.2%, and the Fear & Greed Index was 69 (Greed). The corporate “crypto hoarding” wave intensified: Strategy’s total holdings reached 845,050 BTC, and Strive bought 1,800 BTC, moving it up to become the fifth-largest corporate holder. In terms of ETFs, IBIT, FBTC, and ETHA closed slightly lower.
🥇 Gold
$XAUT was $4,451.22 (+0.06%). Supported by geopolitical tensions and rate-cut expectations, gold prices traded in a range near high levels.
📰 Crypto Headlines
· Strategy bought another 4,603 BTC (about $370 million), bringing total holdings to 845,050 BTC (TheBlock)
· Bitmine bought 53,501 ETH in a single transaction, setting the biggest record since June. Tom Lee called it the best-performing macro asset (TheBlock)
· Treasury yields are nearing 20-year highs; BTC’s volatility increased toward month-end. A US airstrike on Iran did not affect the crypto market (CoinDesk)
· Russia’s Sberbank plans to use ETH and USDT as loan collateral; regulated trading volume in the first year could reach $46 billion (CoinDesk)
🌐 Macro News
· Fed Chair Warsh is concerned about inflation and argues the central bank should be quieter; Hammack said it’s time to raise rates (CNBC)
· China’s August factory activity contracted for the second consecutive month, with the contraction smaller than expected (CNBC)
· South Korea’s August exports surged 68.7% year-on-year, beating expectations (Quick News)
📅 This Week’s Economic Data Preview
Today: US August ISM Manufacturing PMI. Thursday: initial jobless claims. Friday: US August nonfarm payrolls—the biggest highlight of the week.
231
·
--
Overseas hackers launched a DDoS attack on Sun Ge’s exchange due to Sun Ge’s recent actions, causing the withdrawal network to be temporarily suspended.
Overseas hackers launched a DDoS attack on Sun Ge’s exchange due to Sun Ge’s recent actions, causing the withdrawal network to be temporarily suspended.
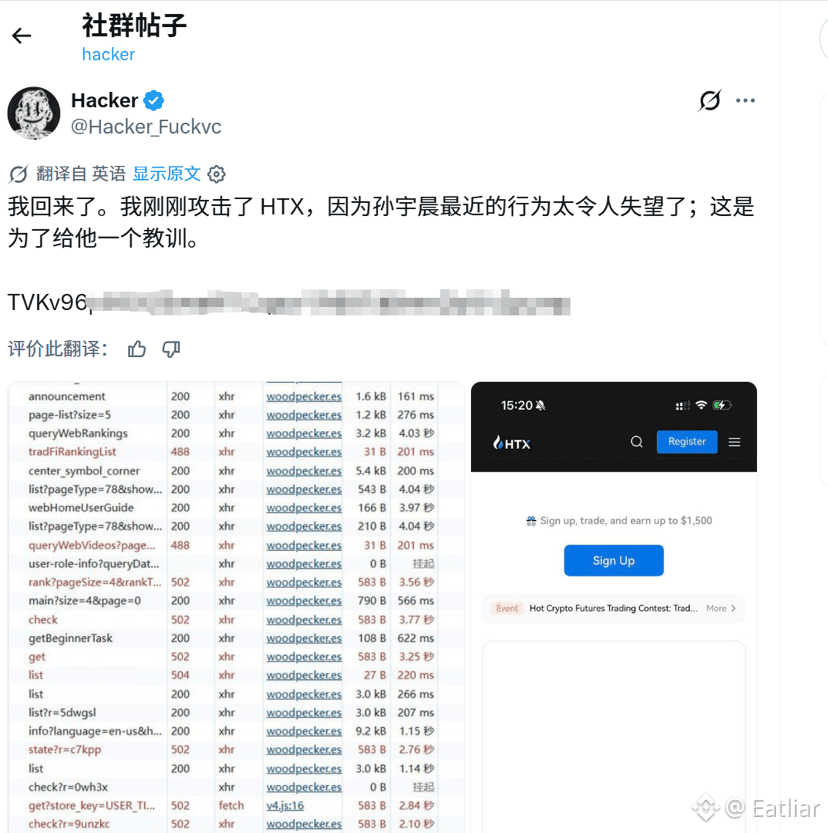
1
1
3.7k
·
--
In last night’s piece “Wosch’s Jackson Hole debut,” I bet he would play a yin-yang game, and the guy instead chose a hawkish script: fight inflation to 2% at all costs. The U.S. dollar strengthened on the spot, the yen fell through 160, and it erased most of the gains from the July joint U.S.-Japan intervention.
The funniest part is the Treasury: Bessent just doubled the buyback of long-dated debt to suppress yields, only to get slapped by its own central bank. The Treasury leans on the long end, the central bank pushes the strong dollar—two forces pulling against each other.
160 has already shifted from a valuation line to a policy line. The Bank of Japan not hiking rates in September is a bottomless pit, and the rate-hike momentum for shorts is the fuel. The biggest highlight of this year’s Jackson Hole isn’t what Wosch said—it’s the matter of dollar credibility: it’s worth more than you’d think, and more fragile than you’d imagine.
In last night’s piece “Wosch’s Jackson Hole debut,” I bet he would play a yin-yang game, and the guy instead chose a hawkish script: fight inflation to 2% at all costs. The U.S. dollar strengthened on the spot, the yen fell through 160, and it erased most of the gains from the July joint U.S.-Japan intervention.
The funniest part is the Treasury: Bessent just doubled the buyback of long-dated debt to suppress yields, only to get slapped by its own central bank. The Treasury leans on the long end, the central bank pushes the strong dollar—two forces pulling against each other.
160 has already shifted from a valuation line to a policy line. The Bank of Japan not hiking rates in September is a bottomless pit, and the rate-hike momentum for shorts is the fuel. The biggest highlight of this year’s Jackson Hole isn’t what Wosch said—it’s the matter of dollar credibility: it’s worth more than you’d think, and more fragile than you’d imagine.
The funniest part is the Treasury: Bessent just doubled the buyback of long-dated debt to suppress yields, only to get slapped by its own central bank. The Treasury leans on the long end, the central bank pushes the strong dollar—two forces pulling against each other.
160 has already shifted from a valuation line to a policy line. The Bank of Japan not hiking rates in September is a bottomless pit, and the rate-hike momentum for shorts is the fuel. The biggest highlight of this year’s Jackson Hole isn’t what Wosch said—it’s the matter of dollar credibility: it’s worth more than you’d think, and more fragile than you’d imagine.
Cerberus-
·
--
Wosh’s Jackson Hole debut: walking a tightrope over cracks in U.S. Treasuries
The Federal Reserve’s new chair’s first annual test: a question about $4 trillion in credit
Tonight at 22:00 (UTC+8), Federal Reserve Chair Kevin Wosh will deliver his first major speech since taking office at Jackson Hole, at the foot of the Grand Teton. In previous years, this was merely the annual gathering of central bank governors worldwide; this year, the market has turned it into a big exam. The 30-year U.S. Treasury yield has just hit a 19-year high; the Treasury Secretary moved to buy bonds before the central bank; and from the podium, this new chair—known for speaking in riddles—could, with every word, rewrite the pricing of assets worth tens of trillions of dollars.
Tonight at 22:00 (UTC+8), Federal Reserve Chair Kevin Wosh will deliver his first major speech since taking office at Jackson Hole, at the foot of the Grand Teton. In previous years, this was merely the annual gathering of central bank governors worldwide; this year, the market has turned it into a big exam. The 30-year U.S. Treasury yield has just hit a 19-year high; the Treasury Secretary moved to buy bonds before the central bank; and from the podium, this new chair—known for speaking in riddles—could, with every word, rewrite the pricing of assets worth tens of trillions of dollars.
83
·
--
Article
Wosh’s Jackson Hole debut: walking a tightrope over cracks in U.S. TreasuriesThe Federal Reserve’s new chair’s first annual test: a question about $4 trillion in credit
Tonight at 22:00 (UTC+8), Federal Reserve Chair Kevin Wosh will deliver his first major speech since taking office at Jackson Hole, at the foot of the Grand Teton. In previous years, this was merely the annual gathering of central bank governors worldwide; this year, the market has turned it into a big exam. The 30-year U.S. Treasury yield has just hit a 19-year high; the Treasury Secretary moved to buy bonds before the central bank; and from the podium, this new chair—known for speaking in riddles—could, with every word, rewrite the pricing of assets worth tens of trillions of dollars.
Wosh’s Jackson Hole debut: walking a tightrope over cracks in U.S. Treasuries
The Federal Reserve’s new chair’s first annual test: a question about $4 trillion in credit
Tonight at 22:00 (UTC+8), Federal Reserve Chair Kevin Wosh will deliver his first major speech since taking office at Jackson Hole, at the foot of the Grand Teton. In previous years, this was merely the annual gathering of central bank governors worldwide; this year, the market has turned it into a big exam. The 30-year U.S. Treasury yield has just hit a 19-year high; the Treasury Secretary moved to buy bonds before the central bank; and from the podium, this new chair—known for speaking in riddles—could, with every word, rewrite the pricing of assets worth tens of trillions of dollars.
Tonight at 22:00 (UTC+8), Federal Reserve Chair Kevin Wosh will deliver his first major speech since taking office at Jackson Hole, at the foot of the Grand Teton. In previous years, this was merely the annual gathering of central bank governors worldwide; this year, the market has turned it into a big exam. The 30-year U.S. Treasury yield has just hit a 19-year high; the Treasury Secretary moved to buy bonds before the central bank; and from the podium, this new chair—known for speaking in riddles—could, with every word, rewrite the pricing of assets worth tens of trillions of dollars.
1
127
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
FedRateWatch
864,242 views
4,116 Discussing
Share & Win Traffic Reward in our Trending Hashtag Campaign
✨Topic: FOMC September, What's The Fed's Next Move?
👉How to Join:
Publish a short post or article with hashtag #FedRateWatch
Create content based on the below angles:
- August core CPI rose 0.3% month-over-month, and the odds of a 25bp hike this week are now close to 90%. Do you anticipate a rate hike this week? Is it a one-off, or the start of a longer hiking cycle?
- If the hike lands, how does it play out for BTC, tech stocks, and gold? Bullish or bearish?
- How are you planning to trade next? Share your BTC, stocks or gold trade/holdings with our trade sharing widget.
⏰Campaign Period:
- 2026-09-15 11:00 - 2026-09-17 3:00 UTC
🎁Reward:
- Qualified posts that comply with the above guidelines and contain more than 100 words will be reviewed and may receive a random traffic boost of 500 to 3,000 views. You will receive a notification from your feed secretary if your post is selected.
- Get a chance to have your article featured on Binance Square Official
Need ideas for your post? Visit the topic page #FedRateWatch or the Square Guide on How to Post for Better Reach.
Binance Square Official
·504 Likes
·1.1M views
BitcoinFalls4%
5,122 views
224 Discussing
SKHynixInTalksToMakeMemoryChipsInUS
1,753 views
53 Discussing