
#lighter
lighter
176,881 views
535 Discussing
Hot
Latest
·
--
Lighter ($LIT) Grabs Attention with High Volume and Strong Community Support
Lighter ($LIT) is trending at #5 with a strong 24-hour trading volume of $88.945M. Despite a slight 2.03% dip, the community is buzzing with activity. $LIT's innovative approach to decentralized finance and its robust ecosystem are driving interest. Traders should keep an eye on this coin as it continues to gain traction. ⚡
Follow for more setups like this.
#HahaProfit #Lighter
Lighter ($LIT ) Grabs Attention with High Volume and Strong Community Support
Lighter ($LIT ) is trending at #5 with a strong 24-hour trading volume of $88.945M. Despite a slight 2.03% dip, the community is buzzing with activity. $LIT 's innovative approach to decentralized finance and its robust ecosystem are driving interest. Traders should keep an eye on this coin as it continues to gain traction. ⚡
Follow for more setups like this.
#HahaProfit #Lighter
Lighter ($LIT ) is trending at #5 with a strong 24-hour trading volume of $88.945M. Despite a slight 2.03% dip, the community is buzzing with activity. $LIT 's innovative approach to decentralized finance and its robust ecosystem are driving interest. Traders should keep an eye on this coin as it continues to gain traction. ⚡
Follow for more setups like this.
#HahaProfit #Lighter
79
·
--
Lighter ($LIT) Gains Momentum with High Volume
Lighter ($LIT) is trending despite a slight 2.06% dip, thanks to its high 24h volume of $88.94M. Currently ranked #5 in trending and #68 in market cap, $LIT is catching the eye of traders. The strong volume suggests significant interest and potential for volatility. With a price of $4.31, $LIT is a coin to watch for its dynamic market activity. If the volume sustains, $LIT could see more movement in the near future. 📊💰
Follow for daily crypto updates.
#DeGenYuv #Lighter
Lighter ($LIT ) Gains Momentum with High Volume
Lighter ($LIT ) is trending despite a slight 2.06% dip, thanks to its high 24h volume of $88.94M. Currently ranked #5 in trending and #68 in market cap, $LIT is catching the eye of traders. The strong volume suggests significant interest and potential for volatility. With a price of $4.31, $LIT is a coin to watch for its dynamic market activity. If the volume sustains, $LIT could see more movement in the near future. 📊💰
Follow for daily crypto updates.
#DeGenYuv #Lighter
Lighter ($LIT ) is trending despite a slight 2.06% dip, thanks to its high 24h volume of $88.94M. Currently ranked #5 in trending and #68 in market cap, $LIT is catching the eye of traders. The strong volume suggests significant interest and potential for volatility. With a price of $4.31, $LIT is a coin to watch for its dynamic market activity. If the volume sustains, $LIT could see more movement in the near future. 📊💰
Follow for daily crypto updates.
#DeGenYuv #Lighter
117
·
--
Bullish
$LIT 🐋 WHALES ARE BACK — AGAIN $5 NEXT? 🚀
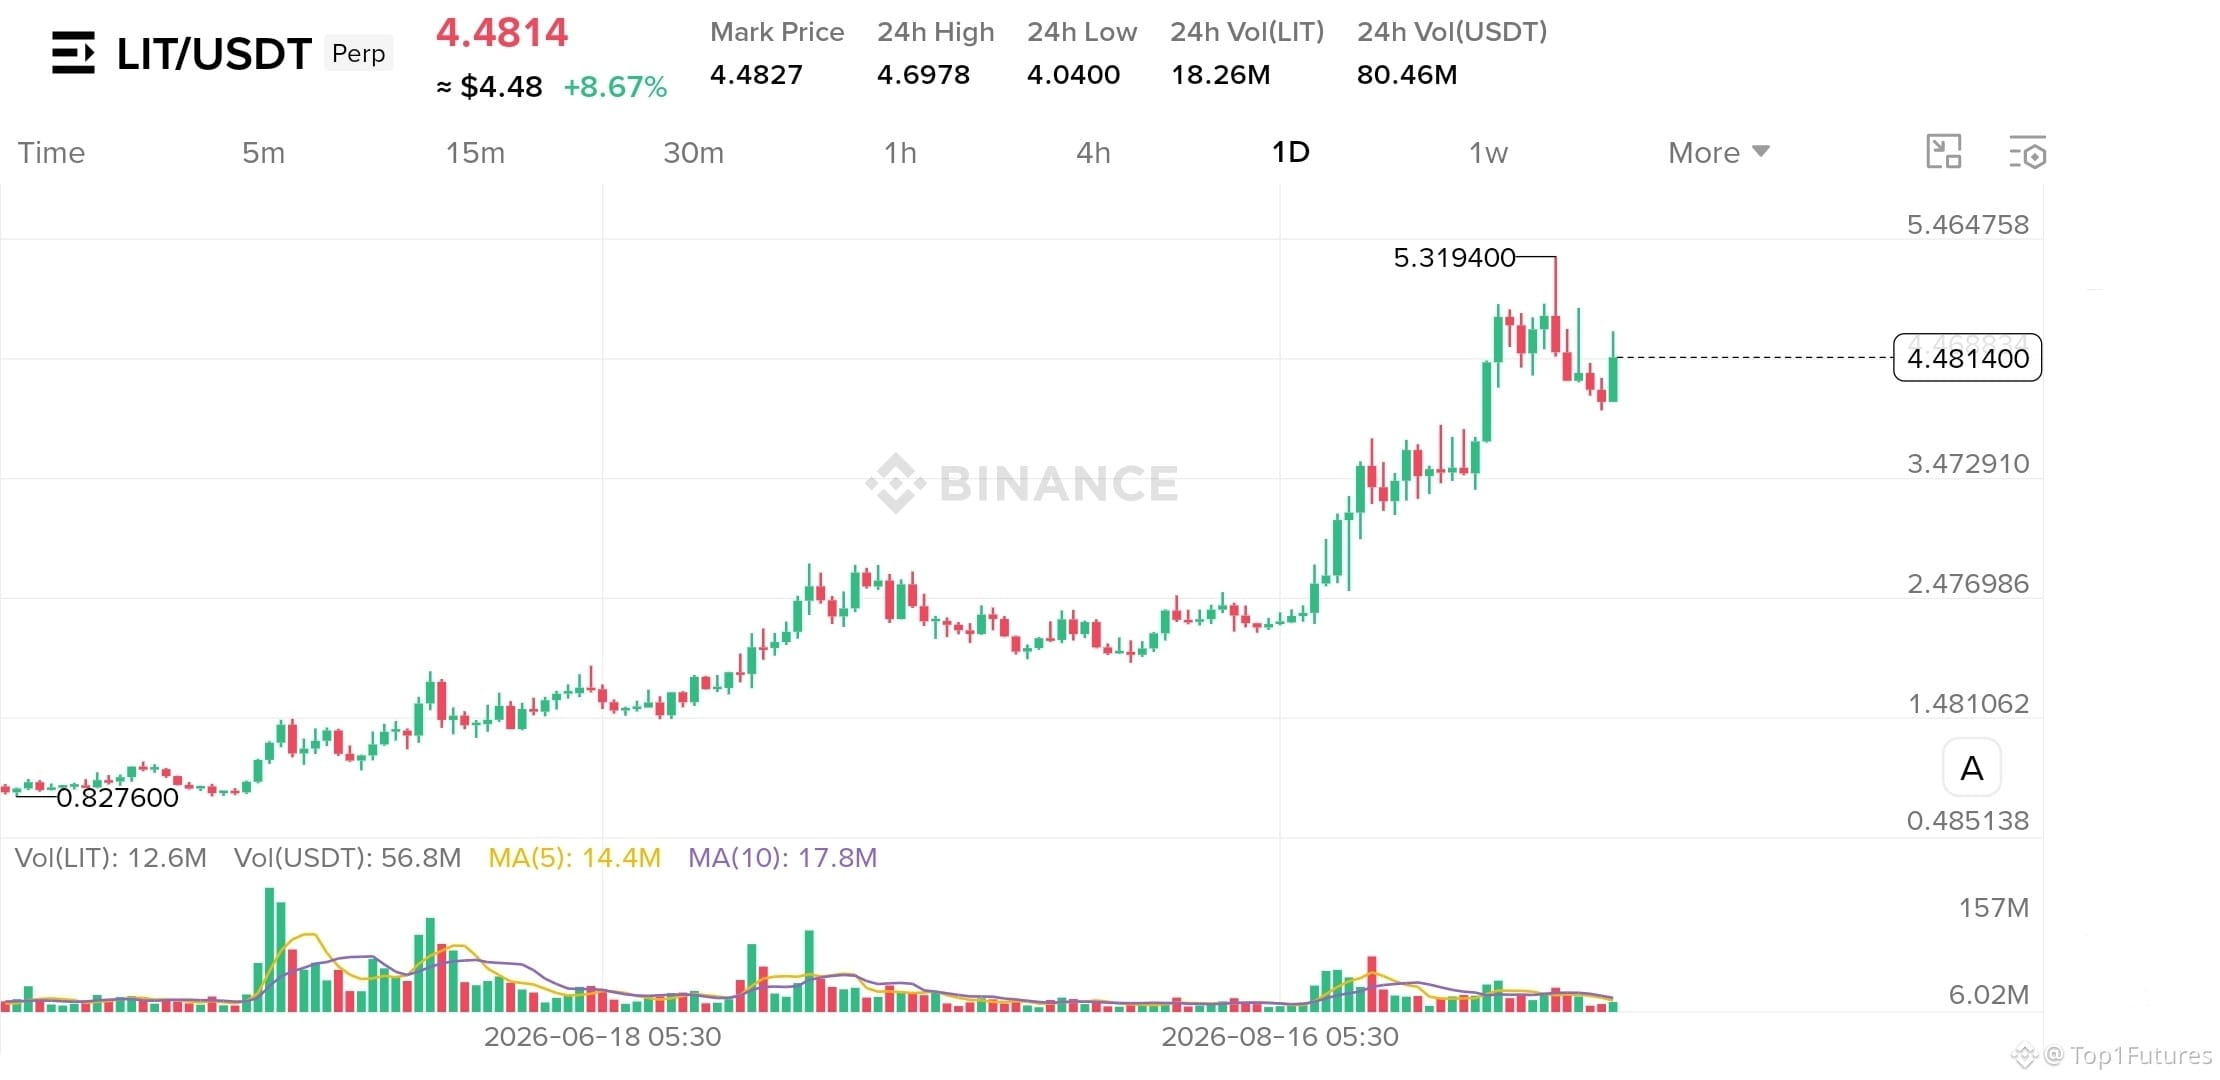
#Lighter is showing signs of a comeback after five days of selling. The token bounced from around $4.00 and jumped 11%, reaching $4.68 before cooling near $4.55.
Trading activity is also picking up, with volume rising sharply, suggesting buyers are becoming more active.
The bigger signal came from a whale, who reportedly withdrew 500K LIT worth about $2.07M. That kind of move can show confidence in higher prices.
Meanwhile, Open Interest climbed 13% to $512M, while derivatives volume jumped 127%.
LIT has also moved back above its short-term moving averages, supporting the bullish momentum.
If buyers can hold above $4.40, another push toward $5 could be possible. 👀
#litu #uptrend #rally
$LIT 🐋 WHALES ARE BACK — AGAIN $5 NEXT? 🚀
#Lighter is showing signs of a comeback after five days of selling. The token bounced from around $4.00 and jumped 11%, reaching $4.68 before cooling near $4.55.
Trading activity is also picking up, with volume rising sharply, suggesting buyers are becoming more active.
The bigger signal came from a whale, who reportedly withdrew 500K LIT worth about $2.07M. That kind of move can show confidence in higher prices.
Meanwhile, Open Interest climbed 13% to $512M, while derivatives volume jumped 127%.
LIT has also moved back above its short-term moving averages, supporting the bullish momentum.
If buyers can hold above $4.40, another push toward $5 could be possible. 👀
#litu #uptrend #rally
#Lighter is showing signs of a comeback after five days of selling. The token bounced from around $4.00 and jumped 11%, reaching $4.68 before cooling near $4.55.
Trading activity is also picking up, with volume rising sharply, suggesting buyers are becoming more active.
The bigger signal came from a whale, who reportedly withdrew 500K LIT worth about $2.07M. That kind of move can show confidence in higher prices.
Meanwhile, Open Interest climbed 13% to $512M, while derivatives volume jumped 127%.
LIT has also moved back above its short-term moving averages, supporting the bullish momentum.
If buyers can hold above $4.40, another push toward $5 could be possible. 👀
#litu #uptrend #rally
1
66
·
--
Lighter ($LIT) Gains Momentum with 10% Surge
Lighter ($LIT) is surging 10% in 24 hours, ranking #2 in trending coins. The community is buzzing with excitement over recent updates and strong volume. With a market cap of $4.5967, $LIT is showing strong momentum and trader interest. The 24-hour volume of $75,367,138 highlights the coin's growing liquidity. Traders should keep an eye on this rising star. ⚡👀
Follow for more setups like this.
#HahaProfit #Lighter
Lighter ($LIT ) Gains Momentum with 10% Surge
Lighter ($LIT ) is surging 10% in 24 hours, ranking #2 in trending coins. The community is buzzing with excitement over recent updates and strong volume. With a market cap of $4.5967, $LIT is showing strong momentum and trader interest. The 24-hour volume of $75,367,138 highlights the coin's growing liquidity. Traders should keep an eye on this rising star. ⚡👀
Follow for more setups like this.
#HahaProfit #Lighter
Lighter ($LIT ) is surging 10% in 24 hours, ranking #2 in trending coins. The community is buzzing with excitement over recent updates and strong volume. With a market cap of $4.5967, $LIT is showing strong momentum and trader interest. The 24-hour volume of $75,367,138 highlights the coin's growing liquidity. Traders should keep an eye on this rising star. ⚡👀
Follow for more setups like this.
#HahaProfit #Lighter
1
·
--
Lighter ($LIT) Gains Momentum with Strong 24h Volume and Price Surge
Lighter ($LIT) is making waves with a 9.70% jump in the last 24 hours. The surge is backed by robust trading volume of $75.3M, indicating strong market interest. As the 68th largest coin by market cap, $LIT is gaining traction. Traders should keep an eye on this momentum and the coin's growing community. ⚡🔥
Follow for daily crypto updates.
#DeGenYuv #Lighter
Lighter ($LIT ) Gains Momentum with Strong 24h Volume and Price Surge
Lighter ($LIT ) is making waves with a 9.70% jump in the last 24 hours. The surge is backed by robust trading volume of $75.3M, indicating strong market interest. As the 68th largest coin by market cap, $LIT is gaining traction. Traders should keep an eye on this momentum and the coin's growing community. ⚡🔥
Follow for daily crypto updates.
#DeGenYuv #Lighter
Lighter ($LIT ) is making waves with a 9.70% jump in the last 24 hours. The surge is backed by robust trading volume of $75.3M, indicating strong market interest. As the 68th largest coin by market cap, $LIT is gaining traction. Traders should keep an eye on this momentum and the coin's growing community. ⚡🔥
Follow for daily crypto updates.
#DeGenYuv #Lighter
98
·
--
Why am I optimistic about Lighter’s $LIT ?
What attracts me most is that Lighter solves the real problems traders care about: cost, speed, and whether the trading rules are transparent.
First, low cost is a tangible competitive advantage. For users who trade frequently, fees continuously affect returns. Lighter offers zero-fee trading for retail users, which gives users a reason to try and migrate. Of course, whether it can retain users depends on depth, slippage, and stability—but low cost is an appealing starting point.
Second, its emphasis on trading transparency is worth paying attention to. According to the official description, Lighter uses ZK technology to provide verifiable proofs for matching and settlement. What I value is that traders can verify how the rules are executed. As on-chain trading evolves, this verifiability has the potential to become a product advantage.
Third, I believe there’s room for Lighter to win on-chain trading users. My judgment is that a platform that balances trading experience, cost, and transparency has the opportunity to attract more users and capital. If Lighter can continue improving liquidity and keep users willing to stay even after incentives are reduced, the quality of its growth will be even more convincing.
As for $LIT, what I’m most looking forward to is the platform’s development gradually translating into clear, sustainable token demand. Product usage is the starting point for value accumulation; how business growth benefits token holders determines the token’s long-term appeal. I will keep an eye on revenue, token utility, value-recapture mechanisms, and unlock schedules.
So my optimism in LIT’s logic comes from seeing Lighter’s ability to win users with its product—and also expecting that this competitive edge ultimately reflects in the token’s value. This is a conditional long-term bullish view: it needs ongoing data to validate, and it also needs a suitable entry valuation.
The first target 6.7U remains unchanged
#lighter #defi $LIT
Why am I optimistic about Lighter’s $LIT ?
What attracts me most is that Lighter solves the real problems traders care about: cost, speed, and whether the trading rules are transparent.
First, low cost is a tangible competitive advantage. For users who trade frequently, fees continuously affect returns. Lighter offers zero-fee trading for retail users, which gives users a reason to try and migrate. Of course, whether it can retain users depends on depth, slippage, and stability—but low cost is an appealing starting point.
Second, its emphasis on trading transparency is worth paying attention to. According to the official description, Lighter uses ZK technology to provide verifiable proofs for matching and settlement. What I value is that traders can verify how the rules are executed. As on-chain trading evolves, this verifiability has the potential to become a product advantage.
Third, I believe there’s room for Lighter to win on-chain trading users. My judgment is that a platform that balances trading experience, cost, and transparency has the opportunity to attract more users and capital. If Lighter can continue improving liquidity and keep users willing to stay even after incentives are reduced, the quality of its growth will be even more convincing.
As for $LIT , what I’m most looking forward to is the platform’s development gradually translating into clear, sustainable token demand. Product usage is the starting point for value accumulation; how business growth benefits token holders determines the token’s long-term appeal. I will keep an eye on revenue, token utility, value-recapture mechanisms, and unlock schedules.
So my optimism in LIT’s logic comes from seeing Lighter’s ability to win users with its product—and also expecting that this competitive edge ultimately reflects in the token’s value. This is a conditional long-term bullish view: it needs ongoing data to validate, and it also needs a suitable entry valuation.
The first target 6.7U remains unchanged
#lighter #defi $LIT
What attracts me most is that Lighter solves the real problems traders care about: cost, speed, and whether the trading rules are transparent.
First, low cost is a tangible competitive advantage. For users who trade frequently, fees continuously affect returns. Lighter offers zero-fee trading for retail users, which gives users a reason to try and migrate. Of course, whether it can retain users depends on depth, slippage, and stability—but low cost is an appealing starting point.
Second, its emphasis on trading transparency is worth paying attention to. According to the official description, Lighter uses ZK technology to provide verifiable proofs for matching and settlement. What I value is that traders can verify how the rules are executed. As on-chain trading evolves, this verifiability has the potential to become a product advantage.
Third, I believe there’s room for Lighter to win on-chain trading users. My judgment is that a platform that balances trading experience, cost, and transparency has the opportunity to attract more users and capital. If Lighter can continue improving liquidity and keep users willing to stay even after incentives are reduced, the quality of its growth will be even more convincing.
As for $LIT , what I’m most looking forward to is the platform’s development gradually translating into clear, sustainable token demand. Product usage is the starting point for value accumulation; how business growth benefits token holders determines the token’s long-term appeal. I will keep an eye on revenue, token utility, value-recapture mechanisms, and unlock schedules.
So my optimism in LIT’s logic comes from seeing Lighter’s ability to win users with its product—and also expecting that this competitive edge ultimately reflects in the token’s value. This is a conditional long-term bullish view: it needs ongoing data to validate, and it also needs a suitable entry valuation.
The first target 6.7U remains unchanged
#lighter #defi $LIT
锤爆鱼头:
靠谱的分析,用了lit就不会再用其它平台交易了😂
2
1
238
·
--
Lighter ($LIT) Gains Traction Despite Market Dips
Lighter ($LIT) is trending at #8, despite a 5.99% drop in 24 hours. The coin's robust 24-hour volume of $37.1M suggests strong interest. $LIT is known for its innovative approach to decentralized finance, focusing on lightweight, fast transactions. With a market cap rank of 70, it's attracting attention from both retail and institutional investors. Keep an eye on community activity and potential partnerships that could drive further momentum. ⚡
Follow for daily crypto updates.
#HahaProfit #Lighter
Lighter ($LIT ) Gains Traction Despite Market Dips
Lighter ($LIT ) is trending at #8, despite a 5.99% drop in 24 hours. The coin's robust 24-hour volume of $37.1M suggests strong interest. $LIT is known for its innovative approach to decentralized finance, focusing on lightweight, fast transactions. With a market cap rank of 70, it's attracting attention from both retail and institutional investors. Keep an eye on community activity and potential partnerships that could drive further momentum. ⚡
Follow for daily crypto updates.
#HahaProfit #Lighter
Lighter ($LIT ) is trending at #8, despite a 5.99% drop in 24 hours. The coin's robust 24-hour volume of $37.1M suggests strong interest. $LIT is known for its innovative approach to decentralized finance, focusing on lightweight, fast transactions. With a market cap rank of 70, it's attracting attention from both retail and institutional investors. Keep an eye on community activity and potential partnerships that could drive further momentum. ⚡
Follow for daily crypto updates.
#HahaProfit #Lighter
37
·
--
Lighter ($LIT) Gains Momentum Despite 24h Dip
Lighter ($LIT) is trending at #8, despite a 5.90% 24h drop. The $37M daily volume and #70 market cap rank signal strong interest. 📊 Traders are watching its ecosystem growth and recent partnerships. 🤝 The community is buzzing with anticipation for upcoming developments. 🚀 Keep an eye on $LIT for potential upside. ⚠️
Follow for more setups like this.
#DeGenYuv #Lighter
Lighter ($LIT ) Gains Momentum Despite 24h Dip
Lighter ($LIT ) is trending at #8, despite a 5.90% 24h drop. The $37M daily volume and #70 market cap rank signal strong interest. 📊 Traders are watching its ecosystem growth and recent partnerships. 🤝 The community is buzzing with anticipation for upcoming developments. 🚀 Keep an eye on $LIT for potential upside. ⚠️
Follow for more setups like this.
#DeGenYuv #Lighter
Lighter ($LIT ) is trending at #8, despite a 5.90% 24h drop. The $37M daily volume and #70 market cap rank signal strong interest. 📊 Traders are watching its ecosystem growth and recent partnerships. 🤝 The community is buzzing with anticipation for upcoming developments. 🚀 Keep an eye on $LIT for potential upside. ⚠️
Follow for more setups like this.
#DeGenYuv #Lighter
65
·
--
🎯 The coins of sustainable DEX quietly doubled in a month
📰 Lighter’s LIT is at $4.49, up 9.5% in 24h and up 99% over the month. Market cap is $110M, breaking into the top 70—still a bit short of the previous high of $7.86
💬 Honestly, decentralized perpetuals have been quietly building momentum. Big firms are bound by compliance, and on-chain perps contracts have become a new favorite for unconventional funds. This track is worth keeping a close eye on
🏷️ #LIT #Lighter #永续DEX #DeFi
🎯 The coins of sustainable DEX quietly doubled in a month
📰 Lighter’s LIT is at $4.49, up 9.5% in 24h and up 99% over the month. Market cap is $110M, breaking into the top 70—still a bit short of the previous high of $7.86
💬 Honestly, decentralized perpetuals have been quietly building momentum. Big firms are bound by compliance, and on-chain perps contracts have become a new favorite for unconventional funds. This track is worth keeping a close eye on
🏷️ #LIT #Lighter #永续DEX #DeFi
📰 Lighter’s LIT is at $4.49, up 9.5% in 24h and up 99% over the month. Market cap is $110M, breaking into the top 70—still a bit short of the previous high of $7.86
💬 Honestly, decentralized perpetuals have been quietly building momentum. Big firms are bound by compliance, and on-chain perps contracts have become a new favorite for unconventional funds. This track is worth keeping a close eye on
🏷️ #LIT #Lighter #永续DEX #DeFi
41

·
--
$LIT This breakout stronger—I don’t think it should be viewed as just a normal pump.
Behind the price approaching an all-time high and a market cap of about $119 million is a relatively rare “revenue–buyback–deflation” loop: the protocol uses real revenue to keep buying back, and it has already repurchased 7% of the circulating supply. Among narrative-driven tokens, this kind of real-money mechanism is quite scarce, which also means the price isn’t driven purely by sentiment.
The other two lines are equally critical. The first is a dual lock on policy and channels—deep involvement in shaping U.S. crypto policy, while also being deeply integrated with Robinhood Chain. It’s like one hand holds the compliance ticket, and the other catches the traffic from traditional retail users. The second is ecosystem spillover: Wick RWA DEX brings the real-world assets track in, with the potential to open a second growth curve for fee revenue.
In the short term, price will be influenced by sentiment, but as long as the buyback flywheel keeps turning and the policy and channel benefits are realized, the market’s pricing logic for it could be rewritten. Chasing after price rises should be done cautiously—it's recommended to make decisions by going back to fundamentals and position management.
#Lighter #RWA #去中心化交易
$LIT This breakout stronger—I don’t think it should be viewed as just a normal pump.
Behind the price approaching an all-time high and a market cap of about $119 million is a relatively rare “revenue–buyback–deflation” loop: the protocol uses real revenue to keep buying back, and it has already repurchased 7% of the circulating supply. Among narrative-driven tokens, this kind of real-money mechanism is quite scarce, which also means the price isn’t driven purely by sentiment.
The other two lines are equally critical. The first is a dual lock on policy and channels—deep involvement in shaping U.S. crypto policy, while also being deeply integrated with Robinhood Chain. It’s like one hand holds the compliance ticket, and the other catches the traffic from traditional retail users. The second is ecosystem spillover: Wick RWA DEX brings the real-world assets track in, with the potential to open a second growth curve for fee revenue.
In the short term, price will be influenced by sentiment, but as long as the buyback flywheel keeps turning and the policy and channel benefits are realized, the market’s pricing logic for it could be rewritten. Chasing after price rises should be done cautiously—it's recommended to make decisions by going back to fundamentals and position management.
#Lighter #RWA #去中心化交易
Behind the price approaching an all-time high and a market cap of about $119 million is a relatively rare “revenue–buyback–deflation” loop: the protocol uses real revenue to keep buying back, and it has already repurchased 7% of the circulating supply. Among narrative-driven tokens, this kind of real-money mechanism is quite scarce, which also means the price isn’t driven purely by sentiment.
The other two lines are equally critical. The first is a dual lock on policy and channels—deep involvement in shaping U.S. crypto policy, while also being deeply integrated with Robinhood Chain. It’s like one hand holds the compliance ticket, and the other catches the traffic from traditional retail users. The second is ecosystem spillover: Wick RWA DEX brings the real-world assets track in, with the potential to open a second growth curve for fee revenue.
In the short term, price will be influenced by sentiment, but as long as the buyback flywheel keeps turning and the policy and channel benefits are realized, the market’s pricing logic for it could be rewritten. Chasing after price rises should be done cautiously—it's recommended to make decisions by going back to fundamentals and position management.
#Lighter #RWA #去中心化交易
51

$LIT Recently strengthened and hit a new historical high. It’s very close to the prior high area near 5.24 USDT—what’s driving this is not just short-term sentiment.
I’m paying attention to three main themes:
First is the policy narrative. Lighter is deeply involved in shaping U.S. crypto policy. Its position in compliant trading infrastructure may be repriced by capital.
Second is ecosystem integration. It is deeply integrated with the Robinhood Chain and may capture traffic from traditional brokerage users entering on-chain trading.
Third is real buybacks. Protocol revenue continues to be used for buybacks. It has already repurchased 7% of the circulating supply, forming a cycle of “revenue growth—reduced sell pressure from buybacks—token value capture.” In addition, expansions such as Wick RWA DEX are also broadening application scenarios.
The current price is about 4.74 USDT. The 24-hour trading volume is about 117.4 million USDT, with a market cap of about 1.19 billion USDT. Volatility near the highs may increase, but several drivers—policy, channels, revenue, and buybacks—are all fermenting at the same time.
#Lighter #RWA #RobinhoodChain
$LIT Recently strengthened and hit a new historical high. It’s very close to the prior high area near 5.24 USDT—what’s driving this is not just short-term sentiment.
I’m paying attention to three main themes:
First is the policy narrative. Lighter is deeply involved in shaping U.S. crypto policy. Its position in compliant trading infrastructure may be repriced by capital.
Second is ecosystem integration. It is deeply integrated with the Robinhood Chain and may capture traffic from traditional brokerage users entering on-chain trading.
Third is real buybacks. Protocol revenue continues to be used for buybacks. It has already repurchased 7% of the circulating supply, forming a cycle of “revenue growth—reduced sell pressure from buybacks—token value capture.” In addition, expansions such as Wick RWA DEX are also broadening application scenarios.
The current price is about 4.74 USDT. The 24-hour trading volume is about 117.4 million USDT, with a market cap of about 1.19 billion USDT. Volatility near the highs may increase, but several drivers—policy, channels, revenue, and buybacks—are all fermenting at the same time.
#Lighter #RWA #RobinhoodChain
I’m paying attention to three main themes:
First is the policy narrative. Lighter is deeply involved in shaping U.S. crypto policy. Its position in compliant trading infrastructure may be repriced by capital.
Second is ecosystem integration. It is deeply integrated with the Robinhood Chain and may capture traffic from traditional brokerage users entering on-chain trading.
Third is real buybacks. Protocol revenue continues to be used for buybacks. It has already repurchased 7% of the circulating supply, forming a cycle of “revenue growth—reduced sell pressure from buybacks—token value capture.” In addition, expansions such as Wick RWA DEX are also broadening application scenarios.
The current price is about 4.74 USDT. The 24-hour trading volume is about 117.4 million USDT, with a market cap of about 1.19 billion USDT. Volatility near the highs may increase, but several drivers—policy, channels, revenue, and buybacks—are all fermenting at the same time.
#Lighter #RWA #RobinhoodChain
56
·
--
$LIT Behind this recent surge is solid fundamentals support—not a purely emotion-driven push.
First is value capture: agreement revenue continues to fuel buybacks. The company has already repurchased 7% of the outstanding shares, forming a genuine, cash-driven deflationary loop.
Second is narrative strength: the team is deeply involved in shaping U.S. crypto policy, giving it regulatory influence that is quite scarce in the industry. At the same time, it is deeply integrated with Robinhood Chain—effectively holding the gateway to a pool of millions of retail users. On the ecosystem side, Wick RWA DEX is also bringing real-world asset tracks into its blueprint.
On the data front: the current price is about $4.74, market cap about $119 million, and 24-hour trading volume of $117 million. The price has just refreshed its all-time high and is nearing the $5.24 level.
With policy, channels, buybacks, and ecosystem all delivering at the same time, whether it can hold above the new high is worth continued monitoring.
#Lighter #RWA #On-chain activity
$LIT Behind this recent surge is solid fundamentals support—not a purely emotion-driven push.
First is value capture: agreement revenue continues to fuel buybacks. The company has already repurchased 7% of the outstanding shares, forming a genuine, cash-driven deflationary loop.
Second is narrative strength: the team is deeply involved in shaping U.S. crypto policy, giving it regulatory influence that is quite scarce in the industry. At the same time, it is deeply integrated with Robinhood Chain—effectively holding the gateway to a pool of millions of retail users. On the ecosystem side, Wick RWA DEX is also bringing real-world asset tracks into its blueprint.
On the data front: the current price is about $4.74, market cap about $119 million, and 24-hour trading volume of $117 million. The price has just refreshed its all-time high and is nearing the $5.24 level.
With policy, channels, buybacks, and ecosystem all delivering at the same time, whether it can hold above the new high is worth continued monitoring.
#Lighter #RWA #On-chain activity
First is value capture: agreement revenue continues to fuel buybacks. The company has already repurchased 7% of the outstanding shares, forming a genuine, cash-driven deflationary loop.
Second is narrative strength: the team is deeply involved in shaping U.S. crypto policy, giving it regulatory influence that is quite scarce in the industry. At the same time, it is deeply integrated with Robinhood Chain—effectively holding the gateway to a pool of millions of retail users. On the ecosystem side, Wick RWA DEX is also bringing real-world asset tracks into its blueprint.
On the data front: the current price is about $4.74, market cap about $119 million, and 24-hour trading volume of $117 million. The price has just refreshed its all-time high and is nearing the $5.24 level.
With policy, channels, buybacks, and ecosystem all delivering at the same time, whether it can hold above the new high is worth continued monitoring.
#Lighter #RWA #On-chain activity
49

The trajectory of this round of $LIT is best understood as a reassessment jointly driven by “policy narrative + buybacks from revenue + ecosystem expansion.”
As the price moves close to $5.24 and hits a new all-time high, trading remains active: 24-hour trading volume is about $117 million and market cap is around $119 million. But more worth watching than the short-term upside is the set of long-term fundamentals behind Lighter:
First, it is deeply involved in U.S. crypto policy discussions, and its ability to connect policy is becoming a source of narrative premium. Second, it is deeply integrated with the Robinhood Chain, positioning it to capture a larger user base and liquidity. Third, protocol revenue continues to be converted into buybacks; it has already repurchased about 7% of the circulating supply, creating deflationary expectations. Fourth, the ecosystem continues to extend into RWA—for example, the expansion of Wick RWA DEX.
When growth no longer depends purely on sentiment, but is supported by revenue, buybacks, and real application scenarios, the token’s price elasticity will naturally be repriced by the market. The key to watch next is the strength of buybacks, growth in on-chain revenue, and the rollout pace of ecosystem projects.
#Lighter #RWA #加密生态
The trajectory of this round of $LIT is best understood as a reassessment jointly driven by “policy narrative + buybacks from revenue + ecosystem expansion.”
As the price moves close to $5.24 and hits a new all-time high, trading remains active: 24-hour trading volume is about $117 million and market cap is around $119 million. But more worth watching than the short-term upside is the set of long-term fundamentals behind Lighter:
First, it is deeply involved in U.S. crypto policy discussions, and its ability to connect policy is becoming a source of narrative premium. Second, it is deeply integrated with the Robinhood Chain, positioning it to capture a larger user base and liquidity. Third, protocol revenue continues to be converted into buybacks; it has already repurchased about 7% of the circulating supply, creating deflationary expectations. Fourth, the ecosystem continues to extend into RWA—for example, the expansion of Wick RWA DEX.
When growth no longer depends purely on sentiment, but is supported by revenue, buybacks, and real application scenarios, the token’s price elasticity will naturally be repriced by the market. The key to watch next is the strength of buybacks, growth in on-chain revenue, and the rollout pace of ecosystem projects.
#Lighter #RWA #加密生态
As the price moves close to $5.24 and hits a new all-time high, trading remains active: 24-hour trading volume is about $117 million and market cap is around $119 million. But more worth watching than the short-term upside is the set of long-term fundamentals behind Lighter:
First, it is deeply involved in U.S. crypto policy discussions, and its ability to connect policy is becoming a source of narrative premium. Second, it is deeply integrated with the Robinhood Chain, positioning it to capture a larger user base and liquidity. Third, protocol revenue continues to be converted into buybacks; it has already repurchased about 7% of the circulating supply, creating deflationary expectations. Fourth, the ecosystem continues to extend into RWA—for example, the expansion of Wick RWA DEX.
When growth no longer depends purely on sentiment, but is supported by revenue, buybacks, and real application scenarios, the token’s price elasticity will naturally be repriced by the market. The key to watch next is the strength of buybacks, growth in on-chain revenue, and the rollout pace of ecosystem projects.
#Lighter #RWA #加密生态
6
·
--
This round of $LIT gaining strength isn’t just short-term sentiment—it looks more like the market is repricing the fundamentals and the narrative at the same time.
The current price is about $4.74, not far from the previous all-time high near $5.24. In the past 24 hours, trading volume was around $117 million, and the market cap is about $119 million, suggesting that capital attention is still increasing.
I focus on four key pillars:
First, deep involvement in U.S. crypto policy discussions. If the regulatory framework continues to become clearer, Lighter has a chance to secure a position in the compliant trading infrastructure space.
Second, deep integration with Robinhood Chain, which suggests it may be able to capture a larger scale of retail users and on-chain liquidity.
Third, continued buybacks driven by protocol revenue. It has already repurchased about 7% of the circulating supply—this is stronger support than simply telling a token-burn story, because it has cash-flow backing.
Fourth, ecosystem expansion. For example, Wick RWA DEX extends the growth boundary from spot trading into the RWA track.
Technically, it’s close to the prior high, so volatility is likely to increase. But if revenue, buybacks, and ecosystem data continue to materialize, the valuation logic for $LIT could shift from a “trading-type token” to a “protocol-revenue asset.” Chasing the price requires position sizing discipline; focus on monitoring trading volume, the buyback pace, and Robinhood Chain ecosystem data.
#Lighter #RWA #Crypto market
This round of $LIT gaining strength isn’t just short-term sentiment—it looks more like the market is repricing the fundamentals and the narrative at the same time.
The current price is about $4.74, not far from the previous all-time high near $5.24. In the past 24 hours, trading volume was around $117 million, and the market cap is about $119 million, suggesting that capital attention is still increasing.
I focus on four key pillars:
First, deep involvement in U.S. crypto policy discussions. If the regulatory framework continues to become clearer, Lighter has a chance to secure a position in the compliant trading infrastructure space.
Second, deep integration with Robinhood Chain, which suggests it may be able to capture a larger scale of retail users and on-chain liquidity.
Third, continued buybacks driven by protocol revenue. It has already repurchased about 7% of the circulating supply—this is stronger support than simply telling a token-burn story, because it has cash-flow backing.
Fourth, ecosystem expansion. For example, Wick RWA DEX extends the growth boundary from spot trading into the RWA track.
Technically, it’s close to the prior high, so volatility is likely to increase. But if revenue, buybacks, and ecosystem data continue to materialize, the valuation logic for $LIT could shift from a “trading-type token” to a “protocol-revenue asset.” Chasing the price requires position sizing discipline; focus on monitoring trading volume, the buyback pace, and Robinhood Chain ecosystem data.
#Lighter #RWA #Crypto market
The current price is about $4.74, not far from the previous all-time high near $5.24. In the past 24 hours, trading volume was around $117 million, and the market cap is about $119 million, suggesting that capital attention is still increasing.
I focus on four key pillars:
First, deep involvement in U.S. crypto policy discussions. If the regulatory framework continues to become clearer, Lighter has a chance to secure a position in the compliant trading infrastructure space.
Second, deep integration with Robinhood Chain, which suggests it may be able to capture a larger scale of retail users and on-chain liquidity.
Third, continued buybacks driven by protocol revenue. It has already repurchased about 7% of the circulating supply—this is stronger support than simply telling a token-burn story, because it has cash-flow backing.
Fourth, ecosystem expansion. For example, Wick RWA DEX extends the growth boundary from spot trading into the RWA track.
Technically, it’s close to the prior high, so volatility is likely to increase. But if revenue, buybacks, and ecosystem data continue to materialize, the valuation logic for $LIT could shift from a “trading-type token” to a “protocol-revenue asset.” Chasing the price requires position sizing discipline; focus on monitoring trading volume, the buyback pace, and Robinhood Chain ecosystem data.
#Lighter #RWA #Crypto market
41
·
--
Lighter buys back real cash and real gold: 7% of the float is repurchased; $LIT has also stepped above $5—behind this is a typical supply contraction.
In the short term, 7% of tradable chips are withdrawn; trading volume shrinks. As long as the buy-side isn’t weak, it’s not surprising that prices get pushed up. The breakout is just the outcome—the real thing to watch is the “quality” of the buyback:
First, where the funds come from and whether they can be sustained. A one-off buyback can ignite sentiment, but how far the market can go depends on whether there is follow-through that becomes normalized.
Second, whether the on-chain tokens are truly locked. Be wary of digital “paper games” where tokens are effectively passed from one side to the other.
Above $5 is both the sentiment “realization” zone and a litmus test. After good news is delivered, chasing highs needs restraint. The key is to see whether the trading volume can absorb the profit-taking orders.
Buybacks can regulate short-term circulating supply, but they can’t replace long-term value. A deflation narrative sounds good, but it shouldn’t be the reason for mindless onboarding.
#山寨币 #Litentry #Lighter
Lighter buys back real cash and real gold: 7% of the float is repurchased; $LIT has also stepped above $5—behind this is a typical supply contraction.
In the short term, 7% of tradable chips are withdrawn; trading volume shrinks. As long as the buy-side isn’t weak, it’s not surprising that prices get pushed up. The breakout is just the outcome—the real thing to watch is the “quality” of the buyback:
First, where the funds come from and whether they can be sustained. A one-off buyback can ignite sentiment, but how far the market can go depends on whether there is follow-through that becomes normalized.
Second, whether the on-chain tokens are truly locked. Be wary of digital “paper games” where tokens are effectively passed from one side to the other.
Above $5 is both the sentiment “realization” zone and a litmus test. After good news is delivered, chasing highs needs restraint. The key is to see whether the trading volume can absorb the profit-taking orders.
Buybacks can regulate short-term circulating supply, but they can’t replace long-term value. A deflation narrative sounds good, but it shouldn’t be the reason for mindless onboarding.
#山寨币 #Litentry #Lighter
In the short term, 7% of tradable chips are withdrawn; trading volume shrinks. As long as the buy-side isn’t weak, it’s not surprising that prices get pushed up. The breakout is just the outcome—the real thing to watch is the “quality” of the buyback:
First, where the funds come from and whether they can be sustained. A one-off buyback can ignite sentiment, but how far the market can go depends on whether there is follow-through that becomes normalized.
Second, whether the on-chain tokens are truly locked. Be wary of digital “paper games” where tokens are effectively passed from one side to the other.
Above $5 is both the sentiment “realization” zone and a litmus test. After good news is delivered, chasing highs needs restraint. The key is to see whether the trading volume can absorb the profit-taking orders.
Buybacks can regulate short-term circulating supply, but they can’t replace long-term value. A deflation narrative sounds good, but it shouldn’t be the reason for mindless onboarding.
#山寨币 #Litentry #Lighter
2
·
--
$LIT This spike in the market is pretty straightforward in its catalyst: Lighter has bought back 7% of the circulating supply. Near-term supply-and-demand expectations tighten quickly, and the price breaks through $5 in step.
The buyback isn’t just empty hype—it uses real buying demand to absorb supply from the market, which can easily strengthen the deflation narrative. But whether it can hold steady afterward depends on the buyback execution, token unlock schedules, trading volume, and whether the ecosystem can generate sustained revenue. After good news is priced in, volatility usually increases—before chasing higher, don’t ignore the risk of a pullback.
#Litentry #Lighter #altcoin
$LIT This spike in the market is pretty straightforward in its catalyst: Lighter has bought back 7% of the circulating supply. Near-term supply-and-demand expectations tighten quickly, and the price breaks through $5 in step.
The buyback isn’t just empty hype—it uses real buying demand to absorb supply from the market, which can easily strengthen the deflation narrative. But whether it can hold steady afterward depends on the buyback execution, token unlock schedules, trading volume, and whether the ecosystem can generate sustained revenue. After good news is priced in, volatility usually increases—before chasing higher, don’t ignore the risk of a pullback.
#Litentry #Lighter #altcoin
The buyback isn’t just empty hype—it uses real buying demand to absorb supply from the market, which can easily strengthen the deflation narrative. But whether it can hold steady afterward depends on the buyback execution, token unlock schedules, trading volume, and whether the ecosystem can generate sustained revenue. After good news is priced in, volatility usually increases—before chasing higher, don’t ignore the risk of a pullback.
#Litentry #Lighter #altcoin
32
·
--
🔥 Lighter carries out a major buyback: 17.5 million $LIT tokens, accounting for 7% of the circulating supply!
This level of力度 is quite rare among copycat coins. Usually, projects’ buybacks are either just for show or a marketing tactic coordinated with selling. But consuming 7% of the float in one go signals that the team has real confidence in its own token—or, more precisely, that it has a clear judgment that the current price is severely undervalued.
After the buyback, token concentration will further increase, and the sell-pressure will be reduced—this is pretty much a sure thing. The key is still to see whether there will be follow-up ecosystem progress and a value-capture mechanism to support the price.
In the short term, sentiment will definitely be a positive. Will the market immediately reflect it? We can observe together.
#Lighter #山寨币
🔥 Lighter carries out a major buyback: 17.5 million $LIT tokens, accounting for 7% of the circulating supply!
This level of力度 is quite rare among copycat coins. Usually, projects’ buybacks are either just for show or a marketing tactic coordinated with selling. But consuming 7% of the float in one go signals that the team has real confidence in its own token—or, more precisely, that it has a clear judgment that the current price is severely undervalued.
After the buyback, token concentration will further increase, and the sell-pressure will be reduced—this is pretty much a sure thing. The key is still to see whether there will be follow-up ecosystem progress and a value-capture mechanism to support the price.
In the short term, sentiment will definitely be a positive. Will the market immediately reflect it? We can observe together.
#Lighter #山寨币
This level of力度 is quite rare among copycat coins. Usually, projects’ buybacks are either just for show or a marketing tactic coordinated with selling. But consuming 7% of the float in one go signals that the team has real confidence in its own token—or, more precisely, that it has a clear judgment that the current price is severely undervalued.
After the buyback, token concentration will further increase, and the sell-pressure will be reduced—this is pretty much a sure thing. The key is still to see whether there will be follow-up ecosystem progress and a value-capture mechanism to support the price.
In the short term, sentiment will definitely be a positive. Will the market immediately reflect it? We can observe together.
#Lighter #山寨币
69
·
--
Lighter has just completed a fairly weighty buyback: 17.5 million $LIT, accounting for 7% of the circulating supply.
This proportion is not a small move among similar projects. Cutting the circulating float directly by 7% has a real impact on the supply-demand structure—provided that the tokens from the buyback are truly burned or locked for the long term, rather than merely moved to another wallet and kept there.
The market is still digesting this news, so the short-term price reaction will depend on what investors expect Lighter to do next: is this a one-off market-cap management move, or the beginning of a sustained buyback plan? The long-term value implications of these two scenarios are completely different.
During altcoin season, a buyback + burn narrative is always easy for capital to play with. But what actually goes far is still determined by the project’s fundamentals and whether its cash flow can support ongoing buybacks.
What do you think about this 7% circulating supply buyback? Is it a short-term positive that has already run its course, or the start of a value rebound?
#Lighter #山寨币
Lighter has just completed a fairly weighty buyback: 17.5 million $LIT , accounting for 7% of the circulating supply.
This proportion is not a small move among similar projects. Cutting the circulating float directly by 7% has a real impact on the supply-demand structure—provided that the tokens from the buyback are truly burned or locked for the long term, rather than merely moved to another wallet and kept there.
The market is still digesting this news, so the short-term price reaction will depend on what investors expect Lighter to do next: is this a one-off market-cap management move, or the beginning of a sustained buyback plan? The long-term value implications of these two scenarios are completely different.
During altcoin season, a buyback + burn narrative is always easy for capital to play with. But what actually goes far is still determined by the project’s fundamentals and whether its cash flow can support ongoing buybacks.
What do you think about this 7% circulating supply buyback? Is it a short-term positive that has already run its course, or the start of a value rebound?
#Lighter #山寨币
This proportion is not a small move among similar projects. Cutting the circulating float directly by 7% has a real impact on the supply-demand structure—provided that the tokens from the buyback are truly burned or locked for the long term, rather than merely moved to another wallet and kept there.
The market is still digesting this news, so the short-term price reaction will depend on what investors expect Lighter to do next: is this a one-off market-cap management move, or the beginning of a sustained buyback plan? The long-term value implications of these two scenarios are completely different.
During altcoin season, a buyback + burn narrative is always easy for capital to play with. But what actually goes far is still determined by the project’s fundamentals and whether its cash flow can support ongoing buybacks.
What do you think about this 7% circulating supply buyback? Is it a short-term positive that has already run its course, or the start of a value rebound?
#Lighter #山寨币
73
·
--
This message is worth breaking down.
$Lighter has repurchased 17.5 million LIT tokens, accounting for 7% of the circulating supply. From the perspective of a single event alone, that’s already significant. This isn’t a symbolic buy—it's genuinely shrinking the circulating float by a notch. In the short term, the impact on the chip/holding structure is direct.
What I care about more is the repurchase route: was it swept directly from the exchange’s secondary market, routed through a market-maker channel, or carved out from the project’s reserve fund pool? Different paths send different signals— the former suggests the team is propping up the market when sentiment is weak, while the latter is more financially oriented in tightening the supply.
In the short term, a 7% reduction in circulating supply, combined with amplified price volatility, can easily produce two extremes: one is that liquidity thins out, causing an upside breakout to happen faster; the other is that once selling pressure returns, rebounds become more fragile.
Over the medium to long term, repurchases are just a “confidence statement.” What truly determines whether it can hold is the product itself—on-chain daily active users, order book depth, and protocol revenue. These are the key factors that determine whether repurchases can be兑现 into valuation support.
For ordinary token holders, rather than chasing a price run-up based on repurchase news, it’s more worth watching the execution details of the buyback and the subsequent disclosures.
#Lighter #altcoin
This message is worth breaking down.
$Lighter has repurchased 17.5 million LIT tokens, accounting for 7% of the circulating supply. From the perspective of a single event alone, that’s already significant. This isn’t a symbolic buy—it's genuinely shrinking the circulating float by a notch. In the short term, the impact on the chip/holding structure is direct.
What I care about more is the repurchase route: was it swept directly from the exchange’s secondary market, routed through a market-maker channel, or carved out from the project’s reserve fund pool? Different paths send different signals— the former suggests the team is propping up the market when sentiment is weak, while the latter is more financially oriented in tightening the supply.
In the short term, a 7% reduction in circulating supply, combined with amplified price volatility, can easily produce two extremes: one is that liquidity thins out, causing an upside breakout to happen faster; the other is that once selling pressure returns, rebounds become more fragile.
Over the medium to long term, repurchases are just a “confidence statement.” What truly determines whether it can hold is the product itself—on-chain daily active users, order book depth, and protocol revenue. These are the key factors that determine whether repurchases can be兑现 into valuation support.
For ordinary token holders, rather than chasing a price run-up based on repurchase news, it’s more worth watching the execution details of the buyback and the subsequent disclosures.
#Lighter #altcoin
$Lighter has repurchased 17.5 million LIT tokens, accounting for 7% of the circulating supply. From the perspective of a single event alone, that’s already significant. This isn’t a symbolic buy—it's genuinely shrinking the circulating float by a notch. In the short term, the impact on the chip/holding structure is direct.
What I care about more is the repurchase route: was it swept directly from the exchange’s secondary market, routed through a market-maker channel, or carved out from the project’s reserve fund pool? Different paths send different signals— the former suggests the team is propping up the market when sentiment is weak, while the latter is more financially oriented in tightening the supply.
In the short term, a 7% reduction in circulating supply, combined with amplified price volatility, can easily produce two extremes: one is that liquidity thins out, causing an upside breakout to happen faster; the other is that once selling pressure returns, rebounds become more fragile.
Over the medium to long term, repurchases are just a “confidence statement.” What truly determines whether it can hold is the product itself—on-chain daily active users, order book depth, and protocol revenue. These are the key factors that determine whether repurchases can be兑现 into valuation support.
For ordinary token holders, rather than chasing a price run-up based on repurchase news, it’s more worth watching the execution details of the buyback and the subsequent disclosures.
#Lighter #altcoin
135
·
--
Lighter ($LIT) Gains Momentum Despite 24h Dip
Lighter ($LIT) is trending despite a 6.37% 24h dip, driven by strong community support and high trading volume. With a market cap rank of 69 and a 24h volume of $93.51M, $LIT is attracting attention from traders. The coin’s robust ecosystem and recent updates are keeping the momentum alive. Traders should keep an eye on this one as it continues to build a solid foundation. ⚡👀
Follow for daily crypto updates.
#HahaProfit #Lighter
Lighter ($LIT ) Gains Momentum Despite 24h Dip
Lighter ($LIT ) is trending despite a 6.37% 24h dip, driven by strong community support and high trading volume. With a market cap rank of 69 and a 24h volume of $93.51M, $LIT is attracting attention from traders. The coin’s robust ecosystem and recent updates are keeping the momentum alive. Traders should keep an eye on this one as it continues to build a solid foundation. ⚡👀
Follow for daily crypto updates.
#HahaProfit #Lighter
Lighter ($LIT ) is trending despite a 6.37% 24h dip, driven by strong community support and high trading volume. With a market cap rank of 69 and a 24h volume of $93.51M, $LIT is attracting attention from traders. The coin’s robust ecosystem and recent updates are keeping the momentum alive. Traders should keep an eye on this one as it continues to build a solid foundation. ⚡👀
Follow for daily crypto updates.
#HahaProfit #Lighter
3
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#SKPoliceRefer18PolymarketUsersToProsecutors
0 views
0 Discussing
2
#FedSEPProjects2026RateAt4.1%
695 views
54 Discussing
3
#USHouseAdvancesBitcoinReserveBill
1,647 views
76 Discussing
4
#AmazonGetsWarrantsToBuyGeneracStock
2,182 views
110 Discussing
5
#DotPlotSignalsOneMoreHikeIn2026
21,472 views
467 Discussing
6
#RobinhoodToSupportCircleArcNetwork
4,652 views
154 Discussing
7
#FedHikes25BpsUSStocksClose
30,095 views
402 Discussing
8
#AaveToLaunchRWAMarketOnAvalanche
7,259 views
173 Discussing
9
#CryptoVCFundingRebounds$5.6BInQ2
8,039 views
43 Discussing
10
#RevolutHackersDemand$3MInMonero
593 views
16 Discussing