

#hbm
hbm
93,111 views
385 Discussing
Hot
Latest

·
--
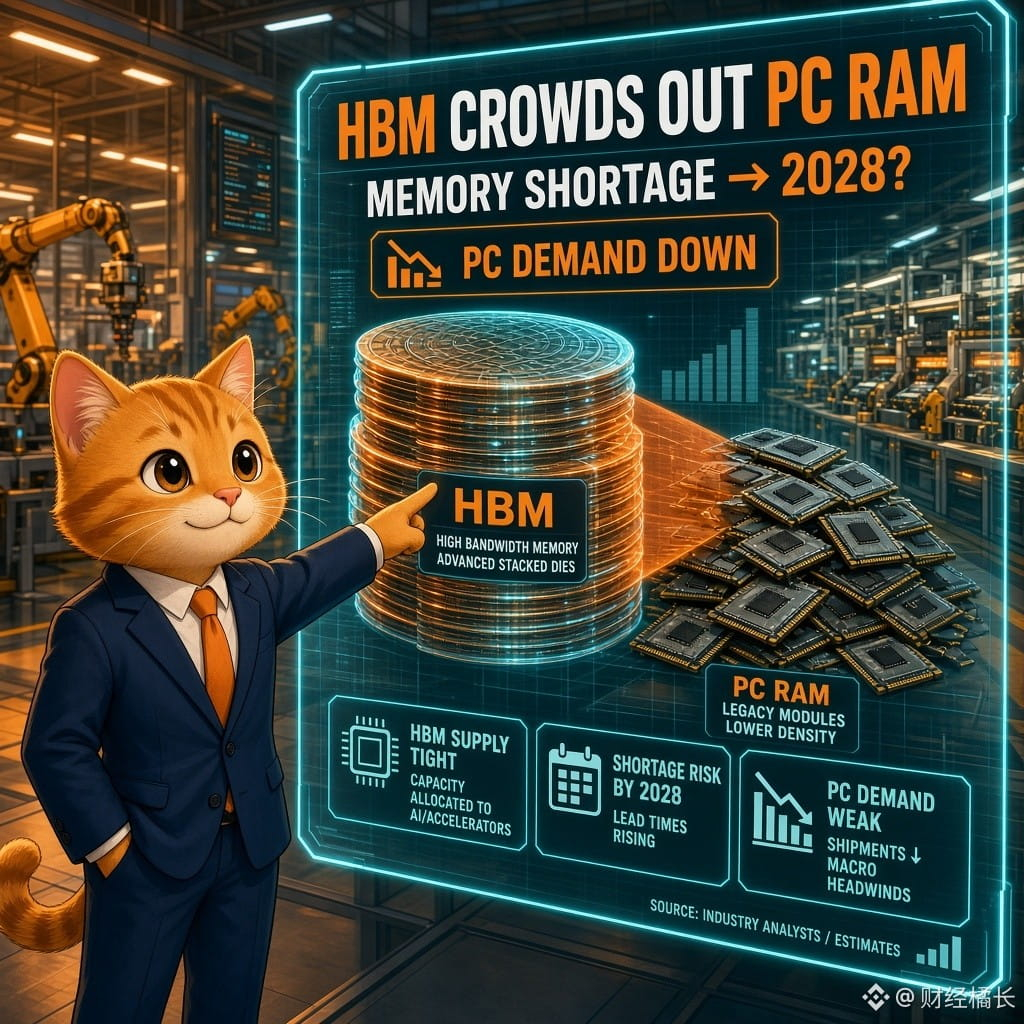
The hidden driver behind Intel’s plunge is a memory shortage: HBM is grabbing capacity, while rising PC memory prices are crushing demand
Samsung, SK Hynix, and Micron are shifting capacity to HBM, making PC memory scarce and more expensive. Global PC shipments fell about 4% year over year in Q2 (Seoul Economic Daily/Reuters/Counterpoint). Intel’s Q3 Client Computing revenue was about $8.1 billion, down 5%; Data Center and AI revenue was about $7.3 billion, up 78%. Its Q4 guidance of $15–16 billion was below the LSEG consensus of about $17.1 billion (company earnings report). Micron’s CEO said about 75% of its 2027 output is already committed and HBM demand has surpassed DRAM demand; a Samsung executive said HBM could account for nearly 30% of DRAM wafer capacity in 2027, up from about 20% this year (Ars/Reuters). Intel expects PC weakness to persist at least through the first half of 2027; Bloomberg reports the PC market could shrink about 12% in 2026 and another 10% in 2027.
【View】Today’s sell-off is hitting Intel, but the underlying issue is “AI memory crowding out consumer memory”—PCs are getting too expensive to sell, causing CPU demand to collapse as well. However strong server CPUs may be, they can’t make up for the PC segment’s roughly half of the market in the short term.
【Opportunities/Risks】The memory shortage supports a favorable pricing cycle, while PC/OEMs and consumer-focused CPUs face pressure. Watch shipment and ASP guidance for the first half of 2027. Risk assets remain tied to tech beta, and $BTC is sensitive to sentiment around the Nasdaq.
Do you think the memory shortage will first hit the phone/PC replacement cycle, or will it first force more HBM capacity expansion?
#内存 #HBM #半导体 #AI $BTC $FET
For reference only; this does not constitute investment advice
156
·
--
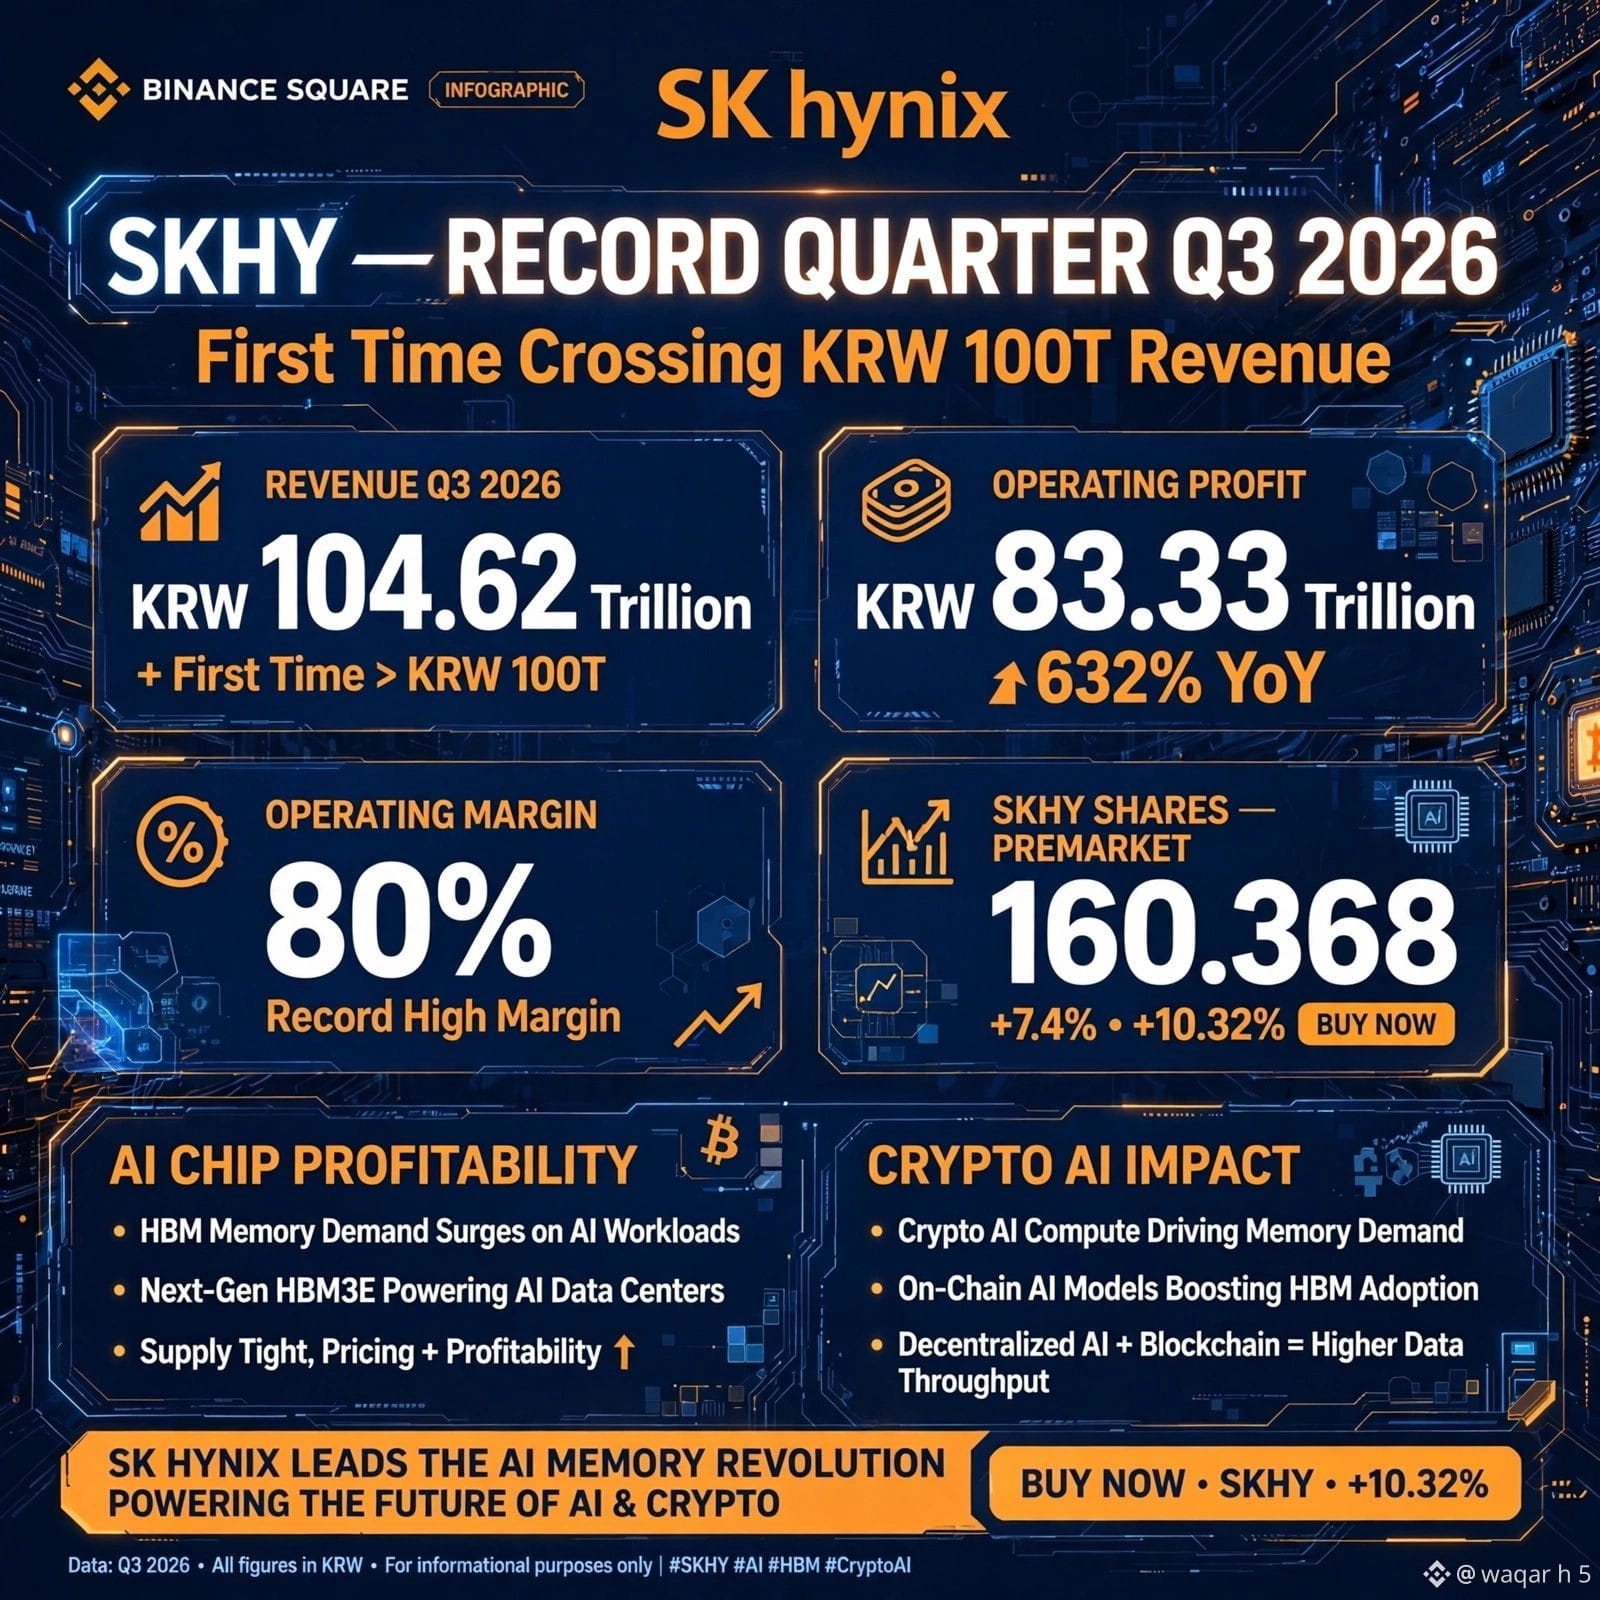
SK Hynix (SKHY) — RECORD QUARTER! Shares +7.4% Premarket 🔥
SK Hynix just delivered one of the STRONGEST earnings in chip sector history — Q3 2026:
📊 Revenue Q3 2026: KRW 104.62 TRILLION — First time ever crossing KRW 100T! 💥
💰 Operating Profit: KRW 83.33 Trillion — UP 632% YoY
📈 Operating Margin: 80% — Record High, showing insane AI chip profitability
🚀 SKHY Shares: 160.368 (+7.4% premarket, +10.32%) — BUY NOW momentum
Why This Matters for Crypto AI?
✅ HBM Memory Demand Surging — AI workloads + Crypto AI compute driving it
✅ Next-Gen HBM3E Powering AI Data Centers — tight supply = higher pricing
✅ Crypto AI Impact: Decentralized AI + Blockchain = Higher Data Throughput, On-Chain AI models boosting HBM adoption
SK Hynix Leads The AI Memory Revolution — Powering Future of AI & Crypto!
Is AI chip boom fueling next Crypto AI rally? 👀
#SKHY #SKHynix #AI #HBM #CryptoAI #Binance #Earnings #ChipStocks
$SKHY $BTC $AI
{future}(SKHYUSDT)
{alpha}(46630x2e8c31162b855a2ffa90f6f8634643ad6f111e18)
SK Hynix (SKHY) — RECORD QUARTER! Shares +7.4% Premarket 🔥
SK Hynix just delivered one of the STRONGEST earnings in chip sector history — Q3 2026:
📊 Revenue Q3 2026: KRW 104.62 TRILLION — First time ever crossing KRW 100T! 💥
💰 Operating Profit: KRW 83.33 Trillion — UP 632% YoY
📈 Operating Margin: 80% — Record High, showing insane AI chip profitability
🚀 SKHY Shares: 160.368 (+7.4% premarket, +10.32%) — BUY NOW momentum
Why This Matters for Crypto AI?
✅ HBM Memory Demand Surging — AI workloads + Crypto AI compute driving it
✅ Next-Gen HBM3E Powering AI Data Centers — tight supply = higher pricing
✅ Crypto AI Impact: Decentralized AI + Blockchain = Higher Data Throughput, On-Chain AI models boosting HBM adoption
SK Hynix Leads The AI Memory Revolution — Powering Future of AI & Crypto!
Is AI chip boom fueling next Crypto AI rally? 👀
#SKHY #SKHynix #AI #HBM #CryptoAI #Binance #Earnings #ChipStocks
$SKHY $BTC $AI
356
·
--
Article
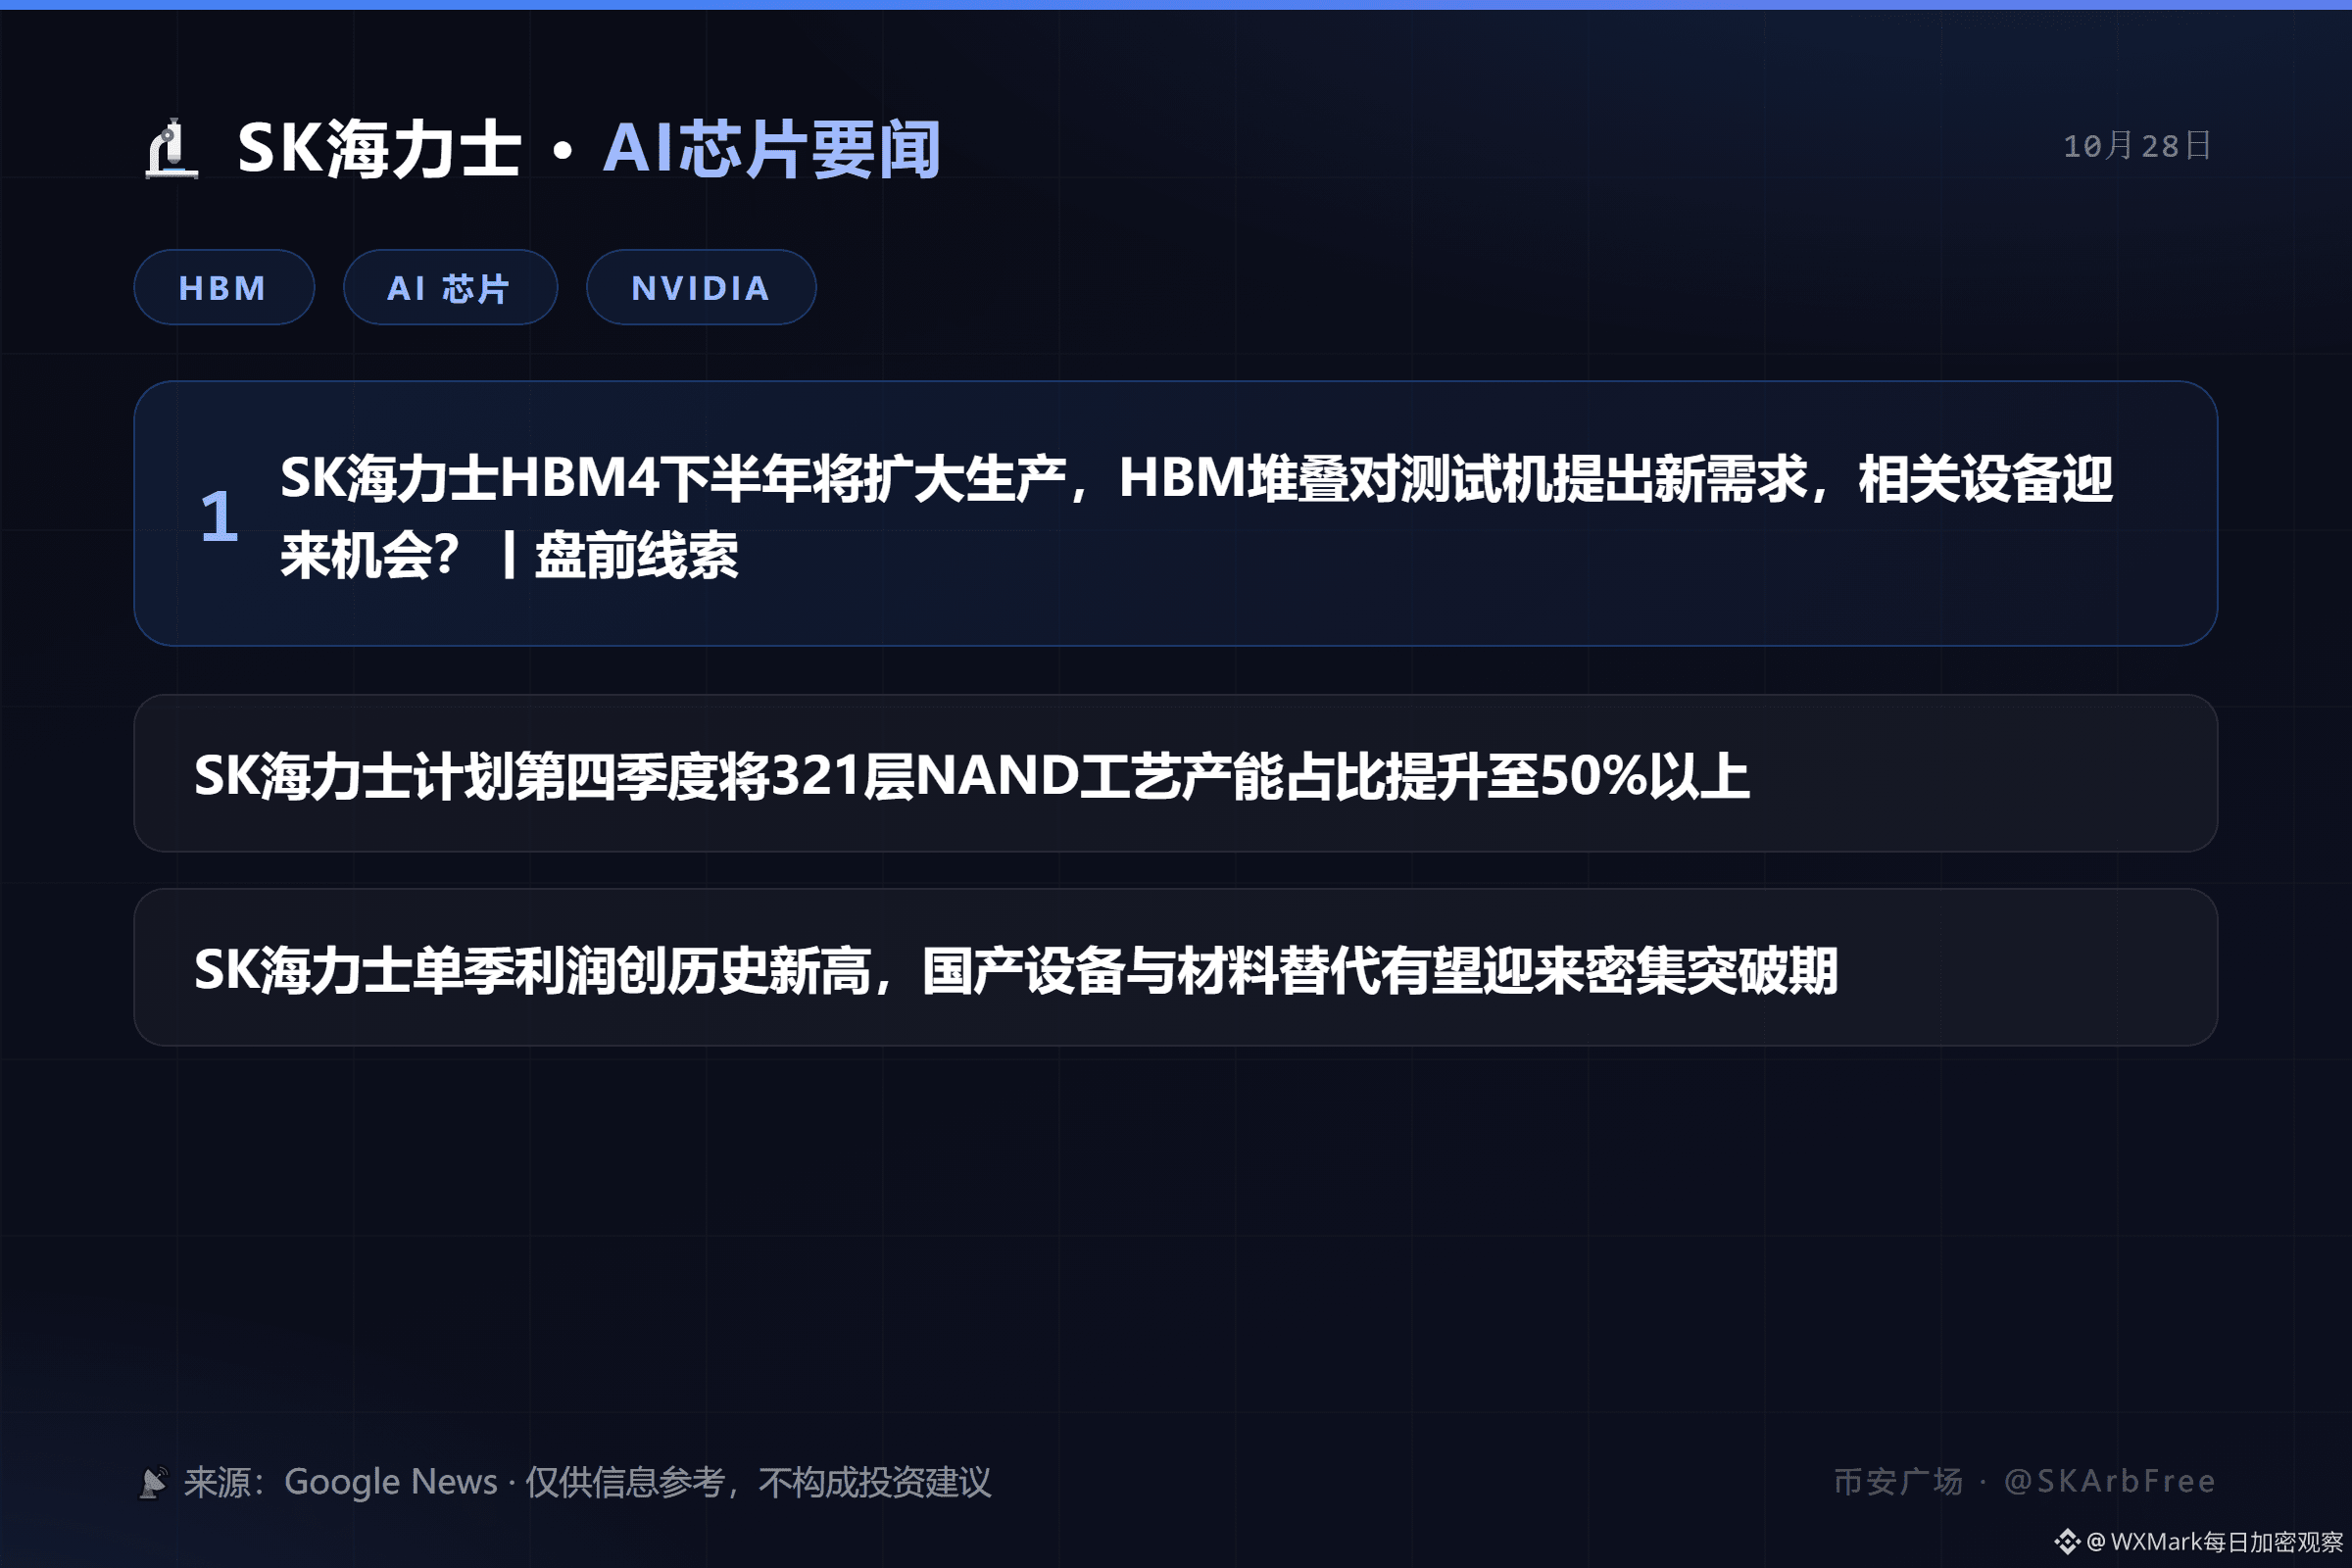
🔬 SK hynix AI Chip Headlines: SK hynix to ramp up HBM4 production in the second half | October 28🔬 SK hynix AI Chip Headlines | October 28
━━━━━━━━━━
1. SK hynix to ramp up HBM4 production in the second half; HBM stacking is creating new demand for testing equipment—an opportunity for related equipment makers? | Pre-market clues
2. SK hynix plans to increase the share of 321-layer NAND process capacity to over 50% in the fourth quarter
3. SK hynix posts record quarterly profit; domestic equipment and materials substitution may be poised for a wave of breakthroughs
📡 Source: Google News (Chinese-language sources)
💡 What to watch: HBM/DRAM supply-and-demand news will directly affect SK hynix’s contracts and ADR; watch for unusual market activity
🔬 SK hynix AI Chip Headlines: SK hynix to ramp up HBM4 production in the second half | October 28
🔬 SK hynix AI Chip Headlines | October 28
━━━━━━━━━━
1. SK hynix to ramp up HBM4 production in the second half; HBM stacking is creating new demand for testing equipment—an opportunity for related equipment makers? | Pre-market clues
2. SK hynix plans to increase the share of 321-layer NAND process capacity to over 50% in the fourth quarter
3. SK hynix posts record quarterly profit; domestic equipment and materials substitution may be poised for a wave of breakthroughs
📡 Source: Google News (Chinese-language sources)
💡 What to watch: HBM/DRAM supply-and-demand news will directly affect SK hynix’s contracts and ADR; watch for unusual market activity
767
·
--
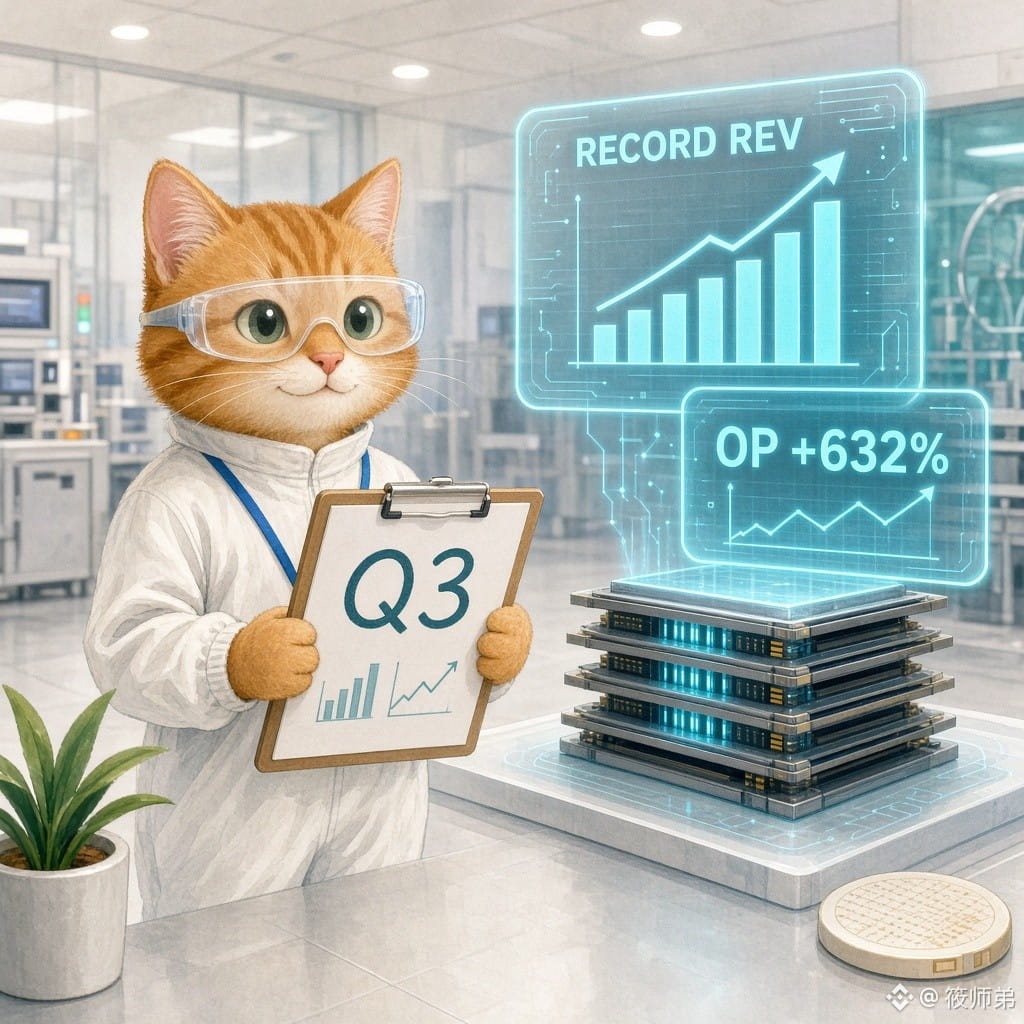
SK Hynix Q3 operating profit soars past expectations to 83.3 trillion won; revenue tops 100 trillion for the first time
【Facts】SK Hynix released its third-quarter results (company announcement/CNBC/JoongAng Ilbo): revenue of 104.62 trillion won (about $78.9 billion), versus expectations of about 98 trillion; operating profit of 83.33 trillion won (about $62.8 billion), versus expectations of about 77 trillion, up 632% year over year and 38% quarter over quarter, with an operating margin of about 80%; and net profit of 39.78 trillion won. Quarterly revenue topped 100 trillion for the first time. Drivers: increased HBM4 shipments, server DDR5, and data-center NAND. The company said it has secured long-term agreements covering more than 50% of capacity for 2027–2028; most of its investment gains from Kioxia will be returned to shareholders, bringing shareholder returns this year to about 100 trillion won; and it expects the memory shortage to potentially continue through 2030.
【View】This is not an ordinary cyclical recovery. AI has turned high-bandwidth memory into a critical bottleneck—and rising volumes and prices, together with long-term capacity commitments, have pushed margins to extreme levels. But net profit came in well below some consensus estimates, so tax expenses and one-off items still need to be examined separately. The market has already priced in some of this record quarter; going forward, attention will be on HBM4’s share of sales and guidance, rather than another huge year-over-year increase.
【Opportunities/Risks】In the short term, watch sentiment around South Korea’s memory stocks and AI infrastructure. Over the medium term, keep an eye on HBM4 delivery, capacity commitments for 2027, and whether tonight’s Microsoft and Google Cloud earnings can sustain the “AI is making money” narrative. Risks: lofty valuations combined with a hawkish FOMC tonight (early Thursday Beijing time), or cloud giants’ capex guidance falling short of expectations, could both reverse the memory premium.
Which matters more to you: this quarter’s nearly 80% margin, or the risk that AI capital spending has peaked?
#AI #半导体 #HBM $RENDER $BTC
For reference only; not investment advice.
94
·
--
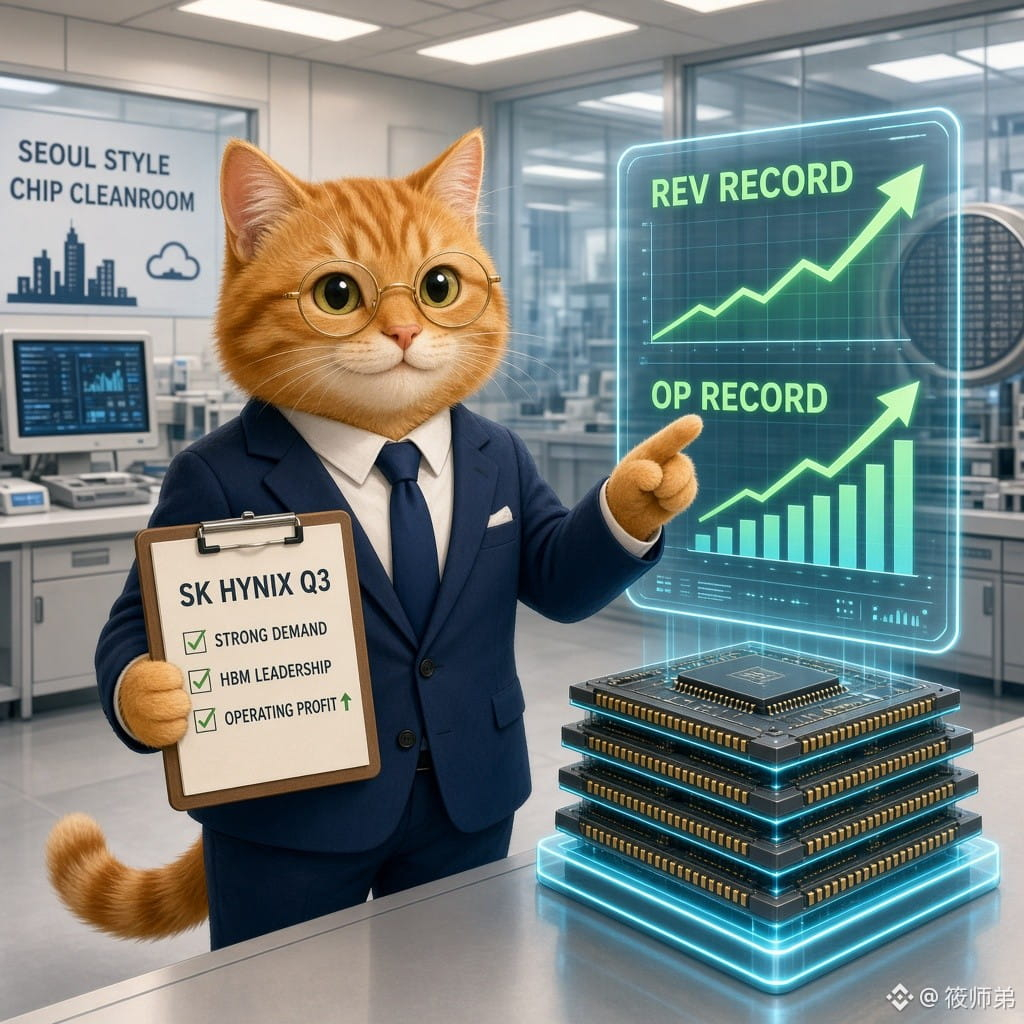
SK Hynix reports Q3 this morning: Revenue and operating profit may both hit records, but shares have already fallen 30%
[Fact] SK Hynix will release its third-quarter results and hold an earnings call today (10/28) at 9 a.m. Seoul time (company 6-K/YTN). FactSet consensus: revenue of about 98.2 trillion won and operating profit of about 77 trillion won, both record highs; net profit of about 61.4 trillion won, nearly 5 times higher year over year (MarketWatch). Yet the share price fell about 33% over the third quarter, and the market is still questioning whether AI capital spending and HBM demand can be sustained. The Fed’s FOMC decision is also due today; Samsung reports Thursday; Solidigm’s U.S. IPO was put on hold last week.
[View] Even record quarterly profit can’t set the price—guidance can. The market is focused instead on the HBM4/Vera Rubin supply ramp, visibility into long-term contracts, and the details of delivering on a commitment to return more than half of FCF to shareholders. A strong set of figures can still come with a falling share price, showing that this market is trading on credibility, not accounting profits.
[Opportunity/Risk] If guidance and buybacks/dividends exceed expectations, sentiment toward memory and the AI computing-power supply chain could recover. If guidance is soft or shareholder returns disappoint, Korean chip stocks and related risk assets could come under further pressure. $BTC is still hovering around 80,000 as investors await the FOMC’s wording; don’t overlook the correlations between risk assets.
Which matters more to you this time: Hynix’s shareholder returns or its HBM4 delivery guidance?
#海力士 #AI芯片 #HBM #财报 $BTC $RENDER
For informational purposes only; not investment advice
156
·
--
Verified
Article
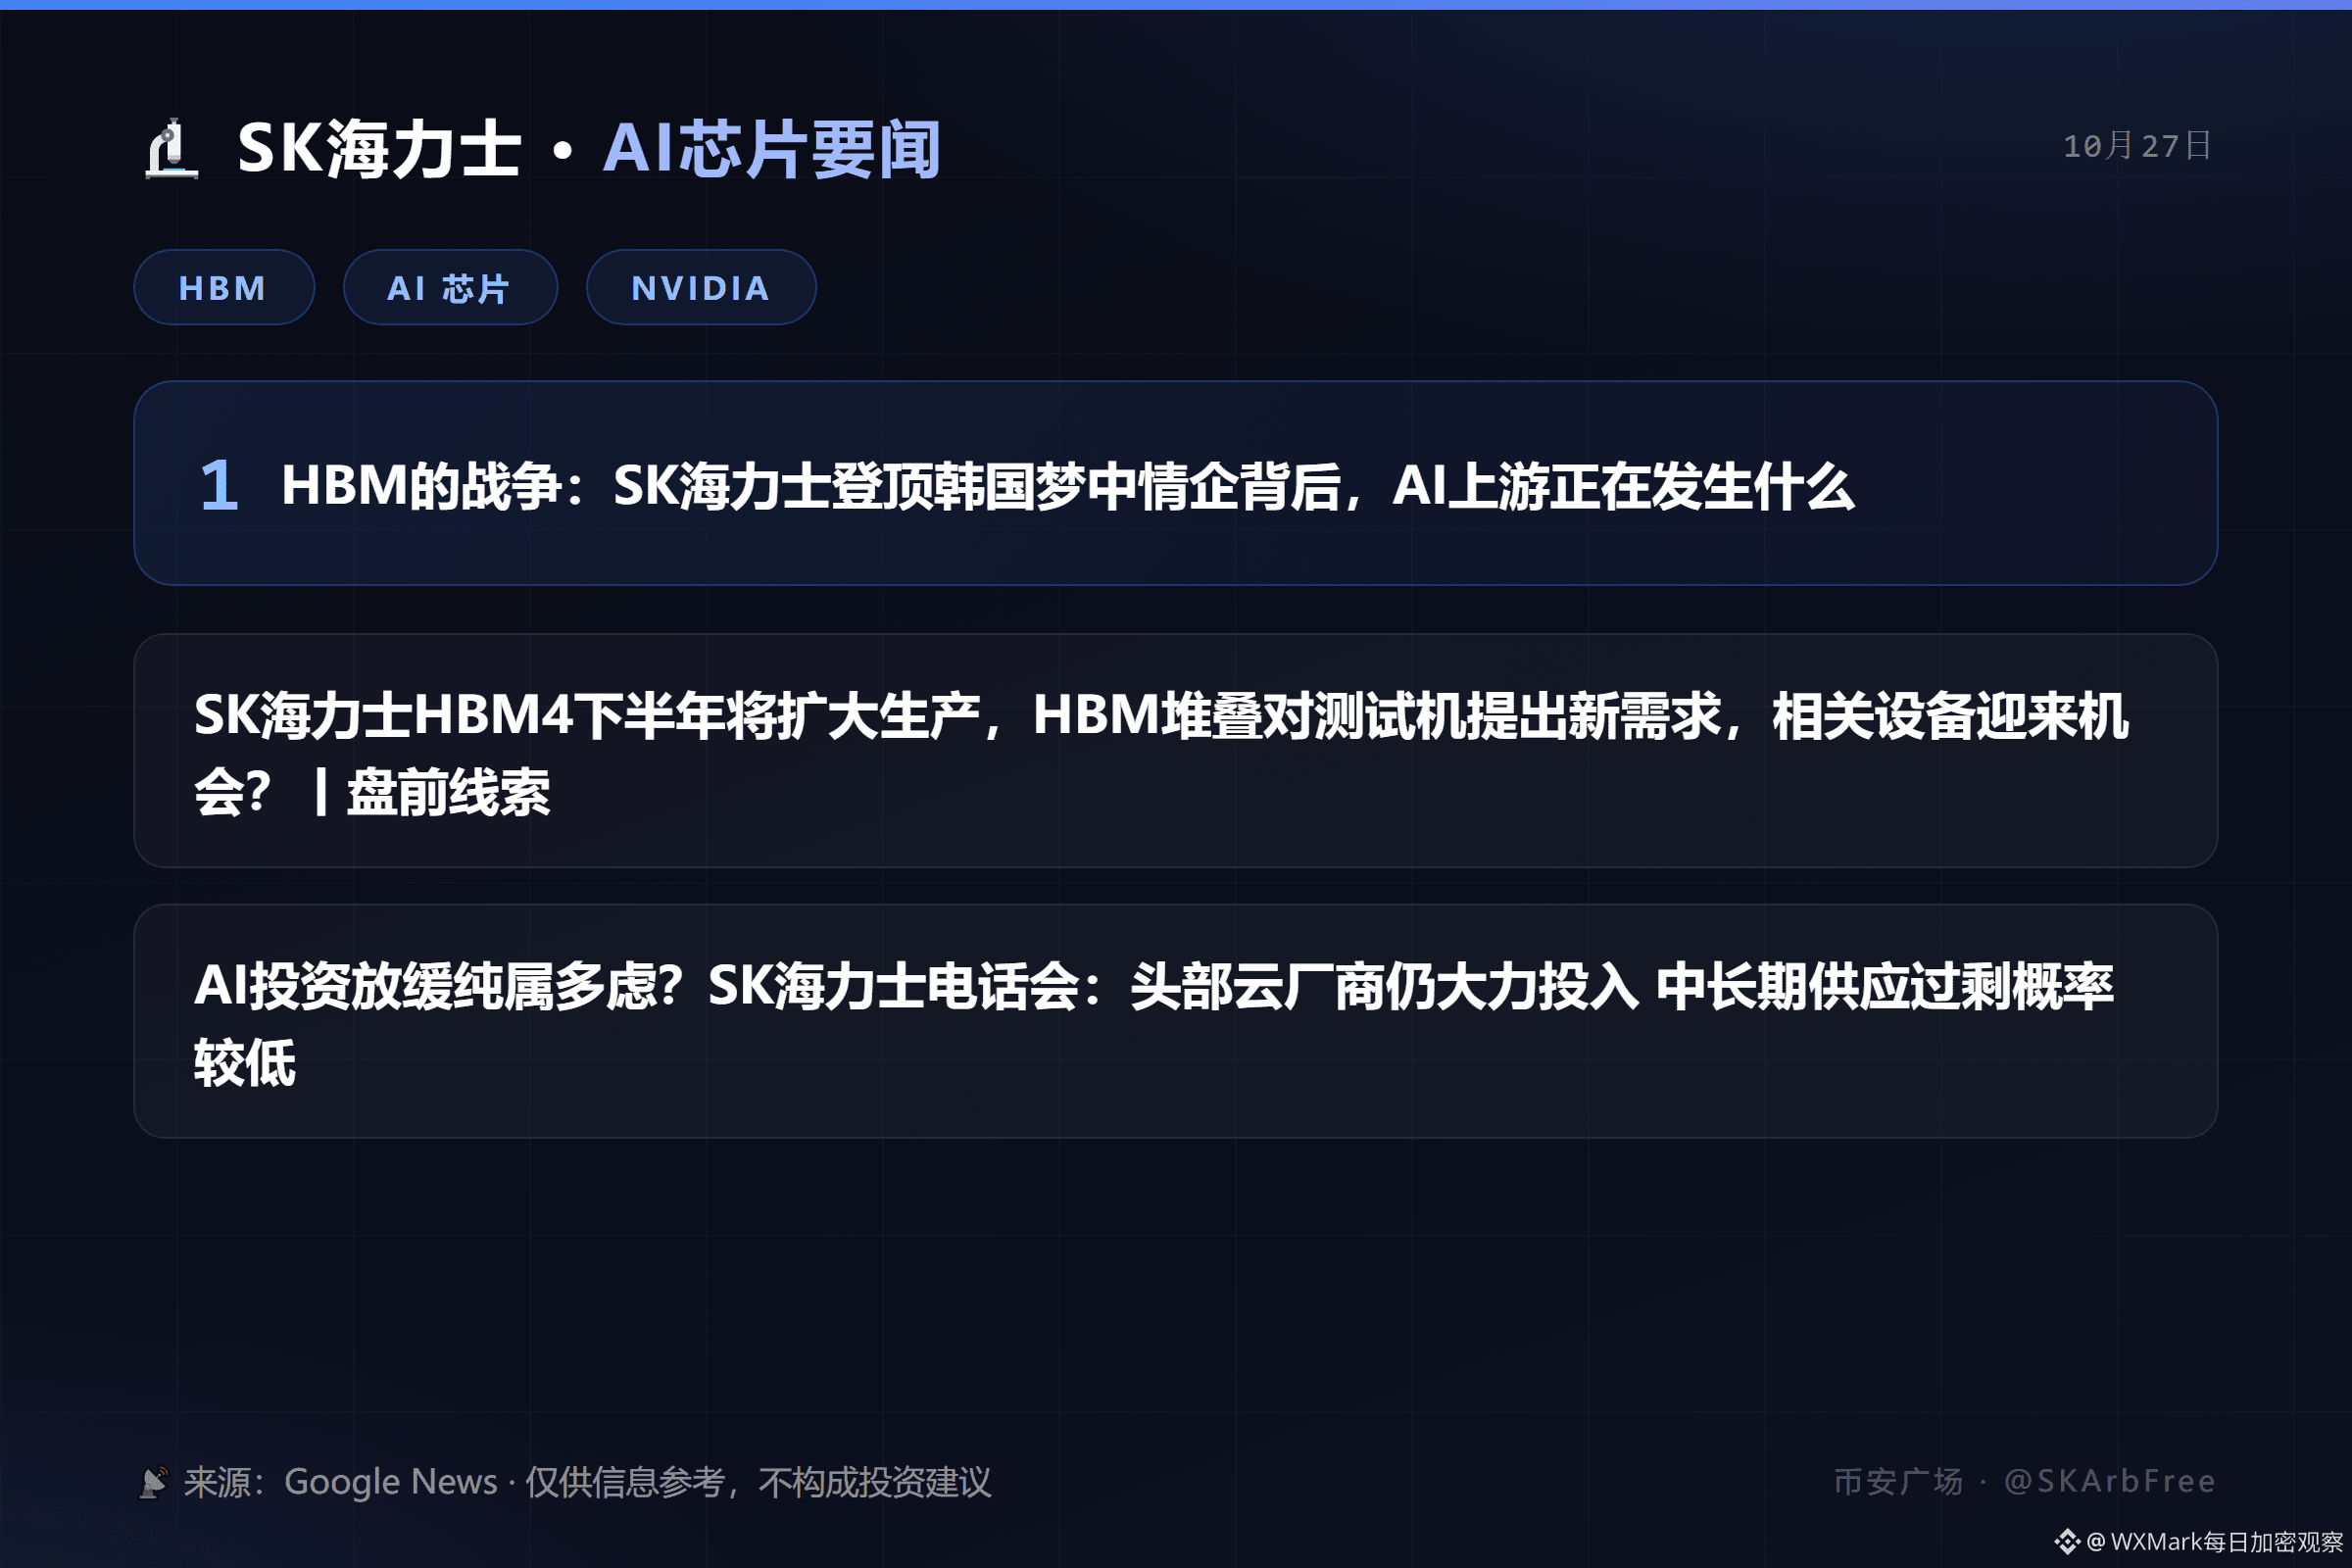
🔬 SK hynix AI Chip Headlines: The HBM Battle: What’s happening behind SK hynix’s rise to become one of Korea’s most coveted companies | October 27🔬 SK hynix AI Chip Headlines | October 27
━━━━━━━━━━
1. The HBM battle: What’s happening in the AI supply chain behind SK hynix’s rise to become one of Korea’s most coveted companies
2. SK hynix to ramp up HBM4 production in the second half; HBM stacking creates new testing equipment requirements, opening up opportunities for related equipment? | Pre-market Brief
3. Are concerns about slowing AI investment overblown? SK hynix earnings call: Major cloud providers are still investing heavily, and the likelihood of a supply glut in the medium to long term is low
📡 Source: Google News (Chinese-language sources)
💡 Watch: HBM/DRAM supply-and-demand news can directly affect SKHYNIX futures and ADRs; keep an eye out for unusual market moves
🔬 SK hynix AI Chip Headlines: The HBM Battle: What’s happening behind SK hynix’s rise to become one of Korea’s most coveted companies | October 27
🔬 SK hynix AI Chip Headlines | October 27
━━━━━━━━━━
1. The HBM battle: What’s happening in the AI supply chain behind SK hynix’s rise to become one of Korea’s most coveted companies
2. SK hynix to ramp up HBM4 production in the second half; HBM stacking creates new testing equipment requirements, opening up opportunities for related equipment? | Pre-market Brief
3. Are concerns about slowing AI investment overblown? SK hynix earnings call: Major cloud providers are still investing heavily, and the likelihood of a supply glut in the medium to long term is low
📡 Source: Google News (Chinese-language sources)
💡 Watch: HBM/DRAM supply-and-demand news can directly affect SKHYNIX futures and ADRs; keep an eye out for unusual market moves
575
·
--
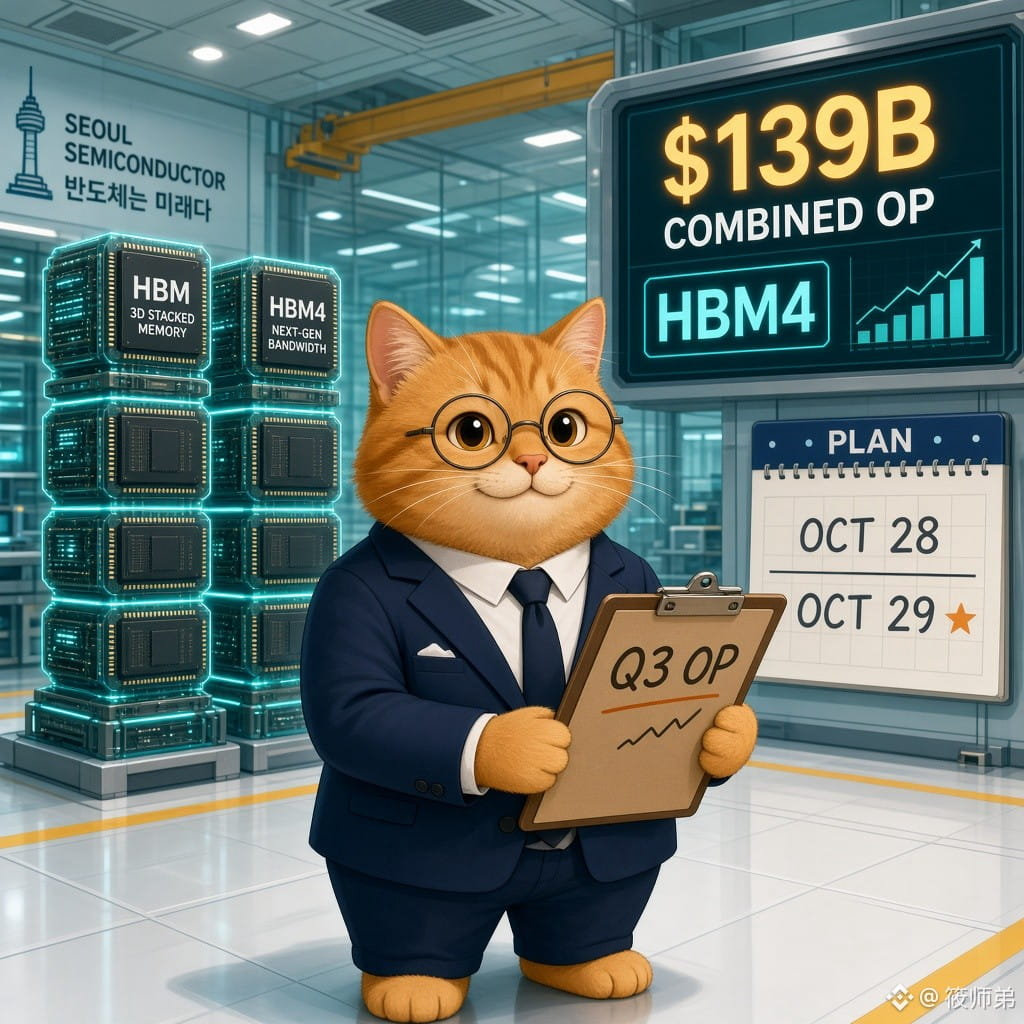
Samsung + SK Hynix Q3 operating profits could total about KRW 184 trillion (around $139 billion)
JoongAng Ilbo/BusinessKorea/Yonhap: Samsung has given preliminary guidance for revenue of KRW 195 trillion and operating profit of KRW 107.4 trillion (up about 783% year over year). FnGuide expects Hynix to post revenue of about KRW 98.2 trillion and operating profit of around KRW 77 trillion. Key drivers include AI-related demand for HBM, as well as TrendForce’s forecast that Q3 contract prices for conventional DRAM will rise 13%–18% quarter over quarter. Both companies are expanding HBM4 supply for Nvidia’s next-generation Vera Rubin accelerators. Hynix will release its full results on Wednesday (10/28), and Samsung on Thursday (10/29).
【View】
As profits hit record highs, the market is increasingly asking: can returns on AI capital spending keep pace? The KOSPI has already seen a sharp correction, and some analysts say the two companies’ P/E ratios have fallen to around 3x. This week’s earnings figures may matter less than investment plans and shareholder returns.
【Opportunities/Risks】
Watch the pace of HBM4 shipments, memory prices next year, and whether there will be large-scale buybacks. Risks include Samsung’s foundry business still being estimated to post a Q3 loss of around KRW 1 trillion, while the cancellation of Solidigm’s IPO has narrowed its financing options. In the short term, risk appetite still hinges on Wednesday’s FOMC remarks.
Which matters more to you this week: validation of HBM profits, or the liquidity signal from Wednesday’s FOMC?
#AI芯片 #HBM #财报周 $RENDER $BTC
For reference only; this does not constitute investment advice.
32
·
--
Article
🔬 SK hynix AI Chip Briefing: SK hynix releases financial results for the second quarter of fiscal 2026 | October 24🔬 SK hynix AI Chip Briefing | October 24
━━━━━━━━━━
1. SK hynix releases financial results for the second quarter of fiscal 2026
2. Are concerns about slowing AI investment overblown? SK hynix earnings call: Major cloud providers still investing heavily; medium- to long-term supply glut unlikely
3. SK hynix Q2 profit surges 557%, but shares plunge
📡 Source: Google News (Chinese-language source)
💡 Key focus: HBM/DRAM supply-and-demand news directly affects SK hynix contract prices and ADRs; watch for unusual market movements
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
🔬 SK hynix AI Chip Briefing: SK hynix releases financial results for the second quarter of fiscal 2026 | October 24
🔬 SK hynix AI Chip Briefing | October 24
━━━━━━━━━━
1. SK hynix releases financial results for the second quarter of fiscal 2026
2. Are concerns about slowing AI investment overblown? SK hynix earnings call: Major cloud providers still investing heavily; medium- to long-term supply glut unlikely
3. SK hynix Q2 profit surges 557%, but shares plunge
📡 Source: Google News (Chinese-language source)
💡 Key focus: HBM/DRAM supply-and-demand news directly affects SK hynix contract prices and ADRs; watch for unusual market movements
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
37
·
--
Partly True
Article
🔬 SK hynix AI chip news: SK hynix releases its second-quarter fiscal 2026 financial report | October 23🔬 SK hynix AI chip news | October 23
━━━━━━━━━━
1. SK hynix releases its second-quarter fiscal 2026 financial report
2. After its “strongest ever” results, SK hynix is finding it harder to beat expectations
3. Are concerns about slowing AI investment overblown? SK hynix earnings call: Leading cloud providers are still investing heavily, and the likelihood of a supply glut over the medium to long term remains low
📡 Source: Google News (Chinese-language sources)
💡 Watch: HBM/DRAM supply and demand news directly affects SKHYNIX contracts and ADRs; keep an eye out for unusual market moves
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
🔬 SK hynix AI chip news: SK hynix releases its second-quarter fiscal 2026 financial report | October 23
🔬 SK hynix AI chip news | October 23
━━━━━━━━━━
1. SK hynix releases its second-quarter fiscal 2026 financial report
2. After its “strongest ever” results, SK hynix is finding it harder to beat expectations
3. Are concerns about slowing AI investment overblown? SK hynix earnings call: Leading cloud providers are still investing heavily, and the likelihood of a supply glut over the medium to long term remains low
📡 Source: Google News (Chinese-language sources)
💡 Watch: HBM/DRAM supply and demand news directly affects SKHYNIX contracts and ADRs; keep an eye out for unusual market moves
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
577
·
--
Verified
🔥 THE MEMORY GAME IS HEATING UP! 💾🚀
Everyone is talking about AI, but the real battle is happening behind the scenes — in memory chips and data storage!
👀 $SKHYNIX
{future}(SKHYNIXUSDT)
is a major player in the High Bandwidth Memory (HBM) market, powering the growing demand for AI infrastructure and data centers.
💡 The big question: Can memory-chip demand keep growing as AI evolves, or will market volatility cool the rally?
📊 Watch the technology, earnings, competition, and market trends before making any investment decisions.
Are you watching the memory-chip sector? 👇
#SKHYNIX #Aİ #HBM #Semiconductors
🔥 THE MEMORY GAME IS HEATING UP! 💾🚀
Everyone is talking about AI, but the real battle is happening behind the scenes — in memory chips and data storage!
👀 $SKHYNIX
is a major player in the High Bandwidth Memory (HBM) market, powering the growing demand for AI infrastructure and data centers.
💡 The big question: Can memory-chip demand keep growing as AI evolves, or will market volatility cool the rally?
📊 Watch the technology, earnings, competition, and market trends before making any investment decisions.
Are you watching the memory-chip sector? 👇
#SKHYNIX #Aİ #HBM #Semiconductors
729

[10/16, 10:48 PM] Meta AI: Here you go — refined, corrected, and ready for Binance Square with visual:
*Ready-to-post caption:*
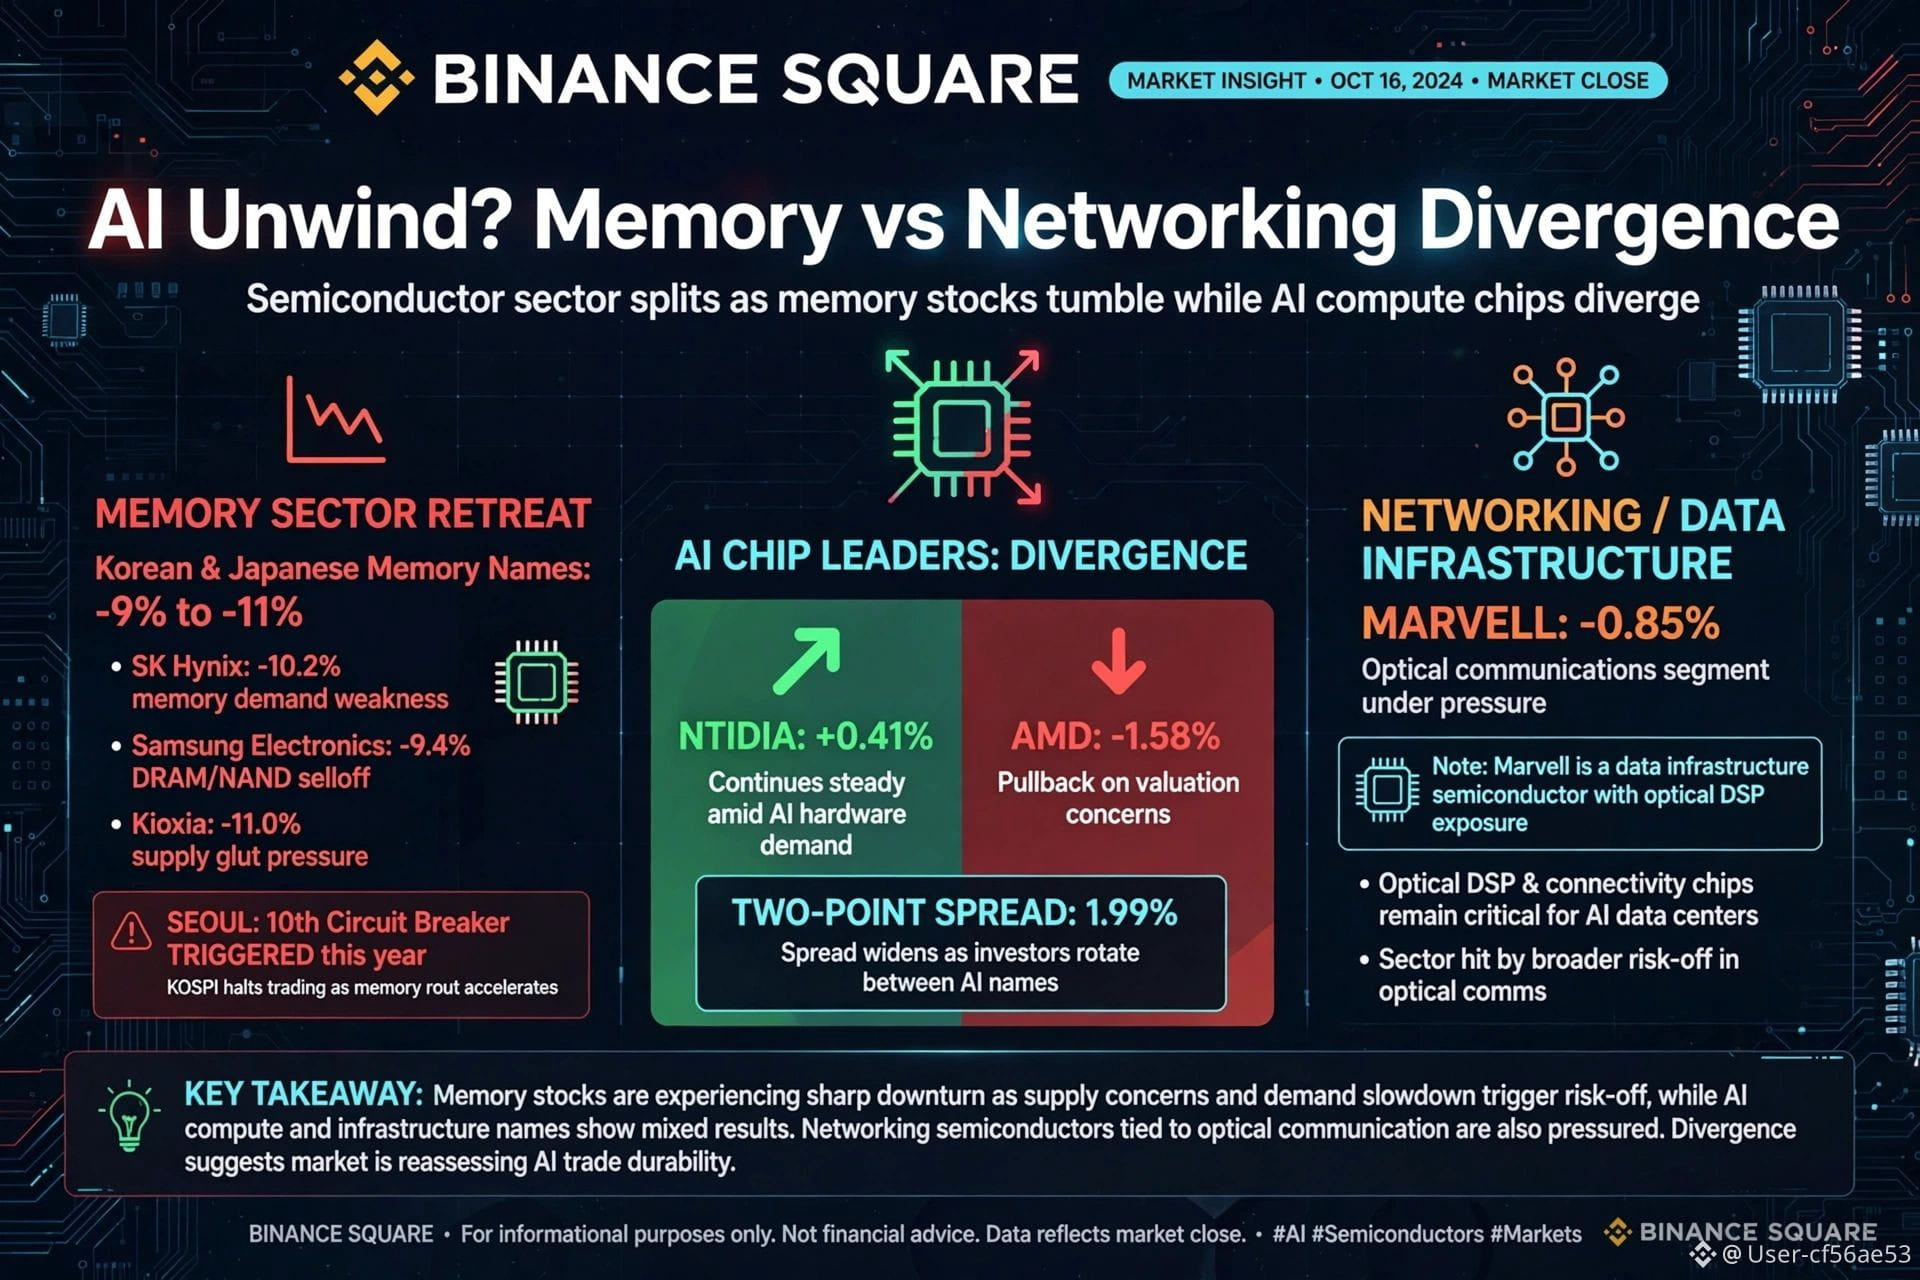
> AI Unwind? Memory vs Networking Divergence
> That Thursday selloff when Korean/Japanese memory names fell 9-11% and Seoul hit its 10th circuit breaker this year looked like a wholesale AI unwind. Today looks more specific.
> Memory pricing + HBM demand is the concern. Networking layer is not being treated the same way.
> • Memory: SK Hynix, Samsung, Kioxia -9% to -11%
> • Nvidia +0.41% vs AMD -1.58% = ∼2pt spread. Usually they move together on AI sentiment, so this divergence is name-specific
> • Marvell -0.85% — not pure optical comms. It's a data infra semiconductor company with optical DSP exposure. Important distinction before publishing.
> My take: Market is rotating _within_ AI, not exiting AI. Memory taking the hit, compute diverging.
#AI #Semiconductors #NVDA #AMD #HBM #BinanceSquare
Want me to remove the Binance Square watermark or add your handle to it?
[10/16, 10:48 PM] Meta AI: This version is publication-ready for Binance — I fixed the classification and tightened the narrative:
*Final Post Text:*
AI unwind? No — AI _rotation_.
Thursday: Korean & Japanese memory names -9% to -11%, Seoul triggers 10th circuit breaker of the year. Looked like wholesale AI unwind.
Today: Much more specific. Memory pricing and HBM demand are the concern. Networking layer is not being treated the same way.
*1. The Spread*
Nvidia +0.41% vs AMD -1.58% = ∼2 point spread in one session.
They usually move together on AI sentiment. A 2-point pre-market divergence = name-specific, not sector call. Low volume though, so weak signal alone.
*2. Fix Before Publishing*
Marvell -0.85% is listed as "optical communications" in source data.
Correct classification: Marvell is a data infrastructure semiconductor with optical DSP exposure — not a pure optical comms name. Don't label it as optical.
Bottom line: Market is punishing memory/HBM beta, sparing compute/networking. That's rotation, not exit
148
A Winter for Edge Devices, a Blaze in the Cloud: HBM’s Countercyclical Saga Through the Lens of the “Cloud Inference” ParadigmSome people think China could rapidly ramp up production capacity within a few years, flooding the memory market. Memory-related stocks have plunged over the past few days.
But if all the computing power used for AI in the future is in the cloud—much like how people casually access ChatGPT or Gemini on their phones today—there won’t be any special requirements for the phones themselves, since all the computing is done in the cloud.
If that’s the case, memory prices in general-purpose devices could indeed collapse. But what about high-end server memory in the same scenario—HBM, which everyone is scrambling to get their hands on right now?
A Winter for Edge Devices, a Blaze in the Cloud: HBM’s Countercyclical Saga Through the Lens of the “Cloud Inference” Paradigm
Some people think China could rapidly ramp up production capacity within a few years, flooding the memory market. Memory-related stocks have plunged over the past few days.
But if all the computing power used for AI in the future is in the cloud—much like how people casually access ChatGPT or Gemini on their phones today—there won’t be any special requirements for the phones themselves, since all the computing is done in the cloud.
If that’s the case, memory prices in general-purpose devices could indeed collapse. But what about high-end server memory in the same scenario—HBM, which everyone is scrambling to get their hands on right now?
267
·
--
Article
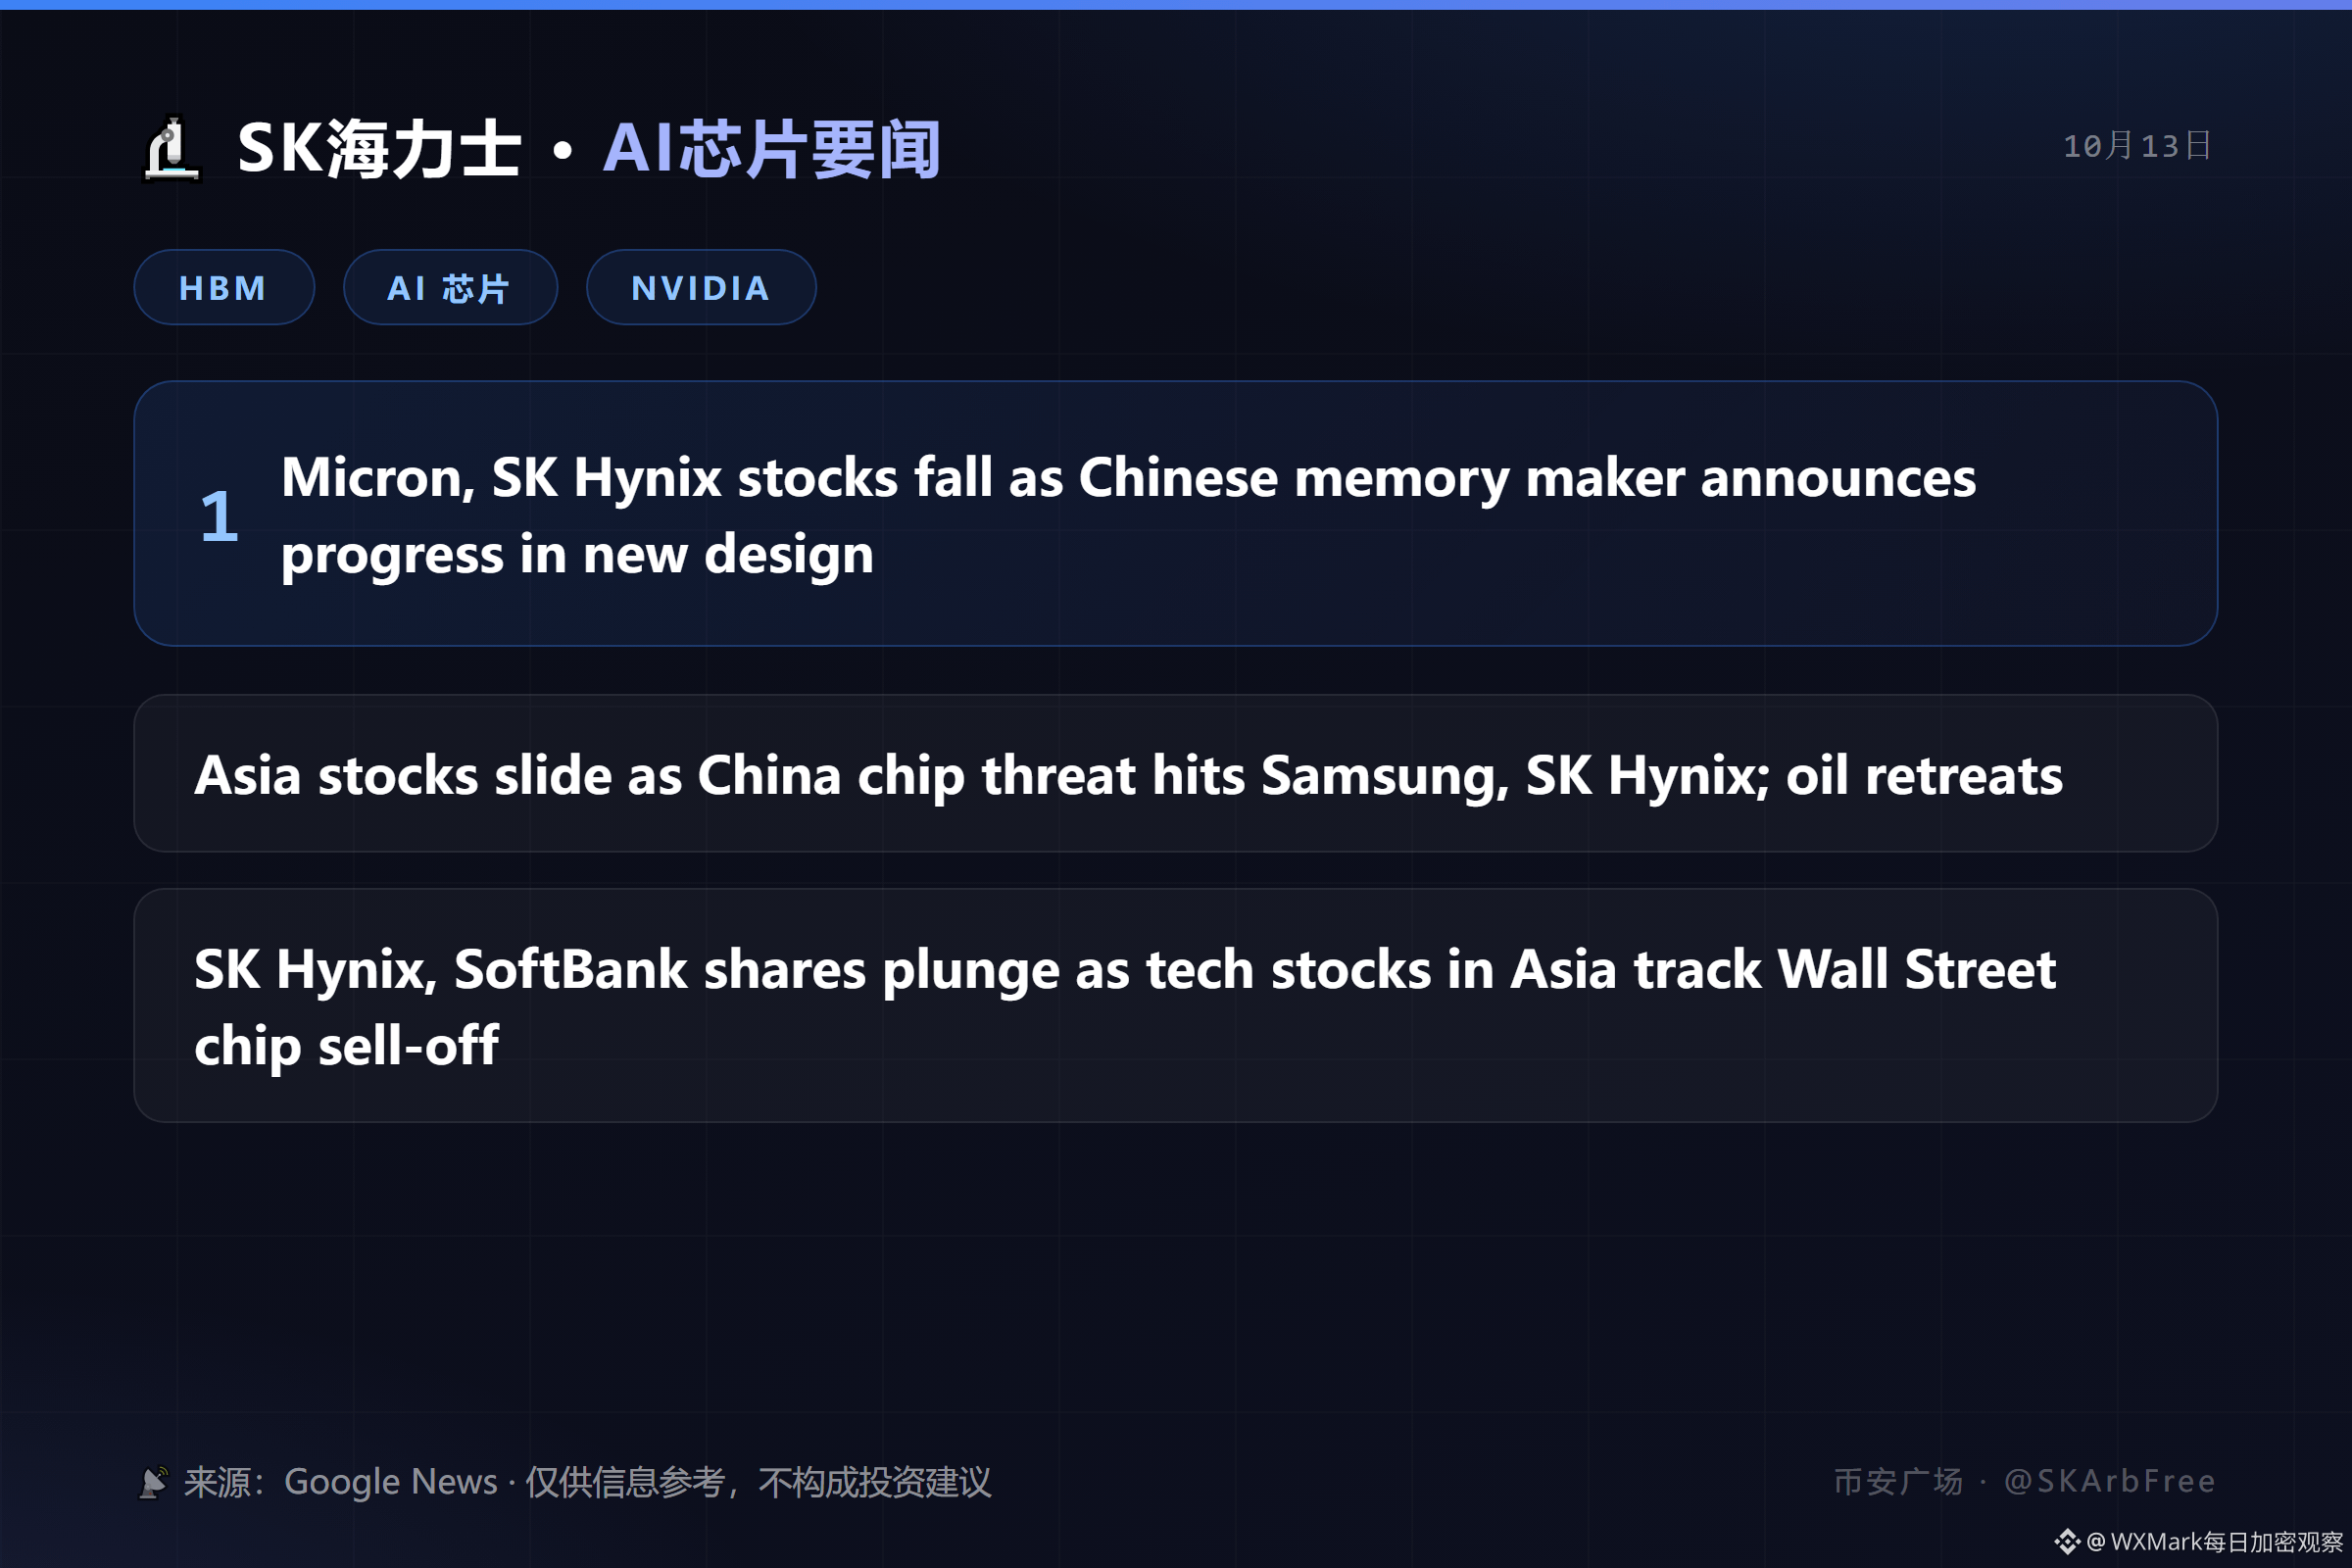
🔬 SK Hynix AI Chip Headlines: Micron, SK Hynix Stocks | October 13🔬 SK Hynix AI Chip Headlines | October 13
━━━━━━━━━━
1. Micron, SK Hynix stocks fall as Chinese memory maker announces progress in new design
2. Asia stocks slide as China chip threat hits Samsung, SK Hynix; oil retreats
3. SK Hynix, SoftBank shares plunge as tech stocks in Asia track Wall Street chip sell-off
📡 Source: Google News
💡 Key focus: HBM/DRAM supply-and-demand news directly affects SK Hynix contracts and ADRs; watch for unusual market movements
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; this is not investment advice
🔬 SK Hynix AI Chip Headlines: Micron, SK Hynix Stocks | October 13
🔬 SK Hynix AI Chip Headlines | October 13
━━━━━━━━━━
1. Micron, SK Hynix stocks fall as Chinese memory maker announces progress in new design
2. Asia stocks slide as China chip threat hits Samsung, SK Hynix; oil retreats
3. SK Hynix, SoftBank shares plunge as tech stocks in Asia track Wall Street chip sell-off
📡 Source: Google News
💡 Key focus: HBM/DRAM supply-and-demand news directly affects SK Hynix contracts and ADRs; watch for unusual market movements
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; this is not investment advice
245
·
--
Article
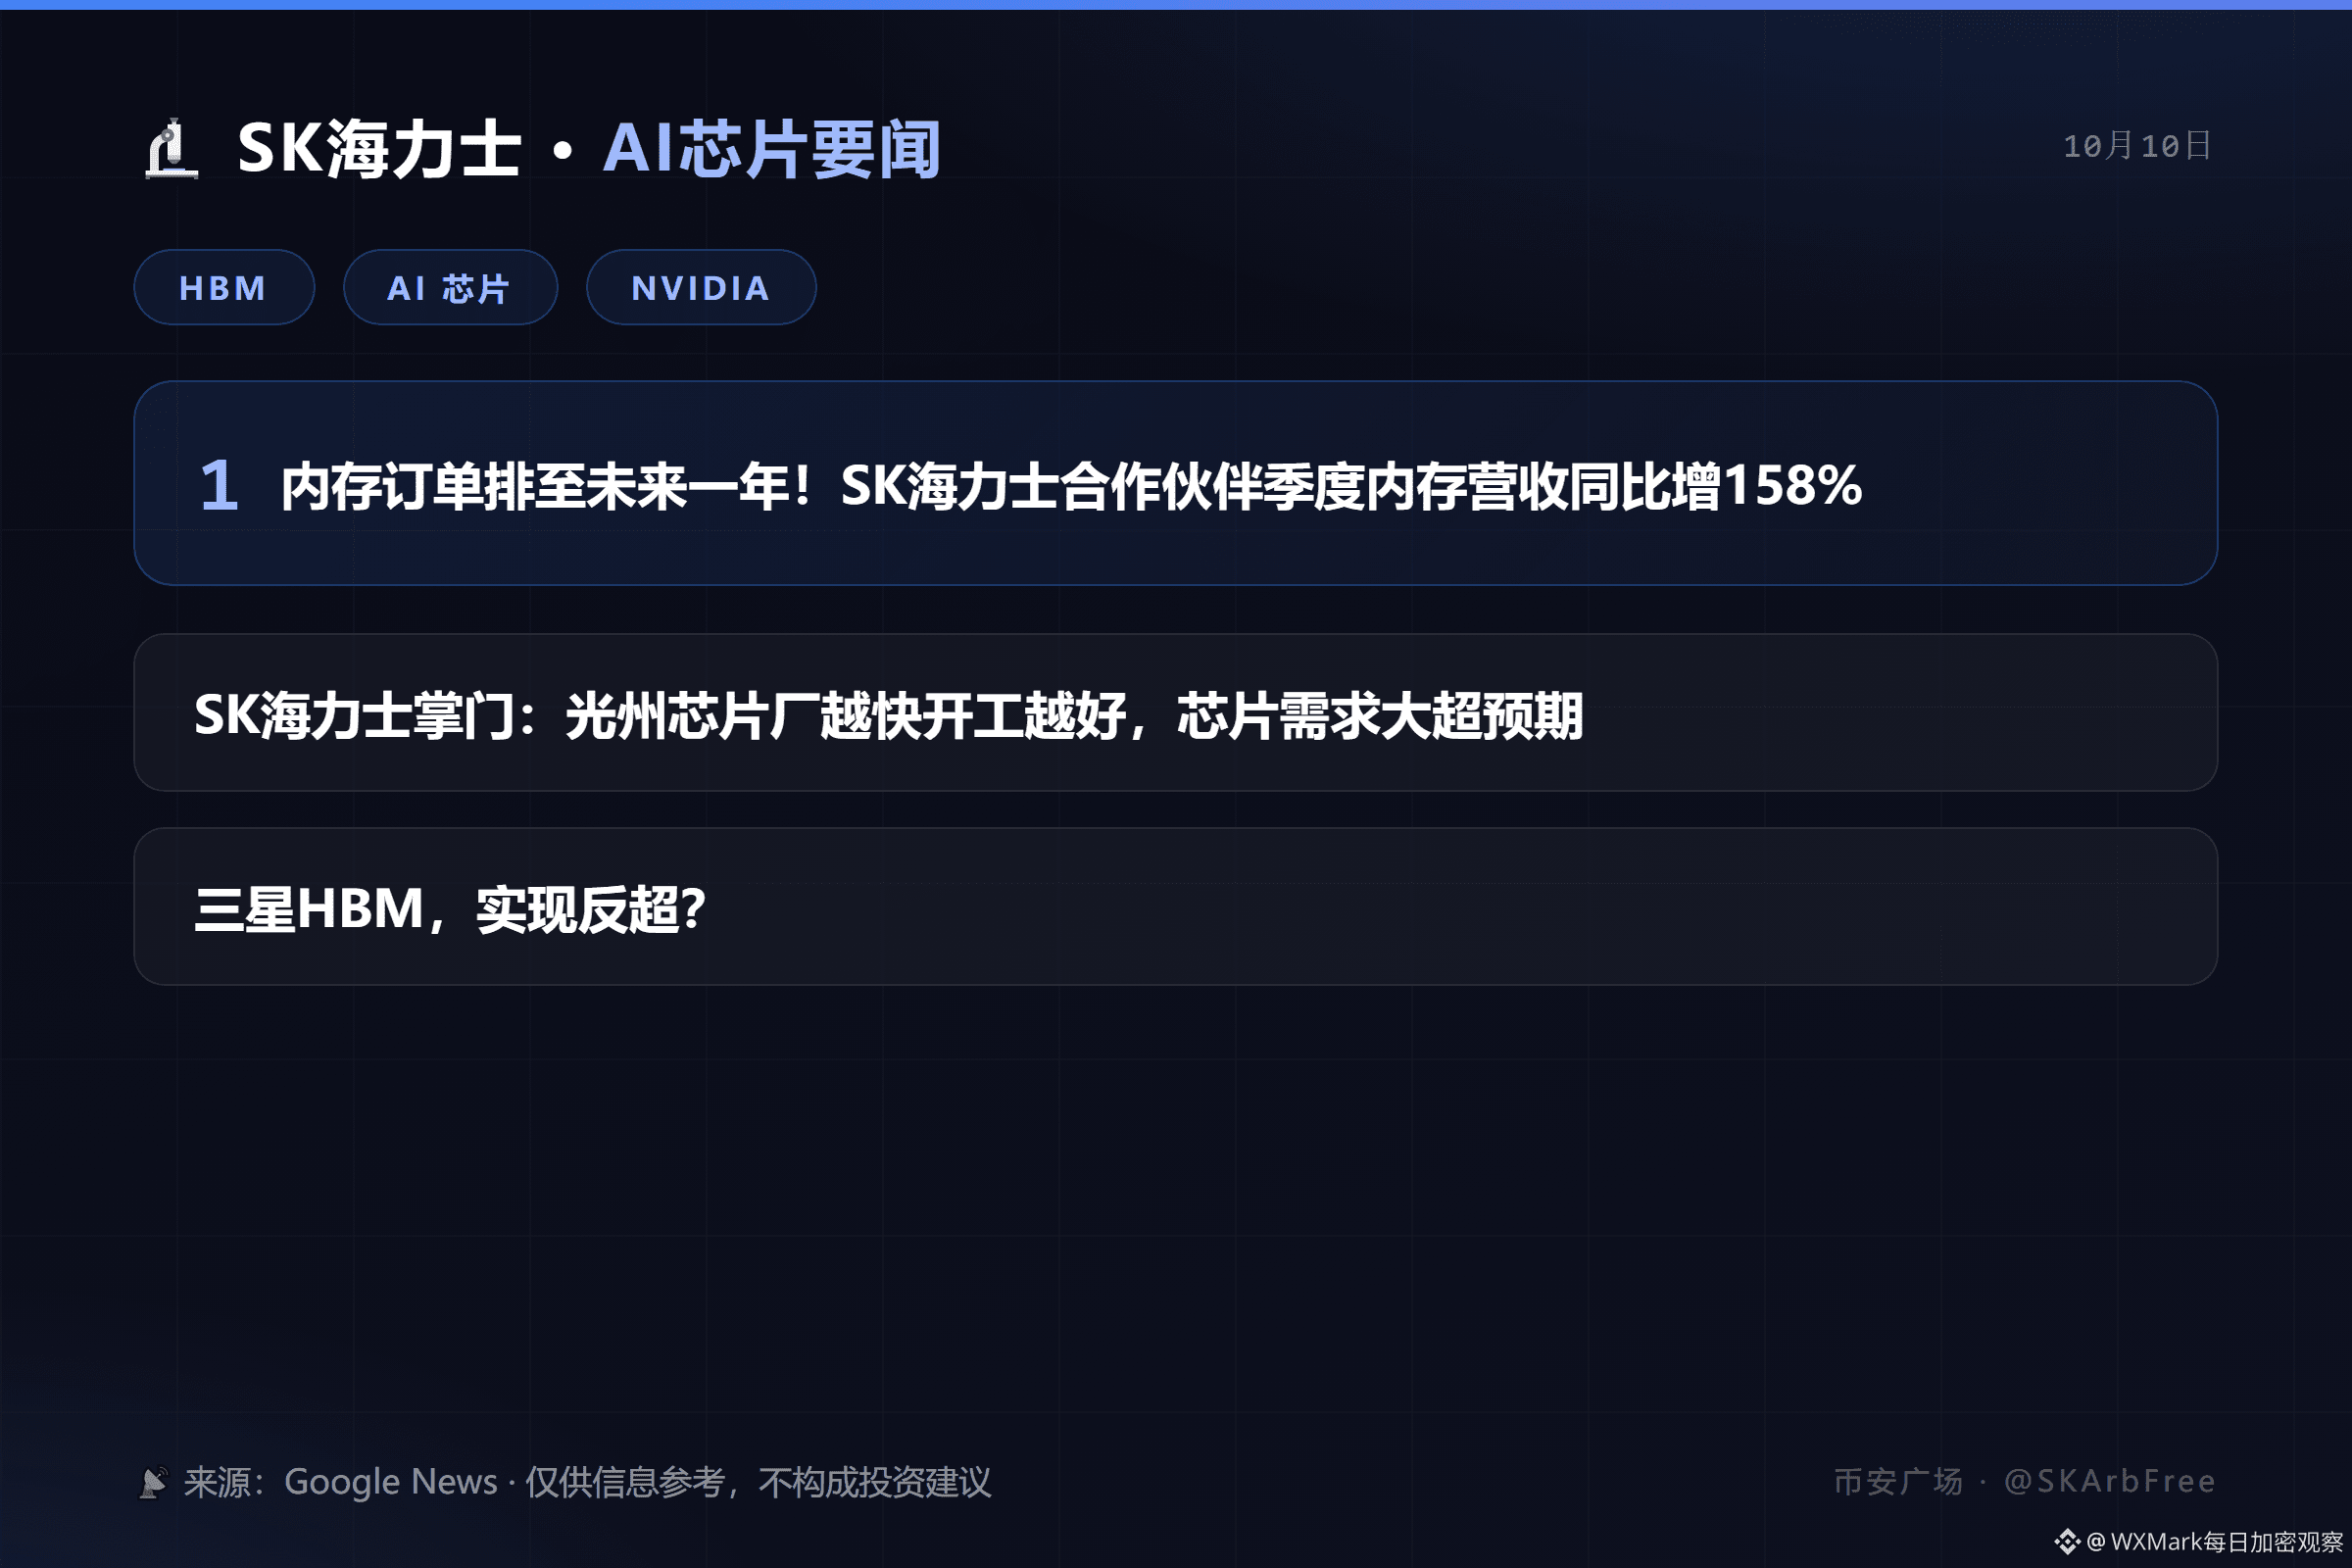
🔬 SK hynix AI Chip Headlines: Memory orders booked through the next year! SK hynix partner's quarterly memory | October 10🔬 SK hynix AI Chip Headlines | October 10
━━━━━━━━━━
1. Memory orders booked through the next year! SK hynix partner's quarterly memory revenue rose 158% year over year
2. SK hynix chief: The sooner the Gwangju chip plant starts construction, the better; chip demand far exceeds expectations
3. Samsung HBM: Has it caught up?
📡 Source: Google News
💡 What to watch: HBM/DRAM supply and demand news directly affects SK HYNIX futures and ADRs; watch for unusual market moves
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
🔬 SK hynix AI Chip Headlines: Memory orders booked through the next year! SK hynix partner's quarterly memory | October 10
🔬 SK hynix AI Chip Headlines | October 10
━━━━━━━━━━
1. Memory orders booked through the next year! SK hynix partner's quarterly memory revenue rose 158% year over year
2. SK hynix chief: The sooner the Gwangju chip plant starts construction, the better; chip demand far exceeds expectations
3. Samsung HBM: Has it caught up?
📡 Source: Google News
💡 What to watch: HBM/DRAM supply and demand news directly affects SK HYNIX futures and ADRs; watch for unusual market moves
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
771
·
--
Article
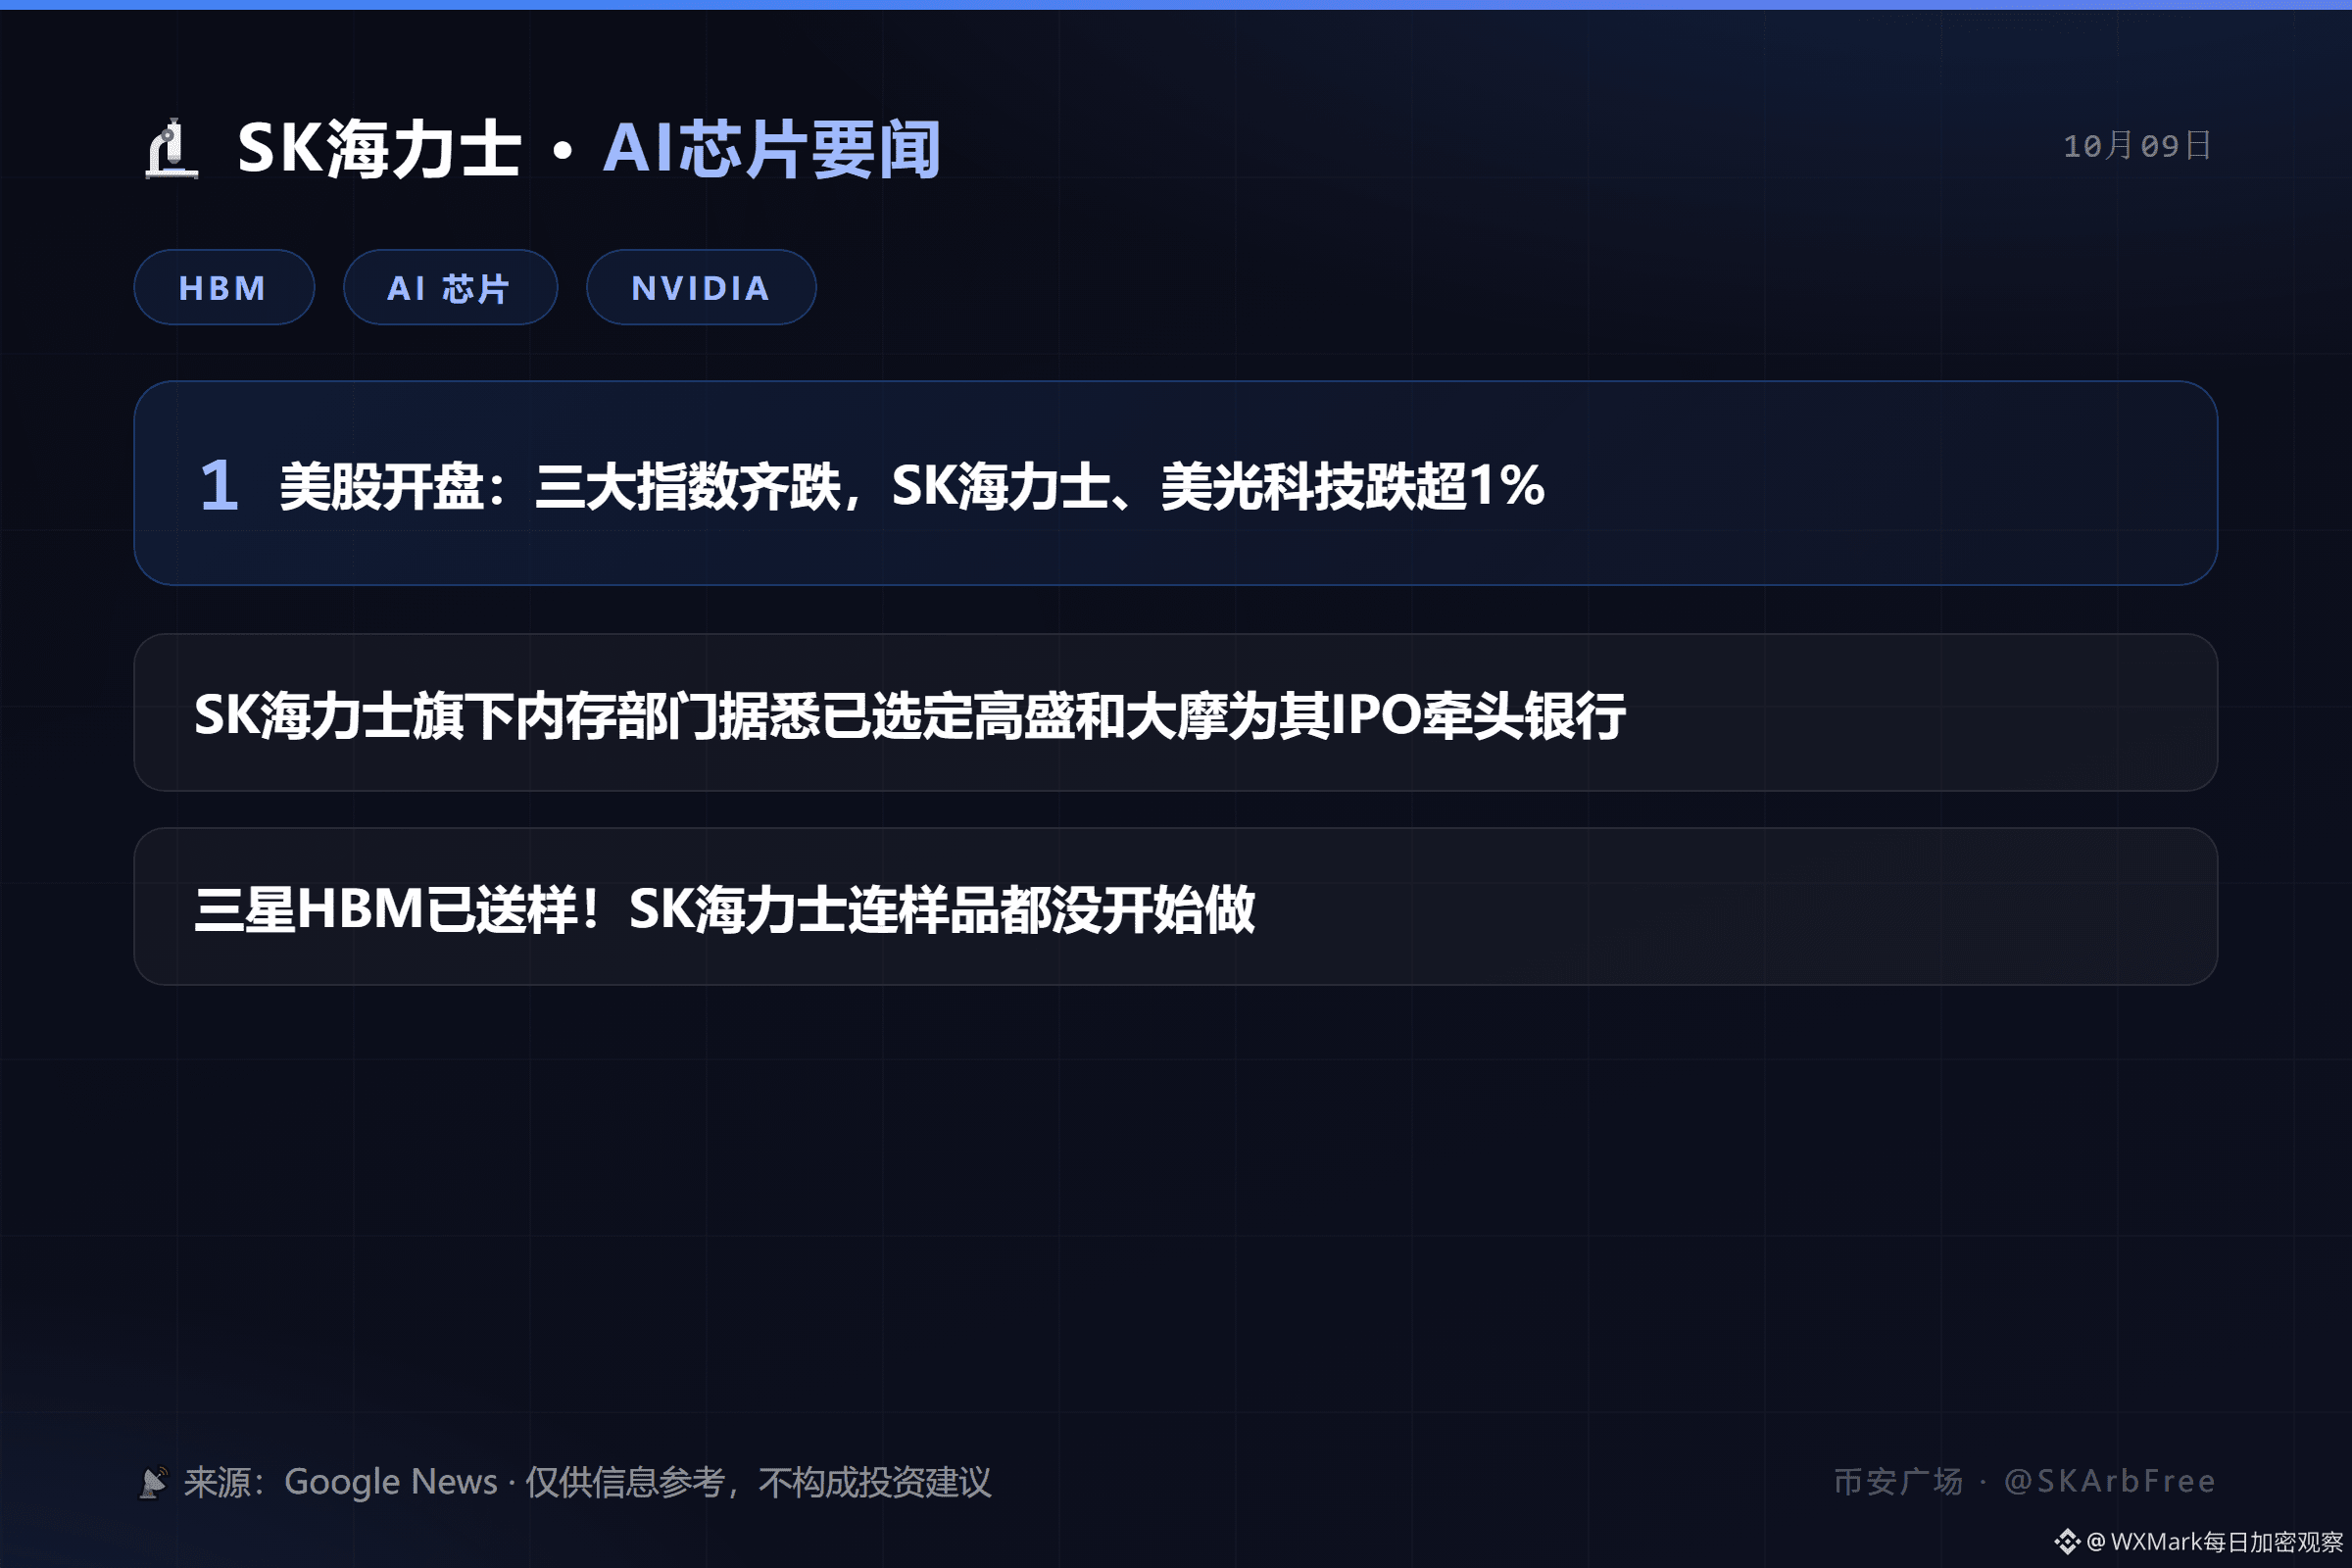
🔬 SK hynix AI Chip Headlines: U.S. stocks at the open: All three major indexes fall; SK hynix and Micron Technology drop more than | October 9🔬 SK hynix AI Chip Headlines | October 9
━━━━━━━━━━
1. U.S. stocks at the open: All three major indexes fall; SK hynix and Micron Technology drop more than 1%
2. SK hynix's memory division reportedly selected Goldman Sachs and Morgan Stanley as lead banks for its IPO
3. Samsung has sent HBM samples! SK hynix hasn't even started making samples
📡 Source: Google News
💡 What to watch: HBM/DRAM supply-and-demand news can directly affect SK hynix's contracts and ADRs; watch for unusual market movements
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
🔬 SK hynix AI Chip Headlines: U.S. stocks at the open: All three major indexes fall; SK hynix and Micron Technology drop more than | October 9
🔬 SK hynix AI Chip Headlines | October 9
━━━━━━━━━━
1. U.S. stocks at the open: All three major indexes fall; SK hynix and Micron Technology drop more than 1%
2. SK hynix's memory division reportedly selected Goldman Sachs and Morgan Stanley as lead banks for its IPO
3. Samsung has sent HBM samples! SK hynix hasn't even started making samples
📡 Source: Google News
💡 What to watch: HBM/DRAM supply-and-demand news can directly affect SK hynix's contracts and ADRs; watch for unusual market movements
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only; not investment advice
417
·
--
Verified
Article
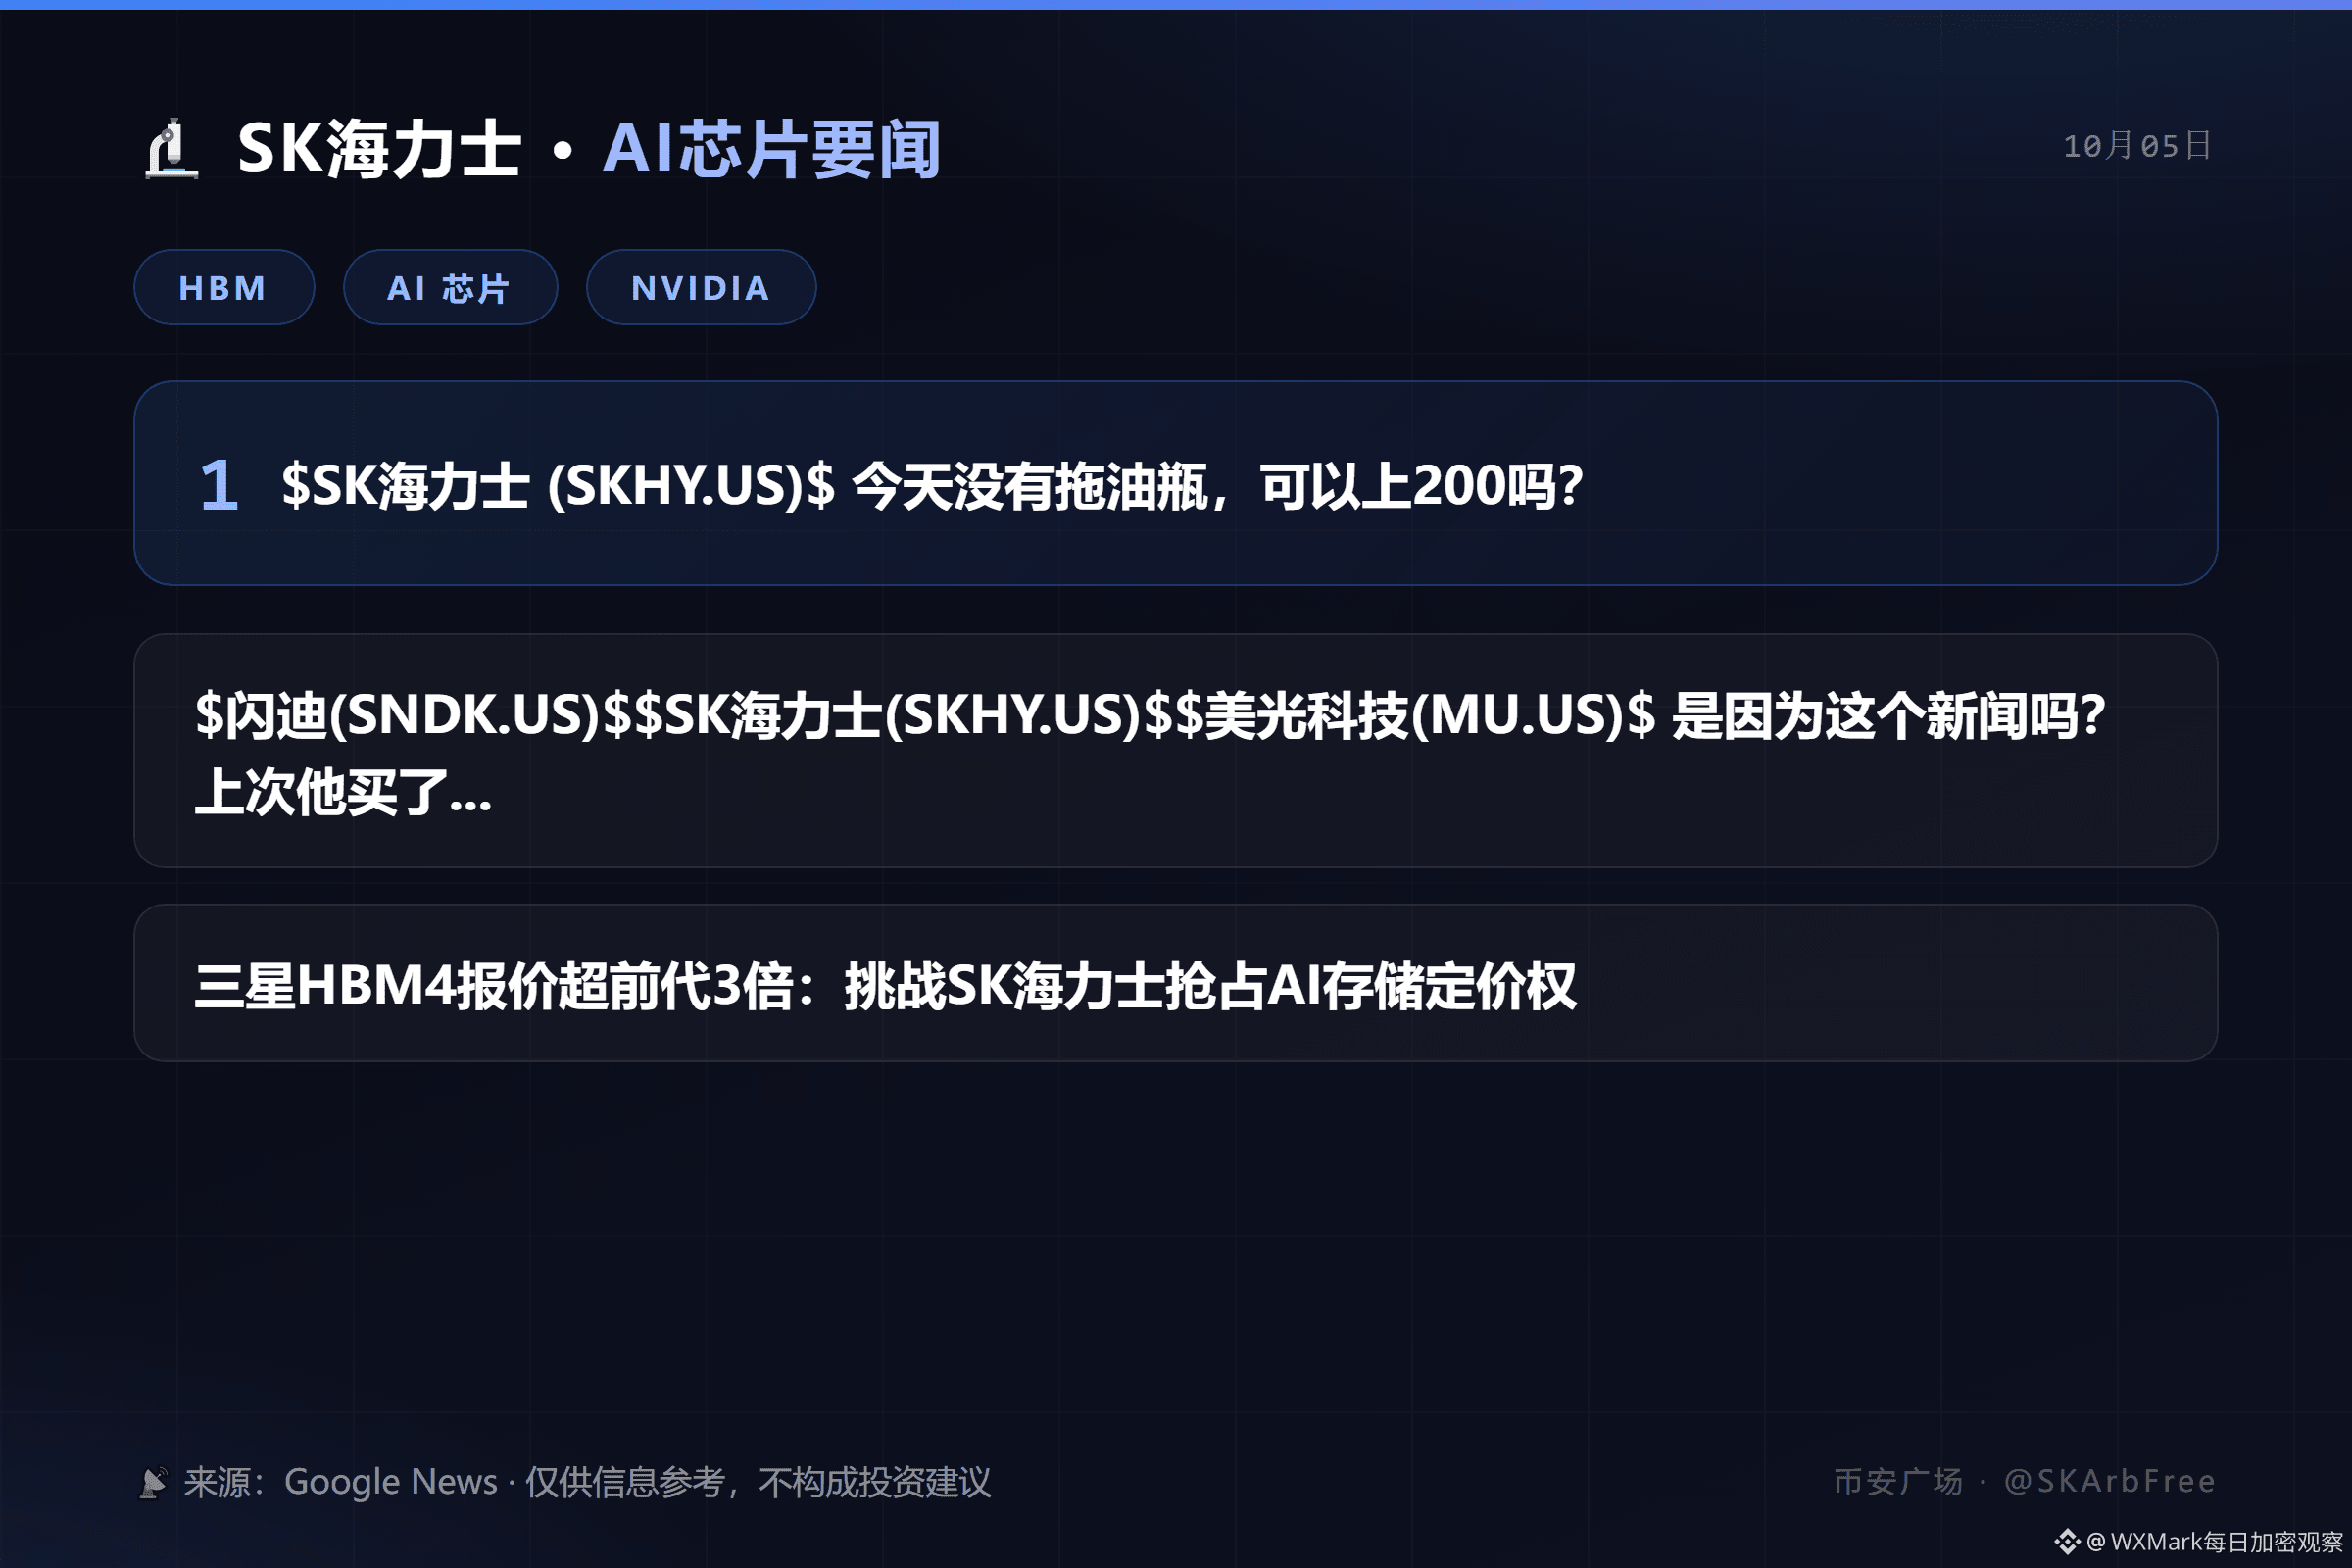
🔬 SK Hynix AI chip news: $SK Hynix (SKHY.US)$ no lag today | Oct 05🔬 SK Hynix AI chip news | Oct 05
━━━━━━━━━━
1. $SK Hynix (SKHY.US)$ Today there’s no drag—can it go up to 200?
2. Is it because of this news? $SanDisk (SNDK.US)$$SK Hynix (SKHY.US)$$Micron Technology (MU.US)$ Last time he bought...
3. Samsung HBM4 pricing is ahead of the previous generation by 3x: challenging SK Hynix to seize pricing power in AI memory
📡 Source: Google News
💡 Key focus: HBM/DRAM supply-and-demand updates will directly link to SKHYNIX contracts and ADRs—watch for unusual moves in the market
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For information only and does not constitute investment advice
🔬 SK Hynix AI chip news: $SK Hynix (SKHY.US)$ no lag today | Oct 05
🔬 SK Hynix AI chip news | Oct 05
━━━━━━━━━━
1. $SK Hynix (SKHY.US)$ Today there’s no drag—can it go up to 200?
2. Is it because of this news? $SanDisk (SNDK.US)$$SK Hynix (SKHY.US)$$Micron Technology (MU.US)$ Last time he bought...
3. Samsung HBM4 pricing is ahead of the previous generation by 3x: challenging SK Hynix to seize pricing power in AI memory
📡 Source: Google News
💡 Key focus: HBM/DRAM supply-and-demand updates will directly link to SKHYNIX contracts and ADRs—watch for unusual moves in the market
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For information only and does not constitute investment advice
1.3k
·
--
Verified
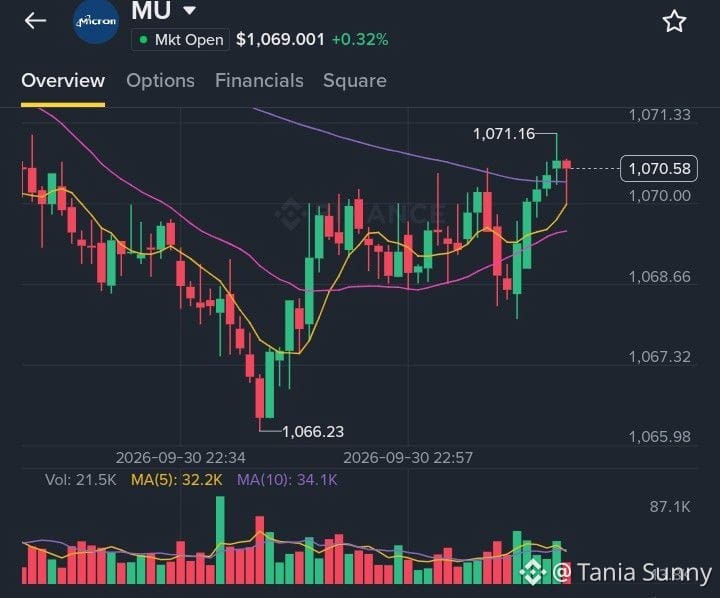
I'm watching $MU closely into Q4 FY2026 earnings today, Sept 30.
The setup is very different from last year. HBM3E demand for AI accelerators is pushing spot prices 4-5x above contract levels (TrendForce data), and Micron is one of the only 3 suppliers who can deliver at scale.
Why I'm bullish on $MU :
{stock_us}(MU.US)
- Data center is now the core story: Nvidia just posted $89B data center revenue (+117% YoY) and AMD's data center also doubled — both need more HBM from Micron.
- Pricing power is back: Reports showing 2026 HBM contracts up ∼20% YoY, which directly supports Micron's push towards 70%+ gross margin.
- Valuation still reasonable vs AI peers despite the run to ∼$180.
Risk is high if guidance disappoints, but the memory upcycle looks intact to me.
Not financial advice. My view on $MU.US
#EarningsSeason #MU #HBM #AIDemand
I'm watching $MU closely into Q4 FY2026 earnings today, Sept 30.
The setup is very different from last year. HBM3E demand for AI accelerators is pushing spot prices 4-5x above contract levels (TrendForce data), and Micron is one of the only 3 suppliers who can deliver at scale.
Why I'm bullish on $MU :
- Data center is now the core story: Nvidia just posted $89B data center revenue (+117% YoY) and AMD's data center also doubled — both need more HBM from Micron.
- Pricing power is back: Reports showing 2026 HBM contracts up ∼20% YoY, which directly supports Micron's push towards 70%+ gross margin.
- Valuation still reasonable vs AI peers despite the run to ∼$180.
Risk is high if guidance disappoints, but the memory upcycle looks intact to me.
Not financial advice. My view on $MU.US
#EarningsSeason #MU #HBM #AIDemand
MU+0.28%
MUUS-4.90%
2
2.1k
·
--
#EarningsSeason
I’ve been watching the memory market for a while, and this cycle feels different from the usual boom-and-bust story.
Micron is heading into its FY2026 Q4 earnings with expectations around $50B in revenue and gross margins around 86%.
The big question for me is:
How much longer can this memory super cycle actually run?
I think there’s still room for the cycle to continue, mainly because AI infrastructure is creating massive demand for memory, especially HBM.
But I don’t think these growth rates can continue forever.
What I’m watching most closely isn’t just Micron’s Q4 numbers. It’s what management says about the next few quarters.
If AI demand stays strong while memory supply remains tight, the cycle could continue much longer than a typical memory cycle.
But if new capacity starts coming online faster than demand grows, margins could eventually be the first warning sign.
So my view is cautiously bullish on the memory story, but I’m not assuming this is an endless cycle.
The next earnings report should give us another important piece of the puzzle.
What are you watching most closely — HBM demand, gross margins, or FY2027 guidance?
#MU #HBM
1
347
·
--
Article
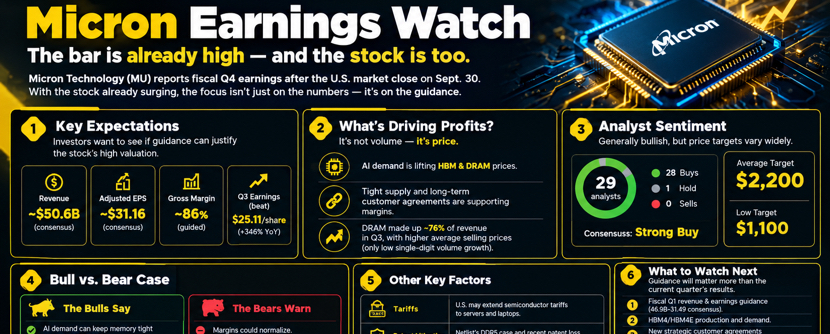
🚨 Micron $MU Earnings: The Bar Is Already HighMicron Technology reports fiscal Q4 earnings after the U.S. market close today, Sept. 30. With the stock already surging, investors are watching guidance more closely than the headline earnings beat.
📊 What matters:
• AI-driven demand continues to lift HBM and DRAM prices.
• Tight supply and long-term customer agreements are supporting margins.
• Analysts expect another strong quarter, but price targets vary widely.
• Bulls see AI demand keeping memory supply tight into 2027 and beyond.
• Bears warn that new capacity could eventually push prices and margins lower.
🔑 Tonight’s key signals:
• Fiscal Q1 revenue and earnings guidance
• HBM4/HBM4E production and demand
• DRAM/NAND pricing trends
• Gross-margin outlook
• New long-term customer agreements
• Management’s view on how long the supply shortage can last
⚠️ Bottom line: Micron doesn’t just need strong numbers—the guidance needs to show that the AI-driven memory boom can continue to justify the stock’s elevated valuation.
$MU #Aİ #HBM #DRAM #Semiconductors
{future}(MUUSDT)
{spot}(MUBUSDT)
🚨 Micron $MU Earnings: The Bar Is Already High
Micron Technology reports fiscal Q4 earnings after the U.S. market close today, Sept. 30. With the stock already surging, investors are watching guidance more closely than the headline earnings beat.
📊 What matters:
• AI-driven demand continues to lift HBM and DRAM prices.
• Tight supply and long-term customer agreements are supporting margins.
• Analysts expect another strong quarter, but price targets vary widely.
• Bulls see AI demand keeping memory supply tight into 2027 and beyond.
• Bears warn that new capacity could eventually push prices and margins lower.
🔑 Tonight’s key signals:
• Fiscal Q1 revenue and earnings guidance
• HBM4/HBM4E production and demand
• DRAM/NAND pricing trends
• Gross-margin outlook
• New long-term customer agreements
• Management’s view on how long the supply shortage can last
⚠️ Bottom line: Micron doesn’t just need strong numbers—the guidance needs to show that the AI-driven memory boom can continue to justify the stock’s elevated valuation.
$MU #Aİ #HBM #DRAM #Semiconductors
241
·
--
Article
🔬 SK Hynix AI chip news: Valuation uncertainty for SK Hynix amid plans for its subsidiary listing | Sep 30🔬 SK Hynix AI chip news | Sep 30
━━━━━━━━━━
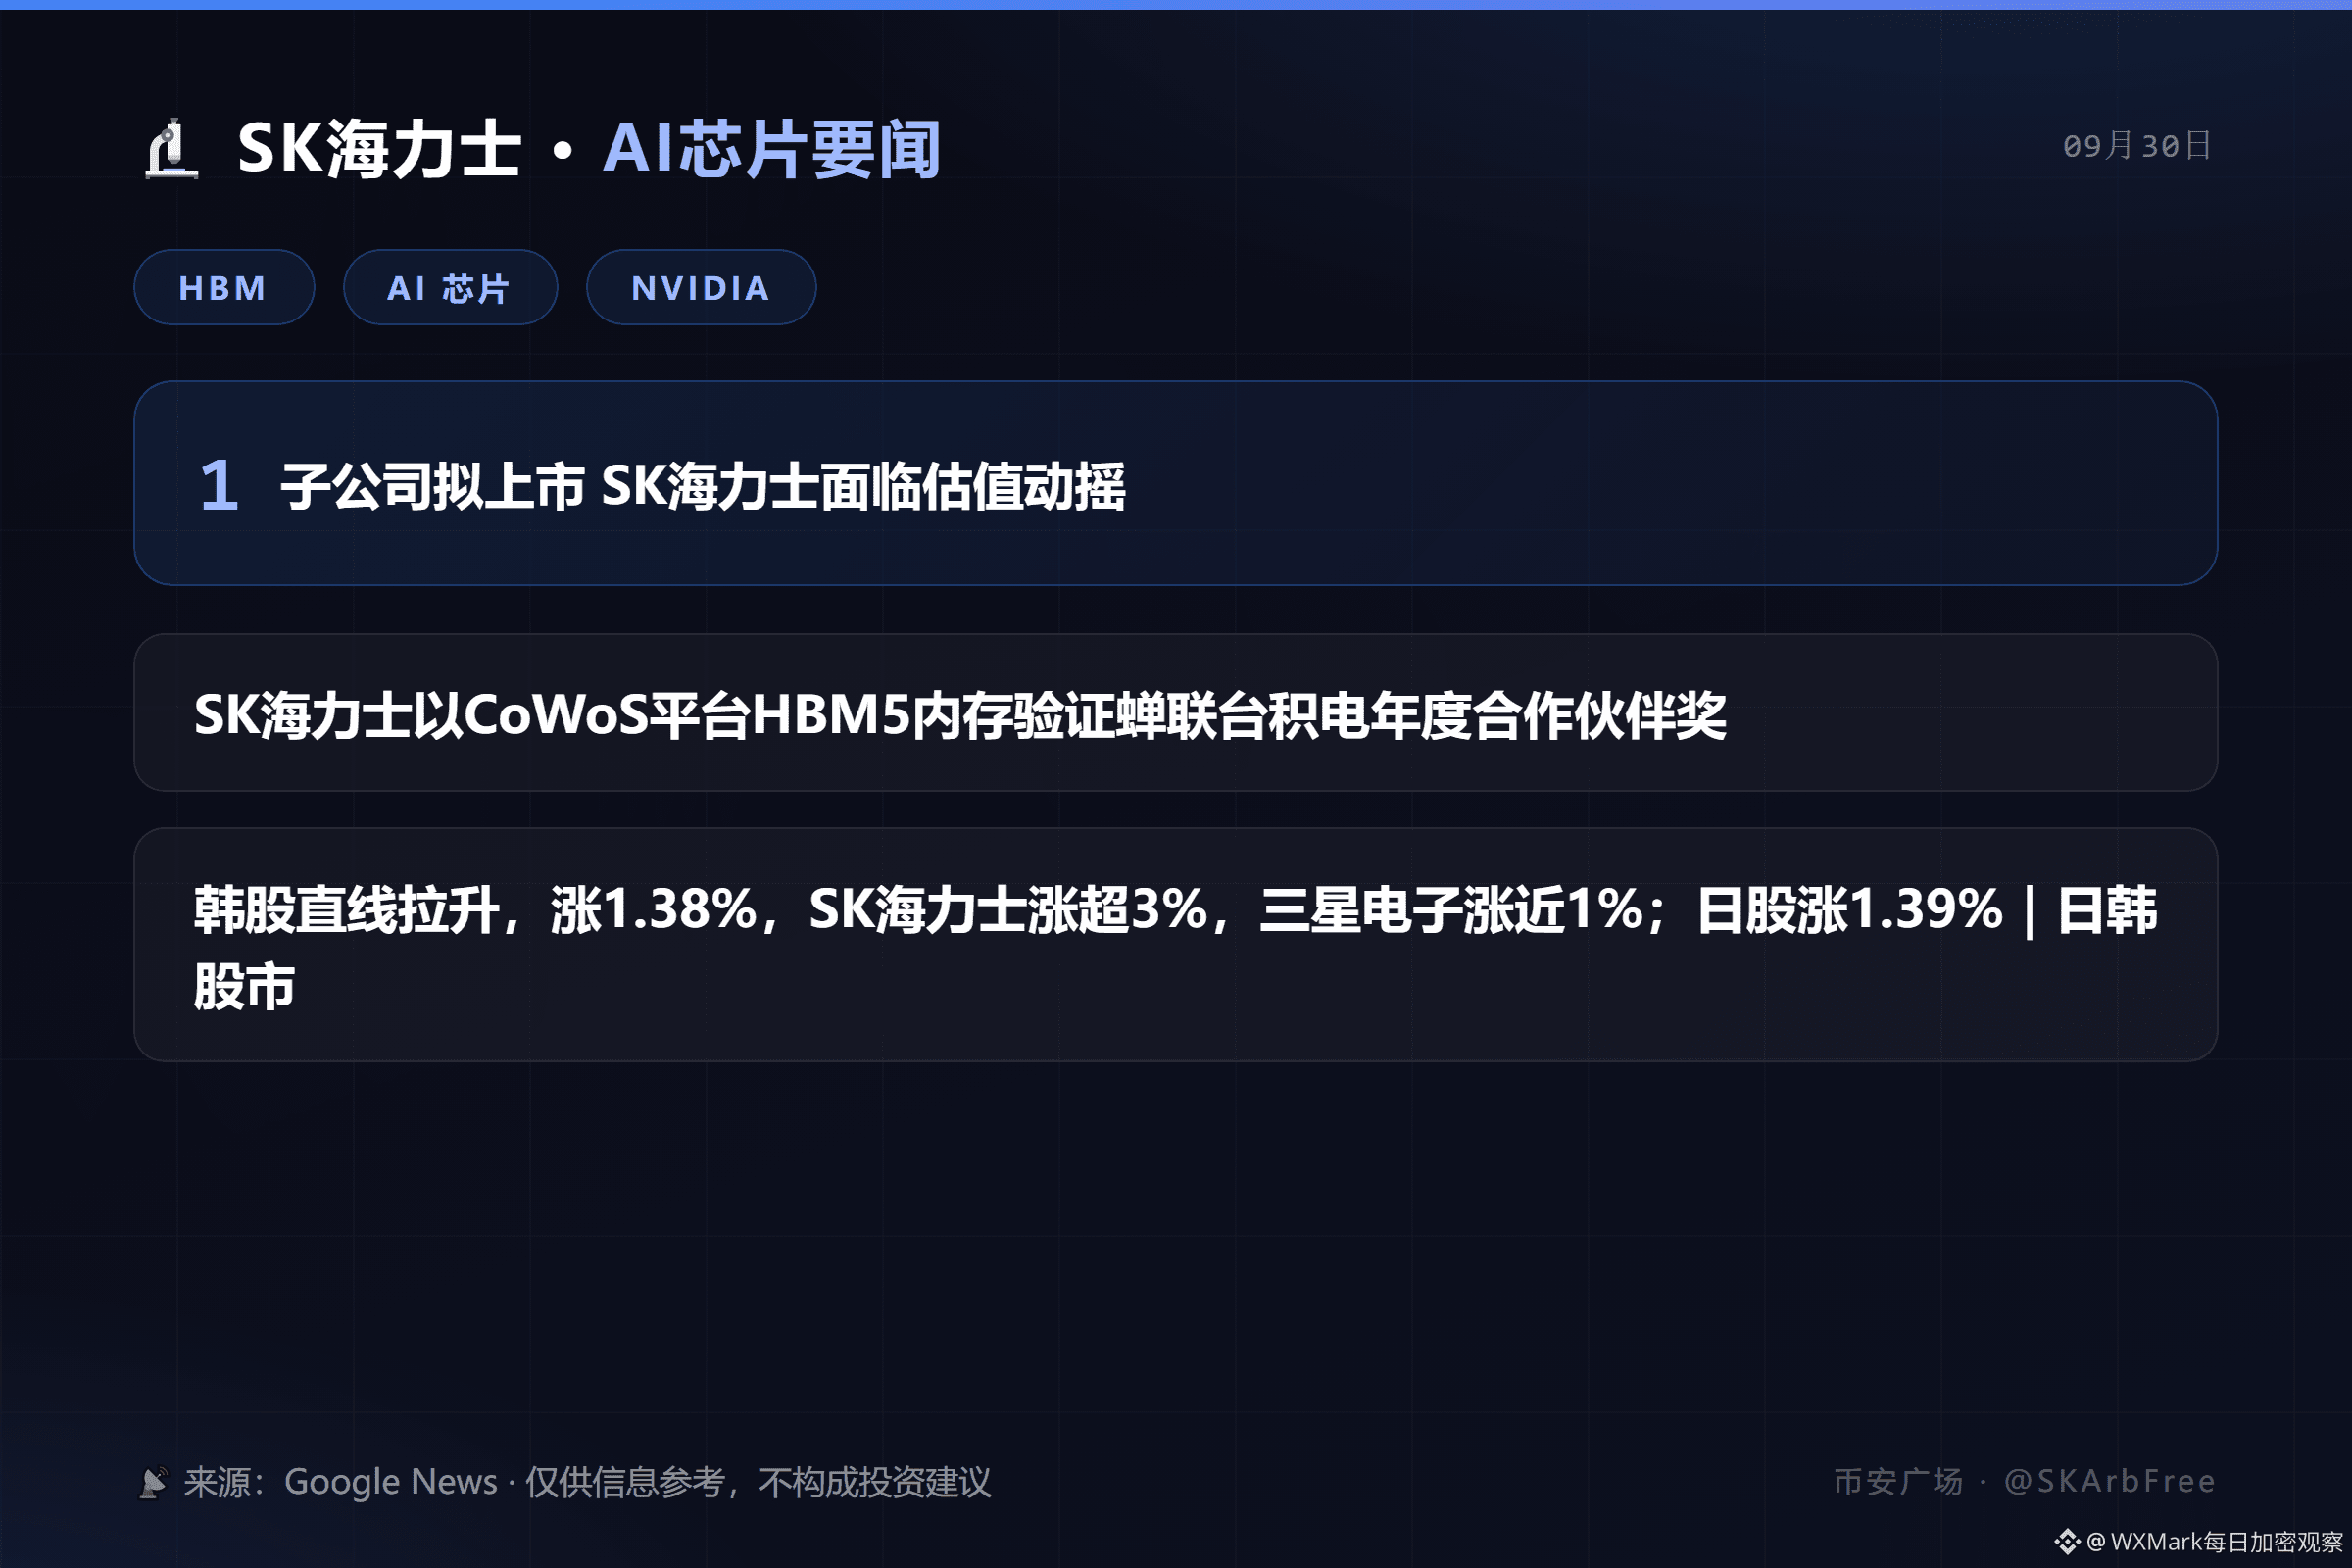
1. A subsidiary plans to list: SK Hynix faces valuation uncertainty
2. SK Hynix, using the CoWoS platform to verify HBM5 memory, wins TSMC’s annual partner award for a consecutive year
3. South Korean stocks surge straight up, up 1.38%; SK Hynix up more than 3%; Samsung Electronics up nearly 1%. Japan stocks up 1.39%|Korean and Japanese stock markets
📡 Source: Google News
💡 Focus: HBM/DRAM supply-and-demand updates will directly affect SK Hynix contracts and ADRs—watch for unusual market moves
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only and does not constitute investment advice
🔬 SK Hynix AI chip news: Valuation uncertainty for SK Hynix amid plans for its subsidiary listing | Sep 30
🔬 SK Hynix AI chip news | Sep 30
━━━━━━━━━━
1. A subsidiary plans to list: SK Hynix faces valuation uncertainty
2. SK Hynix, using the CoWoS platform to verify HBM5 memory, wins TSMC’s annual partner award for a consecutive year
3. South Korean stocks surge straight up, up 1.38%; SK Hynix up more than 3%; Samsung Electronics up nearly 1%. Japan stocks up 1.39%|Korean and Japanese stock markets
📡 Source: Google News
💡 Focus: HBM/DRAM supply-and-demand updates will directly affect SK Hynix contracts and ADRs—watch for unusual market moves
$SKHYNIX $SKHY #SK海力士 #AI芯片 #HBM #Nvidia
⚠️ For informational purposes only and does not constitute investment advice
1
477
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceProcesses$4.65BWithdrawals
9,538 views
78 Discussing
2
#WithdrawalsBack: 15 networks live
5,460 views
112 Discussing
3
#BinanceUpdatesProofofReservesAddresses
95,828 views
1,371 Discussing
4
#BinanceToResumePhaseOneOfWithdrawals
135,170 views
1,494 Discussing
5
#BinanceHadAlreadyCovered$6BofHackLoss
9,157 views
131 Discussing
6
#FBIConfirmsNorthKoreaIsResponsibleForBinanceCryptoHack
45,561 views
143 Discussing
7
#CZDismissesClaimsBinanceHackWasPredicted
66,712 views
678 Discussing
8
#B14gReportsUnauthorizedTransferOfAbout97MCORE
22,073 views
330 Discussing
9
#USSpotETHETFsPost23StraightDaysOfNetOutflows
25,679 views
309 Discussing
10
#IntelHasItsWorstDaySince1974
117,069 views
923 Discussing