
#applovin
applovin
4,997 views
39 Discussing
Hot
Latest
·
--
Bullish
🚀 $APPB
{spot}(APPBUSDT)
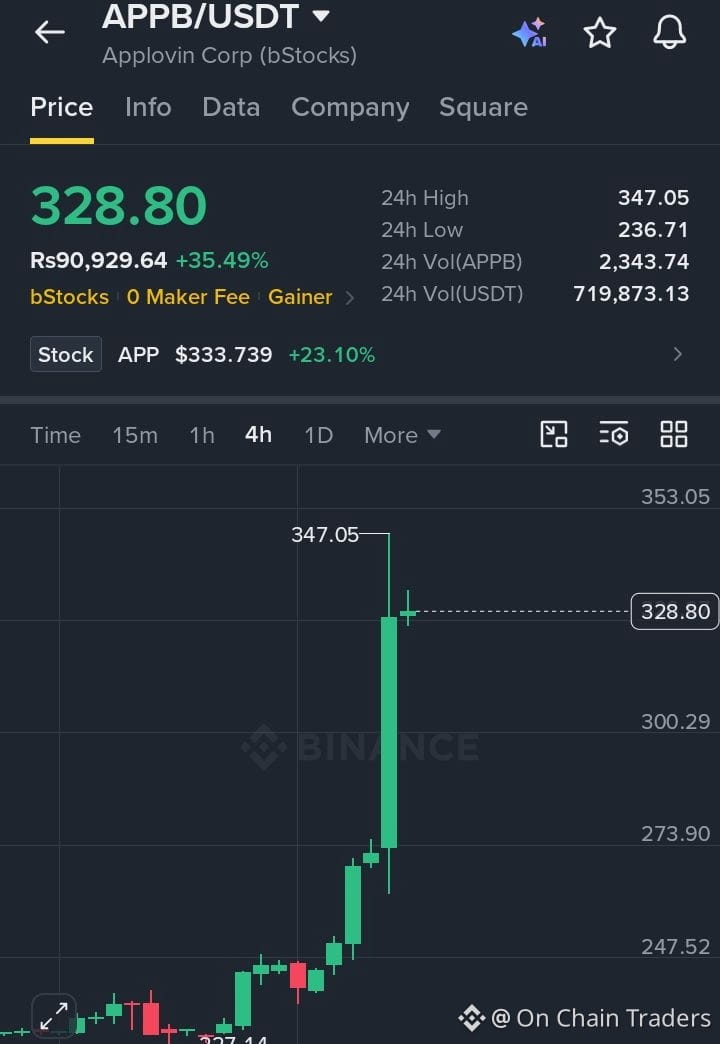
is exploding with strong bullish momentum, up 35.49%! Entry Zone: $315–$329 Targets: $347 / $353 / $365 Stop Loss: $300 Pattern: Bullish breakout with strong buying pressure; a clean break above $353 could extend the rally. Market Outlook: Bullish above $300, but watch for profit-taking after this sharp pump. DYOR.
#APPB #AppLovin #bStocks
🚀 $APPB
is exploding with strong bullish momentum, up 35.49%! Entry Zone: $315–$329 Targets: $347 / $353 / $365 Stop Loss: $300 Pattern: Bullish breakout with strong buying pressure; a clean break above $353 could extend the rally. Market Outlook: Bullish above $300, but watch for profit-taking after this sharp pump. DYOR.
#APPB #AppLovin #bStocks
is exploding with strong bullish momentum, up 35.49%! Entry Zone: $315–$329 Targets: $347 / $353 / $365 Stop Loss: $300 Pattern: Bullish breakout with strong buying pressure; a clean break above $353 could extend the rally. Market Outlook: Bullish above $300, but watch for profit-taking after this sharp pump. DYOR.
#APPB #AppLovin #bStocks
1
52
·
--
Bullish
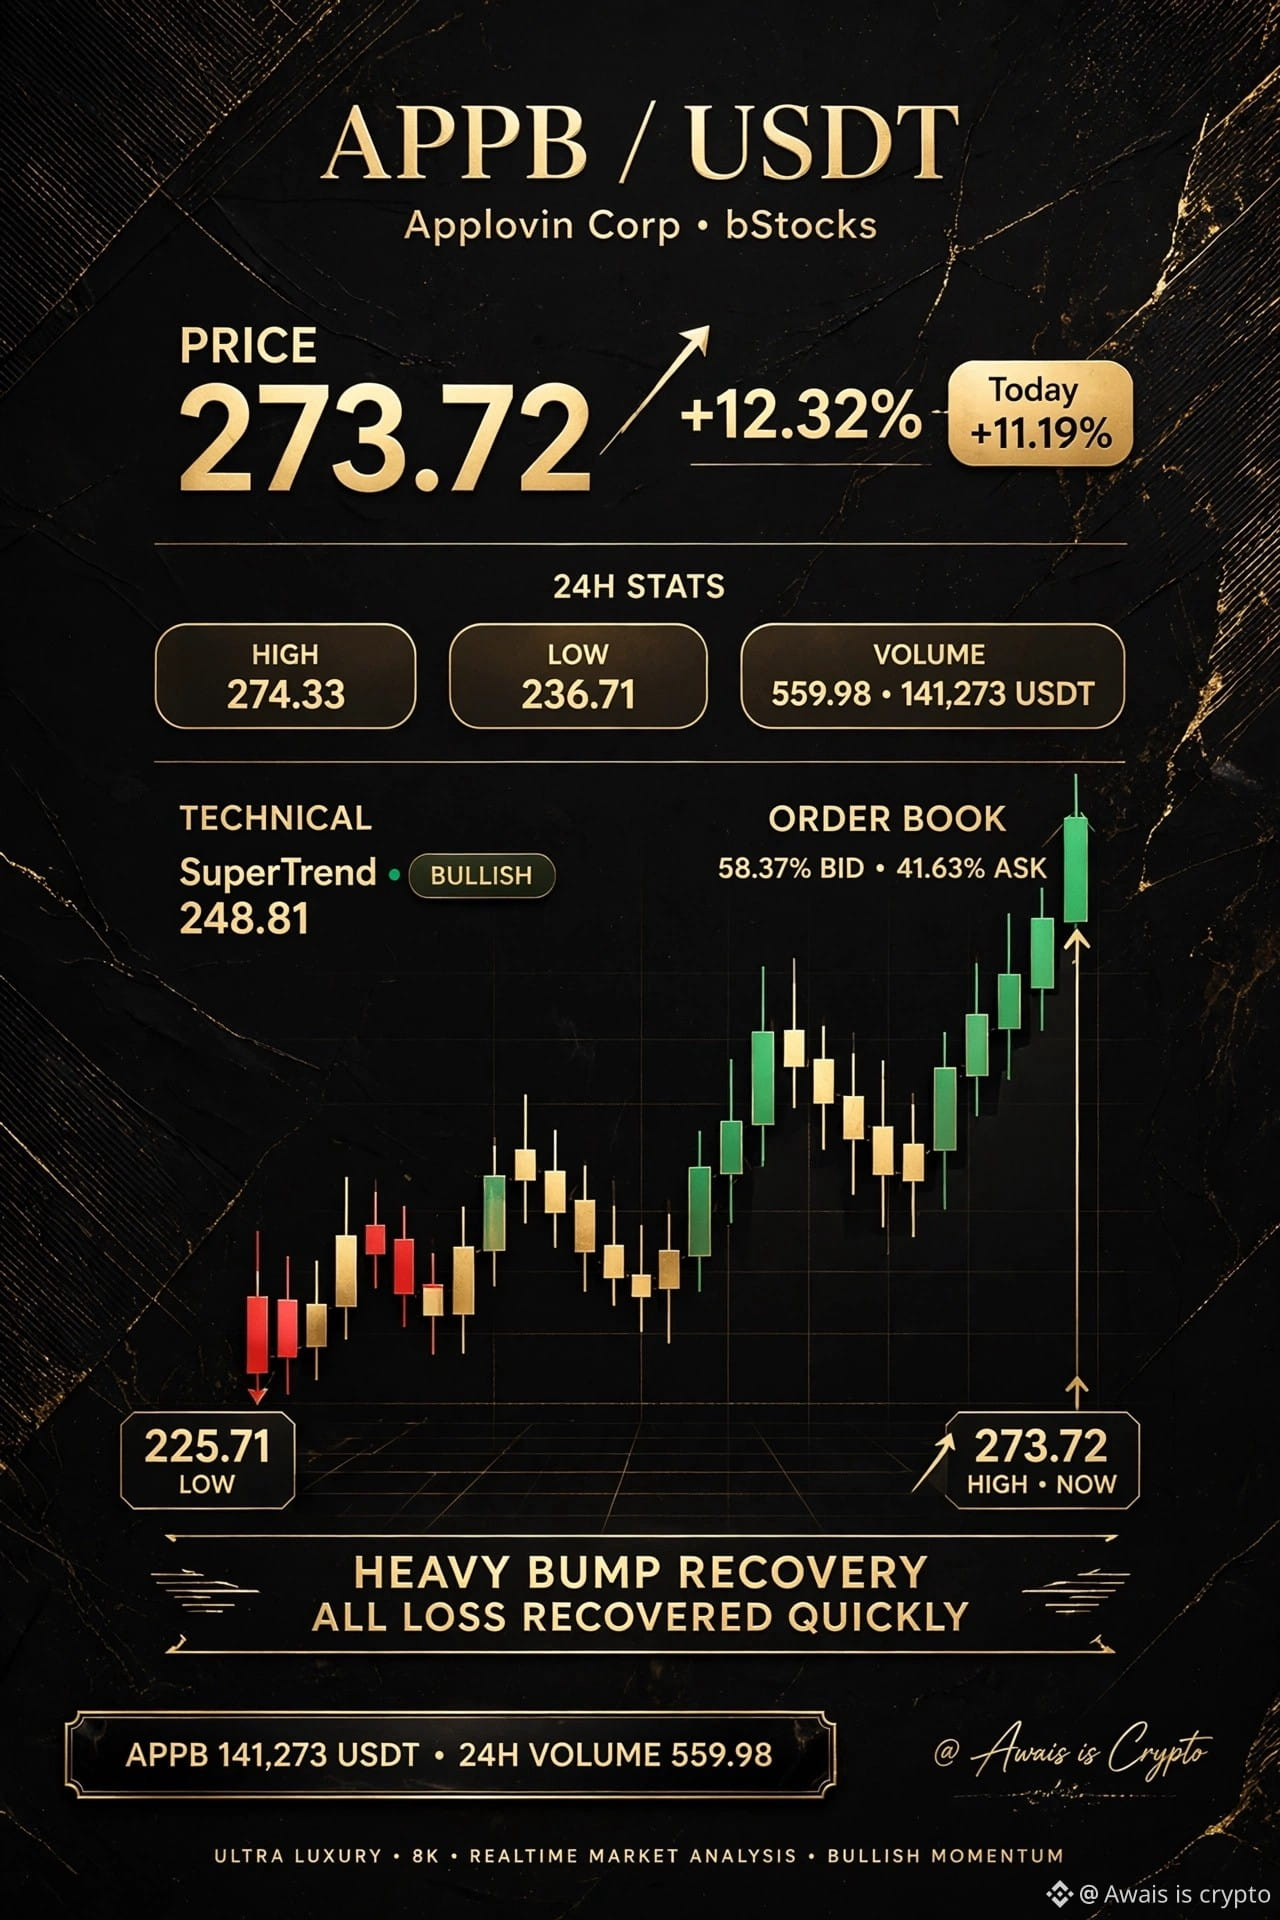
🔥 $APPB /USDT HEAVY BUMP +12.32% 🚀 ALL LOSS RECOVERED QUICKLY!
> 💰 Price: $273.72
> 📈 24H Range: $236.71 - $274.33
> 📊 Volume: 559.98 APPB ($141,273 USDT)
> 📊 SuperTrend: $248.81 - Price Well Above Trend = Strong Bullish ✅
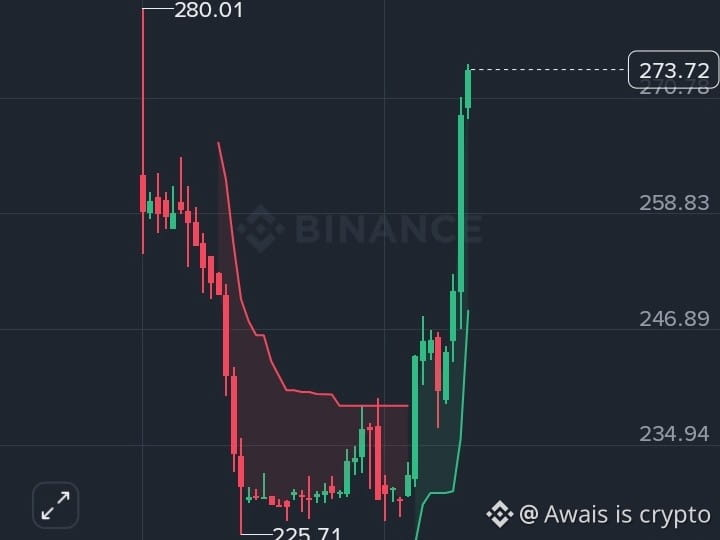
> 🕯️ Chart Story: Red Candles Dump to $225.71 Bottom, Then BIG Green Candles Pump Straight to $273.72!
> HEAVY BUMP = FULL RECOVERY! 💪
> Jo loss hua tha, sab recover ho gaya - Green candles ne game palat di! 🟢🔴
> 📖 Order Book: 58.37% Bid 🟢 | 41.63% Ask 🔴 - Buyers Still Strong!
> 🔥 Performance: Today +11.19%
> Next Target $280.01? 🌙👇
> $APPB
{spot}(APPBUSDT)
#Applovin #APPB #bStocks #Binance
🔥 $APPB /USDT HEAVY BUMP +12.32% 🚀 ALL LOSS RECOVERED QUICKLY!
> 💰 Price: $273.72
> 📈 24H Range: $236.71 - $274.33
> 📊 Volume: 559.98 APPB ($141,273 USDT)
> 📊 SuperTrend: $248.81 - Price Well Above Trend = Strong Bullish ✅
> 🕯️ Chart Story: Red Candles Dump to $225.71 Bottom, Then BIG Green Candles Pump Straight to $273.72!
> HEAVY BUMP = FULL RECOVERY! 💪
> Jo loss hua tha, sab recover ho gaya - Green candles ne game palat di! 🟢🔴
> 📖 Order Book: 58.37% Bid 🟢 | 41.63% Ask 🔴 - Buyers Still Strong!
> 🔥 Performance: Today +11.19%
> Next Target $280.01? 🌙👇
> $APPB
#Applovin #APPB #bStocks #Binance
> 💰 Price: $273.72
> 📈 24H Range: $236.71 - $274.33
> 📊 Volume: 559.98 APPB ($141,273 USDT)
> 📊 SuperTrend: $248.81 - Price Well Above Trend = Strong Bullish ✅
> 🕯️ Chart Story: Red Candles Dump to $225.71 Bottom, Then BIG Green Candles Pump Straight to $273.72!
> HEAVY BUMP = FULL RECOVERY! 💪
> Jo loss hua tha, sab recover ho gaya - Green candles ne game palat di! 🟢🔴
> 📖 Order Book: 58.37% Bid 🟢 | 41.63% Ask 🔴 - Buyers Still Strong!
> 🔥 Performance: Today +11.19%
> Next Target $280.01? 🌙👇
> $APPB
#Applovin #APPB #bStocks #Binance
2
240

$APPB - AppLovin Corp Tokenized Stock
Ye normal meme coin nahi hai, ye US stock ka tokenized version hai.
Current scene:
Price ~$259 ke around hai
Liquidity boht kam hai, isliye 1-2% slip bhi bara lagta hai.
Is type ke token me leverage bilkul mat lena,
aur spot me bhi choti quantity rakho.
Ye educational post hai, koi buy/sell advice nahi.
Kya tumne tokenized stocks try kiye hain?
#APPB #AppLovin #TokenizedStocks #Binance
$APPB - AppLovin Corp Tokenized Stock
Ye normal meme coin nahi hai, ye US stock ka tokenized version hai.
Current scene:
Price ~$259 ke around hai
Liquidity boht kam hai, isliye 1-2% slip bhi bara lagta hai.
Is type ke token me leverage bilkul mat lena,
aur spot me bhi choti quantity rakho.
Ye educational post hai, koi buy/sell advice nahi.
Kya tumne tokenized stocks try kiye hain?
#APPB #AppLovin #TokenizedStocks #Binance
Ye normal meme coin nahi hai, ye US stock ka tokenized version hai.
Current scene:
Price ~$259 ke around hai
Liquidity boht kam hai, isliye 1-2% slip bhi bara lagta hai.
Is type ke token me leverage bilkul mat lena,
aur spot me bhi choti quantity rakho.
Ye educational post hai, koi buy/sell advice nahi.
Kya tumne tokenized stocks try kiye hain?
#APPB #AppLovin #TokenizedStocks #Binance
114
·
--
🔴 $APPB /USDT — SHORT SIGNAL
Applovin Corp (bStocks)
📉 Trade Plan:
Direction: SHORT
Entry: $248.00 – $250.00
Stop Loss (SL): $254.50
🎯 Take Profit Targets:
TP1: $244.00
TP2: $240.00
TP3: $236.00
Trade here $APPB
{spot}(APPBUSDT)
Technical Analysis:
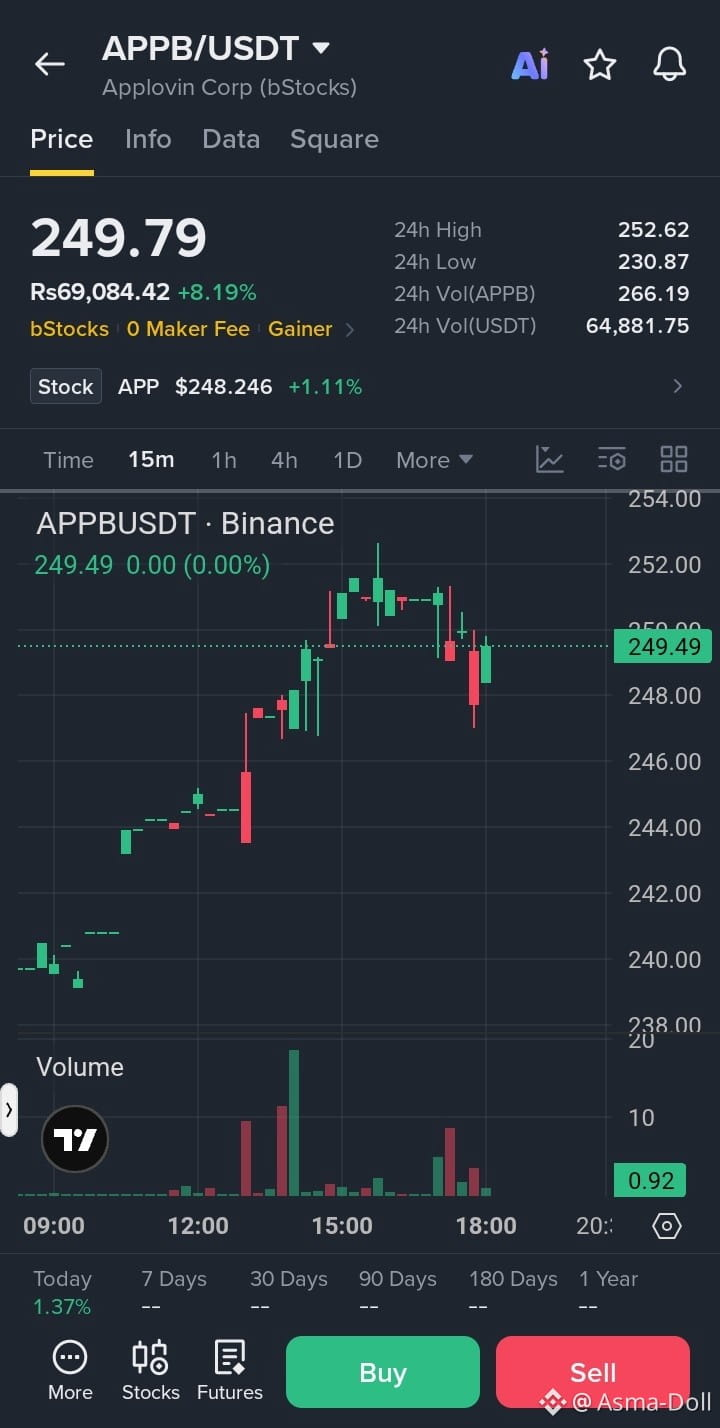
Strong +8.19% daily pump.
Price approaching resistance at $252.62.
Potential rejection near the 252–253 zone.
Profit-taking may trigger a short-term correction.
A breakdown below $248 could increase selling pressure.
Confirmation: Wait for a strong bearish candle below $248 before entering SHORT. Avoid entering if price breaks above $252.62 with strong volume.
Risk-to-Reward: Approximately 1:0.8 to TP1, 1:1.6 to TP2, and 1:2.4 to TP3 (using a $249 entry).
⚠️ Short setup is conditional; the strong daily momentum makes early shorting risky.
#APPB #Applovin #SHORTSignal #BinanceTrading #CryptoSignals
🔴 $APPB /USDT — SHORT SIGNAL
Applovin Corp (bStocks)
📉 Trade Plan:
Direction: SHORT
Entry: $248.00 – $250.00
Stop Loss (SL): $254.50
🎯 Take Profit Targets:
TP1: $244.00
TP2: $240.00
TP3: $236.00
Trade here $APPB
Technical Analysis:
Strong +8.19% daily pump.
Price approaching resistance at $252.62.
Potential rejection near the 252–253 zone.
Profit-taking may trigger a short-term correction.
A breakdown below $248 could increase selling pressure.
Confirmation: Wait for a strong bearish candle below $248 before entering SHORT. Avoid entering if price breaks above $252.62 with strong volume.
Risk-to-Reward: Approximately 1:0.8 to TP1, 1:1.6 to TP2, and 1:2.4 to TP3 (using a $249 entry).
⚠️ Short setup is conditional; the strong daily momentum makes early shorting risky.
#APPB #Applovin #SHORTSignal #BinanceTrading #CryptoSignals
Applovin Corp (bStocks)
📉 Trade Plan:
Direction: SHORT
Entry: $248.00 – $250.00
Stop Loss (SL): $254.50
🎯 Take Profit Targets:
TP1: $244.00
TP2: $240.00
TP3: $236.00
Trade here $APPB
Technical Analysis:
Strong +8.19% daily pump.
Price approaching resistance at $252.62.
Potential rejection near the 252–253 zone.
Profit-taking may trigger a short-term correction.
A breakdown below $248 could increase selling pressure.
Confirmation: Wait for a strong bearish candle below $248 before entering SHORT. Avoid entering if price breaks above $252.62 with strong volume.
Risk-to-Reward: Approximately 1:0.8 to TP1, 1:1.6 to TP2, and 1:2.4 to TP3 (using a $249 entry).
⚠️ Short setup is conditional; the strong daily momentum makes early shorting risky.
#APPB #Applovin #SHORTSignal #BinanceTrading #CryptoSignals
12
·
--
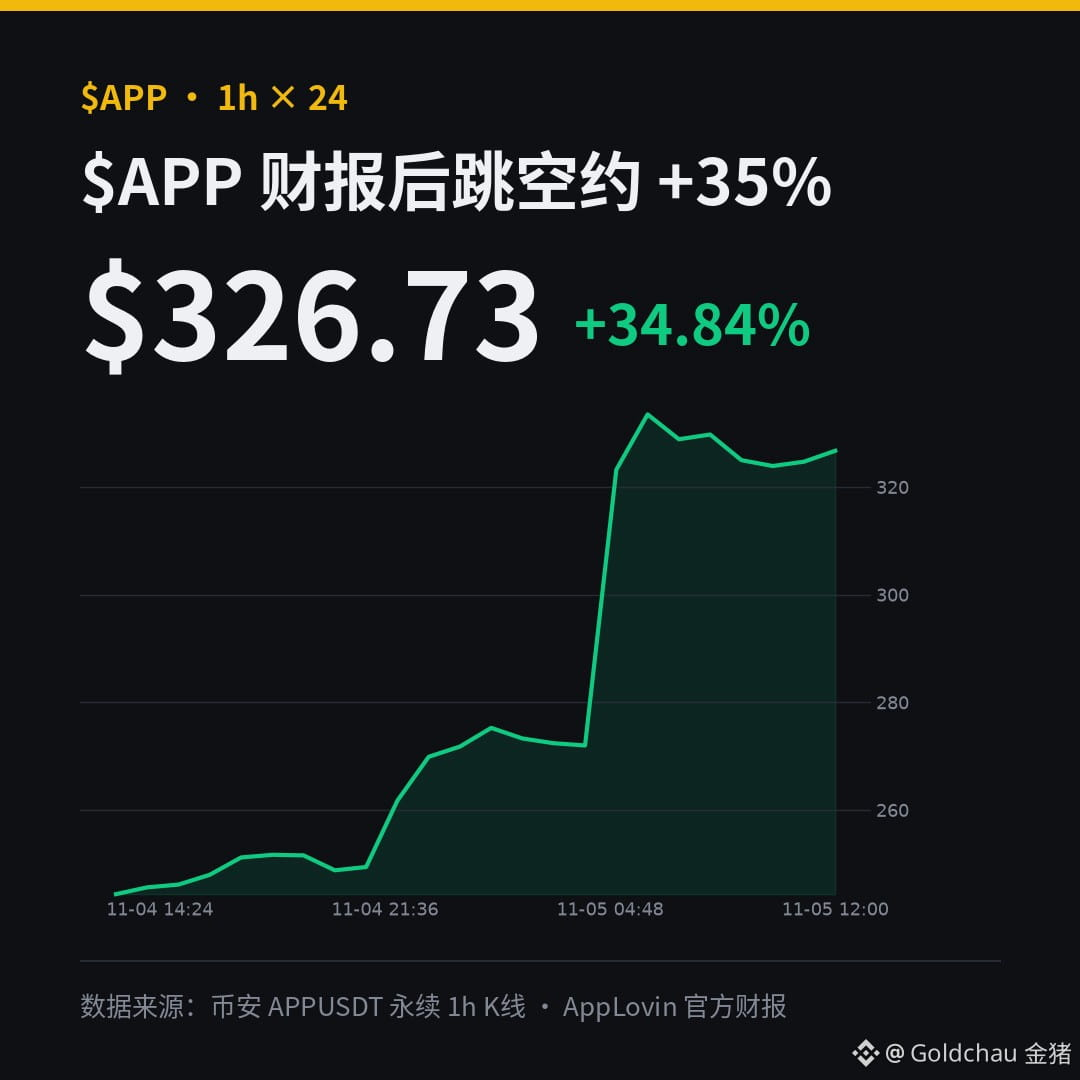
Golden Pig’s take: $APP ’s perpetual contract rose about 35% in a day after earnings. I’m cautiously bullish on this one, but wouldn’t chase the gap-up high here. If it pulls back to around 300 and holds, I’d keep holding; if it falls below 280, I’d reduce my position.
The hard numbers: Q3 revenue was about $2.185 billion, up roughly 55% year over year; net income was about $1.439 billion, up roughly 72% year over year.
More importantly, the guidance: Q4 revenue is expected to be about $2.365–$2.395 billion.
After such a big earnings gap-up, the real test is whether the guidance can be met—not this one big green candle. If you’re looking to get in, at least wait for a pullback and confirmation that support holds; if you’re trading perpetuals, don’t add leverage just because the earnings were good.
After the big post-earnings rally, how would you manage a position in a TradFi perpetual like $APP ?
#APP #AppLovin #财报 $APP $BTC
Data sources: AppLovin’s official Q3 earnings report and Binance market data. DYOR; this is not investment advice.
Golden Pig’s take: $APP ’s perpetual contract rose about 35% in a day after earnings. I’m cautiously bullish on this one, but wouldn’t chase the gap-up high here. If it pulls back to around 300 and holds, I’d keep holding; if it falls below 280, I’d reduce my position.
The hard numbers: Q3 revenue was about $2.185 billion, up roughly 55% year over year; net income was about $1.439 billion, up roughly 72% year over year.
More importantly, the guidance: Q4 revenue is expected to be about $2.365–$2.395 billion.
After such a big earnings gap-up, the real test is whether the guidance can be met—not this one big green candle. If you’re looking to get in, at least wait for a pullback and confirmation that support holds; if you’re trading perpetuals, don’t add leverage just because the earnings were good.
After the big post-earnings rally, how would you manage a position in a TradFi perpetual like $APP ?
#APP #AppLovin #财报 $APP $BTC
Data sources: AppLovin’s official Q3 earnings report and Binance market data. DYOR; this is not investment advice.
The hard numbers: Q3 revenue was about $2.185 billion, up roughly 55% year over year; net income was about $1.439 billion, up roughly 72% year over year.
More importantly, the guidance: Q4 revenue is expected to be about $2.365–$2.395 billion.
After such a big earnings gap-up, the real test is whether the guidance can be met—not this one big green candle. If you’re looking to get in, at least wait for a pullback and confirmation that support holds; if you’re trading perpetuals, don’t add leverage just because the earnings were good.
After the big post-earnings rally, how would you manage a position in a TradFi perpetual like $APP ?
#APP #AppLovin #财报 $APP $BTC
Data sources: AppLovin’s official Q3 earnings report and Binance market data. DYOR; this is not investment advice.
257
·
--
Bullish
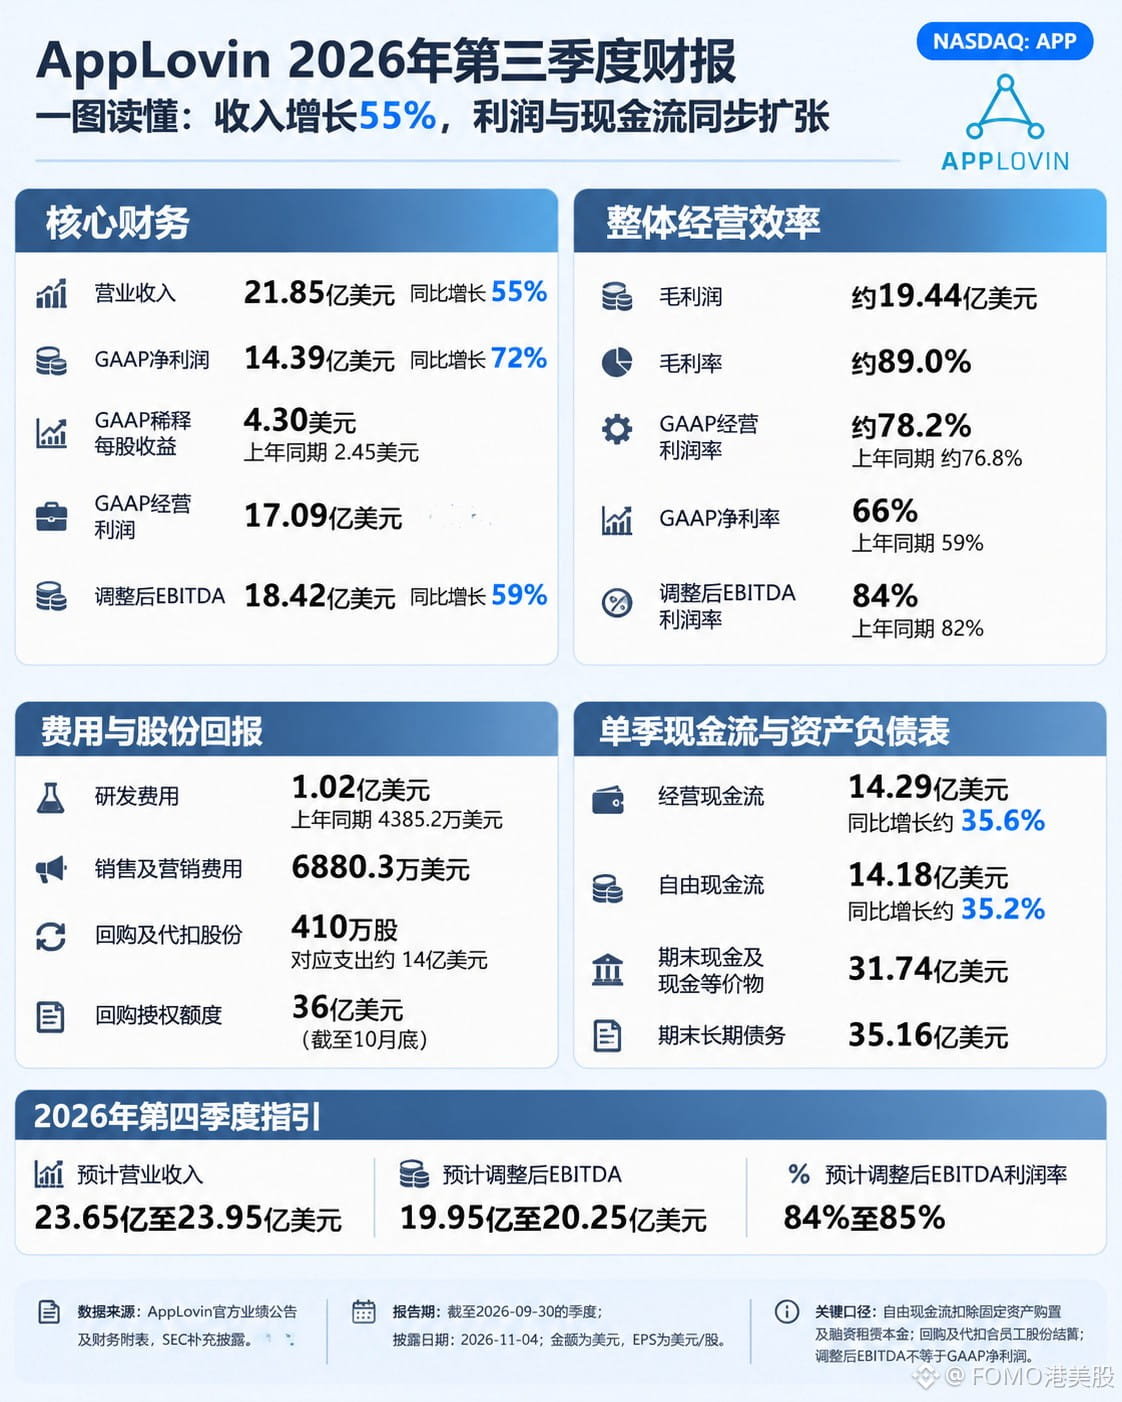
AppLovin $APPB revenue of $2.185 billion, +55%.
Net income rose 72%, while cash flow grew only 36%.
· Reported net income: $1.439 billion, +72%
· Operating income: $1.709 billion, 78% margin
· Operating cash flow: $1.429 billion, +36%
· R&D: $102 million, up from $44 million last year
Margins are still rising.
R&D increased from $44 million to $102 million, but costs are still growing more slowly than revenue. Operating margin climbed from 76.8% to 78.2%.
The scale effect is real.
Whether it can hold onto Q4's 84% margin is key.
Revenue growth slowing to 8% is another story.
{spot}(APPBUSDT)
#AppLovin #BStocks #股票财报季
AppLovin $APPB revenue of $2.185 billion, +55%.
Net income rose 72%, while cash flow grew only 36%.
· Reported net income: $1.439 billion, +72%
· Operating income: $1.709 billion, 78% margin
· Operating cash flow: $1.429 billion, +36%
· R&D: $102 million, up from $44 million last year
Margins are still rising.
R&D increased from $44 million to $102 million, but costs are still growing more slowly than revenue. Operating margin climbed from 76.8% to 78.2%.
The scale effect is real.
Whether it can hold onto Q4's 84% margin is key.
Revenue growth slowing to 8% is another story.
#AppLovin #BStocks #股票财报季
Net income rose 72%, while cash flow grew only 36%.
· Reported net income: $1.439 billion, +72%
· Operating income: $1.709 billion, 78% margin
· Operating cash flow: $1.429 billion, +36%
· R&D: $102 million, up from $44 million last year
Margins are still rising.
R&D increased from $44 million to $102 million, but costs are still growing more slowly than revenue. Operating margin climbed from 76.8% to 78.2%.
The scale effect is real.
Whether it can hold onto Q4's 84% margin is key.
Revenue growth slowing to 8% is another story.
#AppLovin #BStocks #股票财报季
368

·
--
Verified
APP gapped up 35% on earnings night, and shorts are still paying longs
First, where I stand: I’m on the bulls’ side this time, but I’m not chasing it higher.
Let’s start with the numbers.
After the U.S. market closed last night, APP reported Q3 revenue of $2.185 billion, up 55% year over year, versus expectations of just over $2.07 billion.
EPS was $4.30, against expectations of $4.03 and just $2.45 in the same quarter last year.
Net income was $1.439 billion, up 72% year over year, with a 66% net margin. Adjusted EBITDA was $1.842 billion, with an 84% margin.
Put simply, earnings are growing faster than revenue. There’s not much to poke holes in with this report.
Even more impressive was the guidance: Q4 revenue is forecast at $2.365–$2.395 billion, while Wall Street expected around $2.25 billion.
Adjusted EBITDA guidance is $1.995–$2.025 billion, also well above the $1.88 billion consensus.
Free cash flow came in at $1.4 billion for the quarter, and the board added $3.2 billion to its buyback authorization, bringing the total authorization to $3.6 billion.
This goes beyond simply calling it a beat—it was a beat across the board.
By the way, ARM also beat earnings next door, but its perpetual futures still fell 8%, and SOXL was down 12% in a single day.
APP’s 35% move is a solo act, not a sector-wide rally.
The bull case.
The ad business is genuinely making money after upgrades to its AI models. Gaming revenue rose nearly 50% year over year, and consumer spending grew by triple digits.
The explanation for the Q2 miss—that the model upgrade was a few days late—holds up. This quarter, they made up for it and then some.
With the buyback and higher guidance, management isn’t even pretending to be cautious anymore.
The bear case.
But don’t get carried away: APP has been falling from its high of 614 this year, and it even touched 228 last Friday.
At the end of October, UBS cut its price target from 790 to 414, RBC cut theirs from 575 to 500, and Zacks went straight to a Sell rating.
It missed once in Q2. The model-upgrade explanation worked this time, but that doesn’t mean it will work next time.
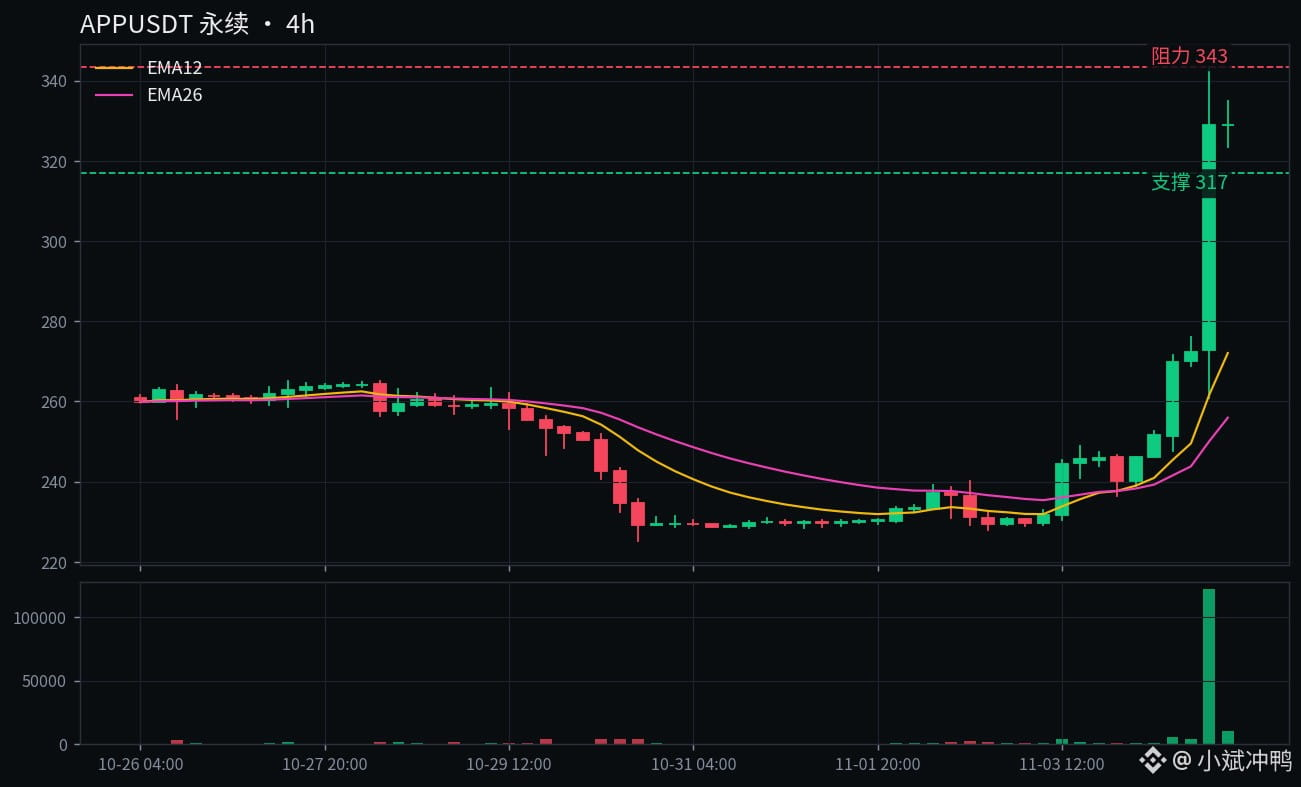
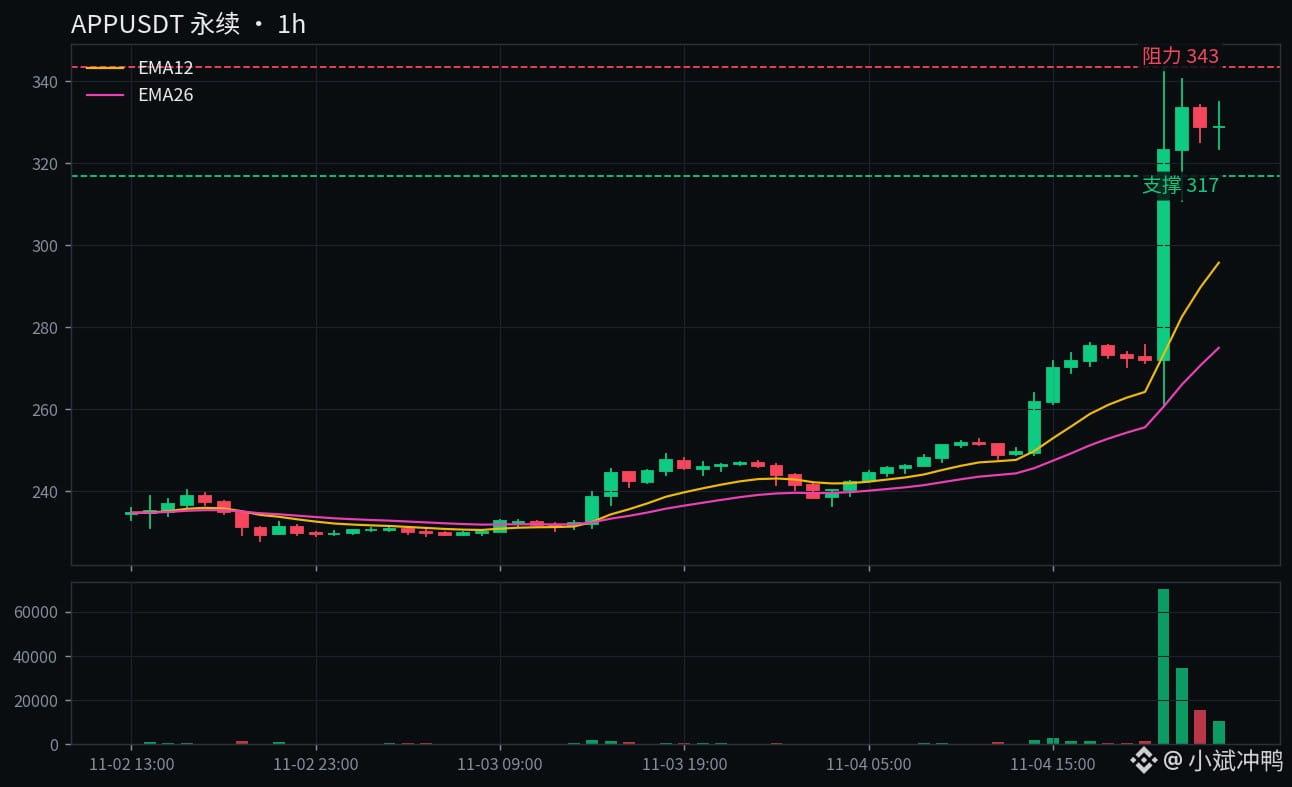
And perpetual futures are already up 35% today. The current price is 329.5, just a hair below the 24-hour high of 343. If you chase it here, you’re just providing an exit for the first buyers from earnings night.
My take.
Both the bulls and bears make good points, but I put more faith in the numbers.
Guidance is 6% above expectations, and the buyback authorization is up to $3.6 billion. Those are real, tangible things—not just talk.
Still, I’m not chasing a 35% gap. With gaps like this, the price could easily pull back to retest the level the same day.
There’s another interesting signal in perpetual futures: the funding rate is -0.52% every 8 hours, meaning shorts are still paying longs.
The spot index is 333, while perpetuals are at 329—perpetuals are actually cheaper than spot, which suggests traders chasing the move in perpetuals aren’t as frenzied as spot buyers.
Here are the scenarios.
If it holds above 343 and closes there, this won’t be just an earnings pop, and a move toward 360 looks pretty likely.
If it breaks below 317, the 24-hour volume-weighted average price, that would mean the earnings momentum has faded, with a move back to 300 to fill the gap.
If it breaks below 300, my bullish thesis in this post is invalidated, and I’ll admit this was just a one-day wonder.
What I’m planning to do.
I never chase a gap, so I’ll watch from the sidelines and wait to see if it holds above 343 or pulls back to 317.
I believe the earnings, but not the price. Chasing it at this level leaves too little room for error.
If you had to pick one: does it hold above 343 and charge toward 360, or break below 317 and fall back to 300 to fill the gap? I’m betting on a run to 360, but I’m not chasing it. What about you?
$APP $ARM $SOXL
#AppLovin #Earnings
APP gapped up 35% on earnings night, and shorts are still paying longs
First, where I stand: I’m on the bulls’ side this time, but I’m not chasing it higher.
Let’s start with the numbers.
After the U.S. market closed last night, APP reported Q3 revenue of $2.185 billion, up 55% year over year, versus expectations of just over $2.07 billion.
EPS was $4.30, against expectations of $4.03 and just $2.45 in the same quarter last year.
Net income was $1.439 billion, up 72% year over year, with a 66% net margin. Adjusted EBITDA was $1.842 billion, with an 84% margin.
Put simply, earnings are growing faster than revenue. There’s not much to poke holes in with this report.
Even more impressive was the guidance: Q4 revenue is forecast at $2.365–$2.395 billion, while Wall Street expected around $2.25 billion.
Adjusted EBITDA guidance is $1.995–$2.025 billion, also well above the $1.88 billion consensus.
Free cash flow came in at $1.4 billion for the quarter, and the board added $3.2 billion to its buyback authorization, bringing the total authorization to $3.6 billion.
This goes beyond simply calling it a beat—it was a beat across the board.
By the way, ARM also beat earnings next door, but its perpetual futures still fell 8%, and SOXL was down 12% in a single day.
APP’s 35% move is a solo act, not a sector-wide rally.
The bull case.
The ad business is genuinely making money after upgrades to its AI models. Gaming revenue rose nearly 50% year over year, and consumer spending grew by triple digits.
The explanation for the Q2 miss—that the model upgrade was a few days late—holds up. This quarter, they made up for it and then some.
With the buyback and higher guidance, management isn’t even pretending to be cautious anymore.
The bear case.
But don’t get carried away: APP has been falling from its high of 614 this year, and it even touched 228 last Friday.
At the end of October, UBS cut its price target from 790 to 414, RBC cut theirs from 575 to 500, and Zacks went straight to a Sell rating.
It missed once in Q2. The model-upgrade explanation worked this time, but that doesn’t mean it will work next time.
And perpetual futures are already up 35% today. The current price is 329.5, just a hair below the 24-hour high of 343. If you chase it here, you’re just providing an exit for the first buyers from earnings night.
My take.
Both the bulls and bears make good points, but I put more faith in the numbers.
Guidance is 6% above expectations, and the buyback authorization is up to $3.6 billion. Those are real, tangible things—not just talk.
Still, I’m not chasing a 35% gap. With gaps like this, the price could easily pull back to retest the level the same day.
There’s another interesting signal in perpetual futures: the funding rate is -0.52% every 8 hours, meaning shorts are still paying longs.
The spot index is 333, while perpetuals are at 329—perpetuals are actually cheaper than spot, which suggests traders chasing the move in perpetuals aren’t as frenzied as spot buyers.
Here are the scenarios.
If it holds above 343 and closes there, this won’t be just an earnings pop, and a move toward 360 looks pretty likely.
If it breaks below 317, the 24-hour volume-weighted average price, that would mean the earnings momentum has faded, with a move back to 300 to fill the gap.
If it breaks below 300, my bullish thesis in this post is invalidated, and I’ll admit this was just a one-day wonder.
What I’m planning to do.
I never chase a gap, so I’ll watch from the sidelines and wait to see if it holds above 343 or pulls back to 317.
I believe the earnings, but not the price. Chasing it at this level leaves too little room for error.
If you had to pick one: does it hold above 343 and charge toward 360, or break below 317 and fall back to 300 to fill the gap? I’m betting on a run to 360, but I’m not chasing it. What about you?
$APP $ARM $SOXL
#AppLovin #Earnings
First, where I stand: I’m on the bulls’ side this time, but I’m not chasing it higher.
Let’s start with the numbers.
After the U.S. market closed last night, APP reported Q3 revenue of $2.185 billion, up 55% year over year, versus expectations of just over $2.07 billion.
EPS was $4.30, against expectations of $4.03 and just $2.45 in the same quarter last year.
Net income was $1.439 billion, up 72% year over year, with a 66% net margin. Adjusted EBITDA was $1.842 billion, with an 84% margin.
Put simply, earnings are growing faster than revenue. There’s not much to poke holes in with this report.
Even more impressive was the guidance: Q4 revenue is forecast at $2.365–$2.395 billion, while Wall Street expected around $2.25 billion.
Adjusted EBITDA guidance is $1.995–$2.025 billion, also well above the $1.88 billion consensus.
Free cash flow came in at $1.4 billion for the quarter, and the board added $3.2 billion to its buyback authorization, bringing the total authorization to $3.6 billion.
This goes beyond simply calling it a beat—it was a beat across the board.
By the way, ARM also beat earnings next door, but its perpetual futures still fell 8%, and SOXL was down 12% in a single day.
APP’s 35% move is a solo act, not a sector-wide rally.
The bull case.
The ad business is genuinely making money after upgrades to its AI models. Gaming revenue rose nearly 50% year over year, and consumer spending grew by triple digits.
The explanation for the Q2 miss—that the model upgrade was a few days late—holds up. This quarter, they made up for it and then some.
With the buyback and higher guidance, management isn’t even pretending to be cautious anymore.
The bear case.
But don’t get carried away: APP has been falling from its high of 614 this year, and it even touched 228 last Friday.
At the end of October, UBS cut its price target from 790 to 414, RBC cut theirs from 575 to 500, and Zacks went straight to a Sell rating.
It missed once in Q2. The model-upgrade explanation worked this time, but that doesn’t mean it will work next time.
And perpetual futures are already up 35% today. The current price is 329.5, just a hair below the 24-hour high of 343. If you chase it here, you’re just providing an exit for the first buyers from earnings night.
My take.
Both the bulls and bears make good points, but I put more faith in the numbers.
Guidance is 6% above expectations, and the buyback authorization is up to $3.6 billion. Those are real, tangible things—not just talk.
Still, I’m not chasing a 35% gap. With gaps like this, the price could easily pull back to retest the level the same day.
There’s another interesting signal in perpetual futures: the funding rate is -0.52% every 8 hours, meaning shorts are still paying longs.
The spot index is 333, while perpetuals are at 329—perpetuals are actually cheaper than spot, which suggests traders chasing the move in perpetuals aren’t as frenzied as spot buyers.
Here are the scenarios.
If it holds above 343 and closes there, this won’t be just an earnings pop, and a move toward 360 looks pretty likely.
If it breaks below 317, the 24-hour volume-weighted average price, that would mean the earnings momentum has faded, with a move back to 300 to fill the gap.
If it breaks below 300, my bullish thesis in this post is invalidated, and I’ll admit this was just a one-day wonder.
What I’m planning to do.
I never chase a gap, so I’ll watch from the sidelines and wait to see if it holds above 343 or pulls back to 317.
I believe the earnings, but not the price. Chasing it at this level leaves too little room for error.
If you had to pick one: does it hold above 343 and charge toward 360, or break below 317 and fall back to 300 to fill the gap? I’m betting on a run to 360, but I’m not chasing it. What about you?
$APP $ARM $SOXL
#AppLovin #Earnings
AudreyGM:
我偏向先震荡洗一轮,负费率是空头交房租,不是多头免死金牌😂 343能不能放量站稳,比直接喊360更有看头。
1
993
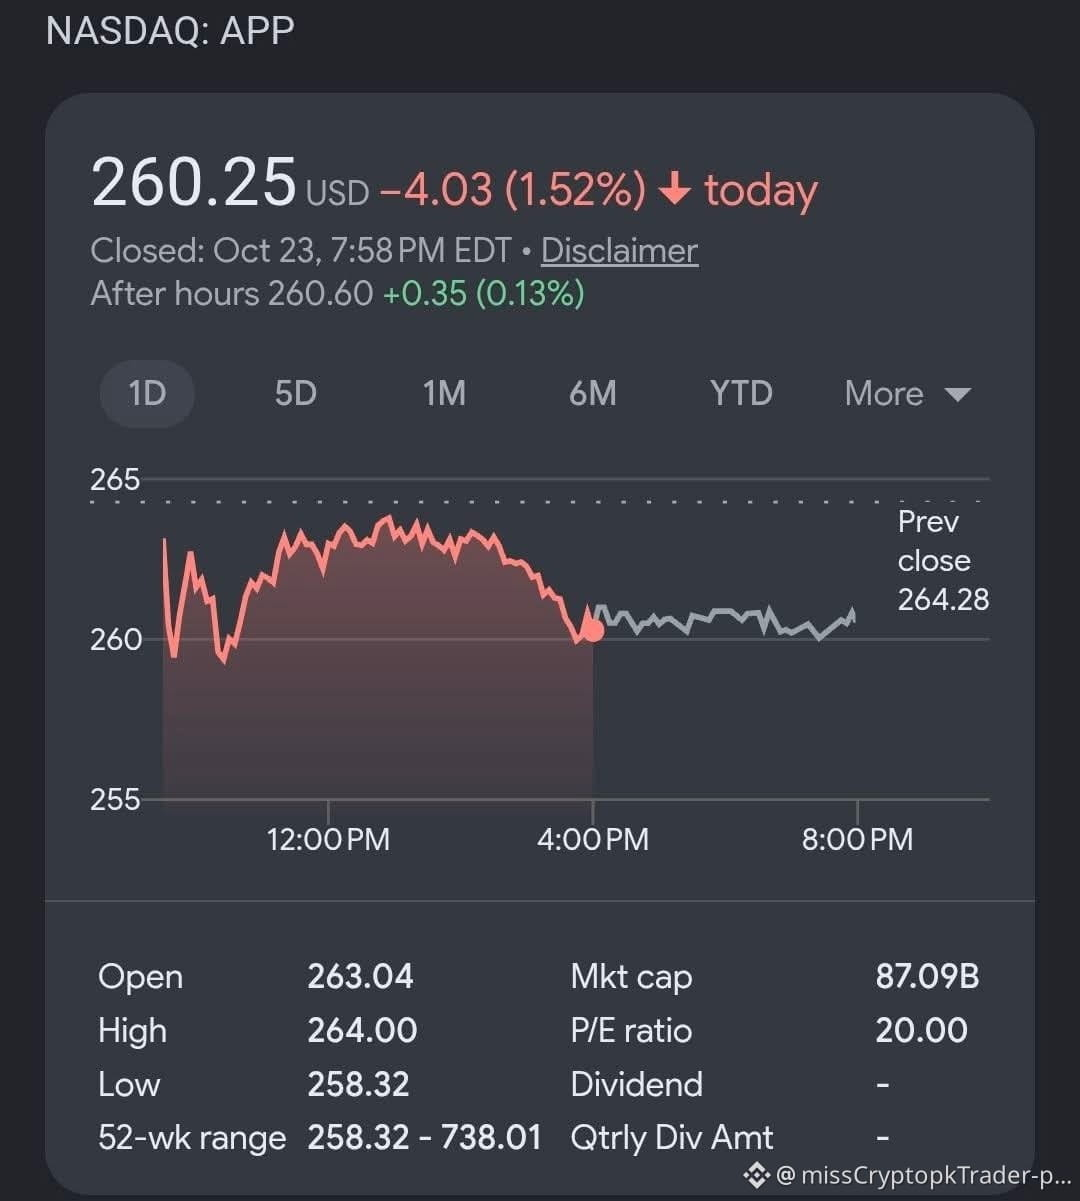
*APPB - $325.42 - $APPB *
AppLovin Corp Tokenized bStocks - A tokenized version of AppLovin (APP) stock on Binance, giving you economic exposure to the real AppLovin stock and convertible into the original stock.
Price: $325.42
Underlying APP stock price: $271.75
52-week high: $738.01
52-week low: $225.19
*Support:*
- Support 1: $303.76
- Support 2: $268.22
- Strong support 3: $234.91
*Resistance:*
- Resistance 1: $338.34
- Resistance 2: $412.31 - 200-day average
- Resistance 3: $490 - Analysts' target
Original stock market cap: $76.47B
APPB circulating supply: ∼6,376
Sector: Media / mobile advertising and AI
*Analysis:*
APP rose +10.69% yesterday, from $245.51 to $271.75, bouncing strongly from the bottom after falling -59% year-to-date due to AI concerns.
APPB is priced at $325.42, above the underlying stock. This is the tokenized pricing difference—focus on the underlying stock price as an indicator.
A break above $338 opens the way to $412, and holding above it would completely change the downtrend.
Warning: The stock is below all major moving averages and still facing class-action lawsuits. High volatility, Beta 2.52.
#APPB #APP #AppLovin
$APPB
{spot}(APPBUSDT)
*APPB - $325.42 - $APPB *
AppLovin Corp Tokenized bStocks - A tokenized version of AppLovin (APP) stock on Binance, giving you economic exposure to the real AppLovin stock and convertible into the original stock.
Price: $325.42
Underlying APP stock price: $271.75
52-week high: $738.01
52-week low: $225.19
*Support:*
- Support 1: $303.76
- Support 2: $268.22
- Strong support 3: $234.91
*Resistance:*
- Resistance 1: $338.34
- Resistance 2: $412.31 - 200-day average
- Resistance 3: $490 - Analysts' target
Original stock market cap: $76.47B
APPB circulating supply: ∼6,376
Sector: Media / mobile advertising and AI
*Analysis:*
APP rose +10.69% yesterday, from $245.51 to $271.75, bouncing strongly from the bottom after falling -59% year-to-date due to AI concerns.
APPB is priced at $325.42, above the underlying stock. This is the tokenized pricing difference—focus on the underlying stock price as an indicator.
A break above $338 opens the way to $412, and holding above it would completely change the downtrend.
Warning: The stock is below all major moving averages and still facing class-action lawsuits. High volatility, Beta 2.52.
#APPB #APP #AppLovin
$APPB
AppLovin Corp Tokenized bStocks - A tokenized version of AppLovin (APP) stock on Binance, giving you economic exposure to the real AppLovin stock and convertible into the original stock.
Price: $325.42
Underlying APP stock price: $271.75
52-week high: $738.01
52-week low: $225.19
*Support:*
- Support 1: $303.76
- Support 2: $268.22
- Strong support 3: $234.91
*Resistance:*
- Resistance 1: $338.34
- Resistance 2: $412.31 - 200-day average
- Resistance 3: $490 - Analysts' target
Original stock market cap: $76.47B
APPB circulating supply: ∼6,376
Sector: Media / mobile advertising and AI
*Analysis:*
APP rose +10.69% yesterday, from $245.51 to $271.75, bouncing strongly from the bottom after falling -59% year-to-date due to AI concerns.
APPB is priced at $325.42, above the underlying stock. This is the tokenized pricing difference—focus on the underlying stock price as an indicator.
A break above $338 opens the way to $412, and holding above it would completely change the downtrend.
Warning: The stock is below all major moving averages and still facing class-action lawsuits. High volatility, Beta 2.52.
#APPB #APP #AppLovin
$APPB
1
94
AppLovin’s earnings report left Wall Street stunned: Q3 revenue was $2.18 billion, up 55% year over year; net income was $1.44 billion, up 72%, with a 66% net margin; free cash flow was about $1.4 billion. Its Q4 guidance of $2.365 billion to $2.395 billion topped the market forecast of $2.25 billion, and the board added $3.2 billion to its buyback program. The stock rose 10.7% intraday to close at $271.75, then jumped another 23% after hours to $334—up about 35% across both sessions from the previous close. But it’s still down nearly 60% for the year, and remains roughly 50% below its June high of $614. So, is this the start of a turnaround, or just a bounce after a steep drop? Pick a side: A. A 66% net margin and better-than-expected guidance—turnarounds start with earnings reports like this; B. A stock down 60% for the year has to bounce 35% just to get back to where it was—don’t rush to call it a turnaround.
$BTC $ETH $SOL
#美股 #财报 #AppLovin
AppLovin’s earnings report left Wall Street stunned: Q3 revenue was $2.18 billion, up 55% year over year; net income was $1.44 billion, up 72%, with a 66% net margin; free cash flow was about $1.4 billion. Its Q4 guidance of $2.365 billion to $2.395 billion topped the market forecast of $2.25 billion, and the board added $3.2 billion to its buyback program. The stock rose 10.7% intraday to close at $271.75, then jumped another 23% after hours to $334—up about 35% across both sessions from the previous close. But it’s still down nearly 60% for the year, and remains roughly 50% below its June high of $614. So, is this the start of a turnaround, or just a bounce after a steep drop? Pick a side: A. A 66% net margin and better-than-expected guidance—turnarounds start with earnings reports like this; B. A stock down 60% for the year has to bounce 35% just to get back to where it was—don’t rush to call it a turnaround.
$BTC $ETH $SOL
#美股 #财报 #AppLovin
$BTC $ETH $SOL
#美股 #财报 #AppLovin
151

AppLovin surged as much as 19% after hours, with both its earnings and next-quarter guidance beating market expectations. It was arguably the strongest AI application performance of this earnings season.
A few personal thoughts:
First, what the market is really rewarding isn’t revenue growth, but the margin expansion driven by the AXON AI engine. Once an ad tech company makes ad targeting efficiency compound, its valuation story shifts from “cyclical ad stock” to “AI application stock.” That’s what drove investors to pay a premium after hours.
Second, AppLovin is deeply tied to mobile gaming and mobile app user acquisition. Its better-than-expected guidance suggests that end-market ad demand is recovering. That’s a marginal positive for GameFi and blockchain gaming: if user acquisition costs remain reasonable, projects will have more room to attract users and survive.
Third, in the context of the crypto market, repeated strong results from U.S. tech giants support overall risk appetite. A stronger Nasdaq and improving sentiment toward risk assets typically benefit high-beta assets like $BTC indirectly. But earnings ultimately drive individual stock performance, so it’s unwise to extrapolate that directly to crypto.
In short, the AI-driven profit potential of traditional tech stocks is building up. A recovery in risk appetite is unlikely to leave the crypto market entirely untouched, but liquidity remains the master switch to watch.
#AppLovin #美股财报 #AI Applications
AppLovin surged as much as 19% after hours, with both its earnings and next-quarter guidance beating market expectations. It was arguably the strongest AI application performance of this earnings season.
A few personal thoughts:
First, what the market is really rewarding isn’t revenue growth, but the margin expansion driven by the AXON AI engine. Once an ad tech company makes ad targeting efficiency compound, its valuation story shifts from “cyclical ad stock” to “AI application stock.” That’s what drove investors to pay a premium after hours.
Second, AppLovin is deeply tied to mobile gaming and mobile app user acquisition. Its better-than-expected guidance suggests that end-market ad demand is recovering. That’s a marginal positive for GameFi and blockchain gaming: if user acquisition costs remain reasonable, projects will have more room to attract users and survive.
Third, in the context of the crypto market, repeated strong results from U.S. tech giants support overall risk appetite. A stronger Nasdaq and improving sentiment toward risk assets typically benefit high-beta assets like $BTC indirectly. But earnings ultimately drive individual stock performance, so it’s unwise to extrapolate that directly to crypto.
In short, the AI-driven profit potential of traditional tech stocks is building up. A recovery in risk appetite is unlikely to leave the crypto market entirely untouched, but liquidity remains the master switch to watch.
#AppLovin #美股财报 #AI Applications
A few personal thoughts:
First, what the market is really rewarding isn’t revenue growth, but the margin expansion driven by the AXON AI engine. Once an ad tech company makes ad targeting efficiency compound, its valuation story shifts from “cyclical ad stock” to “AI application stock.” That’s what drove investors to pay a premium after hours.
Second, AppLovin is deeply tied to mobile gaming and mobile app user acquisition. Its better-than-expected guidance suggests that end-market ad demand is recovering. That’s a marginal positive for GameFi and blockchain gaming: if user acquisition costs remain reasonable, projects will have more room to attract users and survive.
Third, in the context of the crypto market, repeated strong results from U.S. tech giants support overall risk appetite. A stronger Nasdaq and improving sentiment toward risk assets typically benefit high-beta assets like $BTC indirectly. But earnings ultimately drive individual stock performance, so it’s unwise to extrapolate that directly to crypto.
In short, the AI-driven profit potential of traditional tech stocks is building up. A recovery in risk appetite is unlikely to leave the crypto market entirely untouched, but liquidity remains the master switch to watch.
#AppLovin #美股财报 #AI Applications
1

After AppLovin released its earnings, its shares surged as much as 19% in after-hours trading. Revenue and next-quarter guidance both topped market expectations, once again showcasing the remarkable monetization resilience of this AI-ad-engine-driven company.
A few observations:
1. The market had broadly worried that the mobile ad cycle was peaking and growth was slowing. Instead, the company delivered even stronger guidance, suggesting that advertisers’ budgets are continuing to concentrate on automated ad platforms with high ROI—and that the Matthew effect is intensifying.
2. The surge was fundamentally driven by the “expectations gap.” When consensus expectations are pushed low enough, a solid earnings report that beats expectations can be enough to trigger short covering and momentum buying, instantly amplifying the stock’s price sensitivity.
3. Looking at the broader market, earnings beats from tech leaders can help restore overall risk appetite. A recovery in U.S. equity risk sentiment often spills over through both capital flows and investor sentiment, and crypto assets can also benefit from this more permissive trading environment.
The logic of earnings season is actually quite simple: in a high-interest-rate environment, investors are only willing to pay a premium for “real growth that can be delivered.” No matter how compelling the story, it’s less convincing than solid guidance.
#美股 #AppLovin #EarningsSeason
After AppLovin released its earnings, its shares surged as much as 19% in after-hours trading. Revenue and next-quarter guidance both topped market expectations, once again showcasing the remarkable monetization resilience of this AI-ad-engine-driven company.
A few observations:
1. The market had broadly worried that the mobile ad cycle was peaking and growth was slowing. Instead, the company delivered even stronger guidance, suggesting that advertisers’ budgets are continuing to concentrate on automated ad platforms with high ROI—and that the Matthew effect is intensifying.
2. The surge was fundamentally driven by the “expectations gap.” When consensus expectations are pushed low enough, a solid earnings report that beats expectations can be enough to trigger short covering and momentum buying, instantly amplifying the stock’s price sensitivity.
3. Looking at the broader market, earnings beats from tech leaders can help restore overall risk appetite. A recovery in U.S. equity risk sentiment often spills over through both capital flows and investor sentiment, and crypto assets can also benefit from this more permissive trading environment.
The logic of earnings season is actually quite simple: in a high-interest-rate environment, investors are only willing to pay a premium for “real growth that can be delivered.” No matter how compelling the story, it’s less convincing than solid guidance.
#美股 #AppLovin #EarningsSeason
A few observations:
1. The market had broadly worried that the mobile ad cycle was peaking and growth was slowing. Instead, the company delivered even stronger guidance, suggesting that advertisers’ budgets are continuing to concentrate on automated ad platforms with high ROI—and that the Matthew effect is intensifying.
2. The surge was fundamentally driven by the “expectations gap.” When consensus expectations are pushed low enough, a solid earnings report that beats expectations can be enough to trigger short covering and momentum buying, instantly amplifying the stock’s price sensitivity.
3. Looking at the broader market, earnings beats from tech leaders can help restore overall risk appetite. A recovery in U.S. equity risk sentiment often spills over through both capital flows and investor sentiment, and crypto assets can also benefit from this more permissive trading environment.
The logic of earnings season is actually quite simple: in a high-interest-rate environment, investors are only willing to pay a premium for “real growth that can be delivered.” No matter how compelling the story, it’s less convincing than solid guidance.
#美股 #AppLovin #EarningsSeason
·
--
Another earnings-season standout has emerged. Mobile marketing technology company AppLovin surged about 19% after hours. The rationale is straightforward: its latest quarterly revenue and profit both beat market expectations, and its guidance for next quarter also came in above consensus—delivering two surprises at once: results and outlook.
Why is the market willing to assign it such a high premium? The key is its AI-powered ad delivery engine, AXON, which turns algorithmic recommendation capabilities directly into better returns on advertisers’ spending. It boosts efficiency both in customer acquisition and monetization, driving revenue growth and profit margins higher at the same time. In an environment where the aftereffects of high interest rates have yet to fade, few companies can tell both a “growth story” and a “profitability story” convincingly, so investors are naturally willing to pay a premium.
There’s also a takeaway for the crypto world: traditional investors are once again embracing assets with “real cash flow” and the ability to “put AI to work.” Once risk appetite recovers, optimism often spills over, making mainstream risk assets such as Bitcoin more likely to benefit. Of course, an after-hours spike doesn’t mean a trend is firmly established. It remains to be seen whether the company can keep delivering on its guidance, and anyone chasing the rally should still leave a margin of safety.
#AppLovin #美股财报 #AI Applications
Another earnings-season standout has emerged. Mobile marketing technology company AppLovin surged about 19% after hours. The rationale is straightforward: its latest quarterly revenue and profit both beat market expectations, and its guidance for next quarter also came in above consensus—delivering two surprises at once: results and outlook.
Why is the market willing to assign it such a high premium? The key is its AI-powered ad delivery engine, AXON, which turns algorithmic recommendation capabilities directly into better returns on advertisers’ spending. It boosts efficiency both in customer acquisition and monetization, driving revenue growth and profit margins higher at the same time. In an environment where the aftereffects of high interest rates have yet to fade, few companies can tell both a “growth story” and a “profitability story” convincingly, so investors are naturally willing to pay a premium.
There’s also a takeaway for the crypto world: traditional investors are once again embracing assets with “real cash flow” and the ability to “put AI to work.” Once risk appetite recovers, optimism often spills over, making mainstream risk assets such as Bitcoin more likely to benefit. Of course, an after-hours spike doesn’t mean a trend is firmly established. It remains to be seen whether the company can keep delivering on its guidance, and anyone chasing the rally should still leave a margin of safety.
#AppLovin #美股财报 #AI Applications
Why is the market willing to assign it such a high premium? The key is its AI-powered ad delivery engine, AXON, which turns algorithmic recommendation capabilities directly into better returns on advertisers’ spending. It boosts efficiency both in customer acquisition and monetization, driving revenue growth and profit margins higher at the same time. In an environment where the aftereffects of high interest rates have yet to fade, few companies can tell both a “growth story” and a “profitability story” convincingly, so investors are naturally willing to pay a premium.
There’s also a takeaway for the crypto world: traditional investors are once again embracing assets with “real cash flow” and the ability to “put AI to work.” Once risk appetite recovers, optimism often spills over, making mainstream risk assets such as Bitcoin more likely to benefit. Of course, an after-hours spike doesn’t mean a trend is firmly established. It remains to be seen whether the company can keep delivering on its guidance, and anyone chasing the rally should still leave a margin of safety.
#AppLovin #美股财报 #AI Applications
3
Binance is listing five tokenized U.S. stocks tonight at 8: AppLovin, GE Vernova, and Bending Spoons, plus a pair of 2x leveraged long/short SK Hynix ETFs. Longs and shorts go head-to-head—time to place your bets. All five new pairs are USDT-margined and support trading bots, with fee-free instant conversion to BTC within an hour of launch. So, with U.S. markets closed but crypto still trading, are you jumping into AppLovin tonight, or waiting to see the 2x Hynix longs and shorts battle it out before placing your bet? Pick a side in the comments 👇
$BTC $ETH $SOL #币安 #代币化美股 #AppLovin
Binance is listing five tokenized U.S. stocks tonight at 8: AppLovin, GE Vernova, and Bending Spoons, plus a pair of 2x leveraged long/short SK Hynix ETFs. Longs and shorts go head-to-head—time to place your bets. All five new pairs are USDT-margined and support trading bots, with fee-free instant conversion to BTC within an hour of launch. So, with U.S. markets closed but crypto still trading, are you jumping into AppLovin tonight, or waiting to see the 2x Hynix longs and shorts battle it out before placing your bet? Pick a side in the comments 👇
$BTC $ETH $SOL #币安 #代币化美股 #AppLovin
$BTC $ETH $SOL #币安 #代币化美股 #AppLovin
8
AppLovin ($APP ) Stock: 53% Revenue Growth as AI Advertising Expands
AppLovin’s AI-powered Axon platform is driving major growth in digital advertising, while its expansion into e-commerce could open new opportunities.
📊 Q2 2026 Highlights:
- Revenue: $1.924B (+53% YoY)
- Net income: $1.267B (+55%)
- Adjusted EBITDA: $1.614B (+58%)
- Free cash flow: $863.3M
- Adjusted EBITDA margin: 83.9%
- Q3 revenue guidance: $2.055B–$2.085B
📈 What’s next? AI improvements, e-commerce expansion, and Q3 earnings expected November 4.
⚠️ Competition, slower growth, rising computing costs, and advertising-platform changes remain key risks.
Is AppLovin’s AI advertising growth sustainable?
$APP #AppLovin #AI #ArtificialIntelligence #TechStocks #StockMarket
Not financial advice. For informational purposes only.
$APP
AppLovin ($APP ) Stock: 53% Revenue Growth as AI Advertising Expands
AppLovin’s AI-powered Axon platform is driving major growth in digital advertising, while its expansion into e-commerce could open new opportunities.
📊 Q2 2026 Highlights:
- Revenue: $1.924B (+53% YoY)
- Net income: $1.267B (+55%)
- Adjusted EBITDA: $1.614B (+58%)
- Free cash flow: $863.3M
- Adjusted EBITDA margin: 83.9%
- Q3 revenue guidance: $2.055B–$2.085B
📈 What’s next? AI improvements, e-commerce expansion, and Q3 earnings expected November 4.
⚠️ Competition, slower growth, rising computing costs, and advertising-platform changes remain key risks.
Is AppLovin’s AI advertising growth sustainable?
$APP #AppLovin #AI #ArtificialIntelligence #TechStocks #StockMarket
Not financial advice. For informational purposes only.
$APP
AppLovin’s AI-powered Axon platform is driving major growth in digital advertising, while its expansion into e-commerce could open new opportunities.
📊 Q2 2026 Highlights:
- Revenue: $1.924B (+53% YoY)
- Net income: $1.267B (+55%)
- Adjusted EBITDA: $1.614B (+58%)
- Free cash flow: $863.3M
- Adjusted EBITDA margin: 83.9%
- Q3 revenue guidance: $2.055B–$2.085B
📈 What’s next? AI improvements, e-commerce expansion, and Q3 earnings expected November 4.
⚠️ Competition, slower growth, rising computing costs, and advertising-platform changes remain key risks.
Is AppLovin’s AI advertising growth sustainable?
$APP #AppLovin #AI #ArtificialIntelligence #TechStocks #StockMarket
Not financial advice. For informational purposes only.
$APP
1
1
340
·
--
Bullish
✅ The future of #AppLovin (APP) is closely tied to the growth of AI-powered app advertising technology and its expansion into e-commerce
📈 Future growth drivers
AXON AI tool: The core platform that helps optimize advertising performance and maintain high profit margins.
Expansion into e-commerce: Moving beyond traditional mobile gaming to tap into the broader retail market.
Self-service model: The AppLovin Ads platform is open to all advertisers, increasing its reach to more than 1 billion users per day.
✅ The future of #AppLovin (APP) is closely tied to the growth of AI-powered app advertising technology and its expansion into e-commerce
📈 Future growth drivers
AXON AI tool: The core platform that helps optimize advertising performance and maintain high profit margins.
Expansion into e-commerce: Moving beyond traditional mobile gaming to tap into the broader retail market.
Self-service model: The AppLovin Ads platform is open to all advertisers, increasing its reach to more than 1 billion users per day.
📈 Future growth drivers
AXON AI tool: The core platform that helps optimize advertising performance and maintain high profit margins.
Expansion into e-commerce: Moving beyond traditional mobile gaming to tap into the broader retail market.
Self-service model: The AppLovin Ads platform is open to all advertisers, increasing its reach to more than 1 billion users per day.
1
141
·
--
AppLovin plummeted 13% in a single day, and worries in the market about slowing growth in its e-commerce Pixel business have been fully reignited.
The company—once regarded as a benchmark in AI-advertising narratives over the past two years—has largely built its valuation thesis on a second growth curve driven by e-commerce Pixel. Once the marginal performance weakens—such as the number of Pixel merchant partners and conversion data—the high premium is immediately turned against it.
A few signals to pay attention to:
· The overall beta in the ad-tech segment is amplifying; sentiment has switched from “AI beneficiary stocks” to “growth thesis being disproven stocks”
· A slowdown in e-commerce ad spending is a leading indicator of cooling macro consumption
· Pullbacks in high-valuation growth stocks typically spill over into risk assets, including high-beta altcoins in the crypto market
For participants in the on-chain space, this kind of sentiment inflection point in TradFi is worth incorporating into your monitoring framework. Once the US stock AI narrative loosens, AI-themed sectors in crypto often face simultaneous pressure.
In the short term, there’s no need to chase from the left side; waiting for the earnings call to provide a steadier re-interpretation of the Pixel reporting metrics is more prudent.
#AppLovin #AI广告 #Market sentiment
AppLovin plummeted 13% in a single day, and worries in the market about slowing growth in its e-commerce Pixel business have been fully reignited.
The company—once regarded as a benchmark in AI-advertising narratives over the past two years—has largely built its valuation thesis on a second growth curve driven by e-commerce Pixel. Once the marginal performance weakens—such as the number of Pixel merchant partners and conversion data—the high premium is immediately turned against it.
A few signals to pay attention to:
· The overall beta in the ad-tech segment is amplifying; sentiment has switched from “AI beneficiary stocks” to “growth thesis being disproven stocks”
· A slowdown in e-commerce ad spending is a leading indicator of cooling macro consumption
· Pullbacks in high-valuation growth stocks typically spill over into risk assets, including high-beta altcoins in the crypto market
For participants in the on-chain space, this kind of sentiment inflection point in TradFi is worth incorporating into your monitoring framework. Once the US stock AI narrative loosens, AI-themed sectors in crypto often face simultaneous pressure.
In the short term, there’s no need to chase from the left side; waiting for the earnings call to provide a steadier re-interpretation of the Pixel reporting metrics is more prudent.
#AppLovin #AI广告 #Market sentiment
The company—once regarded as a benchmark in AI-advertising narratives over the past two years—has largely built its valuation thesis on a second growth curve driven by e-commerce Pixel. Once the marginal performance weakens—such as the number of Pixel merchant partners and conversion data—the high premium is immediately turned against it.
A few signals to pay attention to:
· The overall beta in the ad-tech segment is amplifying; sentiment has switched from “AI beneficiary stocks” to “growth thesis being disproven stocks”
· A slowdown in e-commerce ad spending is a leading indicator of cooling macro consumption
· Pullbacks in high-valuation growth stocks typically spill over into risk assets, including high-beta altcoins in the crypto market
For participants in the on-chain space, this kind of sentiment inflection point in TradFi is worth incorporating into your monitoring framework. Once the US stock AI narrative loosens, AI-themed sectors in crypto often face simultaneous pressure.
In the short term, there’s no need to chase from the left side; waiting for the earnings call to provide a steadier re-interpretation of the Pixel reporting metrics is more prudent.
#AppLovin #AI广告 #Market sentiment
171
·
--
AppLovin plunges 13% in a single day, with market focus shifting to the slowdown in growth of its e-commerce pixel business.
As a star stock in the ad-tech sector over the past two years, AppLovin’s valuation has largely been built on a second growth curve driven by e-commerce advertising. Once the expansion pace in the number of pixel-connected customers and conversion data hits a turning point, the market’s pricing for the high-growth narrative will quickly retreat.
This isn’t just a problem with one stock—it serves as a warning bell for the entire “AI + ad attribution” track: when incremental customers peak, the platform story has to be sustained by retention and ARPU, and the challenge suddenly becomes much steeper.
The lesson for the crypto community is equally direct—any valuation narrative that relies on “connection numbers/integration numbers” (whether L2, RWA, or AI agents) will not see a gentle drawdown once the growth metrics reverse course. The second derivative of the growth curve is the true pricing anchor.
#AppLovin #广告科技 #增长放缓
AppLovin plunges 13% in a single day, with market focus shifting to the slowdown in growth of its e-commerce pixel business.
As a star stock in the ad-tech sector over the past two years, AppLovin’s valuation has largely been built on a second growth curve driven by e-commerce advertising. Once the expansion pace in the number of pixel-connected customers and conversion data hits a turning point, the market’s pricing for the high-growth narrative will quickly retreat.
This isn’t just a problem with one stock—it serves as a warning bell for the entire “AI + ad attribution” track: when incremental customers peak, the platform story has to be sustained by retention and ARPU, and the challenge suddenly becomes much steeper.
The lesson for the crypto community is equally direct—any valuation narrative that relies on “connection numbers/integration numbers” (whether L2, RWA, or AI agents) will not see a gentle drawdown once the growth metrics reverse course. The second derivative of the growth curve is the true pricing anchor.
#AppLovin #广告科技 #增长放缓
As a star stock in the ad-tech sector over the past two years, AppLovin’s valuation has largely been built on a second growth curve driven by e-commerce advertising. Once the expansion pace in the number of pixel-connected customers and conversion data hits a turning point, the market’s pricing for the high-growth narrative will quickly retreat.
This isn’t just a problem with one stock—it serves as a warning bell for the entire “AI + ad attribution” track: when incremental customers peak, the platform story has to be sustained by retention and ARPU, and the challenge suddenly becomes much steeper.
The lesson for the crypto community is equally direct—any valuation narrative that relies on “connection numbers/integration numbers” (whether L2, RWA, or AI agents) will not see a gentle drawdown once the growth metrics reverse course. The second derivative of the growth curve is the true pricing anchor.
#AppLovin #广告科技 #增长放缓
110
AppLovin’s single-day plunge of 13% has led the market to start questioning the growth “myth” behind its e-commerce Pixel business.
Over the past year, the valuation of $APP was almost entirely built on the dual-wheel narrative of AI ads + e-commerce Pixel. Once Pixel’s merchant coverage growth slows quarter-over-quarter and ROI per customer hits a peak, high PE can’t hold up.
My observations:
· Advertising-tech stocks are fundamentally cyclical; AI is just an amplifier, not a get-out-of-jail card
· The e-commerce traffic tailwind is narrowing, and Shopify-style merchants’ budget growth for ad spend is already slowing
· The pace of institutional profit-taking often runs 2–3 quarters ahead of the underlying fundamentals
It’s also worth thinking about the crypto-market analogy. When overvalued growth stocks in TradFi get de-rated, it usually feeds through to risk appetite and is unfavorable for altcoin sentiment in the short term. On-chain AI segments are especially worth watching out for being liquidated in a “tied-to-the-wrong-crowd” selloff.
I won’t chase the dip, but I’ll put it on the “narrative fading” watchlist.
#AppLovin #广告科技 #Market Sentiment
AppLovin’s single-day plunge of 13% has led the market to start questioning the growth “myth” behind its e-commerce Pixel business.
Over the past year, the valuation of $APP was almost entirely built on the dual-wheel narrative of AI ads + e-commerce Pixel. Once Pixel’s merchant coverage growth slows quarter-over-quarter and ROI per customer hits a peak, high PE can’t hold up.
My observations:
· Advertising-tech stocks are fundamentally cyclical; AI is just an amplifier, not a get-out-of-jail card
· The e-commerce traffic tailwind is narrowing, and Shopify-style merchants’ budget growth for ad spend is already slowing
· The pace of institutional profit-taking often runs 2–3 quarters ahead of the underlying fundamentals
It’s also worth thinking about the crypto-market analogy. When overvalued growth stocks in TradFi get de-rated, it usually feeds through to risk appetite and is unfavorable for altcoin sentiment in the short term. On-chain AI segments are especially worth watching out for being liquidated in a “tied-to-the-wrong-crowd” selloff.
I won’t chase the dip, but I’ll put it on the “narrative fading” watchlist.
#AppLovin #广告科技 #Market Sentiment
Over the past year, the valuation of $APP was almost entirely built on the dual-wheel narrative of AI ads + e-commerce Pixel. Once Pixel’s merchant coverage growth slows quarter-over-quarter and ROI per customer hits a peak, high PE can’t hold up.
My observations:
· Advertising-tech stocks are fundamentally cyclical; AI is just an amplifier, not a get-out-of-jail card
· The e-commerce traffic tailwind is narrowing, and Shopify-style merchants’ budget growth for ad spend is already slowing
· The pace of institutional profit-taking often runs 2–3 quarters ahead of the underlying fundamentals
It’s also worth thinking about the crypto-market analogy. When overvalued growth stocks in TradFi get de-rated, it usually feeds through to risk appetite and is unfavorable for altcoin sentiment in the short term. On-chain AI segments are especially worth watching out for being liquidated in a “tied-to-the-wrong-crowd” selloff.
I won’t chase the dip, but I’ll put it on the “narrative fading” watchlist.
#AppLovin #广告科技 #Market Sentiment
32
·
--

Article
【AppLovin 2026 Q2 Earnings】 One chart to understand: Revenue $1.924 billion, up 53% year over year; adjusted EBITDA margin 84%$APP The strongest part of this Q2 earnings report is that while revenue maintained growth of 50% or more, profit margins were not dragged down. After the ad marketing platform expanded in scale, operating leverage continued to be released, and the Q3 guidance followed the same momentum.
First, let's look at the core data.
This quarter's revenue was $1.924 billion, up 53% year over year; net profit was $1.267 billion, up 55% year over year, with a net profit margin of 66%; diluted EPS was $3.76. Adjusted EBITDA was $1.614 billion, up 58% year over year. The growth rate continued to outpace revenue growth, indicating the revenue increase was not driven purely by scale expansion.
【AppLovin 2026 Q2 Earnings】 One chart to understand: Revenue $1.924 billion, up 53% year over year; adjusted EBITDA margin 84%
$APP The strongest part of this Q2 earnings report is that while revenue maintained growth of 50% or more, profit margins were not dragged down. After the ad marketing platform expanded in scale, operating leverage continued to be released, and the Q3 guidance followed the same momentum.
First, let's look at the core data.
This quarter's revenue was $1.924 billion, up 53% year over year; net profit was $1.267 billion, up 55% year over year, with a net profit margin of 66%; diluted EPS was $3.76. Adjusted EBITDA was $1.614 billion, up 58% year over year. The growth rate continued to outpace revenue growth, indicating the revenue increase was not driven purely by scale expansion.
First, let's look at the core data.
This quarter's revenue was $1.924 billion, up 53% year over year; net profit was $1.267 billion, up 55% year over year, with a net profit margin of 66%; diluted EPS was $3.76. Adjusted EBITDA was $1.614 billion, up 58% year over year. The growth rate continued to outpace revenue growth, indicating the revenue increase was not driven purely by scale expansion.
162
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceReopensWithdrawalsForMoreAssets
675,303 views
3,363 Discussing
2
#BTCRebounds80K
174,160 views
1,628 Discussing
3
#Binance98PercentReplenished
89,524 views
1,096 Discussing
4
#StrategySTRCResumesIssuanceAfterOver170Days
544 views
31 Discussing
5
#ADPUSPrivateEmployersAdd86000JobsInOctober
13,071 views
238 Discussing
6
#SouthKoreaSeeksCryptoTaxDelayUntil2029
3,003 views
45 Discussing
7
#USMidterms-WhatAreMarketsExpecting?
491,232 views
2,516 Discussing
8
#US10YearTreasuryYieldFallsTo4.845%
3,578 views
57 Discussing
9
#ZcashExpectsNU7ToMake$16MSproutZECInaccessible
440 views
10 Discussing
10
#AsianChipStocksRetreat
3,531 views
61 Discussing