
#qualcomm
qualcomm
4,992 views
38 Discussing
Hot
Latest

·
--
Article
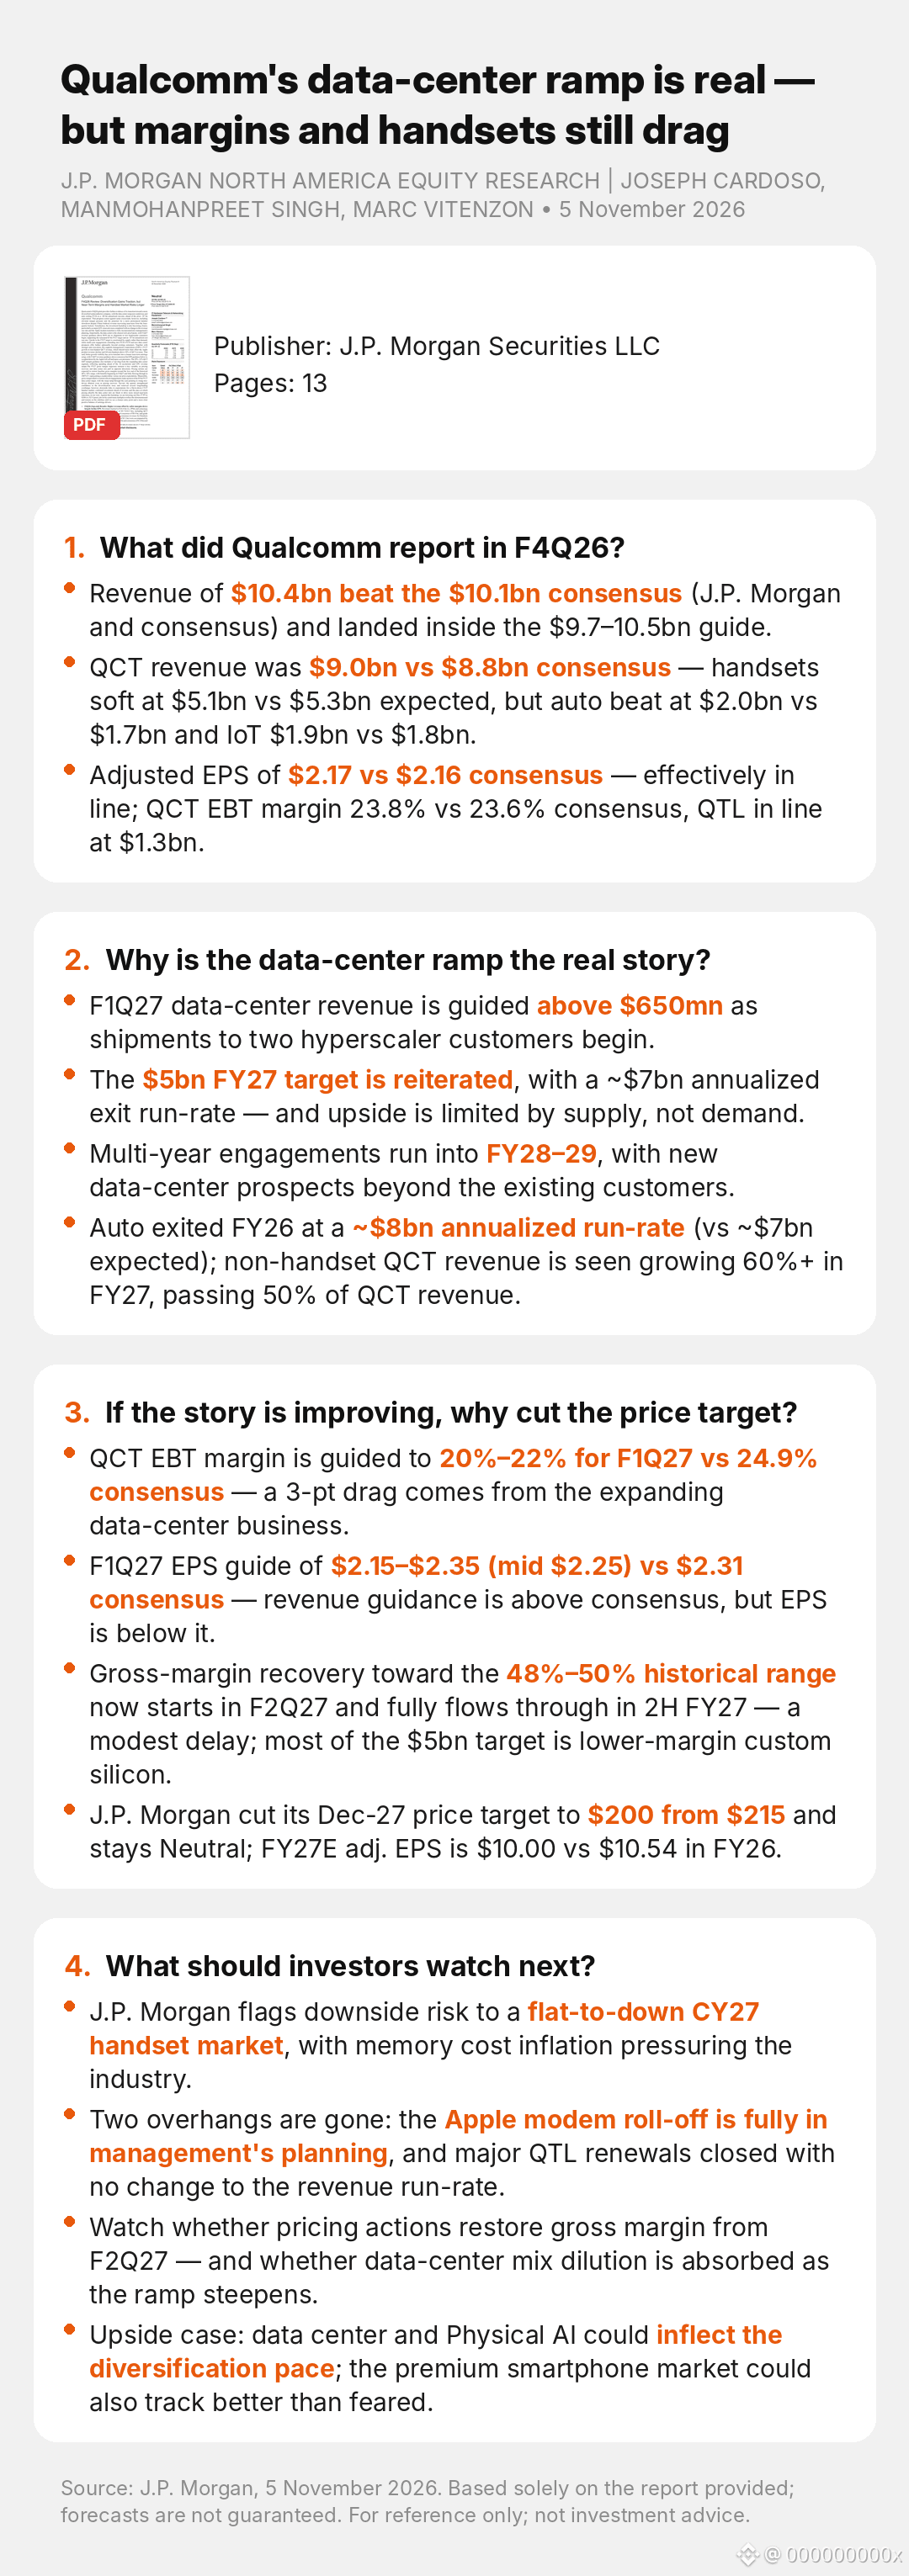
Qualcomm's data-center ramp is real — but margins and handsets still dragQualcomm's data-center ramp is real — but margins and handsets still drag
$QCOM
J.P. MORGAN NORTH AMERICA EQUITY RESEARCH | JOSEPH CARDOSO, MANMOHANPREET SINGH, MARC VITENZON • 5 November 2026
1. What did Qualcomm report in F4Q26?
• Revenue of $10.4bn beat the $10.1bn consensus (J.P. Morgan and consensus) and landed inside the $9.7–10.5bn guide.
• QCT revenue was $9.0bn vs $8.8bn consensus — handsets soft at $5.1bn vs $5.3bn expected, but auto beat at $2.0bn vs $1.7bn and IoT $1.9bn vs $1.8bn.
• Adjusted EPS of $2.17 vs $2.16 consensus — effectively in line; QCT EBT margin 23.8% vs 23.6% consensus, QTL in line at $1.3bn.
2. Why is the data-center ramp the real story?
• F1Q27 data-center revenue is guided above $650mn as shipments to two hyperscaler customers begin.
• The $5bn FY27 target is reiterated, with a ~$7bn annualized exit run-rate — and upside is limited by supply, not demand.
• Multi-year engagements run into FY28–29, with new data-center prospects beyond the existing customers.
• Auto exited FY26 at a ~$8bn annualized run-rate (vs ~$7bn expected); non-handset QCT revenue is seen growing 60%+ in FY27, passing 50% of QCT revenue.
3. If the story is improving, why cut the price target?
• QCT EBT margin is guided to 20%–22% for F1Q27 vs 24.9% consensus — a 3-pt drag comes from the expanding data-center business.
• F1Q27 EPS guide of $2.15–$2.35 (mid $2.25) vs $2.31 consensus — revenue guidance is above consensus, but EPS is below it.
• Gross-margin recovery toward the 48%–50% historical range now starts in F2Q27 and fully flows through in 2H FY27 — a modest delay; most of the $5bn target is lower-margin custom silicon.
• J.P. Morgan cut its Dec-27 price target to $200 from $215 and stays Neutral; FY27E adj. EPS is $10.00 vs $10.54 in FY26.
4. What should investors watch next?
• J.P. Morgan flags downside risk to a flat-to-down CY27 handset market, with memory cost inflation pressuring the industry.
• Two overhangs are gone: the Apple modem roll-off is fully in management's planning, and major QTL renewals closed with no change to the revenue run-rate.
• Watch whether pricing actions restore gross margin from F2Q27 — and whether data-center mix dilution is absorbed as the ramp steepens.
• Upside case: data center and Physical AI could inflect the diversification pace; the premium smartphone market could also track better than feared.
#Qualcomm #Semiconductors #AI #DataCenter #Smartphones
Source: J.P. Morgan, 5 November 2026. Research summary for reference only; forecasts are not guaranteed. Not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-3b12e316dbb84f2c9de3299332384e53-en
Visit unhidea.com for more of the latest sell-side research interpretations.
Qualcomm's data-center ramp is real — but margins and handsets still drag
Qualcomm's data-center ramp is real — but margins and handsets still drag
$QCOM
J.P. MORGAN NORTH AMERICA EQUITY RESEARCH | JOSEPH CARDOSO, MANMOHANPREET SINGH, MARC VITENZON • 5 November 2026
1. What did Qualcomm report in F4Q26?
• Revenue of $10.4bn beat the $10.1bn consensus (J.P. Morgan and consensus) and landed inside the $9.7–10.5bn guide.
• QCT revenue was $9.0bn vs $8.8bn consensus — handsets soft at $5.1bn vs $5.3bn expected, but auto beat at $2.0bn vs $1.7bn and IoT $1.9bn vs $1.8bn.
• Adjusted EPS of $2.17 vs $2.16 consensus — effectively in line; QCT EBT margin 23.8% vs 23.6% consensus, QTL in line at $1.3bn.
2. Why is the data-center ramp the real story?
• F1Q27 data-center revenue is guided above $650mn as shipments to two hyperscaler customers begin.
• The $5bn FY27 target is reiterated, with a ~$7bn annualized exit run-rate — and upside is limited by supply, not demand.
• Multi-year engagements run into FY28–29, with new data-center prospects beyond the existing customers.
• Auto exited FY26 at a ~$8bn annualized run-rate (vs ~$7bn expected); non-handset QCT revenue is seen growing 60%+ in FY27, passing 50% of QCT revenue.
3. If the story is improving, why cut the price target?
• QCT EBT margin is guided to 20%–22% for F1Q27 vs 24.9% consensus — a 3-pt drag comes from the expanding data-center business.
• F1Q27 EPS guide of $2.15–$2.35 (mid $2.25) vs $2.31 consensus — revenue guidance is above consensus, but EPS is below it.
• Gross-margin recovery toward the 48%–50% historical range now starts in F2Q27 and fully flows through in 2H FY27 — a modest delay; most of the $5bn target is lower-margin custom silicon.
• J.P. Morgan cut its Dec-27 price target to $200 from $215 and stays Neutral; FY27E adj. EPS is $10.00 vs $10.54 in FY26.
4. What should investors watch next?
• J.P. Morgan flags downside risk to a flat-to-down CY27 handset market, with memory cost inflation pressuring the industry.
• Two overhangs are gone: the Apple modem roll-off is fully in management's planning, and major QTL renewals closed with no change to the revenue run-rate.
• Watch whether pricing actions restore gross margin from F2Q27 — and whether data-center mix dilution is absorbed as the ramp steepens.
• Upside case: data center and Physical AI could inflect the diversification pace; the premium smartphone market could also track better than feared.
#Qualcomm #Semiconductors #AI #DataCenter #Smartphones
Source: J.P. Morgan, 5 November 2026. Research summary for reference only; forecasts are not guaranteed. Not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-3b12e316dbb84f2c9de3299332384e53-en
Visit unhidea.com for more of the latest sell-side research interpretations.
$QCOM
J.P. MORGAN NORTH AMERICA EQUITY RESEARCH | JOSEPH CARDOSO, MANMOHANPREET SINGH, MARC VITENZON • 5 November 2026
1. What did Qualcomm report in F4Q26?
• Revenue of $10.4bn beat the $10.1bn consensus (J.P. Morgan and consensus) and landed inside the $9.7–10.5bn guide.
• QCT revenue was $9.0bn vs $8.8bn consensus — handsets soft at $5.1bn vs $5.3bn expected, but auto beat at $2.0bn vs $1.7bn and IoT $1.9bn vs $1.8bn.
• Adjusted EPS of $2.17 vs $2.16 consensus — effectively in line; QCT EBT margin 23.8% vs 23.6% consensus, QTL in line at $1.3bn.
2. Why is the data-center ramp the real story?
• F1Q27 data-center revenue is guided above $650mn as shipments to two hyperscaler customers begin.
• The $5bn FY27 target is reiterated, with a ~$7bn annualized exit run-rate — and upside is limited by supply, not demand.
• Multi-year engagements run into FY28–29, with new data-center prospects beyond the existing customers.
• Auto exited FY26 at a ~$8bn annualized run-rate (vs ~$7bn expected); non-handset QCT revenue is seen growing 60%+ in FY27, passing 50% of QCT revenue.
3. If the story is improving, why cut the price target?
• QCT EBT margin is guided to 20%–22% for F1Q27 vs 24.9% consensus — a 3-pt drag comes from the expanding data-center business.
• F1Q27 EPS guide of $2.15–$2.35 (mid $2.25) vs $2.31 consensus — revenue guidance is above consensus, but EPS is below it.
• Gross-margin recovery toward the 48%–50% historical range now starts in F2Q27 and fully flows through in 2H FY27 — a modest delay; most of the $5bn target is lower-margin custom silicon.
• J.P. Morgan cut its Dec-27 price target to $200 from $215 and stays Neutral; FY27E adj. EPS is $10.00 vs $10.54 in FY26.
4. What should investors watch next?
• J.P. Morgan flags downside risk to a flat-to-down CY27 handset market, with memory cost inflation pressuring the industry.
• Two overhangs are gone: the Apple modem roll-off is fully in management's planning, and major QTL renewals closed with no change to the revenue run-rate.
• Watch whether pricing actions restore gross margin from F2Q27 — and whether data-center mix dilution is absorbed as the ramp steepens.
• Upside case: data center and Physical AI could inflect the diversification pace; the premium smartphone market could also track better than feared.
#Qualcomm #Semiconductors #AI #DataCenter #Smartphones
Source: J.P. Morgan, 5 November 2026. Research summary for reference only; forecasts are not guaranteed. Not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-3b12e316dbb84f2c9de3299332384e53-en
Visit unhidea.com for more of the latest sell-side research interpretations.
2

·
--
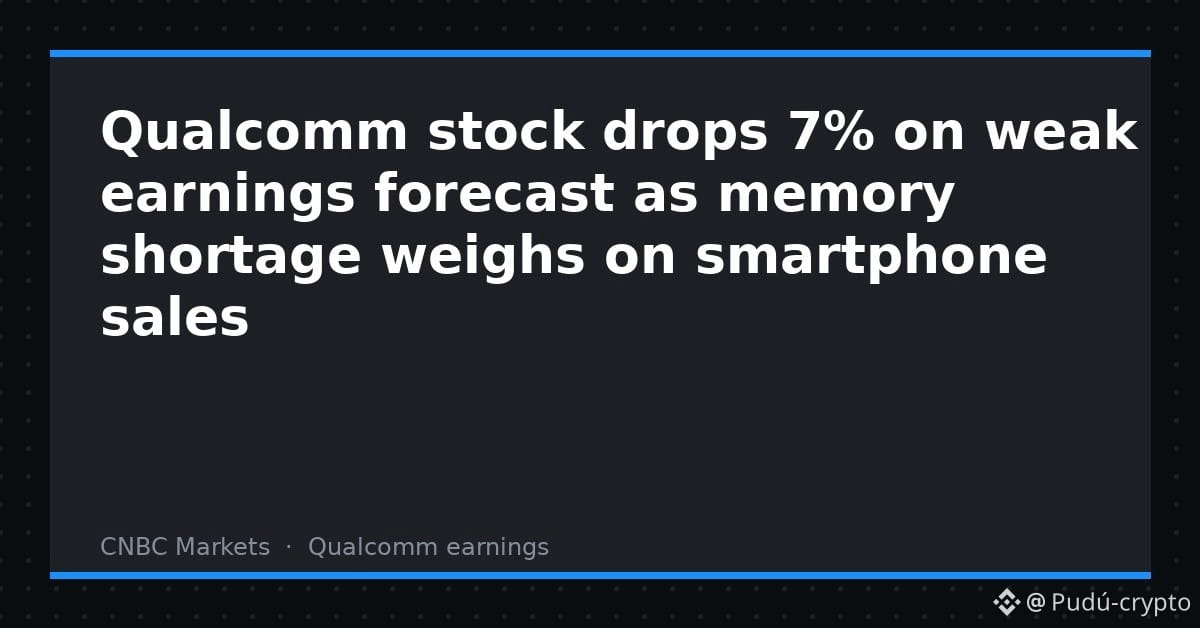
El mercado castigó a $QCOM tras su último informe.
Aunque superaron las expectativas en sus resultados recientes, las proyecciones futuras decepcionaron.
La empresa advirtió sobre una escasez de memoria que complica las ventas de teléfonos.
La acción cayó un 7% apenas se conocieron los números.
Es curioso ver cómo una previsión cautelosa pesa más que los resultados actuales.
¿Qué te parece esta reacción del mercado?
#Qualcomm #Acciones #Mercado
El mercado castigó a $QCOM tras su último informe.
Aunque superaron las expectativas en sus resultados recientes, las proyecciones futuras decepcionaron.
La empresa advirtió sobre una escasez de memoria que complica las ventas de teléfonos.
La acción cayó un 7% apenas se conocieron los números.
Es curioso ver cómo una previsión cautelosa pesa más que los resultados actuales.
¿Qué te parece esta reacción del mercado?
#Qualcomm #Acciones #Mercado
Aunque superaron las expectativas en sus resultados recientes, las proyecciones futuras decepcionaron.
La empresa advirtió sobre una escasez de memoria que complica las ventas de teléfonos.
La acción cayó un 7% apenas se conocieron los números.
Es curioso ver cómo una previsión cautelosa pesa más que los resultados actuales.
¿Qué te parece esta reacción del mercado?
#Qualcomm #Acciones #Mercado
162

·
--
Qualcomm mengalahkan ekspektasi laba — sahamnya justru jatuh lebih dari 7% setelah penutupan. Yang dihukum pasar bukan kuartal yang lewat, tapi panduan ke depan.
Fakta: Qualcomm (QCOM) melaporkan laba fiskal Q4 pada 4 Nov 2026 (Reuters, CNBC): pendapatan adjusted $10,44 miliar (−7% YoY) dan EPS adjusted $2,17 vs konsensus $2,16 — beat tipis. Tapi panduan kuartal Desember: EPS $2,15–$2,35, midpoint $2,25 di bawah ekspektasi $2,27. Saham ditutup naik 5,33% ke $173,19 di sesi reguler, lalu jatuh ke $160,25 (−7,47%) di after-hours. Catatan basis: pendapatan GAAP $10,32 miliar, berbeda dari angka adjusted di atas.
Konteks pasar: ini terjadi di hari pasar saham AS justru reli pasca-pemilu — Dow naik 1.569 poin (+3,03%) ke 53.356, Nasdaq +1,44%. Qualcomm jatuh melawan arus. Di kripto, BTC di sekitar $80.350 saat aku menulis ini, masih konsolidasi pasca-rebound.
Yang aku pantau selanjutnya: apakah penurunan after-hours bertahan di sesi reguler 5 Nov; margin bisnis chip-design yang dipandu 20–22% vs 24% di Q4; dan harga memori — CEO Cristiano Amon bilang ini masalah pasokan, bukan permintaan: "We don't have a demand issue; it's a supply issue."
Opiniku: ceritanya terbagi dua. Bisnis handset — masih yang terbesar — turun 26% ke $5,14 miliar, di bawah ekspektasi $5,21 miliar, karena biaya memori naik dan produsen ponsel menaikkan harga. Tapi otomotif melonjak 89% ke $1,99 miliar dan data center membukukan sekitar $650 juta di kuartal ini, dengan target $5 miliar di fiskal 2027. Pasar hari ini memilih menghukum margin yang tertekan, bukan memberi hadiah pada diversifikasi yang jalan.
Menurut kalian, pasar terlalu keras menghukum Qualcomm, atau panduan margin ini memang alasan yang sah untuk menjauh dulu?
Ini analisisku, bukan nasihat finansial — DYOR selalu.
#Qualcomm #Earnings
Qualcomm mengalahkan ekspektasi laba — sahamnya justru jatuh lebih dari 7% setelah penutupan. Yang dihukum pasar bukan kuartal yang lewat, tapi panduan ke depan.
Fakta: Qualcomm (QCOM) melaporkan laba fiskal Q4 pada 4 Nov 2026 (Reuters, CNBC): pendapatan adjusted $10,44 miliar (−7% YoY) dan EPS adjusted $2,17 vs konsensus $2,16 — beat tipis. Tapi panduan kuartal Desember: EPS $2,15–$2,35, midpoint $2,25 di bawah ekspektasi $2,27. Saham ditutup naik 5,33% ke $173,19 di sesi reguler, lalu jatuh ke $160,25 (−7,47%) di after-hours. Catatan basis: pendapatan GAAP $10,32 miliar, berbeda dari angka adjusted di atas.
Konteks pasar: ini terjadi di hari pasar saham AS justru reli pasca-pemilu — Dow naik 1.569 poin (+3,03%) ke 53.356, Nasdaq +1,44%. Qualcomm jatuh melawan arus. Di kripto, BTC di sekitar $80.350 saat aku menulis ini, masih konsolidasi pasca-rebound.
Yang aku pantau selanjutnya: apakah penurunan after-hours bertahan di sesi reguler 5 Nov; margin bisnis chip-design yang dipandu 20–22% vs 24% di Q4; dan harga memori — CEO Cristiano Amon bilang ini masalah pasokan, bukan permintaan: "We don't have a demand issue; it's a supply issue."
Opiniku: ceritanya terbagi dua. Bisnis handset — masih yang terbesar — turun 26% ke $5,14 miliar, di bawah ekspektasi $5,21 miliar, karena biaya memori naik dan produsen ponsel menaikkan harga. Tapi otomotif melonjak 89% ke $1,99 miliar dan data center membukukan sekitar $650 juta di kuartal ini, dengan target $5 miliar di fiskal 2027. Pasar hari ini memilih menghukum margin yang tertekan, bukan memberi hadiah pada diversifikasi yang jalan.
Menurut kalian, pasar terlalu keras menghukum Qualcomm, atau panduan margin ini memang alasan yang sah untuk menjauh dulu?
Ini analisisku, bukan nasihat finansial — DYOR selalu.
#Qualcomm #Earnings
Fakta: Qualcomm (QCOM) melaporkan laba fiskal Q4 pada 4 Nov 2026 (Reuters, CNBC): pendapatan adjusted $10,44 miliar (−7% YoY) dan EPS adjusted $2,17 vs konsensus $2,16 — beat tipis. Tapi panduan kuartal Desember: EPS $2,15–$2,35, midpoint $2,25 di bawah ekspektasi $2,27. Saham ditutup naik 5,33% ke $173,19 di sesi reguler, lalu jatuh ke $160,25 (−7,47%) di after-hours. Catatan basis: pendapatan GAAP $10,32 miliar, berbeda dari angka adjusted di atas.
Konteks pasar: ini terjadi di hari pasar saham AS justru reli pasca-pemilu — Dow naik 1.569 poin (+3,03%) ke 53.356, Nasdaq +1,44%. Qualcomm jatuh melawan arus. Di kripto, BTC di sekitar $80.350 saat aku menulis ini, masih konsolidasi pasca-rebound.
Yang aku pantau selanjutnya: apakah penurunan after-hours bertahan di sesi reguler 5 Nov; margin bisnis chip-design yang dipandu 20–22% vs 24% di Q4; dan harga memori — CEO Cristiano Amon bilang ini masalah pasokan, bukan permintaan: "We don't have a demand issue; it's a supply issue."
Opiniku: ceritanya terbagi dua. Bisnis handset — masih yang terbesar — turun 26% ke $5,14 miliar, di bawah ekspektasi $5,21 miliar, karena biaya memori naik dan produsen ponsel menaikkan harga. Tapi otomotif melonjak 89% ke $1,99 miliar dan data center membukukan sekitar $650 juta di kuartal ini, dengan target $5 miliar di fiskal 2027. Pasar hari ini memilih menghukum margin yang tertekan, bukan memberi hadiah pada diversifikasi yang jalan.
Menurut kalian, pasar terlalu keras menghukum Qualcomm, atau panduan margin ini memang alasan yang sah untuk menjauh dulu?
Ini analisisku, bukan nasihat finansial — DYOR selalu.
#Qualcomm #Earnings
29

·
--
Bullish
Qualcomm falls around 7% after hours as smartphone sales and margins face pressure
📉 Smartphone chip revenue fell 26% year over year to $5.14 billion in fiscal Q4 2026, missing expectations. Weakness in its core business overshadowed other positive developments.
🧩 AI data center demand is pushing memory costs higher, pressuring phone prices and demand. Qualcomm also faces rising manufacturing, packaging and testing costs.
📊 Next-quarter revenue guidance of $10.4–11.2 billion has a midpoint above expectations. However, adjusted EPS guidance centers on $2.25, below the $2.27 consensus, highlighting profitability pressures.
🚗 Automotive revenue rose 89% to $1.99 billion, supporting diversification. Smartphones still heavily influence overall results.
🔎 Key factors to watch are Qualcomm’s ability to pass higher costs through to customers, smartphone recovery and growth beyond handsets.
#Qualcomm $QCOMB
Qualcomm falls around 7% after hours as smartphone sales and margins face pressure
📉 Smartphone chip revenue fell 26% year over year to $5.14 billion in fiscal Q4 2026, missing expectations. Weakness in its core business overshadowed other positive developments.
🧩 AI data center demand is pushing memory costs higher, pressuring phone prices and demand. Qualcomm also faces rising manufacturing, packaging and testing costs.
📊 Next-quarter revenue guidance of $10.4–11.2 billion has a midpoint above expectations. However, adjusted EPS guidance centers on $2.25, below the $2.27 consensus, highlighting profitability pressures.
🚗 Automotive revenue rose 89% to $1.99 billion, supporting diversification. Smartphones still heavily influence overall results.
🔎 Key factors to watch are Qualcomm’s ability to pass higher costs through to customers, smartphone recovery and growth beyond handsets.
#Qualcomm $QCOMB
📉 Smartphone chip revenue fell 26% year over year to $5.14 billion in fiscal Q4 2026, missing expectations. Weakness in its core business overshadowed other positive developments.
🧩 AI data center demand is pushing memory costs higher, pressuring phone prices and demand. Qualcomm also faces rising manufacturing, packaging and testing costs.
📊 Next-quarter revenue guidance of $10.4–11.2 billion has a midpoint above expectations. However, adjusted EPS guidance centers on $2.25, below the $2.27 consensus, highlighting profitability pressures.
🚗 Automotive revenue rose 89% to $1.99 billion, supporting diversification. Smartphones still heavily influence overall results.
🔎 Key factors to watch are Qualcomm’s ability to pass higher costs through to customers, smartphone recovery and growth beyond handsets.
#Qualcomm $QCOMB
35

Qualcomm Faces a Semiconductor Sentiment Test 📉
Qualcomm slipped 3.74% to $158.30 as semiconductor shares faced renewed pressure following the U.S. midterm results. While major indexes advanced and the Dow reached a one-year high, investors reassessed expectations for AI data-center spending, creating a cautious backdrop for chipmakers.
{spot}(QCOMBUSDT)
{stock_us}(QCOM.US)
Qualcomm’s diversified business offers a different growth story through smartphones, automotive chips, licensing, and edge AI. The key signals ahead are handset demand, automotive expansion, licensing performance, and management’s AI outlook. Stronger edge-AI adoption could help distinguish QCOM from data-center-focused chip stocks, while broader sector valuation pressure may continue to influence sentiment.
$QCOMB $QCOM $QCOM.US #CoinVahini #Qualcomm #SemiconductorStocks #EdgeAI
Qualcomm Faces a Semiconductor Sentiment Test 📉
Qualcomm slipped 3.74% to $158.30 as semiconductor shares faced renewed pressure following the U.S. midterm results. While major indexes advanced and the Dow reached a one-year high, investors reassessed expectations for AI data-center spending, creating a cautious backdrop for chipmakers.
Qualcomm’s diversified business offers a different growth story through smartphones, automotive chips, licensing, and edge AI. The key signals ahead are handset demand, automotive expansion, licensing performance, and management’s AI outlook. Stronger edge-AI adoption could help distinguish QCOM from data-center-focused chip stocks, while broader sector valuation pressure may continue to influence sentiment.
$QCOMB $QCOM $QCOM.US #CoinVahini #Qualcomm #SemiconductorStocks #EdgeAI
Qualcomm slipped 3.74% to $158.30 as semiconductor shares faced renewed pressure following the U.S. midterm results. While major indexes advanced and the Dow reached a one-year high, investors reassessed expectations for AI data-center spending, creating a cautious backdrop for chipmakers.
Qualcomm’s diversified business offers a different growth story through smartphones, automotive chips, licensing, and edge AI. The key signals ahead are handset demand, automotive expansion, licensing performance, and management’s AI outlook. Stronger edge-AI adoption could help distinguish QCOM from data-center-focused chip stocks, while broader sector valuation pressure may continue to influence sentiment.
$QCOMB $QCOM $QCOM.US #CoinVahini #Qualcomm #SemiconductorStocks #EdgeAI
QCOMUS-5.46%
QCOMB+0.82%
36
·
--
Las acciones de $QCOM están sintiendo el golpe hoy.
La compañía enfrenta dos problemas bastante claros ahora mismo.
Por un lado, la pérdida de los pedidos de Apple.
Por otro, los altos costos de la memoria que frenan la demanda de teléfonos.
Es una combinación difícil de manejar para cualquier fabricante.
¿Qué te parece este panorama para la empresa?
#Qualcomm #TechNews
Las acciones de $QCOM están sintiendo el golpe hoy.
La compañía enfrenta dos problemas bastante claros ahora mismo.
Por un lado, la pérdida de los pedidos de Apple.
Por otro, los altos costos de la memoria que frenan la demanda de teléfonos.
Es una combinación difícil de manejar para cualquier fabricante.
¿Qué te parece este panorama para la empresa?
#Qualcomm #TechNews
La compañía enfrenta dos problemas bastante claros ahora mismo.
Por un lado, la pérdida de los pedidos de Apple.
Por otro, los altos costos de la memoria que frenan la demanda de teléfonos.
Es una combinación difícil de manejar para cualquier fabricante.
¿Qué te parece este panorama para la empresa?
#Qualcomm #TechNews
25
🚨 JUST IN: 🇺🇸 Qualcomm ($QCOM) has reportedly signed a multi-year deal with Elon Musk's SpaceX ($SPCX) to help build a new nationwide 5G cellular network.
📡 The partnership could mark a major step forward in next-generation wireless connectivity and expand competition in the U.S. telecom market.
🚀 Could this reshape the future of mobile connectivity?
#Qualcomm #SpaceX #ElonMusk #5G #TechNews
🚨 JUST IN: 🇺🇸 Qualcomm ($QCOM) has reportedly signed a multi-year deal with Elon Musk's SpaceX ($SPCX) to help build a new nationwide 5G cellular network.
📡 The partnership could mark a major step forward in next-generation wireless connectivity and expand competition in the U.S. telecom market.
🚀 Could this reshape the future of mobile connectivity?
#Qualcomm #SpaceX #ElonMusk #5G #TechNews
📡 The partnership could mark a major step forward in next-generation wireless connectivity and expand competition in the U.S. telecom market.
🚀 Could this reshape the future of mobile connectivity?
#Qualcomm #SpaceX #ElonMusk #5G #TechNews
33

QUALCOMM PARTNERSHIP WITH SAMSUNG ELECTRO-MECHANICS IS A GAME CHANGER FOR $QCOM 🔥
Samsung Electro-Mechanics has started mass production of packaging substrates for Qualcomm's AI accelerator, expanding their cooperation into the data center market. This move is expected to improve energy efficiency and accelerate the adoption of AI technology.
The partnership between Qualcomm and Samsung Electro-Mechanics is gaining momentum, with mass production of FC-BGA packaging substrates for the AI200 accelerator underway. This window of opportunity is narrowing fast, will you be investing in $QCOM as it expands into the data center market?
Not financial advice, manage your risk.
#Qualcomm #AI #DataCenter
#LongSetup #TechStocks
⚡️
QUALCOMM PARTNERSHIP WITH SAMSUNG ELECTRO-MECHANICS IS A GAME CHANGER FOR $QCOM 🔥
Samsung Electro-Mechanics has started mass production of packaging substrates for Qualcomm's AI accelerator, expanding their cooperation into the data center market. This move is expected to improve energy efficiency and accelerate the adoption of AI technology.
The partnership between Qualcomm and Samsung Electro-Mechanics is gaining momentum, with mass production of FC-BGA packaging substrates for the AI200 accelerator underway. This window of opportunity is narrowing fast, will you be investing in $QCOM as it expands into the data center market?
Not financial advice, manage your risk.
#Qualcomm #AI #DataCenter
#LongSetup #TechStocks
⚡️
Samsung Electro-Mechanics has started mass production of packaging substrates for Qualcomm's AI accelerator, expanding their cooperation into the data center market. This move is expected to improve energy efficiency and accelerate the adoption of AI technology.
The partnership between Qualcomm and Samsung Electro-Mechanics is gaining momentum, with mass production of FC-BGA packaging substrates for the AI200 accelerator underway. This window of opportunity is narrowing fast, will you be investing in $QCOM as it expands into the data center market?
Not financial advice, manage your risk.
#Qualcomm #AI #DataCenter
#LongSetup #TechStocks
⚡️
110

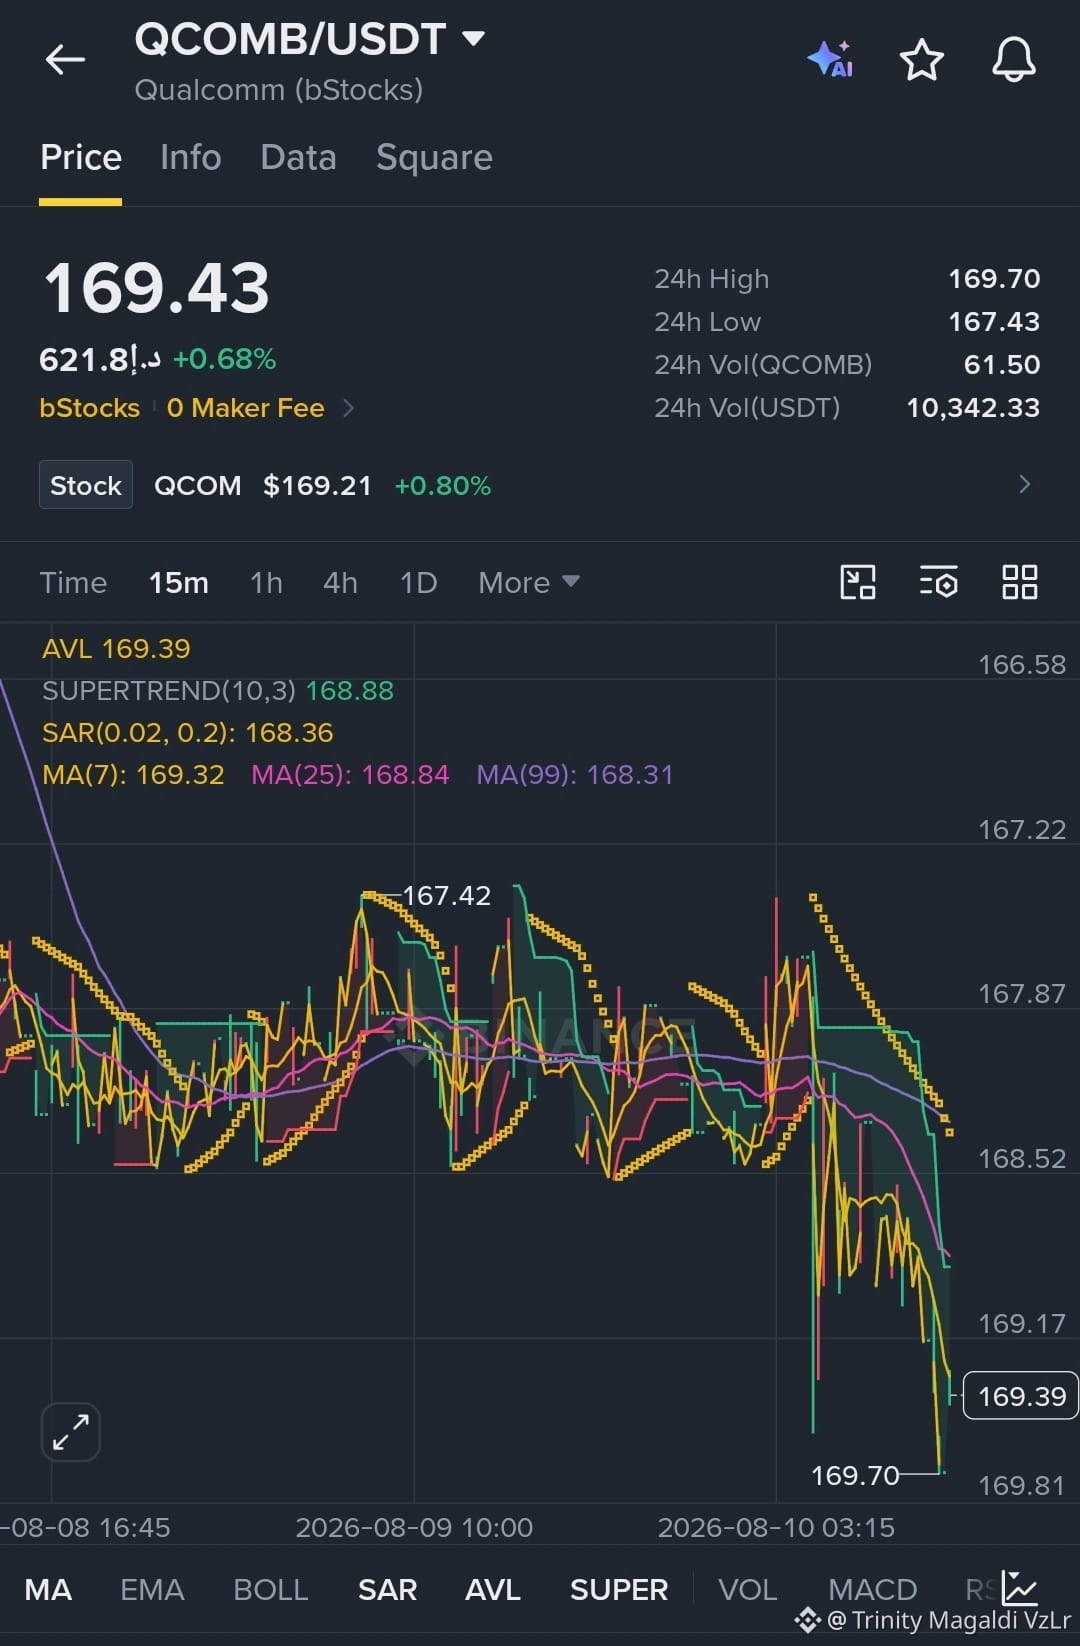
$QCOMB QCOMB is holding strong above key moving averages, with Supertrend support near $168.88 and price pressing $169.70 resistance. A breakout could signal renewed momentum in Qualcomm and related tech stocks. Traders should watch volume closely for confirmation before chasing the move.
#QCOMB #Qualcomm #Crypto #BinanceSquare
$GIGGLE
{spot}(GIGGLEUSDT)
$RIVER
{future}(RIVERUSDT)
$QCOMB QCOMB is holding strong above key moving averages, with Supertrend support near $168.88 and price pressing $169.70 resistance. A breakout could signal renewed momentum in Qualcomm and related tech stocks. Traders should watch volume closely for confirmation before chasing the move.
#QCOMB #Qualcomm #Crypto #BinanceSquare
$GIGGLE
$RIVER
#QCOMB #Qualcomm #Crypto #BinanceSquare
$GIGGLE
$RIVER
1
152
·
--
Qualcomm se mete de lleno en el terreno de los centros de datos.
La empresa acaba de cerrar un acuerdo con Amazon para infraestructura.
Buscan competir en un sector dominado totalmente por $NVDA durante el auge de la IA.
Es un movimiento estratégico bastante claro para diversificar su negocio fuera de los chips móviles.
¿Qué te parece este desafío para Nvidia?
#Qualcomm #Amazon #IA
Qualcomm se mete de lleno en el terreno de los centros de datos.
La empresa acaba de cerrar un acuerdo con Amazon para infraestructura.
Buscan competir en un sector dominado totalmente por $NVDA durante el auge de la IA.
Es un movimiento estratégico bastante claro para diversificar su negocio fuera de los chips móviles.
¿Qué te parece este desafío para Nvidia?
#Qualcomm #Amazon #IA
La empresa acaba de cerrar un acuerdo con Amazon para infraestructura.
Buscan competir en un sector dominado totalmente por $NVDA durante el auge de la IA.
Es un movimiento estratégico bastante claro para diversificar su negocio fuera de los chips móviles.
¿Qué te parece este desafío para Nvidia?
#Qualcomm #Amazon #IA
322
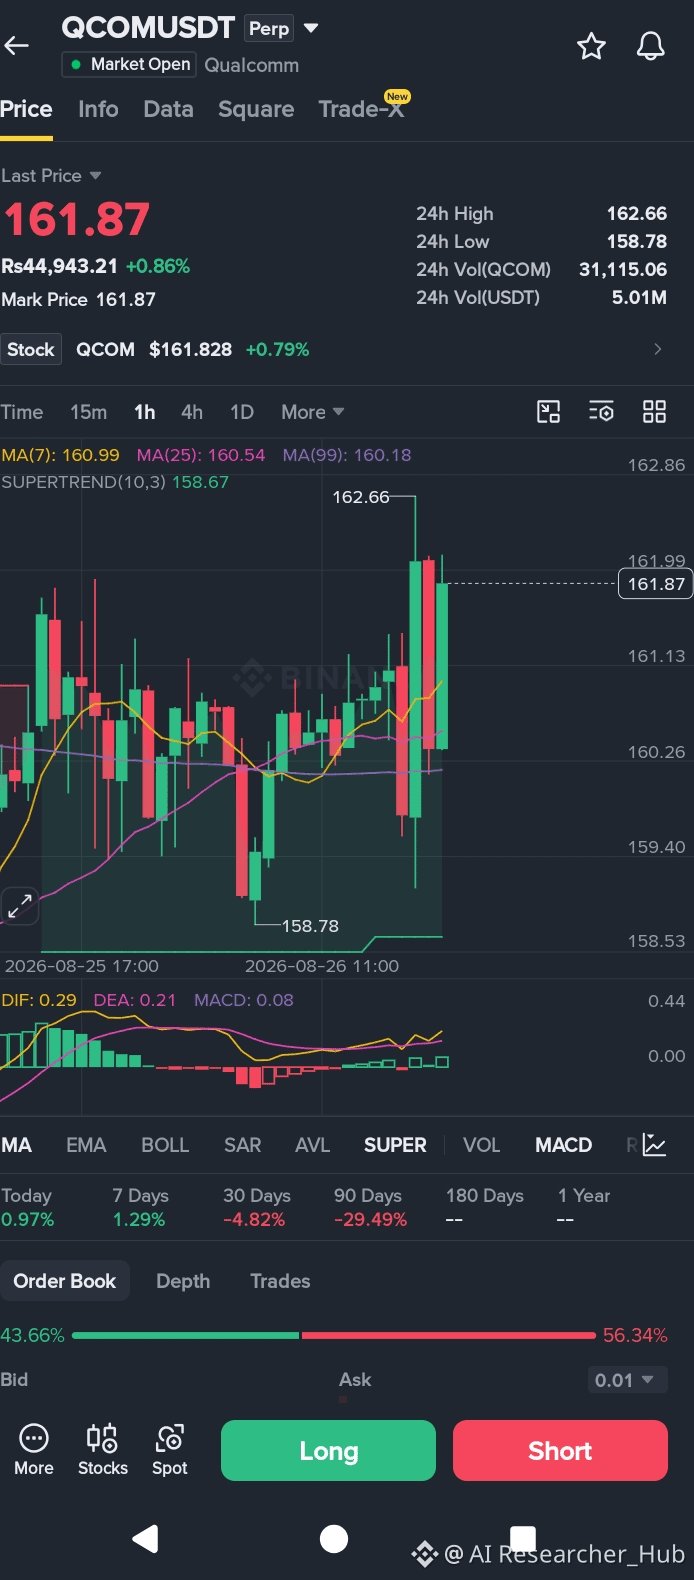
🚀 QCOM LONG SETUP — Bulls Taking Control!
$QCOM is showing strength on the 1H chart, holding above the MA(7), MA(25) & MA(99) with Supertrend still bullish. MACD is also turning positive 📈
🎯 Entry: 161.83
#
🎯 TP: 162.6
🎯 TP: 164.0
🎯 TP: 166.0
🛑 SL: 159.4
If 162.6 breaks with strong volume, QCOM could push higher. 🔥
Click $QCOM here to Trade 👇👇👇
{future}(QCOMUSDT)
#QCOM #Qualcomm #Crypto #BinanceSquare #LongSetup #Trading
🚀 QCOM LONG SETUP — Bulls Taking Control!
$QCOM is showing strength on the 1H chart, holding above the MA(7), MA(25) & MA(99) with Supertrend still bullish. MACD is also turning positive 📈
🎯 Entry: 161.83
#
🎯 TP: 162.6
🎯 TP: 164.0
🎯 TP: 166.0
🛑 SL: 159.4
If 162.6 breaks with strong volume, QCOM could push higher. 🔥
Click $QCOM here to Trade 👇👇👇
#QCOM #Qualcomm #Crypto #BinanceSquare #LongSetup #Trading
$QCOM is showing strength on the 1H chart, holding above the MA(7), MA(25) & MA(99) with Supertrend still bullish. MACD is also turning positive 📈
🎯 Entry: 161.83
#
🎯 TP: 162.6
🎯 TP: 164.0
🎯 TP: 166.0
🛑 SL: 159.4
If 162.6 breaks with strong volume, QCOM could push higher. 🔥
Click $QCOM here to Trade 👇👇👇
#QCOM #Qualcomm #Crypto #BinanceSquare #LongSetup #Trading
1
67
AMD JUST FLIPPED QUALCOMM. 💀
AMD vừa vượt Qualcomm để trở thành hãng bán dẫn fabless lớn thứ 3 thế giới.
Nói đơn giản: AMD không tự xây nhà máy sản xuất chip như Intel Foundry hay TSMC, mà tập trung vào thiết kế chip, sau đó thuê các foundry sản xuất.
Cuộc đua giờ nhìn khá thú vị:
NVIDIA: “AI is mine.”
AMD: “Not so fast.”
Qualcomm: “Wait… where did my #3 spot go?” 💀
AMD đang ngày càng mở rộng từ CPU, GPU sang AI accelerators và data center, khiến vị thế trong ngành bán dẫn tăng mạnh.
AMD DIDN’T BUILD THE FACTORY.
IT JUST BUILT BETTER CHIPS AND TOOK THE SPOT. 💀
Anh em nghĩ AMD có đủ sức đuổi NVIDIA trong cuộc đua AI chip, hay khoảng cách vẫn còn quá lớn?
#AMD #Qualcomm #Semiconductors
$AMDB
{spot}(AMDBUSDT)
AMD JUST FLIPPED QUALCOMM. 💀
AMD vừa vượt Qualcomm để trở thành hãng bán dẫn fabless lớn thứ 3 thế giới.
Nói đơn giản: AMD không tự xây nhà máy sản xuất chip như Intel Foundry hay TSMC, mà tập trung vào thiết kế chip, sau đó thuê các foundry sản xuất.
Cuộc đua giờ nhìn khá thú vị:
NVIDIA: “AI is mine.”
AMD: “Not so fast.”
Qualcomm: “Wait… where did my #3 spot go?” 💀
AMD đang ngày càng mở rộng từ CPU, GPU sang AI accelerators và data center, khiến vị thế trong ngành bán dẫn tăng mạnh.
AMD DIDN’T BUILD THE FACTORY.
IT JUST BUILT BETTER CHIPS AND TOOK THE SPOT. 💀
Anh em nghĩ AMD có đủ sức đuổi NVIDIA trong cuộc đua AI chip, hay khoảng cách vẫn còn quá lớn?
#AMD #Qualcomm #Semiconductors
$AMDB
AMD vừa vượt Qualcomm để trở thành hãng bán dẫn fabless lớn thứ 3 thế giới.
Nói đơn giản: AMD không tự xây nhà máy sản xuất chip như Intel Foundry hay TSMC, mà tập trung vào thiết kế chip, sau đó thuê các foundry sản xuất.
Cuộc đua giờ nhìn khá thú vị:
NVIDIA: “AI is mine.”
AMD: “Not so fast.”
Qualcomm: “Wait… where did my #3 spot go?” 💀
AMD đang ngày càng mở rộng từ CPU, GPU sang AI accelerators và data center, khiến vị thế trong ngành bán dẫn tăng mạnh.
AMD DIDN’T BUILD THE FACTORY.
IT JUST BUILT BETTER CHIPS AND TOOK THE SPOT. 💀
Anh em nghĩ AMD có đủ sức đuổi NVIDIA trong cuộc đua AI chip, hay khoảng cách vẫn còn quá lớn?
#AMD #Qualcomm #Semiconductors
$AMDB
49
" #Alphabet Discloses $548M #Qualcomm Stake as Data Center Expansion Accelerates 👍 "
Institutional tech sector filings highlight strategic corporate positionings across semiconductor and artificial intelligence infrastructure:-
* Stake Disclosure:
Alphabet disclosed a new Qualcomm stake valued at approximately $548 million at the end of the third quarter.
* Premarket Reaction:
Qualcomm shares reacted positively to the filing, rising more than 3% premarket.
{stock_us}(QCOM.US)
* Data Center Strategy:
The regulatory filing reinforces focus on Qualcomm's strategic push beyond mobile smartphones, targeting more than $15 billion in data center revenue by fiscal 2029.
For tech equity analysts, semiconductor investors, and enterprise hardware strategists, tracking big-tech strategic holdings provides valuable insight into long-term hardware supply chains and data center expansion models.
$GOOGLB $QCOMB $GOOGL.US #CoinVahini #Semiconductors #DataCenter
" #Alphabet Discloses $548M #Qualcomm Stake as Data Center Expansion Accelerates 👍 "
Institutional tech sector filings highlight strategic corporate positionings across semiconductor and artificial intelligence infrastructure:-
* Stake Disclosure:
Alphabet disclosed a new Qualcomm stake valued at approximately $548 million at the end of the third quarter.
* Premarket Reaction:
Qualcomm shares reacted positively to the filing, rising more than 3% premarket.
* Data Center Strategy:
The regulatory filing reinforces focus on Qualcomm's strategic push beyond mobile smartphones, targeting more than $15 billion in data center revenue by fiscal 2029.
For tech equity analysts, semiconductor investors, and enterprise hardware strategists, tracking big-tech strategic holdings provides valuable insight into long-term hardware supply chains and data center expansion models.
$GOOGLB $QCOMB $GOOGL.US #CoinVahini #Semiconductors #DataCenter
Institutional tech sector filings highlight strategic corporate positionings across semiconductor and artificial intelligence infrastructure:-
* Stake Disclosure:
Alphabet disclosed a new Qualcomm stake valued at approximately $548 million at the end of the third quarter.
* Premarket Reaction:
Qualcomm shares reacted positively to the filing, rising more than 3% premarket.
* Data Center Strategy:
The regulatory filing reinforces focus on Qualcomm's strategic push beyond mobile smartphones, targeting more than $15 billion in data center revenue by fiscal 2029.
For tech equity analysts, semiconductor investors, and enterprise hardware strategists, tracking big-tech strategic holdings provides valuable insight into long-term hardware supply chains and data center expansion models.
$GOOGLB $QCOMB $GOOGL.US #CoinVahini #Semiconductors #DataCenter
156
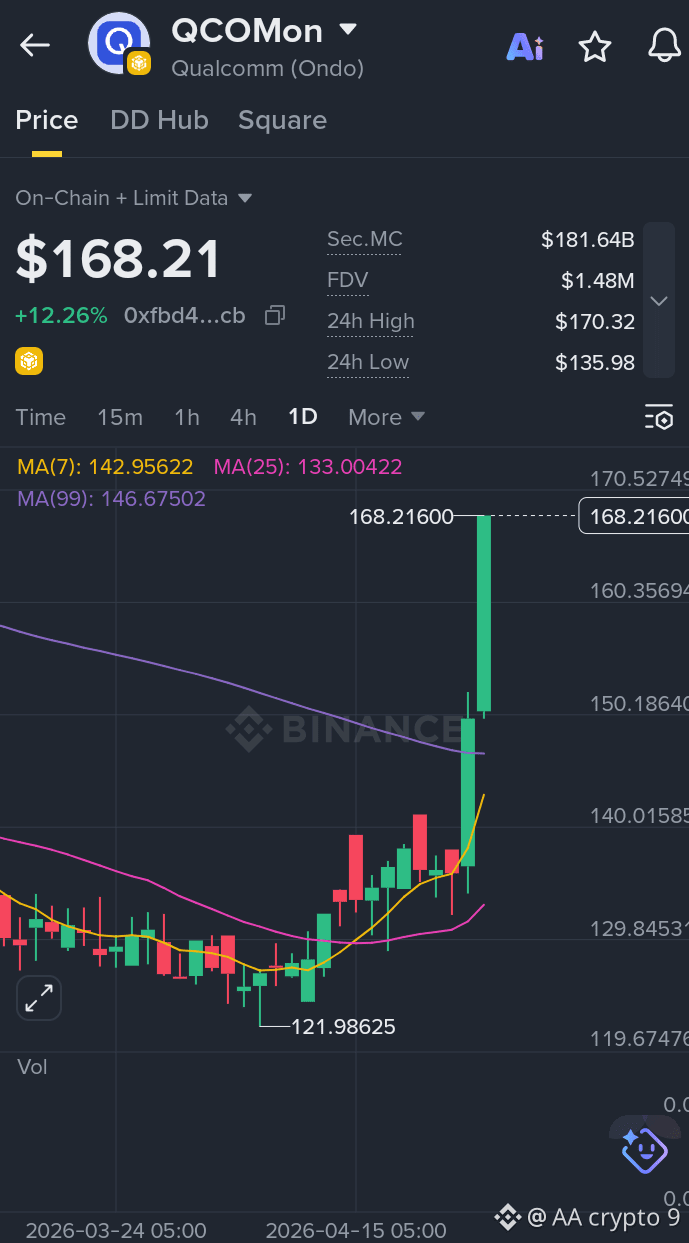
🎯 *Plan*: 🔥🔥
*Bullish While*: Daily holds above $146.67 MA(99)
*Breakout Target*: Daily close above $170.32 → open sky, $180 psychological next
*Support Buy Zone*: $146.67 MA(99) → $142.95 MA(7) on any dip
*Invalidation*: Daily close back under $142.95 MA(7) = fakeout risk
RWA sector waking up. QCOMon leading with Qualcomm exposure on-chain. Don’t chase the wick, but any pullback to MAs is a gift.
Trade Here ..👇
$QCOMon
{alpha}(560xfbd4d681c92ead6af0e49950c8b2e47eeacbb2db)
#RWA #Ondo #Qualcomm #TokenizedStocks #Binance #defi #TechnicalAnalysis #Bullish
🎯 *Plan*: 🔥🔥
*Bullish While*: Daily holds above $146.67 MA(99)
*Breakout Target*: Daily close above $170.32 → open sky, $180 psychological next
*Support Buy Zone*: $146.67 MA(99) → $142.95 MA(7) on any dip
*Invalidation*: Daily close back under $142.95 MA(7) = fakeout risk
RWA sector waking up. QCOMon leading with Qualcomm exposure on-chain. Don’t chase the wick, but any pullback to MAs is a gift.
Trade Here ..👇
$QCOMon
#RWA #Ondo #Qualcomm #TokenizedStocks #Binance #defi #TechnicalAnalysis #Bullish
*Bullish While*: Daily holds above $146.67 MA(99)
*Breakout Target*: Daily close above $170.32 → open sky, $180 psychological next
*Support Buy Zone*: $146.67 MA(99) → $142.95 MA(7) on any dip
*Invalidation*: Daily close back under $142.95 MA(7) = fakeout risk
RWA sector waking up. QCOMon leading with Qualcomm exposure on-chain. Don’t chase the wick, but any pullback to MAs is a gift.
Trade Here ..👇
$QCOMon
#RWA #Ondo #Qualcomm #TokenizedStocks #Binance #defi #TechnicalAnalysis #Bullish
1
56
QUALCOMM ACQUISITION OF MODULAR SIGNALS A SHIFT IN AI HARDWARE EFFICIENCY ⚡
Qualcomm is making a play for the future of AI infrastructure by acquiring Modular to unify their software stack across CPUs, GPUs, and NPUs. This move directly targets the current bottleneck in the industry, which is power efficiency per watt rather than raw capability.
By building a chip-agnostic layer, they are positioning themselves to dominate the transition from data centers to edge computing. This acquisition could redefine how developers deploy models across different hardware architectures over the next few years. How do you think this consolidation will affect the broader AI compute market?
Not financial advice. Always manage your risk.
#AI #Qualcomm #Modular #TechTrends #Crypto
⚡
QUALCOMM ACQUISITION OF MODULAR SIGNALS A SHIFT IN AI HARDWARE EFFICIENCY ⚡
Qualcomm is making a play for the future of AI infrastructure by acquiring Modular to unify their software stack across CPUs, GPUs, and NPUs. This move directly targets the current bottleneck in the industry, which is power efficiency per watt rather than raw capability.
By building a chip-agnostic layer, they are positioning themselves to dominate the transition from data centers to edge computing. This acquisition could redefine how developers deploy models across different hardware architectures over the next few years. How do you think this consolidation will affect the broader AI compute market?
Not financial advice. Always manage your risk.
#AI #Qualcomm #Modular #TechTrends #Crypto
⚡
Qualcomm is making a play for the future of AI infrastructure by acquiring Modular to unify their software stack across CPUs, GPUs, and NPUs. This move directly targets the current bottleneck in the industry, which is power efficiency per watt rather than raw capability.
By building a chip-agnostic layer, they are positioning themselves to dominate the transition from data centers to edge computing. This acquisition could redefine how developers deploy models across different hardware architectures over the next few years. How do you think this consolidation will affect the broader AI compute market?
Not financial advice. Always manage your risk.
#AI #Qualcomm #Modular #TechTrends #Crypto
⚡
QCOMonAlpha
QCOMUS-5.46%
12

·
--
QUALCOMM ACQUISITION OF MODULAR SIGNALS A SHIFT TOWARD AI HARDWARE EFFICIENCY 🎯
The acquisition of Modular by Qualcomm marks a strategic pivot toward optimizing AI inference costs through a hardware-agnostic software stack. By unifying support across CPU, GPU, and NPU architectures, the company is positioning itself to solve the primary constraint currently facing the sector: power efficiency per watt.
This move aims to reduce the total cost of ownership for enterprises by allowing developers to deploy models across diverse environments without rewriting code. As AI scaling shifts from raw capability to cost-effective execution, how do you expect this integration to impact the competitive landscape for edge computing?
Not financial advice. Always manage your risk.
#AI #Qualcomm #TechAnalysis #MarketStructure #Efficiency
🎯
QUALCOMM ACQUISITION OF MODULAR SIGNALS A SHIFT TOWARD AI HARDWARE EFFICIENCY 🎯
The acquisition of Modular by Qualcomm marks a strategic pivot toward optimizing AI inference costs through a hardware-agnostic software stack. By unifying support across CPU, GPU, and NPU architectures, the company is positioning itself to solve the primary constraint currently facing the sector: power efficiency per watt.
This move aims to reduce the total cost of ownership for enterprises by allowing developers to deploy models across diverse environments without rewriting code. As AI scaling shifts from raw capability to cost-effective execution, how do you expect this integration to impact the competitive landscape for edge computing?
Not financial advice. Always manage your risk.
#AI #Qualcomm #TechAnalysis #MarketStructure #Efficiency
🎯
The acquisition of Modular by Qualcomm marks a strategic pivot toward optimizing AI inference costs through a hardware-agnostic software stack. By unifying support across CPU, GPU, and NPU architectures, the company is positioning itself to solve the primary constraint currently facing the sector: power efficiency per watt.
This move aims to reduce the total cost of ownership for enterprises by allowing developers to deploy models across diverse environments without rewriting code. As AI scaling shifts from raw capability to cost-effective execution, how do you expect this integration to impact the competitive landscape for edge computing?
Not financial advice. Always manage your risk.
#AI #Qualcomm #TechAnalysis #MarketStructure #Efficiency
🎯
QCOMonAlpha
QCOMUS-5.46%
1
30
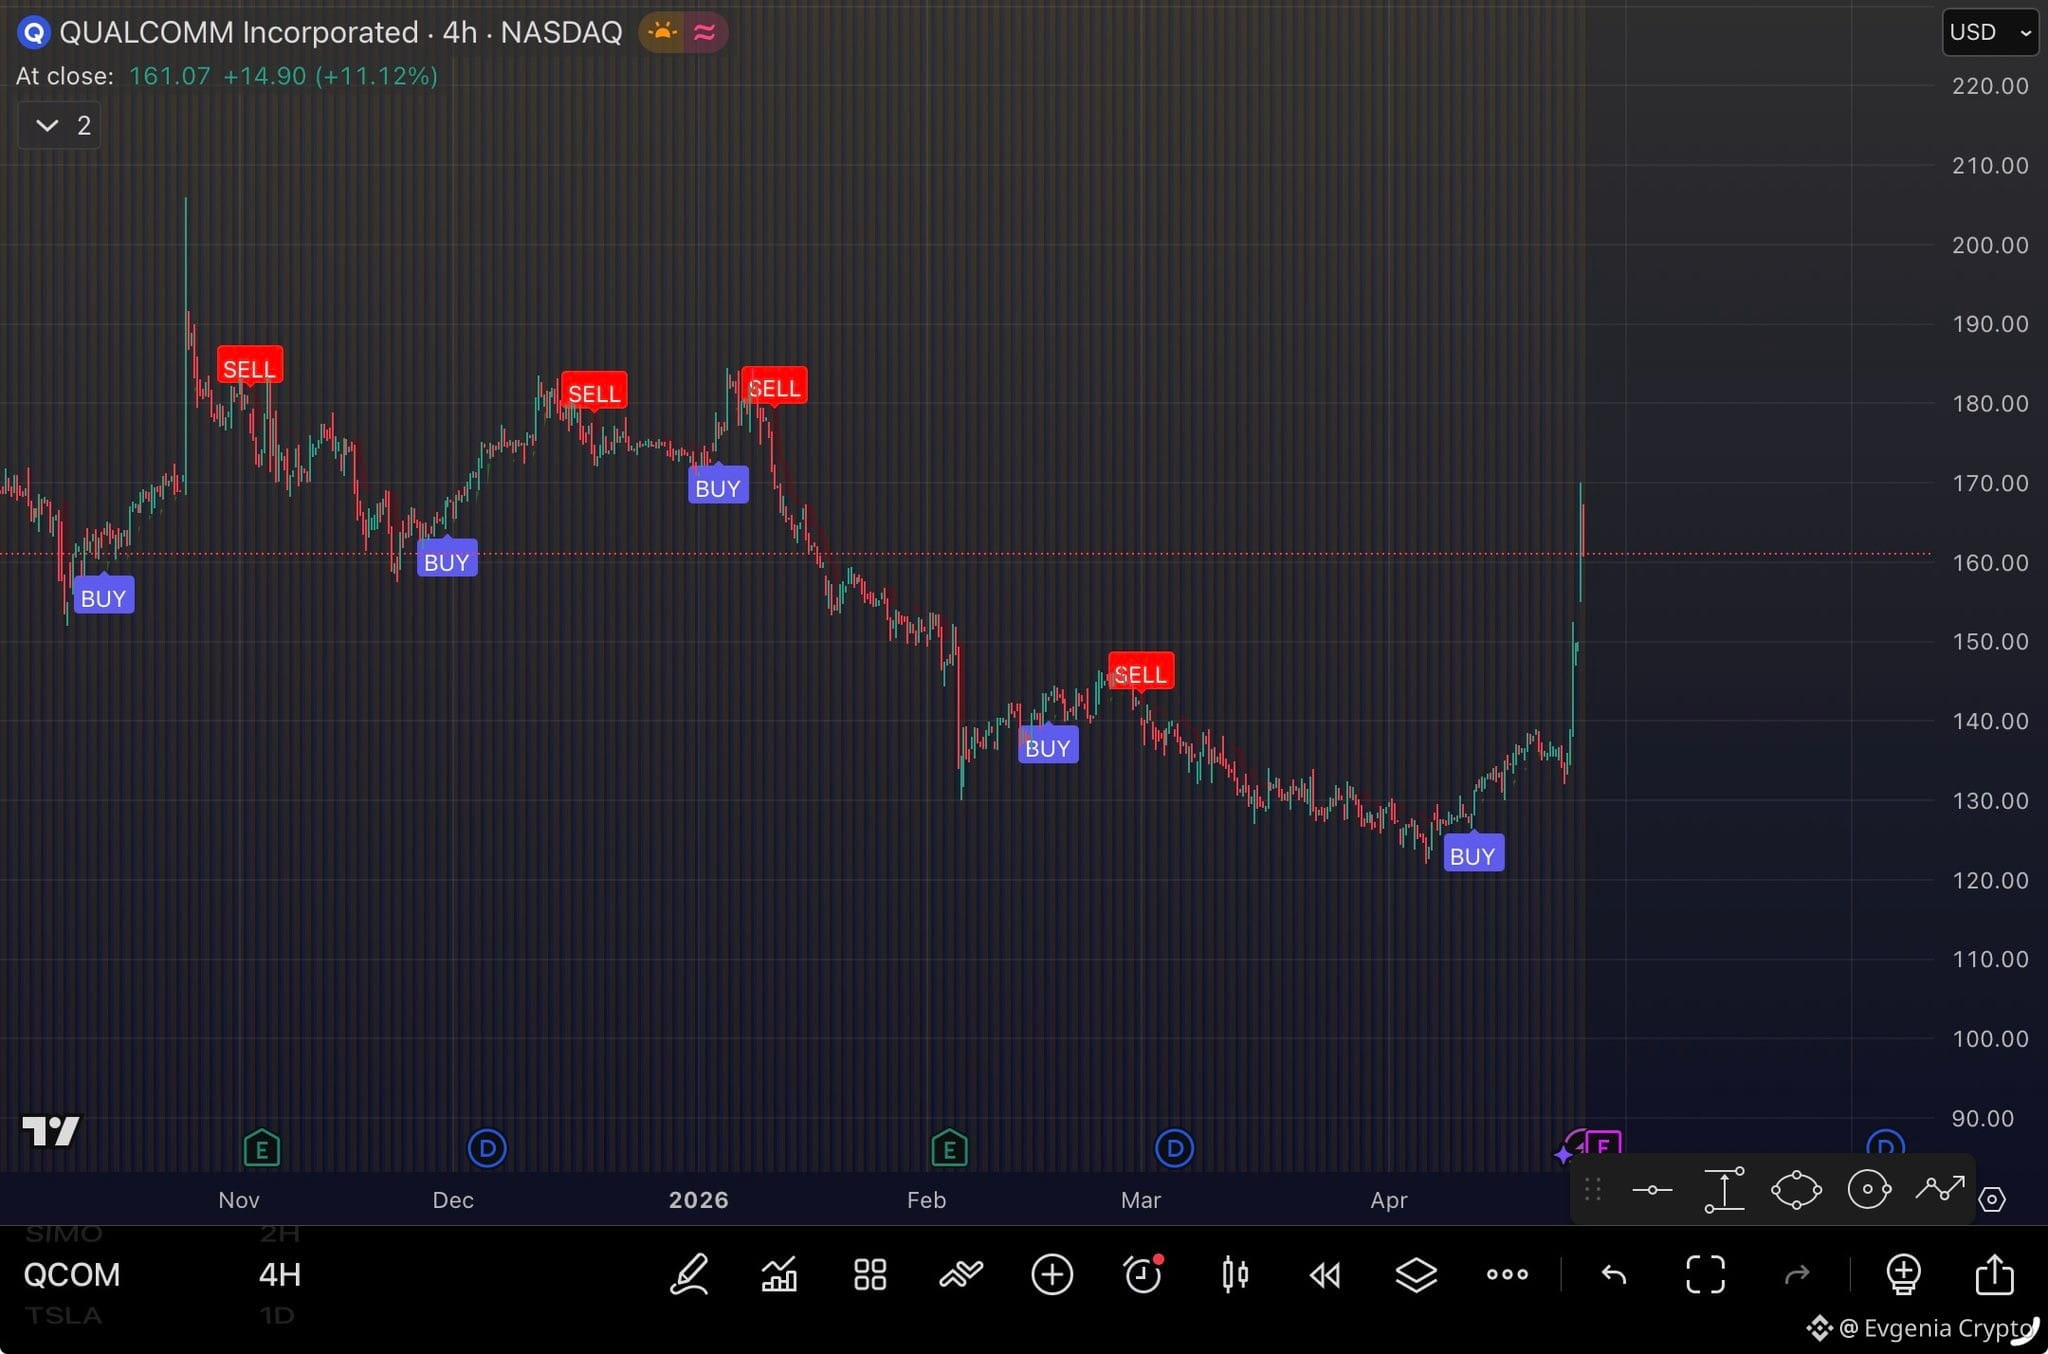
The $QCOMon "Insider Scam" is as blatant as it gets. Imagine dropping a massive $27 MILLION on options right at Friday’s close, only to wake up to a +9% (and climbing) gap up this morning on the OpenAI partnership news.
This isn’t just suspicious; it’s a textbook example of how the game is rigged. The timing is way too perfect to be luck. While retail traders are busy analyzing RSI and drawing trendlines, someone just printed a fortune using info that hadn’t even hit the wires yet.
If you think this is "efficient market hypothesis" at work, I have a bridge to sell you. Is this the peak of corporate corruption, or are we just watching the elites pull another fast one while the SEC sleeps? Drop your take below! 👇🔥
{alpha}(560xfbd4d681c92ead6af0e49950c8b2e47eeacbb2db)
#QCOM #Qualcomm #InsiderTrading
The $QCOMon "Insider Scam" is as blatant as it gets. Imagine dropping a massive $27 MILLION on options right at Friday’s close, only to wake up to a +9% (and climbing) gap up this morning on the OpenAI partnership news.
This isn’t just suspicious; it’s a textbook example of how the game is rigged. The timing is way too perfect to be luck. While retail traders are busy analyzing RSI and drawing trendlines, someone just printed a fortune using info that hadn’t even hit the wires yet.
If you think this is "efficient market hypothesis" at work, I have a bridge to sell you. Is this the peak of corporate corruption, or are we just watching the elites pull another fast one while the SEC sleeps? Drop your take below! 👇🔥
#QCOM #Qualcomm #InsiderTrading
This isn’t just suspicious; it’s a textbook example of how the game is rigged. The timing is way too perfect to be luck. While retail traders are busy analyzing RSI and drawing trendlines, someone just printed a fortune using info that hadn’t even hit the wires yet.
If you think this is "efficient market hypothesis" at work, I have a bridge to sell you. Is this the peak of corporate corruption, or are we just watching the elites pull another fast one while the SEC sleeps? Drop your take below! 👇🔥
#QCOM #Qualcomm #InsiderTrading
1
194

Qualcomm Eyes Top Spot in Auto Chips 👀
Qualcomm’s CFO has signaled that the company is on track to become the largest chip supplier to the automotive industry next year.
Strong growth in its Snapdragon Digital Chassis platform, major deals (including an expanded partnership with BMW for digital cockpits and ADAS), and rising demand for AI-powered vehicle compute are driving the push. Qualcomm has already posted multiple quarters of record automotive revenue and is targeting further expansion in 2027.
A clear shift as the company diversifies beyond smartphones into cars and AI.
{future}(QCOMUSDT)
{spot}(QCOMBUSDT)
$QCOMB $QCOM $QCOM.US #Qualcomm #Automotive #Chips #AI #CoinVahini
Qualcomm Eyes Top Spot in Auto Chips 👀
Qualcomm’s CFO has signaled that the company is on track to become the largest chip supplier to the automotive industry next year.
Strong growth in its Snapdragon Digital Chassis platform, major deals (including an expanded partnership with BMW for digital cockpits and ADAS), and rising demand for AI-powered vehicle compute are driving the push. Qualcomm has already posted multiple quarters of record automotive revenue and is targeting further expansion in 2027.
A clear shift as the company diversifies beyond smartphones into cars and AI.
$QCOMB $QCOM $QCOM.US #Qualcomm #Automotive #Chips #AI #CoinVahini
Qualcomm’s CFO has signaled that the company is on track to become the largest chip supplier to the automotive industry next year.
Strong growth in its Snapdragon Digital Chassis platform, major deals (including an expanded partnership with BMW for digital cockpits and ADAS), and rising demand for AI-powered vehicle compute are driving the push. Qualcomm has already posted multiple quarters of record automotive revenue and is targeting further expansion in 2027.
A clear shift as the company diversifies beyond smartphones into cars and AI.
$QCOMB $QCOM $QCOM.US #Qualcomm #Automotive #Chips #AI #CoinVahini
QCOMUS-5.46%
QCOMB+0.82%
1
515
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#NvidiaLoses$2.7TrillionInMonthAndAHalf
21,495 views
143 Discussing
2
#CanBTCReboundAfterFallingBelow60K?
787,243 views
3,036 Discussing
3
#GlobalStocksFaceLongestLosingStreakSince2023
287,946 views
2,027 Discussing
4
#BlackRockIBITPostsRecord$541MSingleDayOutflow
34,801 views
106 Discussing
5
#AnthropicPlungesTowardIPOPriceonDay2
148,109 views
1,233 Discussing
6
#TwentyOneCapitalAdds172.25BTC
67,960 views
680 Discussing
7
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
9,019 views
50 Discussing
8
#BNBDropsBelow540USDTWith8.46%DailyDecline
80,268 views
659 Discussing
9
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
2,696 views
22 Discussing
10
#BitMineFaces$10.1BUnrealizedETHLoss
5,658 views
28 Discussing