
#stocks
stocks
4.8M views
12,034 Discussing
Hot
Latest

·
--
Disputed
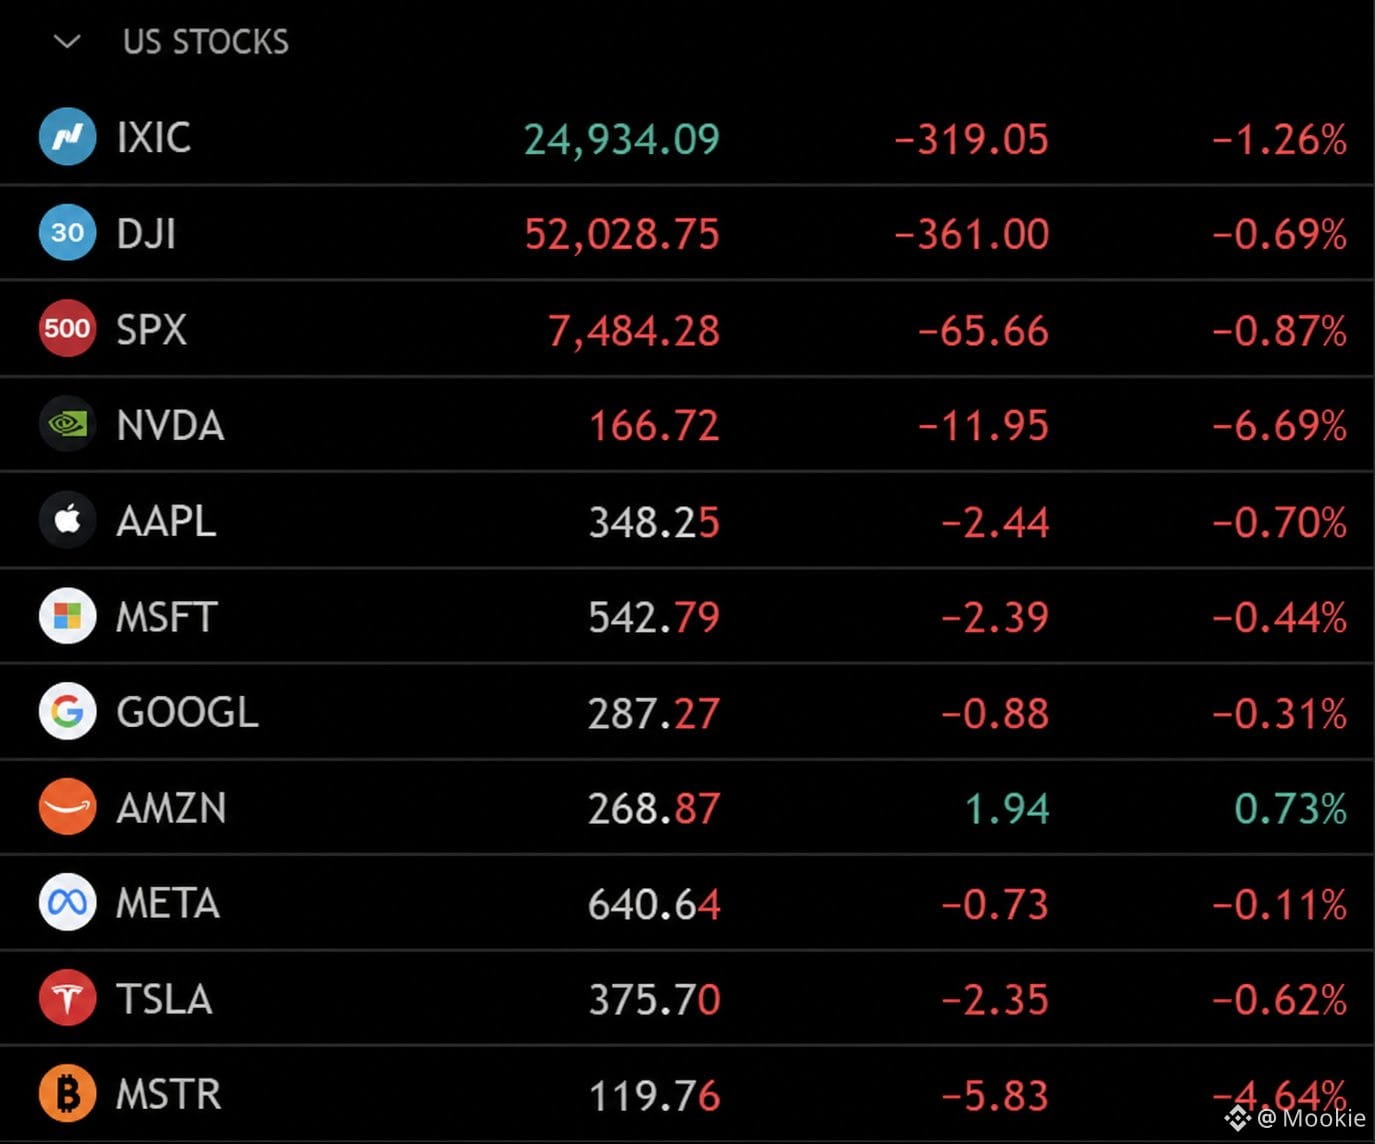
🔻US stocks keep dropping!
Nasdaq: -1.26%
S&P 500: -0.87%
Dow Jones: -0.69%
And of course $NVDAB is down 6.69% again. Another reminder to stay loyal to your wife.
#stocks
🔻US stocks keep dropping!
Nasdaq: -1.26%
S&P 500: -0.87%
Dow Jones: -0.69%
And of course $NVDAB is down 6.69% again. Another reminder to stay loyal to your wife.
#stocks
Nasdaq: -1.26%
S&P 500: -0.87%
Dow Jones: -0.69%
And of course $NVDAB is down 6.69% again. Another reminder to stay loyal to your wife.
#stocks
2
558

·
--
Bullish
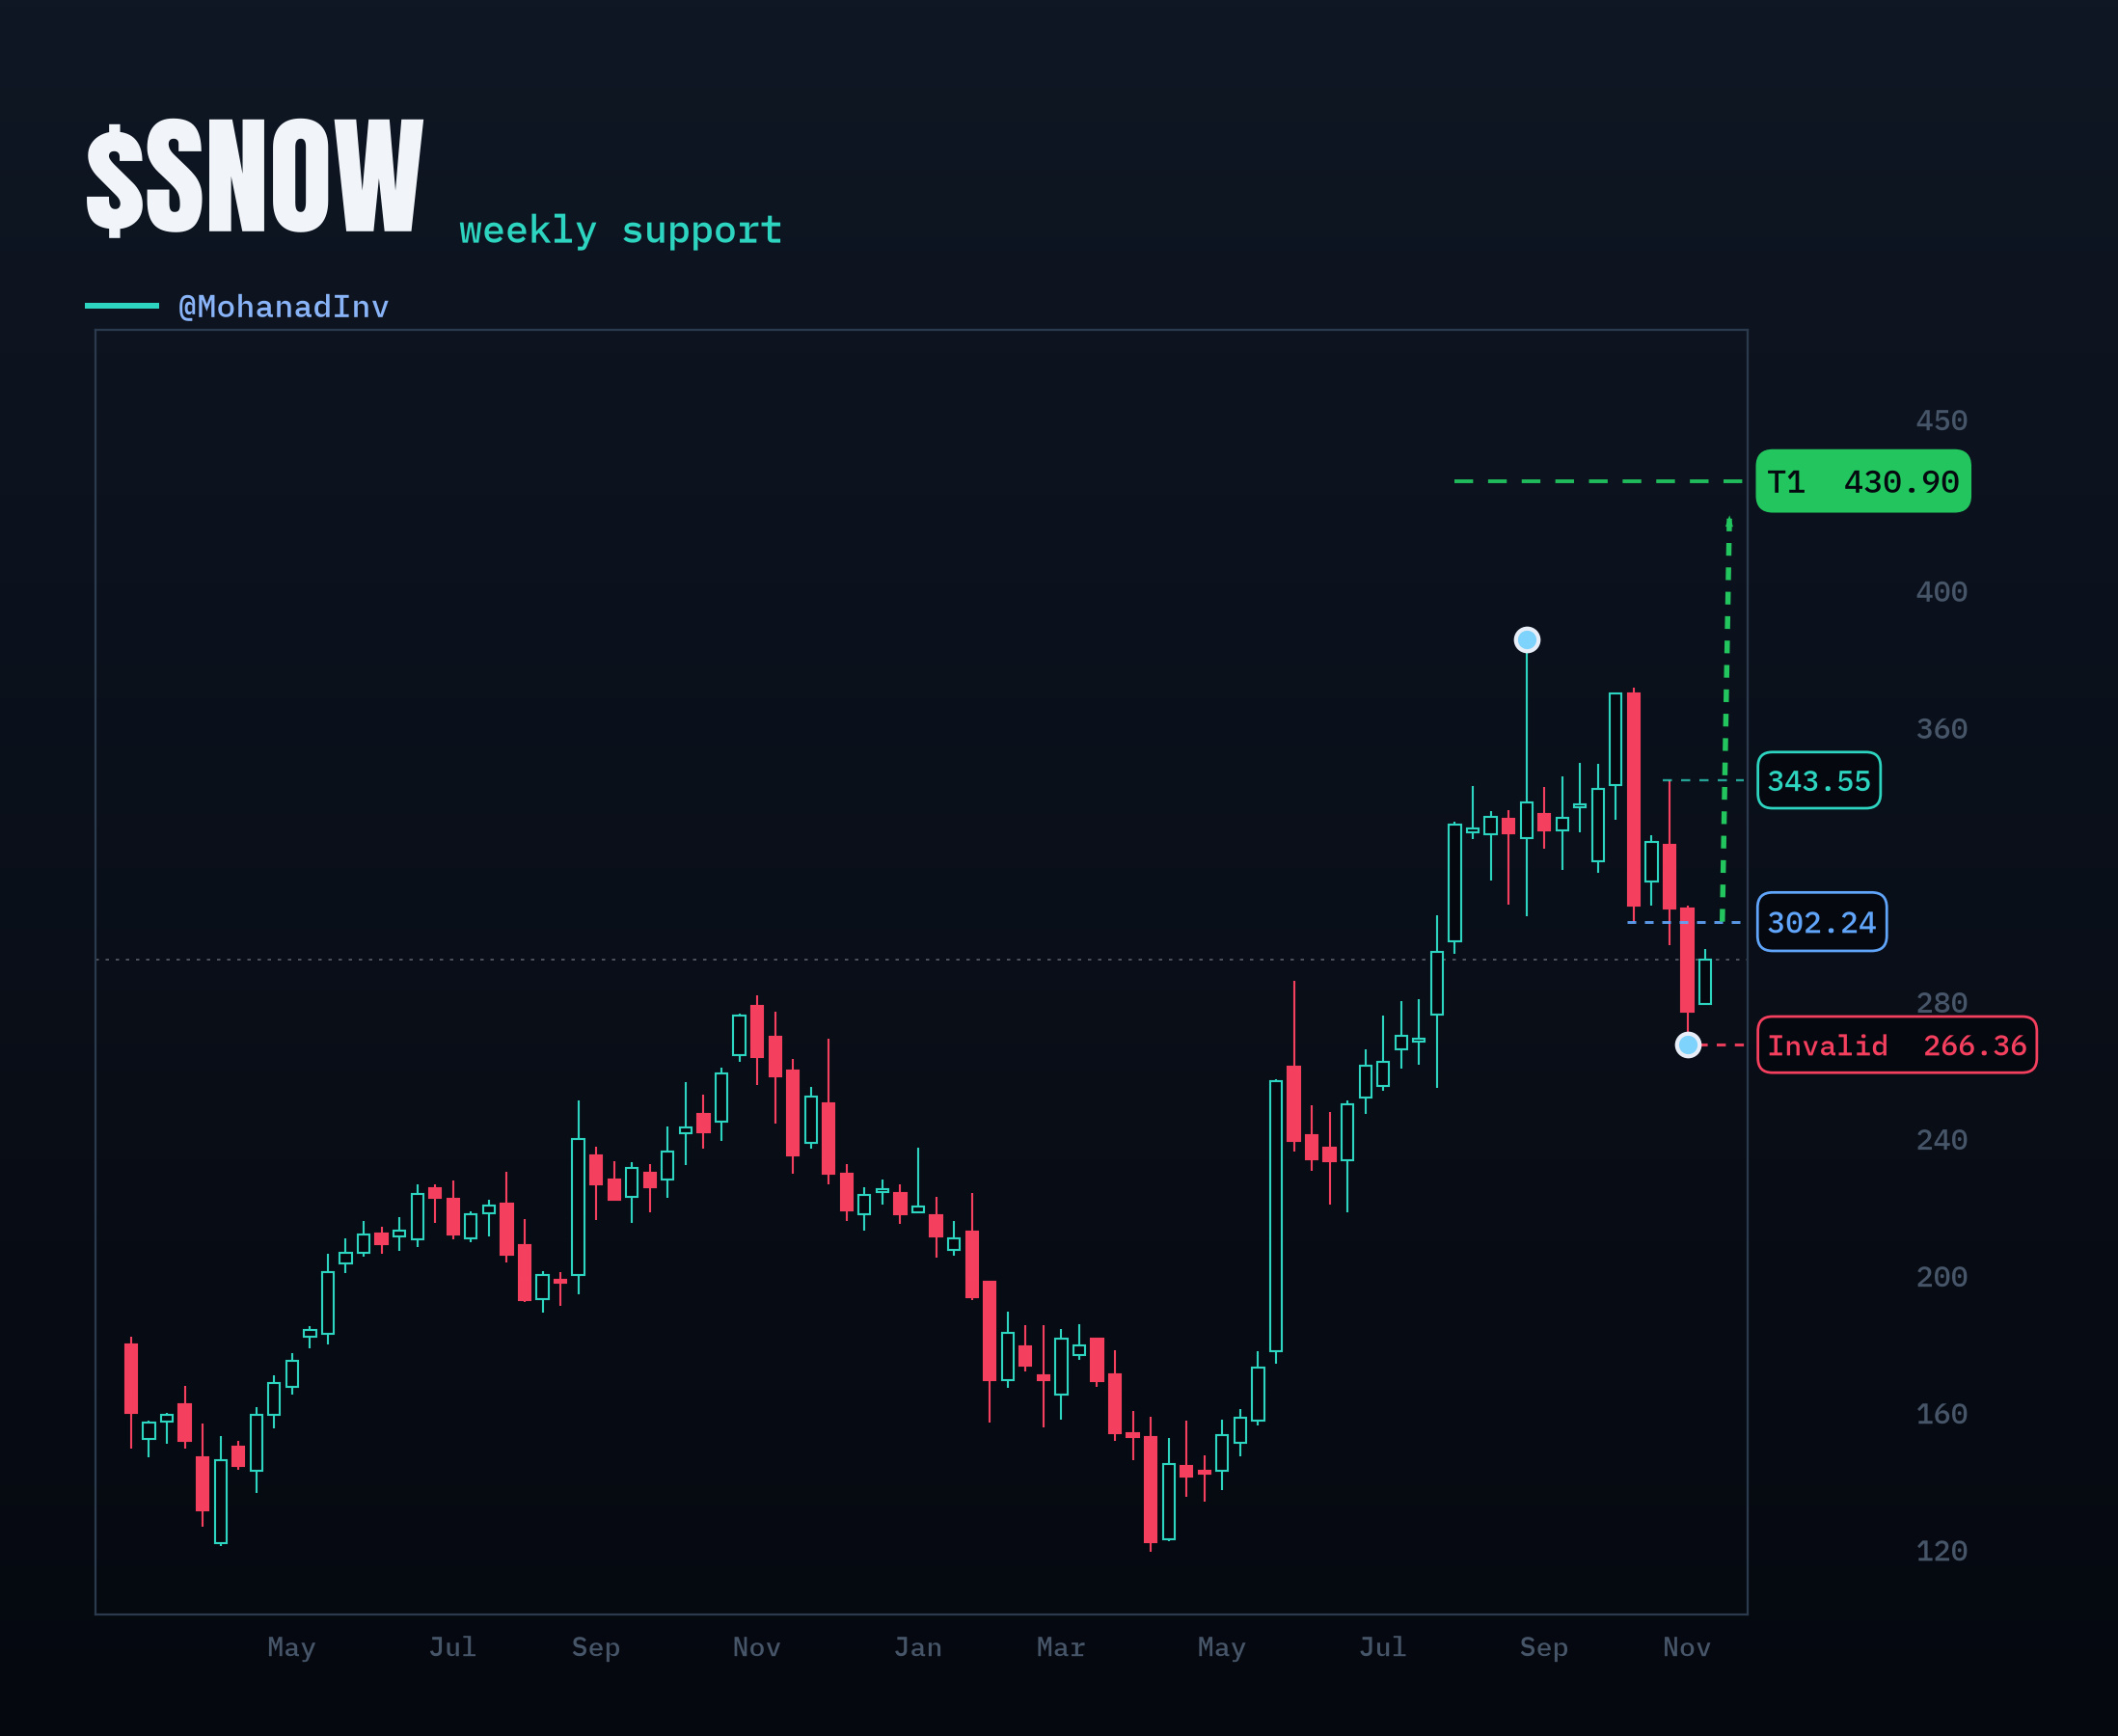
🚨 I SEE 48% UPSIDE IN $SNOW TO 430 👀
Here's why I'm bullish 👇
Last week it bounced off weekly support at 266.36 and closed 275.88 on 30M shares, its heaviest week since late August 🟢
A weekly close over 302.24 opens 343.55 first, then 430.90, where a 61.8% repeat of the April to September rally lands, 48% above Monday's close 🎯
I'm wrong on a weekly close under 266.36 🔴
⚠️ Earnings land Dec 2 after the close
Over 302.24 and it runs, or does 266.36 get tested again? 👇
#stocks
{future}(SNOWUSDT)
🚨 I SEE 48% UPSIDE IN $SNOW TO 430 👀
Here's why I'm bullish 👇
Last week it bounced off weekly support at 266.36 and closed 275.88 on 30M shares, its heaviest week since late August 🟢
A weekly close over 302.24 opens 343.55 first, then 430.90, where a 61.8% repeat of the April to September rally lands, 48% above Monday's close 🎯
I'm wrong on a weekly close under 266.36 🔴
⚠️ Earnings land Dec 2 after the close
Over 302.24 and it runs, or does 266.36 get tested again? 👇
#stocks
Here's why I'm bullish 👇
Last week it bounced off weekly support at 266.36 and closed 275.88 on 30M shares, its heaviest week since late August 🟢
A weekly close over 302.24 opens 343.55 first, then 430.90, where a 61.8% repeat of the April to September rally lands, 48% above Monday's close 🎯
I'm wrong on a weekly close under 266.36 🔴
⚠️ Earnings land Dec 2 after the close
Over 302.24 and it runs, or does 266.36 get tested again? 👇
#stocks
381

·
--
CoreWeave Just Showed Why Hot CPI Matters for AI Infrastructure.
October CPI exceeded expectations: headline +0.4% versus +0.3%, core +0.3% versus +0.2%. Treasury yields jumped.
Hours later, CoreWeave reported:
• Revenue: $3.66B, up 168% YoY
• GAAP operating income: $207M
• Net interest expense: $846M
• Net loss: $709M
• Revenue backlog: $132.5B
• Q4 interest expense guidance: $1.05–1.15B
The striking number isn't revenue growth.
Quarterly interest expense was 4.1 times GAAP operating income.
CoreWeave expects $37–39B in 2026 capex. Its customers are committing to substantial future spending, but the company must finance infrastructure before collecting much of that revenue.
Higher rates don't erase AI demand. They increase the cost of converting that demand into operational capacity.
CoreWeave's backlog provides revenue visibility, but it doesn't eliminate financing costs, execution risk or the timing gap between investment and cash collection.
My investment thesis: AI infrastructure is entering a phase where financing efficiency may matter as much as revenue growth.
The next test isn't another record backlog. It's whether operating earnings and cash generation can catch up with the cost of funding expansion.
#stocks
$CRWV.US
{stock_us}(CRWV.US)
CoreWeave Just Showed Why Hot CPI Matters for AI Infrastructure.
October CPI exceeded expectations: headline +0.4% versus +0.3%, core +0.3% versus +0.2%. Treasury yields jumped.
Hours later, CoreWeave reported:
• Revenue: $3.66B, up 168% YoY
• GAAP operating income: $207M
• Net interest expense: $846M
• Net loss: $709M
• Revenue backlog: $132.5B
• Q4 interest expense guidance: $1.05–1.15B
The striking number isn't revenue growth.
Quarterly interest expense was 4.1 times GAAP operating income.
CoreWeave expects $37–39B in 2026 capex. Its customers are committing to substantial future spending, but the company must finance infrastructure before collecting much of that revenue.
Higher rates don't erase AI demand. They increase the cost of converting that demand into operational capacity.
CoreWeave's backlog provides revenue visibility, but it doesn't eliminate financing costs, execution risk or the timing gap between investment and cash collection.
My investment thesis: AI infrastructure is entering a phase where financing efficiency may matter as much as revenue growth.
The next test isn't another record backlog. It's whether operating earnings and cash generation can catch up with the cost of funding expansion.
#stocks
$CRWV.US
October CPI exceeded expectations: headline +0.4% versus +0.3%, core +0.3% versus +0.2%. Treasury yields jumped.
Hours later, CoreWeave reported:
• Revenue: $3.66B, up 168% YoY
• GAAP operating income: $207M
• Net interest expense: $846M
• Net loss: $709M
• Revenue backlog: $132.5B
• Q4 interest expense guidance: $1.05–1.15B
The striking number isn't revenue growth.
Quarterly interest expense was 4.1 times GAAP operating income.
CoreWeave expects $37–39B in 2026 capex. Its customers are committing to substantial future spending, but the company must finance infrastructure before collecting much of that revenue.
Higher rates don't erase AI demand. They increase the cost of converting that demand into operational capacity.
CoreWeave's backlog provides revenue visibility, but it doesn't eliminate financing costs, execution risk or the timing gap between investment and cash collection.
My investment thesis: AI infrastructure is entering a phase where financing efficiency may matter as much as revenue growth.
The next test isn't another record backlog. It's whether operating earnings and cash generation can catch up with the cost of funding expansion.
#stocks
$CRWV.US
2
·
--
前纽交所总裁Stacey Cunningham加入数字资产平台Bullish担任总裁,看好股票代币化前景!Bullish正收购Equiniti,重点服务股票发行商,这可能是传统金融与加密世界融合的重要一步。$BULL #tokenization #stocks
Former NYSE President Stacey Cunningham joins Bullish as President, bullish on tokenization! Bullish acquiring Equiniti, focusing on stock issuers - this could be a big step for traditional finance meets crypto. $BULL #tokenization #stocks
前纽交所总裁Stacey Cunningham加入数字资产平台Bullish担任总裁,看好股票代币化前景!Bullish正收购Equiniti,重点服务股票发行商,这可能是传统金融与加密世界融合的重要一步。$BULL #tokenization #stocks
Former NYSE President Stacey Cunningham joins Bullish as President, bullish on tokenization! Bullish acquiring Equiniti, focusing on stock issuers - this could be a big step for traditional finance meets crypto. $BULL #tokenization #stocks
Former NYSE President Stacey Cunningham joins Bullish as President, bullish on tokenization! Bullish acquiring Equiniti, focusing on stock issuers - this could be a big step for traditional finance meets crypto. $BULL #tokenization #stocks
7

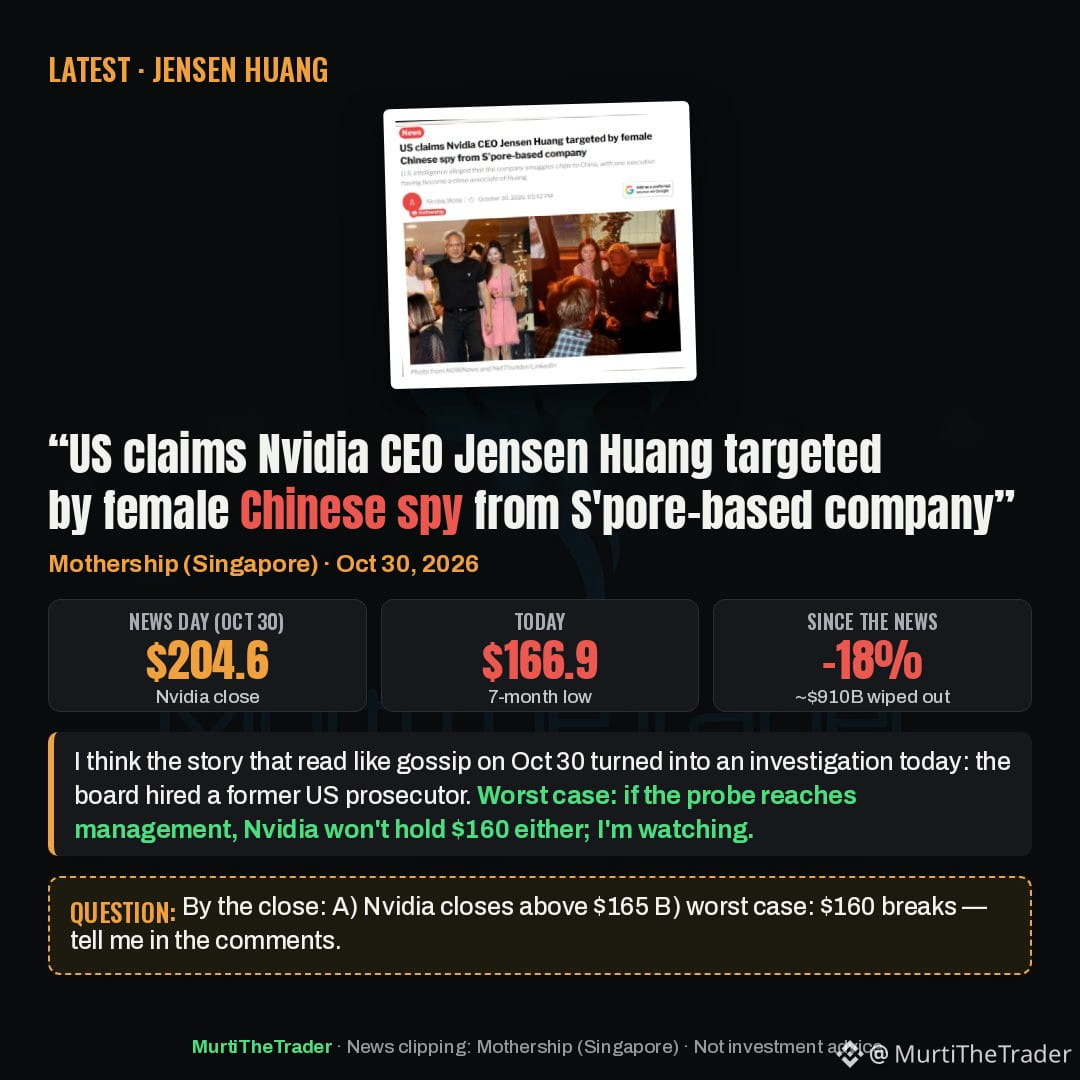
Latest: On Oct 30, Mothership ran the headline "US claims Nvidia CEO Jensen Huang targeted by female Chinese spy from S'pore-based company." Today, the board's independent directors hired a former US prosecutor to investigate.
→ Nvidia was $204.6 on the news day and $166.9 today: down 18%, with ~$910B wiped out
I think the story that read like gossip on Oct 30 turned into an investigation today: the board hired a former US prosecutor. Worst case: if the probe reaches management, Nvidia won't hold $160 either; I'm watching.
By the close: A) Nvidia closes above $165 B) worst case: $160 breaks — tell me in the comments.
#Stocks #Semiconductors
Watching: $NVDA
Latest: On Oct 30, Mothership ran the headline "US claims Nvidia CEO Jensen Huang targeted by female Chinese spy from S'pore-based company." Today, the board's independent directors hired a former US prosecutor to investigate.
→ Nvidia was $204.6 on the news day and $166.9 today: down 18%, with ~$910B wiped out
I think the story that read like gossip on Oct 30 turned into an investigation today: the board hired a former US prosecutor. Worst case: if the probe reaches management, Nvidia won't hold $160 either; I'm watching.
By the close: A) Nvidia closes above $165 B) worst case: $160 breaks — tell me in the comments.
#Stocks #Semiconductors
Watching: $NVDA
→ Nvidia was $204.6 on the news day and $166.9 today: down 18%, with ~$910B wiped out
I think the story that read like gossip on Oct 30 turned into an investigation today: the board hired a former US prosecutor. Worst case: if the probe reaches management, Nvidia won't hold $160 either; I'm watching.
By the close: A) Nvidia closes above $165 B) worst case: $160 breaks — tell me in the comments.
#Stocks #Semiconductors
Watching: $NVDA
132
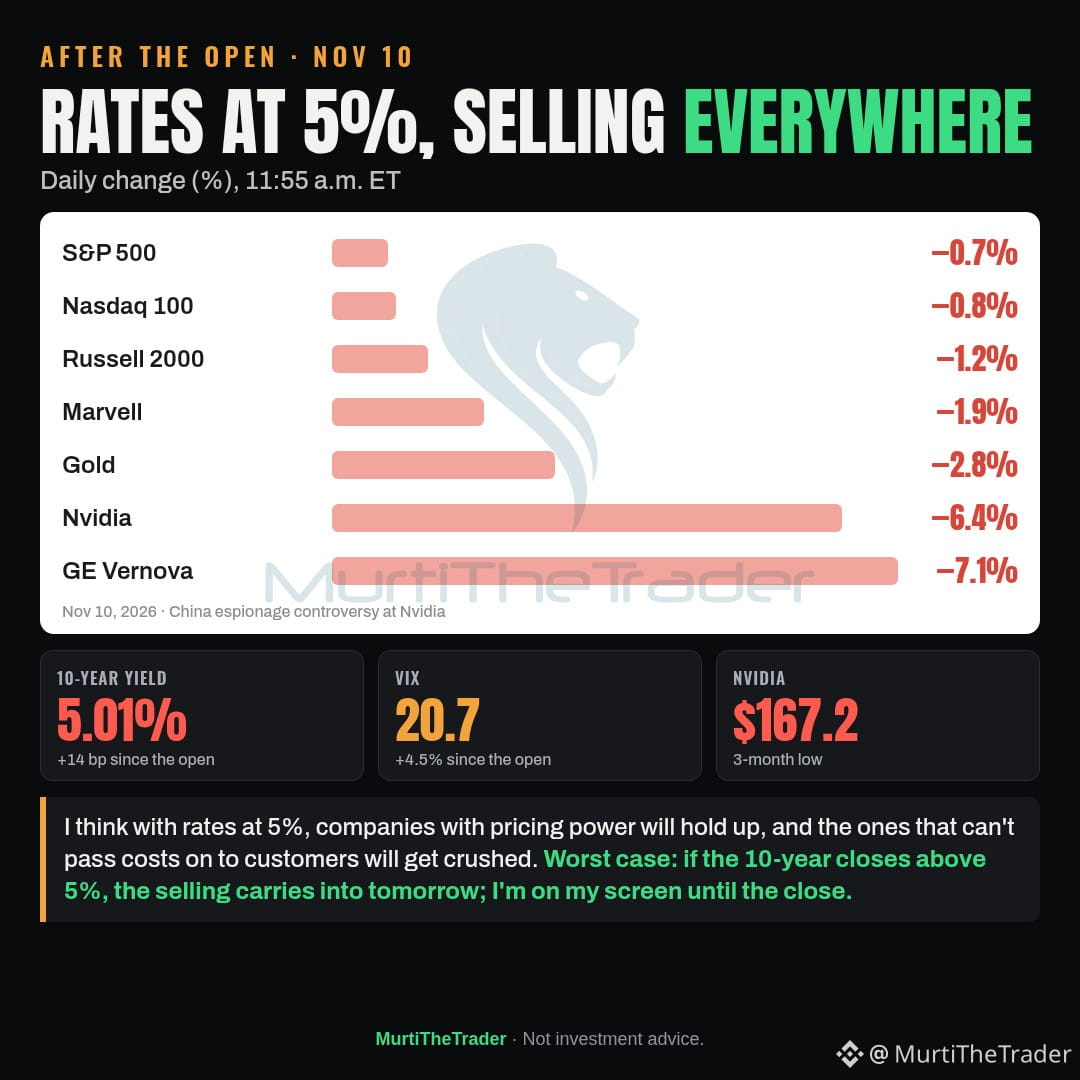
After the open: the 10-year yield broke above 5% (5.01%) and the selling spread to almost everything.
→ A China espionage controversy knocked Nvidia down 6.4% to $167.2
→ GE Vernova down 7.1%, Marvell down 1.9%, Russell 2000 down 1.2%; gold also down 2.8%
→ VIX at 20.7
I think with rates at 5%, companies with pricing power will hold up, and the ones that can't pass costs on to customers will get crushed. Worst case: if the 10-year closes above 5%, the selling carries into tomorrow; I'm on my screen until the close.
#Stocks #Selloff
Watching: $NVDA $GEV $MRVL
After the open: the 10-year yield broke above 5% (5.01%) and the selling spread to almost everything.
→ A China espionage controversy knocked Nvidia down 6.4% to $167.2
→ GE Vernova down 7.1%, Marvell down 1.9%, Russell 2000 down 1.2%; gold also down 2.8%
→ VIX at 20.7
I think with rates at 5%, companies with pricing power will hold up, and the ones that can't pass costs on to customers will get crushed. Worst case: if the 10-year closes above 5%, the selling carries into tomorrow; I'm on my screen until the close.
#Stocks #Selloff
Watching: $NVDA $GEV $MRVL
→ A China espionage controversy knocked Nvidia down 6.4% to $167.2
→ GE Vernova down 7.1%, Marvell down 1.9%, Russell 2000 down 1.2%; gold also down 2.8%
→ VIX at 20.7
I think with rates at 5%, companies with pricing power will hold up, and the ones that can't pass costs on to customers will get crushed. Worst case: if the 10-year closes above 5%, the selling carries into tomorrow; I'm on my screen until the close.
#Stocks #Selloff
Watching: $NVDA $GEV $MRVL
397
·
--
Silicon Slide: NVIDIA bStock Treads Water on Binance Spot 📉
NVIDIA Corp’s tokenized share $NVDAB (NVDAB/USDT) is trading at $172.27 on Binance Spot, down 2.36 % over the past 24 hours. The candle closed near its low, signalling waning buying pressure after a recent rally.
Why it matters: Nvidia remains a bellwether for AI‑driven chip demand, yet muted earnings guidance has cooled enthusiasm across the sector.
Key levels – Support sits around $165.00, a solid psychological floor backed by recent buying clusters. Resistance hovers near $180.00, where sellers previously stepped in. Mid‑range equilibrium is roughly $172.50, acting as a pivot for short‑term bias.
Outlook (cautious): The recent decline looks stretched; a pullback toward the $165 support zone is likely if momentum stalls. Watch volume and any fresh AI‑sector data for confirmation before any upside re‑entry.
#NVDAB #Stocks #BinanceSquare
Silicon Slide: NVIDIA bStock Treads Water on Binance Spot 📉
NVIDIA Corp’s tokenized share $NVDAB (NVDAB/USDT) is trading at $172.27 on Binance Spot, down 2.36 % over the past 24 hours. The candle closed near its low, signalling waning buying pressure after a recent rally.
Why it matters: Nvidia remains a bellwether for AI‑driven chip demand, yet muted earnings guidance has cooled enthusiasm across the sector.
Key levels – Support sits around $165.00, a solid psychological floor backed by recent buying clusters. Resistance hovers near $180.00, where sellers previously stepped in. Mid‑range equilibrium is roughly $172.50, acting as a pivot for short‑term bias.
Outlook (cautious): The recent decline looks stretched; a pullback toward the $165 support zone is likely if momentum stalls. Watch volume and any fresh AI‑sector data for confirmation before any upside re‑entry.
#NVDAB #Stocks #BinanceSquare
NVIDIA Corp’s tokenized share $NVDAB (NVDAB/USDT) is trading at $172.27 on Binance Spot, down 2.36 % over the past 24 hours. The candle closed near its low, signalling waning buying pressure after a recent rally.
Why it matters: Nvidia remains a bellwether for AI‑driven chip demand, yet muted earnings guidance has cooled enthusiasm across the sector.
Key levels – Support sits around $165.00, a solid psychological floor backed by recent buying clusters. Resistance hovers near $180.00, where sellers previously stepped in. Mid‑range equilibrium is roughly $172.50, acting as a pivot for short‑term bias.
Outlook (cautious): The recent decline looks stretched; a pullback toward the $165 support zone is likely if momentum stalls. Watch volume and any fresh AI‑sector data for confirmation before any upside re‑entry.
#NVDAB #Stocks #BinanceSquare
1
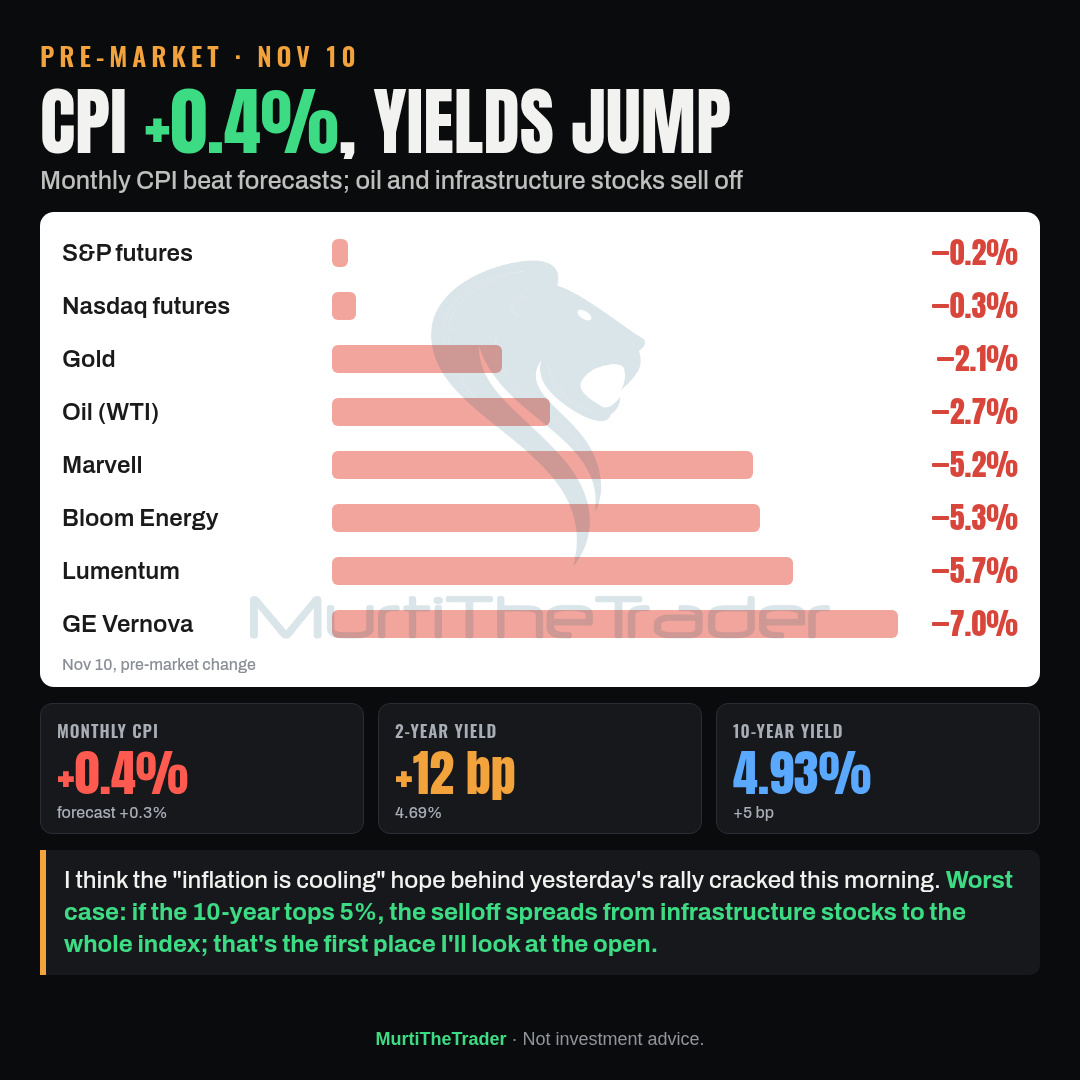
Pre-market: Monthly CPI came in at +0.4%, above forecasts, and the 2-year yield jumped +12 bp to 4.69%.
→ The 10-year rose only +5 bp to 4.93%, and the curve flattened by 7 bp
→ The short end is pricing a rate hike, the long end is pricing growth fears; oil is down −2.7% at $84.50
→ In pre-market, GE Vernova is down −7%, Lumentum −5.7%, Marvell −5.2%
I think the "inflation is cooling" hope cracked this morning. Worst case: if the 10-year tops 5%, the selloff spreads from infrastructure stocks to the whole index; I'm watching 5%.
#Economy #Stocks
Watching: $GEV $LITE $MRVL
Pre-market: Monthly CPI came in at +0.4%, above forecasts, and the 2-year yield jumped +12 bp to 4.69%.
→ The 10-year rose only +5 bp to 4.93%, and the curve flattened by 7 bp
→ The short end is pricing a rate hike, the long end is pricing growth fears; oil is down −2.7% at $84.50
→ In pre-market, GE Vernova is down −7%, Lumentum −5.7%, Marvell −5.2%
I think the "inflation is cooling" hope cracked this morning. Worst case: if the 10-year tops 5%, the selloff spreads from infrastructure stocks to the whole index; I'm watching 5%.
#Economy #Stocks
Watching: $GEV $LITE $MRVL
→ The 10-year rose only +5 bp to 4.93%, and the curve flattened by 7 bp
→ The short end is pricing a rate hike, the long end is pricing growth fears; oil is down −2.7% at $84.50
→ In pre-market, GE Vernova is down −7%, Lumentum −5.7%, Marvell −5.2%
I think the "inflation is cooling" hope cracked this morning. Worst case: if the 10-year tops 5%, the selloff spreads from infrastructure stocks to the whole index; I'm watching 5%.
#Economy #Stocks
Watching: $GEV $LITE $MRVL
197
·
--
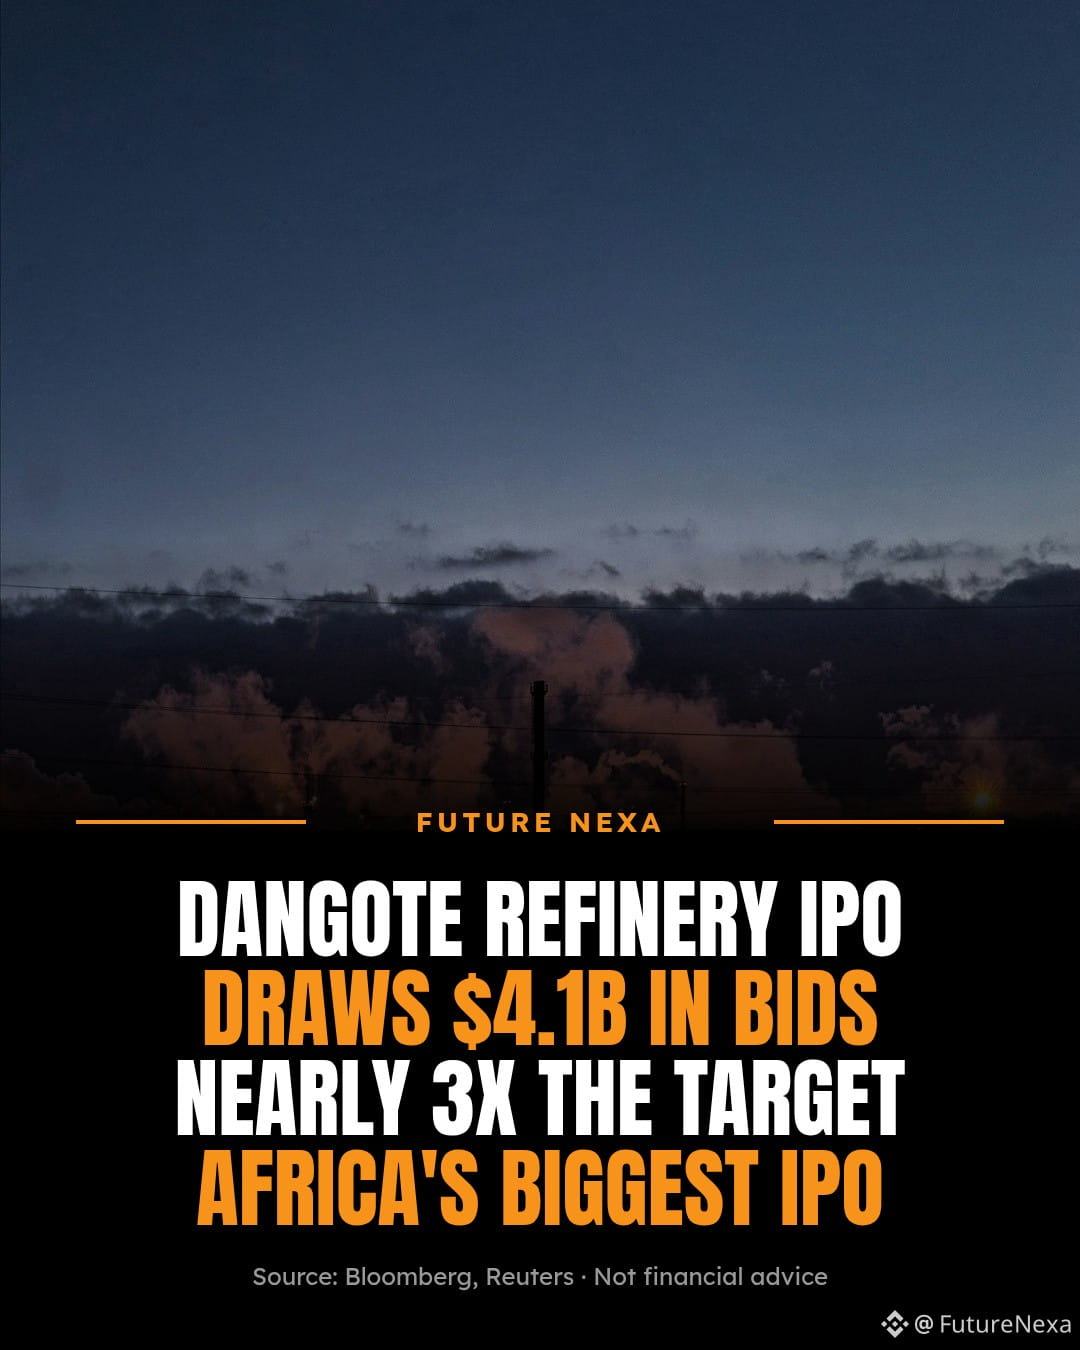
🇳🇬 Dangote Refinery’s IPO drew applications for about 5.85 trillion naira ($4.1B), nearly three times the amount it sought to raise, in Africa’s largest public offering to date, according to Bloomberg, citing people familiar with the matter. Reuters earlier reported orders of about 6.4 trillion naira from Nigerian investors.
The company offered 4.1 billion shares at 525 naira each to raise about 2.15 trillion naira ($1.6B), with applications from 119+ countries including all 54 African nations. With such demand, allotments are expected to be scaled back for large applications.
Big IPO demand shows strong appetite for African energy assets. Next, watch the allotment and the first trading day.
Does global demand like this make you more interested in African markets? 👇
#Dangote #IPO #stocks
Not financial advice. Sources: Bloomberg, Reuters
$BTC
{spot}(BTCUSDT)
🇳🇬 Dangote Refinery’s IPO drew applications for about 5.85 trillion naira ($4.1B), nearly three times the amount it sought to raise, in Africa’s largest public offering to date, according to Bloomberg, citing people familiar with the matter. Reuters earlier reported orders of about 6.4 trillion naira from Nigerian investors.
The company offered 4.1 billion shares at 525 naira each to raise about 2.15 trillion naira ($1.6B), with applications from 119+ countries including all 54 African nations. With such demand, allotments are expected to be scaled back for large applications.
Big IPO demand shows strong appetite for African energy assets. Next, watch the allotment and the first trading day.
Does global demand like this make you more interested in African markets? 👇
#Dangote #IPO #stocks
Not financial advice. Sources: Bloomberg, Reuters
$BTC
The company offered 4.1 billion shares at 525 naira each to raise about 2.15 trillion naira ($1.6B), with applications from 119+ countries including all 54 African nations. With such demand, allotments are expected to be scaled back for large applications.
Big IPO demand shows strong appetite for African energy assets. Next, watch the allotment and the first trading day.
Does global demand like this make you more interested in African markets? 👇
#Dangote #IPO #stocks
Not financial advice. Sources: Bloomberg, Reuters
$BTC
36
·
--
Bank of America has removed Nvidia $NVDA and Micron $MU from its list of top stock picks.
#Stocks #Markets
Bank of America has removed Nvidia $NVDA and Micron $MU from its list of top stock picks.
#Stocks #Markets
#Stocks #Markets
1
273
·
--
Verified
Semiconductors Look Cheap on 2028 Earnings. But Which Earnings Will Survive?
Morgan Stanley reportedly favors AI compute and memory after the selloff, with Nvidia and Broadcom among its preferred names.
The fundamentals are substantial. Nvidia reported 75% gross margins last quarter. Broadcom generated $13.7B in quarterly free cash flow. Micron's FY2026 GAAP gross margin reached 80.7%.
But that creates a valuation problem.
A low multiple on exceptionally high earnings isn't necessarily cheap.
Memory is particularly interesting. Sandisk says new customer agreements will cover roughly two-thirds of its FY2028 bit volume, with minimum financial guarantees and structured pricing. That could make NAND earnings more durable than in previous cycles.
The question is how much protection those contracts provide when supply catches up.
For compute, the equivalent test is whether margins and cash generation hold as AI infrastructure financing becomes more selective.
My hypothesis: the next semiconductor winners won't simply be those with the lowest 2028 P/E.
They'll be the companies whose earnings survive the assumptions embedded in that P/E.
#stocks
$NVDA.US $AVGO.US
{stock_us}(AVGO.US)
{stock_us}(NVDA.US)
Semiconductors Look Cheap on 2028 Earnings. But Which Earnings Will Survive?
Morgan Stanley reportedly favors AI compute and memory after the selloff, with Nvidia and Broadcom among its preferred names.
The fundamentals are substantial. Nvidia reported 75% gross margins last quarter. Broadcom generated $13.7B in quarterly free cash flow. Micron's FY2026 GAAP gross margin reached 80.7%.
But that creates a valuation problem.
A low multiple on exceptionally high earnings isn't necessarily cheap.
Memory is particularly interesting. Sandisk says new customer agreements will cover roughly two-thirds of its FY2028 bit volume, with minimum financial guarantees and structured pricing. That could make NAND earnings more durable than in previous cycles.
The question is how much protection those contracts provide when supply catches up.
For compute, the equivalent test is whether margins and cash generation hold as AI infrastructure financing becomes more selective.
My hypothesis: the next semiconductor winners won't simply be those with the lowest 2028 P/E.
They'll be the companies whose earnings survive the assumptions embedded in that P/E.
#stocks
$NVDA.US $AVGO.US
Morgan Stanley reportedly favors AI compute and memory after the selloff, with Nvidia and Broadcom among its preferred names.
The fundamentals are substantial. Nvidia reported 75% gross margins last quarter. Broadcom generated $13.7B in quarterly free cash flow. Micron's FY2026 GAAP gross margin reached 80.7%.
But that creates a valuation problem.
A low multiple on exceptionally high earnings isn't necessarily cheap.
Memory is particularly interesting. Sandisk says new customer agreements will cover roughly two-thirds of its FY2028 bit volume, with minimum financial guarantees and structured pricing. That could make NAND earnings more durable than in previous cycles.
The question is how much protection those contracts provide when supply catches up.
For compute, the equivalent test is whether margins and cash generation hold as AI infrastructure financing becomes more selective.
My hypothesis: the next semiconductor winners won't simply be those with the lowest 2028 P/E.
They'll be the companies whose earnings survive the assumptions embedded in that P/E.
#stocks
$NVDA.US $AVGO.US
1.4k
·
--
Bearish
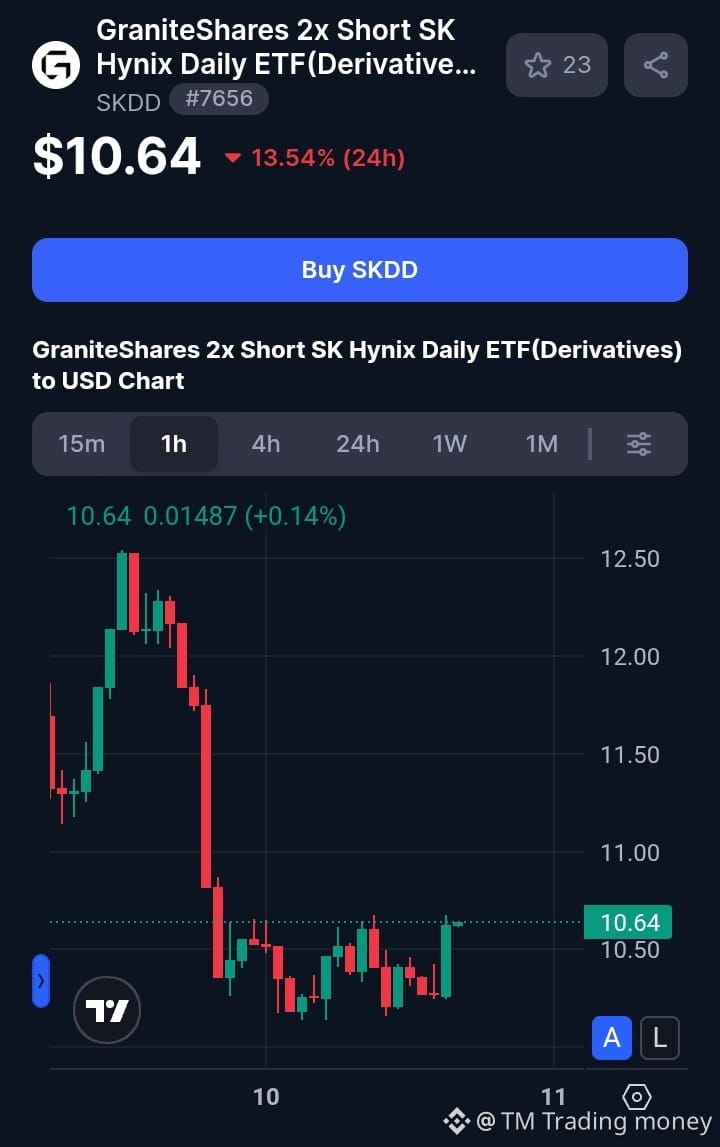
🚨 $SKDD DROPS 13.54% IN 24 HOURS! 🔴
{future}(SKDDUSDT)
GraniteShares 2x Short SK Hynix ETF (SKDD)
💰 Current Price: $10.64
📉 SKDD has faced heavy selling pressure, falling sharply from around $12.50.
📊 The chart now shows consolidation near $10.50 after a major decline.
🎯 Key Support: $10.30
🚧 Resistance: $10.80–$11.00
🔥 Can SKDD recover, or will sellers push it lower?
🐂 BULLISH or 🐻 BEARISH? What's your prediction?
#SKDD #Stocks #Semiconductor #StockMarket #Trading
🚨 $SKDD DROPS 13.54% IN 24 HOURS! 🔴
GraniteShares 2x Short SK Hynix ETF (SKDD)
💰 Current Price: $10.64
📉 SKDD has faced heavy selling pressure, falling sharply from around $12.50.
📊 The chart now shows consolidation near $10.50 after a major decline.
🎯 Key Support: $10.30
🚧 Resistance: $10.80–$11.00
🔥 Can SKDD recover, or will sellers push it lower?
🐂 BULLISH or 🐻 BEARISH? What's your prediction?
#SKDD #Stocks #Semiconductor #StockMarket #Trading
GraniteShares 2x Short SK Hynix ETF (SKDD)
💰 Current Price: $10.64
📉 SKDD has faced heavy selling pressure, falling sharply from around $12.50.
📊 The chart now shows consolidation near $10.50 after a major decline.
🎯 Key Support: $10.30
🚧 Resistance: $10.80–$11.00
🔥 Can SKDD recover, or will sellers push it lower?
🐂 BULLISH or 🐻 BEARISH? What's your prediction?
#SKDD #Stocks #Semiconductor #StockMarket #Trading
124
Verified
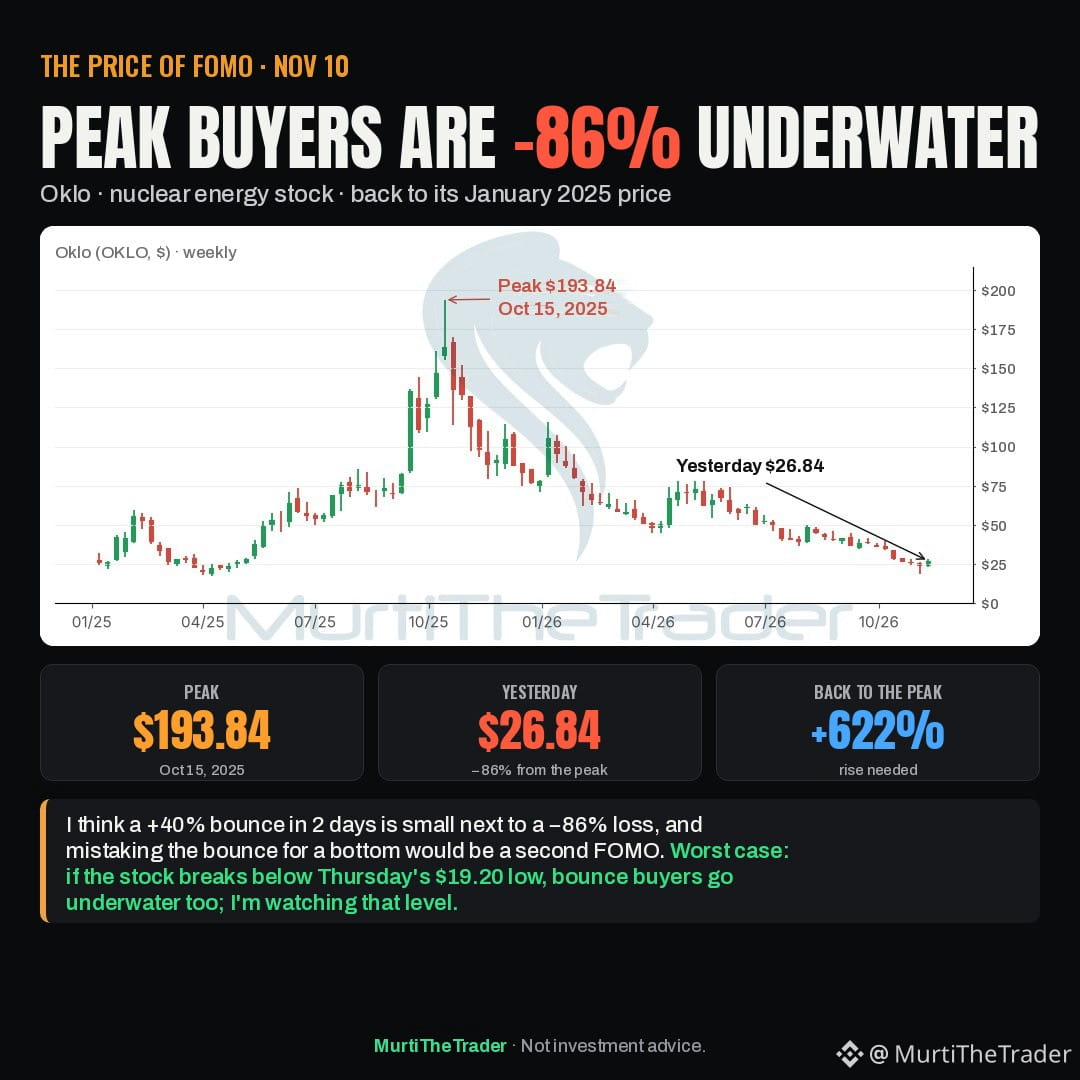
The price of FOMO: Oklo ($OKLO) hit $193.84 on Oct 15, 2025, closed yesterday at $26.84, and peak buyers are down −86%.
→ The stock needs to rise +622% to get back to the peak
→ Price is back to January 2025 levels; the entire nuclear rally is erased
→ It bottomed at $19.20 on Thursday and bounced +40% in 2 sessions
I think a +40% bounce in 2 days is small next to a −86% loss, and mistaking the bounce for a bottom would be a second FOMO. Worst case: if the stock breaks below Thursday's $19.20 low, bounce buyers go underwater too; I'm watching that level.
#Stocks #AI
Watching: $OKLO
The price of FOMO: Oklo ($OKLO ) hit $193.84 on Oct 15, 2025, closed yesterday at $26.84, and peak buyers are down −86%.
→ The stock needs to rise +622% to get back to the peak
→ Price is back to January 2025 levels; the entire nuclear rally is erased
→ It bottomed at $19.20 on Thursday and bounced +40% in 2 sessions
I think a +40% bounce in 2 days is small next to a −86% loss, and mistaking the bounce for a bottom would be a second FOMO. Worst case: if the stock breaks below Thursday's $19.20 low, bounce buyers go underwater too; I'm watching that level.
#Stocks #AI
Watching: $OKLO
→ The stock needs to rise +622% to get back to the peak
→ Price is back to January 2025 levels; the entire nuclear rally is erased
→ It bottomed at $19.20 on Thursday and bounced +40% in 2 sessions
I think a +40% bounce in 2 days is small next to a −86% loss, and mistaking the bounce for a bottom would be a second FOMO. Worst case: if the stock breaks below Thursday's $19.20 low, bounce buyers go underwater too; I'm watching that level.
#Stocks #AI
Watching: $OKLO
750
·
--
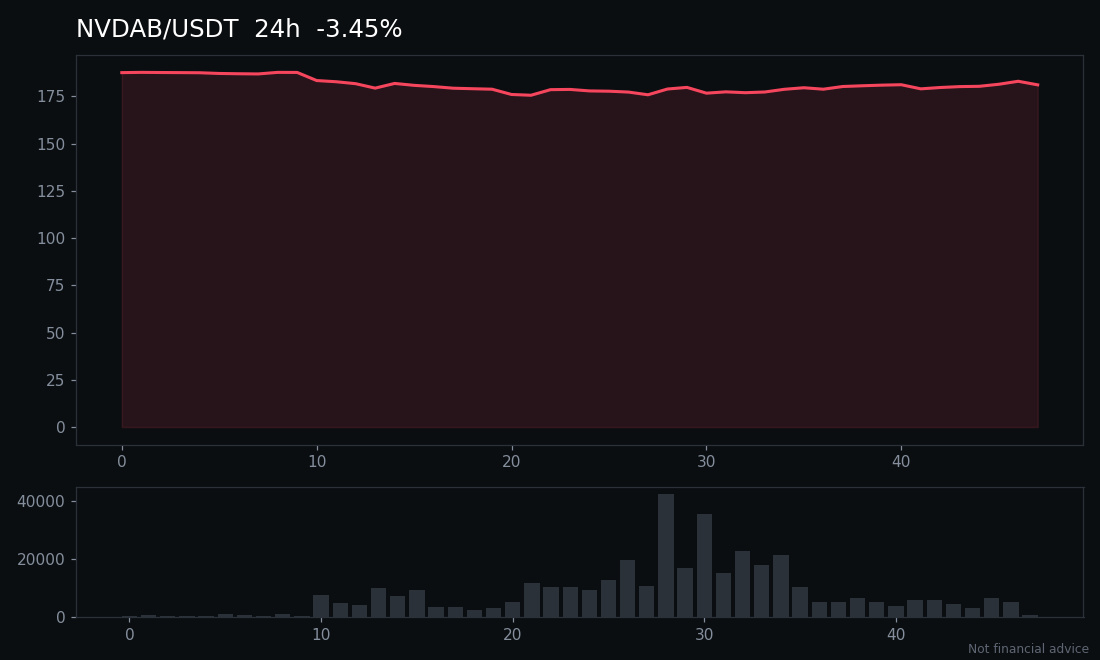
$NVDAB is quietly grinding higher again, up 1.93% to $181.57 on the day with volume north of 53 million shares. The AI bellwether keeps finding buyers on every dip, and the chart is holding its structure while the wider market hesitates. Traders are watching whether this strength can carry through into the next session or whether profit-taking creeps in near recent highs. For now, momentum is with the bulls, but chasing late moves rarely ends well. Let the chart confirm the next leg before sizing up. #BinanceSquare #Crypto #Stocks
Not financial advice.
$NVDAB is quietly grinding higher again, up 1.93% to $181.57 on the day with volume north of 53 million shares. The AI bellwether keeps finding buyers on every dip, and the chart is holding its structure while the wider market hesitates. Traders are watching whether this strength can carry through into the next session or whether profit-taking creeps in near recent highs. For now, momentum is with the bulls, but chasing late moves rarely ends well. Let the chart confirm the next leg before sizing up. #BinanceSquare #Crypto #Stocks
Not financial advice.
Not financial advice.
30
·
--
The industrial metals sector is performing strongly today! Minfa Aluminum hit the daily limit, with Jintian Group, Haomei New Material, and others following suit. The aluminum and metals sectors are rallying together—is a new market upswing about to begin? #股市 #$XAU
Industrial metal sector is on fire today! Minfa Aluminum hit the daily limit, with other metal stocks following suit. Aluminum and metal sectors are rallying - is a new bull round starting? #stocks #$XAU
The industrial metals sector is performing strongly today! Minfa Aluminum hit the daily limit, with Jintian Group, Haomei New Material, and others following suit. The aluminum and metals sectors are rallying together—is a new market upswing about to begin? #股市 #$XAU
Industrial metal sector is on fire today! Minfa Aluminum hit the daily limit, with other metal stocks following suit. Aluminum and metal sectors are rallying - is a new bull round starting? #stocks #$XAU
Industrial metal sector is on fire today! Minfa Aluminum hit the daily limit, with other metal stocks following suit. Aluminum and metal sectors are rallying - is a new bull round starting? #stocks #$XAU
25
·
--
Verified
AI Chipmakers' CDS Spreads Have Overtaken Hyperscalers'. But Who Actually Owns the Risk?
Goldman Sachs trading-desk data reportedly show a basket of Nvidia, Broadcom, AMD and Intel CDS spreads rising to roughly 160bp, above a basket of major AI infrastructure buyers for the first time in three months.
That doesn't prove credit losses are moving upstream. The baskets have different constituents, and GPU depreciation primarily hits whoever owns the hardware.
The more interesting exposure is supplier financing.
A chipmaker can book revenue from selling hardware while also holding equity, loans or guarantees tied to the customer buying it.
If that customer's economics deteriorate, the supplier may face both weaker future orders and losses on its financial exposure.
My hypothesis: investors will increasingly distinguish AI hardware demand funded by independent customer cash flows from demand supported by capital flowing back through the supply chain.
The test is disclosed financing exposure, not CDS spreads alone.
The question isn't just who sells the chips. It's who finances the buyer—and who absorbs the loss if the economics fail.
#stocks
$NVDA.US $AMD.US $INTC.US
{stock_us}(INTC.US)
{stock_us}(AMD.US)
{stock_us}(NVDA.US)
AI Chipmakers' CDS Spreads Have Overtaken Hyperscalers'. But Who Actually Owns the Risk?
Goldman Sachs trading-desk data reportedly show a basket of Nvidia, Broadcom, AMD and Intel CDS spreads rising to roughly 160bp, above a basket of major AI infrastructure buyers for the first time in three months.
That doesn't prove credit losses are moving upstream. The baskets have different constituents, and GPU depreciation primarily hits whoever owns the hardware.
The more interesting exposure is supplier financing.
A chipmaker can book revenue from selling hardware while also holding equity, loans or guarantees tied to the customer buying it.
If that customer's economics deteriorate, the supplier may face both weaker future orders and losses on its financial exposure.
My hypothesis: investors will increasingly distinguish AI hardware demand funded by independent customer cash flows from demand supported by capital flowing back through the supply chain.
The test is disclosed financing exposure, not CDS spreads alone.
The question isn't just who sells the chips. It's who finances the buyer—and who absorbs the loss if the economics fail.
#stocks
$NVDA.US $AMD.US $INTC.US
Goldman Sachs trading-desk data reportedly show a basket of Nvidia, Broadcom, AMD and Intel CDS spreads rising to roughly 160bp, above a basket of major AI infrastructure buyers for the first time in three months.
That doesn't prove credit losses are moving upstream. The baskets have different constituents, and GPU depreciation primarily hits whoever owns the hardware.
The more interesting exposure is supplier financing.
A chipmaker can book revenue from selling hardware while also holding equity, loans or guarantees tied to the customer buying it.
If that customer's economics deteriorate, the supplier may face both weaker future orders and losses on its financial exposure.
My hypothesis: investors will increasingly distinguish AI hardware demand funded by independent customer cash flows from demand supported by capital flowing back through the supply chain.
The test is disclosed financing exposure, not CDS spreads alone.
The question isn't just who sells the chips. It's who finances the buyer—and who absorbs the loss if the economics fail.
#stocks
$NVDA.US $AMD.US $INTC.US
1
3.2k
Verified
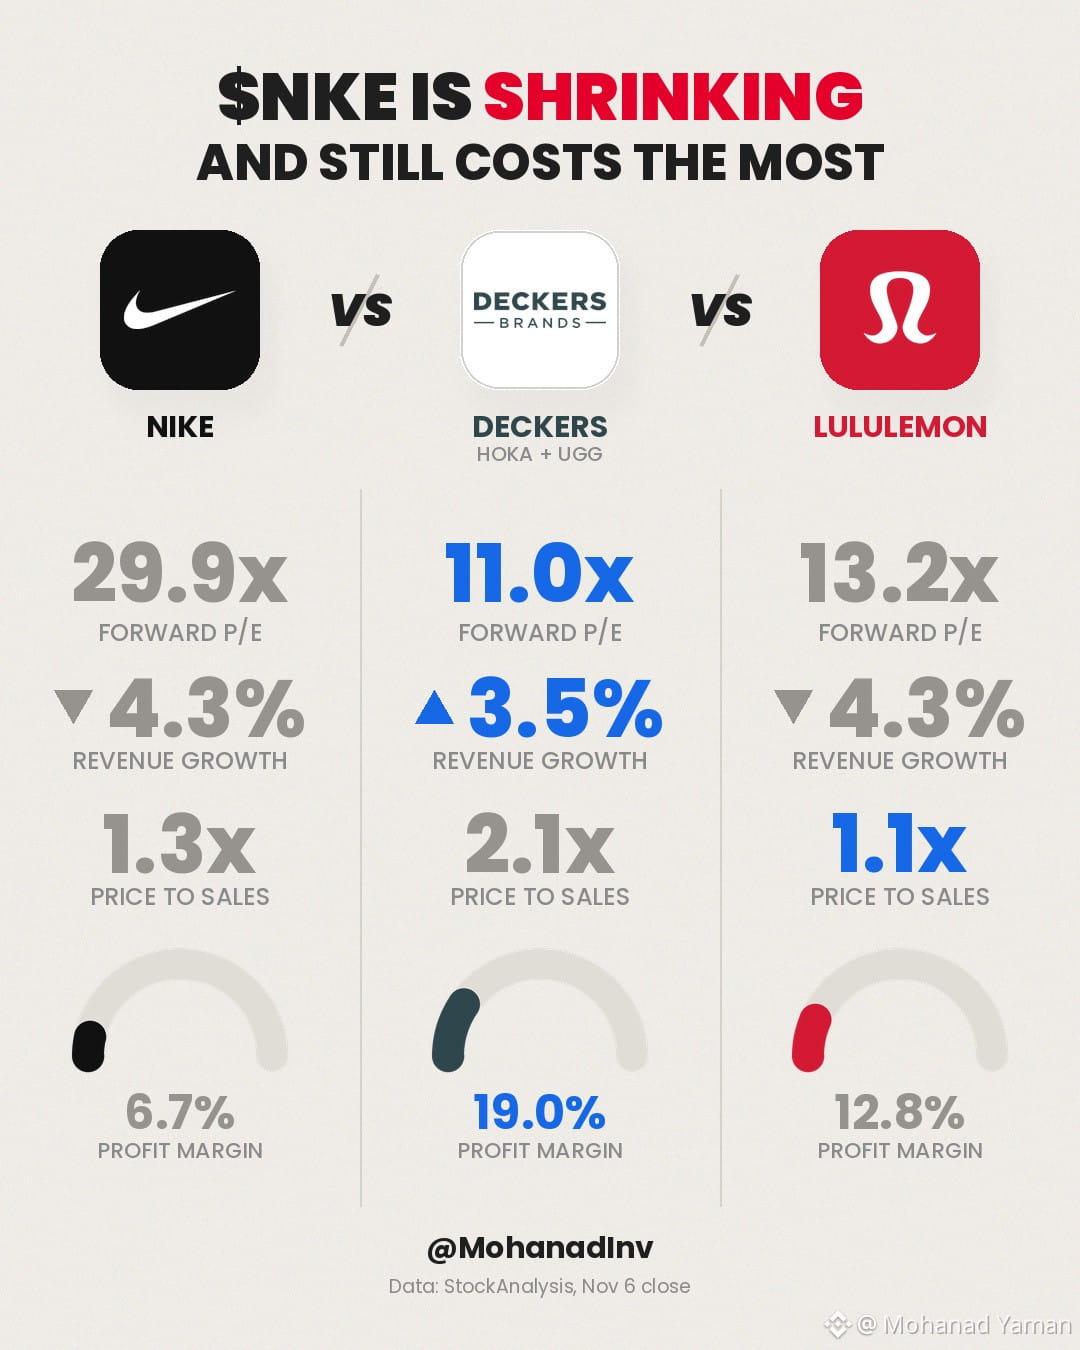
🚨 $NKE IS SHRINKING AND STILL COSTS THE MOST 👟
📈 Revenue growth last reported quarter
🔹 $NKE: down 4.3%
🔹 $LULU: down 4.3%
🔹 $DECK: up 3.5%
🔮 Forward P/E
🔹 $NKE: 29.9
🔹 $LULU: 13.2
🔹 $DECK: 11.0
🏦 Profit margin
🔹 $DECK: 19.0%
🔹 $LULU: 12.8%
🔹 $NKE: 6.7%
Nike is shrinking into a 30x forward multiple. Deckers is growing, keeps nearly 3x Nike's margin, and trades at about a third of the multiple 👀
HOKA grew 6.8% and UGG grew 3.5% last quarter 🧠
Deckers just cut guidance and still trades at 11x. Nike guides lower and trades near 30x 🤔
Paying for the swoosh turnaround, or owning the quiet winner? 👇
#stocks
{future}(NKEUSDT)
🚨 $NKE IS SHRINKING AND STILL COSTS THE MOST 👟
📈 Revenue growth last reported quarter
🔹 $NKE : down 4.3%
🔹 $LULU: down 4.3%
🔹 $DECK: up 3.5%
🔮 Forward P/E
🔹 $NKE : 29.9
🔹 $LULU: 13.2
🔹 $DECK: 11.0
🏦 Profit margin
🔹 $DECK: 19.0%
🔹 $LULU: 12.8%
🔹 $NKE : 6.7%
Nike is shrinking into a 30x forward multiple. Deckers is growing, keeps nearly 3x Nike's margin, and trades at about a third of the multiple 👀
HOKA grew 6.8% and UGG grew 3.5% last quarter 🧠
Deckers just cut guidance and still trades at 11x. Nike guides lower and trades near 30x 🤔
Paying for the swoosh turnaround, or owning the quiet winner? 👇
#stocks
📈 Revenue growth last reported quarter
🔹 $NKE : down 4.3%
🔹 $LULU: down 4.3%
🔹 $DECK: up 3.5%
🔮 Forward P/E
🔹 $NKE : 29.9
🔹 $LULU: 13.2
🔹 $DECK: 11.0
🏦 Profit margin
🔹 $DECK: 19.0%
🔹 $LULU: 12.8%
🔹 $NKE : 6.7%
Nike is shrinking into a 30x forward multiple. Deckers is growing, keeps nearly 3x Nike's margin, and trades at about a third of the multiple 👀
HOKA grew 6.8% and UGG grew 3.5% last quarter 🧠
Deckers just cut guidance and still trades at 11x. Nike guides lower and trades near 30x 🤔
Paying for the swoosh turnaround, or owning the quiet winner? 👇
#stocks
836
Partly True
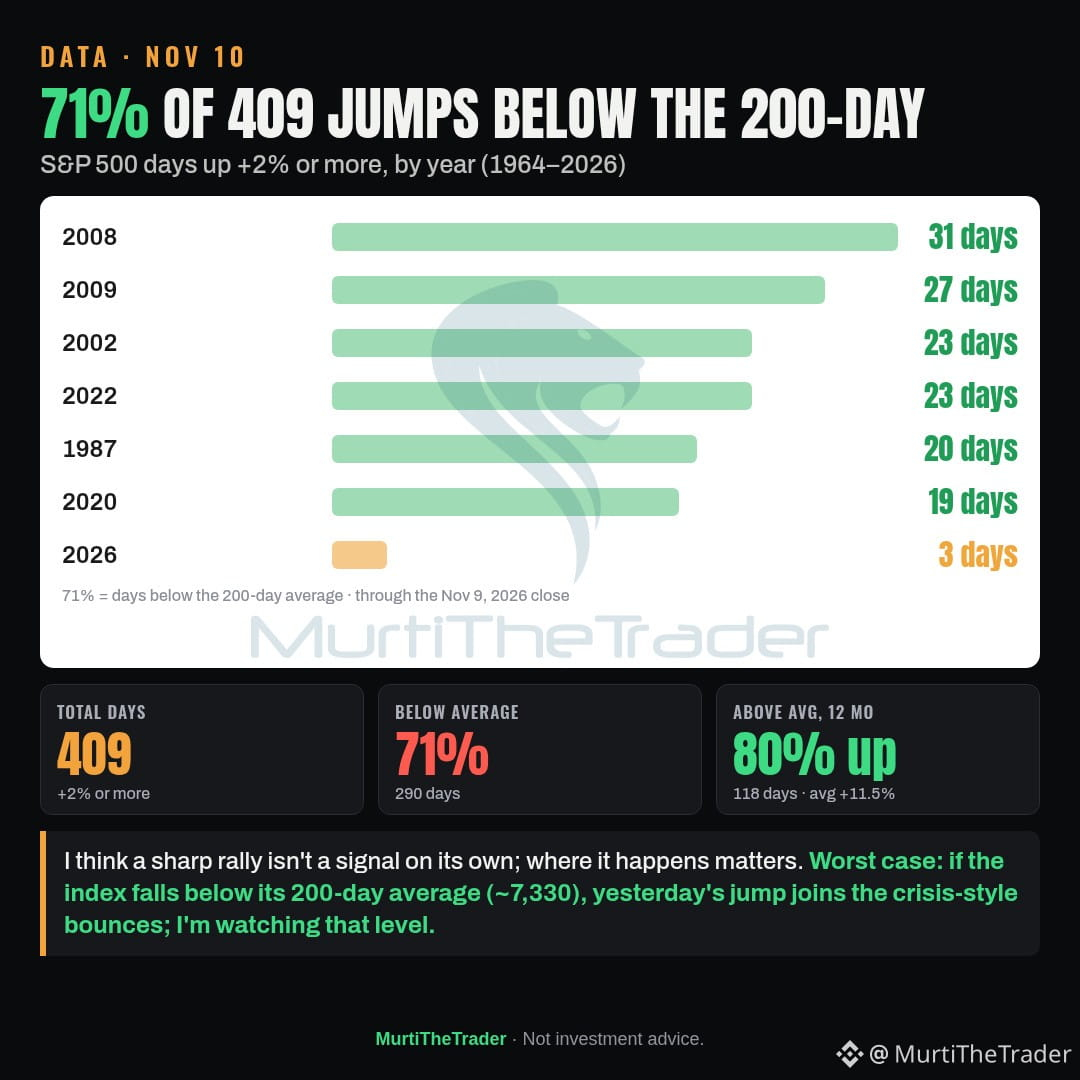
Data: Since 1964, 71% of the 409 days when the S&P 500 rose +2% or more happened below its 200-day moving average.
→ Most in 2008 (31), 2009 (27), and 2002 and 2022 (23 each)
→ Yesterday's +2.35% was one of the 118 such days above the average
→ 12 months after those 118 days: 80% were higher, average +11.5%
I think a sharp rally isn't a signal on its own; where it happens matters. Worst case: if the index falls below its 200-day average (~7,330), yesterday's jump joins the crisis-style bounces; I'm watching that level.
#Stocks #Economy
Watching: $SPY $QQQ
Data: Since 1964, 71% of the 409 days when the S&P 500 rose +2% or more happened below its 200-day moving average.
→ Most in 2008 (31), 2009 (27), and 2002 and 2022 (23 each)
→ Yesterday's +2.35% was one of the 118 such days above the average
→ 12 months after those 118 days: 80% were higher, average +11.5%
I think a sharp rally isn't a signal on its own; where it happens matters. Worst case: if the index falls below its 200-day average (~7,330), yesterday's jump joins the crisis-style bounces; I'm watching that level.
#Stocks #Economy
Watching: $SPY $QQQ
→ Most in 2008 (31), 2009 (27), and 2002 and 2022 (23 each)
→ Yesterday's +2.35% was one of the 118 such days above the average
→ 12 months after those 118 days: 80% were higher, average +11.5%
I think a sharp rally isn't a signal on its own; where it happens matters. Worst case: if the index falls below its 200-day average (~7,330), yesterday's jump joins the crisis-style bounces; I'm watching that level.
#Stocks #Economy
Watching: $SPY $QQQ
878
·
--
Anthropic aims to raise up to $69.3 billion in its initial public offering, according to Reuters. If achieved, the offering could rank among the largest stock market debuts on record.
#Markets #Stocks
Anthropic aims to raise up to $69.3 billion in its initial public offering, according to Reuters. If achieved, the offering could rank among the largest stock market debuts on record.
#Markets #Stocks
#Markets #Stocks
87
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#HotCPIDecemberHikePriced
57,490 views
850 Discussing
2
#AnthropicRejectsIPODelayValuationinQuestion
191,113 views
1,662 Discussing
3
#NvidiaInvestigatesAfterHuang’sAffairApology
469,576 views
3,106 Discussing
4
#CanNvidiaEarningsEaseMarketConcerns?
26,841 views
447 Discussing
5
#ADPWeeklyEstimateShowsUSPrivatePayrollsUp19750
11,336 views
225 Discussing
6
#US-IranTalksFuelStrongStockMarketRebound
117,715 views
581 Discussing
7
#BitcoinFiveWeeklyLosses
488,019 views
3,246 Discussing
8
#AIChipSlumpNasdaq
264,711 views
1,811 Discussing
9
#BitcoinSpotETFsPost$201MNetOutflowForThirdStraightDay
1,872 views
31 Discussing
10
#CryptoLiquidationsReach$1.16BIn24Hours
69,049 views
84 Discussing